



Graphite Electrodes Market: Why APAC & UHP Power the 4.8% CAGR Through 2032

The Graphite Electrodes Market: Strategic Shifts and Commercial Opportunities Through 2032
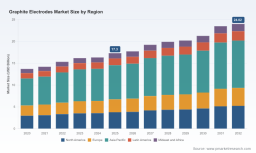
The global graphite electrodes market is entering a phase of structural recalibration, where growth trajectories intersect with trade realignments, raw material volatility, and technological differentiation. Valued at approximately USD 17.3 billion in 2025, the market has expanded from a base of USD 13.68 billion in 2020, reflecting a compound annual growth rate of 4.8 percent through the 2026–2032 forecast horizon. By 2032, revenue is projected to reach USD 24.02 billion, driven by sustained demand from electric arc furnace steelmaking, ladle furnace operations, and ancillary industrial applications. The geographic distribution of value reflects Asia Pacific’s dominant share, followed by North America and Europe, while product segmentation shows ultra-high power electrodes capturing the largest portion of market revenue, with high power and regular power grades representing the remainder. This macro framework masks deeper competitive and supply chain dynamics that will define where value is created and captured over the next several years.
Graphite Electrode Rod Market
Market Snapshot and the Current Inflection Point
The market’s recent growth pattern has not been linear. Post-pandemic recovery phases, shifting steel production economics, and incremental capacity expansions created a rhythm of expansion that is now giving way to more pronounced structural adjustments. Three interconnected challenges stand out as defining inflection points. First, raw material cost volatility has re-emerged as a critical pressure point, with petroleum needle coke prices experiencing significant upward movement in late 2025 tied to tight feedstock availability and broader crude oil dynamics. Second, trade policy is actively reshaping regional price formation and competitive positioning, as demonstrated by recent tariff and duty actions targeting large-diameter imports from China and India into key Western markets. Third, the industry is navigating a sustainability and performance threshold, where ultra-high power grades are increasingly expected to deliver both operational efficiency and documented environmental credentials, raising the bar for product differentiation beyond conventional specifications.
Core Drivers Reshaping the Market
A set of interdependent forces is accelerating the market’s evolution. Understanding how these drivers interact is essential for anticipating where demand will concentrate and where margin opportunities will emerge.
Technological Innovation and Performance Thresholds
The push toward larger-diameter ultra-high power electrodes is one of the most visible technology shifts in the sector. Larger electrodes enable fewer assembly joints, higher thermal efficiency, and improved arc stability in electric arc furnaces, directly translating into productivity gains for steel producers. Recent product validations for 800mm-class electrodes have expanded the addressable furnace base for operators seeking to modernize or optimize batch efficiency. At the same time, environmental product declaration achievements for graphite electrodes have established an official sustainability benchmark, signaling that performance is no longer measured solely by electrical conductivity, mechanical strength, and thermal resistance. The combination of technical performance and verifiable lifecycle data is becoming a competitive differentiator, particularly in markets where procurement teams are under increasing pressure to document Scope 3 impacts and material transparency.
Policy and Regulatory Environment
Trade defense measures and regional regulatory actions are introducing structural shifts in pricing and supply routing. In the United States, petitions for antidumping and countervailing duty investigations filed in early 2026 targeted large-diameter graphite electrode imports from China and India, reflecting concerns about material injury to domestic producers. Subsequent determinations by the U.S. International Trade Commission reinforced the view that these imports are materially affecting the U.S. industry, while also indicating reasonable indication of less-than-fair-value and subsidized imports. In parallel, Japan imposed a provisional anti-dumping duty rate of 95.2 percent on graphite electrodes imported from China effective in early 2025. These actions are not isolated regulatory events; they are reshaping competitive geography by influencing where supply is routed, how pricing is negotiated, and which producers gain or lose access to specific demand pools.
Coal Tar Pitch For Graphite Electrodes Market
Demand-Side Shifts in Steel and Industrial Production
The dominant application segment continues to anchor market growth, with electric arc furnace steelmaking absorbing the largest share of electrode consumption. This reflects broader structural trends in steel production, including the ongoing preference for scrap-based melting in many regions, capacity modernization, and efforts to reduce energy intensity per ton of output. Ladle furnace operations and other industrial applications contribute additional demand, but the strategic weight of the market is closely tied to electric arc furnace deployment and optimization. As steelmakers upgrade furnace configurations, pursue larger electrode diameters, and seek to lower lifecycle operating costs, demand patterns increasingly favor higher-performance grades and suppliers capable of supporting qualification, logistics, and technical service requirements at scale.
Supply Chain and Cost Structure Dynamics
Graphite electrodes are fundamentally linked to petroleum needle coke as the primary upstream feedstock, which means that margin dynamics and pricing strategy are sensitive to coke availability, refining capacity, and crude oil price movements. In late 2025, prices for petroleum coke and needle coke surged amid tight supply conditions and international crude oil fluctuations, adding pressure to input costs across the value chain. This raw material sensitivity has strategic implications. Vertically integrated producers with direct access to needle coke production can better manage cost volatility and protect gross margins, while non-integrated players face greater exposure to spot market swings and supplier negotiations. The resulting cost structure divergence is likely to reinforce competitive advantages for firms that control key upstream inputs and for those that can pass through cost changes with disciplined pricing frameworks.
Competitive Landscape and Strategic Positioning
The market does not exhibit extreme concentration, with the three largest players accounting for roughly one-quarter of revenue and the five largest reaching just over a quarter. This relatively fragmented structure creates room for differentiation through scale, vertical integration, technical service, and regional market access rather than purely through price competition. Several leading companies illustrate how distinct strategic positions are being built.
- GrafTech International Ltd. operates as a major producer and supplier of ultra-high-power graphite electrodes, including super-sized 800mm-diameter electrodes for electric arc furnace steelmaking. Its vertical integration into petroleum needle coke production, with facilities spanning France, Spain, Mexico, and Pennsylvania, supports cost control and supply reliability. Recent actions include an announced price increase on uncommitted volumes, anchored at a minimum of USD 600 to USD 1,200 per metric ton depending on region, alongside the successful launch of 800mm electrodes with completed customer qualifications. This combination of upstream control, large-diameter product capability, and disciplined pricing signals a strategy centered on margin restoration and performance leadership.
- HEG Limited is a leading Indian manufacturer of high-power and ultra-high-power electrodes, anchored by the world’s largest single-site integrated plant. Its focus on large-diameter electrodes for electric arc furnace steel production positions it as a scale-oriented supplier within a region that plays an important role in both domestic demand and export dynamics.
- Tokai Carbon Co., Ltd. maintains a global electrode production footprint across Japan, Europe, and North America, supplying ultra-high-power electrodes for electric arc furnace steelmaking. Capacity adjustments in Japan and Europe illustrate a pragmatic approach to regional competitiveness and asset optimization in response to shifting market conditions.
- Resonac Graphite America Inc. supplies high-quality graphite electrodes for electric arc furnaces, ladle furnaces, and non-ferrous applications, with manufacturing presence across the Americas, EMEA, and Asia. As part of the Resonac Group, it is involved in large-diameter electrode supply and has pursued trade investigations alongside Tokai Carbon GE LLC to address import competition in the United States.
- Tokai Carbon GE LLC, based in North Carolina, produces graphite electrodes and connecting pins up to 32 inches for electric arc furnace steelmaking, reinforcing regional manufacturing capability and direct market access in the United States.
- Graphite India Limited is a major producer of ultra-high-power electrodes for steelmaking with operations in India and Europe, and it is recognized as part of the five largest global producers outside China. Its geographic diversification and grade specialization reflect a strategy aimed at balancing regional demand with export-oriented positioning.
Market Evolution: Consolidation, Differentiation, and Trade-Induced Shifts
The competitive landscape is evolving along three trajectories. First, scale and integration are becoming more valuable as raw material volatility and large-diameter qualification requirements raise barriers to efficient participation. Producers with needle coke access, large-diameter capability, and broad furnace qualification networks are better positioned to capture premium demand. Second, regional realignment is intensifying as trade measures alter import economics and domestic industry protection becomes a more prominent policy theme in key markets. This does not eliminate global trade, but it increasingly conditions it on pricing discipline, duty exposure, and supply chain routing. Third, product differentiation is moving beyond electrical and mechanical performance to include sustainability verification and technical service intensity. Suppliers that can standardize qualification processes, reduce furnace downtime risk, and provide documented environmental data are building an advantage that is harder to replicate through capacity alone.
Strategic Outlook: Trends Shaping 2026–2032
Looking forward, three trends are likely to define the market’s next phase.
PW Consulting Chemical & Energy Research Center
Trend 1: Premiumization toward larger-diameter ultra-high power electrodes. As electric arc furnace operators seek throughput, energy efficiency, and operational stability, demand for larger-diameter and ultra-high power grades is expected to strengthen. This trend favors suppliers with proven qualification records, robust logistics for oversized product handling, and the ability to support furnace-specific configurations. Commercial opportunity lies not just in selling volume, but in bundling technical support, replacement planning, and performance documentation.
Trend 2: Trade policy as a permanent variable in pricing and sourcing. The recent U.S. trade investigation outcomes and Japan’s provisional duty actions indicate that tariff and duty frameworks will remain a meaningful factor in regional price formation. Sourcing strategies will increasingly need to account for duty exposure, alternative routing, domestic supply options, and negotiation leverage tied to local production capability. The commercial implication is a more complex procurement environment where cost optimization depends on legal, logistical, and regional supply considerations in addition to raw material pricing.
Trend 3: Sustainability and data transparency becoming procurement criteria. Environmental product declarations and lifecycle documentation are moving from optional differentiators to expected elements of supplier evaluation in certain customer segments. As downstream buyers face greater scrutiny over material sourcing and embodied impacts, electrode suppliers with verified environmental data and consistent reporting frameworks may gain preference in qualification processes. This opens opportunity for early movers to institutionalize sustainability credentials as part of their commercial value proposition.
These trends carry uncertainty. Raw material price swings can compress margins faster than pricing actions can be implemented. Trade determinations and policy adjustments may shift again, altering competitive access across regions. Demand growth may also be tempered by steel production cycles, scrap availability, and macroeconomic conditions that influence capital spending and furnace modernization timing. The market’s direction is clear enough to plan against, but the pace and intensity of change will depend on how these variables interact.
Implications for Decision Makers
Different stakeholders face distinct strategic priorities, but all share a need to act on more granular intelligence than headline market size can provide.
For Manufacturers and Suppliers
- Prioritize vertical integration or secure needle coke supply arrangements to reduce exposure to feedstock volatility and protect pricing flexibility.
- Invest in large-diameter qualification coverage and technical service capability, since furnace-specific validation and reliable delivery increasingly influence supplier selection for ultra-high power demand.
- Build disciplined regional pricing frameworks that can respond to raw material cost spikes while maintaining customer relationships, using uncommitted volume adjustments and contract structures strategically.
For Investors
- Focus on business models that combine scale, upstream input access, and differentiated product capability, since these traits are better positioned to capture premium demand and manage margin pressure.
- Monitor trade policy outcomes and regional duty exposure as factors that can alter revenue accessibility, competitive intensity, and the relative attractiveness of domestic versus export-oriented production.
- Evaluate sustainability readiness as a longer-term valuation consideration, especially where procurement trends are shifting toward documented environmental performance and supply chain transparency.
For Procurement and Procurement-Led Organizations
- Diversify sourcing with explicit attention to duty exposure, regional supply reliability, and qualification status for larger-diameter electrodes to reduce disruption risk.
- Incorporate total cost of ownership and furnace performance considerations into supplier evaluation, rather than relying solely on spot price comparisons, given the operational impact of electrode quality and service support.
- Track environmental documentation and product transparency as emerging procurement criteria, particularly where internal sustainability commitments or customer requirements are tightening.
Closing Perspective
The graphite electrodes market is expanding, but the more important story is how value is being redistributed across grades, regions, and business models. Ultra-high power electrodes, larger-diameter product capability, needle coke integration, trade policy dynamics, and sustainability verification are collectively reshaping where competitive advantage lies. Organizations that understand these forces at a granular level will be better positioned to price strategically, source resiliently, and capture demand from furnace modernization and performance-driven procurement. For decision makers seeking detailed segmentation data, regional demand breakdowns, competitive benchmarking, and tailored scenario analysis, the full research report provides the depth required to translate these market trends into operational and investment decisions.
For detailed analysis of this topic, please visit the official page: Graphite Electrodes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


