



Flat Glass Market 2026: Why the 6.5% CAGR Trajectory Changes Everything

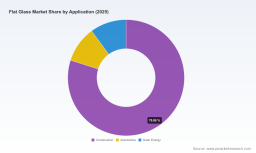
The Flat Glass Market: Strategic Trends and Commercial Opportunities Through 2032
The global flat glass market approaches a defining decade. From a base near 143 billion USD in 2020, the sector expanded steadily to approximately 187 billion USD by 2025, reflecting a trajectory shaped by architectural modernisation, vehicle lightweighting, and the rapid scaling of solar deployments. Forward projections indicate continued growth through the late 2020s, with the market anticipated to reach around 292 billion USD by 2032, supported by a compound annual growth rate of roughly 6.5 percent. This trajectory is not uniform across segments or geographies, nor is it insulated from supply-side volatility and regulatory pressure. For executives planning capacity, sourcing, or capital allocation, the flat glass sector demands a nuanced reading of where structural demand is concentrating, where cost and compliance pressures are intensifying, and which competitive moves are likely to separate durable players from cyclical participants.
Market Snapshots and the Core Tensions Defining the Next Cycle
The headline growth figures mask a more complex reality. Revenue expansion is being driven disproportionately by building envelope upgrades, transportation performance standards, and photovoltaic panel build-outs, yet these same applications intersect with raw material cost variability, energy input exposure, and evolving quality expectations. The market sits at an inflection point where volume growth and value creation are increasingly decoupled: producers that deploy higher-performing, lower-carbon, or application-specific products are capturing margins that commodity-grade lines cannot easily replicate. At the same time, regional demand patterns remain uneven, with some mature markets prioritising replacement and efficiency retrofits while emerging regions accelerate first-build construction and infrastructure.
Three tensions deserve executive attention. First, energy and input cost volatility continues to complicate planning for soda-ash, natural gas, and specialty silica variants, creating margin risk for producers reliant on energy-intensive float lines and for fabricators balancing throughput against unit economics. Second, regulatory and certification frameworks are tightening around optical quality, dimensional tolerances, and safety glazing requirements, raising the bar for thin glass adoption in multi-pane insulated units and for new product claims in building envelopes. Third, the sector’s competitive fabric is undergoing subtle re-sorting, as leading groups reposition around low-carbon production, high-performance coatings, and integrated application portfolios, while regional players and new entrants test niches where volume scale is less decisive than specification capability. Collectively, these dynamics mean that growth alone is no longer a reliable proxy for strategic success; the composition of that growth matters just as much.
The Drivers Reshaping Demand, Cost, and Competitive Value
Technology and Product Differentiation as Margin Engines
Innovation in flat glass is increasingly oriented toward performance attributes that translate directly into end-use value: thermal efficiency, optical clarity, strength-to-weight ratios, and compatibility with advanced building or vehicle assemblies. Float glass remains the volume backbone, but the commercial premium is migrating toward processed and coated variants that meet stricter insulation, daylighting, and safety expectations. Thin and ultra-thin formats are expanding the design envelope for architects and automotive engineers, though their adoption paths are tempered by tempering constraints and certification hurdles in certain multi-pane configurations. For specialty segments, high-transmission and precision-controlled products are opening doors in solar and high-performance construction applications where incremental efficiency gains translate into measurable lifecycle benefits. The strategic implication is clear: differentiation is shifting from pure volume production to specification-driven offerings that can be validated against application-specific standards.
Regulatory and Standards Pressure as a Filter and a Tailwind
Policy and standardisation activity is functioning as both a constraint and an accelerant. Building energy efficiency mandates and sustainability reporting expectations are pushing developers and manufacturers toward lower-embodied-carbon materials and verifiable performance claims. At the same time, technical standards are codifying expectations for dimensional consistency, optical quality, and visual uniformity in building-applied float glass, raising the baseline for acceptable supply. In North America, safety glazing certification continues to influence product choices in insulated glazing units, particularly where thinner configurations encounter tempering or structural acceptance limits. On the low-carbon side, several producers are advancing lines and declarations that reduce embodied carbon intensity, which aligns with procurement requirements in highly regulated markets and supports premium positioning where green credentials are scrutinised. The net effect is a market where compliance capacity and transparent performance data are becoming prerequisites for accessing the most demanding segments.
Float Glass Market
Demand-Side Shifts Toward Efficiency, Durability, and Application-Specific Formats
Demand is being reshaped by decisions at the building, vehicle, and energy-system levels. In construction, the emphasis is moving beyond basic transparency toward envelopes that manage heat transfer, solar gain, and acoustic performance while meeting aesthetic and structural goals. Thisfavors coated, insulating, and laminated configurations that can be integrated into modern facade and fenestration systems. In automotive applications, the push for lighter, stronger, and safer glazing supports continued demand for tempered and laminated formats, with additional interest in specialised optical or structural properties where vehicle architectures allow. In solar, growth in generation capacity is feeding demand for glass that balances transmission, durability, and cost, with low-iron specialty feedstocks gaining attention where performance thresholds are higher. For commercial buyers, the throughline is a preference for solutions that reduce operational risk and operating cost over the asset lifecycle, rather than lowest first-cost alone.
Supply Chain Realities and Cost Structure Sensitivity
The cost architecture of flat glass remains sensitive to energy inputs, soda-ash pricing, and specialty silica availability. Float production lines in Europe and North America have faced mixed price trends and cost volatility in early 2026, underscoring how tightly throughput economics are linked to commodity and energy markets. At the same time, demand from solar applications has influenced pricing for specialised low-iron silica variants, illustrating how cross-sector demand can propagate into raw material markets and alter sourcing strategies for precision grades. For manufacturers, this environment favours procurement flexibility, line efficiency, and process control that can buffer margin compression. For fabricators and system integrators, it elevates the importance of supplier resilience, inventory strategy, and specification discipline to avoid cost shocks being passed unpredictably into end projects.
Competitive Landscape: Positioning, Differentiation, and Evolution
The competitive field spans global producers with broad application portfolios and specialty or regional players that compete on precision, local market access, or specific processing capabilities. Several large groups anchor their positioning in low-carbon production and high-performance architectural, automotive, and solar offerings. Saint-Gobain emphasises float flat glass across architectural, automotive, and solar uses with a clear focus on lower-carbon production pathways, a stance that aligns with regulated building markets and buyers seeking verifiable sustainability attributes. AGC positions around float and processed flat glass, including ultra-thin insulating and low-emissivity products, appealing to markets where thermal performance and design flexibility are priorities. NSG Group’s Pilkington-branded portfolio targets construction, automotive, and high-performance uses, leveraging brand recognition and application breadth.
In North America, Guardian Industries supplies coated and insulated flat glass for architectural and automotive markets, while Cardinal Glass Industries and Pittsburgh Glass Works serve construction and specialty applications with regionally anchored capability. Vitro operates as a major producer with emphasis on energy-efficient and architectural glass, and its disclosed carbon intensity indicators support engagement with efficiency-driven procurement programmes. In Europe and adjacent markets, Şişecam combines broad regional reach with energy-efficient architectural offerings, while Central Glass specialises in high-performance and specialty flat glass, illustrating how niche expertise can coexist with larger-scale players. In Asia, Fuyao Glass and CSG Holding hold strong positions across automotive, construction, and solar segments, supported by large-scale production and global supply chains; Taiwan Glass and Xinyi Glass add further capacity for construction, industrial, solar, and automotive applications. Schott AG remains notable for specialty flat glass, including ultra-thin and high-transmission variants, where precision and performance matter more than volume.
Strategic Patterns Among Leaders
Across these participants, several strategic patterns emerge. The first is application integration: leading producers are increasingly organised around serving construction, automotive, and solar with product lines that are not merely commoditised float, but engineered to meet specific performance, safety, and carbon expectations. The second is the low-carbon differentiator: several groups are advancing production lines and declarations that reduce embodied carbon, using these attributes to align with regulation and procurement preferences in efficiency-sensitive markets. The third is geographic and capability balancing: global scale is paired with regional service depth, processing capability, and certification readiness, which matters because end-use acceptance often depends on local standards and fabricator relationships. Together, these patterns suggest that leadership is being rebuilt around a combination of volume, specification depth, and verifiable sustainability performance rather than capacity alone.
How the Landscape Is Evolving
Market structure is likely to evolve along three directions. Consolidation pressure will persist where scale efficiencies, energy cost management, and R&D amortisation favour larger, multi-application groups, particularly in mature markets where margins reward differentiation. At the same time, segmentation will deepen: specialty producers and regional experts will retain relevance where precision formats, certification complexity, or local service networks create barriers for generalist volume players. New entry and expansion will be selective, concentrated in regions where demand growth and cost positions are favourable, or in niches where thin, coated, or high-transmission products meet emerging architectural, automotive, or solar requirements. Participation in industry events and supply chain gatherings also reflects the importance of channel relationships and specification influence; major trade shows and conferences continuing through 2026 provide forums where manufacturers, fabricators, and dealers align on product roadmaps, supply expectations, and application trends.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
The next half-decade is likely to be defined by the interaction of performance demands, carbon expectations, and cost discipline. The first trend is rising performance specification as a baseline. As building codes, automotive requirements, and solar efficiency targets continue to advance, coated, insulating, laminated, and thin-format products are expected to command a growing share of value even where float glass remains the volume core. This rewards producers and fabricators that can document optical quality, thermal behaviour, and safety compliance with confidence, and it raises the stakes for suppliers that depend on undifferentiated commodity supply.
The second trend is carbon intensity as a commercial variable. Decisions in procurement and project approval are increasingly influenced by embodied carbon considerations and energy efficiency mandates. Producers that can deliver lower-carbon lines, transparent carbon disclosures, and consistent quality are better positioned to participate in regulated or preference-driven segments. This does not eliminate price competition, but it changes the criteria on which bids are won and retained, especially where multiple technically acceptable options exist.
The third trend is cost and supply resilience becoming a core competitive capability. With input cost volatility affecting soda-ash, natural gas, and specialty silica, the ability to manage procurement risk, maintain line efficiency, and ensure dependable delivery will separate stable operators from those exposed to repeated margin compression. For solar-related feedstocks, continued demand growth can tighten availability for low-iron specialty variants, making long-term sourcing strategies and grade discipline increasingly important. These trends point toward opportunities in product portfolios that blend specification value with cost control, in regional supply arrangements that reduce exposure to energy and commodity swings, and in service models that help fabricators and developers navigate certification and performance requirements without sacrificing project timelines.
Uncertainty remains. Energy price paths, raw material availability, certification evolution for thinner glass in multi-pane insulated units, and the pace of policy implementation can all alter the timing and distribution of demand. In construction, rate cycles and renovation activity can shift replacement demand relative to new builds. In automotive, platform architectures and lightweighting roadmaps influence glazing specifications. In solar, generation capacity additions interact with glass demand in ways that depend on technology mix, local content expectations, and feedstock availability. Navigating these variables requires continuous monitoring rather than one-time planning assumptions.
PW Consulting Chemical & Energy Research Center
What Decision-Makers Should Do Now
For Manufacturers and Producers
Prioritise differentiation that is measurable and certifiable. Invest where it strengthens optical, thermal, or structural performance claims and where low-carbon production can be demonstrated with credible disclosures. Balance volume lines with application-specific processing that meets the expectations of construction, automotive, and solar buyers. Strengthen procurement and energy strategies to reduce sensitivity to soda-ash, natural gas, and specialty silica volatility, and ensure that quality systems align with evolving dimensional and optical standards. Use trade and technical gatherings as channels to test specifications, align with fabricators, and signal product roadmaps, but base commercial commitments on resilient cost structures and verified performance rather than short-term demand noise.
For Investors and Capital Allocators
Evaluate exposure by segment composition rather than headline market size. Business models tied to higher-value coated, insulating, laminated, and specialty formats are likely to capture more durable value than undifferentiated volume plays, especially where regulation and procurement preferences reward efficiency and lower embodied carbon. Assess supply chain resilience, energy intensity, and certification readiness as part of operational risk, since these factors increasingly determine margin stability. When evaluating regional expansion or consolidation, consider the interaction of demand growth, input cost environments, and the ability to serve specification-driven applications with local acceptance and support.
For Procurement, Specification, and Supply Chain Leaders
Shift evaluation criteria toward lifecycle performance and supply reliability. Where multiple technically acceptable options exist, weigh embodied carbon, optical and dimensional consistency, and safety compliance alongside first cost. Build sourcing strategies that account for specialty feedstock availability, especially for low-iron and precision grades used in solar and high-performance building applications, and secure relationships that provide visibility into production and certification status. Require clear documentation for performance claims and certification alignment, particularly for thin glass in multi-pane insulated units where tempering and safety acceptance can constrain adoption. Treat trade and standards activity as early signals that can affect specification feasibility and project timelines.
For decision-makers who need segment-level sizing, regional detail, application splits, cost sensitivity analysis, and tailored recommendations aligned to specific products or markets, the full PW Consulting report provides the underlying structure and supporting data to move from directional insight to executable planning.
Optical Glass Market
For detailed analysis of this topic, please visit the official page: Flat Glass Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


