



Paint Protection Film Market: Why 6.4% CAGR and 34% Automotive Share Redefine Growth

Strategic Trajectory: Navigating Growth and Disruption in the Paint Protection Film Market
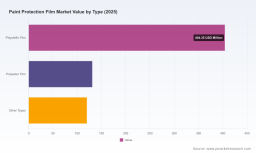
The global Paint Protection Film (PPF) market stands at a critical juncture, defined by robust expansion and evolving technological demands. Valued at USD 655.5 million in 2025, the market is projected to reach USD 1,013.8 million by 2032, reflecting a Compound Annual Growth Rate (CAGR) of 6.4% over the forecast period. This growth trajectory is not merely a function of increasing vehicle production but signals a fundamental shift in how asset protection is perceived across automotive and industrial sectors. From 2020 to 2025, the market demonstrated consistent resilience, overcoming supply chain disruptions to establish a solid revenue base. However, beneath the surface of these optimistic figures lies a complex landscape of material science advancements, regulatory pressures, and intensifying competition that demands strategic attention from industry stakeholders.
Understanding the magnitude of this expansion requires looking beyond the headline numbers. The market has matured from a niche automotive accessory into a broader industrial solution. While the automotive sector remains the primary revenue driver, the diversification into electrical and electronics applications suggests latent potential in high-value asset protection. For decision-makers, the key implication is that reliance on traditional automotive volume growth alone is insufficient. The value pool is expanding through premiumization and application diversification, creating opportunities for players who can innovate beyond standard clear film solutions.
TPU Type Paint Protection Film Market
The Current Landscape and Structural Challenges
Market Concentration and Competitive Density
The industry structure is moderately concentrated, with the top three companies accounting for approximately 45.6% of market revenue, and the top five firms commanding 61.4%. This level of concentration indicates that while dominant players hold significant sway, a substantial portion of the market remains accessible to mid-tier and regional manufacturers. The presence of both established multinational corporations and agile regional specialists creates a dynamic competitive environment. Large incumbents leverage economies of scale and brand equity, while smaller entities often compete on customization, regional availability, and specific technical specifications. For new entrants or existing players looking to gain share, this structure suggests that scale is not the only path to viability; niche specialization and supply chain localization are viable alternative strategies.
Key Challenges at the Inflection Point
Despite the positive growth outlook, the market faces distinct structural challenges that could alter competitive dynamics. First, the dependency on specific raw materials, particularly Thermoplastic Polyurethane (TPU) films, creates vulnerability. TPU is the primary raw material for advanced self-healing and hydrophobic PPF solutions, and polyurethane base films maintain a dominant share in global production. Fluctuations in petrochemical feedstock prices or disruptions in TPU supply chains can directly impact margin stability. Manufacturers unable to secure long-term raw material contracts or develop alternative material formulations risk being squeezed by cost pressures.
Second, the regulatory environment is tightening globally. Recent developments include the Bureau of Indian Standards (BIS) issuing PPF and polymer standards, alongside aligned standards from the United Nations Environment Programme (UNEP). These regulations aim to standardize quality and environmental safety but introduce compliance costs and barriers to entry for manufacturers operating across multiple jurisdictions. Companies that have not prioritized regulatory alignment may find their export capabilities restricted or face reputational risks associated with non-compliance. This regulatory shift is not merely a hurdle but a filter that will likely consolidate the market around compliant, quality-assured producers.
PW Consulting Chemical & Energy Research Center
Third, the market is witnessing a divergence in consumer and enterprise expectations. The demand is shifting from basic protection to enhanced aesthetics and functionality. Buyers increasingly seek films that offer hydrophobic properties, extreme clarity, and multiple finishes without compromising durability. This shift forces manufacturers to balance performance with cosmetic appeal. Balancing these requirements requires advanced R&D capabilities, raising the barrier for commodity-grade producers. Those focusing solely on low-cost, basic protection films may find their addressable market shrinking as premium segments expand.
Core Drivers Shaping Market Dynamics
Technological Innovation and Material Science
Technology remains the primary engine of value creation in the PPF market. The shift toward aliphatic TPU-based films in the USA and other regions exemplifies this trend. Manufacturers are increasingly focusing on self-healing properties that protect against rock chips, scratches, and scuffs, providing tangible value to end-users who prioritize vehicle longevity. The development of hydrophobic coatings and extreme clarity finishes represents a step change in product performance. These advancements are not just incremental improvements; they redefine the value proposition of PPF from a protective afterthought to an integral part of vehicle aesthetics and maintenance. For manufacturers, investment in material science is no longer optional. The ability to offer proprietary formulations that reduce installation complexity or enhance durability serves as a key differentiator in a crowded market.
Demand-Side Evolution and Consumer Behavior
Demand is being reshaped by changing ownership patterns and aesthetic preferences. In the automotive and transportation sector, which remains the largest application segment, the rise of ride-sharing fleets and luxury vehicle ownership in emerging economies drives volume. However, a more nuanced trend is the demand for customization. Leading manufacturers and distributors are now offering bespoke premium colored and clear Paint Protection Film options, catering to consumers who view vehicle modification as a form of expression. This move toward customization requires flexible manufacturing processes and supply chains capable of handling smaller batch sizes without sacrificing quality. Furthermore, the integration of PPF with complementary products such as window tinting and ceramic coatings suggests a bundling strategy that enhances customer lifetime value. Providers who can offer holistic surface protection solutions are better positioned to capture wallet share.
Supply Chain and Cost Structure Adjustments
The supply chain landscape is undergoing reconfiguration driven by regionalization and manufacturing control. Pioneer companies with in-house manufacturing and control over every product line since the mid-1990s have demonstrated the advantages of vertical integration. This control ensures consistency, speeds up time-to-market for new innovations, and mitigates supply chain risks. Conversely, global leaders in automotive-grade TPU films in regions like China are leveraging manufacturing scale to compete on cost. This creates a dual dynamic where high-touch, customized solutions are produced closer to key markets like North America, while commodity volumes are increasingly sourced from efficient Asian manufacturers. Companies must decide where they fit on this spectrum. Those attempting to compete on cost without scale may struggle, while those offering high-value, locally supported solutions can command price premiums. The ability to manage logistics and installation support networks is becoming as critical as the film quality itself.
Competitive Landscape and Strategic Positioning
Differentiation Among Leading Players
The competitive field is characterized by distinct strategic niches. US-based manufacturers such as XPEL Inc. and STEK USA have carved out strong positions by emphasizing self-healing technology and hydrophobic clarity, respectively. Their focus on extreme depth and finishes appeals to high-end automotive consumers and detailing professionals. 3M Company and ORAFOL Europe GmbH leverage their broader brand reputation and material science heritage to offer ranges available in high gloss or matte finishes with unmatched clarity, appealing to enterprise and fleet customers who prioritize reliability and brand trust.
On the other hand, specialized manufacturers like LEGEND® PPF and UPPF-USA focus on specific regional needs. LEGEND® PPF manufactures aliphatic TPU-based film in the USA specifically for North American installers, addressing local supply chain preferences and installation standards. UPPF-USA emphasizes its history of control over every product line, appealing to customers who value consistency and long-term partnership. Pure PPF and Ceramic Pro represent the premium end of the spectrum, offering bespoke colored and clear films or next-evolution durability solutions that target the luxury and performance sectors. Ceramic Pro recently showcased groundbreaking innovations in automotive surface protection including Paint Protection Film at SEMA 2025 with new product lineups and unreleased items, signaling aggressive product development.
In the Asian manufacturing hub, companies like Kehui and Sino Vinyl are positioning themselves as global leaders in Paint Protection Film manufacturing. Kehui focuses on automotive-grade TPU films, while Sino Vinyl emphasizes high-performance Paint Protection Film manufactured to top standards. These manufacturers are not merely cost providers; they are increasingly investing in technology that matches Western standards while retaining cost advantages. TeckWrap International demonstrated dry-install Color Paint Protection Film technology at Autocosmetica 2026, highlighting innovation in application technology that reduces labor costs and installation time.
Market Evolution: Consolidation and Niche Expansion
The market is likely to see further consolidation among large players seeking to secure raw material sources and distribution networks. However, the growth of niche segments suggests that fragmentation will persist in specific areas. The participation of firms like LLumar Films at SEMA Show with demonstrations of immersive Paint Protection Film, window film, and ceramic coatings indicates a trend toward integrated service offerings. Similarly, Global Hi-Tech Films showcased breakthrough Paint Protection Film technologies at FESPA Global Print Expo 2026, suggesting cross-industry technology transfer. The presence of multiple Chinese manufacturers in the global supply chain also points to ongoing integration of Eastern manufacturing capacity with Western distribution channels. The strategic implication is that companies must choose between scaling through acquisition and partnership or deepening their niche expertise. Hybrid models that combine manufacturing efficiency with localized installation support are emerging as a potent strategy.
Window Film Market
Future Outlook: Trends and Opportunities (2026-2032)
Trend 1: Premiumization and Functional Aesthetics
The next five years will see a continued shift toward premium products that combine protection with aesthetic enhancement. The market data indicates a steady upward trajectory in revenue, which will be disproportionately driven by higher-margin segments. Colored PPF, matte finishes, and films with embedded ceramic properties will move from niche offerings to mainstream expectations in the luxury segment. This trend creates opportunities for manufacturers who can master color stability and long-term adhesion without compromising self-healing capabilities. For distributors and installers, offering these premium options requires training and certification, creating a barrier to entry that rewards established networks. The risk lies in imitation products that fail to meet durability standards, potentially damaging consumer confidence in premium segments.
Trend 2: Regulatory Harmonization and Quality Standardization
Regulatory developments such as the BIS standards for PPF materials and UNEP guidelines will accelerate the standardization of quality benchmarks. While this poses initial compliance costs, it ultimately benefits the market by reducing low-quality imports and building trust. Companies that proactively align with these standards will gain a competitive advantage in export markets, particularly in regions like Asia Pacific and Latin America where regulatory frameworks are evolving. This trend favors manufacturers with robust quality control systems and transparent supply chains. Those relying on opaque sourcing or inconsistent quality may find their market access restricted. The opportunity here lies in using compliance as a marketing tool, certifying products to reassure fleet buyers and insurance partners.
Trend 3: Expansion into Adjacent Application Segments
While automotive remains dominant, growth in electrical and electronics applications suggests a pathway for diversification. PPF technology offers protection against environmental degradation and physical damage for sensitive components. As industries such as renewable energy and advanced manufacturing expand, the demand for protective films in non-automotive contexts may grow. This represents a strategic frontier for manufacturers looking to reduce reliance on automotive cycles. However, this expansion requires adapting material properties to different environmental and regulatory requirements. The uncertainty remains in whether these adjacent segments will scale rapidly enough to offset cyclicality in the automotive sector. Early movers who can validate use cases in these industries may secure long-term supply contracts.
Strategic Recommendations for Decision Makers
For Manufacturers and Brand Owners
Focus on technology moats and supply chain resilience. Given the reliance on TPU and polyurethane base films, securing raw material sources through long-term contracts or vertical integration is critical. Invest in R&D that differentiates products through self-healing efficiency, clarity, and application ease. Demonstrate value through certifications and participation in major exhibitions like SEMA to maintain visibility. Consider partnerships with regional installers to ensure market penetration, as seen with US-based manufacturers focusing on local installer support. Diversify product lines to include colored and matte options, but validate durability rigorously. Companies should also monitor regulatory changes closely to ensure compliance costs are factored into pricing strategies.
For Investors and Financial Stakeholders
Evaluate exposure to raw material volatility and regulatory risk. The market concentration suggests that large players offer stability, but significant growth opportunities may exist in specialized manufacturers with strong regional footholds. Look for companies demonstrating vertical integration or proprietary technology, as these attributes protect margins better than commodity producers. Be cautious of segments reliant on low-cost imports that may face regulatory barriers or reputational risks. The shift toward premiumization indicates that valuation multiples may expand for firms with strong brand equity in the luxury automotive segment. Assessing a company's ability to innovate versus simply competing on price is key to identifying sustainable winners.
For Procurement and Fleet Managers
Prioritize total cost of ownership over initial film cost. The durability and self-healing properties of premium films reduce long-term maintenance and repaint costs. Engage with manufacturers who provide comprehensive installation support and warranties. Verify compliance with emerging standards to avoid supply chain disruptions or liability issues. Consider bundling PPF with other surface protection solutions to streamline procurement and maintenance contracts. Investing in high-quality protection for high-utilization vehicles yields measurable ROI through reduced downtime and preserved residual value. Demand transparency regarding material composition and manufacturing origins to align with corporate sustainability goals.
The paint protection film market is entering a phase where strategic clarity matters more than ever. The convergence of material innovation, regulatory evolution, and demand for premium solutions creates a landscape where actionable intelligence is critical for navigating complexity. For stakeholders seeking to capitalize on these dynamics, access to detailed segmentation data and customized strategic scenarios is essential to refine positioning and mitigate risk. Engaging with comprehensive industry research allows decision-makers to validate assumptions against granular market data and anticipate shifts before they become mainstream.
For detailed analysis of this topic, please visit the official page: Paint Protection Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


