



Acoustic Panel Market: Beyond the 6.7% CAGR, What's Fueling $13.68B Growth by 2032

Strategic Shifts and Commercial Opportunities in the Acoustic Panel Market
The acoustic panel market has evolved from a niche building material segment into a strategically significant component of modern interior design, workplace optimization, and healthcare environment planning. Between 2020 and 2025, the market expanded from $6.34 billion to $8.6 billion, reflecting a compound annual growth rate of 6.7 percent through the forecast horizon ending in 2032. That trajectory signals more than incremental demand growth; it indicates a structural reweighting of how organizations approach indoor environmental quality, occupant well-being, and material compliance.
For executives and strategic planners, the question is no longer whether acoustic treatment will be specified, but how procurement, product design, and supplier partnerships will adapt to changing performance expectations, regulatory scrutiny, and material sourcing realities. The market's direction is being shaped by overlapping forces: greener material standards, stricter indoor air quality benchmarks, hybrid workspace acoustics, and a competitive landscape that remains relatively fragmented while rewarding innovation in sustainability and durability.
Market Snapshot and Core Challenges
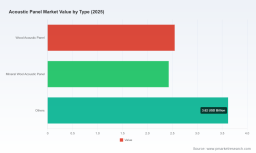
The acoustic panel market’s expansion from $6.34 billion in 2020 to $8.6 billion in 2025 reflects steady, broad-based demand rather than a single sector surge. Growth has been supported by renovations in commercial interior spaces, healthcare facility upgrades, and ongoing residential acoustic improvements. Looking ahead, revenues are projected to climb from $9.2 billion in 2026 to $13.68 billion by 2032, with a 6.7 percent CAGR indicating consistent expansion through the end of the decade.
Floor Panel Market
That growth, however, is unfolding against a backdrop of operational and strategic friction. Three challenges are particularly consequential for market participants.
1. Compliance Pressure Is Becoming a Material Differentiator
Indoor air quality and chemical emissions have moved from secondary considerations to procurement gatekeepers in many commercial and institutional projects. Panels that previously competed primarily on cost or aesthetic flexibility now face scrutiny around volatile organic compound emissions, formaldehyde content, and certified low-emitting performance. This shift raises the bar for suppliers: products must demonstrate compliance, and specifiers increasingly request documentation rather than relying on generic material claims.
The practical consequence is a bifurcation in the market. Manufacturers with established certification pathways, transparent material data, and low-emitting formulations are gaining specification advantage, while lower-cost alternatives risk losing ground in projects where health, wellness, and regulatory compliance carry more weight than unit price.
2. Raw Material and Supply Chain Complexity
Acoustic panels draw from a diverse set of input materials, including wood, mineral wool, fiberglass, polyester, felt, and hybrid composites. That diversity is a strength in product design, but it also exposes manufacturers to varying supply risks. Recycled fabric availability, fiber sourcing consistency, and binder chemistry all influence both cost structure and product positioning. Companies that rely on single-source inputs or narrow supplier bases may face volatility in pricing or lead times, particularly when sustainability requirements demand traceable or recycled content.
At the same time, sustainability claims are becoming more prominent in competitive bids. Materials marketed as biodegradable, recycled, carbon-neutral, or Red List Free can command attention, but they also create expectations for verification. Suppliers that can align material innovation with credible documentation are better positioned to convert sustainability messaging into commercial advantage.
3. Specification Fragmentation Across End-Use Segments
Acoustic needs differ sharply by environment. Commercial and corporate spaces often prioritize speech privacy, aesthetic integration, and modularity. Healthcare and medical facilities may emphasize hygienic surfaces, durability, and low-emission performance. Other applications, ranging from education to residential and specialized industrial settings, introduce additional performance requirements.
This fragmentation makes broad product portfolios attractive, but it also complicates standardization. A panel that performs well in an open-plan office may not align with the cleaning protocols of a medical setting or the environmental constraints of a public building project. Organizations that can tailor product lines to distinct performance profiles, rather than pushing one-size-fits-all solutions, are more likely to secure repeat specification in targeted verticals.
Key Drivers Shaping Market Direction
The market’s momentum is not simply a function of construction activity or interior renovation spending. Several structural drivers are reshaping what buyers ask for and what suppliers must deliver.
Technological and Material Innovation
Innovation in acoustic panels is increasingly centered on material chemistry and performance transparency. Formaldehyde-free binders, natural binder systems, and low-emitting formulations are no longer niche features; they are becoming central to competitive positioning. Fabric-wrapped and hybrid panels are also expanding the design envelope, allowing acoustic treatment to blend into architectural interiors rather than serving as purely functional add-ons.
Recent product activity illustrates this shift. In mid-2025, Kinetics Noise Control introduced Econetic Core, described as the industry’s first DECLARE Red List Free fabric-wrapped fiberglass acoustical panels using a natural formaldehyde-free binder. The same product line was noted for compliance with CDPH 01350 VOC testing standards as a fully wrapped product. This type of launch reflects a broader industry move toward verified low-emission materials and cleaner chemistry, particularly in projects where indoor environmental quality is a priority.
On the material side, recycled content and sustainability claims are becoming part of product identity. Lamvin’s Oceanside fabric-wrapped acoustic panels have been described as using 100 percent post-consumer recycled biodegradable fabric with no formaldehyde content. Autex Composition acoustic wall coverings have been presented with 100 percent PET content, including recycled fiber, alongside carbon-neutral product claims. These examples show how material sourcing and environmental positioning are being woven directly into product narratives rather than treated as optional extras.
Composite Panel Market
Policy, Certification, and Regulatory Expectations
While the acoustic panel market is not governed by a single sweeping regulation, procurement environments are increasingly shaped by indoor air quality standards, low-emitting material requirements, and project-level certification programs. Specifications that reference CDPH 01350 or similar low-emitting performance benchmarks are becoming more common in commercial, institutional, and healthcare settings.
USG’s Halcyon Eco Acoustical Panels, for example, have been noted for certification to meet CDPH 01350 v1.2-2017 for low-emitting performance, with certificates of compliance available. This kind of documentation matters because it reduces risk for specifiers and provides a clearer path to approval in sensitive projects. As a result, regulatory and certification dynamics are not merely compliance costs; they are becoming levers for differentiation and specification confidence.
Demand-Side Behavior and Environment Quality Priorities
Demand patterns are being influenced by changing expectations around workplace comfort, healthcare environments, and interior design sensibility. Organizations are paying more attention to speech privacy, noise distraction, and the broader experience of occupied spaces. That attention is especially visible in corporate and commercial interiors, where acoustic treatment is integrated into workplace strategy rather than treated as an afterthought.
At the same time, aesthetic integration is becoming a demand driver in its own right. Acoustic panels are increasingly expected to function as architectural elements, not just hidden performance components. Slat wood panels with felt backing, textured PET-based designs, fabric-wrapped systems, and sculptural configurations all point to a market where acoustic function and visual identity are converging. Barron Designs’ December 2025 acoustic panel collection, featuring slat wood wall panels with felt backing for residential and commercial sound control, reflects this kind of crossover between acoustic performance and interior design appeal.
PW Consulting Chemical & Energy Research Center
Supply-Base Evolution and Competitive Positioning
The supply side is adapting through product diversification, regional specialization, and incremental consolidation of expertise. Several companies are building reputations around specific material families, such as mineral fiber ceiling and wall systems, PET-based panels, felt-based architectural surfaces, or fiberglass solutions for demanding environments. Others are emphasizing sustainability credentials or specialized performance attributes like durability, hygiene, or industrial-grade noise control.
This is a market where scale alone does not guarantee advantage. Instead, the most visible competitive moves involve targeted product development, documentation strength, and the ability to serve distinct project types with credible performance claims. Companies that combine material innovation with specification-ready transparency are better positioned to convert demand growth into durable market share.
Competitive Landscape and Leading Strategies
The acoustic panel market remains relatively fragmented, with concentration levels that leave room for multiple viable players and differentiated strategies. Rather than a small number of dominant incumbents controlling the field, the market is shaped by companies with distinct material strengths, regional footprints, and application expertise.
Distinct Strategic Profiles
Several companies illustrate how competing firms are carving out positioning through product architecture and performance claims.
- Lamvin operates as a manufacturer of premium acoustical products, including Hushwood, Oceanside, Sonic Sound Block, and Hushtone polyester panels, with an emphasis on interiors and custom applications. Its profile suggests a focus on tailored, design-conscious solutions and material differentiation in fabric-wrapped and polyester-based offerings.
- Sound Seal is positioned as a leading manufacturer of architectural and commercial noise control products, including Poly-Coustix polyester acoustical panels and EchoWool sustainable boards. Its strategy appears centered on broad commercial noise control coverage with sustainable board options.
- Kinetics Noise Control provides fabric-wrapped fiberglass acoustical panels, including Econetic Core and HardSide lines, with attention to voice noise management and durability. Its recent Eco-oriented product development underscores a strategic push toward verified low-emission construction.
- USG Corporation supplies mineral fiber acoustical ceiling and wall panels, including Mars, Juno, Radar Education, and Glacier series, with high NRC and ClimaPlus performance. Its scale and product breadth make it relevant in commercial ceiling and wall systems where standardized performance and documentation are important.
- Armstrong World Industries produces mineral fiber and wood-wool acoustical panels, including SOUNSCAPES SHAPES and SUSTAIN portfolio offerings for sculptural and sustainable applications. Its portfolio reflects a blend of aesthetic flexibility and material sustainability messaging.
- Autex Acoustics designs and supplies PET-based acoustic panels, including Mirage textured series and Composition wall coverings, with carbon-neutral claims. Its positioning leans toward design-forward PET solutions and sustainability-oriented product language.
- CSI Creative manufactures architectural felt wall and ceiling acoustic panels, including WoodLite for high-end commercial interiors. Its focus suggests a premium, design-led segment of the market where finish quality and interior presentation matter.
- Rockfon, under the Rockwool Group , provides acoustical ceiling and wall panels for commercial and industrial applications, reinforcing a strong presence in mineral wool-based systems and broader building ecosystem integration.
- IAC Acoustics manufactures industrial and commercial Noise-Foil panels for harsher environments, indicating a more specialized, performance-heavy position in environments where durability and industrial conditions are central.
Differentiation Through Compliance, Material Claims, and Application Fit
The differentiating factors in this market are becoming more specific. In practice, leading strategies tend to combine three elements: credible low-emission or sustainability performance, clear application fit, and specification-ready documentation.
For example, verified compliance with low-emitting standards can be a meaningful advantage in healthcare, education, and corporate projects where indoor quality documentation is requested early in the specification process. Material stories involving recycled fabric, recycled PET, biodegradable content, or formaldehyde-free binders can support distinct positioning, but they are most effective when paired with accessible compliance information. At the same time, product lines that serve a specific environment well, whether fabric-wrapped systems for commercial interiors, mineral fiber systems for ceiling and wall applications, or industrial-grade panels for demanding settings, can build stronger repeat demand than broadly generic offerings.
How the Landscape Is Evolving
The market is not moving toward a single dominant model. Instead, it is evolving along several axes. One is the continued strengthening of sustainability and emissions documentation as commercial requirements, which raises the importance of certification, testing, and transparent product data. Another is the expansion of design-integrated acoustic products, which broadens the market’s appeal beyond purely technical buyers and into architectural and interior design workflows. A third is the persistence of specialized players alongside larger suppliers, allowing the market to serve both standardized commercial projects and highly tailored environments.
New entry and expansion opportunities remain, particularly for companies that can combine material innovation with strong specification support. At the same time, established players are likely to deepen their portfolio coverage, pursue sustainability-aligned product lines, and reinforce documentation capabilities to protect their position in specification-driven procurement.
Forward-Looking Trends for the Next Three to Five Years
Looking ahead, several trends are likely to shape how the acoustic panel market develops through the late 2020s and into the early 2030s.
1. Low-Emission and Verified Sustainable Materials Will Move From Differentiator to Expectation
As indoor environmental quality becomes a more prominent part of project specifications, low-emitting formulations and credible sustainability documentation are likely to become baseline expectations in many commercial and institutional segments. Panels that can demonstrate compliance with recognized low-emitting standards, provide clear material content information, and reduce concerns around formaldehyde or VOC emissions will be better positioned for repeat specification.
The commercial opportunity lies in turning verified performance into a specification advantage. Suppliers that invest early in certification pathways, transparent documentation, and cleaner material chemistry can reduce friction in the approval process and create stronger relationships with specifiers and procurement teams.
2. Acoustic Products Will Continue Blending Performance With Architectural Identity
The market is increasingly rewarding products that function as visible interior elements rather than concealed treatments. Textured surfaces, wood-based configurations, felt-based architectural panels, and sculptural forms are all part of a broader shift toward acoustic solutions that contribute to spatial design. This trend expands the addressable market by aligning acoustic purchase decisions with design-drivenInterior decisions.
Strategically, this creates opportunities for companies that can pair acoustic performance with aesthetic versatility and format flexibility. It also raises the importance of customization, finish options, and the ability to support design intent without sacrificing performance or compliance.
3. Segment-Specific Solutions Will Outperform Generic One-Size-Fits-All Offerings
Because acoustic requirements vary widely across commercial, healthcare, education, residential, and industrial settings, product strategies that align closely with specific end-use needs are likely to gain traction. Healthcare environments may prioritize hygiene and low emissions. Corporate spaces may prioritize speech privacy and design integration. Industrial settings may prioritize durability and harsh-environment performance.
This trend favors suppliers that organize their portfolios around use-case clarity rather than broad, undifferentiated catalogs. It also creates a role for targeted market intelligence: understanding which applications are expanding, which performance criteria are becoming mandatory, and where documentation or material claims matter most can inform product development and sales focus more effectively than broad generalizations.
Risk and Uncertainty
Several uncertainties could alter the pace or shape of market growth. Material costs and availability may shift if recycled content supply, fiber sourcing, or binder inputs become constrained. Certification and compliance expectations could evolve faster than product development cycles, creating transitional pressure for suppliers with less flexible material portfolios. Demand may also vary by region and project type, particularly if commercial interior spending, healthcare facility investment, or residential acoustic upgrades follow uneven trajectories.
In addition, sustainability claims will face increasing scrutiny. Marketing language around recycled content, carbon neutrality, or biodegradability is more powerful when supported by verifiable data and third-party-aligned documentation. Companies that overstate environmental benefits without supporting evidence risk weakening buyer trust, especially in specification-driven markets.
Strategic Implications for Decision-Makers
The acoustic panel market is large enough and dynamic enough that strategy matters at multiple levels. The most effective actions depend on the role a company plays in the value chain.
For Manufacturers and Product Developers
- Prioritize verified low-emission and sustainability attributes, but treat documentation as part of the product, not an accessory. Compliance-ready data can be as important as the material itself in specification environments.
- Develop products with clear application fit. Differentiating by environment, finish, and performance profile can be more effective than competing solely on price or generic feature lists.
- Monitor material sourcing risk. Recycled content, biodegradable fabric, PET-based inputs, and formaldehyde-free binders can strengthen positioning, but supply consistency and cost control remain essential to scalable execution.
For Investors and Strategic Planners
- Focus on companies with credible compliance documentation, recurring specification relationships, and product lines aligned to expanding end-use segments. In a fragmented market, durable advantage often comes from specification trust and repeat demand rather than headline scale alone.
- Watch for consolidation patterns and portfolio expansion in sustainability-aligned product lines. Firms that can combine material differentiation with strong commercial documentation are better positioned to capture higher-value projects.
- Assess exposure to regulatory and certification trends. Shifts in low-emitting expectations or indoor quality requirements can alter competitive dynamics quickly, creating both risk and opportunity depending on product readiness.
For Procurement Teams and Specifiers
- Evaluate acoustic panels using both performance and material transparency. NRC, durability, and installation fit matter, but so do emissions documentation, binder chemistry, recycled content claims, and compliance certificates where relevant.
- Align product selection with the environment’s operational needs. Healthcare, corporate, education, and industrial settings can have materially different priorities, and the right panel choice often depends on more than appearance or unit cost.
- Request specification-ready documentation early. Products that provide clear compliance evidence and consistent material information reduce project risk and speed approval cycles.
Turning Market Intelligence Into Execution
The acoustic panel market is moving on multiple fronts at once: material chemistry, indoor air quality expectations, design integration, and application-specific performance. That combination creates a market where credible differentiation and specification readiness matter more than ever. For organizations making decisions in this space, the most valuable intelligence is not just a top-line size estimate or a generic growth rate, but a clear view of where demand is concentrated, which product attributes are becoming mandatory, and how leading suppliers are positioning themselves for repeat specification.
For readers who need a deeper breakdown of segment dynamics, regional demand patterns, company-by-company positioning, and forward scenarios through 2032, the full Acoustic Panel Market research report provides expanded data and customized strategic context. It is designed for teams that want to move from high-level trend awareness to specific procurement, product, and investment decisions with more precise segmentation and detail.
For detailed analysis of this topic, please visit the official page: Acoustic Panel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


