



Ultra Fine Copper Powder Market: Why Nano Dominance and 7.4% CAGR Redefine Growth

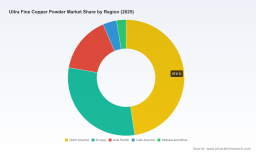
Ultra Fine Copper Powder Market: Strategic Trends and Commercial Opportunities
The ultra fine copper powder market has entered a phase of sustained expansion, driven by the convergence of advanced electronics, energy transition initiatives, and precision manufacturing demands. Historical momentum from 2020 through 2025 established a clear upward trajectory, with the market growing from approximately 183.0 million USD to 260.4 million USD over that span. Forecasts extending through 2032 point toward continued appreciation, with the market projected to reach 428.5 million USD by the end of the period. This translates to a compound annual growth rate of 7.42 percent, a figure that underscores both structural demand and the capital intensity required to meet evolving technical specifications. The scale of opportunity is substantial, yet the path forward is not uniform across regions, applications, or production methodologies. Market participants must navigate a landscape where technological differentiation, regulatory compliance, and supply chain resilience intersect to shape competitive outcomes.
At a macro level, the market structure reveals moderate concentration, with the top three players capturing roughly 35.4 percent of total revenue and the top five reaching 48.2 percent. This degree of concentration suggests that while scale advantages exist, the market remains sufficiently fragmented to allow specialized entrants and regional specialists to carve out defensible niches. The composition of demand across types and applications further illustrates the diversity of use cases. Nano copper particles and micro copper particles each command meaningful shares, reflecting divergent performance requirements across high-precision electronic pathways and more conventional powder metallurgy workflows. Similarly, electrical and electronics applications dominate volume, while energy and power, transportation, medical, and other segments contribute distinct growth vectors that respond to different macroeconomic and technological triggers. Understanding this mosaic is essential for any organization seeking to align product development, capacity planning, or procurement strategies with where value is actually being created.
Key Challenges and Inflection Points
Despite the favorable top-line trajectory, the industry faces structural frictions that will determine which participants capture disproportionate value. The first challenge lies in the regulatory environment, particularly around nanoparticle safety and environmental compliance. European Chemicals Agency data indicates that approximately 52 percent of producers encounter regulatory delays stemming from REACH compliance concerns related to nanoparticle safety and environmental impact. This is not merely an administrative hurdle; it affects time-to-market for new grades, introduces uncertainty around cross-border distribution, and raises the compliance cost baseline for all manufacturers operating in or exporting to regulated markets. Companies that treat compliance as a strategic capability rather than a backend obligation will gain earlier access to customers who require documented safety and environmental performance.
A second inflection point centers on the cost and energy intensity of production. Atomization processes, which dominate high-purity ultra fine copper powder manufacturing, are energy-costly compared to standard copper production. This contributes to higher material pricing and makes producers sensitive to energy price volatility, capacity utilization rates, and process efficiency gains. As demand scales, the ability to optimize energy consumption, improve yield consistency, and selectively invest in pollution control technologies becomes a direct determinant of margin resilience. Stringent environmental regulations on waste and emissions from atomization processes further reinforce this dynamic, requiring capital allocation toward abatement and monitoring systems that may lag behind short-term revenue growth but are essential for long-term operating license and customer qualification.
A third challenge emerges from the tension between accelerating demand and the practical constraints of qualifying new materials in downstream industries. Electrical and electronics applications, which represent the largest demand pool, rely on ultra fine copper powder for conductive pastes, electrode formulations, and advanced interconnect solutions. These applications require rigorous material consistency, purity verification, and performance validation before adoption. The result is a qualification cycle that can slow the translation of market growth into immediate order books, rewarding suppliers who can provide predictable lot-to-lot performance, technical support, and documented process control. In this environment, the market favors organizations that combine production capability with application engineering and customer-facing reliability, not merely volume output.
Key Drivers Analysis
Technological Innovation and Process Breakthroughs
Technological progress remains the most direct lever for market expansion, shaping both the range of viable applications and the economic feasibility of production. Advances in atomization and wet processes have enabled tighter particle size distributions, improved surface characteristics, and more consistent purity levels, which in turn broaden the scope of electronics and advanced materials applications. The ability to produce high-purity grades suitable for multi-layer ceramic capacitor electrode pastes, conductive inks, and high-aspect-ratio flake powders reflects a shift from commodity-style supply to engineered material solutions. Manufacturers that invest in proprietary atomization technology and precision surface treatments can differentiate on performance attributes that matter to downstream designers, such as oxidation resistance, dispersion behavior, and sintering characteristics. Recent product introductions illustrating single surface treatment approaches against oxidation for electronics and conductive applications demonstrate how incremental process innovations can unlock value by reducing handling complexity and improving end-use reliability.
Ultra Fine Copper Market
Capacity expansions targeting specific end markets further signal where technology and demand are converging. Investments aimed at high-purity copper powders for the multi-layer ceramic capacitor market, with an eye toward reduced electronic components in electric and 5G technology, highlight a strategic alignment between material capability and application roadmaps. These moves are not generic capacity additions; they are targeted responses to design trends that favor miniaturization, higher frequency performance, and material efficiency. For competitive analysis, the presence of such targeted expansion indicates that leading producers are actively shaping their portfolios around where technical barriers are highest and where customers are least willing to switch suppliers without compelling justification.
Policy and Regulatory Environment
Policy dynamics are reshaping both demand and supply conditions. On the demand side, EU policies promote copper-based solutions for green technologies, increasing demand for high-purity ultra fine copper powder while simultaneously enforcing compliance. This dual effect creates a structured pull: applications aligned with decarbonization, electrification, and energy efficiency gain preferential market access and policy support, but producers must meet stringent material and environmental standards to participate. The net effect is a market where compliance capability becomes a gatekeeper for high-value opportunities, and where suppliers with robust documentation, traceability, and environmental management systems are better positioned to capture long-term contracts.
On the supply side, regulatory pressure around nanoparticle safety and emissions introduces both cost and timeline implications. Compliance-related delays can affect product launches, market entry timing, and the speed at which new grades reach commercial scale. At the same time, regulations that require investment in pollution control technologies raise the capital intensity of production, which can act as a barrier to casual entry and reinforce the position of established players with existing compliance infrastructure. For market observers, this regulatory layer is not a peripheral concern; it is a structural factor that influences competition, pricing power, and the geography of viable supply.
Demand-Side Shifts in Consumer and Enterprise Behavior
Demand patterns are evolving as downstream industries pursue performance, miniaturization, and material efficiency. In electrical and electronics, the push toward higher component density, improved conductivity, and lower loss characteristics increases the attractiveness of ultra fine copper powders that deliver predictable behavior in pastes, inks, and electrode formulations. The medical segment adds another dimension, where biocompatibility, purity, and controlled surface properties can create specialized demand streams that are less price-sensitive and more focused on certification and consistency. Transportation and energy applications, meanwhile, reflect broader electrification and power infrastructure trends, where copper-based materials support batteries, power electronics, and conductive components.
These demand-side shifts have a strategic implication: value is migrating toward materials that solve specific performance constraints rather than toward generic powder supply. Customers increasingly evaluate suppliers on technical support, quality assurance, and the ability to co-develop grades that match processing conditions. This creates opportunities for producers who can bridge the gap between material science and application engineering, and it raises the stakes for suppliers that compete primarily on volume or price without commensurate differentiation.
Supply Chain and Cost Structure Evolution
Supply chain dynamics are being reshaped by energy costs, capacity geography, and the growing importance of qualified sourcing channels. The energy intensity of atomization makes production costs sensitive to regional energy pricing and to the efficiency of individual plants. This sensitivity encourages a strategic view of capacity placement, where proximity to end markets, access to stable energy supplies, and the ability to operate at high utilization rates become relevant considerations. At the same time, the need for custom purity levels and specialized surface treatments increases the value of flexible, responsive supply arrangements that can accommodate smaller, higher-specification orders alongside larger standard volumes.
Recent developments in dedicated sales channels for ultra fine copper powder manufactured in established facilities illustrate a broader trend toward structured distribution models that emphasize origin, quality assurance, and application fit. For additive manufacturing and industrial uses, such channels reduce search friction and provide buyers with clearer assurance regarding material provenance and specification alignment. This evolution in distribution is significant because it suggests that market access is increasingly mediated by trust, documentation, and channel specialization, not only by production capacity.
Competitive Landscape and Leading Strategies
Strategic Positioning of Core Players
The competitive landscape features a mix of established metallurgy-focused producers, electronics-grade specialists, and regional suppliers with targeted application expertise. Companies with strong positions in electronic components, MLCC electrodes, and battery-related applications have built advantage through advanced atomization and wet processes that support tight specification control and high purity. Their strategic positioning tends to center on materials that require rigorous qualification and consistent performance, where switching costs are high and technical support matters. By aligning production capabilities with specific downstream needs, these players seek to embed themselves in design cycles rather than competing solely as commodity suppliers.
Other producers emphasize high-purity ultra fine copper powders for powder metallurgy, advanced materials, and specialty applications, leveraging proprietary atomization technology to serve markets that value mechanical and physical property consistency. Surface treatment capabilities, including oxidation-resistant treatments for electronics and conductive applications, represent another axis of differentiation. In this context, product launches that address oxidation control or tailored surface chemistry are strategically meaningful because they directly improve handling, storage, and processing outcomes for customers, thereby strengthening supplier value beyond base material characteristics.
Worldwide Ultra-thin Copper Foils Market
A further layer of differentiation comes from electronics-grade focus and capacity scale. Some manufacturers concentrate on ultra-fine powders below specific particle size thresholds for high-volume electronic supply, while others offer custom purity levels and engineered grades for advanced materials, metallurgy, and specialty applications. The presence of producers that provide exclusive sales channels for materials manufactured in US and EU facilities, particularly for additive manufacturing and industrial uses, reflects a strategic emphasis on provenance, quality assurance, and market segmentation. This kind of channel strategy can be especially effective where buyers prioritize supply transparency and where regional compliance or sourcing preferences influence purchasing decisions.
Market Evolution and Entry Dynamics
Market structure appears to be moving along two simultaneous paths. On one hand, targeted capacity expansions and product launches by established players suggest continued specialization, with incumbents strengthening their positions in high-value segments through process refinement and application-specific grades. On the other hand, the presence of multiple regional producers, custom manufacturers, and channel-focused suppliers indicates ongoing fragmentation at the edges, where newer entrants can compete by serving niche specifications, localized demand, or distribution models that larger players may under-serve.
Integration and consolidation are plausible in segments where scale, compliance infrastructure, and application engineering create meaningful barriers, but complete homogenization is unlikely given the diversity of particle size requirements, purity levels, and end-use conditions. New entrants are most likely to find traction by combining technical differentiation with reliable supply, clear compliance posture, and strong customer-facing support. The market is therefore evolving toward a structure where leadership is defined not only by volume but by the ability to deliver engineered solutions, manage regulatory complexity, and sustain qualification trust across demanding applications.
Future Trends and Commercial Opportunities
Engineered Material Solutions as the Norm
Over the next three to five years, the market is likely to shift further toward engineered ultra fine copper powder solutions rather than standardized commodity supply. As downstream design trends continue to favor miniaturization, higher performance, and material efficiency, customers will increasingly specify particle size distributions, surface treatments, purity levels, and processing compatibility as core requirements. This creates commercial opportunity for suppliers that can offer tailored grades, documented performance data, and application support that reduces integration risk. The strategic implication is that product portfolios will need to be managed with more granularity, and that technical service capabilities will become a direct contributor to revenue resilience.
Compliance as a Competitive Moat
Regulatory complexity is expected to remain a defining feature of the market, particularly where nanoparticle safety, environmental emissions, and green technology alignment intersect. Producers that build robust compliance systems, maintain clear documentation, and proactively address REACH-related and environmental requirements will gain an advantage in regulated markets and in customer qualification processes. This trend creates opportunity for organizations that treat compliance as part of product value, using it to shorten approval cycles, expand addressable geographies, and strengthen positioning in applications where material safety and environmental impact are scrutinized. The risk, conversely, is that producers with weaker compliance posture may face delays, restricted access, or qualification failures that erode market share even if production capacity is available.
PW Consulting Chemical & Energy Research Center
Capacity Alignment with Targeted End Markets
Capacity investments are likely to become more purpose-built, with expansions aligned to specific applications such as MLCC electrodes, conductive pastes, energy-related components, and additive manufacturing supply. This alignment creates opportunities for suppliers that can demonstrate clear linkage between capacity, specification control, and end-market demand. At the same time, it introduces risk if demand trajectories shift faster than anticipated or if qualification cycles lengthen under regulatory or technical pressure. Organizations planning capacity additions should therefore weigh not only volume potential but also specification flexibility, regional demand mix, and the cost of maintaining high-purity process control under energy and emissions constraints.
Actionable Guidance for Decision Makers
For Manufacturers and Material Producers
prioritize engineered differentiation over pure volume competition. Invest in process control, surface treatment options, and purity consistency that align with the most demanding applications, particularly in electronics and advanced materials. Build compliance capability early, treating regulatory readiness as a product feature that can accelerate qualification and expand market access. Where capacity expansions are considered, align them with application roadmaps and energy efficiency improvements to protect margins against cost volatility and emissions-related investment requirements.
For Investors and Strategic Allocators
Evaluate exposure not just by market size but by segment sensitivity to compliance, technical differentiation, and demand durability. Segments tied to electrical and electronics, energy and power, and specialized medical applications may offer stronger structural support, but they also require careful assessment of qualification cycles, regulatory timing, and the cost of maintaining high-specification supply. Favor business models that combine production capability with application engineering, quality assurance, and channel specialization, since these attributes are increasingly associated with pricing resilience and customer stickiness.
For Procurement and Supply Chain Leaders
Treat supplier selection as a multi-dimensional decision that includes technical consistency, compliance documentation, energy and emissions posture, and channel transparency. Where applications are specification-sensitive, prioritize suppliers that can provide predictable material behavior, clear traceability, and responsive technical support. Consider diversification across geographies and channel models to reduce dependence on single sources, especially in contexts where regulatory delays or energy cost fluctuations could affect supply continuity. Establish qualification frameworks that allow new grades to be evaluated efficiently without compromising performance or compliance standards.
Conclusion
The ultra fine copper powder market is expanding within a framework that rewards technical precision, regulatory readiness, and application-aligned supply. Growth dynamics are supported by demand from electrical and electronics, energy and power, transportation, medical, and other segments, while the competitive landscape remains balanced between concentrated leaders and specialized entrants. The most consequential decisions for market participants will revolve around how well they convert process capability into engineered value, how effectively they manage compliance and environmental constraints, and how strategically they align capacity with targeted demand. For organizations seeking a deeper, segment-level view of sizing, competitive positioning, and regional dynamics, the full research report provides detailed breakdowns and customized analysis to support planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Ultra Fine Copper Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


