



Lithium Ion Battery Market 2026: The 17.52% CAGR Surge Beyond Size

The Lithium-Ion Battery Market at an Inflection Point: Strategic Trends and Commercial Opportunities
The lithium-ion battery sector has transitioned from a cyclical growth story to a structurally transformative market. Over the past half-decade, the industry has compounded at a pace that defies traditional hardware cycles, driven by the simultaneous electrification of transport and the scaling of stationary storage. As the trajectory extends through the late 2020s and into the next decade, the market is no longer defined by a single technology or application vertical. Instead, it is being reshaped by chemistry diversification, geographic manufacturing realignments, and a tightening regulatory and logistics framework. For executives and investors, the central question has shifted from whether demand will grow to where value will accrue, which chemistries will dominate specific use cases, and how supply chains will adapt to new constraints.
Market Snapshot and Core Challenges
The market has expanded from roughly $184 billion in 2020 to an estimated $326 billion in 2025, with a projected compound annual growth rate of approximately 17.5 percent through 2032. This pace places lithium-ion batteries among the fastest-growing industrial segments globally, underpinned by sustained capital allocation across automotive original equipment manufacturers, utility-scale storage developers, and industrial users. The growth trajectory is broad-based, but it is not uniform. Value creation is increasingly concentrated, and the competitive and operational landscape is becoming more complex as the industry matures.
One of the defining structural features of the current market is a high degree of concentration among leading suppliers. The top three participants account for more than 60 percent of industry revenue, and the top five collectively control a clear majority of market share. This concentration reflects the scale economics of cell manufacturing, the capital intensity of gigafactory construction, and the advantage that integrated players hold in securing supply agreements and industrializing new form factors. For downstream buyers and new entrants, the implication is clear: pricing power, technology roadmaps, and long-term contract availability are increasingly shaped by a small group of incumbents with vertically aligned operations and broad manufacturing footprints.
Lithium-Ion Battery Separator Market
At the same time, the market faces a set of interconnected challenges that will determine the shape of the next growth phase:
Chemistry Fragmentation and Application Fit
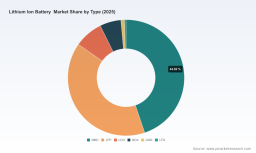
The market is no longer a single-technology story. High-nickel NMC formats remain central to premium and performance-oriented electric vehicles, while LFP chemistry has gained substantial traction where cost, safety, and cycle life are prioritized. Other chemistries occupy narrower but strategically important niches, including industrial equipment, specialty consumer devices, and applications that demand fast charging or extreme thermal tolerance. The challenge for manufacturers and buyers is that chemistry selection now carries long-term implications for pack design, thermal management, procurement strategy, and end-of-life handling. As form factors such as cylindrical and prismatic cells continue to evolve, the alignment between cell architecture and application requirements has become a critical source of differentiation rather than a commodity decision.
Raw Material Volatility and Supply Discipline
Demand-side strength continues to put pressure on upstream inputs. Global lithium production expanded significantly in 2025, reflecting sustained appetite from battery manufacturing, yet pricing dynamics remain sensitive to regional imbalances, refining capacity, and the pace of new project commissioning. Battery-grade lithium carbonate spot prices in China rose over the course of the year, illustrating how even in a production-up cycle, short-term availability and logistics can create cost uncertainty. The broader lesson for commercial teams is that raw material availability is no longer a binary supply question; it is a portfolio management problem involving long-term offtake, geographic diversification, recycling pathways, and chemistry mix decisions that influence metal intensity.
Regulatory and Logistics Tightening
The operational environment is also becoming more regulated in ways that directly affect product design, transport, and deployment. New air transport requirements now limit the state of charge for lithium-ion batteries packed with equipment or vehicles to no more than 30 percent of rated capacity, a change that affects logistics planning, inventory management, and cross-border supply chains. Meanwhile, formal standards for advanced battery development are taking shape in major markets, including the establishment of a national framework in China aimed at accelerating safety, energy density, and commercialization of next-generation cells. These developments are not peripheral; they shape time-to-market, testing requirements, and the cost of compliance for manufacturers and integrators operating across jurisdictions.
Key Growth Drivers Reshaping the Market
The growth trajectory is being propelled by a combination of technology momentum, policy direction, demand-side behavior, and supply chain restructuring. Understanding how these forces interact is essential for identifying where commercial advantage can be captured.
Technology Innovation and Form Factor Evolution
Battery performance and manufacturability are advancing through both chemistry refinement and physical design. High-nickel cathode formulations continue to support energy density goals for vehicles where range and power remain decisive purchase factors. At the same time, LFP-based solutions have broadened the addressable market by offering compelling cost and safety profiles, especially in mass-market vehicles, commercial fleets, and stationary storage. A parallel shift is the acceleration of cylindrical and prismatic cell development, including next-generation cell formats that enable higher packaging efficiency and improved manufacturing throughput. Recent product and partnership activity reflects this focus on the intersection of chemistry and engineering: a major Korean supplier partnered to develop next-generation pack technologies using 46-series cylindrical cells, signaling that formatting choices are now central to performance, cost, and scaling strategy.
Solid-state and advanced electrolyte technologies are also moving from laboratory promise toward structured commercialization pathways. With formal development standards now in effect in China for solid-state batteries, the industry is entering a phase where pilot production, safety qualification, and manufacturing readiness will matter as much as cell-level performance. For companies across the value chain, the opportunity is not simply to chase headline energy density numbers, but to align development with the application requirements, qualification timelines, and cost structures that determine whether new chemistry can scale.
Policy and Regulatory Tailwinds with New Constraints
Policy support remains a powerful accelerant, especially where electrification targets, emissions mandates, and storage deployment goals are tied to infrastructure investment and industrial strategy. At the same time, the regulatory environment is becoming more detailed and operationally specific. The introduction of stricter transport state-of-charge limits is a concrete example: it influences how inventory is handled, how cross-border shipments are planned, and how products are staged for deployment. In parallel, standards development for next-generation cells introduces both a pathway to market acceptance and a compliance burden that will distinguish companies with mature quality systems from those still building them. The broader takeaway is that policy is no longer only a demand-side catalyst; it increasingly shapes product design, logistics, and certification strategy.
Demand-Side Shifts Across Automotive and Storage
Automotive electrification continues to anchor the market, but the demand story is broadening. Utility-scale and commercial battery energy storage is expanding as grid operators, developers, and industrial users seek flexibility, resilience, and capacity optimization. Recent commercial activity underscores this diversification: a major battery supplier signed an agreement for gigawatt-hour-scale battery energy storage systems, reflecting the growing institutionalization of storage procurement. At the same time, industrial and specialty applications are creating demand for batteries that balance energy density, durability, and safety in environments where consumer-electronics assumptions no longer apply. This fragmentation of demand means that product strategy cannot be one-size-fits-all; value creation increasingly depends on matching cell and pack characteristics to the operating profile of the end use.
Supply Chain Restructuring and Cost Strategy
The manufacturing map is being redrawn. Capacity expansion is accelerating in multiple regions, with new automotive-oriented production lines coming online and aiming for substantial annual output. One notable example is the commencement of mass production at a new North American automotive battery factory targeting a high annual gigawatt-hour capacity. Such expansions illustrate a broader trend: localization of supply, tighter integration with vehicle programs, and a strategic emphasis on securing manufacturing scale in key end markets. At the same time, companies are refining cost structures through vertical integration, material sourcing strategies, and engineering choices that reduce sensitivity to volatile inputs. The interaction between capacity timing, utilization rates, and raw material dynamics will be a defining factor in margin trajectories over the coming years.
Competitive Landscape and Leading Strategies
The competitive field is shaped by a group of large, well-capitalized manufacturers with differentiated positioning across chemistry, form factor, integration depth, and geography. Rather than competing solely on price, leading players are building advantage through combinations of scale, technological focus, and customer integration.
Strategic Positioning of Core Players
CATL remains a central force in lithium-ion cell manufacturing for electric vehicles and energy storage, with an integrated model that spans materials through systems. Its scale and breadth give it leverage in securing demand, industrializing new form factors, and shaping volume pricing dynamics. BYD has built a distinctive position around LFP-focused solutions, emphasizing safety and long lifespan across vehicles, storage, and industrial applications. Its Blade battery approach reflects a strategy that ties cell design to practical deployment benefits, not just performance specifications. LG Energy Solution operates as a global supplier of high-energy cylindrical and pouch cells for automotive and storage, using a broad customer base and multiple form factors to adapt to differing vehicle and system requirements. Samsung SDI develops lithium-ion batteries across EVs, stationary storage, and consumer electronics, and has advanced prototypes that point toward future chemistry pathways, giving it optionality in next-generation segments. Panasonic Energy continues to specialize in cylindrical cells for automotive use, with manufacturing expansion in North America reinforcing its alignment with regional vehicle production. SK On focuses on high-nickel NCM cells for EVs and plug-in hybrids, positioning around energy density for applications where range and performance remain priorities. Envision AESC concentrates on high-performance prismatic cells for vehicles and storage, offering an engineering-led approach to application-specific requirements. EVE Energy and Gotion High-Tech both serve the demand for prismatic and cylindrical LFP and NCM cells, with Gotion also extending into enclosed storage systems that target high energy density for utility and commercial deployments.
PW Consulting Chemical & Energy Research Center
Recent Developments as Strategic Signals
Recent corporate activity provides a window into how these strategies are being executed. A storage contract for gigawatt-hour-scale systems highlights the institutionalization of energy storage procurement and the importance of reliable supply commitments for large projects. The unveiling of a high-capacity enclosed storage system points to the push for higher energy density in stationary applications, where footprint, integration, and system-level performance increasingly matter. A partnership to develop next-generation pack technologies using advanced cylindrical cells signals the growing importance of cell format and pack engineering as sources of differentiation. And the start of mass production at a new North American factory illustrates the strategic priority of localized capacity for automotive customers, reducing logistics exposure and supporting regional supply objectives. Taken together, these moves show an industry that is investing not only in volume, but in product specificity, system integration, and geographic alignment with demand.
Market Evolution: Consolidation, Differentiation, and Selective Entry
The industry is likely to continue evolving along three tracks. First, scale and integration will keep rewarding incumbents with the capital and operational capability to sustain high utilization and broad customer coverage. Second, differentiation will intensify as chemistries and form factors are matched more precisely to end-use requirements, making product strategy and application engineering more valuable than generic volume positioning. Third, selective new entry will remain possible in focused niches, particularly where a company can secure a distinct chemistry advantage, a strong application relationship, or a regional manufacturing advantage. The practical effect for buyers and investors is that competitive advantage is increasingly found in the alignment of technology, application, and supply chain geography rather than in cell production alone.
Future Trends and Commercial Opportunities
Looking ahead three to five years, several trends are likely to shape where value is created and where exposure needs to be managed.
Broader Chemistry and Form Factor Rationalization
The market will continue to diversify in the near term, but commercial winners will increasingly be those that can operate across chemistries and formats with clear application focus. LFP is expected to maintain strong relevance in cost-sensitive vehicles and storage, while high-nickel and advanced cylindrical formats remain important where energy density and packaging efficiency matter. Commercial opportunities will arise for companies that can offer flexible sourcing, adaptable pack designs, and credible qualification pathways across multiple chemistries without sacrificing cost discipline. The risk is overexposure to any single chemistry or form factor if demand mix shifts faster than expected.
Storage as a Structural Demand Pillar
Energy storage is increasingly becoming a second anchor for demand growth alongside automotive. As project pipelines mature and procurement becomes more institutionalized, suppliers that can deliver reliable capacity, system-level integration, and predictable lead times will have an advantage. Opportunities include long-term supply agreements, storage-optimized product offerings, and partnerships that connect cell supply with project development and deployment. The uncertainty lies in the pace of grid-related policy implementation, financing conditions for large projects, and the timing of capacity additions relative to demand.
Next-Generation Readiness and Standards-Driven Commercialization
Advanced battery development is moving toward structured commercialization, with standards and pilot production creating a clearer path to market acceptance. Companies that can navigate safety qualification, manufacturing readiness, and application-specific validation will be better positioned to capture value when new technologies reach commercial scale. At the same time, the same standards and logistics changes that enable commercialization can raise the bar for entry and operating complexity. The strategic opportunity is to prepare now for qualification, testing, and supply chain adaptation, rather than waiting for technology maturity to create urgency.
Strategic Actions for Decision-Makers
Different roles in the market face different priorities, but several practical actions apply across the board.
Lithium-ion Battery Recycling Market
For Manufacturers and Technology Developers
- Align chemistry and form factor roadmaps to application requirements rather than generic performance targets, and invest in the engineering and qualification capabilities that make multi-chemistry flexibility commercially viable.
- Treat supply chain resilience as a design input, including long-term material agreements, geographic diversification, and recycling or recovery pathways that reduce exposure to input volatility.
- Prepare operational and compliance capabilities for evolving standards and transport rules now, since these factors increasingly influence time-to-market and deployment logistics.
For Investors and Strategic Capital Allocators
- Focus on the intersection of scale, application fit, and supply alignment when evaluating opportunities, since value creation is increasingly tied to execution across these dimensions rather than to volume alone.
- Track capacity timing and utilization as leading indicators of margin risk, especially where new factories and demand growth are not perfectly synchronized.
- Watch for differentiated positioning in storage and advanced cell formats, where system-level integration and application-specific engineering can create stronger moats than generic cell supply.
For Procurement, OEM, and Deployment Teams
- Diversify sourcing strategies across chemistries and suppliers where feasible, and structure agreements to balance cost, availability, and qualification requirements for the intended application.
- Integrate logistics and compliance constraints, including transport state-of-charge requirements, into inventory and deployment planning rather than treating them as afterthoughts.
- Prioritize suppliers with clear application engineering support and proven system-integration capability, since these attributes increasingly affect project outcomes and total cost of ownership.
The lithium-ion battery market is entering a phase where success depends less on riding a single growth wave and more on navigating a complex set of technology, application, supply, and regulatory choices. For decision-makers who need segmented forecasts, competitive benchmarking, and tailored sourcing or investment scenarios, the full PW Consulting research report provides the deeper data and customization required to act with confidence.
For detailed analysis of this topic, please visit the official page: Lithium Ion Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


