



High Strength Steel Market: Why 7.8% CAGR from Automotive Demand Redefines 2032 Outlook

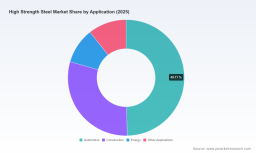
High Strength Steel Market: Strategic Trends and Commercial Opportunities (2026–2032)
Market Landscape and Critical Inflection Points
The global high strength steel market has established itself as a critical enabler of industrial modernization, currently valued at $130.0 million in 2025 and projected to reach $217.2 million by 2032. The sector's 7.8 percent compound annual growth rate reflects a structural shift rather than a cyclical expansion, driven by simultaneous pressures to reduce weight, improve safety, and lower lifecycle emissions across heavy industry and transportation. The market's trajectory is being shaped by concentration dynamics that reward specialized producers while creating volatility for commoditized participants. Industry concentration, with three firms controlling 39 percent of revenue and five firms holding 52 percent, indicates an oligopolistic structure where scale advantages in specialized grade development, capital-intensive processing, and customer qualification programs create meaningful barriers to entry.
PW Consulting Chemical & Energy Research Center
Several inflection points are reshaping how the market operates. First, the price and availability of prime scrap have become central cost drivers, with early-2026 moves by major domestic producers to raise hot-rolled coil prices reflecting underlying raw material inflation. This dynamic compresses margins for buyers while reinforcing the value of high-strength grades that deliver more performance per ton of material consumed. Second, renewed and expanded trade restrictions have altered the competitive geography of steel supply. In the United States, import tariffs on steel were raised to 25 percent in early 2025 and increased to 50 percent by mid-2025, while the European Union moved in early 2026 to reduce duty-free quotas by approximately 47 percent and apply a 50 percent duty above allocated volumes. These measures are rerouting supply patterns, prompting localized production strategies, and elevating the strategic importance of regional manufacturing assets. Third, the technical standards governing high-strength steel applications are evolving in parallel with product innovation. The publication of revised welding electrode classifications under EN ISO 18275:2026 underscores how downstream application ecosystems are maturing, requiring producers and fabricators to align process specifications with new material grades.
For decision-makers, the implication is clear: high strength steel is no longer a commodity input subject to price-only negotiation. It is a performance material whose value depends on grade selection, supply reliability, application engineering support, and alignment with regulatory and technical requirements. Companies that treat the category as a strategic input rather than a purchased commodity are positioned to capture efficiency gains and competitive differentiation.
Key Drivers of Market Evolution
Technological Innovation and Material Performance Breakthroughs
The market's growth is being sustained by a continuous cycle of grade development and application engineering. Producers are moving beyond incremental strength improvements toward multi-functional steels that combine high tensile capability with formability, weldability, and fatigue resistance tailored to specific end-use requirements. In the automotive sector, third-generation advanced high-strength steels and ultra-high-strength grades are enabling designers to consolidate parts, reduce wall thicknesses, and maintain crashworthiness while lowering overall vehicle mass. Recent industry work published by WorldAutoSteel in mid-2026 highlighted how advanced high-strength steels can simplify vehicle architecture by reducing part count and assembly complexity, reinforcing the economic case for grade substitution and design optimization.
Structural and industrial applications are benefiting from parallel advances. Specialized grades optimized for welded structures, offshore environments, and heavy machinery are extending service life and reducing maintenance cycles. The focus has shifted from achieving a single mechanical property to delivering a balanced property set that aligns with the fabrication and operational constraints of each application. This evolution raises the importance of technical collaboration between steel suppliers and engineering teams, turning material selection into a value-creation process rather than a specification exercise.
Policy and Regulatory Environment as a Competitive Variable
Trade policy and regulatory standards are now among the most significant variables shaping market access and competitive positioning. The reinstatement and escalation of import measures in the United States, combined with the European Union's tightened quota and duty framework, have increased the cost of cross-border steel flows and incentivized regional supply strategies. These policies affect everything from mill location decisions to inventory planning, contract structuring, and logistics design. Producers with domestic or near-shore capacity are gaining structural advantages in certain markets, while buyers must navigate a more fragmented and policy-sensitive supply environment.
Regulatory developments also extend into product specifications and compatibility standards. Updated welding classifications and application-specific codes influence how quickly new grades can be qualified and deployed at scale. For manufacturers adopting advanced high-strength steels, the alignment of material grades with fabrication processes, inspection protocols, and certification requirements becomes a critical path item. Companies that invest early in understanding these technical and regulatory interdependencies can reduce time-to-implementation and avoid costly redesign cycles.
High-strength Polyester Thread Market
Demand-Side Shifts in Transportation, Construction, and Energy
Demand is being reshaped by performance and efficiency objectives that transcend any single sector. In transportation, lightweighting and safety compliance remain dominant forces, but the rise of electric vehicle architectures has added new considerations around battery enclosure protection, structural rigidity, and material compatibility with manufacturing processes optimized for new powertrain configurations. Advanced high-strength steels are increasingly evaluated not just for mass reduction but for their ability to support platform simplification, multi-model flexibility, and total cost of ownership.
Structural Steel Market
In construction and infrastructure, demand for high-strength structural steels is tied to durability, span capability, and lifecycle performance. As projects face pressure to use materials more efficiently and extend service intervals, high-strength grades enable lighter sections, faster erection, and reduced material volume without sacrificing load-bearing capacity. In energy applications, high-tensile steels for offshore, pipeline, and infrastructure use continue to be driven by harsh-environment performance requirements and the need to standardize reliable grades across long-duration assets. Across all these segments, the common thread is a demand for materials that deliver measurable operational value over the asset lifecycle, not only at the point of purchase.
Supply Chain and Cost Structure Dynamics
The cost structure of high strength steel production is increasingly sensitive to scrap quality, energy inputs, and capital intensity. Early-2026 pricing actions by domestic producers illustrate how prime scrap cost increases feed directly into mill pricing and customer economics. At the same time, capacity investments in quenching and tempering lines and other specialized processing routes reflect a strategic bet that differentiated grades can command premiums and offset raw material volatility. This dynamic creates a divergence between commoditized volume players and producers with specialized assets, know-how, and customer qualification pipelines.
For procurement and supply planning teams, the operational challenge is to balance cost control with resilience. Concentration in specialized grades means that qualification lead times, supply assurance, and engineering support often matter as much as unit price. Companies that diversify grade options, secure multi-source strategies where feasible, and build closer technical relationships with producers are better positioned to manage both cost and risk in a volatile input environment.
Competitive Landscape and Leading Strategies
Competitive Landscape and Leading Strategies
The market is anchored by a group of globally active producers with distinct strategic footprints. SSAB AB has built a reputation around premium and special steels, including structural grades such as Strenx and automotive advanced high-strength and ultra-high-strength offerings under the Docol brand, positioning itself where performance certification and application engineering matter most. ArcelorMittal operates at scale with high-yield high-strength steels and advanced grades for automotive and construction, and its recent launch of ultra-high-strength steels tailored for electric vehicle chassis reflects a focus on lightweighting and safety compliance. POSCO emphasizes premium structural steels and automotive high-strength products with expanding global sales reach, while Nippon Steel contributes high-tensile offshore plates and ultra-high-tensile sheets for automotive and infrastructure use.
In the North American market, Cleveland-Cliffs stands as a significant supplier of advanced high-strength steels, including third-generation grades for automotive lightweighting, and has announced a substantial investment to expand quenching and tempering capacity at an Alabama facility to support high-strength brands. U.S. Steel complements this landscape with proprietary advanced high-strength grades and ultra-thin lightweight steels designed for electric vehicles and transformers, signaling a focus on differentiated product architecture and emerging application segments.
European and Indian producers round out the competitive field with specialized orientations. thyssenkrupp AG supplies high-strength flat-rolled steels for automotive and industrial applications, and voestalpine AG focuses on premium grades for automotive and machinery, reinforcing the value of application-specific specialization. Tata Steel brings corrosion-resistant high-tensile steels for offshore and maritime applications, extending the market's relevance into demanding environmental conditions.
Recent company actions illustrate how leading producers are translating strategy into tangible moves. In early 2025, ArcelorMittal introduced a line of ultra-high-strength steels for electric vehicle chassis, emphasizing lightweighting and safety compliance. Later in 2025, U.S. Steel outlined a growth-oriented portfolio expansion that included proprietary advanced high-strength steel and ultra-thin lightweight grades for electric vehicles. In late 2025, Cleveland-Cliffs announced a $74 million investment to expand quenching and tempering production capacity for high-strength brands, reinforcing the capital-intensive path to differentiated grade supply. Around the same time, SSAB-related coverage highlighted capacity expansion activity tied to hard-facing and high-strength structural brands, underscoring the alignment between specialized processing assets and premium grade positioning.
The competitive landscape is evolving along several axes. One is consolidation of advantage among producers with specialized assets, strong customer qualification programs, and the ability to co-engineer solutions with end users. Another is the potential for divergence between commoditized volume segments, where price competition remains intense, and premium-grade segments, where performance, certification, and supply assurance differentiate winners. A third dynamic is the role of regional policy in shaping competitive geography; producers with local capacity and compliant supply chains are gaining stature in markets where import costs and quotas have risen sharply. New entrants face steep barriers in high-strength steel because value is created not only through chemistry and processing but also through the long qualification cycles, application testing, and trusted relationships that underpin adoption in automotive, construction, and energy markets.
Future Trends and Commercial Opportunities
Looking ahead three to five years, three trends are likely to define the market's commercial shape. The first is the acceleration of application-driven grade selection. As designers and engineers gain broader access to advanced high-strength steels and as industry studies continue to quantify the benefits of part consolidation and architecture simplification, material selection will become more tightly linked to total system performance. This creates opportunities for producers and service providers that can translate technical properties into application outcomes, offering guidance on grade substitution, fabrication compatibility, and lifecycle value.
The second trend is the deepening influence of trade and regulatory policy on supply strategy. With import duties and quota adjustments already reshaping market access in major regions, companies are likely to place greater weight on regional production, inventory positioning, and contractual flexibility. This environment rewards suppliers with diversified manufacturing footprints and buyers who build supply strategies that account for policy variability rather than assuming stable cross-border flows. The opportunity lies in designing procurement and production networks that remain viable across multiple policy scenarios.
The third trend is the convergence of material innovation with manufacturing process alignment. High-strength steels deliver their greatest value when matched to appropriate welding, forming, and assembly processes, and updated standards such as the revised welding electrode classification increasingly require coordinated planning across material and fabrication choices. Producers and fabricators that invest in joint technical development, process qualification, and education can reduce implementation friction and capture more of the material's potential. This convergence favors participants who operate as solution partners rather than transactional sellers.
These trends point to a set of commercial opportunities. Producers with differentiated grades and strong application support are well positioned to deepen relationships in automotive lightweighting, structural efficiency, and demanding energy environments. Suppliers of fabrication accessories, welding consumables, and process engineering services can benefit from the need to align downstream operations with new grades. Procurement organizations have an opportunity to shift negotiation from unit price to total value, using grade optimization and supply assurance to improve cost-performance outcomes. Investors should watch for capital deployment in specialized processing capacity, regional supply expansion, and portfolio moves that link high-strength steel to growth applications such as electric vehicle platforms and infrastructure modernization.
Risks remain. Raw material volatility can compress margins and create pricing uncertainty, particularly where prime scrap availability and energy costs fluctuate. Policy changes can alter competitive dynamics quickly, rewarding some regions and penalizing others. Technical qualification cycles can slow adoption if fabricators and end users face compatibility or certification hurdles. And in segments where differentiation is limited, price competition may erode returns despite overall market growth. Navigating these risks requires a clear view of where value is created in a given product segment and a disciplined approach to investment, sourcing, and technical collaboration.
Actionable Guidance for Decision-Makers
For manufacturers and engineering-led organizations, the priority is to integrate high-strength steel selection into product development and sourcing strategy rather than treating it as a late-stage specification. Start by mapping where advanced grades can reduce part count, lower assembly complexity, or improve lifecycle performance without compromising manufacturability. Establish early technical dialogue with steel suppliers to align grade choice with welding, forming, and inspection processes, and track evolving standards that affect qualification timelines. Where possible, develop multi-grade options for critical components to preserve design flexibility and mitigate supply risk.
For investors and strategy teams, the focus should be on the structural points of value creation within the market. Differentiated, application-specific grades and specialized processing capacity are likely to command better margins than undifferentiated volume exposure. Regional supply advantages are gaining importance in policy-sensitive markets, making local production footprints and compliant logistics relevant evaluation criteria. Capital allocation decisions should weigh not only demand growth but also the intensity of competition in each segment, the degree of technical differentiation, and the ability of a company to sustain customer qualification programs and application support.
For procurement and supply chain leaders, the effective approach is to balance cost management with resilience and performance. In concentrated, specialized segments, unit price is only one component of total cost; qualification lead time, supply assurance, technical support, and compatibility with fabrication processes often determine the real outcome. Build sourcing strategies that combine competitive negotiation with risk management, including scenario planning around trade policy shifts and raw material cost movements. Where feasible, qualify alternative grades and suppliers for critical applications to preserve optionality and reduce dependence on single points of supply.
For organizations seeking a deeper, customized view of where to focus, a detailed segmentation review can clarify which grade families, applications, and regional pathways offer the strongest alignment with specific business objectives. Fine-grained market sizing, segment-level growth profiles, competitive positioning, and tailored sourcing or investment scenarios help convert the broad market trajectory into concrete action steps. Access to such detailed intelligence supports more precise prioritization, whether the goal is to optimize a material specification, evaluate a supply partnership, assess a capacity investment, or identify the most promising application segments for growth.
The high strength steel market is moving from a period of broad expansion to a phase where advantage is increasingly determined by technical fit, supply resilience, and regional strategy. Companies that align their material choices, partnerships, and sourcing structures with this reality are better positioned to turn a critical input into a durable source of performance and competitive advantage.
For detailed analysis of this topic, please visit the official page: High Strength Steel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


