



Galvanized Steel Wire Market: 7.1% CAGR and $2.96B Outlook Shape Strategy

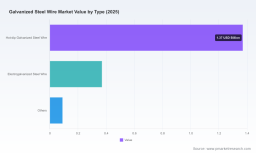
The Galvanized Steel Wire Market: Strategic Shifts, Competitive Dynamics, and Opportunities Through 2032
The galvanized steel wire market has entered a phase of measured but accelerating expansion, driven by a combination of structural demand, coating innovations, and evolving infrastructure priorities. From 2020 through 2025, total revenue climbed steadily, with the base year valuation reaching an estimated USD 1.83 billion. The forward trajectory points toward a compound annual growth rate of 7.1 percent across the 2026–2032 forecast window, tracking toward a market size that approaches USD 3 billion by the end of the period. This growth is not merely a continuation of historical patterns; it reflects a structural reorientation in how coated steel wire is specified, manufactured, and deployed across construction, agriculture, telecommunications, and infrastructure applications.
Beneath the headline growth trajectory lies a market that is consolidating around a handful of large producers while simultaneously fragmenting around application-specific performance requirements. The top three firms collectively control roughly 42 percent of global revenue, with the top five extending that share to just under half. Concentration of this magnitude suggests mature competitive dynamics, but it also masks meaningful divergence in technological positioning, geographic exposure, and product differentiation. For executives and investors, the operational implication is clear: scale alone no longer guarantees resilience. Competitive advantage is increasingly tied to coating chemistry, tensile performance, and the ability to align production capacity with localized demand signals.
Key Challenges and Inflection Points
Three structural challenges are reshaping how market participants plan capacity, pricing, and product roadmaps.
First, raw material volatility remains a persistent pressure on cost structures. Zinc price fluctuations continue to drive production cost variability for galvanized steel wire, forcing manufacturers to balance pass-through pricing with customer retention. This dynamic is particularly acute for producers reliant on conventional hot-dip galvanizing, where coating weight and zinc consumption are directly tied to input costs. Companies that cannot hedge exposure or transition toward more efficient coating architectures face margin compression during periods of commodity instability.
Second, the market is crossing an inflection point where traditional zinc coatings are no longer sufficient for demanding applications. Infrastructure projects, renewable energy installations, and high-stress structural uses are pushing beyond baseline corrosion protection thresholds. This creates a dual challenge: legacy product lines must be defended while next-generation coated wires require capital investment in new coating lines, quality control protocols, and technical sales capabilities. Firms that delay this transition risk ceding premium segments to competitors offering longer service life and higher strength-to-weight performance.
Third, the demand environment is becoming more application-diverse and regionally uneven. Construction remains a foundational demand pillar, but growth rates and specification requirements vary significantly across geographies and project types. Agricultural fencing, telecommunications infrastructure, and increasingly specialized industrial uses each impose distinct performance criteria. Navigating this fragmentation requires production flexibility, inventory strategies that align with project cycles, and commercial teams capable of translating technical specifications into procurement decisions.
Key Demand Drivers and Structural Forces
Technological Innovation in Coating and Wire Performance
Coating technology is moving from a commodity differentiator to a core value driver. The development of Zn-Al-Mg alloy coatings represents a meaningful departure from conventional hot-dip galvanizing, delivering corrosion protection that extends service life by roughly half again in demanding outdoor and marine-adjacent environments. This shift is not incremental; it changes the economics of infrastructure durability by reducing maintenance cycles and enabling wire specifications that withstand harsher exposure without thicker zinc layers. At the same time, high-tensile formulations are pushing mechanical performance upward, with newer products achieving yield strengths approaching 1,000 MPa alongside controlled zinc adhesion and uniform coating distribution.
The commercial significance of these advances lies in their ability to unlock premium pricing and application expansion. Offshore wind farm guy wires, highway safety barriers, seismic-resistant bridge cables, and solar panel frameworks are all environments where failure costs are high and replacement cycles are expensive. When a coated wire can deliver longer protection and higher structural performance, specifiers are more willing to accept elevated unit costs in exchange for lifecycle savings. Producers that have built technical demonstration capabilities, field validation data, and application-specific engineering support are gaining leverage in specification processes that historically defaulted to standard galvanized offerings.
Policy, Regulation, and Infrastructure Priorities
Regulatory and policy environments are shaping demand indirectly but powerfully by influencing project specifications, durability requirements, and public infrastructure spending priorities. Infrastructure programs that emphasize resilience, longer asset life, and reduced maintenance are creating a favorable backdrop for higher-performance coated wires. In parallel, safety standards for bridges, transportation corridors, and energy installations are tightening in ways that reward stronger materials with proven corrosion resistance. These dynamics are not uniform across regions, but they collectively reinforce a preference for coated steel wire that can meet more demanding engineering criteria.
The policy effect also intersects with renewable energy deployment and grid expansion. Solar frameworks, transmission conductors, and wind support infrastructure require materials that can operate reliably under outdoor exposure while maintaining structural integrity over decades. When procurement teams evaluate these applications, coating performance and tensile reliability increasingly enter the decision calculus alongside conventional considerations such as lead time and availability. This creates a tailwind for manufacturers that can document performance advantages and align product portfolios with infrastructure and energy-transition project requirements.
Demand-Side Shifts in End-Use Behavior
Demand patterns are being reshaped by how end users prioritize durability, total cost of ownership, and specification reliability. In construction and agricultural fencing, there is a growing tendency to specify wire based on anticipated service life and environmental exposure rather than lowest upfront price. This is especially visible where projects face corrosive soils, coastal conditions, or long maintenance cycles. In telecommunications and related infrastructure uses, reliability and consistency of supply are gaining weight as networks expand and installation schedules become more time-sensitive.
At the enterprise level, procurement behavior is shifting toward suppliers that can offer technical support, consistent coating quality, and predictable lead times. The commercial implication is that relationship-based selling and specification influence are becoming more valuable than price competition alone. Manufacturers that invest in application engineering, sample programs, and post-sale technical assistance are better positioned to capture and retain demand in segments where performance risk is high.
Supply Chain and Cost Structure Dynamics
Cost structures are being renegotiated by the interaction of raw material exposure, production efficiency, and capacity utilization. Zinc volatility remains a primary driver of production cost fluctuations, and producers are responding with a mix of procurement hedging, coating optimization, and selective pass-through strategies. The broader cost environment also reflects producer price trends in steel wire drawing and coated wire production, which have shown sustained elevation in recent readings. This reinforces the need for disciplined cost management and transparent pricing frameworks that preserve margin without alienating price-sensitive segments.
Supply chain resilience is also emerging as a differentiator. Industrial customers and infrastructure project teams increasingly value dependable availability and the ability to service large orders without disruption. Producers that maintain balanced capacity utilization, regional distribution reach, and responsive customer service can convert supply reliability into competitive advantage, particularly in applications where project timelines and installation schedules leave little room for delay.
Competitive Landscape and Leading Strategies
The market’s competitive architecture is defined by a mix of large integrated producers, specialized coated-wire specialists, and regional manufacturers with strong application footholds. The leading firms are not competing on a single dimension; rather, they are building differentiated positions around coating chemistry, tensile performance, geographic reach, and application-specific service models.
PW Consulting Chemical & Energy Research Center
ArcelorMittal has positioned itself around advanced coated wire solutions, including hot-dip galvanized steel wire and newer Zn-Al-Mg coated products designed for construction, infrastructure, and agricultural fencing. Its strategic emphasis on longer corrosion protection aligns with the broader shift toward durability-driven specifications. Nippon Steel Corporation has concentrated on high-strength galvanized and alloy-coated products, with particular relevance to offshore wind farm guy wires and highway safety barriers. This focus places the company in higher-performance segments where mechanical strength and coating resilience carry premium value.
Tata Steel has built a strong presence in low-carbon and high-tensile hot-dip galvanized wires for fencing, agriculture, and infrastructure, supported by capacity expansion that broadened output in its Jamshedpur facility. United States Steel Corporation has differentiated through specialized high-tensile galvanized offerings, including the ZincGuard® series developed for seismic-resistant bridge cables and solar panel frameworks. Its recent high-tensile product with 1,000 MPa yield strength and a 100 gsm zinc layer illustrates how targeted product engineering can serve demanding structural and energy-infrastructure applications.
Other notable participants include JFE Steel Corporation, which supplies galvanized and coated wire products for industrial and construction use; POSCO, with galvanized steel wire serving automotive components, infrastructure, and agricultural applications; Steel Authority of India Limited, active in hot-dip galvanized wire for fencing and construction; Bekaert, known for agricultural fencing, automotive components, and industrial cable applications; The Heico Companies, with wire mesh, fencing, and specialty industrial products; and Davis Wire Ltd., a producer focused on fencing and wire products.
The competitive landscape is evolving along two reinforcing trends. The first is consolidation of scale and technical capability among the largest producers, who are investing in advanced coatings, high-tensile processing, and application-focused commercial organizations. The second is continued differentiation in regional markets, where local producers maintain advantage through proximity, supply reliability, and familiarity with domestic specification practices. Strategic collaborations are also emerging as a way to commercialize advanced coating technologies more quickly, signaling that even well-resourced firms recognize the value of partnerships in accelerating technical deployment.
For companies evaluating competitive positioning, the strategic takeaway is that leadership is being redefined. It is no longer sufficient to be a low-cost galvanized wire supplier. The firms that are gaining strategic ground are those that can pair coating innovation with tensile performance, document lifecycle benefits, and align capacity with the most valuable end-use segments.
Strategic Implications of Recent Moves
Recent industry activity underscores how competitive advantage is being built. A major Indian producer expanded its galvanized steel wire production facility by 25 percent to increase output of low-carbon and high-tensile hot-dip galvanized wires, reinforcing a strategy centered on scale, cost efficiency, and expanded availability for fencing, agriculture, and infrastructure demand. A leading U.S. steelmaker launched a high-tensile galvanized wire with 1,000 MPa yield strength and a 100 gsm zinc layer aimed at seismic-resistant bridge cables, solar frameworks, and transmission conductors, illustrating a push into performance-oriented segments where specification influence matters. In parallel, a strategic collaboration between two major international producers focused on commercializing high-strength galvanized wires with advanced Zn-Al-Mg coatings, targeting 50 percent longer corrosion protection for offshore wind farm guy wires and highway safety barriers.
These developments collectively point to a market where capacity expansion, product premiumization, and technology partnerships are being used in combination. The pattern suggests that firms are preparing for a future in which demand growth is tied less to volume alone and more to value-added performance in applications where failure is costly and durability is prized.
Forward Outlook: Three Trends Shaping 2026–2032
Trend 1: Premium Coatings Gain Mainstream Relevance
Advanced alloy coatings and engineered zinc architectures are expected to move from niche applications into broader commercial use as infrastructure durability requirements intensify and maintenance costs become more visible in project economics. As specifiers compare total lifecycle cost rather than initial material price, coated wires offering longer corrosion protection and reliable adhesion will capture a growing share of high-value demand. The opportunity for manufacturers lies in building specification relationships early, providing field data, and aligning product lines with the environments where extended protection delivers measurable savings.
The associated risk is execution and adoption velocity. Premium coatings require new processing capabilities, quality assurance rigor, and customer education. If adoption is slower than anticipated, capacity investments in advanced lines may face underutilization, and price differentials may be difficult to sustain in price-sensitive segments.
Steel Wire Rope Market
Trend 2: High-Tensile Wire Expands Into Infrastructure and Energy Applications
High-tensile galvanized wire is poised to play a larger role in bridge cables, solar frameworks, transmission conductors, and safety barrier systems. The combination of higher strength and controlled coating performance allows engineers to reduce material mass while maintaining structural reliability, which is attractive in projects where span, load, and exposure conditions are demanding. Growth in this trajectory is likely to be reinforced by infrastructure modernization, renewable energy deployment, and transportation safety requirements.
The upside is meaningful, but it depends on consistent quality and proven performance in critical applications. Any quality inconsistency or field failure in high-stakes uses could slow specifier confidence and shift procurement toward more conservative choices, at least in the near term.
Trend 3: Regional Demand Divergence and Capacity Rebalancing
Demand growth will not be evenly distributed. Some regions will see stronger pull from construction activity, agricultural expansion, and infrastructure programs, while others will experience more modest growth or project cycle dependency. This divergence will encourage producers to rebalance capacity, adjust export strategies, and tailor product mixes to regional specification norms. Companies that can align regional capacity with local demand signals and maintain dependable supply chains are better positioned to capture disproportionate share in their served markets.
The uncertainty here lies in project timing, macroeconomic conditions, and policy implementation pace. If infrastructure spending or agricultural investment slows in key regions, near-term utilization may soften even as the longer-term growth trajectory remains intact. Producers with flexible capacity and diversified application exposure will be better equipped to manage that variability.
Strategic Actions for Decision Makers
For Manufacturers and Producers
Prioritize coating and tensile differentiation as the core of commercial strategy. The market is rewarding firms that can offer longer corrosion protection and higher mechanical performance in applications where lifecycle value justifies premium pricing. Invest in technical demonstration, field validation, and specification support so that sales teams can compete on performance rather than price alone. At the same time, manage zinc exposure and coating efficiency carefully, since raw material volatility will continue to pressure margins and require disciplined pricing and procurement practices.
Consider capacity decisions through the lens of application mix rather than aggregate volume. Expanding output is valuable only if it aligns with the segments where performance differentiation and reliable supply can be monetized. Where advanced coating or high-tensile lines are justified, ensure that quality control, customer technical support, and application engineering are scaled alongside production capacity.
For Investors
Evaluate exposure based on product positioning and end-use resilience rather than market-level growth alone. The most attractive risk-adjusted opportunities are likely to be found in firms with credible high-tensile and advanced coating portfolios, diversified application bases, and the ability to serve infrastructure, energy, and construction demand with differentiated specifications. Scale remains important, but it should be assessed alongside technological roadmap, margin defense against raw material volatility, and the strength of specification relationships in priority segments.
Watch for consolidation and partnership activity as signals of how the market is maturing. Collaborations around advanced coatings and capacity expansions in high-growth regions can reveal where value is being created and which technological pathways are gaining commercial traction.
Hot-dip Galvanized Steel Market
For Procurement and Supply Chain Leaders
Reassess specification criteria to reflect total cost of ownership, especially in applications exposed to corrosion, structural load, or long maintenance cycles. Where lifecycle performance matters, advanced coatings and high-tensile options may lower long-term risk even if unit costs are higher. Build procurement frameworks that allow for performance-based selection rather than defaulting to lowest initial price in every category.
Strengthen supplier relationships with an emphasis on quality consistency, coating reliability, and delivery dependability. In project-driven environments, supply assurance and technical support often matter as much as price. Diversifying sourcing where appropriate and maintaining visibility into supplier capacity and coating technology roadmaps can reduce risk during periods of raw material volatility or demand surges.
Navigating the Next Phase with Better Intelligence
The galvanized steel wire market is not simply expanding; it is restructuring around performance, durability, and application-specific value. Growth to nearly USD 3 billion by 2032 is plausible, but the distribution of that growth will favor firms and buyers who understand where premium coatings, high-tensile formulations, and regional demand patterns converge. For decision makers, the most valuable next step is to move from market-level awareness to segment-level clarity: which applications are shifting specifications fastest, where coating innovation is translating into commercial advantage, and how capacity and cost structures will evolve as raw material volatility and infrastructure priorities continue to interact.
A deeper dive into regional demand splits, type-level dynamics across hot-dip, electrogalvanized, and other coated wire categories, and application-level growth paths can sharpen strategic planning far beyond what headline figures reveal. Disaggregating the market by region, product type, and end use exposes where concentration risks lie, where premium segments are forming, and which capacity and procurement decisions are best timed now versus later. For executives and investors looking to translate market momentum into concrete action, that level of segmentation and forward scenario detail is where strategy becomes executable.
For detailed analysis of this topic, please visit the official page: Galvanized Steel Wire Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


