



Wind Power Coating Market Surges 10.8% CAGR: What the Data Reveals About Real Drivers

Strategic Trends and Commercial Opportunities in the Wind Power Coating Market
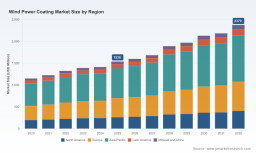
The wind power coating market has reached an inflection point where material performance, regulatory pressure, and turbine scale converge to reshape competitive dynamics. Valued at approximately USD 1.54 billion in 2025, the market expanded from roughly USD 1.15 billion in 2020, reflecting a compound annual growth rate of 10.8 percent through 2032. This trajectory is not merely a function of turbine installation volumes; it signals a structural shift in how operators prioritize asset longevity, maintenance efficiency, and compliance with increasingly stringent environmental standards. For decision-makers, the market presents a clear mandate: coating systems are no longer commoditized afterthoughts but critical enablers of uptime, safety, and total cost of ownership.
Segmentation data underscores where value is concentrating. Polymer-based formulations continue to command the largest share, driven by their versatility in blade manufacturing and field repair applications. Ceramic and metal coatings occupy smaller but strategically important niches, particularly in high-temperature environments and structural corrosion protection. Onshore installations remain the dominant application channel, while offshore deployments are accelerating as projects move into deeper waters and more aggressive operating conditions. Understanding these structural realities is essential for positioning product portfolios, managing supply chain risk, and aligning R&D roadmaps with end-user expectations.
Operational Durability Meets Scale Expansion
One of the most pressing challenges facing the industry is the widening gap between turbine scale and coating durability. As rotor diameters increase and offshore sites expose assets to salt spray, ultraviolet radiation, and mechanical fatigue, traditional coating systems are being tested beyond their historical performance envelopes. Leading-edge erosion, micro-cracking, and delamination can compromise aerodynamic efficiency and force unplanned maintenance, which is especially costly in remote or marine environments. Operators are therefore demanding formulations that balance flexibility with abrasion resistance, while manufacturers face the pressure to reduce cure times and volatile organic compound emissions without sacrificing protection longevity.
A second challenge lies in navigating an evolving regulatory landscape. Regional frameworks targeting solvent-based chemistries and industrial emissions are progressively narrowing the formulation options available to coating producers. Compliance is no longer a static checkbox; it requires continuous reformulation, lifecycle assessment, and documentation that satisfies both manufacturing partners and end-users. This shift rewards companies that invest early in solvent-free or low-emission architectures, while penalizing those that treat regulatory adaptation as a reactive exercise.
A third structural challenge is raw material volatility. Petrochemical-linked inputs such as isocyanates, epoxy resins, and fluoropolymer intermediates have experienced unpredictable pricing and availability fluctuations. Because coating formulations often rely on precise resin blends and specialty additives, cost instability can compress margins and disrupt production scheduling. Companies that lack transparent supplier relationships or alternative material pathways are particularly exposed, making supply chain resilience a strategic priority rather than a back-office function.
Technology Innovation as a Performance Multiplier
Technological breakthroughs are redefining what coatings can deliver in wind turbine applications. Advanced polymer systems are increasingly engineered for faster in-mould curing, higher temperature tolerance, and improved adhesion under variable humidity conditions. These attributes directly translate into higher manufacturing throughput and reduced downtime during blade production. In parallel, elastomeric repair coatings are being reformulated to enable field-applied restoration of leading edges with significantly shorter application windows and enhanced resistance to rain erosion. Such innovations reduce the frequency of major interventions and help operators maintain power curve performance over longer inspection intervals.
Standardization is also accelerating the pace of innovation. New testing methodologies for ice adhesion and hail resistance are bringing greater rigor to coating qualification, particularly for sites in cold or high-storm-frequency regions. As these protocols mature, they create a clearer benchmark for performance claims and help procurement teams compare solutions on a more consistent basis. For coating suppliers, this environment favors those that invest in validated test data and can demonstrate repeatable results across multiple turbine platforms and operating conditions.
The practical implication for manufacturers and service providers is clear: performance differentiation is increasingly tied to quantifiable durability metrics rather than generic product claims. Companies that can show how a coating system performs under standardized erosion, corrosion, and environmental exposure tests will gain credibility with turbine OEMs and asset owners. This, in turn, shortens evaluation cycles and supports premium positioning in segments where failure costs are highest.
Policy and Regulatory Shifts Reshaping Formulation Choices
Policy signals are exerting a powerful influence on coating chemistry, application processes, and supplier selection. Directives targeting industrial emissions and chemical safety are progressively restricting solvent-based systems, steering the market toward high-solids, water-borne, and solvent-free alternatives. This transition is not uniform across regions, but the directional momentum is consistent: formulations that reduce emissions and simplify waste handling are gaining preference in both new-build and retrofit projects.
Worldwide Wind Turbine Blade Anti-Corrosion Coating Market
Corrosion protection standards for steel structures further shape purchasing behavior. Guidance frameworks that define protection system selection for tower and foundation assets encourage operators to specify coatings with documented service life expectations and compatible surface preparation requirements. In offshore contexts, where access for maintenance is expensive and weather-dependent, these specifications increasingly prioritize long-term protection over short-term cost savings. Suppliers that align their technical documentation with recognized standards can reduce friction in qualification processes and position their products as low-risk choices for engineering teams.
For businesses operating in or adjacent to the wind sector, these regulatory dynamics create both constraint and opportunity. Constraint comes from the need to reformulate, retest, and redesignated products to meet evolving requirements. Opportunity emerges for companies that can offer compliant systems without sacrificing application efficiency or durability. Early movers in solvent-free gelcoats, low-emission repair coatings, and standards-aligned corrosion packages are building moats that are difficult for late entrants to replicate quickly.
Demand-Side Shifts and Cost Structure Evolution
Demand-side behavior is changing as asset owners internalize the full lifecycle cost of coatings. Rather than selecting products based solely on unit price, operators are increasingly evaluating protection systems through the lens of maintenance frequency, blade performance retention, and repair logistics. Offshore projects, in particular, amplify this calculus because travel, weather windows, and specialized crew availability make downtime disproportionately expensive. As a result, coatings that extend inspection intervals or simplify field repairs are gaining traction even when their upfront cost is higher.
On the supply side, cost structures are being reshaped by material volatility, energy inputs, and logistics complexity. Petrochemical-derived intermediates remain central to many high-performance formulations, and their pricing sensitivity introduces unpredictability into both production planning and final pricing. At the same time, the push toward faster curing and lower-emission processes is altering energy and consumable requirements at manufacturing sites. Companies that diversify supplier bases, secure long-term feedstock agreements, or develop hybrid formulations with more stable input profiles are better positioned to protect margins through cyclical disruptions.
A notable demand signal is the growing emphasis on repairability. Leading-edge protection and blade restoration systems are attracting attention because they directly address one of the most common degradation modes in operational turbines. Products that enable faster on-site repair, broader application conditions, and improved erosion resistance reduce the total cost of ownership for operators and create recurring revenue streams for coating suppliers and service partners. This shift is expanding the market beyond initial manufacturing coatings into a more service-intensive, maintenance-driven value chain.
Competitive Positioning and Strategic Differentiation
The competitive landscape features a mix of global coating specialists, resin producers, and niche providers focused on blade repair and protection. Leading players are distinguishing themselves through combinations of application expertise, technical documentation, and regionally tailored service networks. One common differentiator is the ability to supply integrated systems that cover both manufacturing-stage protection and in-service maintenance, reducing the number of vendors an operator must manage across a turbine’s lifecycle.
Several companies have built strong associations with blade coatings and repair technologies, where performance claims around leading-edge protection, rain erosion resistance, and cure speed are closely scrutinized. Others emphasize corrosion protection for steel structures, towers, and foundations, aligning their portfolios with recognized corrosion guidance and offshore durability requirements. Resin and polymer suppliers occupy a critical upstream position by controlling key formulation inputs, giving them influence over the performance characteristics that downstream coating makers can deliver.
Recent product activity illustrates how competition is intensifying around application efficiency and compliance. One major coatings provider introduced a fast-curing, solvent-free epoxy in-mould gelcoat designed to support higher temperature applications and accelerate blade production cycles. A separate technical data sheet for the same system reinforced the emphasis on controlled processing and manufacturing optimization. In the repair segment, another specialist launched an improved white version of a leading-edge repair coating, engineered to deliver significantly faster application while enhancing rain erosion resistance and widening the usable application window. These moves reflect a broader industry push to reduce downtime, improve throughput, and meet stricter environmental expectations without compromising protection.
PW Consulting Chemical & Energy Research Center
The market is also showing signs of consolidation and specialization occurring simultaneously. Larger groups are leveraging scale to standardize core technologies across regions, while smaller firms are carving out niches in repair, leading-edge protection, or regional service delivery. New entrants face a high bar because qualification cycles are lengthy, performance data is increasingly standardized, and asset owners prefer suppliers with proven field track records. As a result, successful differentiation tends to come from deep application know-how, validated test results, and the ability to support customers through both manufacturing and operational phases.
Future Outlook: Three Trends Shaping the Next Three to Five Years
The first trend is the acceleration of solvent-free and low-emission coating architectures across both manufacturing and maintenance applications. As regulatory pressure and customer sustainability expectations continue to build, formulations that reduce volatile emissions and simplify handling will become the default choice in many projects. This trend will favor companies with established R&D pipelines in high-performance, low-emission chemistries and those that can demonstrate equivalent or superior durability relative to legacy solvent-based systems.
The second trend is the increasing importance of standardized durability testing as a commercial filter. With maturing protocols for ice adhesion, hail resistance, and corrosion system selection, procurement teams will rely more heavily on comparable performance data when shortlisting suppliers. This will reward firms that invest in robust testing programs and transparent documentation, while raising the cost of entry for players that cannot substantiate performance claims under recognized methods. Over time, this dynamic will likely concentrate share among suppliers that can consistently meet or exceed benchmark expectations.
The third trend is the expansion of service-linked coating business models. As operators seek to reduce maintenance frequency and protect power output, coatings that enable faster repairs and longer protection intervals will create recurring engagement opportunities. Expect more partnerships between coating suppliers, blade service providers, and turbine operators to co-develop repair protocols, train field teams, and optimize application conditions. This service dimension will make coatings a more integrated part of asset management strategies rather than a one-time purchase at commissioning.
Special Epoxy Resin for Wind Power Blades Market
Potential risks remain. Raw material price swings could compress margins if companies cannot adjust formulations or lock in feedstock stability. Regulatory divergence across regions may complicate product launches and require multiple formulation variants, increasing cost and time-to-market. In addition, if standardization efforts outpace the availability of validated products, qualification delays could slow adoption of advanced systems. Businesses should treat these risks as design parameters in their planning rather than external uncertainties to be monitored passively.
Strategic Recommendations for Decision-Makers
For turbine manufacturers and blade producers, the priority is to align coating selection with production efficiency and lifecycle durability. Evaluate solvent-free and fast-curing systems that can reduce mould cycle times while meeting environmental targets, and require suppliers to provide standardized test data for erosion, corrosion, and environmental exposure. Where possible, consolidate supply relationships for both manufacturing coatings and repair solutions to simplify qualification and improve consistency across turbine platforms.
For investors and portfolio managers, attention should focus on companies with differentiated formulation capabilities, strong technical documentation, and exposure to both manufacturing and maintenance segments. Businesses that can demonstrate recurring demand through repair and service offerings, or that control critical resin and polymer inputs, are better positioned to capture value as the market matures. Monitor regulatory trajectories in key regions, since compliance readiness will increasingly separate leaders from laggards.
For procurement teams and asset owners, the most effective approach is to shift evaluation criteria from unit price toward total cost of ownership. Prioritize coatings with documented performance under standardized tests, clear application guidance, and support for field repairs. Establish qualification criteria early in project planning, and request lifecycle-oriented documentation that connects coating performance to inspection intervals, maintenance logistics, and downtime costs. This discipline will help reduce operational risk and improve long-term asset economics.
For organizations seeking to move from strategic insight to execution, detailed segmentation data, regional granularity, and tailored competitive assessments can sharpen planning further. A comprehensive research report can provide the deeper breakdowns and scenario analysis needed to validate product roadmaps, pricing strategies, and market entry decisions. Engaging with that level of detail early enables teams to act with confidence rather than retrofit strategy after market conditions have already shifted.
For detailed analysis of this topic, please visit the official page: Wind Power Coating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


