



Wire Enamels Market: Why 6.8% CAGR and EV Motors Redefine Growth

The Wire Enamels Market: Strategic Trends and Commercial Opportunities Through 2032
The global Wire Enamels Market has entered a phase of structural expansion, defined by steady revenue growth, technological differentiation, and shifting demand patterns across industrial and transportation sectors. From a baseline of approximately 952.5 million USD in 2020, the market scaled to 1287.75 million USD in 2025, reflecting an annualized growth trajectory that positions the segment for continued uplift. Projections for the forecast period spanning 2026 through 2032 indicate revenue will advance toward 2032.1 million USD by the end of the horizon, underpinned by a compound annual growth rate of 6.8 percent. The 2020 to 2025 historical window captured the market’s recovery from supply chain disruptions, followed by a demand rebound driven by motor manufacturing, transformer replacements, and the accelerating adoption of electric drivetrains. As the industry moves into the mid-to-late 2020s, the growth curve is no longer solely dependent on volume expansion; it is increasingly shaped by formulation performance, regulatory compliance, and regional capacity realignment. For executives and investors evaluating exposure to industrial coatings and electrical insulation materials, the market presents a structurally favorable environment, but one that requires disciplined positioning to navigate raw material volatility, evolving compliance mandates, and intensifying product differentiation.
Despite the positive macro trajectory, the industry is confronting a set of inflection points that will determine which participants capture disproportionate value over the next several years. The first challenge lies in balancing performance requirements with cost control. End-users in motors and automotive components increasingly demand insulation systems that withstand higher operating temperatures, improved thermal dissipation, and extended service life, while simultaneously pressuring suppliers for more predictable pricing. This tension is amplified by the second challenge: raw material cost dynamics. Fluctuations in resin feedstocks, pigment supplies, and specialty chemical intermediates have repeatedly raised production expenses across the value chain, prompting manufacturers to reassess procurement strategies and pricing architectures. The third challenge involves the regulatory environment. Stringent environmental standards on solvent-based formulations are accelerating the transition toward low-VOC and solvent-free solutions, forcing incumbents and new entrants alike to invest in reformulation, testing, and compliance documentation. Together, these forces are reshaping competitive benchmarks. Companies that can integrate advanced polymer chemistry, stabilize input costs through strategic sourcing, and align product portfolios with regulatory and performance expectations are best positioned to convert market growth into durable margin expansion.
Technological Innovation and Formulation Breakthroughs
Product innovation is becoming a primary vector of differentiation in the Wire Enamels Market, with advances centered on hybrid architectures, thermal stability, and application-specific reliability. Organic-inorganic hybrid polyamide-imide formulations have emerged as a notable development, offering enhanced insulation performance for high-demand electrical systems where thermal endurance and mechanical resilience are critical. These hybrid systems are particularly relevant for electric vehicle powertrains, wind turbine generators, and other high-performance electrical applications that push conventional enamel limits. Parallel progress in polyesterimide and polyamide-imide chemistries is enabling manufacturers to deliver tailored solutions for magnet wire coatings, allowing winding producers to optimize balance between dielectric strength, flexibility, and cure characteristics. The shift toward formulation precision is also supported by improved process control and closer collaboration between enamel suppliers and winding wire manufacturers. Rather than treating enamels as commodity coatings, leading participants are positioning them as engineered components within larger motor and transformer designs. This approach creates room for premium positioning, especially where customers seek to reduce failure rates, improve energy efficiency, or extend maintenance intervals. Innovation is therefore not only a technical storyline; it is a commercial strategy that links material performance directly to end-product value.
Policy and Regulatory Pressures Reshaping Formulation Paths
Regulatory momentum is exerting a powerful influence on product design and manufacturing choices. Environmental requirements targeting solvent-based wire enamels are encouraging a broader migration toward sustainable low-VOC solutions and solvent-free systems. This transition is not simply a compliance exercise; it affects formulation stability, application behavior, curing requirements, and downstream processing compatibility. Manufacturers must therefore coordinate changes in chemistry with customer production environments to ensure that new coatings perform reliably under real-world winding and impregnation conditions. In parallel, regulatory scrutiny around emissions, workplace safety, and chemical handling is increasing the importance of documentation, testing protocols, and transparent supply chain practices. Companies that proactively align their portfolios with evolving standards can reduce the risk of retrofit costs, specification changes, and market access delays. Conversely, late adaptation can leave suppliers exposed to customer qualification bottlenecks and regional compliance mismatches. The regulatory trajectory also intersects with customer expectations for sustainability, meaning that environmental performance is increasingly part of the purchasing rationale rather than a separate administrative issue.
Demand-Side Shifts in Motors, Automotive, and Electrical Equipment
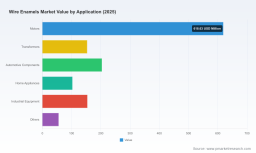
Demand behavior is changing as end-use sectors reassess performance, reliability, and electrification goals. Motors remain the dominant demand anchor, reflecting their pervasive role in industrial machinery, HVAC systems, and increasingly efficient electric drives. Automotive components represent another high-growth demand center, where the expansion of electrified powertrains and the need for robust motor windings are elevating the importance of high-performance insulation materials. Beyond these segments, transformers and industrial equipment continue to contribute meaningfully, supported by grid infrastructure upgrades, industrial automation, and replacement cycles for aging equipment. Home appliances and other smaller-scale applications add breadth to the demand base, though they typically place different emphasis on cost and processing convenience versus extreme thermal or mechanical performance. A key demand-side trend is the growing preference for enamel solutions that can support higher efficiency and reliability without compromising manufacturability. This is prompting closer specification alignment between enamel suppliers and winding producers, as well as more rigorous qualification processes for new formulations. The commercial implication is clear: demand growth is increasingly tied to applications where insulation performance directly affects system outcomes, giving advanced products a stronger value proposition than in lower-specification settings.
Supply Chain Reconfiguration and Cost Structure Dynamics
Cost structure dynamics remain a central factor shaping competitiveness. Volatility in raw material inputs, including resin and pigment pricing, has increased production expenses and complicated margin planning for producers. This environment is encouraging more active procurement strategies, such as multi-source sourcing, long-term supply arrangements, and formulation adjustments that reduce exposure to volatile intermediates without sacrificing performance. Capacity decisions are also being revisited in response to regional demand patterns and cost considerations. Investments in production footprint expansion are being directed toward locations where demand growth is strongest and where manufacturers can better serve local winding wire producers and component manufacturers. At the same time, pricing actions are becoming more selective, with increases tied to specific chemical families and market conditions rather than applied uniformly across all products. These adjustments reflect a broader move toward disciplined portfolio management, where profitability depends on aligning cost recovery with value delivered in each application segment. Supply chain resilience is therefore not just a logistics concern; it is a strategic differentiator that affects pricing credibility, delivery reliability, and the ability to scale advanced formulations.
PW Consulting Chemical & Energy Research Center
Competitive Dynamics and Strategic Positioning
The competitive landscape features a mix of specialty coating manufacturers, large materials companies, and integrated wire and coating suppliers, with no single dominance pattern across all regions or application segments. Market concentration remains moderate, with the top three participants holding a combined share in the mid-twenties and the top five only slightly higher, indicating that differentiation, regional presence, and application-specific expertise still matter greatly. This fragmented-but-specialized structure creates opportunities for companies that can combine formulation strength with strong customer proximity and technical service capabilities. Several leading participants are pursuing distinct strategic angles. One established European-focused manufacturer has built a broad portfolio of high-performance enamels for magnet wire coatings, emphasizing global production sites and custom solutions for motors and electric vehicles. This provider has also taken steps to expand capacity in southern China to align supply with rising regional demand, while implementing selective price adjustments across major chemical families to reflect changing market conditions. Another major coatings company has advanced hybrid polyamide-imide solutions, including a recent launch of an organic-inorganic hybrid wire enamel recognized for its relevance to electric vehicles, wind turbines, and high-performance electrical systems. That product momentum signals a deliberate push into segments where insulation reliability is a critical purchasing criterion. A large U.S.-based materials company has supported its polyesterimide offering through capacity-related expansion tied to an acquisition, reinforcing its ability to supply electric vehicle and industrial motor applications. A Japanese specialist has focused on high-efficiency insulation materials developed in collaboration with electric vehicle component producers, illustrating the value of application-side partnerships in refining product fit. In parallel, an integrated wire and coating supplier serves winding wire manufacturers with enameled wire and enamel offerings, while another global materials producer provides resins and coating inputs that support high-temperature and motor applications. These varied strategies highlight a market where value capture depends on combining chemistry, capacity, and customer-facing engineering rather than competing on price alone.
Market Evolution Toward Integration, Differentiation, and Targeted Entry
The market structure is evolving along several directions at once. Consolidation pressure exists in regions where scale, regulatory compliance, and technical service requirements raise the barrier to effective competition, yet the moderate concentration levels suggest that specialization and regional strength remain viable paths. Differentiation is intensifying around performance classes, with high-performance polyesterimide, polyamide-imide, and hybrid formulations attracting greater attention than lower-specification alternatives in demanding applications. This creates a two-layer competitive environment: one where commodity-adjacent products compete on cost and supply reliability, and another where engineered coatings compete on thermal endurance, dielectric robustness, and application fit. New entry and expansion activity is likely to remain selective, favoring participants with existing chemical expertise, production know-how, and customer relationships in motors, transformers, or automotive components. At the same time, capacity additions are being shaped by regional demand centers, especially where electrification and industrial modernization are accelerating. The overall trend is toward a more segmented market in which success depends on matching product architecture to application requirements, maintaining dependable supply, and adapting to regulatory change without losing commercial momentum.
Outlook: Three Structural Trends Shaping 2026 to 2032
The next several years are likely to be defined by three reinforcing trends. First, high-performance and hybrid enamel formulations will continue to gain share in demanding applications as electric vehicle motors, wind power equipment, and advanced industrial drives push insulation requirements higher. This trend favors suppliers that can demonstrate measurable improvements in thermal resistance, reliability, and process compatibility, and it creates opportunities for premium pricing where performance outcomes are clearly valued by customers. Second, sustainability-driven reformulation and regulatory compliance will become standard elements of competitive capability rather than occasional initiatives. Low-VOC and solvent-free directions will increasingly influence specification decisions, procurement criteria, and regional market access, making formulation agility and compliance readiness a durable advantage. Third, regional capacity alignment will grow in importance as manufacturers seek to serve local demand more efficiently and reduce exposure to input cost disruptions and logistics constraints. Together, these trends suggest a market where growth is not uniform across products or geographies, but is concentrated in segments where performance, compliance, and supply reliability converge. The commercial opportunity lies in identifying those convergence points early and building the technical and operational capabilities required to serve them consistently.
Worldwide Retangular Enameled Wire Market
These trends also carry risks that warrant careful monitoring. Raw material volatility can compress margins if pricing mechanisms lag cost movements, especially in periods when resin and pigment inputs fluctuate sharply. Regulatory changes may outpace reformulation timelines, creating qualification gaps or regional mismatches that slow adoption of new products. Demand intensity can also vary by segment, with electrification-related applications potentially experiencing cyclical or project-driven swings that affect planning accuracy. Additionally, capacity expansion in high-growth regions may intensify competition if multiple suppliers pursue the same demand pockets simultaneously, placing pressure on both pricing and customer qualification cycles. Managing these uncertainties will require scenario-aware sourcing, disciplined product roadmaps, and close engagement with downstream customers to anticipate specification shifts before they become disruptive.
Strategic Actions for Different Decision-Maker Profiles
For manufacturers and product leaders, the priority is to sharpen formulation strategy around the applications that most value performance differentiation. This means investing in hybrid and high-temperature systems where insulation reliability translates into customer benefits, while maintaining a cost-competitive baseline for lower-specification segments. Equally important is building technical service capabilities that help winding wire producers and motor manufacturers integrate new enamels efficiently, since adoption often depends on processing compatibility and qualification support as much as on material properties. For investors and corporate development teams, the focal point should be the intersection of electrification-driven demand, regulatory-driven reformulation, and regional capacity shifts. Opportunities are likely to be strongest where suppliers can demonstrate both product leadership and supply resilience, especially in motors and automotive components. Evaluating exposure should therefore go beyond headline growth figures to include portfolio mix, pricing discipline, compliance readiness, and regional manufacturing alignment. For procurement and sourcing leaders, the practical goal is to balance performance, cost, and continuity risk by diversifying supply where possible, aligning specifications with sustainability and reliability requirements, and monitoring input cost trends that may affect pricing stability. Long-term supply agreements and early engagement on reformulation transitions can help reduce disruption risk while preserving access to advanced insulation materials.
The Wire Enamels Market is moving from steady growth toward a more performance-sensitive and regulation-shaped competitive environment. The companies that capture the most value will be those that align product architecture with demand intensity, operate with resilient cost structures, and respond quickly to compliance and application changes. For decision-makers seeking deeper segmentation detail, regional demand patterns, and customized scenario planning, the full PW Consulting research report provides the additional data and structured analysis needed to translate these strategic themes into precise commercial decisions.
Enameled Wire Market
For detailed analysis of this topic, please visit the official page: Wire Enamels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


