



Rubber Conveyor Belt Market: Why the 4.05% CAGR Path from 2026–2032 Redefines Strategy

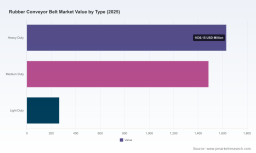
Rubber Conveyor Belt Market: Strategic Trends and Commercial Opportunities (2026–2032)
1. Market Snapshot and Core Challenges
The global rubber conveyor belt market has transitioned from a post-pandemic recovery phase into a period of measured, structurally driven growth. Revenue reached approximately 3.38 billion USD in 2025, expanding from 2.80 billion USD in 2020 at a compound annual growth rate of 4.05 percent. The forecast period through 2032 projects the market to approach 4.46 billion USD, with growth trajectories reflecting both steady baseline demand and periodic accelerations tied to heavy industrial capital cycles. This trajectory signals a market that is no longer defined by volatile rebounds but by operational efficiency imperatives, material handling scale-up, and the gradual replacement of aging infrastructure across mature and emerging economies.
Despite this constructive outlook, the industry faces intersecting challenges that will separate agile operators from stagnant incumbents. First, raw material price volatility and supply chain fragmentation continue to compress margins, particularly for manufacturers reliant on synthetic rubber, carbon black, and steel cord inputs. Second, the regulatory and operational push toward energy efficiency and emissions reduction is forcing end-users to reassess belt specifications, favoring longer-life, lower-friction solutions that carry higher upfront costs but deliver measurable total cost of ownership benefits. Third, market concentration remains pronounced, with the top three players holding roughly 45 percent share and the top five approaching 60 percent. This concentration creates a dual dynamic: established leaders benefit from scale, technical credibility, and service networks, while smaller producers face pressure to differentiate through niche applications, regional agility, or cost-optimized manufacturing footprints.
For executives and investors, the implication is clear. The market is not simply growing; it is restructuring around performance metrics, service intensity, and regional demand shifts. Strategy that ignores these structural forces risks exposure to commoditization, whereas strategy that aligns product portfolios, supply chain resilience, and customer-facing value propositions with the new operating reality can capture disproportionate share.
PW Consulting Chemical & Energy Research Center
2. Key Drivers Reshaping the Market
Technological Innovation and Material Performance
The most consequential driver is the ongoing evolution of reinforcement technology and compound engineering. Steel-cord reinforcement, for example, is forecast to post a 6.05 percent CAGR through 2031, outpacing broader market growth. This acceleration is not a statistical artifact; it reflects a practical shift in how operators design material handling systems. Steel-cord belts provide high tensile strength and low elongation, enabling longer single-flight conveyors that lower energy consumption and reduce maintenance frequency. As mining, cement, and bulk logistics operators seek to minimize downtime and energy intensity, the specification conversation is moving from "replace like-for-like" to "optimize system performance." This shift favors manufacturers with advanced carcass design capabilities, consistent quality control, and the technical service infrastructure to support engineered solutions rather than commodity replacement.
Beyond reinforcement, innovation in cover compounds, abrasion resistance, and heat or oil resistance is expanding the addressable use cases for rubber belts in environments previously dominated by alternative materials. The commercial reality is that value is migrating toward performance-justified pricing, where buyers accept higher unit costs in exchange for extended service life, fewer belt related stoppages, and reduced total energy consumption. Manufacturers that can quantify these benefits and supply evidence-backed specifications will command better margins and stronger customer retention.
Regulatory and Operational Pressure on Efficiency and Safety
Policy and regulatory trends are not acting as blunt constraints; they are reshaping procurement logic. Environmental and workplace safety expectations are increasing scrutiny on dust generation, spillage, and maintenance-related exposure in bulk handling facilities. Simultaneously, energy cost awareness is driving procurement teams to evaluate conveyor systems through a lifecycle lens. In this environment, belt selection becomes a strategic variable rather than a tactical purchase. Industry recognition patterns reflect this shift: ContiTech was named Best Conveyor Belt Supplier for the third consecutive time in Chile in October 2025, with additional recognition for belt cleaners. Such recurring validation in demanding operating environments signals that leading suppliers are being rewarded not merely for product availability but for reliability, local operational support, and complementary system solutions that reduce material carryback and maintenance burden.
For decision-makers, the operational takeaway is that compliance and efficiency are converging. Regulations and corporate sustainability goals are increasingly aligned with the same outcome: fewer failures, less energy waste, and lower exposure to operational risk. Suppliers that can position their offerings within this combined narrative gain access to procurement conversations that were previously locked behind price negotiations.
Demand-Side Shifts in Mining, Manufacturing, and Logistics
Demand is being reshaped by the differing growth rhythms of core application sectors. Mining continues to anchor market volume, supported by bulk material movement in extractives and the need to transport ore, coal, and aggregates across increasingly large site layouts. Manufacturing and logistics and warehousing are expanding on the back of throughput optimization, automation compatibility, and the need for dependable internal material movement in high-lot operations. What unites these segments is a declining tolerance for unplanned downtime and a growing willingness to invest in belts that integrate cleanly with broader conveyor system design.
A notable demand-side change is the shift from reactive replacement to planned lifecycle management. Operators are increasingly aligning belt procurement with maintenance scheduling, conveyor redesign, and site expansion plans. This creates opportunities for suppliers that can offer application engineering, installation guidance, and failure analysis as part of the value proposition. It also raises the barrier for pure price-based competition, because buyers are comparing packages rather than unit prices alone.
Supply Chain and Cost Structure Evolution
Cost structures are being recalibrated by input volatility, logistics complexity, and the strategic reorganization of manufacturing footprints. In response, leading companies are pursuing consolidation of production assets, selective localization, and tighter control over critical inputs. Yokohama Rubber’s consolidation of its conveyor belt subsidiary in China illustrates this direction. The move was designed to further stabilize earnings under its Yokohama Transformation 2026 medium-term plan, reflecting a broader tendency to rationalize regional operations where scale, coordination, and margin stability can be improved. Rather than expanding everywhere, mature players are prioritizing operational coherence and earnings predictability.
At the same time, the supply base is being tested by the need to balance cost competitiveness with specification integrity. Lower-cost production can win short-term procurement rounds, but inconsistent quality creates hidden costs in the field. The market is therefore developing a clearer hierarchy: premium engineered belts for demanding applications, cost-competitive belts for less severe service, and a growing expectation that suppliers clearly differentiate these tiers rather than blur them. The companies that manage this tiering transparently will be better positioned to defend margins while retaining volume.
Heavy Duty Conveyor Belts Market
3. Competitive Landscape and Leading Strategies
Structural Positioning of Core Players
The competitive set reflects a blend of specialized European technology suppliers, large international rubber producers, and increasingly capable Asian manufacturers serving both domestic and export markets. SIG S.p.A. operates as a specialized manufacturer of rubber conveyor belts and elevator belts with textile and steel carcass construction for bulk material handling, positioning itself around application specificity and carcass expertise. ContiTech leverages its broader industrial rubber and materials handling heritage to supply energy-efficient and heavy-duty models for industrial, mining, and materials handling applications, with an emphasis on system-level performance and recognized field reliability.
In China, Zhejiang Double Arrow Rubber Co., Ltd. stands out as a leading producer of fabric, steel cord, solid woven, aramid, and specialized rubber conveyor belts, supported by global sales and ISO certifications. Qingdao Rubber Six Conveyor Belt Co., Ltd. similarly manufactures fabric, steel cord, and heavy-duty rubber conveyor belts under the Rubber Six and Zhonghua brands, reflecting the scale and range available within the Chinese supply base. On the Japan-linked side, The Yokohama Rubber Co., Ltd. manufactures rubber conveyor belts through its wholly owned subsidiary Shandong Yokohama Rubber Industrial Products Co., Ltd., while Bando Chemical Industries, Ltd. supplies conveyor belts and related rubber products for industrial power transmission and materials handling. Fenner Dunlop Conveyor Belting rounds out the landscape with durable rubber and PVC conveyor belts for mining, industrial, and heavy-duty applications, distributed across EMEA and the Americas.
These profiles matter because they reveal two competing axes of advantage. One axis is application depth: companies that emphasize carcass technology, cover compound engineering, and technically supported solutions. The other axis is reach and cost orchestration: companies that combine broad product ranges, certifications, and multi-region distribution with disciplined manufacturing. The strongest players increasingly operate along both axes by offering tiered portfolios, credible technical service, and recognizable reliability in demanding markets.
Differentiation and Strategic Themes
Several strategic themes differentiate the leaders from the rest of the field. First, engineered solution selling is becoming a margin defense mechanism. Suppliers that can size belts to conveyor geometry, material characteristics, and throughput targets reduce the likelihood of under-specification and over-specification, both of which create friction in procurement and maintenance. Second, recognition and repeatability in difficult operating environments build a form of credibility that is hard for new entrants to replicate quickly. Recurrent awards or customer validations in high-stress regions indicate that a supplier’s products and support infrastructure perform under real conditions, not just in specification sheets.
Third, organizational consolidation is becoming a strategic lever. Yokohama Rubber’s subsidiary consolidation in China demonstrates how companies can seek earnings stability and operational focus rather than pursuing undifferentiated geographic expansion. This pattern suggests that future competition will not only be about who has the broadest footprint, but about who manages its footprint with the greatest coherence, quality consistency, and capital discipline. Fourth, complementary system components are gaining attention. Belt cleaners and related accessories are increasingly part of the commercial conversation because they reduce carryback, improve cleanliness, and lower maintenance effort. Recognition of belt cleaner performance alongside belt supply signals a market that is progressively valuing integrated material handling outcomes.
Market Evolution: Consolidation, Fragmentation, and Entry Dynamics
The market is likely to evolve through selective consolidation among scale players seeking margin stability and operational efficiency, alongside continued fragmentation in regional and niche segments where local service, cost positioning, or specialized applications matter. New entry remains possible, but the barriers are rising in the premium engineered segment, where performance history, testing capability, and customer trust compound over time. In the value segment, entry and competition remain more fluid, though price competition alone is increasingly risky as buyers become more aware of lifecycle costs and specification sensitivity.
For manufacturers and investors, the strategic question is where competitive advantage is being created and preserved. In demanding mining and heavy industrial applications, advantage is being built through technical reliability, long-life designs, and service density. In broader industrial and logistics applications, advantage is increasingly tied to consistent quality, predictable delivery, and clear segmentation between duty levels. The companies that can articulate and deliver these distinctions will be better placed to sustain pricing power and customer loyalty.
4. Future Trends and Commercial Implications
Over the next three to five years, three trends are likely to shape commercial outcomes. The first is the continued shift toward steel-cord and high-performance reinforcement in applications where conveyor length, load intensity, and energy efficiency justify the specification. With steel-cord belts forecast to grow at a 6.05 percent CAGR through 2031, the commercial opportunity lies in application engineering, lifecycle justification, and service support that helps operators realize the intended efficiency gains. The revenue opportunity is not simply in selling more belts; it is in aligning product selection with system-level performance so that higher specification becomes a defensible investment rather than a premium price objection.
The second trend is the growing importance of recognized reliability and localized support in key operating regions. Recurring supplier recognition in challenging environments suggests that buyers increasingly value proof of performance and responsive service over generalized brand claims. This creates commercial opportunities for manufacturers that invest in regional technical presence, failure analysis capability, and fast response to field issues. It also raises the stakes for suppliers that depend on remote selling without sufficient local problem-solving capacity, because trust in demanding applications is difficult to build and easy to lose.
The third trend is the rationalization of manufacturing and service footprints around earnings stability and cost discipline. As seen in recent corporate moves to consolidate subsidiaries and focus on medium-term transformation plans, companies are likely to favor operational clarity over unchecked expansion. For buyers and investors, this can translate into more predictable supply, clearer product segmentation, and potentially stronger supplier commitment to quality and service in core markets. For exporters and smaller regional players, the implication is that scale, certification, and consistent execution will matter more than before, especially where buyers are under pressure to reduce total cost of ownership without sacrificing reliability.
Potential risks and uncertainties should be monitored closely. Raw material swings can undermine margin plans even when demand is healthy. Over-investment in heavy industrial capacity during cyclical upswings can create exposure if mining or cement activity soften. Regulatory and sustainability expectations may accelerate specification upgrades, which is favorable for premium suppliers but challenging for cost-focused operators with limited engineering support. Finally, the line between rubber and alternative belt materials in some applications may narrow if competing technologies improve on cost, weight, or maintenance characteristics. Competitive strategy will therefore require continuous reassessment of where rubber belts hold a durable advantage and where substitution risk is rising.
5. Strategic Actions for Decision-Makers
For Manufacturers and Suppliers
Develop a clearly segmented portfolio that separates engineered high-performance solutions from cost-competitive standard offerings, with transparent differentiation in duty, reinforcement, and expected service life. Build the technical service capability needed to justify higher specifications through application engineering, lifecycle analysis, and field failure insights. Prioritize operational coherence in key regions, focusing on quality consistency, delivery reliability, and recognized performance in demanding environments rather than pursuing growth that dilutes margin or control. Where complementary system components such as belt cleaners are relevant, evaluate whether bundling or coordinated solution selling can strengthen customer retention and differentiate from pure product suppliers.
For Investors
Assess exposure not only to top-line market growth, but to the structural forces that determine margin quality: reinforcement mix, application intensity, regional service density, and the ability to defend price through performance justification. Companies with disciplined manufacturing consolidation, credible field recognition, and a defensible position in steel-cord or other faster-growing reinforcement types are better aligned with the market’s direction than generic volume players. Monitor for cyclical risk in mining-anchored demand and for substitution pressure in less severe applications, and weigh these against the durability of engineering-led differentiation and regional reputation.
For Procurement and Operations Leaders
Shift evaluation criteria from unit price to total cost of ownership, incorporating energy efficiency, expected service life, downtime reduction, and maintenance burden. Use specification as a strategic lever: select belt types that match material characteristics and conveyor geometry, and request evidence-backed performance data rather than accepting generic claims. Strengthen supplier relationships where local support, failure analysis, and rapid response are available, because these capabilities increasingly determine operational resilience. Where possible, align belt procurement with planned maintenance and conveyor optimization programs to capture the full value of higher-specification solutions.
Conveyor Belts Market
For decision-makers seeking a deeper, segment-level view of growth trajectories, regional demand dynamics, duty-level breakdowns, and company-level strategic positioning, the full market research report provides the additional granularity needed to translate these trends into customized action plans. The broader market trajectory is clear; the practical advantage lies in the details that connect product strategy, sourcing decisions, and capital allocation to the operating realities shaping the next phase of demand.
For detailed analysis of this topic, please visit the official page: Rubber Conveyor Belt Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


