



Flame Retardant Cable Market: The 4.5% CAGR Shift Reshaping 2032 Demand

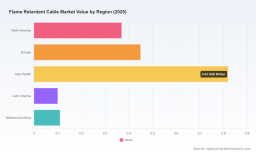
Flame Retardant Cable Market: Strategic Trends and Commercial Opportunities for Forward-Looking Enterprises
The global market for flame retardant cable solutions has entered a phase of mature, steady expansion characterized by shifting regulatory emphasis and evolving end-user performance requirements. Valued at approximately USD 1.85 billion in 2025, the sector has demonstrated a compound annual growth rate of roughly 4.5 percent through the forecast period extending to 2032, with total revenue projected to approach USD 2.5 billion by the end of the decade. This trajectory reflects a market that is no longer driven primarily by volume growth in traditional construction wiring, but rather by incremental value creation through compliance, safety certification, and application-specific engineering. Growth is increasingly concentrated in segments where fire performance is non-negotiable, where circuit integrity must be preserved under extreme thermal load, and where building codes intersect with operational continuity concerns across transportation, energy, and industrial facilities.
Several structural features define the current landscape. Market concentration remains moderate, with the top three players capturing roughly one-third of total revenue and the top five collectively accounting for close to half. This distribution suggests an environment where scale advantages coexist with meaningful regional and technical differentiation, allowing specialized manufacturers to compete on certification portfolios, insulation chemistry, and application engineering rather than price alone. At the same time, the broader cable industry contends with raw material volatility across copper, plastics, rubber, and aluminum, which directly influences manufacturing economics for flame retardant formulations. These input cost dynamics, combined with rising compliance complexity, have raised the bar for execution and are filtering out operators without strong testing infrastructure or established certification relationships.
Against this backdrop, the market is navigating a series of pivotal challenges that will shape competitive positioning over the next several years. The first is the accelerating pace of regulatory revision across major codes. Ongoing updates to fire safety standards are tightening performance thresholds for emergency circuits, increasing concrete encasement requirements in certain jurisdictions, and aligning fire detection and alarm system expectations with more rigorous cable testing protocols. As building codes evolve toward 2026 and beyond, compliance is shifting from a checkbox exercise to a continuous engineering requirement, pressuring manufacturers to maintain up-to-date certification evidence and technical documentation for each installed base.
A second challenge lies in balancing smoke and toxicity management against mechanical and electrical performance. Low smoke zero halogen formulations and other advanced insulation systems are gaining prominence in enclosed transit environments, high-rise residential buildings, and data-centric facilities where occupant evacuation and equipment survivability are paramount. Yet these materials often require precise compounding, controlled curing, and specialized jacketing to achieve target flame propagation and circuit integrity metrics. The technical trade-offs between halogenated and halogen-free architectures, as well as between cost and fire-rated performance, are forcing suppliers to invest in application-specific validation rather than rely on generic product lines.
A third challenge is the growing alignment of fire safety expectations with operational resilience in mission-critical environments. As facilities such as AI data centers, semiconductor plants, and advanced manufacturing sites demand uninterrupted power under fault conditions, the value proposition of flame retardant cable is expanding beyond life safety toward business continuity. This shift introduces new testing requirements, supply chain rigor, and documentation standards that smaller players struggle to meet consistently, while incumbents leverage their engineering depth to secure long-term specification wins. The result is a market in which differentiation is increasingly earned through demonstrated performance under extreme temperatures, validated circuit survival, and reliable delivery of certified product into complex projects.
Key Drivers Shaping Market Momentum
Innovation in Fire-Resistant Insulation and Circuit Integrity Solutions
Technological progress continues to reshape what flame retardant cable can achieve under real-world fire conditions. Recent product commercialization illustrates how insulation chemistry, conductor shielding, and jacketing design can be integrated to sustain power delivery under severe thermal stress. A notable example is the launch of a medium-voltage fire-resistant cable capable of maintaining circuit function at temperatures up to 830°C, developed specifically for AI data centers and semiconductor plants and aligned with updated IEC 60331-4 standards. This type of capability redefines the performance ceiling for critical infrastructure wiring, where even brief loss of power can translate into significant operational and financial consequences.
Flame Retardant Fabric Market
At the same time, fire-resistant and low smoke zero halogen variants are being refined for high-rise residential, transit, and industrial applications where flame propagation control and circuit integrity are specified as part of project approval. Manufacturers that pair material science expertise with in-house testing and certification workflows are better positioned to convert code changes into specification opportunities. The practical implication for buyers and designers is that performance is no longer determined solely by nominal voltage or conductor size; it increasingly depends on validated behavior under fire exposure, which makes detailed technical comparison and certification evidence central to procurement decisions.
Regulatory Evolution and Compliance as a Specification Driver
Policy and code activity remains a primary force behind demand for compliant fire-resistant solutions. Revisions to widely referenced standards are raising the bar for how emergency circuits are installed and protected, including stronger concrete encasement expectations and enhanced testing alignment for fire detection and alarm systems. In parallel, construction product regulations in major markets require manufacturers to demonstrate compliance through documented testing and certification, adding a layer of traceability that influences both product development and sales cycles.
These regulatory dynamics create a dual effect. On the demand side, they increase the addressable scope for certified flame retardant cables by expanding the range of applications where fire performance must be proven. On the supply side, they raise the cost of entry and ongoing compliance, favoring organizations that can maintain current certifications, support specification teams with technical evidence, and adapt product portfolios quickly when standards are updated. For executives overseeing portfolio strategy, the takeaway is that regulatory tracking should be treated as a core commercial function rather than a back-office compliance task, because the timing and substance of code changes often determine which product variants win in upcoming project cycles.
Demand-Side Shifts Toward Resilience in Critical Facilities
End-user behavior is changing as digital infrastructure and advanced manufacturing become more central to economic activity. Data center operators, semiconductor fabricators, and energy facility managers are placing greater emphasis on continuity of supply under fault conditions, which elevates the importance of cables that can maintain function while resisting flame spread. This demand-side shift is not merely a safety preference; it is increasingly an operational requirement tied to uptime commitments, insurance considerations, and facility certification.
In building and construction, the trend is visible in specification practices that favor documented fire performance for vertical risers, transit interchanges, and enclosed public spaces. In automotive and industrial wiring, fire-resistant insulation options are being evaluated for applications where thermal events could compromise both safety and equipment integrity. Across these segments, the common thread is a growing willingness to pay for verified performance when the cost of failure is high. For suppliers, this creates an opportunity to move beyond commoditized pricing by offering application-engineered solutions with clear certification backing and technical support during the design and approval phases.
Supply Chain and Cost Structure Pressures
The economics of flame retardant cable production are being shaped by input cost volatility and the operational demands of maintaining certified product streams. Fluctuations in copper and polymer markets directly influence manufacturing costs, while the need to produce materials with consistent flame retardant and low smoke characteristics adds complexity to sourcing and compounding. These pressures are encouraging consolidation of production capability in facilities that can achieve scale, control quality tightly, and sustain certification evidence across batches.
Worldwide Flame Retardant Masterbatches Market
Capacity investments in specialized fire-resistant lines reflect this reality. For example, expansion of a fire-resistant LSZH cable production facility has increased annual capacity to better serve demand in high-rise residential and transit sectors, signaling that manufacturers are aligning capacity additions with the applications where compliance and performance requirements are most stringent. Such moves illustrate a broader pattern: investment is flowing toward product lines where specification wins are repeatable and where certification and engineering support can be monetized through long-term contracts and recurring project flow.
Competitive Landscape and the Strategies of Leaders
The market is shaped by a mix of global cable leaders and regionally strong specialists, each pursuing distinct strategic positioning. The leading organizations differentiate not only through scale, but through application focus, certification depth, and the ability to integrate fire safety into broader infrastructure solutions. Their recent actions provide a useful lens on how competitive advantage is being built in this segment.
One global group has concentrated on fire-resistant cables, including low smoke zero halogen variants designed for high-rise, transit, and industrial environments, with particular emphasis on circuit integrity and flame propagation compliance. Its recent capacity expansion in the UK demonstrates a deliberate alignment of production capability with demand in high-specification building and transit projects. This approach positions the company to compete on technical reliability and compliance documentation rather than on price alone, and it signals to specifiers that supply continuity for certified product is a priority.
A major European cable manufacturer has pursued a complementary strategy centered on fire-resistant and fire-retardant solutions for critical infrastructure, with an emphasis on the building and energy sectors. Its recent acquisition of a Spanish low-voltage cable producer specializing in fire-resistant building solutions illustrates a willingness to consolidate regional capability and broaden portfolio coverage where code-driven demand is intensifying. By combining organic standard upgrades with targeted acquisitions, this type of player seeks to secure both technical credibility and local specification relationships, which can translate into more resilient project pipelines.
A South Korean manufacturer has focused on high-performance fire-resistant cables that meet IEC 60331 standards, including medium-voltage and energy storage applications. Its commercialization of a medium-voltage fire-resistant cable designed for AI data centers and semiconductor plants highlights how advanced manufacturing and energy-adjacent demand can pull new performance classes into the market. This trajectory suggests that strategic differentiation can emerge from serving emerging high-value applications where fire safety intersects with power continuity and equipment survivability.
Other active participants extend the competitive picture into automotive and industrial wiring systems, where fire-resistant insulation options are increasingly specified, as well as into high- and low-voltage power cables with fire safety features for energy and infrastructure. An additional industrial and energy-focused player rounds out the landscape by supplying fire-resistant and flame-retardant cables for industrial and energy applications. Collectively, these companies illustrate a market where segmentation is blurring at the edges: players are no longer defined solely by commodity cable volume, but by their ability to deliver certified performance into specific end-use contexts.
The market structure is evolving along several axes. Consolidation is evident where acquirers seek to strengthen regional footprints and expand certified portfolios, particularly in segments tied to building infrastructure and energy. Differentiation is intensifying where manufacturers build technical narratives around circuit integrity, smoke management, and extreme-temperature performance. New entry or re-entry remains challenging because of the certification burden and testing requirements, which tend to favor incumbents with established compliance infrastructure. At the same time, mid-tier specialists can still compete effectively by concentrating on a narrow application set and delivering superior documentation, technical support, and delivery reliability.
Future Outlook: Three Trends to Watch
The next three to five years are likely to be defined by the convergence of stricter compliance expectations, higher performance thresholds, and a more selective allocation of capacity toward high-value applications. One trend to monitor is the continued elevation of certification and documentation as core commercial assets. As codes evolve and specification committees place greater weight on validated fire performance, products with current, well-maintained certification evidence and clear technical narratives will gain an advantage in competitive bids. This trend benefits manufacturers that invest in testing agility and transparent compliance communication, while increasing the risk for those that treat certification as episodic rather than operational.
A second trend is the migration of flame retardant cable requirements into mission-critical digital and energy infrastructure. Data centers, semiconductor facilities, and advanced energy installations are driving demand for solutions that preserve circuit function under severe thermal conditions. This shift expands the strategic relevance of medium-voltage and specialized fire-resistant variants, and it creates opportunities for suppliers that can align product capabilities with the continuity requirements of these facilities. The opportunity is not simply to sell cable, but to participate earlier in the design process and to offer performance data that supports specification and approval.
A third trend is the potential for regional divergence in code intensity and enforcement, which may influence where demand grows fastest and where localized compliance capability becomes a competitive necessity. Areas with accelerating construction of high-rise residential, transit, and critical infrastructure may see stronger pull for certified fire-resistant solutions, while regions with slower code adoption could experience more price-sensitive competition. Organizations operating across multiple markets will need to manage these differences carefully, balancing portfolio standardization with local specification readiness.
These trends carry risk. Raw material volatility can compress margins if pricing mechanisms lag cost movements. Regulatory pace and interpretation can vary by jurisdiction, creating uncertainty for product roadmaps and capacity planning. Supply chain disruptions can affect the availability of certified batches, which in turn can jeopardize project timelines and specification commitments. The commercial implication is that resilience depends on diversified sourcing, disciplined cost management, and the ability to sustain certification continuity even as inputs and standards shift.
Actionable Recommendations for Decision-Makers
For manufacturers and product leaders, the priority is to treat certification and application engineering as growth enablers rather than support functions. That means maintaining current alignments with evolving fire safety codes, investing in testing capacity that supports rapid validation of new formulations, and building documentation frameworks that help specification teams justify selection. Companies should also consider targeted capacity and portfolio moves toward applications where circuit integrity and extreme-temperature performance command willingness to pay, especially in data centers, semiconductor facilities, and critical building infrastructure. The guiding question is whether the organization can reliably deliver certified performance into the projects that matter most, and whether its technical narrative is clear enough to win in specification committees.
For investors evaluating exposure to this segment, the key is to distinguish between volume-driven commodity exposure and value-driven compliance exposure. Businesses with strong certification portfolios, application-specific engineering capability, and relationships in high-specification building, transit, and energy markets are better positioned to sustain margins through raw material cycles and code changes. Capacity expansions that target fire-resistant LSZH and medium-voltage fire-resistant lines should be assessed against the durability of demand in the intended end-markets. Due diligence should emphasize the quality of testing and certification processes, the stability of key specification wins, and the company’s ability to adapt product offerings as standards evolve.
For procurement and specification teams, the strategic task is to embed fire performance evidence into early design decisions rather than treating compliance as a last-stage requirement. That includes comparing cable options on validated circuit integrity, smoke and toxicity behavior, and the currency of certification, not just on nominal specifications. Procurement strategies should give weight to suppliers that can demonstrate consistent batch-to-batch compliance, provide timely technical support during approval cycles, and maintain supply continuity for certified product. In environments where downtime costs are high, selecting cable based on documented extreme-temperature performance and circuit survival can reduce operational risk in ways that are not visible on a unit price comparison.
PW Consulting Chemical & Energy Research Center
In a market where regulatory momentum, application criticality, and material economics are reshaping competitive rules, timely access to detailed segmentation data, regional demand signals, and company-level benchmarking becomes a practical necessity. Decision-makers who need granular breakdowns by insulation material, application mix, regional dynamics, and competitor positioning will find that deeper intelligence directly supports portfolio planning, capacity allocation, and specification strategy. For those seeking a more complete view of the Flame Retardant Cable Market—including detailed segmentation data, regional trends, and customized strategic recommendations—PW Consulting’s full research report offers expanded analysis and targeted guidance to support concrete business decisions.
For detailed analysis of this topic, please visit the official page: Flame Retardant Cable Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


