



PVB Film Market 2026: Beyond the 6.98% CAGR Story

The PVB Film Market at a Strategic Inflection Point: Growth, Innovation, and Competitive Realignment
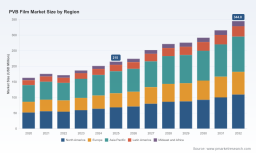
The poly vinyl butyral (PVB) film market has entered a phase of sustained expansion, with global revenue projected to climb from approximately 215.0 million USD in 2025 to 344.8 million USD by 2032, reflecting a compound annual growth rate of 6.98% across the 2026–2032 forecast window. This trajectory builds on a recovery and acceleration pattern observed from 2020 through 2025, during which the market moved from 163.15 million USD to its current scale despite intermittent supply chain disruptions and macroeconomic volatility. The underlying growth is not merely a bounce-back from pandemic-era constraints; it signals a structural shift driven by performance requirements, regulatory pressures, and evolving end-use expectations. For executives and investors, the PVB film sector presents a concentrated yet dynamically evolving landscape where technological differentiation, sustainability credentialing, and supply chain resilience are becoming the primary axes of competition.
At the same time, the market is not sailing into calm waters. Three interlocking challenges define the current operating environment. First, raw material volatility and input cost pressure continue to test margin structures. Key precursors for PVB film production, including butyraldehyde and polyvinyl alcohol, remain exposed to petrochemical price cycles, logistics friction, and currency translation effects. Recent disclosures indicate that exchange rate fluctuations and fuel cost movements have imposed material headwinds on operating profit for major producers, with one leading manufacturer reporting a negative impact quantified in the billions of its local currency during its most recent fiscal reporting period. Second, the industry is navigating a tightening sustainability and transparency mandate. Customers and regulators are increasingly scrutinizing the carbon footprint of interlayers, pushing producers to adopt certified bio-based or recycled content, renewable energy usage, and third-party verification frameworks. Third, demand is bifurcating across application segments, with some verticals demanding higher structural performance and others prioritizing aesthetic customization or cost efficiency. This divergence forces manufacturers to manage multiple product architectures simultaneously, complicating capacity planning and R&D allocation.
Navigating the Core Challenges
The margin challenge is not simply a cost-pass-through exercise. Producers that rely on undifferentiated standard PVB film face intensifying price sensitivity, especially in applications where interlayer performance requirements are modest. At the same time, the shift toward high-performance variants, which command premium positioning, requires incremental investments in formulation science, processing control, and application-specific validation. These investments are non-trivial, and the return profile depends on the ability to secure design wins in automotive programs, specification adoption in architectural projects, and qualification in photovoltaic laminates. The sustainability mandate adds another layer of complexity. Certification achievements and the integration of recycled resin content are becoming table stakes in certain customer conversations, particularly in Europe and North America, where procurement teams are embedding environmental criteria into supplier qualification processes. Producers that treat sustainability as a compliance checkbox rather than a product and process strategy risk losing specification relevance over time.
Demand bifurcation is equally consequential. Automotive applications continue to drive a substantial share of volume, propelled by evolving vehicle architectures, safety expectations, and the gradual redesign of interiors and glazing systems. Architectural usage remains a steady and growing contributor, supported by building codes, renovation activity, and a growing appetite for specialized visual effects in premium and commercial projects. The photovoltaic segment, while smaller in relative terms, is gaining attention as solar module makers explore improved encapsulation and durability characteristics. The strategic implication is clear: growth is available, but it is unevenly distributed, and capturing it requires targeted product roadmaps rather than broad-based volume plays.
Key Drivers Reshaping the PVB Film Market
Three to four core drivers are interacting to reshape the competitive and commercial dynamics of the PVB film market. These drivers do not operate in isolation; they reinforce one another and collectively raise the bar for what constitutes a viable market position.
Technological Innovation and Performance Breakthroughs
Performance differentiation is moving from a nice-to-have to a decisive purchase criterion. In laminated safety glass, the interlayer's role is expanding beyond basic structural bonding and optical clarity.Automotive OEMs and Tier suppliers are seeking interlayers that contribute to acoustic comfort, impact resistance, and shape retention under stress, while architectural specifiers are looking for films that enable thinner glass packages, improved load-bearing characteristics, and distinctive visual finishes. Recent product introductions illustrate this direction. In the spring of 2024, a major producer launched a next-generation interlayer engineered for improved structural capacity, resistance, toughness, and elasticity, signaling a push toward higher-performance standards in safety glass applications. Later in the year, another incumbent introduced a low-carbon film variant that incorporated recycled resin content and leveraged renewable energy in its production process. By the following year, a European-focused manufacturer unveiled a specialized interlayer designed to deliver a refined visual effect suited to minimalistic architectural designs. These launches collectively demonstrate that innovation is branching into both performance engineering and aesthetic customization, broadening the value proposition beyond traditional transparency and adhesion.
The strategic takeaway is that R&D is becoming a direct revenue lever. Manufacturers that can shorten qualification cycles, align product attributes with end-use validation protocols, and communicate performance benefits in customer-relevant terms are better positioned to secure long-term specification loyalty. Conversely, firms that stagnate on product architecture risk being squeezed between premium innovators and cost-oriented competitors.
Policy, Regulation, and Sustainability Credentials
Regulatory and sustainability dynamics are increasingly shaping procurement decisions and competitive access. Certification frameworks that verify the bio-based or recycled content of materials, as well as the sustainability of manufacturing operations, are gaining traction in customer qualification checklists. Recent certification milestones have covered PVB film products and major production sites across Europe, the United States, and Asia, reflecting a deliberate effort by leading players to institutionalize sustainability credentials across their global footprint. This is not merely a public relations exercise; it is becoming a gateway to certain projects and programs where environmental criteria are embedded in sourcing policy. At the same time, producers are deploying financial and operational instruments to manage input volatility, including derivative tools to hedge exposure on strategic raw materials. The combination of sustainability certification and cost-risk management is creating a more resilient operating model, but it also raises the investment threshold for staying competitive.
For decision-makers, the implication is that sustainability is converging with commercial risk management. Procurement teams are weighing not only price and performance but also the compliance and reputational risk associated with material sourcing. Manufacturers that can provide traceable, verified content and energy sourcing data are gaining an advantage in specification discussions, particularly in regions where regulatory and customer expectations are advancing most quickly.
Demand-Side Shifts in Automotive, Architecture, and Energy Applications
Demand-side behavior is evolving across the three primary application areas, each with distinct drivers. In automotive, glazing strategies are being influenced by vehicle electrification, interior redesign, noise and vibration refinement, and the ongoing push for lighter, safer, and more aesthetically cohesive cabin environments. These trends support continued demand for interlayers that can meet stricter performance profiles while enabling designers to achieve new visual and tactile outcomes. In architecture, the drivers are more varied: building energy codes, renovation and retrofit activity, security and safety requirements, and a growing interest in bespoke finishes for commercial and premium residential projects. The photovoltaic application, while representing a smaller share of current demand, is attracting attention as module manufacturers and integrators evaluate encapsulation options that can contribute to longevity, optical consistency, and processing compatibility. The common thread is that customers are becoming more application-literate and are expecting film suppliers to speak to specific use-case requirements rather than offering generic interlayer solutions.
This specificity changes the commercial dynamic. Winning in automotive often requires long lead times, rigorous testing, and program-aligned supply commitments. Winning in architecture frequently depends on specification relationships, visual and performance differentiation, and the ability to support architects and fabricators with consistent quality and aesthetic options. Winning in photovoltaic contexts depends on validation against module-level durability and processing requirements. Each path requires a tailored go-to-market model, and the firms that can orchestrate these models coherently are better positioned to convert demand into durable revenue.
Supply Chain and Cost Structure Evolution
The supply side is being reshaped by the interplay of input volatility, capacity decisions, and regional localization pressures. Key raw materials remain sensitive to petrochemical cycles and logistics costs, and currency movements can materially affect operating results for globally exposed producers. In response, leading manufacturers are pursuing a combination of hedging strategies, production optimization, and selective capacity expansion or rationalization. The objective is to protect margins without sacrificing service levels or quality consistency. There is also a growing emphasis on reducing the carbon intensity of production, which can involve energy sourcing changes, process efficiency improvements, and the integration of recycled or bio-based feedstocks where technically and commercially viable. These efforts are not isolated initiatives; they are increasingly woven into product positioning and customer discussions, blurring the line between operational efficiency and market-facing value creation.
The practical consequence is that cost leadership alone is becoming harder to sustain as a differentiator. While efficiency remains essential, the more durable advantages are emerging from the combination of performance innovation, verified sustainability attributes, and reliable supply assurance. Producers that can deliver this combination are able to command more favorable commercial terms and build deeper relationships with specifiers and procurement organizations.
Competitive Landscape and Leading Strategies
The PVB film market is characterized by a high degree of concentration, with the top three producers accounting for approximately 79% of market value and the top five representing around 85%. This concentration reflects the scale, technical know-how, and qualification infrastructure required to compete effectively across automotive and architectural applications. It also means that competitive dynamics are shaped by a relatively small number of players whose product portfolios, geographic reach, and sustainability commitments directly influence market direction.
Strategic Positioning of Leading Players
Several incumbent companies illustrate the divergent yet overlapping strategies now unfolding. One U.S.-based producer has built a strong association with laminated safety glass interlayers for both automotive and architectural markets, leveraging established brand recognition and a broad application footprint. Recent moves have combined product innovation with sustainability positioning, including the introduction of a low-carbon film variant that incorporates recycled resin content and uses renewable energy in production. The same company has also relied on derivative instruments to manage volatility in the cost of strategic raw materials, highlighting a dual focus on product differentiation and cost-risk control. Another major player, headquartered in Japan, maintains a globally recognized interlayer portfolio and has pursued a parallel path of performance and sustainability advancement. This includes the launch of a next-generation stiff interlayer designed for improved structural capacity and the achievement of sustainability certification covering products and major plants in Europe, the United States, and Asia. A Taiwanese producer contributes a distinct angle through its focus on polyvinyl butyral resins and film for safety glass interlayers, adhesives, and printing inks, reflecting a broader materials orientation that can support integrated supply advantages. A Belgium-based manufacturer has carved out a specialized position in high-quality PVB film for architectural laminated safety glass, with recent attention to refined visual effects tailored for minimalistic design contexts.
These profiles reveal a market in which leaders are not merely competing on volume but are differentiating along multiple axes: performance engineering, aesthetic customization, sustainability verification, and supply chain resilience. The strategic implication is that competitive advantage is becoming multidimensional. A single strength, such as cost efficiency or brand recognition, is less sufficient on its own than it once was. Instead, the most defensible positions combine at least two of the following: application-specific performance leadership, credible sustainability credentials, and reliable, localized supply capability.
Market Structure Evolution: Consolidation, Differentiation, and Entry Dynamics
Given the high concentration and the technical barriers associated with qualification, scale, and application validation, the market is likely to see continued consolidation pressure among smaller or less differentiated participants. At the same time, the bifurcation of demand and the emergence of specialized product attributes are creating space for targeted differentiation, even within a concentrated landscape. New entry remains challenging because of the need to secure design wins, pass validation protocols, and establish supply reliability across demanding customer segments. However, niche opportunities may arise in specialized architectural finishes, high-performance interlayers for specific automotive programs, or application-tailored solutions for photovoltaic encapsulation, where focused innovation and strong specification relationships can offset scale disadvantages. The broader trend is one of strategic segmentation: the market is not becoming uniformly consolidated into a single winners-take-all structure, but rather into a set of performance and application niches where distinct value propositions can command premium positioning.
VCI Film Market
For observers of competitive dynamics, the key question is not whether concentration will persist, but how value will be distributed within that concentrated structure. Leaders that can translate product innovation into specification wins and sustainability credentials into procurement preference will likely capture a disproportionate share of the incremental growth projected through the end of the decade and into the early 2030s.
Forward Outlook: Three Trends to Watch Over the Next Three to Five Years
Looking ahead, the PVB film market is likely to be shaped by trends that connect technological ambition, sustainability expectations, and application-specific demand. These trends carry both opportunity and risk, and they should inform near-term strategic planning.
Performance-Led Premiumization Accelerates
The push toward higher-performance interlayers is expected to intensify as automotive and architectural customers raise their expectations for structural capacity, acoustic behavior, durability, and design flexibility. This trend favors producers that can validate advanced attributes in relevant applications and secure design or specification wins early in program or project cycles. The commercial opportunity lies in building a portfolio of differentiated variants that address specific performance gaps, supported by technical service and application engineering. The risk is that premiumization outpaces the ability to scale qualified production or that customers resist premium pricing in cost-sensitive segments, forcing difficult trade-offs between margin and volume.
Sustainability Becomes a Specification Factor, Not a Differentiator
Sustainability credentials are on a trajectory from optional advantage to expected attribute in several regions and customer segments. Certification coverage across major production sites, the use of recycled or bio-based content, and renewable energy integration are increasingly part of supplier evaluations. The opportunity is to embed sustainability into product identity and process design in ways that are verifiable and customer-relevant, thereby reducing friction in qualification and strengthening preference in competitive bids. The uncertainty lies in the pace and uniformity of adoption. If expectations diverge significantly by region or application, producers may face complex portfolio and compliance decisions. If standards tighten faster than anticipated, firms that have not invested early may find themselves excluded from certain opportunities or forced into catch-up investments at higher cost.
Supply Chain Localization and Cost Discipline Reshape Competitive Resilience
Input volatility, currency exposure, and logistics complexity are likely to keep cost and supply resilience in focus. Producers will continue to pursue a mix of hedging, process efficiency, energy sourcing changes, and selective capacity adjustments. The opportunity for resilient operators is to combine cost discipline with reliable service and consistent quality, building trust with customers who are themselves managing procurement risk. The risk is that overinvestment in capacity in a softening segment or underinvestment in qualifying new variants can distort the portfolio and weaken competitive positioning. Additionally, regional cost structures and regulatory environments may create uneven profitability across geographies, requiring disciplined portfolio management rather than blanket expansion.
PW Consulting Chemical & Energy Research Center
Actionable Implications for Decision-Makers
For manufacturers, the priority is to align product roadmaps with the specific performance and aesthetic requirements of high-value applications while institutionalizing sustainability credentials across production sites. This means treating R&D as a commercial engine, not a back-office function, and ensuring that new variants are supported by validation data, technical service, and clear positioning. It also means building cost-risk management into the operating model, using hedging and process optimization to protect margins without compromising quality or service. Companies that can demonstrate measurable performance benefits and credible sustainability attributes are more likely to secure specification loyalty and defend premium positioning.
For investors, the strategic signal is that growth is real but unevenly distributed across applications and product tiers. The most attractive exposure is likely to be found in producers that combine application-relevant innovation with verified sustainability and disciplined cost management, rather than in undifferentiated volume plays. Due diligence should focus on qualification pipelines, certification coverage, raw material exposure, and the ability to convert product launches into specification wins. Portfolio valuation should account for the possibility that premiumization and sustainability adoption will accelerate in some regions and segments faster than others, creating divergence in growth and margin profiles across the competitive set.
For procurement and sourcing leaders, the practical guidance is to evaluate suppliers on a broader set of criteria that includes performance validation, sustainability verification, and supply assurance, not just unit price. The most resilient sourcing relationships will be those in which the supplier can demonstrate traceability, consistent quality, and the ability to support application-specific requirements over the life of a program or project. Engaging early in design and specification cycles, and aligning on sustainability and performance expectations upfront, can reduce downstream risk and improve total value.
For all of these audiences, the pace of change in the PVB film market argues for timely, granular intelligence. High-level growth figures and concentration ratios provide context, but the commercial decisions that matter most—program qualification, specification strategy, capacity allocation, sustainability investment, and sourcing commitments—depend on detailed segmentation data, regional demand patterns, and company-level trajectories. Accessing deeper, structured analysis can shorten the distance between market awareness and actionable strategy, enabling more precise prioritization of investments, partnerships, and risk mitigation.
PV Ribbon Market
For detailed analysis of this topic, please visit the official page: PVB Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


