



Category: Healthy Lifestyle
The Real Drivers Behind Chlorogenic Acid’s 5.69% Growth Trajectory Through 2032
By PW Consulting, 2026-09-21
Chlorogenic Acid Market: Strategic Shifts and Commercial Opportunities Through 2032
Market Snapshot and Core Challenges
The chlorogenic acid market has evolved from a niche botanical ingredient into a structurally important segment within the broader functional ingredients landscape. Over the past five years, the market has demonstrated steady expansion, moving from a baseline above 160 million USD in 2020 to an estimated 215 million USD in 2025. Looking ahead through 2032, the trajectory points toward continued growth, with values projected to exceed 315 million USD by the end of the forecast period. This translates to a compound annual growth rate of approximately 5.69 percent, a pace that reflects durable demand rather than a short-lived hype cycle. The growth profile suggests an ingredient that is gradually moving from specialized applications into mainstream formulations, supported by both consumer interest and formulator confidence.
Despite this favorable growth backdrop, the market faces several structural challenges that will shape how companies compete and where value is captured. First, raw material exposure remains a persistent vulnerability. Global coffee production has consistently exceeded 11 million tons, with roughly 8 million tons traded internationally and Brazil and Viet Nam accounting for nearly half of total output. This concentration creates a supply chain that is inherently sensitive to weather events, crop disease, logistics bottlenecks, and shifting trade dynamics. For chlorogenic acid processors, the consequence is not simply a pricing issue but a structural dependency on a commodity ecosystem that can swing quickly from surplus to constraint.
Second, regulatory divergence across key markets is adding complexity to formulation and market access strategies. In Europe, specific food products such as coffee substitutes have faced limits on chlorogenic acid content set below 100 mg/L, creating a compliance framework that differs materially from other regions. In the United States, chlorogenic acid is recorded as a dietary substance with no specific quantity restrictions identified in the latest database, reflecting a more permissive posture. This asymmetry means that global ingredient suppliers and finished product manufacturers must manage distinct formulation rules, documentation requirements, and labeling considerations depending on where products are sold. The regulatory gap is not necessarily a barrier to growth, but it does reward companies that can navigate multiple compliance regimes efficiently while disadvantaging those that rely on a single-market assumption.
Third, the market is entering a phase where differentiation is becoming more difficult to sustain through generic claims alone. As awareness of chlorogenic acid spreads across nutraceutical, food and beverage, cosmetics, and pharmaceutical applications, the risk increases that the ingredient becomes a commoditized specification rather than a strategic differentiator. Suppliers that compete primarily on price or broad availability may find margins compressing as the market matures. The strategic question is whether companies can build defensible positions through purity standards, clinical validation, traceability, application-specific functionality, or proprietary processing methods before the market settles into a more homogeneous competitive structure.
Key Drivers Reshaping the Market
Technological Innovation and Processing Precision
A central driver of market evolution is the maturation of extraction and purification technologies that enable higher consistency and purity levels. The ability to deliver high-purity chlorogenic acid extracts, including HPLC 98 percent grades, has shifted the ingredient from a broadly characterized botanical to a defined functional input with repeatable specifications. For formulators, that precision matters because it reduces batch-to-batch variability, supports more accurate dosing, and simplifies regulatory and quality documentation. It also creates room for premium positioning, particularly in applications where bioactive consistency is tied directly to performance claims or clinical credibility.
At the same time, extraction innovation is increasingly linked to supply security and traceability rather than purity alone. Recent capacity and sourcing expansions in key raw-material hubs have demonstrated how processors are tightening control over upstream supply chains. By strengthening relationships with producing regions and improving traceability systems, leading suppliers are attempting to reduce the risk of disruption while also reinforcing the quality narrative that premium buyers increasingly expect. This combination of technical precision and supply accountability is becoming a meaningful competitive lever, especially in applications where ingredient provenance is part of the product story.
Policy and Regulatory Environment
Regulatory dynamics are influencing both the pace and the shape of market growth. The divergence between mature markets and emerging markets means that product developers cannot assume a uniform pathway for chlorogenic acid-rich formulations. European limits in certain food categories require careful application engineering, while the U.S. posture allows more flexibility in dietary and supplement contexts. This landscape encourages companies to invest in regulatory intelligence and application-specific formulation strategies rather than treating chlorogenic acid as a universally interchangeable ingredient.
Trade policy adds another layer of influence. Recent adjustments in U.S. green coffee tariffs have begun to alter import expenditures for key producing regions, affecting cost structures and sourcing decisions for downstream processors. For companies that rely on imported green coffee beans or related botanical inputs, these shifts can affect landed costs, working capital, and the economics of regional sourcing strategies. The implication is that regulatory and trade monitoring is no longer a peripheral activity; it is becoming a strategic input into sourcing, pricing, and market-entry decisions.
Demand-Side Shifts in Consumer and Business Behavior
Demand is being shaped by a broader move toward functional wellness, metabolic health, and plant-based formulation preferences. In nutraceutical and dietary supplement contexts, chlorogenic acid is often associated with metabolic and weight-management narratives, which continue to attract consumer attention and drive product development. In food and beverage, the ingredient is increasingly evaluated for flavor-compatible functional benefits, especially in formats that seek to combine taste with a health-oriented positioning. In cosmetics and personal care, botanical actives with antioxidant and skin-care relevance continue to support interest in chlorogenic acid as part of multi-functional ingredient systems.
Importantly, the demand story is not limited to end consumers. Business buyers are increasingly asking for documented functionality, application support, and supply reliability. This shift raises the bar for ingredient suppliers. Companies that can offer more than raw material, such as formulation guidance, consistency data, and application-specific performance context, are better positioned to secure long-term contracts and defend pricing. The market is therefore rewarding suppliers that treat chlorogenic acid as part of a solutions offering rather than a standalone commodity.
Supply Chain and Cost Structure Dynamics
Cost structures in the chlorogenic acid market are influenced by a mix of agricultural supply conditions, processing complexity, and logistics. The concentration of coffee output among a small number of producing countries heightens the sensitivity of input availability to regional disruptions. When supply is tight, processors face not only higher raw material costs but also the challenge of maintaining consistent specifications. When supply is ample, competition can intensify and pricing pressure can increase, particularly for standard-grade material. This cyclicality means that effective cost management requires more than negotiating favorable purchase prices; it depends on portfolio diversification, inventory strategy, and the ability to shift between supply sources without compromising quality.
The market also benefits from diversified botanical sources beyond green coffee beans. Honeysuckle and eucommia-based inputs contribute additional supply options and can help reduce single-commodity dependency. However, the strategic use of alternative sources is not simply about substitution. It requires understanding how each source compares in terms of yield, purity potential, regulatory acceptance, and application fit. Suppliers that can integrate multiple raw material pathways with consistent processing standards are better equipped to manage volatility while preserving specification integrity.
Ellagic Acid Market
Competitive Landscape and Leading Strategies
The competitive environment in the chlorogenic acid market reflects a blend of globally established botanical ingredient specialists and high-scale producers with strong regional footprints. The market is moderately concentrated, with a meaningful share of activity captured by a limited set of leading suppliers. This concentration suggests that scale, technical capability, and supply-chain control are important determinants of competitive advantage, while also leaving room for differentiated niches in application-specific formulations and premium-grade extracts.
Naturex, part of Givaudan, illustrates a strategy centered on standardized green coffee bean extracts with strong emphasis on traceability and quality compliance. Its focus spans nutraceutical, functional beverage, and cosmetic applications, where consistent specification and documented sourcing are valued by formulators. Recent capacity and sourcing expansions in Ecuador and Viet Nam signal a deliberate effort to strengthen raw-material security and improve traceability across key producing regions. Alongside that, the introduction of high-concentration bioactive solutions for beverage applications shows a push to connect chlorogenic acid more directly with flavor-compatible functional formats. This dual approach, supply resilience paired with application-driven innovation, positions the company to serve buyers who want both reliability and product development support.
Applied Food Sciences has built a distinct positioning around branded green coffee bean extracts with defined chlorogenic acid content, particularly for dietary supplements, weight-management, and metabolic health formulations. This brand-and-specification strategy is well aligned with the demand-side shift toward clear functional claims and repeatable ingredient profiles. By emphasizing defined content and usage clarity, the company appeals to customers who need a recognizable ingredient identity for marketing and formulation purposes. In a market where generic botanical ingredients can be harder to differentiate, branded and specification-led offerings can create stronger customer loyalty and more defensible pricing.
EUROMED SA represents a pharmaceutical- and clinical-grade orientation, emphasizing high-purity botanical extracts for APIs, dietary supplements, and clinical-grade nutraceutical formulations. This positioning places the company closer to regulated and quality-intensive end uses, where documentation, purity, and process control carry greater weight. The strategic value of this approach lies in its alignment with higher-specification applications that often tolerate less price competition and more value on compliance and consistency. As the broader market expands into more demanding use cases, suppliers with credible high-purity capabilities may capture a disproportionate share of value relative to volume.
Sabinsa Corporation rounds out the competitive picture with a science-backed herbal and botanical API focus, including chlorogenic acid extracts supported by clinical validation. Its relevance lies in the intersection of pharmaceutical, nutraceutical, and preventive healthcare markets, where evidence and credibility are central to adoption. Companies operating in this space benefit when the market moves toward more substantiated claims and more rigorous buyer expectations, because clinical backing and scientific positioning become tangible differentiators rather than generic marketing language.
A notable feature of the competitive landscape is the presence of large-scale producers, particularly in China, that have built substantial export-oriented capacity for high-purity chlorogenic acid extracts. Some of these players have established meaningful global market shares and supply footprints across multiple countries. Their strength typically comes from scale, process efficiency, and the ability to serve a wide range of international buyers with defined purity grades. This creates a two-tier competitive dynamic: on one side, suppliers competing on volume, consistency, and price accessibility; on the other, companies competing on branding, clinical narrative, regulatory positioning, and application-specific value. The market is likely to continue supporting both tiers, but with increasing pressure on scale players to demonstrate more than cost leadership if they want to protect margins as the market matures.
The competitive evolution is also being shaped by a broader trend toward integration and specialization. Some suppliers are expanding upstream into sourcing hubs to reduce exposure and improve traceability. Others are developing application-focused product lines to capture more value in specific formats such as beverages or clinical nutraceuticals. At the same time, new entrants can still find opportunities if they bring a clearly defined niche, whether that is a particular purity standard, a specialized botanical source, or a targeted application competency. The most durable strategies appear to be those that combine operational reliability with a specific value proposition, rather than attempting to compete across every segment at once.
Forward Outlook: Three Trends to Watch
One likely trend over the next three to five years is the continued shift from generic chlorogenic acid supply to application-tailored solutions. As the ingredient becomes more familiar, buyers will increasingly expect support for specific formulation challenges, including stability, sensory compatibility, dosage clarity, and regulatory fit. Suppliers that invest in application development and provide practical formulation support are more likely to secure recurring demand and reduce vulnerability to price-based competition. The commercial opportunity here lies in creating defensible relationships with formulators and brands that value solutions over mere material supply.
A second trend is the growing importance of traceability, purity assurance, and documentation as baseline expectations rather than premium extras. This is being reinforced by both regulatory asymmetry and buyer behavior. As more companies sell into multiple markets, the ability to demonstrate consistent quality and clear sourcing becomes a commercial necessity. Suppliers that can standardize quality systems, provide reliable specification data, and maintain transparent sourcing pathways will be better positioned to serve international customers and reduce the friction associated with multi-market compliance. The upside is stronger customer trust and longer contract cycles; the risk is that any lapse in quality or documentation can spread quickly through a tightly connected buyer network.
A third trend is the potential for regional supply-chain reconfiguration as trade dynamics and sourcing economics evolve. Tariff adjustments, logistics costs, and production concentration all influence where and how chlorogenic acid inputs are sourced and processed. Over time, some suppliers may pursue more diversified sourcing strategies or regional processing arrangements to reduce exposure to any single origin or trade channel. For buyers, this could create both opportunities and risks: more sourcing flexibility can improve resilience, but frequent shifts in supply routes can also affect consistency and commercial terms. Companies that proactively monitor these shifts and build flexible sourcing strategies will be better prepared to manage cost and continuity.
Each of these trends carries embedded uncertainty. Regulatory frameworks may tighten in some markets or remain permissive in others, altering where the most attractive growth opportunities appear. Agricultural conditions could disrupt input availability and create pricing volatility that tests the resilience of weaker operators. And as the market expands, competitive intensity may increase in the most accessible segments, compressing the room for undifferentiated suppliers. The companies most likely to benefit will be those that treat these uncertainties as strategic variables to manage rather than external events to simply react to.
Strategic Actions for Decision-Makers
For ingredient manufacturers and suppliers, the priority is to strengthen the link between technical capability and commercial positioning. This means investing in consistent high-purity outputs, reliable traceability systems, and application-relevant support that helps buyers integrate chlorogenic acid more effectively into their products. Companies should also evaluate whether they are overly dependent on a single raw material pathway or a single geographic source, and consider whether portfolio diversification or upstream sourcing relationships can reduce vulnerability. In a market where scale alone is increasingly difficult to monetize, differentiation through quality assurance, formulation support, and application focus is likely to offer better long-term protection.
PW Consulting Health Care Research Center
For investors and strategic capital allocators, the relevant question is where value is likely to accumulate as the market matures. Volume growth is expected to continue, but the most attractive opportunities may lie in suppliers with credible differentiation in purity, clinical or scientific positioning, traceability, or application ownership. It is also worth distinguishing between businesses that depend primarily on commodity-style throughput and those that can capture more value through branded or specification-led offerings. Monitoring regulatory changes, trade policy shifts, and raw material concentration risk should be part of any investment thesis, because these factors can alter cost structures and market access faster than volume trends alone would suggest.
Ferulic Acid Market
For procurement and formulation teams, the practical focus should be on reducing exposure to inconsistency and compliance friction. This includes evaluating suppliers not only on price but also on specification reliability, documentation quality, and the ability to support multi-market requirements. Long-term supply agreements may be more valuable when paired with performance expectations around consistency and traceability. Procurement teams may also benefit from maintaining a diversified supplier base that includes both scale-oriented and specialty-oriented partners, allowing them to balance cost efficiency with resilience and application fit.
For all of these stakeholders, the strategic value of deeper intelligence is clear. The chlorogenic acid market is large enough to matter and dynamic enough to reward informed decisions, but its nuances, from regulatory asymmetry to raw material concentration and competitive differentiation, are difficult to navigate with high-level summaries alone. More detailed segmentation data, company-level positioning, and application-specific dynamics can materially improve sourcing, investment, and product development decisions. A comprehensive research report can provide that granularity, offering a more precise view of where demand is building, how competitive positions are evolving, and which supply and formulation strategies are most likely to withstand market volatility.
For detailed analysis of this topic, please visit the official page: Chlorogenic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Chemotherapy Induced Peripheral Neuropathy Treatment Market: 6.5% CAGR from 2026-2032
By PW Consulting, 2026-09-21
Chemotherapy-Induced Peripheral Neuropathy Treatment Market: Strategic Trends and Commercial Opportunities
The chemotherapy-induced peripheral neuropathy (CIPN) treatment market has reached a critical inflection point. With a total market value of approximately $1.46 billion in 2025 and a projected trajectory to exceed $2.28 billion by 2032, the sector reflects a compound annual growth rate of 6.5 percent over the 2026-2032 period. This expansion is not merely a function of rising oncology volumes. It represents a structural shift in how the pharmaceutical industry approaches symptom management, neurological preservation, and quality-of-life endpoints in cancer care. Chemotherapy remains one of the most widely deployed modalities in oncology, and neuropathy stands among its most persistent and debilitating side effects. Patients receiving platinum-based agents, taxanes, and vinca alkaloids frequently experience progressive sensory loss, pain, balance impairment, and treatment-limiting dose reductions. The market for interventions addressing these outcomes has evolved from a fragmented landscape of off-label symptomatic therapies into a structured pipeline of mechanism-targeted candidates, increasingly shaped by regulatory guidance and clinical evidence standards.
Yet the scale of opportunity is matched by complexity. Stakeholders approaching this space must navigate a market where clinical differentiation, regulatory pathways, pricing dynamics, and oncology practice patterns intersect in non-linear ways. The next phase of growth will likely reward players who can translate mechanism plausibility into robust trial design, align with evolving oncology workflows, and articulate value propositions that resonate beyond symptom relief alone. Understanding where the market stands today, what forces are reshaping it, how competitors are positioning themselves, and where strategic opportunities are likely to emerge provides a necessary foundation for informed decision-making.
Market Landscape and Core Challenges
The CIPN treatment space is characterized by moderate market concentration and a therapeutic mix that still leans heavily on existing symptomatic classes, particularly antidepressants and anticonvulsants, alongside a smaller but strategically important segment of narcotics and emerging alternatives. This composition reflects both historical prescribing habits and the limited number of approved, mechanism-specific interventions. While the broader market size demonstrates steady expansion, the underlying structure reveals a sector that is simultaneously mature in its standard-of-care elements and early-stage in its innovation pipeline. That duality creates both stability and uncertainty, as legacy therapies continue to anchor clinical practice while newer candidates attempt to redefine therapeutic expectations.
A first challenge lies in clinical endpoint definition and trial design. CIPN presents across a spectrum of sensory, motor, and autonomic symptoms, and the field has historically struggled to standardize how improvement, stabilization, or prevention should be measured. Different chemotherapy regimens, cumulative dosing patterns, and patient baseline risk profiles complicate the creation of uniform trial populations. Sponsors that rely on broad symptom scales without mechanistic alignment or clearly defined responder thresholds risk generating data that is difficult to position clinically or commercially. The challenge is not simply demonstrating statistical change. It is demonstrating clinically meaningful change that oncologists, neurologists, and payers can act upon.
A second challenge is the persistent alignment gap between existing symptomatic classes and the underlying neurobiology of nerve injury. Current treatments often address perceived symptom pathways without directly interrupting axonal degeneration, ion channel dysfunction, or inflammatory signaling associated with specific chemotherapeutic agents. As understanding of CIPN mechanisms matures, therapies that are not linked to a plausible biological rationale may face growing pressure in clinical discussion and formulary positioning. This does not render all symptomatic options obsolete, but it does raise the bar for differentiation. The market increasingly favors interventions that can articulate not only what they treat, but why they should work in a particular chemotherapy context.
PW Consulting Health Care Research Center
A third challenge involves the oncology treatment environment itself. Dose adjustments, regimen substitutions, and individualized risk-benefit calculations can influence both the incidence of neuropathy and the perceived value of adjunctive interventions. In practice, neuropathy management does not exist in isolation. It competes for attention alongside tumor response, survival endpoints, and other supportive care priorities. Treatments that can integrate into existing oncology workflows, offer predictable safety profiles, and demonstrate a credible link to preserving chemotherapy delivery are more likely to gain adoption than those positioned as standalone neurological interventions with limited integration into cancer care pathways.
Key Drivers Shaping the Market
Several interconnected factors are accelerating momentum in the CIPN treatment market, and their influence is likely to intensify over the next several years. Rather than acting independently, these forces are reinforcing one another, reshaping both pipeline priorities and commercial expectations.
One of the most consequential drivers is the shift toward mechanistic and targeted approaches. A growing portion of the pipeline is focused on molecular pathways with clearer links to nerve injury, signaling dysregulation, or peripheral nerve repair. Candidates addressing specific ion channels, receptor-mediated protective pathways, and topical delivery strategies reflect an effort to move beyond nonspecific symptom modulation. This trend matters commercially because it creates opportunities for sharper messaging, more defensible clinical narratives, and potential differentiation in a crowded supportive care environment. At the same time, it raises the technical requirement for biomarker strategy, subgroup definition, and endpoint clarity. Sponsors that can connect a mechanism to a meaningful clinical readout are better positioned to justify investment and partnership interest.
Regulatory guidance and pathway signals are a second major driver. The issuance of FDA draft guidance for developing drug and biological products for the prevention and treatment of CIPN has helped establish a more explicit framework for expectations around trial design, population definition, and outcome measurement. Complementary regulatory actions, including Fast Track designations and IND clearances for candidates targeting CIPN, indicate that the agency is engaging with the area more actively. This environment reduces some ambiguity for developers and can improve the perceived credibility of programs that are designed with regulatory expectations in mind. For commercial stakeholders, the implication is that programs aligned early with guidance are more likely to navigate development with fewer late-stage surprises and clearer dialogue with regulators.
A third driver is the changing demand profile within oncology. As cancer therapies improve and patients live longer, the burden of chronic treatment-related effects is becoming more visible. Neuropathy that persists beyond active chemotherapy or limits future treatment options carries significant downstream implications for physical function, independence, and quality of life. This has increased attention to interventions that can prevent symptomatic progression, reduce dose-limiting toxicity, or support patients through longer treatment courses. Demand is not only coming from patient advocacy and clinician concern. It is also being shaped by the broader oncology goal of preserving treatment continuity and minimizing long-term functional impairment.
Supply-side and reimbursement dynamics also play a role, though often in less visible ways. The relative availability of generic symptomatic therapies exerts competitive pressure on pricing and adoption for newer agents, while reimbursement expectations increasingly favor evidence that connects treatment to functional outcomes, reduced downstream costs, or maintained chemotherapy delivery. Cost structures are therefore influenced by both the competitive shadow of established options and the evidentiary requirements of payers and health systems. Programs that can demonstrate practical value in real-world oncology settings are more likely to achieve sustainable market positioning than those relying solely on clinical signals without integration into care economics.
Competitive Landscape and Leading Strategies
The competitive environment reflects a spectrum of developmental maturity and strategic focus. Some companies are advancing candidates with clearer regulatory momentum or later-stage clinical activity, while others are operating in earlier phases or have paused further development after earlier signals. What distinguishes the more strategically positioned players is not only the stage of their programs, but the coherence of their therapeutic rationale, the alignment of their trial design with oncology context, and their ability to use regulatory or partnership leverage to accelerate confidence in their approach.
Dogwood Therapeutics illustrates a company building momentum through a combination of clinical progress and strategic licensing activity. The Halneuron program has moved forward in Phase 2b with reported interim findings and substantial enrollment progress, while the SP16 program has advanced through licensing from Serpin Pharma with IND clearance and planned Phase 1b activity. This dual-track structure suggests an emphasis on diversifying mechanism exposure while maintaining forward progress in a lead candidate. From a strategic standpoint, the company appears to be positioning around both clinical data generation and partnership-enabled capability expansion, which can be valuable in a market where single-asset dependence carries execution risk.
Asahi Kasei Pharma’s ART-123 program takes a prevention-oriented approach in a defined oncology population, focusing on sensory symptom prevention in colorectal cancer patients receiving oxaliplatin. This positioning is strategically notable because prevention can be harder to demonstrate than treatment, but it may also offer stronger clinical integration if the evidence supports a clear reduction in neuropathy burden within a specific chemotherapy context. Targeting a well-defined regimen and patient group can reduce some of the heterogeneity challenges that complicate broader CIPN studies, though it also narrows the initial commercial footprint.
Neuropathy Pain Treatment Market
Sironax’s SIR2501 program has drawn attention through Fast Track designation, signaling regulatory recognition of potential unmet need and development efficiency value. In a market where endpoint complexity can slow progress, regulatory designations can provide useful leverage for development planning, clinical engagement, and partnership conversations. WinSanTor’s topical pirenzepine program, meanwhile, reflects an alternative delivery strategy and a broader peripheral neuropathy focus, with ongoing work extending beyond CIPN. Topical approaches may be attractive if they can reduce systemic exposure or offer localized benefit, but adoption will depend on evidence that supports clinical differentiation and practical usability.
Serpin Pharma’s SP16 program reinforces the growing importance of early-stage financing and academic or institutional support in shaping pipeline viability. The receipt of grant funding to support a Phase 1b trial highlights how non-dilutive resources can help earlier programs reach critical developmental checkpoints. For investors and partners, this is a reminder that the CIPN market includes meaningful activity not only from large-scale commercial developers, but also from smaller, mechanism-focused groups whose evolution may influence future licensing and acquisition dynamics.
Across these players, a few competitive themes emerge. First, there is a clear trend toward programs that are more tightly tied to specific mechanisms or delivery modalities, with the intent of differentiating from nonspecific symptom management. Second, regulatory engagement and guidance alignment are increasingly part of strategic positioning, particularly for companies looking to reduce development risk or improve the credibility of their programs in clinical and investor discussions. Third, the landscape remains open enough for new entrants to find niches, but crowded enough that differentiation must be supported by more than mechanistic plausibility. Credible clinical design, context-specific positioning, and practical integration into oncology care will likely determine which programs translate into durable commercial advantage rather than short-term pipeline interest.
Forward-Looking Trends and Commercial Implications
Over the next three to five years, several trends are likely to shape the direction of the CIPN treatment market. These are not mutually exclusive, and each carries distinct commercial implications.
One likely trend is a sharper separation between prevention-focused and treatment-focused interventions. As clinical programs mature, stakeholders may increasingly differentiate between agents intended to reduce the onset or progression of neuropathy during chemotherapy and those intended to manage established symptoms. This distinction matters for trial design, regulatory positioning, and clinical adoption. Prevention programs may target specific regimens or high-risk populations, while treatment programs may need to demonstrate meaningful benefit in patients with existing neurological impairment. The commercial implication is that value propositions will need to be tailored more precisely to the clinical context in which the intervention is used. Broad, undifferentiated claims may be less effective than narrowly supported, use-case-specific positioning.
A second trend is the increasing importance of topical and targeted delivery approaches alongside systemic therapies. Topical strategies may gain attention if they can offer focused benefit with favorable tolerability or reduced systemic exposure, especially in a population where polypharmacy and cumulative toxicity are concerns. However, clinical adoption will depend on whether these approaches can demonstrate consistent efficacy, ease of use, and integration into oncology supportive care routines. The commercial opportunity is not just in developing a new formulation. It is in proving that the delivery method creates meaningful clinical or operational advantages that clinicians and patients will accept in practice.
A third trend is growing pressure to connect CIPN interventions with functional and care-continuity outcomes. As payer and health system expectations evolve, evidence that goes beyond symptom scores may become more important. Demonstrating associations with maintained chemotherapy dosing, reduced supportive care utilization, or improved day-to-day function could strengthen commercial viability for certain programs. The risk is that companies relying solely on conventional symptom endpoints without a clear link to broader outcomes may find adoption more difficult or reimbursement discussions more complex. This creates a strategic imperative to design evidence generation around the full clinical and economic context of use.
At the same time, uncertainty remains. Trial results may vary by chemotherapy class, baseline risk, and endpoint definition, and not every mechanistic hypothesis will translate into durable clinical benefit. Competitive dynamics may also shift through partnerships, licensing, or consolidation, particularly as earlier-stage programs reach pivotal milestones. Stakeholders should therefore plan for a market that is growing but fragmented in credibility, where selection of partners, programs, or investment targets requires careful assessment of trial design, intended use case, and alignment with oncology practice.
Strategic Recommendations for Decision-Makers
For manufacturers and developers, the priority is to design programs with clear clinical context and regulatory alignment from the outset. This includes defining the intended chemotherapy setting, the relevant patient population, and the endpoint strategy in a way that supports both clinical credibility and commercialization. Mechanism-based differentiation is valuable, but it must be paired with evidence that can withstand scrutiny in real-world oncology settings. Developers should also consider how they will position their intervention relative to existing symptomatic options and whether they can articulate a distinct value proposition around tolerability, delivery, or care integration.
For investors, the opportunity lies in distinguishing programs with defensible execution roadmaps from those that depend primarily on early enthusiasm. Attention should be paid to enrollment feasibility, endpoint clarity, regulatory engagement, and the strength of clinical rationale within a specific chemotherapy context. Programs that combine mechanism interest with sound trial design and credible milestones may offer stronger risk-adjusted prospects than those that emphasize scientific promise without a clear path to clinically actionable evidence. Early-stage licensing and partnership activity may also create optionality, particularly if it enables better-capitalized or more operationally experienced groups to accelerate development.
For procurement and formulary decision-makers, the focus should be on evidence that supports practical adoption and value relative to current care patterns. This means evaluating not only efficacy signals but also safety, ease of integration, and any demonstrated impact on treatment continuity or functional outcomes. As new agents emerge, structured assessment frameworks can help determine which interventions warrant adoption, under what conditions, and where further evidence is needed before broader use. The availability of more standardized guidance and maturing clinical data should support more disciplined evaluation over time.
Worldwide Advanced Cancer Pain Management Market
In a market expanding toward $2.28 billion by 2032, the strategic question is not whether demand for effective CIPN intervention will continue to grow, but which programs, partnerships, and evidence strategies will separate durable value creation from transient pipeline interest. Detailed segmentation data, pipeline benchmarking, and scenario analysis can help organizations move from general market awareness to specific, actionable decisions. Readers interested in deeper breakdowns of market segments, competitive benchmarks, and customized strategic implications can explore the full report available through PW Consulting for more detailed segmentation data and tailored guidance.
For detailed analysis of this topic, please visit the official page: Chemotherapy Induced Peripheral Neuropathy Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Insect Feed Market: How 16.4% CAGR and Aquaculture Demand Reshape 2032 Outlook
By PW Consulting, 2026-09-21
The Insect Feed Market: Strategic Trends and Commercial Opportunities Through 2032
The insect feed sector is transitioning from niche sustainability play to mainstream protein infrastructure. With the global market valued at approximately $147 million in 2025 and projected to reach $425.8 million by 2032, the sector is expanding at a compound annual growth rate of 16.4 percent. This trajectory reflects more than incremental demand growth. It signals a structural recalibration of animal nutrition supply chains, driven by regulatory opening, substrate economics, and the scaling of bioconversion technology. For executives and investors, the question has shifted from whether insect protein will gain traction to how capital, capability, and partnerships will be allocated as the market matures.
Market Landscape and Core Challenges
The revenue arc over the past half-decade illustrates steady acceleration, with growth compounding as production capacity converts from pilot scale to commercial throughput. By the close of the forecast window, the market is on a path toward nearly triple its 2025 baseline. That expansion is uneven rather than uniform, shaped by regional regulatory readiness, feed formulation economics, and the pace at which manufacturing networks achieve cost parity with conventional protein sources. Understanding where the market is heading requires looking past headline figures to the structural constraints that will determine which players capture value.
Navigating Structural Constraints
Several inflection points are shaping the operational reality of the industry. First, substrate sourcing and waste-stream consistency remain foundational bottlenecks. Insect feed production depends on upcycled organic inputs such as food processing byproducts, and the economics of collection, pretreatment, and contamination control vary widely by geography and season. While this model can reduce material costs substantially relative to conventional protein sourcing, the operational discipline required to maintain consistent substrate quality across multiple intake streams is non-trivial. Facilities that fail to standardize input quality encounter downstream variability in yield, nutrient profiles, and regulatory compliance.
Second, regulatory adoption is advancing but remains fragmented. In the European Union, rules governing insect protein in aquaculture are established, and approval pathways for poultry and swine applications have progressed under updated feed frameworks. In the United States, regulatory clearances have extended for select insect proteins in poultry and pet food categories. The pace and scope of these approvals differ by jurisdiction and protein type, creating uneven commercialization timelines. Companies that can navigate multiple regulatory regimes simultaneously, or that align product development with the fastest-opening categories, gain a meaningful time advantage.
Aqua Feed Market
Third, scaling biology is as much an engineering challenge as a biological one. Temperature control, humidity management, disease mitigation, and harvesting logistics all influence yield stability and unit economics. Early-stage producers often underestimate the capex intensity of climate-controlled environments and the operational complexity of continuous rearing systems. As the market moves toward larger facilities, the gap between companies with proven process control and those still refining biological workflows will become more visible in margin performance and supply reliability.
Key Drivers Reshaping the Sector
Several forces are converging to accelerate adoption and reshape competitive dynamics. These drivers are not isolated; they reinforce each other and create a clearer line of sight to commercial scale for operators who align technology, compliance, and customer demand.
Bioconversion and Process Technology
The most consequential technical progress lies in improving rearing efficiency, feedstock flexibility, and downstream processing consistency. Proprietary rearing systems, automation in harvesting and separation, and process controls that stabilize larval growth cycles are reducing variability in protein and lipid outputs. This matters because feed formulators require repeatable nutrient profiles, contamination thresholds, and functional properties. Companies that treat insect production as a manufacturing process rather than an agricultural experiment are gaining credibility with B2B buyers who evaluate suppliers on reliability as much as sustainability credentials.
The commercial significance of this shift is clear when viewed alongside recent market activity. Innovafeed has expanded its operational footprint with a U.S. facility in Decatur, Illinois, marking a step toward localized production in a market where feedstock availability and regulatory timing support scale-up. This move illustrates how technology-enabled producers are positioning themselves closer to end markets in order to reduce logistics friction and respond more quickly to regional demand signals.
Regulatory Opening and Category Expansion
Regulation remains the central gatekeeper for category expansion. Approvals for aquaculture have already enabled commercial use of insect proteins in fish feed, while newer regulatory movements in the EU and U.S. have extended possibilities into poultry and swine nutrition and, in certain contexts, pet food. These changes do not merely open new addressable segments; they reshape feed formulation economics by creating alternatives to soy and fishmeal in categories where substitution pressure is strongest.
The regulatory trajectory also influences procurement behavior. Feed manufacturers and integrators that have been waiting for regulatory clarity are now beginning to test inclusion rates, evaluate supply continuity, and negotiate multi-year arrangements. Protix, for example, signed a multi-year supply agreement with Skretting for black soldier fly meal in salmon feed formulations, a move that signals how regulatory maturity is translating into committed offtake and category-specific product development.
Demand-Side Shifts in Animal Nutrition and Pet Care
Demand is being pulled by multiple end-use pressures. In aquaculture, the need for sustainable protein inputs continues to intensify as marine ingredient supply faces volatility and environmental scrutiny. In poultry and swine nutrition, producers are exploring insect protein not only for sustainability positioning but also for functional benefits and supply diversification. In pet food, consumer interest in novel protein sources and premium formulation is expanding the addressable market for insect-based ingredients, particularly where regulatory clearance and brand acceptance progress together.
This diversification matters strategically because it reduces dependence on any single category’s adoption cycle. Companies with portfolios that span aquaculture, livestock nutrition, and pet food can shift commercialization emphasis as regulatory timing and customer readiness vary by region. The effect is a more resilient demand base and a stronger foundation for long-term contract structures.
Cost Structure and Substrate Economics
The economic case for insect feed is closely tied to substrate cost and plant efficiency. Because insect production can utilize upcycled organic waste streams, input costs can be materially lower than those of conventional protein sources when collection and pretreatment are managed effectively. Life cycle assessments comparing insect-based inputs with soy or fishmeal indicate substantial differences in land and water requirements and lower associated greenhouse gas emissions, reinforcing the sustainability narrative that supports procurement decisions.
However, cost advantage is not automatic. It depends on logistics networks, preprocessing capability, and the ability to maintain consistent substrate composition at scale. Facilities that integrate substrate procurement, pretreatment, and rearing into a coordinated operational model are better positioned to protect margins as volumes increase. This is where competitive differentiation increasingly emerges: not simply in the insect species used, but in the industrial design of the entire value chain.
Competitive Landscape and Leading Strategies
The market remains moderately concentrated, with a small group of established producers accounting for a meaningful share of revenue and an expanding set of regional and specialized entrants competing on niche formulations, geography, or substrate strategies. The strategic posture of leading companies reveals how value is being captured in a market still defining its standards.
Differentiation Through Scale, Technology, and Of ftake
Several patterns distinguish the more advanced players. Protix has built a profile around high-quality insect solutions spanning feed, pet food, aquaculture, and plant care, with a focus on black soldier fly larvae and broad application coverage. Its multi-year agreement with Skretting illustrates a strategy centered on committed customer relationships and category-specific formulation support, which helps stabilize demand and fund capacity expansion.
Innovafeed has emphasized proprietary rearing technology and geographic expansion, including its U.S. facility in Illinois. This reflects a strategy of combining technical differentiation with direct market access, reducing reliance on export logistics and positioning closer to large North American feed markets. Entobel has pursued a similar operational discipline, with long-standing production in Vietnam and a recent certification milestone that reinforces its positioning around sustainability and governance as commercial signals for B2B buyers.
Pet Food Insect Protein Market
Other companies are carving distinct lanes. Beta Hatch has focused on mealworm-based production within a regenerative agriculture framing, highlighting a different species and system design from the black soldier fly-dominant core of the market. Nutrition Technologies, now operating under the Sentara Group name following expansion, has continued to build around black soldier fly ingredients for aquaculture, agriculture, and animal feed, illustrating how rebranding and organizational scaling can accompany capacity growth. Hexafly and nextProtein have emphasized the bioconversion of food waste into protein, oil, and fertilizer, aligning product portfolios with circular-economy value propositions that appeal to customers seeking integrated sustainability outcomes.
Market Evolution: Consolidation, Specialization, and New Entry
The competitive landscape is evolving along several axes. Scale industrialization is concentrating production among companies able to fund large facilities, standardize processes, and secure stable substrate supply. At the same time, specialization remains viable in niches such as pet food formulations, functional ingredients, plant care products, and regional supply arrangements where logistics and regulatory timing favor local production.
New entry continues, but the bar is rising. Early entrants could often compete on concept and pilot output; newer entrants must demonstrate process reliability, regulatory compliance, cost control, and defensible customer relationships. This dynamic is likely to reward operators that combine biological capability with manufacturing discipline and commercial execution. It also suggests that partnerships, offtake agreements, and integration with existing feed supply chains will become more important than standalone brand positioning.
Forward Outlook: Three Strategic Trends for 2026–2032
Looking ahead, several trends are likely to define how value accrues in the insect feed market over the next several years.
Trend 1: Regional Production Clusters and Feedstock-Proximity Manufacturing
Production is likely to consolidate around feedstock availability, regulatory readiness, and end-market demand rather than forming a single global center of gravity. Regions with strong waste-stream infrastructure, supportive feed regulations, and large aquaculture or livestock sectors will attract capacity. This has direct commercial implications: companies that align facility siting with substrate economics and customer proximity will lower logistics costs and improve supply reliability, while those dependent on long-distance substrate or product movement may face margin pressure as the market scales.
Trend 2: Formulation Integration and Category-Specific Product Design
Insect ingredients will increasingly be valued not simply as generic protein but as formulated inputs tailored to specific species, life stages, and functional requirements. As feed manufacturers gain experience with inclusion rates and nutrient performance, demand will shift toward consistent specifications, traceability, and technical support. The commercial opportunity lies in building product architectures around customer formulations rather than selling undifferentiated bulk ingredients. Suppliers that invest in application engineering and quality assurance will be better positioned to defend pricing and deepen relationships.
Trend 3: Regulatory Normalization and Procurement Mainstreaming
As approvals expand and standards mature, insect protein is likely to move from special-case procurement to routine supplier evaluation. That transition will favor operators with established compliance records, auditable quality systems, and supply continuity. It also introduces risk: regulatory timing can shift, inclusion limits can change, and category approvals may not proceed uniformly. Companies that assume a linear regulatory path without scenario planning may misallocate capacity or overcommit to segments that open more slowly than expected.
Associated uncertainties include substrate consistency at scale, biological process control during rapid expansion, and the risk that sustainability narratives alone will not sustain procurement decisions if cost or performance gaps remain. The market’s trajectory is strong, but execution quality will determine which participants convert growth into durable margins.
Implications and Actions for Decision Makers
For executives and investors evaluating the insect feed market, the strategic task is to match ambition with operational readiness and to prioritize the decisions that convert market momentum into competitive advantage.
PW Consulting Health Care Research Center
For Producers and Technology Developers
- Prioritize process control and substrate logistics as the foundation of scale-up. Consistent quality and cost stability matter more to B2B buyers than incremental sustainability claims, so investment should flow toward rearing consistency, harvesting efficiency, and integrated feedstock management.
- Align capacity deployment with regional regulatory timing and customer demand. Expanding too quickly into segments with uncertain approval pathways can create underutilized assets, while sequencing expansion around opening categories supports revenue absorption and learning-curve gains.
- Build formulation support and application data. As customers move from trial to routine use, technical service capability becomes a differentiator. Developing species-specific and application-specific evidence strengthens customer retention and pricing power.
For Investors and Capital Allocators
- Evaluate biological capability alongside manufacturing discipline. The most attractive opportunities are likely to be with teams that can demonstrate repeatable yield, contamination control, and cost trajectory rather than concept-level promise.
- Assess demand visibility through offtake structure and customer diversification. Contracts, pilot-to-commercial conversion rates, and exposure across aquaculture, livestock, and pet food can indicate resilience if one category’s adoption slows.
- Model regulatory and substrate scenarios, not just base-case growth. Because approvals, inclusion limits, and feedstock availability can vary by region, sensitivity analysis around timing and input costs is essential for realistic return expectations.
For Procurement and Feed Formulators
- Treat insect ingredients as part of a supply diversification and sustainability strategy, but validate them through performance trials and supply reliability assessment. The strategic value lies in reducing exposure to conventional ingredient volatility while maintaining nutrient specification and consistency.
- Engage early with suppliers on specification design and traceability. Collaboration on inclusion rates, quality parameters, and auditability can accelerate integration and reduce reformulation risk.
- Structure sourcing with regulatory awareness. Procurement plans should account for category-specific approvals and potential changes in inclusion limits so that supply commitments align with regulatory reality in each market.
Closing Perspective
The insect feed market is entering a phase where growth is increasingly determined by execution rather than narrative. The revenue trajectory through 2032 points to a substantial expansion in addressable demand, but the distribution of value will depend on how effectively companies manage substrate economics, regulatory complexity, process control, and customer integration. For organizations building, funding, or sourcing from this sector, the opportunity is not simply to participate in a high-growth category but to shape a supply chain that can deliver consistent quality at competitive cost while meeting the sustainability expectations of modern animal nutrition. Detailed segmentation, regional dynamics, and company-level benchmarking can sharpen these decisions further, and a full research report can provide the supporting data and structured frameworks needed for planning at the segment and facility level.
For detailed analysis of this topic, please visit the official page: Insect Feed Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Fine Surface Oriented Strand Board FOSB Market: Why 5.85% CAGR Through 2032 Changes Everything
By PW Consulting, 2026-09-18
Fine Surface Oriented Strand Board (FOSB) Market: Navigating Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
The Fine Surface Oriented Strand Board (FOSB) market has established itself as a significant segment within the broader wood-based panels industry, bridging the performance characteristics of traditional Oriented Strand Board (OSB) with the aesthetic and surface quality requirements of finer applications. Over the historical period from 2020 to 2025, the market demonstrated resilient growth, reflecting steady commercialization and increasing adoption across multiple downstream sectors. With the value expanding from approximately 939.85 million USD to 1250.0 Million in 2025, the sector has transitioned from a niche product to a recognized alternative to plywood, medium-density fiberboard (MDF), and particleboard in specific use cases. Projections for the forecast period 2026 through 2032 indicate sustained expansion, driven by broader structural demand for engineered wood products and the material's favorable strength-to-weight properties.
At the macroeconomic level, the market is characterized by a moderate consolidated structure. The top three firms hold a combined share of roughly 28.5 percent, while the top five account for about 39.2 percent of total revenue. This concentration suggests that while global capacity is distributed across multiple geographies, specialized FOSB production is still dominated by a limited number of players with the technical capability to produce fine surface layers at commercial scale. The forecast compound annual growth rate of approximately 5.85 percent through 2032 points to steady but not explosive expansion, implying that value creation will increasingly depend on differentiation, cost efficiency, and alignment with downstream application trends rather than pure volume scaling.
Despite the positive trajectory, the industry currently faces several structural challenges that are shaping competitive positioning. First, raw material security and adhesive cost exposure remain persistent concerns. FOSB production relies on specific feedstock profiles, often fast-growing eucalyptus or selected softwood strands, combined with resin systems that meet stringent surface and emission requirements. Fluctuations in wood supply dynamics and the cost of adhesives, which are influenced by petrochemical feedstock movements, introduce margin variability that producers cannot entirely pass through to downstream buyers.
Second, the market sits at a technical crossover point. FOSB must continuously justify its position against established substitutes such as MDF and high-grade particleboard, particularly in furniture manufacturing and interior finishing, where surface finish, machining behavior, and total installed cost are tightly evaluated. While FOSB offers structural advantages and surface quality improvements over standard OSB, the value proposition must be clearly articulated to specifiers and fabricators who are accustomed to traditional materials.
Third, regulatory and environmental expectations are becoming more granular across major end markets. Low formaldehyde emission classifications and other indoor air quality considerations are increasingly treated as baseline requirements rather than differentiators, especially in furniture and interior construction applications. Compliance is necessary, but it also compresses the space for premium pricing unless accompanied by genuine performance or process advantages.
Key Drivers Shaping the FOSB Market
The growth and evolution of the FOSB market are being shaped by a convergence of technological, regulatory, demand-side, and cost-structure developments. Understanding how these forces interact is essential for identifying where durable advantages can be built.
Technology and process capability remain the most distinctive driver. FOSB is not simply OSB with a cosmetic overlay; it typically integrates an OSB core with fine surface layers engineered for superior finish and structural properties. Producers investing in advanced continuous press technology and precision surface treatment are better positioned to deliver consistent panel quality, reduced variability, and surface characteristics that can compete with more traditionally processed boards. The move toward low-formaldehyde or formaldehyde-free adhesive solutions in selected product lines further illustrates how process innovation can simultaneously address performance, regulatory, and branding objectives. Where these technologies are deployed effectively, they enable FOSB to enter applications that previously favored MDF or laminated particleboard.
On the policy and regulatory side, emission standards and interior-use specifications are acting as both a constraint and an enabler. Low formaldehyde emission grades, such as E0 and E1 classifications, have become standard expectations in major markets for FOSB used in furniture and interior applications. Rather than being treated as optional premium features, these requirements are increasingly embedded in procurement specifications and building practices. This regulatory trajectory favors producers that have already integrated cleaner adhesive systems and quality control processes into their operations, while creating a barrier for capacity that cannot reliably meet tighter emission profiles at scale.
Demand-side dynamics are equally important and are shifting the center of gravity for FOSB adoption. Furniture manufacturing continues to represent a large end-use segment, where surface appearance, stability, and finish compatibility influence material selection. At the same time, construction and renovation activity sustains demand for panels that combine structural performance with improved surface qualities for exposed or semi-exposed applications. A smaller but meaningful portion of demand also comes from packaging and industrial uses, where board consistency and mechanical properties matter. What ties these segments together is a broader move toward engineered wood solutions that can reduce weight, improve dimensional stability, or offer more predictable machining behavior than conventional alternatives.
Cost structure and supply chain factors complete the picture. Wood-based panel economics are sensitive to feedstock availability, log and fiber pricing, energy costs, and resin markets. For FOSB, the use of fast-growing eucalyptus or selected softwood strands and the incorporation of specialized adhesives mean that procurement strategy is tightly linked to product positioning. Recent price signals for OSB and FOSB in key supply regions indicate a market where cost discipline matters, but where differentiation in surface quality and adhesive profile can still support value-based positioning. Producers that manage feedstock mix, press efficiency, and resin usage with greater precision are better insulated against input volatility and more capable of competing on quality rather than price alone.
Competitive Landscape and Leading Strategies
The competitive environment in FOSB is defined by a mix of established OSB producers, regional specialists, and manufacturers actively expanding fine-surface capability. The strategic positioning of leading firms reflects different combinations of technology access, feedstock strategy, geographic presence, and application focus.
Strategic Positioning Among Core Players
PW Consulting Health Care Research Center
Fletcher Building is advancing a focused FOSB strategy that emphasizes the material's superiority over particleboard and MDF in targeted applications. Its planned CEBRO Fine OSB production at the Laminex Taupo site, supported by Dieffenbacher technology, signals an intent to move beyond conventional OSB into higher-value surface panels. The timeline for commissioning of the finishing line, followed by initial board production activity in 2026, indicates a deliberate ramp-up rather than an immediate volume play, consistent with a strategy centered on qualification, application development, and downstream acceptance.
In China, Luli Group represents a scale-oriented approach, with multiple fine OSB lines operational and expanded FOSB capacity coming online through additional fine-OSB lines. The company's emphasis on low-formaldehyde formulations and advanced continuous press technology reflects an alignment with furniture and construction requirements in domestic and export markets. This positions Luli as a player that can address volume demand while maintaining attention to surface and emission specifications.
GuangXi Dekek Group adopts a more specialized premium positioning. Its use of Dieffenbacher equipment, MDI adhesive options, and eucalyptus feedstock points to a product focus on fine surface panels for furniture and decorative uses. By concentrating on premium fine surface panels, Dekek illustrates how feedstock and adhesive choices can be combined with process technology to serve higher-specification end segments rather than competing primarily on commodity board characteristics.
West Fraser and Louisiana-Pacific contribute a different competitive logic. As large North American OSB manufacturers with broad structural and specialty panel portfolios, they bring extensive capacity, supply chain scale, and market access. Their relevance to FOSB lies partly in the structural OSB base that can support fine surface applications and engineered wood product development, offering the potential to leverage existing operational strengths while expanding into higher-value panel grades where requirements permit.
In Europe, Kronospan and Egger bring established wood-based panel expertise and broad construction and furniture market reach. Kronospan's capabilities in OSB with fine surface variants and Egger's wood-based material portfolio indicate that European producers are not merely following North American or Asian FOSB developments but are shaping their own product strategies around regional application needs, emission expectations, and finish requirements.
Market Evolution and Competitive Dynamics
The overall market structure suggests a landscape in transition. With the top five firms accounting for under 40 percent of revenue, there is room for both consolidation and specialist differentiation. New capacity additions in key producing regions indicate that growth is being pursued not only by incumbents expanding within existing footprints but also by producers building dedicated fine surface lines to capture specific application demand. This points toward a market that is likely to remain somewhat fragmented at the global level while becoming more concentrated within premium FOSB niches where technology, feedstock, and qualification matter most.
Competitive advantage is increasingly likely to come from three intertwined elements: the ability to deliver consistent fine surface quality at scale, the capacity to meet low-emission expectations without compromising cost, and the strength of application-specific relationships with furniture manufacturers, construction specifiers, and industrial buyers. Firms that treat FOSB as a distinct product category with its own technical and commercial requirements are better positioned than those that view it simply as a subset of general OSB production.
OSB Sheathing Market
Future Outlook: Trends and Opportunities
Looking ahead to the 2026-2032 period, several interconnected trends are likely to shape the FOSB market and define where commercial value accrues.
The first trend is the gradual narrowing of FOSB's application footprint around segments where its combination of surface quality and structural performance delivers a clear advantage. Rather than displacing all competing boards, FOSB is likely to gain traction in furniture parts, interior fit-out components, and certain construction applications where surface finish, stability, and machining behavior are critical. This selective adoption will reward producers that invest in application development and specifiers' education rather than relying solely on board-level marketing.
The second trend is the growing importance of adhesive technology and emission performance as baseline expectations. As low-formaldehyde and formaldehyde-free options become more common in premium FOSB lines, producers that can control resin usage, achieve consistent bonding, and document emission performance will be better equipped to serve regulated interior markets. This trend also creates opportunities for differentiation through product documentation, testing, and specification support, especially in markets where compliance is expected but implementation quality varies.
Oriented Strand Board (OSB) Market
The third trend concerns supply chain and cost management. With wood and adhesive inputs remaining sensitive to broader commodity dynamics, producers that optimize feedstock mix, press efficiency, and surface layer application are likely to manage margins more effectively. In parallel, regional pricing conditions will continue to influence competitive attractiveness across geographies, meaning that market entry and expansion decisions will need to account for local feedstock availability, logistics, and downstream pricing power.
These trends translate into tangible commercial opportunities. For producers, the opportunity lies in converting technological capability into recognized application fit, particularly in furniture and interior construction, where surface and emission attributes can support value-based positioning. For investors, the opportunity is to distinguish between capacity that is aimed at commodity substitution and capacity that is designed to serve premium fine surface demand with defensible technical and supply chain advantages. For procurement and specification teams, the opportunity is to use FOSB selectively where it reduces downstream processing cost, improves finished-product quality, or enables design choices that are harder to achieve with traditional boards.
Potential risks and uncertainties should not be overlooked. Substitution pressure from MDF, particleboard, and improved OSB grades remains real, particularly where FOSB does not offer a sufficiently compelling cost or performance advantage. Feedstock and adhesive cost volatility can compress margins if not managed proactively. In addition, regulatory expectations may continue to rise, shifting the baseline for what qualifies as acceptable performance and increasing the cost of non-compliance. These factors suggest that confidence in long-term FOSB growth should be paired with disciplined application targeting and cost control.
Strategic Recommendations for Decision-Makers
For manufacturers, the priority is to define FOSB as a distinct product platform rather than a generic panel. This means aligning technology investment, feedstock strategy, and adhesive selection with specific end-use requirements, and building qualification and specification support that helps buyers understand where FOSB adds value. Producers that can demonstrate consistent surface quality, predictable emission performance, and reliable supply are better positioned to secure long-term relationships in furniture and interior construction segments.
For investors, due diligence should focus on the fit between capacity strategy and application reality. The most attractive opportunities are likely to be found where new lines are tied to clear downstream demand, supported by appropriate press and surface technology, and managed with cost structures that can withstand input volatility. Broader OSB capacity expansions should be evaluated separately from dedicated FOSB projects, since the commercial logic and risk profile differ meaningfully.
For procurement and specification teams, the practical path is to evaluate FOSB on a segment-by-segment basis, comparing total installed cost, finish compatibility, machining behavior, and compliance attributes against entrenched alternatives. Where FOSB offers a genuine combination of surface quality, structural performance, and supply reliability, it can be a constructive option; where it does not, traditional boards may remain the better choice.
For stakeholders seeking a deeper, segment-level view of market size, regional dynamics, and company-level positioning, the full PW Consulting report provides structured detail and customized interpretation to support internal planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Fine Surface Oriented Strand Board (FOSB) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Medical Device Package Validation Market: Why 7.2% CAGR Reshapes Compliance
By PW Consulting, 2026-09-18
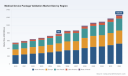
Navigating the Medical Device Package Validation Market: Strategic Shifts and Commercial Opportunities (2026-2032)
Market Overview and Core Pressures
The medical device package validation market has demonstrated consistent expansion over the past five years, growing from a valuation of approximately USD 550 million in 2020 to USD 780 million in 2025. Projections indicate that this trajectory will continue through the forecast window, with the market expected to reach nearly USD 1.27 billion by 2032, representing a compound annual growth rate of 7.2 percent. This sustained growth reflects the critical role that packaging validation plays in the broader medical device lifecycle, where regulatory compliance, patient safety, and product integrity intersect. North America continues to command the largest share of global revenue, followed by Europe and Asia Pacific, while emerging regions such as Latin America and the Rest of World represent smaller but steadily growing demand pools. By test type, seal strength testing and integrity testing account for the majority of commercial activity, with shelf life and stability testing and microbial challenge testing forming the remainder. Packaging formats such as pouches and trays drive the largest portions of testing volume, with blister packs representing a secondary but meaningful segment.
Despite this positive outlook, the industry stands at a pivotal juncture shaped by several structural challenges. First, raw material cost dynamics have introduced new complexity into packaging production and validation planning. Medical-grade polyethylene and polypropylene prices have risen by 15 to 20 percent since 2024, driven by supply dislocations that ripple through manufacturing cost structures and validation sequencing. Second, the regulatory environment is evolving in ways that require validation providers and device manufacturers to reassess their compliance frameworks. While ISO 11607-1 and -2 remain the principal standards governing validation of terminally sterilized medical device packaging systems, state-level extended producer responsibility laws in jurisdictions such as Oregon and California are creating new questions around eco-modulated fees, recyclability expectations, and the scope of exemptions for sterile-labeled Class II and III devices. Third, demand is shifting toward more complex packaging configurations and distribution simulations that test products under increasingly realistic temperature, humidity, and mechanical stress conditions. These pressures are not isolated; they interact to create a landscape where validation is no longer a compliance checkbox but a dynamic strategic function.
For executives and investors, the implication is clear. The market's growth is real, but it is being reshaped by cost volatility, regulatory ambiguity, and higher performance expectations. Organizations that treat validation as a back-end activity risk bottlenecks, while those that integrate validation strategy earlier in design and supply chain planning are better positioned to manage cost, compliance, and speed to market.
Key Drivers of Market Change
Technology Innovation and Testing Sophistication
Advancements in testing methodology are redefining what validation can deliver. Temperature-controlled packaging validation has gained prominence as medical devices with stricter thermal requirements move through broader distribution networks. Testing providers are responding with more refined distribution simulation capabilities, including updates to visual inspection protocols for whole-package evaluation. These improvements allow manufacturers to identify failure modes earlier, reduce field risks, and strengthen confidence in sterile barrier systems before commercialization. The broader trend is a move from minimum compliance testing toward predictive, data-rich validation that supports design decisions and supply chain resilience.
In parallel, the integration of engineering and validation services is becoming a competitive differentiator. Providers that can combine package design, materials evaluation, and performance testing under one roof reduce handoff delays and improve traceability across the validation lifecycle. This convergence is especially valuable for companies introducing novel materials or complex configurations, where traditional siloed testing approaches can slow iteration and increase rework.
Regulatory and Standards Environment
Regulatory clarity is both a stabilizer and a source of new complexity. ISO 11607-1 and -2 continue to anchor validation expectations for terminally sterilized packaging systems, covering design, process validation, and stability testing. However, the broader compliance environment is expanding beyond traditional sterilization and integrity requirements. State-level EPR frameworks are introducing eco-modulated fee structures tied to recyclability, even as many medical device packaging materials remain exempt. For manufacturers and validation partners, this creates a need to monitor jurisdictional nuances, anticipate possible future tightening, and document packaging choices with greater precision. The practical effect is that validation programs must now account not only for performance but also for the evolving sustainability and materials-related expectations that regulators and customers increasingly reference.
Demand-Side Shifts and Device Complexity
Demand for validation is being reinforced by changes on the device side. More devices are being designed for broader distribution footprints, longer shelf life expectations, and more rigorous sterility assurance, all of which raise the bar for packaging performance. At the same time, device manufacturers are under pressure to accelerate development cycles without compromising regulatory submission quality. This creates a dual incentive: reduce time spent on validation rework while ensuring that test programs are robust enough to support submissions and post-market confidence. The result is growing interest in pre-validated packaging approaches, accelerated aging strategies, and integrated testing packages that address multiple requirements simultaneously.
PW Consulting Health Care Research Center
Supply Chain and Cost Structure Dynamics
Cost pressure is reshaping how validation is planned and executed. The recent increase in medical-grade resin prices has affected packaging production economics, which in turn influences validation scope, material selection, and revalidation timing. When material costs rise, the financial penalty of late-stage redesigns or failed validation cycles becomes more significant. This dynamic is pushing organizations to engage validation partners earlier, validate material and process choices more decisively, and consider total cost of ownership rather than testing cost alone. Supply chain disruptions have also underscored the value of distribution simulation and integrity testing that reflect real-world logistics conditions, rather than idealized laboratory settings.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a mix of specialized U.S.-based testing providers, global assurance companies, and integrated service organizations that combine validation with manufacturing or outsourcing capabilities. Market concentration remains moderate, with the top three players accounting for roughly 35 percent of revenue and the top five approaching 49 percent. This level of concentration suggests a market that is still fragmented enough for differentiation, but increasingly attractive for consolidation among players seeking scale, geographic coverage, and expanded service lines.
Several firms illustrate the strategic paths being taken. Westpak has built its position around ISO 11607-compliant validation services, including performance testing, accelerated aging, sterile integrity, and distribution simulation, supported by ISTA-certified testing. Its recent focus on temperature-controlled packaging validation and updated whole-package visual inspection protocols reflects a broader industry shift toward more realistic distribution testing. DDL brings over 35 years of experience as an ISO/IEC 17025 accredited laboratory offering stability, distribution simulation, integrity, and materials testing, positioning longevity and accreditation as trust signals for device manufacturers seeking consistent compliance support. Nelson Laboratories provides end-to-end packaging solutions validation, spanning accelerated and real-time aging, container closure integrity, microbial barrier, strength, and transportation testing, which appeals to customers that want a single partner for multiple validation dimensions.
Packaging Compliance Labs has pursued a more aggressive expansion strategy through acquisition, including the purchase of Quest Engineering Solutions to strengthen East Coast presence and broaden ISO 17025-accredited testing capacity. The opening of PCL East in Billerica, MA, following that acquisition, illustrates how regional coverage and capability expansion are being used to capture demand closer to customers and reduce service friction. Pro-Tech Design & Manufacturing differentiates through a combined model that integrates ISO 13485 and ISO 17025 certified contract manufacturing with packaging validation, assembly, and pre-validated packaging, offering a turnkey route for clients that want to reduce coordination overhead. Life Science Outsourcing adds further variety by pairing package testing and validation with assembly and sterilization services, supported by ISTA-certified lab capabilities, which can be attractive for companies seeking to consolidate multiple operational steps.
On the global side, SGS and TÜV SÜD leverage broad regulatory and testing footprints to serve multinational device manufacturers that need harmonized support across regions and standards. NAMSA rounds out the landscape by embedding packaging validation, seal integrity, simulated distribution, and shelf-life determination within a wider medical device testing portfolio, positioning validation as part of a comprehensive product development and compliance pathway.
The strategic implications are becoming clearer. Leading providers are pursuing one or more of the following advantages: geographic expansion to shorten response times and serve regional demand; capability integration that links validation with design, manufacturing, or sterilization; and service breadth that reduces the number of external handoffs for device companies. At the same time, the market is likely to see continued differentiation between specialists that offer deep, narrowly focused validation expertise and broader service platforms that compete on convenience, scale, and end-to-end continuity. New entrants may find opportunities in regional niches, temperature-sensitive packaging validation, or specialized materials testing, but gaining trust will depend on accreditation, demonstrated compliance support, and the ability to handle increasingly complex device and distribution scenarios.
Future Trends and Commercial Implications
Looking ahead to the next three to five years, several trends are likely to shape the market. First, validation is expected to become more integrated with early-stage package design and supply chain planning. As device manufacturers face higher material costs and more demanding distribution requirements, the cost of late-stage validation failures will continue to rise. This should drive greater adoption of pre-validated packaging concepts, earlier distribution simulation, and more coordinated engineering-test workflows. The commercial opportunity lies with providers that can help customers reduce iteration cycles while maintaining regulatory confidence.
Second, the regulatory and sustainability conversation will keep expanding, even where direct medical device packaging exemptions remain in place. State EPR frameworks and eco-modulation concepts are creating a backdrop in which packaging choices are scrutinized not only for performance but also for materials handling, recyclability, and long-term compliance risk. Validation programs will need to document material selection and performance in ways that support both regulatory submissions and internal sustainability governance. Providers that can bridge performance testing with materials and compliance advisory services will be better placed to capture this growing need.
Sterile Medical Packaging Market
Third, demand for temperature-controlled and distribution-realistic testing is likely to keep rising as devices travel through more complex logistics networks and as visual inspection and integrity testing methods become more refined. This trend creates openings for labs that can deliver clinically relevant simulation, consistent accreditation, and clear reporting that supports both internal decision-making and external submissions. The associated risk is that test expectations may continue to evolve faster than some providers can scale capacity or update protocols, which could create uneven service quality across the market. Organizations should also monitor the possibility of further regulatory or standards updates that could shift validation requirements, particularly in areas related to sterility assurance, stability, and materials documentation.
Plastic Medical Packaging Market
Actionable Recommendations for Decision-Makers
For medical device manufacturers, the priority is to treat package validation as a strategic input rather than a late-stage gate. Engaging validation partners earlier, aligning test plans with distribution realities, and considering materials cost and supply risk during design can reduce rework and shorten time to market. Companies should also document packaging decisions with enough clarity to address both performance requirements and the evolving sustainability and materials context that regulators and customers are increasingly watching.
For investors, the market offers appeal through steady growth, moderate concentration, and ongoing consolidation activity. The most resilient opportunities are likely to be found in providers with strong accreditation, regional expansion momentum, and the ability to integrate validation with adjacent services such as design, assembly, sterilization, or distribution simulation. Due diligence should focus on capacity scalability, protocol update capability, and exposure to raw material and regulatory variability.
For procurement and quality leaders, selecting validation partners should involve more than comparing test cost. Accreditation status, service breadth, geographic coverage, and the ability to support temperature-controlled and distribution simulation testing are all relevant to long-term risk management. Building relationships with providers that can scale with product complexity and supply chain changes will help reduce friction as portfolios grow and distribution requirements become more demanding.
For organizations seeking a deeper, segment-level view of growth rates, regional dynamics, test-type mixes, packaging format trends, and company-level benchmarking, a more granular research perspective can support tailored planning and investment decisions. Detailed datasets and customized scenario analysis can help translate these market-level insights into specific operational priorities, whether the goal is capacity planning, partner selection, or competitive positioning.
For detailed analysis of this topic, please visit the official page: Medical Device Package Validation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Bovine Leather Goods Market: 4.25% CAGR Trajectory and Regional Power Shifts Exposed
By PW Consulting, 2026-09-18
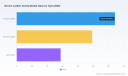
Bovine Leather Goods Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The bovine leather goods market has demonstrated resilient growth over the past half-decade, expanding from approximately $234.66 billion in 2020 to $285.5 billion in 2025. This trajectory reflects a compound annual growth rate of 4.25% through the forecast period extending to 2032, with projected revenues reaching $382.08 billion by the end of the outlook window. The market's expansion is not merely a function of population growth or inflation; it represents a structural shift in how bovine leather is positioned across premium, mid-tier, and specialized industrial applications. However, the growth path is neither linear nor without friction. Industry participants navigating this landscape must contend with a set of interconnected challenges that will define competitive positioning over the next several years.
Leather Market
One of the most pressing inflection points lies in the tension between raw material cost volatility and margin preservation. Hides prices have fluctuated in a narrow but persistent band, hovering around 57 to 59 US cents per pound in early 2026, while wholesale raw hides and skins in the United States have traded within a range of approximately $1.38 to $2.76 per kilogram. These fluctuations, though seemingly modest in percentage terms, compound across complex supply chains where tanning, finishing, and craftsmanship add significant value. Manufacturers operating with thin margins or rigid pricing contracts face residual exposure that can erode profitability even when end-market demand remains robust. The ability to hedge, negotiate long-term supply agreements, or vertically integrate upstream has become a differentiating capability rather than a optional efficiency play.
A second challenge centers on regulatory and sustainability expectations that are reshaping procurement criteria across both consumer and industrial buyer segments. The United States and European Union maintain strict environmental and animal welfare standards for bovine leather production and imports, and compliance is increasingly treated as a baseline requirement rather than a discretionary credential. Tariff structures on imported raw leather materials further complicate cost planning for manufacturers reliant on cross-border sourcing, introducing variability that can disrupt otherwise stable production economics. Companies that treat compliance as a reactive exercise risk facing supply disruptions, reputational friction, or lost contracts with buyers who now embed sustainability and traceability requirements directly into vendor selection frameworks.
A third structural tension involves the market's moderate concentration and the resulting fragmentation of competitive dynamics. With a combined share of roughly 18.5% held by the top three firms and approximately 24.4% by the top five, the industry remains broadly distributed across established luxury houses, specialized tanneries, and regional manufacturers. This dispersion fosters innovation and niche specialization but also means that no single entity exerts decisive pricing or supply control. The result is a market where scale advantages are real but not absolute, and where differentiation through craftsmanship, traceability, or application-specific engineering often matters more than pure volume. For decision-makers, this environment rewards clarity of positioning and penalizes undifferentiated competition.
Key Drivers of Market Change
Several interlocking forces are propelling the bovine leather goods market forward, each reinforcing the others in ways that create both opportunity and strategic urgency. Understanding these drivers is essential for aligning production capacity, sourcing strategy, and product development with where demand and regulatory momentum are actually heading.
Technological Innovation and Processing Breakthroughs
Advancements in tanning chemistry, finishing technologies, and grading consistency are reshaping what bovine leather can deliver across applications. Traditional vegetable and chrome tanning methods continue to anchor premium segments, but newer processes are enabling manufacturers to achieve more uniform surface quality, improved durability, and reduced environmental footprints without sacrificing the tactile and aesthetic qualities that buyers expect. These improvements matter because they expand the usable yield from each hide, lower rejection rates, and allow producers to serve demanding applications such as automotive interiors and high-wear footwear with greater confidence. The practical implication is straightforward: firms that invest in process control and finishing innovation can convert raw material volatility into a more predictable cost-per-output equation, while also meeting stricter performance specifications from commercial buyers.
Policy, Regulation, and Standards Evolution
Regulatory frameworks are not merely constraints; they are increasingly shaping the structure of competition. Environmental and animal welfare standards in major markets create a de facto barrier for producers who lack traceability systems, certified sourcing practices, or documented compliance records. At the same time, industry bodies and exhibition platforms are actively promoting sustainable bovine leather goods, signaling that sustainability is becoming a commercial asset rather than a compliance cost. Participation in major industry gatherings and exhibitions has become a channel for showcasing compliant, traceable, and performance-optimized leather goods to buyers who are actively filtering suppliers through sustainability criteria. For manufacturers and brands, the strategic question is no longer whether to engage with these standards but how to use them as a basis for differentiation in buyer negotiations and market positioning.
Demand-Side Shifts in Consumer and Enterprise Behavior
Demand patterns are evolving on both the consumer and commercial sides. In consumer markets, there is sustained appreciation for bovine leather goods that combine durability with craftsmanship, particularly in footwear, apparel accessories, and luxury-adjacent categories where material provenance and finish quality influence purchase decisions. In enterprise and industrial applications, buyers are prioritizing consistency, traceability, and lifecycle performance, especially in automotive interiors and furniture upholstery where material specifications are tied to brand promises and warranty exposure. This dual dynamic means that bovine leather is no longer competing solely on tradition or aesthetics; it is increasingly evaluated on measurable performance, supply reliability, and alignment with sustainability expectations. Brands and manufacturers that can articulate these value propositions with evidence are better positioned to defend pricing and secure long-term contracts.
Supply Chain and Cost Structure Dynamics
Supply chain reconfiguration is another significant driver. Tariff impacts on imported raw leather materials have introduced cost variability for manufacturers dependent on cross-border sourcing, prompting some firms to reassess supplier geography, inventory buffers, and contract structures. At the same time, raw material pricing remains sensitive to broader agricultural and livestock market conditions, meaning that even well-structured procurement strategies must accommodate periodic fluctuations. Companies are responding by diversifying supplier bases, strengthening relationships with certified tanneries, and in some cases exploring closer coordination with hide suppliers to improve visibility and reduce lead-time uncertainty. The firms that treat supply chain design as a strategic lever rather than a transactional function are gaining an edge in cost stability and delivery reliability, both of which are increasingly weighted in buyer selection.
Competitive Landscape and Leading Strategies
The competitive environment in the bovine leather goods market is defined by a mix of heritage craftsmanship, brand equity, and specialized manufacturing capability. The presence of large luxury groups alongside focused tanneries and regional manufacturers creates a landscape where multiple pathways to differentiation coexist. Understanding how leading players position themselves reveals where value is being captured and how the market is likely to evolve.
Strategic Positioning Among Leading Players
At the premium end, luxury houses such as Hermès International S.A. and Kering S.A. emphasize full-grain bovine and calf leathers, artisanal craftsmanship, and strong brand heritage. Their strategy centers on maintaining perceived scarcity, controlling the narrative around material quality, and using leather goods as anchor products within broader luxury portfolios. LVMH and Prada similarly leverage bovine leather across handbags, wallets, and travel goods, but with a stronger emphasis on volume coordination across brands and collections. These players benefit from brand-driven pricing power and direct consumer relationships, but they also face ongoing pressure to demonstrate sustainability credentials and supply transparency without diluting the exclusivity that underpins their pricing.
Specialized manufacturers and tanneries occupy a different strategic position. Horween Leather Company, for example, focuses on high-quality vegetable and chrome tanned bovine leathers for footwear, bags, wallets, and belts, relying on traditional methods that appeal to brands and consumers who value pedigree and consistency. Rancourt & Co., The Frye Company, Circa of America, Garrett Leather Corp, and Tanner Goods each serve distinct niches, from footwear and boots to accessories and supply-oriented manufacturing. Their advantages typically lie in application knowledge, production flexibility, and the ability to meet specific performance or aesthetic requirements that broader producers may not prioritize. In a market with moderate concentration, these specialized players can compete effectively by deepening relationships with brand partners and delivering reliable quality rather than competing solely on price.
PW Consulting Health Care Research Center
Market Evolution: Consolidation, Differentiation, and New Entrants
The market's moderate concentration suggests room for both consolidation and continued fragmentation, depending on segment and geography. In premium luxury, brand consolidation and portfolio coordination are likely to persist, as large groups seek to balance exclusivity with scale efficiencies across leather goods categories. In mid-tier and specialized manufacturing, the more probable trajectory is differentiation through capability: firms that can combine consistent quality, traceability, and application-specific engineering will capture preferential access to discerning buyers. New entrants and smaller specialized producers may find opportunity in niches where craftsmanship, limited runs, or sustainability credentials command premiums, though they will need to navigate raw material cost variability and compliance requirements carefully. Overall, the competitive dynamic favors players who can articulate a clear value proposition and execute reliably across sourcing, production, and delivery.
Leather Goods Market
Future Outlook and Emerging Trends
Looking ahead over the next three to five years, several trends are likely to shape how the bovine leather goods market evolves and where commercial opportunities emerge. These trends are not speculative abstractions; they are extensions of current pricing behavior, regulatory direction, and buyer expectations already visible in the market.
One prominent trend is the increasing integration of sustainability and traceability into procurement decisions across both consumer-facing and industrial segments. As environmental and animal welfare standards remain strict in major markets and as industry exhibitions continue to highlight sustainable bovine leather goods, buyers are likely to place greater weight on documented compliance, responsible sourcing, and process transparency. The commercial opportunity lies in building verifiable credentials that can be presented in sales cycles and vendor evaluations, turning sustainability from a cost center into a competitive asset. The associated risk is that firms without credible traceability or compliance infrastructure may find themselves increasingly excluded from preferred supplier lists, particularly in segments where brand reputation and regulatory exposure are high.
A second trend is the ongoing refinement of product performance and finish consistency through processing innovation. As tanning and finishing capabilities improve, bovine leather goods can better meet the demands of automotive interiors, footwear, and upholstery applications where durability, appearance retention, and uniformity are critical. This creates opportunities for manufacturers to expand into higher-specification segments and for brands to market leather goods with clearer performance promises. The risk here is that innovation requires investment and process discipline; companies that delay modernization may face yield inefficiencies and reduced competitiveness against more advanced producers.
A third trend involves continued supply chain recalibration in response to cost variability and trade dynamics. With raw hides prices fluctuating and tariff impacts affecting imported materials, firms are likely to pursue more diversified sourcing, stronger supplier partnerships, and greater inventory or contract flexibility. The opportunity is to reduce exposure to sudden cost shocks and improve delivery reliability, both of which strengthen buyer confidence. The risk is that over-concentration in any single sourcing geography or supplier relationship can leave a company vulnerable if conditions shift, making diversification and contingency planning essential rather than optional.
Strategic Recommendations for Decision-Makers
For manufacturers, the priority is to strengthen process control, traceability, and supplier coordination so that raw material volatility can be managed more predictably. Investing in finishing consistency, grading reliability, and documented compliance will improve both margins and buyer confidence, particularly in segments where performance specifications and sustainability expectations are tightening. Building longer-term supplier relationships and diversifying sourcing where feasible can also reduce exposure to tariff and price fluctuations.
For investors, the most compelling opportunities lie in companies that combine clear differentiation with operational discipline. Luxury and heritage brands with strong demand and pricing power remain attractive, but scrutiny should extend to their sustainability readiness and supply transparency. Specialized manufacturers with application expertise, dependable quality, and flexible production may offer resilient exposure to multiple end-use segments, especially where they serve buyers who value reliability and specification compliance over lowest-cost sourcing.
For procurement and sourcing leaders, the strategic imperative is to evaluate suppliers against a broader set of criteria that includes traceability, consistency, and resilience alongside price. Engaging with suppliers who can demonstrate compliance, stable output, and transparent sourcing practices will reduce downstream risk and support brand-level commitments. Maintaining visibility into raw material pricing trends and regulatory developments will also improve negotiation positioning and inventory planning.
Detailed segmentation data, regional breakdowns, and customized scenario analysis can sharpen these decisions further. For teams that need granular revenue splits, application-specific growth patterns, and company-level benchmarking beyond the overview presented here, the full PW Consulting research report provides the deeper dataset and structured frameworks required to translate these market dynamics into precise action plans.
For detailed analysis of this topic, please visit the official page: Bovine Leather Goods Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Projects Penicillin API Market to Reach $385M by 2032, Growing at 5.6% CAGR from $280M in 2025
By PW Consulting, 2026-09-16
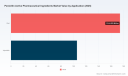
Beyond the Blister Pack: The Strategic Battlefield for Penicillin Active Pharmaceutical Ingredients
The state of global healthcare supply chains is often measured in headlines about finished drugs reaching pharmacy shelves. Yet the true vulnerability and opportunity in the antibiotic sector lie upstream, in the manufacture of the active pharmaceutical ingredients that make those medicines possible. Penicillin APIs remain among the most critical yet geopolitically exposed building blocks in modern medicine. For executives, procurement leaders, and strategy teams navigating the post-pandemic regulatory environment, the decisions made in 2026 will define competitive positioning through the end of the decade.
This article previews our latest market research, designed to give decision-makers a clear view of where the market is heading, which structural forces are shaping it, and where strategic leverage can be gained. The full intelligence, including granular segmentation, company-level capacity maps, and scenario modeling, is available in our published report. Here, we outline the strategic contours that every stakeholder should understand before committing capital, capacity, or supplier relationships.
A Market Defined by Steady Growth and Hidden Complexity
On the surface, the penicillin API market presents a picture of disciplined expansion. Between 2020 and 2025, global revenue climbed from roughly 212.5 million USD to 280.0 million USD, reflecting both the enduring clinical relevance of beta-lactam antibiotics and the gradual recovery of supply chains from earlier disruptions. The forward trajectory through 2032 points to continued momentum, with the market expected to surpass 385.0 million USD by the close of the forecast window. The projected compound annual growth rate of 5.6 percent over this period is neither explosive nor negligible; it is the kind of steady, policy- and demand-driven expansion that rewards companies who move early on capacity, compliance, and supplier diversification.
However, aggregate figures only tell part of the story. Beneath the headline numbers lies a market shaped by distinct product families, delivery formats, and regional production realities that determine margin profiles, supply resilience, and regulatory exposure. The bulk of commercial activity centers on established molecules such as amoxicillin, ampicillin, and penicillin G potassium, supplemented by a broader category of derivatives and specialty intermediates. Demand patterns also diverge sharply across administration routes, with oral formulations commanding the larger share of volume while injectable products sustain a significant and clinically essential footprint. Understanding how these structural elements interact with regional manufacturing capacity is the first step toward building a strategy that can withstand price pressure, regulatory shifts, and geopolitical shocks.
Why 2026 Is a Decision Year for Penicillin API Strategy
The years ahead will not simply be a continuation of past trends. Several intersecting forces make 2026 a pivotal moment for anyone operating in or adjacent to this market. First, the balance between cost efficiency and supply security has fundamentally changed. Organizations that once optimized purely for unit price are now weighing single-source dependency against resilience, particularly where national governments are signaling expectations around domestic or allied-region production of critical medicines.
Second, capital is flowing back into antibiotic API infrastructure, but selectively. Recent facility launches and expansions illustrate how firms are positioning themselves to capture growth while also responding to regulatory and policy tailwinds in specific geographies. At the same time, these investments create capacity additions that may reshape pricing dynamics and competitive intensity over the forecast period. Companies that understand the timing, scale, and certification status of these assets will be better placed to negotiate supply agreements, plan their own production roadmaps, and anticipate shifts in the competitive hierarchy.
Third, raw material and environmental cost structures are exerting renewed pressure on profitability. Changes in export tax treatment on fermentation feedstocks, for example, have raised production costs for some manufacturers, compressing margins that were already tight in a price-sensitive commodity-adjacent market. In parallel, environmental compliance and operating permits have become strategic variables rather than mere administrative hurdles, influencing which plants can run at full capacity and which face interruptions. A 2026 decision framework must therefore integrate cost volatility, regulatory timing, and capacity reliability into a single view, rather than treating them as separate tactical concerns.
The Concentration of Power and the Fragmentation of Risk
Market structure is a central theme for strategy. The penicillin API landscape displays moderate concentration at the top, with the largest players accounting for a significant but not dominant share of global revenue, while the remaining balance is distributed across a wide field of regional and specialized producers. This configuration matters because it shapes bargaining dynamics, switching costs, and the ability of buyers to diversify without sacrificing quality or regulatory compliance.
At one end of the spectrum are fully integrated, high-capacity facilities with strong regulatory credentials and explicit commitments to maintaining production in specific regions. These assets serve as anchor points in the supply chain, offering continuity for customers who prioritize stability and traceability. Elsewhere, particularly in Asia, multiple large-scale producers supply bulk penicillin G potassium and related intermediates to global generic manufacturers, leveraging scale, active regulatory filings, and export-oriented operations. Their presence lowers barriers to access but also introduces concentration risk in feedstock sourcing and downstream dependency.
The strategic implication is nuanced. A market with meaningful concentration can offer efficiency and established quality systems, yet it can also create exposure if policy, environmental events, or operational disruptions affect key sites. Conversely, a more fragmented supplier base can improve diversification but requires stronger quality governance and qualification programs. In 2026, the winning strategies will be those that map this landscape not just by company names, but by capacity, certification status, geographic footprint, and the real-world reliability of each node under stress.
Recent Signals Shaping the Competitive Landscape
Several recent developments underscore how quickly the ground can shift. In Europe, Sandoz completed the final phase of a major investment at its Kundl facility, adding meaningful capacity for penicillin API and finished-dose production while reinforcing its public commitment to safeguard EU-based manufacturing. This move is strategically significant not only because of the capacity added, but because it signals a deliberate choice to maintain a European anchor in a category where production has otherwise migrated toward lower-cost regions.
Penicillin Active Pharmaceutical Ingredients Market
In India, high-profile facility investments and restarts have drawn attention to the country's ambition to expand domestic API capability. A flagship penicillin G production site was inaugurated with national-level visibility and subsequently resumed operations after regulatory approvals following an earlier disruption. Combined with India's broader incentive frameworks, these actions point to a long-term push to reduce import dependency for critical intermediates. Yet they also illustrate the practical realities of capacity ramp-up, environmental permitting, and the time required to achieve stable, certified output at scale.
Beyond individual corporate moves, the supply chain itself reveals structural vulnerabilities that no executive should overlook. Dependence patterns remain pronounced in several directions: downstream generic drug markets in some regions remain heavily reliant on imported penicillin APIs, and leading formulation producers in other markets continue to source the majority of their intermediates from a single upstream origin. These dependencies create efficiency today but elevate risk in a scenario where trade policy, pricing, or operational continuity changes unexpectedly. This is precisely the kind of blind spot that rigorous market intelligence is designed to illuminate before it becomes a crisis.
What Our Research Delivers for Executive Decision-Making
Our full market research is built to translate complex supply chain and competitive dynamics into actionable intelligence. Rather than stopping at high-level totals, the report unpacks the market in ways that support procurement strategy, capacity planning, regulatory risk assessment, and competitive positioning. The following elements are central to the analysis:
Worldwide Penicillin Market
- Forward-looking revenue trajectories across the forecast window, framed to support scenario planning rather than single-point estimates, with explicit attention to the rate and shape of growth as policy and capacity evolve.
- A structured view of product and formulation segments, allowing readers to understand where volume and value concentrate, how mature categories differ from higher-value derivatives, and what that implies for sourcing and differentiation.
- Regional production and demand context that connects manufacturing footprints to regulatory environments, feedstock access, and import-dependency patterns without reducing the picture to simplistic rankings.
- Company profiles and recent operational developments for the key players shaping supply, including fully integrated European producers, large-scale Asian exporters, and specialized international suppliers, with emphasis on capacity, certifications, and strategic intent.
- Market concentration analysis that clarifies the balance between consolidated leadership and broader supplier fragmentation, helping buyers and investors gauge negotiation leverage and resilience options.
- Supply chain and cost dynamics that bring into focus raw material policy changes, environmental permitting risk, and the interplay between upstream intermediates and downstream formulation requirements.
The objective is not simply to describe the market but to enable better decisions. Procurement leaders can use the analysis to evaluate diversification options and qualification pipelines. Executives planning capacity or partnership strategies can benchmark their timing against announced investments and regulatory milestones. Competitive intelligence teams can map where consolidation pressure is likely to intensify and where niche positioning may remain viable. This breadth of practical utility is what distinguishes a strategic study from a conventional data summary.
How to Use This Intelligence in 2026
The most valuable use of this research is not passive reading but active scenario building. We recommend that teams approach the findings with three questions in mind. First, where are the single points of failure in your current supply base, and which alternative nodes are credible from a regulatory, quality, and capacity standpoint? Second, how will announced capacity additions and regional policy commitments alter the bargaining environment over the next two to three years? Third, what cost and margin assumptions remain robust if feedstock economics, environmental compliance, or import-dependency patterns shift further than currently anticipated?
These questions cannot be answered by headlines or isolated statistics. They require a detailed view of how regional dynamics, product categories, supplier capabilities, and regulatory realities interact across the forecast period. That is the level of analysis our report provides, and it is the level at which serious strategic choices are made.
Access the Full Strategic View
The penicillin API market is expanding, but its real significance lies in the strategic choices it forces upon participants: how to balance cost and continuity, how to interpret capacity investments in context, and how to prepare for a supply environment where policy and operational risk are as important as unit price. Our newly released market research offers the depth and structure required to make those choices with confidence.
To explore the complete segmentation, competitive profiles, regional supply dynamics, and forward scenarios that underpin this analysis, please access the full report. The detailed intelligence inside is designed for practitioners who need more than a summary—they need a decision-ready map of the market through 2032.
For detailed analysis of this topic, please visit the official page: Penicillin Active Pharmaceutical Ingredients Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pain Management Drugs Market to Reach $204.9M by 2032, Growing at 3.82% CAGR
By PW Consulting, 2026-09-16
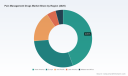
Navigating the Pain Management Drugs Market: Strategic Imperatives for 2026 and Beyond
The global pain management drugs market stands at a critical inflection point. As stakeholders across the pharmaceutical, healthcare, and investment sectors prepare for the 2026–2032 forecast horizon, the intersection of clinical innovation, regulatory evolution, and reimbursement policy is reshaping competitive dynamics at an unprecedented pace. Our latest comprehensive market study delivers the granular intelligence required to navigate this complex landscape, transforming macroeconomic trends into actionable strategic pathways for enterprise decision-makers.
For senior leadership teams evaluating portfolio allocation, partnership opportunities, or geographic expansion, this research provides more than a retrospective analysis. It establishes a forward-looking framework calibrated to the structural shifts that will define commercial viability in the coming years. The following overview outlines the foundational market architecture, the competitive forces at play, and the regulatory levers currently altering the value chain, while intentionally preserving the deeper segmentation analytics and scenario modeling for full access.
Market Trajectory and Structural Fundamentals
Examining the historical performance of the market from 2020 through the base year of 2025 reveals a trajectory of measured but sustained growth. Total market revenue climbed from approximately 131.5 million USD in 2020 to 158.5 million USD by 2025, reflecting consistent demand across both acute and chronic pain indications. This foundational expansion sets a robust baseline for the forecast period, which projects continued appreciation through 2032, with estimated market valuations progressing steadily to 204.9 million USD.
The compound annual growth rate of 3.82 percent across the 2026–2032 window signals a market that is neither stagnant nor explosively volatile. Rather, it is undergoing disciplined maturation, where incremental gains are increasingly tied to therapeutic differentiation, channel optimization, and alignment with value-based care models. Top-line projections alone, however, do not capture the deployment strategy required to capture share. Our analysis decomposes the growth engine into distinct commercial vectors, evaluating how shifts in prescribing behavior, formulation preferences, and regional policy environments interact to redirect capital and research prioritization.
A critical structural indicator is market concentration. With a CR3 of 38.2 percent and a CR5 of 52.1 percent, the landscape exhibits moderate consolidation, leaving meaningful whitespace for specialized entrants and innovative therapeutic platforms. This concentration profile suggests that while incumbent scale confers advantages in pricing leverage and distribution reach, it does not constitute an insurmountable barrier for companies that can articulate clear clinical and economic differentiation. Understanding precisely where concentration is highest, which drug classes are driving share accumulation, and how indication-level demand is reallocating across therapeutic categories requires the full segmentation matrices contained within the complete report.
Competitive Landscape: Incumbents, Innovators, and Positioning Dynamics
The competitive architecture of the pain management market is anchored by a diverse cohort of global pharmaceutical leaders and specialized therapeutic developers. At the core of the market's established footprint are companies that have built enduring franchises around opioid and non-opioid analgesics. Pfizer Inc. continues to maintain a broad analgesic portfolio, leveraging legacy products such as Vicodin alongside a wider pipeline of pain management therapies. Johnson & Johnson maintains a prominent presence in the opioid segment, with Duragesic representing a key asset for moderate to severe pain indications. Endo Health Solutions Inc. has historically anchored its commercial efforts around opioid analgesics including Opana and Percocet, while Teva Pharmaceutical Industries Ltd. balances branded and generic opioid offerings, notably through Nucynta and complementary pain medications. Mallinckrodt plc, operating from its UK headquarters, contributes to the market through opioid products and controlled-substance generics, including formulations related to OxyContin.
Beneath this incumbent tier, a second wave of competitive repositioning is underway, driven by companies emphasizing non-opioid mechanisms and device-enabled delivery. Cumberland Pharmaceuticals Inc. has advanced its non-opioid footprint with the expanded FDA approval of Caldolor for postoperative pain management, reflecting a deliberate strategy to capture procedural pain segments while reducing opioid exposure. Vertex Pharmaceuticals Incorporated is pursuing a more targeted mechanistic approach with Journavx, a first-in-class NaV1.8 inhibitor designed to address moderate to severe acute pain without engaging traditional opioid pathways. Avanos Medical, Inc. occupies a distinct position in the non-pharmacologic and device-assisted recovery space, offering elastomeric infusion pumps and cryo-compression systems that align with evolving recovery protocols and post-acute care economics.
Recent developments underscore how rapidly competitive positioning can shift when regulatory and clinical milestones converge. The FDA's draft guidance issued in late 2025, focused on the development of non-opioid analgesics for chronic pain, has effectively signaled a regulatory environment more receptive to alternative mechanisms. Simultaneously, Vertex's Phase 4 clinical data presentation in early 2026 demonstrated opioid-free recovery outcomes in aesthetic and reconstructive plastic surgery procedures, reinforcing the clinical narrative that non-opioid pathways can meet stringent efficacy expectations. Cumberland's expanded postoperative indication for Caldolor and Avanos's CMS reimbursement confirmation for the Game Ready GRPro 2.1 system further illustrate how policy and product development interact to alter commercial viability. The complete competitive profile section of our study maps each principal company against strategic differentiators, pipeline exposure, and likely tactical responses across the forecast horizon, enabling readers to anticipate where consolidation pressure, partnership activity, or assertion of market leadership is most probable.
Regulatory and Reimbursement Dynamics Redefining Commercial Calculus
No strategic assessment of the pain management market can be constructed without integrating the regulatory and reimbursement architecture that governs adoption. In this cycle, policy developments are acting not merely as compliance constraints but as active demand drivers. The NOPAIN Act framework has emerged as a central lever, and CMS's confirmation of eligibility for multiple pump and compression systems beginning in the 2026 cycle has reinforced the reimbursement pathway for non-opioid pain management solutions in hospital outpatient settings. The separate payment eligibility for non-opioid drugs and biologicals under federal outpatient policy, applicable through the end of 2027, provides a defined window in which hospitals and procedural centers can integrate alternative therapies without absorbing the full cost burden internally.
For pharmaceutical and device manufacturers, this reimbursement environment is not just a pricing consideration; it is a deployment strategy. The availability of separate outpatient payment mechanisms alters the incentive structure for formulary decisions, procurement planning, and clinical protocol design. Companies that align their product development and market access efforts with these reimbursement windows are positioned to secure early adoption advantages, while those that rely solely on traditional inpatient or pharmacy benefit channels may face slower uptake despite clinical merit.
Regulatory guidance is simultaneously shaping trial design and de-risking investment in non-opioid mechanisms. The FDA's draft guidance issued in 2025, which outlines considerations for developing non-opioid analgesics for chronic pain, indicates a willingness to support study designs that can more efficiently demonstrate efficacy without defaulting to opioid comparators in every context. This guidance does not eliminate the evidentiary bar, but it reduces certain development uncertainties that historically discouraged capital allocation toward novel mechanisms. As a result, the innovation pipeline is expected to broaden, intensifying competition among developers pursuing first-in-class targets, reformulation strategies, and device-drug combinations.
Our full market dynamics analysis traces how these reimbursement and regulatory threads intersect with macro demand signals, procurement cycles, and therapeutic substitution trends. By modeling the timing of policy implementation alongside adoption curves, the study identifies the operational implications for commercial teams, health economics specialists, and supply chain planners. The precise interaction between CMS payment windows, hospital procurement behavior, and regional formulary variability is one of several areas where complete segmentation breakdowns are essential for translating policy into executable market access tactics.
Worldwide Advanced Cancer Pain Management Market
Indication and Therapeutic Diversification: Emerging Commercial Vectors
Demand across pain indications is not uniformly distributed, and the relative weight of each segment is shifting as clinical practice evolves. The overall market reflects substantial engagement across arthritic pain, neuropathic pain, cancer pain, chronic back pain, and post-operative pain, with each indication carrying distinct prescribing norms, payer expectations, and lifecycle considerations. Arthritic and neuropathic pain segments, for example, are shaped heavily by chronic management pathways and long-term tolerability profiles, while oncology-related pain management is deeply intertwined with broader supportive care protocols and multidisciplinary treatment plans. Post-operative pain represents a procedural, high-intensity demand environment where non-opioid alternatives and device-assisted recovery are gaining incremental traction.
Parallel to indication-level demand, therapeutic class dynamics are being reconfigured. Opioid and non-steroidal anti-inflammatory drug classes remain foundational, but their relative commercial positioning is increasingly contingent on regional prescribing guidance, formulary restrictions, and perceptions of risk. Antidepressants and anticonvulsants, often deployed in neuropathic and chronic pain contexts, contribute additional therapeutic diversity, while other drug classes capture adjunctive and specialized use cases. The precise distribution of commercial volume across indications and drug classes, including how these splits are evolving year over year, is detailed at a granular level in the complete segmentation framework. That level of detail is essential for businesses evaluating whether to prioritize chronic care partnerships, acute-care procurement relationships, specialty sales channels, or combination therapy positioning.
Importantly, the market's therapeutic diversification is not occurring in isolation. It is being accelerated by the very reimbursement and regulatory developments discussed above, which lower the friction for adopting non-opioid and device-inclusive approaches. Companies that can demonstrate both clinical differentiation and alignment with these structural incentives are best positioned to convert therapeutic overlap into durable share. The complete report maps these indication-class interactions and identifies the commercial inflection points where early alignment yields disproportionate returns.
Strategic Priorities for 2026 Decision-Making
For executive teams, the immediate strategic challenge is to reconcile long-term market growth with the rapidly shifting mechanics of access, acceptance, and competition. The forecast period does not simply extend historical patterns; it introduces new variables around mechanism innovation, reimbursement timing, and regional policy divergence. To act decisively, organizations should consider several foundational priorities.
Pain Management Drugs Market
- Align portfolio and pipeline decisions with the reimbursement and regulatory windows that are currently shaping adoption behavior, especially in outpatient and procedural care settings.
- Evaluate competitive positioning against both scale incumbents and mechanism-focused entrants, weighing the relative advantages of established distribution versus differentiated clinical value propositions.
- Incorporate market concentration dynamics into go-to-market planning, recognizing that moderate consolidation leaves room for specialized strategies in selected indications and geographies.
- Integrate health economics and access considerations early in development and commercialization planning to ensure that product profiles match the evidentiary and payment expectations of relevant stakeholders.
- Monitor regional and institutional procurement patterns, as policy implementation and formulary evolution are likely to proceed unevenly across care settings and markets.
Our report supplies the analytical scaffolding for each of these priorities, combining historical baseline data, forward-looking projections, and company-level competitive context into a unified decision-support framework. Rather than providing a single-point market estimate, the study constructs the scenarios and segmentation insights required to test strategy against plausible outcomes. This includes evaluating where share migration is most likely to occur, which therapeutic and indication combinations present the strongest near-term commercial catalysts, and how regulatory momentum may alter the cost and speed of market entry for non-opioid alternatives.
Conclusion: The Value of Complete Intelligence in a Shifting Market
The pain management drugs market is evolving under a confluence of clinical, regulatory, and reimbursement forces that reward prepared organizations and penalize reactive positioning. A top-line growth trajectory of 3.82 percent CAGR through 2032 signals opportunity, but the real strategic value lies in understanding where that growth is generated, which competitive assets are most exposed, and how policy design is reshaping adoption economics. The published market size progression from 2020 through the forecast horizon provides a useful anchor, yet the decisions that will determine commercial success depend on the deeper segmentation architecture, competitive profiling, and scenario analysis that only the full study delivers.
Organizations that rely on aggregate figures alone risk misallocating capital toward segments where access barriers remain high or where concentration and competition compress margin potential. Conversely, those that integrate the complete market intelligence into portfolio planning, partnership evaluation, and access strategy can identify the highest-probability opportunities for differentiated positioning. The complete version of this market study provides the detailed regional, indication, and drug class breakdowns, the full competitive profile matrix, and the dynamic scenario modeling needed to convert high-level trends into concrete 2026 action plans. For executives and strategy teams seeking to move from awareness to execution, the comprehensive report is the essential next step.
For detailed analysis of this topic, please visit the official page: Pain Management Drugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Wine Glass Market to Hit $220.73M by 2032, Growing at 2.8% CAGR
By PW Consulting, 2026-09-16
Why the Global Wine Glass Market Report Is the Strategic Compass Your Business Needs for 2026
The global wine glass market stands at a quiet but decisive inflection point. Between 2020 and 2025, the sector moved from a post-pandemic recovery phase into steady, compounding growth, with baseline revenues climbing from USD 151.0 million to USD 183.0 million. Projections extending through 2032 outline a market trajectory that approaches USD 220.73 million by the end of the forecast window, supported by a compound annual growth rate of 2.8 percent. These numbers are not abstract industry statistics. They are the raw signals that separate companies that react defensively to margin compression and supply chain shocks from those that position their portfolios in advance. Our newly released market research is engineered to transform those signals into executable strategy for 2026 and beyond.
For executives, procurement leaders, and category managers, the value of this study lies in its decision-ready architecture. Rather than offering a retrospective data dump, the report maps the operational terrain that will shape pricing, sourcing, product mix, and competitive positioning over the next six years. It is a reference document designed for boardroom discussions, capital allocation calls, and commercial planning cycles where precision matters and guesswork must be minimized.
What the Research Delivers: A Practical Operating Framework
The study is structured around the actionable information that decision-makers actually need when they are under pressure to justify line extensions, renegotiate supplier contracts, or evaluate new distribution channels. It moves beyond headline figures to equip leaders with a repeatable analytical process they can apply directly to their own business units.
- Historical baseline and forward trajectory: The report anchors every forecast in a rigorously tracked historical sequence and then maps a forward path that captures the subtle shifts expected across the 2026 to 2032 horizon.
- Segment-level structural insight: Readers receive a clear dissection of product architecture and consumption contexts, helping identify where value is accumulating and where structural bottlenecks are forming.
- Regional demand mapping: Geographic performance is presented as a comparative landscape rather than a static list, enabling teams to understand which territories are driving momentum and which are moderating growth.
- Competitive positioning and concentration metrics: The study examines how market share is distributed among leading manufacturers and what that concentration implies for pricing leverage, entry barriers, and partnership opportunities.
- Regulatory, material, and labor dynamics: External forces are analyzed as active variables, not background noise, so that supply strategy and compliance planning can be integrated rather than bolted on after the fact.
- Recent corporate developments and launch patterns: Fresh on-the-ground activity is synthesized to show how market leaders are adjusting designs, materials, and consumer engagement strategies in real time.
This is not a report meant to sit on a shelf. It is built to guide questions such as where to concentrate innovation spend, how to think about volume versus premiumization, and which operational risks deserve immediate mitigation. The full dataset behind these frameworks is available in the complete study, where the granular breakdowns can be filtered, compared, and applied to your own internal models.
Market Size, Growth Trajectory, and the Real Meaning of a 2.8 Percent CAGR
A compound annual growth rate of 2.8 percent might appear modest at first glance, but in a mature consumer goods category it carries distinct strategic weight. It signals a market that is still expanding, yet doing so in a measured way that rewards disciplined execution over aggressive volume chasing. The revenue progression from 2025 through the early forecast years suggests that growth will not be evenly distributed. Some product families and consumption contexts will advance more quickly, while others will stabilize or face cost-driven friction. The study isolates those divergent paths so that leadership can allocate resources where incremental returns are most defensible.
The implication for 2026 planning is straightforward: a moderate CAGR demands sharper segmentation and more selective sourcing. Companies that treat the entire category as a single growth opportunity risk diluting focus. Those that understand where the structural pull is strongest, and which consumer or commercial channels are expanding faster than the category baseline, can build a more resilient revenue mix. The report gives you the scaffolding to make those distinctions without relying on intuition alone.
Wine Glass Market
Analyzing the Competitive Layer Without Getting Lost in Rhetoric
Strategic advantage in wine glass manufacturing is rarely determined by a single product launch. It comes from understanding who controls what kind of position in the value chain, how differentiated those positions are, and where consolidation or substitution could alter the balance. The research profiles the companies that shape category standards today, including Riedel Tiroler Glashutte GmbH, Libbey Inc., Bormioli Rocco, Schott AG, Josephinenhütte, Gabriel-Glas, and Spiegelau.
These organizations represent different strategic archetypes. Some compete on varietal specificity and sensory optimization, building recognition around performance-driven stemware. Others anchor themselves in durability, commercial service reliability, or universal design philosophies that simplify product ranges. A few emphasize lightweight construction, thermal resistance, or premium hand-finished lines. The study does more than summarize brand narratives. It evaluates how each player's positioning interacts with the broader demand environment, where their approaches converge, and where they deliberately diverge to protect margin or defend distribution.
What recent activity tells us about the near-term direction
Recent corporate actions already signal how the category is being reshaped. Riedel, for example, has continued expanding its consumer engagement footprint with high-profile tasting experiences and new collections that emphasize thinner, machine-blown designs alongside hand-crafted premium lines. Parallel activity in the retail and experiential channel, such as exclusive stemless souvenir introductions at regional wine expos, points to a mindset shift: packaging and vessel design are increasingly treated as part of the tasting moment rather than as passive serving items.
For strategy teams, the practical value lies in pattern recognition. When leading manufacturers adjust material profiles, refine product aesthetics, and invest directly in consumer-facing events, they are testing which value propositions still resonate. The report distills these developments into comparable strategic signals so your organization can judge whether you are aligned with the direction the market is taking or still responding to yesterday's assumptions.
The Regulatory and Supply-Side Reality: Why 2026 Demands Scenario Planning
External pressures are no longer side considerations. They are central inputs into pricing, sourcing, and product design decisions. The study incorporates the most consequential industry dynamics currently affecting the wine glass and broader wine service ecosystem, including regulatory proposals, energy-intensive production realities, tariff exposure, and labor-side capacity adjustments.
- Labeling and transparency pressure: Proposed changes to mandatory alcohol facts statements, including calorie and nutrient disclosures, have the potential to reshape how product information is presented and how consumer expectations evolve around beverage service.
- Production energy intensity: Glass manufacturing remains a high-temperature, energy-heavy process, which has direct implications for cost stability, sustainability narratives, and long-term supply resilience.
- Import cost exposure: Tariff actions affecting imported wine create downstream pressure on packaging and service costs for importers, altering the economics of the broader wine service chain.
- Capacity and labor adjustments: Significant facility closures and workforce reductions among major glass producers highlight how sensitive the supply base can be to demand shifts and cost structures, reinforcing the need for diversified sourcing strategies.
This is exactly why the report includes scenario-oriented analysis rather than a single static forecast. Decision-makers need to understand how an increase in compliance complexity, a change in import economics, or a disruption in production capacity might interact with their own operating model. The research helps translate those external variables into concrete planning questions about supplier redundancy, cost pass-through feasibility, and product design flexibility.
Why the Complete Study Matters for 2026 Decision-Making
Macro indicators and executive summaries can inform a conversation, but they rarely replace the kind of detailed intelligence required to set budgets, choose priorities, or defend a go-to-market plan. The complete market research provides the working-level detail that turns high-level insight into operational readiness. It enables you to compare structural opportunities across product categories, consumption settings, and regional contexts without having to reconstruct the analysis from fragments.
More importantly, the study preserves analytical integrity. It distinguishes what is supported by evidence from what is merely plausible, and it organizes that distinction in a way that is useful for cross-functional teams. Commercial leaders can use it to sharpen assortment thinking. Procurement teams can use it to frame sourcing resilience. Strategy and executive teams can use it to benchmark concentration, competitive behavior, and the likelihood of margin pressure in specific segments.
The report is also designed with a clear purpose: to make your next decision faster and better informed. Whether your team is evaluating a new premium line, analyzing the durability of a commercial channel, or preparing for regulatory cost implications, the research supplies a shared evidence base that reduces internal friction and shortens the path from question to answer.
Looking Ahead: Use This Intelligence to Shape 2026 With Confidence
The wine glass market is not defined by sudden disruption. It is defined by cumulative choices: what to produce, what to source, where to emphasize design, and how to respond when regulatory and supply conditions shift. In that environment, strategic clarity is a competitive asset. The companies that outperform will be the ones that understand the category's growth logic, read competitive signals early, and build operating flexibility into their plans before pressure arrives.
Glassware Market
This market research is intended to give you that clarity at the moment you need it. It provides the structure to assess where the market is heading between 2026 and 2032, the competitive context to interpret who is winning and why, and the external dynamics to stress-test your assumptions against real-world variables. To access the full segmentation detail, comparative regional insight, and company-level intelligence that support these strategic conclusions, refer to the complete PW Consulting market research. The comprehensive dataset is where the operational specifics live, and where your 2026 decisions can be grounded with confidence.
For detailed analysis of this topic, please visit the official page: Wine Glass Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Activin A Market Hits $162M in 2025, Poised for 8.56% CAGR Through 2032
By PW Consulting, 2026-09-16
# Strategic Imperatives in 2026: Navigating the Expanding Activin A Market
Executive Overview: The Inflection Point of 2026
The Activin A market has reached a critical inflection point. As the biopharmaceutical landscape shifts from purely academic exploration toward tangible therapeutic realization, understanding the nuances of this specific protein market is no longer optional for strategic stakeholders. It is a necessity. This report serves as a comprehensive navigational tool for decision-makers operating within the biotechnology, pharmaceutical, and research supply sectors. The trajectory is clear, the demand is scaling, and the competitive dynamics are tightening.
Entering 2026, the industry moves beyond historical baselines into a period of rigorous expansion. For companies relying on Activin A for drug development, stem cell research, or assay standardization, the capacity to access reliable supply chains and understand market drivers determines operational success. This market intelligence briefing synthesizes years of longitudinal data to provide a forward-looking perspective that aligns procurement strategies with long-term growth expectations.
Historical Trajectory and Future Projections
To understand where the market is going, we must first acknowledge where it has been. The historical performance of the Activin A sector demonstrates a consistent upward trend, reflecting the protein's increasing utility in high-value research areas.
Historical Context (2020–2025)
The market has demonstrated robust resilience and growth over the past half-decade. Starting from a foundational position in 2020, the sector has expanded steadily through the pandemic era and into the post-pandemic recovery period. By the base year of our current analysis, the market had solidified its revenue streams, indicating a mature demand structure that is now accelerating into the forecast period. This historical stability provides a reliable baseline for projecting future investments. The progression from the early 2020s to 2025 shows a marked increase in commercialization activity, driven by both academic institutes and emerging biotech firms seeking novel differentiation pathways.
Forecasted Growth (2026–2032)
The forecast period represents a significant escalation in market valuation. The trajectory points toward a Compound Annual Growth Rate (CAGR) that underscores the sector's vitality. As we project through the end of the decade, the cumulative growth suggests a market that is not merely expanding incrementally but is structuring itself for a landmark increase in value. This period will likely be defined by the transition of Activin A products from research use-only models toward GMP-grade standards required for clinical translation.
By the target horizon, the market is expected to reach valuation levels that justify increased capital allocation. The magnitude of this growth indicates that Acts of negation, testing, and development involving Activin A are becoming central to broader biomedical strategies. Stakeholders who analyze the nuances of this growth curve will be better positioned to time their capacity expansions and investment cycles correctly.
Segmentation Dynamics: Understanding the Value Chains
While aggregate numbers provide the macro view, the true strategic insight lies in understanding how value is distributed across product types and applications. This market is not monolithic; it is composed of distinct segments that behave differently based on technological maturity and clinical need.
The landscape includes a diversified array of product configurations, ranging from high-purity recombinant proteins to specialized assay kits. The dominance of certain recombinant formats suggests a market deeply entrenched in rigorous research standards, where quality and reproducibility are paramount. Meanwhile, the presence of assay kits and other specialized types indicates a secondary market dedicated to high-throughput screening and quality control processes. For supply chain managers, this segmentation highlights the necessity of multi-source procurement strategies to mitigate risks associated with single-product dependency. Understanding the specific volume and value contribution of these distinct formats allows procurement officers to negotiate better terms with vendors and anticipate lead time variances.
Vitamin A Market
Clinical Catalysts and Industry Dynamics
The market does not exist in a vacuum. It is propelled by clinical outcomes and regulatory milestones that shift the perception of Activin A from a mere research reagent to a therapeutic target. Recent developments have significantly altered the landscape's gravity.
Activin A Market
Therapeutic Advancements
The most notable shift comes from clinical trials targeting Activin A directly. The progress made by key pharmaceutical players has validated the protein as a potent drug target, rather than just a tool for drug development. For instance, the Phase 3 OPTIMA trial updates regarding garetosmab, a monoclonal antibody neutralizing Activin A, signaled a major breakthrough with significant reduction in heterotopic ossification lesions. The planned regulatory submissions associated with such milestones create a ripple effect across the entire supply chain, increasing demand for high-quality research materials that can support late-stage development and potential commercialization.
Simultaneously, early-stage pipeline developments are feeding the long-term pipeline. Initial topline results from ligand traps inhibiting Activin A and myostatin have shown improvements in body composition and bone formation markers. These early successes encourage biotech companies to invest more heavily in the underlying research infrastructure, thereby sustaining the demand for research-grade and GMP-grade Activin A proteins.
Competitive Landscape and Key Players
The competitive environment is characterized by a concentration of expertise among a select group of global providers. Market concentration metrics indicate that the majority of the market share is held by a few dominant entities, fostering a competitive environment where differentiation through quality and regulatory compliance is essential. The top-tier providers have established themselves as the backbone of the research community, offering products that range from standard research use to clinically compliant GMP standards.
Key players such as Acro Biosystems, R&D Systems, Bio-Techne Corporation, and PeproTech have solidified their positions by offering specialized GMP Human Activin A proteins derived from CHO systems. These offerings are critical for cellular therapeutics and drug development, where consistency and purity are non-negotiable. Stemcell Technologies, based in Canada, continues to support the development sector with human recombinant Activin A for research and cell therapy support.
For companies evaluating partnerships or procurement opportunities, analyzing the specific capabilities of these leaders is vital. The distinction between standard recombinant proteins and GMP-compliant versions is a key differentiator that affects downstream regulatory approval timelines. Strategic buyers must assess whether their current vendors can scale production to meet GMP requirements as therapeutic programs advance from preclinical to clinical phases.
Strategic Implications for 2026 Decision Makers
The data points and trends described above converge into several actionable strategic imperatives for the year 2026. Organizations operating in this space must look beyond simple procurement and consider the broader ecosystem dynamics.
- Supply Chain Resilience: With a high market concentration, reliance on a limited number of suppliers poses a risk. Diversifying the supplier base while maintaining quality standards is crucial. Engaging with multiple key players available in the market ensures continuity of supply even if one market segment faces disruptions.
- GMP Transition Planning: As clinical trials advance, the transition from research-grade to GMP-grade proteins becomes inevitable. Companies should audit their current inventory and future requirements against GMP availability. Early engagement with manufacturers capable of scaling GMP production prevents bottlenecks during critical development windows.
- Application Diversification: The market spans across cancer research, reproductive biology, and other applications. The uptake in therapeutic areas like fibrosis and bone disorders suggests that demand is evolving. Strategic forecasting should account for shifting application priorities based on the latest clinical data, ensuring that research portfolios remain aligned with high-growth therapeutic areas.
- Regulatory Awareness: With regulatory submissions on the horizon for novel Activin A-targeting therapies, the standards for research materials are likely to tighten. Anticipating stricter quality control requirements and integrating them into current operational workflows provides a competitive advantage.
Why This Report Matters
In an environment where information asymmetry can lead to costly strategic errors, this report provides the transparency and depth necessary to make informed decisions. It bridges the gap between raw data and actionable intelligence, offering a structured view of the market that accounts for historical performance, future projections, and competitive realities.
This comprehensive analysis goes beyond surface-level trends. It delves into the operational specifics of product types, the nuances of regional distribution, and the intricate details of the competitive landscape. The goal is to equip stakeholders with the insights needed to navigate the complexities of the Activin A ecosystem confidently. Whether you are assessing market entry opportunities, optimizing procurement strategies, or evaluating investment potential, the detailed breakdown contained within the full study offers the granularity required for rigorous due diligence.
The full dataset, including detailed segmentation splits across regions and applications, provides a granular view that macroeconomic summaries cannot capture. This allows for precise market sizing and opportunity assessment that is tailored to specific business units or geographic targets.
Conclusion
As we advance through 2026, the Activin A market stands as a testament to the growing importance of targeted protein research in the broader biomedical ecosystem. The combination of steady historical growth, promising clinical developments, and a concentrated yet dynamic competitive landscape creates a unique environment for strategic growth. For leaders in the life sciences sector, the opportunity lies in understanding these dynamics in depth and aligning organizational strategy with the market's forward trajectory. The road ahead is defined by precision, quality, and the ability to respond to clinical breakthroughs with supply chain agility.
This report serves as the foundational tool for mastering that environment, ensuring that your organization is prepared for the opportunities and challenges of the coming years. The insights provided herein are designed to spark further investigation and facilitate the strategic conversations necessary to capitalize on the burgeoning value of this sector.
For detailed analysis of this topic, please visit the official page: Activin A Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


