



Category: Healthy Lifestyle
PW Consulting: Commercial Payment Cards Market to Hit $364.76B by 2032, Growing at 6.98% CAGR
By PW Consulting, 2026-09-16
Navigating the Next Wave: Strategic Insights from the Commercial Payment Cards Market Research 2026
The landscape of corporate spending is undergoing a seismic shift. As businesses grapple with inflationary pressures, evolving regulatory frameworks, and the demand for seamless digital integration, the commercial payment card sector has emerged as a critical lever for operational efficiency. For decision-makers navigating the fiscal calendar of 2026, understanding the trajectory of this market is not merely an academic exercise—it is a strategic imperative. PW Consulting is proud to unveil our latest comprehensive market research, designed to equip leaders with the intelligence needed to capitalize on growth opportunities and mitigate emerging risks in the commercial payment ecosystem.
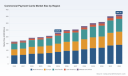
This research is anchored in rigorous data analysis covering historical performance from 2020 through 2025 and extending robust forecasts through 2032. The macro-environment presents a compelling story of resilience and expansion. In 2025, the global revenue for commercial payment cards reached approximately 229.05 billion USD. Looking ahead, the market is projected to climb to 249.66 billion USD in 2026, marking a significant inflection point in corporate adoption rates. Our forecast models indicate a steady compound annual growth rate of 6.98 percent throughout the forecast period, with revenues expected to surpass 364.76 billion USD by 2032. These figures underscore a sustained appetite for flexible payment instruments that bridge the gap between traditional corporate treasury functions and modern procurement needs.
Decoding Market Concentration and Competitive Forces
One of the most critical aspects of our analysis focuses on the competitive dynamics that define the industry. The market is characterized by a moderate level of concentration, where strategic positioning among top-tier players dictates the pace of innovation. Our report details a landscape where the top three companies command a combined market share of roughly 49.5 percent, while the top five entities control approximately 62.8 percent of the revenue pool. This structure suggests that while dominant networks hold significant sway, there remains substantial room for specialized issuers and niche providers to carve out profitable segments.
Plastic Cards Market
The competitive arena is populated by a diverse mix of global network operators and specialized issuers. Giants like American Express, Visa, and Mastercard continue to dominate the infrastructure layer, offering robust networks that support virtual purchase cards and corporate spend management solutions. American Express, headquartered in New York, remains a key player in issuing commercial payment cards including virtual purchase cards for business-to-business procurement. Similarly, Visa, based in San Francisco, operates a global network supporting commercial payment cards including virtual cards for corporate spend management, while Mastercard, located in Purchase, NY, provides network infrastructure with a focus on virtual and single-use variants for B2B transactions.
However, the ecosystem extends far beyond these primary networks. Discover Financial Services, based in Riverwoods, IL, issues commercial payment cards for business expense tracking and virtual solutions, catering to specific expense management needs. International reach is exemplified by JCB in Tokyo and UnionPay in Beijing, the latter facilitating commercial payment cards with contactless and virtual options to support cross-border commerce. On the specialized issuer front, companies like WEX in Minneapolis provide commercial fleet and virtual payment cards for business expenses, whereas Corpay in Nashville issues and manages commercial payment cards for corporate travel and expense programs.
Innovation is also being driven by agile entrants and standards bodies. Engine, based in Denver, recently made waves with the launch of the Engine X Visa-branded corporate charge card specifically for small and mid-sized businesses. This product features spending controls and travel rewards, directly addressing the needs of the SMB segment which often feels overlooked by larger issuers. Furthermore, standards development plays a crucial role in interoperability and security. X9, the standards body in Annapolis, MD, developed and published X9.149 for single-use virtual business-to-business payment cards, aiming to streamline transaction efficiency.
Recent Developments Shaping the 2026 Landscape
Real-time intelligence is vital in a sector moving this fast. Our research integrates the latest developments that are actively reshaping the value proposition for corporate clients. In March 2026, Engine announced the launch of their corporate charge card, featuring spending limits, merchant restrictions, and up to 10 percent rewards on business travel. This move highlights a trend toward incentivizing specific spending categories while maintaining strict control parameters, a balance that many finance teams are seeking.
Simultaneously, the regulatory and standards environment is tightening to support higher efficiency and security. In April 2026, the Accredited Standards Committee X9 published the X9.149 standard for single-use virtual purchase card payment automation. This development is designed to improve B2B transaction efficiency and reconciliation following ISO 20022 messaging standards. Such standardization efforts are critical for reducing friction in accounts payable processes and enhancing the auditability of corporate spending.
Beyond specific product launches, broader industry dynamics are influencing market behavior. The Federal Reserve Board reported on average debit card interchange fees by payment card network in December 2025, providing essential data for cost-benefit analyses of different card programs. Security remains paramount, with the PCI DSS Card Production and Provisioning Physical and Logical Security Requirements defining standards for card manufacturing, transport, and personalization. Additionally, the Payment Card Industry Data Security Standard version 4.0 guides organizations on card data handling and compliance, a critical consideration for any firm integrating payment cards into their IT infrastructure.
Infrastructure costs also play a background role in the economics of payment processing. The American Society of Civil Engineers 2025 Infrastructure Report Card noted that deployment costs for broadband infrastructure increased over 10 percent with materials and labor as primary drivers. While this relates to physical infrastructure, it impacts the broader digital ecosystem supporting payment technologies. Furthermore, macro-level shifts are occurring, as highlighted by the McKinsey Global Payments Report in September 2025, which pointed to growing payment sovereignty initiatives in regions such as Europe and Brazil to reduce reliance on global intermediaries. This trend could influence network selection and localization strategies for multinational corporations.
Segmentation Dynamics and Application Scenarios
Understanding where the revenue is generated is key to allocating resources effectively. Our research delves deep into the segmentation of the market by type and application, revealing distinct growth drivers within each category. The market is segmented by type into Credit Cards, Debit Cards, and Prepaid Cards. Credit cards continue to hold a substantial portion of the market value, reflecting their utility in managing cash flow and earning rewards, while Debit Cards offer a controlled spending mechanism linked directly to funds. Prepaid Cards also represent a significant segment, often utilized for specific budgeting purposes or employee allowances.
From an application perspective, the divide between Large Business Cards and Small Business Cards illustrates the diverse needs across the corporate spectrum. Large Business Cards constitute a major share of the application market, driven by high-volume procurement and complex travel requirements. Small Business Cards, while representing a smaller total revenue share compared to the enterprise segment, are witnessing heightened innovation and competitive pressure from issuers like Engine looking to capture the SME market. Our report provides granular analysis of how these segments interact with regional dynamics and type preferences without exposing the specific numerical splits that constitute our core proprietary intelligence.
Geographic distribution also plays a pivotal role in strategy formulation. The market serves key regions including North America, Europe, Asia Pacific, Latin America, and Mideast and Africa. Each region presents unique regulatory environments, adoption rates, and competitive intensities. For instance, payment sovereignty trends may impact strategies in Europe and Latin America differently than in North America. Our analysis contextualizes these regional variations to help clients prioritize market entry or expansion efforts based on their specific risk tolerance and growth objectives.
The Strategic Value of Comprehensive Intelligence
Why does this level of detail matter for your 2026 planning? In a market projected to grow by over 130 billion USD between 2026 and 2032, the margin for error shrinks as competition intensifies. Access to detailed segmentation data, competitive profiling, and regulatory roadmaps allows organizations to move from reactive spending management to proactive financial strategy. Whether you are a issuer looking to refine your product portfolio, a corporate treasurer optimizing expense policies, or an investor assessing the viability of fintech ventures in the payments space, this report provides the foundational knowledge required to make informed decisions.
The report goes beyond high-level numbers to explore the operational realities faced by market participants. It examines how reimbursement dynamics, influenced by factors such as interchange fee structures, affect the total cost of ownership for corporate card programs. It also assesses how compliance with evolving security standards impacts procurement timelines and vendor selection. By synthesizing data on market concentration, company profiles, and recent developments, we offer a 360-degree view of the ecosystem.
Our analysis of key companies includes detailed profiles covering their headquarters, operational focus, and strategic moves. For example, understanding the focus of WEX on fleet and virtual payment cards versus Corpay's emphasis on corporate travel and expense programs helps tailor partnership or benchmarking strategies. Similarly, tracking the standardization efforts of bodies like X9 ensures that technology investments align with future-proof protocols.
Commercial Payment Cards Market
Unlock the Full Intelligence
The insights summarized here represent only the surface of the comprehensive intelligence available in the full PW Consulting Commercial Payment Cards Market Research. To truly leverage the 6.98 percent CAGR opportunity and navigate the complexities of a market reaching 364.76 billion USD by 2032, decision-makers need access to the complete dataset, detailed forecasts, and proprietary analytical models.
We invite you to access the source webpage to download the full report. There you will find the specific regional growth rates, detailed application segment valuations, and deep-dive competitive benchmarking that cannot be fully disclosed in this overview. Equip your team with the precise data needed to outperform in the evolving commercial payment landscape. Visit our report page today to secure your copy and start transforming market intelligence into strategic advantage.
For detailed analysis of this topic, please visit the official page: Commercial Payment Cards Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cast Film Market to Reach $14.47B by 2032, 4.5% CAGR Amid Food Packaging Demand
By PW Consulting, 2026-09-16
Strategic Imperatives in the Cast Film Market: Navigating Growth and Complexity Through 2032
The global cast film market stands at a critical juncture where material science, regulatory pressure, and sustainability mandates converge. For strategic planners and category leaders, understanding the trajectory of this sector is no longer optional. It is a prerequisite for resilient supply chain design, product portfolio optimization, and long-term competitive positioning. Our latest comprehensive study on the Cast Film Market translates years of historical performance and forward-looking modeling into an executable intelligence framework. This article outlines the structural forces shaping the industry, highlights the operational content embedded in the full report, and demonstrates how executives can leverage these insights to de-risk decisions across the 2026 to 2032 horizon.
Market Trajectory and the Momentum Behind Sustained Expansion
Over the past five years, the cast film sector has demonstrated consistent upward movement, underpinned by expanding packaging demand, continuous extrusion technology improvements, and the material's inherent versatility across food, pharmaceutical, agricultural, and industrial applications. Historical revenue patterns from 2020 through 2025 reflect a steady climb, with the market surpassing the nine-figure million threshold and closing the base year at a level that signals durable commercial relevance. The forward projection reinforces this trajectory. Our forecast modeling indicates that the global market will continue its measured expansion through 2032, supported by volume growth, product innovation, and the gradual penetration of advanced mono-material structures. The compound annual growth rate anchored at 4.5 percent reflects a market that is neither overheated nor stagnant, but rather evolving at a pace that rewards organizations capable of aligning production capacity, feedstock strategy, and downstream application development with shifting end-user requirements.
For decision-makers, this growth profile carries nuanced implications. A mid-single-digit expansion rate suggests that headline market size alone will not differentiate winners. Instead, margin capture, application-level specialization, and regional execution precision will determine which participants convert industry-wide growth into outsized financial returns. The full research deliverable dissects these dynamics across multiple analytical lenses, allowing clients to isolate high-conviction opportunities without getting lost in aggregate figures that mask structural variation.
Segmentation Architecture and Where Strategic Value Actually Resides
Cast film demand does not move uniformly. The market is inherently multi-dimensional, shaped by resin chemistry, end-use performance specifications, and geographic manufacturing footprints. Understanding how these layers interact is essential for capacity planning, pricing strategy, and customer targeting. The study examines the primary segmentation axes that matter most to commercial and operational leaders, focusing on how resin categories, application verticals, and regional ecosystems each present distinct risk-return profiles.
On the material side, polyethylene-based structures continue to anchor a substantial portion of industry volume, reflecting their balanced mechanical properties, processability, and cost competitiveness across broad packaging formats. Polypropylene variants serve a strategically important but more specialized slice of the market, often favored where flexural strength, thermal stability, or specific barrier characteristics are prioritized. Polyester-based cast films occupy a narrower but high-performance niche, typically linked to demanding graphics, labeling, and specialty conversion environments. Rather than treating these categories as static share buckets, the report evaluates how resin selection is increasingly driven by downstream regulatory compliance, recyclability objectives, and converter-level processing economics.
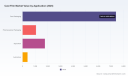
Application-level analysis reveals equally important divergence. Food packaging remains the dominant demand engine, shaped by freshness preservation, print fidelity, and stringent safety standards. Pharmaceutical packaging introduces a different calculus, where consistency, traceability, and regulatory alignment take precedence over pure cost optimization. Agricultural uses add complexity through exposure conditions, durability requirements, and seasonal demand cycles. Automotive and industrial applications, while smaller in aggregate volume, often function as high-specification adoption pathways that influence broader material innovation. The report maps these application environments to operational implications, helping clients anticipate where technical service, qualification lead times, and supply reliability will matter more than price alone.
Geographic dispersion further complicates the picture. Demand concentration varies by manufacturing maturity, export orientation, packaging infrastructure investment, and regional sustainability policy tempo. Instead of presenting narrow regional breakdowns that can obscure strategic context, the study evaluates how macro-regional demand patterns interact with local compliance frameworks, logistics constraints, and competitive density. This approach allows executives to assess where near-term volume growth is most likely to materialize and where longer-term positioning requires patience, partnership, or localized product adaptation.
What the Full Report Delivers Beyond Top-Line Figures
Aggregated market size and growth rates are only the starting point. The research is built around an operational architecture designed to support real decision-making. Inside the full study, clients gain access to a structured set of analysis modules that connect market behavior to executable strategy. The report incorporates:
- A multi-year historical reconstruction that validates trend assumptions and isolates structural shifts from cyclical noise
- Forward-looking demand modeling through the end of the decade, with scenario-aware forecasts that account for feedstock volatility, regulatory acceleration, and technology adoption pacing
- Application-specific demand logic that explains why certain verticals expand faster, resist downturns more effectively, or respond differently to material substitution
- Resin and processing-technology assessments that clarify the commercial relevance of downgauging, mono-material transition, and high-performance extrusion advances
- Competitive profiling that evaluates participant positioning across material supply, film conversion, equipment provision, and specialty application expertise
- Regulatory and compliance mapping that ties policy developments to substrate selection, recycled content requirements, and converter-level risk exposure
- Strategic implication summaries that translate data patterns into capacity, procurement, partnership, and go-to-market recommendations
This structure is intentionally designed to avoid the common trap of presenting data without decision context. Each section is linked to practical questions facing production leaders, procurement teams, R&D groups, and commercial strategists. The objective is to help organizations move from awareness to action, whether that means adjusting resin procurement timing, prioritizing regional expansion,qualifying new mono-material formats, or repositioning product offerings around recyclability and performance.
Competitive Landscape: Diversification of Capability and the Rise of Ecosystem Play
The cast film environment is not defined by a single business model. Instead, it comprises a blend of film converters, resin suppliers, extrusion-technology providers, and specialty solution developers. This diversity matters because competitive advantage increasingly depends on how well an organization can integrate upstream material capability with downstream application performance and regulatory alignment.
Several established participants illustrate the range of strategic postures now shaping the market. Avery Dennison operates with a strong orientation toward professional-grade cast films serving graphics and labeling applications, where print reliability, conformance, and converter usability are central to product value. Profol Group is recognized for custom cast film manufacturing across polypropylene and polyethylene formats, reflecting a conversion-focused model that emphasizes specification flexibility and customer-specific film design. Windmöller & Hölscher contributes from the equipment and process side, producing high-speed cast film extrusion lines and supporting CPP cast film production, which positions the company as an enabler of capacity and throughput improvements across the value chain. SML extends this technology-driven logic further, specializing in high-performance cast film extrusion technology and MDO-PE cast films, where dimensional performance and process efficiency are closely intertwined.
Material suppliers add another critical layer. TotalEnergies provides polymers that support downgauging initiatives for MDO-PE cast films, linking resin development directly to lightweighting and material efficiency objectives. LyondellBasell develops and supplies resins tailored to cast film grades, reinforcing the importance of feedstock-level innovation in achieving targeted mechanical and processing outcomes. Amcor rounds out the landscape as a manufacturer and supplier of cast films for packaging applications, combining conversion capability with broad commercial reach across end-use sectors.
The strategic lesson is clear: competitiveness is increasingly multidimensional. A company may compete on specification customization, extrusion efficiency, resin innovation, or application-oriented service. The full report maps these postures against market demand patterns, enabling clients to identify where partnerships, vertical alignment, or product portfolio adjustments can create defensible positioning.
Recent Innovation Signals and What They Reveal About Market Direction
Recent product activity confirms that the industry is moving toward thinner structures, improved material efficiency, and digitally enabled application formats. These developments are not isolated launches; they reflect a broader shift in how performance, sustainability, and processing economics are being optimized simultaneously.
TotalEnergies and SML collaborated on the development of two innovative downgauging films, including an unlaminated MDO-PE cast film designed for deep-freeze bags with a 35 to 50 percent thickness reduction. This kind of advancement illustrates how resin and technology alignment can deliver measurable material savings without sacrificing functional performance, a theme that will likely intensify as cost pressure and sustainability expectations rise together.
Avery Dennison reinforced the graphics and labeling trajectory by launching MPI 1903, a professional-grade cast film developed for digitally printable applications. This move highlights the growing importance of print compatibility, workflow integration, and specification reliability in higher-value conversion environments.
Amcor introduced Stratos cast film for ultra-lightweight packaging solutions, underscoring the continued emphasis on material efficiency and packaging optimization. Taken together, these developments suggest that the market's next phase of value creation will come less from raw volume expansion and more from engineered improvements that reduce material input, enhance processing performance, and satisfy evolving application requirements.
Industry Dynamics: Raw Material Pressure, Regulatory Acceleration, and Structural Reorientation
No strategic assessment of the cast film market is complete without addressing the external forces that can reshape margins, product design, and procurement timing. Two interlinked dynamics are particularly consequential in the current environment.
First, raw material volatility has become a defining operational challenge. Polypropylene prices rose 34 percent year-to-date through April 2026, driven by feedstock shortages and crude oil and naphtha volatility. For cast film producers and converters, this level of input fluctuation affects cost structures, pricing negotiations, inventory strategy, and product mix decisions. Organizations that rely on rigid procurement models or single-resin dependence face heightened exposure. The study examines how material price sensitivity interacts with application economics and identifies where feedstock diversification, hedging discipline, and product engineering can mitigate risk.
Cast Film Market
Second, regulatory and sustainability frameworks are actively restructuring demand logic. The EU Green Deal and single-use plastic reduction mandates are driving demand for recyclable mono-material cast films, shifting attention away from multi-layer complexity toward structures that are easier to recover and reprocess. At the same time, Extended Producer Responsibility schemes in Europe are requiring higher recycled content in cast films, placing additional pressure on material sourcing, quality consistency, and compliance documentation. REACH chemical restrictions are also tightening substrate compliance for cast film converters, adding another layer of technical and administrative scrutiny.
These forces are not separate noise; they are converging into a structural reorientation of the market. Recyclability, recycled content, chemical compliance, and material efficiency are increasingly embedded in purchasing criteria and product qualification processes. Companies that treat sustainability as a peripheral initiative risk losing relevance in segments where compliance and circularity are becoming commercial gatekeepers. The report integrates these dynamics into the forecast narrative and competitive analysis, ensuring that strategic recommendations reflect the regulatory reality facing the industry.
Why This Research Matters for 2026 Decision-Making
The 2026 planning cycle requires more than retrospective review. It demands forward visibility into where demand will intensify, which material transitions will accelerate, how regulatory pressures will alter qualification cycles, and where competitive differentiation will be won or lost. The Cast Film Market study is built to support that moment of decision. It provides a calibrated view of market size evolution, segmentation behavior, technology relevance, and competitive positioning, while intentionally preserving room for scenario-based interpretation rather than fixed predictions.
For executives, the practical value lies in connection. The research links macro trends to segment-level logic, connects innovation signals to commercial outcomes, and translates raw material volatility and regulatory change into operational implications. Whether the objective is to evaluate capacity expansion, optimize resin sourcing, prioritize application development, or refine regional market entry, the study is designed to reduce ambiguity and sharpen resource allocation.
Casters Market
To access the complete segmentation detail, competitive profiles, forecast tables, regulatory mapping, and strategic recommendation sets, readers are encouraged to explore the full report. The aggregate trends outlined here establish the strategic frame; the full research delivers the execution-level intelligence required to act on it with confidence.
For detailed analysis of this topic, please visit the official page: Cast Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Flavor Enhancer Market Hits $6.8B in 2025, 6% CAGR to $10.06B by 2032
By PW Consulting, 2026-09-16
Strategic Intelligence in the Food Flavor Enhancer Market: Navigating Growth and Complexity Through 2032
The global food flavor enhancer industry is entering a decisive phase of transformation. As consumer preferences shift toward cleaner labels, functional nutrition, and reduced sodium profiles, manufacturers across the value chain face a critical window to align product portfolios with emerging demand signals. PW Consulting's latest Food Flavor Enhancer Market research provides a rigorous, data-grounded framework to support executive decision-making through the 2026-2032 forecast horizon. This report is structured not as a static snapshot, but as a living strategic asset designed to inform capital allocation, competitive positioning, and supply chain resilience in a market that continues to evolve at a measured yet unmistakable pace.
Food Flavor Enhancer Market
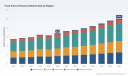
Drawing on verified historical data and forward-looking modeling, the analysis traces a market that expanded from approximately 5.5 billion USD in 2020 to an estimated 6.8 billion USD in 2025, with a projected trajectory toward roughly 10.1 billion USD by 2032. The forecast points to a compound annual growth rate of 6.0 percent over the forecast period, reflecting steady volume expansion supported by industrial food processing, retail convenience formats, and ongoing reformulation efforts in mature and emerging economies alike. Base-year calibration for 2025 anchors the modeling to current operating conditions, while the projection window captures the intersection of consumer behavior shifts, regulatory recalibration, and technological optimization within the flavor ingredients ecosystem.
Market Structure and the Strategic Signal Within the Data
Understanding the architecture of this market requires looking beyond headline revenue figures. Historical movement between 2020 and 2025 reveals how external pressures, commodity dynamics, and product mix adjustments shaped year-over-year performance, including periods of compression and recovery that tested supply chain discipline. The forecast period from 2026 through 2032 maps a sequence of incremental gains, with year-by-year estimates calibrated to reflect realistic adoption curves, capacity announcements, and pricing sensitivity across major end-use channels.
The analytical depth within the full report decomposes these trajectories across the core dimensions that matter to strategy teams: product type, application category, and geographic footprint. Rather than offering generic statements, the study isolates where momentum is concentrating, which segments exhibit structural durability versus cyclical vulnerability, and how category leadership is likely to shift as ingredient platforms mature. Critically, the segmentation analysis is designed to inform product roadmap decisions, pricing strategy, and regional Go-to-Market prioritization without exposing sensitive competitive signals prematurely. Executives seeking the complete set of segment-level estimates, share distributions, and growth attribution breakdowns will find them within the full publication, where each figure is cross-referenced with demand drivers and supply-side constraints.
Competitive Landscape: Consolidation, Differentiation, and the Playbook of Leading Players
The flavor enhancer space is characterized by a concentrated core of globally active ingredient and flavor companies, complemented by regional specialists that compete on formulation expertise, sourcing proximity, or application-specific performance. Concentration metrics within the study indicate that a small group of established players commands a substantial share of total market revenue, underscoring the importance of differentiation through innovation, sourcing reliability, and regulatory readiness. At the same time, the presence of multiple competitors across glutamate-based systems, yeast-derived ingredients, hydrolyzed vegetable proteins, and specialty taste modulation solutions signals a market where technical capability and customer intimacy remain decisive.
Several companies stand out for their scale, technological breadth, and geographic reach. Ajinomoto Co., Inc. remains closely associated with monosodium glutamate production rooted in fermentation-based processes using plant-derived feedstocks, while also expanding its operational footprint in key producing markets. Givaudan SA continues to advance plant-derived and natural alternative platforms, increasingly emphasizing speed-to-market through digital and consumer-insight tools. Kerry Group plc has built a strong position around natural umami and yeast-derived systems suited to processed and savory applications. International Flavors & Fragrances Inc. offers a broad portfolio spanning synthetic and natural enhancement solutions for food processing environments, and Sensient Technologies Corporation supplies integrated flavor systems that support multiple beverage and food categories. Mane SA and Takasago International Corporation contribute specialized ingredient capabilities, while Biospringer by Lesaffre, Ohly, and Angel Yeast Co., Ltd. represent a strong yeast-based value chain that spans both traditional umami enhancement and clean-label positioning. Firmenich SA and Symrise AG round out a competitive set that blends taste modulation science with application-focused formulation support.
Beyond these anchor names, the landscape includes additional suppliers such as American International Foods, Inc., which maintains a strong MSG supply orientation, and Actus Nutrition, whose whey protein-based ingredient portfolio adds another functional dimension to flavor enhancement discussions. Rather than treating this roster as a static directory, the report evaluates each company's strategic posture in terms of capacity decisions, platform launches, geographic expansion, and response to regulatory change. This company-level intelligence is essential for benchmarking, partnership assessment, and competitive threat mapping.
Recent Developments Shaping the 2026 Decision Calendar
Recent operational moves and innovation announcements signal where the industry is placing its bets. In late 2025, Ohly opened a new spray drying tower in Hamburg, Germany, expanding production capacity for yeast-based flavor enhancer products and reinforcing the strategic importance of yeast extract platforms in natural enhancement strategies. Around the same period, Ajinomoto expanded its MSG production footprint across Brazil, Vietnam, and Thailand, a move that strengthens global supply resilience and positions the company closer to demand centers in multiple regions. In the spring of 2025, Fufeng Group introduced a new plant-based MSG product line at a major food additives expo, targeting clean-label and vegan applications and reflecting the broader industry push toward label-friendly presentation without abandoning performance expectations.
Flavor and Fragrance Market
Innovation cadence also accelerated through platform launches and trade show activity. Givaudan showcased Myromi and Consumer Foresight platforms at VivaTech 2025, designed to compress innovation cycles and connect sensory science with consumer trend intelligence. Ajinomoto Health & Nutrition introduced Salt Answer and Palate Perfect platforms aimed at sodium reduction and taste optimization, directly addressing one of the most persistent reformulation challenges in savory and processed food categories. These developments illustrate a market in which competitive advantage is increasingly tied to formulation agility, messaging precision, and the ability to translate scientific advances into commercial-ready solutions.
The full report situates each of these events within a broader strategic context, assessing their implications for capacity utilization, regional supply balance, and the pace of substitution between traditional and alternative enhancer systems.
Regulatory and Supply-Side Dynamics That Cannot Be Ignored
No forward-looking strategy in this sector is complete without accounting for the regulatory environment and feedstock realities that influence cost structures and market access. In early 2026, the U.S. Department of Commerce conducted antidumping duty administrative reviews and released preliminary results concerning imports of monosodium glutamate from China, while the U.S. International Trade Commission subsequently determined that revoking existing antidumping orders on MSG from China and Indonesia would likely lead to continuation or recurrence of material injury. These actions create a complex trade environment with direct implications for pricing, sourcing decisions, and the cost competitiveness of imported versus domestically sourced or regionally produced material.
On the regulatory front, the U.S. Department of Health and Human Services directed the FDA in 2025 to explore rulemaking that could affect the self-affirmed GRAS pathway for food ingredients, including flavor enhancers. Although MSG continues to maintain GRAS status and remains subject to standard ingredient-panel labeling requirements, any tightening or clarification of the pathway for ingredient recognition would have ripple effects across product development timelines, documentation burdens, and the speed at which new enhancer systems can reach market. The report analyzes these dynamics not as isolated headlines, but as structural variables that shape portfolio risk, compliance strategy, and market entry sequencing.
Supply-side considerations are equally important. Corn starch remains the primary feedstock for monosodium glutamate production in China, accounting for a substantial majority of usage in 2025, which ties producer economics to agricultural commodity trends, regional availability, and input cost volatility. For companies dependent on glutamate-based systems, feedstock exposure is a strategic variable that influences both margin stability and geographic sourcing strategy. The study integrates these raw material dynamics into its segment discussion, highlighting where input sensitivity is most acute and where alternative feedstock routes or ingredient platforms may offer greater resilience.
What the Report Delivers: An Action-Oriented Blueprint
PW Consulting's Food Flavor Enhancer Market research is designed to convert complex market information into executable strategy. The publication provides a full historical and forecast series anchored to 2025 base-year conditions and extended through 2032, enabling scenario modeling for revenue planning, capacity planning, and long-cycle investment decisions. The segmentation framework covers the primary type categories, major application domains, and regional markets, with discussion of the demand logic, competitive intensity, and development patterns that differentiate each segment. Rather than offering undifferentiated growth numbers, the analysis connects each segment to the operating conditions that drive performance, giving readers a practical basis for prioritizing resources.
The competitive section combines company profiles, recent development tracking, and strategic interpretation to help readers assess relative positioning, risks, and opportunities across the market. Regional and application-level insights are paired with regulatory and supply-side context so that strategy teams can evaluate not only where growth is happening, but also what conditions must be managed to capture it. This integrated approach is especially valuable for organizations evaluating new formulation platforms, considering geographic expansion, or weighing exposure to trade policy and ingredient recognition changes.
Importantly, the report functions as a decision-support system rather than a standalone dataset. It enables users to test assumptions about category substitution, sodium-reduction reformulation, clean-label positioning, and supply chain localization. By linking market size evolution to underlying drivers, the study helps executives distinguish between temporary fluctuations and durable structural shifts, reducing the risk of overreacting to short-term noise or underestimating longer-term transitions.
Why This Research Matters for 2026 Decision-Making
The 2026-2032 window is shaping up to be a period in which disciplined strategy will separate durable performers from reactive followers. A 6.0 percent CAGR may appear moderate at the headline level, but the composition of that growth matters immensely. Different product types, applications, and regions are advancing at different speeds, and the companies that succeed will be those able to combine technical credibility with supply resilience, regulatory readiness, and sharp customer insight. Recent capacity investments, platform launches, and trade-policy developments already demonstrate that the boardroom agenda in this market extends well beyond volume growth alone.
Executives using this report will be better positioned to answer several critical questions: where to concentrate innovation resources, how to anticipate regulatory and trade-related disruptions, which ingredient platforms offer the strongest long-term alignment with label and health trends, and how to interpret competitor activity without losing sight of proprietary positioning. The complete segmentation data, regional breakdowns, application-level estimates, and company-level intelligence are essential to turning these questions into concrete plans.
For decision-makers who require the full granularity necessary to set budget priorities, define market-entry strategies, and evaluate competitive threats, the complete Food Flavor Enhancer Market research provides the depth and structure needed to act with confidence. The teaser figures and directional insights presented here establish the strategic frame; the full report delivers the operational intelligence required to execute within it.
For detailed analysis of this topic, please visit the official page: Food Flavor Enhancer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Running Watches Market Hits $7.4B in 2025, 9.4% CAGR to $13.9B by 2032
By PW Consulting, 2026-09-16
Navigating the Next Horizon: Strategic Intelligence for the Global Running Watches Market (2026–2032)
The athletic wearables sector has matured rapidly over the past five years, transforming from a niche enthusiast category into a core component of the broader performance technology ecosystem. As we approach the mid-decade inflection point, organizations operating across manufacturing, retail, investment, and strategic planning require a disciplined lens into the structural forces shaping the Running Watches Market. PW Consulting’s latest industry analysis provides a comprehensive, boardroom-ready examination of the landscape from a 2025 base year through a 2032 forecast horizon, translating historical momentum into actionable intelligence. The study maps a clear trajectory from a 4.74 billion USD valuation in 2020 to a projected 13.95 billion USD by 2032, anchored by a compound annual growth rate of 9.4 percent. This document outlines the strategic architecture of the report and demonstrates how decision-makers can leverage its frameworks to navigate competitive intensity, supply chain volatility, and accelerating consumer demands.
A Decade of Acceleration: Mapping the Revenue Trajectory
Historical performance across the 2020 through 2025 window reveals an unbroken expansion curve, with annual valuations climbing from 4.74 billion to 7.43 billion USD. The progression from 5.28 billion in 2021, 5.85 billion in 2022, and 6.11 billion in 2023 demonstrates sustained demand absorption, while the subsequent jump to 6.90 billion in 2024 and 7.43 billion in 2025 confirms that growth has decoupled from post-pandemic recovery dynamics. Looking forward, the forecast model positions 2026 at 8.33 billion USD and extends steadily upward, reaching 9.06 billion in 2027, 9.82 billion in 2028, 10.73 billion in 2029, 11.65 billion in 2030, 12.86 billion in 2031, and ultimately 13.95 billion by 2032. These figures are not isolated projections; they reflect modeled demand elasticity, product cycle cadence, and the structural migration of mainstream fitness consumers toward performance-grade instrumentation. Crucially, the research isolates the primary velocity drivers without oversimplifying the underlying complexity. Readers will find explicit analysis of how GPS-enabled precision, physiological monitoring integration, and multi-sport versatility are reshaping purchase criteria across different user cohorts. The narrative deliberately avoids fragmenting the outlook by slicing the market into isolated regional or application-level percentage shares, because executive strategy demands a first-principles understanding of interaction effects, capacity allocation, and portfolio prioritization rather than static tabular breakdowns.
Portfolio Architecture and Product-Level Innovation
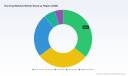
The report dissects the product ecosystem along a structured type framework that captures the full spectrum of running-centric instrumentation. This segmentation spans GPS-native devices, standalone pedometer-focused instruments, dedicated heart-rate monitoring watches, and hybrid GPS plus heart-rate models optimized for continuous athletic tracking. The analysis demonstrates how each architecture serves distinct positioning tiers and how manufacturers are engineering feature convergence to capture overlapping demand pools. Parallel to this, the application landscape is mapped across running, biking, cardio training, climbing, and adjacent use cases, revealing how cross-training behavior, outdoor endurance pursuits, and structured fitness programming are influencing SKU rationalization and platform investment. Rather than presenting these dimensions as disconnected columns, the study examines how product architecture, sensor suites, and software ecosystems must be aligned with consumer use patterns to protect margin profiles and reduce inventory risk. Strategic readers will gain clarity on where engineering investment yields the strongest competitive differentiation, which feature combinations are becoming table-stakes, and how platform modularity is enabling faster iteration cycles without compromising cost discipline.
Running Watches Market
Competitive Architecture and Strategic Positioning
Market concentration remains pronounced, with the top three participants commanding roughly 72.4 percent of aggregate revenue and the top five consolidating approximately 88.0 percent. This concentration underscores the importance of understanding not merely who leads the category, but how incumbents defend share while emerging and adjacent players pursue differentiated value propositions. Garmin continues to anchor the premier performance tier through a disciplined lineup built around the Forerunner 970 and Forerunner 570, alongside the Fenix 8 and Enduro 3 series. Their strategy emphasizes precise training metrics, advanced navigation, and athlete recovery instrumentation, reinforcing a positioning that appeals to serious runners and triathletes who treat their wearables as performance management platforms. COROS has carved a distinct identity in the ultralight endurance space, leveraging the Pace 4, Apex 4, and NOMAD to deliver multi-sensor navigation, extended battery life, and rugged outdoor construction. In August 2025, COROS expanded this footprint with the NOMAD outdoor GPS watch, introducing dual-frequency navigation, detailed mapping, rugged construction, and an Adventure Journaling capability that broadens its utility beyond conventional running sessions. Suunto maintains a strong presence through multisport and running GPS devices, including the Vertical 2, Run, and 9 series, where dive-rated durability, precise heart rate capture, and performance data delivery under extreme conditions differentiate its engineering narrative. Polar approaches the category through advanced physiological monitoring and training optimization, exemplified by the Vantage M3, Street X, and broader Vantage lineup, which integrate heart rate and GPS running capabilities into structured performance feedback loops. Meanwhile, Amazfit represents an increasingly influential affordability-and-functionality axis, with T-Rex 3 Pro, T-Rex Ultra 2, and Active series offerings that balance GPS accuracy, battery endurance, and fitness tracking at accessible price points. In May 2026, iRunFar updated its best GPS running watches guide to reflect the latest 2026 lineup, validating pricing and availability while incorporating models such as the Amazfit T-Rex Ultra 2, signaling how independent verification and consumer media continue to shape purchase consideration.
The research does more than profile product portfolios; it evaluates go-to-market posture, brand equity durability, channel leverage, and innovation cadence. The report examines how premium players protect hardware margins while layering subscription-adjacent services, how mid-tier challengers leverage material efficiency and sensor commoditization to narrow capability gaps, and how value-oriented entrants use packaging, battery longevity, and GPS reliability to defy entry-level stigma. These strategic lenses enable clients to benchmark their own positioning, assess vulnerability to competitive encroachment, and prioritize partnership, acquisition, or product roadmap investments with greater precision.
Smartwatch Market
Structural Shifts: Supply Dynamics and Regulatory Undercurrents
No forward-looking market assessment is complete without addressing the material and policy environments that shape production economics and long-term resilience. In 2025, the U.S. Geological Survey recommended adding copper, silicon, silver, rhenium, and lead to the List of Critical Minerals, directly elevating supply disruption risk for semiconductors, sensors, and precision components embedded in running watches. This development is particularly consequential for manufacturers who depend on tightly integrated electronic assemblies, advanced navigation chipsets, and sensor-grade materials. The same agency’s 2025 methodology for the Critical Minerals List assesses probability-weighted net decreases in U.S. GDP from foreign trade disruptions, prioritizing the monitoring of semiconductor and electronics supply chains. For the running watches sector, this framework signals heightened attention to sourcing diversification, inventory buffering, component substitution feasibility, and geopolitical exposure in downstream electronics manufacturing. The study integrates these supply-side realities into a broader dynamics assessment, showing how raw material classification, trade flow sensitivity, and component lead times can alter cost structures, delay product introductions, and recalibrate competitive advantage for firms that lack flexible procurement architectures. Beyond materials, the analysis considers how ecosystem software, data privacy expectations, firmware update sustainability, and device longevity expectations are becoming structural differentiators. Companies that treat hardware as the entire product are increasingly exposed, while those designing integrated hardware-plus-software experiences with durable update pathways are building more defensible customer relationships and lower churn profiles.
What the Full Research Delivers: Operational Intelligence for 2026 Decision-Making
This report is engineered to function as a working strategic asset rather than a static summary. It combines quantitative modeling with qualitative competitive assessment to support planning cycles across R&D, sourcing, sales, and investment functions. The complete study provides a structured examination of market sizing and forward projections grounded in a consistent 2025 base year and 2032 forecast framework. It details the evolution of product architectures and application demand patterns, helping teams align platform roadmaps with actual usage migration rather than speculative trend narratives. The competitive review places primary emphasis on how leading players structure their value propositions, manage innovation cadence, and defend market share in a concentrated environment. The dynamics section translates critical mineral designations, semiconductor supply considerations, and regulatory monitoring frameworks into implications for procurement strategy, cost planning, and resilience design. The report also addresses how pricing architecture, channel composition, and brand positioning interact to shape profitability, and it maps the practical consequences of independent review cycles and retail validation for launch timing and promotional strategy. Throughout, the analysis is designed to support scenario planning: clients can use the frameworks to test capacity expansion assumptions, evaluate portfolio additions, stress-test supply dependencies, and refine messaging strategies for different consumer tiers. By focusing on the mechanisms that drive the 9.4 percent compound growth trajectory, the study equips teams to make decisions that are robust under multiple demand and cost conditions rather than dependent on a single baseline outcome.
Closing the Intelligence Gap
The Running Watches Market is entering a period in which competitive advantage will be determined less by product availability than by strategic precision. Firms that understand where growth is structurally concentrated, how product architectures are converging, and which supply and regulatory pressures will reshape cost economics will be better positioned to allocate capital, time product introductions, and defend margins. The macro arc from 7.43 billion USD in 2025 toward a 13.95 billion USD endpoint in 2032 is clear, but the strategic value lies in the operational insight beneath that headline: how concentration shapes pricing power, how sensor and navigation innovation changes demand, how material classifications alter sourcing strategy, and how competitive portfolios evolve under sustained scrutiny from both consumers and independent reviewers. PW Consulting’s complete analysis is built to convert these dynamics into executable strategy. Organizations ready to move from observation to decision will find the full dataset, segmentation logic, competitor deep dives, and scenario frameworks essential to shaping their 2026 programs and beyond.
For detailed analysis of this topic, please visit the official page: Running Watches Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Intravesical BCG Market Hits $195M in 2025, Projected 8.97% CAGR Through 2032
By PW Consulting, 2026-09-16
Navigating Supply Chain Complexity and Treatment Demand: Strategic Insights into the Intravesical BCG Market
As the global healthcare landscape continues to evolve, the management of non-muscle invasive bladder cancer remains a critical focal point for urologists, pharmaceutical manufacturers, and healthcare administrators. The Intravesical Bacillus Calmette-Guérin market has experienced steady expansion over the past five years, reflecting both the clinical indispensability of BCG therapy and the structural challenges inherent in biological manufacturing. Our latest market intelligence study provides a comprehensive examination of this evolving landscape, offering executives and strategy teams a rigorous foundation for capital allocation, supply chain planning, and competitive positioning through the 2026 to 2032 forecast horizon.
The therapeutic context for intravesical BCG is unambiguous. Major clinical guidelines continue to position BCG as the preferred adjuvant treatment for intermediate- and high-risk disease presentations, underscoring a durable demand profile that transcends short-term pricing fluctuations or regional reimbursement variations. At the same time, the biological nature of BCG production introduces constraints that have repeatedly tested supply resilience. Understanding how these clinical mandates intersect with manufacturing bottlenecks, regulatory pathways, and regional procurement patterns is precisely the kind of strategic clarity that our research is designed to deliver.
Historical Trajectory and Forecast Outlook
The market has followed a measured but consistent growth curve since the early 2020s, driven by steady adoption in established markets and gradual expansion of access in developing regions. Our historical reconstruction places total market revenue at approximately 150 million dollars in 2020, progressing to 158 million dollars in 2021, 168 million dollars in 2022, 178 million dollars in 2023, and 184 million dollars in 2024. The base year analysis for 2025 reflects continued momentum, with the market reaching 195 million dollars as procurement cycles stabilized and clinical demand maintained its upward trajectory.
Looking forward, our forecast modeling projects the market to exceed 214 million dollars in 2026, followed by progressive expansion toward 237 million dollars in 2027, 241 million dollars in 2028, 279 million dollars in 2029, 292 million dollars in 2030, 315 million dollars in 2031, and 342 million dollars by 2032. The compound annual growth rate across the forecast period is calculated at 8.97 percent, a figure that captures the combined effect of sustained clinical utilization, capacity investments by key manufacturers, and incremental market participation from newly authorized or expanded-access formulations. This trajectory is not merely a statistical projection; it is a strategic signal that underscores the importance of long-term planning for procurement teams, investors, and clinical network operators who must anticipate both volume growth and supply volatility.
Structural Dynamics Shaping Market Behavior
The Intravesical BCG ecosystem is defined by a small number of entrenched manufacturers, each operating within distinct regulatory environments and supply chain architectures. Because BCG is a live biological product, production is inherently sensitive to process validation, strain stability, facility compliance, and distribution logistics. These factors have historically limited the number of viable commercial suppliers and concentrated market participation among a handful of established entities. Our research maps these structural realities in detail, offering decision-makers a clear view of where supply-side constraints originate and how they influence procurement strategies across different clinical settings.
Shortages have been a recurring theme in the market narrative, particularly in regions where a single manufacturer has served as the primary domestic source. This concentration has prompted repeated discussions within clinical guideline bodies regarding dose modification protocols and alternative sourcing strategies when supply disruptions occur. At the same time, recent authorization and supply-agreement developments have begun to diversify the availability landscape, introducing expanded-access programs and cross-border supply arrangements that create new options for treating centers. Our report examines these developments not as isolated announcements, but as interconnected signals that reshape procurement risk, pricing expectations, and competitive dynamics over the forecast period.
The Competitive Landscape: Positioning Among Core Participants
A defining feature of this market is the strategic positioning of its leading commercial participants, each of whom brings a different combination of manufacturing capability, regulatory footprint, and supply-chain response to the table. Our analysis evaluates these participants with a focus on operational readiness, product presentation, and the ability to respond to demand pressure.
One of the most closely watched developments involves the sole U.S.-based manufacturer of a widely recognized intravesical formulation. This company has publicly outlined plans to construct a new production facility intended to significantly expand output capacity, with an operational timeline that positions the expansion to intersect with the later years of our forecast window. The strategic significance of this investment extends beyond volume; it reflects an effort to address persistent supply limitations that have influenced clinical scheduling, procurement planning, and payer discussions for years. Our research explores how this capacity expansion is likely to alter supply risk perceptions and what it implies for market share stability among competing sources.
Alongside this effort, other participants have pursued complementary routes to strengthen availability. One manufacturer and distributor involved in U.S. intravesical administration continues to play a central role in the commercial pathway for a well-established product, maintaining its presence as a key node in the domestic supply chain. In parallel, an Indian-based producer has advanced a lyophilized formulation with broad international authorization for non-muscle invasive bladder cancer treatment, supported by a multi-year shelf-life profile and a presentation designed for practical clinical use. This participant has also been linked to recent regulatory authorization activity that expanded access to a recombinant BCG approach under specific program conditions, signaling a more direct response to shortage-driven demand.
A Japanese manufacturer adds another dimension to the competitive picture through its intravesical offering built on a distinct strain with specific potency characteristics. This supplier's product has been associated with recent supply arrangements intended to broaden availability in key markets, including an exclusive development and supply framework for U.S. activity. These moves illustrate how strain differentiation, dosing conventions, and regional authorization strategies all feed into a competitive environment where supply assurance can be as strategically important as the product itself. Our report unpacks these positioning choices and evaluates how they interact with procurement realities across hospital and clinic settings.
Segmentation Logic and Revenue Concentration Patterns
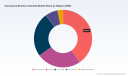
Our segmentation framework is designed to help executives understand where revenue is generated, which product formats dominate commercial activity, and how procurement is distributed across clinical care environments. The study examines product-type dynamics across the principal vial presentations that define commercial supply, with particular attention to how volume concentration differs across dosage forms. The analysis also maps application-level demand patterns, distinguishing between the largest care setting that anchors bulk utilization and the secondary setting that contributes a smaller but strategically meaningful share of total demand.
In addition, the research evaluates regional revenue distribution to identify where commercial activity is most concentrated and where growth potential is emerging. Rather than presenting percentages in isolation, our analysis situates regional data within the broader context of procurement habits, guideline adoption, and supply accessibility, enabling readers to interpret geographic patterns in a way that directly informs market-entry discussions, partnership evaluation, and inventory planning. The report further addresses market concentration metrics to clarify how revenue is distributed among leading participants, providing a realistic picture of the degree to which the market remains consolidated and where competitive pressure may intensify.
Report Contents and Operational Utility for Decision-Makers
This study is structured to support practical decision-making rather than abstract market observation. Readers will find a detailed examination of the demand drivers that shape utilization, the supply-side factors that influence availability, and the regulatory and guideline environment that governs treatment selection. The report includes a comprehensive competitive profiling section that describes each major participant's operational base, product positioning, and strategic response to market constraints. It also provides a forward-looking synthesis of how capacity investments, authorization activity, and supply agreements may alter the balance of availability across the forecast period.
Beyond competitive mapping, the report delivers actionable analytical building blocks for pricing strategy, sourcing diversification, and network planning. Procurement teams can use the segmentation analysis to better understand where demand concentrates and how product formats are distributed across end-use settings. Executive teams can draw on the forecast structure to test scenario assumptions around capacity release, shortage mitigation, and regional expansion. Investors and business development professionals can use the concentration and competitive assessments to evaluate entry feasibility and partnership opportunities without relying on incomplete or anecdotal information.
The study also incorporates discussions of cost considerations and treatment-course economics where relevant to strategic planning, alongside the practical implications of strain potency differences, dosing conventions, and product presentation choices. These details matter because they influence both clinical workflow and procurement behavior, and our report places them in context so that strategic conclusions are grounded in operational reality rather than surface-level market descriptors.
Why This Research Matters for 2026 Strategy
The 2026 to 2032 window represents a period in which the Intravesical BCG market is likely to be shaped as much by supply-side restructuring as by underlying clinical demand. Capacity expansion commitments, authorization pathways, and cross-company supply arrangements are beginning to alter the availability landscape, yet the biological and regulatory complexity of BCG production means that uncertainty will not disappear overnight. In this environment, decision-makers need more than top-line growth figures; they need an integrated view of how product formats, care settings, regional dynamics, and competitive actions combine to create risk and opportunity.
Our report is designed to provide that integrated view. It connects market size progression and forecast expansion to the operational realities behind the numbers, helping organizations anticipate where supply resilience will improve, where dependence on limited sources may persist, and how different procurement strategies may perform under varying shortage and authorization scenarios. For executives planning budgets, sourcing frameworks, or competitive responses in 2026, this research offers the level of detail required to move from reactive positioning to informed strategy.
BCG Vaccine Market
Conclusion and Next Steps
The Intravesical BCG market is at a point where clinical importance, manufacturing complexity, and evolving supply arrangements converge to create both challenge and opportunity. Our study translates that convergence into a structured, forward-looking analysis that supports strategic planning across commercial, operational, and investment decisions. The full report provides the complete segmentation detail, competitive assessment, and forecast architecture needed to evaluate market potential with confidence. Readers interested in the full set of regional breakdowns, application-level revenue patterns, product-type splits, and concentration metrics are encouraged to access the complete study for the comprehensive intelligence required to guide 2026 decision-making.
Intravesical Bacillus Calmette Market
For detailed analysis of this topic, please visit the official page: Intravesical Bacillus Calmette Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Medical Ultrasound Probe Market Hits $215M in 2025, Projected 3.3% CAGR Through 2032
By PW Consulting, 2026-09-16
Navigating the Pulse: Strategic Intelligence for the 2026 Medical Ultrasound Probe Market
The medical ultrasound probe market stands at a critical inflection point as healthcare delivery models shift toward point-of-care diagnostics and advanced imaging integration. For executives and strategy teams planning capital allocation and product roadmaps through 2032, understanding the nuanced trajectory of this sector is not merely analytical—it is imperative. This article introduces PW Consulting's latest comprehensive market research, designed to equip decision-makers with the foresight required to navigate regulatory shifts, competitive realignments, and evolving clinical demands. The following insights distill the executive summary of our full report, highlighting the strategic value embedded within our analysis while preserving the granular data necessary for precise execution available exclusively in the complete document.
Macroeconomic Trajectory and Market Size Evolution
Our analysis covers a robust historical period from 2020 through 2025, extending a forecast horizon to 2032. This longitudinal view allows for the identification of structural trends rather than transient fluctuations. The market has demonstrated consistent growth over the past half-decade, with revenue figures reflecting a steady expansion in diagnostic imaging adoption globally. In 2020, the market valuation stood at approximately 163.15 Million USD. Year-over-year progression saw increases to 167.51 Million USD in 2021, 175.83 Million USD in 2022, and a notable acceleration to 183.64 Million USD in 2023. The recent past indicates a significant jump to 205.21 Million USD in 2024, culminating in an estimated base year valuation of 215.0 Million USD for 2025.
Looking forward, the forecast period projects the market to reach 222.9 Million USD in 2026. The trajectory suggests continued growth, with valuations anticipated to climb toward 236.95 Million USD by 2027. However, strategic planners must note specific variance points within the forecast window. While growth is the overarching theme, the data indicates a slight contraction to 235.1 Million USD in 2028 before resuming an upward trend toward 252.9 Million USD in 2029. Subsequent years show fluctuation, with dips to 247.5 Million USD in 2030, followed by recovery to 266.77 Million USD in 2031 and a projected stabilization near 268.83 Million USD by 2032. The Compound Annual Growth Rate (CAGR) calculated over this forecast period is 3.3 percent. This moderate yet steady growth rate underscores a mature market environment where competitive advantage is derived from segmentation precision and operational efficiency rather than pure volumetric expansion.
Structural Segmentation Overview
To truly leverage market opportunities, one must understand the underlying architecture of demand and supply. Our research dissects the market across three primary dimensions: Region, Type, and Application. Each dimension reveals distinct behavioral patterns and strategic entry points for stakeholders.
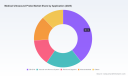
Geographically, the market exhibits significant dispersion. While North American markets have historically commanded strong positions, our data highlights the substantial weight of the Asia Pacific region, followed closely by North America and Europe. Latin America and the Middle East and Africa represent emerging vectors with unique adoption curves. The concentration of revenue across these regions suggests that supply chain resilience and localized regulatory compliance are becoming key differentiators.
In terms of product Type, the landscape is diversified. Convex probes remain a dominant segment, reflecting their broad utility in abdominal and obstetric imaging. Linear probes constitute a significant portion of the revenue mix, driven by vascular and musculoskeletal applications. Specialized categories such as Phased Array and Endocavitary probes serve niche but critical clinical needs, while Other types capture emerging technologies. The distribution across these types indicates that innovation is not solely focused on volume drivers but also on high-value specialized transducers.
Regarding Clinical Application, the demand is heavily influenced by standard diagnostic protocols. OB-GYN applications represent a substantial share, consistent with the global emphasis on maternal health and routine screening. Vascular and Nervous System applications follow as a major demand driver, supported by the rising prevalence of cardiovascular conditions. Renal, Digestive, and Musculoskeletal applications round out the core demand pillars, with Other applications encompassing emerging use cases in emergency medicine and primary care. Understanding the revenue contribution of each application helps manufacturers prioritize R&D and marketing resources effectively.
Competitive Landscape and Strategic Positioning
The market is characterized by a fragmented yet competitive environment. The top three companies hold a combined market concentration of 24.6 percent, while the top five extend this to 26.2 percent. This relatively low concentration ratio implies that no single entity dominates the entire value chain, leaving ample room for specialized players and regional champions to compete on technology, service, and cost.
Our report provides detailed profiles and strategic assessments of key industry participants. Global giants such as GE HealthCare, headquartered in Chicago, Illinois, continue to lead with proprietary diagnostic systems and transducer compatibility, notably within their Voluson Expert series. Koninklijke Philips N.V., based in Amsterdam, maintains a strong presence through its EPIQ and Affiniti series, offering broad diagnostic compatibility. Siemens Healthineers AG, operating from Erlangen, Germany, manufactures MyLab systems and associated probes that serve diverse clinical imaging needs.
Recent Regulatory Milestones and Industry Noise
The regulatory environment remains a pivotal factor in product deployment and market access. Recent months have seen significant activity regarding FDA 510(k) clearances, which directly impact the availability and cycle times for new probe technologies. In January 2025, GE HealthCare announced FDA clearance for enhanced Voluson Expert Series ultrasound systems, including lightweight probes, signaling a push toward ergonomics and portability. Further clearances followed in July 2025 for the Venue Go, Venue Fit, Venue Sprint, and Venue systems, and again in November 2025 for the Voluson Expert 18, 20, and 22 systems under specific K-numbers. Philips also secured FDA clearance in June 2025 for its EPIQ and Affiniti Series diagnostic systems.
Beyond approvals, the industry must also navigate recall dynamics. Recent database entries indicate Class III recalls for multiple Philips ultrasound transducers in early 2026. Such events highlight the importance of quality assurance and risk management in strategic planning. Additionally, service ecosystems are evolving; for instance, in January 2026, Probo Medical secured the inclusion of ultrasound probe repair services on the Federal Supply Schedule via Maclean Group LLC, indicating a growing demand for lifecycle management and repair solutions alongside new equipment sales.
Unlocking Decision-Ready Intelligence
While this overview establishes the strategic context, the full PW Consulting report delivers the depth required for actionable execution. The complete study moves beyond high-level trends to provide specific revenue splits, growth rates by segment, and detailed competitor benchmarking that are essential for tactical planning. By accessing the full intelligence, stakeholders can dissect exactly how regional shifts will impact their supply chains, which probe types offer the highest margin potential in specific clinical settings, and how the competitive moves of entities like FUJIFILM Sonosite, Canon Medical, Samsung Medison, Hitachi Healthcare, Esaote, Mindray, SIUI, and emerging players like Shenzhen Ruqi Technology will reshape the battlefield.
Worldwide Ultrasonic Probe Covers Market
The report integrates real-world data to map out the competitive intensity, identifying where consolidation might occur and where niche players can secure defensible positions. It also analyzes the implications of regulatory clearances on market entry barriers and the strategic value of service contracts in an era of increasing hardware complexity. With the market projected to nearly double from its 2020 levels by the end of the forecast period, the cost of inaction or misinformed strategy is significant.
Medical Ultrasound Probe Market
Call to Action for Strategic Leaders
As we move through 2026, the ability to anticipate market fluctuations—such as the variance projected between 2027 and 2030—will separate market leaders from followers. The data suggests that while the overall CAGR is 3.3 percent, specific segments and regions may outperform or underperform this average based on regulatory adoption and clinical guideline updates. PW Consulting's detailed analysis provides the granular visibility needed to capitalize on these discrepancies.
We invite industry executives, investors, and product strategists to explore the full findings of our Medical Ultrasound Probe Market report. The comprehensive document includes detailed segmentation tables, competitor SWOT analyses, and forward-looking scenarios that go beyond the summary provided here. To gain the competitive edge required for 2026 and beyond, access the complete intelligence package available on the PW Consulting website. Let us guide your strategy with data precision and industry expertise.
For detailed analysis of this topic, please visit the official page: Medical Ultrasound Probe Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Smart Manufacturing Market Hits $215B in 2025, Projected 13.5% CAGR to 2032
By PW Consulting, 2026-09-16
Navigating the Intelligent Factory: Strategic Imperatives for the Smart Manufacturing Market in 2026
The industrial landscape is undergoing a fundamental reset. As enterprises transition from pilot projects to enterprise-wide deployment, smart manufacturing has moved from a competitive advantage to an operational necessity. For executives planning capital allocation, technology roadmaps, and supply chain resilience in 2026, the window for strategic action is narrowing. This introduction outlines the strategic framework embedded in our latest market research, designed to equip decision-makers with the analytical rigor required to navigate an increasingly complex ecosystem.
A Market in Accelerated Expansion
The smart manufacturing sector has demonstrated consistent momentum over the past half-decade, evolving from incremental automation to integrated, data-driven production environments. Our analysis tracks this trajectory from 2020 through the base year of 2025, establishing a clear upward curve that sets the stage for the forecast window extending to 2032. The compound annual growth rate of 13.5 percent across the projection period signals more than incremental uptake; it reflects a structural shift in how manufacturers invest in infrastructure, software, and operational intelligence.
Revenue expansion tells a parallel story. The market crossed the two hundred billion dollar threshold in 2024 and reached approximately two hundred fifteen billion dollars by 2025. Forward momentum carries this trajectory through the mid-to-late 2020s, with valuations climbing steadily toward the three hundred forty billion dollar range by 2032. These figures are not abstract metrics; they represent capital deployment patterns, procurement cycles, and technology prioritization decisions that will define competitive positioning for the remainder of the decade.
Yet macro-level growth is only the starting point. The real strategic challenge lies in understanding how capital flows across technology stacks, how regional supply chains are reconfiguring under policy pressures, and which operational models will prove sustainable as deployment scales. This report is built to answer those questions with precision.
Report Architecture and Operational Utility
A market study earns its value only when it translates into actionable strategy. Our research is structured to serve multiple stakeholder functions simultaneously, from executive briefing to operational planning. The core of the analysis is built around four interconnected pillars:
- Technology segmentation analysis that dissects adoption patterns across control systems, execution platforms, and programmable logic architectures, revealing where investment is concentrating and which capabilities are becoming baseline expectations.
- Component-level evaluation distinguishing hardware procurement cycles from software licensing and services integration, helping procurement and IT leaders align budgeting rhythms with deployment realities.
- End-use industry mapping that highlights how automotive, electronics, aerospace, and defense organizations are tailoring smart manufacturing investments to their specific throughput, compliance, and precision requirements.
- Geographic distribution insights that contextualize regional demand intensity, policy acceleration, and supply chain localization trends without reducing complex dynamics to simplistic rankings.
Beyond segmentation, the report delivers competitor profiling, partnership mapping, and a regulatory watch module that tracks how industrial policy is reshaping procurement and localization mandates. Each section is designed to feed directly into scenario planning, vendor evaluation, and capacity expansion decisions. Readers will find executive dashboards, adoption maturity curves, and investment prioritization matrices that convert raw analysis into boardroom-ready narrative.
Competitive Dynamics Among Market Leaders
The smart manufacturing arena is defined by a concentrated but heterogeneous group of players, each anchoring its strategy around distinct value propositions. Our competitive assessment examines how these organizations position themselves across automation, digital factory platforms, and industrial connectivity.
Smart Factory Market
Siemens AG continues to anchor its offering around integrated digital factory ecosystems, bundling automation, production operations, and Industry 4.0 platforms into a unified deployment model. ABB Ltd has carved a parallel path with a focus on robotics, automation, and AI-driven optimization, positioning intelligent control as a differentiator rather than a feature. Rockwell Automation, Inc. emphasizes industrial automation platforms, MES systems, and digital twin technologies, reflecting a growing enterprise appetite for simulation-led process refinement before physical deployment.
Schneider Electric SE brings an energy-centric lens to the market, developing eco-adaptive infrastructure and smart grid solutions that integrate directly into manufacturing environments. Honeywell International Inc. contributes a connective enterprise perspective, pairing industrial cybersecurity with IIoT platforms to address the operational risk dimension that becomes more acute as factories digitize. Emerson Electric Co. reinforces this momentum with automation solutions, digital twins, and smart equipment designed to streamline industrial operations at scale.
GE has maintained leadership in advanced manufacturing technologies, particularly through industrial IoT and predictive maintenance systems that extend asset life and reduce unplanned downtime. Mitsubishi Electric Corporation complements the field with factory automation, robotics, and IoT-enabled smart factory systems, while Robert Bosch GmbH focuses on industrial automation, IoT, and digital transformation solutions that support smart production across diverse manufacturing modalities.
The competitive field also includes specialized and adjacent players that shape niche but high-impact segments. Applied Materials, Inc. delivers semiconductor equipment and smart manufacturing platforms purpose-built for chip production, an industry where precision and process control carry outsized strategic weight. Cimatron Ltd. supplies CAM software and integrated workflow solutions that bridge design and shop-floor execution. HighByte Inc. addresses the data plumbing challenge directly, providing industrial data management and connectivity software that underpins effective smart factory integration.
Together, these players illustrate a market where differentiation is increasingly tied to integration depth, data interoperability, and sector-specific expertise rather than hardware specifications alone. Understanding these positioning strategies is essential for procurement leaders evaluating vendor roadmaps and for operators assessing which ecosystems are most likely to support long-term scalability.
Policy, Regulation, and Regional Dynamics
Market growth does not occur in a policy vacuum. Industrial strategy, trade dynamics, and regulatory frameworks are actively reshaping where and how smart manufacturing investments are deployed. Recent developments provide a clear signal that governments and standards bodies are accelerating their focus on manufacturing modernization.
China's industrial upgrading program continues to influence global supply chain architecture. By mid-2025, assessments documented substantial progress in localization rates across key sectors, including agricultural machinery and basic materials. At the same time, high-performance computing segments have shown more uneven progress, with import dependency remaining elevated in certain categories. The nine implementation paths associated with the initiative prioritize digitalization of manufacturing equipment, intelligent process design, and green standards aimed at reducing resource consumption. These priorities intersect directly with smart manufacturing adoption, especially in energy-intensive sectors where China already holds dominant production share in lithium-ion batteries and solar modules.
On the other side of the Pacific, policy incentives are reinforcing domestic investment. Analysis released in late 2025 highlighted U.S. government incentives and OEM-led digital transformation efforts as key drivers of smart manufacturing adoption, alongside state-level support mechanisms for pilot programs. This alignment between federal encouragement and corporate deployment is creating a more structured pathway for scaling intelligent manufacturing capabilities.
Standards development is also gaining momentum. India's telecommunications engineering framework introduced a technical report in mid-2025 establishing standards for Industry 4.0 and smart manufacturing integration, reflecting a broader international push to harmonize interoperability expectations and reduce fragmentation in connected factory environments.
Meanwhile, industry events and conference agendas are increasingly centered on autonomy, agentic AI integration, and advanced packaging in semiconductor manufacturing, signaling where practitioner attention and R&D emphasis are converging. These developments do not merely contextualize the market; they shape procurement timelines, compliance strategies, and cross-border investment decisions.
Why This Research Matters for 2026 Decision-Making
Executive teams entering 2026 face a set of interlocking decisions: which technology layers to standardize, how to sequence capital deployment, which vendor ecosystems to align with, and how to hedge against regulatory and supply chain volatility. High-level growth projections can inform optimism, but they cannot replace granular intelligence about adoption bottlenecks, segment-specific demand intensity, and competitive maneuvering.
This report is designed to close that gap. It converts market scale into strategic context, situates competitor moves within broader technology trends, and embeds policy developments into operational planning assumptions. For organizations evaluating factory modernization, capacity expansion, or digital transformation roadmaps, the analysis provides a structured reference point for scenario modeling and risk assessment.
The full study goes further than what an introduction can capture. It contains segment-specific adoption trajectories, regional intensity mapping, detailed competitor positioning tables, procurement cycle insights, and scenario-based forecasts that allow leadership teams to test assumptions against multiple future states. Those elements are essential for converting directional awareness into precise investment logic.
Accessing the Complete Intelligence
The smart manufacturing market is expanding at a pace that rewards disciplined analysis. With a sustained growth trajectory, intensifying competition among established and specialized players, and an evolving policy environment that directly affects localization and standards, the cost of incomplete information is rising. Organizations that enter 2026 with a clear view of technology segmentation, competitive positioning, and regulatory direction will be better positioned to allocate capital efficiently, negotiate from an informed stance, and build manufacturing capabilities that remain resilient as the landscape shifts.
Smart Manufacturing Market
To explore the complete dataset, segmentation breakdowns, and competitor profiles in full detail, download the full report. The complete analysis provides the depth required to move from strategic awareness to execution-ready decision-making.
For detailed analysis of this topic, please visit the official page: Smart Manufacturing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting ESWL Market Hits $381.96M in 2025, Projects 5.5% CAGR to $552.74M by 2032
By PW Consulting, 2026-09-16
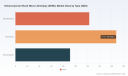
Strategic Horizons in Extracorporeal Shock Wave Lithotripsy: A 2026 Market Perspective
The global landscape for Extracorporeal Shock Wave Lithotripsy (ESWL) is entering a decisive phase of transformation. As healthcare systems worldwide balance cost containment with the demand for minimally invasive urological interventions, understanding the trajectory of this market is no longer optional for strategic planners—it is imperative. This article serves as an executive overview of our latest comprehensive market research, designed to equip stakeholders with the intelligence needed to navigate the forecast period from 2026 through 2032.
Our analysis indicates that the market is on a steady upward path. Following historical growth patterns observed between 2020 and 2025, where revenue climbed from approximately 294.62 Million USD to 381.96 Million USD, the momentum is expected to continue. The forecast period projects a compound annual growth rate (CAGR) of 5.5 percent. By 2032, the market volume is anticipated to reach significant maturity, driven by technological advancements and shifting clinical preferences. However, raw figures only tell part of the story. The real value lies in understanding the underlying dynamics that will dictate profitability, market share, and operational feasibility for providers and manufacturers alike.
Market Dynamics and Operational Realities
The ESWL sector does not operate in a vacuum. It is influenced by a complex interplay of regulatory frameworks, reimbursement structures, and capital expenditure constraints. Our report dives deep into these friction points to provide a realistic view of market entry and expansion opportunities.
Regulatory and Clearance Milestones
Recent regulatory activities highlight the pace of innovation and the hurdles remaining for new entrants. For instance, recent clearance events have validated new devices under specific federal classifications, signaling both opportunity and heightened scrutiny. The approval of specific lithotripters under Class II regulations demonstrates that while the pathway is established, the bar for clinical efficacy and safety documentation remains high. Companies aiming to launch new units must navigate these regulatory corridors with precision. Our research details the specific implications of these clearances for future product pipelines and competitive barriers.
Reimbursement and Economic Viability
Financial sustainability for ESWL procedures relies heavily on reimbursement codes. The economic environment for 2026 suggests varied payment structures depending on the care setting. National average Medicare payments differ significantly between ambulatory surgical centers and hospital outpatient departments. This disparity influences where providers choose to locate their services and how they structure their billing practices. Understanding the nuances of Current Procedural Terminology codes and their associated payment rates is critical for forecasting net revenue. Our report dissects these reimbursement landscapes to help stakeholders model accurate financial projections.
Capital Investment Considerations
The barrier to entry for ESWL technology remains substantial. Initial capital investment for systems varies widely, ranging from mobile units to stationary configurations. The cost differential between these options impacts hospital budgeting cycles and procurement strategies. Mobile units offer flexibility but may limit throughput, while stationary systems provide stability at a higher upfront cost. Strategic decision-makers must weigh these capital costs against expected utilization rates and maintenance expenses. We provide a granular breakdown of cost structures to assist in capital allocation decisions.
Technology Segmentation and Clinical Application
The market is segmented by technology type and clinical application, each presenting distinct growth vectors. While the overall market expands, specific technologies are gaining traction due to improved precision and reduced complications. Similarly, the prevalence of different stone types dictates where demand will concentrate.
Technology Evolution
Different shock wave generation technologies compete on efficacy, durability, and cost. The market includes electrohydraulic, piezoelectric, and electromagnetic systems. Each type carries different implications for maintenance, energy consumption, and patient outcomes. Our analysis evaluates the maturity and adoption rates of these technologies across different healthcare settings. We examine how technological shifts are influencing purchasing decisions among major healthcare providers.
Application Diversity
While kidney stones remain the primary driver of demand, other applications are contributing to market expansion. Ureteral stones, pancreatic stones, and salivary stones represent additional revenue streams that are often overlooked in broader analyses. The clinical protocols for these conditions vary, influencing the type of equipment required and the specialist involved. Our report maps the volume and growth potential across these applications, providing a clear picture of where niche opportunities exist.
The competitive landscape is moderately concentrated, with a few key players holding significant market share. This concentration suggests that while there is room for innovation, competitive pressure on pricing and service levels is intense. Our report provides a detailed competitive intelligence section that profiles the strategies of leading manufacturers.
Key Players and Strategic Moves
Several companies are defining the current market standards. German engineering firms have historically held strong positions, leveraging reputation for durability and precision. Simultaneously, manufacturers from emerging manufacturing hubs are increasing their presence through aggressive pricing and rapid innovation cycles.
-
Dornier MedTech: A longstanding participant known for establishing clinical benchmarks in shock wave technology. Their strategy focuses on maintaining high clinical efficacy standards.
-
Karl Storz GmbH & Co. KG: Integrates ESWL solutions within broader endoscopic and urological portfolios, offering bundled solutions that appeal to comprehensive care centers.
-
Siemens Healthineers: Leverages extensive imaging and diagnostic capabilities to enhance the precision of lithotripsy procedures, positioning technology as a integrated diagnostic-therapeutic solution.
-
Shenzhen Wikkon Precision Technologies Co., Ltd.: Represents the growing influence of manufacturers from the Asia-Pacific region. Recent activities indicate a push towards global regulatory approval and branding.
Extracorporeal Shock Wave Lithotripsy (ESWL) Market
Recent Developments and Market Shifts
Recent actions by key competitors signal shifting strategies. In mid-2025, Shenzhen Wikkon Precision Technologies Co., Ltd. achieved a significant regulatory milestone with FDA 510(k) clearance for their U200 Extracorporeal Shock Wave Lithotripter, specifically indicated for kidney stone treatment. This clearance under 21 CFR 876.5990 opens the US market to this specific device. Following this, in late 2025, the company launched a new brand identity and announced global expansion plans during a meeting of the Chinese Urological Association. These moves suggest a deliberate strategy to scale presence in Western markets while consolidating strength in home regions.
However, competition is not limited to these profiled entities. The market concentration metrics indicate that the top three players hold over half of the market revenue, and the top five control approximately 65 percent. This structure implies that market entry for new players requires significant differentiation, either through cost leadership or proprietary technology. Our report analyzes the strategic postures of these leaders to identify potential vulnerabilities and partnership opportunities.
Strategic Imperatives for 2026 and Beyond
As we look toward the forecast period, several key strategic imperatives emerge for stakeholders involved in the ESWL market. Success will depend on the ability to align technology procurement with reimbursement realities, manage capital expenditures efficiently, and adapt to a competitive landscape that is both concentrated and dynamic.
Optimizing Procurement and Deployment
Healthcare providers must look beyond the sticker price of ESWL systems. The total cost of ownership, including maintenance, disposable components, and energy consumption, must be factored into procurement decisions. With capital costs ranging significantly based on system type, facilities need to model their expected patient volume to justify the investment. Our research provides frameworks for calculating return on investment based on procedure volumes and reimbursement rates specific to different care settings.
Navigating Regulatory Pathways
For manufacturers and distributors, the regulatory environment remains a critical gatekeeper. Recent clearances demonstrate that compliance is achievable, but the process requires robust clinical data. Companies planning product launches must anticipate regulatory timelines and prepare corresponding quality management systems. The report outlines the specific regulatory requirements and recent precedents that will shape future approval processes.
Capitalizing on Regional Variances
Market growth is not uniform across geographies. Different regions exhibit varying levels of adoption based on healthcare infrastructure, reimbursement policies, and disease prevalence. While some regions show higher immediate revenue potential, others may offer faster growth rates due to developing healthcare access. Strategic expansion plans should be tailored to these regional characteristics rather than applying a one-size-fits-all approach. Our report includes detailed regional analysis to guide market entry and resource allocation.
Conclusion
The Extracorporeal Shock Wave Lithotripsy market presents a landscape of steady growth tempered by complex operational challenges. With a projected CAGR of 5.5 percent leading into the next decade, the opportunity for value creation is substantial. However, realizing this potential requires more than superficial market knowledge. It demands a deep understanding of reimbursement mechanics, capital constraints, regulatory pathways, and competitive strategies.
This article has provided a high-level overview of the forces shaping the ESWL market. Yet, the true depth of intelligence lies in the data points, specific segmentation values, and detailed company profiles contained within our full report. For executives and investors who need to make precise decisions regarding market entry, product development, or investment allocation, the granular details are essential. We invite you to access the full market research report to uncover the specific data driving these trends. The complete analysis offers the actionable intelligence required to turn market insight into strategic advantage.
Extracorporeal Shock Wave Therapy Device Market
For detailed analysis of this topic, please visit the official page: Extracorporeal Shock Wave Lithotripsy (ESWL) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Non-Stick Pans Market to Hit $11.9B by 2032 with 8.27% CAGR
By PW Consulting, 2026-09-16
Navigating the Non-Stick Pans Market: Strategic Intelligence for 2026 and Beyond
The global cookware industry stands at a critical inflection point. As consumer preferences shift toward healthier living, regulatory frameworks tighten around chemical safety, and material innovation accelerates, the non-stick pans market has emerged as a dynamic battleground for established manufacturers and emerging disruptors alike. This comprehensive market research report serves as an indispensable strategic compass for executives, product managers, and investors seeking to navigate the complexities of this evolving landscape through 2032.
Our analysis reveals a market characterized by robust growth trajectories, intensifying competitive pressures, and transformative supply chain dynamics. With a projected Compound Annual Growth Rate of 8.27 percent over the forecast period, the sector presents significant opportunities for stakeholders who can align their strategies with emerging consumer demands and regulatory realities. However, capturing these opportunities requires more than surface-level understanding. It demands deep, granular intelligence that only this report delivers.
Market Trajectory: From Recovery to Sustained Expansion
The historical data tells a compelling story of resilience and acceleration. Following a period of market stabilization between 2020 and 2025, the non-stick pans industry has demonstrated consistent revenue growth, building from approximately 4718.44 million USD in 2020 to an estimated 6915.35 million USD in 2025. This upward trajectory reflects not merely post-pandemic recovery patterns but fundamentally shifting consumer behaviors around home cooking, health consciousness, and premiumization trends.
Looking forward, our forecasts indicate that revenue will continue climbing through 2032, with the market expanding from an estimated 7576.05 million USD in 2026 toward the 11900.0 million USD range by the end of the forecast window. This growth is not distributed evenly across all segments or geographies. Premium segments featuring advanced coating technologies are outpacing traditional offerings, while certain regional markets exhibit faster adoption curves driven by urbanization, rising disposable incomes, and evolving culinary preferences. The report deconstructs these growth vectors with precision, enabling decision-makers to identify high-potential pockets of value creation.
Importantly, the research does not merely project numbers. It contextualizes them within broader macroeconomic indicators, raw material cost volatilities, and channel dynamics that will shape actual realized revenues. Stakeholders who rely on top-line projections alone risk making suboptimal allocation decisions. Our granular analysis illuminates the underlying drivers that will determine which companies capture disproportionate share of the expanding pie.
Segmentation Intelligence: Technology, Application, and Geography
One of the most valuable contributions of this report lies in its detailed segmentation framework. The market divides across multiple axes, each carrying distinct strategic implications for positioning, pricing, and channel strategy.
Non-stick Coatings Market
-
Coating Technology: The competitive landscape is shaped by divergent technology pathways, including traditional PTFE-based formulations, anodized aluminum surfaces, ceramic alternatives, and enameled iron options. Each technology carries unique cost structures, performance characteristics, regulatory exposure, and consumer perception profiles. Understanding the relative positioning and trajectory of each category is essential for R&D prioritization and portfolio optimization.
-
Application End-Use: Demand patterns vary considerably between residential and commercial users. Residential consumers prioritize aesthetics, ease of use, and health considerations, while commercial operators focus on durability, heat distribution, and total cost of ownership. The report quantifies these divergent demand drivers and maps them to actionable go-to-market strategies.
-
Geographic Distribution: Regional dynamics play a decisive role in shaping competitive advantage. Markets in North America, Europe, and Asia Pacific each present distinct regulatory environments, retail channel structures, brand loyalty patterns, and price sensitivities. The research unpacks these regional nuances without reducing them to simplistic rankings, offering instead a nuanced view of where and how to compete effectively.
To preserve the competitive advantage our clients derive from this intelligence, we deliberately withhold granular percentage splits and absolute revenue figures for individual segments in this preview. These details are reserved for the full report, where they are presented alongside cross-tabulated analysis, scenario modeling, and sensitivity assessments that reveal the full strategic picture.
Competitive Dynamics: A Fragmented Yet Concentrated Landscape
The non-stick pans market exhibits a fascinating duality. On one hand, market concentration metrics indicate that the top three players command approximately 35.0 percent of total revenue, while the top five firms control roughly 50.0 percent. This concentration suggests meaningful barriers to entry in certain segments and the presence of established brands with strong distribution networks and consumer recognition. On the other hand, the market remains sufficiently fragmented that nimble, innovation-driven challengers can carve out significant niches, particularly in premium and health-focused categories.
Several leading companies exemplify the strategic directions shaping the market. All-Clad, headquartered in Canonsburg, Pennsylvania, has reinforced its premium positioning through offerings like the NS Pro Ceramic line, which combines ceramic interiors with hard-anodized bodies and an EvenPro base designed for consistent everyday performance. Calphalon, based in St. Louis, Missouri, continues to leverage its reputation for hard-anodized non-stick surfaces that deliver even heating and durability across both sets and individual pan offerings. T-Fal, operating in North America as part of Groupe SEB, maintains a broad portfolio spanning hard-anodized and ceramic non-stick pans and pots engineered for easy food release and quick cleanup.
The competitive field also includes influential players pushing the boundaries of non-toxic offerings. GreenPan, with headquarters in the Netherlands and global operations, has built its brand around PFAS-free ceramic non-stick cookware, including the Valencia Pro and Dover series, positioning itself as a leader in toxin-free performance. Caraway, based in New York, markets ceramic-coated cookware sets explicitly framed as non-toxic alternatives to traditional coatings, appealing to health-conscious consumers. OXO, also headquartered in New York, offers ceramic professional non-stick pans such as the OXO Ceramic Professional Nonstick 10-inch Frying Pan, emphasizing scratch-resistant functionality. Additional brands like Anolon, Our Place, and HexClad contribute to a rich ecosystem of innovation, with the Always Pan from Our Place becoming a notable example of versatile non-stick cookware marketed with ceramic or innovative coatings, while HexClad pursues a hybrid approach blending non-stick coating with distinctive surface architectures.
Recent developments underscore the pace of strategic activity. In December 2025, All-Clad launched its NS Pro Ceramic non-stick cookware line, marking a deliberate push toward cleaner everyday cooking solutions. By April 2026, GreenPan expanded the retail availability of its ceramic non-stick cookware, including the GreenPan Dover and Bobby Flay Chef Series lines, signaling a concerted effort to broaden consumer access to PFAS-free options. These moves, among others detailed in the full report, illustrate how companies are actively responding to shifting demand signals and regulatory currents.
Non-Stick Pans Market
Regulatory and Consumer Tailwinds Reshaping the Industry
No strategic assessment of the non-stick pans market can overlook the profound impact of regulatory and consumer trends. The landscape has been fundamentally altered by actions targeting per- and polyfluoroalkyl substances, commonly known as PFAS, which have been used in various non-stick coatings. Minnesota became the first U.S. state to ban the sale of cookware coated with PFAS chemicals as of January 2025, with California, New York, and Connecticut following with similar legislative actions. These regulatory developments are not isolated events but part of an accelerating trend that will increasingly influence product formulation, labeling, and market access across multiple jurisdictions.
Consumer awareness of chemical exposure risks has risen sharply in parallel. A study from the University of North Carolina released in October 2025 linked cookware use to PFAS exposure while highlighting a retail shift toward PFAS-free ceramic non-stick options. This research, alongside updated testing by Consumer Reports in January 2026 showing that worn or scratched non-stick coatings can release PFAS chemicals into food, has intensified consumer scrutiny and reinforced demand for safer alternatives. Retailers, in turn, have responded by expanding PFAS-free non-stick options to meet growing consumer demand for safer cookware.
Regulatory concerns extend beyond PFAS. The FDA issued a warning in December 2025 regarding imported cookware that may potentially leach lead, a development particularly relevant to aluminum-based non-stick products. This alert underscores the importance of rigorous supply chain oversight and quality assurance for manufacturers sourcing materials and finished goods across international borders.
Raw material economics also factor heavily into competitive strategy. Sector analysis on retail pricing trends from 2026 indicates that ceramic non-stick coatings cost approximately twice as much as traditional PTFE-based non-stick coatings. For instance, an 8-inch GreenPan model priced at 19.96 USD compares against a 9.96 USD standard nonstick alternative. This cost differential shapes margin structures, retail pricing strategies, and the value proposition communicated to consumers. Companies must navigate these economics carefully, balancing premium positioning against affordability thresholds in their target segments.
What This Report Delivers: Actionable Intelligence for Decision-Makers
This market research report goes beyond high-level summaries to provide the depth and specificity required for confident strategic decision-making. The following elements represent core components of the analysis:
-
Comprehensive Market Sizing and Forecasting: Historical revenue data from 2020 through 2025 forms the foundation for detailed forecasts extending through 2032. Projections are built using robust methodology that accounts for historical trends, macroeconomic assumptions, regulatory impacts, and technology adoption curves.
-
Segment-Level Deep Dives: The report disaggregates market performance across coating types, application categories, and geographic regions. Cross-sectional analysis reveals interdependencies and migration patterns that inform product development roadmaps and resource allocation decisions.
-
Competitive Profiling and Benchmarking: Detailed profiles of key market participants, including their strategic positioning, product innovations, and recent developments, enable benchmarking against peer activities. Recent events such as product launches, retail expansions, and research-driven market shifts are integrated into the competitive analysis.
-
Regulatory and Compliance Landscape: An examination of current and emerging regulatory frameworks affecting non-stick cookware, including PFAS restrictions, lead leaching concerns, and import requirements. This section helps organizations anticipate compliance costs and adapt product formulations proactively rather than reactively.
-
Consumer Trend Analysis: Insights into shifting consumer preferences around health, sustainability, aesthetics, and performance. These trends inform packaging, branding, and marketing strategies that resonate with target audiences in different segments and geographies.
-
Supply Chain and Raw Material Considerations: Analysis of input cost dynamics, sourcing complexities, and manufacturing considerations that influence margin potential and competitive positioning. Understanding these factors is essential for pricing strategy and profitability planning.
-
Strategic Recommendations: Synthesized insights translated into actionable guidance for product strategy, market entry, expansion planning, and competitive response. These recommendations are grounded in the data and tailored to the specific challenges and opportunities facing stakeholders in this market.
Why This Intelligence Matters Now
The strategic stakes for 2026 and the years ahead have never been higher. Companies that enter this period with a clear, data-backed understanding of market dynamics will be better positioned to allocate capital efficiently, prioritize R&D investments, refine go-to-market strategies, and respond agility to regulatory and competitive shifts. Those that rely on outdated assumptions or incomplete data risk misallocating resources, missing emerging opportunities, or exposing themselves to compliance vulnerabilities.
The non-stick pans market is not a static arena. It is being reshaped by converging forces: technological innovation in coating materials, regulatory pressure on chemical safety, consumer demand for healthier and more sustainable products, and competitive intensity across both established and emerging brands. Success in this environment requires more than intuition. It requires rigorous analysis, forward-looking scenario planning, and a willingness to act on evidence rather than assumption.
This report is designed to equip stakeholders with precisely that capability. It provides the depth, context, and strategic framing necessary to make informed decisions that align with both near-term market realities and long-term growth trajectories. The full report contains the detailed data, segment breakdowns, regional analyses, and competitive assessments that form the foundation for confident strategic planning.
For executives and analysts seeking to position their organizations advantageously in the non-stick pans market, the insights contained in this research represent a critical resource. The complete analysis, including granular segmentation data, detailed company profiles, scenario models, and strategic recommendations, is available through our comprehensive report. We invite you to access the full document to gain the complete strategic intelligence needed to navigate the opportunities and challenges of this dynamic market landscape.
For detailed analysis of this topic, please visit the official page: Non-Stick Pans Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Portable Kayaks Revenue Hits $896M in 2025, Projected CAGR 4.2% Through 2032
By PW Consulting, 2026-09-16
Navigating the Currents: Strategic Insights into the Portable Kayaks Market Through 2032
The portable kayak sector has evolved from a niche recreational corner into a structurally resilient segment of the broader paddlesports industry. Driven by urban densification, the democratization of waterfront access, and a sustained consumer preference for compact, transport-friendly outdoor gear, the market is entering a phase of steady, technology-led expansion. Our latest Portable Kayaks Market research translates this momentum into a decision-ready intelligence framework, designed specifically for executives, product strategists, and channel developers navigating the 2026–2032 horizon.
Worldwide Canoe-Kayak Accessories Market
For decision-makers operating in 2026, the imperative is no longer whether portable kayaks represent an attractive adjacency, but how to position portfolios, pricing architectures, and distribution models against a landscape defined by material innovation, shifting usage patterns, and increasingly concentrated competitive dynamics. This report provides the structural clarity required to separate cyclical noise from durable growth vectors.
Market Trajectory: From Recovery to Sustained Expansion
The historical record from 2020 through 2025 reveals a market that absorbed pandemic-era demand shocks, corrected pricing expectations, and recalibrated around quality and repeatability. By 2025, the sector had stabilized at a revenue base reflecting matured supply chains and a broader consumer base that now treats portable watercraft as a mainstream outdoor accessory rather than a specialist purchase.
Looking forward, the forecast period through 2032 outlines a consistent growth trajectory. The market is projected to expand at a compound annual growth rate of 4.2 percent, reaching a valuation of just under one billion dollars by 2026 and progressing steadily toward a materially larger valuation by the end of the forecast window. This pace of expansion is neither explosive nor speculative; it reflects the compounding effect of product iteration, incremental adoption in emerging usage contexts, and the ongoing substitution of bulky, non-portable alternatives with designs that prioritize on-road convenience and quick deployment.
For strategy teams, the implication is clear. Growth in this segment will be captured by organizations that align product roadmaps with durability expectations, optimize cost-to-volume ratios, and anticipate where portability intersects with performance. The data underscores a market that rewards precision over hype, and our research supplies the dimensional rigor needed to make those judgments with confidence.
Structural Segmentation: Where Demand Actually Concentrates
Portable kayaks are not a monolithic category. The segment decomposes into distinct architectures that serve different performance thresholds, storage constraints, and demographic profiles. Understanding which configuration dominates, why it dominates, and where secondary formats are gaining traction is essential for product planning, inventory strategy, and marketing positioning.
Type-based segmentation reveals a clear preference hierarchy. Inflatable designs command the largest share of overall revenue, reflecting their balance of transport simplicity, storage efficiency, and broad consumer acceptance. Folding constructions occupy a significant but narrower footprint, appealing to buyers who prioritize folding mechanics, assembly speed, and a compromise between rigidity and portability. Rigid portable formats represent a smaller portion of the market, typically serving specialized use cases where weight and trailering constraints are balanced against higher performance expectations. Each architecture carries its own manufacturing complexity, quality assurance requirements, and aftermarket considerations.
Application segmentation further clarifies where commercial energy should be directed. Recreational use remains the dominant demand driver, consistent with the category’s origins and its alignment with casual paddling, weekend excursions, and accessible outdoor leisure. Fishing applications form a meaningful secondary channel, supported by anglers’ need for stable, compact platforms that can be deployed without extensive logistics. Whitewater and other specialized applications occupy more focused niches, often demanding higher material tolerances, tailored hull characteristics, and targeted distribution partnerships.
Geographic distribution adds another layer of strategic context. Consumption patterns vary materially across regions, shaped by local waterway culture, retail infrastructure, seasonal usage cycles, and the pace of outdoor recreation adoption. The research isolates these regional dynamics without reducing them to simplistic rankings, enabling clients to identify where to intensify go-to-market efforts, where to test localized product variants, and where channel consolidation may create near-term barriers or opportunities.
Competitive Landscape: Concentration, Differentiation, and the Innovator’s Edge
The portable kayak market is not a diffusely competitive field. It operates with a meaningful degree of concentration, where leading participants capture disproportionate share through design IP, specialized materials, brand credibility, and tightly managed product ecosystems. This concentration has strategic consequences. It raises the barrier to entry for undifferentiated newcomers, while simultaneously rewarding incumbents that can iterate rapidly, protect performance claims, and reinforce distribution moats.
Among the companies shaping the category, Tucktec Folding Kayaks has built a reputation around hard-shell folding designs that emphasize rapid assembly and road-ready portability without reliance on roof racks or trailers. Their positioning reflects a pragmatic, performance-first approach that addresses the everyday friction points of transport and launch. Oru Kayak, by contrast, has leaned into lightweight construction and space-efficient packaging, utilizing origami-inspired polypropylene architectures designed to withstand extensive repeated folding while maintaining compact storage dimensions. Their product philosophy appeals to urban buyers, apartment dwellers, and users who treat portability as a primary purchasing criterion.
TRAK Kayaks occupies a premium, expedition-oriented tier. Their focus on adjustable rocker, reinforced frame systems, and advanced skin materials positions them at the intersection of portability and serious paddling performance. This higher-spec orientation supports a distinct price architecture and a customer base willing to pay for durability, maneuverability, and expedition-grade reliability. Noisy River Outdoors contributes a different structural answer to portability, developing patented catamaran-style platforms that emphasize stability and integrated functionality for sportsmen and users operating across varied water conditions.
Recent developments in the sector illustrate how product communication and model-level refinement continue to shape market perception. In mid-2025, Tucktec refreshed its product catalog and pricing visibility around its Pro and Jr. models, aligning promotional activity with updated availability and seasonal purchasing cycles. Around the same period, TRAK highlighted its next-generation construction approach through paddling media recognition, reinforcing its positioning around high-performance foldable design and expedition-grade build quality. These moves are not isolated product announcements; they are signals of how leading participants are managing portfolio clarity, performance narrative, and consumer trust in a market where claims must be backed by repeatable user experience.
For clients evaluating partnership, acquisition, or competitive positioning strategies, the research maps these dynamics into actionable intelligence. Concentration levels, brand differentiation levers, and development cadence are all examined in sufficient depth to support scenario planning and risk assessment.
Portable Kayaks Market
Operational Intelligence Embedded in the Report
Market size and trajectory figures are necessary, but they are not sufficient for 2026 decision-making. This research is built around operational usability. It moves beyond high-level estimates to provide a structured view of the levers that actually affect commercial outcomes.
Readers will find detailed analysis covering product type economics, application-specific demand drivers, and regional consumption contexts that inform where to allocate sales effort and marketing investment. The report examines supply-side considerations relevant to manufacturing complexity, material selection, durability expectations, and after-sales support implications. It also addresses channel dynamics, including how specialty retailers, direct-to-consumer models, and seasonal distribution windows interact with product architecture and pricing strategy.
Beyond segmentation, the research integrates competitive profiling that connects company positioning to broader market behavior, helping clients understand not just who occupies which part of the category, but why certain design philosophies and go-to-market approaches succeed or stall. The result is a reference document that can be used for portfolio planning, target market prioritization, pricing architecture reviews, and new product introduction scoping.
Strategic Takeaways for 2026 Decision-Makers
The portable kayaks market in 2026 sits at an inflection where steady growth, design maturity, and competitive concentration intersect. Several strategic conclusions emerge for organizations operating in or adjacent to the category.
- Portability is no longer an accessory feature; it is a primary purchase driver. Consumers increasingly weigh transport friction, storage footprint, and deployment speed alongside on-water performance. Products that reduce everyday friction without sacrificing durability are best positioned for sustained adoption.
- Material and construction choices define brand ceilings and pricing pathways. The divergence between lightweight foldable systems, hard-shell folding designs, and premium expedition-grade builds reflects more than aesthetics. It defines downstream economics, warranty exposure, and the customer segments each product can credibly serve.
- Concentration rewards differentiation, not imitation. With a meaningful share held by established participants, new entrants and expanding incumbents must articulate a defensible performance or convenience claim. Generic portability messaging is unlikely to overcome the trust and repeat-use thresholds already established by leading designs.
- Regional and application context determines execution speed. Demand intensity varies across geographies and usage settings. Strategy teams should avoid one-size market entry assumptions and instead align product variants, channel support, and promotional timing with the specific waterway culture and retail dynamics of each target market.
Why This Research Matters Now
As organizations set priorities for the remainder of the decade, the portable kayak segment offers a rare combination of accessible growth, clear usage rationale, and expanding design sophistication. That combination creates both opportunity and execution risk. The opportunity lies in capturing sustained demand from buyers who want water access without logistical friction. The risk lies in misreading segmentation, overcommitting to undifferentiated product variants, or underestimating how material durability and performance claims shape brand trust over time.
Our Portable Kayaks Market research is designed to reduce that uncertainty. It translates macro trajectory into segment-level logic, clarifies competitive positioning, and maps the operational considerations that determine whether a product, channel, or partnership strategy will hold up under real-world conditions. For executives planning 2026 investments and beyond, the report offers a disciplined foundation for decisions about product architecture, market entry sequencing, pricing strategy, and competitive response.
The full intelligence package provides the detailed segmentation data, regional analysis, competitive profiling, and scenario-based interpretation required to convert broad market momentum into precise commercial action. We invite strategy, product, and commercial teams to consult the complete report for the full analytical depth behind these findings and to apply its structure to their own planning cycles.
For detailed analysis of this topic, please visit the official page: Portable Kayaks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


