



Category: IT & Electronics
PW Consulting: ADAS Market to Hit USD 74.19B in 2026, Driven by 12.8% CAGR
By PW Consulting, 2026-07-08
Automotive ADAS Market 2026: Strategic Imperatives for Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a concise, forward-looking primer that frames the strategic value of our full Automotive ADAS Market study for decisions you will make in 2026. This briefing synthesizes macro trajectories, regulatory inflection points, technology vectors and competitive positioning — demonstrating the practical utility of our work while intentionally withholding granular segment tables and proprietary scorecards to guide you to the full report for transaction-grade intelligence.
Automotive ADAS Market
Why 2026 Is a Pivotal Year
The Advanced Driver Assistance Systems (ADAS) market is shifting from technology proof-points to large-scale industrial deployment. After robust historical expansion — from roughly USD 38.2 billion in 2020 to USD 67.3 billion in 2025 — we expect the market to continue expanding rapidly, reaching an estimated USD 74.2 billion in 2026 and projecting toward roughly USD 149 billion by 2032. That trajectory embodies an aggregate growth profile consistent with a mid-teens expansion rate (our forecast period CAGR is 12.8%), underscoring both opportunity and competitive urgency.
Automotive ADAS Market
For corporate leaders, 2026 is where strategy must pivot from “roadmap and labs” to scalable productization, supplier rationalization, and regulatory-compliant deployment. The pace of adoption — and the corresponding shifts in cost structure, certification overhead, and software lifecycle management — will make or break near-term profitability and long-term platform control.
Automotive ADAS Market
High-Level Market Dynamics
- Technology consolidation and modularization: Suppliers are standardizing on modular ADAS architectures that enable incremental feature sets (L2 → L2+) through software updates and scalable sensor suites. This reduces per-unit integration cost and accelerates OEM time-to-market.
- Software-first monetization: As hardware costs decline and compute becomes commoditized, software differentiation — perception stacks, safety cases, fleet-learned models — will drive margin capture and recurring revenue opportunities.
- Regulatory acceleration: Recent global regulatory activity is tightening minimum safety baselines and establishing certification pathways that favor validated, scalable solutions. This increases the value of suppliers with robust test-and-validation toolchains.
- Concentration with room for specialized challengers: Market concentration remains meaningful, with the top three players controlling a clear majority of market flows and the top five representing an even larger share. This dynamic creates both barriers and opportunities: integration certainty from incumbents versus differentiation through niche specialization.
What the PW Consulting Report Delivers (Practical, Transaction-Ready)
Our full study translates market direction into executable playbooks. It is designed for C-suite leaders, corporate development teams, product and procurement heads, and venture investors evaluating strategic moves in 2026. Key operative deliverables include:
- Actionable market-sizing and demand scenarios calibrated to regulatory timelines and OEM platform cycles — enabling capex and sourcing decisions that are aligned to realistic adoption curves.
- Risk-weighted go-to-market options (build, buy, partner, or white-label) with quantified trade-offs on TCO, speed-to-market and IP control.
- Supplier scorecards and an M&A target shortlist combining technology fit, production readiness, and regulatory compliance maturity — presented as prioritized archetypes rather than a single “best” target.
- Validation frameworks and recommended test matrices mapped to recent NHTSA and UNECE developments, supporting certification planning and in-market safety assurance.
- Procurement negotiation playbooks and modular component roadmaps to protect margin as sensors, compute and software stacks evolve toward commoditization.
Note: while this overview highlights the nature of our operational outputs, the detailed segment-level forecasts, supplier-level valuations, and scenario model datasets are reserved for the full report.
Competitive Landscape: Positioning and Strategic Implications
The ADAS ecosystem today is a mix of legacy Tier-1 scale players, semiconductor and SoC specialists, pure-play perception software companies, and software-first OEMs. Each archetype faces distinct strategic trade-offs.
- Bosch — Competitive posture: modular ADAS ecosystems combining camera-radar fusion, ACC and AEB capabilities, and scalable hardware-software stacks targeting both mass-market and premium vehicles. Strategic implication: their scale and vertical integration make them attractive partners for OEMs seeking predictable supply and deep system integration, but their breadth can slow niche innovation.
- Aptiv — Competitive posture: platform-led Gen 6 ADAS with emphasis on radar and advanced cameras, and modular software tailored for commercial vehicles. Strategic implication: strong candidate for fleet-and-commercial deployments where regulatory and operational requirements differ from passenger cars.
- STRADVISION — Competitive posture: AI-driven vision perception designed for production-ready L2+ deployment. Strategic implication: represents the archetype of vision-specialist players that are attractive acquisition or integration targets for OEMs and Tier-1s pursuing camera-first architectures.
- Mobileye — Competitive posture: SoC and perception stack leader with modular Surround ADAS and EyeQ processors that enable cost-effective L2+ for high-volume platforms. Strategic implication: entrenched value capture via silicon plus software — a blueprint for how vertical integration can preserve margins.
- Continental & ZF Friedrichshafen — Competitive posture: diversified sensor and system integrators offering radar, camera and lidar solutions with software-defined features. Strategic implication: incumbents with deep OEM relationships, but under pressure to accelerate software practices and time-to-market.
- Valeo & Denso — Competitive posture: sensor fusion and advanced safety modules aimed at collision avoidance and lane-keeping. Strategic implication: focused on delivering proven systems for OEMs balancing cost and performance.
- Tesla — Competitive posture: proprietary FSD vision-based system with end-to-end neural stacks and fleet learning. Strategic implication: a high-risk, high-reward model — accelerates software progress but runs into regulatory scrutiny and validation questions.
- NXP & Harman — Competitive posture: SoCs, radar processing and ADAS software platforms that underpin system performance. Strategic implication: critical enablers of scale; supply chain relationships and software ecosystems are decisive.
Recent supplier moves — product launches, OEM selections and commercial rollouts in early 2026 — confirm strategic themes: vendors continue to push higher-performance radar (new radar gens), integrate AI perception into production-ready stacks, and secure OEM wins in both passenger and commercial vehicle segments. These developments validate our emphasis on modular, scalable, and certifiable platforms in the full report.
Regulation, Test Infrastructure and Safety Assurance
Regulatory activity is a defining force shaping 2026 decisions. Key developments influencing strategic planning include widening NCAP ADAS expectations, evolving UNECE guidance on automated driving systems, and domestic regulatory initiatives to modernize safety standards to accommodate ADS-equipped vehicles. Complementing these are investments in advanced test tools and augmented-reality validation methods that change cost and time-to-certify calculations.
For executives, these trends translate into three immediate imperatives:
- Invest in compliance-first architecture: design for traceability, over-the-air safe updates, and audit-ready data pipelines.
- Validate early with rigorous, regulatory-aligned test protocols to avoid post-deployment remediation costs.
- Prioritize partnerships with suppliers demonstrating documented test tooling, scenario coverage and verification capabilities.
Strategic Recommendations for 2026 Decision-Makers
Our research highlights pragmatic choices corporate leaders must weigh this year:
- Pick a primary architecture thesis and double down: Decide whether your competitive vector is sensor fusion leadership, software services, or platform control — then align R&D and M&A to reinforce that thesis.
- Balance build vs. buy with an economic lens: Build core perception IP if you seek sustained margin capture; partner or buy when time-to-market and certification risk dominate.
- Harden validation and compliance capabilities: Allocate budget for advanced test tooling, scenario libraries and safety-case documentation — these are non-discretionary costs that materially impact launch timelines.
- Hedge supplier concentration risk: With market concentration skewed toward a small set of incumbents, design procurement strategies that keep alternatives live while leveraging scale benefits.
- Introduce recurring monetization models: Use software updates, subscription features and validation-as-a-service to offset hardware margin compression.
How PW Consulting Can Accelerate Your 2026 Agenda
Our full Automotive ADAS Market study delivers the confidential, transaction-grade elements that power execution: detailed segment-level forecasts, supplier scorecards, integration checklists, scenario models with sensitivity levers, and a prioritized M&A target list. It maps regulatory timelines to product launch windows and provides a step-by-step roadmap for procurement, product, and compliance teams to act in 2026.
This briefing is designed to signal the strategic pathways and near-term levers available to senior executives. To convert these insights into executable plans and to access the granular datasets and supplier assessments withheld here, visit the PW Consulting report page and request our executive briefing tailored to your business context.
Final Word
ADAS is no longer an adjacent technology initiative — it is a core platform decision that affects product architecture, supplier ecosystems, regulatory exposure and long-term revenue models. In 2026, organizations that marry disciplined regulatory preparedness, software-first product strategies, and pragmatic supplier engagement will secure the disproportionate share of value as the market scales toward the next phase of automation. PW Consulting’s full study provides the operational intelligence you need to make those decisions with confidence.
For detailed analysis of this topic, please visit the official page: Automotive ADAS Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: RF Coaxial Cable Assemblies Market Poised for 6.4% CAGR to 2032
By PW Consulting, 2026-07-08
RF Coaxial Cable Assemblies Market: Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present an evidence-led introduction to our latest RF Coaxial Cable Assemblies Market study. This briefing lays out the strategic value of the research for boardrooms, product teams, procurement leaders and M&A sponsors planning actions in 2026. It is expressly designed as a high‑signal “trailer”: we demonstrate analytical depth, expose the material drivers and decision levers, and deliberately withhold granular segment tables so you will consult the full report for transaction‑grade intelligence.
RF Coaxial Cable Assemblies Market
Why this study matters for 2026 strategy
The RF coaxial cable assemblies market has evolved from a modest, component‑centric industry into a strategically important node in global telecommunications, defense, test & measurement, and automotive systems. Our base year is 2025; the market grew from approximately USD 245 million in 2020 to USD 345 million in 2025 and is forecast to expand to roughly USD 531 million by 2032. That trajectory implies a compound annual growth rate (CAGR) of 6.4% across the 2026–2032 forecast period. These headline numbers frame three hard truths for decision-makers in 2026:
RF Coaxial Cable Assemblies Market
- Demand is growing and diversifying: technical requirements and program lifecycles increasingly favor higher‑value assemblies (phase‑stable, low‑loss, ruggedized, customized harnesses).
- Margin pressure and supply risk are material: raw material price volatility and tightening regulatory constraints are reshaping cost and sourcing models.
- Consolidation and capability differentiation are becoming more decisive: market concentration remains moderate (CR3 ≈ 25%, CR5 ≈ 32%), leaving room for focused players to scale quickly through either capability investment or targeted M&A.
What the report contains (practical, decision‑facing outputs)
The full report is built for practical use in 2026 planning cycles. Key deliverables include:
RF Coaxial Cable Assemblies Market
- Market sizing and validated forecasts (2020–2025 historical, 2026–2032 projections) in USD Million with scenario bands and sensitivity to raw material and regulatory shocks.
- Segment archetypes and buyer personas that map engineering requirements (e.g., insertion loss, VSWR, shielding, flex life), procurement constraints, and replacement cycles across major end‑use families.
- Go‑to‑market playbooks: OEM vs. contract manufacturing strategies, configuration‑to‑order approaches, pricing ladders and margin models for standard vs. engineered assemblies.
- Supply‑chain diagnostics and sourcing levers: dual‑sourcing templates, inventory buffers, long‑lead component identification and supplier qualification checklists tailored for aerospace & defense grades.
- Regulatory and compliance matrix: impact assessments and action plans for standards and procurement rules affecting buyer access and eligible suppliers.
- Competitive heatmaps and strategic positionings, plus a curated M&A checklist identifying capability gaps, inorganic growth targets and integration risk mitigations.
Macro and industry dynamics shaping 2026 decisions
Several contemporaneous forces are driving strategic reprioritization for 2026:
- Raw material pressure: Copper costs escalated materially in recent years (with sector analysis indicating increases on the order of one third), and aerospace/defense grade conductor requirements further amplify cost exposure via minimum order and qualification constraints. Procurement teams must now model multi‑year cost pass‑through mechanisms and experiment with alloy/construct alternatives where performance permits.
- Regulatory tightening: Two developments merit immediate attention. First, the EN IEC 60966‑2‑8:2025 standard introduced technical updates that raise the bar on connector provisions and reflection (return‑loss) performance for certain TV and broadcast applications. Second, FAR 52.204‑25 (effective March 13, 2026) restricts contracting for specified telecommunications equipment—including certain coaxial products used in backhaul—on national security grounds. Together, these change product qualification timelines and eligible supplier lists for government and regulated customers.
- Demand pattern shifts: Telecom 5G densification and private network deployments continue to drive volumes for higher‑performance interconnects; defense and aerospace programs demand qualified assemblies with longer procurement lead times and higher margins; automotive and test & measurement create high‑mix short‑run demand for configurable assemblies.
- Competitive positioning: Market concentration remains moderate (CR3 ≈ 25%, CR5 ≈ 32%), indicating that while leading global suppliers exert influence, there is room for specialty and regional players to capture premium niches through differentiated capabilities.
What leading suppliers are doing — implications for 2026 playbooks
We analyzed the strategic moves and capability footprints of primary incumbents and specialists in the space. The competitive set spans large diversified connectors and interconnect conglomerates, specialist RF houses, and agile contract manufacturers. Representative firms covered in the study include Amphenol, TE Connectivity, Rosenberger, Molex, HUBER+SUHNER, Radiall, Carlisle Interconnect Technologies, Times Microwave, W.L. Gore, Samtec, ZTT, Trigiant, Winchester, L‑Com, Koaxis, RF Industries, Technical Cable Assembly, Star Engineering, Micro‑Coax, Cristek, and Coaxicom.
- Large Tier‑1 players (e.g., Amphenol, TE Connectivity, HUBER+SUHNER) are leveraging global footprint and integrated supply chains to secure large program contracts and to offer systems bundles. Their scale supports long lead time qualification and defense program commitments.
- Specialist RF vendors (e.g., Times Microwave, Rosenberger, Radiall) focus on technical differentiation—low loss, phase stability and high frequency performance—and serve both high‑performance telecom and aerospace segments.
- Nimble contract manufacturers and regional suppliers (including several China‑based and U.S. niche producers) compete on rapid turnaround, customization, and lower complexity assemblies, capturing portions of test & measurement and short‑run automotive demand.
- Market entrants and product innovations are active: two recent developments underscore competitive dynamics—Samtec’s July 2025 launch of a phase‑ and amplitude‑stable Nitrowave coax assembly for demanding environments, and a March 2026 capacity expansion by an Indian producer (SigmaRF) offering rapid delivery for standard and custom builds. These moves collectively compress lead times and expand the set of supply options for OEMs.
Strategic recommendations for 2026 decision cycles
Based on our scenario modeling and supplier assessments, PW Consulting recommends a prioritized set of actions for executives committing resources in 2026:
- Recalibrate sourcing and cost models now: incorporate copper volatility and aerospace grade MOQ constraints into three‑year procurement contracts; evaluate hedging and alloy substitution scenarios; negotiate dual‑sourcing with at least one technical specialist to balance cost and qualification risk.
- Accelerate compliance and product qualification pipelines: fast‑track laboratory validation for EN IEC 60966‑2‑8:2025 compliance where applicable, and sequence customer communication and contractual clauses to address FAR 52.204‑25 exposure for government projects.
- Prioritize product differentiation investments: invest in phase‑stable, low‑loss, and ruggedized assemblies where lifetime value is highest (defense, high‑frequency telecom). For automotive and test markets, emphasize modularizing designs to reduce time‑to‑custom and aftermarket complexity.
- Pursue targeted inorganic options: given moderate concentration, bolt‑on M&A for capability (e.g., phase‑stable cable technologies, rapid‑turn contract assembly capacity, or regional manufacturing footholds) can materially improve win rates against global integrators.
- Design go‑to‑market segmentation by buyer economics: deploy a tiered service model—catalog, configured standard, and fully engineered—with clear margin and lead‑time profiles to optimize production scheduling and improve gross margins.
- Embed regulatory scenario planning in bid approval: create a “regulatory kill switch” in proposal workflows for bids that may run afoul of national procurement restrictions, and maintain a qualified list of alternative suppliers cleared for regulated procurement.
Risk vectors and leading indicators to watch in 2026
Our report includes a prioritized risk matrix; highlights for 2026 include:
- Raw material squeezes: sustained copper escalation or tightened aerospace‑grade supply will be immediate margin squeezers.
- Regulatory shocks: additional procurement restrictions or standards updates could suddenly disqualify suppliers or product families from major programs.
- Capacity shifts: rapid capacity additions by low‑cost regional players (as seen in early 2026) can compress lead times and place pricing pressure on short‑run segments.
- Qualification timelines: new standards or customer‑specific qualification demands can lengthen program timelines and increase NRE costs—monitor certification queues as a leading indicator.
How to use the full PW Consulting study in your 2026 planning
The full research package transforms the insights above into executable tools: vendor scorecards, cost build‑ups, segment profitability maps, M&A target shortlists, and a step‑by‑step compliance checklist tied to contract templates. If you are prioritizing 2026 capital allocation, procurement renegotiation, or an acquisition in the interconnect space, these tools materially reduce execution risk and shorten decision cycles.
PW Consulting’s market model is transparent and auditable: we publish assumptions, sensitivity levers, and scenario outputs (base, upside and downside) tied to copper price curves, regulatory incidence rates and technology adoption paths. That traceability allows you to update forecasts quickly as 2026 events unfold.
Next steps
This briefing aims to equip senior leaders with an operational view of why the RF coaxial cable assemblies market is strategically relevant in 2026 and how to plan for it. For transaction‑level insights (detailed segment sizes, regional and application splits, supplier margins, and customer contract archetypes) please consult the full PW Consulting report—which contains the granular datasets and proprietary vendor assessments required to execute M&A, sourcing, or product roadmap decisions.
Contact PW Consulting to request the complete study, model access, and a tailored briefing workshop for executive teams preparing 2026 budgets or pursuing integration targets in the RF interconnect space.
For detailed analysis of this topic, please visit the official page: RF Coaxial Cable Assemblies Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Battery Design & Manufacturing Software Market Valued at USD 2,950.4 Million in 2025, Poised for 16.62% CAGR to Reach USD 8,638.25 Million by 2032
By PW Consulting, 2026-07-07
Battery Design and Manufacturing Software Market: Strategic Imperatives for 2026
PW Consulting’s latest market research—based on a comprehensive review of historical performance (2020–2025) and forward-looking scenarios across 2026–2032—clarifies a pivotal truth for industrial decision‑makers: software is now the strategic linchpin of battery competitiveness. The market for battery design and manufacturing software has accelerated from just over USD 1.1 billion in 2020 to an estimated USD 2.95 billion in our 2025 base year and is projected to continue expanding at a compound annual growth rate (CAGR) of 16.62% through the 2026–2032 forecast window. By 2032 the sector will be measured in multiple billions of dollars, reflecting the systemic shift to virtual validation, digital manufacturing, and compliance-driven data platforms.
Battery Design And Manufacturing Software Market
Why this report matters for 2026 decision-makers
Enterprise leaders—CIOs, CTOs, manufacturing heads, and corporate strategy teams—face three simultaneous pressures in 2026: rapid capacity scale-up, tighter regulatory reporting obligations, and a bifurcated supplier landscape where incumbent CAE/PLM players compete with specialist MES/BMS vendors and emergent AI-first entrants. This report translates those pressures into operational levers and investment criteria. It does not merely quantify market size; it provides the tactical intelligence required to prioritize capital allocation, vendor selection, and integration sequencing to preserve time-to-market while reducing compliance and safety risk.
Battery Design And Manufacturing Software Market
What the PW Consulting report contains (practical, actionable content)
- Strategic playbooks: Clear short‑, medium‑, and long‑term moves for OEMs, tier‑1 suppliers, battery pack integrators, and captive manufacturing sites—anchored to real business cases and sensitivity analyses.
- Vendor selection framework: A decision matrix that maps functional requirements (simulation fidelity, BMS-integration, MES interoperability, traceability, test lab management) to procurement criteria and total cost of ownership.
- Implementation roadmaps: Stepwise plans for migrating legacy MES/BMS landscapes, integrating digital twins across R&D and production, and de-risking rollouts with staged KPIs.
- Regulatory and compliance playbook: Checklists and data-mapping templates aligned to the latest EU and US regulatory regimes, including digital-reporting formats and MACR-related supply-chain obligations.
- Techno-economic models: Scenario-based TCO and ROI models that quantify the business cases for simulation‑led design, virtual testing, and factory digitization—tuned to different production scales.
- IP and data governance guidance: Best practices for protecting simulation models, anonymizing operational telemetry, and building auditable chains of custody for battery passports.
- Procurement assets: RFP outlines, standard SLA language, interoperability test scripts, and vendor scorecards to accelerate sourcing.
Market structure and competitive dynamics
The software ecosystem supporting battery design and manufacturing is maturing rapidly. Our concentration analysis shows a market that is moderately consolidated: the top three firms account for roughly 42% of vendor revenue, and the top five for about 58%. This profile reflects a balance—large, integrated PLM and CAE vendors retain significant share through end‑to‑end platforms, while specialist providers capture vertical niches (MES, lab automation, BMS toolchains and AI-enabled simulation).
Battery Design And Manufacturing Software Market
Key competitive observations:
- Broader platforms winning adjacent workflows: Major PLM/CAE vendors are bundling materials informatics, cell/pack virtual twins, and manufacturing process simulation, increasing the switching cost for enterprises looking for a single-source digital thread.
- Specialists delivering depth: Niche providers focused on MES, lab management, and real‑time BMS toolchains continue to be indispensable for shop‑floor traceability, test-rig orchestration, and regulatory submissions.
- AI and automation reshaping differentiation: Vendors that integrate AI-driven parameterization, automated meshing, and workflow scripting accelerate model-to-factory cycles—and buyers need to evaluate the maturity and explainability of those AI components.
Vendor landscape: strengths and strategic signals
- Ansys (Canonsburg, PA): Strength in multiphysics battery modeling—thermal, electrochemical and cell-to-pack simulation. Ansys’ suite accelerates virtual validation and shortens test cycles, which is essential for safety certification and early prototype iterations.
- Siemens (Munich): Offers an integrated portfolio that spans detailed cell design through digital manufacturing. Siemens’ completion of a major acquisition designed to combine high‑fidelity simulation, AI, and HPC capabilities signals aggressive consolidation of simulation and factory planning functionality.
- Altair Engineering (Troy, MI): Noted for system‑level multiphysics and AI-powered modeling; recent product releases emphasize automation and safety workflows. Its integration into larger platform portfolios expands options for customers seeking combined CAE + manufacturing execution capabilities.
- COMSOL (Stockholm): Focuses on add‑on physics modules that help design teams iterate electrochemical and thermal behaviors at multiple scales—a useful option for teams needing flexible, customizable physics solvers.
- MathWorks (Natick, MA): Simulink-based simulation and virtual testing remain central for BMS development and parameterization—particularly attractive for teams with heavy control-algorithm workstreams.
- Dassault Systèmes (Vélizy-Villacoublay): Brings a strong virtual twin and materials informatics angle—helpful for firms pushing materials innovation alongside manufacturability and lifecycle analysis.
- GE Vernova (Cambridge, MA): Provides MES-oriented solutions optimized for mixed-continuous and discrete battery processes—key for traceability and yield improvement at scale.
- AVL (Graz, Austria): Combines battery simulation with test-lab management and validation toolchains—valuable for organizations seeking tight coupling between virtual models and physical test infrastructures.
Regulation, traceability and the rise of the digital twin
Regulatory shifts in 2025–2026 materially change the calculus of software investments. New EU implementing rules effective April 2026 require standardized digital reporting formats for technical, chemical, performance, and recycling data. In parallel, U.S. administration rules tied to tax credits impose material supply-chain thresholds that influence sourcing and localization decisions beginning in 2026. These rules create two imperatives: (1) robust data capture and auditable traceability across the lifecycle, and (2) software architectures that can demonstrate provenance and support carbon‑footprint calculations.
Consequently, digital twins and AI-enabled traceability are no longer optional innovation projects; they are foundational compliance and market‑access capabilities. Buyers must assess not only modeling fidelity but also data governance, schema compatibility with battery passport requirements, and the ability to produce audited snapshots for regulators.
Strategic playbook for 2026 (concise action items)
- Immediate (0–12 months): Implement a proof of value that connects one virtual‑to‑physical use case—e.g., simulation-driven thermal management validation tied to one production line’s MES for traceability. Begin mapping data schemas to EU reporting templates.
- Near term (12–24 months): Consolidate vendors around a core platform approach where possible to reduce integration overhead, but retain specialist partnerships for lab automation and BMS toolchains. Update procurement contracts to include regulatory‑compliance SLAs.
- Mid term (2–4 years): Invest in a digital‑twin backbone that spans R&D to operations, with an auditable data lake and role-based access for IP protection. Use scenario-driven TCO models to plan CAPEX amortization and licensing structures.
- Long term (4+ years): Build modular, composable architectures that allow swapping of optimization engines (AI solvers, multiphysics engines) without disrupting traceability or reporting chains—preserving strategic optionality as standards and regulations continue to evolve.
Vendor selection checklist (high‑impact filters)
- Compatibility with mandated reporting schemas (EU battery passport formats).
- Proven ability to link simulation outputs to MES and lab test results for auditable traceability.
- Roadmap for AI features that are explainable and certifiable for safety use cases.
- Interoperability with existing PLM and ERP stacks and support for industry data standards.
- Commercial flexibility—options for on‑prem, cloud, and hybrid deployment to balance IP risk and compute needs.
- Clear SLAs for support during scale‑up phases and for regulatory audits.
How to use this report in boardroom decisions
Executives should use the report as a decision‑support toolkit: apply the procurement framework to narrow vendor shortlists, use the techno‑economic models to stress‑test capital plans under different localization and MACR scenarios, and adopt the compliance checklists to prepare for audits and submissions. For investors and M&A advisors, the report highlights pockets of consolidation and technology gaps where bolt-on acquisitions or partnerships can rapidly accelerate capability stacks—particularly in AI-enabled simulation and lab‑to‑factory integration.
Final note — the strategic gap we observe
There is a widening gap between companies that treat software as engineering support and those that treat it as strategic infrastructure. The latter group—those embedding digital twins, traceability, and advanced simulation into their product and factory lifecycles—will enjoy faster time‑to‑market, more predictable scale‑up, and lower regulatory friction. PW Consulting’s Battery Design And Manufacturing Software Market report equips you to close that gap. For practitioners seeking the granular segmentation, vendor scorecards, and the full suite of financial models and RFP templates, please consult the full report on our website.
For detailed analysis of this topic, please visit the official page: Battery Design And Manufacturing Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Paper-Based Biofuel Cells Market Set for Breakout Growth — 14.46% CAGR Forecast Through 2032
By PW Consulting, 2026-07-07
Paper Based Biofuel Cells Market: Strategic Outlook and Actionable Insights for 2026 Decision-Makers
Executive preview
PW Consulting’s latest market research brief on Paper Based Biofuel Cells distills the commercial, technological, and regulatory inflections that will define competitive positioning through 2032. Built on a quantitative foundation spanning 2020–2025 as the historical window and a 2026–2032 forecast horizon, the research synthesizes market sizing, growth drivers, production-readiness signals, and go-to-market pathways. With a compound annual growth rate of 14.46% embedded in our forecast model, this fast-evolving segment is transitioning from prototyping and pilot deployments toward scaled commercial applications where strategic timing and partnership choices will materially influence value capture.
Paper Based Biofuel Cells Market
Why this report matters for 2026 strategy
-
Accelerating commercialization: 2026 will be a pivotal year in which early technology demonstrations must convert into reproducible manufacturing and repeatable client outcomes. The report provides practical frameworks for evaluating operational readiness—supply chain, quality systems, and certification roadmaps—that directly impact go/no-go investment decisions this year.
Paper Based Biofuel Cells Market -
Risk-calibrated investment: with a clearly defined market trajectory and scenario-based sensitivity analyses, executives can align capital deployment to risk tolerance—whether prioritizing differentiated IP and pilot integration or scaling low-cost, sustainable manufacturing for high-volume disposables.
Paper Based Biofuel Cells Market -
Partnership and M&A playbook: the space is ripe for strategic partnerships that combine material science, low-power electronics, and logistics integration. Our report identifies the commercial archetypes and transaction rationales that will produce near-term commercial synergies and long-term market share advantages.
-
Regulatory and sustainability alignment: increasing regulatory scrutiny on battery waste and single-use electronics creates a structural tailwind for compostable, metal-free alternatives. The report maps regulation-to-revenue pathways so compliance becomes a marketable capability rather than a cost center.
Market trajectory at a glance
Our topline market model quantifies the sector’s evolution from early niche deployments to a broader addressable market. The market size expanded steadily through the historical window and our base-year assessment (2025) captures the moment of inflection: the sector moves from exploratory commercialization to scalable production. Over the forecast period, the model—anchored by a 14.46% CAGR—captures adoption across healthcare diagnostics, wearables, environmental sensing, and emerging smart packaging use cases. The detailed revenue path we model for 2026–2032 includes explicit scenarios built on differing adoption curves and technology maturation timelines, enabling board-level scenario planning and working-capital modeling for 2026–2027 execution windows.
Core themes and strategic implications
-
Material simplicity enables rapid cost-down: cellulose paper substrates combined with enzymatic systems and carbon-based electrodes create an attractive cost and sustainability profile. Companies that secure low-cost, high-quality cellulose supply chains and robust enzyme sourcing will convert prototype advantages into cost-per-unit leadership.
-
Quality and certification are accelerants: ISO 9001 and related quality certifications are no longer optional for scaled production. Certification unlocks tiered procurement opportunities with regulated customers (medical diagnostics, defense, and certain logistics providers) and mitigates counterparty risk in B2B commercialization.
-
System integration is where value migrates: raw device performance matters, but the highest-margin opportunities will accrue to firms that integrate ultra-low-power electronics, energy management, and OEM-friendly form factors into turnkey solutions for end customers.
-
Regulation shapes buyer economics: lifecycle and disposal regulations favor compostable, metal-free designs. Companies that can document end-of-life benefits with third-party validation will shorten procurement cycles and command pricing premia in regulated verticals.
Competitive landscape insights
The market shows early signs of concentration—neither a pure fragmented frontier nor a stable oligopoly. Measured concentration indicators point to a competitive environment with a handful of emerging leaders and a broad tail of specialized innovators. Market concentration metrics indicate that the top three and top five participants hold meaningful shares of current commercial activity, but significant share remains contestable, especially as new entrants mature manufacturing capability and strategic partners accelerate adoption.
Company focus: BeFC and the rise of paper-based enzymatic solutions
Among the names of strategic consequence, BeFC (Bioenzymatic Fuel Cells), headquartered in Grenoble, France, stands as an instructive case of how product, sustainability narrative, and industrialization combine to unlock commercial pathways. BeFC is recognized for pioneering metal-free, paper-based enzymatic biofuel cells that use enzymes and simple sugars to generate low-power electricity for IoT sensors, smart packaging, wearables, and diagnostics. Their product positioning—compostable, ultra-thin, and flexible—directly targets the replacement of small coin-cell batteries in single-use and limited-life applications.
Recent strategic moves illustrate the playbook needed to scale: a partnership to integrate ultra-low-power microcontroller platforms that enable battery-free device operation, public attainment of ISO 9001 quality management certification, and active participation in high-profile trade shows to accelerate commercial validation and OEM engagements. These developments exemplify the three levers the report identifies as critical for market leaders: (1) technology integration partnerships, (2) demonstrable quality systems for manufacturing scale-up, and (3) market-facing activities to shorten commercialization cycles.
What the report delivers (operational, not just observational)
-
Quantitative market model with base-year calibration and scenario runs across conservative, base, and accelerated adoption paths—suitable for financial planning and investment committee review.
-
Manufacturing and supply-chain diagnostics that identify critical inputs, single-source risks, and cost-reduction roadmaps for cellulose, enzymes, and conductive inks.
-
Regulatory and certification playbook outlining required and optional standards by vertical, plus practical timelines and cost estimates to achieve them.
-
Technology readiness and integration matrix assessing enzyme longevity, substrate robustness, power density, and interoperability with ultra-low-power electronics.
-
Commercialization blueprints including go-to-market archetypes, channel strategies for OEMs and packagers, pricing ladders, and sample contractual terms for licensing and co-development.
-
M&A and partnership screening criteria that prioritize complementary IP, manufacturing scale, customer access, and validated pilots—complete with a short-list of acquisition and alliance profiles tailored to strategic buyers.
How corporate leaders should use this intelligence in 2026
-
Portfolio prioritization: use the report’s scenario outputs to allocate R&D and commercialization budgets—decide which product lines should pilot first and where to defer based on cash runway and customer urgency.
-
Partner selection and negotiation: apply the governance templates and commercial models included in the report when negotiating supply agreements or co-development contracts to preserve optionality while accelerating time-to-market.
-
Manufacturing readiness check: adopt the report’s maturity checklist to validate contract manufacturers or to build in-house capability—ISO certification and process controls are early gating criteria to win enterprise customers.
-
Regulatory positioning: integrate the sustainability and end-of-life value propositions into procurement pitches; the report identifies the regulatory levers that can be turned into purchasing preferences for buyers in regulated industries.
Risks and mitigants
-
Technical durability vs. cost: enzyme stability and environmental resilience remain technical risks. Our report provides de-risking approaches—enzyme stabilization techniques, encapsulation options, and warranty structures aligned with customer use cases.
-
Supply concentration: reliance on specific cellulose grades or enzyme suppliers exposes firms to disruption. Recommended mitigants include multi-sourcing strategies, upstream investments, and co-development agreements to secure capacity.
-
Market education: some buyer segments require demonstration of lifecycle benefits before premium adoption. The report offers turnkey pilot templates and turnkey measurement frameworks that accelerate credible proof points.
Next steps: how to convert insights into action
For executives evaluating entry, expansion, or consolidation in paper-based biofuel cells, the logical next step is a focused 30–60–90 day execution agenda. PW Consulting supports rapid turn-key initiatives that translate our findings into commitments: supplier due-diligence, pilot commercialization plans with measurable KPI gates, and M&A screening. Our templates enable procurement, R&D, and business development teams to move from strategy to signed pilots within a single quarter.
Conclusion — the strategic window for 2026
The paper-based biofuel cell market is at a strategic inflection point. With accelerating demand driven by sustainability requirements and the emergence of ultra-low-power integration partners, organizations that act thoughtfully in 2026—prioritizing quality certification, supply-chain resilience, and systems integration—stand to convert early momentum into durable commercial advantage. PW Consulting’s report equips leaders with the data, playbooks, and risk mitigations required to make those choices with confidence.
Get the full intelligence
This preview highlights the analytical depth and practical orientation of our full report while intentionally withholding certain segment-level allocations and proprietary scenario tables that are provided exclusively in the complete publication. To access the full dataset, segment breakdowns, company scorecards, and downloadable financial models, visit our report page or contact PW Consulting’s industry desk for a tailored briefing and licensing options.
For detailed analysis of this topic, please visit the official page: Paper Based Biofuel Cells Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: IT Audit Services Market at USD 16,845.5 Million in 2025, Poised for 11.5% CAGR Through 2032
By PW Consulting, 2026-07-07
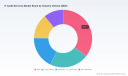
It Audit Services Market — 2026 Strategic Preview
PW Consulting’s latest market research, the It Audit Services Market Report (base year 2025; historical 2020–2025; forecast 2026–2032), provides a forward-looking, execution-oriented view designed to inform boardroom decisions in 2026. The global market for IT audit services has expanded rapidly over the past half-decade — growing from approximately USD 10.25 billion in 2020 to roughly USD 16.85 billion in 2025 — and our modelling anticipates continued acceleration through the forecast window, reaching an estimated USD 36.09 billion by 2032 at a compound annual growth rate (CAGR) of 11.5%. This briefing highlights the strategic consequences for enterprise buyers, service providers, and investors while intentionally withholding the granular segmentation datasets that subscribers will find in the full report.
It Audit Services Market
Why this matters for 2026 decision‑makers
-
Risk tolerance is being re-priced. Elevated cyber losses — with average breach costs in major markets exceeding USD 10 million in recent reporting — mean that IT audit and assurance functions are no longer a back-office checkbox but a balance‑sheet management lever. Audit outputs feed directly into capital allocation, insurance negotiation, and regulatory exposure assessments.
It Audit Services Market -
AI and automation have moved from niche pilots to enterprise-scale vectors of both opportunity and risk. New guidance from standards bodies and recent product launches reflect an ecosystem shift: audit methodologies, tooling, and talent profiles must adapt to review models, datasets, and autonomous processes.
It Audit Services Market -
Regulatory complexity is increasing. Tiered AI compliance regimes, updated IT audit frameworks, and explicit internal‑audit cybersecurity requirements are changing audit scopes and cadence. Organizations that align audit design with emergent regulation gain measurably better control over compliance cost and enforcement risk.
-
Market structure matters for procurement. The IT audit services space sits between specialist boutiques and global advisory firms. While a small group of large firms exerts meaningful influence, the overall market retains room for specialized, technology‑native providers — creating both consolidation opportunities and differentiated sourcing strategies.
What the PW Consulting report delivers — practical, action‑ready content
-
Decision frameworks that translate evolving requirements (AI governance, cloud assurance, continuous auditing) into prioritized audit portfolios and annual planning templates.
-
Operational playbooks for integrating automation and analytics into audit fieldwork, including example control tests, data extraction patterns, and sampling approaches aligned to modern architectures.
-
Vendor evaluation scorecards and sourcing decision trees calibrated to enterprise scale, risk appetite, and transformation objectives — designed to eliminate time‑wasting RFP cycles.
-
Maturity models and roadmap templates that convert audit findings into measurable remediation programs and governance improvements, with KPI dashboards and time‑boxed milestones.
-
Scenario‑based financial impact analyses and TCO models that connect audit investment choices to loss‑avoidance and compliance cost reductions — enabling CFOs and audit committees to quantify ROI.
Because this release follows a “teaser” approach, the full dataset — including detailed regional and service‑line segmentation, supplier matrices, and downloadable dashboards — is available only in the complete report and interactive portal.
Market dynamics: drivers, accelerants and headwinds
-
AI and generative technologies. Standards bodies and market participants are converging quickly on new norms for auditing AI systems. Industry frameworks published in 2026 have expanded audit scopes to cover model lifecycle governance, data lineage, and drift monitoring. Simultaneously, vendors have introduced agentic audit capabilities that promise productivity gains but raise new assurance requirements.
-
Framework updates and guidance. Professional standards have been updated to incorporate cloud, automation, continuous assurance, and AI-specific controls. These updates are reshaping skill expectations for internal audit teams and third-party providers alike.
-
Regulation and enforcement. Emerging AI regulations introduce tiered obligations that require high‑risk systems to be subject to additional audit and control cycles. Entities operating across multiple jurisdictions face growing complexity in audit evidence requirements and reporting obligations.
-
Labor and capability constraints. Demand for auditors with hybrid skillsets — data science, privacy, cloud security, and AI governance — is far outstripping traditional supply, putting upward pressure on labor costs and accelerating adoption of automation to bridge capability gaps.
-
Economic and competitive pressures. Service buyers are balancing the need for deeper, more frequent assurance with budget constraints. This drives demand for outcome‑oriented contracts, technology‑augmented audits, and managed assurance programs.
Competitive landscape — positioning and strategic moves
The It Audit Services Market is characterized by a mix of global professional services firms, specialized consultancies, and regional players. The three largest global firms together account for a meaningful but not dominant share of the market, and the top five do not approach monopoly — our concentration metrics indicate that the market’s leading vendors are influential yet competition remains robust (CR3 ≈ 35.4%; CR5 ≈ 48.2%).
-
Deloitte, PwC, EY and KPMG remain platform leaders with breadth across technology risk, compliance, and advisory services. Their strengths lie in cross‑service integration, scale delivery, and rapid deployment of enterprise controls testing at global scale.
-
Specialists such as Protiviti, RSM US, Grant Thornton, BDO, Cherry Bekaert and Baker Tilly compete on depth of industry knowledge, mid‑market reach, and technology‑enabled assurance solutions. These firms frequently win mandates that require closer alignment to sector‑specific regulation or more hands‑on remediation support.
-
Notable market catalysts in early 2026 include enterprise agentic AI launches from major audit firms and contemporaneous framework updates from standards bodies — moves that are compressing time‑to‑value for technology‑enabled audit services while also elevating expectations for AI assurance capabilities.
Strategic playbook for 2026 — recommendations by stakeholder
-
Boards & Audit Committees: Reframe audit as a risk‑mitigation and value‑creation function. Require scenario analyses that show how audit investments reduce probabilistic loss exposure and enable faster regulatory readiness. Demand visibility into AI governance and continuous assurance mechanisms.
-
CIOs & CISOs: Prioritize controls that enable auditability: robust telemetry, immutable evidence capture, and data lineage. Select vendors that provide integrated assurance across cloud, identity, and model governance rather than siloed point solutions.
-
Chief Audit Executives: Adopt a risk‑tiered audit cadence that reserves intensive field work for high‑impact systems and uses automated continuous audit for stable, lower‑risk environments. Invest in cross‑training programs that combine audit methodology with data science and cloud architectures.
-
Service Providers: Differentiate through proprietary AI assurance modules, repeatable audit playbooks for regulated industries, and outcome‑oriented commercial models. Build partnerships to cover gaps in domain expertise and to accelerate global delivery footprints.
-
Investors & M&A teams: Target firms that combine verticalized content with technology‑first audit tooling. Expect consolidation opportunities where scale and IP can compress delivery costs and increase penetration into regulated accounts.
How PW Consulting’s report accelerates decision‑making
-
Actionable templates: Downloadable audit program templates, test procedures, and remediation trackers that reduce implementation time from months to weeks.
-
Scenario modelling: Pre-built financial and regulatory scenarios that let leaders stress‑test audit investments against litigation, breach, and compliance events.
-
Vendor due diligence kit: A curated RFP framework and scorecard that shortens procurement cycles and clarifies trade‑offs between global scale and specialist depth.
-
Interactive datasets: Subscriber dashboards that allow executives to explore growth drivers and vendor positioning. Note: the press summary omits the granular region/service breakdowns and supplier share tables — these are available in full to report purchasers.
Closing perspective
By 2026, IT audit is evolving from a retrospective compliance exercise into an integral component of operational resilience and strategic governance. The market’s sustained double‑digit growth trajectory signals both pressure and opportunity: organizations that modernize audit frameworks, embrace continuous assurance, and invest in AI governance will reduce exposure and unlock strategic flexibility. Service providers that combine domain depth with automation and clear commercial outcomes will capture disproportionate value.
PW Consulting’s It Audit Services Market Report equips executives with the frameworks, playbooks, and market intelligence required to make informed procurement, investment, and organizational decisions. For access to the full dataset, regional and service‑line segmentation, and the interactive vendor scorecards referenced in this briefing, visit our report page and download the complete study.
For detailed analysis of this topic, please visit the official page: It Audit Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: OpenStack Service Market to Nearly Double from USD 8.25B in 2025 to USD 16.9B by 2032 at 10.78% CAGR — Consulting & Integration Leads at USD 3.91B, North America Tops at USD 3.19B (CR5: 46.2%)
By PW Consulting, 2026-07-07
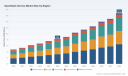
OpenStack Service Market: Strategic Imperatives for 2026 — PW Consulting Preview
As enterprises reassess cloud strategy in 2026, OpenStack-based services are re-emerging as a pragmatic route to control, cost optimization, and infrastructure sovereignty. PW Consulting’s latest OpenStack Service Market report (base year 2025; historical window 2020–2025; forecast 2026–2032) synthesizes vendor evolution, operational economics, and technology direction into an actionable framework for CIOs, CTOs, and procurement leaders. This release is a preview: we surface the high-value findings and strategic implications while reserving the granular segmentation tables, scorecards, and monetized scenario models for the complete report and dataset.
Openstack Service Market
Market at a Glance
After steady recovery and renewed investment in private and hybrid clouds, the OpenStack services market expanded from roughly USD 4.8 Billion in 2020 to USD 8.25 Billion in 2025. Our baseline forecast shows continued momentum through the coming decade, driven by enterprise cloud repatriation, telco NFV/edge initiatives, and platform modernization, implying a compound annual growth rate (CAGR) of approximately 10.78% across the forecast window. Under PW Consulting’s central scenario, the market approaches mid‑double‑digit billions by the early 2030s.
Openstack Service Market
Two structural observations matter for strategic planning. First, the market remains moderately fragmented: leading suppliers represent a meaningful but not dominant share of global spend, leaving ample runway for specialized players and managed service specialists. Second, adoption is being reshaped by platform revitalization—most notably the Open Infrastructure community’s 2026.1 release (Gazpacho)—and a surge in production-scale footprints reported by the community.
Openstack Service Market
- Open Infrastructure momentum: The Open Infrastructure Foundation released OpenStack 2026.1 (Gazpacho) in April 2026, emphasizing operational simplification, intelligent automation, enhanced workload migration, and broader hardware enablement—advances that materially reduce integration friction for heterogeneous infrastructures.
- Scale signals: OpenInfra’s 2025 user survey confirmed a global production footprint exceeding 55 million compute cores—evidence that OpenStack remains a strategic infrastructure choice for large, performance-sensitive deployments.
Why This Matters for Enterprise Decision‑Makers in 2026
For 2026 planning cycles, the implications of these dynamics are practical and immediate:
- Cost predictability and TCO: With renewed emphasis on long-term operational control, organizations must re-evaluate TCO models that include migration costs, managed operations, and energy consumption. Our report supplies a modular TCO methodology that factors hardware refresh timing, energy tariffs, and managed services premiums.
- Vendor selection and risk management: The landscape supports both enterprise-scale vendors and niche specialists. Procurement strategies need to balance consolidation benefits against the flexibility of best-of-breed integrators—particularly where edge or scientific workloads are involved.
- Energy and infrastructure risk: Data center energy demand remains a decisive operational variable. Recent analyses indicate substantial electricity consumption for data centers globally; simultaneous industry moves—such as the March 2026 Ratepayer Protection Pledge by major cloud providers to fund new generation and grid enhancements, and region-specific transmission adjustments—are reshaping availability and pricing risk for large compute deployments.
- Regulatory and grid dynamics: Where capacity and transmission markets are tightening, operators should model regional procurement and resilience strategies. In the U.S., for example, grid operators have introduced special protections and transmission services for data centers in jurisdictions responding to AI-driven load growth—factors we quantify qualitatively in the full study.
- Operational modernization: OpenStack’s renewed automation and migration tooling materially lowers the barrier for enterprises transitioning away from legacy hypervisor silos or proprietary stacks. Our deployment playbooks calibrate effort for lift-and-shift, re-platforming, and hybrid integration scenarios.
What PW Consulting’s Report Delivers
Our full report is structured to convert insight into executable programs for 2026 decision calendars. Major deliverables include:
- Market sizing and validated growth scenarios (conservative / central / aggressive) with methodological transparency tied to cloud spend drivers and compute footprint trends.
- Vendor benchmarking and risk matrices that evaluate commercial models, delivery footprints, open-source stewardship, and partner ecosystems—presented as qualitative scores and decision heuristics.
- TCO and migration calculators with plug‑and‑play inputs for energy pricing, labor rates, migration duration, and managed service tiers.
- Procurement playbooks and RFP templates tailored to managed OpenStack services, consulting & integration engagements, and fixed-price delivery models.
- Operational playbooks that translate OpenStack 2026.1 feature sets into runbooks, automation targets, and SLA negotiation points.
- Energy & capacity stress tests that fold in regional grid constraints and utility‑level programs to assess site-level risk and mitigation levers.
- Case studies and vendor-led proofs-of-concept templates for telco edge clusters, HPC research clouds, and enterprise private cloud rollouts.
Note: Core segment tables (detailed regional splits, service-type revenue breakdowns, and enterprise-size allocations) are intentionally omitted from this preview. These granular datasets, including provider-level revenue estimates and market share scenarios, are available in the full PW Consulting dataset and interactive portal.
Competitive Landscape — Who Matters and Why
The OpenStack service ecosystem in 2026 features a mix of large platform vendors, pure-play specialists, and regional service houses. Each category has strategic value depending on enterprise objectives—control, speed-to-market, cost, or specialized engineering capability.
- Red Hat — As a major commercial steward with an enterprise-grade OpenStack distribution and deep integration into hybrid stacks, Red Hat remains the default choice for organizations prioritizing vendor-led support and a path to Red Hat OpenShift convergence. Recent security advisories in May 2026 underline the company’s operational responsiveness and the importance of timely patching in hybrid environments.
- Mirantis — A pure-play OpenStack specialist, Mirantis continues to invest in managed services and build-operate-transfer (BOT) models that appeal to telcos and large enterprises seeking to internalize operations after third-party incubation. Mirantis’ expansion of managed OpsCare services underscores market demand for production-grade operational SLAs.
- Canonical — Canonical’s Charmed OpenStack and fixed-price consulting packages have gained traction for predictable, automated deployments. Their continued emphasis on enterprise SLAs and automated delivery makes them an attractive supplier for organizations that favor deterministic commercial models.
- Rackspace Technology — Rackspace’s managed cloud experience and Elastic Engineering pods remain compelling for enterprises seeking blended managed/private offerings with rapid escalation paths and multi-cloud integration expertise.
- VEXXHOST and Ultimum Technologies — Regional and specialist providers offer tailored hosted private clouds and migration toolkits for VMware-to-OpenStack transitions; their value is highest in highly regulated, performance-sensitive, or localized hosting scenarios.
- StackHPC — Focused on research computing and containerized architectures, StackHPC is notable where scientific workloads or HPC-like characteristics demand bespoke design consultancy.
- SUSE, IBM, and HPE — Each brings enterprise infrastructure and systems integration breadth: SUSE with its OpenStack distribution, IBM through hybrid consultative services often leveraging Red Hat technology, and HPE through infrastructure alignment and edge-to-core delivery pathways.
Competitive intensity is shaped by a moderate concentration: a small group of providers account for a substantive share of market activity, but the long tail remains relevant for specialized engineering needs and regional compliance nuances. The full report contains provider-level matrices and negotiated contract archetypes to guide selection.
Strategic Playbook — Immediate Actions for 2026
For organizations prioritizing cloud control and predictable costs in 2026, our recommended short list of actions includes:
- Commission a portfolio segmentation to identify workloads suitable for OpenStack: latency-sensitive, data-sovereign, and cost-stable candidates should be prioritized.
- Run three migration pilots (lift-and-shift, re-platform, hybrid integration) using the OpenStack 2026.1 feature set to validate automation and workload transformation assumptions.
- Model energy exposure across target data center locations and incorporate grid/utility risk—especially where capacity markets and transmission changes are active.
- Negotiate managed service contracts with clear runbook handoffs, escalation SLAs, and vendor lock‑in exit clauses (BOT or handback terms).
- Invest in training & workforce transition for platform engineering capabilities; prioritize observability, automation, and security operations for cloud-native operations.
PW Consulting can rapidly deploy a tailored engagement to deliver the TCO model, vendor shortlists, and a 90‑day pilot program blueprint. Our methodology emphasizes measurable KPIs, cost transparency, and producible runbooks ready for procurement.
Next Steps and How to Access the Full Intelligence
This preview captures the strategic inflection points we expect to influence enterprise cloud choices in 2026. For procurement teams, platform engineering leaders, and C‑suite sponsors preparing FY2027 budgets, the full PW Consulting OpenStack Service Market report provides the complete dataset: regional and service‑type splits, provider revenue estimates, downloadable TCO calculators, and negotiation playbooks.
To obtain the full report, dataset access, and an executive briefing tailored to your environment, contact PW Consulting’s Market Intelligence Center. The full content unlocks the granular segmentation and provider scorecards referenced throughout this preview—essential inputs for any major infrastructure decision this year.
For detailed analysis of this topic, please visit the official page: Openstack Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Airborne Mission Management Systems Market Poised to Reach USD 3,651.74 Million by 2032, Growing at a 6.15% CAGR (2026–2032 Forecast)
By PW Consulting, 2026-07-07
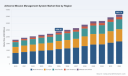
Airborne Mission Management System Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market research on Airborne Mission Management Systems (AMMS) delivers a focused, action-oriented assessment designed to shape procurement, R&D, and M&A decisions in 2026. Built on a base year of 2025 with historical coverage from 2020–2025 and a forward-looking forecast to 2032, the report synthesizes market trajectory, technology inflection points, certification constraints, and vendor positioning into practical guidance for executives, program managers, and investors.
Airborne Mission Management System Market
Market Trajectory: a Mature, Growing Opportunity
The AMMS market is no longer nascent; it has demonstrated steady expansion through the first half of the decade and is forecast to continue growing at a mid-single-digit compound annual growth rate (CAGR). From a measured market size in 2020, the industry expanded through 2025 to a multi-billion-dollar sector (reported in USD millions) and, under PW Consulting’s baseline scenario, is expected to approach a substantially larger market by the end of the 2032 forecast horizon. This trajectory reflects sustained defense modernization, acceleration of ISR and special-mission requirements, and the convergence of high-performance computing, sensors, and data fusion capabilities onboard airborne platforms.
Airborne Mission Management System Market
For decision-makers, that rate of growth represents an environment where steady demand coexists with a dynamic supplier landscape: incumbents must defend platform integrations and lifecycle support contracts while newer entrants chase differentiated software-defined mission capabilities. The investment calculus in 2026 should therefore balance near-term program wins with long-lead technology investments that enable adaptability across both manned and unmanned platforms.
Airborne Mission Management System Market
Why this Report Matters for 2026 Strategy
- Timing for Procurement and Modernization — Several national programs and platform modernization efforts are entering contracting windows. The report identifies how certification timelines and MOSA (Modular Open Systems Approach) compliance drive procurement schedules; leaders who align product roadmaps to these windows can materially shorten fielding cycles.
- Technology Transition Planning — The shift toward software-centric mission management and composable architectures is reshaping integration risk. We map the paths operators should take to migrate legacy airborne processors and mission suites while preserving airworthiness certification.
- Risk-aware Investment Priorities — Our analysis quantifies where investments in compute density, thermal management, and low-SWaP (Size, Weight, and Power) hardware yield the highest mission-return for integrators and OEMs.
- M&A and Partnering Windows — Market dynamics create strategic M&A opportunities for firms seeking capabilities in multi-sensor fusion, ISR payload integration, or mission software ecosystems. The report highlights archetypal targets and integration risks.
Report Contents: What We Deliver (Practical, Executable)
- Concise market sizing and scenario-based forecasts through 2032, with sensitivity to procurement pacing and technology adoption.
- Technology and capability roadmaps that prioritize investable features (e.g., ruggedized edge compute, real-time data fusion, multi-workstation operator environments, secure comms gateways).
- Certification and compliance playbook aligning development checkpoints to RTCA/DO-254 and DO-178C expectations, and practical guidance for ARP4754A process alignment.
- Integration cost and schedule models for typical modernization initiatives, including hardware retrofit vs. full-suite replacement analyses.
- Competitive vendor profiles and capability matrices, including MOSA readiness, software lifecycle practices, and demonstrated mission integrations.
- Procurement and sustainment scenarios that translate technical choices into lifecycle cost-of-ownership implications.
Competitive Landscape: Who Matters and Why
The AMMS ecosystem combines large prime contractors, specialized avionics firms, and increasingly, agile ISR-focused companies. The market exhibits a balance between legacy aerospace integrators and niche technology providers that offer rapid software innovation and sensor fusion expertise.
- Curtiss-Wright Defense Solutions — Offers scalable, MOSA-aligned rugged computing and airborne processors tailored for enduring maritime and long-endurance UAV missions. Its lineage of mission processors and custody of mission-critical programs make it a strategic partner for platform primes.
- General Dynamics Mission Systems – Canada — Known for delivering fully integrated AMMS across fixed and rotary platforms and for modernization programs that couple sensor integration with secure communications and data exploitation chains.
- Saab AB — Provides a flexible airborne C2 and mission management offering designed for high-mission-flexibility roles such as AEW, MPA and SIGINT, emphasizing operator workflow and mission orchestration.
- BIRD Aerosystems / Ondas (post-acquisition) — Brings multi-mode radar and EO sensor integration capabilities and lightweight ISR mission management software; recent acquisition activity positions this capability set for faster commercialization against special-mission platforms.
- Leonardo — Focused on rotary-wing mission suites and tight avionics integration, connecting airborne mission management closely to platform-specific sensors and crew workflows.
- Honeywell Aerospace — Leverages broader avionics and cockpit ecosystems to provide mission manager products that emphasize multi-workstation interoperability and tactical situational awareness.
- Thales Group — Integrates mission management with broader sensor-to-C2 systems, emphasizing naval and multi-domain interoperability in addition to airborne mission processing.
Recent vendor developments illustrate shifting momentum: prime contractors continue to secure program orders tied to legacy platforms and next-gen UAVs; specialist ISR firms are being consolidated to accelerate capability scaling. For procuring agencies and integrators, continuity of sustainment, software supply-chain integrity, and evidence of DO-178C/DO-254 alignment are immediate selection criteria.
Regulatory and Integration Dynamics: Certification is the Clock
Certification realities—specifically DO-254 for airborne hardware and DO-178C for software—are central constraints. Compliance demands rigorous traceability from system requirements through to implementation and verification. Additionally, ARP4754A process alignment remains essential for safely integrating AMMS with platform flight-critical systems.
MOSA is increasingly not just an engineering preference but a policy driver in several defense markets. The practical upshot is that vendors with modular, standards-based interfaces and clear upgrade paths will reduce total cost of ownership and integration risk for platform owners. Conversely, high-performance SWaP-constrained computing remains a persistent bottleneck: achieving edge compute density without compromising thermal or certification margins is a live engineering challenge.
Strategic Imperatives for 2026
- Prioritize MOSA-aligned Roadmaps — Embed open interfaces and upgrade lanes into product plans now to meet procurement mandates and to accelerate secondary market sales.
- Invest in Certification-Ready Toolchains — Adopt lifecycle engineering practices that generate the artifacts required for DO-178C/DO-254 compliance; this shortens approval cycles and reduces program risk.
- De-risk Compute and Integration — Focus R&D on low-SWaP, rugged compute modules and modular sensor adapters that reduce aircraft downtime during upgrades.
- Balance Software Monetization with Lifecycle Support — Transitioning to software-first mission features creates recurring revenue potential but requires robust update, cybersecurity, and RMF/ATO considerations.
- Prepare for Consolidation — Expect continued M&A and strategic partnerships as systems integrators seek to close capability gaps rapidly; have due diligence frameworks ready that stress certification posture and sustainment commitments.
How PW Consulting’s Report Helps You Execute
Our report is intentionally pragmatic: it equips you with decision-ready artifacts rather than abstract forecasts. We translate market growth trends into actionable program timelines, supplier scoring models, and procurement-ready technical specifications. We also include war-gaming scenarios that test supplier resilience under alternative procurement and certification timelines so your team can stress-test investment cases before committing capital or program resources.
Next Steps
If your 2026 strategy depends on competitive positioning in airborne mission capabilities—whether you are a prime contractor, avionics supplier, defense investor, or government program office—this report provides the framework to align technology, certification, and procurement decisions. To access the full dataset, vendor benchmarking, and the executable playbooks referenced above, please visit the PW Consulting report portal for the Airborne Mission Management System Market. The portal includes downloadable tools, vendor scorecards, and scenario models that underwrite program-level decisions.
PW Consulting stands ready to support bespoke briefings, acquisition strategy workshops, and technical due diligence engagements that translate these insights into operational outcomes.
For detailed analysis of this topic, please visit the official page: Airborne Mission Management System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Robotics in Shipbuilding Market to Expand at a 7.5% CAGR
By PW Consulting, 2026-07-06
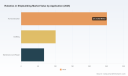
Robotics in Shipbuilding Market: Strategic Outlook and Decision Playbook for 2026
As shipyards confront accelerating demands for throughput, quality, and safety, robotics is moving from niche automation to a strategic infrastructure investment. PW Consulting’s latest market study — with a 2025 base year and a 2026–2032 forecast horizon — quantifies this transition and translates it into executable guidance for executives making investment and procurement decisions in 2026. At a headline level, the global Robotics in Shipbuilding market expanded to an estimated USD 420.0 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 7.5% through the 2026–2032 forecast period (reaching modeled revenue nearing USD 697 Million by 2032). These macro trajectories reflect structural forces that make robotics not a cost center experiment but a strategic lever for competitiveness.
Robotics in Shipbuilding Market
Why 2026 is a Pivotal Decision Year
-
Labor and capacity pressures: Persistent shortages of skilled welders and fabricators have pushed shipbuilders to explore adaptive robotic welding and material handling as capacity-sustaining measures rather than optional efficiency projects.
Robotics in Shipbuilding Market -
Rapid advancement of physical AI: Partnerships and MOUs signed in early 2026 between major naval primes and physical-AI robotics vendors demonstrate a shift from pilot-stage proof-of-concept to integration-scale programs targeting measurable throughput gains.
Robotics in Shipbuilding Market -
Falling component costs and modular architectures: Key enabling components — including six-axis force-torque sensing and integrated control modules — have experienced significant price declines, lowering the entry threshold for complex applications such as force-guided welding and surface preparation.
-
Regulatory and safety tailwinds: Emerging standards for collaborative robots and guarded work cells support human-robot coexistence in shipyards, permitting higher utilization without the traditional safety fencing that fragments workflows.
-
Strategic public investment: Research grants and government commitments to AI-enabled shipbuilding underline national-level priorities to preserve industrial capacity while modernizing labor models.
What the Numbers Mean for Buyers and Investors
The market’s projected 7.5% CAGR and modeled progression from USD 420.0 Million in 2025 toward near-USD 697 Million by 2032 are not abstract forecasts; they are decision triggers. For procurement leads, these numbers imply a near-term imperative to establish vendor roadmaps and pilot sites: early movers will define standards, capture integration learning curves, and reduce long-run TCO. For CFOs, the growth trajectory supports allocating staged capital — a combination of targeted CAPEX for core systems and OPEX for AI/analytics subscriptions — to smooth adoption risk.
From a cost perspective, industrial robotic systems suitable for marine shipbuilding typically fall within a capital range that makes modular rollout an effective strategy: unit hardware expenditures can cluster in a defined mid-five-figure to low-six-figure band, with total installed cost multiples that reflect integration, fixtures, and commissioning. This dynamic favors phased deployments and vendor partnerships that bundle installation and application engineering rather than pure hardware procurement.
Report Offerings — Practical Intelligence, Not Just Projections
PW Consulting’s report is structured around the practical questions executives must answer in 2026. Rather than a catalog of market slices, the deliverables are designed to be directly operationalizable:
-
Executive decision framework: A buyer’s guide to determine build vs. buy, procurement sequencing, and pilot-to-scale criteria tailored to capital budgets and production cadence.
-
Total Cost of Ownership (TCO) models: Scenario-based TCO calculators that incorporate capital, integration, training, productivity uplifts, and maintenance across multi-year horizons.
-
Deployment playbooks: Step-by-step templates for pilot selection, system integration, human-machine-interface (HMI) design, and workforce reskilling plans.
-
Risk and compliance matrix: Practical mitigation strategies for intellectual property, cybersecurity of robotic control systems, and safety certification pathways for cooperative work cells.
-
Vendor selection toolkit: Scorecards and negotiation playbooks to capture lifecycle services, spare-part provisioning, and SLAs that matter in high-mix, low-volume shipyards.
-
Scenario planning and sensitivity analysis: Upside and downside cases tied to raw-material shocks, labor shifts, and policy interventions to stress-test investment decisions.
Competitive Landscape — Who Matters and Why
The market exhibits moderate concentration: the top three vendors account for a meaningful portion of industry revenues, while the top five capture a majority share. This structure yields a dual-path competitive dynamic: major global robotics suppliers continue to dominate core hardware, while specialist and software-first entrants compete on domain-specific capabilities and systems integration.
-
ABB (Switzerland) — A global leader in industrial robotics and automation, ABB supplies integrated welding, material handling, and precision assembly systems designed to scale across large vessel programs. Strategy implication: strong choice for end-to-end automation programs with global service footprints.
-
FANUC Corporation (Japan) — Known for high-precision robots and high-volume reliability, FANUC supports large Asian shipyards where repeatability and throughput are the priority. Strategy implication: preferred where robust, high-duty-cycle hardware is essential.
-
KUKA AG (Germany) — Focused on complex automation tasks, KUKA targets welding, assembly, and handling tasks in constrained, marine-specific environments. Strategy implication: attractive where systems require deep application engineering and advanced path planning.
-
Yaskawa Electric Corporation (Japan) — Delivers Motoman robots with proven arc-welding performance, emphasizing reliability in heavy industrial settings. Strategy implication: strong candidate for retrofit and hybrid human-robot workflows.
-
Kawasaki Heavy Industries (Japan) — Combines robotics with heavy machinery expertise, useful for painting, structural assembly, and integrated production lines. Strategy implication: well-suited for yards integrating robotics across multiple production stages.
-
KRANENDONK (Netherlands) — Specialist provider of intelligent automation for panel, block, and pipe fabrication with adaptive gantries for non-repetitive work. Strategy implication: an option for yards with high product variability.
-
Inrotech (Lincoln Electric, Denmark) — Offers adaptive mobile welding systems that minimize programming requirements and work well in high-variation welding environments. Strategy implication: reduces dependence on high-end programming expertise for variable joints.
-
GrayMatter Robotics (USA) — An AI-driven provider focused on surface preparation, grinding, coating, and inspection; notable for partnerships with naval shipbuilders. Strategy implication: strong for modernization programs emphasizing physical-AI surface workflows.
-
Path Robotics (USA) — Supplies autonomous welding cells driven by physical AI and is active in naval and commercial shipbuilding partnerships. Strategy implication: attractive for programs seeking high autonomy levels in welding operations.
Competitive implications: expect consolidation around systems integrators that can bundle hardware, domain software, and lifecycle services. At the same time, niche innovators that solve discrete pain points — for example, adaptive welding in variable-joint environments or AI-driven surface preparation — can capture premium value through services and repeatable IP.
Recent Industry Signals and Their Strategic Consequences
-
Defense primes integrating physical AI : Partnerships and MOUs in 2026 between major shipbuilders and physical-AI vendors signal naval shipbuilding is accelerating automation adoption to address both labor shortages and production tempo. For commercial yards, these moves lower adoption risk by validating performance at scale.
-
Research and public funding : Multi-million-dollar grants for AI and digital-twin development reinforce a longer-term ecosystem bet on reducing the impact of design deviations and accelerating design-for-assembly approaches.
-
Cost structure evolution : Declines in force-torque sensor pricing and modular controller designs reduce entry barriers for advanced force-guided tasks, enabling more yards to trial collaborative robotic cells for tasks previously considered too complex or costly.
Actionable Recommendations for 2026 Decision-Makers
-
Prioritize pilot projects that de-risk integration — Select two to three high-value, repeatable tasks (e.g., arc welding of repetitive seams, automated surface prep for coatings) and run 6–12 month pilots coupled with TCO measurement and operator upskilling plans.
-
Structure procurement around lifecycle outcomes — Negotiate SLAs that include uptime guarantees, spare parts provisioning, and application engineering hours rather than procuring hardware alone.
-
Develop partnership ecosystems — Combine hardware incumbents with AI-focused integrators and local systems integrators to accelerate knowledge transfer and preserve operational control.
-
Invest in workforce transition — Channel savings from productivity gains into reskilling programs that transition welders and assemblers into robotic operators and QA specialists.
-
Adopt a phased capital plan — Use staged CAPEX aligned to milestone-driven scale-ups to avoid oversized initial investments and to incorporate insights from early pilots into broader rollouts.
Methodology and What’s Behind the Curtain
The study synthesizes historical market activity from 2020–2025 with field interviews, vendor financials, procurement data, and company disclosures. The forecast through 2032 blends bottom-up adoption modeling with scenario-driven macro assumptions around labor availability, policy interventions, and component-cost curves. Concentration metrics and vendor profiles are derived from cross-validated revenue estimates and primary research.
In keeping with the “trailer” principle — designed to provide strategic clarity while preserving actionable granularity for report subscribers — this article highlights the central trends, competitive dynamics, and pragmatic frameworks you need for 2026 decisions. Detailed segment-level breakouts, region-application revenue splits, and vendor-specific market share figures are reserved for the full report and interactive data tools.
Next Steps
For procurement directors, strategy teams, and investors evaluating robotics programs in shipbuilding, PW Consulting’s Robotics in Shipbuilding Market report provides the playbook to convert market momentum into measurable production outcomes. To access the full segment-level analysis, proprietary vendor scorecards, and scenario TCO models, visit the report page or contact a PW Consulting industry specialist to request an executive briefing and sample modules tailored to your operational context.
For detailed analysis of this topic, please visit the official page: Robotics in Shipbuilding Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Real Time Shelf Monitoring System Market to Grow at 13.52% CAGR, Reshaping Retail Analytics by 2032
By PW Consulting, 2026-07-06
Real Time Shelf Monitoring System Market: Strategic Outlook and Decision Framework for 2026
Executive snapshot
By 2025 the real time shelf monitoring system market has transitioned from an emerging automation niche into a mainstream operational capability for retailers and CPG companies. Our base-year analysis (2025) situates the market at a meaningful industry scale, after growing from a modest foundation in 2020. The forecast period (2026–2032) anticipates sustained expansion at a compound annual growth rate (CAGR) of 13.52%, taking the market through the next phase of commercialization, platform consolidation, and cross‑channel integration. For leaders making procurement, architecture and partnership decisions in 2026, this report translates growth dynamics into executable choices — balancing speed-to-shelf visibility with long-term interoperability, privacy compliance and total cost of ownership.
Real Time Shelf Monitoring System Market
Why this report matters for 2026 decision-makers
-
Timing investments: Understand when to pilot, when to scale, and how product roadmaps align with a market expanding at double-digit CAGR — so capital allocation and pilots de‑risk rather than chase hype.
Real Time Shelf Monitoring System Market -
Technology mix: Decide the right blend of sensing technologies (vision, weight/pressure sensing, RFID and hybrid approaches) for different store formats and SKU densities without over-investing in marginal precision.
Real Time Shelf Monitoring System Market -
Vendor selection: Benchmark prospective suppliers on product maturity, integration pathways, deployment velocity and data governance — not just on sample accuracy metrics.
-
Operational integration: Translate shelf-level signals into replenishment and merchandising workflows, defining SLAs and automation thresholds that deliver measurable uplift in on-shelf availability and customer experience.
-
Regulatory and privacy readiness: Build GDPR- and regional-compliance into deployments from day one, minimizing late-stage remediation costs and reputational risk.
What’s inside the report — practical assets for immediate use
Beyond narrative analysis and trend synthesis, the report is designed as a practitioner’s toolkit for 2026 rollouts. Key deliverables include:
-
Deployment playbooks for pilots and scale-ups: step-by-step timelines, resource plans, and milestone-based decision gates tailored to store formats ranging from convenience to large-format grocery.
-
Vendor selection scorecards and RFP templates that weight accuracy, integration effort, edge processing capability, update cadence and data ownership.
-
ROI and TCO modelling templates in Million USD units, enabling scenario analysis for SaaS, CapEx, and hybrid pricing models across typical multi-site rollouts.
-
Integration patterns and API reference architectures for ESL (electronic shelf label) linkages, POS/EPOS, IMS/WMS and ERP systems, plus recommended message schemas and latency targets.
-
Privacy and compliance checklists, including camera placement best practices and anonymization standards that reflect recent vendor approaches to GDPR-sensitive designs.
-
Operational KPIs and dashboard blueprints: recommended leading and lagging indicators, alerting thresholds, and business rules to convert shelf events into replenishment actions.
Market dynamics shaping 2026 choices
Three structural dynamics will determine winners and losers over the next two years.
-
Convergence of sensing and software platforms. Vendors are moving from single-sensor propositions toward software-centric platforms that ingest multiple sensor streams (video, weight sensors, RFID, robotic scans) and normalize events into a common SKU-level view. This trend favors suppliers that can demonstrate robust edge processing and a clear path to systems integration.
-
Commercialization of robotics and continuous scanning. Autonomous shelf scanners and robotic platforms are shifting the cadence of visibility from episodic audits to near-continuous monitoring. Recent product refreshes extend runtime and edge AI capabilities, increasing the frequency of high-quality shelf data and changing replenishment economics.
-
Regulation and standards driving solution design. Privacy-preserving camera architectures and ESL integration patterns are becoming de‑facto expectations in regulated markets. Vendors that embed compliance and standards-based interoperability into their architectures reduce deployment friction and procurement cycles.
Market concentration metrics indicate a moderate level of fragmentation: leading groups occupy meaningful but not dominant combined shares, leaving room for specialized entrants and regional champions while underscoring the importance of vendor due diligence.
Competitive landscape — positioning and strategic implications
-
Trax Retail (HQ: Singapore; major office Boston) — A mature provider of AI-powered image recognition and planogram-compliance analytics. Trax’s strengths lie in retail execution analytics and brand-focused insights. Strategic implication: best considered when planogram compliance and CPG execution are primary KPIs.
-
Focal Systems (HQ: USA) — Offers integrated shelf cameras and a Shelf AI platform tuned for out-of-stock detection and automated replenishment. Strategic implication: attractive for retailers prioritizing a tight replenishment loop and fast edge-to-cloud inference.
-
Pensa Systems (HQ: Austin, Texas) — Vision AI specialist expanding into end-to-end retail supply chain coverage, including back-room and warehouse visibility. Strategic implication: suitable for organizations seeking a single analytics stack across store and supply-chain telemetry.
-
Vispera (HQ: Istanbul) — Delivers image-recognition shelf monitoring optimized for rapid deployment in diverse geographies. Strategic implication: a candidate for multi-market rollouts where deployment speed and retargeting are priorities.
-
VusionGroup / SES-imagotag (HQ: France) — Integrates mini-cameras with electronic shelf labels (Captana), emphasizing privacy-aware, always-on shelf visibility. Strategic implication: best for retailers investing in ESL infrastructure and seeking seamless price-and-stock synchronicity.
-
Simbe Robotics (HQ: San Francisco) — Robotics-led approach with autonomous Tally units and a Store Intelligence platform. Recent iterations focus on longer runtimes and improved edge AI. Strategic implication: compelling for large-format chains seeking high-frequency, wide-coverage scans with limited store staff intervention.
-
ParallelDots (HQ: India) — Offers ShelfWatch AI with global operations; a cost-competitive image-recognition option with focus on CPG and retail execution. Strategic implication: useful for price-sensitive pilots and regional scale.
Recent vendor developments are informative for procurement timing: platform expansions into supply-chain contexts and robotics product refreshes materially change the ROI calculus for 2026 deployments. Buyers should map vendor roadmaps against their own scaling timelines to avoid mid-course integration mismatches.
Strategic recommendations for 2026 procurement and deployment
-
Run a two-stage procurement: a focused 3–6 month pilot to validate accuracy and operational integration, followed by a phased rollout tied to clear replenishment KPIs and financial gates.
-
Adopt hybrid architectures: combine edge inference for latency-sensitive alerting with cloud analytics for cross-store pattern detection, ensuring bandwidth and privacy constraints are respected.
-
Define data ownership and monetization policies up front. Clarify how SKU-level data is shared with CPG partners, anonymized and stored, and what commercial arrangements govern insights sharing.
-
Incentivize suppliers on business outcomes, not only technical accuracy. Link a portion of commercial terms to improvements in on-shelf availability, reduced shrink, or increased sales lift attributable to shelf visibility.
-
Plan ESL and ERP integration in year-one roadmaps if pricing parity and automated price updates are strategic; otherwise define clear manual fallbacks to avoid operational friction.
-
Prioritize privacy-preserving designs in regulated markets. Request vendor evidence of anonymization architecture and compliance mechanisms during RFP evaluation.
Checklist — questions executives should insist vendors answer
-
What is your edge vs cloud inference split, and how does that impact latency, bandwidth and cost?
-
How do you ensure GDPR-compliant camera deployments and avoid capturing PII? Can you provide design artifacts or certifications?
-
What is your ESL and POS integration approach, and do you support standard protocols or require custom adapters?
-
How do you measure and warranty SKU-recognition accuracy in live store conditions, and what are your dispute-resolution mechanisms?
-
What SLAs do you offer for uptime, model update cadence and data delivery, and how are those SLAs priced?
-
Can you provide references for rollouts of comparable scale and complexity to our planned deployment?
Closing — how to use this analysis in 2026
For executives planning investments in 2026, the choice is not simply which sensor to buy but how to convert shelf telemetry into durable operational advantage. The market is expanding quickly — driven by advances in computer vision, robotics and systems integration — but it remains sufficiently fragmented that thoughtful procurement, staged pilots and outcome-based contracting will disproportionately separate success from failure.
Our full report contains the granular segmentation, vendor scoring matrices, downloadable TCO/ROI models (in Million USD units), and the proprietary datasets that informed our forecasts. To examine the detailed breakdowns, compare vendor scorecards side-by-side, and access the templates you can operationalize immediately, please consult the full Real Time Shelf Monitoring System Market report on PW Consulting’s portal.
For detailed analysis of this topic, please visit the official page: Real Time Shelf Monitoring System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Lowdk Glass Fiber Cloth Market Set for 8.15% CAGR During 2026–2032
By PW Consulting, 2026-07-06
Lowdk Glass Fiber Cloth Market: Strategic Imperatives for 2026 — PW Consulting Advance Brief
PW Consulting’s latest industry briefing on the Lowdk Glass Fiber Cloth market synthesizes five years of historical trends (2020–2025) and delivers a forward-looking forecast through 2032. The market’s structural momentum — underpinned by AI-driven demand for high-frequency, low-loss substrates — presents a compelling growth opportunity for executives planning investments, capacity moves, M&A, and go‑to‑market strategies in 2026. Below we summarize the strategic takeaways and the reasons why the full report should be a required input into board- and strategy-level decision-making this year.
Lowdk Glass Fiber Cloth Market
Market Trajectory: Macro Picture and Growth Dynamics
Our model (base year 2025) shows the Lowdk Glass Fiber Cloth market has entered a sustained growth phase. After passing an estimated USD 625.5 Million in 2025, the market is projected to expand at a compound annual growth rate of approximately 8.15% across the 2026–2032 forecast window, reaching an anticipated USD 1,082.5 Million by 2032. The dataset includes a consistent historical series (2020–2025) and a granular, scenario-based projection for 2026–2032 that incorporates demand pull from AI servers, 5G infrastructure, and next‑generation automotive radar and IC packaging.
Lowdk Glass Fiber Cloth Market
Two structural forces drive the growth profile: (1) product substitution toward ultra-low dielectric materials in high-speed digital and RF applications, and (2) a concentration effect where a relatively small set of specialized suppliers capture a disproportionate share of advanced-spec demand. Our concentration analysis indicates the market is moderately consolidated at the top: the leading three suppliers account for a majority share, and the top five capture an even larger portion of advanced product supply — important context for supply risk and competitive positioning.
Lowdk Glass Fiber Cloth Market
Why This Report Matters for 2026 Decisions
- Capital allocation and timing: With mid‑to‑high single-digit CAGR and pronounced short‑term supply tightness in advanced low‑Dk and low‑CTE materials, the timing of capacity investments materially affects return on invested capital. The report’s capital‑project stress-tests and lead‑time scenarios enable CFOs and investment committees to compare accelerated vs. staged expansions under practical price and yield assumptions.
- Supply‑chain risk management: Supplier concentration and regional exposure create geopolitical and operational risk. Our risk matrix quantifies exposure by supplier tier and proposes mitigation levers — dual sourcing, strategic inventory, and supplier co-investment — that materially reduce disruption odds for a 2026 product ramp.
- Pricing and margin modeling: ASP differentials between commodity E‑glass and advanced low‑Dk varieties are substantial. The report includes margin waterfall analyses for NE‑glass, NER‑glass and ultra‑low‑loss grades that help commercial teams set premiums while preserving share in volume-sensitive accounts.
- Go‑to‑market and channel design: As demand moves from commodity laminates to engineered cloths for IC substrates, manufacturers must evaluate direct OEM engagement versus distributor-led models. Our sales motion playbooks are tailored to both incumbent fabricators and new entrants pursuing high-margin IC substrate segments.
Practical Contents — What the Report Provides (Operational, Not Just Theoretical)
- Proprietary demand model (2020–2032) with scenario toggles for AI server intensity, 5G capex cycles, and automotive electrification uptake.
- Supply‑side capacity mapping and lead‑time sensitivity analysis that isolates critical bottlenecks through mid‑2027.
- Price and cost benchmarking with margin impact models across glass types and fabric constructions (commercially actionable ASP and cost drivers are included in the full report).
- Strategic playbooks for capacity expansions, joint ventures, technology licensing, and geographic diversification—each with a pragmatic implementation roadmap and KPI templates.
- M&A playbook focused on bolt‑on targets and technology acquisitions, including valuation templates that reconcile current multiples to projected demand profiles.
- Supplier due‑diligence checklists and an RFP template for procurement teams evaluating advanced low‑Dk material partners.
Note: In keeping with PW Consulting’s “preview” approach, detailed segment tables, site‑level capacity numbers, and client‑ready Excel modules are intentionally omitted from this brief. Access to the full dataset and interactive models is available through the complete report.
Competitive Landscape — Who Matters and Why
The advanced Lowdk Fabric market is shaped by a mix of integrated incumbents, specialty fiber producers, and agile regional fabricators. Key strategic players we profile in the report include longstanding integrated manufacturers that control upstream glass production and newer, nimble firms expanding capacity in demand regions. Recent strategic moves underscore shifting power dynamics:
- Integrated Japanese and Taiwanese suppliers continue to set technical benchmarks for ultra‑low dielectric and low‑CTE offerings; they hold a sizeable portion of advanced specs and maintain preferential relationships with high‑end PCB and IC substrate producers.
- North American specialty fiber producers are investing to secure local supply for on‑shore semiconductor and AI server demand, narrowing geographic risk and shortening lead times for regional customers.
- Regional fabricators and weavers, through partnerships and local capacity expansions, are capturing read‑to‑laminate demand in fast-growing production corridors.
Strategic implications: incumbents benefit from vertical integration and technical moats but are exposed to raw‑material supply constraints and price volatility. New entrants and incumbent fabricators can win commercial traction by optimizing lead times, developing close OEM partnerships, and differentiating on process yields rather than raw material cost alone.
Industry Signals and Recent Developments — What To Watch in 2026
- Price normalization is unlikely in the short term. Leading material suppliers implemented sizeable premium adjustments in 2025 and signaled additional increases in early 2026 amid tightness in advanced yarn supply. Businesses that assume stable ASPs risk margin compression when launching new product lines.
- Capacity expansion announcements and strategic partnerships are accelerating, particularly in North America and select APAC locations. These moves are intended to support semiconductor and AI server ecosystems and to reduce regional supply exposure.
- Lead times for advanced low‑Dk and low‑CTE fabrics remain extended and are expected to persist until mid‑2027 unless incremental brownfield capacity is commissioned faster than currently signaled.
- Order‑of‑magnitude price differentials between commodity glass and advanced low‑Dk glass mean product selection and qualification timelines will materially affect TCO for OEMs moving to next‑generation boards and substrates.
- Geopolitical dynamics and supply concentration in Taiwan and Japan continue to influence corporate decisions around localization and redundancy; manufacturers are evaluating southward CCL strategies and cross‑border collaborations to de‑risk supply chains.
Actionable Strategic Recommendations for 2026
- Prioritize secure supply pathways: Enter multi‑year purchase agreements with tier‑1 suppliers or structure co‑investment arrangements to lock in capacities and preferential lead times. For firms unable to secure long‑term allocations, plan for strategic inventory buffers calibrated against cost of capital and product shelf life.
- Stage capacity investments: Use a staggered investment profile with milestone‑based capital release. This reduces exposure to short‑cycle ASP volatility while preserving market access as demand materializes.
- Accelerate qualification timelines: Parallelize materials qualification with system integration workstreams to shorten time‑to‑revenue for new builds. The report includes a practical 9–12 month qualification checklist that can be executed by small cross‑functional teams.
- Leverage partnerships for speed: Consider technology partnerships or toll‑manufacturing arrangements with established weavers to gain fast access to low‑Dk fabrics without upfront plant risk.
- Hedge through product differentiation: Move up the value chain by developing fabric constructions and resin integrations tailored for high‑value applications (e.g., AI server interposers, high‑frequency CCLs) where ASP premiums and margin sustainability are highest.
- Embed geopolitical scenario planning: Maintain at least two qualified supply sources across political geographies for critical grades and develop contingency plans for southward shifts in CCL and fabrication footprints.
Concluding Note — Where PW Consulting Adds Immediate Value
For 2026, the Lowdk Glass Fiber Cloth market will reward surgical strategic moves: well‑timed investments, supplier certainty, and product differentiation. PW Consulting’s full report provides the operational playbooks, quantitative models, and supplier insights needed to translate market growth into durable competitive advantage. This brief is intentionally selective — the full deliverable contains the data‑rich modules, scenario analyses, and executable templates that boards and executive teams need to move from strategy to implementation.
To obtain the complete dataset, granular segmentation tables, and the interactive financial model referenced in this brief, please consult the full PW Consulting report or contact our industry advisory team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Lowdk Glass Fiber Cloth Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


