



Category: IT & Electronics
PW Consulting: Real Time Shelf Monitoring System Market to Grow at 13.52% CAGR, Reach USD 2,729.75 Million by 2032
By PW Consulting, 2026-07-06
Real Time Shelf Monitoring Systems: Strategic Imperatives for 2026 — Executive Preview from PW Consulting
Introduction
Retail shelf intelligence has moved from experimental pilots to enterprise-grade operations. PW Consulting's latest market study — anchored on a 2025 base year with historical coverage from 2020–2025 and a forward-looking forecast across 2026–2032 — shows the Real Time Shelf Monitoring System market evolving into a high-growth strategic layer within retail and CPG operations. The market reached an inflection point in 2024–2025 and is projected to sustain a high-teens/low-double-digit compound annual growth trajectory through 2032 (projected CAGR ~13.5% for the forecast window). This briefing highlights the report’s strategic utility for executives preparing decisions in 2026, outlines actionable takeaways, and sketches competitive and regulatory dynamics that will shape vendor selection, integration, and ROI realization.
Real Time Shelf Monitoring System Market
Why 2026 Is a Pivotal Year for Decision-Makers
Several simultaneous trends push shelf monitoring from “nice-to-have” to “mission-critical” for retailers, consumer goods companies, and systems integrators in 2026:
Real Time Shelf Monitoring System Market
- Operationalization of computer vision and edge AI that enables continuous, store-level decision automation rather than episodic audits.
- Proven cost-to-value inflection where deployments deliver measurable lift in on-shelf availability, promotional execution, and shrink reduction across multi-format retail estates.
- Interoperability advances — notably with electronic shelf labels (ESL) and existing POS/inventory systems — that unlock downstream use cases (dynamic pricing, automated replenishment triggers).
- Privacy and regulatory considerations — particularly in GDPR-influenced markets — which have catalyzed new product designs that prioritize shelf-only capture and anonymization.
For 2026 planning cycles, these forces mean procurement and technology roadmaps must be redesigned to treat shelf monitoring as an integrated node in retail execution and supply chain orchestration rather than a siloed analytics tool.
Real Time Shelf Monitoring System Market
Market Trajectory — A Macroeconomic Snapshot
Over the 2020–2025 historical period the market scaled rapidly, reflecting accelerating adoption across retail formats and geographies. With a 2025 base year firmly established, our forecast through 2032 projects consistent expansion at a ~13.5% CAGR, driven by broader automation initiatives at retail chains, increased investments by CPG brands in direct-store analytics, and continued improvements in vision AI accuracy and deployment economics.
Two implications for enterprise planning:
- Budgeting: Capital and operating expenditures for shelf monitoring should be treated as multi-year programs with phased rollouts and measurable KPIs linked to sales uplift, lost-sales avoidance, and labor redeployment.
- Vendor strategy: As the market grows, so does vendor differentiation — procurement teams must evaluate not only accuracy claims but integration maturity, scalability, and compliance design.
What the Full PW Consulting Report Contains (Practical, Actionable)
The complete report is structured to support immediate decision-making. Highlights include:
- Executive playbooks for pilot-to-scale roadmaps: step-by-step guidance on proof-of-concept design, KPI selection, pilot sizing, and staged rollouts across store formats.
- Integration checklists: practical technical requirements and data schemas to integrate shelf monitoring outputs with POS, inventory management, ERP, and ESL systems.
- Vendor selection matrix: multi-dimensional scoring that weighs detection accuracy, latency, edge vs. cloud processing, hardware lifecycle economics, and privacy-by-design features.
- Commercial models and ROI templates: templated TCO/ROI calculators that allow teams to model outcomes under conservative, base, and aggressive scenarios over typical multi-year horizons.
- Use-case playbooks: prioritization frameworks to select high-impact use cases (e.g., on-shelf availability recovery, execution compliance for high-margin promotions, automated replenishment triggers) and operational KPIs to track.
- Compliance and risk framework: practical steps for GDPR-aligned deployments, employee and shopper privacy protections, and vendor contractual language to mitigate data governance risk.
- Implementation case studies and lessons learned: anonymized, reproducible examples showing how leading retailers converted pilot data into sustained operational improvements.
Note: the public preview intentionally omits granular region/application split figures and vendor-specific revenue breakdowns; these are detailed in the subscriber dataset and interactive models available through the PW Consulting report portal.
Competitive Landscape — Who Matters and Why
The market balance reflects a mix of specialized vision-AI vendors, robotics providers, and edge-hardware integrators. Market concentration metrics indicate moderate aggregation among the top-tier vendors, with the three largest firms accounting for a significant share of commercial deployments and the top five increasing that reach further. This concentration influences procurement dynamics: incumbent relationships, integration depth, and field-proven scale become differentiators beyond raw algorithmic accuracy.
- Trax Retail (Singapore / Boston) — A long-standing player in image recognition and planogram compliance. Trax’s strength is its enterprise-scale analytics stack and deep retail execution insights, making it a common choice for CPG companies seeking shelf-level visibility aligned to broader execution KPIs.
- Focal Systems (USA) — Focused on shelf cameras and a Shelf AI platform that emphasizes real-time out-of-stock detection and automated replenishment. Focal positions itself on the integration of camera hardware with operational workflows.
- Pensa Systems (Austin, TX) — Known for Vision AI targeted at CPG brands and retailers. Recent platform expansions indicate a strategic move from shelf monitoring toward full retail supply chain visibility, opening new revenue pathways in back-room and warehouse intelligence.
- Vispera (Istanbul) — Offers image recognition-based Shelfsight with strengths in flexibility of camera deployments and regional expansion across emerging retail markets.
- VusionGroup (SES-imagotag) (France) — Integrates mini wireless cameras with electronic shelf labels (ESL), emphasizing a combined hardware+software approach that links real-time shelf imagery with pricing and product metadata while addressing privacy constraints.
- Simbe Robotics (San Francisco) — Differentiated by an autonomous robot approach (Tally) that provides systematic, frequent aisle scans. Recent product iteration (Tally 4.0) extends runtime and edge AI capabilities, improving cadence of shelf data capture.
- ParallelDots (India) — A global operator with a vision-platform approach focused on adaptable deployment models for both retailers and CPGs, competing on cost and regional implementation agility.
Recent vendor developments underscore strategic trajectories: Pensa’s platform expansion into full supply chain contexts (April 2026) and Simbe’s Tally 4.0 launch (January 2026) illustrate two paths to scale — horizontal platform breadth versus hardware-led frequency and operational depth.
Regulatory and Standards Considerations
Privacy and interoperability are no longer afterthoughts. Leading deployments incorporate privacy-by-design architectures that avoid imaging individuals, retain only shelf-relevant metadata, and support data minimization to comply with GDPR and equivalent frameworks. VusionGroup’s Captana product is a prominent example of GDPR-aware design in live deployments.
Standards alignment with ESL systems is accelerating: real-time linkage between shelf imagery, product metadata, and ESLs enables synchronized price and availability signals. Vendors and retailers that master these integrations will unlock compounding value through automated promotional execution and near-real-time price optimization.
Actionable Strategic Recommendations for 2026
- Reframe investment: Treat shelf monitoring as an operational node. Budget for phased rollouts with defined KPI gates and integrating expenditures for systems and change management, not just sensor hardware.
- Select vendors for ecosystems, not point features: Prioritize vendors that demonstrate field-scale integrations with POS, inventory, ESL, and replenishment systems. Request references that match your store formats and operational cadence.
- Build privacy and compliance into the procurement checklist: include contract clauses on data retention, purpose limitation, and third-party auditing to avoid late-stage rework and regulatory exposure.
- Define success with cross-functional KPIs: link shelf monitoring metrics to revenue, lost-sales reduction, promotional compliance uplift, labor redeployment outcomes, and inventory turns.
- Invest in change management and analytics enablement: raw shelf data does not equal impact. Plan training, data pipelines, and decision workflows to convert signals into automated or human-in-the-loop actions.
What PW Consulting’s Full Report Enables
The full PW Consulting report supplies the quantitative backbone and operational playbooks needed to move from strategy to execution in 2026. Subscribers gain access to:
- Interactive scenario models calibrated to your region and store mix (subscriber-only dashboards).
- Vendor scorecards and negotiation levers based on real deployment economics.
- Detailed playbooks for pilot design, rollout cadence, and governance structures that reduce time-to-value.
Our aim is to empower procurement leads, CIOs, retail operations heads, and CPG customer teams to make confident, measurable choices during the critical 2026 planning window.
Closing — Navigating the Next Phase
The Real Time Shelf Monitoring System market is entering a phase where execution excellence, integration depth, and privacy-aware design determine winners. With a strong macro growth trajectory and demonstrable operational benefits, 2026 is the year executive teams must convert interest into disciplined programs. PW Consulting’s full report contains the proprietary datasets, vendor evaluations, ROI templates, and implementation playbooks that senior leaders need to accelerate impact. For organizations deciding on scale, partner selection, and integration strategies this year, the path forward is clear: move beyond pilots, standardize on interoperability and compliance, and measure shelf monitoring by business outcomes — not just technical accuracy.
Access to the complete dataset and subscriber-only tools is available through the PW Consulting report portal. Download the full study to review detailed regional and application breakdowns, vendor revenue analyses, and customizable ROI models to inform your 2026 strategy.
For detailed analysis of this topic, please visit the official page: Real Time Shelf Monitoring System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Lowdk Glass Fiber Cloth Market Poised to Grow at an 8.15% CAGR During 2026–2032
By PW Consulting, 2026-07-06
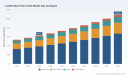
Lowdk Glass Fiber Cloth Market: Strategic Imperatives for 2026
PW Consulting’s new market study on Lowdk Glass Fiber Cloth provides a forward-looking playbook for executives making high-stakes capital, sourcing, and product decisions in 2026. Anchored on 2025 as the base year and spanning historical analysis from 2020–2025 with a forecast through 2032, the report synthesizes macro growth drivers, supplier dynamics, and tactical levers that determine commercial outcomes in a market growing at a compound annual rate of approximately 8.15%.
Lowdk Glass Fiber Cloth Market
Why 2026 is a Pivotal Year
2026 sits at the inflection between immediate capacity shocks and longer-term structural demand led by AI servers, high-performance networking, and next-generation wireless infrastructure. Our models show the total market continuing an uninterrupted expansion from the mid-2020s into the early 2030s, reflecting durable secular demand for ultra low-loss, low-dielectric and low-CTE glass fabrics used in advanced PCBs, IC substrates, and high-frequency interconnects.
Lowdk Glass Fiber Cloth Market
-
Base-year anchoring and scenario-ready outputs: The report uses 2025 as the quantitative anchor and projects through 2032. Readers receive scenario-adjusted revenue curves and sensitivity testing keyed to key inflection points in supply and end-market adoption.
Lowdk Glass Fiber Cloth Market -
Decision horizons mapped to execution windows: We translate the market’s growth trajectory into recommended windows for capex, inventory accumulation, and contractual commitments, aligning procurement and manufacturing timelines with predicted relief in supply constraints.
Market Dynamics: What Is Driving Growth — and What Could Stall It
The structural demand story is clear: the Lowdk glass fiber cloth market is being pulled by higher-performance compute and communications architectures that require progressively lower dielectric constants and tighter thermal-mechanical behavior. This creates a sustained premium tier of materials where average selling prices and margins significantly outpace standard electronic glass products.
-
Demand-side acceleration: AI training clusters, high-speed servers, and next-wave 5G/6G radio and backbone equipment are principal drivers. These end-markets have shifted supplier selection from cost-first to performance-first for critical dielectric and CTE properties.
-
Supply-side constraints: Lead times for advanced low-Dk and low-CTE products have lengthened materially, with capacity tightness expected to persist into mid-2027. Capacity additions will matter less than technology parity: not all new meters of fabric can meet ultra-low-loss specifications.
-
Price dynamics and margin segmentation: Premium glass variants carry a multiple of the ASP of commodity E-glass; the gulf between standard and specialty materials fuels supplier profitability but raises procurement risk for OEMs and CCL makers.
-
Geopolitics and localization: High-end supply remains concentrated among Taiwanese and Japanese producers. Recent southward capacity initiatives and cross-border collaborations are beginning to mitigate geographic concentration, but geopolitical risk and customer preference for supply proximity will continue to influence sourcing strategies.
Competitive Landscape: Who Matters and Why
The competitive map is a mix of integrated glassmakers, specialty fiber producers, and nimble fabricators. Market concentration is meaningful at the top end, with the leading firms collectively controlling a majority share of the advanced product segment — a structural feature that creates both supply-side leverage and opportunities for vertically aligned competitors.
-
Nittobo (Nitto Boseki Co., Ltd.): A Tokyo-based integrated leader that retains dominant positions in advanced NE- and T-glass categories used for high-frequency PCBs and IC substrates. Their product breadth and control over fiber-to-cloth integration make them a bellwether for pricing and availability.
-
AGY: The U.S. specialty glass player is scaling capacity in Aiken, South Carolina, while advancing L-Glass variants targeted at AI-PCB and semiconductor packaging use cases. Recent investments and a partnership to produce North America’s first low-CTE fabric position AGY as a pivotal local source for Western supply chains.
-
Taiwan Glass, Fulltech, and Nan Ya: Taiwanese fabricators are expanding high-end production to capture AI-driven demand. Their proximity to major CCL and PCB clusters and investments in high-performance lines make Taiwan a continued heartland for advanced substrates.
-
Regional fabricators and integrators: Players in China and other Asian markets are expanding scale rapidly. New large electronic glass fiber and fabric lines are coming online, which will increase volume availability but require tight quality governance to meet the top-tier electrical and mechanical tolerances.
Recent industry moves underline the strategic momentum: product launches of next-generation low-dielectric fibers, targeted capacity investments, and cross-company partnerships to localize high-margin fabrics. These developments are creating a bifurcated market where access to validated, high-performance supply chains is a competitive moat.
What the PW Consulting Report Contains: Practical, Executable Tools
Beyond market sizing and forecasts, the report delivers actionable tools that procurement, C-suite, and business development teams can use immediately:
-
Supplier decision matrix: A weighted, validated scorecard covering technical capabilities, capacity timing, geographic resilience, and price elasticity for key suppliers — designed to shorten vendor selection cycles.
-
Capex and inventory timing model: Scenario-driven guidelines for when to commit to brownfield expansions vs. third-party tolling, and recommended buffer inventories by risk profile.
-
Product-roadmap alignment: Mapping of substrate performance thresholds to product architectures — enabling OEMs to prioritize which cloth grades to qualify for near-term designs versus long-range R&D investments.
-
Commercial playbooks: Negotiation levers for buyers, including contractual structures to hedge ASP volatility, joint development arrangements, and tiered pricing linked to verified material performance.
-
M&A and partnership screening: A pragmatic framework for evaluating bolt-on acquisitions or strategic alliances that accelerate route-to-market for specialty fabrics or secure proprietary yarn supply.
-
Regulatory & geopolitical stress tests: Trade-scenario simulations and contingency plans that account for regional concentration of high-end supply and potential export controls.
Strategic Recommendations for 2026
For executives who must act this year, our top-line recommendations are:
-
Prioritize qualification with multiple validated suppliers across geographies: Dual-sourcing reduces execution risk but must be balanced against qualification costs and yield fragmentation.
-
Target selective vertical integration or exclusivity deals for mission-critical cloth grades: Where margin and performance upside are significant, securing priority of supply through equity, JV, or long-term offtake makes commercial sense.
-
De-risk supply by front-loading critical inventory in H1 2026 when justified by end-market backlog and contractual protections — but avoid broad-based stockpiling that locks capital inefficiently.
-
Invest in materials validation capability: Companies that can reduce qualification time from months to weeks gain decisive commercial advantage in a tight market.
-
Monitor ASP dynamics and prepare tiered pricing strategies: Given the steep price dispersion between commodity and specialty glass, price pass-through strategies and product-tier governance are essential.
Implementation Playbooks
PW Consulting provides short-form playbooks tailored by buyer archetype:
-
OEMs & Tier-1s: Fast-track material co-development with a shortlist of high-quality suppliers; condition long-term supply agreements on performance milestones to protect pricing.
-
Material producers: Prioritize capital allocation to lines that materially improve dielectric and CTE performance rather than pure tonnage, and pursue partnerships that provide downstream validation pathways.
-
Private equity & corporate development teams: Use our M&A screening to identify targets that offer unique yarn-to-cloth IP or localized production capability in strategically important geographies.
How This Report Creates Strategic Value
Our study combines granular technical understanding with commercial analytics: it quantifies growth at the total-market level, models capacity cadence, simulates price pathways, and translates these into operationally useful decisions. The report’s strength lies in shaping the tactical choices — timing of investments, supplier prioritization, and contract structures — that materially affect P&L outcomes through 2028 and beyond.
Note: This press article highlights core market architecture, dynamics, and strategic takeaways. Detailed regional and application splits, proprietary price curves, and company-level revenue assumptions are intentionally withheld from this release to preserve the report’s role as a working tool for subscribing clients.
Recent Industry Signals Worth Watching
-
Product innovation and upstream supply: New low-dielectric fiber introductions and yarn-level product launches are shortening the path to higher-performance fabrics for semiconductors and AI servers.
-
Regional capacity & partnerships: Announced investments and strategic partnerships are accelerating local supply options in North America and Asia; these will reshape logistics, qualification lead times, and local sourcing economics.
-
Price and lead-time volatility: Expect ongoing ASP pressure for premium grades and extended lead times through mid-2027, requiring buyers to adopt more sophisticated hedging and contractual protections.
Next Steps
For strategic teams preparing capital plans and procurement strategies in 2026, PW Consulting’s Lowdk Glass Fiber Cloth report is a decision-ready resource. The full report contains the numerical deep-dive, supplier scorecards, and executable templates referenced in this release. To access the complete dataset, model files, and tailored advisory sprints, please visit our official report page.
PW Consulting — turning market complexity into operational advantage for leaders in materials, electronics, and advanced manufacturing.
For detailed analysis of this topic, please visit the official page: Lowdk Glass Fiber Cloth Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Retail Supply Chain IT Transformation Market Poised to More Than Double to USD 27.99 Billion by 2032 (9.85% CAGR)
By PW Consulting, 2026-07-06
Supply Chain IT Transformation Services for Retail: Strategic Imperatives for 2026
PW Consulting’s latest market research — Supply Chain IT Transformation Services for Retail Market (base year 2025, forecast 2026–2032) — is designed as an operational playbook for retail leaders making pivotal investment decisions in 2026. The research synthesizes market dynamics, vendor capabilities, regulatory pressures and pragmatic implementation guidance so executives can convert digital supply chain intent into measurable outcomes. This briefing summarizes the report’s strategic value and points executives to the specific modules in the full study that will accelerate decision-making and de-risk program delivery.
Supply Chain IT Transformation Services for Retail Market
Market trajectory: scale, growth and the investment window
The market for supply chain IT transformation services serving retail has moved from a niche investment to a mainstream strategic priority. Our market sizing shows expansion from roughly USD 9 billion in 2020 to USD 14.5 billion in 2025, with an expected uplift into the mid‑teens in 2026 and a longer-term trajectory that reaches the high‑twenties by 2032. The compound annual growth rate through the forecast window is 9.85%, underscoring sustained vendor investment, growing buyer demand, and an ongoing shift toward platform-centric, analytics‑driven supply chains.
Supply Chain IT Transformation Services for Retail Market
For 2026, the practical takeaway is clear: the market is large enough to support multiple program approaches (internal build, platform partnership, or managed service), but still captures outsized value for organizations that move early to modernize core planning, fulfilment and compliance capabilities. The size and growth imply a robust vendor ecosystem and healthy buyer choice — but success will depend on rigorous vendor selection and staged execution to convert potential into realized value.
Supply Chain IT Transformation Services for Retail Market
Primary drivers shaping 2026 decisions
- AI and visibility acceleration: Industry tracking shows a meaningful step‑change in AI adoption for supply chain visibility — a material share of retailers already embed AI today, and adoption is accelerating year‑over‑year. Expect rapid expansion in projects that fuse AI with real‑time telemetry to reduce stockouts, improve demand sensing and automate exception management.
- Regulatory traceability demands: New rules such as the EU’s Packaging and Packaging Waste Regulation (PPWR), Extended Producer Responsibility (EPR) requirements and similar regional mandates are translating directly into IT requirements for traceability, digital product passports and recycled‑content reporting. These are not peripheral IT upgrades — they require integration across PLM, ERP, WMS and supplier networks.
- Data privacy and governance: GDPR, CCPA and evolving privacy frameworks mean that supply chain telemetry and customer‑linked fulfilment data need robust governance, privacy‑by‑design, and contractual controls with third‑party technology vendors.
- Workforce and operational cost pressures: Rising labor costs and jurisdictional labor reforms — for example, shifts to shorter workweeks or enhanced pay transparency requirements in multiple markets — increase the premium on automation, ergonomics, and workforce optimization features in transformation programs.
- Omnichannel complexity and resilience: Customer expectations and e‑commerce persist as structural drivers; retailers investing in orchestration layer, distributed fulfilment and advanced order management realize differentiated service economics.
2026 strategic priorities — a practitioner’s checklist
- Start with visibility and forecasting: Prioritize projects that reduce lead time and improve demand accuracy. Early wins often come from integrating point‑of‑sale and inventory telemetry with cloud‑based demand engines and a single source of truth for inventory.
- Embed compliance as a feature, not a bolt‑on: Treat traceability, recycled content validation and digital passporting as core functional requirements for any modernization program — this reduces rework and shortens certification timelines.
- Adopt an AI‑first, outcomes‑driven approach: Focus pilots on measurable outcomes (forecast accuracy, inventory turns, order‑fulfilment cost). Use PoCs to validate models and build measurable business cases before enterprise roll‑out.
- Design for hybrid architectures: Balance edge and cloud processing for latency‑sensitive fulfilment tasks while centralizing analytics on cloud platforms for cross‑store optimization and advanced forecasting.
- Prioritize vendor‑partnership models: Choose partners with retail‑specific IP, proven execution references and ecosystem alliances — success is rarely achieved by a single supplier acting in isolation.
Competitive landscape — how to interpret vendor capabilities in 2026
The competitive environment blends global systems integrators, large professional services firms and specialized retail consultancies. Leading integrators bring scale, cross‑industry delivery models and broad platform partnerships; boutique players contribute vertical depth and rapid configuration for retail specifics.
- Tata Consultancy Services (TCS): Noted for end‑to‑end supply chain transformation offerings, TCS combines advisory‑led transformation with AI‑powered optimization and deep platform partnerships. Recent analyst recognition underscores its execution capability on complex retail and CPG programs.
- Cognizant: Positioned on modernization, demand forecasting and resilience initiatives; strong in IT modernization paths that link digital planning with legacy landscapes.
- Accenture: Emphasizes network orchestration, AI and automation across Oracle and other core platforms — a common choice for large, multinational retailers seeking integrated transformation.
- Deloitte and PwC: These firms blend strategic supply chain advisory with systems implementation, and their public guidance emphasizes AI adoption, flexible networks and resilience as central to retail strategy in 2026 and beyond.
- IBM, Brillio and specialist consultancies (e.g., Parker Avery): These players offer combinations of advanced analytics, rapid forecasting capability and hands‑on retail experience for mid‑market and specialist use cases.
For procurement teams, the implication is to evaluate vendors on five dimensions: (1) retail domain IP and referenceability; (2) ability to deliver compliance and data governance; (3) outcome‑based pricing and TCO transparency; (4) integration accelerators and partner ecosystem; and (5) change management and adoption services.
What PW Consulting’s full report delivers (practical, implementation‑oriented)
- Actionable market sizing and trajectory: Granular macro view with base‑year context (2025) and a forward forecast (2026–2032) that shows where investment capacity is expanding and which capability investments index to the strongest growth pockets.
- Decision frameworks and roadmaps: Playbooks for rapid assessment, build vs. buy decision trees, pilot design templates and 12–36 month implementation roadmaps translated into procurement milestones.
- Vendor benchmarking and go‑to‑market playbooks: Comparative profiles, strengths/weaknesses and partnership strategies for integrators, consultancies and niche specialists — accompanied by vendor selection scorecards you can reuse in RFPs.
- Operational tools: TCO and ROI calculators, contract negotiation checklists (including data privacy and compliance clauses), KPI dashboards and implementation risk matrices tailored to retail contexts.
- Scenario and sensitivity modelling: Regulatory impact models (traceability, EPR), AI adoption scenarios (near, medium and long term) and workforce cost sensitivity analyses to inform prioritization and capital allocation.
Importantly, the core segmentation insights (regional, service‑type and application breakdowns) and the more granular vendor share data are intentionally presented in the full report rather than in this briefing. That lets readers access the segmentation tables, heatmaps and downloadable tools that are most actionable for procurement and program planning.
Using the report to shape 2026 investments — recommended sequencing
- Immediate (0–6 months): Conduct a compliance gap assessment (traceability, packaging regulation, privacy). Run a rapid technology audit to identify integration blockers and low‑hanging automation opportunities.
- Short term (6–12 months): Execute focused PoCs on AI‑enabled visibility and demand sensing tied to clear KPIs. Negotiate modular contracts with outcome clauses and convertible pilots that permit scale‑up.
- Medium term (12–24 months): Roll out platform consolidation, integrate supplier data for full traceability, and scale workforce optimization technologies to align with labor regulation changes.
- Metrics to track: forecast accuracy, inventory days of supply, order fulfilment cost per order, compliance cycle time for packaging reporting, and measured ROI for AI pilots.
Concluding view — why 2026 is decisive
2026 represents a moment of convergence: regulatory requirements, rising labor and operational costs, and a clear maturation of AI and cloud technologies create a narrow window where early adopters can realize durable competitive advantage. The market’s growth profile — rising consistently from 2020 through the 2025 base year and forecast to expand materially across the 2026–2032 horizon — validates continued investment. But size alone does not guarantee success: disciplined prioritization, vendor selection finesse and pragmatic execution discipline determine winners.
PW Consulting’s Supply Chain IT Transformation Services for Retail Market report packages the macro market context with a hands‑on set of tools and frameworks to help retail executives make faster, less risky, and more measurable decisions in 2026. We deliberately present this summary as a strategic preview; detailed segmentation, vendor share matrices, downloadable tools and full implementation templates are available in the complete report.
To access the full intelligence, benchmarking tools and implementation playbooks that underpin this briefing, please visit PW Consulting’s report page or contact our advisory team for a tailored briefing. Our analysts are available to walk through scenario models and to co‑design a roadmap aligned to your specific retail operating model and regulatory footprint.
For detailed analysis of this topic, please visit the official page: Supply Chain IT Transformation Services for Retail Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Rapid Expansion of Automotive Multi‑Domain Controller Market with 14.5% CAGR
By PW Consulting, 2026-07-06
Automotive Multi-Domain Controller Market: Strategic Intelligence for 2026 Decision-Making
Executive Summary
PW Consulting's new Automotive Multi-Domain Controller Market report (base year 2025; forecast 2026–2032) condenses independent primary research, supplier roadmaps, and systems-level analysis into a decision-grade toolkit for automotive executives, semiconductor investors, and Tier‑1 partners. The market is on a rapid growth curve — expanding from approximately USD 3.2 billion in 2025 to an estimated USD 8.26 billion by 2032, at a compound annual growth rate (CAGR) of 14.5% over the forecast window. This trajectory underscores a structural shift toward software-defined vehicles (SDVs) anchored by consolidated compute domains — a shift with immediate strategic implications for 2026 planning cycles.
Automotive Multi Domain Controller Market
Why This Report Matters in 2026
-
Time-sensitive strategic choices: 2026 is a hinge year when pilot integrations move to volume programs and chip-level inflections (3nm and heterogeneous compute stacks) enable new architectures. Our report maps these inflection points and the commercial windows they create.
Automotive Multi Domain Controller Market -
Procurement and supplier roadmaps: With concentration metrics indicating a market that is significant but not monopolized (CR3 ~45.2%; CR5 ~62.4%), buyers can influence architecture trajectories through early program awards. We show which supplier capabilities translate to negotiating leverage.
Automotive Multi Domain Controller Market -
Risk management for sourcing and compliance: Regulatory and supply-side dynamics (safety and cybersecurity mandates; memory supply tightness) are already compressing project timelines and costs. The report quantifies these risks and prescribes mitigation playbooks.
Market Trajectory — Macro View (2023–2032)
Our compilation of market sizing shows steadily accelerating adoption: market value rose from the low‑billions in the early 2020s to USD 3.2 billion in 2025, with an expected near‑term uplift to about USD 3.66 billion in 2026 and sustained growth to USD 8.26 billion by 2032. The 14.5% CAGR reflects multiple tailwinds — broader SDV program adoption, consolidation of cockpit/ADAS/gateway functions into multi-domain controllers, and adoption of centralized or hybrid compute topologies by OEMs pursuing software monetization and feature over-the-air (FOTA) strategies.
Key Strategic Implications
-
Architecture selection determines margin capture: Early choices between central, zonal, and domain-first strategies are consequential. OEMs that adopt a clear long-term compute topology and enforce interface standards will preserve option value for software monetization and aftermarket services.
-
Software becomes the monopolistic moat: Value is shifting from hardware BOM to software stacks, continuous integration pipelines, and lifetime update capabilities. Suppliers unable to demonstrate robust safety-certified software and secure update management will face commoditization pressure.
-
Semiconductor partnerships require multi-dimensional alignment: Leading SoC players are moving to automotive-grade advanced nodes and multi-die strategies. For system integrators, aligning supplier roadmaps (process node, ISP/AI accelerators, deterministic cores) with program timing is a mission-critical negotiation lever.
-
Supply-chain resilience is a near-term commercial differentiator: Memory pricing and availability have become program-level risks. The report offers hedging and contract structures that minimize exposure to DRAM tightness and legacy memory price volatility.
Competitive Landscape — Where the Power Lies
The multi-domain controller space is populated by a mix of Tier‑1 systems integrators, traditional automotive electronics suppliers, and high-performance semiconductor vendors. Recent product and program moves in 2024–2026 illustrate the interplay between software, system integration, and silicon leadership.
-
Systems and Tier‑1 integrators (e.g., Continental, Bosch, ZF, Visteon, Aptiv) are consolidating electrical/electronic architecture design capabilities with systems integration and software stacks to capture OEM system premiums. These players leverage their integration scale to bundle safety, functional decomposition, and vehicle-level validation — capabilities that are difficult for pure-play silicon vendors to replicate at scale.
-
Semiconductor incumbents and challengers (e.g., Renesas, NXP, Qualcomm, NVIDIA) are competing on a mix of process-innovation, deterministic compute, and domain-specific accelerators. Notable recent moves include a 3nm automotive multi-domain SoC introduction and the debut of multi-Snapdragon central computer implementations in production intent vehicles — developments that compress the timeline for capability parity across suppliers.
-
Cross-domain winners will be hybrid: suppliers that combine hardened automotive-grade silicon, validated middleware, and demonstrable safety/cybersecurity engineering will be best positioned to win multi-program awards. Partnerships and M&A activity are expected to accelerate as companies fill capability gaps ahead of 2027 program ramps.
Selected Recent Developments That Shape 2026 Choices
-
A leading semiconductor vendor released a 3nm automotive multi-domain SoC capable of concurrent ADAS, IVI, and gateway functions, accelerating the performance baseline for central compute strategies.
-
Major Tier‑1s showcased and implemented high-performance computers in technology vehicles, demonstrating integrated cockpit and vehicle function consolidation at the systems level.
-
OEM and silicon partnerships debuted central-computer architectures leveraging dual high-performance application processors, signaling a move from single-vendor dominance to heterogeneous multi-supplier stacks in candidate production vehicles.
Regulatory, Safety, and Supply Dynamics — Immediate Action Items
-
Regulatory compliance drives architecture: ISO 26262 requirements for ASIL levels and UNECE R155/R156 cybersecurity and software update mandates are non-negotiable design constraints. The report details how architecture choices map to test, validation, and certification effort and cost.
-
Safety plus time-to-market trade-offs: Compliance pathways (toolchains, traceability, ASIL certification routes) materially affect schedule and supplier selection. Early alignment on compliance responsibility between OEMs and suppliers reduces program slippage risk.
-
Memory market perturbations: Automotive DRAM supply tightness led to dramatic price spikes for legacy DDR types in early 2026 — experienced program managers must account for volatility, consider alternative memory mixes, and negotiate flexible supply contracts.
-
Safety mandates such as AEB and NCAP evolutions are increasing the performance floor for controllers supporting ADAS features — buyers must reconcile these performance baselines with cost targets.
What the PW Consulting Report Contains (Practical, Actionable Deliverables)
-
Market sizing and forecast model (2020–2032) with scenario analysis and sensitivity to chip supply, regulatory timing, and OEM architecture choices.
-
Program-level supplier capability matrices mapping compute performance, safety maturity, cybersecurity posture, and software integration readiness.
-
Go-to-market playbooks for OEMs, Tier‑1s, semiconductor vendors, and software providers — including recommended contractual constructs, co‑development modes, and IP-shared strategies for minimizing technical and commercial risk.
-
Cost and BOM impact assessments under alternative memory and SoC roadmaps, with hedging and sourcing tactics to preserve margins amid component price volatility.
-
Validation, test, and certification checklists tied to ISO 26262 and UNECE requirements, with estimated effort and cost buckets (detailed task-level schedules included in the full report).
-
A competitive brief for each major market participant, synthesizing product roadmaps, program wins, and likely near-term strategic moves.
How to Use This Intelligence in 2026 Planning Cycles
-
For OEMs: Treat controller architecture as a multi-year strategic decision — set clear interface standards, select partners on long‑term roadmap alignment, and lock down compliance responsibilities early.
-
For Tier‑1 suppliers: Invest in demonstrable software engineering, safety toolchains, and update-management platforms to avoid being relegated to commodity hardware roles.
-
For semiconductor vendors: Prioritize automotive-grade process nodes and deterministic compute offerings, and package software reference stacks and validation kits to accelerate OEM adoption.
-
For investors: Look for companies with integrated software monetization strategies and resilient supply-chain positioning; concentration metrics suggest there is room for consolidation but also opportunity for nimble challengers.
Trailer: What We Don’t Publish Here (and Why You Need the Full Report)
To preserve the strategic utility of our research and to support actionable commercial negotiations, this public summary omits program-level revenue splits and fine-grained regional/application breakdowns. Detailed segmentation, supplier scorecards with scored sub-criteria, and the interactive forecast model (including scenario toggles for memory pricing and regulatory timing) are reserved for subscribers and licensed clients. These deliverables are the assets you will use directly in supplier selection, contract negotiations, and 2026 capital planning.
Next Steps
PW Consulting is scheduling bespoke briefings for executive teams, program managers, and investors to walk through the model and translate findings into concrete program actions for 2026 and beyond. Contact your PW Consulting representative or visit our report page to arrange a briefing and access the full dataset, interactive scenarios, and the supplier capability library.
Concluding Perspective
The multi-domain controller market is not merely a component market — it is a systems-level battleground that determines who captures long-term value in the software-defined vehicle era. The 2026 planning cycle will determine which OEMs and suppliers seize platform economics and which will be forced into retrofitted strategies. Our report supplies the evidence, the scenarios, and the playbooks you need to make those decisions with confidence.
For detailed analysis of this topic, please visit the official page: Automotive Multi Domain Controller Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Glass Substrate for Hard Disk Drives Market Set to Expand at a 5.85% CAGR, New Report Reveals
By PW Consulting, 2026-07-06
Glass Substrate for Hard Disk Drives Market: Strategic Imperatives for 2026 — PW Consulting Insight Preview
Executive summary
PW Consulting's latest market study on glass substrates for hard disk drive (HDD) platters synthesizes five years of historical performance (2020–2025) with an eight-year forecast (2026–2032) to deliver a decision-grade intelligence package for executives planning capital allocation, supply-chain strategy, and product roadmaps in 2026. The global market has expanded from a modest base in 2020 to USD 520 million in our base year (2025) and is forecast to grow at a compound annual growth rate (CAGR) of 5.85% through 2032, reaching an estimated USD 774.24 million by 2032. This preview outlines the strategic consequences of that trajectory without revealing the granular segmentation contained in the full report — a deliberate "trailer" designed to demonstrate analytical depth and operational relevance while steering readers to our full study for the supporting subsegment datasets and modeling.
Glass Substrate For Hard Disk Drives Market
Why glass substrates matter now
Glass substrates have moved from niche to strategic within the HDD value chain. Technical advantages — thermal stability, rigidity, and the ability to support higher platter counts in thinner designs — are enabling HDD suppliers to push areal density and durability in nearline and enterprise applications. These material-level attributes are also closely aligned with advanced recording technologies (notably HAMR/heat-assisted approaches) and the industry’s push for denser, more reliable nearline storage economics.
Glass Substrate For Hard Disk Drives Market
Commercially, this technological transition coincides with persistent demand in enterprise storage and hyperscale deployments, creating a sustained runway for glass substrate adoption that is reflected in our mid-single-digit CAGR through 2032. For decision-makers, this convergence of technology and demand creates a narrow window to secure preferred supply positions, validate product roadmaps, and align supplier investments with expected capacity timing.
Glass Substrate For Hard Disk Drives Market
Market structure and competitive dynamics
- High concentration, single-source realities: The market exhibits very high concentration: the top three suppliers capture the vast majority of global supply, with the top five approaching near-total market share. Practically, this means buyers face limited supplier choice, and incumbents wield substantial commercial leverage.
- HOYA Corporation as the systemic supplier: HOYA remains the sole global manufacturer with scale in both smaller and larger platter segments, and it is actively increasing capacity to address the nearline opportunity. Notably, HOYA announced in April 2026 an investment of approximately JPY 50 billion to build a new glass substrate plant in Vietnam, targeting completion around 2028 — a material development for supply availability and lead-time planning.
- HDD OEMs advancing product integration: OEMs are rapidly validating multi-disk and stacking technologies that depend on glass substrates to deliver thinner, mechanically stable platters. For example, development milestones and early sampling from major HDD suppliers in late 2025 and early 2026 demonstrate a concrete shift from laboratory feasibility to commercial readiness for higher-capacity nearline drives.
Supply-chain and raw-material considerations
Glass substrate manufacturing is energy- and material-intensive. Soda ash — a key flux — is a meaningful cost driver in many glass applications and has shown price variability in recent industry reports. While public sources report differing short-term price points, the practical implication is consistent: raw-material volatility alters landed cost assumptions and can compress supplier margins or be reflected in pass-through pricing to OEMs. Separately, increasingly stringent environmental regulations on energy-intensive glass production are accelerating investments in cleaner furnace technologies and recycled-content programs — adding both capital intensity and new compliance dimensions to supplier selection.
Strategic implications for corporate decision-makers in 2026
- Procurement and supplier risk management: With a tightly concentrated supply base and a single dominant manufacturer, enterprise buyers and OEMs must build multi-year sourcing agreements, capacity reservation clauses, and escalation mechanisms now. Waiting for spot availability risks prolonged lead times and price volatility as new capacity comes online.
- CapEx timing and location strategy: HOYA’s Vietnam project and similar investments create a multi-year phasing dynamic. Investors and OEMs should align their own investment timelines (e.g., R&D for HAMR-enabled heads or factory retooling) to supplier capacity ramps to avoid misaligned production windows.
- Product and platform roadmaps: HDD OEMs pushing higher platter counts and thinner form factors should bake substrate-availability scenarios into their product roadmaps. Early engagement with substrate manufacturers on qualification, yield ramps, and co-engineering can materially shorten time-to-market for next-generation nearline drives.
- Commercial model innovation: Suppliers and buyers should explore price-stability mechanisms (indexation, hedging), consignment models, and joint investment frameworks to balance supply security with cost control. Strategic partnerships or minority investments in substrate capacity can be value-accretive for OEMs seeking to de-risk supply constraints.
- Regulatory and ESG alignment: The capital intensity of clean-glass production means ESG propositions (carbon footprint, water usage, recycled content) will increasingly affect procurement and finance decisions. Buyers should incorporate measurable ESG KPIs into supplier selection criteria now.
What PW Consulting’s full report delivers (practical, actionable content)
Our full market study is built to be operative for commercial teams, M&A desks, and corporate strategy functions. It combines quantitative demand and supply modeling with qualitative commercial playbooks:
- Proprietary market-sizing and demand-forecast models calibrated to the 2020–2025 historical period and projecting 2026–2032 under multiple scenarios (base, upside, downside).
- Supply-side mapping covering manufacturing capacity, technology readiness levels, geographic footprints, and capital-expansion timelines — including scenario overlays for announced investments.
- Cost-stack and sensitivity analysis highlighting the impact of raw-material price swings and energy/regulatory premiums on unit economics.
- Competitive profiles and capability assessments for incumbent suppliers and potential entrants, with strategic playbooks for OEMs, substrate suppliers, investors, and operators.
- Commercial contracting templates and negotiation levers to secure capacity, manage price risk, and accelerate qualification cycles.
- M&A and partnership screening — prioritized shortlists based on strategic fit, execution risk, and time-to-value.
How to translate findings into a 90-day action plan
- Week 0–4: Run a rapid supplier-risk audit: quantify current sourcing exposure, identify single points of failure, and map contractual maturities. Use our checklist to evaluate supplier lead times, qualification status, and ESG compliance.
- Week 4–8: Initiate dual-track commercial engagement: secure interim capacity through multi-year purchase agreements with priority clauses, while launching joint-qualification programs with strategic substrate providers. Consider staged capex commitments tied to supplier ramp milestones.
- Week 8–12: Align product roadmap and manufacturing schedules to supplier capacity scenarios. Finalize hedging or indexation structures for critical raw materials, and complete one pilot co-investment or strategic partnership contingent on supplier performance metrics.
Decision-grade signals to monitor in 2026
- Capacity ramp updates and capital allocation announcements from substrate manufacturers.
- Qualification and sampling milestones from HDD OEMs that indicate migration from development to production.
- Directional movements in soda ash and energy costs, and any regulatory actions impacting furnace emissions or recycled-content mandates.
- Commercial terms being offered in supplier agreements — especially lead-time guarantees, price adjustment clauses, and ESG-linked incentives.
Final perspective
The glass-substrate market for HDDs represents a strategically important niche with outsized implications for enterprise storage economics. Our analysis shows a stable, mid-single-digit CAGR trajectory from 2026 to 2032 and a structurally concentrated supply base that amplifies the value of early, informed action. Whether you are an OEM aligning product roadmaps, a hyperscaler securing nearline capacity, or an investor evaluating upstream opportunities, the right mix of supplier engagement, contract design, and timing will determine whether you capture upside or suffer supply-induced constraints.
PW Consulting's complete report provides the subsegment-level models, supplier scorecards, and execution templates required to operationalize these insights. For a full briefing, tailored scenario analysis, or an executive workshop to convert this research into a 2026 action plan, please visit our report page or contact your PW Consulting advisor.
For detailed analysis of this topic, please visit the official page: Glass Substrate For Hard Disk Drives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: GaN Wafers Market to More Than Triple from USD 2,550M in 2025 to USD 8,350M by 2032 at 18.5% CAGR — Asia‑Pacific, GaN‑on‑Si and Power Electronics Lead
By PW Consulting, 2026-07-06
GaN Wafers Market 2026 Outlook: Strategic Imperatives from PW Consulting’s New Industry Report
PW Consulting today releases its authoritative GaN Wafers Market report, presenting an evidence-based strategic compass for executive decision-making in 2026. Built on a 2025 base year and a detailed historical review (2020–2025), the study projects the market through 2032 and models an aggressive but attainable compound annual growth rate (CAGR) of 18.5%. The market expanded from approximately USD 1,050 million in 2020 to USD 2,550 million in 2025, and PW Consulting’s forecast sees the total market reaching the order of multiple billions by 2032 — a trajectory that compels commercial actors to re-evaluate capacity, sourcing and partnership strategies now.
Gan Wafers Market
Why this report matters for 2026 planning
-
Timing and scale: With an 18.5% CAGR through our forecast window, GaN wafers are not a niche material — they are a core enabler for high-growth semiconductor segments. Boards and strategy teams must overlay this growth profile onto capital plans and product roadmaps to avoid lost share to better-prepared competitors.
Gan Wafers Market -
Decision-readiness: The report converts macro dynamics into actionable choices — whether that is a fast-follow manufacturing scale-up, targeted vertical integration, supply-security contracts, or focused R&D investments.
Gan Wafers Market -
Risk-adjusted pathways: The GaN ecosystem sits at the intersection of raw-material volatility, geopolitics and rapid technology evolution. Our scenario engine models policy shifts, material shocks and commercialization timetables, enabling executives to prepare contingency budgets and trigger-based actions for 2026.
Data-driven context: growth, concentration and capital intensity
PW Consulting’s market topology demonstrates a rapid expansion in total revenue (USD Million) from 2020 to 2025 and a continued steep growth path through 2032 under base assumptions. The sector shows moderate market concentration: the top three players account for a substantive share of revenue, and the top five exhibit an even larger cumulative presence. This structure implies both significant advantages for established incumbents and a window for differentiated newcomers who can offer cost, performance, or supply differentiation.
Capital intensity and technology complexity are central determinants of competitive position. Moving to larger diameters, advanced epitaxy routes and improved substrate technologies requires significant capex, IP and process know-how. As a result, strategic choices for 2026 should weigh the return horizon for capacity investments against partnership or foundry-based alternatives.
Supply-chain and material risk: gallium and beyond
One of the most immediate strategic exposures for GaN wafer users and producers is raw-material availability and price. Recent developments have injected pronounced volatility into the upstream: policy shifts affecting gallium exports, unit-price inflation of gallium metal, and concentrated primary production have all elevated procurement risk. PW Consulting’s risk matrix underscores that single-supplier or single-region dependence for critical inputs materially increases the likelihood of production disruptions and margin compression.
Specific events in the last 12–18 months — including temporary changes in export policy and step-changes in import volumes for key markets — underline the need for dynamic procurement strategies. For 2026, successful players will be those that combine short-term hedging and inventory levers with medium-term supplier diversification and qualification programs.
Technology inflection points and what they mean for 2026 plays
-
Diameter scaling: Activity to mature larger-diameter substrates and wafer processing is accelerating; several industry milestones announced in 2024–2025 indicate a near-term path to broader adoption. For strategy teams, this translates into decisions on whether to build proprietary capacity for advanced diameters or secure early-access allocations from strategic partners.
-
Substrate innovation: Novel substrates and epitaxy routes (including high-quality bulk GaN, engineered composites and diamond-integrated solutions) are maturing. These alternatives change performance and total-cost-of-ownership calculations for RF, power and optoelectronic applications.
-
Foundry and platform plays: The rapid move of wafer suppliers and device foundries toward co-development and platform offers (e.g., high-voltage GaN device stacks) is redefining go-to-market models. OEMs and device firms should weigh in-house development versus early participation in platform joint-development agreements.
Competitive landscape: players to watch and strategic implications
Our vendor analysis synthesizes company-level capabilities, capacity roadmaps, and strategic intent. While the full vendor scorecards are available only in the report, several firms and recent moves are emblematic of sector dynamics:
-
Eta Research Ltd. (Shanghai) — a bulk GaN producer with HVPE capabilities. Its focus on free-standing GaN wafers and multiple doping options makes it a key upstream source for laser diode and power-device OEMs. Strategy implication: consider long-term supply agreements or technology partnerships with firms that can secure vertical integration into epitaxy-to-device value chains.
-
Sanan Semiconductor — a large-scale GaN-on-Si epiwafer and foundry services provider expanding capacity. For companies targeting fast time-to-market, foundry partnerships with players that offer both epi and wafer services present an efficient growth route.
-
Sumitomo Electric and NGK Insulators — incumbents advancing substrate technology (larger diameter GaN-on-GaN, diamond-enhanced platforms, and low-dislocation methods). These technological differentiators are likely to shape device-level performance and total system costs over the medium term.
-
IQE plc and Wolfspeed — firms with strong epitaxial expertise and RF/power device focus. Their initiatives (including platform JDA and wafer/device integration) signal the increasing importance of end-to-end offerings for automotive, data center and telecom end markets.
We map these firm-level capabilities to strategic options: (1) supplier partnerships to accelerate qualification timelines; (2) minority investments to align incentives; (3) co-development agreements to secure preferred access to new diameters or epitaxial stacks; and (4) selective insourcing for critical, IP-rich processes.
Recent industry developments shaping the 2026 decision landscape
-
Scalable 300mm GaN wafer initiatives and first customer samples from major semiconductor device firms are narrowing the gap between R&D and manufacturing readiness. Executives must evaluate the timing of migration to larger wafers relative to product roadmaps and capital cycles.
-
Demonstrations of GaN-HEMT on novel substrates (including diamond-enhanced stacks) indicate throughput and efficiency gains for communications and high-performance power applications — this raises the bar for thermal management and packaging strategies.
-
Strategic collaborations to develop 650V and other automotive-grade GaN platforms are proliferating. For OEMs and Tier-1 suppliers, pre-emptive qualification of GaN platforms with established wafer partners will accelerate adoption and mitigate supply risks.
What’s in the PW Consulting report (operational highlights)
The PW Consulting GaN Wafers Market report blends rigorous quantitative models with practical decision-support tools designed for 2026 action. Core deliverables include:
-
Transparent market-sizing and price modeling for the historical and forecast periods (methodology, assumptions, sensitivity analysis).
-
Scenario-based financial models that stress-test capex choices, capacity expansion timing and unit-cost trajectories under alternative material-price and policy environments.
-
Full supply-chain maps, critical-path vulnerability matrices and supplier qualification playbooks for procurement and operations teams.
-
Vendor scorecards, capability matrices and a shortlist of strategic M&A and partnership targets (operational and financial rationales included).
-
Go-to-market playbooks tailored by end-market (power electronics, RF, optoelectronics), including channel strategies, qualification timelines and key performance thresholds.
-
Regulatory and trade-impact assessment with trigger-based recommendations for procurement and inventory policies.
Recommended executive actions for 2026
-
Prioritize supply-security actions: secure multi-year off-take or capacity commitments with strategic suppliers, and implement a staged inventory and hedging policy tied to material-price thresholds.
-
Adopt flexible capital plans: favor modular capacity or staged investments that can pivot between wafer diameters and substrate types as technology adoption crystallizes.
-
Engage in early platform partnerships: participate in joint development agreements for next-generation GaN device stacks to shorten qualification windows and lock favorable supply terms.
-
Embed scenario triggers in board-level strategy: create pre-defined governance triggers (e.g., material-price movements, export-policy changes, customer qualification outcomes) that automatically escalate decisions on capex and sourcing.
How to access the full intelligence
This release provides a strategic preview of PW Consulting’s GaN Wafers Market report. The full study contains the granular segmentation, primary-data tables, vendor financial models and downloadable templates necessary to convert strategy into executable programs — intentionally withheld here to preserve the report’s role as a decision-grade asset. PW Consulting clients and subscribers can access the comprehensive dataset, scenario tools and vendor scorecards via our report distribution channels.
For executives planning capital allocation, supply chain redesign or corporate development moves in 2026, the report is designed to be a practical companion — delivering both the "why" and the "how." PW Consulting stands ready to support strategy workshops, due-diligence efforts and implementation roadmaps derived from the report’s findings.
Contact PW Consulting to schedule a briefing and to obtain the full GaN Wafers Market report and its accompanying strategic toolkits.
For detailed analysis of this topic, please visit the official page: Gan Wafers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Special Airport Systems Market to Expand at 6.5% CAGR — From USD 12.5 Billion in 2025 to USD 19.42 Billion by 2032
By PW Consulting, 2026-07-06
Special Airport Systems Market 2026: Strategic Imperatives for Airport Operators, Suppliers and Investors
Executive summary
PW Consulting’s Special Airport Systems Market report (base year 2025, historical 2020–2025, forecast 2026–2032) delivers a focused, actionable roadmap for executives making capital, procurement and partnership decisions in 2026. The special airport systems market demonstrated steady expansion through the mid-2020s — rising from approximately USD 10.7 Billion in 2023 to USD 12.5 Billion in 2025 — and our modelling shows a robust trajectory at a 6.5% compound annual growth rate (CAGR) across the 2026–2032 forecast window, reaching an estimated USD 19.42 Billion by 2032. This pace of growth is sufficient to alter strategic priorities for operators, systems integrators and technology providers: growth is real, concentrated in definable technology clusters, and being reshaped by regulation, digitization and shifting operational models.
Special Airport Systems Market
Why this matters for 2026 decision-makers
For airport owners, concessionaires and vendors, 2026 is a pivotal planning year. The market momentum established through 2023–2025 now requires decisions that will determine who captures the next wave of replacement, capacity expansion and regulatory-compliance spend. Capital budgets that are allocated without a clear systems roadmap risk lock-in to legacy architectures that are expensive to retrofit. Conversely, proactive investment in modular automation, integrated IT/OT platforms and security modernization can produce measurable operational savings and resilience.
Special Airport Systems Market
- Investment timing: The 6.5% CAGR and the 2026–2032 growth envelope indicate an extended upswing rather than a short-term spike — favour staged, interoperable procurements over full rip-and-replace strategies.
- Scope of spend: Demand drivers are concentrated around automation, screening modernization, airfield safety technologies, passenger flow solutions and systems that deliver measurable throughput improvements.
- Competitive implications: Market concentration metrics point to a moderate degree of supplier dominance, but meaningful room exists for focused challengers and specialist integrators that can demonstrate lower total cost of ownership (TCO) and faster time-to-benefit.
Core dynamics reshaping the market
Our research identifies four structural forces that will shape procurement and investment choices in 2026 and beyond.
Special Airport Systems Market
- Regulatory acceleration: Recent and upcoming rule changes — including the IATA revisions to airport handling and baggage manuals effective in 2026 and ICAO’s security amendment activity — are creating hard timelines for screening, baggage and operational-process upgrades. These rules are nudging airports toward integrated “one-stop” and hold-baggage concepts that have direct implications for equipment specifications and systems integration planning.
- Security modernization and consolidation: Airports and governments are prioritizing faster, higher-throughput screening technologies and enterprise security solutions. Partnerships between defense- and security-focused firms and civil contractors are increasing, altering competitive dynamics in the screening and surveillance segments.
- Digitization and IT/OT convergence: The value proposition has shifted from individual components (a baggage conveyor or a scanner) to platform-level capabilities — digital twins, predictive maintenance, unified baggage and passenger-tracking services, and cloud-enabled operational analytics.
- Operational resilience and safety: Investments in runway incursion detection, visual docking guidance, and airfield lighting are being prioritized to reduce risk and insurance exposure, and to support increased traffic volumes as passenger numbers recover and expand over the next decade.
Competitive landscape — strategic positioning and recent moves
The market comprises established industrial-engineering conglomerates, specialist automation vendors, IT-platform providers and defence-heritage firms. Our report profiles each major player, assesses capabilities across R&D, system integration, global delivery and lifecycle services, and identifies where new entrants can disrupt incumbents.
- Integrated engineering and automation leaders — Companies with end-to-end engineering, large-scale BHS capability and global delivery networks remain the default partners for terminal expansions. Their advantage is proven project delivery and deep relationships with Tier-1 airport clients.
- IT-platform and passenger-experience providers — Firms that deliver passenger processing platforms, departure control systems and operational data layers are increasingly central to value capture; they control the data fabric that links hardware assets to operational outcomes.
- Security and defence-aligned suppliers — Vendors with screening and surveillance expertise are leveraging defence-sector heritage and partnerships to win airport security contracts and large-system integrations.
- Specialist challengers — Niche automation and software firms are commercializing focused capabilities (e.g., tote-based sorting, AI-driven baggage tracking, or advanced airfield lighting) and partnering with system integrators to break into larger projects.
Notable recent developments exemplify these trends: new contract awards for next-generation baggage screening equipment and several significant baggage handling system contracts were announced in late 2025 and early 2026, while strategic joint ventures to combine screening and security service portfolios emerged in 2026. These moves underscore a pattern: large-scale airport programs are being awarded to suppliers who bring both proven hardware solutions and demonstrable systems-integration capability.
What the PW Consulting report delivers — practical content for your 2026 playbook
This Special Airport Systems Market report translates market-wide signals into decision-ready outputs. Key operational deliverables include:
- Granular market model: A bottom-up market-sizing and forecasting model (USD, Billion) for 2023–2032, including scenario sensitivity analysis to stress-test CAPEX under different traffic and regulation outcomes.
- Procurement playbooks: Best-practice RFP templates, evaluation matrices, and sample contract clauses to preserve upgradeability, data ownership and service-level accountability.
- Vendor shortlists and capability maps: Comparative assessments that go beyond brand names to map suppliers’ integration strengths, software stacks, lifecycle-service offerings and regional delivery footprints.
- Technology adoption roadmaps: Practical migration strategies for moving from siloed equipment to an interoperable, software-defined operations layer, with timing recommendations keyed to regulatory milestones and traffic thresholds.
- Investment and M&A diagnostic: A structured framework for assessing supplier partnerships, tuck-in acquisitions and strategic alliances that improve platform competitiveness.
- Case studies and unit-economics: Real-world deployments, measured outcomes and TCO analyses to support business-case development and stakeholder buy-in.
Strategic recommendations — three imperatives for 2026
Based on cross-validation of our market model, supplier screens and regulatory timelines, PW Consulting recommends that airport operators, vendors and investors prioritize the following in 2026:
- Design for modularity and data continuity: Tender specifications should mandate modular subsystems, open APIs and data contracts so future upgrades (e.g., new screening technologies or AI-based sorting) can be integrated without wholesale replacement.
- Prioritize integration capability over lowest-capex bids: Given the complexity of combining baggage handling, screening and passenger processing into a single operational flow, the winning suppliers will be those who can demonstrate previous successful integrations and an ability to manage multi-vendor ecosystems.
- Use regulatory timelines as procurement triggers: IATA and ICAO guidance, and targeted runway-safety deployments, create fixed windows for compliance-driven spend. Map procurement cycles to these milestones to accelerate approvals where needed and to avoid last-minute premium costs.
Implications for investors and technology providers
For investors, the market profile indicates attractive returns for platform plays that combine hardware, software and long-term service contracts. Consolidation activity is likely in niches where small specialists can be folded into larger integrators to deliver turnkey solutions. Technology providers should orient product roadmaps toward cloud-native operations, machine-learning-enabled predictive maintenance, and streamlined certification pathways for security screening equipment.
Market concentration metrics in the report highlight a competitive landscape where the top firms account for a meaningful share of revenue, but not an insurmountable dominance — leaving room for targeted M&A, geographic expansion and partnerships to scale quickly.
Next steps — how to use the report
PW Consulting’s Special Airport Systems Market report is structured to support three primary user journeys: (1) operational teams preparing capital plans for terminal projects; (2) vendor strategy teams defining product and channel roadmaps; and (3) corporate development teams evaluating M&A and partnership targets. Each user group will find tailored tools: buildable procurement artifacts, a dynamic market model you can re-run with your assumptions, and a prioritized vendor matrix calibrated to technical and delivery capabilities.
Conclusion — positioning for the decade ahead
The special airport systems market is entering a sustained expansion phase that rewards forward-looking decisions. Airports and suppliers that treat 2026 as a year for architecture and partnership decisions — not only for equipment procurement — will be best positioned to capture operational upside as traffic grows and regulatory frameworks tighten. PW Consulting’s report provides the analytical backbone, procurement playbooks and competitive intelligence required to turn market momentum into measurable operational and financial outcomes.
Access the report
To review the full market model, vendor profiles, and prescriptive procurement tools, visit our report landing page. The public summary outlines methodologies and sample insights; the subscriber edition includes downloadable models and editable procurement templates to accelerate your 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Special Airport Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Broadband Router Market Poised to Reach USD 36,486.14 Million by 2032, Growing at a 7.15% CAGR (2026–2032)
By PW Consulting, 2026-07-06
Broadband Router Market Outlook 2026: Strategic Imperatives for Executive Decision-Making
Executive summary
As broadband infrastructure and home connectivity evolve rapidly, PW Consulting’s latest Broadband Router Market report provides a forward-looking framework for corporate strategy in 2026. Anchored on a 2025 base year and a detailed 2026–2032 forecast, the market is modeled to grow at a compound annual growth rate (CAGR) of 7.15% — rising from a market value in 2025 to a materially larger opportunity by 2032. Our analysis synthesizes regulatory shifts, technology transitions (notably Wi‑Fi 6/6E and Wi‑Fi 7, fiber and fixed wireless access), supply‑chain dynamics, and competitive positioning to convert macro trends into actionable choices for product, channel, and M&A strategies.
Broadband Router Market
Why this report matters for 2026 strategy
-
Regulatory inflection points are forcing near‑term shifts in sourcing and qualification: recent U.S. regulatory actions and judicial rulings have redefined the compliance landscape for device manufacturers and channel partners.
Broadband Router Market -
Technology windows are tightening: vendors must balance investment in next‑gen silicon, mesh/edge software, and cloud management against persistent replacement cycles in consumer and enterprise environments.
Broadband Router Market -
Commercial models are fragmenting between subscription and hardware sales, with operators and retailers experimenting with bundled services, managed Wi‑Fi, and device financing.
Macro trajectory: measured growth, expanding opportunity
PW Consulting’s projections indicate a robust, sustained market expansion over the forecast horizon. With the market base established in 2025 and modeled through 2032, the industry is forecast to grow at a steady mid‑single‑digit to low‑double‑digit pace consistent with a 7.15% CAGR. The combination of ongoing broadband penetration, upgrades to support multi‑gigabit last‑mile services, and the commercial rollout of new wireless spectrum use cases underpins this growth. For executives, the implication is clear: the absolute market remains attractive, but returns will depend on segment and product mix decisions that capitalize on premium upgrade cycles and recurring‑revenue services.
Key growth drivers and structural headwinds
-
Fiber and fixed wireless deployment acceleration. Ongoing fiber rollouts and the use of new mid‑ and upper‑band spectrum for fixed wireless increase addressable homes and businesses. At the same time, material increases in build costs and permitting complexity affect operator capex plans — creating windows for high‑value CPE and managed services.
-
Wi‑Fi generational shifts. Adoption of Wi‑Fi 6/6E and the emergence of Wi‑Fi 7 create upgrade opportunities across consumer and commercial segments, especially where multi‑gigabit broadband has become available.
-
Regulatory and national security dynamics. Policy moves that affect device authorization and the trusted supply chain are introducing sourcing constraints and regional market bifurcation, prompting diversification strategies among OEMs and channel partners.
-
Consolidation pressure and ecosystem partnerships. Moderate market concentration highlights the potential for targeted M&A and strategic alliances, particularly among software, silicon, and cloud orchestration players that can deliver differentiated managed Wi‑Fi offerings.
Regulation and public policy: a new operating reality
Regulatory shifts in early 2026 have significantly altered strategic calculus. Notably, updated government restrictions on certain foreign‑produced consumer devices, paired with selective exemptions, elevate compliance costs and supplier risk for companies engaging in the U.S. market. At the same time, judicial rulings that reclassify broadband services have constrained some federal policy levers, increasing reliance on state and private initiatives to advance network deployment. Policymakers’ ongoing spectrum planning and modifications to major subsidy programs also affect where and how broadband infrastructure — and the routers that sit at its edge — will be purchased and deployed.
Competitive landscape: positioning and strategic implications
The broadband router ecosystem comprises global incumbents, consumer‑focused specialists, and agile newcomers. Our competitive concentration analysis shows a market that is neither tightly consolidated nor wholly fragmented — a dynamic that favors both scale and differentiation. Executives should weigh the following strategic postures:
-
Enterprise and service‑provider incumbents should leverage scale, portfolio breadth, and cloud capabilities to defend large contracts while accelerating software‑defined value propositions.
-
Consumer OEMs must optimize product roadmaps to balance cutting‑edge features (Wi‑Fi 7, multi‑gig backhaul, integrated security) with cost‑effective manufacturing and diversified supply chains to mitigate regulatory interruptions.
-
Channel and platform players that can combine hardware with recurring services (security subscriptions, parental controls, performance guarantees) are best positioned to capture lifetime value and smooth revenue volatility.
Representative vendor dynamics we evaluate in the report include strategic moves from enterprise stalwarts offering cloud‑native broadband routers, consumer brands pushing Wi‑Fi 7 mesh systems, and emerging suppliers targeting industrial and ruggedized applications. Each vendor profile in the full report maps product strengths, go‑to‑market channels, and likely responses to regulatory or supply‑chain shocks.
Recent developments that change near‑term playbooks
-
Regulatory updates in early 2026 created immediate compliance planning requirements for manufacturers, distributors, and service providers, prompting some to accelerate localization or pursue exemptions.
-
Product innovation continues at pace: the market is seeing ruggedized industrial designs, integrated edge compute capabilities, and higher‑density gateways aimed at both consumer and vertical markets.
-
Spectrum and infrastructure policy moves, including planned auctions and subsidy program adjustments, will influence operator capex allocation and therefore timing and scale of CPE refresh waves.
Strategic imperatives for 2026
-
Prioritize portfolio segmentation by value: carve out clear premium, mid‑market, and managed‑service propositions and align channel incentives to those tiers.
-
Harden supply‑chain and compliance capabilities: establish multi‑sourcing playbooks, pursue relabeling or localized assembly where feasible, and maintain proactive engagement with certification bodies.
-
Invest in software and services: embedding security, performance analytics, and subscription services into router platforms materially increases customer stickiness and margins.
-
Use targeted M&A and partnerships to fill capability gaps quickly — particularly in cloud orchestration, security telemetry, and edge compute — where organic development would lag market timing.
-
Scenario‑based planning: build commercial plans that assume a range of regulatory outcomes and spectrum availability timelines to avoid single‑point risks in product launches and channel commitments.
What the PW Consulting report delivers for executives
This report is structured as an executive decision toolkit rather than a raw data dump. Highlights include:
-
A concise executive playbook translating market forecasts into concrete choices for product prioritization, pricing, and channel strategy.
-
Vendor scorecards and strategic options for partnerships, licensing, and bolt‑on acquisitions to accelerate service delivery and SaaS conversion.
-
Scenario models and sensitivity analyses that show how variations in regulatory timing, fiber roll‑out rates, and component availability alter TAM and revenue mix outcomes.
-
Operational checklists for compliance, supply‑chain risk mitigation, and go‑to‑market sequencing for new product introductions.
-
Customer and operator interview summaries that surface buying triggers, tolerance for subscription models, and expectations for supported lifecycles.
Importantly, the report preserves granular regional, technology, and end‑user splits behind a gated dataset — designed so strategic teams can access tailored tables and dashboards that map directly to their commercial territories and product SKUs.
Methodology and data integrity
Our analysis combines historical time‑series (2020–2025), primary interviews with carriers, OEMs, distributors, and retailers, and a bottom‑up product/price model. Forecasts (2026–2032) use scenario weighting that reflects both macroeconomic assumptions and industry‑specific catalysts such as spectrum auctions, subsidy program revisions, and Wi‑Fi generational adoption curves. Market concentration metrics are included to inform competitive strategy, while our risk framework quantifies exposure to regulatory shocks and supply constraints.
Next steps for leaders
For 2026, broadband router strategy must be both adaptive and decisive. PW Consulting’s Broadband Router Market report equips senior leaders to: prioritize investments where margin and adoption converge; set procurement and localization roadmaps; and mobilize M&A or partnering plays to capture emergent service revenues. The public summary above outlines the strategic contours — the full report and interactive data pack convert those contours into executable plans, prioritized initiatives, and scenario‑tested financials.
Access and engagement
PW Consulting is making the full report and its interactive forecasting workbook available to clients and partners. The restricted dataset contains detailed regional, technology, and end‑use segmentation, vendor financial benchmarks, and downloadable scenario models. For boards, investors, and product leaders planning tactical moves in 2026, the report is designed to be the single reference that aligns product roadmaps, procurement decisions, and regulatory risk mitigation across the enterprise.
For detailed analysis of this topic, please visit the official page: Broadband Router Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Workday HCM Consulting Market to Reach USD 6,155.97 Million by 2032 at an 8.85% CAGR, Driven by Implementation Services and Large Enterprises
By PW Consulting, 2026-07-06
PW Consulting: Strategic Brief — Workday Human Capital Management Consulting Service Market (2026)
PW Consulting today publishes an executive-level synthesis of our latest market research report on the Workday Human Capital Management (HCM) consulting services market. Built on a 2025 base year with historical coverage from 2020–2025 and a 2026–2032 forecast horizon, the study quantifies market direction and delivers practical decision tools designed specifically for 2026 strategic planning cycles. Our analysis projects continued, above-market expansion — underpinned by a compound annual growth rate (CAGR) of 8.85% across the forecast period — reflecting the sustained shift of enterprise HR modernization, AI-enabled workforce automation, and regulatory-driven data governance investments. In dollar terms, the global market grows from the multi‑billion-dollar scale in recent years to an expected market size of roughly USD 6,156 million by 2032 (revenue unit: Million USD), offering a clear signal for boards and executive teams to re-evaluate resourcing, vendor strategy, and risk posture this year.
Workday Human Capital Management Consulting Service Market
Why this report matters for 2026 decision‑making
- Tactical clarity for procurement windows: The market trajectory and velocity captured in the report inform procurement windows, preferred contracting models, and the trade-offs between fixed-price implementation engagements, outcome-based managed services, and ongoing optimization retainers.
- Evidence-based vendor selection: With a market landscape that remains moderately concentrated (CR3 ~32.5%; CR5 ~44.8%), organizations must balance the strengths of global systems integrators with the agility of specialist providers when defining scope and delivery governance.
- AI and compliance are now intertwined: Adoption of AI-functionalities in HCM (recruiting, workforce planning, skills mapping) accelerates value capture but elevates legal and reputational risk, making vendor capabilities in explainability, auditability, and joint governance mandatory evaluation criteria.
- Investment timing and sizing: The projected growth path enables CFOs to stress-test multi-year budgets for HCM transformation initiatives and align internal change‑budget phasing with vendor release cycles and capability roadmaps.
What the full report delivers (practical content for immediate use)
- Proven implementation playbooks and deployment timelines tailored to enterprise size and transformation complexity, including phased vs. big‑bang scenarios and hybrid delivery models.
- Vendor evaluation frameworks and a repeatable RFP template that weight technical capabilities, delivery footprint, IP, and shared‑risk commercial terms.
- Financial models: TCO and ROI calculators with configurable assumptions for license mix, third‑party integrations, change management, and multi‑year managed services.
- Capability maps and operating‑model blueprints linking Workday module choices to HR operating model evolution, payroll connectivity, and finance integrations.
- AI readiness and governance checklists specific to high‑risk employment use cases, plus a compliance playbook aligned to new privacy regimes and the EU AI Act requirements.
- Case studies and implementation retrospectives that extract lessons on governance bodies, sprint cadences, and delivery risk mitigation.
- M&A and partner strategy guidance for acquirers and target companies that use Workday as a core HRIS — including integration sequencing and contract harmonization considerations.
Competitive landscape: implications for partner selection
The competitive field spans global systems integrators, multinational consulting firms, and specialized Workday services vendors. Leading global consultancies — including Deloitte, Accenture, KPMG, PwC, Cognizant, IBM Consulting, Capgemini — bring deep end‑to‑end transformation capabilities, global delivery scale, and strong finance‑to‑HR integration experience. Their strengths are particularly evident in complex, multi‑jurisdictional rollouts, enterprise change programs, and large transformation budgets.
Workday Human Capital Management Consulting Service Market
Specialist providers and managed‑services firms — represented by vendors such as OneSource Virtual, Alight, Huron, Slalom, and Surety Systems — offer differentiated value in operationalizing Workday post‑go‑live, delivering agile optimization cycles, and providing industry‑specific templates for faster time‑to‑value. These firms typically excel at long‑tail operational governance, release management, and optimization engagements where bespoke integrations and continuous improvement matter more than one‑off implementations.
Workday Human Capital Management Consulting Service Market
Strategically, the market’s moderate concentration (CR3 ~32.5%; CR5 ~44.8%) indicates that while the big players command scale advantages and deeper pockets for risk sharing, there remains significant space for specialists and regional partners to capture value through niche services, industry templates, and managed service models. For buyers, this means a hybrid sourcing strategy—mixing global integrator muscle for initial transformation and specialist partners for sustained optimization—is often optimal.
Regulation, product evolution and talent dynamics shaping 2026 choices
- Data protection and cross‑border processing: Workday’s recent certifications under the EU‑U.S. Data Privacy Framework (including UK and Swiss extensions) reduce legal friction for cross‑border processing, but enterprise contracts must still embed specific controls and audit mechanisms to meet internal and external compliance obligations.
- State‑level privacy laws in the U.S.: With multiple U.S. states enacting comprehensive privacy rules that affect HR data and AI hiring tools, procurement teams must require granular data handling commitments and breach notification SLA clauses from vendors.
- EU AI Act and high‑risk classification: The EU’s stance on AI in employment contexts elevates vendor responsibility for risk management, documentation, and human oversight — requirements that should be contractualized in 2026 deals.
- Workday product evolution: Recent platform enhancements (including new HRScale offerings and skills‑mapping capabilities) expand the opportunity set for faster automation of talent processes but also require buyers to reassess integration priorities and training investments.
- Talent and labor cost pressure: Specialized Workday skill scarcity — for implementation, release management, and AI‑tuning — continues to drive supplier pricing dynamics and has become a decisive factor in deciding between insourcing vs. managed service arrangements.
Concrete recommendations for executives planning 2026 HCM programs
- Align financing to the market cycle: Use the report’s TCO scenarios to establish multi‑year funding that anticipates iterative optimization rather than a single implementation payout.
- Specify AI governance in contracts: Mandate transparency, model documentation, and remediation SLAs for AI modules used in recruitment and workforce decisions.
- Adopt a blended delivery sourcing strategy: Combine a lead integrator for initial deployment with specialist partners for industry‑specific configuration and ongoing managed services.
- Stress‑test privacy controls: Build contractual data residency and processing clauses into statements of work, reflecting both international frameworks and U.S. state law variability.
- Invest in internal release management capability: Treat Workday as an evolving platform; allocate budget and talent for continuous releases, feature adoption, and skills development to avoid expensive re‑implementations.
- Use procurement levers to align incentives: Evaluate outcome‑based contracting and shared savings models for optimization engagements to better align vendor and client objectives.
How to use this report in your 2026 planning
The report is intended for CHROs, CIOs, CFOs, transformation leads, and procurement heads who must decide on investment sizing, vendor selection, and operating model design in 2026. Practically, teams can use the deliverables to:
- Build defensible business cases and board memos using our ROI templates;
- Run side‑by‑side vendor scoring workshops with the included evaluation framework;
- Accelerate RFP readiness with our templated scopes and commercial clauses; and
- Operationalize AI governance and privacy controls immediately using the provided playbooks and checklists.
PW Consulting’s report is designed with the “preview and probe” principle: we provide the diagnostic frameworks, migration blueprints, and commercial levers that senior teams need to act in 2026 while preserving the proprietary granular market segmentation and vendor scorecards for subscribers. This approach ensures executives receive actionable guidance now and can access the full evidentiary dataset to finalize procurement and budget commitments.
To explore the complete dataset, granular vendor matrices, and the operational toolkits referenced above, please visit our official report page where you can request the full report and supporting Excel models. PW Consulting stands ready to support boards and executive teams in translating this market intelligence into executable program plans that mitigate risk, accelerate value capture, and future‑proof HCM investments in an increasingly regulated and AI‑enabled landscape.
For detailed analysis of this topic, please visit the official page: Workday Human Capital Management Consulting Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Prefabricated & Modular Data Centers to Surge from USD 72.5 Billion in 2025 to USD 210.6 Billion by 2032 at a 16.45% CAGR
By PW Consulting, 2026-07-06
Prefabricated And Modular Data Centers Market: Strategic Intelligence for 2026 Decision-Makers
PW Consulting’s latest market study on Prefabricated And Modular Data Centers (base year 2025) is released at a moment when capital allocation, site-selection, and technology choice decisions will determine enterprise competitiveness for the decade ahead. Between 2020 and 2025 the market scaled rapidly — from roughly USD 34.0 Billion to about USD 72.5 Billion — and our forecast extends that momentum through 2032, reaching an estimated USD 210.56 Billion. The forecast window 2026–2032 is underpinned by a compound annual growth rate of 16.45%. For senior executives, infrastructure planners, and investors, this report reframes modular data center purchasing from tactical procurement to strategic capability building.
Prefabricated And Modular Data Centers Market
Why 2026 Is a Strategic Inflection Point
-
Acceleration of AI and high-density compute: The rapid adoption of AI, HPC, and high-density workloads is reshaping requirements for power delivery, cooling (including liquid cooling), and rack-level infrastructure. Modular systems — factory-built, pretested, and optimized for density — are no longer a niche alternative but a primary deployment model for enterprises needing predictable, rapid capacity.
Prefabricated And Modular Data Centers Market -
Regulatory and utility dynamics: 2026 introduces meaningful regulatory shifts in several jurisdictions where data centers are being required to internalize new infrastructure costs and disclose energy impacts. Multi-state actions and formal pledges by hyperscalers to protect ratepayers are changing the economic calculus for siting and operating facilities. Rising residential electricity prices and utility rate cases in recent years further compress margins and require scenario-driven energy planning.
Prefabricated And Modular Data Centers Market -
Supply chain and factory integration become competitive levers: Organizations that lock early to factory-integrated modular solutions gain control over schedule risk, quality, and integration of advanced cooling and power topologies. Recent product launches and collaborations across major vendors demonstrate a race toward factory-delivered AI-ready modules.
What This Report Delivers — Practical, Actionable Intelligence
This is a market intelligence deliverable designed for operators, CIOs, real estate and facilities heads, M&A teams, and infrastructure investors who must translate macro trends into executable choices in 2026. The report combines macro forecasting with practitioner-grade tools and includes:
-
Quantitative market model (2020–2032) with high-resolution scenario layers. The document traces historical growth, baseline forecasts, and up/down scenarios calibrated to demand drivers including AI adoption curves, edge densification, and policy shocks.
-
Vendor profiles and competitive playbooks. Deep, vendor-specific analyses synthesize product roadmaps, factory capabilities, channel models, and go-to-market strategies — enabling readers to build shortlists matched to technical and commercial constraints.
-
TCO and lifecycle toolkits. Modular CAPEX/OPEX templates, sensitivity calculators, and lifecycle replacement scenarios allow procurement teams to compare prefabricated options against traditional stick-built alternatives on equal footing.
-
Site selection and regulatory risk matrices. Practical checklists and scoring models map grid readiness, permitting timelines, taxation and incentives, and local regulatory exposure to support data-driven location decisions.
-
Implementation playbooks. From factory acceptance testing protocols and shipping logistics to on-site commissioning and phased capacity activation, the report outlines standardized processes that reduce schedule risk and integration costs.
-
Supply chain stress-tests and mitigation strategies. Scenarios model critical component constraints, pricing shocks, and vendor concentration, with recommended sourcing and contractual hedges.
Note: To preserve the value of our original research, the full report contains detailed regional and segment-level breakdowns, and downloadable financial models. Core regional/application-level splits and proprietary segment figures are available in the source report.
Competitive Landscape — Who Matters and Why
The modular data center market is moving from fragmented vendor competition to a more structured marketplace where factory integration, systems engineering, and channel execution matter as much as component performance. While concentration is rising, the market remains contestable: the three largest firms account for a significant portion of the market and the five largest firms approach half of total market share, a dynamic that shapes procurement strategy and negotiating leverage.
-
Schneider Electric — A global systems leader with an established EcoStruxure portfolio and recent product launches tailored to high-density AI workloads. Strong in integrated power and liquid-cooling architectures and in partnerships across hardware ecosystems.
-
Vertiv — A major provider of factory-integrated prefabricated infrastructure with product lines aimed at accelerated AI deployment, and recent global releases and partnerships that signal a push into turnkey, high-capacity factory modules.
-
Huawei — Vendor of containerized and prefabricated modular units optimized for telco, edge, and scalable deployments, with strong supply-chain integration and on-premises product families suited to rapid rollout.
-
Eaton, Delta Electronics — Power-centric suppliers offering modular solutions focused on resilience, UPS, and integrated power delivery — critical where uptime and local power constraints drive architecture.
-
Specialist integrators (BMarko, CenCore, Compu Dynamics Modular, PodTech, TAS) — These firms provide custom and turnkey factory-built solutions focused on edge, secure/TEMPEST-compliant deployments, and tailored high-density implementations for cloud providers, defense, and enterprise colocation.
Recent vendor moves underscore market dynamics: major launches and partnerships in late 2025 and early 2026 have accelerated the availability of AI-optimized prefabricated systems and strengthened factory-to-field value chains. Buyers should expect product roadmaps to be a decisive procurement criterion in 2026.
Strategic Implications for Enterprise Decision-Makers
-
From schedule to strategic capacity: Prefabrication converts months of on-site construction risk into factory-driven timelines. Organizations seeking rapid market entry, predictable OTTR (order-to-ready) windows, or phased capacity expansion will gain measurable advantage.
-
Energy and regulatory exposure must be modeled as a first-order cost. States and utilities are increasingly requiring data centers to fund incremental distribution and generation impacts; incorporate these scenarios into financial models and site comparisons.
-
Interoperability and vendor lock-in are expensive. Insist on modular interface standards, open mechanical and electrical designs where practicable, and contractual rights to migrate workloads across physical modules and vendors.
-
Financing and commercial models will diversify. Expect increased use of OPEX-based offerings, factory financing, and vendor-managed facilities as enterprises and hyperscale operators seek speed without capital overhang.
Five High-Impact Actions to Start Now
-
Embed regulatory scenarios in every site-selection and financial model: model utility rate pass-throughs, infrastructure cost allocation, and permitting timelines across best/worst/likely cases.
-
Require factory acceptance test (FAT) packages and systems-level interoperability clauses in RFPs to reduce integration risk and enable competitive multi-vendor sourcing.
-
Prioritize modular designs that are liquid-cooling ready and support high power density — retrofitting for advanced cooling is often costlier than specifying capability up-front.
-
Negotiate flexible commercial structures: hybrid CapEx/Opex contracts, milestone-linked payments, and warranty terms that align vendor incentives to operational performance.
-
Stress-test procurement against supply-chain shocks: include alternate sourcing, longer lead-time forecasts, and options for localized manufacturing or containerization to mitigate logistics risk.
Why PW Consulting’s Report Is Different
Our analysis couples large-sample quantitative forecasting (2020–2032) with primary interviews, vendor factory visits, and detailed procurement playbooks. The methodology blends macroeconomic drivers, policy simulations, and engineering-level cost models to produce a decision-ready output. Clients receive scenario-ready financial models, procurement templates, and a prioritized roadmap tailored to enterprise profiles — all designed to reduce time-to-decision and the probability of costly rework in deployment.
For strategic buyers and investors preparing plans in 2026, the difference between a playbook and a post-mortem is often the quality of the foresight applied today. This study is crafted to convert foresight into implementable actions.
To access the full report, including regional and segment-level breakdowns, the downloadable TCO tools, and our vendor scorecards, please consult the PW Consulting publication page. The detailed segment matrices and primary-source appendices are held in the full report to preserve the integrity of our proprietary research and to support high-trust client engagements.
PW Consulting — helping leaders translate modular infrastructure momentum into durable competitive advantage for the decade ahead.
For detailed analysis of this topic, please visit the official page: Prefabricated And Modular Data Centers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


