



Category: IT & Electronics
Smart Waste Collection at 13.5% CAGR: The Real Drivers Behind $6.4B Growth
By PW Consulting, 2026-09-18
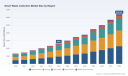
The Smart Waste Collection Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The smart waste collection market has transitioned from a niche urban experimentation space to a mainstream infrastructure priority over the past half-decade. Valued at approximately $2.65 billion in 2025, the sector has expanded from $1.34 billion in 2020, reflecting a compound annual growth rate of 13.5 percent through the forecast horizon ending in 2032. By the close of the projection period, revenue is expected to surpass $6.4 billion, signaling a structural shift rather than a cyclical uptick. This trajectory is anchored in the convergence of municipal budget pressures, regulatory mandates for transparent waste tracking, and the maturation of low-power connectivity ecosystems that make sensor-driven logistics economically viable at scale.
The market expansion, however, masks underlying friction points that decision-makers must navigate carefully. First, the cost of deployment remains a persistent barrier for mid-sized cities and commercial operators. Basic smart bin sensor deployments paired with SaaS platforms typically run between €30 and €60 per bin annually, including sensor amortization. While this figure has declined as hardware commoditizes, the total cost of ownership—encompassing installation, network provisioning, platform licensing, and ongoing maintenance—still constrains rapid adoption in budget-constrained environments. Second, data interoperability and integration complexity continue to fragment the value chain. Fleet management systems, route optimization engines, and municipal ERP platforms rarely share common data models, forcing operators to build custom middleware or accept siloed dashboards that limit cross-functional insight. Third, the regulatory landscape is accelerating faster than standardization. Frameworks such as the UK's mandatory Digital Waste Tracking scheme and updated EU Waste Framework Directive requirements are introducing stricter recycling mandates and purity accountability, but compliance pathways vary by jurisdiction, creating uncertainty for multinational operators and technology vendors alike.
These challenges are not deterrents so much as stress tests that will separate durable solutions from short-lived pilots. Organizations that treat smart waste collection as a data infrastructure play—rather than a hardware replacement project—will be better positioned to extract operational leverage and align with evolving compliance expectations.
Key Drivers Behind Market Acceleration
Several interlocking forces are propelling the smart waste collection market toward sustained double-digit growth. Understanding these drivers is essential for anticipating where capital, partnerships, and product development will converge in the coming years.
Technological Breakthroughs in Sensing and Connectivity
Ultrasonic fill-level sensors, solar-powered compaction units, and low-power wide-area network connectivity have matured into reliable, field-tested components. LoRaWAN networks, widely adopted for smart bin monitoring, are undergoing upgrades in 2026 to support hybrid multi-band connectivity, improving coverage in dense urban corridors and reducing reliance on single-network dependencies. This evolution lowers the risk of connectivity gaps that previously undermined route optimization accuracy. On the software side, predictive analytics and route optimization engines are moving beyond static fill-level thresholds toward dynamic models that incorporate historical collection patterns, traffic conditions, and seasonal waste generation profiles. The result is a measurable reduction in unnecessary collection trips, fuel consumption, and labor allocation.
Policy and Regulatory Momentum
Regulation is reshaping waste management from an operational afterthought into a compliance-critical function. The EU Waste Framework Directive updates introduced in early 2026 impose stricter recycling targets and accountability for waste purity, pushing municipalities and industrial operators to demonstrate traceability across collection, sorting, and disposal stages. In parallel, the UK's mandatory Digital Waste Tracking scheme, effective in 2026, is designed to combat waste crime and support circular economy compliance by requiring digital documentation across the waste chain. These mandates create a clear demand signal for platforms that can capture, validate, and report waste movement data with audit-grade reliability. Vendors that embed compliance workflows directly into their analytics and route optimization tools are gaining a structural advantage, as operators seek to avoid fragmented point solutions that increase administrative overhead.
Demand-Side Shifts in Municipal and Commercial Operations
City governments and commercial property managers are increasingly treating waste collection as a service optimization problem rather than a fixed-cost utility. Public space managers, for example, are deploying solar-powered smart waste and recycling stations with compaction and fill-level sensing to reduce collection frequency in high-traffic areas while maintaining cleanliness standards. The deployment of such stations at Emerald Park in partnership with Panda illustrates how public-private arrangements can share deployment risk and align operational incentives. On the commercial side, facility operators face pressure to reduce service disruptions, improve tenant experience, and demonstrate sustainability commitments. Smart collection platforms that provide real-time visibility into bin status and collection scheduling help operators move from reactive pickup schedules to condition-based service models, which in turn supports labor planning and fleet utilization.
Supply Chain and Cost Structure Evolution
The economics of smart waste collection are gradually improving as hardware components become more standardized and software platforms shift toward subscription-based models. Sensor modules and IoT gateways are benefiting from broader industrial IoT supply chain scale, which has helped moderate unit costs and shorten deployment timelines. Meanwhile, the industry context noise around per-bin annual costs of €30–€60 including sensor amortization reflects a broader trend toward unbundled pricing, where hardware, connectivity, and software are priced separately or packaged in tiered service models. This modularity gives operators flexibility to scale incrementally, but it also requires disciplined vendor evaluation to avoid hidden integration and maintenance expenses. Fleet upgrades are another notable shift. The launch of Cart Smart automated garbage and recycling collection using new smart-equipped trucks demonstrates how vehicle-side intelligence—such as onboard scanning, load verification, and route feedback—can complement bin-side sensors, creating a more complete data loop between collection points and hauling operations.
Competitive Landscape and Leading Strategies
The smart waste collection market remains relatively fragmented, with the top three players accounting for roughly 28.5 percent of revenue and the top five reaching approximately 36.2 percent. This concentration leaves substantial room for differentiation, consolidation, and targeted market entry. The competitive field spans solar-powered smart bins, sensor and IoT modules, and software platforms that span route optimization, fleet management, and citizen engagement. Companies are pursuing distinct strategic positions rather than competing on a single dimension.
- Bigbelly has built a recognizable presence in public-space waste management through solar-powered smart waste and recycling stations that combine compaction with fill-level sensing. Its deployments in municipal and commercial public areas emphasize reduced collection frequency and improved space utilization, positioning the brand around visible, self-contained hardware solutions that simplify procurement for parks, campuses, and downtown corridors.
- Ecube Labs operates from a dual hardware-and-platform angle with solar-powered compacting bins and a network management platform that incorporates ultrasonic fill-level sensing and route optimization. Its approach reflects a strategy of tying bin-level intelligence to centralized dispatch, which appeals to operators seeking a single vendor relationship for both field equipment and analytics.
- Sensoneo offers end-to-end smart waste management spanning ultrasonic sensors, data analytics, and route optimization, with a track record in large-scale municipal deployments and deposit return systems. Its recent involvement in Portugal's national Deposit Return System—powering voucher validation and waste tracking—illustrates a strategy of embedding technology into nationally significant compliance and circular economy programs, which can create durable public-sector relationships and reference deployments.
- Evreka focuses on AI-powered digital platforms for waste collection, fleet management, and citizen engagement, with IoT integration tailored to municipalities and operators. Its emphasis on citizen-facing engagement and operational digitization positions it at the intersection of service communication and field execution.
- Rubicon Technologies centers its offering on software for waste and recycling fleet optimization, route planning, and data analytics, serving cities and businesses with a platform-first model. This software-centric positioning allows the company to integrate with existing fleet and municipal systems without necessarily controlling the bin hardware layer.
- Enevo specializes in sensor-based waste monitoring, predictive analytics, and route optimization for haulers and property managers, targeting the operational efficiency layer where fill-level data translates directly into collection scheduling and cost reduction.
- AMCS Group provides an AI-enabled end-to-end waste management and recycling software platform that includes route optimization and smart collection tools, appealing to operators that want a broader enterprise software footprint across recycling, logistics, and customer management.
- Veolia leverages its global environmental services footprint to integrate smart collection technologies, IoT sensors, and data platforms into municipal and industrial operations. Its strategy is less about standalone product sales and more about embedding intelligence into large-scale service contracts, which can accelerate adoption where operators prefer integrated service delivery over fragmented technology procurement.
These companies illustrate a market that is simultaneously differentiating and converging. Hardware-led providers are expanding into software and network management to capture recurring revenue and deepen customer stickiness. Software-centric players are building integrations with sensors and fleet systems to improve data fidelity and route accuracy. Large environmental services firms are layering smart technologies into existing contracts, using scale and service relationships to deploy solutions across multiple sites. The net effect is a landscape where pure-play hardware vendors face pressure to demonstrate platform-level value, while software vendors must prove they can reliably ingest field data and translate it into operational savings.
Market evolution is also being shaped by the pace of standardization and the growing importance of compliance-ready data. As digital waste tracking and recycling accountability requirements tighten, vendors that can offer auditable data flows, transparent reporting, and configurable compliance workflows will likely command stronger positioning in municipal and industrial segments. At the same time, the presence of multiple viable approaches—solar compacting bins, ultrasonic sensors, route optimization platforms, and fleet-side intelligence—suggests continued fragmentation in the near term, with consolidation more likely around integrated data platforms and regional service partnerships than around any single hardware form factor.
Forward-Looking Trends and Commercial Implications
Looking ahead to the 2026–2032 window, several trends are likely to define where value is created and where risk accumulates.
From Bin-Level Sensing to End-to-End Data Loops
The next phase of market maturation will increasingly reward solutions that close the loop between bin status, collection execution, and downstream waste handling. Bin-side sensors and compaction units will remain important, but their strategic value will depend on how effectively they feed route optimization, fleet verification, and compliance reporting. Operators that can demonstrate measurable reductions in empty runs, improved container utilization, and traceable waste movement will have stronger grounds for contract renewals and expansion. Commercial opportunity lies in platforms that combine fill-level intelligence with vehicle-side confirmation and analytics that tie collection efficiency to cost and emissions metrics.
Garbage Truck Market
Compliance-Driven Procurement as a Growth Catalyst
Regulatory mandates for digital tracking, recycling purity, and circular economy accountability are converting compliance from a cost center into a procurement driver. Municipalities and industrial operators are more likely to prioritize solutions that can support mandated reporting and reduce the administrative burden of manual documentation. This creates openings for vendors that design data capture and reporting into everyday collection workflows rather than treating compliance as an add-on module. The risk is that divergent national and regional requirements could increase integration complexity, especially for operators running multi-jurisdiction fleets. Standardization efforts and interoperable data models will matter more as compliance scope expands.
Modular Pricing and Fleet-Side Intelligence Will Reshape Adoption Paths
The trend toward modular hardware, connectivity, and software pricing will likely continue, giving operators more flexibility to scale in stages. This modularity lowers initial barriers but also places a premium on disciplined evaluation of total cost of ownership, including network dependencies, data integration effort, and maintenance obligations. At the same time, fleet upgrades that bring intelligence onto collection vehicles—such as automated cart handling, onboard verification, and route feedback—are expected to complement bin-side sensing and improve the reliability of dynamic scheduling. Organizations that align bin-side and vehicle-side data streams will be better positioned to optimize labor, fuel, and container lifecycles. The uncertainty here lies in the pace of fleet renewal and the degree to which smaller operators can fund vehicle-side upgrades alongside sensor deployments.
Strategic Recommendations for Decision-Makers
For manufacturers and technology vendors, the priority is to move beyond standalone hardware specifications and articulate how a solution reduces total operational cost while supporting compliance workflows. Product roadmaps that integrate fill-level sensing, route optimization, and auditable reporting into a coherent data architecture will be easier to position in municipal and industrial procurement processes. Vendors should also anticipate interoperability demands by designing open integration points for fleet systems, municipal platforms, and regional connectivity options rather than locking customers into closed stacks.
For investors, the market's growth trajectory is attractive, but value capture will favor companies with durable recurring revenue, demonstrable operational savings, and exposure to compliance-driven procurement. Due diligence should focus on unit economics across hardware, connectivity, and software components, as well as the strength of municipal and industrial references that validate route optimization and cost reduction claims. Portfolio positioning should account for the likelihood of consolidation around integrated data platforms and regional service relationships, especially where regulatory momentum is strongest.
Worldwide Smart Solar Urban Equipment Market
For procurement teams and operational leaders, the most effective adoption strategy starts with a narrowly defined use case—such as high-traffic public spaces, commercial facilities with irregular waste generation, or municipal corridors with high collection costs—and expands only after measurable savings and data reliability are proven. Evaluation criteria should include total cost of ownership, integration effort with existing fleet and reporting systems, and the vendor's ability to support evolving digital tracking and recycling accountability requirements. Building internal capability to interpret collection data and translate it into scheduling and labor decisions will determine whether smart waste collection delivers its intended operational leverage.
Detailed segmentation data, regional deployment patterns, and customized scenario analysis can help stakeholders narrow where to commit resources and how to sequence investments. Comprehensive research on the smart waste collection market is available for teams that need deeper breakdowns across product types, application segments, and regional dynamics, along with tailored guidance for procurement, partnership, and investment decisions.
PW Consulting Information & Electronics Research Center
For detailed analysis of this topic, please visit the official page: Smart Waste Collection Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Smart Seam Tracking Laser Sensors: Why 7.5% CAGR Reshapes Market|2026-2032
By PW Consulting, 2026-09-18
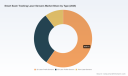
The Strategic Evolution of the Smart Seam Tracking Laser Sensors Market
The global market for smart seam tracking laser sensors has entered a phase of structurally accelerating growth, expanding from approximately 490.2 million USD in 2020 to an estimated 685.0 million USD in 2025, with momentum carrying toward more than 1.13 billion USD by 2032. This trajectory translates to a compound annual growth rate of 7.5 percent across the 2026-2032 forecast window. The growth is neither cyclical nor narrowly tied to a single industrial cycle; rather, it reflects a foundational shift in how automated fabrication, assembly, and inspection workflows are engineered. Seam tracking has transitioned from a niche alignment aid to a core perception layer that enables closed-loop control in robotic welding, hybrid joining, brazing, and precision inspection. As tolerance stacks tighten and production volumes scale across mobility, marine, and advanced manufacturing sectors, the sensor layer has become the differentiating factor between basic automation and adaptive, high-yield processing.
Despite the clear growth path, manufacturers and system integrators are navigating three overlapping challenges that will define competitive outcomes over the next half decade. First, the industry must reconcile performance expectations with real-world variability. Workshop lighting, surface oxidation, gap deviations, and material heterogeneity consistently degrade the robustness of vision-based tracking if algorithms, optics, and illumination are not co-optimized for production environments rather than controlled lab conditions. Second, supply chain fragility has moved from a logistical nuisance to a strategic cost driver. Concentrated sourcing of high-power semiconductor components, laser optics, and specialty substrates introduces exposure to pricing shocks and lead-time elongation, forcing vendors to redesign bill-of-materials strategies and qualification pipelines. Third, integration complexity remains a persistent adoption barrier. While individual sensor specifications are increasingly impressive, the value is realized only when tracking data is fused seamlessly with robot kinematics, process controllers, and quality management systems, a requirement that demands ecosystem readiness rather than stand-alone hardware superiority. Addressing these friction points is no longer an engineering afterthought; it is the central commercial battleground.
Market Architecture and Concentration Dynamics
The revenue base is distributed across a mix of established sensor specialists and application-focused equipment players, with a meaningful share of total volume concentrated among a small group of incumbents. This concentration does not imply a static hierarchy. Instead, it reveals a market where differentiation is increasingly earned through software maturity, cross-platform compatibility, and lifecycle support rather than pure sensor resolution. The three dimensional profile segment commands the largest revenue share, reflecting the broader industry migration from simple line profiling to volumetric perception that can handle complex joint geometries and variable gaps. Two dimensional profile sensors retain strong adoption in high-speed, lower-complexity tasks where cost and cycle time dominate purchasing decisions, while point laser sensors serve targeted displacement and alignment uses. Geographically, demand is broadest across Asia Pacific, followed by Europe and North America, with Latin America and the Middle East and Africa representing smaller but strategically important footprints tied to localized capacity expansion and export-oriented fabrication. Across application domains, automotive manufacturing leads demand formation, reflecting the impact of electrification on joint designs, material mixes, and throughput requirements. Heavy machinery and infrastructure, shipbuilding, and aerospace and defense each contribute sizable demand blocks shaped by durability requirements, regulatory scrutiny, and the rising use of robotic processes in large-scale structures and precision assemblies.
Key Drivers Shaping the Next Growth Cycle
Technology Innovation and Sensor Intelligence
The most consequential driver is the maturation of sensor intelligence itself. Modern systems are no longer simply delivering better point clouds; they are increasingly capable of adaptive interpretation under imperfect conditions. Advances in image processing pipelines, real-time filtering, and edge-based inference have improved seam detection reliability in environments where joint preparation varies, weld spatter is present, or surface finish is inconsistent. The practical effect is a reduction in false rejects, fewer manual interventions, and higher first-pass yield, which directly improves the economics of automated joining. In parallel, hybrid approaches that combine laser profile data with displacement and groove detection are reducing the need for multiple stand-alone sensors on the end effector, simplifying payload management and lowering integration risk. Recent product refreshes that emphasize enhanced image processing for precise seam tracking in automated welding illustrate how vendors are shifting from hardware-centric specifications toward application-tuned performance. This shift matters commercially because it expands the addressable envelope from ideal applications into broader, less forgiving production settings where the return on automation is most contested.
Policy, Standards, and Strategic Industrial Directives
Regulatory and policy environments are quietly but decisively reshaping demand patterns. In shipbuilding and advanced marine fabrication, national guidelines promoting smart shipyard development have created explicit tailwinds for robotic welding precision and integrated laser seam tracking. These directives do not merely encourage automation in principle; they support procurement strategies, modernization programs, and supplier qualification paths that make sensor-enabled joining more bankable for yard operators and tier suppliers. Equally important, quality assurance expectations in aerospace, defense, and safety-critical mobility segments are tightening, which elevates the role of inspection-grade tracking as part of a unified process rather than a separate quality gate. When seam tracking becomes part of the process control logic rather than a post-process verification step, the sensor transitions from an optional accessory to a core process enabler. For decision-makers, the strategic implication is that adoption is increasingly influenced by compliance roadmaps, export requirements, and program-level quality targets as much as by unit cost or cycle time.
Demand-Side Transformation in Mobility and Heavy Fabrication
On the demand side, the most visible change is the structural shift in joining requirements across e-mobility, vehicle architecture evolution, and large-scale fabrication. Electric drivetrains, battery enclosures, lightweight structural elements, and mixed-material assemblies introduce new gaps, thicker coatings, and more varied joint geometries than legacy body-in-white production. Robotic laser welding and hybrid joining are responding to these requirements because they can achieve consistent results while preserving productivity, but they also demand higher robustness from the tracking layer. In shipbuilding and infrastructure-adjacent heavy fabrication, similar pressures exist: longer structural runs, complex edge conditions, and a need to reduce rework in high-value assemblies. The common thread is that tolerance control and process repeatability are becoming more valuable than raw speed alone. As a result, end users are more willing to invest in sensors that demonstrably reduce rework, support adaptive path correction, and provide inspection-grade confidence. This demand evolution favors suppliers that can articulate total process value rather than sensor-only performance metrics.
Supply Chain Realities and Cost Structure Pressures
Cost structures are undergoing a simultaneous push and pull. On one side, raw material and component pressures have intensified. Restrictions and export dynamics affecting gallium and germanium, alongside broader concentration in high-power semiconductor and optics supply, have driven notable price increases in critical inputs, with ripple effects across laser-based and optics-intensive sensor designs. On the other side, integration complexity and qualification cycles can inflate total cost of ownership if the sensor is treated as an isolated component rather than part of a coordinated system. The resulting dynamic favors vendors that can stabilize performance despite component volatility, offer modular designs, and deliver predictable field performance with minimal recalibration burden. For buyers, the cost conversation is shifting from sticker price to resilience: supply assurance, multi-source readiness, software support longevity, and integration compatibility now weigh heavily in evaluation. Suppliers that overlook these factors risk margin erosion even when their core technology is competitive.
Worldwide Security Laser Scanner Market
Competitive Landscape and Differentiation in Practice
The competitive field blends specialized sensor manufacturers, welding-equipment integrators, and emerging players with regional cost advantages and application-specific engineering depth. A defining feature of the leaders is that they do not compete solely on resolution or scan speed; they compete on how well the sensing capability is packaged into the target process. Some firms anchor their positioning in high-speed, high-accuracy vision systems explicitly engineered for laser welding, hybrid welding, and brazing, where real-time joint guidance must keep pace with rapid thermal cycles and moving workpieces. Others emphasize optical seam tracking tuned for automated arc and laser welding, with particular attention to e-mobility and automotive use cases where tolerances and material variability are elevated. A further group integrates laser seam tracking sensors directly with robotic welding torches and joint guidance systems, aiming to reduce end-effector complexity and shorten deployment cycles. This diversity in go-to-market posture reflects a market that is still maturing from component competition toward solution-level competition.
Several strategic differentiators are increasingly decisive. First, cross-platform compatibility is becoming a practical necessity. As customers standardize on major robot brands and seek to deploy tracking across multiple cell designs, sensors that demonstrate reliable interoperability with common controllers and robot ecosystems reduce integration friction and expand addressable reuse within a facility. Second, the ability to support both real-time tracking and downstream inspection functions is gaining commercial weight. Systems that can guide the weld and then contribute to bead profile inspection or displacement verification offer a more complete value proposition, especially where quality records and traceability are mandatory. Third, application specialization is creating defensible niches. Vendors with focus on zero-gap detection for sheet metal, aerospace-oriented sensor lines, or specialized weld bead profiling are building domain credibility that generic specifications cannot easily replicate. This does not mean broad platforms are losing relevance; rather, the most resilient players are pairing broad compatibility with application-specific tuning and support.
Laser Displacement Sensor Market
The competitive evolution is also being shaped by a mix of consolidation logic and new-entry pressure. On one hand, established players are likely to deepen vertical integration around software, service, and integration support, because those layers increasingly determine retention and expansion within existing accounts. On the other hand, regional manufacturers and sensor-focused entrants continue to expand, particularly where localized price-performance ratios, faster engineering responsiveness, and strong relationships with domestic robot integrators create a viable path to scale. A notable early signal is the emergence of sensor lines targeting high-stakes verticals such as aerospace, which reflects both demand maturation and the willingness of large customers to qualify specialized offerings for demanding tolerances. The net direction is not simply toward fewer competitors; it is toward clearer segmentation between general-purpose tracking platforms and application-hardened solutions, with the most competitive firms capable of bridging both through modular architectures and adaptable software stacks. For customers, this means the evaluation framework should weigh ecosystem fit and support capability as heavily as raw sensing performance.
Forward-Looking Trends and the Shape of Opportunity
Over the next three to five years, the market is likely to consolidate around three interrelated trends. The first is the expansion of perception from tracking to closed-loop process control. Seam tracking will increasingly feed adaptive path correction, dynamic parameter adjustment, and inspection feedback within a single workflow, reducing dependence on offline quality sampling and shortening response time to process drift. This creates commercial opportunities for vendors that can deliver reliable sensor data in a form that controllers and quality systems can consume without heavy middleware or custom integration work. The second trend is the continued migration from hardware differentiation toward software and algorithm differentiation. As baseline optical and scanning performance becomes more comparable across competent suppliers, the edge will increasingly belong to systems that perform better under variable joint gaps, surface conditions, and production noise, and that can be updated and tuned without extensive re-qualification. The third trend is a growing emphasis on supply resilience and modular design. Given ongoing component volatility, customers will reward suppliers that can articulate risk-mitigated sourcing, maintain performance continuity across revisions, and offer flexible configuration options aligned with different payload, cycle-time, and budget constraints.
These trends translate into concrete opportunity spaces. For system integrators and equipment builders, the opportunity lies in embedding sensor capability earlier in the design of welding cells and large-scale fabrication lines, so that tracking is planned as a process layer rather than retrofitted as an add-on. For end users, the opportunity is to use tracking data not simply to improve alignment but to unlock higher automation rates in applications that were previously considered too variable for unattended operation. At the same time, uncertainty remains. Pricing pressure on critical optical and semiconductor inputs could compress margins or slow product iteration in segments where cost sensitivity is high. Adoption may also fragment if integration standards and data interfaces remain inconsistent, forcing repeated customization across robot platforms and cell architectures. Finally, the competitive mix may shift quickly where regional players gain traction through strong local support and cost positioning. These dynamics do not threaten the broader growth path, but they do reward participants who can balance technological ambition with deployment practicality.
Strategic Actions for Decision-Makers
For manufacturers and equipment integrators, the priority is to treat seam tracking as part of the core process architecture rather than a peripheral feature. Selection criteria should emphasize robust performance under real production variability, compatibility with existing robot ecosystems, and the ability to support both guidance and inspection use cases within a manageable integration footprint. Suppliers that can demonstrate repeatable outcomes across joint variation and surface conditions will increasingly capture preference over those competing only on peak specifications or isolated lab results. This is also the moment to evaluate whether in-house tracking capability, partnership with a sensor specialist, or bundled equipment offerings best fit long-term process roadmaps.
For investors and corporate strategists, the key is to differentiate between sensor hardware exposure and solution-level exposure. Revenue tied to recurring software support, integration services, and application-specific qualification is likely to be more durable than revenue dependent solely on unit volume in commoditizing segments. Watching which companies expand across multiple verticals while maintaining integration simplicity and supply resilience will provide an early signal of which positions are likely to scale. Capital and partnership decisions should account for the possibility that value capture shifts toward players capable of combining perception hardware with the software, support, and ecosystem relationships needed to keep systems operating in demanding environments.
For procurement and operations leaders, the emphasis should move toward total cost of ownership and deployment reliability. Where possible, qualification should include tests that reflect actual gap variation, surface finish, and noise conditions rather than idealized setups. Multi-source readiness, lifecycle support expectations, and compatibility with the dominant robot and controller platforms in the facility should weigh heavily in purchasing decisions. Tracking investments will deliver the strongest returns when they are aligned with broader automation and quality objectives, allowing process teams to reduce rework, increase automation coverage, and build more consistent inspection evidence from the same data stream. For organizations seeking deeper segmentation data, competitive benchmarking, and customized adoption roadmaps, the full research report provides the detailed breakdowns and scenario analysis needed to translate these trends into precise procurement, investment, and product strategy decisions.
PW Consulting Information & Electronics Research Center
For detailed analysis of this topic, please visit the official page: Smart Seam Tracking Laser Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Mental Health Counseling Service Market: Why 8.12% CAGR Changes Everything
By PW Consulting, 2026-09-18
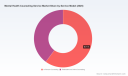
Navigating the Mental Health Counseling Service Market: Strategic Trends and Commercial Opportunities
Market Snapshot: Scale, Growth, and Structural Realities
The global mental health counseling service market has entered a period of sustained expansion, driven by shifting societal attitudes, institutional adoption, and systemic healthcare pressures. Valued at approximately $10.2 billion in 2020, the market crossed $14.8 billion by 2024 and reached $16.5 billion in 2025. Forward projections indicate continued momentum, with revenue expected to approach $17.8 billion in 2026, $20.7 billion by 2028, and $28.5 billion by 2032. This trajectory reflects a compound annual growth rate of 8.12 percent, signaling that demand is not cyclical but structural. The expansion is broad-based, spanning multiple delivery formats, demographic segments, and geographic regions. However, growth alone does not guarantee commercial viability, and the market’s underlying architecture reveals several inflection points that will shape competitive outcomes over the next five years.
One of the most defining characteristics of the sector is its fragmented nature. The top three players collectively account for only 8.5 percent of total revenue, while the top five hold 12.2 percent. This dispersion suggests a market that remains highly accessible to regional providers, specialized practices, and technology-enabled entrants, rather than one dominated by a single platform or national chain. At the same time, fragmentation masks intense operational pressure. Practitioners, clinics, and digital care networks are all wrestling with workforce scarcity, reimbursement variability, and the logistical complexity of scaling consistent care quality across channels. For decision-makers evaluating market entry, partnership, or investment, the macro narrative is clear: demand is robust, but execution risk is elevated.
Several structural challenges are currently reshaping the industry’s trajectory. First, the workforce gap remains a binding constraint on capacity. Even as reimbursement frameworks and public awareness expand, the availability of licensed counselors, therapists, and psychiatric support staff has not kept pace with service demand. This imbalance affects wait times, clinician burnout, and the economics of care delivery, particularly in regions where recruitment and retention are already difficult. Second, the sustainability of insurance reimbursement and public funding continues to create uncertainty. Shifts in coverage policies, grant allocations, and payment schedules introduce volatility for providers who rely on a mix of commercial, public, and out-of-pocket revenue. Third, the market is navigating a delivery-model transition that is still maturing. While digital and remote counseling has moved from a supplementary option to a core channel, many organizations are still aligning operational workflows, clinical protocols, and customer experience standards across both physical and virtual settings. These factors together create a market that rewards scale, efficiency, and differentiated service design, while penalizing fragmented or operationally heavy providers.
PW Consulting Information & Electronics Research Center
Key Drivers: Technology, Policy, Demand, and Cost Architecture
The expansion of mental health counseling services is not occurring in isolation. It reflects converging forces across technology, regulation, consumer behavior, and cost structures. Understanding how these forces interact is essential for identifying where durable advantage can be built.
Technology innovation is fundamentally altering how counseling services are discovered, delivered, and scaled. Digital platforms have reduced friction in patient access, enabling text-based, audio, and video-based care across time zones and schedules. More importantly, technology is becoming embedded in clinical operations. Scheduling automation, matching algorithms, outcome tracking, and asynchronous communication tools are improving throughput and patient engagement while reducing administrative burden. The next wave of differentiation is likely to come from systems that combine clinical quality with operational efficiency: platforms that can connect patients to appropriate clinicians more quickly, retain them through structured care pathways, and capture outcome data that supports both clinical and commercial decisions. Technology-enabled providers that can demonstrate measurable engagement and continuity of care are gaining an advantage in both direct-to-consumer and enterprise contexts.
Policy and regulatory developments are simultaneously shaping the incentives that underpin service delivery. In the near term, reimbursement frameworks for outpatient psychological services are being adjusted, with modest updates to payment rates increasing the commercial attractiveness of insured counseling pathways. At the same time, legislative activity is focused on improving access and reimbursement parity for a broader set of provider types, including mental health counselors, marriage and family therapists, and clinical social workers. These policy shifts matter because they influence who can be paid, at what rate, and through which channels. In parallel, telehealth policy remains a central enabler for behavioral health delivery, with continued support for access-oriented remote care. However, the regulatory environment is not uniformly favorable across all programs and geographies. Some public grant and funding mechanisms have contracted, placing additional pressure on community-based providers and smaller organizations that depend on discretionary support. As a result, the policy landscape is creating both tailwinds and headwinds, rewarding organizations that can adapt to reimbursement complexity and diversify funding sources.
On the demand side, the most significant shift is the broadening normalization of mental health care as a routine component of personal wellness and organizational health strategy. Consumers are no longer treating counseling as an emergency-only service; they are seeking ongoing support for stress, relationship challenges, workplace burnout, and broader emotional well-being. Employers and institutions are increasingly incorporating mental health benefits into broader employee value propositions, recognizing that access to counseling and therapy influences retention, productivity, and overall workforce stability. This demand evolution is expanding the total addressable market beyond traditional clinical referral pathways and encouraging providers to design services that are easier to access, faster to start, and more aligned with varied use cases. The commercial implication is that patient acquisition, retention, and engagement are becoming as important as clinical capability alone.
Cost structure dynamics are also changing. Labor is the dominant operating expense in counseling services, and workforce scarcity has a direct impact on pricing power, margin stability, and scalability. Providers that can improve clinician productivity without compromising care quality—through better caseload design, integrated admin support, or hybrid delivery models—are better positioned to manage this pressure. At the same time, reimbursement and funding variability push organizations toward more balanced revenue mixes. Those relying heavily on a single payer type or grant program face greater exposure to policy shifts. The most resilient operators are increasingly building workflows that can serve insured, self-pay, and employer-sponsored populations with flexible care pathways while keeping fixed costs disciplined. In this environment, operational design is becoming a competitive lever, not just a back-office function.
Competitive Landscape and Leading Strategies
The competitive field in mental health counseling services reflects a wide spectrum of business models, from clinician networks anchored in physical clinics to digital-first platforms serving direct consumers and employer-sponsored markets. What distinguishes leaders is not simply the choice of channel, but the clarity of their value proposition and the consistency with which they execute it at scale.
Intellectual Disabilities Service Market
Large behavioral health organizations that operate across both outpatient clinics and telehealth are building strength through breadth of access and integrated care offerings. By combining therapy, psychiatry, and counseling within a single network, these players can serve a wider range of clinical needs and manage patient pathways across levels of intensity. Their advantage often lies in clinician recruitment capacity, geographic coverage, and the ability to support both insured and direct-to-consumer demand with a unified operational backbone. Where they succeed, they reduce fragmentation for patients and create a more seamless experience across care settings.
Digital counseling and telehealth platforms have pursued a different strategic path, emphasizing convenience, lower barriers to entry, and scalable service design. Some have grown directly with consumers by offering asynchronous messaging, video sessions, and flexible subscription models. Others have expanded their role within employer and health plan channels by positioning mental health care as part of a broader benefits ecosystem. The key differentiator for these platforms is typically access speed, user experience, and the ability to match patients with appropriate clinicians quickly. In a crowded digital care environment, platforms that can demonstrate high engagement, retention, and perceived quality have a stronger foundation for sustainable growth than those competing primarily on price.
A third strategic orientation is emerging among providers that combine in-person accessibility with online extensions and large clinician networks. These organizations aim to capture demand from patients who prefer face-to-face care but still want the convenience of online scheduling, flexible appointment availability, and continuity with the same provider when needed. Their positioning often emphasizes short time-to-appointment, localized access, and caregiver breadth. This model is especially relevant in markets where in-person trust remains important, but digital convenience is now an expected baseline rather than a premium feature.
A related area of strategic differentiation is the integration of digital self-care tools, meditation, and structured mental wellness content alongside counseling and therapy. This approach broadens the service ladder, allowing organizations to serve users at different levels of need and intensity. For employers and health-focused buyers, bundled wellness-plus-care offerings can be attractive because they address prevention and ongoing mental fitness in addition to clinical intervention. The commercial logic here is retention and ecosystem value: users who engage with multiple touchpoints are more likely to remain within a platform and benefit from a more continuous care relationship.
Employer-sponsored mental health benefits represent a distinct competitive space. Several providers have built their models around care navigation, personalized matching, and access to therapy or counseling through organizational partnerships. In this context, success depends less on direct consumer marketing and more on demonstrating measurable access, usage, and outcomes that employers and benefits administrators can trust. Providers that can translate clinical services into a clear organizational value proposition—lower barriers to care, improved employee experience, and structured support—are gaining traction in the enterprise segment. This channel also offers more predictable demand flows when contracts and utilization management are well designed.
Recent market activity illustrates how these strategies are evolving in practice. Strategic partnerships are being used to extend clinical depth and care coordination, particularly in areas such as psychiatric evaluation and medication management. Facility expansion efforts are reinforcing in-person capacity in specific regions, signaling that digital access does not eliminate the need for localized crisis and rehabilitation services. Meanwhile, educational and workforce programs are beginning to address the clinician supply pipeline directly, including apprenticeship-style models designed to create new pathways into mental health counseling. Across these developments, the broader pattern is one of hybridization: organizations are combining delivery formats, clinical disciplines, and partnership structures to build more resilient service networks rather than relying on a single channel or business model.
The competitive landscape is therefore moving in two directions at once. On one hand, scale players are working to consolidate access, expand clinician pools, and integrate service lines. On the other, specialized and digitally native providers continue to enter with focused value propositions around convenience, employer coverage, or particular patient populations. The market’s low concentration leaves room for both dynamics, but it also raises the stakes for differentiation. Providers that cannot clearly define their access model, reimbursement strategy, and clinician operating model will likely struggle to convert growth into durable margin.
Business Management Consulting Service Market
Future Trends and Commercial Implications
Looking ahead three to five years, several trends are likely to define the next phase of market development and create distinct commercial opportunities. First, the market will continue its shift toward hybrid care delivery, with in-person and virtual counseling increasingly treated as complementary rather than competing models. Providers that can move patients smoothly across channels, maintain clinical continuity, and align staffing to demand fluctuations will capture more efficient utilization and stronger patient retention. The commercial opportunity lies in designing end-to-end experience models that make access simple, reduce drop-off between intake and first appointment, and support ongoing care without forcing patients into a single modality.
Second, the workforce constraint will remain central, pushing the industry toward new talent models and productivity-focused operating designs. This includes more structured training pathways, apprenticeship and supervised practice programs, and workflow innovations that allow clinicians to focus more on direct care and less on administrative friction. Organizations that invest in clinician retention, well-designed caseloads, and supportive practice infrastructure will have an advantage in both quality and scale. The opportunity here is not simply hiring more clinicians, but building a more durable care workforce and matching supply to demand in a more intelligent way.
Third, reimbursement and access policy will continue to shape where value accrues. Modest payment improvements and legislative efforts to expand eligible provider reimbursement can improve the economics of insured counseling services, while funding volatility in certain community programs may intensify pressure on smaller providers. As a result, companies that can navigate payer diversity, strengthen billing and contracting capabilities, and maintain flexible funding options will be better positioned to stabilize revenue. The risk is that organizations heavily dependent on a narrow set of funding sources face disproportionate disruption if policy or grant priorities shift further.
These trends point to a market in which access, clinical quality, and operational discipline will increasingly determine who thrives. Commercial winners are likely to be those that treat mental health counseling not as a standalone service line but as an integrated part of a broader care and wellness ecosystem, with clear pathways for patient acquisition, continuity, and outcome measurement. At the same time, uncertainty remains around labor availability, reimbursement consistency, and funding levels in public programs. Decision-makers should plan for a market that is expanding, but also one where execution quality and adaptability will separate durable players from short-lived growth stories.
Strategic Recommendations for Decision-Makers
For executives, investors, and procurement leaders, the current market environment calls for clarity of role and discipline in execution. Three strategic priorities are especially relevant.
- For organizations building or scaling counseling services, prioritize hybrid delivery design and clinician operating models before chasing raw demand. Access speed, continuity across channels, and provider productivity will determine whether growth translates into sustainable economics.
- For investors and capital allocators, assess business models against reimbursement exposure, workforce scalability, and retention dynamics. Platforms and provider networks with diversified revenue streams, strong engagement metrics, and defensible operational advantages are better positioned than those dependent on a single channel or funding source.
- For employers, health plans, and institutional buyers, focus on access reliability and care navigation when evaluating mental health benefits and vendor partnerships. The most valuable partnerships are those that reduce friction to care, support a range of clinical needs, and provide visibility into utilization and follow-through rather than offering only broad access claims.
These decisions are best informed by detailed segmentation data, competitive benchmarking, and scenario analysis tailored to specific operating contexts. Broad market direction is only the starting point; the commercially relevant questions lie in segment economics, channel mix, payer dynamics, and the operational levers that determine margin under different demand conditions. Market participants who obtain structured, granular intelligence early can calibrate expansion plans, partnership choices, and service design with more confidence, while those relying on aggregate trends alone risk misjudging where opportunity and exposure are concentrated.
For detailed analysis of this topic, please visit the official page: Mental Health Counseling Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Flashcard App Market: How 13% CAGR & Platform Shifts Redefine Growth Through 2032
By PW Consulting, 2026-09-18
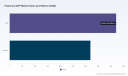
The Flashcard App Market: Strategic Trends and Commercial Opportunities as the Industry Enters a High-Growth Phase
Market Reality at a Crossroads: Size, Momentum, and Structural Challenges
The flashcard application sector has evolved from a niche study utility into a decisive component of the broader digital learning ecosystem. Recent trajectory data shows the market expanding from approximately $385.4 million in 2020 to roughly $740.15 million in 2025, with a projected climb toward $1.74 billion by 2032. This translates into a compound annual growth rate of 13.0 percent across the forecast period, a pace that signals durable demand rather than a temporary pandemic-era surge. The growth story is anchored in habit formation, portability, and the proven cognitive benefits of spaced repetition and active recall. Learners increasingly expect study tools that integrate seamlessly into mobile routines, support collaborative workflows, and adapt to individual pacing. As a result, the category now serves K-12 classrooms, higher education programs, professional certification candidates, and language learners in parallel, each with distinct usage patterns but overlapping expectations for reliability and intelligence.
Despite the headline momentum, the market is navigating several structural pressures that will shape competitive outcomes over the next five years. First, user acquisition costs are rising while retention remains difficult. The low barrier to entry for basic flashcard functionality encourages abundant free alternatives, compressing monetization pathways for standalone apps. Developers must therefore justify premium pricing through differentiated pedagogy, adaptive algorithms, or workflow integration that transcends rote memorization. Second, data governance and cross-border compliance are adding meaningful operational complexity. Educational platforms routinely process personal identifiers, usage telemetry, and in some cases performance records tied to minors or institutional programs. Managing this data under evolving privacy frameworks raises storage and processing overhead, and it forces product teams to reconcile regional requirements with globally distributed user bases. Third, the value proposition is shifting from static card creation toward intelligent, context-aware study experiences. Users increasingly expect generated content, auto-summarized materials, and study flows that connect to notes, documents, and classroom systems. Apps that treat flashcards as isolated objects risk being outpaced by tools that embed memorization into broader knowledge management.
Worldwide Comic Book App Market
These dynamics are also exposing the limits of fragmented ecosystems. Many learners juggle multiple tools for note-taking, flashcard creation, collaboration, and progress tracking, which fragments attention and reduces the perceived ROI of any single app. At the same time, institutional procurement is becoming more deliberate. School districts and universities increasingly weigh accessibility, data residency, integration with learning management systems, and evidence of learning outcomes before adoption. That raises the bar for vendors seeking to move beyond consumer-led growth into structured B2B and institutional channels.
For decision-makers, the implication is clear: the category is large enough to support multiple winners, but growth will accrue to products that can balance open, familiar study mechanics with stronger intelligence, privacy maturity, and institutional integration. Scale alone is not sufficient. The winners will be defined by how well they resolve the tension between low-friction utility and differentiated value.
Key Drivers Reshaping Demand, Product Design, and Margins
Several converging forces are pushing the flashcard app market beyond incremental growth into a phase of product reconstruction. The most visible is the rapid infusion of artificial intelligence into study workflows. Rather than simply digitizing paper cards, leading tools now support automatic conversion of notes, slides, and readings into structured study sets, adaptive scheduling of review items, and contextual hints that reduce friction during practice. This shift matters commercially because it changes the unit economics of content creation. When generation and curation become AI-assisted, the cost of building high-quality decks falls, and the value moves toward curation quality, pedagogical tuning, and trust in the output. It also raises the stakes for differentiation: apps that can reliably turn messy personal materials into usable study assets gain a practical advantage over those that rely entirely on user-built libraries.
At the same time, the regulatory environment is reshaping how apps design data flows and pricing models. Privacy and data-handling requirements for educational tools have increased average storage and processing costs meaningfully for firms that manage personal user data, and they have also introduced cross-jurisdiction compliance considerations for U.S.-based providers operating in European contexts. These dynamics do not just affect legal teams; they influence product architecture, consent design, international rollout sequencing, and the feasibility of certain business models. Companies that treat compliance as a design constraint early gain speed later, while those that retrofit privacy controls face rework and potential delays in expansion. A related infrastructure factor is the expectation of neutral, non-discriminatory access to educational traffic by internet providers. Predictable delivery and low-latency syncing remain important for study apps that depend on frequent, small interactions and real-time collaboration, especially in regions with variable connectivity.
On the demand side, learner behavior is changing in ways that reinforce the category while changing how it is used. Students and professionals increasingly treat flashcards not as isolated memorization aids but as part of an integrated study loop that includes reading, note-taking, self-testing, and review scheduling. This is especially pronounced in higher education and professional certification preparation, where the volume of material is large and the cost of ineffective study is high. In language learning, the appeal lies in repeated exposure and spaced practice, but users also expect content that reflects real-world usage rather than static vocabulary lists. Corporate training and professional upskilling add a third demand vector: learners want short, repeatable practice sessions that fit around work schedules and tie back to measurable competency. Together, these behaviors push vendors to support multiple learning modes, progress tracking, and collaborative deck sharing, rather than a single generic review screen.
Supply-Side and Cost Structure Shifts
On the supply side, development costs are being redistributed. The marginal cost of building a basic flashcard engine has fallen, but the cost of maintaining reliable syncing, moderating community content, ensuring accessibility, and delivering AI features with consistent quality has risen. Open-source roots and community ecosystems can reduce development risk and accelerate trust, but they also require strong stewardship to keep quality and sustainability aligned. Proprietary platforms can move faster on integrated experiences and monetization, but they face higher expectations for polish, support, and data stewardship. In parallel, cloud infrastructure, compliance-related processing, and ongoing content moderation all contribute to a cost base that favors vendors with scale, disciplined product scope, and efficient moderation workflows. The result is that competitive advantage increasingly comes from operational discipline as much as from feature novelty.
Taken together, these drivers point to a market where value is shifting from the presence of flashcards to the quality of the study system surrounding them. The apps that capture durable share will be those that can combine intelligent content workflows with credible privacy practices, dependable performance, and a pedagogy that users can feel working in day-to-day practice.
Competitive Landscape: Strategy, Positioning, and the Shape of Market Evolution
The competitive field is defined by a mix of established study platforms, open-source-rooted tools, and newer entrants focused on AI-enabled content generation. A small group of leaders currently accounts for a majority of market share, reflecting the category’s maturity in consumer adoption and the advantage of scaled content libraries, brand recognition, and institutional relationships. Concentration of this kind is typical in education technology, where network effects in user-generated content and classroom adoption reinforce incumbency. Yet the landscape is not static, because the value frontier is moving toward integration, intelligence, and stewardship rather than raw library size alone.
PW Consulting Information & Electronics Research Center
Quizlet illustrates one dominant playbook: scale through community-generated content paired with product-led classroom workflows and AI features that reduce study setup time. Its recent expansion into an integrated experience inside conversational AI environments reflects a strategy of meeting learners where they already work, turning prompts, notes, and documents into study materials with minimal friction. The strategic logic is straightforward. If creation and retrieval become easier, usage frequency rises, and the platform becomes a default study layer rather than one tool among many. Brainscape takes a more pedagogy-forward posture, emphasizing confidence-based spaced repetition and structured decks designed for long-term retention. Its differentiation rests on the claim that better scheduling and clearer self-assessment produce more efficient learning, which appeals to exam preparation and disciplined self-study. Anki and the broader ecosystem around it occupy a different position: highly customizable, offline-capable, and supported by a strong add-on culture. That model has sustained a loyal user base among learners who want control over card structure, review logic, and local data. The recent transition of day-to-day operations and open-source stewardship to AnkiHub signals a broader pattern in which community-driven projects seek sustainable governance without abandoning openness. AnkiHub’s collaborative deck platform and premium syncing services show how a community-backed tool can evolve toward paid support and shared content while preserving its core value proposition.
Tablet Pc Note App Market
Emerging Hybrids and New Entrants
Newer entrants are exploring a different middle ground. Knowt exemplifies the AI-first content path, focusing on converting existing notes and documents into study sets with spaced repetition features. RemNote blends note-taking and flashcard creation into a single interconnected system, appealing to learners who want their reading, notes, and review loops to belong to one workspace. These hybrids matter because they address a real pain point: study tools often fail when content creation is disconnected from note capture or when review is isolated from the material being learned. By collapsing those steps, hybrid tools reduce setup cost and create more coherent learning workflows.
The market is therefore evolving along two simultaneous axes. On one axis, consolidation incentives are strong: large platforms with broad libraries, classroom integrations, and AI capabilities can pull usage into a single environment and monetize through premium subscriptions, institution-level contracts, and enhanced productivity features. On the other axis, specialization and open ecosystems remain viable, particularly for users who value customization, data locality, and transparent methods. Importantly, new entrants are not just competing on features; they are competing on trust, workflow coherence, and the credibility of their pedagogical claims. That means the next round of competitive differentiation will likely come from evidence of learning impact, reliability of generative outputs, privacy design, and the ability to integrate into broader knowledge workflows rather than from card-making alone.
Forward View: Three Trends That Will Define the Next Three to Five Years
One of the most consequential trends is the shift from flashcard creation to automated study-system assembly. Over the next few years, the most-used tools will likely be those that can ingest notes, slides, and readings, then produce structured review sequences with minimal manual effort. This trend opens commercial opportunities for vendors that can differentiate on curation quality, discipline-specific content templates, and confidence in generated materials. The opportunity is not simply generating more cards; it is reducing the time from raw material to effective review while maintaining accuracy and pedagogical coherence. Companies that nail that workflow can increase engagement and justify premium tiers based on time savings and outcomes rather than simple access.
A second trend is the deepening of privacy, compliance, and trust as competitive differentiators rather than back-office concerns. As expectations around data handling rise and as educational apps continue to operate across jurisdictions, platforms that offer transparent data practices, predictable storage architectures, and clear consent models will gain an advantage in institutional sales and in cautious consumer segments. This is particularly relevant for tools used by K-12 learners and in regulated academic environments, where procurement teams scrutinize data residency, retention, and access controls. The commercial implication is that trust can become a moat: it reduces friction in enterprise procurement, supports international expansion sequencing, and lowers the risk of costly retrofits later.
A third trend is the movement toward integrated knowledge workflows that connect memorization with note-taking, collaboration, and performance tracking. The apps most likely to capture durable share are those that let learners move smoothly from reading to note capture to self-testing to review scheduling, without exporting content between disconnected tools. This favors hybrid architectures and platform-level integrations, especially where classrooms and institutions already rely on collaborative systems. The opportunity lies in becoming the connective tissue for study, not just a card repository. At the same time, this trend carries uncertainty. AI-generated content can introduce quality variability, institutional adoption can slow if evidence of outcomes is thin, and rising compliance costs may pressure margins for smaller players. The market will likely reward disciplined operators who can balance automation with quality assurance and who can prove that their workflows improve retention and throughput rather than simply adding features.
Actionable Implications for Decision-Makers
For product and platform leaders, the priority is to strengthen the study loop end to end. That means investing in content ingestion and generation that is accurate and discipline-aware, refining spaced repetition logic so it feels effective in daily use, and ensuring that syncing, accessibility, and support are dependable enough to underpin institutional confidence. Differentiation should be anchored in workflow coherence and trust, not in the number of card formats alone. For investors, the attraction is in platforms that combine scalable content workflows with credible monetization paths, whether through premium consumer tiers, institutional contracts, or value-added features that reduce learner time-to-results. Due diligence should focus on retention economics, content quality controls, compliance readiness, and the defensibility of integrations that tie study tools into broader learning environments. For procurement and education leaders, the selection process should weigh evidence of learning impact, data governance, and the ability to fit within existing classroom or enterprise systems, since the cost of tool sprawl and data risk can outweigh the appeal of feature richness.
The strategic stakes are rising as the category scales toward broader adoption and more demanding users. Detailed segmentation data, company-level profiles, and scenario-dependent projections can sharpen planning by revealing where growth is most concentrated, which business models are gaining traction, and where compliance or workflow gaps may slow expansion. Readers seeking a deeper dive into segment dynamics, competitive positioning, and tailored strategic options can find the full research report through the reference link below.
For detailed analysis of this topic, please visit the official page: Flashcard APP Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Trends & Commercial Opportunities in the Health Savings Account Provider Market
Market Overview: Scale, Trajectory, and Core Challenges
The Health Savings Account (HSA) provider market has matured into a cornerstone of the U.S. consumer-directed healthcare ecosystem, reflecting both structural shifts in insurance design and evolving consumer expectations around health financing. Measured in constant terms over a five-year baseline through 2025, the market has expanded from roughly 82.5 to 135.0 across the referenced period, with projections extending through 2032 pointing to sustained momentum. The forward trajectory implies a compound annual growth rate of approximately 11.55 percent, lifting the market size to nearly 290.1 by the end of the forecast window. This expansion is not merely a function of inflation or administrative growth; it signals a fundamental recalibration of how households and employers approach healthcare spending, savings, and investment.
Worldwide Financial Wellness Benefits Market
Beneath the headline figures, several structural realities define the current operating environment. First, account distribution is heavily weighted toward employer-sponsored arrangements, which dominate the overall composition, while individual-direct accounts represent a meaningful but smaller share. This split underscores the continued reliance on workplace channels for account origination, even as digital enrollment pathways and direct-to-consumer marketing gradually broaden the addressable base. Second, the provider landscape is fragmented across Banks and Financial Institutions, Insurance Carriers, and FinTech and Third-Party Administrators, with no single category achieving outright dominance. That fragmentation creates both distribution frictions and partnership opportunities, as each provider type brings distinct capabilities in compliance, investment access, and user experience. Third, regional concentration remains pronounced, with North America accounting for the overwhelming majority of activity and the rest of the world representing a negligible fraction, highlighting the deeply U.S.-centric nature of the current regulatory and tax framework.
The market also exhibits meaningful concentration at the top, with the largest players collectively holding roughly 48.2 percent of the landscape and the top five approaching 62.4 percent. Such concentration suggests established incumbents have secured durable advantages in employer relationships, compliance infrastructure, and asset accumulation, yet the remaining share leaves considerable room for differentiated entrants and niche platforms. The challenges ahead are equally clear. Providers must navigate the tension between scale-driven margin improvement and the growing expectation for personalized digital experiences, all while operating within a regulatory perimeter that ties account eligibility to qualifying High Deductible Health Plans. Compounding these dynamics, the shift from pure spend accounts to true investment vehicles is reshaping customer expectations, forcing providers to prove out performance, transparency, and long-term value rather than merely facilitating contributions and withdrawals.
Key Growth Drivers: Technology, Regulation, Demand, and Cost Realities
The most visible catalyst for market expansion is the accelerating convergence of financial services and digital health platforms. Modern HSA architectures increasingly embed self-service dashboards, real-time claim adjudication, automatic investment enrollment, and integrated budgeting tools that treat health spending as part of broader household finance. These capabilities reduce administrative burden for employers and improve engagement among account holders, which in turn supports higher asset retention and deeper investment adoption. The trend toward embedding HSA functionality within broader benefits ecosystems—often layered with flexible spending arrangements, health reimbursement arrangements, and emergency savings features—has transformed the account from a standalone tax-advantaged vehicle into a multi-purpose financial hub. Recent industry reporting highlights that assets reached nearly 174 billion across 41.7 million accounts at year-end 2025, with 19 percent year-over-year asset growth and a rising share allocated to investments, signaling that users and sponsors are increasingly comfortable with longer-horizon financial behaviors.
Regulation continues to shape the speed and structure of adoption, not only by defining eligibility but by setting annual contribution limits that influence household behavior and employer design choices. For 2026, the IRS set HSA contribution limits at 4,400 for self-only coverage and 8,750 for family coverage, parameters that guide recurring contributions and encourage year-end planning. Because HSAs must be paired with a qualifying High Deductible Health Plan to preserve tax advantages, any shift in employer insurance strategy, employee cost sensitivity, or plan design directly influences account origination and asset accumulation. The regulatory backdrop also rewards providers that can demonstrate robust compliance, clean reporting, and seamless integration with plan documents and payroll workflows. In practice, the firms that most effectively translate regulatory requirements into friction-free employer onboarding and employee education capture disproportionate share of new accounts and assets.
Demand-side dynamics reinforce this trajectory. Employers are increasingly weighing total rewards packages that blend clinical coverage with financial wellness, recognizing that HSA participation can influence employee retention, productivity, and financial resilience. Individuals, meanwhile, are becoming more deliberate about health spending, investment growth, and portability as job mobility rises and traditional employer relationships become less sticky. This behavioral shift favors platforms that offer clear fee structures, intuitive investment options, and educational support that demystifies contribution strategies, catch-up provisions for older participants, and the interplay between current spending and future growth. The result is a market where user experience and transparency are no longer differentiators but baseline requirements.
Cost structures and operating models are evolving in parallel. As digital onboarding, automated compliance checks, and platform-based integrations reduce marginal handling costs, providers are gaining latitude to compete on value rather than price alone. At the same time, the economics of managing growing asset balances introduce new considerations around recordkeeping, custody, and investment administration. Companies that can align scalable technology with disciplined cost control are better positioned to sustain margins as the market expands, especially when investment assets increasingly represent a meaningful portion of total value. The strategic implication is straightforward: the winners will be those that turn cost efficiency into better user outcomes, not just internal savings.
Competitive Landscape: Positioning, Differentiation, and Market Evolution
The competitive field is anchored by several well-established players, each leveraging a distinct blend of scale, integration, and product breadth. Fidelity Investments has built a reputation for fee-light HSAs paired with broad investment menus that span stocks, ETFs, and mutual funds, complemented by seamless connectivity to retirement accounts. Its positioning emphasizes low cost and investment flexibility, appealing to account holders who view their HSA as a long-term savings and investment instrument rather than a transactional spend account. HealthEquity has concentrated on employer-sponsored administration at scale, combining compliance rigor with integrated consumer-directed benefits that include FSAs and HRAs. Its strengths lie in analytics, account volume, and enterprise-grade support, and its recent financial results—record revenue of 1.31 billion, over one million new HSAs from sales, and an outlook raised for fiscal 2027 with 17.8 million total accounts and more than 36 billion in assets—illustrate how scale and disciplined execution can compound in a maturing market.
HSA Bank, operating as a division of Webster Bank, blends HSA administration with investment access through brokerage relationships and integrated benefits solutions, while also extending into adjacent pillars of employee financial wellness. Its acquisition of SecureSave to expand into employer-sponsored Emergency Savings Accounts signals a move toward broader financial resilience offerings, allowing employers to bundle health savings with emergency savings in a single wellness narrative. Lively has carved out a modern, digital-first identity with an emphasis on user-friendly tools, transparent pricing, and support for both individuals and small-to-mid employers, positioning itself as an agile alternative to more traditional administrators. Optum Bank leverages its integration within a large health benefits ecosystem to offer HSAs connected to broader care and benefits management, with investment options available through brokerage windows or managed solutions. Bank of America brings a conventional banking footprint with tiered interest rates and basic investment access, appealing to consumers who prioritize familiar banking relationships and integrated account management.
The strategic differences among these players reveal a market that is simultaneously consolidating around scale and differentiating around experience. Incumbents with deep employer relationships and robust compliance infrastructure continue to capture the bulk of new accounts, while newer platforms compete on design, fee clarity, and specialized workflows that reduce administrative overhead for smaller sponsors. The evolution is also visible in product adjacency: providers are extending beyond core HSA administration into emergency savings, wellness incentives, and integrated benefit stacks, recognizing that household financial decisions rarely occur in isolation. This blending of use cases creates opportunities for cross-selling and deeper engagement, but it also raises the bar for operational discipline, as each new feature must be supported by clear governance and reliable user communication.
Concentration patterns suggest that while the largest players enjoy meaningful advantages in distribution and asset accumulation, the market remains open to targeted innovation. The gap between top-tier scale and the long tail of smaller providers creates a natural environment for partnerships, platform integrations, and geographic or segment specialization. At the same time, the expectation for investment adoption and digital fluency is pulling even traditional providers toward more modern interfaces and transparent fee logic. The net effect is a landscape in flux: scale still matters, but differentiation through experience, ecosystem fit, and adjacent financial wellness capabilities is increasingly decisive.
Strategic Outlook: Three Trends Shaping the Next 3-5 Years
First, the HSA will continue its evolution from a spend account to a core investment vehicle within household finance. As assets grow and a larger share is allocated to investments, providers that offer well-structured investment options, clear performance reporting, and educational support will deepen engagement and retention. The commercial opportunity lies in building trust around long-term outcomes, including guidance on contribution strategies, catch-up eligibility, and the interaction between current healthcare spending and future growth. Platforms that can communicate value without complexity are likely to capture more assets and fewer lapses.
Second, financial wellness bundling will become a standard expectation rather than a differentiator. Employers and individuals increasingly view health savings alongside emergency savings, retirement readiness, and benefits transparency as part of a single financial resilience strategy. Providers that can integrate these use cases in a coherent, compliant manner will gain preference in employer selection and individual adoption. The upside is higher engagement and broader account utility; the risk is operational complexity and the potential for feature sprawl that dilutes clarity.
Third, digital experience and fee transparency will increasingly separate leaders from laggards. As account holders compare platforms on usability, investment access, and total cost, providers that invest in self-service design, proactive education, and straightforward fee logic will stand out. The uncertainty here is twofold: regulatory parameters can change with annual limits and eligibility rules, and competitive pressure may compress fee-based economics, pushing providers to rely more on scale, ecosystem partnerships, and value-added services to sustain margins.
Actionable Recommendations for Decision-Makers
For employers and plan sponsors, the priority is to treat HSA design as a strategic component of total rewards rather than an administrative checkbox. That means selecting providers based on integration quality, fee clarity, investment readiness, and employer analytics, while pairing account access with education that improves participation and asset retention. Sponsors should also evaluate adjacent financial wellness capabilities, such as emergency savings integrations, as part of a cohesive offer that supports employee resilience and engagement.
Health Products Market
For investors and market participants, the most durable opportunities lie in platforms that combine scalable compliance infrastructure with modern user experience and credible investment pathways. Attractive theses typically emphasize asset growth, investment adoption trends, and the ability to expand into adjacent wellness use cases without sacrificing operational discipline. Caution is warranted where differentiation rests primarily on marketing claims without transparent fee structures, reliable service levels, or clear employer value.
PW Consulting Information & Electronics Research Center
For technology providers and procurement teams, the mandate is to prioritize interoperability, clean data flows, and enrollment simplicity. Solutions that reduce onboarding friction, automate compliance checks, and deliver actionable reporting will earn preference in a market where scale and experience increasingly converge. Timely, granular intelligence on segment dynamics, provider positioning, and adoption patterns can sharpen procurement decisions and reduce integration risk, especially as the market continues to reward providers that align product design with real user behavior. For those seeking deeper segmentation, competitive benchmarking, and tailored strategic guidance, PW Consulting’s full research report provides detailed breakdowns and customized recommendations to support concrete next steps.
For detailed analysis of this topic, please visit the official page: Health Savings Account (HSA) Provider Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Digital Product Passport Software Market Surges to $285.5M in 2025, 22.5% CAGR to $1.18B by 2032
By PW Consulting, 2026-09-17
The Digital Product Passport Software Market: A Strategic Imperative for 2026 and Beyond
As global regulatory frameworks shift toward unprecedented transparency, the Digital Product Passport Software Market has emerged from a niche sustainability initiative into a core infrastructure requirement for modern enterprises. Based on our latest comprehensive analysis, this sector is not merely growing—it is accelerating at a pace that demands immediate strategic attention from C-suite executives, supply chain leaders, and compliance officers. The transition from voluntary sustainability reporting to mandatory digital traceability represents a fundamental restructuring of how products are manufactured, tracked, and consumed.
Our research indicates that the market revenue, measured in USD Million, has exhibited a compound annual growth rate (CAGR) of 22.5% throughout the forecast period extending from 2026 to 2032. This trajectory underscores a critical reality: Digital Product Passport (DPP) software is no longer a future consideration but a present-day operational necessity. With the overall market size projected to expand significantly from its base year levels in 2025, organizations that delay adoption risk not only regulatory penalties but also competitive obsolescence in increasingly transparent supply chains.
This article serves as a strategic overview of the market dynamics, competitive landscape, and operational considerations detailed in our full report. While we outline the macro-level forces shaping the industry, the specific segmentation data, regional revenue splits, and granular adoption rates are reserved for our licensed intelligence portal. Understanding the breadth of this opportunity requires looking beyond the headline numbers to the structural shifts driving demand.
Regulatory Catalysts and Market Dynamics
The primary engine propelling this market expansion is the tightening regulatory environment, particularly within the European Union. The Ecodesign for Sustainable Products Regulation (ESPR) has established a phased implementation roadmap for Digital Product Passports across priority sectors. Our analysis highlights that batteries are set to become the first mandatory category from 2027, followed by textiles, iron and steel, and other key industries. This regulatory cascade creates a domino effect across global supply chains, compelling manufacturers outside the EU to adopt compliant systems if they wish to maintain access to the European market.
A critical milestone in this regulatory timeline is the operational launch of the central EU DPP Registry. Scheduled to become functional in July 2026, this registry will serve as the central node for market access verification. Organizations must ensure their software infrastructure is interoperable with this registry well before the deadline. The implication for enterprise strategy is clear: compliance is not a checkbox exercise but a data integration challenge that requires robust software architecture capable of communicating with centralized government databases.
However, regulatory pressure is only one side of the coin. The market dynamics are equally influenced by the need for supply chain visibility and consumer engagement. Modern consumers increasingly demand verifiable proof of sustainability claims, driving brands to adopt DPP solutions that offer end-to-end traceability. This dual pressure—regulatory compliance on one end and consumer trust on the other—creates a resilient demand curve that is less susceptible to economic downturns than typical software markets.
Key Industry Developments and Strategic Partnerships
The landscape is evolving rapidly through strategic collaborations and pilot projects that signal the transition from concept to scalable execution. In early 2026, significant moves were observed among key players. For instance, a notable Memorandum of Understanding was signed between DigiProd Pass and Fashion Power Group for a Digital Product Passport pilot project in apparel manufacturing. Such initiatives demonstrate the industry's focus on practical application within the textile sector, which remains a high-priority area for regulation.
Simultaneously, technology giants are entering the fray to provide the infrastructure necessary for scale. A collaboration between Siemens and Accenture has been advancing Digital Product Passports from concept to scalable execution, with a specific focus on data integration. This involvement of major industrial technology firms validates the market's maturity and suggests that DPP software will increasingly become embedded within broader Manufacturing Execution Systems (MES) and Enterprise Resource Planning (ERP) platforms.
Furthermore, sector-specific preparations are underway. Leaders in the textile space have highlighted ongoing DPP pilots and groundwork for production systems ahead of the 2026 registry launch. These updates indicate that early movers are already stress-testing their data pipelines to ensure they can handle the volume and veracity requirements of a fully operational registry. The convergence of regulatory deadlines and technological readiness creates a narrow window for organizations to finalize their vendor selection and implementation strategies.
Market Segmentation and Deployment Preferences
Our report dives deep into how organizations are choosing to deploy DPP solutions. While specific revenue splits are detailed in the full intelligence subscription, the broader trends indicate a strong preference for certain deployment models based on organizational size and complexity. Cloud-based DPP software deployments are becoming the default choice for many entities, particularly Small and Medium-sized Enterprises (SMEs). This preference is driven by lower upfront infrastructure costs and the flexibility of subscription models compared to traditional on-premises solutions.
Digital Product Passport Software Market
The shift toward cloud-based architectures also addresses the scalability challenges inherent in managing vast amounts of product data. However, this introduces new operational considerations. Organizations must remain vigilant about cloud spending efficiency, as reports suggest that unused resources can lead to significant waste in cloud hosting budgets. For scalable DPP platforms reliant on cloud hosting for data management, optimizing these costs is a key operational factor that our research examines in detail.
Industry vertical adoption also varies significantly based on regulatory exposure and supply chain complexity. Sectors such as textiles and apparel, electronics, and automotive batteries are leading the charge. Each sector presents unique challenges regarding data standardization and lifecycle management. For example, the electronics sector must navigate complex chemical compliance data, while the fashion industry focuses heavily on material provenance and labor standards. Our full report provides a comparative analysis of these vertical-specific requirements, helping stakeholders understand which solutions are best tailored to their specific operational context.
Competitive Landscape and Vendor Ecosystem
The market is characterized by a mix of specialized startups, established compliance software providers, and large conglomerates entering the space. Our analysis identifies a fragmented but consolidating landscape, with a handful of key players capturing significant attention. The competitive intensity is high, driven by the race to establish standard-setting positions before the registries go live.
Among the notable entities shaping the market is Spherity, based in Cologne, Germany. Their VERA Digital Product Passport solution is heavily focused on battery passports and compliance with ESPR and REACH regulations. They enable lifecycle management and integrate recycling and resale marketplace functionalities, making them particularly relevant for the battery sector where mandatory compliance begins earliest.
In the textiles and fashion domain, TrusTrace, headquartered in Stockholm, Sweden, delivers an end-to-end DPP compliance solution. Their offering includes supplier traceability, unique IDs, and QR codes designed for standardized consumer interfaces. This focus on verified supply chain data aligns closely with the needs of fashion brands facing intense scrutiny over sustainability claims. Similarly, Arianee, located in Paris, France, offers a blockchain-powered DPP platform specialized in product lifecycle, ownership tracking, and consumer engagement, with a strong foothold in luxury goods and fashion.
Kezzler, from Oslo, Norway, provides a Connected Products Platform (CPP) for digital IDs and DPP across industries including textiles and footwear. Their support for GS1 Digital Link and partnerships for supply chain visibility positions them as a infrastructure-play vendor. On the compliance and chemical safety side, 3E Exchange, based in Carlsbad, California, provides Digital Product Passports integrated with safety, chemical, and regulatory compliance data such as PFAS and RoHS, catering to supply chain visibility and sustainability requirements.
Renoon, operating out of the Netherlands, functions as a DPP infrastructure platform connecting data, compliance, and customer value for fashion and textile brands, with a strong emphasis on operational system integration. iPoint-systems, based in Reutlingen, Germany, offers software solutions for product compliance and sustainability data management supporting DPP requirements, leveraging their long history in compliance software.
Blockchain technology remains a core component for several players. Circularise, also based in the Netherlands, provides blockchain-based Digital Product Passports for material traceability, transparency, and circular economy applications. In the realm of retail and labeling, Avery Dennison, headquartered in Mentor, Ohio, delivers DPP as a Service (DPPaaS) via their atma.io platform for end-to-end product traceability and EU compliance in fashion and retail. Finally, Carbonfact, with a presence in France and the USA, offers an AI-powered platform for LCA-based Digital Product Passports in apparel and footwear, automating environmental data and publishing compliant DPPs.
Market concentration metrics suggest that while no single vendor dominates the entire landscape, there is a moderate level of consolidation among the top players. This fragmentation offers buyers choice but also creates complexity in selecting the right partner. Our full report includes a detailed vendor benchmarking matrix that evaluates these companies based on technology stack, compliance coverage, and scalability.
Strategic Considerations for 2026 Decision Makers
For enterprise leaders planning their 2026 strategies, several critical factors emerge from our analysis. First, the timeline for compliance is non-negotiable. With the EU DPP Registry becoming operational in July 2026, the window for system integration and testing is narrowing. Organizations must prioritize data readiness, ensuring that product information is structured, verifiable, and accessible via API.
Second, data privacy cannot be an afterthought. DPP systems handling personal data must comply with GDPR requirements, including data minimisation, explicit consent, and breach notification within 72 hours. Potential fines can reach up to 4% of global turnover, representing a significant financial risk. Our research outlines the specific data governance frameworks required to mitigate this risk while maintaining the transparency needed for compliance.
Third, the cost of non-compliance is severe. Under ESPR regulations, non-compliance prohibits the market placement of affected products in the EU. Member states are empowered to enforce fines and potential public procurement exclusions. This creates a clear line of sight between DPP software investment and revenue protection. The software is not an IT expense but a license to operate in key markets.
Finally, organizations must consider the long-term scalability of their chosen solution. As the registry expands to include more product categories beyond batteries and textiles, the software must be flexible enough to accommodate new data fields and reporting standards. Vendors that offer modular architectures and strong integration capabilities with existing ERP and PLM systems will likely provide more value over the forecast period.
Conclusion and Access to Full Intelligence
The Digital Product Passport Software Market represents one of the most significant shifts in industrial data management in recent decades. The convergence of regulatory mandates, consumer demand, and technological maturity creates a compelling case for immediate action. With a projected CAGR of 22.5% and a market size expanding into the billions by the end of the decade, the stakes for strategic positioning are high.
However, navigating this landscape requires more than general awareness. Success depends on granular insights into regional adoption rates, specific vendor capabilities, and detailed cost-benefit analyses of deployment models. Our full market research report provides the depth required to make informed investment decisions, including proprietary data on segmentation splits, competitive positioning, and risk assessments that are not available in public summaries.
To access the complete dataset, including detailed regional revenue projections, specific vendor benchmarking scores, and comprehensive regulatory impact analyses, we invite you to explore our dedicated research portal. The intelligence contained within is designed to equip your organization with the precision needed to lead in the era of digital transparency.
Shipping Software Market
For detailed analysis of this topic, please visit the official page: Digital Product Passport Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rare Disease CRO Market Set to Hit $12.8B by 2032 with 10.2% CAGR
By PW Consulting, 2026-09-17
Strategic Intelligence for 2026: Navigating the Rare Disease CRO Service Market
The landscape of clinical research is undergoing a pivotal transformation, driven by the increasing complexity of rare disease development and the urgent need for specialized operational excellence. As we move through 2026, pharmaceutical sponsors and biotech innovators face a critical juncture. The decision of how to partner with Contract Research Organizations (CROs) is no longer merely about cost efficiency; it is about securing access to niche expertise, adaptive trial designs, and global patient networks that can make or break an orphan drug application. Our latest market research report, Rare Disease CRO Service Market, offers a comprehensive lens into this evolving ecosystem, providing the strategic clarity needed to navigate the opportunities and challenges of the forecast period from 2026 to 2032.
This article serves as a strategic preview of our findings. It highlights the macroeconomic trajectory, the shifting competitive dynamics, and the operational realities defining the sector. However, the true depth of our analysis lies in the detailed segmentation, granular regional data, and specific competitive benchmarking available in the full report. For executives planning capital allocation, partnership strategies, or service line expansions in the coming year, this intelligence is not just valuable—it is essential.
Rare Disease CRO Service Market
Macroeconomic Trajectory and Market Momentum
The rare disease CRO service market has demonstrated robust growth over the past half-decade, reflecting the broader industry shift toward specialized therapeutics. Our analysis tracks the market revenue from 2020 through the base year of 2025, projecting a strong upward trend into the next decade. The market reached an estimated value in the mid-six figures million USD range by 2025, building on a consistent compound annual growth rate observed over the historical period. This momentum is expected to accelerate, with the forecast period indicating a sustained CAGR of approximately 10.2 percent.
This growth trajectory is not linear. It is underpinned by specific catalysts that are reshaping demand patterns. The market forecast suggests that revenue volumes will expand significantly by 2032, driven by an increasing pipeline of gene therapies, cell therapies, and targeted small molecules for indications that were previously considered undruggable. For strategic planners, this implies that capacity constraints and specialized talent shortages may become binding factors earlier than anticipated. Understanding where this growth concentrates—whether in specific service lines or therapeutic focuses—is key to anticipating supply-demand imbalances. The full report provides a detailed year-by-year breakdown of these projections, allowing stakeholders to model their resource planning against realistic market expansion scenarios.
Segmentation and Operational Focus
One of the most critical aspects of strategic planning in this sector is understanding where the value is being generated within the CRO service portfolio. The market is not monolithic. It is divided into distinct service categories, each carrying different margin profiles, complexity levels, and strategic importance to sponsors. Our research delineates the market across major service types, including clinical development, regulatory consulting, laboratory services, and patient recruitment.
Clinical development remains a cornerstone of the market, reflecting the heavy lifting required in executing complex protocols. However, the relative weight of regulatory consulting and patient recruitment services is gaining prominence as trials become more intricate. Regulatory pathways for orphan drugs are evolving, and the ability of a CRO to navigate these nuances—from FDA Rare Disease Evidence Principles to EMA guidelines—can add significant value beyond data collection. Similarly, patient recruitment in ultra-rare conditions often dictates the timeline and success of a program, making it a high-stakes service segment.
Therapeutic area segmentation further refines this picture. Oncology has historically dominated rare disease trials, but neurology and metabolic disorders are claiming substantial shares of the CRO landscape. The interplay between these areas and the service types offered is a key focus of our analysis. For instance, the requirements for a metabolic disorder trial may differ significantly from a neurological study in terms of biomarker integration, site selection, and long-term follow-up. By examining the market through these dual lenses—service type and therapeutic area—sponsors can identify partners that offer the right combination of capabilities rather than relying on generalized claims. The complete report offers a detailed split of these segments, enabling a nuanced view of where the largest revenue pools and fastest growth vectors reside.
Competitive Landscape and Strategic Positioning
The competitive environment in the rare disease CRO space is characterized by a mix of established global players and specialized boutiques. Market concentration metrics indicate a moderately fragmented landscape, where a handful of leading firms hold significant share, but numerous niche operators thrive by offering deep domain expertise. Our report profiles a wide array of key companies, analyzing their strategic positioning, service footprints, and recent moves.
Firms like Medpace and Precision for Medicine have built reputations on end-to-end capabilities and specialized approaches such as integrated biomarker and cell/gene therapy services. Others, such as Parexel and PPD (Thermo Fisher Scientific), leverage scale and integrated platforms to support complex trials across diverse indications. The landscape also includes specialized entities like Allucent, Ergomed, and TFS HealthScience, which focus intensely on orphan and rare indications, often providing tailored methodologies for patient location and regulatory success.
Contract Research Organization (CRO) Market
Recent developments in 2025 and 2026 underscore the dynamic nature of this competition. We have observed strategic acquisitions and leadership expansions aimed at bolstering capabilities in advanced therapeutics and broader clinical development support. For example, recent acquisition activity by major players to integrate data solutions, endpoint data platforms, and expanded oncology and FSP capabilities signals a trend toward vertical and horizontal integration. Leadership appointments focused on advanced therapeutics and cell/gene therapy programs highlight the industry's commitment to building centers of expertise for the most challenging indications. These moves are reshaping the competitive hierarchy and altering the value propositions available to sponsors. Our report analyzes these developments in detail, providing context on how each company is positioning itself for the future and what these changes mean for partnership negotiations.
Industry Dynamics and External Pressures
Beyond the core market mechanics, a constellation of external factors is influencing the rare disease CRO sector. Regulatory evolution is a primary driver. Initiatives such as the FDA Rare Disease Innovation Hub and the Rare Disease Evidence Principles introduced in 2025 are providing more flexible evidence standards and harmonized approaches for ultra-rare conditions. These regulatory shifts can reduce barriers to entry for certain programs but also introduce new expectations for data quality and trial design. Similarly, the finalization of ICH E6(R3) Good Clinical Practice guidelines emphasizes risk-based monitoring and flexible designs, which are particularly relevant for complex rare disease trials where traditional monitoring approaches may be impractical.
Data privacy and cross-border complexities remain significant hurdles. Regulatory frameworks like GDPR and HIPAA add layers of complexity and cost to trials involving international patient registries and data sharing, especially when genomic data is involved. Sponsors must weigh the benefits of global patient access against the operational burden of compliance. Additionally, reimbursement landscapes and incentives such as Orphan Drug Act designations and EU equivalents continue to drive outsourcing decisions by offering market exclusivity and development support, making the cost-benefit analysis of CRO partnerships even more critical.
Cost structures in rare disease trials also warrant careful attention. The requirement for specialized navigators, expert clinicians, and tailored recruitment strategies leads to higher per-patient costs. Analysis indicates that per-patient CRO costs for ultra-rare Phase III programs can run significantly higher than standard trials, sometimes reaching multiples of standard rates. This cost differential means that efficiency in trial design, patient retention, and site management is paramount. CROs that can demonstrate superior retention rates, reduced protocol deviations, or faster enrollment in hard-to-reach populations offer a compelling value proposition that goes beyond hourly rates. Our report delves into these dynamics, exploring how cost pressures and regulatory incentives interact to shape outsourcing strategies.
Strategic Implications for 2026 Decision-Makers
As organizations prepare their strategies for the remainder of 2026 and beyond, several actionable insights emerge from our analysis. First, the selection of a CRO partner should be aligned with the specific therapeutic and operational profile of the asset. A one-size-fits-all approach is unlikely to yield optimal results in a market where niche expertise can accelerate development and mitigate risks. Second, the trend toward integration—whether through acquisitions or service bundling—suggests that sponsors may benefit from engaging partners who offer cohesive solutions across clinical, regulatory, and data management functions, reducing the fragmentation that can slow down complex trials.
Third, the growing importance of patient-centric approaches and decentralized models is reshaping recruitment and retention strategies. CROs that have invested in advanced technologies, patient advocacy relationships, and global site networks are better positioned to address the challenges of dispersed patient populations. Fourth, regulatory agility is becoming a competitive differentiator. With evolving evidence standards and guidelines, partners that can anticipate regulatory shifts and incorporate flexible designs into trial protocols will add significant value.
Finally, the market growth trajectory suggests that competition for high-quality sites and specialized talent will intensify. Early engagement with capable partners, clear communication of study requirements, and strategic alignment on milestones can help secure the resources needed for success. The full report provides benchmarking data, detailed company profiles, and segment-specific forecasts that allow decision-makers to evaluate their options with precision.
Conclusion
The Rare Disease CRO Service Market stands at the intersection of scientific innovation, regulatory evolution, and operational complexity. The data indicates strong growth, but realizing value in this environment requires more than just tracking market size. It demands a deep understanding of segmentation, competitive dynamics, regulatory nuances, and cost structures. Our market research report offers a detailed, data-driven exploration of these factors, providing the intelligence needed to make informed strategic decisions.
We invite you to explore the full report to access the complete analysis, including detailed regional breakdowns, precise segment valuations, competitive benchmarking, and actionable recommendations tailored for 2026 planning. The insights contained within are designed to empower your team to navigate the rare disease CRO landscape with confidence and clarity.
For detailed analysis of this topic, please visit the official page: Rare Disease CRO Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Video Inspection Robot Market to Hit $4,158.62M by 2032 at 7.85% CAGR
By PW Consulting, 2026-09-17
Navigating the Visual Frontier: Strategic Intelligence for the Video Inspection Robot Market 2026-2032
The industrial landscape is undergoing a profound transformation driven by the imperative for safety, efficiency, and data accuracy. In this context, the market for video inspection robots has emerged as a critical enabler for infrastructure maintenance, industrial manufacturing, and energy sector operations. As organizations look toward the 2026 fiscal year and beyond, reliance on traditional manual inspection methods is becoming increasingly untenable compared to automated, robot-assisted visual data collection. Our latest market research publication offers a comprehensive strategic roadmap for stakeholders navigating this evolving sector. This article serves as an executive primer, outlining the macroeconomic currents and competitive dynamics that define the industry, while highlighting the specific actionable intelligence available within the full report.
Macroeconomic Trajectory and Market Valuation
Understanding the financial scale and growth velocity of the video inspection robot market is fundamental for capital allocation and long-term planning. The sector has demonstrated consistent resilience and expansion over the past five years. From a respected market size in the base year 2020, the industry has progressed through steady annual increases, reflecting the growing adoption of automated inspection technologies across diverse industrial verticals. By 2025, the market had solidified its position as a multi-billion dollar sector, driven by infrastructure renewal projects and the need for predictive maintenance in manufacturing facilities.
Looking ahead to the forecast period spanning 2026 to 2032, the trajectory indicates sustained growth momentum. The compound annual growth rate (CAGR) observed over this decade-long horizon underscores the structural shift toward robotics in inspection workflows. Organizations that recognize this upward trend early will be better positioned to secure supply chains, invest in compatible technologies, and capture market share before saturation points are reached. The projection extends through 2032, offering a long-term view that encourages strategic patience and sustained investment rather than short-term speculation. Revenue projections throughout this period indicate a significant escalation in total market value, signaling lucrative opportunities for manufacturers, service providers, and investors alike.
Structural Segmentation and Application Drivers
The versatility of video inspection robots is reflected in the diverse segmentation of the market. The technology is not monolithic; rather, it is divided into distinct hardware categories that serve specific operational needs. These include crawler robots designed for confined spaces and pipelines, pole-operated inspection cameras for accessible infrastructure, and aerial inspection drones for hard-to-reach areas. Each type offers unique value propositions depending on the environment and the specific data required by the client. Understanding the revenue split and adoption rates between these hardware categories is essential for product development teams and sales strategists.
Geographically, the market exhibits varied maturity levels and growth potentials. While established regions continue to drive significant volume, emerging markets present untapped opportunities due to rapid urbanization and infrastructure development initiatives. The full report provides a granular analysis of regional performance, highlighting where demand is highest and where regulatory environments are most conducive to deployment. Furthermore, the application landscape is segmented across municipal infrastructure and pipelines, industrial and manufacturing facilities, and petrochemical and energy sectors. Each vertical faces unique challenges regarding safety standards, environmental conditions, and inspection frequency, driving differentiated demand patterns that sophisticated strategies must address.
Competitive Landscape and Strategic Positioning
The vendor landscape is characterized by a mix of specialized niche players and large industrial conglomerates. Market concentration metrics suggest a moderately fragmented environment, where agility and technological innovation often outweigh sheer scale. Key industry participants are headquartered across North America, Europe, and Asia, reflecting the global nature of both manufacturing and service deployment. Companies such as Envirosight LLC and Deep Trekker Inc. have established strong reputations in sewer and pipeline inspection, focusing on high-definition video capabilities and ruggedized robotic designs. Meanwhile, entities like Wuhan Easy-Sight Technology Co., Ltd. and IBAK Helmut Hunger GmbH & Co. KG represent significant manufacturing capabilities in Asia and Europe respectively, offering modular solutions with advanced imaging features.
Worldwide Underwater Inspection Robot Market
Other notable contributors include CUES Inc. and RedZone Robotics in the United States, which focus on municipal and large-diameter pipe solutions, alongside European specialists like Mini-Cam Ltd. and iPEK International GmbH. The presence of large-scale industrial players such as Waygate Technologies (Baker Hughes) adds a layer of industrial-grade reliability to the segment, particularly in hazardous environments. Inspector Systems further diversifies the pool with modular video and laser inspection robots. Understanding the specific strengths, geographical reach, and technological foci of these competitors is vital for any company seeking to enter or expand within this space. Our research provides detailed profiles that go beyond basic information, analyzing competitive advantages and potential vulnerabilities.
Recent Developments and Technological Acceleration
Innovation within the sector is accelerating, driven by the integration of artificial intelligence and advanced sensor fusion. Recent industry activities highlight a clear trend toward automation and enhanced data utility. For instance, in mid-2025, Envirosight launched the ROVVER X HD with AI-assisted defect recognition, signaling a shift from passive video collection to automated analysis. This type of innovation reduces human error and speeds up inspection workflows significantly. Similarly, IBAK Helmut Hunger introduced new generation inspection robots with panoramic 3D laser profiling integrated with video capabilities, enhancing the spatial accuracy of inspections.
Deployment activities also reflect the expanding operational boundaries of this technology. In early 2026, Baker Hughes (Waygate Technologies) deployed ATEX/IECEx-certified explosion-proof pipe inspection robots with video capabilities in offshore facilities, demonstrating the technology's viability in high-risk environments. Additionally, newer market entrants like Multinnov have launched wireless CCTV crawlers, indicating a push toward reducing tether limitations and improving mobility. These developments are not isolated events but symptoms of a broader technological shift. The full research report contextualizes these events within the broader innovation cycle, helping leaders anticipate the next wave of technological disruptions.
External Factors and Risk Mitigation
No strategic plan is complete without accounting for external risk factors. The video inspection robot market is not immune to macroeconomic and geopolitical pressures. Regulatory environments are evolving, with particular attention on trade policies affecting industrial machinery and components. For example, recent investigations into robotics and industrial machinery imports have introduced uncertainty regarding potential tariffs on components like cameras and sensors. These regulatory shifts can impact cost structures and supply chain stability, requiring proactive mitigation strategies.
Supply chain dynamics also remain a critical concern. Disruptions for high-precision sensors and optical components continue to impact lead times and costs, affecting manufacturers' ability to deliver products on schedule. Furthermore, geopolitical tensions have influenced trade flows, with tariffs on imports of electronics components increasing production costs for video inspection systems. These factors necessitate a robust understanding of global trade dynamics and supply chain resilience. Our market research delves into these constraints, offering scenarios and strategic recommendations to navigate regulatory and supply chain headwinds effectively.
Strategic Value of Comprehensive Market Intelligence
In an environment defined by rapid technological change and complex external pressures, intuition is insufficient. Decision-makers require data-driven insights to validate assumptions and mitigate risk. This market research publication is designed to serve as a foundational tool for strategic planning in 2026 and beyond. It moves beyond superficial market sizing to provide actionable intelligence on segmentation trends, competitive positioning, and regulatory impacts. By synthesizing historical data with future projections, the report enables organizations to benchmark their performance against industry standards and identify gaps in their current strategies.
Video Inspection Robot Market
Access to detailed segmentation data, specific regional growth drivers, and deep-dive company profiles allows stakeholders to tailor their approaches with precision. Whether the goal is to launch a new product line, enter a new geographic market, or acquire a competitor, the granularity of this intelligence supports evidence-based decision-making. The report also includes analysis of market concentration and potential barriers to entry, providing a realistic view of the competitive intensity.
Conclusion and Next Steps
The video inspection robot market represents a significant opportunity for growth, but realizing its potential requires a clear understanding of the underlying dynamics. The convergence of AI, regulatory shifts, and infrastructure needs creates a complex landscape where informed strategy is the key differentiator. We invite industry leaders, investors, and strategic planners to utilize this research as a cornerstone for their 2026 planning cycles.
To access the complete dataset, including detailed segmentation splits, proprietary forecasts, and exhaustive competitor analysis, we encourage you to visit the source webpage. There you will find the full executive summary, sample chapters, and the option to acquire the complete report. Equip your organization with the intelligence needed to navigate the visual frontier successfully.
For detailed analysis of this topic, please visit the official page: Video Inspection Robot Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Power Generation Equipment Market to Hit $237.47B by 2032 with 5.1% CAGR
By PW Consulting, 2026-09-16
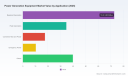
Navigating the Power Generation Equipment Market: Strategic Imperatives for 2026 and Beyond
The global power generation equipment sector is undergoing a structural recalibration unlike any seen in the past decade. As energy demand accelerates and policy frameworks shift, organizations operating across the power value chain must look beyond short-term pricing signals and evaluate the deeper architectural changes reshaping supply, demand, and competitive positioning. At PW Consulting, our latest Power Generation Equipment Market study has been engineered specifically to equip executive teams, procurement leaders, and strategic planners with the analytical rigor needed to navigate this complexity. This overview outlines the strategic contours of the market, previews the operational depth contained in the full report, and demonstrates why access to granular, forward-looking intelligence is no longer optional but essential for 2026 decision-making.
A Market in Transition: Macro Trajectory and Structural Realities
During the 2020-2025 evaluation window, the global market for power generation equipment experienced a pronounced contraction phase, with total revenue declining from an estimated 219.62 billion USD at the start of the period to 175.0 billion USD by 2025. This downward pressure reflected a confluence of project delays, supply chain bottlenecks, and transitional demand patterns as legacy infrastructure phased out and new capacity faced permitting and financing hurdles. However, the trajectory has decisively shifted. Forecast modeling for the 2026-2032 horizon indicates a sustained recovery, with market size projected to climb back to 185.76 billion USD in 2026 and continue expanding at a compound annual growth rate of 5.1 percent. By 2032, the sector is expected to surpass 237 billion USD in revenue, signaling a durable growth cycle rather than a temporary rebound.
For corporate strategists, this inflection carries critical implications. The early-cycle contraction masked underlying demand resilience, while the projected expansion underscores that capacity additions, modernization programs, and distributed generation deployments are aligning into a sustained build-out phase. The 5.1 percent CAGR is not merely a statistical projection; it reflects structural drivers including grid modernization mandates, industrial power demand surges, data center expansion, and the ongoing need for reliable baseload and flexible peaking capacity. Companies that treat the market as a static procurement environment risk misallocating capital, whereas those that map procurement cycles, technology roadmaps, and partnership strategies to this growth trajectory will secure favorable positioning.
The 2026 Decision Architecture: Why This Research Matters Now
Entering 2026, executives are operating at the intersection of multiple compounding forces. Demand forecasts indicate that electricity usage is expected to grow by an average of 5.7 percent annually over the next five years, with peak demand growth reaching 166 GW. Such magnitude of load expansion places unprecedented pressure on generation planning, equipment lead times, and balance-of-plant integration. Simultaneously, cost structures are being reshaped by material input pressures. Tariffs on imported steel and aluminium are elevating costs for power generation equipment and transmission projects, turning historical cost assumptions into unreliable planning benchmarks. Engineering-heavy deployments now require more sophisticated scenario modeling to protect margins and avoid schedule overruns.
On the regulatory front, the policy environment has tightened considerably. A U.S. executive action concluded market-distorting subsidies for unreliable foreign-controlled energy sources in July 2025, accompanied by strict enforcement of tax credit terminations. This development alters the economic calculus for project developers, equipment selectors, and financing structures, particularly for hybrid or transitional assets. In parallel, reliability challenges are surfacing in major load centers. Utilities in New York City have encountered reliability violations linked to peaker plant retirements under stricter emissions requirements, necessitating temporary dual-fuel retention through 2026 to preserve grid stability. These localized stress events are not isolated; they are early indicators of broader reliability-compliance tension that will influence equipment selection criteria, dispatch flexibility requirements, and O&M contract structures throughout the forecast period.
Strategic planners must therefore answer a series of interlocking questions: How should procurement timelines align with projected capacity additions? Which equipment categories will capture the largest share of near-term investment? What regional dynamics will dictate contract negotiation leverage? How are leading incumbents adjusting their portfolios to serve data center, utility-scale, and distributed power demand? The full PW Consulting report is structured to resolve these questions with methodological precision, but the strategic takeaway is already clear: 2026 is a year in which informed anticipation will separate market leaders from reactive followers.
Power Generation Equipment Market
Inside the Research: Operational Depth Designed for Action
Our study is built around the principle that high-level market sizing alone does not drive execution. The report delivers a comprehensive analytical framework covering technology segmentation, application dynamics, regional deployment patterns, competitive positioning, and forward-looking scenario modeling. Readers will find a detailed breakdown of equipment categories spanning turbines, reciprocating engines, boilers, heat exchangers, and power transformers, with emphasis on how each segment is being reshaped by performance requirements, emissions constraints, and system integration needs. The analysis maps how baseload generation, peak generation, combined heat and power, emergency power, and other application classes are diverging in procurement behavior and technology preference, enabling buyers and suppliers to calibrate product strategies accordingly.
The regional dimension is examined with attention to deployment intensity, policy influence, and infrastructure readiness, helping organizations identify where demand concentration is forming and where partnership or localization strategies may be required. Equally important, the study incorporates a realistic appraisal of cost and supply-side headwinds, including the impact of tariff-driven input cost escalation on large engineering projects and the implications of labor and material conditions on delivery schedules. Rather than presenting static snapshots, the report integrates these variables into a cohesive view of market dynamics, allowing readers to stress-test assumptions and prepare for multiple plausible outcomes.
Worldwide Power Generation Engines Market
To preserve the analytical leverage of the complete publication, we intentionally avoid disclosing the specific regional share splits, application-level revenue figures, and segment-level breakdowns in this preview. Those detailed matrices, combined with scenario-adjusted projections and competitive cross-referencing, form the core intelligence layer that decision-makers rely on when sizing investments, negotiating frameworks, and prioritizing technology roadmaps. Accessing the full report ensures that your team can work from the exact percentages, magnitudes, and relational insights necessary for precise planning.
Competitive Landscape: Positioning, Portfolio Moves, and Recent Signals
The market is characterized by meaningful concentration, with the top three players accounting for approximately 58.0 percent of revenue and the top five reaching roughly 62.0 percent. This structure signals a landscape where scale, integrated service offerings, and long-term framework agreements carry disproportionate strategic weight. Yet the competitive field remains diverse, with specialist manufacturers, regional integrators, and technology-focused entrants all pursuing differentiated pathways. The following companies illustrate the range of strategic postures currently shaping the market.
-
Wärtsilä Corporation , headquartered in Helsinki, Finland, continues to expand its footprint through integrated power generation packages, including 2-stroke and 4-stroke engines and gas turbines. Its recent 123 MW power plant order in Odessa, Texas, booked in the first quarter of 2026 for ERCOT grid supply, demonstrates a clear emphasis on grid-serving flexible capacity alongside comprehensive O&M agreements. Wärtsilä’s positioning reflects a strategy centered on delivery reliability, modular plant configurations, and long-term service partnerships.
-
Caterpillar Inc. , based in Irving, Texas, United States, maintains a broad portfolio of reciprocating engines, gas turbines, and large-scale power generation packages. Its strategic relevance is amplified by framework-level commitments, including a 1.4 GW framework agreement secured with Atlas Energy Solutions Inc. for data center and distributed power projects, with initial orders anticipated between 2027 and 2029. Caterpillar’s capacity to anchor multi-year, high-volume deployments underscores its role as a backbone supplier in scaling distributed and industrial generation.
-
2G Energy AG , headquartered in Heek, Germany, specializes in containerized cogeneration and power generation equipment, with a notable focus on natural gas-fired plants for data center applications. In May 2026, its North American subsidiary received a major order for containerized power generation equipment to equip data centers, with deliveries beginning in the second half of 2026. This move highlights the growing importance of packaged, rapidly deployable solutions in high-density power environments.
-
Atlas Energy Solutions Inc. , located in Austin, Texas, United States, operates as a procurer and integrator of high-efficiency natural gas reciprocating engine generators and power generation packages for long-term distributed power solutions. Beyond its March 2026 framework agreement with Caterpillar, Atlas placed an order in November 2025 for 240 MW of power generation equipment, with 4 MW per engine units and delivery scheduled for late 2026. Its strategy illustrates the integrator model, where equipment aggregation, project coordination, and long-term service alignment create value beyond the hardware itself.
-
Liberty Advanced Equipment Technologies LLC , based in Houston, Texas, United States, supplies Bergen Engines-based power generation equipment and balance-of-plant solutions for data center and distributed power projects. In May 2026, the company entered 505 million USD in supply contracts with Bergen Engines, with deliveries planned across 2027 and 2028. This contract scale signals strong confidence in engine-based solutions for near-term capacity deployment and reflects the increasing relevance of balanced plant integration in project economics.
-
Solar Turbines Incorporated , headquartered in San Diego, California, United States, offers factory-packaged gas turbine generator sets ranging from 1 to 39 MW for industrial and utility power generation. Its product range positions the company well for modular industrial deployments and mid-scale utility applications where packaged reliability and simpler commissioning are prioritized.
-
Shanghai Electric Group Company Limited , based in Shanghai, China, provides synchronous condensers, generators, and power generation equipment for grid connection and utility-scale applications. Its focus on grid interfacing and large-scale generation hardware aligns with infrastructure-heavy expansion routes and transmission-linked generation planning.
-
IHI Corporation , headquartered in Tokyo, Japan, is developing ammonia-capable gas turbines and boilers for low-emission power generation equipment. This technological orientation points toward a longer-horizon strategy in which fuel flexibility and emissions performance become central differentiators, especially as procurement criteria increasingly weigh future-proofing against regulatory trajectories.
These profiles demonstrate that competitive advantage is no longer defined by product breadth alone. It is increasingly determined by the ability to secure framework agreements, integrate balance-of-plant components, deliver containerized or modular packages for fast-deployment environments, and align offerings with emerging fuel and emissions pathways. Our full report maps these strategic postures against market share dynamics, order flow indicators, and technology migration patterns, enabling readers to identify where partnerships, procurement shifts, or capacity investments are likely to yield the highest return.
From Intelligence to Execution: What 2026 Demands
The convergence of rapid load growth, material cost volatility, regulatory recalibration, and concentrated supplier power means that 2026 will reward organizations that can move from awareness to action with precision. Procurement teams must anticipate lead-time compression and competition for high-demand equipment categories. Engineering and project developers must build cost models that account for tariff-sensitive input structures and dual-fuel or emissions-compliant configurations where local reliability requirements dictate. Commercial teams must evaluate framework opportunities with a clear understanding of which incumbents are scaling data center and distributed power commitments, and which technology pathways are gaining traction for low-emission or fuel-flexible deployments.
Equally important, executives should treat the market as a system rather than a series of isolated purchases. The interaction between baseload requirements, peaking flexibility, combined heat and power efficiency, and emergency backup needs creates cross-segment dependencies that influence total cost of ownership, dispatch strategy, and service contract design. Understanding how these application classes relate to one another, and how equipment categories such as turbines, engines, boilers, heat exchangers, and transformers are positioned within each, is essential for building resilient investment plans.
Accessing the Full Intelligence: The Strategic Case for the Complete Report
This preview has outlined the market’s direction, the decision environment now taking shape, and the competitive dynamics that will influence outcomes through the end of the decade. Yet the most valuable insights, including the precise regional deployment figures, application-level revenue compositions, segment-level magnitudes, and scenario-adjusted forecasts, are reserved for the complete PW Consulting Power Generation Equipment Market study. By withholding those specifics here, we underscore a simple principle: durable strategic advantage comes from working with the full data architecture, not from partial signals.
Organizations that secure the complete report will be equipped to quantify demand concentration, benchmark competitor positioning, model cost and regulatory scenarios, and align procurement and investment plans with the most probable market pathways. In a sector where growth is returning, concentration is high, and external pressures are intensifying, the difference between reactive purchasing and proactive strategy will be defined by the quality of intelligence underpinning each decision. The full study provides that foundation, enabling your team to move into 2026 with clarity, discipline, and competitive confidence.
For detailed analysis of this topic, please visit the official page: Power Generation Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Solder Preform Market Hits $440M in 2025, Projected 7.4% CAGR to Reach $718M by 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for a Transforming Market: Inside the 2026 Solder Preform Landscape
The solder preform market is entering a decisive inflection point. As manufacturers navigate tighter tolerances, evolving material standards, and shifting supply chain architectures, strategic foresight has become a competitive necessity rather than an analytical luxury. PW Consulting’s latest Solder Preform Market research was designed to meet that exact moment. This study does not merely document historical performance; it translates structural market signals into actionable decision frameworks for 2026 and beyond. For executives, procurement leaders, and product strategists, the report functions as a navigational instrument, aligning capacity planning, sourcing strategy, and innovation roadmaps with the trajectory of a rapidly consolidating industry.
The foundation of this analysis rests on a rigorous examination of market expansion across the recent historical window and into the forward-looking forecast horizon. From 2020 through 2025, the industry demonstrated consistent upward momentum, reflecting steady demand absorption and incremental capacity investments. Looking ahead to the 2026–2032 forecast period, the market is projected to sustain a compound annual growth rate of 7.4 percent, anchored in U.S. dollars and measured in millions of revenue units. This trajectory signals more than simple volume growth; it reflects a structural reallocation toward higher-performance material solutions, precision-form geometries, and application-specific alloy formulations. The reported market valuation has already climbed from 320.0 million in 2020 to 440.0 million in 2025, with the forward estimates extending toward 718.0 million by 2032. These figures establish a clear macro narrative: the solder preform space is expanding, but the drivers of that expansion are increasingly concentrated in specialized segments, stringent certification requirements, and advanced thermal and electrical performance mandates.
Strategic value emerges not from the headline numbers alone, but from understanding how those numbers are distributed across the operational realities that shape procurement, pricing, and capacity decisions. The market structure reflects a moderately fragmented competitive environment, with CR3 concentration at 22.0 percent and CR5 concentration at 32.0 percent. This distribution indicates that no single entity controls the entire value chain, while simultaneously suggesting that scale advantages, tooling libraries, and certification portfolios are becoming meaningful differentiators. For buyers, this means sourcing strategies must balance reliability, technical capability, and resilience. For incumbents, it means the window to expand share through precision manufacturing, custom alloy development, and application-specific preform engineering remains active but increasingly contested. The report unpacks these structural dynamics without reducing them to superficial rankings, instead positioning concentration metrics as indicators of where negotiation leverage, supplier diversification, and partnership models will be most effectively deployed.
What the Research Delivers: Operational Content for Execution-Focused Teams
A market study earns its place on the executive shelf when it converts data into operational clarity. This report is built around that principle. Rather than offering abstract commentary, the analysis maps directly onto the categories that determine day-to-day sourcing and planning decisions. The segmentation architecture examines how product classifications, regional footprints, and end-use application contexts interact to shape demand volatility, lead-time expectations, and qualification pathways. Procurement teams will find structured visibility into the material categories that dominate current procurement flows, while R&D and engineering groups will gain context around the geometry and alloy considerations that influence attachment reliability, thermal management, and bond-line control. The study deliberately avoids presenting segmentation as a static table of proportions; instead, it frames each segment through the operational implications that matter most to decision-makers, including certification requirements, tooling compatibility, and the cost implications of transitioning between material classes.
Equally important is the report’s treatment of supply-side realities. The analysis incorporates the manufacturing and technical capabilities that distinguish leading preform producers, drawing attention to the practical dimensions of die libraries, custom alloy development, thickness control methodologies, and quality system certifications. These are not ornamental details; they determine which suppliers can meet tight tolerance specifications, which can support rapid design changes, and which can sustain consistent output under high-mix production requirements. The study also integrates recent organizational and strategic developments that signal shifting priorities within the competitive field. For example, the June 2025 appointment of a Division Vice President of Sales and Marketing at AMETEK Specialty Metal Products reflects an explicit push toward market expansion and accelerated new product introductions in solder preforms and related custom alloys. Such movements matter because they shape commercial velocity, technical support capacity, and the pace at which new preform configurations reach qualified production status. By tracking these developments, the report helps leaders anticipate where supplier capabilities are likely to strengthen, where commercial engagement models may evolve, and where differentiation will increasingly hinge on technical responsiveness rather than base material availability alone.
Worldwide Composite Preform Market
Competitive Architecture and the Rising Cost of Differentiation
The competitive landscape is defined by a blend of established specialty manufacturers and regional producers, each pursuing distinct positioning strategies within the broader market. Several organizations have built reputations around high-precision preform geometries, broad tooling inventories, and customized alloy solutions intended for demanding end-use environments. One U.S.-based advanced materials group has emphasized ultra-clean preform production across shapes that include squares, rectangles, discs, washers, frames, and custom designs, offering lead-free alloys, gold-tin, and silver-based formulations for microelectronic packaging in aerospace, defense, semiconductor, and high-power applications. Another large-scale manufacturer has positioned itself around the broadest preform range in the industry, supported by an extensive tooling library and specialization in custom alloy configurations for aerospace, defense, high-performance electronics, photonics, automotive, and medical devices. A Japanese producer has focused on versatile geometries such as ribbon, washer, pellet, disc, and chip formats, incorporating design features for bond-line thickness control and optional flux-integrated configurations for simultaneous solder and flux delivery across electronics, automotive, aerospace, and medical contexts. A U.S. materials supplier has advanced preform and thermal management solutions with fixture-stabilizing technologies and certified quality systems aligned to automotive, medical, defense, and power electronics requirements. Historical manufacturers with long operating pedigrees continue to serve industrial, plumbing, electronics, and precision applications through integrated solder and flux portfolios, while specialty electronics solution providers have emphasized sustainability-aligned production environments and metal waste recycling alongside their preform offerings.
Regional manufacturing presence also plays a meaningful role in shaping availability, pricing logic, and qualification pathways. Several dedicated OEM-oriented producers operate around standard and custom preform shapes along with complementary soldering materials such as wires, balls, fluxes, pastes, and powders. Other firms extend their portfolios across electronics and industrial applications as part of broader soldering material ecosystems. These regional capabilities affect not only unit economics but also lead-time predictability, engineering support models, and the practical feasibility of qualification for highly regulated end-markets. The report examines these competitors not as isolated profiles but as strategic reference points within an ecosystem where technical differentiation, certification depth, and customization capacity increasingly determine commercial positioning. Leaders who understand where each supplier concentrates its strengths can structure multi-source arrangements more effectively, align internal qualification roadmaps with supplier readiness, and avoid over-reliance on capabilities that may be vulnerable to capacity constraints or material volatility.
Supply Chain Realities, Material Economics, and Regulatory Friction
The strategic usefulness of a market study depends heavily on its ability to reflect the forces that distort pricing, constrain throughput, and reshape sourcing assumptions. In the solder preform market, material economics have become a central concern. Sustained increases in LME tin pricing have translated into higher preform costs across categories, forcing procurement functions to reinterpret cost forecasts, negotiate contract structures with greater flexibility, and evaluate the trade-offs between alloy selection, geometry standardization, and application performance. At the same time, geopolitical disruption and supply chain concentration in the processing of ultra-high-purity silver powders and related critical materials have surfaced vulnerabilities that extend beyond short-term price movement. These concentration risks affect upstream feedstock availability and can influence lead times, qualification continuity, and the practical resilience of suppliers that depend on narrowly sourced inputs.
Regulatory and trade dynamics add a further layer of complexity. Executive actions affecting ad valorem tariff duties have altered the calculus for cross-border procurement and inventory positioning, especially for organizations balancing regional supply against qualification and compliance requirements. Meanwhile, export controls on gallium and germanium products have implications for upstream feedstock used in certain indium and silver-based preform formulations. Such developments do not simply create headlines; they influence the feasibility of specific alloy pathways, the stability of cost assumptions, and the speed at which alternative material strategies can be validated. The report integrates these macro-level disturbances into the market narrative so that readers can better anticipate where cost pressure may persist, where substitution or qualification efforts will be necessary, and where supplier concentration may create exposure that requires mitigation through diversification or inventory strategy.
Why This Research Matters for 2026 Decision-Making
For organizations operating in or adjacent to the solder preform market, the 2026 planning cycle demands more than retrospective trend analysis. It requires a clear view of where growth is structurally concentrated, which supplier capabilities will determine qualification speed and production reliability, and how material and regulatory forces will reshape cost and risk assumptions. The PW Consulting study is designed to provide that decision-grade context. It enables procurement teams to evaluate sourcing models with greater precision, helps R&D groups align material and geometry exploration with realistic market readiness, and supports executive teams in prioritizing capital, capacity, and partnership investments where the growth trajectory is strongest.
The report also serves as a practical bridge between macro momentum and segment-level realities. By connecting overall market expansion to the operational implications of segmentation, concentration, tooling breadth, certification depth, and material volatility, it helps leaders convert trend awareness into execution strategy. This is particularly valuable in a market where the most consequential decisions often hinge on details that generic analysis overlooks: the availability of specific preform shapes, the flexibility of custom alloy development, the resilience of upstream feedstock channels, and the commercial significance of recent leadership and product-introduction moves within key manufacturing organizations.
Solder Preform Market
Strategic advantage in 2026 will belong to organizations that can align their internal capabilities with the market’s directional signals before those signals become fully priced into competition. The full research delivers the depth required to make that alignment possible. It presents a structured, evidence-based view of market size, growth trajectory, competitive positioning, and operational sensitivities, while preserving the granular intelligence that procurement, engineering, and executive teams need to act with confidence. To access the complete segmentation breakdowns, competitive capability assessments, regional and application-level context, and forward-looking scenario implications, readers are encouraged to visit the source page for PW Consulting’s Solder Preform Market research and obtain the full report.
For detailed analysis of this topic, please visit the official page: Solder Preform Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


