



Category: Machinery & Automotive
Gas Detectors Market Surges Past $6.2B Why the 6.5% Growth Trajectory Changes Everything
By PW Consulting, 2026-09-21
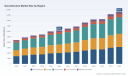
Strategic Trends and Commercial Opportunities in the Global Gas Detectors Market
The global gas detectors market has entered a phase of sustained expansion, driven by tightening safety regulations, technological maturation, and a structural shift toward connected, real-time monitoring solutions. Over the historical period from 2020 through 2025, the market advanced from approximately $4.4 billion to $6.2 billion, reflecting steady year-over-year growth as industrial operators, municipal authorities, and energy infrastructure providers increasingly prioritized early detection and continuous environmental monitoring. Looking ahead to the 2026–2032 forecast window, the trajectory points toward a compound annual growth rate of 6.5 percent, with total market value projected to reach nearly $9.6 billion by the close of the period. This growth is not merely a function of incremental replacement cycles; it represents a broader realignment in how organizations conceptualize safety infrastructure, moving from passive, compliance-driven installations toward active, data-integrated monitoring ecosystems.
Market Structure and Concentration Dynamics
The market demonstrates a moderately concentrated structure, with the top three competitors collectively accounting for roughly 58 percent of overall revenue and the top five firms capturing approximately 72 percent. This concentration signals the presence of entrenched incumbents with established distribution channels, mature product portfolios, and significant brand recognition across industrial and municipal verticals. However, the remaining market share is distributed among a diverse set of regional specialists, application-focused manufacturers, and emerging players targeting niche monitoring requirements. The coexistence of dominant global players and agile niche suppliers creates a competitive environment where differentiation increasingly hinges on connectivity capabilities, regulatory compliance readiness, and application-specific engineering rather than raw sensor performance alone.
Key Challenges and Inflection Points
Despite the favorable growth trajectory, the market faces several structural challenges that will shape competitive outcomes over the next five years. First, the regulatory landscape is fragmenting across jurisdictions, with local building codes, pipeline safety mandates, and occupational health standards imposing divergent performance and installation requirements. Organizations operating across multiple regions must navigate inconsistent certification pathways and compliance timelines, which increases integration complexity and raises total cost of ownership for multi-site deployments. Second, the transition from standalone detection hardware to connected, networked monitoring systems introduces cybersecurity, data interoperability, and lifecycle management concerns that many traditional manufacturers are still addressing through product development and service model adaptation. Third, supply chain volatility for specialized sensing components, calibration gases, and semiconductor-based detector elements continues to pressure margins and constrain rapid scale-up for new product lines. These challenges are not insurmountable, but they require strategic foresight and investment in cross-functional capabilities that extend beyond core hardware engineering.
Key Drivers Shaping Market Evolution
Technological Innovation and Sensor Advancement
Advancements in sensor technology are fundamentally reshaping product capabilities and expanding the addressable use cases for gas detection. Infrared-based sensing, enhanced electrochemical cell designs, and improved catalytic bead configurations have increased detection precision, reduced false alarm rates, and extended operational life in harsh environments. Simultaneously, the integration of wireless communication modules, edge computing capabilities, and cloud-anchored fleet management platforms has transformed portable and fixed detectors from isolated warning devices into interconnected nodes within broader safety and asset monitoring networks. Manufacturers that have embedded connectivity into their product architectures are enabling centralized visibility across large facility footprints, real-time alarm escalation, and predictive maintenance workflows that reduce downtime and improve response coordination.
Policy and Regulatory Momentum
Regulatory activity has accelerated across multiple jurisdictions, creating both compliance-driven demand and opportunities for early-adopting solution providers. Recent municipal and federal requirements have mandated natural gas alarms and zoned detection systems in specific residential and commercial building categories, establishing new installation baselines and product specification thresholds. Pipeline safety rules have further emphasized the need for commercially available leak detection equipment that meets defined performance standards, pushing operators to upgrade legacy monitoring approaches with validated, interoperable solutions. Occupational safety guidelines continue to reinforce the requirement for routine air monitoring in hydrogen sulfide and other hazardous gas environments, with renewed emphasis on training, device qualification, and documented compliance. Collectively, these regulatory shifts are converting safety detection from an optional best practice into a codified operational necessity across housing, energy transport, and industrial processing sectors.
Demand-Side Shifts in Operational Behavior
Demand patterns reflect a broader organizational move toward proactive risk management rather than reactive incident response. Facilities managers, safety directors, and operations leaders are increasingly seeking integrated monitoring strategies that combine area-fixed systems with personal and portable units, enabling layered protection across confined spaces, process zones, and perimeter areas. Fleet operators and emergency response organizations are prioritizing devices that support centralized management, automatic reporting, and integration with existing workforce safety platforms. This behavior shift is particularly pronounced in sectors where downtime carries high financial and reputational costs, and where regulatory scrutiny has intensified following high-profile incidents and investigative reports highlighting gaps in residential and commercial fuel-gas detection practices.
Supply Chain and Cost Structure Considerations
Cost structures are being reshaped by the increasing incorporation of digital services, calibration management programs, and extended warranty or lifecycle support offerings. While core sensor and housing costs remain important, the total value proposition now includes software licensing, data subscription models, remote diagnostics, and on-site service networks. Organizations that have built robust service ecosystems are able to smooth revenue streams and deepen customer stickiness, while those that remain purely hardware-focused face margin compression from price competition and component cost variability. Supply chain resilience has therefore become a strategic differentiator, with leading players investing in component sourcing diversification, inventory buffering for critical sensor elements, and regional manufacturing or assembly footprints to reduce exposure to logistical disruptions.
Competitive Landscape and Leading Strategies
Incumbent Positioning and Differentiation
The market's leading companies have built their positions through a combination of broad product portfolios, established industry credibility, and targeted application specialization. Large diversified manufacturers offer comprehensive fixed and portable solutions spanning multi-gas monitoring, flame detection, and hazardous-area certification, allowing them to serve integrated safety programs across industrial, utility, and mining environments. Specialized safety companies have strengthened their standing through reputation for rugged reliability, confined-space expertise, and strong relationships with industrial customers who prioritize worker protection and compliance documentation. European and North American manufacturers alike have advanced their positions by embedding connectivity into flagship portable and fixed product lines, enabling fleet-wide visibility and compliance tracking. Mid-tier and niche players have carved out defensible positions by focusing on specific gas targets, such as hydrogen-specific monitoring for emerging energy applications, or by delivering bespoke fixed detection engineering for demanding process environments.
Strategic Themes Among Leading Players
Several strategic themes are evident across the competitive field. One is the convergence of personal protection and area monitoring into unified safety architectures, with product lines designed to share communication protocols, data standards, and management interfaces. Another is the emphasis on hydrogen-ready and multi-gas flexible detection, reflecting the expansion of new energy infrastructure and the need for equipment that can adapt to shifting gas compositions and operational scenarios. A third theme is the strengthening of aftermarket and service capabilities, including calibration programs, detector refurbishment, and remote health monitoring, which convert one-time capital purchases into recurring engagement models. Trade show participation and product launch cadence have become important signals of market intent, with companies showcasing fire-rescue, civil protection, and industrial detection solutions at major international events, while simultaneously rolling out new portable monitor series and updated product catalogs to refresh portfolios and address emerging application requirements.
Market Evolution: Consolidation, Differentiation, and Entry Dynamics
The competitive landscape is evolving along multiple axes. Consolidation pressure remains present among mid-sized suppliers seeking scale in manufacturing, distribution, or service delivery, while larger incumbents continue to evaluate targeted acquisitions or technology partnerships that can accelerate connectivity, sensor diversification, or geographic reach. At the same time, market differentiation is increasingly likely to occur at the application and integration level rather than through generic hardware specifications alone. New entrants and regional specialists can find viable openings by addressing underserved gas targets, tailoring solutions to specific regulatory frameworks, or offering lighter-cost portable options for emerging markets and smaller contractors. However, successful entry typically requires credible certification coverage, reliable supply relationships, and a clear path to either service attachment or channel partnership, given the importance of compliance assurance and lifecycle support in customer purchasing decisions.
Future Trends and Commercial Implications
Trend 1: Connected Safety Ecosystems as the New Baseline
Over the next three to five years, connected detection architectures are expected to become a standard expectation rather than a premium differentiator. Fixed and portable devices will increasingly operate as integrated elements within facility-wide safety and operational technology environments, with data flowing into centralized dashboards, automated alarm escalation workflows, and compliance reporting systems. For manufacturers, this trend creates opportunities to expand software and service attach rates, develop interoperable data standards, and position hardware as entry points to broader subscription-based monitoring programs. For end users, the implication is a shift in procurement criteria toward platform compatibility, data retention policies, integration effort, and total lifecycle cost, rather than sensor price alone.
Trend 2: Regulatory Normalization Across Residential, Pipeline, and Industrial Domains
Regulatory momentum across building codes, pipeline safety mandates, and occupational monitoring requirements is expected to continue normalizing gas detection as a codified infrastructure component. As codes and standards become more explicit about installation zoning, performance thresholds, and maintenance obligations, demand for compliant, certifiable equipment will broaden beyond traditional heavy industrial settings into municipal housing, commercial buildings, and energy transport operations. This opens addressable market expansion for manufacturers with proven certification portfolios and documented compliance support, while raising the bar for competitors that lack established testing records or regional code familiarity. Organizations that invest early in aligning product specifications with emerging code expectations will be better positioned to capture procurement cycles as mandates take effect.
Trend 3: Application Expansion Into New Energy and Specialized Environments
The growing focus on hydrogen-related monitoring, combined with continued demand in oil and gas, chemicals, mining, and emergency response contexts, is broadening the application base for both fixed and portable systems. New energy infrastructure, fleet management requirements, and specialized confined-space operations are driving interest in detectors that can handle evolving gas compositions, support rapid deployment, and integrate with existing safety and logistics workflows. This expansion creates opportunities for companies that can deliver application-engineered solutions, flexible calibration and sensor swap options, and clear guidance on deployment best practices. The corresponding risk is that rapid application diversification can strain product development resources and complicate quality assurance if not managed with disciplined platform architecture and careful validation protocols.
Actionable Guidance for Decision-Makers
For Manufacturers and Product Leaders
Prioritize platform-level design that allows sensor modules, communication interfaces, and management software to evolve without requiring full product line replacements. Invest in certification coverage and compliance documentation that align with the most demanding regional requirements, as these credentials increasingly function as market-access prerequisites rather than optional endorsements. Strengthen aftermarket and service capabilities, including calibration programs, remote diagnostics, and detector lifecycle management, to build recurring revenue and deepen customer retention. Evaluate targeted partnerships or technology acquisitions that can accelerate connectivity, data interoperability, or application-specific detection capabilities, particularly where internal development timelines would lag market expectations.
PW Consulting Automotive & Machinery Research Center
For Investors and Strategic Planners
Focus due diligence on companies that demonstrate a credible transition from hardware-only revenue models to integrated hardware-plus-service portfolios, as this shift often correlates with improved revenue visibility and customer lock-in. Assess exposure to regulatory-driven demand across pipeline safety, residential and commercial building codes, and occupational health mandates, since these drivers can create durable procurement cycles that are less sensitive to short-term industrial cyclicality. Monitor competitive signals such as product launch cadence, trade show positioning, and fleet-management integration capabilities, which often indicate which players are executing effectively on market evolution rather than reacting to it. Be attentive to margin dynamics in sensor supply chains and to the cost implications of connectivity features, as these factors will shape profitability trajectories across the forecast period.
For Procurement and Safety Operations Leaders
When evaluating detection solutions, expand evaluation criteria beyond unit price to include total cost of ownership, interoperability with existing safety platforms, data access and retention terms, calibration and service arrangements, and the supplier's ability to support multi-site compliance documentation. Prioritize architectures that enable layered protection across fixed area monitors, portable units, and personal devices, ensuring coverage continuity as personnel and operations move across zones. Require clear evidence of certification alignment with applicable regional codes and standards, and confirm that the solution provider can deliver training, refresher support, and documented maintenance processes that satisfy both internal safety programs and external audit requirements.
Worldwide Carbon Dioxide Detector Market
Closing Perspective
The gas detectors market is moving through a period of meaningful structural change, where growth is being driven not only by incremental replacement demand but by a broader redefinition of safety detection as a connected, compliance-embedded, and application-diversified capability. Organizations that align product strategy, service design, and regulatory readiness with these shifts will be best positioned to capture value as the market advances toward the end of the decade. The commercial opportunities are substantial, but realizing them requires disciplined investment in platform architecture, certification coverage, and lifecycle support, paired with a clear understanding of where regulatory, technological, and demand-side momentum are converging. For decision-makers seeking deeper granularity on segment dynamics, regional demand patterns, competitive benchmarking, and customized scenario planning, a comprehensive research report provides the detailed data and structured analysis necessary to translate these strategic themes into precise, actionable plans.
Radiation Detector Market
For detailed analysis of this topic, please visit the official page: Gas Detectors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
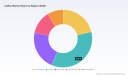
Navigating the Next Wave: Strategic Trends and Commercial Opportunities in the Global Coffee Market
The global coffee market has entered a phase of structural expansion characterized by resilient demand, evolving consumption patterns, and shifting competitive dynamics. Over the past five years, the industry has demonstrated consistent growth, with total market revenue climbing from approximately USD 191.69 billion in 2020 to an estimated USD 249.34 billion in 2025. This trajectory positions the sector on a projected compound annual growth rate of 5.4 percent through 2032, suggesting that the market will likely surpass USD 360 billion by the end of the forecast period. Such expansion is not merely a function of volume increases; it reflects deeper transformations in how coffee is sourced, processed, distributed, and consumed across both developed and emerging economies. For executives and investors, the current landscape presents a mix of substantial opportunity and complex risk, requiring a nuanced understanding of the forces shaping value creation across the supply chain.
PW Consulting Automotive & Machinery Research Center
Despite the optimistic top-line trajectory, the market faces several intersecting challenges that will define strategic decision-making in the near term. First, price volatility remains a persistent feature of the commodity cycle, with recent months illustrating how quickly supply-side improvements can compress margins and alter trading dynamics. Second, regulatory tightening around sustainability and deforestation is introducing new compliance requirements that affect every node from plantation to point of sale, particularly for operators with significant European exposure. Third, the gap between premiumization trends and everyday affordability is widening, forcing producers and retailers to navigate competing consumer expectations while managing input costs. These challenges are not isolated; they interact with each other and with broader macroeconomic conditions, creating a landscape where agility and data-informed positioning matter more than ever.
Key Drivers Reshaping Market Dynamics
Technological Innovation and Processing Breakthroughs
Innovation across the coffee value chain is moving beyond incremental product tweaks to encompass fundamental shifts in how beans are sourced, roasted, packaged, and delivered. Advances in cold-chain logistics, single-serve extraction systems, and ready-to-drink formulation have expanded the reach of coffee beyond traditional hospitality settings and into everyday retail and on-the-go consumption. At the same time, digital tools for traceability, quality control, and demand forecasting are becoming increasingly central to operational efficiency, especially for roasters and distributors managing complex multi-origin portfolios. Recent industry events have highlighted this momentum, with major trade exhibitions showcasing new equipment, product formats, and supply chain connectivity initiatives that connect producers directly with roasters and buyers. These platforms are not merely promotional; they signal a maturing ecosystem where technical differentiation and relationship-based sourcing are converging to create defensible competitive positions.
Espresso Coffee Market
Regulatory and Sustainability Imperatives
Policy and regulatory developments are no longer peripheral concerns; they are central to market access, cost structures, and brand positioning. The introduction and ongoing implementation of due diligence requirements tied to deforestation have raised the compliance bar for coffee imports, particularly within Europe, where traceability and origin verification are becoming table stakes rather than optional differentiators. Parallel trade policy shifts in key importing markets have also begun to alter cost dynamics for specific origin countries, with recent tariff adjustments removing long-standing barriers for certain Southeast Asian coffee exports. These regulatory and trade developments create a dual effect: they increase short-term administrative and verification burdens for supply chain operators, while simultaneously opening new sourcing and distribution pathways for businesses that can adapt quickly. Companies that proactively build compliance infrastructure and diversify origin portfolios are better positioned to convert regulatory pressure into competitive advantage rather than cost drag.
Shifting Consumer and B2B Demand Patterns
Demand-side behavior continues to evolve along two reinforcing axes: premiumization and convenience. Consumers across multiple regions are showing greater willingness to pay for perceived quality, origin transparency, and specialty attributes, while simultaneously expecting faster, more consistent access through ready-to-drink formats, subscription models, and expanded away-from-home channels. For business-to-business buyers, the demand picture is equally dynamic, with foodservice operators, office coffee providers, and retail chains seeking flexible supply arrangements, consistent quality, and menu differentiation that aligns with local taste preferences. The intersection of these trends is reshaping product mix decisions, channel strategies, and pricing architectures. Suppliers that can segment their offerings effectively, balancing premium narratives with accessible everyday options, are capturing a broader share of wallet across consumer and institutional buyers.
Supply Chain Reconfiguration and Cost Structure Evolution
Cost structures in the coffee sector are being reshaped by a combination of commodity cycles, logistics complexity, and origin-level production dynamics. Periods of improved harvest expectations can rapidly lower benchmark prices, creating favorable acquisition conditions for roasters and manufacturers but also compressing returns for producers and intermediaries who depend on price upside. At the same time, the cost of compliance, certification, and sustainable sourcing initiatives is becoming a more visible component of total cost of ownership, influencing which supply relationships are economically viable over the long term. The net effect is a market where supply chain design matters as much as product quality. Companies are increasingly evaluating resilience, traceability, and contractual flexibility alongside traditional cost metrics, recognizing that a lean but brittle supply chain can be more risky than a slightly more diversified and transparent one.
Competitive Landscape and Strategic Positioning
The competitive architecture of the coffee market is defined by a mix of global brands, commodity traders, and specialty-focused operators, each pursuing distinct pathways to scale and differentiation. Large multinational roasters and food-and-beverage companies continue to leverage brand equity, extensive distribution networks, and portfolio breadth to capture share across retail, foodservice, and ready-to-drink channels. Their advantage lies in the ability to standardize quality, manage large-volume procurement, and cross-sell across multiple consumer touchpoints. At the same time, major commodity handlers and green coffee traders occupy a critical intermediary role, providing origination, logistics, and risk management capabilities that link producing regions with industrial and retail buyers. Their strategic relevance is reinforced by the complexity of global sourcing and the growing need for verified, multi-origin supply streams.
Alongside these scale-oriented players, premium and specialty-focused companies are carving out positions based on origin storytelling, quality curation, and direct producer relationships. This segment benefits from the broader premiumization trend and from consumer interest in transparency and authenticity, but it also faces the challenge of balancing margin goals with ethical sourcing commitments. Recent industry gatherings have underscored this dynamic, with producer-roaster forums and specialty product award events highlighting the increasing importance of direct relationships, product innovation, and origin-level differentiation. The competitive landscape is therefore not a simple hierarchy; it is a layered ecosystem where brand power, supply chain control, product quality, and sustainability credentials each contribute to market position in different ways.
Several patterns are emerging in how leading players are adapting. Portfolio expansion into ready-to-drink and single-serve formats is allowing established brands to capture convenience-driven demand without sacrificing core retail and foodservice presence. Vertical integration and strategic sourcing relationships are being used to secure supply, reduce variability, and strengthen traceability narratives. At the same time, the market is seeing both consolidation pressure among mid-tier players seeking scale and fragmentation at the specialty end, where new entrants and regional roasters compete on authenticity, local taste profiles, and agile product development. This coexistence of consolidation and differentiation suggests that the next phase of competition will reward companies that can combine operational scale with credible specialty positioning and adaptive supply chain design.
Forward Outlook: Trends and Opportunities for 2026 and Beyond
Deepening Premiumization with Portfolio Segmentation
The premiumization trajectory is expected to continue, but its manifestation will likely become more segmented rather than uniformly upward. Consumers and business buyers will increasingly differentiate between everyday coffee needs and occasion-driven premium consumption, prompting companies to structure portfolios that serve both segments without cannibalizing each other. This creates opportunities for tiered product architectures, origin-specific lines, and format-specific innovation that align quality signals with price points and channel context. Businesses that invest in clear segmentation logic and can maintain quality consistency across tiers will be better equipped to capture growth without eroding margin integrity.
Supply Chain Transparency as a Commercial Asset
Traceability, sustainability verification, and origin storytelling are transitioning from compliance obligations to commercial assets. As due diligence requirements mature and consumer awareness of sourcing practices deepens, transparent supply chains will increasingly influence purchasing decisions, partnership selection, and brand trust. Companies that embed verification, auditable sourcing, and clear communication into their operations can convert regulatory and reputational pressures into differentiators, particularly in markets where sustainability claims are scrutinized and rewarded. The commercial opportunity lies not only in reducing risk but in using credible transparency to justify premium positioning, secure institutional contracts, and build long-term producer relationships.
Channel Convergence and Format Innovation
The boundary between on-trade and off-trade consumption continues to blur as ready-to-drink products, retail formats, and foodservice offerings converge around convenience, consistency, and experience. This convergence is encouraging product and packaging innovation designed for portability, shelf stability, and rapid preparation, while also requiring companies to manage channel-specific requirements around logistics, pricing, and brand presentation. For operators, the opportunity is to design offerings that travel well across channels without losing their identity, leveraging format innovation to extend reach into new consumption moments. The risk is that channel complexity can erode efficiency if portfolio and supply decisions are not coordinated, making integrated planning essential.
Actionable Guidance for Decision Makers
For manufacturers and roasters, the priority is to align product portfolios with the dual forces of premiumization and convenience while reinforcing supply chain resilience. This means evaluating whether current sourcing and production models can support both premium and value-tier offerings without compromising quality or cost efficiency, and whether traceability capabilities are strong enough to meet evolving compliance expectations and consumer expectations alike. Building flexibility into contracts, diversifying origin exposure, and investing in format innovation can help protect margins during commodity swings while positioning the business to capture new demand moments.
For investors, the strategic focus should be on identifying operators with credible differentiation, disciplined cost structures, and the ability to navigate regulatory and supply chain complexity. Scale alone is not sufficient in a market where premiumization, sustainability requirements, and channel convergence are reshaping competitive logic. Investment theses that account for traceability readiness, portfolio balance across formats and channels, and the quality of producer relationships are more likely to capture durable value. Equally important is monitoring how trade policy shifts and commodity cycles alter relative cost advantages across origin markets, since these dynamics can create both dislocation and entry opportunities.
For procurement and supply chain leaders, the emphasis should be on building sourcing strategies that combine cost discipline with resilience and verification. Relying on a narrow set of origins or suppliers may deliver short-term efficiency but increases exposure to climate variability, regulatory change, and price volatility. Diversifying portfolios, securing multi-year relationships with transparent producers, and integrating compliance requirements early in the sourcing process can reduce disruption risk while strengthening negotiating posture. Procurement decisions increasingly influence not only cost but also brand credibility and market access, making them a strategic lever rather than a purely operational one.
The coffee market is moving into a period where growth will be shaped less by uniform expansion and more by how effectively companies translate shifting consumer behavior, regulatory pressure, and supply chain complexity into coherent strategy. The operators that succeed will be those that treat transparency as a commercial advantage, segment portfolios with discipline, and design sourcing and production systems that can absorb volatility while capturing premium and convenience-driven demand. For decision makers seeking a deeper view of market sizing, segment trajectories, origin-level dynamics, and competitive benchmarking, the full PW Consulting market research report provides a more detailed breakdown of the data and customized recommendations for specific business contexts.
Coffee Machine Market
For detailed analysis of this topic, please visit the official page: Coffee Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Electric Utility Vehicles Market: Why 6.85% CAGR and Lithium-Ion Shift Change Everything
By PW Consulting, 2026-09-21
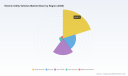
Electric Utility Vehicles Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The electric utility vehicle segment has matured from a niche alternative into a structurally significant market. Total revenue expanded from approximately $13.52 billion in 2020 to $23.86 billion in 2025, reflecting consistent annual growth and deepening commercial adoption across multiple verticals. Forward projections place the market at roughly $25.4 billion in 2026 and climbing toward $38.24 billion by 2032, sustained by a compound annual growth rate of 6.85 percent. This trajectory is not merely a reflection of broader electrification sentiment; it signals a tangible shift in how fleets, facilities, and recreational operators approach mobility economics, maintenance overhead, and regulatory compliance.
Despite the upward momentum, the market faces structural friction that will shape competitive outcomes over the next several years. The first challenge lies in battery chemistry economics and operational range expectations. Lithium-ion platforms, particularly lithium iron phosphate variants, are becoming the default choice for commercial deployments because they lower upfront procurement costs while supporting range extensions beyond forty-five miles. Yet the same chemistry decisions create tension between purchase price, charge cycle longevity, and thermal management requirements. Operators evaluating total cost of ownership must reconcile lower initial expenditures with lifecycle degradation patterns, especially for heavy-duty use cases where duty cycles strain pack durability. The result is a market in which specification choices carry long-term financial consequences, and misjudging application requirements can erode the economic case for electrification.
The second challenge stems from infrastructure readiness and municipal procurement complexity. Electrified roadway pilots, including multi-million-dollar testing corridors with wireless charging installations and extended charging segments, are underway in locations such as Germany and Michigan to validate operational feasibility for heavy utility vehicles. These initiatives demonstrate technical possibility, but they also expose the gap between pilot-scale validation and fleet-wide deployment. Operators must contend with charging access, grid capacity, and route planning constraints that vary significantly by site. Simultaneously, government procurement notices increasingly specify four-wheel-drive electric utility vehicles that meet EPA Tier 4 and CARB standards for municipal and utility fleet deployment. Compliance with these specifications raises the technical bar for suppliers and forces buyers to align vehicle selection with evolving regulatory checklists rather than legacy performance benchmarks alone.
A third challenge is market concentration and the strategic risk it creates for late entrants. The segment remains highly consolidated, with the top three firms capturing roughly 62.4 percent of revenue and the top five reaching approximately 71.2 percent. This concentration rewards scale, established distribution channels, and the ability to meet demanding commercial specifications. It also raises the difficulty of differentiation for new manufacturers unless they bring distinct advantages in platform modularity, retrofit conversion capabilities, or application-specific engineering. Companies that attempt to enter with broadly generic offerings face an uphill battle, while those that target underserved application niches or conversion pathways can find more viable positioning.
Key Drivers of Market Evolution
Technical Innovation and Powertrain Maturation
Powertrain engineering continues to be the primary force reshaping the market’s value proposition. Manufacturers are moving beyond basic electrification toward integrated platform strategies that combine higher-efficiency motors, improved thermal management, and battery architectures tuned to specific duty cycles. Recent updates from John Deere, which refreshed its electric utility vehicle lineup with increased battery runtime and enhanced features showcased at the 2025 GCSAA Conference, illustrate how incremental platform improvements directly address fleet runtime concerns. These enhancements matter because they reduce route interruption, improve uptime predictability, and strengthen the operational argument for electric platforms in demanding environments.
Battery technology is similarly advancing the commercial equation. Lithium-ion batteries and LFP chemistries dominate electric utility vehicle powertrains, with range upgrades to forty-five-plus miles enabling lower upfront costs for commercial users. This combination of extended usable range and reduced entry cost is especially important for fleets that previously hesitated because of range anxiety or high initial expenditure. As range thresholds rise and costs moderate, electric utility vehicles become more competitive against internal combustion alternatives on a total cost basis rather than solely on environmental grounds.
Policy, Regulation, and Incentive Architecture
Regulatory and incentive frameworks are accelerating adoption by reshaping procurement economics and compliance requirements. Government contracts and bids are specifying electric utility vehicles that satisfy EPA Tier 4 and CARB standards, which channels municipal and utility demand toward compliant models and away from legacy platforms. At the same time, incentive programs such as Vermont’s Electrify Your Fleet initiative provide direct support for electric utility vehicle replacements in municipal and business fleets, explicitly tying funding to greenhouse gas emission reduction goals. These mechanisms do more than subsidize purchases; they create procurement pathways that prefer electric options and lower the financial risk for fleet managers making the transition.
Policy momentum also influences design priorities. Because municipal and utility specifications increasingly emphasize environmental compliance, noise reduction, and operational efficiency, manufacturers are tailoring platforms to meet those criteria rather than pursuing generic electrification. This alignment between regulation and product development increases the likelihood that compliance-driven demand will continue to underpin growth, particularly in North America where procurement structures are highly standardized.
Demand-Side Shifts in Commercial and Recreational Use
Buyers are redefining what they expect from utility vehicles as electrification becomes normalized. Commercial operators are prioritizing lower long-term labor and maintenance costs, reduced fuel exposure, and improved site-level air quality. Fleet electrification of municipal and utility vehicles shifts operational maintenance demands, with incentives targeting replacement of internal combustion models to lower long-term labor and fuel expenses. This shift is particularly meaningful for organizations that operate high-utilization fleets, where maintenance downtime and fuel price volatility can significantly affect operating budgets.
Electric Vehicles for Construction, Agriculture and Mining Market
At the same time, recreational and hospitality-adjacent demand is expanding the addressable market beyond traditional industrial applications. Golf courses, resorts, and leisure operators are adopting electric vehicles to improve guest experience, reduce noise, and align with sustainability expectations. This broadening demand base diversifies growth sources and reduces reliance on a single vertical, though it also requires manufacturers to balance differing performance, range, and charging needs across use cases.
Supply Chain Dynamics and Cost Structure Realignment
Cost structure changes are reshaping competitive positioning. As battery supply chains mature and chemistry choices stabilize around proven lithium-ion and LFP options, manufacturers can plan production with greater predictability and lower volatility in key input costs. The transition also alters service economics: fewer moving parts, reduced fuel handling, and simplified maintenance routines change the labor profile of fleet operation. These supply-side improvements support the commercial case for electrification, but they also create a race to the bottom in segments where differentiation is weak. Companies that rely solely on cost competition may find margin pressure intensifying, while those that combine platform efficiency with strong application engineering can preserve value.
Competitive Landscape and Leading Strategies
The market’s competitive architecture is defined by a mix of established utility vehicle specialists, diversified outdoor and agricultural brands, and regional players with strong conversion or modular capabilities. GEM Cars has carved out a focused position in street-legal all-terrain electric utility vehicles and low-speed vehicles, emphasizing fleet electrification through its electric series. This specialization allows the company to appeal directly to municipal and commercial customers that need compliant, purpose-built platforms rather than adapted recreational vehicles.
Polaris Inc. brings a different strategic advantage: the integration of advanced electric powertrains developed through its Zero Motorcycles partnership, deployed across models such as the RZR Pro XD Kinetic and Ranger EV. This powertrain collaboration signals a technology-forward approach that targets performance-conscious utility users and recreational-commercial crossover demand. Textron Specialized Vehicles Inc. competes with a stronger emphasis on commercial fleet solutions and specialized industrial applications, positioning itself where custom configuration and utility-grade durability matter most. John Deere continues to leverage its agricultural and utility brand equity through its Gator series, extending electrification into farm and utility fleet contexts where brand trust and application familiarity reduce adoption friction.
Kubota Corporation adds a construction and farm-grade dimension with its RTV series and expanding electric ranges, appealing to operators who need rugged utility vehicles with a clear path toward electrified options. Alke S.p.A. differentiates through modular electric utility vehicles with enhanced safety and platform features, an approach that supports customization for diverse commercial environments. Club Car remains a strong presence in electric golf, transportation, and utility vehicles, and its expansion into street-legal models for commercial applications shows how an established golf and transport brand can broaden into municipal and facility markets. Kandi Technologies Group focuses on high-clearance electric UTVs for off-road utility use, targeting customers that require greater ground clearance and rugged capability. Groupe Gruau provides a distinct value proposition through utility vehicle conversion and electric retrofit solutions for commercial fleets, an increasingly relevant path for organizations that want to extend the life of existing assets rather than replace them entirely. The Massimo Group is also expanding into electric utility terrain vehicles with debut models planned for 2026, indicating continued entry activity from manufacturers seeking performance and efficiency gains.
PW Consulting Automotive & Machinery Research Center
Recent market activity underscores both product momentum and brand expansion beyond traditional utility vehicle definitions. Kia’s EV9 was named the 2026 Canadian Electric Utility Vehicle of the Year by AJAC and displayed at the Canadian International Auto Show in February 2026, reflecting how larger electric vehicles are gaining recognition in utility-adjacent categories. Jeep introduced the all-electric 2026 Recon SUV as the only fully electric utility vehicle designed to be trail rated, blending recreational utility expectations with electric propulsion. These developments illustrate a broader competitive trend: the boundaries of the electric utility vehicle market are widening as more brands position electric platforms for mixed-use, off-road, and facility-based applications.
Electric Trucks Market
Strategically, the leading companies are pursuing differentiation along several axes. Some emphasize powertrain sophistication and performance credibility to attract buyers who fear electric platforms will underdeliver in demanding conditions. Others focus on compliance, modularity, and application-specific engineering to win municipal, industrial, and fleet contracts. A third group builds value through conversion and retrofit pathways, allowing commercial operators to electrify existing assets where total replacement is financially or operationally impractical. These divergent strategies suggest a market in which multiple legitimate competitive models can coexist, but only if each is anchored in a clear application fit rather than a generic electric vehicle proposition.
The competitive landscape is also evolving through both consolidation pressure and new entry. High concentration advantages the largest players in scale procurement, service networks, and brand trust, but it does not eliminate opportunities for targeted entrants. New manufacturers can compete by addressing niche range requirements, specialized vehicle geometry, or retrofit services that incumbents underserve. At the same time, the widening definition of utility vehicles invites crossover from broader electric vehicle brands, which can intensify competition at the edges of the market while leaving dedicated utility vehicle manufacturers to defend core commercial and industrial segments.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
Trend One: Commercial Electrification Becomes a Total Cost of Ownership Decision, Not a Compliance Purchase
Over the next several years, buying decisions will increasingly center on lifecycle economics rather than regulatory checkbox compliance. As battery range improvements and chemistry maturity reduce upfront barriers, fleet managers will compare electric options against internal combustion alternatives using maintenance labor, fuel exposure, downtime, and site-level operating conditions. This shift favors manufacturers that can document real-world operational savings and provide credible deployment support, while disadvantaging those that rely primarily on environmental messaging. Commercial opportunity lies in packaging vehicles with charging planning, service expectations, and application-specific performance data that make the economic case clear.
Trend Two: Retrofit and Conversion Pathways Gain Strategic Importance
Conversion and retrofit solutions are likely to become more commercially significant as organizations seek to electrify existing fleets without full replacement. Supply chain maturation, incentive structures that reward replacement of internal combustion models, and the desire to manage capital expenditure all support this direction. Companies that can deliver reliable conversion platforms, maintain safety and compliance standards, and integrate electric powertrains into existing vehicle architectures will capture demand from buyers who value flexibility. The strategic risk is that conversion quality and regulatory alignment vary widely, so credible engineering and consistent certification will separate scalable programs from short-lived experiments.
Trend Three: Infrastructure Pilots Move From Validation to Site-Specific Deployment Planning
Electrified roadway experiments and wireless charging installations currently serve as proofs of concept, but the practical value will come from translating pilot findings into site-specific deployment models. As testing expands in locations such as Germany and Michigan, operators will gain better visibility into charging behavior, route constraints, and operational feasibility for heavier utility vehicles. This creates an opportunity for manufacturers and service providers that can help buyers design charging layouts, manage grid interactions, and match vehicle range profiles to actual routes. The uncertainty lies in whether infrastructure investment scales broadly or remains concentrated in selected corridors and demonstration sites, which could limit the pace of heavy-duty adoption in some regions.
Strategic Actions for Decision Makers
For manufacturers, the priority is to anchor platform development in application-specific value rather than broad electrification positioning. This means defining clear target duty cycles, documenting runtime and maintenance advantages, and aligning product roadmaps with compliance requirements that procurement teams now expect. Companies should also evaluate whether modular platforms or retrofit offerings can open additional revenue streams in commercial fleets that need flexibility. Differentiation will increasingly come from engineering credibility, deployment support, and the ability to prove operating savings in realistic conditions.
For investors, the most important question is where durable margin advantage can be sustained as the market scales. Concentration indicates that scale and channel strength matter, but growth also creates room for specialists with strong application fit or conversion capabilities. Due diligence should focus on battery lifecycle economics, compliance readiness, service infrastructure, and the realism of stated range and uptime claims. Capital allocation that favors companies with credible deployment ecosystems and clear use-case targeting is better positioned than capital that chases generic electric vehicle exposure without commercial differentiation.
For procurement leaders and fleet operators, the practical task is to treat electrification as an operational redesign rather than a simple vehicle swap. This includes evaluating route profiles, charging access, maintenance capacity, and regulatory specifications before committing to a platform. Incentive programs and compliance-driven procurement can reduce financial friction, but only when vehicles are matched to actual use requirements. Organizations that build internal competency in deployment planning and lifecycle cost modeling will make better acquisition decisions and avoid overpaying for capabilities they do not need.
Given the pace of product updates, regulatory shifts, and infrastructure experimentation, decision makers benefit from access to detailed segmentation data, competitive tracking, and application-level deployment benchmarks. A complete research view can support more precise planning around battery chemistry choices, regional procurement patterns, vehicle-type demand shifts, and the commercial implications of range thresholds across different operating environments. The full Electric Utility Vehicles Market report provides that deeper segmentation and customized strategic guidance for manufacturers, investors, and procurement teams evaluating their next moves.
For detailed analysis of this topic, please visit the official page: Electric Utility Vehicles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Die Casting Machine Market 2026: Cracking the Real Drivers Behind 6.09% CAGR Growth
By PW Consulting, 2026-09-21
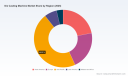
Die Casting Machine Market: Strategic Trends and Commercial Opportunities in a High-Growth Industry
The die casting machine market has entered a phase of structural acceleration. From a baseline of 2,884.21 million in 2020, the sector expanded to 3,863.83 million by 2025, reflecting sustained demand across automotive, consumer electronics, and industrial applications. Looking ahead, the market is projected to reach 5,826.99 million by 2032, with a compound annual growth rate of 6.09 percent. This trajectory is not merely a reflection of cyclical demand recovery; it signals a deeper reconfiguration of manufacturing priorities, technological maturity, and regional capacity allocation. For executives, investors, and procurement leaders, the market offers meaningful expansion potential, but also demands sharper strategic positioning to navigate intensifying competition and shifting operational expectations.
Aluminum Casting Market
Market Context: Scale, Momentum, and Emerging Friction Points
The current market environment is characterized by steady volume growth, increasingly sophisticated equipment requirements, and a gradual shift from commoditized machinery to integrated, intelligence-enabled production systems. Revenue expansion over the past five years has been broad-based, but the pace of growth is beginning to diverge across segments and geographies. While the Asia Pacific region continues to account for the largest share of overall market value, mature markets in North America and Europe are investing in modernization, automation, and higher-precision capacity. This dual dynamic—volume growth in emerging industrial hubs and value-upgrade in established markets—creates a more complex operating landscape than in previous decades.
Despite favorable growth fundamentals, the industry faces several structural challenges that are reshaping decision-making:
- Precision and consistency pressure: End customers increasingly demand tighter tolerances, improved surface quality, and repeatable performance across high-volume production runs. Machines that cannot deliver closed-loop control, stable clamping forces, or integrated quality inspection are losing competitiveness.
- Energy and sustainability expectations: Operators and OEMs are under growing pressure to reduce energy intensity per casting cycle, optimize material yield, and align equipment choices with broader decarbonization goals. This is changing procurement criteria and encouraging electro-mechanical and servo-driven architectures.
- Supply chain fragmentation and lead-time volatility: The complexity of die casting systems—spanning hydraulics, automation, control software, and mold integration—makes equipment delivery sensitive to component availability, engineering bottlenecks, and regional service capacity.
These friction points do not halt growth, but they redefine where value is created. Companies that treat die casting machines as standalone capital equipment are increasingly finding themselves outmatched by suppliers offering integrated process control, faster ramp-up, and lower total cost of ownership.
Core Drivers Reshaping the Market
Technological Innovation and Process Integration
Technology advancement remains the most powerful force in the market. Recent developments illustrate how equipment functionality is expanding beyond basic casting capability. Bühler Group’s Carat series, for example, incorporates nano-coating die technology that enhances aluminum alloy fluidity by 40 percent, enabling more reliable filling and improved lightweight component production. This type of innovation directly addresses one of the persistent constraints in aluminum die casting: balancing fluidity, cycle time, and part quality.
At the same time, intelligent control and automation are becoming baseline expectations rather than premium add-ons. Closed-loop pressure and position control, real-time diagnostic systems, and AI-assisted inspection are increasingly integrated into production lines. Shibaura Machinery’s Hyper Series, equipped with AI vision inspection and a shortened production beat, demonstrates how cycle efficiency and quality verification can be combined within a single ecosystem. Similarly, LK Technology’s large-scale units above 2,800 tons, with real-time closed-loop control accuracy of ±0.01 mm, reflect the industry’s push toward high-tonnage machines that maintain precision at scale.
PW Consulting Automotive & Machinery Research Center
Policy, Standards, and Regulatory Influence
Regulatory and standards frameworks are shaping procurement and engineering decisions in subtle but important ways. Safety and operational standards such as NADCA B152.1-2019 continue to influence machine design, maintenance protocols, and ancillary equipment specifications for high-pressure die casting systems. In parallel, OEM-specific material and heat treatment specifications, including GM Die Material Specifications DC-9999-1 and Ford standard AMTD-DC2010, affect how external casting suppliers design and qualify components. These requirements create a more demanding compliance environment, but they also raise barriers to entry for lower-tier equipment providers and reward manufacturers that can demonstrate repeatable conformance.
Sustainability-oriented expectations are also becoming embedded in purchasing decisions. Equipment that reduces energy consumption, supports scrap reduction, or enables more efficient material usage is gaining preference in tenders and internal capital allocation models. This regulatory and standards-driven pressure is accelerating the shift toward machines that offer measurable efficiency gains rather than incremental capacity increases.
Demand-Side Shifts in End Markets
Demand patterns are changing as downstream industries pursue lighter, more integrated, and more cost-efficient components. Rising demand for lightweight aluminum components is a clear macro trend supporting market growth, particularly in vehicle structures and high-performance consumer products. The automotive sector remains the largest application segment, and its focus on structural part integration is pushing die casting machines toward larger clamping forces and higher throughput stability. At the same time, the 3C industry continues to drive volume demand for precision components, reinforcing the need for machines that can deliver repeatability across complex geometries and shorter production cycles.
Another important shift is the growing interest in large integrated castings, including body and chassis structures that reduce part count and assembly complexity. This trend favors manufacturers with proven capability in ultra-large machines and process control at high tonnage. Ube Industries’ 8,500-ton-class units, which mass-produce 1.8-meter integrated body chassis, illustrate how equipment scale and part integration are converging in practical production environments.
Supply Chain and Cost Structure Dynamics
Cost structures are being reshaped by electrification of machine actuation, digital service models, and the broader push for yield improvement. Electric and servo-driven systems can reduce energy use and improve positioning repeatability, but they also require different maintenance competencies and component supply chains. Companies such as Haitian Plastic Machinery are pursuing direct-drive servo technology with repetitive positioning accuracy of ±0.005 mm, reflecting a wider industry movement toward precision and efficiency in machine architecture.
At the same time, supply chain resilience is becoming a competitive differentiator. Integrated manufacturing capability is increasingly valued because it reduces coordination risk across casting, tooling, and downstream processing. Recent consolidation activity, such as Dynacast’s acquisition of Platinadora Baja to expand integrated manufacturing capabilities, highlights how operators are seeking broader in-house control over the value chain. For machine builders, this means that equipment sales are increasingly evaluated alongside service networks, automation integration, and lifecycle support.
Metal Casting Market
Competitive Landscape and Strategic Positioning
Leaders and Differentiation Themes
The competitive field is defined by a mix of global technology leaders, regional scale players, and specialists focused on specific materials, process types, or application needs. Several distinct strategic positions are visible across the market:
- Scale and high-tonnage leadership: Some manufacturers compete by mastering very large machine architectures and integrated control systems. Ube Industries’ ultra-large two-plate die-casting machines and LK Technology’s large-scale units above 2,800 tons are examples of positioning around high-force capability, precision control, and structural part production.
- Process innovation and material specialization: Other players differentiate through advanced material handling, coating technology, or specialized alloy expertise. Bühler Group’s nano-coating die technology and Frech Group’s pioneering work in magnesium alloy vacuum die-casting show how material-centric innovation can create durable differentiation.
- Digital integration and intelligent operation: A growing group of competitors emphasizes remote diagnostics, IoT-enabled maintenance, and automated quality control. Frech Group’s IoT diagnostic system for 24-hour remote operation and Shibaura Machinery’s AI vision inspection system reflect a shift toward equipment that is managed as part of an intelligent production environment.
- Yield and application-focused engineering: Some manufacturers concentrate on improving output quality for specific end markets. Yizumi’s H-series heavy-duty machines, which achieve 98.7 percent yield for new energy vehicle structural parts, illustrate a focus on outcome-level performance rather than machine specifications alone.
Market Evolution: Consolidation, Integration, and New Entrants
The market is moving toward greater integration at multiple levels. Equipment suppliers are increasingly expected to support automation, inspection, and service workflows, while casting operators are seeking broader capability across molding, robotics, and downstream processing. This is encouraging both vertical integration and selective consolidation. The acquisition landscape, combined with partnerships such as the development of 20,000-ton-class die-casting equipment by Neta and LK Technology, suggests that scale, technology access, and application-specific capability are becoming more tightly linked.
At the same time, the market is not consolidating uniformly. Regional dynamics remain important, and differentiated niches—such as bio-based material die-casting, electric machine architectures, or ultra-large structural casting—continue to attract focused investment. Toyo Machinery & Metal Co., Ltd.’s development of a die-casting machine dedicated to bio-based materials, supported by an Eco-Mode system that reduces energy consumption, shows how specialized innovation can create room for new positioning even in a mature equipment category.
Concentration levels indicate a moderately consolidated market, with leading players holding a meaningful share of revenue. This creates both stability and pressure: established players benefit from brand trust, service networks, and proven large-scale deployments, while challengers must offer clear advantages in precision, efficiency, cost structure, or application fit to gain traction.
Future Trends and Commercial Implications
Trend 1: Precision and Intelligence as Baseline Requirements
Over the next three to five years, precision control, digital monitoring, and integrated quality systems are likely to become standard expectations rather than differentiated extras. Machines that lack real-time control accuracy, repeatable positioning, or connected diagnostics will face increasing resistance in tenders and capital planning. For suppliers, this means investing in control architecture, software, and service integration. For buyers, it means evaluating total performance over the equipment lifecycle rather than focusing solely on initial purchase price.
Trend 2: Larger, More Integrated Casting Solutions
Demand for large integrated components and high-efficiency structural parts is expected to sustain interest in high-tonnage machines and advanced process control. The commercial opportunity lies not only in selling larger machines, but in enabling faster stabilization, fewer defects, and lower assembly complexity for end manufacturers. Companies that can demonstrate reliable large-part production, supported by strong process engineering and service capacity, are well positioned to capture premium demand.
Trend 3: Efficiency, Sustainability, and Material Innovation
Energy efficiency, yield optimization, and material flexibility will become increasingly central to purchasing decisions. Innovations such as nano-coating die technology, electric servo architectures, vacuum die-casting, and eco-mode energy management point toward a market where sustainability and productivity are pursued together. This creates opportunities for equipment that reduces per-part energy use, improves material utilization, or supports new material streams. The main uncertainty lies in the pace of adoption: some operators may prioritize proven reliability over newer efficiency technologies, especially in cost-sensitive environments.
Strategic Recommendations for Decision-Makers
For Machine Manufacturers and Equipment Suppliers
- Prioritize closed-loop precision, digital service capability, and integration with automation and inspection systems. These attributes are increasingly tied to adoption decisions and long-term customer retention.
- Build clear application-facing value propositions. Machine specifications alone are less persuasive than demonstrated yield, throughput stability, and part-quality outcomes in target end markets.
- Strengthen service, training, and parts availability in key regions. Lead-time reliability and local support are becoming important differentiators as equipment complexity increases.
For Investors and Strategic Partners
- Evaluate opportunities based on technology integration and application fit rather than headline capacity alone. Companies that combine scale with precision, efficiency, or specialized material capability are more likely to sustain margin and growth.
- Monitor consolidation signals and partnership activity. Mergers, acquisitions, and joint development agreements can reshape competitive access, especially in large-tonnage and integrated manufacturing segments.
- Pay attention to standards, OEM specifications, and sustainability requirements. These factors influence procurement eligibility and can accelerate demand for higher-compliance equipment.
For Procurement Leaders and Casting Operators
- Assess total cost of ownership, including energy use, yield performance, maintenance requirements, and downtime risk. Precision and efficiency features may justify higher upfront investment if they reduce operating cost and quality variability.
- Align equipment selection with downstream production needs. Integration with robotics, inspection, and molding ecosystems can improve line stability and reduce coordination friction.
- Verify service coverage and training support before committing to large-scale deployments. Complex machines require capable local support to maintain performance over time.
Conclusion
The die casting machine market is advancing on multiple fronts at once: higher precision expectations, larger integrated part production, efficiency-driven machine design, and deeper digital integration. Growth to 5,826.99 million by 2032 at a 6.09 percent CAGR reflects strong underlying demand, but the real strategic question is no longer whether the market will expand. It is which manufacturers, investors, and operators can capture value by aligning equipment capability with application needs, process reliability, and long-term operating efficiency. Companies that treat die casting as a systems challenge—combining machine performance, automation, service, and compliance—will be best positioned to convert market growth into durable competitive advantage.
For decision-makers seeking a more detailed view of segment dynamics, regional value distribution, and company-level positioning, the full market research report provides expanded data and customized analysis. Readers interested in deeper segmentation, competitive benchmarking, and scenario-based planning can access the complete study here .
For detailed analysis of this topic, please visit the official page: Die Casting Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Radiator Hose Market: Why the 3.5% CAGR and Asia Pacific's 89.84M Lead Through 2032
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Radiator Hose Market
Market Snapshot and Structural Challenges
The global radiator hose market has demonstrated steady, predictable growth over the past five years, expanding from approximately $165.0 million in 2020 to $215.0 million in 2025. This trajectory reflects a compound annual growth rate of 3.5 percent through the 2026-2032 forecast horizon. While the growth profile appears conventional for an established automotive component sector, the underlying dynamics reveal a market at a structural inflection point. Revenue expansion is no longer solely a function of vehicle production volumes; it is increasingly shaped by material substitution, regulatory tightening, and shifting channel economics.
Understanding the current market size requires acknowledging that the headline figure masks divergent performance across vehicle platforms, material technologies, and geographies. Silicon-based hoses continue to command the largest revenue share among material categories, driven by their compatibility with high-temperature engine architectures and synthetic coolants. Rubber formulations maintain significant traction in cost-sensitive applications, while emerging material blends are gaining ground as manufacturers respond to durability mandates and environmental specifications. Passenger cars remain the dominant vehicle segment by revenue, though commercial vehicle applications are growing at a faster pace as fleet operators prioritize extended maintenance intervals and thermal reliability.
Hydraulic Hose Market
Beneath these structural patterns, the market confronts three interconnected challenges that will define competitive outcomes over the next several years.
First, the regulatory environment is compounding performance requirements in ways that strain traditional hose design paradigms. Emission standards in major markets now cascade indirectly into thermal management specifications, as tighter engine tuning and advanced combustion strategies demand coolant hoses with tighter temperature tolerances and improved chemical resistance. The effect is not merely incremental; it forces redesign cycles, validation costs, and supply chain re-qualification that compress margins for manufacturers unable to absorb engineering overhead.
Second, trade policy disruption has altered procurement economics. Tariff escalations introduced in 2025 have raised effective import costs on certain hose categories, prompting OEMs and tier suppliers to reconsider geographic sourcing footprints. This has accelerated supply chain diversification efforts but also introduced short-term cost volatility and qualification complexity for alternative supplier bases. Companies that previously optimized for lean inventory and single-source efficiency are now re-evaluating risk-adjusted sourcing models.
Third, the aftermarket channel continues to gain relative importance as global vehicle fleets age and compliance-driven repairs extend service life. While OEM volumes remain the dominant commercial pathway, aftermarket demand is becoming a more meaningful growth lever, particularly for heavy-duty and commercial applications where replacement cycles are lengthening. This shift changes the competitive calculus: aftermarket success depends less on production scale and more on distribution reach, fitment precision, and brand trust in repair ecosystems.
PW Consulting Automotive & Machinery Research Center
Critical Drivers Reshaping the Market
The market’s evolution is being propelled by a combination of technological, regulatory, demand-side, and supply chain forces. Each driver interacts with the others, creating compounding effects that reward companies able to align engineering, sourcing, and commercial strategy.
Technological Innovation and Material Science Advances
Material innovation is the most consequential technical driver in the radiator hose market. Manufacturers are increasingly adopting advanced composites, reinforced silicone constructions, and hybrid rubber-thermoplastic formulations to meet stricter thermal and pressure requirements. The shift is not simply about durability; it is about enabling engine architectures that run hotter, use synthetic coolants, and require hoses capable of maintaining sealing integrity across wider temperature ranges.
Adoption of advanced manufacturing technologies has accelerated this transition by lowering cost barriers. In 2025, the market for eco-friendly automotive radiator hoses grew by more than 15 percent, while advanced manufacturing processes increased adoption by 20 percent to reduce production costs. This combination of performance improvement and cost optimization is significant because it expands the addressable market for higher-specification hoses beyond premium platforms into broader passenger and commercial applications. Companies that can demonstrate equivalent reliability at lower lifecycle cost are positioning themselves to capture share from conventional rubber designs.
Policy and Regulatory Environment
Regulation is reshaping product specifications and channel behavior simultaneously. In China, the GB 18352.6-2024 standard requires improved particulate matter and nitrogen oxide limits, which in turn mandates radiator hose upgrades for ISO 3384 performance and synthetic coolant compatibility. European regulations under Euro 6d-TEMP impose coolant hose materials with precise temperature tolerance of plus or minus 2 degrees Celsius for advanced combustion engines. These requirements raise the technical bar for suppliers and reward those with established material science capabilities and qualified validation infrastructures.
Beyond product specifications, regulatory pressure is also influencing channel mix. OEM and aftermarket channels accounted for 62.4 percent and 37.6 percent of market value respectively in 2025, driven by vehicle fleet aging and emission compliance. Compliance-related service interventions are sustaining aftermarket demand even as new vehicle production cycles fluctuate. For manufacturers, this means regulatory momentum is not only a product engineering challenge but also a commercial opportunity in the service and replacement segment.
Demand-Side Shifts in Consumer and Fleet Behavior
Demand patterns are being shaped by two parallel trends: the expansion of high-performance passenger vehicles and the increasing emphasis on durability in commercial fleets. Passenger car buyers and manufacturers are prioritizing thermal efficiency as engine downsizing and turbocharging become more common, creating demand for hoses that can handle elevated operating conditions without compromising longevity. In parallel, fleet operators are seeking components that reduce downtime and extend service intervals, which favors more robust hose designs and higher-grade materials.
These demand shifts are also influencing purchasing behavior in the aftermarket. As vehicles remain in service longer, repair and replacement decisions are increasingly guided by parts that offer improved reliability and compatibility with modern coolant chemistries. This creates a market environment where product differentiation in the aftermarket is becoming more valuable, especially for suppliers that can provide engineered fitment solutions and clear performance credentials.
Supply Chain and Cost Structure Evolution
Cost structures are being redefined by raw material dynamics, tariff impacts, and manufacturing process improvements. The increased tariff burden on certain imports has forced procurement teams to weigh the trade-offs between cost, risk, and qualification lead times. Some manufacturers are regionalizing supply arrangements, while others are pursuing multi-source strategies to mitigate exposure. These decisions are not purely cost-driven; they reflect a broader shift toward resilience as a strategic priority.
At the same time, efficiency gains from advanced manufacturing are partially offsetting input cost pressures. Companies that can integrate material innovation with process optimization are achieving better margin defense than those relying solely on volume scale. This is particularly relevant for market participants that compete in both OEM and aftermarket channels, where cost discipline and product performance must be balanced across different commercial models.
Competitive Landscape and Leading Strategies
The radiator hose market is characterized by moderate concentration, with the top three players accounting for 28.5 percent of market share and the top five reaching 32.0 percent. This structure suggests a market where scale advantages exist but are not insurmountable, and where specialized capabilities can still generate competitive differentiation. The presence of multiple global manufacturers alongside regionally focused suppliers indicates that both global reach and localized technical service remain valuable.
Several companies illustrate distinct strategic positioning within this landscape. Gates Corporation has built a comprehensive presence across fluid power and engine hose applications, leveraging molded, flexible, and braided constructions to serve both OEM and aftermarket thermal management needs. Its breadth across hose architectures provides flexibility in addressing diverse vehicle requirements. Continental AG, through its ContiTech division, emphasizes advanced materials and integrated sensor technologies, positioning its hose solutions as part of broader vehicle systems rather than standalone components. This systems-oriented approach aligns well with the trend toward tighter performance tolerances and smarter thermal management.
Dayco Products LLC focuses on molded radiator hoses for passenger vehicles and light-duty applications, with an emphasis on durability and OE fitment. This specialization supports strong positioning in segments where precision and reliability are primary purchase criteria. Parker Hannifin Corporation extends its fluid management expertise across industrial, marine, and automotive applications, allowing it to transfer high-pressure and thermal management capabilities across markets. Hutchinson SA stands out for its vertically integrated manufacturing model and strong OEM partnerships in Europe, enabling customized thermal management solutions with close engineering collaboration.
In Asia, Toyoda Gosei and Sumitomo Riko maintain strong ties to regional OEM production, with Toyoda Gosei benefiting from integrated high-volume passenger car applications and Sumitomo Riko supplying Asian manufacturers with precision rubber compounds. Tokyo Rubber Co., Ltd. also plays a significant role as a key Asian OEM supplier focused on precision thermal management components. Goodyear continues to leverage its global supplier reputation with an emphasis on sustainability and multi-year supply agreements, as illustrated by its September 2025 supply agreement with Ford for advanced radiator hoses on global vehicle platforms. Fairchild Industries provides an example of a custom manufacturer that supports engineering design services and direct-to-OEM production, highlighting the value of flexible, design-led engagement in specialized applications.
Recent market activity further underscores the strategic directions shaping competition. In January 2025, Crown Automotive launched a new aftermarket radiator hose line for heavy-duty trucks, signaling continued investment in the commercial aftermarket segment. In February 2025, ACDelco introduced an eco-friendly radiator hose made from recycled rubber and thermoplastics, reflecting the growing importance of sustainable material narratives and regulatory-aligned product claims. These moves illustrate how companies are using product launches and supply agreements not only to secure volume but also to reinforce technological and commercial positioning.
The competitive landscape is evolving along several axes. Integration is visible among manufacturers seeking to control material formulation, production, and qualification within a single value chain, particularly where regulatory compliance and performance validation are becoming more complex. At the same time, there is room for differentiation through application specialization, as companies target specific vehicle segments, regions, or channel models with tailored engineering and service capabilities. New entrants and smaller suppliers may find opportunity in niche applications, custom design services, or sustainable material formulations, especially where larger incumbents are constrained by scale-driven process architectures. The overall trend is toward a market in which competitive advantage will increasingly depend on the ability to combine material expertise, regulatory readiness, sourcing flexibility, and channel-specific commercial execution.
Forward Outlook: Trends and Commercial Implications
Looking ahead to the next three to five years, three trends are likely to shape the radiator hose market’s trajectory and associated commercial opportunities.
The first trend is the continued migration toward higher-specification materials as baseline performance requirements rise. As emission and thermal management standards tighten globally, conventional hose designs will face growing pressure to demonstrate compatibility with synthetic coolants, tighter temperature tolerances, and extended service life. This creates a commercial opportunity for suppliers that can offer validated advanced formulations with cost-efficient manufacturing pathways. Companies that treat material upgrades as a premium feature alone may miss the broader shift toward mainstream adoption of higher-performance hoses in mid-tier vehicle segments.
The second trend is the reconfiguration of supply chains in response to trade policy and risk management priorities. Tariff-driven cost changes and procurement realignment are likely to persist as strategic considerations rather than temporary disruptions. This favors manufacturers with diversified sourcing options, regional production flexibility, and the ability to qualify alternative supplier bases without protracted validation cycles. For buyers, this trend increases the importance of supplier selection criteria that weigh resilience and compliance readiness alongside unit cost. For investors, it suggests that operational agility and supply chain transparency will become more relevant valuation factors than scale alone.
The third trend is the growing commercial significance of the aftermarket as fleets age and compliance-related service needs expand. Replacement demand is increasingly influenced by part reliability, fitment accuracy, and sustainability credentials. Suppliers that can build strong aftermarket distribution, provide clear technical differentiation, and align product claims with environmental expectations are likely to capture disproportionate value in this channel. At the same time, the aftermarket presents risk for participants that depend primarily on OEM volume without a credible service-channel strategy, since channel diversification can buffer demand volatility and improve long-term revenue resilience.
These trends carry potential uncertainties. Regulatory timelines and technical thresholds may shift as standards evolve, altering product development priorities. Material supply constraints or cost volatility could affect margin trajectories, particularly for newer sustainable formulations that depend on specific input streams. Vehicle production cycles, especially in commercial segments, may fluctuate with macroeconomic conditions and infrastructure spending patterns. Competitive responses from incumbents and new entrants could also compress returns in segments where differentiation is difficult to sustain.
Worldwide Oil Hose Market
Strategic Guidance for Decision Makers
For manufacturers, the priority is to align product roadmaps with the intersection of regulatory requirements, material innovation, and channel demand. Engineering investments should focus on hose designs that can meet tighter temperature and chemical compatibility specifications while remaining cost-competitive through advanced manufacturing processes. At the same time, supply chain strategies should incorporate flexibility to respond to tariff-driven cost changes and sourcing diversification needs. Companies that can demonstrate validated performance, sustainable material options, and reliable qualification capability will be better positioned to secure both OEM partnerships and aftermarket credibility.
For investors, the market offers a profile of steady growth with differentiated value creation depending on operational and technological positioning. Interest should be directed toward companies that combine material science capability with process efficiency, strong OEM relationships, and a credible aftermarket presence. The moderate market concentration suggests that specialized players can still generate meaningful returns if they occupy defensible segments or possess unique engineering and service capabilities. However, valuation assumptions should account for regulatory adaptation costs, sourcing realignment risk, and the possibility that material transitions could reshape competitive hierarchies over time.
For procurement and supply chain leaders, the environment calls for a more balanced evaluation of supplier selection criteria. Unit price remains important, but resilience, compliance readiness, and the ability to support evolving material and performance specifications should receive greater weight. Multi-source strategies, regional sourcing options, and suppliers with demonstrated advanced manufacturing efficiency can reduce exposure to tariff volatility and qualification delays. Procurement teams should also monitor aftermarket availability and fitment reliability, particularly for heavy-duty and commercial applications where downtime costs can exceed component price differences.
For stakeholders seeking a more detailed understanding of segment-level dynamics, regional variation, and forward-looking scenario analysis, a comprehensive market research report can provide the granularity needed to translate these strategic themes into execution plans. Deep-dive segmentation data, competitive benchmarking, and customized procurement or investment scenarios can help decision makers move from directional insight to targeted action.
For detailed analysis of this topic, please visit the official page: Radiator Hose Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Automotive Cabin Air Filter Market: Why 5.8% CAGR and Shifting Segments Change Everything
By PW Consulting, 2026-09-21
The Automotive Cabin Air Filter Market: Strategic Trends and Commercial Opportunities
Market Landscape and Core Challenges
The automotive cabin air filter market has evolved from a commoditized replacement component to a strategic element of vehicle health, passenger safety, and OEM value engineering. Revenue across the global market reached approximately $3.5 billion in 2025, building on a steady expansion from roughly $3.0 billion in 2020. The trajectory reflects both volume growth in vehicle parc and a qualitative shift toward higher-performance filtration media, improved sealing, and integrated cabin health features. Forward estimates point to continued expansion through 2032, with a compound annual growth rate of 5.8 percent, indicating that incremental gains will increasingly come from premiumization and regulatory-driven specification changes rather than baseline replacement demand alone.
Europe and Asia Pacific together account for the largest share of revenue, reflecting dense vehicle populations, stringent emissions and air quality frameworks, and relatively fast fleet turnover in key markets. North America remains a meaningful contributor, supported by a high aftermarket penetration and a consumer base that has grown more attentive to in-cabin air quality. Latin America and the Middle East and Africa represent smaller but gradually expanding opportunities, often shaped by aftermarket service patterns and localized air quality concerns. The revenue distribution underscores a market where regional regulatory intensity, vehicle mix, and consumer awareness intersect to determine end-market appetite for advanced filtration.
Behind the top-line growth, the industry faces several structural challenges. First, the overlap between filtration performance, packaging constraints, and serviceability is becoming more complex. Modern vehicle architectures place cabin air filter housings in tighter spaces, sometimes near sensitive components such as wiring harnesses. This creates a design and service risk: a filter change that is intended to be routine can, if executed improperly, damage adjacent systems. Recent safety actions in the United States highlight this tension. A Part 573 safety recall report and a related service information bulletin addressed potential damage to air conditioning wiring harnesses during cabin air filter replacement on certain vehicles. An engineering investigation was initiated after field incidents involving thermal events in model year 2024 vehicles where the filter housing cover sits close to the air conditioning wiring harness. The follow-up bulletin mandated procedure modifications to avoid harness damage during replacement. For OEMs and service networks, these developments add a layer of process control, training, and design-risk management that did not exist when cabin filters were treated as simple consumables.
Second, the regulatory environment is tightening filtration expectations while simultaneously reshaping adjacent vehicle systems. More stringent ambient air quality standards for particulate matter are raising the bar for what consumers and regulators expect from in-cabin filtration. At the same time, the phase-down of high-global-warming-potential hydrofluorocarbons in model year 2025 has accelerated the adoption of advanced cabin air filtration systems as part of broader climate and refrigerant transitions. In Europe, Euro 7-style expectations are pushing particle filtration performance down to very small sizes, influencing both OEM specifications and aftermarket acceptable performance. The cumulative effect is a market where compliance is no longer a checkbox but a continuous performance requirement that can affect material selection, media layering, and validation cycles.
Third, the combination of rising performance expectations and cost sensitivity is reshaping competitive dynamics. Activated carbon and combination products command stronger positioning in segments where odor, gaseous pollutants, and allergen reduction matter, but they also increase material and manufacturing complexity. Electrostatic and media-engineered solutions offer efficiency gains, yet they must be balanced against airflow, load, noise, and service life. Suppliers and buyers alike are navigating a tension between specification ambition and total cost of ownership, especially in commercial fleets and price-sensitive aftermarket channels. The result is a market in transition: growth is real, but it is unevenly distributed across regions, vehicle types, and product tiers, and the competitive winners will be those who can manage performance, service risk, and cost at the same time.
Key Demand Drivers
The market is being pulled forward by a small number of high-impact forces that are reshaping both product design and commercial positioning.
Technology Innovation and Media Engineering
Media architecture remains the central differentiator. The industry is moving beyond basic particulate capture toward layered solutions that combine mechanical filtration, adsorption, and electrostatic effects. Activated carbon media continues to play a central role for odor and gaseous contaminant control, while nanofiber and electrostatically enhanced materials are increasingly used to raise capture efficiency without excessively restricting airflow. Multi-layer designs are also enabling more compact housings and better balance between filtration efficiency and system load. Recent product guidance from leading suppliers shows how these technologies are being adapted to specific vehicle categories, including motorhomes, where activated carbon protection against odors and harmful gases is being emphasized for prolonged cabin occupancy and varied operating environments.
This technology shift matters because it changes the basis of competition. A filter that was once evaluated primarily on particulate arrestance is now judged on odor management, allergen reduction, durability, and ease of integration. That, in turn, creates room for differentiation in both OEM sourcing and aftermarket branding, especially where consumers associate filtration quality with overall cabin health and comfort.
Automotive Cabin Air Quality Sensor Market
Policy and Regulatory Environment
Regulatory pressure is a growing source of demand for higher-efficiency cabin filtration. Stricter ambient particulate matter standards are reinforcing the value proposition of filters that can remove a very high proportion of fine particles. At the same time, tighter vehicle-level emissions frameworks and refrigerant transitions are indirectly raising the importance of cabin air quality, because they encourage broader system changes and a more holistic view of in-cabin environmental control. Europe’s push toward filtration of extremely small particles and the United States’ refrigerant-related transitions both illustrate how policy is influencing product expectations beyond traditional replacement cycles.
For manufacturers and fleet operators, the regulatory trajectory creates two practical effects. One is a rising floor for acceptable performance, which compresses the lowest end of the market and rewards suppliers with validated media and testing capabilities. The other is an opportunity to position advanced filtration as part of a broader safety, health, and compliance narrative, rather than as a standalone part number.
Demand-Side Shifts in Consumer and Fleet Behavior
Passenger car buyers are increasingly aware of air quality as a component of vehicle livability, particularly in urban environments and regions with seasonal pollutant spikes. That awareness has elevated the appeal of combination and activated carbon solutions in premium and mid-tier segments, and it has also influenced service behavior, where filter replacement is being viewed more proactively rather than purely reactively. In commercial vehicles, fleet operators are weighing cabin filtration alongside driver comfort, retention, and operational reliability, especially where vehicles operate in dusty or high-pollution conditions. In two-wheelers, demand is smaller but still growing in markets where exposure to traffic emissions and particulate matter is uneven and where affordable upgrade paths can improve rider experience.
These behavioral changes are important because they expand the conversation beyond technical specs. The commercial case for better filtration is increasingly tied to perceived health benefits, comfort, and brand positioning, which gives suppliers and automakers a stronger storytelling and value-selling platform.
Supply Chain and Cost Structure Evolution
The cost picture is being shaped by the interplay of media complexity, validation requirements, and the need to maintain serviceability. Higher-performance materials and layered constructions can improve capability, but they also create pressure on sourcing, manufacturing consistency, and quality control. At the same time, the service-side incidents discussed earlier are forcing reconfiguration of replacement procedures and, in some cases, packaging or access design. That adds indirect cost in training, documentation, and warranty-related risk management. Suppliers that can standardize high-quality media, control variability, and design for service-friendly installation are better placed to protect margins while meeting performance expectations.
Competitive Landscape and Leading Strategies
The competitive structure is moderately concentrated, with the top three players holding a notable share and the top five extending that advantage further. Concentration at this level indicates that scale, OEM relationships, media expertise, and brand recognition matter, but it also leaves room for specialized players to compete in niches such as performance filtration, aftermarket branding, or specific application segments.
European suppliers remain particularly prominent, reflecting deep OEM integration, strong engineering heritage, and broad coverage across passenger cars, trucks, and off-highway applications. One global filtration specialist has emphasized nanofiber and activated carbon technologies across OEM and aftermarket lines, with recent recommendations tailored to motorhomes that highlight activated carbon protection against odors and harmful gases. Another major German supplier has focused on both original equipment and retrofit applications, spanning particulate and combination filters. A third large industrial and automotive supplier has built a position around high-efficiency particle and activated carbon options for OEM integration, while a fourth German filtration technology company is known for advanced media aimed at protection against pollutants and allergens. Together, these players illustrate how leading vendors combine media science, broad application coverage, and channel strength to defend share.
In Asia, Japanese manufacturers have carved out strong positions through integration with vehicle programs and specialized media approaches. One major Japanese supplier has highlighted multi-layer media designed for optimal airflow and filtration efficiency, including particulate-electrostatic concepts, while another has developed OEM cabin filters integrated into Toyota and Lexus vehicle models. These examples show how regional strengths in manufacturing discipline and OEM relationships can support consistent volume and specification alignment.
North American participants bring a different set of advantages. Some focus on high-efficiency products for automotive and commercial vehicle applications across OEM and replacement markets, while others emphasize specialized filtration media or performance-oriented and washable solutions. A separate aftermarket-oriented group has expanded consumer visibility through branded variants, illustrating how retail presence and brand recognition can complement product capabilities in the replacement channel.
The strategic patterns among leaders are clear. First, differentiation is increasingly tied to media architecture and validated performance rather than commoditized fitment alone. Second, the most resilient players are those that can serve both OEM and aftermarket channels, because OEM programs provide scale and specification influence while aftermarket channels provide reach and margin flexibility. Third, application breadth matters: suppliers that address passenger cars, commercial vehicles, and select two-wheeler or niche segments can smooth cyclicality and capture cross-segment learning. At the same time, the landscape is evolving. Consolidation pressure persists among smaller players that cannot match validation costs or OEM integration requirements, while new entrants and specialist media companies can still gain ground where they offer distinct efficiency, serviceability, or branding advantages. The recent regulatory and serviceability issues also suggest that design integration, documentation, and field support will become more important competitive factors, not just filter performance on a spec sheet.
Future Trends and Commercial Implications
Over the next three to five years, several trends are likely to shape where value is created in this market.
PW Consulting Automotive & Machinery Research Center
Performance Premiumization with Serviceability as a Design Constraint
Demand for higher-efficiency and odor-controlling products should continue to rise, especially where air quality concerns and consumer expectations overlap. However, the most successful offerings will be those that balance performance with accessible replacement design and clear service instructions. The recent safety and service bulletin activity is a reminder that a filter’s value proposition is not limited to filtration efficiency; it also includes the risk profile of the replacement process. Suppliers and vehicle programs that design for both performance and safe service access will be better positioned to reduce field issues and protect customer trust.
Worldwide Automotive Air Filter Housing Market
The commercial opportunity here is twofold: advanced media can support higher-margin product tiers, and service-friendly design can reduce warranty exposure and strengthen OEM and fleet relationships. The risk is that performance gains are undermined by packaging compromises or by replacement procedures that are too easy to mishandle.
Regulatory-Driven Specification Escalation
As ambient air quality standards tighten and vehicle-level expectations evolve, filtration requirements will continue to move up the performance curve. This will likely compress the lowest tier of the market and increase reliance on validated media, repeatable manufacturing, and testing capability. It also creates an opening for suppliers that can translate regulatory requirements into practical, cost-effective product architectures for both OEM and aftermarket use.
The risk is that compliance pressure becomes fragmented across regions and programs, making it harder to scale a single solution globally. Companies that can maintain a core platform while adapting media and sealing options to local requirements will have an advantage in managing complexity without sacrificing margin.
Channel Blending and Aftermarket Brand Building
The aftermarket will remain a major growth driver, but its composition is changing. Consumer awareness is supporting demand for higher-quality replacement filters, while commercial buyers are looking for consistent performance and reduced operational disruption. At the same time, branded aftermarket offerings and performance-oriented products are expanding visibility and choice. This blending of channels means that competitive success will depend not only on supply reliability but also on consumer communication, fitment clarity, and distribution reach.
A key commercial opportunity is to build recognizable value propositions in the replacement channel around health, comfort, and reliability, rather than competing solely on price. A key risk is channel conflict and margin erosion if premium claims are not backed by visibly differentiated performance or service experience.
Strategic Recommendations for Decision-Makers
For manufacturers and product developers, the priority is to treat cabin air filtration as a system-level attribute rather than a low-cost replaceable part. That means investing in media architecture that can address particulate, odor, and allergen concerns while maintaining airflow and durability, and validating designs against real-world service scenarios. It also means coordinating packaging, access, and documentation so that replacement does not create avoidable risk. Companies that can demonstrate consistent performance across OEM and aftermarket use, with clear instructions and robust quality control, will be better positioned as performance expectations rise.
For investors, the most interesting signals are the shift toward premiumized media, the growing importance of regulatory-driven specification changes, and the channel dynamics that favor suppliers with both OEM credibility and aftermarket visibility. Evaluation should focus on whether a company has defensible media technology, the ability to serve multiple applications, and the operational discipline to manage serviceability and compliance risk. In a market growing at a mid-single-digit rate, differentiation and execution quality matter more than volume alone.
For procurement and fleet buyers, the strategic question is not whether to buy a better filter, but how to make filtration choices that align with operating conditions, service processes, and total cost goals. That calls for selecting products with validated performance for the relevant environment, ensuring that replacement procedures are clear and compatible with the vehicle, and avoiding low-cost options that may compromise airflow, seal integrity, or service safety. In commercial operations, standardization can reduce complexity, but it should be paired with enough performance headroom to handle variable pollution and dust exposure.
The market’s direction is becoming clearer: growth will continue, but the most valuable opportunities will belong to those who can integrate filtration performance, regulatory readiness, service safety, and channel execution into a coherent offering. For decision-makers who need detailed segmentation data, company-level positioning, and tailored guidance for specific regions or applications, the full research report provides a deeper evidence base and more granular recommendations to support planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Automotive Cabin Air Filter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
CVT Market 2026-2032: Decoding the 4.5% CAGR Surge and Key Segment Dynamics
By PW Consulting, 2026-09-21
Navigating the Continuously Variable Transmission Market: Strategic Shifts and Commercial Opportunities
The global automotive transmission landscape is undergoing a quiet but consequential transformation. Continuously Variable Transmissions (CVTs) have moved from a niche alternative to a mainstream powertrain choice, driven by endurance efficiency mandates, shifting consumer expectations, and relentless refinement in mechanical design. The market has steadily expanded from approximately $15.6 billion in 2020 to $18.65 billion in 2025, settling into a forecasted compound annual growth rate of 4.5 percent through 2032, when it is projected to reach $25.65 billion. This trajectory is not linear, nor is it guaranteed. It reflects a sector balancing mechanical optimization against electrochemical disruption, regulatory pressure against supply chain fragility, and established dominance against emerging competitive architectures. Understanding where the CVT market stands today, what forces are bending its trajectory, and how incumbents are positioning themselves offers practical guidance for executives, investors, and procurement leaders navigating the next cycle of powertrain strategy.
Worldwide Hydrostatic Transmission Market
The current market structure reveals both maturity and vulnerability. CVT technology now accounts for a meaningful share of light vehicle powertrains, with belt-driven systems commanding the largest typology share, chain-driven variants holding a substantial secondary position, and toroidal and hydrostatic configurations serving specialized niches. Passenger cars remain the dominant application, while light and heavy commercial vehicles contribute incremental but strategically important volumes. Geographically, the market is distributed across mature and emerging regions, with North America and the Asia Pacific region anchoring the largest revenue pools, Europe maintaining steady demand, and Latin America and the Middle East and Africa representing smaller but growing footprints. This broad distribution masks a highly concentrated competitive environment. The top three players control more than half of market revenue, and the top five extend that share past sixty percent, underscoring the advantage of scale, proprietary manufacturing experience, and long-term procurement relationships. Concentration is not merely a statistical observation; it shapes pricing power, innovation pacing, and the barriers that new entrants must clear.
Concentrated Leadership and Structural Fragility
The market operates under a dual reality. On one side, scale players benefit from accumulated learning curves, volume-driven component sourcing, and deep integration with vehicle manufacturers who value predictable pricing and validated reliability. On the other side, the sector remains exposed to component-specific supply constraints, manufacturing cost sensitivity, and the ever-present question of whether internal combustion efficiency improvements will ultimately be overtaken by electrification trajectories. These forces do not cancel each other out; they interact. A firm that has mastered belt-pulley dynamics and launch-gear integration can extract better fuel economy and smoother acceleration, but if the global supply chain for specialized steel push-belts and precision-machined pulleys experiences disruption, production schedules slip and unit costs rise. The result is a market that rewards disciplined operational execution as much as mechanical ingenuity.
Key Challenges and Inflection Points
Three challenges dominate strategic discussions. The first is cost and reliability perception. While modern CVT designs have improved markedly, earlier generations left a residual impression among some consumers and fleet operators. Addressing that perception requires sustained refinement in durability, thermal management, and packaging efficiency, all of which translate directly into warranty exposure and brand trust. The second challenge is regulatory uncertainty intertwined with compliance economics. Regulatory bodies continue to model transmission cost and efficiency at a granular level, and CVT manufacturing cost estimates have been adjusted through learning curve factors in recent compliance demonstrations. Simultaneously, earlier planning scenarios projected minimal CVT penetration under certain compliance pathways, highlighting how regulatory modeling can influence OEM architecture choices. The third challenge is the tension between incremental internal combustion optimization and the broader shift toward electrification. CVTs can improve fuel economy and help automakers meet Corporate Average Fuel Economy standards and emissions targets, but their long-term role must be evaluated against hybrid, plug-in hybrid, and battery electric architectures. This tension is not a binary conflict; it is a strategic calibration problem that requires understanding where CVTs deliver the greatest marginal benefit and where alternative solutions will outcompete them.
The Resilience-And-Recalibration Paradox
The practical implication for decision makers is that the CVT market is not a single trend line but a portfolio of outcomes. Passenger car adoption continues to benefit from smoothness and fuel economy, commercial applications are expanding where torque delivery and efficiency matter, and specialty architectures remain important for specific duty cycles. Yet all of these segments must contend with component availability, cost discipline, and the credibility of the underlying mechanical design. Companies that manage these trade-offs well are not simply selling transmissions; they are selling validated reliability, predictable total cost of ownership, and regulatory alignment. That is the real competitive currency in this market.
Key Drivers Shaping Market Trajectory
Market growth is not speculative; it is being pulled by identifiable forces that interact across technology, regulation, demand, and supply. The strongest drivers are not isolated innovations but layered dynamics that reinforce one another, making the market more attractive to scale players while simultaneously raising the bar for new entrants.
Technical Refinement as a Competitive Multiplier
Continuous improvement in CVT architecture has shifted the conversation from basic functionality to refined performance. Launch gears, wider ratio ranges, reduced friction losses, and enhanced thermal durability have addressed historical concerns about acceleration response and reliability. These refinements matter because they convert a transmission technology into a brand-level asset. A CVT that delivers seamless operation and strong fuel efficiency becomes a selling point in passenger car lineups, while a robust, torque-tolerant design supports commercial vehicle applications where uptime and operating cost are paramount. The mechanical evolution also has a learning curve effect. As cumulative production volumes rise, manufacturing knowledge deepens, tolerances tighten, and unit economics improve. This is precisely why regulatory and industry analyses continue to apply learning curve factors to cost estimates; the trajectory of cost reduction is tied to output and experience, not to static assumptions. The strategic implication is clear: companies with sustained volume and disciplined process control can lower costs faster and pass through competitive pricing or reinvest in further refinement, creating a virtuous cycle that is difficult for low-volume players to replicate.
Regulatory Pressure and Emissions Strategy
Fuel economy standards and emissions targets remain a powerful structural driver. CVTs contribute directly to compliance strategies by enabling engines to operate closer to optimal efficiency across a wider range of vehicle speeds and loads. This makes them relevant not only for consumer perception but for fleet-average compliance economics. At the same time, regulatory documentation continues to provide granular insights into transmission cost, market penetration assumptions, and compliance scenarios. These documents are not mere paperwork; they influence how automakers model portfolio trade-offs, how suppliers anticipate volume commitments, and how investors assess the durability of transmission demand under different compliance regimes. A market participant that understands the interplay between efficiency mandates, compliance cost modeling, and vehicle architecture choices gains an early-warning advantage when regulatory expectations shift or when specific scenarios reweight the attractiveness of CVTs relative to alternative transmissions.
Demand-Side Behavior and Commercial Uptake
Consumer and commercial demand is moving along two tracks. In passenger vehicles, drivers value smoothness, quiet operation, and fuel economy, and manufacturers have leaned into these attributes in widely sold models. In commercial segments, the calculation is more functional: torque delivery, durability, serviceability, and total cost of ownership drive adoption. The commercial track is especially important because it tends to be less fashion-driven and more performance-driven, making it a stabilizing demand base when consumer taste cycles fluctuate. Additionally, commercial adoption often benefits from fleet-scale procurement and longer lifecycle evaluations, which means winners in this segment can secure recurring volume and deeper integration with operating economics. The broader demand signal is therefore dual-polarized: consumer-facing value propositions build volume and brand relevance, while commercial applications build revenue stability and engineering credibility.
Supply Chain Realities and Cost Structure
No discussion of demand and regulation is complete without addressing the physical supply chain. CVT systems depend on specialized global sourcing for steel push-belts, pulleys, and precision components. This dependence creates both leverage and vulnerability. When supply is stable and scale is high, manufacturers can achieve competitive pricing and dependable delivery. When disruptions occur, production schedules are affected and costs rise, sometimes with cascading effects on OEM build plans. Cost structure, therefore, is not just a function of design efficiency; it is also a function of supply continuity, logistics resilience, and multi-sourcing strategy. Companies that treat the supply chain as a strategic asset rather than a transactional input are better positioned to absorb shocks and preserve margin. This is a practical differentiator that often matters more in day-to-day competitiveness than marginal improvements in marketing position.
Competitive Landscape and Leader Strategies
The CVT market is defined by a concentration of capability among a small group of manufacturers and vehicle makers who have built long-standing technical and contractual relationships. The competitive story is less about scattered experimentation and more about deepening expertise, expanding application breadth, and defending reliability perceptions through sustained product refinement.
Japanese Leadership and Differentiated Positioning
Japanese firms continue to anchor the sector. One transmission specialist has built a leading global market share in CVT technology, with product lines such as CVT-X, CVT-XS, and CVT-S for front-wheel-drive vehicles, and a business model centered on design, development, manufacture, and sale of CVT systems. Its strategic advantage lies in vertical focus and a broad application portfolio that can serve multiple OEM platforms. Another major supplier develops and supplies advanced CVT systems for passenger cars, including models equipped with launch gear to improve fuel efficiency and acceleration response. Its differentiation is engineering integration, especially where launch performance and efficiency must coexist. On the automaker side, several large Japanese brands have embedded CVTs deeply into their lineups. One producer offers its Xtronic CVT across models such as Rogue, Sentra, and Altima, and has continued refining reliability and performance through successive generations. Another incorporates CVTs in widely recognized models for seamless operation and fuel efficiency. A third utilizes its Lineartronic CVT across models such as Forester, Crosstrek, and Outback for efficient power delivery and drivability. The common strategic thread is not mere adoption but sustained optimization: each brand uses the CVT as part of a broader value proposition that ties efficiency, ride quality, and model-specific tuning together.
Worldwide Hybrid Dual-Clutch Transmission Market
Evolution of the Field: Consolidation Depth and Niche Expansion
The competitive field is evolving along two tracks. The first is deepening consolidation among scale players who can amortize engineering, tooling, and supply chain commitments over large volumes. High market concentration means that incumbents already control much of the learning curve, supplier relationships, and customer qualification process. New entrants face not just a technical hurdle but an institutional one: OEMs prefer proven durability, predictable supply, and validated warranty performance. The second track is differentiation within specialized applications and architectures. Toroidal, hydrostatic, and other configurations remain smaller in volume, but they matter where specific torque, speed, or duty-cycle requirements make belt-driven or chain-driven designs less suitable. The opportunity here is not to challenge the dominant architectures head-on, but to own a credible position in segments where mechanical requirements or operating conditions reward alternative designs. This is a classic concentration-plus-niche dynamic: scale players defend the mainstream, while specialists preserve optionality and option value in targeted applications.
Recent Market Signal: Confidence Through Refined Reliability Messaging
A telling recent signal is the emphasis on decades of refinement and improved reliability in updated model-year content. In mid-2025, one major automaker released refreshed messaging highlighting twenty years of CVT improvements and the enhanced reliability of its CVT across 2025 and 2026 models such as the Rogue. This kind of communication is strategically meaningful. It does more than promote a product; it attempts to reset a reliability narrative that has lingered in consumer and fleet perception, and it ties mechanical refinement to model-year continuity. From a competitive standpoint, it signals that leading players understand the market is won as much on trust and durability as on efficiency claims. It also suggests that incumbents are actively managing the perception gap as a core part of their go-to-market strategy, not leaving it to dealer networks or word of mouth.
What This Means for Positioning and Entry
For existing leaders, the priority is to protect scale advantages while continuing to improve launch performance, thermal durability, and packaging flexibility. For suppliers, the priority is to integrate more tightly with OEM calibration and vehicle-level efficiency goals, because CVTs are increasingly evaluated within the full powertrain system rather than as standalone components. For potential new entrants, the realistic path is not to commoditize the mainstream but to address underserved niches, alternative architectures, or regional supply gaps where specificity and responsiveness can outweigh scale. The market does not reward generic entry; it rewards credible specialization backed by engineering discipline and supply reliability.
PW Consulting Automotive & Machinery Research Center
Future Trends and Commercial Opportunities
Predicting the next three to five years of the CVT market requires reading the interaction of technical momentum, regulatory direction, supply resilience, and the broader electrification debate. The trends that matter are not isolated forecasts; they are conditions that reshape where value is created.
Efficiency-as-Standard, Reliability-as-Differentiator
The first trend is the normalization of efficiency and the elevation of reliability into a competitive differentiator. As consumers and fleets become more familiar with CVTs, the baseline expectation will shift from novelty to dependability. Companies that can consistently deliver smooth operation, low noise, and durable performance will capture disproportionate trust and repeat adoption. This trend opens commercial opportunities in warranty-optimized design, improved thermal management, and better service diagnostics, all of which can reduce total cost of ownership and strengthen brand confidence. It also suggests that communications around reliability will remain a strategic lever, especially as new model years refresh the narrative and older concerns fade.
Commercial and Specialty Applications as Growth Anchors
The second trend is the incremental but strategically significant expansion of commercial and specialty applications. While passenger cars will continue to drive volume, commercial vehicles and niche architectures offer stability and higher willingness to pay for functional performance. This is where CVTs can build recurring demand that is less sensitive to consumer taste cycles and more aligned with operational economics. The opportunity lies in tailoring designs to specific duty cycles, improving torque handling and serviceability, and positioning CVTs as part of a broader commercial vehicle efficiency strategy. Companies that treat these applications as afterthoughts will miss a valuable anchor; those that invest in application-specific engineering can create defensible positions and longer contract cycles.
Regulatory Modeling and Portfolio Calibration
The third trend is the growing importance of regulatory modeling in portfolio decisions. Compliance documentation continues to provide detailed estimates of transmission cost, penetration assumptions, and scenario-based outcomes. These documents influence how automakers plan architectures and how suppliers anticipate commitment levels. The commercial opportunity here is foresight: firms that can interpret regulatory trajectories, translate them into volume and cost expectations, and align their product roadmaps accordingly will be better positioned to capture demand when scenarios shift in favor of CVTs, and to protect margins when alternative architectures gain relative weight. This is not about betting on a single future; it is about building optionality and responding quickly to changes in compliance expectations.
Risks and Uncertainties to Watch
No forecast is complete without identifying where the model could break. The most immediate risk is supply chain disruption in specialized components, which can affect production continuity and unit cost. A second risk is the ongoing recalibration of electrification strategies, which could alter the relative attractiveness of internal combustion optimization in certain segments. A third risk is perception persistence: if reliability concerns resurface in high-mileage or extreme-duty conditions, brand trust can erode quickly, reversing some of the gains made through product refinement. A fourth risk is regulatory assumption shifts, where modeling scenarios change how CVT penetration is projected under different compliance pathways. Each of these risks is manageable, but only if firms monitor the signals early and build flexibility into sourcing, product design, and portfolio planning.
Strategic Playbook for Decision Makers
The CVT market rewards participants who combine technical credibility with operational discipline and regulatory awareness. The most useful actions are not generic; they are tailored to the role each organization plays in the value chain.
For Manufacturers and Suppliers
- Double down on reliability as a marketable asset. Invest in durability validation, thermal management, and launch performance, and align product messaging with model-year continuity to strengthen consumer and fleet trust.
- Treat the supply chain as a strategic moat. Develop multi-source strategies for critical components, maintain buffer capacity for specialized steel push-belts and pulleys, and coordinate logistics resilience with OEMs to reduce exposure to disruption.
- Expand application-specific engineering where it pays. Focus development on commercial and specialty segments that value torque, duty-cycle performance, and serviceability, and use these segments to stabilize volume and reinforce engineering credibility.
For Investors
- Assess scale and learning curve advantages rather than headline growth alone. Concentration, cumulative production experience, and supplier integration often determine who can sustain cost improvement and margin stability.
- Monitor compliance modeling signals closely. Changes in regulatory assumptions, cost estimates, and penetration scenarios can shift portfolio preferences more quickly than product trends, and early interpretation can create timing advantages.
- Look for durable demand anchors in commercial and specialty applications, where functional value and total cost of ownership can support recurring volume even as consumer preferences fluctuate.
For Procurement and Fleet Decision Makers
- Evaluate CVTs within the full operating context, not just on efficiency claims. Consider warranty performance, serviceability, supplier continuity, and total cost of ownership across the expected vehicle lifecycle.
- Request evidence of durability and reliability improvements, especially for higher-mileage or commercial use, and align procurement criteria with the reliability narrative that manufacturers are actively reinforcing in current model years.
- Build procurement flexibility around specialized components and delivery continuity to reduce exposure to supply disruptions that can affect uptime and operating cost.
The strategic takeaway is that the CVT market is advancing through disciplined refinement, regulatory alignment, and selective application expansion, not through indiscriminate growth. The companies that will capture the most value are those that understand this nuance and act on it: improving reliability, protecting the supply chain, and positioning CVTs where they deliver the strongest marginal benefit. For leaders who need to go beyond directional trends and make precise decisions on segment allocation, cost modeling, supplier selection, or product roadmaps, detailed segmentation data and customized analysis are available in the complete PW Consulting report on the Continuously Variable Transmission market.
For detailed analysis of this topic, please visit the official page: Continuously Variable Transmissions (CVT) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Logistics Robots Market 2032: Why 16.8% CAGR and 63% Palletizing Shift Redefine Growth
By PW Consulting, 2026-09-21
The Logistics Robots Market: Navigating Growth, Innovation, and Strategic Opportunity
The logistics robots market has evolved from a niche automation segment into a foundational pillar of modern supply chain infrastructure. Between 2020 and 2025, the market expanded from approximately $66.8 million to $120.5 million, reflecting a compound annual growth rate of 16.8% that extends through the 2026–2032 forecast window. By the end of the projection period, revenue is expected to approach $295 million, driven by sustained adoption across warehousing, material handling, and last-mile operations. This trajectory is not merely a function of technological novelty; it represents a structural realignment in how goods are moved, sorted, and stored amid persistent labor constraints, rising throughput expectations, and the need for operational resilience.
Within this growth story, concentration patterns reveal a market still in transition. The top three players capture roughly 45% of revenue, while the top five account for 56%, indicating a landscape where established automation vendors coexist with agile, software-driven entrants. The diversity of offerings—from automated guided vehicles and autonomous mobile robots to robotic arms and specialized end-effectors—demonstrates that logistics automation is no longer a one-size-fits-all proposition. Instead, success increasingly depends on how well solutions integrate with existing facility layouts, warehouse management systems, and broader enterprise data architectures.
Market Landscape and Critical Inflection Points
From Isolated Automation to Ecosystem Integration
For much of the past decade, logistics robotics deployments focused on discrete, repeatable tasks within controlled environments. Today, the prevailing shift is toward layered automation ecosystems where mobile platforms, fixed automation, and software orchestration converge. Facilities are no longer evaluating robots as standalone tools; they are assessing how robotic fleets interact with inventory algorithms, demand forecasting models, and labor scheduling systems. This integration imperative is reshaping procurement cycles, implementation timelines, and the value proposition of vendors who can deliver both hardware reliability and intelligent software layers.
Labor Dynamics and Throughput Pressure
Persistent workforce volatility continues to act as a fundamental catalyst. High turnover, shifting labor availability, and escalating training costs have pushed operators to seek automation that augments rather than entirely replaces human activity. At the same time, consumer expectations for faster, more accurate fulfillment have compressed tolerance for bottlenecks. The result is a market where throughput per square foot, error reduction, and flexibility during demand spikes have become central decision criteria. Companies are increasingly treating robotics not as a capital expenditure isolated from operations, but as a lever for stabilizing service levels under variable conditions.
Worldwide Logistics Automatic Robotics Machine Market
Cost Structures and Implementation Complexity
While the promise of automation is clear, the economics of deployment remain uneven. Upfront capital, integration effort, and change management requirements can delay payback periods, particularly for mid-sized operators. Steel tariffs of 25% implemented in 2025 have added pressure to equipment costs across robotics and conveyor systems, with domestic steel price increases partially neutralizing the expected advantages of localized sourcing. These dynamics are pushing buyers to evaluate total cost of ownership more rigorously, favoring solutions that minimize retrofit complexity, support phased rollouts, and offer predictable operating expenses.
Core Drivers Shaping Market Trajectory
Technological Innovation and Embodied Intelligence
The most consequential driver is the maturation of embodied intelligence and AI-enabled navigation. Modern autonomous mobile robots are increasingly capable of dynamic path planning, obstacle recognition, and task adaptation without extensive fixed infrastructure. Recent product introductions illustrate this direction: in May 2026, SEER Robotics launched an AI delivery robot ready for immediate deployment alongside an embodied wheeled humanoid robot base, signaling a push toward versatile platforms that can handle both final-mile delivery and warehouse operations. Similarly, Geek+ introduced its Brain embodied intelligence platform and RoboShuttle V5 at MODEX 2026, reinforcing the industry’s move toward software-defined robotics that can be reconfigured as operational needs change.
These advancements reduce the traditional friction of warehouse automation: fixed guide paths, extensive site preparation, and rigid workflow assumptions. Instead, fleets can be scaled incrementally, retasked across shifts, and coordinated through centralized orchestration layers. For operators, this means automation can follow demand rather than requiring demand to conform to automation design. For vendors, differentiation is shifting from mechanical performance alone to the quality of perception, fleet coordination, and integration APIs.
Policy, Safety Standards, and Regulatory Clarity
Regulatory and standards development is quietly reshaping deployment confidence. The ANSI/A3 R15.06-2025 safety standard, which updates ISO 10218-1:2025, introduces revised risk assessment practices, functional safety expectations, and cybersecurity requirements for industrial robots. As safety frameworks become more explicit, organizations gain clearer guidance for integrating collaborative and autonomous systems alongside workers, reducing ambiguity that historically slowed adoption in mixed human-robot environments.
Policy momentum is also emerging in specific geographies. In the United Kingdom, the 2025 Industrial Strategy and Digital and Technologies Sector Plan introduced reforms including a Regulatory Innovation Office and a clearer route to market for delivery robots. Such developments matter because they reduce time-to-deployment uncertainty for last-mile and urban logistics applications. When regulators provide predictable pathways, innovators can invest with greater confidence, and operators can plan pilots with more reliable approval timelines.
Demand-Side Shifts and the Rise of Robotics-as-a-Service
On the demand side, adoption patterns are broadening beyond large-scale distribution centers. As of November 2025, 60% of U.S. warehouses had integrated AI into their operations, with projections indicating this figure could reach 80% in the coming years. This AI penetration is closely intertwined with robotics adoption because intelligent software layers make robotic fleets more useful: they enable better task allocation, predictive maintenance, and dynamic responsiveness to order profiles.
The economics of adoption are also evolving through Robotics-as-a-Service models, which grew by 42% according to IFR World Robotics 2025 data. IFR reported 102,900 transportation and logistics robots sold in 2024, making this the largest professional service robot application class. RaaS growth reflects a preference among many operators for variable-cost models that lower upfront capital exposure and align automation expenses with utilization. For a market where operational flexibility is paramount, subscription and outcome-based pricing are becoming meaningful differentiators, particularly for seasonal businesses and companies managing multiple sites with varied automation needs.
Supply Chain Realities and Cost Resilience
Supply chain volatility continues to influence purchasing behavior and vendor selection. Beyond steel tariffs, organizations are weighing the resilience of their automation supply chains: component availability, lead times, and service support networks all affect the reliability of robotic deployments. Vendors that provide transparent supply chain strategies, modular hardware designs, and robust remote support capabilities are gaining favor because they reduce the risk of prolonged downtime. In parallel, the push toward software-defined fleets is making it easier to adapt hardware bases to new tasks via firmware and orchestration updates, which helps protect prior investments as operational requirements change.
Competitive Dynamics and Strategic Positioning
Portfolio Breadth Versus Specialized Excellence
The competitive field spans global automation incumbents, AMR specialists, and emerging players focused on embodied intelligence, humanoid platforms, and cloud robotics. Companies such as Amazon Robotics, ABB, KUKA, Toyota Industries, Fanuc, Yaskawa, KION Group, Daifuku, and MiR bring scale, industrial manufacturing heritage, and deep integration experience. Their competitive strength often lies in the ability to combine robotics with broader material handling systems, service networks, and long-standing customer relationships.
At the same time, specialist firms are carving distinct positions. Geek+ has maintained a leading position in AMR and embodied intelligence warehouse logistics, emphasizing full fleet solutions for order fulfillment and storage. Locus Robotics focuses on AI-powered autonomous mobile robots and robots-to-goods picking systems that align closely with labor-constrained picking workflows. Rapyuta Robotics promotes cloud robotics with ASRS and upgraded PA-AMR systems designed for modular warehouse automation, appealing to operators seeking flexibility across site configurations. Addverb Technologies has expanded its footprint with carousel automation and interface robots tailored for high-order storage centers, while Exotec has pushed higher-density storage through next-generation Skypod systems with advanced software and improved space utilization.
Differentiation Through Software, Safety, and Service
Hardware motion is increasingly table stakes; competitive advantage is accruing to firms that excel in fleet orchestration, safety certification, and service economics. The emphasis on updated safety standards and cybersecurity requirements elevates the importance of vendors who can document compliance rigorously and support secure integration with enterprise IT. Service models are equally critical: remote diagnostics, over-the-air updates, and predictable maintenance windows reduce the operational burden on warehouse teams and strengthen the business case for automation. In markets where labor is scarce and skilled technicians are even scarcer, service reliability can be as decisive as robot speed or payload.
Market Evolution: Consolidation, Fragmentation, and New Entrants
The market is unlikely to settle into a single dominant structure. Instead, it is evolving along multiple axes. Large automation groups may consolidate capabilities through acquisitions that add software, vision, or mobile capabilities to fixed automation portfolios. Simultaneously, fragmentation persists at the application layer, where niche players address specific workflows such as tote handling, final-mile delivery, or high-density storage. New entrants are also emerging with humanoid and embodied platforms, expanding the design space beyond traditional pallet and cart movement. This pluralistic structure benefits buyers because it creates options across price points, deployment styles, and integration complexity, but it also complicates vendor selection and underscores the need for clear evaluation criteria aligned with operational goals.
Forward Outlook: Three Trends Defining the Next Wave
Trend 1: Software-Defined Fleets Become the Norm
Over the next three to five years, the market will increasingly separate the value of hardware from the value of orchestration. Robots will be expected to adapt to changing layouts, task mixes, and throughput targets through software upgrades rather than physical reconfiguration. This trend favors platforms with open integration architectures, robust simulation tools, and analytics that help operators optimize task assignment and utilization. The commercial opportunity lies in solutions that can demonstrate measurable improvements in pick density, travel efficiency, and changeover time without requiring major facility redesign.
Trend 2: Broader Application Footprints Beyond Traditional Warehousing
While palletizing, de-palletizing, pick-and-place, and internal transportation remain dominant use cases, the application frontier is expanding. Final-mile deliveries, mixed human-robot collaboration in active aisles, and modular automation for smaller sites are gaining traction. In the United Kingdom, regulatory reforms have opened clearer routes for delivery robots, and product launches in embodied wheeled platforms point toward more versatile machines capable of operating across warehouse and urban environments. As these applications mature, the market will likely see more cross-site deployments where the same platform family supports multiple functions, improving asset utilization and simplifying fleet management.
Trend 3: Cost Optimization and Phased Adoption Models
Given equipment cost pressures and integration complexity, adoption will continue to shift toward phased rollouts and flexible financial models. Operators will favor deployments that prove value in a limited area before expanding, especially when steel tariffs and domestic material costs elevate baseline equipment expenses. Robotics-as-a-Service and outcome-linked pricing will remain attractive for organizations seeking to manage capital exposure and align automation spend with volume variability. Vendors that can offer transparent cost structures, scalable pilots, and rapid time-to-value will be better positioned to convert interest into committed deployments.
PW Consulting Automotive & Machinery Research Center
Risks and Uncertainties to Monitor
Several factors could temper or redirect growth. 만일 steel and component cost pressures persist, payback periods may lengthen for capital-intensive projects, slowing adoption among price-sensitive segments. Regulatory divergence across regions could create uneven deployment paths, particularly for mobile and delivery applications that cross jurisdictional boundaries. Cybersecurity expectations will continue to rise, requiring vendors and operators to invest in secure integration and data governance. Finally, the pace of AI adoption in warehouses will influence how quickly robotic fleets realize their full potential; without strong software integration and change management, advanced hardware can underperform relative to expectations.
Strategic Actions for Decision-Makers
For Manufacturers and Automation Vendors
Differentiate beyond kinematics. The most defensible positions will combine reliable mobile platforms with strong orchestration software, clear safety and cybersecurity documentation, and service models that reduce operational friction. Prioritize integration readiness with existing warehouse management and enterprise systems, and invest in simulation and deployment tooling that shortens implementation cycles. As application diversity increases, modular hardware and flexible tasking capabilities will help customers adapt without discarding prior investments.
For Investors
Look for value creation at the intersection of software, fleet management, and service economics. Companies that can demonstrate repeatable deployment processes, strong utilization metrics, and scalable RaaS or outcome-based models are better aligned with the market’s shift toward flexible cost structures. Pay attention to safety compliance maturity and cybersecurity posture, as these increasingly influence procurement decisions in mixed-use environments. Sector breadth matters too: exposure across warehousing, material handling, and final-mile applications can provide resilience if one segment slows.
For Procurement and Operations Leaders
Define the problem before selecting the platform. Clarify whether the priority is throughput stability, labor augmentation, space efficiency, or flexibility across sites, then evaluate vendors against those outcomes rather than nominal specifications. Favor phased pilots that can validate performance under real order profiles, and model total cost of ownership with realistic integration and service costs. As equipment cost pressures persist, consider flexible financial models and modular deployments that let you scale credible results rather than committing to large fixed installations upfront.
From Insight to Execution
The logistics robots market is moving from rapid expansion to more nuanced value creation. Growth rates remain strong, but the next phase will reward those who can align automation with operational realities: integration complexity, safety expectations, cost pressures, and the need for flexible deployment models. Companies that treat robotics as part of a broader, software-enabled logistics strategy will be better equipped to capture the upside while managing risk.
For decision-makers seeking detailed segmentation data, regional and application-level revenue breakdowns, competitor benchmarking, and customized strategic recommendations, the full PW Consulting research report provides the granular evidence base needed to translate these market dynamics into concrete investment and deployment decisions.
Worldwide Warehouse Robots Market
For detailed analysis of this topic, please visit the official page: Logistics Robots Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Optical Distribution Frame Market: Why 9.5% CAGR and Telecom Shift Change Everything
By PW Consulting, 2026-09-21
The Optical Distribution Frame Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The optical distribution frame market has transitioned from a steady infrastructure component to a critical enabler of next-generation connectivity. Total market revenue is projected to expand from approximately 893 million USD in 2025 to roughly 1,685 million USD by 2032, reflecting a compound annual growth rate of 9.5 percent over the forecast period. Historical momentum through 2025 illustrates a market that accelerated meaningfully after 2023, with revenue climbing at a pace that outpaced broader telecom infrastructure spending in several regions. The trajectory signals a structural shift rather than a cyclical uptick, driven by capacity demands that older distribution architectures were never designed to accommodate.
Despite the favorable top-line outlook, the market faces several inflection points that will separate adaptable players from those locked into legacy configurations. First, the definition of density is changing. Traditional frame designs optimized for incremental port additions are now encountering physical and thermal constraints as single racks and enclosures must support thousands of splice points without compromising maintainability. Second, deployment speed has become a competitive differentiator. Operators and data center developers are no longer willing to accept multi-day commissioning cycles for optical distribution layers, yet many existing product lines still rely on field-terminated assemblies and manual circuit labeling. Third, the supply chain environment continues to reward manufacturers that can balance standardized modularity with rapid customization, while penalizing those exposed to volatile component costs and fragmented logistics networks.
These challenges converge on a single strategic question: how to deliver higher connectivity density, faster time-to-service, and reliable operational performance without inflating total cost of ownership. The market is not simply asking for more ports; it is asking for smarter distribution architectures that integrate identification, validation, and scalability at the point of installation.
Key Drivers Shaping the Market
Technology Innovation and Architectural Breakthroughs
Innovation in optical distribution is increasingly centered on hyperscale density, single-fiber handling, and pre-integrated deployment models. Recent product introductions demonstrate how frame architecture is being re-engineered to support rapid mesh connectivity in AI-driven data center environments. One notable example is a hyperscale optical distribution frame capable of supporting up to 5,760 splices per frame, incorporating single-fiber splicing, tracer fiber circuit identification, and pre-assembled deployment features. This level of integration reduces on-site assembly complexity and improves circuit traceability, both of which are becoming essential as rack-level fiber counts multiply.
Beyond raw port counts, design innovation is shifting toward tool-less installation, full front access, and modular scalability. These attributes matter because they reduce skilled labor dependency and enable repeatable deployment patterns across multiple sites. In practical terms, improved mechanical design and pre-configured connectivity options can compress installation timelines while lowering the risk of human error during splicing and labeling. For operators, that translates into faster service readiness and more predictable operational overhead.
Policy and Regulatory Environment
Policy momentum continues to reinforce fiber-based connectivity as a foundational utility rather than an optional premium service. Government-backed broadband expansion programs, rural connectivity initiatives, and regulatory pressure to close digital access gaps are expanding the addressable base for optical distribution infrastructure. At the same time, data center build-out is being shaped by broader digital policy priorities, including cloud sovereignty, enterprise digitization, and the need for resilient interfacility links.
This environment creates a dual effect. Public-sector and regulated networks often require proven interoperability, long-term supply reliability, and documented maintainability, which favors established platforms and disciplined manufacturing practices. Meanwhile, commercial data center projects prioritize speed and density, pushing vendors to deliver flexible architectures that can be adapted across diverse cabinet form factors and site constraints. The regulatory tailwind is therefore not uniform; it amplifies demand across segments while simultaneously raising the bar for reliability and serviceability.
Demand-Side Shifts in Telecom and Data Centers
Demand is being reshaped by two powerful forces: the relentless scale-up of data center interconnectivity and the continuing evolution of telecom access networks. Data centers are no longer passive consumers of connectivity; they are active fabric nodes that require dense, manageable, and quickly reconfigurable optical distribution layers. The rise of distributed compute, higher rack power densities, and mesh-style network designs is increasing the number of fiber terminations that must be organized, identified, and maintained within compact enclosures.
On the telecom side, fiber deepening into metro and access networks is supporting higher-capacity service offerings and more granular network segmentation. Operators are seeking distribution solutions that can accommodate both traditional indoor termination needs and higher-density configurations aligned with 19-inch or 21-inch cabinet standards. The practical outcome is a market in which demand is broadening across legacy service upgrades and new high-density deployments, but the requirements within each application are becoming more specific and performance-sensitive.
Supply Chain and Cost Structure Dynamics
Cost structure is increasingly determined by design efficiency and deployment simplification rather than component price alone. Pre-assembled configurations, standardized module footprints, and improved fiber management can reduce field labor time and mitigate installation variability. In contrast, solutions that require extensive on-site termination or manual tracing often carry hidden operational costs that emerge during maintenance and reconfiguration.
Supply chain resilience also matters more than ever. Manufacturers that can maintain consistent quality, support multiple cabinet formats, and deliver predictable lead times are gaining an advantage in competitive bid processes. The broader dynamic is a shift in value capture from pure volume production toward integrated solutions that lower total deployment and operating costs. In this environment, pricing power is increasingly tied to demonstrated efficiency gains rather than commodity positioning.
PW Consulting Automotive & Machinery Research Center
Competitive Landscape and Leading Strategies
The market is shaped by a concentrated group of manufacturers with distinct strategic postures. One leading player has positioned itself around hyperscale data center performance, emphasizing extreme splice capacity, single-fiber handling, tracer fiber circuit identification, and pre-assembled deployment for rapid rollout in AI-driven mesh networks. This product direction reflects a clear bet on density and speed as primary purchasing criteria in large-scale facility builds.
Another major provider focuses on indoor fiber termination and splicing across standardized cabinet configurations, offering 48- and 96-core variants designed for 19-inch or 21-inch enclosures. This approach underscores the continued importance of reliable, form-factor-aligned solutions for telecom and enterprise indoor networks, where compatibility, serviceability, and proven performance remain central buying considerations.
A third active manufacturer emphasizes flexible access architectures and modular scalability, with platforms that support full front access, tool-less installation, and ultra-high density connectivity for telecom and data center use. The emphasis here is on adaptability and installation efficiency, targeting buyers who need to balance density with maintainability across diverse deployment contexts.
Together, these positions highlight a market in which differentiation is increasingly defined by how well a product reduces deployment friction while meeting application-specific density and access requirements. The competitive landscape is evolving along several lines:
- Consolidation is likely to continue as larger players pursue cross-platform integration and broader fiber management portfolios, especially where data center and telecom requirements increasingly overlap.
- At the same time, differentiation will create pockets of specialization, with some vendors concentrating on hyperscale high-density frames while others retain strength in indoor termination, modular scalability, or service-friendly access designs.
- New entrants and technology-driven challengers may gain traction by targeting specific pain points such as circuit identification, pre-integration, and faster commissioning, particularly if they can demonstrate measurable reductions in deployment time or maintenance effort.
For incumbents, the strategic imperative is to avoid competing solely on port count or price. The more durable advantages are likely to come from repeatable deployment models, clear serviceability benefits, and the ability to scale across both telecom and data center environments without forcing customers into a single cabinet philosophy.
Future Trends and Strategic Implications
Density Will Become a Design Philosophy, Not Just a Spec Sheet Number
Over the next three to five years, optical distribution frames will be evaluated less by simple port counts and more by how effectively they manage extreme fiber densities in real operating conditions. Expect continued pressure toward higher splices per frame, improved airflow and thermal behavior around dense closures, and more advanced circuit identification methods that reduce troubleshooting time. The commercial opportunity lies in offering architectures that make high density operationally manageable, not merely physically possible. Manufacturers and system integrators that can prove lower error rates, faster reconfiguration, and smoother maintenance at high densities will be well positioned.
Pre-Integration and Rapid Deployment Will Redefine Procurement Value
The trend toward pre-assembled, ready-to-deploy distribution platforms is likely to accelerate as operators and data center developers seek to compress project schedules. Solutions that combine validated fiber paths, pre-labeled or light-guided identification, and tool-less installation will become more attractive in competitive bids, especially where labor availability or on-site expertise is constrained. The strategic implication is that procurement decisions will increasingly weigh installation efficiency and commissioning certainty alongside hardware cost. This creates opportunities for vendors that can standardize high-density modules while still accommodating site-specific configurations.
Segment Blurring Between Telecom and Data Center Requirements
The boundary between telecom access networks and data center interconnect environments is becoming less rigid. Both domains are pushing for higher density, cleaner fiber management, and faster deployment, even if they emphasize different cabinet sizes, access styles, and operational priorities. As a result, product platforms that can flex across these environments without sacrificing reliability or serviceability will capture broader demand. The risk is that manufacturers may over-index on one segment and miss the growing overlap in deployment needs. Buyers, in turn, will benefit from more consistent architectures, but they will also need to assess whether a given platform can scale across future site designs rather than only fitting a current project.
Risks and Uncertainties to Monitor
Several uncertainties could reshape the market’s trajectory. A slowdown in data center expansion, or a shift toward more distributed and less fiber-intensive compute models, could temper the most aggressive density assumptions in certain regions. Regulatory or procurement changes could also influence the balance between standardized platforms and customized solutions, especially if public funding programs impose stricter interoperability or lifecycle requirements. In addition, if labor markets remain tight, the value of tool-less and pre-integrated designs will rise, but any manufacturing bottlenecks that delay complex pre-assembled products could undermine that advantage.
Worldwide Optical Networking IC Market
Actionable Guidance for Decision-Makers
For manufacturers and product strategists, the priority is to align innovation with operational outcomes rather than density alone. Develop platforms that make high-density deployment repeatable, traceable, and service-friendly. Where possible, invest in pre-integrated configurations and modular scalability so that customers can standardize where it matters and adapt where they need to. Differentiation should be anchored in measurable deployment benefits, such as reduced installation time, easier circuit identification, and lower maintenance complexity.
Optical Transceivers Market
For investors, the most compelling exposure is likely to be in capabilities that reduce total cost of ownership across the deployment lifecycle. Evaluate companies not only by revenue momentum, but by the extent to which their product architecture addresses installation speed, density manageability, and cross-application flexibility. Businesses that can serve both telecom and data center demand with coherent platforms may enjoy broader growth optionality, while those overly dependent on a single form factor or application may face more volatile demand patterns.
For procurement and network planning teams, the practical focus should be on future-proofing fiber distribution decisions. Favor solutions that can accommodate rising densities without forcing premature replacement cycles, and evaluate total deployment and maintenance effort rather than hardware price in isolation. Pay close attention to compatibility with cabinet standards, access preferences, and anticipated reconfiguration needs. In high-density environments, circuit identification, splice management, and modular scalability can have as much operational impact as raw port count.
Given the pace of change in product architecture, deployment expectations, and application overlap, detailed segment-level intelligence is increasingly valuable for shaping product roadmaps, investment theses, and purchasing strategies. Comprehensive research can help clarify how demand is shifting across regions, applications, and mounting styles, and where competitive differentiation is likely to be earned or lost. For organizations that need sharper visibility into segment dynamics, forecast ranges, and vendor-specific positioning, the full market study provides a deeper basis for decision-making.
For detailed analysis of this topic, please visit the official page: Optical Distribution Frame Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Trends & Commercial Opportunities in the Tyre Curing Press Market
The tyre manufacturing sector is undergoing a quiet but consequential transformation, and the curing press sits at the center of that shift. Over the past five years, global demand for curing equipment has expanded from roughly $163 million to $215 million, and the trajectory suggests continued growth toward $345 million by 2032. The forward path is anchored by a compound annual growth rate of approximately 4.15 percent through the end of the decade. These figures do not describe a mature, static market. They describe an industry in the middle of a technology transition, a regulatory tightening cycle, and a geographic realignment that is reshaping how manufacturers source, spec, and operate curing systems. For executives planning capital expenditures, investors evaluating industrial equipment exposure, and procurement teams negotiating long-cycle orders, the direction of the market matters more than any single quarter. The next five years will favor players who align equipment strategy with energy efficiency, compliance readiness, and regional demand patterns rather than those who compete purely on price per unit.
Market Overview and Core Challenges
The current market structure reflects a steady but uneven expansion. Base-year sizing places the sector at $215 million, with historical data showing a clear acceleration after 2022. The jump from $172.69 million in 2022 to $193.7 million in 2023, followed by continued movement toward $201.23 million in 2024, indicates a post-pandemic normalization combined with fresh capital spending in tyre production capacity. From there, the forecast builds steadily, with the market crossing $222.74 million in 2026 and reaching $344.8 million by 2032. The consistency of this growth curve is significant: it suggests that curing press demand is being driven by structural factors rather than temporary capacity spikes. At the same time, the market is not concentrated in the hands of a few dominant players. A CR3 of 24.6 percent and a CR5 of 26.2 percent point to a broad competitive field, which reinforces price and technology differentiation as the main differentiators instead of oligopolistic advantage.
PW Consulting Automotive & Machinery Research Center
This broad landscape is also where the central tensions emerge. Three challenges define the current turning point.
- Technology substitution is accelerating, but not uniformly. Hydraulic systems continue to hold meaningful share, while hybrid and electric variants are gaining attention in specific production environments. The market is not eliminating mechanical presses, but it is shifting expectations around cycle consistency, energy draw, and process control.
- Regulatory scrutiny is intensifying around safety, traceability, and plant-level emissions. tyre identification requirements, compliance labeling, and environmental permitting have moved from administrative concerns to operational constraints. Manufacturers and equipment suppliers need to treat compliance as part of product design and deployment, not as a downstream paperwork exercise.
- Regional demand is uneven, creating both overcapacity risk in some areas and supply opportunities in others. Tire production growth, retreading activity, and replacement cycles are not moving in lockstep across geographies, which complicates demand forecasting for equipment suppliers and buyers alike.
For decision makers, the implication is straightforward: curing press strategy must be multifaceted. A unit that performs well in one plant may not be the right answer for another if energy costs, labor availability, regulatory exposure, or end-product mix differ materially. The market is rewarding flexibility and penalizing one-size-fits-all assumptions.
Key Drivers Shaping the Market
Technology Innovation and Process Control
The most consequential driver in the near term is the evolution of curing technology itself. The emergence of modular hydraulic and electric solutions, including next-generation curing platforms and post-cure inflation options, reflects a broader push toward tighter process control and reduced energy intensity. Manufacturers are not simply replacing old machines; they are rethinking the curing step as a variable that affects throughput, quality consistency, and operating cost. The trend is visible in the product mix, where hydraulic equipment leads in value and electric and hybrid formats are expanding their footprint in higher-value or more customized applications.
Trade show activity reinforces the point. Recent appearances by major equipment providers at international tyre and rubber events have highlighted advances in curing technology, manufacturing inspection, and sustainable production methods. These showcases are more than marketing events. They signal where engineering teams and end-users are converging on priorities: repeatable cure profiles, safer operator environments, and equipment that can integrate with automated line architectures. HF GROUP’s ongoing exhibition presence across Vienna, Chennai, and tyre technology events in 2026, along with its earlier participation in India Rubber Expo communications, underscores how suppliers are using live demonstrations to position curing solutions within broader sustainability and productivity narratives.
The commercial takeaway is that equipment choice is increasingly a process decision, not just a mechanical purchase. Plants that pair curing equipment with better control systems and predictive maintenance can reduce scrap, improve throughput, and adapt more easily to product mix changes. That makes the value proposition of advanced curing platforms more defensible than simple unit pricing.
Policy, Compliance, and Permitting Environments
Regulatory dynamics are becoming a more visible market driver than many equipment buyers assume. Traceability and compliance labeling requirements for tyres have created concrete consequences for producers and equipment integrators. Recent federal-level actions involving tire information numbering and curing press identification symbols illustrate how compliance failures can affect product acceptance and market access. This is not an abstract risk. It connects curing press configuration and plant recordkeeping directly to regulatory adherence.
At the same time, environmental permitting at the plant level is influencing where and how new equipment is installed. In several regions, permitting activity for rubber processing facilities and curing presses has been part of broader emissions and operational control frameworks. Authorized installations during 2025 and 2026 reflect a market in which environmental compliance is an integral part of capacity expansion. This matters for suppliers because it shapes the specifications buyers request, and for purchasers because it affects project timelines, operating conditions, and long-run operating costs.
One notable equipment-level example is the introduction of automatic curing press ranges with enhanced safety features, precise control, and mold compatibility for retreading and tyre manufacturing. Such product launches show how suppliers are responding to the dual pressure of operational performance and regulatory or safety expectations. The market is increasingly rewarding equipment that reduces operator risk and supports repeatable, auditable processes.
Demand-Side Shifts in Tire Types and Production Patterns
On the demand side, the market is shaped by what tyres are being produced and where. Passenger vehicle tyres remain the dominant application, supported by replacement demand, new vehicle production, and regional tyre manufacturing footprints. Commercial vehicle tyres, aircraft tyres, and other specialty formats make up meaningful but smaller segments, and they often carry different technical requirements for curing equipment. The mix matters because curing presses are increasingly evaluated by the range of tyre sizes and types they can handle without compromising cycle times or uniformity.
Demand for retreading and specialty tyre production also influences equipment choice. Automatic curing press solutions designed for retreading applications demonstrate how end-use diversification is creating additional demand vectors. Plants that serve both new tyre production and retreading markets need equipment that can switch configurations efficiently while maintaining product integrity. This trend favors flexible platforms and complicates buying decisions for organizations that previously treated curing presses as single-purpose assets.
Supply Chain and Cost Structure Dynamics
Cost structure is evolving as manufacturers balance capital expenditure discipline with operating efficiency. Energy consumption is a recurring theme in curing press evaluations, especially in facilities where electricity costs, cooling requirements, and cycle frequency significantly affect total cost of ownership. Suppliers have responded with press series designed to reduce energy consumption and optimize process control, and those features are becoming more prominent in buying criteria. For capital-intensive equipment, the conversation is shifting from sticker price to lifecycle economics.
Supply chain expansion is another relevant force. Acquisitions and integration moves in the hydraulic sector show how equipment makers are strengthening their capabilities to support broader system requirements. These moves are less about symbolic corporate growth and more about securing technical depth and service support. Buyers benefit when suppliers can deliver integrated hydraulic, mechanical, and automated components with tighter calibration and faster local support. The trend also suggests that the market is moving toward more bundled offerings rather than standalone press purchases, which has implications for vendor selection and contract scope.
Competitive Landscape and Leading Strategies
The market is populated by a diverse set of international players, each with a distinct strategic position. Rather than competing on identical terms, leading companies are building differentiation around product breadth, application focus, and regional presence.
- HF GROUP has built its position around modular hydraulic and electric curing solutions, including established curing platforms, classic press models, and post-cure inflation equipment, with extensive global deployment. Its strategy appears centered on demonstrating innovation through live exhibitions and maintaining a broad installed base that supports serviceability and product evolution.
- Uzer Makina focuses on floating column hydraulic presses and frame-type and mechanical options across a wide size range for passenger, light truck, truck, off-the-road, and agricultural tyre applications. Its recent expansion through acquisition in the hydraulic sector suggests a push toward deeper system capability and broader service support.
- Larsen & Toubro maintains a mechanical tyre curing press range that spans a wide application set, from two-wheelers to passenger cars, light trucks, trucks, tractors, and off-the-road equipment. This breadth positions the company to serve diverse markets, particularly where mechanical press familiarity and application coverage are valued.
- HERBERT Maschinenbau offers hydraulic and mechanical curing presses across passenger to off-the-road sizes, along with post-cure inflators and mold-related equipment. Its introduction of a press series emphasizing reduced energy consumption and optimized process control illustrates a clear response to efficiency and control requirements.
- SCPT Machinery provides tire curing press machines and vulcanizing equipment for varied tyre production needs, supporting a broad equipment portfolio that can appeal to producers seeking standardized vulcanization solutions.
- Cima Impianti markets automatic curing presses, including a product range oriented toward retreading and tyre manufacturing with emphasis on safety, control, and mold compatibility. This positioning addresses both production and aftermarket segments.
- ŽĎAS specializes in tyre curing presses for trucks, tractors, and building machines, reflecting a focused application strategy that serves heavier-duty and industrial tyre segments.
Taken together, the competitive landscape is not coalescing into a single dominant model. Instead, it is differentiating into several strategic approaches: technology-forward modular platforms, application-specific coverage, broader system integration through acquisitions, and sustainability- or efficiency-oriented product lines. This fragmentation is important because it creates choice for buyers, but it also raises the burden of evaluation. Procurement teams need to compare not just press price and capacity, but integration readiness, compliance support, service coverage, and fit with current and future product mixes.
The market evolution is likely to continue along two paths in parallel. In one, larger incumbents will deepen their offerings through product complexity, automation compatibility, and service networks. In the other, specialized suppliers will continue to compete by dominating particular tire types, regional demand patterns, or process configurations. The result is a market where consolidation will be selective rather than sweeping, and where the winners will be those who can articulate a clear operational value proposition rather than those who merely expand factory output.
Future Trends and Commercial Opportunities
Broader Adoption of Efficiency-Focused Curing Platforms
Over the next three to five years, efficiency and control will move from desirable features to baseline expectations. Curing presses that combine reduced energy consumption, predictable cycle management, and safer operation will become more central to procurement decisions, especially in facilities facing tighter operating margins and stricter environmental oversight. The commercial opportunity here is twofold. Equipment suppliers can capture value by selling lifecycle performance rather than commodity machinery, and manufacturers can reduce operating variability while improving throughput consistency. The key uncertainty is the pace at which energy cost volatility and regulatory expectations will accelerate replacement cycles in different regions.
Growth in Segmented and Application-Diverse Demand
Demand will increasingly be segmented by tyre type, production scale, and end-use cycle. Passenger vehicle tyres will continue to anchor volume, but commercial, aircraft, specialty, and retreading formats will create niches where equipment flexibility matters more than headline capacity. This creates opportunities for suppliers that can offer adaptable press configurations and for buyers who plan for mixed-product environments rather than single-line optimization. The risk is that overinvestment in narrowly optimized equipment may leave plants exposed to product mix changes, while underinvesting in flexibility can erode quality and consistency when lines need to switch applications.
Press Machine Market
Closer Integration of Compliance and Plant Equipment Strategy
As traceability, labeling, and permitting issues become more embedded in tyre manufacturing operations, curing press selection and plant strategy will be more tightly linked to compliance readiness. Future investments are likely to incorporate identification protocols, documentation compatibility, and environmental operating constraints as part of the equipment specification process. This trend opens opportunities for suppliers who design compliance-friendly architectures and for buyers who treat equipment planning as part of a broader regulatory strategy. The uncertainty lies in how quickly compliance requirements will change across jurisdictions and how consistently they will be enforced.
Strategic Recommendations for Decision Makers
The market is not simply expanding; it is becoming more conditional. The right curing press strategy depends on the role a company plays in the value chain and the operating pressures it faces. The following actions are most relevant across the three core audiences.
For Manufacturers and Equipment Buyers
- Evaluate curing systems on total operating economics, including energy use, cycle consistency, maintenance burden, and changeover flexibility, rather than on first-cost alone.
- Align press selection with the expected mix of tyre types and production cycles, including new tyre output and retreading activity where relevant, to avoid over-specialized equipment.
- Build compliance and traceability considerations into equipment specifications early, so that curing press configuration supports product identification, documentation, and permitting requirements without later retrofit costs.
For Investors and Strategic Planners
- Watch for differentiation that is tied to real operating gains, such as energy reduction, process control, and integrated service coverage, because those features are more likely to support durable competitive advantage than price-based competition.
- Track regional demand shifts and permitting activity, since market growth may be uneven and driven by local production expansion, environmental approvals, and replacement demand rather than by a uniform global cycle.
- Assess whether targets are building meaningful system capability and service depth or merely broadening product names, because integration and support quality will increasingly determine customer retention and aftermarket economics.
For Procurement and Operations Leaders
- Treat curing press sourcing as a multi-year operating decision, not a transactional purchase. Establish clear criteria for safety, control, mold compatibility, and service response, and use them consistently across bids.
- Prioritize suppliers whose product roadmaps align with your plant’s efficiency and compliance trajectory, especially if you expect tighter energy budgets or stronger environmental oversight in the coming years.
- Use pilot programs and reference installations to validate process outcomes where possible, because curing performance differences can be subtle in specifications but material in daily operations.
The tyre curing press market will continue to expand, but growth alone will not define winners. The companies that navigate this period well will be those that understand how technology transitions, compliance pressures, demand segmentation, and cost structures interact inside real production environments. Broad market sizing and directional trends are useful, but they rarely answer the specific questions that determine capital deployment, vendor selection, and operating risk. Manufacturers planning line upgrades, investors comparing equipment exposures, and procurement teams structuring long-cycle purchases need detailed segmentation data, regional demand context, and company-level capability mapping to move from general direction to actionable decision-making. For that level of detail, the full research report provides a deeper breakdown of market segments, competitive positioning, and development timelines that can support more granular strategy work.
Hydraulic Press Market
For detailed analysis of this topic, please visit the official page: Tyre Curing Press Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


