



Category: Machinery & Automotive
PW Consulting: Hollow Blow Molding Machine Market Set to Hit USD 3,833.9 Million by 2032
By PW Consulting, 2026-06-28
Hollow Blow Molding Machine Market — Strategic Briefing for 2026 Capital Allocation
Executive snapshot
PW Consulting’s latest market intelligence positions the global hollow blow molding machine market at USD 3,000.0 Million in 2025 and growing to USD 3,153.2 Million in 2026, with a compound annual growth rate (CAGR) of 3.6% across the 2026–2032 forecast window. By 2032 the market approaches USD 3,833.9 Million under our base scenarios. These headline figures underscore a stable, industrial-growth profile: steady replacement cycles, selective greenfield investments in packaging and beverage lines, and pockets of accelerated demand driven by sustainability and throughput optimization.
Hollow Blow Molding Machine Market
Why 2026 is a decisive year for investors and equipment buyers
Several converging forces make 2026 a pivotal moment for capital deployment in hollow blow molding equipment:
Hollow Blow Molding Machine Market
- Raw material volatility: PET resin cost shocks and an elevated Producer Price Index for plastics materially affect unit economics for bottle producers, increasing the value of machines that reduce material usage or enable higher recycled-content formulations.
- Regulatory tightening: Region-specific mandates on recycled content and bans on certain food-contact chemistries raise compliance risk for legacy lines and create premium for equipment that supports traceability and multi-resin processing.
- Operational intensity: Leading beverage and packaging customers are prioritizing throughput per square meter and life-cycle cost, shifting procurement criteria from first-cost to total-cost-of-ownership (TCO) and sustainability-enabled value.
Market dynamics — what is driving structural change
Our analysis shows the market is no longer governed solely by cycle-time and capital intensity. The dominant growth vectors in 2026 are:
- Sustainability mandates that force retrofits or replacement to accept higher PCR (post-consumer resin) blends and enable refilling/returnable strategies.
- Material substitution and formulation volatility that reward flexible, adaptive machine platforms with robust process control.
- Consolidation among OEM end-users seeking integrated supply/value chain partnerships rather than point-equipment suppliers.
These drivers are intensified by recent industry events: sharp PET resin price moves in early 2026 and region-level regulatory updates on recycled-content and food-contact chemistries. The combination raises the opportunity cost of deferring investment and increases the strategic value of equipment that demonstrably lowers per-unit material and compliance risk.
Competitive dimensions — how vendors are being differentiated in 2026
In our vendor mapping we evaluate manufacturers along orthogonal competitive dimensions rather than headline market share alone. Key axes determining design wins and long-term customer capture include:
- Technological moat: proprietary extrusion or injection platforms that enable higher cavitation, tighter tolerances, or hybrid processing modes.
- Systems integration capability: the ability to deliver turnkey solutions that align blow molding with filling and downstream inspection to shorten time-to-volume.
- Service and aftermarket network: predictive maintenance, spare-part logistics, and retrofit packages that materially reduce downtime risk.
- Compliance and materials expertise: engineering depth to validate multi-resin runs, facilitate PCR adoption, and support regulatory documentation.
- Price-to-TCO positioning: commercial models that shift value toward lifecycle savings (energy, material yield, labor) rather than just headline capital cost.
Leading OEMs in the ecosystem exemplify different combinations of these capabilities. Some display deep specialization in high-cavitation solutions for lightweight containers; others compete on integrated line delivery and aseptic or high-speed sterile processing. Notable recent vendor moves — including high-cavitation system introductions and high-speed aseptic line installations — confirm that performance-per-footprint and sustainability compatibility are decisive procurement criteria in 2026.
Technology pathways and design-win levers
Purchasers in 2026 evaluate new equipment across a short list of practical technical risks. Machines that win design contracts do so by addressing at least two of these levers:
- Material efficiency: demonstrable reductions in wall variance and scrap rates when running PCR blends or variable-viscosity resins.
- Cycle flexibility: modular platforms that can scale cavitation or switch between extrusion and injection approaches with minimal downtime.
- Energy and thermal management: energy recovery, smarter heater zoning, and process controls that reduce overall energy per bottle.
- Traceability and validation: embedded data capture for regulatory audit trails and rapid qualification of new bottle designs.
Vendors that align these levers with their service economics and spare-parts network are winning larger programs from beverage and packaging customers. PW Consulting tracks a set of product introductions and line commissions in 2025–2026 that underscore these themes and that feed into our competitive scoring methodology.
Report toolkit — what the PW Consulting report delivers to practitioners
This market study is built as an operational playbook for procurement, plant engineering, and corporate strategy teams. Core deliverables include:
- Supply-chain topology and risk heatmaps that trace critical components, single-source exposures, and logistics chokepoints.
- Bill-of-Materials decomposition logic and BOM-level sensitivity matrices (not raw BOM lists)—enabling realistic scenario modeling for cost down and localization trade-offs.
- Yield-adjustment and scrap-reduction models that link machine parameters to factory KPIs, allowing finance teams to quantify TCO impacts without proprietary machine trials.
- Technology roadmaps and upgrade pathways showing migration steps from legacy platforms to hybrid/aseptic-capable setups.
- Commercial negotiation playbooks and warranty/service models tailored to different buyer archetypes (contract fillers, FMCG multinationals, regional bottlers).
Each tool is designed to be actionable in 2026: for example, the supply-chain topology highlights where nearshoring or dual-sourcing materially shortens lead times; the BOM decomposition allows procurement to prioritize parts for qualification ahead of capital delivery, reducing project slippage risk.
Methodology — how PW Consulting builds high-confidence intelligence
Our conclusions are derived through a layered triangulation methodology combining patent-citation analysis, machine-level benchmarking, vendor financials, customs and trade flows, and over 120 confidential interviews with OEM executives, Tier-1 suppliers, and plant engineers. We augment public records with on-site machine audits and controlled BOM teardowns under non-disclosure agreements to reveal failure modes and real-world yield impacts.
We then apply a multi-dimensional calibration process—cross-checking supplier claims with end-user performance data and independent energy and material-use measurements. This mixed-methods approach allows us to reconstruct non-public performance distributions and infer the practical value of different technology choices without releasing raw proprietary data in the public summary.
Practical playbook for 2026 decision-makers
Executives should treat the report as a diagnostic and execution platform. Immediate actions we recommend for 2026 are:
- Run a TCO triage on candidate lines that includes material-sensitivity stress tests and regulatory risk overlays.
- Prioritize pilot deployments that validate PCR and mixed-resin runs before broad-line rollouts.
- Negotiate service SLAs tied to yield and energy KPIs, not only uptime.
- Use the supply-chain heatmap to evaluate dual-sourcing and inventory decoupling for long-lead items.
These steps compress deployment risk and create options value as regulatory and material-price uncertainty plays out through 2026–2028.
Competitive watchlist and recent developments
We monitor a set of incumbent and specialist OEMs whose product and commercial moves are shaping procurement dynamics. Each firm brings distinct strengths—ranging from high-cavitation extrusion platforms to integrated aseptic line delivery and PET stretch-blow specialization. Recent market activity that reinforces our thesis includes high-cavitation system launches and the commissioning of aseptic PET bottling lines at commercial scale. Such events highlight where vendors are placing R&D and go-to-market emphasis in 2025–2026.
PW Consulting’s competitive analysis focuses on the factors that generate durable wins (technical differentiation, aftermarket reach, and compliance depth) rather than projecting confidential 2026 roadmaps. For a comparative matrix of vendor capabilities and our assessment criteria, please consult the full report.
Access the full operational intelligence
For procurement leaders and strategic investors who need the granular maps, regional demand distribution charts, BOM sensitivity dashboards, and vendor capability matrices that support 2026 capital decisions, access the comprehensive report and supporting datasets here: Access the full Hollow Blow Molding Machine Market report .
Closing perspective
2026 is shaping up to be a year where equipment choice has outsized implications for compliance, margin protection, and competitive positioning. PW Consulting’s work converts market-level forecasts and vendor behavior into executable playbooks—without exposing our clients’ confidential inputs in public briefings. The headline market growth is modest but meaningful; the strategic opportunities are concentrated around machines and services that materially lower material risk and speed regulatory alignment. Executives who treat this year as an active decision point—not a passive observation—will capture the largest share of value as the industry transitions.
For detailed analysis of this topic, please visit the official page: Hollow Blow Molding Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Service Robot Market to Surge to USD 344.8 Million by 2032
By PW Consulting, 2026-06-28
Service Robot Market 2026 Outlook: Strategic Playbook for Capitalizing on a 6.98% CAGR
PW Consulting publishes a focused strategic briefing from our new Service Robot Market research, designed for C-suite decision makers, corporate strategy teams, and private investors who must allocate capital in 2026 with confidence. Our analysis synthesizes global supply chains, technology trajectories, and regulatory inflection points into an operational playbook—demonstrating how to convert the sector’s steady 6.98% compound annual growth into defensible revenue and margin outcomes.
Service Robot Market
Market snapshot (2020–2032)
Service robotics is moving from experimentation to structured industrialization. Our base year is 2025 (215.0 Million USD), following a five‑year historical series that begins in 2020 and a forward forecast window covering 2026–2032. The market is projected to expand consistently, reaching an estimated 344.8 Million USD by 2032 under a 6.98% CAGR. These headline metrics capture both recurring adoption in logistics and cleaning and accelerating deployment in healthcare and inspection workflows.
Why this matters in 2026
2026 is a turning point. The sector is simultaneously facing:
- Stronger regulatory requirements for AI and safety (notably the EU AI Act becoming fully applicable for high‑risk systems by August 2026), which raise compliance costs and create certification barriers for late movers.
- Persistent semiconductor constraints that make procurement lead times and bill‑of‑materials (BOM) optimisation a top financial lever for OEMs and integrators.
- Labor scarcity and rising wages in key markets, pushing enterprises to accelerate automation investments to secure predictable OPEX improvements.
These conditions increase the value of timely, operationally relevant insight: suppliers that can demonstrate validated reliability, compliant AI stacks, and predictable total cost of ownership will capture outsized share as procurement committees shift from pilots to scaled contracts.
Strategic themes that will drive winner‑take‑more outcomes
Our report identifies a compact set of strategic imperatives that are decisive in 2026 procurement and M&A decisions. Executives should prioritize actions that reinforce at least one of the following dimensions:
- Supply‑chain control: firms that can map, secure, and shorten critical component paths reduce working capital and mitigate lead‑time risk.
- Design wins and integration depth: modular platforms with configurable software stacks and validated integrations with enterprise systems increase switching costs.
- Regulatory and data governance moat: compliance documentation, validated datasets, and explainable AI become commercial differentiators in regulated deployments (e.g., healthcare, public safety).
- Field proven yield and service economics: demonstrated uptime, repairability and spare‑parts logistics convert pilots into rollouts.
Companies that align product, procurement, and go‑to‑market to these themes are the most likely to translate market growth into sustainable profitability.
How PW Consulting’s tools answer 2026 pain points
We designed the deliverables to be prescriptive without disclosing sensitive model outputs. Key components address the precise operational gaps executives face this year:
- Supply‑chain topology maps that trace single‑point‑of‑failure suppliers for critical ICs and subassemblies, enabling targeted supplier consolidation and dual‑sourcing strategies.
- BOM teardown logic that translates component scarcity into actionable substitution options and cost‑sensitivity scenarios—supporting procurement negotiations when lead times spike.
- Yield adjustment and service‑economics models that convert lab reliability into field warranty risk, informing pricing, service contracts, and capex payback timelines.
- Technology roadmaps and integration matrices that show where to invest R&D for near‑term design wins—without publishing proprietary performance parameters.
These instruments are built to be operational: procurement teams can use BOM guidance to renegotiate contracts; engineering leads can apply yield models to production planning; and corporate development can use integration matrices to prioritize targets.
Competitive landscape: dimensions of advantage (not predictions)
The competitive field is diverse—ranging from humanoid and healthcare specialists to inspection and logistics incumbents. Rather than offering prescriptive 2026 forecasts for each firm, we analyze the competitive dimensions that determine outcomes and where each listed player plays to its strengths:
- Moat type — intellectual property in manipulation and mobility, integrated hardware‑software stacks, and service ecosystems (installation, training, spare parts).
- Design‑win determinants — demonstrated reliability in target environments, ease of systems integration, and validated ROI cases for procurement stakeholders.
- Scale vs. specialization tradeoffs — broad‑market incumbents secure large enterprise deals through channel and systems reach; niche specialists win premium margins in regulated verticals through certification and clinical validation.
- Partnership leverage — alliances with logistics integrators, hospital systems, and facilities managers accelerate deployment velocity and create secondary revenue from services.
To illustrate how these dimensions play out in practice, consider the recent industry moves in 2025–2026: new commercial cleaning products, humanoid demonstrations in factory settings, and record professional unit sales in logistics. These developments validate that design wins are increasingly decided by field performance and compliance readiness, not marketing alone. For a deeper company‑level matrix and our proprietary scoring on these competitive dimensions, Read the full report.
Practical use cases for corporate leaders in 2026
Executives can apply our findings across typical strategic workflows:
- Capital allocation: prioritize investments that reduce BOM risk and accelerate design wins in regulated verticals; apply scenario tests from our yield models to capex requests.
- Procurement and sourcing: implement supplier risk heatmaps and alternative‑component playbooks to stabilize manufacturing throughput despite semiconductor tightness.
- Product strategy: align feature roadmaps to integration matrices that procurement panels value most—interoperability, explainability, and maintainability.
- M&A and partnerships: use our competitive dimensions to filter targets that improve either supply‑chain resilience or field service economics rather than those offering only incremental product features.
Methodology: how we triangulate hard‑to‑get signals
PW Consulting’s approach is layered triangulation rooted in primary and secondary evidence. Our methodology combines:
- Patent landscape and citation analysis to detect nascent technical leadership and identify where R&D investment is concentrated.
- Structured, confidential interviews across OEMs, tier‑1 suppliers, component manufacturers, and systems integrators to capture procurement criteria and supplier timelines.
- Physical BOM teardowns and reverse‑engineering sampling from commercially deployed units to validate component choices and assembly practices.
- Multi‑source data fusion including customs flows, partner channel disclosures, and field service logs to estimate installed base and reliability curves.
We emphasize reproducibility: each high‑impact insight in the report is flagged with the dominant evidence vector (e.g., patent + teardown, or interview + customs) so decision makers understand confidence levels. Importantly, this layered approach allows us to surface commercially sensitive signals—like supplier concentration and subcomponent risk—while preserving client confidentiality and avoiding public disclosure of proprietary data.
Regulatory and ESG considerations
Regulatory compliance and ESG are now commercial levers, not just cost centers. With the EU AI Act becoming enforceable for high‑risk systems by August 2026, buyers and vendors must bake compliance into certification, traceability, and data governance practices. ESG considerations—especially lifecycle impacts of battery and sensor disposal—are increasingly factored into procurement scoring and public tender evaluations.
Our report includes a compliance playbook and an ESG checklist tailored to 2026 procurement processes to help legal, procurement, and sustainability teams converge on contract terms that de‑risk deployments and protect brand reputation.
Next steps: how to apply this insight
Executives who need to act now can use PW Consulting’s report as a near‑term decision tool to:
- Rapidly stress‑test capex proposals with BOM and yield scenarios.
- Prioritize R&D investments that unlock design wins validated by procurement criteria.
- Design M&A screens that favor targets improving supply continuity or service economics.
To obtain the full dataset, interactive supply‑chain maps, and company scoring matrices that underpin this briefing, download the complete Service Robot Market report here: https://pmarketresearch.com/auto/ai-service-robots-market .
About PW Consulting
PW Consulting is a strategy and industry intelligence firm serving global technology and industrial clients. Our Service Robot Market offering combines deep technical expertise, supply‑chain forensics, and commercial diligence to help executives make executable decisions in 2026.
For detailed analysis of this topic, please visit the official page: Service Robot Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: POS Terminals Market Set to Expand at 7.9% CAGR from 2026–2032, Report Finds
By PW Consulting, 2026-06-28
POS Terminals Market — 2026 Strategic Outlook for Capital Allocation
The global POS terminals market is at an inflection point in 2026. After expanding from USD 76.1 Billion in 2020 to USD 123.2 Billion in 2025, the market continues to grow, with PW Consulting modeling a 7.9% compound annual growth rate (CAGR) across the 2026–2032 forecast window and an expected market size of USD 207.6 Billion by 2032. These headline figures underscore both the structural resilience of merchant payments hardware and the accelerating shift toward software-enabled, services-driven terminal economics.
POS Terminals Market
Executive summary
Institutional investors, C-suite leaders of merchant acquirers, and hardware OEMs are making critical allocation decisions in 2026. This briefing highlights the strategic signals our full report delivers without disclosing our proprietary segmentation tables. PW Consulting’s analysis is expressly designed as an action-oriented intelligence product: it shows where value pools are migrating, which operational levers matter most in 2026, and why near-term investments will disproportionately determine multi-year returns.
-
Market momentum: Macro demand and terminal refresh cycles are driving continued top-line expansion; the market size is projected to reach USD 132.8 Billion in 2026, supporting a multi-year expansion path.
-
Concentration profile: The market remains moderately concentrated (CR3: 58.0%; CR5: 62.0%), which preserves pricing power for incumbents while creating niche opportunities for targeted entrants.
-
Capital timing: Regulatory change, certification cycles, and component supply dynamics combine to create a narrow window in 2026 to secure design wins and favorable procurement terms.
Market dynamics shaping 2026 decisions
Three convergent dynamics are determining the most material risks and opportunities for 2026 allocations: regulatory uplift, technology transition, and supply-chain stress. Each has distinct implications for CapEx and M&A planning.
-
Regulatory and certification pressure — PCI PTS v6.0 and regional authentication mandates continue to raise the bar for terminal design and lifecycle management. For buyers, certification timelines translate directly into product roadmaps and revenue recognition schedules.
-
Technology migration — The industry is accelerating Android- and cloud-native terminal deployments while preserving certified hardware stacks for high-security segments. This bifurcation increases the value of flexible software architectures and field upgradability.
-
Supply-chain volatility — Semiconductor supply constraints and lead-time variability persist through 2026, creating a premium on validated multi-sourcing strategies, BOM-level visibility, and inventory optimization protocols.
-
Payments behavior — Rapid adoption of contactless and mobile-present payments is shifting terminal feature sets toward NFC, biometric readiness, and low-touch maintenance models; these shifts affect both unit economics and recurring service revenue potential.
Strategic imperatives for 2026
Clients tell us that three strategic moves separate winners from also-rans when deciding how to deploy capital in 2026. Each is actionable and substantiated in the full PW report by supplier maps, BOM logic and yield models.
-
Move from BOM visibility to BOM control — Executives must operationalize component-level sourcing playbooks. We show how BOM decomposition supports cost-out scenarios, tariff sensitivity analysis, and substitution pathways that preserve certification compliance.
-
Convert certification into a commercial moat — Certification lead times are an entry barrier. Senior leaders should treat certification roadmaps as assets to be monetized through software subscriptions, managed services, and co-branded programs.
-
Design wins as a platform strategy — A single enterprise-grade design win can justify multi-year R&D investment. Winning depends less on raw hardware specs and more on ecosystem integrations (acquirers, processors, ISVs), field service economics, and validator endorsements.
-
Defensive supply chain play — Hedging component risk via validated secondary suppliers and early long-lead procurement materially reduces time-to-revenue volatility and preserves margin capture on refresh cycles.
Operational toolset included in the report
The PW report is not descriptive research; it is a practitioner’s toolkit for 2026 execution. Below are the operational modules that clients repeatedly cite as the most directly ROI-positive.
-
Supply-chain topology map — A layered supplier map identifying single-source nodes, cross-border concentration, and logistics choke points to prioritize de-risking investments.
-
BOM decomposition and substitution logic — A standardized BOM template and rules engine for assessing component replacement scenarios that preserve certification and reduce total delivered cost.
-
Yield adjustment and cost sensitivity models — Factory yield curves, rework cost schedules, and scenario drivers to integrate into CAPEX planning and vendor scorecards.
-
Technology roadmap and certification calendar — A timeline aligning OS/platform migrations, certification milestones, and commercial launch windows to inform timing of procurement and sales campaigns.
-
Partner evaluation framework — A decision matrix for selecting OEM partners and ISV integrations based on integration time, support footprint, and potential for recurring services revenue.
How the report resolves 2026 pain points
Executives are facing three pressing 2026 pain points: rising unit costs, certification complexity, and uncertain time-to-market. The report’s modules address these through practical mechanisms rather than prescriptive numbers:
-
Cost control is addressed by tracing cost drivers to the BOM line item and using substitution levers while quantifying certification requalification risk.
-
Compliance complexity is mitigated through a mapped certification calendar and an approvals playbook that shortens audit cycles.
-
Time-to-market risk is reduced by combining validated secondary sourcing with an OS migration checklist that preserves backward compatibility for legacy deployments.
Competitive landscape — dimensions that matter
Our competitive analysis focuses on competing dimensions rather than binary forecasts. The market is contested along a small number of durable vectors where incumbents and challengers can build defensible positions:
-
Security and certification moat — Firms that embed certified security modules and sustain a predictable re-certification cadence win enterprise trust and premium pricing.
-
Scale manufacturing and distribution — Mass-market players leverage scale to compress lead times and underwrite aggressive customer financing programs.
-
Software and services ecosystems — Companies that transform a hardware sale into a recurring revenue relationship (POS software, analytics, payments orchestration) materially increase lifetime value.
-
Design win mechanics — The decisive factors for design wins are integration ease, local compliance readiness, field repair economics, and proof points from reference deployments rather than raw performance specifications.
Notable vendors in the landscape include global hardware specialists, integrated systems suppliers, and software-first entrants. Recent product launches and certifications demonstrate how players are executing along the dimensions above — these signals are cataloged in the full PW dataset and used to parameterize our scenario models.
For readers ready to assess competitive trajectories in detail, access the full company matrices and the design-win scoring framework here: Access the full POS Terminals Market report .
Regulatory and macro signals—implications for 2026
Regulation and macro behavior are active drivers in 2026. The enforcement of updated PCI PTS v6.0 requirements and continued PSD2-style strong customer authentication regimes make certification timelines a strategic variable. Simultaneously, contactless payment penetration and government subsidy programs for small merchants alter adoption curves. These forces mean compliance and go-to-market planning must be synchronized with procurement and R&D roadmaps.
-
PCI PTS v6.0 increases design and testing cycles; firms without certification pipelines face time-to-market delays.
-
Semiconductor tightness elevates the value of multi-sourcing and secondary vendor qualification.
-
Contactless adoption accelerates terminal feature prioritization and aftermarket service models.
Methodology and evidence base
PW Consulting’s findings rest on a layered triangulation methodology designed to surface actionable, non-public signals while respecting commercial confidentiality. Our approach blends patent and certification citation analysis, customs-based shipment tracking, factory-level yield sampling, and more than 120 structured interviews with OEMs, processors, acquirers and high-volume merchants across major markets.
Key elements of our rigor include:
-
Patent and certification mapping — We trace technology adoption using patent citation clusters and certificate issuance timelines to infer feature diffusion and vendor readiness.
-
Supply-side triangulation — Proprietary supplier interviews (conducted under NDA), component shipment data, and factory audits allow us to estimate lead-time distributions and yield profiles without exposing sensitive customer or vendor contracts.
-
Buyer-side validation — We calibrate vendor scorecards and design-win parameters through merchant procurement interviews and field-deployment audits.
What to do next — a 90-day agenda for 2026
For boards and investment committees, the immediate next moves in 2026 are tactical and time-sensitive. We recommend a 90-day agenda that aligns with our operational tools:
-
Execute a BOM stress-test against your next two product cycles and validate secondary suppliers for critical components.
-
Map certification milestones to commercial launch calendars and allocate funding to shorten audit cycles where ROI-positive.
-
Prioritize design-win targets by ecosystem fit rather than market share alone; secure at least one anchor partner with a multi-year refresh agreement.
PW Consulting’s full POS Terminals Market report provides the executable templates, supplier lists, and scenario models to operationalize the 90-day agenda. For access to the complete dataset, company matrices, and the supply-chain map, please follow this link: Access the full POS Terminals Market report .
In 2026, the difference between a defensive and offensive capital allocation will be determined by who integrates certification, supply-chain control, and software monetization into a single operating rhythm. PW Consulting’s report is built to make that integration repeatable and measurable.
For detailed analysis of this topic, please visit the official page: POS Terminals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Automotive Exhaust System Market to Grow at 5.0% CAGR Through 2032
By PW Consulting, 2026-06-28
Automotive Exhaust System Market — Strategic Outlook for 2026
PW Consulting’s latest market study on the Automotive Exhaust System market sets the strategic agenda for 2026. The market is on a steady recovery path following the 2020–2025 normalization period, with PW’s base-year assessment (2025) placing the global market at 210.0 Million USD and our layered forecasts showing a 5.0% CAGR through 2032, reaching 295.5 Million USD by the end of the projection window. This press release highlights the report’s strategic value for executives preparing 2026 capital allocation, product roadmaps, and M&A playbooks — while intentionally reserving the report’s detailed splits and company-level forecasts for subscribers.
Automotive Exhaust System Market
Why 2026 is an inflection year
Several converging forces make 2026 a decisive year for suppliers, OEMs and investors in exhaust systems:
- Regulatory polarization: Recent heavy-duty aftertreatment mandates in the EU (EU6d) increase demand for advanced SCR and particulate control modules, while some U.S. rule changes in early 2026 alter the compliance calculus for light- and heavy-duty fleets. The result is a bifurcated market where localized compliance programmes drive product complexity.
- Raw-material volatility: Stainless steel and precious-metal pricing remain a material cost vector for converters and manifolds, with metals accounting for a disproportionate share of catalytic converter BOM cost and intermittent price spikes feeding margin pressure.
- Powertrain mix transition: Hybridization and performance-oriented electrified vehicles create new requirements for lightweight exhaust assemblies and modular aftertreatment; concurrently, nascent hydrogen and fuel-cell pathways demand alternative materials and sealing technologies.
- Aftermarket versus OE tension: Strong aftermarket channels persist as a cash-flow and margin stabilizer for many suppliers, even as OEM Design Wins increasingly hinge on integrated, software-aware emissions solutions.
What PW Consulting’s report delivers — practical tools, not platitudes
Our research is built as a practitioner’s toolkit for 2026 decisions. The report is explicitly operational and includes:
- Supply-chain topology maps that identify critical nodes, single-source risks, and substitution pathways across raw-materials, catalyst substrates and fabrication capacity.
- BOM teardown templates and cost-mapping logic that translate component-level choices into supplier negotiation levers without exposing proprietary line-item prices in this release.
- Yield-adjustment and throughput models that quantify the P&L impact of corrosion, weld-rework and catalyst pass-yield on a program’s lifecycle margin.
- Technology roadmaps and maturity matrices that track SCR, DPF, sensor integration and hydrogen-ready architectures — with scenario branches for regulatory tightening or relaxation.
- Design-win scoring and bid-playbook frameworks that convert technical differentiation into procurement success factors for Tier-1s and system integrators.
Each of these modules is packaged with executable checklists and governance templates so procurement, engineering and strategy teams can convert insight into prioritized action in Q1–Q2 2026.
Market trajectory and structural view
PW’s trajectory recognises a steady compound expansion: the market expands from the 2025 baseline of 210.0 Million USD to roughly 295.5 Million USD by 2032 at a 5.0% CAGR. That growth is uneven — pockets of rapid acceleration are tied to regional regulation, heavy-duty aftertreatment retrofits, and fleet renewal cycles, while legacy passenger-car exhaust volumes face headwinds from electrification trends.
Structurally, the sector remains moderately fragmented: three-firm concentration is low, leaving room for regional champions and niche specialists to capture differentiated margins. This fragmentation also underpins strategic consolidation opportunities for buyers seeking vertical integration or scale in catalyst procurement and manufacturing footprint.
Competitive dimensions that determine outcomes (not company predictions)
Our competitive analysis focuses on the dimensions that reliably determine Design Wins and margin sustainability, rather than forecasting specific 2026 moves. Those dimensions include:
- Vertical integration versus modular supply: Firms that control catalyst sourcing and core fabrication can compress lead times and capture more BOM margin, while modular suppliers win on flexibility and faster global coverage.
- Aftermarket strength and brand reach: Companies with deep aftermarket channels use reverse-logistics and data from service networks to sharpen product fit and lifecycle pricing.
- Technology breadth: Leadership in SCR, DPF, lightweight alloys, and sensor-embedded aftertreatment differentiates suppliers when compliance demands increase.
- Program execution capability: Design-for-manufacture, rigorous NVH tuning, and consistent first-pass yields are decisive in obtaining and holding long-term OEM programs.
- Geographic supply footprint: Local manufacturing and logistics matter for mix shifts driven by local trade policy and regulatory enforcement.
Applying these lenses to industry incumbents clarifies where each firm derives its defensive or offensive advantage. For example, suppliers with strong OE relationships and integrated aftertreatment portfolios create defensible corridors for design wins, while aftermarket specialists leverage scale and service data to protect margins. Recent moves in the field — such as FORVIA’s investment in North American clean mobility production and Tenneco’s expansion of CARB-compliant catalytic coverage and lightweight systems — illustrate how incumbents are executing along these competitive vectors without undermining the need for fresh strategic responses from challengers.
For a granular competitive matrix and the full set of company profiles, see our catalogue of firm-level strategic dimensions: https://pmarketresearch.com/auto/automotive-exhaustive-system-market .
Supply-side pressures and procurement imperatives
Raw-material inputs and processing constraints are immediate levers and risks in 2026:
- Stainless steels (notably certain 400-series grades) continue to exhibit multi-band pricing volatility, directly affecting fabrication choices and gauge selection.
- Precious metals remain a concentrated cost element within catalytic substrates; swings in those markets materially change converter margins and inventory strategies.
- Capacity pinch points for high-temperature welding, catalyst loading lines and coating processes create batch-level lead-time variability that must be managed through supplier contracts and secondary sourcing.
PW’s BOM and yield models enable procurement teams to stress-test supplier quotes against commodity shocks and production yield scenarios, identifying hedging and inventory strategies that preserve program NPV without impairing compliance readiness.
Technology roadmaps — scenarios that matter in 2026
Our technology workstream frames three plausible transition pathways and the supplier capabilities each rewards:
- Regulatory-led aftertreatment intensification: Accelerated demand for SCR and DPF hardware, sensor fusion and calibration services.
- Hybrid performance and lightweighting: Increased adoption of thinner gauges and advanced joining methods; materials engineering becomes a source of differentiation.
- Alternative-powertrain peripherals: For hydrogen and fuel-cell vehicles, sealing, corrosion resistance and alternative catalyst chemistries become relevant revenue niches.
The report’s scenario tables and time-to-adoption curves let R&D and corporate development teams prioritize roadmaps consistent with their risk appetite and balance-sheet constraints.
Actionable priorities for 2026 decision-makers
Based on our integrated analysis, PW recommends executives prioritize five actions this year:
- Lock design-win pipelines by demonstrating program-level manufacturability and first-pass yield guarantees — not just prototype performance.
- Institute dynamic commodity hedging and strategic buffer inventories for catalysts and stainless inputs to smooth margin volatility.
- Pursue selective M&A to close capability gaps (e.g., catalyst sourcing, sensor integration) rather than broad horizontal roll-ups that dilute execution focus.
- Deploy compliance-as-a-service capabilities — testing, certification, and documentation — as a revenue-adjacent offering to OEM and fleet customers.
- Invest in modular, software-capable aftertreatment platforms that reduce time-to-approval across multiple regulatory regimes.
Methodology — how we build confidence in the unseen details
PW Consulting’s conclusions are derived from a layered-triangulation methodology that combines primary and secondary evidence streams. We synthesise patent-citation mapping, confidential supplier and OEM interviews, on-site supplier audits, controlled BOM teardowns, and customs and aftermarket sales analytics to validate unit-level economics and supply-chain relationships. This approach allows us to reconstruct program economics and cross-check them across independent data vectors.
Where public data are incomplete, our team supplements with anonymized procurement contracts and aggregated service-part telemetry supplied under NDA. These inputs enable probabilistic estimates of yield distributions, BOM sensitivity to commodity swings, and design-win probability matrices — outputs that are included in the full report but selectively summarised here to preserve proprietary granularity.
Next steps — where to get the full intelligence
PW’s Automotive Exhaust System market report is designed to be immediately usable by strategy, procurement and engineering teams preparing 2026 budgets and playbooks. To access the full set of distribution charts, component- and vehicle-segment allocations, and the complete company-level strategic profiles, visit our report page at https://pmarketresearch.com/auto/automotive-exhaustive-system-market . The full report provides the confidential annexes and executable templates required to operationalize the insights described above.
For detailed analysis of this topic, please visit the official page: Automotive Exhaust System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Mica Paper Market Poised for Rapid Expansion with a 9.1% CAGR, New Insight Reveals
By PW Consulting, 2026-06-28
Mica Paper Market Outlook 2026 — Strategic Imperatives for Capital Allocation
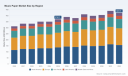
As PW Consulting releases its latest Mica Paper Market Mica Paper Market Mica Paper Market Mica Paper Market Mica Paper Market Mica Paper Market Mica Paper Market Mica Paper Market update for 2026, senior leaders must reconcile a simple fact: the industry is materially larger and more dynamic than conventional vendor briefings suggest. Our base-year benchmarking (2025) places the global mica paper market at USD 670.0 Million, with a projected trajectory to approximately USD 1,180.0 Million by 2032 at a 9.1% CAGR for 2026–2032. This growth profile creates both an investment window and a source of strategic risk for manufacturers, OEMs, and institutional buyers in the coming 18–36 months.
Mica Paper Market
Market Snapshot: Momentum, Not Mystery
The market has experienced steady expansion from 2020 to 2025, reflecting multi-vector demand drivers: electrification of equipment, higher-temperature insulation requirements, and an industrial pivot toward advanced synthetic substrates. These macro signals are not evenly distributed — the market’s center of gravity is shifting — and the winners will be those who translate that directional change into near-term design wins and supply security rather than relying on legacy channel strength.
- Historical scale: the market expanded from a modest base in 2020 to USD 670.0 Million in 2025, reflecting product requalification cycles across multiple industrial end markets.
- Forward momentum: a 9.1% CAGR for 2026–2032 implies accelerating capex and procurement activity through the end of the decade.
- Industry structure: the market exhibits moderate concentration (CR3: 35.2%; CR5: 48.0%), indicating meaningful room for mid-tier players to leverage specialization and for incumbents to consolidate value via downstream integration.
Why 2026 Is a Strategic Inflection Point
For boards and investment committees, 2026 is not “another year.” Three converging forces make it a make-or-break planning horizon:
- Trade and compliance tightening: new regional trade rules and more rigorous material traceability requirements increase the cost of non-compliance and lengthen supplier qualification timelines.
- ESG-driven procurement: end users and financiers are embedding material-level sustainability expectations into contracts, forcing suppliers to demonstrate supply-chain transparency and emissions control at the mica and processed-paper stages.
- Digital manufacturing uplift: AI-enabled process control and yield-management tools are moving from pilot to production, changing the calculus on who can consistently meet tight dielectric and dimensional tolerances at scale.
These trends elevate the value of actionable, operational intelligence over high-level market anecdotes — which is precisely where our Mica Paper Market report delivers immediate ROI for decision-makers.
What the Mica Paper Market Report Provides — Practical Tools, Not Plate Scraps
Our research package is designed as a strategic playbook for 2026 capital allocation and procurement cycles. We deliberately focus on operational instruments that translate into measurable margin and risk reduction while withholding segmented line-item tables in this summary to preserve the “trailer” nature of this release.
- Supply-chain map and tiered BOM decomposition — a visualized supplier topology down to sub-tier mineral feedstocks and critical processing nodes, enabling targeted supplier diversification and concentration risk scoring.
- Bill-of-Materials (BOM) logic and yield-adjustment models — pragmatic templates that show how small shifts in raw-material purity, calendering yield, or lamination throughput cascade to EBITDA under different demand scenarios.
- Technology roadmap and requalification playbook — side-by-side paths for muscovite, phlogopite, and synthetic mica paper adoption that outline requalification timelines, expected test protocols, and likely cost inflection points for 2026 buyers.
- Regulatory & compliance matrix — an actionable checklist to align supplier audits, test-cert chains, and traceability controls with near-term trade and ESG requirements.
Collectively, these modules are purpose-built to answer two executive questions: “How do I reduce cost volatility without jeopardizing reliability?” and “How do I certify compliance for complex, multi-source mica supply chains in time for 2026 product launches?” The report shows the methods and levers; it does not substitute for company-specific parameterization, which we help clients perform via bespoke engagements.
Competitive Landscape — Dimensions of Advantage, Not Scorecards
The market’s competitive topology is best understood through strategic dimensions rather than static rankings. Across the value chain — from raw mica miners to laminated-paper converters and distributor channels — firms compete on a mix of the following defensible attributes:
- Raw-material access and vertical integration: secure upstream feedstock can compress cost and expedite qualification, particularly in markets sensitive to supply disruption.
- Process IP and quality gates: thickness control, dielectric uniformity, and thermal-stability process recipes act as effective technical moats once embedded in OEM qualification lists.
- Customer intimacy and design wins: pre-certification at the component engineering stage accelerates adoption; design-win velocity is often more valuable than short-term price concessions.
- Distribution reach and niche channel strength: some legacy distributors and specialty paper manufacturers retain strong institutional relationships that can be repurposed for mica-based substrates.
For example, a set of small-to-mid-sized suppliers — well-known in adjacent specialty paper markets and select distribution channels — leverages deep customer service, customization capacity, and localized inventory models to capture design wins in educational and instrument-level applications. These players differ materially from converter-integrators who compete primarily on scale, capital intensity, and validated high-voltage performance.
PW Consulting’s field work has observed that design wins in 2026 increasingly favor players who can simultaneously demonstrate technical reproducibility, traceable supply, and low requalification friction. This triad is the dominant axis for near-term market share shifts.
On Adjacent Channels and Retail/Distribution Influence
Certain retailers and specialty-paper distributors retain disproportionate influence in institutional buying cycles and educational channels. While these actors are not typically primary suppliers for high-voltage industrial mica paper, their distribution intelligence and SKU-level customer data are valuable signals for forecasting demand and seasonal inventory needs. PW Consulting integrates such third-party channel intelligence into our demand overlays to refine procurement lead-time assumptions.
To review our full competitive matrices and the company-level strategic dimension maps, access the full report: access the full Mica Paper Market report .
Technology Pathways and Supply Resilience — Tactical Priorities for 2026
Technical and procurement leaders must prioritize three tactical domains this year to convert market growth into resilient margin:
- Qualification velocity: shortening supplier qualification cycles by pre-validating suppliers against modular test suites reduces time-to-market for product launches.
- Yield uplift via AI: adopting proven AI process-control modules for lamination and calendaring can deliver asymmetric upside on yield and scrap reduction within a single six-to-nine-month initiative.
- Sustainable sourcing proofs: establishing verifiable emissions and chain-of-custody proofs for mica feedstocks is no longer optional for capital-backed OEMs and system integrators.
Implementing these priorities requires disciplined experiments and pilot budgets in 1H–2H 2026. The cost of delayed action is not merely lost revenue but increased exposure to supplier rationalization and rising compliance costs.
Methodology — How PW Consulting Sees What Others Miss
Our Mica Paper Market analysis is built on layered triangulation and traceable, replicable evidence collection. Methodological pillars include:
- Patent and standards-citation analysis — mapping process- and material-related patents to active production footprints to detect near-term capacity and capability shifts.
- Layered triangulation — integrating customs trade flows, confidential supplier interviews, third-party lab test logs, and on-site OEM qualification schedules to reconcile demand and supply at a granular level.
- BOM and yield reverse engineering — reconstructing representative Bills of Materials from disassembled samples and production-acceptance criteria to populate our yield-adjustment models.
We obtain non-public inputs through structured NDAs, targeted supplier workshops, and cooperation with independent test labs. These sources enable us to produce forward-looking operational tools rather than static forecasts — a key differentiator when clients must make supply decisions with 12–24 month consequences.
Implications and Recommended Next Steps for Executives
For CFOs, procurement heads, and CTOs, the tactical implication of our 2026 assessment is straightforward: prioritize supplier qualification velocity and invest in targeted yield-improvement pilots now. Specific starting actions include:
- Initiate a 90–120 day supplier assurance sprint to map tier-1 and tier-2 risks, focusing on traceability and requalification windows.
- Allocate a pilot budget for AI-enabled yield-control modules at a single converter site to validate scrap-reduction assumptions before scaling.
- Mature procurement clauses to include verifiable sustainability and traceability deliverables tied to milestone-based payments.
These moves protect near-term deliveries while positioning organizations to capture the upside of a market that PW Consulting expects to be materially larger and more consolidated by 2032.
Access the Full Intelligence
This executive brief is a strategic preview that demonstrates the depth of PW Consulting’s operational insight while preserving the granular segmentation, supplier-level matrices, and scenario parameterizations for the full report. To review the complete dataset, interactive supply-chain maps, and the requalification playbook, visit: access the full Mica Paper Market report .
For detailed analysis of this topic, please visit the official page: Mica Paper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Asia Pacific Leads 2025 Excavator Market at USD 43.4 billion, Driving Global Momentum
By PW Consulting, 2026-06-28
Excavator Market 2026: Strategic Briefing — Why Capital Allocation Decisions This Year Will Define Competitive Leadership
PW Consulting’s latest Excavator Market report (base year 2025) delivers an actionable, decision-grade view of a market that is both mature and rapidly reconfiguring. The global excavator market registers USD 60.4 Billion in 2025 and accelerates to an estimated USD 64.1 Billion in 2026 under a 5.5% compound annual growth rate (CAGR) across the 2026–2032 forecast window. This briefing summarizes the report’s strategic value for executive teams making 2026 capital-allocation, product and supply-chain choices — while intentionally preserving the report’s proprietary segment-level detail to drive further engagement.
Excavator Market
Market Snapshot — Momentum, Concentration, and What It Means for Investors
The market’s multi-year expansion (from roughly USD 46.5 Billion in 2020 to USD 60.4 Billion in 2025) is neither uniform nor incidental. Two structural forces are driving the near-term dynamics:
- End-market pull from infrastructure and reconstruction activity that sustains demand for mid- and heavy-class units.
- Technology and regulation-led replacement cycles (emissions compliance, electrification pilots, and telematics-driven maintenance) that change product lifecycles and margin profiles.
Market concentration remains material: the top-three OEMs capture 56.5% of market value and the top-five capture 70.2%. That level of concentration shapes supplier bargaining power, channel strategies, and the economics of aftersales. For investors and OEM leadership teams, the implication is clear — scale matters, but so do differentiated go-to-market moats that extend beyond pure production capacity.
Strategic Imperatives for 2026
Executives must treat 2026 as an inflection year. Four imperatives are decisive:
- Protect margins against material-cost shocks: escalated steel costs and tariff shifts have materially increased input-price risk for steel-intensive platforms.
- Secure design wins that lock-in lifecycle revenue: beyond headline OEM brand strength, the new battleground is system-level integration (electrified drivetrains, telematics, attachments).
- Accelerate compliance and product roadmap decisions: emissions standards and NRMM rules in key markets are constraining engine choices and creating windows for electrified and hybrid architectures.
- Reshape dealer and rental channel economics: rental fleets and independent dealers are becoming strategic partners for OEMs that want rapid product validation and recurring revenue capture.
Operational Toolkits — What the Report Contains and Why It Matters to 2026 Execution
The report is explicit about the operational instruments that translate strategy into measurable outcomes. Highlights include:
- Supply-chain topology maps that overlay supplier criticality, single-source risks and lead-time variability — enabling procurement teams to model alternate sourcing and buffer strategies.
- BOM (bill-of-materials) tear-down logic and cost-position diagnostic frameworks that reveal the sensitivity of unit economics to steel, electronics and powertrain choices.
- Yield-adjustment and manufacturing throughput models that quantify how incremental OEE (overall equipment effectiveness) improvements affect breakeven and pricing flexibility.
- Technology roadmaps that sequence powertrain electrification, hybridization, and telematics integration according to regulatory timing and TCO parity scenarios.
These tools are configured to address 2026 pain points — most notably cost containment amid raw-material volatility, compliance-driven re-engineering, and the need to accelerate service-attach monetization. The report shows how to use the tools to stress-test capex plans and supplier commitments without disclosing the proprietary node-level metrics reserved for the full analysis.
Competitive Dimensions — How OEMs Will Compete (Not a Share Forecast)
PW Consulting’s company-focused workstreams do not republish public press releases; they evaluate competitive advantage along structured dimensions. Our analysis highlights five durable vectors of competition across the OEM landscape:
- Integrated system engineering: OEMs that integrate powertrain, hydraulics and controls reduce total-cost-of-ownership for fleet customers and win specification-level decisions.
- Aftermarket and telematics ecosystems: firms with deep dealer networks and data-analytics platforms convert equipment uptime into recurring revenue and higher lifetime value.
- Manufacturing footprint and supplier control: proximity to key markets and degree of vertical integration determine exposure to tariffs and material shocks.
- Design-win economics: the ability to lock in fleets depends on demonstrable TCO, retrofit paths and local service capacity.
- Brand and finance muscle: access to captive finance and rental partnerships accelerates large-scale fleet conversions.
Recent product introductions at CONEXPO-CON/AGG 2026 — from next-generation medium and large excavators to refreshed electric mini lines — confirm that OEMs are pursuing these vectors. PW Consulting’s report explains how each vector maps to capital allocation choices, supply-chain restructuring and sales incentives; full firm-level diagnostic matrices and scenario outcomes are available in the report.
For a concise, authoritative assessment of competitive positioning and to see our firm-level diagnostic matrices, click here: Access the full Excavator Market report .
Regulatory & Raw-Material Headwinds — Practical Consequences for 2026 Decisions
Two external dynamics are materially reshaping vendor strategies:
- Raw-material pressure: U.S. hot-rolled coil and expanded tariffs in 2025–2026 are elevating steel-dependent manufacturing costs, compressing margins for standard platforms and accelerating the search for lighter, higher-value materials and modular chassis designs.
- Emissions and compliance: EU Stage V and continued NRMM tightening are increasing the engineering burden for internal combustion options while creating staged opportunities for electric and hybrid deployments.
These drivers produce tactical consequences: procurement teams must model tariff scenarios and multi-sourcing; R&D leaders need staged powertrain roadmaps; and CFOs should re-evaluate equipment-retirement curves. The report’s scenario engines allow users to run these permutations and see P&L and cash-flow outcomes under alternate policy assumptions.
Methodology — How PW Consulting Produces Decision-Grade Intelligence
Our methodology is designed to surface hard-to-find, transaction-level signals and to triangulate them into robust forecasts. Key elements include layered triangulation across public and proprietary sources:
- Patent and regulatory filing analysis to detect nascent technology commitments and emissions compliance timelines.
- Proprietary supply-chain mapping built from verified BOM tear-downs, anonymized supplier interviews under NDA, and customs shipment flows.
- Dealer and fleet telemetry panels that provide utilization, retrofit incidence and uptime statistics; these are cross-checked against OEM service networks and orderbooks.
We emphasize process over black-box outputs: the report documents the calibration steps, the sensitivity bounds used for commodity price shocks, and the governance around anonymized data sources. This transparency ensures clients can replicate scenarios within their corporate planning cycles and trust the directional validity of the insights even when we withhold certain granular segment datapoints to preserve proprietary value.
How to Use This Report in 2026 Planning Cycles
Senior leaders should treat the report as a tactical playbook and a strategic radar. Immediate uses include:
- Capex reprioritization: use the BOM and yield models to re-score manufacturing investments and to re-time EV/hybrid pilots against TCO parity scenarios.
- Procurement playbooks: deploy the supply-chain maps to identify near-term single-source risks and to structure hedges or dual-sourcing agreements.
- Commercial design wins: reconfigure sales incentives and specification packages for high-conversion channels such as rental and large infrastructure contractors.
- Regulatory compliance programs: align product development milestones to NRMM and Stage V windows identified in our policy mapping.
Why Now — The Case for Urgency
2026 is not a routine planning year. Material-cost inflation, tariff-induced price floors, and accelerated electrification pilots combine to narrow the execution window for both OEMs and their capital providers. Decisions on factory retooling, supplier contracts, and product-line rationalization taken in 2026 will crystallize competitive positions for the latter half of the decade.
PW Consulting’s Excavator Market report is engineered to shorten the path from insight to action while maintaining the confidentiality of high-value segment and firm-level projections. Our diagnostic tools transform market-level trends into executable plans without leaking the proprietary nodes that give clients competitive advantage.
To review the full data tables, segment distributions, and the firm-level scenario matrices referenced here, access the complete report: Read the full Excavator Market report .
For detailed analysis of this topic, please visit the official page: Excavator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Water Meter Market to Grow at 7.0% CAGR Through 2032
By PW Consulting, 2026-06-26
PW Consulting Strategic Brief: Water Heater Market — 2026 Outlook and Investment Imperatives
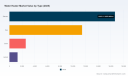
PW Consulting publishes a focused industry briefing derived from our forthcoming Water Heater Market report (base year 2025, forecast 2026–2032). The global market is entering a decisive capital allocation window in 2026: after a 2020–2025 phase of uneven recovery, our model projects the market expanding at a 6.98% CAGR across the 2026–2032 forecast, with the 2025 market value measured at USD 215.0 Million and a projected market size of USD 344.8 Million by 2032. This briefing highlights the strategic value of our full report for executive decision-making while preserving the granular segmentation that is gated behind the full analysis.
Water Meter Market
Executive snapshot — why 2026 is a pivot year
Leaders in manufacturing, distribution and private equity must treat 2026 as a pivot year because three forces collide now: regulatory tightening, raw-material inflation, and accelerated product electrification coupled with AI-enabled efficiency gains. The combined effect amplifies near-term execution risk and raises the premium on early design wins, supply-chain resilience, and regulatory-compliant roadmaps. Our full report quantifies the exposure and opportunity by market node; here we outline the practical implications for 2026 planning.
Market dynamics shaping near-term strategy
-
Regulatory pressure: New U.S. Department of Energy efficiency standards and staggered compliance dates are reshaping product roadmaps and manufacturing cutovers. These rules materially increase the engineering and certification burden for gas-fired instantaneous and commercial models beginning within the next 12–36 months and thus affect product lifecycles and stocking strategies.
-
Input-cost volatility: Early-2026 copper cost jumps (over +18% year-on-year) and tariffs on imported steel and components (15–35% band observed across affected tariff lines) are compressing BOM margins for electrified and heat-pump product architectures.
-
Technology and electrification: Heat-pump and CO2-split architectures are moving from niche proof-of-concept into scaled commercialization. Concurrently, AI-enabled system optimization is reducing operating costs and enabling new aftermarket monetization models.
-
Competitive fragmentation: Market concentration metrics indicate a fragmented landscape (CR3: 24.6%, CR5: 26.2%), which raises the strategic value of targeted design wins and channel partnerships over attempts at large-scale share grabs.
What our full report provides — practical tools for 2026 execution
PW Consulting’s full Water Heater Market report is intentionally operational: it is designed to convert insight into executable actions for procurement, product and corporate strategy teams. Key deliverables include:
-
Supply-chain cartography: mapped supplier tiers, single-source risk flags, and alternative sourcing routes that help procurement reassign critical-path components without compromising lead times.
-
BOM decomposition logic: a reproducible framework for disaggregating finished-unit costs into scalable line items and for simulating SKU-level margin impacts under commodity scenarios.
-
Yield-adjustment and throughput models: scenarios that translate process yield improvements and rework reductions into unit-cost gains across plant footprints.
-
Technology roadmap and design-win playbooks: a matrix of feature-to-value mappings that prioritize which capabilities win in OEM and dealer selection processes, and which require ecosystem partnerships (controls, sensors, service platforms).
Each of these tools is paired with implementation notes and a set of diagnostic checkpoints so that teams can move from assessment to prioritized pilots within an 8–12 week horizon—precisely the timeline that matters for 2026 compliance and cost-control cycles.
How the analysis translates to the C-suite — three decision levers
-
CapEx sequencing: Use scenario-linked CapEx triggers in our model to defer or accelerate equipment upgrades tied to efficiency standards rather than relying on calendar-based plans;
-
M&A & partnership priorities: Target acquisitions or JV structures that provide immediate access to low-cost sourcing of critical components or to validated heat-pump module designs;
-
Channel and service monetization: Shift commercial focus from unit-sale economics to lifecycle-service models that reduce sensitivity to component price shocks and increase aftermarket revenue streams.
Competitive landscape — dimensions that decide winners in 2026
Our analysis covers incumbent and specialist vendors across global markets. Rather than presenting full company forecasts, the report evaluates competitors along repeatable competitive dimensions that determine 2026 outcomes:
-
Technology moat: proprietary thermodynamic designs, patented compressor/heat-exchanger integration, and systems-level control software that translate into measurable energy-performance advantages.
-
Channel strength: depth of professional distribution networks and installer loyalty which can either accelerate or block rapid retrofits and specification changes.
-
Manufacturing footprint flexibility: the ability to re-route assembly or subassembly production to mitigate tariffs and localized input-cost spikes.
-
Design wins mechanics: time-to-spec, certification track records, and integration support (controls + OEM APIs) emerge as the decisive factors in procurement award decisions.
For example, legacy heating manufacturers that combine strong installer relationships with recent investments in electrified platforms are positioned to secure early design wins in residential retrofit programs, while specialist tankless players retain an edge where footprint and delivery speed matter most. Specific company profiles and our triangulated view of their defensive assets are available in the full report.
Recent industry signals we incorporate include product launches and demonstrations through 2026 (e.g., new heat-pump lines and tankless showcases by several major vendors), and these events confirm the migration of R&D dollars towards heat-pump electrification and AI-enabled optimization. For a deeper company-by-company competitive matrix, see the full analysis and supplier scorecards (Download the full report: https://pmarketresearch.com/auto/water-heater-market ).
Methodology — why our findings are actionable and defensible
PW Consulting’s market model synthesizes layered triangulation: a structured fusion of patent landscaping, proprietary procurement-scanner data, confidential interviews with OEM procurement and engineering executives, plant-level yield measurements, and customs/shipments analytics. We calibrate these primary data sources against public filings, testing-lab certifications and trade-show disclosures to produce reconciled node-level estimates.
Where data are not in the public domain, our team leverages anonymized supplier conversations, NDA-protected factory visits and mutually consented telemetry samples from partner fleets to validate throughput and failure-mode assumptions. This multi-source triangulation reduces single-source bias and yields operational models that procurement and manufacturing teams can map directly onto their ERP and MES systems.
Regulatory and supply risks — what to model now
-
DOE efficiency standards: company roadmaps and inventory plans must account for phased compliance windows and certification lead times. Certificate testing capacity and third-party lab queues are non-trivial gating items.
-
Tariff exposure: short-term hedging of critical metals and flexible supplier contracts will be decisive in preserving margin bands during 2026 commodity shocks.
-
Component concentration: identify single-sourced subcomponents and prioritize dual-sourcing or redesign opportunities within the next two product development cycles.
Actionable steps for planners in 2026
-
Run the BOM-decomposition diagnostic across top SKUs to quantify dollar-sensitivity to copper and steel swings and to define minimum viable substitution strategies;
-
Prioritize two design-wins with national installers or channel aggregators within 9 months to lock route-to-market for electrified SKUs;
-
Fast-track one pilot that deploys AI-driven energy optimization on a controlled fleet segment to validate aftermarket revenue potential;
Why PW Consulting’s report is indispensable for 2026 decision-making
Our report translates market-level projections (6.98% CAGR, system-size trajectory to USD 344.8 Million by 2032) into operational playbooks: supply-chain mitigations, product-architecture prioritization and design-win tactics that procurement, R&D and business development teams can implement within quarter cycles. The analysis is deliberately granular in its modeling but curated in this briefing to preserve the competitive intelligence that is gated in the full report.
For procurement directors, product leaders, and investment committees seeking a defensible 2026 allocation thesis and step-by-step execution templates, access the complete datasets, regional distributions and supplier scorecards here: https://pmarketresearch.com/auto/water-heater-market .
For detailed analysis of this topic, please visit the official page: Water Meter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Concrete Vibrator Market to Reach USD 179.6 Million by 2032
By PW Consulting, 2026-06-26
Concrete Vibrator Market 2026 Preview: Strategic Imperatives for Capital Allocation
PW Consulting publishes a focused industry briefing derived from our full Concrete Vibrator Market study, providing decision-makers with the analytic scaffolding required for capital and operational choices in 2026. The market we model uses 2025 as its base year (Market size: 130.0 Million USD) and projects a steady compound annual growth rate (CAGR) of 4.8% across the 2026–2032 forecast window, reflecting a market that is mature but responsive to technology-driven displacement and rental-led demand dynamics.
Concrete Vibrator Market
Why 2026 Is a Pivotal Moment
Several converging forces make 2026 a moment for accelerated, disciplined action by OEMs, rental fleets, private equity, and procurement organizations:
-
Macro rental market expansion: The broader construction equipment rental market is scaling rapidly, increasing counterparty opportunities for concrete vibrator providers and rental operators to capture higher-utilization revenue streams.
-
Regulatory and ESG pressure: Noise and indoor air-quality regulations push contractors toward electrified, high-frequency solutions, reshaping product specification and compliance checklists used in public tenders and large institutional projects.
-
Cost and labor dynamics: Renting continues to be a lever for contractors to lower fixed labor and maintenance exposure; rental models also accelerate technology diffusion (e.g., cordless, battery-backpack units) where capital replacement cycles are shorter.
-
Supply-chain friction and component inflation: Sourcing shocks and lead-time variability mean fleet managers and OEM procurement teams must redesign BOMs and supplier relationships to protect margins and uptime.
What Our Report Delivers — Practical Tools for 2026 Decisions
The full PW Consulting report is intentionally operational. It delivers a suite of diagnostic and execution tools designed to convert insight into action without prescribing one-size-fits-all settings. Highlights include:
-
Supply-chain topology and risk map — a layered view of tier-1 through tier-3 suppliers, critical single-source nodes, and substitution levers for fast re-specification under lead‑time pressure.
-
BOM decomposition logic — a reproducible framework that isolates cost drivers by assembly and supports scenario-based cost simulations (e.g., battery pack vs. combustion engine, actuator frequency packages).
-
Yield and uptime adjustment models — templates to quantify the operational impact of device reliability and service cadence on rental revenue per unit and fleet-level utilization.
-
Technology roadmap and three-staged adoption pathways — an engineering-oriented view aligning high-frequency electrification, battery energy-density improvements, and IoT-enabled predictive maintenance with procurement milestones.
-
Commercial playbooks — procurement scorecards, retrofit vs. replace decision matrices, and rental pricing elasticity models calibrated to current utilization and compliance constraints.
Each tool is designed to be plugged into corporate planning cycles in 2026: procurement managers can run BOM scenarios against supplier contracts; fleet heads can model utilization uplift from targeted electrification pilots; investment committees can rank M&A targets using a common, risk-adjusted scorecard.
Market Structure and Competitive Dynamics
The market exhibits moderate concentration: the top three players account for roughly 33.0% of measured market activity, while the top five reach about 45.0%. This profile indicates a market where national-scale rental networks coexist with specialist and regional providers, and where design wins and service models determine sustainable margins.
Competitive advantage in this segment is multi-dimensional. Our analysis highlights the core vectors on which incumbents and challengers compete:
-
Network scale and availability: Large rental platforms leverage branch density and cross-rental logistics to guarantee lead times for project-critical deliveries.
-
Product breadth and modularity: Suppliers that offer interchangeable head/shaft combinations, multi-frequency platforms, or battery retrofits increase capture rates across heterogeneous job types.
-
Service economics and uptime: Warranty, on-site repair capability, and rapid spare-part fulfillment are decisive in contractor procurement decisions where downtime penalties are material.
-
Data and digital fleet management: IoT-enabled units and telematics allow for predictive maintenance, utilization analytics, and outcome-based rental pricing.
-
Regulatory compliance and specification trust: Providers that demonstrate compliance with noise and indoor-safety norms gain advantage on public infrastructure and institutional projects.
Selected industry participants illustrate these dimensions without disclosing our forward-looking scenario outputs. For example:
-
Large multi-branch rental platforms are competing on scale and logistics efficiency to secure site-level availability.
-
Specialist and regional providers emphasize fleet specialization and rapid shipment services to capture localized demand peaks.
-
Newer entrants and equipment-as-a-service operators focus on cordless/battery product niches and digital customer experiences to win specification-led contracts.
Recent field signals reinforce these dynamics: a prominent rental operator amplified contractor-facing educational marketing in mid‑2025 to increase adoption and reduce misuse-related downtime, while battery-powered backpack applications have been deployed in notable energy‑island construction projects in early 2026, demonstrating commercial viability at scale.
Call to Action
For granular regional and application distributions, fleet-level BOMs, supplier-by-supplier risk scoring, and the full set of forecast tables and sensitivity analyses, access the full report at https://pmarketresearch.com/auto/concrete-vibrator-rental-market .
Methodology — Why Our Findings Are Actionable
PW Consulting applies a Layered Triangulation methodology to this study. We combine patent-citation and standards-mapping to identify emergent technology vectors, customs and shipment analytics to reveal directional trade flows, and fleet-telemetry sampling to measure real-world utilization patterns. These inputs are cross-validated against primary research: structured interviews with procurement leads at rental operators, supplier-level interviews under NDA, and on-site equipment audits.
Our approach prioritizes reproducibility and defensibility. Key elements include:
-
Patent and standards analysis to map technology trajectories and patent clusters that correlate with modular design and battery integration trends.
-
Primary fleet audits and telemetry ingestion to calibrate uptime and mean-time-to-repair parameters against advertised manufacturer claims.
-
Multi-party supplier triangulation combining purchase orders, lead-time samples, and direct supplier interviews to estimate real sourcing flexibility under stress scenarios.
How To Use This Intelligence in 2026
Decision-makers can translate the report's diagnostic outputs into prioritized actions across four portfolios:
-
Capital allocation — use scenario-ready BOM and TCO simulations to decide between selective electrification pilots and broad fleet replacement, prioritizing assets with the highest utilization uplift and compliance exposure.
-
Procurement and supplier strategy — redesign contracts to include dual-sourcing clauses for critical components and embed yield-adjustment triggers to protect margins under input-price volatility.
-
Commercial and service model innovation — pilot outcome-based rental packages and retrofit bundles (battery conversions, IoT modules) to capture premium pricing while preserving unit economics.
-
M&A and partnership screening — apply our scorecard to filter targets by fleet health, retrofitability, and branch-network synergies rather than headline revenue alone.
Each recommended action leverages explicit report modules: the BOM templates feed procurement simulations; the yield-adjustment models quantify service-capex tradeoffs; and the competitive-dimension frameworks inform deal diligence checklists.
Practical Next Steps for Executives
Executives preparing 2026 capital and operational plans should prioritize three near-term initiatives informed by our analysis: align procurement KPIs to lifecycle cost rather than unit price, commit to at least one electrification pilot in each major operating geography, and operationalize telematics for all newly acquired units to accelerate payback on predictive maintenance investments.
PW Consulting’s full dataset and operational annexes provide the numerical underpinnings to execute these initiatives with confidence; the briefing above outlines the why and how at a strategic level and points you to the source materials for definitive scenario inputs.
Closing
In a market that is growing steadily—anchored by a 4.8% CAGR and a demonstrated shift toward electrification and rental-centric deployment—timely, calibrated action will separate winners from laggards. The PW Consulting Concrete Vibrator Market report equips boards, investment committees, and operations leaders with the tools to act decisively in 2026. For the complete dataset, supplier-level analyses, and executable playbooks, visit https://pmarketresearch.com/auto/concrete-vibrator-rental-market .
For detailed analysis of this topic, please visit the official page: Concrete Vibrator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Programmable Stage Lighting Market to Grow at 7.3% CAGR Through 2032
By PW Consulting, 2026-06-26
Programmable Stage Lighting Market 2026: Strategic Intelligence for Capital Allocation and Competitive Positioning
In 2026, the programmable stage lighting market is operating at the intersection of rapid product innovation, tightening regulatory compliance, and supply-chain cost pressure. PW Consulting’s new market study—anchored to base year 2025 and covering historical performance from 2020–2025 with a forward-looking forecast to 2032—shows the industry expanding from USD 120.4 Million in 2020 to USD 158.9 Million in 2025, and projecting a continuation of momentum into 2026 and beyond. Our modeled compound annual growth rate for the forecast period 2026–2032 is 7.3%, a pace that makes near-term capital allocation and strategic repositioning both urgent and potentially rewarding for market participants.
Programmable Stage Lighting Market
Market snapshot: what the headline numbers mean for 2026 decisions
The headline trajectory—measured growth and a mid-single-digit CAGR—masks a complex set of internal dynamics that materially affect product roadmaps, procurement, and M&A timing. Key forces in 2026 include:
Programmable Stage Lighting Market
- Regulatory realignment around laser safety standards, which raises certification costs and shapes product launch windows.
- Concentration and fragmentation dynamics: the market is neither monopolized nor atomized, leaving room for differentiated plays in IP, software, and systems integration.
- Supply-chain sensitivity, especially to laser diode pricing and component lead times, which directly compresses margins for OEMs that lack vertical cost control or alternative sourcing structures.
Why this report matters: actionable intelligence without giving your competitors a playbook
Executives and boards use our study to convert macro growth visibility into executable 12–24 month plans. Rather than distribute raw segment matrices that competitors can immediately exploit, the report provides operational tools and decision frameworks that enable companies to:
- Prioritize capex and R&D investments based on expected regulatory milestones and product certification timelines.
- Quantify supply-chain levers that move gross margin under multiple commodity-price scenarios.
- Calibrate go-to-market sequencing to capture design wins with touring houses, venues, and broadcast partners who are tightening safety and interoperability requirements.
Core deliverables inside the PW Consulting report
The report is constructed as an execution toolkit for 2026, not an academic summary. Key practical modules include:
- Supply-chain map: a layered view showing second- and third-tier suppliers for laser diodes, optics, and thermal-management subsystems, highlighting single-source risks and alternative sourcing corridors.
- BOM decomposition logic: a repeatable methodology for converting teardown observations into procurement levers and cost-sensitivity curves without exposing vendor-specific purchase prices.
- Yield-adjustment model: plug-and-play templates that translate yield improvements into bottom-line impacts under real-world manufacturing constraints.
- Technology roadmap: scenario-based paths that map LED vs. laser-phosphor adoption, safety-control system integration, and software-defined lighting capabilities to time-to-market and regulatory compliance calendars.
These deliverables are built to be immediately actionable in 2026 boardroom decisions—guiding whether to insource critical optics, accelerate firmware development for interoperability, or delay launches pending IEC/ FDA alignment—while intentionally withholding the raw segment-level tables best viewed in the full report.
Regulatory and compliance dynamics: a 2026 imperative
Regulatory change is a material risk and a strategic opportunity in 2026. The withdrawal of legacy U.S. guidance and the industry shift toward IEC-aligned standards has increased the certification burden for programmable laser products. High-power laser projectors, in particular, require careful variance management and documentation for public demonstrations in markets such as the U.S.
- For manufacturers, compliance is now an input to product design rather than a downstream certification task—driving earlier engagement with test labs and documented safety architectures.
- For investors, regulatory complexity creates a barrier to entry that can be converted into a competitive moat if integrated into product development and aftermarket services.
Competitive landscape: dimensions that determine winners in 2026
The company list in this sector ranges from software specialists to vertically integrated fixture manufacturers. PW Consulting’s analysis evaluates competitive position along high-signal dimensions rather than publishing isolated forecasts. Core competitive dimensions we observe are:
- Technical moat: proprietary optics, thermal design excellence, and certified safety subsystems reduce substitution risk for large-scale tours and fixed installations.
- Software & control ecosystem: firms with robust control stacks and backwards-compatible protocols secure recurring revenue through ecosystem lock-in and service contracts.
- Design-win velocity: speed and reliability of field trials, logistics support for touring clients, and pre-certified product configurations determine which suppliers achieve repeat business with major venues.
- Channel and service footprint: global aftermarket support and rental-partner relationships matter as much as product specs in win-rate for large-scale shows.
Illustrative company profiles (selective, high-level):
- Robe Lighting: recognized for high-power laser-phosphor moving heads with environmental ratings that target outdoor and touring use; the company’s IP-rated mechanical and optical architectures are a clear technical differentiator.
- Elation Professional & X-Laser: the acquisition and integration dynamic increases end-to-end capability in programmable laser projectors and accelerates access to the North American aftermarket.
- Pangolin Laser Systems: dominant in control software and scanners; its software ecosystem is a recurring-value asset that influences design-win outcomes.
- Kvant Lasers and Laserworld Group: specialize in high-precision, high-power systems across different price tiers—competition here is shaped by reliability and product-service integration.
- Chauvet, ADJ, Clay Paky: cover complementary segments from entry-level programmable effects to premium theatrical fixtures; each competes on speed-to-spec and channel reach.
These snapshots are used in the report to map relative strengths and to identify where partnerships, bolt-on acquisitions, or capability-building investments yield the highest strategic return—without disclosing the full set of company-specific forecasts from 2026 onward.
Cost and supply risks: where dollars and timelines are most sensitive
Raw-material exposure—most notably to laser diodes, precision optics, and thermal-management components—accounts for a sizable share of manufacturing cost. In 2026, procurement teams must treat these inputs as strategic variables:
- Hedged sourcing and dual-sourcing strategies reduce single-supplier disruption risk but can increase short-term procurement complexity.
- Yield improvement programs, combined with supplier co-investment in test fixtures or burn-in capacity, often produce faster margin recovery than purely price-focused negotiations.
- Nearshoring selective assembly can reduce logistics lead-times for time-sensitive touring orders and improve compliance oversight for regulated products.
Methodology corner: how PW Consulting constructs confidence
PW Consulting’s methodological rigor blends public, proprietary, and primary data streams to deliver defendable, forensic-quality intelligence. We apply a layered-triangulation approach combining patent-citation analysis, controlled teardown BOMs, and confidential supplier invoice and customs flows to reconcile unit economics against reported revenues.
Primary inputs include structured interviews with OEM engineers, rental and touring operations, accredited test laboratories, and trade associations. We complement these with machine-assisted patent and standards-mapping to identify IP overlaps and potential regulatory exposure. Our approach privileges reproducibility—decision frameworks are supplied so clients can re-run sensitivity scenarios under alternate assumptions.
Strategic takeaways for capital allocators and product leaders in 2026
For executive teams deciding where to deploy capital in 2026, the most impactful moves are rarely headline-grabbing. The report recommends prioritizing:
- Investments that accelerate regulatory compliance and pre-certification to shorten time-to-revenue for high-power offerings.
- Software and control-platform investments that create recurring revenue and defend margin under component-cost inflation.
- Targeted vertical integration or exclusive supply agreements for high-sensitivity components like laser diodes where returns justify balance-sheet allocation.
- Operational programs—yield uplift, supplier co-engineering, and tested field-service models—that unlock margin faster than pure cost-cutting.
Next step: access the full execution toolkit
PW Consulting’s full study provides the complete mapping, models, and supplier roll-ups that underpin the findings summarized here. Executives who need to convert the 2026 market trajectory into executable boardroom options can review the report and accompanying scenario models at the official product page: Programmable Stage Lighting Market — Full Report .
Final note: timing and urgency
2026 is a pivotal year: regulatory convergence, concentrated component supply, and accelerating software expectations create both risk and runway for differentiated players. Organizations that act now—leveraging compliance as a moat, codifying software lock-in, and shoring up critical component supply—will capture disproportionate value as the market compounds toward 2032. PW Consulting’s report is designed to turn that urgency into practical milestones and measurable portfolio decisions without exposing your strategic playbook to competitors.
For detailed analysis of this topic, please visit the official page: Programmable Stage Lighting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Melamine Foam Market to Expand at 5.9% CAGR Through 2032 as Acoustic Applications Drive Demand
By PW Consulting, 2026-06-26
Melamine Foam Market — Strategic Outlook for 2026: PW Consulting Intelligence Brief
PW Consulting publishes a targeted intelligence brief on the melamine foam market that frames 2026 as a decisive year for capital allocation, compliance planning and product-platform repositioning. Anchored to a 2025 base year and a seven-year forecast window (2026–2032), the market grows at a compound annual growth rate (CAGR) of 5.9%, moving from a global size of USD 190.6 Million in 2025 toward USD 282.6 Million by 2032. These headline metrics validate demand momentum, but they understate how regulatory shocks, raw-material cycles and technology choices are reshaping winners and losers in real time.
Melamine Foam Market
Why 2026 Is a Strategic Inflection Point
2026 is not just another planning year; it is the year when multiple external vectors converge to force tactical decisions:
Melamine Foam Market
- Regulatory enforcement accelerates: global class and safety rules are imposing phase-outs and retrofit timelines for legacy chemistries, creating discrete demand waves for compliant replacements.
- Supply-cost volatility persists: feedstock price swings and regional manufacturing bottlenecks amplify margin risk for processors with thin hedging or single-source procurement.
- Buyer behaviour shifts toward certified, traceable materials: OEMs and shipowners increasingly demand verifiable material provenance and third-party lab data as procurement prerequisites.
- Design-win timelines compress: procurement windows for retrofit projects and new builds shorten; suppliers that can prove performance and compliance rapidly capture share.
These dynamics create urgency for capital allocation between three competing priorities: compliance upgrades, capacity investment for higher-margin specialty grades, and digital transformation to protect yields and accelerate time-to-design-win.
What the Report Delivers: Practical Tools for 2026 Execution
The report is built as an operational playbook rather than a purely academic forecast. It provides a suite of tools that procurement, R&D and strategy teams can apply immediately to reduce execution risk in 2026:
- Supply-chain topography and node-risk scoring — a visual map that surfaces single-source nodes, transit chokepoints and substitution pathways.
- BOM decomposition logic — a reproducible approach to unbundle finished-product cost into raw-material, transformation and overhead buckets to guide margin recovery strategies.
- Yield-adjustment and sensitivity models — modular templates that let manufacturing leaders test yield-improvement levers against feedstock price scenarios without rebuilding models from scratch.
- Technology roadmaps and capability matrices — comparative assessment of formulations, additive packages and process innovations that define near-term upgrade paths to PFOS-free and other certified chemistries.
- Compliance readiness matrix — stepwise actions covering lab validation, third-party certification and retrofit workflows tied to inspection cycles.
Each tool is purpose-built to address 2026 pain points: quick-certification processes to win OEM approvals, cost-to-serve visibility to justify price adjustments, and yield-improvement playbooks that materially improve margin resilience under volatile feedstock prices.
Market Dynamics & Macro Signals
The market is expanding in absolute terms while remaining structurally fragmented — the top three firms control about 23.5% of industry revenues and the top five account for about 28.7%, indicating meaningful room for specialist players and new entrants with certification-led differentiation. Key structural drivers we track include:
- Regulatory-led retrofit demand — phased bans and replacement requirements accelerate uptake of certified PFOS-free alternatives.
- End-market uplift in acoustic and thermal applications — product design trends in transportation and building retrofits are durable demand anchors.
- Upstream cost cycles — periodic MDI/TDI and polyol swings create windows for margin compression and strategic procurement advantage.
Recent industry developments confirm these directions: new marine-grade production machinery that supports water-resistant formulations; advances in microbial and durability testing that raise acceptance thresholds; and product launches that target durability upgrades for marine flooring. Together, these events increase the commercial premium for validated, certified melamine foam variants in 2026.
Competitive Landscape: Dimensions of Advantage
Our competitive analysis emphasizes the dimensions that determine sustainable wins in 2026 rather than forecasting exact moves. Across the spectrum of players — from custom fabricators to multinational chemical producers — success depends on a small set of defensible capabilities:
- Customer intimacy and customization: companies that combine rapid prototyping, on-site machining and tight OEM integration convert trials into repeat design-wins.
- Formulation IP and certification bandwidth: firms with broad formulation libraries and active certification pipelines reduce friction for buyers focused on compliance.
- Scale and distribution: integrated chemical producers leverage raw-material access, logistics scale and global sales footprints to undercut late movers on price and delivery.
- Service and installation competence: for retrofit-heavy markets, the ability to provide end-to-end service (from material supply to in-field installation guidance) is a decisive differentiator.
Illustrative positioning (not predictive): specialty fabricators excel at tailored flotation and cushioning applications through close customer partnerships; medium-sized converters win by combining flexible manufacturing with rapid certification; major chemical companies leverage formulation IP, multi-region capacity and distribution relationships to capture large OEM accounts. PW Consulting’s proprietary scoring framework quantifies these dimensions to show where each supplier is likely to be most competitive in 2026 without publishing confidential strategic plans.
Regulatory & Raw Material Risk Matrix
Two regulatory facts are central to 2026 planning:
- A prohibition on certain legacy fire-extinguishing media and PFOS-containing materials comes into force, creating mandatory replacement timelines for in-service assets.
- Survey and class-cycle enforcement require existing vessels to present certified replacements at the first post-cutoff inspection under amended SOLAS rules.
Concurrently, raw-material signals include both periodic price spikes and episodes of feedstock surplus that depress specific isocyanate prices. The net effect is a complex procurement environment where timing and supplier selection materially affect realized margin. The report’s risk matrix pairs regulatory milestones with upstream cost scenarios so teams can prioritize capex and sourcing actions by expected impact window.
Methodology: How PW Consulting Builds Confidence
Our findings are the output of a layered triangulation methodology designed to surface non-public commercial realities while ensuring reproducibility. Core elements include patent-landscape analysis, customs and shipment flow examination, plant-level capex tracking, structured interviews with OEM procurement teams and tier-1 converters, laboratory validation of performance claims, and reverse-engineered BOM modeling from sample products. We explicitly track design-win timelines through OEM specification updates and third-party certification filings to map which suppliers are credible for 2026 procurement cycles.
This multi-source approach allows PW Consulting to reconcile official statistics with supplier-disclosed metrics and confidential industry interviews, producing calibrated intelligence that is both rigorous and directly actionable for investment committees and commercial teams.
Actionable Recommendations for 2026 Capital Allocation
Based on the above, PW Consulting recommends that executive teams prioritize a small number of high-impact actions this year:
- Allocate a portion of near-term capex to certification-ready production lines that can validate PFOS-free formulations at scale.
- Implement a targeted feedstock hedging strategy and dual-sourcing plan for critical isocyanates and polyols to smooth margin volatility.
- Invest in digital yield-management and BOM-tracking tools to accelerate margin recovery and reduce time-to-design-win.
- Reassess M&A and partnership targets with an eye toward acquiring specialized converters that bring installation/service competence and certification dossiers.
- Elevate procurement requirements to include traceability and third-party lab evidence as standard pre-qualifiers for supplier selection.
These recommendations are prioritized by implementation speed and expected ROI for 2026, and they are accompanied in the full report by executable playbooks that senior teams can deploy within existing governance cycles.
Next Steps & How to Access Full Intelligence
To obtain the complete regional and application breakdowns, supplier scorecards, downloadable BOM templates, and scenario-ready financial models that underpin the analysis summarized here, visit the report page and download the full deliverable: https://pmarketresearch.com/auto/marine-foam-market . The full report includes interactive exhibits, supplier risk dashboards and an actionable regulator-to-capex timeline calibrated to 2026 inspection cycles.
PW Consulting’s melamine foam intelligence is designed for decision-makers who must translate regulatory pressure, supply volatility and product design cycles into defensible investment choices this year. Our rigor and operational focus equip strategy, procurement and product teams to convert uncertainty into competitive advantage in 2026.
For detailed analysis of this topic, please visit the official page: Melamine Foam Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


