



Category: Machinery & Automotive
PW Consulting: Plastic Bag Market Hits $283M in 2025, Projected 3.5% CAGR Through 2032
By PW Consulting, 2026-09-16
Navigating the Plastic Bag Market in 2026: Strategic Imperatives for Sustainable Growth
The global plastic bag market stands at a critical inflection point. As regulatory frameworks tighten and consumer preferences evolve, industry stakeholders must reconcile structural demand with sustainability mandates. PW Consulting latest market research delivers a comprehensive, data-driven analysis of the plastic bag market from 2020 through 2032, providing executive teams with the strategic clarity required to navigate 2026 and beyond. This report is engineered not merely as a retrospective overview, but as a forward-looking decision architecture that maps growth trajectories, competitive pressures, and operational pivots across material innovation, regional expansion, and compliance readiness.
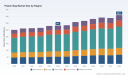
Our analysis draws on rigorous historical tracking and forward-looking modeling to establish a reliable baseline. The global market revenue reached approximately USD 283.00 million in 2025, reflecting a steady expansion from USD 251.00 million in 2020. Moving into the forecast window, the market is projected to cross USD 285.51 million in 2026 and accelerate toward USD 360.10 million by 2032, supported by a compound annual growth rate of 3.5 percent over the forecast period. These aggregate figures signal a market that remains fundamentally resilient, even as regulatory and environmental headwinds reshape traditional consumption patterns. The strategic question for leadership teams is no longer whether demand will persist, but how value will be reallocated across segments, geographies, and material classes.
Report Scope and Practical Utility
This study is structured to support cross-functional decision-making across strategy, procurement, product development, and regulatory affairs. Rather than offering static snapshots, the report embeds actionable frameworks that translate market intelligence into operational plans. The analysis spans the full value chain and is organized to help executives answer three core questions: where will volume and value concentrate, which stakeholder moves will redefine competitive positioning, and what compliance or material shifts must be priced into 2026 planning cycles.
Plastic Bag Market
Inside the report, readers will find:
- A longitudinal review of market performance from 2020 to 2025, establishing baseline momentum and structural change points.
- A detailed forecast model extending to 2032, with scenario sensitivities that account for regulatory acceleration, material substitution, and macroeconomic demand shifts.
- Deep-dive segmentation analysis across material types, application verticals, and regional markets, with emphasis on relative velocity rather than isolated snapshots.
- A competitive benchmarking module that maps incumbent positioning, product specialization, and strategic partnerships shaping near-term market dynamics.
- Regulatory tracking and compliance implications, including material mandates, recycling requirements, and single-use restrictions affecting retail, food service, and industrial channels.
- An operational playbook for navigating material transitions, supplier selection, and product portfolio adjustments in markets exposed to heightened policy scrutiny.
Every section is anchored in data but framed for action. The objective is to equip leadership teams with a defensible view of where competitive advantage will be won or lost, and which decisions made in 2026 will compound through the remainder of the decade.
Market Dynamics: Regulation, Recycling, and Regional Realignment
The 2026 landscape is being reshaped by a convergence of policy enforcement and circular-economy initiatives. In North America, California SB 1053 eliminates all single-use plastic carryout bags at retail beginning January 1, 2026, removing prior thickness-based exemptions and effectively closing loopholes that had allowed certain flexible formats to persist. The California Department of Resources Recycling and Recovery reinforced this shift with retail-facing bans on single-use carryout bags across most grocery and retail outlets, while New Jersey advanced its Plastic Ban Law prohibiting single-use carryout bags and polystyrene foam, accompanied by vendor lists for compliant reusable alternatives. In Asia, China continued executing its national single-use plastic control roadmap, phasing out non-degradable plastic bags and ultrathin variants across cities and markets through 2026. In Europe, the EU Packaging and Packaging Waste Regulation introduced mandates for fully recyclable packaging and minimum post-consumer recycled content for food packaging, intensifying pressure on flexible formats to meet design-for-recyclability standards.
These regulatory developments are not isolated compliance burdens; they are demand disruptors and portfolio stress tests. Retail and consumer-facing applications face the most immediate format transitions, while food and beverage channels must align packaging architecture with recyclability and recycled-content requirements. Industrial users, meanwhile, are evaluating how material specifications and procurement standards will adapt as downstream recycling infrastructure and feedstock availability evolve.
At the same time, practical recycling partnerships are gaining momentum as operational responses to film waste challenges. In March 2026, Scotts Miracle-Gro expanded its partnership with Trex to recycle plastic film waste from production operations into composite decking products. Shortly thereafter, in April 2026, Goodwill Industries of the Chesapeake repurposed millions of plastic bags collected at donation centers into composite decking through its collaboration with Trex Company. These initiatives illustrate a broader pattern: flexible film recovery is moving from pilot ideas to repeatable operational models, particularly where end-of-life pathways can be industrialized. For manufacturers and converters, such models create both opportunity and obligation, especially as brand owners and retailers seek verifiable circularity claims.
Geographically, the market continues to display uneven momentum. Asia Pacific remains a substantial demand center, supported by retail expansion, logistics growth, and broad-based packaging consumption. North America and Europe are defined less by raw volume expansion and more by format substitution, compliance-driven innovation, and consolidation around recyclable or reduced-waste solutions. Latin America and the Middle East and Africa present distinct growth vectors tied to retail modernization, import-driven supply chains, and localized packaging requirements. The report examines how these regional dynamics interact with material availability, conversion capacity, and competitive positioning, helping leaders prioritize where to invest, where to adapt, and where to defend share.
Competitive Landscape: Scale, Specialization, and Strategic Positioning
The plastic bag market is characterized by a concentrated core of large-scale producers alongside a broad field of specialized manufacturers serving retail, foodservice, industrial, and custom packaging niches. Competitive advantage in 2026 will be determined not only by production capacity, but by portfolio flexibility, material expertise, compliance readiness, and the ability to align with downstream recycling and recovery ecosystems.
Among the leaders, Berry Global Group, Inc. maintains a global footprint in plastic packaging, with flexible plastic bags and films serving foodservice, grocery, and retail applications. Novolex Holdings, Inc. operates as a major North American producer of plastic shopping bags, foodservice bags, and specialty packaging, positioning itself across high-visibility retail and consumer channels. Amcor Plc brings globally integrated flexible packaging capabilities with relevance across food, beverage, and consumer products, while Sonoco Products Company contributes industrial and specialty plastics expertise through custom plastic bags and packaging solutions. ProAmpac LLC supports the market through flexible packaging production, including plastic shopping bags and liners via its Hymopac division, and TC Transcontinental Inc. adds scale in flexible packaging, including plastic bags and pouches.
In the specialty and regional segments, Bischof & Klein GmbH & Co. KG focuses on flexible plastic packaging and technical films for product protection, including bags and sacks, while RKW Group provides polyolefin film solutions and manufactures plastic sacks and bags, with active market engagement such as its presentation of comprehensive film solutions and plastic packaging at ProPak Asia 2026 in Bangkok. Reynolds Consumer Products Inc. remains prominent in consumer-facing formats through its Hefty brand plastic trash bags and consumer plastic bags. International Plastic Inc., Inteplast Group, Flair Flexible Packaging Corporation, and Universal Plastic Bag Manufacturing Co. provide a mix of retail shopping bags, poly bags, ziplock bags, custom flexible packaging, totes, and stock solutions, often serving customers that require rapid turnaround, customization, and broad SKU availability. AllState Plastics LLC extends into industrial, foodservice, and medical applications, broadening the use-case base beyond conventional retail formats.
The competitive field also includes players with growing relevance in sustainability-adjacent positioning. Dagöplast AS produces compostable, recycled, and green polyethylene bags, aligning product architecture with emerging environmental expectations. Thantawan Industry Plc. contributes Thai manufacturing capability in plastic bags and packaging products, reflecting the continued importance of Asia-based production and export dynamics. Together, these companies represent the breadth of the competitive landscape, from global integrators to regional specialists and sustainability-focused innovators.
Market concentration remains notable. The top three competitors account for approximately 62.0 percent of market revenue, while the top five represent around 75.0 percent. This concentration implies that scale advantages, distribution relationships, and portfolio breadth can exert persistent pressure on smaller or narrower players. At the same time, the presence of specialized manufacturers indicates that differentiation remains viable in custom formats, technical films, niche applications, and sustainability-oriented product lines. The report assesses how these competitive forces interact with regulatory shifts and material transitions, identifying which capabilities are likely to separate durable leaders from vulnerable incumbents.
Material and Application Considerations: Beyond Simple Volume Tracking
Material composition continues to shape the market structure. Polyethylene remains central to flexible bag manufacturing, supported by established conversion infrastructure and broad applicability across retail, food service, and industrial uses. Polypropylene contributes distinct performance characteristics and continues to hold meaningful share in applications where strength, clarity, or specific barrier attributes matter. Biodegradable formats occupy a strategically important but evolving position, influenced by regulatory expectations, consumer perception, composting infrastructure, and cost competitiveness. The report examines how these material streams interact with demand patterns, compliance pressure, and substitution risk, helping executives assess which formats warrant investment, which require contingency planning, and which may face mounting performance or policy constraints.
Application segmentation further clarifies where growth and disruption will be most pronounced. Retail and consumer channels remain a major demand base, but are also the most exposed to single-use restrictions and reusable alternatives. Food and beverage applications must navigate recyclability mandates and recycled-content requirements while preserving functional performance. Industrial applications offer a different risk-return profile, often with longer specification cycles and more customized requirements, but still subject to broader sustainability expectations and procurement standards. Rather than providing a fixed allocation snapshot, the report focuses on relative momentum, sensitivities, and the operational implications of shifting demand across these channels.
Plastic Cards Market
Why This Research Matters for 2026 Decision-Making
The plastic bag market is no longer a routine volume play. It is a sector in which regulatory timing, material innovation, recycling partnerships, and competitive concentration converge to redefine competitive positioning. Leaders who treat 2026 as a transitional year risk underinvesting in compliance readiness, misallocating product development resources, or missing the windows where regional and application-specific opportunities can be captured. Leaders who approach the market with a structured, evidence-based view can better align portfolios with durable demand, anticipate format substitution, and build supplier and customer relationships that survive policy and infrastructure changes.
This report is designed to support that level of decision-making. It integrates historical performance, forward forecasts, competitive benchmarking, and regulatory context into a coherent framework that can be translated into product planning, procurement strategy, market entry or expansion decisions, and risk mitigation. Most importantly, it identifies where the market is moving and what evidence-based actions will matter most in the next planning cycle.
For executives who need detailed segmentation trajectories, material-level growth differentials, regional demand dynamics, and company-specific competitive positioning, the full study provides the granular intelligence required to move from strategic direction to execution. The complete report, including detailed segmentation splits, competitive profiles, and forward-looking scenario analysis, is available through our official market research portal. We encourage leadership teams, strategy planners, and category decision-makers to access the full publication to align 2026 planning with the most current market evidence.
For detailed analysis of this topic, please visit the official page: Plastic Bag Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Off-Highway Vehicle Engine Market to Hit $1,071.8 Billion by 2032 on 18.5% CAGR
By PW Consulting, 2026-09-16
Navigating the Off-Highway Vehicle Engine Market: Strategic Intelligence for 2026 Decision-Making
The off-highway vehicle engine sector stands at a critical inflection point. As infrastructure development accelerates globally and agricultural mechanization reaches new levels of sophistication, the demand for robust, compliant, and efficient power systems has never been more pronounced. For executives, investors, and strategic planners operating in heavy equipment, construction, and agribusiness, understanding the trajectory of this market is not merely an academic exercise—it is a prerequisite for sustainable growth and competitive positioning.
PW Consulting's latest comprehensive market research on the Off-Highway Vehicle Engine Market delivers the granular intelligence required to navigate this complex landscape. This article serves as a strategic overview, highlighting the macro drivers, competitive forces, and regulatory dynamics shaping the industry through 2032, while demonstrating why access to the full report is essential for informed decision-making in 2026 and beyond.
Market Trajectory and Growth Dynamics
The historical performance of the off-highway engine market reveals a sector characterized by resilience and accelerating expansion. Between 2020 and 2025, the global market demonstrated substantial growth, reflecting increased capital expenditure in infrastructure, mining, and agricultural sectors across both developed and emerging economies. This five-year trajectory established a robust foundation for the forecast period extending through 2032.
Off-road Engines Market
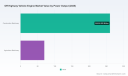
Our analysis projects that this momentum will continue, with the market expected to expand at a compound annual growth rate (CAGR) of 18.5% from 2026 through 2032. By the end of the forecast horizon, the global market valuation is anticipated to surpass significant milestones, reflecting compounded growth driven by replacement cycles, new equipment sales, and the modernization of existing fleets to meet evolving emission standards.
Several structural factors underpin this projected expansion. First, the ongoing global emphasis on infrastructure modernization—particularly in developing economies—continues to drive demand for construction machinery and the engines that power them. Second, the agricultural sector's push toward precision farming and higher productivity requirements is fueling upgrades in tractor and harvesting equipment. Third, mining operations seeking to optimize output while managing operational costs are investing in newer, more efficient mobile equipment.
Off Highway Vehicle Engine Market
Importantly, the growth narrative is not uniform across all segments. Different fuel types, power output categories, and regional markets present distinct opportunities and challenges. The full report provides a detailed breakdown of how these segments interact and where the most attractive value pools are forming, enabling stakeholders to allocate resources with precision.
Regulatory Pressures and Technological Transformation
One of the most significant forces reshaping the off-highway engine landscape is the tightening of emission regulations. In 2025, new EPA Tier 4 Final and EU Stage V emission standards for off-highway engines became fully effective, mandating advanced aftertreatment systems and exhaust gas recirculation technologies. These regulations represent a substantial compliance burden but also create opportunities for manufacturers who can deliver solutions that meet standards without compromising performance or total cost of ownership.
Within the European market, EU Stage V nonroad engine standards specifically require integrated particulate filters and selective catalytic reduction for heavy-duty off-highway vehicles to meet stringent emission limits. Meanwhile, China's Nonroad Stage IV standards, enforced since 2024, introduced mandatory real-world emission testing protocols, adding another layer of complexity for manufacturers seeking access to that market. These regulatory developments are not merely technical hurdles; they are strategic considerations that influence product roadmaps, manufacturing costs, and market entry strategies.
Beyond emissions, the industry is witnessing a broader technological transformation. Sector analysis indicates that hybrid powertrain integration in off-highway engines is accelerating, with the potential to achieve 15-25% fuel efficiency gains in construction and mining applications. While diesel remains the dominant fuel source, the gradual emergence of hybrid and electric solutions signals a shifting competitive landscape. Companies that can navigate this transition—offering a portfolio that spans traditional and alternative powertrains—will be best positioned to capture market share across diverse customer segments.
Cost considerations are also paramount. Advanced aftertreatment components required for Tier 4 Final compliance represent a notable portion of total engine production costs in heavy-duty off-highway segments. Understanding these cost structures and their implications for pricing, margins, and value proposition is critical for both engine manufacturers and equipment OEMs.
Competitive Landscape: Key Players and Strategic Moves
The off-highway engine market features a mix of established multinational manufacturers and specialized players, each competing on technology, reliability, service networks, and compliance capabilities. Market concentration metrics indicate a moderately fragmented environment, providing space for both incumbents and new entrants to differentiate through innovation and strategic partnerships.
Several leading companies exemplify the competitive dynamics at play:
- Caterpillar Inc., headquartered in Deerfield, Illinois, continues to leverage its Cat C13D off-highway engine platform for heavy-duty applications spanning construction, agriculture, and material handling equipment. Its emphasis on integrated solutions and global service infrastructure reinforces its position as a market leader.
- Cummins Inc., based in Columbus, Indiana, supplies the Next Generation X15 off-highway diesel engine and hydrogen internal combustion engine (H2-ICE) solutions for construction, mining, and agricultural off-highway vehicles. Its recent product launches underscore a commitment to performance and alternative fuel readiness.
- John Deere Power Systems, located in Schaumburg, Illinois, provides Tier 4 Final/Stage V certified diesel engines—including the JD4, JD14, and JD18 series—for off-highway tractors, loaders, and forestry equipment. Its deep integration with branded equipment gives it unique insights into end-user requirements.
- Volvo Penta, based in Gothenburg, Sweden, manufactures an industrial off-highway engine range designed for performance-critical applications in construction, agriculture, and marine sectors. Its focus on durability and efficiency resonates with operators in demanding environments.
- Perkins Engines Company Limited, headquartered in Peterborough, United Kingdom, specializes in off-highway engines including the 2600 Series platforms tailored for agricultural and heavy-duty equipment. Its legacy in the sector provides a strong foundation for continued innovation.
- Deutz AG, located in Cologne, Germany, produces the TCD off-highway engine portfolio (including TCD 3.9, TCD 5.2, and TCD 12.8 models) for compact to heavy-duty construction and industrial vehicles. Its broad product range addresses diverse power requirements across multiple applications.
Recent developments highlight the pace of innovation and strategic activity in this space. In April 2024, Cummins launched its Next Generation X15 off-highway diesel engine at Intermat, featuring up to 522 kW and 3200 Nm peak torque—a clear signal of its focus on high-performance solutions for demanding applications. In February 2025, John Deere Power Systems released preliminary details on next-generation Tier 4 Final/Stage V diesel engines, including the JD4 clean-sheet design, at Bauma 2025, demonstrating ongoing investment in clean diesel technology.
Further signaling the dynamic nature of the market, BorgWarner announced in May 2026 a partnership with a world-leading off-highway engine and machine manufacturer for large diesel applications starting in 2026. Meanwhile, Deutz presented its full off-highway engine portfolio at CONEXPO-CON/AGG in February 2026, reinforcing its commitment to comprehensive solutions across the power spectrum. These events illustrate that competitive advantage in this market is increasingly derived from technological leadership, strategic collaborations, and the ability to anticipate customer needs.
Segmentation and Regional Opportunities
A nuanced understanding of market segmentation is essential for identifying growth vectors and tailoring go-to-market strategies. The off-highway engine market can be analyzed across multiple dimensions, including fuel type, power output, and geography. Each dimension reveals distinct demand drivers, competitive intensities, and investment requirements.
By fuel type, the market encompasses diesel, gasoline, and increasingly, hybrid and electric solutions. Diesel continues to dominate in heavy-duty applications where torque, durability, and refueling infrastructure are critical. However, the emergence of hybrid and electric powertrains is reshaping expectations, particularly in scenarios where operational efficiency, emissions reduction, or regulatory compliance are prioritized. Understanding the relative share and growth trajectory of each fuel type—and the conditions under which shifts may occur—is vital for strategic planning.
By power output and application, the market spans construction machinery and agriculture machinery, among other categories. Construction machinery engines must withstand harsh operating conditions, frequent load changes, and extended duty cycles. Agriculture machinery engines, by contrast, often prioritize fuel efficiency, reliability during critical operational windows, and compatibility with precision agriculture technologies. The specific requirements of each application segment influence engine design, aftertreatment configuration, and service support models.
Regional dynamics further complicate the picture. Different geographic markets exhibit varying levels of infrastructure development, regulatory maturity, equipment replacement cycles, and competitive intensity. While some regions demonstrate mature markets with steady replacement demand, others are experiencing rapid growth driven by industrialization and government investment. The full report provides a detailed regional analysis that maps these differences, enabling stakeholders to prioritize markets based on their strategic objectives and risk tolerance.
The Strategic Value of Comprehensive Market Intelligence
In an environment defined by regulatory change, technological disruption, and regional divergence, surface-level data cannot support the depth of analysis required for confident decision-making. PW Consulting's Off-Highway Vehicle Engine Market report offers a level of detail and rigor that empowers stakeholders to move beyond speculation and toward evidence-based strategy.
The report delivers actionable insights across multiple dimensions critical to business success. It provides a thorough examination of market size and growth projections, grounded in historical data and forward-looking assumptions. It dissects segmentation by fuel type, power output, and region, revealing where value is concentrated and where white spaces may exist. It profiles key competitors, analyzing their product portfolios, recent developments, and strategic positioning, allowing readers to benchmark their own capabilities and anticipate competitive moves.
Furthermore, the report integrates an analysis of regulatory developments, technological trends, and cost dynamics, contextualizing these factors within the broader market narrative. This holistic approach ensures that readers understand not just what is happening, but why it matters and how it may evolve. Whether the goal is to assess market entry opportunities, optimize product development roadmaps, refine pricing strategies, or evaluate partnership and acquisition targets, the report provides the foundation for informed choices.
The stakes for 2026 and beyond are high. Companies that invest in understanding the nuances of the off-highway engine market will be better equipped to capitalize on growth, manage risks, and build sustainable competitive advantages. Those that rely on incomplete or outdated information risk misallocating resources, missing emerging opportunities, and falling behind more agile competitors.
Accessing the Full Intelligence
This overview has outlined the macro forces, competitive dynamics, and regulatory context shaping the off-highway vehicle engine market. However, the full depth of analysis—including detailed segmentation data, regional breakdowns, competitive benchmarking, and scenario analysis—is available exclusively in PW Consulting's comprehensive market research publication.
For executives, strategy teams, and investors seeking to navigate this complex and rapidly evolving sector, the report represents an essential resource. It transforms raw data into strategic intelligence, enabling decision-makers to act with confidence and clarity. We invite you to access the complete report to unlock the full insights needed to drive your organization's success in the off-highway engine market through 2032 and beyond.
For detailed analysis of this topic, please visit the official page: Off Highway Vehicle Engine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Battery Operated Grease Gun Market Hits $1.2B in 2025, Projects 6.5% CAGR to 2032
By PW Consulting, 2026-09-16
Battery Operated Grease Gun Market: Strategic Intelligence for Enterprise Decision-Making in 2026
Executive Overview: Why This Market Matters Now
The industrial lubrication landscape is undergoing a structural transformation driven by electrification, operational efficiency mandates, and shifting maintenance paradigms. Battery operated grease guns have transitioned from peripheral workshop accessories to core equipment maintenance assets, particularly in environments where hydraulic lines, pneumatic infrastructure, or manual crank systems create productivity bottlenecks. This market research report positions your organization at the intersection of macro demand acceleration and competitive technology divergence. The findings are engineered for procurement directors, product strategy leads, aftermarket planning teams, and regional expansion managers who must allocate capital, forecast revenue, and anticipate competitive responses in a consolidating equipment segment.
The business case for cordless lubrication tools has evolved beyond convenience. Manufacturers and fleet operators now evaluate battery powered systems against total cost of ownership, maintenance downtime reduction, ergonomic safety requirements, and integration with predictive maintenance workflows. As heavy machinery usage expands and preventive maintenance cycles intensify across automotive, construction, and industrial sectors, demand for reliable, high output, cordless lubrication equipment is accelerating. This report synthesizes historical trajectory, forward looking market projections, competitive positioning, and operational dynamics into a decision ready intelligence package.
Market Trajectory and Forecast Architecture for 2026 and Beyond
Historical performance through 2025 demonstrates consistent expansion, with the market advancing from a 2020 revenue baseline of approximately 900 million USD to an estimated 1,200 million USD by 2025. That trajectory reflects sustained adoption of cordless lubrication technology, improving reliability of battery platforms, and broader acceptance of wireless maintenance tools in professional settings. The forecast period from 2026 through 2032 projects continued growth, reaching a 2026 market size of roughly 1,287 million USD and scaling toward the 1,858 million USD mark by 2032. The implied compound annual growth rate during the forecast window is 6.5 percent, a rate that signals mature but still expanding demand rather than a speculative startup phase.
For enterprise planning, these figures are more than headline numbers. They provide a structural reference for budgeting, revenue forecasting, capacity expansion timing, and scenario modeling. A 6.5 percent CAGR in a specialized industrial tool segment indicates that growth will be earned through product differentiation, service integration, regional execution, and pricing discipline rather than passive market tailwinds. The report translates this top level trajectory into actionable frameworks, allowing leaders to benchmark internal projections against market wide momentum and identify where share gains are realistic versus where defensive positioning is required.
Segment Structure and Where Value Is Concentrated
The market is organized across technology platforms, application environments, and geographic demand clusters. Voltage category segmentation highlights a clear hierarchy in tool capability and user preference. The 12V platform represents the largest revenue pool, reflecting broad compatibility with existing battery ecosystems and wide deployment in light to medium duty maintenance environments. The 18V segment holds substantial weight as a balanced performance tier, while 20V configurations occupy a more specialized position for higher pressure requirements and extended cycle demands. A smaller Other category completes the voltage mix, capturing niche configurations and regional variations.
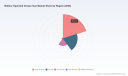
Application segmentation reveals how maintenance workflows shape demand. Automotive lubrication requirements constitute a leading application pool, driven by fleet maintenance, dealership service bays, and mobile workshop operations. Construction represents a significant demand segment, supported by on site equipment servicing, reduced dependency on external power sources, and the need for rapid lubrication during project schedules. Agriculture contributes a meaningful share tied to seasonal equipment maintenance and distributed farm operations. Industrial applications and other end use categories round out the mix, often emphasizing higher pressure performance, integration with lubrication management programs, and specialized dispensing requirements. Regional demand is also uneven, with North America commanding the largest revenue share, Europe maintaining a strong second position, and Asia Pacific representing a smaller but strategically relevant footprint. Latin America and the Middle East and Africa comprise additional regional clusters that present distinct distribution, pricing, and service model considerations.
Battery Operated Grease Gun Market
Importantly, the full segmentation architecture contains detailed value splits that are essential for targeting and resource allocation but are not disclosed in this overview. The complete report quantifies each segment contribution, enabling precise prioritization by region, application, and voltage class without exposing assumptions prematurely.
Competitive Footprint and Consolidation Dynamics
Market concentration is a defining feature of this landscape. The report indicates that the top three competitors collectively account for approximately 55 percent of market revenue, while the top five control around 65 percent. This level of concentration suggests established brand leverage, distribution channel advantages, and recurring service attachment opportunities for incumbent players, while also signaling that disciplined entrants can compete through differentiated performance, bundled service offerings, or regional specialization.
Several companies define the strategic contours of the segment. Makita Corporation, headquartered in Nagoya, Japan, has advanced its battery powered lubrication portfolio with brushless motor technology and high output pressure capabilities. Its recent product activity underscores a focus on high volume lubrication and multi speed control, reinforcing the importance of motor efficiency and flow performance in competitive positioning. Milwaukee Tool, based in Brookfield, Wisconsin, leverages its M18 battery platform and has introduced digital pressure control and LED indicator features that speak to precision and user feedback in professional workflows. DeWalt, operating under Stanley Black & Decker in New Britain, Connecticut, offers two speed cordless grease gun models designed for pressure output and runtime optimization, aligning with users who value versatility across service scenarios.
Industrial lubrication specialists also play an influential role. SKF, headquartered in Göteborg, Sweden, integrates battery powered grease gun solutions with condition based maintenance platforms, reflecting a broader shift toward maintenance intelligence rather than standalone tool sales. Lincoln Industrial, based in St. Louis, Missouri, supplies battery operated grease dispensing systems and cordless models for automotive and industrial use, emphasizing application breadth. Graco Inc., located in Minneapolis, Minnesota, contributes industrial and construction oriented lubrication equipment. Groz Engineering Tools Pvt. Ltd. and Macnaught Pty Ltd., both with Australian operations, address heavy duty industrial and automotive lubrication, with Macnaught emphasizing performance in mining and industrial environments. European and regional players such as Pressol Schmiergeräte GmbH in Germany and SAMOA Industrial, S.A. in Gijón, Spain, complete the competitive field by focusing on workshop lubrication, fluid handling, and application specific battery operated solutions.
The competitive analysis in the full report extends beyond company descriptions to examine positioning, product architecture, channel strategy, and likely reactions to market shifts. This depth is essential for M&A screening, category entry decisions, pricing strategy, and competitive response planning.
Industry Dynamics Reshaping Demand and Supply
Several operational forces are actively reshaping the trajectory of battery operated grease guns. Tariff exposure is a notable pressure point, with import cost increases affecting lithium ion batteries, electric motors, control electronics, and metal components used in tool manufacturing. These cost dynamics influence margin structure, pricing strategy, sourcing decisions, and regional assembly considerations. Companies that rely heavily on imported components may need to evaluate supplier diversification, inventory planning, or value engineering initiatives to preserve competitiveness.
Performance improvements in lithium ion battery technology are supporting broader adoption by extending runtime, reducing recharge interruption, and improving consistency in field use. At the same time, the construction and agricultural machinery boom continues to accelerate demand for efficient cordless lubrication solutions, as dispersed job sites and mobile service requirements make battery powered tools more practical than corded or pneumatic alternatives. Expansion of heavy machinery usage and rising maintenance activities in industrial equipment further reinforce the shift toward battery powered tool adoption, particularly where uptime and service flexibility are critical.
Regulatory and safety considerations also shape market behavior. Product safety notices in the cordless lubrication category highlight the importance of quality control, user instructions, and component reliability. Organizations operating in this space must account for recall risk management, compliance processes, and post market monitoring as part of product launch and lifecycle planning. The interplay between tariff pressure, battery performance progress, end use sector expansion, and safety compliance creates a dynamic environment where operational execution is as important as product specifications.
What the Report Delivers: Actionable Intelligence for Decision Teams
This market research is structured as a practical toolkit for strategic planning rather than a static descriptive summary. The report includes comprehensive market sizing and forecast modeling for the historical and forecast periods, enabling revenue scenario development and benchmarking. Segmentation analysis provides a structured view of demand by voltage platform, application environment, and region, helping teams identify where growth opportunities and competitive exposure are concentrated. Competitive landscape assessment examines major players, product positioning, and market share dynamics, supporting entry strategy, differentiation planning, and partnership evaluation.
Automotive Grease Market
The study also incorporates industry dynamics relevant to procurement, production, and distribution planning, including cost pressures, technology evolution, sector demand drivers, and safety related market events. Vertical and horizontal analysis is designed to help readers understand not only what the market looks like, but how the pieces interact—where margin sensitivity lies, which segments are most exposed to external cost shocks, and which applications are likely to drive durable adoption. For teams evaluating expansion, portfolio adjustment, channel strategy, or competitive response, the report provides the contextual grounding needed to convert market signals into operational decisions.
Detailed value splits by region, application, and type, along with company level positioning and development timelines, are included in the full report. Those specifics are essential for precise planning but are held back from this preview to preserve the depth and differentiation of the complete intelligence package.
Strategic Takeaways for 2026 Planning
For organizations making 2026 decisions, the battery operated grease gun market offers credible growth, recognizable competitive structure, and clear operational complexity. The forecast indicates sustained expansion, but the value of the growth will be captured by firms that understand segment prioritization, regional execution realities, cost exposure, and competitive positioning. Whether the objective is to defend share in a concentrated category, identify entry points in under served segments, optimize sourcing and pricing under tariff pressure, or align product development with evolving maintenance workflows, this report is designed to support those choices with grounded market intelligence.
The complete analysis provides the detailed segmentation values, competitive assessments, and dynamic market context needed to turn strategic intent into executable plans. Readers seeking full segment-level data, company profiles, and forward-looking scenario support will find the complete report essential for rigorous planning and confident execution.
For detailed analysis of this topic, please visit the official page: Battery Operated Grease Gun Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Tubular Steel Wind Tower Market Hits $8.31B in 2025, 7.3% CAGR to 2032
By PW Consulting, 2026-09-16
Navigating the Steel Skeleton of Wind Energy: Strategic Insights for the Tubular Steel Wind Tower Market 2026-2032
Executive Preface: Why This Intelligence Matters Now
The global energy transition is no longer a theoretical trajectory; it is a supply chain imperative. As wind farm developers push for higher capacity factors and greater hub heights, the demand for robust tubular steel wind towers has entered a critical inflection point. Our latest comprehensive study, covering historical performance from 2020 through 2025 and a detailed forecast extending to 2032, provides the analytical rigor required to navigate this complex landscape. This article serves as a strategic preview of that research, designed to equip corporate strategy teams, procurement leaders, and investors with a clear understanding of the market forces at play.
In 2026, decision-making cannot rely on outdated assumptions. The market has demonstrated consistent growth, with revenue figures climbing from approximately 5.84 billion USD in 2020 to a projected 8.66 billion USD in 2026. Looking further ahead, the trajectory points toward 13.61 billion USD by 2032. This represents a compound annual growth rate of 7.3 percent over the forecast period. These numbers are more than statistics; they represent the scale of capital deployment required to meet renewable energy targets. However, understanding the aggregate size is only the starting point. The true value of this report lies in dissecting the underlying drivers, constraints, and competitive maneuvers that will determine market share in the coming years.
Readers should note that while this overview highlights the strategic framework, specific segmentation breakdowns, detailed regional revenue figures, and proprietary competitive scoring are reserved for the full report. This approach ensures that stakeholders who require actionable intelligence for precise investment or sourcing decisions have a compelling reason to engage with the complete dataset.
Market Resilience and Growth Trajectory
The period from 2020 to 2025 established a foundation of stability despite global supply chain disruptions. The market size expanded from 5.84 billion USD to 8.31 billion USD over this historical window, reflecting a steady uptake in wind energy infrastructure. The forecast period from 2026 to 2032 anticipates a continuation of this momentum, with the market expected to breach the 10 billion USD threshold by 2028 and reach 13.61 billion USD by the end of the forecast horizon.
Several macro factors support this outlook. First, the ongoing repowering of older wind farms requires replacement towers that meet modern standards for height and durability. Second, new project approvals in key markets are driving demand for onshore installations, which remain the dominant application type within the tubular steel segment. While offshore wind presents a high-growth opportunity, the sheer volume of onshore deployments continues to anchor the market size.
However, growth is not linear. Project developers must contend with significant variability in input costs. Steel constitutes a substantial portion of tower construction expenses, and volatility in raw material pricing between 660 and 890 USD per ton observed in recent years continues to ripple through project budgets. This cost sensitivity makes accurate forecasting and strategic sourcing essential for maintaining margin integrity. Our report analyzes how these cost structures influence bidding strategies and project viability across different regions.
Structural Segments and Technical Trends
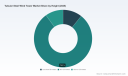
Understanding the market requires looking beyond total revenue to the technical specifications that drive demand. The industry is currently defined by a preference for mid-to-high hub heights. Towers in the 80 to 120 meters range represent a significant portion of the market value, as they offer the optimal balance between energy capture efficiency and transportation logistics. Towers below 80 meters are seeing reduced relative demand as turbines grow larger, while structures above 120 meters are gaining traction for specific high-wind sites, often requiring specialized engineering solutions.
Innovation in tower design is also reshaping the competitive landscape. Traditional tubular steel designs are being augmented by hybrid models. For instance, recent product launches have introduced hybrid steel towers that combine modular segmented steel with tubular sections to achieve higher hub heights without compromising structural integrity. These technological shifts are not merely engineering feats; they alter the supply chain requirements and open new avenues for manufacturers who can adapt their production capabilities.
The report provides a granular analysis of how these technical segments evolve over the forecast period. It examines the trade-offs between cost, logistics, and performance for different tower heights and application types. By understanding these technical drivers, stakeholders can better anticipate future demand patterns and align their production capacities accordingly.
Competitive Landscape and Concentration
The tubular steel wind tower market is characterized by a high degree of concentration. The top three players command a significant share of the market, while the top five entities further consolidate this position. This concentration implies that market dynamics are heavily influenced by the strategic moves of a few key industrial players. Our research profiles several of these critical companies, analyzing their operational footprints, product portfolios, and strategic positioning.
In North America, companies such as Arcosa Wind Towers and Broadwind Energy remain pivotal. Arcosa focuses on manufacturing and supplying tubular steel towers for onshore wind farms across the region, leveraging its location in Dallas, Texas, to serve a broad domestic market. Broadwind Energy, based in Cicero, Illinois, produces tubular steel towers and repowering adapters for turbine OEMs in the United States, positioning itself as a key partner for turbine manufacturers seeking reliable supply chain integration.
Asia Pacific presents a different competitive dynamic, with strong manufacturing bases in South Korea and China. CS Wind Corporation, headquartered in Seoul, supplies tubular steel wind towers and has secured full supply contracts for major US wind projects, highlighting the global nature of modern wind supply chains. In China, Titan Wind Energy in Suzhou and Shanghai Taisheng Wind Power Equipment Co., Ltd. are specialized manufacturers serving both onshore and offshore applications. Qingdao Tianneng Heavy Industries Co., Ltd. is also noted for its emphasis on offshore capabilities, reflecting the region's push into deeper water wind resources.
Europe remains a hub for technological innovation and high-quality manufacturing. ENERCON GmbH, based in Aurich, Germany, provides tubular steel wind towers for its own turbine platforms and hybrid designs. The company's recent introduction of a Hybrid Steel Tower demonstrates the ongoing innovation in this space, aiming to combine the benefits of modular segmentation with the strength of tubular sections for higher hub heights.
The report dives deep into the financial health, capacity expansions, and strategic partnerships of these key players. It also examines recent developments, such as the launch of a new wind tower manufacturing facility in Yanbu, Saudi Arabia, by Al Yamamah Steel Industries in late 2025. This move signals an effort to expand local supply chains in the Middle East, reducing reliance on imported components and potentially altering regional logistics costs.
Regulatory Environment and Trade Dynamics
No strategic analysis of the tubular steel wind tower market is complete without a rigorous examination of the regulatory landscape. Trade policies and anti-dumping duties have become central variables in project economics, particularly in the United States. The US International Trade Commission has recently issued determinations in five-year sunset reviews for utility-scale wind towers from Canada, Indonesia, South Korea, and Vietnam. The commission determined that revoking antidumping duty orders on these imports would likely lead to the continuation or recurrence of material injury to the domestic industry. This decision reinforces the protective trade measures that have been in place, affecting sourcing strategies for developers who might have considered these regions for cost savings.
Furthermore, the US Department of Commerce has amended final determinations on anti-dumping duties for utility-scale wind towers from Spain, setting a rate of 28.55 percent. Such specific duty rates can dramatically alter the landed cost of imported towers, making domestic or non-tariffed supply options more attractive. Additionally, a new federal tariff of 25 percent on imported steel-derivative products, including wind towers, announced in 2025, is already threatening specific projects. Reports indicate that nine wind projects in British Columbia face increased costs due to this tariff, highlighting the cross-border implications of US trade policy on neighboring markets.
These regulatory factors create a complex matrix for compliance and risk management. Companies must navigate not only the direct costs of tariffs and duties but also the potential for retaliatory measures and supply chain disruptions. Our report provides a detailed mapping of these regulatory risks, offering insights into how different regions are affected and what mitigation strategies are being employed by leading market participants. Understanding the legal and political context is as crucial as understanding the technical specifications of the towers themselves.
Why You Need the Full Report
While this overview underscores the magnitude and complexity of the tubular steel wind tower market, it only scratches the surface of the intelligence available in our full study. The market is too dynamic, and the stakes too high, to rely on high-level summaries for critical decision-making. The full report offers a depth of analysis that transforms general market awareness into actionable strategy.
Access to the complete research enables stakeholders to benchmark their performance against detailed market size data segmented by region and application. It provides the specific revenue figures and growth rates for each segment, allowing for precise target setting and resource allocation. The competitive analysis goes beyond company profiles to include market share estimates, strategic moves, and potential vulnerabilities. This level of detail is essential for identifying partnership opportunities, assessing competitive threats, and planning capacity expansions.
Tubular Steel Wind Tower Market
Moreover, the report includes a comprehensive analysis of raw material trends, supply chain risks, and regulatory updates, providing a holistic view of the operating environment. For investors, this data supports valuation models and risk assessments. For manufacturers, it informs production planning and pricing strategies. For developers, it aids in procurement negotiations and project feasibility studies.
In a market projected to reach 13.61 billion USD by 2032 with a CAGR of 7.3 percent, the difference between success and missed opportunity often lies in the granularity of the data. The full report is designed to provide that granularity. We invite you to explore the complete study to unlock the full potential of these insights and ensure your organization is equipped with the intelligence needed to thrive in the evolving wind energy landscape.
Worldwide Wind Turbine Tower Market
For detailed analysis of this topic, please visit the official page: Tubular Steel Wind Tower Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Stainless Steel Cable Ties Market to Reach $390.3M by 2032, Growing at 6.98% CAGR
By PW Consulting, 2026-09-16
Navigating the Next Frontier: Strategic Intelligence for the Stainless Steel Cable Ties Market (2026-2032)
The industrial fastening sector is undergoing a period of disciplined evolution, driven by a convergence of infrastructure modernization, maritime expansion, and increasingly stringent environmental resilience requirements. Within this landscape, the stainless steel cable ties market has emerged as a critical niche where material science meets operational reliability. Over the past half-decade, the market has demonstrated steady consolidation, with historical valuation climbing from approximately $215 million in 2020 to $252.5 million by 2025. As we turn the page to 2026, the trajectory points toward a base valuation of $260.72 million, with a projected compound annual growth rate positioning the sector to reach $390.3 million by the end of 2032.
These figures represent more than macroeconomic arithmetic. They reflect a structural shift in how engineers, procurement directors, and project managers approach cable management in harsh, corrosive, and high-vibration environments. For decision-makers navigating 2026, understanding the underlying drivers, competitive positioning, and regulatory friction points is no longer optional. It requires a granular, forward-looking intelligence framework. The latest PW Consulting Stainless Steel Cable Ties Market research report has been engineered precisely for this purpose.
Stainless Steel Cable Ties Market
Macro Growth Trajectory and the 2026 Inflection Point
The historical performance between 2020 and 2025 tells a story of resilience and deliberate recalibration. Following a period of market adjustment in 2024, evaluated revenue rebounded to $242.08 million before climbing to $252.5 million in 2025, signaling renewed capital allocation across both replacement and greenfield industrial projects. Looking ahead, the forecast horizon from 2026 through 2032 maps a sustained upward curve, with annual valuations expected to accelerate as downstream adoption deepens in electrical infrastructure, marine platforms, and heavy industrial assembly lines.
The headline CAGR of 6.98 percent underscores a market that is neither speculative nor stagnant, but structurally growing. This rate of expansion demands strategic attention. Organizations that rely on backward-looking procurement benchmarks will quickly find themselves misaligned with material availability, pricing dynamics, and certification requirements that are evolving in real time. The 2026 edition of our market research dissects these trajectories not as isolated numbers, but as interconnected signals that inform capacity planning, supplier negotiations, and regional deployment strategies.
Nylon Cable Ties Market
Competitive Architecture and the Rise of Specialized Offerings
The competitive landscape is defined by a concentrated yet differentiated group of manufacturers that have carved distinct value propositions within the stainless steel cable ties ecosystem. Market concentration data indicates a moderately fragmented structure, with the top three firms collectively capturing a modest share and the top five extending that footprint only slightly further. This dispersion suggests ample room for targeted positioning, but it also demands rigorous evaluation of product engineering, coating technologies, and compliance portfolios.
HellermannTyton, headquartered in Germany, has built its reputation on precision-engineered stainless steel cable ties offered across a spectrum of lengths, widths, and tensile specifications. Their approach emphasizes full polyester coating to prevent contact corrosion, paired with protective polyolefin channels designed to mitigate chafing, vibration, and mechanical shock. In critical infrastructure scenarios, their MBT-Series has achieved full-range UL 62275 certification for short-circuit protection, establishing a compliance benchmark that procurement teams increasingly reference during vendor qualification.
Across the Atlantic, Panduit, based in Illinois, has focused on integrated systems rather than standalone components. Their Pan-Steel System consolidates stainless steel cable ties, banding, mounts, identification solutions, and installation tools into a unified workflow tailored for shipbuilding and severe operating environments. The emphasis on smooth, round edges that prevent cable insulation damage reflects a user-centric engineering philosophy that resonates with OEM integrators and field installation teams.
BAND-IT, operating from California, has concentrated on tensile durability and industrial bundling performance through its Ultra-Lok locking style. This mechanical design prioritizes secure, repeatable fastening in high-stress applications, positioning the brand as a go-to for manufacturers that require consistent clamping force under dynamic load conditions.
On the compliance and regional manufacturing front, Hayata distinguishes itself as a US-owned, ISO 9001-certified producer offering 360-degree coated stainless steel cable ties and banding in multiple sizes. Its status as the only such US-based manufacturer serving harsh environment applications provides a tactical advantage for domestic supply chain resilience and procurement teams prioritizing localized production footprints.
Kable Kontrol has carved a niche around flame-retardant Grade 304 stainless steel cable ties featuring an easy-install, low-profile self-locking ball bearing head, with UL listing that streamlines approval cycles for electrical positioning devices. Meanwhile, HUA WEI INDUSTRIAL CO., LTD., based in Taiwan, has expanded its certification footprint to include UL, CSA, GL, CE, and CQC accreditations, aligning its heavy-duty and ball-lock stainless steel cable ties with severe industrial application standards. Their June 2026 participation in ElectroneX, where they showcased stainless steel and heavy-duty cable ties alongside ball-lock variants and polyamide 12 solar cable ties, illustrates how trade presence and product diversification are being leveraged to capture cross-sector attention.
Additionally, Hangzhou Gordon Electric Co., Ltd. was highlighted in April 2026 as a specialized OEM/ODM manufacturer within the top supplier landscape, reinforcing the growing role of contract and custom manufacturing in meeting project-specific fastening requirements across global industrial deployments.
Material Standards, Regulatory Friction, and the Certification Economy
The operational value of stainless steel cable ties is inseparable from the material grades and regulatory frameworks that govern their deployment. Grade 304 and marine-grade 316 stainless steel form the backbone of the category, offering corrosion resistance and thermal tolerance spanning from -100°F to 1000°F. This thermal and chemical resilience is what enables adoption in environments where polymer-based fasteners degrade, where salt exposure accelerates failure, or where electrical safety mandates fire-retardant performance.
Yet material capability alone does not unlock market access. Certification has become a decisive commercial variable. The UL 62275 alignment achieved by HellermannTyton’s MBT-Series, the UL listing secured by Kable Kontrol under File No. E530766, and the multi-accreditation portfolio maintained by HUA WEI INDUSTRIAL CO., LTD. all reflect a market where compliance is a gatekeeper to project eligibility. ISO 9001 certification, as demonstrated by Hayata’s US-based production line, further signals process maturity that procurement and quality teams weigh heavily when qualifying suppliers for long-term contracts.
For 2026 strategy planning, this certification economy introduces both constraint and opportunity. Organizations that internalize the mapping between application requirements, regional regulatory expectations, and supplier certification portfolios will compress approval timelines and reduce downstream rework risk. Our research report layers these dynamics into a practical compliance-and-selection framework, helping teams evaluate not just what a tie does, but what standards it satisfies and where those standards carry the greatest commercial weight.
Why This Report Is Built for 2026 Decision-Making
Market research that merely recites growth percentages fails the modern strategist. The 2026 Stainless Steel Cable Ties Market report is structured to convert intelligence into action. It delivers an operational blueprint that covers:
- Historical performance mapping and forward forecast modeling that contextualizes the 2026-2032 growth arc without reducing it to a single headline figure, enabling scenario-based planning across procurement cycles and capital budgeting windows.
- A structured examination of type, size, application, and regional segmentation dynamics, presented to illuminate where demand density is concentrating and how product configurations are aligning with end-use requirements, while preserving the strategic discretion necessary for competitive positioning.
- A competitive profiling module that dissects product engineering, coating technologies, locking mechanisms, installation ergonomics, and compliance portfolios across the key manufacturers shaping the category, equipping buyers and sellers with a comparative lens for vendor selection and market entry evaluation.
- An integrated view of market concentration and fragmentation trends, providing context for pricing power, negotiation leverage, and the strategic implications of a moderately dispersed supplier base.
- A regulatory and certification tracker that translates recent UL, CSA, GL, CE, CQC, and ISO 9001 developments into actionable guidance for project qualification, export planning, and risk mitigation.
- Material and performance benchmarks anchored in real-world thermal, corrosion, and flame-retardant requirements, enabling engineering and procurement teams to align specification choices with environmental exposure and safety mandates.
The deliberate architecture of this report reflects a core principle: in a market where certification, coating technology, tensile design, and regional compliance expectations are moving in tandem, decision-makers need an integrated intelligence system, not a fragmented data dump. The report is designed to support sourcing strategy, product portfolio alignment, competitive benchmarking, and market-entry assessment with equal rigor.
The Strategic Case for Deeper Intelligence
As 2026 unfolds, the stainless steel cable ties market will continue to reward organizations that treat fastening not as a commodity afterthought, but as a performance-critical component embedded in larger system reliability. The convergence of infrastructure renewal, marine asset expansion, and electrical safety mandates is expanding the addressable base, while certification scrutiny and material differentiation are raising the barrier to entry for undifferentiated players.
The full research report extends beyond the trajectory outlined here. It maps the segmentation architecture across type, size, application, and regional demand patterns, unpacks the competitive positioning of the companies shaping the category, and provides the analytical scaffolding needed to convert market signals into procurement strategy, product development priorities, and expansion planning. To access the complete segmentation breakdown, forecast scenarios, and competitive deep dives, we invite you to explore the full report on our platform. The intelligence required to navigate 2026with precision is available, and the organizations that secure it first will be best positioned to capture the growth ahead.
For detailed analysis of this topic, please visit the official page: Stainless Steel Cable Ties Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aircraft Piston Engines Market to Hit USD 7,152.97M by 2032 at 5.2% CAGR
By PW Consulting, 2026-09-16
Navigating the Sky: Strategic Intelligence for the Aircraft Piston Engines Market (2026-2032)
The global aviation landscape is undergoing a subtle yet profound transformation. While much attention dominates the headlines regarding sustainable aviation fuels and electric propulsion, the heartbeat of general aviation remains steadfastly dependent on the internal combustion piston engine. For stakeholders, investors, and strategic planners, understanding the trajectory of this mature yet evolving market is not merely an academic exercise—it is a critical component of risk mitigation and growth strategy for the 2026 fiscal year and beyond.
PW Consulting is proud to introduce our comprehensive market intelligence report on the Aircraft Piston Engines Market. This document serves as a strategic compass for navigating the complexities of engine manufacturing, aftermarket support, and regulatory compliance over the forecast period extending to 2032. By synthesizing historical data with forward-looking projections, this study provides the granularity required to make informed capital allocation and product development decisions.
Market Trajectory and Historical Context
The resilience of the piston engine sector is evident when examining the revenue trends over the past half-decade. From 2020 to 2025, the market demonstrated a consistent upward trajectory, recovering from global supply chain disruptions and ramping up to meet renewed demand in general aviation. Revenue figures have climbed steadily, reflecting both increased production rates and healthy pricing power within the supply chain.
Looking forward, the market is projected to expand from an estimated 5,270 million USD in 2026 to approximately 7,153 million USD by 2032. This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 5.2 percent throughout the forecast period. This rate suggests a market that is not only recovering but maturing, driven by replacement cycles, fleet expansion in emerging economies, and technological upgrades in existing airframes. For decision-makers, these top-line figures validate the sector as a stable investment vehicle with predictable long-term returns, though the allocation of these revenues across different segments requires deeper analysis provided in our full report.
Segmentation Dynamics: Types, Applications, and Geography
Understanding where value is generated within the market is crucial for targeting investments. The market is divided into distinct categories based on engine architecture, operational application, and regional demand. While specific percentage splits are detailed within the proprietary sections of our study, the structural composition reveals key preferences among manufacturers and operators.
In terms of engine type, the market is anchored by Horizontally Opposed, Inline, and Radial configurations. The dominance of certain architectures often correlates with specific aircraft categories, influencing supply chain requirements and manufacturing capabilities. Similarly, the application landscape is diversified across Training, Aerial Work, and Private and Recreational segments. The training sector, for instance, remains a critical volume driver due to the perpetual need for pilot certification, whereas aerial work demands durability and specific performance metrics. Private and recreational use continues to be a significant contributor, fueled by hobbyist enthusiasm and personal aviation ownership.
Geographically, the demand is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents unique regulatory environments, economic conditions, and fleet ages that dictate consumption patterns. Our analysis highlights how regional discrepancies in certification standards and economic growth rates create varied opportunities for engine manufacturers and service providers.
Competitive Landscape and Key Players
The competitive environment is characterized by a mix of established legacy manufacturers and innovative entrants focusing on alternative fuel capabilities. The market concentration, indicated by a CR5 of 26.2 percent, suggests a moderately fragmented industry where niche players can still carve out significant market share through specialization.
Lycoming Engines, based in Williamsport, Pennsylvania, remains a cornerstone of the industry. Their production of four-, six-, and eight-cylinder piston engines up to 400 horsepower supports a vast array of general aviation, training, and commercial aircraft. Notably, their engines power over half of the world's general aviation fleet, establishing a reputation for reliability that creates high switching costs for operators.
Continental Aerospace Technologies, headquartered in Mobile, Alabama, competes closely with a focus on advanced designs. They manufacture piston engines capable of running on both Jet-A and avgas, accumulating over 12 million flight hours. Their recent moves highlight a strategic pivot towards fuel flexibility and certification in new sectors.
Aircraft Piston Engines Market
BRP-Rotax, located in Austria, serves a specialized niche by developing engines for light sport, ultralight, and training aircraft. Their focus on the lower end of the weight and power spectrum allows them to dominate segments where traditional general aviation engines are too large or costly.
DeltaHawk Engines, based in Racine, Wisconsin, represents the innovative frontier. They manufacture FAA-certified jet-fuel-burning piston engines, such as the DHK180 and DHK6A350. By enabling the use of heavy fuel in piston engines, they address logistical advantages in remote operations and reduce dependency on traditional avgas supplies.
Recent Developments and Technological Shifts
The period leading into 2026 has seen significant activity regarding product launches and certifications that will shape the next cycle of market growth. These events signal a shift towards fuel flexibility and expanded operational envelopes.
In July 2025, Piper Aircraft, Inc. announced the Piper Seminole DX, powered by DeltaHawk's FAA-certified DHK4A180 180-hp heavy fuel engine. The order book opened at EAA AirVenture 2025, marking a tangible entry of heavy-fuel piston technology into multi-engine training and commercial applications. This development is particularly significant given the regulatory backdrop. FAA certification flight testing for the Piper Seminole DX with the DeltaHawk engine commenced in November 2025, with certification expected in Q3 2026. This timeline suggests that full market availability and subsequent fleet integration will accelerate demand in the latter half of the forecast period.
Continental Aerospace Technologies achieved a milestone in April 2026 by receiving EASA approval for the CD-170R Jet-A piston engine for rotorcraft applications. This marks the first certified Jet-A FADEC-controlled helicopter piston engine. By bridging the gap between fixed-wing efficiency and rotary-wing operational needs, this certification opens a new revenue stream that was previously inaccessible to piston engine manufacturers.
Jet Engines Market
Simultaneously, DeltaHawk Engines achieved FAA Type Certification for the DHK180 jet-fuel piston engine in June 2025, with the first flight occurring in a Van's RV-14. This certification validates the technical viability of heavy-fuel piston engines in experimental and general aviation categories, encouraging further adoption among builders and operators seeking fuel security.
These technological strides are supported by broader industry data. The General Aviation Manufacturers Association (GAMA) reported that piston airplane deliveries increased by 4.2 percent in 2024 to 1,772 units. This uptick in unit shipments provides a strong foundational demand signal for engine manufacturers, indicating that airframe production is aligning with engine supply capabilities.
Strategic Implications for 2026 Decision-Makers
For executives and planners preparing budgets and strategies for 2026, several implications arise from this landscape. First, the reliance on avgas remains a strategic vulnerability for many operators, making the adoption of Jet-A capable engines a potential risk mitigation strategy. The certifications achieved by Continental and DeltaHawk in 2025 and 2026 provide viable alternatives that should be evaluated against total cost of ownership and logistics.
Second, the fragmentation of the market means that partnership opportunities exist beyond the top tier. With a CR5 of only 26.2 percent, there is room for specialized manufacturers to thrive, particularly in training and aerial work segments where specific power-to-weight ratios are prioritized over raw horsepower. Supply chain resilience is also paramount; understanding the geographic distribution of demand helps in positioning inventory and service centers to minimize downtime.
Finally, regulatory timelines are critical path items. The expected FAA certification for the Piper Seminole DX in Q3 2026 is a catalyst that could spur orders in the training and commuter segments. Stakeholders should align their procurement and hiring strategies to anticipate the ripple effects of this certification on maintenance training and parts inventory.
Report Scope and Methodology
This strategic insight is derived from a robust methodology that combines primary research with extensive secondary data analysis. The full report offers a deep dive into the factors influencing market growth, including regulatory frameworks, technological innovations, and economic indicators.
Readers of the complete study will gain access to detailed segmentation analysis that breaks down market value by region, type, and application, allowing for precise market sizing. The competitive profiling extends beyond basic company statistics to include strategic positioning, recent M&A activity, and product pipeline assessments. Furthermore, the report addresses the constraints and challenges facing the industry, such as fuel availability, emission standards, and supply chain bottlenecks.
Our analysis covers the forecast period from 2026 to 2032, providing a long-term view that supports capital expenditure planning and technology roadmap development. Whether you are a manufacturer looking to expand your portfolio, an investor assessing market entry barriers, or an operator optimizing fleet composition, the data contained herein is tailored to support those specific objectives.
Conclusion
The Aircraft Piston Engines Market stands at a inflection point where traditional reliability meets modern fuel flexibility. The growth projected through 2032 is not merely a reflection of historical trends but a result of active innovation in engine technology and expanding operational scopes. For organizations aiming to lead in this sector, access to granular, verified data is the differentiator between reactive management and proactive strategy. This report provides the foundation necessary to navigate the coming years with confidence.
For detailed analysis of this topic, please visit the official page: Aircraft Piston Engines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cockpit and Flight Data Recorder Market Hits $170M in 2025, 5.8% CAGR to $257M by 2032
By PW Consulting, 2026-09-16
Strategic Imperatives in the Cockpit Voice and Flight Data Recorder Market: Navigating Growth and Regulatory Shifts Through 2032
The aviation safety ecosystem stands at a pivotal juncture. As aircraft design philosophies evolve and regulatory bodies tighten mandates around data retention and crashworthiness, the Cockpit Voice and Flight Data Recorder market is experiencing a structural realignment that will define procurement strategies, product development roadmaps, and competitive positioning for the next decade. Our latest market research offers a comprehensive, data-driven blueprint for executives, sourcing directors, and engineering leaders who must make capital allocation and compliance decisions in 2026 and beyond.
This publication arrives at a moment when the intersection of technological innovation and regulatory compliance is no longer a peripheral concern, but a central boardroom priority. The insights contained within are designed to transform uncertainty into actionable intelligence, enabling stakeholders to anticipate demand shifts, evaluate supplier capabilities, and align investment timing with the market’s most consequential inflection points.
Market Trajectory: A Decade of Calculated Expansion
Tracing the historical arc from 2020 through 2025 reveals a market that has consistently demonstrated resilience and steady upward momentum, even amid global supply chain disruptions and shifting fleet utilization patterns. The sector has progressed from a baseline valuation in the early 2020s to a substantially expanded footprint by 2025, reflecting sustained airframe deliveries, replacement cycles, and the gradual integration of next-generation recording architectures across both commercial and defense platforms.
Looking forward across our forecast period, the trajectory points toward continued growth, underpinned by heightened safety mandates, fleet modernization programs, and the ongoing proliferation of digital flight data streaming capabilities. The compound annual growth rate projected for this window signals a durable expansion narrative, one that will reward organizations capable of aligning their product portfolios and supply chain strategies with emerging compliance requirements. Critically, the projected valuation milestones across successive forecast years illustrate a market that is not merely expanding in nominal terms, but evolving in complexity, demanding more sophisticated integration, certification readiness, and lifecycle support capabilities from manufacturers and integrators alike.
For enterprise decision-makers, this growth profile carries strategic weight. It suggests that the market will accommodate new entrants and incumbent expansions alike, but that the distribution of opportunity will be uneven. Organizations that treat the recorder segment as a commoditized afterthought risk ceding ground to competitors who recognize it as a high-value, regulation-sensitive domain with significant barriers to entry and long-term revenue visibility.
Regulatory Catalysts Reshaping Demand Profiles
The single most potent force currently restructuring procurement pathways is the regulatory environment. Throughout 2024 and 2025, authorities across major aviation markets moved to codify extended recording durations and enhanced data accessibility standards. A landmark development in early 2026 saw the finalization of a rule mandating twenty-five-hour cockpit voice recorder retention for newly manufactured aircraft across multiple operational categories, with compliance timelines anchored to production dates in mid-2025. This ruling does not merely extend a specification; it fundamentally alters the engineering requirements for manufacturers designing for the commercial airliner, business jet, and commuter segments.
Complementary legislative actions, including provisions embedded in broader aviation reauthorization frameworks, have extended similar twenty-five-hour capability requirements to larger transport-category aircraft and established retrofit compliance horizons extending toward the end of the decade. These mandates create a dual-layer demand structure: an immediate pull from new production lines adapting to revised certification baselines, and a deferred but substantial pull from in-service fleets that must be upgraded or replaced to remain compliant. International standardization efforts have reinforced this trajectory, with global aviation bodies advancing proposals to harmonize flight recorder data download interfaces, reduce analysis friction, and improve cross-manufacturer interoperability. Such initiatives signal a longer-term shift toward data-centric safety architectures that will influence procurement criteria well beyond the current forecast horizon.
For organizations evaluating market entry, product line expansion, or supplier partnerships, the regulatory calendar is not a peripheral detail. It is a scheduling mechanism that dictates certification timelines, production slot allocation, retrofit campaign planning, and ultimately, revenue realization. The strategic implication is clear: companies that map their development cycles and capacity investments against these regulatory milestones will secure competitive advantage, while those that treat compliance as an after-the-fact engineering task will face costly redesigns and delayed market access.
Aerospace and Marine Data Recorders Market
Product Segmentation and Engineering Evolution
The market’s product architecture spans distinct recorder categories, each carrying different engineering demands, certification pathways, and end-user value propositions. Traditional flight data recording units continue to serve as the backbone of operational monitoring and accident investigation, while cockpit voice recording systems have undergone a generational leap in capacity and reliability. The emergence of combined voice and flight data recorder solutions reflects a broader industry preference for integrated, weight-optimized, and simplified installation architectures, particularly in platforms where space, power, and maintenance access are tightly constrained.
Engineering sophistication in this segment has accelerated markedly. Modern recorder families now emphasize extended recording durations, enhanced crashworthiness and fire resistance, faster data retrieval through advanced interface protocols, and optional onboard streaming or rapid-retrieval capabilities that reduce post-event analysis timelines. Ethernet-enabled download pathways, integrated rapid-retrieval information processing systems, and modular designs that accommodate multi-platform certification are increasingly becoming baseline expectations rather than premium differentiators. For integrators and airframe manufacturers, these features translate into reduced certification complexity, streamlined maintenance workflows, and improved alignment with fleet-wide data management strategies.
The implication for market participants is that product differentiation is shifting from standalone recorder specifications toward ecosystem compatibility. Suppliers that can demonstrate seamless integration with existing avionics suites, provide clear retrofit pathways, and offer lifecycle support aligned with extended operational use cases will capture disproportionate share in a market where total cost of ownership and compliance assurance weigh heavily in purchasing decisions.
Cockpit Voice and Flight Data Recorder Market
Competitive Architecture: Who Holds the Edge
The competitive landscape is defined by a concentrated group of established aerospace and defense technology firms that have invested heavily in recorder platforms, certification portfolios, and OEM relationships. Industry analysis indicates a market structure where a relatively small number of participants command a substantial share of revenue, reflecting the high technical barriers, lengthy certification cycles, and long-term supply agreements that characterize this domain. Such concentration rewards companies with proven track records in airworthiness certification, production scalability, and global aftermarket support.
Among the organizations shaping this competitive environment, several stand out for their product architectures and strategic positioning. Honeywell Aerospace has solidified its presence through combined recorder platforms engineered for commercial airliners and business jets, with certification coverage that spans multiple aircraft categories and recording durations aligned with the latest mandates. Curtiss-Wright Defense Solutions contributes through its recording technology divisions, including collaborative development of next-generation recorder series and proprietary systems designed for commercial aviation applications. Universal Avionics has advanced the segment through its fifth-generation recorder line, emphasizing combined unit configurations, Ethernet download options, and modular rapid-retrieval capabilities that align with modern fleet data management needs.
L3Harris Technologies maintains a strong footprint through its recorder and survival recorder families, including series designed for widely deployed airframes with supplemental type certificate coverage on platforms such as the Boeing 737NG and integrated rapid-retrieval systems. HENSOLDT brings European certification expertise and a portfolio spanning combined recorders, standalone flight data units, and voice recording models certified to recognized industry standards. Flight Data Systems has carved a position around lightweight combined recorder designs that meet stringent crashworthiness and fire-resistance requirements while offering optional rapid-retrieval integration. Safran extends its influence through helicopter and fixed-wing recorder solutions, reflecting the diversification of platform requirements across rotorcraft and general aviation segments. Acron Aviation has emerged as a notable player through its recorder series offering extended audio and flight data retention, alongside strategic recognition as an approved solution for major airframer programs and a platform for continuous online procurement of certified avionics components.
The strategic takeaway for procurement and planning teams is that supplier selection increasingly hinges on more than unit pricing. Certification breadth, retrofit readiness, production capacity, global support infrastructure, and alignment with forthcoming data interface standardization all factor into long-term value. Organizations that conduct structured supplier evaluations against these criteria will be better positioned to secure reliable supply, navigate certification dependencies, and capitalize on retrofit and replacement cycles.
Where 2026 Decision-Makers Must Focus
As enterprises calibrate their strategies for the current year and beyond, several priority areas demand focused attention. First, regulatory mapping must become a continuous function rather than a periodic compliance exercise. The staggered compliance dates across new production and retrofit mandates require organizations to sequence procurement, engineering, and fleet planning activities with precision. Second, product evaluation frameworks should incorporate data accessibility, interface compatibility, and aftermarket support as core criteria, reflecting the longer-term shift toward integrated safety data ecosystems.
Third, supply chain resilience warrants heightened scrutiny. The concentration of market share among a limited set of manufacturers underscores the importance of qualifying alternate sources where feasible, securing multi-year agreement structures, and stress-testing production capacity against anticipated demand surges driven by retrofit campaigns and fleet renewal programs. Fourth, forward-looking investment decisions should account for the possibility that standardization initiatives around data download interfaces and interoperability will create new value pools in software, analytics, and service delivery, extending the commercial relevance of recorder platforms beyond hardware sales.
Organizations that embed these considerations into their strategic planning will not only mitigate compliance risk but also unlock opportunities to influence specification development, secure preferred supplier status, and align product roadmaps with the market’s most consequential growth vectors.
What the Full Study Delivers
Our complete market research publication provides a granular, actionable foundation for the decisions outlined above. The report constructs a multi-year market size framework anchored to historical performance data and extended through a detailed forecast horizon, enabling precise scenario planning and investment timing analysis. It decomposes demand across major geographic markets and application segments, illuminating where growth concentration is forming and how regional aviation activity, fleet composition, and regulatory adoption patterns shape local opportunity profiles.
The study delivers deep segmentation analysis by recorder type, clarifying the relative commercial weight of flight data recorders, cockpit voice recorders, and combined systems, while mapping product architecture trends, certification requirements, and technological adoption curves across each category. Application-level examination distinguishes between civil aviation and military aviation demand drivers, including fleet renewal cycles, operational mandates, and platform-specific engineering requirements that influence procurement timing and specification preferences.
A dedicated competitive profiling section evaluates the strategic posture, product capabilities, certification footprints, and recent developments of the leading manufacturers, providing a structured basis for supplier benchmarking, partnership evaluation, and competitive positioning analysis. The report also integrates regulatory trackers, recent product launches, partnership announcements, and procurement developments, offering a continuously updated view of the forces that are actively reshaping purchasing requirements and market access conditions.
For executives seeking to validate capital allocation, guide engineering investment, or refine market entry strategies, the full study translates macro-level trends into specific, segment-level intelligence that can be operationalized across procurement, product management, and strategic planning functions. The most consequential details, including precise regional revenue distributions, application-level valuation breakdowns, and company-specific market share estimates, are reserved for the complete report to ensure that stakeholders receive unfiltered, decision-ready intelligence when they engage directly with the analysis.
The Strategic Case for Early Engagement
The Cockpit Voice and Flight Data Recorder market will not be defined solely by airframe production volumes or cyclical procurement patterns. It will be shaped by the interplay of regulatory mandates, engineering standardization, supplier concentration, and the growing expectation that safety recorders function as integral nodes within broader aviation data architectures. Organizations that act early to align their strategies with these forces will secure advantages in specification influence, supply assurance, and market positioning that will compound as the forecast period unfolds.
This research publication is designed to provide the evidentiary foundation and analytical structure necessary to make those decisions with confidence. By combining historical validation, forward-looking modeling, competitive mapping, and regulatory tracking into a single integrated framework, it equips decision-makers with the clarity required to navigate a market that rewards preparedness and penalizes ambiguity. The complete dataset, segment-level breakdowns, and detailed company assessments are available through the full report, offering the depth required to translate strategic intent into executed action.
For detailed analysis of this topic, please visit the official page: Cockpit Voice and Flight Data Recorder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Earthing Lightning Protection Market to Hit $10.61B by 2032 at 7.3% CAGR
By PW Consulting, 2026-09-16
Navigating the Surge: Strategic Intelligence for the Earthing Lightning Protection System Market in 2026
The global infrastructure landscape is undergoing a critical transformation, driven by the accelerating need for resilient electrical safety systems. As we move deeper into 2026, the Earthing Lightning Protection System Market stands at a pivotal juncture where historical growth trajectories meet new regulatory and technological realities. For industry stakeholders, investors, and strategic planners, understanding the nuances of this evolution is not merely an academic exercise—it is a fundamental requirement for risk mitigation and capital allocation.
This article serves as an executive overview of the comprehensive market research recently published by PW Consulting. Our analysis draws upon a robust dataset spanning from 2020 through 2025, offering a detailed forecast window extending to 2032. The objective is to arm decision-makers with the foresight necessary to navigate a market defined by stringent compliance standards, material innovations, and shifting geographic demands. The following insights represent the high-level strategic value embedded within our full report, highlighting why deep-dive intelligence is essential for capturing the opportunities within this sector.
Lightning Arrester Market
Market Trajectory and Financial Horizons
The financial architecture of the Earthing Lightning Protection System Market demonstrates a consistent upward trend, reflecting the global prioritization of infrastructure safety. Our research indicates that the overall market revenue has seen steady expansion over the past half-decade. Starting from a baseline in 2020, the market has cultivated substantial momentum, reaching significant valuation milestones by 2025. This historical performance sets the stage for a forecast period that analysts view with considerable optimism.
Looking toward the immediate and long-term future, the growth trajectory suggests a compound annual growth rate (CAGR) that underscores the sector's vitality. This expansion is not accidental; it is the result of compounded investments in industrial safety, renewable energy integration, and telecommunications infrastructure. However, raw numbers alone do not tell the whole story. The strategic value lies in understanding the velocity of this growth and the specific drivers that will sustain it beyond 2026. Our report dissects these financial flows to reveal where capital is concentrating and where future revenue streams are likely to emerge, providing a clear lens through which to view investment potential.
Regulatory Frameworks as Growth Engines
One of the most potent catalysts for market expansion is the evolving landscape of international safety standards. Compliance is no longer optional; it is a prerequisite for market entry and operational continuity in many regions. The industry is heavily influenced by established protocols such as the IEC 62305 series, which mandates comprehensive earthing and lightning protection systems for structures and electrical installations. Similarly, the UL 96A standard establishes rigorous requirements for the installation of lightning protection systems, including grounding electrodes, specifically targeting commercial and industrial applications.
These regulations create a structured environment where compliance drives demand. For manufacturers and service providers, alignment with standards like NFPA 780 and UL 96A is critical. Our analysis explores how these regulatory frameworks vary by region and application, creating unique barriers to entry and opportunities for specialization. Companies that can navigate this complex compliance web effectively are positioned to capture greater market share. The report details how these standards influence design choices, material specifications, and installation protocols, ensuring that stakeholders understand the operational implications of regulatory adherence.
Technological Innovations and Material Science
Beyond regulation, the market is being reshaped by advancements in material science and product design. The performance of earthing systems relies heavily on the resistivity of the ground and the conductivity of the materials used. Industry data highlights the importance of copper bonded electrodes in maintaining low resistance grounding performance, often requiring systems to achieve thresholds below 10 ohms. Furthermore, copper conductors and plates are frequently specified for earthing systems to achieve even stricter grounding resistance targets, such as below 4 ohms, in lightning protection setups.
Recent developments indicate a shift toward more application-specific solutions. For instance, recent product announcements have showcased retractable grounding assemblies for storage tanks, addressing niche requirements within oil and gas facilities. Additionally, the release of comprehensive product catalogs and design tools is streamlining the engineering process for contractors and engineers. These innovations reduce installation time and improve reliability, which in turn accelerates adoption. Our research evaluates these technological shifts to determine which innovations are likely to become industry standards and which represent transient trends. Understanding the technical specifications behind these products is crucial for procurement teams and engineering leads.
Competitive Landscape and Key Players
The market structure is characterized by a mix of established multinational corporations and specialized regional manufacturers. Our analysis identifies key companies that are defining the competitive boundaries. These entities range from manufacturers of structural lightning protection components and grounding electrodes to providers of application-specific systems and surge protection integration.
Leading players such as nVent ERICO and DEHN SE are recognized for their specialist capabilities in integrating lightning protection with surge suppression and compliance standards. Meanwhile, firms like Harger Lightning and Grounding and Lightning Eliminators focus heavily on structural components and application-specific assemblies, particularly in the North American market. Other significant contributors include Furse and LPI Group, which provide complete systems across Europe and the UAE, and regional powerhouses like Gravin Earthing & Lightning Protection System and Bahra Electric, which serve specific material and geographic needs.
The competitive dynamics are further influenced by the low market concentration, suggesting ample opportunity for new entrants or niche players who can differentiate through technology or service. Our report provides a detailed competitive benchmarking analysis, evaluating the strategic moves, product launches, and standard updates undertaken by these key entities. By understanding the strategies of these market leaders, organizations can better position themselves to compete or collaborate effectively.
Strategic Segmentation and Application Drivers
Demand for earthing and lightning protection is not uniform across all sectors. The market is segmented by type, region, and application, each with its own growth drivers. The division between Lighting Protection Systems and Earthing Systems represents a fundamental split in product focus, with both segments contributing significantly to overall revenue. However, the application side offers deeper insights into where the immediate demand lies.
Key application areas include industrial factories, solar plants, telecommunications towers, residential homes, and the oil and gas sector. Each of these verticals faces distinct risk profiles and compliance requirements. For example, solar plants require robust earthing to protect significant capital investment in photovoltaic arrays, while factories demand systems that can handle high-voltage industrial loads. Telecom towers, often located in exposed areas, rely heavily on effective lightning protection to ensure network uptime. Our report breaks down these application drivers to reveal which sectors are experiencing the highest velocity of adoption. We analyze the specific needs of each vertical without disclosing the precise revenue splits, encouraging stakeholders to consult the full dataset for actionable allocation strategies.
Earthing Lightning Protection System Market
Regional Dynamics and Growth Variations
Geography plays a crucial role in market performance. Different regions exhibit varying levels of infrastructure development, regulatory strictness, and climatic conditions that influence lightning risk. The market is distributed across major global regions, including North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa.
Asia Pacific, for instance, represents a significant portion of the market volume, driven by rapid industrialization and infrastructure projects. North America and Europe maintain strong demand due to mature regulatory environments and the retrofitting of existing structures. Emerging markets in Latin America and the Mideast and Africa present growth opportunities linked to energy projects and urban development. However, navigating these regions requires an understanding of local standards and supply chain logistics. Our comprehensive study maps these regional nuances, offering guidance on where to focus sales efforts and distribution networks. We highlight the macro trends in each geography while reserving specific regional revenue figures for the detailed report to ensure clients benefit from the complete intelligence package.
Market Concentration and Consolidation Trends
An important aspect of the competitive environment is the level of market concentration. Current data suggests a fragmented landscape where no single entity dominates the entire value chain. This fragmentation indicates that while large players hold significant influence, there is substantial room for competition based on quality, innovation, and regional expertise.
This structure impacts pricing power, supply chain resilience, and merger and acquisition strategies. Companies looking to expand may find opportunities to consolidate smaller regional players to gain market access. Conversely, smaller firms may seek partnerships with larger integrators to broaden their solution offerings. Our analysis examines the implications of this concentration level, providing context for strategic partnerships and M&A activities. Understanding the balance of power among the top competitors is essential for forecasting market stability and pricing trends.
In conclusion, the Earthing Lightning Protection System Market offers substantial opportunities for those equipped with the right intelligence. The convergence of regulatory pressure, technological advancement, and infrastructure development creates a fertile environment for growth. However, realizing this potential requires more than a surface-level understanding of the market. It demands a deep dive into the specific drivers, competitive maneuvers, and regional intricacies that define the landscape.
This article has provided a strategic overview of the key themes shaping the industry in 2026 and beyond. Yet, the full extent of the opportunity lies in the details. The complete PW Consulting market research report offers exhaustive data, precise segmentation analysis, and actionable forecasts that go beyond the macro trends discussed here. For enterprises ready to make informed decisions on product development, market entry, or investment, accessing the full intelligence is the critical next step. We invite you to explore the complete study to unlock the comprehensive insights necessary to lead in this evolving market.
For detailed analysis of this topic, please visit the official page: Earthing Lightning Protection System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Retail Shelving Systems Market Hits $2.64B in 2025, Projects 9.2% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Shelf Space: Navigating the 2026 Retail Shelving Systems Market
The physical storefront remains a critical battleground for consumer brands, even as digital channels expand. While e-commerce captures headlines, the in-store experience continues to drive impulse purchases and brand loyalty, making the infrastructure behind the merchandise more vital than ever. At the center of this infrastructure lies the retail shelving system. It is no longer mere storage; it is a strategic tool for inventory management, visual merchandising, and customer flow optimization. As we move through 2026, understanding the trajectory of this market is essential for stakeholders looking to capitalize on evolving retail dynamics.
This article serves as a strategic overview based on our latest comprehensive research into the Retail Shelving Systems Market. It highlights the macro-economic shifts, competitive pressures, and structural trends defining the industry. However, to maintain the integrity of our proprietary analysis and provide actionable precision for your specific business case, detailed segmentation data and granular forecast figures are reserved for the full report. The following insights are designed to contextualize the opportunity and demonstrate why deep-dive intelligence is necessary for informed capital allocation in the coming years.
Market Trajectory and Economic Context
The retail shelving systems sector has demonstrated remarkable resilience and growth over the past half-decade. Analyzing the historical performance from 2020 through 2025 reveals a consistent upward trend, driven by store expansions, renovations, and the replacement of legacy fixtures with more efficient, modular solutions. The industry has successfully navigated supply chain disruptions and material cost volatility, emerging with a strengthened value proposition centered on durability and flexibility.
Looking ahead, the forecast period from 2026 to 2032 indicates sustained momentum. Our analysis projects a compound annual growth rate (CAGR) of 9.2% throughout this horizon. This growth is not merely a function of inflation or nominal price increases but reflects genuine demand expansion across multiple retail verticals. The total market revenue is expected to scale significantly, crossing substantial thresholds by the end of the decade. For enterprise planners, this trajectory suggests that shelving systems should be viewed as a growth-adjacent investment rather than a maintenance cost. The increasing value of the total addressable market implies greater competition for shelf space, higher standards for fixture quality, and a premium on systems that can adapt to changing planograms without costly retrofits.
It is important to note that while the aggregate numbers paint a picture of robust health, the distribution of this value varies by deployment type, application, and geography. Understanding where the highest value density lies requires a nuanced look at how different retail formats are prioritizing their physical infrastructure. For instance, the shift towards high-density merchandising in certain sectors contrasts with the open, experiential setups preferred in others. Our full research delineates these splits with precision, allowing clients to benchmark their regional or segment-specific performance against the broader market reality.
Operational Dynamics and Segmentation Insights
The market is structurally divided by system type, application, and geographic region, each presenting unique challenges and opportunities. In terms of system architecture, gondola shelving continues to dominate the landscape due to its versatility and standardized integration into grid layouts. However, wall-mount and floor-mount solutions are seeing renewed interest in specialty stores and spaces where perimeter optimization is critical. Corner shelving also represents a significant portion of the mix, addressing the inefficiencies of traditional straight-run aisles in varied store footprints.
By application, supermarkets and hypermarkets remain the heavyweights, consuming the largest share of system deployments due to their high SKU counts and volume-driven models. Yet, apparel stores and specialty retail segments are increasingly investing in higher-specification fixtures that support brand elevation and interactive displays. The distinction here is crucial: a supermarket requires durability and ease of restocking, whereas a specialty boutique may prioritize aesthetics and modularity to facilitate seasonal theme changes. These differing needs drive distinct purchasing behaviors and vendor relationships.
Geographically, the market reflects mature infrastructure in North America and Europe, where replacement cycles and upgrades drive demand. Meanwhile, Asia Pacific and other emerging regions offer growth potential tied to modern retail expansion and the formalization of grocery sectors. Each region carries its own regulatory, logistical, and cultural nuances that impact product specification and deployment speed. A one-size-fits-all strategy is rarely effective. Our detailed regional analysis provides the granularity needed to assess market entry barriers, competitive intensity, and localized demand drivers without relying on broad generalizations.
Competitive Landscape and Strategic Positioning
The competitive environment is characterized by a mix of established legacy manufacturers and agile specialists. The top tier of the market exhibits moderate concentration, with the top three players holding a significant share, and the top five expanding that footprint further. This concentration suggests that scale advantages in manufacturing, distribution, and R&D are becoming increasingly important. However, the presence of numerous specialized competitors indicates that niche expertise and customization capabilities still command loyalty and pricing power.
Several key companies define the current strategic landscape. Lozier Corporation, based in Omaha, Nebraska, stands as a leading manufacturer of modular gondola shelving systems and custom retail fixtures. With over 70 years of vertically integrated production, they serve grocery, pharmacy, and general merchandise retailers, emphasizing supply chain control and consistent quality. Their longevity suggests a strong capability in managing large-scale deployments and adhering to stringent retailer specifications.
Madix Inc., headquartered in Terrell, Texas, focuses on custom-configurable retail display fixtures and shelving systems. Their offering emphasizes sustainability and broad accessory integration, targeting supermarket and convenience store applications. In an era where environmental compliance and waste reduction are becoming procurement criteria, Madix positions itself as a forward-thinking partner for retailers looking to align their physical infrastructure with corporate sustainability goals.
Uniweb Inc., located in Corona, California, has been manufacturing high-density pharmacy and retail shelving since 1970. Their specialization in steel construction for pharmacies and general merchandise highlights a focus on durability and space optimization in high-value product categories. For retailers dealing with sensitive or high-theft items, the structural integrity and security features of such systems are paramount.
Retail Shelving Systems Market
Continental Store Fixture Group operates out of Canada, providing commercial-grade retail shelving and modular fixtures for grocery, pharmacy, hardware, and specialty retail across Canada and the US. Their value proposition includes in-stock inventory and CAD-based store planning, which reduces lead times and streamlines the design process for store planners. Speed to market is a critical differentiator in an industry where store openings and remodels are often scheduled tightly.
DGS Retail, based in Chicago, Illinois, has been a manufacturer and supplier since 1979, offering gondola and display solutions for various retail formats. Their long history implies a deep understanding of evolving retail trends and the ability to adapt product lines to changing consumer behaviors. Similarly, Shelving Depot serves as a provider of retail store shelving solutions across multiple industries, with an emphasis on quality and customization, catering to clients who need flexible specifications without sacrificing structural standards.
Gershel Brothers, located in Philadelphia, Pennsylvania, supplies new and used store fixtures, including gondola shelving and display accessories. Their inclusion of used fixtures introduces a cost-optimization angle to the market, appealing to budget-conscious retailers or those seeking temporary setups. STM Display Sales Inc. acts as a one-stop source for retail merchandising fixtures and store design, leveraging over 30 years of experience to offer integrated solutions that go beyond just hardware.
Worldwide Boltless Shelving Market
LA Darling, based in Albert Lea, Minnesota, manufactures retail merchandising and display systems, including gondola shelving. Following their post-2020 merger integration, they have focused on delivering custom solutions, suggesting a strategic move towards higher-value, tailored offerings rather than commoditized products. Trion Industries and Storflex Fixture Corporation round out the landscape with focuses on display and shelving integration and durable retail fixtures emphasizing quality and efficiency, respectively. These players ensure that the market remains dynamic, with continuous pressure on innovation and cost-effectiveness.
Industry Dynamics and Decision Drivers
The industry is currently influenced by several macro and micro dynamics that planners must account for. First, the emphasis on omnichannel fulfillment is reshaping store layouts. Stores are increasingly serving as fulfillment centers for online orders, requiring shelving systems that can accommodate pick zones, secure storage, and efficient retrieval processes without compromising the customer experience. This dual-use requirement adds complexity to fixture selection and layout planning.
Second, sustainability and material sourcing are moving from nice-to-have to mandatory. Retailers are under pressure to reduce their carbon footprint and waste. This influences the materials used in shelving systems, the longevity of the fixtures, and the ease of recycling or refurbishing old units. Suppliers who can provide certified sustainable materials or take-back programs may gain a competitive edge in procurement negotiations.
Third, labor constraints and operational efficiency are driving demand for systems that are easier to assemble, adjust, and maintain. As labor costs rise and availability fluctuates, fixtures that reduce setup time or allow for quick planogram changes without specialized tools become more valuable. Automation compatibility is also an emerging consideration, as some retailers begin to integrate technology for inventory tracking and shelf monitoring directly into their fixture systems.
Finally, the post-pandemic retail landscape has accelerated the need for hygiene-conscious and flexible designs. Aisles may need to be reconfigured more frequently, and surfaces may need to meet higher sanitation standards. The market players who have adapted their designs to these new realities are better positioned to capture share in the current cycle.
The Strategic Value of Comprehensive Intelligence
While the trends outlined above provide a high-level view, making specific investment or procurement decisions requires a depth of data that only a structured market research report can deliver. Strategic decisions regarding vendor selection, regional expansion, or product development hinge on precise figures regarding market size by segment, growth rates by application, and concentration metrics that reveal competitive vulnerability.
For example, knowing the aggregate market size is useful, but understanding the exact revenue contribution of gondola shelving versus wall-mount systems in the supermarket segment allows for targeted product development. Similarly, recognizing that North America holds a significant revenue share is a starting point, but analyzing the growth rate differential between North America and Asia Pacific informs where to allocate marketing resources or sales force expansion.
The consolidation metrics, such as the CR3 and CR5 percentages, offer insight into the bargaining power of suppliers and the potential for partnership or acquisition opportunities. A market with moderate concentration may leave room for disruptive entrants or niche players to thrive, whereas a highly concentrated market might suggest a need for differentiation through service or technology rather than price.
Our full report dissects these elements with rigorous methodology, providing historical data from 2020 to 2025 as a baseline and detailed forecasts through 2032. It maps the competitive profiles of key companies, analyzing their strengths, weaknesses, and strategic moves. It also includes qualitative assessments of industry drivers, restraints, and opportunities that quantitative data alone cannot capture.
Conclusion and Call to Action
The Retail Shelving Systems Market in 2026 is not merely a supplier market; it is a strategic enabler for the broader retail ecosystem. With a projected CAGR of 9.2% and a total market value trajectory that underscores its importance, the sector offers significant opportunities for those who can navigate its complexities. The key lies in moving beyond general observations to data-backed strategies that align with specific business objectives.
Whether you are a manufacturer looking to optimize your product mix, a retailer planning a network-wide fixture upgrade, or an investor assessing the viability of market entry, the granularity of your intelligence will determine the quality of your outcomes. General trends can guide direction, but precise segmentation, regional analysis, and competitive profiling are required to execute effectively.
We invite you to access the full market research report to unlock the complete dataset and strategic analysis. The full document provides the detailed breakdowns, proprietary forecasts, and actionable recommendations necessary to turn market intelligence into competitive advantage. Do not rely on aggregate figures alone when the nuances of segmentation and regional dynamics can define the success of your initiative. Explore the full report to secure the comprehensive insights needed for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Retail Shelving Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Indoor Air Quality Meter Market to Hit $212M in 2025, Grow at 8.8% CAGR Through 2032
By PW Consulting, 2026-09-16
Navigating the Indoor Air Quality Meter Market: Strategic Intelligence for 2026 and Beyond
As organizations worldwide confront the escalating intersection of public health mandates, workplace safety standards, and sustainability targets, indoor air quality has evolved from a compliance checkbox to a core operational priority. The Indoor Air Quality (IAQ) Meter Market stands at the center of this transformation, serving as the foundational measurement layer for building managers, facility operators, environmental consultants, and product manufacturers. Our latest market research offers a comprehensive, data-driven portrait of this rapidly maturing sector, delivering actionable intelligence that enables executives to allocate capital, position product portfolios, and refine market-entry strategies with precision.
Market Trajectory: From Accelerating Adoption to Sustained Expansion
The historical footprint of the IAQ meter market reveals a sector that has consistently outpaced broader environmental instrumentation growth. Between 2020 and 2025, the market expanded from an estimated 138.5 million USD to 212.0 million USD, reflecting a compound trajectory shaped by heightened health awareness, post-pandemic facility audits, and the institutionalization of ventilation monitoring in commercial real estate. This foundation sets the stage for a forecast period spanning 2026 through 2032, during which the market is projected to reach 381.33 million USD, underpinned by a steady compound annual growth rate of 8.8 percent.
This growth path is not merely a function of unit sales; it reflects a structural shift in how indoor environments are measured, managed, and certified. Organizations are moving from sporadic spot-checks to continuous monitoring architectures, integrating hardware with analytics platforms, and aligning air quality data with broader ESG and tenant-experience metrics. The forecast horizon captures this maturation, mapping revenue expansion across evolving purchasing cycles, procurement frameworks, and deployment models. For decision-makers, understanding the velocity and inflection points of this trajectory is essential to timing product launches, scaling distribution channels, and anticipating competitive pressure.
Report Scope and Practical Deliverables
This research is engineered as a decision-support instrument rather than a static overview. It provides a structured examination of the IAQ meter landscape across multiple dimensions, enabling teams to translate market signals into execution roadmaps. The report encompasses the following operational components:
- Historical performance analysis covering the 2020 to 2025 window, establishing baseline demand patterns, pricing behaviors, and adoption cycles across end-use environments.
- Forward-looking projections through 2032, built on scenario-aware modeling that reflects regulatory pacing, technology substitution curves, and procurement momentum.
- Detailed segmentation mapping across geographic regions, product types, and application verticals, illustrating where volume concentrates, where differentiation is most viable, and where emerging demand is forming.
- Competitive profiling of leading manufacturers, including product architecture, geographic footprint, certification positioning, and strategic signaling.
- Technology and regulatory context analysis, highlighting how sensor validation programs, performance benchmarking initiatives, and certification frameworks are reshaping buyer expectations and vendor requirements.
Each section is designed to be referenced independently by strategy, product, sales, and investment teams, while the integrated narrative reveals the interdependencies that determine market outcomes. The report prioritizes clarity on what is measurable today and what is likely to shift tomorrow, helping leaders separate durable trends from short-term noise.
Competitive Landscape: Eight Pillars Shaping Market Direction
The IAQ meter market is defined by a concentrated yet increasingly dynamic competitive field. Industry structure reflects a mix of established instrumentation specialists, sensor-driven technology entrants, and regional players with strong vertical expertise. The combined influence of leading participants is evident in the market's concentration profile, where a small group of firms commands a substantial share of revenue and standard-setting activity. Understanding the strategic posture of these companies is critical for benchmarking, partnership evaluation, and positioning decisions.
TSI Incorporated continues to anchor its offering in comprehensive measurement coverage, spanning CO2, temperature, humidity, particulate, and ventilation parameters across workplace and residential environments. Their product architecture emphasizes repeatability and multi-parameter integration, reinforcing their relevance for professional auditing and facility validation workflows. Aeroqual Limited concentrates on portable real-time monitoring systems that combine integrated sensors for multiple pollutants, positioning the company around mobility, rapid deployment, and field-grade flexibility. HORIBA, Ltd. contributes advanced instrumentation and systems calibrated for environmental and IAQ monitoring applications, drawing on a heritage of precision measurement and complex ambient analysis.
Testo SE & Co. KGaA brings strong HVAC and building air quality assessment capabilities, aligning its instrument portfolio with inspection, commissioning, and ongoing commissioning use cases. Kanomax USA, Inc. emphasizes practical monitoring solutions for HVAC validation and environmental testing, including dedicated IAQ monitors and handheld odor meters that serve technicians and consultants in field applications. GrayWolf Sensing Solutions, LLC focuses on portable datalogging meters and monitors that address toxic gases, volatile organic compounds, particulates, and multi-parameter testing, appealing to compliance-driven and industrial-adjacent environments.
Air Quality Sensor Market
Airthings has expanded the consumer-to-prosumer boundary with smart radon and IAQ monitors that detect multiple pollutants, including VOCs, PM2.5, CO2, and formaldehyde. Its recent recognition in an independent consumer evaluation for a flagship monitor underscores how sensor integration, user experience, and broad pollutant coverage are increasingly shaping product perception across market segments. Kaiterra targets commercial building markets with wireless and wired IAQ monitors designed for workplace environments, integrating analytics and certification-oriented features tied to frameworks such as WELL and RESET, which reflects the growing importance of performance evidence and documentation in procurement decisions.
The strategic implications of this landscape are clear. Competition is not just about accuracy; it is about integration, portability, certification readiness, analytics usability, and total cost of ownership. Companies seeking to enter or expand within this market must evaluate where they can create defensible differentiation, whether through sensor engineering, software workflows, service ecosystems, or vertical specialization.
Market Dynamics: Regulation, Validation, and the Evidence Economy
A defining feature of the current IAQ meter environment is the increasing emphasis on measurement credibility. Buyers are operating in a context where low-cost and consumer-grade monitors are widely available, yet professional procurement increasingly demands performance evidence. This shift is visible across several evaluation and validation efforts that are actively shaping expectations in the sector. As of November 2025, the EPA Air Sensor Toolbox included evaluations of low-cost IAQ monitors under both controlled and ambient conditions, reflecting a broader public-sector interest in understanding sensor behavior outside laboratory settings.
Alongside this, the Consumer Indoor Air Sensors Evaluation program led by Lawrence Berkeley National Laboratory continues to assess the performance of IAQ sensors for indoor environments. These initiatives are not simply academic exercises; they influence how procurement teams interpret specifications, how vendors support claims, and how certification bodies weigh measurement reliability. In parallel, the AQ-SPEC program administered by the South Coast Air Quality Management District evaluates low-cost air quality sensors under ambient and controlled conditions, contributing another layer of independent benchmarking to the ecosystem.
For commercial strategy, this dynamic matters in several ways. First, it raises the strategic value of transparent performance data and repeatable testing. Second, it creates opportunities for vendors that can bridge the gap between accessible monitoring and professionally defensible results. Third, it encourages buyers to think in terms of system-level reliability rather than isolated sensor features. Organizations that anticipate this shift can strengthen their positioning by aligning product claims, validation documentation, and customer education with the evaluation frameworks that procurement teams are increasingly referencing.
Strategic Priorities for 2026 Decision-Making
The market's projected growth path and competitive intensity make 2026 a pivotal year for planning. Rather than reacting to demand signals after they surface, forward-looking organizations can use the research to prioritize investments and sharpen execution. Key strategic priorities include:
- Timing product and channel moves around forecast inflection points, ensuring that inventory, service capacity, and commercial messaging align with the projected revenue trajectory through 2032.
- Selecting target segments with intention, recognizing that demand patterns vary materially across regions, product types, and application environments, and that the most attractive opportunities may differ by company capability and operating model.
- Building measurement credibility into the value proposition, leveraging independent evaluation context and certification-aligned messaging to reduce friction in professional procurement cycles.
- Differentiating through integration rather than specs alone, connecting hardware performance with analytics, reporting formats, and workflow compatibility that facility teams actually use.
- Monitoring competitive signaling closely, since moves by established instrumentation firms, portable-monitoring specialists, and smart-monitoring entrants can reshape buyer expectations and pricing norms.
The research also supports scenario-based thinking. Because the forecast period extends across a seven-year horizon, executives can stress-test strategies against alternative demand paces, technology adoption speeds, and regulatory emphasis. This kind of structured planning is especially useful for organizations balancing near-term revenue targets with longer-term positioning in a market where hardware, software, and validation expectations are evolving together.
Turning Market Intelligence into Actionable Advantage
The Indoor Air Quality Meter Market is entering a phase where scale, credibility, and ecosystem integration will determine competitive outcomes. Revenue expansion over the forecast period signals durable demand, but the real challenge lies in capturing the right growth with the right positioning. Leaders who approach this market with detailed segmentation insight, validated competitive context, and a clear understanding of the regulatory and evaluation environment will be better equipped to make confident capital and product decisions.
Indoor Air Quality (IAQ) Meter Market
Our full report provides the deeper intelligence required to translate these themes into concrete plans. It details the segmentation architecture, the forward revenue path, the competitive profiles, and the operational trends that collectively define where value is being created. To access the complete dataset, segmentation breakdowns, and extended company analysis, we invite you to explore the full study and secure the intelligence needed for 2026 strategy execution.
For detailed analysis of this topic, please visit the official page: Indoor Air Quality (IAQ) Meter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


