



Category: market research
Vitamin A Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The global Vitamin A market has demonstrated consistent growth over the past five years, expanding from approximately 520 million USD in 2020 to an estimated 665 million USD in 2025. This trajectory reflects a compound annual growth rate of roughly 5.5 percent through the 2026 to 2032 forecast period, positioning the market to approach nearly 970 million USD by the end of the decade. The steady expansion is underpinned by broad demand across nutrition, feed, and fortification applications, yet the industry is navigating a period of structural transition that demands strategic attention from market participants.
One of the most pressing challenges lies in the evolving regulatory and trade landscape. Recent policy shifts in major economies have introduced both protections and constraints for vitamin supply chains. The exemption of Vitamin A from new U.S. tariffs and reciprocal duties under Annex II of recent executive orders has insulated producers from cost volatility that has affected other commodity categories. At the same time, extended regulatory shutdowns at key production facilities, particularly the vitamin A precursor plant in Ludwigshafen, Germany, have constrained EU-origin supply and elevated prices among established suppliers. These dynamics create a fragmented operating environment where regional availability and pricing stability are no longer guaranteed.
A second challenge centers on the tension between natural and synthetic product segments. The market is split between natural Vitamin A sources and synthetic variants, with synthetic products accounting for a larger share of overall revenue. This division is not merely a matter of preference; it reflects deeper questions about sourcing sustainability, consumer perception, and formulation performance. Natural carotenoid-derived Vitamin A has gained traction in food, beverage, and dietary supplement applications, while synthetic forms continue to dominate in animal nutrition and industrial fortification. Companies must navigate the strategic implications of this bifurcation as downstream customers increasingly seek transparency and differentiation in their ingredient portfolios.
The third significant challenge is market concentration. A relatively small group of manufacturers commands a disproportionate share of the market, creating both stability and vulnerability. While concentrated supply ensures quality consistency and technical expertise, it also amplifies the impact of production disruptions, capacity constraints, or strategic decisions by a handful of firms. Buyers and investors alike must account for this concentration when evaluating supply resilience and long-term pricing dynamics.
PW Consulting
Key Growth Drivers
Several interconnected forces are shaping the direction of the Vitamin A market and creating distinct pathways for value creation.
Technological Innovation and Product Formulation
Advancements in microencapsulation and combined formulation technologies are redefining how Vitamin A is delivered across applications. Recent product launches illustrate this shift. A next-generation microencapsulated combined Vitamin A and D3 formulation has been introduced with an extended shelf life under standard storage conditions, addressing long-standing stability challenges in animal nutrition. Such innovations reduce waste, improve handling efficiency, and enable more precise dosing, which in turn supports adoption in cost-sensitive feed markets while also opening doors in human nutrition where stability and bioavailability are critical.
Beyond microencapsulation, the broader trend toward tailored vitamin formulations is gaining momentum. Manufacturers are increasingly moving from commoditized bulk vitamin supply toward value-added solutions that address specific application requirements, whether that means enhanced heat stability, improved mixing characteristics, or compatibility with complex feed matrices. This shift encourages differentiation and supports margin preservation in a market where basic vitamin ingredients face periodic pricing pressure.
Regulatory and Policy Environment
The regulatory backdrop is a decisive factor in market dynamics. The exemption of Vitamin A from recent U.S. tariff actions, including 20 percent duties under specific statutory provisions, has preserved cost stability for producers and downstream users. Most key vitamins, including Vitamin A and a broad range of B-complex and other essential nutrients, are fully exempt from these duties under relevant sections of recent trade policy directives. This exemption reduces the risk of supply chain disruption and supports uninterrupted production scheduling for feed, food, and pharmaceutical applications.
Vitamin D Market
However, regulatory divergence across regions introduces complexity. The extended regulatory shutdown at a major German production site has constrained EU-origin supply, pushing buyers to reconsider sourcing strategies and inventory planning. Such disruptions underscore the importance of regulatory monitoring and the need for flexible procurement models that can adapt to shifting compliance timelines and regional availability.
Demand-Side Shifts in Consumer and Corporate Behavior
Demand patterns are evolving as consumer awareness of nutrition and wellness continues to rise, particularly in food and beverage and dietary supplement categories. Fortification trends are expanding beyond traditional staples into functional foods, beverages, and specialized supplement formats, where Vitamin A plays a supporting role in product positioning and nutritional labeling. In animal feed, the drive for efficient livestock production and balanced nutrition sustains steady demand, while also pushing formulators toward combined vitamin solutions that streamline inclusion rates and improve overall feed performance.
Corporate behavior is also shifting toward greater supply chain resilience. Buyers are increasingly prioritizing suppliers who can offer consistent quality, transparent sourcing, and contingency options. This preference favors established manufacturers with diversified production footprints and technical service capabilities, while also creating openings for newer entrants that can address niche requirements or regional demand gaps.
Supply Chain and Cost Structure Dynamics
Cost structures in the Vitamin A market are influenced by raw material availability, energy inputs, and the geographic concentration of manufacturing capacity. The exemption of Vitamin A from recent tariff pressures has provided a degree of protection, but other cost factors remain in play. Energy costs, logistics constraints, and the operational status of key precursor plants all contribute to pricing variability. The continued shutdown at the Ludwigshafen facility, for example, has elevated prices among established suppliers and reinforced the strategic importance of alternative sourcing routes.
Supply chain resilience is increasingly tied to the ability to manage multi-regional production and distribution. Companies that can balance capacity across regions, maintain buffer inventory where appropriate, and align formulation strategies with regional regulatory realities are better positioned to navigate cost volatility and supply interruptions.
Competitive Landscape and Leading Strategies
The competitive environment is defined by a mix of large-scale synthetic vitamin producers, specialized natural ingredient suppliers, and regional manufacturers with growing international reach. The market is moderately concentrated, with a small group of firms accounting for a significant portion of total revenue. This structure rewards scale, technical capability, and the ability to serve multiple application segments.
Strategic Positioning of Key Players
BASF SE, headquartered in Ludwigshafen, Germany, maintains a leading position in synthetic Vitamin A production for animal nutrition and human fortification. Its recent focus on combined microencapsulated formulations, including a next-generation Vitamin A and D3 product with extended shelf life, reflects a strategy oriented toward formulation differentiation and application-specific performance. By investing in dedicated formulation capabilities within its Verbund site, BASF is reinforcing its role as a solutions provider rather than a commodity supplier.
DSM-Firmenich AG, based in Delft, Netherlands, operates as a major supplier of Vitamin A and derivatives across nutrition and feed applications. The company maintains active portfolio management and market updates, signaling a strategy that emphasizes responsiveness to market conditions and regulatory developments. Its presence across multiple downstream categories supports diversification and provides visibility into shifting demand patterns.
Vitamin Market
Bluestar Adisseo Company, headquartered in Shanghai, China, is a key manufacturer of synthetic Vitamin A products for global feed and food markets. Its strategic value lies in its ability to serve large-volume demand while navigating regional production dynamics. As Asian demand continues to grow, manufacturers with strong regional footprints and export capabilities play an increasingly important role in balancing global supply.
Fenchem Biotek Ltd., also based in China, is an active producer of Vitamin A and related ingredients for industrial and nutritional applications. Its positioning reflects the broader trend of regional manufacturers expanding their ingredient portfolios and seeking integration into global supply chains.
Lycored Ltd., headquartered in Israel, supplies natural carotenoid-derived Vitamin A for food, beverage, and dietary supplement markets. Its focus on natural sourcing aligns with growing consumer and brand preferences for clean-label and traceable ingredients, differentiating it from synthetic-focused competitors and creating niche opportunities in premium fortification and supplement applications.
Market Evolution and Emerging Dynamics
The competitive landscape is evolving along several axes. Integration among large-scale producers continues to reinforce scale advantages in synthetic vitamin production, while differentiation is increasingly driven by formulation technology, application expertise, and regional supply reliability. At the same time, natural ingredient suppliers are carving out distinct positions by addressing demand for transparency and plant-based or carotenoid-derived alternatives.
New entrants and regional manufacturers are gaining relevance where they can offer cost-competitive supply, localized service, or specialized product attributes. However, the concentrated nature of the market means that new entrants must navigate barriers related to production scale, regulatory compliance, and customer qualification processes. The result is a market that rewards both scale and specificity, with successful players often combining broad application coverage with targeted technical differentiation.
Future Trends and Commercial Opportunities
Looking ahead to the 2026 to 2032 period, several trends are likely to shape the Vitamin A market and its commercial opportunities.
Trend One: Formulation-Led Differentiation Will Intensify
As basic vitamin ingredients face periodic pricing pressure and supply variability, the value shift toward tailored formulations is expected to deepen. Microencapsulation, combined vitamin products, and application-specific stabilizers will become more central to competitive positioning. Manufacturers that can offer formulations with extended shelf life, improved stability under processing conditions, and easier integration into feed or food matrices will capture incremental value and strengthen customer loyalty. This trend creates opportunities for suppliers to move up the value chain and for buyers to reduce total cost of ownership through improved performance and reduced waste.
Trend Two: Regional Supply Rebalancing and Sourcing Flexibility
Regulatory disruptions and production constraints in key regions are likely to accelerate efforts to rebalance supply across geographies. Buyers will increasingly seek multi-source strategies, regional inventory buffers, and supplier partnerships that provide continuity during compliance or operational interruptions. This rebalancing favors manufacturers with diversified production footprints and transparent supply chain practices. It also creates opportunities for regional producers to strengthen their role in global supply networks, particularly where they can offer reliable quality and responsive service.
Trend Three: Natural and Synthetic Segments Will Continue to Coevolve
The coexistence of natural and synthetic Vitamin A segments will remain a defining feature of the market. Natural carotenoid-derived options will continue to find traction in consumer-facing applications where clean-label positioning and traceability matter. Synthetic forms will retain strength in high-volume feed and industrial fortification markets where cost efficiency and performance consistency are paramount. The commercial opportunity lies in understanding where each segment adds the most value and in building portfolios or sourcing strategies that align with downstream customer priorities.
Risks and Uncertainties
Several uncertainties warrant attention. Extended regulatory shutdowns or new compliance requirements at major production sites could further constrain supply and elevate pricing. Trade policy changes, while currently favorable for Vitamin A through tariff exemptions, remain subject to revision and could introduce new cost dynamics if exemptions are altered. Demand shifts in animal feed, driven by livestock market conditions or alternative nutrition strategies, could affect volume growth in key segments. Finally, the concentrated supplier base means that strategic decisions by a small number of firms can have outsized effects on availability and pricing, requiring buyers and investors to maintain contingency planning and diversified sourcing approaches.
Actionable Insights for Decision-Makers
For manufacturers and suppliers, the priority is to strengthen differentiation through formulation capability and application expertise. Investing in microencapsulation, combined vitamin products, and stability-enhancing technologies can support margin resilience and customer retention. Equally important is the development of flexible supply strategies that account for regional regulatory dynamics and production variability, ensuring continuity for downstream customers even when specific sites face constraints.
For investors, the market offers steady growth supported by broad demand across nutrition, feed, and fortification, but success will depend on selecting players with scalable production, regulatory agility, and the ability to serve multiple application segments. Concentration in the supplier base creates both reliability and vulnerability, making it essential to evaluate each company's production footprint, formulation pipeline, and exposure to regional disruptions. Long-term value creation is likely to accrue to firms that combine scale with differentiated product capabilities and resilient sourcing models.
For procurement and formulary decision-makers, the key is to balance cost efficiency with supply resilience. Diversifying across suppliers and regions, aligning specification requirements with realistic supply conditions, and engaging suppliers early on formulation and stability needs can reduce exposure to price spikes and availability gaps. Understanding the regulatory status of Vitamin A in key markets, including its exemption from recent tariff actions, helps inform sourcing decisions and inventory planning. Maintaining visibility into production status at major sites and monitoring regulatory developments will support more proactive procurement strategies.
For organizations seeking a deeper understanding of regional demand patterns, application-level dynamics, and customized sourcing or investment scenarios, detailed market intelligence can provide the granularity needed to translate these trends into executable plans. Comprehensive research encompassing segmentation data, competitive assessments, and scenario-based forecasting offers a practical foundation for strategic planning and risk management in a market defined by both steady growth and evolving structural complexity.
For detailed analysis of this topic, please visit the official page: Vitamin A Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Medical Equipment Maintenance Market: Why 9.9% CAGR and Preventive Services Redefine Growth to $110.08B
By PW Consulting, 2026-09-21
The Medical Equipment Maintenance Market: Strategic Trends and Commercial Opportunities (2025–2032)
1. Market Snapshot and Core Challenges
The global medical equipment maintenance market has entered a period of pronounced expansion, with total revenue reaching approximately 57.0 billion in 2025 and projected to climb to 110.08 billion by 2032. This trajectory reflects a compound annual growth rate of 9.9 percent across the forecast horizon, signaling a structural shift rather than a short-term cyclical upturn. Over the past five years, the market has steadily moved from fragmented, reactive repair models toward integrated lifecycle management programs, driven by rising capital intensity in healthcare delivery and an accelerating push toward operational resilience.
Despite this momentum, the sector faces meaningful headwinds that will shape competitive positioning over the next several years. First, the boundary between servicing and remanufacturing continues to generate regulatory and commercial friction. Healthcare providers, OEMs, and third-party operators must navigate evolving guidance on what constitutes acceptable post-market maintenance versus material modification, a distinction that carries direct implications for liability, scope of work, and pricing models. Second, labor constraints and specialized skill shortages are compressing service capacity. The industry relies heavily on trained clinical engineers and field technicians, and the supply of qualified personnel has not kept pace with the volume of installed equipment across aging hospital fleets. Third, installed-base complexity is increasing faster than many organizations’ service capabilities. Devices are becoming more software-defined, interconnected, and modular, which raises the bar for diagnostic precision, parts logistics, and remote intervention.
These challenges are not merely operational footnotes; they define where value will be captured. Organizations that treat maintenance as a predictable, data-enabled discipline will be better positioned to protect uptime, manage total cost of ownership, and align service delivery with clinical and financial performance targets.
2. Key Drivers Shaping Market Direction
Technology Innovation and Intelligent Service Models
Predictive and condition-based maintenance is rapidly moving from pilot programs to mainstream adoption. AI-enabled monitoring, remote diagnostics, and connected device telemetry are allowing service teams to anticipate failures before they affect clinical workflows. Recent activity illustrates how quickly this capability is becoming table stakes. In 2025, GE HealthCare expanded its enterprise software and imaging service footprint through the acquisition of Intelerad Medical Systems Corporation for 2.3 billion, while also entering a seven-year Care Alliance with Sutter Health to deploy AI-powered imaging systems across more than 300 facilities. Separately, a collaboration with IBM Watson Health was announced to launch AI-powered predictive maintenance services for medical imaging equipment. Philips also moved to strengthen its informatics-driven service positioning after securing FDA approval for IntelliSpace Enterprise Edition 6.0, which includes predictive maintenance capabilities for imaging systems.
For commercial leaders, the implication is clear: maintenance is increasingly sold and evaluated as an outcomes-based capability rather than a labor-hours contract. Solutions that can reduce unplanned downtime, extend useful life, and integrate with clinical and operational data are gaining preference, especially in high-acuity environments where device availability directly affects throughput and care continuity.
Regulatory and Standards Evolution
The regulatory environment is tightening in ways that favor disciplined, well-documented service programs. The FDA Quality Management System Regulation became effective in early 2026, incorporating ISO 13485:2016 by reference and applying to manufacturers as well as facilities engaged in remanufacturing or servicing. This alignment raises the expectations for quality systems, traceability, and controlled processes across the service ecosystem. At the same time, the Joint Commission streamlined its accreditation standards effective January 1, 2026, consolidating previous requirements for inspecting, testing, and maintaining medical equipment into a single element of performance that hospitals must ensure essential equipment remains in safe operating condition.
These developments create a dual effect. On one hand, they increase compliance burden and can raise the cost of service delivery for organizations that depend on informal or poorly documented practices. On the other hand, they strengthen the commercial case for providers and OEMs that can demonstrate structured quality management, standardized procedures, and auditable maintenance records. In practical terms, regulatory momentum is rewarding service models that are transparent, repeatable, and integrated with device lifecycle governance.
Demand-Side Shifts in Healthcare Operations
Healthcare providers are under sustained pressure to optimize capital deployment, reduce total cost of ownership, and maintain service levels with constrained operational budgets. These pressures are pushing procurement teams to evaluate service contracts not as ancillary expenses but as strategic levers for equipment reliability and cost predictability. Hospitals and health systems are increasingly seeking bundled programs that combine preventive maintenance, corrective support, and operational oversight, rather than managing multiple fragmented vendor relationships.
This demand-side evolution is also visible in regional capacity expansion. Sodexo India opened a 6,700 square-foot Healthcare Technology Management facility in Kolkata, equipped with six specialized labs designed to support up to 500,000 devices. The move reflects broader interest in building localized service capacity that can respond faster, reduce logistics latency, and improve coverage density. For the market overall, it signals that service delivery is becoming more geographically distributed and more sensitive to response-time expectations.
Cost Structure and Supply Chain Dynamics
Parts availability, labor economics, and reverse logistics continue to shape service margins and contract design. As devices become more software-centric and modular, the economics of repair are shifting. In some categories, rapid diagnostics and component-level replacement can improve asset utilization and reduce total cost, while in others, specialized parts sourcing and calibration requirements tighten margins and extend resolution times. At the same time, remanufacturing and refurbishment pathways are gaining attention as organizations look for ways to extend asset life without compromising performance or compliance.
A recent FDA guidance finalized in 2024 clarified the distinction between remanufacturing and servicing of reusable medical devices, emphasizing that proper servicing is critical to continued performance and overall product lifecycle management. More recently, FDA finalized guidance on Predetermined Change Control Plans for AI/ML-enabled devices, enabling manufacturers to include post-market algorithm update plans in initial submissions. Together, these signals indicate that device lifecycles are being managed more actively, and service providers will need clearer frameworks for supporting evolving software and hardware configurations over time.
3. Competitive Landscape and Leading Strategies
The medical equipment maintenance market remains concentrated, with a small group of large players commanding a substantial share of high-value service contracts. GE HealthCare, Siemens Healthineers, Philips, and Medtronic each bring strong brand recognition, deep installed-base relationships, and the ability to bundle maintenance with device sales, informatics platforms, and clinical workflow solutions. This integration is a defining competitive advantage, because it links service delivery directly to equipment performance data, service history, and lifecycle planning.
Worldwide Heavy Equipment Maintenance Service Market
GE HealthCare has emphasized AI-driven predictive maintenance, imaging and cardiology service, and the expansion of enterprise software portfolios. Siemens Healthineers has focused on diagnostic imaging, laboratory, and therapeutic equipment maintenance with remote monitoring and service contracts tailored to healthcare facilities. Philips has leaned into informatics platforms with predictive capabilities, positioning maintenance as part of a broader clinical technology ecosystem. Medtronic’s service model is particularly relevant in implanted devices, cardiac rhythm management, and minimally invasive surgical equipment, where ongoing service and maintenance contracts intersect with clinical risk and long-term patient outcomes.
Outside the largest OEMs, a second tier of specialists is carving out differentiated positions. B. Braun has concentrated on infusion, dialysis, and related equipment maintenance across hospital settings. STERIS has built a strong identity around sterilization, infection prevention, and equipment maintenance and repair services. Agiliti and TriMedx have taken a more holistic approach to clinical engineering, equipment maintenance, and technology management, often targeting health systems that want to consolidate service oversight or improve asset utilization across diverse device fleets.
PW Consulting
Several strategic themes are shaping how these players compete. First, integration is becoming more important than isolated repair capability. Providers increasingly prefer partners that can combine maintenance with remote monitoring, data analytics, spare-parts logistics, and technology lifecycle planning. Second, AI-enabled service differentiation is accelerating. Predictive maintenance, automated fault diagnosis, and algorithm-driven scheduling are transitioning from innovative features to differentiators that affect contract selection and retention. Third, partnerships and acquisitions are being used to extend reach. The 2025 acquisition by GE HealthCare and collaborations with major health systems and technology partners highlight a pattern of strengthening software, informatics, and enterprise service capabilities rather than competing solely on field labor.
At the same time, the landscape is not static. Regional capacity investments, such as the Healthcare Technology Management facility in Kolkata, point to growing appetite for localized service delivery and specialized lab infrastructure. This suggests an ongoing tension between centralized, OEM-led service models and regional or third-party operators that can offer flexibility, coverage density, or niche device expertise. For buyers and investors, the relevant question is whether a provider’s model can scale while maintaining quality, compliance, and responsiveness across heterogeneous equipment portfolios.
4. Forward Outlook: Three Trends to Watch Through 2032
From Preventive Schedules to Predictive, Data-Connected Service
Preventive maintenance will remain foundational, but its role is likely to evolve from calendar-based tasks toward continuously informed service planning. Devices that generate operational telemetry, error logs, and performance trends will enable more precise intervention windows, which can reduce unnecessary visits while improving readiness. The commercial opportunity lies in contracts and service architectures that reward reliability, faster diagnosis, and deferred capital replacement. Organizations that can operationalize predictive insights across large installed bases will have a clearer path to differentiated pricing, stronger retention, and better asset utilization outcomes.
One risk is uneven data quality and interoperability. Predictive models are only as effective as the underlying device data, integration maturity, and process discipline supporting them. If telemetry coverage is incomplete or service workflows cannot act quickly on alerts, the theoretical gains from AI-driven maintenance may fail to materialize in practice.
Regulation-Driven Professionalization of Service Delivery
As quality management expectations rise and accreditation standards consolidate around safe operating condition requirements, service delivery is likely to become more formalized. Documentation, training, traceability, and controlled procedures will carry greater commercial weight, especially for organizations involved in remanufacturing or servicing activities that intersect with regulatory oversight. The trend favors providers that can standardize processes across sites and demonstrate compliance without imposing excessive administrative burden on clinical staff.
The uncertainty here is speed and consistency of adoption. Regulatory clarity is improving, but implementation varies by facility type, region, and device category. Market participants that assume uniform compliance behavior may misjudge the timeline for contract wins, service standardization, or partnership requirements.
Lifecycle Extension, Modularity, and Strategic Refurbishment
With device complexity rising and capital budgets under pressure, lifecycle management is gaining strategic importance. Maintenance programs are increasingly evaluated not only on uptime but also on whether they enable longer useful life, component-level optimization, and responsible refurbishment where appropriate. This creates opportunities for service providers that can combine repair expertise with parts logistics, calibration, software updates, and disposal or redeployment planning. It also raises the importance of clear boundaries between servicing and remanufacturing, since misclassification can create regulatory, quality, and commercial risk.
A key risk is that lifecycle extension strategies can be undermined by unavailable parts, obsolete software support, or changing clinical requirements. Without strong reverse logistics and lifecycle governance, maintenance programs may extend service duration without improving total cost outcomes.
5. Strategic Actions for Decision-Makers
For manufacturers and OEMs, the priority is to embed service intelligence into the product and contract architecture early. Predictive capabilities, remote diagnostics, and integrated informatics should be treated as core elements of the service offering rather than optional add-ons. Aligning service design with regulatory expectations for quality management and device lifecycle management can reduce downstream friction and strengthen contract positioning. Where possible, manufacturers should also consider how partnerships, acquisitions, and software expansion can broaden enterprise value beyond individual device repairs.
For investors, the market’s expansion is attractive, but differentiation will depend on execution quality. Due diligence should focus on whether a service provider has durable mechanisms for predictive maintenance, compliance readiness, geographic coverage, and parts logistics. Concentration in the market suggests that scale and brand matter, yet there is also room for specialists that address underserved device categories, regional demand, or integrated technology management. The most resilient business models will likely combine recurring service revenue with demonstrated improvements in uptime, total cost of ownership, and operational simplicity for customers.
Worldwide Pharmaceutical Equipment Maintenance Services Market
For healthcare procurement and clinical engineering teams, the decision framework should shift from lowest headline price to total value under real operating conditions. Contracts that provide transparent service levels, remote monitoring, rapid response, and well-documented quality processes can reduce hidden costs associated with downtime, repeated visits, and compliance gaps. Procurement teams should also evaluate whether the service provider can support mixed device portfolios, evolving software configurations, and future lifecycle needs rather than optimizing for a single equipment category in isolation.
Given the pace of regulatory change, technology adoption, and competitive consolidation, timely access to granular market intelligence is increasingly important for shaping contracts, portfolio strategy, and investment priorities. Readers seeking deeper segmentation data, regional expansion patterns, and customized recommendations aligned with specific device portfolios or service models may find value in PW Consulting’s comprehensive research report on the medical equipment maintenance market.
For detailed analysis of this topic, please visit the official page: Medical Equipment Maintenance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Why Waste-to-Energy Market Growth at 3.62% CAGR Shows Reshaping Forces in 2032
By PW Consulting, 2026-09-21
Navigating the Waste-to-Energy Market: Strategic Trends and Commercial Opportunities Through 2032
The waste-to-energy (WTE) sector stands at a critical inflection point. As municipal waste volumes continue to rise alongside growing pressure to decarbonize power generation, the industry is evolving from a niche waste management solution into a structured component of regional energy infrastructure. Market trajectories indicate steady expansion, with a compound annual growth rate of 3.62 percent projected through 2032. Revenue scales from an estimated 311.0 million USD in 2025 to approximately 399.58 million USD by 2032, reflecting a compound annual expansion of 3.62 percent. This growth trajectory is neither linear nor uniformly distributed. While baseline figures suggest consistent upward movement, the underlying dynamics reveal a market shaped by technological differentiation, regulatory recalibration, and shifting operational economics. For executives and investors, the challenge lies in distinguishing structural tailwinds from transitional noise and positioning accordingly.
Market Snapshot and Structural Challenges
The current market environment reflects a mature but unevenly developed landscape. Thermal conversion routes continue to anchor the majority of installed capacity, with incineration accounting for the largest share of revenue. Complementary pathways such as gasification, pyrolysis, and anaerobic digestion represent a collective but growing portion of the market, signaling gradual diversification beyond conventional combustion. Application-wise, electricity generation dominates end-use deployment, while heat production captures a meaningful secondary segment. Regional distribution shows pronounced concentration, with Asia Pacific and Europe collectively representing the bulk of market value, North America maintaining a substantial position, and Latin America and the Middle East/Africa reflecting early-stage development potential.
This macro structure, however, masks several operational and strategic friction points that define the current cycle.
1. Conversion Efficiency and Emissions Compliance Under Scrutiny
Traditional grate-based incineration remains the operational backbone, yet it faces mounting pressure to improve net energy recovery while meeting tighter air emissions thresholds. Facilities that operate with older boiler configurations or suboptimal heat recovery systems struggle to maintain favorable levelized costs, particularly as grid parity expectations rise and carbon accounting becomes embedded in procurement and financing decisions. The industry is being pushed toward higher steam parameters, advanced flue gas treatment, and integrated heat utilization, which raises capital intensity but improves long-term contract economics.
2. Policy Fragmentation and Regulatory Transition Risk
WTE does not operate in a uniform regulatory vacuum. Jurisdictions are simultaneously incentivizing waste-to-energy as a clean generation pathway and imposing stricter monitoring, reporting, and offset obligations on incineration-based systems. This creates a dual dynamic: projects may qualify for clean electricity provisions in one market while encountering emissions compliance costs in another. Organizations with cross-border portfolios or multi-jurisdictional supply chains must navigate divergent definitions of eligibility, differing measurement methodologies, and staggered compliance timelines that can compress margins or delay commissioning.
3. Feedstock Reliability and Contract Structuring Complexity
The economics of WTE projects remain tightly linked to consistent waste supply, calorific value stability, and long-term offtake security. Diversion of recyclables, changes in municipal collection practices, and competition from alternative recovery pathways can alter feedstock composition mid-cycle. In markets where tariff structures, cost recovery mechanisms, or interconnection rules are still being formalized, developers face elevated negotiation risk. Securing bankable feedstock agreements and aligning them with energy revenue routes is increasingly a core strategic task rather than a secondary operational concern.
Key Drivers Reshaping the Sector
The market trajectory is being shaped by a set of mutually reinforcing forces that extend beyond simple waste volume growth or energy demand. Understanding the interaction between technology, policy, customer behavior, and cost dynamics is essential for identifying durable profit pools rather than short-term cycles.
Technology Innovation and System-Level Efficiency Gains
Innovation is moving beyond incremental boiler upgrades toward integrated plant design and alternative conversion routes. Gasification and pyrolysis continue to attract attention for their potential to produce secondary fuels and chemical precursors, while anaerobic digestion is carving out a distinct niche where organic-rich waste streams and heat-on-site applications align. On the thermal side, advanced combustion controls, improved refractory and boiler materials, and better heat recovery integration are helping facilities extract more usable energy per tonne of input. Equipment suppliers and EPC players are increasingly positioned as partners in lifecycle optimization, not just plant builders. The strategic implication is clear: technology choice now influences not only emissions performance but also revenue flexibility, grid qualification, and long-term contract structure.
Policy and Regulatory Reorientation
Recent regulatory developments illustrate how policy is both enabling and disciplining the market. Clean electricity tax credit guidance in the United States has clarified that WTE facilities can qualify when assessed through lifecycle analysis, giving eligible projects a clearer financing pathway and improving project economics for compliant operations. At the same time, emissions-related obligations are becoming more granular. In the United Kingdom, the extended carbon pricing and monitoring scope now captures energy-from-waste and incineration, with reporting obligations beginning and full surrender requirements phased in later in the decade. This creates a compliance dimension that must be modeled into cash flow forecasts rather than treated as a peripheral environmental cost.
In emerging and fast-scaling markets, regulatory clarity is directly shaping project pipelines. Indonesia's presidential regulation setting a fixed electricity purchase price for WTE under a state-backed program, with long-term contract structures and compensation mechanisms for grid connection costs, reduces revenue uncertainty for developers and equipment providers alike. Meanwhile, the Philippines has moved to incorporate WTE into national grid and distribution codes, with provisions for long-term cost recovery and subsidies to support interconnection. These frameworks do not guarantee uniform returns, but they do reduce a major class of financing friction and help convert conceptual pipelines into executable projects.
Demand-Side Shifts and Corporate Behavior
The demand environment is changing on two fronts. First, municipalities and industrial operators are increasingly treating WTE not merely as disposal but as part of integrated resource recovery strategies. Heat utilization, for example, is gaining relevance in contexts where district heating, industrial process heat, or adjacent thermal loads can absorb otherwise wasted energy. Second, corporate procurement of renewable and low-carbon energy is expanding the relevance of generation assets that can offer measurable lifecycle attributes. Facilities that can demonstrate credible emissions performance and stable energy output are better positioned to align with offtake relationships, public-private partnerships, and sustainability-linked financing structures. The commercial opportunity lies in packaging energy recovery with verifiable environmental performance rather than in volume alone.
Cost Structures and Supply Chain Realignment
Capital intensity remains a defining characteristic of the sector, but the composition of cost risk is shifting. Equipment supply, engineering procurement, and construction execution are increasingly influenced by regional project pipelines, localization requirements, and lead-time volatility for critical components. Recent project activity underscores this trend. In Taiwan, a major incinerator unit and equipment supply contract was awarded for a WTE plant under a build-operate-transfer model, highlighting the continuing relevance of proven thermal equipment in structured project delivery. At the same time, full EPC and operational partnerships are favored where developers seek integrated risk transfer rather than fragmented procurement. Cost competitiveness now depends on more than hardware pricing; it depends on execution certainty, emissions compliance readiness, and the ability to align plant design with local grid and feedstock conditions.
Waste-to-Energy Technologies Market
Competitive Landscape and Strategic Positioning
The competitive environment is characterized by a mix of integrated waste and energy service providers, specialized plant equipment manufacturers, and regional project developers with strong deployment track records. Market concentration, with the top three firms holding approximately 42.5 percent of market value and the top five around 55.2 percent, indicates a sector where scale, operational expertise, and relationship depth matter, but where meaningful participation remains feasible for focused players.
Strategic Archetypes Among Leading Players
Several competitive patterns emerge from current positioning and recent activity:
- Integrated service and operations players combine waste management, plant operation, and energy production into end-to-end offerings. This model reduces coordination risk across collection, processing, and generation, and is particularly valuable where long-term municipal contracts and operational continuity are central to revenue stability.
- Equipment and technology specialists concentrate on core conversion hardware, boiler systems, or full plant delivery. Their differentiation often rests on moving grate and combustion technologies, high-efficiency boiler configurations, and the ability to supply standardized yet customizable solutions for BOT and EPC contexts. Strong delivery records and technology familiarity with grid-connected thermal plants remain central advantages.
- Regional developers and EPC-oriented operators focus on large-scale projects in geographies with active municipal build-outs, particularly in Asia and parts of the Middle East. Their value lies in local execution, permitting and stakeholder management, and the ability to structure projects that align with national energy and waste policy directions.
- Advanced conversion and fuel-oriented entrants emphasize alternative outputs such as renewable natural gas or engineered fuels. These players typically target niches where feedstock composition, product flexibility, and premium offtake structures can support differentiated economics.
How the Landscape Is Evolving
The market is not simply consolidating; it is stratifying. Traditional scale players continue to defend positions through operational breadth and integrated service models, but technology differentiation and policy-linked eligibility are creating new competitive axes. Companies that can combine reliable thermal performance with credible emissions management, grid compliance readiness, and flexible energy product offerings are gaining leverage in both tender processes and private financing discussions. At the same time, new entrants and specialized technology providers are carving out segments through alternative conversion routes or modular plant approaches, particularly where conventional capacity is constrained by regulation or community acceptance. The trend suggests a market in which the battleground is shifting from pure capacity addition toward lifecycle value, compliance resilience, and project structuring capability.
Forward Look: Three Trends to Watch
Looking across the current data and recent policy and project signals, three directional trends are likely to shape the next few years.
1. Policy-Linked Project Economics Will Become a Core Differentiator
As jurisdictions clarify eligibility for clean electricity incentives, define emissions monitoring obligations, and establish cost recovery or interconnection provisions, projects with stronger policy alignment will command better financing terms and more predictable revenue paths. The practical implication is that commercial success will increasingly depend on anticipating regulatory definitions, model lifecycle eligibility early, and structuring contracts to withstand compliance evolution rather than assuming static frameworks.
PW Consulting
2. Heat Integration and Multi-Output Designs Will Expand Value Capture
Electricity remains dominant, but the margin between successful and marginal projects may increasingly hinge on the ability to monetize thermal output. District heating linkages, industrial steam supply, and process heat utilization can improve overall plant economics and reduce sensitivity to electricity price volatility. Facilities and partners that design for heat export from the outset, rather than as an afterthought, can unlock incremental returns and strengthen long-term offtake narratives.
Waste Incinerators Market
3. Supply Chain Localization and Execution Discipline Will Matter More as Pipelines Scale
With several large-scale projects advancing in Europe, Asia, and emerging markets, the sector will test its ability to deliver on schedule, within budget, and with compliant emissions performance. Equipment suppliers and EPC organizations that can localize content where required, manage long-lead items effectively, and deliver standardized yet site-adaptive solutions will capture stronger positioning. Developers, meanwhile, will favor partners who can reduce integration risk across permitting, construction, commissioning, and operation.
These trends carry inherent uncertainty. Policy frameworks can shift as political priorities change, feedstock availability can be disrupted by diversion programs or municipal restructuring, and emissions compliance costs may rise if monitoring obligations tighten faster than anticipated. Additionally, community acceptance and landfill diversion trade-offs continue to influence siting decisions in multiple regions, adding a layer of execution risk that cannot be discounted.
Strategic Playbooks for Decision-Makers
For executives and investors evaluating near- to mid-term moves, the following considerations can help translate market signals into actionable positioning.
For Equipment Manufacturers and Technology Providers
- Prioritize designs that balance proven thermal reliability with flexibility for heat recovery and emissions control upgrades, since these features increasingly influence bid selection and lifecycle economics.
- Strengthen delivery and localization capabilities in regions with active WTE pipelines, where execution certainty and regulatory familiarity are becoming as important as hardware performance.
- Develop clear lifecycle and compliance narratives that align with evolving clean electricity and emissions frameworks, enabling customers to justify investment under changing policy conditions.
For Investors and Project Developers
- Focus underwriting on projects with credible feedstock security, aligned policy incentives, and offtake structures that account for both electricity and potential heat value streams.
- Stress-test returns against emissions compliance costs and monitoring obligations, particularly in markets where carbon pricing or MRV requirements are being phased in.
- Evaluate partners not only for capital and technology but also for permitting track record, grid interconnection experience, and ability to manage multi-year commissioning risk.
For Procurement and Municipal Decision-Makers
- Treat WTE as one element of an integrated waste and energy strategy, weighing siting, feedstock continuity, emissions performance, and heat utilization alongside disposal cost reduction.
- Structure contracts to balance long-term cost recovery with performance accountability, ensuring that operational and compliance responsibilities are clearly allocated.
- Request transparent lifecycle and emissions documentation to support public accountability and to future-proof assets against evolving regulatory definitions.
For deeper segmentation data, regional modeling, and tailored scenario analysis, the full PW Consulting research report provides expanded detail across technology pathways, application mixes, and policy-sensitive revenue drivers, along with customized recommendations aligned to specific operational and investment profiles.
For detailed analysis of this topic, please visit the official page: Waste to Energy (WTE) (Waste-to-Energy) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Cleaning Robots Market: Strategic Trends and Commercial Opportunities in an AI-Driven Automation Era
The global cleaning robots market has transitioned from a niche convenience category into a foundational component of the broader automation and facility management landscape. Valued at approximately 5.98 billion USD in 2020 and scaling to 14.8 billion USD by 2025, the sector has demonstrated compounding momentum that reflects deeper structural shifts in how spaces are maintained, managed, and optimized. Forward projections through 2032 point to sustained expansion, with the market trajectory aligning to a 20.6 percent CAGR across the forecast horizon. This growth is not merely a function of hardware adoption; it is being reshaped by software-defined navigation, operational labor economics, and evolving regulatory frameworks that collectively redefine what cleaning automation can deliver and where value is captured.
At the same time, the market stands at a strategic inflection point. Early adoption cycles were driven by consumer curiosity and premium residential upgrades. Today, the commercial and industrial segments are accelerating deployment, but with higher expectations for uptime, safety validation, integration with facility management systems, and measurable return on investment. The companies that navigate this shift successfully will be those that can pair compelling hardware with ecosystem-ready software, proven compliance postures, and service models that reduce total cost of ownership rather than simply lowering sticker prices.
Market Landscape: Growth Trajectory and Strategic Inflection Points
The headline scale of the market masks a more nuanced reality beneath the surface. Growth has been broad-based across product types and end-use contexts, yet the composition of value is shifting as capabilities converge and buyer expectations mature. Floor cleaning robots represent the largest product concentration, underscoring the enduring importance of routine surface maintenance in both homes and commercial premises. At the same time, specialized segments such as pool, lawn, and window cleaning robots are carving out defensible niches by solving specific operational pain points that generalist platforms cannot address efficiently.
One of the defining characteristics of the current market is moderate concentration. The top three players account for roughly 32 percent of total revenue, while the top five capture approximately 37 percent. This dispersion signals a market that is large enough to support multiple viable strategies, but not so fragmented that scale advantages are irrelevant. It also means that positioning, distribution strength, and vertical integration decisions can materially alter competitive outcomes.
Key Challenges and Turning Points
The sector is not simply riding a technological wave; it is contending with several structural challenges that will separate durable players from transient ones.
- From feature parity to reliability economics. Early differentiation was heavily reliant on incremental features, yet buyers now reward consistent performance, simpler maintenance, and fewer service interruptions. As competition intensifies, the cost of warranty claims, spare parts logistics, and field support is becoming a decisive margin lever.
- Navigation and obstacle handling at scale. Real-world environments are cluttered, dynamic, and unpredictable. The market is moving past controlled demonstrations toward deployment in spaces with mixed flooring, moving obstacles, pets, cables, and high-traffic transitions. Robots that can maintain cleaning quality without frequent intervention will increasingly define category leadership.
- Data, privacy, and operational compliance. Cloud-connected robots generate continuous streams of environmental and usage data. This creates value for remote diagnostics and fleet optimization, but it also introduces governance obligations. As privacy expectations rise and safety standards evolve for mobile platforms, compliance is shifting from a back-office concern to a commercial prerequisite.
These challenges are not purely risks; they are also filters. They reward manufacturers that can operationalize reliability, integrate safety-by-design thinking, and build transparent data practices into product architecture.
Core Drivers Reshaping Demand and Competitive Advantage
The market’s momentum is being shaped by four interlocking forces. Understanding how they interact is essential for positioning products, allocating capital, and deciding where to compete.
Technology Innovation and the Software-Defined Cleaning Robot
The most consequential breakthroughs are less about mechanical cleaning and more about perception, planning, and adaptation. High-precision navigation, dynamic obstacle avoidance, and adaptive cleaning modes are transforming robots from pre-programmed floor machines into responsive environment-aware systems. In residential settings, this translates into better results around furniture, pet areas, and transitional spaces. In commercial environments, it enables repeatable cleanliness with reduced supervision.
Artificial intelligence is also expanding the functional envelope of cleaning robots. Stain detection, surface-type recognition, and task-specific mode switching allow a single platform to handle broader scope without sacrificing cleaning quality. This matters because it changes the value proposition from “automation for convenience” to “automation for consistency and coverage,” which is far more defensible in procurement decisions.
Policy and Regulatory Environment as a Competitive Variable
Regulatory and standards activity is increasingly shaping product design and go-to-market timelines. Recent updates to safety requirements for industrial mobile robots, alongside active specifications for commercial cleaning equipment, are reinforcing the importance of functional safety, risk assessment, and performance validation. At the same time, working-stage guidance on dynamically stable mobile platforms is pushing manufacturers to think more carefully about balance performance and safe operation zones.
Beyond hardware safety, data governance has become an integral part of market access. GDPR and CCPA compliance are now baseline expectations for cloud-connected deployments, and independent security certifications are increasingly used as trust signals in commercial procurement. These developments do not simply constrain the market; they raise the bar for entry and reward organizations that build compliance into their engineering and operational processes early.
Demand-Side Shifts in Consumer and Enterprise Behavior
On the residential side, cleaning robots are increasingly evaluated as part of a broader smart-home or household management experience rather than as isolated appliances. Buyers are looking for seamless setup, low-friction maintenance, and cleaning outcomes that perform reliably across varied household conditions. This has raised the importance of user experience, dock intelligence, and maintenance automation, since these factors directly affect long-term satisfaction and retention.
In commercial and industrial contexts, the driver is different but equally powerful: the search for predictable service quality under constrained labor availability. Facility operators are not simply looking to replace labor; they are trying to stabilize outcomes, extend cleaning coverage across shifts, and reduce variability in hygiene standards. This is why commercial-grade platforms that can operate in demanding environments with minimal supervision are gaining traction, and why deployments are increasingly judged by uptime and service-level consistency.
Supply Chain and Cost Structure Evolution
Hardware economics are being reshaped by component availability, integration complexity, and the cost of differentiated software stacks. Commodities such as basic sensors and standard drive components have seen gradual normalization, but high-value differentiation is migrating toward navigation subsystems, AI processing, dock intelligence, and service ecosystems. As a result, manufacturers face a strategic choice: compete on volume and cost efficiency in more standardized segments, or invest in higher-margin platforms that combine superior perception, cleaner software integration, and stronger after-sales value.
This dynamic is also reshaping partnerships. Rather than building every capability internally, some companies are pursuing co-development arrangements and ecosystem alliances to accelerate time-to-market and broaden compatibility. Such moves can reduce development risk and improve product completeness, but they also require careful management of brand positioning, data handling, and long-term dependency.
Competitive Landscape: Positioning, Differentiation, and Evolution
The competitive field reflects the market’s breadth. Players range from consumer-focused leaders with strong brand equity and ecosystem reach to specialist manufacturers concentrated on professional and commercial cleaning, and to diversified electronics companies leveraging robotics as an extension of broader home portfolios.
Strategic Positioning Among Leading Companies
Several patterns are visible among the most influential participants.
Worldwide Toilet Cleaning Robot Market
- Residential AI leadership. Organizations such as iRobot have built strong recognition around home cleaning platforms that combine advanced navigation, self-emptying infrastructure, and multi-function cleaning modes. Their strategic advantage lies in brand trust, recurring attachment through docks and consumables, and a product architecture designed around residential usability.
- Navigation and mop-integration differentiation. Companies like Ecovacs Robotics and Roborock have emphasized high-precision navigation, self-washing mop systems, and AI-based obstacle handling. Their push has centered on improving cleaning completeness while reducing manual intervention, which is increasingly important in premium residential segments and larger indoor spaces.
- Commercial-grade specialization. Manufacturers such as Kärcher and SoftBank Robotics are oriented toward professional and facility-scale applications, where robustness, multi-surface capability, and operational endurance matter more than consumer-friendly packaging. Their value proposition is rooted in integration with facility workflows and the ability to deploy reliably in hotels, hospitals, and large public or industrial premises.
- Broad portfolio extension from consumer electronics. LG and Samsung have approached cleaning robots as part of wider appliance and smart-home ecosystems, using suction performance, self-cleaning infrastructure, and connectivity integration as differentiators. This approach can create cross-selling advantages and platform synergies, especially where consumers already trust the brand in adjacent categories.
- Niche autonomy in specialized environments. In pool cleaning, companies such as Maytronics have maintained relevance through purpose-built autonomy for a distinct use case, showing that specialized navigation and durability in water environments can sustain a strong position even as broader segments consolidate. SharkNinja has similarly leaned into brand-led AI vacuums and mops with features such as self-emptying systems and stain-detection technologies, illustrating how strong consumer branding can support robotics entry and expansion.
How the Landscape Is Evolving
The market is exhibiting a mix of consolidation pressure and deliberate differentiation. Some competitors are expanding into adjacent cleaning contexts, while others are narrowing focus to specific environments where they can command stronger pricing and service relationships. Alliances and co-development initiatives are becoming more common as companies seek to extend capabilities without stretching internal resources too thin. At the same time, new entrants are testing highly targeted solutions for overlooked tasks, particularly in commercial hygiene where labor constraints and cleanliness standards create persistent demand.
Recent developments highlight this direction. Strategic partnerships are being used to combine complementary expertise and accelerate next-generation solutions. Product launches are increasingly focused on autonomous restroom cleaning and expanded commercial fleets, reflecting a move toward higher-complexity environments that demand greater autonomy and task-specific engineering. Milestones such as major commercial scrubber sales thresholds also indicate that demand for professional automation is not theoretical; it is scaling in practice.
In this environment, competitive advantage is increasingly determined by the ability to deliver complete solutions rather than isolated hardware. That includes navigation reliability, maintenance design, safety and compliance documentation, integration with operational systems, and service economics. Companies that can prove they reduce operational friction for the buyer will have a stronger position than those competing primarily on feature lists or price alone.
Forward-Looking Trends and Where Value Will Concentrate
Looking ahead across the next three to five years, the market is likely to be shaped by a small number of durable trends. These trends create both opportunity and risk, depending on how organizations position themselves.
Trend 1: Commercial and Facility-Scale Automation as a Growth Anchor
The commercial segment is poised to become an increasingly important growth engine. Labor availability, consistency requirements, and the operational cost of manual cleaning are pushing facility managers toward autonomous solutions that can supplement or partially replace repetitive maintenance tasks. This trend favors robust platforms, clear service-level commitments, and proven performance in demanding environments. The commercial opportunity is not limited to large venues; it extends to offices, retail spaces, healthcare facilities, and educational environments where standardized cleanliness and coverage matter.
Commercial deployment also raises the stakes for total cost of ownership. Buyers will increasingly compare the combined cost of acquisition, maintenance, consumables, downtime, and supervision rather than focusing solely on unit price. Manufacturers that can document operational savings and reduce intervention requirements will have a stronger commercial narrative.
Trend 2: Convergence of Cleaning and Environmental Intelligence
Cleaning robots are becoming more embedded in broader environmental sensing and facility management workflows. Navigation and perception technologies that support cleaning can also support monitoring, mapping, and task coordination. This opens the door to broader value creation: robots that not only clean but also contribute to space utilization insight, maintenance scheduling, or workflow coordination.
This convergence creates opportunities for differentiated platforms, but it also introduces integration challenges. Data handling, interoperability, and system reliability become more important as robots participate in larger operational ecosystems. Privacy and security expectations will continue to shape what is commercially acceptable, especially in environments where cameras, sensors, or continuous connectivity are involved.
Trend 3: Safety, Compliance, and Trust as Commercial Entry Conditions
Safety standards, performance specifications, and data governance requirements are becoming more visible in procurement and deployment decisions. This is likely to accelerate product maturation, but it may also slow entry for players that lack engineering rigor or documentation discipline. Trust is becoming a competitive asset: operators want platforms that are not only effective, but also safe around people, dependable in varied environments, and transparent in how they handle operational data.
The implication is clear. Companies that treat safety and data governance as engineering and commercial priorities, rather than as legal afterthoughts, will find it easier to scale deployments and win enterprise confidence.
Logistics Robots Market
Risks and Uncertainties
Several uncertainties could shape the pace and shape of growth. Economic volatility may affect both consumer discretionary spending and enterprise capital allocation, influencing adoption timing across segments. Competition could compress margins in more standardized categories if differentiation fails to keep pace. Regulatory and standards developments may change product requirements faster than some organizations can adapt. Finally, the market may see segmentation intensify, where generalist platforms struggle to match the economics and performance of specialists in demanding niches.
Strategic Playbooks for Decision-Makers
The cleaning robots market rewards clarity of purpose. Whether the objective is manufacturing, investment, or procurement, the most useful question is not whether the market is growing, but where value is being created and how to capture it.
For Manufacturers and Product Leaders
- Decide where to win, not just what to build. The market supports both broad consumer platforms and specialized commercial solutions, but managing both without clear differentiation is difficult. Define the environments, tasks, and customer types where the company can credibly outperform, then align navigation, cleaning mechanism, maintenance design, and service model to that target.
- Prioritize reliability economics. Cleaning outcomes, uptime, and service simplicity increasingly determine long-term reputation and margin. Invest in perception robustness, obstacle handling, consumable and dock design, and field support processes that reduce repeat visits and warranty exposure.
- Make compliance and data trust part of the product story. Functional safety, performance validation, and responsible data handling are no longer optional polish. They are part of how commercial buyers evaluate risk and how consumers evaluate long-term trust.
For Investors
Capital allocation should be guided by durability of advantage rather than headline growth alone. The most attractive opportunities are likely to be found where there is a combination of clear demand drivers, defensible technology or niche focus, and economic models that scale through service, software, or specialized hardware rather than relying purely on unit volume. Assess whether a company can sustain differentiation as navigation and cleaning features become more common, and whether its go-to-market model can support commercial deployments where procurement cycles and reliability expectations are stricter. Also pay attention to partnerships and ecosystem moves, since they can accelerate capability but also change dependency structures and competitive positioning.
For Procurement and Operations Leaders
- Evaluate the full operational picture. Compare solutions on cleaning consistency, supervision requirements, maintenance burden, and integration with existing workflows. A lower upfront cost can be outweighed by higher intervention, downtime, or consumable complexity.
- Request evidence relevant to your environment. Demonstrations in idealized settings are useful, but procurement decisions should be informed by performance data, safety documentation, and deployment support that match the specific space type, traffic patterns, and cleanliness standards involved.
- Plan for service and lifecycle management. Autonomous cleaning is not a one-time purchase decision. It is an operational relationship. Assurance around support response, spare availability, software updates, and data handling practices can be as important as the hardware itself.
The Practical Payoff of Deeper Market Intelligence
The dynamics in this market are moving quickly enough that broad directional understanding is necessary but not sufficient. Segment-specific economics, company-level positioning, regional deployment patterns, and emerging product strategies can materially change the attractiveness of a particular opportunity or the risk profile of a given vendor choice. Decision-makers who need to compare options, size entry points, or evaluate competitive threats will benefit from more granular intelligence that connects market structure to actionable choices.
PW Consulting
For organizations looking to move from general awareness to confident execution, a detailed study of segment trends, company strategies, and commercial implications can provide the granularity needed to prioritize investments, shape product roadmaps, and negotiate procurement decisions with greater clarity. Access to more detailed research allows leaders to test assumptions, compare scenarios, and identify where to commit resources before the market shifts further.
For detailed analysis of this topic, please visit the official page: Cleaning Robots Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Traffic Signs Market Forecast 2026-2032: The 7.75% CAGR Reshaping Industry Growth
By PW Consulting, 2026-09-21
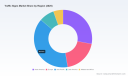
The Traffic Signs Market at an Inflection Point: Strategic Trends and Commercial Opportunities Through 2032
The global traffic signs market is navigating a structural transition. Over the tracking period from 2020 through 2025, the sector expanded from approximately USD 44.59 million to a projected USD 64.76 million, and forward estimates point to continued growth toward nearly USD 110 million by 2032, supported by a compound annual growth rate of 7.75%. The trajectory signals more than routine infrastructure renewal. It reflects a convergence of regulatory tightening, material cost volatility, and the early stages of digital-physical integration in road safety infrastructure. For executives, planners, and investors, the question is no longer whether the market will grow, but which segments of the value chain will capture disproportionate value as standards evolve and procurement models reorganize.
Worldwide Traffic Signal Recognition Market
The numbers outline a market that has recovered from pandemic-era procurement pauses and is now anchored by sustained public investment in road safety, urbanization-driven signage demand, and incremental modernization of legacy traffic control systems. Historical data shows consistent year-over-year expansion, with the jump from 2023 to 2024 indicating a stabilization phase before the 2025 baseline accelerates. The forecast period through 2032 suggests that growth will not be linear; rather, it will be shaped by policy adoption cycles, regional infrastructure pacing, and manufacturers’ ability to navigate input cost pressure while maintaining compliance with evolving visibility and performance standards.
Market Reality and Core Challenges
The market’s expansion is real, but it is unfolding against a backdrop of operational friction. Three challenges stand out as particularly consequential for strategic planning.
Material Cost Volatility and Margin Compression
Aluminum remains the primary substrate for most traffic sign blanks, and its pricing dynamics have introduced a new layer of risk into production planning and bid economics. Through late 2025, Midwest Premium aluminum prices climbed approximately 190% year-over-year, a spike that compresses margins for manufacturers working under fixed-price municipal contracts or competing in price-sensitive procurement environments. This is not merely a cost issue; it reshapes sourcing strategies, inventory timing, and the economics of sign blank production versus finished sign assembly. Companies that rely heavily on coil stock and blank production are exposed to raw material volatility in ways that differentiate their cost structures from firms focused on value-added assemblies, illuminated solutions, or traffic calming systems.
PW Consulting
Regulatory Visibility Standards and Compliance Complexity
Visibility and retroreflectivity requirements are becoming more prescriptive, raising the bar for what qualifies as a compliant permanent traffic control sign. In Ohio, for example, guidance from the Department of Transportation has moved toward recommending Type III retroreflective sheeting for all permanent new traffic control signs on maintained highways, while also requiring Type IV, IX, or XI sheeting in specific contexts. These requirements are part of a broader standardization trend that ties sign performance to measurable visibility outcomes rather than legacy material norms. Compliance complexity is increasing because regulators are not only specifying sheeting grades but also linking them to placement, maintenance cycles, and nighttime performance expectations. For manufacturers and contractors, the operational implication is clear: product specifications that fall behind evolving standards risk disqualification in public tenders, while faster adoption can become a competitive differentiator.
At the same time, the broader framework governing traffic control devices continues to evolve. Recent updates to MUTCD standards are reinforcing visibility, placement, and performance requirements across a range of sign and traffic calming products. That means compliance is no longer a one-time certification exercise; it is an ongoing design constraint that affects product development cycles, testing protocols, and field deployments.
Procurement Fragmentation and the Pressure to Standardize
Traffic sign procurement remains fragmented across municipalities, state agencies, contractors, and cooperative purchasing vehicles. This fragmentation creates both opportunity and inefficiency. On one hand, it allows specialized providers to serve niche applications and regional preferences. On the other hand, it slows the adoption of higher-performance materials and limits scale economies for standardized solutions. The tension is visible in the market’s concentration profile, where a meaningful share of revenue is held by a relatively small group of firms, yet substantial demand still flows through dispersed buyers with varied specifications and purchasing timelines. As cooperative purchasing contracts and multi-agency frameworks expand, the market may tilt toward more standardized product families, but the transition will be uneven across regions and agency types.
Core Drivers Reshaping the Market
Technology Innovation: From Passive Signage to Active Visibility
One of the most significant shifts in the market is the move beyond static signage toward solutions that enhance driver awareness through illumination, flashing elements, and sensor-linked warnings. Solar-powered flashing warning signs, radar speed displays, and pedestrian crossing enhancements are expanding the definition of what a traffic sign can do. This is not a wholesale replacement of traditional signs, but an incremental layering of active visibility features where risk is higher or compliance requires stronger behavioral cues. The commercial relevance is that these products command different margin structures, different installation requirements, and different procurement justifications than passive blanks or reflective signs. Manufacturers that can combine compliance-grade base products with active visibility add-ons are positioned to capture value in applications where safety outcomes are measured and funded more explicitly.
The traffic calming segment illustrates this dynamic well. Products that integrate static signs with radar-based feedback, flashing warnings, and pedestrian-crossing enhancements are increasingly tied to public agency goals around speed management and intersection safety. As these solutions become more standardized and more visibly effective, they create a bridge between traditional sign manufacturing and the broader traffic safety equipment market.
Policy and Regulatory Momentum around Safety Outcomes
Policy is becoming a more direct driver of demand because road safety is increasingly framed around measurable outcomes rather than routine maintenance. Regulatory bodies and transportation departments are sharpening requirements for retroreflectivity, sheeting performance, and device visibility. This policy momentum benefits suppliers that can demonstrate compliance, provide documentation, and align product roadmaps with emerging standards. It also raises the importance of regulatory intelligence as a commercial capability. Companies that anticipate updates to visibility standards, understand regional interpretations, and design products with forward compliance in mind reduce the risk of specification obsolescence and improve their positioning in agency procurement.
A related policy driver is the increasing use of cooperative purchasing frameworks, which can broaden access to compliant products for public agencies while also creating more transparent price discovery. Recent contract awards that expand public agency access to MUTCD-compliant safety solutions show how procurement channels themselves are becoming a strategic lever. For manufacturers, inclusion in such frameworks can shorten sales cycles and increase volume predictability, but it also intensifies competition on specification, availability, and total cost of ownership.
Traffic Signal Controller Market
Demand-Side Shifts in Municipal and Regional Procurement
Demand is being shaped by a shift in how public agencies think about signage and safety infrastructure. Instead of treating signs purely as replacement items, agencies increasingly evaluate them within broader safety programs, work zone management plans, and traffic calming initiatives. That shift changes the sales narrative from unit price to functional outcome. It also expands the relevant buying center, bringing engineering, safety, and maintenance teams into the decision process alongside procurement. As a result, suppliers that can articulate performance benefits, maintenance implications, and compliance documentation are gaining an advantage over those competing primarily on material cost.
In addition, the demand mix is diversifying by application type. Guide and direction signs, warning signs, regulatory signs, and other specialized signage each serve different operational contexts, and the relative importance of each category varies by region and project type. The broader point is that demand is not monolithic. Growth is being distributed across categories with different replacement cycles, specification sensitivity, and installation complexity. Understanding which application categories are tied to higher-frequency renewal cycles versus longer-life installations is essential for revenue forecasting and capacity planning.
Supply Chain and Cost Structure Reconfiguration
The supply chain for traffic signs is being tested by material input volatility, logistics complexity, and the need to maintain consistent quality across reflective sheeting, metal substrates, and ancillary hardware. Cost structure is becoming a strategic differentiator rather than a back-office concern. Manufacturers that can manage blank production efficiently, secure stable sheeting supply, and reduce lead-time variability gain latitude in pricing and bidding. At the same time, regional manufacturing footprints matter more as agencies and contractors look for predictable delivery, localized support, and lower total installed cost. In this environment, the competitive edge often lies in combining material sourcing discipline with application-specific product configuration, rather than pursuing scale alone.
The rise of export-oriented manufacturers also adds a global dimension to supply dynamics. Some producers have built positions serving a wide range of countries with certifications that support cross-border distribution. That creates price and availability competition in certain segments while also giving buyers more options for specification-matched products. The strategic response for established players is not simply to compete on price, but to reinforce compliance assurance, service responsiveness, and product consistency that are harder to replicate through transactional importing.
Competitive Landscape and Leading Strategies
The competitive field includes a mix of specialized U.S. manufacturers, export-oriented producers, and broader traffic systems providers. Several patterns define the current landscape.
A group of North American companies has built its positioning around MUTCD and DOT compliance for static signs, custom reflective aluminum signs, work zone products, and related control signage. These firms compete heavily on specification alignment, availability, and familiarity with public agency procurement requirements. Their differentiation often comes from product breadth within compliant signage categories, responsiveness to municipal and contractor demand, and the ability to supply both standardized and custom configurations. In a market where compliance documentation and material consistency matter, that positioning can be durable, especially when paired with cooperative purchasing access or strong regional distribution.
A second grouping emphasizes traffic calming and active visibility solutions. These providers extend beyond traditional sign blanks into radar speed displays, flashing warning signs, pedestrian crossing enhancements, and related systems. The strategic advantage here is category expansion: by offering products that address speed management and driver awareness directly, these companies can participate in projects where safety outcomes are prioritized and where funding is tied to measurable behavior change or risk reduction. This approach also diversifies revenue beyond replacement-driven signage demand, though it requires investment in product development, testing, and sometimes field support.
A third dimension is represented by broader traffic systems providers with portfolios spanning standard signs, variable message signs, dynamic signage, and illuminated solutions for highways and urban environments. These companies compete by offering integrated capability across static and dynamic categories, which can be attractive for larger projects or regions pursuing modernization programs. Their scale and portfolio breadth allow them to address multiple signage functions within a single engagement, but they must still navigate the same regulatory and material pressures as more specialized players.
Recent market activity shows how these strategies are playing out. One U.S. traffic calming provider expanded access to public agencies through a cooperative purchasing contract, strengthening the procurement channel for MUTCD-compliant safety solutions. Around the same time, the same provider introduced new solar flashing warning signs designed to improve visibility and driver awareness on critical roadways. These moves illustrate a combined strategy of channel expansion and product refresh aimed at active visibility applications. In parallel, an Austrian traffic systems provider previewed next-generation sign solutions at a major industry event, signaling continued investment in advanced signage portfolios for highways and urban deployments. Together, these developments suggest that competition is intensifying not only in price, but in channel access, product modernization, and the ability to meet evolving visibility expectations.
The market is also likely to see continued differentiation between firms that compete primarily as commodity-adjacent sign suppliers and those that position around performance, compliance assurance, and application-specific solutions. Consolidation may occur where scale, sourcing, and distribution advantages can be combined, while fragmentation may persist in specialized or region-specific segments where local service and specification knowledge matter. New entrants are most likely to appear in active visibility and traffic calming niches, where the link between product capability and safety outcome is more direct and where procurement narratives increasingly favor demonstrated performance.
Forward Trends and Commercial Opportunities
Active Visibility and Solar-Enabled Signage Will Move from Niche to Mainstream in Targeted Applications
Over the next three to five years, active visibility features are likely to become more common in high-risk corridors, school zones, pedestrian crossings, and work zone environments. Solar flashing warning signs and radar-linked displays will continue to gain traction where agencies need stronger behavioral cues and where wiring or grid access is impractical. The commercial opportunity lies in bundling these solutions with compliant base signage and installation support, creating offerings that are easier for agencies to adopt as part of broader safety programs. The risk is that active visibility products may face their own specification, maintenance, and durability scrutiny, so suppliers will need to invest in field reliability and documentation as well as initial performance claims.
Regulatory-Driven Material Upgrades Will Reset Product Standards and Replace Legacy Inventory
As visibility and sheeting requirements become more prescriptive, there will be a multi-year cycle of material upgrades and replacement demand. This creates a commercial window for manufacturers and distributors that can supply compliant retroreflective materials, upgrade existing product lines, and help agencies manage transition timelines. It also raises a strategic risk for suppliers whose product portfolios lag behind emerging standards. The opportunity is not just in selling new signs, but in helping buyers navigate the shift from older materials to higher-performance sheeting, including guidance on applicability, installation, and maintenance expectations. Firms that treat regulatory change as a product strategy input rather than a compliance afterthought will be better placed to capture this cycle.
Regional Demand Divergence Will Reward Segment-Specific Positioning
Demand growth will not unfold uniformly. Regions with faster urbanization, more active road safety programs, and stronger cooperative procurement frameworks are likely to show stronger momentum, while other markets may remain dependent on replacement cycles and budget pacing. For manufacturers and investors, this means that broad market averages can obscure where the most attractive opportunities actually sit. The more productive approach is to align product portfolios, distribution capacity, and pricing strategy with regional demand characteristics and procurement behavior. Companies that can tailor offerings to specific application mixes, agency types, and compliance expectations will be better positioned than those relying on a single standardized playbook.
For the materials and cost side, the forward risk is that aluminum and sheeting volatility may persist in cycles, making hedging, sourcing flexibility, and product mix optimization increasingly important. Suppliers that can shift emphasis toward higher-value assemblies, active visibility products, or service-linked offerings may be better insulated than those dependent on low-margin blank production alone.
Strategic Recommendations for Decision Makers
For Manufacturers and Product Leaders
- Align product roadmaps explicitly with evolving visibility and sheeting standards so that compliance becomes a design input rather than a retrofit exercise.
- Expand into active visibility and traffic calming adjacencies where safety outcomes support stronger value propositions and differentiate pricing from commodity sign supply.
- Build sourcing and inventory strategies that reduce exposure to metal input volatility, including flexible blank procurement, regional supply options, and product mixes that balance material-intensive and value-added items.
For Investors and Strategic Capital
- Evaluate exposure to regulatory-driven replacement cycles and active visibility adoption, since these dynamics can shape both revenue durability and margin profiles across different business models.
- Distinguish between players that compete primarily on price and commodity-like supply and those that have defensible positions in compliance, product reliability, channel access, or application specialization.
- Watch for consolidation opportunities where regional distribution, cooperative purchasing access, and product breadth can be combined to improve scale and customer retention.
For Procurement Agencies and Contracting Entities
- Standardize specifications around current visibility and performance expectations to reduce specification lag and improve comparability across bids.
- Evaluate total cost and safety outcomes rather than unit price alone, especially when considering active visibility or higher-performance sheeting that may reduce long-term maintenance or improve driver response.
- Use cooperative purchasing and multi-agency frameworks strategically to expand access to compliant products while maintaining specification rigor and vendor accountability.
The traffic signs market is entering a phase where growth is increasingly tied to how well participants navigate regulatory change, material cost pressure, and the shift toward active visibility. The companies that will capture the most value are those that can combine compliance confidence with product modernization and efficient cost structures, while also understanding how demand differs by region, application, and procurement channel. For executives and investors looking to move from market awareness to detailed segmentation, competitive mapping, and tailored commercial strategy, a full research report can provide the deeper breakdown needed to support decisions with precision.
For detailed analysis of this topic, please visit the official page: Traffic Signs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Calcium Formate Market: The Real Drivers Behind 7.2% CAGR Growth Through 2032
By PW Consulting, 2026-09-21
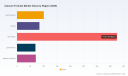
The Calcium Formate Market: Strategic Shifts and Commercial Opportunities Through 2032
The global calcium formate market has entered a period of steady expansion, characterized by consistent value growth and shifting demand patterns across construction, animal nutrition, and industrial applications. Valued at 495.16 million USD in 2020, the market climbed to 701.0 million USD by 2025, reflecting a compound annual growth rate of approximately 7.2 percent through the forecast horizon extending to 2032. By the close of the projection period, market value is positioned to surpass 1.14 billion USD, driven by structural demand in fast-setting construction chemistries, feed preservation formulations, and specialty industrial processes. The trajectory signals a transition from steady commodity positioning toward a more differentiated landscape where grade purity, regional supply reliability, and regulatory compliance increasingly dictate commercial outcomes.
A Market at an Inflection Point
While the headline growth figures suggest uninterrupted expansion, the underlying dynamics reveal a sector navigating several concurrent pressures. First, raw material cost volatility is reshaping margin structures across the value chain. Formic acid serves as the primary feedstock for calcium formate production, and recent pricing actions in European markets have directly altered production economics. A March 2026 price increase of 250 Euro per metric ton on formic acid immediately elevated input costs for downstream calcium formate manufacturers, compressing margins for producers operating without index-linked contracts or hedging mechanisms. This shift forces a reassessment of regional sourcing strategies and accelerates interest in vertically integrated or regionally balanced supply models.
Potassium Formate Market
Second, regulatory frameworks are redefining permissible use levels and creating new pathways for market entry. The formal approval of calcium formate as a feed acidifying agent for swine and poultry at up to 1.2 percent of complete feed marked a significant clarification for formulators and premix suppliers. Simultaneously, a 2026 consultation process in Canada regarding pre-market amendment of the Feeds Regulations, 2024 signals ongoing scrutiny and evolving approval timelines for new feed ingredient categories. For market participants, regulatory clarity expands addressable demand in animal nutrition, but inconsistent regional approval pathways introduce compliance complexity and extended time-to-market for cross-border product rollouts.
Third, demand-side shifts are altering grade prioritization and application mix. Construction chemical formulators continue to prioritize calcium formate for its performance in cold-weather concrete acceleration, tile adhesives, and dry-mix mortar systems, particularly in markets experiencing infrastructure renewal or seasonal construction constraints. At the same time, feed preservative demand is expanding where producers seek alternative acidifiers with favorable handling characteristics and compatibility with existing premix architectures. These parallel demand streams are pulling the market in different technical directions, requiring suppliers to maintain distinct product specifications rather than relying on a single commodity-grade offering.
PW Consulting
The competitive structure remains relatively fragmented, with the top three suppliers accounting for approximately one-quarter of total market value and the top five capturing just over one-quarter. This concentration pattern indicates meaningful room for regional differentiation and specialized positioning, but it also underscores the importance of scale efficiency, technical service capabilities, and supply continuity as competitive differentiators.
Core Drivers Reshaping the Market
Several interconnected forces are redefining how value is created and captured across the calcium formate landscape. Understanding these drivers provides the foundation for investment, sourcing, and product strategy decisions.
Feedstock dynamics and cost architecture. The relationship between formic acid pricing and calcium formate production economics is central to profitability. Recent European formic acid pricing adjustments have illustrated how quickly input costs can shift, particularly when supply is concentrated in specific regional hubs or affected by broader chemical market cycles. Producers with access to captive or long-term feedstock supply, or those positioned in regions with lower feedstock volatility, gain a structural cost advantage. Conversely, manufacturers relying on spot procurement face greater exposure to margin compression. This dynamic is encouraging a reevaluation of sourcing footprints, including regional substitution, dual-supplier strategies, and contractual structures that link cost pass-through to finished-grade pricing.
Regulatory evolution as a demand catalyst and barrier. Regulatory developments are simultaneously unlocking demand and adding compliance complexity. The formal recognition of safe use levels for calcium formate in swine and poultry feed creates a clearer formulation pathway for feed acidifiers, supporting demand in animal nutrition where gut health, preservation, and feed efficiency remain priorities. At the same time, ongoing consultation processes in markets such as Canada demonstrate that ingredient approval is not a one-time event but a continuous regulatory management requirement. Companies that treat regulatory alignment as a core commercial capability—rather than a backend compliance function—can accelerate market access and reduce the risk of reformulation delays.
Construction chemical performance requirements. Demand from construction applications continues to be shaped by performance needs that go beyond simple set acceleration. Formulators increasingly look for calcium formate grades that deliver reliable performance across varying temperature conditions, compatibility with diverse binder systems, and consistency in dry-mix and pre-blended mortar applications. Cold-weather concreting, tile adhesive performance, and corrosion-inhibition considerations in certain applications add technical nuance to procurement decisions. As infrastructure investment cycles and housing activity patterns shift regionally, suppliers that can provide application-specific grade optimization and technical support are better positioned to retain share even when price competition intensifies.
Animal nutrition and feed preservation trends. In the feed segment, demand is influenced by broader livestock production practices, biosecurity concerns, and the search for preservative solutions that integrate cleanly into existing feed formulations. Calcium formate's role as an acidifying and preserving agent aligns with formulator interest in ingredients that support feed stability and handling while meeting defined safety thresholds. The expansion of permitted inclusion levels in certain species has broadened the formulation envelope, allowing feed manufacturers to optimize dosage strategies without compromising compliance. This development is particularly relevant where producers aim to replace or supplement more traditional acidifiers with alternatives offering favorable handling, dust, or storage characteristics.
Competitive Positioning and the Evolution of the Landscape
The supplier landscape spans established multinational producers, specialized chemical manufacturers, and regional players concentrated in Asia Pacific, Europe, and North America. Rather than competing solely on price, leading participants are differentiating through grade specialization, application support, regional supply reliability, and selective expansion into higher-value industrial or feed-grade niches.
Multinational producers with broad chemical portfolios tend to emphasize high-purity calcium formate for construction, adhesives, and industrial uses, leveraging existing distribution networks and technical service capabilities. Their positioning often centers on specification consistency, regulatory documentation, and the ability to support large-formulation customers with product reliability across multiple markets. For these players, scale and portfolio breadth can translate into stronger relationships with specification-driven buyers who prioritize supply continuity and quality assurance.
Formic Acid Market
Specialized producers focused on green or application-specific calcium formate are carving out distinct positions in feed additives and construction chemicals. By aligning product development with sustainability narratives or regional performance requirements, these companies seek to reduce direct price comparison with commodity-grade alternatives. For feed-focused participants, the strategic emphasis is often on formulation compatibility, safe-use documentation, and regional regulatory readiness. For construction-focused participants, differentiation frequently comes through performance consistency in dry-mix mortars, tile adhesives, and cold-weather accelerators, alongside service responsiveness to formulator testing and customization needs.
Regional manufacturers, particularly in Asia Pacific, play an important role in meeting volume demand across feed and construction applications. Their growth trajectory is supported by proximity to feedstock supply, expanding domestic construction activity, and increasing integration into export-oriented supply chains. At the same time, these players face pressure to demonstrate grade consistency, regulatory compliance for destination markets, and reliable logistics performance as customers diversify their sourcing bases. The result is a landscape where regional scale and technical credibility increasingly coexist as prerequisites for broader market access.
Market structure appears to be evolving along several lines. Consolidation is plausible in segments where scale in feedstock procurement, production efficiency, and regional distribution provides durable advantages, particularly among suppliers targeting large construction-chemical or feed premix customers. At the same time, fragmentation is likely to persist where regional demand patterns, regulatory nuances, and application-specific requirements reward localized production and customized grade offerings. New entrants may find opportunities in niche industrial-grade supply, laboratory and research channels, or specialized feed-additive formulations, especially where incumbents are less focused on small-volume, high-specification segments. Recent feedstock pricing dynamics also suggest that competitive advantage will increasingly depend on cost management agility rather than volume alone, favoring companies that can adapt pricing, sourcing, and product mix quickly.
Forward Outlook: Three Trends to Watch Through 2032
Looking ahead, several trends are likely to shape commercial outcomes over the next three to five years. Each trend carries implications for strategy, risk management, and opportunity capture.
Trend 1: Feedstock-linked margin management becomes a core competitive capability. With formic acid pricing subject to regional volatility and periodic sharp adjustments, producers that institutionalize feedstock cost management—through long-term contracts, regional sourcing diversification, index-linked pricing mechanisms, or selective vertical integration—will be better positioned to protect margins. The commercial implication is clear: cost resilience will increasingly differentiate winners from laggards, especially in periods when raw material spikes cannot be immediately passed through to customers. Companies that fail to build flexible cost architectures risk margin erosion and reduced ability to invest in product development or regional expansion.
Trend 2: Regulatory alignment accelerates feed-grade demand in select markets while creating uneven global access. The formalization of safe use levels for calcium formate in swine and poultry feed expands the formulation toolkit for animal nutrition customers and supports demand growth where adoption is already underway. However, the staggered nature of regulatory consultations and approvals across jurisdictions means that market access will remain uneven. Feed-focused suppliers that invest early in regulatory documentation, regional approvals, and customer education are likely to capture first-mover advantages in markets where inclusion levels are clarified or expanded. Conversely, delays in approval pathways can constrain near-term commercialization even when underlying demand is strong.
Trend 3: Application-specific grade differentiation intensifies as construction and feed demand pull in different directions. Construction chemical requirements and feed preservation needs are not converging into a single commodity specification. Instead, they are reinforcing the need for distinct industrial-grade and feed-grade offerings, each with its own quality, handling, and compliance expectations. Suppliers that maintain clear grade separation, robust quality control, and transparent documentation will be better equipped to serve specification-sensitive buyers. This trend also creates opportunities for companies that can bridge multiple end-use segments, provided they avoid dilution of grade integrity or compliance positioning. At the same time, the growing emphasis on performance-specific grades may invite competitive pressure from alternative additives, requiring continuous demonstration of functional value rather than reliance on commodity positioning alone.
These trends are interconnected. Feedstock cost dynamics influence grade pricing and margin capacity for product development. Regulatory developments shape demand readiness in feed applications and affect the pace at which new formulations can be commercialized. Application-specific differentiation determines whether suppliers can sustain premium positioning or are forced into commodity price competition. Taken together, they point to a market where strategic agility, technical credibility, and regional execution matter more than simple volume scale.
Strategic Actions for Decision-Makers
The evolving calcium formate landscape presents distinct priorities depending on a decision-maker's position in the value chain.
For manufacturers and producers: Prioritize feedstock cost resilience and grade discipline. Evaluate sourcing contracts, regional supply options, and pricing mechanisms that reduce exposure to sharp feedstock swings. Maintain clear separation between feed-grade and industrial-grade offerings, supported by consistent quality control and documentation that meets destination-market requirements. Where feasible, build application-specific technical support capabilities to strengthen relationships with construction-chemical formulators and feed premix suppliers. Consider selective expansion into regions or segments where regulatory clarity is improving and where existing supply gaps create room for reliable, specification-driven participation.
For investors and corporate development teams: Assess exposure to feedstock volatility and regional regulatory pathways when evaluating opportunities. Companies with strong cost-management structures, clear grade positioning, and credible regulatory readiness are better placed to capture demand growth without sacrificing margin stability. Pay attention to market fragmentation as both a risk and an opportunity: fragmented markets can reward specialized, well-executed regional players, but they can also pressure undifferentiated suppliers into margin compression. Monitor consolidation signals in segments where feedstock procurement, production scale, or distribution density creates durable advantages, and evaluate whether potential targets have the technical and compliance capabilities to support broader commercial ambitions.
For procurement and supply chain leaders: Diversify sourcing strategies to reduce vulnerability to single-region feedstock disruptions and to improve responsiveness to grade-specific requirements. Establish specification frameworks that distinguish feed-grade and industrial-grade needs clearly, and align supplier selection with documentation, consistency, and delivery reliability rather than price alone. Where long-term supply relationships are in place, consider contractual structures that accommodate feedstock-driven cost movements while preserving budget predictability. Technical collaboration with suppliers can also help optimize dosage, handling, and formulation performance, turning procurement decisions into value-creating partnerships rather than transactional purchases.
Strategic decisions in this market benefit from detailed visibility into regional demand patterns, grade-level pricing dynamics, regulatory calendars, and competitive positioning. A comprehensive view of these variables supports more precise sourcing, investment, and product strategies, particularly as feedstock conditions and regulatory frameworks continue to evolve. For organizations seeking deeper segmentation data, region-level volume and value context, and customized scenario planning, PW Consulting's full market research report provides a structured foundation for next-step decision-making. The complete study extends beyond the trends summarized here, offering granular segmentation detail and tailored recommendations designed to support executive planning, investment evaluation, and supply strategy development.
For detailed analysis of this topic, please visit the official page: Calcium Formate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Feed Yeast Market: Why Live Yeast and Poultry Dominance Drive a 5.1% CAGR Through 2032
By PW Consulting, 2026-09-21
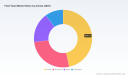
Navigating the Feed Yeast Market: Strategic Trends and Commercial Opportunities Through 2032
The global feed yeast market is entering a phase of measured but deliberate expansion. Over the past five years, the industry has evolved from a commodity-focused segment into a value-driven arena where strain specificity, functional efficacy, and supply chain reliability increasingly dictate purchasing decisions. By 2025, total market revenue reached approximately $150 million, reflecting a sustained upward trajectory from $115 million in 2020. The sector is projected to grow at a compound annual rate of 5.1 percent through 2032, when revenue is expected to approach $210 million. This growth profile signals more than incremental demand; it points to a structural shift in how livestock producers, aquaculture operators, and feed formulators view yeast-based inputs as functional nutrition tools rather than routine additives.
That said, the expansion is uneven, and the landscape carries notable friction. Market concentration remains pronounced, with the top three players accounting for roughly 65 percent of global revenue and the top five capturing over 82 percent. Such concentration reflects the capital intensity of modern fermentation infrastructure, the importance of technical service and veterinarian-level support, and the increasingly regionalized nature of regulatory requirements. For decision-makers, the implication is clear: scale alone no longer guarantees advantage. Differentiation, formulation expertise, and the ability to navigate shifting trade and compliance frameworks are becoming the decisive factors.
PW Consulting
Market Evolution and Structural Pressures
The feed yeast segment has matured along several axes simultaneously. Demand is being reshaped by tighter antibiotic restrictions, heightened scrutiny of gut health performance, and the broader movement toward preventive nutrition in monogastric and ruminant production. At the same time, the product portfolio has diversified beyond traditional live yeast into derivatives and spent yeast streams, each appealing to different technical and economic priorities. This evolution is not merely a story of more SKUs; it reflects a marketplace in which buyers are increasingly willing to trade a modest premium for measurable benefits in digestibility, pathogen binding, or stability during feed pelleting and storage.
Within this environment, a few structural pressures stand out as defining challenges for the next cycle. First, raw material economics create persistent volatility. The fermentation feedstock base that underpins Saccharomyces cerevisiae production remains sensitive to grain and energy inputs, and the average annual price for the core yeast input still ranges between $800 and $1,200 per metric ton as of 2025. This cost structure pressures margins and limits the ability of smaller players to compete on volume without sacrificing consistency or lead times. Second, trade policy is becoming a more material driver of regional pricing and sourcing decisions. In February 2026, a U.S. executive order introduced a 6.4 percent tariff on inactive yeasts under a specific tariff classification, excluding dried brewers’ yeast. While the measure does not apply uniformly across all feed yeast categories, it underscores how rapidly tariff exposure can alter the economics of cross-border supply and encourages buyers to reconsider sourcing portfolios. Third, regional production leadership is shifting the center of gravity in the market. China’s annual output now exceeds 200,000 tonnes and is primarily directed toward Asian and European markets, reinforcing a supply chain dynamic in which volume availability and export logistics play an outsized role in regional pricing behavior.
Core Drivers Reshaping the Market
Several interlocking forces are driving the current trajectory of the feed yeast market. Understanding these drivers is essential for evaluating where growth will materialize and which capabilities will translate into durable advantage.
Technological and Strain-Level Innovation
Innovation in this market is increasingly centered on strain selection, propagation efficiency, and functional reliability under real-world feeding conditions. The competitive edge is shifting from generic yeast inputs toward formulations designed for specific gastrointestinal targets, such as rumen stability, pathogen binding, or resilience during thermal processing. For producers, this means that manufacturing scale must be paired with application science: a large fermentation capacity is valuable, but the ability to document performance in target species and to provide technical guidance on inclusion rates and integration with other additives is what converts production capability into recurring demand. The industry context reinforces the point. Major producers operate fermentation infrastructure with annual capacity above 100,000 tonnes, yet the most differentiated offerings are increasingly defined by their functional claims and the evidence supporting them.
Regulatory and Compliance Environment
Regulatory dynamics are now a strategic variable rather than a background condition. Feed additives face varying approval pathways, renewal cycles, and labeling expectations across major markets. In Europe, for example, Alltech’s Yea-Sacc® yeast culture continues to be authorized for use in cattle feed under EFSA oversight, with renewals ongoing through 2025. Such continuity matters because it shapes buyer confidence in long-cycle procurement, especially for ruminant applications where health claims and compliance documentation carry significant weight. At the same time, the U.S. tariff action on certain inactive yeast categories illustrates the broader point that trade policy can alter the cost base of specific product types and incentivize formulation or sourcing shifts. Companies that actively monitor these regulatory and tariff signals, and that design portfolios with flexibility in mind, are better positioned to absorb shocks and preserve margin.
Yeast Market
Demand-Side Behavior and Animal Nutrition Priorities
The demand landscape is being reshaped by a combination of animal production economics and an evolving nutrition philosophy. Livestock operators are placing greater emphasis on gut health, feed conversion efficiency, and resilience to stress, especially in environments where preventive health strategies are replacing reactive treatments. Yeast-based inputs are increasingly evaluated through that lens: their value proposition is tied not only to nutrient contribution but also to functionality such as stabilization of the gastrointestinal environment, modulation of microbial balance, or binding of undesirable compounds. As a result, procurement decisions are becoming more evidence-driven, and buyers are more likely to seek technical support, trial data, and integration guidance alongside product specifications. This shift favors suppliers that can act as solution partners rather than simple vendors.
Supply Chain and Cost Structure Dynamics
Feed yeast production remains a scale-sensitive business. Fermentation, downstream processing, drying, and logistics all carry capital and operating requirements that reward continuity and keep smaller, underfunded entrants at a disadvantage. At the same time, the rise of integrated and cross-industry ownership is altering the supply base. A notable example is the acquisition of Leiber GmbH by Asahi Group Foods in March 2025, which consolidated brewers’ yeast production for both animal nutrition and food ingredient applications. Transactions of this type are not merely financial; they change operational priorities, improve access to certain raw material streams, and can create new avenues for cross-segment demand. For the feed yeast market, such moves hint at a broader trend in which ingredient producers seek to secure feedstock consistency, expand application portfolios, and reduce exposure to single-market volatility.
Competitive Landscape and Emerging Positioning
The competitive structure of the feed yeast market is dominated by a mix of global animal nutrition specialists, large ingredient companies, and regional producers with strong fermentation capabilities and technical service networks. The top players are not interchangeable; their strategic positioning reflects differences in geography, portfolio depth, application focus, and ownership structure. What unites the stronger performers is a tendency to build advantage around functional reliability and end-user support rather than price alone.
Among the firms shaping the current landscape, several patterns stand out. Angel Yeast has built a broad feed yeast portfolio spanning live yeast, inactive yeast, yeast extracts, and mycotoxin binders, and its scale-oriented production model is reinforced by participation in major trade forums such as SPACE 2025, where it showcased its full range of feed yeast solutions. This combination of volume capability and market-facing visibility helps the company maintain relevance across multiple buyer segments. Alltech continues to emphasize a more focused, science-backed approach through its Yea-Sacc® yeast culture for rumen health, leveraging regulatory continuity in Europe to support confidence in cattle feed applications. Lallemand and Lesaffre contribute from positions grounded in yeast strain expertise and broader animal health portfolios, often competing on the strength of application data and integrated nutrition messaging. Leiber’s position has evolved further following its acquisition, aligning brewers’ yeast capabilities with a larger group’s ingredient strategy and potentially expanding cross-market leverage. ADM, Novus, AB Agri, Chr. Hansen, Nutreco, and DSM-Firmenich each bring their own angles, whether through animal nutrition divisions, yeast cell wall components, or broader feed additive portfolios that incorporate yeast-derived inputs as part of a wider value proposition.
The market is not simply consolidating; it is also differentiating. Some players are moving toward integrated, multi-functional product systems, while others maintain a sharper focus on specific species or functional claims. The trend suggests a bifurcation in which scale and operational reliability protect share in commoditized segments, while application-specific formulation, documentation, and technical service drive growth in more demanding use cases. New entry is likely to remain difficult without access to fermentation capacity, regulatory fluency, and a credible technical narrative. At the same time, acquisition activity and cross-industry ownership may increase, especially where ingredient streams, regional distribution, or application expertise can be combined to create a stronger commercial position.
Worldwide Nutritional Yeast Market
Forward Outlook: Three Trends to Watch
Looking ahead to the 2026–2032 period, three developments are likely to define the commercial trajectory of the feed yeast market.
The first is a gradual shift from generic supplementation toward function-targeted formulations. As buyers increasingly evaluate yeast inputs for specific outcomes—such as rumen performance, gut stability, or resilience under stress—the market will reward products with clearer application narratives and stronger supporting evidence. Companies that invest in species-specific documentation, dosing guidance, and integration with other feed additives are more likely to secure repeat business and price resilience. The commercial opportunity here lies not just in product development but in the ability to translate technical claims into credible, practical recommendations for feed formulators and producers.
The second trend is regional recalibration of sourcing and pricing. Trade policy volatility, including tariff actions on certain inactive yeast categories, combined with concentrated production in key exporting countries, will encourage buyers to diversify supply sources and consider lead-time stability alongside unit cost. Suppliers with reliable export logistics, flexible packaging and specification options, and the ability to serve multiple regions will gain an edge. For manufacturers, regional demand growth will likely remain uneven, with some markets expanding faster as protein production intensifies and as nutrition programs become more preventive in design.
The third trend is continued portfolio and ownership consolidation, particularly where it enhances feedstock access, broadens application coverage, or strengthens technical service. Acquisitions that link yeast production with broader ingredient or food-grade operations can improve supply security and create cross-selling opportunities. At the same time, integration carries execution risk: differences in operating culture, quality systems, and customer expectations can complicate the anticipated benefits. The market will therefore reward operators that can combine scale with disciplined product stewardship and consistent technical support.
These trends carry both upside and uncertainty. Demand for functional nutrition is likely to remain supportive, but the pace of adoption will depend on economic conditions in animal production, the stringency of regulatory approvals, and the ability of suppliers to demonstrate consistent value. Cost pressures from feedstock inputs and the potential for additional trade measures also remain variables that can compress margins or shift competitive dynamics faster than expected. The companies best positioned to navigate this environment will be those that treat regulatory monitoring, supply resilience, and application documentation as core capabilities rather than peripheral concerns.
Strategic Actions for Decision-Makers
For manufacturers, the priority is to align fermentation scale with application credibility. Capacity provides optionality, but differentiation comes from strain performance, stability data, and the ability to guide customers through integration decisions. Building a portfolio that balances core volume products with more specialized, function-oriented offerings can help protect share while opening paths to higher-value engagements. Equally important is the discipline to track regulatory and tariff developments closely, because even narrow policy changes can reshape the economics of specific product types and influence sourcing preferences.
For investors, the market’s concentration pattern warrants attention. The dominance of a few large players suggests that scale, distribution, and technical service networks create meaningful barriers, but the presence of targeted acquisitions and cross-industry ownership also signals that value may be created through strategic combination rather than organic expansion alone. Due diligence should focus on the defensibility of functional claims, the stability of feedstock access, the exposure of each portfolio to trade and regulatory shifts, and the quality of customer support. In this market, durable growth is increasingly tied to reputation for reliability and efficacy, not simply to volume.
For procurement teams and feed formulators, the practical imperative is to evaluate yeast inputs as part of a broader nutrition strategy rather than as interchangeable commodities. Inclusion decisions should weigh functional performance, supply continuity, documentation quality, and the supplier’s ability to support integration with existing formulations. Diversifying sources where feasible can reduce exposure to regional disruptions and tariff fluctuations, while maintaining dialogue with suppliers that can provide species-specific guidance and consistent product quality. In an environment where pricing is influenced by both input costs and trade policy, proactive sourcing and evidence-based selection are likely to yield better outcomes than price-only comparisons.
The feed yeast market is moving toward a more demanding, more differentiated, and more regionally sensitive phase of its development. That shift creates opportunity for operators and buyers who treat functionality, compliance, and supply resilience as strategic assets. For decision-makers seeking a deeper view of segment trajectories, regional nuances, competitive positioning, and scenario-based implications, the full research report provides a more granular breakdown and tailored guidance to support planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Feed Yeast Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Automated Material Handling Equipment: Why $52.16B in 2025 Changes Everything
By PW Consulting, 2026-09-21
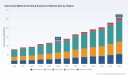
The Automated Material Handling Equipment Market: Strategic Trends and Commercial Opportunities
The global market for automated material handling equipment has reached a decisive inflection point. Valued at approximately $52.16 billion in 2025, the sector has expanded from $32.39 billion in 2020, reflecting a compound annual growth rate of 10.6% through the 2026–2032 forecast horizon. By the end of the projection period, revenue is expected to surpass $101.65 billion. This trajectory is not merely a function of incremental efficiency gains; it signals a structural reorientation of how goods are moved, stored, and sorted across manufacturing, distribution, and e-commerce ecosystems. The equipment category encompasses automated guided vehicles, conveyor and sorting systems, and automated storage and retrieval platforms, each addressing distinct operational pain points but increasingly converging through software-defined control layers and unified fleet orchestration.
Growth has been uneven but persistent across the historical window, with notable acceleration in recent years as labor market pressures, e-commerce fulfillment expectations, and supply chain redundancy requirements aligned. The market remains moderately fragmented, with the top five players collectively accounting for roughly 30% of revenue, indicating ample room for regional specialists, niche innovators, and well-capitalized consolidators. Executive teams evaluating capital allocation, capacity planning, or technology roadmaps must recognize that this is no longer a peripheral automation play. Material handling automation has become a core determinant of throughput scalability, labor flexibility, and real estate optimization. The following analysis examines the structural challenges shaping the market, the forces driving adoption, the evolving competitive architecture, and the strategic implications for operators, investors, and technology decision-makers.
Market Reality and the Defining Challenges
The headline growth figures mask a market navigating several simultaneous tensions. First, the distinction between nominal order value and real demand intensity has blurred. Rising input costs for steel, aluminum, and electronic components have pushed system pricing higher, inflating nominal revenue figures while complicating return-on-investment calculations for end users. Procurement teams are therefore scrutinizing total cost of ownership more rigorously, shifting conversations from unit price to lifecycle economics, energy consumption, and changeover flexibility.
Second, integration complexity remains a persistent barrier. Facilities rarely adopt a single equipment class in isolation. A typical deployment pairs autonomous mobile robots or guided vehicles with conveyor networks, storage retrieval systems, and warehouse execution software. The marginal benefit of each addition depends on data interoperability, safety zone management, and change management across shifts. Organizations that treat automation as a plug-and-play hardware purchase frequently encounter bottlenecks in commissioning, operator training, and downstream process alignment. The gap between purchasing equipment and realizing throughput gains continues to separate experienced integrators from inexperienced buyers.
Third, the operational environment is being reshaped by updated safety and integration expectations. Revised standards for automated guided vehicles have introduced clearer guidance on risk assessment, human-machine interaction zones, and fleet coordination. Compliance is no longer a checkbox exercise; it influences layout design, sensor selection, and software architecture. Companies that internalize these requirements early gain smoother commissioning paths, while those that retrofit controls after deployment face rework costs and schedule delays.
Implications for Decision-Makers
The practical takeaway is that equipment selection must be evaluated within a systems context. Leadership teams should assess whether their facilities have the data infrastructure, maintenance capabilities, and workforce readiness to absorb automation without creating new constraints. Projects that begin with process mapping, bottleneck identification, and clear performance targets tend to outperform those that start with a generic equipment specification.
Forces Reshaping Demand and Deployment
Several interconnected drivers explain why material handling automation is moving from selective adoption to broad-based necessity. Understanding these forces helps separate durable trends from cyclical noise.
Technology convergence is expanding the addressable use case. Autonomous mobile robots and guided vehicles have matured from fixed-path cart replacements to flexible fleet assets capable of dynamic routing, load balancing, and work assignment. Meanwhile, conveyor and sorting systems continue to improve in modularity and throughput density, and automated storage and retrieval platforms are becoming more adaptable to variable SKU profiles and mixed pallet handling. The real breakthrough lies in orchestration: software layers that translate order profiles, labor availability, and equipment status into sequenced movements. Facilities are increasingly evaluating fleets as unified workforces rather than isolated machines, which raises the strategic value of interoperable controls and open architecture.
Labor economics and operational resilience are accelerating adoption. Sustained wage pressure, turnover variability, and the need for consistent shift coverage are pushing operators toward equipment that can sustain throughput without proportional headcount growth. At the same time, supply chain disruptions have reinforced the value of predictable internal flow. Distribution and assembly environments, where speed and accuracy directly affect customer commitments, are leading adoption because automation there translates into measurable service-level improvements and reduced congestion during peak windows.
Regulatory and safety frameworks are maturing. The updated AGV standard provides clearer expectations for safe operation in shared spaces, influencing how vendors design navigation, sensing, and fallback behavior. Facilities that plan around these expectations from the outset can reduce rework and accelerate acceptance from safety teams and floor operators. For vendors, alignment with recognized safety expectations is becoming a competitive differentiator, especially in regulated or unionized environments where documented risk management matters.
Input cost dynamics are reshaping procurement strategies. Higher material and component costs have increased nominal project valuations, but they have also incentivized more disciplined scoping. Buyers are prioritizing incremental deployments, phased rollouts, and equipment that can be repurposed across seasons or product lines. This environment rewards vendors that offer scalable configurations, transparent pricing models, and integration support that reduces hidden failure costs.
What This Means in Practice
Organizations should treat automation decisions as multi-year operating model choices rather than single-cycle capital purchases. The most resilient strategies combine flexible hardware, software visibility, and workforce development plans. Vendors and integrators that can demonstrate measurable improvements in labor utilization, error reduction, and space efficiency will find stronger positioning than those competing solely on hardware features.
PW Consulting
Competitive Architecture and Strategic Positioning
The competitive landscape blends established global integrators, specialized equipment manufacturers, and increasingly ambitious regional players. Daifuku, Jungheinrich, KION Group, SSI SCHAEFER, Toyota Industries, BEUMER Group, Honeywell Intelligrated, Murata Manufacturing, KUKA, Dematic, Hyster-Yale, and Vanderlande each bring distinct strengths, but the market is not settling into a single template. Differentiation increasingly depends on the ability to combine hardware reliability with software orchestration, service responsiveness, and integration discipline.
Japanese and European incumbents with broad intralogistics portfolios continue to benefit from deep engineering heritage and global service networks. Companies offering end-to-end systems—from storage retrieval and sorting to vehicle fleets and control software—are well positioned for large, multi-zone facilities where process continuity matters more than component-level price competition. Their advantage lies in managing complexity across disciplines, reducing the coordination burden on the customer, and maintaining performance across mixed workflows.
Regional specialists and technology-focused entrants are carving out roles by targeting specific pain points or deployment models. Some emphasize omnidirectional handling, compact footprints, or rapid reconfiguration for high-mix environments. Others focus on software-driven fleet management, digital twin visualization, or simplified commissioning workflows. These entrants often win in scenarios where a customer needs a targeted improvement, a pilot-scale validation, or a solution that can be absorbed by a smaller engineering team. The presence of such players increases overall market dynamism and pushes larger incumbents to improve modularity and responsiveness.
Market Evolution Patterns
Consolidation is accelerating where it creates scale in service, software, and project delivery. Recent activity illustrates how ownership changes and brand repositioning are reshaping the landscape. The acquisition of Honeywell’s warehouse and workflow solutions division, including Intelligrated, by American Industrial Partners highlights interest in mature automation capabilities with established deployment track records. At the same time, brand transitions such as Pyramid’s emergence for Matthews Automation Solutions after Duravant’s acquisition signal that portfolio rationalization and clearer market positioning are becoming priorities. These moves matter because they affect post-deployment support, product roadmaps, and the continuity of software updates—factors that customers weigh heavily when selecting partners for multi-year operations.
Exhibition activity and product launches further reveal where innovation is concentrated. Demonstrations of advanced AMR and AGV platforms, omnidirectional pallet forklifts, and digital twin-enabled logistics systems indicate a market increasingly focused on flexibility, visibility, and faster commissioning. Next-generation vehicle introductions and smarter orchestration tools are not isolated events; they reflect an industry-wide push to reduce integration friction and make automation more accessible to facilities that previously considered such projects too complex or too capital-intensive.
Strategic Positioning Takeaways
Winning in this market requires more than hardware competence. Leaders combine dependable equipment with integration services, lifecycle support, and software that helps customers manage mixed fleets and changing order profiles. For customers, the practical question is not which vendor has the broadest catalog, but which partner can own the most difficult parts of deployment, training, and ongoing optimization within the customer’s operating context.
Worldwide Automated Storage Retrieval System Market
Forward Outlook: The Next Three to Five Years
The next phase of growth will be shaped by how the market resolves current tensions and expands into new operational contexts. Three developments are particularly consequential.
Fleet orchestration will become a primary value driver. As facilities operate mixed equipment sets—guided vehicles, autonomous mobile robots, conveyors, and retrieval systems—the competitive edge will shift toward software that coordinates work assignment, exception handling, and performance visibility across asset types. Customers will increasingly evaluate automation based on how smoothly it adapts to demand spikes, product mix changes, and staffing variability. Providers that deliver transparent dashboards, predictive upkeep signals, and configuration flexibility will be better positioned to defend margins and deepen customer relationships.
Modularity and phased deployment will broaden adoption. Large greenfield automation projects will remain important, but a growing share of activity will come from modular upgrades and incremental rollouts. Facilities will favor equipment that can be installed with minimal disruption, expanded as throughput grows, and repurposed when layout or product strategy changes. This trend favors vendors that can offer standardized building blocks, clear integration interfaces, and project plans that reduce downtime during cutover. It also increases the importance of simulation and digital twin tools, which let teams test layouts and workflow changes before physical installation.
Regional growth dynamics will diverge. Asia Pacific continues to represent the largest revenue share, reflecting the scale of manufacturing, distribution modernization, and e-commerce infrastructure investment in the region. Europe and North America remain strong contributors, driven by labor cost pressures, warehouse modernization, and stricter operational expectations. Emerging regions will grow from a smaller base but offer meaningful upside for vendors that can localize support, adapt to varying facility standards, and price solutions appropriately for different maturity levels. The market will not move uniformly; success will depend on aligning product complexity and service models with local buying conditions.
Material Handling Robotics Market Research
Risks and Uncertainties
Several factors could alter the pace or shape of growth. Persistent input cost volatility can compress project budgets or delay decisions if buyers cannot justify commitments under uncertain margin scenarios. Integration risk remains significant; projects that underestimate data compatibility, safety onboarding, or workforce change management may underperform and dampen enthusiasm for subsequent deployments. In addition, standards and safety expectations will continue to evolve, and vendors or customers that lag behind may face rework, compliance friction, or reputational exposure. Finally, the balance between in-house integration capability and outsourced partnering will influence outcomes. Organizations with limited internal expertise may depend heavily on vendors and system integrators, making partner quality and contract structure unusually important.
Actionable Priorities for Decision-Makers
Different stakeholders should focus on distinct but overlapping priorities as they navigate this market.
For manufacturers and operators planning automation: Begin with process clarity before equipment selection. Map the highest-friction flows, identify where variability undermines throughput, and define the operational outcomes that automation must deliver. Prioritize solutions that can integrate with existing control and data environments, and structure deployments in phases that allow performance validation before larger commitments. Invest in operator training and maintenance readiness early; the best equipment underperforms when the team lacks confidence in exception handling or changeover procedures. Where possible, favor modular architectures that allow expansion without full redesign, and evaluate total cost of ownership across energy, maintenance, downtime, and floor space utilization rather than focusing narrowly on purchase price.
For investors and corporate development teams: Value creation will increasingly come from software-enabled differentiation, service scalability, and portfolio alignment rather than hardware volume alone. Assess targets for their ability to manage integrated deployments, maintain software continuity, and support mixed-fleet environments. Watch for ownership changes and brand rationalization as indicators of strategic intent and post-merger service stability. Consider the growing importance of regional execution capability; companies that can localize integration, training, and support often capture share more durably than those competing only on specification sheets. Also monitor the shift toward orchestration and visibility tools, as these create recurring engagement points and can improve customer retention when they demonstrably reduce operational friction.
For procurement and technology buyers evaluating suppliers: Look beyond equipment features to integration discipline and lifecycle support. Ask how a vendor handles mixed-fleet coordination, exception resolution, safety compliance, and post-commissioning optimization. Verify that proposed layouts and workflows have been validated through simulation or pilot evidence where feasible, and clarify ownership of software updates, spare parts availability, and escalation paths. Structured selection processes that weigh deployment risk, service responsiveness, and adaptability to future layout changes will reduce the likelihood of costly rework and improve long-term performance.
Closing Perspective
The automated material handling equipment market is moving from a phase of selective adoption to one of broader operational dependence. Growth to more than $100 billion by the early 2030s reflects a structural shift in how facilities manage labor, throughput, and space under tighter service expectations and more volatile operating conditions. The organizations that benefit most will be those that treat automation as a coordinated system, align equipment choices with process realities, and build the internal capabilities needed to sustain performance after deployment.
Detailed segmentation, regional dynamics, and company-level profiling can materially improve capital planning, supplier selection, and investment prioritization. For teams that require granular data and tailored scenario analysis, the full market research report provides deeper breakdowns and structured guidance to support execution.
For detailed analysis of this topic, please visit the official page: Automated Material Handling Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Navigating the Chicory Market: Strategic Trends and Commercial Opportunities (2026–2032)
The global chicory market is entering a phase of structural acceleration, driven by converging forces in functional nutrition, regulatory clarity, and regionalsupply chain realignment. With a market valuation reaching approximately USD 300 million in 2025 and a projected compound annual growth rate of 7.9 percent through 2032, the sector is transitioning from a niche botanical commodity to a strategically important ingredient in food, beverage, and wellness formulations. For executives, investors, and procurement leaders, the window to shape positioning is narrowing as competitive dynamics tighten and consumer-facing applications multiply.
Understanding where value will concentrate requires looking beyond aggregate growth figures. The market is being reshaped by ingredient innovation, regulatory approvals that unlock new use cases, shifting demand from discretionary wellness to everyday functional consumption, and supply-side restructuring around raw material sourcing and extraction economics. This analysis maps the forces at play, profiles the competitive landscape, and outlines actionable implications for business leaders evaluating chicory-related investments or ingredient strategies.
Current Market Landscape and Core Challenges
The chicory market has sustained steady expansion over the past five years, with revenue trajectories reflecting consistent demand growth across food, beverage, and dietary supplement channels. The upward momentum is expected to continue through the forecast period, supported by broader consumer interest in plant-based fibers, prebiotic ingredients, and coffee-alternative formats. Growth is not uniform across value pools, however. Different segments are maturing at different speeds, and the pace of commercialization depends heavily on regulatory status, formulation compatibility, and end-market adoption cycles.
Several structural challenges are defining the market's next chapter.
Raw Material Geography and Climate Exposure
Chicory root production is geographically concentrated, with Northern Europe historically serving as a core sourcing region for inulin and related functional ingredients destined for global markets. This concentration creates vulnerability to weather variability, crop yield fluctuations, and logistics disruptions. Companies that depend on a narrow supplier base face quality consistency risk and cost volatility, particularly when demand spikes or input costs rise. Diversifying sourcing geographies, building contractual resilience, and investing in yield optimization are becoming pragmatic priorities rather than optional supply chain enhancements.
Regulatory Fragmentation Across Use Cases
The commercial pathway for chicory-derived ingredients varies significantly by application and jurisdiction. Certain forms of chicory root powder and extracts have cleared regulatory thresholds for use in bakery products, beverages, cereals, and grain-based items, with inclusion levels spanning a wide range. Chicory extract has also gained recognition as a color additive, flavor enhancer, and flavoring agent in specific contexts. Meanwhile, native chicory inulin has been evaluated and authorized in select markets as a functional ingredient and, in some regions, under novel food frameworks. These approvals create opportunity, but they also introduce complexity: formulation teams must navigate differing inclusion limits, claim language, and market-specific compliance requirements, which can slow product launches and add cost to regulatory navigation.
Functional Positioning Versus Commmodity Pressure
Chicory is increasingly positioned around functional benefits such as prebiotic fiber content and digestive wellness, yet it also competes in price-sensitive commodity channels where chicory root is used as a bulk ingredient or coffee extender. This dual identity creates strategic tension. Premiumization requires demonstrated efficacy, taste performance, and clean-label compatibility, while commodity-oriented channels pressure margins and incentivize scale. Companies must decide whether to compete on functional differentiation, cost efficiency, or a hybrid model that segments product lines by application and customer type.
Key Drivers Shaping Market Trajectory
Four interconnected drivers are accelerating market evolution and creating pockets of differentiated opportunity.
Ingredient Innovation and Extraction Technology
Technological progress in extraction, fractionation, and formulation is expanding the range of chicory-based inputs available to manufacturers. Advances in processing chicory root into soluble forms, standardized extracts, and functional inulin variants are enabling better taste masking, texture control, and label flexibility. These improvements matter because chicory is often used in categories where organoleptic performance is critical, such as coffee blends, flavored beverages, and baked goods. As ingredient formats become more versatile, the addressable market widens beyond traditional root-based applications and into newer functional food and supplement formats.
Regulatory Progress Opening New Use Cases
A series of regulatory determinations is reducing uncertainty and expanding the commercial menu for chicory ingredients. Recent determinations have supported chicory root powder in bakery products, beverages, cereals, and other grain products at defined inclusion levels. Separate determinations have positioned chicory extract as a color additive, flavor enhancer, and flavoring agent. In parallel, native chicory inulin has been evaluated and authorized in select frameworks, including recognition as a novel food in some regions and scientific assessment by European food safety panels. Collectively, these developments reduce formulation risk and give developers more confidence to build chicory into mainstream products rather than limiting it to niche or premium-only offerings.
Demand-Side Shift Toward Everyday Functional Consumption
Consumer behavior is moving from occasional wellness purchases toward routine integration of functional ingredients into daily diets. Fiber and prebiotic content remain relevant purchase drivers, and chicory fits naturally into this narrative because it can be incorporated into familiar formats such as coffee alternatives, cereals, snacks, and beverages. Importantly, the demand story is not only about supplements. Food and beverage applications continue to represent the largest demand pool, reflecting the ingredient's flexibility and compatibility with everyday consumption occasions. This shift encourages manufacturers to pursue shelf-stable, mass-reachable products instead of relying solely on specialty channels.
Supply Chain Realignment and Cost Structure Pressures
The chicory value chain is undergoing reconfiguration as processors and ingredient companies respond to raw material availability, processing efficiency, and export dynamics. Several producers in India, for example, have built export-oriented operations spanning dried chicory roots, roasted chicory, liquid chicory, and extracts, targeting both coffee blends and nutraceutical markets. At the same time, large-scale ingredient suppliers in North America and Europe continue to emphasize chicory-derived inulin and functional ingredients for food, beverage, and nutraceutical uses. These parallel supply models create both competition and collaboration opportunities. Cost structures are influenced by root quality, drying and roasting methods, extraction yields, and logistics, meaning that margin management increasingly depends on process optimization and sourcing strategy as much as on end-market pricing power.
PW Consulting
Competitive Landscape and Leading Strategies
The chicory market remains moderately fragmented, but competitive positioning is sharpening as participants define clearer boundaries around geography, product format, and end-market focus. Market concentration is not extreme, and the presence of multiple regional processors alongside global ingredient suppliers creates a landscape where differentiation is achievable through specialization rather than scale alone.
Worldwide Fondant Market
Differentiated Positioning Among Established Players
Several companies illustrate how participants are carving out defensible positions.
-
Leroux has built its identity around roasted chicory products, including grains, ground chicory, liquid chicory, and soluble forms for beverages and culinary uses, anchored by a fully French supply chain. The emphasis on origin, roasted formats, and culinary compatibility positions the company in a premium, taste-driven segment where provenance and product consistency matter.
-
Cargill Incorporated leverages scale and ingredient science to produce chicory-derived inulin and functional ingredients for food, beverage, and nutraceutical applications. Its strategic advantage lies in formulation breadth, regulatory and technical support capabilities, and the ability to integrate chicory inputs into larger ingredient portfolios serving multinational customers.
-
Starwest Botanicals focuses on organic chicory root, powder, and extracts for herbal and food ingredient uses. Its positioning targets clean-label, organic, and botanical channels, appealing to buyers who prioritize certification, traceability, and ingredient transparency.
-
Indian processors such as Vashila Industries, Jamnagar Chicory Industries, Pioneer Chicory, Farmvilla Food Industries, and Nature's Gold Production illustrate a robust export- and domestic-oriented ecosystem spanning dried roots, roasted chicory, liquid chicory, cubes, and extracts. These companies compete on cost efficiency, volume supply, and versatility across coffee-blend, food, and nutraceutical channels, often serving as important nodes in global distribution networks.
-
European and UK-based distributors such as Organic Herb Trading Co support the market by supplying organic chicory and related botanicals, reinforcing the importance of distribution networks that connect processors with end users seeking specialty or certified materials.
Strategic Themes Across the Landscape
Across these profiles, several strategic themes emerge.
-
Format specialization is a common differentiator. Some players concentrate on roasted and culinary forms, others on extracts and inulin-type ingredients, and others on organic or herbal-grade materials. This segmentation reduces direct head-to-head competition and allows firms to build reputations around specific customer needs.
-
Supply chain origin is increasingly part of the value proposition. Fully domestic supply chains, regional sourcing clusters, and certification pathways are used to signal quality, consistency, and traceability. In a market where raw material geography matters, origin can support price premiums and customer loyalty.
-
Application breadth versus depth creates different risk-return profiles. Broad-line ingredient suppliers can cross-sell across categories and capture more of the value chain, while focused producers can deepen expertise and serve niche channels more effectively. Both approaches can succeed, but they require different capabilities in regulatory support, technical service, and operational scalability.
Market Evolution Outlook
The competitive landscape is likely to evolve through selective consolidation, entry by ingredient-focused players, and rising importance of technical service and regulatory navigation. As use cases expand, buyers will increasingly value partners that can support formulation, compliance, and scale simultaneously. At the same time, regional processors with strong export capabilities and cost advantages are well placed to capture share in price-sensitive and volume-driven segments. The result is a market where multiple business models can coexist, but where advantage will increasingly depend on execution quality, regulatory readiness, and the ability to match ingredient formats to end-market demand.
Forward-Looking Trends and Commercial Opportunities
Looking ahead three to five years, three trends are particularly consequential for strategic planning.
Expansion of Chicory in Everyday Food and Beverage Formats
Chicory is poised to move further into everyday consumption occasions as formulators leverage soluble forms, roasted formats, and functional extracts to improve taste and texture in mainstream products. Coffee alternatives, fortified cereals, snack applications, and flavored beverages represent channels where chicory can gain incremental share through familiar formats and added functional appeal. The commercial opportunity lies in building product architectures that combine functional messaging with sensory performance, enabling chicory to compete in categories with high purchase frequency rather than remaining confined to specialty wellness niches.
Inulin and Prebiotic Fiber as a Growth Anchor
Inulin-type ingredients derived from chicory continue to benefit from sustained interest in digestive health and fiber enrichment. Scientific evaluation and regulatory recognition in multiple markets support broader adoption, while manufacturing advances make it easier to incorporate these materials into diverse matrices. Growth is likely to be strongest where suppliers can provide consistent quality, clear application guidance, and compliance support. For ingredient companies, the strategic priority is to strengthen technical documentation, customer education, and formulation expertise so that chicory-based inulin becomes a default option in fiber-enrichment projects rather than one option among many.
Cobalt Market
Regional Supply Chain Diversification and Value-Added Processing
The market is likely to see continued diversification in sourcing and processing footprints as participants seek to reduce exposure to concentrated supply regions and capture more value locally. This includes expansion of drying, roasting, extraction, and blending capabilities in key production and export markets, as well as closer partnerships between processors and end-user manufacturers. The opportunity is twofold: buyers can improve resilience and cost predictability by broadening supplier relationships, while processors can differentiate through higher-margin value-added formats rather than competing solely on raw root volume.
Risks and Uncertainties to Monitor
Several factors warrant caution. Input cost volatility and crop variability can pressure margins and disrupt supply continuity. Regulatory complexity across jurisdictions may slow product development or limit claim language in certain markets. Taste and formulation challenges remain relevant in sensitive applications, where performance trade-offs can affect repeat purchase and shelf presence. In addition, competition from alternative fibers, botanical ingredients, and coffee extender substitutes could compress pricing in specific segments. Companies should scenario-plan around these variables and maintain flexibility in sourcing, formulation, and market prioritization.
Strategic Implications for Decision-Makers
The chicory market presents a clear value proposition for leaders willing to align ingredient strategy with application realities and regulatory pathways. The following recommendations are oriented by role.
For Manufacturers and Ingredient Developers
-
Prioritize format-to-application fit. Select roasted, soluble, extract, or inulin-type inputs based on the intended end use, taste requirements, and label goals rather than sourcing by commodity alone. Matching format to application reduces reformulation risk and improves speed to market.
-
Build regulatory and technical support into the commercialization plan. Because inclusion levels, claim opportunities, and compliance expectations differ across markets and product categories, early attention to regulatory status and application guidance can shorten launch timelines and reduce rework.
-
Strengthen supply resilience through diversity and process control. Multi-region sourcing, quality consistency protocols, and processing optimization help mitigate raw material volatility and support margin stability in volume-driven programs.
For Investors
-
Focus on differentiation that compounds over time. Businesses with clear positioning around organic certification, origin credibility, extraction capability, or application expertise are better placed to defend margins than undifferentiated bulk suppliers.
-
Evaluate end-market mix carefully. Exposure to everyday food and beverage channels can provide scale and repeatability, while specialty wellness channels may offer higher unit value but more volatile demand. Understanding the balance between these pools is essential for modeling growth and risk.
-
Watch for consolidation signals and partnership-driven expansion. As use cases broaden, value may migrate toward players that can combine supply reliability, technical service, and regulatory navigation, whether through organic build-out or strategic combinations.
For Procurement and Sourcing Leaders
-
Expand and qualify the supplier base beyond single-region dependence. Diversification across geographies and processing models improves continuity and gives procurement teams more negotiating leverage in volatile conditions.
-
Assess total cost beyond unit price. Processing method, certification requirements, consistency, lead times, and technical support all affect landed value and downstream performance. Evaluating these factors holistically supports better category decisions.
-
Align specifications with application needs early. Defining required formats, inclusion tolerances, and quality parameters before sourcing reduces the risk of mismatched materials and accelerates downstream formulation work.
The strategic picture is clear: chicory is no longer a narrow botanical input but a versatile ingredient set with expanding regulatory support, growing functional relevance, and a competitive landscape that rewards specialization and execution quality. Organizations that act early to define their positioning, secure resilient supply, and align formulation strategy with the strongest end-market opportunities will be best placed to capture value as the market moves toward 2032. For those seeking deeper segmentation data, company-level benchmarking, and tailored scenario analysis, a comprehensive research report can provide the detailed evidence base needed to convert these directional insights into precise commercial decisions.
For detailed analysis of this topic, please visit the official page: Chicory Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Navigating the Petroleum Resin Market: Strategic Trends and Commercial Opportunities Through 2032
The petroleum resin market is entering a phase of measured expansion, characterized by steady demand growth, evolving regulatory pressures, and a competitive landscape that rewards product differentiation over volume alone. Current market sizing places the sector at approximately 218.7 million USD in 2025, with a projected trajectory toward 322.6 million USD by 2032. This growth path reflects a compound annual growth rate of 5.88% across the 2026–2032 forecast window, building on a historical expansion pattern that saw the market move from 185.1 million USD in 2020 through a series of incremental annual gains. The trajectory is not uniform, however. Growth is being reshaped by feedstock volatility, tightening emissions standards, and shifting end-user requirements that are quietly redefining which resin grades will capture premium value in the next cycle.
Rosin Resin Market
For decision-makers, the immediate takeaway is that the market is large enough to support multiple business models but narrow enough that margin capture depends heavily on grade specialization, regional positioning, and compliance readiness. The industry remains moderately consolidated, with the top three players accounting for roughly 29.5% of revenue and the top five reaching approximately 36.8%. This concentration leaves substantial room for localized competitors, niche formulators, and integrated feedstock players to compete on service, technical support, and application-specific performance rather than scale alone.
Key Challenges and Inflection Points
Three structural challenges are currently re-shaping strategic planning across the petroleum resin value chain.
Feedstock exposure and margin sensitivity remain a persistent pressure point. Naphtha-derived C5 and C9 fractions form the backbone of most hydrocarbon resin synthesis routes, and pricing swings in crude oil and naphtha markets transmit quickly into producer cost structures. Because resin grades are often priced against performance benchmarks rather than raw input costs, suppliers with limited hedging flexibility or narrow product portfolios face disproportionate margin compression during volatile periods. The implication is that cost leadership alone is becoming less durable; resilience is increasingly tied to feedstock diversification, integration depth, and the ability to shift production toward higher-margin grades when input costs rise.
Regulatory tightening on emissions and aromatic content is altering the competitive balance between conventional and hydrogenated resins. In adhesive and coating applications, regulatory direction is favoring products with lower volatile organic compound profiles and reduced aromatic residuals. This shift is not merely a compliance issue; it influences formulation choices, customer qualification cycles, and the willingness of converters to standardize on specific resin families. Companies that have already invested in hydrogenation capacity or water-white grade portfolios are positioned to benefit from a transition that will otherwise raise reformulation costs for slower-moving competitors.
Demand fragmentation across end-use sectors is making blanket capacity plays riskier. Growth is not coming from a single application category but from a mix of adhesive systems, rubber compounding, road-marking and industrial coatings, and packaging-related ink and film applications. Each segment has distinct performance requirements, qualification timelines, and price sensitivity. As a result, the market is moving toward a model where revenue growth depends on aligning resin grades with specific technical needs rather than selling generalized intermediates into undifferentiated demand.
Key Drivers Shaping the Market Trajectory
The 5.88% CAGR projected through 2032 reflects a convergence of technical, regulatory, and demand-side forces. Understanding how these drivers interact is essential for identifying where value will accumulate.
- Technology innovation and grade specialization continue to be central to competitive differentiation. Hydrogenated and water-white resins represent a clear example of how processing sophistication translates into market access. By reducing color bodies and residual aromatics, these grades open doors to packaging, hygiene, and high-visibility coating applications that conventional fractions cannot easily serve. At the same time, modification strategies that blend C5, C9, and copolymer architectures are enabling formulators to balance tack, compatibility, and thermal stability more precisely. Innovation is therefore not only about new molecules; it is about creating grades that solve formulation constraints in high-value applications.
- Policy and regulatory environments are accelerating product migration toward cleaner profiles. Rules governing VOC limits, aromatic compound scrutiny, and food-contact extractables are progressively raising the bar for resin selection in adhesives and packaging-adjacent uses. This environment favors producers with ready access to fully hydrogenated options and those capable of documenting compliance across multiple jurisdictions. It also encourages downstream converters to consolidate their supplier base around partners who can provide consistent regulatory documentation and predictable grade performance.
- Demand-side shifts in adhesives and industrial applications are expanding the addressable market for specialized resins. Hot-melt and pressure-sensitive adhesive systems remain significant demand anchors, but the broader story is the continued push toward lighter-weight assemblies, faster processing speeds, and Bondline performance optimization in manufacturing. In parallel, road-marking and industrial coatings demand is supported by infrastructure maintenance cycles and the need for durable, visible markings. These end-use trends reward resin suppliers who can align grade characteristics—such as tack build, openness, and weatherability—with real processing conditions rather than generic specification sheets.
- Supply chain and cost structure changes are reshaping regional competitiveness. Feedstock sourcing, logistics, and local availability of C5/C9 streams influence both cost position and supply reliability. Regions with stronger integration between petrochemical feedstock production and resin manufacturing can respond more flexibly to demand changes and margin pressure. Meanwhile, transportation costs and qualification lead times are reinforcing the value of regional supply relationships, particularly where converters prioritize consistent batch performance and shorter response cycles over marginal price differences.
Recent company-level developments illustrate how these drivers are being addressed in practice. Capacity expansions are being pursued in response to rising global demand for adhesive and coating applications, signaling that at least some major players see sustained volume growth as worth the capital commitment. At the same time, certification and feedstock-innovation moves are becoming part of the differentiation conversation. Notably, ISCC PLUS certification has been achieved at a key production facility for sustainable resin production, and resin derived from used cooking oil has been supplied to an affiliate for synthetic rubber production. These moves point to a market in which sustainability credentials and alternative feedstock pathways are increasingly tied to commercial access, especially where downstream customers are under pressure to document lifecycle and sourcing improvements.
Competitive Landscape and Leading Strategies
The competitive field spans large multinational producers, regional specialists, and application-focused formulators. Strategic positioning varies by feedstock access, hydrogenation capability, geographic footprint, and the depth of technical support offered to converters.
Among the prominent players, a clear divide is emerging between companies competing primarily on broad product breadth and those building advantage around hydrogenated grades, sustainable supply claims, or application-specific modification expertise. Producers with established hydrocarbon resin brands spanning C5, C9, and copolymer lines are leveraging name recognition, global distribution, and long-standing customer qualification relationships. Their challenge is to maintain relevance as end-users increasingly prioritize emissions performance, food-contact compliance, and consistent color quality in sensitive applications.
Hydrogenated resin specialists and producers with water-white portfolios are positioned to capture premium demand where aromatic residuals or color limitations would otherwise restrict material choice. In adhesive and coating grades, the ability to deliver low-color, low-odor, and low-VOC profiles is becoming a commercial advantage rather than a niche feature. This is especially relevant as regulatory expectations tighten and as packaging and hygiene-adjacent applications expand their material requirements.
Regional and China-based producers continue to play an important role in supplying C5 aliphatic, C9 aromatic, and C5/C9 copolymer resins to cost-conscious and volume-driven segments. Their strategic advantage often lies in feedstock proximity, manufacturing scale in specific resin families, and the ability to serve regional adhesive, coating, and rubber compounding markets with shorter supply lines. The key question for these players is whether they can move up the value chain into higher-specification grades without losing cost competitiveness, and whether they can build the documentation and certification infrastructure that multinational converters increasingly require.
The landscape is evolving along several axes. Integration is deepening where feedstock security and conversion efficiency matter most, allowing producers to protect margins during naphtha price swings. Differentiation is intensifying around hydrogenation, modification, and certification, as customers use compliance and performance criteria to narrow their approved supplier lists. New entry and regional specialization remain viable where local demand growth, logistics advantages, or application knowledge create a defensible position, even if global scale is limited. Overall, the market is not trending toward a single dominant model; it is trending toward a segmented structure in which success depends on matching the right grade, the right compliance profile, and the right service model to a specific customer segment.
Future Trends and Commercial Implications
Looking across the 2026–2032 horizon, several trends are likely to define where growth and margin will concentrate.
- Hydrogenated and low-aromatic resins will capture a growing share of high-value demand. As VOC limits tighten and aromatic scrutiny increases, converters in adhesive and coating applications will continue shifting toward fully hydrogenated options that simplify compliance and reduce reformulation risk. This trend favors producers with existing hydrogenation capacity and those able to supply consistent water-white grades at scale. The commercial opportunity lies not just in selling a different resin, but in helping customers qualify faster, reduce audit burden, and standardize on grades that meet multiple regulatory regimes simultaneously.
- Sustainable feedstock and certification pathways will become more commercially meaningful. ISCC PLUS certification and the use of alternative feedstocks such as used cooking oil are moving from pilot-stage signals to operational reality in certain production lines. While these pathways are unlikely to replace conventional naphtha-based synthesis across the board, they will become increasingly important in customer segments where sustainability documentation influences sourcing decisions. The opportunity here is for producers to build credible, auditable supply chains that can support customer claims without overpromising on volume or cost.
- Regional demand growth will reward localized grade portfolios and technical service. Asia Pacific remains a major demand center, but growth is also emerging from infrastructure-related coatings, packaging-adjacent inks and films, and adhesive-intensive manufacturing in multiple regions. In this environment, global product lists matter less than regional readiness: the ability to supply the right grade mix, maintain reliable batch consistency, and provide formulation support in local markets. Producers who can combine product breadth with regional responsiveness are more likely to secure long-term converter relationships than those competing on price alone.
These trends are not without risk. Feedstock volatility can still erode margins quickly, especially for producers with limited hedging or integration. Regulatory change may accelerate faster in some jurisdictions than others, creating uneven compliance costs and fragmented qualification requirements. In addition, overinvestment in generalized capacity could lead to oversupply in commoditized grades while leaving high-specification segments underserved if capital is not directed toward hydrogenation, modification, or certification capabilities. The most resilient strategies will be those that treat these risks as reasons to specialize rather than reasons to retreat.
Strategic Actions for Decision-Makers
The market outlook suggests a period in which disciplined positioning will matter more than aggressive volume chasing. The following actions are most relevant for different roles in the value chain.
PW Consulting
For Manufacturers and Producers
- Prioritize grade portfolios that align with regulatory direction and high-value applications, particularly hydrogenated, water-white, and low-aromatic options where qualification cycles are shortening and customer scrutiny is rising.
- Strengthen feedstock resilience through integration, diversification, or supply agreements that reduce exposure to naphtha price swings, and consider how alternative feedstock pathways can support both cost flexibility and sustainability positioning.
- Invest in technical service and application support as a competitive lever, since converter decisions are increasingly driven by formulation reliability, consistency, and documentation as much as by resin price.
For Investors and Capital Allocators
- Focus on companies with clear differentiation in hydrogenated or specialized grades, credible certification and compliance infrastructure, and the ability to serve high-margin adhesive, coating, and packaging-adjacent demand rather than solely competing in commoditized segments.
- Evaluate feedstock exposure and regional positioning as risk factors, since margin durability will depend on how well companies can manage naphtha-linked volatility and serve demand centers with reliable supply and short response times.
- Watch for consolidation and capability acquisition activity, particularly where smaller producers hold desirable grade expertise, regional relationships, or certification assets that larger players need to expand into premium segments.
For Procurement and Supply Chain Leaders
- Diversify approved supplier lists deliberately between broad-line suppliers and specialists, so that compliance requirements, color/aromatic constraints, and supply continuity can be managed without overrelying on a single source for critical grades.
- Include regulatory readiness, documentation quality, and feedstock sustainability credentials in sourcing evaluations, especially where future VOC limits, aromatic scrutiny, or food-contact requirements could affect qualification and reformulation risk.
- Engage early with suppliers on grade development and qualification timelines, since the market is shifting toward custom-fit solutions where early collaboration can reduce switching costs and protect production schedules.
The strategic picture is clear enough to act on, but the details matter. Market-wide sizing and growth rates provide the backdrop, while the real opportunities are embedded in grade-level demand shifts, regional feedstock dynamics, certification status, and the ability to meet tightening regulatory expectations without sacrificing performance. For organizations that need a sharper view of segment-level volume patterns, regional share dynamics, price/cost sensitivity, and company-level positioning, a more detailed research package can provide the granularity required to translate these trends into concrete sourcing, investment, and product decisions.
C9 Petroleum Resin Market
For detailed analysis of this topic, please visit the official page: Petroleum Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


