



Category: market research
Solar Cell Metal Paste Market: Why 6.5% CAGR and Asia Pacific Lead 2026-2032
By PW Consulting, 2026-09-21
Solar Cell Metal Paste Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
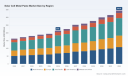
The solar cell metal paste market has demonstrated consistent growth over the past half-decade, evolving from a niche materials segment into a critical enabler of photovoltaic manufacturing efficiency. Revenue expanded from approximately 163.15 million USD in 2020 to 215.0 million USD in 2025, reflecting a compound annual growth rate of 6.5 percent. Projections indicate the market will continue its upward trajectory, reaching 344.8 million USD by 2032. This expansion is not merely a function of installed capacity growth; it is increasingly tied to technology transitions, material substitution debates, and the competitive dynamics of a fragmented supplier base.
At first glance, the growth narrative appears straightforward: more solar cells require more conductive pastes for front-side metallization and back-surface field formation. However, the structural reality is more nuanced. Manufacturing yield optimization, silver intensity reduction, and the shift toward next-generation cell architectures are reshaping how paste suppliers position themselves and how cell manufacturers evaluate material procurement. The market's resilience during periods of raw material volatility underscores both the strategic importance of metallization materials and the persistent tension between performance requirements and cost constraints.
Key Challenges and Inflection Points
Three structural challenges currently define the operating environment for solar cell metal paste participants and downstream manufacturers alike.
First, raw material cost exposure has intensified. Silver, the dominant conductive component in high-performance pastes, experienced unprecedented price appreciation, reaching approximately 121 USD per ounce in January 2026 before averaging around 81 USD per ounce through the year according to J.P. Morgan Global Research. Silver paste formulations can account for up to 30 percent of total solar cell production costs, making paste chemistry and silver-loading strategies a direct contributor to cell-level economics. This exposure forces manufacturers to balance efficiency gains against material input volatility.
Second, the technology transition from legacy crystalline silicon architectures toward TOPCon, heterojunction, and other advanced structures is disrupting paste specification requirements. Formulations optimized for PERC or standard multicrystalline platforms do not automatically translate to higher-efficiency architectures. Suppliers must invest in R&D to develop pastels that maintain adhesion, low contact resistance, and fire-through compatibility under altered thermal profiles and layer stack designs. This creates a divide between suppliers with formulation depth and those competing primarily on price.
Third, the competitive landscape remains structurally fragmented despite pockets of technological leadership. The market's concentration metrics reflect a diffuse supplier environment where differentiation is increasingly tied to application-specific engineering support, formulation customization, and supply reliability rather than commodity volume alone. This fragmentation presents both an opportunity for steady entrants and a risk for those unable to move beyond generic product positioning.
Key Drivers of Market Evolution
Technology Innovation and Formulation Breakthroughs
The most consequential driver of market growth is the simultaneous push toward higher cell efficiencies and lower silver consumption per watt. Advanced metallization pastes are being engineered to reduce sintering temperatures, improve line resistance uniformity, and enable thinner finger spacing without compromising collection efficiency. Formulations designed for PERC, TOPCon, and emerging n-type architectures are moving from qualification stages into volume production, and suppliers capable of delivering consistent performance across multiple technology platforms are capturing disproportionate share within high-value segments.
This technical trajectory intersects directly with silver-saving initiatives. Industry reporting from early 2026 highlighted accelerating efforts across the solar value chain to reduce silver intensity, with metallization paste optimization identified as one of the most actionable levers in cell cost structure. The implication for paste suppliers is clear: the next wave of market growth will not be awarded solely to those with the largest production footprint, but to those with the formulation agility to support lower-silver designs without eroding electrical performance.
Policy and Regulatory Momentum
Policy environments in major markets are reinforcing demand for high-performance photovoltaic materials. The European Union's target of a 40.5 percent renewable energy share by 2030 is driving sustained investment in solar deployment and, by extension, demand for high-performance silver-based pastes in advanced module manufacturing. In the United States, the Inflation Reduction Act has indirectly strengthened the economics of domestic and allied supply chains, encouraging producers to prioritize materials that meet quality, reliability, and traceability expectations for long-life assets.
China's policy stance further shapes the demand picture. Commitment to 20.5 percent non-fossil energy consumption by 2026 supports continued expansion in domestic solar cell production, creating a substantial internal market for both silver and aluminum-based metallization materials. These regulatory signals do not merely boost volume; they influence the premium attached to formulations that enable efficiency, yield, and long-term durability in increasingly competitive deployment economics.
PV Metallization Silver Paste Market
Demand-Side Shifts in Manufacturing Behavior
Cell and module manufacturers are increasingly treating paste selection as a systems-level optimization decision rather than a discrete consumable purchase. As production scales and fab economics tighten, buyers focus on total cost per watt, line yield, and compatibility with high-throughput screen printing or printing-and-fire processes. This behavioral shift advantages suppliers that offer not only material consistency but also process integration support, troubleshooting capability, and the ability to co-develop formulations tailored to specific line configurations.
At the same time, large-scale manufacturing is intensifying sensitivity to supply continuity. Volatility in precious metal markets and geopolitical supply considerations have elevated the importance of qualified secondary sources, regional availability, and inventory strategies. Manufacturers that once tolerated single-source dependency for specialized pastes are actively building supplier redundancy, changing how incumbents must compete against challengers.
Supply Chain and Cost Structure Dynamics
Cost structure pressures are reshaping how paste portfolios are built and priced. Silver price surges have accelerated interest in silver-aluminum hybrid designs, reduced-loading formulations, and aluminum paste alternatives where application constraints allow. At the same time, the cost of delivering advanced formulation performance is rising, as research, quality control, and application engineering become more essential to customer selection criteria.
This dynamic creates a dual pressure: manufacturers want lower input costs, while simultaneously demanding performance that enables next-generation cell economics. Suppliers that can articulate the trade-off between silver loading, fire-through behavior, and contact resistance in a way that maps to customer cost-per-watt calculations are gaining negotiating leverage, even in a price-sensitive environment.
Competitive Landscape and Leading Strategies
The supplier ecosystem spans established specialty material companies, electronics-paste incumbents extending into photovoltaics, and regional manufacturers competing on cost-performance balance. Ten companies illustrate the breadth of strategies currently shaping the market: Heraeus Photovoltaics, DuPont de Nemours, Inc., Giga Solar Materials Corporation, Targray Technology International Inc., Murata Manufacturing Co., Ltd., Hunan LEED Electronic Ink Co., Ltd., Shanghai Transcom Scientific Co., Ltd., Daejoo Electronic Materials Co., Ltd., Agfa-Gevaert N.V., and Noritake Co., Limited.
Strategic Positioning of Leading Players
Heraeus Photovoltaics has built a position around high-performance silver metallization pastes tailored for advanced cell architectures, including PERC, TOPCon, and n-type technologies. Its relevance in the current cycle stems from formulation depth and visibility into the industry's silver-saving agenda, where paste cost and silver intensity are recognized as material contributors to cell economics. The company's focus on architecture-specific formulations positions it well for customers transitioning away from legacy platforms.
DuPont de Nemours, Inc. brings brand recognition and an established Solamet product lineage optimized for high-efficiency solar cells, including PERC and advanced architectures. Its value proposition emphasizes performance consistency and integration with efficiency-focused manufacturing strategies, appealing to producers who prioritize reliability and wafer-level performance in premium segments.
Giga Solar Materials Corporation and Targray Technology International Inc. represent manufacturers emphasizing mass-production practicality. Giga Solar focuses on low-silver and high-efficiency formulations designed for volume fabrication, aligning product development with the industry's cost-reduction imperative while maintaining efficiency targets. Targray differentiates through customization of front- and rear-side conductive materials, aiming to improve yields and efficiency at the cell level rather than competing purely on raw material price.
Legacy electronics-paste expertise provides additional competitive angles. Murata Manufacturing Co., Ltd. and Noritake Co., Limited draw on long-standing electronic paste technology to develop silver pastes for solar cell electrodes, leveraging process know-how and material consistency from adjacent electronic markets. Agfa-Gevaert N.V. contributes specialized metallization paste capabilities for photovoltaic applications, reinforcing the view that metallization performance is increasingly a cross-industry competency.
Cost-Performance Challengers and Regional Dynamics
A parallel set of suppliers competes by narrowing the performance gap with international benchmarks while offering more attractive cost profiles. Hunan LEED Electronic Ink Co., Ltd. produces cost-effective high-temperature silver paste for solar cell electrodes and mass production applications, targeting volume-driven manufacturing environments where formulation reliability and price alignment are both critical. Shanghai Transcom Scientific Co., Ltd. offers competitive formulations with performance approaching international standards at lower cost points, reflecting the broader regional trend of maturing domestic material options.
Daejoo Electronic Materials Co., Ltd. occupies a differentiated position by supplying both silver and aluminum paste solutions for solar cell metallization, providing customers with alternative material paths where back-side or specific electrode requirements favor aluminum-based or hybrid approaches. This kind of portfolio breadth can be strategically valuable as manufacturers experiment with material combinations to manage silver exposure.
Evolution of the Competitive Structure
Market concentration remains relatively modest, with the top three players holding approximately 24.6 percent and the top five about 26.2 percent of revenue. This dispersion indicates that scale advantages exist, but they are not yet dominant enough to prevent specialized or regionally focused entrants from capturing meaningful share. The likely evolution is twofold.
On one side, consolidation pressure will persist among suppliers that lack formulation differentiation, application support, or cost discipline. In a segment where silver intensity, yield, and architecture compatibility directly affect customer economics, undifferentiated commodity positioning becomes increasingly vulnerable. On the other side, fragmentation will endure where regional demand growth, customization requirements, and multi-source procurement strategies create room for additional qualified participants. New entrants and expanding incumbents will need to demonstrate more than production capacity; they will need to show that their products improve total wafer-to-module economics under real factory conditions.
Forward-Looking Trends for 2026 to 2030
Trend One: Silver Intensity Reduction as a Core Design Constraint
Over the next several years, formulation strategies that reduce silver loading without sacrificing electrical performance are expected to become central competitive differentiators rather than optional enhancements. Silver price spikes have already drawn attention to paste cost as a share of total cell expense, and the structural incentive to lower material intensity will persist regardless of short-term price fluctuations. Suppliers able to deliver paste systems that support finer lines, lower contact resistance, and stable fire-through behavior at reduced silver content will align directly with manufacturer priorities.
The commercial opportunity lies in pairing material design with application engineering. Manufacturers will increasingly favor partners who can demonstrate how a formulation change affects not just paste price, but overall cell cost per watt, yield, and compatibility with future printing processes. This shifts competition from bulk pricing toward solution value.
Trend Two: Broader Adoption of Advanced Cell Architectures Driving Paste Specification Upgrades
As TOPCon, heterojunction-related variants, and other advanced architectures move further into mainstream production, metallization requirements will continue to diverge from legacy PERC-era norms. Paste suppliers that maintain a single product focus will face growing friction; those that invest in architecture-aware development and can validate performance across multiple platforms will secure stronger customer relationships. The trend increases the value of technical support, qualification speed, and repeatable scale-up of new formulations.
PW Consulting
For buyers, this trend means that paste selection will become more tightly coupled to fab technology roadmaps. For suppliers, it means that R&D cadence and customer co-development capability will increasingly determine growth potential, especially in regions scaling advanced-cell manufacturing capacity.
Trend Three: Regional Supply Resilience and Multi-Source Procurement as a Structural Shift
Policy support in Europe, the United States, and China is expanding regional manufacturing ambitions, and with that expansion comes greater attention to supply security. Even where global trade remains fluid, manufacturers are incentivized to qualify multiple paste sources, diversify regional availability, and reduce exposure to single-supplier risk for critical materials. This shift favors suppliers with reliable production footprints, transparent quality systems, and the ability to support localized qualification timelines.
The opportunity here is less about displacing incumbents and more about earning qualified status as a reliable secondary or primary source in specific regions or product lines. Suppliers that can combine competitive formulation performance with dependable delivery and regional responsiveness will find expanding procurement interest, particularly among manufacturers building or expanding capacity in policy-supported markets.
Risks and Uncertainties
The forward outlook is contingent on several variables. Silver price volatility remains a persistent risk; sustained high prices could accelerate aluminum-based substitution in applications where performance trade-offs are acceptable, altering demand patterns for silver-dominant paste portfolios. Conversely, if silver prices moderate sharply, cost pressure may ease in the short term but the structural incentive to reduce intensity is unlikely to disappear, given the broader focus on cell-level cost optimization.
Technology adoption rates also introduce uncertainty. The pace at which TOPCon and other advanced architectures scale relative to legacy lines will determine how quickly paste specifications must evolve and how rapidly formulation-dependent suppliers can capture premium demand. Slower-than-expected transitions would extend the relevance of mature formulations but could also delay the demand uplift associated with higher-efficiency architectures. Finally, policy trajectories could shift with political or economic changes, altering the timing and geography of demand expansion.
Actionable Guidance for Decision Makers
For Solar Cell and Module Manufacturers
Treat paste selection as a cost-per-watt optimization problem rather than a commodity procurement decision. Evaluate suppliers based on formulation performance under your specific process conditions, silver-loading flexibility, support for next-generation architectures, and ability to maintain lot-to-lot consistency at production scale. Building qualified multi-source relationships for critical formulations can reduce supply risk while preserving performance standards.
Solder Paste Market
At the same time, use material selection as a lever in your silver-intensity strategy. Where performance allows, collaborate with paste suppliers to test reduced-loading or silver-aluminum hybrid options, measuring impact not just on material cost but on firing yield, contact resistance, and overall cell efficiency. The most valuable partnerships will be those that tie material development directly to fab economics.
For Investors and Strategic Planners
Focus on suppliers whose competitive advantage rests on formulation depth, application support, and architecture adaptability rather than volume alone. In a 6.5 percent CAGR market extending through 2032, growth will increasingly accrue to participants that can align product development with silver-reduction strategies and advanced cell transitions. Companies with credible customization capability, credible qualification pipelines, and the ability to serve both cost-sensitive and efficiency-focused segments are better positioned than those competing purely on price.
Pay attention to the interplay between raw material cycles and product strategy. Sustained silver price pressure is likely to reinforce demand for lower-silver formulations, hybrid designs, and aluminum alternatives in certain applications, expanding the strategic relevance of suppliers that can address this spectrum. Monitoring regional capacity expansion, especially in policy-supported markets, offers early signals about where demand growth and supplier qualification activity will intensify.
For Procurement and Supply Chain Leaders
Prioritize qualification readiness and supply resilience. The cost of line downtime, yield variation, or delayed qualification can outweigh marginal material savings, particularly in high-throughput manufacturing environments. Maintain a structured qualification pipeline for alternative formulations, document performance trade-offs clearly, and align sourcing strategy with your technology roadmap so that paste decisions do not become constraints when architecture transitions accelerate.
Negotiate with an understanding of total value rather than unit price alone. Where suppliers can demonstrate measurable improvements in yield, process stability, or compatibility with lower-silver designs, those benefits may justify a premium that is more than offset by reduced cell-level cost. Structured evaluation frameworks that capture electrical, mechanical, and process metrics will support better sourcing outcomes over time.
Conclusion
The solar cell metal paste market is entering a phase where growth and differentiation are increasingly inseparable. Revenue expansion toward 344.8 million USD by 2032 reflects not only rising deployment but also the intensifying importance of metallization materials in enabling higher efficiency, lower silver intensity, and more resilient manufacturing economics. Suppliers that treat formulation performance, architecture compatibility, and application engineering as core strategic assets will be better positioned to capture value in a fragmented but increasingly demanding landscape.
For manufacturers, investors, and procurement leaders alike, the practical imperative is to look beyond unit prices and short-term price cycles. The most consequential decisions will involve how paste selection supports cost-per-watt objectives, how quickly suppliers can adapt to technology transitions, and how effectively sourcing strategies balance performance with supply resilience. For organizations seeking detailed segmentation data, company-specific assessments, and region-level commercial context to inform those decisions, a full research report can provide the structured depth needed to translate market trends into targeted execution plans.
For detailed analysis of this topic, please visit the official page: Solar Cell Metal Paste Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Slurry Pump Market: Why Asia Pacific's Steady Growth Reshapes Global Dynamics
By PW Consulting, 2026-09-21
Strategic Horizons in the Global Slurry Pump Market: Navigating Growth, Innovation, and Competitive Shifts
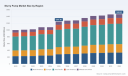
The slurry pump market stands at a pivotal intersection of industrial necessity and technological transformation. As heavy industries worldwide grapple with tougher materials, stricter efficiency mandates, and volatile supply chains, the demand for robust slurry handling solutions continues to evolve. Current projections indicate a moderate but steady expansion trajectory, with the market expected to grow from a base of approximately USD 1,247.48 million in 2025 to around USD 1,468.62 million by 2032, reflecting a compound annual growth rate of 2.5 percent. While this pace may appear subdued compared to high-growth technology sectors, it underscores a mature industry where value creation is increasingly driven by performance differentiation, lifecycle optimization, and regional demand shifts rather than volume alone.
Behind these headline figures lies a complex landscape shaped by contrasting regional dynamics, application-specific requirements, and a competitive field that blends established multinational players with specialized regional manufacturers. For executives, investors, and procurement leaders, understanding the forces reshaping this market is no longer optional—it is essential for capital allocation, product strategy, and operational resilience. This analysis examines the structural challenges defining the industry today, unpacks the core drivers of change, maps the competitive positioning of key players, and outlines the trends that will determine where value concentrates over the next five years.
Market Snapshot and Structural Challenges
The global slurry pump market has demonstrated resilience through a period of fluctuating industrial activity, with revenue figures climbing from roughly USD 1,000.0 million in 2020 to an estimated USD 1,247.48 million in 2025. This growth reflects sustained demand across mining, chemical processing, metallurgical operations, and construction applications, even as broader macroeconomic uncertainty and commodity price volatility tested capital expenditure cycles. The forecast period through 2032 suggests continued expansion, though at a pace that rewards operators who can navigate operational inefficiencies and supply chain constraints rather than simply chasing volume growth.
Several structural challenges are reshaping how companies approach slurry pump procurement and product development. First, the industry faces mounting pressure to balance durability with energy efficiency. Traditional heavy-duty designs have long prioritized wear resistance, but newer performance benchmarks now require hydraulic efficiencies in the 75 to 85 percent range, pushing manufacturers to rethink impeller geometries, casing designs, and material combinations. Achieving these targets without compromising reliability in abrasive or corrosive environments remains a persistent engineering hurdle.
Second, the supply chain for critical wear materials has emerged as a strategic vulnerability. High-chrome white iron alloys and specialized elastomers, which form the backbone of pump linings and internal components, are subject to intermittent shortages and price swings. For operators, this translates into unpredictable maintenance costs and longer lead times, while manufacturers must decide whether to vertically integrate material sourcing, diversify supplier networks, or redesign components to reduce dependency on scarce alloys. The cost dynamics are particularly pronounced for high-chrome variants, which can range from USD 0.50 to USD 1.50 per kilogram and directly influence the wear life expectancy of pump components deployed in mining circuits.
Third, regulatory and certification requirements are tightening across regions, compelling manufacturers to embed quality management and performance validation into their development processes. Compliance with standards such as ISO 9001:2015 and industry-specific hydraulic efficiency benchmarks is increasingly viewed as a baseline for market access, particularly in North America and Europe. Companies that treat certification as a 사후 consideration rather than a design parameter risk exclusion from tenders and long-term service contracts, especially in sectors where downtime costs far exceed equipment purchase prices.
Key Drivers Shaping Market Evolution
Technological Innovation and Material Science Breakthroughs
Innovation in slurry pump design is moving beyond incremental improvements to encompass material science, modular architecture, and application-specific customization. Manufacturers are investing in larger pump configurations tailored for high-flow decarbonization and carbon capture workflows, reflecting the broader industrial push toward emissions reduction. Simultaneously, advances in high-chrome iron alloys and wear-resistant elastomers are extending component lifespans in abrasive environments, reducing the frequency of rebuilds and lowering total cost of ownership for end users. Front pull-out shaft seal designs and gasite iron formulations are examples of engineering refinements that address leakage, maintenance accessibility, and metallurgical performance under extreme-duty conditions.
These technological shifts carry direct commercial implications. Manufacturers that can deliver pumps with demonstrably longer wear life and simpler maintenance procedures gain leverage in competitive bidding, particularly in mining and mineral processing where operational continuity is paramount. For buyers, the trend toward higher-efficiency and longer-life designs means a reevaluation of procurement criteria: upfront price is increasingly secondary to lifecycle cost, availability of replacement parts, and compatibility with existing plant infrastructure.
Policy and Regulatory Pressures
Regulatory frameworks are becoming a decisive factor in product adoption and regional market dynamics. Efficiency mandates and quality certification requirements are no longer optional benchmarks; they function as gatekeepers for participation in public tenders, large-scale infrastructure projects, and regulated industrial sectors. In the power generation and chemical industries, where slurry pumps handle hazardous or high-temperature fluids, compliance with stringent safety and performance standards directly influences vendor selection.
The policy environment also intersects with broader sustainability goals. As industries face increasing scrutiny over energy consumption and carbon footprints, pumps that contribute to lower power draw and reduced maintenance waste align with corporate environmental targets. This creates a dual incentive structure: manufacturers are compelled to design for efficiency and compliance, while end users are motivated to upgrade older, less efficient units to meet internal sustainability metrics and avoid regulatory penalties.
Demand-Side Shifts in Mining, Chemicals, and Industrial Processing
Demand patterns are being reshaped by the geographic redistribution of mining activity, the expansion of chemical processing capacity in emerging markets, and the modernization of aging industrial facilities in developed economies. Mining and mineral processing remain the largest application segment, driven by continuous extraction operations, tailings management requirements, and the need to handle increasingly abrasive ores. Chemical industry applications, meanwhile, demand pumps capable of managing corrosive slurries and precise flow control, pushing manufacturers to develop lined and specialized configurations that resist chemical degradation.
A notable demand-side shift is the growing preference for integrated service models. Operators are less interested in standalone equipment transactions and more focused on partnerships that include installation support, predictive maintenance tools, and rapid parts availability. This evolution reflects the reality that pump downtime in a mill circuit or chemical plant can cascade into significant production losses, making reliability and service responsiveness critical purchase criteria. Manufacturers that build service networks, digital monitoring capabilities, or modular replacement parts programs are positioning themselves to capture recurring revenue streams and deepen customer relationships.
Supply Chain Realignment and Cost Structure Dynamics
The cost structure of slurry pump manufacturing is undergoing recalibration as raw material volatility, regional production strategies, and logistics complexity intersect. Companies are responding by diversifying manufacturing footprints, expanding localized production capabilities, and investing in supply chain resilience. Recent capacity expansions in submersible pump manufacturing, supported by multi-million-dollar investments in North American facilities, illustrate how producers are aligning production capacity with regional demand centers to reduce lead times and mitigate freight cost fluctuations.
At the same time, the availability of specialty alloys and elastomers remains a wildcard. Price volatility in high-chrome materials forces manufacturers to make strategic trade-offs between component performance and cost predictability. Some are exploring alternative material formulations or hybrid lining designs that maintain wear resistance while reducing exposure to single-source suppliers. For the broader market, these supply chain adjustments influence not only product pricing but also the speed at which new models can be brought to market and the reliability of after-sales support.
PW Consulting
Competitive Landscape and Leadership Strategies
The slurry pump market exhibits moderate concentration, with the top three players accounting for approximately 28.5 percent of revenue and the top five collectively holding around 45.2 percent. This structure indicates a market where established leaders maintain strong positions through product breadth, technological pedigree, and global service networks, while regional specialists and niche manufacturers compete effectively in specific applications or geographies. The presence of both multinational firms and focused local players creates a dynamic environment where differentiation often hinges on application expertise, material science capabilities, and responsiveness to regional regulatory demands.
Leading manufacturers have carved distinct strategic identities. Sulzer has emphasized a comprehensive portfolio spanning heavy-duty horizontal and vertical configurations, with recent expansions targeting larger pump sizes for decarbonization and carbon capture workflows. Its investment in submersible manufacturing capacity in the United States reflects a deliberate push to align production with North American demand while reinforcing its value proposition around abrasion and corrosion resistance for mining and metals applications. KSB, through its GIW brand, has focused on extreme-duty mill circuits and tailings applications, leveraging high-chrome gasite iron and front pull-out shaft seal designs to address the most demanding operational environments. The phased North American rollout of its latest slurry pump series underscores a strategy of incremental market penetration supported by material and sealing innovations.
Slurry Tankers Market
In the Americas, Schurco Slurry and EDDY Pump have built reputations around heavy-duty horizontal and vertical centrifugal designs and high-solids handling capabilities, respectively. Schurco Slurry's focus on hard-rock mining and mineral processing, combined with a robust replacement parts offering, positions it as a practical choice for operators prioritizing uptime and component availability. EDDY Pump's emphasis on high-density, high-solids applications in mining, dredging, and wastewater highlights a niche-oriented approach that caters to specialized fluid handling requirements. Meanwhile, Kingda Pump Group has maintained a long-standing presence in engineered heavy-duty slurry and dredge pumps, with recent visibility at major industry exhibitions signaling continued engagement with mining and industrial end users in Latin America and beyond.
Chinese manufacturers such as Kingda Pump Group and Hebei Tobee Pump have expanded their footprint by offering warman-equivalent configurations across vertical, horizontal, and submersible categories, supported by full parts supply chains. This approach appeals to cost-conscious buyers and operators seeking compatibility with established pump standards while maintaining access to localized support. In parallel, companies like Goulds Pumps (ITT) and Metso continue to leverage their industrial scale and mineral processing expertise, offering extra-heavy-duty lined slurry pumps and specialized series tailored to mineral processing circuits.
The competitive landscape is also being shaped by targeted acquisitions and product-line expansions. The acquisition of a peristaltic slurry pump line by a European fluid handling specialist illustrates how firms are broadening their abrasive fluid handling portfolios to capture cross-industry demand, particularly in applications requiring gentle handling or precise dosing. Similarly, the launch of NSF/ANSI 61-certified surface pumps by a U.S.-based manufacturer reflects the growing importance of certification in water-related and regulated industrial applications, where compliance directly influences procurement eligibility.
Looking ahead, the market is likely to see continued consolidation among players seeking to expand geographic reach or application coverage, while specialized entrants may carve out niches in high-solids handling, hygienic processing, or region-specific service models. The differentiation frontier is shifting from pure equipment supply toward integrated solutions that combine material performance, efficiency certification, predictive maintenance tools, and rapid parts availability. Companies that can orchestrate these elements will be better positioned to defend margins and capture share in a market where volume growth alone does not guarantee profitability.
Future Trends and Commercial Opportunities (2026–2032)
Efficiency-Driven Product Refresh Cycles
As regulatory benchmarks and corporate sustainability targets tighten, a wave of equipment upgrades is expected across mining, chemical, and power generation facilities. Older slurry pumps with lower hydraulic efficiency and higher maintenance burdens will face replacement pressure, particularly in regions where energy costs are rising and downtime penalties are severe. This trend creates opportunities for manufacturers offering retrofits, high-efficiency replacements, and service programs that reduce the financial and operational barriers to upgrading. For investors, companies with strong aftermarket service networks and modular upgrade paths may benefit from recurring revenue tied to equipment refresh cycles rather than relying solely on new equipment sales.
Regional Demand Rebalancing and Localized Production
Demand is likely to continue shifting toward Asia Pacific and Latin America, driven by mining investment, infrastructure development, and industrial capacity expansion. In response, manufacturers will further localize production, service hubs, and parts distribution to reduce lead times and respond to regional procurement preferences. This geographic rebalancing presents commercial opportunities for firms that can establish credible local partnerships, navigate import and certification requirements, and offer culturally and operationally aligned support. However, it also introduces risk: companies that overinvest in regions with volatile commodity cycles or regulatory uncertainty may face underutilized capacity, while those that delay localization risk losing share to agile regional competitors.
Material Science and Wear Life as Competitive Differentiators
Advances in alloy formulations, elastomer technology, and lining designs will increasingly determine which manufacturers win in abrasive and corrosive applications. As high-chrome materials remain subject to price volatility and supply constraints, companies that develop alternative material strategies or secure stable supply relationships will gain a structural advantage. For end users, the commercial implication is clear: wear life longevity directly affects maintenance budgets and production continuity, making material performance a key evaluation criterion alongside initial price. Manufacturers that can provide verifiable wear life data, standardized testing results, and predictable replacement part availability will be able to command premium positioning in competitive tenders.
Strategic Recommendations for Decision Makers
For manufacturers and product developers, the priority is to embed efficiency, material resilience, and serviceability into the design phase rather than treating them as aftermarket enhancements. Investing in front pull-out seal architectures, high-chrome gasite iron options, and modular component designs can reduce maintenance friction and extend pump life in demanding circuits. At the same time, companies should evaluate supply chain exposure to critical alloys and elastomers, considering dual-sourcing strategies or alternative material formulations that preserve performance while reducing cost volatility. Building digital monitoring or predictive maintenance capabilities into pump offerings can further differentiate products in markets where operators value uptime and lifecycle cost transparency.
Worldwide Polishing Slurry Market
For investors, the slurry pump market rewards a selective approach that emphasizes companies with strong regional service networks, certification compliance, and application-specific expertise. Firms that combine equipment sales with aftermarket parts, rebuild services, and predictable lead times are better positioned to capture recurring revenue in a moderate-growth environment. Investment theses should also account for regional demand shifts: companies with credible footprints in Asia Pacific and Latin America, or those expanding localized production to serve these regions, may benefit from structural demand growth in mining and industrial processing. Conversely, exposure to single-region dependency or reliance on volatile raw material inputs without mitigation strategies warrants careful scrutiny.
For procurement leaders and plant operators, the buying decision should shift from lowest upfront price to total cost of ownership that accounts for wear life, energy consumption, parts availability, and service responsiveness. Evaluating manufacturers on their ability to provide certified efficiency performance, predictable rebuild schedules, and rapid parts fulfillment can reduce operational risk and avoid costly downtime. Where possible, procurement teams should seek standardized interfaces and compatibility with existing plant infrastructure to simplify future upgrades and minimize integration costs. Establishing long-term service agreements with manufacturers that demonstrate material science competence and regional support capacity can also stabilize maintenance budgets and improve equipment reliability over time.
The slurry pump market is entering a phase where competitive advantage will be defined less by scale alone and more by the ability to deliver technically differentiated, efficiently certified, and reliably supported solutions. As efficiency mandates tighten, material supply chains remain unpredictable, and demand continues to redistribute across regions and applications, organizations that act on these insights with disciplined product strategy, targeted regional investment, and lifecycle-focused procurement will be best positioned to capture value. For those seeking a deeper dive into segment-level dynamics, regional revenue distributions, and customized strategic scenarios, the full research report provides granular data and tailored recommendations to support precise decision-making.
For detailed analysis of this topic, please visit the official page: Slurry Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Borosilicate Glass Tubes Market: Why the 6.8% CAGR Through 2032 Redefines Competition
By PW Consulting, 2026-09-21
Strategic Trends & Commercial Opportunities in the Borosilicate Glass Tubes Market
Market Landscape and Core Pressures
The global borosilicate glass tubes market has demonstrated steady expansion over the past five years, moving from approximately $1.05 billion in 2020 to an estimated $1.54 billion in 2025. The trajectory reflects a compound annual growth rate of roughly 6.8 percent through 2032, with revenue projected to approach $2.4 billion by the end of the forecast period. This growth is not merely incremental; it is reshaping how manufacturers, procurement teams, and investors evaluate capacity, feedstock security, and long-term contract structures.
Behind the headline figures lies a market that is simultaneously broadening in application scope and tightening in operational discipline. Demand is no longer concentrated in traditional laboratory and chemical handling roles. Solar energy collection systems, pharmaceutical primary packaging, and heat-resistant industrial glassware are absorbing a growing share of production capacity. At the same time, the market remains moderately consolidated, with the top five producers accounting for just under half of total revenue. This concentration creates a landscape where scale, certification depth, and regional footprint matter, but it also leaves room for specialized players to compete on niche specifications, localized service, or sustainability credentials.
Key Challenges Shaping Strategic Positioning
Three pressures are forcing a recalibration of how incumbents and new entrants plan their next investment cycles.
- Feedstock volatility and constrained supply alternatives. Boric oxide and high-purity silica sand remain the foundational inputs for borosilicate formulations. The supplier base is limited, and disruptions in logistics or regional demand shifts can quickly translate into price moves at the tube level. Periodic spikes in boron-related costs have already rippled through procurement budgets, particularly when freight rates fluctuate or agricultural and industrial end-users compete for the same material pools.
- Regulatory alignment and certification overhead. Pharmaceutical and medical-grade applications demand strict adherence to quality management systems, including GMP-aligned certifications and traceable manufacturing controls. Maintaining compliance across multiple sites and product lines adds operational complexity. As global sourcing becomes more fragmented, buyers increasingly verify not just product specifications but the certification status of every production node in the supply chain.
- Carbon intensity and energy transition expectations. Energy-heavy melting processes sit at the core of glass tubing production. Rising interest in lower-carbon materials, coupled with procurement policies that factor environmental performance into supplier selection, is pushing manufacturers to reconsider furnace technology, energy sourcing, and process efficiency. Facilities that continue to rely on conventional thermal profiles may face growing friction in tenders where lifecycle emissions or renewable energy usage are evaluated alongside cost and quality.
Core Drivers Propelling Market Evolution
The expansion of borosilicate glass tubes is being pulled by a combination of technical, regulatory, demand-side, and supply-chain forces. Understanding which drivers are structural versus cyclical helps decision-makers prioritize where to allocate capital and operational attention.
Technical Innovation and Process Breakthroughs
Advances in melting technology and product formulation are changing what is commercially feasible. The introduction of all-electric melting furnaces powered by renewable energy represents a meaningful shift in how pharmaceutical-grade tubing can be produced at scale. By reducing reliance on fossil-derived heat, manufacturers can lower process emissions while maintaining the tight tolerances required for vials, cartridges, syringes, and laboratory capillaries. This development is not only an environmental milestone; it also creates a differentiator in procurement discussions where buyers increasingly weigh carbon performance alongside dimensional stability and breakage resistance.
In parallel, continuous improvements in tubing consistency, wall thickness control, and surface quality are expanding the usable range of borosilicate tubes in high-precision applications. For pharmaceutical packaging and laboratory apparatus, reliability across batches is critical. Producers that can demonstrate tighter process control and reliable certification coverage are better positioned to win long-term supply agreements, particularly in regions where local content preferences or risk-mitigation strategies favor domestic or nearshore sourcing.
Policy and Regulatory Environment
Regulatory dynamics are reinforcing demand for certified borosilicate glass in pharmaceutical and medical contexts. Quality management standards, GMP-aligned production requirements, and increasingly rigorous traceability expectations are raising the barrier to entry for non-specialized suppliers. Importantly, these requirements are not static. As health authorities and procurement organizations tighten expectations around material compatibility, contamination control, and supplier validation, the value of established certification portfolios grows.
Trade and sourcing patterns are also evolving. European import flows for borate materials have shown upward movement in recent years, with Türkiye continuing to play a central role as a supply origin. Such patterns highlight the interdependence between regional availability and production planning. Manufacturers that rely on a narrow set of feedstock channels must monitor geopolitical and trade developments closely, since shifts in import volumes or tariff structures can affect both cost and continuity.
Demand-Side Shifts in End-Use Behavior
Demand is being reshaped by how end users prioritize performance, sustainability, and supply resilience. In pharmaceutical packaging, the continued emphasis on primary container integrity and patient safety keeps borosilicate tubing at the center of vial and ampoule production. For laboratory and scientific applications, the need for chemically resistant, thermally stable glass remains a durable base load for the market.
At the same time, new application momentum is emerging from solar energy systems that utilize borosilicate-based tubes, alongside heat-related industrial glassware where temperature resistance and durability are essential. These segments do not just add volume; they change the specification mix. Buyers in these areas often weigh total cost of ownership, operational lifespan, and environmental exposure more heavily than upfront price alone. That shift encourages manufacturers to think beyond commodity supply and toward application-tailored performance, technical support, and longer-cycle partnerships.
Supply Chain and Cost Structure Dynamics
Cost structures are being tested by the intersection of energy pricing, feedstock availability, and logistics. Boron-related pricing has exhibited sensitivity to freight movement and seasonal demand from both glass manufacturing and agriculture, underscoring how even specialized materials can be influenced by broader commodity cycles. Because high-purity silica sand and boric oxide have limited comparable suppliers globally, supply-chain vulnerabilities are not theoretical; they are operational realities that can affect scheduling, margin planning, and customer commitments.
In response, several producers are rethinking geographic distribution of capacity. New facilities and joint ventures in key demand regions are intended to shorten lead times, reduce transport exposure, and improve responsiveness to local specification requirements. This regionalization trend also intersects with customer preferences for lower-risk sourcing, especially where pharmaceutical or regulated applications are concerned. The net effect is a market in which proximity, certification readiness, and feedstock management are becoming as strategically relevant as production scale alone.
Competitive Landscape and Strategic Positioning
The competitive environment is defined by a set of established players with deep application expertise, strong brand recognition in specific verticals, and increasingly visible efforts to align capacity with demand geography and sustainability expectations.
Quartz Tubing Market
Strategic Positioning of Leading Companies
Corning Incorporated continues to assert its position as a leading supplier of Type I borosilicate glass tubing for pharmaceutical primary packaging. Its focus on products such as Corning® 51 and Corning® 33 tubing underscores a strategy centered on regulatory-grade quality, pharmaceutical compatibility, and broad packaging formats including vials, ampoules, cartridges, and syringes. Recent activity includes the inauguration of a new pharmaceutical glass tubing manufacturing facility in India developed with joint venture partner SGD Pharma, alongside a move to strengthen the European production base through SGD Pharma's acquisition of Alphial S.r.l. These steps suggest a deliberate combination of regional capacity expansion and consolidation of pharmaceutical tubing assets.
SCHOTT AG maintains a prominent global presence in Type I borosilicate tubing through the FIOLAX® and DURAN® brands, covering pharmaceutical and laboratory applications across an extensive range of glass types. Its multi-product portfolio and long-standing certification infrastructure position it well for customers who require broad specification coverage and documented quality systems. The emphasis on maintaining ISO 9001 and ISO 15378 (GMP) certifications across tubing production sites reflects a strategic priority on compliance assurance and buyer confidence in regulated markets.
DWK Life Sciences focuses on premium laboratory borosilicate glass 3.3, including DURAN® tubing, rods, and capillaries for scientific, chemical, and industrial use. Its specialization supports a strategy built on application depth in laboratory and chemical contexts, where consistent quality and recognized brand trust matter highly. By concentrating on scientific and industrial performance rather than broad pharmaceutical packaging, DWK Life Sciences occupies a distinct flank in the market.
Nipro Corporation operates as a major global manufacturer of premium borosilicate tubing for pharmaceutical packaging, with multiple production sites supporting scale and regional flexibility. Its product range, including grades such as G38 and NSV51, highlights a pharmaceutical-oriented strategy with geographic breadth. This footprint supports continuity of supply and responsiveness across markets where packaging demand is growing or where localized production is preferred.
Nippon Electric Glass Co., Ltd. supplies BS-series borosilicate tubing for pharmaceutical containers and medical applications, and has recently drawn attention for beginning mass production of pharmaceutical glass tubing using an all-electric melting furnace with renewable energy at its Malaysia facility. This move positions the company at the intersection of quality-focused pharmaceutical supply and lower-carbon manufacturing, a combination that is likely to resonate with buyers assessing both performance and sustainability in their supplier evaluations.
Borosil Limited produces borosilicate glass tubes and rods for laboratory and scientific applications, representing a strong regional presence in a segment where trusted laboratory glassware remains a steady demand center. Its positioning shows how regional specialists can compete by aligning product range, service, and local market knowledge with the expectations of scientific and industrial buyers.
How the Landscape Is Evolving
The market is showing signs of both consolidation and targeted expansion. In pharmaceutical-grade tubing, activity suggests a push toward stronger regional production bases and bundled capability through partnerships or acquisitions. This is consistent with a broader pattern in which leading producers seek to reduce supply-chain distance, reinforce certification continuity, and capture growth in regions where pharmaceutical packaging demand is expanding.
At the same time, differentiation is increasingly multidimensional. Scale alone is no longer sufficient to secure advantage. Buyers compare suppliers on certification depth, energy and carbon profile, application-specific reliability, and logistics resilience. As a result, competition is becoming more segmented: some players compete primarily on pharmaceutical compliance and volume, others on laboratory-grade specialization, and a growing set of evaluators are paying attention to low-carbon process technology as a criterion in supplier selection.
New entrants and regional specialists can still find room by addressing localized needs, offering responsive service, or developing expertise in specific tube grades, dimensions, or end-use requirements. However, the certification burden and feedstock complexity mean that credibility and operational discipline are necessary for durable participation, especially in regulated segments.
Forward-Looking Trends and Commercial Implications
Looking across the 2026–2032 window, several trends are likely to shape where value accrues and where risk concentrates.
Trend 1: Regionalization of Pharmaceutical-Grade Capacity
Pharmaceutical packaging demand is expected to remain a central growth engine, and producers will continue to align capacity more closely with key demand regions. This regionalization reduces exposure to long logistics chains, supports faster response times, and can improve alignment with local sourcing expectations. For commercial actors, the implication is clear: supply relationships will increasingly favor vendors who can demonstrate not only product quality but also production proximity, local certification coverage, and predictable continuity.
Commercial opportunity lies in multi-year supply arrangements, technical co-development around container formats, and resilient backup sourcing strategies. Buyers can use regional capacity to reduce lead-time variability, while producers can use localized facilities to strengthen customer stickiness and expand share in growing markets.
Trend 2: Sustainability as a Procurement Filter
Lower-carbon production methods are moving from experimental narrative to commercial relevance. The adoption of all-electric melting and renewable energy sourcing in pharmaceutical tubing production signals that environmental performance can be integrated into high-precision manufacturing without abandoning the quality demands of regulated applications. As procurement teams broaden evaluation criteria, suppliers with demonstrable energy and emissions advantages may gain preference in tenders, particularly where corporate sustainability commitments or customer expectations create additional pressure.
PW Consulting
This trend creates opportunities for manufacturers to differentiate through process innovation and for buyers to align supply choices with broader environmental targets. The uncertainty lies in how consistently sustainability metrics will be weighted against cost, quality, and reliability across different regions and industries. Producers that invest early in measurable, verifiable improvements are better positioned than those that rely on generalized claims.
Trend 3: Application Diversification and Specification Complexity
demand is gradually broadening beyond traditional laboratory and chemical uses toward solar energy tubes, heat glassware, and other specialized applications. This diversification introduces both opportunity and complexity. Different applications impose different requirements on thermal performance, chemical resistance, dimensional tolerance, and lifecycle durability. Suppliers that can manage specification complexity while maintaining efficient production are more likely to capture margin across a wider set of use cases.
For buyers, the opportunity is to secure materials that fit long-term operational needs rather than simply meeting immediate cost targets. For suppliers, the risk is that spreading capacity across too many divergent specifications can erode efficiency if not managed with disciplined product architecture and demand forecasting.
Risk and Uncertainty Considerations
Several variables could alter the pace or distribution of growth. Feedstock availability and price movement remain a persistent risk, particularly where supplier alternatives are limited. Energy costs and the pace of transition to lower-carbon furnace technology will influence both operating economics and competitive positioning. Trade dynamics, including shifting import volumes and origin patterns for borate materials, can affect cost structures and sourcing strategies. Finally, demand timing in newer applications such as solar-related tubes may be uneven, creating pockets of rapid adoption in some regions or customer segments while remaining more gradual in others.
Borosilicate Glass Market
Strategic flexibility is essential. Organisations that lock into single-source feedstock arrangements, rigid capacity plans, or narrow application bets without monitoring these variables may find themselves exposed to cost shocks or demand mismatches.
Actionable Recommendations for Decision-Makers
Different roles in the value chain should prioritize different decisions, but all benefit from a clearer view of where market momentum is building and where vulnerability is accumulating.
For Manufacturers and Producers
- Align capacity expansion with regional demand centers and regulatory expectations. Where pharmaceutical or laboratory demand is growing, evaluate whether local or nearshore production can improve service levels and reduce logistics exposure.
- Invest in process differentiation that can be verified, not just promoted. All-electric melting, renewable energy integration, and documented certification coverage are examples of attributes that can be demonstrated to buyers and procurement teams with increasing scrutiny.
- Strengthen feedstock strategy. Diversify sourcing where feasible, monitor boron and silica supply dynamics, and build contingency planning into procurement and production schedules to reduce vulnerability to price or availability shocks.
- Manage specification complexity deliberately. Expanding into new application areas can be profitable, but only if product architecture, quality systems, and forecasting are designed to support varied requirements without sacrificing efficiency.
For Investors and Strategic Planners
- Focus on structural drivers rather than short-term volume spikes. The combination of pharmaceutical packaging demand, laboratory stability, and emerging application segments provides a multi-engine growth path, but the durability of each engine depends on regulatory continuity, feedstock stability, and energy economics.
- Evaluate competitive advantage through a broader lens. Scale remains relevant, but certification depth, regional footprint, process sustainability, and application specialization increasingly determine which players can defend pricing and win long-term contracts.
- Track consolidation signals and partnership activity. Joint ventures, facility launches, and acquisitions in pharmaceutical tubing indicate where incumbents believe durable value will be created. These moves can reveal shifts in regional strategy and capacity control.
- Incorporate supply-chain resilience into valuation and planning. Feedstock concentration and energy transition costs can affect margins and operational continuity, making them relevant to risk assessment as well as growth potential.
For Procurement and Sourcing Leaders
- Broaden supplier evaluation criteria. Quality and price remain essential, but certification coverage, production location, energy and carbon profile, and contingency capability should be part of the decision framework, especially for regulated or long-life applications.
- Use regional availability as a risk-mitigation lever. Where possible, balance global sourcing with regional or nearshore options to reduce lead-time variability and improve responsiveness to specification changes or urgent requirements.
- Engage earlier on application requirements. For solar, heat glassware, pharmaceutical packaging, and laboratory use, aligning on performance expectations and lifecycle needs before procurement can reduce rework, incompatibility risk, and total cost over time.
- Plan for feedstock and energy volatility. Build flexibility into contracts and inventory strategies where feasible, and monitor commodity and trade developments that can influence borosilicate tube costs and availability.
Closing Perspective
The borosilicate glass tubes market is moving through a phase in which growth is increasingly tied to application breadth, regulatory confidence, supply resilience, and process sustainability. The market's expansion from roughly $1.05 billion in 2020 toward nearly $2.4 billion by 2032 reflects more than incremental demand; it signals a shift in how value is created and protected. Feedstock constraints, certification expectations, and energy transition pressures are not marginal concerns. They are shaping supplier selection, capacity planning, and the definition of competitive advantage.
For manufacturers, the priority is to match capacity and differentiation with where demand is becoming most durable. For investors, the task is to distinguish structural growth from cyclical noise and to assess whether competitive positioning can withstand feedstock, energy, and trade volatility. For procurement leaders, the opportunity lies in using broader evaluation criteria to secure supply that supports both operational reliability and longer-term strategic goals.
Deeper segmentation data, region-by-region dynamics, application-level demand patterns, and company-specific strategic assessments can sharpen these decisions further. Detailed market intelligence is especially valuable when sizing growth opportunities in newer applications, evaluating the pace of regional capacity shifts, or benchmarking supplier claims against operational realities. In a market where feedstock, regulation, and sustainability expectations are all moving at once, timely and granular insight can make the difference between reactive sourcing and proactive strategy.
For detailed analysis of this topic, please visit the official page: Borosilicate Glass Tubes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Resistant Dextrin Market: Why 6.98% CAGR Signals a Structural Shift Beneath the $317M Forecast
By PW Consulting, 2026-09-21
The Resistant Dextrin Market: Strategic Trends and Commercial Opportunities Through 2032
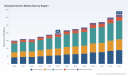
The resistant dextrin market has transitioned from a niche dietary fiber niche to a mainstream functional ingredient category with substantial commercial momentum. Valued at approximately USD 198 million in 2025, the market has demonstrated a compound annual growth rate of 6.98 percent over the historical period and is projected to expand steadily through 2032. This trajectory reflects the convergence of multiple structural shifts: rising consumer awareness of gut health, regulatory recognition of resistant dextrin as a legitimate dietary fiber, and manufacturing innovations that enable broader application across food, beverage, and nutraceutical formats. For executives and investors navigating this landscape, the market presents meaningful opportunities alongside distinct competitive and operational risks that require careful strategic positioning.
Understanding where this market is heading requires looking beyond aggregate revenue figures. The underlying dynamics involve evolving formulation requirements, shifting supply chain cost structures, and an increasingly polarized competitive field where differentiation hinges on clinical validation, regulatory approvals, and application-specific performance. This analysis examines the current market structure, the forces driving change, the competitive landscape, and the strategic implications for stakeholders across the value chain.
Market Landscape and Structural Challenges
The market's expansion over the past several years has been anything but linear. Historical data reveals periods of contraction followed by renewed growth, underscoring the influence of external shocks and demand elasticity. After a moderate decline in 2022, the market rebounded strongly through 2025 and is forecast to accelerate notably in the latter half of the projection period. This pattern suggests that the category is sensitive to macroeconomic conditions, raw material pricing, and the pace of regulatory developments, yet maintains a resilient long-term growth trajectory driven by fundamental demand shifts.
Several structural challenges define the current inflection point for resistant dextrin.
Supply Chain Volatility and Input Cost Pressure
The cost environment for key raw materials has introduced significant uncertainty into margin planning. Corn starch, a primary feedstock for most resistant dextrin production, experienced a sharp price escalation in mid-2025, reaching record levels that placed upward pressure on manufacturing costs across the value chain. For producers operating on thin margins or competing in price-sensitive segments, this volatility complicates inventory management, long-term contracting, and pricing strategies. Companies that fail to implement hedging mechanisms, diversify feedstock sources, or pass through costs effectively risk compressing profitability during periods of sustained input inflation.
Regulatory Fragmentation and Claim substantiation Requirements
While resistant dextrin enjoys growing regulatory acceptance, the path to commercialization remains uneven across jurisdictions and application categories. Regulatory recognition of specific fiber types, permissible health claims, and labeling requirements differ across regions and continue to evolve. In this environment, manufacturers must invest in clinical substantiation and regulatory navigation to secure approvals and defend market access. The increasing emphasis on evidence-backed positioning means that companies without robust clinical data or established regulatory relationships face a higher barrier to entry, particularly in healthcare and nutraceutical segments where claim substantiation is a prerequisite rather than an optional differentiator.
Application-Specific Formulation Constraints
Resistant dextrin is not a one-size-fits-all ingredient. Functional performance varies by source material, processing method, solubility profile, and compatibility with different formulation environments. Food and beverage developers face constraints related to taste modification, texture impact, stability under processing conditions, and interaction with other ingredients. These technical considerations limit the speed at which resistant dextrin can be adopted across new applications and create opportunities for suppliers who can provide application support, customized formats, and formulation guidance. The gap between generic availability and application-ready solutions represents both a challenge and a strategic lever for differentiation.
Key Drivers Shaping Market Dynamics
The growth trajectory of resistant dextrin is propelled by a combination of technological, regulatory, demand-side, and supply chain factors. Each driver carries distinct implications for market participants.
PW Consulting
Technological Innovation and Product Differentiation
Advances in enzymatic processing, starch modification, and purification techniques have expanded the range of resistant dextrin grades available to formulators. Manufacturers now offer variations in fiber content, solubility, particle size, and functional properties that enable tailored solutions for specific applications. These innovations support broader adoption by addressing formulation challenges that previously limited use in sensitive matrices such as low-pH beverages, baked goods, and clear-liquid formats.
Beyond physical properties, the emphasis on clinical validation has become a central dimension of product differentiation. Independent verification of prebiotic activity and gut health benefits through recognized certification programs has emerged as a credibility marker that resonates with both consumers and purchasing managers. Recent certification achievements by leading suppliers demonstrate how clinical evidence can be translated into marketable claims that support premium positioning and facilitate adoption in health-oriented formulations. These developments signal a shift from commodity-driven competition to evidence-based differentiation, where the strength of scientific backing increasingly determines market access and pricing power.
Regulatory Progress and Recognition Expansion
The regulatory environment has been a meaningful tailwind for resistant dextrin adoption. Recognition by major regulatory bodies as a valid dietary fiber, alongside expanded Generally Recognized as Safe status for additional food categories, has reduced ambiguity for formulators and accelerated inclusion in new products. Expanded approvals covering reduced-calorie beverages and other application areas illustrate how regulatory clarity can unlock growth by lowering development risk and enabling faster time-to-market.
Resistant Starch Market
At the same time, the regulatory landscape continues to reward companies that proactively engage with authorities and maintain comprehensive dossiers. Suppliers with established regulatory histories and documented safety profiles are better positioned to support customers through the approval process and navigate emerging requirements. As regulatory scrutiny around health claims and ingredient transparency intensifies, this capability becomes a strategic asset that compounds over time, creating a moat around well-prepared market participants.
Consumer and Enterprise Demand Shifts
Demand for functional ingredients with digestive health benefits has moved from a fringe concern to a mainstream purchasing driver. Consumers increasingly associate gut health with broader wellness outcomes, influencing food and beverage selection across categories. This shift has prompted manufacturers to incorporate fiber and prebiotic ingredients into everyday products, not just specialized health supplements. The result is a broader application footprint for resistant dextrin, spanning everyday beverages, bakery items, confectionery, dairy alternatives, and convenience foods.
On the enterprise side, brands face pressure to deliver products that align with clean-label expectations, sugar reduction goals, and functional benefits without compromising sensory quality. Resistant dextrin offers advantages in this context, including solubility, neutral flavor profiles in certain grades, and compatibility with nutritional goals such as fiber enrichment and calorie management. As product development cycles shorten and consumer expectations rise, ingredient suppliers that can provide technical support, co-development services, and rapid prototyping capabilities gain a competitive edge in securing inclusion in new formulations.
Supply Chain Structure and Cost Dynamics
The supply chain for resistant dextrin is shaped by the availability and pricing of starch feedstocks, the geographic distribution of manufacturing capacity, and logistics considerations. Production is concentrated among established players with integrated starch processing capabilities or long-standing supplier relationships, while emerging manufacturers seek to enter the market through cost-competitive positioning or regional focus. This structure creates both stability and vulnerability.
Record raw material prices illustrate how input cost fluctuations can ripple through the value chain, affecting producer margins, supplier pricing, and ultimately end-product economics. Companies that operate with flexible sourcing strategies, forward contracting, or diversified feedstock portfolios are better equipped to manage these dynamics. Conversely, reliance on single-source inputs or inflexible contract terms heightens exposure to price shocks. Over time, cost structure resilience will likely become a more prominent factor in supplier selection, particularly for large-volume buyers seeking supply security alongside competitive pricing.
Competitive Landscape and Strategic Positioning
The resistant dextrin market is characterized by a mix of established multinational ingredient suppliers and specialized manufacturers, with a notable degree of concentration among leading players. This concentration reflects the technical and regulatory barriers to entry, as well as the importance of scale, application expertise, and regulatory track records in securing market share.
Maltodextrin Market
Leading Players and Strategic Differentiation
Several companies occupy prominent positions by leveraging distinct strengths. Global ingredient manufacturers with broad portfolios and established relationships across food, beverage, and pharmaceutical channels benefit from scale, regulatory experience, and the ability to support customers across multiple markets. These players often differentiate through comprehensive technical service, co-development capabilities, and the credibility that comes with long-standing regulatory recognition.
Specialized producers have carved out positions by focusing on specific formats, source materials, or certification-backed claims. Companies offering resistant dextrin derived from corn or tapioca, with options spanning powder, liquid, and agglomerated formats, address varied formulation needs and enable customers to select grades suited to their application constraints. The availability of non-GMO, kosher, and other quality certifications further expands market access, particularly in segments where these attributes carry significant purchasing weight.
Increasingly, the competitive battleground is shifting toward evidence-based positioning. Suppliers that invest in clinical substantiation and secure independent verification of functional benefits are able to command stronger brand recognition and support customer claims with defensible data. This trend favors companies with the resources to conduct or commission clinical research and the regulatory expertise to translate findings into approved claims and certification status.
Market Consolidation and Emerging Entrants
The market structure suggests ongoing consolidation pressure, driven by the economies of scale associated with production, regulatory investment, and global distribution. Larger players are well positioned to absorb input cost volatility, fund application research, and expand capacity in response to demand growth. At the same time, regional manufacturers and distributors can find opportunities by serving localized demand, offering cost-advantaged products, or focusing on niche segments where broader players may not prioritize investment.
New entrants face meaningful hurdles. Establishing regulatory recognition, building clinical credibility, and securing consistent feedstock supply require capital and time. However, partnerships with established producers, contract manufacturing arrangements, and focused geographic strategies can provide pathways for incremental market participation. The presence of distributors and bulk suppliers that aggregate products from multiple producers also adds a layer of intermediation, which can benefit end-users seeking simplified sourcing while introducing additional considerations around quality control and supply traceability.
Forward Outlook: Trends and Opportunities (2026–2032)
Looking ahead, several trends are likely to shape the resistant dextrin market over the next several years, each carrying distinct commercial implications.
Accelerated Adoption in Everyday Food and Beverage Formats
As regulatory recognition expands and formulation capabilities improve, resistant dextrin is poised to move further into mainstream food and beverage applications. Categories that were once considered challenging for fiber enrichment, such as clear beverages, confectionery, and shelf-stable products, are becoming more accessible as ingredient grades and processing techniques evolve. This broadening application base supports volume growth and creates opportunities for suppliers who can demonstrate application-specific performance and provide formulation support that reduces development friction.
For brands, the opportunity lies in leveraging resistant dextrin to meet multiple objectives simultaneously: fiber enrichment, sugar reduction, texture management, and functional benefits. Success in this environment depends on selecting grades that align with product requirements and on communicating benefits in ways that resonate with target consumers without overstepping regulatory boundaries.
Evidence-Based Positioning as a Core Competitive Lever
The emphasis on clinical evidence and independent certification is expected to intensify. As consumers and purchasing managers become more sophisticated about ingredient claims, suppliers with verified functional benefits and documented safety profiles will hold an advantage in securing inclusion in premium and health-oriented products. Certification programs that evaluate prebiotic function and other claimed benefits provide third-party validation that can differentiate products in crowded markets and support premium pricing where justified.
This trend also introduces risk for companies that rely on generic positioning without substantive clinical backing. As the category matures, differentiation will increasingly depend on the credibility of functional claims and the quality of supporting data, making investment in research and regulatory documentation a strategic priority rather than an optional enhancement.
Supply Chain Resilience and Sourcing Strategy Recalibration
Input cost volatility and the concentration of feedstock supply are likely to drive recalibration of sourcing strategies across the value chain. Buyers and producers alike will place greater emphasis on supply security, long-term contracting, feedstock diversification, and regional capacity considerations. These dynamics may encourage investment in additional production capacity in key markets, as well as closer collaboration between ingredient suppliers and end-product manufacturers to manage risk and ensure consistent availability.
For market participants, the strategic implication is clear: resilience in supply chain design will increasingly influence competitiveness. Companies that build flexibility into sourcing, maintain transparent quality systems, and develop contingency plans for input disruptions will be better positioned to sustain operations and customer relationships through periods of volatility.
Potential Risks and Uncertainties
Despite the favorable long-term outlook, risks remain. Regulatory shifts, including changes to fiber recognition criteria or health claim requirements, could alter market access conditions. Raw material cost fluctuations may compress margins for players without effective risk management. Competitive intensity could increase as new entrants attempt to capture share through price competition, potentially pressuring returns in segments where differentiation is weaker. Additionally, consumer trends are subject to change, and categories that appear promising today may face headwinds if broader wellness preferences shift or if alternative ingredients gain traction.
Navigating these uncertainties requires continuous monitoring of regulatory developments, input market conditions, and competitive activity. Strategic agility, grounded in accurate intelligence, will be essential for capitalizing on opportunities while mitigating downside exposure.
Strategic Implications for Decision-Makers
The resistant dextrin market presents distinct considerations for manufacturers, investors, and procurement professionals. Each group faces different priorities and time horizons, but all stand to benefit from a clear understanding of market dynamics and a proactive approach to positioning.
For Ingredient Manufacturers and Formulators
- Invest in application-specific value propositions. Differentiate beyond basic fiber content by demonstrating performance in target matrices, offering multiple formats, and providing technical support that reduces customer development time.
- Strengthen regulatory and clinical credibility. Proactively pursue regulatory recognition for new applications, maintain comprehensive safety documentation, and consider independent verification of functional claims to support differentiation and customer confidence.
- Build supply chain resilience. Evaluate feedstock sourcing options, consider forward contracting or diversification strategies, and assess how input cost volatility may affect margins under different scenarios.
For Investors and Strategic Capital Allocators
- Assess differentiation quality, not just scale. Evaluate companies based on their regulatory track records, clinical substantiation, application expertise, and ability to command premium positioning rather than volume alone.
- Monitor consolidation dynamics and capacity investments. Track which players are expanding capacity, entering new geographies, or securing certifications, as these moves often signal strategic intent and can reshape competitive balance.
- Consider downstream integration and partnership models. Opportunities may exist in companies that offer integrated solutions, co-development services, or distribution models that simplify sourcing for end-users, particularly as demand broadens across applications.
For Procurement and Sourcing Professionals
- Prioritize supply security alongside cost. Evaluate suppliers on feedstock flexibility, production capacity, quality certifications, and contingency capabilities, recognizing that input volatility can affect availability and pricing over time.
- Leverage application support in supplier selection. Suppliers that provide formulation guidance, technical service, and co-development resources can reduce time-to-market and improve product outcomes, adding value beyond the ingredient itself.
- Stay informed on regulatory and claim developments. Understanding evolving recognition status and certification options enables more confident product positioning and helps avoid compliance risks associated with unsupported claims.
Conclusion
The resistant dextrin market is at a point where fundamental demand drivers, regulatory progress, and technological capability are aligning to support sustained growth. The projected expansion through 2032 reflects not only increasing volume but also the broadening of applications and the deepening of competitive differentiation around evidence, format flexibility, and supply reliability. For stakeholders across the value chain, the path to capturing value lies in understanding these dynamics in detail and acting with strategic precision.
Aggregate market figures provide a useful baseline, but the real strategic complexity resides in segment-level dynamics, regional regulatory variations, application-specific performance requirements, and the evolving cost structure of feedstock supply. Accessing granular data on subsegments, competitive benchmarks, and scenario-based forecasts can materially improve decision quality, whether the objective is product development, capacity planning, investment allocation, or sourcing strategy. Deeper intelligence enables more confident navigation of a market that is simultaneously expanding and becoming more competitive.
For detailed analysis of this topic, please visit the official page: Resistant Dextrin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Artificial Blood Vessel Market: How 5.38% CAGR Redefines Growth Trajectories to 2032
By PW Consulting, 2026-09-21
The Artificial Blood Vessel Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape: Scale, Momentum, and Structural Challenges
The artificial blood vessel market has entered a phase of steady, compounding growth. The overall market size reached approximately $2.38 billion in 2025, expanding from $1.83 billion in 2020 at a compound annual growth rate of 5.38 percent. The trajectory points toward $3.45 billion by 2032, with the forecast period from 2026 through 2032 reflecting a consistent upward slope. This expansion is not accidental; it reflects a convergence of clinical necessity, material science advancement, and shifting procurement dynamics across healthcare systems.
Despite the encouraging headline numbers, the market faces structural headwinds that will define competitive outcomes over the next several years. Three challenges stand out as particularly consequential for decision-makers.
First, reimbursement fragmentation remains a persistent drag on adoption velocity. Advanced graft technologies, particularly tissue-engineered and bioengineered variants, carry unit costs that far exceed conventional synthetic alternatives. Without consistent, transparent payment pathways across payers and procedures, volume adoption lags behind clinical approval. The gap between regulatory clearance and real-world utilization is where many promising products stall.
Second, the supply chain for specialized vascular materials is vulnerable to cost volatility and manufacturing complexity. Certain polymer-based and biologic grafts require tightly controlled production environments, validated sterilization processes, and cold-chain logistics. Any disruption in raw material availability or scaling bottlenecks can compress margins and delay hospital deliveries. Companies that treat these operational constraints as strategic risks rather than back-office issues are better positioned to protect market share.
Third, clinical preference and procedural heterogeneity create uneven adoption patterns. Not all vascular indications demand the same performance profile. Hemodialysis access, peripheral artery disease interventions, aortic reconstruction, and trauma revascularization each carry distinct hemodynamic, durability, and handling requirements. A product optimized for one pathway does not automatically translate across others. Decision-makers must recognize that broad market growth can coexist with highly segmented demand realities.
The market concentration profile reflects a moderately consolidated environment. The top three players hold a combined share of approximately 35.2 percent, while the top five reach roughly 42.5 percent. This structure suggests that incumbents retain meaningful scale advantages in reimbursement negotiations, clinical education, and distribution reach. At the same time, the remaining share dispersion leaves room for differentiated entrants, particularly those bringing breakthrough technology or targeted clinical value propositions to underserved indications.
Key Drivers: What Is Propelling Change
Technology Innovation and Clinical Performance Shift
Material science and bioengineering are reshaping the performance envelope of vascular grafts. Traditional synthetic materials have long served as workhorse solutions, but next-generation options are expanding what clinicians can achieve in complex anatomy and high-risk patient populations. Acellular tissue-engineered vessels, cryopreserved allografts, and collagen-based grafts each address different unmet needs, from reduced thrombogenicity to better endothelialization potential and improved handling in contaminated fields.
The commercial signal from recent product milestones is instructive. Humacyte Global advanced its acellular tissue-engineered vessel, Symvess, through FDA approval for use in adults as a vascular conduit for extremity arterial injury when urgent revascularization is needed and autologous vein is not feasible. The approval pathway, executed via Biologics License Application, reflects a shifting regulatory recognition of engineered tissue products as viable conduits in trauma and reconstruction settings. The product subsequently received priority designation for vascular trauma treatment from the U.S. Secretary of Defense, underscoring a dual commercial and defense-relevant use case. In May 2025, Symvess was submitted for a New Technology Add-On Payment with a potential start for discharges on October 1, 2025, and was priced at $29,500 per unit. Notably, that list price compares against the inflated 2024 cost equivalent of autologous vein harvest, estimated at approximately $37.45 per minute. The economics argument is not abstract; it is being quantified in procedural time, complication risk, and downstream resource utilization.
For manufacturers, the implication is clear: performance differentiation must be paired with economic justification. A graft that reduces harvest time, lowers re-intervention risk, or simplifies operative workflow can command premium positioning if the value story is coherent across the care pathway.
Policy and Regulatory Environment as a Catalyst and Gatekeeper
Regulatory design and reimbursement architecture increasingly determine which innovations reach scale. Approval pathways for biologics and tissue-engineered devices are becoming more defined, but they remain demanding. Companies that secure priority designations, navigate biologic licensing frameworks, and proactively engage payment mechanisms stand to compress the time between clearance and commercial uptake.
The Humacyte trajectory illustrates this dynamic in practice. Beyond the FDA approval and defense designation, the planned marketing authorization application for Symvess in Israel, announced in January 2026, signals an intent to broaden geographic access after establishing a U.S. foothold. International expansion is rarely a simple replication exercise; it requires alignment with local regulatory expectations, payer structures, and clinical adoption patterns. Still, the company's sequential moves suggest a deliberate strategy: validate in a high-value domestic market, secure payment recognition, then pursue regional authorizations where unmet need and procurement readiness intersect.
For the broader market, policy momentum around vascular trauma, dialysis access, and peripheral revascularization is likely to sustain regulatory attention. The challenge is that reimbursement reforms often lag product innovation. Executives should monitor where add-on payment mechanisms, coverage with evidence development pathways, and national pricing dialogues are evolving, because these are the levers that convert clinical differentiation into volume growth.
Demand-Side Shifts in Clinical Practice and Patient Populations
Demand is being propelled by both epidemiological trends and procedural evolution. Rising prevalence of peripheral artery disease, expanding dialysis populations, and increasing complexity of aortic and peripheral reconstructions are widening the addressable base for vascular grafts. At the same time, surgeons are seeking alternatives to autologous vein harvest in scenarios where donor tissue is unavailable, unsuitable, or associated with excessive operative burden.
This shift is not uniform across indications. Hemodialysis access continues to drive consistent volume, particularly where arteriovenous graft salvage and lower extremity bypass options are needed. Peripheral artery disease interventions benefit from grafts that can accommodate challenging distal targets. Aortic and peripheral reconstructive procedures increasingly favor materials with predictable handling and durable patency characteristics. The common thread is a growing preference for solutions that reduce procedural complexity while maintaining or improving clinical outcomes.
Vascular Graft Market
From a commercial standpoint, this means market growth is being pulled by specific clinical workflows rather than a single generalized demand surge. Companies that map their product portfolios to procedure-level economics and surgeon decision criteria are more likely to convert adoption interest into repeat utilization.
Supply Chain and Cost Structure Realignment
Cost structures in the artificial blood vessel market are being redefined by material inputs, manufacturing intensity, and logistics requirements. Conventional synthetic grafts benefit from mature production ecosystems, while advanced biologics and engineered tissues carry higher unit costs and more complex upstream dependencies. The resulting margin profile is diverging across product categories, and procurement teams are increasingly scrutinizing total cost of care rather than sticker price alone.
This environment favors organizations that can manage the full operational chain with discipline. Reducing variability in raw material sourcing, standardizing sterilization and packaging, and anticipating cold-chain or specialized storage needs are not mere cost-center activities; they are competitive differentiators. When unit economics are under pressure, reliability and scalability become the difference between sustainable market presence and episodic, margin-eroding sales.
Competitive Landscape: Positioning, Differentiation, and Evolution
The competitive field is defined by companies with distinct clinical footprints and strategic priorities. Rather than competing on a single dimension, leaders are building portfolios and positioning statements around specific use cases, material platforms, and procedural contexts.
Humacyte Global has concentrated on acellular tissue-engineered vessels, with Symvess as its flagship offering for extremity arterial injury when autologous vein is not feasible. The company's strategic posture emphasizes regulatory validation, payment recognition, and targeted trauma and reconstruction applications. By pursuing FDA approval through a biologic pathway, securing a defense-related priority designation, and engaging NTAP processes, Humacyte is attempting to anchor a premium-priced technology in a reimbursement framework that acknowledges its differentiated cost and clinical profile. The planned 2026 authorization application in Israel extends this playbook internationally, indicating a phased geographic rollout rather than simultaneous global expansion.
Artivion operates in the cryopreserved allograft space, with CryoArtery Aortoiliac Artery and CryoArtery Femoral Artery positioned for below-knee revascularization and peripheral vascular repair. Its differentiation rests on the use of preserved biological tissue for scenarios where synthetic options are less favorable, particularly in complex peripheral reconstructions. The cryopreserved allograft angle requires robust tissue handling, preservation logistics, and surgeon familiarity, but it opens access to patient populations where matching biological properties to the repair site matters.
PW Consulting
LeMaitre Vascular offers the Artegraft Collagen Vascular Graft, a bovine carotid artery product used for hemodialysis access, AV graft salvage, and lower extremity bypass. Its positioning emphasizes a collagen-based biological graft in a segment where access durability and salvage options are clinically important. Participation in upcoming investor conferences in June 2026 suggests continued attention to capital markets and strategic communications alongside product activity. In a market where dialysis access remains a steady volume driver, a biologically derived graft with a defined salvage and access role can maintain relevance, especially when hospitals seek alternatives to synthetic access options in selected patients.
B. Braun Melsungen AG brings warp-knitted polyester vascular prostheses through its Silver Graft and Silver Graft Helix lines, targeting aortic and peripheral reconstructive procedures. Its strength lies in established synthetic manufacturing capabilities, broad distribution, and product lines designed for reconstructive consistency. In many healthcare systems, such polyester-based prostheses serve as reliable defaults for aortic and peripheral repair, benefiting from surgeon familiarity, inventory stability, and procurement economics. The strategic challenge for incumbents of this type is to sustain utilization while anticipating the slow but real migration toward advanced materials in select indications.
Terumo Medical Corporation has been building around bioengineered vascular grafts within a broader innovative product portfolio for vascular surgery. Its approach reflects an integrated device company posture, where vascular grafts complement a wider surgical offering and benefit from cross-portfolio distribution, clinical support, and procurement relationships. For a company of this scale, vascular grafts can function as both a stand-alone growth avenue and a reinforcing element within a broader vascular surgery ecosystem.
Man-made Vascular Graft Market
Market structure is evolving along several axes. Consolidation pressure exists where scale advantages in reimbursement, education, and distribution favor larger platforms. At the same time, fragmentation persists because different product technologies address different clinical niches, and breakthrough entrants can capture meaningful share in targeted areas without displacing incumbents across the entire market. New entrants with tissue-engineered, bioengineered, or biologically derived platforms are most likely to succeed when they pair regulatory and payment readiness with a clear procedural value proposition. The middle ground, where companies offer incremental improvements without a compelling clinical or economic story, is the most vulnerable to margin compression and share erosion.
Future Outlook: Three Trends Shaping 2027 to 2032
Trend One: Premium, Engineered Grafts Gain Traction Where Economics Can Be Defended
Over the next three to five years, advanced grafts are likely to expand beyond early adoption clusters into broader procedural use, but not uniformly. The commercial ceiling for premium-priced solutions will be set by the ability to demonstrate value in procedural time savings, reduced complications, and lower downstream costs. Indications where autologous alternatives carry high harvest burden, where contamination risk makes biocompatible options attractive, or where re-intervention costs are material will be the most receptive.
The commercial opportunity lies in building indication-specific evidence packages and payment narratives. Companies that can quantify the total care pathway impact, rather than defend list price in isolation, will be better positioned to secure utilization in hospitals and integrated delivery networks. The risk is overreliance on regulatory milestones without parallel progress on reimbursement and real-world evidence, which can leave even approved products with constrained volume trajectories.
Trend Two: Regional Divergence and Strategic Geographic Expansion
Market growth will not be geographically even. Regions with mature reimbursement systems, established vascular surgery volumes, and procurement frameworks that recognize advanced device economics will adopt more quickly. Areas where access to vascular care is expanding but payment pathways are less developed may show slower volume conversion despite rising procedural need.
This divergence creates two distinct strategic opportunities. First, companies with strong domestic positions can pursue measured international expansion where authorization processes, clinical demand, and procurement readiness align. Second, manufacturers that anticipate regional reimbursement gaps can design market access strategies that include evidence generation, pilot programs, and payer engagement tailored to local structures. The downside is that uncoordinated geographic expansion can dilute resources and create fragmented launch execution, especially when regulatory and payment systems differ substantially from one market to the next.
Trend Three: Consolidation of Distribution and Service, Alongside Niche Innovation
The market is likely to see continued tension between scale-oriented consolidation and niche innovation. Larger platforms may pursue distribution, service, and portfolio synergies that reduce selling costs, improve hospital support, and strengthen procurement positioning. In parallel, smaller or more specialized innovators can capture value by targeting unmet needs in trauma, dialysis access, distal revascularization, or biologic graft alternatives.
For decision-makers, this implies a market where broad portfolios and narrow, high-value technologies can both thrive, but under different playbooks. Scale players must protect relevance by maintaining clinical credibility and supply reliability. Specialist entrants must justify premium positioning with clear clinical and economic differentiation. The risk for both is complacency: incumbents that assume synthetic defaults will remain unchallenged may lose select indications, while entrants that underestimate reimbursement complexity may struggle to convert innovation into sustained revenue.
Actionable Guidance for Decision-Makers
The artificial blood vessel market is expanding with moderate but dependable momentum, and the most consequential decisions will be shaped by how well organizations align product strategy, market access, and operational execution. A few priorities stand out across stakeholder groups.
- For manufacturers, the priority is to design indication-specific value propositions that connect clinical performance to procedural economics. Where a graft reduces harvest burden, simplifies handling, or lowers re-intervention likelihood, that story must be supported by evidence and communicated in terms that resonate with surgeons, hospital administrators, and procurement teams. Equally important is operational discipline: supply reliability, manufacturing scalability, and logistics readiness should be treated as core commercial capabilities rather than operational afterthoughts.
- For investors, the most durable opportunities are likely to be found where regulatory progress is matched by reimbursement engagement and geographic rollout discipline. A product with approval, payment recognition, and a defined expansion path offers a stronger risk-adjusted profile than one relying on clinical promise alone. Attention should also be paid to differentiation durability: technologies that can defend premium pricing through demonstrable total-cost advantages are better positioned than those competing solely on novelty.
- For procurement and clinical decision-makers, the focus should be on evaluation frameworks that capture total cost and outcomes rather than unit price alone. Where advanced grafts reduce operative time, lower complication risk, or address cases where autologous options are impractical, they may offer value that is not visible in a sticker-price comparison. Building institutional familiarity through targeted education and procedure-level evaluation can improve adoption decisions and reduce reliance on default product choices.
The market is large enough, and the product landscape varied enough, that a single generalized strategy will not fit all players. The organizations that will capture disproportionate value are those that combine clinical clarity, payment readiness, operational reliability, and a disciplined view of where advanced grafts truly outperform defaults. Because reimbursement pathways, regulatory rhythms, and regional procurement dynamics continue to evolve, timely access to granular segmentation data, company-level tracking, and tailored scenario analysis can materially improve capital allocation and commercial planning. For decision-makers seeking a deeper, more customized view of pricing dynamics, regional variation, and segment-specific opportunity sets, the full research report provides the supporting detail and structured analysis needed to translate these trends into concrete action.
For detailed analysis of this topic, please visit the official page: Artificial Blood Vessel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Hydrogen Fuel Cell Gas Diffusion Layer Market Hits $2B, 5 Shifts Reshaping Growth Through 2032
By PW Consulting, 2026-09-21
Hydrogen Fuel Cell Gas Diffusion Layer Market: Strategic Trends and Commercial Opportunities Through 2032
The hydrogen economy has graduated from pilot programs and regulatory mandates to a phase where material science and component reliability directly determine commercial viability. At the heart of every proton exchange membrane fuel cell lies the gas diffusion layer, a deceptively thin component that governs water management, reactant transport, electrical conductivity, and long-term durability. While often treated as a commodity within fuel cell stacks, the gas diffusion layer market has matured into a strategically distinct segment where performance trade-offs, supply chain resilience, and sustainability credentials increasingly separate winners from the rest. Market trajectory data from 2020 through 2032 point to a sustained expansion from approximately 700 million USD in 2020 to the 2 billion USD threshold in 2025, with continued growth projected at a compound annual growth rate of 13.18 percent through the 2026 to 2032 window, reaching the 4 billion USD mark by 2032. This trajectory reflects more than demand pull; it signals a structural shift in how hydrogen technologies are engineered, manufactured, and scaled across automotive, stationary, and emerging portable applications.
The current landscape is defined by accelerating adoption in heavy-duty mobility and distributed power, yet it is simultaneously pressured by material complexity, regulatory divergence, and concentrated manufacturing know-how. The industry is not simply searching for cheaper substrates; it is recalibrating the performance envelope to support higher current densities, colder start-up conditions, longer stack lifetimes, and tighter environmental standards. Understanding where the market is heading requires looking past headline sizing and into the operational realities that shape procurement, R&D prioritization, and competitive positioning.
Market Landscape and Core Challenges
Sizing the Opportunity Without Losing Sight of the Complexity
The hydrogen fuel cell gas diffusion layer market has expanded from roughly 700 million USD in 2020 to about 2 billion USD in 2025, with projections indicating further growth to 2.27 billion USD in 2026 and a steady climb toward 4 billion USD by 2032. This growth path is underpinned by a compound annual growth rate of 13.18 percent, reflecting cumulative demand from fuel cell electric vehicles, stationary power systems, and a broadening set of specialized applications. The expansion is not uniform across segments or geographies. Asia Pacific continues to anchor a substantial portion of volume, driven by manufacturing scale and policy-backed deployment, while North America and Europe contribute strongly through technology-intensive applications and stringent durability requirements. Carbon-based substrates remain the dominant material family, with carbon paper securing the largest share of the market, supported by carbon cloth and a smaller but strategically important pool of alternative formats. Automotive applications lead demand, followed by stationary power generation and portable power segments that, while smaller in absolute terms, provide valuable entry points for differentiated product strategies.
Beyond the numbers, the market is defined by a high degree of concentration. A relatively small group of established players commands a dominant share of total revenue, reflecting the technical barriers associated with fiber architecture, microporous layer formulation, and hydrophobic treatment consistency. This concentration gives incumbents an advantage in qualification cycles and volume supply, but it also exposes the market to fragility when disruption arrives in the form of material substitution, regulatory pressures, or regional trade dynamics.
Key Challenges and Inflection Points
The first challenge is performance versus durability trade-offs under real operating conditions. Gas diffusion layers must balance effective gas transport with water removal and electron conduction, all while enduring mechanical compression, thermal cycling, and chemical exposure over thousands of hours. As stack designs push higher power density and faster load acceptance, the tolerance for inconsistency narrows. Any mismatch in thickness uniformity, pore distribution, or hydrophobic treatment can manifest as localized flooding, mass transport losses, or accelerated degradation. The market is therefore shifting from acceptable baseline performance toward application-tuned solutions, which increases complexity in both manufacturing and qualification.
The second challenge is the material sustainability and regulatory environment. Traditional gas diffusion layers rely heavily on carbon fiber paper or cloth treated with perfluorinated hydrophobic agents such as PTFE to manage water repellency. While effective, these chemistries face increasing scrutiny in certain markets, and supply chains are being tested by environmental policy direction, potential trade barriers, and the broader push toward circular material strategies. This is not merely an environmental narrative; it is a sourcing risk and a design constraint. Manufacturers and system integrators must now consider whether existing material choices will remain viable under future regulatory frameworks, and whether alternative hydrophobic approaches can deliver equivalent performance without compromising cost or lifecycle expectations.
The third challenge is supply chain concentration and geopolitical exposure. Because a limited number of suppliers and specialized raw material streams support the sector, regional trade constraints and component-level bottlenecks can disrupt lead times and pricing. For program planners and procurement teams, the implication is clear: single-source dependency is increasingly risky, and qualification strategies need to account for geographic diversification and alternative material pathways without sacrificing stack performance.
Together, these challenges create a market inflection point. Demand is strong enough to justify investment, but the value is shifting toward suppliers and system integrators who can manage durability, regulatory compliance, and supply resilience simultaneously. The question is no longer whether the market will grow, but which players can turn material innovation and supply chain strategy into durable competitive advantage.
Key Drivers Shaping the Market
Technology Innovation as a Performance Multiplier
Material and process innovation remains the most powerful driver of market evolution. The gas diffusion layer is moving from a standardized component toward a performance-critical enabler of stack efficiency and system cost. Research and development activity is increasingly focused on tuning fiber architecture, optimizing microporous layer distribution, and refining hydrophobic treatments to reduce mass transport losses while preserving mechanical integrity. Equally notable is the emergence of fluorine-free hydrophobic approaches that explore interpenetrating networks of graphene, cellulose fiber, and modified polypropylene fiber. These alternatives are not simply substitutes; they represent a broader push to decouple water management performance from perfluorinated chemistry, potentially lowering long-term regulatory exposure while opening new performance windows.
In parallel, production innovation is gaining strategic relevance. Pilot lines using recycled carbon fibers have been introduced to reduce raw material waste, with some programs targeting reductions in waste by up to 40 percent. This matters because GDL manufacturing is sensitive to fiber quality, fiber alignment, and treatment consistency. The ability to preserve performance while expanding recycled content can improve cost structures and supply flexibility, while also responding to customer and regulatory expectations around circularity. In practical terms, material innovation is no longer confined to the lab; it is becoming a commercial lever that influences qualification success, total stack cost, and long-term supply viability.
Policy and Regulatory Direction as a Deployment Accelerator
Policy remains a foundational driver, but its influence is evolving from general hydrogen support to more specific requirements around durability, sourcing, and environmental compatibility. Public incentives, zero-emission vehicle mandates, and hydrogen infrastructure programs continue to stimulate demand across mobility and stationary power. At the same time, regional policy divergence is shaping procurement strategies. In Europe, the push for green energy policies and the possibility of trade barriers for certain GDL materials are encouraging supply chain localization and material differentiation. In the United States and China, trade constraints on critical components can affect availability and cost, making regional capability and supplier diversification more valuable than ever.
For commercial decision-makers, the policy environment is not just about volume; it is about compliance risk and time-to-market. Stack developers that design with regulatory trajectory in mind can reduce the probability of late-stage redesigns, whereas those dependent on materials or chemistries facing future restrictions may face higher qualification costs and shorter product lifecycles. Policy is therefore a demand driver, but also a design constraint that shapes the strategic value of material choice.
Demand-Side Shifts Toward Reliability and Total Cost
Demand behavior is maturing on both the consumer and enterprise sides. In automotive applications, the focus has moved beyond proving feasibility to optimizing total cost of ownership, stack longevity, and cold-start reliability. Fleets and OEMs increasingly evaluate fuel cell components not by unit price alone but by their impact on maintenance intervals, degradation rates, and system uptime. In stationary power generation, demand is influenced by grid resilience needs, backup power requirements, and the desire for low-emission distributed generation. Portable power applications, while smaller, contribute to a broader commercial ecosystem where reliability and specific performance characteristics can justify differentiated products.
This shift changes how gas diffusion layers are valued. A GDL that is marginally more expensive but improves water management under dynamic load or extends stack life can be commercially superior to a lower-cost alternative that introduces performance variability. As a result, demand-side behavior is rewarding suppliers that can provide application-specific optimization, consistent quality, and evidence of durability under real operating conditions.
Supply Chain and Cost Structure Realignment
Supply chain dynamics are being reshaped by the interaction of material specialization, regional production capability, and cost pressure. Carbon fiber-based substrates remain central, yet the cost structure of these materials is sensitive to precursor availability, processing efficiency, and the degree of customization required by fuel cell manufacturers. As volumes scale, there is increasing pressure to improve throughput, reduce waste, and standardize dimensions and treatment protocols without sacrificing performance. At the same time, demand for resilience is encouraging dual-sourcing, geographic diversification, and greater transparency into material provenance.
The cost conversation is therefore moving from unit price to total economic value. Suppliers that can offer stable lead times, reproducible quality, and material strategies aligned with future regulatory expectations gain leverage even if their nominal pricing is not the lowest. Conversely, initiatives that reduce waste, increase recycled content, or streamline treatment steps can create meaningful cost advantages while also strengthening sustainability positioning. In this environment, supply chain strategy is a competitive differentiator rather than a back-office concern.
Competitive Landscape and Leading Strategies
Incumbents and the Architecture of Advantage
The market features a mix of specialized material suppliers, broader industrial composites players, and application-oriented distributors, with a clear tilt toward a concentrated group of established leaders. Companies such as SGL Carbon, Toray Industries, Freudenberg Group, AvCarb LLC, Caplinq Corporation, Technical Fibre Products Ltd, Mitsubishi Chemical Corporation, Fuel Cells Etc, Mott Corporation, and GKD Gebr. Kufferath AG each occupy distinct positions in the value chain, balancing scale, specialization, and customer proximity.
SGL Carbon remains a notable leader in carbon paper and carbon cloth gas diffusion layers, with product families built around microporous layer and PTFE treatment for PEM hydrogen fuel cells. Its strategic advantage is rooted in material expertise, manufacturing discipline, and the ability to support qualification programs with consistent product performance. Recent capacity expansion activity has also signaled a forward-looking approach to sustainability, including pilot production using recycled carbon fibers to reduce raw material waste. This combination of performance credibility and supply-side innovation helps reinforce its position in a market where qualification cycles and reliability matter as much as unit economics.
Toray Industries brings a strong composites and advanced materials heritage, with carbon paper GDL products supporting both PEM fuel cells and water electrolyzers. Its presence across hydrogen-related applications gives it broader exposure to the hydrogen ecosystem and an ability to align material development with adjacent technology demand. Participation in industry exhibitions and technical exchanges has reinforced its focus on communicating product capability for PEM fuel cell and electrolyzer use, emphasizing the link between material performance and system-level outcomes.
Freudenberg Group contributes a broad fuel cell gas diffusion layer portfolio spanning carbon cloth and paper types. Its advantage often lies in systems-level thinking and application breadth, which can support differentiated offerings for specific operating environments. AvCarb LLC and Caplinq Corporation occupy more specialized positions in the North American market, with product lines that include carbon cloth and carbon paper-based GDLs and conductive plastic alternatives. These companies often compete on responsiveness, customization, and the ability to serve research, pilot, and production needs with flexible supply.
Technical Fibre Products Ltd, Mitsubishi Chemical Corporation, Fuel Cells Etc, Mott Corporation, and GKD Gebr. Kufferath AG round out a diverse competitive field. Some focus on carbon fiber cloth and felt-based diffusion layers, others on porous substrates or mesh-based configurations, and some on distribution and broader component availability. Their presence illustrates that the market is not monolithic; there is room for both generalized scale players and specialized suppliers, depending on application requirements, volume, and regional service expectations.
Differentiation and Strategic Positioning
The competitive edge in this market is increasingly multidimensional. Performance consistency and durability remain foundational, but differentiation now also depends on material sustainability, supply resilience, and application-specific engineering support. Leaders tend to combine several of the following capabilities:
Hydrogen and Fuel Cells Market
- Advanced control over fiber structure and microporous layer uniformity to support predictable electrochemical performance
- Hydrophobic treatment strategies that balance water management with regulatory and sustainability considerations
- Production flexibility that enables both standardized high-volume products and tailored solutions for demanding applications
- Supply chain transparency and geographic or sourcing diversification to reduce exposure to trade and material constraints
- Technical engagement with stack developers and system integrators to align material properties with real operating conditions
In practical terms, this means the most resilient players are not necessarily those with the simplest cost structure, but those that can translate material know-how into reliability, compliance readiness, and customer-specific value.
Evolution of the Competitive Structure
The market is likely to experience both consolidation and fragmentation pressure over the next several years. On one hand, scale advantages in material production, qualification support, and global supply can favor larger incumbents and encourage integration across the component value chain. On the other hand, niche applications, regional demand pockets, and material innovation pathways create opportunities for specialized entrants and for suppliers that can move faster on sustainability-driven redesigns. New entrants that bring fluorine-free hydrophobic concepts, improved recycled content strategies, or novel porous architectures may find traction in specific performance segments, especially where incumbents are constrained by legacy chemistry or older production lines.
Worldwide Bipolar Plate Fuel Cell Market
At the same time, distributors and multi-brand providers will continue to play a useful role in lowering entry barriers for research teams, pilot programs, and smaller-scale deployments. However, the strategic center of gravity remains with suppliers that can support volume production with consistent quality and a credible path through changing regulatory and sustainability expectations. The market is thus evolving from a relatively narrow competition around material type into a broader contest over reliability, compliance, and supply resilience.
Future Trends and Commercial Opportunities
Trend One: Performance-Tailored GDL Design Becomes the Norm
As stack requirements diverge by application, the market is moving toward more application-tuned gas diffusion layers rather than one-size-fits-all substrates. Automotive stacks with high dynamic load cycles, stationary systems with long-duration operating profiles, and specialized portable units each impose distinct water management, compression, and durability demands. Suppliers that can configure pore structure, thickness, and treatment characteristics to match these profiles will be better positioned to capture value. The commercial opportunity lies in moving from transactional component supply to engineered solution partnerships, where performance data, validation support, and lifecycle outcomes become part of the commercial proposition.
Trend Two: Sustainability-Driven Material Redesign Gains Commercial Weight
Regulatory direction and customer expectations are increasing the strategic importance of fluorine-free hydrophobic approaches and recycled or lower-waste production methods. Material redesign is not only an environmental initiative; it is a risk management and differentiation lever. Suppliers that can demonstrate equivalent or superior performance with alternative chemistries or improved material efficiency can open access to customers seeking to reduce future compliance exposure and improve sustainability narratives. The opportunity is to align R&D with market-facing requirements early, so that material alternatives are commercially viable when needed rather than arriving too late to influence program decisions.
Trend Three: Regionalization and Supply Diversification Become Structural Requirements
Given the concentration of expertise and material streams, regional demand growth will increasingly encourage localized supply capabilities, dual sourcing, and more resilient qualification pathways. Trade dynamics and component-level constraints can stretch lead times or complicate sourcing, making geographic diversification a pragmatic hedge. For suppliers, the commercial opportunity is to build regional service depth, maintain reproducible quality across sites, and offer credible alternatives when program planners seek to reduce single-source exposure. For buyers, the opportunity is to secure performance without locking into fragile supply arrangements.
Risks and Uncertainties to Factor Into Planning
Despite the positive trajectory, several uncertainties warrant attention. Material substitution may take longer than anticipated if alternative hydrophobic chemistries or new fiber architectures struggle to meet durability and cost thresholds at scale. Policy divergence could create uneven demand across regions, with some markets accelerating while others face compliance or trade complications that slow deployment. Supply chain disruptions affecting carbon fiber precursors, treatment chemicals, or specialized manufacturing equipment can create cost and timing volatility. In addition, if fuel cell adoption in certain segments underperforms relative to expectations, even a strong overall market can hide segment-level weakness that affects supplier revenue mix. Decision-makers should therefore treat momentum as real but conditional, and design strategies that can adapt to changes in regulation, material availability, and application demand.
PW Consulting
Strategic Recommendations for Decision-Makers
For Manufacturers and Material Suppliers
Prioritize performance consistency and durability evidence as the basis for commercial differentiation. As qualification cycles lengthen and application requirements diversify, the ability to demonstrate reproducible behavior under real operating conditions becomes a decisive advantage. At the same time, invest early in material innovation that addresses sustainability and regulatory trajectory, including fluorine-free hydrophobic options and waste-reducing production approaches. Building flexibility into product architecture and manufacturing processes will allow faster response to changing customer needs and reduce the risk of being locked into legacy chemistries.
For Investors and Strategic Partners
Focus on companies and technologies that combine material expertise with supply resilience and a credible path through regulatory change. The most attractive opportunities are likely to sit at the intersection of performance reliability, sustainability alignment, and regional supply capability. In diligence, look beyond near-term revenue and assess whether a supplier can sustain quality, support qualification, and adapt material strategies as policy and customer expectations evolve. Portfolio exposure to hydrogen applications should also account for segment variability, since automotive, stationary, and portable demand can follow different adoption rhythms.
For Procurement and System Integrators
Treat gas diffusion layer sourcing as a strategic decision rather than a commodity purchase. Evaluate suppliers on quality consistency, application fit, lead-time reliability, and alignment with future regulatory expectations. Where possible, diversify sourcing and establish qualification pathways that allow alternative materials or regions to be introduced without disrupting program timelines. The goal is to secure stack performance while reducing exposure to single-source dependency and material chemistry risk.
The strategic significance of the hydrogen fuel cell gas diffusion layer market is growing alongside its size. Demand momentum is clear, but long-term value will accrue to those who manage the intersection of performance, sustainability, and supply resilience with discipline. For decision-makers who need deeper segmentation, competitive benchmarking, regional demand detail, and scenario-based planning data, the full PW Consulting market research report provides the structured, granular intelligence needed to translate these trends into concrete business decisions.
For detailed analysis of this topic, please visit the official page: Hydrogen Fuel Cell Gas Diffusion Layer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The KNX Products Market: Strategic Trajectories and Commercial Imperatives
The KNX products market represents a mature yet rapidly evolving segment within the broader building automation ecosystem. As buildings worldwide transition from passive structures to intelligent, interconnected environments, KNX-certified solutions have solidified their position as a benchmark protocol for integrated control systems. The market has demonstrated consistent growth over the past half-decade, expanding from approximately 127.0 million USD in 2020 to an estimated 164.19 million USD in 2025. Projections indicate this trajectory will accelerate through the end of the decade, with the market reaching roughly 180.25 million USD in 2026 and climbing to 338.0 million USD by 2032. This expansion reflects a compound annual growth rate of approximately 10.94 percent, signaling that demand is not merely sustaining but compounding as architectural, technological, and regulatory forces converge.
Such growth is not uniform across all vectors. The market's composition reveals a balanced but increasingly specialized demand structure, where sensors command the largest share of product allocation, followed by actuators, system devices, and ancillary product categories. Application-wise, lighting control remains the dominant use case, with HVAC control, energy management, shutter and blind control, and access and security systems forming a tightly interwoven secondary tier. Geographically, the market has historically been anchored in Europe, which accounts for the largest revenue share, while North America, Asia Pacific, Latin America, and the Middle East and Africa each contribute distinct but growing portions of total demand. The competitive arena remains moderately fragmented, with the top three players commanding roughly 24.0 percent of market revenue and the top five collectively holding about 36.0 percent. This concentration suggests a landscape where established incumbents retain substantial influence but where differentiation, regional adaptation, and technological refinement continue to create openings for strategic positioning.
Key Challenges and Inflection Points
Despite the favorable growth outlook, the KNX products market is navigating several structural challenges that will shape competitive outcomes over the next several years. The first challenge lies in protocol harmonization and interoperability expectations. While KNX enjoys strong recognition as a standardized, open protocol, building owners and system integrators increasingly expect seamless connectivity across heterogeneous ecosystems, including IP-based networks, cloud platforms, and proprietary IoT extensions. Manufacturers that treat KNX as a standalone control layer without addressing cross-protocol bridging risk losing relevance in projects where unified dashboards, remote accessibility, and data interoperability are non-negotiable requirements.
A second challenge emerges from the tension between standardization and customization. KNX-certified devices offer reliability and compatibility advantages, but many high-value commercial and luxury residential projects demand bespoke integration scenarios, localized regulatory compliance, and aesthetic differentiation. Suppliers must balance the efficiency of standardized product lines with the flexibility required for specialized deployments. Over-indexing on either extreme can erode margins or reduce market reach.
Third, the market faces an inflection point around skills and installation capacity. As KNX solutions expand from advanced residential projects into broader commercial, institutional, and multi-family environments, the availability of trained integrators and electricians becomes a bottleneck. The protocol's technical rigor is an asset for system performance, but it also raises the barrier to rapid deployment. Companies that invest in simplified configuration tools, stronger partner enablement, and clearer commissioning workflows are better positioned to scale adoption without compromising quality.
Key Drivers of Market Change
Technological Innovation and Protocol Evolution
Technology advancement is the most visible driver reshaping the KNX products market. The convergence of traditional KNX bus architecture with IP connectivity and IoT-enabled extensions is widening the addressable use cases for sensors, actuators, and system devices. Recent industry activity underscores this direction. In March 2026, the KNX Association showcased its member ecosystem at Light + Building, where multiple companies presented the latest KNX IoT and intelligent energy management solutions. This exhibition signaled a clear strategic emphasis: KNX is evolving beyond isolated control functions toward integrated energy intelligence, remote management, and data-aware building operations.
For manufacturers, this shift is not merely a feature upgrade. It reframes the value proposition of KNX-certified devices from static control components to enablers of measurable energy performance and operational insight. Sensors that once served localized detection functions are now being positioned as inputs for broader automation logic, while actuators and system devices are increasingly designed to interface with centralized analytics and demand-response strategies. Companies that embed connectivity, software-friendly interfaces, and upgrade pathways into their hardware portfolios are likely to capture disproportionate share in projects where building owners prioritize future-proofing over lowest initial cost.
Policy and Regulatory Momentum
Regulatory pressure is a powerful accelerant for KNX adoption, particularly in regions with aggressive building decarbonization targets. Policy frameworks are increasingly tying building performance to measurable energy outcomes, and automation systems have become essential instruments for compliance and optimization. The EU Energy Performance of Buildings Directive, for example, highlights that buildings account for approximately 40 percent of EU energy consumption and 36 percent of energy-related CO2 emissions. This regulatory context creates direct demand for control systems capable of monitoring, balancing, and reducing consumption across lighting, HVAC, shading, and security functions.
Within this environment, KNX-certified products are gaining relevance because they align with established energy performance assessment standards. Certified products can enable up to 50 percent energy savings in building automation when deployed in accordance with top Energy Performance Class requirements under EN 15232. This capacity is not a marginal benefit; it is becoming a core procurement rationale for public tenders, large-scale commercial developments, and retrofit programs where compliance and documented efficiency gains carry financial and reputational weight. For suppliers, regulatory tailwinds are most valuable when paired with clear documentation, certification transparency, and application guidance that helps project teams translate compliance goals into system design choices.
Smart Building Market
Demand-Side Shifts in Building Ownership and Operations
Demand patterns are also changing as building owners and facility operators reevaluate the role of automation in total cost of ownership. The traditional purchase logic centered on hardware price is giving way to a broader assessment that includes energy savings, comfort, maintenance predictability, and integration with corporate sustainability commitments. In residential segments, buyers are increasingly treating smart control not as a premium add-on but as a baseline expectation for new developments and high-end renovations. In commercial environments, operational resilience and energy cost control are driving facility managers to favor systems that can centralize control across multiple subsystems without creating vendor lock-in.
This shift has implications for product mix and go-to-market strategy. Lighting control remains the largest application area, but demand is increasingly cross-linked with HVAC control, energy management, and access and security workflows. Buyers are less interested in isolated subsystems and more interested in coherent environments where shading, climate, illumination, and security can respond to occupancy patterns and external conditions in a coordinated manner. As a result, suppliers offering integrated yet modular KNX portfolios are better aligned with how projects are being specified and evaluated.
Supply Chain and Cost Structure Considerations
Supply chain dynamics continue to influence competitive positioning, particularly for hardware-heavy product categories. The market's reliance on sensors, actuators, and system devices means that component availability, manufacturing efficiency, and logistics stability directly affect time-to-market and margin preservation. While the sector has not faced the same level of disruption as some consumer electronics segments, cost volatility and lead-time variability remain practical concerns for both producers and integrators. The companies most effectively managing these pressures are those that combine disciplined sourcing with product architectures that allow regional adaptation without excessive rework.
Cost structures are also being reshaped by the growing importance of software-supported configuration, remote diagnostics, and service-enabled offerings. As building automation becomes more data-centric, the economic value of a KNX product is increasingly tied to the surrounding ecosystem: documentation quality, integration support, training, and post-installation service. Manufacturers that treat these elements as part of the core offering, rather than as after-sales extras, can differentiate more effectively in a market where hardware specifications alone are becoming less sufficient as a competitive moat.
Competitive Landscape and Leading Strategies
Incumbent Positioning and Differentiation
The competitive field in the KNX products market features a broad set of established manufacturers, many of whom anchor their KNX offerings in certified actuators, sensors, and control devices spanning lighting, heating, ventilation, and security applications. German and French firms feature prominently in this landscape, reflecting the deep integration of KNX within European building culture and procurement norms. Companies such as ABB AG through its BUSCH-JAEGER and STOTZ-KONTAKT units, Albrecht Jung GmbH & Co. KG, 4ba GmbH, Berker, B.E.G. Brück Electronic GmbH, Busch-Jaeger, Gira, Hager Group, MDT Technologies, Theben AG, and Siemens AG represent a strong presence of organizations with well-defined automation portfolios and established distribution relationships.
Beyond these, the landscape includes Legrand and Schneider Electric from France, Somfy from France, and a wider circle of specialists and regional players such as Eelectron, HDL Automation, IPAS GmbH, Lime International, STEINEL, Urmet, Weinzierl Engineering, Zennio Avance y Tecnologia S.L., and GVS. While their individual product emphasis varies, the collective profile suggests a market where many manufacturers compete on similar foundational capabilities: KNX certification, application breadth, and reliability. Differentiation therefore tends to emerge through brand strength, regional channel reach, design language, integration partnerships, and the ability to support complex project requirements end to end.
PW Consulting
Leading incumbents are increasingly distinguishing themselves not just by what they sell, but by how they enable deployment. Stronger technical documentation, expanded accessory ecosystems, integration with planning tools, and more intuitive commissioning processes can reduce friction for integrators and specifiers. In practice, this means that a manufacturer's strategic advantage may depend as much on its support infrastructure and partner network as on the specifications of individual devices. In a market where the top five players collectively hold around 36.0 percent of revenue, sustained leadership will likely belong to those who convert certification and product range into repeatable project wins and long-term specification loyalty.
Market Evolution: Consolidation, Specialization, and New Entry
The competitive landscape appears poised for selective consolidation and parallel specialization. On one hand, the moderate concentration levels indicate room for continued fragmentation, especially in regional markets where local service, compliance knowledge, and distributor relationships remain decisive. On the other hand, the increasing complexity of connected building projects favors larger portfolios, stronger R&D resources, and broader international support capabilities. This dynamic may encourage consolidation among mid-tier players seeking scale, while also creating space for niche specialists who excel in particular application areas such as lighting control, shading, or energy management.
New entrants and adjacent players are also likely to influence the market, especially where KNX intersects with IoT platforms, smart metering, and remote building management. The competitive threat is not necessarily direct displacement of KNX devices, but rather the expansion of expectations around what those devices must connect to and communicate with. Companies that can position KNX as the dependable field-level backbone within a broader digital architecture are likely to preserve and extend their relevance. Conversely, players that fail to adapt to cross-platform expectations may find their products confined to narrower, more price-sensitive segments.
Future Trends and Commercial Opportunities
Trend 1: Energy Intelligence as a Core Product Dimension
Over the next three to five years, energy management is expected to transition from a supporting application to a central design driver for KNX product strategies. Regulatory pressure, operating cost sensitivity, and corporate sustainability commitments are aligning to make measurable energy performance a priority in both new builds and retrofits. KNX systems that can coordinate lighting, HVAC, shading, and security while feeding usable data into building-level energy oversight will likely see stronger specification rates. The commercial opportunity lies in developing product combinations and configuration models that make energy outcomes easier to design, validate, and maintain. Suppliers that can demonstrate credible savings pathways and align their portfolios with recognized performance classes will have an advantage in tender processes and high-value projects.
Trend 2: Greater Emphasis on Interoperability and Remote Management
A second trend is the growing expectation that KNX deployments should integrate smoothly with broader digital building environments. This includes IP-based communication, cloud-connected monitoring, and interfaces that allow facility teams to manage multiple sites or subsystems from unified platforms. The commercial opportunity is not simply to add connectivity features, but to reduce the operational burden of KNX integration. Products that are easier to commission, easier to monitor, and easier to expand will appeal to integrators and building owners alike. This trend also creates opportunities for service-oriented models, where ongoing diagnostics, firmware management, and configuration support become part of the value chain rather than peripheral activities.
Trend 3: Regional Acceleration and Application Diversification
The third trend concerns the geographic and application broadening of demand. While Europe remains the strongest revenue base, regions such as Asia Pacific, North America, Latin America, and the Middle East and Africa are contributing increasing shares as building modernization programs, premium residential development, and commercial automation projects expand. At the same time, application demand is spreading beyond lighting control into HVAC control, shutter and blind control, energy management, and access and security control. The commercial opportunity here is twofold: manufacturers can pursue regional adaptation strategies that reflect local building norms, and they can develop application-focused bundles that mirror how projects are actually specified. Companies that treat regional growth as a replication of the European playbook may underappreciate the importance of local integration practices, certification expectations, and procurement channels.
Risks and Uncertainties
These opportunities are accompanied by meaningful uncertainties. One risk is that rapid software-centric innovation could shift value toward platform providers and integrators, compressing hardware margins if manufacturers are unable to justify premium pricing through differentiated performance or services. Another is regulatory variation: while some regions are tightening building performance requirements, others may move more slowly or prioritize different compliance mechanisms, creating uneven demand growth. A third risk relates to execution complexity. As products become more connected and application combinations more intricate, the potential for installation errors, commissioning delays, and support burdens increases. Companies that expand their portfolios without strengthening the corresponding enablement and service infrastructure may find that growth brings operational drag rather than profitable scale.
Strategic Implications for Decision Makers
For Manufacturers and Product Leaders
Manufacturers should prioritize building portfolios that combine KNX certification credibility with clear pathways for connectivity, energy management, and integration support. Rather than treating IoT capabilities as optional add-ons, they should be designed into the product architecture from the outset so that devices can function as dependable field-level components within broader digital building strategies. Equally important is the enablement ecosystem: planning tools, configuration guidance, commissioning support, and partner training can determine whether a strong product lineup translates into repeat specification and successful project outcomes. In a market where concentration remains moderate, differentiation through deployment ease and application coherence can be as important as hardware specifications.
For Investors and Strategic Capital
Investors should evaluate opportunities with attention to companies that can bridge hardware reliability and software-enabled value creation. The most attractive positions may be found where firms can demonstrate durable certification advantages, strong regional channel relationships, and the ability to serve cross-application demand such as lighting, HVAC, and energy management in a coordinated way. Capital allocation should also account for the growing importance of service, training, and integration support as margin contributors. In a market growing at a double-digit CAGR, value capture will increasingly depend on whether a company can convert demand growth into specification loyalty and repeatable project execution rather than one-time product sales.
For Procurement and Integration Leaders
Procurement and integration teams should approach KNX selection with a broader project lens. The lowest unit price may not deliver the best outcome if it increases commissioning complexity, limits future expandability, or weakens energy performance alignment. Evaluation criteria should include certification transparency, compatibility with planned energy management goals, ease of integration with existing or anticipated building platforms, and the quality of supplier support. Given the increasing importance of compliance and operational efficiency, procurement decisions should weigh how well a chosen product set can support documented performance goals over the building lifecycle. Early engagement with suppliers that can provide clear application guidance and integration pathways can reduce project risk and improve long-term value.
Conclusion
The KNX products market is entering a phase where growth is being reinforced by regulatory pressure, technological extension, and shifting expectations around energy performance and interoperability. The market's expansion from roughly 127.0 million USD in 2020 to an projected 338.0 million USD by 2032 reflects more than incremental demand; it reflects a structural realignment in how buildings are specified, commissioned, and operated. Sensors, actuators, and system devices remain foundational, but their commercial value is increasingly tied to how effectively they support lighting control, HVAC control, energy management, shading, and security within integrated environments.
IO-Link Market
For companies operating in this space, the strategic question is no longer whether KNX remains relevant, but how to position within a market that is becoming more connected, more performance-driven, and more application-integrated. The leaders who gain durable advantage will likely be those who combine certified product excellence with stronger enablement, clearer energy-performance alignment, and the ability to serve regional and application diversity without losing coherence. Detailed segment-level data, company-level comparisons, and customized strategic guidance can help decision makers convert these trends into concrete plans. For those seeking a deeper operational view of segmentation, competitive positioning, and forward demand pathways, the full research report provides a more granular foundation for strategy development.
For detailed analysis of this topic, please visit the official page: KNX Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Dicalcium Phosphate Market Insights: Decoding 5.0% CAGR Growth Drivers to 2032
By PW Consulting, 2026-09-21
Navigating the Dicalcium Phosphate Market: Strategic Imperatives for the Next Decade
The global Dicalcium Phosphate market enters the late 2020s at a critical juncture. Between 2020 and 2025, the industry expanded from approximately $900 million to over $1.1 billion, reflecting sustained demand across feed, food, and pharmaceutical applications. Forward projections through 2032 indicate a trajectory toward $1.56 billion, underpinned by a compound annual growth rate of roughly 5.0 percent. These figures do not tell a simple growth story. They reveal a market undergoing structural realignment, where value creation increasingly depends on grade specialization, regulatory compliance, and supply chain resilience rather than volume alone.
Tricalcium Phosphate Market
Market Snapshot and Underlying Tensions
Historically, Dicalcium Phosphate benefited from predictable procurement cycles in animal nutrition and steady utilization in food fortification. The recent acceleration, however, has been uneven. Feed-grade volumes remain the largest share of total revenue, but food-grade and pharmaceutical-grade streams are gaining relative importance as downstream industries prioritize purity, traceability, and functional performance. The market remains moderately concentrated, with the top three players collectively controlling a substantial portion of output and the top five firms capturing the majority of traded supply. This concentration creates both stability for established buyers and friction for new entrants seeking scale.
Three structural tensions currently shape the operating environment. First, the industry must reconcile volume-driven economics with tightening quality thresholds. Feed applications demand cost efficiency, while food and pharmaceutical applications impose rigorous impurity limits, moisture control, and documentation standards. Second, geographic demand is shifting in ways that stress traditional logistics networks. Emerging agricultural intensification and expanding food processing capacity in Asia Pacific and Latin America are creating pull that legacy European and North American production hubs must route efficiently. Third, the sector faces margin pressure from raw material volatility, which interacts with regulatory compliance costs to reshape the profitability equation for mid-tier producers.
The practical implication is clear: competitive advantage no longer belongs to generic producers. It accrues to firms that can manage multiple grade specifications within the same facility, convert compliance into a commercial differentiator, and align production footprints with regional demand centers.
Key Drivers Reshaping the Market
Technology and Process Innovation
Advancements in precipitation control, drying, and particle engineering are redefining what Dicalcium Phosphate can deliver in end-use applications. Fine-tuning of crystal morphology and moisture content is improving flowability and compressibility for tablet formulations, while also supporting consistent phosphorus bioavailability in feed premixes. Producers that invest in process automation and inline quality monitoring are better positioned to reduce batch variability, minimize rework, and meet the increasingly strict documentation expectations of food and pharmaceutical buyers. Over time, these operational improvements translate into lower total cost of ownership for customers, which is becoming a decisive factor in vendor selection.
PW Consulting
Regulatory and Policy Environment
Regulatory frameworks are acting as both a barrier and a catalyst. In the European Union, stringent purity thresholds for feed additives have elevated quality expectations across the supply chain, effectively filtering out producers that cannot sustain consistent compliance. Meanwhile, food and pharmaceutical applications are governed by recognized monographs and food additive standards that define limits for heavy metals, microbial load, and related substances. These frameworks increase the cost of entry, but they also create a durable moat for capable manufacturers. In markets where regulatory harmonization is advancing, compliant producers can command premium positioning because buyers treat quality assurance as a non-negotiable input to their own brand risk management.
Demand-Side Behavior Shifts
The demand picture is changing on both the animal nutrition and human nutrition fronts. In feed, the growth of intensive livestock and aquaculture operations is driving consistent phosphate requirements, but buyers are also more selective, favoring suppliers that can guarantee specification stability across seasons and shipments. In food fortification and supplements, rising awareness of bone health, mineral supplementation, and clean-label sourcing is encouraging manufacturers to seek Dicalcium Phosphate grades with documented purity and predictable functionality. Pharmaceutical and related applications continue to value excipient performance and regulatory traceability. Across these segments, the common thread is a shift from price-first procurement toward value-first partnerships, where reliability, certificate-of-analysis consistency, and responsiveness matter as much as unit cost.
Worldwide Diethyl Chlorophosphate Market
Supply Chain and Cost Structure Dynamics
Phosphate rock remains the dominant cost input in Dicalcium Phosphate production, with estimates placing it at roughly 60 to 70 percent of operating expenses. The sensitivity of margins to raw material prices is therefore significant. Recent commodity data shows mine-level pricing hovering in the vicinity of $80 per metric ton on an f.o.b. basis, while domestic production volumes in major supplying countries remain substantial. This cost structure favors producers with secure rock access, efficient beneficiation, and the ability to hedge or contract feedstock intelligently. At the same time, logistics costs and regional energy dynamics can either amplify or dampen the impact of raw material prices. Companies that design supply chains around proximity to demand, flexible routing, and integrated quality systems are better able to protect margins during cycles of input volatility.
Competitive Landscape and Strategic Positioning
The competitive field is diversified by geography and by grade focus. Some manufacturers emphasize branded excipients and specialty formats for food, beverage, supplement, and tablet applications, building reputation around consistency and application support. Others concentrate on anhydrous and feed-grade volumes, leveraging multi-site production across Europe, North Africa, and South America to serve industrial and animal nutrition customers at scale. Additional players in China, India, and Japan maintain a strong presence in feed, food, and pharmaceutical grades, with several firms oriented toward active pharmaceutical ingredient and dihydrate formats. This mix creates a market where scale, specialization, and regional reach each provide distinct advantages.
Differentiation Levers Among Leading Players
Leading firms tend to differentiate along three axes. The first is grade breadth: the ability to serve feed, food, and pharmaceutical requirements from integrated operations reduces customer burden and increases stickiness. The second is compliance and documentation: robust quality systems, traceable sourcing, and alignment with recognized monographs and food/feed standards allow producers to enter more sensitive applications. The third is geographic fit: locating production closer to key demand clusters shortens lead times, reduces freight exposure, and improves service levels. When these levers are combined, suppliers transition from commodity vendors to application partners, which is where pricing power and long-term contracts become achievable.
Evolution of the Market Structure
The landscape is likely to trend toward selective consolidation among mid-tier producers who lack scale or compliance depth, while specialized players continue to carve out niches in food-grade and pharmaceutical-grade segments. Greenfield and expanded capacity announcements, such as recent initiatives tied to animal feed supplement production with regional government support, indicate that new entrants and existing players alike see room for targeted investment where demand is growing and logistics align. At the same time, the presence of multiple capable suppliers in Asia and India suggests that competitive intensity will remain strong on price and availability, pushing differentiated players to compete more explicitly on quality, service, and specification control. The net effect is a market that is not simply consolidating, but stratifying: commodity volumes remain contested, while higher-value grades increasingly reward precision and credibility.
Forward Outlook: Three Trends to Watch
Trend One: Grade Specialization as the New Growth Engine
Over the next three to five years, incremental growth is expected to come less from undifferentiated volume and more from higher-purity grades and application-tailored formats. Food fortification and pharmaceutical-related uses are likely to outpace pure feed growth rates in relative terms, driven by stricter quality expectations and demand for consistent functional performance. For producers, this means the most resilient revenue streams will be those supported by documented purity, controlled particle characteristics, and reliable certificate-of-analysis outcomes. The commercial opportunity lies in building grade-specific capacity and marketing supply as a quality-assured input rather than a bulk commodity.
Trend Two: Regional Rebalancing of Supply and Demand
Demand growth is expected to remain strongest where food processing, animal nutrition, and supplement manufacturing are expanding rapidly, while established markets will focus on replacement, reformulation, and premiumization. This rebalancing encourages investment in production and blending capabilities that are closer to emerging demand hubs. It also rewards logistics agility, because buyers increasingly value shorter, more predictable supply paths. Firms that align footprint decisions with regional demand trajectories can reduce transit risk, improve service levels, and capture share from distant suppliers that are more exposed to freight and timing variability.
Trend Three: Compliance as a Commercial Asset
Regulatory scrutiny and buyer diligence are unlikely to ease. The practical consequence is that compliance infrastructure, audit readiness, and documentation consistency will become explicit buying criteria rather than background requirements. Producers that institutionalize quality assurance and can demonstrate alignment with food and feed standards will find it easier to enter and retain sensitive applications. The risk is equally clear: any lapse in specification control or documentation can quickly erode customer trust in these grades. Organizations that treat compliance as a strategic capability rather than a cost center will be better positioned to defend margins and expand into higher-value channels.
Strategic Actions for Decision Makers
For manufacturers, the priority is to clarify grade strategy and invest where differentiation is defensible. Facilities that can flexibly serve feed, food, and pharmaceutical requirements with rigorous quality controls will capture more resilient demand than those locked into a single price-competitive segment. Process automation, inline monitoring, and clean documentation workflows should be treated as enablers of premium positioning, not merely operational improvements. Where raw material exposure is high, securing reliable rock supply and designing efficient production routes can help stabilize margins during price swings.
For investors, the opportunity is to evaluate exposure through the lens of grade mix and compliance depth rather than total capacity alone. Assets tied to higher-purity food and pharmaceutical applications, or to regionally balanced production footprints, tend to offer more durable growth profiles than undifferentiated volume plays. Due diligence should emphasize feedstock arrangements, quality system maturity, and customer concentration in sensitive applications, because these factors determine whether a business can convert market growth into sustainable returns.
For procurement and supply chain leaders, the mandate is to reweight supplier evaluation toward specification reliability, documentation quality, and service predictability. Multi-grade sourcing strategies can reduce single-supplier dependency while maintaining access to premium materials when needed. Establishing clear acceptance criteria, audit expectations, and contingency routing will help protect production continuity in food and pharmaceutical contexts where variability carries disproportionate risk. In feed applications, total cost of ownership should incorporate not only unit price but also consistency, lead-time reliability, and the cost of non-conformance.
The market’s next phase will reward participants who can read these shifts early and act on them with discipline. While the headline trajectory points to steady expansion, the real strategic value lies in understanding how grade demand, regulatory intensity, and regional supply dynamics interact at the segment level. For decision makers seeking a fuller picture of sub-segment sizes, regional pathways, and company-level positioning to inform investment and procurement choices, the detailed research report provides the granular data and customized analysis needed to move from broad direction to executable plan.
For detailed analysis of this topic, please visit the official page: Dicalcium Phosphate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
CNT Market’s 14.88% CAGR Trajectory: What Structural Shifts Are Really Driving It
By PW Consulting, 2026-09-21
Carbon Nanotube Market Strategic Trends and Commercial Opportunities: A 2025–2032 Outlook
Carbon nanotubes have moved beyond laboratory promise into a phase of commercial scaling defined by structural demand, repeated capacity expansions, and increasing integration into mainstream material portfolios. Over the historical period from 2020 through 2025, the global carbon nanotube sector expanded from roughly 500 million USD to approximately 1.75 billion USD, reflecting a marked acceleration in the later years of the timeline. Current forecasting places the market on a 14.88 percent compound annual growth trajectory through 2032, with revenue projected to reach 4.59 billion USD by the end of the forecast window. This growth curve is not linear. It reflects a bimodal pattern in which early development years gave way to a step-change in commercialization as battery manufacturers, electronics assemblers, and advanced composite engineers began standardizing carbon nanotube additives into production processes.
For executives and investors, the central question has shifted from whether carbon nanotubes will scale to how the value chain will organize itself around scale. The answer increasingly depends on how quickly producers can translate capacity additions into consistent quality, how industrial buyers absorb new formulations without disrupting existing lines, and how regulatory frameworks mature around exposure, handling, and reporting requirements.
Market Context and Critical Inflection Points
The market is experiencing a transition from fragmented early-stage adoption to a more concentrated, application-led growth structure. Concentration among the leading participants remains significant, with the top three firms accounting for a substantial share of total revenue and the top five approaching a majority of market activity. This concentration is not accidental. It reflects the technical complexity of producing carbon nanotubes at consistent purity, the capital intensity of expanding production, and the importance of established supplier relationships in validation-heavy industries such as electronics, energy storage, and structural composites.
Two inflection points are shaping the near-term trajectory. The first is the move from pilot-scale validation to volume integration, especially in batteries and conductive formulations. As production capacity expands across multiple geographies, the limiting factor is no longer whether carbon nanotubes can be made, but whether dispersion quality, dust control, and batch-to-batch consistency can meet industrial acceptance thresholds at scale. The second inflection point is the growing intersection of nanomaterials with regulatory oversight. Carbon nanotubes are increasingly treated as a distinct class requiring documented risk and exposure data, which raises the compliance burden for manufacturers and processors while simultaneously reinforcing the advantage of established producers who already operate with structured quality systems and reporting processes.
The third pressure point is cost-driven selectivity among buyers. As more suppliers enter the market and capacity grows, industrial users are becoming more discerning about grade, dispersion format, and performance claims. This is a healthy maturation signal, but it also means that generic product offerings will face margin compression. The commercial battleground is now differentiating by capability rather than by availability alone.
Core Drivers Reshaping the Carbon Nanotube Market
Technological Innovation and Performance Breakthroughs
The most consequential technical shift is the migration of carbon nanotubes from niche enhancement materials to standard constituents in demanding applications. High-conductivity grades and tailored dispersions are now being positioned for lithium-ion battery anodes and cathodes, conductive plastics, and advanced composite systems. The strategic value lies in incremental but compounding performance gains: lower internal resistance, improved charge-transfer pathways, stronger mechanical reinforcement at lower loading levels, and formulation designs that reduce processing complexity.
Recent progress in dispersion engineering and co-catalyst development illustrates this trend well. Rather than chasing raw capacity alone, leading producers are increasingly focused on formulations that improve dispersibility, lower dust generation, and simplify downstream integration. That matters because industrial adoption often hinges on manufacturability. A material that delivers exceptional lab properties but is difficult to handle at scale will lose to a slightly less exotic alternative that behaves predictably in continuous production environments.
Policy and Regulatory Environment
Regulatory dynamics are becoming a defining part of the operating landscape. Under evolving chemical oversight frameworks, manufacturers, importers, and processors of carbon nanotubes are increasingly expected to submit risk and exposure data, and some jurisdictions have introduced reporting thresholds relevant to production and handling facilities. State-level surveys have also identified where carbon nanotubes are used across semiconductor, composite, and nanotechnology manufacturing sites, which signals a more active monitoring environment.
This regulatory trajectory has two practical implications. First, it adds a layer of compliance cost and administrative rigor, particularly for new entrants or smaller producers with less mature environmental, health, and safety infrastructure. Second, it creates a differentiation advantage for producers that can provide documented traceability, controlled manufacturing conditions, and formulation support that simplifies downstream compliance. In effect, regulatory maturation is pushing the market toward quality assurance as a strategic asset rather than a back-office function.
Worldwide Carbon Nano Cold Cathode Tube Market
Demand-Side Shifts in Electronics, Energy, and Advanced Materials
Demand is being pulled by several converging industrial priorities. In electronics and semiconductors, the push for more efficient conductive pathways and miniaturized components is creating steady interest in nanotube-based inks, formulations, and functional materials. In energy storage, battery performance, cycle life, and thermal behavior remain central engineering concerns, which makes conductive additives attractive when they can be integrated without compromising existing manufacturing economics. In structural composites and polymer systems, formulators are looking for reinforcement and conductivity improvements that can be achieved at practical loading levels without undermining processability.
What makes this phase different is the combination of volume and specificity. Buyers are not simply asking for carbon nanotubes; they are asking for grades that match particular processing routes, dispersion formats that minimize disruption, and performance consistency that survives scale-up. As a result, demand growth is increasingly tied to supplier capability in application engineering, not just tonnage.
Supply Chain and Cost Structure Dynamics
The cost structure of the market is evolving as production scales and geographic diversification increases. Capacity expansions across multiple regions are reshaping supply resilience, while the industrial focus on dispersion quality and low-dust formulations is changing what counts as a commercially viable product. In practical terms, the total delivered value of a carbon nanotube offering now depends on more than purity and price per kilogram. It includes the downstream burden of handling, dispersion, integration, and performance validation.
PW Consulting
Supply chains are also becoming more application-specific. Producers that can offer standardized dispersion formats and formulation support reduce the adoption friction for buyers, while those operating only at the powder level may face longer qualification cycles. This is gradually shifting the competitive center of gravity from raw production alone toward integrated material solutions.
Competitive Landscape and Strategic Positioning
The competitive field is increasingly defined by scale, application focus, and formulation capability. A small group of major producers is driving much of the capacity expansion and product standardization activity, while a broader set of specialized firms competes in high-purity, electronics-grade, or research-oriented segments. This dual structure is important: volume leadership is becoming more valuable in battery and conductive-additive markets, while specialty differentiation remains essential in semiconductors, printed electronics, and high-specification composites.
Several strategic patterns are visible across the leading participants.
-
Vertical integration around capacity and geography is a common theme. Firms are expanding plant networks to support growing demand from energy storage and conductive applications, while also positioning themselves closer to key downstream markets. This reduces logistical friction and strengthens supply reliability for large buyers.
-
Formulation and dispersion capability is becoming a differentiator. The ability to supply ready-to-use dispersions, low-dust grades, and iron-free or otherwise tailored formulations matters because it shortens adoption cycles and simplifies integration into battery and polymer processes.
-
Product-line diversification is widening the addressable market. Leading producers are building portfolios that span battery additives, conductive plastics, coatings, and composite reinforcements, which helps buffer demand volatility across end-use sectors.
Boron Nitride Nanotubes (BNNT) Market -
Specialization remains a viable path. Companies focused on high-purity semiconducting grades or research-grade materials continue to play an important role in enabling emerging uses, particularly where performance specificity outweighs volume considerations.
Capacity expansion is a dominant theme in recent industry activity. One major producer commissioned an additional facility that lifted total operating capacity by a significant margin, reflecting a deliberate push to support battery and conductive additive demand. Another volume-focused producer initiated a new cathode material project with phased capacity coming online in the near term. A leading single-walled carbon nanotube producer scaled dispersion capacity substantially through partner-based expansion in China. These moves are not isolated. They indicate a market where producers are racing to secure both volume and application proximity.
The competitive evolution is also likely to produce consolidation pressure over time. As the market matures, larger, well-capitalized producers with multi-application portfolios and strong formulation capabilities will be better positioned to absorb demand cycles and compliance requirements. At the same time, specialized entrants can still thrive where performance requirements are highly specific and switching costs are high. The net effect is a market that is simultaneously consolidating at the top and fragmenting in niche segments where precision and technical support matter more than scale.
Forward Trends and Strategic Implications for 2026–2032
Trend One: Battery and Energy Storage Applications Will Anchor Volume Growth
Energy storage remains one of the most important demand anchors for carbon nanotubes, particularly as conductive additives become more embedded in battery electrode design. The practical opportunity is not only in improved conductivity, but also in engineering gains such as reduced internal resistance and better material integration. As battery manufacturers continue to optimize performance and throughput, nanotube-based additives are likely to see broader acceptance where they can demonstrate measurable process and performance benefits.
The commercial implication is clear: producers that can consistently supply battery-grade formulations with strong quality control and application support will capture disproportionate value. Buyers, in turn, should evaluate supplier capability in dispersion design and qualification support rather than treating carbon nanotubes as a commodity input.
Trend Two: Regulatory and Handling Standards Will Reshape Sourcing Decisions
As reporting expectations and oversight mechanisms become more defined, sourcing decisions will increasingly factor in compliance readiness, exposure documentation, and handling characteristics. This trend does not necessarily slow the market, but it does raise the bar for operational maturity. Producers with structured quality systems and transparent documentation will have an advantage, while less organized participants may find it harder to enter regulated supply chains.
For industrial users, this means that supplier selection should incorporate compliance, safety, and handling considerations alongside performance metrics. For producers, it means that documentation, traceability, and formulation support are no longer optional enhancements; they are part of commercial competitiveness.
Trend Three: Formulation, Dispersion, and Application Engineering Will Outperform Raw Powder Competition
As capacity grows, the market will increasingly reward solutions that reduce integration risk. Dispersion quality, dust control, batch consistency, and ready-to-use formats will become more valuable than price alone. This is a typical maturation pattern in advanced materials: early competition centers on basic availability, and later competition centers on reliability, usability, and performance assurance at scale.
Strategically, this favors companies that invest in formulation know-how and customer-facing technical support. It also creates opportunities for partnerships between material producers and downstream formulators who can co-develop application-specific solutions.
Risks and Uncertainties
Several uncertainties could shape the pace and distribution of growth. Regulatory requirements may evolve faster than some producers can adapt, especially if exposure and risk assessment expectations expand. Overcapacity in certain grades could pressure margins if demand does not keep pace with new capacity, particularly where differentiation is weak. Application adoption may also be slower than anticipated in some sectors if validation cycles remain long or if alternative materials improve rapidly. Finally, supply chain concentration in specific geographies could create vulnerability if logistics, trade conditions, or local operating environments shift.
These risks do not undermine the broader growth outlook, but they justify disciplined capacity planning, strong application engineering, and careful attention to regulatory readiness.
Actionable Guidance for Decision Makers
For manufacturers and product developers, the priority is to treat carbon nanotube selection as an integration decision, not just a material purchase. Qualifying a supplier should include dispersion behavior, dust and handling characteristics, batch consistency, and the supplier's ability to support scale-up. Where feasible, co-developing formulations with experienced producers can reduce qualification time and improve performance predictability in production environments.
For investors, the most durable value creation is likely to come from companies that combine scalable capacity with formulation strength and multi-application portfolios. Pure capacity expansion without application support may generate volume but not necessarily margin resilience. Due diligence should therefore assess not only capacity milestones, but also dispersion capability, customer qualification progress, regulatory readiness, and the degree to which a company is embedded in high-value demand segments such as batteries and conductive materials.
For procurement and sourcing leaders, the market now rewards technical evaluation over simple price comparison. Evaluation criteria should include documented quality systems, handling and safety posture, dispersion formats, and track record in the specific application of interest. Diversifying across suppliers with different strengths can also reduce exposure to single-source risk, particularly where supply is concentrated or where regulatory and compliance expectations are tightening.
As the market moves deeper into this phase of scaling and standardization, the competitive edge will belong to organizations that can align material capability with operational reality. The most useful next step is to map current application requirements against supplier capabilities, identify where dispersion, quality, and compliance readiness matter most, and prioritize engagement with producers that can demonstrate measurable integration value rather than generic availability. Detailed segmentation data, supplier benchmarking, and application-specific pathway analysis can further sharpen these decisions and support more targeted commercial strategy.
For detailed analysis of this topic, please visit the official page: Carbon Nanotube (CNT) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
SPD Market Insights: Why 6.98% CAGR and $344.8M Value Redefine 2026 Growth
By PW Consulting, 2026-09-21
The Surge Protection Device Market at a Strategic Crossroads: Growth, Regulation, and the Shift Toward Integrated Infrastructure Protection
The global surge protection device (SPD) market has entered a phase of steady expansion, with total revenue crossing the $215 million mark in 2025 and a projected compound annual growth rate of 6.98 percent through 2032. The trajectory reflects a market that has evolved from a peripheral electrical accessory into a core component of resilient power infrastructure. Between 2020 and 2025, revenue climbed from approximately $163 million to $215 million, a pace that accelerated as building codes tightened, industrial automation expanded, and end users grew more sensitive to equipment downtime. Looking ahead, the market is expected to scale toward roughly $345 million by 2032, driven by a blend of regulatory mandates, electrification trends, and a structural shift toward smarter, more visible protection devices. Yet growth alone does not guarantee profitability or competitive advantage. The SPD landscape is shaped by a fragmented supplier base, shifting cost dynamics, and a regulatory environment that increasingly rewards devices with clear end-of-life signaling and fail-safe performance. For executives, investors, and procurement leaders, the question is no longer whether the market is expanding, but how value is being captured across regions, product categories, and end-use segments, and where strategic positioning can create durable differentiation.
A Market Characterized by Broad Adoption and Concentrated Competition
The overall market size has grown consistently over the past half-decade, with the most pronounced step-up occurring between 2022 and 2025. That acceleration aligns with a broader push toward protective infrastructure in both new construction and retrofit projects, as well as increased awareness of transient overvoltage risks in sensitive industrial and commercial environments. The forecast period through 2032 points to continued expansion, though the pace suggests a maturing market rather than a hypergrowth phase. Revenue growth is expected to be supported by higher penetration in industrial and commercial applications, where the cost of downtime and equipment damage far exceeds the upfront expense of protection devices. At the same time, residential adoption is expanding more gradually, constrained by installation complexity and cost sensitivity among homeowners.
Competition in the SPD market remains moderately concentrated, with the top three firms accounting for roughly 24.6 percent of revenue and the top five reaching about 26.2 percent. This concentration level indicates that while established players hold meaningful share, a long tail of regional and specialized manufacturers continues to compete on price, application-specific engineering, and local service relationships. The market structure creates both opportunity and vulnerability. Incumbents with broad product portfolios and strong compliance credentials can leverage scale and brand trust, while smaller firms can win in niche segments by addressing specific signal-level protection, hazardous-area needs, or localized regulatory requirements. The net effect is a market where differentiation is increasingly tied to integration, certification agility, and lifecycle visibility rather than standalone surge suppression performance alone.
Key Challenges and Inflection Points Shaping the Market
Several structural pressures are redefining how SPDs are specified, purchased, and maintained. The first is the growing emphasis on end-of-life visibility and proactive maintenance. Regulatory expectations and engineering best practices are pushing devices toward clear status indication, remote monitoring, and fail-safe disconnection. This shift is changing procurement criteria: buyers are no longer evaluating SPDs solely on surge current ratings and certification, but also on how easily a device can be inspected, replaced, and integrated into maintenance workflows. The second challenge involves cost dynamics at the installation and ownership level. Whole-house and commercial panel-mounted SPDs typically require professional electrician labor, which adds meaningful upfront expense and can slow adoption in price-sensitive residential and small commercial segments. At the same time, energy and raw material cost pressures are being passed through the supply chain, raising the sticker price of premium units and creating a tension between protection quality and budget constraints. The third inflection point is the regulatory and standards environment itself. Updated editions of key safety and performance standards are reshaping product design requirements, particularly around testing, classification, and lifecycle behavior. Manufacturers must navigate a landscape where compliance is not static; it evolves with each standards cycle, affecting product roadmaps, certification timelines, and competitive parity across regions. Together, these forces are moving the market from a transactional hardware business toward a more service-aware, compliance-driven, and integration-focused market.
Worldwide Ethernet Surge Protector Market
Key Drivers of Market Change
The market's trajectory is being shaped by four interlocking drivers: technological innovation, regulatory momentum, shifting demand-side behavior, and supply-side cost structures. Each driver influences not only volume growth but also the mix of products that win in different applications.
Technological Innovation: From Standalone Suppression to Integrated, Intelligent Protection
Innovation in SPDs is increasingly centered on integration, miniaturization, and lifecycle management rather than raw surge-handling capability alone. Modular and plug-in architectures are reducing installation friction by enabling faster replacement and panel-level integration without extensive rewiring. Narrow-profile designs are gaining traction in space-constrained distribution boards and control panels, where engineers must balance protection with physical layout constraints. At the device level, thermally protected MOV-based solutions and gas discharge tube combinations continue to evolve, with an emphasis on fail-safe disconnection that prevents a degraded device from becoming a hazard after repeated stress events. Equally important is the move toward end-of-life signaling and remote indication. As maintenance teams face higher labor costs and more complex asset portfolios, SPDs that can communicate status or provide clear visual indicators are becoming more valuable because they reduce inspection uncertainty and support planned replacement. This trend is especially relevant in commercial and industrial environments, where downtime avoidance is a primary purchase driver and where SPDs are increasingly specified as part of a broader power quality and resilience strategy rather than as isolated hardware.
Policy and Regulatory Environment: Standards as a Design and Competitive Force
Regulatory frameworks are no longer just compliance checkpoints; they are actively shaping product architecture and procurement standards. Updated editions of UL 1449 have reinforced expectations around end-of-life visibility, pushing manufacturers to design devices with clearer status feedback and more predictable maintenance behavior. Complementary updates to IEC standards for low-voltage AC SPDs have refined performance parameters, making it easier to compare devices across international supply chains while also raising the bar for consistent test compliance. In parallel, electrical code cycles and regional building requirements continue to influence where SPDs are mandated or strongly recommended, particularly in new construction and major renovations. The practical effect is twofold. First, compliance credentials are becoming a more significant competitive moat, because certification timelines and test coverage can delay product launches and affect market access. Second, specifiers are increasingly writing requirements around lifecycle behavior and maintenance readiness rather than surge rating alone, which rewards manufacturers that can demonstrate robust design, clear documentation, and reliable post-event behavior.
Demand-Side Shifts: Electrification, Downtime Sensitivity, and Professionalization of Installation
Demand is being reinforced by several structural changes in how power is consumed and protected. Industrial automation, data-dependent commercial operations, and the proliferation of sensitive electronics have raised the cost of transient overvoltage events, making protection a more visible line item in facility planning. In commercial and industrial settings, SPDs are increasingly bundled into broader power distribution and switchgear discussions, which shortens specification cycles when devices are already aligned with recognized panel or switchgear platforms. At the same time, installation patterns are shifting toward a more professionalized model. Whole-house and larger commercial installations often require qualified electricians, and that labor requirement introduces both cost and scheduling considerations for end users. As a result, demand is strongest where the protection value is easy to quantify, where installation can be streamlined, or where devices are integrated into equipment that is already being purchased for other reasons. Residential demand is growing more slowly, partly because the value proposition must overcome both cost sensitivity and installation friction, though it is supported by broader home resilience trends and insurance-related awareness.
Supply Chain and Cost Structure: Material Pressures, Pricing, and Value Perception
On the supply side, energy costs and raw material prices have been moving through the value chain, affecting both manufacturer margins and end-user pricing. Premium surge protection devices are not immune to these pressures, and in some cases the price increase has created hesitation among cost-conscious buyers. That dynamic is important because it can widen the gap between basic and advanced devices, potentially slowing adoption of higher-specification products unless their value is clearly communicated. At the same time, periodic maintenance and component replacement introduce recurring cost considerations, especially where maintenance teams must inspect and replace elements such as MOVs or gas discharge tubes over time. These factors are nudging the market toward designs that reduce inspection burden, simplify replacement, and provide better visibility into device health. The broader implication is that cost is no longer just an upfront purchase decision; it is increasingly a total-cost conversation that includes installation labor, maintenance effort, downtime risk, and the reliability of end-of-life handling.
Competitive Landscape and Leading Strategies
The competitive field is anchored by a group of large, diversified electrical and power management companies, alongside specialized players with strong application-specific engineering. The market's moderate concentration suggests room for both broad-portfolio scale play and targeted differentiation. Several recent product and documentation moves illustrate how leading firms are positioning themselves.
Incumbent Strategies: Integration, Compliance Breadth, and Application-Specific Solutions
Schneider Electric has emphasized integration into commercial and industrial distribution boards, extending plug-in SPD offerings that fit into existing panel ecosystems without requiring additional bolt-on enclosures or upstream devices. The strategic intent is clear: make surge protection easier to specify and install by aligning it with recognized load centre and panel platforms, while also improving visibility through end-of-life monitoring and remote indication. This approach targets the commercial and industrial segments where downtime avoidance and maintenance planning matter most. Siemens has taken a related but distinct path, embedding ground reference monitoring into low-voltage switchgear and panels and positioning residential and commercial SPD families as part of a broader protection and power distribution conversation. By tying SPD functionality closer to the equipment already present in the system, Siemens is reinforcing an integrated-infrastructure narrative rather than treating surge protection as an add-on. Eaton continues to focus on high short-circuit current ratings and UL 1449 compliance within power distribution systems, UPS, and switchgear, appealing to buyers who want protection tightly coupled with rated distribution equipment and clear compliance credentials. ABB offers a broad type coverage across Type 1, Type 2, and Type 3 devices, including modular and industrial overvoltage ranges aligned with IEC and UL standards, which supports customers seeking multi-tier protection across different installation points. Mersen has concentrated on thermally protected, fail-safe designs and updated its technical documentation to reflect current UL 1449 and NEC expectations, signaling an emphasis on lifecycle safety and code-aligned specification support. Phoenix Contact has extended its surge protection range toward process automation, measurement and control signals, and hazardous-area environments, including ultra-narrow modular formats and designs optimized for industrial Ethernet and emerging communication protocols. This strategy targets the more specialized end of the market, where space constraints, signal integrity, and environmental requirements create higher engineering barriers.
The pattern across these players is not simply broader product lines; it is a strategic move toward integration points where protection can be specified more naturally, maintained more easily, and justified more clearly. Devices that fit into established panel systems, communicate status, or address signal-level protection in demanding environments are gaining traction because they reduce friction in both specification and operation.
Market Evolution: Integration, Specialization, and the Competitive Middle
The competitive landscape appears to be evolving along three axes. First, there is a push toward integration with existing infrastructure, whether in load centres, switchgear, UPS, or automation panels. This reduces installation burden and improves specification flow, but it also raises the importance of platform compatibility and cross-product validation. Second, there is continued specialization in high-value niches such as signal-level protection, hazardous-area environments, and narrow-profile modular devices. These segments reward engineering depth and can command stronger margins when the application is clearly defined. Third, the market's moderate concentration leaves space for regional and application-focused competitors to compete on service, price, and local specification relationships, especially where procurement teams value responsiveness and localized support. The likely outcome over the next few years is not a simple shakeout, but a more layered competitive environment in which broad incumbents compete on integration and compliance breadth, specialists compete on application performance and environmental fit, and regional players compete on service and speed. Success will increasingly depend on how well a company can align product design, certification readiness, and lifecycle messaging with the way buyers actually specify and maintain SPDs.
Future Trends and Commercial Opportunities
Looking ahead three to five years, three trends are likely to shape where growth and margin opportunities emerge.
Trend 1: Lifecyle-Aware SPDs as a Specification Default
End-of-life visibility, remote indication, and fail-safe disconnection are moving from differentiating features to expected attributes in commercial and industrial applications. As maintenance labor costs rise and downtime becomes more expensive, buyers are likely to favor devices that reduce inspection ambiguity and support planned replacement. The commercial opportunity lies not only in selling hardware, but in aligning product design with maintenance workflows and specification language. Manufacturers that can clearly communicate lifecycle behavior and maintenance readiness may find an advantage in tenders and engineering specs, particularly where facility teams are responsible for large asset bases and limited inspection windows.
Trend 2: Integration into Distribution, Switchgear, and Automation Ecosystems
SPD adoption is likely to accelerate where protection can be incorporated into equipment that is already being procured for other reasons. Plug-in architectures, narrow-profile modular devices, and panel-aligned designs reduce installation friction and make surge protection easier to bundle into broader infrastructure decisions. This trend creates opportunity for suppliers that can demonstrate compatibility, streamline specification, and reduce labor burden. It also creates a challenge for more standalone offerings, which may face longer specification cycles unless they solve a clearly differentiated application need. The strategic implication is that integration is becoming a growth multiplier, especially in commercial and industrial segments where the value of protection can be tied directly to uptime and equipment protection.
Trend 3: Standards-Driven Product Cycles and Regional Divergence
As standards continue to evolve, product cycles will be shaped less by a single breakthrough and more by recurring compliance updates, test coverage, and documentation rigor. Companies that can manage certification agility and keep pace with evolving requirements will be better positioned to maintain market access across regions. At the same time, regional differences in code adoption, installation practice, and preferred product formats will continue to create uneven opportunity sets. In some markets, residential and small-commercial growth may remain constrained by labor cost and price sensitivity, while industrial and larger commercial deployments continue to expand at a steadier pace. The opportunity here is to treat standards and regional requirements as a design input rather than an afterthought, especially for manufacturers with global ambitions or multi-market portfolios.
Risks and Uncertainties
Several uncertainties could alter the pace or shape of growth. Persistent raw material and energy cost pressure could keep upward pressure on pricing, potentially slowing adoption of premium devices in cost-sensitive segments. Labor availability and installation cost may continue to constrain residential and small-commercial uptake, especially where whole-house solutions require professional installation. Standards evolution can also create transitional friction, as products are updated, re-tested, or repositioned to meet revised requirements. Finally, the market's moderate concentration means competitive dynamics can shift if regional players gain traction through service, pricing, or localized specification relationships. These risks do not undermine the growth outlook, but they do suggest that execution quality around compliance, integration, and cost communication will matter as much as product performance.
Implications for Decision Makers
The SPD market is no longer just a story about surge current ratings and basic certification. It is increasingly a story about how protection is specified, installed, maintained, and integrated into broader infrastructure. That shift creates different implications for different roles.
For Manufacturers
Differentiate through integration and lifecycle visibility rather than hardware specifications alone. Devices that fit naturally into established panel, switchgear, or automation ecosystems, and that provide clear status feedback or fail-safe behavior, are better positioned for specification in commercial and industrial environments. Equally important is certification readiness and documentation discipline, since evolving standards can influence both market access and buyer confidence. Manufacturers should also consider how installation labor and maintenance effort affect total cost perception, because reducing friction at deployment and inspection can be as valuable as improving surge-handling performance. Where possible, targeting high-value niches such as signal-level protection, hazardous-area environments, or narrow-profile modular formats can create stronger margins and more defensible positioning.
For Investors
Focus on business models and product strategies that benefit from recurring specification pull rather than one-off hardware sales. Value is likely to accrue to companies that can align with integration points, demonstrate compliance agility, and communicate total-cost advantages in downtime-sensitive segments. The market's moderate concentration suggests that scale alone does not guarantee outsized share gains; differentiation through application fit, lifecycle design, and specification alignment may be more durable. Investors should also watch how standards updates affect product roadmaps and regional access, because compliance execution can become a competitive differentiator or a launch bottleneck depending on the company's readiness.
PW Consulting
For Procurement and Specification Teams
Move the evaluation conversation beyond upfront price and basic ratings. Include installation labor, maintenance visibility, replacement simplicity, and compliance documentation in the selection criteria, because these factors increasingly determine real-world total cost and operational risk. Where possible, favor devices that integrate with existing distribution or panel platforms, and verify that end-of-life signaling or status indication aligns with your maintenance processes. In commercial and industrial contexts, specify for lifecycle behavior and downtime avoidance as much as for surge handling, since the clearest value often comes from reducing inspection uncertainty and planned replacement friction. In residential or small-commercial settings, weigh installation complexity and labor cost carefully, because these can be the main barriers to adoption even when the protection rationale is sound.
Surge Arresters Market
Strategic Intelligence as a Decision Multiplier
The SPD market is moving through a period in which growth is real, but value capture is uneven. Companies that treat surge protection as an integrated, lifecycle-aware, and standards-aligned part of infrastructure planning are better positioned to win specification, reduce installation and maintenance friction, and build credibility with buyers who are increasingly focused on uptime and operational resilience. For organizations making build, buy, partner, or specification decisions, the most useful intelligence is granular: it connects regional requirements, product formats, end-use dynamics, and competitive moves to the specific segments where a strategy will actually be tested. Detailed segmentation data, competitive profiling, and scenario analysis can help turn broad market direction into concrete commercial choices. For readers seeking a deeper dive into subsegment breakdowns, regional nuances, and customized strategic implications, the full PW Consulting market research report provides the structured detail needed to support planning and execution at the segment level.
For detailed analysis of this topic, please visit the official page: Surge Protection Device (SPD) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


