



Category: market research
Traffic Signs Market Forecast 2026-2032: The 7.75% CAGR Reshaping Industry Growth
By PW Consulting, 2026-09-21
The Traffic Signs Market at an Inflection Point: Strategic Trends and Commercial Opportunities Through 2032
The global traffic signs market is navigating a structural transition. Over the tracking period from 2020 through 2025, the sector expanded from approximately USD 44.59 million to a projected USD 64.76 million, and forward estimates point to continued growth toward nearly USD 110 million by 2032, supported by a compound annual growth rate of 7.75%. The trajectory signals more than routine infrastructure renewal. It reflects a convergence of regulatory tightening, material cost volatility, and the early stages of digital-physical integration in road safety infrastructure. For executives, planners, and investors, the question is no longer whether the market will grow, but which segments of the value chain will capture disproportionate value as standards evolve and procurement models reorganize.
Worldwide Traffic Signal Recognition Market
The numbers outline a market that has recovered from pandemic-era procurement pauses and is now anchored by sustained public investment in road safety, urbanization-driven signage demand, and incremental modernization of legacy traffic control systems. Historical data shows consistent year-over-year expansion, with the jump from 2023 to 2024 indicating a stabilization phase before the 2025 baseline accelerates. The forecast period through 2032 suggests that growth will not be linear; rather, it will be shaped by policy adoption cycles, regional infrastructure pacing, and manufacturers’ ability to navigate input cost pressure while maintaining compliance with evolving visibility and performance standards.
Market Reality and Core Challenges
The market’s expansion is real, but it is unfolding against a backdrop of operational friction. Three challenges stand out as particularly consequential for strategic planning.
Material Cost Volatility and Margin Compression
Aluminum remains the primary substrate for most traffic sign blanks, and its pricing dynamics have introduced a new layer of risk into production planning and bid economics. Through late 2025, Midwest Premium aluminum prices climbed approximately 190% year-over-year, a spike that compresses margins for manufacturers working under fixed-price municipal contracts or competing in price-sensitive procurement environments. This is not merely a cost issue; it reshapes sourcing strategies, inventory timing, and the economics of sign blank production versus finished sign assembly. Companies that rely heavily on coil stock and blank production are exposed to raw material volatility in ways that differentiate their cost structures from firms focused on value-added assemblies, illuminated solutions, or traffic calming systems.
PW Consulting
Regulatory Visibility Standards and Compliance Complexity
Visibility and retroreflectivity requirements are becoming more prescriptive, raising the bar for what qualifies as a compliant permanent traffic control sign. In Ohio, for example, guidance from the Department of Transportation has moved toward recommending Type III retroreflective sheeting for all permanent new traffic control signs on maintained highways, while also requiring Type IV, IX, or XI sheeting in specific contexts. These requirements are part of a broader standardization trend that ties sign performance to measurable visibility outcomes rather than legacy material norms. Compliance complexity is increasing because regulators are not only specifying sheeting grades but also linking them to placement, maintenance cycles, and nighttime performance expectations. For manufacturers and contractors, the operational implication is clear: product specifications that fall behind evolving standards risk disqualification in public tenders, while faster adoption can become a competitive differentiator.
At the same time, the broader framework governing traffic control devices continues to evolve. Recent updates to MUTCD standards are reinforcing visibility, placement, and performance requirements across a range of sign and traffic calming products. That means compliance is no longer a one-time certification exercise; it is an ongoing design constraint that affects product development cycles, testing protocols, and field deployments.
Procurement Fragmentation and the Pressure to Standardize
Traffic sign procurement remains fragmented across municipalities, state agencies, contractors, and cooperative purchasing vehicles. This fragmentation creates both opportunity and inefficiency. On one hand, it allows specialized providers to serve niche applications and regional preferences. On the other hand, it slows the adoption of higher-performance materials and limits scale economies for standardized solutions. The tension is visible in the market’s concentration profile, where a meaningful share of revenue is held by a relatively small group of firms, yet substantial demand still flows through dispersed buyers with varied specifications and purchasing timelines. As cooperative purchasing contracts and multi-agency frameworks expand, the market may tilt toward more standardized product families, but the transition will be uneven across regions and agency types.
Core Drivers Reshaping the Market
Technology Innovation: From Passive Signage to Active Visibility
One of the most significant shifts in the market is the move beyond static signage toward solutions that enhance driver awareness through illumination, flashing elements, and sensor-linked warnings. Solar-powered flashing warning signs, radar speed displays, and pedestrian crossing enhancements are expanding the definition of what a traffic sign can do. This is not a wholesale replacement of traditional signs, but an incremental layering of active visibility features where risk is higher or compliance requires stronger behavioral cues. The commercial relevance is that these products command different margin structures, different installation requirements, and different procurement justifications than passive blanks or reflective signs. Manufacturers that can combine compliance-grade base products with active visibility add-ons are positioned to capture value in applications where safety outcomes are measured and funded more explicitly.
The traffic calming segment illustrates this dynamic well. Products that integrate static signs with radar-based feedback, flashing warnings, and pedestrian-crossing enhancements are increasingly tied to public agency goals around speed management and intersection safety. As these solutions become more standardized and more visibly effective, they create a bridge between traditional sign manufacturing and the broader traffic safety equipment market.
Policy and Regulatory Momentum around Safety Outcomes
Policy is becoming a more direct driver of demand because road safety is increasingly framed around measurable outcomes rather than routine maintenance. Regulatory bodies and transportation departments are sharpening requirements for retroreflectivity, sheeting performance, and device visibility. This policy momentum benefits suppliers that can demonstrate compliance, provide documentation, and align product roadmaps with emerging standards. It also raises the importance of regulatory intelligence as a commercial capability. Companies that anticipate updates to visibility standards, understand regional interpretations, and design products with forward compliance in mind reduce the risk of specification obsolescence and improve their positioning in agency procurement.
A related policy driver is the increasing use of cooperative purchasing frameworks, which can broaden access to compliant products for public agencies while also creating more transparent price discovery. Recent contract awards that expand public agency access to MUTCD-compliant safety solutions show how procurement channels themselves are becoming a strategic lever. For manufacturers, inclusion in such frameworks can shorten sales cycles and increase volume predictability, but it also intensifies competition on specification, availability, and total cost of ownership.
Traffic Signal Controller Market
Demand-Side Shifts in Municipal and Regional Procurement
Demand is being shaped by a shift in how public agencies think about signage and safety infrastructure. Instead of treating signs purely as replacement items, agencies increasingly evaluate them within broader safety programs, work zone management plans, and traffic calming initiatives. That shift changes the sales narrative from unit price to functional outcome. It also expands the relevant buying center, bringing engineering, safety, and maintenance teams into the decision process alongside procurement. As a result, suppliers that can articulate performance benefits, maintenance implications, and compliance documentation are gaining an advantage over those competing primarily on material cost.
In addition, the demand mix is diversifying by application type. Guide and direction signs, warning signs, regulatory signs, and other specialized signage each serve different operational contexts, and the relative importance of each category varies by region and project type. The broader point is that demand is not monolithic. Growth is being distributed across categories with different replacement cycles, specification sensitivity, and installation complexity. Understanding which application categories are tied to higher-frequency renewal cycles versus longer-life installations is essential for revenue forecasting and capacity planning.
Supply Chain and Cost Structure Reconfiguration
The supply chain for traffic signs is being tested by material input volatility, logistics complexity, and the need to maintain consistent quality across reflective sheeting, metal substrates, and ancillary hardware. Cost structure is becoming a strategic differentiator rather than a back-office concern. Manufacturers that can manage blank production efficiently, secure stable sheeting supply, and reduce lead-time variability gain latitude in pricing and bidding. At the same time, regional manufacturing footprints matter more as agencies and contractors look for predictable delivery, localized support, and lower total installed cost. In this environment, the competitive edge often lies in combining material sourcing discipline with application-specific product configuration, rather than pursuing scale alone.
The rise of export-oriented manufacturers also adds a global dimension to supply dynamics. Some producers have built positions serving a wide range of countries with certifications that support cross-border distribution. That creates price and availability competition in certain segments while also giving buyers more options for specification-matched products. The strategic response for established players is not simply to compete on price, but to reinforce compliance assurance, service responsiveness, and product consistency that are harder to replicate through transactional importing.
Competitive Landscape and Leading Strategies
The competitive field includes a mix of specialized U.S. manufacturers, export-oriented producers, and broader traffic systems providers. Several patterns define the current landscape.
A group of North American companies has built its positioning around MUTCD and DOT compliance for static signs, custom reflective aluminum signs, work zone products, and related control signage. These firms compete heavily on specification alignment, availability, and familiarity with public agency procurement requirements. Their differentiation often comes from product breadth within compliant signage categories, responsiveness to municipal and contractor demand, and the ability to supply both standardized and custom configurations. In a market where compliance documentation and material consistency matter, that positioning can be durable, especially when paired with cooperative purchasing access or strong regional distribution.
A second grouping emphasizes traffic calming and active visibility solutions. These providers extend beyond traditional sign blanks into radar speed displays, flashing warning signs, pedestrian crossing enhancements, and related systems. The strategic advantage here is category expansion: by offering products that address speed management and driver awareness directly, these companies can participate in projects where safety outcomes are prioritized and where funding is tied to measurable behavior change or risk reduction. This approach also diversifies revenue beyond replacement-driven signage demand, though it requires investment in product development, testing, and sometimes field support.
A third dimension is represented by broader traffic systems providers with portfolios spanning standard signs, variable message signs, dynamic signage, and illuminated solutions for highways and urban environments. These companies compete by offering integrated capability across static and dynamic categories, which can be attractive for larger projects or regions pursuing modernization programs. Their scale and portfolio breadth allow them to address multiple signage functions within a single engagement, but they must still navigate the same regulatory and material pressures as more specialized players.
Recent market activity shows how these strategies are playing out. One U.S. traffic calming provider expanded access to public agencies through a cooperative purchasing contract, strengthening the procurement channel for MUTCD-compliant safety solutions. Around the same time, the same provider introduced new solar flashing warning signs designed to improve visibility and driver awareness on critical roadways. These moves illustrate a combined strategy of channel expansion and product refresh aimed at active visibility applications. In parallel, an Austrian traffic systems provider previewed next-generation sign solutions at a major industry event, signaling continued investment in advanced signage portfolios for highways and urban deployments. Together, these developments suggest that competition is intensifying not only in price, but in channel access, product modernization, and the ability to meet evolving visibility expectations.
The market is also likely to see continued differentiation between firms that compete primarily as commodity-adjacent sign suppliers and those that position around performance, compliance assurance, and application-specific solutions. Consolidation may occur where scale, sourcing, and distribution advantages can be combined, while fragmentation may persist in specialized or region-specific segments where local service and specification knowledge matter. New entrants are most likely to appear in active visibility and traffic calming niches, where the link between product capability and safety outcome is more direct and where procurement narratives increasingly favor demonstrated performance.
Forward Trends and Commercial Opportunities
Active Visibility and Solar-Enabled Signage Will Move from Niche to Mainstream in Targeted Applications
Over the next three to five years, active visibility features are likely to become more common in high-risk corridors, school zones, pedestrian crossings, and work zone environments. Solar flashing warning signs and radar-linked displays will continue to gain traction where agencies need stronger behavioral cues and where wiring or grid access is impractical. The commercial opportunity lies in bundling these solutions with compliant base signage and installation support, creating offerings that are easier for agencies to adopt as part of broader safety programs. The risk is that active visibility products may face their own specification, maintenance, and durability scrutiny, so suppliers will need to invest in field reliability and documentation as well as initial performance claims.
Regulatory-Driven Material Upgrades Will Reset Product Standards and Replace Legacy Inventory
As visibility and sheeting requirements become more prescriptive, there will be a multi-year cycle of material upgrades and replacement demand. This creates a commercial window for manufacturers and distributors that can supply compliant retroreflective materials, upgrade existing product lines, and help agencies manage transition timelines. It also raises a strategic risk for suppliers whose product portfolios lag behind emerging standards. The opportunity is not just in selling new signs, but in helping buyers navigate the shift from older materials to higher-performance sheeting, including guidance on applicability, installation, and maintenance expectations. Firms that treat regulatory change as a product strategy input rather than a compliance afterthought will be better placed to capture this cycle.
Regional Demand Divergence Will Reward Segment-Specific Positioning
Demand growth will not unfold uniformly. Regions with faster urbanization, more active road safety programs, and stronger cooperative procurement frameworks are likely to show stronger momentum, while other markets may remain dependent on replacement cycles and budget pacing. For manufacturers and investors, this means that broad market averages can obscure where the most attractive opportunities actually sit. The more productive approach is to align product portfolios, distribution capacity, and pricing strategy with regional demand characteristics and procurement behavior. Companies that can tailor offerings to specific application mixes, agency types, and compliance expectations will be better positioned than those relying on a single standardized playbook.
For the materials and cost side, the forward risk is that aluminum and sheeting volatility may persist in cycles, making hedging, sourcing flexibility, and product mix optimization increasingly important. Suppliers that can shift emphasis toward higher-value assemblies, active visibility products, or service-linked offerings may be better insulated than those dependent on low-margin blank production alone.
Strategic Recommendations for Decision Makers
For Manufacturers and Product Leaders
- Align product roadmaps explicitly with evolving visibility and sheeting standards so that compliance becomes a design input rather than a retrofit exercise.
- Expand into active visibility and traffic calming adjacencies where safety outcomes support stronger value propositions and differentiate pricing from commodity sign supply.
- Build sourcing and inventory strategies that reduce exposure to metal input volatility, including flexible blank procurement, regional supply options, and product mixes that balance material-intensive and value-added items.
For Investors and Strategic Capital
- Evaluate exposure to regulatory-driven replacement cycles and active visibility adoption, since these dynamics can shape both revenue durability and margin profiles across different business models.
- Distinguish between players that compete primarily on price and commodity-like supply and those that have defensible positions in compliance, product reliability, channel access, or application specialization.
- Watch for consolidation opportunities where regional distribution, cooperative purchasing access, and product breadth can be combined to improve scale and customer retention.
For Procurement Agencies and Contracting Entities
- Standardize specifications around current visibility and performance expectations to reduce specification lag and improve comparability across bids.
- Evaluate total cost and safety outcomes rather than unit price alone, especially when considering active visibility or higher-performance sheeting that may reduce long-term maintenance or improve driver response.
- Use cooperative purchasing and multi-agency frameworks strategically to expand access to compliant products while maintaining specification rigor and vendor accountability.
The traffic signs market is entering a phase where growth is increasingly tied to how well participants navigate regulatory change, material cost pressure, and the shift toward active visibility. The companies that will capture the most value are those that can combine compliance confidence with product modernization and efficient cost structures, while also understanding how demand differs by region, application, and procurement channel. For executives and investors looking to move from market awareness to detailed segmentation, competitive mapping, and tailored commercial strategy, a full research report can provide the deeper breakdown needed to support decisions with precision.
For detailed analysis of this topic, please visit the official page: Traffic Signs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Calcium Formate Market: The Real Drivers Behind 7.2% CAGR Growth Through 2032
By PW Consulting, 2026-09-21
The Calcium Formate Market: Strategic Shifts and Commercial Opportunities Through 2032
The global calcium formate market has entered a period of steady expansion, characterized by consistent value growth and shifting demand patterns across construction, animal nutrition, and industrial applications. Valued at 495.16 million USD in 2020, the market climbed to 701.0 million USD by 2025, reflecting a compound annual growth rate of approximately 7.2 percent through the forecast horizon extending to 2032. By the close of the projection period, market value is positioned to surpass 1.14 billion USD, driven by structural demand in fast-setting construction chemistries, feed preservation formulations, and specialty industrial processes. The trajectory signals a transition from steady commodity positioning toward a more differentiated landscape where grade purity, regional supply reliability, and regulatory compliance increasingly dictate commercial outcomes.
A Market at an Inflection Point
While the headline growth figures suggest uninterrupted expansion, the underlying dynamics reveal a sector navigating several concurrent pressures. First, raw material cost volatility is reshaping margin structures across the value chain. Formic acid serves as the primary feedstock for calcium formate production, and recent pricing actions in European markets have directly altered production economics. A March 2026 price increase of 250 Euro per metric ton on formic acid immediately elevated input costs for downstream calcium formate manufacturers, compressing margins for producers operating without index-linked contracts or hedging mechanisms. This shift forces a reassessment of regional sourcing strategies and accelerates interest in vertically integrated or regionally balanced supply models.
Potassium Formate Market
Second, regulatory frameworks are redefining permissible use levels and creating new pathways for market entry. The formal approval of calcium formate as a feed acidifying agent for swine and poultry at up to 1.2 percent of complete feed marked a significant clarification for formulators and premix suppliers. Simultaneously, a 2026 consultation process in Canada regarding pre-market amendment of the Feeds Regulations, 2024 signals ongoing scrutiny and evolving approval timelines for new feed ingredient categories. For market participants, regulatory clarity expands addressable demand in animal nutrition, but inconsistent regional approval pathways introduce compliance complexity and extended time-to-market for cross-border product rollouts.
Third, demand-side shifts are altering grade prioritization and application mix. Construction chemical formulators continue to prioritize calcium formate for its performance in cold-weather concrete acceleration, tile adhesives, and dry-mix mortar systems, particularly in markets experiencing infrastructure renewal or seasonal construction constraints. At the same time, feed preservative demand is expanding where producers seek alternative acidifiers with favorable handling characteristics and compatibility with existing premix architectures. These parallel demand streams are pulling the market in different technical directions, requiring suppliers to maintain distinct product specifications rather than relying on a single commodity-grade offering.
PW Consulting
The competitive structure remains relatively fragmented, with the top three suppliers accounting for approximately one-quarter of total market value and the top five capturing just over one-quarter. This concentration pattern indicates meaningful room for regional differentiation and specialized positioning, but it also underscores the importance of scale efficiency, technical service capabilities, and supply continuity as competitive differentiators.
Core Drivers Reshaping the Market
Several interconnected forces are redefining how value is created and captured across the calcium formate landscape. Understanding these drivers provides the foundation for investment, sourcing, and product strategy decisions.
Feedstock dynamics and cost architecture. The relationship between formic acid pricing and calcium formate production economics is central to profitability. Recent European formic acid pricing adjustments have illustrated how quickly input costs can shift, particularly when supply is concentrated in specific regional hubs or affected by broader chemical market cycles. Producers with access to captive or long-term feedstock supply, or those positioned in regions with lower feedstock volatility, gain a structural cost advantage. Conversely, manufacturers relying on spot procurement face greater exposure to margin compression. This dynamic is encouraging a reevaluation of sourcing footprints, including regional substitution, dual-supplier strategies, and contractual structures that link cost pass-through to finished-grade pricing.
Regulatory evolution as a demand catalyst and barrier. Regulatory developments are simultaneously unlocking demand and adding compliance complexity. The formal recognition of safe use levels for calcium formate in swine and poultry feed creates a clearer formulation pathway for feed acidifiers, supporting demand in animal nutrition where gut health, preservation, and feed efficiency remain priorities. At the same time, ongoing consultation processes in markets such as Canada demonstrate that ingredient approval is not a one-time event but a continuous regulatory management requirement. Companies that treat regulatory alignment as a core commercial capability—rather than a backend compliance function—can accelerate market access and reduce the risk of reformulation delays.
Construction chemical performance requirements. Demand from construction applications continues to be shaped by performance needs that go beyond simple set acceleration. Formulators increasingly look for calcium formate grades that deliver reliable performance across varying temperature conditions, compatibility with diverse binder systems, and consistency in dry-mix and pre-blended mortar applications. Cold-weather concreting, tile adhesive performance, and corrosion-inhibition considerations in certain applications add technical nuance to procurement decisions. As infrastructure investment cycles and housing activity patterns shift regionally, suppliers that can provide application-specific grade optimization and technical support are better positioned to retain share even when price competition intensifies.
Animal nutrition and feed preservation trends. In the feed segment, demand is influenced by broader livestock production practices, biosecurity concerns, and the search for preservative solutions that integrate cleanly into existing feed formulations. Calcium formate's role as an acidifying and preserving agent aligns with formulator interest in ingredients that support feed stability and handling while meeting defined safety thresholds. The expansion of permitted inclusion levels in certain species has broadened the formulation envelope, allowing feed manufacturers to optimize dosage strategies without compromising compliance. This development is particularly relevant where producers aim to replace or supplement more traditional acidifiers with alternatives offering favorable handling, dust, or storage characteristics.
Competitive Positioning and the Evolution of the Landscape
The supplier landscape spans established multinational producers, specialized chemical manufacturers, and regional players concentrated in Asia Pacific, Europe, and North America. Rather than competing solely on price, leading participants are differentiating through grade specialization, application support, regional supply reliability, and selective expansion into higher-value industrial or feed-grade niches.
Multinational producers with broad chemical portfolios tend to emphasize high-purity calcium formate for construction, adhesives, and industrial uses, leveraging existing distribution networks and technical service capabilities. Their positioning often centers on specification consistency, regulatory documentation, and the ability to support large-formulation customers with product reliability across multiple markets. For these players, scale and portfolio breadth can translate into stronger relationships with specification-driven buyers who prioritize supply continuity and quality assurance.
Formic Acid Market
Specialized producers focused on green or application-specific calcium formate are carving out distinct positions in feed additives and construction chemicals. By aligning product development with sustainability narratives or regional performance requirements, these companies seek to reduce direct price comparison with commodity-grade alternatives. For feed-focused participants, the strategic emphasis is often on formulation compatibility, safe-use documentation, and regional regulatory readiness. For construction-focused participants, differentiation frequently comes through performance consistency in dry-mix mortars, tile adhesives, and cold-weather accelerators, alongside service responsiveness to formulator testing and customization needs.
Regional manufacturers, particularly in Asia Pacific, play an important role in meeting volume demand across feed and construction applications. Their growth trajectory is supported by proximity to feedstock supply, expanding domestic construction activity, and increasing integration into export-oriented supply chains. At the same time, these players face pressure to demonstrate grade consistency, regulatory compliance for destination markets, and reliable logistics performance as customers diversify their sourcing bases. The result is a landscape where regional scale and technical credibility increasingly coexist as prerequisites for broader market access.
Market structure appears to be evolving along several lines. Consolidation is plausible in segments where scale in feedstock procurement, production efficiency, and regional distribution provides durable advantages, particularly among suppliers targeting large construction-chemical or feed premix customers. At the same time, fragmentation is likely to persist where regional demand patterns, regulatory nuances, and application-specific requirements reward localized production and customized grade offerings. New entrants may find opportunities in niche industrial-grade supply, laboratory and research channels, or specialized feed-additive formulations, especially where incumbents are less focused on small-volume, high-specification segments. Recent feedstock pricing dynamics also suggest that competitive advantage will increasingly depend on cost management agility rather than volume alone, favoring companies that can adapt pricing, sourcing, and product mix quickly.
Forward Outlook: Three Trends to Watch Through 2032
Looking ahead, several trends are likely to shape commercial outcomes over the next three to five years. Each trend carries implications for strategy, risk management, and opportunity capture.
Trend 1: Feedstock-linked margin management becomes a core competitive capability. With formic acid pricing subject to regional volatility and periodic sharp adjustments, producers that institutionalize feedstock cost management—through long-term contracts, regional sourcing diversification, index-linked pricing mechanisms, or selective vertical integration—will be better positioned to protect margins. The commercial implication is clear: cost resilience will increasingly differentiate winners from laggards, especially in periods when raw material spikes cannot be immediately passed through to customers. Companies that fail to build flexible cost architectures risk margin erosion and reduced ability to invest in product development or regional expansion.
Trend 2: Regulatory alignment accelerates feed-grade demand in select markets while creating uneven global access. The formalization of safe use levels for calcium formate in swine and poultry feed expands the formulation toolkit for animal nutrition customers and supports demand growth where adoption is already underway. However, the staggered nature of regulatory consultations and approvals across jurisdictions means that market access will remain uneven. Feed-focused suppliers that invest early in regulatory documentation, regional approvals, and customer education are likely to capture first-mover advantages in markets where inclusion levels are clarified or expanded. Conversely, delays in approval pathways can constrain near-term commercialization even when underlying demand is strong.
Trend 3: Application-specific grade differentiation intensifies as construction and feed demand pull in different directions. Construction chemical requirements and feed preservation needs are not converging into a single commodity specification. Instead, they are reinforcing the need for distinct industrial-grade and feed-grade offerings, each with its own quality, handling, and compliance expectations. Suppliers that maintain clear grade separation, robust quality control, and transparent documentation will be better equipped to serve specification-sensitive buyers. This trend also creates opportunities for companies that can bridge multiple end-use segments, provided they avoid dilution of grade integrity or compliance positioning. At the same time, the growing emphasis on performance-specific grades may invite competitive pressure from alternative additives, requiring continuous demonstration of functional value rather than reliance on commodity positioning alone.
These trends are interconnected. Feedstock cost dynamics influence grade pricing and margin capacity for product development. Regulatory developments shape demand readiness in feed applications and affect the pace at which new formulations can be commercialized. Application-specific differentiation determines whether suppliers can sustain premium positioning or are forced into commodity price competition. Taken together, they point to a market where strategic agility, technical credibility, and regional execution matter more than simple volume scale.
Strategic Actions for Decision-Makers
The evolving calcium formate landscape presents distinct priorities depending on a decision-maker's position in the value chain.
For manufacturers and producers: Prioritize feedstock cost resilience and grade discipline. Evaluate sourcing contracts, regional supply options, and pricing mechanisms that reduce exposure to sharp feedstock swings. Maintain clear separation between feed-grade and industrial-grade offerings, supported by consistent quality control and documentation that meets destination-market requirements. Where feasible, build application-specific technical support capabilities to strengthen relationships with construction-chemical formulators and feed premix suppliers. Consider selective expansion into regions or segments where regulatory clarity is improving and where existing supply gaps create room for reliable, specification-driven participation.
For investors and corporate development teams: Assess exposure to feedstock volatility and regional regulatory pathways when evaluating opportunities. Companies with strong cost-management structures, clear grade positioning, and credible regulatory readiness are better placed to capture demand growth without sacrificing margin stability. Pay attention to market fragmentation as both a risk and an opportunity: fragmented markets can reward specialized, well-executed regional players, but they can also pressure undifferentiated suppliers into margin compression. Monitor consolidation signals in segments where feedstock procurement, production scale, or distribution density creates durable advantages, and evaluate whether potential targets have the technical and compliance capabilities to support broader commercial ambitions.
For procurement and supply chain leaders: Diversify sourcing strategies to reduce vulnerability to single-region feedstock disruptions and to improve responsiveness to grade-specific requirements. Establish specification frameworks that distinguish feed-grade and industrial-grade needs clearly, and align supplier selection with documentation, consistency, and delivery reliability rather than price alone. Where long-term supply relationships are in place, consider contractual structures that accommodate feedstock-driven cost movements while preserving budget predictability. Technical collaboration with suppliers can also help optimize dosage, handling, and formulation performance, turning procurement decisions into value-creating partnerships rather than transactional purchases.
Strategic decisions in this market benefit from detailed visibility into regional demand patterns, grade-level pricing dynamics, regulatory calendars, and competitive positioning. A comprehensive view of these variables supports more precise sourcing, investment, and product strategies, particularly as feedstock conditions and regulatory frameworks continue to evolve. For organizations seeking deeper segmentation data, region-level volume and value context, and customized scenario planning, PW Consulting's full market research report provides a structured foundation for next-step decision-making. The complete study extends beyond the trends summarized here, offering granular segmentation detail and tailored recommendations designed to support executive planning, investment evaluation, and supply strategy development.
For detailed analysis of this topic, please visit the official page: Calcium Formate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Feed Yeast Market: Why Live Yeast and Poultry Dominance Drive a 5.1% CAGR Through 2032
By PW Consulting, 2026-09-21
Navigating the Feed Yeast Market: Strategic Trends and Commercial Opportunities Through 2032
The global feed yeast market is entering a phase of measured but deliberate expansion. Over the past five years, the industry has evolved from a commodity-focused segment into a value-driven arena where strain specificity, functional efficacy, and supply chain reliability increasingly dictate purchasing decisions. By 2025, total market revenue reached approximately $150 million, reflecting a sustained upward trajectory from $115 million in 2020. The sector is projected to grow at a compound annual rate of 5.1 percent through 2032, when revenue is expected to approach $210 million. This growth profile signals more than incremental demand; it points to a structural shift in how livestock producers, aquaculture operators, and feed formulators view yeast-based inputs as functional nutrition tools rather than routine additives.
That said, the expansion is uneven, and the landscape carries notable friction. Market concentration remains pronounced, with the top three players accounting for roughly 65 percent of global revenue and the top five capturing over 82 percent. Such concentration reflects the capital intensity of modern fermentation infrastructure, the importance of technical service and veterinarian-level support, and the increasingly regionalized nature of regulatory requirements. For decision-makers, the implication is clear: scale alone no longer guarantees advantage. Differentiation, formulation expertise, and the ability to navigate shifting trade and compliance frameworks are becoming the decisive factors.
PW Consulting
Market Evolution and Structural Pressures
The feed yeast segment has matured along several axes simultaneously. Demand is being reshaped by tighter antibiotic restrictions, heightened scrutiny of gut health performance, and the broader movement toward preventive nutrition in monogastric and ruminant production. At the same time, the product portfolio has diversified beyond traditional live yeast into derivatives and spent yeast streams, each appealing to different technical and economic priorities. This evolution is not merely a story of more SKUs; it reflects a marketplace in which buyers are increasingly willing to trade a modest premium for measurable benefits in digestibility, pathogen binding, or stability during feed pelleting and storage.
Within this environment, a few structural pressures stand out as defining challenges for the next cycle. First, raw material economics create persistent volatility. The fermentation feedstock base that underpins Saccharomyces cerevisiae production remains sensitive to grain and energy inputs, and the average annual price for the core yeast input still ranges between $800 and $1,200 per metric ton as of 2025. This cost structure pressures margins and limits the ability of smaller players to compete on volume without sacrificing consistency or lead times. Second, trade policy is becoming a more material driver of regional pricing and sourcing decisions. In February 2026, a U.S. executive order introduced a 6.4 percent tariff on inactive yeasts under a specific tariff classification, excluding dried brewers’ yeast. While the measure does not apply uniformly across all feed yeast categories, it underscores how rapidly tariff exposure can alter the economics of cross-border supply and encourages buyers to reconsider sourcing portfolios. Third, regional production leadership is shifting the center of gravity in the market. China’s annual output now exceeds 200,000 tonnes and is primarily directed toward Asian and European markets, reinforcing a supply chain dynamic in which volume availability and export logistics play an outsized role in regional pricing behavior.
Core Drivers Reshaping the Market
Several interlocking forces are driving the current trajectory of the feed yeast market. Understanding these drivers is essential for evaluating where growth will materialize and which capabilities will translate into durable advantage.
Technological and Strain-Level Innovation
Innovation in this market is increasingly centered on strain selection, propagation efficiency, and functional reliability under real-world feeding conditions. The competitive edge is shifting from generic yeast inputs toward formulations designed for specific gastrointestinal targets, such as rumen stability, pathogen binding, or resilience during thermal processing. For producers, this means that manufacturing scale must be paired with application science: a large fermentation capacity is valuable, but the ability to document performance in target species and to provide technical guidance on inclusion rates and integration with other additives is what converts production capability into recurring demand. The industry context reinforces the point. Major producers operate fermentation infrastructure with annual capacity above 100,000 tonnes, yet the most differentiated offerings are increasingly defined by their functional claims and the evidence supporting them.
Regulatory and Compliance Environment
Regulatory dynamics are now a strategic variable rather than a background condition. Feed additives face varying approval pathways, renewal cycles, and labeling expectations across major markets. In Europe, for example, Alltech’s Yea-Sacc® yeast culture continues to be authorized for use in cattle feed under EFSA oversight, with renewals ongoing through 2025. Such continuity matters because it shapes buyer confidence in long-cycle procurement, especially for ruminant applications where health claims and compliance documentation carry significant weight. At the same time, the U.S. tariff action on certain inactive yeast categories illustrates the broader point that trade policy can alter the cost base of specific product types and incentivize formulation or sourcing shifts. Companies that actively monitor these regulatory and tariff signals, and that design portfolios with flexibility in mind, are better positioned to absorb shocks and preserve margin.
Yeast Market
Demand-Side Behavior and Animal Nutrition Priorities
The demand landscape is being reshaped by a combination of animal production economics and an evolving nutrition philosophy. Livestock operators are placing greater emphasis on gut health, feed conversion efficiency, and resilience to stress, especially in environments where preventive health strategies are replacing reactive treatments. Yeast-based inputs are increasingly evaluated through that lens: their value proposition is tied not only to nutrient contribution but also to functionality such as stabilization of the gastrointestinal environment, modulation of microbial balance, or binding of undesirable compounds. As a result, procurement decisions are becoming more evidence-driven, and buyers are more likely to seek technical support, trial data, and integration guidance alongside product specifications. This shift favors suppliers that can act as solution partners rather than simple vendors.
Supply Chain and Cost Structure Dynamics
Feed yeast production remains a scale-sensitive business. Fermentation, downstream processing, drying, and logistics all carry capital and operating requirements that reward continuity and keep smaller, underfunded entrants at a disadvantage. At the same time, the rise of integrated and cross-industry ownership is altering the supply base. A notable example is the acquisition of Leiber GmbH by Asahi Group Foods in March 2025, which consolidated brewers’ yeast production for both animal nutrition and food ingredient applications. Transactions of this type are not merely financial; they change operational priorities, improve access to certain raw material streams, and can create new avenues for cross-segment demand. For the feed yeast market, such moves hint at a broader trend in which ingredient producers seek to secure feedstock consistency, expand application portfolios, and reduce exposure to single-market volatility.
Competitive Landscape and Emerging Positioning
The competitive structure of the feed yeast market is dominated by a mix of global animal nutrition specialists, large ingredient companies, and regional producers with strong fermentation capabilities and technical service networks. The top players are not interchangeable; their strategic positioning reflects differences in geography, portfolio depth, application focus, and ownership structure. What unites the stronger performers is a tendency to build advantage around functional reliability and end-user support rather than price alone.
Among the firms shaping the current landscape, several patterns stand out. Angel Yeast has built a broad feed yeast portfolio spanning live yeast, inactive yeast, yeast extracts, and mycotoxin binders, and its scale-oriented production model is reinforced by participation in major trade forums such as SPACE 2025, where it showcased its full range of feed yeast solutions. This combination of volume capability and market-facing visibility helps the company maintain relevance across multiple buyer segments. Alltech continues to emphasize a more focused, science-backed approach through its Yea-Sacc® yeast culture for rumen health, leveraging regulatory continuity in Europe to support confidence in cattle feed applications. Lallemand and Lesaffre contribute from positions grounded in yeast strain expertise and broader animal health portfolios, often competing on the strength of application data and integrated nutrition messaging. Leiber’s position has evolved further following its acquisition, aligning brewers’ yeast capabilities with a larger group’s ingredient strategy and potentially expanding cross-market leverage. ADM, Novus, AB Agri, Chr. Hansen, Nutreco, and DSM-Firmenich each bring their own angles, whether through animal nutrition divisions, yeast cell wall components, or broader feed additive portfolios that incorporate yeast-derived inputs as part of a wider value proposition.
The market is not simply consolidating; it is also differentiating. Some players are moving toward integrated, multi-functional product systems, while others maintain a sharper focus on specific species or functional claims. The trend suggests a bifurcation in which scale and operational reliability protect share in commoditized segments, while application-specific formulation, documentation, and technical service drive growth in more demanding use cases. New entry is likely to remain difficult without access to fermentation capacity, regulatory fluency, and a credible technical narrative. At the same time, acquisition activity and cross-industry ownership may increase, especially where ingredient streams, regional distribution, or application expertise can be combined to create a stronger commercial position.
Worldwide Nutritional Yeast Market
Forward Outlook: Three Trends to Watch
Looking ahead to the 2026–2032 period, three developments are likely to define the commercial trajectory of the feed yeast market.
The first is a gradual shift from generic supplementation toward function-targeted formulations. As buyers increasingly evaluate yeast inputs for specific outcomes—such as rumen performance, gut stability, or resilience under stress—the market will reward products with clearer application narratives and stronger supporting evidence. Companies that invest in species-specific documentation, dosing guidance, and integration with other feed additives are more likely to secure repeat business and price resilience. The commercial opportunity here lies not just in product development but in the ability to translate technical claims into credible, practical recommendations for feed formulators and producers.
The second trend is regional recalibration of sourcing and pricing. Trade policy volatility, including tariff actions on certain inactive yeast categories, combined with concentrated production in key exporting countries, will encourage buyers to diversify supply sources and consider lead-time stability alongside unit cost. Suppliers with reliable export logistics, flexible packaging and specification options, and the ability to serve multiple regions will gain an edge. For manufacturers, regional demand growth will likely remain uneven, with some markets expanding faster as protein production intensifies and as nutrition programs become more preventive in design.
The third trend is continued portfolio and ownership consolidation, particularly where it enhances feedstock access, broadens application coverage, or strengthens technical service. Acquisitions that link yeast production with broader ingredient or food-grade operations can improve supply security and create cross-selling opportunities. At the same time, integration carries execution risk: differences in operating culture, quality systems, and customer expectations can complicate the anticipated benefits. The market will therefore reward operators that can combine scale with disciplined product stewardship and consistent technical support.
These trends carry both upside and uncertainty. Demand for functional nutrition is likely to remain supportive, but the pace of adoption will depend on economic conditions in animal production, the stringency of regulatory approvals, and the ability of suppliers to demonstrate consistent value. Cost pressures from feedstock inputs and the potential for additional trade measures also remain variables that can compress margins or shift competitive dynamics faster than expected. The companies best positioned to navigate this environment will be those that treat regulatory monitoring, supply resilience, and application documentation as core capabilities rather than peripheral concerns.
Strategic Actions for Decision-Makers
For manufacturers, the priority is to align fermentation scale with application credibility. Capacity provides optionality, but differentiation comes from strain performance, stability data, and the ability to guide customers through integration decisions. Building a portfolio that balances core volume products with more specialized, function-oriented offerings can help protect share while opening paths to higher-value engagements. Equally important is the discipline to track regulatory and tariff developments closely, because even narrow policy changes can reshape the economics of specific product types and influence sourcing preferences.
For investors, the market’s concentration pattern warrants attention. The dominance of a few large players suggests that scale, distribution, and technical service networks create meaningful barriers, but the presence of targeted acquisitions and cross-industry ownership also signals that value may be created through strategic combination rather than organic expansion alone. Due diligence should focus on the defensibility of functional claims, the stability of feedstock access, the exposure of each portfolio to trade and regulatory shifts, and the quality of customer support. In this market, durable growth is increasingly tied to reputation for reliability and efficacy, not simply to volume.
For procurement teams and feed formulators, the practical imperative is to evaluate yeast inputs as part of a broader nutrition strategy rather than as interchangeable commodities. Inclusion decisions should weigh functional performance, supply continuity, documentation quality, and the supplier’s ability to support integration with existing formulations. Diversifying sources where feasible can reduce exposure to regional disruptions and tariff fluctuations, while maintaining dialogue with suppliers that can provide species-specific guidance and consistent product quality. In an environment where pricing is influenced by both input costs and trade policy, proactive sourcing and evidence-based selection are likely to yield better outcomes than price-only comparisons.
The feed yeast market is moving toward a more demanding, more differentiated, and more regionally sensitive phase of its development. That shift creates opportunity for operators and buyers who treat functionality, compliance, and supply resilience as strategic assets. For decision-makers seeking a deeper view of segment trajectories, regional nuances, competitive positioning, and scenario-based implications, the full research report provides a more granular breakdown and tailored guidance to support planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Feed Yeast Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Automated Material Handling Equipment: Why $52.16B in 2025 Changes Everything
By PW Consulting, 2026-09-21
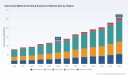
The Automated Material Handling Equipment Market: Strategic Trends and Commercial Opportunities
The global market for automated material handling equipment has reached a decisive inflection point. Valued at approximately $52.16 billion in 2025, the sector has expanded from $32.39 billion in 2020, reflecting a compound annual growth rate of 10.6% through the 2026–2032 forecast horizon. By the end of the projection period, revenue is expected to surpass $101.65 billion. This trajectory is not merely a function of incremental efficiency gains; it signals a structural reorientation of how goods are moved, stored, and sorted across manufacturing, distribution, and e-commerce ecosystems. The equipment category encompasses automated guided vehicles, conveyor and sorting systems, and automated storage and retrieval platforms, each addressing distinct operational pain points but increasingly converging through software-defined control layers and unified fleet orchestration.
Growth has been uneven but persistent across the historical window, with notable acceleration in recent years as labor market pressures, e-commerce fulfillment expectations, and supply chain redundancy requirements aligned. The market remains moderately fragmented, with the top five players collectively accounting for roughly 30% of revenue, indicating ample room for regional specialists, niche innovators, and well-capitalized consolidators. Executive teams evaluating capital allocation, capacity planning, or technology roadmaps must recognize that this is no longer a peripheral automation play. Material handling automation has become a core determinant of throughput scalability, labor flexibility, and real estate optimization. The following analysis examines the structural challenges shaping the market, the forces driving adoption, the evolving competitive architecture, and the strategic implications for operators, investors, and technology decision-makers.
Market Reality and the Defining Challenges
The headline growth figures mask a market navigating several simultaneous tensions. First, the distinction between nominal order value and real demand intensity has blurred. Rising input costs for steel, aluminum, and electronic components have pushed system pricing higher, inflating nominal revenue figures while complicating return-on-investment calculations for end users. Procurement teams are therefore scrutinizing total cost of ownership more rigorously, shifting conversations from unit price to lifecycle economics, energy consumption, and changeover flexibility.
Second, integration complexity remains a persistent barrier. Facilities rarely adopt a single equipment class in isolation. A typical deployment pairs autonomous mobile robots or guided vehicles with conveyor networks, storage retrieval systems, and warehouse execution software. The marginal benefit of each addition depends on data interoperability, safety zone management, and change management across shifts. Organizations that treat automation as a plug-and-play hardware purchase frequently encounter bottlenecks in commissioning, operator training, and downstream process alignment. The gap between purchasing equipment and realizing throughput gains continues to separate experienced integrators from inexperienced buyers.
Third, the operational environment is being reshaped by updated safety and integration expectations. Revised standards for automated guided vehicles have introduced clearer guidance on risk assessment, human-machine interaction zones, and fleet coordination. Compliance is no longer a checkbox exercise; it influences layout design, sensor selection, and software architecture. Companies that internalize these requirements early gain smoother commissioning paths, while those that retrofit controls after deployment face rework costs and schedule delays.
Implications for Decision-Makers
The practical takeaway is that equipment selection must be evaluated within a systems context. Leadership teams should assess whether their facilities have the data infrastructure, maintenance capabilities, and workforce readiness to absorb automation without creating new constraints. Projects that begin with process mapping, bottleneck identification, and clear performance targets tend to outperform those that start with a generic equipment specification.
Forces Reshaping Demand and Deployment
Several interconnected drivers explain why material handling automation is moving from selective adoption to broad-based necessity. Understanding these forces helps separate durable trends from cyclical noise.
Technology convergence is expanding the addressable use case. Autonomous mobile robots and guided vehicles have matured from fixed-path cart replacements to flexible fleet assets capable of dynamic routing, load balancing, and work assignment. Meanwhile, conveyor and sorting systems continue to improve in modularity and throughput density, and automated storage and retrieval platforms are becoming more adaptable to variable SKU profiles and mixed pallet handling. The real breakthrough lies in orchestration: software layers that translate order profiles, labor availability, and equipment status into sequenced movements. Facilities are increasingly evaluating fleets as unified workforces rather than isolated machines, which raises the strategic value of interoperable controls and open architecture.
Labor economics and operational resilience are accelerating adoption. Sustained wage pressure, turnover variability, and the need for consistent shift coverage are pushing operators toward equipment that can sustain throughput without proportional headcount growth. At the same time, supply chain disruptions have reinforced the value of predictable internal flow. Distribution and assembly environments, where speed and accuracy directly affect customer commitments, are leading adoption because automation there translates into measurable service-level improvements and reduced congestion during peak windows.
Regulatory and safety frameworks are maturing. The updated AGV standard provides clearer expectations for safe operation in shared spaces, influencing how vendors design navigation, sensing, and fallback behavior. Facilities that plan around these expectations from the outset can reduce rework and accelerate acceptance from safety teams and floor operators. For vendors, alignment with recognized safety expectations is becoming a competitive differentiator, especially in regulated or unionized environments where documented risk management matters.
Input cost dynamics are reshaping procurement strategies. Higher material and component costs have increased nominal project valuations, but they have also incentivized more disciplined scoping. Buyers are prioritizing incremental deployments, phased rollouts, and equipment that can be repurposed across seasons or product lines. This environment rewards vendors that offer scalable configurations, transparent pricing models, and integration support that reduces hidden failure costs.
What This Means in Practice
Organizations should treat automation decisions as multi-year operating model choices rather than single-cycle capital purchases. The most resilient strategies combine flexible hardware, software visibility, and workforce development plans. Vendors and integrators that can demonstrate measurable improvements in labor utilization, error reduction, and space efficiency will find stronger positioning than those competing solely on hardware features.
PW Consulting
Competitive Architecture and Strategic Positioning
The competitive landscape blends established global integrators, specialized equipment manufacturers, and increasingly ambitious regional players. Daifuku, Jungheinrich, KION Group, SSI SCHAEFER, Toyota Industries, BEUMER Group, Honeywell Intelligrated, Murata Manufacturing, KUKA, Dematic, Hyster-Yale, and Vanderlande each bring distinct strengths, but the market is not settling into a single template. Differentiation increasingly depends on the ability to combine hardware reliability with software orchestration, service responsiveness, and integration discipline.
Japanese and European incumbents with broad intralogistics portfolios continue to benefit from deep engineering heritage and global service networks. Companies offering end-to-end systems—from storage retrieval and sorting to vehicle fleets and control software—are well positioned for large, multi-zone facilities where process continuity matters more than component-level price competition. Their advantage lies in managing complexity across disciplines, reducing the coordination burden on the customer, and maintaining performance across mixed workflows.
Regional specialists and technology-focused entrants are carving out roles by targeting specific pain points or deployment models. Some emphasize omnidirectional handling, compact footprints, or rapid reconfiguration for high-mix environments. Others focus on software-driven fleet management, digital twin visualization, or simplified commissioning workflows. These entrants often win in scenarios where a customer needs a targeted improvement, a pilot-scale validation, or a solution that can be absorbed by a smaller engineering team. The presence of such players increases overall market dynamism and pushes larger incumbents to improve modularity and responsiveness.
Market Evolution Patterns
Consolidation is accelerating where it creates scale in service, software, and project delivery. Recent activity illustrates how ownership changes and brand repositioning are reshaping the landscape. The acquisition of Honeywell’s warehouse and workflow solutions division, including Intelligrated, by American Industrial Partners highlights interest in mature automation capabilities with established deployment track records. At the same time, brand transitions such as Pyramid’s emergence for Matthews Automation Solutions after Duravant’s acquisition signal that portfolio rationalization and clearer market positioning are becoming priorities. These moves matter because they affect post-deployment support, product roadmaps, and the continuity of software updates—factors that customers weigh heavily when selecting partners for multi-year operations.
Exhibition activity and product launches further reveal where innovation is concentrated. Demonstrations of advanced AMR and AGV platforms, omnidirectional pallet forklifts, and digital twin-enabled logistics systems indicate a market increasingly focused on flexibility, visibility, and faster commissioning. Next-generation vehicle introductions and smarter orchestration tools are not isolated events; they reflect an industry-wide push to reduce integration friction and make automation more accessible to facilities that previously considered such projects too complex or too capital-intensive.
Strategic Positioning Takeaways
Winning in this market requires more than hardware competence. Leaders combine dependable equipment with integration services, lifecycle support, and software that helps customers manage mixed fleets and changing order profiles. For customers, the practical question is not which vendor has the broadest catalog, but which partner can own the most difficult parts of deployment, training, and ongoing optimization within the customer’s operating context.
Worldwide Automated Storage Retrieval System Market
Forward Outlook: The Next Three to Five Years
The next phase of growth will be shaped by how the market resolves current tensions and expands into new operational contexts. Three developments are particularly consequential.
Fleet orchestration will become a primary value driver. As facilities operate mixed equipment sets—guided vehicles, autonomous mobile robots, conveyors, and retrieval systems—the competitive edge will shift toward software that coordinates work assignment, exception handling, and performance visibility across asset types. Customers will increasingly evaluate automation based on how smoothly it adapts to demand spikes, product mix changes, and staffing variability. Providers that deliver transparent dashboards, predictive upkeep signals, and configuration flexibility will be better positioned to defend margins and deepen customer relationships.
Modularity and phased deployment will broaden adoption. Large greenfield automation projects will remain important, but a growing share of activity will come from modular upgrades and incremental rollouts. Facilities will favor equipment that can be installed with minimal disruption, expanded as throughput grows, and repurposed when layout or product strategy changes. This trend favors vendors that can offer standardized building blocks, clear integration interfaces, and project plans that reduce downtime during cutover. It also increases the importance of simulation and digital twin tools, which let teams test layouts and workflow changes before physical installation.
Regional growth dynamics will diverge. Asia Pacific continues to represent the largest revenue share, reflecting the scale of manufacturing, distribution modernization, and e-commerce infrastructure investment in the region. Europe and North America remain strong contributors, driven by labor cost pressures, warehouse modernization, and stricter operational expectations. Emerging regions will grow from a smaller base but offer meaningful upside for vendors that can localize support, adapt to varying facility standards, and price solutions appropriately for different maturity levels. The market will not move uniformly; success will depend on aligning product complexity and service models with local buying conditions.
Material Handling Robotics Market Research
Risks and Uncertainties
Several factors could alter the pace or shape of growth. Persistent input cost volatility can compress project budgets or delay decisions if buyers cannot justify commitments under uncertain margin scenarios. Integration risk remains significant; projects that underestimate data compatibility, safety onboarding, or workforce change management may underperform and dampen enthusiasm for subsequent deployments. In addition, standards and safety expectations will continue to evolve, and vendors or customers that lag behind may face rework, compliance friction, or reputational exposure. Finally, the balance between in-house integration capability and outsourced partnering will influence outcomes. Organizations with limited internal expertise may depend heavily on vendors and system integrators, making partner quality and contract structure unusually important.
Actionable Priorities for Decision-Makers
Different stakeholders should focus on distinct but overlapping priorities as they navigate this market.
For manufacturers and operators planning automation: Begin with process clarity before equipment selection. Map the highest-friction flows, identify where variability undermines throughput, and define the operational outcomes that automation must deliver. Prioritize solutions that can integrate with existing control and data environments, and structure deployments in phases that allow performance validation before larger commitments. Invest in operator training and maintenance readiness early; the best equipment underperforms when the team lacks confidence in exception handling or changeover procedures. Where possible, favor modular architectures that allow expansion without full redesign, and evaluate total cost of ownership across energy, maintenance, downtime, and floor space utilization rather than focusing narrowly on purchase price.
For investors and corporate development teams: Value creation will increasingly come from software-enabled differentiation, service scalability, and portfolio alignment rather than hardware volume alone. Assess targets for their ability to manage integrated deployments, maintain software continuity, and support mixed-fleet environments. Watch for ownership changes and brand rationalization as indicators of strategic intent and post-merger service stability. Consider the growing importance of regional execution capability; companies that can localize integration, training, and support often capture share more durably than those competing only on specification sheets. Also monitor the shift toward orchestration and visibility tools, as these create recurring engagement points and can improve customer retention when they demonstrably reduce operational friction.
For procurement and technology buyers evaluating suppliers: Look beyond equipment features to integration discipline and lifecycle support. Ask how a vendor handles mixed-fleet coordination, exception resolution, safety compliance, and post-commissioning optimization. Verify that proposed layouts and workflows have been validated through simulation or pilot evidence where feasible, and clarify ownership of software updates, spare parts availability, and escalation paths. Structured selection processes that weigh deployment risk, service responsiveness, and adaptability to future layout changes will reduce the likelihood of costly rework and improve long-term performance.
Closing Perspective
The automated material handling equipment market is moving from a phase of selective adoption to one of broader operational dependence. Growth to more than $100 billion by the early 2030s reflects a structural shift in how facilities manage labor, throughput, and space under tighter service expectations and more volatile operating conditions. The organizations that benefit most will be those that treat automation as a coordinated system, align equipment choices with process realities, and build the internal capabilities needed to sustain performance after deployment.
Detailed segmentation, regional dynamics, and company-level profiling can materially improve capital planning, supplier selection, and investment prioritization. For teams that require granular data and tailored scenario analysis, the full market research report provides deeper breakdowns and structured guidance to support execution.
For detailed analysis of this topic, please visit the official page: Automated Material Handling Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Navigating the Chicory Market: Strategic Trends and Commercial Opportunities (2026–2032)
The global chicory market is entering a phase of structural acceleration, driven by converging forces in functional nutrition, regulatory clarity, and regionalsupply chain realignment. With a market valuation reaching approximately USD 300 million in 2025 and a projected compound annual growth rate of 7.9 percent through 2032, the sector is transitioning from a niche botanical commodity to a strategically important ingredient in food, beverage, and wellness formulations. For executives, investors, and procurement leaders, the window to shape positioning is narrowing as competitive dynamics tighten and consumer-facing applications multiply.
Understanding where value will concentrate requires looking beyond aggregate growth figures. The market is being reshaped by ingredient innovation, regulatory approvals that unlock new use cases, shifting demand from discretionary wellness to everyday functional consumption, and supply-side restructuring around raw material sourcing and extraction economics. This analysis maps the forces at play, profiles the competitive landscape, and outlines actionable implications for business leaders evaluating chicory-related investments or ingredient strategies.
Current Market Landscape and Core Challenges
The chicory market has sustained steady expansion over the past five years, with revenue trajectories reflecting consistent demand growth across food, beverage, and dietary supplement channels. The upward momentum is expected to continue through the forecast period, supported by broader consumer interest in plant-based fibers, prebiotic ingredients, and coffee-alternative formats. Growth is not uniform across value pools, however. Different segments are maturing at different speeds, and the pace of commercialization depends heavily on regulatory status, formulation compatibility, and end-market adoption cycles.
Several structural challenges are defining the market's next chapter.
Raw Material Geography and Climate Exposure
Chicory root production is geographically concentrated, with Northern Europe historically serving as a core sourcing region for inulin and related functional ingredients destined for global markets. This concentration creates vulnerability to weather variability, crop yield fluctuations, and logistics disruptions. Companies that depend on a narrow supplier base face quality consistency risk and cost volatility, particularly when demand spikes or input costs rise. Diversifying sourcing geographies, building contractual resilience, and investing in yield optimization are becoming pragmatic priorities rather than optional supply chain enhancements.
Regulatory Fragmentation Across Use Cases
The commercial pathway for chicory-derived ingredients varies significantly by application and jurisdiction. Certain forms of chicory root powder and extracts have cleared regulatory thresholds for use in bakery products, beverages, cereals, and grain-based items, with inclusion levels spanning a wide range. Chicory extract has also gained recognition as a color additive, flavor enhancer, and flavoring agent in specific contexts. Meanwhile, native chicory inulin has been evaluated and authorized in select markets as a functional ingredient and, in some regions, under novel food frameworks. These approvals create opportunity, but they also introduce complexity: formulation teams must navigate differing inclusion limits, claim language, and market-specific compliance requirements, which can slow product launches and add cost to regulatory navigation.
Functional Positioning Versus Commmodity Pressure
Chicory is increasingly positioned around functional benefits such as prebiotic fiber content and digestive wellness, yet it also competes in price-sensitive commodity channels where chicory root is used as a bulk ingredient or coffee extender. This dual identity creates strategic tension. Premiumization requires demonstrated efficacy, taste performance, and clean-label compatibility, while commodity-oriented channels pressure margins and incentivize scale. Companies must decide whether to compete on functional differentiation, cost efficiency, or a hybrid model that segments product lines by application and customer type.
Key Drivers Shaping Market Trajectory
Four interconnected drivers are accelerating market evolution and creating pockets of differentiated opportunity.
Ingredient Innovation and Extraction Technology
Technological progress in extraction, fractionation, and formulation is expanding the range of chicory-based inputs available to manufacturers. Advances in processing chicory root into soluble forms, standardized extracts, and functional inulin variants are enabling better taste masking, texture control, and label flexibility. These improvements matter because chicory is often used in categories where organoleptic performance is critical, such as coffee blends, flavored beverages, and baked goods. As ingredient formats become more versatile, the addressable market widens beyond traditional root-based applications and into newer functional food and supplement formats.
Regulatory Progress Opening New Use Cases
A series of regulatory determinations is reducing uncertainty and expanding the commercial menu for chicory ingredients. Recent determinations have supported chicory root powder in bakery products, beverages, cereals, and other grain products at defined inclusion levels. Separate determinations have positioned chicory extract as a color additive, flavor enhancer, and flavoring agent. In parallel, native chicory inulin has been evaluated and authorized in select frameworks, including recognition as a novel food in some regions and scientific assessment by European food safety panels. Collectively, these developments reduce formulation risk and give developers more confidence to build chicory into mainstream products rather than limiting it to niche or premium-only offerings.
Demand-Side Shift Toward Everyday Functional Consumption
Consumer behavior is moving from occasional wellness purchases toward routine integration of functional ingredients into daily diets. Fiber and prebiotic content remain relevant purchase drivers, and chicory fits naturally into this narrative because it can be incorporated into familiar formats such as coffee alternatives, cereals, snacks, and beverages. Importantly, the demand story is not only about supplements. Food and beverage applications continue to represent the largest demand pool, reflecting the ingredient's flexibility and compatibility with everyday consumption occasions. This shift encourages manufacturers to pursue shelf-stable, mass-reachable products instead of relying solely on specialty channels.
Supply Chain Realignment and Cost Structure Pressures
The chicory value chain is undergoing reconfiguration as processors and ingredient companies respond to raw material availability, processing efficiency, and export dynamics. Several producers in India, for example, have built export-oriented operations spanning dried chicory roots, roasted chicory, liquid chicory, and extracts, targeting both coffee blends and nutraceutical markets. At the same time, large-scale ingredient suppliers in North America and Europe continue to emphasize chicory-derived inulin and functional ingredients for food, beverage, and nutraceutical uses. These parallel supply models create both competition and collaboration opportunities. Cost structures are influenced by root quality, drying and roasting methods, extraction yields, and logistics, meaning that margin management increasingly depends on process optimization and sourcing strategy as much as on end-market pricing power.
PW Consulting
Competitive Landscape and Leading Strategies
The chicory market remains moderately fragmented, but competitive positioning is sharpening as participants define clearer boundaries around geography, product format, and end-market focus. Market concentration is not extreme, and the presence of multiple regional processors alongside global ingredient suppliers creates a landscape where differentiation is achievable through specialization rather than scale alone.
Worldwide Fondant Market
Differentiated Positioning Among Established Players
Several companies illustrate how participants are carving out defensible positions.
-
Leroux has built its identity around roasted chicory products, including grains, ground chicory, liquid chicory, and soluble forms for beverages and culinary uses, anchored by a fully French supply chain. The emphasis on origin, roasted formats, and culinary compatibility positions the company in a premium, taste-driven segment where provenance and product consistency matter.
-
Cargill Incorporated leverages scale and ingredient science to produce chicory-derived inulin and functional ingredients for food, beverage, and nutraceutical applications. Its strategic advantage lies in formulation breadth, regulatory and technical support capabilities, and the ability to integrate chicory inputs into larger ingredient portfolios serving multinational customers.
-
Starwest Botanicals focuses on organic chicory root, powder, and extracts for herbal and food ingredient uses. Its positioning targets clean-label, organic, and botanical channels, appealing to buyers who prioritize certification, traceability, and ingredient transparency.
-
Indian processors such as Vashila Industries, Jamnagar Chicory Industries, Pioneer Chicory, Farmvilla Food Industries, and Nature's Gold Production illustrate a robust export- and domestic-oriented ecosystem spanning dried roots, roasted chicory, liquid chicory, cubes, and extracts. These companies compete on cost efficiency, volume supply, and versatility across coffee-blend, food, and nutraceutical channels, often serving as important nodes in global distribution networks.
-
European and UK-based distributors such as Organic Herb Trading Co support the market by supplying organic chicory and related botanicals, reinforcing the importance of distribution networks that connect processors with end users seeking specialty or certified materials.
Strategic Themes Across the Landscape
Across these profiles, several strategic themes emerge.
-
Format specialization is a common differentiator. Some players concentrate on roasted and culinary forms, others on extracts and inulin-type ingredients, and others on organic or herbal-grade materials. This segmentation reduces direct head-to-head competition and allows firms to build reputations around specific customer needs.
-
Supply chain origin is increasingly part of the value proposition. Fully domestic supply chains, regional sourcing clusters, and certification pathways are used to signal quality, consistency, and traceability. In a market where raw material geography matters, origin can support price premiums and customer loyalty.
-
Application breadth versus depth creates different risk-return profiles. Broad-line ingredient suppliers can cross-sell across categories and capture more of the value chain, while focused producers can deepen expertise and serve niche channels more effectively. Both approaches can succeed, but they require different capabilities in regulatory support, technical service, and operational scalability.
Market Evolution Outlook
The competitive landscape is likely to evolve through selective consolidation, entry by ingredient-focused players, and rising importance of technical service and regulatory navigation. As use cases expand, buyers will increasingly value partners that can support formulation, compliance, and scale simultaneously. At the same time, regional processors with strong export capabilities and cost advantages are well placed to capture share in price-sensitive and volume-driven segments. The result is a market where multiple business models can coexist, but where advantage will increasingly depend on execution quality, regulatory readiness, and the ability to match ingredient formats to end-market demand.
Forward-Looking Trends and Commercial Opportunities
Looking ahead three to five years, three trends are particularly consequential for strategic planning.
Expansion of Chicory in Everyday Food and Beverage Formats
Chicory is poised to move further into everyday consumption occasions as formulators leverage soluble forms, roasted formats, and functional extracts to improve taste and texture in mainstream products. Coffee alternatives, fortified cereals, snack applications, and flavored beverages represent channels where chicory can gain incremental share through familiar formats and added functional appeal. The commercial opportunity lies in building product architectures that combine functional messaging with sensory performance, enabling chicory to compete in categories with high purchase frequency rather than remaining confined to specialty wellness niches.
Inulin and Prebiotic Fiber as a Growth Anchor
Inulin-type ingredients derived from chicory continue to benefit from sustained interest in digestive health and fiber enrichment. Scientific evaluation and regulatory recognition in multiple markets support broader adoption, while manufacturing advances make it easier to incorporate these materials into diverse matrices. Growth is likely to be strongest where suppliers can provide consistent quality, clear application guidance, and compliance support. For ingredient companies, the strategic priority is to strengthen technical documentation, customer education, and formulation expertise so that chicory-based inulin becomes a default option in fiber-enrichment projects rather than one option among many.
Cobalt Market
Regional Supply Chain Diversification and Value-Added Processing
The market is likely to see continued diversification in sourcing and processing footprints as participants seek to reduce exposure to concentrated supply regions and capture more value locally. This includes expansion of drying, roasting, extraction, and blending capabilities in key production and export markets, as well as closer partnerships between processors and end-user manufacturers. The opportunity is twofold: buyers can improve resilience and cost predictability by broadening supplier relationships, while processors can differentiate through higher-margin value-added formats rather than competing solely on raw root volume.
Risks and Uncertainties to Monitor
Several factors warrant caution. Input cost volatility and crop variability can pressure margins and disrupt supply continuity. Regulatory complexity across jurisdictions may slow product development or limit claim language in certain markets. Taste and formulation challenges remain relevant in sensitive applications, where performance trade-offs can affect repeat purchase and shelf presence. In addition, competition from alternative fibers, botanical ingredients, and coffee extender substitutes could compress pricing in specific segments. Companies should scenario-plan around these variables and maintain flexibility in sourcing, formulation, and market prioritization.
Strategic Implications for Decision-Makers
The chicory market presents a clear value proposition for leaders willing to align ingredient strategy with application realities and regulatory pathways. The following recommendations are oriented by role.
For Manufacturers and Ingredient Developers
-
Prioritize format-to-application fit. Select roasted, soluble, extract, or inulin-type inputs based on the intended end use, taste requirements, and label goals rather than sourcing by commodity alone. Matching format to application reduces reformulation risk and improves speed to market.
-
Build regulatory and technical support into the commercialization plan. Because inclusion levels, claim opportunities, and compliance expectations differ across markets and product categories, early attention to regulatory status and application guidance can shorten launch timelines and reduce rework.
-
Strengthen supply resilience through diversity and process control. Multi-region sourcing, quality consistency protocols, and processing optimization help mitigate raw material volatility and support margin stability in volume-driven programs.
For Investors
-
Focus on differentiation that compounds over time. Businesses with clear positioning around organic certification, origin credibility, extraction capability, or application expertise are better placed to defend margins than undifferentiated bulk suppliers.
-
Evaluate end-market mix carefully. Exposure to everyday food and beverage channels can provide scale and repeatability, while specialty wellness channels may offer higher unit value but more volatile demand. Understanding the balance between these pools is essential for modeling growth and risk.
-
Watch for consolidation signals and partnership-driven expansion. As use cases broaden, value may migrate toward players that can combine supply reliability, technical service, and regulatory navigation, whether through organic build-out or strategic combinations.
For Procurement and Sourcing Leaders
-
Expand and qualify the supplier base beyond single-region dependence. Diversification across geographies and processing models improves continuity and gives procurement teams more negotiating leverage in volatile conditions.
-
Assess total cost beyond unit price. Processing method, certification requirements, consistency, lead times, and technical support all affect landed value and downstream performance. Evaluating these factors holistically supports better category decisions.
-
Align specifications with application needs early. Defining required formats, inclusion tolerances, and quality parameters before sourcing reduces the risk of mismatched materials and accelerates downstream formulation work.
The strategic picture is clear: chicory is no longer a narrow botanical input but a versatile ingredient set with expanding regulatory support, growing functional relevance, and a competitive landscape that rewards specialization and execution quality. Organizations that act early to define their positioning, secure resilient supply, and align formulation strategy with the strongest end-market opportunities will be best placed to capture value as the market moves toward 2032. For those seeking deeper segmentation data, company-level benchmarking, and tailored scenario analysis, a comprehensive research report can provide the detailed evidence base needed to convert these directional insights into precise commercial decisions.
For detailed analysis of this topic, please visit the official page: Chicory Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Navigating the Petroleum Resin Market: Strategic Trends and Commercial Opportunities Through 2032
The petroleum resin market is entering a phase of measured expansion, characterized by steady demand growth, evolving regulatory pressures, and a competitive landscape that rewards product differentiation over volume alone. Current market sizing places the sector at approximately 218.7 million USD in 2025, with a projected trajectory toward 322.6 million USD by 2032. This growth path reflects a compound annual growth rate of 5.88% across the 2026–2032 forecast window, building on a historical expansion pattern that saw the market move from 185.1 million USD in 2020 through a series of incremental annual gains. The trajectory is not uniform, however. Growth is being reshaped by feedstock volatility, tightening emissions standards, and shifting end-user requirements that are quietly redefining which resin grades will capture premium value in the next cycle.
Rosin Resin Market
For decision-makers, the immediate takeaway is that the market is large enough to support multiple business models but narrow enough that margin capture depends heavily on grade specialization, regional positioning, and compliance readiness. The industry remains moderately consolidated, with the top three players accounting for roughly 29.5% of revenue and the top five reaching approximately 36.8%. This concentration leaves substantial room for localized competitors, niche formulators, and integrated feedstock players to compete on service, technical support, and application-specific performance rather than scale alone.
Key Challenges and Inflection Points
Three structural challenges are currently re-shaping strategic planning across the petroleum resin value chain.
Feedstock exposure and margin sensitivity remain a persistent pressure point. Naphtha-derived C5 and C9 fractions form the backbone of most hydrocarbon resin synthesis routes, and pricing swings in crude oil and naphtha markets transmit quickly into producer cost structures. Because resin grades are often priced against performance benchmarks rather than raw input costs, suppliers with limited hedging flexibility or narrow product portfolios face disproportionate margin compression during volatile periods. The implication is that cost leadership alone is becoming less durable; resilience is increasingly tied to feedstock diversification, integration depth, and the ability to shift production toward higher-margin grades when input costs rise.
Regulatory tightening on emissions and aromatic content is altering the competitive balance between conventional and hydrogenated resins. In adhesive and coating applications, regulatory direction is favoring products with lower volatile organic compound profiles and reduced aromatic residuals. This shift is not merely a compliance issue; it influences formulation choices, customer qualification cycles, and the willingness of converters to standardize on specific resin families. Companies that have already invested in hydrogenation capacity or water-white grade portfolios are positioned to benefit from a transition that will otherwise raise reformulation costs for slower-moving competitors.
Demand fragmentation across end-use sectors is making blanket capacity plays riskier. Growth is not coming from a single application category but from a mix of adhesive systems, rubber compounding, road-marking and industrial coatings, and packaging-related ink and film applications. Each segment has distinct performance requirements, qualification timelines, and price sensitivity. As a result, the market is moving toward a model where revenue growth depends on aligning resin grades with specific technical needs rather than selling generalized intermediates into undifferentiated demand.
Key Drivers Shaping the Market Trajectory
The 5.88% CAGR projected through 2032 reflects a convergence of technical, regulatory, and demand-side forces. Understanding how these drivers interact is essential for identifying where value will accumulate.
- Technology innovation and grade specialization continue to be central to competitive differentiation. Hydrogenated and water-white resins represent a clear example of how processing sophistication translates into market access. By reducing color bodies and residual aromatics, these grades open doors to packaging, hygiene, and high-visibility coating applications that conventional fractions cannot easily serve. At the same time, modification strategies that blend C5, C9, and copolymer architectures are enabling formulators to balance tack, compatibility, and thermal stability more precisely. Innovation is therefore not only about new molecules; it is about creating grades that solve formulation constraints in high-value applications.
- Policy and regulatory environments are accelerating product migration toward cleaner profiles. Rules governing VOC limits, aromatic compound scrutiny, and food-contact extractables are progressively raising the bar for resin selection in adhesives and packaging-adjacent uses. This environment favors producers with ready access to fully hydrogenated options and those capable of documenting compliance across multiple jurisdictions. It also encourages downstream converters to consolidate their supplier base around partners who can provide consistent regulatory documentation and predictable grade performance.
- Demand-side shifts in adhesives and industrial applications are expanding the addressable market for specialized resins. Hot-melt and pressure-sensitive adhesive systems remain significant demand anchors, but the broader story is the continued push toward lighter-weight assemblies, faster processing speeds, and Bondline performance optimization in manufacturing. In parallel, road-marking and industrial coatings demand is supported by infrastructure maintenance cycles and the need for durable, visible markings. These end-use trends reward resin suppliers who can align grade characteristics—such as tack build, openness, and weatherability—with real processing conditions rather than generic specification sheets.
- Supply chain and cost structure changes are reshaping regional competitiveness. Feedstock sourcing, logistics, and local availability of C5/C9 streams influence both cost position and supply reliability. Regions with stronger integration between petrochemical feedstock production and resin manufacturing can respond more flexibly to demand changes and margin pressure. Meanwhile, transportation costs and qualification lead times are reinforcing the value of regional supply relationships, particularly where converters prioritize consistent batch performance and shorter response cycles over marginal price differences.
Recent company-level developments illustrate how these drivers are being addressed in practice. Capacity expansions are being pursued in response to rising global demand for adhesive and coating applications, signaling that at least some major players see sustained volume growth as worth the capital commitment. At the same time, certification and feedstock-innovation moves are becoming part of the differentiation conversation. Notably, ISCC PLUS certification has been achieved at a key production facility for sustainable resin production, and resin derived from used cooking oil has been supplied to an affiliate for synthetic rubber production. These moves point to a market in which sustainability credentials and alternative feedstock pathways are increasingly tied to commercial access, especially where downstream customers are under pressure to document lifecycle and sourcing improvements.
Competitive Landscape and Leading Strategies
The competitive field spans large multinational producers, regional specialists, and application-focused formulators. Strategic positioning varies by feedstock access, hydrogenation capability, geographic footprint, and the depth of technical support offered to converters.
Among the prominent players, a clear divide is emerging between companies competing primarily on broad product breadth and those building advantage around hydrogenated grades, sustainable supply claims, or application-specific modification expertise. Producers with established hydrocarbon resin brands spanning C5, C9, and copolymer lines are leveraging name recognition, global distribution, and long-standing customer qualification relationships. Their challenge is to maintain relevance as end-users increasingly prioritize emissions performance, food-contact compliance, and consistent color quality in sensitive applications.
Hydrogenated resin specialists and producers with water-white portfolios are positioned to capture premium demand where aromatic residuals or color limitations would otherwise restrict material choice. In adhesive and coating grades, the ability to deliver low-color, low-odor, and low-VOC profiles is becoming a commercial advantage rather than a niche feature. This is especially relevant as regulatory expectations tighten and as packaging and hygiene-adjacent applications expand their material requirements.
Regional and China-based producers continue to play an important role in supplying C5 aliphatic, C9 aromatic, and C5/C9 copolymer resins to cost-conscious and volume-driven segments. Their strategic advantage often lies in feedstock proximity, manufacturing scale in specific resin families, and the ability to serve regional adhesive, coating, and rubber compounding markets with shorter supply lines. The key question for these players is whether they can move up the value chain into higher-specification grades without losing cost competitiveness, and whether they can build the documentation and certification infrastructure that multinational converters increasingly require.
The landscape is evolving along several axes. Integration is deepening where feedstock security and conversion efficiency matter most, allowing producers to protect margins during naphtha price swings. Differentiation is intensifying around hydrogenation, modification, and certification, as customers use compliance and performance criteria to narrow their approved supplier lists. New entry and regional specialization remain viable where local demand growth, logistics advantages, or application knowledge create a defensible position, even if global scale is limited. Overall, the market is not trending toward a single dominant model; it is trending toward a segmented structure in which success depends on matching the right grade, the right compliance profile, and the right service model to a specific customer segment.
Future Trends and Commercial Implications
Looking across the 2026–2032 horizon, several trends are likely to define where growth and margin will concentrate.
- Hydrogenated and low-aromatic resins will capture a growing share of high-value demand. As VOC limits tighten and aromatic scrutiny increases, converters in adhesive and coating applications will continue shifting toward fully hydrogenated options that simplify compliance and reduce reformulation risk. This trend favors producers with existing hydrogenation capacity and those able to supply consistent water-white grades at scale. The commercial opportunity lies not just in selling a different resin, but in helping customers qualify faster, reduce audit burden, and standardize on grades that meet multiple regulatory regimes simultaneously.
- Sustainable feedstock and certification pathways will become more commercially meaningful. ISCC PLUS certification and the use of alternative feedstocks such as used cooking oil are moving from pilot-stage signals to operational reality in certain production lines. While these pathways are unlikely to replace conventional naphtha-based synthesis across the board, they will become increasingly important in customer segments where sustainability documentation influences sourcing decisions. The opportunity here is for producers to build credible, auditable supply chains that can support customer claims without overpromising on volume or cost.
- Regional demand growth will reward localized grade portfolios and technical service. Asia Pacific remains a major demand center, but growth is also emerging from infrastructure-related coatings, packaging-adjacent inks and films, and adhesive-intensive manufacturing in multiple regions. In this environment, global product lists matter less than regional readiness: the ability to supply the right grade mix, maintain reliable batch consistency, and provide formulation support in local markets. Producers who can combine product breadth with regional responsiveness are more likely to secure long-term converter relationships than those competing on price alone.
These trends are not without risk. Feedstock volatility can still erode margins quickly, especially for producers with limited hedging or integration. Regulatory change may accelerate faster in some jurisdictions than others, creating uneven compliance costs and fragmented qualification requirements. In addition, overinvestment in generalized capacity could lead to oversupply in commoditized grades while leaving high-specification segments underserved if capital is not directed toward hydrogenation, modification, or certification capabilities. The most resilient strategies will be those that treat these risks as reasons to specialize rather than reasons to retreat.
Strategic Actions for Decision-Makers
The market outlook suggests a period in which disciplined positioning will matter more than aggressive volume chasing. The following actions are most relevant for different roles in the value chain.
PW Consulting
For Manufacturers and Producers
- Prioritize grade portfolios that align with regulatory direction and high-value applications, particularly hydrogenated, water-white, and low-aromatic options where qualification cycles are shortening and customer scrutiny is rising.
- Strengthen feedstock resilience through integration, diversification, or supply agreements that reduce exposure to naphtha price swings, and consider how alternative feedstock pathways can support both cost flexibility and sustainability positioning.
- Invest in technical service and application support as a competitive lever, since converter decisions are increasingly driven by formulation reliability, consistency, and documentation as much as by resin price.
For Investors and Capital Allocators
- Focus on companies with clear differentiation in hydrogenated or specialized grades, credible certification and compliance infrastructure, and the ability to serve high-margin adhesive, coating, and packaging-adjacent demand rather than solely competing in commoditized segments.
- Evaluate feedstock exposure and regional positioning as risk factors, since margin durability will depend on how well companies can manage naphtha-linked volatility and serve demand centers with reliable supply and short response times.
- Watch for consolidation and capability acquisition activity, particularly where smaller producers hold desirable grade expertise, regional relationships, or certification assets that larger players need to expand into premium segments.
For Procurement and Supply Chain Leaders
- Diversify approved supplier lists deliberately between broad-line suppliers and specialists, so that compliance requirements, color/aromatic constraints, and supply continuity can be managed without overrelying on a single source for critical grades.
- Include regulatory readiness, documentation quality, and feedstock sustainability credentials in sourcing evaluations, especially where future VOC limits, aromatic scrutiny, or food-contact requirements could affect qualification and reformulation risk.
- Engage early with suppliers on grade development and qualification timelines, since the market is shifting toward custom-fit solutions where early collaboration can reduce switching costs and protect production schedules.
The strategic picture is clear enough to act on, but the details matter. Market-wide sizing and growth rates provide the backdrop, while the real opportunities are embedded in grade-level demand shifts, regional feedstock dynamics, certification status, and the ability to meet tightening regulatory expectations without sacrificing performance. For organizations that need a sharper view of segment-level volume patterns, regional share dynamics, price/cost sensitivity, and company-level positioning, a more detailed research package can provide the granularity required to translate these trends into concrete sourcing, investment, and product decisions.
C9 Petroleum Resin Market
For detailed analysis of this topic, please visit the official page: Petroleum Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Solar Cell Metal Paste Market: Why 6.5% CAGR and Asia Pacific Lead 2026-2032
By PW Consulting, 2026-09-21
Solar Cell Metal Paste Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The solar cell metal paste market has demonstrated consistent growth over the past half-decade, evolving from a niche materials segment into a critical enabler of photovoltaic manufacturing efficiency. Revenue expanded from approximately 163.15 million USD in 2020 to 215.0 million USD in 2025, reflecting a compound annual growth rate of 6.5 percent. Projections indicate the market will continue its upward trajectory, reaching 344.8 million USD by 2032. This expansion is not merely a function of installed capacity growth; it is increasingly tied to technology transitions, material substitution debates, and the competitive dynamics of a fragmented supplier base.
At first glance, the growth narrative appears straightforward: more solar cells require more conductive pastes for front-side metallization and back-surface field formation. However, the structural reality is more nuanced. Manufacturing yield optimization, silver intensity reduction, and the shift toward next-generation cell architectures are reshaping how paste suppliers position themselves and how cell manufacturers evaluate material procurement. The market's resilience during periods of raw material volatility underscores both the strategic importance of metallization materials and the persistent tension between performance requirements and cost constraints.
Key Challenges and Inflection Points
Three structural challenges currently define the operating environment for solar cell metal paste participants and downstream manufacturers alike.
First, raw material cost exposure has intensified. Silver, the dominant conductive component in high-performance pastes, experienced unprecedented price appreciation, reaching approximately 121 USD per ounce in January 2026 before averaging around 81 USD per ounce through the year according to J.P. Morgan Global Research. Silver paste formulations can account for up to 30 percent of total solar cell production costs, making paste chemistry and silver-loading strategies a direct contributor to cell-level economics. This exposure forces manufacturers to balance efficiency gains against material input volatility.
Second, the technology transition from legacy crystalline silicon architectures toward TOPCon, heterojunction, and other advanced structures is disrupting paste specification requirements. Formulations optimized for PERC or standard multicrystalline platforms do not automatically translate to higher-efficiency architectures. Suppliers must invest in R&D to develop pastels that maintain adhesion, low contact resistance, and fire-through compatibility under altered thermal profiles and layer stack designs. This creates a divide between suppliers with formulation depth and those competing primarily on price.
Third, the competitive landscape remains structurally fragmented despite pockets of technological leadership. The market's concentration metrics reflect a diffuse supplier environment where differentiation is increasingly tied to application-specific engineering support, formulation customization, and supply reliability rather than commodity volume alone. This fragmentation presents both an opportunity for steady entrants and a risk for those unable to move beyond generic product positioning.
Key Drivers of Market Evolution
Technology Innovation and Formulation Breakthroughs
The most consequential driver of market growth is the simultaneous push toward higher cell efficiencies and lower silver consumption per watt. Advanced metallization pastes are being engineered to reduce sintering temperatures, improve line resistance uniformity, and enable thinner finger spacing without compromising collection efficiency. Formulations designed for PERC, TOPCon, and emerging n-type architectures are moving from qualification stages into volume production, and suppliers capable of delivering consistent performance across multiple technology platforms are capturing disproportionate share within high-value segments.
This technical trajectory intersects directly with silver-saving initiatives. Industry reporting from early 2026 highlighted accelerating efforts across the solar value chain to reduce silver intensity, with metallization paste optimization identified as one of the most actionable levers in cell cost structure. The implication for paste suppliers is clear: the next wave of market growth will not be awarded solely to those with the largest production footprint, but to those with the formulation agility to support lower-silver designs without eroding electrical performance.
Policy and Regulatory Momentum
Policy environments in major markets are reinforcing demand for high-performance photovoltaic materials. The European Union's target of a 40.5 percent renewable energy share by 2030 is driving sustained investment in solar deployment and, by extension, demand for high-performance silver-based pastes in advanced module manufacturing. In the United States, the Inflation Reduction Act has indirectly strengthened the economics of domestic and allied supply chains, encouraging producers to prioritize materials that meet quality, reliability, and traceability expectations for long-life assets.
China's policy stance further shapes the demand picture. Commitment to 20.5 percent non-fossil energy consumption by 2026 supports continued expansion in domestic solar cell production, creating a substantial internal market for both silver and aluminum-based metallization materials. These regulatory signals do not merely boost volume; they influence the premium attached to formulations that enable efficiency, yield, and long-term durability in increasingly competitive deployment economics.
PV Metallization Silver Paste Market
Demand-Side Shifts in Manufacturing Behavior
Cell and module manufacturers are increasingly treating paste selection as a systems-level optimization decision rather than a discrete consumable purchase. As production scales and fab economics tighten, buyers focus on total cost per watt, line yield, and compatibility with high-throughput screen printing or printing-and-fire processes. This behavioral shift advantages suppliers that offer not only material consistency but also process integration support, troubleshooting capability, and the ability to co-develop formulations tailored to specific line configurations.
At the same time, large-scale manufacturing is intensifying sensitivity to supply continuity. Volatility in precious metal markets and geopolitical supply considerations have elevated the importance of qualified secondary sources, regional availability, and inventory strategies. Manufacturers that once tolerated single-source dependency for specialized pastes are actively building supplier redundancy, changing how incumbents must compete against challengers.
Supply Chain and Cost Structure Dynamics
Cost structure pressures are reshaping how paste portfolios are built and priced. Silver price surges have accelerated interest in silver-aluminum hybrid designs, reduced-loading formulations, and aluminum paste alternatives where application constraints allow. At the same time, the cost of delivering advanced formulation performance is rising, as research, quality control, and application engineering become more essential to customer selection criteria.
This dynamic creates a dual pressure: manufacturers want lower input costs, while simultaneously demanding performance that enables next-generation cell economics. Suppliers that can articulate the trade-off between silver loading, fire-through behavior, and contact resistance in a way that maps to customer cost-per-watt calculations are gaining negotiating leverage, even in a price-sensitive environment.
Competitive Landscape and Leading Strategies
The supplier ecosystem spans established specialty material companies, electronics-paste incumbents extending into photovoltaics, and regional manufacturers competing on cost-performance balance. Ten companies illustrate the breadth of strategies currently shaping the market: Heraeus Photovoltaics, DuPont de Nemours, Inc., Giga Solar Materials Corporation, Targray Technology International Inc., Murata Manufacturing Co., Ltd., Hunan LEED Electronic Ink Co., Ltd., Shanghai Transcom Scientific Co., Ltd., Daejoo Electronic Materials Co., Ltd., Agfa-Gevaert N.V., and Noritake Co., Limited.
Strategic Positioning of Leading Players
Heraeus Photovoltaics has built a position around high-performance silver metallization pastes tailored for advanced cell architectures, including PERC, TOPCon, and n-type technologies. Its relevance in the current cycle stems from formulation depth and visibility into the industry's silver-saving agenda, where paste cost and silver intensity are recognized as material contributors to cell economics. The company's focus on architecture-specific formulations positions it well for customers transitioning away from legacy platforms.
DuPont de Nemours, Inc. brings brand recognition and an established Solamet product lineage optimized for high-efficiency solar cells, including PERC and advanced architectures. Its value proposition emphasizes performance consistency and integration with efficiency-focused manufacturing strategies, appealing to producers who prioritize reliability and wafer-level performance in premium segments.
Giga Solar Materials Corporation and Targray Technology International Inc. represent manufacturers emphasizing mass-production practicality. Giga Solar focuses on low-silver and high-efficiency formulations designed for volume fabrication, aligning product development with the industry's cost-reduction imperative while maintaining efficiency targets. Targray differentiates through customization of front- and rear-side conductive materials, aiming to improve yields and efficiency at the cell level rather than competing purely on raw material price.
Legacy electronics-paste expertise provides additional competitive angles. Murata Manufacturing Co., Ltd. and Noritake Co., Limited draw on long-standing electronic paste technology to develop silver pastes for solar cell electrodes, leveraging process know-how and material consistency from adjacent electronic markets. Agfa-Gevaert N.V. contributes specialized metallization paste capabilities for photovoltaic applications, reinforcing the view that metallization performance is increasingly a cross-industry competency.
Cost-Performance Challengers and Regional Dynamics
A parallel set of suppliers competes by narrowing the performance gap with international benchmarks while offering more attractive cost profiles. Hunan LEED Electronic Ink Co., Ltd. produces cost-effective high-temperature silver paste for solar cell electrodes and mass production applications, targeting volume-driven manufacturing environments where formulation reliability and price alignment are both critical. Shanghai Transcom Scientific Co., Ltd. offers competitive formulations with performance approaching international standards at lower cost points, reflecting the broader regional trend of maturing domestic material options.
Daejoo Electronic Materials Co., Ltd. occupies a differentiated position by supplying both silver and aluminum paste solutions for solar cell metallization, providing customers with alternative material paths where back-side or specific electrode requirements favor aluminum-based or hybrid approaches. This kind of portfolio breadth can be strategically valuable as manufacturers experiment with material combinations to manage silver exposure.
Evolution of the Competitive Structure
Market concentration remains relatively modest, with the top three players holding approximately 24.6 percent and the top five about 26.2 percent of revenue. This dispersion indicates that scale advantages exist, but they are not yet dominant enough to prevent specialized or regionally focused entrants from capturing meaningful share. The likely evolution is twofold.
On one side, consolidation pressure will persist among suppliers that lack formulation differentiation, application support, or cost discipline. In a segment where silver intensity, yield, and architecture compatibility directly affect customer economics, undifferentiated commodity positioning becomes increasingly vulnerable. On the other side, fragmentation will endure where regional demand growth, customization requirements, and multi-source procurement strategies create room for additional qualified participants. New entrants and expanding incumbents will need to demonstrate more than production capacity; they will need to show that their products improve total wafer-to-module economics under real factory conditions.
Forward-Looking Trends for 2026 to 2030
Trend One: Silver Intensity Reduction as a Core Design Constraint
Over the next several years, formulation strategies that reduce silver loading without sacrificing electrical performance are expected to become central competitive differentiators rather than optional enhancements. Silver price spikes have already drawn attention to paste cost as a share of total cell expense, and the structural incentive to lower material intensity will persist regardless of short-term price fluctuations. Suppliers able to deliver paste systems that support finer lines, lower contact resistance, and stable fire-through behavior at reduced silver content will align directly with manufacturer priorities.
The commercial opportunity lies in pairing material design with application engineering. Manufacturers will increasingly favor partners who can demonstrate how a formulation change affects not just paste price, but overall cell cost per watt, yield, and compatibility with future printing processes. This shifts competition from bulk pricing toward solution value.
Trend Two: Broader Adoption of Advanced Cell Architectures Driving Paste Specification Upgrades
As TOPCon, heterojunction-related variants, and other advanced architectures move further into mainstream production, metallization requirements will continue to diverge from legacy PERC-era norms. Paste suppliers that maintain a single product focus will face growing friction; those that invest in architecture-aware development and can validate performance across multiple platforms will secure stronger customer relationships. The trend increases the value of technical support, qualification speed, and repeatable scale-up of new formulations.
PW Consulting
For buyers, this trend means that paste selection will become more tightly coupled to fab technology roadmaps. For suppliers, it means that R&D cadence and customer co-development capability will increasingly determine growth potential, especially in regions scaling advanced-cell manufacturing capacity.
Trend Three: Regional Supply Resilience and Multi-Source Procurement as a Structural Shift
Policy support in Europe, the United States, and China is expanding regional manufacturing ambitions, and with that expansion comes greater attention to supply security. Even where global trade remains fluid, manufacturers are incentivized to qualify multiple paste sources, diversify regional availability, and reduce exposure to single-supplier risk for critical materials. This shift favors suppliers with reliable production footprints, transparent quality systems, and the ability to support localized qualification timelines.
The opportunity here is less about displacing incumbents and more about earning qualified status as a reliable secondary or primary source in specific regions or product lines. Suppliers that can combine competitive formulation performance with dependable delivery and regional responsiveness will find expanding procurement interest, particularly among manufacturers building or expanding capacity in policy-supported markets.
Risks and Uncertainties
The forward outlook is contingent on several variables. Silver price volatility remains a persistent risk; sustained high prices could accelerate aluminum-based substitution in applications where performance trade-offs are acceptable, altering demand patterns for silver-dominant paste portfolios. Conversely, if silver prices moderate sharply, cost pressure may ease in the short term but the structural incentive to reduce intensity is unlikely to disappear, given the broader focus on cell-level cost optimization.
Technology adoption rates also introduce uncertainty. The pace at which TOPCon and other advanced architectures scale relative to legacy lines will determine how quickly paste specifications must evolve and how rapidly formulation-dependent suppliers can capture premium demand. Slower-than-expected transitions would extend the relevance of mature formulations but could also delay the demand uplift associated with higher-efficiency architectures. Finally, policy trajectories could shift with political or economic changes, altering the timing and geography of demand expansion.
Actionable Guidance for Decision Makers
For Solar Cell and Module Manufacturers
Treat paste selection as a cost-per-watt optimization problem rather than a commodity procurement decision. Evaluate suppliers based on formulation performance under your specific process conditions, silver-loading flexibility, support for next-generation architectures, and ability to maintain lot-to-lot consistency at production scale. Building qualified multi-source relationships for critical formulations can reduce supply risk while preserving performance standards.
Solder Paste Market
At the same time, use material selection as a lever in your silver-intensity strategy. Where performance allows, collaborate with paste suppliers to test reduced-loading or silver-aluminum hybrid options, measuring impact not just on material cost but on firing yield, contact resistance, and overall cell efficiency. The most valuable partnerships will be those that tie material development directly to fab economics.
For Investors and Strategic Planners
Focus on suppliers whose competitive advantage rests on formulation depth, application support, and architecture adaptability rather than volume alone. In a 6.5 percent CAGR market extending through 2032, growth will increasingly accrue to participants that can align product development with silver-reduction strategies and advanced cell transitions. Companies with credible customization capability, credible qualification pipelines, and the ability to serve both cost-sensitive and efficiency-focused segments are better positioned than those competing purely on price.
Pay attention to the interplay between raw material cycles and product strategy. Sustained silver price pressure is likely to reinforce demand for lower-silver formulations, hybrid designs, and aluminum alternatives in certain applications, expanding the strategic relevance of suppliers that can address this spectrum. Monitoring regional capacity expansion, especially in policy-supported markets, offers early signals about where demand growth and supplier qualification activity will intensify.
For Procurement and Supply Chain Leaders
Prioritize qualification readiness and supply resilience. The cost of line downtime, yield variation, or delayed qualification can outweigh marginal material savings, particularly in high-throughput manufacturing environments. Maintain a structured qualification pipeline for alternative formulations, document performance trade-offs clearly, and align sourcing strategy with your technology roadmap so that paste decisions do not become constraints when architecture transitions accelerate.
Negotiate with an understanding of total value rather than unit price alone. Where suppliers can demonstrate measurable improvements in yield, process stability, or compatibility with lower-silver designs, those benefits may justify a premium that is more than offset by reduced cell-level cost. Structured evaluation frameworks that capture electrical, mechanical, and process metrics will support better sourcing outcomes over time.
Conclusion
The solar cell metal paste market is entering a phase where growth and differentiation are increasingly inseparable. Revenue expansion toward 344.8 million USD by 2032 reflects not only rising deployment but also the intensifying importance of metallization materials in enabling higher efficiency, lower silver intensity, and more resilient manufacturing economics. Suppliers that treat formulation performance, architecture compatibility, and application engineering as core strategic assets will be better positioned to capture value in a fragmented but increasingly demanding landscape.
For manufacturers, investors, and procurement leaders alike, the practical imperative is to look beyond unit prices and short-term price cycles. The most consequential decisions will involve how paste selection supports cost-per-watt objectives, how quickly suppliers can adapt to technology transitions, and how effectively sourcing strategies balance performance with supply resilience. For organizations seeking detailed segmentation data, company-specific assessments, and region-level commercial context to inform those decisions, a full research report can provide the structured depth needed to translate market trends into targeted execution plans.
For detailed analysis of this topic, please visit the official page: Solar Cell Metal Paste Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Slurry Pump Market: Why Asia Pacific's Steady Growth Reshapes Global Dynamics
By PW Consulting, 2026-09-21
Strategic Horizons in the Global Slurry Pump Market: Navigating Growth, Innovation, and Competitive Shifts
The slurry pump market stands at a pivotal intersection of industrial necessity and technological transformation. As heavy industries worldwide grapple with tougher materials, stricter efficiency mandates, and volatile supply chains, the demand for robust slurry handling solutions continues to evolve. Current projections indicate a moderate but steady expansion trajectory, with the market expected to grow from a base of approximately USD 1,247.48 million in 2025 to around USD 1,468.62 million by 2032, reflecting a compound annual growth rate of 2.5 percent. While this pace may appear subdued compared to high-growth technology sectors, it underscores a mature industry where value creation is increasingly driven by performance differentiation, lifecycle optimization, and regional demand shifts rather than volume alone.
Behind these headline figures lies a complex landscape shaped by contrasting regional dynamics, application-specific requirements, and a competitive field that blends established multinational players with specialized regional manufacturers. For executives, investors, and procurement leaders, understanding the forces reshaping this market is no longer optional—it is essential for capital allocation, product strategy, and operational resilience. This analysis examines the structural challenges defining the industry today, unpacks the core drivers of change, maps the competitive positioning of key players, and outlines the trends that will determine where value concentrates over the next five years.
Market Snapshot and Structural Challenges
The global slurry pump market has demonstrated resilience through a period of fluctuating industrial activity, with revenue figures climbing from roughly USD 1,000.0 million in 2020 to an estimated USD 1,247.48 million in 2025. This growth reflects sustained demand across mining, chemical processing, metallurgical operations, and construction applications, even as broader macroeconomic uncertainty and commodity price volatility tested capital expenditure cycles. The forecast period through 2032 suggests continued expansion, though at a pace that rewards operators who can navigate operational inefficiencies and supply chain constraints rather than simply chasing volume growth.
Several structural challenges are reshaping how companies approach slurry pump procurement and product development. First, the industry faces mounting pressure to balance durability with energy efficiency. Traditional heavy-duty designs have long prioritized wear resistance, but newer performance benchmarks now require hydraulic efficiencies in the 75 to 85 percent range, pushing manufacturers to rethink impeller geometries, casing designs, and material combinations. Achieving these targets without compromising reliability in abrasive or corrosive environments remains a persistent engineering hurdle.
Second, the supply chain for critical wear materials has emerged as a strategic vulnerability. High-chrome white iron alloys and specialized elastomers, which form the backbone of pump linings and internal components, are subject to intermittent shortages and price swings. For operators, this translates into unpredictable maintenance costs and longer lead times, while manufacturers must decide whether to vertically integrate material sourcing, diversify supplier networks, or redesign components to reduce dependency on scarce alloys. The cost dynamics are particularly pronounced for high-chrome variants, which can range from USD 0.50 to USD 1.50 per kilogram and directly influence the wear life expectancy of pump components deployed in mining circuits.
Third, regulatory and certification requirements are tightening across regions, compelling manufacturers to embed quality management and performance validation into their development processes. Compliance with standards such as ISO 9001:2015 and industry-specific hydraulic efficiency benchmarks is increasingly viewed as a baseline for market access, particularly in North America and Europe. Companies that treat certification as a 사후 consideration rather than a design parameter risk exclusion from tenders and long-term service contracts, especially in sectors where downtime costs far exceed equipment purchase prices.
Key Drivers Shaping Market Evolution
Technological Innovation and Material Science Breakthroughs
Innovation in slurry pump design is moving beyond incremental improvements to encompass material science, modular architecture, and application-specific customization. Manufacturers are investing in larger pump configurations tailored for high-flow decarbonization and carbon capture workflows, reflecting the broader industrial push toward emissions reduction. Simultaneously, advances in high-chrome iron alloys and wear-resistant elastomers are extending component lifespans in abrasive environments, reducing the frequency of rebuilds and lowering total cost of ownership for end users. Front pull-out shaft seal designs and gasite iron formulations are examples of engineering refinements that address leakage, maintenance accessibility, and metallurgical performance under extreme-duty conditions.
These technological shifts carry direct commercial implications. Manufacturers that can deliver pumps with demonstrably longer wear life and simpler maintenance procedures gain leverage in competitive bidding, particularly in mining and mineral processing where operational continuity is paramount. For buyers, the trend toward higher-efficiency and longer-life designs means a reevaluation of procurement criteria: upfront price is increasingly secondary to lifecycle cost, availability of replacement parts, and compatibility with existing plant infrastructure.
Policy and Regulatory Pressures
Regulatory frameworks are becoming a decisive factor in product adoption and regional market dynamics. Efficiency mandates and quality certification requirements are no longer optional benchmarks; they function as gatekeepers for participation in public tenders, large-scale infrastructure projects, and regulated industrial sectors. In the power generation and chemical industries, where slurry pumps handle hazardous or high-temperature fluids, compliance with stringent safety and performance standards directly influences vendor selection.
The policy environment also intersects with broader sustainability goals. As industries face increasing scrutiny over energy consumption and carbon footprints, pumps that contribute to lower power draw and reduced maintenance waste align with corporate environmental targets. This creates a dual incentive structure: manufacturers are compelled to design for efficiency and compliance, while end users are motivated to upgrade older, less efficient units to meet internal sustainability metrics and avoid regulatory penalties.
Demand-Side Shifts in Mining, Chemicals, and Industrial Processing
Demand patterns are being reshaped by the geographic redistribution of mining activity, the expansion of chemical processing capacity in emerging markets, and the modernization of aging industrial facilities in developed economies. Mining and mineral processing remain the largest application segment, driven by continuous extraction operations, tailings management requirements, and the need to handle increasingly abrasive ores. Chemical industry applications, meanwhile, demand pumps capable of managing corrosive slurries and precise flow control, pushing manufacturers to develop lined and specialized configurations that resist chemical degradation.
A notable demand-side shift is the growing preference for integrated service models. Operators are less interested in standalone equipment transactions and more focused on partnerships that include installation support, predictive maintenance tools, and rapid parts availability. This evolution reflects the reality that pump downtime in a mill circuit or chemical plant can cascade into significant production losses, making reliability and service responsiveness critical purchase criteria. Manufacturers that build service networks, digital monitoring capabilities, or modular replacement parts programs are positioning themselves to capture recurring revenue streams and deepen customer relationships.
Supply Chain Realignment and Cost Structure Dynamics
The cost structure of slurry pump manufacturing is undergoing recalibration as raw material volatility, regional production strategies, and logistics complexity intersect. Companies are responding by diversifying manufacturing footprints, expanding localized production capabilities, and investing in supply chain resilience. Recent capacity expansions in submersible pump manufacturing, supported by multi-million-dollar investments in North American facilities, illustrate how producers are aligning production capacity with regional demand centers to reduce lead times and mitigate freight cost fluctuations.
At the same time, the availability of specialty alloys and elastomers remains a wildcard. Price volatility in high-chrome materials forces manufacturers to make strategic trade-offs between component performance and cost predictability. Some are exploring alternative material formulations or hybrid lining designs that maintain wear resistance while reducing exposure to single-source suppliers. For the broader market, these supply chain adjustments influence not only product pricing but also the speed at which new models can be brought to market and the reliability of after-sales support.
PW Consulting
Competitive Landscape and Leadership Strategies
The slurry pump market exhibits moderate concentration, with the top three players accounting for approximately 28.5 percent of revenue and the top five collectively holding around 45.2 percent. This structure indicates a market where established leaders maintain strong positions through product breadth, technological pedigree, and global service networks, while regional specialists and niche manufacturers compete effectively in specific applications or geographies. The presence of both multinational firms and focused local players creates a dynamic environment where differentiation often hinges on application expertise, material science capabilities, and responsiveness to regional regulatory demands.
Leading manufacturers have carved distinct strategic identities. Sulzer has emphasized a comprehensive portfolio spanning heavy-duty horizontal and vertical configurations, with recent expansions targeting larger pump sizes for decarbonization and carbon capture workflows. Its investment in submersible manufacturing capacity in the United States reflects a deliberate push to align production with North American demand while reinforcing its value proposition around abrasion and corrosion resistance for mining and metals applications. KSB, through its GIW brand, has focused on extreme-duty mill circuits and tailings applications, leveraging high-chrome gasite iron and front pull-out shaft seal designs to address the most demanding operational environments. The phased North American rollout of its latest slurry pump series underscores a strategy of incremental market penetration supported by material and sealing innovations.
Slurry Tankers Market
In the Americas, Schurco Slurry and EDDY Pump have built reputations around heavy-duty horizontal and vertical centrifugal designs and high-solids handling capabilities, respectively. Schurco Slurry's focus on hard-rock mining and mineral processing, combined with a robust replacement parts offering, positions it as a practical choice for operators prioritizing uptime and component availability. EDDY Pump's emphasis on high-density, high-solids applications in mining, dredging, and wastewater highlights a niche-oriented approach that caters to specialized fluid handling requirements. Meanwhile, Kingda Pump Group has maintained a long-standing presence in engineered heavy-duty slurry and dredge pumps, with recent visibility at major industry exhibitions signaling continued engagement with mining and industrial end users in Latin America and beyond.
Chinese manufacturers such as Kingda Pump Group and Hebei Tobee Pump have expanded their footprint by offering warman-equivalent configurations across vertical, horizontal, and submersible categories, supported by full parts supply chains. This approach appeals to cost-conscious buyers and operators seeking compatibility with established pump standards while maintaining access to localized support. In parallel, companies like Goulds Pumps (ITT) and Metso continue to leverage their industrial scale and mineral processing expertise, offering extra-heavy-duty lined slurry pumps and specialized series tailored to mineral processing circuits.
The competitive landscape is also being shaped by targeted acquisitions and product-line expansions. The acquisition of a peristaltic slurry pump line by a European fluid handling specialist illustrates how firms are broadening their abrasive fluid handling portfolios to capture cross-industry demand, particularly in applications requiring gentle handling or precise dosing. Similarly, the launch of NSF/ANSI 61-certified surface pumps by a U.S.-based manufacturer reflects the growing importance of certification in water-related and regulated industrial applications, where compliance directly influences procurement eligibility.
Looking ahead, the market is likely to see continued consolidation among players seeking to expand geographic reach or application coverage, while specialized entrants may carve out niches in high-solids handling, hygienic processing, or region-specific service models. The differentiation frontier is shifting from pure equipment supply toward integrated solutions that combine material performance, efficiency certification, predictive maintenance tools, and rapid parts availability. Companies that can orchestrate these elements will be better positioned to defend margins and capture share in a market where volume growth alone does not guarantee profitability.
Future Trends and Commercial Opportunities (2026–2032)
Efficiency-Driven Product Refresh Cycles
As regulatory benchmarks and corporate sustainability targets tighten, a wave of equipment upgrades is expected across mining, chemical, and power generation facilities. Older slurry pumps with lower hydraulic efficiency and higher maintenance burdens will face replacement pressure, particularly in regions where energy costs are rising and downtime penalties are severe. This trend creates opportunities for manufacturers offering retrofits, high-efficiency replacements, and service programs that reduce the financial and operational barriers to upgrading. For investors, companies with strong aftermarket service networks and modular upgrade paths may benefit from recurring revenue tied to equipment refresh cycles rather than relying solely on new equipment sales.
Regional Demand Rebalancing and Localized Production
Demand is likely to continue shifting toward Asia Pacific and Latin America, driven by mining investment, infrastructure development, and industrial capacity expansion. In response, manufacturers will further localize production, service hubs, and parts distribution to reduce lead times and respond to regional procurement preferences. This geographic rebalancing presents commercial opportunities for firms that can establish credible local partnerships, navigate import and certification requirements, and offer culturally and operationally aligned support. However, it also introduces risk: companies that overinvest in regions with volatile commodity cycles or regulatory uncertainty may face underutilized capacity, while those that delay localization risk losing share to agile regional competitors.
Material Science and Wear Life as Competitive Differentiators
Advances in alloy formulations, elastomer technology, and lining designs will increasingly determine which manufacturers win in abrasive and corrosive applications. As high-chrome materials remain subject to price volatility and supply constraints, companies that develop alternative material strategies or secure stable supply relationships will gain a structural advantage. For end users, the commercial implication is clear: wear life longevity directly affects maintenance budgets and production continuity, making material performance a key evaluation criterion alongside initial price. Manufacturers that can provide verifiable wear life data, standardized testing results, and predictable replacement part availability will be able to command premium positioning in competitive tenders.
Strategic Recommendations for Decision Makers
For manufacturers and product developers, the priority is to embed efficiency, material resilience, and serviceability into the design phase rather than treating them as aftermarket enhancements. Investing in front pull-out seal architectures, high-chrome gasite iron options, and modular component designs can reduce maintenance friction and extend pump life in demanding circuits. At the same time, companies should evaluate supply chain exposure to critical alloys and elastomers, considering dual-sourcing strategies or alternative material formulations that preserve performance while reducing cost volatility. Building digital monitoring or predictive maintenance capabilities into pump offerings can further differentiate products in markets where operators value uptime and lifecycle cost transparency.
Worldwide Polishing Slurry Market
For investors, the slurry pump market rewards a selective approach that emphasizes companies with strong regional service networks, certification compliance, and application-specific expertise. Firms that combine equipment sales with aftermarket parts, rebuild services, and predictable lead times are better positioned to capture recurring revenue in a moderate-growth environment. Investment theses should also account for regional demand shifts: companies with credible footprints in Asia Pacific and Latin America, or those expanding localized production to serve these regions, may benefit from structural demand growth in mining and industrial processing. Conversely, exposure to single-region dependency or reliance on volatile raw material inputs without mitigation strategies warrants careful scrutiny.
For procurement leaders and plant operators, the buying decision should shift from lowest upfront price to total cost of ownership that accounts for wear life, energy consumption, parts availability, and service responsiveness. Evaluating manufacturers on their ability to provide certified efficiency performance, predictable rebuild schedules, and rapid parts fulfillment can reduce operational risk and avoid costly downtime. Where possible, procurement teams should seek standardized interfaces and compatibility with existing plant infrastructure to simplify future upgrades and minimize integration costs. Establishing long-term service agreements with manufacturers that demonstrate material science competence and regional support capacity can also stabilize maintenance budgets and improve equipment reliability over time.
The slurry pump market is entering a phase where competitive advantage will be defined less by scale alone and more by the ability to deliver technically differentiated, efficiently certified, and reliably supported solutions. As efficiency mandates tighten, material supply chains remain unpredictable, and demand continues to redistribute across regions and applications, organizations that act on these insights with disciplined product strategy, targeted regional investment, and lifecycle-focused procurement will be best positioned to capture value. For those seeking a deeper dive into segment-level dynamics, regional revenue distributions, and customized strategic scenarios, the full research report provides granular data and tailored recommendations to support precise decision-making.
For detailed analysis of this topic, please visit the official page: Slurry Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Borosilicate Glass Tubes Market: Why the 6.8% CAGR Through 2032 Redefines Competition
By PW Consulting, 2026-09-21
Strategic Trends & Commercial Opportunities in the Borosilicate Glass Tubes Market
Market Landscape and Core Pressures
The global borosilicate glass tubes market has demonstrated steady expansion over the past five years, moving from approximately $1.05 billion in 2020 to an estimated $1.54 billion in 2025. The trajectory reflects a compound annual growth rate of roughly 6.8 percent through 2032, with revenue projected to approach $2.4 billion by the end of the forecast period. This growth is not merely incremental; it is reshaping how manufacturers, procurement teams, and investors evaluate capacity, feedstock security, and long-term contract structures.
Behind the headline figures lies a market that is simultaneously broadening in application scope and tightening in operational discipline. Demand is no longer concentrated in traditional laboratory and chemical handling roles. Solar energy collection systems, pharmaceutical primary packaging, and heat-resistant industrial glassware are absorbing a growing share of production capacity. At the same time, the market remains moderately consolidated, with the top five producers accounting for just under half of total revenue. This concentration creates a landscape where scale, certification depth, and regional footprint matter, but it also leaves room for specialized players to compete on niche specifications, localized service, or sustainability credentials.
Key Challenges Shaping Strategic Positioning
Three pressures are forcing a recalibration of how incumbents and new entrants plan their next investment cycles.
- Feedstock volatility and constrained supply alternatives. Boric oxide and high-purity silica sand remain the foundational inputs for borosilicate formulations. The supplier base is limited, and disruptions in logistics or regional demand shifts can quickly translate into price moves at the tube level. Periodic spikes in boron-related costs have already rippled through procurement budgets, particularly when freight rates fluctuate or agricultural and industrial end-users compete for the same material pools.
- Regulatory alignment and certification overhead. Pharmaceutical and medical-grade applications demand strict adherence to quality management systems, including GMP-aligned certifications and traceable manufacturing controls. Maintaining compliance across multiple sites and product lines adds operational complexity. As global sourcing becomes more fragmented, buyers increasingly verify not just product specifications but the certification status of every production node in the supply chain.
- Carbon intensity and energy transition expectations. Energy-heavy melting processes sit at the core of glass tubing production. Rising interest in lower-carbon materials, coupled with procurement policies that factor environmental performance into supplier selection, is pushing manufacturers to reconsider furnace technology, energy sourcing, and process efficiency. Facilities that continue to rely on conventional thermal profiles may face growing friction in tenders where lifecycle emissions or renewable energy usage are evaluated alongside cost and quality.
Core Drivers Propelling Market Evolution
The expansion of borosilicate glass tubes is being pulled by a combination of technical, regulatory, demand-side, and supply-chain forces. Understanding which drivers are structural versus cyclical helps decision-makers prioritize where to allocate capital and operational attention.
Technical Innovation and Process Breakthroughs
Advances in melting technology and product formulation are changing what is commercially feasible. The introduction of all-electric melting furnaces powered by renewable energy represents a meaningful shift in how pharmaceutical-grade tubing can be produced at scale. By reducing reliance on fossil-derived heat, manufacturers can lower process emissions while maintaining the tight tolerances required for vials, cartridges, syringes, and laboratory capillaries. This development is not only an environmental milestone; it also creates a differentiator in procurement discussions where buyers increasingly weigh carbon performance alongside dimensional stability and breakage resistance.
In parallel, continuous improvements in tubing consistency, wall thickness control, and surface quality are expanding the usable range of borosilicate tubes in high-precision applications. For pharmaceutical packaging and laboratory apparatus, reliability across batches is critical. Producers that can demonstrate tighter process control and reliable certification coverage are better positioned to win long-term supply agreements, particularly in regions where local content preferences or risk-mitigation strategies favor domestic or nearshore sourcing.
Policy and Regulatory Environment
Regulatory dynamics are reinforcing demand for certified borosilicate glass in pharmaceutical and medical contexts. Quality management standards, GMP-aligned production requirements, and increasingly rigorous traceability expectations are raising the barrier to entry for non-specialized suppliers. Importantly, these requirements are not static. As health authorities and procurement organizations tighten expectations around material compatibility, contamination control, and supplier validation, the value of established certification portfolios grows.
Trade and sourcing patterns are also evolving. European import flows for borate materials have shown upward movement in recent years, with Türkiye continuing to play a central role as a supply origin. Such patterns highlight the interdependence between regional availability and production planning. Manufacturers that rely on a narrow set of feedstock channels must monitor geopolitical and trade developments closely, since shifts in import volumes or tariff structures can affect both cost and continuity.
Demand-Side Shifts in End-Use Behavior
Demand is being reshaped by how end users prioritize performance, sustainability, and supply resilience. In pharmaceutical packaging, the continued emphasis on primary container integrity and patient safety keeps borosilicate tubing at the center of vial and ampoule production. For laboratory and scientific applications, the need for chemically resistant, thermally stable glass remains a durable base load for the market.
At the same time, new application momentum is emerging from solar energy systems that utilize borosilicate-based tubes, alongside heat-related industrial glassware where temperature resistance and durability are essential. These segments do not just add volume; they change the specification mix. Buyers in these areas often weigh total cost of ownership, operational lifespan, and environmental exposure more heavily than upfront price alone. That shift encourages manufacturers to think beyond commodity supply and toward application-tailored performance, technical support, and longer-cycle partnerships.
Supply Chain and Cost Structure Dynamics
Cost structures are being tested by the intersection of energy pricing, feedstock availability, and logistics. Boron-related pricing has exhibited sensitivity to freight movement and seasonal demand from both glass manufacturing and agriculture, underscoring how even specialized materials can be influenced by broader commodity cycles. Because high-purity silica sand and boric oxide have limited comparable suppliers globally, supply-chain vulnerabilities are not theoretical; they are operational realities that can affect scheduling, margin planning, and customer commitments.
In response, several producers are rethinking geographic distribution of capacity. New facilities and joint ventures in key demand regions are intended to shorten lead times, reduce transport exposure, and improve responsiveness to local specification requirements. This regionalization trend also intersects with customer preferences for lower-risk sourcing, especially where pharmaceutical or regulated applications are concerned. The net effect is a market in which proximity, certification readiness, and feedstock management are becoming as strategically relevant as production scale alone.
Competitive Landscape and Strategic Positioning
The competitive environment is defined by a set of established players with deep application expertise, strong brand recognition in specific verticals, and increasingly visible efforts to align capacity with demand geography and sustainability expectations.
Quartz Tubing Market
Strategic Positioning of Leading Companies
Corning Incorporated continues to assert its position as a leading supplier of Type I borosilicate glass tubing for pharmaceutical primary packaging. Its focus on products such as Corning® 51 and Corning® 33 tubing underscores a strategy centered on regulatory-grade quality, pharmaceutical compatibility, and broad packaging formats including vials, ampoules, cartridges, and syringes. Recent activity includes the inauguration of a new pharmaceutical glass tubing manufacturing facility in India developed with joint venture partner SGD Pharma, alongside a move to strengthen the European production base through SGD Pharma's acquisition of Alphial S.r.l. These steps suggest a deliberate combination of regional capacity expansion and consolidation of pharmaceutical tubing assets.
SCHOTT AG maintains a prominent global presence in Type I borosilicate tubing through the FIOLAX® and DURAN® brands, covering pharmaceutical and laboratory applications across an extensive range of glass types. Its multi-product portfolio and long-standing certification infrastructure position it well for customers who require broad specification coverage and documented quality systems. The emphasis on maintaining ISO 9001 and ISO 15378 (GMP) certifications across tubing production sites reflects a strategic priority on compliance assurance and buyer confidence in regulated markets.
DWK Life Sciences focuses on premium laboratory borosilicate glass 3.3, including DURAN® tubing, rods, and capillaries for scientific, chemical, and industrial use. Its specialization supports a strategy built on application depth in laboratory and chemical contexts, where consistent quality and recognized brand trust matter highly. By concentrating on scientific and industrial performance rather than broad pharmaceutical packaging, DWK Life Sciences occupies a distinct flank in the market.
Nipro Corporation operates as a major global manufacturer of premium borosilicate tubing for pharmaceutical packaging, with multiple production sites supporting scale and regional flexibility. Its product range, including grades such as G38 and NSV51, highlights a pharmaceutical-oriented strategy with geographic breadth. This footprint supports continuity of supply and responsiveness across markets where packaging demand is growing or where localized production is preferred.
Nippon Electric Glass Co., Ltd. supplies BS-series borosilicate tubing for pharmaceutical containers and medical applications, and has recently drawn attention for beginning mass production of pharmaceutical glass tubing using an all-electric melting furnace with renewable energy at its Malaysia facility. This move positions the company at the intersection of quality-focused pharmaceutical supply and lower-carbon manufacturing, a combination that is likely to resonate with buyers assessing both performance and sustainability in their supplier evaluations.
Borosil Limited produces borosilicate glass tubes and rods for laboratory and scientific applications, representing a strong regional presence in a segment where trusted laboratory glassware remains a steady demand center. Its positioning shows how regional specialists can compete by aligning product range, service, and local market knowledge with the expectations of scientific and industrial buyers.
How the Landscape Is Evolving
The market is showing signs of both consolidation and targeted expansion. In pharmaceutical-grade tubing, activity suggests a push toward stronger regional production bases and bundled capability through partnerships or acquisitions. This is consistent with a broader pattern in which leading producers seek to reduce supply-chain distance, reinforce certification continuity, and capture growth in regions where pharmaceutical packaging demand is expanding.
At the same time, differentiation is increasingly multidimensional. Scale alone is no longer sufficient to secure advantage. Buyers compare suppliers on certification depth, energy and carbon profile, application-specific reliability, and logistics resilience. As a result, competition is becoming more segmented: some players compete primarily on pharmaceutical compliance and volume, others on laboratory-grade specialization, and a growing set of evaluators are paying attention to low-carbon process technology as a criterion in supplier selection.
New entrants and regional specialists can still find room by addressing localized needs, offering responsive service, or developing expertise in specific tube grades, dimensions, or end-use requirements. However, the certification burden and feedstock complexity mean that credibility and operational discipline are necessary for durable participation, especially in regulated segments.
Forward-Looking Trends and Commercial Implications
Looking across the 2026–2032 window, several trends are likely to shape where value accrues and where risk concentrates.
Trend 1: Regionalization of Pharmaceutical-Grade Capacity
Pharmaceutical packaging demand is expected to remain a central growth engine, and producers will continue to align capacity more closely with key demand regions. This regionalization reduces exposure to long logistics chains, supports faster response times, and can improve alignment with local sourcing expectations. For commercial actors, the implication is clear: supply relationships will increasingly favor vendors who can demonstrate not only product quality but also production proximity, local certification coverage, and predictable continuity.
Commercial opportunity lies in multi-year supply arrangements, technical co-development around container formats, and resilient backup sourcing strategies. Buyers can use regional capacity to reduce lead-time variability, while producers can use localized facilities to strengthen customer stickiness and expand share in growing markets.
Trend 2: Sustainability as a Procurement Filter
Lower-carbon production methods are moving from experimental narrative to commercial relevance. The adoption of all-electric melting and renewable energy sourcing in pharmaceutical tubing production signals that environmental performance can be integrated into high-precision manufacturing without abandoning the quality demands of regulated applications. As procurement teams broaden evaluation criteria, suppliers with demonstrable energy and emissions advantages may gain preference in tenders, particularly where corporate sustainability commitments or customer expectations create additional pressure.
PW Consulting
This trend creates opportunities for manufacturers to differentiate through process innovation and for buyers to align supply choices with broader environmental targets. The uncertainty lies in how consistently sustainability metrics will be weighted against cost, quality, and reliability across different regions and industries. Producers that invest early in measurable, verifiable improvements are better positioned than those that rely on generalized claims.
Trend 3: Application Diversification and Specification Complexity
demand is gradually broadening beyond traditional laboratory and chemical uses toward solar energy tubes, heat glassware, and other specialized applications. This diversification introduces both opportunity and complexity. Different applications impose different requirements on thermal performance, chemical resistance, dimensional tolerance, and lifecycle durability. Suppliers that can manage specification complexity while maintaining efficient production are more likely to capture margin across a wider set of use cases.
For buyers, the opportunity is to secure materials that fit long-term operational needs rather than simply meeting immediate cost targets. For suppliers, the risk is that spreading capacity across too many divergent specifications can erode efficiency if not managed with disciplined product architecture and demand forecasting.
Risk and Uncertainty Considerations
Several variables could alter the pace or distribution of growth. Feedstock availability and price movement remain a persistent risk, particularly where supplier alternatives are limited. Energy costs and the pace of transition to lower-carbon furnace technology will influence both operating economics and competitive positioning. Trade dynamics, including shifting import volumes and origin patterns for borate materials, can affect cost structures and sourcing strategies. Finally, demand timing in newer applications such as solar-related tubes may be uneven, creating pockets of rapid adoption in some regions or customer segments while remaining more gradual in others.
Borosilicate Glass Market
Strategic flexibility is essential. Organisations that lock into single-source feedstock arrangements, rigid capacity plans, or narrow application bets without monitoring these variables may find themselves exposed to cost shocks or demand mismatches.
Actionable Recommendations for Decision-Makers
Different roles in the value chain should prioritize different decisions, but all benefit from a clearer view of where market momentum is building and where vulnerability is accumulating.
For Manufacturers and Producers
- Align capacity expansion with regional demand centers and regulatory expectations. Where pharmaceutical or laboratory demand is growing, evaluate whether local or nearshore production can improve service levels and reduce logistics exposure.
- Invest in process differentiation that can be verified, not just promoted. All-electric melting, renewable energy integration, and documented certification coverage are examples of attributes that can be demonstrated to buyers and procurement teams with increasing scrutiny.
- Strengthen feedstock strategy. Diversify sourcing where feasible, monitor boron and silica supply dynamics, and build contingency planning into procurement and production schedules to reduce vulnerability to price or availability shocks.
- Manage specification complexity deliberately. Expanding into new application areas can be profitable, but only if product architecture, quality systems, and forecasting are designed to support varied requirements without sacrificing efficiency.
For Investors and Strategic Planners
- Focus on structural drivers rather than short-term volume spikes. The combination of pharmaceutical packaging demand, laboratory stability, and emerging application segments provides a multi-engine growth path, but the durability of each engine depends on regulatory continuity, feedstock stability, and energy economics.
- Evaluate competitive advantage through a broader lens. Scale remains relevant, but certification depth, regional footprint, process sustainability, and application specialization increasingly determine which players can defend pricing and win long-term contracts.
- Track consolidation signals and partnership activity. Joint ventures, facility launches, and acquisitions in pharmaceutical tubing indicate where incumbents believe durable value will be created. These moves can reveal shifts in regional strategy and capacity control.
- Incorporate supply-chain resilience into valuation and planning. Feedstock concentration and energy transition costs can affect margins and operational continuity, making them relevant to risk assessment as well as growth potential.
For Procurement and Sourcing Leaders
- Broaden supplier evaluation criteria. Quality and price remain essential, but certification coverage, production location, energy and carbon profile, and contingency capability should be part of the decision framework, especially for regulated or long-life applications.
- Use regional availability as a risk-mitigation lever. Where possible, balance global sourcing with regional or nearshore options to reduce lead-time variability and improve responsiveness to specification changes or urgent requirements.
- Engage earlier on application requirements. For solar, heat glassware, pharmaceutical packaging, and laboratory use, aligning on performance expectations and lifecycle needs before procurement can reduce rework, incompatibility risk, and total cost over time.
- Plan for feedstock and energy volatility. Build flexibility into contracts and inventory strategies where feasible, and monitor commodity and trade developments that can influence borosilicate tube costs and availability.
Closing Perspective
The borosilicate glass tubes market is moving through a phase in which growth is increasingly tied to application breadth, regulatory confidence, supply resilience, and process sustainability. The market's expansion from roughly $1.05 billion in 2020 toward nearly $2.4 billion by 2032 reflects more than incremental demand; it signals a shift in how value is created and protected. Feedstock constraints, certification expectations, and energy transition pressures are not marginal concerns. They are shaping supplier selection, capacity planning, and the definition of competitive advantage.
For manufacturers, the priority is to match capacity and differentiation with where demand is becoming most durable. For investors, the task is to distinguish structural growth from cyclical noise and to assess whether competitive positioning can withstand feedstock, energy, and trade volatility. For procurement leaders, the opportunity lies in using broader evaluation criteria to secure supply that supports both operational reliability and longer-term strategic goals.
Deeper segmentation data, region-by-region dynamics, application-level demand patterns, and company-specific strategic assessments can sharpen these decisions further. Detailed market intelligence is especially valuable when sizing growth opportunities in newer applications, evaluating the pace of regional capacity shifts, or benchmarking supplier claims against operational realities. In a market where feedstock, regulation, and sustainability expectations are all moving at once, timely and granular insight can make the difference between reactive sourcing and proactive strategy.
For detailed analysis of this topic, please visit the official page: Borosilicate Glass Tubes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Resistant Dextrin Market: Why 6.98% CAGR Signals a Structural Shift Beneath the $317M Forecast
By PW Consulting, 2026-09-21
The Resistant Dextrin Market: Strategic Trends and Commercial Opportunities Through 2032
The resistant dextrin market has transitioned from a niche dietary fiber niche to a mainstream functional ingredient category with substantial commercial momentum. Valued at approximately USD 198 million in 2025, the market has demonstrated a compound annual growth rate of 6.98 percent over the historical period and is projected to expand steadily through 2032. This trajectory reflects the convergence of multiple structural shifts: rising consumer awareness of gut health, regulatory recognition of resistant dextrin as a legitimate dietary fiber, and manufacturing innovations that enable broader application across food, beverage, and nutraceutical formats. For executives and investors navigating this landscape, the market presents meaningful opportunities alongside distinct competitive and operational risks that require careful strategic positioning.
Understanding where this market is heading requires looking beyond aggregate revenue figures. The underlying dynamics involve evolving formulation requirements, shifting supply chain cost structures, and an increasingly polarized competitive field where differentiation hinges on clinical validation, regulatory approvals, and application-specific performance. This analysis examines the current market structure, the forces driving change, the competitive landscape, and the strategic implications for stakeholders across the value chain.
Market Landscape and Structural Challenges
The market's expansion over the past several years has been anything but linear. Historical data reveals periods of contraction followed by renewed growth, underscoring the influence of external shocks and demand elasticity. After a moderate decline in 2022, the market rebounded strongly through 2025 and is forecast to accelerate notably in the latter half of the projection period. This pattern suggests that the category is sensitive to macroeconomic conditions, raw material pricing, and the pace of regulatory developments, yet maintains a resilient long-term growth trajectory driven by fundamental demand shifts.
Several structural challenges define the current inflection point for resistant dextrin.
Supply Chain Volatility and Input Cost Pressure
The cost environment for key raw materials has introduced significant uncertainty into margin planning. Corn starch, a primary feedstock for most resistant dextrin production, experienced a sharp price escalation in mid-2025, reaching record levels that placed upward pressure on manufacturing costs across the value chain. For producers operating on thin margins or competing in price-sensitive segments, this volatility complicates inventory management, long-term contracting, and pricing strategies. Companies that fail to implement hedging mechanisms, diversify feedstock sources, or pass through costs effectively risk compressing profitability during periods of sustained input inflation.
Regulatory Fragmentation and Claim substantiation Requirements
While resistant dextrin enjoys growing regulatory acceptance, the path to commercialization remains uneven across jurisdictions and application categories. Regulatory recognition of specific fiber types, permissible health claims, and labeling requirements differ across regions and continue to evolve. In this environment, manufacturers must invest in clinical substantiation and regulatory navigation to secure approvals and defend market access. The increasing emphasis on evidence-backed positioning means that companies without robust clinical data or established regulatory relationships face a higher barrier to entry, particularly in healthcare and nutraceutical segments where claim substantiation is a prerequisite rather than an optional differentiator.
Application-Specific Formulation Constraints
Resistant dextrin is not a one-size-fits-all ingredient. Functional performance varies by source material, processing method, solubility profile, and compatibility with different formulation environments. Food and beverage developers face constraints related to taste modification, texture impact, stability under processing conditions, and interaction with other ingredients. These technical considerations limit the speed at which resistant dextrin can be adopted across new applications and create opportunities for suppliers who can provide application support, customized formats, and formulation guidance. The gap between generic availability and application-ready solutions represents both a challenge and a strategic lever for differentiation.
Key Drivers Shaping Market Dynamics
The growth trajectory of resistant dextrin is propelled by a combination of technological, regulatory, demand-side, and supply chain factors. Each driver carries distinct implications for market participants.
PW Consulting
Technological Innovation and Product Differentiation
Advances in enzymatic processing, starch modification, and purification techniques have expanded the range of resistant dextrin grades available to formulators. Manufacturers now offer variations in fiber content, solubility, particle size, and functional properties that enable tailored solutions for specific applications. These innovations support broader adoption by addressing formulation challenges that previously limited use in sensitive matrices such as low-pH beverages, baked goods, and clear-liquid formats.
Beyond physical properties, the emphasis on clinical validation has become a central dimension of product differentiation. Independent verification of prebiotic activity and gut health benefits through recognized certification programs has emerged as a credibility marker that resonates with both consumers and purchasing managers. Recent certification achievements by leading suppliers demonstrate how clinical evidence can be translated into marketable claims that support premium positioning and facilitate adoption in health-oriented formulations. These developments signal a shift from commodity-driven competition to evidence-based differentiation, where the strength of scientific backing increasingly determines market access and pricing power.
Regulatory Progress and Recognition Expansion
The regulatory environment has been a meaningful tailwind for resistant dextrin adoption. Recognition by major regulatory bodies as a valid dietary fiber, alongside expanded Generally Recognized as Safe status for additional food categories, has reduced ambiguity for formulators and accelerated inclusion in new products. Expanded approvals covering reduced-calorie beverages and other application areas illustrate how regulatory clarity can unlock growth by lowering development risk and enabling faster time-to-market.
Resistant Starch Market
At the same time, the regulatory landscape continues to reward companies that proactively engage with authorities and maintain comprehensive dossiers. Suppliers with established regulatory histories and documented safety profiles are better positioned to support customers through the approval process and navigate emerging requirements. As regulatory scrutiny around health claims and ingredient transparency intensifies, this capability becomes a strategic asset that compounds over time, creating a moat around well-prepared market participants.
Consumer and Enterprise Demand Shifts
Demand for functional ingredients with digestive health benefits has moved from a fringe concern to a mainstream purchasing driver. Consumers increasingly associate gut health with broader wellness outcomes, influencing food and beverage selection across categories. This shift has prompted manufacturers to incorporate fiber and prebiotic ingredients into everyday products, not just specialized health supplements. The result is a broader application footprint for resistant dextrin, spanning everyday beverages, bakery items, confectionery, dairy alternatives, and convenience foods.
On the enterprise side, brands face pressure to deliver products that align with clean-label expectations, sugar reduction goals, and functional benefits without compromising sensory quality. Resistant dextrin offers advantages in this context, including solubility, neutral flavor profiles in certain grades, and compatibility with nutritional goals such as fiber enrichment and calorie management. As product development cycles shorten and consumer expectations rise, ingredient suppliers that can provide technical support, co-development services, and rapid prototyping capabilities gain a competitive edge in securing inclusion in new formulations.
Supply Chain Structure and Cost Dynamics
The supply chain for resistant dextrin is shaped by the availability and pricing of starch feedstocks, the geographic distribution of manufacturing capacity, and logistics considerations. Production is concentrated among established players with integrated starch processing capabilities or long-standing supplier relationships, while emerging manufacturers seek to enter the market through cost-competitive positioning or regional focus. This structure creates both stability and vulnerability.
Record raw material prices illustrate how input cost fluctuations can ripple through the value chain, affecting producer margins, supplier pricing, and ultimately end-product economics. Companies that operate with flexible sourcing strategies, forward contracting, or diversified feedstock portfolios are better equipped to manage these dynamics. Conversely, reliance on single-source inputs or inflexible contract terms heightens exposure to price shocks. Over time, cost structure resilience will likely become a more prominent factor in supplier selection, particularly for large-volume buyers seeking supply security alongside competitive pricing.
Competitive Landscape and Strategic Positioning
The resistant dextrin market is characterized by a mix of established multinational ingredient suppliers and specialized manufacturers, with a notable degree of concentration among leading players. This concentration reflects the technical and regulatory barriers to entry, as well as the importance of scale, application expertise, and regulatory track records in securing market share.
Maltodextrin Market
Leading Players and Strategic Differentiation
Several companies occupy prominent positions by leveraging distinct strengths. Global ingredient manufacturers with broad portfolios and established relationships across food, beverage, and pharmaceutical channels benefit from scale, regulatory experience, and the ability to support customers across multiple markets. These players often differentiate through comprehensive technical service, co-development capabilities, and the credibility that comes with long-standing regulatory recognition.
Specialized producers have carved out positions by focusing on specific formats, source materials, or certification-backed claims. Companies offering resistant dextrin derived from corn or tapioca, with options spanning powder, liquid, and agglomerated formats, address varied formulation needs and enable customers to select grades suited to their application constraints. The availability of non-GMO, kosher, and other quality certifications further expands market access, particularly in segments where these attributes carry significant purchasing weight.
Increasingly, the competitive battleground is shifting toward evidence-based positioning. Suppliers that invest in clinical substantiation and secure independent verification of functional benefits are able to command stronger brand recognition and support customer claims with defensible data. This trend favors companies with the resources to conduct or commission clinical research and the regulatory expertise to translate findings into approved claims and certification status.
Market Consolidation and Emerging Entrants
The market structure suggests ongoing consolidation pressure, driven by the economies of scale associated with production, regulatory investment, and global distribution. Larger players are well positioned to absorb input cost volatility, fund application research, and expand capacity in response to demand growth. At the same time, regional manufacturers and distributors can find opportunities by serving localized demand, offering cost-advantaged products, or focusing on niche segments where broader players may not prioritize investment.
New entrants face meaningful hurdles. Establishing regulatory recognition, building clinical credibility, and securing consistent feedstock supply require capital and time. However, partnerships with established producers, contract manufacturing arrangements, and focused geographic strategies can provide pathways for incremental market participation. The presence of distributors and bulk suppliers that aggregate products from multiple producers also adds a layer of intermediation, which can benefit end-users seeking simplified sourcing while introducing additional considerations around quality control and supply traceability.
Forward Outlook: Trends and Opportunities (2026–2032)
Looking ahead, several trends are likely to shape the resistant dextrin market over the next several years, each carrying distinct commercial implications.
Accelerated Adoption in Everyday Food and Beverage Formats
As regulatory recognition expands and formulation capabilities improve, resistant dextrin is poised to move further into mainstream food and beverage applications. Categories that were once considered challenging for fiber enrichment, such as clear beverages, confectionery, and shelf-stable products, are becoming more accessible as ingredient grades and processing techniques evolve. This broadening application base supports volume growth and creates opportunities for suppliers who can demonstrate application-specific performance and provide formulation support that reduces development friction.
For brands, the opportunity lies in leveraging resistant dextrin to meet multiple objectives simultaneously: fiber enrichment, sugar reduction, texture management, and functional benefits. Success in this environment depends on selecting grades that align with product requirements and on communicating benefits in ways that resonate with target consumers without overstepping regulatory boundaries.
Evidence-Based Positioning as a Core Competitive Lever
The emphasis on clinical evidence and independent certification is expected to intensify. As consumers and purchasing managers become more sophisticated about ingredient claims, suppliers with verified functional benefits and documented safety profiles will hold an advantage in securing inclusion in premium and health-oriented products. Certification programs that evaluate prebiotic function and other claimed benefits provide third-party validation that can differentiate products in crowded markets and support premium pricing where justified.
This trend also introduces risk for companies that rely on generic positioning without substantive clinical backing. As the category matures, differentiation will increasingly depend on the credibility of functional claims and the quality of supporting data, making investment in research and regulatory documentation a strategic priority rather than an optional enhancement.
Supply Chain Resilience and Sourcing Strategy Recalibration
Input cost volatility and the concentration of feedstock supply are likely to drive recalibration of sourcing strategies across the value chain. Buyers and producers alike will place greater emphasis on supply security, long-term contracting, feedstock diversification, and regional capacity considerations. These dynamics may encourage investment in additional production capacity in key markets, as well as closer collaboration between ingredient suppliers and end-product manufacturers to manage risk and ensure consistent availability.
For market participants, the strategic implication is clear: resilience in supply chain design will increasingly influence competitiveness. Companies that build flexibility into sourcing, maintain transparent quality systems, and develop contingency plans for input disruptions will be better positioned to sustain operations and customer relationships through periods of volatility.
Potential Risks and Uncertainties
Despite the favorable long-term outlook, risks remain. Regulatory shifts, including changes to fiber recognition criteria or health claim requirements, could alter market access conditions. Raw material cost fluctuations may compress margins for players without effective risk management. Competitive intensity could increase as new entrants attempt to capture share through price competition, potentially pressuring returns in segments where differentiation is weaker. Additionally, consumer trends are subject to change, and categories that appear promising today may face headwinds if broader wellness preferences shift or if alternative ingredients gain traction.
Navigating these uncertainties requires continuous monitoring of regulatory developments, input market conditions, and competitive activity. Strategic agility, grounded in accurate intelligence, will be essential for capitalizing on opportunities while mitigating downside exposure.
Strategic Implications for Decision-Makers
The resistant dextrin market presents distinct considerations for manufacturers, investors, and procurement professionals. Each group faces different priorities and time horizons, but all stand to benefit from a clear understanding of market dynamics and a proactive approach to positioning.
For Ingredient Manufacturers and Formulators
- Invest in application-specific value propositions. Differentiate beyond basic fiber content by demonstrating performance in target matrices, offering multiple formats, and providing technical support that reduces customer development time.
- Strengthen regulatory and clinical credibility. Proactively pursue regulatory recognition for new applications, maintain comprehensive safety documentation, and consider independent verification of functional claims to support differentiation and customer confidence.
- Build supply chain resilience. Evaluate feedstock sourcing options, consider forward contracting or diversification strategies, and assess how input cost volatility may affect margins under different scenarios.
For Investors and Strategic Capital Allocators
- Assess differentiation quality, not just scale. Evaluate companies based on their regulatory track records, clinical substantiation, application expertise, and ability to command premium positioning rather than volume alone.
- Monitor consolidation dynamics and capacity investments. Track which players are expanding capacity, entering new geographies, or securing certifications, as these moves often signal strategic intent and can reshape competitive balance.
- Consider downstream integration and partnership models. Opportunities may exist in companies that offer integrated solutions, co-development services, or distribution models that simplify sourcing for end-users, particularly as demand broadens across applications.
For Procurement and Sourcing Professionals
- Prioritize supply security alongside cost. Evaluate suppliers on feedstock flexibility, production capacity, quality certifications, and contingency capabilities, recognizing that input volatility can affect availability and pricing over time.
- Leverage application support in supplier selection. Suppliers that provide formulation guidance, technical service, and co-development resources can reduce time-to-market and improve product outcomes, adding value beyond the ingredient itself.
- Stay informed on regulatory and claim developments. Understanding evolving recognition status and certification options enables more confident product positioning and helps avoid compliance risks associated with unsupported claims.
Conclusion
The resistant dextrin market is at a point where fundamental demand drivers, regulatory progress, and technological capability are aligning to support sustained growth. The projected expansion through 2032 reflects not only increasing volume but also the broadening of applications and the deepening of competitive differentiation around evidence, format flexibility, and supply reliability. For stakeholders across the value chain, the path to capturing value lies in understanding these dynamics in detail and acting with strategic precision.
Aggregate market figures provide a useful baseline, but the real strategic complexity resides in segment-level dynamics, regional regulatory variations, application-specific performance requirements, and the evolving cost structure of feedstock supply. Accessing granular data on subsegments, competitive benchmarks, and scenario-based forecasts can materially improve decision quality, whether the objective is product development, capacity planning, investment allocation, or sourcing strategy. Deeper intelligence enables more confident navigation of a market that is simultaneously expanding and becoming more competitive.
For detailed analysis of this topic, please visit the official page: Resistant Dextrin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


