



Category: market research
Optical Transceivers Market 2026: How 13.5% CAGR Reshapes Data Center Competition
By PW Consulting, 2026-09-21
The Optical Transceivers Market: Strategic Trends and Commercial Opportunities in a High-Speed Era
The global optical transceivers market has entered a phase of accelerated expansion, driven by an unprecedented surge in data traffic and the rapid deployment of high-performance computing infrastructure. From 2020 to 2025, the market experienced a compound annual growth rate that significantly outpaced broader semiconductor sectors, culminating in an estimated annual revenue of USD 13.9 billion for the base year 2025. This trajectory is projected to continue through the forecast period ending 2032, with the market size expected to more than double from its 2025 base. The sustained momentum suggests a CAGR of approximately 13.5 percent over the forecast horizon, indicating that optical connectivity is transitioning from a supporting component to a critical bottleneck and enabler of digital infrastructure.
However, this growth is not linear. The industry stands at a complex inflection point where technological capability, regulatory friction, and supply chain realities intersect. While demand signals from hyperscale data centers and telecommunications providers remain robust, the path to capturing value is fraught with challenges that require strategic navigation rather than passive participation. Understanding these dynamics is essential for executives and investors looking to position themselves advantageously in the coming cycle.
Market Landscape and Core Challenges
The current market environment is characterized by intense demand for higher bandwidth densities, yet this demand is mediated by significant structural constraints. The market size evolution from 2020 to 2032 reflects a compounding effect of data center expansion and network modernization, but the concentration of revenue among top players indicates a mature competitive field. With the top three and top five companies holding an identical market concentration share, the barrier to entry for new competitors remains high, while existing players must defend share through continuous innovation and cost efficiency.
Several key challenges define the current operational landscape. First, the transition to higher data rates such as 400G and 800G has introduced substantial complexity in manufacturing tolerances. Precision photonic components, including laser diodes and photodetectors, require stringent production controls. These technical requirements contribute to elevated unit costs, creating a cost structure that can strain margins if volume scaling does not materialize as expected. High manufacturing costs and component supply chain vulnerabilities result in elevated unit costs for 400G and 800G modules, making price sensitivity a relevant factor despite strong overall demand.
Worldwide Copper Transceivers Market
Second, geopolitical friction is reshaping supply chain strategies. US-China Technology Export Restrictions are disrupting supply chains for key optical components, forcing manufacturers to reconsider sourcing strategies and regional footprints. This regulatory environment introduces uncertainty regarding component availability and potential delays in product rollouts. Simultaneously, the EU's Push for Digital Sovereignty is stimulating local manufacturing and innovation in optical transceivers, creating divergent regional incentives that complicate global standardization efforts.
Third, the industry must reconcile the pace of technological obsolescence with capital investment cycles. As hyperscale operators push for next-generation interconnects to support AI workloads, the window for profitable deployment of specific transceiver generations narrows. Companies must balance the risk of investing in standards that may evolve rapidly against the risk of falling behind in performance capabilities required by key customers. The industry must navigate the tension between performance leadership and manufacturing readiness, particularly as specifications move toward 1.6T and beyond.
Key Drivers of Market Evolution
The expansion of the optical transceivers market is underpinned by a convergence of technological, regulatory, and demand-side factors. Understanding the interplay between these drivers provides a clearer picture of where growth will originate and how value will be captured over the next several years.
Technological Innovation and Breakthroughs
The primary engine of growth remains the relentless push for higher data throughput per lane. The industry is shifting from 100G and 200G per lane architectures toward 400G and 800G standards, with early developments pointing toward 1.6T capabilities. This shift is not merely an incremental upgrade; it requires fundamental changes in transceiver design, including the adoption of advanced modulation formats, silicon photonics integration, and co-packaged optics.
Recent developments illustrate the pace of this innovation. In April 2025, Coherent Corp. demonstrated its 1.6T-SR8 optical transceiver based on advanced 200G VCSELs at OFC 2025. This demonstration highlights the industry's focus on pushing the limits of vertical-cavity surface-emitting laser technology to achieve higher densities without compromising power efficiency. Such advancements are critical for hyperscale AI data centers, where power and space constraints are as binding as bandwidth requirements.
Concurrently, the move toward co-packaged optics represents a structural shift in how optical interfaces are integrated with switching silicon. By moving the optical engine closer to the ASIC, vendors can reduce electrical interconnect losses and improve energy efficiency. Broadcom Inc. announced the shipment of its industry's first 102.4 Tbps co-packaged optics Ethernet switch with 200 Gbps per channel performance in October 2025. This milestone signals that co-packaged optics are moving from conceptual demonstrations to commercial shipments, opening new design paradigms for AI infrastructure. These technological breakthroughs directly influence market composition by creating demand for specialized transceiver modules and integrated optical engines that differ from traditional pluggable form factors.
Policy and Regulatory Environment
Regulatory frameworks are increasingly shaping market dynamics, influencing both supply chains and demand patterns. On one hand, trade restrictions and export controls are fragmenting the global supply base. The disruption of supply chains for key optical components creates divergence between regions that can access advanced manufacturing capabilities and those that face constraints. This environment incentivizes regionalization of production, as companies seek to mitigate risk by establishing local manufacturing hubs or securing supply from allied jurisdictions.
On the other hand, policy initiatives aimed at digital infrastructure development are stimulating demand. The EU's Push for Digital Sovereignty is stimulating local manufacturing and innovation in optical transceivers, while harmonized regulation under the European Electronic Communications Code is streamlining spectrum allocation and infrastructure deployment approvals. These regulatory improvements reduce friction for network operators deploying new capacity, indirectly boosting the addressable market for transceivers in European telecommunications and enterprise networks. Additionally, national strategies in Asia and North America continue to prioritize data center expansion and broadband connectivity, providing a stable policy backdrop for long-term infrastructure investment.
Demand-Side Dynamics
Demand for optical transceivers is driven by distinct but complementary applications. Data centers remain the largest application segment, fueled by the exponential growth of AI model training, cloud services, and content delivery networks. The concentration of revenue in this segment reflects the capital intensity of hyperscale facilities and their need for high-speed interconnects to manage massive datasets and distributed computing workloads.
Telecommunications networks form a significant secondary driver, as operators upgrade backbone and access networks to support 5G densification, fixed wireless access, and growing enterprise connectivity requirements. The need for coherent transceivers in long-haul and metro networks is sustained by the requirement to maximize capacity over existing fiber assets while preparing for future bandwidth demands. Enterprise networks also contribute to demand, particularly as organizations modernize LAN and WAN infrastructures to support hybrid work models, IoT deployments, and security requirements that demand higher throughput and lower latency.
Across all segments, the common thread is the expectation of sustained bandwidth growth. Users and enterprises are increasingly data-hungry, and applications such as high-definition video, real-time collaboration, and AI-driven services continue to push traffic volumes upward. This demand-side resilience provides a buffer against short-term cyclical fluctuations, ensuring that the underlying driver for optical connectivity remains strong.
Supply Chain and Cost Structure Changes
The supply chain for optical transceivers is undergoing structural adjustments in response to demand signals and geopolitical pressures. Manufacturers are investing in capacity expansion and geographic diversification to secure supply and reduce dependency on single-source regions. For example, Applied Optoelectronics, Inc. is expanding U.S. manufacturing capacity to meet high-volume demand for 800G and 1.6T datacom transceivers, reflecting a broader trend toward nearshoring or friend-shoring critical optical component production.
Cost structures are also evolving as technologies mature and volumes increase. While initial units for new generations like 1.6T carry premium pricing due to low yields and complex assembly, continued investment in automated manufacturing and photonic integration is expected to drive down per-bit costs over time. Companies that can achieve superior yield rates and scalable production processes will gain a competitive advantage in pricing power and margin retention. However, the need for stringent manufacturing tolerances and high-quality precision photonic components means that cost reduction cannot come at the expense of performance reliability, creating a narrow operational window for suppliers.
Competitive Landscape and Leading Strategies
The competitive environment in the optical transceivers market is defined by a mix of established multinational players, specialized optical component manufacturers, and region-specific challengers. Market concentration remains high, indicating that scale, technological leadership, and ecosystem relationships are critical determinants of success. Companies are pursuing differentiated strategies to capture value across various segments of the market.
Strategic Positioning of Key Players
Several companies illustrate the range of strategic approaches currently in play. Coherent Corp. has focused on vertically integrated silicon photonics, VCSEL arrays, and coherent transceivers, including 1.6T-DR8 modules for hyperscale AI data centers and enterprise interconnects. Their strategy emphasizes deep technological integration and the ability to deliver high-performance solutions that address the specific needs of AI-driven workloads. By demonstrating advanced 200G VCSEL-based transceivers, Coherent is positioning itself at the forefront of next-generation lane speeds.
Broadcom Inc. is pursuing a co-packaged optics platform strategy, developing optical I/O engines for AI infrastructure with direct chip-to-chip integration. Their announcement of a 102.4 Tbps co-packaged optics Ethernet switch underscores a commitment to rearchitecting the interconnect layer for future AI clusters. This approach targets the highest end of the market where performance and energy efficiency are paramount, potentially reshaping the form factor and integration model of optical transceivers over time.
Cisco Systems, Inc. continues to leverage its comprehensive portfolio of pluggable transceivers supporting 100G to 800G+ Ethernet in data center and metro networks. The acquisition of CoreOptics in March 2025 expanded its optical networking engineering teams in Europe and Asia, signaling a strategy of strengthening internal capabilities and geographic reach. Cisco's approach relies on breadth of product offerings and strong customer relationships across enterprise and service provider segments.
Lumentum Holdings Inc. focuses on 800G and 1.6T OSFP and coherent transceivers with hybrid photonic integrated circuits for data center interconnects. Their emphasis on hybrid integration reflects an effort to combine the benefits of different photonic technologies to achieve performance and manufacturability goals. Meanwhile, Accelink Technology Co., Ltd. and Eoptolink Technology Inc. are emerging as significant forces in the Asia-Pacific region, offering 800G and 1.6T silicon photonics OSFP transceivers and active optical cables for AI and data center networks. Their growth highlights the increasing capability and competitiveness of regional manufacturers.
Huawei Technologies Co., Ltd. offers the StarryLink series of 400G and 800G pluggable optical modules for intelligent computing and data center interconnect scenarios. Their strategy is closely tied to the broader ecosystem of intelligent computing platforms, which can provide integrated solutions for customers building large-scale compute clusters. Sumitomo Electric Industries, Ltd. emphasizes low-power, compact designs for optical transceiver modules, targeting applications where energy efficiency and form factor are critical constraints.
High Speed Optical Transceiver Market
Other notable players include Source Photonics, Inc., which provides 200G-per-lane 1.6T and 800G PAM4 transceiver families for telecommunications and data connectivity, and Infinera Corporation, known for intelligent coherent pluggable transceivers in the ICE series for long-haul and metro optical networks. NeoPhotonics Corporation focuses on photonic integrated circuit-based transceivers for high-performance networking applications. These companies illustrate the diversity of technological approaches and application focuses within the market. Credo Technology Group Holding Ltd entered the space with its ZeroFlap optical transceiver line in November 2025, delivering secure high-speed connectivity for 400G, 800G, and 1.6T network speeds, indicating that security features are becoming a differentiator in certain segments. Jabil Inc. launched 1.6T transceivers in April 2025 for AI/ML, HPC, and high-speed data center interconnects, demonstrating that large-scale manufacturing services firms are also entering the market with high-speed solutions.
Evolving Market Dynamics
The competitive landscape is likely to evolve along several axes. First, consolidation may continue as larger players acquire specialized technologies or talent to fill gaps in their portfolios, as seen with Cisco's acquisition of CoreOptics. Such moves can accelerate capability development but also intensify competition for key intellectual property and engineering resources.
Second, the market may see divergence between highly integrated solutions for AI hyperscale customers and more standardized pluggable modules for broader enterprise and telecom use. Companies that can serve both ends of the spectrum or choose a focused niche will need to align their R&D and manufacturing strategies accordingly. The rise of co-packaged optics and chip-to-chip integration suggests that the boundary between transceivers and switching silicon may blur, creating opportunities for players with expertise in both optical and electronic integration.
Third, regional dynamics will play an increasing role. Manufacturers in China are expanding their capabilities in high-speed silicon photonics and transceiver modules, potentially capturing significant share in regional data center and telecom markets. At the same time, regulatory pressures and the push for local manufacturing in regions like Europe and North America may lead to a more fragmented supply base, with local content requirements influencing procurement decisions. Companies that can navigate these regional nuances while maintaining global quality and performance standards will be better positioned to scale.
Future Trends and Commercial Opportunities
Looking ahead over the next three to five years, several trends are likely to shape the optical transceivers market and create distinct commercial opportunities. Anticipating these trends allows decision-makers to align investments, product roadmaps, and partnership strategies with the direction of market evolution.
Acceleration of High-Speed Lane Rates and Form Factor Evolution
The transition toward 1.6T and potentially higher lane rates will accelerate as AI workloads continue to demand greater interconnect bandwidth. This trend will drive demand for transceiver modules that can support 200G per lane and beyond, while also pushing the industry to develop new form factors that balance density, power, and thermal management. Commercial opportunities lie in developing transceivers that offer superior energy efficiency per bit, as power consumption becomes an increasingly critical constraint in dense data center environments. Vendors that can demonstrate meaningful improvements in watts per gigabit will find strong demand from hyperscale operators seeking to manage total cost of ownership.
Additionally, the proliferation of co-packaged optics may create opportunities for suppliers of optical engines and integrated photonic modules that differ from traditional pluggable formats. Companies that can deliver reliable, scalable co-packaged solutions with strong integration support will be well-positioned to participate in next-generation switch architectures. However, this transition also introduces risk, as the adoption rate of co-packaged optics may vary across customer segments, and standards maturity could influence deployment timelines.
Regionalization and Supply Chain Resilience
The trend toward regionalization of manufacturing and supply chains is expected to continue, driven by both regulatory pressures and customer preferences for resilient sourcing. This creates opportunities for manufacturers that invest in local production capabilities or secure partnerships within target regions. Companies that can offer transparency, flexibility, and compliance with regional content requirements may gain preferential access to key accounts in government, telecommunications, and enterprise sectors. Conversely, suppliers heavily reliant on single-geography supply chains may face increasing challenges in serving global markets, necessitating strategic adjustments in sourcing, distribution, and partnerships.
For investors, this trend suggests that companies with diversified manufacturing footprints or strong alignment with regional digital infrastructure initiatives may offer more resilient growth profiles. The ability to navigate export controls and trade restrictions while maintaining product availability will be a valuable competitive attribute. Companies that can demonstrate robust supply chain management and compliance frameworks will differentiate themselves in an environment where geopolitical risk is a material consideration.
Integration of Advanced Features: Security, Intelligence, and Modulation Flexibility
As networks become more complex and security requirements intensify, transceivers that incorporate advanced features beyond raw bandwidth will gain relevance. The launch of secure high-speed connectivity solutions indicates that authentication, encryption, and tamper resistance are emerging as value-added attributes for certain customer segments. Commercial opportunities exist for vendors that can embed security features without significant penalties in power, cost, or performance. Similarly, transceivers with flexible modulation capabilities or software-defined configurations may appeal to operators seeking to optimize network resources dynamically across different traffic patterns and service requirements.
Intelligent transceivers that provide telemetry, diagnostics, and proactive maintenance capabilities may also find demand in large-scale networks where operational efficiency is paramount. The ability to monitor performance parameters in real time and predict failures can reduce downtime and optimize capacity planning, creating value for network operators managing diverse infrastructure. Vendors that integrate these capabilities into their product offerings can differentiate beyond price and performance specifications.
Potential Risks and Uncertainties
Despite the positive growth outlook, several risks warrant attention. The pace of adoption for next-generation standards such as 1.6T may be influenced by the readiness of host devices, switch ecosystems, and fiber plant capabilities. If the broader infrastructure does not evolve in lockstep, demand for ultra-high-speed transceivers could be delayed or concentrated in a narrower set of applications. Additionally, macroeconomic conditions affecting capital expenditure cycles could alter the timing of deployments, particularly in enterprise and telecom segments that are more sensitive to budget constraints than hyperscale data centers.
Technological risk remains significant, as rapid innovation can render current product generations obsolete faster than anticipated. Companies must balance the cost of R&D and capacity investment against the uncertainty of standards evolution and customer adoption. Overinvestment in a specific technology path that loses out to an alternative approach could lead to stranded assets. Finally, the regulatory environment remains fluid, with potential for further trade restrictions, changes in spectrum policy, or shifts in digital sovereignty initiatives that could impact supply chains and market access. Navigating these uncertainties requires continuous monitoring, scenario planning, and agile strategic responses.
PW Consulting
Strategic Guidance for Decision-Makers
The optical transceivers market offers substantial opportunities for those who can align their strategies with the underlying drivers of demand, technological change, and regulatory evolution. The following actions provide a starting point for manufacturers, investors, and procurement organizations seeking to capitalize on this dynamic environment.
For Manufacturers and Technology Providers
Invest in scalable manufacturing capabilities that can support high-speed lane rates while maintaining stringent quality and yield targets. Modular architectures that allow for flexibility across form factors and speeds may provide a hedge against standards volatility. Strengthen supply chain resilience by diversifying sourcing, exploring regional production options, and developing contingency plans for component availability. Differentiate through value-added features such as security, power efficiency, and integration support, particularly for customers building AI and high-performance computing infrastructure. Monitor co-packaged optics and silicon photonics developments closely, as these technologies may reshape the competitive landscape and create opportunities for new product categories.
For Investors and Financial Stakeholders
Evaluate companies based on their ability to execute on high-growth segments such as 800G and 1.6T transceivers, their manufacturing scalability, and their exposure to resilient demand applications like AI data centers. Consider the geographic diversification of their supply chains and their alignment with regional digital infrastructure initiatives as indicators of long-term sustainability. Assess R&D pipelines and partnerships that provide access to next-generation technologies, as technological leadership will be a key determinant of market share in a concentrated industry. Recognize that the market may see periods of volatility as standards mature and adoption cycles vary, requiring a balanced view of near-term execution and long-term positioning.
For Procurement and Network Operators
Develop a multi-vendor strategy that balances performance requirements with supply chain risk mitigation. Engage early with suppliers on roadmap alignment, particularly for high-speed transceivers that may impact system design and thermal management. Evaluate total cost of ownership, including power consumption and operational efficiency, rather than focusing solely on unit price, as energy costs and density constraints become increasingly important in high-density deployments. Stay informed about evolving standards and regulatory developments that could affect component availability, compliance requirements, and regional sourcing options. Building relationships with suppliers that offer transparency, flexibility, and advanced feature sets can provide strategic advantages in managing network evolution.
Navigating the Opportunity Horizon
The optical transceivers market is at a pivotal moment where sustained demand growth intersects with rapid technological advancement and shifting geopolitical dynamics. The projected market expansion through the end of the decade underscores the strategic importance of optical connectivity in the broader digital infrastructure ecosystem. However, realizing value in this environment requires more than recognizing the growth trajectory; it demands a nuanced understanding of the competitive landscape, supply chain realities, and the specific technological and regulatory factors that will shape outcomes.
For stakeholders seeking to deepen their understanding of market segments, regional nuances, company-specific profiles, and detailed forecasts, accessing comprehensive research reports can provide the granular data and customized insights needed to refine strategies. Detailed segmentation data, competitive benchmarking, and scenario analysis can help translate high-level trends into actionable plans tailored to specific business contexts. Engaging with specialized market intelligence allows decision-makers to move from general awareness to precise execution, ensuring that investments and initiatives are aligned with the most relevant opportunities and risks in the optical transceivers market.
For detailed analysis of this topic, please visit the official page: Optical Transceivers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Isophthalonitrile Market 2026: 5.5% CAGR and the Real Drivers Shaping Demand to 2032
By PW Consulting, 2026-09-21
Isophthalonitrile (INP) Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The Isophthalonitrile (INP) market has demonstrated steady expansion over the past half-decade, evolving from a specialized chemical intermediate into a strategically significant segment tied to advanced materials and agrochemical supply chains. Valued at approximately $163.15 million in 2020, the market grew to $215.0 million by 2025, reflecting a compound annual growth rate of 5.5 percent. Projections through 2032 indicate the market will surpass $311 million, driven by accelerating demand in high-performance polymers, pharmaceutical intermediates, and specialty crop protection formulations. While the trajectory appears consistent, the underlying dynamics reveal a market at an inflection point, where growth is no longer guaranteed by volume alone but increasingly dependent on technological adaptation, regulatory navigation, and supply chain resilience.
Several structural challenges are shaping how market participants operate today. First, the concentration of supply among a handful of established producers creates both stability and vulnerability. With the top three and top five players collectively controlling the majority of global output, pricing power and capacity allocation are heavily influenced by strategic decisions from a small group of manufacturers. This concentration limits the ability of downstream buyers to negotiate favorable terms during periods of tight supply, while simultaneously raising the barrier for new entrants seeking to achieve meaningful scale.
Second, raw material price volatility continues to disrupt cost forecasting and margin stability. The production of INP relies on specialized precursor chemistry, and fluctuations in petrochemical feedstocks, energy costs, and catalytic materials introduce unpredictable swings in manufacturing expenses. These swings are particularly acute for producers operating in regions with less diversified supply networks or weaker hedging capabilities, forcing them to balance competitive pricing against the risk of margin compression.
Third, the regulatory environment is becoming increasingly complex, especially for producers and exporters navigating cross-border material controls. Recent export restrictions on critical semiconductor-related materials in major Asian markets have introduced uncertainty into broader chemical supply chains, prompting buyers and manufacturers alike to reassess sourcing strategies, inventory buffers, and alternative formulation pathways. These overlapping pressures mean that simply tracking market size is insufficient; understanding how capacity, regulation, and input costs interact is essential for making informed commercial decisions.
Worldwide 4-Brombenzonitrile Market
Key Drivers Shaping Market Trajectories
Technological Innovation and Process Optimization
Advancements in synthetic chemistry and manufacturing efficiency are reshaping the value proposition of INP across multiple end-use sectors. Improved catalytic processes and purification techniques have enabled producers to achieve higher consistency at elevated purity levels, which matters significantly for applications in synthetic resins and electronic-grade materials where impurity tolerances are extremely tight. As downstream manufacturers demand more reliable specifications, suppliers that invest in process control, analytical quality assurance, and continuous improvement are positioned to capture premium segments rather than competing solely on price.
Beyond purification, innovation is also expanding the practical utility of INP in higher-margin applications. Research into advanced polymer architectures and specialty intermediates has reinforced the role of INP as a foundational building block for m-xylylenediamine and related derivatives, which in turn support high-performance engineering plastics and coatings. The convergence of material science requirements and chemical manufacturing capability is creating a positive feedback loop: as end-use applications become more demanding, the incentive to invest in better production methods grows, and those investments in turn unlock new commercial pathways.
Policy and Regulatory Evolution
The regulatory landscape is no longer a background condition; it is a direct determinant of market access, sourcing flexibility, and long-term planning. Export controls and material security policies in several key production regions have already begun influencing how chemical manufacturers structure their supply networks. While these measures are often framed around critical minerals and compound semiconductors, their ripple effects extend into adjacent chemical markets where reliability of supply, traceability, and compliance documentation are increasingly scrutinized.
For INP market participants, this means that regulatory readiness is becoming a competitive attribute. Companies that proactively align with evolving export compliance requirements, maintain transparent documentation practices, and diversify their customer base across jurisdictions are better positioned to avoid disruption. At the same time, regulatory divergence between regions can create uneven playing fields, where producers in one jurisdiction face different cost structures or approval timelines than those in another. Strategic leaders are treating regulatory forecasting as part of their core operational planning rather than a reactive compliance exercise.
Shifting Demand-Side Behavior
Demand for INP is being shaped less by a single end market and more by a combination of performance requirements across diverse applications. In the agrochemical sector, the push for more targeted and efficient crop protection solutions continues to support steady consumption of specialty intermediates. At the same time, pharmaceutical and fine chemical manufacturers are increasingly looking for reliable, high-specification inputs that can support complex synthesis routes without introducing variability. These demand-side shifts favor suppliers that can offer consistent quality, technical support, and flexible order structures.
There is also a growing preference among downstream buyers for supply partners that can provide visibility into capacity, lead times, and contingency plans. This is not simply a cost consideration; it is a risk-management decision. As global supply chains have become more sensitive to geopolitical tension, logistics disruption, and energy volatility, procurement teams are placing greater weight on reliability and strategic alignment. Suppliers that can demonstrate operational resilience and transparent communication are gaining preferential access to long-term contracts and repeat business.
Supply Chain Restructuring and Cost Dynamics
The cost structure of INP production is being reshaped by broader changes in global manufacturing geography and logistics. Some producers are consolidating operations to achieve economies of scale, while others are expanding or relocating capacity to balance proximity to key customers with access to raw materials and energy. These decisions are not purely about production cost; they are about reducing exposure to transport bottlenecks, aligning with regional regulatory frameworks, and strengthening relationships with end markets.
Simultaneously, the market is witnessing a gradual recalibration of inventory strategies. Buyers that once prioritized minimal inventory and just-in-time procurement are increasingly maintaining strategic buffers for critical intermediates. This shift changes the rhythm of demand signals reaching producers and encourages capacity planning that accounts for both baseline consumption and surge scenarios. The companies that can interpret these signals accurately and adjust production schedules accordingly are gaining an advantage in both service levels and cost efficiency.
Competitive Landscape and Leading Strategies
The competitive environment for INP is defined by a small group of active producers, each pursuing distinct strategic positions based on geography, application focus, and operational strengths. Mitsubishi Gas Chemical Company, Inc. has maintained a notable presence through its focus on synthetic resins and electronics-related applications, leveraging an integrated chemicals business model that emphasizes reliability, quality consistency, and long-term customer relationships. Its positioning reflects an emphasis on high-value applications where specification stability and technical support matter more than bare volume.
In China, Jiangsu Weunite Fine Chemical Co., Ltd. has built its relevance around fine chemical intermediates supporting agrochemicals and electronics, aligning with regional demand patterns and production scale advantages. Its strategy underscores the importance of matching manufacturing capabilities to the application priorities of nearby downstream industries, which can shorten lead times and improve responsiveness. Similarly, Suli Co., Ltd. focuses on pharmaceutical and fine chemical intermediates, positioning itself in segments where purity, documentation, and process control are particularly critical. This application-specific focus illustrates how producers are differentiating not just by price, but by the fit between their technical capabilities and the requirements of their chosen markets.
The market structure is evolving along several axes. On one hand, the concentration of output among leading producers creates a relatively stable but potentially inflexible environment, where incremental capacity additions and quality improvements can have outsized influence on pricing and availability. On the other hand, the growing importance of compliance, specialty applications, and supply reliability is opening space for differentiation that goes beyond conventional scale economies. New entrants or expanding producers that can combine cost discipline with strong technical execution and regulatory readiness have the potential to capture meaningful share in specific segments, particularly where existing supply is constrained or where customers are prioritizing resilience over lowest unit cost.
Strategic leadership in this environment is increasingly defined by the ability to balance multiple priorities simultaneously: maintaining cost competitiveness, investing in process and quality capabilities, managing regulatory exposure, and building trusted relationships with downstream customers. Companies that treat these as interconnected rather than isolated priorities are better equipped to sustain margins and protect market position as the landscape matures.
Forward-Looking Trends and Commercial Opportunities
Over the next three to five years, several trends are likely to shape how value is created and captured in the INP market. One prominent trend is the continuing premiumization of demand in high-specification applications. As electronics-related materials and advanced synthetic resins become more performance-sensitive, the share of demand tied to higher purity and tighter quality assurance is expected to grow. This creates opportunities for producers that can consistently meet elevated specifications and for downstream manufacturers that can secure reliable access to these grades without compromising supply continuity.
A second trend is the deepening role of regulatory and supply chain resilience as commercial differentiators. Buyers are increasingly evaluating suppliers not only on price and volume, but on their ability to provide stable delivery under shifting trade conditions, maintain compliant documentation, and support contingency planning. Suppliers that invest in visibility, flexibility, and compliance infrastructure can translate these capabilities into stronger customer retention and more favorable contract terms. This trend also opens the door for regional supply strategies that reduce exposure to cross-border friction while maintaining access to key demand centers.
PW Consulting
A third trend is the gradual re-balancing of capacity and sourcing strategies as raw material dynamics and energy costs continue to fluctuate. Market participants that diversify input sourcing, strengthen hedging approaches, or align production with regions offering more predictable cost structures will be better positioned to protect margins. At the same time, there is opportunity for producers to capture value by offering application-specific solutions that reduce the total cost of ownership for buyers, rather than competing purely on the headline price of the intermediate itself.
These trends are not without risk. Concentration in supply means that unexpected capacity constraints or strategic decisions by a small number of producers can quickly affect availability and pricing. Raw material volatility remains a persistent threat to cost predictability, particularly if energy prices or precursor availability shift abruptly. Regulatory divergence could also introduce uneven compliance burdens, affecting competitiveness across regions. Companies that prepare for these uncertainties by building flexibility into sourcing, capacity planning, and customer engagement will be better positioned to navigate them.
Strategic Implications for Decision-Makers
For manufacturers and producers, the priority is to strengthen the link between process capability and commercial positioning. Investing in purification consistency, analytical control, and production flexibility can unlock access to higher-value applications where specification reliability is a gating factor. At the same time, building a clear regulatory and sourcing strategy helps reduce exposure to input volatility and trade-related disruption. Producers that can articulate a dependable supply narrative and back it with operational discipline are more likely to secure long-term relationships in applications where downtime or variability carries significant downstream cost.
For investors, the most relevant question is not simply whether the market is growing, but where value is concentrating and why. Growth is increasingly tied to segments with higher specification demands and to suppliers that can combine scale with reliability and compliance readiness. Evaluating potential opportunities therefore requires looking beyond headline volume and examining the quality of customer relationships, the durability of cost structures, and the ability to adapt to regulatory and supply chain shifts. Companies with diversified application exposure and clear technical differentiation are more likely to sustain competitive advantage than those dependent on a single cost-sensitive channel.
For procurement and sourcing leaders, the strategic imperative is to balance cost efficiency with resilience in a market where concentration and volatility raise the stakes of supply disruption. Diversifying supplier relationships, understanding the regulatory posture of each source, and securing visibility into capacity and contingency plans can reduce risk without abandoning cost discipline. In practice, this means treating supplier selection as a multi-dimensional decision that includes technical fit, delivery reliability, compliance transparency, and the ability to support changing demand patterns over time.
As the market continues to evolve, the availability of detailed, segment-level intelligence becomes a critical input to decision-making. Granular visibility into application dynamics, regional demand shifts, purity-grade movement, and supplier-specific strategies can clarify where competitive advantage is being created and where exposure is accumulating. For teams responsible for planning, sourcing, or investment allocation, access to comprehensive and regularly updated analysis can reduce uncertainty and improve the quality of strategic choices. PW Consulting's full research report on the Isophthalonitrile market provides a more detailed breakdown of these dynamics, including deeper segmentation, competitive profiling, and scenario-based guidance for navigating the next phase of market development.
Polyacrylonitrile (PAN) Market
For detailed analysis of this topic, please visit the official page: Isophthalonitrile (INP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Thermal Barrier Coatings Market: Why a 5.1% CAGR Redefines Strategic Entry
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Thermal Barrier Coatings (TBC) Market: A 2025 Executive Brief
The thermal barrier coatings market has matured into a critical enabler of industrial efficiency and emissions compliance across multiple heavy-industry verticals. As of 2025, the global market has crossed the $18.1 billion threshold, building on a consistent growth trajectory from the 2020 baseline of approximately $13.5 billion. The sector is projected to sustain a compound annual growth rate of 5.1% through the 2032 horizon, reaching roughly $25.3 billion by the end of the forecast period. This expansion is not merely cyclical; it reflects structural shifts driven by regulatory tightening, operational cost pressures, and incremental breakthroughs in coating architecture and application methods.
For decision-makers operating in manufacturing, energy, aerospace, or capital equipment supply chains, the TBC landscape presents both defensive and offensive opportunities. Below is a strategic assessment of market realities, core drivers, competitive positioning, forward-looking trends, and actionable implications.
Market Snapshot and Core Challenges
A Market at an Inflection Point
The segment has moved past the post-pandemic recovery phase. After crossing the $15.6 billion mark in 2023, the market accelerated noticeably in 2024 and 2025, reflecting renewed industrial capex, expanded turbine fleets, and higher adoption rates in downstream applications. The forecast arc through 2032 suggests compounding gains, though the growth profile is uneven across disciplines and value chains. Sustained momentum will depend on whether manufacturers can address persistent input cost pressures, integrate higher-performance material architectures, and navigate a regulatory environment that simultaneously pushes adoption and constrains certain production pathways.
SiC and TaC Coated Graphite Market
Constraint One: High Input Costs and Material Economics
The procurement cost of advanced coating inputs remains a structural headwind. High-purity ceramic compounds and specialized mixed-metal alloys carry significant production complexity, and their price sensitivity is amplified in regions where raw material supply chains are fragmented. For operators running high-volume thermal spray lines, raw material expenditure directly compresses margins unless offset by yield improvements, process automation, or premium product positioning. This cost pressure is particularly acute for mid-tier applicators that lack scale advantages in powder procurement or process repeatability.
Constraint Two: Environmental Compliance in Manufacturing
Regulatory expectations extend beyond end-use performance to the manufacturing process itself. Certain coating production routes generate hazardous waste streams that require controlled disposal and compliance management. As environmental oversight tightens, firms must invest in containment, waste minimization, and process redesign. This adds a layer of operational complexity and cost that can delay expansion plans for smaller service providers and increase the barrier to entry for new capacity additions.
Constraint Three: Customer Adoption Under Cost and Qualification Scrutiny
Demand-side adoption is ultimately gated by return-on-investment calculations. Industrial operators weigh coating performance gains—higher inlet temperatures, extended component life, reduced cooling requirements—against upfront application cost and downtime. In sectors with long qualification cycles or conservative risk tolerance, even compelling performance data can stall procurement decisions unless supported by robust service-level commitments, repeatability evidence, and lifecycle cost modeling. The challenge is not market awareness; it is commercial proof at scale.
Key Drivers Shaping Market Trajectory
Technological Innovation and Process Maturation
Performance differentiation increasingly depends on process precision and material architecture. Advanced ceramic formulations continue to anchor the largest share of coating value, while metallic and hybrid systems provide targeted benefits in specific thermal and mechanical environments. The market is seeing greater emphasis on process controllability—particularly in plasma spray and related deposition methods—where temperature management, particle velocity, and layer uniformity determine the balance between thermal protection and mechanical durability. Improvements in line automation, particulate control, and in-line inspection are reducing variability and improving throughput, making high-performance coatings more economically viable across broader application sets.
Regulatory and Policy Momentum
Emission regulations on combustion systems are tightening globally, prompting governments and industrial regulators to introduce increasingly stringent performance norms for engines and industrial turbines. These rules incentivize technologies that improve fuel efficiency, reduce thermal stress, and extend component longevity—characteristics that TBC solutions directly support. Policy signals are further reinforced by broad industrial budgeting patterns: a meaningful share of industrial capital allocation is now directed toward energy efficiency improvements, creating a supportive backdrop for coating adoption in both new-build and retrofit scenarios. At the same time, manufacturers must manage the dual-edged nature of regulation, balancing end-use compliance benefits against the operational requirements of cleaner production practices and waste handling.
Worldwide Long-lasting Thermal Insulation and Cooling Coating Market
Demand-Side Shifts in High-Value Verticals
Demand is being reshaped by the operational priorities of aerospace, power generation, automotive, oil and gas, and industrial service providers. In aerospace, higher turbine operating temperatures and extended on-wing performance expectations continue to drive TBC utilization in engine components. In power generation, efficiency targets and cycle upgrades support coating adoption in gas turbines and related hardware. Industrial combustion and processing equipment are also seeing increased retrofit activity as operators seek to reduce fuel consumption and thermal degradation without full asset replacement. A useful market lens is the concentration of enterprise value: a relatively small group of large players accounts for a substantial share of revenue, indicating that scale, certification depth, and service breadth still matter greatly in winning major programs.
Supply Chain and Cost Structure Evolution
Supply-side dynamics are being re-shaped by regional capacity decisions, powder sourcing strategies, and service network expansion. Vertically integrated players that control powder production alongside application services are better positioned to manage input variability and co-develop formulation changes with end customers. Meanwhile, specialized powder suppliers and dedicated service shops compete on purity, availability, and certification readiness. Cost structure improvements are increasingly coming from process digitization, optimized spray parameters, and tighter quality controls rather than from broad commodity-style input deflation. As a result, competitive advantage is shifting toward firms that can combine material expertise with repeatable service delivery and regional proximity to key customer clusters.
A concrete example of this shift is visible in ongoing advanced collaboration between major thermal spray operators and engine manufacturers to integrate digital process workflows into TBC production. The move toward a smarter thermal spray factory—linking process data, quality feedback, and production scheduling—illustrates how the industry is moving from isolated application services to integrated, data-driven manufacturing models. Such arrangements aim to improve throughput, reduce rework, and enhance traceability, which is increasingly important for customers operating under rigorous qualification and maintenance regimes.
Competitive Landscape and Leading Strategies
How Leading Players Differentiate
The market is characterized by a mix of diversified surface technology providers, specialist coating applicators, and material suppliers. Several patterns define how leading firms compete:
- Vertical integration across powder and service : Companies that combine specialty powder supply with thermal spray and coating services can align material selection with application performance, reduce dependency on third-party inputs, and respond more quickly to customer formulation requirements. This model is especially valuable in aerospace and gas turbine work where material traceability and consistency are central procurement criteria.
- Process capability as a moat : Providers with advanced deposition capabilities, including controlled plasma spray and related high-precision methods, gain an edge when customers require repeatable microstructures, tightly managed porosity, and certification-ready documentation. Process maturity also supports higher-value service work such as repair, strip, and re-coat operations.
- Service network scale and certification depth : Global coverage and broad facility footprints help capture both OEM programs and MRO demand. In segments where turnaround time and regional support matter, a wide network of qualified facilities can be as important as raw coating performance.
- Industrial surface expertise across multiple end markets : Some firms compete by offering a broad service portfolio across aerospace, industrial, and regional maintenance applications. This diversification can stabilize revenue against cyclicality in a single vertical while enabling cross-learning across coating requirements.
- Application focus on civil engine maintenance : Certain players emphasize air plasma spray and high-velocity processes tailored to civil engine MRO, positioning around maintenance reliability, turnaround efficiency, and compliance with aviation standards.
- OEM-aligned service facilities : Providers with plasma spray facilities qualified by major OEMs compete on program access, repeatability, and the ability to support production and aftermarket demand under established quality frameworks.
- Regional MRO specialization : Smaller and mid-market applicators often win by offering certified TBC coating and repair services close to customer bases, serving regional maintenance demand with FAA-aligned processes and lower overhead than global networks.
- Powder and process specialization for regional demand : Specialized applicators focusing on plasma spray and high-velocity processes fill niche demand in regional MRO and industrial service, competing on agility, responsiveness, and cost-competitive service packaging.
Market Structure and Evolution Trends
The revenue concentration pattern—where a relatively small set of large players accounts for a significant share of total market value—signals that scale, certification infrastructure, and service breadth remain decisive. This does not imply a stagnant market, however. Several evolutionary dynamics are visible:
- Consolidation of high-value service capacity : Major players continue to strengthen integrated offerings that span powder supply, deposition equipment, and coating services, particularly where digital process control and smart factory capabilities can be leveraged to improve consistency and throughput.
- Segmentation between global platforms and regional specialists : While large global providers target OEM relationships and multi-region demand, regional and mid-market applicators maintain relevance by serving localized MRO needs, offering shorter lead times, and competing on service agility.
- Rising importance of process digitization : As customers demand better traceability, quality predictability, and cost control, firms that embed digital process monitoring, data feedback, and standardized operational workflows are better positioned to command premium service contracts and reduce variability.
- Material supplier positioning : High-purity ceramic powder suppliers play a critical upstream role. Their value is tied to purity, batch consistency, and the ability to support advanced coating designs. Where powder availability or quality fluctuates, downstream applicators face both cost and performance risk, making supplier relationships strategically important.
Forward-Looking Trends for the Next 3–5 Years
Trend One: Energy Efficiency as a durable Demand Anchor
Tightening combustion emissions expectations and broader industrial efficiency goals are likely to keep TBC adoption on a positive trajectory. Components that enable higher thermal operating margins, lower cooling penalties, and longer service intervals will remain attractive to operators managing fuel cost and asset utilization. Over the next several years, this should sustain demand across gas turbines, engine hardware, and industrial combustion systems, particularly where retrofit economics favor partial upgrades over full replacement. The commercial opportunity lies in packaging performance benefits with clearly modeled lifecycle savings and service commitments that reduce perceived procurement risk.
Trend Two: Process Intelligence and Quality Consistency as Value Multipliers
The market is increasingly rewarding providers that can demonstrate repeatable outcomes rather than only superior nominal coating properties. Process digitization, statistical process control, and improved inspection discipline are expected to become more central to competitive positioning. Smart factory-style integration—linking deposition parameters, quality data, and production scheduling—can reduce rework, improve yield, and strengthen customer confidence in high-stakes applications. Providers that build these capabilities will be better placed to secure long-term service agreements, expand into higher-value repair work, and differentiate against lower-cost competitors whose process variability limits premium positioning.
PW Consulting
Trend Three: Regional Capacity Realignment and Service Proximity
Demand patterns are pushing a more nuanced geography of service capacity. While global platforms continue to serve multinational OEM and industrial programs, regional MRO demand remains strong and often favors providers with local certified facilities, shorter logistics cycles, and flexible service packaging. Over the forecast window, some capacity may consolidate around major customer hubs, while regional specialists may capture growth by aligning closely with local maintenance calendars, fleet renewal schedules, and industrial upgrade cycles. Companies that balance global technical credibility with regional responsiveness are likely to gain share in mixed-demand environments.
Uncertainties to Monitor
- Raw material cost volatility and supply continuity for advanced ceramic and alloy powders could compress margins or slow expansion for cost-sensitive segments.
- Environmental compliance requirements may tighten further, increasing operational complexity for manufacturing processes that generate hazardous waste and raising the cost of compliance management.
- Qualification cycles and procurement caution in conservative customer segments can slow adoption even when technical benefits are well established.
- Competitive intensity may rise as integrated players expand service networks and regional applicators improve process discipline, compressing differentiation windows in commoditizing application segments.
Strategic Recommendations for Decision-Makers
For Coating Manufacturers and Service Providers
Strengthen the link between material capability and repeatable service delivery. Where possible, align powder sourcing, deposition process control, and inspection workflows to reduce variability and support premium service contracts. Invest in digital process monitoring and quality traceability to improve consistency, reduce rework, and strengthen qualification readiness. For regional operators, prioritize certified capacity near key maintenance clusters and develop service packages that balance turnaround speed with documentation rigor. For larger platforms, pursue selective integration—whether through advanced process partnerships, digital factory capability, or expanded regional service presence—to reinforce both performance credibility and responsiveness.
For Investors and Strategic Capital Allocators
Evaluate exposure based on value-chain positioning rather than headline market size alone. Businesses that combine material expertise, process maturity, and a credible path to cost control are better insulated from input cost pressure and better placed to capture premium MRO and OEM-linked demand. Monitor the impact of efficiency-driven capex and emissions-driven upgrade cycles on end-market demand, while tracking the risk side: regulatory compliance burdens in manufacturing, raw material volatility, and the potential for value migration toward digitally enabled service models. Diversification across verticals can stabilize returns, but differentiated process capability remains the stronger long-term differentiator.
For Procurement and Asset Operators
Treat TBC adoption as a lifecycle decision rather than a unit-cost purchase. Evaluate total cost of ownership including thermal performance gains, component life extension, maintenance downtime, and qualification support. Prioritize suppliers that can provide documented process repeatability, robust service-level commitments, and clear evidence of performance consistency across production lots. In retrofit and upgrade scenarios, quantify fuel savings, cooling reductions, and maintenance interval improvements to justify investment. Where operational risk is high, prefer partners with established certification records and regional support capacity to reduce execution risk during installation and maintenance windows.
Closing Perspective
The thermal barrier coatings market is moving from a phase of steady expansion to one where performance reliability, process intelligence, and regulatory alignment determine competitive outcomes. Growth through the early 2030s is supported by efficiency mandates, turbine and engine performance requirements, and continued industrial investment in energy-saving technologies. At the same time, margin pressure from high-cost inputs, compliance demands on manufacturing, and customer scrutiny of lifecycle value will reward operators that can deliver consistent quality, strong service networks, and credible economic justification. For executives and investors, the most valuable intelligence is not simply how large the market will become, but where differentiation is being created along the value chain and which capabilities will command premium positioning in a maturing, increasingly digitized competitive environment.
For detailed analysis of this topic, please visit the official page: Thermal Barrier Coatings (TBC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Aseptic Packaging Market: Why 10.5% CAGR and 156 Billion Scale Redefine Growth
By PW Consulting, 2026-09-21
Aseptic Packaging Market: Strategic Trends and Commercial Opportunities Through 2032
The global aseptic packaging sector has cemented its status as a critical infrastructure layer across food, beverage, and pharmaceutical value chains. Between 2020 and 2025, the market expanded from approximately $45.7 billion to $78.3 billion, reflecting sustained demand for shelf-stable, contamination-resistant containment solutions. Forward-looking estimates project the market to surpass $156 billion by 2032, underpinned by a compound annual growth rate of 10.5 percent. This trajectory signals more than incremental growth; it reflects a structural reconfiguration of how liquids and sensitive goods are preserved, distributed, and consumed across geographies.
Yet the figures only sketch the surface. Beneath the headline expansion lies a sector navigating material science transitions, regulatory realignments, and shifting distribution economics. Decision-makers who treat aseptic packaging as a static commodity risk missing both margin compression and strategic positioning opportunities. Understanding the forces reshaping the market is essential for aligning capital allocation, product development, and supply chain strategy with the next phase of industry evolution.
Market Snapshot and Core Challenges
The aseptic packaging market operates at the intersection of food safety, pharmaceutical integrity, and logistical efficiency. Cartons and bags/pouches collectively represent the dominant format categories, while food and beverage applications account for the majority of end-use demand. Regional demand is distributed across developed and emerging markets, with Asia Pacific and North America capturing substantial share, supported by mature dairy and juice ecosystems as well as expanding ready-to-drink and nutritional supplement segments.
Despite robust top-line growth, the industry is approaching several inflection points that warrant strategic attention.
Material Compliance and Recyclability Pressures
Regulators and brand owners are increasingly treating end-of-life performance as a design constraint rather than an afterthought. The EU Packaging and Packaging Waste Regulation entered into force in February 2025 and establishes recyclability requirements for packaging placed on the European market, with detailed design-for-recycling criteria expected to be finalized through delegated acts by 2028. For aseptic packaging specifically, compliance pathways are pushing manufacturers toward aluminum layer minimization and mono-material component architectures. This shifts the competitive basis from mere barrier performance to total recyclability yield and compliance documentation.
Material Substitution and Barrier Technology Race
Traditional aseptic structures have long relied on multi-layer laminates incorporating aluminum foil to achieve microbial barrier and extended shelf life. The push toward recyclable mono-material systems is intensifying investment in paper-based barriers, polymer alternatives, and advanced sealing technologies. Companies pioneering aluminum-free or low-aluminum solutions are betting that recyclability, brand owner ESG commitments, and potential extended producer responsibility cost structures will reward early movers. However, the technical challenge remains substantial: maintaining sterility, oxygen and light barrier properties, and seal integrity without compromising recyclability.
Capacity Realignment and Regional Demand Divergence
Investment patterns indicate a deliberate expansion of aseptic carton and filling capacity in markets serving dairy, shelf-stable beverages, and emerging consumer categories. Simultaneously, pharmaceutical-grade vial, ampoule, and sterile transit packaging demand is being shaped by biologics growth, cold-chain complexity, and regulatory scrutiny. The divergence between high-volume food-grade aseptic systems and precision pharma packaging creates different capital intensity profiles, lead-time expectations, and quality assurance requirements, complicating one-size-fits-all capacity planning.
Key Drivers Shaping Market Trajectory
Several interlocking forces explain why the market is advancing at a double-digit growth cadence while simultaneously restructuring around compliance and material innovation.
Technological Innovation in Barrier and Filling Systems
The most consequential technical shift is the transition from conventional aluminum-dependent aseptic structures to recyclable mono-material and aluminum-minimized designs. Tetra Pak’s EUR 60 million investment in a new pilot plant in Lund, Sweden, focused on paper-based barrier technology to replace aluminum foil in aseptic cartons illustrates how incumbents are reallocating R&D toward recyclable architectures. SIG has similarly rolled out aluminum-free aseptic carton solutions in select European markets, targeting improved recycling yield for dairy and juice applications. On the equipment side, aseptic filler and bottling line providers are refining PET and flexible format lines to handle new material specifications without sacrificing throughput or sterility assurance. The implication is clear: aseptic packaging is becoming a materials-and-engineering problem as much as a containment problem, and differentiation will increasingly derive from demonstrable recyclability, performance consistency, and line compatibility.
Regulatory Environment Reshaping Design and Sourcing
Regulatory momentum is no longer confined to safety and labeling; it now directly influences structural design and procurement strategies. The EU PPWR’s phased application timeline creates a near-term compliance window that favors firms able to redesign structures, validate recycling streams, and document design-for-recycling criteria ahead of delegated act finalization. For multinational manufacturers and brand owners, this regulatory environment introduces both cost and opportunity: early alignment can reduce future redesign fatigue, mitigate potential compliance penalties, and strengthen sustainability claims in markets where packaging performance is scrutinized by retailers and consumers alike. Conversely, lagging players may face restructuring costs, stranded assets in non-compliant formats, and slower market access in regulated regions.
Sterile Medical Packaging Market
Demand-Side Evolution in Food and Beverage
Consumer and retail behavior continues to reinforce demand for shelf-stable, portable, and clean-label compatible packaging. Aseptic cartons and pouches remain attractive for dairy, juices, plant-based beverages, and liquid foods because they combine protection with supply chain flexibility. Recent product category expansions, such as SIG’s entry into camel milk with new aseptic carton solutions, highlight how format adaptability enables penetration into niche and regional dairy segments that demand both sterility and cultural product specificity. Beyond traditional categories, the broader trend toward functional beverages, premium juices, and ready-to-consume nutrition products is expanding the addressable space for aseptic systems that can preserve product quality without preservatives or continuous refrigeration.
Supply Chain and Cost Structure Realignment
Aseptic packaging economics are being reshaped by raw material dynamics, regionalized production, and the cost of compliance. The emergence of large-scale carton manufacturers in Asia, including publicly listed players now ranking among the world’s largest aseptic carton producers, adds scale competition and regional sourcing alternatives. At the same time, investments in Mexico and other nearshore locations, such as SIG’s additional US$ 35 million expansion of its Querétaro aseptic carton plant, reflect a strategic emphasis on serving regional demand with localized capacity, shorter logistics routes, and tariff or trade-flow optimization. For converters and brand owners, the result is a more distributed supply base that can improve resilience but also requires tighter quality governance, specification alignment, and vendor qualification discipline.
Competitive Landscape and Leadership Strategies
The competitive field is shaped by a mix of global incumbents with integrated packaging and filling capabilities, specialized format providers, and equipment manufacturers whose technology choices influence downstream material adoption. Market concentration remains moderate, with the top three firms holding a substantial share and the top five collectively representing just over forty percent of the market. This structure suggests room for both differentiated positioning and consolidation, particularly where scale, regional presence, and technology licensing create advantages.
Differentiated Positioning Among Leading Players
Several strategic archetypes are visible across the leadership group. One focuses on integrated aseptic systems spanning carton formation, filling, and downstream support, with strong positions in dairy and liquid foods. Another emphasizes extended shelf-life plastic bottles and specialized barrier features, including UV protection and longer durability windows for specific beverage applications. A third centers on flexible bag-in-box and spouted bulk systems tailored for industrial and liquid handling use cases. A fourth stream involves sterilized transit packaging and pharma-oriented solutions, where the value proposition rests on contamination control, regulatory alignment, and handling precision rather than mass-market retail volume. Equipment specialists further shape the ecosystem by determining which packaging formats can be manufactured efficiently at scale, effectively acting as adoption accelerators for new materials and structures.
Strategic Moves and Recent Developments
Recent activity underscores how companies are translating strategy into capacity and product decisions. Tetra Pak’s Lund pilot plant investment targets paper-based barrier replacement for aluminum foil, an explicit bet on recyclable carton architecture. SIG’s aluminum-free aseptic carton rollout in Europe and its camel milk category entry show simultaneous focus on structural compliance and category diversification. SIG’s Querétaro expansion reflects a regional capacity build to support dairy and shelf-stable beverage demand closer to end markets. On the exhibition and ecosystem side, companies such as ASEPTO and Steriline have showcased aseptic liquid packaging innovations and advanced filling lines at major industry events, signaling continued emphasis on technology visibility, customer engagement, and solution-level selling. These moves collectively indicate that leadership is increasingly defined by the ability to combine material innovation, regional capacity alignment, and application-specific portfolio breadth.
Market Structure Evolution: Consolidation, Fragmentation, and New Entrants
The market is likely to evolve along two concurrent paths. In mature format segments, scale advantages, integrated service models, and compliance readiness may encourage consolidation or strategic partnerships, particularly where recyclability mandates increase the cost of lagging behind. In parallel, specialized niches and emerging regions may see continued fragmentation, with new entrants targeting specific applications, local material supply chains, or cost-competitive manufacturing models. The presence of large Asian carton producers and regional capacity investments suggests that price competition and localized service will matter alongside technology leadership. For customers, this means the supplier base is becoming more varied in terms of risk-return profiles, and procurement strategies will need to balance scale, compliance assurance, and regional responsiveness rather than defaulting to a single incumbent.
Future Outlook: Three Trends to Watch
Looking toward 2027 and beyond, the market appears headed toward a period in which recyclability, material substitution, and regional capacity alignment become central to commercial performance. Three trends are especially salient.
Bulk Aseptic Packaging Market
Trend 1: Recyclability-Driven Format Redesign Becomes Commercial Mainstream
As delegated design-for-recycling criteria crystallize and brand owners face mounting expectations from retailers, consumers, and regulators, recyclable mono-material and aluminum-minimized aseptic structures are likely to move from pilot and select-market usage to broader commercial deployment. This trend creates opportunities for providers that can prove equivalent barrier performance, reliable seal integrity, and compatible recycling streams. It also introduces risk for formats that cannot meet recyclability thresholds without significant redesign or process changes. Companies that establish validated recycling pathways and transparent compliance documentation will be better positioned to secure long-term brand owner contracts, particularly in Europe and other regulated markets.
Trend 2: Regionalized Capacity and Category-Specific Portfolio Expansion
Investments in localized production and category-focused solutions are expected to continue as firms seek to reduce logistics exposure, serve emerging dairy and beverage segments, and respond to trade and tariff dynamics. This regionalization will likely coincide with more targeted product development, such as carton solutions tailored to specialty milks, plant-based beverages, and nutrition liquids. The commercial opportunity lies in pairing capacity proximity with format flexibility, enabling faster response to regional demand shifts. The uncertainty is whether regional capacity builds will generate sufficient scale to offset higher unit costs in smaller markets, or whether demand concentration will remain uneven across geographies.
Trend 3: Integration of Equipment, Materials, and Service as a Competitive Moat
As material specifications become more complex and regulatory expectations rise, the ability to offer compatible filling equipment, technical support, and compliance assistance will matter more than ever. Equipment providers and packaging suppliers that coordinate material behavior with line performance, sterility assurance, and changeover efficiency can reduce customer adoption friction for new formats. This creates a strategic path for incumbents and enables differentiated service models. One risk is that integration complexity may raise barriers for smaller customers, potentially slowing diffusion of advanced recyclable formats in price-sensitive segments unless financing, training, and transition support evolve alongside the technology.
Strategic Guidance for Decision-Makers
For manufacturers, brand owners, and investors, the current environment rewards proactive positioning across material strategy, regional capacity planning, and supplier selection.
-
Manufacturers and converters should prioritize recyclable structure readiness before regulatory deadlines tighten. Investing in material testing, recycling stream validation, and design-for-recycling documentation can reduce future redesign costs and improve negotiating leverage with brand owners. Where aluminum replacement is technically feasible, piloting should be paired with line compatibility checks to ensure that new substrates perform reliably on existing filling equipment.
-
Brand owners and procurement leaders should treat supplier evaluation as a compliance-and-performance decision, not just a cost decision. Criteria should include recyclability pathway clarity, regional capacity proximity, quality assurance discipline, and ability to support format transitions. Diversifying the supplier base across scale incumbents, regional producers, and specialized format providers can improve resilience while preserving access to advanced solutions.
PW Consulting -
Investors and strategic planners should focus on companies demonstrating coordinated moves across materials, capacity, and application breadth. The strongest positioning is likely to belong to firms that can combine recyclable format leadership with regional production alignment and supportive equipment or service ecosystems. Monitoring capacity announcements, pilot plant outcomes, and regulatory milestone progress will provide early signals of which players are converting innovation into commercially scalable advantage.
The aseptic packaging market is entering a phase where growth and restructuring occur simultaneously. Demand expansion provides a favorable backdrop, but the real strategic value will be captured by those who anticipate material compliance requirements, align capacity with regional demand realities, and select partners capable of delivering both performance and transition support. Detailed segmentation data, regional nuances, and tailored scenario planning can sharpen these choices further for organizations preparing investments or portfolio decisions.
For detailed analysis of this topic, please visit the official page: Aseptic Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
LTCC Ceramic Substrates Market: 6.3% CAGR Trajectory and Regional Shifts to 2032
By PW Consulting, 2026-09-21
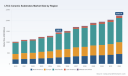
Navigating the LTCC Ceramic Substrates Market: Strategic Trends and Commercial Opportunities Through 2032
The low-temperature co-fired ceramic (LTCC) substrates market has entered a decisive growth phase, driven by the convergence of high-frequency connectivity, automotive electrification, and advanced packaging demands. Between 2020 and 2025, global revenue expanded from approximately 1,022.6 million USD to 1,458.2 million USD, reflecting sustained investment in miniaturized, high-reliability interconnect solutions. The forward trajectory points to a compound annual growth rate of 6.3 percent, with the market projected to reach 2,230.8 million USD by 2032. This expansion is not uniform; it is concentrated among a handful of established manufacturers, with the top three players capturing roughly 65 percent of revenue and the top five accounting for approximately 75 percent. The market structure signals both maturity and opportunity: incumbents hold significant technical and capacity advantages, while lingering pockets of regional and application-specific demand create room for targeted differentiation and strategic entry.
Understanding this landscape requires moving beyond aggregate numbers. The pace of growth, the concentration of supply, and the shifting priorities of end-use industries all carry direct implications for procurement planning, capacity investment, and competitive positioning. The following analysis distills the structural forces shaping the LTCC substrate market, the competitive behaviors defining the leading cohort, and the strategic choices that decision-makers should prioritize as the market moves through 2026 and beyond.
Market Landscape and Core Challenges
The LTCC substrate market has navigated a period of steady expansion, but the current environment is defined less by raw growth and more by the quality and direction of that growth. Over the past five years, demand have been supported by the adoption of multilayer ceramic architectures in applications requiring high integration density, stable dielectric performance, and robust thermal characteristics. The market's ability to grow at a mid-single-digit pace through 2032 suggests that LTCC substrates are becoming an embedded component in several technology roadmaps rather than a cyclical beneficiary of a single end market.
Despite this favorable trajectory, the industry faces three interconnected challenges that will shape competitive outcomes in the near term:
-
Demand diversification across applications and regions. Revenue is increasingly distributed among multiple application categories, with consumer electronics representing the largest segment, followed by automotive electronics, aerospace and military use, and a smaller residual category. This dispersion means that no single application can be treated as a universal proxy for market health. Suppliers must manage distinct qualification cycles, performance requirements, and volume profiles simultaneously, which complicates capacity planning and margin management.
-
Market concentration and the risk of complacency. With the top three and top five firms holding significant revenue shares, the market exhibits characteristics of a consolidated value chain. Concentration can yield scale efficiencies and consistent quality, but it also raises the bar for differentiation. Incumbents must continuously invest in material formulations, process control, and integration capabilities to defend positions, while smaller players must identify niches where specialized performance, lead-time advantages, or regional proximity offer defensible value.
-
Technology and qualification pressures in high-reliability segments. As LTCC substrates expand into automotive radar, 5G RF modules, and advanced semiconductor packaging, the tolerance for variability narrows. Meeting automotive and defense-grade expectations requires rigorous process consistency, advanced dielectric control, and documented supply-chain traceability. These requirements lengthen time-to-revenue for new designs and increase the cost of quality, pressuring firms to balance innovation with certified repeatability.
A secondary but material consideration is the stability of the input environment. Alumina feedstock prices have remained stable, with no reported increases or disruptions affecting LTCC production in 2025 and 2026. The broader alumina supply chain showed no force majeure events or capacity constraints as of early 2026, and there have been no new export controls or tariffs specifically targeting alumina or LTCC ceramic substrates in major economies during this period. Compliance with ISO 9001 and automotive AEC-Q200 standards continues as a baseline requirement without recent regulatory changes, and no new environmental restrictions or transport surcharges on key precursors have been reported. This relative calm in raw material and regulatory conditions provides a stable backdrop for investment, but it also means that competitive advantage will be determined more by process know-how and product architecture than by input cost arbitrage.
PW Consulting
Key Drivers Shaping Market Dynamics
Technological Innovation and Material Advancements
The most compelling driver of market evolution is the ongoing refinement of LTCC materials and multilayer architectures. LTCC technology enables high-density interconnect with embedded passive elements, controlled impedance, and thermal performance suited to demanding RF and power applications. Recent product activity illustrates how manufacturers are translating material science into commercial advantage. In April 2026, a major ceramics supplier announced the commercialization of a breakthrough multilayer ceramic core substrate for advanced AI semiconductors, featuring high rigidity and circuit miniaturization, with an unveiling planned at ECTC 2026. This development signals a deliberate push to extend LTCC beyond traditional RF and sensor applications into advanced packaging domains where dimensional stability and mechanical robustness are critical.
Simultaneously, peers have focused on expanding the performance envelope for connectivity and mobility. In May 2025, a leading manufacturer introduced a next-generation ceramic substrate optimized for high-frequency 5G modules and automotive radar applications. This launch reflects the broader requirement to support wider bandwidths, tighter integration, and consistent signal integrity in environments where electrical performance and mechanical reliability must coexist. Capacity decisions reinforce this direction: in July 2025, another major player expanded production capacity for multilayer ceramic capacitors integral to LTCC substrate performance to meet automotive and telecommunications demand. These moves indicate that substrate suppliers are not only improving individual product attributes but are also aligning capacity and component availability to support system-level integration.
Ceramic Substrate Market
Policy and Regulatory Environment
The policy backdrop has been a stabilizing force rather than a disruptive one. The absence of new export controls or targeted tariffs on alumina or LTCC ceramic substrates in 2025 and 2026 has reduced the likelihood of sudden cost shocks or supply fragmentation. Equally important, the regulatory expectations that do exist—such as ISO 9001 and automotive AEC-Q200 compliance—are well established and continuously applied across active producers. For decision-makers, this means that qualification frameworks are predictable, but they still represent meaningful barriers. Firms that have matured their quality systems and documentation processes are better positioned to win automotive and defense-related programs, while newer entrants face a steeper path to certification. The policy environment therefore favors disciplined, process-oriented operators and rewards long-term investment in quality infrastructure.
Demand-Side Shifts in Consumer, Automotive, and High-Reliability Markets
On the demand side, the market is being reshaped by the needs of three broad clusters. Consumer electronics continue to provide the largest revenue base, driven by the ongoing need for compact, high-integration solutions in mobile and connectivity-oriented devices. Automotive electronics represent the second-largest segment, fueled by the expansion of advanced driver-assistance systems, radar-based sensing, and power management modules that require substrates with strong reliability profiles. Aerospace and military applications, while smaller in absolute terms, contribute disproportionately to requirements for thermal endurance, dimensional stability, and long-term consistency. The "others" category captures additional niche demands, but together these application groups highlight a market where volume and value are distributed across very different qualification and performance regimes.
This diversification matters because it changes how suppliers should allocate engineering resources. A substrate designed for high-volume consumer modules must balance cost and throughput, whereas an automotive radar substrate must prioritize repeatable RF behavior and qualification evidence. An aerospace or defense program may emphasize traceability and environmental robustness more than unit-cost optimization. The ability to serve multiple demand profiles without diluting process control is increasingly a defining capability.
Supply Chain and Cost Structure Dynamics
Cost structure dynamics have been characterized by input stability and process-driven differentiation. Stable alumina feedstock pricing and the absence of force majeure events in the global supply chain through early 2026 have kept variable cost risk contained. However, LTCC substrate economics are increasingly influenced by factors beyond raw materials: layer count, via formation precision, dielectric consistency, yield management, and integration of embedded components all affects the cost-to-performance ratio. Firms that can raise performance while maintaining yield and minimizing rework will capture margin advantages, even in a stable input environment. This is why capacity expansions are often paired with product launches and material innovation rather than treated as standalone volume plays. The market rewards integrated improvements rather than isolated scaling.
Competitive Landscape and Leading Strategies
The competitive field is dominated by a dense cluster of Japanese manufacturers, complemented by notable European, U.S., and select Asian players. This geographic concentration reflects decades of accumulated expertise in ceramic materials, multilayer processing, and high-frequency component integration. The major firms have built strong positions by aligning substrate capabilities with adjacent component businesses, such as multilayer capacitors, RF modules, and precision sensors, which allows them to serve system integration requirements more holistically.
Several strategic patterns emerge among the leaders:
-
Vertical alignment with component ecosystems. Leading manufacturers often combine LTCC substrates with complementary passive and active components. This integration supports higher-density designs and reduces the customer's need to manage multiple supplier interfaces for highly interdependent functions. It also creates switching costs for end-users who value validated subsystem performance.
-
Application-specific material and process leadership. Some firms emphasize high-rigidity ceramic cores for advanced semiconductor packages, while others prioritize dielectric formulations for high-reliability RF front-end modules, antennas, and power electronics. Specialized producers focus on automotive sensors, industrial electronics, or high-frequency and power applications, building reputations around reproducible performance in targeted domains.
-
Certification and reliability as market access tools. Companies serving automotive, aerospace, and defense applications treat quality certification as a core competitive asset. Adherence to established standards is not merely a compliance activity; it is a gating factor for program participation. Firms that have institutionalized these systems can secure long-cycle contracts that smaller, less certified rivals cannot easily enter.
HTCC Ceramic Substrates Market -
Regional specialization and proximity advantages. European and U.S.-based producers often compete by offering tailored custom substrates, turnkey fabrication up to high layer counts, and close collaboration with customers in defense, medical, and high-reliability industrial sectors. Chinese and Taiwanese manufacturers participate in the consumer and telecom supply chains, leveraging scale and proximity to volume-driven programs.
Recent corporate activity reinforces these strategies. The April 2026 commercialization of a high-rigidity multilayer ceramic core substrate for advanced AI semiconductors illustrates how incumbents are extending their technology into next-generation packaging requirements. The July 2025 capacity expansion for multilayer ceramic capacitors tied to LTCC performance, and the May 2025 launch of a substrate optimized for 5G and automotive radar, both demonstrate a pattern of synchronized product and capacity moves aimed at capturing demand in high-growth connectivity and mobility segments.
Looking forward, the market structure is likely to evolve along three lines. First, consolidation pressure will persist among smaller players who lack the scale or certification depth to compete across multiple applications, potentially leading to selective acquisitions or capacity partnerships. Second, differentiation will increasingly hinge on architectural innovation—layer count, via precision, thermal-mechanical performance, and embedded component integration—rather than on basic substrate supply. Third, new entrants and regional specialists may find opportunities in high-mix, lower-volume niches, especially where proximity, customization speed, or domain-specific expertise outweighs the advantages of the largest incumbents. The overall trajectory suggests a market that is consolidating at the top while remaining open to specialized value creation below the leading tier.
Future Trends and Commercial Implications (2026–2032)
Expansion into Advanced Packaging and AI-Enabled Semiconductor Systems
One of the most significant trends is the extension of LTCC substrates into advanced packaging domains associated with AI and high-performance computing. The commercialization of high-rigidity ceramic core substrates with circuit miniaturization indicates that LTCC is being evaluated for structural and interconnect roles beyond conventional RF modules. As semiconductor architectures continue to push thermal and dimensional requirements, LTCC's combination of stability and integration density can create opportunities in packages that demand precise alignment, mechanical robustness, and embedded functionality. For suppliers, this is a route to higher value-add and longer program lifecycles; for end-users, it may offer a pathway to consolidate interconnect functions and reduce packaging complexity.
Continued Growth in Automotive and High-Frequency Connectivity Applications
Automotive electronics and high-frequency connectivity are expected to remain central growth engines. The expansion of radar-based sensing, 5G-related RF modules, and power electronics in vehicles supports steady demand for substrates with consistent RF behavior and strong reliability credentials. At the same time, consumer electronics will continue to provide volume, though margin profiles may differ. The commercial implication is that suppliers must be able to straddle both high-volume cost sensitivity and high-reliability performance requirements without compromising quality. Companies that can manage these dual demands with disciplined process control and application-specific engineering will be better positioned to capture share.
Stabilization of Input Conditions Likely to Shift Competition Toward Process and Integration Capability
With alumina feedstock prices stable, no reported force majeure events in the supply chain, and no new tariffs or export controls targeting LTCC materials, the immediate cost environment is unlikely to be a differentiating shock factor. This shifts the source of advantage toward manufacturing precision, yield management, material formulation, and integration capability. Firms that can deliver higher performance per layer, reduce defect rates, and offer validated subsystem-level solutions will capture more value than those competing primarily on price. For procurement teams, this means that supplier selection should weigh process maturity and qualification depth as heavily as unit economics.
Potential Risks and Uncertainties
Several uncertainties warrant attention. First, while the input environment has been calm, any future disruption in alumina availability or precursor logistics could quickly alter cost dynamics and lead-time reliability, particularly for high-volume programs. Second, the trajectory of automotive and telecom demand is subject to broader macroeconomic and cycle risks; a slowdown in vehicle production or a shift in telecom capex could temporarily soften demand in specific segments. Third, as LTCC substrates extend into advanced packaging and higher-performance domains, qualification and technical validation requirements may intensify, increasing time-to-revenue and raising the cost of failure. Firms should plan for scenario variability in both demand and validation timelines.
Strategic Actions for Decision-Makers
For Manufacturers and Substrate Suppliers
-
Invest in differentiated architectural capabilities. Prioritize improvements that raise performance without sacrificing yield, such as advanced dielectric control, via precision, layer integration, and thermal-mechanical robustness. Product launches paired with targeted capacity expansion, as seen in recent 5G and automotive radar moves, are more effective than undifferentiated volume increases.
-
Deepen application-specific qualification and documentation. Strengthen ISO 9001 and AEC-Q200-aligned processes where relevant, and build evidence packages that support automotive, aerospace, and defense participation. Reliable certification infrastructure is a market-access advantage in high-reliability segments.
-
Align capacity with high-growth demand clusters. Use demand signals from consumer, automotive, and connectivity segments to calibrate expansions. Synchronizing substrate capacity with complementary component availability can improve system-level value and reduce customer integration friction.
For Investors and Strategic Partners
-
Focus on firms with material and process differentiation rather than pure scale plays. In a stable input environment, the companies most likely to capture margin and share are those with proprietary ceramic formulations, high layer-count capability, and proven high-reliability qualification. Evaluate pipeline activity, such as advanced packaging substrate development, as an indicator of future value creation.
-
Monitor integration and geographic diversification. Track how leading players extend into adjacent component businesses and how regional specialists position around customization and proximity. Consolidation among smaller firms and selective partnerships may create opportunities for entry at favorable valuations or with strengthened capability sets.
For Procurement and Engineering Leaders
-
Prioritize supplier capability depth over headline price. In LTCC substrates, process consistency, qualification evidence, and integration support often determine long-term total cost more than initial unit price. Assess suppliers on yield stability, layer-count capability, RF and thermal performance consistency, and ability to support custom requirements.
-
Plan for multi-application supply strategies. Because demand spans consumer, automotive, and high-reliability segments, consider dual-sourcing or application-specific supplier assignments to balance volume needs with qualification requirements. Engage suppliers early in design cycles to align material and process choices with end-system performance goals.
The LTCC ceramic substrates market is entering a phase where growth is sustained, but the nature of competition is becoming more refined. Stable input conditions, predictable regulatory expectations, and a concentrated but still diversified supplier base create a setting in which process excellence, application-specific engineering, and integration capability will determine who captures durable advantage. The companies and organizations that prepare for these dynamics now—by investing in differentiated capabilities, strengthening qualification infrastructure, and aligning supply strategies with application realities—will be better positioned to convert market growth into commercial value through 2032 and beyond.
For teams seeking a deeper, segment-specific view of regional demand distribution, application splits, type-based revenue patterns, concentration benchmarks, and detailed company profiles, a comprehensive research report provides the structured data and tailored scenarios needed to support precise planning. Detailed breakdowns and customized recommendations can help translate these strategic trends into concrete operating decisions.
For detailed analysis of this topic, please visit the official page: LTCC Ceramic Substrates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Lithium-Sulfur Battery Market: Why 25.7% CAGR and Asia Pacific Lead the 2032 Outlook
By PW Consulting, 2026-09-21
The Lithium-Sulfur Battery Market: Strategic Trends and Commercial Opportunities Through 2032
1. Market Context and Core Challenges
The lithium-sulfur battery sector has transitioned from laboratory curiosity to commercial imperative over the past half-decade. Market revenue expanded from approximately $16.9 million in 2020 to an estimated $53.0 million in 2025, reflecting a compound annual growth rate of 25.7 percent across the historical period. Projections extend the trajectory through 2032, with revenue climbing toward $262.8 million as manufacturing scale, application diversification, and cost advantages converge. This pace of expansion outstrips conventional lithium-ion growth in adjacent segments, signaling a structural shift rather than a cyclical upturn.
Several inflection points define the current landscape. The first is the narrowing gap between laboratory performance and manufacturable cell specifications. Early lithium-sulfur designs wrestled with rapid capacity decay, polysulfide shuttling, and cycle life limitations that confined them to academic papers. Recent product announcements and supply chain milestones indicate that chemically stable configurations, advanced anode protection, and sulfur cathode engineering are moving into pilot and early commercial production. The second inflection point concerns application timing. High-altitude unmanned systems, defense payloads, and specialized aerospace platforms are adopting the technology faster than mainstream passenger vehicles, because they tolerate bespoke thermal and packaging constraints while demanding extreme gravimetric energy density. The third challenge revolves around ecosystem maturity. Cell manufacturers seek cathode material consistency, electrolyte formulations with proven longevity, and recycling pathways that align with emerging regulatory expectations. Firms that resolve these integration hurdles will capture disproportionate value as downstream markets scale.
2. Key Drivers Reshaping the Landscape
Technology innovation remains the central catalyst. Advances in three-dimensional graphene scaffolds, nano-encapsulated sulfur cathodes, and glass-protected lithium-metal anodes have substantially improved energy density targets and cycle stability. Companies are now reporting cell-level energy densities that meaningfully exceed conventional lithium-ion benchmarks, with designs targeting ranges between 380 and 500 Wh/kg and development roadmaps that aim substantially higher for aviation and specialized use cases. These performance gains are not merely technical milestones; they change the economics of weight-sensitive applications, enabling longer endurance for drones, lighter battery packs for electric vehicles, and reduced structural load for aerial mobility concepts.
PW Consulting
Policy and regulatory dynamics are reinforcing the technology narrative. In the European Union, carbon footprint declarations for industrial rechargeable batteries exceeding 2 kWh capacity became mandatory as of February 2026, intensifying the focus on lifecycle emissions and supply chain transparency. At the same time, U.S. policy has preserved investment tax credit eligibility for hybrid battery energy storage systems through 2035 under the One Big Beautiful Bill Act of 2025, supporting project economics for stationary storage deployments. Public-sector programs have also sharpened cost-reduction targets, including long-duration storage goals that seek to drive levelized cost of storage toward 5 cents per kWh by 2030 through advanced battery chemistries. These frameworks favor chemistries with lower material footprints and clearer decarbonization pathways.
Demand-side behavior is shifting as well. Aerospace and defense operators prioritize energy density and supply chain sovereignty over pure cost minimization, making them early adopters of sulfur-based cells. Automotive programs are increasingly interested in lithium-sulfur architectures for next-generation platforms, particularly where cobalt, nickel, and manganese reduction aligns with procurement, sustainability, and cost goals. Stationary storage developers are evaluating the chemistry for applications where cycle life, safety, and eventual cost parity can be demonstrated. The common thread is a willingness to qualify new chemistries in high-value segments before broader commercial adoption.
Supply chain and cost structures provide a powerful underpinning. Sulfur cathode active material costs are exceptionally low relative to traditional cathode chemistries, with industry estimates placing sulfur-based material costs around 7 cents per kWh, roughly one-third of lithium-ion equivalents. Domestic sourcing of sulfur and lithium-metal anodes can support tariff-free manufacturing flows, which strengthens supply chain resilience and reduces exposure to geopolitical trade frictions. These cost characteristics, combined with improving manufacturing maturity, give lithium-sulfur a credible path to competitive pack-level economics once yield and cycle life meet operational requirements.
Lithium-Metal Secondary Battery Market
3. Competitive Landscape and Leading Strategies
The competitive field spans dedicated lithium-sulfur developers, materials innovators, and research organizations bridging academia and production. Several firms have defined clear strategic positions. One U.S.-based manufacturer has emphasized proprietary three-dimensional graphene architectures and domestic cell sourcing, targeting drones, defense, electric vehicles, satellites, and stationary storage. Recent activity underscores its integrated approach: beginning U.S. production of battery-grade lithium-metal foil to localize supply chains, launching a drone propulsion system designed around American-made cells for national security applications, and securing more than $200 million in additional equity investment to accelerate manufacturing expansion. Its binding agreement to acquire a European battery recycling plant further illustrates a strategy that pairs capacity growth with material circularity.
Another U.S. developer has focused on sulfurized-carbon cathodes paired with three-dimensional metallic lithium anodes, achieving cell-level energy density near 450 Wh/kg without cobalt, nickel, or manganese. Its partnership with a major automotive group to co-develop lithium-sulfur EV cells highlights the growing interest from incumbent automakers in chemistries that reduce critical mineral dependence while raising gravimetric energy density. A third company has commercialized ultrahigh-energy-density cells approaching 380 Wh/kg at the cell level, with applications spanning energy storage, electric vehicles, and multi-domain transport. Its messaging emphasizes versatility across ground, air, and sea use cases rather than concentration in a single vertical.
International entrants are pursuing differentiated routes. An Australian firm has centered on nano-encapsulated sulfur cathode materials designed to be compatible with existing lithium-ion manufacturing infrastructure, targeting stationary storage and industrial applications. This compatibility thesis lowers adoption friction for established cell lines. A German company has advanced sulfur crystal batteries with polymer-host anodes, emphasizing ultra-fast charging, very high energy density targets, and aviation applications including eVTOL concepts as well as stationary power. A U.S. firm has concentrated on thin glass-protected lithium-metal anodes and advanced electrolyte development, reporting cells exceeding 400 Wh/kg. Another U.S. developer has promoted a lithium-sulfur platform targeting around 500 Wh/kg for EV and aerospace customers, while a separate U.S. manufacturer has expanded into advanced pouch and cylindrical cell production for energy storage and electric vehicles. Research-oriented organizations continue to underpin the field, with one DOE-funded group pursuing improvements in cycle life and energy density for EV and grid storage, and a European research institute operating pilot production of advanced lithium-sulfur cells and materials.
Worldwide Organic Polysulfide Market
The market structure remains moderately fragmented but shows early concentration signals. The top three players account for roughly 34 percent of market revenue, and the top five approach nearly 46 percent. This dispersion suggests room for consolidation, but also indicates that multiple technology routes still coexist. The strategic implication is that differentiation will increasingly come from application-specific fit, manufacturing scalability, supply chain localization, and the ability to demonstrate cycle life under real operating conditions. Firms that integrate materials, cell production, and recycling or end-of-life pathways are likely to build stronger moats than those offering only one link in the value chain.
4. Future Trajectory and Strategic Implications
The next three to five years will likely be defined by three interlocking trends. First, application sequencing will favor high-value, weight-sensitive segments before mass-market mobility. Unmanned aerial systems, defense payloads, and aerospace programs will continue to serve as beachheads, generating revenue and operating data that reduce qualification risk for broader automotive and storage adoption. This sequencing matters commercially because early deployments create reference cases that shape procurement standards and accelerate downstream adoption.
Second, manufacturing localization and supply chain resilience will become strategic differentiators. Recent production and sourcing moves indicate a clear direction toward domestic or regionally anchored lithium-metal foil, sulfur cathode materials, and recycling capacity. This localization lowers tariff exposure, supports security-sensitive customers, and aligns with policy environments that reward supply chain transparency. Companies that secure stable inputs and demonstrate consistent cell quality will be better positioned to win multi-year contracts, particularly in defense and infrastructure applications where reliability and traceability are paramount.
Third, regulatory pressure on carbon intensity and material sourcing will intensify. Carbon footprint declaration requirements in the European Union and extended storage cost targets in the United States will push developers to document lifecycle performance and reduce reliance on expensive or constrained critical minerals. Lithium-sulfur’s low sulfur material cost and potential for reduced critical mineral content provide a structural advantage, but only if manufacturers can substantiate claims with verified data and consistent production. Firms that invest early in lifecycle documentation, recycling integration, and defensible sourcing will convert regulatory pressure into competitive leverage.
These trends translate into clear commercial opportunities. Manufacturers can pursue application-focused product tiers that match energy density, cycle life, and safety requirements to specific end markets, rather than competing solely on headline specifications. Investors can evaluate differentiated technology narratives against tangible milestones such as localized foil production, recycling capacity acquisition, automotive co-development agreements, and verified energy density outcomes. Procurement organizations can use the current transition to secure access to next-generation cells while diversifying supply risk, especially in segments where sulfur-based chemistry offers weight, cost, or sovereignty advantages. The principal uncertainty lies in the pace at which cycle life, calendar stability, and manufacturing yields reach the thresholds required for high-volume mobility and grid storage. Until those thresholds are demonstrated at scale, adoption will remain weighted toward applications that can absorb higher unit costs and tolerate specialized thermal and management requirements.
5. Guidance for Decision-Makers
Manufacturers should prioritize alignment between chemistry roadmaps and application realities. Instead of pursuing a single universal specification, leaders can structure product portfolios that match energy density, cycle life, and cost to the tolerance and value profile of each segment. Building or securing localized supply for lithium-metal foil and sulfur cathode materials, while planning for recycling integration, will reduce exposure to tariffs and supply disruptions and strengthen the value proposition for security-conscious customers. Establishing verifiable performance data under operational conditions will also accelerate commercial qualification in defense, aerospace, and storage markets.
Investors should assess not only technical ambition but execution evidence. Funding decisions are best informed by milestones that demonstrate supply chain control, manufacturing scale-up, and customer co-development rather than headline energy density alone. Special attention should be given to firms that combine material innovation with cell production capacity and end-of-life strategies, because these integrated models are more resilient as the market matures and as regulatory expectations around carbon footprint and material recovery rise. Portfolio diversification across applications can balance the earlier revenue visibility of aerospace and defense against the larger but longer-cycle opportunity in automotive and stationary storage.
Procurement teams should treat the current period as a qualification window rather than a procurement emergency. Early engagement with developers can secure access to cells that meet specific weight, duration, and sovereignty requirements, while establishing testing protocols that confirm performance under real operating conditions. Evaluating total cost of ownership—including weight savings, thermal management implications, maintenance, and eventual recycling pathways—will produce more accurate comparisons than cell-level price alone. Structuring pilot agreements with clear data-sharing and performance milestones can reduce adoption risk while preserving flexibility as the technology evolves.
For leaders who need segment-level detail, granular forecasts, competitive benchmarking, and tailored recommendations, the full PW Consulting report provides the deeper segmentation, regional and application breakdowns, and customized analysis required to translate these trends into execution plans.
For detailed analysis of this topic, please visit the official page: Lithium-Sulfur Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Whole-house Ventilation System Market: How 6.52% CAGR Reshapes Residential Growth
By PW Consulting, 2026-09-21
The Whole-house Ventilation System Market: Strategic Trends and Commercial Opportunities Through 2032
The global whole-house ventilation system market has entered a phase of structural expansion, driven by tightening building codes, growing awareness of indoor air quality, and the broader transition toward energy-efficient residential design. Valued at approximately 3.84 billion USD in 2025, the market has grown steadily from 2.8 billion USD in 2020, reflecting a compound annual growth rate that positions it for sustained momentum through the end of the decade. Projections indicate revenue will reach roughly 5.97 billion USD by 2032, underpinned by a CAGR of 6.52 percent across the forecast period. This trajectory is not merely a function of incremental demand growth; it reflects a fundamental shift in how buildings are designed, regulated, and operated. Ventilation is no longer treated as a passive exhaust function but as an integrated component of indoor environmental quality, energy management, and occupant health.
PW Consulting
The market's expansion is geographically uneven, with mature regulatory environments and high construction activity driving adoption in certain regions, while emerging markets are accelerating uptake as building standards converge with international best practices. Product segmentation reveals a clear preference for heat recovery and energy recovery technologies, which together dominate revenue share due to their ability to balance fresh air intake with thermal efficiency. Residential applications account for the largest share of demand, reflecting both new construction requirements and retrofit activity in existing housing stock. Commercial and industrial segments, while smaller in absolute terms, are growing as facility operators prioritize air quality compliance and energy performance in larger building portfolios. Despite this growth, the market remains moderately fragmented, with the top three players capturing less than a quarter of total revenue and the top five holding a similarly limited share. This fragmentation suggests room for consolidation, strategic positioning, and differentiation as the market matures.
Key Challenges and Inflection Points
The industry faces several structural challenges that will shape competitive dynamics over the next forecasting cycle. First, regulatory fragmentation across jurisdictions creates compliance complexity for manufacturers and distributors. While a growing number of U.S. jurisdictions now require whole-house ventilation systems in new single-family and multifamily construction, the specific standards, testing protocols, and enforcement mechanisms vary widely. This patchwork increases product adaptation costs and complicates market entry strategies for firms targeting multiple regions. Second, the market is experiencing a technology transition as builders and homeowners weigh the performance characteristics of heat recovery versus energy recovery systems. Each approach offers distinct advantages in different climate conditions, and the optimal choice depends on local humidity profiles, energy costs, and design priorities. Misalignment between product capabilities and regional requirements can lead to underperformance, warranty claims, and reputational risk. Third, the industry must navigate supply chain and cost pressures that affect both manufacturing economics and end-user affordability. Component availability, material cost volatility, and labor constraints can compress margins and delay project timelines, particularly in high-growth segments where demand outpaces production capacity.
Key Drivers of Market Change
Technological Innovation and Performance Breakthroughs
Advances in heat and energy recovery technologies are reshaping the value proposition of whole-house ventilation systems. Modern units are achieving higher sensible and latent recovery efficiencies while reducing fan power consumption, enabling builders to meet stringent energy codes without sacrificing indoor air quality. Innovations in enthalpy exchange media, modular design, and integrated controls allow systems to adapt to variable operating conditions and maintain performance across seasonal shifts. Cold-climate optimization has become a particular focus, as manufacturers develop units that maintain recovery efficiency and condensate management in low-temperature environments. These technical improvements are not incremental refinements; they are expanding the addressable market by making ventilation systems viable in regions where earlier generations of equipment struggled to deliver consistent performance.
Policy and Regulatory Environment
Regulatory momentum is one of the strongest catalysts for adoption. Building code adoptions across multiple U.S. jurisdictions now require whole-house ventilation in new single-family and multifamily homes, embedding these systems into the baseline design of new construction rather than treating them as optional upgrades. California's 2025 Energy Code exemplifies this shift by prohibiting exhaust-only systems in new multifamily construction and mandating fault indicator displays for HRV and ERV systems, which raises the bar for monitoring and maintenance. Acceptance testing protocols, such as the 2025 NRCA-MCH-23-A standard, verify airflow, sensible recovery, and fan power compliance for multifamily buildings, creating a more rigorous validation framework. At the national level, ASHRAE Standard 62.2 continues to serve as the reference for minimum ventilation rates in residential mechanical systems, providing a consistent technical baseline that manufacturers can align with. Together, these regulatory developments are converting ventilation from a discretionary specification into a code-driven requirement, which stabilizes demand and encourages standardized product architectures.
Demand-Side Shifts in Consumer and Builder Behavior
Demand is being reinforced by changing expectations around indoor environmental quality. Homebuyers and commercial facility operators increasingly view air quality, humidity control, and ventilation performance as integral to health, comfort, and asset value. This perspective is amplified by greater public awareness of airborne contaminants and the role of mechanical ventilation in managing indoor pollutant levels. Builders are responding by specifying ventilation systems earlier in the design process, integrating them with HVAC architectures to simplify installation and improve balanced air exchange. In multifamily projects, developers are recognizing that compliant, efficient ventilation systems can reduce operational liabilities and support certification goals tied to energy performance and occupant well-being. The result is a demand environment that values not just airflow volume but measurable recovery efficiency, reliability, and ease of commissioning.
Residential Ventilation Systems Market
Supply Chain and Cost Structure Dynamics
Cost structures are evolving as manufacturers scale production, optimize component sourcing, and invest in design-for-manufacturability. Economies of scale are beginning to moderate unit costs for high-volume product lines, though premium segments with advanced controls or specialized climate adaptations remain relatively pricey. The supply chain for core components, including heat exchange media, fans, and control electronics, is maturing but remains sensitive to material price fluctuations and logistics constraints. Firms that secure reliable sourcing, standardize subassemblies across product families, and align production capacity with regional demand patterns are better positioned to protect margins. At the same time, installation and commissioning complexity can affect total cost of ownership for end users, making turnkey solutions and dealer support networks increasingly important competitive factors.
Competitive Landscape and Leading Strategies
The competitive field is populated by a mix of established HVAC manufacturers, specialized ventilation brands, and regional players with strong climate-specific engineering. Carrier offers energy-efficient HRV and ERV ventilator systems designed for whole-house indoor air quality and balanced ventilation, leveraging its broader residential portfolio to integrate ventilation with familiar HVAC platforms. Zehnder America focuses on the ComfoAir series of ERV and HRV units engineered for whole-house fresh air supply with high efficiency, emphasizing performance consistency and installer-friendly design. Panasonic contributes WhisperComfort ERV and related heat and energy recovery systems tailored for whole-house residential use, drawing on its reputation for quiet operation and reliability in connected home environments.
Broan-Nutone and RenewAire both target residential applications with integrated ventilation products and balanced ERV systems, respectively, with an emphasis on whole-house indoor air quality and fresh air exchange. Lifebreath has carved out a position around cold-climate ERV and HRV systems optimized for whole-house ventilation performance, addressing markets where temperature extremes demand robust recovery and defrost management. EXINDA provides HVI-certified ERV units for whole-house fresh air solutions that comply with North American standards, appealing to specifiers seeking verified performance and code alignment. Trane integrates whole-house ventilation with its broader HVAC offerings to improve IAQ and balanced air exchange, positioning ventilation as part of a unified climate control strategy rather than a standalone add-on.
In Europe, STIEBEL ELTRON offers the LWZ series of central ventilation systems with enthalpy heat exchangers for whole-house indoor air quality, reflecting a design philosophy that centralizes air handling for larger or more complex residential layouts. Aereco differentiates through hybrid ventilation systems with room-by-room demand control, targeting applications where adaptive airflow can reduce energy use while maintaining air quality in specific zones. These varied approaches illustrate how companies are aligning product architectures with regional climate needs, installation practices, and buyer expectations.
Strategic Positioning and Differentiation
Leading firms are differentiating along several axes. Some emphasize integration with existing HVAC ecosystems, reducing installation friction and enabling unified controls. Others focus on certified performance, climate-specific engineering, or demand-controlled airflow to appeal to performance-driven specifiers and code-conscious developers. Brand trust, warranty support, and dealer network strength also play outsized roles, particularly in residential markets where installers influence equipment selection. Companies that combine high recovery efficiency with low fan power, clear fault indication, and straightforward commissioning are gaining traction in jurisdictions where testing and compliance requirements are becoming more stringent.
Market Evolution: Consolidation, Fragmentation, and New Entrants
The market's moderate concentration leaves space for both consolidation and targeted fragmentation. Larger HVAC players may pursue acquisitions to fill geographic gaps, expand product lines, or acquire specialized engineering capabilities in cold-climate or demand-control ventilation. At the same time, niche entrants can thrive by serving specific climate zones, certification requirements, or application segments where standardized offerings fall short. New entrants from adjacent industries, including building automation and indoor air quality monitoring, may seek to bundle ventilation with sensing and control platforms, creating integrated solutions that address both air quality and energy performance. The likely outcome is a maturing landscape where scale advantages matter more, yet differentiated technical positioning remains a viable path to growth.
Future Trends and Commercial Opportunities
Trend 1: Code-Driven Standardization and Certification as a Competitive Moat
As more jurisdictions adopt ventilation requirements and acceptance testing protocols, compliance will become a baseline expectation rather than a differentiator. Products that demonstrate verified airflow, sensible recovery, and fan power performance will be preferred in bid processes and inspections. This trend favors manufacturers that invest in third-party certification, clear documentation, and repeatable commissioning procedures. Commercial opportunity lies in designing product families that can be configured to meet multiple regional standards without extensive custom engineering, reducing time-to-market and installation risk.
Trend 2: Integration of Ventilation with Smart Controls and IAQ Monitoring
The next phase of value creation will come from linking ventilation hardware with sensing, controls, and building management platforms. Demand-controlled ventilation, fault detection, and adaptive recovery strategies can optimize energy use while maintaining air quality targets. This convergence creates opportunities for bundled offerings that combine ventilation equipment with monitoring endpoints and control logic, appealing to homeowners who want visibility and to commercial operators who need centralized management. The risk is that integration complexity can raise costs and create dependency on software ecosystems, so interoperability and open communication pathways will be important to sustain adoption.
Trend 3: Climate-Specific Engineering and Regional Product Strategies
Climate diversity will continue to reward specialized engineering. Cold-climate HRV and ERV performance, humid-region latent load management, and mixed-climate flexibility will remain critical purchase criteria. Companies that maintain distinct product variants for key climate bands, rather than offering a one-size-fits-all lineup, are better positioned to capture regional demand without compromising performance. The associated opportunity is to build regional go-to-market strategies that pair the right product architecture with local installer training, warranty support, and code alignment. A potential risk is over-segmentation, which can inflate inventory and manufacturing complexity; disciplined platform design with modular options is the balance point.
Actionable Guidance for Decision Makers
For Manufacturers and Product Leaders
Prioritize platform strategies that allow climate-specific and code-specific variants to be derived from a common core. Invest in certified performance data, fault indication, and commissioning simplicity, as these features are increasingly tied to approval and installers' willingness to specify. Strengthen dealer and installer support, because in residential markets the installation ecosystem often determines repeat business and brand reputation. Evaluate where integration with HVAC platforms or smart controls adds genuine value versus where it introduces unnecessary complexity, and focus differentiation on the attributes that most directly affect compliance, energy performance, and reliability.
For Investors and Strategic Allocators
Look for companies with clear climate adaptation capabilities, credible certification footprints, and distribution relationships that can scale with code-driven demand. Favor business models that can expand revenue through add-on controls, maintenance services, or retrofit solutions, as these can improve lifetime value without requiring constant new construction volume. Monitor consolidation signals, particularly where larger HVAC portfolios seek to absorb specialized ventilation brands to broaden geographic reach or technical coverage. Be mindful of regulatory variability across regions, which can create uneven revenue trajectories even within a single national market.
For Procurement and Specification Teams
Specify ventilation systems with verified performance, clear fault indication, and documented compliance with relevant standards, rather than relying on nominal airflow claims. Evaluate total cost of ownership including installation complexity, commissioning requirements, and ongoing maintenance, since these factors often determine operational outcomes more than equipment price alone. Where possible, align product selection with regional code trajectories and climate conditions to avoid over-engineering in mild climates or under-specifying in extreme ones. Build relationships with installers and service providers early in the specification process to ensure that selected systems can be deployed and maintained effectively.
The whole-house ventilation system market is moving from optional specification to code-embedded infrastructure, with technological improvements, regulatory momentum, and demand-side expectations reinforcing one another. The firms and investors that understand these dynamics, and that align product strategy with regional requirements and performance verification, are best positioned to capture value as the market expands toward 2032 and beyond. For decision makers seeking detailed segmentation data, regional breakdowns, and customized strategic recommendations, the full PW Consulting report provides the granular analysis needed to translate these trends into concrete action plans.
Energy Recovery Ventilation System Market
For detailed analysis of this topic, please visit the official page: Whole-house Ventilation System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Trends and Commercial Opportunities in the Metallocene Catalyst Market
1. Market Landscape and Core Challenges
The metallocene catalyst market has entered a phase of structured expansion, characterized by steady revenue growth and broadening commercial adoption across polymer value chains. Valued at approximately 230.45 million USD in 2020, the sector has progressed to an estimated 302.45 million USD by 2025. Forward projections indicate continued momentum, with the market expected to approach 477.3 million USD by 2032, translating to a compound annual growth rate of 6.85 percent over the forecast horizon. This trajectory reflects a maturing technology base transitioning from specialized applications to mainstream polyolefin manufacturing, supported by performance advantages that conventional catalyst systems struggle to replicate.
Beneath the aggregate growth figures, the market exhibits notable structural characteristics. Concentration metrics indicate that the top three participants control roughly 58 percent of total revenue, while the top five firms account for approximately 68 percent. This distribution suggests a landscape where established players command significant commercial leverage, yet sufficient fragmentation remains to allow targeted disruption. The commercialization pathway for metallocene catalysts continues to balance performance differentiation against cost premium positioning, creating a market where technical capability and application engineering increasingly determine commercial success.
Key Challenges and Inflection Points
The first major challenge centers on cost-structure navigation amid raw material volatility. Metallocene catalysts carry an approximate cost premium of 30 to 40 percent relative to conventional Ziegler-Natta systems used in LLDPE production. This premium creates persistent pressure on converters and polymer producers to justify the incremental expense through demonstrable performance gains, such as enhanced film strength, improved processing efficiency, or downgauging potential. When upstream feedstock costs fluctuate or polymer pricing compresses, the economic calculus for catalyst selection becomes more stringent, forcing suppliers to continuously validate value propositions across diverse operating conditions.
The second inflection point involves regulatory-driven application shifts that reshape demand patterns. The European Union's Packaging and Packaging Waste Regulation mandates recyclable and mono-material packaging by 2030, while stricter environmental rules on single-use plastics compel converters to pursue recyclable monomaterial solutions. These policy frameworks directly influence catalyst demand by elevating the importance of precision chemistry capable of producing polyolefins with tailored rheological and mechanical profiles. Manufacturers that can align catalyst formulations with recyclability requirements and mono-material architecture stand to capture disproportionate demand growth, while those dependent on legacy application mixes face structural headwinds.
A third challenge emerges from regional price dynamics and competitive intensity. Recent market data from March 2026 shows that mLLDPE prices in Northeast Asia reached 1.19 USD per kilogram, reflecting a 2.5 percent downward movement driven by declining upstream ethylene and metallocene catalyst feedstock costs at key producing facilities. While lower input costs can improve margin flexibility, they also intensify price competition and compress differentiation opportunities. Suppliers must therefore manage the dual tension of benefiting from favorable cost environments while defending against commoditization pressures that erode the premium positioning historically associated with metallocene technology.
2. Key Drivers Shaping Market Dynamics
Technological Innovation and Performance Breakthroughs
Advancements in catalyst design and activation chemistry continue to expand the functional envelope of metallocene systems. Single-site metallocene catalysts enable tighter molecular weight distribution and controlled comonomer incorporation, which translates into polyethylene and polypropylene grades with superior film performance, higher extrusion rates, and the ability to produce thinner gauge materials without sacrificing mechanical integrity. Suppliers such as Univation Technologies have commercialized catalyst platforms supporting gas-phase single-site PE production that enable thinner films and higher throughput, demonstrating how catalyst innovation directly addresses converter economics. Similarly, W.R. Grace and Company supplies ActivCat® catalysts and custom-synthesized metallocenes tailored for activation in PE and PP platforms, while LyondellBasell Industries provides Avant single-site metallocene catalysts for specialty metallocene PP and PE products. These technology trajectories indicate that performance differentiation remains a primary engine of commercial adoption, particularly in applications where processing efficiency and end-use properties command premium pricing.
The evolution toward dinuclear metallocene architectures and customized ligand structures further broadens application scope. Nouryon custom-manufactures complex organics including ligands and metallocenes for single-site catalysts and other specialty chemicals, illustrating how upstream chemical synthesis capabilities complement catalyst commercialization. As manufacturers pursue grades optimized for specific film structures, packaging formats, and recycling compatibility, catalyst developers that can rapidly iterate formulations and translate laboratory advances into scalable production gain a strategic edge. This dynamic elevates the importance of R&D agility and application engineering support, shifting competitive advantage beyond raw catalyst performance toward integrated solution delivery.
Regulatory Environment and Sustainability Mandates
Policy frameworks are reshaping demand by imposing structural requirements on packaging and polymer end-use markets. The European Union's Packaging and Packaging Waste Regulation requires recyclable and mono-material packaging by 2030, creating a regulatory tailwind for polyolefins produced with metallocene catalysts that enable precise property control and compatibility with recycling streams. Stricter EU environmental regulations on single-use plastics further compel converters to seek recyclable monomaterial packaging solutions requiring metallocene catalyst precision chemistry. These mandates do not merely influence product specifications; they alter the economics of packaging design by rewarding material architectures that simplify recycling, reduce multi-layer complexity, and maintain performance with mono-material constructions. Catalyst suppliers positioned to support such architectures benefit from a regulatory-driven demand shift that is both durable and geographically concentrated in advanced markets, though its influence increasingly spreads as other jurisdictions adopt similar packaging circularity objectives.
Metallocene Polyethylene Market
The regulatory dimension also interacts with cost dynamics. As converters invest in recyclable solutions, they become more willing to absorb catalyst premiums when the resulting polymer grades enable compliance and preserve functionality. However, this willingness is conditional on clear performance validation and total cost-of-ownership analysis. Suppliers must therefore articulate how metallocene-enabled grades reduce downstream processing costs, support downgauging, or enable recycling-friendly structures, linking catalyst selection to broader sustainability and cost objectives rather than presenting it as an isolated material upgrade.
Demand-Side Shifts in Consumer and Industrial Behavior
End-market demand patterns are increasingly shaped by packaging efficiency, film performance expectations, and sustainability commitments. The launch of new metallocene PE grades illustrates how demand-side priorities translate into product commercialization. In October 2024, TotalEnergies SE launched the Advanced Supertough 12AST05 VLLDPE grade for film and packaging applications, targeting performance attributes that align with converter needs for toughness, sealability, and process reliability. Such product introductions reflect broader trends in which film and packaging manufacturers prioritize materials that support thinner gauges, improved mechanical properties, and compatibility with high-speed converting lines. As consumer brands pursue packaging lightweighting and recyclability goals, demand for polyolefins with tailored properties rises, indirectly strengthening the role of metallocene catalysts in grade development.
Industrial behavior also shifts as producers seek to optimize extrusion throughput and reduce energy intensity. Catalysts that support higher extrusion rates and consistent polymer quality help manufacturers increase line efficiency and reduce per-unit processing costs. When these operational benefits align with product performance gains, the adoption case for metallocene catalysts strengthens across both commodity and specialty segments. This dual benefit—processing efficiency plus end-use performance—makes catalyst selection increasingly strategic, as it affects not only material properties but also production economics and capacity utilization.
Supply Chain and Cost Structure Dynamics
Cost structures in the metallocene catalyst market are influenced by feedstock availability, upstream chemical pricing, and regional production economics. The March 2026 observation that Northeast Asia mLLDPE prices declined amid falling upstream ethylene and catalyst feedstock costs highlights how input-cost movements cascade through the value chain. Lower feedstock expenses can ease margin pressure for polymer producers and, by extension, improve the affordability of catalyst-driven grade upgrades. Yet the same environment can also intensify competition, as lower costs reduce the financial barrier to adopting alternative technologies or increasing output with conventional systems.
Supply chain resilience further shapes commercial strategy. Catalyst manufacturers that maintain reliable access to precursor chemicals, ligand synthesis capacity, and activation support services are better positioned to sustain supply continuity and respond to customer-specific grade requirements. Companies such as Chevron Phillips Chemical, which supplies metallocene catalysts for ethylene polymerization, and Asia-based producers including Mitsui Chemicals, Ube Industries, Prime Polymer, Zibo Xinsu Chemical, Daelim Industrial, SK Chemicals, and Mitsubishi Chemical, reflect a diversified production base spanning multiple geographies and application segments. This geographic breadth supports regional supply security and enables manufacturers to tailor offerings to local demand conditions, though it also requires coordinated management of technology transfer, quality consistency, and customer support across markets.
3. Competitive Landscape and Leading Strategies
Strategic Positioning of Core Players
The competitive field combines global specialty chemical firms, integrated polymer producers, and regional catalyst manufacturers, each pursuing distinct positioning strategies. Univation Technologies, headquartered in Houston, Texas, offers the XCAT™ metallocene catalyst portfolio for gas-phase single-site PE production, with a value proposition centered on enabling thinner films and higher extrusion rates. Its selection by Indian Oil Corporation Ltd. in September 2024 for a world-scale PE production line at Paradip, India, underscores how catalyst suppliers can secure landmark deployments that validate technology credibility and expand reference bases in high-growth markets. Such wins are strategically significant because they combine large-scale commercial proof with regional market entry, creating a template for subsequent adoption in adjacent geographies and applications.
W.R. Grace and Company, based in Columbia, Maryland, emphasizes activation chemistry through ActivCat® catalysts and custom-synthesized metallocenes designed to optimize single-site catalyst performance in PE and PP platforms. This approach highlights a strategic focus on the enabling chemistry layer rather than solely on final polymer grades, allowing Grace to serve as a critical partner in catalyst system design and activation optimization. LyondellBasell Industries, headquartered in Rotterdam, Netherlands, provides Avant single-site metallocene catalysts for specialty metallocene PP and PE products, aligning catalyst offerings with high-value specialty applications where property precision commands premium economics. Nouryon, also based in Arnhem, Netherlands, custom-manufactures complex organics including ligands and metallocenes, positioning within the upstream synthesis segment that supports catalyst developers and specialty chemical programs.
In the Asia-Pacific region, several firms have built substantial capabilities. Mitsui Chemicals, Ube Industries, Prime Polymer, and Mitsubishi Chemical each develop and supply metallocene catalysts for olefin polymerization and polyolefin applications, while Zibo Xinsu Chemical manufactures catalysts for industrial polyolefin applications in China. South Korean participants include Daelim Industrial and SK Chemicals, which provide metallocene catalysts for polymer and polyolefin resin production. Chevron Phillips Chemical, headquartered in The Woodlands, Texas, supplies metallocene catalysts for ethylene polymerization, reinforcing the presence of large integrated chemical companies in the catalyst supply chain. This multi-venue competitive structure means that technology leadership, scale, and regional proximity all influence commercial outcomes, and no single positioning dominates across all application segments.
Differentiation Advantages and Commercial Logic
Differentiation in this market typically rests on a combination of performance precision, application support, and scale economics. Leading suppliers distinguish themselves by delivering catalyst systems that produce consistent polymer properties across production scales, reducing variability and supporting customer quality targets. Equally important is the ability to provide grade-specific guidance, processing recommendations, and troubleshooting support, which transforms catalyst sales from a commodity transaction into a solution relationship. Companies that integrate ligand synthesis, catalyst activation, and application engineering can shorten development cycles for new grades and improve customer retention by embedding themselves in the customer's product development workflow.
Scale and supply reliability constitute another differentiation axis. Large-volume producers benefit from manufacturing efficiency and the ability to support world-scale projects, while regional manufacturers can compete on responsiveness, localized technical service, and cost structures aligned with local feedstock conditions. The market's concentration pattern indicates that scale advantages matter, but they do not automatically determine outcomes, because application-specific performance requirements and regulatory-driven grade demands create niches where tailored solutions outperform generic offerings. As a result, competitive success increasingly depends on aligning catalyst capabilities with the precise requirements of target applications rather than competing on broad specification statements alone.
Evolution of Market Structure
The market is evolving through a combination of consolidation pressure, regional capability expansion, and selective new-entry activity. Existing leaders maintain advantage through established customer relationships, proven large-scale deployments, and integrated technical services. At the same time, regional producers continue to strengthen presence in Asia and other growth markets, where expanding polymer capacity and local content preferences create demand for domestic catalyst supply. New entrants and niche specialists can gain traction by targeting specific application segments, such as recyclable packaging grades or specialty film formulations, where precision chemistry and rapid customization deliver disproportionate value. This dynamic suggests a landscape that is neither fully consolidated nor highly fragmented, but rather stratified into tiers defined by scale, application focus, and regional reach.
PW Consulting
Over the forecast period, the structure is likely to tilt toward stronger coordination between catalyst suppliers and polymer producers as grade development becomes more intertwined with regulatory compliance and sustainability targets. Partnerships, technology licensing, and integrated project commitments may become more common, particularly in large-scale capacity expansions where catalyst selection influences both product economics and long-term competitiveness. The result is a market in which strategic alignment and solution orientation matter as much as baseline catalyst performance.
4. Future Trends and Commercial Implications
Trend One: Sustainability-Linked Grade Development as a Growth Catalyst
Over the next three to five years, regulatory mandates and brand owner commitments are expected to accelerate demand for polyolefin grades designed for recyclability and mono-material packaging architectures. Metallocene catalysts that enable precise property control will play a central role in this shift, because they support the rheological and mechanical characteristics required for downgauging, seal performance, and compatibility with recycling streams. Commercial opportunity lies in developing grade families that explicitly address recyclable packaging requirements, supported by documentation and testing that demonstrate compliance and performance. Suppliers that build sustainability-aligned product portfolios can secure longer-term demand visibility and differentiate from competitors reliant on conventional specification competition. The primary risk is regulatory variation across regions, which can create uneven adoption patterns and require flexible product strategies rather than a single global grade architecture.
Trend Two: Processing Efficiency and Throughput Optimization
A second trend centers on the economic appeal of catalysts that improve extrusion throughput, reduce energy intensity, and enable consistent quality at high line speeds. As polymer producers seek to optimize capacity utilization and lower operating costs, catalyst systems that support higher extrusion rates and stable process windows gain strategic relevance. This trend benefits both commodity and specialty segments, but the strongest opportunity emerges where processing gains can be quantified and linked to total cost reduction. Companies that can demonstrate measurable efficiency improvements through catalyst selection are better positioned to justify premium pricing and expand share in cost-sensitive environments. A related uncertainty is that cost compression in upstream feedstocks can shift attention toward short-term price competition, temporarily weakening the emphasis on performance-driven procurement unless suppliers maintain robust efficiency evidence and application support.
Trend Three: Regionalization of Supply and Application Expertise
The third trend involves increasing regionalization of catalyst supply and technical service, driven by expanding production capacity in Asia and other growth markets, as well as by customer preferences for localized support. Regional manufacturers are likely to deepen capabilities in ligand synthesis, catalyst formulation, and application engineering, while global players will continue to leverage scale and broad technology portfolios. This dual structure creates opportunities for suppliers that can combine global technology credibility with regional responsiveness, particularly in large-scale projects and custom grade development. The commercial implication is that proximity to customer operations, rapid iteration on grade requirements, and strong local technical teams become competitive differentiators. The risk is that regional fragmentation can complicate quality consistency and technology transfer, making supply chain governance and standardized development processes essential for maintaining trust across markets.
5. Strategic Actions for Decision-Makers
For Polymer Manufacturers and Catalyst Users
Manufacturers should evaluate catalyst selection through a total value lens that combines product performance, processing efficiency, and compliance alignment rather than focusing solely on unit cost. Quantifying how metallocene-enabled grades support downgauging, line speed increases, or recyclable packaging structures can clarify the economic case and reduce the perceived burden of the catalyst premium. Building internal capability to test and validate new grades against specific application targets will accelerate adoption of performance-advantaged materials. Where large-scale capacity expansions are planned, engaging catalyst suppliers early in process design and grade definition can improve integration and reduce downstream rework. Timely access to detailed segmentation data, regional pricing dynamics, and competitor capability profiles supports more precise sourcing and product planning decisions.
Worldwide Metallocene Based Polyethylene Market
For Investors and Strategic Planners
Investors should monitor demand shifts tied to packaging regulation, recyclability requirements, and regional capacity additions, because these forces shape the pace and location of catalyst demand growth. Evaluating potential investments or partnerships requires attention to technology differentiation, application engineering strength, and the ability to secure landmark deployments that validate scale and reliability. Companies with strong positions in single-site activation chemistry, ligand synthesis, or specialty grade development may present attractive exposure to higher-value segments, while regional producers with growing technical service capabilities can offer growth optionality in expanding markets. Understanding concentration dynamics and recent commercial milestones helps assess which players are gaining momentum versus those facing pressure from cost competition or slower application adoption.
For Procurement and Supply Chain Leaders
Procurement teams should balance cost objectives with supply resilience and technical support quality, recognizing that catalyst performance variability can affect downstream polymer consistency and production efficiency. Diversifying supplier relationships across global and regional sources can mitigate concentration risk while preserving access to specialized grades. Establishing clear performance criteria, qualification protocols, and cost-totalization frameworks enables more disciplined evaluation of premium catalyst options. Tracking upstream feedstock price movements and regional polymer price trends provides early warning of shifts in cost pressure and competitive intensity, helping procurement calibrate negotiation strategy and inventory timing. Access to current market data and forward indicators strengthens the ability to anticipate supply conditions and align procurement plans with evolving demand requirements.
The metallocene catalyst market is moving toward a more performance-and-compliance-driven competitive environment, where technological precision, application alignment, and regional responsiveness determine commercial outcomes. Decision-makers who integrate catalyst strategy into broader product, cost, and sustainability objectives will be better positioned to capture the value created by this transition. For those seeking deeper segmentation detail, regional breakdowns, and customized strategic recommendations, the full research report provides more granular data and tailored analysis to support specific business decisions.
For detailed analysis of this topic, please visit the official page: Metallocene Catalyst Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Power Without Interruption: Strategic Trends Reshaping the UPS Market
The uninterruptible power system market has graduated from a commodity infrastructure play to a strategic enabler of digital transformation. As organizations push data center density, electrify healthcare networks, and digitize industrial operations, power protection is no longer a line item of last resort—it is now a foundational dependency. The industry's expansion signals that reliable continuity is becoming inseparable from performance, safety, and grid interactivity.
The market generated approximately $180.25 million in 2025, building on a consistent recovery from the $130.45 million recorded in 2020. Growth has accelerated through 2024 and into 2025, reflecting deployment momentum across digital, healthcare, and manufacturing environments. Projections extend through 2032, with the market positioned to reach $265.95 million by the end of the forecast horizon. This trajectory corresponds to a compound annual growth rate of 5.85 percent, a pace that underscores structural demand rather than a cyclical uptick. Momentum is broad-based but uneven, with opportunities concentrated where uptime criticality, energy efficiency, and connectivity converge.
Beneath the headline figures, the market faces meaningful pressure points. Power architecture expectations are changing faster than legacy products can adapt, forcing suppliers to reconcile reliability with efficiency, footprint, and sustainability targets. Supply-chain volatility for critical components, combined with evolving energy storage safety standards, creates execution risk for product rollouts and project timelines. At the same time, procurement is shifting from discrete unit purchases toward integrated continuity solutions, rewarding players that can deliver lifecycle performance, remote readiness, and compliance assurance.
Technological Innovation as the New Basis of Competition
UPS design is evolving from simple backup conversion to intelligent, adaptive power delivery. Advances in power electronics, thermal management, and battery chemistry are reshaping what customers expect from a single unit. Compact form factors, higher power density, and modular architectures are enabling deployments in space-constrained and distributed environments, from edge computing rooms to on-premises workstations. At the high end, medium-voltage solutions are eliminating the need for multiple conversion stages in large facilities, reducing energy losses and simplifying infrastructure around intensive compute operations.
A recent wave of product introductions illustrates how targeted innovation is aligning with use-case realities. Vertiv expanded its portfolio across the density spectrum, introducing compact systems for connected homes and workspaces while simultaneously announcing industrial-grade options tailored to manufacturing, transportation, oil and gas, pharmaceuticals, food and beverage, packaging, and steel operations. This dual-track approach shows how manufacturers are segmenting by environment rather than treating the market as a single volume game. The emphasis on distributed digital environments and industrial continuity suggests a broader shift: UPS solutions are increasingly designed for specific operating profiles, thermal conditions, and load dynamics rather than generic backup.
Battery technology is another critical axis of differentiation. The move toward lithium-ion and optimized energy storage configurations is enabling faster response, longer service life in selected duty cycles, and easier integration with distributed IT and edge deployments. This evolution matters because battery selection affects lifetime cost, footprint, maintenance cadence, and compliance. As customers weigh total cost of ownership against resilience requirements, the ability to match storage technology to application risk profiles becomes a competitive lever.
Policy, Safety Standards, and the Compliance Opportunity
Regulatory and safety frameworks are becoming more consequential in procurement decisions, particularly where energy storage interfaces with the grid or occupies shared infrastructure. Certification milestones are increasingly used as trust signals, not just technical checkboxes. The industry's first UL 9540 certification for energy storage safety and performance, achieved on a medium-voltage UPS platform, marked a notable shift in what is expected from large-scale power protection systems. Such certifications can reduce integration friction for data center operators seeking to connect directly to higher-voltage grid infrastructure while maintaining documented safety and performance assurance.
The broader implication is that compliance capability is becoming part of the value proposition. Projects that can demonstrate standardized safety certification, interoperability with microgrid-ready architectures, and documented integration with battery storage and renewable inputs are better positioned in bidding processes that emphasize operational risk reduction. For manufacturers, this opens a strategic path: align product roadmaps with certification pathways early, and use compliance achievements as differentiators in segments where procurement teams are increasingly risk-averse around energy storage and electrical safety.
Demand-Side Shifts: Critical Load Growth and Operational Continuity
Demand is being restructured by the expansion of critical digital infrastructure, healthcare digitization, and the modernization of industrial systems. Data centers remain a primary demand engine, but the nature of that demand is changing as operators manage higher rack densities, tighter space constraints, and more complex cooling and power interactions. Telecommunications networks continue to require resilient back-up as they expand coverage, support edge connectivity, and adapt to evolving service-level expectations. Healthcare environments are increasingly dependent on uninterrupted power for clinical systems, imaging, monitoring, and building operations, elevating UPS from facility support to patient-safety-adjacent infrastructure.
Industrial manufacturing represents another growth vector, driven by automation, process control sensitivity, and the cost of downtime. Transportation, pharmaceuticals, food and beverage, packaging, and steel operations all share a common vulnerability: brief interruptions can disrupt quality, throughput, and safety protocols. This reality is encouraging adoption of industrial-grade UPS solutions that can tolerate harsh environments, vibration, and variable loads while maintaining availability. Residential and distributed workspace applications are also gaining attention, particularly as home offices, small server rooms, and connected environments seek compact solutions that balance protection with usability.
Behaviorally, buyers are placing more weight on lifecycle continuity than on lowest upfront price. The conversation is increasingly framed around availability targets, maintenance access, remote monitoring readiness, and the ability to scale as loads evolve. For suppliers, this means product portfolios must support not only the initial deployment but also ongoing operational needs, including diagnostics, serviceability, and compatibility with broader facility or data center ecosystems.
Supply Chain and Cost Structure: Building Resilience Into Delivery
Cost structures in the UPS market are shaped by component availability, manufacturing scale, and the economics of power-dense designs. Semiconductor availability, transformer lead times, and battery cell supply can influence both product launch timing and margin stability. Suppliers that diversify sourcing, standardize modular architectures, and design for manufacturability are better able to absorb volatility without sacrificing delivery performance. The operational implication is straightforward: resilience now applies to the supply chain as much as to the end equipment, and procurement teams are increasingly attuned to supplier continuity when evaluating partners.
Cost pressure is also being counterbalanced by efficiency expectations. In larger deployments, reducing conversion losses and simplifying grid connection can yield meaningful operational savings over the life of the installation. This convergence of supply-chain discipline and efficiency optimization favors organizations that can deliver standardized, certified solutions with predictable lead times and installation complexity. It also pushes mid-tier and regional players to clarify their position: compete on customization and service responsiveness, or focus on volume segments with streamlined product lines and strong distribution partnerships.
Competitive Landscape: Differentiated Positioning in a Concentrated Market
The UPS market is moderately concentrated, with a small group of established players commanding a significant share of revenue. This concentration reflects the advantages of scale, broad application coverage, and deep integration with larger power management and infrastructure ecosystems. Yet concentration does not imply uniformity. Leading companies are carving out distinct positions through technology focus, application specialization, and ecosystem breadth.
Industrial UPS Market
Schneider Electric continues to strengthen its position by expanding its power protection lineup for high-density IT and industrial applications, including the release of one of the most compact 3-phase UPS units in its class. Its approach leans on integration with broader energy and digital infrastructure capabilities, positioning UPS as part of an overall facility or data center strategy rather than an isolated device. Eaton maintains a strong presence through its emphasis on power management and operational continuity across commercial and industrial environments, with a focus on reliability and lifecycle service. Vertiv is executing a notably broad segmentation strategy, covering compact home and workspace systems as well as industrial-grade platforms and standby series for distributed digital environments. This breadth allows Vertiv to address multiple demand profiles simultaneously, from consumer-adjacent protection to heavy process loads.
ABB is differentiating through high-voltage and medium-voltage innovation, including medium-voltage UPS solutions that enable direct grid connection for large AI-related data center loads. Its certification achievement and microgrid-ready architecture signal an intent to compete where power levels, safety certification, and grid integration complexity are highest. Delta Electronics and Riello UPS bring application-specific depth, often emphasizing efficiency, thermal performance, and industrial durability. Huawei and Toshiba contribute to a diverse supplier base with strong regional footprints and technology heritage, while Piller and Kehua Data provide additional depth in specialized power and data-centric environments. Falcon Electric and Active Power round out the landscape with focused offerings that can compete on niche requirements, rapid deployment, and specific operational profiles.
The competitive trend is moving toward both consolidation and segmentation. Consolidation is likely where customers seek single-vendor accountability across power, cooling, monitoring, and service. Segmentation is equally strong, as product families are increasingly tuned to particular environments, voltage levels, and load characteristics. New entrants and regional players can still succeed by targeting underserved niches, offering agile delivery, or combining hardware with differentiated service and monitoring capabilities. The key is clarity: companies that attempt to serve every segment with a generic portfolio often struggle to communicate value against more focused competitors.
Outlook for the Next Three to Five Years
Several trends are likely to define the next phase of market development. The first is the continued expansion of high-power-density and medium-voltage solutions for large digital infrastructure projects. As compute-intensive environments scale, the ability to connect more directly to higher-voltage sources while maintaining safety certification and reducing conversion losses will become more valuable. Suppliers that can combine high-voltage capability with reliable certification and integration support will capture a meaningful share of complex, high-stakes deployments.
The second trend is the growth of distributed and edge-oriented protection, supported by compact form factors and battery technologies optimized for smaller, decentralized deployments. This shift reflects the broader decentralization of digital infrastructure and the need for continuity outside centralized data centers. Expect increased attention to systems that are easy to deploy, quiet, serviceable, and compatible with distributed IT rooms and workspace environments.
The third trend is the increasing blend of power protection with intelligence and energy integration. Monitoring readiness, fault diagnostics, lifecycle service, and compatibility with battery storage or renewable inputs will increasingly influence purchasing decisions. As operators look to reduce operational risk and improve asset visibility, UPS platforms that can participate in broader energy and facility management ecosystems will gain preference.
PW Consulting
These trends carry clear commercial opportunities. Manufacturers that align product roadmaps with high-density compute needs, industrial ruggedness, and distributed deployment realities can capture demand across multiple segments. Investors should assess where portfolio breadth, certification strength, and service capabilities create durable differentiation, rather than assuming growth will accrue evenly across the market. For procurement and operations leaders, the opportunity lies in selecting solutions that balance immediate protection with long-term scalability, compliance confidence, and integration readiness.
Risks and uncertainties remain. Lead-time volatility, component constraints, and certification timelines can delay launches and affect project economics. Regulatory expectations around energy storage safety may evolve, changing the compliance burden for certain solution classes. In addition, rapid load growth in some digital infrastructure segments could outpace supply capacity in specific geographies or form factors, creating delivery challenges even in a favorable demand environment. Companies that rely on narrow product lines or single-source dependencies will be more exposed to these pressures.
Uninterrupted Power Supply (UPS) Market
Actionable Guidance for Decision-Makers
For manufacturers, the priority is to sharpen segmentation without losing operational efficiency. Product architectures should support distinct deployment contexts—compact distributed environments, high-density IT, and harsh industrial settings—while sharing enough platform commonality to keep manufacturing and service scalable. Certification strategy should be treated as a market access tool, not a back-office task, especially where safety and grid-integration requirements are becoming procurement thresholds. Service and monitoring capabilities should be designed in from the start, because availability and lifecycle support increasingly determine competitive outcomes.
For investors, the most compelling opportunities are likely to appear where product differentiation is anchored in real operational value: power density, safety certification, industrial durability, and integration with energy storage or facility ecosystems. Due diligence should examine how well a company's portfolio matches the demand profiles likely to grow fastest, and whether its supply and certification capabilities can sustain delivery in a tightening environment. Companies with focused positioning and credible compliance achievements are better placed to defend margins and capture complex deals.
For procurement and operations leaders, the focus should shift from unit price to total continuity value. Selection criteria should weigh availability requirements, environmental suitability, certification status, serviceability, and compatibility with existing monitoring or energy management systems. Where possible, prefer solutions that can scale with load growth and support future integration needs, reducing the risk of premature replacement or retrofit. In critical environments, standardization around a smaller set of proven, certified platforms can simplify maintenance, training, and risk management.
Detailed segment-level data, regional deployment dynamics, and company-specific positioning can help translate these strategic signals into precise plans. A more granular view of application mixes, product family performance, and competitive moves by region provides the context needed to prioritize investments, refine sourcing strategies, and align product roadmaps with where demand is actually forming. Readers seeking that level of detail can explore the full market research report for deeper segmentation data and tailored recommendations.
For detailed analysis of this topic, please visit the official page: Uninterruptible Power System (UPS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Trends and Commercial Opportunities in the Global Train Bogies Market
The train bogies market has entered a phase of structural transformation, driven by shifting infrastructure priorities, technological modernization, and evolving regulatory demands across rail networks worldwide. Valued at approximately 215.0 million USD in 2025, the market has steadily expanded from 163.15 million USD in 2020, reflecting consistent capital allocation toward rolling stock modernization and new fleet deployments. Looking ahead, the sector is projected to grow at a compound annual growth rate of 4.2 percent through 2032, reaching an estimated 344.8 million USD. This trajectory signals more than incremental demand; it reflects a foundational shift in how rail operators approach reliability, energy efficiency, and lifecycle management. For executives and investors navigating capital-intensive transportation sectors, the bogies market offers a clear lens into broader rail industry dynamics, where component-level innovation increasingly determines fleet performance and total cost of ownership.
Rail Wheels Market
Despite this positive trajectory, the industry faces several structural friction points that will shape competitive positioning over the next decade. First, raw material volatility continues to pressure manufacturing economics. Steel remains the dominant material in conventional bogie frames, and price fluctuations directly affect production margins and aftermarket pricing models. Second, tightening safety and emissions frameworks are accelerating procurement cycles while raising compliance thresholds. Operating environments now demand stricter adherence to interchange standards, and regional policy shifts are actively redirecting investment toward electrified and lower-emission rail architectures. Third, aftermarket service and refurbishment are becoming strategic battlegrounds. As operators extend fleet lifespans to manage capital constraints, the ability to deliver high-quality overhaul programs, predictive maintenance capabilities, and standardized component compatibility is increasingly decisive. These challenges are not isolated headwinds; they are redefining what qualifies as a competitive offering in the bogies space.
Material Choices and Manufacturing Cost Dynamics
Material strategy has become one of the most consequential decisions in bogie design and procurement. Conventional steel-based frames continue to dominate many applications, but their cost profile is increasingly exposed to commodity volatility and weight-related performance trade-offs. In parallel, composite and lightweight material adoption is gaining traction in specific segments where energy efficiency, acceleration performance, and passenger comfort are prioritized. Reducing structural weight can lower energy consumption and improve operational flexibility, which matters most in urban transit and high-speed configurations where lifecycle operating costs outweigh initial capital considerations. However, material transitions also introduce new considerations around production scalability, repair protocols, and supply chain maturity. Manufacturers that can standardize lightweight components without compromising structural integrity or serviceability will be better positioned to capture premium segments while managing cost exposure.
Regulatory Pressure and Fleet Electrification Pathways
Regulatory evolution is actively reshaping demand patterns across regional rail markets. Stricter safety, wheel-set, and interchange compliance requirements are raising the bar for bogie specifications, particularly in markets where interoperability and cross-border operations are expanding. At the same time, emissions-driven policies are accelerating the transition away from diesel-heavy fleets in certain jurisdictions, stimulating demand for bogie systems designed for electric traction and compatible with modern rolling stock architectures. In regions where locomotive operating restrictions have come into force, rail operators are forced to reevaluate fleet composition and component compatibility sooner than planned. This creates both procurement urgency and longer-term design implications, as bogie suppliers must align product roadmaps with electrification timelines and evolving compliance expectations. For market participants, regulatory momentum is no longer a background variable; it is a direct demand driver.
Train Seat Market
Aftermarket, Refurbishment, and Operational Lifecycle Value
The aftermarket dimension of the bogies market is growing in strategic importance as operators balance new orders with existing fleet preservation. Overhaul programs, component regeneration, and condition-based maintenance are becoming essential levers for controlling total cost of ownership. Recent activity in the sector highlights how service-oriented engagements can anchor long-term customer relationships while generating predictable revenue streams. High-volume refurbishment projects, particularly for established regional fleets, demonstrate that performance restoration and extended service life can be commercially viable when executed with standardized processes and skilled labor capacity. As operators seek to defer greenfield capital expenditures, suppliers capable of delivering reliable overhaul solutions, digital health monitoring, and consistent quality assurance will capture disproportionate value in the service layer of the market.
Key Drivers Shaping Market Evolution
The market’s expansion is not uniform across all applications or geographies. Growth is being pulled by a combination of technological capability, policy mandates, shifting procurement behavior, and evolving supply chain economics. Understanding which forces are structural rather than cyclical is essential for anticipating where demand will concentrate and which capabilities will command pricing power.
Technological Innovation and System Integration
Bogie design is increasingly treated as an integrated system rather than a mechanical subassembly. Digital health monitoring, active suspension concepts, and advanced frame engineering are moving from experimental initiatives into operational use. Real-time condition data enables operators to plan maintenance with greater precision, reducing unplanned downtime and optimizing spare parts requirements. At the same time, innovations in frame architecture are improving ride quality and load distribution, especially in applications where speed, passenger comfort, and infrastructure compatibility matter most. These advancements are not merely product upgrades; they are shifting the value proposition from component supply to performance assurance. Suppliers that combine mechanical reliability with digital visibility can differentiate themselves in a market where operators increasingly prioritize availability and lifecycle cost over lowest initial price.
Policy Environment and Compliance Requirements
Rail policy is acting as both a constraint and a catalyst. Compliance with interchange and safety standards is becoming more rigorous, forcing manufacturers and operators to align specifications across fleets and procurement cycles. In parallel, regional emissions policies are indirectly pulling demand toward electric-compatible bogie architectures and modernized fleets. Where diesel operation faces restrictions or phase-down timelines, procurement strategies are adjusted to favor rolling stock and component configurations that support electrification goals. This regulatory environment tends to favor established players with documented certification experience, while also creating entry points for suppliers whose designs are built to meet evolving compliance baselines from the outset. Policy-driven demand is often less price-sensitive and more specification-driven, which can support margin stability for suppliers able to demonstrate conformity and operational reliability.
Demand-Side Shifts Across Application Types
Application demand is reshaping where bogie volume and value are concentrated. High-speed and passenger-oriented rail systems continue to absorb a significant share of market activity, reflecting ongoing commitments to mobility modernization and urban connectivity. Freight applications, while smaller in relative share, remain important where logistics networks depend on durable, heavy-duty bogie assemblies suited to load-bearing and interchange requirements. Urban transit and metro deployments add another layer of demand, characterized by high utilization rates and strong expectations for reliability, low noise, and energy efficiency. These application segments differ not only in volume but in performance priorities. Passenger-focused systems reward comfort, safety, and digital monitoring, while freight configurations emphasize durability, interchange compatibility, and total lifecycle durability. As a result, suppliers are increasingly expected to tailor engineering and service strategies to distinct operating profiles rather than rely on a single standardized offering.
Supply Chain and Cost Structure Realignment
Cost structures across the bogies market are being tested by input volatility, skilled labor availability, and the economics of scale. Steel price fluctuations remain a material consideration for conventional frame production, influencing both manufacturer margins and downstream pricing negotiations. At the same time, the shift toward specialized materials and advanced manufacturing processes can raise upfront investment requirements, even as they improve long-term operating economics. labor intensity in overhaul and precision assembly operations also matters, particularly where facilities must sustain skilled roles over multi-year service programs. Organizations that can secure stable input sourcing, optimize production throughput, and maintain skilled service capacity will be better positioned to manage cost variability while meeting specification demands. In practice, supply chain resilience is becoming a competitive attribute in its own right, not just an operational concern.
Competitive Landscape and Leading Strategies
The bogies market remains relatively fragmented in terms of concentration, with no single group dominating overall share. This fragmentation creates room for differentiation through engineering capability, service depth, and regional execution quality. Leading participants are pursuing different strategic paths, and the most successful will likely be those that align product architecture with the operational realities of their target segments.
Strategic Positioning Among Key Players
Several established manufacturers have built recognizable positions around specific strengths. Alstom has emphasized passenger train bogies with a focus on safety, reliability, and comfort, supported by substantial production and overhaul capacity. Recent contract activity and facility milestones illustrate a strategy centered on long-term fleet support and high-volume service execution, reinforcing customer retention through lifecycle engagement. CRRC has pushed into lightweight structural innovation, introducing carbon fiber composite frame approaches and advanced bogie concepts for metro and high-speed applications. Its trajectory suggests a focus on material modernization and production automation as differentiators in segments where weight reduction and throughput matter. Siemens has leaned into integration and digital monitoring, positioning its bogie systems as part of broader operational health and performance management capabilities. This approach aligns with operators seeking visibility into asset condition and predictive maintenance. Other participants, including Amsted Rail, Stadler Rail, Bombardier Transportation, Wabtec Corporation, Voith GmbH, Kawasaki Heavy Industries, Tatravagónka a.s., Titagarh Rail Systems Limited, Hyundai Rotem, and regional specialists such as Titagarh, contribute to a diverse competitive field by targeting freight, urban transit, and international rail programs with varied product and service emphases. Rather than a single dominant model, the landscape reflects multiple viable strategies: production scale, lightweight innovation, digital integration, freight durability, and regional service strength.
Market Structure Evolution
Over time, the market is likely to see selective consolidation around players that can combine engineering credibility, service reach, and compliance readiness. At the same time, new entry remains possible in niche applications where lightweight materials, specialized urban transit requirements, or regional manufacturing incentives lower traditional barriers. The more probable outcome is differentiation rather than uniform consolidation: incumbents will defend positions through service ecosystems and product reliability, while targeted innovation will open pockets of advantage in specific application or regional contexts. For buyers and investors, this means that competitive advantage will increasingly come from capability depth and execution consistency, not merely from scale or brand recognition.
Future Trends and Commercial Implications
The next three to five years are likely to be defined by three interlocking trends: broader adoption of lightweight and composite frame technologies in targeted applications, deeper integration of digital health and condition monitoring into bogie systems, and continued acceleration of aftermarket and refurbishment as strategic revenue centers. Each trend carries distinct commercial implications and associated risks.
Trend One: Selective Lightweight Material Adoption
Composite and lightweight structural solutions will expand beyond pilot use into operational deployments where energy efficiency, speed, and ride quality justify the investment. This shift offers clear advantages in metro and high-speed contexts, where reduced mass can improve acceleration, lower energy consumption, and support passenger comfort goals. The commercial opportunity lies in building scalable production methods and service protocols that make lightweight components practical over full lifecycle use. The risk is that material transitions remain costly or operationally complex if repair, inspection, and supplier support ecosystems lag behind initial deployment. Executives should therefore evaluate lightweight adoption not only on performance merits, but also on long-term maintainability and supply continuity.
Trend Two: Digital Monitoring as a Standard Capability
Condition monitoring and digital health data are moving from optional features to expected components of modern bogie systems. As operators seek to reduce downtime and optimize maintenance schedules, real-time visibility into component state will increasingly influence procurement decisions. This trend favors suppliers that can integrate sensing, data interpretation, and maintenance planning into their offerings, translating hardware supply into service-led value creation. The commercial upside is stronger customer stickiness and higher-margin service relationships. The uncertainty lies in data interoperability, cybersecurity expectations, and the operational burden of managing digital infrastructure across mixed fleets. Success will depend on delivering monitoring capabilities that are practical, reliable, and compatible with existing operator workflows.
Trend Three: Aftermarket and Refurbishment as Strategic Focus
As capital constraints persist in many rail markets, preserving existing fleets through high-quality overhaul and refurbishment will remain a priority. This creates durable demand for service capacity, standardized component processes, and skilled labor execution. Organizations with established overhaul facilities, proven quality controls, and strong customer relationships can transform aftermarket work into a stable revenue base while reinforcing long-term procurement relevance. The risk is operational scaling: maintaining consistency across large refurbishment programs requires disciplined process management and trained workforces. Entities that can demonstrate repeatable quality and timely delivery will be better placed to capture this demand.
Actionable Guidance for Decision-Makers
For manufacturers, the priority is to align product roadmaps with the applications and compliance environments where demand is most durable. Investing in lightweight structural options, digital condition monitoring, and service-ready design will strengthen positioning in passenger and urban transit segments. Equally important is building cost resilience through stable input sourcing and scalable production, particularly where steel and specialized materials remain central to conventional designs. Companies should also treat overhaul and refurbishment capability as a strategic asset, not a secondary activity, because service execution increasingly determines long-term customer retention.
For investors, the market’s 4.2 percent growth trajectory suggests steady expansion, but value creation will likely concentrate among participants with differentiated engineering, service depth, and regional execution strength. Opportunities are most compelling where suppliers can combine product innovation with recurring service revenue and where regulatory momentum supports electrification and modernization spending. Due diligence should focus on capability maturity, aftermarket exposure, and the ability to manage input cost volatility rather than on headline market size alone.
For procurement and rail operators, the emphasis should be on total lifecycle value rather than initial purchase price. Bogies that deliver reliability, maintainability, and compatibility with digital maintenance systems can reduce operational disruption and support fleet planning over longer horizons. Procurement strategies should also account for compliance readiness and service support, especially where emissions policies and interchange standards are reshaping fleet composition. In markets with active modernization programs, establishing clear specifications and long-term service expectations early can reduce downstream integration risk.
The strategic picture is clear: the train bogies market is expanding, but the real competition is shifting toward performance assurance, service capability, and technology integration. Organizations that understand where value is being created across applications, materials, and aftermarket service will be better equipped to make targeted investment and procurement decisions. For a more detailed view of segment-level dynamics, regional demand patterns, application splits, and company-specific positioning, the full PW Consulting research report provides the deeper segmentation data and customized strategic guidance needed to translate these trends into operational plans.
PW Consulting
For detailed analysis of this topic, please visit the official page: Train Bogies Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


