



Category: market research
PW Consulting: Phosphonate Market USD 1,050M in 2025 to USD 1,572M by 2032 at 5.5% CAGR
By PW Consulting, 2026-08-02
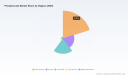
Phosphonate Market 2026: A Strategic Preview for Decision-Makers
As companies prepare capital allocation, supplier strategies, and product investments for 2026, a clear, actionable understanding of the phosphonate market becomes a differentiator. PW Consulting’s latest industry study — with a 2025 base year and a forecast horizon through 2032 — synthesizes historical performance (2020–2025), scenario-based forecasts (2026–2032), and a pragmatic playbook that converts market intelligence into executable choices. At the macro level the industry is forecast to expand at a compounded annual growth rate of 5.5% across our forecast window, with the market expanding from a 2025 base of approximately USD 1,050 million to an estimated mid-single-billions figure by 2032. This preview explains the strategic value of the study for 2026 corporate decision-making while intentionally reserving detailed segment-level tables and region/application splits for the complete report.
Phosphonate Market
Why this report matters for 2026 planning
-
Timing and scale: 2026 is the first forecast year in our model, and early-year decisions lock in supply chains, contract tenors, and capacity commitments. With the market exhibiting steady historical growth and a 5.5% CAGR outlook, misjudging demand side momentum or raw-material exposure can materially affect margins and working capital.
Phosphonate Market -
Regulatory inflection points: Multiple policy and trade developments in 2025–2026 are reshaping supply-side economics and trade flows. Companies need a short, focused intelligence input to stress-test sourcing and market-entry scenarios.
Phosphonate Market -
Competitive repositioning: The market concentration profile shows meaningful room for mid-sized players to defend and expand margins through technical differentiation, yet also signals consolidation opportunities for strategic acquirers. Our report maps those opportunities to real-world valuation and integration considerations.
What the macro data tells us (and what it doesn’t disclose here)
Readers of this preview will find the following high-level implications drawn from our market sizing and trend analysis:
-
Base-year momentum: The phosphonate market grew steadily through 2020–2025, reflecting continued demand in traditional anchors such as water treatment, industrial cleaning, and oil & gas, and emerging uptakes in specialty industrial applications. Momentum into 2026 is positive, with our short-term forecast showing recovery and expansion consistent with the 5.5% CAGR we project for 2026–2032.
-
Structural durability: End-market diversity provides resilience. While some downstream verticals exhibit cyclical sensitivity, the aggregate market demonstrates low-to-moderate volatility attributable to broad-based demand in municipal and industrial water management plus specialty process chemistries.
-
Concentration and competitive spacing: Market concentration metrics indicate that the top three firms account for roughly one-third of market revenue, and the top five approach two-fifths. This structure creates a dual dynamic: clear competitive leaders with scale benefits, and ample runway for differentiated smaller suppliers to capture niche technical or regional advantages.
Key market dynamics shaping 2026 decisions
-
Regulation and trade policy: Recent anti-dumping inquiries and trade measures targeting phosphorus-related inputs are raising transactional and compliance overhead for importers and formulators. Simultaneously, incentives such as selective VAT export rebates introduced by some governments alter relative cost structures for exporters. These developments oblige procurement teams and strategy functions to model policy scenarios into sourcing and pricing strategies.
-
Raw material volatility: Changes in upstream feedstock costs — for example, observable moderations in price for specific phosphorus feedstocks in 2025 — are transmitting to margins differently across product grades. Understanding feedstock-to-product margin pass-through is essential for negotiating indices, hedging programs, and pass-through clauses in customer contracts.
-
Customer requirements and ESG: Buyers in municipal and industrial water management are increasingly embedding sustainability criteria and life-cycle assessments into supplier selection. Suppliers who can demonstrate lower embodied carbon, responsible sourcing, and circularity credentials will enjoy pricing advantages and preferred-supplier status in many accounts.
-
Technology and formulation differentiation: Proprietary formulations and combined chemistries (e.g., polymer-phosphonate blends) are a source of margin expansion and customer lock-in. Investment in technical service capabilities and field trials can yield outsized commercial returns versus competing on price alone.
Competitive landscape — who matters and why
In the absence of exhaustive segment tables here, the report dissects competitive positioning across a curated universe of manufacturers and suppliers. A sample of competitive insights we develop includes:
-
Aquapharm Chemicals — A vertically integrated producer with manufacturing presence spanning India and North America. Strengths include cost-efficient production for standard grades and close customer relationships in water treatment. Strategic priorities for 2026 likely center on scaling exports and deepening service agreements in key industrial accounts.
-
Italmatch Chemicals — Known for established branded phosphonates and a strong European footprint. Recent corporate momentum, including recognition for climate performance and successful refinancing, supports selective capex and M&A flexibility. Expect a continued focus on premium, differentiated product lines and industrial service offerings.
-
Shandong Taihe and other Chinese manufacturers — Leading domestic producers with breadth across common phosphonate chemistries. Policy shifts such as export rebates can sharpen their price competitiveness internationally; the strategic response from Western buyers will be a mix of nearshoring and supplier diversification.
-
Zschimmer & Schwarz and Giovanni Bozzetto — Players with differentiated formulations and tailored industrial solutions. Their technical depth positions them well for higher-margin segments where performance and regulatory compliance matter more than raw price.
-
Specialty manufacturers (e.g., Changzhou Kewei) and contract-capable providers — These firms enable customization and flexible batching for downstream formulators, which is increasingly valuable as customers demand tailored chemistries and traceability.
Practical, action-oriented content in the full report
The full PW Consulting report is structured to convert insight into action. Key operational deliverables include:
-
A validated market-size model with transparent assumptions spanning 2020–2032, permitting sensitivity runs on volume, pricing, and feedstock shocks;
-
Scenario analyses (regulatory shock, feedstock shock, accelerated water-management investment) with P&L and cash-flow implications for producers, distributors, and integrated chemical companies;
-
Supplier-risk heatmaps and procurement playbooks that prioritize contract terms, dual-sourcing strategies, and inventory policies tailored to lead times and raw-material intensity;
-
Commercial playbooks for product managers: go-to-market segmentation, technical service propositions, differentiated pricing tactics, and academic/field trial templates;
-
M&A screening and valuation heuristics for strategic buyers versus financial sponsors, including integration-risk checklists and a shortlist of acquisition themes;
-
Regulatory monitoring and compliance trackers that map pending investigations, trade remedies, and raw-material policy changes to supplier risk scores;
-
CapEx and capacity planning guidance — when to expand, retrofit, or outsource — anchored to projected demand trajectories and margin sensitivity.
Risks, mitigation and near-term watch items for 2026
-
Policy risk: Anti-dumping probes and classification disputes can trigger sudden cost increases or volume displacements. Mitigation: proactive engagement with trade counsel, diversified supplier panels, and short-term contractual flexibility.
-
Feedstock swings: Downstream margins are sensitive to phosphorus feedstock availability and price dynamics. Mitigation: explore indexation clauses, strategic raw-material inventories, and supplier co-investment options.
-
Reputational/ESG exposure: Procurement choices in municipal and industrial water customers increasingly reflect sustainability screening. Mitigation: invest in third-party verification, publish supplier sustainability data, and prioritize lower-impact chemistries where possible.
-
Competitive consolidation: Mid-sized players may be targets for consolidation. Mitigation: develop defensive partnerships, joint-venture alternatives, and integration-ready operational playbooks.
Recent events that shape near-term strategy
-
Corporate signals: Italmatch’s public recognition for climate performance and successful refinancing are strategic signals that capital-efficient growth and ESG alignment remain central to premium positioning.
-
Trade shows and knowledge exchange: Participants such as Zschimmer & Schwarz and technology providers presenting at sector conferences continue to accelerate cross-border technology diffusion and customer education — a relevant channel for market-entry and product-awareness campaigns.
-
Technical innovation forums: Presentations from process-engineering specialists highlight opportunities to convert commodity streams into differentiated packaged solutions — a recurring theme for margin enhancement.
How to use this preview and next steps
This preview is designed to orient executive teams and strategy functions ahead of 2026 planning cycles. Use it to prioritize internal deep dives: procurement should model three sourcing scenarios; product teams should rank high-value trials for differentiated chemistries; corporate development should refresh acquisition screens aligned to concentration and segment growth metrics.
PW Consulting’s full Phosphonate Market report contains the granular segmentation tables, regional and end-use breakdowns, supplier-by-subscriber profiles, and downloadable models that are deliberately excluded from this preview. That detailed intelligence is what enables profit-impacting tactical moves — from contract structures and hedging to targeted capex and bolt-on acquisition diligence.
Accessing the complete intelligence
For strategy teams preparing budgets and mandates for 2026, the full report provides the actionable data and scenario tools needed to move from analysis to execution. The preview you have read highlights the strategic thrusts and risks; our full deliverable supplies the segment-level metrics, supplier scorecards, and downloadable financial models you will use to implement decisions. Contact PW Consulting to obtain the complete dataset and tailored advisory engagement for your organization.
For detailed analysis of this topic, please visit the official page: Phosphonate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PPR market to hit USD 7,557.7M by 2032 at 6.98% CAGR; Asia Pac USD 2,140.6M
By PW Consulting, 2026-08-02
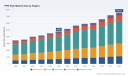
PPR Pipe Market 2026 Strategic Brief: Navigating Growth, Margin Pressure, and Competitive Positioning
Executive snapshot
As PW Consulting’s lead industry analyst, I present a concentrated strategic briefing designed to orient C-suite and strategy teams for decisions that will shape 2026 and beyond. The global PPR pipe market has entered a phase of steady expansion, driven by steady demand in building water systems, infrastructure programs in emerging markets, and incremental product innovations around thermal stability and leak mitigation. Our underlying model quantifies the industry’s rise from approximately USD 3,471 million in 2020 to USD 4,800 million in the base year 2025, with a compound annual growth rate of 6.98% over the 2026–2032 forecast horizon. By 2032, the market is projected to approach roughly USD 7,558 million—an expansion that is meaningful in scale for incumbents and challengers alike.
PPR Pipe Market
Why this matters for 2026 decisions
-
Timing: 2026 sits at an inflection point where product technology improvements (e.g., PP‑RCT grades, composite constructions) intersect with macro supply‑chain normalization post-commodity volatility. Companies that recalibrate capacity and procurement strategies now will avoid cost whipsaws and capture share as mid- and long-term demand re-accelerates.
PPR Pipe Market -
Margin leverage: Feedstock swings—tied to crude/naphtha and reflected in regional polypropylene pricing—are exerting pressure on production margins. Strategic buyers and producers can protect margin through forward purchasing, regional sourcing diversification, and selective premiumization of performance grades.
PPR Pipe Market -
Portfolio prioritization: With the market growing at just under 7% CAGR, resource allocation must be surgical. Firms should prioritize high-return initiatives (product upgrade programs, installation‑efficiency services, and solutions that reduce whole-life cost) over low-yield volume chasing.
-
Competitive playbook: Market concentration is moderate—top three players account for roughly 30% of value and the top five about 35%—leaving meaningful room for differentiated strategies (regional leadership, product specialization, or integrated service offers) to scale fast.
Observed trajectories and practical implications
The market’s trajectory through 2020–2025 shows consistent recovery and growth, with 2025 serving as a robust base year. This momentum is expected to continue into 2026 and beyond, but growth will not be uniform. Strategic choices that will matter most in 2026 include:
-
Capacity and footprint optimization: Where to expand or contract production is becoming a question of proximity to large infrastructure programs, feedstock availability, and labor/equipment cost. Investments in flexible micro‑capacity and local compounding can be decisive for fast-moving regional demand.
-
Product differentiation: Technical advances—such as stabilized high-heat formulations, composite cores for reduced thermal expansion, and pre-insulated systems—are shifting procurement preferences from lowest-price to total cost of ownership. Prioritize R&D paths that enable installers to save time and reduce rework.
-
Service and installer economics: The installer channel remains a strategic gatekeeper. Programs that reduce installation time (simpler joints, fusion training, prefabricated manifolds) and channel economics (credit, supply reliability) provide outsized returns on sales and loyalty.
-
M&A and partnership criteria: Given a moderate concentration profile and vibrant regional incumbents, M&A should target capabilities gaps—technical compounding, prefabrication, digital tools for specification—or rapid channel ownership in high-growth corridors rather than generic capacity buys.
What the full report delivers (practical and operational)
PW Consulting’s PPR Pipe Market study combines quantitative forecasting with executable playbooks. Core modules include:
-
Market sizing and trend analysis (2020–2025 historic, 2026–2032 forecast) with scenario-based sensitivity to feedstock price paths and major policy shifts.
-
Demand drivers mapped to procurement cycles—residential, commercial, and industrial—and demand elasticity by installation economics.
-
Cost‑to‑serve models for regional supply chains, including logistics, compounding, and fabrication cost overlays to inform pricing and margin strategies.
-
Risk matrix and mitigation playbook covering feedstock volatility, regulatory compliance (water contact standards, fire rating norms), and construction cycle exposure.
-
Actionable tactical templates: capacity decision framework, product roadmaps, channel engagement packages, and a prioritized M&A screening checklist.
-
Competitive benchmarking and win-loss analysis that synthesizes capabilities across manufacturing, technical support, and installer economics.
To preserve commercial value for clients and encourage direct engagement, this overview intentionally omits the full segment-by-segment numerical breakdowns and the granular regional/application splits contained in the paid report. Those detailed tables drive the specific sizing, margin, and opportunity maps that operational teams will use to build budgeted business cases for 2026.
Competitive landscape—how to interpret incumbent moves
The competitive set blends global manufacturers with strong European engineering brands and agile regional champions. A few strategic observations:
-
Aquatherm (United States): Recognized for leadership in PP‑RCT and high-end system integration, Aquatherm’s advanced fusion techniques and positioning in radiant and industrial applications make it a benchmark for premium system performance. Their playbook emphasizes reliability and lifecycle claims—useful for benchmarking premium product launches.
-
Wefatherm & REHAU (Germany): These manufacturers demonstrate the value of German engineering credentials and certification depth. REHAU’s innovations around assembly technology (O‑ring free compression-sleeve systems) illustrate how installation economics and specification ease can create stickiness with specifiers.
-
Wavin, Georg Fischer, and Aliaxis: These European suppliers underscore a platform strategy—broad product suites, technical support, and sustainability positioning. Georg Fischer’s recent integration moves to add pre‑insulated piping highlight the trend toward system selling where thermal efficiency becomes a differentiated attribute.
-
Uponor: Focused on PP‑RCT and installation efficiency, Uponor’s inclusion within broader building flow platforms points to consolidation opportunities for firms that can combine product breadth with integrated services.
-
Indian players (APL Apollo, Fusion Industries, Supreme, Finolex, Ashirvad, Astral, Prince Pipes): These firms are driving scale and price competitiveness in large-volume markets. Recent capacity expansions and product launches in India signal that low-cost regional champions will continue to shape global cost curves and win share in price-sensitive segments.
Recent industry signals and operational consequences
-
Capacity and consolidation: Public announcements in early 2025—capacity add‑backs, brand integrations, and localized production pushes—suggest a two-track market: premium system expansion in developed markets and cost-competitive volume growth in emerging markets. Strategy teams must balance margin capture with share protection.
-
Product innovation: New launches focused on high-heat stabilization and mass‑flow designs are reducing technical failure modes linked to thermal cycling. Prioritize accelerated validation cycles and field trials to bring these attributes into commercial specs for 2026 tenders.
-
Raw material volatility: Polypropylene price oscillations during 2024–2025 have tightened producer margins and forced more dynamic feedstock strategies. For manufacturers, hedging, diversified procurement, and selective pass-through pricing mechanisms are now essential tactical elements.
-
Regulatory and standards alignment: PPR materials comply with well-established DIN and ISO standards for potable and hot/cold water systems and meet fire performance requirements in construction codes. Certification and documented compliance will continue to be gating factors for specification in public and institutional projects.
Actionable next steps for 2026 planning
-
Undertake a three‑month procurement tuning exercise: map exposure to PP feedstock, create prioritized supplier hedges, and model cost pass-through scenarios for major markets.
-
Run a product-portfolio stress test: identify SKUs to upgrade to premium grades, retire low-margin SKUs, and pilot factory prefabrication for manifold and joint assemblies to shorten installation time.
-
Deploy an installer economics program: pilot training, bundled logistics, and conditional financing in two representative markets to measure uplift in specification share and reduce payback on channel investments.
-
Use M&A selectively: target capabilities rather than capacity—compounding, digital tools for specification, or prefabrication assets that accelerate route-to-market and reduce unit installation time.
Closing—strategic vantage
The PPR pipe market’s steady mid‑single-digit compound growth masks a landscape that rewards timely investments and penalizes strategic drift. Where firms act with data‑driven procurement, focused product differentiation, and installer-centric go‑to‑market programs, 2026 will be a year of capture and share expansion. PW Consulting’s full PPR Pipe Market report contains the granular segmentation, region‑by‑application matrices, and actionable financial templates necessary to convert the macro picture above into 2026 budgeted initiatives. For teams preparing capital allocation, product roadmaps, or M&A screens for next year, the full dossier is the toolset you’ll need to move from strategy to execution.
For detailed analysis of this topic, please visit the official page: PPR Pipe Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Organic Milk Market to Expand at 5.12% CAGR Through 2032
By PW Consulting, 2026-08-02
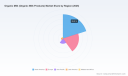
Organic Milk Market — 2026 Strategic Preview
Introduction
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a concise strategic preview of our new Organic Milk (Organic Milk Products) Market study. This briefing distills the research essentials that corporate leaders, investors, and category managers must act on in 2026. It demonstrates the methodological rigor and practical insight within the full report while intentionally withholding granular segmentation tables and detailed regional shares to preserve the value of the complete study.
Organic Milk (Organic Milk Products) Market
Why this research matters for 2026 decisions
- Clear growth trajectory. The organic milk market has expanded consistently over the 2020–2025 historical window and enters 2026 from a materially larger base. Our base-year estimate for 2025 places the global market firmly above the 2020–2024 trendline, and our forecast takes that momentum forward: using a 5.12% compound annual growth rate across the forecast horizon, the market is projected to reach a substantially higher level by the end of the 2026–2032 period. These headline numbers validate both defensive and growth-oriented strategic choices in 2026.
- Strategic inflection in 2026. Several concurrent forces—product premiumization, supply-side constraints, targeted public support programs, and trade/regulatory shifts—create an environment in which tactical actions taken in 2026 will disproportionately determine market share and margin trajectories through 2032.
- Actionable, risk-focused intelligence. The study combines scenario-based forecasts, cost-and-price modeling, and primary interviews with processors and retailers to convert raw data into executable decision options for the near term and mid term.
Executive takeaways for executives and investors
- Growth is reliable—but segmented. Organic milk demand is broadening beyond classic fluid milk into higher-value variants and formats. Expect steady topline expansion at the market level, but diverging performance across product types and channels. The full report maps the trajectories and elasticities by SKU class and route-to-market.
- Supply-side pressure is real and measurable. Input-cost dynamics in early 2026—marked increases in forage and feed prices and elevated all-milk price benchmarks—are compressing margins for exposed producers. Our cost model quantifies the impact on processor margins at multiple milk-price and feed-cost scenarios, enabling procurement teams to evaluate hedging, fixed-cost conversion, and index-linked contracting.
- Policy support reduces downside, but trade shifts open upside. Recent changes in organic dairy support programs and international trade frameworks have improved certainty for exporters and high-volume processors. These policy moves lower some downside revenue risk but also invite intensified competition in exportable product segments.
- Concentration remains moderate. Market concentration metrics indicate a moderately fragmented supplier base, creating opportunities for scale-driven integration and premium-brand differentiation. The competitive landscape section of the report provides tailored value-capture plays for players at each scale (cooperatives, regional processors, global brands).
- Operational risk is front-of-mind: recall and QA systems matter. Product recalls in early 2026 among established firms underline the strategic importance of end-to-end traceability and defensive quality systems. Our playbook prescribes organizational changes and investment priorities that materially reduce recall frequency and reputational damage over three-year horizons.
What the full report delivers (practical modules)
- Market sizing and verified historicals (2020–2025) and conservative/central/accelerated forecasts (2026–2032) with transparent assumptions and model files.
- Price and cost toolkit: SKU-level price ladders, input-cost trend scenarios (feed, labor, energy), margin sensitivity matrices, and short-term hedging recommendations.
- Segmentation and consumer-cluster analysis: product-format economics, channel dynamics (retail, foodservice, co-pack), and willingness-to-pay by consumer cohort. (Note: full segment tables and regional shares are available in the complete report.)
- Supply-chain and capacity maps: farm-gate sourcing economics, transport/cold-chain risk nodes, co-packer capacity, and alternative sourcing pathways (imports, toll-processing).
- Competitive benchmarking and M&A playbook: valuations, synergies, integration risk, and five pragmatic acquisition targets by strategic objective.
- Regulatory and trade tracker: payments and subsidy flows, sanitary/phytosanitary (SPS) requirements, and implications of recent U.S.–EU trade arrangements.
- Operational risk matrix and recall-response framework with template playbooks for crisis communications and remediation.
- Methodology annex: primary research notes, sample weighting, and data sources suitable for internal audit and investment committees.
Competitive landscape — implications and recommended moves
We profile leading firms across the value chain and convert their strategic positions into practical implications for competitors, suppliers, and buyers. Below are distilled, advisory-level assessments for named participants (full company dossiers in the report).
Organic Milk (Organic Milk Products) Market
- Aurora Organic Dairy (U.S.). Strengths: vertically integrated pasture holdings and traceability from feed to carton. Strategic implication: competitors should assume Aurora will defend bulk supply contracts while selectively expanding branded SKUs. Recommended response: pursue differentiated co-packing agreements and premium branded partnerships rather than head-to-head capex races on acreage.
- Organic Valley (U.S.). Strengths: largest cooperative model with deep farmer network and recent product innovation (high-protein ultra-filtered milk). Strategic implication: expect continued investment in value-added SKUs and premium positioning. Recommended response: retail buyers should use multi-tier promotional strategies to protect margin while offering premium varieties that capture growing protein-focused demand.
- Horizon Organic Dairy (U.S.). Strengths: broad national retail footprint. Recent development: a limited voluntary recall in early 2026 highlighted packaging and QA exposure. Strategic implication: near-term attention to packaging suppliers and QA process audits is required across the industry. Recommended response: all players should accelerate traceability pilots and supplier audits; opportunistic players can capture shelf space if an incumbent faces prolonged distribution disruption.
- Dairy Farmers of America (U.S.). Strengths: cooperative scale and diverse brand channels. Strategic implication: DFA will be an active participant in supply stabilization and co-manufacturing. Recommended response: processors should evaluate partnership models with DFA for supply smoothing while preserving product differentiation.
- Emmi Roth USA and WhiteWave/Silk (U.S.). Strengths: global brand expertise and product formulation capabilities. Strategic implication: these firms will target premium and alternative formats, leveraging cross-border sourcing. Recommended response: domestic producers should defend home-market premium niches through freshness and provenance marketing.
- Yeo Valley and Stonyfield (U.K./U.S.). Strengths: strong sustainability and farm-to-table credentials with selective export strategies. Strategic implication: these brands are well-positioned to win premium natural-food consumers. Recommended response: retail buyers and distributors should balance imported premium lines with domestic options to optimize margins and assortment diversity.
Macro and regulatory context that will shape 2026 tactics
- Input-cost signals. Recent price movements in forage and feed, together with a higher all-milk benchmark, are tightening margins across the board. Our model translates these inputs into per-unit margin impacts across common processing configurations.
- Targeted public supports. Expanded organic-dairy marketing assistance and related payments have materially reduced downside revenue volatility for eligible producers, changing the risk calculus on investments in traceability and premium production capacity.
- Trade and regulatory shifts. A recent U.S.–EU framework agreement has lowered barriers to certain dairy flows and streamlined sanitary requirements, opening export opportunities for scale-oriented players and new competition in formerly protected niches.
- Price floors and regional mechanisms. Certain European markets continue to operate guaranteed-price mechanisms that support farm incomes and stabilize local supply—a factor multinational buyers must account for in sourcing strategies.
Immediate 90-day playbook for 2026
- Conduct a supplier QA and packaging-supplier audit to reduce recall exposure; fast-track traceability pilots with smart-contract provenance for high-risk SKUs.
- Hedge a portion of the next 12 months’ feed exposure using indexed contracts and evaluate pass-through pricing clauses with major retail partners.
- Prioritize SKU-level assortment pruning: retire low-velocity SKUs and reallocate shelf and promotional investment to premium, high-margin formats identified in our elasticity analysis.
- Initiate pre-due-diligence on one acquisition target or co-manufacturing partnership focused on capacity or route-to-market expansion, using our M&A checklist.
How to obtain the full intelligence
This preview demonstrates the analytical depth and pragmatic orientation of PW Consulting’s full Organic Milk Market study. The complete report contains the proprietary segmentation tables, regional and product-level shares, forecasting models with scenario toggles, and exhaustive competitive dossiers that we intentionally withhold here to preserve actionable value. Purchase or licensing of the full study provides the specific tables and model files you need to operationalize the strategies outlined above.
Organic Milk (Organic Milk Products) Market
Closing
For CFOs, heads of procurement, and category leaders, the decisions you take in 2026 will compound over the next six years. Use the insights summarized here to prioritize quality systems, secure supply economics, and capture premiumization upside. PW Consulting stands ready to translate this market intelligence into transaction support, competitive-play advisement, and implementation roadmaps tailored to your organization.
— PW Consulting, Strategic Advisory & Industry Analysis
For detailed analysis of this topic, please visit the official page: Organic Milk (Organic Milk Products) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Montan Wax Market to Reach USD 182.02M by 2032 at 4.2% CAGR
By PW Consulting, 2026-08-02
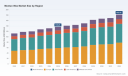
Montan Wax Market — 2026 Strategic Outlook: A PW Consulting Executive Brief
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a forward-looking introduction to our Montan Wax Market study — an actionable intelligence product built for the high-stakes decisions companies must take in 2026. This brief frames the strategic value of the full report, highlights the macro dynamics that will shape commercial outcomes over the 2026–2032 forecast window, and lays out the practical implications for producers, converters, distributors and industrial buyers.
Montan Wax Market
Why 2026 Matters: an Inflection Point for Market Structure and Cost Pass‑Through
-
Base dynamics are shifting from steady commodity growth to strategic allocation of capital and feedstock. The Montan wax market has expanded from an estimated USD 112.45 Million in 2020 to USD 136.25 Million in our base year 2025 (USD, Million). Over the forecast horizon we expect compound annual growth of approximately 4.2% (2026–2032), with the market reaching roughly USD 182.02 Million by 2032 under our base scenario.
Montan Wax Market -
That moderate but consistent growth masks critical cost-side stressors: European carbon regimes (including the operationalization of CBAM in January 2026) and rising CO2 price volatility are beginning to be reflected in conversion and import economics. At the same time, supply-side constraints rooted in lignite extraction policy and regional mining capacity are creating forward-buying behavior in some buyer segments.
Montan Wax Market -
For 2026 planning cycles, this mix of steady demand, concentrated upstream feedstock exposure and increasing carbon-related input costs converts a classical commodity decision into a strategic, cross-functional question — one that combines procurement, industrial policy, operations and commercial strategy.
Macro View: Growth Profile and What It Implies
From 2020 through 2025 the market expanded consistently; our modeling translates this into an addressable opportunity that grows by about 4.2% annually in the forecast window. This trajectory is neither explosive nor stagnant — it signals a maturing specialty-chemical segment where innovation, product differentiation and supply security will determine winners more than sheer volume plays.
Key takeaways from the macro sizing:
-
Moderate, reliable demand across core end uses (industrial polishes and coatings, plastics processing, and specialty personal care formulations) supports margins for differentiated, higher-value montan grades and micronized products.
-
Profit pools will increasingly concentrate in refined and modified waxes and in value-added services such as technical support for polymer formulations and micronization technologies.
-
Price-setting and pass-through dynamics will be governed by a handful of structural levers: feedstock access, processing/refining capability, ability to absorb or pass on carbon costs, and proximity to large conversion clusters.
Industry Dynamics to Watch in 2026
-
Carbon pricing and CBAM: European carbon regimes remain a decisive variable. Prices in recent cycles have fluctuated materially, reinforcing the need for carbon sensitivity in contracting, capital appraisal and pricing clauses.
-
Feedstock stability: Lignite/bitumen feedstock pricing has remained regionally stable in recent months, but localized extraction restrictions (notably in Germany) are extending lead times. Expect procurement volatility where regional mining constraints collide with export demand.
-
Supplier concentration: Market concentration metrics show that the top three players account for a majority share of the market, with the top five capturing a clear supermajority. This creates both bargaining power for incumbents and acquisition opportunities for firms seeking scale.
-
Global supply chain divergence: Producers with integrated access to lignite resources, or with advanced refining/speciation capabilities, will be the first movers when converters demand substitute or upgraded grades for high-performance applications.
Competitive Landscape — Who Moves Price and Product
The competitive field is a mix of Europe-based legacy producers, specialized additives firms, global chemical majors and regional producers in Asia and North America. Each archetype plays a distinct strategic role:
-
Integrated lignite-based producers (e.g., firms with deep ties to lignite deposits) retain structural cost and supply advantages for crude and certain refined grades. Their ability to manage extraction-to-refinery logistics is a moat in constrained supply scenarios.
-
Specialist additives and blends manufacturers (providers focused on tailored wax blends and processing aids) capture margin through technical differentiation and stable, high-value contracts with plastics and coatings converters.
-
Large chemical conglomerates who produce modified and derivative montan waxes can leverage global distribution and R&D to open new performance applications — an advantage in premium segments such as high-performance polymers and cosmetic actives.
-
Regional low-cost producers supply robust export flows into local industrial markets; their scale and proximity to growing conversion hubs makes them important margin anchors in price-competitive segments.
Among named players we profile in the full study, you will find detailed company-level positioning, capability maps and a supplier scorecard framework to evaluate strategic fit. Our competitive synthesis indicates a moderately concentrated market — the top three players control a majority share, and the top five extend that dominance — a structure that both disciplines price competition and creates runway for select acquisitions and capacity plays.
What the Full Report Delivers: Practical, Executable Outputs
PW Consulting’s full Montan Wax Market study is built as a boardroom toolset rather than an academic exercise. Highlights include:
-
Transparent market-sizing and methodology notes — historical data (2020–2025), base year calibration (2025), and scenario-driven forecasts through 2032. We provide downloadable models so you can run your own sensitivity checks.
-
Price and cost analytics — an anonymized industry cost curve, feedstock breakouts, and scenario tables showing the impact of stepped carbon pricing on converter margins.
-
Supply-chain stress tests — concentration risk maps, forward lead-time indicators, and contingency playbooks for feedstock disruption.
-
Competitive scorecards — capability and risk assessments for leading suppliers, with acquisition rationales and integration risk profiles for M&A planning.
-
Commercial templates — take-or-pay contracting frameworks, indexation clauses that reflect carbon and lignite cost pass-throughs, and sample supply agreements tuned to 2026 market realities.
-
Actionable go-to-market strategies — product prioritization frameworks for producers and tactical channel strategies for distributors targeting growth in higher-margin specialty end uses.
Note: This executive brief intentionally omits the granular regional and application-level splits and company-specific volume tables that are part of the proprietary datasets in the full report. Those high-resolution tables are available in the complete study and are purposefully gated to ensure clients get precise, operational intelligence.
Practical Priorities for 2026 Planning — A Manager’s Checklist
-
Secure feedstock through diversified contracts and evaluate toll-refining options to mitigate extraction disruption risk.
-
Quantify carbon exposure in bid and contract models; test indexation mechanisms that can shift a portion of carbon price risk to customers where market structures allow.
-
Invest selectively in refining/modification capacity that addresses premium demand segments (micronized additives, esters, modified waxes) where margin expansion is most visible.
-
Screen M&A targets using our proprietary scorecard: feedstock access, technical capability, regulatory compliance, and distribution footprint.
-
Stress-test your sales pipeline against scenarios of both constrained supply and sudden price normalization — and prepare commercial playbooks for each.
Scenario Outlook & Key Risks
Our modeling presents three high-level scenarios: a base case aligned with the 4.2% CAGR, a downside characterized by accelerated carbon pricing and tighter lignite access causing near-term price spikes and slower volume growth, and an upside where accelerated innovation (e.g., expanded micronized wax adoption in engineering plastics) drives premiumization and faster value growth. Each scenario carries distinct implications for capital allocation, inventory strategy and commercial terms.
How to Use This Study in Boardroom Decisions
-
Capital allocation: prioritize investments that increase ability to supply refined and modified grades or that materially lower carbon intensity per tonne produced.
-
Procurement: move from single-year spot procurement to multi-year contracts with carbon-adjusted price mechanisms and performance-based clauses.
-
M&A: use our acquisition scorecards to prioritize bolt-ons that add feedstock resilience, technical capability or regional distribution scale.
-
Commercial: redesign pricing terms and value propositions for converters to reflect total cost of ownership inclusive of carbon and logistics risk.
In short, the Montan wax market in 2026 requires companies to combine traditional commodity discipline with capabilities more commonly associated with specialty chemicals — technical differentiation, contract engineering and regulatory strategy.
Next Steps
This brief is a strategic preview. The full PW Consulting Montan Wax Market report contains the proprietary datasets, scenario models, supplier scorecards and downloadable spreadsheets that enable operational execution. For teams preparing 2026 budgets, M&A pipelines or procurement strategies, the full study provides the calibrated inputs and decision templates needed to convert market insight into measurable outcomes.
Contact PW Consulting to access the complete report and the supporting Excel models — the granular regional and application splits, supplier volumes, and price ladders are included only in the full deliverable.
For detailed analysis of this topic, please visit the official page: Montan Wax Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: 3D Optical Surface Profilers Market to Reach USD 237.6M by 2032 at 3.83% CAGR
By PW Consulting, 2026-08-02
3D Optical Surface Profilers (Profilometers) Market — Strategic Insights for 2026 Decision‑Makers
As the metrology layer that underwrites quality, yield and certification across precision manufacturing, 3D optical surface profilometry is transitioning from a niche laboratory capability to a mission‑critical production discipline. Our latest PW Consulting market study — anchored on a 2025 base year and projecting through 2032 — finds that the global market has demonstrated steady expansion over the 2020–2025 period and is positioned to continue growing at a compound annual growth rate of 3.83% in the forecast window. By 2025 the market reached a clear six‑figure magnitude in USD Million terms and is modeled to approach a substantially larger figure by 2032, reflecting measurable demand acceleration in select use cases and a maturing supplier landscape.
3D Optical Surface Profilers (Profilometers) Market
Why this analysis matters for corporate strategy in 2026
-
Investment prioritization: Capital allocation toward R&D, factory automation and aftermarket services must be informed by a market that is growing modestly overall but unevenly across product types and end‑use intensity.
3D Optical Surface Profilers (Profilometers) Market -
M&A and partnership scouting: A concentrated supplier base combined with pockets of capability gaps presents targeted acquisition and alliance opportunities to accelerate access to software, in‑line integration, and service networks.
3D Optical Surface Profilers (Profilometers) Market -
Product roadmap decisions: Differentiation is shifting from pure hardware performance to measurement software, standards compliance and workflow integration — a shift that should drive product development priorities in 2026 and beyond.
-
Supply chain and production risk mitigation: Raw material constraints and component price volatility now pose a crystallized risk to capacity expansion and time‑to‑market for new metrology systems.
-
Regulatory and customer compliance: Standards and regulation (notably ISO 25178 and region‑specific device regulations) are altering procurement specifications — buyers increasingly treat areal surface texture as a contractual requirement, not an optional capability.
High‑level market dynamics — what is driving change
Four structural forces are shaping the market’s trajectory in 2026:
-
Standards and regulatory elevation. Areal surface texture standards such as ISO 25178 are being embedded into engineering drawings and quality specifications, while semiconductor industry roadmaps and medical device regulations mandate advanced 3D metrology for process control and device safety. These developments are creating non‑optional demand for certified measurement traceability and repeatability.
-
Technology convergence. Suppliers who combine optical hardware with robust surface analytics, automation for sub‑micron repeatability, and industry‑specific measurement libraries are pulling ahead. Buyers increasingly value systems that integrate seamlessly into automated production lines and factory data environments.
-
Supply‑side friction. Component shortages and raw material price volatility are constraining some vendors’ ability to scale production quickly. Strategic buyers and suppliers must assume lead‑time variability and diversify procurement to protect critical launches and contractual commitments.
-
Consolidation and concentration. The market exhibits high concentration among a small set of incumbent players, driving premium pricing for trusted, field‑proven systems and creating both barriers and opportunities for challengers seeking to enter via software, service, or niche application specialization.
Competitive landscape — who matters and how they compete
The competitive field blends large instrumentation houses, specialized metrology firms and agile niche players. The market’s concentration metrics indicate a dominant share commanded by a few leaders (top‑three and top‑five concentration levels are materially high), which has strategic implications for pricing power, channel control and warranty/service economics.
-
Bruker Corporation (Billerica, MA). Bruker’s offering emphasizes precision measurement across materials and semiconductor workflows, pairing established interferometric platforms with growing analytics ecosystems. Their strength lies in cross‑portfolio integration and strong field service footprints.
-
Zygo Corporation (Middlefield, CT). Zygo continues to be positioned around high‑accuracy interferometry for optical manufacturing. Recent trade show activity reinforced their focus on non‑contact surface measurement for precision optics and semiconductor inspection workflows.
-
Taylor Hobson (Leicester, UK). With a long history in surface and form metrology, Taylor Hobson is advancing automation and setup speed for aspheric and freeform measurements — a 2026 product update introduced automatic centre and level features that accelerate throughput in optical production.
-
Sensofar (Barcelona, Spain). Sensofar is notable for flexible, application‑focused systems targeted at industrial research and production, emphasizing software‑driven measurement recipes for surface texture and defect analysis.
-
Onto Innovation / 4D Technology (Tucson, AZ). Combining interferometric and wavefront metrology competencies, Onto Innovation competes on high‑precision solutions for semiconductor and optical fabs where integration with process control is critical.
-
Mahr GmbH (Göttingen, Germany). Mahr leverages a strong European installed base and focuses on industrial metrology solutions that marry robust hardware with serviceability and factory integration.
-
Nanovea (Irvine, CA). Nanovea’s value proposition emphasizes flexible profilometry for both laboratory and shop‑floor use, with modular systems that address diverse material types and testing standards.
-
Evident (Olympus) (Tokyo, Japan). Evident’s portfolio targets materials science and industrial microscopy applications where 3D surface data supplements imaging and failure analysis workflows.
-
Keyence Corporation (Osaka, Japan). Keyence offers integrated measurement and automation platforms that appeal to high‑volume manufacturing customers seeking rapid, rugged measurement on the production line.
-
Michelyne (France) and FRT GmbH (Germany). These specialist suppliers focus on tailored metrology solutions for surface characterization, often serving regional niches or high‑precision research markets.
Recent vendor activity in early 2026 — including product updates that reduce setup time for complex optics and trade‑show showcases of next‑generation non‑contact profilers — underlines an industry pivot toward throughput, ease of use and production readiness.
Strategic playbook — eight practical moves for 2026
-
Map compliance to product roadmaps. Align new product development to ISO 25178 parameter coverage and semiconductor/metrology chapter recommendations; make certification and traceable reporting a sales enabler, not an afterthought.
-
Invest in software and workflow IP. Differentiate on measurement analytics, automated reporting and API‑level integration to factory execution systems — buyers now prize turnkey measurement recipes as much as optical resolution.
-
Prioritize supply‑chain resilience. Lock long‑lead components, qualify secondary suppliers and build inventory buffers for critical optical and electronic subassemblies to avoid production disruption.
-
Design for modularity and serviceability. Offer modular instrument architectures that can be upgraded in the field to protect customer investment and create recurring aftermarket revenue.
-
Pursue targeted M&A or partnerships. Consider tuck‑ins that add analytics, software or regional service reach rather than broad, unfocused acquisitions; bolt‑on capabilities accelerate go‑to‑market faster than greenfield builds.
-
Monetize data and calibration services. Develop subscription models for data analytics, remote diagnosis and calibration services that capture higher lifetime value per install.
-
Segment go‑to‑market by use case. Industrial buyers in high‑mix, low‑volume sectors value flexibility and service; high‑volume semiconductor and optics fabs prioritize throughput and automation — tailor sales motions accordingly.
-
Build standards leadership. Contribute to standards bodies and publish white papers and validated measurement protocols to shape buyer requirements and lower procurement friction.
What PW Consulting’s full report delivers
This research is designed for boards, corporate strategy teams, product leaders and M&A professionals who need decision‑ready intelligence for 2026. Key practical deliverables include:
-
Market sizing and scenario modeling (2020–2032) with baseline and upside/downside cases that reflect component constraints and regulatory shifts.
-
Vendor scorecards and positioning maps that assess technology differentiation, service networks, and go‑to‑market DNA without compromising confidentiality of proprietary benchmarks.
-
Application playbooks with buyer decision criteria, procurement checklists and CapEx templates tailored for semiconductor, optical, medical device and transportation OEMs.
-
Technology roadmaps for interferometry, confocal and hybrid approaches, including maturity curves and integration levers for automation and AI‑based analysis.
-
Supply‑chain risk heatmaps and mitigation playbooks that translate component volatility into concrete sourcing and inventory tactics.
-
Strategic M&A screening matrices and valuation heuristics calibrated to the market’s concentration realities and service‑led revenue potential.
-
Actionable recommendations for sales, service and product teams to convert standards compliance and certification investments into measurable revenue uplift.
Closing — how to use this insight in 2026
For companies that manufacture, integrate or buy 3D optical profilometers, 2026 is a year to translate recognition of metrology’s strategic importance into disciplined execution: shore up supply chains, double down on software and services, and align product investments with rising regulatory and industry measurement requirements. This market is concentrated enough that targeted moves — whether a partnership, an acquisition of analytics IP, or an operational pivot to modularity — can materially change competitive position.
PW Consulting’s report functions as a tactical roadmap and a strategic radar: it reveals the direction of travel and equips leaders with the tools needed to convert metrology requirements into competitive advantage. For the full suite of segmentation tables, granular regional‑and‑application demand analysis, vendor financial proxies and the downloadable vendor scorecards that underpin our recommendations, please consult the full report on our publication page.
For detailed analysis of this topic, please visit the official page: 3D Optical Surface Profilers (Profilometers) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Medical Audiometers Market to Reach USD 302.56M by 2032 at 5.2% CAGR
By PW Consulting, 2026-08-02
Medical Audiometers (Diagnostic Audiometer) Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present a concise, insight-driven preview of our new Medical Audiometers (Diagnostic Audiometer) Market study. This preview is designed to communicate the strategic value of the full report for corporate leaders planning resource allocation, product roadmaps, regulatory strategy, and M&A in 2026 — while preserving the detailed, commercially sensitive segment-level data that we reserve for the full publication.
Medical Audiometers (Diagnostic Audiometer) Market
Why this report matters for 2026
The diagnostic audiometer market is at an inflection point where steady clinical demand, evolving reimbursement and regulatory frameworks, and incremental technology innovation converge. Our modeling shows a resilient market with a compound annual growth rate (CAGR) of 5.2% over the 2026–2032 forecast window, built on a historical base that spans 2020–2025. The market size increased from USD 153.75 Million in 2020 to USD 215.0 Million in 2025 (base year), and our outlook projects continued expansion through 2032, with modeled year-by-year projections reflecting both steady baseline demand and upside from telehealth-enabled services and device modernization. Executives who prioritize evidence-driven strategy in 2026 will use the report to translate these macro trajectories into investment priorities and go-to-market choices.
Medical Audiometers (Diagnostic Audiometer) Market
Market trajectory snapshot (contextual numbers)
- Historical context (2020–2025): The sector grew from USD 153.75 Million in 2020 to USD 215.0 Million in 2025, demonstrating recovery and incremental adoption during the latter half of the historical window.
- Near-term outlook (2026–2032): Using 2025 as the base year, our forecast anticipates market expansion at a 5.2% CAGR through 2032, with year-specific model points that reflect conservative and aggressive adoption scenarios for digital audiometry, cloud-enabled deployments, and hybrid business models.
- Concentration dynamics: Market concentration is moderate—our CR3 and CR5 metrics indicate that the top three and top five firms hold a meaningful but not dominant share of the market (CR3: 47%, CR5: 57%), signaling both entrenched incumbency and continued opportunities for mid-sized challengers and specialized new entrants.
How PW Consulting’s report supports 2026 strategic choices
- Portfolio prioritization: We translate market trajectories into a decision matrix that helps product and corporate strategists choose where to accelerate R&D (e.g., advanced diagnostic platforms, integrated OAEs, or portable tele-audiometry kits) and where to rationalize SKUs.
- Regulatory and reimbursement readiness: The report maps near-term regulatory changes and reimbursement pathways so device manufacturers can timetable submissions, audits, and labeling updates with precision.
- M&A and partnership playbooks: We identify target archetypes, valuation heuristics, and integration risk factors that are actionable for corporates and financial sponsors evaluating tuck-ins or platform acquisitions.
- Market-entry and commercial tactics: For companies expanding geographically or into adjacent clinician- and consumer-facing service models, we provide go-to-market sequencing and pricing frameworks tailored to 2026 market realities.
Key industry dynamics that change the game in 2026
Several regulatory and reimbursement developments crystallize as critical inputs to near-term strategy:
Medical Audiometers (Diagnostic Audiometer) Market
- Regulatory simplifications and controls: Historical shifts (e.g., past FDA reclassifications) have reduced certain premarket burdens for select hearing-related devices. At the same time, a significant procedural change takes effect beginning February 2, 2026: PMA and HDE submissions and related preapproval inspections will be evaluated against an ISO 13485-based Quality Management System Regulation. This elevates QMS alignment as a gating factor for advanced device approvals and requires companies to prioritize systems-level compliance investments.
- CPT code overhaul and telehealth permanence: The American Medical Association’s code restructuring (effective January 1, 2026) that replaced older audiology codes with a new suite of professional service codes materially alters billing pathways for hearing device-related professional services. Complementing this, proposed CMS rules for 2026 include the permanent inclusion of certain telehealth audiology codes (e.g., CPT 92622), which increases the commercial attractiveness of tele-audiology-enabled devices and subscription services.
- 510(k) throughput and clearance patterns: The FDA continues to process a high volume of device submissions (CDRH authorized over 3,200 510(k)s in 2025), reflecting an active clearance environment. Manufacturers should anticipate both steady review activity and heightened scrutiny tied to QMS expectations.
Competitive landscape — what the report reveals (high level)
The market structure comprises established clinical audiology device manufacturers, regional specialists, and emergent software-enabled entrants. Our competitive module evaluates market positioning, product portfolios, commercial channels, and strategic initiatives for each named player — allowing readers to assess competitive threats and partnership opportunities without disclosing granular market-split figures.
- Grason-Stadler (Eden Prairie, MN): Longstanding reputation in diagnostic audiometers, tympanometry, and OAE devices. Strengths include clinician trust and clinical-grade product lines; watch for moves to integrate cloud data workflows and service bundles.
- MAICO Diagnostics (Eden Prairie, MN): Broad portfolio spanning diagnostic and screening audiometry. Their channel depth in public health and occupational screening makes them a natural partner for scaled screening deployments.
- MedRx (Largo, FL): Noted for comprehensive diagnostic series (e.g., AVANT A2D lineage). Product engineering and modularity are strategic assets for facilities seeking integrated ENT test suites.
- Amplivox (United Kingdom): Recently launched the Model 270+ (May 2025), which emphasizes accuracy across air, bone, and speech audiometry. Product refreshes such as this are reshaping clinical expectations for measurement precision and workflow efficiency.
- Sibelmed (Sabadell, Spain): Offers compact diagnostic platforms focused on clinician ergonomics and noise-robust testing, appealing to outpatient clinics and private practices across target regions.
- Happersberger Otopront (Hohenstein, Germany): Positioned in the advanced ENT diagnostic segment, with strengths in engineering and integration for hospital-grade audiology suites.
Our competitor analysis synthesizes public disclosures, product launches (such as Amplivox’s May 2025 release), and Q4/2025–Q1/2026 commercial signals to build scenario-based threat maps. The report’s annex contains head-to-head product feature matrices, patent landscaping, and channel-margin benchmarks (available only in the full report).
What the full report contains — practical components for immediate use
- Detailed market sizing and forecast model (historical 2020–2025; base year 2025; forecast 2026–2032) with downloadable model inputs to run custom scenarios.
- Segmental analysis by device type, application, and region, each presented with demand drivers, adoption hurdles, and upside risk cases. (Segment tables and regional splits are reserved for the full report.)
- Competitive profiles and product mapping for the leading suppliers, plus capability assessments and acquisition targets.
- Regulatory and reimbursement playbook, translating code changes, QMS expectations, and telehealth policy into tactical timelines for product labeling, clinical trials, and payer engagement.
- Commercial playbooks for direct sales, distributor partnerships, and hybrid subscription models—complete with pricing elasticity tests and launch checklists.
- Supply chain risk register that flags single-source components, calibration instrument dependencies, and logistics vulnerabilities that commonly affect audiometer manufacturers.
- Executive decision tools: M&A scoring matrix, internal investment prioritization framework, and a one-page board-ready strategic recommendation.
Executive takeaways — priorities for 2026
- Invest in QMS maturity now. With ISO 13485-based evaluation anchored in regulatory review processes beginning in early 2026, QMS readiness is not optional for companies seeking PMA/HDE pathways or international market access.
- Embed telehealth capabilities into product value propositions. Permanent inclusion of tele-audiology billing codes materially increases the market for remote diagnostic solutions and recurring service revenue models.
- Monitor clearance backlog and 510(k) trends. Clearance throughput remains robust; plan submission timing and premarket evidence generation to minimize time-to-market slippage.
- Targeted product refreshes beat broad proliferation. Given moderate market concentration and the continued importance of clinician trust, prioritizing upgrades that materially improve measurement accuracy, workflow, or tele-integration will yield better returns than broad SKU expansion.
- Use M&A selectively to fill capability gaps. Mid-sized M&A can accelerate access to software platforms, telehealth delivery models, or regional channels—our report provides a shortlist of archetypal targets and valuation guidance.
Where the trailer leads
This preview has demonstrated the methodological rigor and practical orientation of our full Medical Audiometers market study: credible base-year calibration (2025 = USD 215.0 Million), transparent historical series (2020–2025), and a robust forecast that reflects a 5.2% CAGR through 2032. It surfaces regulatory inflection points, competitive motions, and near-term commercial levers that matter to leaders in 2026. For CFOs, Heads of Product, BD teams, and Corporate Development officers, the full report converts these insights into executable actions and ready-to-use financial models.
To access the segment-level forecasts, regional and application splits, granular competitor benchmarking, and proprietary scenario model downloadable files, please refer to the full PW Consulting study. The complete deliverable is designed to be used at the board level and in operational planning cycles across 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Medical Audiometers (Diagnostic Audiometer) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sodium Percarbonate Market to Reach USD 705M by 2032 at 4.5% CAGR
By PW Consulting, 2026-08-02
Sodium Percarbonate Market 2026: Strategic Imperatives for Decision-Makers
Executive snapshot
As PW Consulting’s lead industry analyst, I present a concise, decision-focused view of the sodium percarbonate landscape to inform 2026 corporate strategy. Our market model—anchored to a 2025 base year and spanning historical data from 2020–2025 with forecasts through 2032—shows the market has strengthened materially over the past half-decade and is expected to continue expanding at a steady mid-single-digit cadence (CAGR 4.5% over the forecast window). From recovery and rebalancing following 2020–2021 disruptions to renewed demand traction in 2024–2025, the market’s macro momentum and structural attributes create distinct opportunities and hazards for producers, downstream formulators, and investors planning moves in 2026.
Sodium Percarbonate Market
Why this study matters for 2026 strategic choices
-
Timing matters: With the market already larger in 2025 than in prior years and projections extending growth toward the end of the decade, 2026 is a pivotal year for capacity, pricing and partnership decisions that will lock in relative competitive position for the next planning cycle.
Sodium Percarbonate Market -
Profitability under pressure: Feedstock volatility and regional demand swings are squeezing margins episodically; near-term cost management and commercial tactics will determine which players convert volume growth into sustainable earnings.
Sodium Percarbonate Market -
Regulatory and trade policy noise is elevated: Chemical registration, anti-dumping actions and evolving environmental expectations are reshaping sourcing and market access strategies—requiring proactive compliance and country-level playbooks.
-
Consolidation potential: The market concentration profile indicates that a relatively small number of firms capture a meaningful share of global supply—creating both acquisition targets and strategic scale advantages for incumbents and entrants.
Market trajectory: what the numbers tell us (high-level)
Our topline market model tracks a clear expansion from the early-2020 baseline through a firm 2025 base year, followed by steady growth across the forecast period. This trajectory—underpinned by a 4.5% compound annual growth rate—reflects a combination of durable household and commercial demand, incremental industrial use cases, and an ongoing shift toward higher-value, stabilized product grades within detergent and cleaning formulations. For executives, the implication is simple: volume growth is real, but margin capture depends on product mix, channel strategy and cost control.
Report contents — practical, action-first deliverables
Our full study is built for practitioners who must act in 2026. It includes:
-
Topline market sizing and demand-driver analysis (2020–2025 history; 2026–2032 scenarios) with sensitivity runs around feedstock and pricing.
-
Segmentation frameworks by form and application that map to supply chain, logistics and margin pools—presented in a way that supports SKU-level commercial decisions (note: detailed splits and unit-level price curves are available in the full report).
-
Channel and end-customer mapping, highlighting how detergent makers, industrial launderers, water treatment operators and household product OEMs procure and value differentiated grades.
-
Cost-to-serve models and break-even analyses to support pricing and make-versus-buy choices.
-
Regulatory matrix and trade-risk heatmap, cross-referenced to likely compliance actions and fast-deploy remediation pathways.
-
Competitor playbooks and inorganic opportunities: due diligence checklists, valuation benchmarks and a prioritized target list for bolt-on or transformative acquisitions.
Dynamics shaping 2026 — what to watch
-
Feedstock volatility: Sodium percarbonate production is sensitive to sodium carbonate and hydrogen peroxide availability and pricing. During 2025 feedstock trends were uneven, and our monitoring shows continued volatility into 2026—requiring hedging and flexible procurement arrangements for producers and formulators alike.
-
Short-term price movement in China: In Q1 2026 the domestic price index registered a quarter-over-quarter uptick driven by export demand and restocking. Such short-run price moves can compress margins or, if managed via contractual adjustments, can be converted into improved returns.
-
Regulatory scrutiny and compliance: European registration dossiers remain active for established trade names, emphasizing dossier hygiene, REACH-aligned testing, and forward-looking substitution evaluations for downstream customers that increasingly prioritize compliant sources.
-
Trade remedies: Anti-dumping measures in certain markets have altered competitive dynamics and redirected trade flows—an ongoing variable that companies must incorporate into supply and go-to-market strategies.
Competitive landscape — how to interpret positioning
The sodium percarbonate supplier base combines established global majors, regional champions and specialized niche players. Market concentration is meaningful: the top three suppliers collectively capture a majority of the market’s supply, while the top five increase that coverage substantially—creating clear scale advantages but also room for focused challengers.
-
Solvay (Brussels, Belgium): Global footprint and branded high-stability grades make it a go-to supplier for premium laundry and industrial bleaching customers. Their strength lies in global logistics and R&D-backed formulations.
-
Evonik (Essen, Germany): Competes on technology-enabled grades geared to cold-water washing and eco-detergent trends—positioning that aligns well with western detergent innovation agendas.
-
OCI (Seoul, South Korea): Large-scale capacity and a focus on detergent and bleaching markets provide cost and supply security advantages, particularly in Asia-Pacific corridors.
-
Specialists such as Kandelium and Chinese producers: These firms offer deep product know-how and cost-competitive supply, with strong positions in coated and tailored grades; they are important partners or rivals depending on regional market access and quality requirements.
-
Other regional players (Turkey, India, China): These firms support local industrial, textile and water treatment demand and have export ambitions; they are often the flexible swing suppliers in spot markets.
Strategic implications and recommended 90-day actions for 2026
-
Immediate procurement hedges and supplier diversification: Lock flexible offtake terms with multiple origins to weather feedstock-driven spikes. Short-term index-linked contracts combined with conditional volume agreements reduce exposure.
-
Prioritize higher-margin, differentiated grades: Accelerate development and commercialization of stabilized/coated grades where technical barriers and brand trust allow price premium capture.
-
Regulatory readiness: Update dossiers, engage early with authorities in target markets, and build an evidentiary base for eco-claims—this reduces market-access latency and supports premium positioning.
-
M&A and partnership screening: Use market concentration and capacity maps to identify bolt-ons that either shore up regional supply or add specialized product lines.
-
Commercial playbook refresh: Re-segment customers by margin-to-serve and technical requirements; deploy targeted pricing and logistics offers to strategic OEMs and formulators.
-
Scenario and contingency planning: Model downside stress cases for feedstock shocks and trade disruptions; prepare temporary production re-routing plans and emergency inventory protocols.
What we leave for the full report (and why)
True to the “trailer” principle of this introduction, we have showcased the strategic depth required to act in 2026 while deliberately withholding the granular segmentation tables, SKU-level pricing decks, region-by-region breakdowns and confidential company share matrices that materially affect tactical decisions. These datasets are compiled in the full report and are essential for precise commercial modelling, buyer-specific negotiations and M&A valuation work.
How PW Consulting supports your 2026 execution
We combine a quantified market model, primary-sourced procurement intelligence and transaction advisory experience to convert the insights above into executable programs. Whether you need a rapid supply-security retrofit, a tailored product commercialization plan, or a buy-side diligence package, our team delivers integrated workstreams that tie forecast scenarios to P&L impact and implementation milestones.
Next step
If you are considering capacity moves, pricing resets, or acquisitive growth in 2026, request the full Sodium Percarbonate Market report for detailed segmentation tables, company share analytics, price decks and the defensive playbooks that are omitted from this preview. The full toolkit is designed to convert the macro picture and competitive intelligence above into immediate actions that protect margin and accelerate market share.
For detailed analysis of this topic, please visit the official page: Sodium Percarbonate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Vaccine Refrigerators Market to Reach USD 932 Million by 2032 at 8.5% CAGR
By PW Consulting, 2026-08-02
Vaccine Refrigerators Market — Strategic Outlook and Decision Framework for 2026
As global immunization agendas accelerate and health systems prioritize resilient cold chains, the vaccine refrigerators market has entered a sustained growth phase. After expanding from a historical base of approximately USD 350 million in 2020 to a 2025 market size of USD 525 million, the sector is positioned to nearly double by the end of the 2026–2032 forecast window. Our modeling indicates a compound annual growth rate of roughly 8.5% across the forecast period, reflecting a mix of replacement demand, programmatic expansion in emerging markets, and technology-driven upgrades in mature markets. For executive teams planning capital allocation, product roadmaps, go-to-market pivots, or M&A activity in 2026, this landscape requires finely-tuned strategy that balances regulatory compliance, service economics, and supply-chain resilience.
Vaccine Refrigerators Market
Why this Report Matters for 2026 Decision-Making
- Translates macro momentum into operational choices: We map where growth is most durable and what capabilities (certifications, energy profiles, service networks) convert market tailwinds into revenue.
- Reduces technical and regulatory uncertainty: With WHO PQS and CDC guidelines increasingly shaping procurement, the report clarifies compliance thresholds that materially affect win rates in institutional tenders and international immunization programs.
- Prioritizes capital-efficient product development: We identify product attributes and service models that maximize lifetime value (LTV) under realistic OPEX and labor-cost scenarios.
- Supports M&A and partnership screening: The analysis highlights target profiles, integration risks, and value-creation levers for roll-up or cross-border alliance plays.
Report Contents — Practical, Actionable, and Executable
- Market sizing and topline projections from 2020 through 2032, with scenario analysis calibrated to regulatory shifts, energy-cost volatility, and programmatic funding cycles.
- Market dynamics and segmentation logic that explain where and why demand concentrates — without exposing proprietary client-level splits in the public summary.
- Regulatory and standards matrix: PQS, CDC/NSF guidance, annual verification cycles, and their procurement implications across buyer types.
- Competitive benchmarking and product scorecards covering temperature performance, freeze-protection, energy use, solar-direct-drive readiness, and serviceability.
- Commercial playbooks: pricing strategies, tender bid-shaping, LRP (long-range planning) for spare parts, and aftermarket service-as-a-product models to improve margins.
- Supply-chain vulnerability assessment and mitigation strategies for critical inputs (e.g., insulation formulations) and logistics to remote installations.
- Investment thesis and M&A screening templates, including stress-tested valuations under three demand scenarios.
- Implementation roadmaps with KPIs, operating models, and pilot design templates for 12–24 month execution cycles.
Market Dynamics and Near-Term Catalysts
Three structural forces are converging to define the market through 2026 and beyond. First, public-health funding and routine immunization programs continue to expand, driving baseline demand for certified storage capacity. Second, mature markets are accelerating replacement cycles to meet more stringent energy- and safety-related standards, elevating the share of higher-specification units. Third, off-grid immunization efforts and remoteness considerations are increasing demand for solar-capable and robust solar-direct-drive designs.
Vaccine Refrigerators Market
Regulatory frameworks are a critical gating factor. WHO PQS performance specifications (notably for E003-category refrigerators) now emphasize Grade A freeze protection and solar compatibility — a requirement that directly influences product architectures and supplier selection for many international tenders. In parallel, CDC guidance in the United States continues to set behaviorally binding expectations for vaccine storage, requiring purpose-built solutions that meet defined standards.
Vaccine Refrigerators Market
On the input side, material and labor dynamics are non-trivial. Polyurethane foam insulation remains a core material, and supply-chain pressure has driven OEMs to innovate toward more energy-efficient formulations that reduce both material costs and operating energy. Additionally, the labor-intensive nature of installation and maintenance in remote geographies increases total deployment costs, making service models and local partnerships a decisive competitive advantage.
Competitive Landscape — Profiles and Strategic Implications
- Helmer Scientific (Noblesville, Indiana) — Purpose-built medical-grade refrigerators and freezers designed to meet CDC recommendations. Helmer’s emphasis on temperature uniformity and recovery positions it well in high-regulation clinical and hospital channels. Recent product introductions into ultra-low temperature segments expand their addressable market and reinforce a hospital- and research-focused distribution footprint. ( https://www.helmerinc.com/)
- B Medical Systems (Hosingen, Luxembourg) — Offers a broad portfolio including ice-lined and solar direct-drive options compliant with WHO guidelines and PQS certification paths. Their recent product releases add capacity and water-pack freezer options, signaling a push into higher-volume, program-oriented tenders. ( https://www.bmedicalsystems.com/)
- PHC Europe B.V. (PHCbi) (Etten-Leur, Netherlands) — Pharmaceutical-grade cold solutions with emphasis on precise temperature control and energy efficiency, appealing to pharmaceutical companies, central labs, and academic research sites. ( https://www.phchd.com/)
- Haier Biomedical (Qingdao, China) — A full-range provider targeting both commercial and programmatic cold-chain systems, including solar and integrated system solutions for immunization programs. Their manufacturing scale and integrated product lineup make them a natural partner in large rollouts. ( https://www.haiermedical.com/)
- Vestfrost Solutions (Esbjerg, Denmark) — Specialized in PQS-approved self-regulating refrigerators suitable for professional and tropical use. Recent PQS prequalification further validates their suitability for international procurement programs. ( https://www.vestfrostsolutions.com/)
- Aucma (Qingdao Aucma Global Medical) — WHO PQS-certified offerings and designated supplier status for certain immunization equipment categories; their presence signals continued competition from scale-oriented Asian OEMs. ( https://www.aucmamedicalglobal.com/)
The competitive structure is moderately concentrated: the top three firms capture a meaningful but not dominant share of the market, and the top five increase concentration further. This opens room for specialist players to win in focused niches (e.g., ultra-low temperature, solar-direct-drive for off-grid markets, or high-service-margin hospital channels) while larger OEMs drive scale-based advantages in price and distribution.
Strategic Playbook for 2026
- For OEMs: Accelerate PQS and equivalent certifications; prioritize modular designs that enable local assembly and reduce freight costs; develop adjustable service contracts with predictive maintenance and remote monitoring to convert CAPEX buyers into recurring revenue streams.
- For investors and acquirers: Target mid-sized specialists with proven PQS/NSF compliance and established local-service footprints. Value creation can be realized by combining product portfolios, centralizing spare-parts logistics, and cross-selling managed services.
- For procurement agencies and NGOs: Shift evaluation criteria from purchase price to total cost of ownership and serviceability, with explicit scoring for freeze-protection, energy efficiency, and solar readiness. Prioritize suppliers with demonstrated compliance histories and local maintenance partners.
- For service providers: Invest in remote telemetry, field-service training programs, and bundled spare-part subscriptions — particularly for deployments in regions where labor and logistics are costly.
- For materials and components suppliers: Explore long-term supply agreements and co-development of lower-GWP, higher-performance insulation blends to meet both regulatory and energy objectives.
Operational Levers and Risk Mitigation
Decision-makers should stress-test plans against four primary risks: raw-material volatility (insulation and refrigerants), labor and installation cost escalation in remote installs, tightening or evolving regulatory standards (including annual PQS re-evaluations), and the risk of technology obsolescence as energy-efficiency expectations rise. Mitigation measures include dual sourcing for key materials, modular product platforms to enable rapid certification updates, local-assembly partnerships to reduce logistics burdens, and piloting service-as-a-product models with built-in telemetry to reduce onsite visits and accelerate issue resolution.
How PW Consulting’s Study Enhances Your 2026 Playbook
Our full study blends quantitative forecasts with practical tools — procurement scorecards, certification checklists, supplier due-diligence templates, and investment case models — designed to be used directly by product leaders, procurement heads, and investors. We maintain a clear separation between strategic narrative and proprietary segment-level datasets; the former is provided here to inform immediate choices, while the latter is bundled in the full report to enable transaction-level and bid-level decision-making.
In summary, 2026 represents a pivotal year: the broader market momentum (8.5% CAGR across the forecast) provides attractive upside, but realization of that upside will be uneven and dependent on certification readiness, service capability, and supply-chain agility. Organizations that operationalize the recommendations in this report — prioritizing compliance, modularity, service monetization, and strategic partnerships — will be best positioned to capture the most profitable growth pockets.
Next Steps
- Access the complete PW Consulting Vaccine Refrigerators Market report for regional and application-level forecasts, supplier scorecards, and downloadable decision templates.
- Engage with our advisory team for a tailored briefing and a 6–12 month implementation roadmap aligned to your organization’s objectives and risk tolerance.
For the detailed datasets, granular regional and application breakdowns, and the full competitive scorecards referenced in this executive preview, please visit our report page or contact PW Consulting’s life sciences practice for a confidential briefing.
For detailed analysis of this topic, please visit the official page: Vaccine Refrigerators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Roof Coating Market to Grow 3.8% CAGR to USD 3,350M by 2032
By PW Consulting, 2026-08-02
Roof Coating Market 2026: Strategic Imperatives and Decision-Ready Insights
Executive summary — why this study matters to boardrooms and deal teams in 2026
As organizations reassess capital allocation and product strategies for the post‑pandemic recovery, the roof coating market presents a mix of steady growth, supply‑side stressors and regulatory uncertainty that will materially influence near‑term commercial outcomes. PW Consulting’s latest Roof Coating Market study (base year 2025; historical series 2020–2025; forecast 2026–2032) synthesizes quantitative trend lines and qualitative, actionable intelligence to help executives make high‑confidence decisions on pricing, sourcing, product positioning, and M&A through 2026 and beyond.
Roof Coating Market
Key macro anchors from the study: global market value climbed from roughly USD 2,200 Million in 2020 to an estimated USD 2,570 Million in 2025, and PW Consulting’s scenario modelling indicates expansion toward the low‑to‑mid USD 3,000 Millions by the early 2030s, riding a compound annual growth rate (CAGR) of about 3.8% over the forecast window. Market structure is moderately concentrated (CR3 ≈ 55%, CR5 ≈ 72%), which creates both incumbent power and opportunity for focused challengers.
Roof Coating Market
How this research converts to 2026 decisions
- Procurement & supply strategy: The report maps supplier risk across raw materials and polymer chemistries, enabling procurement teams to prioritize dual‑sourcing and hedging strategies where margin exposure and supply disruption risk are highest.
- R&D and product road‑mapping: With regulatory pressure on VOCs and hazardous constituents intensifying, the report identifies priority reformulation pathways that balance performance, compliance, and cost.
- Commercial & pricing playbooks: Dynamic pricing scenarios and price‑elasticity modelling in the study give commercial leaders the tools to test price moves against volume, margin, and warranty exposure.
- M&A and portfolio moves: The concentration profile and company‑level value drivers spotlight pockets where bolt‑on acquisitions or capability purchases can deliver disproportionate returns.
- Go‑to‑market optimization: The research overlays product, channel and end‑user logic to recommend where to invest in contractor incentives, specification campaigns, or OEM partnerships.
Market trajectory & implications
Growth over the past five years has been steady but nonlinear. Recovery patterns in construction activity, periodic raw material price shocks, and pronounced changes in building‑performance requirements have created distinct windows of opportunity for technology upgrades and higher‑value coatings. The study’s baseline projection (CAGR ~3.8% for 2026–2032) reflects a market that favors incremental innovation, selective premiumization, and regulatory‑driven product migration rather than explosive expansion.
Roof Coating Market
For 2026 decision cycles this implies three practical imperatives: prioritize margin resilience through supply chain and product design; align new product introductions with tightening emissions and chemical regulations; and focus channel investments where specification and retrofit demand converge.
Critical dynamics shaping 2026 outcomes
- Raw material pressure: Tight supplies of methyl methacrylate (PMMA) and silicone resin feedstocks are generating upward price pressure and longer lead times for certain formulation pathways. The report quantifies supplier concentration, lead‑time variability and sensitivity of different product classes to these inputs, enabling supply‑chain mitigation planning.
- Regulatory acceleration: National and regional authorities are advancing rules on volatile organic compounds (VOCs) and hazardous chemical content. The report includes a regulatory impact matrix that translates pending rules into shelf‑level formulation and labelling implications for 2026 product launches.
- Consolidation and competitive positioning: With a mid‑range market concentration profile, scale and specialty chemistry matter. The study’s competitive framework explains why certain global players can defend margins through integrated supply chains while niche manufacturers can succeed by optimizing life‑cycle cost performance for specific roofing systems.
Competitive landscape — what incumbents and challengers are doing
The study provides a granular, decision‑oriented assessment of incumbent strategies and challenger playbooks. PW Consulting evaluated a cross‑section of leading manufacturers, from large diversified chemical and coatings groups to regionally focused specialists. The analysis highlights business models, channel focus, technical differentiation, and near‑term strategic moves that will determine competitive advantage in 2026.
- Specialty silicone-focused manufacturers: Firms that produce OH‑functional silicone polymers and related elastomeric technologies are positioned to capture premium retrofit and high‑performance commercial segments—subject to securing resilient silicone feedstock supply chains.
- Performance coatings groups and diversified players: Large coatings and chemical companies leverage scale in R&D, distribution and integrated raw material sourcing to defend share across multiple product families. Their ability to internalize raw‑material volatility and amortize regulatory compliance investments is a key advantage.
- Regionally focused manufacturers and installers: Companies that combine in‑house manufacturing with installation services can capture lifetime value via warranty extensions and maintenance contracts; they also face unique working‑capital dynamics and concentration risk in local supply ecosystems.
To illustrate how the competitive analysis is structured, the full report includes company profiles (headquarters, core value propositions, and go‑to‑market orientation) for major players, alongside an assessment of their strategic strengths, vulnerabilities and likely 12‑24 month plays. As an example, Progressive Materials is profiled for its silicone roof coatings and trade show engagement; similarly, a set of global chemical and coatings groups are evaluated for their product platforms and supply integration. The report synthesizes public developments and interview intelligence to produce strategic theses for each firm.
Report contents — operational modules that executives use
PW Consulting’s Roof Coating Market study is constructed as an operational toolkit rather than a pure data dump. Key modules include:
- Demand modelling (scenario‑based) that ties macro drivers—new construction, retrofits, roofing lifecycles—to product demand and revenue outcomes across 2026–2032;
- Price‑and‑cost sensitivity analyses exposing margin exposure to key feedstocks, freight and energy;
- Supply‑chain heatmaps and supplier scorecards with mitigation playbooks for critical raw materials and specialty polymers;
- Regulatory impact matrix linking pending rules to formulation, labelling and testing requirements in priority markets;
- Competitive benchmarking and strategic option maps (organic R&D, partnerships, acquisitions) tailored to different company archetypes;
- Go‑to‑market playbooks segmented by channel (contractors, specifiers, distributors) and commercial model (product vs. product+service);
- Innovation and sustainability roadmap that prioritizes reformulation, circularity and warranty design to meet customer willingness‑to‑pay and compliance thresholds;
- Deal screening and valuation addenda for M&A teams, spotlighting acquisition targets, synergy sources and integration risk.
Each module is designed to be extracted into board materials, investor memos or 100‑day integration plans—delivering both the “what” and the “how” to act. Importantly, the report intentionally refrains from publishing some core sub‑segment datapoints in summary outlets; PW Consulting’s source portal houses the full split‑level datasets and model access for clients.
Practical recommendations for 2026 action plans
- Immediately: stabilize feedstock exposure. Activate alternative sourcing, strategic inventory buffers, and contractual protections for PMMA and silicone resins where your formulations are most exposed.
- Next 90 days: compliance readiness sprint. Use the report’s regulatory matrix to triage SKUs for reformulation, testing and labelling ahead of new VOC and hazardous‑content rules.
- Within 6 months: refine product and channel mix. Reallocate commercial investments toward higher margin segments and specification channels identified in the study’s demand modelling outputs.
- Over 12–18 months: pursue capability M&A selectively. Target acquisitions that deliver raw‑material access, formulation know‑how, or contractor channel control—using the report’s deal screening filters to prioritize targets with the fastest path to accretion.
Data integrity and methodology
PW Consulting’s approach combines primary interviews with manufacturers, distributors and major contractors; bottom‑up revenue mapping; and cross‑validation with trade‑level shipment and raw‑material flow data. The study’s market size time series (2020–2025 historical and 2026–2032 forecast) is expressed in USD Million and is anchored to a 2025 base year to align corporate planning cycles for 2026. Scenario sensitivity tests and a transparent assumptions appendix enable clients to re‑run the core model under bespoke internal hypotheses.
Closing — a strategic invitation
For executives, the question is not whether the roof coating market will grow—our baseline shows ongoing expansion at a mid‑single‑digit CAGR—but how to capture durable value in a market defined by raw‑material tightness, regulatory change, and a mix of scale and niche competition. PW Consulting’s Roof Coating Market study translates these macro truths into a practical, priority‑ranked playbook for 2026 actions: stabilise supply, de‑risk compliance, reprice with discipline, and pursue capability buys where integration economics are clear.
To access the full dataset, detailed sub‑segment analytics and the company‑level decision memos that are intentionally withheld from summary briefings, visit the PW Consulting client portal or contact our industry team. The intelligence in the report is designed to be the operational backbone for the next 18 months of strategic choices—equipping CEOs, CFOs, and business unit leaders to convert market transparency into competitive advantage.
For detailed analysis of this topic, please visit the official page: Roof Coating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Sprocket Market Outlook 2026: Strategic Imperatives from Our 2025 Base-Year Study
As firms prepare budgets, M&A roadmaps, and product strategies for 2026, the ability to translate validated market signals into targeted choices will be the differentiator between opportunistic gains and costly missteps. PW Consulting’s latest Sprocket Market study—anchored on a 2025 base year and a rigorous 2020–2025 historical analysis—provides that translation. In short: the market is sizeable, recovering from near-term cyclical noise, and positioned for steady expansion at a mid-single-digit compound annual growth rate through 2032. This briefing outlines the strategic value of the study for 2026 decision-making while intentionally preserving our segmented intelligence behind the report paywall.
Sprocket Market
Why this study matters for 2026
Decision cycles in 2026 will be dominated by three realities: constrained capital allocation, supply-chain reconfiguration, and accelerating product differentiation driven by materials and manufacturing technology. Stakeholders need a single, defensible view of demand drivers, supplier economics, and concentration dynamics to prioritize actions. Our report synthesizes primary interviews, demand modelling, cost mapping, and scenario stress-tests into a practical guide for executives, corporate development teams, procurement officers, and R&D leaders.
Sprocket Market
- Validated market trajectory: Using 2025 as the base year, we show the market’s recovery after a brief softening and its expected expansion through the forecast horizon—culminating in an estimated market size in 2032 that confirms durable mid-term growth at a 6.8% CAGR.
- Decision-focused outputs: Rather than broad commentary, the study provides explicit levers—sourcing, pricing, product mix, and partnership playbooks—that can be executed within an 18–24 month planning horizon.
- Risk-first scenarios: Multiple macro- and micro-scenarios quantify downside and upside outcomes for capital-intensive moves (e.g., new plant builds, acquisitions), enabling contingency planning that is realistic and actionable for 2026 budgets.
Market trajectory: what the macro numbers tell you
Our consolidated market model places the industry at a clear inflection point. After tracking historical output through 2020–2025, the market stabilized into 2025—reflecting a mix of demand rebounds in certain end-markets and cost pressures elsewhere. From this position, the market is forecast to grow at a compound annual growth rate of 6.8% over the 2026–2032 forecast window, reaching a materially larger size by the end of the period.
Sprocket Market
For executives, two interpretations matter. First, sustained mid-single-digit growth supports selective capacity expansion, particularly where differentiated product or service models can realize premium pricing. Second, the pace of growth is not so rapid as to eliminate the value of consolidation and efficiency plays; disciplined inorganic moves and operational optimization remain compelling.
Concentration and competition: reading the market structure
Market concentration in the Sprocket sector is moderate. The top three players capture a meaningful share of revenue, and the top five widen that lead further—indicators of established incumbency yet also of accessible share for well-executed challengers. Specifically, the three-firm concentration and five-firm concentration metrics validate a market where scale matters but niche specialization and service differentiation can still create defensible positions.
- Implication for M&A: Targets should be assessed not only on immediate revenue synergies but on capability adjacencies that accelerate time-to-premium (e.g., coatings, higher-tolerance machining, aftermarket services).
- Implication for suppliers: Tiered procurement strategies that blend strategic partnerships with agile spot sourcing will reduce supply disruption risk without eroding margin capture.
- Implication for new entrants: Entry opportunities exist where product-performance improvements or logistics/service models materially change customer economics.
Key dynamics shaping strategy in 2026
- End-market oscillation: Automotive and industrial demand patterns are diverging in pace and quality of demand. Firms must map product portfolios to the elasticity of each end-market and avoid one-size-fits-all pricing or capacity decisions.
- Material-technology push: Advances in metallurgy, surface engineering, and precision manufacturing are compressing lifecycle costs for premium offerings. R&D investments focused on weight, durability, and lifecycle serviceability will unlock margin expansion.
- Supply-chain resilience: Geographic diversification of critical suppliers, nearshoring of key processes, and digital traceability are no longer optional—they are a requirement to maintain customer trust and preserve contractual penalties in tighter delivery ecosystems.
- Service and aftermarket: Monetization beyond initial sale—spare parts, predictive maintenance, and integration services—is a high-leverage channel to stabilize revenues as capital spending cycles fluctuate.
From insight to action: four tactical priorities for 2026
Based on our modeling and interviews, PW Consulting recommends four tactical priorities to ensure 2026 initiatives are high-impact and low-regret.
- Calibrate capacity investments to validated demand pockets: Use the report’s localized demand scenarios to sequence CAPEX. Prioritize flexible lines and modular tooling that allow quick shifts between product families.
- Reprice with value, not cost: Implement a value-based pricing framework for product tiers that captures technical differentiation and aftermarket potential. Our workshop templates show how to convert performance delta into price premiums with customer segmentation.
- Accelerate supply-partner consolidation where it reduces complexity: Consolidate low-value transactional relationships and build strategic alliances with vendors who can co-invest in resilience and quality improvement programs.
- Make targeted M&A bets for capability, not scale alone: Look for bolt-ons that close capability gaps (e.g., proprietary coatings, localized logistics hubs) rather than acquisitions that merely add symmetrical capacity without improving margin mechanics.
What the full PW Consulting Sprocket Market study includes
To make these recommendations executable, the full report contains a comprehensive package of practical deliverables. Highlights include:
- Granular demand forecasts across region, material, and application dimensions (historic and forecast), including sensitivity ranges and lead indicators to watch in real time;
- Detailed cost-to-serve and supplier economics models that allow buyers to stress-test contract terms and identify immediate cash-saving levers;
- Value-chain maps with supplier risk scores, interchangeability assessments, and recommended near-term mitigations;
- Commercial playbooks: go-to-market strategies for premiumization, aftermarket growth, and geographic rollout—each articulated with P&L impact estimates and implementation checklists;
- M&A playbook: target screening matrix, valuation multipliers calibrated to current market multiples, and integration checklists designed to capture synergies in 12–18 months;
- Interactive dashboards and downloadable datasets to allow teams to run custom scenarios aligned to internal KPIs.
Note: While we preview the report’s architecture here, the granular segment-level forecasts and the downloadable datasets are made available exclusively within the full report package to ensure confidentiality and integrity of our models.
How to use the report in your 2026 planning cycle
The study is structured to slot directly into typical corporate planning workflows. Tactical usage patterns we recommend:
- Q4 2025 / Q1 2026 budgeting: Use the base-case scenario and sensitivity bands to set conservative vs. aggressive budget lines for revenue and CAPEX.
- M&A diligence: Apply our target-screening criteria and valuation frameworks during initial screening to avoid overpaying for scale without capability uplift.
- Procurement renegotiations: Deploy the supplier economics models in supplier scorecards and renegotiation playbooks to secure firm, resilient commitments.
- R&D prioritization: Map product development pipelines against the forecasted premium segments to rationalize investments that will pay back within a 24–36 month window.
Closing perspective: where opportunity and discipline meet
The Sprocket market today presents a classic strategic trade-off: measured growth and moderate concentration reward both scale and focused differentiation. For 2026, success will be defined neither solely by the size of a firm’s balance sheet nor by aggressive capacity expansion, but by its ability to invest selectively—locking in capabilities and partnerships that convert moderate demand growth into lasting competitive advantage.
PW Consulting’s study is engineered to be the operating manual for that choice process. It combines a defensible macro view—anchored to the 2025 base year and articulated through a 6.8% CAGR forecast—with the tactical playbooks and datasets teams need to act quickly and confidently.
Next steps
For immediate access to the full segmented forecasts, company-level profiles, interactive dashboards, and implementation materials referenced above, visit the PW Consulting report page. If you prefer a tailored briefing, our consulting team can run a 90-minute executive workshop to translate the study’s findings into a 12–24 month action plan calibrated to your organization’s priorities.
For detailed analysis of this topic, please visit the official page: Sprocket Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


