



Category: market research
PW Consulting: Wireless WAN Solutions Market to Rise from USD 7,650 Million in 2025 to USD 19,713.74 Million by 2032 at a 14.48% CAGR — 5G and Hardware Lead Growth as Top 5 Hold 62.3%
By PW Consulting, 2026-07-13
Wireless WAN Solutions Market 2026: Strategic Imperatives for Enterprise Decision‑Makers
Executive summary
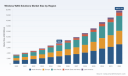
As organizations accelerate distributed digital transformation, wireless wide area network (Wireless WAN) solutions have moved from tactical redundancy to strategic infrastructure. PW Consulting’s latest Wireless WAN Solutions Market report (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes quantitative market sizing—anchored by a 2025 market of USD 7,650 million and a 2026 projected step to roughly USD 8,727 million—with qualitative frameworks that directly inform enterprise decisions in 2026. The market exhibits a robust compound annual growth rate (CAGR) of 14.48% across the forecast window, signaling continued vendor investment, rising service adoption, and expanding solution breadth.
Wireless Wan Solutions Market
This briefing article is intentionally a “trailer”: it reveals the analytic logic, strategic insights, and practical levers that will shape procurement, architecture and M&A choices in 2026, while preserving the report’s proprietary segment-level detail to motivate access to the full deliverable.
Wireless Wan Solutions Market
What the full report delivers (practical, actionable contents)
- Market sizing and growth scenarios — deterministic and three-statement scenario analyses that reconcile historical uptake with technology inflection points and macro drivers.
- Demand archetypes and buyer personas — enterprise decision pathways for retail edge, industrial OT, multi-site healthcare, and mobile-first field services, mapped to procurement triggers and SLAs.
- Technology and architecture playbooks — decision matrices for selecting between hybrid SD‑WAN + cellular uplinks, private 5G, and managed cellular access, including TCO modeling templates and deployment phasing guides.
- Regulatory and spectrum impact maps — concise summaries of jurisdictional constraints, spectrum availability, and export-control exposures that materially affect vendor selection and supply chain design.
- Vendor benchmarking and competitive scorecards — qualitative and quantitative assessment across commercial, technical, and operational dimensions, paired with a vendor risk heatmap.
- M&A and partnership screening tools — bespoke scoring models for inorganic growth targets and alliance prioritization, aligned to integration complexity and revenue synergy timelines.
- Operational checklists and KPIs — pilot acceptance criteria, measurable service-level definitions (latency, throughput, resiliency), and an operations playbook for multi-vendor orchestration.
- Customizable financial models and dashboards — downloadable spreadsheets to stress-test procurement scenarios under variance in spectrum cost, small-cell deployment CAPEX, and vendor pricing.
Market trajectory and strategic implications
The Wireless WAN market’s trajectory from the early 2020s into 2026 reflects two reinforcing dynamics: first, a secular shift to edge-first applications that demand ubiquitous, low-latency connectivity; second, vendor commercialization of 5G and advanced SD‑WAN integration. PW Consulting’s baseline projection shows meaningful expansion from the mid‑2020s into the early 2030s, culminating in an expected market size of approximately USD 19.7 billion by 2032 under the primary scenario.
Wireless Wan Solutions Market
For enterprise strategists planning 2026 budgets, three implications flow directly from the CAGR and trajectory:
- Strategic window for capability capture: with ~14.5% CAGR, 2026 is an inflection year where early adopters of combined private 5G and resilient SD‑WAN architectures can secure differentiated performance before broad market commoditization.
- Unit costs will change shape: economies emerge in software and service layers faster than hardware, shifting procurement from CAPEX-heavy rollouts to hybrid CAPEX/OPEX models and managed service consumption.
- Vendor selection matters more than price alone: the speed of vendor evolution—driven by network integrations, protocol support, and ecosystem partnerships—creates asymmetric switching costs that favor forward-compatible platforms.
Competitive landscape — structure, players and recent moves
The market demonstrates moderate concentration: the top three vendors account for nearly half of industry revenue, and the top five capture over 60%—a posture that mixes established systems integrators and network operators with niche specialist vendors. That structure produces both stability and opportunity: enterprises can source from proven incumbents for scale projects, while specialist providers accelerate vertical-specific innovation.
Key vendor dynamics to watch in 2026:
- Cisco Systems (San Jose, CA) — leverages integrated routing and SD‑WAN stacks with increasingly ruggedized hardware for industrial deployments. Recent product updates reinforce cellular uplink and orchestration capabilities for hybrid WANs.
- Ericsson (Stockholm) — continues to push 5G RAN and core advancements that lower barriers for private and shared wireless WAN deployments, including low‑power and reduced‑capability device profiles that expand IoT coverage.
- Nokia (Espoo) — its investments in standalone 5G core and edge routing strengthen its role for carriers and large enterprises requiring high throughput backhaul and service chaining.
- Huawei Technologies (Shenzhen) — remains a major supplier of integrated RAN and edge networking equipment, with deep cost and integration offers in markets where regulatory constraints permit widespread adoption.
- Major US carriers (Verizon, T‑Mobile and the incumbent Sprint legacy) — provide differentiated managed services, private 5G options, and urban mmWave capacity; their nationwide rollouts and protocol activations materially expand enterprise choice sets.
- Specialists (Pepwave, VMware/Broadcom) — multi‑WAN bonding, sophisticated cellular failover, and cloud‑native SD‑WAN orchestration remain critical for multi-site resiliency and rapid deployment scenarios.
- Consumer/mobile-focused operators (Cricket Wireless et al.) — increasingly participate in enterprise segments via wholesale and MVNO models to serve mobile broadband needs.
Recent vendor developments through 2024–2025 underscore these trends: product launches that support reduced-capability IoT devices, expanded 5G standalone deployments, ruggedized industrial routers with sub‑6GHz 5G support, and broadened mmWave urban coverage. These moves tighten the roadmap for enterprises evaluating pilot-to-production timelines in 2026.
Regulatory, spectrum and infrastructure context (what keeps CFOs and CTOs awake)
Regulatory and infrastructure factors will materially influence 2026 decisions. Recent and relevant items include mid-band spectrum allocations that underpin densification strategies, network‑neutrality regimes that affect traffic management and SLAs in certain jurisdictions, export controls that constrain supplier choice for cryptography‑enabled equipment, and evolving 3GPP releases that introduce public safety and ultra‑reliable low‑latency communications (URLLC) features.
On the cost side, small-cell deployment remains a non‑trivial component for densified urban backhaul—enterprise planners must account for multi‑site site lease, power, and backhaul integration expenses when modeling rollout economics. PW Consulting’s models stress‑test these variables to expose breakeven points for private 5G versus managed cellular and hybrid SD‑WAN options.
Actionable strategic recommendations for 2026
- Prioritize hybrid architectures: adopt an SD‑WAN-first approach that can natively integrate cellular uplinks and private 5G. This minimizes rip-and-replace risk and preserves workload portability across cloud and edge.
- Run a two‑track procurement process: simultaneously engage incumbent-scale vendors for core orchestration and niche suppliers for edge resilience to reduce single‑vendor dependence while maintaining integration discipline.
- Embed regulatory and spectrum contingencies into RFPs: require vendor responses to include alternative supplier paths and cryptography compliance statements to mitigate export-control and spectrum-access risks.
- Structure pilots for measurable learning: define acceptance criteria tied to latency, failover recovery, and operational overhead. Use short, multi‑site pilots to validate orchestration and monitoring before capex commitments.
- Optimize finance models: favor vendor contracts with flexible consumption tiers and network-as-a-service options to convert upfront CAPEX into manageable OPEX during the growth phase.
- Invest in operational readiness: build cross-functional runbooks covering multi‑SIM management, edge security, and life‑cycle firmware control to reduce mean time to repair and compliance exposure.
- Monitor consolidation and partner moves: given the market concentration dynamics, expect continued M&A and alliances; keep vendor‑management options open to leverage bargaining power during contract renewals.
How PW Consulting’s report supports 2026 decision-making
The report is designed to be directly operational for 2026 procurement cycles: it provides vendor scorecards that map to procurement clauses, downloadable TCO and ROI models tuned to current small‑cell cost ranges and spectrum availability assumptions, and a regulatory appendix that clarifies country‑level constraints. For executive teams, the report distills strategic choices into a one‑page roadmap that aligns architecture, sourcing, and investment timing with risk appetite.
For security and compliance leads, the vendor risk heatmap and export-control matrix offer immediate filters to accelerate shortlists. For network and operations teams, the deployment blueprints and pilot acceptance checklists shorten time to production while preserving observability and resilience targets.
Next steps and access
PW Consulting’s Wireless WAN Solutions Market report is the prescriptive intelligence package for enterprises finalizing 2026 network strategy. This article outlines the report’s analytical foundations and strategic value; the full publication contains the fine-grained segment insights, downloadable models, and vendor scorecards withheld here to preserve proprietary value.
Visit the PW Consulting market portal to access the full report, scenario spreadsheets, and a companion executive workshop package that helps translate findings into a 90‑day implementation plan. For tailored briefings, PW Consulting offers strategy sessions that apply the report’s models to your topology, regulatory footprint, and financial constraints.
For detailed analysis of this topic, please visit the official page: Wireless Wan Solutions Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Microbes Protein Hydrolysates Market Poised for 6.45% CAGR, New Insights Reveal
By PW Consulting, 2026-07-13
Microbial Protein Hydrolysates: Strategic Imperative for 2026 — A PW Consulting Industry Brief
As the microbial protein hydrolysates market accelerates into a phase of commercial maturation, executive teams face a narrow window in which to convert early technical advantages into durable competitive positions. PW Consulting’s latest market analysis — anchored on a 2025 base and a 2026–2032 forecast horizon — shows the market moving from an estimated USD 465.5 Million in 2025 toward a materially larger opportunity in the coming decade, growing at a compound annual growth rate (CAGR) of 6.45% through 2032 and approaching roughly USD 721.0 Million by the end of the forecast period. These macro trends are already informing investment, regulatory and go-to-market choices across verticals that include feed, food & beverage, pharma/biotech and agricultural biostimulants.
Microbes Protein Hydrolysates Market
Executive snapshot — what senior leaders must know
-
Growth trajectory. The market’s mid-single-digit CAGR masks important inflection points tied to regulatory approvals, commercial-scale plant commissioning, and feedstock availability that will determine winners and losers in 2026–2028.
Microbes Protein Hydrolysates Market -
Commercial readiness. Several technology paths — gas fermentation (methanotrophs), autotrophic CO2-based processes, and yeast fermentation — have moved from pilot to commercial output in selected applications, especially animal nutrition and selected human-food demonstrations.
Microbes Protein Hydrolysates Market -
Regulatory gating. Recent approvals and organic-system recognitions are lowering entry barriers for feed use, but full mainstreaming in human food and pharma remains contingent on regional regulatory clarity and clinical substantiation for specialized hydrolysates.
-
Market structure. The competitive landscape is characterized by dynamic specialization rather than a single dominant incumbent; top suppliers account for a meaningful share of supply, but there remains room for targeted entrants and partnerships.
Why our 2026 strategic planning must account for microbial hydrolysates
-
Timing matters more than absolute scale. While the market remains sub‑billion-dollar in near-term revenue terms, the pace of technological scale‑up and the discrete nature of approvals means first movers can lock-in valuable offtake agreements, feedstock contracts, and channel partnerships that yield outsized returns as the market expands.
-
Feedstock and energy are strategic levers. Producers using methane, CO2 + H2 (electricity-driven), or sugar feedstocks face different risk profiles: access to low‑cost methane or renewable electricity/green hydrogen and CO2 streams will materially affect unit economics and sustainability credentials.
-
Product differentiation is technical and regulatory. Suppliers who can combine consistent amino-acid profiles with functional claims (digestibility, bioavailability, peptide functionality) and validated health outcomes will secure premium placement in food, pharma and specialty feed applications.
-
Partnerships beat solo scale-ups. Joint ventures, toll manufacturing and strategic alliances with established feed and ingredient players are the fastest routes to commercial traction and risk mitigation in 2026 planning cycles.
Competitive landscape — profiles and strategic implications
-
Unibio (Denmark) — Uniprotein via gas fermentation: regulatory momentum in aquaculture and early commercial shipments position Unibio as a lead commercializer for methanotrophic single‑cell protein in feed. Strategic implication: incumbents and integrators should evaluate aquaculture pilot partnerships and regional feed trials where approvals exist.
-
Calysta Inc. (United States) — FeedKind and scaled JV output: Calysta’s recent shift from R&D pilots in the US/UK to concentrated commercial manufacturing in its China JV reflects a pragmatic move to optimize CAPEX utilisation and unit costs. Strategic implication: firms evaluating supply should prioritize assured commercial supply agreements and consider geographic production footprints when modeling supply risk.
-
Solar Foods (Finland) — Solein (CO2 + H2): its product demonstrations for next‑generation protein beverages show the attractiveness of electricity-driven production for human-food applications. Strategic implication: consumer-facing brands seeking low-land-use, decarbonized protein should open co-development dialogues now to secure formulation windows.
-
Angel Yeast (China) — Yeast-derived hydrolysates: breakthrough research on nutrient synergies (e.g., peptides + mineral absorption) indicates value-add pathways into functional foods and nutraceuticals. Strategic implication: formulators and supplement companies should evaluate trial programs to exploit differentiated health claims.
-
Kerry Group, DSM‑Firmenich, Corbion, Lallemand, Alltech — ingredient and fermentation incumbents: these firms offer scale, channel access and formulation expertise, and are natural acquirers or partners for smaller microbial protein innovators. Strategic implication: buyers and investors should map alliance and M&A strategies against these firms’ capability footprints.
Recent industry moves that shape 2026 playbooks
-
Regulatory wins for feed use and organic status in some jurisdictions are already de‑risking pilot-to-commercial transitions for methanotrophic proteins; companies should monitor approvals as triggers for expansion.
-
Operational consolidation by certain innovators toward fewer, larger manufacturing sites signals a shift to manufacturing-first playbooks — raising the importance of long-term feedstock/energy contracts and plant reliability data for offtakers.
-
Visible product showcases from CO2‑based producers into consumer-facing beverage prototypes indicate an emerging pathway for microbial proteins into mainstream human nutrition — but commercialization timelines will hinge on cost curves and consumer acceptance pilots.
What the PW Consulting report delivers — actionable components
-
Market sizing and demand scenarios: top‑down and bottom‑up forecasts from 2020 baseline through 2032, including sensitivity runs that quantify impact of regulatory approvals, feedstock pricing shocks, and CAPEX scaling.
-
Technology and cost models: CAPEX/OPEX build-ups for gas fermentation, CO2‑based autotrophy, and yeast fermentation pathways; energy and feedstock cost elasticities; break‑even curves under multiple price and scale assumptions.
-
Regulatory and standards matrix: approval timelines, labeling considerations, and organic/animal‑feed certification pathways across priority jurisdictions — with recommended engagement sequences for 2026 regulatory filings.
-
Competitive intelligence dossiers: strategic profiles of active players, recent developments, partnership maps and capability heatmaps to support target screening and JV sourcing.
-
Commercialization playbooks: pilot-to-scale roadmaps, sample offtake and tolling contract clauses, procurement scorecards, and go‑to‑market segmentation frameworks for feed, food, pharma and agri-biostimulant customers.
-
Investment and M&A guidance: red-flag risk checklist, valuation drivers for providers at different maturity stages, and prioritized target lists based on capability gaps, IP position and go-to-market synergies.
How to use this intelligence in 2026 planning cycles
-
Board & capital committees — integrate a two-track capital allocation approach: preserve optionality for rapid scale via JV/tolling while selectively funding proprietaryscale where unique feedstock or IP advantages exist.
-
Commercial teams — secure binding offtake windows for pilot volumes now and include escalation clauses tied to published regulatory milestones to hedge price risk as units scale.
-
R&D & regulatory — prioritize dossiers that unlock the largest near-term revenue pools (e.g., aquaculture/animal feed approvals) while planning parallel human‑food safety and labeling studies for medium-term expansion.
-
Procurement & operations — model feedstock scenarios (natural gas/methane, sugar streams, renewable H2 + CO2) and secure long‑dated supply or capture agreements for critical inputs to protect margins in a tightening market.
-
M&A and partnerships — use a capability-first lens: ingredient formulators and feed integrators should target microbial producers that can demonstrate repeatable scale, validated quality systems, and defensible supply contracts.
Priority next steps — a 90‑day action plan for executives
-
Run a feedstock sensitivity analysis across your portfolio and price points to identify exposure and opportunity under three energy/commodity scenarios.
-
Initiate pilots with at least two different microbial suppliers that use different process pathways (gas vs yeast vs CO2‑based) to evaluate functional equivalency and cost-to-formulation.
-
Engage regulatory counsel to map the fastest viable route for product claims and labeling in target markets; prioritize regions where approvals provide immediate commercial access.
-
Open dialogues with incumbent ingredient players for JV or tolling arrangements to accelerate market entry without absorbing full CAPEX burden.
Conclusion: The microbial protein hydrolysates market is no longer a speculative niche — it is an emergent supply domain with distinct commercial pathways and embedded strategic choices for 2026. The macro numbers point to steady expansion, but the commercial winners will be those who align technology selection, feedstock strategy and regulatory sequencing with disciplined partnership and offtake execution.
For full datasets, detailed segment-level intelligence, cost models and candidate target lists to inform 2026 decisions, access PW Consulting’s full Microbial Protein Hydrolysates Market report and supporting appendices on our web portal.
For detailed analysis of this topic, please visit the official page: Microbes Protein Hydrolysates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Consumer Electronic BMS Chip Market Set to Expand at 7.5% CAGR — From USD 2,450 Million in 2025 to USD 4,064.7 Million by 2032, Led by Asia‑Pacific (USD 1,217.1M)
By PW Consulting, 2026-07-13
Consumer Electronic BMS Chip Market — Strategic Preview for 2026 Decisions
Executive summary
PW Consulting’s forthcoming market research on Consumer Electronic Battery Management System (BMS) chips synthesizes a unique combination of quantitative market modeling and hands‑on commercial frameworks to inform executive decisions in 2026. Our base-year analysis uses 2025 as the grounding point (market size: USD 2,450 million), with historical trend mapping across 2020–2025 and a forward-looking forecast to 2032. The market is modeled to grow at a steady 7.5% CAGR over the forecast horizon, reaching roughly USD 4,065 million by 2032 under our central scenario. This briefing outlines the strategic value of the report for product, supply‑chain and M&A choices in 2026 while deliberately withholding granular sub‑segment tables — these are available in full on the report landing page.
Consumer Electronic Battery Management System Bms Chip Market
Why this matters for 2026 planning
-
A predictable mid‑single‑digit-to‑high‑single‑digit CAGR creates a planning horizon where product investments and supply commitments can be staged over multi‑year cycles rather than requiring immediate, full‑scale reallocation. Our model shows an accelerated compound expansion from the 2025 base through 2032 that makes phased R&D and capacity contracts a viable way to balance risk and opportunity.
Consumer Electronic Battery Management System Bms Chip Market -
Macro policy and supply‑chain idiosyncrasies are creating asymmetric risk profiles. Regulatory requirements (notably new EU rules) and export control regimes are shifting where and how high‑value functionality (e.g., advanced fuel gauging, AI‑enabled estimators) can be developed and shipped — a dynamic that has direct implications for 2026 sourcing, localization and partnership choices.
Consumer Electronic Battery Management System Bms Chip Market -
Market concentration is meaningful but not insurmountable: the top three players hold a material share of market value, and the top five are well positioned across product platforms. Competitive entry by focused analog and mixed‑signal vendors continues to compress margins in commoditized nodes while premium feature sets command ASP resilience.
Report contents — what you get (practical, decision‑ready modules)
-
Market model and scenarios — a calibrated bottom‑up revenue model (2020–2032), three demand scenarios, and sensitivity dashboards that let finance and product teams stress‑test revenue by price, device penetration, and regulatory adoption curves.
-
ASP and cost curves — dynamic ASP tracking (including 2025 observations) and component cost breakouts to support negotiating positions with IDM and fab partners.
-
Product and roadmap playbook — comparative feature maps across cell protection, fuel gauging, integrated BMS+charger solutions and low‑power wearables variants; vendor capability matrices for quick vendor short‑lists.
-
Supply‑chain risk map — lead time heatmaps, single‑sourcing points, raw material exposures and mitigation levers (dual‑sourcing, design requalification pathways, buffer stock models).
-
Regulatory and compliance navigator — obligations tracking (including near‑term deadlines for state‑of‑health reporting), impact scoring and compliance roadmaps for product teams and legal/compliance functions.
-
Commercial playbooks — go‑to‑market strategies for OEMs, ODMs, and semiconductor suppliers including pricing playbooks, bundling options and co‑engineering engagement templates to accelerate adoption.
-
M&A and partnership pipeline — target screening criteria, valuation heuristics and a prioritized list of tuck‑ins and technology partners aligned to different strategic objectives (time‑to‑market, IP, customer access).
Competitive landscape — who’s shaping the market
Our competitive analysis synthesizes public product portfolios, reference designs, recent product moves and go‑to‑market posture to generate battle‑cards for each major supplier. Market concentration metrics indicate an environment where leading analog and mixed‑signal specialists retain structural advantages, but differentiated system suppliers and highly focused niche players create corridors for growth.
-
Texas Instruments (Dallas, TX) — Strengths: deep analog portfolio, broad BQ family with cell balancing, protection and fuel gauge logic. Strategic posture: platforming for OEMs and power‑bank / laptop use cases. Recent move: late‑2025 launches expanded multi‑cell monitors targeting higher‑cell‑count consumer packs.
-
Analog Devices (Wilmington, MA) — Strengths: precision monitoring and state‑of‑charge algorithms; strong presence in multi‑cell stacks. Strategic posture: positioning LTC series as the premium monitoring solution for mid‑to‑high end portables. Recent move: 2025 sampling activity to accelerate design wins in wearables and multi‑cell devices.
-
STMicroelectronics (Geneva) — Strengths: low‑power, system‑level integration for wearables and IoT. Strategic posture: reference designs and developer ecosystems to speed adoption of single‑cell BMS in mass‑market consumer earbuds and sensors. Recent move: reference design releases for TWS earbuds to lower customer integration hurdles.
-
NXP Semiconductors (Eindhoven) — Strengths: controller platforms for consumer battery packs with emphasis on pack‑level management and communications. Strategic posture: leveraging automotive‑grade qualifications to win higher‑reliability consumer segments. Recent move: product qualification wins to broaden addressable markets.
-
Renesas Electronics (Tokyo) — Strengths: high‑accuracy monitoring and strong reliability pedigree. Strategic posture: targeting notebook and professional portable segments by adapting automotive‑grade architectures to consumer reliability expectations.
-
Infineon Technologies (Neubiberg) — Strengths: ASIC and multi‑cell solutions for drones and power tools; communications architectures for daisy‑chaining cells. Strategic posture: bringing industrial robustness into premium consumer categories.
-
Maxim Integrated (Analog Devices, San Jose) — Strengths: single‑cell fuel gauge and protector products for ubiquitous devices such as earbuds and single‑cell wearables. Strategic posture: deep OEM relationships on single‑cell power management.
-
Monolithic Power Systems (Kirkland) — Strengths: integrated charging+protection controllers for portable devices with compact BOM impacts. Strategic posture: cost‑effective integration and fast time‑to‑market for consumer electronics makers.
Recent industry developments shaping 2026 tactics
-
Product cadence is accelerating: several vendors announced sampling or launches through 2024–2025, bringing higher cell counts and integrated functionality to consumer packs. These moves compress product windows and make early design wins materially more valuable.
-
Pricing and ASP behavior: the unit ASP for consumer BMS ICs rose meaningfully in 2025 (our market monitoring flagged a rise to approximately USD 1.20/unit driven by demand for AI‑enabled fuel gauging). That trend supports near‑term revenue resilience for differentiated chips while commoditized parts face margin pressure.
-
Supply‑chain and raw‑material frictions: wafer fab lead‑times spiked (20–24 weeks in Q4 2025 for automotive‑grade wafers) and palladium shortages extended qualification cycles for analog ICs — factors that increase the time and cash required to bring new designs to production.
-
Policy and geopolitical constraints: export‑control measures have real, measurable impact on the ability to transfer advanced BMS technologies across borders; our mapping estimates roughly 15% of global consumer supply is affected by recent export rules. This changes where OEMs can source advanced nodes and puts a premium on localized design capacity.
-
Regulatory mandate: the EU has set out a timeline for consumer devices to report state‑of‑health data beginning in 2027. Product and compliance roadmaps need to account for firmware, security and data‑handling obligations now to avoid late‑stage rework.
Strategic actions PW Consulting recommends for 2026
-
Lock design windows, not just capacity: given extended qualification lead times for new analog designs, secure multi‑phase commitments with preferred vendors and include requalification corridors. Shorten time‑to‑design‑win via early reference design partnerships.
-
Prioritize regulatory readiness: incorporate state‑of‑health telemetry and secure reporting into platform architectures now to meet near‑term mandates without feature trade‑offs.
-
Adopt a differentiated ASP strategy: exploit premium ASP resilience for AI‑enabled and multi‑cell solutions while aggressively cost‑optimizing single‑cell and commoditized SKUs.
-
De‑risk supply chains: build dual‑source strategies for critical analog components, evaluate localized wafer sourcing for sensitive designs and use staged buffer inventory for long‑lead items.
-
Use M&A and alliances tactically: prioritize tuck‑ins that provide IP for fuel gauging, state‑estimation algorithms, or compliance stacks rather than only capacity targets.
Methodology, confidence and where to look next
The report’s base year is 2025 with historical coverage from 2020–2025 and a forecast window through 2032. Our approach blends bottom‑up bill‑of‑materials modelling, primary interviews with OEM/ODM/power‑IC suppliers, and triangulation from semiconductor market trackers and policy databases. We present three forecast scenarios plus a comprehensive sensitivity matrix so teams can test alternative ASP and penetration assumptions. Confidence intervals are provided at the product family level; the full report contains the granular tables, segment‑level forecasts and vendor revenue splits that are intentionally not excerpted here.
Conclusion and call to action
For executives making 2026 capital allocation, product roadmap or M&A decisions, this PW Consulting report offers an operationally actionable synthesis: a proven growth trajectory from USD 1.75 billion in 2020 to USD 2.45 billion in 2025, and a modeled expansion to roughly USD 4.07 billion by 2032 at a 7.5% CAGR. The combination of evolving regulation, supply‑chain constraints and selective vendor consolidation means that well‑timed, targeted moves in 2026 can secure durable advantage. To access the full dataset, segment breakdowns, vendor financials and our prioritized short‑list of targets and suppliers, consult the report landing page for subscription access and bespoke advisory engagements.
For detailed analysis of this topic, please visit the official page: Consumer Electronic Battery Management System Bms Chip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Intelligent Fire Emergency Lighting Market to Grow from USD 3,450 Million in 2025 to USD 6,107 Million by 2032 at an 8.5% CAGR
By PW Consulting, 2026-07-13
Intelligent Fire Emergency Lighting and Evacuation Indication Systems: Strategic Imperatives for 2026 — PW Consulting Market Preview
PW Consulting today releases a strategic preview of our upcoming market research on the Intelligent Fire Emergency Lighting and Evacuation Indication System market. As organizations prepare procurement, product, and regulatory strategies for 2026, this analysis synthesizes multi-year market trajectories, regulatory inflection points, technology adoption vectors, and competitive dynamics to inform C-suite and business unit decision-making. The full report contains the confidential segment-level datasets and vendor scorecards referenced below; this preview highlights the operationally relevant insights while deliberately withholding detailed revenue splits to drive direct engagement with the source report.
Intelligent Fire Emergency Lighting And Evacuation Indication System Market
Market trajectory at a glance
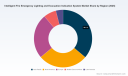
The market for intelligent fire emergency lighting and evacuation indication systems has transitioned from steady recovery into structurally accelerated adoption. Our baseline shows market size rising from approximately USD 2,348 Million in 2020 to about USD 3,450 Million in 2025. Under our central forecast, the market continues to expand through the coming decade, reaching roughly USD 6,107 Million by 2032 — representing a compound annual growth rate (CAGR) in the forecast window. This growth reflects converging forces: stricter safety standards, broader adoption of adaptive escape lighting and positioning technologies, and increasing integration of emergency illumination with building management, fire alarm and communications systems.
Intelligent Fire Emergency Lighting And Evacuation Indication System Market
Why this matters for 2026 decisions
- Budgeting and CapEx prioritization: Facilities and infrastructure owners should assume elevated baseline investment in intelligent emergency lighting through 2026 as compliance cycles and retrofit programs accelerate. Early alignment of budgets with multi-year upgrade pathways reduces disruption and secures preferential procurement terms.
- Product roadmap alignment: Manufacturers and OEMs must prioritize features that regulators now explicitly recognize — adaptive lighting, automatic self-test and reporting capabilities, and personnel-positioning interfaces — to avoid product obsolescence in multiple major markets.
- Channel and partner strategy: Integration with fire detection, voice evacuation and BMS platforms is becoming table stakes. Strategic partnerships with established fire-system integrators and property-management software vendors will materially shorten sales cycles in 2026.
- M&A and investment screening: The market concentration data indicates room for consolidation and regional champions. Investors should focus on targets that combine hardware competence with software and certification capabilities.
Key trends driving the market
- Adaptive and dynamic evacuation solutions: Adaptive escape lighting that responds to incident conditions and directs occupant flow is moving from niche to normative in major jurisdictions. This creates demand for centralized control architectures and intelligence at the luminaire level.
- Integration and interoperability: Buyers increasingly demand turnkey solutions that integrate emergency lighting with fire alarms, voice alarm systems, access control and building management to enable coordinated evacuations and post-event analytics.
- Digitalization and self-testing: Automated testing, remote reporting and predictive maintenance — often cloud-enabled — are shifting service models from time-based maintenance to condition-based operations, reducing lifecycle cost and improving compliance evidence.
- Positioning and personal safety features: Bluetooth-based personnel positioning and wayfinding functions are now recognized in several regulatory and standards updates, creating new use cases for occupant-level guidance and rescue coordination.
- Energy and LED performance: Advances in LED efficiency and battery technology continue to improve lumen output, runtime and lifecycle cost, accelerating replacement of conventional emergency luminaires in retrofit cycles.
Regulatory inflection points and compliance timing
Regulatory momentum is a central near-term driver. Several recent updates materially affect product specifications, certification pathways and the timeline for compliance:
Intelligent Fire Emergency Lighting And Evacuation Indication System Market
- National certification rules in certain markets now expand the scope of mandatory certification for emergency lighting distribution equipment, and introduce explicit expectations for Bluetooth-based functions, personnel positioning, and enhanced self-test capabilities. Compliance calendars set conversion deadlines that create a finite window for suppliers and systems integrators to certify legacy product lines.
- European standards have been revised to incorporate luminous and functional requirements for adaptive escape lighting and related safety signage, with national conflicting standards scheduled for withdrawal on a defined timeline. Suppliers targeting cross-border sales must map these transitions into product design and documentation plans.
- Standards strengthening in areas such as risk assessment, documented design and periodic illuminance measurement raise the bar for professional services and testing providers. This expands serviceable revenue streams for vendors who can offer certified test and maintenance programs.
Competitive landscape: who matters and why
The space is a mix of large multinational systems integrators, specialized EU/UK innovators, and regional manufacturers. Market concentration metrics indicate a landscape where top-three vendors hold a meaningful but not dominant share, with wider opportunity for regional champions and specialized suppliers. The following firms illustrate the different strategic archetypes operators and investors should consider:
- Siemens (Munich, Germany) — Established systems integrator delivering high-performance intelligent emergency lighting and evacuation guidance integrated tightly with fire alarm ecosystems. Strength: end-to-end building systems integration and global service capability. ( https://www.siemens.com)
- Honeywell (Charlotte, NC, USA) — Offers intelligent detection and life-safety platforms with integrated emergency lighting capabilities for connected buildings. Strength: deep channel and enterprise building relationships. ( https://buildings.honeywell.com)
- Eaton (Dublin, Ireland) — Known for adaptive evacuation central battery systems and control panels enabling dynamic evacuations linked to fire and voice systems. Strength: power systems and resilient design expertise. ( https://www.eaton.com)
- Mircom (Concord, Ontario, Canada) — Integrates emergency lighting within broader fire detection and life-safety portfolios, emphasizing North American market needs. ( https://mircom.com)
- Evaclite (United Kingdom) — Specialist in dynamic exit signage and adaptive evacuation indication systems with strong product innovation in directional guidance. ( https://evaclite.com)
- Leading Chinese suppliers (examples) — Several China-based manufacturers provide complete centralized control solutions and have been active in certification and volume markets; they are increasingly relevant for global sourcing strategies.
- Technical-specialist vendors (Advanced, Orena, Sanjiang, Beijing Mingri) — These companies offer targeted products (addressable automatic test systems, rechargeable luminaires, centralized control with testing capabilities, integrated monitoring) that form the modular pieces of larger integrated solutions.
For procurement teams the implication is clear: route-to-market and installed-base service capability matter as much as unit-cost. Systems that can be integrated into existing alarm and building management layers reduce time-to-value and compliance risk.
What the PW Consulting report contains (practical, actionable deliverables)
The full PW Consulting market study is structured to enable direct operational execution across procurement, product, regulatory, and M&A decisions. Key deliverables include:
- Macro market sizing and seven-year forecast with scenario analysis and sensitivity to regulation, technology adoption, and macroeconomic variables (note: detailed segment revenue tables and geographic/application splits are available in the report appendix).
- Vendor scorecards and capability matrices that assess product breadth, integration capability, channel reach, and certification readiness.
- Compliance playbooks aligned to the latest standard updates — including technical checklists, testing regimens, and documentation templates to accelerate certification and audit readiness.
- Procurement playbooks and TCO models that compare centralized vs. decentralized architectures, retrofit vs. new build economics, and the impact of remote-monitoring service contracts.
- Go-to-market roadmaps for vendors and integrators — prioritizing segments and channel strategies to maximize 2026 growth while balancing certification investment.
- M&A and investment heatmaps identifying bolt-on capabilities, regional consolidation targets, and strategic partnership opportunities.
How to use this intelligence in 2026
- For facility owners/operators: Launch compliance gap assessments now that map existing systems to forthcoming standards; prioritize pilot deployments of adaptive evacuation solutions in high-occupancy assets to validate operations and occupant behavior assumptions.
- For OEMs and suppliers: Accelerate firmware and interoperability roadmaps to meet adaptive lighting, self-test and personnel-positioning expectations; secure certifications in priority markets ahead of the enforced conversion deadlines to protect revenue.
- For system integrators and channel partners: Expand managed-services capabilities around automated testing, reporting and predictive maintenance; these will become differentiators in long-term service contracts.
- For investors and acquirers: Prioritize targets with proven certification programs, software-enabled service revenue, and flexible manufacturing that can scale into retrofit demand waves.
Recent regulatory and standards milestones to watch
- National certification updates in major markets now require broader product scope and include new functional expectations such as Bluetooth-enabled positioning and enhanced self-test capabilities; transitional timelines impose a hard deadline for certificate conversions.
- European standard revisions now codify adaptive escape lighting performance and luminous requirements, with a defined withdrawal schedule for conflicting national standards. Parallel updates to national codes are already in process in several jurisdictions.
- Standards strengthening around design documentation and periodic illuminance verification will increase demand for third-party testing and certified maintenance programs.
Conclusion — a decision point for 2026
2026 is not simply another planning year — it is a decision point. The convergence of regulatory tightening, functional evolution toward adaptive, networked solutions, and an evolving competitive map creates both risk and optionality. Organizations that treat emergency lighting and evacuation indication as an integrated safety and digitalization initiative will capture efficiency, compliance and resilience benefits. Conversely, delayed response to certification timelines and interoperability expectations will create retrofit cost waterfalls and contractual exposure.
PW Consulting’s full report provides the granular segmentation, regional and application breakouts, vendor rankings, and financial models needed to operationalize these insights. For procurement-ready matrices, certification playbooks and the complete data tables that underpin these strategic recommendations, please refer to the full report on our website or contact PW Consulting directly for enterprise licensing and bespoke advisory engagements.
For detailed analysis of this topic, please visit the official page: Intelligent Fire Emergency Lighting And Evacuation Indication System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Solid-State Cooling Market Set to Hit USD 2,019.32 Million by 2032, Growing at a 12.48% CAGR
By PW Consulting, 2026-07-13
Solid State Cooling Market: Strategic Imperatives for 2026 — PW Consulting Release
As organizations across electronics, healthcare, automotive and industrial verticals reassess their thermal management roadmaps for 2026, PW Consulting’s new Solid State Cooling Market report delivers the pragmatic intelligence leaders need to translate technological promise into executable strategy. Built on a rigorous historical baseline (2020–2025), scenario modelling for 2026–2032 and primary company interviews, the study synthesizes market trajectories, competitive positioning, technology inflection points and actionable go-to-market playbooks designed for boards, corporate strategy teams and investors.
Solid State Cooling Market
Why 2026 Is a Decision Point
Solid-state cooling is moving from niche to selective scale. Our market model — expressed in constant USD (millions) — shows a pronounced expansion from the 2020 baseline through 2025 and into the forecast window: the market more than doubles on the 2020 base by the end of the 2032 horizon under our central scenario, driven by an expected compound annual growth rate of 12.48% across 2026–2032. That pace reflects converging forces: tightening regulations on traditional refrigerants, accelerating demand for compact, vibration-free thermal solutions in sensitive electronics and medical applications, and fresh material-science breakthroughs that may materially alter device efficiency curves.
Solid State Cooling Market
What the Report Contains — Practical, Executable Insight
- Proprietary market sizing and scenario modelling: annualized market values and stress-tested trajectories calibrated to multiple adoption pathways through 2032.
- Technology roadmaps and performance benchmarks: comparative thermal metrics, projected efficiency gains, and sensitivity analysis tied to material innovations.
- Supply-chain and raw-material risk heatmaps: inputs, sourcing concentration and mitigation levers for critical components such as thermoelectric semiconductor materials.
- Commercial playbooks: segment-specific go-to-market strategies, pricing frameworks and channel models for OEMs, module suppliers and systems integrators.
- Competitive intelligence and M&A landscape: vendor scorecards, capability matrices and scenarios for consolidation and partnership.
- Regulatory and standards matrix: implications of refrigerant phase-downs, ASHRAE guidance and IEC compliance on product design and market access.
- Case studies and pilot evaluation templates: eight real-world deployments across data center, medical refrigeration and precision industrial control, with measurable KPIs and NPV-style investment tests.
We intentionally present high-level, actionable frameworks in this release; the report contains the granular segmentation tables, vendor-level revenue splits and unit economics required for transaction diligence and program budgeting.
Solid State Cooling Market
Competitive Landscape — Leaders, Challengers and Strategic Gaps
The solid-state cooling domain remains a mixture of specialized incumbents, system integrators and emerging materials innovators. Market concentration is moderate: the top three players capture a meaningful but not dominant share (CR3 ~38.4%), with the top five together representing just over half of the market (CR5 ~52.2%). That structure creates both competitive stability at scale and opportunities for targeted disruption.
- Ferrotec Holdings Corporation (Japan) — a major manufacturer of thermoelectric modules and assemblies. Ferrotec’s scale and vertical integration in module manufacturing give it a core advantage in industrial and medical OEM channels, particularly where supply security and custom assembly expertise are critical.
- Coherent Corp. (United States) — with legacy assets from II‑VI Marlow, Coherent brings precision thermal management expertise that aligns with high-reliability electronics and laboratory applications. Their strength is in engineered thermal solutions rather than commodity modules.
- Laird Thermal Systems (United States) — known for thermoelectric coolers and integrated systems, Laird is well positioned to capture demand where packaged solutions and speed-to-market matter most.
- Phononic, Inc. (United States) — focused on solid-state refrigeration systems for electronics, data centers and cold chain; highlights the category’s move beyond component sales to system-level solutions.
- Delta Electronics, Inc. (Taiwan) — a large power and thermal management player integrating solid-state cooling into broader systems, signaling an industrialization route for the technology.
- Specialists and regional producers — companies such as Solid State Cooling Systems, TECA, TE Technology, CUI Devices, Kryotherm, RMT and several other regional suppliers maintain important positions in recirculating chillers, lab equipment and bespoke industrial cooling. Their agility and niche focus make them preferred partners for pilot projects and customized applications.
Collectively, the competitive picture points to a two-track market: a consolidating layer of scaled module and system providers focused on data center, healthcare and automotive electrification; and a diverse field of niche vendors serving specialized laboratory, instrumentation and industrial segments. For buyers and investors, the strategic question is which track aligns with their required time-to-market, risk tolerance and margin profile.
Technology and Material Inflection — The CHESS Disruption
One of the most consequential inputs to our 2026 advisory is the emergence of nano-engineered thin-film thermoelectric materials. In mid-2025, the Johns Hopkins Applied Physics Laboratory (APL) publicized CHESS thin-film materials that, in laboratory refrigeration testing with a major industry partner, nearly doubled the efficiency of commercial solid-state cooling devices. The development was subsequently validated with a high-profile award later that year.
Strategic implications are immediate:
- Efficiency improvements accelerate use-case expansion: higher COP (coefficient of performance) can make solid-state solutions competitive in higher-capacity applications previously dominated by vapor-compression systems.
- IP and licensing become choke points: firms with early access to, or licenses for, next-generation materials will enjoy a multiyear window to capture premium segments.
- Supply-chain reorientation: thin-film processes may reduce reliance on bulk bismuth telluride for some configurations, but broader adoption still depends on scale-up, manufacturability and thermal interface engineering.
Our full report maps plausible adoption timelines for next-gen materials and quantifies the sensitivity of market size and margin expansion to these technology milestones — a critical input for R&D portfolio prioritization in 2026.
Regulatory and Standards Context
Two policy and standards themes underpin the sector’s near-term acceleration: regulatory pressure on HFC refrigerants and tightening environmental, safety and performance standards in electronics cooling. Industry norms such as ASHRAE thermal guidelines for high-density electronics, and compliance with IEC laboratory safety standards, shape allowable architectures and verification protocols for product certification. PW Consulting’s regulatory matrix aligns these rules with design constraints, providing product teams with an actionable compliance-to-market timeline.
Strategic Playbook for 2026
Executives and investors must translate the market trajectory and technology inflection into prioritized bets. Our recommended 2026 agenda, drawn from the report’s executive playbooks, includes:
- Portfolio triage: identify which product lines and markets will benefit most from incremental efficiency gains versus those that require step-change materials breakthroughs.
- Partnerships and licensing: pursue selective material-IP partnerships and early licensing to secure performance advantages without shouldering full-scale manufacturing risk.
- Hybrid system development: invest in engineering hybrid architectures that combine solid-state modules with conventional refrigeration to unlock interim use cases and lower total cost of ownership.
- Supply resilience: implement raw-material sourcing plans and dual-sourcing contracts for critical thermoelectric inputs while exploring thin-film suppliers as hedges.
- M&A scouting: target complementary module manufacturers, systems integrators and thermal interface specialists to accelerate time-to-market and capture value across the stack.
- Pilot-first commercialization: use staged pilots in high-value segments (medical, precision lab, data center) to build references, optimize thermal management software and validate total-cost models.
Decision-Quality Outputs for 2026 Planning
Boards and strategy teams will find the report particularly valuable for three planning functions: capital allocation (R&D and M&A sizing), commercial go-to-market design (pricing, channel and partner economics), and risk management (supply chain and regulatory stress-testing). We provide modular tools — including a customizable NPV template, thermal-performance sensitivity tables and a vendor negotiation checklist — to move from insight to procurement and engineering decisions within 60–90 days.
Next Steps
PW Consulting’s Solid State Cooling Market report is designed as an active decision support asset for 2026. This press release highlights the analysis framework, high-level market trajectory and strategic recommendations; the full report contains the granular segmentation, vendor scorecards and financial models required for transaction-level diligence and program execution. For teams preparing budgets, R&D roadmaps or M&A pipelines for 2026, the report is the operational intelligence you should base your first-mover, fast-follow or defensive play on.
Contact PW Consulting or visit our Solid State Cooling Market research page to request the full dataset, vendor benchmarking annex and executive briefings tailored to your organization’s role in the value chain.
For detailed analysis of this topic, please visit the official page: Solid State Cooling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 8.75% CAGR for Networked Pulse Oximeter Market in 2026–2032
By PW Consulting, 2026-07-13
Networked Pulse Oximeter Market: Strategic Imperatives for 2026
As PW Consulting’s senior strategy advisor and chief industry analyst, I present a concise, actionable briefing drawn from our new Networked Pulse Oximeter Market report. The connected oximetry market is moving from early adoption to structural deployment across acute and home settings. Our baseline analysis places the market at USD 1,150.8 Million in 2025, with a compound annual growth rate (CAGR) of 8.75% over the 2026–2032 forecast period, driving the market toward a multi‑billion dollar opportunity by 2032. This brief outlines the strategic implications for executives preparing budgets, product roadmaps, regulatory strategies, and partnerships in 2026 — while reserving the granular segment-level intelligence for the full report.
Networked Pulse Oximeter Market
Why 2026 is an Inflection Year
-
Regulatory tightening and clearer guidance: The FDA’s January 2025 draft guidance on pulse oximeters — which elevates expectations around non‑clinical and clinical performance testing, inclusive skin pigmentation studies, and labeling — raises the bar for medical-grade connected devices. Manufacturers who align their R&D and regulatory pathways now will avoid costly rework and accelerate time-to-market in 2026.
Networked Pulse Oximeter Market -
Reimbursement tailwinds: Remote patient monitoring (RPM) coding and reimbursement updates through CMS (2025–2026), including new short‑term reading codes, materially improve the payback profile for networked oximetry programs. Health systems and device-makers that can demonstrate automated data uploads and clinical workflow integration will be first to capture payer-aligned use cases.
Networked Pulse Oximeter Market -
Technology convergence: Bluetooth, Wi‑Fi and cellular connectivity, combined with low‑power wearable form factors and cloud analytics, are enabling continuous, networked SpO2 monitoring across settings. The commercialization cadence in 2024–2025 (new product launches and clearances) signals that 2026 will shift from pilots to scaled deployments.
Market Dynamics Executives Must Prioritize
-
Clinical performance and equity: Expect buyers and regulators to demand robust clinical validation across diverse skin tones and physiologic states. Investment in controlled desaturation studies and transparent labeling is no longer optional; it is a market entry ticket.
-
Interoperability and cybersecurity: Compliance with IEC 60601‑1‑2 EMC standards plus FDA cybersecurity expectations should be baked into design and premarket dossiers. Interoperability with hospital information systems (HIS), EHRs, and RPM platforms will be a decisive procurement criterion.
-
Operational and commercial models: Vendors must present not only device performance but also deployment playbooks — logistics for device provisioning, cellular or Wi‑Fi management, clinical escalation pathways, and billing workflows to capture RPM revenues.
-
Consolidation pressure and competitive concentration: The market exhibits a moderate level of concentration among the top vendors. Strategic partnerships, selective acquisitions, and OEM/ODM arrangements will continue to shape who controls clinical workflows versus who supplies sensing components.
Competitive Landscape — How Leading Players Are Positioning
-
Masimo Corporation — Continues to leverage its clinical-grade sensor platforms and wireless PPG offerings, extending into wearable ecosystems and partnerships to broaden reach across acute and ambulatory care. Expect continued emphasis on proprietary signal processing and multi‑parameter integration as differentiators.
-
Medtronic (Nellcor) — Maintains strength in bedside and integrated monitoring, reinforcing presence in acute care networks where established clinical trust matters. Integration into central monitoring systems remains a core advantage.
-
Koninklijke Philips — Focused on modular sensor components and enterprise integrations that connect oximetry data into broader digital health platforms and hospital IT investments. Partnerships and platform playbook choices will drive adoption among health systems.
-
GE HealthCare — Pursuing wearable and wireless backbones that integrate into enterprise monitoring and EHR workflows; strategy emphasizes breadth of clinical device portfolio plus software analytics.
-
Nonin Medical — Strengthening connected consumer‑grade and clinical fingertip offerings with targeted accuracy claims and app ecosystems to serve both OTC and telehealth channels.
-
Nihon Kohden — Reinforces hospital-centric monitoring, focusing on sensor reliability and compatibility with central station monitoring architectures prevalent in Asia and regions with legacy monitoring infrastructure.
-
Contec Medical and Shenzhen Viatom — Chinese producers are scaling Bluetooth‑enabled devices and obtaining incremental regulatory clearances to expand into Western markets; their trajectory is toward cost‑competitive connected devices for telehealth and value care programs.
-
Prevounce Health and OxiWear — Emerging innovators targeting specific remote monitoring niches: cellular‑connected standalone devices and ear‑worn continuous oximetry, respectively. These form factors and connectivity models can disrupt traditional device-to-workstation paradigms.
Recent Developments Shaping 2026 Decisions
-
FDA regulatory guidance (Jan 2025) clarifying testing expectations and labeling requirements for diverse skin pigmentation — impacting device validation plans and clinical study designs.
-
Notable market entries and clearances in 2024–2025, including new cellular and ear‑worn devices and multiple FDA 510(k) clearances, that broaden form factor choices for RPM and continuous monitoring programs.
-
CMS reimbursement updates extending RPM CPT codes and introducing a short‑period readings code in 2026 — creating new revenue levers for providers deploying automated oximetry data capture.
-
Regulatory emphasis on EMC and cybersecurity conformity for wireless devices, accelerating demand for security-by-design and validated communication stacks.
Strategic Playbook — Immediate Actions for 2026
-
Manufacturers: Prioritize robust clinical validation programs aligned with FDA recommendations and ISO standards; package regulatory readiness with interoperability and cybersecurity evidence to shorten procurement cycles.
-
Health systems & IDNs: Pilot cellular and Bluetooth models in RPM pathways that map to updated CPT reimbursement; insist on turnkey operational plans (device lifecycle, patient onboarding, escalation protocols) in vendor RFPs.
-
Payers: Define evidence thresholds for reimbursement that include automated data ingestion, clinical escalation outcomes, and health equity measures. Consider coverage pilots tied to value-based contracts.
-
Investors & M&A teams: Target assets that combine validated sensing technology with software platforms enabling chronic care management and billing automation. Pay special attention to firms with cleared form factors (ear, wearable, cellular) and demonstrated clinical integrations.
-
Technology partners & integrators: Build secure, standards‑based middleware that solves data normalization (SpO2, pulse rate, device metadata), low latency alerting, and audit trails required by both clinicians and regulators.
What PW Consulting’s Report Delivers
-
Proprietary market sizing and forecast models (2020–2032) that quantify the macro opportunity and sensitivities under alternative regulatory and reimbursement scenarios.
-
Vendor scorecards and a competitive action matrix that evaluates technology, regulatory readiness, go‑to‑market capability, and strategic fit for OEM, enterprise and consumer channels.
-
Operational playbooks for scaled RPM deployments, including device provisioning, connectivity management (cellular + Bluetooth + Wi‑Fi), clinical escalation templates, and billing workflows aligned to CPT coding changes.
-
Regulatory and compliance toolkit: checklists for FDA premarket submissions, IEC/EMC and cybersecurity evidence, and labeling that addresses performance across diverse populations.
-
M&A and partnership heatmaps identifying high-value targets by capability and geography, plus scenario-based ROI models for tuck‑ins versus greenfield development.
Using the Report to Inform 2026 Budgets and Roadmaps
Executives preparing 2026 plans should use the report to: align R&D and clinical validation spend to regulatory timelines; sequence product launches that combine validated sensing with interoperability and cybersecurity credentials; design commercial pilots tied to RPM reimbursement mechanics; and prioritize partnerships that complement in‑house strengths. The report’s sensitivity runs and scenario playbooks will help CFOs and strategy leaders stress-test investment cases under conservative and accelerated adoption curves.
Final Observations
The networked pulse oximeter market is maturing into a strategically significant layer of the clinical monitoring stack. With a projected CAGR of 8.75% and the market on a trajectory to materially expand through 2032, organizations that integrate regulatory foresight, clinical validation, interoperable engineering, and pragmatic deployment models will convert technical capability into sustainable commercial advantage. Our full Networked Pulse Oximeter Market report contains the granular segmentation, regional and end‑user breakouts, and vendor-level datapoints needed to operationalize these recommendations.
For PW Consulting clients and prospective subscribers seeking the complete dataset, vendor scorecards, and tailored advisory engagements that convert this market intelligence into 2026 action plans, please visit our report page or contact our industry team for a briefing.
For detailed analysis of this topic, please visit the official page: Networked Pulse Oximeter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Lock Market to Expand at a 6.15% CAGR from 2026–2032
By PW Consulting, 2026-07-13
Lock Market 2026: Strategic Imperatives from PW Consulting’s New Market Study
Executive preview — why this report matters to decision-makers in 2026
PW Consulting’s Lock Market report (base year 2025; historical window 2020–2025; forecast 2026–2032) synthesizes market-scale modeling, competitive mapping, and practical go-to-market playbooks tailored for industrial, commercial, and residential security stakeholders. The global lock market reached an estimated USD 38,500 Million in 2025 and, under our central forecast, expands at a 6.15% compound annual growth rate (CAGR) to exceed USD 58,400 Million by 2032. These macro dynamics — combined with mounting input-cost pressures and a shifting competitive topology — make the report an operational tool for procurement chiefs, product heads, M&A teams, and public-sector buyers planning for 2026 and beyond.
Lock Market
Headline market signals
- Structural growth, but uneven conversion: After a recovery phase through 2024–2025, the market enters a consistent mid-single-digit CAGR period to 2032. Adoption of digital and electromechanical access systems is an important growth engine, but mechanical solutions remain resilient across many end markets.
- Fragmented supply base: Market concentration remains low—our CR3 is 18.5% and CR5 is 25.4%—indicating opportunities for consolidation as well as room for specialized niche players to capture premium pockets of demand.
- Cost and trade shocks are material: Elevated tariffs on steel and aluminum (including a U.S. Section 232 increase to 50% in mid‑2025) and new import measures affecting North American supply chains have materially raised procurement risk and compressed margins for incumbents that rely on commodity metals.
- M&A and portfolio reshaping are accelerating: Strategic bolt‑on acquisitions—especially in high‑security and electromechanical segments—are being prioritized by large OEMs seeking to broaden technology stacks and route-to-market.
What’s in the report — practical deliverables for 2026 action
The study is designed as an executive playbook, not an academic exercise. Key operational components include:
Lock Market
- Top-line market modeling (historical 2020–2025, base year 2025) and scenario forecasts (2026–2032) with sensitivity testing for raw-material shocks and policy shifts.
- Competitive heat maps and strategic profiles for the leading OEMs and challengers, with acquisition overlays and capability matrices to support partner selection and M&A screening.
- Channel and commercial playbooks: pricing levers, retrofit vs. new‑build go‑to-market strategies, and a modular partner model for system integrators and value-added resellers.
- Procurement & supply-chain checklist: sourcing alternatives, near‑shoring decision matrix, and hedging recommendations tuned to metal-price volatility and tariffs.
- Technology adoption roadmap: product and services blueprints for migrating customers from mechanical to electromechanical and connected access systems while mitigating cybersecurity and regulatory risk.
- Deal flow and valuation appendices: comparable-transactions framework, synergy templates, and an anonymized short list of targets and partners suitable for strategic buyers and private equity.
Competitive landscape — who matters and why
The market is populated by a mix of global platform players, regional champions, and specialized security houses. The report’s competitive section does not simply rank suppliers by size; it evaluates strategic moats, channel reach, product breadth, and integration risk. Highlights:
Lock Market
- Global platform leaders: Long-established multinational groups are leveraging scale to combine mechanical, electromechanical, and digital offerings into bundled enterprise solutions. These incumbents are the default choice for customers prioritizing global supply consistency and wide service networks.
- Regional and brand-centric players: Well‑known North American and APAC brands maintain strong consumer and commercial positions through retail, locksmith channels, and localized manufacturing advantage—important when tariffs and shipping costs bite.
- Specialists and high‑security houses: Niche firms focused on patented cylinders, safe locks, and government/industrial credentials are becoming prime targets for acquisitions by platform players seeking to add certified high‑security capabilities quickly.
Recent market activity underscores these dynamics. A case in point: the integration of an established high‑security lock specialist into a global group in late 2025–early 2026 has accelerated consolidation in certified security segments and creates new cross‑sell opportunities within institutional and government channels. For buyers and investors, this validates a two-track strategy: (1) scale through platform consolidation of complementary technologies; and (2) defend margins by owning premium, patented product lines that command structural price protection.
Regulatory and input-cost headwinds — operational implications
Three near-term themes require active mitigation planning in 2026:
- Tariff risk and sourcing flexibility: Tariff increases and trade measures introduced in 2025 disproportionately impact lock makers that source heavy-gauge steel or import finished locksets. The report’s procurement playbook maps practical near‑term actions: dual-sourcing, regional manufacturing pivots, and contract clauses for pass‑through pricing.
- Raw-material volatility: Steel price swings increase working capital needs and inventory risk. We outline inventory hedging strategies and just‑in‑time vs. just‑in‑case sourcing tradeoffs for different product families.
- Certification and procurement policy: Government and institutional tenders are increasingly looking for certified, traceable supply chains. Firms that can rapidly demonstrate chain-of-custody, anti-counterfeit measures, and compliance with procurement regimes will gain a procurement premium.
Technology and product strategy — seize the transition
The shift toward electromechanical and connected access is both a growth lever and an operational challenge. The report provides an action framework for 2026 that includes:
- Product roadmaps balancing legacy mechanical offerings (serviceable, price-sensitive) with higher-margin smart-lock systems (subscription and software revenue potential).
- Integration templates for cybersecurity hardening, lifecycle software updates, and cloud/on-premise hybrid deployment options demanded by enterprise and government buyers.
- Aftermarket and services monetization models: managed access services, retrofit kits, and long-term maintenance contracts that smooth cyclicality and increase customer lifetime value.
Dealmaking and capital allocation — where to place bets in 2026
Given a fragmented market and mid-single-digit CAGR tailwinds, our advisory view for boards and private investors centers on three portfolio plays:
- Buy-and-build in high-security niches: Acquire certified specialist firms to obtain IP, channel trust, and contract stickiness in government and critical infrastructure markets.
- Scale digital offerings through partnerships: Pursue strategic tie-ups with cloud and cybersecurity vendors to accelerate time-to-market for connected access platforms while preserving manufacturing independence.
- Operational resilience investments: Allocate capital to regional manufacturing and inventory flexibility to protect margins from tariff shocks and metal-price volatility.
Practical recommendations for 2026 decision-makers
- Prioritize a supply‑chain stress test in Q1 2026 that models tariff, shipping, and steel‑price scenarios; implement rapid contingency actions for single‑source components.
- Accelerate product modularization so mechanical and electromechanical components can be mixed-and-matched without long redesign cycles—this reduces time-to-revenue for retrofit opportunities.
- Formalize an M&A screening funnel focused on patented high‑security technologies, cloud‑native access management, and regional manufacturing platforms.
- Invest in service capabilities and recurring-revenue offers (managed access, software subscriptions) to soften capital spending cyclicality among OEM customers and landlords.
- Engage proactively with procurement authorities and certification bodies to shape standards that favor traceable, anti‑counterfeit manufacturing and secure update channels.
How to use the PW Consulting report
This release is a strategic preview intended to orient boards, executive teams, and investors. The full PW Consulting Lock Market report provides the granular segmentation, channel breakouts, and scenario spreadsheets necessary to execute the recommendations above. In keeping with our “trailer” approach, we intentionally reserve proprietary sub‑segment percentages and granular regional/application-level figures for the full publication—these are provided with source data, spreadsheets, and an implementation workbook to buyers of the report.
Final note — timing and next steps
2026 is a year of choices: react defensively to input-cost and tariff pressure, or act offensively to capture long-term value from digitalization and consolidation. PW Consulting’s Lock Market report equips leaders with modeled outcomes, prioritized initiatives, and executable templates to make those choices with confidence. For teams that want immediate tactical support, we offer advisory sprints to operationalize procurement resilience, product roadmaps, and M&A diligence informed by the study’s confidential annexes.
To access the full study, scenario files, and the implementation workbook, please consult PW Consulting’s Lock Market report page or contact our industry practice for a briefing and customized executive summary tailored to your strategic priorities.
For detailed analysis of this topic, please visit the official page: Lock Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Kraft Paper Bag Market to Expand at 5.45% CAGR Through 2032 Amid Asia‑Pacific Demand Surge
By PW Consulting, 2026-07-13
Kraft Paper Bag Market — Strategic Imperatives for 2026
Executive snapshot
As global packaging strategies pivot toward circularity and regulatory accountability, the kraft paper bag market is moving from niche sustainability signaling to core packaging strategy. PW Consulting’s latest market study finds that the industry has expanded materially over the past half-decade, rising from an estimated USD 4,850.3 million in 2020 to roughly USD 6,080.0 million in 2025. Our baseline forecast projects the market to reach approximately USD 6,478.8 million in 2026 and to continue growing at a compound annual growth rate (CAGR) of 5.45% through the 2026–2032 forecast window, reaching an estimated USD 8,815.2 million by 2032.
Kraft Paper Bag Market
Why 2026 is a pivotal planning year
-
Regulatory inflection points are changing economics. Expanded Extended Producer Responsibility (EPR) schemes in multiple U.S. states and evolving EU packaging regulations are accelerating cost internalization for producers and favoring recyclable, fiber-based alternatives.
Kraft Paper Bag Market -
Raw material volatility and cost dynamics are re-shaping supplier strategies. Recent market readings (e.g., kraft pulp prices and producer price indices for unbleached kraft paper) are increasing the premium on procurement agility and cost pass-through mechanisms.
Kraft Paper Bag Market -
Supply-side capacity and technology investments are concentrated among established global players — creating opportunities for strategic partnerships, regional capacity plays, and premium product differentiation.
What this means for corporate decision-makers
For industrial manufacturers, retailers, private equity investors, and packaging OEMs, 2026 is the year to convert sustainability positioning into resilient commercial advantage. The market’s steady CAGR underlines predictable, investable demand; however, return on capital will depend on how organizations align three vectors: cost-to-serve, regulatory compliance readiness, and product differentiation.
-
Procurement and raw-material hedging — Build actionable scenarios around kraft pulp price volatility and domestic pulp availability. Short-term contracts and regional supplier diversification reduce exposure, while longer-term offtake agreements can secure feedstock for premium, certified product lines.
-
Product strategy — Prioritize product architectures that simplify downstream recycling streams and meet evolving recyclability criteria. Demand is increasingly bifurcating between commodity industrial sacks and value-added, engineered kraft solutions for retail and e-commerce.
-
Operations and capacity planning — Evaluate capital allocations between retrofit upgrades (to add recycled-content compatibility and barrier-free coatings) and greenfield capacity in growth corridors. Recent facility investments by major players demonstrate continued appetite for capacity expansion tied to e-commerce and industrial logistics.
-
Regulatory compliance and extended producer responsibility — Anticipate compliance costs and reporting obligations; embed EPR impact into product pricing models, and use design-for-recycling to mitigate future fees and brand risk.
Market dynamics — drivers and near-term headwinds
Our analysis identifies five principal dynamics shaping the kraft paper bag market in 2026:
-
Policy-driven demand elasticity: Packaging regulations in EU and U.S. markets are lifting the relative appeal of fiber-based solutions and creating downstream incentives for recyclable primary packaging.
-
Cost trajectory and feedstock tightness: Market indicators point to elevated kraft pulp pricing and producer price index pressure for unbleached kraft paper, making cost management a strategic priority for low-margin bag products.
-
Consolidation vs. specialization: Market concentration metrics show a moderately fragmented landscape at the global level, with the top few firms holding meaningful but not dominant shares — a structure that favors both scale plays and specialist challengers.
-
Customer segmentation evolution: End-users are demanding higher performance (moisture resistance, tamper evidence) alongside better environmental profiles; suppliers who can deliver certified and engineered solutions will capture premium pockets of demand.
-
Supply chain resilience: Logistics cost variability and regional capacity investments are driving nearshoring and multi-hub sourcing strategies for critical customers in foodservice, retail, and industrial segments.
Competitive landscape — who to watch
The competitive field is dominated by integrated and vertically oriented players with global footprints, plus regional champions focused on service and customization. Key companies covered in our analysis include:
-
Mondi Group (Vienna, Austria; significant UK/US operations) — a global leader in sustainable packaging with high-tech kraft paper bag production and a pronounced focus on recyclable fiber solutions. Recent activity includes a new, high-capacity production facility in the U.S. designed to serve e-commerce and industrial channels.
-
International Paper (Memphis, Tennessee, USA) — one of the world’s largest renewable fiber-based packaging producers, offering an extensive suite of kraft bag formats and certified-fiber options aimed at large-scale industrial and retail customers.
-
Smurfit WestRock (Dublin, Ireland / Atlanta, Georgia, USA) — integrated paper and packaging provider combining kraft bags with corrugated and retail solutions, emphasizing scale and supply-chain integration.
-
Novolex (including Duro Bag) (Charlotte, North Carolina, USA) — a North American leader focused on certified and recycled-content kraft offerings, with strong presence in foodservice and retail channels.
-
Billerud (Solna, Sweden) — specialist in high-quality kraft papers and engineered paper bag solutions with a strong sustainability narrative built into product R&D.
-
DS Smith (London, UK) — significant European footprint focused on circular economy design and supply-chain optimization for paper-based packaging.
-
Georgia-Pacific LLC (Atlanta, Georgia, USA) — integrated pulp and paper producer with capabilities across kraft paper and bag production for industrial customers.
-
ProAmpac (Cincinnati, Ohio, USA) — flexible packaging specialist offering custom kraft bag solutions, often positioned as a technical partner for brand owners.
-
Ronpak (USA) — regional supplier with strong service orientation for retail and foodservice paper bag requirements.
-
Oji Holdings Corporation (Tokyo, Japan) — large Japanese paper and packaging manufacturer with global export capabilities and technology transfer across markets.
Recent developments with strategic relevance
-
Mondi Group’s April 2026 opening of a state-of-the-art paper bag facility in the U.S. highlights both the role of capacity expansion to serve e-commerce and the premium placed on proximity to key logistics hubs.
-
Billerud’s 2025 sustainability reporting underscores continuous product innovation in fiber-based packaging — a pattern likely to accelerate as brands pursue verified environmental claims.
-
Policy movements (EU packaging rules and expanding U.S. EPR laws) and commodity signals (e.g., kraft pulp price and producer price index levels) collectively increase the value of regulatory foresight, certified supply chains, and recyclable product credentials.
What PW Consulting’s report delivers — practical contents
Our study is structured to move beyond description into decision-ready analysis. The report includes:
-
Market sizing and top-line forecasting with scenario analysis that captures regulatory, raw-material, and demand shocks;
-
Supply-chain and cost-to-serve modeling (including sensitivity to pulp pricing and converting equipment utilization);
-
Commercial segmentation frameworks and customer-value maps to prioritize SKU rationalization and channel strategies (note: detailed segment-level datasets and regional/application splits are reserved for the full report);
-
Competitive intelligence dossiers and capability heat maps for leading suppliers, with actionable M&A and partnership screens;
-
ESG and compliance playbooks — readouts on EPR readiness, recyclability design guidance, and certification pathways;
-
Investment decision tools — capex prioritization matrices, break-even analyses for retrofit vs. new-build, and go-to-market playbooks for premium kraft offerings.
How to use this intelligence in 90/180/360-day planning
-
90 days — Run a cost-exposure assessment to pulp and processing inputs; secure short-term supply deals where volatility is high; update sustainability claims and labeling to reflect regulatory requirements in priority markets.
-
180 days — Align product roadmaps to recyclable-design criteria; pilot premium engineered kraft bag SKUs with select retail and e-commerce customers; begin supplier consolidation or diversification as dictated by cost curves.
-
360 days — Execute targeted capacity investments or M&A based on validated demand clusters; embed EPR cost models into pricing and commercial contracts; formalize long-term feedstock strategies (recycled content procurement, certified fiber agreements).
Final perspective — where returns will accrue
Between now and 2032, the value in the kraft paper bag market will be captured by players who can combine certified, traceable raw-material sourcing with manufacturing agility and regulatory foresight. The market’s steady CAGR reflects enduring demand, but margin expansion will hinge on premiumization, operational efficiency, and the ability to demonstrate credible circularity. For investors and corporate strategists, the immediate task is to convert regulatory disruption and raw-material uncertainty into differentiated offerings and resilient supply chains.
Next steps
PW Consulting’s full report includes the complete segmentation datasets, company-level benchmarking, and downloadable models required to operationalize the insights above. For access to the comprehensive dataset, proprietary scenario models, and our bespoke advisory services to translate findings into executable roadmaps, please visit the PW Consulting report portal or contact our industry practice team.
For detailed analysis of this topic, please visit the official page: Kraft Paper Bag Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Children's Medical Equipment Market Set to Expand at a 6.95% CAGR, Driving Next‑Gen Pediatric Care
By PW Consulting, 2026-07-13
Children’s Medical Equipment Market — PW Consulting Strategic Outlook for 2026
As health systems, device manufacturers and investors plan for the post‑pandemic capital cycle, the children’s medical equipment market is a distinct growth frontier that demands a specialized strategic playbook. Our new PW Consulting market study (base year 2025, historical 2020–2025, forecast 2026–2032) shows the market continuing to expand at a steady compound annual growth rate of 6.95%. With total market value approaching the mid‑2020s landmark and multi‑year projections extending into 2032, the market’s trajectory creates immediate strategic choices for 2026 budgets, R&D roadmaps, and M&A pipelines.
Childrens Medical Equipment Market
Why this report matters for 2026 decisions
-
It translates macro momentum into decision‑grade implications: where to allocate R&D dollars, which product platforms to scale, and which go‑to‑market models will deliver margin in a more value‑driven procurement environment.
Childrens Medical Equipment Market -
It aligns regulatory and reimbursement headwinds with product development timelines so clinical evidence generation and regulatory filings are synchronized with market windows.
Childrens Medical Equipment Market -
It surfaces practical procurement and supply‑chain interventions—critical for devices that require pediatric‑specific materials and tighter quality tolerances.
-
It benchmarks competitive positioning and identifies partnership and bolt‑on acquisition targets to expand pediatric portfolios rapidly without reinventing core capabilities.
Market trajectory and strategic implications
Across the 2020–2025 historical window and into the 2026–2032 forecast, the market exhibits durable, above‑average growth driven by three structural forces: rising neonatal and pediatric service utilization in emerging markets, accelerating migration of certain therapies from inpatient to home settings, and ongoing device miniaturization enabling broader pediatric application of diagnostics and monitoring. The market’s medium‑term CAGR of 6.95% underpins a predictable runway for firms that time investment in manufacturing scale and regulatory clearance cycles appropriately.
Concentration metrics indicate a moderately consolidated supplier landscape—enough market share among leaders to set commercial standards, but with clear opportunity for challengers and focused specialists to capture share through clinical differentiation, service models, or cost leadership. This creates a favorable environment for targeted M&A or licensing plays that complement a core franchise.
Regulatory and reimbursement dynamics — immediate actions for 2026
-
Regulatory design requirements for pediatric devices are stricter and increasingly explicit. US FDA requirements under quality system regulations and human factors testing for devices intended for children (0–12 years) must shape clinical and usability programs. Companies should front‑load pediatric human‑factors studies to shorten review cycles and avoid rework.
-
Recent FDA guidance and recall history have elevated expectations for bias testing and performance across skin tones for non‑invasive monitors. Manufacturers of pulse oximetry and similar sensors must incorporate bias and diverse‑population validation into product claims and labeling to avoid disruptive market actions.
-
Reimbursement pathways remain decisive for capital procurement. Public payers continue to bundle neonatal and pediatric care under DRG constructs that influence hospital purchasing priorities. Generating procedural‑level health economics and outcomes evidence will materially accelerate hospital adoption.
Supply chain and input cost considerations
Pediatric products require tighter material and component tolerances (biocompatibility, smaller form factors), which increases exposure to raw‑material price volatility. For example, medical‑grade silicones used in pediatric catheters command a premium and are subject to certification requirements. In 2026, procurement teams should pursue dual‑sourcing strategies, long‑dated offtake agreements with key compounders, and design‑for‑supply approaches (e.g., common subassemblies across age ranges) to protect margins and launch timelines.
Competitive landscape — positioning and recent moves
The market features established global medtech leaders alongside specialized pediatric device innovators. Key strategic players demonstrate a mix of organic innovation and targeted commercial wins that are instructive for 2026 planning:
-
GE HealthCare (Chicago, IL): Continued investment in pediatric imaging with child‑centric MRI platforms and low‑dose imaging features underscores the importance of experience design and radiation stewardship in procurement decisions.
-
Philips Healthcare (Amsterdam): Portfolio moves in neonatal ventilators and infant monitoring reflect an integrated systems approach—bundling hardware, software and workflow features to lock in clinical pathways.
-
Medtronic (Dublin): Clinical program outcomes for pediatric structural heart devices signal the value of long‑term evidence generation as a commercial accelerant in high‑complexity pediatric care.
-
Draeger (Luebeck): Specialized neonatal ventilators and NICU equipment highlight the continued opportunity in critical‑care niches where device performance and clinician trust are primary buying criteria.
-
BD, Smiths Medical, Atom Medical, Natus, Masimo, Fisher & Paykel Healthcare: These firms illustrate how focused device and consumable portfolios, sensor miniaturization, and respiratory interface design are becoming essential differentiators. Recent product launches, FDA clearances and hospital contracts across these vendors confirm an active market for both innovation and procurement competition.
Recent industry developments—from pediatric MR system launches and FDA 510(k) clearances to clinical study publications and notable hospital contracts—signal a market balancing product innovation with accelerated clinical validation and health‑system adoption. Companies that can compress the cycle from bench to bedside while demonstrating cost‑of‑care advantages will win tender rounds and long‑term service relationships in 2026.
What the PW Consulting report delivers (practical, execution‑focused)
-
Transparent market sizing and growth scenarios (base year and forecast span) with sensitivity analysis to help stress‑test investment cases.
-
Regulatory and reimbursement playbooks tailored to pediatric evidence, including recommended timelines for human‑factors testing, bias validation, and labeling strategy aligned to FDA and international standards.
-
Commercial frameworks: tender and procurement playbooks, hospital decision‑unit maps, pricing and service‑model case studies (capex vs. opex models, rental/subscription approaches).
-
Supply‑chain risk matrix and mitigation templates for specialty materials and pediatric‑grade components.
-
Competitive heatmaps, partner archetypes and M&A target screening criteria that identify high‑leverage bolt‑ons.
-
Actionable go‑to‑market roadmaps for product launches, including required clinical evidence packages and stakeholder engagement plans.
-
Practical appendices: regulatory checklist, clinician persona profiles, procurement negotiation scripts, and a prioritized implementation backlog for 12–24 months.
Priority recommendations for 2026 (what to do next)
-
Prioritize human‑factors and bias testing now—delay increases regulatory risk and slows hospital adoption.
-
Convert clinical evidence into economic value propositions: invest in real‑world evidence that maps device use to reduced length of stay or readmission for payers and hospital CFOs.
-
Secure long‑lead materials and qualify secondary suppliers for pediatric‑grade components to avoid launch slippage.
-
Consider targeted M&A or licensing in monitoring software and sensor miniaturization capabilities to accelerate product breadth without the full cost of greenfield development.
-
Design commercial offers around service uptime and outcome guarantees—health systems increasingly pay for demonstrable outcomes rather than hardware alone.
Accessing the full intelligence
This executive overview is a strategic preview. The full PW Consulting Children’s Medical Equipment Market report contains the granular segment analysis, regional and application breakdowns, vendor revenue estimates, and downloadable decision‑support tools that procurement, product and corporate development teams require to act in 2026. For access to the complete dataset, scenario models and tailored executive briefings, please visit our report page or contact PW Consulting to schedule a briefing with our industry lead analysts.
2026 will be a year of choice: firms that align product design, clinical evidence and commercial execution for pediatric care will convert the market’s steady growth into durable share and superior margins. Our study provides the operational playbook to do exactly that—helping executives move from insight to action with precision and speed.
For detailed analysis of this topic, please visit the official page: Childrens Medical Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Clinical Laboratory Tests Market to Reach USD 377.37 Billion by 2032, Posting a 6.15% CAGR
By PW Consulting, 2026-07-13
Clinical Laboratory Tests Market: Strategic Outlook for 2026 — Executive Preview
As PW Consulting’s senior strategic advisor and chief industry analyst, I present an executive preview of our latest Clinical Laboratory Tests Market report — a decision-quality briefing designed to shape commercial, M&A and regulatory strategies through 2026 and beyond. The global clinical laboratory tests market has moved from recovery to structural expansion: after rising from USD 182.45 Billion in 2020 to USD 248.50 Billion in 2025, our model forecasts continued growth across the 2026–2032 horizon at a compound annual growth rate (CAGR) of 6.15%, reaching an estimated USD 377.37 Billion by 2032. This trajectory creates both near-term execution challenges and medium-term strategic optionality for payers, providers, diagnostics vendors, and investors.
Clinical Laboratory Tests Market
Why this report matters for 2026 decisions
-
Actionable foresight tied to near-term inflection points: 2026 will be defined more by regulatory and reimbursement re‑calibration than by a single technological breakthrough. Firms that align product roadmaps, pricing models and compliance programs with the new regulatory reality and updated fee schedules will materially outcompete peers.
Clinical Laboratory Tests Market -
Data-driven scenario planning: our baseline, upside and downside scenarios quantify revenue and margin implications across macro and clinical test drivers — enabling CFOs and business unit leaders to stress-test capital allocation, volume assumptions and pricing tactics against plausible 24–36 month outcomes.
Clinical Laboratory Tests Market -
Competitive playbooks calibrated to fragmentation: market concentration remains modest (CR3 ~14.9%; CR5 ~19.4%), signaling persistent opportunity for scale players to consolidate while specialty and regional labs defend niche advantages. The report translates concentration metrics into prioritized M&A and partnership targets by capability and geography.
Core market dynamics shaping 2026 strategies
-
Decoupling of volume and value: demographic aging and chronic disease prevalence continue to drive baseline volume growth, while value accrues to providers who can deliver faster, higher-value molecular and biomarker testing tied to therapeutic decision-making.
-
Automation and throughput optimization: instrument manufacturers and high-volume labs are investing to consolidate test menus, increase throughput, and reduce per-test cost. Vendors launching systems that materially improve end-to-end workflow will be in a position to command premium placement in core labs.
-
Regulatory recalibration and LDT uncertainty: after legal developments in 2025 the regulatory environment for laboratory-developed tests (LDTs) remains in flux. Enforcement discretion, state-level oversight mechanisms and evolving FDA considerations require active compliance strategies and scenario-based product positioning.
-
Reimbursement displacements: the 2026 Clinical Laboratory Fee Schedule updates — including new Proprietary Laboratory Analysis (PLA) codes and HCPCS/CLIA edits — create short-term pricing variability and medium-term pathways for differentiated assays to capture value. Organizations must redesign reimbursement intelligence and coding workflows to protect margin and accelerate commercial uptake for novel assays.
-
Convergence of diagnostics, therapeutics and value-based care: clinically actionable diagnostics (e.g., blood‑based biomarkers for neurodegeneration, oncology panels) are becoming integral to care pathways and contracting discussions with payers, requiring diagnostics providers to build real-world evidence and outcomes partnerships.
Competitor landscape — strategic implications
The market is populated by a mix of global reference labs, regional consolidated networks, instrument and reagent OEMs, and highly specialized providers. Our competitive analysis focuses on strategic positioning, growth vectors, and likely responses to regulatory and reimbursement moves.
-
Quest Diagnostics Incorporated (Secaucus, NJ): a broad diagnostic services platform with deep routing and esoteric menus and a strong brand in clinician-facing services. Its resilience and reputational strength make it a natural consolidator in moves that accelerate national network optimization.
-
Laboratory Corporation of America Holdings (Labcorp) (Burlington, NC): the company continues to expand higher-value biomarker portfolios (e.g., blood-based Alzheimer’s biomarkers), positioning itself to capture therapy-linked testing demand. Expect intensified commercialization of specialty assays and partnerships with biopharma.
-
Sonic Healthcare Limited (Sydney): strong regional networks and integrated lab-pathology services create defensive moats in countries where local clinical integration and service quality drive referral patterns. Strategic play: deepen integration with hospital systems and diagnostic imaging to protect referral channels.
-
Eurofins Scientific (Luxembourg) and SYNLAB International (Munich): pan‑European scale players with growing clinical genomics capabilities — well-positioned to leverage cross-border service models and centralized sequencing platforms.
-
ARUP Laboratories and Mayo Clinic Laboratories : reference-lab strengths in esoteric and high-complexity diagnostics. Their clinical credibility and academic linkages make them essential partners for validation studies and for building clinical utility evidence.
-
NeoGenomics , OPKO/BioReference and specialized oncology/genetics labs: their niche focus on oncology and molecular diagnostics creates strategic optionality through partnerships with therapeutic developers and targeted payer contracts.
-
Instrument and reagent firms ( Siemens Healthineers , Abbott , Roche and others): product launches enhancing throughput and integration (for example, the recent generations of high-throughput systems) will influence lab CAPEX decisions and accelerate menu consolidation.
Recent developments to factor into 2026 planning
-
Regulatory: Court actions and policy reversals in 2025 created renewed uncertainty around LDT oversight; stakeholders should expect phased regulatory activity and continued enforcement discretion for certain legacy tests.
-
Reimbursement: CMS’s 2026 updates (including PLA code rollouts and CLIA edits) create a transient period of MAC-coded pricing and regional variance that requires active reimbursement monitoring and coding agility.
-
Product and commercial moves: instrument upgrades and novel assay launches over late 2024–2025 materially affect lab modernization timetables and clinical adoption curves. Labs should synchronize instrument refresh plans with assay commercialization roadmaps to maximize ROI.
-
Reputational and talent signals: recognition of large labs and academic reference centers underscores persistent value in clinical quality, data governance, and clinical liaison capabilities — factors that influence clinician referral loyalty and payer trust.
What the PW Consulting report delivers (practical content)
-
Top-line market sizing and trajectory models from 2020 through 2032, with baseline and alternate scenarios to stress-test revenue and margin outcomes.
-
Commercial and reimbursement playbooks: step-by-step guides for assay commercialization, coding strategy, evidence generation and payer negotiation under the 2026 fee schedules.
-
Regulatory decision matrix for LDTs: pathways and contingencies keyed to likely FDA and state-level enforcement permutations, including practical compliance checklists and clinical validation standards.
-
Competitive heat maps and capability benchmarking (technology, geography, service mix), plus prioritized M&A and alliance targets informed by strategic fit, integration risk and expected synergies.
-
Operational playbooks for lab modernization: capital planning templates, ROI calculators for automation and instrument upgrades, and labor productivity models.
-
Case studies and implementation milestones from leading labs and OEMs illustrating successful adoption and commercialization patterns for high-value tests.
Recommendations for 2026 executive action
-
Align commercial launches with reimbursement readiness: ensure coding, evidence, and payer engagement tracks are completed before wide launch windows to avoid revenue erosion during PLA code pricing cycles.
-
Prioritize interoperability and data assets: clinical utility and payer contracts increasingly depend on longitudinal evidence. Invest in data capture, outcomes studies and partnerships with health systems.
-
Targeted consolidation and capability buys: acquisition appetite should focus on complementary capabilities — molecular labs, oncology/genetics specialty assets, and rapid‑throughput automation — rather than replicating commodity testing capacity.
-
Regulatory hedge: build LDT governance playbooks and modular validation pipelines so tests can be adapted to evolving regulatory criteria without halting commercial momentum.
-
Scenario-based capital planning: use the report’s scenario models to set three-tiered CAPEX plans tied to leading indicators (payer coverage decisions, instrument availability, test adoption rates).
Next steps and where to find the full analysis
This preview highlights the strategic contours you need to prioritize for 2026. The full PW Consulting Clinical Laboratory Tests Market report contains the comprehensive dataset, segmented models, downloadable financial templates, and detailed competitor dossiers that underpin these recommendations. To preserve competitive confidentiality and to protect our proprietary modeling, we have deliberately withheld certain segment-level financial tables and regional splits from this preview — the full dataset and Excel workbooks are available through the official PW Consulting report page.
For executive briefings, bespoke scenario runs, or to commission a tailored annex (e.g., M&A target screening, payer strategy playbook, or lab modernization ROI study), contact our industry practice leads at PW Consulting. Use the report to convert market momentum into defensible market share and measurable margin expansion in 2026.
For detailed analysis of this topic, please visit the official page: Clinical Laboratory Tests Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


