



Category: market research
Soy Sauce Market Beyond the 5.4% CAGR: Strategic Shifts Reshaping Asia Pacific Dynamics
By PW Consulting, 2026-09-21
The Strategic Soy Sauce Market: Navigating the Next Wave of Growth
The global condiments sector has long relied on soy sauce as a foundational ingredient, but the current market trajectory suggests a more sophisticated evolution than simple volume expansion. As the industry moves through a period of steady revenue growth and shifting consumption patterns, strategic decision-makers must look beyond headline numbers to understand the structural forces reshaping supply chains, competitive positioning, and consumer expectations. The market has demonstrated consistent momentum over the past half-decade, with revenue figures climbing steadily and a projected compound annual growth rate signaling continued expansion through the early 2030s. Yet this growth masks underlying complexities that demand careful navigation.
From a macro perspective, the industry has transitioned from a mature, regionally concentrated category into a more globally integrated space where premiumization, geographic diversification, and operational scale intersect. Total market revenue has grown from the high twenty-nines billion range in 2020 to surpass the forty-one billion mark by 2025, and forward projections indicate continued upward movement, with the market expected to approach the sixty-billion threshold by 2032. This trajectory reflects more than population growth or basic culinary adoption; it points to a category gaining relevance in modern food preparation, ethnic cuisine globalization, and industrial food formulation. For executives and investors, the headline growth rate of approximately 5.4 percent annually provides a useful baseline, but the real strategic value lies in understanding where growth concentrates, what threatens it, and how incumbents are adapting.
Several structural tensions currently define the industry's inflection point. First, the sector operates within a moderately concentrated environment where a limited number of large producers command meaningful share, yet smaller specialty manufacturers continue to carve out profitable niches through authenticity, craftsmanship, and geographic specificity. This coexistence of scale and specialization creates both competitive friction and partnership opportunities. Second, raw material cost dynamics introduce volatility that can compress margins or force pricing strategies that risk alienating price-sensitive buyers. Third, regulatory divergence across key markets means that compliance requirements, labeling rules, and ingredient transparency expectations differ sharply depending on where a product is manufactured, distributed, or consumed. These three forces, market concentration, input cost variability, and regulatory asymmetry, form the backdrop against which strategic choices must be made.
Understanding the Market Landscape and Its Pressures
The global soy sauce market has matured into a multi-regional industry where cultural familiarity, foodservice integration, and retail convenience collectively drive demand. Asia Pacific remains the dominant revenue contributor, reflecting both deep culinary tradition and large population bases, but growth is increasingly visible in regions where Asian cuisine adoption continues to expand among mainstream consumers. The category is no longer confined to traditional home cooking; it now flows through packaged food manufacturing, restaurant operations, and cross-cultural food experimentation. This broader application footprint has helped stabilize demand even as certain mature markets face slower household penetration growth.
Three challenges stand out as particularly consequential for strategic planning:
Soy Milk Market
- Margin pressure from input cost volatility: Soybeans and fermentation inputs are subject to agricultural cycles, weather disruptions, and commodity trading dynamics. When harvest forecasts shift or trade flows adjust, producers must decide whether to absorb cost increases, renegotiate supplier agreements, or pass changes through to customers, each path carrying commercial risk.
- Regulatory fragmentation: Labeling, nutritional disclosure, and ingredient transparency rules vary across jurisdictions. A product positioned for global distribution must comply with differing standards on GMO disclosure, nutritional labeling, and processing classifications, which can complicate packaging, marketing, and market-entry sequencing.
- Competitive differentiation in a crowded category: Traditional large-scale brewing, accelerated production methods, and artisanal fermentation all compete for shelf space and foodservice contracts. Consumers and professional buyers increasingly evaluate flavor complexity, sodium content, authenticity claims, and sourcing ethics, raising the bar for what constitutes competitive advantage.
These challenges are not insurmountable, but they do require a more deliberate approach to product architecture, supply chain resilience, and geographic prioritization. Companies that treat the category as a single homogeneous proposition risk missing the opportunities hidden in regional taste preferences, application-specific formulations, and regulatory arbitrage where compliant positioning can become a market-access advantage.
Core Drivers Shaping the Next Growth Cycle
The market's forward momentum is not accidental; it is being propelled by a combination of technological advancement, shifting consumer behavior, supply-side restructuring, and evolving regulatory frameworks. Each driver interacts with the others, creating a landscape where advantages compound for organizations that align product strategy with operational readiness.
Innovation in Production and Product Architecture
Fermentation science and process control have progressed beyond the traditional binaries of naturally brewed versus chemically accelerated production. Modern manufacturers are investing in controlled fermentation environments, strain selection, and analytical quality systems that improve consistency while preserving the flavor profiles consumers associate with authenticity. At the same time, product architecture has expanded to include reduced-sodium formulations, cleaner-label variants, and flavor-specialized offerings tailored to specific culinary applications. This innovation is not merely technical; it is commercial. Producers that can deliver consistent taste, adaptable viscosity, and stable shelf performance gain advantages in both retail and industrial food service settings.
Regulatory Divergence as a Strategic Variable
Regulatory environments are not moving in unison, and this divergence has become a meaningful factor in market strategy. In some markets, soy sauce benefits from exemptions or lighter labeling burdens, while in others, GMO disclosure, nutritional labeling, or deeply processed product classification introduces additional compliance steps. These differences shape where companies choose to launch first, how they design packaging, and which ingredient claims they can safely make. For global players, the capability to modularize compliance by region, rather than treating labeling as a single global template, can reduce time-to-market friction and avoid costly reformulation cycles. For smaller brands, understanding regulatory thresholds early can determine whether a product can scale internationally or remains regionally constrained.
Demand-Side Shifts Toward Authenticity and Application Versatility
Consumer and buyer behavior continues to tilt toward products that signal authenticity, craftsmanship, and culinary specificity. This does not mean every segment seeks premium pricing; rather, it means that trust, origin narrative, and flavor reliability increasingly influence purchase decisions. At the same time, foodservice operators and packaged food manufacturers demand ingredients that perform consistently across large batches and varied recipes. The dual demand for artisanal credibility and industrial reliability pushes manufacturers to build portfolios that serve both ends of the spectrum. Brands that can articulate a clear position, whether as a heritage fermented product or a dependable industrial ingredient, are better placed to secure shelf space, contract stability, and repeat procurement.
Pasta Sauce Market
Supply Chain and Cost Structure Realignment
Soy sauce production depends on soybean supply, brewing infrastructure, logistics, and regional labor and energy costs. Agricultural price forecasts for the coming marketing years point to higher season-average soybean prices compared with the prior year, which signals potential cost pressure for upstream inputs. This does not automatically translate into market-wide margin erosion, but it does reward organizations that secure forward contracts, diversify sourcing, and optimize plant utilization. Companies with geographically distributed production footprints can shift volume among facilities, hedge against localized disruptions, and respond more flexibly to currency or logistics shocks. In practical terms, supply chain resilience is becoming a competitive differentiator rather than a back-office function.
Competitive Dynamics and Strategic Positioning
The industry's competitive field is shaped by a mix of long-established brewing specialists, large regional manufacturers, and smaller innovators pursuing distinctive flavor profiles or niche market positions. The largest producers combine scale, export capability, and multi-plant infrastructure, while others compete through premium positioning, regional brand equity, or specialized product development. This structure supports a market where share is contestable but not easily overturned, because scale advantages in brewing capacity, distribution relationships, and ingredient procurement are difficult to replicate quickly.
Several strategic postures are visible across the leading set. One is geographic expansion through local production, which reduces shipping costs, shortens lead times, and signals commitment to a market. A second is premiumization through naturally brewed positioning and taste differentiation, which targets consumers and foodservice buyers willing to pay for perceived quality and culinary authenticity. A third is portfolio breadth across light, dark, and specialty variants, allowing a manufacturer to serve multiple culinary applications and capture demand across different cooking traditions. A fourth is innovation in small-batch, distinctive flavor profiles that can command premium pricing and build loyal following among chefs, specialty retailers, and consumer enthusiasts.
Recent operational developments illustrate how these strategies are playing out in practice. A major Japanese producer with significant U.S. manufacturing presence has been progressing a new American production facility, with first shipments anticipated in the fall of 2026 after groundwork laid in 2024. This kind of investment signals confidence in sustained demand and a desire to deepen local supply capability rather than relying solely on export flows. Meanwhile, in the Chinese market context, leading domestic brands have continued to showcase light, dark, and standard varieties through major trade platforms, reinforcing the importance of category breadth and export visibility for manufacturers seeking broader international reach.
Market structure appears likely to evolve along two parallel paths. Consolidation pressure will persist where scale economics, distribution leverage, and sourcing advantages favor larger operators, especially in price-competitive segments and high-volume foodservice channels. At the same time, fragmentation will remain viable in premium, regional, and specialty segments where authenticity, craft narrative, and differentiated flavor profiles create defensible positions. New entrants that can combine a clear brand story with disciplined production quality, or that can serve an underserved application such as a specific culinary format or a clean-label requirement, can still gain traction without directly challenging the largest incumbents on volume alone.
Forward-Looking Trends for the 2026 to 2032 Window
Looking ahead, several trends are likely to shape how growth is captured and where value accrues. These trends are grounded in current market data, recent operational moves, and the regulatory and demand environment already in motion.
PW Consulting
Local Production and Regional Capacity Expansion
As demand broadens beyond traditional strongholds, the economics of long-distance export versus local manufacturing become more consequential. Additional production capacity in key markets can improve responsiveness, reduce logistics exposure, and support labeling or formulation adaptation to regional requirements. Over the next several years, more manufacturers are likely to evaluate where to place capacity based on demand density, input availability, and regulatory clarity. The strategic implication is that presence in a market will increasingly be judged not just by brand recognition but by supply reliability and local compliance readiness.
Premiumization Paired with Functional Positioning
Premium products will continue to grow in relevance, but premiumization alone will not define success. The most durable growth will likely come from products that combine authentic fermentation or distinctive flavor with practical benefits such as lower sodium, cleaner ingredient lists, or application-specific performance. This pairing allows manufacturers to address both consumer-facing premium demand and buyer-facing formulation needs. Brands that can communicate flavor quality while meeting functional expectations will have a stronger chance of commanding price resilience and repeat usage.
Regulatory Clarity as a Market Access Multiplier
Because regulatory requirements differ across markets, companies that proactively align product design and labeling with local rules can turn compliance into a market-entry advantage. In regions where nutritional labeling is not required, simpler packaging and broader claim flexibility may be available; in regions with stricter disclosure, early adaptation can prevent reformulation delays and protect brand consistency. Over time, the ability to navigate multiple regulatory regimes efficiently will become part of the competitive baseline for companies pursuing international distribution.
These trends carry uncertainty. Cost volatility in soybean supply could compress margins for producers with less flexible sourcing or pricing strategies. Regulatory changes could shift faster than anticipated in some markets, altering labeling obligations or ingredient disclosure expectations. Consumer taste preferences may evolve toward lower-sodium or plant-forward alternatives, requiring manufacturers to innovate without diluting the category's core identity. Each of these risks is manageable with the right data, scenario planning, and operational agility.
Strategic Actions for Decision-Makers
For manufacturers, the priority is to align product architecture with both flavor differentiation and operational resilience. That means evaluating whether portfolio breadth, premium positioning, or local production offers the best return in each target market, and ensuring that sourcing and facility strategy can absorb input cost variability without sacrificing consistency. For investors, the opportunity lies in identifying organizations that combine credible brand equity with scalable production and a clear regional expansion plan, while monitoring where margin exposure to raw material costs and regulatory complexity may create downside risk or require additional capital discipline. For procurement and foodservice buyers, the practical focus should be on supplier reliability, formulation consistency, and compliance alignment, since these factors increasingly determine whether a soy sauce supplier can support large-scale operations across multiple markets without disruption.
Access to detailed segmentation data, regional revenue splits, and granular competitive movement can sharpen each of these decisions. Broad market trajectories provide direction, but precise allocation decisions require clearer visibility into where growth concentrates, how share is shifting among product types, and which operational investments are likely to yield durable advantage. The full research report offers that level of detail, including segmented data, company-level developments, and market-access considerations that support tailored commercial planning.
The soy sauce market is entering a phase where growth is real, but competitive advantage will depend on how well organizations align innovation, compliance, and supply chain readiness with the specific markets and applications they choose to serve. Companies that treat the category as a strategic platform rather than a routine ingredient business are better positioned to convert steady industry expansion into defensible share and healthier margins.
For detailed analysis of this topic, please visit the official page: Soy Sauce Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Clinical Mass Spectrometry Market: Why 9.35% CAGR and LC-MS Dominance Redefine Growth
By PW Consulting, 2026-09-21
The Clinical Mass Spectrometry Market: Strategic Trends and Commercial Opportunities Through 2032
Market Status and Core Challenges
The clinical mass spectrometry market has transitioned from a specialized scientific instrument segment into a mainstream clinical diagnostic modality over the past half-decade. Market valuation moved from approximately 785.0 million USD in 2020 to 1260.0 million USD in 2025, representing a compound annual growth rate of roughly 8.2 percent across the historical window. Current trajectory models indicate expansion to 1346.99 million USD in 2026 and continued acceleration toward 2360.0 million USD by 2032, with a forecast-period CAGR of 9.35 percent. This growth profile reflects a market that has crossed the chasm from research-grade adoption into routine clinical workflows, driven by the superior specificity and multiplex capability of mass-based quantification compared with traditional immunoassays.
The regional distribution of demand reveals a mature anchor in North America, which accounts for the largest revenue share at 562.22 million USD, followed by Europe at 319.65 million USD and Asia Pacific at 234.95 million USD. Latin America and the Middle East and Africa together represent a combined base of 143.18 million USD, signaling early-stage penetration with substantial room for expansion as healthcare infrastructure and reimbursement frameworks mature. By technology type, liquid chromatography-mass spectrometry dominates installed value at 801.16 million USD, while gas chromatography-mass spectrometry holds 212.76 million USD and matrix-assisted laser desorption/ionization time-of-flight contributes 198.12 million USD, with other modalities rounding out the remainder. Across applications, therapeutic drug monitoring represents the largest clinical use case at 555.11 million USD, newborn screening follows at 315.55 million USD, and hormonal testing, hemoglobin testing, and other indications collectively account for the balance. The market remains moderately concentrated, with the top three players capturing 52.0 percent of revenue and the top five holding 62.0 percent, a structure that preserves room for differentiated entrants while rewarding scale incumbents.
Despite the favorable growth backdrop, the industry faces three structural challenges that will define capital allocation and product strategy in the near term.
Challenge 1: The Complexity-Reimbursement Gap
Mass spectrometry delivers analytical performance that routine immunoassays cannot match, but that performance often carries operational complexity that limits throughput and increases per-test cost. Many clinical laboratories still treat mass spectrometry as a specialized, limited-access service requiring highly trained operators, dedicated sample preparation, and careful method validation. When reimbursement structures do not commensurately reward this complexity, laboratories hesitate to expand mass-based panels, and manufacturers face pressure to simplify platforms without sacrificing analytical rigor. The gap between what the technology can do and what payers and laboratory economics will sustain remains the central friction point in market expansion.
MALDI-TOF Mass Spectrometer Market
Challenge 2: Regulatory Fragmentation Across Indications and Jurisdictions
Clinical mass spectrometry spans diverse indications, each with distinct evidentiary requirements, validation expectations, and regulatory pathways. A system cleared for microorganism identification does not automatically translate into a cleared workflow for therapeutic drug monitoring or hormone quantification. This fragmentation slows portfolio scale-up, increases time-to-market for new assays, and creates uneven competitive advantages across regions. Companies that can navigate a multi-indication, multi-jurisdiction regulatory landscape more efficiently than peers will capture disproportionate share in high-value applications.
Challenge 3: Workflow Integration and Standardization
As clinical mass spectrometry moves from reference laboratories into decentralized hospital and multi-site networks, standardization becomes a binding constraint. Variability in sample handling, chromatography conditions, ionization performance, and data interpretation can undermine comparability across sites and erode confidence in results. The market is increasingly rewarding vendors that offer integrated hardware-software-reagent systems, simplified operator interfaces, and traceable quality controls, while penalizing those that require extensive in-house method development for routine testing.
Key Drivers of Market Change
Technological Innovation and the Push Toward Automation
The most consequential technical shift is the move from manually intensive, laboratory-developed workflows toward automated, integrated platforms that reduce operator dependence and improve reproducibility. Quantitative software suites purpose-built for clinical analysis now accompany single quadrupole and tandem mass spectrometry systems, enabling biomarker verification, precision medicine workflows, and routine quantification with less hands-on intervention. In microorganism identification, software and sample handling innovations are compressing turnaround time and improving the reliability of organism differentiation directly from clinical specimens. These advances directly address the complexity-reimbursement gap by making high-performance mass spectrometry more compatible with high-volume clinical operations.
A concrete illustration of this trajectory is the broad expansion of reagent and assay menus on automated clinical mass spectrometry platforms. Recent milestones include CE Mark approval for an antibiotics drug monitoring reagent pack that broadens an automated mass spectrometry menu to 39 tests covering immunosuppressants, antibiotics, steroids, and vitamin D metabolites. In parallel, regulatory classification progress has lowered operational barriers: steroid assays for mass spectrometry have been classified as moderate complexity under CLIA, which expands the population of laboratories and operators able to run these tests without specialized staffing. Together, these developments demonstrate how regulatory easing and workflow automation can unlock routine clinical access for assays that previously required limited, expert-run environments.
Regulatory and Reimbursement Environment as an Accelerant and a Gatekeeper
Regulatory and coding dynamics are reshaping the commercial landscape for clinical mass spectrometry on two fronts. On the access side, moderate-complexity classification for selected mass spectrometry assays is expanding the addressable laboratory base by removing the requirement for highly specialized operators in routine settings. On the coding side, revisions to CPT codes for mass spectrometry-based testing are influencing reimbursement mechanics. Updated codes such as CPT 82542 for quantitative column chromatography/mass spectrometry reflect ongoing efforts to align coding with current practice, while reimbursement continues to vary by payer and analyte. For manufacturers and laboratory customers alike, the direction of travel matters: clearer, more predictable coding and broader complexity allowances reduce adoption friction, but analyte-specific reimbursement variability still demands careful health-economic justification for each test menu.
These dynamics also create a differentiated advantage for companies that pursue regulatory clearance proactively across multiple indications and regions. A vendor that secures clearance for therapeutic drug monitoring reagents, hormone panels, and microorganism identification systems in sequence can cross-sell across clinical departments, increase installed-base stickiness, and establish reference standards that competitors must match. The regulatory environment is thus not merely a compliance backdrop; it is increasingly a competitive moat.
Demand-Side Shifts in Clinical Practice and Patient Management
Clinical demand is being reshaped by three interrelated forces. First, precision medicine workflows are increasing the need for accurate quantification of biomarkers, drug concentrations, and metabolic markers that mass spectrometry is uniquely suited to measure. Second, the management of complex medication regimens, including antibiotics and immunosuppressants, is driving sustained demand for therapeutic drug monitoring in hospital and specialty settings. Third, early detection programs and screening protocols, including newborn screening, continue to provide a stable and high-volume demand base that rewards throughput, reliability, and standardized workflows.
At the same time, healthcare delivery is shifting toward consolidated networks and standardized testing protocols. Larger laboratory systems are seeking platforms that can support multiple indications on a single instrument footprint, reduce training burden, and provide traceable quality controls across sites. This demand-side consolidation is pushing vendors toward modular, software-centric architectures and multi-test menus, and away from single-application, laboratory-developed approaches that are difficult to scale across a health system.
PW Consulting
Supply Chain and Cost Structure Evolution
Cost structure is becoming a more explicit competitive variable as installed bases grow and laboratories compare total cost of ownership across platforms. The economics of clinical mass spectrometry depend not only on instrument price but on reagent costs, consumables durability, calibration frequency, service coverage, and the labor required to maintain compliance. Vendors that can reduce per-test operating cost through automation, longer calibration intervals, integrated reagents, and remote diagnostics are increasingly favored in procurement decisions, particularly in cost-sensitive environments.
Supply chain resilience is also under scrutiny. Platforms that reduce dependence on highly customized sample preparation steps and that offer standardized reagent packs tend to be more resilient to staffing volatility and consumable supply disruptions. As a result, the market is rewarding designs that prioritize workflow robustness and predictable consumable economics over maximal analytical flexibility alone.
Competitive Landscape and Leading Strategies
Incumbent Positioning and Differentiation
Thermo Fisher Scientific continues to anchor its strategy in quantitative clinical analysis and precision medicine workflows. Its LCQUAN quantitative software paired with ISQ EM/EC single quadrupole LC-MS systems is positioned for quantitative clinical analysis, biomarker verification, and precision medicine applications. The strategic emphasis is on software-driven quantification and a platform that supports accurate routine workflows and biomarker work, appealing to laboratories that want a credible quantitative foundation with room to extend into precision medicine use cases.
Waters Corporation leans into therapeutic drug monitoring and biomarker applications with its MassTrak LC-MS/MS platform and related solutions. A distinguishing element is the availability of FDA-cleared systems for TDM and biomarker workflows, which directly addresses the regulatory-access driver in the market. This clearance-centric approach is strategically important because it shortens the path for laboratories seeking validated, regulatorily recognized workflows rather than building laboratory-developed methods from scratch.
Bruker Daltonics differentiates through microorganism identification and differentiation, with MBT Compass HT CA software, MBT FAST Shuttle US IVD, and clinical microorganism mass spectrometry systems. The FDA clearance of its microorganism identification and differentiation system as Class II under special controls formalizes a regulatory pathway and supports adoption in clinical microbiology workflows. Bruker's positioning reflects the value of a focused application with clear clinical identity, which can be expanded within microbiology departments and integrated with broader laboratory information systems.
Roche Diagnostics International AG is pursuing a broad multi-indication IVD strategy on an automated clinical mass spectrometry platform. Its cobas Mass Spec solution with Ionify reagent packs spans therapeutic drug monitoring for antibiotics, steroid hormones, and vitamin D metabolites, supported by the Cobas i601 analyzer and an expanding IVD menu. The strategic signal is clear: Roche is using automation, a wide test menu, and regulatory milestones to position mass spectrometry as a routine clinical workhorse rather than a niche specialty tool.
Market Evolution: Consolidation, Differentiation, and New Entrants
The competitive landscape is evolving along three vectors. First, consolidation pressure is rising among scale incumbents that can cross-sell across applications and leverage installed bases to lower service and consumable costs. The top-three concentration near 52.0 percent and top-five near 62.0 percent indicates that leading players already hold meaningful share, but the remaining 38.0 percent is large enough to support specialized entrants with differentiated applications or regional strengths.
Second, differentiation is shifting from raw analytical capability toward integrated, regulatory-cleared, workflow-friendly solutions. In this environment, a vendor's ability to deliver cleared assays, simplified operator experience, and multi-test menus on a single platform is becoming as important as instrument performance alone. This favors companies that can orchestrate hardware, software, reagents, and regulatory clearance as a unified clinical solution.
Third, new entrants and regional players are finding openings in specific applications or geographies. Lower-concentration regions such as Latin America and the Middle East and Africa present early-stage demand where localized service, pricing, and workflow simplicity can be decisive. Similarly, application niches with clear clinical identity and regulatory clarity, such as microorganism identification or antibiotic TDM, can support focused entrants who build depth rather than breadth.
Future Trends and Commercial Opportunities
Trend 1: Routine Clinical Access Will Expand as Complexity Barriers Lower
Over the next three to five years, regulatory classification progress and automation will continue to broaden the laboratory base able to run mass spectrometry assays. Moderate-complexity classification for selected steroid and other assays is an early indicator of a broader shift toward routine access. The commercial opportunity lies in panels and platforms that can scale across diverse laboratory types without requiring specialized operators, supported by clear coding pathways and defensible health economics. Vendors and laboratory customers that invest early in these accessible workflows will capture utilization before the market consolidates around a smaller set of standardized platforms.
Trend 2: Multi-Indication, Software-Centric Platforms Will Become the Default Architecture
Healthcare systems increasingly prefer platforms that support multiple indications on one footprint with consistent software, quality controls, and data management. This favors architectures that separate application expansion from hardware replacement, allowing laboratories to add tests through software and reagent updates rather than capital upgrades. The commercial opportunity is for vendors that can package multi-test menus, traceable QC, and integration with laboratory information workflows as a cohesive solution, while laboratory buyers can reduce capital intensity and standardize operations across departments.
Worldwide High Resolution Mass Spectrometry System Market
Trend 3: Therapeutic Drug Monitoring and Steroid/Immunosuppressant Panels Will Remain Central Growth Engines
Therapeutic drug monitoring is already the largest application segment, and the strategic rationale is strong: managing antibiotics, immunosuppressants, and steroid-related markers requires precise quantification with clinical turnaround that mass spectrometry can provide. As automated reagent packs and cleared workflows expand, these panels can move from specialized use into more routine hospital and specialty settings. The commercial opportunity lies in full-panel strategies that bundle antibiotics, steroids, immunosuppressants, and vitamin D metabolites around a single platform, creating cross-department utilization and stronger laboratory retention.
Risks and Uncertainties
Several risks temper the outlook. Reimbursement variability by payer and analyte can slow adoption for specific tests even when analytical performance is strong. Regulatory timelines and classification outcomes remain uncertain across indications and regions, meaning portfolios that depend on a single clearance event face concentration risk. In addition, if automation and software do not deliver the expected reduction in operating cost and training burden, the complexity-reimbursement gap will persist and limit throughput gains. Finally, coding and reimbursement updates can shift the economics of specific assays, requiring continuous health-economic monitoring rather than one-time justification.
Strategic Recommendations for Decision Makers
For Manufacturers and Platform Providers
- Prioritize integrated, software-centric architectures that allow multi-test expansion without hardware replacement, and pair them with cleared or clearly regulatory-tracked workflows for high-value indications such as TDM, steroid panels, and microorganism identification.
- Design for operational simplicity and total cost of ownership, not just analytical performance. Reduce training burden, automate sample preparation where feasible, and offer predictable reagent and calibration economics to win procurement decisions in consolidated laboratory networks.
- Build multi-indication, multi-region regulatory strategies in advance. Early and sequential clearances across applications and jurisdictions can become a defensible competitive moat and accelerate cross-sell within health systems.
For Investors and Strategic Partners
- Focus on companies that convert regulatory and workflow advantages into installed-base growth and recurring consumable revenue, particularly where moderate-complexity classification, cleared assays, and broad test menus expand the addressable laboratory base.
- Evaluate exposure to reimbursement and coding risk at the analyte level. Investments tied to panels with clearer coding pathways and stronger health-economic support are less exposed to reimbursement variability than narrow, single-test offerings.
- Watch for consolidation opportunities in regional markets where service capability, pricing, and workflow simplicity matter more than cutting-edge analytical novelty. Localized execution can be a durable advantage in earlier-stage regions.
For Procurement and Laboratory Decision Makers
- Evaluate platforms based on total cost of ownership, regulatory status of assays, and the ability to standardize across multiple indications and sites, rather than instrument specifications alone. A platform that supports several cleared panels with integrated QC and data management can reduce operational risk and capital intensity.
- Assess training burden, staffing resilience, and service coverage as part of the sourcing decision. Workflows that lower dependency on specialized operators and offer predictable maintenance are better suited to high-throughput environments and decentralized networks.
- Monitor coding and reimbursement developments for the specific analytes you plan to run, and align test menu expansion with clear reimbursement pathways and health-economic justification to avoid adoption friction later.
The clinical mass spectrometry market is moving from specialist adoption to routine clinical integration, and the winners will be those who align analytical performance with workflow simplicity, regulatory clarity, and defensible economics. For decision makers who need granular segmentation, region-by-region dynamics, per-application growth drivers, and customized strategic scenarios, a detailed research report can provide the depth required to translate these trends into concrete plans. To access the full segmentation breakdown, competitive benchmarking, and tailored recommendations, request the complete PW Consulting report on the Clinical Mass Spectrometry Market.
For detailed analysis of this topic, please visit the official page: Clinical Mass Spectrometry Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tax Software Market: Why Cloud Adoption and 9% CAGR Shift the Competitive Landscape
By PW Consulting, 2026-09-21
Navigating the Tax Software Market: Strategic Trends and Commercial Opportunities
The global tax software market is undergoing a structural transformation driven by technological advancement, regulatory complexity, and shifting user expectations. Valued at approximately $17.6 billion in 2025, the market has expanded steadily from $10.2 billion in 2020, reflecting a compound annual growth rate of 9.0 percent through 2032. By the end of the forecast horizon, total market revenue is projected to approach $32.3 billion, underscoring sustained institutional and consumer demand for digital tax solutions. This growth trajectory is not merely a function of population expansion or inflation; it represents a fundamental shift in how tax compliance, reporting, and advisory services are delivered. Organizations that understand the underlying drivers, competitive dynamics, and emerging friction points will be best positioned to capture value in the coming years.
Market Landscape and Core Challenges
The market's expansion has been broad-based, with cloud-based solutions now representing the largest share of revenue, reflecting a decisive migration away from legacy on-premises deployments. Individual tax filing continues to anchor volume, while business and corporate tax management segments contribute meaningful but more specialized revenue streams. Geographically, adoption patterns vary significantly, with mature markets showing high penetration and emerging regions accelerating digital onboarding as regulatory frameworks modernize and internet infrastructure improves.
Despite the favorable growth backdrop, the industry faces several structural challenges that will shape competitive outcomes over the next five years. First, regulatory fragmentation and compliance velocity are intensifying. Tax authorities across jurisdictions are updating filing formats, validation rules, and electronic submission requirements at an accelerating pace. Software vendors must continuously align their platforms with IRS Modernized e-File standards, state-level franchise tax mandates, and error-checking protocols. The operational burden of maintaining compliance across multiple jurisdictions creates a high barrier to entry and rewards vendors with robust regulatory monitoring and rapid update cycles.
Second, user experience expectations are rising faster than legacy architectures can accommodate. Both individual filers and professional preparers increasingly expect intuitive interfaces, guided workflows, automated data ingestion, and real-time error feedback. Platforms that rely on manual form entry or fragmented dataflows risk losing adoption to solutions that reduce cognitive load and accelerate filing turnaround. This shift is particularly pronounced among self-employed professionals and small business owners who prioritize simplicity and predictable pricing.
Third, cost structure pressures are reshaping procurement decisions. Professional-grade tax software typically carries annual licensing costs in the range of $700 to $1,275 for multi-user access, a meaningful expense for smaller firms and independent preparers. While these investments deliver compliance assurance and workflow efficiency, margins remain sensitive to pricing models, update frequency, and the perceived value of advanced features. Vendors must balance feature richness with affordability, particularly as free or low-cost guided filing options expand for eligible taxpayers and raise expectations for baseline functionality across the market.
These challenges intersect at a critical inflection point: the market is moving from a compliance-centric model toward an experience- and outcomes-centric model. The winners will be those that convert regulatory complexity into simplified user journeys, maintain update reliability at scale, and deliver clear return on investment for both professional firms and end users.
Key Drivers Shaping Market Evolution
Several interconnected forces are accelerating demand and redefining value propositions across the tax software ecosystem.
Technological Innovation and Workflow Automation
Cloud-native architectures, automated form population, and integration with financial data sources are reducing manual effort and error rates. Guided preparation workflows, predictive error checks, and rapid e-filing feedback loops are becoming table stakes rather than differentiators. For professional preparers, annual software updates that incorporate new tax laws, form revisions, and validation enhancements are essential to maintaining throughput and compliance accuracy. The release cadence and update transparency of leading platforms directly influence user retention and referral momentum within accounting and tax practices.
Policy and Regulatory Environment
Regulatory modernization is both a constraint and a catalyst. Tax authorities are progressively mandating electronic submissions, enhanced error validation, and structured data formats to improve processing efficiency and reduce rejection rates. Providers must demonstrate compliance with assurance testing systems and maintain approved status to operate within official filing channels. At the same time, tiered access models, such as no-cost guided preparation for eligible income brackets, expand the addressable user base while pressuring vendors to offer clear differentiation for premium features. The net effect is a more standardized compliance baseline, with competitive advantage shifting toward usability, advisory extensions, and multi-jurisdiction coverage.
Demand-Side Behavior Shifts
End users are increasingly treating tax software as an annual operating tool rather than a one-time filing utility. Individuals and small business owners value continuity, data portability, and time savings. Professional firms seek platforms that scale across seasons, support diverse client profiles, and integrate with broader practice management workflows. The preference for cloud delivery amplifies these expectations by enabling remote access, collaborative preparation, and centralized document management. As a result, switching costs are rising for users who have invested in historical data, trained workflows, and integrated ecosystems, favoring vendors that can deepen lifetime value through reliability and extensibility.
Cost Structure and Procurement Dynamics
The economics of tax software procurement are evolving as firms weigh licensing fees against labor costs, error remediation, and seasonal capacity constraints. Multi-user access models, update subscriptions, and support expectations shape total cost of ownership. For smaller practices, predictable annual pricing and straightforward update processes can be decisive, while larger firms prioritize scalability, role-based access, and audit-ready documentation. The market is gradually rewarding vendors that offer transparent pricing, efficient update delivery, and demonstrable time savings, particularly in environments where preparer labor remains a significant cost driver.
Competitive Landscape and Leading Strategies
The market is characterized by a concentrated core of established vendors alongside a long tail of specialized providers serving distinct user segments. Intuit maintains a prominent position in the individual and self-employed segments, leveraging broad brand recognition, guided filing experiences, and a wide distribution footprint. H&R Block complements this landscape with a strong retail and digital presence, emphasizing accessible filing pathways and small business support. In the professional segment, Wolters Kluwer and Thomson Reuters serve accounting firms and tax practitioners with comprehensive preparation and practice management tools, focusing on regulatory update cadence, multi-form coverage, and workflow integration. Smaller but focused providers, including Drake Software, TaxAct, TaxSlayer, On-Line Taxes, CFS Tax Software, and Advanced Tax Solutions, differentiate through niche functionality, pricing clarity, or specialized professional workflows.
Accounting Software Market
Strategic differentiation is increasingly defined by three dimensions: compliance reliability, user experience, and ecosystem fit. Leading vendors invest heavily in maintaining approved e-filing status, delivering timely updates aligned with tax law changes, and providing error validation that reduces rework. Equally important is the design of preparation workflows, including guided prompts, document capture, and transcript integration that lower the skill threshold for complex filings. Finally, ecosystem fit matters as firms evaluate how well a platform aligns with existing practice management, client communication, and data storage preferences. Vendors that excel across all three dimensions tend to retain multi-year loyalty, while laggards face churn when competitors demonstrate faster update cycles or smoother user journeys.
The competitive landscape is evolving through both consolidation and fragmentation. Larger platforms are expanding their feature sets to serve adjacent user segments, blurring the line between individual and professional tools. At the same time, specialized providers continue to carve out defensible positions by focusing on specific form sets, regional compliance requirements, or price-sensitive professional markets. New entrants face a steep climb given the importance of approval status, historical data accumulation, and trusted update cycles, but they can gain traction by targeting underserved workflows, offering transparent pricing, or delivering superior onboarding experiences. Overall, the market is moving toward a bifurcated structure in which broad-platform leaders compete on scale and integration while focused providers compete on specificity and cost clarity.
PW Consulting
Future Trends and Commercial Opportunities
Looking ahead to the next three to five years, three trends are likely to determine where value concentrates and how competitive advantage is built.
Trend One: Compliance-as-a-Service and Continuous Update Models
Regulatory change will continue to accelerate, and the ability to deliver reliable, audited updates will become a core commercial asset. Platforms that institutionalize continuous compliance monitoring, automated test suites, and rapid deployment pipelines will reduce the risk of filing rejections and user friction. This trend creates opportunities for vendors to monetize update assurance, compliance documentation, and proactive regulatory alerts as part of premium service tiers. For buyers, the commercial implication is clearer visibility into total compliance risk and a stronger basis for vendor selection based on update reliability rather than feature count alone.
Trend Two: Guided Experiences and Tiered Offerings
User expectations will keep shifting toward guided, low-friction preparation, particularly among individuals and small business owners who value speed and certainty. Tiered pricing models will likely deepen, with no-cost or low-cost guided pathways for eligible users coexisting alongside premium advisory and comprehensive preparation features. Vendors that design seamless handoffs between free, guided, and professional-grade workflows can expand reach while preserving margin through upsell into data continuity, multi-state filing, and practice-oriented tools. The strategic opportunity lies in using guided experiences as an entry point that builds trust and historical data retention, then converting that engagement into recurring, higher-value relationships.
Worldwide Tax & Revenue Collection Software Market
Trend Three: Integration with Broader Financial Workflows
Tax preparation is increasingly viewed as one node within a larger financial operations workflow. Connections to accounting data, bank and payment records, payroll information, and document storage reduce duplicate entry and improve accuracy. Platforms that enable secure data exchange, standardized imports, and role-based collaboration will capture additional stickiness and reduce seasonal onboarding costs. This trend opens commercial pathways for vendors to position tax software as part of a year-round financial toolkit, rather than a seasonal utility, potentially expanding cross-sell opportunities and lengthening the customer lifecycle.
These trends carry inherent uncertainties. Regulatory decisions can alter filing requirements or reimbursement structures, shifting demand patterns unexpectedly. Rapid update cycles can strain support resources if error validation or form coverage is incomplete. Pricing pressure from free or low-cost guided options may compress margins in volume-driven segments. And integration ambitions can collide with data privacy expectations and interoperability constraints. Organizations that monitor these variables closely and maintain flexible product roadmaps will be better equipped to pivot as conditions evolve.
Strategic Actions for Decision Makers
The following recommendations are intended to help different stakeholder groups translate market dynamics into practical actions.
For Software Vendors and Product Leaders
Prioritize update reliability and compliance assurance as foundational differentiators. Invest in automated testing, transparent release notes, and rapid remediation processes to reduce filing rejections and user friction. Simultaneously, refine user journeys to lower the cognitive burden of complex forms, and design tiered offerings that preserve accessibility while creating clear paths to premium features. Evaluate integration points with accounting, document management, and client communication tools to strengthen year-round relevance and reduce seasonal switching risk.
For Investors and Strategic Allocators
Focus due diligence on vendors with durable update cycles, approved filing status, and evidence of user retention beyond a single season. Assess whether a company's pricing model aligns with the cost sensitivities of its target segment, and whether its roadmap anticipates regulatory complexity rather than reacting to it. Favor platforms demonstrating clear product-led growth signals, such as multi-year data continuity, expanding form coverage, and measurable time savings for professional preparers. Monitor consolidation potential among specialized providers whose workflows could be absorbed into broader platforms.
For Procurement Teams and Practice Owners
Evaluate tax software based on total compliance risk, update cadence, and workflow fit rather than headline pricing alone. Ask vendors how they validate form changes, how quickly updates reach users, and how error feedback is delivered during filing windows. Consider the long-term value of data portability, role-based access, and integration with existing practice tools. Where eligible, explore guided filing options to reduce preparation time for straightforward returns, while reserving professional-grade platforms for complex cases that require multi-state coverage, entity-level filings, or advisory extensions.
Market conditions in tax software are being reshaped by the intersection of regulatory modernization, cloud adoption, and rising user expectations. The organizations that thrive will be those that treat compliance reliability as a product foundation, design for sustained user engagement, and position their offerings within broader financial workflows. Detailed segmentation data, vendor scorecards, regional demand patterns, and customized strategic recommendations are available in the full research report, which provides the granular evidence base needed to support planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Tax Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Data Center Busway Market 2026: 9% CAGR Means the Competition Just Changed
By PW Consulting, 2026-09-21
Data Center Busway Market 2025–2032: Strategic Shifts, Power Density, and the Path to Sustainable Scalability
The data center busway market has entered a phase of accelerated structural transformation, driven by the convergence of artificial intelligence workloads, hyperscale expansion, and evolving power distribution requirements. Valued at approximately USD 215.0 million in 2025, the market has grown from USD 163.15 million in 2020, reflecting a compound annual growth rate of 9.0 percent across the forecast horizon through 2032, when revenues are projected to reach USD 344.8 million. This trajectory is not merely a function of incremental capacity additions. It reflects a fundamental rethinking of how power is routed, tapped, and managed within increasingly dense and modular computing environments. For executives, investors, and procurement leaders, the busway segment represents both a direct response to next-generation infrastructure demands and a lens through which broader shifts in data center design, material economics, and regulatory compliance can be understood.
The market’s expansion has been relatively consistent in recent years, yet the composition of growth is shifting. Historical performance from 2020 to 2025 illustrates steady upward movement, with particular acceleration in the most recent intervals as AI-driven deployment cycles matured. The forward outlook suggests that the pace will be sustained, though not uniformly distributed across all end-use contexts or product configurations. Rather than treating busway systems as commoditized electrical distribution components, industry participants are increasingly positioning them as integral elements of high-density, rapidly deployable, and energy-aware data center architectures. This reframing is reshaping competitive dynamics, procurement criteria, and long-term investment theses.
Market Landscape and Core Challenges
The current market environment is characterized by robust demand signals, but also by structural frictions that will define competitive outcomes over the next several years. Three intersecting challenges stand out as particularly consequential for operators, suppliers, and capital allocators alike.
Power Density and Architectural Compression
The transition toward high-density computing environments is compressing traditional layout assumptions. As rack power densities increase and AI clusters demand higher amperage distribution, legacy cable-based or fixed-tray approaches are encountering spatial, thermal, and installation constraints. Busway systems are gaining relevance because they offer modular tap-off flexibility, shorter deployment cycles, and the ability to adapt to evolving white-space configurations. However, this shift is not automatic. Integrating high-ampacity busway into prefabricated or containerized data center pods requires coordinated engineering across power, cooling, and structural dimensions. The challenge for suppliers is to deliver systems that balance current-carrying capacity, footprint efficiency, and ease of modification without introducing complexity that undermines the very speed advantages busway is meant to provide.
Material Cost Volatility and Conductor Selection
Raw material dynamics are becoming a more prominent factor in busway economics. Copper prices moved to 15-month highs in 2025 amid supply disruptions and sustained data center demand, placing upward pressure on manufacturing costs for copper-dependent systems. At the same time, aluminum conductor options are gaining attention for their weight and installation labor advantages in high-density deployments. This creates a strategic tension: copper remains the default expectation for many mission-critical specifications, while aluminum-based designs can reduce weight and installation effort when properly engineered and certified. Manufacturers and procurement teams must navigate performance expectations, total installed cost, and long-term reliability rather than relying on material conventions alone.
PW Consulting
Regulatory and Compliance Pressures
Regulatory expectations are increasingly shaping infrastructure upgrade decisions. In Europe, the Energy Efficiency Directive has drawn attention to the need for data center operators to modernize infrastructure, including busway replacement and upgrades in certain contexts, to support compliance objectives. In parallel, safety and reliability expectations in mission-critical facilities continue to elevate the importance of certified solutions. For example, UL listing requirements for specific busway offerings have become a meaningful differentiator for operators seeking assured reliability in data center applications. These dynamics do not simply add cost; they reshape the value proposition of busway systems by linking power distribution decisions to broader energy, safety, and operational resilience goals.
Key Drivers Reshaping the Market
The growth trajectory of the data center busway market is being propelled by a set of reinforcing drivers that extend beyond simple capacity expansion. Understanding how these forces interact is essential for anticipating where demand will concentrate and which product strategies will gain traction.
Technology Innovation in High-Ampacity, Modular Distribution
Product development is increasingly focused on scalable, high-current busway architectures that can adapt to rapidly changing white-space layouts. One of the most notable shifts is the move toward systems capable of supporting amperage levels well beyond conventional server room distributions, including solutions designed for environments where high-ampacity busway systems exceeding 4000A are required. This trend is closely tied to hyperscale AI data center construction, where power distribution must accommodate dense compute clusters while preserving flexibility for future expansion.
Innovation is also evident in toolless tap-off designs, double-stack configurations, and integrated monitoring capabilities. Double-stack busway systems, for instance, are being introduced to support growing AI data center demands while preserving white space, effectively enabling higher power density without proportionally increasing the floor footprint. At the same time, modular plug-in tap designs are reducing installation friction and enabling faster reconfiguration as workloads evolve. These advances are not isolated product features; they collectively support a broader architectural shift toward busway as a dynamic distribution layer rather than a static electrical accessory.
AI-Driven Demand and Hyperscale Deployment Patterns
The most powerful demand-side force is the proliferation of AI-focused infrastructure. Hyperscale AI data center construction is driving demand for high-ampacity busway systems, particularly in environments where power distribution must scale in lockstep with accelerated compute density. This is altering procurement priorities: speed of deployment, modularity, and compatibility with prefabricated modules are increasingly valued alongside raw current-carrying capacity.
The trend is visible in recent product and exhibition activity. New EcoStruxure Pod Data Center solutions have been introduced with high-power busway integrated alongside liquid cooling and prefabricated modules for AI cluster deployments, illustrating how busway is being embedded into broader pod-level architectures. Similarly, scalable high-capacity double-stack track-style busway systems have been announced to address growing AI data center demands while preserving white space. At major industry gatherings, multiple manufacturers have showcased modular data center solutions that emphasize busway power distribution as a core element of next-generation AI infrastructure. These developments suggest that busway is no longer a peripheral consideration; it is becoming a defining component of AI-ready data center design.
Policy, Efficiency Mandates, and Certification-Driven procurement
Policy and regulatory frameworks are influencing both retrofit and greenfield decisions. Efficiency mandates and energy-related directives are pushing operators to evaluate infrastructure upgrades more holistically, including busway replacement where it contributes to compliance or operational improvement. At the same time, certification and listing requirements are becoming more salient in procurement processes for mission-critical facilities. This is especially relevant where reliability, safety, and interoperability must be demonstrable through recognized standards.
The practical effect is a more discerning buyer environment. Operators are not simply seeking the lowest upfront cost; they are increasingly weighing lifecycle performance, compliance readiness, and integration with broader facility systems. For suppliers, this means that product leadership is increasingly defined by the ability to provide certified, monitored, and easily integrated solutions rather than by volume alone. In this context, busway systems that combine protection, metering, monitoring, and modular tap-off functionality are well positioned to align with evolving procurement criteria.
Supply Chain and Cost Structure Considerations
Supply chain conditions and material economics continue to shape product strategy and pricing dynamics. Copper price movements have introduced cost variability that affects both manufacturers and end users, particularly in segments where copper remains the dominant conductor choice. This has reinforced interest in aluminum conductor options, which can reduce weight and installation labor in high-density deployments. The strategic implication is that conductor selection is becoming a more explicit trade-off analysis, balancing electrical performance, mechanical handling, certification requirements, and installed cost.
In parallel, the broader supply chain emphasis on modularity and prefabrication is encouraging busway designs that can be shipped, assembled, and commissioned with minimal on-site customization. This aligns with the pace demands of hyperscale and colocation projects, where schedule certainty is often as valuable as technical performance. Suppliers that can standardize high-value configurations while maintaining flexibility for site-specific requirements are likely to capture disproportionate advantage in a market where deployment speed is a critical success factor.
Competitive Landscape and Leading Strategies
The competitive environment in the data center busway market is moderately concentrated, yet it is evolving quickly as suppliers differentiate around architecture, integration, and application-specific engineering. With a combined share held by the top three players at approximately 24.6 percent and the top five at about 26.2 percent, the market remains relatively fragmented at the top, leaving room for specialized positioning, regional strength, and targeted innovation. The strategic question is not simply who holds the largest share today, but which companies are building durable advantages in high-growth subsegments tied to AI, modularity, and compliance-driven upgrades.
Leading Players and Strategic Positioning
Several established manufacturers are defining the market’s direction through product architectures that explicitly address high-density AI workloads, modular deployment, and integrated monitoring. Their approaches illustrate how busway is being repositioned from a utility product to a strategic infrastructure component.
Schneider Electric has emphasized integrated pod-level solutions that combine high-power busway with prefabricated modules and liquid cooling for AI cluster deployments. Its recent product launch of EcoStruxure Pod Data Center solutions featuring high-power busway integrated with liquid cooling and prefabricated modules reflects a strategy centered on holistic, rapid-deployment architectures. The company’s exhibition activity has also highlighted busway integration with power shelf concepts for 48V AI systems, signaling attention to evolving power architectures as well as traditional distribution.
Eaton Corporation has focused on modular tap-off flexibility and scalable white-space optimization through track-style busway systems. Its Pow-R-Way III and PowerWave 2 platforms are positioned around modular tap-off for scalable white-space and high-density power distribution. By showcasing modular data center solutions including busway power distribution at Data Center World 2026, Eaton reinforced a strategy that aligns busway with adaptable facility layouts and repeatable deployment patterns.
Vertiv has advanced high-capacity, space-efficient designs with its PowerBar Track and double-stack busway systems. Its offerings support high current levels with copper and aluminum options and emphasize toolless tap-offs for AI data center white-space optimization. The recent announcement of a scalable high-capacity double-stack PowerBar Track busway system for growing AI data center demands illustrates a clear focus on density, scalability, and space preservation.
ABB Ltd has concentrated on integrated protection, metering, and monitoring within low-voltage busway systems for server room distribution. Its Lmax-T systems are designed to support data center server room distribution with integrated protection, metering, and monitoring up to 86 kW per rack. This positions ABB around operational visibility and localized power management, which is increasingly valued in environments where granular monitoring supports efficiency and reliability objectives.
Siemens AG has pursued smart monitoring and strategic power distribution partnerships, with aluminum-based busway systems designed for high-density AI data centers. Its approach underscores the growing importance of monitoring-enabled systems and collaborative ecosystem positioning in high-value segments.
LS Cable & System has built a differentiated presence around modular plug-in taps and UL listing for high-capacity AI and energy-efficient data center power distribution. Its Data-way™ busway with modular plug-in taps and UL listing emphasizes mission-critical reliability and readiness for next-generation AI data centers, a positioning reinforced by its exhibition presence at Data Center World 2026.
Other notable participants contribute additional variety to the competitive field. Legrand offers data center busway solutions for modular power distribution in mission-critical facilities. nVent provides custom medium- and high-voltage bus systems for industrial and data center power applications, expanding the scope beyond standard low-voltage distribution. EAE Electric offers busway systems up to 6300A with data center-specific solutions for power distribution, highlighting the persistent demand for very high-current configurations in specialized environments.
Strategic Differentiation and Evolving Market Structure
Across these players, differentiation is increasingly rooted in four dimensions: current capacity and conductor flexibility, modularity and deployment speed, integration with monitoring and protection, and certification or listing readiness for mission-critical use. Companies that can combine these attributes within repeatable, prefabrication-friendly architectures are gaining leverage in a market where AI-driven projects reward both performance and schedule certainty.
The market structure appears likely to evolve through a mix of consolidation, specialization, and ecosystem positioning rather than through a single dominant wave of unification. Large, globally integrated suppliers benefit from breadth, engineering resources, and cross-selling potential across power management portfolios. At the same time, specialized or regionally strong players can compete effectively by emphasizing certification, customized high-current solutions, or rapid responsiveness to local procurement requirements. New entrants and adjacent players may also find openings by targeting specific niches such as very high-ampacity systems, aluminum-based designs, or modular pod-integrated busway solutions. The overall trend is toward a more application-aware competitive landscape, where Winning strategies depend on how well a product aligns with the operational, regulatory, and architectural priorities of the end facility.
Future Trends and Commercial Opportunities
Looking ahead to the next three to five years, several trends are likely to shape the data center busway market and create distinct commercial opportunities. These trends are interconnected, and their combined effect will determine which product categories, geographies, and use cases capture the most value.
Trend 1: High-Ampacity, AI-Optimized Busway as a Default Consideration
As AI workloads continue to drive higher power densities, high-ampacity busway systems will become less of a specialized option and more of a baseline consideration for new hyperscale and large colocation builds. The practical opportunity lies in designing for scalability from the outset: systems that can accommodate future power increases, support modular tap expansion, and integrate with cooling and prefabricated infrastructure will command stronger interest than fixed, single-purpose configurations. Commercially, this favors suppliers that can offer proven high-current performance, conductor flexibility, and documented compatibility with AI cluster layouts. The risk is that demand may become concentrated in a narrower set of high-specification systems, intensifying competition among suppliers that can meet those requirements at scale.
Trend 2: Material Strategy and Total Installed Cost as Competitive Levers
Material economics will continue to influence product design and procurement decisions. Copper price volatility and the practical benefits of aluminum conductor options in high-density deployments will encourage more explicit total cost evaluations, including weight, handling, installation labor, and long-term maintainability. This creates an opportunity for manufacturers to differentiate through engineered solutions that justify material choices with measurable installation and operational advantages. It also introduces a risk: if certification, customer familiarity, or application-specific performance requirements strongly favor one conductor type in certain segments, the ability to substitute may be limited. The most resilient strategies will likely involve offering credible options across conductor types while clearly mapping each to specific use cases and total cost profiles.
Busway-Bus Duct Market
Trend 3: Compliance, Monitoring, and Lifecycle Value as Procurement Differentiators
Regulatory efficiency expectations and mission-critical reliability standards are likely to elevate the importance of compliance-ready, monitored busway systems. As operators align infrastructure upgrades with energy efficiency and operational resilience goals, busway solutions that incorporate protection, metering, and monitoring will be better positioned to support both compliance and operational management objectives. The commercial opportunity here extends beyond hardware sales to includes integrated value propositions that reduce lifecycle risk, support audits or reporting, and simplify future modifications. A key uncertainty is the pace and uniformity of regulatory adoption across regions, which could create uneven demand patterns and require suppliers to remain agile in different compliance environments.
Data Center Rack Market
Actionable Implications for Decision Makers
The data center busway market is evolving from a component-level discussion into a strategic infrastructure question. The following implications are most relevant for manufacturers, investors, and procurement leaders seeking to act on current dynamics rather than react to them.
For Manufacturers and Solution Providers
- Prioritize architectures that combine high-current capability with modular tap flexibility and toolless or low-friction installation, especially where AI-driven white-space optimization is a priority.
- Develop clear conductor strategies that address both copper and aluminum use cases, supported by certification, testing, and documented total installed cost arguments rather than relying on convention alone.
- Strengthen integration narratives around monitoring, protection, and prefabricated module compatibility, since these attributes increasingly align with procurement criteria for mission-critical and efficiency-focused facilities.
For Investors
- Focus on companies with credible positioning in high-ampacity, AI-related deployments and evidence of product momentum through launches, trade presence, or qualified project pipelines.
- Assess exposure to material cost dynamics and supply chain resilience, particularly where product portfolios depend heavily on a single conductor type or limited sourcing pathways.
- Look for differentiation that is difficult to replicate quickly, such as certified solutions, integrated monitoring capabilities, or strong alignment with modular/pod-based data center architectures.
For Procurement and Infrastructure Leaders
- Evaluate busway options against total lifecycle criteria, including deployment speed, reconfiguration flexibility, monitoring and protection integration, and compliance readiness, rather than basing decisions solely on initial price.
- Plan for future power density increases by specifying systems that can scale in amperage and tap capacity without requiring wholesale redesign of the distribution layer.
- Verify certification and listing status early in the selection process, especially where mission-critical reliability and regulatory alignment are explicit project requirements.
The breadth of forces shaping this market—from AI-driven power density and material economics to efficiency mandates and modular deployment models—makes detailed, up-to-date segmentation and company-level intelligence highly valuable. For decision makers evaluating market entry, capacity expansion, product roadmap priorities, or procurement strategies, a fuller view of subsegment dynamics, regional variation, and competitive movements can materially improve planning accuracy. More comprehensive data and tailored analysis are available through the complete PW Consulting market report, which provides deeper segmentation detail and customized strategic guidance for specific business contexts.
For detailed analysis of this topic, please visit the official page: Data Center Busway Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PRP Market Analysis: How 10.5% CAGR to $1B Reshapes Orthopedics and Aesthetics
By PW Consulting, 2026-09-21
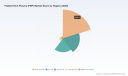
The Platelet-Rich Plasma Market: Strategic Trends and Commercial Opportunities in Autologous Biologics
The global platelet-rich plasma (PRP) market has evolved from a niche regenerative modality into a structured commercial ecosystem, driven by clinical adoption across orthopedics, sports medicine, aesthetics, and wound care. With historical revenue expanding from approximately $236.5 million in 2020 to $512.0 million in 2025, and a projected trajectory toward $1,032.3 million by 2032, the sector reflects a compound annual growth rate of 10.5 percent. This growth is neither uniform nor accidental. It emerges from a convergence of technological maturation, shifting reimbursement pathways, regulatory clarification, and demand-side preferences that favor autologous, minimally processed biologics. For executives, investors, and procurement leaders, the current moment represents a transition from early experimentation to scaled commercialization. The challenge lies in navigating a fragmented supply base, inconsistent coverage models, and evolving clinical evidence while capturing value in segments where efficacy, workflow integration, and reimbursement alignment intersect.
The market structure reveals a moderately concentrated landscape, with the top three players accounting for roughly 47.2 percent of revenue and the top five reaching 52.8 percent. This concentration suggests that scale, regulatory clearance, and system integration confer meaningful advantages, yet substantial runway remains for differentiated technologies and regional expansion. Growth is not evenly distributed across applications or geographies. Orthopedic and sports medicine use cases continue to anchor demand, while aesthetic and wound care applications present distinct reimbursement and clinical-evidence dynamics. The following analysis examines the forces shaping this transition, the strategic postures of leading participants, and the practical implications for decision-makers seeking to capitalize on the next phase of market development.
Plasma Protein Therapeutics Market
Market Snapshot: Growth Trajectory and Structural Realities
Over the 2020–2025 period, the PRP market expanded at a pace that outpaced many adjacent medical device and biologics segments. Revenue climbed from $236.5 million to $512.0 million, and forward projections indicate continued expansion through 2032, with annual figures moving from $579.7 million in 2026 to $1,032.3 million in 2032. This trajectory implies a sustained 10.5 percent CAGR, reflecting both underlying volume growth and incremental adoption of point-of-care preparation systems. The market’s composition spans multiple product formats, including pure PRP, leukocyte-rich variants, platelet-rich fibrin, and ancillary systems, alongside application breadth that covers orthopedic reconstruction, sports injury management, cosmetic procedures, and chronic wound care.
Despite the favorable headline numbers, the market operates within a set of structural constraints that shape commercial strategy. First, clinical evidence remains uneven across indications, with stronger data in select musculoskeletal and wound applications and more limited consensus in aesthetic and certain orthopedic injection contexts. Second, reimbursement pathways are partial and indication-specific, creating adoption friction in settings where providers cannot reliably pass through preparation costs. Third, regulatory classification creates a dual-track environment: FDA-cleared preparation devices enable compliant autologous use, while off-label applications depend on provider discretion and often lack broad coverage. Together, these realities mean that market growth is increasingly tied to workflow efficiency, evidence generation, and reimbursement alignment rather than to scientific novelty alone.
Key Challenges and Inflection Points
The PRP sector stands at several inflection points that will determine which participants capture durable value. One central challenge is the evidence-to-reimbursement gap. While point-of-care systems have improved consistency and reduced preparation variability, payers and institutions increasingly require indication-specific data, standardized protocols, and transparent cost accounting. Without these, adoption remains concentrated in cash-pay, sports medicine, and high-income aesthetic segments, limiting broader institutional uptake.
A second challenge involves cost structure and sterilization logistics. Single-use processing components, hemapheresis kits, and point-of-care consumables depend on gamma sterilization and small-batch manufacturing, which elevate unit costs and constrain margin flexibility. Suppliers must balance clinical-grade reliability with economic scalability, particularly as volume expectations rise and hospital procurement teams normalize total-cost-of-ownership assessments.
A third inflection point is regulatory clarity versus clinical flexibility. Autologous PRP devices are classified as Class II under 21 CFR 864.9245 and require 510(k) clearance, while PRP itself is regulated as a blood product by FDA CBER and is generally considered investigational for most non-wound applications. This framework ensures compliance for cleared autologous use but leaves many orthopedic and aesthetic injections in a provider-discretion zone without broad insurance coverage. The result is a market where device clearance, coding specificity, and clinical protocol design are increasingly intertwined commercial variables rather than purely regulatory checkboxes.
Core Drivers of Market Change
Technology Innovation and Workflow Integration
The most consequential technological shift is the move toward point-of-care systems that combine high platelet yields, customizable formulations, and rapid preparation workflows. Automated separation platforms, double-syringe kits, and single-spin systems have reduced preparation time and improved reproducibility, making PRP more viable in busy clinical environments. Systems that enable up to 18x platelet concentration at the point of care, or that deliver supraphysiologic concentrating with customizable formulations, address two practical barriers: clinical consistency and operational throughput. These capabilities matter because adoption in orthopedics and sports medicine often hinges on whether preparation can be embedded into existing procedure workflows without disrupting scheduling or staffing.
Technology differentiation is also moving toward application-specific optimization. In wound care, fibrin-based matrices and gel preparations that support exuding cutaneous wounds represent a distinct value proposition from injection-focused systems used in musculoskeletal settings. This specialization is creating a broader ecosystem in which device architecture, kit composition, and preparation protocol are increasingly matched to clinical use cases rather than sold as generic autologous blood products.
Policy and Regulatory Environment
Regulatory and coding developments are reshaping commercial viability. FDA clearance of PRP preparation systems establishes a compliance pathway for autologous use, while the broader classification of PRP as a blood product under FDA CBER keeps many non-wound applications in an investigational category. This duality means that device-level clearance does not automatically translate into coverage for every indication. Instead, commercial success increasingly depends on aligning cleared indications with coding structures and payer policies.
Worldwide Platelet Rich Plasma (PRP) Kit Market
Reimbursement dynamics are evolving in parallel. For chronic non-healing diabetic wounds, Medicare covers autologous PRP prepared with FDA-cleared devices under HCPCS G0465, with required invoice documentation for the PRP supply kit and an in-house processing fee. This creates a structured, if narrow, coverage pathway that rewards cleared devices and documented supply chains. At the same time, Category III coding such as 0232T applies to PRP injections across sites, including image guidance, harvesting, and preparation, with some payers requiring separate billing for supplies. These coding nuances affect provider economics and influence which systems are preferred in outpatient and institutional settings.
Demand-Side Shifts in Provider and Consumer Behavior
Demand is being reshaped by a preference for autologous biologics that minimize immunogenicity concerns and align with regenerative care models. In sports medicine and orthopedics, providers seek options that can be deployed during same-session procedures, reducing reliance on off-site processing and supporting rapid turnaround. In aesthetics, consumer interest in minimally invasive rejuvenation continues to drive volume, though this segment remains more sensitive to evidence messaging, pricing transparency, and outcomes consistency. In wound care, the demand driver is clinical necessity: chronic ulcers and non-healing wounds create a persistent care burden, and autologous PRP-based matrices offer a biologically aligned adjunct where standard dressings and therapies may be insufficient.
Across these settings, the common thread is a growing expectation that PRP should be reproducible, documented, and economically legible. Providers and procurement teams increasingly evaluate systems not only on platelet concentration claims but also on sterility assurance, kit reliability, ease of use, and compatibility with existing billing and documentation workflows.
Supply Chain and Cost Structure Evolution
Supply chain economics are becoming a strategic variable. Gamma sterilization requirements and small-batch manufacturing for single-use kits raise input costs, which can compress margins for manufacturers and increase total cost for providers. This environment favors participants that can standardize kit architectures, secure reliable sterilization pathways, and design systems that minimize waste or redundant consumables. It also rewards vertical alignment between device platforms and consumable supply, since fragmentation can introduce variability in both cost and clinical performance.
At the same time, distribution partnerships are altering market access. Agreements that place PRP systems under established brand channels can accelerate reach in specific clinical segments, particularly where wound care or orthopedic procurement is consolidated. Such arrangements can reduce the commercial burden on smaller manufacturers while expanding the availability of cleared systems within trusted distribution networks.
Competitive Landscape and Leading Strategies
Strategic Positioning Among Core Participants
The competitive set reflects a mix of device-focused manufacturers, biologics integrators, and specialty developers pursuing differentiated preparation architectures. Several participants have built their positioning around point-of-care concentration performance and workflow reliability. EmCyte Corporation emphasizes a supraphysiologic concentrating system for point-of-care autologous PRP preparation with customizable formulations and high platelet yields, appealing to settings that value concentration control and formulation flexibility. Arthrex, Inc. focuses on an automated PRP system and double-syringe kits designed for orthopedic applications, enabling high platelet concentration at the point of care and integrating preparation into procedure workflows. Zimmer Biomet emphasizes integrated PRP systems and biologics kits that support orthopedic reconstruction and soft-tissue procedures, leveraging the advantages of an established orthopedic portfolio. Terumo BCT targets point-of-care PRP systems and related kits for rapid autologous preparation, with an emphasis on workflow speed and clinical usability.
PW Consulting
In parallel, several developers have pursued application-specific differentiation. Regen Lab S.A. focuses on PRP kits and systems optimized for clinical use in regenerative medicine applications, aligning product design with practitioner workflows. Royal Biologics has concentrated on fibrin-based PRP and PRF systems for wound management and bone graft handling, including a PRF wound matrix that recently received FDA clearance for management of exuding cutaneous wounds, including diabetic and venous ulcers. Nuo Therapeutics, Inc. has built a wound care and biodynamic therapy focus, with its PRP system distributed through private-label arrangements to Smith+Nephew in the U.S. wound care market. Gale Force Aesthetics, LLC emphasizes a single-spin system designed for high-volume platelet capture and rapid preparation, while Forever Labs, Inc. focuses on an automated separator for safe, rapid autologous PRP preparation at the point of care. Royal Wound-X, Inc. concentrates on a PRF-matrix system for rapid PRP gel preparation from peripheral blood for wound management.
These positions illustrate two strategic paths. One path concentrates on concentration performance, automation, and orthopedic or sports medicine integration, where procedural efficiency and reproducibility are paramount. The other path emphasizes wound care and regenerative applications, where matrix properties, clearance status, and reimbursement compatibility can create more defined commercial pathways. Both paths require disciplined alignment between device capability, kit economics, and clinical protocol design.
Market Evolution: Consolidation, Differentiation, and New Entry
The market is evolving along multiple axes. Consolidation pressure is rising where scale, distribution reach, and regulatory clearance create advantages, particularly in segments where procurement is centralized or where private-label distribution can rapidly expand availability. Differentiation is intensifying around workflow integration, concentration consistency, and indication-specific design, as generic autologous blood preparation becomes less distinctive in a maturing market. At the same time, new entrants continue to appear, often bringing novel spin architectures, automated separation concepts, or niche wound care formulations that challenge established incumbents on speed, yield, or use-case fit.
A notable dynamic is the increasing importance of commercial alignment beyond pure product performance. Recent developments such as exclusive private-label distribution agreements in wound care and FDA clearances for specific wound matrix indications demonstrate how regulatory milestones and channel partnerships can reshape market access. In wound care especially, clearance for exuding cutaneous wounds and diabetic or venous ulcers can materially change the commercial profile of a system by enabling more defensible positioning within reimbursement-eligible pathways. In orthopedics and aesthetics, the absence of broad coverage for many off-label applications means that competitive advantage often depends on provider education, protocol standardization, and total cost management rather than on clearance alone.
Forward Outlook: Trends Shaping the Next Three to Five Years
Trend 1: Indication-Specific Commercialization Becomes the Norm
The next phase of growth will likely reward participants that align device design, coding strategy, and clinical evidence with specific indications rather than treating PRP as a single homogeneous category. Wound care offers a concrete example: where cleared devices and defined coverage pathways exist, commercialization can be structured around documented supply chains, processing fees, and matrix-based protocols. In musculoskeletal and aesthetic settings, growth may remain stronger in cash-pay and sports medicine channels unless evidence and coding evolve further. The commercial implication is clear: companies that build indication-specific value propositions, including protocol support and billing compatibility, are better positioned to convert adoption into repeatable revenue.
Trend 2: Automation and Workflow Integration Will Separate Leaders from Laggards
Point-of-care automation, rapid preparation, and high-yield concentration are increasingly baseline expectations rather than differentiators. The next competitive frontier is end-to-end workflow integration: systems that minimize hands-on time, reduce variability, and fit cleanly into existing clinical routines. This matters because clinical adoption is often constrained by operational friction as much as by clinical interest. Manufacturers that can demonstrate reliable kit performance, straightforward preparation steps, and compatibility with institutional procurement and documentation requirements will have an advantage in converting trial use into sustained adoption.
Trend 3: Reimbursement Architecture and Cost Transparency Will Shape Segment Economics
As payers, institutions, and providers scrutinize cost, the economics of PRP will depend more heavily on coding clarity, supply-chain documentation, and processing-fee structures. Narrow coverage pathways can be commercially attractive where they are well-defined, but they also demand rigorous invoice and kit documentation. In segments where coverage is limited, cost transparency and predictable kit economics will influence whether providers continue to adopt PRP or redirect spend to alternative biologics or procedures. The risk is that uneven reimbursement and variable sterilization-driven costs create instability in margin planning and adoption forecasting.
Opportunities and Uncertainties
These trends open several commercial opportunities. There is room for differentiated systems that combine automation with application-specific performance, particularly where wound care clearance or orthopedic workflow integration can be clearly demonstrated. Distribution partnerships and private-label arrangements can accelerate access in consolidated procurement environments. There is also opportunity in standardizing kit economics and sterilization pathways to improve margin resilience. At the same time, uncertainties remain: evidence gaps in select indications, reliance on provider discretion for many off-label applications, and cost pressures from gamma sterilization and small-batch manufacturing can all temper growth expectations. Participants should also monitor regulatory developments, since device clearance does not automatically broaden coverage, and coding practices may continue to diverge across payers and regions.
Strategic Implications for Decision-Makers
For Manufacturers and Technology Developers
- Align product development with indication-specific workflow needs, prioritizing automation, reproducibility, and kit reliability over concentration claims alone.
- Invest in documentation-ready supply chains and clear billing compatibility, especially where coverage pathways such as wound care codes create structured economic models.
- Pursue distribution partnerships or private-label channels where procurement is consolidated, using cleared indications and proven reproducibility to gain entry into institutional workflows.
- Plan for cost structure resilience by standardizing single-use components, securing reliable sterilization pathways, and reducing consumable waste wherever possible.
For Investors
- Evaluate companies on the strength of their regulatory positioning, reimbursement alignment, and workflow integration rather than on market-level growth narratives alone.
- Favor business models that can convert clinical interest into repeatable economics, including recurring kit demand, stable sterilization and manufacturing pathways, and defensible channel access.
- Monitor segment-specific dynamics closely, since wound care, orthopedics, sports medicine, and aesthetics each face different evidence, coverage, and pricing constraints.
- Assess whether a company’s differentiation is durable in the face of automation becoming a baseline expectation, and whether its cost structure can withstand single-use kit economics.
For Procurement and Clinical Leaders
- Evaluate PRP systems against total cost of ownership, including kit reliability, preparation time, sterility assurance, and billing documentation requirements.
- Match system selection to the intended indication and clinical protocol, recognizing that wound care, orthopedic, and aesthetic applications often require different performance and coverage considerations.
- Require transparent documentation for supply kits, processing fees, and device clearance status to support compliance and reimbursement where applicable.
- Prioritize vendor support that includes protocol guidance, staff training, and consistent kit availability, since workflow friction can undermine adoption even when clinical interest is strong.
The PRP market is moving from broad enthusiasm to disciplined commercialization. Growth is increasingly determined by the intersection of cleared device pathways, reimbursement compatibility, workflow integration, and cost transparency. In that environment, the most valuable intelligence is segment-specific: how clearance status interacts with coding, how kit economics behave under sterilization and small-batch constraints, and where distribution partnerships can open durable access. Detailed segmentation data, competitive benchmarking, and customized scenario planning can help decision-makers translate these dynamics into concrete investment, product, and procurement choices. For leaders seeking a fuller view of the market’s subsegments, regional trajectories, and company-level positioning, accessing the complete research dataset and methodology notes provides the granularity needed to act with confidence.
For detailed analysis of this topic, please visit the official page: Platelet Rich Plasma (PRP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
ESP Market 2026–2032: Why 6.4% CAGR and Power Generation Dominance Redefine Strategy
By PW Consulting, 2026-09-21
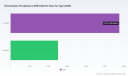
Navigating the Electrostatic Precipitators Market: Strategic Trends and Commercial Opportunities Through 2032
The electrostatic precipitator (ESP) market is entering a phase of measured but meaningful expansion, driven by tightening emissions standards, aging infrastructure demands, and incremental technological upgrades. Between 2020 and 2025, the global market grew from 6,500.0 million USD to 8,300.0 million USD, reflecting steady demand across utility and industrial sectors. Looking ahead to the 2026-2032 forecast period, the trajectory points toward a compound annual growth rate of 6.4%, with revenue projected to reach 12,790.0 million USD by 2032. This growth is not uniform. It is concentrated among a handful of established players, as reflected in a CR3 of 38.2% and CR5 of 55.0%, indicating that scale, technical expertise, and long-term service relationships continue to shape competitive dynamics. The market’s structure favors firms that can deliver not only hardware but also lifecycle support, performance upgrades, and integration with broader emission control systems.
Behind the headline numbers lie structural tensions that will define how companies position themselves over the next several years. The first challenge centers on the balance between capital intensity and operational efficiency. Advanced ESP configurations increasingly rely on digital control modules, corrosion-resistant materials, and hybrid filtration approaches, all of which raise upfront investment. At the same time, electrical energy consumption in large-scale installations remains substantial, translating into ongoing operating costs that plant operators must justify against performance gains. The second challenge is regulatory fragmentation. While federal and regional standards continue to push particulate limits downward, the pace and specifics of compliance requirements vary by jurisdiction and by industrial application, creating uneven demand cycles and complicating long-term planning. The third challenge involves the shift from greenfield installations to retrofit and rebuild activity. Many existing plants are prioritizing incremental upgrades that restore or exceed original collection efficiency without full system replacement, reshaping procurement patterns and service expectations.
Market Structure and the Shift Toward Service-Enabled Solutions
The ESP market’s evolution is increasingly defined by how suppliers manage the entire asset lifecycle rather than by initial equipment sales alone. Rebuild contracts, performance optimization, and integration with flue gas treatment systems are gaining weight in commercial negotiations. Companies that can demonstrate consistent collection efficiency, lower operating expenditure, and predictable maintenance intervals are finding stronger positioning in both utility and industrial segments. This shift is visible in recent contract activity and network expansion moves, where the emphasis is on extending service reach, supporting existing installations, and delivering measurable efficiency improvements. For decision-makers, the implication is clear: competitive advantage is moving from hardware specification to total cost of ownership and performance reliability over time.
Key Drivers Reshaping the ESP Market
Regulatory Pressure as a Baseline Demand Catalyst
Emissions regulations are the most consistent force behind ESP demand, and recent regulatory actions reinforce that trajectory. In the United States, the EPA’s Mercury and Air Toxics Standards require coal-fired power plants to contain filterable particulate emissions at 0.03 lb/MMBtu, accelerating the deployment of ESP systems that can meet or exceed those limits. At the same time, federal regulations on particulate matter emissions from industrial sources continue to compel facilities to adopt ESP technologies for compliance. These requirements do not merely create one-time purchase cycles; they establish a compliance floor that encourages operators to invest in systems capable of sustained performance, particularly where future tightening is anticipated. For suppliers, this environment rewards proven high-efficiency collection capability and the ability to document compliance outcomes.
Technological Innovation: Efficiency, Control, and Integration
Technological progress in ESP systems is increasingly focused on improving collection efficiency while moderating energy use and simplifying integration with downstream gas cleaning. High-efficiency collection up to 99.9% is now a benchmark that several leading providers reference, and achieving that level consistently often depends on advanced electrode design, better discharge management, and refined control logic. Equally important is the move toward smarter operation. AI-enhanced control systems and digital monitoring are being embedded into ESP platforms to adjust operating parameters in response to load changes, dust characteristics, and process conditions. This reduces wasted energy, stabilizes performance, and improves predictability for plant operators. Integration with flue gas conditioning and NOx reduction technologies further extends the value of ESP installations, especially in coal-fired utility settings where multi-pollutant control is a priority.
Recent developments illustrate how these innovations are being commercialized. Babcock & Wilcox secured more than 18 million USD in wet and dry ESP rebuild contracts for utility and industrial plants across the U.S. and Europe, emphasizing collection efficiency up to 99.9%, a clear signal that performance-led upgrades remain commercially attractive. FLSmidth expanded its service center network with a new facility in Dammam, Saudi Arabia, to support advanced emission control technologies including electrostatic precipitators, reflecting a strategy of positioning service capability closer to key industrial demand centers. Mitsubishi Heavy Industries delivered an ESP unit for a 700,000-tonne chemical pulp project in China, while Valmet shipped electrostatic precipitators to Nordic Paper’s Swedish Backhammar recovery boiler with completion targeted by the end of 2025. These activities show that demand is not limited to power generation; pulp and paper, chemical pulp production, and broader industrial recovery systems are also active deployment areas where ESP performance matters.
Demand-Side Shifts Across Power and Industrial Applications
Demand for ESP systems continues to be anchored by power generation, particularly where coal-fired and biomass-linked facilities must meet strict particulate limits or extend the viable operating life of existing assets. Beyond power, industrial applications are expanding the addressable market. Cement and lime processing, waste-to-energy and biomass, chemical and petrochemical operations, and specialized sectors such as pulp and paper recovery boilers all present distinct dust characteristics and operating conditions that shape ESP selection. The commercial implication is that a single ESP architecture rarely fits all applications. Suppliers that can tailor electrode design, gas flow management, and cleaning methods to specific process environments are better positioned to capture demand across multiple verticals. This is also where wet and dry system choices become strategically important, with selection driven by dust properties, moisture content, and downstream process constraints.
PW Consulting
Cost, Energy, and Supply Chain Considerations
Despite the positive demand outlook, cost and energy dynamics remain central to commercial decision-making. High capital and maintenance costs for advanced ESP systems incorporating digital control modules, corrosion-resistant materials, and hybrid filtration technologies require substantial upfront investment. Electrical energy consumption in electrostatic precipitators can also be substantial, with resulting high operating costs for large-scale installations. These factors encourage a more disciplined approach to procurement, where operators evaluate not only collection performance but also energy profile, maintenance intervals, and 부품 or material availability over the system’s lifespan. Supply chain considerations are becoming more prominent as well, particularly for specialized materials and control hardware. Providers that can streamline sourcing, localize support, and reduce downtime through predictable maintenance planning are likely to gain preference in competitive bidding situations.
Competitive Landscape and How Leading Players Differentiate
The ESP market is moderately concentrated, with a limited group of established companies holding meaningful share and long-standing relationships across utility and industrial markets. Market leadership is less about unit volume alone and more about the breadth of application coverage, demonstrated efficiency, service reach, and the ability to offer integrated emission control solutions. Several firms have built their positioning around high-efficiency systems, rebuild and retrofit capabilities, and sector-specific expertise. For example, some leaders emphasize wet and dry ESP systems for utility and industrial power generation with global installation experience, while others specialize in advanced ESP technologies integrated with gas cleaning systems for industrial emission control. Custom wet and dry ESP manufacturing for power, cement, and steel applications remains a differentiator for firms serving heavy industrial environments, and AI-enhanced control systems are increasingly part of the value proposition for providers targeting cement and industrial applications.
Worldwide Dry Electrostatic Precipitator Market
Company activity over the past two years highlights three strategic themes. First, performance-led rebuilds are a commercially meaningful pathway, as shown by major rebuild contracts focused on restoring or improving collection efficiency in existing plants. Second, geographic and service expansion is being used to reduce response times and strengthen relationships in important demand regions, including the Middle East. Third, sector-specific project wins in pulp, chemical pulp, and recovery boiler environments indicate that specialization can open doors beyond the largest power generation markets. Together, these moves suggest a market where incumbents are reinforcing their positions through service proximity, proven efficiency claims, and application-specific execution rather than relying solely on equipment pricing.
Consolidation, Fragmentation, and Entry Dynamics
The ESP market is not experiencing dramatic consolidation at the top, but it is showing signs of functional consolidation around capabilities. Buyers increasingly value suppliers that can handle design, installation, commissioning, and ongoing optimization under a coordinated framework. At the same time, niche players remain relevant where specialized applications, local support needs, or custom engineering demands create room for focused offerings. New entry is challenging but not impossible, especially where a company brings a clear technical advantage, such as a novel control approach, improved energy management, or a distinctive material solution that lowers lifecycle cost. In practice, the most resilient competitors are those that combine technical credibility with commercial flexibility, allowing them to serve both large-scale utility projects and smaller industrial retrofits without losing operational focus.
Forward Outlook: Trends Likely to Shape the Next 3-5 Years
Trend 1: Efficiency and Energy Management Will Become the Central Battleground
As regulations tighten and operating costs remain under scrutiny, the most important competitive differentiator will be the ability to deliver high collection efficiency without inflating energy consumption. Systems that can modulate power use intelligently, sustain efficiency across variable loads, and integrate with broader plant controls will be favored in both new installations and upgrades. This trend creates commercial opportunities for providers that can quantify energy savings, reduce maintenance burden, and show compliance durability over time. It also raises the stakes for suppliers still relying on static operating profiles, since plants are increasingly reluctant to accept high operating costs as a fixed requirement.
Electrostatic Chucks (ESCs) Market
Trend 2: Retrofit, Rebuild, and Life Extension Will Outweigh Greenfield Demand in Many Markets
In many regions, the near-term opportunity lies less in replacing entire systems and more in restoring performance, adapting to new fuel or process conditions, and extending service life. Rebuild contracts and targeted upgrades are likely to remain a significant share of activity, especially where plants need to meet current standards or prepare for future limits without committing to full replacement. This shift rewards vendors with strong field service capabilities, modular upgrade paths, and the ability to diagnose existing installations efficiently. For investors and manufacturers, it suggests that service-oriented revenue streams and upgrade kits may be as strategically important as flagship new-system sales.
Trend 3: Regional Service Footprints and Application Specialization Will Determine Access to Demand
Demand is geographically and sectorally uneven, and access to projects will increasingly depend on local presence and application knowledge. Expansion of service centers, local support teams, and region-specific engineering capacity can reduce friction in procurement and commissioning while improving responsiveness during operation. At the same time, companies that understand the dust and process nuances of specific industries will be better positioned to win in segments such as cement, waste-to-energy, chemical, and pulp and paper applications. The commercial opportunity here is to build repeatable sector playbooks rather than treating each project as a standalone customization exercise.
Risks and Uncertainties to Monitor
Several uncertainties could alter the pace or shape of market growth. Regulatory timelines may shift, particularly if compliance deadlines are adjusted or if enforcement emphasis changes across jurisdictions. Energy pricing and availability can affect operating economics, especially for large installations where power use is a major cost element. Material availability and lead times for specialized components may influence project scheduling and total cost. Finally, changes in fuel mix, plant retirement decisions, and the balance between coal, biomass, and alternative generation pathways can reshape where ESP demand appears and how quickly it materializes. Companies that monitor these variables closely will be better prepared to adjust pipeline planning and service capacity.
Strategic Recommendations for Decision-Makers
For ESP Manufacturers and Solution Providers
- Prioritize total-cost-of-ownership positioning by documenting efficiency outcomes, energy behavior, and maintenance predictability, not just collection performance at a point in time.
- Invest in service and rebuild capabilities, since retrofit and upgrade activity is likely to remain a durable source of revenue and customer contact.
- Build application-specific engineering playbooks for cement, waste-to-energy, chemical, and pulp and paper environments, where process conditions shape system selection and value claims.
For Investors and Strategic Partners
- Evaluate providers based on their ability to sustain high-efficiency claims in the field, expand service reach, and capture multi-pollutant integration opportunities rather than equipment scale alone.
- Watch for commercial signals in rebuild activity, regional service expansion, and sector project wins, as these often indicate where demand is becoming more concrete.
- Assess exposure to energy-intensive operating profiles and specialized material supply, since these factors influence margin stability and project execution risk over the forecast period.
For Plant Operators and Procurement Teams
- Select ESP solutions with a clear view of lifecycle cost, including energy consumption, maintenance intervals, and the feasibility of future upgrades as regulations or processes change.
- Use rebuild and retrofit pathways where feasible to meet current compliance targets while preserving capital flexibility for other plant priorities.
- Request performance evidence tied to operating conditions similar to your own, especially for dust characteristics, load variability, and integration with existing gas treatment systems.
The ESP market is moving toward a more performance-intensive, service-oriented, and application-aware phase of growth. That shift rewards companies that can combine proven collection efficiency with smarter operation, local support, and credible lifecycle economics. For organizations seeking to navigate this environment with greater precision, deeper segmentation data, company-level benchmarks, and customized strategic guidance can clarify where to commit resources and how to sequence next steps. Access the full PW Consulting report on the Electrostatic Precipitators market to explore detailed segmentation, competitive profiles, and forward-looking scenarios built for planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Electrostatic Precipitators (ESP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Robotic Polishing Machine Market: Why the 12.6% Growth Trajectory Redefines Competition
By PW Consulting, 2026-09-21
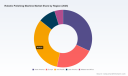
Robotic Polishing Machine Market: Strategic Shifts, Competitive Dynamics, and Value Creation Horizons
The global market for robotic polishing machines is entering a phase of accelerated structural transformation. Between 2020 and 2025, market revenue expanded from approximately $163 million to $215 million, reflecting sustained adoption across precision manufacturing and surface finishing workflows. The trajectory forward indicates a compound annual growth rate of 12.6% through 2032, with projected revenue approaching $345 million by the end of the forecast horizon. This growth is not merely a function of incremental automation adoption; it reflects a fundamental rethinking of how surface quality, throughput, and labor constraints interact in modern production environments. For executive teams and capital allocators, the implication is clear: robotic polishing is transitioning from a niche productivity tool to a strategic capability that shapes product quality, operational resilience, and competitive positioning.
Market Snapshot and Structural Challenges
The market’s expansion over the past half-decade has been broad-based, with steady year-over-year increases that signal deepening integration rather than speculative cycles. Revenue climbed from roughly $174 million in 2021 to nearly $208 million in 2024, before stabilizing near $215 million in 2025. The forward path suggests continued momentum, with the market expected to cross $250 million by 2027 and approach $290 million around 2030. Yet this headline trajectory masks a more nuanced reality. Growth is uneven across use cases, and the market is navigating several inflection points that will separate winners from laggards.
One of the most pressing challenges is the tension between standardization and application-specific customization. Polishing requirements vary dramatically by material, geometry, tolerance thresholds, and finish specifications. A solution that performs exceptionally on high-volume automotive components may struggle with delicate electronics housings or irregularly shaped stone surfaces. Manufacturers are therefore forced to balance the cost efficiencies of modular, repeatable systems against the precision demanded by specialized workflows. This creates a strategic fork: companies that over-index on rigid automation risk losing high-margin niches, while those that overengineer custom solutions may sacrifice scalability and total cost of ownership advantages.
A second challenge lies in workforce transition and operational integration. Deploying robotic polishing is not simply a hardware purchase; it requires reconfiguration of upstream and downstream processes, recalibration of quality control protocols, and upskilling of operators who must interface with systems that blend mechanical execution with sensor-driven adaptation. Facilities with strong internal automation competency are absorbing these transitions relatively smoothly, but organizations with fragmented production planning or limited engineering bandwidth are experiencing longer payback periods and higher initial friction. The market is increasingly rewarding operators who treat robotic polishing as a process transformation initiative rather than a point solution.
A third challenge is the evolving regulatory and safety environment. Industrial robotics deployments are subject to stringent operational safety requirements, and robotic polishing systems introduce additional complexity due to dynamic force application, tool wear, and interaction with delicate or irregular workpieces. Compliance frameworks now emphasize risk assessments, protective measures, and system-level integration checks. While these standards are essential for safe, scalable deployment, they also raise the barrier to entry for smaller integrators and increase the importance of designing for compliance from the outset rather than retrofitting it after the fact.
Core Drivers Reshaping the Market
Several interconnected forces are accelerating the shift toward robotic polishing, and each carries distinct strategic implications for how companies should position themselves.
Technology Innovation and Adaptive Control
The most consequential technical shift is the move from static, pre-programmed finishing routines to adaptive, sensor-informed polishing. Advanced systems increasingly combine multi-axis motion with force control, vision-based inspection, and closed-loop feedback that adjusts pressure, speed, and tool engagement in real time. This capability directly addresses one of the long-standing limitations of automation in surface finishing: the inability to maintain consistent quality when workpieces vary or when tool wear introduces drift. AI-enabled platforms are pushing this further by scanning surfaces, mapping deviations, and automating path generation without extensive manual programming. The result is faster setup, reduced rework, and more repeatable finishes on complex geometries. For manufacturers, the strategic takeaway is that value is increasingly created not just by the robot arm itself, but by the intelligence layer that governs how polishing decisions are made during production.
Regulatory and Safety Expectations
As robotic systems become more capable and more widely deployed, safety and compliance expectations are becoming a defining element of market acceptance. Governing standards for industrial robots now require structured risk assessments and protective measures that account for force-controlled interactions, tool changes, and human proximity in shared workspaces. This is particularly relevant in polishing applications where unpredictable material response and tool wear can create operational variability. Systems designed with integrated safety logic, documented risk controls, and modular compliance features are gaining preference, especially in regulated industries and in deployments where multiple stakeholders must validate automation before scaling. Compliance is no longer a checkbox; it is becoming a competitive differentiator that influences procurement decisions, deployment speed, and long-term operational risk.
Demand-Side Shifts in Quality, Throughput, and Consistency
On the demand side, manufacturers are under increasing pressure to deliver higher consistency at lower defect rates while maintaining throughput. Automotive production, electronics assembly, hardware tooling, and household product manufacturing all place distinct demands on surface finish, but they share a common requirement: quality cannot be treated as a variable that is inspected in at the end of the line. It must be engineered into the process. Robotic polishing supports this shift by reducing dependence on manual skill variability, enabling repeatable finishes across shifts and facilities, and freeing skilled workers for higher-value tasks. At the same time, end customers and OEM partners are increasingly specifying finish tolerances and appearance standards that are difficult to meet reliably with manual or semi-automated methods. This demand-side pressure is expanding the addressable use case set beyond high-volume commodity finishing into precision and brand-sensitive applications where finish quality directly affects perceived value and downstream performance.
Supply Chain and Cost Structure Dynamics
Cost structures are also evolving in ways that reshape ROI calculations for automation. Labor availability, wage dynamics, and training burdens continue to push manufacturers toward solutions that reduce dependence on highly skilled manual finishing labor. At the same time, improvements in component availability, tooling ecosystems, and system integration practices are gradually lowering the total cost of deployment for well-scoped projects. The most compelling economics are emerging where robotic polishing is used not only to replace labor but to compress cycle times, reduce scrap and rework, and stabilize output quality across production runs. Companies that evaluate ROI narrowly through headcount replacement often underestimate the operational value of consistency, uptime, and reduced quality leakage. The market is increasingly favoring deployments that are justified through a broader set of operational benefits rather than labor cost alone.
Competitive Landscape and Leading Strategies
The competitive environment is shaped by a mix of established automation suppliers, specialized tooling and finishing companies, and newer entrants bringing software-centric approaches to surface finishing. Several firms stand out for the way they are positioning their offerings around different value propositions.
Acme Manufacturing has built a strong focus on robotic polishing machines with advanced belt polishing heads, targeting high-volume producers that need repeatable finishes on complex shapes. Its strategic emphasis is on throughput and consistency for demanding production environments, where the ability to maintain finish quality across large batches is a core purchasing driver. This positioning reflects a broader trend: in high-volume segments, reliability and repeatability are often more valuable than flexibility, and suppliers that can demonstrate proven performance at scale gain traction.
Mirka Ltd offers a more complete system view, combining robotic polishing and sanding systems with tools and automation solutions for industrial surface finishing. By presenting an integrated tool-plus-automation proposition, Mirka addresses customers who want fewer integration handoffs and a more coordinated hardware ecosystem. This approach reduces ambiguity in tool selection, process setup, and maintenance planning, which can be especially valuable for organizations that prefer to simplify supplier complexity and standardize finishing workflows.
GrayMatter Robotics has differentiated itself with AI-powered robotic polishing systems that scan surfaces and automate polishing to support manufacturing capacity and quality enhancement. This software-led approach centers on reducing programming effort and enabling faster adaptation to variation, which appeals to environments where part diversity or setup changeovers make conventional programming costly. The strategy highlights a growing market segmentation: systems that emphasize intelligence, scanning, and automated path generation are gaining relevance wherever flexibility and responsiveness are prioritized over fixed, high-volume routines.
Dinosaw Machine manufactures 6-axis robotic arms and systems for stone grinding and polishing, with a focus on force control and precision tooling. Its emphasis on precision control and material-specific applications illustrates the importance of domain specialization. In materials such as stone, where structural variability and surface behavior can differ significantly from metallic or synthetic workpieces, force-controlled accuracy and tooling precision are central to performance. This specialization also aligns with the broader regulatory and safety expectations for industrial robots, where force control and protective integration are increasingly viewed as prerequisites for reliable deployment.
American Siepmann Corporation supplies automated CNC polishing machines and robotic systems for high-precision industrial finishing. Its positioning reflects demand for tightly controlled processes in environments where tolerance, repeatability, and integration with CNC workflows matter. The company’s focus on precision industrial finishing underscores the fact that robotic polishing is not a single market but a family of use cases, each with its own performance priorities and procurement logic.
Recent market developments reinforce these strategic directions. In late 2025, Dinosaw Machine presented a detailed analysis of stone polishing robot technology, emphasizing 6-axis force control and safety integration. That activity reflects a broader industry emphasis on controlling force dynamically while meeting safety expectations for industrial robotics. Meanwhile, Mirka Ltd updated its robotic solutions materials to highlight automated polishing, sanding, and grinding systems, signaling continued investment in integrated finishing offerings and a desire to make automation more accessible across a wider set of applications. These kinds of moves suggest that leading players are expanding system completeness, reinforcing safety and control capabilities, and refining the way they communicate value to customers who are evaluating automation across multiple use cases.
PW Consulting
The market structure itself is moderately concentrated, with the top firms accounting for a majority of revenue. This concentration does not imply stagnation; rather, it suggests that scale, integration depth, and brand trust still matter in a market where deployment risk and process reliability are significant concerns. At the same time, the landscape is open enough to permit differentiation through technology depth, application specialization, and software-enabled flexibility. New entrants and niche specialists can compete by solving specific finishing problems better than broader incumbents, particularly in high-value or technically demanding segments. Consolidation is likely to continue where larger players seek to broaden their system capabilities, but fragmentation will persist where application diversity and regional manufacturing patterns reward localized specialization.
Outlook: Key Trends for the Next Three to Five Years
Looking ahead, several trends are likely to shape how the market evolves and where commercial opportunities will concentrate.
-
Adaptive, intelligence-led finishing will become a baseline expectation rather than a premium feature. Systems that can scan, measure, and adjust polishing behavior in real time will increasingly be favored because they reduce programming burden, improve robustness to variation, and support faster changeovers. Over the next few years, the strategic question will shift from whether to adopt robotic polishing to how much adaptive control is necessary for a given application and how to integrate that capability into quality workflows.
-
Application specialization will intensify, with suppliers and end users aligning solutions more tightly to material and process requirements. Polishing for automotive components, electronics, hardware tools, household products, and stone or specialty materials each carries distinct demands. Companies that build deep domain expertise, tool ecosystems, and demonstration cases in specific verticals are likely to earn stronger customer trust and pricing power than those that attempt to serve all segments with generic solutions. This trend creates opportunities for focused innovators and for established players that can credibly claim leadership in a defined application set.
-
Integration and compliance will increasingly operate as joint value drivers. As deployments scale, customers will care not only about the polishing module but about how it connects to upstream machining, downstream inspection, tooling maintenance, and operational safety. Systems that are designed with documented safety integration, risk-control logic, and interoperability in mind will face lower deployment friction and will be easier to scale across facilities. In practice, this means that the most successful offerings will be those that reduce the total integration burden rather than simply optimizing a single machine’s performance.
These trends create clear commercial opportunities, but they also carry risks. One risk is overinvestment in automation before process maturity is sufficient to absorb it. Facilities that lack stable upstream processes, clear quality specifications, or operational discipline may experience disappointing results even with capable hardware. Another risk is market fragmentation driven by application diversity: too much customization can erode scalability, while too little can leave high-value segments underserved. A third risk is the pace of regulatory and safety expectations, which may continue to evolve and raise the standard for what counts as a deployable system. Organizations that treat safety, integration, and process design as afterthoughts will face higher costs and slower adoption curves.
Strategic Implications for Decision Makers
For manufacturers evaluating robotic polishing, the first priority should be to define the operational problem with precision. The strongest business cases typically emerge where finishing variability, rework, or throughput constraints are well understood and where automation can be introduced into a process that already has clear quality targets and stable upstream conditions. Rather than starting with the hardware, leaders should start with the finish specification, the tolerance for variation, the frequency of changeovers, and the cost of quality leakage. That framing makes it easier to determine whether a repeatable high-volume system, an adaptive AI-driven platform, or a precision-focused CNC-integrated solution is the better fit.
For investors and strategic planners, the opportunity lies in identifying where value is being created along the chain. Revenue growth is meaningful, but the more important question is where margins, differentiation, and recurring value are forming. Companies that control the combination of hardware, tooling, adaptive software, and integration know-how are likely to capture more durable value than those competing primarily on unit pricing. Equally important is the ability to demonstrate measurable outcomes in targeted applications. Investors should favor exposure to players that can connect their technology to defensible use cases, repeatable deployments, and clear operational benefits, rather than to broad claims that are not anchored in specific finishing problems.
Worldwide Glass Polishing Powder Market
For procurement and operations leaders, the emphasis should be on total deployment risk rather than initial sticker price. That means evaluating tooling ecosystems, programming and changeover burden, safety and compliance posture, and the service and maintenance model alongside the core machine. A system that appears marginally more expensive may offer materially lower integration risk and faster ramp-up if it reduces programming time, simplifies tooling management, or embeds safety and quality logic more effectively. Procurement decisions that incorporate these factors tend to produce more reliable outcomes and fewer hidden costs after deployment.
For all of these audiences, the value of detailed, current market intelligence is rising. The market is moving quickly enough that broad assumptions about adoption, pricing, and competitive positioning can become outdated within a short period. Segment-level demand patterns, technology substitutions, regulatory expectations, and supplier strategies can differ significantly across regions and applications, and these differences shape where opportunities are real and where they are overstated. Organizations that use detailed, structured intelligence to map their specific application, cost structure, and competitive environment are better positioned to calibrate investment timing, prioritize use cases, and avoid committing to solutions that do not fit their operational reality.
As the robotic polishing market continues its shift from incremental automation to capability-driven competitiveness, the leaders who benefit most will be those who approach it as a strategic decision rather than a tactical purchase. The combination of adaptive technology, application specialization, safety-aware integration, and disciplined ROI framing will determine which organizations capture durable value. For decision makers seeking a deeper view of segment-level dynamics, regional variation, and tailored scenario planning, the full PW Consulting research report on the robotic polishing machine market provides a more detailed foundation for those decisions.
Robotic Polishing Cells Market
For detailed analysis of this topic, please visit the official page: Robotic Polishing Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Fibrinogen Concentrates Market: Why a 5.96% CAGR Reshapes the $704.96M Outlook by 2032
By PW Consulting, 2026-09-21
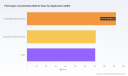
Strategic Trends and Commercial Opportunities in the Fibrinogen Concentrates Market
The global fibrinogen concentrates market has evolved from a specialized niche into a strategically significant segment within the broader plasma-derived therapeutics landscape. Market valuation reached approximately USD 468.38 million in 2025, reflecting a compound annual growth rate of 5.96 percent over the historical evaluation period and positioning the sector for continued expansion through 2032, when projected revenues approach USD 705 million. This trajectory is not merely a function of demographic demand or clinical adoption; it reflects structural shifts in surgical standards, regulatory pathways, manufacturing efficiency, and the economics of hemostatic care. For executives navigating biologics markets, fibrinogen concentrates present a case study in how concentrated therapeutic classes can scale while navigating plasma supply constraints, reimbursement complexity, and competitive differentiation.
PW Consulting
At the same time, the market is not without friction. Growth trajectories must be weighed against manufacturing bottlenecks, cost barriers for end users, and the evolving reimbursement environment that determines real-world utilization. Understanding where value is being created, which strategic moves are compounding advantage, and where uncertainty remains is essential for companies allocating capital, shaping product roadmaps, or evaluating partnership and acquisition targets in hemostasis and plasma-derived therapies.
Market Dynamics and Core Challenges
The current market structure reflects a mature but still expanding therapeutic category. Demand is distributed across surgical bleeding management, congenital fibrinogen deficiency, and a broad set of acquired and specialized applications. The product mix continues to favor powdered formulations, while liquid presentations are gaining incremental traction as reconstitution and storage considerations are addressed through formulation innovation. Geographically, developed markets continue to anchor the largest revenue shares, but the growth profile increasingly depends on expanded access in regions where hemophilia and bleeding disorder infrastructure is maturing.
Human Fibrinogen Market
Several forces are converging to define the near-term inflection points for the industry:
- Plasma supply and fractionation economics remain the dominant cost constraint. Fibrinogen-rich plasma inputs account for more than half of total production costs, which means that supply chain resilience, yield optimization, and donor plasma economics directly influence pricing power and margin stability.
- Reimbursement and coding frameworks are evolving rapidly in key markets. Recent HCPCS designations and expanding clinical approvals are reshaping the administrative and financial pathways that hospitals and payers use to authorize fibrinogen concentrate use, influencing both volume and substitution patterns.
- Clinical adoption is expanding beyond congenital indications into acquired fibrinogen deficiency and acute bleeding settings, but evidence requirements, institutional protocols, and cost consciousness create uneven adoption curves across health systems.
These dynamics create a market that rewards operators who can align product formulation, regulatory strategy, and market access planning rather than treating each as a separate silo. The ability to navigate plasma cost volatility while securing reimbursement clarity is becoming a competitive differentiator rather than a baseline expectation.
Key Drivers Shaping the Market
Technological Innovation and Formulary Differentiation
Innovation in fibrinogen concentrates is increasingly centered on presentation formats, viral inactivation robustness, reconstitution convenience, and indication expansion. Manufacturers are advancing refined purification and pathogen reduction processes that support confidence in efficacy and safety, while new packaging options are designed to meet the operational needs of surgical theaters and emergency settings. The introduction of specialized gram-level presentations reflects a broader trend toward tailoring product formats to clinical workflows and dosing requirements. These advances are not cosmetic; they affect procurement decisions, storage logistics, dosing precision, and the speed with which fibrinogen can be deployed in time-sensitive bleeding scenarios.
From a commercial standpoint, formulation and presentation strategy has become a lever for market access. Products that reduce handling complexity, improve dosing flexibility, or support specific patient populations can gain preference even in a category where therapeutic class equivalence is often assumed. The practical implication is that innovation must be paired with evidence generation and reimbursement alignment to translate clinical value into market share.
Regulatory and Reimbursement Dynamics
Regulatory progress continues to expand the addressable patient population. Recent approvals in the United States have broadened the use of fibrinogen concentrates for acquired fibrinogen deficiency and acute bleeding episodes, while separate regulatory actions have reinforced product-specific coding pathways. These developments matter because they influence prescribing confidence, hospital procurement policies, and payer coverage decisions. A product that moves from a narrower congenital indication into acquired and acute bleeding settings can unlock substantially larger utilization, provided the supporting evidence and coding environment enable consistent reimbursement.
The same regulatory environment introduces complexity. Stringent plasma collection, testing, and fractionation requirements raise the barrier to entry and increase the operational burden for manufacturers. Simultaneously, payers and health systems are scrutinizing cost-effectiveness, dosing efficiency, and the relationship between fibrinogen concentrate use and broader hemostatic management protocols. Companies that proactively shape clinical evidence, real-world utilization data, and coding narratives are better positioned to mitigate reimbursement friction and sustain volume growth.
Demand-Side Transformation in Surgical and Bleeding Care
Demand for fibrinogen concentrates is being shaped by several interrelated clinical and institutional trends. Surgical bleeding management remains a central application, supported by growing recognition of fibrinogen’s role in perioperative hemostasis and the desire to reduce transfusion-related risks and complications. At the same time, congenital fibrinogen deficiency continues to anchor a consistent base of demand, while acquired fibrinogen deficiency is emerging as an area of expanding clinical interest across trauma, cardiac, obstetric, and critical care settings.
Hospital procurement behavior is also shifting. Procurement teams are increasingly balancing clinical efficacy, supply reliability, presentation convenience, and total cost of care. In many institutions, formulary decisions are not made solely on price per gram; they incorporate workflow fit, stability, reconstitution requirements, and the availability of dosing options that match patient weight and bleeding severity. This suggests that demand growth will not be uniform across products or settings. Instead, adoption will favor manufacturers who can demonstrate clinical reliability, practical usability, and a clear value proposition relative to alternatives in the hemostatic toolkit.
Supply Chain and Cost Structure Pressures
Cost structure remains a defining feature of the market. The economics of plasma fractionation mean that plasma acquisition and processing represent the largest share of manufacturing cost, with fibrinogen-rich materials contributing a substantial portion of total expense. This creates sensitivity to plasma supply variability, donor availability, fractionation yields, and overhead associated with compliance and testing. For manufacturers, the challenge is not simply reducing unit cost; it is managing a cost stack that is partially exposed to external supply dynamics while maintaining consistent product availability and quality.
The cost implication for end users is equally important. At typical dosing levels, fibrinogen concentrate therapy can represent a meaningful expense for hospitals, particularly in lower-income regions or resource-constrained settings. That pricing pressure does not eliminate demand, but it shapes substitution decisions, protocol design, and the pace at which fibrinogen concentrate use expands beyond well-resourced centers. Commercial strategies that account for tiered access, presentation efficiency, and strong pharmacoeconomic justification are more likely to sustain growth across diverse market conditions.
Competitive Landscape and Leading Strategies
The market is characterized by a concentrated group of established plasma-derived biologics manufacturers alongside regional players seeking to establish or expand fibrinogen concentrate offerings. Leading organizations differentiate themselves through combinations of indication breadth, presentation options, regulatory milestones, manufacturing scale, and market access positioning. Rather than competing on a single dimension, successful players are aligning product portfolios with clinical workflows and reimbursement realities.
Several strategic positions are evident in the current landscape:
- Indication expansion as a growth lever. Companies that secure approvals for acquired fibrinogen deficiency or acute bleeding episodes broaden the clinical contexts in which their products can be used, increasing the addressable volume beyond congenital deficiency alone.
- Presentation flexibility as an operational advantage. Introducing dosing options and formulations tailored to specific settings can reduce friction in procurement, compounding, and bedside administration, strengthening hospital preference and formulary retention.
- Regulatory and coding alignment as a commercial enabler. Clear coding pathways and reimbursement language can reduce administrative barriers and accelerate institutional adoption, especially when paired with clinical evidence that supports appropriate use.
- Plasma-derived manufacturing credibility and supply resilience. Established fractionation capabilities and robust quality systems matter in a category where consistency, safety, and supply continuity are paramount for both clinicians and purchasers.
Recent developments illustrate how regulatory and product-level moves are reshaping competitive positioning. In late 2025, a major plasma therapeutics company secured FDA approval for a fibrinogen concentrate in acute bleeding episodes for pediatric and adult patients with congenital fibrinogen deficiency. Shortly thereafter, in early 2026, another key player gained FDA approval for a new 2-gram presentation of its fibrinogen concentrate for bleeding patients with acquired fibrinogen deficiency, building on earlier expanded approval activity in the prior year. These milestones are not isolated product events; they signal a broader shift toward wider clinical use, more flexible dosing formats, and increased competitive intensity around indication coverage and market access.
The market concentration profile suggests that scale and regulatory experience still matter, with a relatively concentrated share structure among leading participants. However, the landscape is also evolving through targeted launches, indication-specific differentiation, and regional capacity development. New entrants and regional manufacturers can compete by focusing on specific geographies, cost-efficient presentations, or locally relevant indications, particularly where access gaps remain or where procurement dynamics favor regional supply resilience. Consolidation may continue over time as larger players seek to strengthen portfolio depth and manufacturing reach, but differentiation through formulation, indication strategy, and market access capability will remain central to winning share.
Future Trends and Commercial Implications
Broader Clinical Use Will Drive Volume, but Distribution Will Be Uneven
Over the next three to five years, the most consequential trend is likely to be the continued migration of fibrinogen concentrate use beyond narrowly defined congenital indications into acquired deficiency and acute bleeding management. This broadening reflects both regulatory momentum and clinical interest in targeted fibrinogen replacement. The commercial implication is that total volume potential increases, but adoption will depend on local protocols, evidence dissemination, and reimbursement clarity. Markets with mature bleeding disorder infrastructure and established surgical hemostasis pathways are likely to absorb new indications faster, while regions where plasma-derived therapy access remains constrained will see more gradual uptake. Companies that invest in clinical education, guideline engagement, and site-level implementation support can convert indication expansion into sustained utilization more effectively than those relying on label expansion alone.
Presentation Innovation and Workflow Fit Will Influence Preference
As the category matures, product format will increasingly serve as a differentiator. Liquid formulations, specialized gram presentations, and packaging designed for rapid deployment in surgical and emergency settings can reduce logistical friction and improve fit within institutional workflows. This does not eliminate the importance of clinical efficacy and safety, but it adds a practical layer to procurement and formulary decisions. The trend favors manufacturers that treat product design as part of the value proposition, aligning presentation choices with real-world usage patterns. For hospitals and health systems, the opportunity lies in standardizing fibrinogen concentrate use in a way that supports both clinical outcomes and operational efficiency.
Cost, Access, and Reimbursement Will Remain Strategic Variables
Cost pressures are unlikely to disappear. Plasma-dependent manufacturing economics will continue to expose the category to input cost volatility, while high per-dose treatment costs will keep affordability and pharmacoeconomic justification in focus for payers and hospital administrators. The trend here is not a simple price war; it is a more sophisticated market access environment in which coding, coverage, evidence, and total cost of care arguments influence adoption. For manufacturers, the strategic response should include robust health economics support, dosing efficiency narratives, and proactive engagement with reimbursement frameworks. For investors, the durability of margins will depend on yield management, supply resilience, and the ability to secure favorable access arrangements rather than on volume growth alone.
Hemodialysis Concentrates Market
Potential Risks and Uncertainties
Several uncertainties could alter the pace or shape of growth. Plasma supply disruptions, donor availability constraints, or fractionation bottlenecks can affect availability and cost. Reimbursement changes, stricter utilization management, or shifts in payer policy could slow expansion in specific settings. Competitive intensity may increase as new presentations, regional entrants, or alternative hemostatic therapies influence treatment choices. In addition, clinical evidence expectations may evolve, requiring more robust real-world data to support use outside traditional indications. These risks do not negate the growth outlook, but they highlight the need for contingency planning around supply, access, and evidence strategy.
Actionable Guidance for Decision Makers
The fibrinogen concentrates market rewards strategic discipline across product, regulatory, and access dimensions. For executives and investors, four priorities stand out.
- For manufacturers, align formulation innovation with indication strategy and reimbursement planning. Product launches should be built around clinical workflow fit, dosing flexibility, and a credible market access narrative, not solely around regulatory milestones.
- For investors, focus on supply resilience, fractionation efficiency, and access-enabled growth. Companies that can manage plasma cost exposure, maintain consistent availability, and convert indication expansion into reimbursed utilization are better positioned for durable value creation.
- For procurement and clinical leaders, evaluate fibrinogen concentrate options based on total workflow impact and total cost of care, including presentation efficiency, dosing suitability, and evidence supporting appropriate use in relevant patient populations.
- For all stakeholders, treat market access and evidence development as ongoing capabilities. Reimbursement pathways, coding frameworks, and clinical adoption patterns are shifting quickly, and timely intelligence can reduce execution risk and improve planning accuracy.
Given the pace of regulatory updates, presentation innovation, and reimbursement evolution, decisions made on incomplete market intelligence carry avoidable risk. For organizations that need deeper segmentation, pricing and reimbursement detail, competitive benchmarks, and scenario planning across regions and indications, more granular analysis can help translate these trends into actionable plans. Detailed data sets, company-specific evaluations, and tailored commercial scenarios are available through PW Consulting’s full Fibrinogen Concentrates Market report, which provides the structured intelligence needed to support product strategy, investment decisions, and procurement planning with greater precision.
For detailed analysis of this topic, please visit the official page: Fibrinogen Concentrates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Polyphenylene Sulfide Fibers Market: How 4.7% CAGR and Filtration Demand Reshape 2032
By PW Consulting, 2026-09-21
The Polyphenylene Sulfide Fibers Market: Strategic Trends and Commercial Opportunities in a High-Performance Materials Landscape
The global market for polyphenylene sulfide fibers has entered a phase of steady, value-driven expansion. Valued at approximately 151.2 million USD in 2020 and reaching roughly 189.6 million USD by 2025, the market is projected to grow to around 259.8 million USD by 2032, reflecting a compound annual growth rate of 4.7 percent over the forecast period. This trajectory signals a mature yet resilient industry where demand is increasingly tied to high-performance applications rather than volume-led commoditization. For executives, investors, and procurement leaders, the question is no longer whether PPS fibers will grow, but how the competitive landscape, cost structure, and regulatory environment will reshape who captures value in the next cycle.
Despite the consistent growth profile, the market is navigating several structural inflection points. First, margin compression is becoming a reality as energy-intensive production collides with tightening environmental controls and rising utility costs. Second, geopolitical and trade dynamics are introducing uncertainty around cross-border sourcing, particularly as major economies reassess anti-dumping frameworks and regional supply dependencies. Third, demand is shifting from generic filtration uses toward more specialized, specification-driven applications that reward technical differentiation and consistent quality. These forces are redefining the baseline for competitive performance and forcing companies to rethink scale, innovation, and supply chain architecture.
Innovation at the Fiber Level: Performance Trumps Volume
Technical advancement remains the most powerful growth lever in this market. The industry is moving beyond baseline heat and chemical resistance toward engineered fiber architectures that solve specific operational pain points. Trilobal cross-section designs, for example, have demonstrated measurable improvements in dust collection efficiency for filtration systems, while new flame-retardant grades are opening pathways into high-voltage electrical insulation where safety margins are non-negotiable. Simultaneously, bio-based feedstock initiatives are beginning to reshape the sustainability narrative, offering a credible route for buyers under pressure to reduce embodied carbon without sacrificing performance. These innovations are not incremental tweaks; they are creating application-specific value pools that command pricing resilience and longer-term customer lock-in.
Regulatory Realignment and the Trade Policy Variable
Policy and regulatory shifts are becoming a decisive factor in sourcing strategy. Environmental controls in key production regions have already influenced raw material pricing, with p-dichlorobenzene costs rising sharply in 2024 as tightened standards constrained supply. At the same time, trade policy dynamics are entering a new phase. The initiation of a sunset review investigation into anti-dumping measures on imports of polyphenylene sulfide from Japan and other countries signals that tariff and duty environments may be recalibrated in the near term. For multinational buyers and producers alike, this creates a dual challenge: maintaining supply continuity while preparing for potential cost volatility and redirected logistics. Companies that treat compliance and trade exposure as strategic variables rather than administrative hurdles will be better positioned to navigate procurement disruptions.
Demand-Side Transformation: From Filtration Dominance to High-Performance Diversification
End-use demand continues to be anchored by filtration applications, which remain the largest consumption segment. Bag filters in industrial dust collection and emission control systems represent a core demand driver, supported by stricter air quality standards and the need for durable, high-temperature-resistant media. However, the most notable shift is the growing interest in insulation materials and engineering applications where PPS fibers are being evaluated for thermal stability, chemical resistance, and long service life. Procurement behavior is also evolving: buyers are increasingly specification-driven, evaluating total cost of ownership rather than unit price alone. This change rewards suppliers that can demonstrate consistent grade quality, technical support, and application engineering capability. It also creates an opening for fiber producers to expand into adjacent high-performance segments where differentiation is achievable.
Cost Structure and Supply Chain Pressure
The economics of PPS fiber production are increasingly sensitive to energy intensity and raw material availability. Producing one metric ton of PPS requires approximately 3,200 kWh of electricity, which places a premium on regional energy tariffs and grid reliability. In markets with high or volatile electricity costs, this translates directly into margin pressure and can influence plant location decisions, capacity timing, and pricing strategies. At the same time, the supply chain is experiencing selective consolidation and regional rebalancing. Capacity expansions and targeted acquisitions are being used to strengthen local market access and reduce exposure to long logistics chains. These moves reflect a broader industry recognition that resilience and proximity to key end markets are becoming as important as scale alone.
Competitive Landscape and Strategic Positioning
The market is moderately concentrated, with the top three players accounting for roughly 35.8 percent of share and the top five reaching approximately 42.6 percent. This concentration suggests a landscape where scale and brand recognition matter, yet enough fragmentation remains to allow differentiated entrants to compete on technical performance, regional presence, or application specialization. Leadership in this market is increasingly defined by how effectively a company aligns product architecture, capacity strategy, and regional access with the evolving needs of specification-driven buyers.
Japanese and European Incumbents: Engineering Heritage and Application Depth
Several established manufacturers have built strong positions by emphasizing application-specific fiber grades and long-standing technical credibility. Leading PPS fiber producers have focused on high-temperature and chemical-resistant grades tailored for bag filters and insulation, reinforcing their relevance in industrial filtration and demanding engineering environments. Other major players offer PPS fiber variants with superior heat, chemical, and hydrolysis resistance across yarn, fabric, and non-woven formats, broadening their reach into both filtration and high-performance industrial uses. A notable differentiator in the market has been the development of trilobal cross-section fibers designed specifically to improve dust collection efficiency, a clear example of structural innovation translating into measurable performance gains. European suppliers have also maintained a presence with fiber grades suitable for monofilament and multifilament extrusion in high-performance engineering applications, positioning themselves in niches where precision and consistency are critical.
Phosphorus Pentasulfide Market
Regional Expansion and Capacity Strategy
Capacity and supply chain strategy are becoming central to competitive positioning. Recent activity includes the completion of an acquisition of a regional PPS fiber manufacturing plant in Southeast Asia, a move aimed at strengthening supply chain resilience and improving market access. In parallel, capacity expansions by major producers in China are signaling a continued push to serve both industrial and automotive-adjacent demand more efficiently. These developments point to a market that is not only growing but also reconfiguring its geographic footprint. For buyers and investors, regional capacity additions can reduce lead times and logistics risk, but they also intensify local competition and may pressure margins in oversupplied segments.
Product Innovation as a Competitive Moat
Recent product launches illustrate how innovation is being used to defend and extend market position. One major Japanese manufacturer introduced a new flame-retardant PPS fiber grade specifically designed for high-voltage electrical insulation, targeting an application space where reliability and safety certification create strong barriers to entry. Meanwhile, a European supplier announced an eco-friendly PPS fiber line using bio-based feedstocks, aligning product development with sustainability goals in markets where procurement teams face increasing pressure to document lifecycle impacts. In a related high-performance direction, a partnership between a global chemical company and an aerospace OEM has focused on co-developing ultra-high-performance nanocomposite PPS fibers, suggesting that the upper end of the market is moving toward tailored, application-engineered materials rather than standardized grades.
PPS Resin Market
Market Structure Evolution: Consolidation, Differentiation, and New Entrants
The competitive trajectory appears to be moving toward a hybrid structure. On one side, consolidation and capacity acquisitions are strengthening the scale and regional reach of incumbents. On the other, product differentiation and application specialization are enabling companies to compete without relying solely on volume. New and expanding entrants, particularly in China, are increasing production capacity for filtration and industrial uses, which broadens available supply but also raises the importance of quality consistency and technical support. Over the next few years, the market is likely to reward players that can combine reliable scale with clear application advantages, while those competing primarily on price in commoditized segments may face intensifying pressure.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
The next phase of growth will be shaped by the interaction of technical differentiation, cost resilience, and regulatory uncertainty. Three trends stand out as particularly consequential for commercial strategy.
PW Consulting
Trend 1: Application-Specific Value Pools Will Outperform Generic Segments
As buyers increasingly prioritize total cost of ownership and performance reliability, specification-driven applications are expected to capture a disproportionate share of margin growth. High-voltage insulation, advanced filtration media, and engineered industrial textiles are likely to see stronger demand for premium grades that solve clear operational problems. This trend favors producers with strong application engineering capabilities and consistent grade control, and it creates opportunities for companies that can demonstrate measurable performance advantages in targeted use cases. The broader implication is that growth will be less about expanding volume across all segments and more about winning in high-value niches where customers are willing to pay for proven performance.
Trend 2: Cost and Energy Dynamics Will Drive Regional Strategy Decisions
Given the electricity intensity of PPS production and ongoing raw material price volatility, regional cost structures will increasingly influence where capacity is added, how production is scheduled, and which suppliers are preferred in tender processes. Producers in regions with stable, cost-competitive energy and efficient logistics may gain a structural advantage, while high-energy-cost regions could see margin pressure unless offset by premium product positioning or local demand strength. For downstream buyers, this trend underscores the importance of multi-region sourcing strategies and scenario planning for energy and input cost fluctuations. It also suggests that near-market capacity expansions could become a differentiator for suppliers seeking to reduce lead times and improve supply assurance.
Trend 3: Sustainability and Regulatory Compliance Will Become Commercial Inputs
Sustainability is transitioning from a reputational consideration to a procurement requirement in several end markets. Bio-based feedstock development and other eco-aligned product initiatives are likely to gain traction among buyers who need to document environmental performance across their supply chains. At the same time, trade and regulatory reviews will continue to shape cross-border sourcing, potentially altering duty exposure and supply routes. The commercial implication is clear: sustainability claims and regulatory readiness will increasingly influence supplier selection, especially in sectors where compliance, safety, and lifecycle documentation carry operational weight. Companies that can provide credible, verifiable product attributes and maintain agile sourcing options will be better positioned to retain and expand share.
Risks and Uncertainties to Monitor
Despite the constructive growth outlook, several risks warrant attention. Continued raw material price volatility, especially for key precursors, could compress margins if not managed through pricing strategy or supply contracts. Energy cost escalation in certain regions may affect production economics and plant utilization decisions. Trade policy reviews and potential duty adjustments could introduce short-term sourcing disruption and pricing uncertainty. Finally, the risk of overcapacity in specific regional segments could intensify price competition, particularly in more commoditized filtration applications. Navigating these risks will require a combination of technical differentiation, flexible sourcing, and disciplined capacity planning.
Strategic Implications for Decision-Makers
For manufacturers, the priority is to align product development with the applications that command the strongest performance requirements and willingness to pay. Investing in grade consistency, application-specific fiber architectures, and credible sustainability attributes can create meaningful differentiation. At the same time, capacity and energy strategy should be evaluated in the context of regional cost structures and customer proximity, rather than scale alone. Companies that can combine reliable supply with clear technical advantage will be best placed to defend pricing and expand into higher-value segments.
For investors, the market offers a profile of steady growth with pockets of higher-margin opportunity in specialized applications. Due diligence should focus on the durability of product differentiation, the exposure of production costs to energy and raw materials, and the ability of target companies to navigate trade and regulatory shifts. Regional capacity moves and acquisitions may improve supply chain resilience, but they also require scrutiny around utilization, local competition, and end-market demand quality. Selective exposure to engineered fiber segments and application-led growth appears more attractive than undifferentiated volume plays.
For procurement and supply chain leaders, the strategic task is to reduce exposure to single-source dependency and price-only purchasing logic. Evaluating suppliers on the basis of grade consistency, technical support, energy and regulatory resilience, and sustainability documentation can lower total risk and improve long-term cost stability. Building multi-region sourcing options and maintaining visibility into trade policy developments will help mitigate disruption if duty environments or input costs shift. In practice, procurement strategies that treat PPS fibers as a performance-critical input rather than a commodity are more likely to secure reliable supply and better commercial outcomes.
The market is entering a period where technical value, cost resilience, and regulatory readiness will separate durable participants from price-takers. For decision-makers seeking a deeper, segment-level view of demand dynamics, competitive positioning, and scenario-based planning parameters, a more detailed research compendium can provide the granularity needed to translate these strategic trends into specific operational choices.
For detailed analysis of this topic, please visit the official page: Polyphenylene Sulfide Fibers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Surgical Blades & Scalpels Market 2026: Why 5.2% CAGR and Disposable Blades Reshape Strategy
By PW Consulting, 2026-09-21
The Surgical Blades & Scalpels Market: Strategic Trends and Commercial Opportunities Through 2032
The global market for surgical blades and scalpels has entered a phase of steady, structurally supported expansion. Valued at approximately $172.5 million in 2020, the market reached $219.8 million in 2025 and is projected to climb to $312.3 million by 2032, reflecting a compound annual growth rate of 5.2 percent. This trajectory mirrors broader shifts in surgical practice, infection control standards, and procurement economics. While the product category itself is mature, the competitive and operational dynamics beneath the surface are evolving quickly. For executives, investors, and procurement leaders, the market presents a paradox: top-line growth is predictable, yet margin structures, channel control, and innovation pathways are being reshaped by regulation, safety mandates, and regional supply chain reconfiguration.
The market is heavily concentrated. The top three players account for roughly 60 percent of revenue, and the top five capture about 72 percent. This concentration signals scale advantages in manufacturing, sterilization, distribution, and compliance management. Yet the remaining share is fragmented across regional manufacturers, specialty blade producers, and safety-focused innovators, creating both pressure and opportunity depending on a company's positioning. The following analysis examines the core challenges, demand and supply drivers, competitive strategies, and forward-looking opportunities that will shape decision-making through the end of the decade.
Market Landscape and Core Challenges
A Mature Category Operating Under Structural Efficiency Pressure
The surgical blades and scalpels market is not experiencing explosive growth, but it is benefiting from persistent procedural volume expansion, a shift toward single-use sterile disposables, and tightening safety standards. The overall revenue path from 2020 through 2032 shows consistent year-over-year gains, with the steepest incremental increases expected in the latter half of the forecast period. This pattern is consistent with a category where volume growth, product mix shifts, and regional procurement changes compound rather than spike.
One of the most pressing challenges is the tension between cost containment and safety compliance. Hospitals and surgical centers are under sustained pressure to reduce indirect costs, yet regulatory and occupational safety expectations continue to favor single-use sterile blades and safety scalpels. The result is a procurement environment where price sensitivity exists alongside mandatory or strongly encouraged adoption of safety-engineered products. Manufacturers that can deliver standardized, compliant, and competitively priced disposable blades are better positioned than those relying on premium differentiation alone.
PW Consulting
A second challenge lies in the regulatory asymmetry across regions. In the United States, scalpel blades and scalpels are generally classified as Class I exempt devices, meaning most models do not require a premarket submission, but establishments must still register and list with the appropriate authorities. Manufacturing facilities are expected to meet ISO 13485 quality management expectations, and EU markets impose stricter single-use validation protocols under the Medical Device Regulation framework. This duality creates a compliance burden for companies selling across multiple jurisdictions, especially when validation documentation, sterilization records, and traceability requirements differ. The cost of maintaining multi-region compliance can erode margins for smaller producers while reinforcing the position of established players with mature quality systems.
A third challenge is the absence of dedicated reimbursement codes for blades and scalpels. Costs are typically embedded within global surgical procedure fees rather than billed as standalone items. This structure pushes procurement decisions toward total cost of procedure rather than device-level price comparisons, and it places a premium on reliability, inventory turnover, and integration with broader perioperative workflows. Suppliers that can demonstrate predictable availability, reduced sharps injury risk, and compatibility with existing surgical workflows gain leverage in a reimbursement environment that does not isolate blade economics.
Key Demand and Supply Drivers
Safety Standards and the Shift Toward Single-Use Sterile Disposables
A major driver of market evolution is the continued migration from reusable blades to single-use sterile disposables. This shift is reinforced by occupational safety mandates and international standards for safety scalpels, which aim to reduce sharps injuries among surgical staff. Facilities are increasingly standardizing on disposable sterile blades not only for clinical reasons but also to streamline infection control protocols and minimize reprocessing costs. The practical effect is a product mix that tilts toward disposable blades in many general surgery settings, while reusable blades retain relevance in specific use cases where reprocessing infrastructure and cost equations remain favorable.
Double Edges Blades Market
The commercial implication is clear: manufacturing capacity, sterilization capability, and distribution reliability for disposable blades are becoming strategic assets. Companies that can scale sterile disposable production while maintaining tight dimensional tolerances and consistent sharpness profiles are better positioned to capture share in a market where safety standards are accelerating adoption. At the same time, safety scalpel designs and retractable or shielded options are gaining attention in procurement specifications, giving an edge to suppliers with differentiated safety portfolios.
Regulatory Classification and Quality System Expectations
Regulatory classification shapes both entry barriers and operating economics. The Class I exempt status of most scalpel blades and scalpels in the United States lowers the premarket submission burden for many models, but it does not remove the need for establishment registration, listing, and robust quality management. ISO 13485 certification is effectively a baseline expectation for manufacturing facilities, and EU requirements add further validation rigor for single-use devices. These conditions favor manufacturers with mature quality infrastructure and disciplined documentation practices.
Worldwide Surgical Saw Blades Market
This environment also affects innovation incentives. Since many conventional blade models face a lighter regulatory pathway, competition often centers on manufacturing consistency, packaging, sterilization reliability, and supply continuity rather than dramatic product redefinition. By contrast, safety-engineered scalpels and specialty micro blades can involve more complex design validation, creating a higher barrier but also a stronger differentiation opportunity for companies that can demonstrate clinical and operational value.
Procurement Economics and the Embedded Cost Reality
Because blades and scalpels are generally absorbed into broader surgical procedure costs rather than reimbursed under dedicated codes, procurement decisions are influenced by total procedure economics. Surgical teams and purchasing departments evaluate availability, standardization, waste reduction, and injury prevention alongside unit price. This creates an environment where bundling compatibility, inventory management support, and safety alignment can be as important as the blade itself.
Demand-side behavior reflects this embedded cost reality. Hospitals seek to minimize variation across surgical service lines, which encourages standardization on a limited set of blade and handle configurations. At the same time, specialty procedures and microsurgical applications sustain demand for precision blades and ophthalmic knives. The net effect is a market where volume flow favors standardized disposable products, while higher-value niches reward precision engineering and application-specific design.
Manufacturing Scale, Regional Sourcing, and Cost Structure Dynamics
Cost structure remains a decisive competitive lever. Blade manufacturing requires precise metallurgy, controlled edge geometry, reliable sterilization, and consistent packaging. Companies with integrated production and quality systems can manage unit costs more effectively, while smaller or regionally focused producers must compete on flexibility, local service, or niche applications. Regional sourcing strategies are gaining importance as procurement teams look to reduce logistics risk, improve lead-time predictability, and align with local compliance expectations.
Recent distribution developments illustrate how channel strategy is evolving. For example, in early 2025, a Canadian distribution agreement expanded exclusive coverage for a major blade and scalpel portfolio, signaling a push to strengthen regional availability and service reliability. Moves like this reflect a broader pattern: established manufacturers are investing in distribution density and localized support to protect share in regulated, service-intensive markets, while emerging producers pursue export growth and selective partnerships to enter new regions.
Competitive Landscape and Leading Strategies
Strategic Positioning Among Core Players
The competitive field combines long-established multinational manufacturers, precision-focused producers, and regional exporters with growing scale. The leading companies differentiate along several axes: product range breadth, safety portfolio depth, metallurgical precision, sterilization and sterile packaging capability, and integration into broader perioperative or specialty workflows.
Several strategic profiles are visible across the market. One group emphasizes heritage, broad blade and handle ranges, and comprehensive sterile disposable offerings. These players often compete on consistency, distribution reach, and the ability to serve General Surgery and multiple specialty segments with standardized products. Another group focuses on precision manufacturing and high-sharpness stainless steel products, with particular attention to safety scalpel lines and micro blade options. This positioning appeals to surgical specialties that require fine edge control and reliable performance in delicate procedures.
A third profile is built around regional export strength and cost-competitive sterile disposable manufacturing. These companies have expanded their footprint by offering full lines of carbon steel and stainless steel blades and scalpels, targeting price-sensitive procurement environments while meeting international quality expectations. A fourth profile lies in specialty focus, where ophthalmic surgical knives, micro blades, and dental-oriented scalpel systems create differentiated value in narrower but higher-specification applications. Finally, some broader perioperative solution providers incorporate scalpel blades and handles into integrated surgical workflows, using device availability and service continuity as part of a larger institutional relationship.
Market Structure Evolution: Consolidation Pressure and Targeted Expansion
The high concentration at the top of the market indicates that scale, compliance, and distribution maturity matter. Larger players benefit from the ability to standardize quality systems, manage sterilization at volume, and maintain inventory across multiple regions. At the same time, the long tail of smaller and regional manufacturers remains active, particularly where localized service, flexible order sizes, or specialty products create room for differentiation.
The evolution of the landscape is likely to continue along two tracks. First, established manufacturers will keep strengthening distribution partnerships and regional coverage to protect share and improve service levels. Second, targeted expansion by efficient regional producers and specialty innovators will pressure incumbents in specific segments, especially where disposable adoption is rising and procurement is open to alternative suppliers that can meet compliance requirements at competitive cost. M&A and rebranding activity also reshape the landscape indirectly, as companies reposition portfolios to emphasize safety, specialty precision, or perioperative integration.
Given the embedded cost structure and safety-driven adoption trends, competitive advantage increasingly comes from the ability to deliver standardized sterile disposables with reliable lead times, consistent quality, and safety-aligned design features. In specialty niches, the advantage shifts toward precision, application fit, and clinical trust. Companies that can operate effectively across both tracks—scale-driven standard products and higher-specification specialty offerings—are best placed to defend and expand their positions.
Forward Trends and Commercial Opportunities Through 2032
Continued Mix Shift Toward Sterile Disposable and Safety-Aligned Products
Over the next three to five years, the product mix is expected to keep moving toward single-use sterile disposables and safety-oriented scalpels where protocols and procurement specifications allow. This trend is supported by safety standards, infection control expectations, and the operational simplicity of disposables in high-volume surgical environments. For suppliers, the opportunity lies in scaling sterile disposable capacity, improving packaging and traceability, and aligning product lines with the safety expectations that hospitals are increasingly embedding into purchasing criteria.
A related opportunity is the expansion of safety scalpel adoption in settings that have historically relied on conventional blades. Education, workflow integration, and cost acceptance will influence the pace of adoption, but the direction of travel favors designs that reduce handling risk and support standardized disposal procedures.
Regional Growth and Supply Chain Localization
Regional dynamics will continue to shape growth patterns. North America remains the largest market, supported by established surgical volumes, safety adoption, and mature distribution. Europe follows with substantial demand and stricter validation expectations that reinforce quality and traceability requirements. Asia Pacific represents a meaningful growth path, driven by expanding surgical capacity, increasing procurement professionalism, and growing export competitiveness among efficient manufacturers. Latin America and the Middle East and Africa remain smaller in absolute terms but offer incremental opportunities where access, service, and compliance alignment improve.
Commercially, this points to a strategy of regional reinforcement rather than uniform global rollout. Companies that invest in localized distribution, predictable lead times, and documentation readiness for multiple regulatory environments can capture share more effectively than those relying solely on product price. For investors, regional scalability and channel control are likely to be critical indicators of long-term resilience.
Precision, Specialty, and Workflow-Integrated Positioning
While standardized disposables drive volume, specialty applications sustain higher-margin opportunities. Ophthalmic knives, micro blades, and application-specific scalpel systems require tighter tolerances and greater clinical confidence, which can support differentiated pricing when performance and reliability are demonstrable. At the same time, broader perioperative providers can create value by integrating blade and scalpel availability into larger surgical workflow solutions, making supply reliability and service continuity part of the value proposition.
This bifurcation suggests a practical strategic path: maintain a strong core in standardized sterile disposables to capture volume and safety-driven adoption, while building or strengthening specialty lines that serve precision procedures and specialized surgical workflows. The risk is spreading too thin across unrelated segments; the opportunity is to align precision and workflow integration with genuine clinical need rather than broad but shallow expansion.
Risks and Uncertainties
Several uncertainties could alter the trajectory. Regulatory and validation expectations may tighten further in certain markets, raising compliance costs and slowing the pace at which new entrants can scale. Procurement pressure could intensify if hospitals prioritize cost over safety features in specific budget cycles, temporarily dampening the shift toward premium safety designs. Supply chain disruptions, raw material cost volatility, and sterilization capacity constraints could also affect margin stability and service levels. Finally, because reimbursement does not isolate blade costs, demand can be indirectly affected by changes in surgical procedure volumes, service line economics, and broader healthcare spending patterns.
Strategic Implications for Decision Makers
For Manufacturers
Prioritize the operational foundations that convert market growth into defensible share. That means investing in sterile disposable capacity, quality system maturity, and distribution reliability, while maintaining enough precision capability to serve specialty segments. Standardize core blade and handle configurations where hospital procurement favors consistency, but preserve differentiated safety and micro blade options where clinical value supports them. Build regional channel strength through partnerships or localized service capacity, especially in markets where lead time and documentation readiness influence purchasing decisions.
For Investors
Evaluate businesses on their ability to manage compliance, scale sterile production, and control distribution across regions. Concentration in the market indicates that scale and quality infrastructure matter, but growth opportunities also exist for efficient producers and specialty innovators that can meet safety expectations at competitive cost. When assessing potential investments or partnerships, look for evidence of ISO 13485-aligned quality systems, reliable sterilization and traceability processes, and channel strategies that reduce reliance on a single geography or customer type. Also consider exposure to procedural volume cycles, since blade demand is tied to surgical activity even though reimbursement does not itemize the device separately.
For Procurement and Supply Chain Leaders
Treat blade and scalpel selection as part of total procedure economics rather than an isolated unit-price exercise. Standardize where clinical workflows allow, but preserve access to safety-aligned disposables and precision options for specialties that require them. Evaluate suppliers on consistency, injury-prevention design, inventory reliability, and documentation readiness as much as on price. Where possible, align purchasing specifications with occupational safety standards and infection control goals to reduce downstream operational risk.
Closing Perspective
The surgical blades and scalpels market is moving through a period where growth is steady, safety expectations are rising, and competitive advantage depends on execution quality as much as product design. The mix shift toward sterile disposables, the regulatory and validation environment, and the embedded cost structure of surgical procedures all point in the same direction: future success will belong to organizations that can combine scale, compliance discipline, and targeted precision where it matters most. For leaders navigating this landscape, the most valuable next step is to ground strategy in detailed, segment-level intelligence—covering regional demand patterns, product mix economics, channel dynamics, and competitor positioning—so that decisions on capacity, portfolio focus, and market entry are calibrated to the opportunities and risks that lie ahead.
For detailed analysis of this topic, please visit the official page: Surgical Blades & Scalpels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


