



Category: market research
PW Consulting: Anti‑Tamper Software Market Poised to Reach USD 2,014.9 Million by 2032, Expanding at a 15% CAGR
By PW Consulting, 2026-07-13
Anti-Tamper Software Market 2026: Strategic Imperatives for Risk-Aware CIOs and Product Leaders
Executive preview
PW Consulting’s latest market study—anchored on a 2025 base year and covering historical performance (2020–2025) with a forecast window through 2032—provides a data-driven strategic compass for organizations buying, building, or investing in anti-tamper software in 2026. At the macro level, the global anti-tamper software market has accelerated from a low hundreds of USD Million in 2020 to a substantially larger base in 2025 and is projected to grow at a 15.0% compound annual growth rate (CAGR) through 2032, reaching just over USD 2.0 Billion (USD Million units). This trajectory reflects rising commercial, regulatory, and national-security drivers that make tamper-resilience a board-level priority rather than a niche engineering concern.
Anti Tamper Software Market
Why this matters for 2026 decision-making
-
Risk posture is shifting from perimeter-only defenses to application and endpoint assurance. Anti-tamper controls—ranging from code obfuscation and runtime application self-protection (RASP) to hardware-integrated sensors and cryptographic cores—are now core to preserving product integrity, monetization models, and exportability of strategic systems.
Anti Tamper Software Market -
Regulatory and procurement forces are converging with technical risk: defense directives and program protection policies, together with industry-specific compliance requirements and an expanding patchwork of state-level privacy laws, are increasing the compliance premium for demonstrable tamper protection.
Anti Tamper Software Market -
Market concentration indicates a competitive landscape where a handful of specialist vendors and broader platform providers account for a meaningful share of value—creating clear opportunities and trade-offs for buyers evaluating vendor lock-in, technical depth, and lifecycle support models.
What the report contains (practical, operational deliverables)
-
Executive decision frameworks that translate threat scenarios into procurement requirements and technical acceptance criteria—designed for CISOs, heads of product security, and procurement leads.
-
Vendor scorecards and use-case mappings that compare candidate solutions across protection techniques (obfuscation, RASP, white-box cryptography, hardware sensors), deployment models, and integration effort—presented without vendor revenue breakdowns in the public summary but fully detailed in the full report.
-
ROI and TCO modeling templates calibrated to the 2026 cost environment—covering development lift, DevSecOps upskilling, maintenance, and incident-reduction benefits.
-
Procurement and contract playbooks with model SOWs, acceptance tests, and IP/escrow clauses for both commercial and defense-context purchases.
-
Scenario-driven roadmaps for tiered adoption: protect-first (critical IP), integrate-first (DevSecOps), and platform-first (cloud-native/no-code) strategies—each with milestones, staffing, and budgetary guardrails.
-
Technical annexes detailing attack taxonomies, detection heuristics, and recommended telemetry for continuous assurance.
Competitive landscape — practical implications
The market mixes specialist application-shielding firms, platform vendors offering embedded anti-tamper as a module, and hardware-focused players providing tamper-resistant IP and cryptographic cores. Select observations with direct procurement relevance:
-
Established application-protection specialists provide deep, multi-platform protections (mobile, desktop, IoT, gaming). Their strengths lie in mature obfuscation, runtime integrity checks, and toolchains that integrate into CI/CD pipelines—reducing time-to-hardening for legacy portfolios.
-
No-code and low-code entrants have emerged as accelerants for organizations with limited native security engineering capacity. These solutions dramatically reduce integration friction for mobile and web apps, but buyers must validate long-term maintainability and licensing models in enterprise contexts.
-
Hardware and SoC-focused vendors are increasingly relevant where anti-tamper must cross the software/hardware boundary—defense, high-value IP, and safety-critical industrial systems. Their offerings are complementary to software shielding and often required to meet classified or export-controlled program protection requirements.
-
M&A and asset transactions are reshaping supplier capabilities. Recent asset sales and partnerships have consolidated mobile protection portfolios under specialist vendors, while recognition in user-review platforms is amplifying momentum for cloud-friendly, automated shielding providers. Buyers should expect continued consolidation and should include change-of-control and transition clauses in multi-year contracts.
Vendor highlights (selection)
-
Digital.ai — Broad in-app protection across mobile, IoT, web, and enterprise endpoints; suitable for organizations seeking an integrated application protection component within a broader app lifecycle suite.
-
Guardsquare — Mobile security focus with specialized tooling for Android and iOS; attractive for mobile-first product teams that require deep, platform-specific hardening.
-
Verimatrix — Provider of media and application shielding; note recent strategic asset activity that signals portfolio reshaping in the mobile protection space.
-
Appdome — No-code, automated approach with strong momentum in user reviews; a practical choice for organizations prioritizing rapid deployment and limited in-house security engineering.
-
Irdeto (Denuvo) — Recognized in gaming and media anti-piracy; relevant where runtime integrity and anti-piracy are commercial imperatives.
-
Specialist hardware/IP players (Secure-IC, Rambus, and others) — Required where anti-tamper must live inside silicon, or where side-channel resistance and trusted processing are non-negotiable.
Regulatory and procurement dynamics shaping 2026 choices
-
Defense and program protection policies increasingly mandate anti-tamper measures as part of acquisition and exportability strategies—buyers supporting defense programs should align implementation plans with current directives and program protection instructions.
-
Regulatory compliance across finance, healthcare, and public sectors is elevating the bar for demonstrable application integrity; anti-tamper controls are now often cited in audit narratives and incident post-mortems.
-
State-level privacy laws and evolving data-residency requirements increase the complexity of cloud vs on-premises deployment decisions for integrity tooling. Legal and procurement teams must coordinate early in vendor selection.
Actionable recommendations for 2026
-
Map protection needs to attacker models. Start with a prioritized asset register (IP, monetization flows, safety-critical functions), then select protection techniques proportionate to the threat and program value.
-
Adopt a layered protection architecture. Combine software shielding, runtime integrity monitoring, telemetry for anomaly detection, and hardware-level controls where required. Avoid single-point reliance on obfuscation alone.
-
Embed anti-tamper into the SDLC. Allocate budget for DevSecOps training and CI/CD integration to make protection repeatable and maintainable—this materially reduces long-term lifecycle costs versus ad-hoc hardening.
-
Negotiate continuity protections. Given recent and ongoing market consolidation, insist on transition, escrow, and step-in rights in multi-year contracts to mitigate vendor-risk.
-
Validate operational metrics. Require vendors to supply verifiable telemetry and incident-case histories, and run adversarial acceptance tests (red-team scenarios) as part of procurement acceptance criteria.
-
Plan for workforce uplift. Implementation of advanced anti-tamper and AI-enabled detection capabilities requires specialist skills; include training and third-party services in initial procurement planning.
How PW Consulting’s report adds value
-
We translate macro projections (15.0% CAGR through 2032 and an overall market scale that crosses the USD Billion threshold in our forecast) into specific procurement, architecture, and M&A decision levers for 2026.
-
Our vendor evaluations combine technical test results, customer-feedback analysis, and commercial risk scoring—producing pragmatic shortlists aligned to enterprise constraints and program-specific threat models.
-
The report’s tactical annexes include contract language templates, CI/CD integration checklists, and red-team playbooks that buyers can operationalize within 90 days.
Next steps
This article is a strategic preview. The full report contains the comprehensive regional and vertical segmentation, vendor-by-vendor financial and technical scorecards, and downloadable decision-support templates that enterprise teams and investors need to execute in 2026. To access the complete analysis—including the detailed segmentation and the proprietary vendor matrix—visit the PW Consulting report page.
For detailed analysis of this topic, please visit the official page: Anti Tamper Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Flat Panel Loudspeaker Market Set to Grow at a 6.81% CAGR Through 2032
By PW Consulting, 2026-07-13
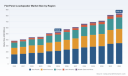
Flat Panel Loudspeaker Market: Strategic Intelligence to Frame 2026 Decisions
Executive summary
PW Consulting’s new Flat Panel Loudspeaker Market report synthesizes five years of historical performance (2020–2025) with a seven‑year forecast (2026–2032) to deliver decision-ready insight for manufacturers, systems integrators, investors and specification‑driven buyers. The market has expanded from USD 385.12 Million in 2020 to USD 529.09 Million in 2025, and our modeling shows continued expansion into the next decade — with the market projected to grow at a 6.81% CAGR over 2026–2032, approaching roughly USD 839.09 Million by 2032. This trajectory masks substantial technology- and channel‑level shifts that will determine winners and losers in 2026 and beyond.
Flat Panel Loudspeaker Market
Why this matters for 2026 planning
- Market momentum: The recent step‑change in absolute market scale between 2023 and 2025 signals a transition from early adoption to scaling commercial opportunities across select verticals. Companies planning launches, capacity investments, or strategic pivots in 2026 need demand‑validated roadmaps — not intuition.
- Technology differentiation: Multiple flat panel wave‑generation technologies (bending‑wave/DML derivatives, planar magnetic, piezo/magnetostatic variants and hybrid BMR designs) are converging in capability but diverge on manufacturability, cost‑to‑serve, and channel fit. Technology choice will be a primary determinant of margin performance and commercial traction in 2026 product portfolios.
- Concentration and opportunity: The market exhibits a moderate concentration profile (top‑3 and top‑5 firm CR metrics indicate mid‑range consolidation). This creates pockets where focused scale and distribution partnerships can unlock outsized returns without needing category‑leading share.
Market dynamics and near-term shocks
Several structural and transitory forces will shape 2026 outcomes:
Flat Panel Loudspeaker Market
- Tariff complexity: Recent U.S. tariff actions have created what industry participants describe as a "tariff inversion" — in some cases higher duties on components than on finished loudspeakers — materially affecting offshoring economics and assembly footprints. Sensitivity to tariff scenarios must be built into 2026 sourcing plans and supplier negotiations.
- Semiconductor and amplifier IC volatility: Lead‑times for DSP and Class‑D amplifier ICs have at times exceeded 26 weeks into 2025, and platform redesigns to accommodate alternative ICs have incurred development costs in the USD 50,000–200,000 range per platform, plus delayed launches up to six months. Procurement strategies and design modularity are therefore immediate priorities for 2026 roadmaps.
- Specification vs. perception: As flat panel solutions migrate from niche audiophile and museum roles into mainstream AV and automotive consideration sets, procurement teams will increasingly require third‑party verification of coverage, speech intelligibility, and distortion metrics. Vendors that codify and publish verifiable performance credentials will shorten sales cycles in 2026.
Competitive landscape — strategic takeaways
Our report profiles the vendors shaping the category and decodes practical implications for partners and competitors. Highlights:
Flat Panel Loudspeaker Market
- FlatPanel Audio (San Jose): A DML‑centric supplier positioning for professional AV installations. Their DML500 family — including weatherized and in‑ceiling/ceiling variants — is optimized for diffuse soundfields and reverberant spaces. For 2026, FlatPanel Audio’s playbook is instructive for companies targeting specification channels: marry product variants to installer workflows and complementary subwoofer/amplifier ecosystems.
- Magnepan (White Bear Lake): A high‑end planar magnetic incumbent focused on audiophile and reference‑grade deployments. Their value proposition emphasizes handcrafted quality and fidelity improvements. For businesses evaluating premium segments in 2026, Magnepan demonstrates the value of brand equity and field‑proven performance as margin protection.
- Flatt Speakers (Phoenix): Thin, durable planar transducers with strong directivity and weather resistance suited to intelligibility‑critical installs. Their MCMA technology underscores a category pathway where robustness and reduced unit counts deliver TCO advantages for system integrators.
- Tectonic Audio Labs (Woodinville): Developer of bending‑wave and BMR solutions with a broad addressable set across pro audio, consumer and automotive. Their recent product showcases illustrate how component‑level innovation (drive units, exciters) can open platform licensing and OEM supply opportunities — a potential strategic axis for 2026 revenue diversification.
- Brown Innovations & Wisdom Audio: Brown’s directional ceiling/tiling form factors and Wisdom’s high‑performance planar line‑source offerings highlight two profitable roles vendors can adopt — targeted, specification‑driven systems for museums and exhibits (Brown) versus high SPL, multi‑octave performance for premium home and commercial installs (Wisdom).
Recent product and channel movements to watch
- Tectonic’s CES 2025 showcase and new drive units signal renewed OEM interest in flat diaphragm solutions for both immersive and distributed applications; expect OEM licensing conversations and sample programs to accelerate in 2026.
- Brown Innovations’ 2025 trade show activity demonstrates the ongoing strength of the directional audio niche — companies that can pair focused hardware with installation‑grade control and accessibility options will secure repeat institutional business.
- FlatPanel Audio’s 2024 InfoComm debut is emblematic of a broader trend: vendors are increasingly selling through architect/specification channels; success demands bundled system design, training and reference builds rather than single SKU transactions.
Strategic recommendations for 2026 (what to do now)
PW Consulting recommends a three‑layer approach for executives planning 2026 moves — Protect, Pivot, and Prove.
- Protect (supply chain resilience)
- Run tariff sensitivity scenarios and re‑price BOMs under inversion stress cases. Consider near‑shoring select assembly steps where labor and tariff math justify localized integration.
- Execute dual‑sourcing for critical ICs or modularize power and DSP subassemblies to enable rapid board swaps without full‑platform redesigns.
- Pivot (portfolio and GTM)
- Identify two commercial plays to pursue in 2026: a high‑value specification channel for commercial/professional builds and a volume play for targeted consumer/automotive partnerships. Each requires distinct productization, channel incentives and returns thresholds.
- Prioritize product roadmaps that reduce total installed cost (fewer drivers per coverage area, integrated mounting, weatherization options) to expedite acceptance in AV/architectural specs.
- Prove (commercial credibility)
- Invest in third‑party acoustic validation and speech intelligibility testing to shorten procurement evaluation cycles. Publish installation case studies and verifiable performance data tied to real‑world environments.
- Where applicable, develop OEM/technology licensing offers (drive units, exciters, subwoofer pairings) to monetize IP while minimizing capital outlays for scale.
What PW Consulting’s report delivers (practical content)
This release is designed as an operational playbook, not an academic paper. Key deliverables include:
- Top‑down market sizing and CAGR forecasts with sensitivity scenarios calibrated to tariff and component‑supply volatility.
- Segmentation frameworks by region, technology and application with strategic implications and go‑to‑market maps (note: detailed numeric splits and proprietary model outputs are available in the full report).
- Vendor diligence dossiers (product roadmaps, distribution footprints, go‑to‑market strengths and weaknesses) for the major players shaping the category.
- Supply‑chain risk matrix and mitigation playbooks addressing tariffs, semiconductor lead times and alternative sourcing strategies.
- Commercial tools: market entry checklists, ROI templates for platform investments, M&A screening criteria and 12‑month tactical milestones for scaling in specification channels.
How to use the analysis in boardroom and product planning
For CEOs and product chiefs, the report turns market forecasts into prioritized decisions: where to allocate R&D, whether to pursue licensing versus direct manufacturing, and how to structure channel incentives for 2026. For CFOs and corporate development teams, the CR3/CR5 concentration context and scenario P&L models inform valuation assumptions for M&A and JV negotiations. For supply‑chain and procurement leads, the tariff and semiconductor modules provide executable contingency plans with clear cost and timing tradeoffs.
Next steps and how to get the full intelligence
PW Consulting’s executive summary above is intentionally selective: we reveal market scale and the directional forces you must plan around, while preserving the granular, model‑level outputs that clients use to operationalize strategy. Access to the full report unlocks the detailed segment matrices, regional demand projections, commercial model spreadsheets and vendor scorecards necessary to execute confidently in 2026.
- If you are evaluating portfolio moves, supply‑chain redesigns, or inorganic transactions in the flat panel loudspeaker space for 2026, PW Consulting can provide targeted briefings, scenario workshops and custom financial models derived from the full study.
- Visit the PW Consulting report page to request the full report, schedule a briefing, or commission a bespoke strategic due diligence tailored to your organization’s role in the ecosystem.
In an industry where product form factor, directivity and manufacturability now intersect with trade policy and chip scarcity, 2026 will reward companies that combine engineering clarity with pragmatic commercial design. Our analysis equips leaders to make those choices with confidence — and to act quickly while the market’s growth and disruption windows remain open.
For detailed analysis of this topic, please visit the official page: Flat Panel Loudspeaker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Camouflage Netting Market to Expand at a 7.25% CAGR as Defense Demand Drives Growth
By PW Consulting, 2026-07-13
Camouflage Netting Market — Strategic Outlook for 2026: Tactical Intelligence for High‑stakes Decisions
PW Consulting’s new Camouflage Netting Market report is the definitive strategic resource for executives, procurement leads, product teams, and investors who must make decisions in 2026 with multi‑year consequences. At a market size of USD 745.2 Million in our 2025 base year and an expected expansion to approximately USD 812.6 Million in 2026, the sector is set to grow at a compound annual growth rate (CAGR) of 7.25% through 2032, when our forecast reaches roughly USD 1.22 Billion. These headline figures understate a far more important story: a market being reshaped by multispectral sensor threats, defence procurement windows, raw material volatility, and a rapidly diversifying set of commercial end‑uses. This briefing explains why those who act in 2026 will create asymmetric advantage through positioning, partnerships, and targeted capability investments.
Camouflage Netting Market
Why this report matters for 2026 decision cycles
-
Timing matters: Defence procurement cycles and a renewed emphasis on multispectral signature management are translating into near‑term demand spikes for advanced netting solutions. Companies that align production, certification and tender readiness in 2026 will capture outsized share during follow‑on contract awards.
Camouflage Netting Market -
Technology is a differentiator: Modern camouflage systems now compete on their ability to defeat visual, near‑IR, shortwave IR, thermal and radar sensors simultaneously. The winners combine materials science, modularity and platform integration rather than competing on price alone.
Camouflage Netting Market -
Supply chain sensitivity: Polyester‑based materials remain the backbone of the category because they balance strength, weight and cost. At the same time, resin price volatility materially affects margins and must be modelled into 2026 budgets and supplier agreements.
-
Sustainability and new markets: Pressure to incorporate recycled feedstocks and plant‑based fibres is growing—creating both product development risk and an opportunity to win non‑defence commercial contracts with demonstrable ESG credentials.
What the PW Consulting report delivers — practical, transaction‑grade insight
This is a hands‑on strategy product, not a high‑level summary. The report equips decision makers with:
-
Tactical procurement playbooks tailored to defence and commercial buyers, including checklist templates for testing multispectral performance, contract clauses to mitigate raw material price swings, and ramp‑up timelines to support urgent orders.
-
Supplier capability matrices and a vetted shortlist process to identify partners by technical capability, production scale, and geopolitical footprint. (Note: our public summary highlights capabilities; detailed segment‑level supplier shares and financials are available in the full dataset.)
-
Product roadmaps and R&D priorities that reconcile performance targets (e.g., thermal suppression at scale) with manufacturability and unit economics.
-
Scenario modelling (three demand/risk scenarios through 2032), plus sensitivity analyses that quantify the P&L impact of raw material price swings and procurement timing shifts.
-
An M&A and partnership playbook highlighting adjacencies (advanced textiles, sensor defeat coatings, modular concealment architectures) and valuation frameworks appropriate to this mid‑market vertical.
Competitive landscape — capabilities to watch in 2026
The market exhibits a mixed structure: concentrated technology leadership at the top and a broad base of specialized regional and niche suppliers. Our concentration metrics show that leading firms capture meaningful share, yet there remains ample room for strategic challengers and consolidators.
-
Saab (Barracuda): Global leader in multispectral systems. Saab’s Barracuda family epitomizes high‑performance, lightweight solutions designed for platform integration and broad spectrum signature management. Their strength is R&D depth and established relationships with major defence integrators.
-
Fibrotex Technologies / Fibrotex USA Inc.: A major supplier of ultra‑lightweight multispectral systems with deep engagement in modern army programs. Recent contract awards and integrations into national camouflage programs underscore their tactical positioning.
-
CamoSystems: A flexible manufacturer focused on treated/coated nets for multispectral suppression and private‑label manufacturing. Their recent product launches signal an aggressive push into IR suppression across both defence and hunting/commercial channels.
-
Camonets and J & S Franklin: Established specialty suppliers providing certified flame‑retardant and entertainment/wildlife solutions. Their niche focus preserves margins and keeps them relevant for non‑tactical market segments.
-
Seyntex, Miranda Military, Nitex and regional players such as Sterlite Camotech: These firms bring differentiated technologies (anti‑radar/3D systems, localized manufacturing footprints, competitive pricing) that matter in procurement decisions where proximity and sovereign supply are valued.
Recent market activity underscores these dynamics: major contract awards to leading multispectral manufacturers, multiple product launches focused on IR suppression, and public tenders from defence departments testing expeditionary and netting systems. For 2026 procurement strategists, monitoring supplier announcements and active tenders is operationally essential.
Market structure implications: concentration and consolidation
The market exhibits moderate concentration: a handful of firms collectively represent a significant portion of commercial activity while a larger group serves specialty and regional demand. For incumbents, this points to three realistic strategic plays: deepen technology differentiators to defend share; pursue targeted acquisitions to broaden capability; or double down on low‑cost manufacturing for volume business. New entrants should focus on narrow performance niches or high‑growth commercial adjacencies to avoid head‑on competition with entrenched multispectral incumbents.
Supply chain and raw material risk — actionable mitigation
-
Hedge and contract: Given the exposure to polyester resin and polymer price swings, buyers and manufacturers should consider multi‑year supply agreements with price bands, indexed pass‑throughs, or financial hedges where liquid instruments exist.
-
Dual sourcing and nearshoring: Where defence programmes require assured supply, build redundancy across geopolitical boundaries and qualify local suppliers for surge capacity testing.
-
Sustainable alternatives as an insurance policy: Pilot recycled and plant‑based yarns in non‑critical commercial lines first. Capture lessons on durability and sensor performance before scaling to defence applications.
A 2026 strategic playbook — four prioritized moves
-
For manufacturers: Accelerate certification paths for multispectral performance and create modular product families that can be rapidly configured for specific platform footprints. Lock in strategic raw material agreements this year to stabilize 2027 cost forecasts.
-
For defence contractors/OEMs: Integrate camouflage systems as a configurable subsystem with clear performance acceptance criteria. Pre‑qualify multiple suppliers to maintain negotiating leverage during tender awards.
-
For distributors and commercial brands: Leverage product differentiation (thermal suppression coatings, fire retardancy, private‑label flexibility) to expand into film, events and wildlife markets, where higher margins can subsidize R&D for tactical products.
-
For investors and M&A teams: Target bolt‑on acquisitions that add multispectral capability, seal supply chain risk, or provide access to defence channels. Valuations should reflect the time value of certification and procurement lead times—expect integration horizons of 12–24 months.
Risk scenarios to stress‑test 2026 plans
-
Defence surge scenario: Accelerated procurement leads to supply shortages and price inflation for raw materials—mitigate with supplier contracts and surge manufacturing plans.
-
Material shock scenario: Volatile polyester inputs compress margins—use cost sensitivity models to determine price‑pass mechanisms or product redesigns using alternative substrates.
-
Regulatory and sustainability push: Stricter environmental requirements force reformulation—accelerate laboratory testing and stagger commercial and defence roll‑outs to manage certification risk.
How to use the full PW Consulting dataset
Our public briefing demonstrates the analytical frame and tactical granularity you need, while intentionally reserving the full segment‑level breakdowns that commercial users require to execute. The complete report provides year‑by‑year market sizing, validated supplier profiles, detailed segmentation across materials and applications, and an annex with sourcing scorecards and bid response templates. If your 2026 plan requires precise allocation by material, region or application (the inputs used to build procurement commitments, inventory plans and capex), those tables and model files are available through the full report package on our website.
Concluding recommendation
2026 is a pivotal year: market growth is healthy, but the competitive landscape and supply chain realities mean that first movers with disciplined risk management and focused capability investments will outperform. PW Consulting’s Camouflage Netting Market report translates sector dynamics into executable decisions—tender readiness, supplier selection, product development prioritization and M&A targets—without sacrificing the confidentiality you need for negotiation. For teams preparing 2026 budgets and strategic plans, the question is simple: do you want directional insight, or the transaction‑grade, segment‑level intelligence required to win the next contract?
Contact PW Consulting to access the full dataset, supplier scorecards and the tactical playbooks that will convert market growth into sustainable advantage.
For detailed analysis of this topic, please visit the official page: Camouflage Netting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Lead‑Based Rare Earth Alloy Market to Grow at 5.0% CAGR Through 2026–2032
By PW Consulting, 2026-07-13
Lead-Based Rare Earth Alloy Market: Strategic Imperatives for 2026 — Preview of PW Consulting’s Market Intelligence
Executive snapshot
As PW Consulting’s lead industry strategist, I present a forward-looking synthesis of our latest Lead Based Rare Earth Alloy Market report — the one-stop strategic playbook designed to inform executive decisions in 2026. The global market has demonstrated steady expansion from our historical baseline (2020–2025) and, with a projected compound annual growth rate (CAGR) of 5.0% over the 2026–2032 forecast window, is expected to move from a 2025 base of USD 306.0 Million to a materially larger market by 2032. This preview outlines the principal dynamics that will shape near-term corporate choices, while reserving our full segment-level intelligence — pricing scenarios, regional and application splits, and detailed financial models — for the full report.
Lead Based Rare Earth Alloy Market
Why this market matters now
Lead-based rare earth alloys remain a niche but strategically important material class. They sit at the intersection of traditional heavy-industry demand (notably battery grids and radiation shielding) and emerging supply-chain sensitivities driven by rare earth feedstock availability and geopolitical shifts. For manufacturers, battery OEMs, materials traders, and private investors, the coming 24 months will be decisive: supply-side constraints, regulatory pressures, and input price volatility will determine who captures margin and who is forced into defensive positions.
Lead Based Rare Earth Alloy Market
Market trajectory and what the headline numbers mean
-
Historical momentum: The market expanded meaningfully across 2020–2025, reflecting both steady end-use demand and incremental substitution of specialty alloys in traditional applications.
Lead Based Rare Earth Alloy Market -
Base year and forecast baseline: With 2025 as our reporting base (USD 306.0 Million), our scenarios model a 5.0% CAGR across 2026–2032 under a central-case macro environment — an outcome consistent with continued industrial demand and moderate expansion of downstream capacity.
-
Strategic implication: The scale and pace of growth are sufficient to justify selective capacity additions and targeted M&A, but not to support indiscriminate expansion — firms must prioritize efficiency, input security, and product differentiation.
Dynamics shaping 2026 decisions
Several high-impact dynamics converge as companies plan capital allocation, sourcing strategies, and product roadmaps for 2026:
-
Upstream feedstock volatility — rare earth concentrate pricing has become a defining input risk. Recent industry-level benchmarks show a sharp quarter-over-quarter increase in negotiated concentrate prices in Q2 2026, reflecting tighter supply and active repositioning by major rare earth producers. That trajectory compresses gross margins for alloy makers that cannot rapidly pass costs through.
-
Policy and reshoring incentives — government financing and loan programs (notably initiatives in 2025 supporting rare earth metallization and separation) are beginning to alter the global supply chain map. These policies reduce concentration risk over the medium term but create transitional winners and losers in 2026 as new capacity and domestic processing lines come online.
-
Regulatory and sustainability pressure — lead toxicity remains a material regulatory constraint. Environmental, health, and transport regulations shape both production cost and market access. Firms that invest in cleaner processing, occupational safety, and traceable supply chains will find premium market access and lower regulatory risk.
Competitive landscape — who matters and why
The market exhibits moderate concentration (CR3 approximately 42.2%; CR5 approximately 58.4%), indicating notable incumbent scale advantages but also room for niche specialists. Our competitive assessment highlights several archetypes:
-
Integrated major producers: Large, vertically integrated firms with upstream lead and rare earth inputs command cost and security advantages. These players typically supply battery-grid markets and industrial alloys through integrated logistics and captive feedstocks.
-
Resource-backed smelters and refiners: Companies with adjacent non-ferrous metals portfolios (zinc, germanium, copper) use cross-commodity synergies to optimize yield and diversify raw material risk, often offering specialized alloy grades for industrial customers.
-
Specialist alloy fabricators: Niche manufacturers focus on higher-value forms — master alloys, wires, foils, and custom purity grades — serving customers with strict metallurgical specs. These players can command margin premiums for product breadth and technical service.
Representative firms we profile in the full report include established integrated producers and specialist fabricators, each with differentiated strengths in feedstock integration, product portfolio, and route-to-market. Our corporate scorecards evaluate capex plans, technological capabilities, balance-sheet resilience, and likely 12–24 month strategies — from capacity ramp-up to selective divestment.
Supply chain and pricing — tactical levers for 2026
Executives must treat feedstock procurement and pricing as front-line strategic issues. Our research shows that the most effective immediate actions include:
-
Negotiate multi-year offtake agreements with price collars to smooth input cost volatility;
-
Pursue vertical tie-ups or minority stakes in upstream concentrate production where feasible to secure allocation;
-
Invest in downstream product differentiation (specialty alloys and forms) to reduce pure commodity exposure and enhance margin capture;
-
Implement incremental efficiency and decarbonization projects that also mitigate regulatory risk related to lead handling.
Sector opportunities and strategic playbook
Based on scenario modeling, we identify four pragmatic strategic plays companies should evaluate in 2026:
-
Secure-to-grow: For firms with balance-sheet capacity, targeted capacity additions near stable power and logistics hubs can capture demand upside while controlling quality and emissions.
-
Niche leadership: Technical specialization (e.g., high-purity master alloys, tailored strip/foil forms) enables margin expansion without heavy capex-led exposure.
-
De-risk and hedge: Financial and physical hedging of rare earth feedstocks, plus contractual customer protections, reduce earnings volatility during input-price shocks.
-
Collaborative resilience: Strategic alliances — joint ventures for separation, recycling partnerships, and shared processing platforms — address both feedstock scarcity and regulatory compliance costs.
What PW Consulting’s full report delivers (practical, actionable assets)
Our research is built for decision-makers. The full report provides:
-
Granular market sizing and a transparent bottom-up model covering 2020–2032 (base year 2025) with scenario toggles to stress-test demand and price assumptions;
-
Segmentation matrices by region, type, and application with defensible assumptions and sensitivity analysis (note: segment tables and exact percentage splits are available in the full report);
-
Company scorecards and an M&A shortlist with an assessment of strategic fit, value creation potential, and integration risks;
-
Supply-chain maps highlighting choke points in concentrate supply, processing capacity, and logistics, plus tactical playbooks for procurement and offtake negotiations;
-
Regulatory and ESG risk register with mitigation options and costed compliance pathways;
-
Go-to-market frameworks for product differentiation, channel strategy, and customer contracting (including a 100-day rapid-response plan for price-shock events).
Risk matrix — what keeps CFOs awake
Key downside risks we model include prolonged rare earth concentrate tightness, accelerated regulatory restrictiveness on lead use, and abrupt demand erosion in legacy applications. Upside risks are faster-than-expected domestic processing capacity additions (reducing supply concentration) and technical breakthroughs that increase rare-earth utilization efficiency in alloys. Each risk is quantified in the full report and mapped to concrete mitigation steps.
Implications for boardroom decisions in 2026
For executives preparing 2026 capital and commercial plans, the strategic takeaway is straightforward: act with precision, not breadth. Prioritize actions that improve feedstock certainty, product margin, and regulatory resilience. Consider the following near-term moves:
-
Revisit capital allocation: prioritize projects with short payback that improve product mix or lower unit costs;
-
Intensify commercial contracting: renegotiate key customer and supplier agreements to include indexation and protection clauses;
-
Pursue targeted partnerships: joint ventures for separation or recycling can materially lower feedstock exposure;
-
Accelerate compliance investments: early adopters of best-practice environmental controls gain market access and avoid costly retrofits.
Final note — why PW Consulting’s intelligence is different
This report blends detailed financial modeling with on-the-ground intelligence from plant-level capacity audits, procurement channel interviews, and patent analysis. We combine quantitative forecasts (5.0% CAGR baseline, full model anchored to 2025 base-year sizing) with qualitative scenario narratives that operational teams can convert into a 90–180 day action plan. Importantly, while this preview highlights the strategic contours, the full report contains the segment-level breakouts, company profiles, and downloadable models you will need to operationalize these insights.
Call to action
Executives considering investments, partnerships, or restructuring in the lead-based rare earth alloy space should request the full PW Consulting report to access: the downloadable financial model, proprietary supply-chain maps, and our prioritized M&A shortlist. Our team is available for tailored briefings and scenario workshops to translate the research into executable 2026 strategies.
For detailed analysis of this topic, please visit the official page: Lead Based Rare Earth Alloy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Corrugating Grease Market Poised to Reach USD 295.56 Million by 2032, Says New Insights
By PW Consulting, 2026-07-13
Corrugating Grease Market — 2026 Strategic Outlook and Decision Playbook
Executive summary
As corrugated packaging rebounds and industrial maintenance priorities refocus on uptime and lifecycle cost, corrugating greases are moving from a commoditized maintenance item to a strategic input for plant reliability and packaging safety. PW Consulting’s latest market study, built on a 2020–2025 historical base and a 2026–2032 forecast horizon, quantifies the market and translates that data into a practical playbook for management teams preparing 2026 budgets and strategic choices.
Corrugating Grease Market
Key macro markers: the global corrugating grease market shows clear expansion into the latter half of the decade, underpinned by a steady compound annual growth rate (CAGR) of 4.62% across our forecast window and a base-year market size that informs FY-2026 planning. Our research triangulates demand-side recovery in corrugated packaging volumes, technology shifts in high-temperature greases, and raw-material structural changes to surface the highest-impact decision levers for 2026.
Corrugating Grease Market
Why this matters for 2026 decisions
- Procurement and operations leaders face a narrow window (next 12–18 months) to lock in lubricant strategies that affect maintenance intervals, inventory carrying costs, and operational safety through 2030.
- Suppliers and OEMs must align product roadmaps and service propositions around heat-resistant chemistries and certifications relevant to food-contact packaging lines.
- Private equity and corporate M&A teams will find the sector’s current concentration and margin dynamics useful for identifying consolidation or joint-service opportunities.
Market dynamics and structural drivers
Several structural themes are shaping the corrugating grease market:
Corrugating Grease Market
- Packaging recovery: The corrugated packaging market’s rebound supports sustained maintenance spend on corrugating equipment, creating a predictable baseline for grease demand.
- Formulation pressure from raw materials: Lithium soap and lithium complex thickeners remain significant components of global grease production, but volumes have experienced near-term pressure amid competing demand (notably from electric-vehicle battery supply chains) and a broader shift to alternative thickeners. Tighter upstream controls and regulatory scrutiny on lithium extraction are accelerating formulation experimentation across suppliers.
- Regulatory and certification pull: NSF H1 registration and similar food-contact certifications are material procurement differentiators for grease used on corrugating lines involved in packaging foodstuffs. Certification status is increasingly a must-have in commercial negotiations with major packagers.
- Supplier concentration and bargaining dynamics: The market exhibits a moderate degree of concentration among leading suppliers, creating both opportunities for premium, service-led offerings and vulnerability for buyers that rely on a narrow supplier base.
Technology and formulation trends
High-temperature, low-volatility chemistries continue to dominate technical conversations. Fully fluorinated PFPE/PTFE-based greases remain the benchmark for single-facer and heated-roll applications because of their film strength and thermal stability at elevated temperatures. At the same time, synthetic hydrocarbon and other engineered high-temperature synthetics are making inroads where cost or regulatory considerations require alternatives to fluorinated systems.
Manufacturers must weigh trade-offs: top-tier PFPE systems offer superior thermal performance and maintenance interval extensions but come with higher upfront material cost and tighter supplier concentration. Non-fluorinated high-temperature synthetics and novel thickener-systems provide cost and regulatory latitude, but require thorough compatibility and wear testing before plant-wide conversion.
Competitive landscape — what leading suppliers are doing
PW Consulting’s competitive review highlights differentiated strategies from incumbents and specialist suppliers:
- Chemours (Krytox) leverages its Krytox Performance CORR product family to anchor premium positioning: established industry standards for high-temperature corrugator bearings and strong brand recognition among maintenance teams. Their value proposition is thermal performance combined with proven uptime benefits.
- FUCHS Lubricants (including Nye Lubricants) competes on a combined product-and-service model. Their food-grade, PTFE-thickened solutions and Total Corrugator Plant Lubrication service illustrate a route to lock-in through plant conversions and lifecycle services that reduce total cost of ownership for buyers.
- LUBCON and IKV Tribologie operate as focused specialists, targeting technical niche applications and compliance-driven segments with NSF H1-registered products, quick-response technical support, and regional presence that appeals to converters with specific certification needs.
- Adjacent chemistry and materials developments — for example, coatings and inks with improved grease resistance showcased by suppliers in late-2025 — change the operational interface between grease and substrate. These cross-supply chain interactions are emerging negotiating points between packaging material suppliers and lubrication providers.
Strategic implications and recommended moves for 2026
For executive teams building 2026 plans, the report highlights a set of prioritized actions that create optionality and de-risk exposure to raw-material and regulatory shocks:
- Procurement diversification: Establish dual-source contracts for premium high-temperature greases and map alternative-thickener suppliers to mitigate single-supplier risk. Include supply continuity clauses and multi-year pricing collars tied to raw-material indices.
- Certification roadmap: Require NSF H1 (or equivalent) compliance where lines produce food packaging. Make certification a gate in supplier RFPs and include periodic re-audits in vendor terms.
- Service-led conversions: For converters aiming to reduce downtime, pilot plant conversions using service packages (lubrication audits, conversion trials, and predictive monitoring) rather than spot-product switches. Track maintenance interval improvements and capture actual TCO impacts to justify roll-outs.
- R&D and testing protocols: Allocate budget to qualification testing for non-fluorinated alternatives — including thermal cycling, wear particles monitoring, and substrate interaction tests — before committing to fleet-wide changes.
- Cross-supply chain coordination: Coordinate procurement and technical teams with ink and coating suppliers to ensure grease compatibility, particularly as packaging surface technologies evolve.
- Scenario planning and hedging: Use scenario-based planning to model upstream raw-material constraints and regulatory changes (including potential REACH-like actions) and build contingency capex and inventory strategies accordingly.
What PW Consulting’s report delivers (practical content)
The full report is built for action: it combines robust market-sizing and forecast models with operationally focused tools that can be executed during 2026 planning cycles. Highlights include:
- A verified market-size baseline and a transparent CAGR forecast to 2032, enabling finance teams to quantify near-term budget envelopes for lubricant spend.
- Supplier scorecards and a competitive playbook describing product portfolios, certification coverage, service models, and win-loss patterns observed in customer conversions.
- A regulatory and raw-material risk map with trigger points for formulation sensitivity and sourcing contingency options.
- Technical evaluation templates and an equipment-level pilot checklist for safe, repeatable grease qualification in plant environments.
- Commercial negotiation levers and contracting templates designed to protect buyers from supply shocks while allowing suppliers to monetize performance improvements.
- Scenario analytics that connect packaging demand forecasts to grease consumption patterns under multiple recovery and cost-inflation assumptions.
How to use this intelligence in 2026 planning cycles
Executives, procurement leads, and plant managers should use the report in three immediate ways:
- Inform the 2026 procurement RFP: use supplier scorecards and certification filters to structure RFPs that prioritize continuity, compliance, and demonstrable performance gains.
- Design pilot programs: deploy the report’s pilot checklist across representative lines to measure real-world maintenance interval shifts, lubricant consumption, and interfacing risks with inks and substrates.
- Support capital allocation: feed forecast scenarios into maintenance-capex planning to determine whether investments in bearings, seals, or advanced lubrication systems produce superior ROI versus repeated lubricant-based interventions.
Decision primers for specific stakeholders
- C-suite and strategy teams — incorporate supplier concentration metrics and sensitivity to raw-material regulation in portfolio scenarios and M&A screening.
- Procurement — implement multi-source strategies with contractual protections linked to performance metrics and certification maintenance.
- Operations — prioritize pilot-based conversions and embed grease compatibility checks into change-control procedures.
- R&D — accelerate qualification of non-lithium thickener systems and alternative synthetics where regulatory or cost risk is material.
Conclusion and next steps
The corrugating grease market is not a niche of purely technical interest — it is a lever for uptime, packaging safety, and cost control. Our research shows a clear growth trajectory through the rest of the decade and identifies the practical interventions that create value in 2026 planning cycles. PW Consulting’s full report contains the granular segmentation, supplier-by-supplier benchmarking, and downloadable operational templates that decision teams need to execute with confidence.
To access the complete dataset, segmentation tables, supplier contact map, and the operational playbook, download the full report or contact PW Consulting’s Industrial Lubricants practice. For immediate inquiries and enterprise licensing options, visit: pwconsulting.com/reports/corrugating-grease-market.
For detailed analysis of this topic, please visit the official page: Corrugating Grease Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rare Earth Metal Recycling to Grow at 17.5% CAGR, Reach USD 773.06 Million by 2032 — Asia‑Pacific Leads with USD 134.7M in 2025
By PW Consulting, 2026-07-13
Rare Earth Metal Recycling Market: Strategic Outlook for 2026 — PW Consulting Preview
Executive summary
PW Consulting’s latest Rare Earth Metal Recycling Market report (base year 2025; historical period 2020–2025; forecast 2026–2032) delivers a tactical playbook for corporate leaders, investors, and policy-makers preparing for a market that is transitioning from pilot stage to industrial scale. The market has expanded rapidly—from approximately USD 110 million in 2020 to USD 250 million in 2025—and our modelling projects continued rapid growth through the forecast horizon, yielding a multi-fold increase by 2032 under a scenario-driven compound annual growth rate (CAGR) of 17.5% for the forecast period. This growth trajectory is underpinned by technology maturation, supportive industrial finance, and geopolitical realignment of critical minerals supply chains.
Rare Earth Metal Recycling Market
Why this report matters for decisions in 2026
-
Action timing: 2026 is a pivot year for rare earth recycling as several projects move from demonstration to commercial commissioning. Decisions on plant siting, feedstock agreements, and offtake partnerships taken in 2026 will determine competitive positioning for the remainder of the decade.
Rare Earth Metal Recycling Market -
Capital allocation: Our analysis connects capital deployment to near-term capacity additions and price sensitivities. Companies and financiers who deploy capital with the right technology-, feedstock- and policy-alignment stand to capture outsized returns as the recycling supply pool scales.
Rare Earth Metal Recycling Market -
Risk management: Regulatory shifts and raw-material price volatility are already affecting economics. The report supplies scenario-based stress tests that inform hedging, inventory, and vertical-integration choices that should be considered by 2026 planners.
Macro picture — what the numbers tell us
The rare earth recycling market has moved beyond niche recovery to a structurally growing industry. Measured in USD Million, the market more than doubled between 2020 and 2025, and our forecast shows a clear path to substantially larger market value by 2032 under a 17.5% CAGR across 2026–2032. That pace is consistent with accelerating collection programs, technology improvements in recovery yields, and rising economics driven by magnet demand in electrification and renewables.
Concentration metrics are notable: the three largest recyclers control a meaningful share of the market, while the top five firms consolidate an even greater portion. That concentration profile creates both opportunity and incumbent risk—opportunity for new entrants who can unlock differentiated feedstock access or proprietary recovery routes, and risk for smaller players exposed to feedstock or capital constraints.
Market drivers and near-term disruptors
-
Supply-side restructuring: Government financing and industrial policy in the U.S. and allied markets have catalyzed commercial projects and recycling hubs. Public-private capital is reducing project financing barriers, accelerating timelines for select facilities.
-
Raw material economics: Prices for Nd-Pr alloys and related rare earth inputs have experienced acute upward pressure in early 2026, materially improving the economics of recycling projects and shortening payback periods for higher-capex processes.
-
Technology differentiation: Multiple technical routes—hydrogen-based processes, chromatography, proprietary solvent and pyrometallurgical hybrids—are proving competitive in different feedstock and scale contexts. Technology choice drives plant footprint, capital intensity, and product specification.
-
Regulatory and geopolitical dynamics: Export controls, licensing rules, and extraterritorial provisions introduced by key producing nations are reshaping trade flows and compliance burdens. Parallel supportive measures from buyer-country governments are accelerating domestic recycling capability.
Competitive landscape — who to watch
The market is populated by a combination of specialist recyclers, incumbent mineral producers pivoting into circularity, and technology-focused start-ups. Key companies profiled in our report include established and scaling operators with differentiated approaches to feedstock, chemistry, and value capture. Highlights include:
-
Cyclic Materials — advancing mixed rare earth oxide production through proprietary processes and expanding capacity in North America to capture end-of-life magnet flows from EVs, wind turbines, and electronics.
-
Neo Performance Materials — integrating recycling capabilities with magnet production, with international plant activity that signals a hybrid upstream–downstream strategy.
-
REEcycle Inc. — commercializing a high-efficiency process to recover rare earths from NdFeB magnets in batteries and e‑waste.
-
HyProMag (Maginito/Mkango partnership) — deploying hydrogen-based short-loop recycling for NdFeB scrap with commercial-scale plans in the U.S. market.
-
ReElement Technologies — using chromatography-based processing, supported by strategic defence funding to scale U.S. processing capacity.
-
Global industrial players (Umicore, Hitachi Metals, Lynas, MP Materials) — expanding recycling as part of broader critical-material strategies, leveraging existing refining, manufacturing, or mining positions to offer integrated supply solutions.
-
Specialist recyclers and new entrants (Oryx Metals, RarEarth) — developing niche, low-hazard chemistries for motor and magnet recycling in regional markets.
Recent 2026 developments underscore the move to industrialization: large announced campus investments, site selections for magnet manufacturing with closed-loop recycling, and university-industry facility launches demonstrate that commercially meaningful capacity is being deployed now—accelerating feedstock demand for collectors and processors alike.
Strategic implications and recommendations for 2026 decision-makers
-
Secure strategic feedstock partnerships now. Early long-term agreements with OEMs, motor remanufacturers, and e‑waste aggregators provide cost and quality visibility that materially improves project returns. Our scoring matrices identify the differentiated value of short-loop (scrap) versus long-loop (end-of-life) feedstock.
-
Match technology to feedstock and offtake. Not all recovery technologies are equal across feedstock streams. Our techno-economic roadmaps quantify break-even yields and product specifications; match technology selection to your targeted product stream rather than selecting technology independently.
-
Layer capital strategies: blend measurable public financing opportunities with staged private capital to shorten time-to-commercial while de‑risking scale-up. We map grant/loan programs against project timelines and provide a practical funding playbook for 2026–2028 execution.
-
Design for product quality and standards. Magnet-grade outputs require tight impurity control; recycling projects must incorporate downstream purification or partner with magnet manufacturers to realize premium pricing. Our recommended process flows include pragmatic quality checkpoints to retain value.
-
Develop compliance and trade contingency plans. With export controls and extraterritorial licensing in flux, build compliance-first sourcing and technology governance frameworks. The report includes a jurisdictional risk matrix and a checklist for contract language that protects IP and supply continuity.
-
Consider industrial clustering to capture scale. Co-location with magnet manufacturing, battery plants, or existing refining capacity reduces logistics and intermediate handling costs—our location decision model weights cost, feedstock availability, and policy incentives.
What the report contains — operationally useful deliverables
This report is intentionally practical. It is designed to be a working tool for 2026 planning and includes:
-
Market sizing and growth scenarios (2020–2032) with transparent assumptions and sensitivity analyses for pricing, collection rates, and technology adoption.
-
Technology evaluation frameworks that compare recovery yield, unit economics, capital intensity, and environmental footprint across leading process routes.
-
Commercial due diligence templates for feedstock agreements, offtake contracts, and EPC procurement specific to recycling plants.
-
Project financial models with modular inputs for plant size, feedstock grade, and product mix—enabling rapid scenario testing for 2026 investment decisions.
-
A competitive intelligence chapter profiling market players, their strategic moves, and a forward-looking map of announced capacities and likely commercialization timelines (redacted at segment granularity in this preview to protect proprietary forecasting detail).
-
Regulatory and policy appendices summarizing recent export controls, public financing programs, and recommended compliance actions.
How to use this intelligence in 2026
Leaders should use the report to create an executable 24–36 month plan aligned with capital cycles and policy windows. We recommend three immediate actions:
-
Run a rapid portfolio fit exercise using our technology–feedstock matrix to prioritize piloting vs. partnering vs. building.
-
Begin targeted feedstock negotiations with the top local collectors/OEMs identified in our market map, locking minimum viable throughput to de-risk financing conversations.
-
Engage with funding stakeholders—public and private—using our investor-ready capex and cash-flow models to secure trancheable finance tied to measurable performance milestones.
Why PW Consulting’s forecast is strategically distinct
Our approach blends granular project-level techno-economics with system-level trade-flow analysis and a disciplined policy-risk overlay. The report’s forecasts are not a single baseline; they are a suite of scenarios that reflect the key variables we see driving 2026 outcomes—feedstock collection efficacy, technology learning rates, policy levers, and raw material price dynamics. We show not only where value pools are likely to emerge but also the tactical moves that can capture them.
Trailer principle — what this preview omits and where to find it
This press release intentionally highlights strategic implications and high-level market trajectory. To preserve the utility of the intelligence for commercial decision-making, detailed segment-level tables (regional splits, application shares, and company-level revenue estimates) and the full project-by-project capacity schedule are reserved for subscribers of the full report. Those exhibits include the exact flows, unit economics, and sensitivity tables that corporate planners need to execute in 2026.
Next steps
Executives preparing decisions in 2026 should contact PW Consulting to access the full Rare Earth Metal Recycling Market report and the accompanying financial model. Our advisory team is available to run a tailored 48-hour strategic diagnostics session, deploying the report’s datasets against your assets, partner list, and capital constraints to produce an actionable 90‑day plan.
About PW Consulting
PW Consulting is a strategy advisory and industry analysis firm specializing in critical-materials value chains. Our Rare Earth Metal Recycling Market report synthesizes technical, commercial, and policy intelligence to help clients convert market transition into competitive advantage.
For detailed analysis of this topic, please visit the official page: Rare Earth Metal Recycling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 7.38% CAGR for Metal Ion Free (MIF) Photoresist Developer Market Through 2032
By PW Consulting, 2026-07-13
Metal Ion Free (MIF) Photoresist Developer Market — Strategic Imperatives for 2026
Executive summary
PW Consulting’s new market study on Metal Ion Free (MIF) Photoresist Developers delivers the evidence-based framework executives need to make high-stakes semiconductor materials decisions in 2026. Built on a 2020–2025 historical baseline with 2025 as the base year and a 2026–2032 forecast horizon, the report quantifies a sustained growth trajectory: the global MIF developer market expands from under USD 1.0 Billion in 2020 to roughly USD 1.40 Billion in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 7.38% through the 2026–2032 forecasting window, approaching the low‑to‑mid USD 2.3 Billion range by 2032. These macro dynamics create discrete opportunities and risks for process engineers, procurement leads, and corporate strategists preparing for the 2026 budget cycle and beyond.
Metal Ion Free (MIF) Photoresist Developer Market
Why 2026 is a decisive inflection point
-
Node migration and yield sensitivity: As semiconductor manufacturers consolidate mature nodes and ramp advanced logic, the tolerance for ionic contamination tightens — elevating the strategic importance of MIF developers for device reliability and yield. 2026 is when many capital and process decisions finalized in 2024–25 will enter execution, making timely vendor choices critical.
Metal Ion Free (MIF) Photoresist Developer Market -
Supply-side dynamics and cost pass-through: Upstream feedstock (notably tetramethylammonium hydroxide, TMAH) and regional demand swings have resulted in directional price softness in early‑to‑mid 2025. Buyers and planners must decide in 2026 whether to lock long-term supply agreements, pursue spot procurement, or invest in formulation co-development to secure predictable margins.
Metal Ion Free (MIF) Photoresist Developer Market -
Regulatory and sustainability inflection: Emphasis on low-ionic, environmentally compliant developers has accelerated vendor product launches and partnerships. 2026 procurement strategies should explicitly incorporate environmental compliance, recyclability of process chemistries, and vendor roadmaps for lower-environmental-impact formulations.
Market trajectory and what it means for decisions
The market’s historical compounding and our forecasted 7.38% CAGR together indicate steady, above‑inflation growth driven by semiconductor production resilience and incremental yield-driven migrations to MIF chemistries. For 2026 planning this translates into three practical implications:
-
Invest in qualification pipelines now: Lead times for developer qualification—lab evaluations, pilot production runs, and inline integration—can exceed a single fiscal year when combining supplier audits, wafer‑level testing, and supply agreements. Firms that begin cross-functional qualification in early 2026 can materially shorten time-to-production for critical nodes in 2027.
-
Prioritize supplier portfolio design: Given the market concentration metrics (the top three suppliers capture a majority share and the top five an even larger portion), strategic sourcing should balance performance specialization with supplier diversification to mitigate single‑source exposure.
-
Embed price and supply scenarios in budgeting: Because raw material pricing exhibited softness in Q2 2025, 2026 procurement should model both continued softening and potential rebound scenarios tied to demand cycles in foundry and memory segments.
Key market dynamics shaping 2026 strategies
-
Feedstock concentration: TMAH remains the dominant upstream input with standard normalities used across most MIF developer formulations. Any supply disruption or regulatory action affecting TMAH will have an outsized impact on downstream availability and qualification schedules.
-
Regulatory and purity drivers: MIF developers are increasingly the default where ionic purity matters (chemically amplified and DNQ-based resists, sub‑0.5 µm work). Decision-makers must align product selection with device reliability specifications rather than price alone.
-
Product differentiation: Vendors are competing not just on purity and normality but on adjunct performance attributes—wetting agents, residue control, and compatibility with immersion or in‑line track systems. Procurement and process teams should score suppliers against a multidimensional performance matrix instead of a unit price list.
-
Sustainability and compliance: Recent launches and partnerships show suppliers investing in eco‑friendlier MIF formulations. Incorporating environmental KPIs into supplier scorecards will be a differentiator for OEMs and fabs pursuing sustainable manufacturing mandates.
Competitive landscape — what matters to buyers and strategists
The MIF developer vendor ecosystem blends large, vertically integrated chemical companies with fast‑moving specialty formulators and distribution partners. PW Consulting’s analysis identifies several strategic postures that matter in 2026:
-
Global chemistry leaders: Long‑standing players with broad portfolios offer scale, technical support, and global logistics that suit high-volume foundries. Their recent moves include eco‑friendly product introductions and strategic partnerships to support customized process solutions—important for partners seeking co‑development and security of supply.
-
Regional and specialty formulators: Smaller manufacturers and niche suppliers provide quick‑turn customization and lab‑scale to production transition capability. These firms are ideal partners for product differentiation and pilot projects where fast iteration matters.
-
Distributors and lab-to-production bridges: Specialized distribution companies play a critical role in bringing major brands into small/mid‑volume fabs and R&D labs, offering technical dispersion and local regulatory navigation.
For procurement and strategy teams: evaluate suppliers across three dimensions—technical fit (compatibility with resist systems and track equipment), operational resilience (lead times, multi-site supply), and strategic flexibility (co‑development, IP, and environmental roadmap).
Recent vendor activity and implications
-
Product launches focused on environmental performance and process compatibility indicate vendors expect sustainability and compliance to be purchasing criteria in 2026. Buyers should request detailed life‑cycle and regulatory documentation during RFPs.
-
Partnerships between major suppliers and device manufacturers suggest a trend toward collaborative product customization. Corporates considering process differentiation should assess the strategic value of exclusive or semi‑exclusive development agreements.
-
Price signals from 2025 and early 2026 imply buyers can achieve short‑term cost relief, but should guard against complacency—securing long‑term stability often requires premium terms or co‑investment in qualification and supply resilience.
Actionable 2026 playbook — recommendations at a glance
-
Start an accelerated qualification sprint: Launch cross‑functional (procurement, process, quality) trials for at least two supplier candidates per critical node. Target pilot completion within 6–12 months and align budget approvals to that timeline.
-
Adopt a layered sourcing strategy: Combine one lead global supplier for scale and two regional/specialty partners for flexibility. Include contractual clauses for price review tied to key raw material indices, and inventory buffers for critical ramp periods.
-
Negotiate co‑development and IP terms: Where process differentiation matters, structure agreements that secure priority access to new MIF formulations while retaining manufacturing rights or preferred status during ramp phases.
-
Integrate sustainability KPIs: Require transparency on formulation lifecycle impacts and vendor roadmaps for lower environmental footprint chemistries as a condition for long-term sourcing commitments.
-
Scenario test budgets: Build P&L sensitivity for sustained price softness, short-term supply shocks, and accelerated demand—update capital and working capital models quarterly in 2026.
What PW Consulting’s report includes (practical deliverables)
The full market study translates these strategic implications into operational tools: a validated market sizing and forecast model (USD, revenue expressed in Million units), segmentation by region/chemistry/application, vendor profiles and capability maps, supply‑chain heat maps, raw‑material pricing scenarios, regulatory impact analysis, a risk matrix, M&A and partnership targets, and an execution playbook for procurement and process teams. Importantly, the report pairs numerical forecasts with qualification checklists, supplier scoring templates, and a buyer’s negotiation playbook that clients can deploy immediately.
Accessing the full intelligence
This release is a strategic “trailer”: it surfaces the evidence and frameworks that will shape successful 2026 strategies while preserving the granular segmentation and supplier‑level data that our clients rely on for tactical decisions. For procurement teams, process engineering leads, corporate development professionals, and investors preparing commitments in 2026, the full report provides the downloadable datasets, interactive models, and due‑diligence appendices necessary to act with confidence.
Contact
To request an executive briefing or to license the complete PW Consulting MIF Photoresist Developer Market Report (including the downloadable forecast model and supplier scorecards), contact our Industry Strategy Desk at insights@pwconsulting.com. Time‑sensitive advisory slots for 2026 strategy sessions are available on a limited basis.
For detailed analysis of this topic, please visit the official page: Metal Ion Free (MIF) Photoresist Developer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Liposomal Glutathione Market to Expand at 8.79% CAGR Through 2032
By PW Consulting, 2026-07-13
Liposomal Glutathione Market 2026 Strategic Outlook — Actionable Intelligence for Corporate Decision-Makers
PW Consulting’s latest market intelligence on Liposomal Glutathione synthesizes five years of historical performance with a rigorous 2026–2032 forecast to inform near-term corporate strategy. The global market recorded steady expansion through 2020–2025, reaching an estimated USD 186.15 Million in the base year (2025). Our model anticipates continued momentum at a compound annual growth rate (CAGR) of 8.79% for 2026–2032, with the market evolving from roughly USD 206.29 Million in 2026 to an expected USD 335.89 Million by 2032. These macro trajectories create both clear opportunities and strategic challenges for incumbent players, new entrants, ingredient suppliers, and channel partners.
Liposomal Glutathione Market
Why this report matters for 2026 planning
-
Decision support under uncertainty: the market is in a structural growth phase driven by bioavailability demand, premium consumer positioning, and formulation innovation. Our scenarios quantify upside and downside pathways to help allocate CAPEX and commercial spend.
Liposomal Glutathione Market -
Operational risk mitigation: the report identifies supply-chain pinch points and proposes sourcing strategies for reduced L‑glutathione and phospholipid inputs — critical for continuity in 2026 procurement cycles.
Liposomal Glutathione Market -
Go‑to‑market design: we map effective commercial models (DTC, specialty retail, practitioner channels, and B2B formulation licensing) and provide playbooks for rapid execution.
-
M&A and partnership intelligence: our competitive analysis and concentration metrics highlight likely target profiles and timing windows for acquisitive growth or strategic alliances.
What you will find in the report — practical, executable deliverables
-
Dynamic market model (2020–2032) delivered in Excel, enabling user-defined scenarios and sensitivity testing of pricing, penetration, and channel mix assumptions.
-
Commercial playbooks tailored for product types and route-to-market strategies, including sample promotional narratives and positioning frameworks for premium vs. mass segments.
-
Supply-chain scorecards and a supplier short-list for raw glutathione and phosphatidylcholine, with risk heatmaps and recommended mitigation levers.
-
Regulatory and labeling toolkit that translates DSHEA-era constraints into compliant marketing language and evidence strategies that support allowable structure–function claims.
-
Product development checklist covering formulation choices, stability testing, PK/PD study templates, and third-party validation pathways to substantiate bioavailability claims.
-
Competitive intelligence dossier on leading brands and manufacturer profiles, plus a prioritized list of M&A/partnership targets and value-creation hypotheses.
Macro and market-structure takeaways (data‑driven)
The category has transitioned from niche to mainstream over the last five years. The growth profile through 2025 reflects rising consumer awareness of antioxidant strategies and a premium willingness to pay for demonstrable bioavailability improvements. Our forecasted 8.79% CAGR captures sustained adoption across channels and iterative product innovation rather than a one‑time spike.
Market concentration is moderate: the top three players account for a meaningful share, while the top five increase that share further but leave room for disruptive entrants and mid-sized specialists. This structure implies the sector is neither a pure oligopoly nor highly fragmented; strategic consolidation and brand consolidation remain highly plausible, particularly for companies that can pair formulation IP with distribution scale.
Competitive landscape — positioning and strategic implications
-
Quicksilver Scientific — Known for liquid and spray formats emphasizing enhanced bioavailability. Strategic strengths: clinician awareness and formulation recognition. Strategic implication: further investment in comparative bioavailability data and clinician education can solidify premium pricing and justify channel exclusives.
-
LivOn Laboratories — Proprietor of a recognized liposomal encapsulation technology marketed for oral delivery. Strategic strengths: proprietary processing and brand equity with nutraceutical formulators. Strategic implication: consider licensing models to monetize technology across adjacent antioxidant ingredients or pursue selective co‑branded partnerships.
-
Seeking Health — Positions on ingredient sourcing (non‑GMO sunflower phospholipids) and practitioner channels. Strategic strengths: supply‑chain story and clinician trust. Strategic implication: opportunity to expand practitioner-led educational programs and evidence-generation to defend premium segment share.
-
Core Med Science — Focused on high-potency formulations across capsules and liquids. Strategic strengths: product potency claims and broad format offering. Strategic implication: vertical integration or supply agreements for reduced L‑glutathione could protect margins as raw-material pricing evolves.
-
Empirical Labs — Active in liquid formulations for detox and antioxidant positioning. Strategic strengths: niche detox audience and targeted marketing. Strategic implication: cross-selling into adjacent detox or functional wellness bundles and clinical partnerships can expand lifetime value.
Regulatory, raw-material and research context
Key regulatory reality: in the U.S., liposomal glutathione is marketed as a dietary supplement under DSHEA and is not subject to pre-market FDA approval. This creates a compliance landscape where labeling, substantiation of claims, and advertising rigor are decisive competitive differentiators rather than product approval gates. Companies must adopt conservative claim language, maintain audit-ready documentation, and implement robust adverse event monitoring.
Raw-material dynamics are central. Reduced L‑glutathione produced via yeast fermentation is the predominant source, while liposomes are typically formed from phosphatidylcholine derivatives. Supply tightness, quality divergence across suppliers, and geopolitical sourcing risk for phospholipids can all materially affect cost of goods sold and product shelf stability. Our supply‑chain module provides a prioritized mitigation plan including secondary sourcing, long‑term contracts, and on‑site QC protocols.
Research and promotional constraints: standard consumer-facing disclaimers remain necessary. Investing in human PK/PD and bioavailability studies is a high‑leverage move: credible clinical data enables stronger trade partnerships, premium pricing, and reduced risk during regulatory or marketing scrutiny.
Prescriptive strategic moves for 2026
-
Invest selectively in human bioavailability data and third‑party validations to convert curiosity into enduring willingness to pay.
-
Secure diversified supply lines for reduced L‑glutathione and phospholipids now; consider multi-year offtake agreements to stabilize input costs.
-
Prioritize GMP-certified manufacturing and transparent QC reporting to differentiate on quality — not just marketing.
-
Adopt hybrid commercial models that blend practitioner endorsement with DTC storytelling for maximal reach and margin control.
-
Pursue bolt‑on M&A for formulation IP or channel capability rather than headline-grabbing buyouts; small strategic acquisitions can accelerate scale at lower valuation multiples.
-
Systematize compliance and claims governance across markets to avoid costly reworks or enforcement actions as the category matures.
-
Explore licensing of liposomal platforms to white-label partners as a lower-capex route to enlarge addressable market footprint.
The PW Consulting difference — how we support 2026 decisions
Our Liposomal Glutathione Market report is designed as an operational toolkit for corporate leaders: the deliverable set includes a flexible financial model, a competitor and supplier database, regulatory compliance templates, and a prioritized roadmap of initiatives keyed to ROI and timing. For firms preparing 2026 budgets, the combination of modeled scenarios and tactical playbooks reduces execution risk and accelerates time-to-market for prioritized initiatives.
Note: this release presents high‑confidence macro results and strategic guidance. To preserve the tactical value of the dataset for subscribers and to encourage direct engagement, detailed segmental breakdowns, regional splits, application-level datapoints, and company market-share tables are withheld here. The full report and supporting Excel model contain the granular tables and heatmaps that decision-makers require to execute precise, investable strategies.
Next steps
-
If you are evaluating portfolio moves, distribution strategies, or sourcing arrangements for 2026, begin with a scenario workshop using our model to identify breakeven investment levels and prioritized actions.
-
Contact PW Consulting to access the full report and the downloadable market model; the detailed segmentation, company share tables, and supplier shortlists are available to subscribers and advisory clients.
2026 will be a defining year for companies that convert formulation credibility, supply‑chain resilience, and disciplined commercial execution into defensible market positions. PW Consulting’s Liposomal Glutathione Market intelligence equips leaders with the foresight and tools to act decisively — without revealing the proprietary segmentation that makes those actions investable.
For detailed analysis of this topic, please visit the official page: Liposomal Glutathione Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Polarizer for OLED Market to Expand at a 10.32% CAGR Through 2032
By PW Consulting, 2026-07-13
Polarizer for OLED Market — Strategic Briefing (PW Consulting)
Executive summary
As companies set budgets and strategic priorities for 2026, the polarizer segment for OLED displays sits at a pivotal inflection point. PW Consulting’s forthcoming Polarizer for OLED Market report synthesizes robust quantitative modelling with on-the-ground commercial intelligence to inform executive decisions on product development, capacity allocation, sourcing, and M&A. At the macro level, the OLED polarizer market is recovering and re-accelerating: the global market reached roughly USD 2.19 billion in our 2025 base year and is projected to expand at a compound annual growth rate (CAGR) of about 10.32% across our 2026–2032 forecast horizon — reaching a materially larger market size by 2032. This growth coexists with accelerating substitution risks from polarizer-less technologies, concentrated supplier structures, and raw-material cost volatility — factors that together make 2026 a make-or-break year for many OEMs and suppliers.
Polarizer for OLED Market
Why this matters for 2026 planning
-
Timing of investment: With a strong near-term growth trajectory, suppliers face trade-offs between capacity expansion and preserving capital for R&D into alternate optical stacks. The opportunity to capture incremental volume in 2026 is real, but so is the risk of overbuilding for a market being reshaped by pol-less innovations.
Polarizer for OLED Market -
Risk management: Raw-material exposure (notably PVA and iodine) creates a dual challenge — cost-pass-through limits with end customers, and supply concentration risks. Companies that lock flexible sourcing arrangements or integrate upstream are positioned to protect margins in 2026.
Polarizer for OLED Market -
Customer alignment: Panel-makers and system OEMs continue to pilot polarizer-free architectures for specific product segments. Suppliers must prioritize cross-functional partnerships with display integrators in 2026 to retain design-ins and avoid being disintermediated.
Market snapshot (high level)
Our model, calibrated to 2020–2025 historical performance and updated through early 2026 intelligence, quantifies a market that has grown steadily from the 2020 base and stands at approximately USD 2.19 billion in 2025. Under the central forecast scenario the market expands at a 10.32% CAGR during 2026–2032, reflecting continued OLED adoption across consumer electronics, large-format displays, and specialized automotive/industrial applications. The market remains moderately concentrated: the top three suppliers account for roughly 68% of market share and the top five approach the mid‑80s percent range — a structure that creates both resilience and vulnerability depending on how quickly substitution trends proceed.
Note: This briefing intentionally omits detailed segmentation figures by region, product type, and application. The full report contains the granular splits, growth rates by segment, and model sensitivities that underpin the scenarios summarized here.
Competitive landscape — strategic implications
Supplier competition is bifurcating into (1) scale-focused incumbents maintaining cost and supply leadership, and (2) specialist innovators pursuing ultra-thin, flexible and high-contrast solutions. Key companies we track exhibit distinct positioning:
-
Nitto Denko Corporation (Japan) — A global leader in ultra-thin polarizers with strong IP and long-standing design relationships in smartphones and premium displays. Nitto’s scale and product breadth make it a de facto partner for panel-makers migrating toward flexible and foldable form factors.
-
Sumitomo Chemical (Japan) — Focused on high-performance PVA-based films for premium applications. Its strengths are in optical performance and material science, positioning it to defend premium price points but leaving it exposed to raw-material inflation unless hedged.
-
LG Chem / Shanjin Optoelectronics (Korea/China) — Retains OLED-specific manufacturing capabilities, particularly for larger-size and flexible panels. Close ties with panel ecosystems give LG Chem strategic leverage for volume commitments and co-development.
-
Samsung SDI (Ace Digitech) (Korea) — Notable for polarizers tailored to foldable and premium OLEDs and for potential strategic moves tied to Samsung’s broader display roadmap. Business positioning is subject to ongoing strategic review, but the company’s integration into a major panel ecosystem is a competitive differentiator.
-
BenQ Materials (Taiwan) — Specialist in bendable circular polarizers, gaining share in the foldable segment. Smaller scale than the largest incumbents but high relevance in fast-growing subsegments.
-
Other regional manufacturers (Japan, China, Taiwan, Korea) — A cadre of medium and smaller players are expanding capacity and capability, often targeting cost-sensitive segments or regional OEMs. Their growing presence contributes to supply competition and to the industry’s ability to respond to regional trade shifts.
Strategic takeaway: market concentration gives incumbents pricing power in the near term but does not insulate them from technology-driven commoditization. Partnerships with panel-makers, selective capex, and focused R&D into flexible/ultra-thin materials will be decisive in 2026.
Technology disruption and demand substitution
Three concurrent trends are reshaping demand:
-
Polarizer-less innovations: Independent market analyses forecast meaningful adoption of polarizer-free OLED modules in certain device classes over the coming decade. Pilots and awards (e.g., recent recognitions for polarizer-free display innovations) indicate commercial momentum that could materially reduce some polarizer volumes, particularly where thickness and cost are paramount.
-
Alternative optical stacks: Approaches such as OLED Transmittance Control Film (OTF) are gaining traction in specific TV applications as a way to optimize cost and thinness. These alternatives do not instantly negate the polarizer market but change the mix of required optical films and the value chain.
-
Segment-specific trajectories: Replacement risk is uneven — some applications (e.g., high-contrast smartphone panels, certain automotive displays) will maintain polarizer demand longer due to optical performance requirements, while others may move faster toward pol-less designs.
Supply chain and input risk
Manufacturing of polarizer films is materially dependent on polyvinyl alcohol (PVA) and iodine for dyeing and performance. Key observations for 2026 planning:
-
Input concentration: The iodine supply chain is concentrated geographically; this creates price volatility and raises secure-supply concerns. Market-level estimates suggest the iodine sector itself will be a multibillion-dollar market in 2026, with major national suppliers accounting for a large share of output.
-
Margin pressure: Historical gross margins for polarizer operations at several Chinese and Taiwanese producers cluster in the mid‑teens to low‑twenties percent. That margin band constrains the ability of suppliers to fully absorb raw-material spikes without contractual or commercial consequences.
-
Trade & tariff dynamics: Policy shifts — such as potential changes to previously tariff-free treatments of polarizers and sub-films — plus ongoing US-China trade tensions create sourcing and competitiveness implications. Companies should stress-test 2026 supplier strategies against alternative tariff scenarios.
Actionable recommendations for 2026
-
Prioritize dual-track investment: allocate a portion of R&D and capex budgets to defend core polarizer technology (ultra-thin, flexible, circular polarizers) while funding targeted pilots for pol-less optical solutions with key panel customers.
-
Hedge raw-material exposure: secure multi-year supply agreements for PVA and iodine, consider strategic inventory buffering, and evaluate upstream investments or alliances to stabilize cost and availability.
-
Forge closer OEM partnerships: negotiate long-term design-in commitments, co-development agreements, and risk-sharing contracts with panel-makers to protect revenue streams as optical architectures evolve.
-
Reassess geographic footprint: model tariff scenarios and re-align production footprints and sourcing to mitigate trade risk while preserving access to growth markets.
-
Targeted M&A and JV playbook: prioritize acquisitions or minority investments that fill capability gaps (e.g., pol-less optics, flexible substrates, or iodine/PVA upstream exposure) and that can be integrated rapidly to capture 2026 market opportunities.
-
Adopt scenario-driven planning: use our three-tier scenarios (conservative, central, rapid substitution) to set contingency budgets and trigger points for capacity adjustments across 2026.
What the PW Consulting report contains (practical deliverables)
-
Market sizing and forecasts (2020–2032) with driver decomposition and sensitivity modelling for pol-less adoption rates and component substitution.
-
Supplier scorecards and cost-to-serve benchmarking for the top global firms, including capability maps and strategic positioning assessments.
-
Supply-chain heatmaps identifying raw-material risk, single points of failure, and mitigation levers for 2026 procurement cycles.
-
Commercial playbooks for OEMs and suppliers: pricing strategies, contract templates for long-term sourcing, and co-development agreement templates.
-
M&A screen: prioritized targets, valuation heuristics, and integration risk checklists to accelerate 2026 deal-making.
-
Regulatory and geopolitical impact analysis with tariff sensitivity scenarios and alternative sourcing strategies.
-
Executive dashboards and negotiation-ready slide decks to support board-level decision-making in 2026.
Closing perspective
2026 represents both an opportunity window and a stress test for players across the polarizer value chain. The macro trajectory is favorable — double-digit CAGR through our forecast period — yet the pace and shape of technology substitution, input volatility, and trade dynamics will determine winners and losers. PW Consulting’s Polarizer for OLED Market report provides the quantitative backbone and commercial playbooks necessary to make high-conviction decisions in 2026 without waiting for perfect foresight.
To access the complete analysis, including the withheld segment-level intelligence and supplier-specific scorecards, please consult the full Polarizer for OLED Market report on our website or contact our industry team for an enterprise briefing.
For detailed analysis of this topic, please visit the official page: Polarizer for OLED Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Marine Electric Motor Market to More Than Double to USD 16.42 Billion by 2032 on a 12.25% CAGR
By PW Consulting, 2026-07-13
Marine Electric Motor Market — 2026 Strategic Brief: Why this report will shape your electrification decisions
PW Consulting’s latest Marine Electric Motor Market report (base year 2025) synthesizes quantitative projection models, supplier intelligence, technology roadmaps and procurement-grade decision tools to guide boardroom and commercial teams through the critical 2026 planning window. The market is transitioning from niche retrofit projects to mainstream vessel architectures: global demand has more than doubled since 2020 and is projected to expand at a compound annual growth rate of approximately 12.25% into the forecast horizon. On a headline basis, the market grew from around USD 4.1 billion in 2020 to roughly USD 7.3 billion in 2025 and is forecast to exceed USD 8.3 billion in 2026, accelerating toward an estimated USD 16.4 billion by 2032. These dynamics create discrete tactical and strategic inflection points for shipowners, OEMs, suppliers and investors in 2026.
Marine Electric Motor Market
Why this matters to executives in 2026
- Investment timing: With robust near-term growth, capital allocation decisions made in 2026 will determine access to constrained production capacity and the ability to secure preferential OEM engagement.
- Procurement strategy: Rapid product evolution and supply-side concentration on critical raw materials mean single-source procurement or late contracting can significantly raise TCO and delivery risk.
- Product roadmap alignment: From small recreational outboards to high-power inboard systems, technology choices made now (type of motor, magnet technology, integration strategy) will lock in lifecycle efficiency and retrofit flexibility for a decade.
- Regulatory compliance and commercial opportunity: New IMO measures and tightened energy-efficiency planning raise both compliance risk and market demand; early movers capture first-mover commercial advantages in retrofit and newbuild segments.
What the PW Consulting report delivers — practical, decision-ready content
- Proprietary demand model with scenario variants (base, accelerated decarbonization, supply-constrained) and downloadable forecast datasets calibrated to 2020–2025 historicals and extended to 2032.
- Fully auditable financial templates: capex/opex lines, TCO calculators, and payback analyses tailored to propulsion and auxiliary installations across vessel archetypes.
- Supplier scorecards and negotiation playbooks: capability matrices, technology readiness, warranty and service footprints, and recommended commercial terms segmented by buyer profile.
- Supply-chain heatmaps and risk registers: material exposure (magnets, copper), manufacturing bottlenecks, and logistics vectors—plus mitigation options such as strategic inventory, long-term offtake, and co-investment models.
- Technology deep dives: permanent-magnet architectures, synchronous/asynchronous options, novel topologies (including recent trapezoidal stator radial-flux designs), and integration pathways for hybrid-electric systems.
- Case studies and implementation roadmaps: sample retrofit and newbuild programs with stepwise milestones, certification checklists, and expected operational outcomes.
- M&A and partnership screening tools: valuation heuristics for target assessment, strategic fit matrices and playbooks for technology licensing or joint development agreements.
Market dynamics shaping 2026 opportunity
- Regulatory push: The IMO’s 2025–2027 policy package — including a global fuel standard and strengthened SEEMP requirements — creates a deterministic demand tailwind for low- and zero-emission propulsion. These rules enter force in 2027 and are already prompting fleets to accelerate electrification pilots and design-for-electrification in newbuild contracts.
- Raw material and energy supply constraints: The industry faces concentration risk for rare earth elements used in high-power permanent-magnet motors, with primary production concentrated in a small number of jurisdictions. Parallel pressure on copper supply driven by broader electrification increases material cost volatility and project scheduling risk in 2026.
- Technology maturation and product proliferation: Smaller, higher-power-density motor topologies and integrated pod and inboard systems are moving from prototype demonstrations to catalog entries, shortening the commercialisation curve for advanced propulsion units.
- Capital markets and financing: Growing availability of green financing and incentive structures for decarbonization makes financed electrification projects more accessible — but lenders increasingly require robust lifecycle models and demonstrated supplier security before funding.
Competitive landscape — who matters and what to watch
The market is characterized by a mix of large industrial incumbents and agile specialist challengers. Leading global suppliers and a cohort of fast-moving innovators are each carving distinct strategic plays; together they shape OEM sourcing, pricing dynamics and integration choices.
Marine Electric Motor Market
- ABB (Zurich, Switzerland) — Strengths: integrated electric propulsion systems and strong installed base in commercial and specialized vessels. Strategic implication: ABB is a default partner for operators seeking turnkey electrification in larger vessel segments; competitors should anticipate bundled solutions and lifecycle service contracts.
- Siemens (Munich, Germany) — Strengths: high-efficiency motors and integrated drives for heavy maritime and offshore applications. Strategic implication: Siemens will continue to anchor large-scale projects where electrification is paired with complex power management and automation.
- Ingeteam / Indar (Zamudio, Spain) — Strengths: broad power range and proven reliability on merchant and specialized ships. Strategic implication: strong contender for retrofits and mid-to-high power newbuilds where established marine credibility is required.
- TECO-Westinghouse (Round Rock, USA) — Strengths: rugged marine-grade motors and long heritage in shipboard systems. Strategic implication: appeals to fleets prioritizing durability and long service lifecycles, particularly in demanding operating profiles.
- Torqeedo, ePropulsion, Evoy, Elco Motor Yachts — Strengths: nimble innovation in outboards, pod drives and leisure/commercial segments with high-efficiency small- to medium-power units. Strategic implication: these firms are accelerating product cycles for small craft and will influence standards, charging/installation norms and aftersales partnerships.
- WEG, Nidec — Strengths: scale manufacturing capability and adaptable motor platforms. Strategic implication: positioned to provide cost-competitive alternatives and to support OEMs requiring volume production and global service footprints.
Recent product and trade-show activity through 2025–2026 demonstrates two parallel flows: incumbents scaling proven architectures for large vessels, and smaller players accelerating power-density improvements and integration for leisure and short-haul commercial craft. Expect continued alliance activity between system integrators and magnet or inverter specialists as manufacturers seek performance-density gains while managing supply-chain exposure.
Marine Electric Motor Market
Supply-chain and technology risk mitigation
- Diversify magnet sourcing and consider magnetless architectures where lifecycle economics and reliability support substitution. Contractual hedges, consortia purchasing, and strategic equity stakes in upstream suppliers are viable options for materially exposed buyers.
- Lock early delivery slots with high-quality manufacturers for 2026–2027 production windows; consider staggered procurement to manage cashflow and avoid single-point delivery risk.
- Invest in holistic TCO models that incorporate commodity volatility, maintenance intervals and potential regulatory penalties to ensure procurement decisions are resilient across scenarios.
Six strategic recommendations for 2026 decision-makers
- Run fast pilots with clear metrics: short-run retrofit pilots (6–18 months) with pre-agreed data sharing enable suppliers and shipowners to derisk full-scale rollouts.
- Adopt a layered supplier strategy: combine a primary systems partner for integration with two qualified secondary suppliers for critical components and aftersales to manage continuity risk.
- Embed material-hedging clauses into supplier contracts: indexed pricing bands, capped pass-throughs and minimum acceptance quantities reduce exposure to rare earth and copper swings.
- Use PW Consulting’s scenario tools to stress-test fleet electrification pathways against regulatory timelines and fuel-cost scenarios before committing to fleet-wide conversion plans.
- Pursue strategic partnerships with inverter and battery suppliers early to capture integration benefits and improve certification timelines.
- Prioritise modularity in design specifications to enable technology refreshes without full-system replacement, protecting investments against rapid product evolution.
How PW Consulting supports execution
Our Marine Electric Motor Market report bundles the quantitative forecast workbook with actionable deliverables — vendor scorecards, procurement RFx templates, capex/opex calculators and a step-by-step implementation playbook. The deliverables are designed for rapid hand-off to procurement, technical and finance teams so that 2026 programs move from approval to contract award with control over timing, cost and compliance exposure.
For decision-makers planning capital allocation, supplier negotiations or M&A activity this year, the report provides the calibrated market view and negotiation playbooks required to convert the current growth trajectory into durable competitive advantage. To access the full dataset, segmented intelligence and the downloadable toolset, please visit PW Consulting’s Marine Electrification insights page to obtain the complete report and advisory options.
For detailed analysis of this topic, please visit the official page: Marine Electric Motor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


