



Category: market research
PW Consulting: Micronized Rubber Powder Market to Reach USD 279.34 Million by 2032 at 6.5% CAGR
By PW Consulting, 2026-07-12
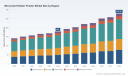
Micronized Rubber Powder Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s senior strategic advisor and industry analyst, I present an executive preview of our latest Micronized Rubber Powder (MRP) Market study — a decision-oriented intelligence product tailored for executives preparing capital, commercial and M&A moves in 2026. This preview demonstrates the analytical depth and operational focus you will find in the full study while intentionally withholding core sub-segment datapoints that are reserved for subscribers and clients.
Micronized Rubber Powder Market
Why this study matters for 2026
-
A compact but fast-growing market. The MRP market has expanded from an estimated USD 142 million in 2020 to USD 180 million in the base year 2025, and our forecast models project a compound annual growth rate (CAGR) of 6.5% over 2026–2032. Under baseline assumptions, the market is expected to reach approximately USD 279 million by 2032, with the 2026 opening-year projection at roughly USD 193 million.
Micronized Rubber Powder Market -
Decision window for capacity and partnerships. The combination of steady growth and tightening feedstock/regulatory dynamics means that investment choices made in 2026 will materially shape competitive position through the 2026–2032 horizon.
Micronized Rubber Powder Market -
From compliance to competitive advantage. Beyond volume demand, high-value attributes — including particle morphology, product traceability, and lifecycle credentials — are the new battlegrounds for margin and adoption in downstream applications such as asphalt modification, polymer compounding and specialty coatings.
What the PW MRP study delivers (practical, transaction-ready intelligence)
-
Market sizing & validated forecast model: detailed historical series (2020–2025) and multi-scenario forecasts (2026–2032) with sensitivity levers for feedstock costs, regulatory adoption rates and product mix shifts.
-
Segment playbooks: actionable value-creep maps for particle-size strategies, application use-cases, and regional go-to-market priorities (note: full sub-segment metrics are available in the paid report).
-
Production economics and cost curves: bottom-up cost models for cryogenic and ambient processing lines, with breakouts for capex, energy, labor and critical consumables.
-
Supply-chain and feedstock risk matrix: mapping of tyre collection networks, logistics bottlenecks, and feedstock quality variance — with mitigation options (offtake contracts, co-located collection hubs, and pre-processing partnerships).
-
Lifecycle & sustainability dossier: LCA benchmarking templates, carbon-intensity levers, and certification pathways (EPD, product declarations) tailored to asphalt and construction end-markets.
-
Competitive landscaping and capability matrix: granular profiles of incumbent and emerging producers, their processing technologies, IP positions and commercial strategies.
-
M&A and partnership targets: screened targets across geographies and technologies, with valuation frameworks and integration risk checklists.
-
Commercial playbook and contracts library: sample offtake agreements, pricing models indexed to feedstock and energy, and specification templates for customers and regulators.
Key dynamics that will define 2026 strategies
-
Cost structure centers on nitrogen and energy. For cryogenic MRP producers, liquid nitrogen is a significant variable cost driver — industry data indicates it often represents roughly 28–35% of variable production cost. Recent process improvements have reduced nitrogen usage per ton by an estimated 15–20% over the last five years, but operators remain sensitive to spot nitrogen and energy price volatility.
-
Premium for cryogenic product attributes. Cryogenic-grade MRP consistently commands a price premium over ambient-produced grades — reflecting superior particle morphology and surface area that aid compatibility with polymer matrices. Market evidence suggests a meaningful premium range, which makes technology choice (and process optimization) a primary determinant of margin strategy.
-
Regulation and circularity are demand multipliers. Regulatory pressure on end-of-life tyre management and public procurement requirements for recycled content continue to create higher-value outlets for MRP. European frameworks and product-level disclosures (e.g., EPDs) are already influencing procurement in construction and public infrastructure projects.
-
Moderate market concentration leaves room for scale players. The market concentration profile shows a moderately fragmented industry: the top three players account for around one-third of market volume, and the top five just over two-fifths. This structure favors consolidation, strategic alliances, and technology-based differentiation.
Competitive snapshot — what incumbents signal about strategic trajectories
-
Lehigh Technologies (Michelin Group): a technology-driven leader with a clear upstream–downstream integration play; recent lifecycle assessment work underscores a push to monetize carbon-reduction benefits in asphalt and polymer applications.
-
Genan: large-scale EOL tyre recycling specialist with focus on ultra-fine powders and premixed asphalt solutions; product certification moves indicate a strategy to command specification-driven uptake in infrastructure projects.
-
Tinna Rubber & Infrastructure: integrated producer with strong regional collection networks and high mesh capability; its scale in certain geographies creates cost and feedstock advantages.
-
Entech Inc.: long-tenured U.S. operator offering breadth across particle sizes and services — a playbook focused on customer intimacy and integrated services (hauling to compounding).
-
Rubberjet Group: differentiates via high-pressure water-jet technology, targeting morphology-sensitive applications and alternative feedstock profiles.
Recent industry moves underscore the strategic themes above: Lehigh’s October 2025 LCA publication seeks to translate carbon credentials into premium pricing and procurement wins, while Genan’s October 2025 EPD certification for an asphalt premix product shows the path from certification to specification-driven demand.
Strategic plays we recommend for 2026 (practical, prioritized)
-
Invest selectively in cryogenic capability where margin delta and off-take economics justify the premium. Use a staged-capex approach (demo → modular lines → scale) to de-risk and accelerate time-to-market.
-
Secure feedstock via hybrid models: a mix of long-term collection agreements, co-invested collection hubs and partnerships with tyre dealers. Prioritize quality consistency clauses to reduce processing variability.
-
Monetize sustainability credentials: implement EPDs/LCA claims early, use those credentials in bid strategies for infrastructure contracts, and develop carbon or circularity premium pricing where spec-driven purchasing exists.
-
Diversify technology exposure: pair cryogenic capability with ambient or water-jet processing to serve distinct application tiers and improve asset utilization.
-
Value chain integration: for mid-sized players, evaluate vertical integration into compounding or asphalt premix blending to capture downstream margin and reduce sensitivity to spot pricing.
-
M&A and alliances: pursue bolt-on acquisitions to secure regional feedstock or proprietary processing IP; alternatively, structure JV agreements with offtakers to derisk demand and capex.
-
Commercial sophistication: adopt indexed pricing contracts linking MRP prices to feedstock and energy baskets, include quality-based premiums, and provide technical support packages to accelerate adoption in new end-markets.
Scenario planning, KPIs and what to track in 2026
-
Scenarios we model: baseline growth consistent with a 6.5% CAGR (2026–2032), a policy-accelerated upside (faster adoption tied to procurement mandates and certifications), and a downside (feedstock/logistics shocks or commodity-price shocks). Each scenario includes NPV, IRR and payback estimates for greenfield lines, retrofits and strategic acquisitions.
-
Operational KPIs to monitor: specific production cost per ton (with nitrogen and energy lines), product yield by particle-size distribution, feedstock quality variance, on-time delivery to offtakers, and certification status (EPD/LCAs).
-
Market KPIs to monitor: specification wins in target sectors (e.g., asphalt mixes and polymer compounding), contract tenor and price realization relative to spot, and share shifts among top players (watch CR3/CR5 movement as a proxy for consolidation).
Closing — how PW Consulting can accelerate your 2026 plan
This preview demonstrates the strategic vantage offered by our full Micronized Rubber Powder Market study: a fusion of market forecasting, production economics, certification roadmaps, competitor intelligence and transaction-ready playbooks. In 2026, executives must navigate a market where operational efficiency (notably nitrogen and energy management), product differentiation (morphology and LCA), and feedstock security will determine winners.
To unlock the full dataset, granular regional and application splits, and executable annexes (including financial models, contract templates and target lists), access the complete report and advisory engagement options on our website. The full report contains the precise sub-segment metrics and scenario spreadsheets needed to finalize capex decisions, structure partnerships and execute M&A with confidence.
For detailed analysis of this topic, please visit the official page: Micronized Rubber Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Heating Furnace Market Poised for 5.5% CAGR Through 2032
By PW Consulting, 2026-07-12
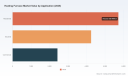
Heating Furnace Market — Strategic Preview for 2026 Decision-Makers
As Pw Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a high-level briefing on our Heating Furnace Market study that positions executive teams to make decisive, risk-calibrated moves in 2026. Built on a robust historical window (2020–2025) and a detailed forecast horizon (2026–2032), this analysis synthesizes macro growth trajectories, regulatory inflection points, raw-material pressures, competitive positioning, and product/technology vectors that will determine winners and laggards through the end of the decade.
Heating Furnace Market
Market at a Glance — What the Numbers Tell Us
The heating furnace market reached a substantive base in 2025, and our model projects a compound annual growth rate (CAGR) of 5.5% through 2032 under the central scenario. That pace reflects a mix of retrofit activity, new construction demand, technology upgrades driven by energy-efficiency standards, and selective industrial investment in advanced heating technologies. By 2032 the market is forecast to be meaningfully larger than the 2025 baseline, creating a multi-billion dollar opportunity pool for suppliers, integrators, and service specialists who align product roadmaps and channel strategies to the emerging regulatory and fuel-price landscape.
Heating Furnace Market
Why This Report Matters to 2026 Strategy
-
Actionable timing: The 2026–2032 forecast period overlays a critical regulatory cascade and commodity cycle that will drive product obsolescence and create windows for premiumization. Companies that allocate capex and R&D in 2026 with these timelines in mind will capture disproportionate share in the early-adoption tranche.
Heating Furnace Market -
Policy-driven premiums: New efficiency mandates and updated industry standards are reshaping product architectures. Our study translates those mandates into product-level technical requirements, compliance timelines, and estimated retrofit volumes — enabling procurement, product and regulatory teams to prioritize investments that protect margin.
-
Supply chain resilience: Rising commodity costs and supply constraints for key inputs (notably steel) are compressing supplier margins. The report provides scenario-tested procurement strategies and supplier-sourcing playbooks that reduce exposure while maintaining launch schedules.
-
Competitive intelligence: We map winners by capability (high-efficiency combustion platforms, induction heating for industrial users, and digital-integrated solutions for the residential channel) and identify whitespace where late entrants can establish new footholds.
Report Contents — Practical Deliverables (Summary)
-
Market sizing and growth drivers: historical decomposition and bottom-up forecast models capturing demand levers across channels and end-markets for 2026–2032.
-
Regulatory impact analysis: scenario modeling of efficiency standards, codes, and guidance (including major published rules and ASHRAE guidance) and their timing impacts on product lifecycles and cost pass-through.
-
Technology and product roadmaps: competitive benchmarking of combustion, electric, induction, and hybrid heating technologies, with R&D priorities and cost-to-performance trajectories.
-
Go-to-market playbooks: channel segmentation, pricing strategies, aftermarket and service monetization blueprints, and digital value propositions for 2026 rollouts.
-
Supply-chain and procurement risk maps: critical-input exposure assessments, hedging strategies, and alternative sourcing scenarios tuned to 2026 supply dynamics.
-
M&A and partnership pipeline: prioritized target archetypes, valuation heuristics, and integration risks for roll-up or capability-acquisition plays.
-
Decision-support tools: ROI calculators, sensitivity analyses, and playbook checklists designed for board-level decision cycles in 2026.
Competitive Landscape — Forces Shaping Market Structure
The market exhibits moderate concentration: the leading three firms account for under one third of market share, while the top five remain below the 40% threshold. This structure favors firms capable of scale in manufacturing, differentiated product platforms, or superior channel access — but it also leaves meaningful room for regional specialists and engineered-solution providers to disrupt.
-
Carrier — a leader in high-efficiency gas and electric furnaces, leveraging variable-speed technology and ENERGY STAR positioning. Carrier’s strength is in system-level integration and channel reach; their playbook for 2026 should emphasize lifecycle services and bundled efficiency solutions for premium segments.
-
Trane Technologies — through the Trane and American Standard brands, they emphasize reliability, high AFUE performance, and integrated smart controls. The strategic lever for Trane is pushing system integration with building controls, enabling recurring revenues via service and controls subscriptions.
-
Lennox International — known for premium, quiet, and modulating models. Lennox’s advantage lies in differentiated product performance; defensive moves in 2026 should include expanding value-added installation training and optimizing compressor/electronics supply chains to protect margin on high-end SKUs.
-
Rheem Manufacturing — a value-to-performance player offering durable constructions across gas and electric lines. Rheem can increase share by streamlining aftermarket parts availability and reinforcing installer loyalty programs in growth geographies.
-
Goodman Manufacturing — competes on affordability and dependable performance. Goodman’s strategic opportunity in 2026 is to couple cost leadership with modular, upgradable electronics that enable an eventual premium services attach without undermining price positioning.
-
Inductotherm Group — a specialist in industrial induction heating for metal processing. Inductotherm benefits from capital-equipment tailwinds where energy efficiency and process repeatability are mission-critical; their 2026 play should focus on digital process monitoring and vertical partnerships with metal processors.
Recent Industry Moves and Their Strategic Bearings
-
Product launches at industry shows in 2025 signaled a push toward next-generation burners, compact system furnaces, and installation/diagnostic tools — all pre-positioning vendors for retrofit waves and stricter efficiency expectations. These launches create short-term differentiation but will be table stakes if regulations tighten as expected.
-
Commodity-pressure events in 2025 increased unit cost volatility for steel and other inputs. Tactical purchasing strategies and contract renegotiations are essential in 2026 to preserve gross margins without sacrificing availability.
-
Published standards and guidance from regulatory bodies and ASHRAE are converging toward uniform efficiency and safety practices. The timing of these policies creates predictable windows for product obsolescence and forced retrofits — windows that can be exploited for margin-rich replacement cycles if firms are operationally prepared.
Key Strategic Imperatives for 2026
-
Prioritize compliance-led product refreshes: Prepare engineering and supply chains in 2026 to meet impending efficiency thresholds. Delaying retooling beyond 2026 risks compressed timetables and elevated replacement costs.
-
Monetize services and digitalization: Build subscription and predictive-maintenance offers tied to smart controls and diagnostics. These revenue streams insulate firms from cyclical capex swings and enhance customer retention.
-
Hedge raw-material exposure: Implement layered sourcing, strategic stockpiling for critical components, and supplier partnerships that include cost-sharing mechanisms to absorb short-term price spikes.
-
Invest selectively in electrification and induction capabilities: While gas-fired solutions remain central today, the long-term vector favors electrified and induction offerings in select industrial and premium residential segments. Early entrants to hybrid platforms will secure attractive pricing power.
-
Optimize channel economics: Rebalance investments between direct-installation programs, contractor incentives, and OEM distribution to ensure profitable installation throughput as retrofit demand accelerates.
-
Use M&A to plug capability gaps: Targets that expand controls, digital services, or induction expertise will accelerate time-to-market and are generally less capex-intensive than greenfield R&D investments.
Risk Factors and Contingencies
-
Regulatory timing risk — accelerated or delayed adoption of efficiency mandates materially affects replacement cadence and inventory strategies.
-
Fuel-price dynamics — projected shifts in relative electricity vs gas pricing alter total-cost-of-ownership calculations and customer switching behavior; companies should stress-test pricing and product mixes against both higher and lower electricity-to-gas scenarios.
-
Supply-chain shocks — single-source dependence for critical components elevates vulnerability; diversification is a priority.
Next Steps — How Executives Should Use This Preview
This briefing outlines the strategic shape of the market and the levers that leaders must pull in 2026 to create defensible growth. Our full report contains the granular segmentation, regional and application breakdowns, product-level compliance requirements, and executable 90–180–360 day playbooks that are intentionally withheld from this preview to preserve proprietary insights. For teams developing 2026 budgets, crafting M&A pipelines, or revising R&D roadmaps, the full dataset and scenario models are indispensable.
Pw Consulting is prepared to walk leadership teams through tailored briefings, readiness assessments, and rapid-deployment playbooks grounded in the report’s findings. For those prioritizing decisive action in 2026, the time to translate scenario visibility into execution capability is now.
For detailed analysis of this topic, please visit the official page: Heating Furnace Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Vein Finder Market to Hit USD 574M by 2032 at 5.15% CAGR — PW Consulting
By PW Consulting, 2026-07-12
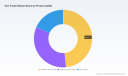
Vein Finder Market 2026: Strategic Imperatives for Decision-Makers
Executive snapshot
As health systems globally seek to reduce procedural failure rates, improve patient throughput and lower per-procedure costs, the vein finder market has moved from niche adjunct to operationally material medical device category. Our PW Consulting Vein Finder Market research (base year 2025; historical 2020–2025; forecast 2026–2032) shows the market achieving steady expansion at a compound annual growth rate (CAGR) of 5.15%. Measured in USD millions, the market is recorded at USD 405.0 Million in 2025 and is modeled to progress meaningfully through the forecast window, reflecting steady clinical adoption and incremental technology improvements.
Vein Finder Market
Why this study matters for 2026 decisions
- Timing: 2026 is the first full year after multiple supplier refreshes and regulatory milestones that materially alter supplier capacity and product availability. Procurement cycles that began in 2024–25 will be assessed and renewed this year—making 2026 strategy decisions pivotal.
- Operational impact: Incremental improvements in imaging fidelity and device ergonomics are unlocking new use cases (e.g., emergent vascular access in high-throughput departments) that directly influence capital allocation and staffing models.
- Market structure clarity: Our market concentration analysis shows a market in which the top three firms control a plurality but not a monopoly (CR3 ≈ 47.3%), and the top five account for a clear majority (CR5 ≈ 61.9%), creating a competitive environment where scale matters but agility and product differentiation can still win.
Market trajectory and structural implications
The Vein Finder market’s steady CAGR reflects a classic medical-technology maturation curve: sustained clinical validation, gradual price erosion on legacy technologies, and a steady stream of incremental innovations that expand addressable use cases. Between 2020 and 2025 the market expanded consistently, and our forecasts through 2032 anticipate continued growth as hospitals embed vein visualization into standard vascular access protocols and as outpatient and home-care settings adopt portable solutions.
Vein Finder Market
For executives, the practical takeaway is twofold. First, strategic investments—whether in product development, sales infrastructure, or clinical education—must be planned on a multi-year horizon to capture compounded returns. Second, scale remains an advantage for pricing and distribution, but differentiated product characteristics (battery life, imaging depth, ease of disinfection, integration with EHR/workflow) can overturn incumbency in targeted clinical pockets.
Vein Finder Market
Technology and clinical adoption dynamics
- Modular innovation: Near-infrared (NIR) and transillumination technologies continue to be the primary performance vectors. Recent device launches emphasize improved imaging algorithms, longer battery and field durability, and easier sterilization protocols—attributes that shorten training curves and reduce total cost of ownership.
- Shifting use cases: While vascular access remains the dominant clinical application driving unit uptake, secondary use cases (dermatology, surgical planning, pediatric and geriatric care) are growing. Adoption is often incremental—starting with high-volume wards and expanding laterally as clinicians gain confidence.
- Form factor segmentation: Handheld and portable systems are taking share in ambulatory and emergency care settings due to flexibility and lower upfront procurement friction; stationary, projection-based systems retain an advantage in procedural suites and specialized departments where integration and multi-user access are priorities.
Competitive landscape — what to watch in 2026
The competitive field contains a mix of established specialty vendors and nimble regional players. Core competitors in the space include long-standing specialists that have introduced next-generation systems, as well as newer entrants focused on localized regulatory approvals and cost-competitive portfolios.
- AccuVein Inc. continues to invest in next-gen handheld NIR systems, launching an AV600 model in early 2026 that emphasizes enhanced imaging and field durability—an explicit signal that incumbents are prioritizing product robustness for clinical throughput environments.
- Christie Medical Holdings retains its presence with projection-style systems tailored to high-volume procedural settings; attention to cleaning and compatability instructions in its device guides signals an operational focus required by large hospital clients.
- TransLite and other transillumination specialists keep competing on simplicity and focused performance for specific clinical niches such as EMS and pediatric use.
- China-based manufacturers and other regional players (including those updating catalogs or securing local regulatory clearances) are expanding addressable markets by offering competitive price-performance tradeoffs—which will accelerate adoption in emerging markets and price-sensitive channels.
Recent industry events in early-to-mid 2026—product launches, catalog updates and first-mover regulatory clearances in emerging markets—are reshuffling procurement conversations. Companies that can couple product improvements with clear clinical evidence and robust service models will command leverage in hospital negotiations.
Regulatory and procurement environment
- Regulatory posture: Many non-contact projection and certain LED-based visualization devices continue to qualify for lower-risk regulatory pathways in major markets, which reduces time-to-market for new entrants. Simultaneously, device-specific cleaning compatibility and hospital infection-control expectations are becoming decisive procurement filters.
- Procurement dynamics: Hospitals are shifting from unit-by-unit purchases to portfolio-level sourcing—favoring vendors who offer predictable maintenance, integrated training programs, and demonstrable throughput improvements. Pricing discussions are increasingly tied to service-level metrics and failure-rate reductions rather than hardware list price alone.
- Emerging-market nuance: Local regulatory clearances in high-growth countries are enabling domestic manufacturers to compete effectively on price and distribution speed; multinational suppliers must decide between direct investment, distribution partnerships, or licensing strategies to maintain presence.
Actionable strategic playbook for 2026
PW Consulting’s analysis produces a set of high-confidence actions for executives who need to convert market intelligence into deliverables this year.
- Prioritize clinical evidence tied to operational KPIs. Sponsor and publish cohort studies that quantify first-attempt success improvements, procedure-time reductions and downstream cost avoidance. These metrics win procurement conversations faster than imaging-resolution specifications alone.
- Segment go-to-market by clinical workflow, not by department names. Target high-throughput wards (e.g., emergency, dialysis, pediatric floors) with tailored propositions—bundled devices, training and service commitments—rather than one-size-fits-all offers.
- Design differentiated pricing models. Introduce outcome-linked pricing for high-volume clients and subscription-based models for outpatient chains. These reduce procurement friction and align incentives for device uptime and service performance.
- Invest selectively in product robustness and cleaning compatibility. Hospital infection-control requirements and device longevity directly affect total cost of ownership and purchasing decisions—make these explicit selling points backed by test data.
- Establish regional playbooks. For emerging markets, consider licensing or local manufacturing relationships to accelerate regulatory clearances and meet price-performance expectations. For mature markets, double down on integration, bundled service and clinical training.
- M&A and partnering discipline. With CR5 around 61.9%, there is room for bolt-on acquisitions that extend clinical reach or broaden portfolio breadth. Prioritize targets with complementary clinical data, robust service networks, or unique form-factor IP over purely geographical roll-ups.
What the PW Consulting report delivers (practical components)
This study is crafted to be directly actionable for product, commercial, and corporate development teams. Deliverables include:
- A robust market model (historical 2020–2025; forecast 2026–2032) with scenario toggles for adoption rates, price erosion and service revenue assumptions;
- A competitive playbook detailing product positioning, service propositions and go-to-market templates for both mature and emerging markets;
- Regulatory and procurement risk-mapping by market cluster, including recommended mitigations for device cleaning, classification and local registration timelines;
- Commercial templates—provider ROI calculators, contract language frameworks and clinical-evidence study protocols—designed to shorten sales cycles and strengthen negotiation positions.
Importantly, while this introduction highlights directional insights and strategic implications, detailed sub-segment tables and confidential supplier share estimates are intentionally reserved for the full report. Those granular views are essential for transaction-level decisions and are accessible through our research portal.
How to use this intelligence in Q2–Q4 2026
- Rapid portfolio review: Use the market model to stress-test product roadmaps against conservative and optimistic adoption curves, then prioritize R&D and capital accordingly.
- Commercial pilots: Launch high-impact pilots in targeted clinical pockets where you can demonstrate measurable throughput benefits within 90–180 days.
- Regulatory pathway alignment: If entering new jurisdictions, map registration timelines to procurement cycles to avoid missed contracting windows.
- M&A readiness: Prepare an acquisition checklist that emphasizes clinical evidence dossiers, service coverage maps and IP transferability to accelerate deal execution in a moderately consolidated market.
Closing — the strategic value of evidence-led action
The vein finder market offers predictable, above-inflation growth driven by practical clinical benefits and a wave of incremental product innovation. For 2026, success will flow to organizations that combine rigorous evidence generation, targeted commercial execution and operational readiness to support clinicians. PW Consulting’s Vein Finder Market research provides the modeling, competitive context and executable tools to translate these market dynamics into defensible strategic moves—while leaving the detailed, transaction-critical sub-segment datasets to the full report for subscribers and clients.
For organizations preparing budgets, evaluating M&A opportunities, or planning product launches in 2026, this study is designed to shorten decision cycles and reduce execution risk.
For detailed analysis of this topic, please visit the official page: Vein Finder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Car Audio Speakers Market to Hit USD 10.27B by 2032 at 7.21% CAGR
By PW Consulting, 2026-07-12
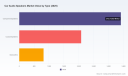
Car Audio Speakers Market — Strategic Brief for 2026 Decisions
PW Consulting’s latest market study on Car Audio Speakers (base year 2025; historical window 2020–2025; forecast 2026–2032) is designed as a decision-grade intelligence package for executive teams planning moves in 2026. The market is expanding at a steady compound annual growth rate (CAGR) of 7.21%, having grown from a multi-billion-dollar global base in 2020 to an estimated USD 6,310 Million in 2025, and is projected to exceed USD 10 Billion by 2032. This brief summarizes the strategic value of that research, highlights the commercial inflection points executives must address this year, and previews the actionable workstreams contained in the full report — while deliberately withholding the granular segment tables and region/application splits to encourage direct access to the underlying models.
Car Audio Speakers Market
Why 2026 Is a Critical Decision Window
-
Consolidation and concentration: Market concentration is meaningful — the largest three players control a substantial share and the top five an even larger portion — creating both barriers for scale and openings for focused differentiation. This structural reality shapes pricing power, channel leverage, and M&A calculus.
Car Audio Speakers Market -
Product premiumization meets platform integration: OEMs are increasingly looking for speaker solutions that are tuned for vehicle interiors and integrated into factory audio stacks. At the same time, aftermarket demand is bifurcating between value-oriented upgrades and high-end, experience-driven systems (high-resolution audio, advanced subwoofers, and tunable component arrays).
Car Audio Speakers Market -
Trade and supply volatility: Recent tariff actions, changing import duties, and supply pressure on critical components have already prompted pricing adjustments across the supply base. These dynamics are feeding margin pressure and are forcing suppliers and OEMs to revisit sourcing strategies and pricing models in 2026.
-
Technology and vehicle trends: Electrification, increased in-cabin time, and greater on-board compute enable richer audio features (active filtering, software-defined equalization, and vehicle-level sound staging). Manufacturers who translate acoustics into perceived in-cabin value will capture premium dollars.
What the Full Report Delivers (Operational Contents)
-
Proprietary market sizing and forecast model (2020–2032) with scenario toggles for tariff, material-cost, and EV-adoption trajectories. The model is provided in a downloadable workbook so commercial teams can re-run forecasts against their own assumptions.
-
Demand-driver diagnostics: a layered view of consumer and OEM drivers, elasticities across price tiers, and a short-list of high-impact product attributes that change purchase intent.
-
Competitive and product benchmarking: product family mapping, value propositions across price tiers (entry, mid, premium), and a vendor capability matrix focused on engineering, distribution, and OEM relationships.
-
Go-to-market playbooks for OEM-supply and aftermarket channels, including channel economics, recommended margin structures, and sample commercial terms for 12-, 36-, and 60-month engagements.
-
Supplier risk heatmap and sourcing strategies identifying node-level exposure (tariffs, single-source parts, lead-time sensitivity) with recommended hedging and dual-sourcing approaches.
-
M&A and partnership screening framework: prioritized target profiles, valuation heuristics, and integration checklists tailored to capture incremental shelf-space in premium OEM programs and aftermarket distribution.
Competitive Dynamics — What Leading Vendors Are Doing
Industry leaders are executing distinct but overlapping plays. Some are doubling down on OEM integration and factory-fit programs; others are sharpening aftermarket propositions with series-level product families engineered for specific use cases.
-
Pioneer and Alpine are positioning around complete system offerings that serve both factory-fit and upgrade scenarios. Their product roadmaps show emphasis on system-level integration and interior tuning.
-
High-performance brands like Rockford Fosgate and JL Audio continue to stress power handling and fidelity for enthusiasts and install-heavy aftermarket segments.
-
Consumer electronics incumbents (e.g., Sony) leverage brand recognition and high-resolution audio credentials to move upmarket within factory-specified programs.
-
Specialist premium audio firms (e.g., Focal, Hertz) focus on timbre accuracy and plug-and-play high-fidelity kits, often targeted at premium OEM trims and performance-oriented aftermarket customers.
Recent industry moves underscore this dynamism: Hertz introduced compact and sport-tuned models in early-to-mid 2026, Pioneer announced a flagship integrated interior audio system in March 2026, and Sony refreshed its GS speaker and subwoofer lineup in 2025. These product actions illustrate how vendors are responding to both engineering demands and channel opportunities.
Strategic Implications for 2026 Decision-Makers
-
Portfolio prioritization: Firms must decide whether to compete on system integration, niche/high-fidelity performance, or cost-driven aftermarket solutions. Our report’s product-level profitability matrices help prioritize SKUs and engineering investment through 2028.
-
Channel strategy: With OEMs seeking tightly integrated systems and aftermarket channels fragmenting by specialty stores and e-commerce, manufacturers should adopt differentiated channel mixes with dedicated SKUs and pricing to avoid channel conflict.
-
Sourcing and pricing under tariff uncertainty: Short-term pricing actions taken in 2025–2026 reflect supplier constraints and tariff responses. The report provides hedging playbooks and scenario pricing that finance teams can use to renegotiate long-term contracts and rebalance landed-cost exposure.
-
M&A and partnerships: Where scale matters (distribution, OEM relationships), bolt-on acquisitions and licensing partnerships can accelerate access. We provide an acquisition target heatmap and integration milestones to de-risk such moves.
-
R&D and feature roadmap: Investment in tuning tools, software-defined audio features, and scalable subwoofer/component architectures will yield differentiated propositions — particularly for EV platforms where cabin acoustics differ materially from ICE vehicles.
How Executives Should Use This Research in 2026
-
Run the provided financial model against three internal scenarios (base, tariff-stress, high-EV-adoption) and translate outcome deltas into prioritized capex and commercial milestones for the next 18 months.
-
Use vendor benchmarking and supplier heatmaps to renegotiate supply agreements; prioritize contingency capacity or dual-sourcing for high-exposure components identified in our risk mapping.
-
Adopt a two-track product strategy: protect OEM relationships with integration-ready platforms while investing in a modular aftermarket line that can be rapidly deployed through e-commerce and specialty channels.
-
Prepare preemptive M&A diligence on targets that unlock distribution, engineering IP, or specialized fabrication capabilities — the report’s acquisition heatmap narrows this list to the highest-value targets for fast follow-up.
Where This Brief Fits in Your 2026 Planning Cycle
This document is an executive primer: it synthesizes the macro trajectory (7.21% CAGR and a market expected to surpass USD 10 Billion by 2032), competitive moves, and the near-term commercial variables that will shape profitability in 2026 and beyond. The full PW Consulting report contains the granular segmentations, region- and application-level breakdowns, SKU-level price elasticity matrices, and vendor scorecards you will need to operationalize strategy. Those detailed datasets are intentionally gated to ensure clients extract maximum commercial advantage from the analysis.
Next Steps — How to Access the Full Intelligence
For teams preparing budget submissions, supplier renegotiations, or M&A screening in 2026, the complete report and the accompanying financial model are practical tools that turn insight into executable plans. Reach out to PW Consulting to obtain the full study, unlock the segmentation tables, and receive a tailored briefing that maps findings directly to your P&L and product roadmap.
PW Consulting’s Car Audio Speakers Market study is built to be a working document for leadership teams — not a static read. In a market where product refreshes, trade policy, and vehicle platform changes can shift outcomes quickly, access to a validated model and prioritized action lists is the difference between reacting and leading.
For detailed analysis of this topic, please visit the official page: Car Audio Speakers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Reverse Transcriptase Market to reach USD 1,659.9M in 2026 at 6.69% CAGR
By PW Consulting, 2026-07-12
Reverse Transcriptase Market — Strategic Briefing for 2026 Decision Makers
As life-science buyers, product leaders and corporate strategists set budgets and allocate R&D priorities for 2026, the Reverse Transcriptase market presents both a predictable growth runway and a set of breaking inflection points. PW Consulting’s latest market study, anchored on a 2025 base year and forecasting through 2032, synthesizes hard market-sizing (the global market grew from USD 1,102.5 Million in 2020 to USD 1,530.0 Million in 2025) with scenario-led insights. The model projects a continued expansion into the forecast window (the market is forecast to reach USD 1,659.9 Million in 2026 and USD 2,408.5 Million by 2032) at a compound annual growth rate of 6.69% over 2026–2032.
Reverse Transcriptase Market
Why this matters for 2026 decisions
-
Budgeting and portfolio prioritization: The market’s steady CAGR and the step-change in absolute size between 2025 and the early forecast years create a predictable base for multi-year capex and manufacturing planning. Firms that align capacity with the early part of the 2026–2028 growth curve can lock-in scale advantages and shorten time-to-revenue for incremental enzyme launches and integrated kits.
Reverse Transcriptase Market -
M&A and partnership timing: With a concentrated supplier landscape (CR3 ~65%, CR5 ~75%), mid-sized innovators face clear barriers to scale. 2026 is a window for targeted bolt-on acquisitions that deliver product differentiation—enzyme engineering, improved thermostability, or integrated workflow compatibility—without competing directly on commodity pricing.
Reverse Transcriptase Market -
Commercial channel and differentiation: The market expansion is occurring alongside faster adoption of RNA-centric workflows, decentralized molecular diagnostics and higher-throughput sequencing. Vendors that offer validated end‑to‑end workflows (enzyme + buffer chemistry + support documentation) will capture disproportionate share in tender-driven institutional channels in 2026.
Market evolution — key quantitative signals (high-level)
-
Scale and momentum: The market more than doubled in size across the 2020–2032 window in absolute terms. The 2025 base provides a robust starting point for ROI modeling, and the first forecast year (2026) shows measurable uplift as new diagnostic programs and research investments come online.
-
Concentration and competitive dynamics: The market concentration metrics indicate that a small number of global players command the majority of commercial volumes. That creates favorable economics for incumbents but also a structural opportunity for challengers that can deliver differentiated performance or cost-to-serve advantages.
-
Volatility vectors: Pricing pressure in mature procurement channels, supply-chain fragility for cold-chain biologicals, and accelerating regulatory scrutiny around molecular diagnostic components are the primary risk levers that could compress near-term margins if not proactively hedged.
Practical contents of the PW Consulting report
The study is designed as a pragmatic decision tool for commercial and corporate leadership. It includes:
-
A transparent market model with historicals (2020–2025) and an integrated forecast (2026–2032) that can be re-run with alternate macro assumptions and input parameters.
-
Scenario analysis (three tiers) that quantifies outcome ranges under differing adoption curves for molecular diagnostics, sequencing demand, and RNA therapeutics R&D spend.
-
Go-to-market playbooks for six strategic moves: premium product differentiation, cost leadership at scale, channel reconfiguration, regional market entry, M&A playbook, and contract-manufacturing partnerships.
-
Operational toolkits: SKU rationalization templates, manufacturing capacity planning matrices, and a supply‑chain resilience checklist mapped to typical biological reagent constraints.
-
Commercial KPIs and scorecards used to benchmark product launches, tender success rates, and partner performance—structured so internal teams can plug in corporate-level targets and obtain actionable gap analyses.
Competitive landscape — profiles and strategic postures
Our competitive analysis focuses on the vendors that shape product expectations and procurement decisions in reverse transcriptase supply chains. Below is a high-level characterization of each firm’s strategic posture (detailed vendor scorecards and validated capability matrices are available in the full report).
-
New England Biolabs (Ipswich, MA, USA) : Known for a technical-first product portfolio emphasizing enzyme innovation, NEB’s strengths are in reagent performance claims, robust application notes and developer community engagement. Their play is defense through technical differentiation and community adoption.
-
Thermo Fisher Scientific (Waltham, MA, USA) : Thermo Fisher leverages broad channel reach and integrated workflow offerings—tying enzyme products into end-to-end solutions for high-throughput labs and diagnostic manufacturers. Expect them to push bundled solutions and leverage global service capabilities.
-
QIAGEN (Hilden, Germany) : QIAGEN positions itself where molecular diagnostics and sample-to-answer workflows converge. Their competitive edge lies in validated kits and regulatory know-how, making them a preferred partner for clinical-lab customers and regulated diagnostic OEMs.
-
Merck KGaA (Darmstadt, Germany) : Merck’s advantage is breadth—suited to customers seeking supply reliability and broad reagent portfolios. They play the scale card and are a logical supplier for multi-site labs or contract manufacturers prioritizing continuity and certification.
-
Promega Corporation (Madison, WI, USA) : Promega is recognized for assay development support and application-driven reagents. Their go-to-market is often collaborative, helping customers co-develop assays and thus locking in product use through application dependence.
-
Takarabio (Takara Bio, Otsu, Japan) : Takara’s strengths are in enzyme engineering and market segments that require high-fidelity or specialty reverse transcriptases. Their route to growth in 2026 will be through targeted partnerships and niche clinical applications.
Strategic plays we see winning in 2026
-
Move from component selling to workflow selling. Vendors that convert single‑sku enzyme sales into validated, documented workflows (reagents + protocols + technical support) secure higher margins and stickier revenue streams.
-
Pursue modular scale-up via CMO partnerships. For firms without excess biologics capacity, partnering with qualified CMOs for fill/finish and cold-chain logistics reduces capital intensity while preserving speed to market.
-
Embed regulatory and clinical evidence into product launches. Products launched with pre-validated claims and clear regulatory pathways (e.g., companion diagnostic compatibility) accelerate procurement cycles in clinical settings.
-
Use targeted M&A to fill capability gaps. Small to mid-sized enzyme developers with novel chemistries are attractive acquisition targets for incumbents that need differentiation without developing in-house capabilities over many quarters.
Risk management and operational readiness
Our analysis highlights three operational risks that require attention in 2026 planning cycles: (1) supply-chain concentration for bespoke reagents and packaging materials; (2) margin compression driven by tender-led pricing dynamics in larger institutional channels; and (3) faster regulatory expectations for traceability and quality systems. The report includes a supplier-risk heatmap, working-capital scenarios, and a price-elasticity framework to quantify the likely impact of each risk on EBITDA under alternate adoption cases.
How to translate these insights into action
For corporate strategy teams: incorporate the PW Consulting market model into your 2026 financial plan to test acquisition payback periods under optimistic and conservative adoption curves. For commercial leaders: adopt the workflow-selling playbook and pilot a bundled-offer in two high-opportunity accounts in H1–2026. For R&D leaders: prioritize enzyme features that reduce total assay cost and shorten warm-up times—these attributes are repeatedly cited by procurement and lab managers as escalation factors during vendor selection.
Accessing the withheld intelligence
This briefing intentionally omits granular sub-segment tables and procurement-level pricing matrices to preserve the value of the complete study. The full PW Consulting Reverse Transcriptase Market report contains the segment-level demand model, region-by-application dynamics, detailed vendor scorecards, and template transaction models (including synergies and due-diligence checklists) that are essential for execution in 2026. Visit our report page to obtain the full dataset, interactive model, and a customized briefing with our lead analysts.
For detailed analysis of this topic, please visit the official page: Reverse Transcriptase Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Video Live Streaming Market to Reach USD 5.38B by 2032 at 4.65% CAGR
By PW Consulting, 2026-07-12
Video Live Streaming Solution Market — Strategic Preview for 2026 Decision‑Makers
As enterprises, broadcasters, platform owners, and systems integrators prepare their 2026 roadmaps, the Video Live Streaming Solution Market is shifting from a growth story into a strategic battleground. Our PW Consulting preview frames that transition: a market that has expanded steadily from a measured base in the early 2020s to a predictable, mid‑single‑digit growth trajectory (CAGR 4.65%) through the coming planning window. This briefing highlights why that trajectory matters for 2026 decisions, what competitive and regulatory forces will shape choices, and how our full Video Live Streaming Solution Market study converts industry signals into executable actions — while intentionally reserving the granular segmental figures that are available in the full report.
Video Live Streaming Solution Market
Market trajectory and what the headline numbers mean
Using 2025 as the base year, our historical review (2020–2025) and modeled outlook (2026–2032) show the market moving from an early recovery and consolidation phase into a steadier, innovation‑led expansion. The market’s headline trend is straightforward: steady expansion underpinned by ongoing investment in cloud video infrastructure, codecs and edge delivery, and by the penetration of live streaming into non‑media verticals.
Video Live Streaming Solution Market
-
The steady CAGR (4.65%) masks heterogeneity: pockets of rapid innovation (AI‑enabled workflows, avatar and interactive video), alongside legacy segments that are being rationalized through consolidation and SaaS migration.
Video Live Streaming Solution Market -
Market concentration remains low relative to many enterprise software markets — the top three and top five vendors collectively hold under one‑third of revenue — signaling a fragmented supplier landscape and opportunity for differentiated propositions.
-
From a planning perspective, the implied increase in aggregate market scale through the forecast window is sufficiently material to justify multi‑year investments, but not so large as to eliminate the need for careful prioritization of use cases and cost control.
Why this study matters for 2026 strategic decisions
Leaders who postpone a hard look at their live streaming strategy risk three outcomes: fragmented technology stacks and higher TCO; missed monetization and engagement opportunities enabled by AI and interactive video; and unexpected compliance or spectrum constraints that disrupt delivery economics. The full market study is designed explicitly to convert macro trends into 2026 playbooks — enabling procurement teams, product leaders, and M&A groups to make evidence‑based choices during budgeting cycles.
-
Capital allocation: Understand which investments (edge delivery, low‑latency codecs, AI orchestration, security/DRM) will materially alter unit economics over a 24–36 month horizon.
-
Partnerships and vendor strategy: Determine when to partner, when to build, and when to acquire based on supplier fragmentation and capability gaps.
-
Regulatory and infrastructure hedges: Align live streaming roadmaps with spectrum availability, 5G roll‑outs, and evolving broadcast‑streaming rights frameworks.
Competitive landscape — players to watch and tactical implications
The supplier field blends legacy broadcast‑grade specialists with cloud‑native platform providers and nimble middleware vendors. Our examination of core providers highlights differentiated strategies and near‑term initiatives that should inform vendor selection and product roadmap choices.
-
Haivision Systems Inc. — With roots in mission‑critical contribution and remote production, Haivision continues to strengthen hardware‑centric, low‑latency contribution capabilities. Recent product additions emphasize configurable encoder/decoder platforms suitable for hybrid broadcast workflows, making them a logical partner when deterministic quality and interop are priorities.
-
Wowza Media Systems, LLC — Positioned as an infrastructure and on‑premises engine specialist, Wowza appeals to enterprises needing customizable streaming engines and tight control over delivery logic. They remain relevant where on‑prem latency, regulatory constraints, or bespoke integrations outweigh the convenience of pure cloud services.
-
Brightcove Inc. — A cloud‑centric platform vendor aggressively integrating AI into monetization and captioning workflows. Their 2026 roadmap and AI Suite updates signal a push to commoditize higher‑order ad personalization and live captioning, which matters for OTT players and publishers optimizing yield.
-
Telestream, LLC — Focused on production and channel management tools, Telestream bridges live production workflows with streaming delivery. Their product family is often chosen where production quality control and operational continuity are the highest priorities.
-
Kaltura, Inc. — Evolving into conversational and avatar‑enabled video experiences, Kaltura’s recent launches underscore a broader industry pivot into interactive, persona‑driven live experiences — particularly relevant for education, corporate communications, and certain entertainment formats.
Strategic takeaway: vendor choice is increasingly use‑case dependent. Procurement strategies that assume "one‑size fits all" platforms will face integration debt and missed feature opportunities. Instead, multi‑vendor architectures or wholesale acquisitions of targeted capabilities will dominate near‑term decisions.
Regulatory and infrastructure dynamics that will shape 2026 investments
The live streaming ecosystem does not operate in a vacuum. Recent regulatory and spectrum developments introduce both risk and opportunity for planners:
-
Spectrum reallocation and auctions to support next‑gen 5G introduce timing risks for broadcasters that still rely on traditional distribution bands. Planned auctions and orders on spectrum sharing will accelerate terrestrial 5G deployments — improving mobile delivery economics but also compressing legacy broadcaster margins.
-
Regulatory scrutiny of sports rights and the competitive dynamics between streaming platforms and traditional broadcasters is changing rights valuation and distribution strategies. Organizations that depend on premium live sports must model alternative distribution and rights strategies now.
-
Policy on spectrum sharing between satellite broadband and terrestrial networks opens new technical integration pathways. Architectures that blend satellite contribution with 5G terrestrial distribution will become viable in specific geographies.
In practice, these dynamics mean capital planners must coordinate spectrum/infra intelligence with streaming architecture choices — from codec roadmaps to edge caching strategies — to avoid stranded assets and to exploit new delivery modes.
What the PW Consulting report delivers — practical modules for execution
This study is purposely structured as a pragmatic toolkit for 2026 execution. It couples market modeling with decision templates and technical guidance to accelerate the time from insight to deployment. Key operational elements include:
-
Decision frameworks (build vs buy vs partner) tailored to enterprise scale, latency tolerance, and content economics.
-
Reference architectures for hybrid cloud / edge streaming, with trade‑off analyses for latency, cost, redundancy, and compliance.
-
Vendor scorecards and selection rubrics that map capability clusters (e.g., contribution, encoding, orchestration, AI analytics, monetization) to procurement priorities.
-
ROI and TCO models including sensitivity analyses for bandwidth, CDN, and CDN/edge strategies under different audience growth scenarios.
-
Regulatory risk matrices and mitigation playbooks aligned to spectrum auctions, rights changes, and cross‑border compliance.
-
Go‑to‑market playbooks for product teams looking to launch interactive/AI‑enhanced live experiences, plus sample KPIs and AB test designs.
Note: The preview above is deliberately high level. The full report contains the detailed subsegment analysis, regional splits, application breakdowns, and vendor financial benchmarks that underpin the models and recommendations.
How organizations should use this preview in 2026 planning cycles
Decision makers should treat this briefing as the starting point for a three‑step execution cadence:
-
Validate internal priorities: map business objectives (audience growth, monetization, latency targets, cost reduction) to the technology and vendor archetypes outlined above.
-
Stress‑test architectures and budgets: use scenario runs (e.g., accelerated mobile adoption, rights fragmentation, constrained spectrum) to identify breakpoints in current plans.
-
Build a 12–24 month tactical plan: sequence investments so that early wins (captioning, ad personalization, CDN rationalization) fund strategic bets (edge pools, avatar/interactive experiences, M&A or strategic partnerships).
For teams considering M&A or strategic partnerships, the fragmented market concentration makes targeted tuck‑ins and capability acquisitions attractive ways to accelerate roadmap delivery while controlling cash outflow.
Conclusion — the strategic choice for 2026
The video live streaming market in 2026 presents a classic strategic inflection: continuing, predictable growth overall, but powerful micro‑disruptions from AI innovation, interactive video formats, and spectrum/regulatory shifts that will reconfigure winners and losers. The full PW Consulting Video Live Streaming Solution Market study translates these macro forces into actionable vendor shortlists, technical blueprints, and commercial scenarios designed to be operational in 90–180 days. If your 2026 plans depend on dependable delivery, differentiated viewer experiences, or rights and distribution engineering, the next step is to consult the detailed intelligence and proprietary subsegment models in the full report.
Visit the source report to access the complete dataset, subsegment splits, and the tactical annexes that power procurement, product, and M&A decisions for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Video Live Streaming Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Chromium Oxide Green to Reach USD 776.2M by 2032 at 5.2% CAGR
By PW Consulting, 2026-07-12
Chromium Oxide Green Market — A 2026 Strategic Preview for Executive Decision-Makers
PW Consulting’s latest Chromium Oxide Green Market study (base year 2025; historical window 2020–2025; forecast 2026–2032) provides the actionable intelligence senior executives need to set course in 2026. The market reached approximately USD 546.5 Million in 2025 and, under our central scenario, grows at a 5.2% CAGR through the 2026–2032 forecast period to reach roughly USD 776.2 Million by 2032. This preview outlines why the report matters for boardrooms and strategy teams this year — and what practical levers it contains — while intentionally reserving the granular segment-level datapoints for the full research package.
Chromium Oxide Green Market
Why this study should shape your 2026 agenda
-
Timing: 2026 is a pivot year for chromium supply economics — energy, feedstock, and regulatory headwinds are converging to create both operational risk and strategic opportunity.
Chromium Oxide Green Market -
Decision focus: procurement contracts, capital allocation for compliance and emissions control, product portfolio prioritization (pigment vs. metallurgical vs. refractory), and M&A / partnership scouting.
Chromium Oxide Green Market -
Clarity on growth: with a mid-single-digit CAGR in our baseline, executives need to distinguish durable demand pockets from price-driven volume swings.
Macro drivers and market dynamics
The Chromium Oxide Green market is shaped by three interconnected vectors: end-use demand, feedstock and production capacity, and regulatory / ESG pressure.
-
End-use demand: Chromium oxide’s role across coatings, ceramics, rubber, metallurgical and refractory applications continues to anchor baseline consumption. Incremental gains are coming from improved formulation stability in high-performance coatings and demand tied to construction and industrial refurbishment cycles.
-
Feedstock and capacity: Production relies heavily on sodium dichromate feedstock and benefits from an installed global capacity base that, by industry estimates, supports tens of thousands of tonnes annually. That underlying capacity provides a buffer to sudden demand shocks, but the concentration of primary feedstock sources creates susceptibility to regional supply interruptions and price volatility.
-
Cost inflation and price transmission: Energy, freight and raw-material pressures have driven supplier repricing actions in 2026. Notably, one major producer announced a significant price increase in March 2026 — a market signal that should trigger scenario planning for procurement and margin management.
Regulatory and ESG landscape — constraints and catalysts
Chromium chemistry is under heightened regulatory scrutiny. Recent updates include mandatory registrations and safety dossier refreshes under European frameworks, and a substantial share of manufacturers reporting higher compliance costs. In parallel, nearly half of production facilities face stringent emission standards that materially increase operating expenditure or force capital investment.
-
Compliance baseline: Key jurisdictions now require formal registration and updated safety data for Chromium(III) oxide; enterprises sourcing globally must validate REACH and comparable registrations in their supplier due diligence.
-
Cost of compliance: Around half of manufacturers report rising compliance costs — this is not a niche line item but a recurring operating burden that should be built into supplier TCO models.
-
Strategic implication: ESG-driven cost pressure is accelerating consolidation among producers with the capital to retrofit emission controls, while creating opportunity for suppliers who can credibly certify low-emission, high-purity material.
Competitive landscape — profiles and strategic postures
The market shows a moderate degree of concentration: leading global suppliers together command just over half of the market value, making supplier strategy a critical element of risk management. The competitive field includes established European, North American and Asian producers, plus regional specialists serving industrial-grade channels.
-
LANXESS (Cologne, Germany) — Global leader with high-purity pigment lines produced in flagship sites; emphasizes quality and eco-focused manufacturing. Its 2026 pricing action underscores the influence large producers have on market direction.
-
Elementis (London, UK) — Strong European position across pigment and metallurgical offerings, with a reputation for consistent quality and technical service.
-
Venator (United States) — Supplies across coatings, plastics and refractories with a sustainability narrative in its product lines, relevant for customers seeking certified low-impact inputs.
-
Vishnu Chemicals (India), Hebei Chromate and other Chinese producers — Competitive cost structures and high-purity refractory/metallurgical grades make these suppliers critical to volume markets and export flows.
-
Hunter Chemical (United States) and Cofermin (Germany) — Niche and speciality players with FDA- or industry-approved portfolios targeting high-specification applications.
-
Regional suppliers (MidUral, Aktyubinsk, Hubei Zhenhua, Jirong) — Provide industrial scale supply into domestic and adjacent export markets; relevant for customers balancing cost, lead-time and regulatory alignment.
What the full report delivers — practical, deal-ready content
PW Consulting’s full study is designed as a toolkit for immediate 2026 execution. Highlights include:
-
Robust market-sizing and methodology: transparent top-down and bottom-up approaches, reconciled to public filings and proprietary channel data for the 2020–2025 historical series and 2026–2032 forecasts.
-
Scenario modeling: three strategic demand scenarios (baseline, upside, downside) with sensitivity levers for energy prices, feedstock disruption, and accelerated regulatory tightening.
-
Supplier scorecards: operational, regulatory and sustainability KPIs for major producers, enabling rapid shortlisting for dual-sourcing or strategic partnership.
-
Procurement playbook: negotiation templates, indexation clauses, hedging and inventory strategies calibrated to the observed mid-single-digit growth environment.
-
CapEx and compliance blueprint: benchmarking of emissions control, wastewater treatment and process upgrades, with indicative timelines and cost buckets to support capex approval cycles.
-
Commercial and product roadmaps: go-to-market options for pigment vs. metallurgical grade offerings, formulation guidance, and downstream customer segmentation to prioritize sales efforts.
-
M&A and partnership screening: acquisition targets and strategic alliances mapped by technological capability, geographic footprint and regulatory posture.
-
Risk matrix and mitigation playbooks: supply interruption scenarios, regulatory shock playbooks, and contingency procurement plans for 30/60/90-day disruptions.
Key implications for corporate strategy in 2026
-
Procurement and sourcing: move from price-only sourcing to total cost of ownership models that include compliance and emissions capex. Add dual-sourcing from at least one geographically diversified supplier and one low-emission certified supplier.
-
Product strategy: accelerate formulation work for high-value coatings and specialty ceramics where margin expansion is most feasible, and evaluate premium “eco” lines for customers with sustainability mandates.
-
Capex planning: plan for staged investments in emissions controls where in-house production exists; where investments are not viable, consider longer-term contracting with certified producers.
-
M&A and JV diligence: prioritize targets that provide either technical differentiation (high-purity grades) or strategic geographic access to reduce lead times and tariff exposure.
-
Commercial risk management: incorporate surcharge pass-through clauses tied to relevant indices, and maintain strategic inventory buffers to weather short-term supplier pricing actions.
-
Regulatory readiness: embed REACH and comparable jurisdiction checks into product approvals and supplier onboarding; prepare SDS and hazard communication updates as part of product compliance governance.
How to use this preview
This article is a strategic preview intended to demonstrate analytical depth and to frame the executive decisions that need to be made in 2026. The full PW Consulting Chromium Oxide Green Market report contains the proprietary segmentation, regional and application splits, company-level KPIs, and downloadable data tables that underpin the scenarios and recommendations summarized here.
For procurement leads, R&D heads, corporate development teams and C-suite sponsors, the study provides an integrated playbook: validated market numbers, supplier intelligence, compliance roadmaps and tactical templates to turn insight into executable plans. If you are preparing budgets, supplier contracts or a strategic M&A pipeline in 2026, this research will materially shorten your decision cycle and improve outcome predictability.
PW Consulting’s approach combines industry-level capacity assessments, primary supplier interviews, regulatory scans, and proprietary demand overlays. We have intentionally withheld the granular segment-specific figures from this preview to preserve the value of the full dataset and to ensure you obtain the actionable, auditable numbers required for board-level decisions.
To access the full dataset, supplier scorecards, and scenario models that operationalize the implications above, please consult the complete Chromium Oxide Green Market report. The full report is structured to get your team from insight to action within 30 days — from contract language to capex planning to M&A shortlists.
For detailed analysis of this topic, please visit the official page: Chromium Oxide Green Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Car Amplifiers Market to Hit USD 620.9 Million by 2032 at 7.0% CAGR
By PW Consulting, 2026-07-12
Car Amplifiers Market — 2026 Strategic Preview
Opening Frame: Why this preview matters for 2026 decision cycles
As companies reallocate R&D, manufacturing, and commercial resources for the post‑pandemic recovery, the car amplifiers market sits at an inflection point. PW Consulting’s latest market research — built on a 2020–2025 historical base and a 2026–2032 forecast horizon — provides the empirical ballast that boards and executive teams need to make confident bets in 2026. The headline mathematics are clear: the market expanded from roughly 302.5 million USD in 2020 to about 386.3 million USD in 2025, and our model projects growth to approximately 427.9 million USD in 2026 and toward 620.9 million USD by 2032 at an underlying CAGR of 7.0% for the forecast window. These macro dynamics are the starting point; the strategic value of the full study is in turning that trajectory into defensible commercial choices.
Car Amplifiers Market
Market snapshot and interpretive headline risks
Historical momentum through 2025 reflects two structural forces: continued aftermarket demand for high‑performance audio and deeper OEM integration of premium audio systems. Looking ahead, growth is driven by product premiumization (DSPs, class‑D efficiency gains, and multi‑channel solutions), tighter testing and verification expectations, and evolving vehicle architectures that place new constraints and opportunities on amplifier design. At the same time, market concentration metrics indicate meaningful scale advantages: the top three players command over half of the market, and the top five approach three quarters. This concentration amplifies the strategic importance of brand, OEM relationships, and validated performance claims.
Car Amplifiers Market
At the policy and standards layer, voluntary but widely referenced testing standards continue to shape buyer trust. Updated testing protocols and independent verification—alongside vendor certifications—are becoming de‑facto entry hurdles for premium segments. For manufacturers and investors, the interplay of certification, verified performance, and perceived product quality will increasingly determine which platforms secure OEM slots and which secure long‑term aftermarket loyalty.
Car Amplifiers Market
What corporate leaders will find immediately useful in this research
- Proven, audit‑ready market sizing and forecasting model that links macro fleet and vehicle mix trends to amplifier demand drivers.
- A supplier benchmarking framework that ranks vendors across technology (DSP, thermal, EMI, class architecture), OEM traction, aftermarket distribution effectiveness, and validated performance certifications.
- Modular go‑to‑market playbooks for OEM engagements, specialist aftermarket channels, and direct‑to‑consumer premium strategies.
- Operational intelligence: component cost build‑ups, typical BOM margins by product architecture, and manufacturing footprint tradeoffs informed by labor‑and‑supply realities.
- Scenario and sensitivity analyses — including upside/downside cases tied to regulation, certification changes, and raw‑material price shocks — with actionable trigger points for M&A and capacity decisions.
Competitive landscape — who matters and why
The market is populated by a mix of legacy electronics majors, audio‑specialist independents, and OEM‑facing Tier 1 groups. Each cluster pursues a distinct strategic play:
- Premium independents (examples included): position on audio fidelity and lifestyle cachet — often supporting marine‑rated or specialty vehicle integrations and leveraging brand equity in enthusiast channels.
- Performance brands: focus on power density, thermal management and demonstrable peak output for aftermarket installers and show cars; proof points such as independent certifications and high‑profile show unveilings are common tactics.
- Japanese consumer electronics incumbents: balance broad OEM relationships with a wide aftermarket portfolio; scale in supply chain and integration expertise is their competitive moat.
- OEM integrators and Tier‑1s: embed amplifiers within complete infotainment clusters and take advantage of vehicle‑level validation resources and multi‑year contracts.
Selected vendor patterns from our coverage: certain premium firms emphasize DSP and reference‑level audio processors, while performance‑oriented brands showcase highest‑output 12V architectures for the aftermarket. Several players strengthen market credibility through catalog refreshes, high‑visibility demonstrations at mobility and tuning festivals, and targeted product introductions at industry shows. Independently verified performance (third‑party measurement and Klippel‑style validation) has emerged as a differentiator for high‑end claims.
Recent market signals that matter to 2026 planning
- Product and catalogue refreshes by specialist audio vendors signal continued investment into acoustics and integration tools for premium installs.
- Showcase launches at major trade events underscore an ongoing aftermarket appetite for headline‑making power amplifiers; these launches often precede dealer and installer demand surges.
- Independent testing standards and the first vendor certifications under new verification regimes are sharpening the edge between marketing claims and measurable performance — a factor that is changing procurement language in OEM RFQs.
- Manufacturing concentrations and labor footprints in Asia remain an operational reality; labor and capacity considerations are already influencing sourcing decisions and contingency planning for new entrants and incumbents alike.
How to translate the research into a 2026 action playbook
Companies that convert market growth into sustainable profit will do three things well: align product architecture to validated vehicle constraints; prioritize verified performance and certifications; and ensure supply‑chain resilience. For 2026 decisions, we recommend a phased set of actions:
- Immediate (0–6 months): validate product claims through recognized third‑party measurement; re‑baseline pricing and warranty agreements to reflect verified performance; and stress‑test supplier continuity plans.
- Near term (6–18 months): accelerate modular platform development for scalable channel variants (OEM‑grade, premium aftermarket, specialist installs), and pursue targeted partnerships with infotainment Tier‑1s and select automakers.
- Medium term (18–36 months): selectively invest in capacity or M&A to shore up market positions where scale and certification lead to durable OEM slots; deploy localized manufacturing buffers to head off regional disruptions.
Risk matrix — what to watch in 2026
- Standards uptake and certification expectations: delayed or inconsistent adoption by vendors can impair access to premium OEM contracts.
- Component supply and labor dynamics: concentration of production and episodic labor cost volatility can compress margins or force price increases.
- Technological substitution: efficiency gains (e.g., more efficient amplifier classes or integrated amplifier‑infotainment ASICs) could compress demand for discrete amplifier units in certain vehicle classes.
- Channel friction: misaligned incentive structures between OEM integration teams and aftermarket distribution networks can limit scale‑up of new products.
What is deliberately left for the full report
This preview outlines the analytical scaffolding and strategic implications. The full PW Consulting report contains the detailed segmented market model, vendor scorecards, product‑level profitability matrices, region‑by‑region demand curves, and downloadable financial models that underpin the forecasts. We intentionally withhold the granular segmentation tables and explicit regional/application allocations here so that decision‑makers access the comprehensive data package with full context and interactive spreadsheets available on the report portal.
Final counsel for executives preparing 2026 plans
2026 will be a year when execution against validated claims and supply resilience will separate winners from laggards. Executives should move beyond topline growth narratives and ask three operational questions: (1) Can we prove our claims under recognized test protocols? (2) Do we have the modular architecture to serve both OEM leverage and aftermarket margin pools? (3) Are our sourcing and manufacturing playbooks hedged against regional labor and component concentration risks? The full PW Consulting Car Amplifiers Market report equips leadership teams with the models, verification frameworks, and strategic playbooks to answer these questions, prioritize investments, and present defensible roadmaps to boards and investors.
To unlock the full dataset, vendor rankings, and interactive scenario models that drive the 2026 strategic recommendations, access the complete report and supporting Excel tools on our research portal.
For detailed analysis of this topic, please visit the official page: Car Amplifiers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Germanium Market at USD 320M in 2025, poised for 3.5% CAGR to 2032
By PW Consulting, 2026-07-12
Germanium Market 2026: Strategic Imperatives from PW Consulting’s Market Outlook
As critical minerals rise toward the top of corporate and national security agendas, germanium has moved from niche specialty to strategic input for fiber optics, infrared optics, semiconductors, and next‑generation solar technologies. PW Consulting’s Germanium Market study—anchored on a 2025 base year and extending through 2032—translates raw data into decision frameworks. Our core macro finding: the global germanium market has expanded from a modest revenue base in 2020 to a substantially larger market by 2025, and is forecast to continue growing through 2032 at a compound annual growth rate (CAGR) of 3.5% under our central scenario. This report is designed to help executives convert that trajectory into concrete procurement, investment, and geopolitical risk decisions in 2026.
Germanium Market
Why this report matters for 2026 corporate strategy
-
Procurement resilience: With supply‑side policy shocks becoming more frequent, procurement teams need multi‑vector sourcing roadmaps and contract structures that reflect tight supply buffers and higher volatility.
Germanium Market -
Capital allocation: Investors and corporate development teams require forward‑looking scenario analysis to decide on capacity expansions, recycling investments, and M&A targets in an environment of rising strategic support for domestic production.
Germanium Market -
Product roadmaps: R&D and product groups must assess material design choices (e.g., germanium‑containing vs. alternative materials) against cost curves and supply risk profiles to prioritize development timelines.
-
Regulatory and geopolitical planning: Supply disruptions driven by export controls and trade measures require playbooks that align lobbying, contingency sourcing, and domestic production incentives.
High‑level market trajectory (what the macro data tells us)
Our top‑line market sizing traces a steady recovery and expansion: the market value moved up between 2020 and 2025 and, under the central forecast, continues to trend upward through 2032. The CAGR of 3.5% across the 2026–2032 forecast window points to a market that is growing steadily rather than explosively—creating strategic opportunities that reward early, targeted moves rather than reactive catch‑up plays. Importantly, market concentration metrics show a moderately consolidated supplier base (CR3 at roughly one‑third of market share and CR5 approaching half the market), which amplifies the impact of individual supplier moves and policy levers on global availability and pricing.
Key market dynamics shaping 2026 decisions
-
Policy and trade: Since 2023, export licensing and direct export restrictions from major producing countries have reframed supply risk. Complementing these controls, a series of policy instruments enacted elsewhere—ranging from executive orders to tariff measures—are accelerating government‑backed incentives for domestic processing capacity. Together, these trends increase the strategic value of near‑term investments in localized refining and recycling.
-
Price volatility: Recent market developments demonstrate pronounced price volatility. Buyers should assume a higher base price environment and build hedging and contract flexibility into purchasing strategies. Our scenarios quantify upside price shocks and the economic thresholds at which demand substitution or accelerated recycling becomes viable.
-
Supply augmentation and substitution: Private and public capital are already moving to expand capacity and recycling. Notable capacity expansions and strategic acquisitions in early 2026 indicate escalated efforts to secure domestic primary and secondary sources—actions that will gradually relieve pressure but require multi‑year timelines.
-
Technological and demand shifts: Applications across fiber optics, IR optics, and electronics/solar continue to drive end‑use demand. Small shifts in adoption rates across these verticals can have outsized effects on Germanium balances given overall market scale and concentration dynamics.
Competitive landscape — who matters and why
The market’s competitive set is a mix of integrated primary producers, refiners/recyclers, and specialty materials firms. Key players include established miners and refiners with integrated value chains, as well as specialty manufacturers and recyclers that can rapidly scale purified product flows. Recent corporate moves—capacity expansions in North America, offtake agreements linking recycling technologies to downstream processors, and the transfer of primary asset ownership—have shifted the strategic map in ways that matter for buyers and investors.
-
Integrated primary producers with upstream access maintain strategic leverage over raw flows and are obvious partners or targets for downstream players seeking security of supply.
-
Refiners and recyclers that can produce high‑purity germanium act as swing suppliers in constrained markets; investments in recovery technology and offtake partnerships materially change availability over a multi‑year horizon.
-
Specialty manufacturers and compound producers retain commercial advantages where proprietary processing yields differentiated product forms or lower contamination risk—critical for semiconductor and optical applications.
Report contents — what executives will find inside
This study blends market intelligence, structured scenario analysis, and practical playbooks to support immediate and medium‑term decisions. Highlights include:
-
Market sizing and demand modeling from 2020 through 2032, including a central forecast and two alternative scenarios for upside and downside demand/policy outcomes.
-
Supply‑side analysis that maps primary, secondary, and emerging recovery channels; a supplier matrix with operational footprints and capacity indicators; and concentration metrics that identify single‑point risks.
-
Price‑formation framework and sensitivity testing: an operational model that ties raw supply shocks and policy shifts to end‑market price responses across our forecast horizon.
-
Regulatory and geopolitical risk assessment, with stress‑test outcomes under different trade restriction and subsidy regimes.
-
Transaction and operational playbooks: M&A screening criteria, JV templates, recycling investment cases, procurement contracting checklists, and capex prioritization matrices.
-
Proprietary datasets and dashboards: time‑series market values, demand drivers by application group, supplier profiles and recent corporate developments, and an executive heatmap of near‑term supply risks.
Practical implications and recommended actions for 2026
Translate insight into prioritized action across three horizons:
-
Immediate (0–6 months): Run a supplier‑risk audit, secure staggered offtake contracts with optionality, and fast‑track small‑scale recycling pilots to create a local buffer. Update procurement KPIs to incorporate geopolitical risk scores and supplier concentration exposure.
-
Near term (6–24 months): Pursue strategic partnerships with refiners or recyclers, evaluate targeted bolt‑on acquisitions to de‑risk supply, and model product redesign options where substitution can be achieved without degrading performance.
-
Medium term (2–5 years): Consider greenfield refining or shared regional assets with public or private co‑investors where strategic national policy supports domestic capacity; integrate advanced recycling and recovery technologies into core materials strategy.
How PW Consulting’s intelligence changes the odds
Our analysis does not simply report historical trends—it quantifies the levers that matter in 2026: policy shifts, supplier capacity moves, recycling scale‑up, and demand elasticity across end markets. Clients using our models can run bespoke scenarios that answer questions such as: At what price threshold does demand pivot toward substitution? Which supplier disruption scenarios create systemic shortage risk? Where is it optimal to invest in domestic capacity versus signing long‑term offtake contracts?
What we intentionally leave for report access
Consistent with the “trailer” principle behind this overview, we have showcased the analytical architecture and strategic utility of the study while preserving the report’s granular datasets and proprietary split tables for subscribers. The full report contains downloadable tables, regional and application breakdowns, supplier share matrices, and financial models for immediate use by procurement, corporate development, and strategy teams.
To convert these insights into operational advantage in 2026—securing supply, optimizing capital allocation, and managing policy risk—access the full PW Consulting Germanium Market study and datasets on our website. The complete product provides the granular segmentation, supplier scorecards, and model inputs necessary to execute the playbooks outlined above.
For detailed analysis of this topic, please visit the official page: Germanium Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Ultra‑High Performance Concrete (UHPC) Market — Strategic Primer for 2026 Decision‑Makers
Executive summary
As capital allocation and infrastructure programs accelerate in 2026, Ultra‑High Performance Concrete (UHPC) is transitioning from a niche engineering specialty into a scalable proposition for bridge preservation, precast manufacturing, architectural façades, and select industrial uses. PW Consulting’s latest market synthesis frames this transition with a quantified top‑line and an actionable set of diagnostic tools designed for corporate strategists, infrastructure owners, and technology investors.
Ultra-High Performance Concrete (UHPC) Market
Key headline: the global UHPC market, measured on a USD Million basis with 2025 as the reference year, has expanded from the low hundreds in 2020 to an estimated USD 500.0 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 7.6% through our 2026–2032 forecast horizon. That trajectory yields an expected market size of roughly USD 553.0 Million in 2026 and around USD 831.0 Million by 2032 — a clear signal that demand and commercial viability are converging.
Ultra-High Performance Concrete (UHPC) Market
Why this matters for 2026 strategic choices
- Timing: 2026 is a pivotal year in which pilot projects, standards maturation, and early commercial rollouts will determine whether UHPC options move from bespoke to mainstream procurement lots.
- Risk vs. reward: A sustained high‑single digit CAGR suggests attractive topline growth, but returns will be concentrated among players that control formulation IP, scalable supply, and installation capabilities.
- Competitive posture: Market concentration metrics indicate meaningful aggregation among a small number of specialist suppliers — an environment that benefits providers with proven performance credentials and distribution reach, and that poses a barrier for late entrants without partnership strategies.
Market trajectory — the numbers that drive strategy
Our time series analysis (2020–2025 historical; 2026–2032 forecast) shows consistent expansion from an earlier base toward a mid‑to‑high hundreds of millions of USD within the forecast window. The 7.6% CAGR reflects a compound effect of three concurrent dynamics: accelerating infrastructure maintenance programs, materials innovation that reduces lifecycle cost, and standardization efforts that lower procurement friction.
Ultra-High Performance Concrete (UHPC) Market
For decision‑makers, the numerical implications are twofold. First, the market scale is now large enough that establishing a meaningful share is financially material to specialized producers and attractive to mainstream concrete suppliers seeking adjacent growth. Second, the growth rate is steady but not exponential — making first‑mover investments in manufacturing scalability, installation expertise (e.g., sprayable UHPC systems), and low‑carbon formulations a differentiator that compounds over several planning cycles.
Key market dynamics shaping 2026 actions
- Standards and regulatory tailwinds: The publication of a proposed ASTM test method in mid‑2025 clarifies the boundary between fibre‑reinforced concrete variations and UHPC for structural applications. That clarity reduces technical procurement risk and enables public agencies and large developers to include UHPC in bid specifications with predictable acceptance criteria.
- Deployment innovations: Sprayable UHPC applications have moved from demonstration to operational use (notably an FHWA‑supported bridge repair in early 2025). Sprayability and rapid set/earlier return‑to‑service are unlocking bridge preservation programs that prioritize minimized traffic disruption — a major demand lever in jurisdictions with mature asset management policies.
- Decarbonization and product differentiation: Leading material suppliers introduced low‑carbon UHPC variants in 2025, reducing embodied carbon while retaining mechanical properties. This addresses two buyer priorities simultaneously: lifecycle emissions targets and long‑term durability.
- Consolidation of supply: Measured concentration among the top three and five suppliers indicates that incumbents are leveraging formulation IP, authorized licensing, and localized production to protect margins. New entrants must therefore evaluate partnership, licensing, or white‑label models rather than attempting a standalone scale build‑out in the short term.
Competitive landscape — what to watch in 2026
The UHPC competitive set is a mix of global cement/construction chemicals majors, regional licensed formulators, and specialized systems providers. Firms with vertically integrated offerings or proprietary fiber‑reinforced formulations are best positioned to influence specification and capture value across the supply chain.
- Ductal by Holcim (Switzerland): A widely recognized branded UHPC solution with patented fiber‑reinforced formulations focused on bridge preservation, precast, and architectural uses. Their 2025 enhancements toward lower‑carbon formulations signal an offensive posture on sustainability credentials.
- Sika AG (Switzerland): Operates a pre‑blend UHPC product line tailored to bridge and infrastructure projects; its strength lies in a global sales and admixture distribution footprint that can accelerate project adoption once standards align.
- BASF SE (Germany): Through its construction solutions, BASF provides admixtures and specialized mixes. Their R&D pipeline and chemical know‑how enable performance tuning for specific use cases (e.g., high early strength, durability under aggressive environments).
- GCP Applied Technologies (United States): Focuses on specialty admixtures that enable local UHPC production; their business model supports precast and contractor partners looking for turnkey mix solutions.
- RAMPF, Cor‑Tuf, Densit, ceEntek, Gulf Precast, Steelike: These regional and application‑focused players offer solutions ranging from UHPC systems for machine beds and offshore strengthening to carbon‑enhanced low‑carbon mixes and architectural all‑white UHPC. Their value is often in niche applications, local manufacturing, and rapid response to project timelines.
Recent developments to monitor:
- Federal Highway Administration promotion under EDC‑6 and the first U.S. sprayable UHPC bridge abutment repair (early 2025) — proof of operational readiness for preservation use‑cases.
- Product launches in 2025 emphasizing lower‑carbon UHPC formulations and spray‑applied systems — signaling commercial readiness for larger, sustainability‑driven contracts.
- ASTM’s mid‑2025 proposed test method — reducing technical procurement risk and enabling public agencies to specify UHPC with measurable acceptance criteria.
What the PW Consulting UHPC report delivers (operational highlights)
Our full study is built around the information architecture that corporate decision‑makers need to convert market opportunity into profitable action. Highlights include:
- Robust top‑line modeling (2020–2032) with sensitivity scenarios that test macroeconomic, infrastructure funding, and technology adoption assumptions.
- Commercial playbooks: go‑to‑market options for producers, precasters, admixture suppliers, and contractors — including licensing vs. own‑plant economics and margin waterfall analysis.
- CapEx and Opex models for production scale‑up, including mix formulations, fiber sourcing, and plant footprint trade‑offs.
- Supply chain and raw material risk map, identifying single‑source exposures and cost levers (e.g., steel fiber, silica fume, admixtures).
- Regulatory and standards impact assessment, quantifying the procurement and project pipeline effects of ASTM updates and FHWA programs.
- Commercial case studies and pilot project dossiers that translate technical performance into lifecycle cost and maintenance savings for asset owners.
- Competitive benchmarking and M&A heatmaps: where strategic partnerships, licensing, or bolt‑on acquisitions make economic sense by 2026–2028.
What we deliberately withhold here — and why
In keeping with a “trailer” approach to this primer, we surface the macro trajectory, competitive dynamics, and actionable frameworks while withholding granular segment‑level figures and detailed regional/application splits that constitute the core, decision‑grade intelligence in the full study. This includes the precise regional and application allocations and certain proprietary channel economics. Those subsegment tables and the underlying vendor financial models are available in the complete report and accompanying data pack for subscribers.
Strategic recommendations for 2026
- For producers and admixture suppliers: Prioritize licensed manufacturing partnerships and small‑scale local plants to shorten delivery lead times. Invest in low‑carbon formulations and certification pathways aligned with ASTM developments to capture public procurement demand.
- For precast manufacturers and contractors: Develop installation competency (including spray application and accelerated curing techniques) and partner with branded UHPC formulators to mitigate formulation risk while offering turnkey solutions to owners.
- For infrastructure owners and asset managers: Pilot sprayable UHPC in bridge preservation and overlay programs where lifecycle cost and reduced traffic disruption create easily demonstrable ROI. Use ASTM test method adoption as a procurement trigger to standardize acceptance criteria.
- For private equity and strategic investors: Target firms with IP on fiber‑reinforced mixes, established licensing models, or regional manufacturing footprints. Expect consolidation opportunities where CR3/CR5 concentration affords premium valuation for incumbents.
Why PW Consulting’s study is decision‑relevant for 2026
We designed this research to bridge technical materials science and boardroom strategy. The combination of a quantified top‑line (2020–2032), concentration metrics, a mapped competitive set, and pragmatic commercial tools creates a single reference for investment memos, procurement pilots, and M&A evaluation. For executives facing capital allocation choices in 2026, the study reduces uncertainty around standards, deployment methods, and supplier economics — and lays out clear options to capture the growth opportunity implied by the projected 7.6% CAGR.
To move from insight to action, stakeholders will need the granular subsegment data, vendor financials, and scenario models contained in the full report. PW Consulting’s UHPC market package includes those deliverables, along with a bespoke advisory session to translate findings into a 90‑day implementation plan tailored to your role in the value chain.
Next steps
- Review the full report for regional, type, and application breakouts and the downloadable data pack.
- Book a strategy workshop to convert our models into a prioritized action plan for your organization in 2026.
For detailed analysis of this topic, please visit the official page: Ultra-High Performance Concrete (UHPC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


