



Category: market research
Full Body Scanner Market to Reach USD 745M by 2032, Growing at 9.8% CAGR - PW Consulting
By PW Consulting, 2026-07-09
Full Body Scanner Market 2026: Strategic Preview for Decision-Makers
As organizations plan capital allocations and operational strategies for 2026, the Full Body Scanner market is moving from niche security investment to a scalable, programmatic procurement category. PW Consulting’s upcoming Full Body Scanner Market study — anchored on a 2025 base year, a 2020–2025 historical window and a 2026–2032 forecast horizon — synthesizes market forces, regulatory inflection points, vendor dynamics and deployment playbooks to inform board-level and procurement-level choices. At a macro level, the market has expanded from roughly USD 200 million in 2020 to about USD 390 million in 2025 and is forecast to grow to approximately USD 745 million by 2032, representing a compound annual growth rate of 9.8%. That trajectory creates a different strategic calculus for 2026 investments: this is planning for scale, not one-off pilots.
Full Body Scanner Market
Why this matters for 2026 decision cycles
-
Budgeting and multi-year procurement: The market’s near-term growth profile forces organizations to move from episodic buys to multi-year procurement frameworks that lock in price, support and upgrade paths.
Full Body Scanner Market -
Programization of security screening: Airports, mass-transit hubs and correctional systems increasingly treat full body scanners as program-level assets. That shifts procurement criteria toward lifecycle cost, throughput optimization and integration with existing security stacks.
Full Body Scanner Market -
Regulatory and certification risk: Certification timelines and government procurement windows will define winners in 2026—approved systems get accelerated deployment where standards or event-driven demand emerges.
Market dynamics and regulatory inflection points
Three dynamics are shaping near-term demand and vendor positioning: regulatory standardization, event-driven procurement, and technology convergence.
-
Regulatory standardization: Over the past two years regulatory bodies and authorities have clarified certification pathways and baseline performance expectations. Notable examples include updated checkpoint guidance from major aviation authorities in 2025 and multiple vendor certifications against pan-European standards in 2024–2025. For procurement teams, this reduces technical uncertainty but raises the bar for interoperability and compliance documentation.
-
Event-driven and sovereign demand: Major international events and geopolitical drivers create concentrated procurement windows. In 2026, several high-visibility contracts and deployments illustrate how event timetables and national security priorities accelerate adoption.
-
Technology and data integration: Advances in millimeter-wave imaging, AI-based object detection, and non-ionizing screening techniques are converging. Vendors that can fuse software-led detection with a defined hardware upgrade path will capture larger program contracts.
Technology posture: what matters to operators
For operators and security architects, technology choice is no longer purely a “type” decision. Procurement decisions hinge on a set of operational attributes:
-
Throughput and false alarm rates — affecting staffing and checkpoint design.
-
Safety and privacy profile — non-ionizing alternatives and anonymized detection outputs are increasingly mandatory in public deployments.
-
Integration and upgradeability — APIs, software update cadence and on-site service footprints determine lifecycle TCO.
-
Certification and interoperability — cleared systems attract accelerated deployment in certified environments such as aviation checkpoints.
These attributes explain why several suppliers have differentiated along both hardware and software axes, offering certified systems with AI-assisted detection, walk-through form factors and non-ionizing modalities that address throughput and privacy simultaneously.
Competitive landscape: fragmented but feature-led
The Full Body Scanner market is characterized by a relatively fragmented vendor base (industry concentration metrics indicate low top-three and top-five shares), which creates room for both incumbent defense/aviation suppliers and fast-follow specialized vendors. Competition is feature-led rather than purely price-led, with differentiation around certification status, throughput guarantees, fleet support and integration capabilities.
-
Smiths Detection (Hemel Hempstead, UK) positions itself around non-invasive transmission X-ray screening series designed to detect concealed objects. Their product set answers demands where penetration and material discrimination remain critical to threat detection strategies.
-
Rohde & Schwarz (Munich, Germany) has anchored a strong position in millimeter-wave walk-through systems with AI-assisted detection and full body coverage. Recent contract awards and certification milestones have reinforced their airport and high-capacity venue credentials.
-
Leidos (Reston, VA, USA) brings a high-throughput, non-ionizing people-screening solution with a software-first detection layer, appealing to large-scale checkpoint operators seeking throughput and low health-risk profiles.
Recent vendor developments that have immediate strategic implications for 2026 include multi-site contract awards and certification achievements that reduce deployment friction. These wins shift the procurement conversation from “prototyping” to “rollout,” and they create second-order effects on support ecosystems and aftermarket services.
Recent developments to watch (implications for procurement)
-
Certification progression for walk-through systems removed a barrier for continuous passenger flow screening in airports, opening high-throughput architectures for major terminals.
-
Updated checkpoint guidance from major aviation authorities has clarified hardware and data-handling expectations; procurement teams must align RFP language with these updated standards to avoid rework.
-
Legislative activity at state levels has broadened the addressable market for custodial and correctional security deployments, with pilot authorizations creating initial demand pockets.
-
Recent vendor contract awards tied to major events demonstrate that certified suppliers with demonstrated logistics and global support can capture accelerated, high-value deployments.
Strategic choices for 2026 — an operator playbook
For 2026, we recommend five concurrent actions for organizations that intend to operationalize full body scanning capability at scale:
-
Move from pilot to program procurement: shift contract structures to include multi-year service-level agreements, defined upgrade paths and performance-based incentives.
-
Prioritize certification-aligned products: require proof of certification in initial RFPs and contract clauses for maintaining compliance as standards evolve.
-
Design for integration: require vendor commitments for open APIs, cybersecurity attestations and third-party integration tests to lower long-term integration risk.
-
Model total cost of ownership, not unit price: include spares provisioning, software licensing, data storage, and field service in TCO models to avoid budget surprises.
-
Define staged rollouts linked to measurable KPIs: incremental performance and user-acceptance gates de-risk full rollouts and provide negotiation levers.
What PW Consulting’s full study delivers (actionable content)
The full PW Consulting report translates market dynamics into procurement-grade intelligence. Highlights of the deliverables include:
-
Market sizing and validated forecast models (2020–2032) with scenario sensitivity for event-driven surges and accelerated certification adoption.
-
Technology roadmaps and vendor capability matrices that compare detection modalities, throughput, privacy profiles and upgrade paths.
-
Regulatory compliance mapping and an acquisition checklist aligned to recent international standards and national guidance.
-
Vendor scorecards and procurement templates — RFP language, SLA clauses, maintenance schedules and service credits — to shorten procurement cycles.
-
Operational deployment playbooks — checkpoint redesign, staffing models, and KPI frameworks for first 24 months post-installation.
-
Commercial models — detailed TCO, financing options, and leasing vs. capital purchase comparisons tailored for operators and governments.
-
M&A and partnership radar — candidate profiles, capability gaps and investment theses for investors seeking consolidation plays in a fragmented market.
To honor the “trailer” principle: this preview demonstrates the depth and practical focus of our work while reserving the full tranche of sub-segmentation tables, region/application breakdowns, vendor scorecard weightings and model assumptions for the full report. Those deliverables contain the granular procurement levers and numeric appendices clients use directly in negotiations and CAPEX approvals.
Conclusion — strategic posture for 2026
Entering 2026, the Full Body Scanner market is at a pivot: certification clarity, feature convergence and strategic procurement windows are converging to make large-scale deployments a rational option for governments and commercial operators. The market’s sustained near-double-digit CAGR and forecasted expansion through 2032 mean that decisions made in 2026 — about vendors, contract structures, and integration blueprints — will lock in cost and capability implications for years.
PW Consulting’s full study equips procurement leaders, security program executives and investors with the forward-looking models, vendor benchmarking and playbooks needed to convert market opportunity into repeatable, secure deployments. For readers preparing procurement strategies, contract specifications, or investment memos for 2026, the full report is the operational manual you’ll reference in bid committees and boardrooms.
Access the complete report page for the full data appendices, segmentation tables and executable templates that power 2026 decision-making.
For detailed analysis of this topic, please visit the official page: Full Body Scanner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PGMEA for Electronic Materials to Reach USD 207.08M by 2032 (6.2% CAGR)
By PW Consulting, 2026-07-09
Propylene Glycol Methyl Ether Acetate (PGMEA) for Electronic Materials — Strategic Preview for 2026 Decision Makers
As global electronics supply chains reassess resilience, cost and regulatory risk entering 2026, Propylene Glycol Methyl Ether Acetate (PGMEA) continues to be a strategically critical specialty solvent across semiconductor manufacturing, photoresist chemistry, and display production. This briefing frames the strategic value of PW Consulting’s full market study for executives making capital allocation, procurement, and M&A decisions in 2026. It highlights the structural drivers underpinning market growth, the levers that will determine competitive advantage, and the practical, actionable analyses the full report delivers—while intentionally reserving granular tables and proprietary segmentation to the paid report.
Propylene Glycol Methyl Ether Acetate (PGMEA) for Electronic Materials Market
Market trajectory at a glance
- Recovery and momentum: The PGMEA market has shown sustained expansion from the early-2020s into the mid-decade, reflecting the electronics industry’s recovery and structural demand from advanced semiconductor and display processes.
- Size and pace: On a macro basis, the market expanded from approximately 101 million USD in 2020 to roughly 136.8 million USD by the 2025 base year, and is projected to reach just over 207 million USD by 2032 under the central scenario—a compound annual growth rate (CAGR) of about 6.2% over the forecast window.
- Implication for 2026 planning: That growth profile translates into predictable incremental demand for high‑purity grades, but also amplifies supply‑chain and regulatory pressures that will shape supplier selection and investment timing in 2026 and beyond.
Why this market matters to your 2026 playbook
- Strategic input to high-value manufacturing: PGMEA is not a commodity in electronics contexts—electronic‑grade specifications and manufacturing controls materially affect wafer yields and downstream device performance. Procurement decisions therefore have direct operational and quality implications for chip fabs and advanced packaging lines.
- Price and margin lever: Electronic-grade PGMEA commands a purity premium in the high single-digit dollars per kilogram range—an input cost that can erode or protect margin depending on sourcing strategy, hedging, and specification management.
- Exposure to upstream volatility: Production costs are sensitive to propylene oxide and acetic acid feedstock moves. Volatile feedstock pricing has historically transmitted quickly to contract and spot terms, creating timing risk for buyers and opportunity for producers who can hedge or vertically integrate.
- Regulatory and emissions constraints: Tighter emissions rules in North America and Europe, and chemical notification requirements such as those under US TSCA for novel grades, add compliance cost and time-to-market risk—important inputs for capex scheduling and product launch planning.
Competitive landscape: concentration, capabilities, and recent shifts
The PGMEA value chain exhibits a measurable degree of concentration: the top three producers control a meaningful share of global market volumes, and the top five account for a clear majority. This concentration creates both negotiating power for large buyers and an elevated strategic premium for incumbents who can guarantee ultra-high purity, on-time shipments, and regulatory compliance.
Propylene Glycol Methyl Ether Acetate (PGMEA) for Electronic Materials Market
- Major integrated chemical players dominate supply: Multinational producers with integrated propylene-based operations and established global distribution networks (examples include large petrochemical and specialty chemical groups) hold the manufacturing scale and logistical reach that many electronics customers require.
- Specialists in high‑purity grades maintain differentiation: Several specialist producers and chemistry-focused firms have developed refined purification and quality control platforms that are valued by semiconductor and display manufacturers.
- Recent industrial moves: Notable capacity expansions in Asia-Pacific by leading specialty chemical producers (announced in 2025) reflect a strategic bet on continued electronics-driven demand and a push to secure regional supply for OEMs and fabs in the Asia supply cluster.
Supply‑chain and regional dynamics—what keeps CEOs awake
- Geography matters: Asian production hubs continue to be the primary global source for PGMEA volumes, creating freight, insurance, and tariff differentials that raise landed cost for North American and European purchasers. For global procurement teams, regional sourcing decisions now require integrated landed-cost modeling—not just unit-price comparisons.
- Feedstock and cost transmission: Propylene oxide and acetic acid remain the upstream cost drivers. Sharp moves in these feedstocks can rapidly compress producer margins or pass through to buyers, depending on contract structures and inventory strategy.
- Regulatory overlay: Pre‑manufacture notifications and evolving emissions standards introduce time and compliance costs. These factors are increasingly part of supplier selection criteria for risk‑averse OEMs.
What PW Consulting’s full report delivers (practical, transaction‑ready content)
PW Consulting’s comprehensive study translates market intelligence into operational decision tools for 2026. Key deliverables designed for immediate executive and C-suite use include:
Propylene Glycol Methyl Ether Acetate (PGMEA) for Electronic Materials Market
- Granular demand and growth scenario models—multiple demand scenarios calibrated to semiconductor fab build-outs and display industry trajectories (note: granular region/application tables and underlying assumptions are provided in the paid report).
- Supplier scorecards and risk maps—qualitative and quantitative assessments of manufacturing capability, quality systems for electronic‑grade production, on‑time performance, regulatory compliance posture, and logistics risk.
- Cost and margin playbooks—bottom‑up cost models that decompose COGS drivers, feedstock sensitivity analyses, and threshold pricing required to justify new capacity investments or long‑term offtake deals.
- Procurement and contracting frameworks—recommended contract structures for 2026 (fixed/variable blends, indexation approaches tied to feedstock, inventory commitments), and a ready‑to‑use supplier due‑diligence checklist tuned to high‑purity solvents.
- M&A and capex prioritization guidance—valuation multiples, earn‑outs, and go/no‑go IRR thresholds for greenfield versus bolt‑on acquisitions in regions where growth or supply security is most urgent.
- Regulatory compliance playbook—roadmap for TSCA notifications, EU/NA emissions compliance, and best practices for product stewardship and customer specification management to accelerate qualification in semiconductor supply chains.
Strategic recommendations for 2026 (actionable, prioritized)
Below are prioritized moves for key stakeholder groups based on PW Consulting’s analysis.
- For producers and investors:
- Prioritize capacity investments in proximity to major electronics clusters while coupling expansions with rigorous quality systems—scale alone will not win business without documented ultra‑high purity performance.
- Implement feedstock hedging programs or secure long‑term upstream offtakes to stabilize margins. Consider vertical integration opportunities where economics support capex payback within acceptable investment horizons.
- Assess targeted M&A to acquire purification know‑how or local logistics assets that reduce landed cost exposure for key customers.
- For semiconductor and display OEMs / large consumers:
- Move from spot buying to portfolio contracting: blend strategic long‑term supply agreements for core volumes with spot opportunities to capture favorable pricing windows.
- Invest in multi‑sourcing where feasible to mitigate regional disruption risk; evaluate local blending/packaging hubs to reduce freight and tariff impact.
- Embed supplier auditing for regulatory compliance (TSCA and regional emissions) as a mandatory gating criterion pre-qualification step.
- For private equity and strategic buyers:
- Screen assets for quality‑process differentiation and existing customer relationships within semiconductor value chains—these attributes command multiples above generic solvent assets.
- Use the PW Consulting cost models to stress-test valuation under commodity feedstock swings and tightening regulatory scenarios.
Risks, blind spots and watch‑points for 2026
- Feedstock shocks remain the single most material short‑term risk to both margins and contract pricing—scenario stress tests in the full report demonstrate asymmetric impacts across different contracting strategies.
- Regulatory developments could lengthen qualification cycles for new grades or suppliers; buyers should allow for regulatory lead time in their supplier onboarding timelines.
- Geopolitical shifts and trade measures that affect freight and tariff regimes could quickly invert landed-cost advantages—dynamic sourcing strategies and regional stocking can mitigate but not eliminate this risk.
Competitive profiles (what executives need to know)
Leading chemical producers combine scale, global logistics, and integrated feedstock access, while specialist firms focus on purification and single‑source reliability for electronic processes. Recent capacity expansions in Asia and ongoing investments in quality and environmental controls highlight where incumbents are placing strategic bets. PW Consulting’s supplier dossiers provide executive briefs on manufacturing footprints, product portfolios, quality certifications, and commercial posture—synthesized into procurement negotiation playbooks.
Conclusion — how to use this preview in 2026 planning
This briefing establishes the strategic contours of the PGMEA market that matter for 2026 decisions—stable mid‑single digit CAGR growth, concentration among incumbent chemical producers, material procurement and regulatory risk, and a clear premium for electronic‑grade performance. The full PW Consulting report converts these insights into executable work streams: sourcing strategies, contract templates, cost models, and M&A screening filters tailored for executives who must commit capital or lock in supply in 2026.
For boards, procurement leaders, and corporate development teams preparing 2026 plans, the next step is a targeted review of the full report’s proprietary segmentation tables, supplier scorecards, and quantitative scenario outputs. These deliverables are intentionally gated to provide clients with actionable, defensible intelligence when negotiating contracts, sizing investments, or pursuing transactions in this strategically important specialty chemicals space.
To obtain the full dataset, supplier dossiers, and executable tools referenced in this preview, visit PW Consulting’s Propylene Glycol Methyl Ether Acetate (PGMEA) for Electronic Materials Market report page or contact our advisory desk for a tailored briefing and model package.
For detailed analysis of this topic, please visit the official page: Propylene Glycol Methyl Ether Acetate (PGMEA) for Electronic Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Thioctic Acid (Alpha Lipoic Acid, ALA) Market: Strategic Imperatives for 2026
As PW Consulting’s lead industry analyst, I present a concise but incisive preview of our full-market study on Thioctic Acid (Alpha Lipoic Acid, ALA). This briefing is designed to demonstrate the analytical rigor and practical orientation of the research while reserving the granular, transaction-grade intelligence for the full report. For corporate leaders planning 2026 allocations—R&D, sourcing, M&A, or commercialization—this note explains why ALA deserves prioritized strategic attention this year.
Thioctic Acid (Alpha Lipoic Acid) (ALA) Market
Executive snapshot
- The global ALA market has expanded meaningfully from the early 2020s into the mid-decade, reaching a base-year total of approximately USD 985 million in 2025. Our forecast, built on a blend of bottom-up capacity modelling and demand-side adoption curves, projects compound annual growth of 5.92% across the 2026–2032 horizon, lifting the market toward roughly USD 1.47 billion by 2032 under the base scenario.
- Market structure shows a mid-level concentration: the top three producers control material share of the market, with the top five firms approaching half of global supply—enough to shape pricing and access dynamics, but not so dominant as to preclude targeted entrants and contract manufacturers from capturing niche value.
- Critical drivers are changing rapidly: form differentiation (stereoisomer and formulation science), regulatory trajectories in major jurisdictions, and upstream raw-material volatility together create both risk and arbitrage opportunities for agile players.
Why this matters for 2026 corporate decisions
Companies that treat ALA as a commodity will be outcompeted by those that take a portfolio approach—aligning technical differentiation (R-ALA vs other forms), supply resilience, and regulatory strategy. With the market passing the USD 900–1,000 million threshold in 2025 and clear mid-single-digit growth ahead, 2026 is the inflection year for commitments: securing long-term supply contracts, investing in stabilized-enantiomer capabilities, and standing up regulatory playbooks for market access. Timing matters: lead times for qualified suppliers, capacity expansion, and dossier development for certain geographies all intersect in the 12–24 month window.
Thioctic Acid (Alpha Lipoic Acid) (ALA) Market
Market trajectory and interpretation of the numbers
- Historical momentum: The market expanded materially between 2020 and 2025, reflecting rising consumer and clinical interest in antioxidant and neuroprotective applications, broader supplementization in aging populations, and incremental adoption in cosmeceutical formulations.
- Forecast logic: Our 5.92% CAGR is scenario-weighted—combining a base case that assumes stable commodity inputs and conservative regulatory outcomes, with downside and upside variants tied to raw-material price shocks and regulatory rulings. The plan-of-record projection to 2032 therefore signals durable, investible demand rather than a transient fad.
- Concentration implications: With the top echelons of suppliers controlling a meaningful portion of available capacity, pricing power will reside with those who can credibly pledge supply continuity and quality certifications. That creates a premium for suppliers that can demonstrate solvent-free processes, enantiomeric purity, or clinical-grade manufacture.
Market dynamics: where immediate risks and opportunities lie
- Raw-material and cost pressure: Conversion economics for ALA are sensitive to inputs such as medium-chain fatty feedstocks. Recent swings in octanoic-acid-related inputs (driven by El Niño effects in 2024–2025) produced double-digit percent swings in upstream costs, narrowing supplement margins and forcing repricing or reformulation decisions. Buyers should stress-test margin models against +/- 20% raw-material volatility.
- Regulatory headwinds and marketing constraints: In the U.S., limitations on certain nutrient claims have already narrowed permissible marketing language, a trend likely to continue as regulators scrutinize structure–function assertions. In the EU, ongoing Article 8 evaluations could materially curtail permitted uses of ALA in supplements in certain scenarios—our modelling includes a sensitivity that quantifies material market contraction if adverse determinations are issued.
- Reimbursement and clinical channels: Compounded ALA retains a role in certain pharmacy compounding pathways in the U.S., and clinical use in neuropathy and metabolic support continues to underpin pharmaceutical interest. Companies that bifurcate strategies—one for consumer-facing supplements and another for clinical/pharmaceutical channels—stand to capture higher-value product placement.
- Supply-chain concentration: Two Chinese suppliers supplied a very large share of global ALA capacity in 2025, creating geographic single points of failure. Events such as shipping disruptions in strategic maritime chokepoints amplified that risk during the prior 18 months. Buyers should evaluate dual-sourcing, strategic inventory, and alternative-route logistics to immunize programs against episodic outages.
Competitive landscape: what the leading players reveal about strategy
The report benchmarks key manufacturers and brand owners across product purity, form portfolio, geographic footprint, and go-to-market approach. Highlights include:
Thioctic Acid (Alpha Lipoic Acid) (ALA) Market
- Sabinsa Corporation (East Windsor, NJ): Known for high-purity ALA targeted at cosmeceutical and nutraceutical customers. Their playbook focuses on branding around ingredient pedigree and application support for formulators—valuable for partnerships in premium SKUs.
- AlzChem Group AG (Trostberg, Germany): A strategic differentiator is its solvent-free, Alipure® manufacturing claim—positioning for pharmaceutical and dietary-supplement channels that prioritize low residual solvents and consistent crystalline profiles.
- GeroNova Research Inc.: Commercializes stabilized R‑lipoic acid enantiomer forms. Their approach demonstrates the commercial value of enantiomer-specific R&D and how clinical substantiation translates into a pricing premium.
- Jarrow Formulas and other branded supplement houses: These players convert ingredient-level differentiation into consumer messaging (nerve support, antioxidant benefits). Their success underscores the importance of evidence-backed claims and supply certainty.
- Large-volume suppliers in China and India (several contract and bulk manufacturers): They deliver scale and cost leadership but introduce concentration and quality narrative challenges for western buyers—creating an opening for near-shore or regionally certified providers who can bridge cost and compliance.
Overall, the ecosystem reveals three viable competitive plays: (1) premium technical differentiation (clinical-grade R‑ALA, solvent-free processes), (2) cost-and-scale supply leadership, and (3) branded consumer product differentiation. Most successful strategies combine elements of two of these plays rather than pure single-axis competition.
What the PW Consulting report delivers (practical, transaction-ready content)
Our full study is engineered for decision-makers who need executable outputs for 2026 action plans. Key deliverables include:
- Demand and supply models with SKU- and form-aware forecasting to 2032, including upside/downside scenarios tied to regulatory and raw-material shocks.
- Supplier scorecards and a CR3/CR5 concentration map that identifies substitution levers, qualification lead times, and risk-adjusted capacity.
- Regulatory decision trees for major jurisdictions (U.S., EU, Asia) with contingency roadmaps and dossier checklists to accelerate market defense or entry.
- Pricing sensitivity analysis and margin impact matrices to inform pricing strategy and contract negotiation thresholds.
- M&A and partnership heatmaps, highlighting targets and acquirers by strategic fit—technical capabilities, geographic profile, and certification footprint.
- Commercial playbooks—go-to-market trajectories for branded supplements, cosmeceuticals, and pharmaceutical channels, including recommended clinical-investment thresholds to achieve premium positioning.
- Supply-chain stress tests and inventory-optimization templates to model resilience at given service levels and cost-of-capital assumptions.
Strategic recommendations for 2026 (prioritized)
- Lock in supply diversity: Execute at least one long-form offtake or capacity reservation with an alternate-region supplier while qualifying a domestic/regional backup. The concentration profile makes this a first-order risk-mitigation action.
- Invest selectively in differentiation: For firms targeting premium channels, prioritize R‑ALA capabilities or partnerships with suppliers who hold solvent-free/clinical-grade claims. The ability to substantiate efficacy and purity is increasingly monetizable.
- Prepare regulatory playbooks now: Anticipate constrained marketing language and potential EU Article 8 impacts. Pre-emptive dossier harmonization and targeted clinical endpoints will shorten time-to-market if regulators require additional evidence.
- Model cost shocks into your pricing: Run scenario analyses that stress raw-inputs by +/-20% and quantify pass-through versus margin compression. Use indexed contract clauses where feasible to share volatility risk with suppliers or customers.
- Explore M&A selectively: Look for bolt-on manufacturers that close geographic supply gaps or brands with sticky direct-to-consumer channels to capture downstream margin.
Conclusion — the 2026 decision window
With a base-year market approaching USD 1 billion and a mid-single-digit growth trajectory through 2032, ALA represents a market with real scale and differentiated value pools. The strategic playbook for 2026 is clear: secure supply flexibility, invest in credible product differentiation, and build regulatory resilience. PW Consulting’s full report provides the granular maps—by form, application, and region—plus supplier-level intelligence and operational templates you need to move from strategy to execution.
Next steps
To access the complete datasets, breakouts, and executable tools (including our supplier scorecards, scenario models, and M&A heatmap), please visit the PW Consulting report page. The full intelligence package is structured to accelerate your 2026 planning and to convert uncertainty into prioritized, fundable actions.
For detailed analysis of this topic, please visit the official page: Thioctic Acid (Alpha Lipoic Acid) (ALA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Acrylic Rubber Market to Rise to USD 2,670M by 2032 at 6.98% CAGR
By PW Consulting, 2026-07-09
Acrylic Rubber Market 2026: Strategic Preview for Executive Decision-Making
Executive Teaser
As the acrylic rubber (ACM) market enters a new phase of maturation and technical differentiation, 2026 will be a pivotal year for commercial and capital decisions. This preview synthesizes the most consequential, data-driven signals from PW Consulting’s full market study (base year 2025; historical 2020–2025; forecast 2026–2032) to equip senior leaders with the strategic framing needed to act quickly and confidently. The market expanded from roughly USD 1.29 billion in 2020 to USD 1.685 billion in 2025 and is forecast to reach about USD 2.67 billion by 2032, implying a compound annual growth rate of approximately 6.98% through the forecast horizon. While this briefing surfaces the strategic implications, detailed segment-level tables, regional and application breakdowns, and proprietary scenario models are reserved for the full report.
Acrylic Rubber Market
Why 2026 Matters — The Inflection Points
-
Acceleration of technical differentiation: Demand is shifting from commodity acrylic rubbers toward specialized grades that combine heat, oil and low-temperature performance. Manufacturers that can demonstrate certified performance in demanding end-use environments are gaining pricing power and share.
Acrylic Rubber Market -
Supply-side consolidation and concentration: The market shows meaningful concentration among a handful of global producers, with the top three and five players commanding substantial combined shares. This structure creates asymmetric advantages for firms with scale, integrated feedstock access, and global manufacturing footprints.
Acrylic Rubber Market -
Raw material and energy dynamics: Early 2026 pricing and tariff signals are already reshaping sourcing calculations and capital plans for energy-intensive production.
Market Fundamentals — What the Numbers Tell Us
Between 2020 and 2025, the industry grew steadily, reflecting resilient end-demand from automotive sealing systems, industrial machinery, and specialty oil-engine applications. Looking forward to 2032, the market’s near 7% CAGR reflects a composite of steady replacement demand, incremental new specifications (notably in powertrain and industrial sealing for electrified systems), and margin-accretive migration to higher-value grades.
At the same time, market concentration metrics point to an environment where mid- and long-term profitability will increasingly hinge on technical differentiation, operational scale, and proximity to feedstock and strategic customers. These dynamics create both defensive rationales for incumbent players and acquisition opportunities for growth-seeking entrants.
Dynamics to Watch — Inputs, Regulations, and Cost Signals
-
Raw materials: Upstream volatility has returned as a primary driver. Analysts reported that butyl acrylate prices in April 2026 were firm across major hubs, with China and India showing elevated price points after Q1 pressures driven by higher acrylic acid costs and constrained supply. For manufacturers, this underlines the need for robust feedstock hedging and alternative sourcing strategies.
-
Energy and transmission economics: Regulatory developments are altering manufacturing cost structures. Notably, a tariff proposal published in late 2025 adjusted transmission tariffs for high-voltage customers—creating differentiated energy cost outcomes for large plants depending on their connection class. Firms that lock favorable power contracts or re-optimize plant locations may secure a structural competitiveness advantage.
-
End-market evolution: Automotive OEMs continue to demand lower-emission profiles and higher durability in sealing systems, while industrial customers prioritize longer service intervals and improved solvent and oil resistance—trends that are increasing the share of high-performance and specialty ACM in procurement specifications.
Competitive Landscape — Profiles and Strategic Implications
The competitive map is dominated by established polymer and specialty chemical players that combine proprietary grades, regional manufacturing footprints, and close OEM relationships. Three representative suppliers illustrate the archetypes and strategic playbooks we examine in the full study:
-
Zeon Corporation (Tokyo) — A technology-led producer with a portfolio of ACM grades targeted at both heat-resistant and low-temperature applications. Zeon’s strategy relies on regional manufacturing capabilities (including sites in Asia and North America) and grade-level differentiation. Its multi-site capacity and product breadth make it a natural partner for global OEM programs and a difficult competitor to displace on performance-spec accounts.
-
Mitsui Plastics, Inc. (Tokyo) — A specialty orientation emphasizing high-purity acrylic esters and advanced grades (low-Mooney, epoxy- and carboxyl-modified, cold-resistant variants). Mitsui’s technical depth and product customization capabilities position it to win development contracts where specification and processing characteristics matter as much as unit price.
-
Unimatec Chemicals Europe GmbH (Germany) — Focuses on ACM grades engineered for automotive seals, gaskets and hose applications demanding heat and oil resistance. Unimatec’s value proposition is a mix of performance certification and close European OEM integration.
Collectively, the competitive environment rewards integrated capabilities—product R&D, regional manufacturing flexibility, and secure feedstock access. The market’s concentration levels also mean that targeted M&A, JV strategies and selective capacity investments are viable paths to rapid share gains for well-capitalized challengers.
What the Full Report Contains — Practical, Actionable Elements
PW Consulting’s full Acrylic Rubber Market study translates these dynamics into executable tools for C-suite and commercial leaders. Highlights include:
- Granular demand models and scenario-based forecasts through 2032 (by region, type, and application) with sensitivity testing for raw material and energy shocks.
- Supply-side mapping: plant-by-plant capacity, vintage, throughput economics and retrofit potential.
- Price and margin analytics: historical pass-through patterns, break-even curves, and recommended commercial hedges for common feedstocks.
- Competitor scorecards: capabilities, strategic intent, and likely next-move playbooks for the leading suppliers.
- Regulatory and ESG checklists tailored to production and downstream applications, including capex implications and compliance timing.
- 90-day to 24-month action frameworks for procurement, R&D prioritization, go-to-market and inorganic growth.
These modules are delivered with an integrated financial model and customizable scenario dashboards to support board-level investment and M&A decisions.
Strategic Recommendations for 2026 Decision Cycles
Based on the market trajectory and the competitive dynamics above, PW Consulting recommends executive teams prioritize the following in 2026:
-
Secure feedstock options and hedge selectively: Given the early-2026 firmness in butyl acrylate and related feedstocks, firms should institutionalize multi-supplier contracts, consider regional sourcing hedges, and evaluate partial fixed-price agreements to stabilize input cost exposure.
-
Prioritize high-value grade deployment: Redirect R&D and commercial focus toward grades that address rising OEM specifications—especially heat- and oil-resistant variants—where margin uplift and longer-term contracts are achievable.
-
Re-evaluate plant footprints against tariff and energy regimes: Transmission tariff adjustments create a window for optimizing large-site economies. Model energy contract renegotiations and potential relocation or capacity toggling for vulnerable plants.
-
Use M&A and JVs to close capability gaps: Acquire or partner to fast-track access to specialty grades, regional customer lists, or feedstock integration—especially where organic timelines would miss 2026 commercial windows.
-
Implement customer co-development pilots: Lock multi-year offtakes by sharing development costs and guaranteeing performance milestones—this is particularly effective with OEMs specifying higher-performing sealing solutions for electrified vehicles and industrial equipment.
Risk Factors and Contingencies
Key uncertainties that should be stress-tested in every strategic plan include prolonged upstream constraints, abrupt regulatory shifts affecting energy tariffs or chemical use, and faster-than-anticipated substitution of ACM by competing elastomers in certain niche applications. Our full report contains scenario matrices and decision-tree guidance to assess capex and commercial outcomes under each contingency.
Conclusion — What to Do Next in 2026
The acrylic rubber market presents both defensive imperatives and offensive opportunities this year. Leaders who align procurement discipline with targeted investments in differentiated grades, while preserving tactical flexibility on capacity and energy exposure, will capture disproportionate upside. PW Consulting’s full study provides the granular segmentation, supplier-level intelligence, and transaction-ready financial models you need to convert these insights into actionable 2026 plays.
For the complete data tables, segmented forecasts, plant-level maps, and a downloadable Excel model, please consult the full report landing page. The detailed breakdowns and proprietary scorecards are intentionally reserved for the full study to preserve the integrity of our client-grade analysis and to enable tailored consulting engagements.
For detailed analysis of this topic, please visit the official page: Acrylic Rubber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Steel Market Poised for $163.6M by 2032 at 3.1% CAGR
By PW Consulting, 2026-07-09
Automotive Steel Market — Strategic Outlook for 2026: An Executive Preview
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present this executive preview of our Automotive Steel Market study to frame the decisions that will define supplier, OEM and investor success in 2026. This piece is intentionally forward-looking and diagnostic: it synthesizes macro dynamics, competitive positioning and actionable strategic options while withholding the granular segment tables that form the core of the full study. Consider this a high-fidelity trailer that demonstrates our analytical depth and the practical value of the complete report—available on our site for decision-grade implementation.
Automotive Steel Market
Market snapshot: what the headline numbers mean for strategy
Using 2025 as the analytical base year, the automotive steel market has moved from a documented industry size in 2020 through steady growth to reach USD 131.2 Million in 2025. Our forecast covers 2026–2032 and projects that the market will expand at a compound annual growth rate (CAGR) of 3.1%, culminating in a modeled market size of approximately USD 163.6 Million by 2032.
Automotive Steel Market
Two practical implications follow. First, the market is growing but not explosively—3.1% CAGR implies a need for efficiency, differentiation and share capture rather than reliance on a booming demand tailwind. Second, absolute expansion creates pockets of opportunity: premium high-strength and value-added coated products, localized supply for regional vehicle programs, and specialized processing services are likely to deliver disproportionate returns if timed to OEM electrification and lightweighting program windows.
Automotive Steel Market
Dynamics shaping 2026 decisions
-
Supply-side consolidation and concentration: Our analysis shows a concentrated supplier landscape with a small set of integrated and specialist producers controlling a meaningful share of capacity. For procurement, this means counterparty selection and contract design are strategic levers—price, allocation guarantees and service-level commitments matter as much as unit cost.
-
Raw-material and spot-price volatility: Early 2026 activity underscores persistent input-cost risk. Notably, a major North American producer announced a hot-rolled coil spot price of USD 960 per short ton in January 2026, and producers have responded with capacity reallocations. Buyers must assume price shocks and design hedging or fixed-price contracts where possible.
-
Supply allocation and capacity moves: Several suppliers announced expansions and dedicated automotive allocations in 2026. Capacity announcements that combine expansion with contractual OEM allocations mean that timing and bilateral relationships influence whether a given automaker or tier supplier secures priority access.
-
Regulatory and contractual hedging: Some firms have moved to multi-year fixed-price agreements to mitigate tariff and volatility risk for OEM customers. Procurement and legal teams should update playbooks to balance price certainty against flexibility for product specification shifts (e.g., toward higher grades for EV structures).
-
Technology diffusion: Symposiums and technical forums in 2026 expanded OEM awareness of press-hardened and advanced high-strength steels (AHSS). Firms that convert R&D into qualification and short lead-time supply capture the OEM program windows that matter for 2026–2028 vehicle launches.
Competitive landscape — positioning and likely 2026 moves
-
ArcelorMittal (Luxembourg) — A leader in advanced high-strength and coated flat-rolled products. Strategic strength: R&D pipeline and global OEM relationships for body-in-white components. Expect continued investment in press-hardening and value-added coatings to defend pricing power on premium segments.
-
Nucor Corporation (Charlotte, NC, USA) — North America’s major EAF-based producer with a sustainability and domestic-sourcing narrative. Strategic strength: flexibility and shortening supply chains. Recent price signals and a dedicated automotive allocation at a new mill indicate a push to capture program-level contracts and to influence regional pricing via capacity allocation.
-
Nippon Steel (Tokyo) and JFE Steel (Tokyo) — Japanese producers with deep OEM integrations across Asia. Strategic strength: material qualification pipelines and supply reliability. Expect continued collaboration with Japanese and Korean OEMs on AHSS and coated product series for next-wave chassis and safety systems.
-
Tata Steel (India) and China Baowu (Shanghai) — Large integrated groups emphasizing cost-competitive micro-alloyed and galvanized solutions. Strategic strength: scale and regional cost advantage. Their role in global supply chains will intensify as OEMs and tier suppliers look to diversify sourcing sources and lower billet costs.
-
POSCO (Seoul) and Hyundai Steel (Seoul) — Focused on high-performance and lightweight grades with strong OEM ties in Korea and beyond. Expect partnerships with local OEMs and expansions into coating and surface treatments to capture higher-margin opportunities.
-
Cleveland-Cliffs (Cleveland, OH) — A vertically integrated U.S. player and the largest domestic supplier of automotive steel. Recent multi-year supply contracts and supplier awards with major automakers highlight a strategic focus on long-term contractual security and value-added galvanizing capabilities for exposed panels.
-
voestalpine (Linz) — A specialist in advanced grades with a premium positioning. Strategic strength: niche, high-margin products for safety-critical components. Their playbook centers on technical collaboration and rapid qualification for specialized programs.
Across these players, the strategic tension for 2026 is between scale-driven cost advantage and capability-driven premiumisation. Firms with integrated upstream assets can hedge input swings, but adjacency plays—coating, press-hardening lines, localized slitting/galvanizing—will determine whose capacity becomes program-critical.
What the full report contains — practical outputs for 2026 action
-
Proprietary demand model (2020–2032) with scenario variants for EV penetration, lightweighting adoption and regional vehicle production shifts.
-
Price and cost modelling including raw-material pass-through mechanics, break-even curves for EAF vs. integrated producers, and sensitivity runs tied to energy and coking coal indices.
-
Supplier benchmarking and playbooks: capability maps, qualification lead-time matrices and contract templates for multi-year allocation agreements, indexed pricing clauses and capacity booking options.
-
Commercial and procurement strategies: negotiation levers, hedging instruments, and a decision tree to optimize between spot purchasing, fixed-price contracts and risk-sharing JV arrangements.
-
M&A and partnership heatmaps identifying likely consolidation targets, niche specialists for bolt-on acquisitions and strategic JV partners for regional capacity or tech transfer.
-
Operational levers for OEMs and tier suppliers: co-development frameworks, processing investment prioritization (e.g., press-hardening, galvanizing), and timelines to align with vehicle program windows.
-
Regulatory and emissions advisory: carbon accounting methodologies, low-embodied-carbon sourcing routes and decarbonization investment ROIs tied to anticipated policy shifts.
Immediate, 12-month and 24–36 month actions for 2026 executives
-
Immediate (0–6 months) : Secure allocation via multi-year supply agreements with clearly defined quality, allocation and escalation provisions. Where possible, include caps and floor pricing to mitigate sudden spot-price spikes. Prioritize qualification of one alternative supplier per key grade to preserve bargaining power.
-
12 months : Invest selectively in on-site processing or co-investment with suppliers (slitting, galvanizing, press-hardening) to reduce lead times and capture margin on value-added processing. Launch pilot projects to swap mass for cost via AHSS and tailored coatings in upcoming vehicle program launches.
-
24–36 months : Consider strategic vertical integration or long-term JV structures where scale and contract certainty provide measurable ROI—particularly for automakers seeking to localize supply and insulate programs from global shocks. Formalize carbon-reduction commitments into sourcing criteria to align with increasingly stringent OEM sustainability mandates.
Why this matters for 2026: decision urgency and the opportunity window
The market’s modest growth profile combined with supplier concentration creates a classic environment where timing and contractual design determine winners. OEMs and tier suppliers that secure material access and accelerate qualification of advanced grades will reduce program risk and create cost leverage. Meanwhile, steelmakers with the right mix of scale, technical differentiation and regional presence are positioned to convert capacity investments and contractual awards into durable revenue streams—evidence already appearing in early-2026 supply awards and capacity reallocations.
Because core program qualification cycles for vehicle launches often span 18–36 months, 2026 is a decisive year: choices made now—over supplier selection, contract structure, co-development timelines and processing investments—will materially affect program budgets, launch readiness and supplier competitiveness through 2028.
Next steps and how to access the full intelligence
This preview highlights the lines of strategic debate and the tactical responses that will matter in 2026. PW Consulting’s full Automotive Steel Market report contains the detailed segment tables, regional and application splits, supplier share matrices and downloadable financial models that operationalize the recommendations summarized above. We have intentionally withheld those granular splits from this preview to protect the actionable value of the primary research and to invite a direct engagement where we can tailor the models to your specific procurement, product and M&A priorities.
To access the full dataset, scenario models and the step-by-step playbook for supplier contracting and capacity hedging, visit our report page or contact our Automotive Materials practice. In a market defined by tight windows and concentrated supply, timely, data-driven action will be the differentiator.
For detailed analysis of this topic, please visit the official page: Automotive Steel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Insulated Lunch Box Market 2026: Strategic Preview for Executive Decision-Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused preview of our new Insulated Lunch Box Market study — a practitioner-grade intelligence asset designed to inform executive choices in 2026. This preview demonstrates the analytical depth and practical orientation of the full report while intentionally withholding core segment-level tables and proprietary splits to guide you to the complete dataset on our site.
Insulated Lunch Box Market
Why this study matters for 2026
The insulated lunch box market has transitioned from a niche accessory category into a strategic product segment sitting at the intersection of consumer health trends, sustainability policy, and supply-chain sensitivity. From 2020 to PW Consulting’s base year (2025), the global market expanded meaningfully, moving from approximately USD 130.5 million in 2020 to an estimated USD 185.0 million in 2025. Building on this momentum, our forecast shows continued growth through the 2026–2032 horizon at a compound annual growth rate (CAGR) of 6.4%.
Insulated Lunch Box Market
For corporate strategists, product managers, and M&A teams, this profile matters because the category is now large enough to justify targeted investment but sufficiently fragmented that disciplined moves — premiumization, materials innovation, channel optimization, and regulatory-readiness — can materially shift competitive position within a short window. The 6.4% CAGR over the forecast period implies both steady demand and attractive tailwinds for firms that can execute on differentiation and operational resilience.
Insulated Lunch Box Market
High-level market trajectory (what the numbers imply)
-
Historical momentum: The market recorded consistent year-on-year increases from 2020–2025, confirming structural demand drivers rather than one-off spikes.
-
Near-term continuity: The model projects a continued climb beyond the base year, with the market expanding further through 2032 under normal macro assumptions and current regulatory trajectories.
-
Concentration context: The sector remains moderately concentrated — our concentration metrics show that the top three and top five players control meaningful, but not dominant, shares. This creates room for fast-followers and niche specialists to scale quickly when they combine product excellence with smarter go-to-market moves.
Core strategic drivers shaping 2026 decisions
-
Regulatory reshaping of product compliance: Recent food-contact rules in major jurisdictions are raising the compliance bar for materials and manufacturing processes. Firms that proactively align product development and supplier contracts to these standards will avoid costly product recalls and gain trust among health-conscious consumers.
-
Trade and duty dynamics: Changes in tariff classification and duty treatment for insulated bags have already altered landed cost calculations for import-heavy portfolios. Procurement and sourcing teams must re-evaluate total landed cost models and possible near-shoring or diversification tactics to protect margins.
-
Material substitution and sustainability: Policy pressure to reduce single-use plastics, coupled with consumer preference for durable, hygienic materials, is accelerating demand for alternative constructions. Manufacturers that invest in stainless steel, verified food-safe composites, and recyclable packaging are likely to capture premium positioning.
-
Consumer behavior: The growth of at-home cooking, health-conscious meal prep, and hybrid work/school patterns sustain demand for portable, temperature-controlled meal containers. Buyers are now prioritizing leak-proof designs, thermal performance, and easy-clean materials alongside aesthetic and lifestyle attributes.
-
Channel evolution: Product discovery and purchase journeys increasingly blend e-commerce reviews, editorial testing, and social proof. Recent independent testing and review cycles spotlight how media evaluations can accelerate or erode adoption for new models within months.
Competitive landscape — who moves the market
The category features a blend of legacy consumer-goods brands, outdoor-performance players, and newer design-led entrants. Each archetype brings different strengths: manufacturing scale, premium performance engineering, sustainability credentials, or lifestyle design. Key global players included in our competitive map are examples of these archetypes and are analyzed in the full report for capability, channel mix, innovation cadence, and partnership potential.
-
Incumbent specialists: Brands with deep heritage in insulated foodware continue to compete on thermal performance and product reliability. Their advantage is brand trust and repeat purchase behavior among conservative segments.
-
Outdoor-performance incumbents: Firms historically rooted in outdoor gear extend vacuum-insulation and ruggedization expertise into lunch solutions, attacking both premium and professional user groups.
-
Design and lifestyle entrants: Companies focused on city consumers and daily commuters compete on aesthetics, convenience, and limited-edition collaborations — often leveraging direct-to-consumer channels effectively.
-
Mass-market and value players: Large diversified consumer brands and legacy outdoor manufacturers serve broad channels with cost-optimized SKUs, providing volume and channel reach that shape baseline pricing dynamics.
Our competitive profiles include company overviews, HQ locations, public positioning and product highlights. We also trace recent independent review cycles and editorial mentions that materially affect consumer perception and channel velocity. Notably, several consumer-review outlets updated comparative testing in 2025, accelerating visibility for new entrants and revised models.
Report contents — what the PW study delivers (practical, action-focused)
-
Market sizing and validated historical series (2020–2025) and baseline for 2026–2032 forecasts with scenario sensitivity to raw material and trade shocks.
-
Segment-level frameworks (by material, product type, end-use and channel) with go-to-market implications — the report intentionally reserves detailed split tables and the exact share numbers for subscribers to protect proprietary modeling and to support consultative engagement.
-
Regulatory and trade impact matrix: a playbook for procurement and compliance teams covering the latest food-contact safety rules and tariff reclassifications, and how they affect unit economics.
-
Competitor benchmarking: strategy trees for differentiated positioning — premium performance, sustainable premium, urban convenience, and volume-oriented value — including capability gaps and partnership targets.
-
Channel and pricing analytics: SKU-level pricing bands, margin pressure points, and promotional risk indicators for retailers and brand owners.
-
Go-to-market toolkits: product-roadmap templates, sampling/test protocols, and media strategy playbooks aligned to the review cycles of influential outlets.
-
M&A and partnership heatmap: targets and rationale for bolt-on acquisitions or licensing arrangements to accelerate capability build or channel access.
Strategic recommendations for executives in 2026
-
Prioritize material and compliance readiness: Map your supplier base to the latest food-contact requirements and create a prioritized upgrade plan for SKUs that face regulatory risk. Early compliance is a defensible moat in B2C and institutional channels.
-
Rebalance sourcing and landed-cost models: Use the recent tariff and classification changes as an opportunity to renegotiate supplier terms and re-run landed-cost scenarios; consider dual-sourcing for high-risk components.
-
Segment investment by return profile: Deploy R&D and marketing resources into two clear plays — high-margin premium performance products for outdoor/professional users and durable, eco-positioned ranges for health-conscious urban consumers. Volume SKUs should be optimized for cost and channel efficiency.
-
Leverage editorial and test cycles: Coordinate product launches with independent test calendars and key editorial moments. Early favorable reviews have outsized impact on DTC flow and wholesale listing velocity.
-
Prepare for consolidation opportunities: Given the market’s moderate concentration, well-capitalized players can use M&A to leapfrog capability gaps — look for targets that offer manufacturing scale, proprietary insulation tech, or direct channel access.
How to use this preview and next steps
This preview is intentionally selective. It synthesizes the structural trends, regulatory drivers, competitive archetypes, and strategic levers you need to consider in 2026 — while preserving the granular segment data and proprietary split models that form the foundation of precise decision-making. If your team needs:
-
Exact segment shares, region-by-region forecasts, SKU-level price bands, and a downloadable set of model inputs — access to the full report and dataset will provide these details.
-
Custom scenario modeling (raw-material shocks, accelerated plastic bans, rapid premiumization) — PW Consulting offers bespoke engagements to quantify outcomes and build implementation roadmaps.
-
Competitor deep dives or acquisition target screening — our advisory team can deliver prioritized lists and valuation-range matrices based on confidential client mandates.
Closing perspective
The insulated lunch box market has evolved from a functional commodity to a strategic product category shaped by health, sustainability, and performance narratives. The macro trajectory is positive and steady: the market has expanded substantially since 2020 and is forecast to continue growing at a mid-single-digit CAGR across our forecast horizon. Yet, within that growth corridor, decisive action in materials strategy, regulatory compliance, channel orchestration, and product differentiation will determine who captures disproportionate value.
PW Consulting’s full Insulated Lunch Box Market report is built to turn this high-level understanding into executable plans. For executives preparing budgets, revising product roadmaps, or assessing M&A targets in 2026, this study is designed to reduce uncertainty and accelerate decision cycles. To access the complete dataset, segment breakdowns, and our scenario tools, please visit the report page or contact our industry advisory desk for a briefing.
For detailed analysis of this topic, please visit the official page: Insulated Lunch Box Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Floor Panel Market to Reach USD 299.2M by 2032 at 6.56% CAGR
By PW Consulting, 2026-07-09
Floor Panel Market — 2026 Strategic Brief
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present this strategic introduction to our latest Floor Panel Market study. Grounded in a rigorous base year of 2025 and a forward-looking 2026–2032 forecast horizon, this brief highlights the decision-relevant intelligence executives must factor into 2026 planning cycles. The narrative demonstrates the analytical depth available in the full report while intentionally withholding granular segment-level outputs — the precise splits, channel shares and line-item forecasts are reserved for the report portal to preserve the “trailer” experience and drive direct engagement with our interactive model.
Floor Panel Market
Market trajectory you need to plan around
Our bottom-up model tracks a focused industry definition measured in USD (Million). The floor panel market expanded from approximately 143.2 million in 2020 to 195.4 million in 2025, reflecting rebound and structural demand across commercial infrastructure, data centers and flexible office refits. Looking out, we project growth to roughly 299.2 million by 2032, implying a compound annual growth rate of 6.56% over the forecast period. The step-change between 2025 and subsequent years is driven by concentrated investment in resilient, serviceable flooring systems that integrate cabling, airflow management and sustainability credentials.
Floor Panel Market
Note: broader industry publications cite larger aggregate valuations for the “flooring” universe (for example, industry sources report a global floor panels market in the multi-billion-dollar range in 2025). PW Consulting’s scope isolates market activity consistent with the product and application definitions used throughout our modeling — a clarity that delivers actionable, enterprise-grade insights for capital allocation and product strategy.
Floor Panel Market
Why this study matters for 2026 corporate decisions
-
Timing and capital allocation: With 2026 budgets being finalized, the trajectory embedded in our 2026–2032 scenarios helps boards and business unit leaders justify or re-prioritize investment in manufacturing capacity, digital configuration tools, and service platforms.
-
Procurement and supply-chain resilience: Raw-material sourcing and supplier concentration are primary cost and lead-time risks. Our analysis identifies where procurement concentration and regulatory standards are likely to exert the greatest pressure on lead times and margin stability.
-
Product, specification and standards alignment: Compliance regimes (notably EN ISO 20326:2018 and its subsequent A1:2020 amendment) are raising entry barriers for loose-laid and certain engineered systems. Specification-driven procurement in commercial and mission-critical applications means manufacturers who can demonstrate certified compliance will capture disproportionate value.
-
Go-to-market design: The convergence of modularity, low-profile systems and integrated cable/airflow features is reshaping buyer requirements — particularly among data-center operators and flexible-office landlords. The study transforms these trends into executable GTM and commercialization playbooks.
What the full report delivers — a practical toolkit for executives
-
Market sizing and validated forecasts (2020–2025 historical; 2026–2032 forward) built from primary interviews, capacity-mapping and transactional datapoints.
-
Scenario suite: base, upside, downside and disruption cases with sensitivity to raw-material price shocks, regulatory tightening, and accelerated green-spec adoption.
-
Modularity and product roadmaps: specification checklists, performance trade-off matrices (load vs. acoustics vs. ventilation), and quick-win product changes to increase sell-through and margin capture.
-
Channel and commercial playbooks: specifier engagement templates for architects and MEP consultants, distributor incentive models, and installer enablement programs optimized for 2026 procurement cycles.
-
Supplier scorecards and concentration heat maps that identify single-source risks and near-term disruption vectors across polymer, metal and composite inputs.
-
M&A and partnership screen: capability-first criteria for targets that accelerate access to high-growth applications or deliver fill-in capabilities (e.g., ventilation-ready panels, low-profile systems, or zero-VOC laminated ranges).
-
Interactive dashboards and an accompanying financial model that allow users to test custom scenarios and evaluate the P&L impact of strategic choices.
Key themes and strategic implications
-
Demand concentration in infrastructure-sensitive applications. Investment in mission-critical environments (e.g., data centers) and high-availability commercial spaces is a major demand engine. These buyers prioritize serviceability, airflow management and certified fire/structural performance over lowest-cost solutions.
-
Material and design differentiation are decisive. Lightweight metals, engineered wood cores and calcium-based composites each offer distinct value propositions. Manufacturers that can combine performance with sustainability credentials (e.g., low VOCs, recycled content) will gain specification advantages.
-
Standards compliance is a gatekeeper. EN ISO 20326 and its amendments are increasingly referenced by architects and procurement teams; compliance is non-negotiable for high-margin specifications.
-
Service orientation expands margins. Warranty upgrades, on-site maintenance contracts, and predictive maintenance enabled by sensor integration convert commoditized panels into annuity-like services.
-
Market structure remains fragmented. Despite some national champions and specialized exporters, the top-three and top-five manufacturers account for a relatively modest share of total market revenue — a dynamic that preserves M&A opportunities for consolidation and capability plays.
Competitive landscape — focused profiles and strategic inference
-
Tate Access Floor (Columbia, MD, USA) : Tate’s ConCore® raised access panels are positioned as premium solutions for commercial office and data center segments, with variants engineered for heavy loading and integrated ventilation. Their strategy emphasizes certified performance, specification-driven sales and sustainability features. Strategic implication: Tate should continue deepening specifier relationships, extend service contracts for mission-critical applications, and invest selectively in ventilation-enabled R&D to protect premium unit economics.
-
FreeAxez (Delran, NJ, USA) : FreeAxez markets low-profile modular steel systems designed for flexible workspaces, emphasizing integrated cable management and rapid reconfigurability. This proposition aligns with hybrid-office trends and end-user demand for agility. Strategic implication: FreeAxez can scale by building installer networks, licensing modular sub-assemblies to global partners, and adding digital configuration tools that reduce specification friction.
-
Swiss Krono (Menznau, Switzerland) : Known for high-quality laminated panels with zero-VOC options, Swiss Krono competes on durability, indoor air quality and installation flexibility—attributes prized in commercial fit-outs. Strategic implication: Swiss Krono’s pathway to higher value lies in expanding European spec channels, integrating circular-sourcing claims and certifying products for leading green building programs.
Recent industry association activity underscores shifting supply-chain relationships: in May 2026 several upstream and downstream players joined major trade associations, signaling both consolidation of specification dialogue and potential collaboration on compliance and sustainability initiatives. For manufacturers and buyers, these moves can shorten time-to-standardization or accelerate raw-material alignment — both of which affect 2026 procurement choices.
Decision playbook for 2026
-
Prioritize product lines that combine serviceability and compliance. Shift R&D emphasis to ventilation-ready and low-profile systems where ROI timelines match procurement cycles.
-
Lock in strategic suppliers where single-source risk is material. Negotiate long-term agreements with key polymer and metal suppliers and build dual-sourcing options for critical inputs.
-
Commercialize services alongside products. Pilot maintenance-as-a-service offerings in one major account to validate pricing and operational models.
-
Target bolt-on acquisitions that fill capability gaps (e.g., sensor integration, modular pedestals, or installer networks) rather than purely revenue-dilutive roll-ups.
-
Operationalize compliance: institute a certification roadmap tied to product launch milestones and integrate compliance checkpoints into warranty and contract language.
Why PW Consulting’s study is different
Our report blends primary commercial intelligence, supplier and installer interviews, and a transaction-level model calibrated to 2020–2025 observed performance and a 2026–2032 forecast calibrated to macro and micro indicators. The study provides an executable playbook — not just high-level views — including procurement templates, M&A screens and a live financial model. For executives preparing 2026 capex requests, GTM shifts or M&A dossiers, the report converts trend signals into dollarized outcomes and operational checklists.
To preserve the consultative value of the work and to guide senior buyers toward tailored insights, we reserve granular segmentation tables and the complete dataset for the report portal. Readers seeking specific regional, type and application splits — and the downloadable scenario model used to generate the forecasts above — should access the PW Consulting report center for full access and an onboarding walkthrough by our analyst team.
In closing: 2026 will be a year of selective investment and specification-led competition in the floor panel market. Executives who blend product compliance, service monetization and supply-chain resilience into their strategic plans will turn the market’s growth trajectory into durable competitive advantage.
For detailed analysis of this topic, please visit the official page: Floor Panel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Paracetamol market to reach USD 15.3B by 2032, growing at 4.5% CAGR
By PW Consulting, 2026-07-09
Paracetamol Market — Strategic Preview for 2026 Decision Makers
PW Consulting’s latest Paracetamol Market study (base year: 2025; historical coverage: 2020–2025; forecast: 2026–2032) frames the commercial and operational choices that will determine winners and laggards through the next planning cycle. At the headline level, the global market is estimated at USD 11,500 Million in 2025 and is projected to grow to approximately USD 15,300 Million by 2032, tracking a compound annual growth rate (CAGR) of about 4.5% over the forecast horizon. This briefing summarizes the strategic implications of that trajectory, outlines the macro risks and opportunities that will shape 2026 decisions, and previews the practical, decision-ready outputs contained in the full PW Consulting report. (Note: this article intentionally omits detailed segment-level figures and regional splits; those are available in the complete study.)
Paracetamol Market
Why this research matters for 2026
-
Supply risk has migrated from academic concern to boardroom priority. Raw-material concentration and geopolitical instability mean procurement, inventory and contract strategies must be rethought now, not later.
Paracetamol Market -
Regulatory and labeling changes in major markets are shifting cost structures for finished products — companies that anticipate and internalize these changes gain a pricing and margin advantage.
Paracetamol Market -
Product- and channel-level innovation (e.g., orodispersible formats, pediatric formulations) are creating differentiated revenue pools despite a broadly stable market growth rate. Execution speed matters.
Interpreting the headline numbers: growth with structural asymmetry
A CAGR of 4.5% implies steady, mid-single-digit expansion of the total Paracetamol market across 2026–2032. In absolute terms the market climbs from the 2025 baseline (USD 11.5 billion in revenue terms, reported in USD Million) toward a roughly USD 15.3 billion total by 2032. That trajectory is healthy for incumbents and new entrants alike, but it masks heterogeneity: growth drivers are concentrated around specific dosage forms, regulatory categories and patient groups, while other areas remain volume-stable or face pricing pressure. The full PW Consulting study decomposes the headline into operationally-relevant scenarios — including upside and downside demand pathways tied to clinical findings, pediatric guidance and pandemic-resilience behaviour — enabling executives to size investments and timing with confidence.
Key dynamics shaping supply and pricing in 2026
-
Raw-material concentration: The predominant intermediate for Paracetamol, para-aminophenol (PAP), remains heavily concentrated in China. Public reporting cites China’s dominant role in PAP supply and meaningful direct-import dependency in several large markets. That concentration transmitted vulnerability in 2025 and 2026, and it will continue to shape procurement bargaining power and lead times.
-
Supply shocks and logistics: 2025–2026 supply events — including export control measures and regional conflicts causing vessel shortages — produced material upward pressure on precursor and API pricing in key manufacturing hubs. Certain markets reported raw-material price increases exceeding 20% in short windows, forcing manufacturers to make quick choices between margin compression and price increases.
-
Domestic policy and pricing regimes: In price-sensitive markets, national agencies and production-linked incentives materially influence final market prices. Recent policy interventions have accelerated price volatility for manufacturers that source ingredients opportunistically.
-
Regulatory cost inflation: Amendments to monographs and labeling requirements in major jurisdictions in 2026 create additional fixed and per-unit compliance costs. These are predictable and quantifiable, and they will disproportionately affect companies with thin OTC margins or complex product portfolios.
Competitive landscape — implications for strategy
Market concentration is moderate: the three largest groups account for roughly 35% of the market while the five largest account for around 45%. This structure supports both scale advantages and differentiated plays by agile mid-sized players.
-
API- and volume-centric producers (examples include Granules India Limited, IOL Chemicals & Pharmaceuticals, and Farmson Pharmaceutical) retain cost and scale advantages in high-volume finished-dosage supplies. Their strategic levers include backward integration, capacity scheduling and long-term offtakes for precursors.
-
Integrated global pharma and branded OTC players (examples include Sun Pharmaceutical Industries, Cipla, GSK and Sanofi) combine marketing reach, formulation capability and regulatory expertise. These firms are well-positioned to monetize premium formats, combination products and brand trust in consumer segments.
-
Regional producers such as Mallinckrodt have legacy positions in specific markets; their strategic responses vary from portfolio rationalization to selective partnerships.
Recent clinical and safety literature published in 2025–2026 (including bioequivalence studies for orodispersible formulations and meta-analyses on prenatal safety) has reduced some demand risk and opened product innovation windows. The full report synthesizes these developments into demand-impact matrices for different end-user channels (OTC retail, hospital, pediatric care), enabling forward-looking SKU and channel strategies.
Operational playbook: immediate and near-term moves
Companies that treat 2026 as a year for both defense and selective offense will materially outperform peers. Below is a practical six-month roadmap that our consulting teams have operationalized with clients in adjacent therapeutic categories.
-
Supply audit and concentration mapping — map supplier tiers for PAP and API; quantify single-point-of-failure exposure; identify alternate sources and their certification timelines.
-
Secure strategic inventory and forward buys — implement staged forward purchasing tied to price collars and supplier performance; prioritize continuity of supply over near-term unit-cost minimization where customer disruption risk is high.
-
Regulatory cost pass-through modeling — run bottom-up scenario models that incorporate monograph and labeling cost increments to determine optimal price adjustments by channel and geography.
-
Accelerate product differentiation — fast-track orodispersible and pediatric formats where clinical and bioequivalence data reduce go-to-market friction; align marketing with recent safety literature to rebuild/extend consumer confidence.
-
Partnerships and targeted M&A — identify bolt-on API capacity or contract manufacturing organizations (CMOs) that close critical supply gaps; consider joint-venturing with local players in constrained geographies to mitigate trade policy risk.
-
Scenario-based commercial planning — create three demand/price scenarios (base, upside, downside) tied to precursor availability and regulatory cost shifts; link P&L and cashflow plans to each scenario with trigger-based decision rules.
What the PW Consulting report delivers — practical outputs for 2026 planning
The full PW Consulting study is expressly designed for executives and strategy teams who must translate macro trends into executable plans. Core deliverables include:
-
Market model and multi-scenario forecasts by geography, product type and application for 2026–2032 (base year 2025);
-
Supplier heatmaps and risk scoring for precursors (PAP) and API; procurement and inventory playbooks with contract templates and hedging options;
-
Regulatory impact analysis with cost estimates for labeling and monograph changes in major markets;
-
Competitive diagnostic and capability matrix for the principal global and regional players (profiles, strategic posture, likely moves);
-
Commercial scenarios linking clinical-safety study outcomes to demand elasticity and pricing power; and
-
M&A target-screen and integration checklist focused on de-risking supply and accelerating access to premium formulations.
To preserve the strategic value of this briefing and to ensure commercial sensitivity, we have withheld the granular tables and segment revenue splits in this preview. The full dataset — including detailed regional and application-level revenue series, pricing bands and supplier cost curves — is available in the complete PW Consulting report.
Final strategic takeaway
Paracetamol remains a core, high-volume category with predictable headline growth. But the next three years will be defined less by demand growth than by who secures resilient supply chains, anticipates regulatory cost shifts and moves fastest to capture differentiated product premiums. At a headline CAGR of 4.5% and with the total market expanding from the USD 11.5 billion baseline in 2025 toward USD 15.3 billion by 2032, the winners will be those who treat procurement and regulatory strategy as central to commercial planning, not as back-office functions.
PW Consulting’s Paracetamol Market report converts these strategic imperatives into an executable plan — from immediate procurement and inventory moves to a multi-year M&A and innovation roadmap. For teams planning budgets, capital allocation or M&A in 2026, the study provides the quantitative models and qualitative playbooks to convert market knowledge into competitive advantage.
For detailed analysis of this topic, please visit the official page: Paracetamol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: X-Ray Security Scanner Market — 6.5% CAGR to USD 11.5B by 2032
By PW Consulting, 2026-07-09
X-Ray Security Scanner Market: Strategic Imperatives for 2026 Decision-Makers
As organizations re-evaluate security postures and capital expenditure plans in 2026, the X-Ray security scanner sector is emerging from steady maturation into a phase of selective, high-value replacement and capability expansion. PW Consulting’s X-Ray Security Scanner Market study (base year 2025; forecast to 2032) quantifies that transition and translates it into concrete decision levers for procurement, operations, and technology strategy. The market is forecast to grow at a compound annual growth rate (CAGR) of about 6.5% from the 2025 base, expanding from a mid‑single‑digit billion USD market in 2025 toward roughly an eleven-plus billion USD market by 2032. This briefing highlights the strategic value of the research for 2026 plans while deliberately withholding the granular tables and segment-level figures reserved for the full report.
X-Ray Security Scanner Market
Why this research matters for 2026
-
Timing and scale: Organizations contemplating checkpoint and cargo screening investments in 2026 must reconcile near-term regulatory pressures with multi-year modernization timelines. Our market sizing shows a steady upward trajectory, signaling both continued replacement cycles and pockets of greenfield demand that can justify immediate procurement.
X-Ray Security Scanner Market -
Procurement lens: The study converts macro growth into procurement playbooks—when to accelerate purchases driven by regulation, when to delay for newer CT models, and when to consider retrofit or service-augmentation options that preserve capital.
X-Ray Security Scanner Market -
Risk-to-reward frame: With modest market concentration (CR3 and CR5 metrics indicating a broadly competitive supplier field), buyers gain negotiating leverage but must manage supplier reliability, certification timelines, and after-sales service risk—each addressed in the report’s supplier risk matrix.
Market snapshot (concise, decision-focused)
-
Base year context: The research uses 2025 as the analytical baseline. The market in 2025 sits comfortably in the single-digit billion USD range and is projected to expand to the low double-digit billion range by 2032 under the central scenario.
-
Growth tempo: A 6.5% CAGR through the forecast period reflects steady replacement cycles, technology refresh (notably CT and 3D imaging adoption), and growth in cargo and border screening use cases.
-
Concentration: Market concentration is modest; the top three and top five vendors together account for only a quarter or so of the market, indicating fragmented demand and opportunities for niche innovation and regional players.
Key dynamics shaping 2026 strategy
-
Regulation as a primary accelerant: New rules requiring volumetric imaging for heavier freight and related mandates are reshaping the upgrade road map of logistics hubs and airports. The report models the timing and regional velocity of regulatory-driven replacements so you can prioritize deployments.
-
Public funding cycles and procurement windows: Government allocations and programmatic buys (notably in aviation security) create multi‑year procurement windows. Our scenario work clarifies how to align supplier discussions and delivery schedules to avoid capacity bottlenecks.
-
Cost differentials by technology: Computed Tomography (CT) checkpoint machines command materially higher per‑unit pricing and total cost of ownership than legacy dual‑view tunnels—an economic reality that drives hybrid strategies (CT for high‑risk streams, tunnels for throughput-intensive lanes). The report provides TCO models that capture acquisition, maintenance, and throughput trade-offs.
-
Privacy and public acceptance: Privacy objections have curtailed some detection modalities, accelerating adoption of millimeter-wave alternatives in public venues. Our analysis maps social acceptance risks against technology choices for commercial and stadium operators.
-
Supply-chain and trade policy effects: Recent tariff shifts have prompted re-evaluation of sourcing strategies for pallet and container scanners. The research includes scenario-based supplier sourcing plans and mitigation steps for procurement leaders.
Competitive landscape — what to watch
The vendor map is diverse, with established defense and industrial players, specialized imaging firms, and growing niche innovators. The full report contains vendor scorecards, capability matrices, and procurement‑suitable shortlists. Below are high‑level profiles of vendors that consistently influence competitive dynamics and procurement outcomes.
-
Rapiscan Systems (United States) — Known for integrated baggage and vehicle inspection platforms and mobile threat detection capabilities. Recent order activity and product certifications signal continued demand for their mixed portfolio.
-
Smiths Detection (United Kingdom) — A long‑standing checkpoint and cargo X‑ray provider whose HI-SCAN and SDX families remain relevant to airport and freight screening modernization programs.
-
L3Harris Technologies (United States) — Brings defense-grade screening systems to aviation and security markets; strong systems integration capabilities make them a go‑to for complex deployments.
-
Nuctech Company Limited (China) — Competes across airports and cargo with high‑throughput systems; competitive pricing and broad product lines influence purchasing dynamics in multiple regions.
-
Gilardoni S.p.A. (Italy) — European supplier specializing in baggage and parcel x‑ray scanners with a focus on tailoring to commercial and postal screening needs.
-
3DX‑Ray (United Kingdom) — Niche player focused on portable and cabinet scanners, useful for specialized frontline and secondary inspection applications.
-
Analogic Corporation (United States) — Provides advanced imaging technology; their solutions are relevant where imaging fidelity and algorithmic processing matter most.
-
Leidos (United States) — Systems integrator with a broad security portfolio; useful in multi‑vendor, programmatic procurements requiring integration and managed services.
-
Astrophysics Inc. (United States) — U.S.-made scanners for mission‑critical infrastructure with an emphasis on robustness and serviceability.
-
VOTI Detection (Canada) — Offers 3D perspective imaging focused on borders and cargo screening where dimensional analysis and automated detection are mission‑critical.
Recent vendor developments in 2026 (orders and certifications) underline two important points: there is active procurement momentum across governments and logistics operators, and certification pathways remain a differentiator for market access. Procurement teams should verify certification roadmaps when evaluating suppliers.
What PW Consulting’s report delivers (operational and strategic tools)
-
Market sizing and validated forecast to 2032 with transparent methodology—useful for capital planning and board-level forecasting.
-
Procurement playbooks—when to buy, when to lease, and when to phase-in CT versus tunnel upgrades based on throughput, risk profile, and budget cadence.
-
Vendor scorecards and negotiation levers—technical and commercial criteria prioritized by deployment archetype (airport, cargo hub, border crossing, commercial venue).
-
TCO and ROI models—configurable worksheets that let you stress-test scenarios (e.g., increased freight volumes, accelerated regulatory compliance timelines, tariff shocks).
-
Regulatory and certification tracker—mapping of regional mandates and the certifications that unlock procurement funding and airport deployment windows.
-
Supply‑chain resilience playbook—practical steps to de‑risk sourcing and installation schedules, and to manage lead‑time volatility for critical sub‑assemblies.
-
Technology deep dives—comparative analysis of CT, dual‑view tunnels, millimeter‑wave, and 3D perspective systems, including algorithmic detection trends and integration pathways for AI‑based threat detection.
-
Case studies and buyer checklists—real deployments that show cost elements, timelines, stakeholder alignment, and operational outcomes.
How to use this research in 2026 decision cycles
-
Prioritize regulatory-driven upgrades: Use the report’s regulatory timing overlays to sequence purchases and avoid premium rush pricing during concentrated program buys.
-
Adopt hybrid technology strategies: Where throughput is paramount, balance CT investment with optimized tunnel deployments; the report’s TCO tools make these trade-offs explicit.
-
Design procurement windows around supplier capacity: Our vendor capacity mapping helps avoid delivery slippage and identify alternative suppliers that meet certification needs.
-
Manage lifecycle costs actively: Include maintenance, software upgrades, and training in multi‑year budgets—our scenario analysis quantifies the impact of different post‑warranty support models.
-
Build privacy and public engagement into rollouts: Anticipate social objections and include mitigation (privacy-enhanced modes, opt‑out options, communication plans) as part of deployment approval packages.
Next steps and how the full report helps
This briefing is intended as an executive preview that surfaces the strategic insights procurement and security leaders need to act in 2026. The full PW Consulting X-Ray Security Scanner Market report contains the granular segmentation tables, interactive dashboards, procurement-ready vendor shortlists, and downloadable financial models that operational teams will use to execute. To move from insight to action, stakeholders should pair the report’s scenario outputs with internal workload forecasts and certification requirements—and sequence procurements to align with both regulatory deadlines and supplier lead times.
For teams preparing 2026 procurement cycles, the report is specifically designed to: reduce decision uncertainty, shorten procurement evaluation time, and demonstrate the ROI of alternative deployment paths. Request access to the full dataset and the procurement playbooks to convert this market momentum into durable security capability upgrades.
For detailed analysis of this topic, please visit the official page: X-Ray Security Scanner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
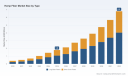
Hemp Fiber Market 2026 Briefing: Strategic Imperatives for Leaders
As PW Consulting’s senior industry analyst, my objective in this briefing is to translate our latest Hemp Fiber Market research into the decision frame that matters most for executives planning moves in 2026. The market is transitioning from niche to scale: after rising from roughly USD 0.4 billion in 2020 to an estimated USD 1.8 billion in 2025 (base year), modelled growth projects the market to reach the mid-single-digit billions by the early 2030s under an 18.5% CAGR. Those headline dynamics matter, but the value for busy leaders is practical line-of-sight: where to allocate capital, how to design resilient supply chains, and which commercial partnerships and capabilities will determine winners over the next 24 months.
Hemp Fiber Market
Why this study matters for 2026 decision-making
-
Clarity in a high-growth window: The market’s compound annual growth rate near 18.5% creates a compressive time frame in which scale and market access matter disproportionately. Late entrants face not only higher cost of capture but increasing technical and regulatory barriers to entry.
Hemp Fiber Market -
Intersection of agriculture, industrial processing and textiles: Hemp fiber is not a single-technology play; it requires orchestration across farm production, decortication/processing, fiber refinement, and end-market integration (textiles, composites, construction and specialty industrial uses). Decisions that ignore any node in this value chain create downstream margin leakage.
Hemp Fiber Market -
Regulatory inflection points: Federal and state policy changes in 2025–2026 materially alter commercial viability and compliance cost structures. Firms that align strategy to the evolving regulatory landscape unlock faster go-to-market than those that react after the fact.
Market trajectory — a strategic reading
Our topline model uses 2025 as the base year. The market expanded rapidly during 2020–2025, reflecting both new processing capacity and growing end-market adoption. The forecast through 2032 shows continued acceleration driven by textile re-shoring, increasing use of natural fiber composites in mobility and construction, and premiumisation in sustainable apparel. For corporate leaders this means a two-tier decision horizon: tactical investments to secure feedstock and processing capacity in 2026–2027, and strategic investments (R&D, brand partnerships, and plant scale) for 2028 onward.
Key demand and supply dynamics (executive summary)
-
Demand drivers: Sustainability mandates in apparel and automotive sectors, rising consumer preference for natural-fiber content, and regulatory encouragement for low-carbon building materials are collectively broadening demand beyond legacy niche buyers.
-
Supply evolution: U.S. open-field fiber hemp production is rising—our reference data shows production increasing in 2025, with measured growth and an average grower price signal that keeps raw material economics attractive for processors and composite manufacturers.
-
Processing bottlenecks: Decortication and fiber refinement capacity remains the gating factor. Investments in low-impact technologies that can produce textile-grade fibers at scale are the differentiator between commodity and premium product strategies.
-
Fragmented supplier base: Market concentration is low; the top three players capture only about a quarter of the market, and the top five roughly one-third. This fragmentation creates opportunities for consolidation and for buyers to secure preferential supply via partnerships and offtake agreements.
Regulatory and policy context — immediate implications
-
Enforcement timing matters: USDA’s delayed enforcement of DEA-registered laboratory testing until December 31, 2026, effectively creates a short window of regulatory uncertainty. Firms should plan compliance upgrades but can use the delay to test and scale traceability, lab partnerships, and QA workflows.
-
Farm Bill language: Draft 2026 Farm Bill provisions that clarify industrial hemp as an agricultural commodity are likely to reduce producer-level regulatory burdens. This will encourage farm acreage expansion and vertical integration by processors seeking feedstock security.
-
State-level variance: States are moving at different paces on retail registration and labeling. Firms scaling to new states must account for asymmetric compliance processes and potential product-retail restrictions.
Competitive landscape — strategic profiles and recent moves
The market’s present structure includes vertically integrated firms, specialized processors, and technology-driven textile startups. The competitive landscape is best read as a set of capability clusters rather than pure product players: (1) raw-material aggregators and decorticators, (2) refinement and textile innovators, and (3) downstream integrators focusing on composites and construction systems.
-
IND HEMP, LLC (Fort Benton, Montana): A decortication and export-oriented operator that has been active in building trade relationships with textile manufacturers in Asia. Recent April 2026 MOU activity to integrate U.S.-grown fiber into Vietnam’s textile supply chain signals a play to bridge premium U.S. feedstock with cost-competitive downstream textile capacity.
-
American Hemp, BastCore, Hemp Inc., BaFa, Konoplex (U.S.): These players emphasize vertical integration—scaling decortication and processing while pursuing offtake with textile and construction customers. Their strategy centers on securing feedstock, optimizing processing yields, and reducing unit costs per kilogram of usable fiber.
-
Canvaloop & Ecofibre : Technology-led incumbents focused on low-impact conversion and textile-grade outputs. Product launches and IP around waste-to-fiber processes position them as suppliers for premium yarn and fabric producers.
-
Dun Agro Hemp Group & Cavac Biomateriaux (Europe): European processors and materials specialists that emphasize construction and composite systems, offering partnership potential for market entrants seeking regional manufacturing capacity and regulatory know-how.
Recent signals to watch: capacity expansions (e.g., new textile plants aimed at U.S. hemp fiber adoption), product launches of textile-grade yarns, and trade shows where technologies for decortication and refined fiber are showcased. These are early indicators of which players will move from pilot to industrial scale in 2026–2027.
Strategic playbook — recommended actions for 2026
-
Secure feedstock through diversified offtake and tolling agreements. Given rising production and remaining processing capacity constraints, buyers should lock in multi-year procurement agreements but avoid single-source dependency.
-
Invest selectively in processing intelligence. Rather than building large decortication plants outright, consider strategic minority investments in technology providers or capacity-as-a-service models that can scale with demand.
-
Pursue co-development with textile and composite manufacturers. Early-stage product integration and co-design reduce time-to-market and allow firms to codify quality specs that become de facto industry standards.
-
Operationalize regulatory readiness. With federal and state rules in flux, dedicate a compliance pod to track lab-testing requirements, labeling rules, and cross-border documentation to prevent costly market access delays.
-
Design for modular expansion. Capex in 2026 should favor modular plants and flexible processing lines to pivot between textile-grade and industrial-grade outputs as demand signals solidify.
Risks and watchlist for C-suite
-
Regulatory reversals or tightening: If federal enforcement timelines change or state-level restrictions proliferate, markets and offtake timelines could be disrupted.
-
Quality and standardization shortfalls: Inconsistent fiber quality and lack of agreed industry standards can slow adoption by mainstream textile and automotive OEMs.
-
Feedstock concentration shocks: Weather events or input-price volatility at the farm level could create short-term scarcity and margin pressure; hedging and geographic diversification are essential mitigants.
-
Competitive consolidation: Roll-ups by stronger cash-rich players could change the negotiating landscape quickly; mid-sized players should be clear about exit or scale-up thresholds.
What the full PW Consulting report delivers (practical scope)
-
Granular demand modelling by application pathways and adoption scenarios through 2032, with sensitivity analysis under alternative policy outcomes.
-
Capex and Opex benchmarking for decortication, refining and textile conversion, with unit economics for common plant sizes and processing technologies.
-
Supplier and buyer due-diligence templates and a playbook for structuring offtake and tolling agreements tailored to hemp fiber.
-
Competitive profiles with capability matrices, patent and technology mapping, and M&A heatmaps to support inorganic growth decisions.
-
Regulatory scenario planning tools and a compliance roadmap aligned to USDA, state-level requirements and likely Farm Bill outcomes.
To preserve the report’s commercial value and to respect partner confidentiality, this briefing intentionally omits detailed split data across regions, finer application percentages, and proprietary segment-level revenue tables. Those elements—critical for transaction diligence and operational planning—are available in the full report.
Concluding guidance
2026 is a make-or-break year for organizations aiming to lead in the hemp fiber value chain. The macro trajectory—marked growth from a small base and an 18.5% CAGR—creates high reward for the firms that combine supply security, processing capability, and early partnerships with textile and composite buyers. Companies that move too slowly risk being commodity suppliers to a set of integrated players that already control scale processing and preferential trade channels.
If your board’s 2026 agenda includes new materials, low-carbon product lines, or sustainable sourcing commitments, treating the hemp fiber market as a strategic growth frontier—not a tactical experiment—will materially change outcomes. PW Consulting’s full Hemp Fiber Market report provides the data, operational tools, and negotiation templates you need to convert opportunity into competitive advantage. Contact our research access desk to obtain the complete dataset and modelling workbooks that support the recommendations outlined here.
For detailed analysis of this topic, please visit the official page: Hemp Fiber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


