



Category: market research
PW Consulting: Gunshot Detection Market to Reach USD 2,254M by 2032 at 11.8% CAGR
By PW Consulting, 2026-07-09
Gunshot Detection Systems Market: Strategic Imperatives for 2026
As organizations reassess security postures in a post-pandemic, geopolitically fraught environment, gunshot detection systems (GDS) have moved from niche military and tactical use-cases to mainstream components of public safety and critical-infrastructure protection. PW Consulting’s latest market study — anchored on a 2025 base year and projecting through 2032 — quantifies a market mid‑cycle that is both fast-growing and strategically fragmented: the global GDS market is projected to grow at an 11.8% CAGR, rising from approximately USD 1.04 billion in 2025 to over USD 2.25 billion by 2032.
Gunshot Detection Systems Market
Why this study matters for enterprise decision-makers in 2026
-
Timing: 2026 will be a pivotal procurement year for municipalities, school systems, transit authorities, and commercial operators. Several funding streams and regulatory requirements are converging, creating windows of accelerated deployment — but winners will be those who align technology selection with operational workflows and funding cycles.
Gunshot Detection Systems Market -
Risk & resilience: Organizations that view GDS as an isolated sensor purchase will underperform. The rapidly maturing market rewards integrators who can combine acoustic/energy sensing, AI-driven event classification, video-forensics linkage, and automated response orchestration.
Gunshot Detection Systems Market -
Competitive positioning: Technology vendors now differentiate on multi‑mode sensing, ML-backed false-positive reduction, and platform openness. Buyers who insist on validated performance metrics, supply‑chain traceability, and clear upgrade paths will preserve long‑term value.
Market trajectory — a high‑growth, consolidating landscape
From a purely numerical standpoint, the GDS market demonstrates sustained expansion. With a 2025 base estimated at about USD 1.04 billion, forecasted growth at an 11.8% CAGR drives a market size surpassing USD 2.25 billion by 2032. This doubling-plus trajectory is not evenly distributed across use-cases; instead it reflects accelerating civilian adoption of military‑grade sensing, the scaling of urban deployments, and the emergence of perimeter and vehicle-mounted solutions that unlock new addressable markets.
Concentration metrics further refine this picture: the market displays a mid-to-high level of consolidation, with the top three vendors controlling a significant share of commercially deployed systems and the top five commanding a larger majority. In practice, that means large incumbents shape procurement standards and channel structures, while innovative challengers push the envelope on algorithmic performance and integration flexibility.
Forces shaping 2026 procurement decisions
-
Regulatory gating and certification: Certification pathways — notably the DHS SAFETY Act in the United States and formal equipment cataloguing requirements in the UK — increasingly determine eligibility for government and critical infrastructure contracts. Vendors lacking these certifications face substantial market access barriers.
-
Public funding & reimbursement: Federal and sub‑national grant mechanisms, such as Bureau of Justice Assistance programs, remain central to deployment economics in jurisdictions prioritizing crime‑reduction interventions. Effective bid strategies will routinely couple technology proposals with reimbursement roadmaps.
-
Shift from acoustic-only to fused sensing: Multi‑mode systems that combine acoustic, infrasound, infrared, and energy-based detection — paired with edge AI to reduce false positives — are moving from R&D demos into fielded solutions. Buyers should prioritize architectures that offer sensor fusion and open APIs to avoid vendor lock‑in.
-
Integration with operational ecosystems: The strategic value of GDS is realized when events are operationalized — integrated with access control, video management systems, CAD dispatch, and mass notification platforms. Procurement decisions in 2026 should require demonstrable end‑to‑end workflows, not just sensor performance specs.
Competitive landscape — incumbents, challengers, and the innovation frontier
The competitive field combines legacy defense contractors, specialized sensor manufacturers, and software-centric AI firms. Several illustrative vendor archetypes emerge:
-
Defense-origin incumbents: Companies with military pedigrees bring hardened, field‑proven products and established government channels. Their strengths include ruggedized platforms, tested localization algorithms, and procurement familiarity with defense buyers.
-
Commercial innovators: Firms that began in civilian markets have prioritized false‑positive reduction, cloud‑native analytics, and integrated emergency workflows. Their pace of feature delivery and customer experience orientation make them attractive to institutional buyers.
Key players profiled in our study exemplify these archetypes and the strategic moves to watch:
-
ACOEM Group — With a focus on acoustic threat detection, ACOEM has advanced single‑sensor intelligence engines that enrich situational awareness for critical infrastructure and law enforcement buyers.
-
EAGL Technology — An energy-based detection specialist that emphasizes adaptive response and direct integration with access control and video systems; regulatory approvals have strengthened its government market candidacy.
-
Hyperion Technology Group — Focused on infrasound sensing, Hyperion targets military and industrial applications where long‑range detection and environmental robustness are critical.
-
QinetiQ — Known for soldier‑worn localization systems, QinetiQ’s deployed unit volumes and combat‑proven heritage make it influential in defense procurement circles and in technology transfer to civilian contexts.
-
Raytheon — A defense prime with vehicle‑mounted and tactical solutions, Raytheon continues to iterate on threat response features for mission critical platforms.
-
Shooter Detection Systems (SDS) — SDS has broadened from indoor solutions to perimeter systems, leveraging multi‑mode sensing and machine learning; its recent product introductions and industry recognition underscore rapid product evolution.
-
SoundThinking (formerly ShotSpotter) — A market pioneer in city‑scale acoustic detection, it continues to expand AI capabilities and law‑enforcement integrations, shaping expectations for municipal deployments.
-
Safety Dynamics — A specialist focused on public safety applications, contributing to the diversity of product offerings available to institutional buyers.
Recent product launches and platform upgrades (including multi‑mode perimeter systems and enhanced acoustic intelligence engines) illustrate a market where innovation is both rapid and operationally driven. For buyers, this means procurement cycles must include performance validation in representative environments rather than reliance on lab claims.
Operational & procurement playbook for 2026
-
Define outcomes before technology: Start with incident‑to‑resolution workflows. Specify how an alert becomes a verified event, how it propagates through command and control, and what success metrics (response time, false alarm rate reduction, evidence capture) will govern acceptance.
-
Insist on measurable performance: Require vendors to demonstrate detection/localization accuracy and false‑positive rates under portfolio‑relevant conditions. Where certification exists, make it a contractual prerequisite.
-
Plan for lifecycle economics: Account for sensor refresh, software subscription, cloud costs, and integration fees. Grants can offset capital outlays but often don’t cover sustained operational expenses.
-
Architect for interoperability: Favor solutions with open APIs, standardized event schemas, and proven integrations with VMS and CAD systems to future‑proof investments.
-
Field‑validate under realistic conditions: Pilot programs must include evaluation windows long enough to stress test AI classifiers across seasonal and ambient noise variations.
What PW Consulting’s report delivers — practical, decision‑ready analysis
This study is built to support 2026 strategic decisions. Highlights of the deliverables include:
-
A validated market model from 2020 through 2032 with scenario analysis capturing conservative, base, and accelerated adoption paths (base year 2025).
-
Vendor benchmarking across technology architecture, sensing modalities, certification status, channel strategies, and go‑to‑market motion.
-
Procurement playbooks tailored to municipal, education, transit, and critical‑infrastructure buyers that translate technical specs into RFP language and evaluation matrices.
-
Integration and operations checklists that map incident workflows to system features, uncovering hidden costs and operational bottlenecks.
-
Risk registers addressing privacy, legal, and community acceptance factors, with mitigation options that vendors and buyers can implement immediately.
-
Case studies and validated field performance tests that illustrate success factors and failure modes across multiple deployment archetypes.
Strategic questions for leaders in 2026
-
Are you procuring a short‑term headline solution or investing in an interoperable platform that scales with evolving threats?
-
Have you aligned funding timelines (grants, capital budgets) with vendor roadmaps and certification milestones to avoid deployment delays?
-
Can your operations team absorb and operationalize real‑time alerts, or do you need to bundle managed verification services to translate alerts into action?
Closing — the trailer: why read the full report
PW Consulting’s Gunshot Detection Systems Market report equips decision‑makers with the market sizing, vendor intelligence, procurement templates, and field evidence required to make defensible 2026 investments. The analysis reveals where growth pockets will develop and which vendor capabilities translate into operational advantage — without giving away the proprietary segmentation and contract‑level details that buyers and suppliers find most actionable.
For readers who want the complete dataset (including detailed regional and application splits, vendor financial outlooks, and downloadable RFP templates), the full report is available through PW Consulting’s market portal. Consider this article your operational preview: it highlights the strategic contours and immediate decision levers — the full document contains the granular figures and model inputs necessary to finalize budgets, vendor selections, and pilot designs for 2026 rollouts.
For detailed analysis of this topic, please visit the official page: Gunshot Detection Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Solar Encapsulation Market to Reach USD 9.95B by 2032 at 7.83% CAGR
By PW Consulting, 2026-07-09
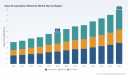
Solar Encapsulation Materials Market — Strategic Preview for 2026 Decision-Makers
As PV module architectures evolve rapidly — from bifacial and TOPCon to heterojunction and tandem concepts — so too does the role of encapsulation materials. This preview synthesizes the macro trajectory and strategic inflection points from PW Consulting’s Solar Encapsulation Materials Market study (base year 2025), highlighting the precise decision levers executives, procurement leads, and investors must act on in 2026. The full report contains the granular segmentation, supplier scorecards, price-volatility scenarios and downloadable datasets; consider this a high-fidelity trailer designed to inform immediate strategic choices while guiding you to the full intelligence package for operational execution.
Solar Encapsulation Materials Market
Executive snapshot — macro trajectory in two sentences
- Market momentum: The global solar encapsulation materials market expanded from approximately USD 4.0 billion in 2020 to USD 5.87 billion in 2025, reflecting steady growth through technology adoption and module upgrades.
- Forward outlook: Our forecast points to continued expansion through 2032, with the market approaching roughly USD 10.0 billion by 2032 under a compound annual growth rate of about 7.8% across the 2026–2032 forecast window.
Why this study matters for 2026 corporate decisions
- Capital allocation: Whether you are sizing new film extrusion lines, investing in POE chemistry R&D, or underwriting downstream lamination capacities, 2026 is a make-or-break year to align plant openings with the next phase of module rollouts. Our model flags timing windows where incremental capacity risks overhang and where demand pull is strongest.
- Supplier selection and risk management: The sector shows clear consolidation dynamics among leading suppliers. Buyers who move from transactional sourcing to partnership-based agreements — including capacity reservation, joint R&D, and long-term raw-material clauses — will secure both quality and price predictability.
- Product roadmaps & warranty alignment: Module manufacturers offering 25‑year warranties now require encapsulants meeting more stringent PID resistance and moisture-barrier metrics. Product teams must re-prioritize formulations and validation protocols in 2026 to avoid warranty friction and performance penalties in the field.
- M&A and JV timing: With visible capacity expansions and regional localization drives, 2026 is primed for strategic acquisitions (technology tuck-ins, regional footprint) and JVs that lock in route-to-market for advanced encapsulant types tailored to high-efficiency modules.
Key market dynamics shaping 2026
- Technology-driven demand: The shift to high-efficiency cell technologies (e.g., TOPCon, HJT) plus the growing adoption of bifacial modules increases technical requirements on encapsulants — moisture ingress resistance, PID mitigation, adhesion under thermal cycling, and UV stability.
- Premiumization and differentiated value: Advanced co-extruded films and specialty formulations command a premium because they enable measurable module-level efficiency and reliability improvements. Capturing that premium depends on validated in-field performance and clear warranty value propositions.
- Localization and supply-chain resilience: Policy and commercial imperatives are driving localization strategies in key end markets. Companies that establish resilient regional supply — be it through greenfield lines, licensing agreements, or partnerships — reduce logistics friction and tariff exposure while supporting rapid module ramp plans.
- Concentration and competition: Market leadership is clustered; top suppliers capture a majority of market share. This concentration creates both opportunities (stable long-term supply) and risks (pricing power, capacity bottlenecks) that buyers must anticipate in procurement strategies.
What the PW Consulting report delivers (practical, implementable content)
- Verified market-sizing (2020–2025 historical) and forward-volume and revenue forecasts (2026–2032) with scenario overlays for upside/downside demand shocks.
- Supply-side heatmaps: capacity by technology family, lead-times, and bottleneck risk scores — built for procurement and operations planners.
- Supplier diagnostic and scorecards: technical capabilities, certification readiness, R&D pipelines, and commercial posture for the leading global and regional encapsulant producers.
- Product and application fit matrices: guidance on material selection by module architecture and warranty targets, including lab-to-field validation checklists.
- Price and raw-material sensitivity models: pass-through scenarios and contract clauses to mitigate monomer and polymer feedstock volatility.
- Investment playbooks: step-by-step checklists for greenfield builds, capacity debottlenecking, and capex prioritization; includes pro forma capex/IRR examples under multiple demand curves.
- M&A watchlist and partnership templates: prioritized targets, valuation benchmarks and a short-list of complementary technologies for bolt-on acquisitions.
- Regulatory and compliance matrix: what to monitor globally for warranty, end-of-life, and environmental disclosure requirements.
Competitive landscape — who matters and why (a strategic reading)
The market is populated by a mix of global specialty-chemical corporations, regionally dominant polymer film manufacturers, and nimble local players. The competitive dynamic is best understood through three capability axes: materials R&D (formulations and co-extrusion), scale/manufacturing footprint, and module-maker partnerships.
Solar Encapsulation Materials Market
- Technology & scale leaders: A small number of established firms combine deep formulation expertise with large-scale film production and global customer relationships. These players set performance benchmarks and often lead in validating new encapsulant types for next-gen cell architectures.
- Regional challengers & fast followers: Several companies are focused on meeting localized demand with rapid product iterations and tailored thermo-mechanical profiles. They are increasingly important for speed-to-market and price-competitive supply in growth corridors.
- Specialists & advanced-material innovators: A subset of firms concentrates on niche solutions — UV-stable chemistries, perovskite tandem encapsulation, or ultrafast-cure films — enabling module makers to extract incremental efficiency or manufacturing throughput gains.
Our report profiles the principal companies operating in the space — from long-standing global suppliers to up-and-coming regional players — assessing their technical positioning, capacity expansion plans, and strategic intent. The public highlights include commercialization of next-gen co-extruded films, regional facility expansions aimed at supply-chain resilience, and launches of tandem-perovskite and BC module encapsulation technologies. These developments are catalysts for realignment in supplier selection and partnership strategies in 2026.
Solar Encapsulation Materials Market
Strategic implications and recommended 2026 actions
- Short-term (0–12 months): Lock in supply via multi-year contracts for critical encapsulant grades tied to defined quality metrics; introduce technical annexes that align material specs with 25-year warranty testing protocols.
- Medium-term (12–24 months): Execute at least one regionalization play — either through a JV, take-or-pay agreement, or minority investment — to secure localized supply for high-growth module programs and to mitigate logistics/tariff exposure.
- Long-term (24+ months): Invest in differentiated product capabilities (e.g., co-extruded barrier films, next‑gen POE variants, or perovskite-compatible laminates) and align R&D roadmaps with key module partners to capture premium segments.
- Operationally: Implement a supplier scorecard that weights technical validation, capacity flexibility, and total landed cost; pair this with scenario-driven inventory policies to smooth feedstock volatility.
- For investors: Prioritize targets with demonstrable technology IP, validated field performance data, and scalable manufacturing footprints. Valuation uplifts accrue to firms with integrated upstream feedstock access or secured offtakes from module OEMs.
How to use this research — a practical checklist
- Procurement teams: Run a “stress test” of existing contracts against the report’s downside and upside volume scenarios for 2026–2028.
- R&D/product teams: Map current material specs to the report’s application-fit matrix and prioritize two material developments with the highest ROI potential.
- Strategy & corporate development: Use the M&A watchlist and deal comparables to short-list acquisition targets or JV partners for capacity or capability gaps identified in 2026 plans.
- Investors & lenders: Apply the report’s sensitivity models to underwrite capex and to size working-capital facilities that absorb raw-material swings without margin erosion.
Methodology & data integrity
The report combines bottom-up capacity audits, supplier financials, proprietary primary interviews with module manufacturers and film producers, and demand modeling anchored to historical module installations. Historical revenue series and the forecast path (2026–2032) are reconciled against macro PV deployment scenarios and validated with trade data and company disclosures. For operational adoption, the report also supplies the underlying modeling workbook and a scoring rubric used for supplier diagnostics.
Final note — what this preview intentionally withholds
Following the “trailer” design, this article presents the strategic signal and the critical levers procurement, product, and corporate development teams need for 2026. The full PW Consulting report contains the detailed regional/type/application splits, price curves, supplier-specific capacity tables, and downloadable datasets required to operationalize these recommendations. Access to the full dataset and the supplier scorecards is available on the report page and is the necessary next step for teams that must translate strategy into contracts, capex approvals, and product roadmaps in 2026.
For executives preparing investment and sourcing decisions this year, the choice is clear: use this preview to prioritize the right strategic questions — and consult the full report to execute answers with the granularity and traceable data that operational teams will require.
For detailed analysis of this topic, please visit the official page: Solar Encapsulation Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Airbag Market Poised for USD 29.79B by 2032 at 7.25% CAGR
By PW Consulting, 2026-07-09
Airbag Market 2026: Strategic Imperatives from PW Consulting
Executive snapshot
As global mobility evolves, the airbag market is entering a decisive phase for corporate strategy. PW Consulting’s latest Airbag Market study (base year 2025, forecast period 2026–2032) synthesizes five years of historical performance with forward-looking scenarios to equip executives making allocation, sourcing, product and M&A choices in 2026. The market has expanded from roughly USD 12.9 billion in 2020 to an estimated USD 18.3 billion in 2025 and is forecast to reach nearly USD 29.8 billion by 2032, implying a compounded annual growth rate of about 7.25% across the 2026–2032 horizon. These headline dynamics mask material complexity: rising product innovation, shifting end‑use mixes, regulatory headwinds, and concentrated supplier power that will shape winners and losers over the next three to five years.
Airbag Market
Why this study matters for 2026 decision cycles
-
Prioritization under capital constraints — The projected mid‑single‑digit to high‑single‑digit growth provides a sufficiency of opportunity but requires careful prioritization of program investments, given competing demands from electrification, ADAS and lightweighting. Our study translates market growth into program-level demand trajectories so CFOs and product heads can rank investments by payback and regulatory urgency.
Airbag Market -
Supply‑chain resilience and compliance — New export control rules and supply‑chain security requirements for connected vehicle ICTS (U.S. Department of Commerce, Jan 2025) complicate global supplier footprints. The report maps where regulatory friction is most likely to affect sourcing and provides mitigation templates for 2026 supplier negotiations.
Airbag Market -
Capital allocation for innovation — Recent product launches in 2026 (wearable airbags, cyclist/pedestrian protection, integrated truck curtains) indicate expanding addressable use cases beyond traditional automotive occupant protection. Our findings identify where R&D and partnership investments can unlock new adjacencies without undermining core OEM relationships.
-
Regulatory and environmental liability management — Updated hazardous waste guidance for recalled airbags (U.S. EPA interim rule, Oct 2025) changes end‑of‑life cost structures and recall economics. The study quantifies recall-management sensitivity and offers operational playbooks to reduce liability and accelerate circularity pilots.
What the report contains — practical, action-oriented deliverables
-
Market sizing and trajectories: A transparent, reproducible model from 2020 through 2032 showing topline demand, scenario variants (baseline, constrained supply, accelerated EV adoption) and sensitivity to key drivers used by procurement and strategy teams.
-
Vendor landscape & capability benchmarking: A playbook that crosswalks supplier capabilities to program needs (inflator chemistry, module integration, electronics and ICT controls, repairability), supported by supplier scorecards and decision matrices tailored for OEM sourcing panels.
-
Cost and input‑material intelligence: Price‑curve analysis for critical polymers and propellants, including the observed price volatility drivers for nylon 6,6, and practical hedging and contract strategies procurement teams can operationalize in 2026.
-
Regulatory impact mapping: A compliance toolkit translating export and waste regulations into project‑level actions — from contractual clauses to engineering design constraints — with templated mitigation measures for near‑term product programs.
-
Opportunity pipelines and M&A screening: A prioritized list of strategic plays (technology partnerships, bolt‑on acquisitions, capacity ventures) with financial and integration checklists to accelerate 2026 deal processes.
Competitive landscape: who matters and why
The airbag ecosystem remains concentrated: the top three suppliers command a significant share of the global market, and the top five together represent an even larger portion, creating structural advantages for incumbent suppliers when securing OEM programs. For market participants and new entrants, understanding each competitor’s technical depth, program footprint and strategic posture is essential.
-
Autoliv (Stockholm, Sweden) — The industry’s long‑standing leader in passive safety. Deep OEM relationships, scale in module production and a strong pipeline of injury‑mitigation innovations (e.g., expanded cyclist/pedestrian protection) make Autoliv a reference competitor for program wins and premium OEM contracts.
-
Joyson Safety Systems (Auburn Hills, USA) — A global mobility safety player with broad product breadth across airbags and related restraint systems. Their scale and cross‑regional footprint make them a key barometer of price pressure and capacity availability.
-
ARC Automotive (Knoxville, USA) — A specialist inflator manufacturer. For firms focused on inflator supply or seeking vertical integration opportunities, ARC’s technology roadmap and capacity allocation decisions are consequential.
-
Daicel Corporation (Osaka, Japan) — A critical supplier of inflator chemistry and pyrotechnic components with a growing footprint in non‑traditional applications; recent work on wearable airbags signals diversification of addressable markets.
-
Toyota Boshoku, Nihon Plast, Toyoda Gosei (Japan) — Strong incumbent suppliers with particular proximity to Asian OEMs and advantages in interior integration, cost control and logistical coordination within regional supply chains.
-
Hyundai Mobis, ZF Friedrichshafen, Continental — Large systems integrators and technology providers whose combined systems expertise (electronics, sensing, integration) will increasingly shape the winner set for advanced occupant protection systems that blur lines between passive and active safety.
Recent product and market developments shaping 2026 strategies
-
Daicel’s May 2026 launch of a wearable airbag product, developed with academic and technology partners, shows how inflator and sensor know‑how can be repurposed into consumer safety segments — an instructive model for product diversification.
-
Autoliv’s April 2026 release of a second‑generation cyclist/pedestrian protection airbag illustrates continuous improvement in external protection systems and signals OEM appetite for expanded active/passive hybrid safety solutions.
-
Volvo Trucks’ industry‑first integrated side curtain airbag for heavy trucks (Feb 2026) is a reminder that commercial vehicle platforms remain fertile ground for higher‑value, differentiated safety modules.
Key strategic implications and recommended actions for 2026
-
Supply‑chain rebalancing: Map single‑source exposures to critical polymers, inflator chemistries and ICT components and execute a prioritized supplier diversification plan. Include contractual language to address export control compliance (per Jan 2025 rules) and implement joint audit programs where ICTS exposure exists.
-
Targeted R&D partnering: Invest selectively in sensor‑inflator co‑development and simulation capabilities. Partnerships with adjacent tech firms, as demonstrated by recent product launches, can accelerate time‑to‑market while sharing development risk.
-
Regulatory‑driven product roadmaps: Reassess product lifecycles and recall economics given the EPA’s hazardous waste guidance. Where feasible, redesign for safer end‑of‑life handling and enable take‑back pilots to reduce recall costs and improve OEM brand resilience.
-
Commercial strategy refinement: Use the report’s vendor scorecards to refine tender evaluation criteria — emphasis should shift from price per unit to total cost of ownership, including warranty exposure, end‑of‑life costs and compliance risk premia.
-
M&A and capacity plays: Given the market’s concentration, acquisitive moves or strategic minority investments in regionally advantaged suppliers can be an efficient way to secure capacity and proprietary technology. The report provides a prioritized screening list matched to integration risk profiles.
Where this leaves executives planning for 2026
2026 will be a year of tradeoffs: balancing near‑term program delivery against investment in new‑use cases and regulatory compliance. The airbag market’s healthy growth trajectory — from the mid‑teens in the past five years to the near‑30 billion USD horizon by 2032 under our baseline — presents significant upside, but extracting value requires disciplined strategy execution across procurement, engineering and regulatory functions.
PW Consulting’s Airbag Market study provides the analytical scaffolding — reproducible models, supplier scorecards, regulatory playbooks and M&A screening — that executives need to convert macro growth into calibrated business decisions. To maintain competitive optionality in 2026, firms should move now to shore up supply chains, prioritize modular innovations, and align commercial terms to reflect evolving environmental and compliance costs.
Next steps
This article highlights the strategic contours of the market and the operational levers that matter for 2026. The full PW Consulting Airbag Market report contains the granular segment-level dashboards, supplier share tables, price curves and scenario models that are essential to implement the actions outlined here. Access the full dataset and operational annexes on our report page to convert these insights into executable plans.
For detailed analysis of this topic, please visit the official page: Airbag Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Blue Laser Diodes Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As demand for higher-power, more efficient blue laser diodes accelerates across industrial, medical, automotive and consumer segments, senior executives must decide where to allocate capital, whom to partner with, and how to shape supply chains resilient to geopolitical and raw-material shocks. PW Consulting’s latest Blue Laser Diodes Market study (base year 2025, forecast 2026–2032) synthesizes market sizing, technology trajectories, and competitive positioning to support those decisions. This preview outlines the study’s strategic value for 2026 decision-makers while preserving the granular subsegment intelligence available only in the full report.
Blue Laser Diodes Market
Market trajectory in one glance
Between 2020 and 2025, the blue laser diodes market expanded from approximately USD 120.5 million to USD 188.5 million—reflecting rapid technology adoption and an improving efficiency-cost profile for GaN-based devices. Our forecast for the 2026–2032 period projects continued momentum, with the market expected to grow at a compound annual growth rate (CAGR) of 8.15%, reaching roughly USD 326.0 million by 2032. These top-line numbers frame a market that is substantial enough to attract strategic investments, yet still concentrated and technically nuanced, where leadership advantages can be sustained through focused R&D, manufacturing scale, and proprietary process control.
Blue Laser Diodes Market
Why this study matters for 2026 strategic planning
- Actionable market sizing and scenario-ready forecasts: The report provides base-year calibration (2025) and probabilistic forecasts across 2026–2032 to support capital allocation, product roadmap prioritization, and M&A valuation. The forecast enforces a clear growth baseline and alternative scenarios tied to material access, regulatory change, and defense procurement shifts.
- Risk-adjusted supply-chain diagnostics: With critical inputs such as gallium subject to pricing volatility and export controls, the study quantifies exposure points and models the cost and lead-time impacts of different sourcing strategies.
- Competitive playbooks: We map incumbent capabilities, product roadmaps, and manufacturing footprints so executives can prioritize partnerships, licensing, or in-house development to secure performance differentials (e.g., wall-plug efficiency, output power, lifetime).
- Regulatory and demand catalysts: The analysis highlights how defense procurement, medical device regulation, and automotive safety standards create both immediate demand and long-term technology requirements—essential inputs for product-planning and pipeline funding.
Report contents — what you’ll find inside
The full PW Consulting report blends quantitative models, primary interviews, and executable recommendations. Key deliverables include:
Blue Laser Diodes Market
- Comprehensive market sizing (historical 2020–2025; base year 2025) and demand forecasts to 2032 with scenario sensitivity to raw-material pricing and export constraints.
- Segmentation by region, device type (single-mode, multi-mode, other) and end-use application (industrial, medical, consumer electronics, automotive, and others), with demand drivers and buyer behavior analysis—note: detailed subsegment tables are available in the full report.
- Supply-chain mapping and cost-stack analysis, including GaN epitaxy, substrate sourcing, packaging, and test—highlighting where margin compression may occur and where scale can unlock outsized returns.
- Technology roadmap and performance benchmarking, including wall-plug efficiency, optical power scaling, thermal management, and life-cycle reliability parameters critical to different use cases.
- Regulatory, export-control and procurement risk analysis—quantifying the near-term implications of controls on critical precursors and major public-sector procurement programs.
- Detailed competitive landscaping and strategic scenarios for market entrants, incumbents, and potential consolidators, including acquisition and partnership targets.
- Go-to-market playbooks and pricing strategy guides tailored to OEM, aftermarket, and direct-to-system integrator channels.
Competitive landscape — who matters and why
The market is moderately concentrated, such that a handful of manufacturers capture a majority share of revenue; our concentration metrics (CR3 and CR5) show a market where strategic moves by leading firms quickly ripple across the value chain. Below we summarize the positioning of core players covered in the study and the strategic implications for partnerships, procurement, and competitive response.
- Nichia Corporation (Anan, Tokushima, Japan) — Nichia’s focus on high-power blue laser diodes and long-standing expertise in GaN epitaxy position it as a technology and supply anchor for industrial and projector applications. Their product depth and manufacturing scale make them a preferred partner for integrators seeking a reliable supply and robust product specs.
- ams-OSRAM AG (Premstätten, Austria) — With recent product introductions pushing wall-plug efficiencies higher, ams-OSRAM is playing a dual role: improving the efficiency floor for industrial and medical applications and challenging incumbents on cost-per-watt. Their March 2025 launch of a high-power 455 nm device with competitive optical power and efficiency underscores a tactical shift toward value-rich, industrial-grade diodes.
- Sharp Fukuyama Laser Co., Ltd. (Fukuyama, Hiroshima, Japan) — Sharp supplies blue diodes tuned for consumer and automotive applications where integration, thermal packaging, and manufacturing consistency are paramount. Their channel relationships and volume-production experience make them attractive for high-volume OEMs.
- Sony Semiconductor Solutions Corporation (Atsugi, Kanagawa, Japan) — Sony’s strengths in optical storage, projector technologies, and automotive systems give it an edge in application-specific engineering. Expect Sony to compete on system-level integration and application certification rather than on raw device throughput alone.
- KYOCERA SLD Laser, Inc. (Goleta, California, USA) — KYOCERA SLD focuses on GaN-based high-performance diodes for lighting, fiber-coupled systems, and automotive headlights. Their US presence and product mix make them a candidate for defense and aerospace partnerships where domestic sourcing is prioritized.
- BluGlass Limited (Silverwater, Australia) — A smaller, technology-driven player, BluGlass is notable for its GaN processing innovations and targeted applications in defense, quantum, and biotech. For buyers seeking niche performance characteristics or early-access to new manufacturing concepts, BluGlass represents a strategic R&D partner.
Industry dynamics that will shape 2026 decisions
- Raw-material and pricing dynamics: Gallium, a critical precursor for GaN devices, has exhibited price volatility and divergent pricing between domestic and export markets due to export licensing regimes. Companies must model procurement exposure—short-term spot volatility can materially affect margins, while longer-term access constraints may necessitate upstream integration or alternative material sourcing.
- Regulatory and trade controls: Export controls and licensing on gallium are shifting the cost and availability landscape. Firms with global manufacturing footprints will need to evaluate compliance risk, customs delays, and inventory strategies to avoid production interruptions.
- Public-sector procurement tailwinds: Large photonics procurement programs—most notably defense allocations—are a near-term demand accelerator for high-reliability blue laser diodes. These programs also raise the bar for domestic-sourcing requirements, certification, and long-tailed aftermarket commitments.
- Technology-driven differentiation: Wall-plug efficiency, lifetime under elevated temperatures, and fiber-coupling capability are the primary axes of competition. Vendors that can deliver convincing system-level advantages (e.g., lower system cooling costs, longer maintenance intervals) command premium pricing.
Immediate strategic recommendations for 2026
- De-risk supply of critical inputs: Secure multi-sourced gallium contracts, consider strategic investments or upstream partnerships, and build buffer inventories aligned with scenario analyses provided in the full report.
- Prioritize application-led product development: Allocate R&D dollars to improve metrics that matter to high-value buyers (efficiency, lifetime, fiber-coupling). Use co-development agreements with key OEMs to shorten time-to-certification in medical and automotive segments.
- Assess near-term M&A and JV opportunities: Identify small technology players that can accelerate efficiency or packaging improvements and evaluate tuck-in acquisitions to secure IP and accelerate product differentiation.
- Prepare for defense procurement demands: If defense or homeland-security customers are strategic, invest in domestic manufacturing capacities and compliance programs—contracts can be significant but come with higher qualification thresholds and longer payment cycles.
- Adopt a dynamic pricing and channel strategy: Use the report’s pricing models to segment customers by willingness-to-pay and risk tolerance; deploy value-based pricing where system-level savings are demonstrable.
What we deliberately withhold in this preview
To preserve the strategic value of the full study for subscribing clients, this preview does not disclose detailed regional or application-level revenue splits, nor the granular company market-share tables and price-by-performance curves. Those critical inputs—used for valuation, supply-chain stress-testing, and go-to-market planning—are presented in the full report alongside downloadable models and an executive dashboard.
How to use the full report for execution in 2026
Executives should use the full PW Consulting report to: (1) validate and stress-test board-level capital allocation scenarios; (2) develop supplier scorecards and contingency plans; (3) identify M&A candidates with technical fit and manufacturability; and (4) construct commercial strategies that align product roadmaps to defense and industrial OEM procurement cycles. The report’s scenario modules can be plugged into CFO and operations planning cycles to quantify cash-flow timing, margin resilience, and inventory needs under various raw-material and regulatory outcomes.
For access to the complete dataset, segmentation matrices, competitive market-share tables, and the executable appendices (including supplier shortlists and a roadmap for securing GaN supply), please visit our Blue Laser Diodes Market report page or contact your PW Consulting account lead. The full intelligence package is designed to convert uncertainty into a playbook for sustained leadership through 2032.
For detailed analysis of this topic, please visit the official page: Blue Laser Diodes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Underfill Market Poised for 9% CAGR to USD 944.6M by 2032 — PW Consulting
By PW Consulting, 2026-07-09
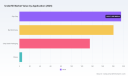
Underfill Market 2026: Strategic Imperatives from PW Consulting’s Preview
Executive preview
As the semiconductor ecosystem intensifies its focus on heterogeneous integration, advanced packaging, and optical interconnects, underfill materials have moved from a commoditized adhesive to a strategic enabler. PW Consulting’s Underfill Market study (base year 2025) synthesizes five years of historical dynamics (2020–2025) and a forward-looking forecast (2026–2032) to quantify that transition. The market evolves at an approximate compound annual growth rate (CAGR) of 9.0% and is denominated in USD (revenue unit: Million). By presenting growth trajectories, supplier positioning, material supply risks, and actionable decision frameworks, this preview outlines the most consequential questions corporate leaders must answer in 2026 — and why access to the full report will materially change how they invest, source, and partner.
Underfill Market
Market trajectory and the strategic context
Between 2020 and 2025 the underfill market demonstrated resilience and steady expansion, reflecting broader semiconductor capex cycles and a structural shift toward flip‑chip, WLCSP, and other high-density packaging topologies. By the 2025 base year the market reached a clear inflection point driven by demand from AI/HPC, silicon photonics, and high-reliability consumer and automotive segments. The PW forecast through 2032 models continued expansion — nearly doubling aggregate revenue over the forecast window — underpinned by sustained adoption of advanced underfill formulations that prioritize low-stress, rapid flow, thermal conductivity, and optical clarity.
Underfill Market
For corporate strategists, this macro picture carries three immediate implications for 2026 planning: (1) underfill is a performance lever, not a commodity; (2) supplier selection must be considered alongside packaging roadmaps and reliability qualification cycles; and (3) materials supply chains are a source of margin volatility and strategic fragility. Each implication is amplified by ongoing regulatory and raw‑material pressures that the report maps in operational detail.
Underfill Market
Why this matters for 2026 decision-making
-
R&D and product roadmaps: Developers of advanced packages must synchronize polymer formulation choices with substrate, die‑attach, and thermal architecture roadmaps. Investments in low-viscosity, optically clear, or highly thermally conductive underfills have long qualification lead times; choosing the wrong technology in 2026 risks multi-year requalification costs.
-
Procurement and cost engineering: Spot and contracted epoxy resin prices have been volatile due to feedstock disruptions and duty actions. Procurement teams should redesign sourcing playbooks to include blended contracts, supplier hedges, and regional contingency capacity — not simply chase the lowest unit price.
-
M&A and partnerships: The market exhibits moderate concentration with a limited set of global formulators holding meaningful scale. Strategic M&A, JV, or co-development agreements remain potent levers for OEMs and OSATs to secure differentiated formulations and prioritize capacity.
-
Reliability and compliance: New eco‑formulation requirements and anti-dumping regimes across jurisdictions mean that compliance and long-run availability must be integrated into supplier scorecards.
What the PW Underfill Market report delivers (practical components)
-
Robust topline and scenario forecasts (2026–2032) calibrated to packaging adoption curves and end-market drivers, enabling capital allocation and sensitivity analysis for a range of demand outcomes.
-
Qualitative decision frameworks and scorecards for supplier selection that combine technical fit, supply resilience, regulatory compliance, and total landed cost — designed for procurement and packaging engineering teams to use in vendor rationalization exercises.
-
Benchmarked product differentiation matrices: viscosity, cure profile, Tg, coefficient of thermal expansion (CTE) compatibility, thermal conductivity, optical properties, and reworkability. These matrices are accompanied by use-case mapping to help prioritize formulation selection against target packages (e.g., large-body flip-chip, image sensors, silicon photonics).
-
Supply chain risk maps highlighting critical feedstocks, concentration points, logistics chokepoints, and mitigation levers — including alternative chemistries, near‑shoring scenarios, and strategic inventory playbooks.
-
Competitive intelligence dossiers on the leading suppliers, recent commercialization events, and likely strategic moves across the next 18–24 months to help clients initiate partnership or procurement dialogues from an informed position.
Competitive landscape — who to watch and why
The competitive environment is populated by specialty formulators and legacy adhesive companies that have invested to serve high-reliability electronics. While the market is not highly consolidated, a handful of players combine formulation depth, global supply chains, and strong reliability track records. PW’s study provides profiles and strategic implications for each major player; below are synthesized highlights that illustrate competitive dynamics without disclosing proprietary market shares.
-
Henkel AG & Co. KGaA (Düsseldorf) — Henkel’s Loctite Eccobond series (including capillary flow underfills engineered for large-body advanced packaging) underscores a strategy of aligning product roadmaps to AI/HPC and complex flip-chip assemblies. Their emphasis on rapid flow and high reliability positions them as a partner for OSATs pursuing dense interconnects.
-
NAMICS Corporation (Kyoto) — Deep in capillary and flip‑chip formulations, NAMICS differentiates through stress‑optimized chemistries. Their regional strength and technical focus make them a credible co-development partner for manufacturers pursuing package‑level stress control.
-
H.B. Fuller Company (St. Paul) — H.B. Fuller targets PCB assembly and device-level robustness with fast-flow, reworkable epoxies tailored for BGA/WLCSP/FlipChip. Their value proposition is centered on production yield improvements and reworkability options important to contract manufacturers.
-
Parker LORD Corporation (Cary) — Parker LORD’s thermoset and anhydride-free options are built for densely populated flip-chip ecosystems where encapsulation chemistry contributes to long-term reliability. They are often selected where thermal cycling endurance is mission‑critical.
-
Epoxy Technology, Inc. (Billerica) — With optically clear, low-stress underfills, Epoxy Technology targets photonic and optoelectronic applications, where clarity and minimal induced stress directly translate into optical performance and yield.
-
Master Bond Inc. (Hackensack) — Master Bond’s nano-filled, thermally conductive formulations are pitched to aerospace-grade assemblies and MEMS, combining vibration resistance with thermal shock durability.
-
YINCAE Advanced Materials (Albany) — YINCAE has been notably active with a sequence of product launches in 2024–2025 and into 2025–2026 that expand their footprint in optical, high‑conductivity, and large‑chip flow-ready underfills — signals of an aggressive product development cadence aligned to silicon photonics and large flip-chip trends.
Recent commercial moves and why they matter
-
Product launches of optically clear and highly thermally conductive underfills (announced across 2024–2025) demonstrate suppliers’ pursuit of differentiated chemistries that map to silicon photonics, AR/VR modules, and high-power logic packages. These launches shorten the path for OEMs to adopt non-standard underfill properties but require earlier engagement for qualification.
-
Innovations emphasizing room‑temperature flow and rapid cure for large chips materially reduce thermal exposure during assembly, improving yields for sensitive die and substrates — an operational advantage for volume production.
-
Nano‑filled and vibration-resistant formulations are beginning to pull aerospace and defense‑grade requirements into commercial electronics, raising the bar for reliability testing and procurement specifications.
Regulation, raw-material shocks, and operational risk
Material and trade policy shocks have reshaped the cost and availability landscape for underfill producers. Regulatory drivers such as EU directives encouraging reduced hazardous content are accelerating reformulation efforts. Simultaneously, anti‑dumping investigations and duties across multiple jurisdictions have altered trade flows for epoxy resins, while episodic supply disruptions of epichlorohydrin and elevated freight costs have driven spot prices and margin pressure for smaller formulators.
These dynamics create a layered risk environment for 2026: procurement cost risk, qualification risk if suppliers shift chemistries, and geopolitical risk tied to trade remedies. The full PW report maps these risks by origin, potential duration, and mitigants, enabling supply-chain and sourcing strategies that are defensible under stress scenarios.
Actionable recommendations for executives
-
Integrate underfill selection into early-stage packaging decisions. Treat underfill as a design constraint and reliability enabler rather than an afterthought.
-
Restructure supplier evaluation metrics to incorporate material‑specific qualifications, regional supply resilience, and regulatory alignment. Prioritize multi-sourced architectures for critical chemistries.
-
Accelerate co-development agreements with suppliers that have demonstrated roadmaps in optical clarity and thermal conductivity if your product roadmap includes photonics, AR/VR, or high‑power compute modules.
-
Hedge exposure to feedstock volatility through blended procurement strategies, targeted safety inventories, and contractual clauses that share commodity risk.
-
Use the report’s scenario forecasts to stress-test CAPEX plans for OSATs and OEMs, ensuring manufacturing capacity commitments align with plausible demand trajectories.
Next steps and how to use this preview
This preview is intentionally selective: it highlights strategic inflection points, supplier differentiation, and the macro picture — while preserving the granular segmentation and proprietary supply maps that are essential for transaction-level decisions. For teams planning supplier negotiations, R&D investments, or M&A activity in 2026, the full PW Consulting Underfill Market study provides the concrete segment-level data, regional demand models, and supplier scorecards required to operationalize the recommendations above.
Engage with PW Consulting to obtain the full dataset, scenario workbooks, and a tailored briefing that maps the findings directly to your product line, sourcing footprint, or M&A thesis. In a market growing at an estimated 9.0% CAGR and facing both opportunity and structural risk, the right intelligence in 2026 will separate prudent operators from reactive followers.
For detailed analysis of this topic, please visit the official page: Underfill Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Oligosaccharide Market to Expand at 6.5% CAGR Through 2032
By PW Consulting, 2026-07-09
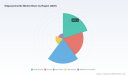
Oligosaccharide Market 2026: Strategic Preview for Executive Decision-Making
Introduction — Why this study matters in 2026
As PW Consulting’s lead industry analyst, I present a strategic preview of our latest Oligosaccharide Market study designed to guide executives making resource allocation, M&A, and go-to-market decisions in 2026. The global oligosaccharide market is transitioning from niche functional-ingredient status to a broader, multi-channel growth engine driven by advances in precision fermentation, regulatory alignment in major markets, and rising demand across infant nutrition, functional foods, and specialty animal nutrition. Our macro view shows an industry that expanded from approximately USD 122 million in 2020 to USD 170 million in 2025 and is projected to reach roughly USD 261 million by 2032, representing a compound annual growth rate of about 6.5% across the forecast horizon.
Oligosaccharide Market
What this preview delivers — the strategic value for 2026
- Rapid situational awareness for executives who must prioritize investment and commercial initiatives in a competitive, partially consolidated market (CR3 ≈ 34.2%; CR5 ≈ 45.8%).
- A synthesis of demand-side shifts (infant nutrition, functional foods, dietary supplements and beyond) and supply-side dynamics (feedstock volatility, synthesis routes, capacity expansions) that materially affect margin and time-to-market.
- Actionable decision frameworks — scenarios, supplier scorecards, and regulatory playbooks — that allow leaders to test strategic choices under realistic cost and demand assumptions without wading through every granular data table in the full report.
Market trajectory and what it implies for 2026 choices
The market’s steady trajectory to 2032 is not homogeneous: growth pockets are concentrated in segments benefiting from regulatory acceptance of oligosaccharides as functional ingredients and from technology-driven unit‑cost reductions. For 2026 planning, implications are clear:
Oligosaccharide Market
- Scale matters: mid-sized producers with flexible production technologies will retain optionality to serve both high-margin infant nutrition applications and high-volume food and beverage customers.
- Technology mix will be a differentiator: enzymatic synthesis and precision fermentation are no longer experimental—precision fermentation in particular is being commercialized at scale, reducing time-to-spec HMO production and enabling entrants to access infant formula value pools more rapidly.
- Regulatory alignment accelerates commercialization: harmonization around Codex-based standards and explicit national updates to infant formula guidance shorten market entry timelines for fortified formulas, but nuanced safety and claim approvals remain a gating factor.
Key demand and regulatory drivers to factor into 2026 strategies
- Infant nutrition is a strategic lever. Recent regulatory moves—EU rules that permit specific GOS–FOS blends in infant formula formulations, and national-level standard updates aligning with Codex in large markets—have lowered policy uncertainty and expanded addressable formulations. Companies must build regulatory dossiers and clinical evidence plans now to capture formulation shelf-space later in the decade.
- Functional foods and supplements continue to grow as consumers seek microbiome-directed health benefits. This creates parallel channels where product claims and substantiation requirements differ; firms should tailor evidence generation (clinical vs mechanistic) to channel economics.
- Feedstock and energy cost exposure is non-trivial. Sucrose feedstock price swings, coupled with industrial electricity differentials (notably in regions where costs exceed USD 0.15 per kWh), materially influence enzymatic synthesis unit economics. Procurement and location strategy must integrate realistic energy- and feedstock-price scenarios.
- Regulatory gating remains: agencies such as EFSA maintain stringent safety verification and health-claim endorsement processes. Building robust safety dossiers and engaging regulators early will shorten approval timelines and protect commercial claims.
Competitive landscape — who matters and why
The market’s competitive topology is a mix of ingredient majors with deep technical capabilities, specialized enzyme and fermentation players, and regional producers focused on cost-competitive prebiotics. The leading firms we profile in the full study demonstrate three distinct strategic postures:
Oligosaccharide Market
- Global ingredient integrators that combine R&D, clinical evidence, and global supply chains to target infant nutrition and high-value clinical segments (examples include producers commercializing HMOs such as 2'-fucosyllactose via fermentation routes).
- Specialized prebiotic manufacturers that leverage feedstock-anchored supply advantages and scale in FOS/GOS to serve food and supplement customers, often offering both powder and syrup forms to address formulation needs.
- Emergent precision-fermentation entrants and partnerships that compress time-to-market for HMOs and bespoke oligosaccharide structures, creating new competitive pressure on incumbent enzymatic-synthesis producers.
Understanding these archetypes allows companies to select a realistic strategic posture: integrate forward into formulation partnerships, double down on low-cost feedstock production, or partner with precision-fermentation specialists to capture premium infant-nutrition premiums.
Selected company implications (strategic takeaways)
- BASF SE and large ingredient houses: Their capacity to produce HMOs and branded 2'-FL via fermentation positions them to serve infant formula customers who demand secure, traceable supply and regulatory support. For competitors, this raises the bar for evidence generation and supply assurance commitments.
- DSM‑Firmenich and similar integrators: Portfolio breadth in HMOs and formula partnerships means acquisition or co-development moves will remain likely; buyers should model defensive and offensive M&A scenarios around complementary enzyme or fermentation capabilities.
- Specialists like Galam Ltd., BENEO, FrieslandCampina Ingredients and regional manufacturers: They will continue to capitalize on prebiotic demand through capacity expansions, product variants (short-chain FOS, GOS) and flexible supply formats. Their agility creates tactical advantages for fast-moving CPG partners.
- Regional Chinese and other low-cost producers: Domestic regulatory harmonization and scale investments mean these suppliers will remain central to cost-sensitive categories; international buyers should weigh tolling, JV, and procurement contingency options.
Recent developments that will shape 2026 dynamics
- Commercialization moves: Partnerships and launches expanding global HMO supply chains signal the start of a new, larger revenue pool accessible via fermentation-produced HMOs.
- Capacity builds: Announcements of additional FOS production lines and facility expansions reflect producers’ confidence in sustained prebiotic demand and create near-term supply-side pressure on prices for commodity prebiotics.
- Facility upgrades in adjacent ingredient groups (e.g., whey protein and membrane ingredient expansions) matter because co-location and integrated supply capabilities can alter procurement and collaboration economics for infant-nutrition formulators.
What the full PW Consulting report contains — practical, executable content
Our full study is structured to move beyond observation to enable execution. It includes:
- Segment-level forecasts and demand-scenarios (2026–2032) with sensitivity to feedstock and energy prices — provided as interactive models so teams can stress-test their P&L and capital plans.
- Supplier and technology scorecards that evaluate scale, regulatory readiness, cost position, and partnership fit for both enzymatic and precision-fermentation routes.
- Regulatory playbook and timelines for major markets, including evidence requirements for infant-formula claims and pathways for health-claim endorsements.
- Commercial playbooks tailored to three strategic options: scale (cost leadership), premium (HMO and clinically substantiated products), and partnership (co-development with fermentation specialists).
- M&A and partnership target shortlists, with deal rationale, valuation benchmarks, and integration risk matrices.
- Supply-chain resilience checklists and procurement strategies to mitigate sucrose/energy exposure, including tolling, hedging, and alternative feedstock scenarios.
Note: in this preview we intentionally withhold the granular subsegment allocations, regional shares, and detailed price curves that underpin the models — these are available in the full report and are essential for transaction-grade diligence.
Strategic recommendations for 2026
- Prioritize regulatory and clinical evidence investments now. For firms targeting infant nutrition or clinical supplements, the cost of delayed evidence generation materially exceeds near-term CAPEX savings.
- Diversify feedstock and technology exposure. Combine short-term enzymatic supply agreements with a staged commitment to precision fermentation to balance cost risk and access to premium HMOs.
- Reassess procurement and location strategy with energy-price scenarios. Production footprint decisions should be stress-tested against scenarios where industrial electricity and sugar prices fluctuate meaningfully.
- Use capacity announcements as tactical signals. Recent line expansions indicate where near-term sourcing pressure may appear; buyers should secure multi-source contracts or consider strategic equity stakes where supply is tight.
- Prepare measured M&A and partnership plays. Given partial consolidation (CR3 and CR5 levels that indicate room for scale consolidation), opportunistic bolt-ons and co-development agreements can accelerate market entry without full-scale greenfield investments.
Final note — how to use this preview
This executive preview is designed to accelerate decision cycles in 2026. It synthesizes macro growth, competitive dynamics, and regulatory inflection points to help you prioritize options and allocate scarce resources. For teams preparing investment-grade business cases, M&A diligence, or product-launch roadmaps, the full PW Consulting Oligosaccharide Market report provides the necessary granular forecasts, supplier-level benchmarking, and scenario models. Access to those tables and interactive models will convert the strategic directions above into executable budgets and timelines.
For immediate next steps, assemble a cross-functional steering group (R&D, regulatory, procurement, commercial) to use the scenarios above as inputs to a 90-day action plan: secure regulatory advisors for targeted dossiers, open option conversations with fermentation-capable partners, and field-test procurement hedges for feedstock exposure.
For detailed analysis of this topic, please visit the official page: Oligosaccharide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Particle Size Analyzers Market — USD 512M (2025), 6.5% CAGR to 2032
By PW Consulting, 2026-07-09
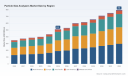
Particle Size Analyzers Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
As organizations finalize budgets and strategic roadmaps for 2026, particle size analysis is shifting from a specialist laboratory function to a strategic capability that underpins R&D productivity, regulatory compliance and process optimisation across pharmaceuticals, advanced materials, and industrial manufacturing. Our PW Consulting Particle Size Analyzers Market study — anchored on a 2025 base year with historical coverage 2020–2025 and forward-looking projections through 2032 — quantifies this transition and translates it into actionable decision levers for executive teams.
Particle Size Analyzers Market
Key macro trajectory: the global market expanded from approximately USD 350 million in 2020 to USD 512 million in 2025, and is projected to continue growing to roughly USD 796 million by 2032, corresponding to a compound annual growth rate (CAGR) of 6.5% over the forecast period. Concentration metrics show a market with influential leaders but substantial niche and regional competitors (CR3 ≈ 38%, CR5 ≈ 42%), a dynamic that has important implications for procurement, partnership and M&A strategies.
Particle Size Analyzers Market
Why this report matters for 2026 strategy
- CapEx prioritisation: Our analysis translates market growth and technology adoption curves into prioritized capital investment timelines. For organisations balancing hospital or laboratory capital budgets under constrained reimbursement environments, this helps pinpoint when to replace, upgrade, or decentralise instrumentation without sacrificing compliance or throughput.
- Product development and formulation: Particle sizing decisions materially affect drug dissolution, bioavailability and excipient performance. We map instrument capabilities to formulation risk profiles so R&D leaders can select measurement approaches that de-risk scale-up and regulatory submissions.
- Procurement & vendor selection: Given the mixed landscape of global incumbents and cost-effective regional suppliers, the study provides a pragmatic framework for vendor shortlists based on technical fit, lifecycle cost and service footprint — critical in environments where instrument uptime and certification matter.
- M&A and partnership scouting: The market’s mid-level concentration and a long tail of specialised players create fertile ground for bolt-on acquisitions and strategic alliances. The report identifies capability gaps and adjacency plays that most acquirers target when building portfolios for laboratory and process analytics.
- Regulatory & compliance planning: We translate standards and certification dynamics into procurement checklists so that organisations using particle size analyzers in regulated workflows satisfy traceability, repeatability and audit requirements efficiently.
What the study delivers — practical, executable assets
This is not a high-level forecast alone. PW Consulting’s deliverables are designed for immediate operational use across functions:
Particle Size Analyzers Market
- Customisable financial model (USD Million base) with scenario toggles for adoption rate, instrument lifetime, service revenue and replacement cycles across our 2026–2032 forecast horizon.
- Vendor scorecards and an RFP template tuned to regulated workflows (pharmaceutical and clinical laboratory requirements), including certifications, warranty, service SLAs and validation support.
- CapEx decision tree and ROI calculators that convert instrument performance attributes into net present value and payback periods under multiple utilisation and reimbursement constraints.
- Regulatory & validation checklist mapped to ISO and CE expectations — enabling compliance-ready procurement for clinical and pharma customers.
- Go-to-market playbooks for instrument manufacturers and distributors, covering segmentation, channel strategy, aftermarket service design and bundling tactics to capture recurring revenue.
- Supply-chain risk heatmaps and mitigation playbooks addressing sourcing of precision optics, medical-grade electronics and other critical components required for high-end laser diffraction systems.
- Scenario analysis and stress-testing: alternative demand paths (conservative, base, and accelerated adoption) with triggers for strategic pivots such as price, innovation or consolidation events.
Market dynamics shaping strategic choices
- Standards and methodological rigor: ISO 13320 remains the established benchmark for laser diffraction particle size analysis, ensuring traceability and repeatability for pharmaceutical and clinical applications. Our report explains how adherence to the standard affects instrument selection, contract wording and validation timelines.
- Regulatory footprint and certification: Manufacturers and buyers alike must navigate CE marking and ISO systems for instruments used in regulated workflows. We outline the certification ladder and downstream implications for procurement cycles and service requirements.
- Capital constraints in clinical settings: Particle size analyzers are classified as laboratory capital equipment and lack dedicated billing codes; acquisition decisions are therefore subject to hospital CapEx cycles and competing priorities. Our analysis converts these constraints into practical procurement windows and financing alternatives for suppliers and institutional buyers.
- Component and supply risk: Precision optics and medical-grade electronics are critical inputs for top-tier laser diffraction instruments. We assess supplier concentration in these upstream markets and offer mitigation strategies — from dual-sourcing to component redesign — that preserve instrument performance while reducing single-source exposure.
Competitive landscape — who matters and why
The ecosystem comprises established instrument manufacturers, platform integrators and regional value players. The leading global manufacturers combine strong instrument portfolios with validated pharma-facing products; regional and cost-driven vendors compete on price and speed-to-deploy for industrial and academic customers. Our competitive profiles include strategic positioning and capability assessments for the key industry players:
- Malvern Panalytical (United Kingdom) — A world-leading supplier of laser diffraction systems with a recognized presence in pharmaceutical particle characterization and instruments tailored for dissolution and bioavailability workflows.
- Danaher Corporation / Beckman Coulter (United States) — Offers a mix of Coulter principle and laser diffraction instruments focused on clinical and pharmaceutical lab environments, leveraging broad life sciences channel reach.
- HORIBA Scientific (Japan) — Delivers laser diffraction solutions spanning sub-micron to larger particle ranges for laboratory research and industrial R&D.
- Anton Paar GmbH (Austria) — Known for precision instrumentation and automation features that appeal to high-throughput labs and process monitoring use cases.
- Bettersize Instruments Ltd. (China) — Competes on cost-effectiveness and entry-level adoption for both lab and industrial applications.
- Microtrac (United States) — Provides a diversified portfolio including laser diffraction, DLS and imaging, useful for organisations needing hybrid measurement capabilities.
- Sympatec GmbH (Germany) — Focused on process monitoring and powder/granule analysis with established systems for continuous measurement.
- Shimadzu, Fritsch, Mettler Toledo and Scitek Global — Each brings complementary strengths in lab instrumentation, sample preparation and market reach; their strategic moves often influence distribution and aftermarket models.
For procurement teams, the competitive implication is straightforward: negotiate beyond instrument price to include validation support, spare parts, training and uptime guarantees. For corporate strategy, opportunities lie in service differentiation and software-enabled analytics that convert single-sale instruments into recurring revenue platforms.
Strategic implications and recommended actions for 2026
- Adopt a phased capital plan: Use the report’s adoption curves and lifecycle models to phase purchases, matching validation timelines and budget cycles while minimising stranded asset risk.
- Design procurement for total cost of ownership: Prioritise suppliers that demonstrate strong service networks, local calibration capabilities and spare-part availability; include performance-based warranty clauses tied to uptime and measurement reproducibility.
- Invest in measurement interoperability: Standardise data outputs and analytical workflows to enable cross-site comparability and faster regulatory filings.
- Explore partnerships and bolt-ons: For manufacturers and investors, pursue acquisitions that extend software analytics, aftermarket service capability or regional distribution to capture higher-margin recurring revenue.
- Mitigate supply-side vulnerabilities: Build supplier scorecards for critical components and integrate alternative sourcing into procurement contracts to avoid disruptions in instrument availability.
How PW Consulting’s study supports your 2026 decisions
Our study is calibrated to the decision cycles that matter in 2026: capital planning, product roadmap prioritisation, vendor contracting and M&A screening. It delivers quantitative forecasts grounded in a 2025 base year, practical tools (financial models, RFPs, checklists) and qualitative insights — enabling cross-functional teams to move from vendor selection to deployment and validation with confidence.
We intentionally keep this preview at a strategic level — the detailed segmentation, vendor scorecards, regional deployment curves and financial-line items are available in the full report and interactive data pack on our website. For teams that need to convert the market trajectory and supplier dynamics into procurement specifications, investment memoranda or M&A targets, the full PW Consulting dataset is designed to be plug-and-play into your 2026 planning processes.
Next steps
Contact PW Consulting to access the complete report and the accompanying Excel model. With the market poised for steady growth at a 6.5% CAGR and clear competitive dynamics, the time to translate measurement strategy into commercial advantage is now.
For detailed analysis of this topic, please visit the official page: Particle Size Analyzers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Medical Cyclotron Market to hit USD 398M by 2032 at 6.9% CAGR
By PW Consulting, 2026-07-09
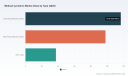
Medical Cyclotron Market 2026: Strategic Primer for Executive Decision-Making
As the medical cyclotron market moves from niche infrastructure into mainstream precision-medicine supply chains, 2026 is shaping up as a pivotal year for strategic choices. This preview, prepared by PW Consulting’s industry practice, synthesizes the macro trajectory, competitive dynamics, regulatory inflections, and the pragmatic levers that should guide board- and C-suite-level decisions. The analysis draws on our proprietary market model (base year 2025), historical trends (2020–2025) and an explicit forecast window through 2032 to highlight where measurable opportunities and systemic risks converge.
Medical Cyclotron Market
Why this market matters in 2026
Medical cyclotrons are no longer solely production assets for local tracer supply; they are capacity nodes in expanding theranostics ecosystems, enablers of on-site manufacturing for next‑generation alpha and beta therapies, and strategic anchors for integrated radiopharmaceutical businesses. Our market model shows an expanding global market, propelled by consistent mid-single-digit expansion—the model uses a 6.9% CAGR across the forecast horizon—indicating both scale and investability for institutions that align clinical, manufacturing, and reimbursement strategies.
Medical Cyclotron Market
From a numbers perspective, the industry has recorded steady growth from the start of the decade and reached a clear inflection by 2025; our forecast to 2032 reflects accelerating adoption as regulatory approvals and reimbursement policies unlock broader clinical use. These aggregate dynamics make 2026 a critical window to capture first-mover advantages in capacity, partnerships, and regulatory positioning.
Medical Cyclotron Market
What the PW Consulting report delivers (practical contents)
- Integrated market-sizing model (USD, Million) with historical series (2020–2025) and scenario-based forecasts (2026–2032).
- Decision-ready commercial playbooks for hospitals, independent radiopharmacies, and device manufacturers (site selection, capex phasing, throughput sizing).
- Regulatory pathway maps and timelines for cyclotron‑produced isotopes and theranostic combinations relevant to 2026–2028 approvals.
- Reimbursement intelligence: billing code mapping, payer positioning tactics, and margin-sensitivity analyses for Ga-68, Lu-177 and emerging alpha emitters.
- Competitor benchmarking and capability matrices juxtaposing technology, service models, installed base, and aftermarket support.
- Supply chain resilience assessment, including critical components, single‑source risks, and mitigation strategies (spare parts, service contracts, and second‑tier suppliers).
- M&A and partnership scouting toolkits with prioritized target archetypes and valuation drivers for 2026 deal activity.
- Operational readiness checklists for running a compliant on‑site radiopharmacy tied to cyclotron deployment.
Each module is built to be executable: executive dashboards, investor-ready slides, and an operational transition plan are included to accelerate board approvals and execution.
Market trajectory: what the numbers say (macro view)
Key macro takeaways from our forecast: the market shows resilient, above-sector growth aligned with broader adoption of PET/SPECT diagnostics, expansion into alpha-therapy production, and national initiatives to localize isotope supply. The base year (2025) is calibrated to recent installations and announced capacity expansions; our scenarios factor in regulatory approvals that are expected to broaden clinical indications and payer access through 2026–2028.
For strategic planning, two implications stand out. First, aggregate growth supports multi-year capacity investments for organizations that can de-risk early through partnerships or service agreements. Second, while the market is growing, it remains concentrated among a limited number of technology providers—creating both competitive pressures and predictable vendor selection processes for deployers.
Competitive landscape — who matters and why
The supplier ecosystem is characterized by a mix of global incumbents, specialized high-output manufacturers, and emergent compact‑cyclotron innovators. The market concentration metrics indicate that the three largest vendors control a dominant share of installed capacity, and the top five together represent substantially more—an important consideration for procurement, service-level agreements, and long-term spare‑parts planning.
- IBA (Louvain‑la‑Neuve, Belgium) — A market leader in particle accelerator technology, IBA combines a broad product portfolio with deep experience in PET/SPECT isotope production and early leadership in targeted alpha therapy enabling technologies. Recent product launches targeting industrial-scale production of Astatine‑211 underscore their push into alpha-emitter supply chains.
- GE HealthCare (Chicago, IL, United States) — A major OEM with strong installed base through its PETtrace series; GE is focused on enabling on-site radiopharmaceutical production that integrates with hospital workflows and theranostic development programs.
- Advanced Cyclotron Systems Inc. (ACSI) (Richmond, Canada) — Known for high-output cyclotrons designed for robust radioisotope throughput; recent investments in dedicated manufacturing facilities point toward scaling for global supply contracts.
- Ionetix (Lansing, MI, United States) — Compact superconducting cyclotron specialist offering smaller-footprint solutions and integrated radiopharmaceutical services—well positioned for decentralized manufacturing models and clinical sites with limited floor space.
- Sumitomo Heavy Industries, Ltd. (Tokyo, Japan) — Supplier of compact, reliable units with strong service and delivery capabilities in mature Asian markets; attractive to buyers prioritizing reliability and local support.
Recent industry moves—product launches, installations, and new facility construction—are consistent with vendors moving to secure demand for isotopes used in both diagnostics and therapy. These tactical plays by suppliers will shape competitive dynamics through 2028 and should inform counter‑strategies by buyers and investors.
Regulatory and reimbursement inflection points
Several regulatory and payer events are contiguous to 2026 and materially affect demand for cyclotrons:
- Regulatory approvals and clearances for cyclotron-produced Ga‑68 tracers and new theranostic pathways are lowering the barrier to hospital adoption and third-party production contracts.
- Recent FDA decisions and scheduled action dates for diagnostic kits tied to cyclotron-produced isotopes create discrete decision points for payers and hospital system investment committees.
- Reimbursement coding for cyclotron-produced isotopes is maturing, enabling clearer revenue models for on‑site production versus outsourced supply—a critical input to capex return models.
- Approvals of radioligand therapies requiring specific isotopes (e.g., Lu‑177) have already created guaranteed clinical demand that feeds cyclotron deployment and long-term supply contracts.
For 2026 strategy, these dynamics mean that procurement and clinical teams must co‑ordinate with regulatory and finance stakeholders earlier in the acquisition process than in past cycles.
Practical strategic implications for 2026 decision-makers
Below are actionable recommendations that senior leaders should consider when integrating cyclotron investments into corporate strategy this year:
- Align capital allocation with regulatory timelines: time major capex decisions to coincide with expected approvals and coding recognition to avoid stranded capacity.
- Prioritize partner models to share technical and regulatory risk: contract manufacturing organizations and technology providers can accelerate time-to-clinic while spreading operational obligations.
- Design redundancy into supply chains: a hybrid model—on‑site micro‑production for just-in-time tracers plus regional high-output hubs for therapeutics—optimizes resilience and margin capture.
- Negotiate service and spare‑parts agreements that reflect concentration risks: given the vendor landscape, long-term service contracts and localized maintenance capabilities materially affect total cost of ownership.
- Use scenario-based valuations for M&A: target assets that either add capacity at scale or provide unique therapeutic-enabling capabilities (alpha-emitter readiness, integrated radiopharmacy). Our report contains scoring matrices for both archetypes.
- Embed payer engagement early: secure coding and coverage pathways in parallel with clinical adoption to avoid revenue timing mismatches post-installation.
Key decision triggers and KPIs
- Regulatory milestones (clearances, approval dates) tied to specific isotopes or production processes.
- Commercial contracts or supply agreements with major radiopharmaceutical developers.
- Utilization thresholds and throughput targets for installed cyclotron capacity.
- Service-level metrics and mean-time-to-repair targets that impact clinical uptime.
- Reimbursement realization rates and payer coverage decisions.
Monitoring these triggers with the appropriate cadence (monthly regulatory watch, quarterly commercialization reviews, and continuous operational KPIs) will materially improve execution certainty.
Closing — why read the full PW Consulting report
This primer outlines the strategic stakes and near-term decision architecture for 2026. The full PW Consulting Medical Cyclotron Market report provides the proprietary models, granular regional and application splits, supplier-by-supplier installed-base analyses, and downloadable decision‑support templates that senior teams need to convert insight into action. If your 2026 roadmap includes cyclotron deployment, theranostics partnerships, or supply‑chain redesigns, the full study is designed to shorten your path from decision to deployment while protecting margin and clinical uptime.
Accessing the full report will reveal the detailed segmentation matrices, price and margin scenarios, and vendor comparison tools we deliberately omit here to preserve the commercial value of our primary research and to ensure readers obtain the executable intelligence they need.
For detailed analysis of this topic, please visit the official page: Medical Cyclotron Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Daylight Fluorescent Pigments Market to Reach USD 787.5M by 2032 at 8.2% CAGR
By PW Consulting, 2026-07-09
Daylight Fluorescent Pigments Market — Strategic Preview for 2026 Decision-Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, this briefing distills the high-impact, decision-ready intelligence executives need when approaching the Daylight Fluorescent Pigments market in 2026. It demonstrates the analytical depth of our full market study while preserving the proprietary segment-level data and modelling that we reserve for subscribers. Consider this a strategic trailer: enough evidence to shape near-term choices and validate hypotheses — and a clear invitation to access the full dossier for transaction-grade inputs.
Daylight Fluorescent Pigments Market
Market at a glance
The Daylight Fluorescent Pigments market sits at an inflection point. After steady expansion through 2020–2025, the market reached approximately USD 465.4 Million in our 2025 base year and is forecast to grow at a compound annual growth rate (CAGR) of 8.2% across the 2026–2032 horizon. Under our baseline scenario this trajectory takes market size from the mid-2020s into the high hundreds of millions by 2032, reflecting both product adoption in existing applications and incremental demand driven by sustainability-driven reformulation and specialty resin systems.
Daylight Fluorescent Pigments Market
This macro momentum masks important structural dynamics — moderate supplier concentration, regulatory pressure in major consuming geographies, and raw material cost volatility — all of which materially influence strategic calculus for suppliers, formulators, downstream brand owners, and investors.
Daylight Fluorescent Pigments Market
Why this matters for 2026 decisions
- Portfolio prioritization: With reformulation pressure mounting (especially in jurisdictions tightening legacy chemistries), companies must decide which formulations to advance to commercialization in 2026 and which legacy SKUs to phase out. Time-to-market for compliant, eco-oriented alternatives will determine commercial share over the next three to five years.
- R&D and CapEx allocation: The 8.2% forecast growth justifies selective investment in resin co-development, dispersion technologies, and colorfastness for LED and high-temperature applications. But capital must be targeted: build-outs focused on differentiated, sustainable chemistries will generate higher ROIC than capacity expansions of commodity streams.
- Supply chain resilience: Petrochemical input inflation and tariff rulings introduced in 2025 have raised the cost of goods sold and created sourcing-risk asymmetries. Contract renegotiation, dual-sourcing strategies, and local inventory buffers will be higher priorities for procurement teams entering 2026.
- M&A and partnership playbook: The market shows moderate concentration (top-tier incumbents control a majority share), creating space for bolt-on acquisitions to buy technical IP and channel access. Strategic buyers should favor targets with validated formulations that meet upcoming regulatory thresholds.
- Commercial model evolution: Pricing flexibility, value-based contracting for high-performance grades, and co-development agreements with OEMs or coatings formulators will be decisive in capturing margin expansion as the market transitions.
Report coverage — what the full study delivers
Our full market report is designed as an operational toolkit for 2026 — not just a descriptive paper. Key deliverables include:
- Transparent market sizing and scenario-based forecasts (2026–2032) with sensitivity testing around raw material inflation and regulatory shocks.
- Demand-driver analysis by application class and polymer system, with go-to-market implications for each buyer persona.
- Supplier benchmarking and scorecards covering technological depth, sustainability posture, geographic footprint, and commercial reach — enabling shortlisting for partnerships and M&A.
- Regulatory impact matrix and reformulation roadmaps, including an EU REACH compliance playbook and North America/Asia tactical guidance.
- Pricing model templates, margin simulators, and break-even analyses to stress-test investment choices under different commodity price trajectories.
- Supply chain mapping and risk heatmaps, including tariff and logistics scenarios introduced in 2025.
- Practical annexes: formulation compatibility matrices, test protocols for accelerated weathering and LED exposure, and sample RFP language for sourcing strategic pigment grades.
Each module is delivered with the primary evidence base, modelling assumptions, and an editable Excel kit that supports immediate executive workshops and board-level decision cycles.
Competitive landscape: who matters and why
The market is shaped by a mix of legacy specialists, regional producers, and niche innovators. High-level positioning insights for leading players (derived from public disclosures, recent product launches, and on-the-ground checks) are summarized below to help prioritize engagements and competitive responses.
- DayGlo Color Corp (Cleveland, Ohio) — The original, largest named player with broad product breadth across pigments, dispersions, inks and toners. DayGlo’s 2025 launch of an eco-friendly daylight fluorescent series indicates a deliberate pivot toward bio-based raw materials and packaging/textile applications. Expect continued emphasis on brand-strength and channel partnerships with coatings and safety-equipment manufacturers.
- Radiant Color N.V. (Houthalen, Belgium) — A technology-driven contender focused on special-effect pigments and resin-integrated solutions. The 2025 opening of a Resin Centre of Excellence signals an investment to defend premium positioning in cosmetics and specialized industrial applications that require regulatory and resin compatibility expertise.
- Wanlong Chemical Co., Ltd. (Ruian, Zhejiang) — A high-volume regional manufacturer pushing advanced AX Series grades for plastics and rubber. Active trade show participation and broadened product marketing suggest a strategy centered on scale and cost-competitive specialty grades for converters in Asia.
- SINLOIHI (Japan) — Concentrating on ultra-bright, durable pigments for coatings and LED-decorative paints, with recent formulations tailored to LED exposure. Their R&D focus aligns with premium architectural and decorative segments where colorfastness to new light sources is a differentiator.
- Regional specialists and newcomers — Companies such as Aron Universal (India), LuminoChem, and several Chinese manufacturers continue to close technical gaps. LuminoChem’s positioning around aqueous, eco-safe chemistries and Huangshan Jiajia’s capacity expansions for packaging/textiles merit attention from sustainability-driven brand owners.
Market concentration is meaningful: the top three firms command a clear majority of volume, with the top five extending that majority further. This structure creates entry barriers for new independent players and increases the strategic value of partnerships or technology licensing for mid-tier companies seeking scale.
Dynamics, regulatory shocks, and operational risk
- Regulatory tightening: The EU’s REACH program is systematically restricting legacy azo-based chemistries; analogous environmental scrutiny is rising in North America and parts of Asia. These trends enforce an investment imperative: reformulate or risk market exclusion in key geographies.
- Input-cost pressure: Petrochemical-derived inputs (e.g., melamine and toluene derivatives) have shown upward pricing pressure in 2024–2025. This inflates production costs and squeezes margins for commodity grades—pushing players toward value-added specialties where premium pricing can be sustained.
- Trade and tariff frictions: New tariff classifications and customs rulings effective in mid-2025 have altered landed-costs for certain supply chains, prompting near-term dual-sourcing and nearshoring discussions among global customers.
- Technological shifts: The rise of LED lighting and higher-temperature polymer processing demands pigment chemistries with different stability profiles. Suppliers that have validated LED and high-thermal grades will capture disproportionate share in premium applications.
Practical decision checklists for 2026
Below are concise, tactical checklists tailored to the major stakeholder groups to convert the market view into executable next steps:
- For suppliers: accelerate reformulation pipelines; prioritize resin co-development; establish raw-material hedging; score products for regulatory compliance and margin potential.
- For formulators/OEMs: qualify multiple pigment suppliers under updated regulatory specs; mandate traceability clauses; co-invest in accelerated weathering and LED exposure testing.
- For brand owners/packaging buyers: request sustainability dossiers, biodegradability claims validation, and supply continuity guarantees as pre-qualification criteria.
- For private equity and strategic buyers: target tuck-ins with differentiated IP, validated regulatory-compliant formulations, or footholds in under-penetrated regional channels.
Next steps — where the full intelligence unlocks value
This preview highlights the strategic contours and the operational levers that will determine winners and laggards through 2026 and beyond. If your board needs transaction-ready models, supplier scorecards, or a tailored go-to-market playbook, the full PW Consulting report contains the granular segmentations, company-level financial proxies, and downloadable Excel models required to validate investment memos and to run supplier selection exercises.
Accessing the complete study will provide: drillable segment revenue streams, segment-level growth drivers, proprietary supplier ratings, and formatted RFP templates — all the elements necessary to turn the strategic direction above into a 90–180 day execution plan.
PW Consulting stands ready to support executive workshops, M&A diligence, or bespoke modelling built on the report’s core datasets. For teams preparing 2026 budgets and strategic roadmaps, acting on these high-conviction recommendations early will materially influence market position as the sector transitions toward sustainable, high-performance pigment chemistries.
For detailed analysis of this topic, please visit the official page: Daylight Fluorescent Pigments Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Diesel Particulate Filter (DPF) Market — 2026 Strategic Outlook and Executive Brief
Executive snapshot
As global decarbonization and air-quality regulations intensify, the Diesel Particulate Filter (DPF) market is entering a phase of sustained, technology-driven growth. Our PW Consulting baseline places the global market at USD 21,500 Million (base year 2025), growing to an estimated USD 34,480 Million by 2032 — a compound annual growth rate (CAGR) of 6.98% over the 2026–2032 forecast window. This trajectory reflects a confluence of regulatory enforcement, retrofit activity, material-technology transitions and aftermarket monetization.
Diesel Particulate Filter (DPF) Market
Why this study matters for 2026 decision-making
- Time-sensitive regulatory compliance: 2026 is a tipping point for fleets and OEMs facing tightened verification regimes and fuel-quality prerequisites in major markets.
- Technology inflection: material choices (e.g., silicon carbide substrates and advanced catalyst coatings) are redefining performance, total cost of ownership (TCO) and product roadmaps.
- Market structure dynamics: a comparatively fragmented supplier base creates windows for targeted M&A, strategic alliances and scale-based cost advantages.
- Operational posture: procurement, manufacturing footprint, and service models need recalibration to capture recurring aftermarket and retrofit revenues while hedging raw-material exposure.
What PW Consulting’s DPF report delivers — practical, transaction-grade content
- Rigorous market sizing and seven-year forecast (2026–2032) with scenario variants calibrated to decarbonization and fuel policy outcomes (currency: USD, revenue units: Million).
- Technology deep dives: substrate materials, coating chemistries, passive vs. active regeneration strategies, and integration with engine and aftertreatment control systems.
- Regulatory mapping and compliance playbook: country- and segment-specific verification requirements, retrofit approvals and enforcement risk matrices to prioritize market entry.
- Supply chain and raw-material risk assessment: critical nodes, supplier concentration, SiC availability, price-sensitivity models and mitigations.
- Aftermarket and retrofit economics: unit-economics models, total lifecycle service opportunities and fleet-conversion business cases.
- Competitive landscaping and capability benchmarking: strategic profiles, product-technology positioning, R&D focus and partnership ecosystems for the leading participants.
- M&A and partnership playbook: target screening criteria, valuation sensitivities, integration risks and synergy capture roadmaps designed for financial sponsors and strategic buyers.
- Implementation guides and KPIs: procurement scorecards, validation testing protocols and production ramp templates for 2026 execution.
Regulatory and technology dynamics to watch in 2026
Regulation continues to be the single largest demand determinant for DPFs. The US EPA’s active verification list (updated January 2026) and CARB’s continued application-specific approvals confirm that verified retrofit systems remain a sanctioned pathway for emissions abatement across heavy-duty and non-road fleets. Practical implications for suppliers and fleet operators include tightened fuel-quality preconditions (e.g., ULSD with maximum sulfur thresholds) and exclusion clauses for certain OEM-equipped engines — factors that materially influence marketable retrofit solutions.
Diesel Particulate Filter (DPF) Market
On the technology front, silicon carbide (SiC) substrates are rapidly maturing as a premium alternative to traditional cordierite monoliths. SiC offers materially higher particulate-number reduction (frequently exceeding 99% in validated testing) and substantially improved thermal stability, widening operational envelopes and supporting more aggressive regeneration strategies. These performance gains, however, introduce new sourcing and cost considerations that must be quantified at the product and portfolio level.
Diesel Particulate Filter (DPF) Market
R&D intensification by catalyst specialists and materials firms — exemplified by recent capacity and capability investments — is compressing the timeline for next-generation coatings and process technologies. This creates a two-track market: incumbent low-cost platforms with predictable margins, and premium, higher-margin systems that command ecosystem-level integration.
Competitive landscape — who matters and why
The DPF ecosystem combines materials innovators, Tier‑1 system integrators, engine OEMs and aftermarket specialists. Market concentration metrics point to a fragmented environment: CR3 is 24.6% and CR5 is 26.2%, indicating no dominant oligopoly and significant room for scale plays and consolidation.
- Materials and catalyst leaders (e.g., firms with deep chemistry and substrate portfolios) are competing on coating performance, substrate innovation and licensing. Investments in centralized catalyst R&D and solids-processing capabilities are a clear strategic priority.
- System integrators and Tier‑1s (global automotive suppliers and exhaust specialists) are consolidating system design, control-electronics and integration services to lock OEM programs and volume contracts.
- Engine manufacturers and component OEMs leverage in‑house capabilities to create platform-level differentiation, particularly for heavy-duty and off-highway applications.
- Aftermarket and retrofit specialists maintain critical access to fleet operators and regulatory approvals, keeping the retrofit channel a vital commercial route for emissions reduction initiatives.
Recent corporate activity underscores these dynamics: select players have announced new development centers and capability expansions, signaling intensified competition in catalyst and process technologies. These moves point to a market where upstream material advantages translate directly into system-level performance and commercial wins.
Strategic implications and recommended plays for 2026
- For OEMs and Tier‑1s: prioritize modular DPF platforms that reduce integration time across vehicle families and enable clear upgrade pathways for SiC substrates. Lock multi-year supply agreements with upstream material suppliers to mitigate price and availability volatility.
- For suppliers: invest selectively in coating IP and testing infrastructure that can shorten verification timelines; pursue targeted partnerships with retrofit specialists to capture early-adopter retrofit volumes in regulated regions.
- For fleet operators and service providers: evaluate retrofit vs. replacement trade-offs using lifecycle TCO models under alternative fuel-quality and regulatory scenarios; leverage verified systems to access government retrofit incentives.
- For investors and PE: screen for mid-market targets with defensible technology or aftermarket distribution assets. The fragmented market profile implies attractive roll-up opportunities with clear synergies in procurement and service networks.
- Cross-cutting action: implement raw-material stress tests into new-product business cases and procure conditional offtake or hedging arrangements for high-demand substrates (e.g., SiC).
Scenario analysis and risk calibration
The report includes multiple scenario pathways to stress-test strategic plans under divergent outcomes: a baseline regulatory-growth scenario; an accelerated retrofit wave driven by stringent enforcement; an electrification-led contraction in certain applications; and a raw-material shock scenario that raises substrate costs. Each scenario quantifies impacts on addressable markets, margin compression, payback timelines for retrofit programs, and capex requirements for manufacturing scale-ups. These scenario outputs are designed to convert into decision-ready inputs for board-level strategy reviews in 2026.
How to use this report in your 2026 planning cycle
- Executive summary and board pack: extract the strategic plays and scenario exposures to inform capital allocation and partnership decisions.
- Product and R&D roadmap: map technology roadblocks and supplier dependencies against the recommended material and coating investments.
- Procurement and operations: deploy the supply‑risk matrices and cost models to renegotiate supplier terms and prioritize manufacturing footprints.
- M&A diligence: utilize the target-screening framework, synergy calculators and integration checklist to accelerate deal execution while preserving valuation discipline.
What we intentionally withhold here — and why it matters
To preserve the report’s role as a transaction-grade intelligence product, this executive introduction deliberately omits detailed regional and application-level splits, unit economics by substrate and vehicle type, and raw numeric breakdowns that constitute the report’s proprietary core. These segmented datasets are essential for scenario tailoring, competitive benchmarking and bid-level procurement strategies — and are available in full through the report portal.
Next steps
For executives and investors preparing for 2026, the choice is straightforward: incorporate material-technology risk, regulatory verification timelines and aftermarket monetization into strategic planning now. PW Consulting’s full DPF market study provides the calibrated datasets, company-level profiles and executable playbooks required to move from insight to action. Access to the complete dataset and implementation templates can be arranged through our report page and advisory desk.
For detailed analysis of this topic, please visit the official page: Diesel Particulate Filter (DPF) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


