



Category: market research
Game Engines Market 2026: Strategic Preview for Executive Decision-Making
Executive summary
As the real-time 3D infrastructure underpinning games, simulation, and an expanding set of non-gaming use cases, game engines have evolved from developer tooling into strategic platforms. By the 2025 base year the market had moved firmly into mainstream commercial scale and is forecast to continue a steady, mid-single-digit expansion through the 2026–2032 horizon. This report introduction lays out why decisions made in 2026 about platform partnerships, R&D allocation, M&A, and go-to-market design will materially shape outcomes across entertainment, enterprise, and the creator economy.
Game Engines Market
Why this research matters for 2026 priorities
-
Timing of technology inflection points: 2025–2026 marks a transition where generative AI, cloud-native rendering, and live-service backends converge to change how assets are produced, distributed, and monetized. Executives who understand the timing and amplitude of these shifts will avoid costly platform lock-in and capture first-mover economics.
Game Engines Market -
Platform strategy trade-offs: Selecting an engine in 2026 is no longer a purely technical decision. Licensing models, creator ecosystems, cross-platform distribution partnerships, and long-term cost of ownership factor into product roadmaps and revenue models. Our report maps the decision levers you need to weigh against 3- to 5-year business targets.
Game Engines Market -
Risk-adjusted investment: With consolidation tendencies among leading vendors and new entrants accelerating capabilities (notably AI-assisted pipelines), capital allocation must be optimized not only for feature parity but for ecosystem access, developer mindshare, and IP protection strategy.
Market at a glance (strategic macro view)
Between the start of the 2020s and the 2025 base year the game engines market expanded from early commercial scale to a materially larger industry cohort. By 2025 the industry reached a clear commercial milestone, and the market is projected to grow at an approximate 6.8% compound annual rate over the 2026–2032 forecast window. That growth reflects persistent demand from video games alongside accelerating adoption in non-gaming verticals — automotive simulation, industrial training, healthcare visualization, and immersive marketing — each driving different commercial and technical requirements for engine vendors and integrators.
What this report delivers (practical, action-oriented content)
-
Consolidated market sizing and topline forecasts calibrated to 2025 base-year reality, with scenario analysis that stress-tests adoption under accelerated AI tooling and alternative regulatory paths.
-
Go-to-market and monetization playbooks for vendors, platform partners, and enterprise buyers: licensing strategies, tiered support models, cloud-render economics, and creator-driven revenue shares.
-
Buyer personas and procurement checklists for studios, automotive OEMs, training providers, and XR enterprises — including integration roadmaps, TCO templates, and KPIs that matter for stakeholder buy-in.
-
Partner ecosystem maps and M&A thesis: technology adjacencies (AI content tooling, multiplayer backend, analytics/telemetry), high-value integration targets, and recommended divestiture/bolt-on scenarios.
-
Regulatory and IP risk playbook: compliance guardrails, piracy and licensing enforcement options, and operational controls to reduce exposure in jurisdictions with active enforcement or elevated piracy risk.
-
Case studies and implementation blueprints: multi-year migration pathways for legacy engines, hybrid cloud/local rendering deployments, and live-ops architectures that prioritize retention and monetization.
Competitive landscape — not just who, but what they enable
Understanding vendor intent and ecosystem reach is essential for executives deciding on partnerships or competitive responses.
-
Unity Technologies — As the engine with the broadest developer footprint across mobile, indie, XR, and enterprise, Unity remains central to scale strategies that prioritize a vast creator base and cross-device compatibility. Recent co-development and platform integration deals illustrate Unity’s continued attempt to deepen publisher relationships while expanding addressable enterprise workloads.
-
Epic Games (Unreal Engine) — Unreal continues to lead with photoreal rendering and live-service capabilities attractive to AAA publishers and high-fidelity enterprise simulators. Epic’s ecosystem, including its flagship live platform, creates alternative distribution and creator-economy value chains that companies must model into revenue share and content strategy decisions.
-
Godot Foundation — The open-source engine represents a strategic alternative for price-sensitive developers and organizations prioritizing code ownership and extensibility. Its presence forces incumbents to refine licensing narratives and support propositions for open-standards and transparent roadmaps.
-
Pragma — Specialized providers of live-service backend suites show how the market is fragmenting vertically; out-of-the-box solutions for multiplayer, matchmaking, and social retention are accelerating time-to-market for publishers and creating new partnership opportunities for engine vendors.
Collectively, the top-tier vendors control a substantial portion of platform dynamics, and competitive positioning is increasingly defined by ecosystem services (analytics, monetization, cloud tooling) not just core rendering. Our report provides vendor-specific strategic implications and decision trees that help buyers and investors translate product roadmaps into business outcomes without exposing confidential segment-level metrics in this preview.
Recent developments and near-term disruptors
-
AI-driven asset creation is moving from prototype to production. Industry players launched and announced AI engines that can generate 3D content from text, images or sketches in minutes — a capability that reshapes production pipelines and shifts cost structures for content-heavy projects.
-
Strategic partnerships among incumbents and major publishers have accelerated cross-platform publishing and creator-economy access, blurring ecosystem boundaries and opening alternative distribution gates that buyers must evaluate.
-
Commercial and IP activity continues to rise: partnerships between platform vendors and enterprise integrators signal an acceleration in non-gaming vertical adoption, while technology filings indicate R&D investments focused on AI-assisted rendering and real-time substitution of traditional engine functions.
-
Regulatory and enforcement environments are tightening in key markets. IP protection and licensing compliance are now operational concerns for platform operators and large buyers; enforcement activity in certain regions underscores the need for proactive legal and technical controls.
Strategic implications and recommended executive actions for 2026
-
Adopt a portfolio stance toward engine dependence. Design migration and co-existence pathways that allow you to change rendering backbones over a defined multi-year horizon while preserving asset portability and minimizing rework.
-
Invest in AI-enabled pipeline pilots now. Run constrained production pilots to validate quality, speed, and governance controls for AI-generated assets before scaling to avoid costly rework and IP exposure.
-
Negotiate partnership terms that prioritize creator access and distribution optionality. With platforms creating alternative channels to end users, contractual flexibility can protect monetization upside.
-
Map vendor ecosystems to your monetization and retention levers. The technical fit of an engine must be evaluated alongside analytics, live-ops tooling, and cloud rendering economics.
-
Prepare for regulatory friction. Build compliance checklists into procurement and integration plans to reduce downstream legal and operational risk.
Methodology and confidence framing
The report uses a base-year of 2025 and draws on a five-year historical window to establish demand trajectories and supply-side shifts. Forecasts span 2026–2032 with scenario bands that reflect variations in AI tooling penetration, enterprise adoption rates, and regulatory scenarios. Our confidence intervals are informed by primary interviews, vendor disclosures, patent and partnership tracking, and a rigorous triangulation of market intelligence.
How to use this research
-
C-suite and investment committees: Use the strategic playbooks and M&A theses to prioritize resource allocation and evaluate portfolio fit against a disciplined, scenario-based view of the market.
-
Product and technology leaders: Leverage the integration blueprints and TCO templates to plan migrations and cloud investments with predictable cost and risk profiles.
-
Business development and partnerships teams: Apply the vendor maps and negotiation frameworks to structure deals that preserve long-term optionality.
Next steps
This introduction surfaces the strategic contours you need to act in 2026. The full PW Consulting Game Engines Market report contains the detailed segment-level forecasts, vendor scorecards, and playbooks referenced here. For executives planning capital deployment, product pivots, or partnership strategies, the full dataset and appendices provide the granular inputs necessary to operationalize these recommendations. Access the full study to unlock the confidential segmentation, scenario spreadsheets, and vendor matrices that underpin the analysis presented in this preview.
For detailed analysis of this topic, please visit the official page: Game Engines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hoverboard Scooters Market Poised for 4.85% CAGR Through 2032
By PW Consulting, 2026-07-08
Hoverboard Scooters Market — Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a focused preview of our comprehensive Hoverboard Scooters Market study. This briefing is designed to equip leaders with the high-level strategic implications they must act on in 2026—while reserving the full, actionable detail for the complete report. The study uses 2025 as the base year, traces historical performance across 2020–2025, and projects through 2026–2032. At the macro level, the market exhibits steady expansion (a compound annual growth rate of 4.85%), having grown from roughly USD 280 million in 2020 to approximately USD 349 million in 2025, with a forecast path that reaches nearly USD 479 million by 2032. These headline dynamics frame the decisions organizations must make next year.
Hoverboard Scooters Market
Why this study matters for 2026
-
2026 is the hinge year for allocation decisions. Manufacturers, distributors, and investors will either consolidate gains from early micro‑mobility adoption or face margin erosion from commoditization and regulatory friction.
Hoverboard Scooters Market -
The market’s steady CAGR masks important inflections: battery cost trajectories, software-enabled differentiation, and shifting retail economics are all accelerating. Companies without a clear response will see diminishing returns on incumbent product lines.
Hoverboard Scooters Market -
For corporate strategists, this research converts market-level growth into operational priorities: which products to scale, where to invest in engineering or brand, and how to structure partnerships and M&A to secure supply, distribution, and IP advantages.
Macroeconomic and industry drivers
-
Urban micro‑mobility adoption continues to broaden consumer demographics beyond early adopters. Leisure and last‑mile use cases remain important anchors for demand, but the path to mainstream commuting use is conditional on safety, weather resistance, and perceived reliability improvements.
-
Battery technology and cost improvements are the dominant cost & performance lever. Incremental energy density gains and safer chemistries materially alter product roadmaps and after‑sales liabilities. Companies that secure stable battery supply and invest in thermal management will reduce warranty burdens and win premium segments.
-
Channel economics are shifting: direct‑to‑consumer digital models coexist with traditional retail and marketplace distribution. Winning players will balance acquisition costs, return logistics, and in‑market support through hybrid channel strategies.
-
Regulatory scrutiny on portable electric rideables—covering safety standards, testing protocols, and transport regulations—has increased. Compliance now represents both a cost and a moat: firms that invest early in certification and transparent testing see accelerated retail acceptance.
-
Market structure remains fragmented. Concentration metrics indicate a market led by several visible brands but with ample room for smaller, regionally focused players and new entrants. This structure creates opportunity for consolidation, selective specialization, and differentiated service models.
Competitive landscape — strategic profiles
-
Ninebot Limited (Beijing) — Scale and integration. Ninebot leverages platform engineering and scale manufacturing to iterate across product tiers. Its strength is product breadth and rapid model refresh, which supports channel penetration and OEM partnerships. Strategic implication: competitors should assess whether to compete on scale, niche differentiation, or partnerships that offset Ninebot’s sourcing advantages.
-
Swagtron (United States) — Brand and product breadth. Swagtron’s focus on both standard and off‑road models enables access to lifestyle segments. Its brand recognition in key markets supports premium and specialty models. Strategic implication: prioritize brand-led variants and lifestyle collaborations to capture higher ASPs where competency exists.
-
Hover‑1 (United States) — Retail‑oriented positioning. Hover‑1 combines in‑house manufacturing with retail distribution strategies. Its value proposition centers on accessible price points and broad retail channel coverage. Strategic implication: margin-sensitive players must optimize cost-to-serve and after‑sales pathways to sustain unit economics.
-
GOTRAX (United States) — DTC and product execution. GOTRAX emphasizes a direct relationship with consumers and a tight value chain for electric rideables. Its approach highlights the importance of digital marketing, user experience and warranty responsiveness. Strategic implication: invest in CRM, logistics, and digital product experiences to increase lifetime value.
Competitive implications and near-term moves
-
Portfolio rationalization: Given modest market growth coupled with product commoditization risk, firms should cull underperforming SKUs and reallocate R&D to higher-margin, software‑enabled features (safety sensors, OTA updates, companion apps).
-
Supply‑chain defensibility: Diversify battery suppliers, qualify second‑source PCB and motor vendors, and pursue long‑lead agreements for critical components to avoid production bottlenecks and margin volatility.
-
Certifications and standards: Invest in independent testing and certifications now to unlock large retail chains and institutional buyers later. Certification also materially reduces warranty/recall risk and supports premium pricing.
-
Channel mix optimization: Adopt a hybrid DTC + select retail strategy to control customer experience while leveraging retail for trial and scale. Optimize return logistics and field service to reduce churn and warranty costs.
-
M&A and partnerships: Use bolt‑on acquisitions to acquire niche tech (sensor fusion, battery management), service capabilities (in‑market repair networks), or distribution footprints rather than large market share buys which are expensive in a fragmented market.
Operational playbook for 2026 — prioritized actions
-
Product: Shift R&D spending to safety, battery management, and software differentiators. Define a two‑track roadmap—cost‑optimized SKUs for mass channels and feature‑rich models for premium segments.
-
Manufacturing & supply: Qualify alternate suppliers for batteries and power electronics; embed cost‑down initiatives; model scenarios for raw material price shocks.
-
Go‑to‑market: Trial pop‑up experience centers in high footfall urban districts to increase conversion; deploy subscription or extended warranty offerings to monetize aftersales.
-
Service & returns: Build modular designs that reduce repair time and lower warranty costs. Outsource field repairs to certified partners where capex is prohibitive.
-
Data & software: Start collecting anonymized operational telematics to improve product safety, inform feature roadmaps, and enable new revenue streams (insurance partnerships, usage analytics).
-
Finance & risk: Stress‑test models against three scenarios (base CAGR continuation, conservative slowdown, and accelerated adoption) and align capex/opex flex to maintain cash runway through cyclical dips.
Metrics to monitor in 2026
-
Unit economics: gross margin by SKU, contribution margin per unit, and ASP trends across channels.
-
Customer metrics: CAC by channel, repeat purchase rate, and average warranty claim cost.
-
Operational KPIs: lead times for batteries, supplier fill rate, and field‑repair turnaround time.
-
Safety & quality: failure rate per 1,000 units in first 12 months and thermal incident frequency—these materially affect brand equity and distribution access.
What the full PW Consulting report contains (practical deliverables)
-
Comprehensive market sizing and forecast models (2020–2032) with downloadable worksheets and sensitivity scenarios to support internal financial planning.
-
Segment and regional breakouts (detailed revenue splits, growth by subcategory and use case) and an interactive dashboard for scenario testing.
-
Competitive benchmarking across product, pricing, distribution and service dimensions, including SWOT profiles of market leaders and challenger brands.
-
Go‑to‑market playbooks tailored to manufacturer, distributor, and retailer archetypes—each with stepwise implementation guidance for 12–24 months.
-
Supply chain and sourcing map with identified single‑point‑of‑failure components and recommended mitigation actions.
-
Regulatory & certification matrix across key jurisdictions and practical checklists for compliance and testing programs.
-
M&A target shortlist and partnership frameworks for buyers seeking inorganic growth or capability augmentation.
-
Primary interview insights from industry leaders and field operational findings that validate model assumptions and reveal near‑term risks.
Closing guidance — what to act on now
For executives preparing 2026 plans, three immediate actions are non‑negotiable: (1) lock in battery and power‑electronics sourcing with contingency clauses; (2) fund a minimal viable investment in software/telemetrics to begin creating serviceable data assets; and (3) perform an SKU profitability review to reallocate spend to higher margin and defensible product lines. These steps materially reduce downside while preserving upside in a market that is growing modestly but becoming increasingly technology- and standards-driven.
Our full PW Consulting report converts these strategic imperatives into executable initiatives with templates, vendor lists, and a prioritized roadmap. For teams responsible for 2026 budgets, the report is designed to turn ambiguity into a concrete investment plan—without overcommitting resources to low‑return SKUs. To obtain the complete analysis and the supporting datasets that detail segment and regional dynamics, request the full report from PW Consulting’s market research desk.
For detailed analysis of this topic, please visit the official page: Hoverboard Scooters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Tool Steel Market to Reach USD 9.94 Billion by 2032 at 6% CAGR
By PW Consulting, 2026-07-08
Tool Steel Market — Strategic Brief for 2026 Decisions
As Pw Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused, action-oriented introduction to our Tool Steel Market study. This brief translates the study’s core macro signals into concrete decision levers for executives preparing strategy, investments, and operations in 2026. It demonstrates the analytical depth of the full report while intentionally preserving the detailed segment-level outputs—so your team will know what to test and where to deploy capital, but will need the full report to execute with precision.
Executive snapshot: What the macro facts tell you
- The tool steel market demonstrates a durable recovery and steady expansion trajectory. Using 2025 as the base year, our historical series (2020–2025) and forward-looking forecast (2026–2032) show a consistent compound annual growth rate of roughly 6.0% through the forecast horizon.
- Measured on the aggregate level, the market has grown from the mid-single-digit billions in 2020 to a stronger position in 2025, and our baseline forecast reaches a near-ten-billion-dollar scale by 2032. This trend signals both steady end-demand and structural drivers that support multi-year investment horizons.
- Market structure is neither a pure commodity nor a highly concentrated oligopoly. Our concentration metrics (CR3 ≈ 30%; CR5 ≈ 45%) indicate a moderately fragmented landscape where leading producers hold meaningful scale advantages but sizeable value remains with regional and specialized players.
Why this study matters for 2026 strategic decisions
2026 will be a pivot year for tool steel participants for three reasons. First, secular demand drivers—industrial electrification, higher-performance mobility components, and continued automation of manufacturing—are transitioning procurement and product roadmaps from cost-centric to performance- and sustainability-centric criteria. Second, supply-side forces such as alloy innovation, recycling economics, and capacity rationalization are consolidating margins and reshaping negotiating power. Third, the 6% CAGR baseline creates a planning envelope that makes moderate-capacity and capability investments viable—but only if directed at the right subsegments and geographies.
In practical terms, this report converts those macro realities into decision-ready outputs: supplier-scorecards for procurement negotiations, capex scenarios tied to demand elasticity assumptions, product roadmaps aligned with alloy innovation timelines, and M&A playbooks that prioritize integrability and margin expansion. The depth of the analysis supports both defensive moves (securing feedstock, hedging alloy premiums) and offensive plays (new high-value grades, downstream integration into tooling and service).
Key strategic implications across the value chain
- Procurement and input risk management — The predictable growth envelope enables procurement to move from ad hoc spot buys to multi-year sourcing frameworks. The report provides tooling for quantifying exposure to alloy-cost volatility and for structuring forward contracts and recycling partnerships to reduce earnings variability.
- Capacity and footprint planning — With the market expanding forecasted through 2032, capacity expansion should be calibrated to grade complexity rather than sheer volume. Our scenario models show greater ROI when investments target advanced high-speed and specialty grades or near-market finishing capacity versus undifferentiated long products.
- R&D and product strategy — Prioritizing development in machinability, wear resistance, and heat-treatment compatibility yields outsized commercial payback. The study outlines timing windows where incremental composition improvements unlock premium pricing in tooling applications.
- Commercial and go-to-market — Sales and service capabilities (engineering support, remanufacturing, field trials) are decisive in capturing premium segments. The full report includes commercial playbooks for converting engineering relationships into recurring revenue streams.
- M&A and partnership screening — The market concentration metrics suggest fertile ground for bolt-on acquisitions that bring differentiated technologies, regional market access, or downstream customer intimacy. We provide a scoring matrix to prioritize targets based on technology fit, cultural integration risk, and immediate margin accretion potential.
- ESG and circularity — Material lifecycle economics improve under tighter recycling loops and alloy standardization. The study quantifies potential cost offsets from reclaimed alloy streams and recommends contractual constructs to share upside across the value chain.
Competitive landscape — how to read today’s leaders
The full competitive analysis maps capability clusters and strategic postures rather than repeating commoditized product lists. Below are concise strategic profiles of three incumbent players that exemplify distinct competitive models featured in the study.
- Proterial, Ltd. (Tokyo, Japan) — A specialty tool steel manufacturer with a portfolio that includes grades for cold working molds, high-speed cutting, hot-work dies, and precision blades. Proterial’s strengths are deep material expertise for high-performance tooling and a value proposition focused on application-specific alloy solutions. Strategically, competitors and customers should watch for how Proterial converts specialty-grade know-how into system-level services (tooling design partnerships, aftermarket optimization).
https://www.proterial.com - voestalpine High Performance Metals (Vienna, Austria) — Operating globally under recognized brands, voestalpine combines a broad product set for hot, cold, and high-speed applications with distribution reach. Its playbook centers on brand-enabled premiumization and integrated supply chains. For challengers, the strategic question is whether to compete on breadth or double-down on niche specializations where technical entry barriers are higher.
https://www.voestalpine.com - Hitachi Metals, Ltd. (Tokyo, Japan) — Known for advanced grades for molds and dies, Hitachi Metals has historically invested heavily in alloy innovation and quality control. Its strategic footprint is strongest where precision and reliability matter most—high-value tooling and components. Competitors should note that R&D-led differentiation remains a durable moat if paired with commercial scale.
https://www.hitachi-metals.com
Collectively, these companies illustrate the two primary axes shaping industry competition in 2026: technological depth (grade and process innovation) and go-to-market scale (distribution, service, and integration). Our report’s competitor matrices translate these axes into playbooks for entrants and incumbents alike.
What the full report contains — practical, operational outputs
The Pw Consulting Tool Steel Market study is engineered for decision-makers. Highlights include:
- Macro demand scenarios (baseline, upside, downside) calibrated to a 6.0% CAGR baseline and stress-tested for recession, raw-material shock, and accelerated electrification vectors.
- Segment-level demand modeling by region, product type, and application—presented as decision rules and allocation levers (note: detailed segment tables are reserved for the full report).
- Supplier and competitor scorecards with standardized KPIs: technology differentiation, margin profile, capacity flexibility, service and aftermarket capability, and integration risk.
- Capex and M&A playbooks including payback thresholds, post-merger integration checklists, and regulatory risk overlays for cross-border deals.
- Procurement tools: hedging calculators, alloy-price sensitivity matrices, and sample contract constructs that align incentives for recycling and long-term supply stability.
- Commercial frameworks for premiumization: price-to-performance maps, customer segmentation logic, and service-bundling approaches that demonstrate margin uplift opportunities.
- Implementation templates: 18‑month milestones, KPIs for a center-of-excellence, and a roadmap for piloting supply-chain and product initiatives in 2026.
How to use this study in your 2026 planning cycle
Here are three concrete use cases the report is designed to support:
- Capital allocation — Use the capex scenarios to stress-test plant expansions and R&D programs under the 6.0% CAGR baseline and alternative demand shocks. The report identifies where incremental capacity delivers margin expansion versus where it dilutes returns.
- M&A targeting — Apply our target-scoring matrix to prioritize acquisition candidates that close capability gaps (e.g., finishing, heat treatment, alloy know-how) rather than simply adding volume.
- Commercial optimization — Implement the supplier scorecards and pricing frameworks to renegotiate customer contracts, introduce value-based pricing for high-performance grades, and build service-based revenue streams.
What we intentionally withhold here — and why
To preserve the strategic value of the full study, this brief purposefully omits the granular segmentation tables and the specific regional/application revenue breakdowns that inform high-precision procurement and M&A bids. Those tables are the operational inputs teams need to size opportunities by geography and application and are available in the full report along with downloadable financial models and scenario files.
Final takeaways
As companies finalize their 2026 plans, the Tool Steel Market offers a clear strategic paradox: the macro growth outlook supports investments, but success will hinge on choosing the right kind of investments—those that emphasize grade differentiation, service integration, and supply-chain resilience instead of volume alone. Pw Consulting’s study equips leaders to make those choices with confidence, providing both the high-level framing and the decision-grade tools needed to act.
For clients and decision-makers ready to convert these insights into immediate action, the full report provides the guarded segmentation data, downloadable models, and implementation templates that convert strategic intent into measurable outcomes. Contact Pw Consulting to access the complete Tool Steel Market study and the supporting decision toolset.
For detailed analysis of this topic, please visit the official page: Tool Steel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Tetramethyl Ammonium Hydroxide Market to Expand at 5.2% CAGR Through 2032
By PW Consulting, 2026-07-08
Tetramethyl Ammonium Hydroxide (TMAH) Market — Strategic Preview for 2026 Decision-Makers
PW Consulting presents a strategic preview of the Tetramethyl Ammonium Hydroxide (TMAH) market designed to orient executives, investors, and corporate strategy teams as they make high‑stakes decisions in 2026. This briefing synthesizes our market modelling, regulatory mapping, and competitive intelligence into actionable implications, while intentionally withholding detailed segment-level datapoints to encourage stakeholders to consult the full report for transaction‑grade detail.
Tetramethyl Ammonium Hydroxide Market
Why TMAH matters now
TMAH is a mission‑critical specialty chemical across semiconductor photolithography, display manufacturing, and a range of industrial and laboratory uses. After steady expansion through the early 2020s, our updated market model shows the industry growing from roughly USD 374 million in 2020 to approximately USD 487.3 million in the base year 2025, and continuing on a compound annual growth path of about 5.2% through the 2026–2032 forecast horizon. Under our baseline assumptions, the market nears USD 702 million by 2032.
Tetramethyl Ammonium Hydroxide Market
For 2026 decision cycles, that growth trajectory creates a window where strategic moves — capacity investments, supply‑chain reconfiguration, product differentiation and targeted M&A — can materially alter competitive positioning. But realizing upside requires careful management of three tightly linked vectors: raw‑material exposure, regulatory & safety risk, and product‑quality differentiation for electronic‑grade applications.
Tetramethyl Ammonium Hydroxide Market
Core dynamics shaping 2026 strategy
-
Raw‑material and input volatility. TMAH production is fundamentally linked to trimethylamine feedstocks derived from methanol and ammonia. Historical shocks — notably the 2021 methanol price surge that increased TMAH solution costs and compressed supplier margins — underline the sensitivity of producer economics to upstream commodity swings. Firms with limited input hedging or spot exposure experienced margin erosion during that period.
-
Regulatory and hazardous‑materials overhead. TMAH is classified as highly toxic and corrosive across major jurisdictions. Compliance regimes (including EU REACH SVHC obligations, US TSCA certification, and China’s Dangerous Chemicals regulations) create recurring compliance costs and capex requirements for storage, transport, emergency response and waste treatment. Noncompliance risk or underinvestment in safety infrastructure can lead to operational disruption and reputational damage — a material consideration for buyers and financiers.
-
Policy‑driven demand reallocation. Recent policy moves matter: China’s 2026 Semiconductor Equipment Industry Development Guide explicitly lists electronic‑grade TMAH as a priority and introduces subsidies for downstream purchases of domestic material; parallel public investment — including sizable allocations from a national semiconductor fund — aims to accelerate local R&D and capacity. These interventions create both demand pull and competitive pressure for non‑Chinese suppliers and influence long‑term supplier selection dynamics.
-
Market concentration and competitive dynamics. The TMAH market shows measurable concentration: our analysis indicates the top three players account for roughly 62% of industry sales, and the top five about 68%. This concentration amplifies the strategic importance of relationships with tier‑one suppliers, and makes targeted partnerships, strategic equity stakes, or selective capacity expansion effective levers to secure supply and pricing advantages.
What the full report delivers — practical, transaction‑ready outputs
To translate the dynamics above into executable decisions, the complete PW Consulting TMAH report contains the following operational tools and analyses (summarised here at a headline level):
- Bottom‑up market model (2020–2032) with scenario toggles (base, upside, downside) that drive demand, pricing and margin forecasts suitable for valuation and capex planning.
- Segmented demand forecasts by grade and application plus differentiated pricing curves for electronic, industrial and laboratory grades — available in the full dataset.
- Supply‑chain mapping and concentration heatmaps, including production locations, capacity utilisation, and logistics sensitivity by trade lane.
- Raw‑material cost driver analysis with input cost pass‑through models and recommended hedging mechanisms tailored to common contracting structures in the sector.
- Regulatory impact assessment (EU, US, China and key Asia Pacific jurisdictions) identifying compliance capex, certification timelines, and probable inspection risk points.
- Supplier and customer scorecards — financial health, quality certifications, production tech, and compliance track records — to support vendor selection and due diligence.
- M&A playbook and valuation comparables for buyers and sellers, including synergies from vertical integration (e.g., ammonium sourcing, on‑site chemical recycling) and bolt‑on opportunities in wet‑chemicals for semiconductor fabs.
- Operational checklists for safe handling, storage and disposal aligned with international best practice — critical for insurance and financing approval.
Note: this introduction deliberately omits segment‑level market shares and granular revenue splits. The full report contains downloadable tables and interactive models for subscribers and clients.
Competitive landscape — strategic takeaways
Our company intelligence covers global incumbents and regional specialists. Several observations are pivotal for 2026 strategy:
-
Incumbents with electronic‑grade focus enjoy structural advantages. Producers that combine ultra‑clean production processes with geographically proximate capacity to semiconductor fabs capture premium pricing and lower logistics risk. Investments in chlorine‑free synthesis methods and cleanroom graded operations are differentiators that translate into higher switching costs for downstream fab customers.
-
Regional champions are leveraging policy to scale. Firms with strong domestic positions and localised manufacturing are best positioned to capture subsidy flows and fast follower demand where governments prioritise semiconductor materials. This dynamic is reshaping supplier selection, particularly for large downstream purchasers seeking secure supply under incentivised procurement frameworks.
-
Niche specialists serve high‑margin laboratory and analytical channels. Reagent‑grade and pentahydrate suppliers that target research and analytical markets maintain distinct value pools separated from commodity industrial volumes; these channels remain attractive for companies seeking margin diversification without large incremental capex.
-
Consolidation risk is real but selective. Given current concentration metrics, targeted consolidation — particularly acquisitions that bring electronic‑grade expertise, proprietary processes, or regional footprint — can rapidly shift local market power. However, integration risks (quality harmonisation, regulatory alignment) are non‑trivial and must be priced into transaction models.
Strategic options for 2026 — decision frameworks
For executives preparing capital allocation and sourcing strategies this year, we recommend evaluating five near‑term options through a structured decision framework that balances supply security, margin protection and regulatory resilience:
-
Hedge & partner. Negotiate multi‑year offtake contracts with indexed pass‑throughs plus input‑price collars. Combine contractual protection with strategic minority investments in key suppliers to align incentives without full integration.
-
Localise selectively. Where policy subsidies or procurement regimes materially improve economics, consider greenfield or JV options to locate electronic‑grade capacity within incentive geographies — but only after scenario testing for demand concentration and contractual lock‑in.
-
Differentiate on quality and services. For suppliers: move up the value chain by certifying for the highest grades, offering customised formulations, and providing fab‑level service agreements that include contamination control and emergency response.
-
Verticalise inputs. Integrate upstream where feasible to reduce exposure to methanol/ammonia price cycles — acquisition of trimethylamine capacity or long‑term feedstock contracts can be decisive during commodity shocks.
-
Stress test scenarios. Run decision trees against three plausible 2026‑2028 outcomes: continued steady growth (baseline, ~5.2% CAGR), accelerated domestic substitution driven by policy, and downside stress from trade disruption or raw material shock. Quantify working‑capital demand, cash‑flow timing, and covenant risk for each.
Operational cautions and risk mitigants
Two operational realities consistently undercut strategy execution:
-
Underestimating compliance capex. Many entrants under‑invest in storage, secondary containment, and emergency response, creating latent liabilities that can derail expansion plans and increase insurance costs.
-
Ignoring logistics complexity. TMAH movement requires specialised carriers, packaging and routing to comply with hazardous‑goods rules; failing to secure qualified logistics partners can result in delivery delays and contractual penalties.
Mitigants include long‑lead procurement of compliant infrastructure, third‑party logistics partnerships with hazardous‑materials specialisation, and explicit contract clauses allocating responsibility for transport and storage compliance.
Next steps for 2026 decision‑makers
PW Consulting’s full TMAH report is structured to move teams from awareness to action: it couples rigorous market models (2020–2032) with supplier scorecards, regulatory playbooks, and financial templates for both organic and inorganic growth paths. For firms evaluating capex in 2026, or planning supplier selection and risk management programs, the report provides the scenario outputs and deal‑level artefacts needed for board‑level approvals and lender diligence.
If your 2026 strategic plan requires securing electronic‑grade supply, sizing a manufacturing investment, or assessing acquisition targets, the full dataset and advisory support will reduce execution risk and compress the decision cycle. This preview highlights the levers; the comprehensive intelligence pack delivers the transactional detail.
How to proceed
Access to the full report and the interactive models is available through PW Consulting. The detailed segmentation, regional allocation, price curves and downloadable forecasts are intentionally gated — they are provided to clients and subscribers to ensure decision‑grade confidentiality. Engage with our team for a tailored briefing and scenario run‑through calibrated to your company’s exposure and strategic ambitions.
For detailed analysis of this topic, please visit the official page: Tetramethyl Ammonium Hydroxide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Oil Country Tubular Goods (OCTG) Market — 2026 Strategic Preview
Executive snapshot
As the upstream energy sector recalibrates for a complex 2026, OCTG remains a cornerstone of project execution and field performance. Our PW Consulting baseline shows the global OCTG market expanding from roughly USD 17.4 Billion in 2020 to an estimated USD 24.5 Billion in 2025, and continuing along a growth trajectory that reaches close to USD 39.0 Billion by 2032 — a compound annual growth rate of 6.8% across the forecast window. These headline dynamics reflect a mix of recoveries in exploration and production activity, accelerated investment in high-spec applications and selective infrastructure awards that demand premium tubular solutions.
Oil Country Tubular Goods (OCTG) Market
Why this research matters for 2026 decision cycles
- Investment prioritization: Capital allocation for 2026–2028 must account for the OCTG market’s steady growth profile and the accelerating portion of demand that requires premium materials and services. Understanding where pricing and specification inflation will occur is now a board-level concern.
- Procurement and sourcing: Trade policy shifts, standard updates and raw-material volatility are compressing lead times and margin buffers. Procurement strategies that ignore these dynamics will face increased supply risk or unexpected cost inflation.
- Competitive positioning: The market exhibits moderate concentration — the top three and five suppliers account for a meaningful share of global supply — creating both entry barriers and targeted opportunities for differentiated players.
Market trajectory and structural drivers
Two complementary forces are driving the OCTG market through 2026 and beyond. First, the recovery and selective expansion of upstream activity in target basins are lifting volumetric demand and underpinning long-term contracts. Second, there is a structural uplift in demand for higher-spec tubulars — corrosion-resistant alloys, premium connections and engineered solutions for complex wells — that pushes average selling prices upward even as producers seek cost efficiencies.
Oil Country Tubular Goods (OCTG) Market
Our historical series (2020–2025) captures the market’s path through cyclical stress and incremental recovery, while scenario-led forecasts (2026–2032) stress-test outcomes under competing commodity price, policy and project-award assumptions. The 6.8% CAGR embedded in our central scenario is not uniform across all product classes or geographies; rather, it masks a re-weighting toward premium, high-value applications that will have outsized implications for supply chain design and margin capture.
Oil Country Tubular Goods (OCTG) Market
Dynamics and near-term risks
- Trade and regulatory shocks: Recent antidumping and countervailing duty investigations initiated by the U.S. Department of Commerce (April 2026) have already begun to reshape sourcing strategies for OCTG imports. These proceedings can materially alter competitive advantages across suppliers and should be factored into bilateral and long-term contracts.
- Standards and specification updates: The American Petroleum Institute published a new foundational line pipe standard in June 2026, while ISO technical work on casing, tubing and drill pipe remains active. Specification changes tend to produce procurement lag, testing bottlenecks and short-term demand spikes for compliant stock.
- Raw material and pricing volatility: Market data indicate movements in FOB pricing for OCTG on North American terms earlier this year. Even modest per-ton swings feed directly into producer margins and can trigger pass-through clauses in supplier contracts.
- Project-driven concentration of demand: Large upstream awards and regional pipelines create episodic demand concentration that benefits suppliers with scale or local footprint — and penalizes those with longer lead times or single-source exposure.
Competitive landscape — supplier implications
The competitive field combines global integrated steelmakers, specialized tubular manufacturers and regional players with export capabilities. Each archetype brings distinct value propositions and risk profiles that buyers and investors must map to project requirements.
- Tenaris (Buenos Aires, Argentina) — Tenaris’s portfolio emphasizes seamless and welded casing/tubing, premium connections (Hydril®), corrosion-resistant alloys and a growing service layer (Rig Direct®, OCTG Experience workshops). Their dual focus on technology and service enables value capture beyond the transaction, making them a natural partner for operators prioritizing performance and reliability.
- Vallourec (Courbevoie, France) — Vallourec remains oriented toward high-spec seamless carbon steel OCTG and proprietary connection systems (VAM®). Recent contract awards for major energy projects and targeted product deployments demonstrate the company’s ability to convert engineering-led solutions into project wins — a model that favors close integration with EPCs and national oil companies.
- United States Steel Corporation (Pittsburgh, USA) — As an integrated supplier with a domestic manufacturing footprint, U.S. Steel offers seamless and ERW casing/tubing options tailored to U.S. energy demand. Their position is strategically relevant when trade interventions or security-of-supply considerations drive onshore sourcing preferences.
- TMK Group (Moscow, Russia) — TMK’s mix of welded and seamless OCTG, premium connections and international distribution capability positions it well for cross-border projects and markets where long-established relationships and logistics proficiency are decisive.
- Borusan Pipe (Istanbul, Turkey) — Borusan’s core strength lies in welded OCTG solutions and a competitive manufacturing cost base, which supports both regional supply and export-led contracts. For buyers seeking balance between cost and delivery performance, regional players like Borusan are often pivotal.
Recent corporate developments exemplify strategic pathways: a leading supplier’s technical workshops aimed at E&P decision-makers, and significant line-pipe awards tied to offshore developments. Such events are not isolated PR items; they materially influence procurement timetables, specification adoption and local content negotiations.
What the full PW Consulting OCTG report delivers (operative content)
- Validated market-sizing and a five-scenario forecast (2026–2032) calibrated to commodity, capex and policy levers.
- Demand-by-product and application modeling with sensitivity analyses for pricing, specification shifts and project award cadence (note: detailed splits for region/product/application are available in the full report).
- Supplier landscaping and scorecards — manufacturing footprint, technical capability, premium-connection patents, lead-time maps and financial resilience indicators.
- Procurement playbook — contract templates, hedging approaches for raw-material exposure, SLAs for run-ready deliveries and risk allocation matrices.
- Operational toolkits — inventory optimization algorithms for tubulars, CapEx sizing for consolidation or nearshoring, and a checklist for technical compliance with the latest API/ISO updates.
- Strategic M&A and partnership opportunities — target screening for bolt-on technologies (CRA, premium connections), geographic expansion candidates and JV structures that de-risk market entry.
Strategic imperatives for executive teams in 2026
- Re-price contractual exposure: Incorporate granular indexation and triggers for raw-material movements and trade policy shifts to avoid profit erosion.
- Prioritize supplier segmentation: Classify suppliers by capability (e.g., premium connections, CRA proficiency, service integration) and allocate volumes accordingly — not all suppliers should be treated as fungible.
- Invest in specification governance: Centralize engineering approval and standard-change monitoring to shorten procurement cycles when API or ISO updates come into force.
- Build contingency capacity: Identify near-shore or strategic stock points for critical tubulars to mitigate disruption from trade actions or freight volatility.
- Monetize services: Operators and suppliers that move up the value chain with training, run-ready services and field-engineering capture higher margin pools and reduce total cost of ownership for clients.
- Use M&A as a means to secure technology: Acquihires or minority stakes in premium-connection or CRA specialists can unlock performance differentiation without full-scale greenfield investment.
How to use this preview — and where to go next
This preview is designed as a strategic roadmap for 2026 planning cycles: it signals where the market is heading, what risks are materializing, and which supplier archetypes will be decisive. For procurement leaders, project sponsors and strategic investors seeking executable intelligence, the full PW Consulting OCTG market study provides the underlying data, segmented demand models and supplier scorecards needed to convert insight into contract and investment decisions.
We have deliberately withheld granular regional and application splits in this extract to preserve the commercial value of the underlying models. Accessing the full dataset will enable scenario runs tailored to your specific exposure — whether you are evaluating a Gulf basin development, a North American shale program, or an export-led pipeline project.
Final note — timing matters
Regulatory filings, standard revisions and a handful of large project awards will compress decision windows through 2026. Firms that align procurement, technical governance and commercial strategy now — informed by rigorous market models and supplier intelligence — will convert the OCTG market’s predictable growth into durable competitive advantage. PW Consulting’s full report provides the tools to do exactly that.
For detailed analysis of this topic, please visit the official page: Oil Country Tubular Goods (OCTG) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rare Earth Magnet Market to Reach USD 17.85 Billion by 2025
By PW Consulting, 2026-07-08
Rare Earth Magnet Market — Strategic Outlook for 2026 Decision-Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present this executive introduction to our Rare Earth Magnet Market study, calibrated for C-suite and investment teams finalizing 2026 playbooks. Built on a 2025 base year with a 2026–2032 forecast window, the study synthesizes five years of historical trends (2020–2025) into scenario-driven, transaction-ready insight. The headline: the global rare earth magnet market has expanded from roughly USD 12.5 billion in 2020 to USD 17.9 billion in 2025 and is projected to reach approximately USD 29.3 billion by 2032, growing at a compound annual rate of about 7.25%. That momentum, coupled with policy interventions and rapid capacity additions, creates a landscape where near-term commercial decisions will materially determine competitive position and supply security through the decade.
Rare Earth Magnet Market
Why This Study Matters for 2026 Decisions
-
Immediate procurement and sourcing choices will lock in cost and availability profiles for multi-year programs. With market growth accelerating and new western capacity coming online in 2025–2026, firms must decide whether to preserve flexibility through diversified sourcing or secure long-term supply via vertical partnerships.
Rare Earth Magnet Market -
Regulatory and defense-driven incentives are reshaping economics. Public-private initiatives, domestic tax and incentive programs, and export-control dynamics are compressing the time-to-market for non-China supply chains. The report maps how these policy levers change breakeven calculations for onshore plants, recycling projects, and offtake contracts.
Rare Earth Magnet Market -
Technology and material composition choices (e.g., grades and magnet formulations) are increasingly strategic. R&D and recycling will decide not just cost but also product eligibility for automotive and defense procurement. Our analysis provides the decision frameworks purchasing, product, and R&D leaders need to align engineering choices with procurement realities.
Market Dynamics & Forecast — What the Numbers Tell Us
The market’s circa 7.25% CAGR to 2032 reflects a blend of sustained demand growth in electrification, industrial automation and renewables, and dynamic supply-side change driven by new capacity and policy support. After the 2020–2025 expansion to roughly USD 17.9 billion in 2025, PW Consulting’s baseline forecast anticipates steady growth to an estimated USD 18.8 billion in 2026 and continuing to about USD 29.3 billion by 2032 under our core scenario.
That rate of expansion is not uniform: the market will experience phases of capacity-driven price compression, short-cycle tactical tightness tied to feedstock availability, and mid-cycle structural tightening as higher-performance magnet grades capture disproportionate value. The report models these phases under three scenarios — Conservative, Baseline, and Accelerated — and quantifies impacts on margin, unit cost, and supply risk for buyers and producers.
Competitive Structure — Who Matters and Why
The competitive landscape is evolving rapidly. A mix of legacy magnet specialists, integrated miners/processors, and new entrants focused on onshore production is creating differentiated pathways to market. Leading public and private firms we profile include MP Materials, Lynas Rare Earths, Noveon Magnetics, USA Rare Earth, Neo Performance Materials, EM&T, Arnold Magnetic Technologies, Vacuumschmelze (VAC), Electron Energy Corporation, and Stanford Magnets. The report offers plant-level intelligence, strategic positioning, and capability mapping for each.
-
MP Materials has moved from miner to integrated supplier with a high-profile public-private partnership that materially accelerates US magnet capacity and creates offtake arrangements engineered to underpin long-term domestic magnet supply chains.
-
Lynas continues to optimize separation and downstream processing across Australia and Malaysia, targeting automotive and industrial OEMs that require non-Chinese supply origins and demonstrated chain-of-custody.
-
Neo Performance Materials has established a major European magnet facility with the explicit aim of serving EV and wind markets — a direct response to OEM localization pressure in Europe.
-
USA Rare Earth has commissioned domestic sintered NdFeB capacity and is pursuing vertical integration, signaling that first-mover onshore production can be achieved at commercial scale when combined with targeted capital and project execution.
-
EM&T and several specialized US players are scaling sintered and bonded magnet capacity specifically to meet defense supply-chain requirements and anticipated procurement rules, creating an alternative supplier base for mission-critical applications.
Collectively, the market shows meaningful concentration among established leaders and rapid fragmentation as new capacity comes online. Our competitive section does more than list names: it assesses technological competencies (bonded vs. sintered, high-temperature grades), qualification cycles for OEMs and defense primes, and expected ramp profiles — all essential when evaluating supplier risk and lead times.
Report Contents — Practical, Transaction-Ready Deliverables
PW Consulting’s full study is built for immediate application. Highlights include:
- Executive summary with decision briefs tailored for procurement, operations, and corporate development teams.
- Scenario-based market and price models (Conservative, Baseline, Accelerated) with downloadable spreadsheets to stress-test procurement bids, offtake proposals, and investment cases.
- Plant-by-plant capacity tracker and time-phased production ramps, together with supplier readiness scoring and qualification timelines.
- Regulatory tracker mapping policy levers (incentives, export controls, domestic content rules) and their quantified effect on unit economics under policy-shock scenarios.
- Supply-chain risk matrix including feedstock concentration, technology dependency, recycling potential, and geopolitical exposure.
- Practical procurement playbooks: template term-sheet language for offtake contracts, negotiating levers for price floors and indexation, and contingency sourcing strategies.
- Investment and M&A playbook for private equity and corporate buyers, with valuation sensitivity to capacity utilization, price decks, and domestic content incentives.
To preserve commercial value for subscribers, the report’s full segmentation tables — regional, type and application splits, and plant-level economics — are available in the complete report. This introduction intentionally omits those granular tables to encourage validation of model assumptions in the detailed dataset.
Policy, Regulation and Supply-Chain Signals You Can’t Ignore in 2026
-
Public-private partnerships and defense procurement preferences are shifting the equilibrium toward onshore production in several markets. Where governments are underwriting downstream build-outs, the commercial calculus for long-term offtake and equity participation changes rapidly.
-
Export control developments and diplomatic oscillations have introduced short-run price volatility and raised the strategic value of traceable, non-controversial supply chains. Our regulatory module quantifies the expected frequency and scope of such interventions and models mitigation strategies.
-
Recycling and material substitution are nascent but accelerating levers to reduce feedstock exposure. DOE and national funding programs are beginning to make recycling projects financeable on compelling unit-cost bases for certain high-grade magnets; the report includes payback models for these projects under multiple price decks.
How Corporates Should Use This Research — 90 Days to 36 Months
-
90 days: Run the PW scenario models against existing supply contracts. Re-prioritize short-list suppliers by qualification timing and domestic-content exposure. Begin contingency conversations for bridging supply if your programs are capacity-sensitive.
-
6–12 months: Negotiate term sheets that incorporate staged price floors, volume-flexibility clauses, and qualification milestones. Evaluate minority equity stakes in ramping facilities where government incentives materially de-risk the build.
-
12–36 months: Implement vertical- or near-vertical integration strategies where technical differentiation (high-temperature grades, specialty assemblies) creates persistent margin advantages. Deploy recycling pilots for high-value scrap streams and lock in offtake for circular feedstocks.
Conclusion — The Strategic Imperative for 2026
2026 is a pivot year: new western capacity, defense-driven procurement, and active policy support converge with steady demand growth to create a market where winners will be defined as much by supply-chain architecture and contracting sophistication as by manufacturing cost. PW Consulting’s Rare Earth Magnet Market study converts aspirational strategy into executable programs — delivering the models, plant-level intelligence, and negotiation playbooks buyers and investors need to turn 2026 choices into durable competitive advantage.
For access to the full dataset, plant-level capacity tables, segmentation breakdowns, and downloadable scenario models, consult the complete PW Consulting report and data annex — the granular evidence base you’ll need to quantify risk and finalize 2026 commitments.
For detailed analysis of this topic, please visit the official page: Rare Earth Magnet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Carbon Brush Market Poised for USD 399.99M by 2032 at 4.1% CAGR
By PW Consulting, 2026-07-08
Carbon Brush Market — 2026 Strategic Outlook: A PW Consulting Executive Preview
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present this executive preview of our Carbon Brush Market research to highlight the strategic choices facing industrial manufacturers, OEMs, procurement leaders, and investors in 2026. Grounded in a rigorous assessment with base year 2025, our study traces developments across 2020–2025 and provides a scenario-driven forecast for 2026–2032. The market, which expanded from roughly USD 250 Million in 2020 to about USD 301 Million in 2025, is modeled to grow at a 4.1% CAGR through the forecast window and approach the USD 400 Million mark by 2032. These macro dynamics — and the competitive structure that places the top three suppliers at just under half of the market and the top five at roughly mid‑fifties concentration — set the context for the tactical decisions we expect organizations to take in 2026.
Carbon Brush Market
Why this market matters to 2026 decision-makers
-
Strategic leverage: Carbon brushes remain a small but mission‑critical component across motors, generators, signal and current transmission assemblies, and grounding systems. Even modest shifts in brush life, wear rates, or unit pricing can materially affect total cost of ownership for fleets of motors or high‑value rotating equipment.
Carbon Brush Market -
Timing of inflection points: 2026 represents an operational inflection driven by ongoing electrification of industrial systems, incremental renewables deployment (notably wind and related generator systems), and steady modernization of material‑handling and process equipment. These trends heighten demand for reliable, lower‑wear carbon solutions and aftermarket service models.
Carbon Brush Market -
Supply‑side fragility: Graphite raw material sourcing is geographically concentrated, and episodic supply constraints have already led to price volatility and lead‑time risk. Procurement teams must reconcile near‑term availability with multi‑year volume needs.
Key drivers and headwinds shaping 2026 strategies
-
Demand drivers: Continued modernization of industrial motors, electrification of transport and off‑highway equipment, increased deployment of variable‑speed drives, and growth in heavy industrial applications drive base demand. At the same time, the aftermarket for brush replacement, refurbishment, and condition‑based maintenance is a rising share of vendor revenue.
-
Material and cost pressures: Graphite feedstock is concentrated in a handful of producing countries, creating episodic price and availability risk during demand spikes. Successful players are investing in material substitution strategies, recycling initiatives, and upstream partnerships to stabilize input costs.
-
Technology substitution and product evolution: Brushless motor topologies continue to displace some brush applications, particularly in consumer and certain automotive subsegments. Conversely, large rotating equipment (including wind turbine generators, heavy industry motors, and specialized traction systems) continues to rely on engineered carbon brush solutions, often with premium formulations for extended life and reduced maintenance.
-
Regulatory and quality bar: OEM specifications and manufacturing quality systems matter. Compliance with standards — including detailed specifications for dimensions, electrical performance, and wear (as captured in norms such as ISO, DIN and ASTM regimes) — plus ISO 9001:2015 manufacturing controls, are table stakes for suppliers seeking long‑term OEM contracts.
What this means for procurement, product, and corporate strategy in 2026
-
Procurement playbook: Lock in diversified graphite supply through multi‑tier contracts, implement strategic buffer stock levels tied to risk scenarios, and qualify secondary suppliers in non‑core geographies. Incorporate clause structures that allow for targeted cost pass‑throughs and performance‑linked rebates for long‑term agreements.
-
Product and R&D priorities: Invest in materials science that reduces wear and friction without compromising conductivity — for example, high‑density electrographitic formulations and hybrid composites. Pilot predictive‑maintenance enablement (sensors and brush wear telemetry) with strategic customers to create sticky aftermarket revenue.
-
Commercial and M&A moves: Expect mid‑market consolidation and bolt‑on plays focused on technical capabilities (e.g., advanced formulations, precision machining) and channel coverage. Buyers should prioritize targets that bring proprietary materials, OEM approvals, or strong position in high‑growth verticals like renewables and traction systems.
-
Operational resilience: Upgrade supplier qualification frameworks to include material traceability, sustainability criteria, and audit schedules. Manufacturing footprint decisions should balance nearshoring to reduce lead times with regional capabilities for specialty brush formulations.
Practical deliverables in the full PW Consulting report
-
Robust market sizing and methodology: Transparent assumptions and reproducible demand models covering historical 2020–2025 performance and scenario outputs for 2026–2032, including high/medium/low adoption pathways.
-
Actionable go‑to‑market playbooks: Step‑by‑step procurement, product development, and aftermarket commercialization plans calibrated by strategic priority and resource intensity.
-
Supplier landscape and scorecards: Comparative capability matrices, risk heatmaps, and supplier selection templates to accelerate qualification and bidding processes.
-
Financial and valuation tools: Pricing and margin benchmarks, unit economics templates, and M&A screening criteria that translate market dynamics into transaction readiness.
-
Compliance and testing checklist: Practical templates to align product specifications with OEM and international standards, reducing time to qualification for new brush grades.
Competitive landscape: positioning the leading players
The market exhibits moderate concentration: the leading three suppliers together account for a significant share, and the top five extend that hold into the mid‑fifties. This configuration fosters both competitive innovation and selective partnership opportunities.
-
Ohio Carbon Industries — a custom‑capability leader: Strong in bespoke brushes, grounding solutions and machined graphite for defense, aviation, and transit systems. Their value proposition centers on engineered solutions for mission‑critical applications and close collaboration with OEMs on specifications and testing.
-
St Marys Carbon — engineering depth in heavy‑duty applications: Well‑regarded for carbon graphite brushes, bearings, and mechanical carbon components across industrial and defense markets. St Marys' historical depth in manufacturing and material know‑how makes it a natural partner for reliability‑focused OEMs.
-
Helwig Carbon Products — broad product systems and aftermarket focus: Offers brush holders, spring assemblies and shaft grounding systems along with brush products — an integrated approach attractive to clients seeking single‑source supplier relationships for assemblies and spares.
-
Sinotech — specialist in small and precision motors: Custom engineering for miniature, stepper, and servo motors positions Sinotech well as industries pushing for higher precision and lower friction at small scales.
-
Anglo Carbon & Contacts — regional OEM relationships: Known for fractional‑horsepower solutions and earthing products, with deep ties to transport and domestic appliance segments in its home geography.
-
Aupac and Toyo Tanso — Asia technical platforms: Both companies supply micro‑motor and small appliance segments with high throughput manufacturing and established local OEM relationships.
-
Resonac and CFC Carbon — advanced materials and new‑generation carbon: These players emphasize high‑value graphite composites, felt, and pyrolytic materials, offering pathways for performance improvements and thermal/electrical integration in advanced devices.
-
Mersen — electrographite and industrial breadth: Mersen’s electrographitic lines and targeted product launches for heavy manufacturing reflect a playbook of higher‑end industrial applications and lifecycle performance gains. Their recent high‑density brush series, introduced in 2024, illustrates the industry’s push for reduced wear and extended lifecycles.
-
Schunk Group — renewables and environmental hardening: With an explicit focus on wind turbine generator systems and an expanded renewable energy portfolio announced in late 2024, Schunk has positioned itself to capture premium demand in offshore and harsh environment applications.
Technology, compliance and supply considerations you cannot defer
-
Raw material traceability: Given the concentration of graphite mining in a small set of countries, buyers should require chain‑of‑custody statements and engage in dual‑sourcing where possible.
-
Standards and factory credentials: ISO 9001:2015 certification and compliance with OEM specifications (standardized norms covering dimensions, electrical performance and wear characteristics) are non‑negotiable for tier‑one contracts.
-
Sustainability and circularity: Reuse, recycling and reduced material intensity will increasingly influence procurement decisions, both for cost reasons and to satisfy end‑customer ESG requirements.
2026 decision calendar — a pragmatic sequence
-
Q1: Rapid diagnostics — conduct a supplier risk and inventory audit, quantify exposure to material concentration, and run a stress test of 12‑ and 24‑month demand scenarios.
-
Q2: Secure and diversify — negotiate long‑lead contracts with primary suppliers, qualify secondary sources, and pursue validated substitution pilots for high‑risk components.
-
Q3: Deploy tech pilots — trial high‑density and low‑wear brush formulations with select accounts; implement condition‑monitoring pilots to prove value of predictive maintenance offerings.
-
Q4: Scale and lock — finalize commercialization and aftermarket pricing models, secure certifications for new grades, and sequence rollout across prioritized verticals.
Our full PW Consulting Carbon Brush Market report provides the granular segmentation, regional and application splits, supplier financial profiles, and Excel‑based models that operationalize the recommendations above. This executive preview is intended to equip leaders with the strategic framing necessary for decisive action in 2026; the detailed tables, scenario spreadsheets, and supplier scorecards in the full study will convert strategy into executable steps. Visit PW Consulting’s Carbon Brush Market page to access the complete research package, consulting playbooks, and subscription access to our dynamic forecast models.
For detailed analysis of this topic, please visit the official page: Carbon Brush Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Hardware Security Modules (HSM) Market: Strategic Implications for 2026 Decision-Making
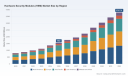
As enterprises accelerate digital transformation and governments tighten cryptographic standards, HSMs have moved from “nice-to-have” infrastructure components to mission-critical strategic assets. PW Consulting’s new HSM Market research (base year 2025; forecast 2026–2032) captures this transition with a data-first perspective: the market has expanded rapidly over the past five years and is forecast to sustain double-digit growth through the next decade at a 13.5% CAGR. In plain terms, the sector more than doubled in scale since 2020 and is projected to approach multi‑billion-dollar scale by 2032—conditions that materially affect procurement timing, vendor selection, risk planning, and architecture decisions in 2026.
Hardware Security Modules (HSM) Market
Why this research matters in 2026
-
Regulatory inflection points are forcing action. Recent updates—PCI DSS 4.0’s tightened HSM requirements and U.S. Treasury mandates requiring FIPS 140‑3 Level 3 certified hardware for certain government financial systems—mean many organizations cannot defer HSM refresh cycles without regulatory and contractual risk.
Hardware Security Modules (HSM) Market -
Quantum and post‑quantum cryptography (PQC) are now procurement drivers. NIST’s finalization of PQC algorithms (notably ML‑KEM and ML‑DSA) has created a hardware refresh imperative for federal agencies and operators of critical infrastructure; most vendors today provide external PQC support, while only a few are redesigning hardware/firmware for genuine quantum-safe operations.
Hardware Security Modules (HSM) Market -
Cloud, AI, and confidential computing create new demand patterns. Enterprises protecting large AI datasets and models, and those adopting confidential compute architectures, look to HSMs for model and key protection—driving demand for both cloud-hosted and on-premise appliances that integrate with modern orchestration frameworks.
-
Supplier concentration and certification complexity introduce procurement risk. The top industry players command the majority of market share (the three largest vendors account for a significant portion and the top five for an even larger share), creating both leverage and single‑vendor risks for large buyers.
Structural dynamics and growth drivers
-
Payments and financial services remain foundational demand vectors, but enterprise use-cases—PKI, database encryption, authentication, IoT and embedded security (notably automotive OTA and V2X), and AI model protection—are broadening the end-market footprint.
-
Cloud adoption is changing consumption models. Dedicated cloud HSM offerings and HSM-as-a-service are maturing, delivering FIPS-validated, managed hardware for teams that prefer operational flexibility. At the same time, regulated workloads continue to push investment into certified on-premise HSMs.
-
Cost and supply-chain pressures persist. Specialized silicon, secure elements, and certified manufacturing increase unit costs and create procurement lead times that buyers must build into IT roadmaps.
-
Certification and lifecycle complexity raise TCO. FIPS 140‑3, PCI requirements, and emerging PQC validation paths add non-recurring engineering and validation costs for vendors—costs that are often passed along or reflected in integration timelines.
Competitive landscape — who matters and how
The market exhibits a mix of long-established incumbents, specialized cryptographic suppliers, cloud giants, and emerging vendors focused on confidential compute and AI security. Broadly, vendor differentiation today falls into four vectors: certification pedigree, hardware architecture (dedicated appliance vs. embedded module vs. FPGA/SoC), cloud-native integration and service models, and PQC readiness.
-
Large system vendors and traditional HSM specialists—such as Thales Group (Paris), Entrust (Dallas), IBM (Armonk), and Utimaco (Aachen)—remain go‑to suppliers for regulated, high-assurance deployments. These vendors combine product breadth, formal certifications, and long experience in payments and PKI markets.
-
Cloud hyperscalers—AWS and Microsoft Azure—provide managed CloudHSM offerings providing fast time‑to‑value and compliance-certified hardware for enterprise cloud-native workloads. Their strength is operational speed; their questions are often around isolation, lifecycle portability and some regulatory nuances.
-
Specialists and embedded suppliers—Infineon, Yubico, Securosys, Lattice Semiconductor, ETAS and others—focus on secure elements, microcontrollers, and FPGA-based modules for embedded, IoT, and automotive use-cases where size, power, and integration matter.
-
Next-gen entrants—Fortanix, Futurex—target confidential compute, AI data protection and cloud-native cryptography, combining software-defined controls with HSM-grade protections and emerging PQC capabilities.
-
Defense and critical-infrastructure vendors—Motorola Solutions, Ultra Electronics, Atos—continue to win specifications where bespoke hardware, rigorous certification and national security requirements are decisive.
Recent vendor activity illustrates the market’s evolution. A notable product launch in late 2025 introduced high‑performance multi‑tenant HSMs with explicit PQC readiness and industry-targeted features (notably for smart metering and automotive). In 2026 several vendors completed or updated FIPS 140‑3 certification paths—strengthening procurement propositions for government and regulated buyers—while alliances emerged to integrate HSM-driven key management into AI data infrastructure ecosystems. These developments underscore three trends: faster product iteration toward PQC, the strategic importance of modern multi‑tenancy and cloud integration, and the material impact of certification milestones on procurement preferences.
What PW Consulting’s report provides (practical deliverables)
-
Forward-looking market sizing and scenario forecasts calibrated to 2025 base-year data and a 2026–2032 projection horizon, with sensitivity analysis for regulatory and quantum adoption timelines.
-
Vendor scorecards and a capability matrix covering certification coverage, PQC roadmap, performance benchmarks, multi‑tenancy and cloud integration features, and managed service maturity.
-
Procurement playbooks and TCO models that capture capital, integration, compliance, and lifecycle renewal costs—designed for CISOs, procurement leads and CFOs to evaluate replacement vs. retrofit strategies.
-
Migration and integration blueprints for common enterprise architectures: on‑prem clustered HSMs, hybrid cloud HSM strategies, edge/embedded deployments for IoT and automotive, and confidential compute architectures for AI workloads.
-
Compliance checklists and acceptance test plans for PCI DSS, FIPS 140‑3 Level 3, and PQC migration validation—mapped to procurement contract clauses and SLA language.
-
Risk registers and mitigation playbooks that address supplier concentration, lead‑time exposure, and supply‑chain cost volatility.
-
Executive decision frameworks and board‑level briefing templates to accelerate internal alignment when HSM investments compete with other security and infrastructure priorities.
Actionable recommendations for 2026 enterprise decisions
-
Treat HSM strategy as part of your cryptographic lifecycle roadmap. Given regulatory timetables and PQC developments, create a prioritized replacement or retrofit path for ‘must‑replace’ systems and a second tranche for ‘can‑defer’ systems, with explicit timelines tied to compliance deadlines.
-
Prioritize vendors with demonstrable FIPS 140‑3 Level 3 coverage and a clear hardware‑level PQC plan. External or “bolt‑on” PQC options reduce short‑term risk but do not substitute for a vendor roadmap that addresses firmware and silicon changes where required.
-
Design for modularity and portability. Use abstraction layers and key management protocols that enable workload portability between on‑prem HSMs and cloud HSMs, reducing lock‑in and simplifying audit and incident response.
-
Hedge supplier concentration: combine strategic partnerships with primary suppliers and secondary spot-capacity agreements or managed services to mitigate delivery delays and certification gaps.
-
Factor full integration costs into TCO: hardware purchase is only the beginning—plan for integration, application changes (PKI, payment pipelines, DB encryption), testing, certification evidence collection, and staff training.
-
Embed PQC testing into procurement pilots now. Establish lab testbeds that validate vendor PQC claims against your specific application stack and performance SLAs before enterprise-scale rollouts.
-
For AI and confidential compute use-cases, evaluate vendors that provide end‑to‑end protection for datasets and model keys—HSMs alone are necessary but not sufficient; orchestration, attestation and key lifecycle tooling are equally important.
How to use this research
This analysis is intended to inform board-level prioritization, procurement strategies, and architecture roadmaps for 2026. It exposes the strategic levers and pragmatics you must control—regulatory deadlines, PQC migration, supplier risk, and integration cost—while reserving granular segment tables and vendor share breakdowns for the full report. For procurement teams and CTO offices that need the complete decision toolkit (detailed regional and application splits, downloadable TCO models, vendor scorecards and contract language templates), the full study provides the necessary datasets and executable artifacts to move from strategy to procurement within quarters rather than years.
In an environment where policy, quantum-readiness and cloud-native architectures converge, a deliberate, data-driven HSM strategy is not optional—it is a competitive and compliance imperative. PW Consulting’s HSM Market research gives you the strategic view and the practical tools to act decisively in 2026.
For detailed analysis of this topic, please visit the official page: Hardware Security Modules (HSM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Microfiber Cleaning Cloths Market to Reach USD 1,117.43 Million by 2032 (4.5% CAGR)
By PW Consulting, 2026-07-08
Microfiber Cleaning Cloths Market 2026: Strategic Preview for Enterprise Decision-Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused industry briefing designed to orient executive decisions for 2026. This article distills the strategic implications from our full Microfiber Cleaning Cloths Market study — situating market momentum, competitive posture, regulatory drivers, and operational levers that will matter most to manufacturers, distributors, retailers, and investors over the next planning horizon.
Microfiber Cleaning Cloths Market
Why this study matters for 2026
-
Timing: The market is moving from recovery into structural growth. With a compound annual growth rate projected at 4.5% across our forecast window (2026–2032), the microfiber cloths category is re-establishing demand patterns and opening margins for innovation-led players.
Microfiber Cleaning Cloths Market -
Decision focus: Companies that act in 2026 will define channel footprints, supply resilience, and sustainability positioning for the coming cycle. Our study turns market-level trends into executable choices — which SKUs to prioritize, which channels to expand, where to invest in production technology, and when to pursue M&A.
Microfiber Cleaning Cloths Market -
Risk/reward calibration: The market shows moderate concentration — the top three players control a meaningful share and the top five expand that edge — creating both scale advantages and white-space opportunities for focused challengers. Understanding this competitive geometry is critical to both defensive and offensive strategies.
Market snapshot (what the macro picture tells us)
-
Base year and trajectory: Using 2025 as the analytical base, the global microfiber cleaning cloths market has rebounded from pandemic-related volatility and is forecast to expand steadily through 2032. The study models demand drivers and elasticity across household, commercial, industrial and precision-cleaning use cases.
-
Growth profile: A steady mid-single-digit CAGR through our forecast reflects a balance of tailwinds — regulatory shifts toward reusables, improved manufacturing economics, and consumer preferences for chemical-free cleaning — against headwinds such as raw material cycles and channel commoditization.
-
Concentration and competitive dynamics: Market concentration metrics indicate an industry where established brands retain scale advantages, but fragmentation at the lower-price tiers keeps distribution and private-label opportunities fluid. This combination incentivizes differentiated product performance, sustainability claims, and channel-specific playbooks.
Key demand drivers and regulatory context
-
Regulatory redirection: Policies to curtail single-use plastic waste — including directives in Europe and parallel measures at national/state levels in other advanced markets — are accelerating substitution toward high-performance reusable textiles. This regulatory momentum is not binary; it changes procurement specifications in commercial cleaning, hospitality and institutional purchasing.
-
Consumer behavior: A durable swing toward reusable, chemical-free cleaning solutions has elevated premium microfiber positioning. Buyers increasingly value demonstrable lifecycle benefits (durability, washability, biodegradability) alongside efficacy claims.
-
Manufacturing innovation: Advances in fiber splitting and blend engineering are shrinking the cost premium for higher-performance microfiber, making technical upgrades feasible at commercial scale. This creates a practical path to upgrade product mixes without sacrificing gross margin.
Channel and commercialization implications
-
Retail mix: The household segment continues to be shaped by e-commerce assortment strategies, private label competition, and value bundles. Retailers that combine performance messaging with demonstrable sustainability credentials win higher attachment rates and lower returns.
-
Commercial procurement: Bids in institutional cleaning and healthcare increasingly specify technical performance and life-cycle cost — favoring vendors that can validate lab-tested efficacy and supply-chain traceability.
-
Specialty and precision niches: Eyewear, electronics, and medical applications demand tighter specifications and enable premium pricing. Companies that develop tailored offerings backed by certification and co-marketing arrangements can create defensible niches.
Competitive landscape — strategic positioning and implications
The market features incumbent brand power and nimble specialists. Below are strategic vignettes that highlight how different player archetypes are shaping the competitive field and what that means for strategy.
-
Global diversified incumbents (example: 3M Company) — Strengths: broad distribution, cross-category credibility, and multi-channel reach. Strategic implication: these firms can use brand trust to expand into professional and household segments simultaneously; challengers should seek vertical specializations or cost leadership to compete.
-
Premium sustainable specialists (example: Norwex) — Strengths: sustainability narrative, proprietary treatments (e.g., antimicrobial, plant-based enhancements), and direct-to-consumer relationships. Strategic implication: high-margin, mission-led players can pressure mainstream brands on premium segments and force regulatory-compliant product innovation.
-
Technical material leaders (example: Toray Industries) — Strengths: advanced fiber technology and precision products suitable for specialty cleaning. Strategic implication: partnerships with OEMs and medical suppliers open higher-margin channels where technical specifications limit competition.
-
Commercial solutions providers (examples: Freudenberg, Unger) — Strengths: integrated systems for facilities management and professional cleaning. Strategic implication: bundling cloths with services and equipment increases switching costs and improves lifetime value per customer.
-
Niche and wholesale players (examples: E-Cloth, Zwipes, Atlas Graham Furgale, Microfiber Wholesale) — Strengths: focused product portfolios, cost-competitive supply chains, and rapid response to channel demand. Strategic implication: they can erode share in value tiers or act as acquisition targets for scale players seeking product breadth.
-
Specialized healthcare suppliers (example: Medline Industries) — Strengths: regulatory credentials and distribution into hospitals/clinics. Strategic implication: compliance and certification create entry barriers for non-healthcare players, making this an attractive route for premiumization.
Recent industry moves to watch
-
Product innovation and reviews are influencing purchase flows: independent testing and review platforms continue to identify best-in-class products across price tiers, impacting short-term demand spikes.
-
Notable launches highlight two simultaneous trends: biodegradable and plant-infused microfiber formulations, and precision-targeted collections for eyewear and electronics — both signaling segmentation by sustainability and use-case performance.
-
Manufacturers are publicly advancing production technologies that reduce labor and material intensity, compressing cost curves and enabling more sustainable blends at scale.
Where value will accrue in 2026 — strategic playbook
-
Product architecture: Prioritize a two-track portfolio — a performance line for institutional and precision use cases, and a sustainability-branded retail line for households. Ensure modular packaging and SKU rationalization to minimize SKU proliferation costs.
-
Supply chain and manufacturing: Invest selectively in fiber-splitting and finishing capabilities that deliver measurable durability and wash-life gains. Seek backward integration or long-term supplier contracts to mitigate polymer price volatility.
-
Channel strategy: Accelerate partnerships with B2B distributors and facilities management firms while optimizing DTC and e-retail presence. Use data-driven assortment testing in e-commerce channels to identify top-converting claims (e.g., chemical-free, reusable X washes).
-
Commercial and institutional sales: Develop RFP-ready documentation, lab certifications, and lifecycle cost calculators to win specification-based contracts.
-
M&A and partnerships: Target bolt-on acquisitions that add technical capability (fiber tech or specialty finishing) or expand access to institutional contracts. Strategic partnerships with certification labs and sustainability NGOs can speed time-to-market for premium claims.
What the full PW Consulting report delivers
-
Practical toolkits — go-to-market playbooks for the four major end-use clusters, pricing sensitivity matrices, and SKU rationalization templates.
-
Channel and distribution models — scenario-modeled demand by retail vs. commercial channels, with prescribed inventory and promotional strategies for 2026.
-
Cost and margin analytics — raw-material passthrough scenarios, manufacturing technology ROI models, and break-even analyses for premium vs. value product lines.
-
Competitive maps — positioning matrices, capability heatmaps for the leading and emerging players, and acquisition target shortlists with synergy estimates.
-
Regulatory and sustainability playbook — compliance checklists, certification pathways, and consumer communication frameworks to translate policy shifts into market share gains.
Actionable recommendations for 2026
-
For manufacturers: Prioritize a capital allocation plan that balances incremental upgrades in production technology with immediate investments in product-testing and certification to win institutional contracts.
-
For retailers and distributors: Re-assess private-label margins against branded sustainability propositions; deploy targeted assortments and bundle offers in e-commerce channels to capture premium buyers without eroding value tiers.
-
For investors: Screen opportunities for platform buys that consolidate regional wholesale suppliers or acquire fiber-technology specialists that can be scaled across existing retail relationships.
-
For innovators: Focus on validated claims (biodegradability, wash-life, antimicrobial efficacy) and prepare a certification roadmap before large-scale commercial rollouts.
Closing — the strategic line for 2026
The microfiber cleaning cloths market in 2026 is a classic market of steady growth and strategic inflection. Regulatory pressures and consumer preferences favor reusable, higher-performing products; manufacturing innovations lower the cost to play at a premium; and the competitive landscape rewards both scale and technical differentiation. PW Consulting’s full report converts these dynamics into replicable actions — from SKU-level decisions to M&A targets and channel tactics.
To access the detailed segment-level models, proprietary demand scenarios, supplier scorecards, and downloadable execution toolkits that underpin these recommendations, consult the full Microfiber Cleaning Cloths Market report on our site. The public preview you have read is designed to establish the analytical framing — the full intelligence contains the tactical granularity required to execute effectively in 2026.
For detailed analysis of this topic, please visit the official page: Microfiber Cleaning Cloths Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Parylene Market Outlook: 7.8% CAGR Sparks Growth Opportunities for PW Consulting
By PW Consulting, 2026-07-08
Parylene Market 2026: Strategic Preview for Executive Decision-Making
As PW Consulting’s lead industry analyst, I present a strategic preview of our comprehensive Parylene Market research (base year 2025). This briefing is written to inform executive teams, corporate development leaders, and investment committees about the material choices and strategic trade-offs that will shape commercially meaningful outcomes in 2026. It reveals the macro trajectory, competitive architecture, regulatory inflection points, and practical playbooks that should guide near-term capital allocation — while intentionally withholding the granular segment tables that are available in the full report to preserve its practical value for subscribers.
Parylene Market
Why Parylene matters in 2026
- Parylene’s role as a vapor-deposited conformal coating places it at the intersection of several high-growth technology vectors: miniaturized medical implants, ruggedized electronics for autonomous systems, and high-reliability aerospace and defense systems. These end-markets are accelerating requirements for ultra-thin, uniform, and biocompatible barriers.
- From a market sizing perspective, the Parylene ecosystem is a mid-sized but fast-growing specialty chemicals and services market. With 2025 as our reporting base year and a compound annual growth rate (CAGR) of approximately 7.8% through the forecast horizon, the market is moving from a niche engineering solution toward broader adoption across adjacent industries that prize longevity and regulatory compliance.
- Concentration is meaningful: the market is neither fully fragmented nor tightly monopolized. The top-three and top-five providers together account for a material majority of industry revenue, which creates both stability and opportunity for consolidation-led strategies.
What this research gives you (operationally usable)
The full PW Consulting report is structured to be immediately actionable for decision-makers. Key deliverables include:
Parylene Market
- Validated market sizing and forward projections (2026–2032) with scenario sensitivity analysis tied to macroeconomic and technical adoption vectors.
- Commercial segmentation maps (by product type, application class, and region) with demand drivers and leading use-case archetypes — presented as decision matrices to support go/no-go product investments.
- Supply-side diagnostics: raw material cost drivers, typical capex envelopes for new coating lines, and breakeven throughput models for contract coating vs. in-house deposition.
- Regulatory and standards playbook: mapping of USP, ISO, REACH/RoHS, and other certifications relevant to medical, electronics, and aerospace qualification timelines.
- Competitive landscaping and capability benchmarking of leading providers, plus an M&A tracker and an integration checklist for buyers.
- Commercial playbooks covering pricing strategies, service bundling (e.g., coatings + testing), and channel approaches for contract coating providers versus dimer manufacturers.
Note: This preview purposefully omits the granular numeric splits for each segment and region. Those detailed tables, supplier scorecards, and primary-interview transcripts are held for the full report and subscriber portal.
Parylene Market
Market Dynamics Driving Strategic Decisions
Regulatory momentum and substitution dynamics
- Tightening PFAS scrutiny and evolving RoHS/REACH enforcement have elevated Parylene’s regulatory attractiveness in certain medical and electronics uses. Parylene C is often positioned as a non-PFAS compliant alternative to fluoropolymers in sensitive wire and device coatings.
- Parylene’s alignment with biocompatibility standards (USP Class VI and ISO 10993) is a commercial accelerant in medical-device qualification programs; again, this is a differentiator for customers prioritizing regulatory certainty over raw cost-per-unit.
- Environmental considerations are becoming operational risks: while Parylene waste is currently categorized as a non-biodegradable industrial polymer, the sector faces growing pressure to document disposal pathways and invest in greener operations — an area where early movers can convert compliance into pricing power.
Raw materials and cost dynamics
- Raw-parylene dimers represent a significant input cost and are heterogeneous by type and quality. Suppliers that control dimer production enjoy margin resilience and improved supply security. Buyers should stress-test procurement strategies for scenarios in which dimer availability tightens or premium grades command wider spreads.
- Given the cost variability across dimer types and grades, there is a clear strategic rationale for vertical integration or long-term offtake contracts if you are scaling coatings capacity for high-volume applications.
Concentration and consolidation
- Industry concentration is meaningful: the leading vendors collectively control a substantial share of the market, enabling them to set technical standards and institutionalize preferred supplier status with OEMs in regulated industries.
- This dynamic raises the value of targeted M&A or partnership strategies for new entrants or regional players seeking rapid market access. Strategic acquisitions can deliver immediate credentialing (e.g., USP/ISO approvals), installed capacity, and OEM relationships.
Competitive Landscape — Who matters and why
The competitive field contains a mix of verticalized coating specialists, contract services providers, and materials firms. Here are the strategic profiles that should factor into any strategic review or vendor shortlist:
- Specialty Coating Systems (Indianapolis) — Global leader in Parylene services and a manufacturer of its own dimers. Their integrated model (material + service) creates a high barrier to entry and a template for margin capture.
- Curtiss‑Wright Surface Technologies (USA) — Strongly integrated into aerospace and defense supply chains; certifications and supply chain pedigree make them a go-to for high‑assurance programs.
- HZO Inc (USA) — Focuses on ultra-thin coatings for mission-critical electronics; their differentiation is in process control for thin-film uniformity on PCBs and assemblies used in robotics and UAVs.
- Kayaku Advanced Materials / Paratronix (USA) — Precision coatings and proprietary branded solutions target medical-electronics convergence scenarios.
- VSi Parylene (USA) — Known for on-demand systems and medical device focus; a useful model for servitization (coating-as-a-service) and local high-touch support.
- Parylene Engineering (San Clemente) — Military-spec providers with MIL-I credentialing, valuable for defense supply chain integrators.
- KISCO Ltd (Japan) and Penta Technology (Suzhou) — Regional champions with capabilities tailored to high-volume electronics and medical customers in Asia — useful partners for capacity scaling and cost-competitive supply.
Recent industry developments also hint at strategic inflection points. For example, an Asia-based coating supplier achieved ISO 14001 certification in early 2026, signaling how environmental credentials are becoming part of the commercial conversation — not just a compliance checkbox.
Strategic Imperatives for 2026
We recommend a three-axis decision framework to translate market realities into near-term action.
1) Protect and extend product/market fit
- Medical device OEMs: Prioritize suppliers with documented USP/ISO qualification and biocompatibility testing. Time-to-qualification is a non-linear cost; mitigate by partnering with accredited coaters or securing co‑development arrangements.
- Electronics & consumer OEMs: Invest in ultra-thin deposition capabilities and test automation to differentiate on performance and speed-to-market.
2) Secure supply and cost control
- Pursue diversified sourcing or take minority equity positions in dimer producers to stabilize costs and secure capacity.
- For players scaling coating capacity, run a comparative analysis between contract coating expansion vs. greenfield lines — factoring in certification timelines, customer pull-through, and regional regulatory regimes.
3) Use ESG and standards as commercial leverage
- Accelerate environmental management certifications (ISO 14001) and transparent waste-handling programs to reduce procurement friction with enterprise customers.
- Package sustainability credentials with product warranties and lifecycle-value arguments to justify premium pricing where reliability and compliance are critical.
How PW Consulting can help
Our full Parylene Market report delivers the numeric granularity, supplier scorecards, and negotiated sourcing templates that operational teams need to execute the strategic imperatives above. If you are evaluating capital investment, M&A, or supplier rationalization in 2026, the report’s scenario models will quantify the ROI timelines and the sensitivity of returns to raw material price swings, certification lead times, and adoption rates in key end-markets.
For readers of this preview: the topline macro trajectory, growth rate, and concentration metrics are intentionally disclosed to frame strategic urgency. The specific segment tables, regional breakdowns, and revenue-by-application numbers that underpin procurement or M&A recommendations are available only in the full report and subscriber portal.
Next steps
- Contact PW Consulting for the full report and a tailored 90-minute executive briefing focused on your strategic options (capacity build vs. buy vs. partner).
- Commission a supplier diligence package if you are contemplating an acquisition or long-term supply agreement; we combine technical audits with commercial valuation models.
- Request our certification acceleration playbook if your roadmap requires rapid entry into regulated medical or aerospace programs.
In 2026, Parylene will reward firms that pair technical know-how with commercial discipline: secure inputs, certify early, and convert compliance into a premium service offering. The market’s trajectory creates multiple windows of opportunity — but those windows close as standards, scale, and supplier relationships harden. PW Consulting’s full study provides the proprietary detail you need to move decisively.
For detailed analysis of this topic, please visit the official page: Parylene Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


