



Category: market research
PW Consulting: Luggage Market to Reach USD 101.01 Million by 2032 at 8.3% CAGR
By PW Consulting, 2026-07-08
Luggage Market 2026: Strategic Imperatives from PW Consulting’s Forward-Looking Analysis
As global mobility re-enters a period of structural expansion, executives must navigate an environment shaped by accelerating consumer expectations, supply-chain turbulence and renewed regulatory friction. PW Consulting’s latest Luggage Market study—anchored on a 2025 base year, a five-year historical window (2020–2025) and a seven-year forecast (2026–2032)—translates macro momentum into 10 strategic decisions that corporate leaders should treat as immediate priorities for 2026. The study combines robust market-sizing, scenario-driven forecasting and practitioner-ready playbooks to convert insight into action.
Luggage Market
Why this report matters for 2026 decision-making
-
Market momentum: The luggage market demonstrated consistent expansion across the 2020–2025 period and is projected to continue growing through 2032 under an 8.3% CAGR (forecast period 2026–2032). Our base-year sizing and trajectory models show more than a doubling of market value from early-decade levels to the end of the forecast horizon—confirming a durable market opportunity for both incumbents and new entrants.
Luggage Market -
Consolidation dynamics: Market concentration is meaningful. The top three players account for roughly two-thirds of market value, and the top five approach three-quarters—conditions that favor scale-driven producers but also create whitespace for focused specialists and digitally native brands.
Luggage Market -
Regulatory and cost shock risk: New tariff measures implemented in 2025 broadened coverage to components such as frames, handles and wheel housings. The policy shift has already created observable cost pressure for importers and small manufacturers, prompting workforce adjustments and capex reallocation—risks that should be priced into 2026 planning.
What the study delivers (operational and strategic value)
-
Macro and scenario-based market sizing: Rolling base-year valuations and conservative/central/aggressive scenarios to stress-test demand in three macro states (soft travel recovery, structural premiumization, and constrained-cost inflation).
-
Go-to-market playbooks: Channel-specific strategies for premium, mid-market, and value tiers—coverage includes wholesale partnerships, direct-to-consumer scaling, and marketplace optimization with practical KPIs and conversion benchmarks.
-
Supply-chain risk maps: Component-level exposure tables (tariff-sensitive items, single-supplier risks, lead-time criticality) and prioritized mitigations such as dual-sourcing, nearshoring pilots and inventory-financing options.
-
Competitive playbook and M&A screen: Comparative profiles of incumbent players, archetypal disruptors, and specialty brands—scoring for strategic fit across brand equity, channel overlap, manufacturability and margin synergy potential.
-
Pricing and promotional models: Elasticity matrices and markdown optimization templates to protect margin while sustaining share in promotional-heavy channels.
-
Sustainability and circularity roadmaps: Practical implementation steps (materials substitution pilot prioritization, repair and refurbishment programs, take-back monetization) and financial case templates for ESG-linked investments.
-
Regulatory tracker and scenario playbooks: Monitoring and response frameworks for tariff, trade and materials-regulation developments—designed to shorten decision cycles when policy shocks occur.
Competitive landscape: who matters and what they signal
The market is anchored by established global brands alongside digitally native and specialty players. Leading incumbents combine scale manufacturing, broad distribution and recognizable consumer propositions—durability and design remain dominant purchase drivers. Several strategic patterns emerge from our company-level analysis:
-
Scale incumbents (e.g., long-standing global manufacturers) leverage distribution breadth and B2B channel depth to defend share, but face margin pressure from rising input costs and retail consolidation.
-
Premium specialists emphasize brand equity and after-sales service (lifetime guarantees and repair networks) as defensible differentiators; their pricing power, however, depends on sustained travel demand among higher-velocity cohorts.
-
Digital-first entrants adopt a direct-to-consumer model with rapid product cycles and integrated accessory ecosystems; these players accelerate category innovation but must overcome unit economics challenges as acquisition costs rise.
-
Adventure and specialty brands place emphasis on ruggedization and functional differentiation, an approach that becomes a natural hedge when leisure travel segments favor experiential trips.
Recent corporate activity underscores these dynamics. One specialty brand recently increased its profile via major event sponsorships, signaling a pivot to brand-led growth even as it navigates macro cost pressures. For leaders evaluating competitors or potential partners, the full report contains detailed company profiles, channel mix diagnostics, and acquisition candidate screens designed to shorten the time from diligence to deal execution.
Regulatory shocks and supply-chain playbook
Fiscal 2025–2026 introduced sharper trade-policy volatility that directly affects the luggage value chain. Expansion of tariffs to include structural components—such as frames, telescopic handles and wheel housings—has materially altered landed costs for imports. Some manufacturers have publicly disclosed attempts to recover tariff-related expenses, while smaller firms have reported layoffs and expenditure cuts in response to widened margins pressure.
For 2026, PW Consulting recommends a three-layer mitigation strategy:
-
Short term (0–6 months): Rapid cost-forensics to identify tariff-exposed SKUs, temporary repricing tests, and a targeted mix-shift toward higher-margin SKUs where possible.
-
Medium term (6–18 months): Supply diversification—nearshoring pilot programs, contract renegotiation with tier-1 component suppliers, and inventory hedging to smooth input-cost volatility.
-
Long term (18+ months): Vertical moves where economically viable (strategic in-sourcing or joint ventures for high-exposure components) and investing in design-to-cost initiatives to reduce dependence on tariff-sensitive bill-of-material elements.
Strategic priorities for executives in 2026
Based on our integrated analysis, the following priorities should guide executive agendas next year:
-
Prioritize resilience over optimization alone: Rebalance cost-efficiency programs with investment in redundancy for critical nodes to prevent single-point failures during policy or demand shocks.
-
Segment the portfolio with discipline: Use customer and margin analytics to rationalize SKUs—double down on high-growth, high-margin archetypes while considering divestiture or licensing for underperforming lines.
-
Monetize services: Expand repair, refurbishment and subscription offerings to extend lifetime value and differentiate against commoditized competitors.
-
Accelerate channel transformation: Invest selectively in first-party digital capabilities to capture margin improvements, while preserving strategic wholesale partnerships for scale.
-
Embed sustainability as commercial strategy: Material innovation and circular services should be pursued not just for compliance but as a source of product differentiation and PR value.
-
Calibrate M&A to concentration economics: With significant share controlled by a small number of players, acquisitions should prioritize capability adjacency (e.g., digital marketing, materials science) or geographic footholds to move the needle on market share.
How the report helps you act now
PW Consulting’s Luggage Market study is intentionally practical. Beyond strategic conclusions, the appendices include templates for scenario P&L, a supplier-risk heatmap, a prioritized regulatory watchlist and a 90-day execution checklist for operations, marketing and M&A teams. We designed these tools so leadership teams can transition from insight to implementation without reinventing analytic wheels.
To preserve competitive value and adhere to our “trailer” principle, this executive introduction highlights the study’s core findings and recommended actions while withholding granular segment-level allocations and price-by-channel matrices. Those detailed breakdowns, including regional and application splits and the full financial model, are available in the full report.
Suggested next steps for 2026 planning
-
Immediate: Convene a cross-functional rapid-response team to stress-test your 2026 plan against three PW-defined scenarios. Use our 30–90 day checklist to identify immediate margin recovery levers and tariff mitigations.
-
Near term: Request the full report to access the supplier-risk heatmap, SKU-level pricing elasticity models and the M&A target shortlist tailored to your strategic profile.
-
Ongoing: Subscribe to our regulatory tracker for monthly alerts on trade policy changes that affect component-level cost exposure.
PW Consulting’s Luggage Market study is targeted at CEOs shaping portfolio strategy, CFOs quantifying mid-term capital needs, COOs reworking supply chains, and CMOs building brand growth roadmaps. If you are positioning your organization for the next wave of market expansion or defending against policy-driven cost shocks, the full report provides the granular analytics and operational playbooks to make confident, fast decisions in 2026.
Access to the complete dataset, company profiles and executable templates is available through the PW Consulting research portal—visit the source page to download the full report and supporting workpapers.
For detailed analysis of this topic, please visit the official page: Luggage Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: EV Traction Motor Market Poised for 29.14% CAGR Through 2032
By PW Consulting, 2026-07-08
EV Traction Motor Market — Strategic Outlook for 2026 Decision-Making
Executive snapshot
The EV traction motor market is transitioning from niche electrification projects into mainstream powertrain architecture. PW Consulting’s analysis — built on a 2025 base year and a seven‑year forecasting horizon (2026–2032) — quantifies that transition: the addressable market expanded from USD 12.0 Million in 2020 to USD 27.28 Million in 2025 and is projected to exceed USD 35.42 Million in 2026, continuing to grow at a compound annual growth rate (CAGR) of 29.14% through 2032, when the market reaches an estimated USD 163.42 Million (USD Million units). This trajectory reflects accelerating EV adoption, rising electrification of commercial fleets, and increasingly diversified motor architectures that are being embedded across vehicle platforms.
EV Traction Motor Market
Why this study matters for 2026 strategic choices
For executives planning capital allocation, product architecture, and supply chain commitments in 2026, the market dynamics captured in this report are decisive. Rapid top‑line expansion combined with a relatively low concentration among incumbents (CR3 ~22.5%, CR5 ~30.0%) creates a window where well‑timed investments can secure outsized returns — but only if companies align strategy with near‑term constraints in raw materials, manufacturing scale, and regulatory requirements.
EV Traction Motor Market
- Timing capital expenditure: The steep growth implied by 2026–2032 forecasts compresses the payback horizon for new manufacturing lines and COGS reduction programs.
- Technology selection: Investments in axial‑flux, in‑wheel, e‑axle or modular central drives should be prioritized based on program pipelines and integration complexity — not just intellectual interest.
- Supply security: Raw material and magnet availability will determine which motor chemistries and design families are practical to deploy at scale within 12–24 months.
Market dynamics and risk matrix
The macro drivers are straightforward: electrification mandates, fleet electrification economics, and falling battery costs. The differentiators lie in supply‑side frictions and regulatory shifts that have outsized consequences on unit economics.
EV Traction Motor Market
- Raw materials: Rare earths remain a dominant cost input for many high‑efficiency motor topologies; sector analysis indicates rare earths can represent nearly 40% of the traction motor core production cost. Geographic supply actions — for example, export restrictions on heavy rare earths introduced in 2025 — have already widened sourcing premiums and require immediate procurement adjustments.
- Regulation & policy: Jurisdictions are tightening critical‑materials governance. The EU announced a set of measures in mid‑2025 targeting supply chains for EV motors and batteries, while U.S. federal roadmaps set manufacturing cost targets that are now baseline constraints for OEM supplier negotiations (e.g., DOE targets for a 100 kW on‑road traction drive system have established clear cost expectations).
- Material & manufacturing bottlenecks: Electrical steel lead times extended by 30–45 days during 2025 supply disruptions. Near‑term capacity investments (e.g., automated winding lines, modular assembly cells) will be the gating factor for meeting 2026 production ramps.
- Opportunity windows: New suppliers of sintered magnets and magnet processing capacity are entering the market with commercial deliveries scheduled in mid‑2026, relieving pressure if OEMs secure offtake agreements early.
Competitive landscape — who matters and how they are moving
The competitive field is a mix of large global Tier‑1s scaling existing product portfolios and specialized innovators carving niches in performance, packaging or integration:
- ABB Ltd. (Zurich, Switzerland) — Offers configurable traction systems and recently launched motor‑inverter packages that demonstrably reduce motor losses on heavy vehicles. Their strategy centers on system optimization for commercial vehicles and buses, leveraging inverter‑motor co‑development.
- YASA Ltd. (Kidlington, U.K.) — A specialist in axial‑flux permanent magnet designs; public OEM programs show their motors being used in high‑performance variants, indicating a premium, performance‑led go‑to‑market approach.
- Protean Electric (Coventry, U.K.) and Elaphe Propulsion Technologies (Ljubljana, Slovenia) — Leaders in in‑wheel direct‑drive technology; their value proposition emphasizes packaging, modularity and new vehicle architecture possibilities but faces trade‑offs in unsprung mass and durability engineering.
- Turntide Technologies (Gateshead, U.K.) — Pursuing axial flux and systems integration with recent product introductions and vehicle integrations targeting specialty vehicles and commercial platforms.
- Nidec Corporation (Kyoto, Japan) — Executing scale plays, with production expansions that increase annual output capacity and prioritize cost competitiveness for high‑volume OEM programs.
- European powertrain Tier‑1s (ZF, MAHLE, Continental, Valeo) — Competing with integrated e‑axle and inverter portfolios that emphasize platform‑level modularity and OEM systems responsibility.
- AC Propulsion — A niche, performance‑oriented player with deep controls and power electronics expertise.
Recent strategic moves illustrate where competitive advantage is being built. Several companies announced product launches and integration wins between 2025 and early 2026 (axial‑flux EDU launches, e‑axle packages for buses, and expanded high‑capacity motor winding lines). These moves signal two parallel plays: (1) scale cost efficiency through manufacturing investments; and (2) differentiated performance/packaging through topology innovation.
Strategic playbook for 2026
We recommend C‑suite and business unit leaders adopt a three‑pronged approach to position for the accelerated growth window beginning in 2026:
- Secure supply and manage material exposure: Lock in magnet and electrical steel offtake with tier‑2 strategic partners; evaluate vertically integrated options where upstream margins justify investment; and build dual‑sourced tooling recipes for the most magnet‑intensive platforms.
- Optimize portfolio sequencing: Prioritize product families that can deliver first cash flow within 18 months while keeping optionality for higher‑margin architectures as material economics evolve. Use modular e‑axle platforms to reduce integration cost and speed up OEM adoption.
- De‑risk production through staged scale: Combine contract manufacturing for initial production ramps with a phased capital program to bring incremental capacity online only as validated orders materialize. Embed advanced automation (e.g., robotic winding, cell‑level testing) to meet DOE‑style cost targets over the medium term.
- Commercial & partnership strategies: Pursue OEM strategic partnerships where co‑development reduces validation time and creates switching friction. For niche players, co‑branding or licensing can accelerate market penetration without requiring scale investments.
- M&A and alliances: With market concentration still modest, targeted acquisitions of complementary IP (controls, power electronics, magnet processing) or bolt‑on capacity can be accretive and defensible against fast‑moving incumbents.
What PW Consulting’s EV Traction Motor Market study delivers (practical modules)
The full PW Consulting report provides the operational intelligence necessary for deployment decisions in 2026. Core deliverables include:
- A granular demand model (historical 2020–2025, base year 2025) and a scenario‑based forecast 2026–2032 with sensitivity to material pricing, OEM program cadence and regulatory interventions.
- Supplier and competitor intelligence dossiers: product roadmaps, validated OEM integrations, production footprints and recent corporate events.
- Unit cost models and cell‑level sensitivity analysis that isolate the drivers of motor system COGS under multiple magnet and steel price paths, plus a path to meet leading government cost targets.
- Manufacturing & supply chain stress tests: lead‑time simulations, capacity adequacy assessments, and mitigation playbooks for material disruptions and export constraints.
- Commercial playbooks for OEM engagement, tier‑1 partnerships, and aftermarket strategies, including contracting templates and price indexation approaches.
- Strategic scenarios and decision trees for M&A, joint ventures, CAPEX timing, and production footprint optimization.
Note: This summary intentionally omits the detailed segmentation tables and supplier scorecards included in the full report (to preserve the utility of the complete dataset for purchasing clients). The full study contains the regional, application and technology splits required to model program‑level revenue and margin outcomes; these elements are only available in the paid deliverable.
How to use the intelligence in 2026 boardroom decisions
Executives should translate the report’s insights into a short list of board‑level actions for 2026:
- Approve conditional capital allocations for capacity based on milestone‑driven triggers tied to validated OEM contracts and material hedges.
- Establish a cross‑functional Magnet & Steel Task Force to secure multi‑year supply and develop cost‑reduction plans aligned to DOE targets and EU regulatory expectations.
- Implement a “fast follower” or “specialist niche” product strategy depending on corporate scale: larger OEMs should pursue integrated e‑axle systems; specialized suppliers should double down on axial‑flux/in‑wheel niches where technical differentiation yields margin.
- Prioritize short‑cycle customer wins that validate manufacturing processes, then scale via staged CAPEX to capture volume benefits without overcommitting before 2027 demand inflection points.
Conclusion — the window for defining market leadership
The EV traction motor market’s rapid expansion offers a rare opportunity to shape future powertrain economics and capture lasting OEM relationships. However, the path to leadership is neither automatic nor evenly distributed: it depends on pragmatic supply assurance, disciplined capital sequencing, and choosing the right technical bets. PW Consulting’s EV Traction Motor Market study converts the broad growth narrative (CAGR 29.14%; USD 27.28 Million base in 2025 and a projected USD 163.42 Million by 2032) into executable decisions for 2026. For teams preparing budgets, negotiating supply contracts, or evaluating M&A targets this year, the right intelligence will materially change outcomes.
Next steps
To access the full dataset, segmentation tables, supplier scorecards and proprietary cost models that underpin these conclusions, request PW Consulting’s complete EV Traction Motor Market report. The full deliverable contains the program‑level detail and downloadable models executives use to finalize 2026 investment and sourcing decisions.
For detailed analysis of this topic, please visit the official page: EV Traction Motor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Saw Palmetto Extracts Market to Reach USD 132.4M by 2032 at 4.9% CAGR
By PW Consulting, 2026-07-08
Saw Palmetto Extracts Market — Strategic Outlook for 2026 (PW Consulting)
Executive snapshot
As companies prepare budgets and strategic roadmaps for 2026, the saw palmetto extracts market deserves attention as a small but steadily expanding ingredient category with outsized implications for sourcing, formulation and channel strategies. Our market model (base year 2025) estimates the global market at approximately 95.0 Million USD in 2025 and projects growth to roughly 132.4 Million USD by 2032, reflecting a compound annual growth rate (CAGR) of about 4.9% across the 2026–2032 forecast window. The historical series in our model captures a clear recovery and structural step-up from the 2020 baseline, driven by renewed interest in prostate and hormone-related wellness, incremental pharmaceutical demand, and fast-follow adoption in specialized supplement formats.
Saw Palmetto Extracts Market
Why this matters for 2026 decision-makers
-
Sourcing & cost control: Saw palmetto is a commodity with acute seasonality and geographically constrained harvests. Supplier selection, forward buying windows and harvest-permit compliance materially affect landed cost and availability. Buyers who lock predictable supply through multi-year purchase agreements and partner-level traceability capture margin and reduce formulation risk.
Saw Palmetto Extracts Market -
Formulation differentiation: Extraction methods (lipidosterolic free fatty acid concentrates, supercritical CO₂ extracts, cold-pressed oils, powders) create distinct claims, stability profiles and unit economics. R&D roadmaps that align extract chemistries to clinical endpoints or label claims can justify premium positioning in crowded supplement assortments.
Saw Palmetto Extracts Market -
Regulatory & certification risk: Harvest and trade controls, particularly in source regions, affect legal compliance and ESG reporting. Firms that operationalize harvest-permit verification, chain-of-custody documentation and third-party testing will outpace peers as regulatory scrutiny intensifies.
-
M&A and partnership timing: Market concentration is meaningful but not insurmountable — the top three players account for a substantial share of sales, and the top five capture a majority. For strategic buyers, 2026 is a moment to consider bolt-on acquisitions of specialized extract makers or upstream suppliers to secure differentiated technologies and supply continuity.
What PW Consulting’s full report delivers (operational, not academic)
-
Proprietary market model: A validated bottom-up and top-down model covering 2020–2025 history and 2026–2032 forecasts by format, route-to-market and end-use. The dataset is granular enough to stress-test scenarios but published without selective bias.
-
Demand-driver heatmaps and scenario analyses: Four near-term scenarios quantifying the impact of regulatory tightening, a raw-material shock, accelerated clinical evidence, and an e‑commerce adoption wave on volumes, pricing and channel mix.
-
Supply-chain playbook: Sourcing strategies by risk appetite — from transactional spot markets to integrated procurement and equity partnerships. Includes recommended contract terms, inbound hedging approaches and supplier scorecards to operationalize supply resilience.
-
Commercial diligence templates: Go-to-market playbooks for B2B ingredient suppliers and finished-goods brands, segmentation-led pricing ladders, and retailer mise-en-place for 2026 launches.
-
Quality & regulatory compendium: Suggested specification thresholds, stability and bioavailability considerations by extract chemistry, and a compliance checklist for harvest permits, organic claims and GMP audits.
-
Competitive intelligence: Profiles and capability assessments for leading suppliers and challengers, patent landscaping, and an M&A screening framework for strategic acquirers.
Competitive landscape — who matters and why
The market balances a few well-established ingredient houses with a broader base of commodity suppliers. Concentration metrics indicate the top three firms capture roughly half the market, and the top five exceed the majority threshold — a structure that rewards scale in manufacturing, regulatory compliance and channel coverage, yet still leaves niches for technology-differentiated players.
-
Valensa International: A U.S.-based specialty supplier known for branded, USP-verified lipidosterolic extracts produced with supercritical CO₂ processes. Valensa’s recent product updates and marketed “triple-action” claims reflect a deliberate move up the value chain toward patented formulations for urinary and sexual function support. For buyers, Valensa represents a reliable partner when clinical-grade verification and traceability are gating criteria.
-
Vidya Herbs: An India-based extractor that has invested in supercritical CO₂ technology and secured intellectual property for a standardized extract. Its patent position strengthens bargaining power for formulations that want proprietary claims on bioactive standardization. Firms evaluating exclusivity or licensing should monitor Vidya’s commercial rollout and geographic coverage.
-
BulkSupplements.com: A large-volume supplier focused on white‑label and bulk powder distribution for supplement manufacturers. They illustrate the low-margin, high-turnover side of the market — appropriate for scale manufacturers that prioritize price and speed over differentiated claims.
-
Nature In Bottle: A niche supplier emphasizing organic, cold‑pressed oil formats from U.S.-sourced berries. Its focus on organic certification and artisanal extraction offers premium positioning for brands targeting natural and traceable label attributes.
Recent moves that reshape 2026 playbooks
-
Patents and product launches: Patented extract formulations and refreshed “pro” product lines from established firms signal a shift to higher-margin, claim-based competition. For acquirers and brand teams, intellectual-property mapping is now a core part of diligence.
-
New upstream entrants: A wave of resellers and berry consolidators has appeared, seeking to capture raw-batch supply flows. While they can stabilize short-term availability, they can also introduce price volatility and quality heterogeneity unless contract terms and testing regimes are tightened.
-
Regulatory force multipliers: Source-region harvest permits and emerging traceability expectations are elevating the transactional cost of doing business. Firms that bake permit verification and chain-of-custody into standard operating procedures will reduce compliance friction and protect brand reputation.
Supply-side volatility and margin dynamics
Raw-material calendars and localized harvest rules create pronounced seasonality in supply. Processors command a sizable uplift versus raw berries; the value conversion from berry to extract is substantial and explains why extraction method and yield optimization directly translate to margin. Wholesale extract prices have historically displayed wide swings; smart procurement teams employ multi-supplier strategies, purchase options and modest inventory cushions to mitigate risk without overcapitalizing on inventory.
Priority actions by stakeholder group for 2026
-
Ingredient buyers / CPG formulators: (a) Run a two-tier sourcing strategy combining a preferred certified supplier for high‑claim SKUs and a cost-optimized pool for mass-market SKUs; (b) specify extract chemistry to match label claims and shelf-life needs; (c) include harvest-permit verification and third-party testing in RFQs.
-
Processors & extractors: (a) Consider scaling capacity for higher-margin standardized extracts and exploring licensing of patented formulations; (b) invest in yield improvements and solvent-free extraction where feasible; (c) formalize supply agreements with upstream berry consolidators to smooth seasonality.
-
Retailers & brand owners: (a) Differentiate with clinically-aligned formulations and transparent supply chains; (b) prepare merchandising tiers—commodity vs. premium traceable SKUs; (c) monitor direct-to-consumer claims and substantiation to avoid regulatory pushback.
-
Private equity & corporate development: (a) Screen targets that provide supply certainty (upstream growers, consolidators) or IP-led differentiation (patented extracts); (b) model scenarios with supply shocks and claim-driven premiumization; (c) plan earn-outs tied to certification and GMP milestones.
How to use the PW Consulting report in practice
Treat the full report as a playbook rather than a presentation deck. It provides the quantitative backbone (detailed segmentation by format and channel, supplier-level revenue estimations, and scenario-based P&L impacts) and the qualitative context (regulatory primers, sourcing checklists and competitive scorecards) needed to convert strategic intent into executable 12–24 month plans. We have intentionally kept this introduction at a high level; the full dataset and segment-level tables — including regional and application breakdowns, price ladders and supplier benchmarking — are available through the PW Consulting release portal for clients performing due diligence or preparing capital allocations for 2026.
Final note — a 2026 decision horizon
For executives making allocation decisions in 2026, the saw palmetto extracts market represents a low-to-mid-growth category with meaningful upside for players who can secure differentiated chemistries, lock reliable supply and translate technical attributes into verifiable consumer claims. The category’s moderate concentration favors strategic moves — targeted M&A, exclusive licensing or integrated supply agreements — over scattershot volume plays. PW Consulting’s full report equips decision-makers with the evidence, templates and risk mitigants needed to translate market opportunity into measurable returns while avoiding common pitfalls around supply volatility and regulatory compliance.
For detailed analysis of this topic, please visit the official page: Saw Palmetto Extracts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Luxury Hotels Market Set to Reach USD 185.6 Billion by 2032
By PW Consulting, 2026-07-08
Luxury Hotels Market — Strategic Imperatives for 2026 Decision‑Makers
Executive snapshot
After a volatile half‑decade of disruption and recovery, the global luxury hotels market reached an inflection point in 2025. Our base‑year synthesis shows the market size crossing the low‑hundreds (USD, base‑year 2025) and, under a central scenario, expanding at a compound annual growth rate (CAGR) of roughly 5.1% across the 2026–2032 forecast window. That trajectory drives a material uplift in absolute market value by the end of the decade and cements luxury lodging as the hospitality complex’s primary growth engine.
Luxury Hotels Market
This briefing introduces the strategic value of PW Consulting’s full Luxury Hotels Market study for corporate leaders, investors, and portfolio managers planning 2026 actions. It highlights why the report is decision‑critical while deliberately withholding the granular segment tables and raw regional splits available in the full package — a curated “teaser” designed to demonstrate analytical depth and drive targeted engagement.
Luxury Hotels Market
Why this research matters for 2026
- Timing and capital allocation: With demand indicators (ADR and RevPAR) showing premium outperformance versus lower tiers, investors must re‑calibrate capex and development priorities to capture faster cash‑flow recovery in luxury assets.
- Portfolio optimization: Operators and owners face tradeoffs between brand‑led repositioning and asset conversion; understanding how premium segments rebound across scenarios determines ROI and hold/sell decisions.
- Competitive positioning: Brand architecture moves and consolidation activity in early 2026 mean immediate reassessment of distribution, loyalty alignment, and brand partnerships is necessary to defend or capture market share.
- Tech and labor planning: Labor cost pressures and emergent AI frameworks are reshaping staffing models and guest personalization; management teams must translate regulatory and technology futures into 12–24 month implementation roadmaps.
What the full report delivers (practical, operational outputs)
- Detailed market sizing and multi‑scenario forecasts (2026–2032) validated against historical performance and macro scenarios.
- Segmented demand and revenue models by region, product type and revenue stream — with downloadable financial model templates that let teams stress‑test price, occupancy and mixed‑use strategies.
- Competitive benchmarking with profile dossiers on leading global groups, recent portfolio moves and capability maps (brand positioning, loyalty reach, distribution strengths, and wholesale vs direct channel exposures).
- Revenue management playbooks that align ADR and packaging tactics to segmented willingness‑to‑pay and length‑of‑stay dynamics; includes sample rate fences and upsell architectures developed from transaction‑level proxies.
- Operational KPIs and cost‑base diagnostics (labor, energy, maintenance) with normalized comparables and gap‑analysis templates for asset owners and operators.
- Investment and M&A decision aids: valuation sensitivity matrices, accretion/dilution frameworks for brand acquisitions, and an opportunities scoreboard calibrated to risk appetite.
- Technology and ESG roadmaps: prioritized digital investments (guest personalization, housekeeping automation, predictive maintenance) and sustainability targets tied to capital planning.
Competitive landscape — what top players are doing and why it matters
The global luxury field remains meaningfully fragmented: a small number of global groups hold a meaningful share of aggregate revenue but do not dominate the market the way global players do in some other industries. That structure creates both opportunity and competitive complexity: strong brands enjoy scale economies in distribution and loyalty, while independents and boutique collections capture premium pricing through distinctive experiences.
Luxury Hotels Market
- Marriott International — Continuing to elevate its top brands through formal segmentation strategies, Marriott is sharpening the value proposition of its flagship luxury banners to reinforce premium rate integrity and loyalty uplifts. Expect a stronger focus on differentiated experiences and curated cross‑brand itineraries.
- Hilton Worldwide — The completed integration of a premier boutique collection into Hilton’s luxury fold has already translated into expanded distribution and membership acceleration for boutique properties. That integration creates downstream pressure on smaller independent operators to either join platforms or double down on ultra‑niche positioning.
- Hyatt — Hyatt continues to leverage its upper‑upscale and luxury brand stack to pursue selective growth, prioritizing experiential stays, branded residences and co‑developed F&B concepts.
- IHG, Accor and other global groups — These chains balance global scale with regional brand acquisitions and partnerships to secure market access, particularly in markets where luxury demand recovery is uneven.
- Ultra‑luxury and boutique independents (Mandarin Oriental, Rosewood, Capella, Four Seasons, curated collections) — These groups are doubling down on distinctiveness: localized storytelling, residential offers, and experiential F&B/spa programming that command rate premiums and drive loyalty among high‑net‑worth clientele.
Recent 2026 initiatives — from new flagship openings to brand integrations — are not cosmetic. They redesign distribution curves, alter pricing elasticities, and shift competitive arbitrage for owners and operators. The full report contains a tactical impact matrix for each major move, helping teams decide whether to reposition, reflag, or defend.
Key market dynamics and near‑term risks
- Demand resilience and pricing power: Luxury RevPAR and average daily rate metrics have outperformed mass leisure and economy tiers in the post‑pandemic rebound. That trend underpins stronger cash generation potential but also raises expectations on service delivery and product refresh cycles.
- Labor and cost inflation: Wage pressures remain a structural headwind. Operators that invest in productivity enhancing technology (while preserving high‑touch guest service where it matters most) will sustain margins; those who do not face margin compression or must trade service for efficiency.
- Consumer preference shift: Affluent travelers are increasingly allocating spend to curated experiences over ownership. The implication is that experiential F&B, wellness and bespoke excursions are high‑return investments for operators looking to grow ancillary revenues.
- Regulation and technology governance: The emergence of global AI frameworks for personalization and operational efficiency implies compliance complexity but also new levers for margin expansion. Early movers who deploy governed, privacy‑conscious personalization will capture disproportionate wallet share.
- Macro and geopolitical exposures: Regional demand shock sensitivities remain heightened. Scenario planning — including soft, central, and aggressive growth paths — should be embedded in all 2026 capital allocation decisions.
Strategic imperatives for 2026 (what leaders should do this year)
- Recalibrate capex and renovation windows: Prioritize product refreshes that unlock price elasticity (guest rooms, signature F&B, wellness offerings) and delay or re‑scope projects with uncertain demand horizons.
- Monetize experiences: Convert guest recognition data into higher‑margin ancillary revenue streams (bespoke excursions, in‑residence dining, long‑stay packages) while testing premium packaging at scale.
- Adopt governed AI where it pays: Deploy personalization engines for upsell conversion and housekeeping/maintenance predictive tools to mitigate labor inflation. Ensure regulatory‑first governance to avoid compliance back‑slides.
- Optimize distribution mix: Reduce dependency on rate‑diluting channels through loyalty, direct booking incentives and localized partnerships with luxury travel advisors.
- Refine M&A and brand strategies: Use the current market window to evaluate tuck‑ins that fill capability gaps (spa brands, experiential operators, technology platforms) and to assess accretive flag conversions versus leaseback models.
- Institutionalize scenario planning: Convert the report’s scenario outputs into concrete trigger points for capital deployment, hiring plans, and brand repositioning decisions.
How to use the full study — next steps
PW Consulting’s full Luxury Hotels Market report contains the granular split tables, regional and application forecasts, downloadable financial models, and company‑level impact assessments that underpin the strategic guidance summarized here. If your 2026 planning cycle requires actionable investment cases, a customized competitor impact analysis, or a workshop to convert the model outputs into board‑level decisions, the full report and our advisory teams are configured to deliver tailored outputs within a 4–6 week engagement.
In short: the luxury segment offers accelerated growth and elevated margin potential in the current cycle, but extracting that value requires disciplined product investment, intelligent use of technology, and strategic responses to a shifting competitive field. Our full study gives you the granular inputs and operational playbooks to make those calls. For access to the complete dataset, segment tables and bespoke advisory engagements, please visit the source page linked in PW Consulting’s distribution channels.
For detailed analysis of this topic, please visit the official page: Luxury Hotels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Superalloy Market: Strategic Imperatives for 2026 — PW Consulting Briefing
As aerospace programs ramp toward next‑generation propulsion, power‑generation operators push efficiency thresholds, and additive manufacturing (AM) becomes standard for critical hot‑section components, the superalloy sector has entered a phase where strategic choices made in 2026 will disproportionately determine market leadership through the next planning cycle. Our Superalloy Market study — anchored on a 2025 base year with a historical window covering 2020–2025 and a forward projection through 2026–2032 — offers executives a decision‑grade synthesis of market trajectories, supplier dynamics, raw‑material risk, and technology inflection points.
Superalloy Market
Market snapshot (what the headline numbers mean)
-
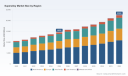
Macro growth: The global superalloy market expanded from approximately USD 10.6 billion in 2020 to USD 14.6 billion in 2025, and is modeled to reach roughly USD 22.5 billion by 2032. The forecast period (2026–2032) assumes a compound annual growth rate (CAGR) of 6.5%.
Superalloy Market -
Concentration and structure: The market remains moderately fragmented — our competitive concentration metrics show that the top three and top five firms collectively control a meaningful but not dominant share, leaving substantial room for specialist players and regional champions to scale.
Superalloy Market -
Why the numbers matter: At a 6.5% CAGR, incremental demand and price movements translate into material shifts in EBIT for both upstream alloy producers and downstream component manufacturers. This trajectory underscores why 2026 is a pivotal planning year for capacity, sourcing, and innovation investments.
Why this study is essential for C‑suite decisioning in 2026
-
Strategic timing: 2026 is when near‑term program awards, capital budgets, and multi‑year supply agreements signed pre‑2025 begin to re‑rate. Firms that align capacity and product roadmaps now will capture disproportionately higher margin pools through 2028–2030.
-
Risk crystallization: Raw‑material volatility and new export controls that emerged in 2024–2025 introduce discrete supply‑risk scenarios. The right mix of hedging, vertical integration, and sourcing diversification reduces project execution risk and protects margins.
-
Technology arbitrage: Additive manufacturing and powder metallurgy are shifting value toward alloy formulators and powder suppliers. Firms investing in AM‑compatible chemistries and qualification playbooks will shorten time‑to‑revenue in aerospace and high‑value industrial segments.
What the PW Consulting report delivers (practical, executable outputs)
-
Decision frameworks: Portfolio prioritization matrices that map product lines against technological defensibility, margin potential, and supplier exposure to raw‑material shocks.
-
Demand scenarios and volume ramps: Three demand trajectories (conservative, baseline, and accelerated) tied to macroeconomic, regulatory, and programmatic milestones that inform capacity planning and inventory strategies.
-
Supply‑chain heatmap: A layered view of input risk — from nickel and cobalt pricing cycles to geographic concentration of melt and forging capacity — with playbooks for rapid mitigation.
-
Technology and route‑to‑market playbooks: Practical guidance for integrating AM powders, vacuum melting, investment casting, and post‑processing capabilities into existing manufacturing footprints.
-
M&A and capex pipeline: Target profiles (technology, geography, scale) and valuation benchmarks for bolt‑on acquisitions, joint ventures, and greenfield expansions, plus a prioritized list of capability gaps buyers should close in 2026–2028.
-
Commercial tools: Negotiation levers for long‑term offtake, index‑linked pricing clauses, and contract templates that align incentives across the value chain.
Macro and raw‑material dynamics shaping 2026 strategies
-
Nickel: Recent cycles showed softening in average nickel prices into 2025, driven by inventory and production moves. Increased mine production and higher refined output in key producing countries altered sellers’ pricing power and opened short‑term cost breathing room for alloy makers. For planners, the implication is twofold: (1) windows for cost‑competitive sourcing may appear intermittently and should be leveraged for long‑lead orders; (2) long‑term hedging strategies must balance price volatility with potential supply disruptions.
-
Cobalt: The sector experienced structural oversupply through 2024 and early 2025, followed by abrupt policy shocks. Government measures in producing countries created episodic export constraints that produced sharp price swings — a reminder that commodity exposure is as much a geopolitical risk as a market one. Scenario planning should include quota and export‑control cases that materially affect cobalt‑intensive grades.
-
Recycling and secondary supply: Increasingly attractive economics for reclaiming high‑value nickel and cobalt from end‑of‑life components and process scrap offer both mitigation and margin opportunities. Investments in closed‑loop recovery should be evaluated against the cost of primary metal exposure and anticipated regulatory developments.
Competitive landscape: capabilities that matter in 2026
-
Incumbent producers that combine metallurgy, semi‑finished production, and component manufacturing retain advantages in qualification speed and program integration. Firms with proven aerospace pedigrees and established qualification records continue to command premium access to blue‑chip programs.
-
Specialists focused on powders, AM readiness, and high‑temperature alloys are increasingly pivotal. Recent developments — capacity expansions in additive manufacturing and new powder introductions — are shifting where technical differentiation accrues along the value chain.
-
Notable recent moves: several tier‑one firms commissioned new AM and vacuum melting lines in 2024–2025; independent technology players launched commercial nickel‑based powders and advanced machining methods for tough alloys. Such actions compress qualification cycles and lower time‑to‑adoption for new alloys.
-
Market concentration metrics indicate meaningful headroom for consolidation and vertical integration: incumbents can pursue targeted acquisitions to plug technological gaps, while nimble specialists can scale through strategic partnerships with OEMs and AM platforms.
Five strategic imperatives for executives in 2026
-
1) Convert short‑term price relief into strategic advantage. Use transient nickel price softness to secure multi‑year supply agreements and to stabilize input costs for longer program lifecycles.
-
2) Diversify cobalt exposure. Pursue alloy substitution where performance allows, invest in recycling, and build supplier redundancy to manage policy shocks from producing countries.
-
3) Accelerate AM‑capability adoption. Prioritize investments in powder qualification, component design for additive workflows, and supply‑chain partnerships that reduce certification timelines.
-
4) Right‑size capacity with staged expansion. Favor modular, flexible capital that can be scaled in response to validated orders and evolving technology standards rather than large, single‑phase greenfield investments.
-
5) Adopt contract structures that align incentives. Index‑linked pricing, volume‑commitment floors with flexibility clauses, and collaborative R&D milestones help stabilize supplier economics and accelerate co‑development.
M&A and investment outlook
-
Consolidation will be selective and capability‑led. Expect deals that deliver either critical process technology (powder atomization, VIM/VAR melting) or specialized manufacturing (investment casting, precision forgings for hot sections), rather than scale only.
-
Private equity interest will focus on platform plays that combine technical IP with recurring revenue streams — for example, powder supply contracts tied to long‑term AM programs.
-
Deal diligence must stress raw‑material exposure, patent strength, qualification backlog, and customer concentration. Regulatory and export‑control risk are non‑trivial and should be stress‑tested in valuation models.
What we intentionally withhold here — and why you need the full report
-
We have deliberately omitted granular segment‑level revenue splits, regional and application percentages, and individual product price trajectories from this briefing. Those sub‑segment figures are core competitive intelligence and are included only in the full report, where they are presented alongside confidential supplier scorecards and a quantitative risk model.
-
If your team needs roll‑up tables that translate segmental demand into material flows, supply commitments, and EBITDA sensitivity by scenario, the complete dataset and interactive models in our full study are the only place you will find them.
Next steps for senior leaders
-
Use 2026 to convert optionality into positions: secure strategic long‑term supply where it matters, fast‑track AM qualification on prioritized platforms, and pursue targeted capability acquisitions where you lack defensibility.
-
Engage our practice for a tailored session: we will map the full report’s scenario outputs to your product portfolio, quantify margin impact across procurement and technology levers, and build a prioritised implementation roadmap for 2026–2028.
PW Consulting’s Superalloy Market study translates headline growth and technology trends into executable commercial and technical strategies. For teams preparing 2026 budgets, supply agreements, or acquisition roadmaps, the work you do now will determine your competitive position for the remainder of the decade. Contact PW Consulting to access the full report, interactive models, and bespoke advisory support.
For detailed analysis of this topic, please visit the official page: Superalloy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: OSB Market to Hit USD 334.7 Million by 2032 at a 5.48% CAGR
By PW Consulting, 2026-07-08
Oriented Strand Board (OSB) Market — Strategic Briefing for 2026 Decision Makers
As operating conditions normalize but structural uncertainty persists across timber markets, the OSB sector occupies a pivotal role in decisions that will determine competitive positioning through the next business cycle. PW Consulting’s latest market study — grounded in a 2020–2025 historical base and projecting out to 2032 — synthesizes market-scale dynamics, supply adjustments, regulatory inflection points, and competitive manoeuvres into a decision-ready framework for executives, investors, and policy teams planning for 2026 and beyond.
Oriented Strand Board (OSB) Market
Why this study matters for 2026 strategy
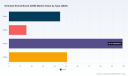
Two simple facts make the case. First, the overall OSB market expanded materially during 2020–2025, growing from USD 143.5 Million in 2020 to USD 210.0 Million in 2025. Second, our forecast projects a continuation of that trajectory, with the global market reaching approximately USD 334.7 Million by 2032 at a compound annual growth rate (CAGR) of 5.48% over the 2026–2032 horizon. Those macro numbers translate into a mid-single-digit structural tailwind for manufacturers and downstream integrators — but the opportunity is uneven, and execution matters.
Oriented Strand Board (OSB) Market
For 2026, the study is specifically designed to support four types of executive decisions: capacity and operations planning; price and raw-material risk management; portfolio and channel strategy; and M&A / partnership prioritization. Each of these decision areas requires credible demand scenarios, short- and mid-term price outlooks, and company-level benchmarking — elements that are central to the report.
Oriented Strand Board (OSB) Market
How PW Consulting structures the insight
- Market sizing and scenarios: A reconciled historical series (2020–2025) and three forward paths for 2026–2032 (base, upside, downside) that quantify demand drivers and sensitivity to housing starts, renovation cycles, and industrial wood-product substitution.
- Supply-side mapping: A plant-level supply atlas, capacity utilization models, and throughput curves that allow rapid simulation of idling, restarts, and new-line ramp timing under different log-supply and labor scenarios.
- Price and cost analytics: Rolling price decks and published-commodity reconciliation (including recent country-level OSB price observations and strand fiber cost volatility) to support forward-margin and breakeven analysis.
- Regulatory and standards impact: A practical legal/regulatory primer showing where exemptions and certifications materially affect product acceptance and cost of compliance in major markets.
- Competitive benchmarking and strategic levers: Comparative matrices for capacity, product differentiation, vertical integration, and channel footprint — with playbooks for near-term actions and longer-term strategic options.
Key takeaways that will shape 2026 choices
- Growth is real but heterogeneous: The market’s mid-single-digit CAGR masks concentrated pockets of opportunity and risk. Players who refine volume plans using facility-level economics (rather than top-line forecasts alone) will capture outsized margin improvements.
- Capacity rationalization is an active force: Recent curtailments and idlings demonstrate that producers are already managing capacity to address log supply constraints and short-term demand softness. Understanding the timing and permanence of these moves is essential for short-cycle pricing and for any company considering expansion or exit.
- Input-cost volatility cuts both ways: Strand fiber and sawmill feedstock swings—exacerbated by biomass demand and regional sawmill curtailments—create margin variability that can wipe out gains from favorable volume trends. A disciplined hedging and sourcing playbook is required.
- Standards and exemptions reshape product economics: Recent regulatory clarifications have practical consequences: certain structural OSB products certified to voluntary standards are exempted from some composite-wood emission requirements, reducing compliance burden and preserving market access in key jurisdictions.
- Consolidation threshold is moderate: The industry remains concentrated at the top (our concentration metrics show a meaningful CR3 and CR5 position), which creates a dual dynamic: incumbent producers can exert pricing and distribution influence, but acquisitive mid-tier players can still achieve scale benefits by targeting complementary assets.
Competitive landscape — what to watch in 2026
The report profiles the major incumbent groups that define structural OSB supply and influence market dynamics — firms with large integrated operations, multi-site footprints, and differentiated product lines. Rather than a simple roll call, PW Consulting’s analysis evaluates each company across four strategic dimensions: capacity adequacy and flexibility; product differentiation and brand equity; logistics and channel reach; and financial resilience to raw-material cycle risk. Recent, actionable developments are particularly instructive:
- Capacity expansions underway in select geographies indicate player confidence in long-term demand, with projects aiming to bring new lines online in the mid-decade window.
- Large producers have announced idlings and curtailments tied to log supply and operational optimization, underscoring the asymmetric response to regional raw-material constraints.
- Targeted capital projects focused on optimization — not just incremental capacity — reveal a strategic shift toward efficiency gains and product mix enhancement.
For decision-makers, the implication is clear: tracking announced project timelines and actual ramp performance is as important as headline capacity numbers. Our company-level scorecards and scenario models enable rapid recalibration of competitor behavior and its pricing implications.
Regulatory and market noise that could alter 2026 outcomes
- Regulatory clarifications: Recent agency rulings have practical implications for product certification and compliance costs. For example, certain structural OSB products made to voluntary standards continue to be exempt from specific formaldehyde emission rules in major jurisdictions, which materially affects both manufacturing choices and customer acceptance.
- Price signals: Published market data show elevated OSB prices in some sourcing regions in early 2026, driven by constrained wood supply — a trend that, if sustained, will compress margins for non-integrated producers and create cross-border arbitrage opportunities.
- Input volatility: Strand-fiber and feedstock price swings in 2025 highlight the need to plan for peak-to-trough scenarios in procurement and tolling agreements.
What the report delivers — practical outputs for 2026
Piloting through 2026 requires tools, not just insight. Our report contains items you can put to work immediately:
- Demand-stress scorecards and 18-month rolling shipment curves you can plug into working capital and procurement plans.
- Plant-level breakeven templates (including labor, energy, resin, and logistics inputs) to evaluate restart vs. idle decisions and to size investment returns for efficiency upgrades.
- Negotiation playbooks for timber-supply contracts and third-party tolling arrangements that reflect real-world contract levers and penalty structures.
- M&A screening matrices and valuation comparables that prioritize targets by synergies (supply chain, market access, product fit) rather than headline capacity alone.
- Regulatory compliance matrices showing certification pathways that reduce market friction in major buying regions.
How executives should use the intelligence
Three priority uses for the 2026 planning cycle:
- Scenario-driven capacity planning: Layer our supply atlas and utilization curves over your asset base to test staged restarts or conversions; prioritize investments that shorten payback under downside scenarios.
- Dynamic pricing and procurement: Use the report’s price decks and component-cost indices to set forward price collars, negotiate timber contracts with indexed clauses, and optimize resin buying windows.
- M&A and partnership execution: Target transactions that close channel or feedstock gaps and run our valuation stress tests to ensure deal resilience to input-price shocks.
Limitations and where the full study adds value
This briefing is intentionally selective. To preserve the strategic value of the primary research and to protect proprietary segmentation models, we have not reproduced the full regional and application-level splits or certain granular commercial datapoints here. The full PW Consulting study includes the exhaustive tables, plant-level models, and interactive scenario tools that power the recommendations summarized above.
Next steps for leaders planning in 2026
- Integrate scenario outputs into CapEx and procurement cycles now — lead times for mill projects and resin contracts mean decisions made in H1 2026 drive financial outcomes through 2027.
- Prioritize contracts and investments that increase feedstock optionality and logistics flexibility to mitigate concentrated regional supply risk.
- Use competitor development tracking (announced curtailments, expansions, and optimizations) as a tactical input to pricing and tender strategies — small timing gaps create large short-term margin opportunities.
PW Consulting’s OSB market study is built to be an operational tool as well as an analytical reference. For teams that must convert market insight into tactical actions in 2026—whether by optimizing plant runs, hedging material exposure, or evaluating M&A—this study offers the models, benchmarks, and playbooks to act with confidence. Access to the full dataset, plant-level models, and interactive scenario workbooks is available in the complete report.
Contact PW Consulting to arrange a briefing, license the interactive models, or commission bespoke scenario work tailored to your asset and market footprint.
For detailed analysis of this topic, please visit the official page: Oriented Strand Board (OSB) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Mechanical Keyboards Market to Reach USD 2,560.7M by 2032 at 12.1% CAGR
By PW Consulting, 2026-07-08
Mechanical Keyboards Market 2026 — Strategic Preview for Decision Makers
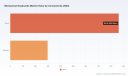
As companies prepare budgets and roadmaps for 2026, understanding where the mechanical keyboards market will travel next is a strategic imperative. PW Consulting’s latest study frames that trajectory: the global mechanical keyboards market, measured at the close of our base year (2025), sits comfortably above the billion‑dollar mark and is forecast to more than double by the end of the 2026–2032 horizon, growing at a compound annual growth rate (CAGR) of 12.1%. This preview distills the report’s strategic value for executive teams — highlighting high‑impact opportunities, looming risks, and the practical decisions that will shape outcomes next year — while reserving the granular segment and regional breakouts for the full report.
Mechanical Keyboards Market
What this preview delivers
- An executive lens on how macro growth translates into 2026 commercial and operational priorities.
- A concise competitive assessment of incumbent OEM/ODM and enthusiast brands shaping supplier economics and innovation pathways.
- Actionable playbooks for procurement, product, go‑to‑market, and M&A leaders to exploit the next 12–18 months.
- A calibrated risk matrix covering tariffs, supply chain geopolitics, and raw‑material volatility — with mitigation pathways that companies can implement today.
Why this market matters in 2026
The mechanical keyboards category is transitioning from a niche “enthusiast + gaming” product set into a broader set of premium input devices serving productivity, creative work, and enterprise customization. That broadening addressable market underpins the forecast strength: after crossing the one‑billion‑USD threshold in our 2025 base year, the market’s projected trajectory through 2032 implies sustained, above‑average expansion driven by product premiumization, wireless adoption, and diversified use cases.
Mechanical Keyboards Market
For strategy teams, this means two immediate implications. First, volume alone will not guarantee value capture: margin structure will increasingly depend on product differentiation (materials, switch technology, software/firmware ecosystems) and supply‑chain control. Second, rising demand creates room for adjacency plays — services, customization, and after‑market ecosystems — that can materially enhance lifetime value per customer.
Mechanical Keyboards Market
Key dynamics shaping the next 12–18 months
- Premiumization of hardware and materials: Demand for aluminum cases, polycarbonate plates, and high‑quality PBT keycaps continues to push product specifications upward. Reported material price swings have lifted production costs in certain premium categories, altering supplier pricing power and requiring revised bill‑of‑materials assumptions for 2026 models.
- Switch innovation and product differentiation: Magnetic and other novel switch architectures are moving from enthusiast prototypes to OEM offerings. Firms that combine innovative switching systems with scalable manufacturing stand to win both enthusiast and mainstream segments.
- Connectivity and form factors: Wireless models are gaining meaningful consideration for productivity and living‑room gaming use cases; however, wired models remain the backbone for performance‑sensitive segments. Portfolio design must balance latency concerns, battery strategy, and industrial design costs.
- Geopolitical and trade risk: Policy signals in 2025 and early 2026 — including open letters and tariff contingencies affecting imports from China/Hong Kong — elevate the probability of trade‑cost shocks. These dynamics, combined with shifting regional manufacturing footprints, are already affecting lead times and sourcing decisions.
- Supply‑chain complexity: Component sourcing is increasingly dispersed across China, Taiwan, and Southeast Asia. Geopolitical friction and capacity shifts translate into higher lead‑time volatility and selective supplier consolidation.
Competitive landscape — where power sits
The market is concentrated among a handful of established OEM/ODM suppliers and specialist brands that control manufacturing scale, tooling, and relationships with switch vendors and component houses. Leading players — including firms with strong OEM/ODM capabilities based in Guangdong and Shenzhen — have built portfolios spanning custom builds, gaming lines, and enthusiast sub‑brands. These suppliers’ strengths are their manufacturing depth, design adaptability, and go‑to‑market flexibility (white‑label and branded channels).
Concentration metrics in our analysis indicate a market where the top three and top five suppliers collectively command a substantial share of industry revenue. That configuration creates both barriers for new entrants and opportunities for incumbents to extract scale benefits through component purchasing, tooling amortization, and channel leverage.
Representative company snapshots included in the full study:
- Shenzhen‑based OEMs that combine custom keyboard services with enthusiast sub‑brands and switch partnerships, enabling a dual play in volume OEM orders and higher‑margin branded offerings.
- Dongguan manufacturers with end‑to‑end production and accessory ecosystems designed for white‑label programs.
- Shenzhen firms specializing in wireless and magnetic‑switch variants, targeting both gaming and premium desktop audiences.
- Custom builders offering broad layout support (ANSI/ISO/ABNT) and flexible small‑batch production — an attractive option for enterprise and niche retail contracts.
Operational and commercial playbook for 2026
To convert market growth into sustained market share and margin improvement next year, leadership teams should prioritize five parallel tracks:
- Supply‑chain resilience: Introduce multi‑sourcing for critical components (switches, PCBs, cases), negotiate flexible lead‑time contracts, and evaluate localized buffer inventories for high‑value SKUs. Scenario‑based procurement models in the full report show the trade‑offs between inventory carrying costs and service levels under tariff shocks.
- Product segmentation and SKU rationalization: Focus R&D spend on two differentiators — switch experience (including magnetic innovations) and materials/finish. Prune low‑velocity SKUs and reallocate capex to platforms that are modular and support rapid localization for regional compliance.
- Pricing and channel optimization: Tighten MAP and channel incentives for D2C vs. reseller pathways. Consider subscription and customization services (keycap sets, tuning services) to expand recurring revenue.
- M&A and partnership scouting: Target small design houses with IP in switch mechanics or firmware ecosystems, and evaluate bolt‑on acquisitions of accessory makers to broaden margins.
- Enterprise and B2B engagement: Build a tailored proposition for corporate procurement (branded or white‑label bulk orders, managed customization, warranty and service tiers) to capture higher‑ticket institutional deals.
Risk scenarios and mitigation
Three near‑term scenarios merit board attention:
- Tariff shock: A sudden imposition of increased import tariffs would compress margins for China‑sourced production. Mitigants include shifting final assembly to alternative jurisdictions, adjusting retail prices in staged increments, and renegotiating long‑term supplier pricing to smooth impacts.
- Raw‑material price spike: With certain premium materials having seen double‑digit cost moves, firms should incorporate dynamic BOM pricing or indexation into supplier contracts and prioritize redesigns that reduce dependence on the most volatile inputs.
- Component shortages and lead‑time elongation: Use demand‑shaping (preorder programs), increase safety stocks for critical parts, and expand qualification processes for alternate suppliers to reduce single‑source risk.
Where to prioritize investment in 2026
- R&D for switch experience and firmware ecosystems that lock in end users through software‑driven customization.
- Quality and materials engineering to justify premium pricing and to differentiate in B2B procurements.
- Channel investments that balance D2C branding with strategic retail and distributor partnerships to scale internationally without sacrificing margin.
- Operational investments in supplier qualification and nearshoring pilots to reduce tariff and geopolitical exposure.
What the full PW Consulting report provides (selected features)
- Proprietary market model (2020–2032) with scenario toggles for tariffs, material price inflation, and adoption curves — enabling bespoke forecasts tailored to corporate assumptions.
- Supplier scorecards and OEM/ODM capability matrices to accelerate supplier selection and supplier‑development programs.
- Price‑band and margin ladders by product archetype, and a recommended SKU rationalization pathway for mid‑sized brands.
- Go‑to‑market playbooks for D2C, retail, and enterprise channels, including suggested promotional calendars and key metrics for CAC and LTV.
- M&A heatmaps highlighting target profiles, expected revenue uplift, and integration risk checklists.
Final note — the strategic vantage for 2026
The mechanical keyboards market offers a rare combination of robust macro growth and actionable micro opportunities. The central strategic decision for 2026 is not whether the market will grow — our forecast makes that clear — but whether a company will capture disproportionate share and margin through product differentiation, supply‑chain design, and channel execution. PW Consulting’s full study supplies the data, models, and tactical playbooks to move from intent to implementation.
To access the complete forecasts, segmented analysis, supplier scorecards, and the interactive scenario model (which includes downloadable worksheets for procurement and product teams), consult the full Mechanical Keyboards Market report. The preview above highlights the strategic levers; the full study contains the subsegment tables, regional splits, and detailed company profiles that operational teams need to execute confidently in 2026.
For detailed analysis of this topic, please visit the official page: Mechanical Keyboards Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Walkie Talkie Market to Reach USD 7.94B by 2032 at 6.98% CAGR
By PW Consulting, 2026-07-08
Walkie Talkie Market 2026: Strategic Preview for Decision-Makers
Executive snapshot
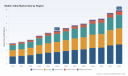
As PW Consulting’s lead industry analyst, I present a condensed strategic preview of our forthcoming Walkie Talkie Market study — a practical intelligence brief designed to influence capital allocation, product roadmaps, and regulatory planning for 2026. The global market has shown steady expansion from the early 2020s and reached approximately USD 4.87 Billion in our base year (2025). With a modeled compound annual growth rate (CAGR) of 6.98% across the 2026–2032 forecast window, the market is poised to approach roughly USD 7.9 Billion by the end of the forecast period. Those headline numbers frame a market that is neither niche nor fully mature: it is commercially substantial, concentrated in a handful of meaningful suppliers, and being reshaped by digitalization, regulation, and new service models.
Walkie Talkie Market
Why this research matters for 2026 decisions
- Timing is convergent: 2026 is the inflection year when software-enabled capabilities (AI, cloud-assisted incident workflows) and spectrum policy updates will materially affect procurement specifications and supplier selection.
- Scale meets complexity: With mid-single-digit CAGR growth and clear leader concentration, buyers and investors must evaluate not just price and features but ecosystem integrations, lifecycle economics, and regulatory resilience.
- Actionable competitive context: Vendors are differentiating through AI, network convergence, and vertical-specific service bundles — the right partner choices in 2026 will determine fielded interoperability and future upgrade paths.
Market trajectory & macro interpretation
Between 2020 and 2025 the market expanded consistently, reflecting recovering infrastructure investment, continued demand from public safety and industrial end-users, and a growing consumer segment for outdoor and recreational use. Our base-year sizing (2025) provides a stable platform to model scenarios through 2032. The projected compound annual growth rate of 6.98% indicates predictable, moderate expansion driven by technology refresh cycles (analog-to-digital migrations), the gradual adoption of IP and LTE/5G complementary solutions, and increasing spend on integrated incident management services rather than hardware alone.
Walkie Talkie Market
From a capital-allocation standpoint, this dynamic supports a portfolio approach: maintain exposure to core hardware incumbents while selectively underwriting software- and services-oriented entrants that can capture recurring revenue and post-sale value.
Walkie Talkie Market
Competitive landscape — what to watch
The market demonstrates measurable concentration among the leading suppliers. Buyers should expect three-to-five vendor dynamics to dominate mission-critical procurement, with regional vendors and low-cost manufacturers remaining relevant on price and distribution in non-mission-critical channels.
- Motorola Solutions (Schaumburg, Illinois) — Strategic posture: premium mission-critical systems, expanding into AI-enabled operational workflows. Recent rollouts of AI-assisted incident narrative capabilities illustrate a move from pure communications hardware to platform-driven, data-centric offerings. Strategic implications: buyers targeting integrated public safety solutions will prioritize Motorola for end-to-end interoperability and ongoing software innovation; however, software dependency and subscription economics will need careful contracting.
- Hytera Communications (Shenzhen) — Strategic posture: broad product breadth across analog and digital systems with an accelerating push into converged networks and smart-city integrations. Recent trade-show activities highlight an emphasis on hybrid deployments that bridge legacy land-mobile-radio (LMR) and IP networks. Strategic implications: Hytera can be an attractive partner for scale deployments in mixed-network environments, but buyers should assess roadmap alignment for long-term digital migrations.
- Sepura Limited (Cambridge) — Strategic posture: deep expertise in mission-critical digital standards such as TETRA and LTE; positions itself on reliability and standards compliance. Strategic implications: Sepura’s strength is resilience in regulated mission-critical segments; organizations with strict interoperability and compliance obligations will find its portfolio compelling.
- ICOM, JVCKENWOOD, Uniden, Retevis, Rocky Talkie — Strategic posture: these vendors populate a spectrum from professional-grade niche suppliers to consumer and value-channel providers. Strategic implications: expect bifurcation — premium, certified solutions for public safety and regulated environments vs. low-cost, high-volume options for consumer and light-industrial deployments. Procurement teams must codify requirements to avoid inappropriate substitutions.
Recent vendor moves and what they signal
- Motorola’s early-2026 AI feature rollout signals the acceleration of analytics and automation as differentiators — not merely accessories. Expect contracting shifts toward performance-based metrics for AI-assisted features and increased emphasis on data governance.
- Hytera’s presence at large trade forums in 2026 underscores the vendor strategy to win municipal and smart-city projects where radio systems converge with urban IoT and broadband networks.
Regulatory and standards dynamics — practical consequences
Regulation is a persistent structural influence for walkie talkie supply and deployment. Two themes are central for 2026 planning:
- Spectrum integrity and compliance risks: Recent regulatory actions, including product recalls tied to pre-programmed licensed frequencies, demonstrate enforcement intensity. Procurement teams must require suppliers to provide compliance artifacts, firmware provenance, and mechanisms for secure configuration management.
- Allocation and standards shifts: National frequency plans and international standards evolve — updates to spectrum plans and enforcement frameworks can change permissible device behavior and certification requirements. For organizations operating cross-border or in multi-jurisdictional contexts, compliance risk translates directly into service interruption risk and potential recall liabilities.
How PW Consulting’s full report converts insight into action
Our comprehensive Walkie Talkie Market report (base year 2025; historical 2020–2025; forecast 2026–2032) is structured to transition senior leaders from awareness to execution. Highlights include:
- Quantitative market sizing and scenario modeling through 2032, with macro baselines and sensitivity around technology adoption and regulation.
- Vendor scorecards that evaluate product breadth, R&D posture, channel strength, financial resilience, and service economics.
- Technology roadmap analysis covering analog-to-digital migration, DMR/TETRA/LTE convergence, AI-enabled workflow layers, and interoperability constraints.
- Use-case playbooks and procurement templates tailored for public safety, industrial, commercial, and defense buyers — including lifecycle cost models and upgrade-path decision trees.
- Regulatory matrix and compliance checklists per major jurisdiction, plus a recall-risk mitigation framework to protect operations and reputations.
- M&A and partnership candidate shortlists driven by gap analysis (capability, geography, and service model) and an actionable 100-day integration playbook.
Importantly, the full report embeds primary interviews, vendor-validated product maps, and a proprietary market-concentration assessment to guide competitive positioning. (Our concentration analysis shows a market architecture where the top three and top five vendors account for a meaningful share of revenue — a structural reality buyers must account for in tender design and partnership strategies.)
Practical recommendations for 2026
- Revise procurement RFQs: Include clauses for firmware provenance, AI performance SLAs, and clear upgrade economics to avoid vendor lock-in or mid-cycle compliance surprises.
- Prioritize interoperability pilots: Before enterprise-wide rollouts, execute cross-vendor interoperability tests that include digital and converged-network scenarios.
- Build a migration roadmap: Treat analog-to-digital transition as a staged program with discrete decision gates linked to spectrum clarity and budget cycles.
- Underwrite regulatory risk: Conduct jurisdictional spectrum and certification audits for any device intended for cross-border use; factor recall insurance or supplier indemnities into contracts.
- Explore software and services capture: Evaluate vendors’ ability to provide recurring services (analytics, incident management, training) rather than one-off hardware deliveries.
How to use this preview
Consider this document a strategic trailhead. It synthesizes macro sizing, growth assumptions, competitive moves, and regulatory inflections so executives can prioritize which lenses to apply in 2026: procurement discipline, vendor risk, service transformation, or M&A. The full PW Consulting Walkie Talkie Market report unlocks the underlying segmentation detail, scenario matrices, and vendor-level models that readers will need to operationalize these strategic directions.
Closing perspective
The walkie talkie market in 2026 is a study in contrasts — stable demand and modest growth at the market level, accelerating technology-driven differentiation, and an elevated regulatory bar that can reprice entire product categories overnight. For decision-makers, success will hinge on marrying disciplined procurement and compliance practices with agile partnerships that embrace software-enabled value. In short: buy hardware where reliability matters, but buy the future with software and services that secure recurring advantage.
PW Consulting’s full market study provides the granular intelligence and executable playbooks required to make those choices with confidence. Access to the complete dataset and vendor modeling is available on our report page.
For detailed analysis of this topic, please visit the official page: Walkie Talkie Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hair Loss & Growth Market to Expand at 5.98% CAGR Through 2032
By PW Consulting, 2026-07-08
Strategic Outlook: Hair Loss & Growth Treatments and Products Market — A 2026 Playbook
As companies recalibrate strategies for 2026, the hair loss and growth treatments market presents a mixture of steady demand, accelerating clinical innovation, and regulatory complexity. Our new PW Consulting market research (base year 2025; forecast period 2026–2032) quantifies a clear expansion trajectory: the global market has grown from a mid-hundreds million USD base in 2020 to roughly USD 267 million in 2025 and is projected to approach USD 405 million by 2032, reflecting a compound annual growth rate of approximately 5.98% over the forecast window. This briefing highlights the research’s strategic value for 2026 decision-makers, outlines the actionable contents of the report, summarizes competitive and regulatory developments to watch, and proposes pragmatic moves that leaders should consider now.
Hair Loss & Growth Treatments and Products Market
Why this research matters for 2026 corporate decisions
-
Predictable, investable growth: The market’s mid-single-digit CAGR signals a stable but competitive growth environment. Organizations that blend clinical differentiation with commercial discipline can capture outsized returns against a backdrop of steady total-market expansion.
Hair Loss & Growth Treatments and Products Market -
Pipeline-driven market reshaping: Late-stage therapeutic advances — spanning topical biologics, oral non-hormonal agents, and immune-modulating therapies for autoimmune hair loss — are changing product mix, channels, and payer conversations. These shifts require companies to reassess R&D prioritization, launch sequencing, and cross-functional readiness now.
Hair Loss & Growth Treatments and Products Market -
Regulatory and safety noise demands active mitigation: Public health communications and agency alerts around compounded products have elevated regulatory and reputational risk. Companies must align clinical evidence strategies with regulatory engagement and communications plans to avoid commercial and compliance setbacks.
-
Moderate market concentration: The market exhibits mid-level concentration among leading firms, which means dominant players can shape standards, but gaps exist for focused entrants and differentiated offerings.
What PW Consulting’s report delivers (practical, execution-focused content)
-
Comprehensive market sizing and multi-scenario forecasting (2026–2032) with sensitivity analyses for clinical success rates, pricing scenarios, and reimbursement dynamics.
-
Go-to-market playbooks tailored to product archetypes — prescription therapeutics, over-the-counter cosmetics, and device-led interventions — covering channel strategy, physician engagement, and DTC marketing considerations.
-
Regulatory pathway mapping and decision trees, including risk mitigation templates for compounded product narratives and evidence packages aligned to FDA expectations.
-
Clinical landscape atlas: trial timelines, mechanism-of-action maps, endpoints comparison, and adoption curves that help prioritize indications and sequence launches.
-
Commercial benchmarking and pricing frameworks that reconcile R&D investment profiles with expected payer behaviors and consumer willingness-to-pay.
-
M&A and partnership playbooks with candidate screening criteria, valuation sensitivities, and integration checklists for quickly moving from diligence to deal-close.
-
Primary research insights: interviews with key opinion leaders, dermatology clinic directors, payers, and distribution partners to inform pricing, reimbursement, and promotional tactics.
Competitive landscape: who’s shifting the market and why it matters
-
Pelage Pharmaceuticals (Los Angeles) — advancing PP405, a topical stem cell reactivation therapy. Positive Phase 2a results in 2025 and a Phase 3 initiation in 2026 signal an intent to compete in the high-value topical therapeutics corridor. For incumbents, Pelage’s approach reflects a strategy to differentiate on mechanism and clinical durability rather than price alone.
-
Veradermics (New Haven) — developing VDPHL01, an oral non-hormonal agent for pattern hair loss. Completion of Phase 3 enrollment in early 2026 indicates a near-term potential for a new oral option that could shift prescribing patterns and broaden patient segments willing to pursue pharmacologic therapy.
-
Nektar Therapeutics (United States) — pursuing an IL‑2 receptor–modulating biologic (rezpegaldesleukin/Rezpeg) for severe-to-very-severe alopecia areata. The reported long-term topline data in 2026 show deepening regrowth responses, underscoring the rising role of immune‑modulating biologics in autoimmune hair loss and the subsequent implications for specialist care pathways and reimbursement.
-
Cosmo Pharmaceuticals (Dublin) — developing clascoterone (Breezula) topical solution with Phase 3 topline results reported in late 2025 and ongoing safety follow-up into 2026 ahead of planned regulatory submission. This program exemplifies the classic pharmaceutical pathway: late-stage data to underpin label differentiation and premium pricing.
Collectively, these programs highlight two strategic realities for 2026: (1) clinical differentiation will increasingly determine commercial outcomes, and (2) timing and sequencing around Phase 3 readouts and regulatory submissions will create windows of opportunity for partnerships, distribution agreements, and targeted marketing investments.
Regulatory dynamics and market risk
-
Recent agency communications have drawn attention to safety risks tied to compounded topical formulations. These advisories have elevated scrutiny on compounding practices and created both near-term reputational risk and longer-term opportunity for approved, standardized alternatives.
-
The absence of regulatory approvals for certain topical formulations commonly used in practice increases uncertainty for existing compounding-based channels and highlights the commercial advantage for firms that can bring approved, clinically-validated products to market.
-
For 2026, companies should anticipate intensified regulatory engagement, including expectations for post-approval safety follow-up and real-world evidence commitments that could shape launch timetables and promotional claims.
Strategic implications and recommended actions for 2026
-
For biotech and pharma: Prioritize regulatory-readiness and dossier quality. If you have late-stage assets, build parallel commercial preparations (payer dossiers, KOL networks, specialty distribution) ahead of approval decisions. Consider staged market entry to manage manufacturing scale-up and formulary negotiations.
-
For consumer brands and OTC players: Invest in clinical differentiation and consumer trust signals (clinical claims substantiation, clinic partnerships). Leverage digital channels to shorten trial-to-purchase cycles and capture demand from early adopters seeking non-prescription solutions.
-
For device manufacturers: Differentiate through integrated ecosystems — devices plus monitoring apps, clinician portals, and subscription models — to raise switching costs and create recurring revenue streams.
-
For investors and private equity: Target bolt-on acquisitions that provide clinical credibility or unique distribution access. Use scenario models that stress-test valuation under delays to pivotal trials and varying reimbursement outcomes.
-
Cross-cutting moves: enact a three-layer playbook: (1) evidence acceleration — pre-launch RWE studies and registries; (2) regulatory engagement — proactive safety communications and labeling strategy; (3) channel hedging — diversify between specialty clinics, retail, and DTC to balance risk.
Where winning competitive advantage will emerge
-
Biologic and immune-modulating therapies for alopecia areata — deep clinical efficacy will reconfigure specialist referral patterns and payer strategies.
-
Non-hormonal oral agents and novel topical mechanisms — those that combine convenience with demonstrated durability of response will broaden market penetration beyond traditional dermatology patients.
-
Integrated care models — combining diagnostics, teledermatology, and adherence-enabled products — will increase lifetime customer value and support premium pricing.
-
Validated, regulatorily cleared alternatives to compounded products — as safety concerns persist, evidence-backed, standardized products will capture share from informal compounding channels.
How PW Consulting turns insight into 2026 action
-
We translate the macro trajectory and competitive events into executable plans: launch readout calendars, payer engagement timelines, and contingency scenarios that map directly onto 2026 boardroom milestones.
-
Our report’s scenario modeling quantifies P&L and valuation impacts across a range of clinical and regulatory outcomes, enabling executives to prioritize capital allocation under uncertainty.
-
We provide deal-ready diligence packages and integration playbooks for M&A, licensing, and co-promotion arrangements that respect the compressed timelines around pivotal data readouts in 2026.
To lead in 2026 you need more than market sizing — you need a playbook that aligns clinical timelines with commercial execution, regulatory positioning, and capital strategy. PW Consulting’s full report contains the granular segmentation, channel-specific models, and primary research that will let your team operationalize the moves outlined here. For companies planning launches, partnerships, or portfolio reshapes in 2026, these are not theoretical levers — they are immediate decision points. Visit our report page to access the full dataset, interactive scenario models, and bespoke advisory options tailored to your organization’s role in the evolving hair loss and growth market.
For detailed analysis of this topic, please visit the official page: Hair Loss & Growth Treatments and Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Computer-on-Module (COM) Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
As companies place heavier bets on edge computing, industrial automation, and AI-enabled devices, the Computer-on-Module (COM) market has entered a phase of steady expansion and technical consolidation. Our latest PW Consulting study (base year 2025, forecast 2026–2032) shows the market expanding at a compound annual growth rate (CAGR) of 5.2% from the recent base, progressing from roughly USD 1.48 billion in 2020 to about USD 1.92 billion in 2025, and projected to reach approximately USD 2.72 billion by 2032. These headline figures frame a market large enough to matter strategically, yet nuanced and fragmented enough to reward targeted plays.
Computer On Module (COM) Market
Why this research matters for strategic choices in 2026
-
Capital allocation: The modest but durable CAGR signals that organizations should favor staged investments — prioritizing modular architectures and software-enablement over one-off hardware bets.
Computer On Module (COM) Market -
Product roadmaps: With the market trajectory through 2032 now quantified, R&D and platform teams can size multi-year design-win campaigns, justify validation budgets, and sequence silicon and carrier-board commitments against demand curves.
Computer On Module (COM) Market -
M&A and partnerships: A market exhibiting mid-single-digit growth with clear concentration dynamics (CR3 ~55%, CR5 ~65%) points to consolidation opportunities — bolt-on acquisitions or strategic alliances can accelerate scale and fill capability gaps.
-
Supply-chain & sourcing strategies: Forecasted expansion supports rethinking dual-sourcing, strategic inventory buffers, and long-lead procurement of critical components (SoCs, power-management ICs, high-speed interconnects) to reduce time-to-market risk.
Market dynamics and growth trajectory
The COM market’s growth is driven by the convergence of several structural forces: persistent demand for compute at the edge, the industrialization of AI inferencing, and the need for modular, long-life embedded platforms across regulated sectors (medical, transportation, industrial). These forces underpin a reliable expansion profile rather than a speculative boom — the 5.2% CAGR reflects steady adoption across adjacent domains rather than a single vertical spike.
Crucially for planners in 2026, the projected path to ~USD 2.72 billion by 2032 implies a market that will reward scale, repeatable design wins, and ecosystem depth (carrier boards, SDKs, lifecycle support). At the same time, the pace of growth underscores the importance of winning early projects in high-value segments (edge AI, industrial automation, regulated medical devices) where price premium and longer product lifecycles justify development effort.
Strategic themes shaping vendor and buyer behavior
-
Modularity as a multiplier: Customers increasingly buy platform-level solutions — COM modules paired with carrier boards and validated software stacks — to accelerate time-to-deployment. Vendors offering strong reference designs and long-term modular roadmaps capture higher lifetime value.
-
AI and heterogeneous compute: Recent product introductions — especially modules built around next-generation Intel Core Ultra-class processors and COM-HPC form factors — highlight the market’s move toward AI-capable edge compute. Expect GPU/accelerator support, multi-lane PCIe, and optimized SDKs to become standard differentiation vectors.
-
Miniaturization and ruggedization: Demand for compact, low-power COMs that still deliver determinism and thermal resilience is growing. Rugged modules and validated environmental profiles are increasingly decisive in industrial and transportation OEM selection processes.
-
Lifecycle and regulatory stewardship: Long-term availability, secure firmware update paths, and compliance support (medical/automotive) matter as much as raw performance for customers who design products with multi-year certification cycles.
-
Consolidation & specialization: Market concentration metrics indicate that a handful of vendors command material share, but there remains space for specialized players that excel at customization, vision/graphics, or ultra-low-power ARM solutions.
Competitive landscape — what recent moves signal
The competitive field blends large, diversified embedded suppliers with nimble specialists. Several contemporaneous developments illuminate strategic directions:
-
Portfolio scale and consolidation: The expansion of COM portfolios following module-business transactions and new product families underscores vendor efforts to offer full-stack, cross-form-factor choices — a clear play to capture platform-level engagements across industrial and medical OEMs.
-
Processor-led product refreshes: Multiple vendors announced modules based on the latest Intel Core Ultra-class processors in late 2025 and January 2026, signaling that the migration cadence of edge-class compute is accelerating. Buyers should therefore assume a shortening window for legacy silicon availability and plan roadmap alignments accordingly.
-
Edge AI specialization: Vendors emphasizing edge-AI SDKs, multi-lane PCIe, and GPU support are positioning to win workloads that require local inferencing and low-latency vision processing. Strategic buyers should demand software stacks and validated inference benchmarks as part of procurement.
Representative vendor positioning (non-exhaustive): established module providers are doubling down on form-factor breadth and customization services; industrial specialists emphasize rugged and long-lifecycle modules; niche players focus on vision/graphics and ultra-custom, OEM-specific designs. Detailed profiles and vendor scorecards are included in the full study.
What the PW Consulting report delivers (practical, actionable content)
-
Robust market-sizing model (historical 2020–2025 and forecast 2026–2032) with scenario drivers and sensitivity tests — designed for CFOs and product leaders to stress-test CAPEX and roadmap assumptions.
-
Module-level technology stack analysis: SOC roadmaps, interconnect trends (PCIe, high-speed SerDes), power/thermal trade-offs, and software-enablement requirements for AI workloads.
-
Go-to-market playbooks: OEM procurement templates, validation checklists, and sample TCO models comparing custom SoC boards versus COM-led architectures.
-
Risk and resilience matrices mapping supplier concentration, component lead-time exposure, and mitigation levers (dual-sourcing, strategic buffer, design-to-availability choices).
-
M&A & partnership heatmaps: target profiles, valuation heuristics for tuck-ins, and a shortlist of strategic capabilities that move the needle in 2026–2028.
-
50+ vendor intelligence profiles and recent-activity tracking — including product launches, portfolio expansions, and platform integrations — to support supplier selection and negotiation.
-
Practical case studies and engineering appendices: validated carrier-board reference designs, thermal benchmarks, and upgrade pathways to COM-HPC and AI-accelerated modules.
High-impact recommendations for 2026 leadership teams
-
Adopt a modular-first architecture for new platform designs. The upfront cost of standard COM integration is offset by faster design cycles, vendor flexibility, and reduced obsolescence risk.
-
Prioritize software and validation: insist on SDK maturity and long-term BSP support in supplier contracts to protect product lifecycles and service revenue streams.
-
Lock down strategic silicon and high-speed interconnect components early. The market’s steady growth supports planned commitments; late procurement increases technical and schedule risk.
-
Pursue bolt-on acquisitions or JV arrangements to bridge capability gaps in edge AI, thermal management, or ruggedization rather than attempting in-house buildouts for every functional block.
-
Use CR metrics and vendor scorecards to design tiered sourcing: a primary vendor for scale, a specialist for differentiation, and a trusted contingency partner for risk mitigation.
Accessing the full intelligence
This preview outlines the strategic implications and high-level evidence base for the COM market through 2032 — enough to guide executive debates and immediate tactical shifts. The full PW Consulting report contains the granular segmentation, regional and application breakouts, vendor market shares, downloadable models, and vendor-by-vendor SWOTs that procurement, R&D, and corporate development teams need to convert strategy into execution.
To evaluate specific entry points, supplier-term scenarios, or to obtain the full dataset and model access, please follow the report link on our site. The complete package is designed as a practical playbook for decision-making in 2026 and beyond — not just analysis for analysts.
For detailed analysis of this topic, please visit the official page: Computer On Module (COM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


