



Category: market research
PW Consulting: Rubber Track Market to Reach USD 2,850 Million by 2032 at 6.0% CAGR
By PW Consulting, 2026-07-08
Rubber Track Market 2026: Strategic Intelligence Briefing for Executive Decision-Makers
As Senior Strategy Advisor and Chief Industry Analyst at PW Consulting, I present an executive briefing that frames the strategic choices industry leaders must make in 2026. This piece previews the full Rubber Track Market study: it demonstrates the analytical depth you will receive while intentionally withholding granular segmentation detail — the exact figures, regional splits and application-level line items remain reserved for the full report accessible from our source page.
Rubber Track Market
Why this study matters for 2026 decisions
Rubber track systems are no longer a niche replacement part; they have become a strategic lever across construction, agriculture, rental fleets, defense and specialty mobility platforms. Decisions you make in 2026 about sourcing, product roadmaps, channel structure, and M&A will be determined by three converging forces: a mid-single-digit market growth trajectory, persistent commodity and regulatory pressure in natural rubber supplies, and a competitive environment that is increasingly defined by differentiated materials chemistry and OEM integration.
Rubber Track Market
-
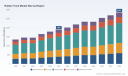
Market growth is steady and predictable: the industry is operating from a base year of 2025 where total global revenues stood at approximately USD 1,900 Million (Million USD). PW Consulting’s forecast models project a compound annual growth rate of about 6.0% through the 2026–2032 horizon, driving the market to roughly USD 2,850 Million by 2032. That combination of scale and steady growth creates favorable conditions for longer-term strategic investments, but also heightens the importance of cost and supply resilience.
Rubber Track Market -
Commodity and regulatory shocks are not theoretical: an anticipated supply gap in natural rubber and upward pressure on raw rubber prices will compress margins for commodity-exposed participants and raise the cost of entry for new product formats without secured feedstock plans.
-
Competition is shifting from price to integrated solutions: suppliers that pair proprietary compounds, reinforced cord technologies, and OEM-certified integration are capturing differentiated value.
Market dynamics shaping 2026 strategy
Four dynamics deserve immediate attention from senior management and procurement teams.
-
Raw material constraints. Industry data indicate a persistent global shortfall in natural rubber production relative to demand by 2026. That gap creates systemic price upside and increases the value of vertical supply assurance — forward contracts, strategic inventories, geographically diversified sourcing, and partnerships with plantation cooperatives now materially affect unit economics.
-
Regulation and traceability. New regulations in premium markets — notably requirements that demand plot-level traceability and auditable sourcing for natural rubber — are changing supplier selection criteria. Compliance is no longer a cost item to be deferred; it has become a table-stakes qualification for access to high-value customers and export markets.
-
Price trajectory and procurement exposure. Forecasts point to mid-single-digit percentage price increases in benchmark natural rubber grades in 2026. Procurement teams must decide whether to absorb, hedge, or pass through those costs; each choice has distinct implications for channel relationships and competitive positioning.
-
Technology and product differentiation. Advances in compound chemistry, reinforced cord systems and metal link interfaces are altering product life, traction performance and repairability. OEM-led co-development and patented formulations are increasingly used to lock in higher-margin, vehicle-integrated solutions.
Competitive landscape — what leading players reveal
The industry profile is a mix of specialized manufacturers, global OEM suppliers, and aftermarket solution providers. PW Consulting’s analysis highlights how a handful of firms are pursuing three distinct strategic plays:
-
OEM partnership and high-spec supply: established industrial suppliers with OEM-facing capabilities are doubling down on volume integration and technical validation. Their value proposition centers on product certification, long lifecycle performance, and tightly managed quality controls.
-
Materials and IP differentiation: companies investing in proprietary compound formulations and steel-cord/metal-link architectures are shifting competition from commodity price to product performance. Patented compounds and integrated track constructions create entry barriers and enable premium pricing.
-
Aftermarket and channel specialization: distributors and replacement-focused firms are optimizing for installation convenience, dealer networks and fast replenishment cycles. Their go-to-market excels in rental, local service and tiered warranty offerings.
Representative firms from each cluster — manufacturers that supply to OEMs, specialized compound innovators, and aftermarket/retailer-focused players — are described in the full study with supplier scorecards that cover capacity, technology assets, geographic strength, and go-to-market models. Recent industry moves in early 2026 further validate these trends:
-
Trade show participation by multiple suppliers underscores the continuing importance of channel and rental relationships as demand generators.
-
Investment in R&D facilities in North America signals an intensifying race to support OEMs with local validation labs and co-engineering capability.
-
Active product launches and demonstrations reflect supplier strategies that prioritize demonstrable performance improvements over price-only competition.
What the PW Consulting report delivers — practical, executable content
The full report blends rigorous data with actionable frameworks designed to support board-level and operational decisions in 2026. Key deliverables include:
-
Market sizing and validated forecasts: multi-scenario revenue projections through 2032, including sensitivity runs that adjust for raw-material price and regulatory adoption timelines.
-
Supplier scorecards and strategic positioning lenses: comparative assessments across technology, capacity, supply security, and go-to-market alignment.
-
Supply chain risk heatmaps: mapped vulnerabilities at the feedstock, conversion and logistics layers, with contingency playbooks for short- and medium-term disruption.
-
Commercial levers and pricing playbooks: actionable approaches for procurement and sales to manage pass-through decisions, hedging strategies, and value-based contracting with OEM customers.
-
M&A and partnership screen: a prioritized pipeline of acquisition and JV targets based on capability gaps, regional access, and IP synergies.
-
Implementation roadmaps: quarter-by-quarter recommendations for supply security, product development, channel investments, and regulatory compliance across a 24–36 month horizon.
Strategic implications and recommended actions for 2026
Based on our synthesis, we recommend that executives prioritize four programmatic responses in 2026. Each is designed to convert market growth and disruption into competitive advantage.
-
Secure feedstock and manage price exposure. Adopt a layered procurement approach: short-term inventory buffers, medium-term forward contracts indexed to quality grades, and long-term strategic partnerships with diversifying suppliers. Parallel investments in alternative compound R&D can reduce sensitivity to natural rubber price shocks.
-
Pursue premium integration with OEMs. Where feasible, convert product relationships into co-development engagements and certified-supplier arrangements. These contracts increase switching costs and enable price differentiation tied to validated lifecycle performance.
-
Invest in traceability and compliance systems. Implement traceability technologies and third-party audit pathways now to capture access to premium markets that demand plot-level provenance. Non-compliance will progressively restrict market access and invite reputational risk.
-
Design for channel segmentation. Separate commercial models for OEM, rental/dealer and DIY aftermarket channels. Tailor warranties, installation services and inventory programs to the economics and adoption drivers of each channel.
How PW Consulting supports your 2026 execution
For companies evaluating strategic moves this year, our full Rubber Track Market study provides the proprietary models, supplier evaluations and playbooks required to move from insight to implementation. We combine market-first data, validated supplier intelligence and hands-on scenario tools that let leadership stress-test decisions under alternative commodity, regulatory and demand scenarios.
Note: this briefing intentionally summarizes themes and strategic recommendations while withholding the granular regional and application-level splits, precise supplier market shares and certain unit-cost schedules. Those items are included only in the full report, along with downloadable models that you can use in your planning cycles.
Next steps
-
Download the full benchmark report to access the complete datasets, supplier scorecards and downloadable scenario models.
-
Engage with PW Consulting for a tailored workshop: we will run a one-day executive session using your cost and supplier data to produce a 90-day action plan.
-
Consider commissioning a targeted due diligence or supplier audit if you plan to pursue M&A or supplier consolidation in 2026.
PW Consulting’s Rubber Track Market study is designed to be the operational intelligence anchor for leaders who must make high-consequence supply, product and channel decisions in 2026. For access to the full data, segmentation tables, and supplier-level insights, please visit the report page or contact our industry practice team.
For detailed analysis of this topic, please visit the official page: Rubber Track Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Herbal Medicine Market set to hit USD 344.8B by 2032 at 8.37% CAGR
By PW Consulting, 2026-07-08
Herbal Medicine Market 2026: Strategic Imperatives for Decisions That Matter
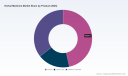
As global interest in botanicals and plant-derived therapeutics accelerates, 2026 represents a pivotal year for corporate strategists, investors and policy teams shaping portfolios and go-to-market models. PW Consulting’s latest Herbal Medicine Market study — anchored on a 2025 base year, covering historical performance from 2020–2025 and projecting through 2032 — crystallizes the market’s trajectory and the cross-cutting forces that will determine winners and laggards. The market’s compound annual growth rate in the forecast window stands at 8.37% (2026–2032), and the report maps a recovery and expansion path that moves total global revenues markedly higher from the mid‑2020s baseline into the early 2030s.
Herbal Medicine Market
Why this research matters for 2026 corporate decision-making
-
Strategic prioritization under uncertainty: Executives face a choice between scaling existing consumer-facing herbal lines, investing in evidence-backed phytopharmaceuticals, or pivoting toward high‑growth channels like e‑commerce and specialty professional distribution. Our study provides a scenario-driven framework that translates top‑line growth expectations and regulatory trajectories into actionable portfolio and investment thresholds for 2026 decisions.
Herbal Medicine Market -
Capital allocation and M&A playbook: With fragmented market structures and evolving concentration dynamics, the report helps acquirors and private equity sponsors size targets, assess integration risk, and price synergies—without disclosing proprietary segment tables in this introduction. It includes valuation sensitivities keyed to differing regulatory and clinical‑evidence outcomes.
Herbal Medicine Market -
Regulatory and clinical roadmap alignment: The window for converting botanical tradition into regulated therapeutic claims is open—but timing and evidence requirements vary by jurisdiction. The study synthesizes recent regulatory shifts and translates them into tactical playbooks for R&D sequencing, clinical investment, and dossier preparation prioritized for 2026 launches.
-
Channel and digital acceleration: Consumer shifts toward online purchasing, subscription models and health‑professional telechannels are reshaping distribution economics. The research quantifies channel elasticities and proposes migration roadmaps that preserve margin while expanding reach.
High‑level market dynamics you need to lock into strategy
From a macroscopic perspective, the herbal medicine market has grown from a documented baseline in the early 2020s and reached a substantial scale by 2025, after which it is forecast to expand at an annualized rate of 8.37% through 2032. That growth profile reflects multiple reinforcing vectors: rising consumer interest in preventive health, increased regulatory clarity enabling higher‑value therapeutic positioning, and the maturation of global supply chains for consistent botanical raw materials. Yet these opportunities coexist with structural challenges—quality and traceability requirements, evolving regulatory thresholds for clinical evidence, and a marketplace where distribution innovation (notably digital platforms and practitioner channels) reshapes competitive advantage.
Importantly, the market remains commercially diverse and not highly concentrated at the top—an attribute that creates both M&A opportunities for scale seekers and competitive openings for digitally native specialists to capture niche leadership. Our full report quantifies concentration metrics and disaggregated segment growth; this introduction focuses on the strategic implications rather than the granular tables.
Regulatory inflection points: the new playbook for botanical therapeutics
-
Harmonization momentum: Multilateral initiatives—including recent WHO engagements on regulatory cooperation—are accelerating efforts to standardize labeling and quality requirements. For 2026 planning, that means firms should anticipate greater cross‑border harmonization in dossier expectations and prepare global regulatory strategies rather than ad‑hoc national submissions.
-
EU and EMA guidance: The European Medicines Agency’s Committee on Herbal Medicinal Products (HMPC) has published a multi‑year work plan and active meeting schedule to refine scientific guidance for marketing authorization. Companies targeting European therapeutic claims must align 2026 R&D roadmaps to these timelines to avoid late‑stage rework.
-
US pathway clarity: The FDA’s Botanical Drug Development guidance released in late 2025 clarified trial design and evidence thresholds for botanical drugs. Developers can now better estimate time‑to‑market and resource requirements for switching from dietary supplement claims to drug‑level approvals—this is a central lever in our valuation and go‑to‑market models.
-
Emerging market regulatory cooperation: Recent partnerships and regulatory initiatives in markets such as Nigeria and Pakistan indicate growing capacity for local trials and approvals. Multinational firms should incorporate local regulatory acceleration opportunities into market entry strategies, especially where traditional medicine systems are broadly accepted.
What the report contains: practical, transaction‑ready deliverables
-
Market sizing and forecast model (2020–2032) with scenario toggles for regulatory stringency, consumer sentiment shifts and supply disruptions. The base and scenarios are calibrated to observed 2020–2025 historical performance and the forecast CAGR through 2032.
-
Channel economics and margin impact matrices that allow users to simulate the P&L effects of shifting sales from traditional retail to e‑pharmacies, practitioner channels and direct‑to‑consumer subscriptions.
-
Prioritized R&D and dossier roadmaps that map clinical evidence needs to target jurisdictions and claim sets, including suggested trial designs aligned with regulatory expectations in major markets.
-
A 360° competitive intelligence module profiling leading global players—covering business models, route‑to‑market, manufacturing footprints and recent strategic moves—plus a shortlist of potential M&A targets and partnership candidates sorted by strategic fit.
-
Supply chain resilience and sustainability playbooks: botanical sourcing risk heatmaps, traceability frameworks, and cost‑benefit cases for vertical integration versus contract manufacturing.
-
Commercial playbooks for premiumization and label claim strategies, including pricing levers, promotional mechanics and consumer segmentation insights designed for rapid operationalization in 2026.
Competitive landscape: what leading firms are telling us
The competitive field spans multinational network marketers, heritage herbal manufacturers, phytopharmaceutical specialists and digitally native brands. Several archetypes stand out and have distinct strategic implications:
-
Multi‑level marketing incumbents (e.g., firms with extensive distributor networks): These players leverage broad direct‑selling footprints and high customer loyalty. Their advantages are rapid market reach and recurring revenue mechanics; constraints include regulatory scrutiny over claims and limited appeal to institutional buyers. For partnership strategies, they are attractive distribution partners but often require careful compliance alignment.
-
Heritage Ayurvedic and traditional medicine manufacturers (notably large India‑based firms): These companies offer deep indigenous knowledge, established supply chains for botanicals and strong domestic brand equity. Opportunities lie in internationalization and clinical evidence upgrades; scaling often hinges on modernizing manufacturing standards and dossier capabilities.
-
Phytopharmaceutical and regulated herbal product specialists (European and Japanese firms in particular): These companies focus on evidence‑based formulations intended for therapeutic positioning. Their strengths are regulatory readiness and clinician acceptance; their playbook is instructive for firms seeking to elevate product claims and enter reimbursed markets.
-
Consumer wellness and supplements specialists (US, Australia and digitally native brands): These firms excel in branding, innovation in formats (e.g., extracts, concentrated formulations) and direct digital acquisition. Their trajectory underscores that premiumization, certification (organic, clinical support) and agile supply chains can command higher margins.
Across these archetypes, common strategic differentiators include: investment in clinical evidence, traceable and sustainable sourcing, digital acquisition and subscription mechanics, and regulatory capabilities to multi‑jurisdictionally manage product claims. Our full report profiles each major player, comparing their positioning and likely strategic moves through 2028—information essential for partnership or competitive response planning.
Actionable recommendations for 2026 planners
-
Prioritize investments in evidence generation for at least one product line if you aim for therapeutic claims in regulated markets. The incremental margin uplift and channel diversification opportunities justify upfront clinical spend, but timing matters—align trials to regulatory calendars identified in our dossier playbooks.
-
Embed traceability and sustainability as non‑negotiable attributes of sourcing. Buyers and regulators are increasingly demanding verifiable supply chains; resilience here mitigates both reputational and regulatory risk.
-
Design a two‑track distribution model: preserve traditional retail and practitioner channels while aggressively scaling e‑commerce and subscription services. Our channel elasticity models show that blended approaches optimize reach without sacrificing margin.
-
Use targeted M&A to accelerate capability acquisition—particularly for regulatory expertise and manufacturing that meets global standards. The market’s mid‑tier fragmentation creates opportunities for bolt‑on acquisitions to consolidate scale quickly.
-
Build a regulatory surveillance function to monitor evolving guidance from EMA HMPC, FDA botanical guidance, WHO harmonization outputs and emerging market regulators. Near‑term wins will accrue to firms that can anticipate and adapt to these shifts in 2026 rather than react.
Closing: where PW Consulting adds value
PW Consulting’s Herbal Medicine Market study is structured to convert macro forecasts and regulatory context into executable 90‑, 180‑ and 360‑day plans for executives planning capital deployment in 2026. The report’s blended methodology—combining historical market performance, a robust forecast model, scenario planning, competitor intelligence and regulatory playbooks—delivers the clarity needed to make high‑stakes decisions with confidence.
To preserve strategic differentiation and encourage rigorous due diligence, this introduction highlights directionally the opportunities and risks without reproducing the granular segment tables and proprietary company score‑cards contained in the full research package. For the complete data sets, segmentation tables, competitor profiles, and transaction‑ready recommendations, PW Consulting’s full report provides the operative detail required to execute in 2026.
For detailed analysis of this topic, please visit the official page: Herbal Medicine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Surface Enhanced Raman Spectroscopy (SERS) Market: Strategic Briefing for 2026 Decisions
As companies reassess their analytical capabilities and product roadmaps for 2026, Surface Enhanced Raman Spectroscopy (SERS) is rapidly moving from specialist labs into commercial, field, and regulated environments. This briefing — prepared by PW Consulting — outlines why our new SERS Market study is a must-read for executives, R&D leaders, and corporate development teams planning investment, partnership, or go-to-market activity in the coming 18 months. It previews the report’s analytical depth and practical outputs while preserving the report’s proprietary segmentation and model outputs to encourage direct download for complete, transaction-ready intelligence.
Surface Enhanced Raman Spectroscopy (SERS) Market
Why SERS matters to 2026 strategy
SERS delivers molecular sensitivity and specificity that materially changes how organizations detect trace compounds — from contaminants in food and pharma to illicit substances in security screening. The technology’s relevance intersects with three strategic priorities that will dominate 2026 board agendas: (1) rapid, decentralized testing; (2) regulatory-compliant analytical platforms; and (3) cost-efficient, scalable sensing solutions that reduce time-to-decision.
Surface Enhanced Raman Spectroscopy (SERS) Market
Our market model shows a sustained expansion path for the overall SERS market, with a compound annual growth rate (CAGR) of approximately 8.3% across the forecast horizon. The market has grown notably in the 2020–2025 period and is projected by our model to continue scaling through 2032, reflecting accelerating adoption in applied testing, industrial monitoring, and regulated product workflows. For executives, that growth profile converts to concrete decisions on allocation of CapEx for instrumentation, recurring revenue models for consumables (substrates and reagents), and the timing of product introductions that require regulatory clearances.
Surface Enhanced Raman Spectroscopy (SERS) Market
What the PW Consulting SERS study delivers (practical, executable deliverables)
- Proprietary market-sizing and demand model (historical 2020–2025; forecast 2026–2032) with scenario toggles for adoption speed and regulatory gating.
- Commercial playbooks for suppliers and end users: procurement checklists, validation protocol templates, and SLA clauses for substrate consistency and instrumentation performance.
- Technology roadmaps mapping substrate approaches, excitation wavelengths, and miniaturization trends to likely commercial use-cases over 3–6 year horizons.
- Regulatory navigation guide for deploying SERS-enhanced Raman systems in regulated environments, including an FDA-compliance checklist and submission pathways that differ by use-case.
- Partnering and M&A scorecards to identify high-leverage bolt-on technologies, fabrication capability gaps, and near-term tuck-in targets.
- Operational KPIs for quality and reproducibility — recommended sample sizes, averaging strategies, and workforce training metrics to reduce measurement variance.
- Commercial segmentation maps with buyer personas, procurement cycles, and price sensitivity analysis (note: the full segmentation tables and underlying figures are retained in the full report).
Market dynamics: drivers, friction points, and tactical implications
- Adoption drivers: demand for rapid, label-free molecular fingerprinting across life sciences, chemical safety, food integrity, and anti-counterfeit applications; improved substrate fabrication; and instrument miniaturization enabling field deployments.
- Regulatory gating: commercial and industrial deployment increasingly requires FDA-registered Raman systems when SERS is part of a regulated workflow. This raises the bar for vendors seeking enterprise and clinical contracts; understanding submission pathways and partnering with FDA-experienced integrators will materially shorten sales cycles.
- Reproducibility constraints: intrinsic variability in hot-spot distributions and substrate uniformity remains a practical hurdle. Industry-level measurements indicate significant spot-to-spot enhancement variability and, in practice, operators may need to average many measurements to achieve statistical confidence. This directly impacts throughput and total cost of ownership (TCO) assumptions.
- Human capital: a notable proportion of organizations report shortages of staff experienced in SERS methods. Investing in training programs, certified workflows, and user-friendly interfaces is an immediate lever to accelerate adoption.
- Consumable economics: substrate batch consistency, shelf-life, and handling standards are a recurring procurement pain-point. For buyers, supplier qualification should include accelerated-aging studies and lot-to-lot performance metrics as standard contract terms.
Competitive landscape: who to watch and where to partner
The SERS ecosystem blends established spectroscopy OEMs, optical-component suppliers, and specialist substrate/kit providers. Market concentration remains modest; the top three players account for roughly a quarter of market value while the top five approach a third. This dispersion signals opportunity for focused product differentiation and well-executed M&A.
- Horiba (Kyoto, Japan) — A full-spectrum Raman systems provider with integrated SERS-capable platforms and nanostructured substrates. Strengths: deep system-engineering expertise and high-throughput solutions tailored to laboratory and industrial customers.
- Ocean Optics (Orlando, FL, USA) — Supplies a broad line of SERS substrates and laser-compatible chips aimed at repeatable trace detection in narcotics, food safety, and anti-counterfeit work. Strengths: ready-to-use substrate kits and multi-wavelength compatibility targeting applied users.
- Thorlabs (Newton, NJ, USA) — Expanding into textured SERS substrates as part of its optics portfolio. Strengths: supply-chain breadth and component-level integration for instrument builders.
- Renishaw (New Mills, UK) — Integrates SERS into robust Raman platforms aimed at research, forensics, and pharmaceutical customers. Strengths: reputation in regulated workflows and high-performance instrumentation.
- B&W Tek (Newark, DE, USA) — Focused on portable and component-based instruments with SERS compatibility for field and industrial deployments. Strengths: portability and industrial-grade packaging.
- Elodiz & DialAct (UK / USA) — Partners providing modular, and in some cases FDA-registered, configurations that support SERS-enhanced applications for research and regulated environments.
- Teledyne Vision Solutions (USA) — Offers imaging and spectroscopy solutions with explicit SERS capabilities, relevant for applications requiring integrated imaging-sensing workflows.
Recent vendor activity reinforces strategic priorities: Thorlabs expanded substrate offerings in mid‑2024, HORIBA introduced a high-throughput Raman plate reader optimized for SERS in early 2025, and DialAct with Elodiz launched FDA-registered systems mid‑2025. These moves highlight two concurrent competitive plays — push into consumables and substrates for application-specific workflows, and system-level innovation aimed at throughput and regulatory compliance.
Executive actions for 2026: a concise playbook
- Prioritize substrate QC and supplier qualification: require accelerated-aging and lot-to-lot performance data in purchase agreements; build in accept/reject criteria tied to field validation outcomes.
- Adopt phased deployment with measured KPIs: pilot SERS in lower-regulated use-cases to validate workflows and operational throughput before scaling into FDA-regulated contexts.
- Invest in workforce enablement: create certification programs or partner with instrument vendors to close the knowledge gap and reduce dependency on specialist operators.
- Consider strategic partnerships for regulatory routes: when targeting clinical or food-safety contracts, favor partners with FDA experience or validated system-level submissions to shorten procurement cycles.
- Lock in consumable margins via long-term supply agreements: design contracts that include volume-based pricing and rapid replacement clauses to protect supply continuity for high-throughput customers.
- Scan for acquisition targets that fill capability gaps: focus on substrate fabricators with reproducibility IP, niche instrument makers enabling portability, or software firms that automate signal processing and QA for SERS data.
How to use this study to win in 2026
Think of our SERS Market study as a decision-support system: it combines a transparent forecast model with tactical modules you can plug into procurement, R&D planning, and M&A diligence. If you are building a product roadmap, the study’s technology timing matrices and adoption scenarios will help you prioritize features and certification investments. If you are a buyer or laboratory manager, the vendor scorecards and procurement checklists will reduce sourcing risk and shorten validation timelines.
We intentionally present this briefing as a directional preview: the full report contains the underlying tables, granular segmentation, downloadable model workbooks, fact-checked company profiles and references, and ready-to-use contract appendix templates. These are the elements that convert strategic insight into executable programs and defensible investment decisions.
Next steps
- Download the full SERS Market report for complete segmentation, regional and application models, and detailed vendor benchmarks.
- Schedule a briefing with PW Consulting’s Industry Advisory team to walk through a customized sensitivity analysis for your product or procurement scenario.
- Engage our M&A team to receive curated target lists and valuation frameworks based on the study’s proprietary market model.
In a market growing at a steady, double‑digit adjusted pace relative to adjacent analytical segments, the difference between leadership and lagging adoption will be determined by how quickly organizations address substrate reproducibility, regulatory readiness, and workforce capability. Our report is designed to make those decisions measurable and actionable — download the full study to convert this strategic preview into a concrete investment plan for 2026.
For detailed analysis of this topic, please visit the official page: Surface Enhanced Raman Spectroscopy (SERS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Stent Grafts Market 2026 Preview: Strategic Imperatives for Executives
Executive snapshot
PW Consulting’s latest industry briefing on the global stent grafts market positions 2026 as a decisional inflection point. The market has demonstrated steady expansion through the pandemic recovery period and into the mid-2020s, growing from a multi‑billion dollar base in 2020 to a larger market size by our 2025 base year. Our baseline projection shows continued expansion across the 2026–2032 forecast window at a compound annual growth rate (CAGR) of approximately 5.15%, producing meaningful upside for clinical innovators, device manufacturers, and strategic investors who act with calibrated timing.
Stent Grafts Market
Why 2026 matters — the strategic context
Executives entering 2026 face a market shaped by three converging forces: tightening regulatory scrutiny on materials and device lifecycle events, active product refresh and disruptive approvals, and shifting economic incentives in procedure reimbursement. These forces alter near‑term commercial performance and determine who can scale safely into complex anatomy solutions (arch, thoracic, fenestrated/branched systems) over the next half decade.
Stent Grafts Market
From a pure market‑size perspective, the stent graft market shows resilience and a sustained growth trajectory through the 2020–2025 historical window and into our 2026 forecast. That trajectory underpins capacity expansion, R&D pipelines, and M&A strategies — but it is the interplay with regulatory, reimbursement and material constraints that will determine winners and losers.
Stent Grafts Market
What this report delivers — hands‑on, actionable intelligence
- Comprehensive market model: a transparent base‑year model with historical granularity (2020–2025) and scenario‑based forecasts (2026–2032), enabling management to run bespoke revenue and ROI sensitivity analyses without exposing confidential regional or application slices in this preview.
- Commercial playbooks: segment‑specific go‑to‑market blueprints for established OEMs, mid‑tier challengers, and new entrants — including channel strategies, pricing optimization levers, hospital procurement negotiation tactics, and growth levers for complex endograft portfolios.
- Regulatory & reimbursement roadmaps: timeline overlays for recent and imminent guidance (materials, labeling, coding) and a decision matrix that links regulatory events to potential commercial impact windows.
- Clinical evidence gap analysis: a prioritized list of trials, registries, and post‑market surveillance designs that materially improve payer and clinician adoption for higher‑complexity devices.
- Strategic M&A and partnership targets: a curated shortlist of technology adjacencies, manufacturing partners, and niche innovators that accelerate access to multi‑branch, arch and thoracic solutions.
- Supply‑chain & materials risk map: stress‑tested scenarios around raw‑material constraints (particularly PTFE/ePTFE alternatives), supplier concentration, and compliance risks under evolving PFAS guidance.
- Board‑ready presentations and investor decks: distilled value‑creation narratives tied to quantified revenue impacts and timing to support capital allocation decisions in 2026.
Competitive landscape — who to watch
The market remains concentrated: the top three players control a majority share, while the top five account for nearly four‑fifths of industry revenue. This structure creates high barriers to entry for full‑spectrum aortic systems but leaves white space in modular, anatomically tailored and lower‑cost platforms.
- Medtronic (Dublin) — A dominant incumbent with broad product families for both abdominal and thoracic applications. Recent labeling updates that expand indications or adjust warnings can rapidly change adoption patterns; the removal of certain warnings in 2026 is an example of how regulatory decisions can directly influence clinical take‑up.
- Terumo Corporation (Tokyo) — A strong regional and niche player with established thoracic offerings; proven capability to iterate delivery systems quickly in response to clinical feedback.
- W. L. Gore & Associates (Flagstaff) — Materials expertise (ePTFE) and differentiated design execution underpin sustained relevance in thoracic portfolios; material policy shifts will be particularly consequential for firms with deep ePTFE exposure.
- Cook Medical (Bloomington) — A major developer of fenestrated and thoracic solutions; recent field actions illustrate the operational and reputational downside of coating or component issues.
- Artivion / Endospan, Endologix, MicroPort, Lombard, BD — Collectively these firms represent agile innovators, regional scale players and materials specialists whose approvals and designations (including Breakthrough Device and PMA events in early 2026) are reconfiguring competitive dynamics in complex anatomy therapeutics.
Taken together, incumbency advantages coexist with windows of opportunity for agile competitors who can demonstrate superior clinical results, simplified supply chains, or lower total cost of care.
Regulatory, coding, and reimbursement dynamics shaping near‑term strategy
- Materials oversight: FDA guidance on PFAS (effective August 2025) increases due diligence requirements for PTFE/ePTFE‑based components and suppliers. Firms must accelerate material qualification programs, build substitute material pathways, and prepare robust biocompatibility dossiers to avoid supply disruptions.
- Coding changes: CPT 2026 introduced new and revised codes for thoracic endovascular repair that broaden the definition of billable pre‑procedure sizing and imaging guidance. Whereas coding clarity can support higher facility reimbursement, these code changes also shift the metrics by which procedural efficiency is measured.
- Reimbursement pressure: CMS adjustments reduced physician work RVUs for certain thoracic stent graft codes as of 2026, reflecting efficiency gains. Manufacturers and hospital systems must therefore recalibrate economic models that previously assumed stable physician reimbursement contribution to procedure profitability.
- Device safety events: high‑visibility recalls and removals (multiple manufacturers experienced component and deployment issues in 2025–2026) elevate the importance of supply‑chain traceability, post‑market surveillance systems, and clinician training programs. Escalation of one product recall into a Class I regulatory notice demonstrates regulatory downside risk that can cascade across the category.
Technology & materials: tactical priorities for R&D and procurement
ePTFE remains the predominant graft covering for its clinical performance profile, but heightened regulatory focus on PFAS/related chemistries requires parallel paths: rigorous qualification of existing materials, accelerated testing of low‑PFAS alternatives, and contingency sourcing strategies. Digital tools for sizing, planning and device deployment (integrated imaging and navigation) are becoming essential differentiation levers; competitors that marry device design to workflow‑reducing software will compound procedural efficiency advantages, which is particularly important given reimbursement headwinds.
Risk and scenario planning — what to stress test in 2026
- Regulatory escalation scenario: a major recall or Class I notice affecting a platform class that drives temporary clinician hesitancy; stress test market share erosion and countermeasures (e.g., intensified training, extended warranties, expedited device modifications).
- Material constraint scenario: ePTFE supply interruption combined with protracted alternative qualification timelines; model output shows which commercial segments are most exposed and which product SKUs should be prioritized for stockpiling or redesign.
- Coding & reimbursement squeeze: if physician RVU reductions persist or expand, evaluate bundled procedure pricing, hospital margins, and possible manufacturer concessions (consumable pricing, bundled services) to preserve volume.
- Competitive acceleration: rapid adoption of a Breakthrough‑designated or newly PMA‑approved arch/branch system that shortens the clinical adoption curve, forcing incumbents to accelerate their own launches or consider licensing/partnerships.
How senior teams should use this report in 2026
- CEO/CXO: Align capital allocation to prioritized R&D programs and M&A options illuminated in the report’s deal‑flow analysis and watchlist.
- Head of R&D: Use the materials risk matrix and qualification playbook to prioritize substitute materials and accelerated test regimes.
- Commercial leadership: Leverage the go‑to‑market playbooks and payer negotiation templates to defend margin under new CPT and RVU environments.
- Corporate development: Apply the target screening framework and valuation scenarios for opportunistic bolt‑on acquisitions and licensing of complex‑anatomy solutions.
Conclusion — a call to disciplined action
The stent graft market entering 2026 is neither a free‑for‑all nor a closed club. Market scale and predictable growth provide a runway, but regulatory shifts, reimbursement recalibration, and episodic safety events create tactical urgency. Firms that pair rigorous materials governance, targeted clinical evidence generation, and nimble commercial models will translate the underlying market growth into sustained share gains. PW Consulting’s full Stent Grafts Market study supplies the granular modeling, risk stress tests, and commercial playbooks necessary to make those 2026 decisions with conviction.
To access the full dataset, segment breakdowns, and downloadable commercial tools referenced in this preview, please consult the report landing page and supporting appendices.
For detailed analysis of this topic, please visit the official page: Stent Grafts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Surface Mount Technology (SMT) Equipment Market — Strategic Outlook for 2026 Decision-Makers
Executive snapshot
Surface Mount Technology equipment sits at the intersection of electronics manufacturing scale-up, automation intensity, and materials volatility. Our PW Consulting market model — anchored to a 2025 base year and drawing a five‑year historical series (2020–2025) into a 2026–2032 forecast window — shows the global SMT equipment market expanding steadily, supported by continued demand from consumer electronics refresh cycles, automotive electrification, advanced packaging, and higher automation penetration across contract manufacturers. The market grows from about USD 6.1 Billion in 2025 to just over USD 10 Billion by 2032, implying an annualized expansion near a 7.5% CAGR across the forecast period.
Surface Mount Technology (SMT) Equipment Market
Why this research matters for 2026 corporate strategy
-
Timing capital: 2026 is a hinge year for many manufacturers — component packaging transitions, investments in unmanned lines, and regional sourcing shifts mean that a narrowly timed CapEx decision can lock in five- to seven-year productivity differentials.
Surface Mount Technology (SMT) Equipment Market -
Supplier selection and configuration: Equipment choice today defines throughput, flexibility, and total cost of ownership (TCO) across several product cycles. The research decodes vendor roadmaps and maps them to factory architectures that are likely to be dominant through 2032.
Surface Mount Technology (SMT) Equipment Market -
Risk-adjusted sourcing: Raw-material and export-control dynamics are elevating supply‑chain risk premiums. Our work translates those macro risks into specific mitigation levers — dual sourcing, vertical integration, buffer strategies — that are actionable in 2026 procurement plans.
-
M&A and partnership playbooks: For corporate development teams, the market’s structure and growth vector point to targeted tuck-ins and strategic alliances (automation software, 3D inspection, high-speed placement niches) that accelerate near-term capabilities without three‑ to five‑year organic build cycles.
What’s in the full PW Consulting SMT Equipment Market report
-
Transparent market sizing and methodology: historical series (2020–2025) and a detailed 2026–2032 projection with scenario variants (base, accelerated automation, constrained-supply scenarios).
-
Practical CapEx playbook: prioritized equipment investments by factory archetype, expected payback ranges, and sensitivity to utilization and labor-cost assumptions.
-
Supplier scorecards and vendor fit-maps: comparative assessments across throughput, flexibility, integration readiness (SMT + AOI + reflow), software maturity, and aftermarket economics.
-
Technology adoption roadmap: when and where to introduce hybrid placers, jet dispensing, inline 3D AOI/AXI, and automatic kitting to achieve optimal mix of yield, speed, and floor-space efficiency.
-
Supply-chain risk matrix: granular impact scenarios for raw-material price swings (notably silver and critical minerals), export control episodes, and feeder/component lead-time stress tests.
-
M&A and partnership investment memos: target profiles, valuation comparables, and integration checklists for strategic acquisitions or joint ventures in automation and inspection.
-
Operational diagnostics library: benchmarking KPIs, throughput calculators, and a modular checklist for retrofitting legacy lines into semi-autonomous cells.
Market structure and competitive dynamics — what to watch
The SMT equipment market is fragmented relative to many mature machinery sectors: the top three vendors account for roughly a quarter of market revenues, and the top five for around thirty percent — a structure that keeps innovation cycles competitive and creates room for niche specialists. That fragmentation favors buyers who can assemble heterogeneous lines optimized by function rather than adopt single-vendor mono-lines indiscriminately.
-
Fuji Corporation — Japan-based Fuji continues to push automation at the cell level. Recent product developments such as a compact all‑in‑one placement machine and an automated kitting station signal an intentional move to enable unmanned, high-mix production cells. Their strategy is to marry modular hardware with line automation to reduce indirect labor and improve line uptime.
-
Yamaha Motor — Yamaha’s portfolio spans mounters to printers to smart-factory software. New hybrid placers and entry-level printers indicate a two-pronged approach: defend share in high-throughput lines while capturing growth among smaller, automation-hungry contract manufacturers.
-
Juki — Juki’s high-speed flexible mounters underscore the persistent demand for speed in areas where component densities rise quickly. Their speed leadership remains a selling point for high-volume electronics OEMs.
-
ASMPT — ASMPT is positioning SIPLACE and DEK as combined productivity levers, promoting hybrid solutions that bridge oversized board handling and semiconductor/SMT integration — an important play as packaging convergence accelerates.
-
Inspection and niche leaders — Vendors such as Koh Young, Viscom, Mirtec, Saki, and TRI remain central to quality assurance. Their 3D AOI/AXI capabilities and inline X-ray inspection are becoming required investments as component miniaturization makes visual inspection insufficient.
-
Process specialists — Firms including Nordson and Heller continue to anchor materials dispensing and thermal processing respectively; their upgrades in precision dosing and thermal profiling are critical to defect reduction and cycle-time optimization.
-
Mid‑market and modular vendors — Europlacer, Mycronic, Hanwha, and other modular-system providers offer configurable approaches, which are attractive to contract manufacturers and regional OEMs pursuing staged automation investment.
Recent vendor moves — what they signal for buyers
-
Product launches emphasizing hybrid placers, compact all‑in‑one machines, and auto‑kitting are a clear signal: vendors are optimizing for unmanned, flexible production cells that can be deployed rapidly and scaled modularly.
-
Showcase improvements in throughput (productivity uplifts announced at trade shows) indicate that incremental productivity gains — in the 20–30% range from specific vendor claims — will be a key short-term driver of replacement cycles for mid-life lines.
-
Awards and strategic initiatives around die placement and semiconductor integration demonstrate vendors’ response to cross-domain demand as advanced packaging and IDM/OSAT needs influence SMT equipment design.
Headwinds and structural risks for 2026 planning
-
Materials cost inflation: Elevated prices for silver and other critical inputs have increased both BOM costs for solder pastes and the price of consumables (feeders, nozzles). Buyers must factor higher per-board material cost into payback analyses and negotiate longer-term supply contracts.
-
Export controls and concentration risk: Recent export restrictions on certain minerals and semiconductor-related materials have increased supply concentration and created jurisdictional risk for sourcing. Manufacturers should run jurisdictional stress tests and consider geographic diversity for critical spares.
-
Component availability and feeders: Lead-time volatility for feeders and certain components is contributing to longer procurement cycles; strategic inventory and supplier bifurcation are practical mitigations.
-
Regulatory compliance: New export control measures affect equipment with semiconductor-capable functions, requiring tighter legal review in procurement contracts and potential licensing workflows for cross-border sales.
How to use this research in your 2026 decision cycle
-
Layer the report’s scenario outputs against your plant-level capacity plan to prioritize which lines to upgrade in 2026 versus 2027–2028.
-
Use our supplier scorecards to design mixed-vendor lines that maximize throughput and resilience, and to negotiate bundling discounts on service agreements and spares.
-
Apply the CapEx playbook to model replacement versus retrofit decisions, including sensitivity to silver price swings and utilization thresholds that affect payback.
-
Leverage the M&A memos to identify targets that can deliver missing capabilities (e.g., inline 3D inspection, jet printing, or automatic kitting) without protracted internal development.
What we intentionally withhold (and why)
To preserve the value of the research package and direct users to the full dataset, this preview deliberately omits granular regional and application split tables, and the detailed subsegment revenue and share figures that underpin our vendor positioning and scenario analytics. Those granular breakouts — including regional demand curves, application-specific unit economics, and vendor-specific revenue tables — are included in the full report and interactive dashboards available from PW Consulting.
Next steps — how to get actionable insight now
-
Download the full report package to access interactive models and vendor scorecards, or schedule a workshop with our SMT practice to run the model against your factory-level data.
-
Commission a rapid 4‑week diagnostic if you require a CapEx road‑map aligned to your product mix and regional risks; our engagement combines the report’s quantitative backbone with on-site productivity and maintenance audits.
-
Subscribe to our quarterly SMT monitoring brief for vendor-release tracking, commodity-price alerts, and regulatory-watch updates to keep procurement and operations teams aligned through 2026.
In 2026, SMT equipment choices will determine not just throughput but flexibility, compliance posture, and the ability to capture higher-value assembly work. PW Consulting’s SMT Equipment Market research provides the decision-grade inputs to align procurement, operations, and corporate development to that reality — combining a transparent market model, supplier intelligence, and practical execution playbooks tuned for the next technology and geopolitical inflection points.
For detailed analysis of this topic, please visit the official page: Surface Mount Technology (SMT) Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Load Bank Market: Strategic Preview for 2026 Decision-Makers
As organizations across critical infrastructure, healthcare, hyperscale computing and industrial end-markets re-evaluate resilience and uptime strategies, load bank procurement and services are shifting from technical line-item to strategic lever. PW Consulting’s forthcoming Load Bank Market research — covering historical performance (2020–2025) and an in-depth forecast horizon (2026–2032) — synthesizes market sizing, regulatory drivers, supplier economics and go-to-market frameworks designed to inform board-level and commercial decisions in 2026.
Load Bank Market
Market snapshot you can act on
- Market trajectory: The load bank market has demonstrated steady growth through the recent historical window and, on our base metrics, is projected to continue expanding during the 2026–2032 forecast. PW Consulting’s topline model expresses that trend as a mid-single-digit compound annual growth rate for the forecast period (4.97% CAGR, USD denominated, revenue units in Millions), reflecting both replacement purchases and the growth of testing and services demand tied to resilience programs.
- Fragmentation and scale: Competitive concentration remains relatively low — the three- and five-firm concentration ratios indicate a market where regional specialists, component suppliers and a handful of global players coexist. That structure creates opportunities for targeted consolidation and margin expansion for firms that can achieve operational scale or deliver differentiated service models.
- Regulatory tailwinds: Compliance requirements (including NFPA 110-style test regimes that mandate staged, nameplate-proportion tests for critical facilities) are institutionalizing recurring testing programs in hospitals, data centers and federal facilities — a structural demand driver for both equipment and testing services.
Why this research matters for 2026 strategic planning
- From CapEx to recurring revenue: For equipment manufacturers and distributors, the market is evolving from one-off sales toward bundled testing-as-a-service and maintenance contracts that lock in multi-year revenue streams. Procurement teams, in turn, must evaluate total lifecycle cost, not just upfront price.
- Regulation equals opportunity: Requirements for periodic, documented generator load testing create predictable service windows that can be monetized through rental fleets, long-term service agreements and managed testing programs — especially in healthcare and mission-critical facilities where compliance is non-negotiable.
- Technology and segmentation inflection: Advances in cooling (including liquid-cooled high-capacity units), power electronics, and remote monitoring are changing the product-definition and O&M economics — favoring suppliers who invest in higher-capacity, lower-footprint solutions and cloud-enabled telemetry for preventive maintenance.
- M&A and supply-chain strategies: Low market concentration and rising aftermarket value make roll-up strategies and selective acquisitions attractive. The recent acquisition activity in adjacent power-equipment segments highlights appetite for bolt-on capabilities that accelerate entry into testing services and rental operations.
Key market dynamics and strategic implications
Several dynamics will shape winners and losers over the next 18–36 months:
Load Bank Market
- Compliance-driven recurring revenue: NFPA-style standards that specify staged generator load tests create predictable intervals for testing activity. This turns what was often a capital purchase decision into a recurring-service opportunity — an important consideration for pricing, fleet sizing and field service capabilities.
- Performance-driven product innovation: High-capacity data-center testing is accelerating demand for liquid-cooled systems and hybrid load banks that combine resistive and reactive elements. Vendors that can deliver reliable, compact solutions with integrated controls will win where site constraints and testing windows are tight.
- Channel and rental economics: Rental models are becoming the preferred option for customers seeking to avoid large upfront spend and for vendors seeking higher asset turnover and recurring margins. Properly engineered rental fleets and remote diagnostics can materially change lifetime profitability.
- Supply chain balance: The ecosystem includes component specialists, contract manufacturers and vertically integrated suppliers. Managing sourcing risk — especially where critical resistive elements and cooling technologies are concerned — will be a tactical priority for 2026.
- Market structure and consolidation potential: With modest top-firm concentration, the market is ripe for strategic consolidation — especially for buyers seeking national footprints, service capabilities or product diversity. Private equity and strategic acquirers will find attractively sized targets across geographies and product niches.
Competitive landscape — firms to monitor
The market combines legacy OEMs, specialized component suppliers and emerging international players. PW Consulting’s vendor benchmarking in the full report evaluates firms across product breadth, service capability, technology roadmap and channel reach. Highlights:
Load Bank Market
- Trystar (USA) — Known for custom and industry-standard load banks distributed through specialized channels; strong presence in hospital and utility-testing projects. ( https://www.trystar.com)
- Universal Load Banks (USA) — Focus on AC/DC solutions for emergency power systems in medical facilities; tight product fit for compliance-driven buyers. ( https://www.universalloadbanks.com)
- Power House Manufacturing (USA) — Offers a mix of standard and custom AC/DC units; attractive for fleet buyers needing configurability. ( https://powerhousemanufacturing.com)
- Avtron Power Solutions (USA) — Increasingly influential in high-capacity testing with recent liquid-cooled product introductions targeted at data centers and mission-critical sites. ( https://avtronpower.com)
- Rata Load Banks (China) — Cost-competitive wholesale and custom suppliers; important in global supply chains for OEM and rental fleet builders. ( https://www.cnloadbank.com)
- TUTCO Farnam (USA) — Specialist in open-coil resistive elements and bespoke designs; an important supplier for high-reliability generator manufacturers. ( https://farnam-custom.com)
- Sephco (USA) — Focus on permanently installed and periodic testing solutions for standby generators and UPS systems; durable installed-solutions play. ( https://www.sephco.com)
- Ohmite Manufacturing (USA) — Component supplier of power resistors and cooling subsystems; strategic for firms designing custom resistive banks. ( https://www.ohmite.com)
- Crestchic Limited (UK) — Specialized in healthcare and backup-power rental solutions; notable for integrated service and rental business models. ( https://loadbanks.com)
Recent developments that shape 2026 tactics
- Product innovation: In January 2026, a market player introduced new liquid-cooled, high-capacity models specifically aimed at data center and high-capacity testing — a signal that vendors are prioritizing power density and cooling efficiency in product roadmaps.
- M&A activity: Notable transactions in 2025 indicate strategic buyers’ interest in integrating load bank manufacturing into broader power-equipment portfolios — an important precedent for private equity and strategic acquirers assessing roll-up plays.
- Policy and procurement levers: Public procurement programs and federal contract eligibility tied to generator maintenance are expanding the addressable market for certified providers of testing services.
What PW Consulting’s full report provides (practical, not just descriptive)
- Topline market model with historical (2020–2025) reconciliation and forward-looking forecasts (2026–2032) at aggregate and segmented levels — built for direct integration into financial models.
- Scenario-based demand cases and sensitivity analysis for unit economics, rental fleet utilization and service-margin scaling.
- Regulatory and procurement playbook mapping NFPA-derived compliance windows to likely service volumes and contract timing (critical for sales planning and fleet deployment).
- Vendor benchmark with capability scoring, price-positioning, and route-to-market diagnostics to support supplier selection or partnership decisions.
- Go-to-market templates for rental operators, OEMs and service providers — including sample commercial terms, maintenance schedules and telemetry-enabled SLAs.
- Actionable M&A pipeline and valuation frameworks with prioritized target archetypes and integration risk checklists (detailed company profiles and deal comparables are reserved for report subscribers).
Recommended strategic actions for 2026
- Prioritize service and rental expansion before broad CapEx commitments: Lock in recurring revenue while maintaining optionality on fleet composition as product innovation unfolds.
- Invest selectively in high-capacity, liquid-cooled and hybrid systems for hyperscale and colocation accounts where time-to-test and space constraints command premium pricing.
- Build compliance-led sales strategies targeting healthcare, federal and critical infrastructure accounts — align sales cycles to mandated testing windows to maximize fleet utilization.
- Pursue targeted M&A or distribution partnerships to attain regional service coverage and accelerate aftermarket penetration rather than broad, unfocused acquisitions.
- Secure supply-chain redundancy for critical resistive and cooling components, balancing cost advantages from offshore suppliers with near-shore or domestic capabilities for mission-critical clients.
- Leverage remote monitoring and predictive maintenance to convert hardware sales into sticky service revenue with measurable uptime guarantees.
How PW Consulting can support your 2026 roadmap
We provide advisory services that translate this research into executable plans: bespoke market-entry models, vendor due diligence, M&A advisory, rental-fleet optimization and RFP support for complex public and private procurement. Our deliverables include the full dataset behind the topline forecast, scenario-ready financial models and a prioritized action plan calibrated to your current footprint and ambitions.
PW Consulting’s Load Bank Market research is intentionally structured as a decision-ready product: the executive briefing you have here highlights the strategic contours; the full study contains the granular, segment-level data, tables and playbooks necessary to operationalize these recommendations. For access to the detailed segmentation, vendor scores and downloadable financial models, please visit our report page or contact our industry practice team.
For detailed analysis of this topic, please visit the official page: Load Bank Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Nurse Call Systems to hit USD 413M by 2032 at 9.88% CAGR
By PW Consulting, 2026-07-08
Nurse Call Systems Market — Strategic Briefing for 2026 Decision-Makers
As healthcare providers and technology vendors enter 2026, Nurse Call Systems have evolved from discrete alarm boxes into platform-grade, interoperable elements of clinical workflow and patient-safety ecosystems. This briefing synthesizes PW Consulting’s latest market study (base year 2025) to highlight the strategic choices executives must prioritize this year. It is designed as a high-value preview: we surface the trends, competitive dynamics, and decision frameworks that will shape procurement, product roadmaps, and M&A through the 2026–2032 forecast horizon — while reserving the granular segment tables and vendor scorecards for the full report.
Nurse Call Systems Market
Market Snapshot: Growth trajectory and structure
Between 2020 and 2025 the global Nurse Call Systems market scaled meaningfully, reflecting both steady replacement cycles in mature care settings and accelerating greenfield investments in digital hospitals. Our model shows the market growing from a historical figure in 2020 to a substantially larger base by 2025, and continuing on an upward trajectory through the forecast window. PW Consulting’s forecast anticipates a compound annual growth rate (CAGR) of approximately 9.9% during the projection period, delivering a market size that more than doubles by the end of the forecast horizon.
Nurse Call Systems Market
Market concentration is material but not prohibitive: the top three vendors control a clear majority of revenue, and the top five command an even larger share. This structure yields both stability (for enterprise buyers seeking proven partners) and room for specialist innovators — especially those focused on mobility, integrated communications, and software-led services.
Nurse Call Systems Market
Why this study matters for 2026 strategic decisions
- Procurement and CapEx planning: The accelerating replacement cycle for legacy systems and the move toward integrated communication platforms mean that hospitals face non-linear CapEx timing risks in 2026. Our scenario-based forecasting lets you stress-test purchase schedules and prioritize pilots vs. full rollouts.
- Vendor selection and partnership strategy: With platform-enabled solutions and tighter regulatory coupling (see UL and FDA activity below), selection criteria have shifted from discrete hardware reliability to integration, lifecycle services, and standards compliance. The study’s vendor benchmarking and interoperability matrix help buyers align supplier selection with long-term roadmaps.
- Product and R&D roadmaps: For device OEMs and software providers, the research identifies feature-level demand vectors (e.g., mobility-first communications, RTLS integration, alarm management harmonization) that should influence 18–36 month development prioritization.
- M&A and commercial diligence: Given the market’s concentration metrics and the rising importance of software and services, the report equips corporate development teams with valuation-adjusted scenarios and integration risk checklists tailored to nurse-call targets.
Key market dynamics shaping 2026 choices
- Platform convergence: Nurse call is increasingly a module in broader clinical communication and alarm-management platforms. Buyers are asking for APIs, EMR integration, RTLS compatibility, and common user interfaces across devices.
- Mobility and clinician workflows: Demand for mobile notifications, smartphone apps, and bedside touchscreen controls is rising, accelerating shifts away from button-only architectures to hybrid, software-centric solutions.
- Regulatory and safety standards: Recent updates to the UL 1069 standard and parallel regulatory activity have raised the compliance bar for hospital signaling equipment. Suppliers and procurers must factor new electrical and alarm-management requirements into deployment specifications and acceptance testing.
- Software-driven differentiation: With clinical workflow optimization and alarm fatigue mitigation now top procurement objectives, software analytics, prioritization logic, and closed-loop communication capabilities drive value beyond raw hardware costs.
Competitive landscape — what incumbents and challengers are doing
The competitive map combines long-established alarm manufacturers with clinical-IT incumbents and nimble software/mobile specialists. The leading players profiled in our study illustrate three strategic archetypes:
- Platform integrators (example: Rauland/AMETEK, Hill‑Rom/Baxter): These firms are bundling nurse call with care-coordination suites and RTLS, targeting enterprise accounts that prefer single-vendor ecosystems. Recent product releases and platform upgrades emphasize workflows and interoperability with clinical systems.
- Clinical-IT specialists with mobile-first offerings (example: Ascom): Emphasize smartphone clients, secure messaging, and device integration. They are attractive to health systems prioritizing mobility and rapid feature delivery via software updates.
- Hardware-rooted suppliers modernizing legacy strengths (example: Jeron, Austco, TekTone, Stanley Healthcare): Continue to leverage their field-proven reliability in acute and long-term care while adding touchscreens, VoIP capabilities, and integration adapters to compete for replacement business.
Recent market developments underscore vendor activity relevant to procurement and partnership strategies. A leading supplier introduced new touchscreen annunciators late in 2024, reinforcing the trend to richer bedside interfaces. Platform vendors have pursued clinical integration approvals and releases in early 2026, signaling readiness to participate in enterprise-level integrations. Combined with updated UL standards and third‑party alarm-management clearances, these moves accelerate buyer evaluation cycles — particularly for systems that promise verified interoperability and compliance.
Regulatory and standards tailwinds — what to factor into 2026 plans
- UL 1069 and related national implementations have been updated, and the new editions include tightened requirements that affect product design, installation practice, and acceptance testing.
- FDA 510(k) activity and clearance of clinical platforms with nurse-call integration capability create precedent for how integrated solutions will be evaluated in procurement contracts.
- Third‑party alarm-management clearances and policy positions from clinical software vendors require hospitals to reassess their alarm response strategies and interoperability contracts.
For buyers and suppliers alike, compliance is now a strategic differentiator: non-compliant equipment increases integration risk, drives longer commissioning cycles, and can materially affect total cost of ownership.
What the PW Consulting report delivers (practical, actionable content)
PW Consulting’s full study is built as an execution tool for C-suite and procurement teams. Highlights include:
- Proprietary demand model: Scenario-driven market forecasts with sensitivity to replacement cycles, greenfield hospital builds, and regulatory shock scenarios.
- Vendor benchmarking and capability matrix: Multi-dimensional supplier assessment across product architecture, interoperability, deployment complexity, services, and compliance posture.
- Implementation playbooks: A step-by-step rollout framework covering site surveys, technical acceptance criteria tied to updated standards, clinician training plans, and alarm-management optimization guides.
- TCO and ROI calculators: Configurable tools that translate technical choices (on-premise vs. cloud, mobile client licensing, RTLS add-ons) into multi-year cost and labor-impact forecasts.
- Procurement templates and contractual clauses: Draft RFP language, SLAs, and interoperability requirements aligned to UL and regulatory updates, designed to reduce negotiation timelines and integration risk.
- M&A diligence kit: Financial and technical checklists, integration risk heatmaps, and post-deal synergies framework for strategic buyers and private equity investors.
Note: This briefing intentionally omits the granular segmented revenue tables and share-by-application/region values that appear in the full study — those detailed splits are provided in the downloadable dataset and interactive dashboard bundled with the report.
Recommended strategic moves for 2026
- For health system CIOs/CNOs: Treat nurse call procurement as a clinical-IT integration project, not a facilities purchase. Mandate open APIs, EMR integration proofs, and compliance evidence as pre-conditions to pilots.
- For vendor product leaders: Prioritize modular APIs, secure mobile clients, and UL-compliant hardware revisions. Demonstrable interoperability with voice, RTLS, and alarm-management partners shortens sales cycles with enterprise accounts.
- For commercial teams: Shift from hardware-centric proposals to outcome-based offers that quantify alarm-fatigue reduction, response-time improvements, and staff efficiency gains — supported by case-study evidence and TCO modeling.
- For investors and M&A teams: Focus diligence on software-as-a-service adjacencies and installation/service margins. Targets that can demonstrate certified interoperability and recurring software revenue command a premium.
How to use this research in your 2026 planning cycle
In practice, clients tell us the most valuable applications of the report are:
- Shortlisting vendors for enterprise-wide rollouts using the vendor capability matrix and compliance checklist;
- Building multi-year procurement roadmaps that align replacement schedules with IT refresh cycles and regulatory milestones;
- Stress-testing integration architectures and contractual terms using the included TCO models and acceptance-test templates;
- Prioritizing R&D investments based on scenario analyses that link feature adoption curves to revenue upside.
Closing perspective
2026 is a pivotal year for Nurse Call Systems. The combination of accelerating platform expectations, regulatory tightening, and sustained market growth creates both timing risk and opportunity. PW Consulting’s market study offers the forecasting rigor, vendor intelligence, and practical playbooks that leaders need to make defensible choices — whether negotiating enterprise contracts, designing product roadmaps, or evaluating acquisition targets.
For executives and procurement teams seeking the full dataset, vendor scorecards, and implementation templates, the complete report and interactive dashboard are available through PW Consulting’s Nurse Call Systems market page. The detailed segmental breakdowns, scenario inputs, and downloadable tools are intentionally provided there to support operational execution and vendor selection.
For detailed analysis of this topic, please visit the official page: Nurse Call Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Silicon Metal Market — Strategic Preview for 2026 Decision Makers
Why this briefing matters now
As companies reset industrial strategies for the mid-2020s, silicon metal has re-emerged as a cross‑sector choke point: it is simultaneously a feedstock for aluminum alloys, silicones, polysilicon and select semiconductor applications, and a barometer for energy- and trade-driven supply risk. PW Consulting’s new Silicon Metal Market study (base year 2025; historical coverage 2020–2025; forecast period 2026–2032) crystallizes that complexity into actionable insight for executive teams planning capital allocation, procurement, and geopolitical risk mitigation in 2026.
Silicon Metal Market
Market at a glance (directional)
- The global silicon metal market, measured in USD million, demonstrated steady growth through the early 2020s and crossed the two‑billion USD threshold in 2025.
- Our forecast model projects a medium‑term compound annual growth rate (CAGR) of 5.5% for 2026–2032, driven by demand elasticity in energy‑transition and electronics value chains and by policy incentives favoring low‑carbon domestic production.
- Market concentration is moderate: the top three producers account for a little over one‑third of market share, and the top five under half — a structure that supports both strategic partnerships and targeted capacity expansion by mid‑sized players.
What this study delivers — practical, transaction‑ready outputs
Our objective was to create a study that senior leaders can use immediately to inform procurement strategies, capital project prioritization, and M&A/partnership screens. We do not publish raw granular invoices or confidential contract terms; instead, the report provides:
Silicon Metal Market
- Proprietary scenario models that map price, input‑cost and policy shocks to EBITDA and cash‑flow profiles across typical silicon‑using plants (aluminum‑alloy smelters, silicone manufacturers, polysilicon operations).
- Supply‑chain stress tests showing node‑level vulnerability to export controls, trade remedies, and regional energy price volatility. Each test produces a ranked mitigation playbook (sourcing diversification, inventory policy, strategic offtake, localized processing, and flexible feedstock clauses).
- A rolling capital‑project ROI matrix that converts capacity expansions, brownfield upgrades, and low‑carbon retrofit projects into NPV and payback timelines under three energy‑price and carbon‑policy regimes.
- Commercial negotiation templates and procurement KPIs tailored to silicon metal spot, term and tolling frameworks — including clauses to protect buyers during regional pricing dislocations and regulatory actions.
- Competitive supplier assessments and a prioritized shortlist for joint ventures, off‑take, and technology licensing, each backed by operational and ESG due‑diligence checklists.
Key strategic implications for 2026
Executives should treat 2026 as a hinge year. The interplay of trade measures, regional industrial policy, and rising input costs has created both near‑term price volatility and durable incentives to reorient supply chains. From a decision‑making perspective, three priorities rise to the top:
Silicon Metal Market
- De‑risk procurement with a dual approach: secure near‑term term contracts to cap exposure and concurrently develop optionality through geographic diversification and technology partnerships (for example, low‑emission electrochemical routes, waste‑heat integration).
- Reassess capital projects through a policy lens: new incentives in large markets for domestic or low‑carbon production change expected returns on retrofits and greenfield investments; projects that were marginal under previous assumptions can become value‑creating under incentive scenarios.
- Build regulatory intelligence into commercial clauses: antidumping and countervailing actions, import licensing changes, and strategic‑materials classifications now materially affect price spreads and delivery risk. Contract design must reflect dynamic tariff and licensing exposure.
Competitive landscape — who matters and why
The industry remains dominated by a mix of vertically integrated aluminum/ferrosilicon groups, specialized silicon producers, and regional exporters. Each class brings different strategic value to buyers:
- Large vertically integrated groups offer scale and downstream integration but are sensitive to alumina/electrolytic aluminum cycles and commodity price swings. When such groups pivot to secure domestic or low‑carbon outputs, they can reshape regional supply cost curves.
- Independent high‑purity specialists provide product quality and technical service for electronics and photovoltaics — a premium segment where long‑term agreements and technical collaboration deliver the most value.
- Regional exporters fill short‑term supply gaps and are often price‑competitive; however, these suppliers can be subject to trade actions and demand‑side concentration risk, which has implications for procurement resilience.
Notable firms profiled in our analysis include European integrated producers with multi‑continent footprints, large Nordic and Chinese suppliers focused on high‑purity streams, U.S. niche refiners with strategic domestic shares, and Latin American exporters serving global markets. For each company we map asset location, feedstock exposure, product-grade mix, recent strategic moves and ESG posture — and we translate that into a buyer‑facing capability matrix that ranks suppliers on reliability, price risk, and low‑carbon transition readiness.
Recent market moves that reshape 2026 planning
Several developments in 2025–early 2026 altered the playing field and are reflected in our scenario work:
- New production technologies and product launches: entrant firms and established producers announced low‑carbon or low‑emission silicon product lines using electrochemical or renewable‑powered routes. These innovations change the cost and carbon calculus of long‑term offtake contracts and create opportunities for branded low‑carbon feedstocks in supply agreements.
- Capacity adjustments and commercial linking: incumbents expanded capacity in select jurisdictions while some regional producers secured long‑term commercial agreements with downstream manufacturers — moves that alter short‑term tightness and the visibility of supply for buyers in strategic value chains.
- Trade and regulatory action: antidumping and countervailing duty filings, and formal determinations by trade authorities, have widened regional price spreads and prompted re‑routing of trade flows. Separately, policy moves classifying silicon metal as a strategic raw material, and new export‑licensing regimes for related critical inputs, have increased the value of onshore capacity and secure supply chains.
Price and input cost environment
Energy and quartz ore cost trends are the dominant upstream drivers. Recent regional price upticks tied to energy and feedstock shortages underscore how supply‑side shocks in one region can transmit globally by shifting trade flows and prompting policy reactions. Our modeling shows that even moderate cost inflation erodes margins for spot buyers but can improve returns on investments in localized, low‑carbon capacity when coupled with production incentives.
What we intentionally withhold (and why)
True to the “trailer” principle of this preview, we demonstrate methodological depth while withholding the granular, segment‑level matrices and the full supplier scoring tables that constitute the study’s proprietary value. Specifically, we do not publish detailed region‑by‑region or application‑by‑application line items in this briefing. Those segmented figures are available only in the complete report and underlying data package. This protects commercial confidentiality of sources and preserves the strategic advantage for subscribers who require transaction‑level specificity.
How executives should use the full study in 2026
- Procurement leaders: deploy the procurement playbooks and contract templates immediately to hedge exposure for H2 2026, reprice term sheets and institute force‑majeure/articulation clauses tied to trade measures and licensing regimes.
- Strategy and corporate development teams: use the ROI matrix to re‑rank greenfield and brownfield projects; the report’s M&A screen identifies targets by technical capability and policy fit rather than headline volume alone.
- Government and public‑affairs teams: leverage the regulatory scenarios and supplier intelligence to inform advocacy and to design incentive requests that are credible and quantified for policymakers.
Final word for 2026 planning
Silicon metal sits at the intersection of decarbonization, electronics scaling, and trade geopolitics. The market has demonstrated resilience and a steady growth trajectory through 2025, and our forecast to 2032 at a mid‑single‑digit CAGR reflects continued structural demand from energy‑transition technologies and electronics. However, the real strategic battleground in 2026 will be around supply certainty and low‑carbon credentialing: companies that move now to lock flexible supply, redeploy capital to policy‑aligned projects, and embed trade‑aware clauses into commercial contracts will convert today’s volatility into multi‑year advantage.
Next steps
For boards and executive teams preparing 2026 plans, PW Consulting offers targeted briefings that pair the full Silicon Metal Market study with a workshop to translate findings into one‑page decisions — from immediate procurement actions to a 36‑month capital allocation roadmap. Contact PW Consulting to access the full report, the underlying datasets, and a customized strategic session tailored to your company’s position in the silicon value chain.
For detailed analysis of this topic, please visit the official page: Silicon Metal Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
LTCC Market 2026 Strategic Briefing — A PW Consulting Introductory Insight
Low Temperature Co-fired Ceramic (LTCC) substrates and packages are transitioning from niche enablers into strategic building blocks for high-frequency communications, advanced automotive electronics, and next‑generation semiconductor modules. This introductory briefing outlines why our comprehensive PW Consulting LTCC Market study — anchored on a 2025 base year, a 2020–2025 historical series, and a detailed 2026–2032 forecast horizon — is essential for any executive making capital, sourcing, or product roadmap decisions in 2026. The market we model expands from roughly USD 163.2 million in 2020 to USD 215.0 million in 2025, and our baseline forecast projects a steady compound annual growth rate (CAGR) of 5.8% through 2032, culminating in a market size approaching USD 345 million by 2032. These headline figures frame a market that is growing steadily, yet is being reshaped by raw‑material pressures, regulatory shifts, and selective consolidation.
Low Temperature Co-fired Ceramic (LTCC) Market
Why this study matters for 2026 decisions
-
Timing: The next 12–18 months will determine who secures long‑lead raw materials, who localizes capacity, and who locks in strategic partnerships for 5G/6G and automotive-qualified LTCC. The 5.8% CAGR is healthy but not explosive — growth will be uneven across segments and geographies, making prioritization essential.
Low Temperature Co-fired Ceramic (LTCC) Market -
Strategic tradeoffs: Firms must weigh near‑term margin protection against longer‑term product differentiation. Decisions about in‑house manufacturing versus outsourced fabrication, material standardization, and co‑development with OEMs will materially affect margins and time‑to‑market.
Low Temperature Co-fired Ceramic (LTCC) Market -
Investment sizing: Our forecast and scenario work provide the necessary confidence intervals for CapEx and procurement commitments. Whether building a greenfield line, retrofitting existing ceramic fabs, or acquiring a specialist contract manufacturer, the report translates market growth into investment thresholds and payback profiles.
Macro drivers and near‑term shocks reshaping LTCC economics
-
Raw‑material dominance: Alumina remains the principal feedstock in LTCC formulations. Industry data show that raw alumina powder and metallization account for roughly 60% of LTCC production costs. That concentration of cost in one input creates a tight coupling between raw‑material markets and final‑product economics.
-
Supply volatility: Temporary shortages of alumina during 2024–2025 pushed unit prices materially higher — industry reports indicate price spikes up to ~20% in that period. Firms unable to hedge or qualify alternative suppliers faced margin compression or production delays.
-
Energy and regulatory delta: Sintering is energy‑intensive, and energy price differentials matter. Sintering energy costs in Europe have been measured as roughly 25% higher than in Asia‑Pacific, which combined with the EU’s Carbon Border Adjustment Mechanism (effectively imposing about USD 90 per ton CO2‑equivalent on imports) alters location economics for both raw material supply and final assembly.
-
Demand concentration and technology cycles: Growth drivers include telecommunications (5G/6G), automotive electrification and ADAS, and advanced semiconductor packaging. These end markets reward low‑loss materials, miniaturization, and high‑reliability process control — capabilities that some suppliers are already leveraging to capture premium segments.
Competitive landscape — capabilities, openings, and tactical moves
The LTCC ecosystem is a mix of materials suppliers, specialty fabricators, and integrated component manufacturers. Market concentration metrics indicate that the top three suppliers account for a majority share (CR3 ~65%), and the top five push that toward high concentration (CR5 ~82%), signaling a market where scale and specialized capability matter.
-
Vibrantz Technologies Inc. (Houston, TX) — a materials and paste supplier with a focus on low‑loss dielectrics and conductor systems. Recent technical presentations and conference activities suggest Vibrantz is positioning its L8 and A6M‑E systems as preferred options for high‑frequency multilayer substrates. For companies seeking material performance gains (loss tangent, thermal stability), Vibrantz represents an attractive partner for co‑development.
-
IMST GmbH (Kamp‑Lintfort, Germany) — a producer of LTCC modules with in‑house prototyping. IMST’s European presence and microwave/RF specialization make it well‑positioned for regional telecommunications and defense programs that prioritize proximity, qualification timelines, and small‑volume engineering runs.
-
NEOTech Inc. (Chesterfield, MO) — differentiated by custom fabrication, embedded passives and hermetic sealing. NEOTech is a contender for customers requiring high‑reliability packaging and tight electrical tolerances for high‑frequency applications.
-
Fralock Corporation (Clinton, SC) — a fabricator that works across multiple material systems (Ferro, DuPont, Heraeus) and offers secondary brazing capabilities. Fralock’s flexibility is a strategic asset for OEMs needing rapid material qualification and mixed‑technology assemblies.
-
TTM Technologies (Santa Ana, CA) — provides turnkey LTCC manufacturing compatible with major material systems. TTM is notable for scale and integration, suitable for OEMs aiming to outsource at higher volumes while retaining engineering control.
-
Murata Manufacturing, Kyocera, TDK (Japan) — these large, vertically integrated electronics players combine materials expertise with high‑volume production, portfolio breadth, and global customer reach. Recent developments — Murata’s new production building (completed April 2026) and continued product launches targeted at automotive applications — underscore the speed at which incumbents can mobilize capacity for priority markets.
Strategic implication: smaller specialists can win premium engineering programs through speed and customization, while larger incumbents will compete on scale, reliability, and bundled component offerings. Expect continued deal activity in 2026 (partnerships, tolling agreements, targeted M&A) as firms pursue capability gaps.
What the full PW Consulting LTCC report delivers — practical, executable outputs
-
Financial model: A dynamic market model (2020–2032) with scenario toggles for demand elasticity, material‑price shocks, and regulatory cost pass‑through. The model quantifies upside and downside pathways around our 5.8% CAGR baseline.
-
Supply‑chain stress tests: Cost build‑ups with raw‑material sensitivity (alumina and metallization), labor, energy, and logistics. We simulate the P&L and cash‑flow impact of up to 20% raw‑material price volatility observed in 2024–2025 and the effect of carbon‑adjusted import costs.
-
Supplier scorecards: Comparative capability matrices for materials suppliers, contract fabricators, and integrated component manufacturers — including qualification timelines, production scale, design support, and risk profiles.
-
Regulatory and energy impact analysis: Regionally differentiated plant economics that incorporate energy‑cost deltas and CBAM‑style tariffs to guide site selection and near‑term localization choices.
-
Commercial playbooks: Go‑to‑market and procurement templates for securing feedstock, setting contractual protections, and structuring long‑term supply agreements. Also included are negotiation levers for OEMs and CMs.
-
Investment cases and M&A roadmaps: Valuation contours, potential synergy capture levers, and integration checklists particular to LTCC capabilities (e.g., embedded passives, hermetic sealing, low‑loss dielectrics).
Note: This briefing intentionally avoids republishing granular segment tables or confidential supplier revenue splits. The full report contains the detailed segmentation, downloadable datasets, and supplier scorecards that power the above outputs.
Strategic imperatives for leadership teams in 2026
-
Secure feedstock through diversified suppliers and contractual hedging — given alumina’s outsized share of production cost and recent price volatility, procurement strategy is now a strategic moat.
-
Quantify and price regulatory risk into product bids — especially for companies selling into or sourcing from Europe where CBAM and higher sintering energy costs increase landed cost.
-
Prioritize low‑loss materials and co‑development for high‑frequency markets — LTCC value increasingly accrues to firms that can offer demonstrable electrical performance benefits for 5G/6G and advanced RF subsystems.
-
Right‑size capacity regionally — use our regional plant economics and energy sensitivity analyses to decide whether to localize production, toll‑manufacture, or outsource.
-
Evaluate targeted consolidation and partnership plays — CR3/CR5 concentration signals room for meaningful M&A and strategic alliances to secure volume, market access, or specialized capabilities.
-
Invest in energy efficiency and process control — reductions in sintering energy and yield improvements directly expand margin in a market where input costs dominate.
How to use this briefing and next steps
-
For strategy teams: Use the forecast scenarios and supplier benchmarks to prioritize product roadmaps and capital allocation over a 36–60 month horizon.
-
For procurement: Apply our cost‑build templates to renegotiate supplier contracts and to design hedging strategies for alumina and metallization purchases.
-
For business development and M&A teams: Leverage the supplier scorecards and investment cases as a baseline due diligence toolbox for potential transactions or JV partners.
-
Engagement options: PW Consulting can provide the full report with downloadable datasets, run a tailored sensitivity analysis for your portfolio, or facilitate supplier selection workshops based on our benchmarking framework.
Conclusion — The LTCC market sits at a crossroad of steady end‑market growth and heightened input‑ and policy‑driven risk. Our baseline projection sees the market continuing to expand from a 2025 base of roughly USD 215 million, growing at a 5.8% CAGR through 2032. The difference between winners and laggards in 2026 will be defined less by exposure to demand and more by the robustness of feedstock plans, regulatory foresight, and execution capability on materials performance. For the full segmentation, supplier profiles, downloadable models, and tactical playbooks that operationalize these insights, please consult the PW Consulting LTCC Market report on our website or reach out to request a customized executive briefing.
For detailed analysis of this topic, please visit the official page: Low Temperature Co-fired Ceramic (LTCC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Caramel Color Market at USD 570M in 2025, 1.6% CAGR to 2032
By PW Consulting, 2026-07-08
Caramel Color Market — Strategic Outlook for 2026
As PW Consulting’s senior strategist and lead industry analyst, I present a guided synthesis of our new Caramel Color Market study—an executive-grade briefing tailored to inform high-stakes decisions in 2026. This introduction surfaces the report’s strategic rationale, the macro trends that will shape near-term commercial outcomes, and the practical tools included to convert insight into action. The full study contains the granular segmentation, transaction-ready models, and source datasets that procurement, R&D, and corporate development teams will need to execute with confidence.
Caramel Color Market
Why this study matters now
The caramel color market has demonstrated resilience through recent economic cycles. Measured on a consistent base-year (2025), global revenues rose from approximately USD 500 Million in 2020 to roughly USD 570 Million in 2025. From a planning horizon perspective the market is forecast to expand at a modest compound annual growth rate of 1.6% over the 2026–2032 period, reaching a forecasted market size in the mid-600s (USD Million) by 2032.
Caramel Color Market
These headline figures mask important structural shifts: where previously incremental volume changes drove supplier outcomes, the current cycle places a premium on formulation agility, regulatory diligence, and supply-chain resilience. With the three largest suppliers capturing just under half of market revenues (CR3 ~48%) and the top five approaching mid-50s concentration (CR5 ~56%), competitive dynamics remain meaningful but leave room for targeted differentiation and consolidation plays.
Caramel Color Market
What the PW Consulting study delivers (practical content)
- Demand Scenarios & Strategic Forecasts — Three alternative scenarios (baseline, accelerated natural-adoption, and raw-material shock) that stress-test growth assumptions through 2032 and quantify upside/downside revenue bands.
- Commercial Playbooks — Go-to-market recommendations for ingredient suppliers and co-packers, including segmentation-based pricing frameworks, customer-tiering approaches, and margin-protection tactics for key channels.
- Product & Portfolio Analytics — A decision matrix for portfolio optimization that links class/type positioning, sensory attributes, and application readiness to margin and volume outcomes (NPD prioritization tool included).
- Supply-Chain Risk & Sourcing Toolkit — Supplier scorecards, geographic risk heatmaps, and a molasses-cost sensitivity model that translate raw-material movements into EBITDA exposure scenarios.
- Regulatory & Compliance Heatmaps — Jurisdiction-by-jurisdiction regulatory risk layering with early-warning triggers and reformulation cost estimates to inform label, claims, and reformulation strategies.
- M&A and Partnership Diagnostics — Target-screening templates, valuation multipliers contextualized to market concentration and growth prospects, and integration playbooks focused on capacity, formulation IP, and commercial channels.
- Commercial Due Diligence Annex — Ready-to-run slides and data extracts to accelerate buyer/seller diligence cycles, including benchmarking against the top industry players.
Competitive landscape — who’s shaping outcomes
The market’s competitive architecture combines multinational ingredient integrators, specialized caramel producers with deep process know-how, and regional players focused on cost-competitive supply. Several strategic archetypes emerge from our review of market leaders:
- Innovation & Portfolio Integrators — Companies such as Sensient Technologies and DDW The Color House emphasize natural color innovation and broad formulation capability. Their strategic advantage lies in R&D-driven product differentiation and upstream customer relationships with major beverage and food manufacturers.
- Legacy Specialists — Firms with long technical histories in caramelization processes (for example, well-established manufacturers that offer a full class range in both liquid and powder formats) hold embedded process IP and customer trust, particularly in industrial and foodservice supply chains.
- Scale & Ingredient Houses — Large ingredient conglomerates that include caramel color in broader portfolios (notably major agribusiness and food-ingredient suppliers) provide distribution breadth, co-manufacturing options, and integrated commodity sourcing benefits.
- Regional & Cost-Focused Producers — Select suppliers based in growth regions or with recently expanded capacity compete on cost and local service responsiveness; some have also invested in new plants to capture nearby demand while reducing freight and lead-time exposure.
Recent public developments underscore these strategic vectors: established specialist producers commercialized new powder and sensorial blends that open dry-spice and specialty applications; ingredient leaders launched branded ranges that couple color with flavor-sensory claims; and at least one regional player announced a significant capital expansion to increase European capacity. Concurrently, large food manufacturers are accelerating reformulation programs toward natural colors, signaling sustained demand for differentiated caramel solutions.
Regulatory and raw-material dynamics — the guardrails for 2026 strategies
Regulation and raw-material volatility are two levers that materially affect both unit economics and product positioning. From a regulatory perspective, caramel color enjoys a permissive status in several jurisdictions—e.g., exempt from certification under certain U.S. rules—while European regimes apply quantum satis principles with explicit limits on reaction by-products in specific caramel classes. Past regional regulatory actions (notably state-level listings) have prompted reformulation waves, which in turn altered supplier mixes and formulation costs.
On raw materials, molasses has been a focal point. Mid-2025 price levels for molasses were materially firmer than several prior years, driven by competing industrial uses such as ethanol and livestock feed. Our scenario models show that sustained molasses price pressure, or disruption in alternative sugar-syrup supply chains, can compress gross margins for manufacturers who cannot fully pass costs through to customers or adapt formulations rapidly.
Strategic implications for decision-makers in 2026
- Prioritize formulation agility. Build a rapid reformulation pipeline to respond to both customer-directed naturalization and jurisdictional 4‑MEI thresholds. Short-cycle pilot lines and modular process investments yield outsized optionality relative to full-scale greenfield expansions.
- Hedge raw-material exposure. Establish dual-sourcing arrangements, negotiate index-linked supply contracts where possible, and stress-test supplier continuity in procurement RFPs. Small changes in molasses sourcing economics can swing margins materially under the current market growth profile.
- Focus M&A on complementary barriers. Targets that add sensory differentiation, application-specific know-how, or regional capacity near key customers deliver faster integration returns than pure-volume plays in a mid-growth market.
- Commercialize claims with evidence. When promoting “natural” or “reduced-reaction by-product” claims, invest in independent testing and customer co-validation to reduce commercial friction and protect pricing.
- Adopt scenario-based pricing. Implement dynamic pricing playbooks that link to commodity indices, regulatory events, and client-tier elasticity so price increases are defensible and timed to market tolerance.
- Use concentration to your advantage. For established suppliers, the mid-range market concentration supports selective price discipline and strategic partnerships. For challengers, targeted investments in service excellence and niche applications present viable routes to premium positioning.
Why PW Consulting’s full report is the operational advantage
Our study is designed not as an overview, but as an operational toolkit for 2026 decision cycles. Clients receive: calibrated financial models (base-year 2025), scenario dashboards for 2026–2032, supplier and customer scorecards, regulatory impact quantifications, and acquisition screening matrices. We deliberately present top-line trajectories and strategic diagnostics here while reserving the detailed segment-level breakdowns, regional allocations, and per-application elasticities for the full report—these are the data assets that procurement and strategy teams use to construct negotiating positions and investment cases.
In practice, buyers of the full report tell us they value three capabilities most: the ability to translate regulatory changes into specific reformulation costs, fast identification of high-value targets in low-cost regions, and a pricing playbook that ties commodity pass-through to contract architecture. The analysis and templates in the full PW Consulting deliverable are built to be plug-and-play into Q1 2026 commercial planning cycles.
Next steps
For executive teams preparing 2026 budgets, R&D roadmaps, or M&A pipelines, the strategic actions above should be operationalized within 60–90 day planning sprints. If your organization is considering portfolio prioritization, supplier renegotiation, or an acquisition in this sector, PW Consulting can provide tailored modules of the study—ranging from a regulatory deep-dive to a full buyer’s diligence pack—so you can move from insight to transaction with certainty.
Contact PW Consulting to access the full Caramel Color Market report and the accompanying analytical assets. The detailed segment disclosures, interactive charts, and custom scenario outputs are available to support immediate decision-making in 2026.
For detailed analysis of this topic, please visit the official page: Caramel Color Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


