



Category: market research
PW Consulting: Solar Mobile Light Tower Market to Expand at 8.5% CAGR as Fully Solar Solutions Drive Momentum
By PW Consulting, 2026-07-07
Solar Mobile Light Tower Market: Strategic Insights for 2026 Decision-Makers
PW Consulting’s new Solar Mobile Light Tower Market report (base year: 2025; historical coverage: 2020–2025; forecast horizon: 2026–2032) equips executives with the forward-looking intelligence required to convert growing sustainability mandates into commercial advantage. This briefing highlights the report’s strategic value for decisions planned in 2026 — demonstrating analytical depth while reserving the proprietary segment-level data that will be available through our full report and interactive models.
Solar Mobile Light Tower Market
Market at a glance — validated, accelerating, investible
After a steady expansion through the early 2020s, the solar mobile light tower market reached USD 315.5 Million in the 2025 base year, up from USD 200.0 Million in 2020. Under our central scenario the market continues to broaden at a compound annual growth rate (CAGR) of 8.5% across the 2026–2032 forecast window, reaching an estimated USD 558.49 Million by 2032. These figures reflect a market that is moving from niche substitution toward mainstream adoption as diesel-driven alternatives are progressively replaced in environmentally sensitive and noise-regulated sites.
Solar Mobile Light Tower Market
Market structure metrics further clarify competitive dynamics: the top three suppliers account for a meaningful but not dominant share (CR3: 35.2%), while the top five collectively approach half of market revenue (CR5: 48.9%). Taken together, growth momentum and moderate concentration point to robust opportunities for incumbent expansion and acquisitive consolidation alike.
Solar Mobile Light Tower Market
Fundamental forces propelling this shift are well documented. Public data shows utility-scale and distributed solar deployment has expanded rapidly — the U.S. Department of Energy reports solar energy deployment grew on average roughly 42% annually over the last decade — creating a favorable technology spillover for mobile solar systems. Parallel advances in high-efficiency photovoltaic modules, LiFePO4 and GEL battery chemistries, and high-lumen LED fixtures now allow multi-day autonomy and true zero-fuel operation for many use cases, intensifying the competitive pressure on diesel units.
Why this report matters for 2026 strategic choices
- Timing major investments: The 8.5% CAGR and our scenario analysis identify 2026 as an inflection period when product, services, and rental strategies should shift from experimentation to scaling.
- Capital allocation: OEMs and investors must decide whether to accelerate product refreshes, expand battery and PV sourcing, or prioritize M&A to access distribution and service footprints.
- Go-to-market pivots: Rental companies and contractors can use the report’s TCO and ROI frameworks to justify fleet replacement programs to corporate buyers and public agencies.
- Regulatory readiness: Procurement and compliance teams will benefit from our assessment of noise and emissions trends that are already reshaping tender requirements in highly regulated sites.
- Supply-chain resilience: Sourcing strategies for batteries and high-efficiency PV are now a strategic lever; the report shows where supplier risk most materially affects unit economics.
What PW Consulting’s report delivers — practical, transaction-ready outputs
This report is built as an operator’s playbook rather than an academic exercise. Key deliverables include:
- Proven market-sizing methodology and demand models (top‑down and bottom‑up reconciliation) tied to scenario-based forecasts across 2026–2032.
- Commercially focused competitive benchmarking: vendor scorecards, product feature matrices, service footprint maps, and go-to-market archetypes.
- Technology and product roadmaps that compare runtime, battery chemistry, PV performance, lighting optics, mast engineering, and telematics capabilities.
- Actionable TCO and ROI calculators (CapEx/Opex templates) designed for procurement and rental decision-makers.
- Procurement instruments including RFP question sets, warranty and service-level frameworks, and retrofit-vs-replace decision guides.
- Scenarios and sensitivity analysis that quantify impacts from battery cost declines, PV efficiency gains, and changes in rental utilization rates.
- Investment and M&A playbooks: target profiling, integration risk checklists, and valuation sensitivity inputs for deal teams.
- Operational modules: field deployment checklists, predictive-maintenance pathways, and aftermarket parts planning tools.
To preserve competitive value for subscribers, detailed regional/application splits and the full interactive model are available exclusively in the full report and online portal.
Competition and capability map — profiles and strategic implications
The market features a mix of diversified industrial OEMs, specialized regional manufacturers, and rapid-growth scale players. Core vendor archetypes include global industrial leaders, North American specialists, European niche innovators, and high-volume Chinese manufacturers. Representative firms analyzed in the report include Atlas Copco (Sweden), Generac Mobile (USA), Wanco (USA), Trime (Italy), Larson Electronics (USA), Progress Solar Solutions (USA), SOLTECH (USA), ArmorLogix (USA), Biglux Innovation (China), and MPMC Powertech (China). For company details and links, the full report provides vendor dossiers and supplier scorecards.
Recent market activity underlines product-led differentiation and hybridization. For example, Atlas Copco’s March 2025 enhancement introduced solar-and-battery units with extended runtimes designed for construction and disaster-response missions, while Generac’s January 2025 GLT Series emphasized hybrid options and improved energy economics. Such moves illustrate two persistent tactical directions: (1) extending autonomy through battery and PV improvements, and (2) broadening addressable use cases via hybrid configurations and smarter controls.
Competitive advantage in 2026 will derive from several measurable dimensions: battery chemistry and energy density, PV efficiency and packaging, telematics-enabled fleet management, modularity for rental operations, noise and emissions performance, after-sales service density, and financing/rental options. Firms that combine superior product economics with deep service networks and creative financing will capture disproportionate share growth as buyers prioritize lifecycle economics over headline CapEx.
Strategic recommendations for 2026 — where to act first
- OEMs: Prioritize investment in battery systems (LiFePO4), PV packaging optimization, and telematics. Build modular platforms that simplify upgrades to higher-energy packs or hybrid genset integration.
- Rental operators: Launch controlled pilots to convert a percentage of fleet each year; use our TCO templates to create procurement cases that win municipal and enterprise tenders.
- Project developers and contractors: Integrate solar light towers into site-emissions plans and bid packages to differentiate on sustainability and noise compliance.
- Investors and PE: Target mid-market players that combine product IP with regional service networks — CR3/CR5 concentration indicates room for roll-up strategies to build national footprints.
- Supply‑chain managers: Lock multi-year agreements for battery cell supply and high-efficiency PV modules; incorporate dual-sourcing to mitigate geopolitical disruption risks.
- Policymakers and large buyers: Consider incentives and standardized testing that accelerate fleet electrification while safeguarding lifecycle environmental benefits.
How to use this intelligence in 90–180 days
- 90-day actions: Run a rapid TCO audit on current rental and fleet assets using our downloadable calculator; identify 1–2 pilot sites for solar-led conversions where noise or emissions restrictions are binding.
- 180-day actions: Finalize supplier contracts for battery and PV volume discounts; set targets for fleet conversion or new-product launches to align with procurement cycles in your core markets.
Next steps — get the full playbook
This article has summarized the strategic signals and operational levers that matter for 2026. The complete PW Consulting Solar Mobile Light Tower Market report contains the detailed regional and application segmentation, revenue and unit forecasts by scenario, full vendor scorecards, and the interactive model you’ll need to stress-test strategies against alternative futures. To access the full dataset, segmentation details, and our scenario builder — or to commission a bespoke briefing for your executive team — visit our report portal or contact a PW Consulting analyst.
PW Consulting synthesizes market rigor with transaction-ready guidance. For decision-makers who must move from intention to execution in 2026, this report is designed to be the blueprint that turns sustainability imperatives into competitive advantage.
For detailed analysis of this topic, please visit the official page: Solar Mobile Light Tower Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Medical Device Calibration Market Poised to Expand at a 9.25% CAGR During 2026–2032
By PW Consulting, 2026-07-07
Medical Device Calibration Service Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
PW Consulting’s new market research brief on the Medical Device Calibration Service market synthesizes regulatory, operational, and competitive intelligence to inform capital allocation and go-to-market decisions in 2026. The market has transitioned from a niche technical service to a mission-critical component of clinical continuity and regulatory defensibility. Our analysis shows the market expanding from roughly USD 1.39 billion in 2020 to about USD 2.16 billion in 2025, and we forecast it to reach approximately USD 4.01 billion by 2032, reflecting a compound annual growth rate (CAGR) of 9.25% over the 2026–2032 forecast window. Market concentration remains low — the top three providers account for under one-fifth of revenue and the top five below one-third — underscoring fragmentation and opportunity for scale-driven consolidation.
Medical Device Calibration Service Market
Why this market matters for 2026 strategy
- Regulatory compliance is now a board-level exposure: Requirements such as ISO/IEC 17025 accreditation for laboratories, ISO 13485 for device quality systems, and FDA obligations (including 21 CFR Part 820.72 and programs like ASCA) are raising the technical bar for calibration evidence used in design, production and premarket submissions.
- Operational resilience and clinical uptime are monetized: Hospitals and OEMs treat calibration as a service that reduces clinical risk and prevents revenue losses from equipment downtime. This has created new pricing and contract models beyond time-and-materials.
- Technology integration is shifting value capture: Predictive maintenance, digital asset management, and remote calibration capabilities change the unit economics of service and create differentiation for providers who can combine field service with software and data analytics.
Market dynamics driving decisions in 2026
- Regulatory tightening and harmonization. Accreditation and traceability to national standards are now prerequisites for defensible measurement data in regulated submissions. The FDA’s ASCA pathway is enabling accredited labs to support premarket evidence, while 21 CFR Part 820.72 continues to obligate device manufacturers to maintain traceable calibration programs. These regulatory facts are shaping supplier selection criteria and elevating ISO/IEC 17025 as a de facto ticket-to-play.
- Infrastructure expansion in growth markets. Public and academic investments in national metrology and mobile calibration facilities are accelerating capacity in emerging geographies. New apex-level facilities and mobile labs expand market accessibility for hospitals and OEMs, reducing the logistical premium for reliable field calibration in regional markets.
- Service model evolution. Third-party providers, OEM service arms and internal hospital biomedical departments are reconfiguring their value propositions: bundled managed services, guaranteed uptime contracts, and asset-as-a-service offerings are displacing transactional calibration engagements.
- Fragmentation enables M&A and roll-up strategies. With a CR3 below 20% and CR5 under 30%, strategic acquirers can capture scale benefits through consolidation, regional coverage, and technical center-of-excellence plays. Recent bolt-on acquisitions and lab aggregations validate this thesis.
Competitive landscape — what the leaders are doing
The competitive set includes international calibration specialists, OEM service divisions, and regional biomedical service firms. Across this landscape we see three convergent plays:
Medical Device Calibration Service Market
- Scale and accreditation: Global providers are investing in ISO/IEC 17025-accredited laboratory networks and traceable measurement systems to win regulated customers and ASCA-eligible work.
- Coverage and speed: Regional roll-ups and acquisitions are being used to densify field-service footprints, shorten lead times, and support hospital networks with guaranteed response SLAs.
- Product-service integration: OEM-focused players leverage their product knowledge to offer prioritized service and lower mean-time-to-repair for their installed base, while independent providers emphasize multi-brand capability and impartiality.
Representative company positioning:
Medical Device Calibration Service Market
- Trescal (France): A full-service international calibration provider with ISO 17025 capabilities and a clear emphasis on traceability and regulatory compliance for life science and clinical equipment. Their multi-country lab-and-field model positions them to serve global OEMs and hospital systems seeking uniformity of practice.
- Transcat, Inc. (United States): Aggressively expanding through laboratory acquisitions to densify regional coverage for healthcare customers. Their recent lab roll-ups are consistent with a regional consolidation strategy that shortens response times and builds testing capacity adjacent to OEM and hospital clusters.
- Tektronix and Fluke Biomedical (United States): Both blend instrumentation expertise with service. Their strength is in multi-brand calibration and the ability to couple test instruments with accredited workflows — attractive for facilities that demand technical rigor and minimal clinical disruption.
- Specialist regional players (e.g., JM Test Systems, Calyx Met, Biomedical Technologies Inc. and others): These providers deliver focused capabilities — from diagnostic imaging calibration to on-site biomedical support — and often compete on accredited traceability and personalized service for hospitals and labs.
Recent developments that recalibrate 2026 plans
- Laboratory acquisitions and roll-ups continue to accelerate — exemplified by multi-site acquisitions in mature markets to build regional test capacity and field networks.
- Public investments in calibration infrastructure and mobile labs in markets such as India expand addressable demand and lower the cost of entry for regulated testing and field service.
- Strategic acquisitions of calibration boutiques by larger service providers and equipment service companies indicate a shift from ad-hoc engagements to packaged compliance solutions.
What PW Consulting’s report delivers — practical assets for 2026 action
This is not an academic exercise. Our report provides tools that operational and commercial leaders can use immediately:
- Go-to-market playbooks tailored for OEMs, third-party service providers and hospital systems, including contract language templates for uptime guarantees, sample SLAs, and escalation paths.
- Regulatory compliance checklists and accreditation roadmaps that map ISO/IEC 17025 and ISO 13485 obligations into discrete operational tasks and audit evidence packages.
- Financial models—CapEx/Opex breakouts, ROI scenarios for insourcing vs. outsourcing, and valuation heuristics for M&A target screening.
- Service portfolio optimization frameworks to prioritize high-impact device classes and clinical use-cases (note: granular device and regional splits are intentionally omitted here — full segmentation available in the paid dataset).
- Operational playbooks for field-force structuring, calibration interval optimization, asset tagging and digital integration strategies for CMMS and predictive analytics.
- Vendor scorecards and due-diligence templates, including accreditation, traceability, SLA performance, and sample audit questionnaires for procurement teams.
Strategic recommendations for 2026 decision cycles
- For OEMs: Convert calibration from a compliance checkbox into a differentiator — bundle accredited calibration services into extended warranty and service contracts to capture recurring revenue and reduce aftermarket leakage.
- For service providers: Prioritize investments in accreditation, digital asset management and regional lab capacity. Pursue bolt-on acquisitions to close coverage gaps and capture scale-sensitive accounts.
- For hospitals and health systems: Reassess the economics of centralized biomedical shops versus accredited third-party partnerships, with particular focus on workload seasonality, regulatory evidence needs, and supply-chain resilience.
- For investors and PE sponsors: Seek platform plays that combine accredited labs, field-service networks, and software-enabled asset-management capabilities; target subsegments where clinical criticality supports premium pricing and contracted recurring revenue.
Data rigor and methodological notes
PW Consulting’s estimates are built on a bottom-up inventory of device populations, calibration frequency benchmarks, accreditation prevalence and service pricing norms, reconciled with provider revenue disclosures and recent M&A activity. The base year is 2025; the forecast period spans 2026–2032 using a 9.25% CAGR assumption. We also quantify market concentration and competitive positioning to support M&A diligence — note that high-granularity regional and device-level splits are part of the paid dataset and are intentionally not reproduced in this preview.
How to use this research in 2026 planning
- Prioritize compliance-sensitive product lines for service bundling and ASCA-ready testing partnerships.
- Run a rapid triage of your calibration footprint against the accreditation map in the report to identify single points of failure in regulatory evidence.
- Use the vendor scorecards to streamline RFPs and shorten procurement cycles by focusing on accreditation, turnaround, and digital integration capabilities.
- Leverage the financial playbooks to model buy-versus-build decisions for both labs and software components of a modern calibration service.
Conclusion — a tactical edge for 2026
Calibration is no longer a back-office technical function: it is a convergence point for regulatory risk management, clinical uptime, and service monetization. With the market expanding at a double-digit growth trajectory into the early 2030s and a fragmented supplier base, organizations that invest selectively in accreditation, regional capacity, and digital integration will capture outsized share and margin. PW Consulting’s full report equips executives with the pathway to convert calibration from cost center to strategic asset.
Next steps
For the full dataset, regional and device-level segmentation, vendor benchmarking matrices, and downloadable operational templates referenced here, consult the PW Consulting report landing page. This release intentionally omits detailed split-values to safeguard the strategic granularity contained in the paid report — an approach designed to protect actionable intelligence and maximize utility for subscribing clients.
For detailed analysis of this topic, please visit the official page: Medical Device Calibration Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Power over Ethernet (PoE) Chipset Market Poised to Grow at a 14.05% CAGR, Driving Next-Gen Networking Adoption
By PW Consulting, 2026-07-07
Power Over Ethernet (PoE) Chipset Market: Strategic Imperatives for 2026 — PW Consulting Preview
As enterprises accelerate edge compute deployments, modernize building infrastructure, and scale AI-driven networking, PoE chipsets have emerged as a practical, high-leverage technology for delivering power and data over a single Ethernet cable. PW Consulting’s upcoming PoE Chipset Market report (base year 2025, historical scope 2020–2025, forecast 2026–2032) synthesizes primary research, vendor interviews, and supply-chain stress-testing to deliver an actionable roadmap for procurement, product planning, and capital allocation in 2026.
Power Over Ethernet Poe Chipset Market
Market Trajectory at a Glance
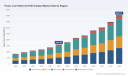
Our firm-level modeling shows sustained expansion of the global PoE chipset market. After recovering from early-decade volatility, total industry revenues climbed to approximately USD 1.61 billion in 2025 and are projected to reach roughly USD 1.79 billion in 2026, with a compounded annual growth rate (CAGR) of 14.05% through the forecast window. By 2032 the market is modeled to exceed USD 4.0 billion — a near-tripling over the decade driven by higher-power PoE classes, enterprise networking refresh cycles, and cross-domain adoption spanning IP video, lighting, industrial automation, and next-generation Wi‑Fi and IoT endpoints.
Power Over Ethernet Poe Chipset Market
Why This Matters for 2026 Strategic Decisions
- Timing investments: The forecasted acceleration in 2026 means device OEMs and system integrators can no longer treat PoE as a marginal option; it should be central to product roadmaps and channel incentives for the next three years.
- Technology selection: With IEEE 802.3bt and higher-power variants enabling previously impractical use-cases (from advanced PTZ cameras to PoE lighting), architecture decisions made in 2026 will determine compatibility and upgrade paths through 2032.
- Supply chain posture: Extended semiconductor lead times and component competition from AI and EV sectors make 2026 the year to institute multi-tier sourcing, safety stocks, and design-for-availability strategies.
- Vendor negotiation and consolidation risk: Market concentration metrics indicate a non-trivial portion of revenues are controlled by leading chipset vendors — a structural factor buyers should fold into contract cadence and contingency planning.
What the Report Contains — Practically Applicable Deliverables
PW Consulting’s report is designed as a decision-support toolkit for executives, product managers, CIOs, and procurement teams. The deliverables include:
Power Over Ethernet Poe Chipset Market
- Top-line market forecast and scenario analyses (base, upside, and downside) for 2026–2032 with sensitivity to lead-time disruption and standard adoption rates.
- Vendor scorecards and an actionable vendor-selection matrix that balances technical performance (efficiency, thermal profile, power limits) with commercial levers (pricing bands, support, roadmap commitments).
- Supply-chain stress tests and mitigation playbooks that quantify the impact of 30–42 week lead times on BOM timing and propose replenishment policies and dual-sourcing templates.
- TCO and ROI calculators tailored to common enterprise use-cases (campus Wi‑Fi, large-scale camera deployments, smart lighting retrofits, and industrial edge controllers).
- Integration checklists and thermal/EMC design guidance for 802.3bt and higher-power designs, including recommendations on DC-DC conversion strategies and heat management to preserve device reliability.
- Regulatory and standards map aligning ENERGY STAR, IEEE evolutions, and national semiconductor policies with product compliance milestones.
- Commercial playbooks for channel partners, including bundling strategies, certification pathways, and ENERGY STAR positioning for midspan and switch-integrated PoE offerings.
Competitive Landscape — Who Matters and Why
The PoE chipset market is populated by a mix of broad-based semiconductor titans and targeted specialists. The competitive dynamic is shaped by the need for highly reliable power-management analog, embedded detection algorithms, and efficient DC-DC conversion at growing power levels. Key competitors analyzed in our report include:
- Texas Instruments Incorporated (Dallas, USA) — a long-standing supplier of PSE and PD controllers with proven series implementations that support the full suite of IEEE PoE standards. TI’s depth in analog power and system-level reference designs makes it a strategic option for customers prioritizing integration and ecosystem support.
- Analog Devices Inc. (Wilmington, USA) — offers integrated PSE/PD controllers including high-efficiency DC-DC capabilities and LTPoE++ support up to higher wattages. Their strength lies in tightly integrated analog front-ends and robust detection schemes suited to industrial and enterprise segments.
- Microchip Technology Inc. (Chandler, USA) — notable for end-to-end PoE solutions and recent product launches geared to intelligent multi-port PSE management and ENERGY STAR‑compliant midspan devices. Microchip’s combined silicon and software approach is attractive for OEMs seeking turnkey subsystems.
- STMicroelectronics N.V. (Geneva, Switzerland) — supplies system-in-package solutions for high-power PD implementations and mid-power controllers, with an emphasis on thermal efficiency and power density.
- onsemi (Scottsdale, USA), Silicon Labs (Austin, USA), Broadcom (San Jose, USA), NXP (Eindhoven), Monolithic Power Systems (Kirkland), Semtech (Camarillo), and Kinetic Technologies (San Jose) — each brings differentiated competencies, from highly cost-optimized PD controllers for IoT to enterprise-grade switching silicon that embeds PoE management. Broadcom’s recent announcements linking PoE functionality into AI-scale switching platforms are particularly noteworthy for large campus and data-center edge strategies.
Collectively, the top three firms account for a meaningful share of market value, while the top five concentrate well over half the market — a structural reality that shapes pricing leverage, roadmap influence, and certification requirements. PW Consulting’s vendor matrix scores these firms across 12 criteria including technical performance, roadmap clarity, supply resilience, and partner ecosystem depth.
Regulatory, Supply, and Technology Dynamics to Watch in 2026
- Standards evolution: IEEE 802.3bt (and higher-power extensions) has unlocked new applications by supporting higher wattage and Autoclass power reporting. Buyers must lock in standard compatibility now to avoid costly reworks later.
- Efficiency and thermal budgets: Advances in DC-DC conversion now routinely deliver efficiencies approaching industry-leading thresholds; however, thermal constraints remain the first-order design limiter for many PDs and compact PSEs.
- Component lead-time pressure: A broader semiconductor demand surge — amplified by AI and EV applications — pushed lead times for key analog and power components into multi-month ranges in early 2026. Design teams should plan for qualified alternates and prioritized allocation agreements.
- Geopolitical and policy drivers: National semiconductor strategies and shifting trade policies continue to reconfigure sourcing footprints. Regional diversification and local assembly options are now valid risk-mitigation levers for mission-critical deployments.
Actionable Recommendations for 2026
- Adopt a two-track sourcing model: Combine strategic long-term agreements with a spot-market contingency to reduce fill-rate risk while managing cost.
- Prioritize standards-compatible platforms: Invest in 802.3bt-compliant PSE/PD silicon for greenfield projects and ensure firmware upgradeability for evolving Autoclass and power reporting features.
- Embed thermal and efficiency KPIs in procurement: Specify conversion efficiency and thermal derating thresholds in RFPs to avoid downstream reliability costs.
- Model TCO over 5–7 years: Account for energy savings, reduced cabling and labor, and maintenance differentials when comparing PoE-enabled architectures to traditional power distribution.
- Monitor vendor roadmaps and concentration risk: Use PW Consulting’s vendor scorecard to identify partners with demonstrated supply robustness and product continuity commitments.
What PW Consulting’s Report Does Not Reveal Here
This preview purposefully surfaces the high-level market trajectory, competitive contours, and the operational levers that will matter in 2026. To preserve the strategic value of the proprietary analysis — including regional and application segmentation breakdowns, detailed vendor market shares, unit shipment forecasts, and downloadable procurement templates — full datasets and interactive models are available exclusively in the complete report.
Final Note: How to Use This Intelligence in 2026
For executives and product leaders making 2026 decisions, the imperative is clear: move from ad hoc PoE pilots to structured deployment strategies that align technical choices with commercial resilience. The PoE chipset market’s projected growth and concentration dynamics create both opportunity and risk — opportunity for vendors and integrators who can deliver reliable, efficient, and standards-compliant silicon; risk for buyers who delay sourcing and integration choices into 2027 and beyond.
PW Consulting’s full PoE Chipset Market report equips decision-makers with the data, vendor assessments, and playbooks necessary to operationalize this strategy. Use the preview insights above to prioritize immediate actions (sourcing, standards alignment, thermal design constraints) and consult the full report for the granular segmentation, scenario-specific ROI tools, and vendor scorecards that will dictate winners and losers through 2032.
For detailed analysis of this topic, please visit the official page: Power Over Ethernet Poe Chipset Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: DC Permanent Magnet Motor Market to Reach USD 65,063.92 Million by 2032, Growing at 6.5% CAGR — Asia Pacific Leads with USD 19,768.43 Million in 2025
By PW Consulting, 2026-07-07
Dc Permanent Magnet Motor Market: Strategic Outlook for 2026 — PW Consulting Exclusive Preview
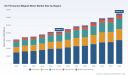
As global electrification and automation accelerate, permanent magnet DC (PMDC) motors have moved from niche components to central enablers across automotive, industrial, consumer and medical ecosystems. Our latest Dc Permanent Magnet Motor Market report — anchored on a 2025 base year and informed by historical trends from 2020–2025 — finds the market at roughly USD 42 billion in 2025, and projected to expand at a compound annual growth rate (CAGR) of about 6.5% through the 2026–2032 forecast horizon. That pace positions the market to surpass the mid‑sixty billion USD mark by the end of our forecast window, creating intense strategic opportunities and new operational risks for manufacturers, OEMs, suppliers and investors alike.
Dc Permanent Magnet Motor Market
Why this report matters for 2026 decision-makers
-
Actionable foresight for capital allocation. With robust mid‑single‑digit growth and evolving product mixes, timing investments in capacity, automation and downstream services will be decisive to preserve margins as product lifecycles shorten.
Dc Permanent Magnet Motor Market -
Regulatory inflection points. New efficiency standards are being rolled out across major markets — most notably expanded energy conservation requirements in the U.S. — with staged compliance deadlines that make 2026 the pivotal year for product roadmapping and compliance investments.
Dc Permanent Magnet Motor Market -
Supply‑chain sensitivity. Magnet supply and rare‑earth dynamics have amplified input risk. Manufacturers must balance near‑term sourcing stability against long‑term strategic approaches such as material substitution, recycling and vertical integration.
-
Competitive reshaping. The market remains fragmented: leading industrial groups provide scale and integrated solutions, while specialty players carve profitable niches in precision, miniature and high‑torque segments. This combination fuels both consolidation and targeted bolt‑on M&A opportunities.
What’s inside the report — practical intelligence you can use
We designed the study as a hands‑on playbook for executives who must make definitive 2026 choices. The full report contains:
-
Scenario‑based market sizing and global demand forecasts (2026–2032) with sensitivity runs on commodity, policy, and adoption variables.
-
Demand segmentation by motor type, application and region, with prioritized growth pockets and margin differentials clearly identified. (Note: detailed segment tables are reserved for the full report.)
-
Supply‑side mapping including Tier‑1 to niche suppliers, contract manufacturing footprints, and logistics chokepoints.
-
Technology and product benchmarking—efficiency ladders, control electronics trends, and system‑level tradeoffs between brushless and brushed architectures.
-
Cost and BOM models that illustrate the impact of magnet alloy cost swings and electronics content on total cost of ownership across typical motor classes.
-
Regulatory impact assessment and a compliance roadmap aligned to announced and expected efficiency standards.
-
Competitive landscaping with company profiles, capability heatmaps, and strategic options tailored to market entrants, incumbent producers and suppliers of raw materials.
-
M&A and partnership opportunity screening, including synergy estimates and integration risks.
-
A 12‑month tactical plan and a three‑year strategic playbook for manufacturers, OEMs and investors focused on revenue protection, margin recovery and growth acceleration.
Competitive landscape — leaders, specialists and the strategic implications
The PMDC landscape is defined by a mix of global industrial conglomerates, precision niche specialists and regional/custom manufacturers. Our analysis highlights distinct positioning and strategic moves among the principal players:
-
Global industrial leaders (examples include Nidec, ABB and Siemens) leverage broad product portfolios and deep channel access to supply large industrial and automotive programs. Their strengths are scale, system integration and established customer relationships—advantages that favor participation in large electrification projects and industrial automation rollouts.
-
Precision and application specialists (such as Maxon Motor, Portescap and Johnson Electric) command premium niches in medical devices, robotics and aerospace. These firms compete on miniaturization, torque density, and quality assurance—segments where technical differentiation enables above‑average margins.
-
Regional and custom manufacturers (including selected OEM‑focused players and geographically diverse suppliers) provide configurable solutions and localized manufacturing advantages. Their agility makes them attractive partners for OEMs seeking customized designs, rapid prototyping or local content compliance.
-
Newer entrants and technology upstarts are pushing advanced magnet geometries, slotless architectures and integrated motor‑drive packages, accelerating the product evolution curve.
Recent industry activity underscores these dynamics: several manufacturers refreshed product catalogs and showcased PMDC solutions at major automation and production expos; others strengthened certification portfolios for critical markets. These moves signal intensified competition on product breadth, compliance and proximity to system integrators.
Supply‑chain and raw‑material dynamics to watch in 2026
Rare‑earth magnet availability and pricing volatility remain structural themes. Export controls and geopolitical concentration of supply create strategic premium for secure sourcing. For many firms, 2026 is the year to operationalize procurement hedges—long‑term offtake agreements, recycled magnet programs, or alliance models with magnet manufacturers. Technology levers—such as reduction of rare‑earth content through topology changes, improved motor control algorithms and hybrid materials—offer mid‑term mitigation but require R&D investment and qualification cycles.
Regulatory and standards headwinds — planning horizon for compliance
Efficiency mandates in key markets are shifting the competitive baseline. Manufacturers that proactively redesign platforms to meet the next generation of efficiency standards will capture shelf‑space and program wins with major OEMs. The report includes compliance timelines, product impact matrices and costed implementation pathways to guide engineering and procurement calendars through 2027–2029 rulemaking windows.
Strategic moves we recommend for calendar‑year 2026
-
Lock strategic magnet supply now: convert a portion of spot exposure into multi‑year relationships or structured supply to reduce upside price shocks.
-
Prioritize electrification product families where system integration and software enable differentiation (e.g., motors + embedded drives + diagnostics), not commodity replacement.
-
Accelerate compliance readiness for announced efficiency rules: perform targeted platform redesigns on the highest‑volume SKUs and validate with pilot customers.
-
Explore bolt‑on acquisitions to acquire precision capabilities, magnet knowledge or regional manufacturing footholds rather than greenfield capacity expansion.
-
Deploy cost‑to‑serve programs tied to product complexity—rationalize SKUs where aftermarket or customization costs erode margins.
-
Invest in circularity pilots: magnet recycling and remanufacturing programs can reduce material exposure and become customer selling points.
How PW Consulting supports 2026 decision execution
Our engagement model bridges deep market analytics with transaction and delivery capability. We offer tailored modules including commercial due diligence, supply‑chain redesign, regulatory compliance roadmaps, technology scouting and divestiture/acquisition execution. For clients seeking rapid alignment, we provide a focused 8‑week "Market to Roadmap" sprint that delivers prioritized investments, a two‑year implementation timeline and a quantified case for change.
Next steps
This preview highlights the strategic value of our Dc Permanent Magnet Motor Market report for organizations that need to make consequential 2026 decisions. To preserve the integrity of our forward work and the proprietary value of segment‑level tables, the full dataset, granular regional and application splits, company benchmarking matrices and interactive scenario tools are available only in the complete report.
Contact PW Consulting to request the full report, schedule an executive briefing, or commission a bespoke strategy workshop tailored to your product portfolio and supply‑chain footprint. Our experts will walk you through the model, validate your assumptions against our scenario set, and help translate insight into 12‑ and 36‑month action plans that protect margin while capturing growth.
For detailed analysis of this topic, please visit the official page: Dc Permanent Magnet Motor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ai Chat Bot Market Poised for Breakout Growth — 24.5% CAGR Forecast for 2026–2032
By PW Consulting, 2026-07-07
Ai Chat Bot Market 2026: Strategic Imperatives from PW Consulting’s Market Intelligence Brief
Executive snapshot
PW Consulting’s latest Ai Chat Bot Market study — a comprehensive market intelligence brief with base year 2025 and a forecast horizon of 2026–2032 — synthesizes five years of historical data (2020–2025) and forward-looking scenario analysis to equip executives making strategic decisions in 2026. The market is expanding rapidly: from a modest base in 2020 it reached multi‑billion dollar scale by 2025, and our model projects continued acceleration through the forecast period at a compound annual growth rate of 24.5%. Underneath that headline growth lie concentrated supplier positions (CR3 ~35.5%, CR5 ~48.2%), shifting regulatory guardrails, and material infrastructure cost dynamics that collectively re-shape vendor selection, deployment architecture, and go-to-market timing.
Ai Chat Bot Market
Why this brief matters for 2026 decision-makers
-
Timing and investment sizing: whether you are allocating capital for internal chatbot R&D, planning a SaaS procurement, or evaluating M&A targets, the growth trajectory and volatility drivers in our analysis enable defensible spend windows and staging milestones for 2026 investment cycles.
Ai Chat Bot Market -
Vendor and risk strategies: the market concentration metrics and vendor capability heatmaps in our report help procurement and legal teams separate platform powerhouses from specialized challengers — a critical distinction for negotiating SLAs, IP terms, and data governance clauses.
Ai Chat Bot Market -
Regulatory readiness: with the EU AI Act effective and emergent U.S. state-level disclosure requirements, the brief identifies the compliance implications that must be operationalized in 2026 to avoid deployment delays and reputational exposure.
-
Total cost of ownership (TCO) clarity: we translate high-level compute and data costs into scenario-based TCO ranges for common enterprise architectures, enabling CFOs to compare cloud-first approaches vs. hybrid/on‑premises strategies under plausible price paths.
What the report contains (practical, executable modules)
-
Executive decision playbook — A 12‑month roadmap for procurement, pilots, scale-up and governance checkpoints tailored for enterprise, mid-market and digital-native firms.
-
Vendor assessment framework — Standardized scorecards covering model capability, integration maturity, data protection posture, licensing flexibility, and upgradability to new model families.
-
ROI and TCO models — Buildable financial models that convert compute runs, expected query volumes, developer integration effort and maintenance into comparable NPV/IRR outputs for alternative deployment choices.
-
Compliance & risk playbooks — Template risk assessments and transparency statements aligned to the EU AI Act and recent U.S. state privacy amendments; practical steps to operationalize model audits and red-team exercises.
-
Procurement language and contracting levers — Practical negotiation language for licensing (including datum usage, model fine-tuning rights, and indemnities) and recommended SLA thresholds for latency, model freshness, and hallucination mitigation.
-
Technology stack decision matrix — Guidance on when to adopt hosted API-first chat platforms versus building on open weights or hybrid offerings, informed by workload profiles and data-residency constraints.
-
Scenario playbook for 2026 — Three credible market scenarios (Consolidation, Platform Dominance, and Decentralized Edge) showing implications for revenue, risk and hiring through 2028.
Competitive landscape: who matters for enterprise adoption
The market is dominated by a mix of cloud platform incumbents, research-driven model providers, and newer consumer‑facing entrants. In our competitive maps we profile both strategic capabilities and enterprise-readiness:
-
OpenAI — Leader in generative chat models with strong enterprise integration options; primary strength lies in rapid model improvements and wide partner ecosystem for CRM and contact-center integrations.
-
Anthropic — Differentiates on safety-first model design, making it attractive for regulated industries and analytical workflows where explainability and conservative behavior are priorities.
-
Google (Gemini) — Deep integration into productivity stacks and search, offering compelling value for enterprises heavily invested in Google Workspace and Android ecosystems.
-
Microsoft — Strength in enterprise productivity and platform bundling, embedding Copilot across Azure, Office 365 and partner CRS like Salesforce for end-to-end adoption at scale.
-
xAI — Faster experimental routes to user-facing chat experiences with real-time signal orientation; notable for differentiated UX and social reach via integrated platforms.
-
IBM (watsonx) — Focused on hybrid deployments and industry-specific solutions, appealing for firms requiring on‑premises control or sector specializations (e.g., financial services).
-
Amazon (Q and Lex) — Robust for voice/text pipelines and deep AWS integration, offering operational advantages where voice or multimodal interfaces are strategic.
-
Meta — Strong at scale for social and messaging channels; Llama-derived models support cost-effective, in-house experimentation for platforms already embedded in consumer touchpoints.
Recent product and partnership moves — notable releases and integrations through late 2025 — materially change competitive calculus. Examples include enhanced reasoning and enterprise features from leading model providers, workspace integrations from major cloud players, and multimodal updates enabling richer user interactions. These dynamics feed directly into vendor risk assessments and preferred supplier lists for 2026 procurement cycles.
Regulatory, infrastructure and market dynamics to watch
-
Regulatory shift: The EU AI Act categorizes certain chatbots as high‑risk and mandates transparency and risk assessment processes. Enterprises deploying cross-border conversational systems must embed compliance as a product requirement rather than an afterthought.
-
Privacy & disclosure: U.S. state-level changes now require clearer consumer disclosures about AI usage, influencing consent flows and audit trails in customer-facing bots.
-
Compute economics: Training large foundational models remains capital intensive; industry benchmarks place single-run costs for LLM-scale training on high-end GPU clusters in the tens of millions range, which explains the continued appeal of API-first or fine-tuning partnerships for many enterprises.
-
Data sovereignty: Jurisdictions with in‑country data residency rules impose architectural constraints that can alter deployment cost and vendor choice; hybrid arrangements and localized inference will be decisive for many international rollouts.
-
Market concentration: With a CR3 of approximately 35.5% and a CR5 near 48.2%, the market shows meaningful clustering around a few major providers. This concentration affects negotiation leverage, dependency risk, and innovation diffusion timelines.
-
Reimbursement reality: Outside narrowly scoped healthcare pilots, there are no broad government reimbursement mechanisms for commercial chatbot deployments — a practical consideration for monetization models and pricing strategies.
Practical strategic recommendations for 2026
-
Adopt a risk-tiered deployment model: For high-risk use cases (regulated advice, financial decisioning), require safety-assured models with audit logs and on‑premises or hybrid hosting. For low-risk workflows, prioritize time-to-value with API-first models and managed services.
-
Hedge compute exposure: Where long-term model control is strategic, stagger investments in fine-tuning and consider co-investment in private inference fleets. For most enterprises, structured vendor contracts with predictable pricing tiers reduce capital intensity.
-
Embed compliance as a product requirement: Map regulatory checkpoints to sprint cycles; require vendor attestations and model cards in procurement packs to avoid costly retrofits.
-
Vendor negotiation playbook: Insist on data usage and IP clarity, rollback/rollback testing for model updates, and defined escalation paths for harmful output incidents.
-
Talent and ops: Build dual competencies — prompt engineering and production‑grade MLOps — and appoint a cross-functional trustee for chatbot governance to balance product, security and legal perspectives.
-
M&A and partnerships: Use the report’s valuation overlays and scenario stress tests to price targets and to assess integration complexity for deals or strategic alliances.
The PW Consulting advantage: what makes our brief different
Our research pairs granular vendor intelligence with executable financial and legal artifacts to move organizations from strategic intent to operational execution within 90–180 days. Importantly, while this release highlights market scale and macro concentration metrics to establish context, our full intelligence suite preserves detailed segment-level breakdowns and proprietary vendor rankings behind the report portal to maintain data integrity and client exclusivity.
Next steps and how to access the full intelligence
For procurement teams, C-suite sponsors, and technology leaders preparing budgets and roadmaps for 2026, this brief is the decision foundation. To access the full dataset, vendor scorecards, downloadable TCO models, and tailored scenario toolkits — including the withheld segment-level splits and regional deployment economics — visit the PW Consulting report page or contact our research desk for a licensed copy. Our analysts are available for bespoke briefings and procurement support to translate the report’s insights into contractual and operational artifacts.
For detailed analysis of this topic, please visit the official page: Ai Chat Bot Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hydrogen Cooling Synchronous Condenser Market Poised to Grow at a 5.86% CAGR Through 2032
By PW Consulting, 2026-07-07
Hydrogen-Cooled Synchronous Condenser Market: Strategic Intelligence for 2026 Decision-Making
PW Consulting’s latest market research report on the Hydrogen Cooling Synchronous Condenser Market positions 2026 as a decisive inflection point for utilities, original equipment manufacturers (OEMs), investors and system integrators navigating the transition to renewable-dominant grids. Built on a 2020–2025 historical baseline with a forward-looking forecast to 2032, the study combines quantitative market sizing, scenario-driven technology assessments, vendor benchmarking and actionable procurement playbooks to inform capital and operational choices in the year ahead.
Hydrogen Cooling Synchronous Condenser Market
Why 2026 Matters: Market Trajectory and Strategic Implications
The market for synchronous condensers incorporating hydrogen cooling has shown steady expansion through the mid-2020s and enters 2026 with clear momentum. From the early-2020s baseline, aggregate market value climbed materially by 2025, and our forecast indicates continued growth through the end of the 2026–2032 horizon at a compound annual growth rate (CAGR) of approximately 5.86%. In dollar terms, the market trajectory underlines a multi-year ramp that will meaningfully influence procurement cycles, manufacturing capacity planning and aftermarket service strategies for incumbent and emerging suppliers alike.
Hydrogen Cooling Synchronous Condenser Market
For corporate strategists and utility planners, this trajectory translates into three practical realities for 2026 decisions:
Hydrogen Cooling Synchronous Condenser Market
- Procurement windows are compressing as grid operators accelerate system-strength projects; lead times for hydrogen-capable rotating machinery must be baked into multi-year project timelines.
- Manufacturing and supply-chain scale-up is required to capture share; firms that de-risk hydrogen handling, sealing and purity supply chains stand to gain negotiating leverage in upcoming tenders.
- Risk-adjusted capital allocation should incorporate hydrogen-specific O&M profiles and safety compliance costs—factors that materially affect lifecycle economics compared to air- or TEWAC-cooled alternatives.
What the Report Contains: Practical, Executable Intelligence
PW Consulting’s report is structured around decision-centric outputs designed to be used at the boardroom and project-execution levels. Key deliverables include:
- Market sizing and validated forecasts (base year 2025; forecast horizon 2026–2032) with scenario analyses that stress-test volumes and revenue outcomes against decarbonization pace, policy changes and technology substitution.
- Technology deep dives comparing cooling architectures (with special emphasis on hydrogen-cooled systems), system-level thermal performance, failure modes, and lifecycle maintenance considerations.
- Practical procurement playbooks and specification templates tailored to transmission operators and independent power producers, including risk controls for hydrogen handling, seal maintenance and purity monitoring.
- Vendor benchmarking including capabilities mapping, delivery footprints, EPC archetypes and aftermarket service models—presented to enable “shortlist-to-RFP” conversion within six months.
- Financial modelling tools and sensitivity matrices that integrate capex, opex, spare-part provisioning and reliability assumptions—designed to yield transparent payback and IRR implications under multiple grid evolution scenarios.
- Case studies and lessons-learned from recent global projects, illustrating deployment challenges, construction sequencing and commissioning protocols in high-renewables environments.
Competitive Landscape: Who Matters and Why
The hydrogen-cooled synchronous condenser market exhibits a concentrated leader set, with the top three to five suppliers accounting for a substantial share of industry revenue. This concentration creates both opportunities and constraints for market participants: established manufacturers enjoy scale and legacy expertise in large rotating machinery, while specialized suppliers and regional players compete on responsiveness and local content.
Notable market participants profiled in the report include long-standing rotating machinery manufacturers and power-electronics integrators that have direct or transferable experience with hydrogen-cooled systems. These firms bring complementary strengths:
- Historical expertise in hydrogen-cooled large machines and global project delivery (e.g., firms with legacy hydrogen-cooled generator portfolios).
- Turnkey capabilities that pair synchronous condenser hardware with system controls, reactive-power management and inertia emulation solutions.
- Regional manufacturing and service networks that reduce logistical friction on large station-class equipment.
Recent procurement and contractual developments underscore market dynamics that corporate leaders should note. In the past 18 months, multiple major awards and EPC appointments demonstrate active demand for synchronous condensers to shore up grid strength as thermal synchronous plants retire and renewables scale. These transactions validate the technology choice in renewal programs and highlight the importance of delivery certainty and local content in award evaluations.
Industry Dynamics: Technology, Regulation and Supply-Chain Realities
Hydrogen cooling is favored in large-scale utility rotating machinery for its high thermal conductivity and low density—qualities that enable higher continuous ratings and favorable thermal performance compared to air-cooled alternatives. However, hydrogen introduces distinct engineering, safety and operational disciplines:
- Hydrogen handling requires robust sealing systems, purity control regimes and leak-detection infrastructure; failure modes differ from air-cooled systems and can affect maintenance periodicity and spare-part strategies.
- Regulatory and procurement frameworks vary: some transmission operators explicitly prefer non-hydrogen-cooled solutions to avoid the complexity and lifecycle costs associated with hydrogen management; others specify hydrogen cooling to achieve higher unit ratings and efficiency.
- Policy programs that enable high-capacity renewable integration—such as state-level Renewable Energy Zones—are accelerating demand in certain markets and shaping tender specifications around system strength deliverables (inertia, short-circuit power, dynamic reactive support).
For strategists, the interplay of these dynamics implies that technology choice is not purely technical—tender language, regulatory risk, and operating-environment factors will often drive whether hydrogen-cooled synchronous condensers are the optimal solution for a particular grid project.
Strategic Recommendations for 2026
Our analysis yields a set of prioritized actions for stakeholders planning near-term commitments in 2026:
- Utilities and system operators: Accelerate early engagement with suppliers to lock delivery windows and define hydrogen-specific acceptance tests. Introduce explicit lifecycle clauses in tenders that cover hydrogen seal maintenance, purity monitoring and emergency procedures.
- OEMs and EPCs: Parallelize capacity expansion with targeted investments in sealing technology, sensorized hydrogen monitoring and local service hubs. Prioritize modular designs that permit retrofitting of cooling architectures where regulatory or site constraints emerge.
- Investors and financial sponsors: Stress-test project models with hydrogen-specific O&M assumptions and scenario-based downside analyses that reflect alternative cooling architectures. Consider partnering with service providers to capture aftermarket margin streams tied to hydrogen management.
- Policy-makers and regulators: Provide clarity on safety standards, inspection cadences and allowable leakage thresholds to reduce tender-to-contract uncertainty and accelerate project bankability.
Risk Map: What Keeps Buyers and Sellers Up at Night
The report’s risk matrix synthesizes the material threats that could derail projects or compress returns:
- Operational risk from hydrogen leakage or seal degradation leading to unplanned outages or extended maintenance windows.
- Procurement risk stemming from ambiguous tender specifications or late-stage shifts away from hydrogen cooling in favor of air-cooled alternatives.
- Supply-chain risk for critical components (specialized seals, purity monitoring instrumentation) that have limited global suppliers.
- Regulatory risk where differing national and regional codes create fragmentation and increase compliance costs for multinational vendors.
Each risk is accompanied in the full report by mitigation strategies, contract clauses, and sample inspection protocols designed to be directly incorporated into procurement documents.
Execution Playbook: From Shortlist to Commissioning
One of the report’s most operationally valuable sections is a step-by-step execution playbook tailored for 2026 projects. It covers:
- Pre-RFP design checks and site-suitability assessments, including hydrogen-safety zoning and ventilation modelling.
- Bid evaluation scorecards that weight delivery certainty, hydrogen risk controls, and aftermarket support.
- Factory-acceptance-test (FAT) templates and commissioning sequences that prioritize hydrogen-system integrity and protection settings tuning for inertial response.
- Aftermarket service schedules and digital monitoring architectures to minimize unplanned downtime and extend interval lengths between invasive maintenance.
These templates are intentionally prescriptive so that procurement and project teams can reduce bid-to-operation timelines while preserving risk transfer and performance guarantees.
Conclusion: Positioning for the 2026 Inflection
As the synchronous condenser market shifts from pilot-phase deployments to mainstream utility adoption, 2026 will reward organizations that integrate technical rigor with commercial foresight. The market’s upward trend—reflected in our validated historical series and 2026–2032 forecast at a mid-single-digit CAGR—creates opportunity windows for suppliers able to prove hydrogen-handling competence and for buyers who structure tenders to monetize capability while controlling operational exposure.
PW Consulting’s Hydrogen Cooling Synchronous Condenser Market report is designed to be an executable bridge between strategy and operations—equipping executives with the market context, vendor intelligence and contractual instruments needed to make confident, de-risked decisions in 2026. To access the full dataset, proprietary segment analysis, and downloadable procurement templates, please visit the PW Consulting report landing page and request the complete report package.
For detailed analysis of this topic, please visit the official page: Hydrogen Cooling Synchronous Condenser Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Low Voltage Motor Control Center Market to Reach USD 8.68 Billion by 2032 on a 6.1% CAGR, with Asia‑Pacific Holding a USD 2.21 Billion Lead in 2025
By PW Consulting, 2026-07-07
Low Voltage Motor Control Center Market 2026: Strategic Imperatives from PW Consulting’s New Industry Brief
Executive snapshot
PW Consulting publishes an in-depth industry brief on the Low Voltage Motor Control Center (LV MCC) market designed to be the operational playbook for 2026 corporate decision-making. Our analysis synthesizes historical performance (2020–2025), validates a base year of 2025, and models a seven-year forecast horizon (2026–2032). The LV MCC market reached roughly USD 5,736 million in 2025 and is modeled to grow at a compound annual growth rate (CAGR) of 6.1% through 2032, driven by replacement cycles, safety upgrades, and accelerated uptake of intelligent, energy-optimizing solutions. Market concentration is moderate: the combined share of the top three firms sits under 40%, while the top five account for just over half the market — a structure that supports both consolidation and niche-specialist opportunity.
Low Voltage Motor Control Center Market
Why this brief matters for 2026 decision-makers
-
Timing and capital allocation: With a steady mid-single-digit CAGR and clear pockets of acceleration across digitalized and arc-resistant solutions, the 2026 investment window rewards purposive CAPEX aligned to energy-efficiency and safety mandates rather than blanket greenfield spending.
Low Voltage Motor Control Center Market -
Vendor selection and supplier risk: The market’s moderate concentration means procurement teams must balance scale advantages from global manufacturers with the technical fit and customization strengths of regional OEMs and remanufacturers.
Low Voltage Motor Control Center Market -
Integration and retrofits: Many industrial operators face decisions about retrofitting VFDs, intelligent starters, and IoT gateways versus full MCC replacement. Our brief provides decision frameworks that map technical benefit, labor disruption, and total cost of ownership across realistic deployment scenarios for 2026–2028.
-
Regulatory and insurance alignment: Strengthened safety expectations and insurance requirements for arc-resistant constructions are reshaping spec language. The brief translates standards and emerging insurance triggers into procurement-ready specifications and risk-avoidance checklists.
What’s inside the report: actionable, non-theoretical intelligence
-
Granular decision frameworks: Step-by-step guides that a plant-level electrical engineer or a procurement lead can use to evaluate retrofit versus replacement—covering labor, downtime, spare parts, and integration with control systems and energy management platforms.
-
Supplier scorecards and commercial playbooks: Qualitative and quantitative performance assessments across technology, delivery, aftermarket support, and digital-readiness — plus negotiation levers and contracting templates tailored to 2026 market dynamics.
-
TCO and payback models: Customizable spreadsheets that incorporate capital cost, installation, downtime, energy savings, and maintenance profiles for conventional and intelligent MCC options. These models are parameterized to reflect prevailing raw material and logistics cost environments.
-
Scenario planning and stress-testing: Three demand scenarios for 2026–2032 (base, accelerated digital adoption, and capital-constrained) with associated supply-chain stress tests, sensitivity to steel-price fluctuations, and contingency playbooks.
-
Integration blueprints: Practical checklists and sequencing guides for integrating VFDs, soft starters, IoT telemetry, and predictive-maintenance analytics into existing MCC footprints with minimal operational disruption.
-
Compliance and design guidance: Interpreting IEC 61439 and arc-resistant requirements into engineering acceptance criteria, factory test plans, and vendor QA clauses.
-
M&A and partnership signals: Criteria identifying targets for bolt-on acquisitions or strategic partnerships, and an M&A playbook with valuation sensitivities tied to product mix, service attach rates, and digital recurring revenue potential.
Market dynamics driving near-term strategy
Three convergent forces should shape corporate strategy in 2026. First, regulatory and insurer-driven safety requirements are accelerating investments in arc-resistant designs and associated features such as optical arc detection and zone selective interlocking. Second, energy efficiency mandates and plant-level decarbonization targets are increasing the adoption of intelligent MCCs embedded with VFDs, energy monitoring, and predictive analytics. Third, input-cost volatility—most notably steel—continues to influence manufacturing lead times, margin profiles, and procurement timing. Collectively, these dynamics are altering procurement cadences and making the choice of vendor and configuration a consequential strategic decision rather than a routine engineering exercise.
Competitive landscape: how to read incumbent moves
-
Global integrators and electrification specialists (ABB, Schneider Electric, Siemens, Eaton): These players are leaning into modular architectures, arc-mitigation designs, and digital ecosystems that promise faster commissioning and predictable lifecycle costs. Their global service networks and compliance credentials make them default choices for multinational projects and high-safety sectors.
-
Automation leaders (Rockwell Automation): Positioning centers on real-time diagnostics and energy monitoring platforms that layer onto MCC hardware — attractive for brownfield sites seeking incremental value through uptime and energy optimization rather than full replacement.
-
Regional and niche suppliers (WEG, Mitsubishi Electric, Powell, Tesco Controls, RESA): These firms compete on customization, local service responsiveness, remanufacturing, and price competitiveness. For industrial operators in regions with localized standards or constrained logistics, regional suppliers present compelling total-cost and schedule advantages.
-
OEM differentiation vectors: Across the board, successful vendors articulate a mix of: arc-resistant safety credentials, modularity and plug-and-play starters, interoperable IoT stacks, and aftermarket service models. Recent product and trade-show activity — including launches that emphasize real-time data and energy savings — underscores that innovation is as much about connectivity and lifecycle economics as it is about hardware.
Recent industry moves that matter for 2026
-
Product introductions and exhibitions highlight where R&D budgets are being allocated: examples include launches focused on modular IEC-compliant MCCs with enhanced real-time data capabilities, showcased at major industrial expositions.
-
Manufacturers’ trade-show participation in 2026 reaffirmed the sector’s pivot toward energy transition narratives and digitalized motor control strategies.
-
Steel price trends remain an input risk; procurement teams should anticipate periodic spikes that can materially affect enclosure and chassis costs and thus project economics.
Practical guidance for corporate leaders in 2026
-
Define procurement intent early: Decide whether the primary objective is safety compliance, energy reduction, digital enablement, or uptime improvement. Each objective drives materially different vendor shortlists and contracting strategies.
-
Use staged deployments: For large facilities, pilot intelligent MCC units in high-value lines to validate integration and quantifiable energy/uptime gains before committing to a plant-wide rollout.
-
Lock long-lead components and hedge raw-material risk: Negotiate supplier clauses that share steel and logistics variances, or secure multi-year pricing for critical components where feasible.
-
Prioritize service and data: Given the increasing importance of predictive maintenance and energy monitoring, attach-weight service SLAs and data interoperability requirements to procurement evaluations.
-
Evaluate remanufacture and retrofit economics: For many operators, a hybrid approach—retrofitting control modules and adding communications to existing MCC shells—delivers the best near-term ROI versus full replacement.
Why PW Consulting’s brief is uniquely actionable
Our methodology combines bottom-up equipment modeling, supplier capability mapping, and primary interviews across procurement, engineering, and maintenance functions. We stress-test scenarios against raw-material sensitivity analyses, regulatory trajectories (notably IEC 61439 family compliance and arc-resistant design adoption), and emerging insurance expectations. The brief translates these tests into executable templates: procurement RFP language, acceptance test plans, and integration sequencing charts that can be used directly by project teams and C-suite sponsors.
Invitation: see the full intelligence
This release intentionally highlights strategic conclusions and operational frameworks while omitting the full set of segmented figures and unit-level models that underpin our recommendations. PW Consulting’s complete LV MCC report includes detailed segmentation, supplier benchmarking matrices, and downloadable TCO models — all designed to enable confident, auditable decisions in 2026 and beyond. For access to the full report, proprietary appendices, and client-only modeling tools, please visit our report page or contact our advisory desk to schedule a briefing tailored to your company’s deployment horizon.
For detailed analysis of this topic, please visit the official page: Low Voltage Motor Control Center Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Train Locomotive Suspension Market to Expand at 4.62% CAGR, Surpassing USD 1.262 Billion by 2032
By PW Consulting, 2026-07-07
Train Locomotive Suspension Market 2026 Outlook: Strategic Imperatives for Industrial Leaders
Executive Snapshot
PW Consulting’s latest market study — the Train Locomotive Suspension Market Report (base year 2025, forecast 2026–2032) — delivers a practice-oriented playbook for executives shaping product, procurement, and investment decisions through 2026 and beyond. The global market has demonstrated steady expansion from an estimated USD 735.12 Million in 2020 to USD 920.45 Million in 2025 and, under current assumptions, is projected to grow at a compound annual growth rate (CAGR) of 4.62% over the 2026–2032 forecast window, reaching roughly USD 1.26 Billion by 2032 (USD Million). Our research combines time-series market sizing, supplier-level capability mapping, regulatory and materials risk assessment, and scenario-led strategic options tailored for OEMs, Tier-1 suppliers, and asset owners.
Train Locomotive Suspension Market
Why this report matters to 2026 decision-makers
-
Actionable translation of macro momentum into boardroom decisions — The study converts market growth trajectories and concentration metrics (CR3 ~34.2%; CR5 ~47.85%) into three strategic choices: defend, diversify, or consolidate. These choices reflect realistic trade-offs for firms of different scale and margin profiles in 2026.
Train Locomotive Suspension Market -
Focus on operational levers with immediate ROI — Beyond demand forecasting, the report emphasizes near-term levers such as lifecycle services, refurbishment pathways, and specification upgrades that unlock value within typical 12–36 month investment cycles.
Train Locomotive Suspension Market -
Integration of regulatory and materials dynamics — With heightened scrutiny from safety authorities and persistent raw-material volatility, the report embeds compliance and input-cost scenarios into product roadmaps and sourcing strategies.
What the report contains (practical, use-case driven)
-
Robust market sizing and scenario models: time-series estimates for 2020–2025 and a probabilistic forecast for 2026–2032 that allow sensitivity testing under alternative inflation, commodity, and demand scenarios.
-
Segment structure and delta analysis: segmentation by region, component, and locomotive type, with a concise interpretation of which segments are structurally attractive and which require tactical defense. (Note: detailed segment-level tables and granular values are reserved for report subscribers.)
-
Competitive capability map: comparative assessment of incumbent technology stacks, manufacturing footprint, aftermarket capacity, and R&D pipelines across leading suppliers, enabling quick benchmarking and target-setting for partnerships or M&A.
-
Procurement playbook: supplier risk heatmaps, alternative-material sourcing options, price pass-through clauses, and tactical hedging instruments calibrated for common lead-times and contract cycles in rail programs.
-
Product and engineering roadmaps: prioritized R&D themes (e.g., elastomer composite longevity, sealed hydraulic dampers, modular bogie interfaces) with estimated implementation timelines and tech-readiness checkpoints for 2026 planning.
-
Aftermarket and service strategies: monetization models for refurbishment, predictive maintenance, and long-term service agreements designed to offset OEM cyclicality and to capitalize on fleet modernization programs.
-
Regulatory compliance matrix: requirements mapping (including key standards and inspection regimes) with operational impact and certification timelines to support procurement and product validation schedules.
-
Executive playbook and decision trees: step-by-step guidance for determining whether to invest, partner, or divest across prioritized markets and technologies.
Competitive landscape: what to watch in 2026
Our benchmarking identifies a mix of diversified industrial incumbents and specialized niche suppliers shaping the suspension value chain. Leading players combine engineering depth, long lifecycle product programs, and aftermarket capabilities — a profile that favors firms able to deliver certified, durable hardware plus long-term service agreements.
-
Technology-integrated incumbents: Companies with broad portfolios in springs, air-suspension systems, and rubber-metal composite assemblies maintain advantages in OEM qualification and system integration. Their strength is reinforced by established refurbishment programs that protect margin over long asset lives.
-
Specialist damper and shock manufacturers: Dedicated hydraulics and friction-control suppliers offer differentiated ride-quality solutions and rebuildable assemblies. Their value proposition is higher unit-level engineering intensity and potential for lucrative aftermarket contracts tied to ride-performance upgrades.
-
Spring specialists and regional fabricators: Precision spring manufacturers and local suppliers remain critical to heavy-haul and regional fleets, particularly where customization, short lead-times, or local content rules influence procurement.
Representative firms covered in the report include market-leading and specialist names across Europe, North America, and Asia-Pacific. For executives preparing 2026 sourcing strategies, the report’s supplier profiles highlight where proprietary IP, refurbishment capability, and service networks concentrate, and where partnership or near-shore manufacturing could materially shorten delivery cycles.
Market dynamics and macro risks
-
Fleet modernization and retrofit demand — Major locomotive contracts and modernization programs (including sizable multi-year deals announced in 2025) are driving near-term demand for upgraded suspension and bogie systems. Suppliers should anticipate procurement windows aligned with locomotive delivery and mid-life overhaul schedules.
-
Alternative-fuel program uncertainty — Pauses or funding shifts in hydrogen or other alternative-fuel rolling-stock programs can create asymmetric demand shocks for suspension components tailored to new architecture. Firms with balanced portfolios across conventional and alternative platforms will be better insulated.
-
Regulatory tightening and certification timelines — Safety authorities have reaffirmed inspection and validation requirements for suspension and bogie systems. Compliance-driven design changes and extended testing protocols will require capital and calendar adjustments in 2026.
-
Raw-material and supply-chain volatility — High-grade steel, elastomers, and hydraulic fluids remain cost drivers; price and availability fluctuations can compress margins or lengthen lead-times. The report quantifies probable cost-pass-through thresholds and recommends tactical and strategic mitigants.
Strategic implications and recommended actions for 2026
-
For OEMs: Prioritize modularity and serviceability. Design decisions made in 2026 should reduce lifecycle retrofit costs and enable standardized service modules that third-party maintainers can support — a practical lever to lengthen revenue tails from the installed base.
-
For Tier-1 suppliers: Invest selectively in high-durability elastomer composites and sealed damper technologies that extend maintenance intervals. Coupling technical upgrades with performance-based warranties will win procurement evaluations where total cost of ownership dominates.
-
For private-equity and M&A teams: Target scale-additive acquisitions that increase aftermarket reach or secure specialized technologies (e.g., long-life hydraulic dampers, OEM-quality air-spring refurbishment). The market concentration metrics indicate room for value creation through consolidation in specific subsegments.
-
For procurement and supply-chain leaders: Implement multi-sourcing strategies for critical inputs and embed commodity-price contingency clauses in contracts. Near-shore manufacturing or strategic inventory buffers for elastomers and high-grade steels can reduce exposure to delivery disruptions.
-
For R&D and product teams: Shortlist technologies that respond to both regulatory requirements and operator pain points — noise, ride comfort, and lifecycle cost. Rapid validation pathways and early engagement with certification bodies should be built into product roadmaps to avoid rework delays.
Case-in-point evidence from recent developments
Large-scale rolling-stock contracts and modernization agreements announced in 2025 illustrate the real-world demand drivers for suspension upgrades and services. Simultaneously, strategic pauses in alternative propulsion projects highlight the need for portfolio resilience. PW Consulting’s report translates these signals into timing implications for kit deliveries, aftermarket revenue phasing, and supplier capacity planning — all calibrated to 2026 procurement cycles.
How executive teams should use this analysis
-
Board-level strategy sessions: Use our decision trees to set a clear 12–24 month posture (accelerate technology investment, pursue bolt-on acquisitions, or monetize aftermarket assets) tied to explicit financial thresholds.
-
Commercial and bid teams: Apply the report’s win-the-bid playbook to structure offers that balance capex, service-level commitments, and certification deliverables — an advantage in long-duration locomotive contracts.
-
Supply-chain operations: Implement the procurement playbook to reduce single-source exposure and to align contractual incentives with supplier capacity expansions or regional content requirements.
Next steps — where to get the full intelligence
This briefing is designed to preview the depth and practical utility of the full PW Consulting Train Locomotive Suspension Market Report. In order to preserve the commercial value of granular segment tables, supplier scorecards, and model inputs — which form the basis for operational decisions — we reserve those datasets for subscribers and clients. The full report contains downloadable scenario models, supplier shortlists, and executable implementation checklists tailored to 2026 procurement and investment calendars.
Contact and access
Senior executives and strategy teams looking to incorporate these findings into 2026 planning cycles are invited to download the full report or request a bespoke briefing with PW Consulting’s rail practice. Our analysts will walk through the scenario models, validate assumptions against your fleet or product portfolio, and co-develop 12–36 month roadmaps aligned with your strategic priorities.
For detailed analysis of this topic, please visit the official page: Train Locomotive Suspension Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: IT Spending on Clinical Analytics to Expand at 13.45% CAGR, Market Reaches USD 22,500 Million in Base Year 2025
By PW Consulting, 2026-07-07
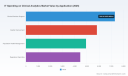
It Spending On Clinical Analytics Market — 2026 Strategic Preview from PW Consulting
Executive summary
PW Consulting’s new market study on IT Spending on Clinical Analytics Market (base year 2025) frames 2026 as a decisive year for health systems, payers, life-sciences firms and technology vendors. Our analysis projects sustained double‑digit expansion driven by AI-enabled clinical use cases, cloud maturation, and growing pressure on outcomes and cost containment. The market expanded to an estimated USD 22,500 Million in 2025 and is projected to continue growing at a compound annual growth rate (CAGR) of 13.45% through our 2026–2032 forecast horizon — a trajectory that doubles down on analytics as a strategic, rather than purely operational, investment.
It Spending On Clinical Analytics Market
Why this matters for enterprise decision-makers in 2026
- Budget prioritization: When IT and clinical leaders allocate capital in 2026, analytics investments will compete directly with platform modernization, AI infrastructure and regulatory compliance. Our report quantifies the overall market scale and growth velocity to help CFOs and CIOs benchmark spending ambition and justify multi‑year investment plans.
- Vendor strategy: The market exhibits moderate concentration (top‑three share ~28.4%; top‑five ~36.2%), implying a healthy mix of incumbents and specialized challengers. That structure creates opportunities for strategic partnerships, targeted procurement, and selective M&A — but it also requires careful vendor risk assessment.
- Regulatory and infrastructure cost exposure: New energy and data‑center regulations, plus DOJ restrictions on bulk health‑data transfers, materially affect sourcing and cloud‑hybrid decisions. We translate these dynamics into practical sourcing constraints and scenario stress tests.
Key market signals — headline metrics
PW Consulting’s headline findings offer a compact, decision‑ready view: the market reached USD 22.5 billion (2025, USD Million base) and is forecast to grow at a 13.45% CAGR across the 2026–2032 period. By 2032, our model anticipates a substantial market expansion reflecting the cumulative effect of AI platform adoption, expanded analytics services and growing demand for integrated clinical workflows. These macro figures are designed to anchor portfolio planning, vendor engagement and M&A sizing exercises.
It Spending On Clinical Analytics Market
What the report contains — practical, actionable modules
Our report is organized for immediate use by strategy, procurement and clinical leadership teams. It includes:
It Spending On Clinical Analytics Market
- Market sizing and demand drivers: a transparent, reproducible model that ties spending to provider, payer and life‑science adoption curves.
- Adoption scenarios and financial impact models: three forward scenarios (base, accelerated, constrained) that translate technology adoption into operational KPIs such as avoidable admissions, readmission reduction and cost per case improvements.
- Vendor and capability mapping: a practice‑oriented taxonomy that aligns vendor capabilities to buyer use cases (e.g., clinical decision support, population management, quality programs) while preserving our proprietary segment-level intelligence behind a gated analysis.
- Procurement playbooks and contract guardrails: negotiation templates and service-level checklists for cloud, managed‑service and software purchases, emphasizing data residency, model governance and energy‑cost pass‑through clauses.
- Regulatory, energy and data governance playbooks: scenario planning templates that quantify potential carrying costs associated with evolving state‑level data‑center rules and DOJ data‑transfer limitations.
- M&A and partnership scorecards: diligence frameworks and synergy valuation approaches tailored for acquirers and target companies in clinical analytics and adjacent segments (imaging, EHR, RWE).
Competitive landscape — what to watch in 2026
The clinical analytics ecosystem is a blend of large platform incumbents, specialist analytics firms, and adjacent diagnostic and device players. We profile leaders across these archetypes and evaluate strategic positioning, strength corridors, and risk exposures:
- Optum Inc. (UnitedHealth Group): Leverages deep claims and clinical data assets to monetize population‑level analytics and risk‑stratification capabilities. Strengths include scale of data, payer‑provider integration and end‑to‑end managed services; watch for integration and regulatory scrutiny as these platforms expand.
- Oracle Health (formerly Cerner): Emphasizes integrated EHR + analytics offerings and recent platform expansion moves. Their playbook targets hospital efficiency and clinician decision support; integration cadence and cloud migration economics are key adoption triggers.
- Epic Systems Corporation: Continues to embed analytics within enterprise EHR workflows, offering tight clinician integration and real‑world evidence capabilities. Epic’s installed base creates natural retention, but interoperability and third‑party analytics partnerships will define its competitive edges.
- IQVIA: Positioned at the intersection of life sciences and clinical data, IQVIA drives RWE and outcomes research; expect increasing collaboration between life sciences analytics and provider decision support.
- SAS Institute Inc. and Health Catalyst: Both offer strong analytics platforms — SAS with advanced statistical modeling and Health Catalyst with integrated clinical/financial datasets aimed at quality improvement and cost reduction.
- GE HealthCare and Siemens Healthineers: Diagnostic and imaging vendors are doubling down on analytics to link imaging and monitoring data into clinical workflows, a powerful vector for enterprise clinical insight monetization.
- Merative, Koninklijke Philips, Veradigm and McKesson: Each brings differentiated strengths — data consolidation, connected care, ambulatory analytics, and supply‑chain analytics respectively. Their strategies reflect horizontal integration and vertical market plays.
Across vendor types, our analysis highlights three tactical themes for buyers: (1) demand for composable analytics that fit existing EHR ecosystems; (2) growing importance of managed services for AI model ops; and (3) the emergence of outcome‑linked commercial models.
Dynamics, risks and externalities shaping 2026 decisions
Several non‑functional dynamics are reshaping how analytics spending converts to outcomes:
- Data center and AI infrastructure costs: Independent analysis shows substantial hidden external costs associated with data centers supporting AI and analytics workloads. These costs are increasingly internalized via energy surcharges and grid‑impact tariffs in state regulation, altering TCO for cloud versus on‑prem choices.
- State‑level data‑center regulation: A wave of U.S. state actions in 2025–2026 is shifting the burden of new energy and transmission infrastructure to large data center operators. Organizations relying on public cloud providers should re‑evaluate contract clauses and geographic resilience assumptions.
- DOJ restrictions on bulk health data transfers: New rules limiting bulk transfers of sensitive health data to certain jurisdictions materially influence cross‑border analytics collaborations and vendor selection for multinational projects.
- Macro AI infrastructure investment: With broad industry estimates putting AI infrastructure spending in the hundreds of billions in 2026, competing priorities around talent, GPU capacity, and sustainability objectives will shape execution timelines for advanced clinical models.
Strategic recommendations for 2026 — three priorities
- Adopt a quadrant funding approach: Allocate investments across foundational data ops, clinical use‑case pilots, scalable platform subscriptions and regulatory/compliance contingencies. Use our scenario models to size staged investments tied to measurable clinical KPIs.
- Design contracts for volatility: Insist on energy‑cost pass‑through protections, data residency guarantees and clear model governance obligations. Where possible, build outcome‑based clauses to align vendor incentives with clinical and financial goals.
- Pursue modular vendor architectures: Favor composable, API‑driven analytics stacks that permit swapping of components (e.g., model providers, MLOps, visualization) without wholesale rip‑and‑replace, reducing strategic lock‑in and improving negotiation leverage.
How to use this report in boardrooms and strategy sessions
PW Consulting’s market report is designed for immediate translation into governance and investment artifacts. Typical uses include:
- Capital allocation templates for the CFO office that reconcile analytics spend to expected quality and margin improvements;
- Procurement scorecards that incorporate vendor risk on data residency, energy cost exposure and model validation;
- M&A diligence checklists to size revenue synergies and integration risk vis‑à‑vis clinical workflow adoption;
- Regulatory scenario decks for compliance teams that map new state and federal legislative actions into sourcing outcomes.
Conclusion — the strategic value of the report in 2026
For leaders making allocation and sourcing decisions in 2026, understanding the macro scale and growth trajectory of clinical analytics spending is table stakes. PW Consulting’s study provides that top‑line perspective — alongside pragmatic modules for procurement, governance and scenario planning — while carefully preserving segment‑level intelligence to be accessed via the full report. In an environment of accelerating AI investments, tightening regulatory constraints and shifting energy economics, this study is intended to be the neutral, evidence‑based input for executives deciding not just what to buy, but how to build sustainable, auditable and outcome‑oriented analytics capability.
Get the full analysis
This press overview highlights our methodological approach, headline market sizing and the strategic lenses we apply. Detailed segment breakdowns, vendor scorecards, and downloadable modeling workbooks are available in the full PW Consulting report. Contact our research team or visit the report page to obtain the complete dataset and bespoke advisory engagement options.
For detailed analysis of this topic, please visit the official page: It Spending On Clinical Analytics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Endodontics Market 2026 Outlook: Strategic Imperatives for Manufacturers, Payers and Providers
Executive summary
PW Consulting’s Endodontics Market report (base year 2025) frames the coming seven-year window as a period of steady expansion and structural change. The global endodontics market reached approximately USD 1.85 billion in 2025, having grown from roughly USD 1.35 billion in 2020. At a forecast compound annual growth rate (CAGR) of 6.5% for 2026–2032, the market is projected to surpass USD 2.8 billion by 2032. These headline metrics reflect a blend of demand-side drivers — demographic shifts and rising disease burden — and supply-side evolution in materials, instruments, and workflow integration. For executives making 2026 strategic choices, the window for capturing sustainable share is open but requires targeted investment across product, regulatory and commercial domains.
Endodontics Market
Why this matters for 2026 decision cycles
-
Portfolio prioritization: With predictable market growth, fiscal 2026 is the moment to prioritize product roadmaps that align with single-use, bioceramic, and integrated digital workflow trends. The difference between defendable and vulnerable roadmaps will be how well product development addresses infection-control expectations and streamlined clinical workflows.
Endodontics Market -
M&A and partnership timing: Moderate market concentration and the accelerating pace of workflow-centric launches create attractive windows for bolt-on acquisitions and strategic partnerships, especially for companies that can combine instrumentation with obturation, irrigation and digital guidance.
Endodontics Market -
Regulatory and reimbursement planning: New and harmonized standards around obturation materials and dimensional requirements, together with expanding dental reimbursement in mature markets, change commercialization tactics — from labeling and clinical validation to payer engagement.
Market dynamics that will shape competitive advantage
-
Clinical demand: Global demographic aging and the persistent prevalence of dental caries and pulpal disease sustain procedure volumes. This is not a short-term spike but a secular trend that supports premiumization of clinical techniques and materials over time.
-
Standards-driven product evolution: EN ISO 6876:2025 and related proposed adoptions (notably an ANSI/ADA proposal mirroring ISO 6877:2025) sharpen technical requirements for sealing materials and obturating devices. Manufacturers who proactively align R&D and quality systems to these standards will reduce time-to-market friction and streamline payer conversations.
-
Infection-control and single-use adoption: Heightened infection-control regulations in several developed markets are accelerating the shift toward single-use endodontic instrumentation and consumables. This trend has implications across unit economics, supply-chain design and environmental policy risk — all of which should be modelled into 2026 budgets.
-
Workflow integration and digitalization: The market is moving beyond component sales to systems thinking — motors, file systems, obturation devices and imaging tied to simplified clinical workflows. Recent product introductions underscore a supplier emphasis on workflow-solutions versus standalone tools.
-
Reimbursement tailwinds: Incremental increases in dental insurance coverage for advanced endodontic procedures in several major markets underpin willingness to adopt higher-cost, higher-value therapies. Commercial teams should prioritize payer evidence-generation plans in 2026.
Competitive landscape: what leading players are doing
The competitive field combines global platform leaders, regional specialists and fast-moving innovators. Leading manufacturers have broadened plays from files and obturation materials into motors, digital devices and integrated disposables. At the same time, companies with deep materials science expertise are leveraging bioceramics and sealers to capture higher-margin segments. Recent product and partnership activity illustrates these strategic themes:
-
Dentsply Sirona: Continuing to position itself as a systems provider, the company’s recent launches (most notably a new endo file system and a next-generation wireless endo motor) accentuate a platform approach that integrates instrumentation, motors and imaging. Expect Dentsply Sirona to press on cross-sell and workflow bundling as a primary growth lever.
-
Envista/Kerr: With product introductions focused on simplified obturation and carrier systems, this player emphasizes ease-of-use and clinic efficiency. Their approach signals the commercial appeal of “faster, simpler, reliable” solutions in general practice settings.
-
Ultradent and material specialists: Firms with bioceramic and irrigation portfolios are directing R&D toward material performance and disinfection efficacy, creating differentiation that supports premium pricing if clinical and regulatory evidence are marshalled.
-
European and Japanese specialists (COLTENE, FKG, VDW, MANI, Micro‑Mega, etc.): These firms often lead on niche technical innovations (advanced NiTi metallurgy, heat treatments, and workflow concepts) and are increasingly attractive partners for distribution and co-development agreements.
-
Smaller and agile innovators: Companies focusing on heat-treated NiTi files, obturation consumables and device ergonomics remain important sources of disruptive capability, particularly when they can integrate with established distributors or clinical networks.
Recent product and partnership highlights — reading the signals
-
New file systems and motors announced across the industry in 2025–2026 signal an emphasis on procedural efficiency and clinician ergonomics. Expect further convergence between instrumentation and drive systems as vendors pursue higher attach-rates for consumables.
-
Commercial partnerships and distribution pacts — seen in recent alliances — indicate a preference for go-to-market breadth over standalone R&D. For buyers and investors, partnerships can accelerate access to regional channels without immediate heavy capital outlays.
What PW Consulting’s report delivers — practical, transaction-ready outputs
PW Consulting’s Endodontics Market report is structured to support executable decisions in 2026. Key deliverables include:
-
Top‑line market sizing and forecasts (2020–2032) at global and major market levels, with scenario modeling to stress-test reimbursement, regulatory and product adoption assumptions.
-
Technology and product landscape maps that benchmark instrumentation, obturation, irrigation, imaging and consumables by clinical role, maturity and adoption drivers.
-
Regulatory and standards tracker (including implications of EN ISO 6876:2025 and related standards) with compliance impact matrices for product development, labeling and clinical validation plans.
-
Commercial playbooks for manufacturers and distributors: pricing levers, bundling strategies, channel mapping and provider segmentation to optimize 2026 go-to-market plans.
-
M&A and partnership screening tool: prioritized target profiles, valuation heuristics and integration risk assessments for buyers and strategic partners.
-
Competitive profiles and a deal/innovation chronology capturing the most consequential moves through early 2026.
Note: this release intentionally provides a high-level synopsis. Detailed segment tables, historical annualized revenue by subsegment and granular company market share tables are reserved for the full report and our online data portal.
Actionable recommendations for each stakeholder group
-
Manufacturers: Prioritize modular product architectures that enable both disposable and reusable elements; accelerate compliance programs for new sealing material standards; and build evidence-generation plans to support payer coverage discussions in key markets.
-
Distributors and dental chains: Reconfigure inventory and logistics to support single-use adoption and bundled workflow solutions; invest in clinician training to speed adoption of new file systems and obturation techniques.
-
Investors and M&A teams: Target bolt-on acquisitions that add workflow elements (motors, obturation devices, imaging) or proprietary materials that raise switching costs. Due diligence should stress-test regulatory readiness and clinical evidence pipelines.
-
Payers and policy makers: Recalibrate coverage policies to incentivize evidence-based, higher-value endodontic procedures that reduce long-term restorative and extraction costs, while monitoring environmental and waste implications of single-use adoption.
-
Clinicians and academic centers: Evaluate integrated workflow offerings that demonstrably reduce chair time or improve outcomes; participate in registries and post-market surveillance to strengthen the real-world evidence base.
Conclusion — the strategic takeaway for 2026
Endodontics is moving from component sales to systems-driven solutions in a market that is both growing and maturing. The predicted 6.5% CAGR through 2032 creates a predictable growth platform, but competitive advantage will accrue to organizations that can combine product innovation, regulatory foresight, and commercial execution. Whether the objective is to defend share, accelerate growth through partnerships, or execute an acquisition, 2026 is a pivotal planning year: the investments and alliances made now will determine who captures the upside of workflow integration, bioceramic differentiation and standards-aligned product portfolios.
How to access the full analysis
This briefing is an executive preview. For the complete dataset, segmented forecasts, company market shares and interactive scenario models, access PW Consulting’s full Endodontics Market report and data portal. Our clients receive customizable workshops and one-on-one advisory for translating these insights into commercially executable plans for 2026.
For detailed analysis of this topic, please visit the official page: Endodontics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


