



Category: market research
PW Consulting: Intellectual Disabilities Services Market Poised for 6.19% CAGR Through 2032, New Report Shows
By PW Consulting, 2026-07-02
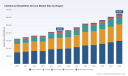
Intellectual Disabilities Service Market — 2026 Strategic Preview
Executive overview
PW Consulting’s newest market study, Intellectual Disabilities Service Market: 2026–2032, is released with a clear executive imperative: translate market momentum into executable strategies for the coming planning cycle. Anchored on a base year of 2025 and a historical review from 2020–2025, the study quantifies a market that has expanded markedly over the past half-decade and that our modelling projects will continue to grow at a compound annual growth rate of 6.19% through 2032. In plain terms, the market moved from roughly USD 325.5 billion in 2020 to about USD 424.5 billion in 2025 and is projected to approach USD 646.8 billion by 2032.
Intellectual Disabilities Service Market
Why this report matters for 2026 decision-making
2026 is a pivot year for operators, payors, investors, and policymakers in the intellectual disabilities services ecosystem. Converging forces — demographic demand, regulatory updates to HCBS quality and ICF/IID conditions of participation, wage and labor market shifts, and the rapid adoption of digital therapy platforms — mean that strategic choices made in 2026 will determine financial resilience and mission impact for the rest of the decade. This report is designed to convert broad market signals into concrete actions: where to invest in service delivery, how to redesign workforce models for retention and quality, how to approach M&A and partnerships, and how to structure contracts and reimbursement negotiations in an increasingly value-driven environment.
Intellectual Disabilities Service Market
What’s inside: operational, decision-ready content
-
Proprietary market sizing and scenario forecasts (base year 2025; forecast 2026–2032) with three alternative macroeconomic and policy scenarios to stress-test investment cases.
Intellectual Disabilities Service Market -
Service delivery playbooks that map workforce models, technology adoption timelines, and clinical integration checklists for residential, HCBS, vocational, and therapeutic settings.
-
Reimbursement and contracting guide: payer archetypes, negotiation levers, and a forensic framework for rate-setting and outcome-based contracting (national and state-level playbooks included).
-
M&A and partnership playbook: target screening criteria, valuation drivers, integration checklist, and post-merger operating model templates for scaling community-based services.
-
Practical KPIs and a 90–180 day operational roadmap for service providers to improve quality scores, reduce DSP vacancy, and prepare for managed care transitions.
-
Risk and regulatory heatmaps (including CMS HCBS quality measure changes and ICF/IID compliance obligations), plus mitigation playbooks for executives and boards.
-
Case studies and validated templates: sample RFIs/RFPs for payors, supplier contracting terms, and workforce compensation models aligned to state funding realities.
Market trajectory and strategic implications
The aggregate market trajectory — a recovery and step-up from 2023 into 2024–2025 and steady expansion into the early 2030s — reflects both structural demand (aging cohorts, earlier diagnosis and intervention, increasing service intensity) and policy-driven flows (Medicaid program design, HCBS evolution). The projected 6.19% CAGR through 2032 signals a market with both scale and fragmentation. For strategic planning in 2026, that implies three practical priorities: (1) define a defensible service footprint and partnership model; (2) reconfigure workforce strategy to manage labor cost inflation and retention risk; and (3) invest judiciously in digital modalities that demonstrably reduce cost-per-outcome.
Competitive landscape — who to watch and why
The sector remains highly fragmented; top-three and top-five concentration metrics confirm ample room for regional consolidation and new entrants. Several incumbent organizations and networks are shaping the competitive environment through acquisitions, partnerships, and platform launches:
-
Sevita (including The MENTOR Network and ResCare Community Living) — a national-scale operator focused on person-centered residential and HCBS models. The recent aggregation of capabilities positions Sevita as a fulcrum for continuity-of-care strategies across geographies.
-
BrightSpring Health Services — active on both the acquisition and portfolio-management fronts; its movement in and out of community living operations demonstrates a playbook of building integrated care offerings while optimizing asset portfolios.
-
Mosaic — a mission-driven operator with deep state-level proficiency in residential and 24-hour supports; representative of organizations translating scale into improved community inclusion outcomes.
-
The Arc of the United States — an advocacy and networked delivery model that can accelerate supported employment and policy influence when aligned with provider partners.
-
Keystone Human Services, Community Options, AbleLight, Devereux, Easterseals, KenCrest, Bayada, Lifeworks, and UCP — these organizations together illustrate the spectrum from national networks to regional specialists, each bringing distinct operating models, funding relationships, and community integration strategies.
Recent transactions and platform launches underscore strategic themes: consolidation for geographic scale and payer contracting leverage; digitization of therapy and tele-rehabilitation; and public–private collaboration to manage Medicaid transitions. Representative developments include BrightSpring’s portfolio moves and the rollout of tele-rehab platforms that expand access and change cost-per-session economics.
Regulatory, reimbursement, and labor dynamics shaping 2026 choices
-
Reimbursement: State Medicaid flows remain the dominant revenue engine for many service models. As an illustrative datapoint, New York State’s OPWDD reported Medicaid spending of approximately USD 9.1 billion in 2023 to serve over 130,000 individuals — an indicator of the scale and the degree to which state policy shifts can rapidly alter provider economics.
-
Regulation: Federal updates to HCBS quality measurement and the ongoing application of Medicare/Medicaid Conditions of Participation for ICF/IID settings increase compliance complexity and require board- level governance attention.
-
Labor cost and workforce: State-funded rate reforms, where present, have demonstrably reduced DSP vacancy in jurisdictions investing in rates and wages. Building flexible staffing models and embedding training-to-career pathways are essential 2026 actions to stabilize operations.
-
Managed care and program design: The expansion of managed care models in select states alters contract negotiation dynamics and necessitates robust outcomes measurement and care coordination infrastructure.
Strategic playbook — recommended actions for 2026
-
Providers: Prioritize revenue diversification and payer mix optimization; implement a phased digital-therapy deployment to realize productivity gains; redesign DSP roles with tiered certification and career ladders to reduce turnover.
-
Payors: Standardize outcome metrics in contracts, pilot shared-savings programs for supported employment and community inclusion, and require interoperable care plans to reduce care fragmentation.
-
Investors and acquirers: Focus on assets with proven state contracting relationships, scalable HCBS platforms, and embedded clinical governance; use scenario models from this report to stress-test reimbursement sensitivity.
-
Policymakers and system architects: Target funding reforms that tie rate increases to measurable quality gains, accelerate HCBS measurement implementation, and finance workforce development programs that reduce vacancy risk.
How PW Consulting’s report converts analysis into action
This report was constructed for operators who must make capital allocation, network design, and contracting decisions in 2026 with imperfect information. It combines a quantitative core (market sizing and scenario modeling), primary research (provider and payer interviews), and operational templates (integration checklists, procurement forms, KPI dashboards). In practical terms, a CEO can use the forecast and scenario outputs to re-weight capital plans; a payer can use the contracting templates to pilot outcome-based agreements; and an investor can use the valuation sensitivity models to price deals under alternative reimbursement regimes.
Market structure: fragmentation presents opportunity
Concentration metrics show the sector remains fragmented — a structural signal that consolidation, platform roll-ups, and strategic partnerships will continue to be strategic value-creation levers in 2026. Low top-player shares mean acquirers that can pair clinical quality with operational scalability will capture disproportionate bargaining power with payors and buyers.
Takeaway and next steps
PW Consulting’s Intellectual Disabilities Service Market: 2026–2032 is a tool for translating macro trends into boardroom-ready decisions. The market’s scale and growth trajectory create both opportunity and urgency: organizations that align workforce strategy, digital capability, and payer contracting in 2026 will be positioned to capture outsized value as the market expands over the next decade.
To preserve the utility of our strategic insights while protecting the detailed segmentation and primary-data tables that underpin robust decision-making, this piece intentionally highlights high-level findings and practical implications. The full report includes detailed regional and service-setting splits, payor-channel analyses, state-level reimbursement matrices, and downloadable operational templates to support immediate implementation.
Accessing the full analysis
Executives seeking the full dataset, segmented forecasts, and turnkey implementation assets should visit the PW Consulting report page to download the complete study and arrange a bespoke briefing. The full deliverable is designed to be operationalized within 30–90 days and includes a tailored decision-support session to apply the findings directly to your 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Intellectual Disabilities Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Naloxone Market Poised for Robust 8.2% CAGR Through 2032
By PW Consulting, 2026-07-02
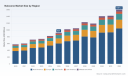
Naloxone Market: Strategic Imperatives for 2026 — PW Consulting Insights
As PW Consulting’s Senior Strategic Advisor and Head Industry Analyst, I present a high-conviction briefing derived from our new Naloxone Market research — a report built for decision-makers preparing for 2026. The market reached approximately USD 920.0 Million in 2025 (base year) and, under our central scenario, expands to roughly USD 1,022.6 Million in 2026. Our forecast period (2026–2032) applies an 8.2% CAGR to project medium-term demand trajectories and to stress-test strategic options for manufacturers, distributors, public-sector buyers, and investors.
Naloxone Market
Why 2026 is a Strategic Inflection Point
-
Policy and access have shifted decisively. FDA authorization of over-the-counter naloxone nasal spray (effective 2023) and subsequent reimbursement moves — such as Medicare Part D coverage without prior authorization — have accelerated retail-level demand and broadened payer involvement. These changes convert naloxone from a largely institutional, prescription-supported product into a mass-market public health commodity.
Naloxone Market -
Demand is driven by an acute public-health necessity. Provisional national data show more than 81,000 opioid-related overdose deaths in the 12 months ending October 2023, prompting sustained government procurement and distribution programs. Supply commitments by national health authorities and stockpiles materially alter manufacturer revenue visibility and procurement dynamics.
Naloxone Market -
Supply-side friction remains a core risk. Intermittent listing of naloxone injection on the FDA drug shortage database through 2024 underscores fragile manufacturing and raw-material bottlenecks at times of surge demand. At the same time, manufacturing quality events and recalls in recent years highlight operational risk that can quickly translate into lost market share and reputational damage.
-
Market structure is moderately concentrated. Our concentration metrics indicate that the top three and top five players account for meaningful shares of supply, creating competitive pressure on pricing while leaving space for niche device innovation and regional players to capture adjacent channels.
What Our Report Delivers — Practical, Transactional, and Actionable
The report is designed as an execution toolkit for 2026. It combines robust macro forecast outputs with operational playbooks and decision-grade intelligence. Key deliverables include:
-
Executive synthesis of market drivers, barriers, and windows of opportunity for 2026 execution plans.
-
Top-line historical and forecast market sizing (2020–2025 history; 2026–2032 projections) with scenario modeling under alternative policy, pricing, and supply assumptions. Note: detailed segment-level numeric tables and regional/application splits are reserved for the full report to preserve client value and are not reproduced in this release.
-
Competitive intelligence dossiers and supplier scorecards covering regulatory posture, manufacturing capacity, unit economics, and go-to-market capabilities.
-
Commercial playbooks: channel-pricing scenarios for OTC vs. prescription channels; tender response templates for government procurements; retailer shelving and patient access strategies.
-
Supply-chain resilience matrix: risk heat maps, alternative sourcing options, and tactical contingencies for shortage events and quality incidents.
-
M&A and partnership screening: prioritized target lists and valuation heuristics for manufacturing scale, device IP, and distribution reach.
-
Regulatory and reimbursement navigation guides tailored to North America, Europe, and other priority jurisdictions emphasizing timelines and levers to expedite market access.
Competitive Landscape — Strategic Implications for Key Players
Our competitive analysis distills how incumbents and new entrants are likely to behave in 2026, and what that means for challengers and partners.
-
Emergent BioSolutions — As the maker of the leading OTC-branded nasal spray, Emergent benefits from strong brand recognition and over-the-counter distribution roll-out. Strategic imperatives for Emergent include defending retail shelf space, optimizing twin-pack consumer offerings for point-of-sale conversion, and fortifying supply agreements with public-sector agencies. Their OTC capability creates a high barrier to entry for branded competition but also makes them a primary target for price competition from generics.
-
Amphastar Pharmaceuticals — A core injectable supplier with extensive emergency-medical-use reach. Amphastar’s manufacturing footprint and product formats are vital to institutional channels. However, historical quality events and recalls have operational and reputational implications; remediation and transparent capacity assurances will be central to regaining and expanding institutional contracts in 2026.
-
Teva, Viatris, Hikma, Pfizer (Hospira), and Sandoz — These multinational generics and institutional players exert downward pricing pressure in both nasal and injectable segments. Their strengths are scale manufacturing, established pharma distribution networks, and tender participation capabilities. Expect intensified bidding behavior in public procurements and a continued shift of naloxone into the low-margin, high-volume generics domain, particularly as more generic nasal equivalents gain regulatory approvals.
-
New entrants and device innovators — Autoinjector and user-friendly delivery innovations are a strategic wedge. While current autoinjector penetration remains limited, device differentiation can command premium pricing in specific channels (e.g., institutional, first-responder kits) and open licensing or partnership opportunities.
-
Recent industry developments sharpen these dynamics: nationwide OTC availability of branded nasal formulations and FDA approval of generic nasal sprays in 2024 have lowered barriers for mass-market uptake; large-scale government procurements (e.g., multi-million-dose stockpile purchases) reinforce the importance of contract supply capability; and intermittent injection shortages keep agility and redundancy on the forefront of buyer evaluations.
2026 Playbook — Concrete Actions by Stakeholder
-
Manufacturers : Prioritize dual-channel strategies (OTC retail + institutional tenders). Invest now in capacity redundancy, quality systems, and spot-source flexibility. Consider licensing or bolt-on acquisitions that bring device differentiation or large-scale sterile injectable capacity.
-
Distributors & Retailers : Reconfigure merchandising to treat naloxone as a public-health staple (visibility, consumer education materials, payer-facing signage). Negotiate volume-based procurement terms tied to reimbursement flows.
-
Government & Payers : Balance stockpiling with rotational inventory models to mitigate expiry waste. Use multi-vendor contracting to reduce single-source risk and include supply-performance clauses tied to quality and delivery KPIs.
-
Investors & M&A Teams : Target assets that reduce manufacturing risk (sterile production lines), add device IP (autoinjectors), or expand low-cost generics capacity in jurisdictions with favorable reimbursement rules. Value accretion will come from operational scaling and integration into public-procurement pipelines.
-
Nonprofits & Community Programs : Leverage OTC availability and payer coverage to expand community distribution while building training and outcome-tracking partnerships with local health systems to demonstrate impact and secure public funding.
How PW Consulting Supports 2026 Execution
Our practice combines health-policy, operations, and commercial execution expertise. For clients moving into 2026 we offer a suite of fast-start services:
-
Rapid market-entry assessment and prioritized channel playbook (30-day deliverable).
-
Supply-chain stress-test and contingency design, including dual-sourcing roadmap and capacity build vs. outsource decision framework.
-
Competitive benchmarking and tender-response playbooks tailored to major public-procurement formats.
-
M&A diligence focusing on manufacturing quality, regulatory history, and integration risk mitigation.
-
Investor-facing valuation scenarios incorporating reimbursement tails and device-premium forecasts.
Closing — The Intelligence You Need (and Where to Get It)
Naloxone’s market is transitioning from episodic institutional demand to a sustained, multi-channel public-health market. The headline numbers — a near-term rise from approximately USD 920.0 Million in 2025 to about USD 1,022.6 Million in 2026, and an 8.2% CAGR across our forecast window — capture the scale of the opportunity. But strategic success in 2026 will be determined at the intersection of manufacturing resilience, channel economics, regulatory navigation, and partnership execution.
In this briefing we have intentionally presented high-level, decision-oriented intelligence while withholding detailed segment-level and regional tables to preserve the actionable value of our proprietary analysis. The full report contains the granular slicings of the market, segmented forecast models, supplier-level financial proxy sheets, and downloadable tender templates that clients need to operationalize plans in 2026.
To obtain the complete Naloxone Market report, schedule a briefing, or commission a tailored 90-day execution roadmap for 2026, please visit our official release page or contact PW Consulting’s Health & Life Sciences team for a confidential consultation.
For detailed analysis of this topic, please visit the official page: Naloxone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Plastic Roof Cement Market to Grow from USD 945.5 Million in 2025 to USD 1,317.15 Million by 2032 at a 4.85% CAGR — North America (USD 380.62M) and Asphalt-based Cement (USD 617.08M) Lead, Top 5 Hold 45.15%
By PW Consulting, 2026-07-02
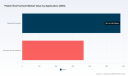
Plastic Roof Cement Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
PW Consulting’s latest market study on Plastic Roof Cement distills a comprehensive, decision-ready view of an industry at the intersection of infrastructure demand, volatile feedstock markets, and tightening product standards. Anchored to a 2025 base year, the report shows the global market reached approximately USD 945.5 Million in 2025 and is expected to expand at a compound annual growth rate (CAGR) of 4.85% over the 2026–2032 forecast window. By 2032 the market is projected to surpass USD 1.3 Billion, creating a predictable runway for strategic moves across product development, procurement, and channel investment.
Plastic Roof Cement Market
What this report delivers — practical, operational intelligence
- Forward-looking market sizing and a flexible forecasting engine calibrated to 2020–2025 historical performance and macro scenarios for 2026–2032.
- Demand-driver analysis that links end-market construction activity, roofing replacement cycles, and maintenance spend to product segment dynamics.
- Supply-side diagnostics covering raw-material exposure (bitumen/asphalt, solvents, fibers), regional sourcing risk, and cost pass-through levers.
- Commercial playbooks for manufacturers and distributors: price elasticity models, channel segmentation, and product-packaging optimization templates.
- Competitive benchmarking and capability maps that prioritize technical differentiators (e.g., fiber reinforcement, wet/dry adhesion, low-solvent formulations) and route-to-market strength.
- Transaction support tools — M&A screens, integration checklists and valuation sensitivities keyed to concentration metrics and margin dynamics.
- Operational toolkits: inventory hedging scenarios, supplier scorecards, contract-clause language for feedstock volatility, and a regulatory compliance checklist.
Note: This release outlines the strategic framework and high-level results. Detailed segment tables and company-level share data (the granular numbers that drive go/no-go capital allocation) are intentionally reserved for the full report and downloadable models available via our source page.
Plastic Roof Cement Market
Top strategic takeaways for 2026 decision-makers
- Size investments to a stable growth baseline: The market’s mid-single-digit CAGR (4.85%) and the 2025 market level provide a defensible growth trajectory for capacity and R&D decisions. Capital deployed to expand differentiated product lines (fiber-reinforced, low-solvent, wet/dry mastics) should be sized against the 2032 upside while preserving flexibility for downside scenarios.
- Hedge raw-material exposure now: Bitumen and solvent price volatility materially affect margins. The report provides scenario models demonstrating how short-term spikes in bitumen can erode gross margins unless procurement establishes fixed-term purchase agreements, regional sourcing diversification, or indexed pass-through pricing with channel partners.
- Prioritize product reformulation to meet standards and commercial demand: Regulatory and buyer expectations around asbestos-free, low-solvent formulations (e.g., ASTM D4586 Type I and Federal Spec SS-153 Type I) are non-negotiable in many commercial tenders. Reformulation is both a compliance necessity and an opportunity to claim premium positioning on safety and environmental attributes.
- Differentiate at the channel level: Retail/DIY and contractor channels value different attributes — packaging convenience and cartridge formats for retail; robustness and performance granularity for contractors. Tailor SKUs, pack sizes, and technical collateral to channel economics to improve sell-through and margin capture.
- Use industry concentration to inform M&A and partnership strategies: The market shows a moderate concentration profile at the top end. This creates tactical windows for bolt-on acquisitions that add specialized chemistries, geographic footprints, or distribution access without large-scale market distortion.
- Operationalize sustainability and cost-efficiency together: Reducing VOCs and solvent intensity not only addresses regulatory risk but can lower logistics and handling costs. The report maps technology pathways where sustainability and unit-cost improvements are mutually reinforcing.
Competitive landscape — who matters and why
The market is populated by established manufacturers and building-material brands with complementary strengths in product formulation, distribution reach, and brand recognition. PW Consulting’s qualitative benchmarking assesses core players on formulation technology, channel coverage, and tactical agility:
Plastic Roof Cement Market
- Henry Company (El Segundo, CA; https://www.henry.com) — Known for premium trowel-grade asphalt-based sealants engineered for durability; strong technical specs for flashing and repair applications.
- GAF (Parsippany, NJ; https://www.gaf.com) — Leverages large roofing-system portfolios and dealer networks; broad-based product that targets general-purpose repair and maintenance use cases.
- Karnak Corp. (Clark, NJ; https://www.karnakcorp.com) — Specialist trowel-applied compounds with seasonal grade variants; product depth in flat-roof repair and professional-grade applications.
- Gardner-Gibson (Tampa, FL; https://www.gardner-gibson.com) — Market presence in all-weather repairs and cross-substrate adhesion opportunities (metal, asphalt).
- Rust-Oleum (Vernon Hills, IL; https://www.rustoleum.com) — Offers fibered asphalt-based solutions; packaging breadth (cartridges to pails) supports multi-channel distribution.
- Polyglass U.S.A., Inc. (Deerfield Beach, FL; https://polyglass.us) — Positions products for ASTM-compliant asphalt roof repairs and flashing applications; strong systems orientation.
- PrimeSource / Grip-Rite (Irving, TX; https://grip-rite.com) — Emphasizes wet-or-dry adhesion and contractor convenience — a commercial differentiator in repair markets.
- TAMKO (Joplin, MO; https://www.tamko.com) — Broad roofing portfolio with products targeted to roofing contractors and distributors.
Market concentration is meaningful but not prohibitive: top-tier firms account for a substantive share of demand, leaving room for specialized entrants and private-label programs. PW Consulting’s competitive matrices reveal where incumbents are vulnerable (e.g., margin pressure from feedstock volatility, slower adaptation to low-solvent chemistries) and where challengers can win (niche formulations, localized supply assurance, or superior channel economics).
Raw-material volatility: an operational risk and strategic lever
Raw-material dynamics are front and center. Observed data points underscore the speed and scale of recent swings: bitumen traded at 4,403 CNY/T as of 3 April 2026 (a rapid monthly and yearly uptick), regional differentials in petroleum bitumen prices were recorded in mid‑2025 (with the United States and Southeast Asia showing divergent trends), and U.S. Producer Price Indices for asphalt manufacturing have ticked up as well. These inputs create three predictable effects — compressing margins when unhedged, accelerating SKU rationalization toward less bitumen-intensive formulations, and raising the strategic value of secured long-term supply contracts. The report translates these market moves into operational thresholds and procurement decision rules.
Regulatory and product-spec dynamics — compliance as competitive advantage
Compliance with ASTM D4586 Type I and Federal Spec SS-153 Type I is already embedded in buyer requirements for large-scale and institutional projects. For manufacturers, meeting these specifications is table stakes; exceeding them through low-solvent, lower-VOC formulations—or demonstrating improved cold-weather performance—creates a premium wedge. The report includes a compliance roadmap and timelines to help product teams prioritize R&D sprints and labeling/certification sequences.
Why PW Consulting’s report matters to your 2026 plan
- It converts macro trajectories (baseline-market levels, a 4.85% CAGR) into operational thresholds for procurement, R&D, and go-to-market resource allocation.
- It provides executable templates (contract language, hedge triggers, SKU rationalization matrices) you can deploy immediately to protect margin and secure supply.
- It identifies high-probability M&A targets and partnership plays aligned to concentration dynamics and capability gaps.
- It equips commercial teams with price elasticity and channel segmentation models that optimize trade spend and pricing ladders under realistic feedstock scenarios.
PW Consulting’s Plastic Roof Cement Market study is structured to be a working document for 2026 — not a passive read. If your 2026 plan depends on supply continuity, competitive positioning, or disciplined capital allocation in this segment, the full report and the downloadable Excel model contain the granular inputs, sensitivity runs, and company-level diagnostics you’ll need to act with confidence.
Next steps
For access to the full dataset, company-level benchmarking tables, and the downloadable forecast model, visit our report page. PW Consulting stands ready to convert these insights into a tailored implementation program — from supplier negotiation playbooks to commercial pilots for differentiated, low-solvent product launches.
For detailed analysis of this topic, please visit the official page: Plastic Roof Cement Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Shadowless Lamps Market to Grow from USD 3,185.0 Million in 2025 to USD 4,633.2 Million by 2032 at a 5.5% CAGR (2026–2032)
By PW Consulting, 2026-07-02
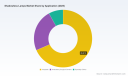
Shadowless Lamps Market 2026: Strategic Intelligence to Power Operational and Investment Decisions
PW Consulting today publishes the executive brief for our forthcoming Shadowless Lamps Market research report — a practitioner-oriented, decision-focused study designed to guide hospital procurement teams, medical device OEMs, private equity investors, and healthcare systems as they finalize 2026 strategies. Drawing on a validated market model covering 2020–2025 as the historical base and projecting through 2032, the report synthesizes market sizing, competitive dynamics, technology trajectories, and pragmatic tools that convert insight into action.
Shadowless Lamps Market
Quick Market Frame
The global shadowless lamps market has demonstrated steady expansion through the early 2020s, with PW Consulting’s model estimating an overall market of approximately USD 3.19 billion in the base year 2025 and a compound annual growth rate of 5.5% across the 2026–2032 forecast horizon. Our projections show continued momentum driven by operating room modernization, LED adoption, and integration of imaging and digital workflow capabilities — culminating in a projected market size north of USD 4.6 billion by 2032. Market concentration metrics indicate a moderately consolidated landscape (CR3 ≈ 38.5%; CR5 ≈ 52.3%), signaling meaningful opportunities for both tier-1 incumbents and well-positioned challengers.
Shadowless Lamps Market
What This Means for 2026 Decision-Makers
-
Capital Planning and Procurement Priorities
Hospitals and health systems finalizing 2026 CapEx plans should prioritize modular, upgradeable lighting platforms that reduce lifecycle cost through lower energy consumption and easier serviceability. Our report offers an ROI framework calibrated to contemporary OR utilization scenarios, enabling procurement teams to compare total cost of ownership (TCO) implications of legacy halogen retrofits versus modern LED platforms under multiple utilization curves.
Shadowless Lamps Market -
Product Strategy for OEMs
Manufacturers contemplating R&D or portfolio rationalization in 2026 will find our segmentation of value pools and feature elasticity essential. The market shows premiumization around integrated imaging (in-light 4K cameras), advanced optics (multi-lens matrices and 3D shadow compensation), and OR connectivity. We map willingness-to-pay against feature sets and provide a product road-mapping tool that helps prioritize developments that materially expand addressable share.
-
M&A and Partnership Playbook
The moderate CR5 highlights opportunity for inorganic growth. PW Consulting’s M&A playbook evaluates targets across strategic intent — geographic expansion, software-embedded lighting, and aftercare/servicing platforms — and prescribes valuation multipliers and integration checkpoints relevant to 2026 market conditions.
-
Commercial & Channel Strategy
Given the capitalized nature of surgical lighting purchases within OR infrastructure budgets, our commercial guidelines recommend hybrid go-to-market strategies combining tender competency for large hospital systems with agile distribution for ambulatory surgical centers and specialty clinics. The report includes negotiation levers, bundling approaches, and service contract templates tuned to procurement cycles common in 2026.
-
Clinical Adoption & Outcomes Alignment
Clinical champions remain a decisive force in lighting procurement. We provide a clinical evidence playbook that aligns lighting features to procedural categories and surgeon workflows, together with metrics to quantify throughput and documentation benefits attributable to integrated imaging and ergonomic improvements.
Competitive Landscape: Who’s Shaping the Next Wave
The competitive map remains populated by established global players and agile regional manufacturers. Stryker has continued to invest in platform-level lighting innovations, introducing multi-mode systems aimed at consistent high-quality illumination and operative visibility. TRUMPF Medical’s (Hillrom/Baxter) iLED and TruLight series emphasize adaptive light management and modular optics targeted at varied surgical environments. STERIS and Getinge remain focal incumbents integrating LED systems with OR ecosystem compatibility and imaging readiness.
European technology specialists such as KLS Martin and Dräger are notable for high-color-rendering optics and ergonomics — Dräger’s Polaris series, for example, has been broadened to the US market with modular upgrade paths and has recently garnered design recognition. China-based manufacturers, including Mindray and other specialized producers, continue to compete intensely on value, feature parity, and rapid local scaling, offering OEMs and distributors alternative sourcing strategies.
Across vendor profiles, three dynamics are noteworthy for 2026:
- Platformization: Leading OEMs are shifting from single-product offerings to modular platforms that support incremental upgrades (cameras, controls, sterilization-friendly interfaces).
- Systems Integration: Vendors that can demonstrate seamless connectivity to OR AV, documentation workflows, and hybrid OR controls capture a premium in hospital procurement deliberations.
- Service Economics: With capital budgets pressured, aftersales service contracts and uptime guarantees are decisive differentiators — manufacturers offering performance-based service agreements are seeing improved stickiness.
Recent Developments and Their Strategic Implication
PW Consulting tracks industry developments that materially affect competitive positioning and product roadmaps. Recent product launches and market entries emphasize three trends: (1) enhanced optics and shadow compensation for complex procedures, (2) inclusion of high-fidelity in-light imaging for documentation and tele-mentoring, and (3) design and ergonomics awards that accelerate adoption in premium accounts. For organizations planning 2026 investments, these developments signal where to allocate R&D and commercial focus to preserve relevance in high-growth segments.
Report Contents — Practical, Executable, and Built for 2026
Our full report is structured to support immediate action. Key deliverables include:
- Proprietary market model (2020–2032) with scenario analysis and sensitivity testing to stress-test planning assumptions.
- Decision-support tools: TCO calculators, procurement ROI templates, and upgrade vs. replace evaluation matrices tailored to hospital and ambulatory settings.
- Vendor scorecards and comparators that align product attributes with buyer priorities, including upgradeability, imaging integration, service economics, and ergonomics.
- Regulatory and compliance checklist covering medical device pathways and electrical safety standards relevant to OR deployment.
- M&A playbook and valuation frameworks for strategic buyers and financial sponsors seeking exposure to lighting platforms and aftercare services.
- Operational playbooks for clinical adoption, including surgeon engagement scripts and proof-of-concept designs for hybrid OR pilots.
To preserve the integrity of client-sensitive commercial insights, we have deliberately kept granular segment-level figures (by region, application, and specific feature revenue splits) and certain competitive unit economics exclusively within the full report and the downloadable model. This “trailer” approach lets you validate strategic direction here while accessing the full intelligence package through our report portal.
Market Dynamics, Risks and 2026 Watch-Items
-
Regulatory Environment
Surgical lighting systems sit within established regulatory frameworks (e.g., medical device premarket pathways and electrical safety standards). Compliance complexity affects time-to-market for upgrades that integrate cameras and wireless connectivity — a critical consideration for firms planning 2026 product introductions.
-
Technology Convergence
The integration of 4K in-light cameras, advanced optics, and OR connectivity is reshaping value propositions. Firms that can deliver validated clinical workflows and interoperable APIs gain preferential consideration in CAPEX cycles.
-
Capital Allocation Pressures
Hospital budget timing and prioritization of OR modernization versus other capital needs will influence demand curves. Our scenario analysis highlights sensitivity to shifts in surgical volumes and hospital investment cycles, enabling financial planners to model deferred vs. accelerated replacement strategies.
-
Competitive Disruption
Modular entrants and low-cost competitors from high-volume markets create price pressure in some channels. Conversely, evidence-driven premiumization around integrated imaging and advanced optics creates margins for differentiated players.
How to Use This Intelligence in 2026
For healthcare systems: prioritize platforms that balance immediate clinical impact with upgrade pathways. Use our TCO and clinical adoption tools to justify CapEx in board discussions.
For OEMs: align 2026 R&D investments to interoperability, modular design, and service models that offer recurring revenue. Our feature elasticity maps help tailor SKUs for segmented go-to-market approaches.
For investors: evaluate targets against the M&A framework and consider bolt-ons that expand service footprints or add digital capabilities to lighting platforms.
Next Steps
PW Consulting’s full Shadowless Lamps Market report provides the granular segmentation, vendor benchmarks, and downloadable financial model needed to operationalize these insights. We intentionally present this executive preview to demonstrate the report’s strategic value while reserving core segmented datasets for the full deliverable. To obtain the complete report, including the Excel-based market model and vendor scorecards, please visit our report page.
As healthcare delivery continues to evolve, properly aligning lighting strategy with clinical, operational, and financial objectives will be a differentiator in 2026. PW Consulting’s analysis equips leaders with the frameworks and tools to make those decisions confidently.
For detailed analysis of this topic, please visit the official page: Shadowless Lamps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: 5G Radome Market to Surge with a 13% CAGR, Led by Asia‑Pacific Demand
By PW Consulting, 2026-07-02
5G Radome Market: Strategic Imperatives for 2026 — PW Consulting
As service providers, infrastructure OEMs, and systems integrators plan capital deployment for the next wave of 5G densification, radome strategy is transitioning from a procurement afterthought to a deliberate product and site-level decision. PW Consulting’s latest 5G Radome Market study — using 2025 as the base year and projecting through 2032 — quantifies this shift and translates it into practical guidance for 2026 decision-making. The market has more than doubled since 2020 and enters a high-growth phase: our forecast shows a compound annual growth rate (CAGR) of 13.0% for the 2026–2032 period, lifting the addressable market to roughly USD 1,753.87 Million by 2032 (revenue unit: Million, currency: USD).
5G Radome Market
Why radomes matter now
Radomes are no longer purely mechanical enclosures. In 5G architectures — where mmWave, mid-band densification, and heterogeneous deployments coexist — radomes materially influence RF performance, thermal behavior, serviceability, and total cost of ownership. Decisions about materials, form factors, and integration strategies cascade into site acquisition timelines, CapEx efficiency, and long-term network quality. PW Consulting’s study positions radomes as a lever that stakeholders can use to reduce rollout friction, protect yield on spectrum investments, and optimize lifecycle economics.
5G Radome Market
Market trajectory and what it implies for 2026 decisions
-
Scale and momentum. The market expanded sharply in the 2020–2025 period, with the base-year size reaching USD 745.5 Million in 2025. The projected 13.0% CAGR for 2026–2032 signals sustained demand driven by macro deployments and retrofit cycles as operators densify networks and upgrade to higher-frequency assets.
5G Radome Market -
Concentration and competitive dynamics. Market concentration is moderate: the top-three players account for roughly 42.1% of the market, and the top-five for approximately 58.6%. These metrics suggest room for both established suppliers and specialist entrants, particularly in niche product lines (e.g., high-performance mmWave enclosures, lightweight airborne radomes, or low-cost small-cell shells).
-
Timing matters. For capital-intensive network rollouts planned in 2026, procurement windowing and supplier selection for radomes must align with equipment delivery schedules and permitting timelines. Regulatory initiatives and spectrum availability discussed below will compress or expand these windows; radome lead times and qualification plans must be synchronized accordingly.
Competitive landscape — who matters and where they play
Our competitive mapping synthesizes company capabilities, product strategies, and recent moves. Key vendors include global infrastructure suppliers and specialized composite manufacturers. Notable profiles from the report:
-
CommScope (United States) — Well-established in telecom infrastructure with radome offerings engineered for RF transparency and weather protection optimized for base station deployments. Their scale is an advantage where integrated antenna/radome packages are procured at program level ( https://www.commscope.com).
-
Exel Composites (Finland) — Focused on patented composite radome solutions that aim to minimize signal attenuation in high-frequency environments. Their recent IP development is targeted at deployment pain points for mmWave corridors ( https://exelcomposites.com).
-
Saint-Gobain (France) — Through its SHEERGARD range, the company supplies a breadth of structural systems (solid laminate, sandwich, fabric tensioned) with a focus on hydrophobic performance for outdoor and small-cell use cases ( https://www.saint-gobain.com).
-
General Dynamics Mission Systems (United States) — Brings aerospace/defense-grade radome expertise to high-frequency communications and mission-critical applications ( https://gdmissionsystems.com).
-
Laird Connectivity (United States) — Recently launched Radome5™ Poly, an injection-molded thermoplastic radome designed for indoor mmWave scenarios and small cells, signaling the commercialization of polymer-based, high-volume cost alternatives ( https://www.laird.com).
-
Supporting-material and component specialists — Companies such as Diab Group (core materials), Competition Composites, Pacific Radomes, and several regional manufactures (including Chinese suppliers) continue to supply the material and fabrication backbone for radome assemblies.
These vendor profiles are accompanied in the full report by supplier scorecards, capability heatmaps, and procurement playbooks that are actionable for OEM sourcing teams. To preserve strategic value for clients, the report provides deeper benchmarking and negotiation targets behind a paywall — an intentional guardrail aligned with the “trailer” principle of this release.
Technology, materials and product trade-offs
Material choice is the dominant trade-off axis. Glass-fiber composites, fluoropolymer laminates (e.g., PTFE), and engineered thermoplastics each offer distinct RF transparency, mechanical performance, manufacturability, and cost footprints. The optimal choice depends on site class (urban small cell vs. macro tower vs. airborne platform), intended frequency bands, environmental exposure, and serviceability constraints.
-
RF vs. durability: Higher RF transparency materials may increase sensitivity to impact or weathering; protective coatings and structural cores can mitigate those risks at an incremental cost.
-
Scale economics: Injection-molded thermoplastics can reduce per-unit cost for high-volume indoor small-cell runs but require upfront tooling investments and careful thermal/RF validation.
-
Repairability and lifecycle: For mission-critical or hard-to-access installations, repair-friendly systems and modular radome designs reduce lifecycle OPEX despite higher upfront cost.
The full study contains parametric cost models, lifecycle TCO calculators, and RF performance case studies to help engineering and procurement teams quantify these trade-offs for specific rollout plans.
Deployment economics and regulatory context
Two external dynamics will shape radome economics in 2026:
-
Infrastructure and spectrum policy. Regulatory moves to expedite buildouts, such as recent agency proposals to streamline approvals, coupled with planned mid-band spectrum auctions, are likely to accelerate densification programs and raise short-term demand for integrated radome/antenna solutions. Firms planning 2026 rollouts must factor regulatory cadence into supplier selection and site qualification timelines.
-
CapEx environment and cost pressure. Industry-wide 5G CapEx reached a multi-year inflection point, and total sector CapEx is estimated at approximately USD 250 billion by 2025. Deployers face equipment cost pressure, supply-chain volatility, and rising labor/material expenses (including fiber backhaul input costs). These forces increase the importance of radome cost-to-performance optimization and may prompt creative procurement models such as volume-tiered pricing, leasing, or integration contracts that bundle radomes with antennas and radios.
Operators and integrators should treat radomes not as passive line items but as strategic inputs that influence permitting speed, aesthetic compliance, and long-term maintenance budgets.
Risks, uncertainties and mitigation levers
-
Supply-chain concentration: While the market is not hyper-concentrated, lead times for specialized composite materials and tooling can introduce schedule risk. Mitigation includes multi-sourcing strategies, regional stocking hubs, and supplier qualification pre-approval.
-
Regulatory drag: Local permitting delays remain a persistent risk for urban densification. Early community engagement, standardized box designs, and pre-certified enclosures can materially shorten approval cycles.
-
Technology shifts: Advances in antenna integration (e.g., conformal arrays) and changes in preferred frequency bands can alter radome requirements mid-cycle. Designing modularity and upgradeability into radome choices reduces stranded-asset risk.
What the PW Consulting report delivers — practical outputs for 2026 action
This is a practical study designed for the program manager and the CFO as much as the RF engineer. Key deliverables include:
-
A concise market-sizing model (historical 2020–2025 and forecast 2026–2032) with scenario toggles for alternate rollout speeds and spectrum auction outcomes.
-
Supplier scorecards and CR-based concentration analysis to support shortlists and dual-sourcing decisions.
-
Radome selection playbooks that map site typologies to material choices, TCO outcomes, and RF performance trade-offs.
-
Procurement templates, expected qualification timelines, and a unit-cost sensitivity tool that incorporates tooling, materials, and logistics variables.
-
Case studies and failure-mode analysis from recent commercial deployments and defense-grade applications.
In keeping with the “trailer” approach of this release, we present high-level findings here to orient strategic decision-making while reserving the full set of segmented tables, region-by-application breakdowns, and supplier-specific price benchmarks for subscribers and report purchasers.
Actionable recommendations for 2026
-
Integrate radome strategy into the early procurement phase. Treat radomes as a performance and schedule risk in rollout planning rather than a downstream enclosure choice.
-
Pre-qualify at least two suppliers per major product class (composite, fluoropolymer laminate, engineered thermoplastic) and maintain a local inventory buffer to absorb short-term lead-time variation.
-
Commission RF-vs.-TCO pilots for high-volume small-cell and critical macro sites to generate empirical data that informs national deployment templates.
-
Engage with regulators proactively, leveraging standardized, pre-certified radome designs to accelerate permitting and reduce localized delays tied to aesthetics or environmental concerns.
-
Monitor vendor IP activity and product launches—recent examples such as the Laird Radome5™ Poly product introduction and Exel Composites’ European patent highlight the pace of innovation and the potential for design-led differentiation.
Conclusion — the strategic cliff notes
Radomes are a disproportionate value lever in 5G rollouts: modest design or procurement improvements can deliver outsized gains in schedule, spectrum efficiency, and lifecycle cost. The market is growing rapidly (13.0% CAGR for 2026–2032), with mid-term scale making supplier strategy, material selection, and regulatory alignment essential components of any successful 2026 deployment plan. PW Consulting’s 5G Radome Market report equips executives with the models, vendor insights, and procurement tools needed to translate these dynamics into defensible program decisions.
For the complete dataset, granular segmentation tables, supplier benchmarking matrices, and downloadable procurement templates, access the full report on PW Consulting’s portal. The detailed intelligence is designed to be directly actionable for 2026 budget cycles and rollout plans.
For detailed analysis of this topic, please visit the official page: 5G Radome Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Magnetic Clamping Technology Market to Expand at a 6.45% CAGR Through 2026–2032
By PW Consulting, 2026-07-02
Magnetic Clamping Technology Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
Executive summary
Magnetic clamping technology is transitioning from a niche workholding solution to a mainstream enabler of automation, multi-face machining, and faster mold-change workflows. Our new market study — which covers 2020–2025 historic performance and provides a 2026–2032 forecast — quantifies that transition while translating it into actionable choices for procurement, R&D, and M&A leaders preparing for decisions in 2026. The sector demonstrates a steady compound annual growth rate (CAGR) of 6.45% over the forecast window, with the market expanding from a mid-single hundred million USD base in recent years toward a substantially larger opportunity by 2032. At the same time, concentration metrics indicate meaningful room for competitive maneuver: the top three players account for roughly 42% of the market and the top five for about 58% — evidence of both established incumbents and prospective challengers.
Magnetic Clamping Technology Market
Why 2026 is a pivotal year for corporate decision-makers
-
Capital cycles and procurement calendars across manufacturing industries are aligning with advanced automation investments scheduled for 2026. Organizations that lock in supplier relationships and technology roadmaps this year will gain a window of competitive uptime through the late 2020s.
Magnetic Clamping Technology Market -
Raw material dynamics are changing the cost and availability profile of magnetic systems. Neodymium oxide — a critical rare-earth input for high-performance permanent magnets — traded above USD 112,000 per tonne in 2026 amid demand pressures from electric vehicles and wind turbines. This tightness has direct implications for BOM engineering, long‑lead sourcing and hedging strategies.
Magnetic Clamping Technology Market -
Regulatory and safety standards are maturing: ISO 23582-1:2023 establishes essential safety requirements for magnetic clamping systems used on plastics and rubber machinery, and cleanroom compatibility (ISO Class 7 and 8) is increasingly referenced in product specifications for electro‑permanent systems. These developments create compliance thresholds that influence supplier selection, qualification timelines, and warranty conditions.
Market trajectory — a disciplined growth story
Our quantitative model shows consistent market expansion across the historical period into the forecast horizon, driven by adoption in molding, metalworking, and automation sectors. The calibrated CAGR of 6.45% reflects a combination of steady demand for faster setups, the growing footprint of electro‑permanent solutions, and incremental performance gains in magnet materials and control electronics. For strategy teams, this trajectory supports medium‑term investments (2–5 year paybacks) in both product development and capacity expansion, while leaving room for faster, targeted bets in aftermarket services and retrofit applications.
Core dynamics shaping supplier economics
-
Material cost volatility: The rare-earth market — valued at roughly USD 19.5 billion in 2024 — remains a cost driver. Firms that secure diversified supply, explore magnet formulation alternatives, or invest in design measures that reduce rare‑earth content will lower unit volatility risk.
-
Standards and safety: ISO 23582-1:2023 and cleanroom compliance requirements elevate the baseline for test documentation, traceability, and integration support. This increases the non-recurring engineering (NRE) and validation effort for suppliers and adopters alike.
-
Automation and systems integration: Magnetic clamping’s role in enabling deformation‑free holding, uniform force distribution, and rapid clamping for 5‑sided machining accelerates its adoption as part of integrated cell designs. Buyers should evaluate suppliers not only on magnet performance but on control interfaces, diagnostics, and serviceability.
Competitive landscape — what leading players bring to the table
The market is characterized by a mix of engineering-centric incumbents and regional specialists. Our competitive benchmarking evaluates product families, system compatibility, safety features, and go‑to‑market models.
-
SCHUNK GmbH & Co. KG (Germany) — Known for the MAGNOS suite, SCHUNK emphasizes uniform clamping for 5‑sided machining and vibration reduction. Strengths: application engineering and deep integration with milling centers.
-
Stäubli International AG (Switzerland) — Offers quick mold‑change magnetic systems (QMC series) with active safety and clamping force measurement. Strengths: solutions tailored for injection molding with a focus on small‑tonnage press compatibility.
-
AMF (Andreas Maier GmbH & Co. KG) (Germany) — Focuses on high holding forces for complex part geometries and close integration with zero‑point systems. Strengths: energy‑efficient platforms and strong presence in 5‑axis machining workflows.
-
ROEMHELD GmbH (RIVI M‑TECS) (Germany) — Supplies magnetic plates engineered for mold change, die casting and forming with attention to temperature resilience and safety during rapid tooling swaps.
-
Mag‑Autoblok Tecnomagnete (Italy) — A long-standing leader in electropermanent systems and customized solutions, with recent hybrid chuck developments signaling product modularity trends.
-
Earth‑Chain Enterprise (Taiwan) and regional specialists such as WALMAG, Eclipse Magnetics, Assfalg, Pascal Engineering, Braillon, Magnetool, Flaig and Spreitzer — collectively these firms contribute manufacturing breadth, niche applications expertise, and aftermarket services. Strengths include cost-competitive manufacturing, EEPM chucks for CNC machining, and localized technical support.
Our analysis shows a market neither perfectly consolidated nor fragmented; incumbency delivers scale, but technical differentiation and application depth create opportunities for focused challengers and partnership plays.
Recent industry movements to watch
-
Trade show activity in early 2026 (GLOBAL INDUSTRIE, BIEMH) underscores a resumed appetite for cross‑technology demonstrations — magnetic clamping paired with zero‑point, hydraulic, and vacuum solutions.
-
Product innovations such as hybrid self‑centering chucks and battery‑operated lifting magnets indicate a broader productization trend: buyers now expect plug‑and‑play modules that simplify retrofits and reduce footprint.
-
Company profile updates and distribution expansions highlight the push into new geographies and channel partnerships, amplifying aftermarket potential.
What the PW Consulting report delivers (practical content designed for action)
-
Market sizing and validated forecasts (2020–2032) with scenario sensitivity to raw‑material costs and adoption rates.
-
Regulatory and standards matrix (including ISO 23582‑1:2023 and cleanroom guidance) mapped to product development and procurement checklists.
-
Vendor scorecards that benchmark technical features, safety, service footprint, and unit economics — enabling rapid shortlists for RFPs.
-
Supply‑chain risk dashboard that quantifies exposure to rare earths and proposes hedging and sourcing strategies.
-
Commercial playbook for OEMs and systems integrators: pricing levers, aftermarket revenue models, and cross‑selling pathways into automation cells.
-
M&A and partnership framework: valuation multipliers, capability gaps to prioritize, and integration checklists for bolt‑on acquisitions or JV formations.
-
Field‑tested implementation guides and acceptance test procedures to reduce time‑to‑value post‑installation.
Strategic recommendations for 2026 decision-makers
-
Prioritize supplier assessments that include material traceability and ISO/cleanroom compliance evidence. Compliance is increasingly non‑negotiable and will shorten integration timelines.
-
Hedge rare‑earth exposure through multi‑source contracts, recycled magnet programs, or alternative magnet formulations where feasible. Factor raw‑material stress tests into total cost of ownership models.
-
Invest selectively in electro‑permanent magnetic (EEPM) platforms and control integration capabilities — these architectures combine low running energy with operational safety, making them attractive for automated production cells.
-
Design aftermarket and service offerings early. Rapid mold changes, diagnostic capabilities, and predictable maintenance windows translate directly into higher utilization and stickier customer relationships.
-
Use the market concentration profile to calibrate partner vs. competitor strategies: where incumbents dominate, focus on complementary modules and service differentiation; where fragmentation remains, pursue aggressive channel expansion and targeted acquisitions.
How to use this report in your 2026 planning cycle
Procurement teams: use the report’s vendor scorecards and acceptance checklists to reduce sourcing lead time and contractual risk. R&D and product: prioritize magnet formulations and control electronics that reduce rare‑earth dependency and support diagnostics. Corporate strategy and M&A: apply our valuation and integration framework to identify targets that either shore up supply or accelerate entry into adjacent automation markets.
Conclusion — the strategic payoff
Magnetic clamping technology will play a tactical and strategic role in factory modernization through the remainder of the decade. For executives making 2026 commitments, the critical choices are not binary “buy vs. build” questions but portfolio choices: which suppliers to lock in, which technologies to standardize on, and where to allocate R&D versus channel investments. Our report provides the quantified backdrop and the playbooks necessary to turn market momentum into measurable operating and financial outcomes.
Next steps
This preview highlights the report’s strategic value while withholding detailed segment-level disclosures and company-specific revenue splits. To access the full dataset, vendor profiles, and scenario models — and to obtain a tailored briefing for your executive team — please visit the PW Consulting report page for Magnetic Clamping Technology Market or contact your PW Consulting representative.
For detailed analysis of this topic, please visit the official page: Magnetic Clamping Technology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electroporation Buffer Market to Grow from USD 225.88 Million in 2025 to USD 366.32 Million by 2032 at a 7.15% CAGR
By PW Consulting, 2026-07-02
Electroporation Buffer Market — Strategic Roadmap for 2026 Decision Makers
Executive Overview
PW Consulting’s latest Electroporation Buffer Market report (base year 2025; historical window 2020–2025; forecast 2026–2032) delivers an action-oriented blueprint for executives planning resource allocation, product strategy, and M&A through 2026 and beyond. The market shows a clear expansion trajectory, growing from an estimated market size in 2025 to a materially larger market by the end of the forecast window under a compound annual growth rate (CAGR) of 7.15%. That growth, combined with a moderately concentrated supplier landscape (CR3 ~45.5%, CR5 ~58.2%), creates both predictable opportunities and emergent operational risks for suppliers, instrument OEMs, contract manufacturers and end-users in the clinical and manufacturing value chains.
Electroporation Buffer Market
Why this report matters for 2026 decisions
- Market momentum: The market’s steady CAGR signals reliable demand expansion for electroporation consumables and formulation innovation across research and manufacturing workflows — a signal to commit to medium-term investments rather than short-lived tactical plays.
- Regulatory inflection: Recent regulatory moves and standards are compressing time-to-clinical readiness for buffers, which changes product roadmaps, labeling strategies and supply qualification timelines for companies targeting clinical or GMP use.
- Supply-cost volatility: Key raw material dynamics and trade policy shifts are changing cost structures; this necessitates more sophisticated procurement, hedging and nearshoring choices in 2026.
- Consolidation opportunity: Moderate market concentration suggests that well‑timed M&A or commercial partnerships can accelerate scale advantages while preserving margin in an innovation-driven space.
Data-driven insights you can action in 2026
Our report integrates a quantitative market model (historical 2020–2025, forecasts 2026–2032) and scenario analyses that translate macro trends into operational levers. Key high-level datapoints included in the report allow you to:
Electroporation Buffer Market
- Stress-test pricing and margin under multiple raw-material and tariff scenarios derived from recent trade actions and commodity movements.
- Prioritize R&D and regulatory investment by comparing adoption curves for research-use vs. clinical/GMP buffer variants.
- Estimate ROI on automation‑focused SKUs and high-throughput packaging formats introduced by instrument OEMs and reagent suppliers.
What’s inside PW Consulting’s operational playbook
The report is deliberately practical. It goes beyond high-level forecasting and includes templates, benchmarks and executable roadmaps that teams can plug into 2026 planning cycles:
Electroporation Buffer Market
- Market model and downloadable datasets with base-case and upside/downside scenarios for 2026–2032.
- Segment-level demand drivers and adoption curves (note: detailed segment share tables and granular values are available in the full report page).
- Supply‑chain map with single‑supplier risk flags, alternative chemistries and validated second-source lists for key inputs.
- Regulatory matrix covering RUO vs. clinical labeling, ISO and GMP pathways, plus a checklist for transitioning formulations to clinical-grade supply.
- Commercial playbooks: pricing sensitivity analyses, channel strategy for OEM bundling, and GTM templates for selling into academia vs. contract manufacturing organizations.
- Competitive scorecards and M&A target shortlists augmented by financial, technical and operational risk indicators.
- Procurement negotiation templates and hedging scenarios tied to raw-material price curves.
Competitive landscape — what to watch in 2026
The report synthesizes publicly available intelligence and proprietary benchmarking on the principal market participants. Several firms are strategically positioned to shape the market dynamic over the next 12–24 months:
- Merck KGaA (MilliporeSigma) — long-standing developer of optimized buffer systems and recent producer-level certifications that increase credibility in regulated manufacturing.
- Thermo Fisher Scientific — rapid SKU expansion aimed at automation and high‑throughput workflows, which compresses cycle time for customers and raises switching costs for consumables.
- Lonza Group — focused on application-specific buffer stability and upgrades for newer electroporation platforms, strengthening OEM tie‑ins for hard-to-transfect primary and stem cells.
- Bio‑Rad Laboratories — leverages compatibility with existing electroporation hardware to preserve installed base attachment and broaden addressable applications.
- BTX (Harvard Bioscience) — targets niche segments with specialized buffer formulations for bacterial and mammalian workflows where price-performance matters.
Recent company-level actions — for example, upgraded buffer stability for next‑gen nucleofection systems, ISO 13485 certification at a major production facility, and automation‑focused SKU launches — are examples of how incumbents are converting technical differentiation into commercial defensibility. Our competitive framework assesses these moves across three vectors: technical defensibility, channel control and regulatory readiness.
Supply chain, regulatory and cost dynamics that will shape 2026
- Raw materials: Key osmotic stabilizers and excipients have shown price volatility. Spot price movements for certain inputs have increased near-term unit costs, making supplier diversification and longer-term contracts a priority for high-volume manufacturers.
- Regulation: Emerging limits on impurity profiles in cell-culture reagents tighten quality requirements for buffer makers aiming at clinical pipelines. This raises the bar for process controls, supplier audits and documentation required for GMP transition.
- Trade and logistics: New tariff lines and trade measures affecting buffer-related chemical headings are increasing landed costs for some supply chains, incentivizing re-routed sourcing or partial onshoring for companies targeting clinical and commercial volumes.
- Labeling and market access: Products labeled for research use only (RUO) face strict restrictions for clinical adoption; manufacturers must plan parallel regulatory and quality tracks if they intend to address both markets.
Prioritized recommendations for executives in 2026
- Immediate (next 6–9 months): Lock supply via multi-year purchase agreements for volatile excipients and initiate dual-sourcing pilots; accelerate regulatory audits for facilities supplying clinical-grade buffers; conduct SKU rationalization to support automation-friendly packaging.
- Medium term (9–18 months): Invest in formulation stability to support OEM platform upgrades, pursue targeted co-development agreements with instrument manufacturers, and set aside capex for modular production capacity that can be quickly validated for GMP use.
- Strategic/M&A (12–24 months): Evaluate tuck-in acquisitions that add validated clinical-grade capability or proprietary optimized formulations; prioritize targets that close gaps in the top‑five supplier set to amplify economies of scale in a moderately concentrated market.
- Commercial execution: Create segmented value propositions (research vs. clinical), introduce subscription or reagent-as-a-service pricing for high-throughput customers, and deploy field trials that quantify efficiency gains from certified buffer/instrument pairings.
How PW Consulting’s report equips your 2026 planning process
The report is designed to be a decision-support toolkit for senior leadership, product teams and corporate development. It includes executable templates, scenario calculators and a curated list of tactical moves that can be operationalized in quarterly roadmaps. If your 2026 planning cycle involves cost containment, regulatory transitions, or inorganic growth, the report provides the masked data and decision rules that enable rapid prioritization while protecting commercial sensitivities.
Next steps
PW Consulting’s Electroporation Buffer Market report contains the full segmentation tables, company scorecards, downloadable model files and a step-by-step playbook referenced in this executive summary. The public preview above is intentionally selective — it highlights the strategic implications and operational levers relevant to 2026 without disclosing the granular segment and regional breakdowns that form the core intelligence in our datasets. For access to the full dataset, scenario models, and bespoke advisory engagements, please visit the PW Consulting report page or contact our industry team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Electroporation Buffer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Market Insight: Baical Skullcap Extract Industry Poised for 6.45% CAGR in 2026–2032
By PW Consulting, 2026-07-02
Baical Skullcap Extract Market 2026 Outlook: Strategic Imperatives for Suppliers, Brand Owners and Investors
PW Consulting’s latest Baical Skullcap Extract Market report provides a practical, decision-grade roadmap for corporate leaders preparing for 2026 and beyond. Drawing on a rigorous historical baseline (2020–2025) and a seven‑year forecast window (2026–2032), the study quantifies market momentum, maps supplier capabilities, and distills operational playbooks that turn botanical market intelligence into commercial advantage. At the macro level, the market is projected to grow at a compound annual growth rate (CAGR) of 6.45%, expanding from the 2025 base year and approaching a near‑billion USD market by 2032—dynamics that require tactical adjustments across procurement, product development and route‑to‑market strategies.
Baical Skullcap Extract Market
Why this report matters for 2026 decisions
-
Clarity on scale and pace: The report models demand and revenue trajectories across a seven‑year horizon, enabling finance and corporate development teams to stress‑test investments against a 6.45% CAGR scenario and alternate volatility paths.
Baical Skullcap Extract Market -
Operational readiness: Buyers and formulators face concrete supply‑chain challenges (quality assurance, crop variability and regulatory friction). Our report supplies checklists, audit templates and supplier scorecards designed for near‑term execution.
Baical Skullcap Extract Market -
Risk‑to‑opportunity translation: We convert macro risks—such as raw material concentration and climate variability—into prioritized mitigation actions that can be implemented within 90–180 days.
-
M&A and partnership prioritization: With a market that remains moderately concentrated (top‑three firms command a meaningful share and top‑five firms account for roughly half of market revenue), the study identifies where consolidation or strategic partnerships most rapidly create scale or capability gaps for potential acquirers.
Market snapshot (what the headline numbers mean)
Our bottom‑line modelling confirms a resilient market with steady expansion through 2032. Practically, the projected growth implies expanding shelf space for natural actives, increasing institutional procurement volumes for high‑purity extracts, and rising buyer interest in standardized ingredient specifications. For 2026 planning cycles, that translates into three immediate implications: (1) procurement teams should lock conditional supply agreements to secure quality at scale; (2) R&D teams should prioritize formulation work using standardized grades that simplify regulatory clearance; and (3) business development functions should aggressively qualify partners across the value chain to hedge supply and accelerate market entry.
What’s inside the report: operational intelligence, not just charts
-
Actionable supplier due‑diligence templates: audited KPIs, certificate verification workflows, and factory audit checklists that can be used as a baseline for vendor onboarding.
-
Commercial negotiation playbook: benchmark pricing levers, minimum order structuring, and escalation clauses that protect buyers during raw‑material scarcity.
-
Scenario‑based price and availability model: an interactive framework projecting impacts from crop shocks, regulatory shifts and demand surges—calibrated to multiple sensitivity bands.
-
Regulatory & claims matrix: mapping global labeling constraints, safety incident history, and recommended clinical/analytical substantiation pathways for claims used in pharmaceuticals, personal care and nutraceutical formulations.
-
Portfolio prioritization tool: a decision algorithm that ranks product concepts by ease‑to‑market, margin potential and supply resilience.
-
M&A target scorecards: shortlists and valuation drivers for strategic acquirers, including capability gaps that command premium multiples.
Supply dynamics & raw material risk (what keeps buyers awake)
The Baical Skullcap value chain remains tightly coupled to agricultural production patterns. Most commercial volumes of Scutellaria baicalensis continue to originate from concentrated growing regions, and climate variability—droughts, floods and shifting seasonal patterns—has translated into meaningful yield variance. These risks are compounded by periodic changes in agricultural and export policy in key producing countries. For 2026 risk plans, firms must move beyond single‑sourcing and adopt tiered procurement strategies that blend contractual security with spot market flexibility.
-
Diversification is actionable: the report prescribes a phased sourcing play—establish primary suppliers with multi‑year contracts, secondary suppliers with rolling capacity guarantees, and a vetted roster of tertiary suppliers for emergency fill.
-
Traceability & quality: we recommend investing in traceability coupled with batch‑level analytics (COA harmonization and targeted HPLC assays) to reduce batch rejection and protect downstream manufacturing continuity.
-
Geographic hedges: producers are already exploring new cultivation zones to de‑risk supply. For buyers, early engagement with emerging producers can secure preferential allocations and price stability.
Regulatory and safety context
Regulatory attention to herbal actives is pragmatic and increasing. Historical safety signals tied to complex combination products have raised the bar on safety dossiers and post‑market surveillance. A notable precedent is an older recall related to a combination product that included Baical Skullcap extract—while causality was not definitively established for the extract itself, the episode underscores the commercial consequences of insufficient pharmacovigilance and unclear attribution in multi‑ingredient products. The report outlines practical dossiers and post‑launch monitoring protocols that substantially reduce regulatory friction and reputational risk.
Competitive landscape: what leading suppliers are signalling
The market is served by a blend of long‑standing manufacturers, vertically integrated suppliers, and compliant, certification‑focused traders. Key industry participants provide varying mixes of scale, certification, and specialty high‑purity capabilities:
-
Large, vertically integrated producers offer scale, pharma‑grade GMP compliance and near‑term capacity availability—valuable for buyers that require high‑purity standardized extracts and documented supply chains.
-
Regional premium players emphasize harvest‑to‑extract traceability and seasonal sourcing practices tailored to cosmetic and supplement customers seeking differentiated claims.
-
Specialty suppliers and organic‑focused traders prioritize certification (organic, Kosher, Halal) and smaller minimum orders—appealing to emerging brands and private‑label users that require flexibility and verified COAs.
Our competitive profiling in the report goes beyond corporate blurb: it assesses manufacturing footprints, certification stacks (GMP, ISO, HACCP, organic), intellectual property positions, and product breadth—then translates those attributes into procurement fit‑matrices for five buyer archetypes (pharma, large CPG, premium naturals, nutraceuticals and private label).
Strategic plays for 2026: prioritized, time‑bound actions
-
Quarter 1: Conduct a supplier resilience audit using our checklist; secure primary supplier contracts covering at least 60% of forecasted 2026 volume with defined quality acceptance criteria.
-
Quarter 2: Fast‑track formulation trials for standardized grades that shorten regulatory timelines; deploy post‑launch safety monitoring routines for any new product introductions.
-
Quarter 3: Execute a hedged procurement program (mix of contracts and defined spot exposure) and lock strategic buffers in logistics to mitigate seasonal crop variability.
-
Quarter 4: Reassess portfolio against market growth projections and initiate targeted M&A or alliance conversations to fill capability gaps (high‑purity extraction, certification or downstream packaging).
How companies use this report in practice
Leading procurement teams have repurposed the PW Consulting playbooks to reduce batch rejection rates, shorten sourcing cycles and negotiate tougher warranty clauses with suppliers. R&D organizations have used our prioritization tool to cut time‑to‑market for new formulations by focusing on ingredients with the most favorable regulatory footprint and supply resilience. Corporate development teams use our competitive maps and scorecards as a rapid triage tool to identify and vet acquisition targets that offer immediate integration benefits.
Methodology and confidence
The study triangulates demand estimates from end‑market indicators, supplier revenue modeling and trade flow analysis, anchored by a conservative baseline in 2025. Forecast paths incorporate both steady‑state and stress scenarios to ensure planners can pivot between optimistic demand capture and defensive supply preservation strategies. The report’s proprietary sensitivity model allows users to simulate the impact of crop failures, export controls and demand shocks on pricing and availability.
Next steps: what PW Consulting recommends
-
Download the full report and interactive models to obtain segment‑level breakdowns, supplier scorecards and the downloadable supplier audit checklist (these detailed datasets are intentionally gated to provide secure, verifiable downloads for clients and registered users).
-
Schedule a strategy workshop with our industry team to tailor the procurement playbook to your organization’s tolerance for supply risk and commercial growth targets in 2026.
-
Adopt our three‑tier sourcing and quality assurance framework before executing new product launches where Baical Skullcap is a functional ingredient.
PW Consulting’s Baical Skullcap Extract Market report is designed as a working tool for 2026 planning cycles—delivering both the macro evidence (growth trajectory and market concentration metrics) and the micro‑operational instruments (contractual templates, audit checklists and scenario models) that convert insight into execution. For companies that need to protect margins, accelerate launches, or evaluate acquisition targets in this ingredient space, the report provides the strategic clarity required to move from uncertainty to action.
For detailed analysis of this topic, please visit the official page: Baical Skullcap Extract Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: 5‑Sulfoisophthalic Acid Monosodium Salt Market Set to Reach USD 564.6 Million by 2032
By PW Consulting, 2026-07-02
PW Consulting Releases Strategic Brief: 5-Sulfoisophthalic Acid Monosodium Salt Market — Critical Insights for 2026 Decision-Making
Executive Snapshot
PW Consulting today publishes a strategic industry brief derived from our comprehensive 5-Sulfoisophthalic Acid Monosodium Salt (NaSIP / NaSSIPA) market study (base year 2025, historical window 2020–2025, forecast 2026–2032). The study reveals a market that has expanded steadily through the early 2020s and is set to continue growing at a mid-single-digit compound annual growth rate (CAGR) of 5.15% across the forecast horizon. From a market size in the high hundreds of million USD in 2025, our models project continued expansion through 2032, underscoring an attractive, investment-grade market environment for firms planning capacity, product, and commercial strategies in 2026.
5 Sulfoisophthalic Acid Monosodium Salt Market
Why This Market Matters for 2026 Strategic Plans
Monosodium 5-sulfoisophthalate has moved from a niche specialty monomer to a mission-critical intermediate across polyester modification, water-borne polyurethanes and resins, inks and coatings, and a growing set of adhesive and specialty polymer applications. Two broad trends elevate its strategic priority for 2026 planning:
5 Sulfoisophthalic Acid Monosodium Salt Market
- Performance-driven polymer differentiation: formulators are integrating sulfonated monomers to deliver dyeability, hydrophilicity, and improved dispersion properties without compromising bulk polymer mechanics — features that map directly to premium product positioning and higher-margin downstream applications.
- Regulatory-driven repositioning: select grades benefit from established regulatory recognition for indirect food contact applications, creating jump‑start opportunities for firms targeting packaging adhesives and coatings where regulatory clearance is a barrier to entry.
Market Trajectory — What the Macro Numbers Tell Us
Our topline market modelling shows the 5-sulfoisophthalic acid monosodium salt market expanding from a mid‑three‑hundreds million USD value in 2025 to a materially larger market by 2032, driven by both application penetration and incremental use rates per tonne in advanced polymers. The steady 5.15% CAGR in our central forecast reflects a balance of demand pull from specialty polymerization and incremental supply-side efficiency gains (process optimization and economies of scale). Importantly, the market displays moderate concentration: the top three players account for a significant share of capacity, and the top five increase that concentration further — a structure that supports coordinated pricing dynamics and signals attractive M&A rationales for larger chemical companies and strategic investors.
5 Sulfoisophthalic Acid Monosodium Salt Market
Supply Chain and Manufacturing Dynamics
Understanding the production pathway is essential to assessing cost, reliability, and potential bottlenecks. Industry best-practice routes convert sulfonated intermediates into the monosodium salt through neutralization with alkali at elevated temperatures, followed by sequential hydrolysis, crystallization and dehydration. These unit operations make the product reliant on:
- Consistent feedstock quality and access to sulfonation intermediates;
- Process thermal reliability and crystallization control (which influence yield and grade distribution); and
- Operational choices on packaging and distribution (drums vs. bulk bags) that affect market reach and customer suitability in specialty versus industrial segments.
From an industrial strategy perspective, these elements translate to specific levers: upstream partnerships for feedstock security, targeted capital investment in crystallization and drying capacity to protect high‑purity yields, and logistics planning to support just‑in‑time supply for downstream formulators.
Regulatory & Application Considerations
Regulation shapes addressable markets. Notably, monosodium 5‑sulfoisophthalate is listed in authoritative inventories for indirect food contact substances in key jurisdictions — a fact that materially lowers market entry friction for adhesives and coatings aimed at packaging. For 2026 planners, three practical implications follow:
- Regulatory clearance creates a defensible premium segment. Firms with documented food-contact acceptability may pursue higher-margin packaging and specialty adhesive contracts.
- Regulatory divergence still requires active management. Market access and labeling must be reconciled across regions and customer supply chains.
- Sustainability profiling (e.g., lower solvent, waterborne systems) aligns with end-customer decarbonization and VOC reduction goals — an increasingly common procurement requirement.
Competitive Landscape — Who Matters and Why
The competitive map includes a mix of global chemical producers and regional specialists. Our qualitative assessment highlights the strategic positioning of several industry participants:
- FutureFuel Corporation (United States) — Markets a high‑purity monomer positioned for polyester and polyamide value chains, with a portfolio that includes multiple packaging and supply formats suited to both specialty and larger batch orders. Their product focus on purity and diverse downstream applications supports premium targeting and partnership opportunities with fiber and coating manufacturers.
- GO YEN CHEMICAL INDUSTRIAL CO., LTD. (GYC Group, Taiwan) — Supplies high‑purity grades and emphasizes applications such as dyeable polyester and food‑contact adhesives. Their FDA‑aligned use cases and high‑purity positioning make them a natural partner for formulators pursuing regulatory-dependent segments.
- Maruti Chemicals Company (India) — A regional supplier serving printing inks, saturated polyester resins and textile sectors. Their presence in large polymer hubs positions them as a low‑cost, high‑availability competitor for industrial grade demand.
- Chung Hwa Chemical (Taiwan) — Focused on aqueous polyester and polyurethane resin applications, serving formulators migrating to amine‑free and waterborne systems.
Collectively, the market’s concentration metrics indicate that a small number of players command a material share of capacity. For 2026, this dynamic suggests that strategic moves (capacity expansions, off‑take agreements, tolling arrangements, and selective M&A) by a handful of firms could shift regional supply balances and pricing dynamics.
What the PW Consulting Report Delivers — Practice-Focused Content
The published study is structured to support actionable decision-making for commercial leaders, R&D heads, procurement and corporate development teams looking ahead to 2026 and beyond. Key operative deliverables include:
- Top‑line demand forecasts with scenario modelling across our 2026–2032 horizon that translate macro demand drivers into near‑term capacity and inventory implications;
- Supply‑side maps and process benchmarking that identify yield, energy and capital intensity differentials between grades and production routes;
- Regulatory mapping and product‑application matrices that decode pathways to specialty end‑markets (including packaging adhesives and waterborne coatings);
- Competitive intelligence dossiers with strategic profiles, route‑to‑market assessments and partner prioritization frameworks;
- Commercial playbooks and investment case templates — from greenfield capacity to strategic tolling — designed to accelerate boardroom decisions in 2026.
In keeping with the “trailer” principle, the public brief showcases the methods and strategic conclusions while preserving granular regional and application split data in the full report — the level of detail procurement teams and M&A advisors need to finalize contracts and bid documents.
Strategic Recommendations for 2026
Based on our synthesis of demand drivers, supply dynamics and competitive positioning, PW Consulting recommends that industry stakeholders prioritize the following actions in 2026:
- Secure feedstock and intermediate supply via multi-year off‑takes or partnerships. Given the process sensitivity and thermal steps in production, upstream availability and quality control materially impact margin and grade mix.
- Differentiate by grade and regulatory qualification. Invest selectively in high‑purity crystallization and drying assets if pursuing food‑contact and specialty polymer segments — a route that supports premium pricing and customer lock‑in.
- Explore regional capacity rebalancing through tolling or JV structures. For companies seeking rapid market share gains, partnering with established regional producers can accelerate access without full greenfield risk.
- Align product development with waterborne and low‑VOC transitions in downstream markets. Reformulation support and technical service capabilities will be decisive in winning long‑term supply contracts with formulators.
- Monitor consolidation opportunities. The market’s concentration profile and the capital intensity of upgrade projects create a favorable environment for bolt‑on acquisitions that deliver immediate scale or technical capabilities.
How to Use This Intelligence in Boardroom Decisions
For corporate strategists and investors preparing 2026 budgets, the brief functions as a decision accelerator: it translates a defined CAGR and multi‑year growth trajectory into near‑term capital, procurement and commercial scorecards. Use it to stress‑test capacity proposals, prioritize R&D roadmaps for specialty grades, and build commercial playbooks for targeting high value channels such as food‑contact adhesives or dyeable polyester systems.
Conclusion & Next Steps
PW Consulting’s 5‑Sulfoisophthalic Acid Monosodium Salt market study offers a pragmatically oriented intelligence package for executives preparing to act in 2026. The sector combines steady market growth, application-driven premiumization, regulatory gateways for specialty markets, and a concentrated supplier base — all features that reward disciplined, strategically timed investment.
To review the full dataset, regional and application splits, company scorecards, and downloadable investment templates, access the complete report and supplementary materials on the PW Consulting client portal. The full report contains the detailed segmentation and model outputs required to finalize procurement contracts, capital project approvals, and M&A diligences.
For detailed analysis of this topic, please visit the official page: 5 Sulfoisophthalic Acid Monosodium Salt Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Norbornane Diisocyanate (NBDI) Market: Strategic Intelligence for 2026 Decision-Making
As chief industry analyst at PW Consulting, I present an executive briefing shaped to inform boardroom priorities and operational playbooks for 2026. This release distills the strategic implications from our full Norbornane Diisocyanate (NBDI) Market study (base year 2025; historical review 2020–2025; forecast horizon 2026–2032), showing the market’s trajectory, structural dynamics, and actionable levers for manufacturers, buyers, and investors. The full report contains granular segment-level data, regional splits, and supplier-level scorecards; this summary demonstrates our analytical depth while reserving those granular datasets for subscribers and web-access requests.
Norbornane Diisocyanate (NBDI) Market
Market Snapshot: Macro Trajectory You Need to Anchor On
PW Consulting projects the global NBDI market to expand steadily through the forecast period 2026–2032. With a base year of 2025 and an observed historical window spanning 2020–2025, the market is forecast to grow at a compound annual growth rate (CAGR) of 5.24%. In revenue terms (USD Million), NBDI’s total market moved into the mid-200s by 2025 and is forecast to reach the mid-300s by 2032. That pace reflects a balanced combination of structural demand in high-performance applications and a relatively concentrated supply base that moderates price volatility but raises strategic supply risk considerations.
Norbornane Diisocyanate (NBDI) Market
Why NBDI Matters Strategically in 2026
- Specialty performance drives premium demand: NBDI’s unique rigid bicyclic molecular architecture supports demanding end-uses—optical-grade polymers, specialty coatings with enhanced durability and clarity, and high-performance elastomers—creating sustained willingness to pay for differentiated performance.
- Concentration intensifies supplier power dynamics: Market concentration metrics indicate a highly consolidated supplier landscape, which has direct implications for contract negotiation, capacity expansion decisions, and long-term off-take strategies.
- Downstream innovation cycles are catalytic: Advances in optical materials, electronic devices requiring improved polymer clarity, and specialty coating formulations are primary demand multipliers for the coming investment cycle.
- Regulatory and feedstock considerations shape near-term risk: NBDI’s regulatory footprint and precursor chemistry materially affect sourcing, cost structure, and compliance planning for 2026.
Key Dynamics Shaping 2026 Strategy
Below are the four dynamics that PW Consulting judges to be most consequential for 2026 strategic planning.
Norbornane Diisocyanate (NBDI) Market
- Supply concentration and bargaining power. Our analysis indicates clear supplier dominance in NBDI production. High concentration scores underscore the need for downstream actors to adopt diversified sourcing strategies, long-term offtake agreements, or co-investments in capacity to mitigate supply-side shocks.
- Feedstock and synthesis pathway constraints. NBDI is derived from norbornene-based precursors, with the bicyclic core typically assembled through Diels–Alder pathways involving cyclopentadiene derivatives. This chemistry links NBDI’s availability and cost to the upstream availability of cycloalkene feedstocks and to fluctuations in process economics for Diels–Alder routes. Procurement teams should layer feedstock market intelligence into pricing models and scenario planning.
- Regulatory and toxicology profile. NBDI is listed on major inventories (e.g., TSCA, DSL, ECL) and carries a documented toxicity profile that includes acute toxicity endpoints and irritation data. While listings facilitate market access, the documented hazard data make proactive compliance and communication critical—particularly for exporters and formulators serving regulated end-markets with stringent registration requirements.
- Demand composition and application pull-through. Growth is being led by high-value applications—optical lenses, specialty coatings, and precision elastomers—where performance characteristics command formulation preference. For 2026, commercialization roadmaps that emphasize formulation trials, co-development partnerships with end-users (e.g., optical manufacturers), and demonstrable lifecycle benefits will unlock disproportionate uptake.
Competitive Landscape: What the Structure Means for Strategy
The NBDI marketplace is highly consolidated. PW Consulting’s market concentration analysis signals that a few manufacturers account for an overwhelming majority of production capacity and commercial supply. For executives, this suggests three immediate strategic imperatives:
- Supplier relationship management: Establish preferred-vendor frameworks, secure multi-year contracts with volume and pricing mechanisms, and consider technical alliances that tie supplier incentives to product performance milestones.
- Risk-sharing and backward integration: Evaluate strategic investments in feedstock access or in-joint ventures for precursor manufacturing to insulate margins and secure capacity during upcycles.
- Competitor intelligence and contingency planning: Maintain up-to-date visibility on capacity additions, planned brownfield expansions, and technology shifts at incumbent producers—this should be central to procurement and M&A playbooks for 2026.
One supplier merits particular attention in this ecosystem. Mitsui Chemicals, Inc., headquartered in Tokyo, is positioned as the primary commercial producer and supplier of Norbornane Diisocyanate (NBDI™, 2,5(6)-Bis(isocyanatomethyl)bicyclo[2.2.1]heptane). The company’s product positioning emphasizes NBDI as a high-performance specialty aliphatic diisocyanate tailored to polyurethane elastomers, coatings, and optical applications, leveraging the rigid bicyclic structure for performance differentiation. For negotiators and technical teams, Mitsui’s leadership role implies that contractual terms and technical access to product grades will be a core determinant of downstream competitiveness in 2026.
Actionable Scenarios for 2026 Decision Cycles
PW Consulting frames three practical, prioritized scenarios that companies should evaluate when setting 2026 budgets and strategic initiatives:
- Protect-and-Optimize (Defensive manufacturing and procurement): For buyers with limited margin flexibility, prioritize securing multi-year supply, negotiate volume-derived pricing, and invest in second-source qualification programs. Operational teams should optimize formulations to reduce NBDI loadings while retaining required performance, thus lowering procurement exposure.
- Capture-and-Scale (Growth-oriented formulators and intermediates producers): Invest in co-development with end-market leaders (optics, specialty coatings) to lock early adoption. Consider targeted capital allocations to secure committed capacity or equity stakes in production facilities, and deploy application-specific demos that quantify lifecycle or performance advantages to justify premium pricing.
- Integrate-and-Insulate (Vertical risk mitigation): For integrated chemical players and strategic investors, evaluate backward integration into norbornene precursor streams or strategic alliances with feedstock producers. This reduces exposure to upstream bottlenecks and enables tighter control over quality for high-purity grades.
What Our Full Report Delivers (Practical, Executable Intelligence)
The PW Consulting NBDI Market report is designed as a working tool for 2026 strategy, containing:
- Multi-year market model (historical and forecast) with scenario toggles and sensitivity to feedstock cost and demand elasticity assumptions.
- Supplier scorecards featuring technical capabilities, capacity baselines, margin projections, and deal-play recommendations.
- Demand-mapping by application and by grade (high-purity vs industrial), including adoption curves, commercialization barriers, and time-to-market estimates for new formulations.
- Regulatory and safety dossier overview with compliance checklists by jurisdiction and recommended communication templates for formulators and downstream marketers.
- Procurement playbook with contract templates, risk allocation clauses, and negotiating levers for securing favorable terms in a concentrated market.
Note: This briefing deliberately omits granular regional and application-specific revenue splits and other segment-level figures to preserve the value of the full dataset. Subscribers and web visitors will find the complete tables, charts, and supplier-level metrics in the source report.
Recommendations for C-Suites and Strategy Teams
- Embed NBDI exposure in 2026 risk registers: Translate market concentration and feedstock dependencies into quantified supply-risk scenarios and stress-test P&L impacts.
- Prioritize technical validation projects: Allocate resources to joint-development trials with leading end-users to accelerate adoption and create switching costs.
- Negotiate for optionality: Structure contracts with clauses for scale-up, quality upgrades, and flexible delivery windows tied to production forecasts rather than fixed volumes.
- Monitor regulatory developments continuously: Keep product stewardship teams funded to respond quickly to any classification or labeling changes that could affect market access.
- Consider strategic capital moves: For players seeking growth or insulation, evaluate minority investments or long-term purchase agreements with incumbent producers to secure preferential access.
Conclusion — How to Use This Intelligence in 2026
NBDI is a specialty, performance-driven chemical with a structurally constrained supply base and steadily growing demand. Our model shows the market expanding at a CAGR of 5.24% from a 2025 base through 2032, reflecting persistent application-led growth tempered by supply concentration. For 2026, companies that combine disciplined procurement, technical co-development, and proactive regulatory stewardship will be best positioned to convert this growth into durable margin and market share gains.
For boards and strategy teams that require the full quantitative backbone—region-by-region forecasts, application revenue slices, supplier capacity maps, and supplier negotiation playbooks—please access the full NBDI Market report on the PW Consulting website. The full deliverable contains the confidential segment tables and the detailed financial model you will need to finalize budgets, procurement strategies, and capex decisions for 2026.
Contact PW Consulting to request the complete report and to schedule an executive briefing tailored to your organization’s exposure and strategic objectives.
For detailed analysis of this topic, please visit the official page: Norbornane Diisocyanate (NBDI) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


