



Category: market research
PW Consulting: Dispensing Robot Market Poised to Grow at a 9.24% CAGR Through 2032, New Report Finds
By PW Consulting, 2026-07-02
Dispensing Robot Market — Strategic Insights for 2026 Decision-Makers
Executive summary
As health systems, retail pharmacy chains, and high-volume fulfillment centers confront persistent labor shortages, margin compression, and pressure to improve medication safety, automation has moved from pilot projects to enterprise-grade procurement decisions. PW Consulting’s latest Dispensing Robot Market report (base year 2025) quantifies this transition and provides a practical, decision-ready playbook for executives planning CapEx and operational transformation in 2026.
Dispensing Robot Market
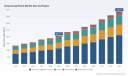
Key macro takeaways from the research: the global dispensing robot market reached approximately USD 2,073.6 Million in 2025 and is forecast to expand at a compound annual growth rate (CAGR) of 9.24% through the 2026–2032 period, with global market size projections approaching USD 3,849.5 Million by 2032. Market concentration remains moderate — the top three players account for roughly 22% of market spend, and the top five about 36% — indicating both incumbent strength and room for disruptive entrants.
Dispensing Robot Market
Why this report matters for 2026 planning
- Timing and prioritization: 2026 is a pivot year for many health systems that are revising capital budgets under constrained financial conditions. Our analysis translates macro spending pressures into tactical decision pathways for dispensing automation investments.
- Actionable investment criteria: beyond headline forecasts, the report delivers financial models (TCO and payback templates), risk scenarios, and vendor-selection scorecards that let procurement and clinical leaders rapidly move from vendor short-listing to approval-ready business cases.
- Competitive differentiation: with a market that is growing yet not highly concentrated, first-mover deployment strategies in specific operational workflows can yield outsized returns. We map those opportunity windows and the capability gaps suppliers must close.
Market dynamics and drivers
The growth trajectory for dispensing robots is driven by three converging forces: operational distress in the workforce, expanding clinical complexity and pharmaceutical volume, and the search for predictable, auditable medication distribution workflows.
Dispensing Robot Market
- Workforce pressures and efficiency mandates: Automation investments are increasingly justified as a response to staffing shortages and clinician burnout. Recent industry polling indicates that a meaningful share of health system leaders now prioritize automation and efficiency as a mitigation strategy. This has accelerated interest in solutions that can standardize dispensing tasks and reduce error-prone manual handling.
- Spending environment and capital availability: The broader hospital capital-spend landscape is mixed — a significant portion of health systems report plans to reduce capital expenditure while a smaller set plans increases — forcing nuanced, risk-adjusted investment decisions. For pharmacy leaders, however, category spend is on an upward trajectory: pharmacy expenditures are estimated to grow at roughly an 8% annual clip, buoyed by expansion in infusion, specialty, and hospital-based pharmacy services.
- Technology consolidation and demand for end-to-end workflows: Buyers are focused on end-to-end automation stories that link dispensing, inventory management, and electronic medication records. As purchasing shifts from single-module proof-of-concept buys to enterprise rollout programs, suppliers that can demonstrate robust integration, validated workflows, and predictable service economics will command a premium.
Segment-level view (what we reveal — and what we hold back)
Our report decomposes the market by product architecture, application, and geographic corridor and identifies adoption patterns, unit economics, and procurement cycles for each slice. In keeping with the “trailer” ethos of this release, we present the high-level growth rates and structural conclusions here while preserving granular segment shares and region-by-region figures for report subscribers. This approach lets readers appraise strategic trajectories without undermining the report’s role as the definitive source for procurement teams and investors who need precise allocations and supplier-level benchmarks.
Competitive landscape — who matters and why
The dispensing robot ecosystem spans established healthcare automation leaders, pharmacy-focused specialists, and systems integrators. Our competitive matrix evaluates companies across product breadth, integration capability, service footprint, regulatory track record, and channel economics.
- Omnicell, Inc. (Mountain View, California) — Omnicell brings a comprehensive pharmacy automation portfolio that spans central pharmacy dispensing, IV compounding automation, and medication management systems. Strengths include deep integration with hospital workflows and a product roadmap oriented to hospital system scale.
- Becton, Dickinson and Company (BD) — BD leverages its broad clinical portfolio and established relationships with hospitals and pharmacies. Its BD Rowa™ dispensing platform and Parata central-fill integrations reflect a strategy of bundling high-throughput dispensing with replenishment automation to serve central-fill environments.
- Capsa Healthcare — Capsa’s compact automated dispensing solutions target outpatient and retail settings where footprint and workflow flexibility are critical. Their emphasis on modular deployments makes them a pragmatic option for incremental modernization.
- Swisslog Healthcare (KUKA Group) — Swisslog emphasizes warehouse-scale automation, storage and retrieval, and robotics that support hospital and health-system logistics. Their value proposition centers on large-scale, integrated automation programs.
- ScriptPro LLC, Yuyama, Parata Systems (BD Parata), ARxIUM, Baxter, and McKesson — Each of these vendors occupies specific niches from high-speed vial filling and central-fill automation to dispensing cabinets and full-service distribution solutions. The competitive field is defined by specialization, integration depth, and service models rather than simple price competition.
Recent market activity underscores vendor innovation and go-to-market shifts. For example, late-2025 product introductions highlighted capabilities in high-speed boxed medication dispensing with automated replenishment — a clear signal that suppliers are prioritizing throughput, replenishment automation, and operator ergonomics for large-scale pharmacy operations.
How purchasers should use the report in 2026
- Align CapEx with clinical ROI: Use our scenario-based ROI templates to stress-test projects under variable volume, labor cost inflation, and capital availability assumptions. This is critical where hospitals are tightening budgets but pharmacy volumes continue to rise.
- Vendor short-listing and contracting: Apply the supplier-selection scorecards and service-level templates to negotiate performance-based contracts that align payments with uptime, throughput, and integration milestones.
- Phased deployment playbooks: Adopt our phased implementation checklists and workforce transition plans to minimize disruption. The report details pragmatic roll-out sequencing — from single-unit validation to enterprise-scale central-fill conversions — without exposing sensitive commercial benchmarks in this release.
- Regulatory and compliance mitigation: Integrate the report’s compliance checklist and validation protocols into procurement clauses to reduce time-to-service and regulatory risk during installation and go-live.
Report contents — practical deliverables
PW Consulting’s Dispensing Robot Market report offers a full suite of operational tools designed for immediate use by procurement teams, clinical leaders, and investors:
- Market sizing and seven-year forecast (2026–2032) with scenario analyses and sensitivity testing.
- Segmentation analysis by product architecture, application, and geography, with adoption curves and TCO comparisons (note: granular segment-level figures are available in the full report).
- Competitive benchmarking: vendor profiles, technology roadmaps, partnership networks, and procurement scorecards.
- Implementation playbooks: site selection criteria, integration checklists for EMR/Pharmacy systems, project governance templates, and workforce transition plans.
- Finance-ready tools: TCO models, payback calculators, and CapEx vs. Opex leasing comparisons tailored to common hospital and retail procurement frameworks.
- Risk and compliance frameworks: validation protocols, quality assurance steps, and post-implementation performance monitoring indicators.
Outlook and strategic recommendations
For 2026, we offer three clear recommendations grounded in the report’s quantitative and qualitative analysis:
- Prioritize deployments that deliver both labor relief and measurable safety improvements. Projects with clear error-reduction metrics and predictable labor substitution profiles achieve faster executive buy-in even amid constrained CapEx.
- Negotiate outcome-linked contracts. Given the mixed capital outlook across health systems, structuring deals with uptime guarantees and milestone-linked payments lowers procurement friction and aligns supplier incentives with clinical objectives.
- Invest in integration and change management early. The largest execution risks we observed arise from poor systems integration and inadequate site-level workflow redesign. Treat integration budgets and training plans as core line items in any procurement request.
Conclusion — the strategic value of the research
PW Consulting’s Dispensing Robot Market report is designed as an execution-oriented intelligence product — not simply a market snapshot. It equips leaders with the forecasting, procurement tools, and operational frameworks needed to make defensible 2026 investment decisions in a financially constrained and operationally urgent environment. The report’s detailed segment-level datasets, vendor scorecards, and TCO calculators are intentionally retained for subscribers to preserve the research’s value and to enable precise procurement and negotiation activities.
To access the full dataset, vendor matrices, and downloadable decision tools that underpin the insights summarized here, please refer to the full report at the PW Consulting insights portal.
For detailed analysis of this topic, please visit the official page: Dispensing Robot Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Potassium Cocoyl Hydrolyzed Collagen Market Poised to Reach USD 322.48 Million by 2032, Expanding at a 5.25% CAGR
By PW Consulting, 2026-07-02
Potassium Cocoyl Hydrolyzed Collagen Market — Strategic Outlook for 2026: PW Consulting Executive Brief
PW Consulting’s latest industry study on the Potassium Cocoyl Hydrolyzed Collagen market provides a compact but actionable intelligence package tailored for commercial leaders, procurement chiefs, R&D heads and corporate strategists preparing decisions in 2026. Anchored on a 2020–2025 historical review and a 2026–2032 forecast horizon, the study quantifies where the market stands today and where it is headed: the global market expanded from roughly USD 175 million in 2020 to an estimated USD 225.4 million in 2025, and under our central case it grows at a 5.25% CAGR to reach approximately USD 322.5 million by 2032. These macro dynamics create both opportunity and risk for firms active in personal-care formulations and ingredient supply chains; this brief highlights the levers senior teams should prioritise in 2026.
Potassium Cocoyl Hydrolyzed Collagen Market
Why 2026 Is a Pivotal Year
-
Regulatory inflection points: Two developments are changing the compliance landscape. First, the US FDA’s early-2025 removal of coconut from its major allergen list materially reduces labeling friction for coconut-derived ingredients—opening faster go-to-market routes across tens of thousands of SKUs. Second, the CIR Expert Panel’s 2025 Tentative Amended Safety Assessment for cocoyl hydrolyzed collagens signals renewed scrutiny and the need for additional supplier safety data on sensitization. Together these trends lower some commercial barriers while raising the bar for documented safety and supplier transparency.
Potassium Cocoyl Hydrolyzed Collagen Market -
Raw-material and supply risks: Climate-driven yield shocks (notably an El Niño-related decline in coconut production) pushed crude coconut oil prices materially higher and introduced supply volatility in 2024–2025. Simultaneously, public and private support programs in producing countries (for example, recent fertilization programs) aim to rebuild resilience—creating a multi-year period of elevated price and availability uncertainty.
Potassium Cocoyl Hydrolyzed Collagen Market -
Market structure that rewards focus: The category displays moderate concentration: leading suppliers collectively control a meaningful share of supply, creating both upward pricing power in constrained windows and opportunities for challengers who can guarantee quality, compliance, and availability.
What the PW Consulting Report Delivers (Practical, Board-Ready Tools)
-
Robust macro sizing and scenario forecasts (base year 2025, historical 2020–2025, forecast 2026–2032) with three demand-pressure scenarios and elasticity sensitivities tied to raw-material price shocks.
-
Supplier dossiers and scorecards: operational footprints, regulatory dossiers, product positioning, recent product updates and catalog releases, and a scored assessment on supply resilience and traceability.
-
Regulatory risk matrix mapped to sourcing and formulation choices, and a playbook for rapid response to CIR or equivalent assessor requests.
-
Procurement and pricing playbooks including hedging scenarios, contractual clauses, and inventory optimisation tools validated against empirical price volatility observed in 2024–2025.
-
Commercial go-to-market modules for brands: claim frameworks that reconcile “mild/conditioning” positioning with safety substantiation, plus consumer-test templates and launch timing calendars aligned to regulatory changes.
-
M&A and partnership screens that flag targets by capability (manufacturing scale, specialty derivative portfolios, vertical feedstock exposure) and deliver a short list for diligences.
Competitive Landscape: What the Leading Suppliers Signal for 2026
-
BASF Personal Care (Germany) — a formulation-focused incumbent that positions Potassium Cocoyl Hydrolyzed Collagen derivatives such as co‑surfactant condensates for mild cleansers and shampoos. Recent product- and datasheet updates indicate investment in specification clarity and claims support for formulators. For buyers, BASF’s depth in formulation science is an asset when rapid reformulation or claims substantiation is required; suppliers like BASF are also likely to use technical support as a differentiator if raw-material tightness continues.
-
SEIWA KASEI Co., Ltd. (Japan) — pursuing an “upcycled ingredient” narrative: their HAZUMI-HADA and Promois series emphasize anti‑aging and sustainability credentials derived from fish-scale upcycling. Their recent catalog refresh underscores a twin strategy of NPD and traceability storytelling—an approach that will resonate with brand teams prioritising circularity and premium claims.
-
Active Concepts (USA) — a specialist ingredient house offering ISO‑aligned foaming collagen derivatives aimed at mild, hair- and skin-friendly formulations. Their positioning is tactical for private-label brands and smaller formulators who value ready-to-use ingredient formats and compliance conformity.
-
Strategic implication: The market’s competitive topology rewards either deep formulation-support services (for larger suppliers) or nimble, niche differentiation (for specialist houses). Expect continued product literature updates and catalog refreshes as players sharpen claims and safety dossiers in response to CIR inquiries and buyer demand.
2026 Procurement and Sourcing Playbook — Recommended Immediate Actions
-
Reassess contracts and adopt flexible volume bands: renegotiate force‑majeure, lead‑time clauses and pricing floors that anticipate elevated coconut-derivative cost windows.
-
Multi-sourcing and regional dual-sourcing: institute qualified second-source arrangements and raw-material substitution feasibility studies to reduce single-supplier exposure.
-
Obtain supplier-level safety and impurity data: accelerate data-sharing agreements to be able to respond within CIR timelines and to reduce product launch risk.
-
Engage in collaborative forecast-and-replenishment pilots with strategic suppliers to reduce inventory holdings while improving fill rates during supply shocks.
R&D, Claims and Product Strategy — Where to Invest in 2026
-
Prioritise substantiation that aligns with both mildness and conditioning claims. With regulatory scrutiny focused on sensitization, invest in targeted in-vitro and controlled-use studies that can be deployed across product portfolios.
-
Leverage ingredient-format strategies: salt forms and pre-blended complexes change handling, cost-in-use and shelf-life profiles. Our report maps these trade-offs and provides time-to-market impact estimates for typical reformulations.
-
Capitalize on the allergen-list change: update packaging and claims roadmaps to capture incremental SKU opportunities unlocked by eased labeling constraints—while ensuring transparency to maintain consumer trust.
Scenario-Based Financial Planning
-
Model three price-transmission scenarios: baseline (moderate inflation of feedstock), adverse (sustained high prices with intermittent shortages), and upside (stabilization as producing countries scale resilience programs). Each scenario in our deliverable includes P&L and cash-flow impacts for typical small, mid and large formulators across a 24‑month planning window.
-
Use the scenario outputs to set trigger points for tactical actions—e.g., when to institute permanent multi-sourcing, when to convert to longer-term fixed-price agreements, and when to accelerate product reformulations to lower-cost substitutes.
How Boards and Strategy Teams Should Use This Report in 2026
-
As a procurement playbook: adopt the report’s supplier scorecards and contract clause templates to renegotiate supplier terms and reduce short-term exposure.
-
As an R&D roadmap: prioritise clinical and safety studies highlighted in the report to expedite product launches and defend claims in a tightened regulatory context.
-
For M&A and partnership screening: deploy the report’s shortlist and valuation-ready models to identify targets that deliver feedstock security, formulation IP or entry into niche premium segments (e.g., upcycled collagen derivatives).
-
For investor and external communications: convert scenario outputs into stress-test narratives that explain how the company will mitigate commodity and regulatory risks.
PW Consulting’s deep-dive report is built to be operational: it combines a clear macro view (historical evolution to 2025 and a 2026–2032 forecast at a 5.25% CAGR), practitioner tools, and supplier-level intelligence that together enable rapid, risk-calibrated decision-making. We intentionally present high-level findings here to guide immediate priorities; the full report contains the granular segmentations, supplier dossiers, Excel modelling files and step-by-step playbooks you will need to implement a winning 2026 program.
Next Steps
-
If your team is allocating budgets or revising sourcing strategies for 2026, schedule a briefing with PW Consulting to review the full dataset, bespoke scenario runs and a priority checklist tailored to your organisation’s exposure.
-
For immediate operational use, request the procurement clause templates and supplier-scorecard workbook included in the full report package to begin contract and supplier capacity assessments this quarter.
Contact PW Consulting to access the full Potassium Cocoyl Hydrolyzed Collagen Market report, including detailed segmentation, supplier profiles, downloadable modelling workbooks and our recommended playbooks to turn 2026 uncertainty into competitive advantage.
For detailed analysis of this topic, please visit the official page: Potassium Cocoyl Hydrolyzed Collagen Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Handheld Microphones Market Poised for 5.42% CAGR During 2026–2032, New Report Reveals
By PW Consulting, 2026-07-02
Handheld Microphones Market — PW Consulting Strategic Brief for 2026 Decisions
PW Consulting’s latest market study on handheld microphones delivers a high-impact, decision-ready briefing for executives planning product, supply chain, and M&A moves in 2026. The global market reached USD 2,845.5 Million in 2025 and, under our base forecasting assumptions, is expected to expand at a 5.42% CAGR through the 2026–2032 horizon, reaching approximately USD 4,117.36 Million by 2032. These headline numbers frame a market that is large enough to matter to audio incumbents and newcomers alike, yet sufficiently fragmented to reward targeted strategic plays.
Handheld Microphones Market
Why this brief matters for 2026
- Rapid technology migration (wireless systems, digital RF, integrated IEM compatibility) is reshaping product roadmaps and aftermarket value streams.
- Supply-side shocks and regulatory inflection points in 2024–2026 are forcing manufacturing, sourcing and compliance choices that will lock cost positions for years.
- Market concentration is moderate: the top three vendors do not dominate the landscape, leaving room for acquisition-driven scale or product-led disruption.
- Our report is designed as a practical playbook — not just a forecast — so leaders can convert insight into near-term actions with quantified risk/reward trade-offs.
Headline, data-driven takeaways
After recovering from pandemic-era distortions, handheld microphone demand shows steady, mid-single-digit growth driven by the convergence of three durable trends: continued professional live-audio recovery, accelerated adoption among content creators and broadcasters for wireless digital solutions, and a premiumization trend in higher-fidelity condenser and modular handhelds. PW Consulting’s base model projects the market to grow from USD 2,845.5 Million in 2025 to roughly USD 4,117.36 Million by 2032 at a 5.42% CAGR (forecast period 2026–2032). Market concentration metrics indicate opportunity: the three largest firms control around 42% of value, and the top five just under 60% — signaling a competitive arena with meaningful room for bolt-on consolidation, brand differentiation, and channel innovation.
Handheld Microphones Market
What the PW Consulting report contains — practical, executable deliverables
- Market sizing & forecast model (interactive): top-line scenario runs, sensitivity to input-cost inflation and wireless spectrum dynamics.
- Go-to-market playbooks: product positioning templates for premium, mid-tier and value handhelds; channel & pricing tactics for distributors vs. direct-to-creator approaches.
- Competitive scorecards: strategy, product roadmap signals, strengths/weaknesses, and likely strategic moves for every major vendor in the space.
- Supply chain & procurement playbook: dual-sourcing matrices, long-lead component hedging templates, and a supplier risk heat map linked to real-world contract clauses.
- Regulatory & compliance checklist: practical steps to meet imminent directives and export-control constraints, including engineering workarounds and certification timelines.
- M&A screening toolset: proprietary target-filter that combines technical differentiation with accretive revenue and cost-synergy estimates.
- Implementation timelines and KPIs: 90/180/360 day action plans with measurable milestones for product launches, factory retooling and channel rollout.
Note: the full report contains the detailed segment and regional splits, model spreadsheets, and the granular company financial proxies that underpin our recommendations; those are intentionally reserved for report subscribers and clients.
Handheld Microphones Market
Competitive landscape — who matters and why
The handheld microphone arena is served by a mix of heritage audio brands and agile challenger firms. PW Consulting’s qualitative and quantitative assessment highlights the following strategic positions:
- Shure Incorporated (Niles, Illinois) — A market leader in professional handhelds and wireless transmitters. Recent product activity signals continued focus on wireless interoperability and transmitter ecosystems. Shure’s legacy models remain strong anchors for live-sound customers, but component scarcity has prompted limited production runs on some wired classics, underscoring supply vulnerabilities.
- Sennheiser (Wedemark, Germany) — Strong in high-end stage and broadcast applications, with an evident push into fully digital wireless systems and integrated monitoring. Their trade-show and product update cadence suggests a platform approach—bundling mics with wireless and monitoring solutions.
- Audio‑Technica (Stow, Ohio) — Demonstrating iterative expansion in digital wireless SKUs. Their strategy mixes cost-conscious options for events and higher-margin digital handheld systems for broadcasters.
- AKG (Harman) & other legacy audio OEMs — Lean on brand recognition for stage and studio, while integrating product roadmaps into broader audio ecosystems (mixers, IEMs, processing).
- Neumann, DPA, Beyerdynamic — Niche and premium specialists focused on fidelity, modularity, and theater/studio applications where margin and brand trust are decisive.
- Rode, Samson — Aggressive at the content-creation and budget segments, pushing wireless sampling and compact systems to capture the long tail of creators and journalists.
Our company profiles in the full report combine product-level intelligence, patent analytics, dealer-channel mappings, and readiness scores that identify which firms are acquisition targets, likely consolidation leaders, or vulnerable to technology disruption.
Supply, regulation and cost dynamics to watch in 2026
- Raw-material pressure: a marked increase in magnetic-material costs in 2024 tightened transducer economics — event-driven price spikes for neodymium altered BOM cost structures and pushed some suppliers to re-evaluate magnet sourcing.
- Regulatory inflection: an EU restriction tightening lead content in solder joints takes effect mid-2026, requiring engineering redesigns or new assembly processes for products sold into that market.
- Geopolitical friction: export-control measures around rare earths and related components require stricter supplier due diligence and, in many cases, alternate sourcing pathways.
- Labor and location economics: rising manufacturing wages in Southeast Asia are changing the calculus for low-cost assembly; nearshoring and automation are back on the table for firms focused on margin protection.
- Legacy SKU disruption: supply disruptions have already forced limited productions of high-volume legacy mics, creating secondary-market demand and brand risk if availability is not managed.
Each of these dynamics is modeled in our stress-test scenarios so leaders can understand P&L sensitivity, product margin erosion, and time-to-market risk under plausible downside cases.
Actionable strategic playbook for 2026
- Short-term (0–6 months): secure multi-year commitments for critical transducer inputs; prioritize RoHS-compliant redesigns for major SKUs; freeze spectrum- and firmware-level requirements for wireless launches.
- Medium-term (6–18 months): accelerate modular-platform investments that allow shared baskets of parts across wired/wireless SKUs; expand service/firmware revenue streams to offset hardware margin pressure.
- Capital allocation & M&A: target tuck-ins that add wireless RF expertise, digital codecs, or service platforms rather than purely geographic expansion; use our M&A screening tool to size likely accretion and integration costs.
- Channel & product: for brands balancing pro and creator segments, adopt tiered SKUs with clear upgrade paths (hardware + subscription) to maximize lifetime value while protecting channel margins.
- Supply risk mitigation: combine dual-sourcing, qualified substitutions, and contract hedges; evaluate nearshoring for high-variability SKUs and automation investments where labor inflation is material.
Decision scenarios: prioritized first steps
- Manufacturer planning a new wireless handheld line: lock RF/codec standards, validate supplier roadmaps for rare-earth components, and negotiate conditional ROI-based tooling investments.
- Distributor optimizing inventory for 2026: prioritize high-turn, wireless-compatible SKUs and secure returnable-stock flex to manage legacy-model scarcity.
- Private equity evaluating targets: favor businesses with software/firmware platforms or proprietary RF stacks that offer post-sale monetization and defensible margins in a consolidating field.
Conclusion — the strategic value of the PW Consulting report
For leaders making pivotal 2026 decisions, the value of this study is its combination of rigorous market projection (USD 2,845.5 Million base in 2025; 5.42% CAGR 2026–2032) and operationally focused playbooks that translate scenarios into executable tactics. Whether managing product roadmaps, securing supply chains, or evaluating M&A, the report equips teams with the models and templates to act decisively while preserving strategic optionality.
To access our full company scorecards, segment and regional splits, interactive forecast models, and the complete set of implementation resources, consult the full PW Consulting Handheld Microphones Market report. Our subscription service also includes tailored advisory calls to adapt the insights to your balance-sheet and go-to-market realities.
For detailed analysis of this topic, please visit the official page: Handheld Microphones Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Customer Support Training Software Market Poised to Hit USD 2.71 Billion by 2032 with 12.85% CAGR as Cloud-Based Solutions Lead with USD 1.01 Billion in 2025
By PW Consulting, 2026-07-02
Customer Support Training Software Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As enterprises recalibrate customer experience investments for 2026, the market for customer support training software has entered a clearer, faster-moving phase. PW Consulting’s forthcoming market study — anchored on a 2025 base year and projecting through 2032 — shows a sustained double-digit trajectory (compound annual growth rate of 12.85%) and a material expansion from the mid‑2020s into the early 2030s. For boards, CHROs, heads of customer success, and procurement leads, the findings translate into urgent strategic choices: how to select platforms that accelerate time‑to‑competency, protect customer data, and demonstrate measurable ROI while navigating a still‑fragmented vendor landscape.
Customer Support Training Software Market
Why 2026 Is a Decision Point
Customer expectations, product complexity, and regulatory pressure are converging to make support training more than a soft‑skill line item: it is a business continuity and growth lever. PW Consulting’s model places the 2025 market at an important inflection level and shows a multi‑year uptrend through 2032, underscoring the opportunity for organizations that make pragmatic investments now. The market’s growth rate signals that investment windows are being established — those that delay risk paying a premium for rapid catch‑up later.
Customer Support Training Software Market
What the Report Delivers (Practically)
Rather than a theoretical overview, this study is designed as an operational playbook for buyers and strategists. Highlights include:
Customer Support Training Software Market
- Vendor evaluation frameworks tailored to enterprise procurement cycles, including security and compliance checkpoints specific to training platforms.
- RFP templates and scoring rubrics that translate business outcomes (reduction in average handle time, ticket deflection, first‑contact resolution improvements) into procurement criteria.
- Implementation roadmaps and phased rollout plans that minimize business disruption and accelerate measurable learning outcomes.
- ROI modeling tools that account for training program amortization, agent ramp time, and support cost savings under different adoption scenarios.
- Content and curriculum blueprints for blended learning — combining microlearning, role‑play simulations, and on‑the‑job coaching for support teams.
- Change management playbooks addressing manager enablement, trainer certification, and governance for learning content updates.
Market Structure and Competitive Dynamics — What You Need to Know
The competitive picture remains moderately fragmented: the top three and top five vendors account for meaningful but not dominant portions of the market, leaving room for specialization, verticalized solutions, and consolidation. For 2026 procurement strategies, fragmentation implies three pragmatic approaches: partner with platform leaders to de‑risk scale, test specialized vendors for capability gaps, or build hybrid stacks that integrate best‑of‑breed training engines with enterprise LMS and CRM layers.
Key vendors profiled in the report include market‑leading and specialist platforms whose positioning matters to buyers:
- Skilljar — strong in customer education and branded academies designed to reduce support load and drive product adoption.
- Docebo — brings AI‑augmented LMS capabilities geared toward scalable enterprise learning and partner enablement.
- TalentLMS — a cloud‑native solution noted for rapid deployment, content management ease, and mobile access.
- LearnUpon — emphasizes automation for external education, an important consideration for partner and customer onboarding.
- Northpass, Absorb LMS, 360Learning — each occupies differentiated niches from customer success academies to compliance-driven enterprise training and collaborative peer learning.
- iSpring, eloomi, AcademyOcean, Comm100, Seismic Learning — provide a spectrum of authoring tools, simulation capabilities, and blended learning features that are mission‑critical for support teams.
Our qualitative vendor analysis compares go‑to‑market focus, product architecture, extensibility, security posture, and ecosystem integrations. The report also synthesizes recent vendor signals — platform reviews, market rankings, and public presentations — that indicate shifting priorities (for example, emphasis on interactive content, AI assistance, and measurable ROI metrics).
Industry Dynamics Shaping Vendor Selection
Four converging dynamics are driving buyer behavior and should shape strategic procurement in 2026:
- AI adoption in support workflows — A significant portion of organizations have implemented formal AI training for experience teams, changing expectations for agent assist, personalized learning pathways, and adaptive assessments. Platforms that offer real‑time assist, scenario simulation, and AI‑driven personalization will have a strategic edge.
- Data protection and regulatory obligations — Evolving privacy rules require demonstrable staff training on data handling. Vendors must support fine‑grained access controls, audit trails, and compliance reporting to be considered for regulated industries.
- Labor economics and speed to competency — AI tools are increasingly reducing cognitive load and compressing ramp time for new hires. Buyers should quantify the training‑to‑productivity curve and prioritize solutions that measurably shorten it.
- Fragmentation and specialization — The market’s current structure rewards both horizontal platforms and specialist providers. Enterprises must decide whether to consolidate on fewer platforms for governance or assemble modular stacks for capability precision.
Recent Market Signals and Their Strategic Implications
- Vendor evaluations and product comparisons released in early 2026 reflect a stronger emphasis on interactive and product‑centric training capabilities, highlighting providers that combine authoring tools with simulation features.
- Industry rankings that call out measurable ROI are shifting procurement conversations from feature checklists to outcome‑based contracts tied to operational KPIs.
- Thought leadership from large support software vendors underscores that AI integration is not a buzzword — it is a capability buyers must validate end‑to‑end (from content creation to in‑ticket assist).
Actionable Guidance for 2026 Decision‑Makers
PW Consulting recommends a pragmatic, risk‑managed path to capture the upside of the expanding market while controlling implementation risk:
- Start with outcome definitions: quantify the business benefits you expect (ticket deflection, handle time reduction, NPS uplift) and translate them into minimum acceptable vendor SLAs and KPIs.
- Run short, instrumented pilots that stress test AI assistance, simulation fidelity, and interoperability with CRM and knowledge bases. Measure time‑to‑competency and customer impact, not just course completion rates.
- Require vendors to demonstrate compliance features and provide evidence of secure data handling; insist on encryption, role‑based access, and comprehensive audit logs for training data flows.
- Favor modular architectures where possible: decouple authoring and delivery from long‑term content governance so you can swap components without retraining content teams.
- Negotiate outcome‑linked commercial terms for larger deals — license fees tied to adoption thresholds or performance milestones align vendor incentives with business objectives.
- Invest in internal capability: appoint a cross‑functional learning governance team (support ops, product management, security, and HR) to maintain content relevance and compliance over time.
How PW Consulting’s Report Supports Your 2026 Roadmap
The full PW Consulting report is structured to accelerate decision cycles. It combines quantitative forecasting, vendor due diligence, procurement tools, and implementation playbooks into a single actionable resource. Key deliverables in the full report include:
- Detailed scenario‑based forecasts and sensitivity analysis to stress‑test investment cases across adoption curves.
- Vendor scorecards and integration matrices to reduce evaluation time and surface hidden technical risks.
- Operational templates — RFPs, pilot plans, curriculum outlines, and success measurement dashboards — that you can tailor and deploy immediately.
- Change management and governance frameworks designed to lock in training benefits and continuously update content in response to product and regulatory changes.
Final Perspective
For 2026, market signals are unambiguous: customer support training software is shifting from discretionary spend to strategic infrastructure. The market’s robust growth rate and multi‑year upside create a compelling case for proactive investment, but success depends on disciplined procurement, measurable pilots, and vendor governance anchored in compliance and AI‑capability validation. PW Consulting’s analysis and playbooks are built to help leaders make those decisions with speed and confidence.
To access the comprehensive vendor scorecards, the full segmentation analysis, and proprietary forecasting models (including downloadable procurement templates and ROI calculators), request the complete PW Consulting Customer Support Training Software Market report through our official distribution channels.
For detailed analysis of this topic, please visit the official page: Customer Support Training Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Refractory Bricks Market to Rise from USD 21,450.5M (Base year 2025) to USD 29,426.6M by 2032 at 4.62% CAGR; Asia‑Pacific Leads with USD 10,225.3M
By PW Consulting, 2026-07-02
Refractory Bricks Market: Strategic Intelligence for 2026 Decision‑Making
Executive preview
PW Consulting’s latest Refractory Bricks Market report synthesizes hard market metrics, supply‑chain stress testing, regulatory mapping, and competitive playbooks into a single operational guide for executives planning 2026 actions. The shaped‑brick market has moved from roughly USD 17.1 billion in 2020 to an estimated USD 21.45 billion in 2025 and is projected to continue expanding through the forecast horizon — reaching an estimated USD 29.4 billion by 2032. That trajectory corresponds to a 2026–2032 compound annual growth rate (CAGR) of approximately 4.62% and reflects the interplay of industrial growth, raw‑material price dynamics, and accelerating decarbonization pressures.
Refractory Bricks Market
Why this report matters for 2026 planning
-
Actionable foresight, not academic theory: The report translates market forecasts and scenario work into decision levers that procurement, operations, and corporate strategy teams can act on within the coming 12 months.
Refractory Bricks Market -
Span of influence: Coverage crosses the value chain — from raw‑material sourcing and processing economics to kiln operations, shaped brick production, and aftermarket services — enabling cross‑functional alignment on CapEx, sourcing, and service models.
Refractory Bricks Market -
Stress‑tested scenarios: We present three pragmatic scenarios (baseline, price‑shock, and decarbonization acceleration) with quantified P&L and cash‑flow sensitivities so leaders can prioritize hedges and investment phasing in 2026.
-
Competitive playbooks: The analysis identifies where scale wins, where specialization is defensible, and where regional logistics and services form sustainable moats.
Market trajectory and implications
The market’s recent expansion and the forecast path underline two simultaneous dynamics: steady demand driven by foundational industries and episodic supply‑side volatility tied to raw materials and regulation. Our base estimates show the industry recovering and growing post‑pandemic, with an anticipated step‑up in absolute market value through the late 2020s. For 2026, the key implication is simple: demand is neither collapsing nor hyper‑booming — it is growing with structural tailwinds and distinct pockets of stress that can be exploited by well‑positioned players.
For corporate planners this means prioritizing flexibility: investment decisions should favor modular capacity increases, dual‑sourcing strategies for critical feedstocks, and service offerings that capture aftermarket value (installation, predictive maintenance, and refractory recycling). Organizations that treat refractories as a dynamic cost and service channel — rather than a static line item — will preserve margin and open adjacent revenue streams.
Key drivers, risks, and regulatory context
-
Raw‑material exposure: Production economics remain heavily dependent on core inputs — alumina, magnesia, silica — which can represent the majority of production cost. Price volatility in these commodities materially affects both manufacturing margins and buyers’ LCC (lifecycle cost) calculations.
-
Regulatory pressure: Emissions and trade policy are material. Notably, European ETS provisions that treat the firing of ceramic products as a regulated activity and rising import duties in certain producing countries have already re‑shaped supplier economics and trade flows. Procurement teams must incorporate regulatory pass‑through risk into supplier evaluations.
-
End‑market linkage: Global steel production acts as a demand barometer for many refractory types. Changes in steel output, furnace technology adoption, and service life expectations feed directly into refractory demand and composition.
-
Decarbonization dynamics: There is an emerging bifurcation between vendors who invest in low‑carbon inputs/processes and those that aim for cost leadership. Awards and pilot projects in carbon‑capture‑linked refractory initiatives signal that sustainability investments are both reputational assets and potential commercial differentiators.
Competitive landscape — who matters and why
The market structure is characterized by a mix of global integrated producers and nimble regional specialists. Our competitive analysis profiles the strategic posture of major players and identifies the routes they are using to protect or expand value:
-
RHI Magnesita (Vienna): A vertically integrated leader with broad shaped‑brick capabilities and global footprint. Investment in low‑carbon projects and project award wins signal its intent to lead on sustainability as well as scale.
-
Vesuvius PLC (London): Focused on high‑performance solutions for metals and foundry customers; its strength lies in specialized products and applications engineering.
-
Shinagawa and Krosaki Harima (Japan): Technology‑driven producers with strong product breadth and export capabilities, especially in high‑performance alumina and specialty bricks.
-
Saint‑Gobain Performance Ceramics & Refractories (France): Offers advanced ceramic and fused‑cast solutions for the most demanding thermal environments, emphasizing premium product segments.
-
Regional champions (HarbisonWalker, IFGL, Resco, Puyang, Chosun, etc.): These players combine local market knowledge with custom‑shape engineering and responsive aftercare services — a competitive advantage in time‑sensitive furnace operations.
Market concentration is moderate: the top tier of firms captures a meaningful but not overwhelming share of market value, leaving room for specialists and regional consolidators to capture profitable niches. Recent M&A and capacity actions — including targeted acquisitions and brownfield expansions — underscore a market where scale, service reach, and raw‑material access are strategic differentiators.
Recent market moves and what they signal for 2026
-
Acquisitions expanding distribution and regional inventory point to a tactical race for service density in time‑sensitive territories.
-
Capacity investments at monolithic and shaped facilities reflect a dual play: some firms are betting on demand growth while others are aiming to shorten lead times and improve margin capture through vertical integration.
-
Sustainability awards and pilots indicate the early commercial value of low‑carbon refractory systems; buyers and investors will increasingly prize technologies with verifiable carbon credentials.
What the PW Consulting report contains (operationally usable)
-
Validated market model: Annual market size series, demand drivers by end‑use, and a seven‑year forecast framework, calibrated to industry KPIs and plant‑level economics.
-
Scenario playbooks: Three executable scenarios with quantified P&L impacts and recommended tactical responses for procurement, manufacturing, and commercial teams.
-
Supplier risk matrix: A short‑list of critical supplier risk exposures and actionable mitigation levers, including contract clauses, inventory strategies, and supplier development pathways.
-
CapEx and plant optimization guidance: Benchmarks for kiln utilization, refractory yield improvement initiatives, and a roadmap for modular capacity expansion with estimated payback bands.
-
Aftermarket commercialization toolkit: Pricing architecture, service bundling options, and a field‑service playbook to convert short replacement cycles into recurring revenue.
-
Regulatory and trade play sheets: Country‑level regulatory risk profiles, anticipated compliance costs, and trade‑flow sensitivities that should inform sourcing and local‑investment decisions.
Practical recommendations for 2026
-
Make raw‑material exposure a Board item: Establish quarterly stress tests that feed into working capital and pricing decisions.
-
Prioritize dual‑sourcing and strategic inventories for critical minerals in regions with trade volatility.
-
Invest in service density: Expand regional inventories and rapid‑response teams to capture aftermarket margin and shorten furnace downtime.
-
Allocate a small strategic R&D/CapEx bucket to low‑carbon refractory pilots — the technology premium is emerging and will widen with regulatory tightening.
-
Use modular capacity investments for optionality: favor brownfield add‑ons that can be scaled to demand without large initial write‑offs.
How this report functions as a decision tool
PW Consulting’s report is structured to move executives from insight to action within a six‑ to twelve‑month horizon. It translates macro forecasts into procurement actions, capital timing decisions, and commercial tactics. For CFOs and Heads of Procurement, the raw‑material scenarios and supplier risk matrices provide immediate inputs to budget and hedge discussions. For COOs and plant managers, the kiln‑level optimization guidance and aftermarket monetization playbooks are road‑tested templates that can be deployed with limited pilot CAPEX.
Closing note — the trailer principle
The material above highlights the strategic contours and operational levers in the refractory bricks market. To preserve the commercial value of granular segmentation, supplier shares, and proprietary sub‑segment forecasts, the report holds the detailed split tables, plant‑level economics, and vendor scoring matrices for the full report package. PW Consulting clients and report purchasers gain access to those detailed models, downloadable scenario files, and an executive workshop designed to convert insight into a 90‑day tactical plan.
Next steps
-
Download the full report or contact PW Consulting to schedule a bespoke executive briefing and a 90‑day implementation roadmap tailored to your operating footprint.
-
For immediate tactical use, request the supplier risk matrix and the price‑shock scenario worksheet — these are available separately and intended to be integrated into 2026 budget cycles.
For detailed analysis of this topic, please visit the official page: Refractory Bricks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Poultry Farm Equipment Market Poised for a 5.2% CAGR in the 2026–2032 Forecast
By PW Consulting, 2026-07-02
Poultry Farm Equipment Market: Strategic Imperatives for 2026 — PW Consulting Industry Brief
As global protein supply chains continue to recalibrate, PW Consulting’s newly released Poultry Farm Equipment Market report — with base year 2025 and a forecast horizon through 2032 — delivers a practical, decision-grade roadmap for executives planning capital allocation, product strategy, and M&A through 2026. Our analysis finds the market reached approximately USD 5,213.6 Million in 2025 and is expected to expand at a compound annual growth rate (CAGR) of 5.2% across the 2026–2032 forecast window, reaching roughly USD 7,434.4 Million by 2032. This brief highlights the strategic value of the report for executive teams while preserving the proprietary segment-level detail that sits behind our paywall.
Poultry Farm Equipment Market
What this means for 2026 decisions
-
Predictable mid-single-digit growth provides a stable planning base: A 5.2% CAGR supports multi-year capital planning without requiring defensive retrenchment, but it also demands differentiation and productivity gains to outpace peers.
Poultry Farm Equipment Market -
Moderate market concentration: The top three players account for a meaningful but not dominant share of the market (CR3 ~31.4%), and the top five reach roughly 42.8% (CR5), implying healthy room for regional specialists, disruptive entrants, and consolidators.
Poultry Farm Equipment Market -
Operational decisions must balance capex and service: Given the capital-intensive nature of equipment and the growing importance of aftermarket services and automation, 2026 should be the year to lock in long-term service and lifecycle-revenue strategies alongside hardware investments.
-
Volatility requires scenario-ready procurement: Historical year-to-year movement (2020–2025) underscores susceptibility to input cost swings and demand cycles — procure and hedge with scenario-triggered contracting clauses and modular procurement paths.
Industry dynamics shaping near-term strategy
-
Labor dynamics accelerating automation adoption — Persistent labor shortages and high turnover in repeatable hatchery and processing tasks are pushing operators toward robotics, automated catching, and automated sexing solutions. The report quantifies the labor-driven ROI thresholds that make automation purchase decisions compelling in 2026.
-
Raw material and component price pressure — Fluctuations in steel and component costs materially affect equipment BOMs. Our stress-testing models show at what exposure levels manufacturers must redesign product architecture, move to alternative alloys, or shift sourcing geographies to preserve margins.
-
IoT and smart farming as table stakes — Temperature, ventilation, feed, and water monitoring are rapidly migrating from optional upgrades to procurement requirements in larger integrator and commercial farm tenders. The report maps incremental revenue opportunities from sensor-enabled retrofits and SaaS-based monitoring.
-
Energy and sustainability levers — From scalding operations to climate control, emerging energy-efficiency designs are not only compliance tools but margin protectors. We quantify energy cost sensitivity and payback periods for typical retrofits commonly considered in 2026 budgets.
Practical content inside the report
PW Consulting’s market study is structured as an operational playbook rather than a descriptive summary. Key deliverables include:
-
Transparent market-sizing methodology with historical reconciliations (2020–2025), definitional clarity, and forecast scenarios through 2032.
-
Scenario-based financial models: base, upside, and downside paths that incorporate labor trends, raw material shocks, energy-price shocks, and regulatory shifts.
-
Capital budgeting toolkits and TCO calculators for major equipment classes — enabling finance teams to run payback, IRR, and sensitivity analyses with customer-specific inputs.
-
A procurement and supplier-risk playbook: supplier scorecards, contract structures, and contingency sourcing maps to de-risk supply chains.
-
Commercial go-to-market frameworks for equipment OEMs and service providers, including pricing strategies for retrofit-as-a-service and subscription-based monitoring.
-
Due-diligence checklists for investors and M&A teams, plus a prioritized list of acquisition archetypes that accelerate access to aftermarket revenue and digital capabilities.
-
Operator-facing implementation roadmaps: phased automation pathways, workforce re-skilling templates, and KPI dashboards for roll-out governance.
Competitive landscape — who to watch
The market is populated by established, geographically diverse OEMs and a growing cohort of regional cost-competitive suppliers. Our report profiles each major player with a focus on product footprint, R&D trajectory, service capabilities, and M&A posture. Highlights include:
-
Big Dutchman International GmbH (Germany) — recognized for comprehensive housing, feeding, ventilation, and manure management systems. Recent trade-show reveals indicate continued investment in mechanical innovations for broiler breeders and strengthened IP in chain feeding designs.
-
Vencomatic Group (Netherlands) — strong in housing automation and egg handling; well-positioned where welfare-driven regulatory standards increase procurement complexity.
-
Chore-Time (CTB, USA) and Valco Companies (USA) — North American stalwarts whose strengths are modular feeding/watering solutions and local aftermarket service networks that matter to large integrators.
-
OFFICINE FACCO & C. Spa and Tecno Poultry Equipment (Italy) — turnkey capability and climatic adaptability make them preferred partners in regions with diverse ambient conditions.
-
Roxell and Petersime (Belgium) — focused plays: Roxell on feed/drink efficiency and animal welfare; Petersime on incubation and hatchery systems, an increasingly strategic node as integrators aim to control early-life productivity.
-
Germany’s LUBING, Farmer Automatic, and a group of China-based producers (e.g., Hightop, Retech) — each occupies distinct positions along the cost-performance curve; Chinese OEMs continue to capture share in labor-constrained, cost-sensitive markets.
Recent corporate signals we track: Big Dutchman’s January 2026 product showcase at IPPE highlighted mechanical innovation; JBT Marel’s late-2025 reporting confirmed upward momentum in poultry equipment volumes and synergy realization; and Tecno’s readiness statements signal continued European technology supply. Our vendor matrix assigns capability and momentum scores that help buyers and investors prioritize opportunities.
Strategic playbook by stakeholder
-
Equipment OEMs — Prioritize modular, retrofit-friendly designs and embed digital services. Shift from one-off hardware sales to lifecycle contracts that smooth revenue and raise customer switching costs.
-
Large poultry producers/integrators — Use 2026 budgets to pilot automation in high-turnover operations (e.g., hatchery sequencing, catching) where the labor ROI is immediate. Reserve capital for energy-efficiency retrofits in processing to lock-in operating cost reductions.
-
Investors and PE — Target assets with strong aftermarket service penetration or digital monitoring capabilities; avoid pure-play hardware businesses without aftermarket or data monetization paths unless pricing power is clear.
-
Policymakers and lenders — Consider incentives for energy-efficient and welfare-enhancing equipment; blended financing and leasing can accelerate adoption while spreading technical obsolescence risk.
Scenarios and watchpoints for 2026
-
Automation acceleration: If regional labor shortages intensify or minimum wage pressures rise, expect accelerated capex cycles for automation — leading indicators are tender volumes for automated catching/sexing equipment and spike in retrofit orders.
-
Raw material shock: A sustained rise in steel/component prices would force OEMs to pass costs to buyers or compress margins; watch supplier lead times and inventory-to-sales ratios as early warnings.
-
Regulatory/welfare-driven capex: New welfare standards in major consuming regions can transform procurement specifications almost overnight. Monitor draft regulations and large integrator RFP language for early signals.
-
Energy price volatility: Sudden increases in energy costs will accelerate adoption of energy-efficient designs — our report provides trigger thresholds and retrofit prioritization matrices.
Why PW Consulting’s report is decision-grade
Our study is designed for the executive who needs to translate market intelligence into capital decisions in 2026. We combine a transparent, auditable market-sizing base (2020–2025), forward-looking scenarios through 2032, proprietary vendor benchmarking, and highly practical tools — from TCO calculators to supplier risk matrices and implementation roadmaps.
To preserve competitive value for clients who rely on PW Consulting for repeatable, actionable insight, the full dataset and segment-level detail (product, region, and poultry-type splits) are accessible on our portal. The public brief above intentionally avoids disclosing those granular allocations so that procurement teams and investors can rely on our verified source material when underwriting investments or launching new product programs.
Next steps
-
Download the executive summary and request our interactive model to stress-test your CAPEX plan.
-
Engage PW Consulting for a tailored 48–72 hour strategic sprint: scenario calibration, capex prioritization, and a supplier shortlist aligned to your risk appetite.
For direct inquiries and to access the full report with segment-level tables, vendor scores, and interactive tools, please visit the PW Consulting report page or contact our Poultry Equipment practice lead. Use 2026 to transform procurement, capture aftermarket revenue, and convert automation into measurable margin improvement — PW Consulting’s analysis shows the pathways; the fieldwork in the full report tells you which to prioritize.
For detailed analysis of this topic, please visit the official page: Poultry Farm Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Liquid Hazardous Waste Management Market to Expand at 6.08% CAGR Through 2032
By PW Consulting, 2026-07-02
Liquid Hazardous Waste Management Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
As corporate boards and public-sector planners finalize budgets and capital allocation for 2026, the liquid hazardous waste management market is emerging as a clear, measurable growth corridor. PW Consulting’s latest market study — built on a five-year historical base (2020–2025) and a forward-looking forecast (2026–2032) — projects sustained expansion at a mid-single-digit compound annual growth rate (6.08% CAGR). The global market, which was assessed at approximately USD 48.5 billion in our 2025 base year, is expected to exceed USD 73 billion by the close of the 2032 forecast window. These headline metrics frame an investment environment where scale, regulatory agility, and technology differentiation will determine winners.
Liquid Hazardous Waste Management Market
Why this report matters to 2026 decision-makers
-
Timing matters: 2026 is the inflection point for several converging dynamics — accelerating regulatory change, capital reallocation toward resilience, and a concentrated wave of capacity investments and acquisitions. Companies that read these signals and align near-term investments will unlock disproportionate optionality through the decade.
Liquid Hazardous Waste Management Market -
Risk management meets growth opportunity: With predictable market growth and an uneven competitive landscape, firms can simultaneously reduce compliance and reputational risk while pursuing accretive revenue streams from liquid hazardous waste handling, treatment, and recovery.
Liquid Hazardous Waste Management Market -
Operational levers are actionable: The economics of liquid waste management are driven by plant throughput, treatment mix, transport logistics, and disposal cost variability. Our report translates macro growth into the practical performance metrics that CFOs and COOs can act on within 12–24 months.
Key market dynamics shaping 2026 strategy
-
Regulatory acceleration. Recent rulemaking efforts and international treaty amendments are raising compliance thresholds and changing cross-border flows of hazardous streams. Notably, federal-level moves toward electronic-only manifest systems and expanded waste category treatment obligations are moving compliance timelines forward — creating both compliance risk for unprepared generators and commercial opportunities for service providers with digital and logistics capabilities.
-
Consolidation and capacity build-out. Strategic M&A and greenfield capacity investments over the last 18 months have reshaped regional footprints. Select vertically integrated players are expanding high-temperature treatment capacity and securing feedstock access through acquisitions and offtake agreements, compressing optionality for smaller regional operators.
-
Technology and circularity. Incineration, physico-chemical processing, solvent recovery, and recycling/recovery methods remain core tools, but the fastest value capture will accrue to operators that combine energy recovery, solvent reclamation, and validated circular pathways with rigorous environmental controls.
-
Fragmented competitive structure. The market retains significant fragmentation: national champions coexist with specialized niche providers (medical, radioactive, industrial solvents), creating pockets of high-margin specialization alongside a low overall concentration across the sector. This fragmentation creates acquisition arbitrage and roll-up potential for scale-minded strategists.
What PW Consulting’s report delivers — practical, executable intelligence
-
Market sizing and forward scenarios. A robust base-case projection anchored in macroeconomic drivers and granular industry indicators, complemented by downside and upside scenarios to stress-test capex and M&A plans.
-
Treatment economics playbook. Comparative cost and throughput models for prevailing treatment methods, including sensitivity analyses for feedstock composition, transport distance, and thermal versus non-thermal treatment choices.
-
Regulatory tracker and compliance impact matrix. Timelines and impact assessments for pending and enacted rules (domestic and international), with recommended compliance levers for generators, processors, and logistics providers.
-
Competitive intelligence dossiers. Company-level profiles, capability maps, and strategic intent signals for major incumbents and fast-scaling challengers — designed to inform M&A screening, partner selection, and threat assessment.
-
Site-level feasibility templates. A step-by-step capital and operating model for new treatment assets, covering permitting risk, environmental controls, community engagement, and expected payback windows under different throughput assumptions.
-
Commercial playbooks. Go-to-market frameworks for corporates and service providers, including contracting structures (volume guarantees, take-or-pay, shared investments), pricing strategies, and digital enablement approaches (e-manifest integration, customer portals, operational telematics).
-
Investor-ready M&A readiness tools. Due-diligence checklists, valuation comparators, and integration risk frameworks tailored to hazardous liquid assets.
Competitive landscape: who to watch and what they signal
-
Global integrated operators. Multinational environmental services leaders are accelerating US and international footprint expansion through strategic acquisitions and large-scale thermal treatment investments. Recent transactions and capacity projects underscore a bet on higher-throughput, high-temperature treatment capacity as a strategic moat for complex liquid streams.
-
North American platform players. Regional champions focused on hazardous liquid streams are reinforcing collection networks and emergency response capabilities, embedding full-service offerings that increase customer switching costs and create bundled revenue opportunities.
-
Specialists and niche players. Firms concentrating on regulated medical, radioactive, or industrial solvent streams are capitalizing on regulatory complexity and high-barrier treatment requirements. Their technical expertise and permit portfolios make them attractive targets for consolidation or long-term partnerships.
-
Energy-from-waste and resource recovery entrants. Operators that combine hazardous treatment with energy recovery or solvent reclamation are differentiating on total lifecycle economics, offering lower net disposal costs for generators and new revenue lines tied to recovered materials or energy credits.
Recent sector moves provide a clear illustration of these dynamics: leading multinationals have announced large-scale acquisitions and capacity expansions; specialty firms have secured major permit upgrades to scale mixed-waste processing; and strategic partnerships are being formed to secure guaranteed treatment capacity. These actions confirm that the market’s next phase will be defined as much by network control and treatment optionality as by traditional price competition.
Regulatory and geopolitical watchlist for 2026
-
Transition to digital manifests. Federal mandates toward electronic-only manifests will accelerate digitization across generators and transporters, changing invoicing, chain-of-custody, and data governance practices.
-
Expanding waste categories and treaty impacts. National rulemaking and international agreements are widening the scope of regulated materials, affecting cross-border logistics and the classification of mixed and electronic waste streams.
-
State-level moratoria and siting restrictions. Localized policy moves can materially delay capacity expansions and raise development costs; effective siting strategies and advanced community engagement are therefore critical for on-time project delivery.
Strategic priorities for executives in 2026
-
Mobilize a two-track M&A strategy: (1) bolt-on acquisitions that extend collection and logistics reach, and (2) selective investments in thermal and recovery capacity to control treatment bottlenecks. Use our valuation toolkit to prioritize targets by integration value and permit defensibility.
-
Fast-track digital compliance. Implement e-manifest readiness and integrate digital chain-of-custody into customer portals to reduce administrative costs and create friction for competitors.
-
Pursue differentiated service bundles. Combine emergency response, vacuum collection, reclamation, and validated destruction certificates to capture higher-margin, compliance-sensitive customers.
-
Underwrite siting risk rigorously. Incorporate state and municipal political risk overlays into CAPEX forecasts; structure development with contingent milestones and community benefit commitments.
-
Deploy scenario-based capacity planning. Align capex phasing to demand corridors revealed by our scenario models to avoid underutilized assets while securing throughput certainty through strategic partnerships.
How PW Consulting’s brief positions you for decisive action
Our report is designed as a decision-focused asset for 2026 planning cycles: not only does it quantify near-term market momentum and mid-term upside, it also equips leaders with the operational metrics, regulatory foresight, and competitive intelligence required to convert market growth into durable value. We surface where scale matters, where specialization pays, and where regulatory timing can be monetized or mitigated.
To preserve the commercial value of our segment-level analyses and proprietary models — and to ensure rigorous use of sensitive operational assumptions in client decision-making — detailed breakdowns of regional/application splits, unit price tables, and drill-down financial models are available through our gated report package and client workshops. For executive summaries, board briefings, or tailored scenario runs, PW Consulting is offering a limited set of bespoke advisory engagements to translate the market view into executable 90–180 day plans.
Contact PW Consulting to request the full Liquid Hazardous Waste Management Market report and to schedule a strategy session with our senior industry analysts. The 2026 planning window is narrow; organizations that act on the right intelligence now will capture the structural advantages that will define the market through 2032.
For detailed analysis of this topic, please visit the official page: Liquid Hazardous Waste Management Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Enzalutamide API Market to Grow at 8.01% CAGR, from USD 329.23 Million in 2025 to USD 564.25 Million by 2032
By PW Consulting, 2026-07-02
Enzalutamide API Market Outlook 2026: A Strategic Playbook for Pharma Manufacturers and Investors
PW Consulting’s latest Enzalutamide API Market report delivers a time-sensitive strategic perspective for executives planning capital allocations, supply-chain adjustments, and commercial entry strategies in 2026. The market has moved from a niche oncology API into a predictable growth corridor—driven by generic launches, regulatory clarity in key export hubs, and shifting reimbursement landscapes. Our analysis synthesizes historical performance, near-term inflection points and actionable playbooks to convert the coming wave of opportunity into sustainable advantage.
Enzalutamide Api Market
Snapshot: Macro trajectory that matters for 2026 planning
Between 2020 and 2025 the global Enzalutamide API market expanded materially, reflecting both increased generic activity and rising unit demand for finished-dose formulations. PW Consulting’s model shows the market at roughly USD 329 million in 2025, with an expected compound annual growth rate (CAGR) of 8.01% across our 2026–2032 forecast horizon. By 2032 our baseline projection places the market in the mid-hundreds of millions of USD—illustrating a multi-year growth runway that supports medium-term capacity investments, regulatory filings, and commercial partnerships.
Enzalutamide Api Market
Why 2026 is a strategic inflection year
-
Patent and generic timing: With principal composition patents approaching expiry in the 2026–2027 window, 2026 will be the critical year for establishing supply lines, securing DMFs/registrations and positioning for first-mover generic advantages.
Enzalutamide Api Market -
Regulatory validation matters: A dense registry of Drug Master Files (DMFs) for Enzalutamide—largely originating from Indian API manufacturers—has created a transparent path for finished-dose applicants, but also intensifies competition among API suppliers. For 2026 entrants, having defensible quality documentation and inspection-ready facilities will shorten commercial lead times.
-
Reimbursement tailwinds: Changes in reimbursement policy in recent years have expanded commercial viability for generics in major payer systems, increasing the addressable market volume that new API suppliers and CDMOs can capture post-launch.
-
Cost volatility and input concentration: Key intermediates constitute a significant portion of API production cost structures—exposing producers to petrochemical price swings. Firms that implement hedging strategies or vertically integrate critical intermediates will enjoy margin resilience in 2026.
What the PW Consulting report delivers — practical, transaction-oriented insights
-
Investment-ready financial models: Scenario-based P&L and cash-flow models calibrated to different market-entry timings, regulatory outcomes and raw-material price regimes—designed to inform greenfield CAPEX and M&A valuations.
-
Regulatory and DMF playbook: A stepwise checklist for DMF preparation, common inspection findings observed across recent inspections, and an assessment framework for regulators’ expectations on nitrosamine impurities and impurity controls.
-
Supply-chain resiliency matrix: Supplier due-diligence templates, dual-sourcing triggers, and an actionable roadmap to shift from spot-buy to contract pricing without jeopardizing capacity commitments to key customers.
-
Commercial partnering blueprints: Templates for offtake agreements, tolling/CDMO arrangements, and licensing term structures that reflect realistic launch windows and pricing pressure from generics.
-
Operational benchmarks: Yield, cycle-time and unit-cost benchmarks for high-purity production ( >99% grade) versus standard grades, and recommendations on when to prioritize investment in ultra-purification capabilities for value capture.
Competitive dynamics — who matters and why
The supplier map for Enzalutamide API is defined by well-known Indian manufacturers and contract providers that have converted regulatory approvals into supply momentum. Key companies profiled in our report include:
-
MSN Laboratories Pvt. Ltd. (Hyderabad) — a leading producer with USFDA-approved DMFs and ANDA support, demonstrating commercial-scale production and supply readiness.
-
Hetero Drugs Ltd. (Hyderabad) — vertically integrated API producer that has executed U.S. market entry strategies using in-house capacity to support generic launches.
-
Aurobindo Pharma Ltd. (Hyderabad) — with US FDA tentative approvals and a track record of scaling API output to match ANDA cycles.
-
Sun Pharmaceutical Industries Ltd. (Mumbai) — leveraging a global API business unit to supply finished-dose partners across regulated markets.
-
Dr. Reddy’s Laboratories Ltd. (Hyderabad), Lupin Ltd. (Mumbai), and Piramal Pharma Solutions (Mumbai) — each offering regulatory-compliant manufacturing footprints and CDMO models tailored to oncology generic programs.
Recent company-level moves underline commercial momentum: regulatory approvals and generic launches have progressed throughout 2023–2024, validating that supply capability and regulatory readiness are now table stakes for competing in primary markets. Our competitive chapter evaluates each supplier’s risk profile across regulatory history, inspection readiness, capacity elasticity, and contractual flexibility for partners.
Risks, mitigants and strategic playbooks for 2026
-
Regulatory risk — nitrosamine-related import alerts and impurity findings can disrupt shipments. Mitigation: implement enhanced analytical controls, expedite impurity-related validation packages, and preemptively engage with regulators to shorten hold times.
-
Concentration risk — a small number of suppliers currently serve much of the market. Mitigation: pursue strategic dual-sourcing, invest in niche purification capabilities, or negotiate exclusivity-light offtake contracts to lock in demand without overcommitting capacity.
-
Price and input-cost risk — volatility in petrochemical-linked intermediates drives margin compression. Mitigation: hedging programs for critical intermediates, backward integration for key steps, and contract structures that share risk with buyers.
-
Commercial timing risk — mis-timed capacity expansion relative to patent expiry or reimbursement shifts can leave idle assets. Mitigation: adopt staged-capex approaches, design modular manufacturing that can be repurposed, and align investment tranches with regulatory milestones.
Action recommendations for distinct executive agendas
-
For API manufacturers considering expansion: prioritize regulatory-compliant, inspection-ready capacity that can be commissioned rapidly in H2 2026; secure intermediate supply contracts with price collars to stabilize margins.
-
For CDMOs: develop flexible tolling propositions tailored to oncology generics, offer bundled regulatory support for DMF preparations, and market your ability to fast-track ANDA-enabling supply.
-
For finished-dose generic players and private equity: evaluate strategic investments in API assets only with full visibility of DMF coverage and supplier audit outcomes; favor deals that include offtake de-risking or staged payments tied to regulatory milestones.
-
For procurement and supply-chain leads at brand and generic companies: implement supplier scorecards focused on impurity control, shipment reliability, and contingency capacity to insulate launches against short-term import disruptions.
Why PW Consulting’s report is indispensable for 2026 decisions
Our Enzalutamide API Market report is structured to support decisions with both breadth and executional depth. Alongside high-level forecasts and scenario analysis, the deliverable includes transaction-ready financial templates, regulatory filing checklists, supplier diligence frameworks, and operational KPIs. The research balances public-source intelligence with proprietary interviews and validated production benchmarks—so readers receive not only market sizing but the operational levers required to act.
To preserve commercial sensitivity and to comply with the “preview” approach, this article intentionally omits granular regional and application-level breakouts that are contained in the full report—including proprietary segmentation tables, per-region demand curves and unit-cost waterfalls. These datasets and the underlying assumptions are essential for detailed modeling and are only available in the comprehensive PW Consulting report.
Final takeaways
Enzalutamide API represents a high-conviction opportunity in the oncology generics complex for 2026: the market profile combines healthy CAGR, imminent patent-driven openings, and payer-driven volume upside. However, the path to long-run returns requires disciplined regulatory execution, supply-chain resilience, and thoughtful timing of capacity commitments.
For executives preparing capital plans, negotiating supply or assessing acquisition targets, our report functions as an operational playbook—bridging market intelligence and actionable steps to convert growth forecasts into realized, risk-mitigated outcomes.
PW Consulting’s full Enzalutamide API Market report contains the actionable data tables, supplier scorecards and model templates referenced here. Contact our research team to access the complete dataset and customized advisory services tailored to your strategic objectives in 2026.
For detailed analysis of this topic, please visit the official page: Enzalutamide Api Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: EDTA Solution Market to Hit USD 1,141.4M by 2032 at 4.38% CAGR — Asia Pacific Leads with USD 307.6M in 2025; Tetrasodium EDTA Dominates, Top‑5 Hold 58.4%
By PW Consulting, 2026-07-02
Edta Solution Market 2026: Strategic Imperatives for Executives — PW Consulting Market Preview
By the PW Consulting Strategy & Industry Analysis Team
The global EDTA solution market is at a strategic inflection point entering 2026. Our latest market model shows the industry expanding from USD 845.5 million in 2025 to an estimated USD 922.7 million in 2026, and, under our baseline forecast, growing at a 4.38% CAGR through 2032 to reach roughly USD 1,141.4 million. These headline figures mask a complex mix of regulatory pressure, raw-material volatility, supply-chain disruption and active product innovation — dynamics that will determine winners and losers over the next three to five years.
Edta Solution Market
Why this report matters to corporate decision-makers in 2026
-
Timing and allocation: With aggregate market growth steady but uneven across value chains, capital allocation decisions — capacity investments, M&A, joint ventures and greenfield projects — must be informed by granular scenario analysis rather than headline demand growth alone.
Edta Solution Market -
Regulatory and reputational risk: New and evolving restrictions are reshaping permitted use cases, labeling requirements and product formulations, with direct implications for product portfolios, marketing and litigation exposure.
Edta Solution Market -
Procurement and price strategy: Feedstock price swings and trade policy measures are altering cost curves and import economics; procurement teams must embed scenario hedges and supplier diversification playbooks into annual sourcing plans.
-
R&D and product strategy: Demand for biodegradable chelating alternatives and certified potable-water products creates commercial upside for firms that can retool formulations and accelerate regulatory approvals.
Headline drivers shaping 2026 strategy
-
Regulation is forcing technical change. The EU’s REACH Annex restriction on EDTA concentration in detergents (effective January 2025) and California’s Proposition 65 listing (requiring warning labels for reproductive toxicity) are not isolated market events — they fundamentally change formulators’ compliance burden and brand managers’ exposure in major consumer markets.
-
Trade policy is reconfiguring sourcing economics. The U.S. International Trade Commission’s imposition of anti-dumping duties (25% on certain imports beginning July 2025) has immediate implications for sourcing strategies, landed costs and incumbent supplier relationships for U.S.-facing manufacturers.
-
Raw-material pressure is squeezing margins. Key feedstock costs rose materially in early 2026 — for example, formaldehyde jumped approximately 15% to about USD 1,450/MT in Q1 2026 — increasing production costs and forcing pricing and formulation responses across the value chain.
-
Product innovation and certification are differentiators. Recent moves by established producers to launch biodegradable chelates and to secure potable-water certifications underscore two commercial pathways: (1) substitution and formulation change to meet sustainability mandates, and (2) premium certified products for water treatment and other regulated end-markets.
Competitive landscape — who matters and why
The EDTA solution market is moderately concentrated. The top three global players capture roughly 42% of market revenue, while the top five account for approximately 58%, creating a competitive dynamic where scale, branded chemistry and distribution reach matter. Several archetypes exist within the competitive set:
-
Integrated chemicals majors: Companies with broad chemical portfolios and branded chelates (examples include manufacturers supplying recognized product families used in industrial water treatment and detergents) leverage scale, downstream relationships and capacity flexibility. Recent capacity investments signal intent to defend share where demand remains robust.
-
Specialty and formulation-focused players: Firms offering liquid EDTA formulations tailored to food, pharmaceutical, cosmetic and textile customers compete on quality, regulatory dossiers and traceability. Their competitive moat is often built around formulation know-how and customer approvals.
-
Laboratory and high-purity suppliers: Distributors and laboratory reagent manufacturers serve clinical, biotech and high-purity industrial segments where product grade and chain-of-custody are decisive. Their value proposition is technical support, inventory availability and regulatory documentation.
Recent corporate developments illustrate these strategic behaviors. Some players have launched biodegradable chelate alternatives to capture demand in regulated personal-care markets; others have pursued product certifications for potable water applications, opening access to new higher-value channels. Capacity expansions by established producers demonstrate a defensive posture toward detergent and industrial cleaning demand even as entrants explore lower-environmental-impact chemistries.
Report deliverables — what PW Consulting provides (practical, operational, non-obvious)
Our full market study is structured to enable rapid operationalization by commercial, procurement and R&D teams. Highlights include:
-
Demand and supply models: Dynamic market-sizing with scenario toggles for regulatory stringency, feedstock shocks and trade-policy outcomes. (These core segmentation tables and granular regional/application splits are intentionally reserved for the full report.)
-
Price-impact simulations: A suite of margin models quantifying the P&L sensitivity of common EDTA formulations to feedstock price moves, using the latest market datapoints and supplier cost proxies.
-
Regulatory playbook: Decision trees and compliance checklists for EU and North American regulatory scenarios, including product relabeling, reformulation thresholds, and documentation requirements for potable-water certification and Proposition 65 mitigation.
-
Supplier heatmaps and negotiation scripts: A performance matrix benchmarking suppliers on capacity, geographic exposure, certification portfolio and innovation pipeline, plus procurement scripts to secure long-term pricing collars and supply guarantees.
-
M&A and partnership screening: A prioritized list of capability gaps and criteria for inorganic expansion — from specialty-formulation tuck-ins to capacity-centric bolt-ons — with valuation and synergy frameworks.
-
Go-to-market templates: Channel segmentation, pricing strategy options for premium certified products, and marketing frameworks for repositioning legacy EDTA-containing products under new label and safety regimes.
Five immediate strategic actions for 2026
-
Audit formulations for compliance and reformulation opportunity: Conduct a rapid portfolio review to identify SKUs exposed to REACH limits and Prop 65 labeling. Prioritize reformulation for high-volume consumer products and identify candidate SKUs for substitution with biodegradable chelates.
-
Lock in feedstock and logistics: Negotiate conditional long-term contracts or option-based hedges for formaldehyde and other key feedstocks to protect margins against further price spikes and logistic bottlenecks.
-
Pursue certification where it creates premium access: For water-treatment and potable applications, target relevant certifications early — the commercial upside from certified products can outstrip the near-term certification cost for manufacturers and distributors.
-
Reconfigure sourcing to address trade-policy risk: Reassess supply chains exposed to anti-dumping duties and develop contingency suppliers or nearshoring options to mitigate landed-cost inflation and customs delays.
-
Invest selectively in sustainability-focused innovation: Allocate R&D budget to accelerate biodegradable chelate alternatives and to create hybrid formulations that reduce regulatory exposure while preserving performance.
How PW Consulting’s analysis supports executive decision-making
Our approach combines quantitative market modeling with qualitative industry expertise to translate macro trends into board-level decisions and operational actions. The core value for 2026 leaders is twofold: first, a defensible view of where overall demand is headed (our baseline model captures both the recent recovery to USD 845.5 million in 2025 and the projected trajectory to roughly USD 1,141.4 million by 2032 at a 4.38% CAGR); second, a practical playbook that converts that view into procurement, product and GTM moves that protect margin and create growth opportunities.
Importantly, we adopt a “trailer” approach in public communications — providing sufficient analytical depth to inform early strategy while withholding the detailed granular regional and application splits that are part of the full, subscription-level deliverable. That structure is deliberate: it protects the commercial value of proprietary modeling while giving senior teams confidence about market direction and operational levers.
Next steps
For companies preparing their 2026 budgets, supplier negotiations and product roadmaps, the PW Consulting Edta Solution Market Report offers the analytical foundation and the playbooks needed to act decisively. The full report contains the granular segmentation, supplier scorecards, downloadable models and executable templates referenced above. Clients and prospective subscribers are invited to contact PW Consulting for access to the complete dataset and an executive briefing tailored to specific strategic priorities.
As the EDTA solutions landscape continues to evolve under regulatory, cost and innovation pressures, the decisions firms take in 2026 will materially affect market share, margin trajectories and regulatory exposure over the next business cycle. Our analysis equips leaders to move from reaction to structured, value-accretive action.
For detailed analysis of this topic, please visit the official page: Edta Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: RF EAS Label Market to Rise from USD 644.11M in 2025 to USD 847.02M by 2032 at a 3.99% CAGR — Europe (USD 213.33M), Deactivatable Labels (USD 448.99M) and Apparel Drive Growth
By PW Consulting, 2026-07-02
RF EAS Label Market: Strategic Imperatives for 2026 — Executive Brief from PW Consulting
Executive summary
As retailers and brands confront accelerated theft, tighter sustainability mandates and the next wave of checkout automation, RF electronic article surveillance (EAS) labels are shifting from commodity security items to strategic enablers across loss prevention, packaging compliance and omnichannel operations. Our new Rf Eas Label Market report — grounded on a 2020–2025 historical base and forward-looking through 2026–2032 — quantifies this transition and translates it into decision-grade guidance for 2026 investments.
Rf Eas Label Market
Key macro takeaways: the global RF EAS label market reached an estimated USD 644.11 Million in the base year (2025) and is forecast to expand to roughly USD 847.02 Million by 2032, reflecting a compound annual growth rate (CAGR) of about 3.99% over the projection window. Market concentration is material enough to make vendor selection consequential: the top three suppliers account for roughly 41.5% of market revenue and the top five approach 57%, indicating a landscape where a limited set of established providers retain scale advantages while a broad field of regional and specialist players continues to innovate.
Rf Eas Label Market
Why this matters for 2026 decision-makers
- Procurement and vendor strategy: With structural growth but mid-level concentration, procurement teams must balance scale (price, global service) against specialized capabilities (metal-tolerant labels, micro labels, sourcing flexibility). Our report explains how to construct multi-vendor sourcing frameworks that reduce single‑supplier risk while capturing unit-cost benefits.
- Loss prevention & store operations: Recent product premieres integrating RF EAS with checkout and cloud platforms point to a near-term shift: EAS is becoming part of store IT architecture, not merely a peripheral security device. This changes CAPEX/OPEX dynamics and the skills required to manage these systems.
- Sustainability and compliance: Extended Producer Responsibility (EPR) schemes and emerging EU packaging rules are raising the operational cost of packaging components. Labels — their substrates and embedded circuits — are now implicated in compliance and end-of-life reporting. Companies need to align label design and supplier contracts with sustainability KPIs to avoid fee escalations and reporting burdens.
Market trajectory and what the numbers conceal (and reveal)
The market’s steady CAGR of approximately 3.99% signals mature, demand-driven expansion rather than speculative spurts. Growth is being fueled by three intertwined vectors: retailers’ ongoing investments in shrink prevention, the migration of tagging to the point of manufacture (source tagging), and the operationalization of RF technologies into omnichannel flows (from inventory reconciliation to automated checkout). Yet growth is uneven: pockets of accelerated demand emerge in geographies and product categories that prioritize visible tagging, metal-tolerant solutions, or deep RFID integration.
Rf Eas Label Market
Importantly, headline totals do not tell the whole story. Unit economics differ widely by label type, manufacturing technique and value chain placement (in-line factory application versus in-store application). That variance is the strategic lever for both suppliers and buyers: small design or process changes can shift margin and compliance outcomes materially. Our report models these dynamics and provides scenario outputs to stress-test budget plans under alternative price, raw-material and recycling-fee trajectories.
Drivers, constraints and regulatory dynamics
- Organized retail crime (ORC) and shrink: Intensifying theft patterns are prompting retailers to invest in higher-detection and specialized labels (e.g., metal-capable forms, anti-human shielding variants). Suppliers are responding with product-level innovation aimed at detection performance without increasing label profile or cost unduly.
- Checkout and systems integration: The trend toward integrating EAS with RFID and POS — exemplified by recent point-of-sale antenna premieres and cloud management platforms — is changing product specifications, installation practices and service models.
- Materials and supply chain pressure: Typical RF soft labels rely on paper substrates with aluminum or copper conductors. Volatility in these commodity inputs, combined with sustainability requirements, means buyers must now manage upstream risk and recyclability trade-offs as part of label procurement.
- Regulation and EPR: Extended Producer Responsibility frameworks — already present in multiple US states and evolving across the EU — impose new obligations and potential fees tied to packaging components, including labels. The EU’s Packaging and Packaging Waste Regulation and state-level schemes (e.g., recent US state adoptions) are elevating the cost of non-recyclable or mixed-material label constructions.
Competitive landscape — leading players and strategic archetypes
The market is a mix of global incumbents with broad portfolios and regional innovators focused on specialized use cases. Several archetypes stand out:
- Portfolio incumbents with scale and R&D depth: Firms offering broad RF EAS portfolios — spanning grocery, apparel, cosmetics and auto‑apply at source — are positioned to serve global retailers seeking standardized deployments and integrated services. Their advantages include in-house manufacturing, multi-tech product stacks and established service networks.
- Specialist source-tagging and custom providers: Some US and China-based players focus on source tagging for apparel and hard goods, customizable SuperLabels and micro labels for high-shrink items. They compete on customization, time-to-market and tight integrations with garment and packaging processes.
- Technology-driven challengers: Companies introducing metal-detection hybrids, RF + metal systems, and POS-integrated antennae are redefining performance expectations. Recent product launches and trade-show demonstrations show a competitive pivot toward solutions that close the gap between loss prevention and checkout efficiency.
Recent company moves provide a window into tactical priorities. One established global supplier premiered an RFID-capable checkout antenna and, in the prior year, launched a cloud-centered store operations platform — moves that underscore strategy to own both hardware and the software layer that organizes in-store RF devices. A manufacturer from Hangzhou introduced a combined RF + metal detection system and used a major retail technology trade show to highlight product maturity after multi-year development. These events are not isolated: they signal supplier efforts to convert technical differentiation into commercial deployment at scale.
What the PW Consulting report delivers (practical components)
This study is designed as an operational playbook for 2026 decision-making, not merely an academic forecast. Deliverables include:
- Volume and revenue outlooks across 2026–2032 with scenario-based sensitivities that factor raw-material pricing, EPR fee escalations and adoption rates of source tagging and POS-integrated systems.
- Supplier benchmarking and capability heatmaps that evaluate R&D, manufacturing footprint, product breadth (metal-tolerant labels, micro forms, etching craft), systems integration and service models.
- Procurement frameworks and multi-supplier contracting templates that balance total-cost-of-ownership, compliance obligations and supplier innovation roadmaps.
- Technology decision matrices to guide trade-offs between RF, RFID convergence, and hybrid metal-detect solutions, including ROI case models tailored to apparel retailers, grocery chains and pharmacy formats.
- Implementation playbooks and sample RFP language for source‑tagging programs, labeling automation at packhouses and rollout of POS-integrated antannae.
- Regulatory impact analysis mapping EPR/PPWR exposure, likely fee trajectories and label design levers to mitigate costs while improving recyclability.
Strategic recommendations for 2026
- Adopt a layered vendor strategy: Lock core volumes with proven global suppliers for unit cost and supply continuity, while retaining niche vendors for metal-tolerant or micro-label needs. Insist on transparency for raw-material sourcing and recyclability metrics.
- Prioritize integration pilots: Run controlled pilots that combine EAS antennas with RFID checkpoints and cloud device management in a subset of high-shrink stores. Use these pilots to validate operational savings and refine labor flows.
- Embed compliance in specifications: Update technical specs to mandate recycled-content reporting and end-of-life handling terms. Tie a portion of supplier compensation to improved recyclability or EPR fee avoidance metrics.
- Reassess TCO with new product classes: Include software subscription, cloud management and POS integration costs in TCO models — not just label unit price. Recent product launches signal that vendors will increasingly monetize software and service layers.
- Use the report’s scenario outputs for budgeting: Stress-test loss-prevention and packaging budgets against alternative EPR fee scenarios and raw-material shocks; build contingencies into 2026 procurement cycles.
How to use this research — next steps
For strategy teams, loss-prevention leaders and procurement heads planning 2026 budgets, this report functions as both a market map and an operational toolkit. It provides the evidence base for vendor shortlisting, the templates for RFP execution, and the scenario modeling to align capital plans with regulatory and retail reality.
PW Consulting’s Rf Eas Label Market report intentionally presents deep methodological transparency and actionable guidance while reserving granular segment-level revenue and regional splits for the full study. That granular intelligence — including supplier scorecards, price curves and downloadable contracting templates — is available through our research portal for clients and subscribers.
Concluding note
RF EAS labels are no longer only about preventing shoplifting. They sit at the intersection of store operations, packaging sustainability and retail systems integration. For 2026, the companies that win will be those that treat label strategy as a cross-functional investment: aligning procurement, packaging, IT and loss prevention around a unified roadmap that anticipates regulation, leverages supplier innovation and captures the operational upside of integrated RF ecosystems.
For detailed analysis of this topic, please visit the official page: Rf Eas Label Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


