



Category: market research
PW Consulting HVAC Air Filter Market to Hit $316.2M by 2032, Rising at 5.6% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence for HVAC Air Filter Market: Navigating the 2026 Decision Landscape
The global HVAC air filter market stands at a pivotal inflection point. As infrastructure modernization accelerates, indoor air quality regulations tighten, and supply chain dynamics continue to reshape procurement strategies, organizations across residential, commercial, and industrial sectors face a complex array of strategic choices. Our latest comprehensive market research report provides executives, procurement directors, and industry strategists with the analytical framework needed to navigate this evolving landscape with confidence. This overview outlines the strategic value embedded within the study, demonstrating how data-driven insights can directly inform capital allocation, competitive positioning, and long-term growth planning for 2026 and beyond.
Market Trajectory and Structural Evolution
Over the past half-decade, the HVAC air filter industry has demonstrated remarkable resilience and steady expansion. From a baseline of approximately 178.5 million USD in 2020, the total addressable market has steadily climbed through successive years, reaching 216.5 million USD by 2025. This trajectory reflects sustained demand across multiple end-use verticals, driven by heightened health consciousness, stricter building performance standards, and the ongoing replacement cycles inherent to filtration infrastructure. The report projects continued momentum through the 2026-2032 forecast window, with the market anticipated to advance toward 316.2 million USD by the terminal year. This growth is underpinned by a compound annual growth rate of 5.6 percent, a figure that signals not only stability but also the emergence of structural tailwinds that astute organizations can leverage for competitive advantage.
Air Filters Market
Importantly, this expansion is not merely a function of population growth or new construction activity. Underlying shifts in material preferences, performance expectations, and regulatory compliance requirements are fundamentally reshaping how filtration solutions are specified, manufactured, and maintained. Organizations that understand these underlying drivers will be better positioned to anticipate demand fluctuations, optimize inventory strategies, and align product development roadmaps with market realities.
Key Demand Catalysts and Industry Dynamics
Several interconnected forces are accelerating transformation within the HVAC air filtration sector. First, regulatory frameworks continue to evolve with increasing precision, placing greater emphasis on measurable performance outcomes. Recent updates to recognized testing methodologies have established more rigorous evaluation protocols for air cleaning technologies, addressing concerns around secondary emissions such as ozone and formaldehyde. Concurrently, updated compliance guidelines for healthcare environments mandate minimum filtration efficiencies that directly influence procurement specifications across institutional buyers. Energy efficiency certification programs have also introduced new performance criteria, compelling manufacturers and end-users alike to balance filtration effectiveness with operational cost considerations.
Second, the post-pandemic era has permanently altered procurement priorities. Building managers, facility operators, and residential homeowners now approach air quality with a heightened level of scrutiny, recognizing filtration as a critical component of occupant wellbeing and operational continuity. This cultural shift has elevated the strategic importance of filtration systems from routine maintenance items to essential infrastructure investments.
Third, technological innovation cycles are compressing. Recent industry gatherings and product launches have showcased advanced filtration media, improved airflow dynamics, and smarter replacement scheduling tools. Manufacturers are increasingly differentiating through specialized product lines that address specific application requirements, from high-capacity commercial environments to precision-sensitive industrial facilities. These developments create both opportunities and risks: organizations that rapidly adopt performance-leading solutions can capture market share, while those relying on legacy specifications may face compliance gaps or operational inefficiencies.
Pricing dynamics further complicate the decision environment. Basic filtration options remain accessible, but premium-grade solutions with enhanced particle capture capabilities command significantly higher price points and distinct replacement intervals. Understanding where specific applications fall on this value spectrum is essential for cost-effective procurement and long-term total cost of ownership optimization.
Segmentation Insights and Strategic Positioning
While aggregate market figures provide a useful top-line perspective, the true strategic value of our research lies in its granular segmentation analysis. The report dissects demand patterns across multiple dimensions, revealing how material preferences, application requirements, and regional procurement behaviors intersect to shape market outcomes.
Material composition remains a critical differentiator. Synthetic polymer-based solutions continue to dominate volume share, reflecting their balance of performance, durability, and manufacturing scalability. Fiberglass alternatives retain relevance in cost-sensitive applications, while carbon and metal media serve specialized niches where chemical filtration, thermal resistance, or extended service life are prioritized. The research examines how these material categories perform across varying operational conditions, enabling organizations to align specification choices with actual environmental demands rather than convenience or legacy habits.
Application segmentation further illuminates demand concentration. Residential settings represent a substantial volume driver, but commercial and industrial applications introduce distinct performance thresholds, procurement cycles, and compliance considerations. The report evaluates how different end-use environments interact with filtration requirements, offering guidance on where value creation is most pronounced and where competitive intensity is highest.
Regional analysis reveals equally important patterns. North American and Asian markets exhibit robust demand fundamentals shaped by construction activity, regulatory environments, and established distribution networks. European procurement behavior reflects a strong emphasis on energy efficiency and sustainability metrics, while emerging markets in Latin America and the Middle East and Africa present evolving opportunities tied to infrastructure development and growing awareness of indoor environmental quality. The study contextualizes these regional dynamics without reducing them to simplistic comparisons, instead providing the nuanced understanding necessary for market entry, expansion, or resource allocation decisions.
Market concentration metrics indicate that the industry remains moderately fragmented, with the top three players collectively commanding approximately 45 percent of revenue and the top five reaching just over 52 percent. This structure suggests that while established incumbents hold meaningful share, there remains sufficient openness for strategic entrants, specialized niche players, and well-positioned distributors to compete effectively through differentiation, service excellence, or regional focus.
Competitive Landscape and Strategic Implications
The HVAC air filter market features a diverse array of participants, each pursuing distinct strategic approaches to capture value. Understanding these competitive postures is essential for any organization seeking to benchmark its positioning or identify partnership opportunities.
HVAC Air Filter Market
Several established manufacturers operate with a clear emphasis on customization and specialized engineering. Companies such as Universal Air Filter and Air Filters Inc. have built reputations around tailored filtration solutions designed for demanding environments, appealing to clients who require precise performance characteristics beyond standard catalog offerings. Similarly, Filterbuy and Filter King maintain strong positions in the replacement and distribution space, leveraging broad product availability and brand recognition to serve both consumer and commercial buyers.
Global and regional leaders like AAF International and Camfil USA occupy the premium performance segment, emphasizing high-efficiency filtration and clean air solutions for applications where air quality directly impacts critical operations. These organizations typically invest heavily in research, testing validation, and technical support, creating competitive moats around performance credibility and long-term customer relationships.
Energy management and lifecycle optimization represent another strategic axis. Nalco Water, operating within broader environmental and water treatment portfolios, integrates filtration technologies with energy-efficient filter life cycle management, appealing to organizations seeking to minimize operating expenses while maintaining compliance. Meanwhile, manufacturers like EAWAY and AirSan Corporation provide specialized product ranges that serve both commercial and industrial applications, often emphasizing media packs, pre-filters, and pocket filter configurations that address specific airflow and contaminant profiles.
Legacy manufacturers such as Glasfloss Industries bring historical manufacturing depth and domestic production capabilities, while specialized suppliers like Tex-Air Filters and Brookaire Co. focus on industrial-commercial segments and extensive MERV-rated inventory, respectively. Factory Direct Filters illustrates another viable model: direct-to-customer distribution of custom-sized filtration products for residential and commercial applications, bypassing traditional intermediaries to capture margin and enhance responsiveness.
Recent market activities underscore the pace of competitive maneuvering. Industry exhibitions have highlighted continuous innovation in filtration technology, with major players showcasing advanced solutions for HVAC applications. Product catalog expansions, including new pre-filter, pleated, and pocket filter lines, reflect ongoing efforts to broaden addressable markets and capture incremental demand. Simultaneously, standardization bodies have introduced updated assessment protocols that will influence how products are evaluated, compared, and ultimately specified by buyers. Organizations that proactively align their offerings with these evolving benchmarks will be better positioned to maintain or improve market standing.
Research Architecture and Operational Utility
The comprehensive report is structured to deliver immediate, actionable intelligence alongside strategic foresight. Our methodology combines rigorous quantitative modeling with qualitative industry assessment, ensuring that findings are both statistically grounded and contextually relevant.
Key components of the study include a detailed historical analysis covering the 2020-2025 period, providing context for recent market behavior and establishing baseline trends that inform forward-looking projections. The forecast framework extends through 2032, offering scenario-aware estimates that account for potential variations in regulatory implementation, economic conditions, and technological adoption rates.
Segmentation chapters dissect market composition by region, material, and application, revealing not just where demand is concentrated but why it concentrates there. These analyses are designed to support product portfolio planning, geographic expansion evaluations, and sales territory prioritization. Competitive profiling extends beyond basic company descriptions, examining strategic focus areas, product philosophies, and likely response patterns to market shifts. Recent developments tracking integrates regulatory announcements, trade show innovations, product launches, and standardization milestones, ensuring that readers understand the immediate forces shaping buyer behavior and manufacturer strategy.
The report also incorporates practical guidance on procurement considerations, including the cost and replacement implications of different filtration grades, the performance expectations associated with various media types, and the compliance implications of evolving testing and certification standards. By connecting technical specifications with financial and operational outcomes, the study enables decision-makers to evaluate trade-offs systematically rather than reactively.
Translating Intelligence into 2026 Action
Access to high-quality market intelligence is valuable only when it translates into concrete strategic action. For 2026 planning cycles, the insights contained within this research can inform a range of critical decisions. Procurement teams can use segmentation and pricing analyses to refine specification guidelines, negotiate more effectively with suppliers, and balance upfront costs against long-term performance and replacement frequency. Product development and innovation groups can identify whitespace opportunities where existing solutions fall short of emerging requirements, particularly as regulatory standards place greater emphasis on comprehensive emission assessment and energy efficiency metrics.
Strategic planners and executives can leverage regional demand patterns and competitive concentration data to evaluate market entry feasibility, partnership potential, and resource allocation priorities. Organizations supplying filtration manufacturers or adjacent HVAC components can use the report's application and material breakdowns to anticipate order volume shifts and align production or inventory accordingly. Investors and analysts will find the revenue trajectory, growth rate context, and competitive structure analysis useful for evaluating sector attractiveness and identifying leading indicators of market maturation.
Ultimately, the report is designed to reduce uncertainty without oversimplifying complexity. It provides the analytical depth required to make informed choices while maintaining the clarity necessary for executive-level communication and cross-functional alignment.
Conclusion
The HVAC air filter market is entering a phase where performance expectations, regulatory scrutiny, and strategic differentiation will increasingly separate leading organizations from those that merely follow. Our comprehensive research report delivers the structured, data-informed perspective needed to navigate this environment with precision. From historical trajectory analysis and forward-looking growth modeling to detailed segmentation evaluation and competitive landscape assessment, every component of the study is purpose-built to support high-stakes decision-making. For leaders seeking to transform market complexity into strategic advantage, the full report offers the complete intelligence foundation required to move from awareness to action.
For detailed analysis of this topic, please visit the official page: HVAC Air Filter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: B Flam Retardants Market to Hit $1,695M by 2032, 7.65% CAGR
By PW Consulting, 2026-09-16
Strategic Imperatives in the BDP Flame Retardants Market: A 2026 Outlook
The global chemical landscape is undergoing a seismic shift. As industries pivot toward sustainability and stringent safety protocols, the demand for high-performance materials has never been more critical. Within this complex ecosystem, Bisphenol A bis(diphenyl phosphate), commonly known as BDP, has emerged as a cornerstone solution for halogen-free flame retardancy. For stakeholders navigating the chemical value chain, understanding the trajectory of the BDP market is not merely an academic exercise but a fundamental requirement for strategic planning in 2026 and beyond.
PW Consulting is pleased to introduce our comprehensive market research study on the BDP Flame Retardants Market. This document serves as a strategic overview, highlighting the macroeconomic currents, competitive dynamics, and regulatory pressures that are defining the sector. While this preview outlines the structural framework of the industry, the full report provides the granular intelligence necessary to capitalize on emerging opportunities.
Market Trajectory and Macroeconomic Context
The BDP Flame Retardants Market has demonstrated remarkable resilience and growth over the past five years. Our analysis tracks historical performance from 2020 through 2025, establishing a robust baseline for forecasting future trends. During this historical window, the industry has navigated supply chain disruptions, raw material volatility, and shifting regulatory landscapes to achieve consistent expansion.
Looking ahead, the forecast period spanning 2026 to 2032 paints a picture of sustained momentum. The market is projected to grow at a compound annual growth rate (CAGR) of 7.65 percent throughout this forecast horizon. This growth trajectory suggests that the industry will expand significantly beyond its current valuation, driven by the dual engines of electrification in transportation and the stringent safety requirements in electrical and electronics sectors.
Fiscal milestones in the near term indicate steady consolidation of market value. By 2026, the market is expected to reach a valuation of approximately 1062.38 Million USD. This upward curve continues as we move through the late 2020s, with projections suggesting the market will surpass 1504.22 Million USD by 2030. Ultimately, the sector is poised to approach 1695.0 Million USD by the end of the forecast period in 2032. These figures underscore the long-term viability of BDP as a critical chemical intermediate and finished additive.
Such macroeconomic indicators are essential for capacity planning and investment decisions. However, top-line numbers only tell part of the story. To truly leverage this growth, enterprises must understand the specific drivers within material types, application sectors, and geographic regions, all of which are dissected in the full PW Consulting report.
Industry Dynamics: The Shift Toward Halogen-Free Solutions
The fundamental force propelling the BDP market is the global regulatory crackdown on halogenated flame retardants. For decades, brominated compounds served as the industry standard due to their efficacy and cost structure. However, environmental persistence and toxicity concerns have triggered a regulatory wave that is reshaping procurement strategies across multiple industries.
Recent industry intelligence highlights a stark divergence in cost structures between traditional brominated solutions and phosphorus-based alternatives like BDP. Specifically, the price of decabromodiphenyl ethane, a common brominated flame retardant, has seen significant escalation, rising from approximately 30,000 yuan/ton in 2017 to around 60,000 yuan/ton in recent years. This price inflation is largely attributable to policy restrictions that have constrained production and increased compliance costs for brominated manufacturers.
In contrast, the PC+BDP system is gaining traction due to its economic advantages. Recent data indicates that the PC+BDP system offers a cost advantage of roughly 0.18 million yuan/ton compared to ABS+bromine alternatives. This economic efficiency, combined with performance parity, makes BDP an increasingly attractive option for compounders and OEMs looking to optimize material costs without compromising safety standards.
Furthermore, the raw material landscape supports this transition. Global ABS production capacity currently stands at 7.35 million tons, whereas PC capacity is at 5.56 million tons. Despite the capacity differential, the strategic advantage of integrating BDP into PC-based alloys lies in the ability to meet UL94 V0 compliance standards efficiently. This dynamic is forcing downstream expansion, not just due to policy mandates, but because cost factors are actively driving increased demand for phosphorus-based flame retardants.
Competitive Landscape and Key Players
The BDP market is characterized by a moderately concentrated competitive environment. Analysis indicates that the top three companies hold a CR3 of 35.2 percent, while the top five players command a CR5 of 42.8 percent. This structure suggests that while large players dominate significant market share, there is ample room for specialized manufacturers to capture niche segments through technological differentiation and supply chain reliability.
BDP Flame Retardants Market
Several key enterprises are actively shaping the market through production capacity expansion, product innovation, and strategic marketing. Oceanchem Group Limited, based in Weifang, Shandong, stands out as an active supplier of phosphorus-based halogen-free flame retardants. With a substantial production capacity of 40,000 tpa, Oceanchem focuses on BDP used in PC/ABS and engineering plastics for UL94 V0 compliance. Their recent activity includes updating product data sheets to clarify application details for fire-retardant use, signaling a commitment to technical transparency.
In the Zhejiang province, Hangzhou Mei Wang Chemical Co., Ltd. has been particularly active in 2025. They manufacture Mflam BDP specifically for PC/ABS resins, typically requiring a 10-15 percent dosage to achieve UL94 V0 at 1.6 mm thickness. Their market presence was highlighted by successful participation in major industry events such as K Show 2025 in Düsseldorf and KOPLAS 2025 in South Korea. These exhibitions showcased innovative flame retardant solutions, emphasizing their role in pioneering solutions for challenging PC/ABS systems. Additionally, their participation in ChinaPlas Shenzhen 2025 marked the introduction of latest flame retardant products to the market.
Other notable manufacturers include Jining Green Mountain Chemical Co., Ltd., which supplies BDP non-halogen flame retardants for engineering plastics including PC/ABS, PPO/HIPS, and ABS, emphasizing low volatility and high thermal stability. Ningbo Haopu Chemical Co., Ltd. produces BDP for a wide range of engineering plastics and thermoplastics alloys, including ABS, HIPS, PC, and PPO. International presence is maintained by DAI HACHI Chemical Industry Co., Ltd. in Japan, which manufactures CR-741 (BDP) phosphorus flame retardant for plastics. Additionally, Sinobio Chemistry operates as a key manufacturer and supplier of BDP Bisphenol A bis(diphenyl phosphate) CAS 5945-33-5 for halogen-free applications.
These companies are not merely producing chemicals; they are engaging in active collaboration and development. Presentations at 2025 K-SHOW focused on future development and collaboration opportunities for halogen-free flame retardants, indicating a shift toward partnership-driven innovation rather than isolated manufacturing.
Segmentation and Application Drivers
Understanding where the demand originates is crucial for targeted market entry. The BDP market is segmented by type, application, and region. In terms of material type, the market is driven by specific engineering plastic systems. PC/ABS blends represent a significant portion of demand, leveraging BDP for flame retardancy without sacrificing mechanical properties. PCB/Epoxy systems and Polyphenylene Oxide Alloys also constitute vital segments, each requiring tailored formulation strategies to achieve optimal performance.
By application, the Electrical & Electronics sector remains a primary consumer of BDP flame retardants. As devices become more compact and powerful, the need for materials that prevent fire propagation without releasing toxic halogenated smoke becomes paramount. The Automotive sector is another critical growth vector, driven by the electrification of vehicles where battery enclosures and interior components require high-level fire safety. Wires & Cables, Building & Construction, and Transportation sectors also contribute to the aggregate demand, each with unique regulatory and performance requirements.
Geographically, the market is well-distributed. North America, Europe, and Asia Pacific each represent significant shares of the global revenue landscape. Asia Pacific, in particular, reflects the manufacturing hub status of the region, while North America and Europe are key markets for high-end engineered solutions driven by strict safety regulations. Latin America and the Middle East and Africa represent emerging territories with growing industrialization needs.
To fully understand the nuance of these segments, including specific growth rates and volume distributions for each category, stakeholders require the detailed breakdown provided in our full analysis. The aggregate data suggests a balanced but dynamic growth pattern across these verticals.
Strategic Recommendations for 2026 Decision Making
For corporate strategists and procurement leaders, the 2026 outlook for BDP Flame Retardants presents both risks and opportunities. The clear trend is away from halogenated chemistry and toward phosphorus-based systems. Companies that fail to adapt their supply chains to accommodate halogen-free alternatives may face regulatory hurdles and cost inefficiencies as brominated materials become increasingly expensive and scarce.
Procurement strategies should focus on securing stable partnerships with manufacturers who have demonstrated capacity and technical competence, such as those detailed in our competitive landscape analysis. With CR3 concentration at 35.2 percent, diversification of supply sources is advisable to mitigate risk, while also engaging with specialized players who offer superior technical support for specific polymer systems like PC/ABS.
Furthermore, R and D investments should align with the cost advantages identified in recent raw material analyses. The economic benefit of PC+BDP systems over traditional alternatives provides a strong business case for material substitution in new product designs. Companies should evaluate their current material portfolios against the latest regulatory standards and cost structures to identify immediate areas for optimization.
Market entry timing is also critical. With the forecast period extending to 2032, early movers who establish supply relationships and product specifications now will be better positioned to capture market share as the total market size expands toward 1695.0 Million USD. Waiting until regulatory pressures peak may result in higher input costs and limited supplier availability.
Accessing Complete Market Intelligence
This article provides a strategic framework for understanding the BDP Flame Retardants Market in the context of 2026 planning. We have explored the macroeconomic growth trajectory, the regulatory shift away from brominated compounds, the competitive dynamics among key manufacturers, and the segmentation drivers that define demand. However, successful execution requires data depth that goes beyond these high-level summaries.
Fire Retardant Additives Market
PW Consulting's full BDP Flame Retardants Market Report offers the granularity needed to make informed, high-stakes decisions. From detailed historical data series covering 2020 to 2025 to precise forecasts through 2032, our research provides the numerical backbone for your strategic models. The report delves into specific volume splits, regional nuances, and company-level profiling that cannot be fully disclosed in this preview.
To secure your competitive edge and gain access to the complete dataset, including detailed segmentation splits and comprehensive company profiles, we invite you to visit the source webpage for this study. Equip your organization with the precise intelligence needed to navigate the evolving flame retardant landscape.
For detailed analysis of this topic, please visit the official page: BDP Flame Retardants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Contract Lifecycle Management Market Hits $1.99B in 2025, 11.5% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Intelligence in the Contract Lifecycle Management System Market: Navigating the 2026 Decision Landscape
In an era where enterprise velocity is increasingly measured by the speed and reliability of contractual execution, Contract Lifecycle Management (CLM) systems have evolved from administrative utilities into strategic infrastructure. The latest PW Consulting market research on the CLM System Market delivers a comprehensive, forward-looking intelligence architecture designed specifically for executives, procurement leaders, legal operations directors, and technology strategists who must allocate capital, select vendors, and shape compliance frameworks in 2026 and beyond.
This research does not merely report historical trends. It constructs a decision-ready lens through which organizations can evaluate platform maturity, competitive positioning, regulatory exposure, and technology adoption pathways. By triangulating historical performance, forward-looking trajectory, ecosystem dynamics, and operational cost drivers, the study provides the analytical rigor required to move from reactive contract administration to proactive value creation.
The Macro Trajectory: A Market in Accelerated Transition
Over the past half-decade, the CLM sector has demonstrated a consistent upward trajectory, reflecting the broader enterprise shift toward digitized, auditable, and AI-augmented contracting processes. Historical performance from 2020 through 2025 reveals a market that has steadily expanded its revenue base, moving from a foundational phase into a period of compounding growth. The most recent year closed with a market valuation that underscores how deeply contract management has become embedded in enterprise operating models.
Looking ahead, the forecast window extending through 2032 projects a sustained growth rhythm, with a compound annual growth rate that signals robust institutional adoption rather than speculative hype. The projected expansion indicates that CLM investments will continue to outpace broader enterprise software averages, driven by regulatory complexity, cross-border transaction volume, and the operational imperative to extract structured intelligence from unstructured contractual text. For decision-makers, this trajectory carries immediate implications: the window for opportunistic platform evaluation is narrowing, and the cost of delayed modernization is rising in tandem with market maturity.
The growth narrative is not uniform across deployment models, functional applications, or geographies. Rather, it reflects a market in which certain structural preferences are consolidating while others remain in flux. Cloud-native architectures have clearly dominated contemporary procurement preferences, reflecting the broader enterprise appetite for scalable, continuously updated, and API-connected environments. At the same time, on-premise and hybrid deployments retain meaningfulpresence in contexts where data residency, legacy integration, or stringent security postures dictate alternative pathways. This duality means that vendor selection cannot be reduced to a single architectural checklist; it requires a nuanced assessment of organizational risk tolerance, integration reality, and long-term total cost of ownership.
What the Research Delivers: From Insight to Execution
PW Consulting’s CLM System Market report is structured to convert high-level market intelligence into actionable executive guidance. The study is organized around several interlocking analytical layers, each designed to support a distinct dimension of strategic decision-making.
- Demand and Deployment Architecture Analysis: The report examines how organizations are structuring their CLM investments across functional domains and operational models. Rather than treating the market as a monolith, the analysis differentiates usage patterns across legal and compliance workflows, procurement and supplier contracting, and commercial functions such as sales and marketing. This functional decomposition helps leaders identify where contract lifecycle friction is most acute and where platform capabilities must be prioritized.
- Competitive Benchmarking and Vendor Positioning: A detailed evaluation of leading CLM providers maps each contender’s architectural philosophy, AI integration strategy, vertical focus, and partnership ecosystem. The research goes beyond feature lists to assess how vendors are differentiating in a crowded field—whether through no-code configurability, obligation tracking depth, procurement-native integration, signature-to-management continuity, or AI-powered extraction and analytics.
- Regulatory and Compliance Dynamics: The study contextualizes market growth within a rapidly evolving compliance environment. It examines how emerging regulatory expectations are reshaping contract clause configuration, data handling requirements, audit trail integrity, and cross-border agreement structures. For organizations operating in multiple jurisdictions, this dimension is not peripheral; it is central to platform selection and process design.
- Operational Cost and Labor Considerations: Beyond license and implementation expenditure, the research addresses the human capital dimension of CLM adoption. It evaluates how specialized labor for contract review, compliance monitoring, and AI configuration continues to shape operating economics, helping leaders forecast realistic adoption timelines and resource requirements.
- Forward-Looking Scenario Framing: The report integrates market trajectory, competitive movement, and regulatory signals into a cohesive forward view. This enables executives to stress-test investment assumptions, anticipate platform evolution, and align CLM strategy with broader enterprise technology roadmaps.
Competitive Landscape: Strategic Differentiation in a Consolidating Field
The CLM vendor ecosystem is characterized by a mix of specialized platforms, incumbent enterprise software providers, and technology giants extending contract capabilities into broader business networks. Market concentration data indicates that while leading players hold meaningful share, the field remains sufficiently distributed to reward organizations that evaluate vendors against precise operational requirements rather than brand familiarity alone.
Several market participants illustrate the breadth of strategic positioning shaping the 2026 landscape. Agile, highly configurable platforms have gained traction among legal operations teams seeking no-code customization and obligation management capabilities that can adapt to varied contracting workflows without heavy professional services dependency. AI-native contract intelligence providers have positioned themselves around governance, compliance reporting, and post-signature performance management, targeting global enterprises that require consistent contract visibility across complex organizational structures. Other platforms emphasize buy-side and sell-side complexity, focusing on obligation tracking and automated performance management for organizations where contract execution directly affects revenue recognition and supply continuity.
Workflow-driven CLM solutions have carved out a distinct position by targeting in-house legal teams with fast approval paths, collaboration tools, and AI assistants designed to compress cycle times. Meanwhile, procurement-centric and spend-management platforms have increasingly embedded CLM functionality into broader sourcing and supplier ecosystems, leveraging AI agents and orchestration layers to connect contract execution with operational procurement flows. Establishing CLM as a natural extension of electronic signature and agreement execution remains a proven entry point for organizations that prioritize creation, negotiation, and execution continuity. Large enterprise software vendors continue to offer CLM capabilities tightly integrated with procurement, supply chain, financial systems, and acquisition workflows, appealing to organizations that favor unified vendor relationships and deep backend integration. AI-powered analytics and data extraction tools, often built on established cognitive platforms, provide specialized review and extraction capabilities that complement broader CLM deployments. Government-focused contract management specialists maintain a dedicated presence by emphasizing compliance, risk management, and regulatory alignment for public-sector and defense-adjacent contracting environments.
Recent market movements underscore how rapidly this landscape is being reshaped by AI productization and partnership strategy. One configurable CLM provider democratized access to enterprise-grade contract AI through a free tier while advancing obligation management features, signaling an intent to expand adoption beyond traditional enterprise buyers. Another AI-native contract intelligence vendor expanded a strategic partnership with a major technology platform to advance contract intelligence capabilities, and separately earned recognition in a prominent peer review program while broadening collaboration with an enterprise software vendor for public-sector CLM use cases. A workflow-oriented CLM vendor released updates spanning AI agents, integrations, workflow administration, and contract data management, while also crossing a notable annual recurring revenue threshold that reflects a broader shift toward AI-led growth models.
For enterprise buyers, these developments convey a clear message: vendor differentiation is increasingly defined by the depth of AI integration, the flexibility of configuration, the strength of ecosystem partnerships, and the ability to support compliance-intensive workflows. Selecting a platform therefore requires more than comparing feature matrices; it demands an evaluation of how each vendor’s trajectory aligns with an organization’s governance requirements, integration architecture, and scale ambitions.
Market Dynamics: Regulation, Risk, and the Operating Cost Reality
The CLM market is not expanding in a vacuum. It is being restructured by regulatory expectations that make contract configuration, evidence retention, and clause governance more complex than ever. In the European context, emerging AI governance requirements are pushing organizations to classify risk and document responsibilities when contracting with AI system vendors, directly influencing how CLM platforms must support clause configuration and compliance verification. Parallel obligations under data protection frameworks require demonstrable contractual presence in international agreements, with mandatory fields and workflows that must be tracked and enforced within CLM environments. Sustainability reporting obligations add another layer of complexity, as ESG-related clauses increasingly need to be systematically captured, configured, and reported across supplier contracts.
At the same time, enterprise security expectations continue to raise the bar for platform trustworthiness. CLM systems are expected to maintain rigorous compliance postures, supported by immutable audit trails and certified control environments that protect sensitive contract data throughout its lifecycle. For procurement and legal leaders, these requirements are no longer optional checkboxes; they are foundational criteria that influence vendor shortlisting, implementation design, and ongoing operational governance.
Beneath the technology conversation lies a persistent operational reality: specialized human labor remains a significant cost driver. Contract review, compliance monitoring, and the setup of AI-assisted workflows require expertise that is not yet fully commoditized. Organizations that underestimate this dimension risk overstating automation benefits and under-scoping change management effort. The research addresses this by framing CLM adoption as a socio-technical transformation in which platform capability, process redesign, and skilled configuration must advance together.
Strategic Implications for 2026 Decision-Makers
For executives navigating CLM strategy in 2026, the market presents both urgency and opportunity. The growth trajectory indicates that contract lifecycle modernization is moving from isolated legal-tech initiatives to enterprise-wide capability building. That shift raises the stakes for vendor selection, integration planning, and compliance alignment. It also creates leverage: organizations that deploy CLM with clear functional priorities, realistic adoption horizons, and disciplined evaluation criteria can convert contract processes from cost centers into structured sources of operational intelligence.
Several strategic priorities emerge from the broader market picture. First, organizations should define CLM requirements through the lens of workflow reality rather than abstract platform promises. Legal, procurement, and commercial functions experience contract lifecycle friction differently, and platform value is maximized when deployment aligns with the most consequential pain points. Second, AI capabilities should be evaluated for practical contract outcomes—obligation visibility, extraction accuracy, workflow acceleration, and governance consistency—rather than as generic feature statements. Third, compliance and security requirements must be treated as primary selection criteria, particularly for organizations managing cross-border agreements, AI-related vendor relationships, or sustainability-linked contractual obligations. Fourth, vendor partnerships and ecosystem integration should be assessed as strategic assets, since the ability to connect CLM with procurement, financial, signature, and analytics environments increasingly determines long-term platform usefulness.
Contract Lifecycle Management System Market
Supplier Relationship Management System Market
Why This Research Matters Now
Market intelligence is most valuable when it is structured for action. PW Consulting’s CLM System Market research is designed to help leaders move beyond surface-level vendor comparison and toward a disciplined, evidence-based strategy. By combining historical context, forward trajectory, functional segmentation, competitive profiling, regulatory dynamics, and operational cost considerations, the report equips decision-makers with the perspective needed to prioritize investments, reduce selection risk, and align contract technology with broader enterprise objectives.
The full study provides the detailed segmentation analysis, vendor evaluation frameworks, regulatory impact mapping, and implementation-oriented guidance required to translate market awareness into confident decision-making. For organizations preparing CLM investments, platform evaluations, or compliance-driven contract transformations in 2026, the complete research offers the depth necessary to support executive alignment and board-level justification.
To access the full market intelligence, segmentation detail, competitive assessments, and forward-looking strategic recommendations, explore the complete PW Consulting Contract Lifecycle Management System Market research package.
For detailed analysis of this topic, please visit the official page: Contract Lifecycle Management System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Magnesium Die Casting Hits $2.72B in 2025, 5.6% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Imperatives in the Automotive Parts Magnesium Die Casting Market: A 2026 Outlook
The automotive industry stands at a critical inflection point where lightweighting mandates intersect with stringent emission regulations. For stakeholders monitoring the Automotive Parts Magnesium Die Casting Market, the convergence of technological capability and regulatory pressure is reshaping competitive positioning. Our latest market research provides a comprehensive analysis designed to guide executive decision-making throughout the 2026 to 2032 forecast horizon. This report serves as a foundational intelligence asset, translating complex industry dynamics into actionable strategic roadmaps for OEMs, Tier suppliers, and investment groups.
Operationalizing Market Intelligence for Executive Teams
Understanding the trajectory of magnesium die casting requires more than surface-level observation. It demands a rigorous examination of production capabilities, alloy innovations, and downstream integration. The automotive sector is increasingly relying on magnesium alloys to achieve fuel efficiency standards and reduce greenhouse gas emissions. As manufacturers pivot toward electrified and lightweight platforms, the demand for high-pressure and vacuum die casting processes is intensifying. Our research framework captures these nuances, offering a granular view of how pressure die casting and vacuum die casting serve as primary processes due to their superior precision and repeatability. This operational focus ensures that leadership can evaluate supplier capabilities with confidence.
The market intelligence encapsulated in this study extends beyond aggregate figures. It dissects the mechanisms driving growth, including the integration of magnesium components into body panels, engine parts, and transmission components. By analyzing the interplay between structural integrity requirements and weight savings, the report equips strategists with the context needed to assess risk and opportunity. Whether evaluating new capacity investments or negotiating supply contracts, having access to verified industry data is paramount. The following sections outline the core pillars of our analysis, demonstrating why this report is an essential tool for navigating the coming years.
Market Landscape and Growth Trajectory
The economic landscape for automotive magnesium die casting has demonstrated robust expansion over the recent historical period. Our analysis tracks market revenue trends from 2020 through the base year of 2025, establishing a validated baseline for future projections. The data indicates a consistent upward movement, reflecting the automotive industry's commitment to material optimization. As we extend the forecast period to 2032, the study projects sustained momentum, underpinned by a Compound Annual Growth Rate that underscores the strategic importance of this material segment.
Worldwide Automotive Magnesium Alloy Wheel Market
This growth is not merely a function of volume but is deeply tied to value creation through engineering innovation. The report highlights how the market valuation evolves as manufacturers scale production of integrated magnesium components. From the initial baseline years to the projected peak in the early 2030s, the trajectory suggests a maturing market where efficiency and scale converge. For decision-makers, understanding the magnitude of this expansion is crucial for capital allocation. The research details the revenue pathways without exposing the granular segmentation tables, ensuring that subscribers gain a holistic view of the economic environment before diving into specific regional or application-based calculations available in the full document.
Dynamics Driving Industry Participation
Several key dynamics are fueling the widespread adoption of magnesium die casting in automotive applications. Foremost among these is the imperative for weight reduction. Magnesium die casting enables significant weight reduction in automotive components, directly supporting fuel efficiency standards and greenhouse gas emission regulations. This regulatory tailwind is a persistent force, compelling manufacturers to seek solutions that do not compromise performance. Furthermore, high-pressure die casting of magnesium alloys complies with automotive safety standards for structural integrity in body and powertrain applications. This dual benefit of lightness and strength is a powerful value proposition that the report analyzes in depth.
Infrastructure and process technology also play a pivotal role. The industry relies heavily on pressure die casting and vacuum die casting as primary processes used for automotive magnesium die casting due to superior precision and repeatability. These technical specifications determine the quality of output in engine parts, transmission components, and body panels. Our research examines how these processes are optimized across different manufacturing environments. By mapping the technological landscape, we provide insights into which production methods are gaining traction and how they align with the demands of modern vehicle architectures. This section of the report is critical for assessing the technical readiness of potential partners or internal production lines.
Competitive Landscape and Key Incumbents
The market structure is characterized by a mix of established global players and specialized firms focusing on lightweighting solutions. Our analysis identifies key companies that are shaping the competitive environment. Leaders such as GF Casting Solutions and Nemak are prominent for their focus on high-pressure die-cast components and lightweighting solutions, respectively. GF Casting Solutions operates with a focus on high-pressure die-cast aluminum and magnesium components for global automotive OEMs, including powertrain and structural parts. Similarly, Nemak focuses on lightweighting solutions with magnesium die casting components for the global automotive industry, showcasing innovations such as cross car beams and oil sumps with significant weight reduction properties.
Automotive Parts Magnesium Die Casting Market
Regional specialization is evident among other key participants. In North America, firms like Shiloh Industries, Pace Industries, Meridian Lightweight Technologies, Kinetic Die Casting Company, and ZD Metal Products contribute to a diverse ecosystem. Shiloh Industries focuses on high-pressure and high-vacuum structural die castings, while Pace Industries offers full-service magnesium die casting for automotive parts, ranging from prototypes to long-term production. Meridian Lightweight Technologies concentrates on innovative die cast magnesium solutions and assemblies, and Kinetic Die Casting Company targets magnesium die casting for lightweight automotive parts. ZD Metal Products rounds out this group with a focus on high-performance magnesium die castings for automotive Tier I and Tier II suppliers.
In Asia, Haitian Die Casting stands out as a major force. Headquartered in Ningbo, China, the company focuses on high-pressure magnesium alloy forming technology and integrated magnesium die-cast components for automotive mass production. The report provides a detailed competitive profiling of these entities, examining their strategic moves, technological deployments, and market positioning. Understanding the scope of operations for these incumbents allows stakeholders to benchmark their own strategies and identify gaps in the supply chain.
Recent Strategic Developments and Innovation
The competitive landscape is dynamic, with recent events highlighting the pace of innovation. Our research integrates recent developments to show how key players are executing their strategies. In 2025, Haitian Die Casting was active with multiple milestones. They debuted magnesium alloy forming technology at the 5th China Foundry Association Die Casting CEO Annual Meeting and Nonferrous Casting Lightweight Forum. Shortly thereafter, they powered the mass production of the world's largest integrated magnesium rear body for SERES vehicles. Additionally, Haitian signed a strategic partnership with Guangdong Hongte Technology Co., Ltd. for comprehensive collaboration in magnesium die casting and showcased aluminum and magnesium forming solutions at automotive industry forums in Wuhan and Hefei.
Moving into 2026, Nemak continued this trend of showcasing advanced components. At the 2026 China Die Casting Congress in Wuhan, they showcased an HPDC Magnesium Cross Car Beam with 53% weight reduction and an HPDC Magnesium Oil Sump with 24% weight reduction and creep resistance. These examples illustrate the tangible progress being made in component engineering. The report contextualizes these developments within the broader industry narrative, helping readers understand how specific technological breakthroughs translate into market share and capability expansion. By tracking these events, the study offers a real-time perspective on where the industry is heading.
Market Concentration and Industry Structure
An understanding of market concentration is vital for assessing competitive intensity and barriers to entry. Our research provides data on the concentration levels within the industry, indicating the share held by leading firms. The analysis reveals a landscape where a significant portion of market revenue is captured by top-tier players, yet ample space remains for specialized innovators. This structure suggests that while scale is important, technological differentiation and service integration are equally critical for success. The report elaborates on these concentration metrics to help stakeholders evaluate the risk of supplier dependency and the potential for consolidation.
This structural insight is complemented by a review of supply chain dynamics. The interplay between major suppliers and automotive manufacturers is complex, influenced by quality requirements, delivery timelines, and cost pressures. By mapping the relationships and dependencies within the value chain, the report supports better vendor selection and risk management strategies. The concentration data serves as a benchmark for understanding the balance of power in the market and informs decisions regarding partnership or acquisition opportunities.
Conclusion: Value for Decision-Makers
The Automotive Parts Magnesium Die Casting Market represents a sector where strategic foresight can yield significant competitive advantage. As regulations tighten and vehicle architectures evolve, the ability to anticipate market shifts is invaluable. This report delivers the depth of analysis required to navigate these complexities. From the macroeconomic growth drivers to the micro-level innovations showcased by key companies, every section is designed to support informed decision-making. The integration of historical data with forward-looking projections ensures that stakeholders have a reliable compass for the forecast period.
For executives seeking to understand the full scope of opportunities and risks, the detailed segmentation analysis offers the necessary granularity. The complete study unpacks regional variations, application-specific demands, and type-based market splits, providing the precise data points needed for detailed planning. We invite industry leaders to leverage this comprehensive intelligence to refine their strategies. Accessing the full report will unlock the specific breakdowns and strategic recommendations that underpin this executive overview, enabling a data-driven approach to growth in the automotive magnesium die casting sector.
For detailed analysis of this topic, please visit the official page: Automotive Parts Magnesium Die Casting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: BIM Market Hits $113M in 2025, Projected 13.05% CAGR to $267.4M by 2032
By PW Consulting, 2026-09-16
The Digital Backbone of Construction: Unlocking Strategic Value in the 2026 BIM Market
The construction industry stands at a critical inflection point, where digital transformation is no longer optional but existential. Building Information Modeling (BIM) has evolved from a niche technological advantage into the central nervous system of modern infrastructure development. As we navigate through 2026, understanding the trajectory of this market is vital for stakeholders ranging from civil engineering firms to software investors. Our latest comprehensive market research provides a granular look at this ecosystem, offering the intelligence required to navigate the next cycle of growth.
Recent historical data underscores the resilience and accelerating momentum of the sector. The market has demonstrated consistent expansion over the past half-decade, moving from a valuation of 60.0 million USD in 2020 to approximately 113.0 million USD in 2025. This historical trajectory sets the stage for a forecast period defined by robust acceleration. Projections indicate that the market will reach 128.71 million USD by the end of 2026, eventually climbing toward 267.4 million USD by 2032. This growth pattern corresponds to a compound annual growth rate of 13.05 percent during the forecast horizon, signaling a high-confidence environment for capital allocation and strategic planning.
However, top-line numbers only tell a fraction of the story. The true value for enterprise decision-makers lies in understanding the underlying mechanics driving this expansion. Our report dissects the ecosystem to reveal where value is being created, which geographies are leading the charge, and how the competitive landscape is consolidating. This article serves as a strategic preview of those findings, highlighting the critical dynamics that will define success in 2026 and beyond.
Market Trajectory and Growth Drivers
The forecast period from 2026 to 2032 is expected to be characterized by a shift from adoption to optimization. While the initial push for BIM was driven by regulatory compliance and basic digitalization, the current phase is fueled by efficiency mandates and integrate data workflows. The steady increase from 146.71 million USD in 2027 to 208.68 million USD in 2030 suggests that demand is becoming less sensitive to economic fluctuations, embedding itself deeper into operational budgets.
Our analysis identifies several key catalysts propelling this growth. The industry is moving beyond static 3D modeling toward dynamic information management. This shift is not merely technological but procedural, requiring firms to rethink how data is handled from preconstruction through postconstruction phases. The research highlights that while certain phases traditionally dominate revenue share, the growth rate is accelerating in areas related to lifecycle management and digital twin integration. Understanding these shifts is crucial for vendors positioning their solutions and for firms selecting partners to ensure long-term compatibility.
Furthermore, the revenue unit analysis indicates a significant reliance on specific type segments. The market remains heavily weighted toward software solutions compared to services, reflecting a preference for scalable digital tools over manual consultancy. Yet, the services segment continues to play a pivotal role in implementation and customization, ensuring that organizations can actually derive value from the software licenses they purchase. This balance between software and services is a key consideration for investors assessing recurring revenue models versus one-off service engagements.
Regional Dominance and Emerging Hubs
Geographic distribution remains a critical component of market strategy. Current analyses point to a mature landscape in developed economies, yet the potential for expansion in emerging regions is substantial. North America continues to command a significant share of the global revenue, reflecting early adoption rates and a high density of large-scale infrastructure projects. Europe follows as a strong second, driven by stringent regulatory frameworks and public sector mandates for digital delivery.
Asia Pacific represents a dynamic growth engine, with rapid urbanization and increasing investment in smart infrastructure fueling demand. While the share values vary, the momentum in this region often outpaces mature markets in terms of percentage growth. Latin America and the Middle East and Africa, while currently representing smaller portions of the total revenue, are identified as areas where strategic entry could yield high long-term returns. Our report provides a detailed breakdown of these regional nuances, helping entities identify where to focus sales efforts or where to seek partnership opportunities.
It is essential for decision-makers to recognize that regional preferences are not static. Local regulations, labor costs, and technological infrastructure influence how BIM is deployed. For instance, markets with higher labor costs may prioritize automation and clash detection tools to reduce rework, whereas developing regions might focus on basic coordination and documentation capabilities. The research delves into these behavioral differences to provide a localized view of global trends.
Building Management System Market
Competitive Landscape and Key Players
The BIM market is defined by a mix of established giants and specialized innovators. Market concentration metrics indicate a moderately fragmented environment, with the top three players capturing a combined share of approximately 25.5 percent and the top five holding around 30.2 percent. This suggests that while there are dominant forces, there is still ample room for niche players or specialized solutions to thrive, particularly in vertical-specific applications.
Autodesk remains a cornerstone of the ecosystem, headquartered in San Francisco. Their portfolio, including Autodesk Revit for parametric 3D modeling and Autodesk Forma, continues to set industry standards. Recent updates in 2026 have focused on enhancing modeling workflows and cloud-based cost management. The company has also expanded its API ecosystem to drive third-party integration, reinforcing its platform strategy and recurring revenue potential. Their continuous updates, such as the Revit 2026 launch with accelerated graphics and the BIM 360 Cost Management update, demonstrate a commitment to maintaining technological leadership.
Bentley Systems , based in Exton, Pennsylvania, maintains a strong focus on infrastructure and digital delivery. Their offerings like ProjectWise for data governance and SYNCHRO for 4D planning are integral to large-scale engineering projects. The emphasis on digital twins through iTwin positions them uniquely for lifecycle management beyond the construction phase. As the industry moves toward information-centric standards, Bentley's focus on data governance aligns well with emerging regulatory requirements.
Nemetschek Group in Munich operates as a powerful conglomerate with diverse holdings including ALLPLAN. Their recent 2026 updates for ALLPLAN emphasize multilayer finishes modeling and BIM-compliant detailing, reflecting a push toward granular construction accuracy. Additionally, the transition of subsidiary Graphisoft away from perpetual licenses toward subscription models signals a broader industry shift toward recurring revenue streams, changing how customers access and pay for architectural tools like Archicad.
Graphisoft , headquartered in Vienna, continues to innovate in the architectural space. The release of Archicad 29 in late 2025 introduced AI Assistant features and enhanced MEP Designer toolkits. However, their decision to terminate perpetual licenses by the end of 2026 forces a market-wide transition to subscription licensing. This move impacts cash flow planning for many firms and underscores the industry's pivot toward cloud-based, continuously updated software environments.
Dassault Systèmes brings a different dimension with their 3DEXPERIENCE platform. Based in France, they focus on integrating BIM with broader digital twin capabilities across the AEC industry. Their use of CATIA for integrated BIM suggests a strong orientation toward complex manufacturing and high-precision building requirements, appealing to clients who need deep engineering integration.
Regulatory Shifts and Operational Dynamics
The regulatory environment is undergoing a significant transformation that directly impacts market dynamics. The release of the ISO 19650:2026 Draft International Standard marks a pivotal shift from model-centric to information-centric lifecycle management. This revision emphasizes information management over traditional BIM terminology, introducing new requirements for data validation, exchange, and lifecycle maintenance. For organizations, this means compliance is no longer just about producing a model but about ensuring the integrity and usability of data throughout the asset's life.
Simultaneously, cloud hosting and data privacy rules are reshaping workflows. New rules effective February 2026 regarding Revit Cloud Model downloads require updates to workflows for unpublished linked files. Compliance in cloud-based BIM environments is now more complex, necessitating careful attention to data governance. Additionally, Autodesk's platform consolidation using Forge APIs aims to drive third-party integration, which benefits the ecosystem but also increases dependency on specific cloud architectures. These technical and regulatory shifts create barriers to entry but also solidify the moats for platforms that can ensure seamless compliance.
Report Scope and Strategic Utility
To fully capitalize on these opportunities, stakeholders need more than high-level trends. Our comprehensive report offers a deep dive into the operational specifics that drive decision-making. The study is structured to provide actionable intelligence across multiple dimensions, ensuring that readers can translate data into strategy.
- Historical and Forecast Analysis: Detailed year-over-year data from 2020 through 2032, allowing for trend extrapolation and budget forecasting.
- Segmentation Deep Dives: Comprehensive breakdowns by application, type, and region, revealing where growth is concentrated without relying on surface-level aggregates.
- Company Profiling: In-depth profiles of key market participants, including their strategic positioning, recent product launches, and technological focus.
- Regulatory Impact Assessment: Analysis of how new standards like ISO 19650:2026 and cloud compliance rules affect operational workflows and vendor selection.
- Growth Drivers and Restraints: Identification of the specific factors accelerating adoption versus those posing challenges, such as labor shortages or integration complexity.
This research is designed for chief strategy officers, market analysts, and investment managers who require precision. Whether you are evaluating market entry, assessing competitor moves, or planning long-term R&D investments, the granularity provided in the full report is essential. We have intentionally omitted specific percentage splits and exact revenue figures for segments in this overview to preserve the proprietary value of the full dataset.
Conclusion: The Path Forward
The BIM market in 2026 is defined by convergence—of data, regulations, and platforms. The growth from 113.0 million USD to a projected 267.4 million USD by 2032 is not just a number; it represents a fundamental restructuring of how the built environment is designed, constructed, and managed. Success in this environment requires a clear understanding of where the market is heading and who is leading the way.
Building Information Modeling (BIM) Market
Our full market research report provides the detailed compass needed to navigate this landscape. By securing access to the complete intelligence package, your organization can move beyond speculation and make decisions grounded in rigorous data. We invite you to explore the full findings to unlock the specific insights required to drive your strategic agenda in this evolving digital construction era.
For detailed analysis of this topic, please visit the official page: Building Information Modeling (BIM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: High-Purity IPA Market to Reach $344.8M by 2032 at 6.98% CAGR
By PW Consulting, 2026-09-16
Strategic Imperative in High-Purity Isopropyl Alcohol: Navigating the 2026 Market Landscape
In the rapidly evolving landscape of advanced materials, High-purity Isopropyl Alcohol (IPA) stands as a critical enabler for two of the most transformative sectors of the 21st century: semiconductor manufacturing and pharmaceutical production. As industries push toward nanometer-scale precision and stringent regulatory compliance, the demand for solvents with ultra-high purity specifications has never been more acute. PW Consulting is pleased to introduce our latest comprehensive market intelligence report, designed to equip strategic decision-makers with the foresight required for 2026 and beyond. This analysis delves into the complex interplay of technological advancement, supply chain resilience, and shifting regional dynamics that define the high-purity IPA market.
Our research provides a granular examination of the market from 2020 through 2025, establishing a baseline of historical performance, before projecting trends across the forecast period from 2026 to 2032. For corporate strategists, investors, and procurement leaders, the ability to distinguish between transient fluctuations and structural shifts is vital. This report offers more than just top-line figures; it delivers a diagnostic of the competitive environment, regulatory currents, and raw material volatilities that will dictate margin structures and supply security over the coming years. The strategic value of this intelligence lies in its capacity to transform raw data into actionable roadmaps, enabling stakeholders to anticipate demand surges, evaluate supplier viability, and optimize cost structures in an increasingly competitive global arena.
Market Trajectory: Resilience and Acceleration
The macroeconomic environment for high-purity IPA has demonstrated remarkable resilience over the past half-decade, characterized by a steady upward trajectory in revenue. From a base of 163.15 million USD in 2020, the market has navigated various challenges, including pandemic-induced disruptions and logistics bottlenecks, to reach a valuation of 215.0 million USD by 2025. This historical progression underscores the inelastic nature of demand in core application areas, particularly where high-purity solvents are non-substitutable inputs for critical processes.
Looking ahead to the forecast period, the market is poised for accelerated expansion. Starting from 235.07 million USD in 2026, the revenue landscape is projected to climb consistently, reaching 344.8 million USD by 2032. This growth trajectory is underpinned by a Compound Annual Growth Rate (CAGR) of 6.98 percent, reflecting sustained investment in advanced electronics, clean energy technologies, and life sciences. The forecast is not merely a linear extrapolation; it accounts for the varying maturation rates of market segments and the impact of capacity expansions by key industry participants. Stakeholders analyzing these figures must look beyond the aggregate numbers to understand the divergent growth vectors within the market. The report dissects these nuances, offering scenario-based insights that help organizations prepare for both baseline expectations and high-growth contingencies.
Segmentation Drives Strategic Differentiation
While the overall market growth is impressive, the true strategic opportunity lies in the segmentation of demand. The high-purity IPA market is not monolithic; it is defined by distinct purity thresholds and application specificities that command different pricing dynamics and supply chain requirements. By purity, the market spans from standard high-purity grades to ultra-high-purity electronic grades that meet rigorous parts-per-billion impurity limits. The report evaluates the competitive positioning of grades such as the 99.9% to 99.99% high-purity range, which caters to broad industrial needs, against the premium Electronic Grade (>99.99%) segment, which is essential for semiconductor wafer fabrication and advanced packaging. Additionally, the "Other Grades" category, including pharmaceutical and specialty variants, represents a vital niche where regulatory compliance and certification become key differentiators.
The application landscape further illustrates the market's bifurcation. Semiconductor wafer cleaning remains the dominant driver of value, fueled by the relentless scaling of logic and memory chips, the rise of advanced packaging techniques, and the need for defect-free surface preparation. However, the Pharmaceutical and Cosmetics sector, as well as Electronics Assembly and Cleaning, contribute significant and growing demand streams. Each application vertical imposes unique specifications regarding water content, acidity, and organic impurities. For instance, the report details how semiconductor manufacturers are imposing increasingly stringent requirements, such as keeping C7-12 acetal impurities below 100 parts per billion per USP/EP monographs to support 2nm node cleaning processes. Similarly, pharmaceutical-grade IPA must meet strict FDA cGMP standards, including maximum 0.5% water content and acidity under 0.002%. These technical barriers create moats for suppliers capable of consistent quality assurance, influencing sourcing strategies and vendor selection criteria.
Recovered Isopropyl Alcohol Market
Regional dynamics add another layer of complexity. The market analysis examines consumption patterns across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. The Asia Pacific region, home to a dense concentration of semiconductor fabs and pharmaceutical manufacturers, exhibits distinct demand characteristics and supply chain interdependencies. Europe and North America maintain strong positions driven by established industrial bases and robust regulatory frameworks. Emerging regions present both opportunities for expansion and risks related to infrastructure maturity. Our segmentation analysis provides the framework to assess regional exposure, identify arbitrage opportunities, and align supply networks with demand centers without oversimplifying the geopolitical and logistical realities on the ground.
Competitive Landscape and Capacity Evolution
The competitive environment for high-purity IPA is characterized by a mix of global chemical majors, specialized electronics material suppliers, and regional players. With a CR3 of 24.6 percent and CR5 of 26.2 percent, the market remains relatively fragmented, allowing for active competition and innovation, yet concentration is gradually increasing in high-value segments. Key players such as ExxonMobil Chemical, Eastman Chemical Company, LyondellBasell Industries, Dow Inc., Mitsubishi Chemical Corporation, LCY Chemical Corporation, Tokuyama Corporation, LG Chem Ltd., Shell Chemicals, BASF SE, INEOS Group, and GJ Chemical are actively shaping the market through capacity expansions, product innovation, and strategic partnerships.
Recent developments highlight the strategic importance of ultra-high-purity capabilities. For example, ExxonMobil Chemical announced a significant USD 100 million investment in March 2025 to upgrade its Baton Rouge plant, targeting the production of 99.999% ultra-high-purity IPA starting in 2027 to support semiconductor chip manufacturing. This move reflects a broader industry trend where integrated supply chains and plant upgrades are prioritized to secure the "EastaPure-equivalent" grades demanded by leading fabs. Similarly, Eastman Chemical Company has reinforced its position by introducing its EastaPure™ ultrahigh-purity IPA (4N grade) in its active catalog, specifically targeting semiconductor wafer fabrication wet cleaning and drying applications. These product launches underscore the race to capture market share in the premium electronic grade segment.
Capacity expansions are not limited to the United States. LyondellBasell Industries expanded its Texas facility IPA production by 25 percent in November 2025 to meet growing North American demand, underscoring the region's strategic focus on domestic supply security. In Asia, LCY Chemical Corporation launched its LCY Advanced Formulations portfolio in September 2025, including electronic-grade high-purity IPA for advanced packaging and wafer cleaning, while Tokuyama Corporation continues to supply ultra-high-purity grades essential for 2nm semiconductor cleaning processes. Other players like Mitsubishi Chemical, LG Chem, and Deepak Fertilisers are also upgrading facilities to enable full-scale production and export of high-grade pharma-certified IPA, signaling a global alignment of supply capabilities with end-market needs. The report provides a deep-dive company profile for each major participant, analyzing their product portfolios, geographic footprint, recent investments, and competitive differentiators, offering readers the intelligence needed to benchmark suppliers and anticipate shifts in market power.
Market Dynamics: Raw Materials and Regulatory Pressures
A sophisticated market analysis must address the underlying forces that influence pricing, availability, and risk. Raw material dynamics play a pivotal role in the economics of high-purity IPA, given its chemical derivation from acetone via hydrogenation. Acetone price volatility can propagate through the value chain, affecting production costs and margin stability. Our research integrates current market intelligence on acetone pricing, noting that CIF acetone prices in North America have observed significant levels, with Northeast Asia FOB prices showing distinct regional differentials. Furthermore, geopolitical events have impacted supply flows; disruptions linked to the US-Iran conflict in 2025 tightened Middle East acetone supply, which in turn elevated European CIF acetone prices. These fluctuations highlight the importance of monitoring upstream commodity markets and securing diversified sourcing strategies. The report explores how suppliers manage these cost pressures through long-term contracts, integration, and hedging, and how these strategies affect the pricing power of high-purity grades.
Regulatory compliance constitutes another formidable driver of market structure. The transition to advanced technology nodes in semiconductors has necessitated tighter control over impurities, with industry standards increasingly referencing USP/EP monographs and ISO 9001 certifications. The requirement for <100 ppb C7-12 acetal impurities in high-purity IPA for 2nm node cleaning exemplifies the technical chasm between standard grades and electronic grades. In the pharmaceutical sector, adherence to FDA cGMP regulations, including limits on water content and acidity, is not optional but a license to operate. These regulatory frameworks create high entry barriers, rewarding suppliers with robust quality management systems and advanced purification technologies. BASF SE, for instance, supplies high-purity IPA grades for pharmaceutical and electronic applications leveraging advanced purification tech, while INEOS Group produces high-purity IPA including bio-based variants to meet evolving sustainability and performance metrics in EU and global markets. The report analyzes how these regulatory and technological demands shape supplier selection, contract negotiation, and the overall cost of quality.
Unlocking the Full Intelligence: Why This Report Matters for 2026
As we move deeper into 2026, the margin for error in strategic planning is shrinking. The high-purity IPA market is influenced by a confluence of factors: rapid technological advancement in semiconductors, evolving regulatory landscapes, volatile raw material inputs, and shifting geopolitical trade patterns. Decision-makers cannot afford to rely on outdated benchmarks or generalized industry narratives. PW Consulting's High-purity Isopropyl Alcohol Market report is engineered to provide the depth, accuracy, and actionable insights required to navigate this complexity.
This report offers a comprehensive toolkit for strategic analysis. It includes detailed market sizing and forecasts that isolate growth drivers by purity and application, enabling precise demand modeling. It profiles the key companies, detailing their recent developments, capacity strategies, and product innovations, allowing you to assess competitive threats and partnership opportunities. It maps the regulatory environment, identifying compliance risks and standards that will impact your supply chain eligibility. It examines raw material dynamics, providing context on cost structures and price volatility drivers. And it analyzes regional dynamics, helping you optimize your geographic exposure and logistics strategy.
Crucially, the report does not merely present data; it interprets it. The segmentation splits, historical performance, and forecast trajectories are woven into a narrative that highlights strategic implications. You will gain an understanding of which purity grades are seeing the most aggressive capacity investment, which applications are driving the highest value growth, and how regulatory shifts are redefining quality benchmarks. You will see where market concentration is building and where fragmentation offers agility. You will understand the interplay between acetone pricing, geopolitical supply disruptions, and the premium pricing of electronic-grade materials.
However, the full strategic value of this intelligence is realized only through access to the complete dataset, scenario analyses, and detailed regional and segment-level forecasts. The overview provided here is a preview of the analytical rigor and strategic relevance embedded in the full report. To secure your competitive advantage in 2026 and build a resilient, forward-looking strategy, we invite you to access the complete PW Consulting High-purity Isopropyl Alcohol Market report. The detailed intelligence within will empower your organization to make informed decisions on procurement, capacity planning, supplier qualification, and market entry, ensuring you are not just reacting to market changes, but anticipating and shaping them.
The high-purity IPA market is at a pivotal juncture. The convergence of semiconductor scaling, pharmaceutical innovation, and supply chain recalibration creates a landscape rich with opportunity for those equipped with the right intelligence. PW Consulting stands ready to provide the clarity and depth you need to lead in this dynamic market. Explore the full report to unlock the actionable insights that will drive your success.
High-purity Isopropyl Alcohol (IPA) Market
For detailed analysis of this topic, please visit the official page: High-purity Isopropyl Alcohol (IPA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Trailer Refrigeration Market Hits $544.07 Million in 2025, Projected 5.67% CAGR to 2032
By PW Consulting, 2026-09-16
Navigating the Cold Chain: Strategic Imperatives in the Trailer Refrigeration System Market (2026–2032)
The global supply chain stands at a critical inflection point. As logistics networks strive for greater resilience, efficiency, and environmental compliance, the trailer refrigeration system market has emerged as a vital enabler of modern cold chain integrity. From temperature-sensitive pharmaceuticals to perishable food shipments crossing continents, the reliability of transport refrigeration directly influences product safety, regulatory adherence, and commercial viability. PW Consulting's latest in-depth market analysis, Trailer Refrigeration System Market: Global Industry Outlook 2026–2032 , offers a comprehensive strategic roadmap for executives, investors, and supply chain leaders seeking to navigate this rapidly evolving landscape.
Trailer Refrigeration System Market
This report is engineered not merely as a statistical compendium, but as a decision-support instrument. Drawing on rigorous primary research, proprietary modeling, and granular competitive intelligence, the study quantifies market trajectories, dissects segment-level value drivers, and evaluates the operational and regulatory forces reshaping the industry. For organizations operating in 2026, when capital allocation, product roadmapping, and compliance strategy demand precision, this analysis delivers the contextual clarity needed to move beyond reactive tactics and toward sustained competitive advantage.
Market Trajectory: A Decade of Measured Expansion
The historical trajectory of the trailer refrigeration system market reflects a sector characterized by steady organic growth, punctuated by technological modernization and regulatory evolution. Between 2020 and 2025, global revenue expanded from approximately 406.5 million USD to 544.1 million USD, demonstrating consistent demand absorption across developed and emerging logistics corridors. This upward momentum is projected to continue through the 2026–2032 forecast horizon, with the market expected to surpass 789.7 million USD by the close of the decade.
At the core of this expansion lies a compound annual growth rate of 5.67 percent, a figure that signals more than nominal market scaling. It indicates structural demand amplification driven by cold chain formalization, e-commerce fulfillment requirements, and the ongoing transition toward temperature-controlled freight solutions. For industry participants, this growth profile carries strategic weight: it suggests a market that is neither saturated nor speculative, but rather one where disciplined investment, product differentiation, and regional execution discipline can yield meaningful returns.
The forecast period also reveals nuanced dynamics that warrant executive attention. Growth is not uniform; it is being reshaped by shifting equipment preferences, ambient performance expectations, and the accelerating adoption of connected refrigeration platforms. Organizations that align their strategy with these underlying currents will be better positioned to capture share in a market where incremental operational efficiencies translate directly into margin preservation and customer retention.
Strategic Segmentation: Where Value Is Created and Captured
The report's segmentation framework is designed to illuminate how revenue flows through distinct equipment configurations, application verticals, and geographic corridors. Rather than treating the market as a monolith, the analysis isolates the structural factors that determine unit economics, competitive positioning, and long-term growth potential.
- Equipment Architecture: The market continues to be shaped by a diversified mix of power architectures, including electric, diesel, and hybrid configurations. Each pathway presents distinct trade-offs in total cost of ownership, emissions performance, grid dependency, and operational range. The analysis examines how fleet operators weigh these variables against deployment environments, regulatory exposure, and sustainability commitments, offering insight into where capital is naturally gravitating as infrastructure and policy conditions mature.
- Application End-Market Demand: Food and beverage logistics remain the dominant commercial driver, reflecting the scale and frequency of perishable goods movement. Simultaneously, pharmaceuticals and chemicals represent a high-value, compliance-intensive segment where temperature excursion risk carries disproportionate financial and reputational consequences. The report evaluates how these verticals differ in procurement behavior, service expectations, and receptivity to advanced monitoring and electric platform adoption.
- Regional Demand Patterns: Geographic distribution of demand is influenced by freight volume concentration, cold chain maturity, regulatory intensity, and local manufacturing or assembly ecosystems. The analysis maps how these factors intersect to create uneven but predictable growth pockets, helping stakeholders prioritize market-entry sequencing, service-network design, and partnership strategies without relying on blunt regional generalizations.
By contextualizing segmentation through an operational lens, the study equips readers to identify which sub-markets offer the most favorable risk-adjusted opportunities, where product specifications must evolve to meet segment-specific requirements, and how pricing architecture should adapt to preserve value across heterogeneous customer bases.
Road Transport Refrigeration Equipment Market
Competitive Dynamics: Incumbents, Innovation, and Consolidation Signals
Market structure analysis reveals a moderately concentrated landscape, with the top three participants collectively accounting for nearly half of total industry revenue and the leading five firms representing over 71 percent of market value. This concentration underscores the competitive advantage held by established players with scaled manufacturing capacity, broad service networks, and deep engineering heritage. Yet concentration alone does not dictate competitive outcomes; it intensifies the premium on differentiation, compliance readiness, and ecosystem integration.
Several core participants define the current competitive baseline. Carrier Transicold, headquartered in Charlotte, North Carolina, maintains a comprehensive portfolio spanning single-temperature and multi-temperature trailer refrigeration units, electric and stationary configurations, and heating platforms, reinforced by its ecoForward sustainability technologies. Thermo King, based in Woodridge, Illinois, competes with its Precedent trailer solutions, T-90 Series architecture, ConnectedSuite telematics capabilities, and TriPac auxiliary power units, while expanding its all-electric and e-reefer offerings with an emphasis on emissions-compliant performance. Polar King Mobile, operating from Fort Wayne, Indiana, has carved a distinct position with all-electric compact refrigerated trailers engineered for modular deployment, E-Track readiness, and NATM compliance, utilizing refrigeration systems capable of maintaining precise temperature bands across demanding transit conditions.
The competitive narrative is further shaped by recent product and regulatory milestones that illustrate how the market is evolving in real time. In early 2026, Utility Trailer Manufacturing Company and Cargobull North America introduced next-generation hybrid transport refrigeration units designed for enhanced cooling performance and efficiency within their 3000R refrigerated trailer lineup. Around the same period, Polar King previewed fresh trailer innovations at a major industry expo, signaling continued product iteration in the compact electric segment. These developments unfold against a backdrop of tightening regulatory architecture, including updated cold appliance emissions standards and refrigerant guidance that increasingly steer procurement decisions toward lower-global-warming-potential solutions and zero-emission transition pathways.
For corporate strategists, the implication is clear: competitive advantage in this market is increasingly determined by how effectively firms integrate regulatory foresight into product design, align service and telematics capabilities with fleet customer expectations, and communicate verifiable sustainability performance without sacrificing operational reliability.
Regulatory and Technological Currents Reshaping the Market
No strategic assessment of the trailer refrigeration system market is complete without a rigorous examination of the regulatory environment. Compliance is no longer a peripheral concern; it is becoming a primary determinant of equipment eligibility, total cost of ownership, and long-term asset viability. Over the past several years, regulators have steadily tightened emissions expectations for transport refrigeration units, with particular emphasis on refrigerant global warming potential thresholds, particulate emission controls, and registration and reporting obligations for owners and large facilities.
These regulatory pressures are compounded by evolving refrigerant chemistry and component standards. The industry's shift toward lower-GWP refrigerant blends reflects a broader transition toward systems that can meet compliance mandates without compromising cooling capacity or serviceability. At the same time, telematics and connected monitoring are transitioning from value-added features to operational necessities, enabling fleet managers to track temperature excursions, optimize preventive maintenance, and demonstrate compliance documentation with greater precision.
The interaction between regulation and technology creates a distinctive strategic environment. Equipment that meets current compliance thresholds may still face retrofit risk or shortened service life if future amendments tighten standards further. Conversely, platforms designed with forward-looking architecture can reduce transition costs, preserve resale value, and strengthen supplier credibility with compliance-sensitive customers. The report evaluates these dynamics in detail, helping organizations distinguish between compliance-driven costs and strategic investments that build durable market positioning.
What This Report Delivers for 2026 Decision-Makers
PW Consulting's market study is structured to convert complex industry data into actionable strategic intelligence. The analysis extends beyond high-level sizing to address the operational and commercial questions that executives face when allocating resources, evaluating competitive threats, and planning product or service expansion. Key deliverables include:
- Market sizing and forecast architecture that provides a transparent view of historical performance and projected growth pathways, enabling scenario planning around demand sensitivity, adoption pacing, and external shocks.
- Segment-level evaluation that isolates the structural drivers behind equipment type preferences, application-specific procurement patterns, and regional demand concentration, supporting more precise go-to-market and investment decisions.
- Competitive profiling that maps the strategic positioning, product offerings, and recent activity of leading participants, with context on how innovation, service capability, and compliance readiness influence share dynamics.
- Regulatory and technology impact assessment that connects emissions standards, refrigerant transitions, telematics adoption, and enforcement trends to practical procurement, design, and service implications.
- Strategic recommendation frameworks tailored to manufacturers, component suppliers, fleet operators, and investors, helping each audience translate market signals into prioritized actions for capacity planning, R&D focus, partnership strategy, and risk mitigation.
By integrating quantitative forecasts with qualitative market intelligence, the report enables readers to stress-test assumptions, identify where consensus expectations may understate or overstate opportunity, and build strategies that remain robust across a range of plausible futures.
Conclusion: Turning Market Intelligence into Strategic Action
The trailer refrigeration system market in 2026 is defined by a convergence of forces: durable cold chain demand, accelerating sustainability mandates, technological differentiation in electric and hybrid platforms, and a competitive field where scale and service quality remain powerful advantages. Growth projections indicate that the sector will continue expanding toward the high-700-million-USD range by 2032, but the more consequential question for decision-makers is not simply how large the market will become, but how value will be distributed across segments, regions, and competitive tiers.
Organizations that treat this market as a purely mechanical equipment category risk overlooking the strategic levers that determine long-term performance: compliance architecture, telematics-enabled service differentiation, segment-specific product customization, and disciplined regional execution. Those that approach it as a strategically layered ecosystem will be better positioned to protect margins, win compliance-sensitive contracts, and build defensible relationships with fleet customers who increasingly evaluate suppliers on total value rather than unit price alone.
This report provides the depth, structure, and forward-looking context required to make those judgments with confidence. To access the full dataset, detailed segmentation analysis, competitive benchmarking, and scenario-based strategic guidance, we invite executives and research buyers to visit the source page for the complete PW Consulting market intelligence package.
For detailed analysis of this topic, please visit the official page: Trailer Refrigeration System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Beauty Devices Market to Hit $176.36M by 2032, 11.54% CAGR Drives 2026-2032 Forecast
By PW Consulting, 2026-09-16
Navigating the Inflection Point: Strategic Intelligence for the 2026 Beauty Devices Market
The global beauty devices market stands at a decisive inflection point. After a period of contraction that tested supply chains, compressed margins, and forced a hard reset in consumer expectations, the industry is now preparing for a sustained, technology-led expansion. For executives, investors, and product leaders operating in 2026, the question is no longer whether the category will rebound, but how to position across the right segments, geographies, and regulatory pathways before the next wave of competition compresses differentiation.
This introduction frames the strategic rationale behind our latest Beauty Devices Market research. The full study is designed to convert macroeconomic signals into executable decision frameworks. What follows is a preview of the analytical architecture, the competitive terrain we map, and the market dynamics that will shape portfolio strategy in the years ahead.
The Trajectory: A Contraction That Forged Discipline, and a Forecast Built for Scale
The historical record tells a story of correction. Between 2020 and 2025, the market navigated a demanding cycle, with revenue compressing through the post-pandemic recalibration period before stabilizing into a new baseline. That contraction was not merely a temporary dip; it functioned as a market-wide stress test. It separated durable innovation from short-lived novelty, exposed fragile channel strategies, and reshaped how consumers evaluate efficacy, safety, and long-term value in at-home and professional treatment devices.
From that reset, the forward outlook is notably constructive. The market is projected to grow from an estimated 88.56 million USD in 2026 to approximately 176.36 million USD by 2032, supported by a forecasted compound annual growth rate of 11.54 percent across the 2026 to 2032 period. This trajectory reflects more than top-line recovery. It signals structural momentum driven by converging forces: the maturation of home-use aesthetics, escalating demand for non-invasive and minimally invasive modalities, and the steady integration of intelligent diagnostics into both consumer and professional devices.
Beauty Devices Market
For leadership teams, the strategic implication is clear. Planning in 2026 cannot rely on category-level optimism alone. It requires a granular understanding of which subsegments are absorbing investment, which use cases are expanding fastest, and where regional adoption curves are diverging. The full report is built to provide that clarity without forcing executives to extrapolate from surface-level headlines.
What the Study Delivers: Operational Intelligence Over Generic Narrative
A market overview can confirm direction. It cannot, on its own, guide capital allocation, channel construction, or product roadmap choices. Our research is structured to bridge that gap. The study moves beyond high-level trend commentary to deliver a decision-ready architecture that organizations can plug directly into strategy sessions, board discussions, and annual planning cycles.
The report combines macro market modeling with segmentation frameworks that dissect the landscape across device categories, end-use environments, and geographic markets. Rather than presenting static snapshots, the analysis is designed to help leaders pressure-test assumptions. It connects historical volatility to forward-looking scenarios, allowing readers to evaluate how shifts in consumer behavior, clinical adoption, and distribution models could alter growth outcomes across the forecast horizon.
Equally important, the study treats the beauty devices ecosystem as a competitive system rather than a collection of isolated product lines. It examines how technology roadmaps, brand positioning, and regulatory milestones interact to shape market access. The intent is to give executives a working map of where differentiation is still achievable, where consolidation pressure is building, and where emerging standards may redefine what counts as a defensible product proposition.
Competitive Architecture: Incumbents, Specialists, and the Reconfiguration of Advantage
The competitive field in beauty devices is defined by a blend of global personal care and electronics incumbents, focused aesthetic technology specialists, and a growing set of clinically oriented entrants pursuing regulatory validation as a moat. Market concentration remains moderately distributed, with the top three players accounting for roughly 24.6 percent of market share and the top five reaching approximately 32.0 percent. That concentration profile matters strategically: it suggests the category is large enough to support multiple viable positions, but competitive enough that differentiation must be engineered deliberately rather than assumed.
Several established names illustrate the diverse strategic postures now competing for share. L'Oréal S.A., based in Clichy, France, has extended its portfolio into AI-driven skin analysis and nano-resurfacing through devices such as Perso, Lumea, and Cell BioPrint. Philips, headquartered in Amsterdam, Netherlands, has built recognition around adaptive tone recognition within its hair removal and skincare device lines. FOREO, from Stockholm, Sweden, has advanced its Luna series of microcurrent and LED facial devices while pairing product development with AI-powered skin analysis and circular economy programs.
Alongside these consumer-facing ecosystems, a parallel competitive dynamic is unfolding in professional and hybrid aesthetic platforms. InMode Ltd., in Irvine, California, develops radiofrequency-based aesthetic platforms for facial and body treatments. Sofwave Medical, based in San Clemente, California, supplies SUPERB ultrasound devices for non-invasive skin lifting and toning. Cutera, Inc., in Brisbane, California, produces laser and RF systems spanning skin rejuvenation, hair removal, and vascular treatments. NuFACE, part of the Carol Cole Company in Vista, California, focuses on microcurrent facial toning devices for non-invasive anti-aging applications. CLASSYS Inc., in Seoul, South Korea, offers radiofrequency-based medical aesthetic platforms such as Volnewmer, including CE MDR certification. Dermalogica, Alma Lasers, Accure Acne, Inc., and SkinHealth Systems further widen the competitive spectrum, each pursuing a distinct blend of clinical credibility, treatment specificity, and channel alignment.
This is not a market where scale alone guarantees advantage. The strategic edge increasingly comes from how well a company connects device performance, user experience, evidence generation, and regulatory readiness. The full report evaluates these players through that operational lens, tracing how their technology choices, launch cadence, and certification activity position them relative to the next generation of entrants and the shifting expectations of both professional and home users.
Aesthetic Devices Market
Regulatory Momentum and Technology Signals as Strategic Variables
One of the most consequential dynamics for 2026 planning is the accelerating cadence of regulatory and technology milestones. In this category, clearance and certification activity is not simply a compliance event; it often functions as a market-access trigger, a credibility signal, and at times a competitive barrier. The study tracks these developments as strategic inputs rather than background news.
Recent regulatory progress illustrates the point. Accure Acne, Inc. secured FDA clearance for its laser system for the long-term treatment of mild to severe inflammatory acne vulgaris. CLASSYS received CE MDR approval for its Volnewmer radiofrequency-based anti-aging system, a notable milestone as the first radiofrequency aesthetic device to achieve that designation in Europe. Ultherapy PRIME obtained FDA clearance for use on the abdomen and arms with real-time visualization across face, neck, décolleté, and body applications. Cutera's truFlex clearance expanded into rehabilitation and therapy applications. In parallel, Dermalogica's PRO Pen microneedling system secured FDA clearance, with launch planned in the US in 2026.
These events are not isolated. They reflect a broader pattern in which regulatory validation, device precision, and treatment specificity are increasingly intertwined. For companies operating in or entering the market, this creates a dual strategic question: how to build products that meet clinical and consumer expectations, and how to navigate a landscape where approvals, certifications, and evidence standards can alter the pace of adoption in specific segments. The report integrates these dynamics into its forward analysis so that leadership teams can better anticipate where access, messaging, and investment priority should shift.
Why This Research Matters for 2026 Decision-Making
The beauty devices market in 2026 rewards disciplined strategy over broad positioning. Organizations that succeed will be those able to align product development with validated demand, construct channel strategies that reflect regional and application-level realities, and interpret regulatory signals as part of competitive planning rather than as a separate compliance track.
This study is designed to support exactly that kind of decision-making. It provides the structural context needed to evaluate where growth is likely to concentrate, how the competitive field is rearranging itself, and which strategic levers will matter most as the forecast period unfolds. By connecting historical volatility to a forward CAGR of 11.54 percent and a projected 2032 revenue trajectory of roughly 176.36 million USD, the research frames the market as both a recovery story and a reallocation story. In other words, the real strategic task is not simply to capture growth, but to capture the right growth.
The full report goes further. It delivers the segmentation detail, company-level analysis, and market-structure insight necessary to translate high-level momentum into actionable plans. For executives evaluating expansion, product roadmap priorities, partnership strategy, or market-entry timing, the complete analysis is built to reduce uncertainty and sharpen judgment.
Conclusion: From Category Outlook to Executable Strategy
The beauty devices sector is entering a phase in which insight quality will separate durable players from reactive ones. The market's path from contraction to expansion is now backed by a credible growth trajectory, but realizing that opportunity will depend on how precisely organizations can read the subsegments, competitive moves, and regulatory developments shaping the landscape. This research begins with that premise and is structured to help leaders act on it.
To access the complete segmentation framework, competitive assessment, and forward-looking scenario analysis, we invite you to explore the full Beauty Devices Market research. The detailed intelligence within is intended to serve as a working resource for 2026 planning and beyond.
For detailed analysis of this topic, please visit the official page: Beauty Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Blade Fuse Market to Reach $1.96B by 2032, CAGR 5.8%
By PW Consulting, 2026-09-16
Navigating the Automotive Blade Fuse Market: Strategic Intelligence for 2026 Decision-Making
The automotive electrical ecosystem is undergoing a structural transformation driven by electrification, advanced driver-assistance systems, and increasingly complex in-vehicle power architectures. At the foundation of these circuits lies a critical yet often overlooked component: the automotive blade fuse. As vehicle manufacturers and aftermarket suppliers navigate tightening reliability standards, fluctuating raw material costs, and shifting regional demand patterns, the need for precise, forward-looking market intelligence has never been more acute. Our latest Automotive Blade Fuse Market research delivers exactly that, translating historical trajectories and multi-year projections into actionable strategic frameworks for 2026 and beyond.
This analysis is designed specifically for executives, procurement leaders, product planners, and competitive intelligence teams who require more than headline figures. The study anchors its methodology in verified historical data spanning 2020 through 2025, then extends the analytical lens across a forecast period from 2026 to 2032. Over the historical window, the market demonstrated steady expansion, moving from approximately 0.99 billion USD in 2020 to 1.31 billion USD by 2025. The trajectory continues into the forecast horizon, with 2026 projections reaching 1.43 billion USD and sustained growth anticipated through 2032, when the market is expected to approach 1.96 billion USD. These figures reflect a compound annual growth rate of 5.8 percent, a pace that signals consistent demand expansion rather than speculative volatility.
Such macro-level momentum creates both opportunity and complexity. Growth is not uniformly distributed across product categories, application segments, or geographic corridors. Manufacturers must understand how pricing dynamics, regulatory compliance, supply chain localization, and vehicle architecture shifts interact to shape revenue pools. Our report dissects these intersections without overwhelming readers with fragmented statistics, instead presenting a structured narrative that clarifies where strategic focus will yield the highest return on investment.
What the Research Delivers: Operational Intelligence for Product, Pricing, and Portfolio Strategy
A market study is only as valuable as its applicability to real-world decision cycles. This report is built around operational utility. It moves beyond generic industry commentary to provide structured assessments that can be integrated directly into annual planning, sourcing evaluations, and competitive positioning exercises. Readers will encounter detailed evaluations of product architecture trends, including the continued dominance of blade-style configurations in contemporary vehicle electrical designs, alongside comparative insights into glass tube and other specialized fuse formats. The analysis examines how form factor preferences align with OEM specifications, aftermarket replacement cycles, and regional certification requirements.
The research also maps the evolution of application-driven demand. Passenger vehicle platforms remain the primary consumption base, reflecting high production volumes and extensive electrical component integration. Commercial vehicle segments introduce distinct load profiles, environmental durability expectations, and maintenance intervals that influence fuse selection and procurement frequency. Other application corridors, including specialty mobility platforms and emerging aftermarket service networks, are evaluated for their incremental contribution to overall market expansion. By contextualizing these segments within broader vehicle production forecasts and fleet turnover cycles, the study enables stakeholders to anticipate demand shifts rather than react to them.
Pricing architecture and value chain dynamics receive equal attention. The report explores how automotive-grade manufacturing standards, testing protocols, and certification pathways influence cost structures and competitive positioning. It examines the interplay between volume-driven OEM supply agreements and the margin characteristics of aftermarket distribution, highlighting how players optimize portfolio mix to balance volume stability with profitability. Supply chain considerations are addressed through the lens of component sourcing, production capacity allocation, and the increasing importance of regional supply resilience.
Forecasting methodology is transparent and grounded in observable industry indicators. Projections integrate historical growth patterns, vehicle production outlooks, electrification roadmaps, and regulatory trajectories to construct a multi-scenario view of market development. This approach allows decision-makers to stress-test internal assumptions against external baselines, reducing exposure to overconfidence or missed inflection points.
Competitive Landscape: Concentration, Positioning, and Strategic Differentiation
Market structure plays a decisive role in pricing power, innovation pacing, and customer access. The automotive blade fuse sector exhibits meaningful concentration, with a compact group of established manufacturers capturing a substantial share of global demand. The report profiles the companies that define this landscape, analyzing their geographic footprints, product specializations, certification capabilities, and go-to-market strategies.
Littelfuse, Inc., headquartered in Rosemont, Illinois, operates as a broad-line manufacturer of automotive blade fuses and related circuit protection products, serving both OEM and aftermarket channels with a focus on standardized reliability and integrated protection solutions. Eaton Corporation, based in Cleveland, Ohio, leverages its Bussmann series to deliver blade fuse offerings tailored for automotive and marine overcurrent protection, combining engineering heritage with extensive distribution networks. Mersen S.A., headquartered in Courbevoie, France, supplies automotive fuses including blade types, positioning itself within electrical protection portfolios that emphasize material performance and application-specific engineering.
Beyond North America and Western Europe, the competitive field includes highly specialized manufacturers with strong regional anchors and global supply relationships. Pacific Engineering Corporation (PEC), located in Ogaki, Gifu, Japan, manufactures automotive blade fuses supplied to global vehicle makers, underscoring the importance of precision manufacturing and long-term OEM collaboration. MTA SpA, based in Codogno, Italy, produces certified automotive blade fuses and power distribution components, aligning product quality with rigorous automotive certification expectations. Conquer Electronics Co., Ltd., in New Taipei City, Taiwan, operates as a designer and manufacturer of automotive and other fuses including blade types, reflecting the role of flexible manufacturing and export-oriented production in the broader supply ecosystem.
European specialist producers further diversify the landscape. ESKA Erich Schweizer GmbH, headquartered in Kassel, Germany, produces miniature and automotive fuses including blade designs, emphasizing compact form factors and application-sensitive engineering. SIBA, based in Lünen, Germany, manufactures high-quality fuses for automotive and industrial applications, reinforcing the market's emphasis on durability and compliance. AEM Components (USA), Inc., located in San Diego, California, supplies automotive-grade surface mount and blade fuses, addressing niche requirements that span conventional and advanced electrical architectures.
Thermal Fuse Market
The report evaluates how these players compete across dimensions that matter most to procurement and strategy teams: certification breadth, production scalability, OEM relationship depth, aftermarket penetration, and responsiveness to regional specification variations. It also examines the structural implications of market concentration, where a limited number of large suppliers shape baseline pricing expectations and technology adoption rhythms. Understanding this concentration is essential for identifying negotiation leverage, assessing entry barriers, and evaluating partnership or sourcing diversification strategies.
Industry Dynamics Shaping 2026 and the Forecast Horizon
No market develops in isolation. The automotive blade fuse sector is influenced by overlapping forces that alter demand timing, product requirements, and supplier competitiveness. Vehicle electrification continues to redefine electrical load characteristics, increasing the importance of reliable circuit protection across hybrid, battery-electric, and conventionally powered platforms. At the same time, the proliferation of electronic control units, connectivity modules, and advanced sensors expands the number of protected circuits within a single vehicle, changing fuse density requirements and replacement patterns.
Regulatory and safety expectations further tighten the operational environment. Automotive-grade certification, thermal performance validation, and environmental durability standards influence both product design and supplier qualification processes. These requirements create meaningful differentiation between general-purpose and certified automotive offerings, affecting how manufacturers structure their portfolios and how buyers evaluate total cost of ownership.
Supply chain configuration is another critical dynamic. Regional production footprints, logistics resilience, and material availability shape lead times and cost predictability. As manufacturers and Tier-1 suppliers increasingly prioritize supply security, the ability to source from trusted, certified producers with stable capacity becomes a strategic advantage rather than a tactical preference. The report places these dynamics in context, showing how they interact with demand growth to influence market outcomes over the 2026 to 2032 window.
Automotive Blade Fuse Market
Aftermarket behavior also remains a steady demand engine. Vehicle fleet aging, service interval patterns, and the replacement of legacy electrical components sustain consumption even as new vehicle architectures evolve. The interplay between OEM volume cycles and aftermarket replacement demand creates a multi-layered market rhythm that rewards companies capable of balancing both channels effectively.
Why This Research Matters for 2026 Strategy
The strategic value of this study lies in its ability to convert market complexity into structured decision support. For product planning teams, it clarifies where blade fuse demand is most likely to intensify and how application requirements are shifting. For procurement and sourcing leaders, it provides context on concentration, certification, and supply chain resilience that can inform supplier evaluation and contract negotiation. For competitive strategy groups, it outlines how established players position themselves and where differentiation opportunities may emerge.
Most importantly, the report is designed to prevent strategic overreach. Market growth at a 5.8 percent CAGR is meaningful, but it does not eliminate risk. Regional variation, application segmentation, and competitive concentration mean that aggregate growth can mask divergence at the segment level. Companies that rely on headline numbers alone may misallocate resources or underestimate the operational requirements needed to capture demand in specific corridors. By integrating historical performance, forward-looking projections, and competitive context, this research equips stakeholders to make calibrated decisions rather than assumptions.
The complete study expands on every dimension introduced here, offering detailed market sizing across historical and forecast periods, segmentation analysis that identifies where growth concentrates, competitive profiling that maps supplier strengths and positioning, and strategic implications tailored to product, pricing, and sourcing decisions. It is built for teams that require a rigorous baseline before committing capital, capacity, or commercial strategy.
For executives planning 2026 initiatives, the strategic question is no longer whether the automotive blade fuse market is expanding, but how to position within that expansion with precision. This report provides the analytical foundation to answer that question with confidence, while the full dataset and segment-level intelligence remain available for teams that need to ground strategy in complete, validated market intelligence.
For detailed analysis of this topic, please visit the official page: Automotive Blade Fuse Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Well Completion Equipment Market to Reach $18.5B by 2032, Growing at 5.13% CAGR
By PW Consulting, 2026-09-16
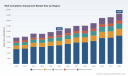
Navigating the Next Wave: Strategic Insights into the Well Completion Equipment Market Through 2032
The global energy landscape is entering a phase of calculated expansion, where efficiency, compliance, and technological resilience dictate competitive advantage. For operators, service providers, and investors, the well completion equipment market represents more than a transactional supply chain. It is a critical inflection point where geological complexity, regulatory evolution, and engineering innovation converge. As we move deeper into the 2026 decision cycle, understanding the structural drivers, competitive tensions, and material constraints shaping this sector is no longer optional. It is foundational to capital allocation, portfolio optimization, and long-term operational readiness.
Our latest market research on well completion equipment delivers a comprehensive, forward-looking assessment designed specifically for strategic planners and senior leadership teams. Spanning historical performance from 2020 through 2025 and projecting market trajectories through 2032, this study maps the revenue architecture, equipment specialization, application distribution, and regional footprint of a market that has consistently demonstrated resilience amid volatility. The analysis is structured to cut through noise, isolate actionable intelligence, and provide decision-makers with the clarity required to navigate an increasingly fragmented and regulation-intensive operating environment.
Market Architecture: Scale, Trajectory, and Structural Shifts
The well completion equipment market has evolved from a cyclical procurement category into a strategically calibrated segment of the broader oilfield services ecosystem. Over the past half-decade, revenue progression has reflected a combination of disciplined operator spending, accelerated unconventional development, and the gradual integration of intelligent completion technologies. The market closed the historical baseline year at approximately 12.22 billion USD, building on a compound annual growth trajectory that signals sustained demand across multiple development phases. Looking ahead to the 2026-2032 forecast window, the sector is projected to expand at a measured yet consistent compound annual growth rate of 5.13 percent, ultimately reaching an estimated 18.54 billion USD by the end of the forecast period.
This growth profile is not uniform. It is shaped by shifting capital priorities, the maturation of certain shale plays, and the steady push toward higher-pressure, higher-temperature well architectures in both established and emerging basins. The revenue curve reflects periods of consolidation, selective capacity expansion, and the gradual reallocation of expenditure toward completion systems that deliver longer operational lifecycles, improved zonal isolation, and greater conformance with evolving emissions standards. For corporate strategists, these patterns underscore a central reality: the market is rewarding suppliers and operators who can align equipment selection with long-term well performance rather than short-term cost minimization.
The study contextualizes these macro trends within a highly concentrated competitive environment. Market leadership is distributed across a handful of dominant players, with the top three firms collectively accounting for nearly half of total industry revenue and the top five firms capturing approximately two-thirds of the market. This concentration reflects the technical barriers to entry, the capital intensity of advanced manufacturing, and the entrenched relationships between equipment manufacturers and major operating companies. Yet concentration does not equate to homogeneity. The report dissects how differentiated product portfolios, regional service capabilities, and technology roadmaps are reshaping competitive positioning across equipment categories and application domains.
Equipment Specialization and Application Dynamics
Well completion equipment is not a monolithic category. It is a portfolio of specialized tools, each tied to distinct operational objectives, reservoir conditions, and completion philosophies. The research provides a granular breakdown of the principal equipment segments that define market structure, examining how demand patterns differ across packers, sand control tools, multi-stage fracturing equipment, liner hangers, and valve systems. Rather than presenting static share figures, the analysis focuses on the functional drivers that determine segment growth, including reservoir complexity, well architecture design, and the increasing reliance on staged completion methodologies in horizontal and extended-reach wells.
Packers continue to anchor the equipment landscape, serving as the foundation for zonal isolation, pressure management, and intervention readiness. Their performance characteristics directly influence well integrity, production optimization, and long-term asset reliability. Sand control tools remain critical in formations where particulate production threatens operational continuity, driving sustained demand for advanced filtering, gravel packing, and hybrid completion approaches. Multi-stage fracturing tools have gained structural importance as operators pursue higher recovery factors through precise stimulation sequencing, while liner hangers and valve systems support the mechanical and flow-control architecture that underpins safe, efficient well completion.
Application-side analysis further clarifies how completion strategies diverge across operating environments. Onshore development continues to represent the dominant demand center, reflecting the scale of unconventional resource development, the prevalence of horizontal drilling programs, and the ongoing optimization of mature fields. Offshore operations, while representing a smaller share of total activity, carry disproportionate strategic weight due to higher technical complexity, stricter safety and environmental standards, and the growing deployment of subsea completion architectures. The report examines how these application profiles shape procurement cycles, service expectations, and technology adoption curves, providing operators and suppliers with a clearer view of where demand is most durable and where performance differentiation matters most.
Competitive Landscape and Strategic Positioning
The competitive dynamics of the well completion equipment market are defined by a blend of global scale, technical specialization, and targeted regional expansion. Leading participants operate across a spectrum of service models, from integrated completion offerings to focused manufacturing of high-performance tools. The study profiles the core companies shaping market direction, analyzing their strategic footprint, product capabilities, and recent operational developments that signal shifting priorities.
Major integrated service organizations maintain a central role through broad equipment portfolios, proprietary completion technologies, and extensive field support networks. Their strategies increasingly emphasize intelligent completion systems, flow control solutions, and subsurface safety architectures that align with operator demands for real-time monitoring, improved well control, and extended intervention intervals. Alongside these broader service providers, specialized manufacturers and completion-focused firms contribute critical technological niches. Their product lines often target specific operational challenges, including high-pressure and high-temperature environments, multistage horizontal completions, expandable isolation technologies, and advanced sleeve systems designed for precision fracturing sequences.
Recent corporate activity highlights the pace of strategic adaptation within the sector. Expansion into international markets, targeted product launches, and the introduction of specialty systems for demanding well conditions all point to a competitive environment where differentiation is increasingly tied to engineering capability and geographic responsiveness. The report integrates these developments into a broader competitive assessment, examining how recent launches, delivery milestones, and portfolio broadening initiatives influence market positioning. By tracking these movements, the analysis provides a practical framework for evaluating which companies are strengthening their foothold in core segments, which are extending into adjacent application areas, and where partnership or procurement opportunities may emerge.
Worldwide Intelligent Well Completion Market
Regulatory Pressures, Material Constraints, and Operational Realities
Strategic planning in the well completion equipment market cannot be separated from the regulatory and material conditions that shape procurement decisions. Over the past year, the operating environment has been influenced by updated emissions requirements, revised performance standards, and shifting raw material cost dynamics. These factors do not merely affect compliance costs. They influence equipment specifications, design priorities, and the economic calculus behind technology selection.
Regulatory developments have placed renewed emphasis on reduced-emission completion practices and tighter performance expectations for hydraulically fractured wells. Updated federal guidance and extended performance standards have required operators to align completion workflows with broader environmental objectives, reinforcing the importance of equipment that supports emissions management, pressure control, and well integrity verification. At the same time, industry standards continue to serve as a baseline for equipment validation, ensuring that critical components such as subsurface safety valves and packers meet established requirements for personnel protection, environmental safeguarding, and asset reliability. The research maps these regulatory and standards-driven considerations into practical implications for equipment procurement, service planning, and long-term compliance strategy.
On the supply side, material cost dynamics have introduced a notable restraint in certain equipment categories. Fluctuations in metal pricing, influenced by global oversupply conditions, have affected input costs for components used in completion tools and packer manufacturing. While these cost pressures are not uniform across all product lines, they highlight the vulnerability of equipment economics to commodity market cycles and procurement timing. The study addresses these influences not as isolated headwinds, but as structural variables that affect pricing strategy, inventory planning, and supplier negotiations. By placing material constraints within the broader market context, the analysis equips decision-makers with a more realistic assessment of cost trajectories and procurement risk.
Well Completion Equipment Market
What the Report Delivers: An Executive Toolkit for 2026 Decisions
This market research is designed as an operational decision-support asset, not a passive overview. It translates broad market movement into a structured intelligence framework that can be applied to budgeting, procurement strategy, technology evaluation, and competitive benchmarking. The report integrates historical performance data, forecast modeling, segmentation analysis, competitive profiling, and market-structure indicators into a single coherent narrative. Its objective is to give executives and planning teams a clearer view of where demand is building, which equipment categories are gaining functional relevance, and how regulatory and material conditions are reshaping the cost and performance equations.
Readers will find detailed segmentation analysis that clarifies how equipment categories and application environments diverge in demand behavior, without reducing the market to simplistic share rankings. The study also examines regional demand patterns, mapping the distribution of activity across major geographic zones to highlight where market intensity is concentrated and where growth opportunities may develop. Competitive profiling extends beyond corporate descriptions, placing each key participant within the context of product focus, recent strategic moves, and market influence. This approach allows users to assess not only who leads today, but how competitive dynamics are likely to evolve as technology adoption, regulatory compliance, and regional expansion continue to reshape the field.
Importantly, the report is structured to support scenario-based planning. Forecast data, market concentration metrics, and equipment-level trends are presented in a way that allows leadership teams to test assumptions about capital deployment, supplier selection, and technology investment. Whether the priority is optimizing completion efficiency, managing compliance exposure, or identifying suppliers with proven capability in demanding well environments, the research provides the contextual foundation needed to make informed, forward-looking decisions.
Conclusion: Positioning for Durable Advantage
The well completion equipment market is entering a period where performance, compliance, and strategic agility will separate resilient organizations from those reacting to short-term cycles. With a forecast trajectory extending through 2032, a concentrated competitive landscape, and evolving regulatory and material conditions, the sector rewards those who can read structural signals early and align equipment strategy with long-term operational goals. This research study is built to support that objective. It offers a disciplined, data-grounded perspective on market scale, segmentation, competitive dynamics, and the external forces shaping procurement and technology choices.
For leadership teams preparing 2026 capital plans, supplier evaluations, and completion strategy reviews, the report delivers the analytical depth required to move beyond surface-level market narratives. Detailed segmentation breakdowns, equipment-level demand drivers, regional activity patterns, and full competitive profiling are available in the complete study. Explore the full market intelligence framework to access the precise data, forecasts, and strategic assessments needed to guide your next decisions with confidence.
For detailed analysis of this topic, please visit the official page: Well Completion Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


