



Category: market research
PW Consulting Report: 2-Mercaptoethanol Market Forecasts CAGR of 5.5% from 2026-2032
By PW Consulting, 2026-09-16
Navigating the 2-Mercaptoethanol Market: Strategic Intelligence for 2026 and Beyond
The chemical industry landscape in 2026 is defined by a complex interplay of supply chain realignment, regulatory tightening, and strategic capacity expansions. For stakeholders involved in the production and utilization of 2-Mercaptoethanol, understanding these shifts is not merely an academic exercise but a critical component of risk management and growth planning. Our latest market research publication serves as a comprehensive guide through this evolving terrain, offering the granularity needed to make informed decisions in a sector characterized by volatility and specialized demand.
2-Mercaptoethanol Market
This report is designed for senior leadership teams, procurement strategists, and market entry analysts who require more than surface-level data. By dissecting the historical performance and future trajectory of the 2-Mercaptoethanol market, we provide a framework for anticipating supply constraints, pricing fluctuations, and regulatory impacts. The analysis spans a historical review from 2020 through the base year of 2025, extending into a robust forecast period reaching to 2032. This long-view approach allows organizations to align their capital allocation and operational strategies with the realistic demands of the coming decade.
Market Trajectory and Historical Context
The overarching narrative of the 2-Mercaptoethanol market over the past half-decade reflects a period of contraction followed by a poised recovery. Historical data indicates that market revenue experienced a downward trend from 2020 through 2025. This compression was driven by a combination of factors including global economic headwinds, shifts in downstream demand, and adjustments in production capacities across key manufacturing hubs. Despite these challenges, the market is now positioned at an inflection point.
Looking forward, the forecast period from 2026 to 2032 suggests a return to growth. The market is projected to expand at a Compound Annual Growth Rate of 5.5 percent during this interval. This rebound is not uniform but is instead underpinned by specific industrial recoveries and strategic investments in chemical infrastructure. For decision-makers, this growth rate signals a timely opportunity to reassess supply agreements and vertical integration strategies. The transition from a contracting market to an expanding one requires a nuanced understanding of where the demand is originating and which production nodes are becoming reliable.
Revenue figures throughout the analysis are denominated in USD Millions, providing a standardized metric for comparing investment opportunities across different regions and sectors. The scale of the market, while specialized, possesses sufficient liquidity to attract significant industrial interest. Understanding the total addressable market size without getting lost in fragmented data allows executives to gauge the potential return on investment for new capacity or distribution networks.
Segmentation and Demand Drivers
A critical value of this research lies in its detailed segmentation analysis. We have broken down the market by region, type, and application to reveal where the actual value creation is occurring. However, the strategic insight goes beyond simple percentage splits. It involves understanding the structural reasons behind these divides.
In terms of product purity, the market distinguishes between high-grade and standard grades. The premium segment, often defined by purity levels of 99 percent or higher, commands a significant share of the revenue. This reflects the stringent requirements of downstream applications where impurities can compromise product performance. Conversely, the lower purity segment serves industrial uses where cost efficiency is paramount. The balance between these two types dictates pricing power and margin potential for manufacturers.
Application-wise, the demand is heavily skewed towards specific industrial processes. PVC production remains a cornerstone consumer of 2-Mercaptoethanol, utilizing the chemical primarily for stabilizers and intermediates. Alongside this, the polymer and rubber sectors, along with food industry applications and water treatment processes, contribute to the diverse demand base. Agrochemicals and other specialty uses round out the consumption profile. Each of these segments faces its own regulatory and economic pressures. For instance, changes in PVC manufacturing standards or shifts in agricultural chemical regulations can ripple through the 2-Mercaptoethanol supply chain. Our report details how these application segments are evolving individually and collectively.
Geographically, the market is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. While the aggregate data shows a global footprint, the density of consumption and production varies significantly. Asia Pacific represents a substantial portion of the global volume, reflecting the region's heavy industrial base. North America and Europe maintain strong positions driven by high-specification industrial and laboratory needs. Emerging regions in Latin America and the Middle East and Africa offer incremental growth opportunities. The report elaborates on the logistical and tariff implications of these regional distributions without exposing the exact volume splits, encouraging a deeper dive into the regional chapters for specific procurement planning.
Competitive Landscape and Strategic Positioning
The competitive environment for 2-Mercaptoethanol is characterized by a mix of large-scale chemical integrators and specialized laboratory suppliers. Market concentration metrics indicate that the top three players hold a combined share of approximately 35 percent, while the top five extend this to 45 percent. This level of concentration suggests that while there is room for niche players, the bulk of industrial supply is controlled by established entities with significant capital and technical resources.
Key industry participants include major chemical corporations such as Chevron Phillips Chemical and BASF SE. Chevron Phillips Chemical, headquartered in The Woodlands, Texas, operates as an active producer and supplier of 2-Mercaptoethanol for PVC stabilizers, agrochemical intermediates, corrosion inhibitors, and oilfield applications. Their integration into the oilfield and PVC supply chains provides them with a stable demand baseline. Similarly, BASF SE, based in Ludwigshafen, Germany, is a pivotal supplier for PVC production, organotin stabilizers, crop protection, and oilfield chemicals. BASF's operational footprint was notably strengthened when their new 10,000 metric tons per year 2-Mercaptoethanol production plant at the Ludwigshafen Verbund site achieved regular operations in the fourth quarter of 2021. This capacity addition significantly altered the supply dynamics in the European region, providing a benchmark for production efficiency and scale.
On the laboratory and research side, the market is served by specialized suppliers including Molecular Toxicology Inc., Sigma-Aldrich International GmbH, Thermo Fisher Scientific, Carl Roth GmbH + Co. KG, and Cambridge Isotope Laboratories. These entities, located across the USA and Germany, focus on providing laboratory-grade 2-Mercaptoethanol for research use only. Their role is critical for R and D sectors, including molecular biology and toxicology studies, where purity and certification are the primary purchase drivers rather than bulk industrial volume. Companies like Sunion Chemical and Hefei TNJ Chemical Industry in China also maintain a presence as active manufacturers for industrial and specialty applications, adding a layer of competitive pressure on pricing and availability in the Asian supply chain.
Strategic interactions among these players involve not just price competition but also securing raw material streams and navigating regulatory compliance. For a new entrant or an existing player looking to expand, understanding the barrier to entry in both the industrial and laboratory segments is vital. The report provides a detailed competitive benchmarking section that evaluates these companies based on capacity, geographic reach, and product portfolio depth.
Regulatory Dynamics and Production Technology
Regulatory compliance remains a defining factor in the 2-Mercaptoethanol market, particularly for entities operating within or exporting to the European Union. The chemical is subject to REACH Annex XVII R3 restriction. This regulation imposes specific usage limits and safety requirements that can impact formulation choices and market access for downstream customers. Compliance costs and the administrative burden of adhering to these restrictions create a moat for larger producers who can absorb regulatory overhead, while potentially squeezing out smaller operators who lack robust compliance infrastructure. Our analysis examines how these regulations are reshaping the competitive landscape and influencing procurement decisions in regulated markets.
On the production side, the industrial synthesis of 2-Mercaptoethanol typically involves the reaction of ethylene oxide with hydrogen sulfide. This process utilizes thiodiglycol and zeolites as catalysts. The efficiency of this reaction, along with the availability and cost of ethylene oxide and hydrogen sulfide, directly impacts production margins. Fluctuations in the petrochemical feedstock market can transmit volatility to 2-Mercaptoethanol pricing. Furthermore, advancements in catalytic technology and process optimization are areas of continuous development. Manufacturers investing in more efficient 촉매 systems or waste reduction technologies may gain a cost advantage. The report delves into the technical nuances of production methods and how they correlate with regional cost structures and environmental standards.
Strategic Implications for 2026 Decision Makers
For organizations planning their strategy in 2026, the insights provided in this market research report translate into several actionable imperatives. First, supply chain resilience must be prioritized. Given the concentration of production among a few key players and the regulatory complexities in regions like Europe, relying on a single source of supply introduces significant risk. Diversification across geographies, balancing between Asian industrial producers and Western integrated chemical manufacturers, can mitigate disruption risks.
Second, pricing strategy needs to be dynamic. The shift from a contracting market to a growing one implies that pricing power may gradually return to suppliers. However, this is contingent on the ability to meet specific purity standards and regulatory requirements. Businesses must evaluate whether they are positioned to capture the premium segment or if they should compete on volume in the standard grade market. Understanding the margin implications of the purity segmentation is essential for portfolio management.
Third, investment in R and D or capacity expansion should be timed against the forecast growth trajectory. The projected CAGR of 5.5 percent suggests steady demand growth, but capital allocation should be targeted towards the applications and regions showing the highest momentum. For instance, sectors related to PVC and organotin stabilizers may require different investment horizons compared to laboratory-grade supply chains. The long-term forecast to 2032 helps in smoothing out short-term volatility and identifying genuine long-term trends versus temporary fluctuations.
Finally, regulatory intelligence is non-negotiable. Compliance with regulations such as REACH Annex XVII R3 is not just a legal requirement but a market access prerequisite. Companies must assess their exposure to restricted substances and prepare for potential tightening of norms. The report includes a dedicated section on regulatory trends, helping stakeholders anticipate changes that could affect product formulation or export eligibility.
Conclusion
The 2-Mercaptoethanol market in 2026 stands at a crossroads. While historical data reflects a period of contraction, the forward-looking indicators point to recovery and growth driven by specific industrial applications and strategic capacity additions. Success in this environment requires a granular understanding of segment dynamics, competitive positioning, and regulatory frameworks.
Mercaptoacetic Acid Market
This market research report offers the depth and breadth required to navigate these complexities. It provides the macroeconomic context while drilling down into the operational details that matter for day-to-day decision-making. However, the full spectrum of data, including precise regional volume splits, exact application revenue contributions, and detailed company profiling, is reserved for the comprehensive study. To fully equip your organization with the intelligence needed to capitalize on the opportunities outlined here and mitigate the associated risks, we invite you to access the complete report via our source webpage. There you will find the detailed tables, charts, and strategic analyses that form the backbone of this executive summary.
Navigate the complexities of the 2-Mercaptoethanol market with confidence. Access the full detailed intelligence to secure your strategic advantage in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: 2-Mercaptoethanol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Intelligence in the Intelligent Electronic Devices Market: Navigating Growth Through 2032
Executive Overview
The global landscape for Intelligent Electronic Devices is undergoing a structural transformation, driven by the accelerating digitalization of electrical infrastructure and the urgent need for reliable, secure, and interoperable control systems. As utilities, industrial operators, and transportation networks modernize their legacy architectures, the demand for next-generation protection, monitoring, and automation hardware continues to reshape competitive positioning across the sector. Our latest market research publication provides a comprehensive, data-driven examination of this evolving landscape, offering executives and strategy teams a clear line of sight into the commercial trajectories, regulatory pressures, and technology adoption curves that will define strategic decision-making in 2026 and beyond.
Built on an extensive baseline of historical performance spanning 2020 through 2025, the study projects market evolution across a seven-year forecast horizon extending to 2032. The analysis captures the compounding effect of infrastructure modernization programs, the integration of advanced sensing and control electronics into substation and distribution environments, and the broader shift toward intelligent, software-defined operational frameworks. For organizations seeking to align capital allocation, product development roadmaps, and market-entry strategies with empirical evidence rather than speculation, this report delivers the rigor required to navigate an increasingly complex ecosystem.
Macro Market Trajectory: Compounding Growth and Structural Inflection Points
Over the past half-decade, the Intelligent Electronic Devices market has demonstrated consistent expansion, with total global revenue climbing steadily from 2020 through 2025. That historical momentum establishes a robust foundation for the forecast period, during which the market is expected to maintain a compound annual growth rate of 7.53 percent. This growth trajectory reflects more than incremental adoption; it signals a structural inflection as critical infrastructure operators prioritize grid resilience, automation depth, and cybersecurity readiness in equal measure.
By 2026, the market is projected to surpass the 186-million-dollar threshold, marking a decisive step up from the preceding year's baseline. The subsequent years of the forecast period reveal an accelerating cadence of expansion, with revenue scaling toward higher plateaus as capital projects mature and deployment cycles compound across multiple end-use sectors. The midpoint and latter years of the outlook period show sustained upward movement, culminating in a market valuation that underscores the entrenched role these devices now play in modern electrical and industrial ecosystems.
This macro trajectory is not merely a function of unit volume growth. Pricing dynamics, technology premiumization, and the shift toward integrated hardware-software bundles all contribute to the revenue expansion captured in our modeling. Organizations that understand how these value drivers intersect with regional deployment timelines and application-specific procurement cycles will be better positioned to anticipate demand fluctuations and tailor their commercial strategies accordingly.
Intelligent Control Market
Segmentation Landscape: Product Typologies and Application Vectors
The Intelligent Electronic Devices market is inherently multidimensional, with demand distributed across a diverse set of hardware categories and operational use cases. Our research dissects this landscape through multiple analytical lenses, enabling decision-makers to identify which product families and application segments are generating the strongest pull, where substitution dynamics are intensifying, and how technological convergence is reshaping traditional category boundaries.
Intelligent Electronic Devices Market
On the product side, the market encompasses a broad spectrum of intelligent control and protection hardware. Digital relay platforms continue to anchor a significant share of demand, reflecting their centrality to substation automation and fault management architectures. Voltage regulation devices represent another major pillar, serving applications where precise electrical parameter control is essential for system stability. Protection relay solutions maintain a strong presence, particularly as operators upgrade legacy electromechanical installations with microprocessor-based alternatives that offer enhanced diagnostic capabilities and communication integration.
Beyond these core categories, the market includes a range of specialized control and switching devices that support increasingly granular grid management requirements. Circuit breaker control platforms, load tap changer controllers, recloser controllers, and capacitor bank switching equipment each address distinct operational needs within distribution and transmission networks. The presence of additional niche product categories further illustrates the breadth of the ecosystem, with innovation increasingly concentrated at the intersection of hardware reliability and digital communication readiness.
Application-side demand is equally varied. Automation remains the dominant deployment vector, as operators seek to reduce manual intervention, improve response times, and integrate device-level intelligence into centralized control environments. Condition monitoring applications represent a substantial and growing demand stream, driven by the industry's shift toward predictive maintenance methodologies and real-time asset health assessment. Traction signaling and control systems constitute another critical application domain, particularly as rail and transit electrification programs expand and require highly reliable signaling electronics. Water supply and management systems also represent a meaningful application segment, where intelligent control devices support distribution efficiency, leakage detection, and operational resilience.
The challenge for commercial leaders is that these segmentation dynamics do not operate in isolation. Product adoption is increasingly influenced by application-specific performance requirements, regional regulatory mandates, and the pace at which interoperability standards are enforced across procurement specifications. Our report maps these cross-currents in detail, allowing organizations to calibrate their product positioning and sales focus without relying on oversimplified category assumptions.
Competitive Dynamics: Enterprise Positioning and Strategic Differentation
The competitive environment in the Intelligent Electronic Devices market is characterized by a carefully balanced concentration structure. The three largest firms collectively account for approximately thirty-five percent of total market revenue, while the top five players extend their combined share to roughly forty-two percent. This structure indicates a market where scale, technological maturity, and global distribution capabilities confer meaningful advantages, yet sufficient fragmentation remains to enable specialized players to compete on engineering depth, regional responsiveness, and application-specific expertise.
Among the leading enterprises, several global technology and industrial groups hold prominent positions, each leveraging distinct strategic assets to reinforce their market presence. ABB Ltd., headquartered in Zurich, maintains a strong footprint in intelligent device portfolios designed for substation automation and protection applications, with an emphasis on integrating device-level intelligence into broader grid-edge ecosystems. Schneider Electric SE, based in France, continues to advance its offering through architectures that align intelligent electronic hardware with energy management platforms and digital service layers, appealing to operators seeking unified operational visibility. Siemens AG, operating from Munich, draws on its established industrial automation and electrification heritage to deliver device solutions that emphasize interoperability, engineering integration, and lifecycle support across complex infrastructure projects.
GE Vernova, headquartered in the United Kingdom, contributes a focused presence in intelligent device solutions tied to power generation, transmission, and distribution modernization initiatives, with product strategies that reflect the operational priorities of utilities managing large-scale asset fleets. Eaton Corporation plc, based in Ireland, advances its position through offerings that combine protection, control, and power management functionalities, often emphasizing compact form factors and integration with broader electrical distribution architectures. Honeywell International Inc., headquartered in the United States, brings relevant expertise from adjacent industrial control and automation domains, supporting demand in environments where intelligent electronics must operate under stringent reliability and safety conditions.
Schweitzer Engineering Laboratories, Inc., also based in the United States, is widely recognized for its specialized focus on protection and control engineering, with product portfolios that resonate strongly in markets where technical differentiation, engineering support, and substation-level customization are valued by procurement teams. Hitachi Energy, headquartered in Zurich, rounds out this competitive field with offerings that connect intelligent device capabilities to broader power system transformation initiatives, including high-voltage applications and grid-scale digitalization programs.
What distinguishes leading players in this market is not merely product breadth, but the ability to align hardware offerings with cybersecurity expectations, interoperability requirements, and lifecycle service models. Procurement teams increasingly evaluate vendors based on support for standardized communication frameworks, firmware update pathways, and documentation that facilitates compliance with critical infrastructure protection mandates. Organizations that can demonstrate consistent conformance, transparent engineering credentials, and reliable deployment support are more likely to secure long-term contract relationships in an environment where operational downtime carries substantial financial and reputational consequences.
Regulatory and Standards-Driven Dynamics
The Intelligent Electronic Devices market is increasingly shaped by standards and regulatory expectations that influence both product design and procurement eligibility. A significant recent development is the publication of the IEEE Standard for Intelligent Electronic Devices Cybersecurity Capabilities, including Corrigendum 1, released in December 2025. This update reinforces the cybersecurity capabilities expected of devices deployed in critical infrastructure environments, reflecting a broader industry consensus that intelligent electronics must be evaluated not only for electrical performance, but also for their resilience against digital threats. For vendors, this means that security features, configurable access controls, and documented vulnerability management practices are becoming integral components of product competitiveness rather than optional enhancements.
In parallel, conformance with IEC 61850-6 remains a fundamental expectation for devices intended for substation automation environments. Interoperability is no longer a desirable feature; it is a prerequisite for integration into modern communication-centric substation architectures. As operators standardize on communication protocols and data modeling approaches, devices that cannot demonstrate reliable conformance risk exclusion from tenders and system integration programs. These standards dynamics create both a compliance burden and a strategic opportunity: organizations that invest early in rigorous testing, transparent conformance documentation, and integration-ready product design can differentiate themselves in markets where system architects are under pressure to reduce integration risk.
Beyond formal standards, the broader regulatory environment is reinforcing the importance of operational reliability, secure update pathways, and long-term support commitments. Infrastructure operators managing critical networks are increasingly attentive to supply chain continuity, firmware lifecycle management, and the ability to maintain device performance over extended deployment horizons. These concerns are reshaping vendor evaluations and encouraging a shift from transactional purchasing toward relationship-based procurement models centered on lifecycle assurance.
Operational Contents and Decision-Support Architecture
This market research publication is designed to serve as a practical strategic tool rather than a static reference document. The analysis is structured to support a range of enterprise decisions, from portfolio planning and market prioritization to competitive benchmarking and risk assessment. The report integrates historical performance data, forecast modeling, segmentation analysis, and competitive profiling into a coherent framework that can be applied across multiple functional teams.
Readers will find detailed demand analysis across product categories and application segments, with emphasis on the factors that are accelerating adoption in certain environments while restraining growth in others. The competitive assessment goes beyond aggregate positioning to examine how leading firms structure their offerings, where they appear to be investing in capability development, and how their strategic footprints align with the macro trends shaping the market. Regional demand patterns are also examined, with attention to the differences in deployment pacing, procurement behavior, and infrastructure modernization priorities that influence where growth opportunities are most concentrated.
The report further incorporates an assessment of the strategic implications of evolving standards and cybersecurity expectations, helping organizations anticipate how compliance requirements may affect product design priorities, sales cycles, and long-term support obligations. By connecting regulatory developments to commercial consequences, the analysis provides a clearer basis for investment decisions, partnership strategies, and go-to-market planning.
For product leaders, the study offers insight into where category growth is most durable and which performance attributes are becoming non-negotiable in competitive bids. For commercial and sales teams, it provides context on the procurement drivers shaping demand across major application domains. For executive planners, it delivers a consolidated view of market size trajectories, concentration dynamics, and the structural forces that will influence profitability and share movement over the forecast period.
Strategic Imperatives for 2026 Decision-Making
Entering 2026, organizations operating in or adjacent to the Intelligent Electronic Devices market face a landscape defined by simultaneous opportunities and constraints. Demand is expanding at a steady compound rate, but the composition of that demand is shifting as automation priorities deepen, monitoring capabilities become more sophisticated, and cybersecurity expectations move from advisory guidance toward procurement requirements. In this environment, the ability to interpret market signals accurately is a decisive advantage.
One clear imperative is to align product and service strategies with the integration expectations of modern infrastructure projects. Devices that support standard communication frameworks, documented cybersecurity capabilities, and reliable lifecycle management are better positioned to meet the evaluation criteria of system integrators and utility procurement teams. A second imperative is to monitor segmentation dynamics with sufficient granularity to avoid overreliance on broad category assumptions. Demand strength varies meaningfully across product families and application domains, and commercial strategies that account for these differences are more likely to capture high-value opportunities.
A third imperative involves competitive positioning. In a market where the largest firms hold a substantial but not dominant share, differentiation can be achieved through engineering depth, regional execution quality, and the ability to reduce integration and compliance risk for customers. Organizations that understand where incumbents are strong and where customer unmet needs persist can identify viable entry points and partnership opportunities. Finally, leadership teams should treat standards evolution as a strategic input rather than a compliance afterthought. Anticipating how cybersecurity specifications and interoperability requirements will shape future procurement criteria can help organizations avoid reactive redesign cycles and position their offerings ahead of tender clarifications.
Conclusion
The Intelligent Electronic Devices market is entering a phase in which growth is supported by durable infrastructure modernization needs, yet competitive outcomes will increasingly depend on how well firms navigate integration standards, cybersecurity expectations, and application-specific demand shifts. Our comprehensive market research publication provides the analytical foundation required to make those strategic judgments with confidence. By combining historical context, forecast projections, segmentation intelligence, and a detailed competitive assessment, the report equips decision-makers with the insights needed to prioritize investments, refine market strategies, and respond effectively to the operational realities of 2026 and the years that follow.
For executives and strategy professionals seeking a complete picture of market size trajectories, segmentation dynamics, regional demand patterns, and vendor positioning, the full study offers the depth and specificity necessary to translate high-level trends into actionable business decisions. Detailed figures, segment-level breakdowns, and extended competitive profiles are available in the complete report, which can be accessed through our official research portal for teams requiring comprehensive intelligence to support planning, procurement strategy, and long-range investment decisions.
For detailed analysis of this topic, please visit the official page: Intelligent Electronic Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Hearing Aid Market to Hit $233M by 2032 with 7.05% CAGR from $144M in 2025
By PW Consulting, 2026-09-16
The Hearing Aid Market in 2026: Strategic Intelligence for the Next Wave of Growth
The global hearing aid market stands at a decisive inflection point. As regulatory frameworks evolve, consumer expectations shift toward self-directed care, and artificial intelligence becomes embedded in sound processing, manufacturers and healthcare stakeholders must navigate a landscape defined by both opportunity and complexity. PW Consulting’s latest Hearing Aid Market research delivers the analytical foundation required to make informed decisions in 2026 and beyond. Drawing on a structured historical review from 2020 through 2025 and a forward-looking forecast spanning 2026 to 2032, this report translates macro trends into actionable intelligence. The market’s trajectory reflects steady expansion, with overall revenue climbing from approximately 114.14 million USD in 2020 to an estimated 144.21 million USD in 2025. The forecast period projects continued momentum, reaching roughly 158.55 million USD in 2026 and advancing to 233.05 million USD by 2032, supported by a compound annual growth rate of 7.05 percent. These figures are not merely retrospective markers; they are the baseline against which product roadmaps, market entry strategies, and partnership decisions will be measured.
For executives planning 2026 initiatives, the strategic value of this research lies in its ability to connect structural shifts with operational execution. The industry is being reshaped by overlapping forces: an accelerating transition toward digital architectures, intensifying competition among established manufacturers and agile over-the-counter entrants, and a regulatory environment that is actively redrawing the boundaries of self-fitting devices. Reimbursement transformation adds another layer of strategic urgency, as professional service coding reforms alter the economics of patient access and provider engagement. Understanding how these dynamics interact is essential for prioritizing investment, refining positioning, and anticipating competitive responses. This report is designed to provide that clarity.
Market Trajectory and Structural Shifts
A market of this scale and growth profile cannot be interpreted through headline figures alone. The historical data reveals a pattern of resilience and rebalancing. After steady increases through 2020 to 2023, the 2024 period reflects a temporary recalibration before the market resumes expansion in 2025. This sequence is instructive for planners because it underscores the importance of distinguishing cyclical adjustments from durable demand shifts. The forecast to 2032 suggests that growth will not be evenly distributed across time or product categories. Instead, it will be shaped by adoption cycles, technology maturation, and the pace at which self-fitting models penetrate broader consumer segments.
Adult Hearing Aids Market
Within this trajectory, the digital transformation of hearing aids remains a defining theme. Digital solutions continue to command a dominant share of the application landscape, reflecting ongoing demand for adaptive sound processing, connectivity, and personalized listening experiences. At the same time, the type landscape is undergoing its own realignment. Receiver-in-canal architectures have gained substantial prominence, while behind-the-ear, in-the-ear, and completely-in-canal formats each occupy distinct positions based on clinical needs, aesthetic preferences, and fitting workflows. These structural patterns matter because they influence product design priorities, inventory strategy, and the allocation of research and development resources. The report explores these splits in detail, allowing decision-makers to assess where demand is consolidating and where emerging formats may create new openings.
Hearing Aid Market
Competitive Landscape: Innovation, Consolidation, and Positioning
The hearing aid sector remains concentrated, with the largest players controlling a significant portion of market value. This concentration does not imply uniformity. On the contrary, the competitive environment is increasingly differentiated by technology strategy, channel approach, and the ability to integrate clinical credibility with consumer convenience. The report profiles the companies shaping this landscape, including Starkey Laboratories, Sonova, WS Audiology, GN Store Nord, MED-EL, Cochlear Limited, Demant, Eargo, Sivantos, Rion, and Envoy Medical. Each occupies a distinct strategic position, and their recent moves offer a practical window into where the industry is heading.
Several developments from late 2025 and early 2026 illustrate this divergence. Envoy Medical advanced its fully implanted cochlear implant program when the FDA approved expansion of the pivotal clinical trial for the Acclaim CI to its final stage, signaling continued momentum in implantable innovation. Cochlear secured FDA approval for the Nucleus Nexa smart cochlear implant system, emphasizing upgradeable firmware and future-ready feature expansion. Sivantos moved forward with the launch of Insera models under its Smile platform, complementing the Moxi line with AI-trained Integra OS designed to optimize sound detection. ReSound, under GN Store Nord, released the Enzo iA power hearing aid as a new high-output BTE option for severe hearing loss. Meanwhile, Eargo and hearX completed a strategic merger to form LXE Hearing, reinforcing the push toward self-fitting OTC solutions. These events are not isolated product announcements; collectively, they map a competitive field in which AI-enabled personalization, self-fitting convenience, implantable differentiation, and firmware upgradability are becoming central battlegrounds.
For 2026 planning, the competitive analysis in this report helps answer a set of critical questions. Which players are strengthening their positions through technology integration rather than portfolio breadth alone? Where are the pressure points for incumbents as self-fitting models gain traction? How are implantable and semi-implantable solutions expanding the addressable market for patients who may not be fully served by conventional devices? By examining company profiles alongside recent developments, the report provides a disciplined framework for evaluating partnership opportunities, competitive threats, and white-space positioning.
Regulation, Reimbursement, and the Changing Rules of Access
Strategic planning in this market requires more than an understanding of product innovation. The regulatory and reimbursement environment is actively reshaping how hearing aids are classified, fitted, reimbursed, and adopted. The report integrates these forces into its market dynamics assessment because they directly affect demand patterns, channel strategy, and compliance requirements.
On the regulatory side, self-fitting OTC hearing aids continue to operate within a structured FDA framework. Devices in this category generally require 510(k) clearance to demonstrate substantial equivalence to predicate devices, supported by clinical data on usability and performance that is comparable to audiologist-fitted options. FDA-cleared self-fitting models must also comply with labeling and indication requirements under 21 CFR 874.3325, ensuring safe use by adults 18 and older with perceived mild-to-moderate hearing loss. As Class II devices, most OTC hearing aids proceed through premarket notification, while some preset-based models follow a lighter registration pathway. In parallel, bone-conduction and semi-implantable systems continue to receive periodic clearances, reflecting ongoing expansion in patient indications and device performance. These regulatory realities are not static background conditions; they define the feasible pace of market entry, the credibility of self-fitting claims, and the differentiation potential for manufacturers that can align innovation with compliance.
Equally important is the reimbursement transformation underway in professional hearing service coding. The longstanding CPT codes for hearing aid services, historically covering codes 92590 through 92595, are being replaced by a new set of 12 codes for professional services related to hearing aids and hearing devices, effective January 1, 2026. This shift has direct implications for how services are documented, billed, and valued. For manufacturers, it affects the broader ecosystem in which products are fitted and supported. For providers, it influences workflow design and service economics. For investors and strategists, it introduces a variable that can alter adoption incentives and channel dynamics. The report examines these dynamics not as isolated regulatory updates, but as interconnected factors that will shape demand realization and market access throughout the forecast period.
What the Report Delivers for 2026 Decision-Making
This research is built for execution, not just observation. It combines macro market sizing, segmentation analysis, competitive profiling, and regulatory context into a single structured reference that supports product, commercial, and investment decisions. The report’s practical value comes from how it connects data to decision points.
- Historical and forecast market sizing that establishes a credible baseline for 2026 planning and long-range scenario modeling through 2032
- Segment-level analysis across regions, product types, and application categories, enabling a clearer view of where demand is concentrated and how structures are shifting
- Competitive profiling of major manufacturers and emerging players, with attention to technology direction, product releases, and strategic consolidation
- Recent industry developments mapped to their strategic implications, including implantable trial progress, cochlear implant approvals, OTC mergers, and new power BTE introductions
- Regulatory and reimbursement dynamics that clarify the operating rules for self-fitting devices, implantable systems, and professional service coding reform
- Market concentration context that helps assess competitive pressure and the room available for new entrants or differentiated positioning
Importantly, the report is organized so that readers can move from high-level direction to the details that matter for specific decisions. Rather than presenting numbers in isolation, it frames them within the operational realities of product development, channel strategy, and market access. This approach allows executives to use the research as a working tool: to validate assumptions, compare strategic options, and identify the questions that still need internal answers.
Why Strategic Foresight Matters Now
The hearing aid market is not simply expanding; it is being reorganized around technology, regulation, and changing user expectations. That reorganization creates both risk and reward. Companies that treat 2026 as a continuation of past playbooks may miss the significance of self-fitting adoption, firmware-driven product lifecycle management, implantable market expansion, and the reimbursement changes that influence how services are delivered and paid for. Companies that act on rigorous, up-to-date intelligence can position themselves more precisely, whether through product differentiation, partnership strategy, geographic prioritization, or targeted entry into underserved patient segments.
PW Consulting’s Hearing Aid Market research is designed to support that decision-making with depth and discipline. It provides the market context necessary to interpret competitive moves, the segmentation insight needed to assess demand patterns, and the regulatory understanding required to plan within the rules of the next cycle. The macro figures tell the story of growth; the report’s deeper analysis tells you what that growth means for your strategy.
To access the complete segmentation data, competitive benchmarking, regulatory detail, and region-specific interpretations that support 2026 planning, visit the full report page. The complete intelligence package is structured to help teams move quickly from insight to action while maintaining the analytical rigor required for high-stakes decisions.
Access the full Hearing Aid Market research report
For detailed analysis of this topic, please visit the official page: Hearing Aid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: SSPS Market Hits $215M in 2025, Projected 6.98% CAGR to $344.8M by 2032
By PW Consulting, 2026-09-16
Strategic Imperatives in the Soluble Soybean Polysaccharides Market: A 2026 Outlook
The global functional ingredients landscape is undergoing a structural shift, driven by clean-label demands, protein stabilization challenges in acidic environments, and the relentless search for cost-effective texturizers. Within this complex ecosystem, Soluble Soybean Polysaccharides (SSPS) have emerged as a critical enabler for food formulators and pharmaceutical developers alike. As we navigate the forecast period from 2026 through 2032, understanding the trajectory of this market is not merely an academic exercise but a strategic necessity for stakeholders across the supply chain.
PW Consulting's latest market research report on the Soluble Soybean Polysaccharides Market offers a comprehensive lens into this evolving sector. This article serves as a strategic overview, highlighting the key macro trends, competitive dynamics, and operational variables that will define decision-making in 2026. However, to truly equip your organization with the granularity required for precise planning, we invite you to explore the full intelligence contained within our complete study.
Market Trajectory and Growth Fundamentals
The SSPS market has demonstrated resilience and steady expansion over the recent historical period. Our analysis covers historical data from 2020 to 2025, providing a robust baseline for understanding current market velocities. In 2020, the global market valuation stood at approximately 163.15 million USD. By 2025, this figure has escalated to 215.0 million USD, reflecting a compound annual growth rate that underscores the ingredient's increasing adoption in high-value applications.
Looking forward, the forecast period from 2026 to 2032 projects continued upward momentum. The market is expected to reach 223.12 million USD in 2026, climbing steadily to 344.8 million USD by 2032. This trajectory implies a CAGR of 6.98 percent throughout the forecast window. Such growth is not accidental; it is rooted in the technical advantages SSPS offers over traditional stabilizers, particularly in beverage systems where protein precipitation is a common failure mode. For corporate strategists, this growth rate signals a maturing market where early movers in capacity expansion or application development may secure significant share advantages before saturation occurs.
Segmentation Dynamics and Application Versatility
A key strength of our research lies in its detailed segmentation analysis. The market is not a monolith; it is fractured by type, application, and geography, each with distinct demand drivers. Our report dissects these segments to reveal where value is being created and where volume is accumulating.
Regarding product types, the market is categorized into low molecular weight, high molecular weight, and other types. Each variant serves different rheological needs. Low molecular weight variants are often preferred for specific beverage clarity and stability profiles, while high molecular weight options may serve distinct thickening requirements. Similarly, the application landscape is diverse. The food and beverages sector remains the dominant consumption channel, leveraging SSPS for protein stabilization in acidic drinks and low-viscosity applications. Beyond this, the pharmaceuticals sector utilizes these polysaccharides for their bioactive potential, while other applications continue to explore novel industrial uses.
PPS Resin Market
Geographically, the market spans North America, Europe, Asia Pacific, Latin America, and Mideast and Africa. While aggregate data suggests broad global interest, regional nuances in regulatory environments, raw material access, and consumer preference shapes distinct growth pockets. Our full report provides a deep dive into these regional variances, allowing clients to identify high-potential zones for distribution partnerships or localized production.
Competitive Landscape: Key Players and Strategic Positioning
The competitive environment for SSPS is characterized by a mix of specialized pioneers and broader biological industry players. Market concentration metrics indicate a relatively fragmented landscape, with the top three players holding a CR3 of 24.6 percent and the top five representing a CR5 of 26.2 percent. This fragmentation suggests opportunities for consolidation or for smaller players to carve out niches through specialized application expertise.
Among the notable entities shaping this space is Fuji Oil Co., Ltd., headquartered in Osaka, Japan. As a pioneer developer and commercial producer of SSPS from soybean pulp, Fuji Oil supplies food-grade SSPS specifically for protein stabilization in acidic beverages and low-viscosity applications. Their technical heritage positions them as a benchmark for quality and application science in the sector.
In China, several active producers are scaling capabilities to meet regional and export demand. Guangzhou Fofiber Biological Industry Co., Ltd. operates as a significant producer, offering SSPS as an emulsifier, thickener, and dietary fiber. Their process involves enzyme-treated extraction from soybean dregs, highlighting the industry's focus on valorizing by-products. Similarly, Jiangsu Yiming Biological Technology Co., Ltd. focuses on protein stabilization and beverage applications, supplying food-grade SSPS for acidic protein drinks.
Other key participants include Guangzhou Hisoya Biological Science & Technology Co., Ltd., which supplies SSPS powder with an emphasis on emulsification and stabilization for both industrial and food uses. Pingdingshan Jinjing Biological Technology Co., Ltd., based in Henan, focuses on derivatives from soybean by-products, targeting protein stability and refreshing taste in drinks. Additionally, Jiahe Xuri Food Co., Ltd. in Hebei produces SSPS for diverse food applications, including formulations such as bun wrappers.
Recent developments underscore the ongoing innovation in this space. In October 2025, Jiahe Xuri Food Co., Ltd. was noted for supplying SSPS for improving steamed stuffed bun wrapper quality and shelf life, a finding published in new food chemistry literature. Such developments illustrate how SSPS applications are expanding beyond beverages into broader textural and preservative roles, opening new revenue streams for producers and users alike.
Industry Dynamics: Raw Materials, Regulations, and Costs
Strategic planning in the SSPS market cannot occur in a vacuum; it must account for the volatile raw material environment and regulatory frameworks that govern production and usage. Soybean-derived ingredients are inherently tied to agricultural cycles, trade policies, and processing economics.
Raw material costs remain a critical sensitivity. For context, Soy Protein Isolate (SPI) prices, often correlated with SSPS production economics, ranged from USD 2,800 to USD 4,200 per metric ton in 2026. This volatility is driven by soybean futures and complex trade dynamics, including U.S.-China relations. Production costs for soy protein isolate have been observed between USD 1,900 and USD 3,000 per metric ton, with raw material costs accounting for a substantial 60 to 75 percent of finished isolate costs. While SSPS is a distinct product, these cost structures influence the broader soybean processing margin environment, affecting the availability and pricing of the soybean pulp and dregs from which SSPS is often extracted.
On the supply side, macroeconomic factors such as harvest yields play a role. Brazil's 2025/26 soybean harvest reached a record 177 to 178 million metric tons, temporarily easing crush margins for soy protein isolate. Such supply abundance can ripple through the supply chain, potentially stabilizing input costs for polysaccharide producers who rely on soybean processing by-products.
Regulatory compliance is another pillar of market access. SSPS is recognized as a food additive under China's Ministry of Health No. 13 announcement (2008), alongside national standards issued in 2005 for soluble soybean polysaccharides. For global players, navigating differing regulatory regimes is essential. Furthermore, the trend toward clean labels and organic certification introduces additional cost layers. Organic soy protein isolate certification, for instance, requires compliance with USDA or EU standards, prohibiting synthetic pesticides and GMOs. This requirement increases raw soybean costs by 30 to 50 percent. While specific to isolate, this premium signals the cost pressure facing organic-compliant soy derivatives broadly, a factor SSPS formulators must weigh when pricing premium product lines.
Strategic Value of the Full Report
While this overview captures the macro essence of the Soluble Soybean Polysaccharides Market, the devil is in the details. For decision-makers in 2026, aggregate growth rates are insufficient. You need to know the specific revenue contributions of each region, the precise market share of each application segment, and the nuanced cost structures that differentiate competitors.
Our full report provides the actionable intelligence required to mitigate risk and capitalize on opportunity. It includes detailed breakdowns of regional market sizes, enabling targeted expansion strategies. It offers granular segmentation data, revealing exactly which product types are outperforming in specific applications. It profiles key companies with depth, analyzing their production capacities, technological advantages, and recent strategic moves. Moreover, it contextualizes raw material fluctuations and regulatory shifts within a forward-looking framework, helping procurement and R&D teams anticipate cost changes and compliance requirements.
In a market projected to grow from 223.12 million USD in 2026 to over 344 million USD by 2032, the window for strategic positioning is open but narrowing. Competitors are investing in capacity, and formulators are increasingly aware of the functional benefits of SSPS. To make informed decisions that align with your organization's growth objectives, you need the complete picture.
We invite you to access the full PW Consulting market research report on the Soluble Soybean Polysaccharides Market. There, you will find the detailed data tables, comprehensive company profiles, and deep-dive regional analyses that transform high-level insights into executable strategy. Let us help you navigate the complexities of this market with confidence.
Soluble Soybean Polysaccharides (SSPS) Market
For detailed analysis of this topic, please visit the official page: Soluble Soybean Polysaccharides (SSPS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Polyimide Foam Market Hits $250M in 2025, Eyeing $388.5M by 2032 with 6.5% CAGR
By PW Consulting, 2026-09-16
Strategic Imperative: Navigating the Polyimide Foam Market Outlook 2026-2032
The specialty materials landscape is undergoing a structural transformation, driven by stringent performance requirements in transportation, electronics, and industrial infrastructure. At the center of this shift is the polyimide foam sector, a niche yet critical segment valued for its exceptional thermal stability, fire resistance, and acoustic damping properties. As enterprises map out capital allocation and product development roadmaps for 2026, relying on fragmented data or outdated assumptions poses significant strategic risk. Our latest comprehensive study, the Polyimide Foam Market Research, provides the granular intelligence necessary to navigate this evolving terrain with confidence.
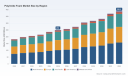
This market is not merely expanding; it is consolidating around high-performance applications where failure is not an option. Based on historical trajectory and forward-looking modeling, the total market revenue is projected to grow from a baseline of approximately 257.8 Million USD in 2026 to nearly 388.5 Million USD by 2032. This trajectory reflects a Compound Annual Growth Rate (CAGR) of 6.5 percent over the forecast period. Such growth is not uniform; it is heavily concentrated in sectors demanding superior safety profiles and energy efficiency. For decision-makers, understanding the drivers behind these numbers is far more critical than the figures themselves.
Decoding the Growth Trajectory and Historical Context
The market has demonstrated resilience and steady accumulation of value over the past five years. Historical data from 2020 through 2025 shows a consistent upward trend, moving from 182.47 Million USD to a consolidated 250.0 Million USD in the base year. This historical momentum provides a sturdy foundation for the forecast period extending through 2032. However, raw historical data only tells part of the story. The real strategic value lies in understanding the inflection points anticipated in the coming years.
Our analysis identifies key catalysts expected to accelerate adoption rates between 2026 and 2032. These include the tightening of global fire safety standards, the electrification of automotive platforms requiring advanced thermal management, and the relentless miniaturization of electronic components necessitating superior insulation materials. The report dissects these drivers to reveal where volumetric growth will materialize and where margin pressure may intensify. By examining the historical baseline alongside forward-looking scenarios, organizations can better align their supply chain strategies and R&D investments with actual market demand rather than speculative trends.
Comprehensive Report Architecture and Operational Content
To support complex business decisions, this research deliverable is structured to provide actionable intelligence rather than abstract macro-level observations. The document serves as an operational playbook for sourcing managers, product strategists, and financial analysts. It covers the full spectrum of market intelligence required to validate business cases and mitigate entry risks.
The study details the production technologies underpinning current market offerings, including variations in polymerization chemistry and blowing agents. It evaluates the trade-offs between performance metrics and manufacturing costs, providing a clear view of cost structures across different production methods. Furthermore, the report conducts a thorough value chain analysis, tracing the flow from raw material suppliers of aromatic diamines and dianhydrides to converters and end-user integrators. This end-to-end perspective is crucial for identifying bottlenecks and supply chain vulnerabilities.
Key sections include:
- Technological Roadmap: Assessment of emerging production methods, including water-blown and supercritical CO2 processes, and their impact on scalability and environmental compliance.
- Application Suitability Analysis: Detailed mapping of material properties against specific use-case requirements in aerospace, automotive, and electronics, highlighting where performance justifies premium pricing.
- Regulatory Impact Assessment: A deep dive into compliance burdens across major jurisdictions, including REACH requirements in Europe and FAA standards in North America, evaluating their effect on time-to-market and operational costs.
- Pricing Dynamics: Analysis of raw material cost volatility and its transmission through the value chain, offering frameworks for negotiating long-term supply agreements.
Competitive Landscape and Strategic Positioning
The polyimide foam market is characterized by a high degree of concentration, with the top three competitors controlling approximately 80 percent of the market share and the top five holding 82 percent. This concentration indicates a mature market where established relationships and proprietary technology create significant barriers to entry. For new entrants or existing players looking to expand share, understanding the specific capabilities and strategic moves of incumbents is vital.
Several key players define the current landscape. Boyd Corporation, based in Pleasanton, California, develops and converts proprietary SOLIMIDE polyimide foam for aerospace, marine, and thermal or acoustic insulation. Their offerings emphasize high-temperature fire-resistant open-cell foam with minimal smoke, catering to safety-critical environments. Similarly, Trelleborg in Sweden operates as an authorized distributor and fabricator of SOLIMIDE polyimide foam, supplying fire-resistant insulation panels for marine, rail, and industrial applications, leveraging distribution networks to expand market reach.
Saint-Gobain Performance Plastics, headquartered in Auburn, Massachusetts, produces and fabricates polyimide foam products for high-performance thermal, acoustic, and sealing applications spanning aerospace, automotive, and industrial sectors. Their recent capacity expansion investments signal a strong commitment to meeting growing demand. On the other side of the Pacific, Ube Industries and Nitto Denko Corporation in Japan produce high-performance foam grades and flexible formats for aerospace, automotive, and building applications, respectively. Chinese manufacturers such as Solver Polyimide and Yancheng Polyimide Insulation Co., Ltd. are also active, manufacturing foam sheets, rods, and insulation products primarily for commercial marine and high-temperature uses.
Distribution International rounds out the competitive set by supplying and fabricating marine-grade insulation panels and sheets, offering various thicknesses and facings. These companies represent a mix of material science giants, specialized converters, and regional manufacturers. Our research provides a comparative assessment of their product portfolios, geographic coverage, and recent strategic moves, such as capacity expansions in Singapore, Germany, and North America observed in early 2025. This competitive profiling allows firms to identify potential partners, assess threat levels, or locate gaps in the market offerings.
Regulatory and Environmental Dynamics Shaping the Market
Regulatory compliance is no longer a back-office function; it is a primary driver of product design and market access. The polyimide foam sector operates under intense scrutiny regarding fire safety and environmental impact. Stringent fire safety regulations across mass transportation, construction, and electronics sectors require materials to meet and exceed FAA standards such as FAR 25.853 for low smoke and flame resistance. Compliance with these standards is a non-negotiable prerequisite for entry into aerospace and rail markets, effectively acting as a filter that favors established, certified suppliers.
In European markets, REACH substance registration requirements add significant documentation burdens for aromatic diamine precursors used in production. This regulatory layer influences supply chain sourcing decisions and can impact the availability of specific chemical inputs. Additionally, EPA regulations on volatile organic compound emissions during foam manufacturing constrain solvent-based production methods. Consequently, there is a shifting preference toward water-blown or supercritical CO2 processes, which aligns environmental compliance with operational efficiency.
Furthermore, stringent EU environmental regulations drive innovation toward sustainable production methods with a focus on water-based polymerization chemistry to reduce emissions. These regulatory pressures are not merely constraints; they are reshaping the competitive landscape by rewarding companies that invest early in cleaner technologies. Our report analyzes how these regulatory trends will impact cost structures and market entry barriers over the forecast period, enabling organizations to anticipate compliance costs and integrate them into their financial modeling.
Strategic Recommendations for 2026 Decision-Makers
As organizations prepare for the 2026 fiscal year and beyond, several strategic imperatives emerge from the data. First, supply chain resilience must be prioritized. Given the concentration of market share and the complexity of raw material sourcing, reliance on single-source suppliers exposes firms to significant risk. Diversification and long-term contracts with key converters or manufacturers are advisable to secure capacity amidst growing demand.
Polyimide (PI) Market
Second, R&D investment should focus on application-specific formulations. The data suggests that growth is not uniform across all applications. Sectors like aerospace and automotive are driving demand for specialized grades that meet exacting thermal and safety profiles. One-size-fits-all approaches are less likely to succeed in this environment. Companies should align their product development efforts with the specific performance gaps identified in high-growth segments.
Third, sustainability is becoming a competitive differentiator. With regulatory trends pushing toward water-based chemistry and reduced emissions, manufacturers who can demonstrate superior environmental credentials may gain preferential access to certain markets, particularly in Europe. Integrating sustainability metrics into procurement and production strategies is no longer optional but a requirement for maintaining market relevance.
Finally, pricing strategies must be dynamic. Raw material costs, priced between 30 and 150 USD per cubic meter depending on quality and application, introduce volatility. Organizations need robust mechanisms to monitor input cost trends and adjust pricing models accordingly to protect margins without losing competitiveness. The report provides frameworks for understanding these pricing dynamics and positioning products effectively within different value segments.
Polyimide Foam Market
Accessing Detailed Intelligence
While this overview highlights the macro trends and strategic considerations defining the polyimide foam market, the full depth of the analysis resides in the complete research publication. The narrative provided here is designed to illustrate the scope and rigor of the study, demonstrating the professional depth required to make informed 2026 decisions. However, the specific segment splits, regional revenue breakdowns, detailed company profiles, and proprietary forecasting models are contained within the full report.
For procurement leaders evaluating supplier options, the granular data on regional capacity and manufacturer capabilities is essential. For investors assessing the viability of market entry, the detailed segmentation by type and application provides the necessary validation for financial models. The complete document offers the specific intelligence needed to move from strategic understanding to tactical execution.
To obtain the full Regional Splits, detailed Type and Application breakdowns, and comprehensive competitor benchmarking data, please access the source webpage for the complete Polyimide Foam Market Research. The detailed intelligence contained in the full report is the key to unlocking precise market positioning and securing a competitive advantage in the years leading up to 2032. Secure your copy to ensure your strategic decisions are backed by the most accurate and actionable data available.
For detailed analysis of this topic, please visit the official page: Polyimide Foam Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Seamless Copper Tubes Market to Reach USD 304.47 Million by 2032, Growing at 5.1% CAGR
By PW Consulting, 2026-09-16
Executive Summary: Navigating the Seamless Copper Tubes Market Amidst Global Transformation
The global infrastructure landscape is undergoing a seismic shift, driven by rapid urbanization, stringent environmental regulations, and the accelerating electrification of transport. At the heart of this transformation lies a critical component: the seamless copper tube. As industries demand higher efficiency and durability, the Seamless Copper Tubes Market has emerged as a pivotal sector for strategic investment and operational planning. PW Consulting's latest comprehensive market research provides a detailed roadmap for navigating these complexities, offering indispensable intelligence for stakeholders aiming to capitalize on the opportunities projected through 2032.
Macroscopic Market Trajectory and Growth Signals
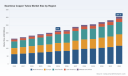
Understanding the broader economic currents is essential for any strategic decision-maker. Our analysis tracks the market evolution from 2020 through the forecast horizon ending in 2032. The data indicates a consistent upward trajectory, reflecting the material's indispensable role in modern engineering. In 2020, the market valuation stood at approximately 163.15 Million USD. This figure has demonstrated resilience and growth, reaching an estimated 215.0 Million USD in 2025.
Looking forward, the momentum is set to continue. The market is projected to attain a valuation of around 218.35 Million USD in 2026, signaling a stable baseline for the forecast period. By the end of the forecast window in 2032, the market size is anticipated to reach 304.47 Million USD. This growth represents a Compound Annual Growth Rate (CAGR) of 5.1 percent over the forecast period. Such metrics suggest a mature yet expanding market where strategic positioning can yield significant returns. The consistency in growth underscores the reliability of seamless copper tubes across various high-demand sectors, making this report a vital tool for long-term capacity planning and investment allocation.
Key Industry Dynamics Reshaping the Landscape
The market does not exist in a vacuum. Several macroeconomic and regulatory forces are actively reshaping the demand and supply dynamics for seamless copper tubes. Our research delves deep into these drivers to help clients anticipate disruptions and leverage trends.
Regulatory Pressures and Environmental Standards
Global regulatory bodies are enforcing stricter environmental and energy efficiency standards, particularly within the HVAC and refrigeration sectors. These regulations mandate the use of seamless copper tubes that comply with rigorous international safety certifications. Manufacturers must ensure their product lines meet these evolving compliance requirements to maintain market access. Our report analyzes the specific certification landscapes across key regions, enabling companies to audit their compliance readiness.
The Electric Vehicle Revolution
A significant macro trend identified in our research is the increasing adoption of seamless copper tubes in electric vehicle (EV) battery cooling systems. As EVs become mainstream, the thermal management requirements for battery packs have intensified. High-performance seamless copper tubes are critical for dissipating heat efficiently, ensuring safety and longevity. This shift represents a high-growth niche within the broader market, attracting innovation from major tube manufacturers.
Raw Material Volatility and Geopolitical Factors
Supply chain stability remains a critical concern. Copper prices exhibited notable volatility in 2025, driven by supply chain disruptions and fluctuating demand from industrial sectors. Furthermore, geopolitical tensions, including US-China trade dynamics and export restrictions in copper-producing nations like Chile and Peru, impact raw material availability. Our analysis provides a nuanced view of these risks, helping procurement teams develop hedging strategies and diversify supply sources to mitigate potential bottlenecks.
Infrastructure Development in Emerging Markets
Urbanization and infrastructure development in emerging markets continue to drive requirements for durable seamless copper tubes, particularly in plumbing and HVAC applications. As cities expand and living standards improve in developing economies, the demand for reliable piping infrastructure escalates. This trend offers substantial growth potential for manufacturers with the logistical capability to serve these regions effectively.
Competitive Arena: Key Players and Strategic Moves
The competitive landscape is characterized by a mix of established global giants and agile regional specialists. With a CR3 of 32.0 percent and a CR5 of 40.0 percent, the market exhibits moderate concentration, allowing for competitive dynamics while rewarding scale and innovation. Our research profiles key enterprises that are defining the market trajectory.
Major Industry Participants
Our report provides detailed profiles of leading companies including Mueller Industries, Inc. , headquartered in Memphis, TN, known for their comprehensive offering in the sector. Wieland Group from Suhl, Germany, represents a major European force with significant technological capabilities. The Italian market is well-represented by KME Group S.p.A. based in Milan. In Asia, Kobe Steel, Ltd. and Furukawa Electric Co., Ltd. from Tokyo, along with Mitsubishi Materials Corporation , showcase Japan's strong presence in high-quality copper products. Luvata , based in Pori, Finland, and Cerro Flow Products, LLC from Saint Louis, MO, are noted for their specialized manufacturing expertise. The Chinese market influence is highlighted by Golden Dragon Precise Copper Tube Group Inc. in Henan, Hailiang Group in Zhejiang, and Shanghai Metal Corporation in Shanghai. Additionally, MetTube Sdn Bhd in Malaysia and MM Kembla Copper Tube Pty Ltd in New South Wales, Australia, round out the global perspective.
Recent Strategic Developments
The velocity of corporate activity in this sector is high. Our intelligence tracks recent moves that signal shifting strategies. In March 2025, Wieland Group announced a 500 million USD expansion at their copper and copper alloy facility in East Alton, Illinois, underscoring a commitment to North American capacity. Also in early 2025, Mueller Industries, Inc. successfully integrated recent acquisitions of Nehring Electrical Works and Elkhart Products, expanding their product line and manufacturing capacity. February 2025 also saw KMCT Corporation expand their line of smooth-bore and inner-groove copper tubing for HVAC and refrigeration systems, responding directly to efficiency demands. By June 2025, Luvata launched high-performance copper tubes specifically designed for electric vehicle cooling systems, marking a strategic pivot toward the EV sector. Furthermore, Golden Dragon Precise Copper Tube Group Inc. completed an expansion of their manufacturing facility in Mexico in June 2025 to increase output, signaling a strengthening of supply chains closer to the US market.
Precision Tubes Market
Understanding these movements is crucial for benchmarking and competitive positioning. Our report dissects these developments to reveal underlying strategic intents, whether they be capacity expansion, technological differentiation, or geographic diversification.
Segmentation Insights: Beyond the Aggregate Numbers
While the overall market size provides a top-down view, true strategic advantage comes from understanding the nuanced segmentation of the market. Our research breaks down the market by Type, Application, and Region to identify where the value pools are deepest.
Product Types and Applications
The market is differentiated by various tube types and end-use applications. HVAC and Refrigeration remains a dominant application area, driven by the need for energy-efficient cooling solutions. Plumbing continues to be a steady contributor, supported by infrastructure development. Additionally, other specialized applications are gaining traction. On the product side, distinctions such as Straight Length Tubes and Capillary Tubes serve different technical requirements. Our analysis quantifies the relative importance of these segments without exposing raw data prematurely, guiding clients on where to focus their R&D and marketing resources. The interplay between product specifications and application requirements is critical for product-market fit in a competitive environment.
Seamless Copper Tubes Market
Regional Distribution
Geographically, the market is spread across North America , Europe , Asia Pacific , Latin America , and Mideast and Africa . Each region presents unique challenges and opportunities. North America shows significant activity driven by industrial demand and recent capacity expansions. Europe faces regulatory pressures that drive high-specification product demand. Asia Pacific remains a hub for both manufacturing and consumption, influenced by rapid industrialization. Our regional analysis helps companies tailor their market entry strategies and optimize their distribution networks to match local demand patterns and regulatory environments.
The PW Consulting Advantage: Actionable Intelligence for 2026
In an era of information overload, precision is paramount. This market research report is not merely a collection of data points; it is a strategic asset designed to inform decision-making at the highest levels. The forecast period from 2026 to 2032 is critical. Companies that act on accurate intelligence today will define the market standards of tomorrow.
Our methodology combines rigorous quantitative analysis with qualitative industry expertise. We synthesize data from primary and secondary sources to ensure reliability. The report covers historical data from 2020 to 2025, providing a solid baseline for trend analysis, and extends forward to 2032 to facilitate long-term planning. All financial figures are presented in USD Million, ensuring consistency and comparability.
Key deliverables include detailed demand forecasts, supply chain risk assessments, and competitive benchmarking. We examine the impact of raw material price volatility on margins and provide scenarios for various geopolitical outcomes. For product managers, the segment analysis offers clarity on which tube types and applications offer the highest growth potential. For strategists, the regional breakdowns inform expansion plans and partnership opportunities.
The insights contained within this document are intended to reduce uncertainty. Whether you are a manufacturer looking to optimize capacity, a supplier seeking stable vendors, or an investor evaluating market potential, this research provides the foundational knowledge required to navigate the complexities of the seamless copper tubes industry. The 5.1 percent CAGR suggests steady growth, but capturing that growth requires understanding the specific drivers behind the numbers.
Access to granular data regarding regional specific values, application splits, and detailed company profiling is essential for crafting a winning strategy. The macroeconomic trends and competitive movements outlined here are only the surface level of the intelligence available. To fully leverage this information for your corporate planning, detailed access to the complete dataset is required.
The seamless copper tube market is poised for evolution. Regulatory shifts, technological advancements in EVs, and infrastructure growth will dictate the pace of change. Partners who understand these dynamics early will secure a competitive edge. PW Consulting stands ready to provide the depth of analysis necessary to turn market intelligence into corporate success.
For detailed analysis of this topic, please visit the official page: Seamless Copper Tubes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Backer Board Market to Hit $3.23B by 2032, Growing at 5.85% CAGR
By PW Consulting, 2026-09-16
Decoding the Backer Board Market: Strategic Intelligence for 2026 and Beyond
The construction and renovation landscape is undergoing a period of intense recalibration, driven by shifting material costs, evolving regulatory frameworks, and a persistent demand for durable building envelopes. At the heart of this transformation lies the backer board market, a critical component in tile installations, wall cladding, and moisture-prone structural applications. For executives, procurement leaders, and strategic planners, navigating this space requires more than surface-level trends. It demands a rigorous, data-backed understanding of where the market has been, where it is accelerating, and how competitive forces will reshape value chains through 2032.
Backer Board Market
Our newly released Backer Board Market research report is designed precisely for that purpose. It distills years of historical tracking, forward-looking modeling, and on-the-ground industry intelligence into a single, actionable intelligence platform. Rather than offering generic market commentary, the study maps the structural drivers, material substitution patterns, and regional demand intensities that will dictate capital allocation, sourcing strategy, and product positioning in the coming cycle.
The Macro Trajectory: A Market in Structural Expansion
Over the past half-decade, the backer board sector has demonstrated consistent volume growth, underpinned by steady residential remodeling activity, commercial retrofit cycles, and the broader push toward moisture-resistant building standards. Historical tracking from 2020 through 2025 reveals a clear upward arc, with total market revenue climbing from approximately 1.5 billion USD to 2.09 billion USD. This progression was not linear; it reflected periods of supply chain normalization, fluctuating raw material pricing, and varying regional construction activity. Yet the overarching pattern is unambiguous: demand has solidified, and adoption curves have steepened as contractors and developers prioritize long-term durability over short-term cost avoidance.
Looking ahead, our forecasting model projects the market to reach 2.25 billion USD in 2026, with continued expansion through the end of the decade. By 2032, the sector is anticipated to approach the 3.2-billion-USD threshold, sustained by a compound annual growth rate of 5.85 percent. This trajectory is not merely a function of population growth or housing starts; it reflects deeper shifts in specification practices, code enforcement intensity, and the gradual migration toward engineered substrate solutions that outperform legacy alternatives. For strategic decision-makers, the implication is clear: the backer board category is transitioning from a commoditized auxiliary material to a differentiated, specification-driven product segment where early positioning yields measurable competitive advantage.
What the Report Delivers: Operational Intelligence, Not Just Headlines
Market research at its best should function as a decision-support system, not a static snapshot. Our study is structured to provide granular, actionable clarity across every dimension that influences sourcing, pricing, and go-to-market strategy. The report examines the full spectrum of product architectures, mapping the performance profiles, installation characteristics, and end-use suitability of the dominant material families that define the category. It evaluates how each type performs under varying moisture conditions, load-bearing requirements, and finish compatibility standards, enabling procurement teams to align material selection with project-specific risk profiles and lifecycle cost expectations.
The application layer receives equal scrutiny. We dissect how substrate demand bifurcates across tile installation environments, wet-area specifications, floor underlayment requirements, and countertop support systems. By tracing volume distribution across these use cases, the report highlights where adoption is accelerating, where substitution threats are emerging, and where specification lock-in is creating durable demand pools. This application-level breakdown is particularly valuable for manufacturers seeking to optimize product mix, distributors aiming to align inventory with regional project pipelines, and contractors evaluating material trade-offs against labor efficiency and warranty exposure.
Regional demand intensity is analyzed through a lens of economic activity, building code enforcement, and import dependency dynamics. Rather than presenting static share percentages, the study prioritizes directional movement, identifying which geographies are experiencing structural demand expansion, which are plateauing due to market saturation or regulatory headwinds, and which are emerging as high-growth corridors fueled by infrastructure modernization and renovation cycles. This geographic intelligence is cross-referenced with supply chain logistics, freight cost sensitivity, and localized raw material availability, providing a practical foundation for regional capacity planning and distribution network optimization.
Beyond segmentation, the report embeds a comprehensive competitive landscape assessment. We profile the market’s leading participants, evaluating their product portfolio breadth, manufacturing footprint, innovation cadence, and strategic positioning. The analysis captures how incumbents are leveraging brand recognition, technical support networks, and specification relationships to defend core share, while also tracking how newer entrants and niche players are exploiting gaps in lightweight alternatives, moisture-specific formulations, and sustainability-aligned material profiles. The result is a clear view of where competitive pressure is concentrating, where margin pools are most defensible, and where partnership or acquisition logic may emerge as the market matures.
Competitive Architecture: Incumbents, Differentiators, and the Innovation Frontier
The backer board market’s competitive structure is defined by a mix of established building material conglomerates, specialized substrate manufacturers, and regional brands with strong distribution ties. Leading the field are companies that have built long-standing relationships with contractors, distributors, and specification channels, leveraging decades of product iteration and technical support infrastructure. United States Gypsum Company, for instance, anchors its position through dedicated cement and fiber cement backer board offerings that emphasize structural compatibility and widespread specification acceptance. James Hardie, with its dual headquarters structure and deep North American operational presence, has cultivated a similarly entrenched footprint, reinforced by product lines that align closely with exterior and interior moisture-management standards.
Back Glue Market
Parallel to these incumbents, specialized players are carving out distinct positioning through material innovation and niche application focus. Grip-Rite has advanced its portfolio with magnesium oxysulfate-based substrate solutions designed to offer lightweight handling, improved durability, and reduced reliance on traditional cement formulations. PermaBASE Building Products has concentrated on cement backer board variants that balance installation efficiency with performance consistency, while Gold Bond Building Products has pushed into gypsum-based tile backer alternatives that address mold resistance and interior finish compatibility. National Gypsum Company operates at a critical junction in this ecosystem, functioning as an exclusive service provider for key product lines and reinforcing the interconnected nature of manufacturing, distribution, and specification support.
Recent product and platform developments underscore how quickly the innovation frontier is moving. In mid-2025, Grip-Rite introduced a mineral-based, eco-conscious backer board and underlayment line, emphasizing reduced chemical complexity, improved weight characteristics, and durability aligned with modern installation expectations. Later that year, James Hardie expanded its contractor and homeowner engagement toolkit through an AI-driven exterior design customization platform, reflecting a broader industry shift toward digital specification support and end-user visualization. These moves are not isolated product launches; they signal a strategic reorientation toward sustainability messaging, installation efficiency, and specification-friendly digital tools, all of which are reshaping how buyers evaluate substrate options.
Market Dynamics: Cost Pressures, Regulatory Flux, and Material Economics
No strategic assessment of the backer board market is complete without confronting the macroeconomic and regulatory currents that influence material pricing, project feasibility, and procurement behavior. Cement and mineral-based substrates sit at the intersection of building material supply chains that are highly sensitive to trade policy, energy costs, and industrial capacity utilization. Recent trade actions have introduced tariff structures that affect cement imported from neighboring trading partners, with industry advocates cautioning that such measures could elevate project costs, delay infrastructure timelines, and complicate energy and security-related construction planning. These dynamics do not merely influence headline pricing; they alter contractor margin calculations, developer budgeting assumptions, and the relative attractiveness of alternative substrate formulations.
At the project level, builder associations have estimated that recent tariff-driven cost effects can add substantial per-home expenses, pressuring affordability thresholds and nudging specification decisions toward materials that balance performance with total installed cost. Simultaneously, higher input prices and intermittent availability constraints for certain raw materials are eroding purchasing power and tempering discretionary spending in segments where cost sensitivity is acute. Yet the broader production environment has shown resilience, with recent index movements indicating sustained industrial activity and capacity utilization that support ongoing material availability, albeit within a volatile pricing landscape.
These intersecting forces create a highly contextual demand environment. In high-end residential and commercial specification segments, performance and durability often justify premium substrate choices, insulating demand from short-term cost fluctuations. In more price-sensitive remodeling and volume development contexts, however, buyers are increasingly scrutinizing the trade-offs between traditional cement-based boards, lightweight alternatives, and gypsum-composite variants. The result is a market where material economics, installation labor considerations, and warranty expectations are being re-evaluated simultaneously, and where suppliers that can articulate clear total-cost-of-ownership advantages will capture disproportionate specification share.
Strategic Implications for 2026 Decision-Making
For executives operating in or adjacent to the backer board sector, the current environment demands a disciplined, data-informed approach to portfolio planning, sourcing strategy, and competitive positioning. The growth trajectory through 2032 is robust, but the path is uneven, shaped by regional construction cycles, regulatory adjustments, and material substitution dynamics that will vary significantly across application types and customer segments. Companies that treat the market as a monolithic commodity space risk misreading where margin pools are forming, where innovation premiums are sustainable, and where distribution leverage is most critical.
Our research is designed to convert that complexity into clarity. It provides the structural framework needed to evaluate product mix decisions, anticipate specification shifts, and align go-to-market investments with the segments where demand is most durable. By integrating historical performance tracking with forward-looking modeling, competitive profiling, and real-time industry developments, the report equips decision-makers with the context required to navigate pricing volatility, evaluate substitution threats, and identify partnership or expansion opportunities before the market fully prices them in.
The full study goes deeper, offering detailed segmentation analysis, company-level benchmarking, application-specific demand mapping, and scenario-based forecasting that unpacks the variables most likely to influence the next several years of market evolution. For procurement leaders, product strategists, and investment planners, that depth is not optional; it is the difference between reactive adjustment and proactive positioning.
To explore the complete dataset, competitive profiles, and forward-looking scenario analysis, access the full Backer Board Market research report. The detailed intelligence contained within is structured to support immediate strategic application, from sourcing renegotiation and product portfolio optimization to regional expansion planning and specification strategy refinement.
For detailed analysis of this topic, please visit the official page: Backer Board Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Real Estate Software Market Hits $10.6B in 2025, Poised for 8.95% CAGR Growth to 2032
By PW Consulting, 2026-09-16
Navigating the Next Wave: Strategic Intelligence for the Real Estate Software Market in 2026 and Beyond
The real estate technology landscape is undergoing a structural transformation. As property operations grow more complex and capital allocation becomes more scrutinized, software is no longer a back-office utility; it is the operational nervous system of modern real estate portfolios. At PW Consulting, we have published a comprehensive research study on the Real Estate Software Market, designed to equip executive teams, investors, and technology strategists with the decision-grade intelligence required to navigate 2026 and the subsequent forecast horizon through 2032.
This article previews the strategic architecture of that study. It outlines the market's directional momentum, the competitive forces reshaping vendor ecosystems, the regulatory and operational dynamics that will define procurement decisions, and the practical analytical frameworks contained in the full report. Per the preview methodology, we present the structural insights needed to evaluate opportunity and risk, while reserving the granular segmentation data and detailed quantitative breakdowns for the complete publication. To access the full intelligence suite, including region-level sizing, application-specific revenue splits, and company-level scenario modeling, readers are directed to the source publication page.
Market Trajectory and the Strategic Case for 2026
The macroeconomic backbone of this study rests on a clear, sustained growth arc. Historical revenue data from 2020 through the 2025 base year demonstrates consistent expansion, validating the sector's resilience through shifting interest-rate environments and evolving asset management priorities. Building on that historical foundation, the forecast period projects continued upward momentum, anchored by a compound annual growth rate of 8.95 percent across the 2026–2032 window.
What does this trajectory mean for enterprise decision-making? First, it signals that demand for real estate software is not cyclical in the traditional sense; it is being structurally reinforced by automation, data centralization, and the operational complexity of managing fragmented portfolios. Second, the forecast's forward curve implies that market consolidation and capability differentiation will accelerate in parallel with top-line growth. Organizations that delay technology evaluation or treat software selection as a purely tactical procurement exercise will face compounding integration costs and capability gaps as the market matures.
The full research quantifies this trajectory across the forecast horizon, mapping year-by-year revenue progression and contextualizing the inflection points where adoption accelerates. Rather than presenting a single headline figure, the study decomposes momentum into the drivers that matter for planning: deployment velocity, workflow automation penetration, and the shifting balance between property-level and enterprise-grade system adoption. These are precisely the variables that determine whether a technology investment compounds value or becomes a stranded asset.
Competitive Landscape: Nine Leaders Defining the Modern Stack
Market growth is always mediated by competitive dynamics, and this sector is no exception. Our analysis centers on a core group of established and rapidly evolving vendors whose product roadmaps, Go-to-market strategies, and recent corporate moves collectively define the shape of the market. The study profiles nine companies whose positioning spans property management automation, enterprise resource planning, customer relationship management, commercial real estate data and analytics, brokerage and transaction workflows, and marketplace-driven search and valuation tools.
Each profile is structured to answer the questions that procurement and strategy teams actually ask. What workflow layer does the vendor own today? Where is the product extending next? How does the company's historical capability translate into near-term differentiation in an environment where AI-assisted operations are becoming table stakes? The study evaluates each organization's operational emphasis, from AI-powered automation and mobile-first workflows to tenant screening, lease tracking, maintenance request orchestration, leasing marketing tools, resident engagement, multifamily workforce automation, portfolio-level commercial operations, marketplace search and agent tools, and transaction management with property valuation capabilities.
Beyond static profiles, the report integrates recent corporate and product developments that signal strategic intent. In May 2026, MRI Software advanced its thought leadership around building versus energy management systems and the operational distinctions between lease and license frameworks, reinforcing its focus on nuanced property operations. The same month, the company appointed Dermot Briody as Chief Revenue Officer, a move aligned with scaling global growth and intensifying client-success execution. These developments illustrate a broader pattern: leading vendors are simultaneously deepening domain expertise and expanding commercial capability to convert technical differentiation into market share.
Property Management Software Market
The competitive timeline continues with notable product and corporate actions in the first half of 2026. In April, RealPage introduced an AI-powered workforce management tool designed to automate leasing, finance, and resident engagement tasks, reinforcing the operational automation trend at the multifamily layer. In January, CoStar Group announced a comprehensive AI deployment across its marketplace platforms to enhance user experience and sharpen competitive positioning, while also authorizing a new $1.5 billion share repurchase program as part of an accelerating AI-driven growth strategy. These moves are not isolated product announcements; they are indicators of how incumbents are reallocating capital and engineering focus in response to intensifying platform competition and elevated user expectations.
The full study goes further by mapping these companies against concentration signals in the market. With the top three firms commanding a substantial share of total revenue and the top five extending that footprint even further, the environment rewards both deliberate vendor selection and an understanding of where platform extensibility will create switching-cost dynamics. Enterprise buyers must assess not only current functionality but also the probability that a given vendor will become a long-term portfolio anchor versus a specialized component in a multi-vendor architecture.
What the Competitive Analysis Enables
- A structured comparison of vendor emphasis across property management, enterprise resource planning, customer relationship management, commercial real estate analytics, and brokerage and marketplace tools, so teams can align software selection with operational priorities rather than feature checklists.
- Product roadmap signaling derived from recent launches and thought leadership, helping organizations anticipate where automation, compliance support, and data integration will mature fastest.
- Capital-allocation context from corporate actions, including leadership changes and platform investment decisions, which provide leading indicators of where vendors intend to compete most aggressively.
- Concentration-aware procurement strategy, enabling buyers to weigh platform breadth, integration risk, and long-term negotiation leverage when structuring technology stacks.
Segment-level revenue distribution, regional breakdowns, and application-specific sizing are included in the full publication to support precise budgeting and market-entry planning. They are intentionally held back from this preview because their strategic value is best realized when paired with the complete analytical framework, scenario assumptions, and methodology notes available in the source report.
Market Dynamics Shaping Procurement and Adoption
Revenue growth alone does not determine outcomes. The sector's trajectory is being remolded by regulatory mandates, operational constraints, and data-governance pressures that alter both demand and implementation risk. The study treats these dynamics as first-order variables in forecasting, not as footnotes.
On the regulatory front, compliance expectations are increasingly encoded into software requirements. The implementation of the EU Corporate Sustainability Reporting Directive is compelling real estate companies to build comprehensive ESG data collection and reporting capabilities into their operations, making sustainability-focused data architecture a procurement consideration rather than an optional add-on. In parallel, the General Data Protection Regulation continues to drive investment in compliance-oriented software across real estate workflows, particularly where tenant, owner, and transaction data intersect with cross-border operations and sensitive personal information.
Data privacy and security concerns are also shaping growth patterns by demanding specialized compliance and cybersecurity measures within real estate software environments. As platforms consolidate more operational, financial, and resident data into unified systems, the attack surface expands, and the cost of inadequate controls rises. The study addresses how these requirements affect vendor evaluation, implementation timelines, and the relative attractiveness of platforms with mature governance frameworks versus those still maturing their security posture.
A second dynamic constraint is talent. The shortage of skilled practitioners in data analytics and AI deployment is cited as a primary brake on adoption and implementation quality. Even when software capabilities are available, organizations can struggle to extract value if internal teams lack the analytical fluency to configure, interpret, and continuously optimize platforms. This has two strategic implications. First, it elevates the importance of vendor-provided enablement, onboarding rigor, and ongoing support models. Second, it raises the premium on solutions that reduce the analytical burden through intuitive workflows, guided configuration, and automation that delivers outcomes without requiring deep in-house data science capacity.
These dynamics do not cancel growth; they channel it. Markets expand fastest where technology providers and enterprise buyers can jointly reduce implementation friction, satisfy compliance obligations by design, and convert operational data into actionable insight. The full research assesses how these dynamics interact with segmentation, regional maturity, and application-level demand to explain where adoption is most likely to accelerate and where execution risk remains elevated.
What the Full Study Delivers
The report is built for executives who need to move from directional awareness to actionable planning. It combines market sizing, forecast architecture, competitive profiling, and dynamics analysis into a single decision framework, with enough operational specificity to inform budgeting, vendor selection, product strategy, and market-entry evaluation.
Operational content in the study includes:
- Historical and forecast revenue architecture spanning the base year through 2032, with year-by-year progression that supports multi-horizon planning rather than single-point estimation.
- Structural segmentation analysis that explains how the market divides across regional environments, software types, and application settings, providing the context needed to evaluate where demand concentrates and where whitespace may exist.
- Company-level profiles and recent-event integration for the core competitive set, allowing teams to benchmark vendors against workflow coverage, automation orientation, and strategic intent.
- Market concentration analysis that clarifies the balance between incumbent strength and competitive openness, helping buyers and investors gauge platform leverage, substitution risk, and consolidation potential.
- Regulatory and operational dynamics assessment, including ESG reporting requirements, data protection obligations, privacy and security expectations, and workforce capability constraints, all linked to their practical impact on adoption and implementation.
The study is intended to support a range of decisions: whether to consolidate around a unified platform or maintain a modular stack; how to sequence implementation to manage compliance, security, and change-management risk; which vendor capabilities represent durable advantages versus transient feature leadership; and how to align software strategy with portfolio composition and growth targets. By integrating quantitative direction with qualitative competitive and regulatory context, the report is designed to reduce the gap between market awareness and execution planning.
Why This Report Matters for 2026 Decision-Making
2026 is a pivotal year because the market's growth rate, competitive intensity, and regulatory expectations are converging at the same moment. Organizations that treat real estate software as a static procurement category will underestimate the pace at which automation, data governance, and platform consolidation are reshaping operating models. Organizations that wait for perfect clarity will find themselves competing against peers who made earlier, better-informed technology commitments.
The strategic value of this study lies in its ability to convert a high-level growth narrative into structured decision support. The 8.95 percent compound annual growth trajectory signals that the opportunity is large and durable, while the concentration patterns and competitive developments indicate that not all platforms will capture that opportunity equally. The regulatory and operational dynamics explain why some implementations accelerate and others stall, and why software selection has become closer to portfolio strategy than to IT procurement.
For investors, the report provides a basis for assessing where platform economics, product extensibility, and regulatory tailwinds align. For enterprise buyers, it offers a framework for evaluating vendor durability, integration risk, and implementation readiness. For technology strategists, it maps the capability gradients that separate short-term feature play from long-term operational advantage.
Accessing the Complete Intelligence
This preview has outlined the strategic logic, competitive structure, and dynamic pressures that define the real estate software market as it moves through 2026 and toward 2032. It has presented the macro growth arc, the vendor behaviors that signal where competition is intensifying, and the regulatory and talent dynamics that will shape adoption outcomes. What it has not done is unlock the full quantitative segmentation, regional and application-level revenue distribution, or the detailed scenario analysis that supports precise planning.
Those elements are contained in the complete study. To access the full set of market sizes, forecast breakdowns, segmentation insights, company profiles, concentration metrics, and dynamics analysis, please visit the source publication page. There, the complete intelligence is available in a form designed for executive review, strategy workshops, procurement evaluation, and investment analysis.
The real estate software market will continue to reward organizations that combine operational discipline with clear-eyed technology strategy. PW Consulting's research is intended to provide exactly that clarity: enough depth to trust the direction, enough structure to act on it, and enough detail to make 2026 decisions with confidence.
Real Estate Software Market
For detailed analysis of this topic, please visit the official page: Real Estate Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Smart Office Market to Hit $99.87M by 2032 with 7.98% CAGR - PW Consulting Insights
By PW Consulting, 2026-09-16
Unlocking the Next Wave: Strategic Intelligence in the Smart Office Market (2026-2032)
As organizations navigate the post-pandemic normalization of hybrid work, the definition of the modern workplace is undergoing a fundamental reconstruction. The smart office is no longer a futuristic concept; it has become a critical determinant of operational resilience, cost efficiency, and employee retention. At PW Consulting, we recognize that capital allocation decisions made in 2026 will define competitive positioning for the remainder of the decade. Our latest market research release, Smart Office Market 2026-2032, is designed not merely as a statistical compendium but as a strategic compass for executives, investors, and technology leaders.
This article serves as a strategic preview, outlining the macro-economic trajectory, competitive structures, and dynamic forces shaping the ecosystem. By understanding the broader contours, decision-makers can better appreciate the depth of intelligence available in the full report, where granular segmentation and actionable forecasts reside.
The Macro-Economic Trajectory: Growth Anchored in Digital Transformation
The smart office market is experiencing a robust expansion phase driven by the convergence of IoT, AI, and sustainability mandates. Our analysis, anchored in historical data from 2020 through 2025 and projecting forward to 2032, reveals a consistent upward trajectory that defies broader economic volatility. The market valuation has demonstrated steady acceleration, moving from approximately 40.1 million USD in 2020 to an estimated 58.65 million USD in 2025. This historical performance sets the stage for a significant growth phase in the forecast period.
Looking ahead to 2026 and beyond, the momentum is expected to intensify. The market is projected to reach 62.88 million USD by 2026, with continued expansion toward the 99.87 million USD range by 2032. This growth path reflects a compound annual growth rate of 7.98 percent over the forecast period. Such a rate indicates that smart office technologies are transitioning from discretionary upgrades to essential infrastructure. For enterprise leaders, this trajectory suggests that delaying investment carries an opportunity cost, not only in terms of operational inefficiency but also in missing the window of early-adopter advantage.
It is crucial to note that these figures represent the broader market aggregate. The full report at PW Consulting decomposes this growth into nuanced segments that reveal where capital is flowing most aggressively. Early indicators suggest that certain categories are outpacing the average CAGR, driven by specific technological breakthroughs and regulatory pressures. However, identifying the precise winners and losers within vertical and geographic splits requires the detailed breakdowns provided in our paid intelligence suite. The aggregate numbers provide the confidence to invest; the segmentation provides the roadmap for allocation.
Competitive Dynamics: A Consolidated Battlefield
The market structure is characterized by a high degree of concentration, signaling maturity and the need for scale. Our analysis indicates that the top three competitors hold a combined market share of approximately 55.0 percent, while the top five entities control 62.0 percent. This concentration suggests that while the market is growing, the battleground for share is intense among established giants and specialized disruptors alike. Understanding the strategic positioning of these key players is vital for companies seeking partnerships or assessing competitive threats.
The landscape is dominated by large industrial and technology conglomerates that leverage diverse portfolios. Johnson Controls, headquartered in Milwaukee, Wisconsin, focuses heavily on IoT-enabled building management platforms that integrate occupancy sensing with HVAC and lighting automation. Similarly, Honeywell International, based in Charlotte, North Carolina, provides AI-powered occupancy sensors and integrated platforms designed for energy optimization in hybrid environments. Siemens AG, from Munich, Germany, offers IoT-enabled suites tailored for human-centric spaces, emphasizing adaptive systems for enterprise retrofits. Schneider Electric, located in Rueil-Malmaison, France, delivers building automation platforms that focus on multi-parameter environmental monitoring and energy management.
Beyond the heavy industrial players, the ecosystem includes specialized technology providers. Signify N.V., based in Eindhoven, Netherlands, manufactures the Interact Office occupancy intelligence platform, utilizing dense sensor networks for utilization optimization. Cisco Systems, from San Jose, California, integrates networking and security with IoT solutions to create connected hybrid workspaces. IBM, headquartered in Armonk, New York, develops Intelligent Workplace Management System platforms focused on space utilization analytics and cost reduction. Crestron Electronics, in Rockleigh, New Jersey, provides next-generation control systems with touchless interfaces and automation.
Smart Building Market
A second layer of innovation comes from niche players and software-focused firms. Framery, based in Helsinki, Finland, supplies smart seating and workspace solutions with real-time Space Overview software for booking management. Envoy, from Austin, Texas, offers workplace management software platforms addressing hybrid-work dynamics and visitor experience. Density, located in San Francisco, California, specializes in plug-and-play occupancy sensors for real-time people counting. viaim, also in San Francisco, develops AI-powered hardware including earbuds and tools for voice recording and transcription. Butlr, based in New York, New York, provides thermal occupancy sensors for anonymous people counting. XY Sense, also in San Francisco, manufactures enterprise occupancy sensors for utilization and sustainability integration.
Our full report provides a detailed comparative analysis of these entities, including their strategic moves, product roadmap alignment, and vulnerability assessments. For instance, recent developments such as viaim's launch of AI voice recorder earbuds and NoteKit tools in June 2025, or Framery's software launch for real-time free-space booking in January 2025, signal shifting priorities toward seamless collaboration and flexibility. Furthermore, industry bodies like AVIXA published guidelines in August 2025 regarding IoT security solutions, highlighting the critical intersection of connectivity and risk. These events are markers of the rapidly evolving competitive terrain that our analysis tracks in real-time.
Market Dynamics and Critical Friction Points
Growth is not without its complexities. The expansion of smart office infrastructure introduces significant dynamics around security, privacy, and regulatory compliance that can impact deployment strategies. As organizations deploy sensors and connected devices, the data generated can reveal patterns about employee behavior, workspace usage, and company operations. This sensitivity necessitates robust cybersecurity measures. The NIST Cybersecurity Framework provides flexible guidelines for identifying, protecting, detecting, responding to, and recovering from cyber incidents in these environments. Ignoring these protocols can expose firms to reputational and financial risk.
Data privacy remains another pivotal concern. GDPR requires transparent handling of personal data and empowers individuals with rights over their information in smart office IoT deployments. Compliance is not optional; it is a foundational requirement for scaling smart office solutions, particularly in regions with stringent data protection laws. Our report delves into the specific compliance landscapes that vary by jurisdiction, offering guidance on how to structure deployments that satisfy regulatory bodies without stifling innovation.
On the structural side, material costs and implementation strategies play a crucial role. Retrofit implementations of smart office solutions enable organizations to improve existing systems without the significant expenses tied to new construction. This factor is accelerating adoption rates among companies with legacy buildings. Additionally, regulatory frameworks are acting as demand pullers. The European Commission Directive 2024/1275 on the Energy Performance of Buildings imposes binding renovation quotas that pull forward demand for building automation in smart offices. These regulatory tailwinds are reshaping the investment thesis, making energy-efficient smart office technologies a compliance necessity as well as an operational choice. Determining the exact impact of these directives on regional demand requires the granular analysis found in the complete market study.
Smart Office Market
Operational Utility and Content Depth of the Report
PW Consulting's Smart Office Market report is engineered for immediate application. It moves beyond high-level trends to provide the specific intelligence required for budgeting, vendor selection, and market entry strategies. The report covers a forecast period from 2026 to 2032, building on a historical baseline from 2020. This long-view perspective allows strategists to model multiple scenarios and stress-test their plans against market volatility.
Inside the full document, readers will find detailed segmentation analysis that dissects the market by region, type, and application. While the aggregate market size provides the macro view, the segmentation reveals the specific drivers behind the numbers. For example, the report examines the relative performance of categories such as Security and Access Control Systems, Energy Management Systems, Smart HVAC Control Systems, Smart Lighting and Controls, Audio-Video Conferencing Systems, and Other Products. Understanding the revenue contribution and growth momentum of each category helps technology leaders prioritize R&D and procurement. Similarly, the application segmentation covers Corporate Offices, SMEs, Educational Institutions, Government Offices, and Healthcare Facilities. Identifying which application sector is driving the highest value capture is essential for solution providers targeting their sales efforts.
Furthermore, the report includes a rigorous analysis of regional dynamics. Global expansion patterns are influenced by local infrastructure readiness, funding availability, and regulatory environments. The full intelligence brief breaks down the market presence across key geographies, allowing multinational corporations to tailor their rollout strategies. We also provide a comprehensive competitor benchmarking matrix that evaluates market share, product portfolio strength, and strategic alliances. This tool is indispensable for M&A due diligence and partnership evaluation.
The report also integrates qualitative insights from industry experts and recent development tracking. We analyze product launches, software updates, and guideline publications that alter the competitive balance. For instance, the recent focus on cybersecurity standards by AVIXA and the continuous innovation from companies like Density and XY Sense in sensor technology are tracked to help clients anticipate market shifts. These insights are synthesized into actionable recommendations for navigating the complexities of project implementation, vendor negotiation, and risk management.
Why This Intelligence Matters for 2026 Decision-Making
In the current economic climate, precision is paramount. General market knowledge is insufficient for securing budget approval or defining a technology roadmap. Stakeholders require evidence-based forecasts that account for regulatory changes, technological disruptions, and competitive responses. The 7.98 percent CAGR and the projected growth toward 99.87 million USD by 2032 provide a strong narrative for growth, but the strategic value lies in knowing exactly where that growth is concentrated.
For investors, the market concentration metrics and competitor profiles offer a lens into market stability and potential consolidation opportunities. For technology vendors, the segmentation data highlights underserved niches and high-growth applications. For end-user organizations, the analysis of retrofit feasibility and energy mandates informs capital expenditure planning. The full report at PW Consulting consolidates these disparate data points into a coherent strategy document.
We invite you to explore the complete Smart Office Market 2026-2032 research. The preview above outlines the scope and strategic relevance, but the proprietary data, detailed segmentation splits, and actionable recommendations are available exclusively through our source page. Access the full report to gain the competitive edge needed to navigate the evolving landscape of the smart workplace.
For detailed analysis of this topic, please visit the official page: Smart Office Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cryogenic Freezers Market Hits $150M in 2025, 5.9% CAGR to $221.6M by 2032
By PW Consulting, 2026-09-16
Unlocking Strategic Value: The Cryogenic Freezers Market Outlook for 2026 and Beyond
The global cryogenic freezers market stands at a pivotal juncture in 2026. As life sciences research accelerates, biopharmaceutical manufacturing scales, and clinical biobanking becomes a cornerstone of modern healthcare infrastructure, the demand for ultra-low temperature storage solutions has never been more critical. For enterprises operating in this ecosystem, navigating the complexities of market growth, competitive positioning, and regulatory compliance requires more than superficial market summaries. It demands a rigorous, data-backed strategic intelligence framework.
This article serves as a strategic primer for our latest comprehensive market research on the Cryogenic Freezers Market. By synthesizing historical performance trends, forward-looking growth trajectories, competitive dynamics, and real-time procurement signals, this report equips decision-makers with the analytical depth required to make informed investments, capacity planning, and partnership strategies throughout the 2026-2032 forecast horizon.
Worldwide Cryogenic Market
Market Trajectory: From Recovery to Sustained Expansion
The cryogenic freezers market has demonstrated a clear upward trajectory over the past half-decade, reflecting the compounding effects of biological sample preservation mandates, increased clinical trial activity, and the expansion of advanced therapy manufacturing. Historical data from 2020 through 2025 reveals a market that has consistently expanded its revenue base, accelerating from approximately 115.0 million USD in 2020 to roughly 150.0 million USD by 2025. This growth underscores a structural shift rather than a temporary cycle, as institutions worldwide continue to invest in cold-chain resilience and long-term specimen archiving capabilities.
Looking ahead, the forecast period spanning 2026 to 2032 projects continued expansion with a compound annual growth rate of 5.9 percent. By 2032, the market is positioned to reach an estimated 221.6 million USD. This trajectory is not linear; it reflects evolving procurement cycles, regional deployment patterns, and the gradual adoption of higher-efficiency storage architectures. For strategic planners, this growth curve signals both opportunity and timing sensitivity. Early movers who align their product portfolios, service infrastructure, and distribution networks with the forecasted demand inflection points will be best positioned to capture market share as the decade progresses.
Structural Dynamics Shaping Competitive Advantage
The cryogenic freezers market is characterized by a moderately concentrated competitive landscape. Industry analysis indicates that the top three players command a combined market share of approximately 60 percent, while the top five collectively control around 65 percent of total revenue. This concentration reflects the capital-intensive nature of cryogenic equipment manufacturing, the importance of regulatory certifications, and the long-term contracts typical of laboratory and clinical procurement cycles. Yet the remaining 35 percent of the market remains accessible to specialized manufacturers, regional suppliers, and innovators who can differentiate through application-specific engineering, energy efficiency, or service agility.
Several structural dynamics are actively reshaping how value is created and captured in this space. First, regulatory compliance has emerged as a decisive gatekeeper. Manufacturers whose cryogenic freezers and associated storage units maintain formal listings with the Food and Drug Administration, or have secured recent FDA approvals for specific models such as helium-based cryogenic units, are gaining preferential access to hospital networks, government procurement programs, and regulated biopharma supply chains. Second, procurement signals from public health institutions are illustrating a broader trend: defense and military medical facilities are increasingly specifying liquid nitrogen-type cryogenic freezers for pathology and specimen storage, reinforcing the strategic importance of reliable cold-chain infrastructure in government health systems.
Third, product innovation cycles are accelerating. Recent product launches highlight a clear industry focus on ergonomics, high-efficiency cooling architectures, and specialized form factors designed for fertility clinics, biorepositories, and clinical laboratories. These developments are not merely engineering milestones; they represent strategic responses to end-user workflow constraints, space limitations, and the growing demand for operator-safe handling of liquid nitrogen systems. Companies that integrate these operational considerations into their product roadmaps are likely to secure stronger customer retention and more favorable procurement positioning.
Operational Intelligence Embedded in the Full Report
Beyond macro-level growth projections and competitive concentration metrics, the complete market research report delivers a granular operational playbook tailored for commercial, R&D, and procurement leaders. The study systematically maps out the segmentation architecture that defines how customers evaluate, procure, and deploy cryogenic freezing technologies. Readers will gain access to detailed breakdowns that clarify which equipment categories dominate current procurement pipelines, how different application sectors prioritize storage specifications, and which geographic markets exhibit the strongest near-term deployment momentum.
The report also incorporates a rigorous competitive profiling framework. Each major participant is evaluated across dimensions that matter to enterprise decision-makers: geographic presence, core product capabilities, recent developmental milestones, and strategic positioning within regulated and research-intensive segments. Profiles cover manufacturers specializing in liquid nitrogen vapor freezers, controlled-rate freezing systems, automated storage architectures, and hybrid cascade refrigeration solutions. By examining these profiles in context, the report enables readers to identify partnership opportunities, assess competitive threats, and benchmark their own strategic posture against established incumbents.
In addition, the full study integrates regulatory tracking, procurement intelligence, and product launch monitoring into a unified analytical structure. This means readers do not need to piece together fragmented press releases or manually cross-reference bidding notices. Instead, they receive a consolidated view of how regulatory approvals, government invitations for bids, and commercial product introductions are interacting to shape demand timing, supply chain readiness, and competitive intensity across the forecast window.
Competitive Landscape: Established Leaders and Evolving Positioning
The competitive environment in cryogenic freezers is anchored by a set of well-established manufacturers with deep roots in life sciences, biomedical storage, and specialized cold-chain equipment. Several of these companies have built reputations around liquid nitrogen-based storage systems, ultra-low temperature freezers, and controlled-rate freezing platforms that serve clinical, research, and biopharmaceutical applications. Their product portfolios reflect a strategic emphasis on long-term sample integrity, operational reliability, and compatibility with regulated laboratory workflows.
Cryogenic Freezers Market
At the same time, the landscape is not static. Hybrid refrigeration technologies, helium-enabled cryogenic designs, and automated storage solutions are expanding the technical boundaries of what end-users expect from modern cryogenic infrastructure. Some manufacturers are pushing into highly specialized niches, such as high-efficiency series designed for fertility clinics and biorepositories, while others are reinforcing their standing through FDA clearances or targeted government procurement eligibility. This diversification of technological approaches and end-market focus is creating a more multidimensional competitive arena, where success depends not only on hardware performance but also on compliance readiness, service coverage, and alignment with institutional procurement cycles.
The report's competitive analysis digs into these nuances. Rather than presenting static company summaries, it evaluates how each organization is adapting to shifting demand signals, regulatory expectations, and application-specific requirements. Readers will be able to discern which manufacturers are strengthening their positions through product launches, which are expanding their footprint through specialized storage systems, and where potential whitespace opportunities may exist for new entrants or existing players seeking to broaden their addressable market.
Why This Research Matters for 2026 Decision-Making
For executives, procurement strategists, and market entry planners, 2026 represents a critical year for calibrating cryogenic storage strategies. The convergence of sustained market growth, regulatory-driven procurement preferences, and accelerating product innovation means that timing, positioning, and evidence-based forecasting are more important than ever. Companies that rely on outdated market snapshots or generalized industry narratives risk misallocating capital, overlooking emerging demand pockets, or entering competitive segments without a clear differentiation strategy.
This market research report is designed to remove that uncertainty. It translates historical performance data into actionable forward-looking insights, contextualizes competitive concentration within real-world procurement dynamics, and highlights the regulatory and operational factors that are currently shaping buyer behavior. Whether the objective is to evaluate capacity expansion, assess partnership or acquisition targets, refine product development roadmaps, or strengthen bids for institutional contracts, the study provides the analytical scaffolding needed to make defensible, data-informed decisions.
Importantly, the report also helps organizations anticipate where demand will likely concentrate and how competitive intensity may evolve as the decade progresses. By understanding which segments are gaining momentum, which regulatory developments are altering procurement eligibility, and how leading manufacturers are adjusting their portfolios, enterprises can build more resilient strategies that account for both near-term opportunities and longer-term structural shifts.
Path Forward: Turning Intelligence into Action
The cryogenic freezers market is entering a phase where strategic clarity will separate leaders from followers. The next several years will reward organizations that combine operational discipline with sharp market intelligence, that respect the importance of regulatory readiness, and that align their capabilities with the practical needs of laboratories, clinical facilities, and biopharmaceutical operations. Our comprehensive report provides the depth, structure, and forward-looking perspective required to navigate this environment with confidence.
For decision-makers seeking a complete view of market sizing, segmentation dynamics, competitive positioning, regulatory tracking, and procurement intelligence across the 2026-2032 period, the full study offers the detailed evidence base needed to support strategic planning and execution. We invite you to access the complete report to obtain the granular data, segment-level analysis, and actionable recommendations that will inform your next strategic moves in this evolving market.
For detailed analysis of this topic, please visit the official page: Cryogenic Freezers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


