



Category: market research
PW Consulting Report: Prosthetic Foot Market Hits $830M in 2025, Projecting 6.4% CAGR to 2032
By PW Consulting, 2026-09-16
Navigating the Next Wave: Strategic Intelligence for the Prosthetic Foot Market (2026–2032)
The prosthetic foot market stands at a critical inflection point. Beyond the first prosthetic foot enabling basic ambulation, modern solutions are now engineered to restore high-impact mobility, adapt to variable terrains, and seamlessly integrate with the user’s biomechanical profile. As healthcare systems evolve, reimbursement frameworks tighten, and demographic shifts accelerate demand, stakeholders require more than surface-level market summaries. They need a precise, forward-looking intelligence framework that translates macro trends into actionable commercial and clinical strategies. The forthcoming Prosthetic Foot Market research delivers exactly that: a rigorous, evidence-based roadmap designed to inform capital allocation, product portfolio decisions, and go-to-market positioning through 2032.
Macro Trajectory: How Structural Shifts Are Reshaping the Market
Over the past half-decade, the prosthetic foot sector has demonstrated steady, compounding growth, recovering strongly from pandemic-era supply and demand disruptions and entering a phase of sustained expansion. From a baseline established in 2020, the market has tracked a consistent upward curve, crossing the 700-million threshold by 2023 and accelerating toward an estimated 830 million in 2025. Forward projections indicate that this momentum will carry the market well past the one-billion milestone during the late 2020s, ultimately approaching a valuation near 1.27 billion by 2032. The compound annual growth rate underpinning this trajectory sits at 6.4 percent, a figure that reflects not only rising prevalence of limb loss conditions but also the broadening adoption of advanced prosthetic technologies, improved reimbursement accessibility, and an expanding pipeline of active, mobility-focused end users.
This growth is not uniform across product categories or patient demographics, and that uneven distribution holds vital strategic implications. Advanced microprocessor-controlled prosthetic feet are capturing an increasing share of clinical preference, driven by superior gait symmetry, fatigue reduction, and adaptability to complex environments. Yet mechanical feet remain foundational, sustaining broad volume across diverse payer environments and activity-level classifications. Meanwhile, the demand base is bifurcating: adult users continue to anchor core volume, while pediatric and adolescent segments are growing as early-intervention protocols mature and long-term mobility outcomes gain prominence in clinical guidelines. Understanding how these demand streams interact—and where margin pools actually concentrate—requires granular, segment-level analysis that goes far beyond headline numbers.
What the Research Delivers: Actionable Intelligence for 2026 Decision-Makers
This study is built for practitioners who must make time-sensitive, resource-intensive decisions in a highly regulated, technology-intensive market. Rather than offering retrospective summaries, the report anchors its analysis in a structured forecast architecture covering the 2026–2032 horizon, calibrated against a transparent historical baseline spanning 2020 through 2025. The methodology is intentionally designed to support scenario planning, portfolio rationalization, and competitive positioning with precision.
Readers will find a multidimensional dissection of demand drivers, sales channels, and end-use adoption patterns, with particular attention to how activity-level classifications shape product-mix economics. The analysis unpacks the interplay between rehabilitation trajectories, payer policies, and prosthetic design requirements, enabling manufacturers, distributors, and service providers to anticipate where volume and value will shift next. Pricing architectures, reimbursement sensitivity, and component-level substitution dynamics are examined to clarify which product formats carry durable margin resilience and which face structural compression under evolving payer scrutiny.
Equally important, the research supplies the operational scaffolding needed to translate market signals into execution. Demand forecasts are mapped against realistic penetration ceilings, capacity considerations, and regional procurement behaviors. Strategic questions—such as whether to prioritize modular design ecosystems, where to concentrate advanced-technology commercialization efforts, and how to align clinical education campaigns with payer-aligned prescribing patterns—are addressed through a lens of commercial realism rather than theoretical optimism.
Competitive Arena: Where Leaders Are Winning—and Where the Gaps Remain
The competitive landscape is defined by a concentrated set of established players, each leveraging differentiated engineering philosophies, clinical relationships, and geographic footprints. Market concentration underscores this reality, with the top three firms collectively representing a substantial share of total revenue, and the top five extending that dominance even further. This structure rewards companies that can combine product reliability, clinical validation, and responsive commercialization while penalizing those that rely on undifferentiated volume plays.
Ottobock SE & Co. KGaA continues to reinforce its position through a dual-track portfolio that pairs mechanical strength with intelligent adaptation. Its Taleo and Evanto mechanical prosthetic feet target active users who demand durability and predictable energy transfer, while its microprocessor-controlled offerings extend the company’s reach into higher-complexity mobility scenarios. This balance allows Ottobock to serve both cost-sensitive and performance-oriented procurement pathways without diluting brand coherence.
Össur hf has built its reputation on dynamic, terrain-responsive design, and its current lineup reflects that philosophy with precision. The Proprio Foot, Pro-Flex family, Balance Foot, and Cheetah series are engineered to address variable walking conditions and high-activity demands. By emphasizing gait adaptability and user confidence across uneven surfaces, Össur positions itself squarely in the performance segment where functional outcomes often dictate purchasing decisions.
Blatchford Limited takes a different route, focusing on high-impact resilience and modular engineering. Its BladeXT e-carbon foot and Echelon series are oriented toward users who push beyond routine ambulation, requiring robust load handling and responsive energy return. The emphasis on active and high-demand user profiles gives Blatchford a clear niche in markets where clinical protocols prioritize return-to-activity outcomes.
College Park Industries contributes to the competitive mix with a focus on biomechanically tuned dynamic feet. The Soleus and Trustep lines highlight energy return and hydraulic modeling, meeting the needs of users who require smoother gait transitions and durable daily-use performance. This orientation appeals to clinicians seeking reliable, functionally versatile options across a broad activity spectrum.
Fillauer LLC strengthens the field with performance-oriented modular solutions. Its Aeris Performance line, alongside bio-attributed PVC shell designs, speaks to an expanding appetite for customizable, modular foot systems that can be adapted to individual residual limb characteristics and activity requirements. This modularity-centric approach aligns with broader industry trends favoring adaptability and component-level servicing.
WillowWood Global LLC has moved to deepen its market relevance through both product engineering and partnership strategy. Its MetaShock dynamic feet and modular component sets are designed for users operating at K3 and K4 activity levels, while its December 2025 strategic partnership with Click Medical signals a clear push toward user-specific prosthetic solutions. Such collaborations reflect a wider industry shift toward personalized fitting workflows and integrated care models.
Worldwide 3D Printed Prosthetic Hands Market
Streefedered KG rounds out the competitive picture with modular systems built for customization. Its Vari-Flex line and modular foot configurations cater to practitioners who value flexible component selection and patient-specific tuning, reinforcing the market’s ongoing emphasis on individualized mobility solutions. Endolite adds further depth with its broad portfolio of components and feet engineered for varied amputation levels, supporting clinical teams that require scalable, level-appropriate solutions across diverse patient populations.
The strategic implication for stakeholders is clear: pricing power, channel access, and clinical adoption will increasingly favor companies that can integrate product differentiation with reimbursement alignment and service scalability. Firms that treat these dimensions as separate workstreams will find themselves outmaneuvered by competitors who treat them as a unified commercial architecture.
2026 Reimbursement Realities: Why Policy Is Now a Product Strategy Variable
One of the most consequential developments shaping near-term decision-making is the reconfiguration of payer coding and reimbursement pathways. In March 2026, the Centers for Medicare & Medicaid Services announced final determinations for lower extremity prosthetics, including the introduction of a new HCPCS code, L5992. Effective April 1, 2026, this code is designated for replacement of foot shells in modular or non-solid ankle cushion heel prosthetic feet and is separately payable at a rate of 127.11 dollars. The same determinations clarify that foot covers remain included within base foot component codes and are not separately payable.
For manufacturers, distributors, and prosthetic service providers, this is not merely a compliance update. It is a structural input into product economics, service-model design, and portfolio prioritization. Separately payable foot-shell replacement creates a distinct revenue touchpoint that can influence how modular systems are positioned, how service contracts are structured, and how clinical teams approach long-term component maintenance. At the same time, the explicit exclusion of foot covers from separate reimbursement reinforces the importance of base-component pricing discipline and value communication.
These reimbursement dynamics interact directly with broader market concentration and product-mix trends. In a market where a limited number of firms already command the majority of revenue, reimbursement shifts can accelerate consolidation advantages, reward companies with clearer modular articulation, and pressure players whose economics depend on blended, less-transparent pricing. Companies that fail to map reimbursement changes onto their product architecture risk mispricing innovation, misaligning sales incentives, or under-serving the maintenance needs that drive long-term patient retention.
Where Strategic Focus Should Land in 2026
As the market advances toward the 2032 horizon, the most successful organizations will be those that treat product development, reimbursement intelligence, and commercial execution as tightly coupled systems. Several strategic priorities stand out.
First, segmentation precision must move from retrospective reporting to forward-looking portfolio design. Volume concentration across adult and pediatric populations, and across mechanical and microprocessor-controlled categories, will shape where R&D dollars produce the strongest commercial returns. Companies that can identify the highest-value intersection of activity level, reimbursement compatibility, and clinical preference will deploy capital more efficiently than those pursuing blanket expansion.
Second, reimbursement navigation is now a core competitive capability. The L5992 pathway, along with broader payer scrutiny on component-level billing, demands that commercial teams understand not just price points but the operational logic of claims, coverage rules, and service cycles. Alignment between clinical messaging, product documentation, and reimbursement architecture will differentiate firms that can secure consistent procurement from those that face repeated reimbursement friction.
Third, partnership and modularity strategies will increasingly determine market agility. The recent WillowWood–Click Medical collaboration illustrates a broader pattern: the market is moving toward more individualized fitting, integrated service delivery, and component ecosystems that reduce friction across the patient journey. Firms that can embed themselves in these workflows—through engineering compatibility, distribution relationships, or joint solution design—will be better positioned to capture sustained demand.
Prosthetic Foot Market
Finally, competitive positioning will hinge on the ability to communicate differentiated clinical value without overpromising on outcomes that payers and clinicians will scrutinize. High-impact designs, terrain-adaptive mechanics, and microprocessor intelligence each solve real user problems, but their commercial success depends on clear reimbursement alignment, credible clinical evidence, and service models that sustain performance over time. In a concentrated market, reputation and reliability can be as decisive as feature sets.
Why the Full Report Matters Now
The prosthetic foot market is no longer defined solely by volume growth. It is being reshaped by reimbursement architecture, product modularity, competitive concentration, and the accelerating expectation that prosthetic solutions should support high-function, real-world mobility. The 6.4 percent CAGR and multi-year revenue trajectory signal opportunity, but opportunity without segmentation insight, reimbursement literacy, and competitive clarity can easily translate into misallocated investment or missed positioning windows.
This research was designed to close that gap. It provides the analytical depth required to evaluate where demand is genuinely expanding, which product and service architectures are most resilient under current payer conditions, and how leading players are structuring their portfolios to defend or extend market share. The macro numbers offer direction; the segment-level dynamics, competitive profiles, and reimbursement-sensitive economics offer the precision needed to act.
Organizations preparing product launches, portfolio reviews, capacity planning, or regional market entry in 2026 will find the full report essential for stress-testing assumptions and prioritizing moves with the highest strategic payoff. Complete segmentation breakdowns, forward scenario analysis, and detailed competitive benchmarking are available in the full study. Readers seeking the complete intelligence framework, including the granular data necessary to translate these market signals into execution-ready plans, are encouraged to access the full report through the source page.
For detailed analysis of this topic, please visit the official page: Prosthetic Foot Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Speed Reducers Market to Hit $18.79B by 2032, Growing at 8.4% CAGR
By PW Consulting, 2026-09-16
Strategic Outlook 2026: Navigating the Speed Reducers Market Landscape
Executive Summary
The global industrial landscape is undergoing a profound transformation, driven by automation, efficiency mandates, and supply chain realignments. At the heart of these mechanical systems lie speed reducers, critical components that ensure precise torque control and operational reliability across diverse sectors. As we move deeper into 2026, understanding the trajectory of this market is no longer optional for strategic planners; it is a necessity. This article serves as a precursor to our comprehensive market research report, offering a high-level view of the forces shaping the industry while highlighting the depth of intelligence available to stakeholders who seek a competitive edge.
The speed reducers market has demonstrated remarkable resilience and growth over the past half-decade. Based on our analysis, the market value reached approximately 10,681.55 million USD in 2025, building upon a steady historical trajectory from 2020. The momentum shows no signs of slowing, with projections indicating a climb toward 18,786.21 million USD by 2032. This expansion is underpinned by a Compound Annual Growth Rate (CAGR) of 8.4 percent during the forecast period of 2026 to 2032. Such figures suggest more than mere inflation; they point to genuine industrial uptake and technological integration that demands attention from C-suite executives and investment committees alike.
Speed Reducers Market
Market Trajectory and Macro-Economic Drivers
Understanding the historical context is vital for validating future projections. The market valuation has consistently escalated from 7,136.54 million USD in 2020 to the 2025 baseline. This upward curve reflects broader industrial health, yet the forecast period introduces new variables. The growth from 11,235.94 million USD in 2026 to over 18,000 million USD by 2032 implies a significant acceleration in demand. This is not merely a continuation of past trends but suggests a shift in how power transmission systems are valued and utilized in modern engineering contexts.
Several macroeconomic factors are fueling this expansion. The push for energy efficiency in manufacturing plants requires machinery that minimizes power loss during transmission. Speed reducers play a pivotal role here, converting high-speed motor output into high-torque, low-speed application requirements. Furthermore, the ongoing modernization of legacy infrastructure in developed economies, coupled with rapid industrialization in emerging markets, creates a dual-engine growth scenario. However, navigating this landscape requires more than top-line numbers; it requires an understanding of where the value is concentrated and how risks are distributed.
Competitive Landscape and Corporate Intelligence
The market structure is characterized by a moderate level of concentration, indicating a mix of dominant players and specialized niche providers. Our analysis indicates that the top three companies hold a significant portion of the market share, while the top five extend this influence further. This concentration suggests that while there is room for innovation, scale and established distribution networks remain critical advantages. The competitive field is global, featuring legacy manufacturers from Europe and North America alongside agile innovators from Asia.
Prominent entities such as SEW-Eurodrive, headquartered in Bruchsal, Germany, continue to set standards in integrated drive systems. Their focus on combining helical, worm, and bevel-helical reducers with electric motors highlights a trend toward simplification and ease of integration for industrial automation. Similarly, Sumitomo Heavy Industries in Tokyo maintains a strong foothold in heavy-duty sectors, supplying large speed reducers and cycloidal units for mining and steel applications. These companies represent the established backbone of the industry, providing reliability for high-load environments.
On the precision front, Nidec Corporation and Harmonic Drive LLC are pivotal. Nidec Shimpo's focus on planetary and cycloidal reducers for robotics and machine tools aligns with the broader automation surge. Harmonic Drive, based in Peabody, Massachusetts, specializes in strain-wave technology, catering to the stringent requirements of medical equipment and precision machinery. Meanwhile, North American manufacturers like Bonfiglioli, ABB Baldor, Boston Gear, and Nord Drivesystems offer comprehensive solutions ranging from standard components to custom-industrial packages. Companies like Winsmith and Broadwind focus on heavy-duty custom assemblies, ensuring that specific torque and load requirements are met without compromise.
Recent activity among these key players underscores the dynamic nature of the sector. In early 2026, Winsmith announced a new line of aluminum round and square speed reducers, signaling a shift toward lightweight materials and modular housing designs. Participation in major trade events such as IPTEX GRINDEX and AISTech by entities like Regal Rexnord and various gear specialists demonstrates the industry's commitment to showcasing metal industry solutions and high-speed epicyclic units. These developments are not isolated; they are signals of strategic pivots toward material innovation and specific industry vertical solutions.
Segmentation Dynamics: Type and Application
To make informed decisions, one must look beyond the aggregate number. The market is divided by technology type, with gear reducers historically commanding the largest share due to their versatility and durability. Worm wheel reducers, planetary gears, cycloid reducers, and harmonic drives each serve distinct operational niches. For instance, while planetary gears offer high efficiency and compactness suitable for robotics, cycloid reducers are preferred for heavy-duty shock load resistance. Understanding the share and growth potential of each type is crucial for product portfolio planning.
Application sectors also drive demand diversity. The industrial sector remains the primary consumer, reflecting the broad use of speed reducers in general machinery and automation. However, significant volume is also generated by the food industry, mining industry, and construction industry. Each sector imposes unique constraints. Food processing requires hygiene-compliant materials and sealing, mining demands extreme durability under abrasive conditions, and construction needs mobility and ruggedness. A strategic supplier must align its product engineering with these specific application demands. Our research delves into the revenue contribution and growth rates of each application segment, identifying where the highest margins and fastest growth intersect.
Regional Insights and Supply Chain Considerations
Geographically, the market is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Asia Pacific represents a massive volume hub, driven by manufacturing capacity and local industrial growth. North America and Europe remain critical for high-value, precision applications and aftermarket services. Latin America and the Middle East and Africa offer emerging opportunities tied to infrastructure projects. However, regional performance is not just about sales volume; it is about supply chain resilience.
The cost of raw materials remains a primary concern. High-grade cast iron, steel forgings, and specialized alloys constitute a significant majority of the manufacturing cost for speed reducers. Volatility in these inputs can compress margins significantly. Strategic procurement and vertical integration are becoming differentiators. Companies that secure stable supply lines for critical alloys or invest in additive manufacturing for complex gear components may gain a cost advantage. Furthermore, logistics and localization strategies are evolving to mitigate geopolitical risks and reduce lead times for customers in critical regions.
Regulatory Frameworks and Technical Standards
Compliance is another layer of complexity defining the 2026 landscape. Technical standards ensure interoperability and safety, but they also act as barriers to entry for non-compliant manufacturers. The American Gear Manufacturers Association (AGMA) continues to provide essential classifications for designing and maintaining reliable power transmission systems. Adherence to these standards is often a prerequisite for tendering in large industrial projects.
Beyond general manufacturing standards, specific operational regulations are coming into force. The ISO 15016:2025 specification for the assessment of speed and power performance by analysis of speed trial data entered into force on May 1, 2026. This regulation impacts how performance is validated, particularly in marine and mobile applications. Additionally, MEPC.403(83) requires EEDI-relevant speed trials for newbuilding vessels to utilize ISO 15016:2025 or specific recommended procedures from the same date. For companies supplying reducers to marine or offshore sectors, alignment with these updated specifications is immediate and critical. Failure to comply can result in exclusion from key contracts or regulatory penalties.
Strategic Implications for 2026 Decision Makers
The convergence of growth, competition, and regulation creates a complex decision matrix for 2026. For investors, the 8.4 percent CAGR presents an attractive entry point, but due diligence must extend beyond top-line growth to assess the competitive positioning of individual firms. For manufacturers, the focus must shift to differentiation through material innovation, such as the aluminum housing trends noted in recent product launches, and precision enhancements in planetary and harmonic technologies.
Procurement leaders face the challenge of balancing cost against reliability. With raw material costs representing a large fraction of manufacturing expenses, supplier stability is as important as unit price. Partners with robust supply chains and adherence to evolving ISO and AGMA standards offer lower risk profiles. Additionally, the regional distribution of revenue suggests that a multi-region strategy may be necessary to hedge against localized economic downturns or supply disruptions.
RV Reducer Market
Conclusion: The Value of Complete Intelligence
The speed reducers market in 2026 is a landscape of opportunity tempered by technical and regulatory complexity. While the macro indicators point to a robust expansion toward nearly 19 billion USD by 2032, the real strategic value lies in the nuances. Which specific technology type is outperforming in the robotics sector? Which region is seeing the fastest adoption of high-efficiency worm reducers? How do the latest regulatory changes specifically impact offshore gear supply contracts?
This article has outlined the framework of the market, highlighting the key players, the regulatory environment, and the macroeconomic drivers. However, actionable strategy requires granular data. Our full market research report provides the detailed segmentation analysis, historical volume data, company profiles, and competitive benchmarking necessary to transform these insights into execution. To access the complete intelligence required for precise planning and investment decisions in this evolving sector, we invite you to explore the full study. The depth of data available there will empower your team to navigate the 2026 landscape with confidence.
For detailed analysis of this topic, please visit the official page: Speed Reducers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Wall Protection Market Hits $1.17B in 2025, Projects 5.5% CAGR to 2032
By PW Consulting, 2026-09-16
The Wall Protection Market 2026 Strategic Outlook: Navigating Growth Amid Regulatory Shifts and Manufacturing Consolidation
The global wall protection market has transitioned from a passive infrastructure maintenance category to a strategically critical component of facility design and risk management. As organizations prepare their operational roadmaps for 2026, understanding the underlying forces shaping this sector is no longer optional. Our latest market research delivery provides executive teams with a structured, forward-looking intelligence framework designed specifically to support capital allocation, supply chain planning, and competitive positioning across the forecast horizon.
Drawing on a rigorous historical baseline spanning 2020 through 2025, the analysis maps an established trajectory of consistent expansion. The market closed the baseline year with total industry revenue of approximately USD 1,170 million, reflecting steady demand accumulation across commercial, institutional, and industrial environments. Forward-looking projections indicate that this momentum will sustain through the 2026 to 2032 outlook period, anchored by a forecast compound annual growth rate of 5.5 percent. By the close of the modeling window, industry revenues are positioned to approach USD 1.71 billion. This expansion trajectory is not merely a function of incremental construction activity. It reflects deeper structural shifts in safety compliance, aging infrastructure renewal cycles, and evolving material specifications across high-traffic environments. The strategic implication is clear: wall protection is increasingly evaluated through the lens of lifecycle performance, regulatory alignment, and total cost of ownership rather than initial procurement price.
Market Dynamics: The Convergence of Specification Pressure and Material Economics
Several interlocking dynamics are reshaping procurement behavior and manufacturer strategy as the 2026 planning cycle unfolds. At the regulatory level, institutional buyers are operating within increasingly precise technical specifications. The U.S. Department of Defense UFGS 10 26 00 standard continues to establish a high-performance benchmark for wall guards, crash rails, and bed locators, requiring minimum impact resistance, defined fire resistance ratings, integral coloration, and explicit chemical, stain, fungal, and bacterial resistance. These requirements are not limited to defense-adjacent projects. They are steadily influencing municipal procurement guidelines, healthcare facility standards, and commercial building specifications across multiple jurisdictions. Healthcare patient safety frameworks have similarly tightened expectations, with recent guidance mandating tested handrails, wall protection assemblies, and toilet accessories in both medium-risk and low-risk care zones. Compliance is no longer treated as a checkbox exercise. It is becoming a baseline qualification for market access.
Parallel to specification tightening, raw material price volatility remains a persistent operational pressure point for manufacturers. Fluctuations in polymer feedstocks, metal alloys, and specialty coatings directly affect production costs and margin stability. Companies that have embedded flexible sourcing strategies, forward procurement agreements, and material substitution capabilities are better positioned to absorb input cost swings without eroding competitive pricing. Conversely, producers relying on rigid supply chains face mounting challenges in maintaining consistent delivery timelines and price predictability. For procurement and facilities leadership, this creates a dual imperative: evaluate supplier resilience alongside product performance, and structure contracts with appropriate escalation mechanisms to preserve long-term project economics.
Segment Architecture: How Product, Application, and Regional Factors Shape Demand
The market’s structure reveals a highly differentiated demand landscape, where product categories serve distinct functional priorities across end-use environments. Among core product families, corner guard solutions represent the largest revenue share, reflecting their universal deployment in high-impact contact zones across institutional, commercial, and healthcare settings. Wall guard assemblies and handrail systems form the next tier of demand concentration, each addressing specific safety and accessibility requirements that vary significantly by facility type and regional building code expectations. Additional product lines, including chair rail profiles and decorative or functional wall covering systems, capture meaningful utilization in specialized applications where aesthetics, impact mitigation, and ease of maintenance must be balanced simultaneously.
Application-side demand is distributed across several high-intake environments, with healthcare facilities and educational institutions consistently ranking among the most intensive users. These sectors share overlapping specifications related to durability, hygiene, and occupant safety, yet their procurement cycles, budgetary constraints, and renovation cadences differ in ways that materially affect purchasing velocity. Commercial and hospitality environments contribute a substantial and sustained demand stream driven by brand presentation standards, guest safety expectations, and high-traffic wear patterns. Industrial sites, while smaller in absolute volume, present distinct performance requirements where heavy-duty impact resistance and chemical exposure tolerance dictate material selection.
Geographically, the market continues to reflect mature demand centers alongside expanding adoption in emerging infrastructure corridors. North American and European procurement ecosystems remain deeply integrated with established specification standards, certified product listings, and long-standing supplier relationships. In contrast, Asia Pacific and Latin American markets exhibit different growth drivers tied to urbanization, public facility modernization programs, and evolving institutional procurement frameworks. Each regional context requires a tailored commercial approach that accounts for local compliance expectations, installation service availability, and sensitivity to total installed cost versus unit pricing.
Worldwide Wall Cladding Market
Because exact regional revenue splits, product family breakdowns, and application-level valuations are mapped in detail within the full report, we focus here on the structural relationships that matter for strategy. The critical insight for 2026 planning is that pricing power, channel access, and specification wins increasingly depend on demonstrating performance differentiation rather than competing solely on availability or initial cost. Buyers are evaluating vendors on documented compliance records, installation efficiency, replacement cycle predictability, and environmental product declarations that align with internal sustainability targets.
Competitive Landscape: Consolidation, Certification Leadership, and Specialized Product Positioning
Market concentration provides an additional lens for understanding competitive behavior and customer decision-making. The sector is anchored by a relatively consolidated group of established manufacturers, with the top three players collectively accounting for approximately 72 percent of total industry revenue, while the top five extend that share to around 85 percent. This concentration pattern reflects the strategic advantages held by companies with broad specification libraries, diversified product portfolios, and mature distribution networks. It also underscores the importance of channel relationships and technical specification support as primary competitive differentiators.
Leading participants have built their positions around distinct capability sets that align with high-demand application segments. Inpro Corporation operates as a prominent U.S.-based provider with a broad portfolio spanning door and wall protection, corner guards, handrails, crash rails, and full wall guard systems tailored for commercial, healthcare, and education environments. Koroseal Interior Products maintains a focused commercial wall protection line that includes corner guards, protective wallcovering materials, Korogard sheets, Flex Decorative Wall Protection, and Fusion Wall Protection, positioning the company across both functional protection and aesthetic integration use cases. SPM Professionnels, headquartered in France, serves as a specialist in wall protections and handrails for healthcare, education, hospitality, industry, and retail, offering PVC panels, plates, bumpers, and recently introduced Fin'Line profile systems alongside its DECOCHOC bestseller. Acrovyn contributes a recognized wall protection line featuring corner guards, handrails, crash rails, wall and door protection products, and Rubstrips supported by NSF-certified environmental product declarations. Pawling Systems emphasizes heavy-duty wall protection systems for commercial environments, utilizing rubber and stainless steel constructions across wall guards, corner guards, crash rails, and bed head protection applications. Protek Systems and Durable Corporation both maintain strong positions in metal and extruded guard solutions, with Protek focused on stainless steel and metal systems across guards, corner guards, handrails, crash rails, and door and frame protection, while Durable targets commercial and industrial settings including loading docks through extruded wall guards and rubber corner guards. Wallprotex completes the competitive field with a broad offering of bumper guards, corner guards, wall guards, wall sheets, and handrails.
Recent industry activity highlights how certification validation and product refreshes are being used to reinforce market positions. In December 2025, NSF Product and Service Listings confirmed the ongoing validity of environmental product declarations for multiple Acrovyn wall protection products, including Rubstrips, wall covering sheets, wall panels, and BG crash rails, with coverage extending through December 2030. During the same period, an Inpro Corporation coverage gap report verified core wall protection and door protection listings valid into January 2026. In July 2025, SPM Professionnels released a new e-catalogue and introduced the Fin'Line elegant profile to enhance panel applications for wall protection deployments. These developments matter because documented environmental compliance, specification continuity, and catalog modernization directly influence procurement confidence, especially in healthcare and public-sector environments where auditability and lifecycle documentation are increasingly scrutinized.
Report Coverage: What the Full Intelligence Package Delivers
This market research is structured to support practical decision-making rather than abstract market description. The complete study provides a detailed segmentation architecture covering product types, application environments, and regional markets, allowing teams to isolate the demand drivers most relevant to their operating context. Historical performance data from 2020 through 2025 establishes a reliable baseline for validating internal forecasts, while the 2026 through 2032 projection window offers forward estimates calibrated to current specification trends, renovation cycles, and procurement conditions.
Competitive analysis within the report examines company positioning across product capability, end-use alignment, certification status, and market concentration dynamics. It also evaluates how recent developments, including environmental product declaration continuity and new profile introductions, are shaping supplier selection criteria. Beyond competitive mapping, the report addresses the regulatory and materials environment that frames purchasing behavior, including specification benchmarks, patient safety expectations, and raw material cost influences on production economics. Procurement strategy, channel dynamics, installation service requirements, and total cost of ownership considerations are assessed to help organizations identify where specification leadership, supply resilience, or value engineering can create measurable advantage.
For strategy, product, and procurement teams, the study is designed to answer questions that generic market summaries cannot. Which application environments are expanding most rapidly as a function of compliance-driven renovation rather than new construction? Where are material specifications trending toward monolithic impact-resistant systems versus modular replaceable components? Which certification and environmental documentation requirements are most likely to influence bid eligibility over the forecast window? How should organizations balance portfolio breadth against specialized performance credibility when positioning for healthcare, education, hospitality, or industrial buyers? These are the kinds of operational questions the full analysis is built to address.
Strategic Implications for 2026 Decision-Making
As organizations move into the 2026 planning cycle, the wall protection market presents a clear set of strategic priorities. First, specification alignment is becoming a prerequisite for volume capture. Vendors and buyers alike must treat compliance documentation, impact testing, fire ratings, and environmental product declarations as core commercial assets rather than supplementary credentials. Second, total cost of ownership frameworks should replace narrow unit-price comparisons. In high-traffic healthcare and educational environments, replacement labor, downtime, cleaning protocols, and expected service life can materially alter the economic case for different product systems. Third, supply chain resilience deserves elevated attention given ongoing raw material price sensitivity and the concentration of leading manufacturers. Diversifying qualified suppliers, understanding regional installation capabilities, and building flexibility into procurement terms can protect project timelines and margin expectations.
Finally, the competitive environment rewards clarity of positioning. With a concentrated market structure dominated by a small group of broad-line providers and complemented by specialized players serving heavy-duty, aesthetic, or hygiene-critical applications, buyers benefit from mapping supplier capabilities directly to their facility risk profiles. Suppliers, in turn, are increasingly differentiating through documented environmental performance, modular design efficiency, and application-specific specification support.
Wall Protection Market
The complete market intelligence package expands every dimension discussed here into a directly actionable research framework, with granular segmentation, forward forecasts, competitive profiling, and regulatory and materials context mapped for immediate integration into capital planning, sourcing strategy, and product portfolio decisions. For teams seeking a precise, evidence-based foundation for 2026 and beyond, the full report provides the detailed breakdowns, scenario-ready projections, and competitive intelligence necessary to move from awareness to execution.
For detailed analysis of this topic, please visit the official page: Wall Protection Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ozone Disinfection Market Hits $1.22B in 2025, Projected to Reach $1.89B by 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for 2026: Navigating the Ozone Disinfection Machine Market
Executive Summary: The Imperative for Precision Decision-Making
As the global landscape for infection control and environmental safety continues to evolve, the Ozone Disinfection Machine Market stands at a critical inflection point. For executive leadership, capital allocators, and strategic planners, the period spanning 2026 through 2032 represents more than a linear growth trajectory; it is a complex ecosystem defined by regulatory tightening, technological differentiation, and shifting application priorities. PW Consulting has released a comprehensive market research study designed to provide stakeholders with the granular intelligence necessary to navigate these dynamics. This analysis serves as a strategic primer, outlining the macro-economic foundations, competitive structures, and regulatory realities that will shape investment and operational decisions in the coming years. The full report offers a level of detail that transcends surface-level trends, providing the actionable data required to secure a competitive advantage in a market that is rapidly maturing.
Macro-Economic Trajectory and Market Valuation
The quantitative foundation of this market research underscores a robust expansion profile. Tracing the historical performance from 2020 through 2025 provides a stable baseline for forecasting, revealing consistent revenue growth that has accelerated into the current fiscal year. The market valuation, denominated in USD millions, has demonstrated resilience against broader economic headwinds, driven primarily by the non-negotiable demand for effective disinfection solutions across critical industries. Looking forward, the forecast period from 2026 to 2032 projects a sustained compound annual growth rate of 6.5 percent. This growth rate is not merely a percentage figure; it represents the cumulative impact of increasing health awareness, stricter municipal water standards, and the integration of ozone technologies into advanced medical and food processing workflows. The trajectory suggests that by the end of the forecast horizon, the total revenue will have expanded significantly from the 2025 base, reflecting a market that is scaling in both volume and value. Stakeholders who understand the nuances behind this macro growth will be better positioned to capture market share, while those relying on generic industry estimates risk misallocating resources.
Spatial Distribution and Regional Nuances
While the aggregate market data provides the overarching narrative, the geographical distribution of demand reveals distinct operational landscapes for manufacturers and distributors. The market is not uniformly distributed; rather, it reflects the varying stages of industrialization, regulatory maturity, and infrastructure development across different zones. North America and Europe continue to anchor a significant portion of global revenue, driven by established healthcare systems, stringent environmental regulations, and high adoption rates of advanced sterilization technologies. However, the Asia Pacific region presents a dynamic growth vector, characterized by rapid urbanization and expanding industrial capacity that demands scalable water treatment and purification solutions. Emerging markets in Latin America and the Middle East and Africa, while currently representing smaller revenue shares, offer long-term potential as public health infrastructure improves and regulatory frameworks align with international standards. The full research delves into the specific drivers within each region, analyzing import-export dynamics, local manufacturing capabilities, and the penetration rates of different ozone generator types without relying on superficial regional generalizations. Understanding these spatial nuances is essential for companies planning market entry strategies or evaluating supply chain resilience.
Product Typology and Application Segmentation
A core pillar of the market analysis lies in the breakdown of technology types and end-use applications. The market is primarily bifurcated between Corona Discharge Ozone Generators and Ultraviolet Ozone Generators, with other emerging types contributing to the remainder of the revenue mix. Corona discharge technology remains dominant, favored for its efficiency and scalability in large-volume applications such as municipal water treatment and industrial processing. Ultraviolet generators, while holding a smaller share, are critical in specific medical and laboratory contexts where precise ozone output and minimal byproduct formation are required. The distinction between these types is not merely technical; it dictates cost structures, maintenance requirements, and suitability for specific regulatory environments.
On the application front, water treatment constitutes the largest revenue driver, reflecting the universal need for safe drinking water and wastewater management. Air purification and medical applications, including food processing and clinical sterilization, represent significant and growing segments. The interplay between application requirements and technology selection is complex. For instance, medical-grade disinfection demands strict adherence to safety protocols and output limitations, whereas industrial water treatment prioritizes throughput and chemical reduction. The report provides a deep dive into how these segmentation splits interact, offering insights into which combinations of type and application yield the highest margin potential and growth velocity. By avoiding a one-size-fits-all view, the research enables clients to identify niche opportunities and optimize their product portfolios for specific high-value segments.
Ozone Disinfection Machine Market
Competitive Dynamics and Industry Structure
The market exhibits a moderately fragmented but highly specialized competitive environment. The concentration ratios indicate that while no single entity dominates the landscape, a core group of specialized manufacturers holds substantial influence, particularly in the medical and high-end industrial sectors. The CR3 and CR5 metrics suggest that there is room for consolidation and strategic maneuvering, but also that niche players with strong technical credentials can thrive. The competitive advantage in this market is increasingly derived from compliance, certification, and proven efficacy rather than price competition alone.
Key industry participants include Hänsler Medical GmbH, based in Iffezheim, Germany, which specializes in medical-grade ozone generators for hospital disinfection, instrument sterilization, and clinical ozone therapy. Their product portfolio, including the OZOMED smartline, OZONOSAN alphaplus, and OZOMED photonik, exemplifies the focus on clinical precision and safety. In Israel, Medozons Ltd. offers medical ozone generators tailored for research, sterilization, and disinfection in clinical and therapeutic settings, emphasizing flexibility for healthcare providers. Faraday Ozone, headquartered in Canada, produces advanced ozone generators and disinfection systems specifically for healthcare and medical applications, leveraging technical expertise to meet rigorous health standards. Aquapure Ozone, operating from the United States, manufactures clinic-grade and medical ozone generators using corona discharge technology, focusing on reliability and disinfection efficacy for medical environments. Additionally, OzoneLab Instruments in Canada develops customizable, CE-marked ozone generators and peripherals, catering to medical research and laboratory disinfection needs.
Ozone Generator Market
The competitive landscape is further shaped by recent strategic activities. For example, Hänsler Medical GmbH recently participated in MEDICA 2025 in November, showcasing new product displays including their OZOMED smartline, OZONOSAN alphaplus, and OZOMED photonik ozone generators. Such events highlight the industry's focus on visibility, networking, and the continuous rollout of advanced solutions. The full report analyzes the strategic positioning of these and other key players, evaluating their product pipelines, geographic reach, and response to market pressures. This competitive intelligence is vital for companies assessing partnership opportunities, potential acquisition targets, or threats from emerging entrants.
Regulatory Frameworks and Safety Standards
Regulatory compliance is a defining force in the ozone disinfection market, influencing product design, market access, and operational protocols. Authorities and health agencies have established guidelines that directly impact the deployment of ozone technologies, particularly in indoor and medical environments. For instance, the FDA requires that the ozone output of indoor medical devices be no more than 0.05 ppm, a threshold that shapes engineering specifications and validation processes for manufacturers targeting the healthcare sector. Similarly, CDC guidelines note that ozone mists are an emerging technology for environmental disinfection but require further research for routine hospital use, signaling a cautious but open regulatory stance that rewards evidence-based innovation.
Certification and adherence to international safety standards also play a critical role in market credibility. Hänsler Medical products feature medical-grade ozone generators compliant with clinical protocols and international safety standards, reinforcing trust among healthcare buyers. Furthermore, CE-marked ozone generators from manufacturers like Medozons and OzoneLab are utilized in medical facilities across 70 countries, demonstrating the importance of harmonized certification for global market expansion. These regulatory and certification dynamics create both barriers to entry and opportunities for differentiation. Companies that can navigate the complex web of requirements, invest in rigorous testing, and maintain transparent compliance records are better equipped to secure long-term contracts and expand into regulated markets. The research provides a detailed mapping of these regulatory requirements by region and application, helping stakeholders anticipate compliance milestones and avoid costly delays.
Report Scope and Operational Utility
This market research study is engineered to deliver practical value to a wide range of stakeholders, including investors, strategic planners, procurement leaders, and product developers. The report offers a granular exploration of the market that goes beyond high-level summaries. It includes a comprehensive segmentation analysis that dissects revenue flows across technology types, applications, and regions, allowing users to model scenarios based on their specific areas of interest. The competitive analysis section provides detailed profiles of key companies, evaluating their market share, product capabilities, recent developments, and strategic direction. This enables benchmarking and helps organizations identify gaps in their own offerings or areas where competitors may be vulnerable.
In addition to structural analysis, the report examines market drivers and restraints, providing a balanced view of the forces accelerating growth and the challenges that could impede expansion. Topics such as raw material availability, technological innovation cycles, regulatory shifts, and consumer behavior are integrated into a cohesive narrative that supports risk assessment and opportunity identification. The research also includes forward-looking insights based on the forecast period, helping clients align their planning horizons with market realities. Whether the goal is to evaluate market entry potential, refine a product roadmap, optimize pricing strategies, or assess the competitive threat landscape, the study supplies the data and context needed to make informed decisions. The analysis is structured to be actionable, with clear implications for operational planning and strategic positioning.
Strategic Vision for 2026 and Beyond
The Ozone Disinfection Machine Market is entering a phase where precision, compliance, and strategic agility will determine success. The projected growth trajectory offers substantial opportunities, but realizing value in this environment requires more than an appreciation of aggregate trends. Companies must understand the intricate relationships between technology types, application requirements, regional dynamics, and regulatory constraints. The competitive field is shaped by players who invest in specialized capabilities, maintain rigorous safety standards, and respond proactively to emerging needs in healthcare, water treatment, and industrial processing. Strategic decisions regarding R&D focus, market prioritization, partnership formation, and capacity expansion must be grounded in robust intelligence to avoid missteps and maximize returns.
PW Consulting's research provides the depth and clarity needed to navigate this complexity. By leveraging the insights contained in the full report, organizations can sharpen their strategic focus, anticipate shifts in demand, and position themselves to capitalize on the evolving landscape. The market will reward those who can combine technical excellence with operational discipline and regulatory awareness. For decision-makers seeking to secure a strong position in the ozone disinfection sector during 2026 and the years ahead, this study offers a vital foundation for planning and execution. Investing in comprehensive market intelligence is not merely an analytical exercise; it is a strategic necessity for sustaining growth and achieving competitive differentiation in a market that continues to expand and mature.
For detailed analysis of this topic, please visit the official page: Ozone Disinfection Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Luxury Yacht Market Hits $11.0B in 2025, Poised for 6.98% CAGR Through 2032
By PW Consulting, 2026-09-16
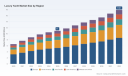
Navigating the Blue Horizon: Strategic Intelligence for the Global Luxury Yacht Market in 2026
The global luxury yacht industry stands at a pivotal inflection point as it moves deeper into the second half of the decade. Characterized by high net worth individual demand, complex manufacturing ecosystems, and increasingly stringent regulatory environments, the sector requires more than mere observation. It demands rigorous, data-driven strategic intelligence.
Luxury Yacht Market
This article serves as a comprehensive introduction to PW Consulting latest market research publication: the Luxury Yacht Market Report 2026–2032 . Designed for executives, investors, and industry stakeholders, this study dissects the forces shaping revenue trajectories, competitive positioning, and operational risks across the superyacht value chain. Below, we outline the strategic value proposition of this research, preview the macro-economic landscape, and demonstrate why access to the full intelligence suite is critical for 2026 decision-making.
The Macro Landscape: Growth Trajectory and Market Scale
Understanding the broad contours of the market is the first step toward informed strategy. Based on historical data from 2020 through 2025 and our proprietary forecast models extending to 2032, the luxury yacht sector has demonstrated consistent resilience and expansion, even amidst global economic volatility.
The market has evolved from a revenue base of approximately 6.58 billion USD in 2020 to an estimated 11.0 billion USD by 2025. This expansion reflects not only recovery from pandemic-era disruptions but also a structural shift in high-net-worth consumption patterns, with a marked preference for experiential luxury and asset-based wealth preservation. Looking forward, our analysis projects the global market revenue to reach 17.91 billion USD by 2032.
This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 6.98 percent over the forecast period. Such a rate indicates healthy organic expansion, though it also signals intensifying competition for new builds, charter inventory, and after-sales service contracts. For stakeholders, this trajectory suggests that volume-based strategies must be balanced with margin protection, as raw growth alone will not guarantee profitability in an increasingly sophisticated buyer environment.
Why This Report Matters for 2026 Decision-Makers
Strategic planning in the yacht industry cannot rely on aggregated headlines. Manufacturers, brokers, charter operators, and financial institutions need granular visibility into segmentation dynamics, regional nuances, and competitive maneuvering. Our report is engineered to provide this visibility without overwhelming decision-makers with raw data tables. Instead, it translates complex datasets into actionable strategic narratives.
Comprehensive Coverage of Build, Demand, and Application Segments
The study examines the market through multiple analytical lenses. We analyze the revenue contribution of motor yachts versus sailing yachts, highlighting how design preferences and performance requirements drive distinct supply chains and pricing architectures. The breakdown of yacht size categories—from vessels up to 50 meters to those exceeding 100 meters—reveals shifting demand among owners who increasingly seek both coastal luxury and long-range expedition capabilities.
Furthermore, the report explores application splits between personal use and commercial charters. This distinction is critical as the line between private asset ownership and revenue-generating investment blurs. Understanding the commercialization trends, including crewed charters and corporate hospitality vessels, provides insight into secondary revenue streams that can alter total lifecycle value assessments.
Regional Intelligence and Demand Geography
While the global headline figures provide the macro context, regional demand patterns dictate where investments, showrooms, and service hubs should be located. Europe remains a dominant center of gravity for both manufacturing heritage and high-net-worth buyer concentration. North America represents a significant and growing demand hub, influenced by coastal wealth clusters and regulatory frameworks specific to US imports. Meanwhile, the Asia Pacific region, Latin America, and the Middle East and Africa each present unique growth vectors with distinct client profiles, financing environments, and logistical considerations.
Our regional segmentation analysis avoids superficial generalizations. Instead, it maps demand intensity against supply chain proximity, identifying where market friction—such as import tariffs or fragmented customs regimes—may impact final pricing and delivery timelines.
Competitive Dynamics: An Oligopolistic Battlefield
The luxury yacht manufacturing sector is characterized by high barriers to entry, substantial capital requirements, and long lead times for vessel delivery. These factors have fostered a moderately concentrated landscape, where a select group of established shipyards and brands command a significant share of total revenue.
Our analysis estimates that the top three competitors collectively represent approximately 55 percent of the market, while the top five firms account for roughly 62 percent. This concentration underscores the importance of brand equity, engineering reputation, and the ability to deliver bespoke or semi-custom vessels at scale.
Key Players and Their Strategic Postures
The report provides detailed profiles of the organizations that define the competitive arena:
- Feadship (Makkum, Netherlands) continues to anchor its identity on pure custom creation, a philosophy maintained since its founding in 1949, appealing to ultra-high-net-worth clients who demand unique hull forms and interiors.
- Lürssen (Bremen, Germany) remains a premium builder of complex custom motor and sailing yachts, known for technical sophistication and large-scale project execution.
- Sunseeker (Poole, United Kingdom) leverages its position as a world-leading luxury motor yacht brand with strong emphasis on design and engineering excellence, catering to a broad spectrum of luxury buyers.
- Ferretti Group (Forlì, Italy) operates multiple luxury motor yacht lines, including the Riva and Pershing brands, blending Italian design heritage with diversified product portfolios.
- Sanlorenzo (Viareggio, Italy) and Benetti (Viareggio, Italy) both offer semi-custom and full-custom superyacht solutions, competing on flexibility, quality, and the ability to tailor vessels to specific owner preferences.
- Azimut-Benetti Group (Viareggio, Italy) delivers bespoke and semi-custom vessels, often competing on styling, performance, and integrated ownership experiences.
- Oceanco (Makkum, Netherlands) has carved a niche in advanced expedition and custom motor yachts, focusing on capability and autonomy for long-range cruising.
- Heesen Yachts (Gorinchem, Netherlands) is recognized for aluminum hybrid and custom motor yachts, emphasizing speed, efficiency, and innovative hull construction.
- Gulf Craft (Moss Point, United States) produces luxury megayachts and private cruisers, expanding the reach of American-built or assembled premium vessels.
- Tankoa Yachts (Ancona, Italy), Amels (Makkum, Netherlands), Hakvoort Shipyards (Makkum, Netherlands), and Cantiere delle Marche (Macerata, Italy) each bring specialized expertise in semi-custom designs, large motor yachts up to 100 meters, sail and motor combinations, and custom engineering.
Additionally, the report tracks emerging activity from brands such as Valhalla Boatworks (South Portland, United States), known for luxury powerboats delivering Viking-quality motor yachts, illustrating how specialized builders are capturing niche segments within the broader market.
Recent Moves and Market Signals
The competitive landscape is not static. Recent activity at major industry events underscores the pace of product innovation and brand refreshment. At the Cannes Yachting Festival in September 2025, multiple manufacturers unveiled significant launches. Groupe Beneteau introduced 19 new models and 14 world premieres, including a new Sealoft range for Jeanneau, signaling aggressive portfolio expansion. Tankoa Yachts debuted the T450 luxury yacht, Benetti presented the Class 44M, and Cantiere delle Marche showcased the Prestige M7. Each of these launches reflects strategic efforts to capture shifting buyer preferences, refresh brand relevance, and compete for delivery slots in a market where wait times and customization are key differentiators.
Luxury Furniture Market
Our report goes beyond event summaries. It evaluates how such product launches influence order pipelines, pricing power, and competitive positioning, helping readers assess which manufacturers are likely to gain or lose share in the near term.
Regulatory and Economic Headwinds: Navigating Complexity
While demand fundamentals remain positive, the operating environment is becoming more complicated. Regulatory shifts and macroeconomic pressures are reshaping cost structures, compliance obligations, and market access. The report dedicates substantial attention to these dynamics, as ignoring them can lead to erroneous forecasts and strategic missteps.
Regulatory Evolution and Safety Standards
Regulatory frameworks are tightening across multiple jurisdictions. Malta revised its Commercial Yacht Code (CYC) in 2025, with the updated provisions taking effect on 1 July 2025. This code now governs commercial yachts—typically those carrying up to 12 passengers—through modernized design, safety, manning, and welfare standards. For charter operators and owners operating under commercial registries, these changes directly affect operational compliance and cost.
At the same time, the 2026 Yacht Code took effect from 1 January 2026, applying enhanced safety requirements to all vessels of 500 GT and above. Among the notable updates are mandatory fire safety provisions for lithium-ion equipment storage. As yachts increasingly incorporate advanced battery systems and hybrid technologies, compliance with these provisions becomes a design and procurement imperative rather than an afterthought.
Environmental Pressures and Carbon Pricing
The expansion of the EU Emissions Trading System (ETS) to the maritime sector, rolled out during 2024–2025, now applies carbon pricing to fuel emissions for superyachts operating in EU ports. This development introduces a new cost dimension for operators and owners who frequently navigate European waters. While the full financial implications depend on usage patterns and emission intensities, the directional signal is clear: environmental compliance is moving from voluntary sustainability narratives to hard operational cost factors.
Trade Policy and Regional Fragmentation
Trade dynamics are also adding friction. New US tariffs of 15 percent now apply to most goods imported into the United States, increasing costs for components built outside the country destined for luxury yachts sold to American buyers. For builders that rely on cross-border supply chains, this tariff structure affects both pricing strategies and sourcing decisions. Simultaneously, EU customs rules remain fragmented as of 2026, leaving superyacht owners exposed to potential VAT billing complications on high-value transactions. This fragmentation can complicate cross-border purchases, relocation of vessels, and ownership structuring.
Our report contextualizes these regulatory and trade elements within the broader market narrative, assessing how they interact with demand elasticity, buyer geography, and shipyard sourcing strategies. The full edition provides detailed mapping of risk exposure by region and vessel category.
What You Will Gain from the Full Report
This preview has highlighted the macro trajectory, competitive structure, and regulatory context that define the current luxury yacht market. However, strategic advantage lies in the details that cannot be fully unpacked in an introduction. The complete PW Consulting report delivers:
- Granular segmentation analysis that breaks down revenue contributions, growth rates, and strategic implications across type, size, application, and region, enabling precise go-to-market and investment decisions.
- Deep-dive competitive assessments that evaluate market share movement, brand positioning, product pipeline strength, and operational capabilities of key players, including their recent launches and development trajectories.
- Scenario-based forecasting that links regulatory developments, tariff structures, and carbon pricing mechanisms to financial outcomes, helping organizations model best-case, base-case, and stress-case scenarios.
- Practical recommendations for manufacturers, brokers, charter operators, and financial institutions, covering pricing architecture, supply chain resilience, compliance planning, and market entry or expansion strategies.
- Data-driven insights on how personal use demand and commercial charter dynamics are evolving, supporting asset valuation models and fleet planning decisions.
For organizations operating in or adjacent to the luxury yacht ecosystem, the difference between reactive management and proactive strategy is access to reliable, nuanced market intelligence. This report is designed to bridge that gap.
Conclusion: Positioning for the Next Phase of Growth
The luxury yacht market is on a clear growth path, with revenue expanding from levels observed in the early 2020s toward nearly 18 billion USD by 2032 and a CAGR of 6.98 percent guiding the forecast window. Yet growth alone does not win markets. Success in 2026 and beyond will depend on the ability to interpret segmentation signals, anticipate regulatory costs, navigate trade frictions, and align product strategy with the evolving expectations of high-net-worth buyers and commercial operators.
PW Consulting Luxury Yacht Market Report provides the comprehensive intelligence necessary to make those decisions with confidence. By combining historical context, forward-looking forecasts, competitive analysis, and regulatory assessment into a single cohesive study, it equips stakeholders to move beyond assumptions and act on evidence.
To explore the full segmentation breakdowns, competitive profiles, regional intelligence, and scenario models, we invite you to access the complete report on the PW Consulting portal. The detailed data and strategic frameworks contained within are tailored for decision-makers who require precision, not generalities, as they plan for the years ahead.
For detailed analysis of this topic, please visit the official page: Luxury Yacht Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Residential Interior Door Market to Hit $20.95 Billion by 2032 at 5.5% CAGR
By PW Consulting, 2026-09-16
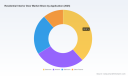
Navigating the Residential Interior Door Market: Strategic Intelligence for 2026 Decision-Makers
The residential interior door market is undergoing a quiet but significant transformation. No longer viewed as a commoditized building component, interior doors are increasingly recognized as critical elements of home performance, privacy, acoustics, design identity, and sustainability compliance. As construction cycles recover, renovation activity accelerates, and consumer expectations evolve toward smarter, healthier, and more customized living spaces, manufacturers, distributors, contractors, and private investors face a complex landscape that rewards foresight over guesswork.
Pw Consulting’s latest Residential Interior Door Market study is designed to cut through this complexity. Rather than offering superficial trends, the report delivers a structured, execution-ready intelligence framework that connects macro market trajectories with granular competitive positioning, segment-specific growth vectors, and regulatory-driven shifts in material and manufacturing preferences. For executives formulating 2026 operating plans, capital allocation strategies, and product roadmaps, this research serves as both a diagnostic tool and a forward-looking navigation system.
Market Trajectory: A Decade of Steady Expansion with 2026 as a Strategic Inflection Point
Historical performance and forward-looking projections place the residential interior door category on a consistent growth path. The market has expanded from approximately $9.95 billion in 2020 to an estimated $14.3 billion in 2025, reflecting resilient demand across housing turnover, remodeling cycles, and design-led replacement programs. Looking ahead, the study maps the market toward a projected valuation exceeding $20.9 billion by 2032, anchored by a compound annual growth rate of 5.5 percent throughout the forecast window.
These figures are not merely aggregate indicators; they reflect underlying momentum that varies meaningfully across product architectures, application contexts, geographic demand centers, and buyer segments. For leadership teams, the strategic implication is clear: growth is real, but it is unevenly distributed. Companies that treat the category as a uniform market risk misallocating resources, entering overheated segments, or overlooking high-margin niches. Exact regional shares, application-level breakdowns, and material-specific revenue contributions are addressed in depth within the full report, where they are modeled alongside pricing elasticity, channel dynamics, and competitive intensity to reveal where profitable expansion is most achievable.
2026 Dynamics: What Is Shaping Demand, Pricing, and Go-to-Market Strategy
Several concurrent forces are redefining how residential interior doors are specified, manufactured, and sold. Understanding their interaction is essential for strategic planning.
Sustainability and Material Standards as Demand Drivers
Responsibly sourced wood, low-VOC finishes, and certified manufacturing practices are transitioning from differentiators to baseline expectations. Buyers, retailers, and increasingly regulated building programs are prioritizing products that align with broader environmental and indoor-air-quality goals. At the same time, updated energy-efficiency considerations and evolving material standards are elevating interest in advanced composite formulations and sustainable door cores. The report dissects how these preferences are reshaping sourcing economics, product architecture choices, and brand positioning across competing portfolios.
Renovation Activity and Housing Demand as Volume Anchors
A robust pipeline of home improvement projects and sustained housing activity continues to underpin steady transactional volume for interior door products. While new-build cycles fluctuate, the renovation channel has proven more resilient, often favoring variety, finish customization, and solution-based selling. The study evaluates how renovation-led demand differs from new-construction demand in terms of order characteristics, specification behavior, and competitive vulnerability, enabling readers to calibrate sales and inventory strategies accordingly.
Trade Friction, Sourcing Strategy, and Cost Pressure
Trade restrictions on imported wood and door components remain a persistent variable in pricing and supply planning. For U.S.-based manufacturers, these dynamics influence raw material availability, finished-goods cost structures, and the relative attractiveness of domestic versus imported supply chains. The analysis examines how leading players are adapting their procurement footprints and product mix decisions in response, and where margin protection is becoming a competitive differentiator.
Smart-Home Integration and Evolving Specification Behavior
Consumer expectations are increasingly shaped by the broader smart-home ecosystem and the desire for doors that contribute to acoustic comfort, privacy, and integrated home functionality. This is not always a matter of embedded electronics; it increasingly involves specification alignment, finish coordination, sound-reduction capabilities, and design compatibility with connected-home aesthetics. The report assesses how these expectations are influencing product development priorities and retail specification strategies.
Segmentation Architecture: Where the Growth Dividends Are Concentrated
One of the study’s core analytical strengths is its segmentation framework. The market is evaluated across multiple dimensions that matter operationally: material preferences, application contexts, and regional demand centers. Each axis reveals a distinct competitive logic.
Material strategies continue to define both cost structure and brand identity. Wood remains a foundational reference point for premium positioning and custom specification, while composite alternatives are gaining traction where durability, consistency, and sustainability credentials intersect. Glass, steel, and other specialty materials occupy targeted niches tied to design statements, acoustic requirements, or specific residential applications. Rather than presenting static shares, the report layers these material preferences against pricing behavior, channel fit, and regional demand intensity to expose where category leadership is being contested and where white space remains.
Application-level analysis is equally critical. Interior doors are specified differently depending on whether they serve private sleeping areas, high-use transitional spaces, moisture-adjacent environments, or secondary rooms with distinct functional and aesthetic requirements. Each application carries its own drivers for privacy, acoustics, moisture resistance, style coordination, and replacement frequency. The study maps these nuances to reveal which applications exhibit the strongest renewal cycles, which are most sensitive to design trends, and which offer the most attractive unit economics for manufacturers and distributors.
Regional demand patterns further complicate the picture. Mature markets display different growth mechanics than emerging demand centers, and local building norms, renovation intensity, trade exposure, and channel maturity all shape how products are positioned and sold. The complete report quantifies these regional dynamics with sufficient granularity to support market-entry decisions, distribution planning, and localized product strategy without revealing the precise splits here, preserving the analytical exclusivity that enterprise buyers expect.
Residential Interior Door Market
Competitive Landscape: Differentiation in a Moderately Concentrated Market
The market structure reflects a moderate level of concentration, with the top three players accounting for approximately 35 percent of revenue and the top five reaching roughly 42 percent. This indicates that while scale players hold meaningful share, a substantial portion of the market remains accessible to specialized manufacturers, regional champions, and design-led brands that compete through customization, craftsmanship, and portfolio breadth.
The competitive set illustrates the diversity of strategic approaches now defining the category. JELD-WEN continues to leverage a broad product architecture spanning wood, composite, and molded interior doors, with solid-core options positioned around sound reduction and consistent specification. Masonite complements this landscape with premium fiberglass and wood offerings, including series designed for elevated aesthetics and residential performance. TruStile Doors differentiates through custom stile-and-rail interiors that span premium MDF, wood, glass, resin, leather, and metal options, appealing to buyers seeking tailored design outcomes. Simpson Door Company draws on a long heritage of handcrafted custom wood doors, reinforcing craftsmanship as a competitive asset. Lynden Door aligns with sustainability-minded procurement through green-certified materials and custom wood offerings, while Rogue Valley Door emphasizes interactive design tools that support specification and customization. Woodgrain competes on breadth of design expression through stile-and-rail and router-carved interiors with extensive design libraries. Andersen Windows and Doors and Pella Corporation integrate interior door offerings within broader residential portfolios, using cross-category relationships as a commercial advantage. ProVia positions professional-class interior doors with customizable cores and overlays, appealing to specification-driven projects.
Recent corporate activity reinforces the strategic tempo of the category. In early 2026, Therma-Tru introduced new ¾-Lite Shaker interior doors and sidelites, signaling continued interest in refined, specification-friendly designs. Later in the year, Masonite showcased its Calden three-panel interior door at a major builders’ event, highlighting the ongoing push toward visually differentiated, multi-panel configurations that resonate with design-led residential projects. These launches are not isolated product updates; they are indicators of where manufacturers are placing bets on aesthetics, functionality, and channel appeal. The full report contextualizes each major competitor’s positioning, product emphasis, and strategic vulnerabilities, enabling readers to benchmark their own portfolios and identify adjacency opportunities without relying on generic competitive summaries.
What the Report Delivers: A Practical Toolkit for 2026 Strategy
This study is built for action. It is structured to help leadership teams answer the questions that matter most when planning product investments, channel expansion, pricing strategy, and competitive response. The report includes:
- A demand-and-supply assessment that connects historical performance to forward projections, with scenario-based views that account for renovation intensity, housing activity, and trade-related cost pressure.
- Multi-dimensional segmentation analysis covering material categories, application contexts, and regional demand patterns, designed to reveal where growth is strongest, where margins are most defensible, and where competitive intensity is rising.
- A competitive profiling section that evaluates leading manufacturers by product emphasis, differentiation logic, and strategic positioning, providing a comparative lens for portfolio planning and market-entry evaluation.
- An examination of market dynamics, including sustainability mandates, certification expectations, material sourcing constraints, and smart-home-aligned specification trends, framed in terms of commercial impact rather than abstract observation.
- Strategic implications for manufacturers, distributors, builders, and investors, with guidance on where to concentrate resources, which customer segments warrant deeper engagement, and how to align product roadmaps with emerging demand signals.
Throughout, the analysis maintains a disciplined focus on decision utility. Figures, shares, and forward estimates are presented with enough context to support judgment, but the most sensitive segmentation data and regional revenue distributions are reserved for the full report. This approach ensures that the complete intelligence product remains a proprietary asset for teams that need to make specific capital, sourcing, and positioning decisions with confidence.
Why This Study Matters for 2026 Planning
The residential interior door market is not defined by a single megatrend. It is shaped by the interplay of renovation economics, material sustainability expectations, trade-driven cost dynamics, design-led specification behavior, and a competitive field that rewards both scale and specialization. In that environment, generalization is a liability. Winning strategies require clarity on which applications are expanding, which materials are gaining pricing power, which regions offer the best risk-adjusted opportunity, and how competitors are translating product innovation into commercial advantage.
Pw Consulting’s Residential Interior Door Market report is intended to provide that clarity. It gives executives a structured, evidence-based foundation for 2026 decision-making, while preserving the deeper segmentation and competitive intelligence needed to convert insight into action. For organizations that need to know not only where the market is heading, but where to place bets now, the full study offers the granularity, benchmarking, and strategic framing necessary to move from awareness to execution.
The market trajectory is visible; the competitive and segmentation details that determine success are not. Accessing the complete analysis is the next step for teams ready to align their 2026 plans with the realities of a maturing, increasingly differentiated residential interior door category.
Wood Interior Doors Market
For detailed analysis of this topic, please visit the official page: Residential Interior Door Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Smart Vending Machines Market Hits $8.82 Billion in 2025, Projecting 10.6% CAGR to 2032
By PW Consulting, 2026-09-16
The Smart Vending Machines Market in 2026: Strategic Intelligence for Enterprise Decision-Makers
The global smart vending machines market is undergoing a structural transformation that goes far beyond the traditional convenience retail model. As automated retail intersects with artificial intelligence, contactless payment infrastructure, and mission-critical dispensing in healthcare and public health settings, organizations face a pivotal moment. This research provides the strategic foundation needed to make informed capital allocation, partnership, and market-entry decisions across the 2026-2032 forecast horizon.
Worldwide Vending Machine Payment System Market
For executives evaluating whether to deploy, invest in, or partner with smart vending infrastructure, the question is no longer whether automation will reshape point-of-sale access. The question is where value will concentrate, which applications will command pricing power, and how regulatory and reimbursement dynamics will shape viable business models. This report has been designed to answer those questions with the granularity and commercial relevance that enterprise strategy teams require.
A Market Built on Accelerated Adoption and Structural Tailwinds
Over the historical review period from 2020 through 2025, the smart vending machines market demonstrated consistent, compounding growth. Total revenue expanded from approximately 5.32 billion USD in 2020 to 8.82 billion USD by 2025, reflecting an industry that has moved beyond early experimentation into mainstream operational integration. The growth trajectory is not merely incremental. It is supported by a convergence of demand-side forces: consumer expectation for 24/7 autonomous access, enterprise demand for inventory visibility, and the emergence of specialized dispensing use cases in medical and public health environments.
Looking forward, the forecast period from 2026 through 2032 projects continued expansion at a CAGR of 10.6 percent, with market revenue reaching 10.08 billion USD in 2026 and climbing to 18.09 billion USD by 2032. These figures reflect a market that is growing through both organic retail automation and the diversification of vending into strategic, non-traditional endpoints. For decision-makers, the strategic implication is clear: this is a market where timing and positioning matter. The organizations that act with a precise understanding of where growth is accelerating, and why, will be better placed to capture share and avoid misallocated capital.
It is worth emphasizing that the headline figures only tell part of the story. Behind the aggregate numbers lies a multidimensional landscape shaped by product category performance, deployment environments, regional maturity, and the regulatory context in which automated dispensing operates. The full report isolates these dimensions so that strategy teams can move from directional awareness to targeted action.
What the Report Delivers: Operational Intelligence, Not Generic Observation
This market research has been constructed for practitioners who need to make investment, procurement, partnership, and rollout decisions under real commercial constraints. Rather than offering a high-level summary, the study provides a structured analytical framework that connects market sizing to market logic. The following components are central to the analysis:
- Historical revenue performance and forward-looking market sizing across the 2026-2032 forecast window, enabling multi-year planning and scenario-based budgeting
- Segment-level evaluation across product categories and application environments, with attention to how demand patterns differ by context and what that means for deployment strategy
- Regional market structure and maturation pathways, helping organizations understand where adoption is advanced, where growth momentum is strongest, and where infrastructure or regulatory conditions shape opportunity
- Competitive positioning analysis that examines the strategies, capabilities, and recent moves of leading participants across commercial vending, healthcare dispensing, and public health applications
- Market dynamics assessment covering technological enablement, operational requirements, reimbursement behaviors, and regulatory classification considerations that influence market entry and scaling
- Practitioner-oriented synthesis designed to translate analytical findings into strategic options for vendors, investors, facility operators, and public-sector stakeholders
The intent is to provide a usable decision-support tool. Whether your interest lies in evaluating a new product rollout, assessing a potential acquisition target, identifying underserved application areas, or mapping competitive vulnerability, the report is built to connect quantitative structure with qualitative commercial reasoning.
Competitive Landscape: A Market Shaped by Diverse Motivations
One of the most strategically important features of the smart vending machines market is the diversity of participants and motivations shaping its evolution. The competitive space is not dominated by a single business model or end-use logic. Instead, it brings together commercial technology providers, healthcare institutions, academic and public-health operators, and community-facing organizations, each with distinct objectives and deployment strategies.
Recent activity illustrates this divergence clearly. In the commercial technology segment, providers are advancing AI-enabled platforms that emphasize real-time inventory monitoring, contactless payment integration, and flexible placement models for businesses and healthcare facilities. These developments signal a shift toward smarter operational control, lower friction for end users, and more adaptable economics for site partners. At the same time, healthcare and public-health institutions are expanding automated dispensing solutions for time-sensitive, access-critical needs, including overdose prevention supplies and wellness resources.
Several developments from late 2025 through early 2026 highlight this dual trajectory. A commercial provider expanded its AI-powered smart vending platform with enhanced inventory monitoring and contactless payment capabilities, reinforcing the growing importance of software-defined vending operations. In parallel, health systems and public health departments have advanced the deployment of naloxone dispensing machines across hospital campuses and community sites, with early installations reporting substantial utilization within their first months of operation and subsequent expansion to additional locations. These deployments show that automated vending is increasingly embedded in mission-driven contexts where availability, anonymity, and 24/7 access are core to the value proposition.
Smart Vending Machines Market
This landscape has meaningful implications for market structure. The level of concentration suggests that while leading players hold significant share, there remains room for specialization, regional deployment advantages, and differentiated application expertise. Enterprise stakeholders therefore need to assess competitors not only by scale, but by application fit, regulatory readiness, partnership model, and operational sophistication. The report examines these competitive dimensions in depth, enabling readers to understand where incumbency advantages exist and where targeted entrants may find viable openings.
Regulatory and Operational Dynamics That Will Shape Strategy
Smart vending strategy cannot be separated from the operational and regulatory environment in which equipment is deployed. In particular, the medical and public-health dimensions of automated dispensing introduce requirements that differ substantially from commercial convenience retail. Automated dispensing units used in medical contexts are classified as Class II medical devices by the U.S. Food and Drug Administration and require 510(k) clearance. This classification is not a minor compliance detail; it affects development timelines, product validation, market access, and the cost structure of healthcare-oriented vending solutions.
At the same time, reimbursement and procurement behaviors are evolving. Hospitals and clinics are increasingly deploying automated dispensing units for over-the-counter medications, personal protective equipment, and wellness products, indicating a broader institutional acceptance of vending as an operational tool rather than a novelty. In the public-health space, harm reduction vending machines for naloxone and related supplies operate under state and county public health guidelines, with basic dispensing arrangements not requiring additional federal reimbursement updates. These dynamics create an environment in which compliance readiness, institutional alignment, and deployment flexibility can be as important as hardware performance.
Infrastructure realities also shape opportunity. Vending placements are not uniform in content or economics. Even within adjacent markets, product mix and site-specific utilization patterns can diverge significantly, influencing revenue potential and machine design. For organizations planning market expansion or portfolio optimization, these factors underscore the need to evaluate each opportunity through the appropriate operational lens. The full report examines these dynamics as part of a broader integrated view, so that strategy teams can incorporate regulatory exposure, procurement behavior, and site-level complexity into their planning assumptions.
Why This Research Matters for 2026 Decision-Making
The 2026 decision environment demands more than awareness of top-line growth. Enterprises are being asked to evaluate where to commit capital, which deployment models are defensible, how to interpret competitive moves across both commercial and health-facing segments, and what regulatory pathways will define feasible scale. A market expanding toward the projected 2032 revenue level will not reward undifferentiated participation. It will reward organizations that can align their strategy with the underlying structure of demand, the economics of deployment, and the compliance realities of the application areas they pursue.
This report is designed to support exactly that kind of strategic clarity. It translates market structure into actionable perspective: where growth is concentrated, how applications differ in their value logic, what distinguishes leading operators in their respective domains, and which dynamics are likely to shape the next phase of market evolution. By integrating historical evidence, forward-looking sizing, competitive intelligence, and operational context, the study gives decision-makers a more reliable foundation for planning than headline figures alone can provide.
Access the Full Strategic Assessment
The analysis presented here outlines the strategic importance of the smart vending machines market and the essential questions this research addresses. However, the full report goes further. It provides the segmented evaluation, competitive detail, regional maturation context, and operational dynamic mapping that organizations need before making investment or deployment commitments. For strategy, operations, and commercial leadership teams preparing for 2026 and beyond, the complete market intelligence is essential.
To access the full dataset, segmentation evidence, competitive profiles, and application-specific strategic implications, visit the source page for the complete Smart Vending Machines Market research. The complete report is designed to support concrete decision-making, from market-entry assessment to partnership evaluation and deployment prioritization.
For detailed analysis of this topic, please visit the official page: Smart Vending Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Proline Market Report: $595.9M in 2025, Projected $907.91M by 2032, 6.65% CAGR
By PW Consulting, 2026-09-16
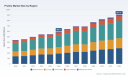
Strategic Intelligence for the L-Proline Market: Navigating Growth and Complexity in 2026 and Beyond
The global amino acid landscape is undergoing a structural transformation, driven by shifting consumer preferences, evolving pharmaceutical demands, and increasingly complex supply chain economics. At the center of this evolution lies L-proline, a non-essential amino acid that has quietly transitioned from a specialized biochemical intermediate to a strategic commodity with broad industrial, nutritional, and therapeutic applications. As enterprises recalibrate their market positioning and supply chain resilience strategies for the coming years, decision-makers require more than surface-level industry commentary. They need granular, forward-looking intelligence grounded in rigorous primary research and validated market modeling.
Our newly released Proline Market report delivers precisely that. Designed for executives, strategy planners, procurement leaders, and investment analysts, this study maps the trajectory of the global L-proline sector across a comprehensive historical and forecast horizon. The findings illuminate not only where the market has been, but where it is structurally headed, providing a decision-ready framework for navigating volatility, capturing emerging demand, and executing competitive positioning with precision.
The 2026 Decision Imperative: Why Timing and Context Matter
Market entry, capacity expansion, partnership formation, and procurement strategy all depend on accurate contextual awareness of macroeconomic and sector-specific dynamics. For L-proline, the convergence of several forces creates a uniquely critical planning window for 2026. Post-pandemic supply chain recalibration has forced manufacturers to reevaluate sourcing dependencies, while rising demand for non-animal-derived ingredients, sports nutrition formulations, and pharmaceutical intermediates has accelerated product development cycles across multiple downstream industries.
The structural shift toward plant-based and fermentation-derived amino acid production continues to reshape cost architectures and competitive moats. Simultaneously, regulatory scrutiny around raw material sourcing, manufacturing transparency, and quality standardization is elevating compliance from a back-office function to a boardroom priority. In this environment, strategic decisions made without a clear view of market velocity, concentration patterns, and application-level demand trajectories carry heightened risk.
Our analysis is calibrated to this reality. By anchoring projections in a multi-year historical baseline and extending the forecast through 2032, the report provides a disciplined, evidence-based pathway for leaders who must act decisively rather than speculate.
Proline Market
Market Trajectory and Structural Signals
The global L-proline market has demonstrated consistent expansion over the past half-decade, with total revenue climbing from approximately $441 million in 2020 to an estimated $596 million in 2025. This growth reflects sustained demand across health and dietary supplement formulations, animal feed nutrition, and pharmaceutical synthesis pathways. Looking ahead, the market is projected to advance at a compound annual growth rate of 6.65 percent, reaching a valuation of roughly $643 million in 2026 and continuing its upward trajectory toward approximately $908 million by 2032.
Several structural signals underpin this momentum. First, downstream demand for amino acid-enabled formulations has broadened beyond traditional food and beverage applications. Nutritional science advancements, clinical research into amino acid metabolism, and consumer wellness trends have collectively expanded the addressable market for proline-based compounds. Second, manufacturing innovation—particularly in fermentation efficiency, strain optimization, and downstream purification—has improved yield economics and expanded grade flexibility for industrial buyers. Third, manufacturing geography continues to evolve, with production capacity increasingly distributed across major industrial corridors to mitigate single-region risk exposure.
For strategic planners, these trends carry actionable implications. Procurement teams must assess whether incumbent suppliers can sustain cost competitiveness as fermentation technology scales. Product developers need visibility into grade availability, purity specifications, and regulatory status across target applications. Investors and corporate development teams require clarity on concentration dynamics, capacity expansion signals, and the pace at which emerging players can scale. Our report addresses each of these dimensions with targeted analysis designed for execution.
Worldwide Prolactin Market
What the Proline Market Report Delivers
This study is engineered for practical use, not academic abstraction. It provides a complete analytical architecture that organizations can integrate directly into forecasting models, market entry evaluations, competitive benchmarking, and supply chain planning workflows. The report covers:
- Historical performance tracking (2020–2025): Year-over-year revenue progression, volume and value trends, and macroeconomic demand drivers that shaped the baseline period.
- Forward-looking forecast (2026–2032): Market size projections, growth rate trajectories, and structural inflection points that decision-makers should monitor as planning horizons extend.
- Type segmentation analysis: A detailed comparison of plant-based and animal-based proline supply streams, including production methodology distinctions, grade suitability, cost structures, and demand migration patterns across end-use sectors.
- Application-level demand mapping: Cross-sector evaluation of how proline is deployed in health and dietary supplements, animal feed, and pharmaceutical formulations, with emphasis on consumption drivers, formulation trends, and regional purchasing behavior.
- Regional market intelligence: Assessment of demand concentration, supply chain geography, trade dynamics, and localization trends across key industrial markets, including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa.
- Competitive landscape profiling: Detailed company profiles, operational focus areas, production capabilities, and strategic positioning of leading manufacturers and emerging participants.
- Concentration and competitive intensity metrics: Structured analysis of market share distribution among top-tier players, indicating where consolidation pressure exists and where fragmentation creates entry or disruption opportunities.
Each section is designed to enable direct integration with internal strategy processes. Whether your team is evaluating supplier diversification, assessing a potential M&A target, modeling product launch scenarios, or stress-testing cost assumptions against raw material volatility, the report provides a defensible foundation for those decisions.
Competitive Dynamics and the Manufacturing Frontier
The L-proline competitive landscape reflects a blend of established multinational amino acid producers, specialized fermentation manufacturers, and regional players with strong downstream integration. The market’s top three participants collectively account for approximately 48.5 percent of revenue, while the top five extend their combined share to roughly 62.3 percent. This concentration profile indicates a market with clear incumbency advantages in scale, process know-how, and downstream customer relationships, but also suggests room for competitive repositioning as regional capacity expands and application-specific demand fragments.
Leading manufacturers demonstrate distinct strategic orientations. Ajinomoto Co., Inc., headquartered in Tokyo, Japan, has built its proline capability around industrial-scale fermentation processes designed for bulk amino acid supply across food, pharmaceutical, and nutrition channels. Evonik Industries AG, based in Essen, Germany, positions L-proline as a non-animal-derived, non-essential amino acid available in multiple industrial grades, serving feed, pharmaceutical, and specialty applications. Meihua Holdings Group Co., Ltd., operating from China, leverages corn fermentation routes to supply proline as an upstream raw material for human medical purposes, sports nutrition food, and special medical applications. KYOWA HAKKO BIO CO., LTD., also based in Tokyo, focuses on amino acid manufacturing including related proline compounds through innovative industrial fermentation methods.
Regional production capability continues to deepen. Sichuan Tongsheng Amino Acid Co., Ltd. manufactures L-proline as part of a broader amino acid portfolio targeting food, pharmaceutical, and animal nutrition markets. Zhejiang NHU Co., Ltd. produces L-proline through fermentation for use in the food industry, human medical purposes, and pharmaceutical intermediates. Shijiazhuang Jirong Pharmaceutical Co., Ltd. supplies L-proline as upstream raw material for drugs treating chronic diseases and related pharmaceutical applications. Together, these participants illustrate how proline manufacturing is not only a commodity play but also a capability-dependent business where fermentation efficiency, grade versatility, and downstream integration shape competitive durability.
Strategic buyers and competitors should pay close attention to how these manufacturers differentiate on grade availability, scale economics, supply reliability, and regulatory alignment. In a market where certain amino acids have become increasingly problematic due to high inclusion rates, elevated pricing, limited global production volumes, or manufacturing complexity, proline’s relative positioning depends on continued process optimization and supply chain transparency. The report provides structured evaluations that help organizations determine which suppliers can support long-term contractual commitments and which represent tactical sourcing options under specific demand scenarios.
Raw Material Pressures and the Cost Architecture Reality
No analysis of the L-proline market is complete without addressing input-side economics. Amino acid manufacturing remains highly sensitive to feedstock pricing, fermentation yield variability, downstream purification costs, and logistics exposure. Industry assessments have highlighted that six amino acids—serine, glutamine, asparagine, histidine, proline, and arginine—have emerged as particularly challenging due to a combination of high inclusion rates, elevated prices, low global production volumes, and manufacturing complexity.
This context matters because cost pressure is rarely uniform across the amino acid portfolio. For proline specifically, competitive advantage increasingly hinges on production efficiency, feedstock flexibility, and the ability to deliver consistent grade quality at scale. Organizations that rely on proline as an upstream input for pharmaceutical synthesis or nutrition formulations must understand how cost volatility transmits through their supply chain and where strategic buffers, alternative sourcing arrangements, or specification adjustments can preserve margin integrity.
Our report integrates these dynamics into the broader market framework, examining how raw material exposure, production complexity, and regional capacity trends interact with pricing behavior and buyer negotiation leverage. Rather than offering static cost snapshots, the analysis maps the structural variables that will shape procurement economics and manufacturing competitiveness over the forecast period.
Why This Report Is Built for 2026 Strategy Execution
Decision-making in 2026 will be shaped by the intersection of demand expansion, supply chain recalibration, technological advancement in fermentation, and increasing transparency requirements across food, nutrition, and pharmaceutical value chains. In that environment, organizations need intelligence that is simultaneously broad enough to capture macro momentum and precise enough to guide category-level actions.
The Proline Market report is structured to meet that standard. It combines historical validation with forward-looking forecasting, maps competitive and application-level dynamics, and provides the analytical scaffolding necessary to translate trend observation into strategic action. More importantly, it preserves strategic discretion: by identifying where the largest decision-relevant opportunities and risks reside, it helps leaders prioritize the questions that matter most before committing capital, capacity, or commercial resources.
Access the Full Intelligence Architecture
The complete Proline Market report extends well beyond the strategic overview presented here. It contains detailed segmentation breakdowns, regional demand and supply mappings, company-level capability assessments, and forecast scenarios designed for internal planning, investment evaluation, and procurement strategy. For teams that require defensible numbers, structured competitive context, and actionable market direction, the full study is the necessary reference point.
To access the complete dataset, segmentation detail, and full competitive profiles, visit the Proline Market research page on the PW Consulting platform. There, you can review the full scope of the analysis, evaluate the report against your internal planning requirements, and secure the intelligence needed to make 2026 and beyond decisions with confidence.
For detailed analysis of this topic, please visit the official page: Proline Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electroporator Market Poised to Hit $344.8M by 2032 on 5.67% CAGR
By PW Consulting, 2026-09-16
Strategic Imperatives in the Evolving Electroporator Market: A 2026 Outlook
The global electroporator market stands at a critical inflection point as we navigate through 2026. For executive leaders, investment committees, and strategic planners, understanding the trajectory of this sector is no longer optional—it is a prerequisite for capitalizing on emerging opportunities in cell therapy, gene editing, and precision medical devices. PW Consulting is pleased to present our comprehensive Electroporator Market research, designed to equip decision-makers with the intelligence necessary to navigate the complexities of the forecast period spanning 2026 to 2032.
As we analyze the historical data from 2020 to 2025, a clear trend of consistent growth emerges. The market revenue has demonstrated resilience and expansion, reflecting the increasing adoption of electroporation technologies across both research and clinical applications. This upward trajectory is projected to continue, driven by technological advancements, regulatory shifts, and the expanding footprint of biotechnology manufacturing. Our latest report delves into these dynamics, offering a granular view of the forces shaping the market landscape.
This article serves as a strategic preview, highlighting the core themes and analytical depth contained within our full market study. While we share high-level insights to establish the context, the specific quantitative breakdowns, regional nuances, and detailed company profiling are reserved for our comprehensive report. For stakeholders seeking actionable intelligence to inform capital allocation, product development, and market entry strategies, the full document provides the granular data required for confident decision-making.
Market Trajectory and Growth Dynamics
The electroporator market has transitioned from a niche laboratory tool to a cornerstone technology enabling breakthrough therapies. Historical performance over the last five years indicates a steady acceleration in revenue generation. Building on this foundation, our forecasts indicate sustained growth through the end of the decade. The projected Compound Annual Growth Rate (CAGR) underscores the market's robust expansion potential, signaling that demand is not merely cyclical but rooted in fundamental shifts within the biotechnology and medical device sectors.
Electroporator Market
This growth is fueled by several converging factors. The rise of cell and gene therapies has amplified the need for reliable, scalable transfection methods. Electroporation has emerged as a preferred technique for delivering genetic material into cells, offering advantages in efficiency and versatility compared to alternative methods. Furthermore, the clinical application of irreversible electroporation (IRE) for tissue ablation represents a significant value driver, expanding the addressable market beyond research laboratories into hospital settings.
Our analysis covers the forecast horizon from 2026 to 2032, a period in which we anticipate increased commercialization of advanced electroporation platforms. Stakeholders must understand the magnitude of this growth to position their portfolios effectively. The revenue projections suggest a market that will more than double its current size by the end of the forecast period, creating substantial opportunities for vendors who can align their offerings with the evolving needs of end-users. However, realizing this value requires a nuanced understanding of market segments, competitive pressures, and regulatory environments, which our full report details extensively.
Technology and Application Landscapes
The electroporator market is characterized by diverse technology types and a wide array of applications. Our research examines the prevailing categories that define the competitive landscape. In terms of product types, the market includes various film-based and specialized electroporation solutions catering to different throughput and efficiency requirements. These include established technologies that dominate volume usage as well as emerging variants designed for specialized workflows. The interplay between these types influences pricing, performance expectations, and adoption rates across different user segments.
Application diversity is another critical dimension. The market serves multiple end-use sectors, ranging from semiconductor manufacturing processes to biopharmaceutical production and clinical interventions. High-volume applications drive significant revenue, while niche uses often command higher margins and foster innovation. Our segmentation analysis explores how demand varies across these applications, identifying which areas are experiencing the fastest adoption and where growth bottlenecks may exist. Understanding these application-specific dynamics is essential for companies looking to target their marketing efforts or develop new product lines that address unmet needs.
It is important to note that while we discuss the structure of the market, the detailed regional and application-level revenue figures, as well as specific market share percentages by type, are disclosed in our full report. These data points are vital for granular strategic planning, allowing clients to benchmark their position against the broader market and identify high-potential regions or segments for expansion. The report provides a complete breakdown of these splits, enabling a precise assessment of where value is being generated.
Regulatory Framework and Industry Compliance
The regulatory environment plays a pivotal role in shaping the electroporator market, influencing product development cycles, market access, and reimbursement prospects. Recent years have seen increased regulatory activity, particularly concerning medical device clearances and compliance standards. Our report integrates the latest regulatory intelligence to help clients anticipate changes and ensure their strategies remain compliant.
A key development in this space involves the clearance of electroporation systems for specific clinical indications. For instance, recent FDA actions have expanded the use of irreversible electroporation devices for tissue ablation, including applications in prostate tissue. Such clearances validate the clinical utility of the technology and open new revenue streams for device manufacturers. Additionally, other electroporation systems have received clearance as substantially equivalent to predicate devices, streamlining the path to market for compatible technologies.
Beyond device-specific approvals, broader regulatory standards impact product design and validation. Standards related to sterilization validation, such as ISO 11135 for ethylene oxide and ISO 11607 for primary packaging, are critical for ensuring the safety and sterility of medical devices. Similarly, biocompatibility testing in accordance with ISO 10993-1 and FDA guidance remains a cornerstone of regulatory submissions. Our report highlights how adherence to these standards affects time-to-market and competitive positioning.
In the context of reimbursement and coding, specific procedural codes are increasingly relevant for the adoption of irreversible electroporation procedures. For example, CPT codes designated for percutaneous and open irreversible electroporation ablation with imaging guidance are used for billing purposes. Awareness of these coding structures is essential for companies marketing to healthcare providers, as it influences the economic viability of procedures for hospitals and clinics. Our full analysis discusses the implications of these regulatory and reimbursement factors on market demand.
Electroporation Buffer Market
Competitive Landscape and Strategic Positioning
The electroporator market features a mix of established life science corporations, specialized technology providers, and innovative medical device companies. Competitive intensity is shaped by the diverse capabilities of these players, ranging from broad-spectrum research instruments to highly specialized clinical systems. Our report provides an in-depth profile of the key companies driving the market, analyzing their strategic moves, product portfolios, and growth trajectories.
Among the notable players, Thermo Fisher Scientific stands out for its comprehensive offering of electroporation instruments, including systems designed for high-efficiency transfection in research, bioprocessing, and cell therapy workflows. These solutions are integral to many laboratory and manufacturing environments, reflecting the company's strength in supporting a wide range of applications. Similarly, Bio-Rad Laboratories maintains a strong presence with electroporation systems that facilitate cell transfection, nucleic acid delivery, and gene editing across various cell types, solidifying its reputation for reliability and performance.
Lonza Group contributes to the competitive landscape through platforms that support gene editing, cell engineering, and therapeutic development. Its solutions are particularly relevant in the context of advanced therapy medicinal products, where efficient and reproducible cell modification is critical. Eppendorf AG offers compact systems tailored for the transformation of microorganisms, addressing the needs of academic and industrial research labs focused on microbial genetics and bioprocessing.
Specialized companies also play a vital role. AngioDynamics designs and manufactures the sole FDA-cleared irreversible electroporation device for tissue ablation, with recent expansions covering prostate tissue use. This focused approach highlights the clinical potential and regulatory pathway specific to IRE applications. MaxCyte develops scalable electroporation platforms for cell therapy, gene editing, and large-scale manufacturing, addressing the growing demand for scalable solutions in the biopharmaceutical sector. Other players like Mirus Bio and BTX provide distinct solutions for transfection of challenging cell types and delivery of genes, drugs, and proteins, respectively. Harvard Bioscience supplies systems and accessories for cell transfection and gene delivery, catering to research applications.
Recent market activities underscore the dynamism of this landscape. For example, the FDA clearance expansion for the NanoKnife System in late 2024 marked a significant milestone for clinical electroporation. Similarly, other companies have achieved regulatory milestones that enhance their market access. Our full report analyzes these developments in the context of competitive strategy, assessing how such events shift market share dynamics, influence partnerships, and create new standards for technology adoption. We also examine the market concentration metrics to provide insights into the level of competition and the dominance of major players.
Strategic Insights for 2026 and Beyond
As we look toward the remainder of 2026 and the forecast period extending to 2032, several strategic implications emerge for market participants. The growth trajectory suggests that demand will continue to outpace supply in certain high-value segments, creating opportunities for companies that can innovate effectively and scale their operations. However, success will depend on more than just product quality; it will require a deep understanding of the end-user ecosystem, including regulatory hurdles, reimbursement realities, and integration with existing workflows.
For researchers and bioprocessing companies, the availability of scalable and efficient electroporation platforms will be a key differentiator. As cell therapies move from clinical trials to commercial manufacturing, the ability to perform transfection at scale with consistent results becomes paramount. Vendors who can demonstrate robust performance, reproducibility, and regulatory compliance will be well-positioned to capture this growing need.
In the medical device sector, the expansion of clinical indications for irreversible electroporation offers a pathway to new revenue streams. Companies that can navigate the regulatory landscape, secure necessary clearances, and educate healthcare providers on the benefits of these procedures will drive adoption. The interplay between device performance, clinical outcomes, and reimbursement codes will shape the pace of uptake in hospital settings.
Our report also explores regional variations in market development. While global growth is robust, certain areas exhibit higher maturity and adoption rates, while others are emerging as potential growth engines. Understanding these regional nuances allows companies to tailor their market entry strategies, prioritize distribution partnerships, and allocate resources where they can achieve the highest return on investment. The detailed regional data provided in our full study enables a precise mapping of these opportunities.
Furthermore, the competitive dynamics will likely evolve as larger conglomerates leverage their broad portfolios and as specialized firms carve out niches with innovative technologies. Mergers, acquisitions, and strategic partnerships may reshape the industry structure. Our analysis tracks these potential shifts and provides a framework for assessing the impact of competitive actions on market positioning.
Navigating the Market with Precision Intelligence
The electroporator market represents a convergence of scientific innovation, clinical need, and commercial opportunity. For organizations operating in or investing in this space, the ability to anticipate trends, understand competitive pressures, and align strategies with market realities is essential. PW Consulting's Electroporator Market report is designed to be the definitive resource for achieving this alignment.
This article has provided a high-level overview of the market forces, growth drivers, regulatory context, and competitive landscape. However, to fully capitalize on the insights presented, stakeholders require the detailed quantitative data and granular analysis that form the core of our research. The complete report includes exhaustive segmentation breakdowns, precise revenue forecasts by segment, comprehensive company profiles with strategic assessments, and in-depth analysis of regional markets. These elements are critical for developing specific, actionable strategies.
We invite executives, analysts, and investors to access the full market research for a complete understanding of the electroporator market's potential. Our team is available to discuss how the findings can be tailored to your specific strategic needs, whether you are evaluating market entry, assessing competitive threats, or planning product development roadmaps. In a rapidly evolving market, having access to precise, up-to-date intelligence is the key to unlocking value and achieving sustainable growth.
For detailed analysis of this topic, please visit the official page: Electroporator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Engineered Stone Market Hits $26.5B in 2025, 7.1% CAGR to $42.8B by 2032
By PW Consulting, 2026-09-16
Strategic Intelligence Report: Navigating the Engineered Stone Market Expansion Through 2032
Executive Overview
The engineered stone sector stands at a pivotal juncture as we move through 2026. Marked by sustained revenue growth, evolving regulatory frameworks, and intensifying competitive dynamics, the market demands a nuanced strategic lens. Our latest Engineered Stone Market research report provides decision-makers with a comprehensive, data-grounded view of where the industry has been, where it is heading, and how leading enterprises are positioning themselves to capture durable competitive advantage.
Drawing on historical performance data from 2020 through 2025 and a forward-looking forecast window extending to 2032, this study translates macroeconomic momentum into actionable intelligence. The global engineered stone revenue trajectory has demonstrated consistent expansion, advancing from approximately 18.81 billion USD in 2020 to an estimated 26.5 billion USD in 2025. Looking ahead, the market is projected to reach roughly 29.28 billion USD in 2026 and continue its upward climb toward 42.83 billion USD by 2032, supported by a compound annual growth rate of 7.1 percent. These figures represent more than sequential growth; they reflect structural shifts in consumer preferences, building material innovation, and manufacturing localization strategies that will define market leadership over the next decade.
Why This Report Matters for 2026 Decision-Making
Enterprise strategy in engineered stone cannot rely on static assumptions. Regulatory mandates are reshaping production standards. Trade policy interventions are altering supply chain architectures. Competitors are investing heavily in next-generation surface technologies and sustainable material formulations. In this environment, a forward-looking, multi-dimensional analysis is not optional; it is foundational to capital allocation, market entry planning, product portfolio optimization, and risk mitigation.
Our report is designed to serve as a strategic compass for executives navigating this complexity. Rather than offering a static snapshot, the analysis integrates historical performance patterns, forward-looking demand signals, competitive positioning assessments, and regulatory trajectory mapping into a single, cohesive intelligence framework. The goal is to equip leaders with the clarity required to make informed decisions in 2026 and beyond, while recognizing that the market's evolution will reward those who anticipate change rather than react to it.
Importantly, this preview offers a strategic orientation and methodological outline. The full report contains the granular segmentation breakdowns, precise regional revenue distributions, type-level and application-level market shares, and detailed forecasting models that enable precise scenario planning. Those deeper data layers are essential for operationalizing the trends described here and are available through the complete research release.
Macro Trajectory and Growth Architecture
The engineered stone market's expansion over the past half-decade has been characterized by steady, compounding growth rather than episodic spikes. Revenue progressed from 19.77 billion USD in 2021, to 20.99 billion USD in 2022, and 22.6 billion USD in 2023, before accelerating to 24.83 billion USD in 2024. This progression reflects underlying demand resilience across residential and commercial end-use sectors, alongside manufacturing scale-up and product innovation cycles that have broadened the material's application footprint.
Engineered Stone Market
The forecast horizon suggests that momentum will be maintained, though not uniformly. Growth is expected to advance through 2027 with revenue approaching 30.34 billion USD, then continue toward 31.78 billion USD in 2028 and 34.69 billion USD in 2029. By 2030, the market is projected to reach 36.1 billion USD, with a notable acceleration phase anticipated through 2031 and 2032, culminating in an estimated 41.11 billion USD and 42.83 billion USD respectively. The 7.1 percent compound annual growth rate across the forecast period signals a market that is scaling on the back of both volume expansion and value enhancement, as premium surface solutions and technologically advanced material formulations gain stronger market penetration.
For strategic planners, the implication is clear. Growth will not be evenly distributed across product types, end-use applications, or geographies. The full research delves into how these growth vectors differ by segment, revealing where demand is maturing, where it is accelerating, and where competitive intensity is likely to reshape share dynamics. That segmentation intelligence is critical for companies evaluating capacity investments, distribution expansion, and product-mix adjustments.
Market Concentration and Competitive Architecture
The engineered stone landscape is marked by meaningful concentration, with a small group of established players commanding a substantial share of industry revenue. The market's top three competitors collectively represent approximately 62.5 percent of total market value, while the top five extend that footprint to roughly 67.2 percent. This concentration reflects the strategic advantages of scaled manufacturing, brand recognition, proprietary surface technologies, and established channel relationships.
Several core enterprises define the competitive frontier. Caesarstone, headquartered in Israel, has built its reputation on premium engineered quartz surfaces with an emphasis on health-compliant formulations and global distribution reach. Its recent operational moves underscore a dual focus on regulatory readiness and commercial expansion. In early 2026, the company launched a full collection of zero crystalline silica quartz surfaces in Australia to align with evolving regulatory standards for worker safety, and later in the year announced first-quarter earnings that highlighted digital platform development and production expansion. The company also introduced an eco-friendly quartz surface line incorporating recycled glass and bio-resins, signaling a broader strategic orientation toward sustainability-led product differentiation.
Cambria, based in the United States, competes with an emphasis on American-made engineered quartz surfaces, innovative design portfolios, lifetime residential warranties, and a strong positioning around natural aesthetics. At a major industry showcase in 2026, Cambria unveiled what it described as the leading edge of quartz innovation, including new designs and application concepts that point toward broader usage scenarios and premiumization within the quartz category.
Cosentino, operating from Spain, stands as a global leader in engineered stone surfaces, with its Silestone quartz and Dekton ultracompact stone offerings anchored by sustainable HybriQ technology. The company demonstrated its innovation cadence by debuting the first collection of its Éclos surface brand alongside new Dekton collections at a prominent 2026 industry event. Its investment posture also reflects long-term capacity planning; in 2025, Cosentino committed 120 million euros to expand Dekton ultracompact stone production capacity through new production lines, an indication of confidence in sustained demand for high-performance surface materials.
LG Hausys, headquartered in South Korea, manufactures Viatera quartz engineered stone surfaces with domestic United States production capabilities and premium collections, reinforcing the strategic importance of localized manufacturing in serving key demand markets. MSI Surfaces, also United States-based, offers Q Premium Natural Quartz engineered stone countertops with domestic manufacturing in South Carolina and a broad color portfolio, underscoring the continued relevance of manufacturing proximity, product variety, and countertop-centered demand in the broader engineered stone ecosystem.
These competitive dynamics illustrate a market where brand equity, technology differentiation, compliance readiness, and production footprint are increasingly intertwined. The full report provides detailed company profiling, strategic positioning analysis, and competitive interaction mapping that help executives benchmark their own capabilities and identify whitespace opportunities.
Regulatory Tailwinds and Constraints
Regulation is now a first-order strategic variable in engineered stone, influencing product design, manufacturing processes, distribution strategies, and market access. The regulatory environment in 2026 reflects heightened attention to worker safety, material composition, and import-related industry impacts, creating both compliance obligations and competitive differentiators for firms that adapt early.
One notable development involves health and safety standards tied to crystalline silica content. Caesarstone's 2026 launch of a zero crystalline silica quartz surface collection in Australia was explicitly oriented toward regulatory compliance, illustrating how product formulation strategies are being reshaped by jurisdictional safety requirements. In parallel, California's occupational safety framework advanced toward a more restrictive posture, with a state board voting to adopt a petition banning the fabrication of engineered stone containing more than 1 percent crystalline silica. These actions point to a broader trajectory in which material composition, fabrication practices, and downstream worker protection are becoming central to product viability in certain markets.
Trade and import dynamics are also exerting strategic pressure. A United States trade commission determination in April 2026 concluded that increased quartz surface imports were causing serious injury to the domestic industry. This finding introduces potential trade remedy implications that could affect import volumes, pricing structures, and competitive positioning between domestically manufactured and imported surfaces. For market participants, the implications extend beyond immediate tariff or duty considerations to longer-term questions about supply chain localization, production capacity planning, and competitive exposure in the US market.
These regulatory vectors do not affect all regions, product types, or applications equally. Their strategic impact depends on manufacturing origin, product formulation, end-market exposure, and the pace at which compliance requirements are adopted and enforced. The report's regulatory analysis section maps these developments against market segments and company profiles, enabling leaders to assess exposure, anticipate compliance costs, and identify potential competitive advantages for firms that proactively align product and process strategies with emerging standards.
Engineered Quartz Stone (EQS) Market
Product Innovation, Sustainability, and Application Evolution
Innovation in engineered stone is increasingly multidimensional. It spans formulation science, aesthetic design, durability performance, sustainability credentials, and application breadth. The companies profiled in this research are investing across these dimensions, and the resulting product landscape is becoming more differentiated.
Zero crystalline silica formulations represent one clear innovation pathway, particularly for markets where worker safety regulation is tightening. Eco-friendly surface lines that integrate recycled glass and bio-resins reflect another axis of differentiation, aligning material innovation with broader sustainability expectations from specifiers, builders, and end consumers. Ultracompact stone technologies and new surface brands introduced at major industry events indicate that manufacturers are also expanding the performance envelope of engineered surfaces, targeting applications that demand higher mechanical resilience, weather resistance, or design flexibility.
Application-wise, countertops remain a central demand anchor within the engineered stone ecosystem, supported by residential renovation activity, new housing construction, and commercial fit-out requirements. Flooring and other application categories contribute additional growth channels, though their relative weighting and growth trajectories vary by region and by product type. The full report examines how these application categories interact with product types and regional demand profiles, providing the kind of segmented insight needed to prioritize go-to-market focus and product development resources.
Strategic leaders should note that innovation Leadership is not solely about launching new collections. It is about aligning product roadmaps with regulatory trajectories, sustainability expectations, distribution channel capabilities, and the aesthetic and performance requirements of construction and design professionals. The report's innovation analysis section evaluates these alignments across the competitive set, helping executives anticipate where product differentiation will translate into share gains versus where it may simply raise the baseline for market entry.
What the Full Study Delivers
This report is structured to support complex strategic decisions with layered, practical intelligence. Beyond the macro growth narrative and competitive context outlined here, the complete study provides:
- Detailed historical and forecast revenue analysis across the full 2020 to 2032 window, including year-by-year projections that support budgeting, capacity planning, and investment timing.
- Segment-level market size and growth assessment by product type, application, and region, enabling targeted market entry, expansion, and portfolio prioritization decisions.
- Competitive profiling of core market participants, including strategic positioning, product and technology emphasis, production footprint considerations, and recent commercial developments.
- Regulatory and trade policy mapping that connects compliance developments to market access, formulation strategy, and competitive exposure across key jurisdictions.
- Industry dynamics analysis that integrates demand drivers, supply-side constraints, innovation trends, and sustainability shifts into a cohesive strategic framework.
- Scenario-ready insights that help leadership teams evaluate alternative growth paths, assess risk concentration, and align operational plans with market reality.
The objective is not simply to describe the market, but to make it legible as a strategic arena. For CEOs, business unit leaders, investors, and strategy professionals, the report is designed to reduce ambiguity around where growth is coming from, which competitors are best positioned to capture it, and what structural factors will shape profitability and market access over the forecast period.
Closing Perspective
The engineered stone market in 2026 is defined by a combination of durable demand growth, accelerating regulatory specificity, and competitive intensification among scaled, innovation-focused players. Revenue expansion from recent historical levels toward a projected 42.83 billion USD by 2032 reflects a sector that is evolving in both substance and strategy. Success in this environment will depend on the ability to interpret market signals early, align product and production strategies with regulatory and sustainability expectations, and deploy capital with precision into the segments and geographies where competitive advantage can be sustained.
This report provides the intelligence architecture required to make those decisions with confidence. To access the full segmentation data, detailed company profiles, regional and type-level breakdowns, and the complete forecast models that underpin the analysis, please refer to the complete Engineered Stone Market research release.
For detailed analysis of this topic, please visit the official page: Engineered Stone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


