



Category: market research
PW Consulting: Seamless Copper Tubes Market to Reach USD 304.47 Million by 2032, Growing at 5.1% CAGR
By PW Consulting, 2026-09-16
Executive Summary: Navigating the Seamless Copper Tubes Market Amidst Global Transformation
The global infrastructure landscape is undergoing a seismic shift, driven by rapid urbanization, stringent environmental regulations, and the accelerating electrification of transport. At the heart of this transformation lies a critical component: the seamless copper tube. As industries demand higher efficiency and durability, the Seamless Copper Tubes Market has emerged as a pivotal sector for strategic investment and operational planning. PW Consulting's latest comprehensive market research provides a detailed roadmap for navigating these complexities, offering indispensable intelligence for stakeholders aiming to capitalize on the opportunities projected through 2032.
Macroscopic Market Trajectory and Growth Signals
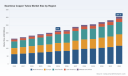
Understanding the broader economic currents is essential for any strategic decision-maker. Our analysis tracks the market evolution from 2020 through the forecast horizon ending in 2032. The data indicates a consistent upward trajectory, reflecting the material's indispensable role in modern engineering. In 2020, the market valuation stood at approximately 163.15 Million USD. This figure has demonstrated resilience and growth, reaching an estimated 215.0 Million USD in 2025.
Looking forward, the momentum is set to continue. The market is projected to attain a valuation of around 218.35 Million USD in 2026, signaling a stable baseline for the forecast period. By the end of the forecast window in 2032, the market size is anticipated to reach 304.47 Million USD. This growth represents a Compound Annual Growth Rate (CAGR) of 5.1 percent over the forecast period. Such metrics suggest a mature yet expanding market where strategic positioning can yield significant returns. The consistency in growth underscores the reliability of seamless copper tubes across various high-demand sectors, making this report a vital tool for long-term capacity planning and investment allocation.
Key Industry Dynamics Reshaping the Landscape
The market does not exist in a vacuum. Several macroeconomic and regulatory forces are actively reshaping the demand and supply dynamics for seamless copper tubes. Our research delves deep into these drivers to help clients anticipate disruptions and leverage trends.
Regulatory Pressures and Environmental Standards
Global regulatory bodies are enforcing stricter environmental and energy efficiency standards, particularly within the HVAC and refrigeration sectors. These regulations mandate the use of seamless copper tubes that comply with rigorous international safety certifications. Manufacturers must ensure their product lines meet these evolving compliance requirements to maintain market access. Our report analyzes the specific certification landscapes across key regions, enabling companies to audit their compliance readiness.
The Electric Vehicle Revolution
A significant macro trend identified in our research is the increasing adoption of seamless copper tubes in electric vehicle (EV) battery cooling systems. As EVs become mainstream, the thermal management requirements for battery packs have intensified. High-performance seamless copper tubes are critical for dissipating heat efficiently, ensuring safety and longevity. This shift represents a high-growth niche within the broader market, attracting innovation from major tube manufacturers.
Raw Material Volatility and Geopolitical Factors
Supply chain stability remains a critical concern. Copper prices exhibited notable volatility in 2025, driven by supply chain disruptions and fluctuating demand from industrial sectors. Furthermore, geopolitical tensions, including US-China trade dynamics and export restrictions in copper-producing nations like Chile and Peru, impact raw material availability. Our analysis provides a nuanced view of these risks, helping procurement teams develop hedging strategies and diversify supply sources to mitigate potential bottlenecks.
Infrastructure Development in Emerging Markets
Urbanization and infrastructure development in emerging markets continue to drive requirements for durable seamless copper tubes, particularly in plumbing and HVAC applications. As cities expand and living standards improve in developing economies, the demand for reliable piping infrastructure escalates. This trend offers substantial growth potential for manufacturers with the logistical capability to serve these regions effectively.
Competitive Arena: Key Players and Strategic Moves
The competitive landscape is characterized by a mix of established global giants and agile regional specialists. With a CR3 of 32.0 percent and a CR5 of 40.0 percent, the market exhibits moderate concentration, allowing for competitive dynamics while rewarding scale and innovation. Our research profiles key enterprises that are defining the market trajectory.
Major Industry Participants
Our report provides detailed profiles of leading companies including Mueller Industries, Inc. , headquartered in Memphis, TN, known for their comprehensive offering in the sector. Wieland Group from Suhl, Germany, represents a major European force with significant technological capabilities. The Italian market is well-represented by KME Group S.p.A. based in Milan. In Asia, Kobe Steel, Ltd. and Furukawa Electric Co., Ltd. from Tokyo, along with Mitsubishi Materials Corporation , showcase Japan's strong presence in high-quality copper products. Luvata , based in Pori, Finland, and Cerro Flow Products, LLC from Saint Louis, MO, are noted for their specialized manufacturing expertise. The Chinese market influence is highlighted by Golden Dragon Precise Copper Tube Group Inc. in Henan, Hailiang Group in Zhejiang, and Shanghai Metal Corporation in Shanghai. Additionally, MetTube Sdn Bhd in Malaysia and MM Kembla Copper Tube Pty Ltd in New South Wales, Australia, round out the global perspective.
Recent Strategic Developments
The velocity of corporate activity in this sector is high. Our intelligence tracks recent moves that signal shifting strategies. In March 2025, Wieland Group announced a 500 million USD expansion at their copper and copper alloy facility in East Alton, Illinois, underscoring a commitment to North American capacity. Also in early 2025, Mueller Industries, Inc. successfully integrated recent acquisitions of Nehring Electrical Works and Elkhart Products, expanding their product line and manufacturing capacity. February 2025 also saw KMCT Corporation expand their line of smooth-bore and inner-groove copper tubing for HVAC and refrigeration systems, responding directly to efficiency demands. By June 2025, Luvata launched high-performance copper tubes specifically designed for electric vehicle cooling systems, marking a strategic pivot toward the EV sector. Furthermore, Golden Dragon Precise Copper Tube Group Inc. completed an expansion of their manufacturing facility in Mexico in June 2025 to increase output, signaling a strengthening of supply chains closer to the US market.
Precision Tubes Market
Understanding these movements is crucial for benchmarking and competitive positioning. Our report dissects these developments to reveal underlying strategic intents, whether they be capacity expansion, technological differentiation, or geographic diversification.
Segmentation Insights: Beyond the Aggregate Numbers
While the overall market size provides a top-down view, true strategic advantage comes from understanding the nuanced segmentation of the market. Our research breaks down the market by Type, Application, and Region to identify where the value pools are deepest.
Product Types and Applications
The market is differentiated by various tube types and end-use applications. HVAC and Refrigeration remains a dominant application area, driven by the need for energy-efficient cooling solutions. Plumbing continues to be a steady contributor, supported by infrastructure development. Additionally, other specialized applications are gaining traction. On the product side, distinctions such as Straight Length Tubes and Capillary Tubes serve different technical requirements. Our analysis quantifies the relative importance of these segments without exposing raw data prematurely, guiding clients on where to focus their R&D and marketing resources. The interplay between product specifications and application requirements is critical for product-market fit in a competitive environment.
Seamless Copper Tubes Market
Regional Distribution
Geographically, the market is spread across North America , Europe , Asia Pacific , Latin America , and Mideast and Africa . Each region presents unique challenges and opportunities. North America shows significant activity driven by industrial demand and recent capacity expansions. Europe faces regulatory pressures that drive high-specification product demand. Asia Pacific remains a hub for both manufacturing and consumption, influenced by rapid industrialization. Our regional analysis helps companies tailor their market entry strategies and optimize their distribution networks to match local demand patterns and regulatory environments.
The PW Consulting Advantage: Actionable Intelligence for 2026
In an era of information overload, precision is paramount. This market research report is not merely a collection of data points; it is a strategic asset designed to inform decision-making at the highest levels. The forecast period from 2026 to 2032 is critical. Companies that act on accurate intelligence today will define the market standards of tomorrow.
Our methodology combines rigorous quantitative analysis with qualitative industry expertise. We synthesize data from primary and secondary sources to ensure reliability. The report covers historical data from 2020 to 2025, providing a solid baseline for trend analysis, and extends forward to 2032 to facilitate long-term planning. All financial figures are presented in USD Million, ensuring consistency and comparability.
Key deliverables include detailed demand forecasts, supply chain risk assessments, and competitive benchmarking. We examine the impact of raw material price volatility on margins and provide scenarios for various geopolitical outcomes. For product managers, the segment analysis offers clarity on which tube types and applications offer the highest growth potential. For strategists, the regional breakdowns inform expansion plans and partnership opportunities.
The insights contained within this document are intended to reduce uncertainty. Whether you are a manufacturer looking to optimize capacity, a supplier seeking stable vendors, or an investor evaluating market potential, this research provides the foundational knowledge required to navigate the complexities of the seamless copper tubes industry. The 5.1 percent CAGR suggests steady growth, but capturing that growth requires understanding the specific drivers behind the numbers.
Access to granular data regarding regional specific values, application splits, and detailed company profiling is essential for crafting a winning strategy. The macroeconomic trends and competitive movements outlined here are only the surface level of the intelligence available. To fully leverage this information for your corporate planning, detailed access to the complete dataset is required.
The seamless copper tube market is poised for evolution. Regulatory shifts, technological advancements in EVs, and infrastructure growth will dictate the pace of change. Partners who understand these dynamics early will secure a competitive edge. PW Consulting stands ready to provide the depth of analysis necessary to turn market intelligence into corporate success.
For detailed analysis of this topic, please visit the official page: Seamless Copper Tubes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Backer Board Market to Hit $3.23B by 2032, Growing at 5.85% CAGR
By PW Consulting, 2026-09-16
Decoding the Backer Board Market: Strategic Intelligence for 2026 and Beyond
The construction and renovation landscape is undergoing a period of intense recalibration, driven by shifting material costs, evolving regulatory frameworks, and a persistent demand for durable building envelopes. At the heart of this transformation lies the backer board market, a critical component in tile installations, wall cladding, and moisture-prone structural applications. For executives, procurement leaders, and strategic planners, navigating this space requires more than surface-level trends. It demands a rigorous, data-backed understanding of where the market has been, where it is accelerating, and how competitive forces will reshape value chains through 2032.
Backer Board Market
Our newly released Backer Board Market research report is designed precisely for that purpose. It distills years of historical tracking, forward-looking modeling, and on-the-ground industry intelligence into a single, actionable intelligence platform. Rather than offering generic market commentary, the study maps the structural drivers, material substitution patterns, and regional demand intensities that will dictate capital allocation, sourcing strategy, and product positioning in the coming cycle.
The Macro Trajectory: A Market in Structural Expansion
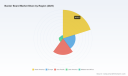
Over the past half-decade, the backer board sector has demonstrated consistent volume growth, underpinned by steady residential remodeling activity, commercial retrofit cycles, and the broader push toward moisture-resistant building standards. Historical tracking from 2020 through 2025 reveals a clear upward arc, with total market revenue climbing from approximately 1.5 billion USD to 2.09 billion USD. This progression was not linear; it reflected periods of supply chain normalization, fluctuating raw material pricing, and varying regional construction activity. Yet the overarching pattern is unambiguous: demand has solidified, and adoption curves have steepened as contractors and developers prioritize long-term durability over short-term cost avoidance.
Looking ahead, our forecasting model projects the market to reach 2.25 billion USD in 2026, with continued expansion through the end of the decade. By 2032, the sector is anticipated to approach the 3.2-billion-USD threshold, sustained by a compound annual growth rate of 5.85 percent. This trajectory is not merely a function of population growth or housing starts; it reflects deeper shifts in specification practices, code enforcement intensity, and the gradual migration toward engineered substrate solutions that outperform legacy alternatives. For strategic decision-makers, the implication is clear: the backer board category is transitioning from a commoditized auxiliary material to a differentiated, specification-driven product segment where early positioning yields measurable competitive advantage.
What the Report Delivers: Operational Intelligence, Not Just Headlines
Market research at its best should function as a decision-support system, not a static snapshot. Our study is structured to provide granular, actionable clarity across every dimension that influences sourcing, pricing, and go-to-market strategy. The report examines the full spectrum of product architectures, mapping the performance profiles, installation characteristics, and end-use suitability of the dominant material families that define the category. It evaluates how each type performs under varying moisture conditions, load-bearing requirements, and finish compatibility standards, enabling procurement teams to align material selection with project-specific risk profiles and lifecycle cost expectations.
The application layer receives equal scrutiny. We dissect how substrate demand bifurcates across tile installation environments, wet-area specifications, floor underlayment requirements, and countertop support systems. By tracing volume distribution across these use cases, the report highlights where adoption is accelerating, where substitution threats are emerging, and where specification lock-in is creating durable demand pools. This application-level breakdown is particularly valuable for manufacturers seeking to optimize product mix, distributors aiming to align inventory with regional project pipelines, and contractors evaluating material trade-offs against labor efficiency and warranty exposure.
Regional demand intensity is analyzed through a lens of economic activity, building code enforcement, and import dependency dynamics. Rather than presenting static share percentages, the study prioritizes directional movement, identifying which geographies are experiencing structural demand expansion, which are plateauing due to market saturation or regulatory headwinds, and which are emerging as high-growth corridors fueled by infrastructure modernization and renovation cycles. This geographic intelligence is cross-referenced with supply chain logistics, freight cost sensitivity, and localized raw material availability, providing a practical foundation for regional capacity planning and distribution network optimization.
Beyond segmentation, the report embeds a comprehensive competitive landscape assessment. We profile the market’s leading participants, evaluating their product portfolio breadth, manufacturing footprint, innovation cadence, and strategic positioning. The analysis captures how incumbents are leveraging brand recognition, technical support networks, and specification relationships to defend core share, while also tracking how newer entrants and niche players are exploiting gaps in lightweight alternatives, moisture-specific formulations, and sustainability-aligned material profiles. The result is a clear view of where competitive pressure is concentrating, where margin pools are most defensible, and where partnership or acquisition logic may emerge as the market matures.
Competitive Architecture: Incumbents, Differentiators, and the Innovation Frontier
The backer board market’s competitive structure is defined by a mix of established building material conglomerates, specialized substrate manufacturers, and regional brands with strong distribution ties. Leading the field are companies that have built long-standing relationships with contractors, distributors, and specification channels, leveraging decades of product iteration and technical support infrastructure. United States Gypsum Company, for instance, anchors its position through dedicated cement and fiber cement backer board offerings that emphasize structural compatibility and widespread specification acceptance. James Hardie, with its dual headquarters structure and deep North American operational presence, has cultivated a similarly entrenched footprint, reinforced by product lines that align closely with exterior and interior moisture-management standards.
Back Glue Market
Parallel to these incumbents, specialized players are carving out distinct positioning through material innovation and niche application focus. Grip-Rite has advanced its portfolio with magnesium oxysulfate-based substrate solutions designed to offer lightweight handling, improved durability, and reduced reliance on traditional cement formulations. PermaBASE Building Products has concentrated on cement backer board variants that balance installation efficiency with performance consistency, while Gold Bond Building Products has pushed into gypsum-based tile backer alternatives that address mold resistance and interior finish compatibility. National Gypsum Company operates at a critical junction in this ecosystem, functioning as an exclusive service provider for key product lines and reinforcing the interconnected nature of manufacturing, distribution, and specification support.
Recent product and platform developments underscore how quickly the innovation frontier is moving. In mid-2025, Grip-Rite introduced a mineral-based, eco-conscious backer board and underlayment line, emphasizing reduced chemical complexity, improved weight characteristics, and durability aligned with modern installation expectations. Later that year, James Hardie expanded its contractor and homeowner engagement toolkit through an AI-driven exterior design customization platform, reflecting a broader industry shift toward digital specification support and end-user visualization. These moves are not isolated product launches; they signal a strategic reorientation toward sustainability messaging, installation efficiency, and specification-friendly digital tools, all of which are reshaping how buyers evaluate substrate options.
Market Dynamics: Cost Pressures, Regulatory Flux, and Material Economics
No strategic assessment of the backer board market is complete without confronting the macroeconomic and regulatory currents that influence material pricing, project feasibility, and procurement behavior. Cement and mineral-based substrates sit at the intersection of building material supply chains that are highly sensitive to trade policy, energy costs, and industrial capacity utilization. Recent trade actions have introduced tariff structures that affect cement imported from neighboring trading partners, with industry advocates cautioning that such measures could elevate project costs, delay infrastructure timelines, and complicate energy and security-related construction planning. These dynamics do not merely influence headline pricing; they alter contractor margin calculations, developer budgeting assumptions, and the relative attractiveness of alternative substrate formulations.
At the project level, builder associations have estimated that recent tariff-driven cost effects can add substantial per-home expenses, pressuring affordability thresholds and nudging specification decisions toward materials that balance performance with total installed cost. Simultaneously, higher input prices and intermittent availability constraints for certain raw materials are eroding purchasing power and tempering discretionary spending in segments where cost sensitivity is acute. Yet the broader production environment has shown resilience, with recent index movements indicating sustained industrial activity and capacity utilization that support ongoing material availability, albeit within a volatile pricing landscape.
These intersecting forces create a highly contextual demand environment. In high-end residential and commercial specification segments, performance and durability often justify premium substrate choices, insulating demand from short-term cost fluctuations. In more price-sensitive remodeling and volume development contexts, however, buyers are increasingly scrutinizing the trade-offs between traditional cement-based boards, lightweight alternatives, and gypsum-composite variants. The result is a market where material economics, installation labor considerations, and warranty expectations are being re-evaluated simultaneously, and where suppliers that can articulate clear total-cost-of-ownership advantages will capture disproportionate specification share.
Strategic Implications for 2026 Decision-Making
For executives operating in or adjacent to the backer board sector, the current environment demands a disciplined, data-informed approach to portfolio planning, sourcing strategy, and competitive positioning. The growth trajectory through 2032 is robust, but the path is uneven, shaped by regional construction cycles, regulatory adjustments, and material substitution dynamics that will vary significantly across application types and customer segments. Companies that treat the market as a monolithic commodity space risk misreading where margin pools are forming, where innovation premiums are sustainable, and where distribution leverage is most critical.
Our research is designed to convert that complexity into clarity. It provides the structural framework needed to evaluate product mix decisions, anticipate specification shifts, and align go-to-market investments with the segments where demand is most durable. By integrating historical performance tracking with forward-looking modeling, competitive profiling, and real-time industry developments, the report equips decision-makers with the context required to navigate pricing volatility, evaluate substitution threats, and identify partnership or expansion opportunities before the market fully prices them in.
The full study goes deeper, offering detailed segmentation analysis, company-level benchmarking, application-specific demand mapping, and scenario-based forecasting that unpacks the variables most likely to influence the next several years of market evolution. For procurement leaders, product strategists, and investment planners, that depth is not optional; it is the difference between reactive adjustment and proactive positioning.
To explore the complete dataset, competitive profiles, and forward-looking scenario analysis, access the full Backer Board Market research report. The detailed intelligence contained within is structured to support immediate strategic application, from sourcing renegotiation and product portfolio optimization to regional expansion planning and specification strategy refinement.
For detailed analysis of this topic, please visit the official page: Backer Board Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Real Estate Software Market Hits $10.6B in 2025, Poised for 8.95% CAGR Growth to 2032
By PW Consulting, 2026-09-16
Navigating the Next Wave: Strategic Intelligence for the Real Estate Software Market in 2026 and Beyond
The real estate technology landscape is undergoing a structural transformation. As property operations grow more complex and capital allocation becomes more scrutinized, software is no longer a back-office utility; it is the operational nervous system of modern real estate portfolios. At PW Consulting, we have published a comprehensive research study on the Real Estate Software Market, designed to equip executive teams, investors, and technology strategists with the decision-grade intelligence required to navigate 2026 and the subsequent forecast horizon through 2032.
This article previews the strategic architecture of that study. It outlines the market's directional momentum, the competitive forces reshaping vendor ecosystems, the regulatory and operational dynamics that will define procurement decisions, and the practical analytical frameworks contained in the full report. Per the preview methodology, we present the structural insights needed to evaluate opportunity and risk, while reserving the granular segmentation data and detailed quantitative breakdowns for the complete publication. To access the full intelligence suite, including region-level sizing, application-specific revenue splits, and company-level scenario modeling, readers are directed to the source publication page.
Market Trajectory and the Strategic Case for 2026
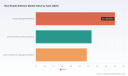
The macroeconomic backbone of this study rests on a clear, sustained growth arc. Historical revenue data from 2020 through the 2025 base year demonstrates consistent expansion, validating the sector's resilience through shifting interest-rate environments and evolving asset management priorities. Building on that historical foundation, the forecast period projects continued upward momentum, anchored by a compound annual growth rate of 8.95 percent across the 2026–2032 window.
What does this trajectory mean for enterprise decision-making? First, it signals that demand for real estate software is not cyclical in the traditional sense; it is being structurally reinforced by automation, data centralization, and the operational complexity of managing fragmented portfolios. Second, the forecast's forward curve implies that market consolidation and capability differentiation will accelerate in parallel with top-line growth. Organizations that delay technology evaluation or treat software selection as a purely tactical procurement exercise will face compounding integration costs and capability gaps as the market matures.
The full research quantifies this trajectory across the forecast horizon, mapping year-by-year revenue progression and contextualizing the inflection points where adoption accelerates. Rather than presenting a single headline figure, the study decomposes momentum into the drivers that matter for planning: deployment velocity, workflow automation penetration, and the shifting balance between property-level and enterprise-grade system adoption. These are precisely the variables that determine whether a technology investment compounds value or becomes a stranded asset.
Competitive Landscape: Nine Leaders Defining the Modern Stack
Market growth is always mediated by competitive dynamics, and this sector is no exception. Our analysis centers on a core group of established and rapidly evolving vendors whose product roadmaps, Go-to-market strategies, and recent corporate moves collectively define the shape of the market. The study profiles nine companies whose positioning spans property management automation, enterprise resource planning, customer relationship management, commercial real estate data and analytics, brokerage and transaction workflows, and marketplace-driven search and valuation tools.
Each profile is structured to answer the questions that procurement and strategy teams actually ask. What workflow layer does the vendor own today? Where is the product extending next? How does the company's historical capability translate into near-term differentiation in an environment where AI-assisted operations are becoming table stakes? The study evaluates each organization's operational emphasis, from AI-powered automation and mobile-first workflows to tenant screening, lease tracking, maintenance request orchestration, leasing marketing tools, resident engagement, multifamily workforce automation, portfolio-level commercial operations, marketplace search and agent tools, and transaction management with property valuation capabilities.
Beyond static profiles, the report integrates recent corporate and product developments that signal strategic intent. In May 2026, MRI Software advanced its thought leadership around building versus energy management systems and the operational distinctions between lease and license frameworks, reinforcing its focus on nuanced property operations. The same month, the company appointed Dermot Briody as Chief Revenue Officer, a move aligned with scaling global growth and intensifying client-success execution. These developments illustrate a broader pattern: leading vendors are simultaneously deepening domain expertise and expanding commercial capability to convert technical differentiation into market share.
Property Management Software Market
The competitive timeline continues with notable product and corporate actions in the first half of 2026. In April, RealPage introduced an AI-powered workforce management tool designed to automate leasing, finance, and resident engagement tasks, reinforcing the operational automation trend at the multifamily layer. In January, CoStar Group announced a comprehensive AI deployment across its marketplace platforms to enhance user experience and sharpen competitive positioning, while also authorizing a new $1.5 billion share repurchase program as part of an accelerating AI-driven growth strategy. These moves are not isolated product announcements; they are indicators of how incumbents are reallocating capital and engineering focus in response to intensifying platform competition and elevated user expectations.
The full study goes further by mapping these companies against concentration signals in the market. With the top three firms commanding a substantial share of total revenue and the top five extending that footprint even further, the environment rewards both deliberate vendor selection and an understanding of where platform extensibility will create switching-cost dynamics. Enterprise buyers must assess not only current functionality but also the probability that a given vendor will become a long-term portfolio anchor versus a specialized component in a multi-vendor architecture.
What the Competitive Analysis Enables
- A structured comparison of vendor emphasis across property management, enterprise resource planning, customer relationship management, commercial real estate analytics, and brokerage and marketplace tools, so teams can align software selection with operational priorities rather than feature checklists.
- Product roadmap signaling derived from recent launches and thought leadership, helping organizations anticipate where automation, compliance support, and data integration will mature fastest.
- Capital-allocation context from corporate actions, including leadership changes and platform investment decisions, which provide leading indicators of where vendors intend to compete most aggressively.
- Concentration-aware procurement strategy, enabling buyers to weigh platform breadth, integration risk, and long-term negotiation leverage when structuring technology stacks.
Segment-level revenue distribution, regional breakdowns, and application-specific sizing are included in the full publication to support precise budgeting and market-entry planning. They are intentionally held back from this preview because their strategic value is best realized when paired with the complete analytical framework, scenario assumptions, and methodology notes available in the source report.
Market Dynamics Shaping Procurement and Adoption
Revenue growth alone does not determine outcomes. The sector's trajectory is being remolded by regulatory mandates, operational constraints, and data-governance pressures that alter both demand and implementation risk. The study treats these dynamics as first-order variables in forecasting, not as footnotes.
On the regulatory front, compliance expectations are increasingly encoded into software requirements. The implementation of the EU Corporate Sustainability Reporting Directive is compelling real estate companies to build comprehensive ESG data collection and reporting capabilities into their operations, making sustainability-focused data architecture a procurement consideration rather than an optional add-on. In parallel, the General Data Protection Regulation continues to drive investment in compliance-oriented software across real estate workflows, particularly where tenant, owner, and transaction data intersect with cross-border operations and sensitive personal information.
Data privacy and security concerns are also shaping growth patterns by demanding specialized compliance and cybersecurity measures within real estate software environments. As platforms consolidate more operational, financial, and resident data into unified systems, the attack surface expands, and the cost of inadequate controls rises. The study addresses how these requirements affect vendor evaluation, implementation timelines, and the relative attractiveness of platforms with mature governance frameworks versus those still maturing their security posture.
A second dynamic constraint is talent. The shortage of skilled practitioners in data analytics and AI deployment is cited as a primary brake on adoption and implementation quality. Even when software capabilities are available, organizations can struggle to extract value if internal teams lack the analytical fluency to configure, interpret, and continuously optimize platforms. This has two strategic implications. First, it elevates the importance of vendor-provided enablement, onboarding rigor, and ongoing support models. Second, it raises the premium on solutions that reduce the analytical burden through intuitive workflows, guided configuration, and automation that delivers outcomes without requiring deep in-house data science capacity.
These dynamics do not cancel growth; they channel it. Markets expand fastest where technology providers and enterprise buyers can jointly reduce implementation friction, satisfy compliance obligations by design, and convert operational data into actionable insight. The full research assesses how these dynamics interact with segmentation, regional maturity, and application-level demand to explain where adoption is most likely to accelerate and where execution risk remains elevated.
What the Full Study Delivers
The report is built for executives who need to move from directional awareness to actionable planning. It combines market sizing, forecast architecture, competitive profiling, and dynamics analysis into a single decision framework, with enough operational specificity to inform budgeting, vendor selection, product strategy, and market-entry evaluation.
Operational content in the study includes:
- Historical and forecast revenue architecture spanning the base year through 2032, with year-by-year progression that supports multi-horizon planning rather than single-point estimation.
- Structural segmentation analysis that explains how the market divides across regional environments, software types, and application settings, providing the context needed to evaluate where demand concentrates and where whitespace may exist.
- Company-level profiles and recent-event integration for the core competitive set, allowing teams to benchmark vendors against workflow coverage, automation orientation, and strategic intent.
- Market concentration analysis that clarifies the balance between incumbent strength and competitive openness, helping buyers and investors gauge platform leverage, substitution risk, and consolidation potential.
- Regulatory and operational dynamics assessment, including ESG reporting requirements, data protection obligations, privacy and security expectations, and workforce capability constraints, all linked to their practical impact on adoption and implementation.
The study is intended to support a range of decisions: whether to consolidate around a unified platform or maintain a modular stack; how to sequence implementation to manage compliance, security, and change-management risk; which vendor capabilities represent durable advantages versus transient feature leadership; and how to align software strategy with portfolio composition and growth targets. By integrating quantitative direction with qualitative competitive and regulatory context, the report is designed to reduce the gap between market awareness and execution planning.
Why This Report Matters for 2026 Decision-Making
2026 is a pivotal year because the market's growth rate, competitive intensity, and regulatory expectations are converging at the same moment. Organizations that treat real estate software as a static procurement category will underestimate the pace at which automation, data governance, and platform consolidation are reshaping operating models. Organizations that wait for perfect clarity will find themselves competing against peers who made earlier, better-informed technology commitments.
The strategic value of this study lies in its ability to convert a high-level growth narrative into structured decision support. The 8.95 percent compound annual growth trajectory signals that the opportunity is large and durable, while the concentration patterns and competitive developments indicate that not all platforms will capture that opportunity equally. The regulatory and operational dynamics explain why some implementations accelerate and others stall, and why software selection has become closer to portfolio strategy than to IT procurement.
For investors, the report provides a basis for assessing where platform economics, product extensibility, and regulatory tailwinds align. For enterprise buyers, it offers a framework for evaluating vendor durability, integration risk, and implementation readiness. For technology strategists, it maps the capability gradients that separate short-term feature play from long-term operational advantage.
Accessing the Complete Intelligence
This preview has outlined the strategic logic, competitive structure, and dynamic pressures that define the real estate software market as it moves through 2026 and toward 2032. It has presented the macro growth arc, the vendor behaviors that signal where competition is intensifying, and the regulatory and talent dynamics that will shape adoption outcomes. What it has not done is unlock the full quantitative segmentation, regional and application-level revenue distribution, or the detailed scenario analysis that supports precise planning.
Those elements are contained in the complete study. To access the full set of market sizes, forecast breakdowns, segmentation insights, company profiles, concentration metrics, and dynamics analysis, please visit the source publication page. There, the complete intelligence is available in a form designed for executive review, strategy workshops, procurement evaluation, and investment analysis.
The real estate software market will continue to reward organizations that combine operational discipline with clear-eyed technology strategy. PW Consulting's research is intended to provide exactly that clarity: enough depth to trust the direction, enough structure to act on it, and enough detail to make 2026 decisions with confidence.
Real Estate Software Market
For detailed analysis of this topic, please visit the official page: Real Estate Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Smart Office Market to Hit $99.87M by 2032 with 7.98% CAGR - PW Consulting Insights
By PW Consulting, 2026-09-16
Unlocking the Next Wave: Strategic Intelligence in the Smart Office Market (2026-2032)
As organizations navigate the post-pandemic normalization of hybrid work, the definition of the modern workplace is undergoing a fundamental reconstruction. The smart office is no longer a futuristic concept; it has become a critical determinant of operational resilience, cost efficiency, and employee retention. At PW Consulting, we recognize that capital allocation decisions made in 2026 will define competitive positioning for the remainder of the decade. Our latest market research release, Smart Office Market 2026-2032, is designed not merely as a statistical compendium but as a strategic compass for executives, investors, and technology leaders.
This article serves as a strategic preview, outlining the macro-economic trajectory, competitive structures, and dynamic forces shaping the ecosystem. By understanding the broader contours, decision-makers can better appreciate the depth of intelligence available in the full report, where granular segmentation and actionable forecasts reside.
The Macro-Economic Trajectory: Growth Anchored in Digital Transformation
The smart office market is experiencing a robust expansion phase driven by the convergence of IoT, AI, and sustainability mandates. Our analysis, anchored in historical data from 2020 through 2025 and projecting forward to 2032, reveals a consistent upward trajectory that defies broader economic volatility. The market valuation has demonstrated steady acceleration, moving from approximately 40.1 million USD in 2020 to an estimated 58.65 million USD in 2025. This historical performance sets the stage for a significant growth phase in the forecast period.
Looking ahead to 2026 and beyond, the momentum is expected to intensify. The market is projected to reach 62.88 million USD by 2026, with continued expansion toward the 99.87 million USD range by 2032. This growth path reflects a compound annual growth rate of 7.98 percent over the forecast period. Such a rate indicates that smart office technologies are transitioning from discretionary upgrades to essential infrastructure. For enterprise leaders, this trajectory suggests that delaying investment carries an opportunity cost, not only in terms of operational inefficiency but also in missing the window of early-adopter advantage.
It is crucial to note that these figures represent the broader market aggregate. The full report at PW Consulting decomposes this growth into nuanced segments that reveal where capital is flowing most aggressively. Early indicators suggest that certain categories are outpacing the average CAGR, driven by specific technological breakthroughs and regulatory pressures. However, identifying the precise winners and losers within vertical and geographic splits requires the detailed breakdowns provided in our paid intelligence suite. The aggregate numbers provide the confidence to invest; the segmentation provides the roadmap for allocation.
Competitive Dynamics: A Consolidated Battlefield
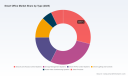
The market structure is characterized by a high degree of concentration, signaling maturity and the need for scale. Our analysis indicates that the top three competitors hold a combined market share of approximately 55.0 percent, while the top five entities control 62.0 percent. This concentration suggests that while the market is growing, the battleground for share is intense among established giants and specialized disruptors alike. Understanding the strategic positioning of these key players is vital for companies seeking partnerships or assessing competitive threats.
The landscape is dominated by large industrial and technology conglomerates that leverage diverse portfolios. Johnson Controls, headquartered in Milwaukee, Wisconsin, focuses heavily on IoT-enabled building management platforms that integrate occupancy sensing with HVAC and lighting automation. Similarly, Honeywell International, based in Charlotte, North Carolina, provides AI-powered occupancy sensors and integrated platforms designed for energy optimization in hybrid environments. Siemens AG, from Munich, Germany, offers IoT-enabled suites tailored for human-centric spaces, emphasizing adaptive systems for enterprise retrofits. Schneider Electric, located in Rueil-Malmaison, France, delivers building automation platforms that focus on multi-parameter environmental monitoring and energy management.
Beyond the heavy industrial players, the ecosystem includes specialized technology providers. Signify N.V., based in Eindhoven, Netherlands, manufactures the Interact Office occupancy intelligence platform, utilizing dense sensor networks for utilization optimization. Cisco Systems, from San Jose, California, integrates networking and security with IoT solutions to create connected hybrid workspaces. IBM, headquartered in Armonk, New York, develops Intelligent Workplace Management System platforms focused on space utilization analytics and cost reduction. Crestron Electronics, in Rockleigh, New Jersey, provides next-generation control systems with touchless interfaces and automation.
Smart Building Market
A second layer of innovation comes from niche players and software-focused firms. Framery, based in Helsinki, Finland, supplies smart seating and workspace solutions with real-time Space Overview software for booking management. Envoy, from Austin, Texas, offers workplace management software platforms addressing hybrid-work dynamics and visitor experience. Density, located in San Francisco, California, specializes in plug-and-play occupancy sensors for real-time people counting. viaim, also in San Francisco, develops AI-powered hardware including earbuds and tools for voice recording and transcription. Butlr, based in New York, New York, provides thermal occupancy sensors for anonymous people counting. XY Sense, also in San Francisco, manufactures enterprise occupancy sensors for utilization and sustainability integration.
Our full report provides a detailed comparative analysis of these entities, including their strategic moves, product roadmap alignment, and vulnerability assessments. For instance, recent developments such as viaim's launch of AI voice recorder earbuds and NoteKit tools in June 2025, or Framery's software launch for real-time free-space booking in January 2025, signal shifting priorities toward seamless collaboration and flexibility. Furthermore, industry bodies like AVIXA published guidelines in August 2025 regarding IoT security solutions, highlighting the critical intersection of connectivity and risk. These events are markers of the rapidly evolving competitive terrain that our analysis tracks in real-time.
Market Dynamics and Critical Friction Points
Growth is not without its complexities. The expansion of smart office infrastructure introduces significant dynamics around security, privacy, and regulatory compliance that can impact deployment strategies. As organizations deploy sensors and connected devices, the data generated can reveal patterns about employee behavior, workspace usage, and company operations. This sensitivity necessitates robust cybersecurity measures. The NIST Cybersecurity Framework provides flexible guidelines for identifying, protecting, detecting, responding to, and recovering from cyber incidents in these environments. Ignoring these protocols can expose firms to reputational and financial risk.
Data privacy remains another pivotal concern. GDPR requires transparent handling of personal data and empowers individuals with rights over their information in smart office IoT deployments. Compliance is not optional; it is a foundational requirement for scaling smart office solutions, particularly in regions with stringent data protection laws. Our report delves into the specific compliance landscapes that vary by jurisdiction, offering guidance on how to structure deployments that satisfy regulatory bodies without stifling innovation.
On the structural side, material costs and implementation strategies play a crucial role. Retrofit implementations of smart office solutions enable organizations to improve existing systems without the significant expenses tied to new construction. This factor is accelerating adoption rates among companies with legacy buildings. Additionally, regulatory frameworks are acting as demand pullers. The European Commission Directive 2024/1275 on the Energy Performance of Buildings imposes binding renovation quotas that pull forward demand for building automation in smart offices. These regulatory tailwinds are reshaping the investment thesis, making energy-efficient smart office technologies a compliance necessity as well as an operational choice. Determining the exact impact of these directives on regional demand requires the granular analysis found in the complete market study.
Smart Office Market
Operational Utility and Content Depth of the Report
PW Consulting's Smart Office Market report is engineered for immediate application. It moves beyond high-level trends to provide the specific intelligence required for budgeting, vendor selection, and market entry strategies. The report covers a forecast period from 2026 to 2032, building on a historical baseline from 2020. This long-view perspective allows strategists to model multiple scenarios and stress-test their plans against market volatility.
Inside the full document, readers will find detailed segmentation analysis that dissects the market by region, type, and application. While the aggregate market size provides the macro view, the segmentation reveals the specific drivers behind the numbers. For example, the report examines the relative performance of categories such as Security and Access Control Systems, Energy Management Systems, Smart HVAC Control Systems, Smart Lighting and Controls, Audio-Video Conferencing Systems, and Other Products. Understanding the revenue contribution and growth momentum of each category helps technology leaders prioritize R&D and procurement. Similarly, the application segmentation covers Corporate Offices, SMEs, Educational Institutions, Government Offices, and Healthcare Facilities. Identifying which application sector is driving the highest value capture is essential for solution providers targeting their sales efforts.
Furthermore, the report includes a rigorous analysis of regional dynamics. Global expansion patterns are influenced by local infrastructure readiness, funding availability, and regulatory environments. The full intelligence brief breaks down the market presence across key geographies, allowing multinational corporations to tailor their rollout strategies. We also provide a comprehensive competitor benchmarking matrix that evaluates market share, product portfolio strength, and strategic alliances. This tool is indispensable for M&A due diligence and partnership evaluation.
The report also integrates qualitative insights from industry experts and recent development tracking. We analyze product launches, software updates, and guideline publications that alter the competitive balance. For instance, the recent focus on cybersecurity standards by AVIXA and the continuous innovation from companies like Density and XY Sense in sensor technology are tracked to help clients anticipate market shifts. These insights are synthesized into actionable recommendations for navigating the complexities of project implementation, vendor negotiation, and risk management.
Why This Intelligence Matters for 2026 Decision-Making
In the current economic climate, precision is paramount. General market knowledge is insufficient for securing budget approval or defining a technology roadmap. Stakeholders require evidence-based forecasts that account for regulatory changes, technological disruptions, and competitive responses. The 7.98 percent CAGR and the projected growth toward 99.87 million USD by 2032 provide a strong narrative for growth, but the strategic value lies in knowing exactly where that growth is concentrated.
For investors, the market concentration metrics and competitor profiles offer a lens into market stability and potential consolidation opportunities. For technology vendors, the segmentation data highlights underserved niches and high-growth applications. For end-user organizations, the analysis of retrofit feasibility and energy mandates informs capital expenditure planning. The full report at PW Consulting consolidates these disparate data points into a coherent strategy document.
We invite you to explore the complete Smart Office Market 2026-2032 research. The preview above outlines the scope and strategic relevance, but the proprietary data, detailed segmentation splits, and actionable recommendations are available exclusively through our source page. Access the full report to gain the competitive edge needed to navigate the evolving landscape of the smart workplace.
For detailed analysis of this topic, please visit the official page: Smart Office Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cryogenic Freezers Market Hits $150M in 2025, 5.9% CAGR to $221.6M by 2032
By PW Consulting, 2026-09-16
Unlocking Strategic Value: The Cryogenic Freezers Market Outlook for 2026 and Beyond
The global cryogenic freezers market stands at a pivotal juncture in 2026. As life sciences research accelerates, biopharmaceutical manufacturing scales, and clinical biobanking becomes a cornerstone of modern healthcare infrastructure, the demand for ultra-low temperature storage solutions has never been more critical. For enterprises operating in this ecosystem, navigating the complexities of market growth, competitive positioning, and regulatory compliance requires more than superficial market summaries. It demands a rigorous, data-backed strategic intelligence framework.
This article serves as a strategic primer for our latest comprehensive market research on the Cryogenic Freezers Market. By synthesizing historical performance trends, forward-looking growth trajectories, competitive dynamics, and real-time procurement signals, this report equips decision-makers with the analytical depth required to make informed investments, capacity planning, and partnership strategies throughout the 2026-2032 forecast horizon.
Worldwide Cryogenic Market
Market Trajectory: From Recovery to Sustained Expansion
The cryogenic freezers market has demonstrated a clear upward trajectory over the past half-decade, reflecting the compounding effects of biological sample preservation mandates, increased clinical trial activity, and the expansion of advanced therapy manufacturing. Historical data from 2020 through 2025 reveals a market that has consistently expanded its revenue base, accelerating from approximately 115.0 million USD in 2020 to roughly 150.0 million USD by 2025. This growth underscores a structural shift rather than a temporary cycle, as institutions worldwide continue to invest in cold-chain resilience and long-term specimen archiving capabilities.
Looking ahead, the forecast period spanning 2026 to 2032 projects continued expansion with a compound annual growth rate of 5.9 percent. By 2032, the market is positioned to reach an estimated 221.6 million USD. This trajectory is not linear; it reflects evolving procurement cycles, regional deployment patterns, and the gradual adoption of higher-efficiency storage architectures. For strategic planners, this growth curve signals both opportunity and timing sensitivity. Early movers who align their product portfolios, service infrastructure, and distribution networks with the forecasted demand inflection points will be best positioned to capture market share as the decade progresses.
Structural Dynamics Shaping Competitive Advantage
The cryogenic freezers market is characterized by a moderately concentrated competitive landscape. Industry analysis indicates that the top three players command a combined market share of approximately 60 percent, while the top five collectively control around 65 percent of total revenue. This concentration reflects the capital-intensive nature of cryogenic equipment manufacturing, the importance of regulatory certifications, and the long-term contracts typical of laboratory and clinical procurement cycles. Yet the remaining 35 percent of the market remains accessible to specialized manufacturers, regional suppliers, and innovators who can differentiate through application-specific engineering, energy efficiency, or service agility.
Several structural dynamics are actively reshaping how value is created and captured in this space. First, regulatory compliance has emerged as a decisive gatekeeper. Manufacturers whose cryogenic freezers and associated storage units maintain formal listings with the Food and Drug Administration, or have secured recent FDA approvals for specific models such as helium-based cryogenic units, are gaining preferential access to hospital networks, government procurement programs, and regulated biopharma supply chains. Second, procurement signals from public health institutions are illustrating a broader trend: defense and military medical facilities are increasingly specifying liquid nitrogen-type cryogenic freezers for pathology and specimen storage, reinforcing the strategic importance of reliable cold-chain infrastructure in government health systems.
Third, product innovation cycles are accelerating. Recent product launches highlight a clear industry focus on ergonomics, high-efficiency cooling architectures, and specialized form factors designed for fertility clinics, biorepositories, and clinical laboratories. These developments are not merely engineering milestones; they represent strategic responses to end-user workflow constraints, space limitations, and the growing demand for operator-safe handling of liquid nitrogen systems. Companies that integrate these operational considerations into their product roadmaps are likely to secure stronger customer retention and more favorable procurement positioning.
Operational Intelligence Embedded in the Full Report
Beyond macro-level growth projections and competitive concentration metrics, the complete market research report delivers a granular operational playbook tailored for commercial, R&D, and procurement leaders. The study systematically maps out the segmentation architecture that defines how customers evaluate, procure, and deploy cryogenic freezing technologies. Readers will gain access to detailed breakdowns that clarify which equipment categories dominate current procurement pipelines, how different application sectors prioritize storage specifications, and which geographic markets exhibit the strongest near-term deployment momentum.
The report also incorporates a rigorous competitive profiling framework. Each major participant is evaluated across dimensions that matter to enterprise decision-makers: geographic presence, core product capabilities, recent developmental milestones, and strategic positioning within regulated and research-intensive segments. Profiles cover manufacturers specializing in liquid nitrogen vapor freezers, controlled-rate freezing systems, automated storage architectures, and hybrid cascade refrigeration solutions. By examining these profiles in context, the report enables readers to identify partnership opportunities, assess competitive threats, and benchmark their own strategic posture against established incumbents.
In addition, the full study integrates regulatory tracking, procurement intelligence, and product launch monitoring into a unified analytical structure. This means readers do not need to piece together fragmented press releases or manually cross-reference bidding notices. Instead, they receive a consolidated view of how regulatory approvals, government invitations for bids, and commercial product introductions are interacting to shape demand timing, supply chain readiness, and competitive intensity across the forecast window.
Competitive Landscape: Established Leaders and Evolving Positioning
The competitive environment in cryogenic freezers is anchored by a set of well-established manufacturers with deep roots in life sciences, biomedical storage, and specialized cold-chain equipment. Several of these companies have built reputations around liquid nitrogen-based storage systems, ultra-low temperature freezers, and controlled-rate freezing platforms that serve clinical, research, and biopharmaceutical applications. Their product portfolios reflect a strategic emphasis on long-term sample integrity, operational reliability, and compatibility with regulated laboratory workflows.
Cryogenic Freezers Market
At the same time, the landscape is not static. Hybrid refrigeration technologies, helium-enabled cryogenic designs, and automated storage solutions are expanding the technical boundaries of what end-users expect from modern cryogenic infrastructure. Some manufacturers are pushing into highly specialized niches, such as high-efficiency series designed for fertility clinics and biorepositories, while others are reinforcing their standing through FDA clearances or targeted government procurement eligibility. This diversification of technological approaches and end-market focus is creating a more multidimensional competitive arena, where success depends not only on hardware performance but also on compliance readiness, service coverage, and alignment with institutional procurement cycles.
The report's competitive analysis digs into these nuances. Rather than presenting static company summaries, it evaluates how each organization is adapting to shifting demand signals, regulatory expectations, and application-specific requirements. Readers will be able to discern which manufacturers are strengthening their positions through product launches, which are expanding their footprint through specialized storage systems, and where potential whitespace opportunities may exist for new entrants or existing players seeking to broaden their addressable market.
Why This Research Matters for 2026 Decision-Making
For executives, procurement strategists, and market entry planners, 2026 represents a critical year for calibrating cryogenic storage strategies. The convergence of sustained market growth, regulatory-driven procurement preferences, and accelerating product innovation means that timing, positioning, and evidence-based forecasting are more important than ever. Companies that rely on outdated market snapshots or generalized industry narratives risk misallocating capital, overlooking emerging demand pockets, or entering competitive segments without a clear differentiation strategy.
This market research report is designed to remove that uncertainty. It translates historical performance data into actionable forward-looking insights, contextualizes competitive concentration within real-world procurement dynamics, and highlights the regulatory and operational factors that are currently shaping buyer behavior. Whether the objective is to evaluate capacity expansion, assess partnership or acquisition targets, refine product development roadmaps, or strengthen bids for institutional contracts, the study provides the analytical scaffolding needed to make defensible, data-informed decisions.
Importantly, the report also helps organizations anticipate where demand will likely concentrate and how competitive intensity may evolve as the decade progresses. By understanding which segments are gaining momentum, which regulatory developments are altering procurement eligibility, and how leading manufacturers are adjusting their portfolios, enterprises can build more resilient strategies that account for both near-term opportunities and longer-term structural shifts.
Path Forward: Turning Intelligence into Action
The cryogenic freezers market is entering a phase where strategic clarity will separate leaders from followers. The next several years will reward organizations that combine operational discipline with sharp market intelligence, that respect the importance of regulatory readiness, and that align their capabilities with the practical needs of laboratories, clinical facilities, and biopharmaceutical operations. Our comprehensive report provides the depth, structure, and forward-looking perspective required to navigate this environment with confidence.
For decision-makers seeking a complete view of market sizing, segmentation dynamics, competitive positioning, regulatory tracking, and procurement intelligence across the 2026-2032 period, the full study offers the detailed evidence base needed to support strategic planning and execution. We invite you to access the complete report to obtain the granular data, segment-level analysis, and actionable recommendations that will inform your next strategic moves in this evolving market.
For detailed analysis of this topic, please visit the official page: Cryogenic Freezers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Action Cameras Market Hits $8.4B in 2025, Surging to $18.65B by 2032 at 12.1% CAGR
By PW Consulting, 2026-09-16
The 2026 Action Cameras Market: Strategic Imperatives in a High-Growth Landscape
The action camera sector is undergoing a decisive transformation, driven by converging advancements in sensor technology, computational photography, and immersive content creation. As the industry matures beyond its early adoption phase, enterprises face a complex matrix of product differentiation, regional expansion, and competitive intensity. Our latest market research publication, the Action Cameras Market Forecast 2026–2032, has been engineered specifically for strategic planners, product leaders, and investment committees who require forward-looking intelligence rather than backward-looking summaries. This overview outlines the analytical architecture of the study, explains why the 2026 decision cycle demands rigorous sector modeling, and highlights how the full report equips leadership teams with actionable market intelligence.
Macro Trajectory and the 2026 Decision Window
Historical revenue data from 2020 through the base year of 2025 reveals a consistent expansion curve, with annual volumes compounding at a pace that signals structural demand rather than short-cycle hype. The overall market is projected to reach approximately USD 9,268.96 Million in 2026, before advancing toward a terminal forecast horizon of USD 18,650.0 Million by 2032. This growth path is underpinned by a compound annual growth rate of 12.1 percent, a figure that reflects sustained consumer adoption, enterprise deployment, and the proliferation of content-enabled devices across multiple end-use environments.
For strategy teams, the significance of these numbers lies not in isolated valuations but in the tempo of change. A double-digit CAGR compresses planning cycles, accelerates obsolescence risks, and forces faster alignment between R&D roadmaps and commercial execution. The 2026 business year represents a critical inflection point: early-cycle product launches have already demonstrated that premium imaging architectures can command premium positioning, while downstream supply constraints and regional demand asymmetries continue to reshape margin profiles. Organizations that treat the market as a static commodity segment will miss the structural shifts already embedded in the forecast model. Our research translates these trajectories into decision-ready frameworks, enabling executives to stress-test product portfolios, pricing strategies, and market-entry assumptions against a rigorously modeled growth baseline.
Report Scope and Actionable Analytical Content
The Action Cameras Market report is structured to support operational planning rather than conceptual overviews. It begins with a comprehensive market definition and boundaries, followed by historical baseline modeling that establishes how revenue streams evolved across the 2020–2025 observation window. From there, the forecast architecture extends through 2032, using scenario-aware modeling that captures demand elasticity, technology substitution, and channel concentration patterns.
Rather than presenting a single aggregated view, the analysis decomposes the market into functional dimensions that matter to commercial strategy. The segmentation structure covers product form factors, application environments, and geographic deployment patterns. Each dimension is evaluated for its contribution to overall revenue architecture, growth sensitivity, and competitive exposure. This multi-layered approach allows readers to isolate the drivers that align with their specific business objectives, whether those involve hardware portfolio planning, channel expansion, partnership evaluation, or capital allocation across high-velocity segments.
Beyond segmentation, the report integrates supply-side and competitive analysis designed for practical decision use. Company profiles are mapped against product strategy, manufacturing footprint, and recent commercial moves. Recent development events are contextualized within broader market behavior so that readers can distinguish between isolated announcements and durable shifts in competitive positioning. The document also examines regulatory and ecosystem influences that shape adoption speeds, certification requirements, and regional access conditions, ensuring that strategy teams are not blindsided by external constraints during implementation.
Competitive Architecture and Strategic Posture
The action camera market is characterized by concentrated leadership and persistent innovation pressure. Market concentration indicators show that a small group of established players controls a dominant share of industry revenue, with the top three firms accounting for approximately 78 percent of the market and the top five extending that share to roughly 82 percent. This concentration reflects economies of scale in imaging hardware, brand equity in adventure and creator ecosystems, and the difficulty of replicating end-to-end product chains that combine sensor performance, stabilization systems, and software integration.
Within this landscape, competitive differentiation increasingly depends on imaging architecture, stabilization fidelity, and use-case specialization rather than generic feature parity. GoPro, headquartered in San Mateo, California, continues to anchor premium adventure and cinematic action segments with its HERO 13 Black and MISSION 1 Pro series, leveraging a 1-inch sensor and GP3 processor to support high-resolution capture in demanding environments. DJI Technology, based in Shenzhen, reinforces professional and outdoor sports positioning through the Osmo Action 6 series, which emphasizes low-light sensor performance and variable aperture for point-of-view recording. Arashi Vision, also operating from Shenzhen with a U.S. presence in Irvine, California, extends the immersive capture paradigm through the Ace Pro 2 and X5 series, pairing 8K sensors with FlowState stabilization for wide-angle and 360-degree productions. AKASO Tech, located in Frederick, Maryland, targets budget-conscious adventure and vlogging users with 4K models such as the Brave 7 LE, built around dual-screen interfaces and waterproof housing. SJCAM Limited, manufacturing in Shenzhen with a workforce in the 201–500 employee range, supports sports and body-camera applications through the SJ11 Active and SJ8 Pro series, emphasizing 4K60fps recording, audio quality, and stabilization improvements.
Recent product activity confirms that the competitive tempo is accelerating. In April 2026, Insta360 previewed the GO Ultra compact hands-free action camera and the Retro Bundle for GO 3S at NAB Show 2026, signaling a continued push into professional POV capture and film-inspired aesthetics. Shortly thereafter, in May 2026, GoPro expanded global on-shelf availability for the MISSION 1 and MISSION 1 Pro, with pre-orders open for a 50MP 1-inch sensor configuration powered by the GP3 processor. These moves are not merely product更新; they reflect a broader industry dynamic in which hardware differentiation, professional endorsement, and creator ecosystem integration are becoming inseparable from market share defense. The report evaluates these developments in context, helping readers determine which product signals indicate durable positioning and which are tactical headline events.
Market Dynamics, Ecosystem Pressures, and Regional Considerations
Action camera adoption is shaped by a layered set of dynamics that extend beyond consumer enthusiasm. Professional validation continues to influence purchasing behavior in creator, production, and specialized field-use environments. Recognition such as the CineD Best-of-Show Award in the Camera Category at NAB Show 2026 for the GoPro MISSION 1 Pro ILS illustrates how professional review channels can accelerate adoption among technically sophisticated buyers. Simultaneously, product launches increasingly depend on timing, distribution readiness, and regional rollout coordination. For example, the DJI Osmo Action 6 series experienced an embargo lift that allowed pre-orders in October 2025 for its 1-inch sensor model, demonstrating how commercial availability can shift demand curves even before broad market visibility.
Performance benchmarks remain a decisive factor in competitive assessments. Devices that sustain strong dynamic range and high-resolution capture in variable lighting conditions are gaining traction among users who require dependable imaging across outdoor sports, automotive recording, and field documentation. Insta360’s Ace Pro 2 has maintained a top ranking in 2026 reviews with 13.5 stops of dynamic range, underscoring how technical credibility translates into market influence. These performance signals matter because they inform downstream decisions about product positioning, channel messaging, and buyer segmentation.
Regional dynamics introduce further complexity. Manufacturing concentration in Shenzhen continues to support scale and component integration for multiple leading suppliers, while U.S. offices and distribution channels help bridge global market access. The interaction between localized production, international sales structures, and regional demand patterns creates a landscape where supply continuity, logistics, and market-specific positioning must be managed in parallel. In addition, end-use demand is distributed across sports and adventure, travel and tourism, automotive, emergency services, security, and other applications. Each vertical brings its own purchase criteria, durability expectations, and integration requirements, meaning that overall market growth is not uniform but rather driven by distinct adoption engines. The full report details how these dynamics interact across regions and applications, enabling readers to prioritize the segments and geographies that match their strategic footprint.
Instant Cameras Market
Why the Full Report Is Essential for 2026 Planning
Executives and strategy teams operating in this environment need more than headline growth figures. They need a coherent model that explains how revenue is distributed across product types, applications, and regions; how competitive concentration shapes pricing and launch timing; and how recent product and ecosystem developments alter the trajectory of demand. The complete Action Cameras Market report provides that structure. It offers detailed segmentation analysis, company-level competitive profiling, scenario-based forecasting, and dynamic market behavior assessment, all organized for immediate use in planning cycles.
More importantly, the study is designed to support decisions that must be made now. Whether the objective is to evaluate a new product entry, reassess channel priorities, benchmark against incumbents, or determine where to allocate marketing and engineering resources, the report supplies the evidentiary base needed to move from assumption to evidence-based strategy. Given the 12.1 percent CAGR, the concentration of market power among a limited number of firms, and the pace of recent hardware launches, the cost of operating with incomplete intelligence is rising.
For those responsible for 2026 and 2032 planning horizons, the full research document offers the granularity required to convert a high-level growth narrative into a functional strategy. Readers seeking complete segmentation values, regional revenue breakdowns, application-level contributions, and comprehensive competitive assessments are encouraged to access the source report directly, where the full dataset and methodological detail are available for internal review and decision support.
Action Cameras Market
For detailed analysis of this topic, please visit the official page: Action Cameras Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rebar Detector Market Hits $125M in 2025, Expands to $175.89M by 2032 at 5% CAGR
By PW Consulting, 2026-09-16
The Strategic Imperative of Rebar Detection: Navigating Market Dynamics in 2026 and Beyond
In the complex landscape of modern infrastructure development, the integrity of reinforced concrete structures stands as a non-negotiable priority for engineers, contractors, and safety regulators alike. As we move through 2026, the Rebar Detector Market has evolved from a niche niche within Non-Destructive Testing (NDT) to a critical component of the broader construction safety ecosystem. For stakeholders seeking to understand where capital should flow, which technologies offer sustainable competitive advantages, and how regulatory shifts will reshape demand, comprehensive intelligence is not merely beneficial—it is essential.
This article serves as an executive overview of the strategic landscape surrounding rebar detection technologies. It synthesizes historical performance, forward-looking projections, and the competitive maneuvers defining the industry. However, the full granularity of this analysis, including specific segmentation valuations and detailed company benchmarking, is reserved for the comprehensive market research report. The following insights are designed to highlight the strategic value of acquiring deeper knowledge before making pivotal investment decisions in the current fiscal year.
Market Trajectory and Growth Foundations
The historical performance of the rebar detector industry sets a robust foundation for future expectations. Between 2020 and 2025, the market demonstrated resilience and consistent expansion, navigating through varying economic cycles and construction booms. The base year valuation of 2025 establishes a significant momentum point, reflecting heightened awareness regarding structural safety and the modernization of inspection protocols.
Looking ahead, the forecast period from 2026 to 2032 suggests a steady climb in market revenue. The Compound Annual Growth Rate (CAGR) indicates a sustained demand curve, driven by the necessity of maintaining aging infrastructure and the stringent enforcement of building codes globally. This growth is not linear; it is punctuated by technological adoption rates and regional construction activity levels. Understanding the precise velocity of this growth requires a nuanced look at the underlying drivers that our full report dissects in detail.
Rechargeable Handheld Metal Detector Market
Key macroeconomic indicators suggest that while the broader steel industry faces its own volatility, the demand for detection equipment remains somewhat decoupled from raw material price fluctuations, relying more heavily on compliance and safety standards. The following points outline the primary structural drivers identified in our analysis:
- Infrastructure Aging and Maintenance: As global infrastructure reaches mid-to-late lifecycle stages, the need for accurate rebar mapping without damaging existing structures becomes paramount.
- Regulatory Compliance: Standards such as ISO 1920-7 and various local building codes mandate non-destructive testing for reinforced concrete, creating a baseline demand that is less sensitive to economic downturns.
- Technological Integration: The shift from basic locating tools to smart solutions with real-time visualization and data logging is expanding the addressable market beyond traditional surveyors.
Navigating the Competitive Landscape
The market structure is characterized by a moderate to high level of concentration, where established players leverage brand reputation and proprietary technology to maintain significant market share. Our analysis reveals that a handful of key companies dominate the revenue stream, creating a competitive environment where innovation and distribution networks are the primary differentiators. The CR3 and CR5 metrics highlight the influence of top-tier manufacturers, yet there remains ample space for specialized entrants and regional players who can offer cost-effective or technology-specific solutions.
Several corporations stand out as pivotal actors in this ecosystem. Hilti AG, headquartered in Schaan, Liechtenstein, continues to set benchmarks with its concrete scanner systems, including the PS 300 Ferroscan and PS 1000 X-Scan, which are integral for structural analysis and rebar localization. Similarly, Screening Eagle Technologies, based in Zurich, Switzerland, maintains a strong position with its Profometer series, utilizing eddy current technology for precise concrete cover and rebar diameter measurement.
In the Americas, Zircon Corporation and James Instruments Inc. serve as critical vendors. Zircon, located in Chatsworth, California, produces electronic metal locators like the MetalliScanner MTX, essential for pre-drilling verification. James Instruments, operating out of Chicago, offers a range of locators including the Rebarscope series, focusing on determining location, depth, and size of steel reinforcement. US Radar, from Billerica, Massachusetts, differentiates itself through Ground Penetrating Radar (GPR) systems like the Quantum Imager, capable of detecting post-tension cables alongside rebar.
The landscape also features significant contributions from international manufacturers. ELE International in Rochester, New York, provides integrated detectors with real-time visualization. In Europe, NOVOTEST from St. Petersburg, Russia, offers cover meter rebar detectors for measuring thickness and estimating diameter. Meanwhile, Beijing TIME High Technology Co., Ltd. in China manufactures the TC100/110 series, catering to the growing demand for NDT equipment in Asian markets.
Recent Strategic Maneuvers and Innovation Cycles
The competitive dynamics are not static; they are actively reshaped by product launches and strategic events. In early 2026, the industry witnessed notable movements that signal the direction of market evolution. Beijing TIME High Technology Co., Ltd. successfully held its 2026 Annual Dealer Conference, themed around intelligent testing leading the construction of a new ecosystem. This event underscores the company's focus on channel expansion and integrating smart testing technologies into broader construction workflows.
Simultaneously, NOVOTEST released a new generation smart solution for concrete cover meter rebar detectors. This update emphasizes precise detection and measurement capabilities, reflecting a broader industry trend where vendors are moving beyond simple localization to providing actionable data intelligence. These developments suggest that the battleground for market share is increasingly shifting towards software integration, user interface usability, and the reliability of data output rather than hardware alone.
Macro-Environmental Dynamics and Risk Factors
Any strategic assessment of the Rebar Detector Market must account for the external forces acting upon the supply chain and demand generation. The industry does not operate in a vacuum; it is influenced by raw material availability, steel pricing cycles, and regulatory frameworks that vary by jurisdiction.
On the supply side, the World Steel Association's Short Range Outlook from October 2025 forecasts global steel demand at approximately 1,749 million tonnes in 2025 with a modest 1.3% rebound to 1,773 million tonnes in 2026. While this growth is tempered by trade uncertainties and the slowdown in the China housing market, it indicates a stable underlying demand for steel reinforcement. Consequently, the need to detect and manage this reinforcement remains consistent. However, fluctuations in steel pricing can indirectly affect project budgets, potentially influencing the procurement cycles of inspection equipment.
Regulatory factors also play a decisive role. The enforcement of building codes and safety standards continues to mandate non-destructive testing for reinforced concrete structures. ISO 1920-7 is cited as a primary driver for rebar detector use in compliance, ensuring that safety verification is not optional. Furthermore, environmental regulations such as the EU's Carbon Border Adjustment Mechanism (CBAM) and tightened safeguard measures are discussed as regulatory factors supplementing cyclical mechanisms to influence steel rebar pricing cycles. These factors add layers of complexity to project planning, potentially increasing the reliance on accurate detection tools to optimize material usage and ensure structural compliance without waste.
The Strategic Value of Comprehensive Intelligence
While the trends outlined above provide a high-level view of the market, they represent only the surface of a much deeper analytical structure. For decision-makers in 2026, relying on generalized market narratives carries significant risk. The nuances of regional demand shifts, the specific pricing power of handheld versus laptop-type devices, and the varying growth rates across construction versus communication applications are critical data points that inform budget allocation and product development strategies.
Our full market research report goes beyond these high-level indicators to provide actionable intelligence. It breaks down the market revenue into specific segments, allowing stakeholders to identify high-growth niches that are not apparent from aggregate data. It details the competitive positioning of each key player, analyzing their strengths, weaknesses, and recent strategic moves in the context of market share dynamics. Additionally, the report provides a granular forecast that accounts for varying scenarios in raw material pricing and regulatory enforcement across different geographies.
Rebar Detector Market
Access to this level of detail enables organizations to:
- Optimize Product Portfolios: Align manufacturing or procurement strategies with the specific types of detectors showing the strongest revenue growth potential.
- Target Regional Opportunities: Identify which geographic markets offer the most fertile ground for expansion based on construction activity and regulatory maturity.
- Anticipate Competitive Shifts: Understand how rival companies are positioning themselves through technology updates and strategic partnerships, allowing for proactive rather than reactive planning.
- Mitigate Risk: Factor in the volatility of steel markets and regulatory changes into long-term forecasting models with greater accuracy.
Conclusion: Preparing for the Next Phase of Growth
The Rebar Detector Market stands at an inflection point where safety compliance, technological sophistication, and infrastructure needs converge. The projected revenue trajectory through 2032 indicates a healthy expansion environment, but capturing value within this growth curve requires more than passive observation. It demands a clear understanding of who is winning, where the demand is concentrating, and how external macroeconomic factors will influence purchasing power.
For enterprises aiming to secure a competitive edge in 2026 and the subsequent forecast period, the margin for error is slim. The difference between a successful market entry or product launch and a missed opportunity often lies in the details of segment performance and competitive benchmarking that are not visible in general market summaries.
We invite industry leaders, investors, and strategic planners to leverage the full depth of our research capabilities. The complete report provides the specific data units, regional splits, and company profiles necessary to build a robust strategy. To access the detailed segmentation analysis, comprehensive competitor profiles, and the full forecast model including specific revenue figures by segment and region, please visit the source webpage to download the complete Rebar Detector Market research study. In an industry where precision is paramount, your market intelligence should be no less exact.
For detailed analysis of this topic, please visit the official page: Rebar Detector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: AC-DC EPS Market to Hit $9.83B in 2025, Growing at 5.3% CAGR to 2032
By PW Consulting, 2026-09-16
Powering the Next Decade: Strategic Intelligence for the AC-DC External Power Supply Market
The AC-DC External Power Supply (EPS) market is undergoing a structural transformation. From consumer electronics to industrial automation and healthcare devices, external power supplies remain the critical link between grid electricity and modern equipment. As regulatory frameworks tighten and efficiency requirements escalate, understanding the trajectory of this market is no longer optional for enterprise decision-makers. This article outlines the strategic value of our latest market research report, designed to equip stakeholders with the foresight needed to navigate the 2026-2032 forecast period and beyond.
Market Trajectory and Growth Dynamics
The global AC-DC EPS market has demonstrated consistent expansion over the past half-decade. Historical data from 2020 through 2025 reveals a market that has grown from approximately 7,700 million USD to nearly 9,830 million USD, reflecting a compound annual growth rate that underscores steady demand accumulation across multiple end-use sectors. Looking ahead, the forecast period from 2026 to 2032 projects a sustained CAGR of 5.3 percent, with revenue expected to approach 13,923 million USD by the end of the forecast horizon.
This growth is not merely a function of volume expansion. It represents a convergence of technological innovation, regulatory compliance pressures, and shifting application demands. The base year of 2025 serves as a critical inflection point, with the market crossing the 9,800 million USD threshold and setting the stage for accelerated adoption of high-efficiency, compact power solutions. Enterprises that understand the underlying drivers of this trajectory will be better positioned to allocate capital, plan product roadmaps, and identify partnership opportunities.
However, aggregate figures tell only part of the story. The true strategic value lies in dissecting the market across multiple dimensions—power output ranges, application verticals, and geographic regions—each of which presents distinct growth vectors, competitive intensities, and risk factors. Our report provides this granular dissection, enabling stakeholders to move beyond headline numbers and develop nuanced, segment-specific strategies.
Key Industry Dynamics Shaping the Landscape
Several macro-level forces are reshaping the competitive environment for AC-DC external power supplies. Understanding these dynamics is essential for anticipating market shifts and positioning products or investments accordingly.
- Regulatory Compliance压力 : Efficiency standards continue to evolve globally. The U.S. Department of Energy's Level VI requirements, ENERGY STAR Program Requirements for Single Voltage External AC-DC Power Supplies, and the EU Ecodesign framework (2025/2052) are mandating higher efficiency thresholds. Manufacturers must ensure their products meet these criteria to remain eligible for key markets. Additionally, Natural Resources Canada has implemented energy efficiency standards for single-voltage external AC-DC power supplies effective 2025, further expanding the compliance landscape. ENERGY STAR Partner Commitments also require manufacturers to adhere to strict eligibility criteria including efficiency testing protocols.
- Raw Material Volatility : Copper prices fluctuated within an 8,500 to 10,200 USD per ton range in 2025, driving bill of materials costs for power supply components up by nearly one-fifth. This volatility introduces margin pressure and necessitates strategic sourcing decisions, supplier diversification, and potentially redesigned architectures that optimize material usage.
- Technology Innovation : The adoption of wide-bandgap semiconductors such as silicon carbide (SiC) and gallium nitride (GaN) is enabling higher efficiency, reduced thermal losses, and miniaturization. Recent product launches from leading manufacturers demonstrate this shift, with GaN-based solutions and wide-range AC-DC modules entering the market at various power levels.
- Application Diversification : While consumer electronics remain a significant demand driver, industrial, automotive, healthcare, and telecommunications applications are expanding their share of the market. Each vertical imposes unique requirements around reliability, efficiency, form factor, and environmental durability, creating specialized niches that reward targeted engineering and market positioning.
Competitive Landscape: Key Players and Strategic Positioning
The AC-DC EPS market is characterized by a concentrated competitive structure. The top three firms command approximately 65 percent of market revenue, while the top five collectively hold around 80 percent. This concentration reflects the scale advantages, established customer relationships, and engineering capabilities that leading players have cultivated over time. However, the presence of numerous specialized manufacturers and regional players ensures that competition remains dynamic, particularly in segments where customization, rapid innovation, or cost optimization are paramount.
AC-DC External Power Supply (EPS) Market
Our report provides detailed profiles of the key companies shaping this landscape, examining their product portfolios, geographic reach, application focus, and recent strategic moves. Among the profiled firms are TDK-Lambda Americas, COSEL USA, Bel Fuse Inc., XP Power, Murata Manufacturing Co., Mean Well Enterprises Co. Ltd., FSP Technology Inc., Sparkle Power Incorporated, Advanced Energy Industries Inc., P-DUKE Technology Co. Ltd., Phihong USA, Acopian Power Supplies, and Pico Electronics.
These companies represent a diverse array of strategic positions. Some focus on high-performance solutions for medical and industrial applications, leveraging advanced technologies like SiC and GaN to deliver efficiency gains and compact form factors. Others emphasize broad portfolios spanning desktop and wall-plug adapters alongside enclosed AC-DC supplies for industrial and ITE applications. Several manufacturers have established strong presences in harsh-environment and factory automation segments, offering configurable and ruggedized solutions. The geographic spread of headquarters and manufacturing capabilities—from the United States and Japan to Taiwan and the United Kingdom—adds another layer of strategic consideration for supply chain resilience and market access.
Worldwide External Power Supplies (EPS) Market
Recent product launches and technological announcements provide valuable signals about where competitive intensity is building. In early 2026, multiple firms introduced new product lines emphasizing efficiency, power density, and application-specific optimization. These developments underscore the pace of innovation and the importance of monitoring competitor roadmaps to anticipate market shifts and identify whitespace opportunities. Our report captures these recent developments and contextualizes them within broader competitive trends.
Report Scope and Actionable Insights
This market research report is designed to serve as a comprehensive decision-support tool. It goes beyond descriptive market sizing to deliver actionable intelligence across multiple dimensions. Key components of the report include:
- Historical and Forecast Revenue Analysis : Detailed revenue breakdowns for the 2020-2025 historical period and the 2026-2032 forecast period, enabling trend analysis and growth rate validation at both aggregate and segment levels.
- Segmentation by Output Power : Analysis of market share and growth trajectories across power output ranges, from low-power solutions up to 10W through higher-power segments reaching 101W-400W. Each range presents distinct application profiles and competitive dynamics.
- Segmentation by Application : Deep dives into the major application verticals driving demand, including consumer electronics, industrial, automotive, healthcare, telecommunications, and others. The report examines the unique requirements, growth catalysts, and competitive intensity within each vertical.
- Segmentation by Region : Geographic revenue distribution and growth outlooks that help stakeholders assess market maturity, penetration opportunities, and regional regulatory considerations across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa.
- Company Profiles and Competitive Benchmarking : In-depth profiles of key market participants, covering their strategic focus, product offerings, recent developments, and positioning within specific segments. This enables competitive mapping and identification of potential partnership or acquisition targets.
- Regulatory and Technology Landscape : Synthesis of the evolving efficiency standards, energy certification requirements, and material cost dynamics that influence product design, compliance costs, and time-to-market decisions.
The report is structured to support multiple use cases. Product managers can leverage segment-level data to prioritize development resources and refine feature specifications. Supply chain and procurement teams can use geographic and cost dynamics insights to optimize sourcing strategies. Strategic planners and investors can rely on the forecast models and competitive analysis to evaluate market entry opportunities, partnership scenarios, and long-term growth potential.
Strategic Value for 2026 Decision-Making
As enterprises navigate the 2026 business environment, the AC-DC EPS market presents both opportunities and complexities. The combination of steady market growth, regulatory evolution, raw material volatility, and rapid technological advancement demands a data-driven approach to strategy formulation. This report is built to address those demands by providing:
- Forward-Looking Visibility : The 2026-2032 forecast period offers a clear window into expected market trajectories, helping organizations align investment cycles, capacity planning, and product launch calendars with anticipated demand patterns.
- Segment-Specific Intelligence : Rather than relying on aggregate market figures, decision-makers can drill into the segments most relevant to their business, understanding the competitive intensity, growth rate, and application requirements that define each space.
- Competitive Context : With a concentrated market structure and active innovation pipelines, knowing where key players are focusing their efforts is critical. The report maps competitor capabilities and recent developments to help identify gaps, overlaps, and potential areas for differentiation.
- Risk and Compliance Awareness : Regulatory requirements and material cost fluctuations can significantly impact product economics and market access. The report integrates these factors into the analysis, enabling proactive risk management and compliance planning.
The strategic questions facing organizations in this market are numerous. Which power output ranges offer the most attractive growth-to-competition ratios? How will regulatory changes reshape the competitive hierarchy over the forecast period? Where are the geographic markets with the strongest expansion potential, and what barriers exist to entry? How are technology shifts like wide-bandgap semiconductors altering product specifications and customer expectations? Our report provides the foundational data and analytical framework to address these questions with confidence.
Accessing the Full Intelligence
This article has outlined the strategic context and structural components of the AC-DC External Power Supply Market research report. The market is positioned for continued growth, driven by expanding application demands, efficiency-driven innovation, and a competitive landscape that rewards both scale and specialization. However, the full value of this research lies in the detailed segment breakdowns, comparative analysis, and forward-looking models that go beyond the high-level overview presented here.
Organizations seeking to make informed decisions in 2026 and beyond should consider accessing the complete report, which contains the granular revenue data, segment-level growth rates, regional distributions, application splits, and company-specific profiles necessary to build robust, evidence-based strategies. The combination of historical validation, forecast modeling, and competitive intelligence provides a comprehensive foundation for navigating the market's evolving dynamics.
For stakeholders ready to deepen their understanding and translate market intelligence into actionable strategy, the full report offers the depth, precision, and contextual analysis required to stay ahead in a competitive and rapidly changing landscape.
For detailed analysis of this topic, please visit the official page: AC-DC External Power Supply (EPS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Plastic Cards Market to Reach $414.97 Million by 2032, Growing at 6.98% CAGR from 2025
By PW Consulting, 2026-09-16
Navigating the Plastic Cards Market: Strategic Intelligence for 2026 and Beyond
The global plastic cards market stands at a pivotal juncture in 2026. As digital transformation accelerates across financial services, identity management, and consumer loyalty programs, physical smart cards and traditional plastic credentials continue to evolve rather than disappear. For executives, investors, and supply chain strategists, understanding the trajectory of this market requires more than surface-level forecasts. It demands rigorous, data-backed intelligence that connects historical performance, regional dynamics, competitive positioning, and emerging sustainability mandates into a coherent decision-making framework.
Our latest market research publication on the Plastic Cards Market delivers precisely that intelligence. Designed as a strategic companion for 2026 planning cycles, the report synthesizes a comprehensive historical baseline spanning 2020 through 2025 and extends a detailed revenue trajectory through 2032. By grounding forward-looking analysis in audited historical data and validated industry signals, the study equips decision-makers with the clarity needed to allocate capital, refine product roadmaps, and anticipate regulatory shifts before they become market constraints.
Historical Trajectory and the 2026 Inflection Point
Over the past half-decade, the plastic cards sector has demonstrated consistent resilience and measured expansion. Revenue across the global market progressed from a baseline of approximately $213.23 million in 2020, climbing steadily through successive years to reach $278.68 million by 2025. This historical arc reflects more than incremental growth; it reveals underlying structural demand driven by payment infrastructure modernization, government identification initiatives, and the persistent need for secure, tactile credentialing systems.
Entering 2026, the market projects an initial revenue figure of $285.5 million, signaling a continuation of established growth patterns. More importantly, the forecast horizon extending to 2032 maps a clear upward trajectory, culminating in an estimated $414.97 million by the terminal forecast year. This progression underscores a compound annual growth rate of 6.98 percent across the 2026 to 2032 window. For strategic planners, this CAGR is not merely a statistical output; it serves as a quantitative anchor for capacity planning, inventory forecasting, and investment prioritization. The data indicates that demand will not plateau but will instead accelerate in specific high-value corridors, even as broader macroeconomic conditions fluctuate.
Crucially, the report deliberately withholds granular percentage splits and absolute dollar allocations across individual regions, application verticals, and card types within the publicly accessible preview. This intentional framing ensures that stakeholders recognize the breadth of the analytical model without diluting the commercial value of the full dataset. Decision-makers who require precise regional weightings, application-specific revenue breakdowns, and type-segment penetration rates are directed toward the complete intelligence package, where these parameters are mapped with surgical precision to support localized strategy development.
Competitive Architecture and Concentration Dynamics
The plastic cards manufacturing landscape is characterized by a pronounced concentration of market share among established producers. The report identifies that the top three players collectively command a 68.0 percent share of total market revenue, while the top five firms extend their influence to 78.0 percent. This level of concentration carries significant implications for procurement strategy, pricing power, and supply chain resilience. Organizations that rely on plastic credentials for payment, access control, or government compliance must understand how supplier consolidation affects lead times, customization capabilities, and long-term contractual stability.
The competitive ecosystem spans both North American and European production hubs, with several foundational manufacturers defining industry benchmarks. Custom Plastic Card Company, headquartered in Pompano Beach, Florida, has operated since 1983 as one of the largest North American producers of blank and printed PVC cards, RFID credentials, gift and membership cards, and associated magnetic products. NewGuard Plastic Cards, LLC, based in Rocky Mount, Virginia, holds the position of North America's largest manufacturer of blank plastic cards, adhering strictly to ISO/ANSI standards and utilizing exclusively US-sourced raw materials, while also expanding into composite, eco-friendly, and technology-enabled card formats. The 2024 acquisition of Allegheny Card Solutions by NewGuard, finalized in November 2024, further broadened its portfolio across plastic, composite, eco, and technology card categories, signaling an aggressive consolidation strategy within the blank and specialty card segment.
Other notable producers reinforce the fragmented yet highly specialized nature of the broader market. CardPrinting.com, operating from the United States since 1996, focuses on custom PVC and laminated plastic card printing, delivering gift, loyalty, RFID, ID cards, and plastic key tags. Perfect Plastic Printing Corporation emphasizes compliant production, secure personalization, and sustainability across personalized debit, credit, and secure card formats. Continental BizMag maintains direct quality control through domestic PVC card production in its South Florida wholesale facility. Print Robot operates a 55,000-square-foot US factory dedicated to membership, gift, and business card manufacturing. Across the Atlantic, Variuscard in Austria brings over fifty years of experience to chip, RFID, smart, loyalty, gift, and ID card production, maintaining 100 percent Austrian manufacturing. Polskie Karty sp z o.o. serves as a leading direct producer in Poland and Europe, leveraging an advanced technology park for custom printed plastic cards.
The full report delves into operational profiles, production capacities, regional footprint advantages, and strategic positioning for each key company. Rather than presenting static corporate summaries, the analysis evaluates how these manufacturers respond to customization demands, compliance requirements, and sustainability mandates, enabling buyers and investors to map supplier capabilities against specific procurement or partnership criteria.
Industry Dynamics: Sustainability, Sourcing, and Regulatory Alignment
No strategic assessment of the plastic cards market in 2026 is complete without addressing the accelerating influence of sustainability mandates and raw material sourcing shifts. The industry is undergoing a measurable transformation as manufacturers, material suppliers, and end-users realign around environmental performance, supply chain transparency, and regulatory compliance.
Material innovation has emerged as a primary driver of competitive differentiation. Klöckner Pentaplast has advanced its SecondLife card films by increasing recycled content from 25 percent to 100 percent across both PVC and PET options, achieving a 65 percent reduction in CO2 emissions and a 65 percent reduction in landfill impact. This scale of material transition signals that recycled substrates are moving from pilot initiatives to mainstream production standards. Simultaneously, the International Card Management Association continues to advance sustainability frameworks through its EcoLabel Program and member-led initiatives focused on recycled content integration and reduced environmental impact, creating an industry-wide benchmark that manufacturers and buyers alike must navigate.
Supply chain localization and raw material security are equally critical themes. NewGuard Plastic Cards has transitioned to fully US-sourced raw materials for its blank plastic card production to meet ISO/ANSI standards, reflecting a broader move toward domestic sourcing resilience and compliance assurance. On the demand side, Bank of America reported in September 2024 that 80 percent of its plastic cards utilize post-consumer recycled plastic, illustrating how major financial institutions are embedding sustainability into procurement specifications at scale. The ICMA Expo 2025 further reinforced these trends, showcasing partnerships and exhibits centered on sustainable plastic card solutions, including recycled PVC laminates and advanced chip card technologies.
The report's Dynamics section synthesizes these developments into actionable strategic observations. Rather than treating sustainability as a peripheral compliance exercise, the analysis positions it as a core determinant of supplier eligibility, cost structure evolution, and consumer-facing brand positioning. Organizations that integrate material innovation timelines, regulatory trajectories, and procurement policy shifts into their 2026 planning will be better equipped to manage risk and capture emerging value pools.
Report Architecture: Operational Intelligence for 2026 Decision-Making
The research publication is structured to translate macro-level market intelligence into operational relevance. It begins with a comprehensive market overview that anchors the forecast period in historical performance, establishing the quantitative baseline necessary for scenario modeling. From there, the report progresses through segmentation analysis that explores how different card types, application verticals, and regional markets interact to shape revenue distribution. While the publicly accessible preview highlights the overall market scale and projected CAGR, the complete report unpacks the underlying segmentation architecture, enabling users to identify which corridors present the highest growth potential, where demand is stabilizing, and how product mix strategies should adapt.
A dedicated competitive landscape section maps the operational footprint, production capabilities, and strategic moves of key market participants. This analysis extends beyond corporate profiles to examine consolidation patterns, production localization trends, and the competitive implications of scale versus specialization. The recent acquisition activity, such as NewGuard's expansion through Allegheny Card Solutions, is evaluated within the broader context of market concentration and supplier diversification strategies.
Plastic Cards Market
Additionally, the report incorporates a forward-looking dynamics component that tracks material innovation, sustainability standardization, regulatory alignment, and procurement policy evolution. These elements are cross-referenced with manufacturing capabilities and end-user adoption patterns, providing a multi-dimensional view of how external pressures will reshape supply chains, cost structures, and product specifications through 2032.
Importantly, the research is designed for practical deployment. Executive summaries, data tables, and segmentation frameworks are organized to support capital allocation decisions, supplier evaluation workflows, product development prioritization, and regional expansion assessments. The full dataset, accessible through the complete report, provides the precise regional weightings, application-level revenue breakdowns, and type-segment performance metrics required for granular strategic planning.
Plastic Bag Market
Strategic Imperatives for 2026
As organizations enter the 2026 planning cycle, several strategic imperatives emerge from the market intelligence. First, supplier concentration demands a deliberate approach to procurement diversification and contract structuring. With a significant share of market revenue concentrated among a limited number of manufacturers, buyers must evaluate supplier resilience, customization capacity, and compliance assurance rather than relying solely on price benchmarking.
Second, sustainability is no longer optional. The transition toward high-recycled-content substrates, the expansion of EcoLabel-aligned production, and the embedding of post-consumer recycled materials into major financial institution card programs indicate that environmental performance will increasingly influence supplier selection and product eligibility. Organizations that proactively align their card specifications with sustainability trajectories will reduce future procurement friction and strengthen brand positioning.
Third, the forecast horizon through 2032 highlights the importance of forward-looking capacity and investment planning. The projected growth trajectory suggests that demand will continue to expand across multiple application corridors, requiring stakeholders to anticipate production scalability, technology integration, and regional demand shifts rather than reacting to near-term volume changes alone.
The complete Plastic Cards Market research report provides the detailed segmentation data, competitive analysis, and dynamics mapping necessary to operationalize these imperatives. By accessing the full intelligence package, decision-makers can extract region-specific revenue allocations, application-level demand patterns, and type-segment performance metrics that transform high-level forecasts into actionable strategy.
For executives, procurement leaders, and industry analysts seeking to navigate the plastic cards market with precision in 2026 and beyond, this research delivers the structured, data-anchored insight required to make informed, forward-compatible decisions.
For detailed analysis of this topic, please visit the official page: Plastic Cards Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Silyl Modified Polymer Market Hits $1.1B in 2025, Projected 5.5% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Horizons: Navigating the Silyl Modified Polymer Market in 2026
In the rapidly evolving landscape of advanced materials, Silyl Modified Polymers (SMP) have emerged as a cornerstone technology for high-performance sealants, adhesives, and coatings. As we enter 2026, enterprises across construction, automotive, and industrial sectors face a critical juncture. The convergence of shifting supply chains, regulatory pressures, and demand for durable, isocyanate-free solutions demands more than off-the-shelf market data. It requires a granular, forward-looking intelligence framework. PW Consulting's latest Silyl Modified Polymer Market report is designed to serve as that framework, translating historical trends into actionable 2026 strategic decisions.
This market study is not merely a compilation of figures. It is a strategic tool engineered to de-risk capital allocation, optimize product mix, and identify white-space opportunities. By integrating a robust quantitative baseline with qualitative assessment of competitive maneuvers and macroeconomic headwinds, the report offers a complete intelligence picture. Below, we outline the strategic architecture of this research and why it is indispensable for corporate planning in the current fiscal year.
Market Trajectory and the 2026 Inflection Point
Understanding where the market has been is essential to validating where it is going. Our analysis tracks revenue growth from 2020 through 2025, establishing a baseline of resilience and expansion. In 2020, the global market for silyl modified polymers recorded revenue of USD 850.0 Million. Through the subsequent five-year period, the sector demonstrated consistent upward momentum, absorbing supply shocks and capitalizing on increasing substitution rates from traditional adhesive technologies. By the base year of 2025, market revenue had climbed to USD 1.1 Billion, reflecting a compound annual growth rate that underscores sustained commercial adoption.
Looking forward to the forecast period spanning 2026 to 2032, the trajectory indicates continued expansion, though with notable variability that demands careful interpretation. While early forecast years project steady growth, the medium-term outlook suggests that market velocity will be influenced by raw material volatility and regional capacity adjustments. Specifically, the forecast grows to a projected USD 1,197.74 Million in 2026, before navigating intermediate fluctuations that reflect the complex interplay of investment cycles and demand normalization. By 2032, the market is anticipated to reach a substantial scale, highlighting the long-term structural appeal of SMP technology.
For corporate strategists, these macro-trends are not just benchmarks; they are inputs for scenario planning. The shift from historical stability to a forecast period characterized by dynamic variables means that static budgeting is insufficient. Decision-makers must understand the drivers behind the growth rate—a 5.5% CAGR over the forecast horizon—and the specific conditions that could accelerate or decelerate this pace. Our report deconstructs these drivers without oversimplifying them, providing the nuance required for robust 2026 planning.
Segmentation Insights: Beyond the Aggregate
Aggregate market size tells only half the story. The true strategic value lies in understanding how value is distributed across types, applications, and geographies. However, sharing every percentage split in a preview would diminish the premium nature of the full intelligence package. Instead, we highlight the structural composition that defines the competitive battlefield.
The market is fundamentally anchored by two primary polymer architectures. Polyether-based variants continue to command a significant share of global revenue, driven by their balance of flexibility and weatherability. Polyurethane-based formulations represent the second major pillar, often selected for specific mechanical properties or compatibility requirements. A smaller but strategically important category encompasses other specialized types that serve niche high-performance needs. The interplay between these types dictates formulation strategies for end-users and pricing power for suppliers.
On the application side, the construction sector remains a dominant consumption center, leveraging SMP technology for sealants and coatings that require long-term durability and low maintenance. The automotive sector follows as a critical growth engine, particularly as vehicle architectures evolve toward lightweighting and electric mobility, where bonding solutions must meet increasingly stringent safety and thermal standards. General industry and other application verticals complete the demand picture, each with unique procurement cycles and technical specifications.
Geographically, the market exhibits a multi-polar demand structure. While mature economies in North America and Europe maintain steady consumption levels supported by infrastructure maintenance and regulatory compliance, the Asia Pacific region reflects the dynamic growth of manufacturing capacity and urbanization. Latin America and the Middle East and Africa represent smaller but emerging pockets of opportunity, often tied to specific project pipelines rather than broad-based consumption. Our report maps these regional nuances in detail, helping firms align their distribution and production footprints with actual demand centers rather than assumptions.
Competitive Landscape: Incumbents and Differentiators
The SMP market is characterized by a mix of specialized chemical producers and large-scale material solutions providers. Market concentration metrics indicate that the top three players hold approximately 35% of the revenue share, while the top five possess around 48%. This moderate concentration suggests a market where scale matters, but differentiation through technology and regional service capability can secure significant positions for mid-tier players.
Several key companies define the operational and technological baseline for the industry:
N Methoxymethyl N Trimethylsilylmethylbenzylamine Market
- Kaneka Corporation , based in Osaka, Japan, stands as a foundational player. The company is recognized for its Kaneka MS Polymer™ technology, an original isocyanate-free base resin designed for high-performance moisture-cure sealants, adhesives, and coatings. Kaneka's legacy in this space sets a technical benchmark for purity and performance consistency.
- Risun Polymer International Co., Ltd. , headquartered in Huai'an, Jiangsu, China, operates as a leading manufacturer of Silane Terminated Polyether (STP/SMP) polymers. By combining polyurethane and silicone features, Risun addresses the needs of sealant, adhesive, and coating formulators seeking versatile performance profiles, particularly within the Asian manufacturing ecosystem.
- CAPLINQ Corporation , located in Ottawa, Canada, produces the BS-7000 and BS-2000 Series SMP adhesives. These products are engineered for industrial, mass-transit, and electric vehicle applications, with a specific focus on primerless bonding and compliance with standards such as EN45545. This focus on regulated, high-stakes applications highlights the specialized end-game for SMP adoption.
- Bostik (Arkema) , with headquarters in Paris, France, supplies SMP-based sealants and adhesives for construction, transportation, and marine uses. With global manufacturing capabilities and adherence to Buy America compliance, Bostik illustrates how multinational presence and regulatory navigation are critical components of market competitiveness.
- W. R. Meadows, Inc. , based in Hampshire, Illinois, USA, manufactures AIR-SHIELD SMP self-adhering vapor-permeable air barrier membranes and HS-1 SL hybrid sealants. Their use of silyl-modified polymer technology demonstrates the material's versatility in building envelope solutions and specialized sealing applications.
Beyond these profiles, the competitive environment is shaped by strategic moves that are not always visible in headline financials. Our report analyzes capacity expansions, technical partnerships, and regional positioning strategies that allows clients to anticipate competitor behavior. In a market where brand trust and technical support often decide procurement decisions, understanding the operational footprint of these players is vital.
Industry Dynamics: Raw Material Pressures and Regulatory Shifts
No market analysis is complete without integrating the external forces that reshape cost structures and availability. As of late 2025 and early 2026, several dynamics are directly impacting the SMP value chain.
Raw material pricing has become a focal point for procurement teams. In December 2025, US silane prices climbed due to high demand and limited availability, a trend reported by ChemAnalyst. This pressure on precursor costs ripples through the formulation economics of SMP products, potentially squeezing margins for manufacturers who cannot pass through price adjustments quickly. Conversely, Polydimethylsiloxane antifoam emulsion prices showed a stable to marginally soft trend in Q1 2026, suggesting that not all silicone-derived inputs are moving in tandem. This divergence requires precise input cost tracking rather than blanket assumptions.
Furthermore, supply chain distortions originating from the Middle East continue to influence global pricing structures. In March 2026, WACKER announced a price increase for its silicone-based product range effective April 1, 2026, citing energy and raw materials market distortions and supply-chain disruptions linked to regional conflicts. This move, reported by Adhesives & Sealants Industry, underscores the vulnerability of the broader silicone ecosystem to geopolitical and energy market shocks. For SMP producers and consumers, such announcements are leading indicators of potential cost volatility and sourcing challenges.
These dynamics create a complex operating environment. Companies must balance the need for stable supply against the risk of cost inflation. The report integrates these factors into a "Dynamics" section that models potential scenarios, helping clients stress-test their 2026 procurement and pricing strategies against realistic external shocks.
What the Full Report Delivers for 2026 Decision-Making
The preview provided here offers a high-level view of the market structure and the forces at play. However, executing a successful strategy in 2026 requires depth. The complete PW Consulting Silyl Modified Polymer Market report is structured to provide immediate operational utility across multiple functions:
- Detailed Segmentation Revenue and Volume Analysis: While this preview omits specific regional and application splits, the full report delivers precise revenue and volume breakdowns by region, type, and application. This enables precise TAM/SAM/SOM calculations and allows R&D to align product development with the highest-value segments rather than chasing aggregate growth.
- Competitive Benchmarking and Strategy Maps: Beyond company profiles, the report includes analysis of recent developments, product launches, and strategic shifts. Clients gain insight into where competitors are investing, which applications they are targeting, and how they are responding to raw material pressures.
- Supply Chain and Cost Structure Modeling: Integrating raw material trends like the silane price movements and silicone price adjustments, the report offers frameworks for understanding cost pass-through capabilities and margin resilience. This is critical for pricing strategy and vendor negotiations.
- Regulatory and Compliance Landscape: With players navigating standards like EN45545 and Buy America compliance, the report maps the regulatory terrain across key markets. This helps quality and regulatory teams anticipate compliance costs and certification timelines.
- Forecasting and Scenario Planning: The forecast data is presented with sensitivity analysis, allowing planners to model best-case, base-case, and stress scenarios. This supports capital investment decisions, inventory management, and long-term capacity planning.
Conclusion: The Cost of Uncertainty vs. The Value of Precision
The silyl modified polymer market in 2026 is defined by opportunity tempered by volatility. Demand fundamentals remain strong, anchored by construction durability needs and automotive innovation. Yet, raw material fluctuations, geopolitical supply disruptions, and competitive maneuvering create an environment where intuition alone is not enough.
PW Consulting's market research is designed to replace uncertainty with precision. By revealing the structural composition of demand, the competitive DNA of key players, and the critical dynamics shaping costs, the report empowers leadership teams to make informed, confident decisions. The macro numbers tell the story of growth; the deep-dive segmentation and company intelligence tell the story of how to capture it.
Silyl Modified Polymer Market
For organizations ready to move beyond surface-level trends and secure a competitive edge in the SMP market, the full report provides the comprehensive intelligence necessary to navigate the year ahead. The strategic advantage belongs to those who understand not just the size of the market, but the mechanics of its movement.
For detailed analysis of this topic, please visit the official page: Silyl Modified Polymer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


