



Category: market research
PW Consulting: Hydraulic Power Unit Market to Reach $18.2B by 2032, Growing at 5.5% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence for the Next Decade: Navigating the Hydraulic Power Unit Market
The global industrial landscape is undergoing a profound transformation. As machinery becomes increasingly sophisticated and energy efficiency mandates tighten, the Hydraulic Power Unit (HPU) market stands at a critical inflection point. For executives, investors, and strategic planners, understanding the trajectory of this sector is not merely an academic exercise but a prerequisite for capitalizing on emerging opportunities. PW Consulting has prepared a comprehensive market research report designed to equip decision-makers with the actionable intelligence needed to navigate the period from 2026 through 2032.
This analysis serves as a strategic compass. It moves beyond superficial market summaries to deliver a granular understanding of revenue streams, competitive positioning, and the operational dynamics that will define success in the coming years. By synthesizing historical performance data with forward-looking projections, this report offers a robust framework for assessing risk and identifying high-growth vectors within the hydraulic power ecosystem.
Macro Growth Trajectory and Economic Context
The financial narrative of the Hydraulic Power Unit market is characterized by steady expansion and resilience. Based on rigorous analysis of historical data from 2020 to 2025, the market has demonstrated a consistent upward trend, overcoming various supply chain challenges and economic fluctuations. The baseline year of 2025 establishes a solid foundation, with the total market revenue reflecting the accumulated demand from key industrial sectors.
Looking forward, the forecast period spanning 2026 to 2032 indicates a favorable growth environment. The Compound Annual Growth Rate (CAGR) is projected to remain robust, driven by modernization efforts in legacy infrastructure and the adoption of advanced hydraulic systems in new applications. Throughout this forecast horizon, the market is expected to witness a significant increase in total valuation, reaching new milestones by 2032. This growth is not linear; it is punctuated by periods of acceleration linked to technological breakthroughs and regulatory shifts.
It is crucial for stakeholders to recognize that while the aggregate numbers suggest stability, the underlying composition of this growth varies significantly across different vectors. The total revenue figures mask the divergent performance of specific technology types and application verticals. Our full report dissects these layers to reveal where the true value is being generated, ensuring that your strategic investments are aligned with the highest potential segments rather than the average market performance.
Market Dynamics and Operational Pressures
Success in the HPU market requires a sophisticated understanding of the external forces shaping production and procurement. Several key dynamics are currently influencing the sector, creating both headwinds and tailwinds for market participants.
-
Regulatory Frameworks: Compliance is no longer optional. Standards such as ISO 4413:2010 specify general rules and safety requirements for hydraulic fluid power systems and components used on machinery. Furthermore, the Harmonised Standard EN ISO 12100:2010 is utilized for guidance in hydraulic power unit risk assessments. Adherence to these protocols affects design cycles, certification costs, and market access, particularly in regions with stringent safety enforcement.
-
Raw Material Volatility: The cost structure of HPU manufacturing is sensitive to commodity markets. Volatility in steel and copper prices can shift HPU production costs by up to 20%. This level of fluctuation demands agile procurement strategies and robust hedging mechanisms to protect margins. Companies that fail to account for this volatility in their pricing models risk eroding profitability during periods of supply tightness.
-
Technology Shift: There is a marked transition toward electrification and efficiency. The industry is gradually moving away from purely combustion-based solutions in favor of systems that offer reduced energy consumption and lower operational footprints. This shift is reshaping the product roadmap for manufacturers and altering the procurement criteria for end-users who are under pressure to meet sustainability targets.
These dynamics create a complex operating environment. The report provides a detailed examination of how these factors interact with regional supply chains and pricing strategies, offering scenarios that help leaders prepare for various economic conditions.
Hydraulic Power Unit Market
Diverse Offerings and Technology Segmentation
The competitive arena is defined by a wide array of product technologies. The market is not monolithic; it is split between distinct power sources and delivery mechanisms, each catering to specific operational needs.
On one hand, electric hydraulic power units represent a significant portion of the market, driven by the demand for cleaner, more efficient solutions suitable for indoor and precision applications. On the other hand, diesel and gasoline hydraulic power units retain strong relevance in mobile and remote settings where grid power is unavailable or reliability in harsh conditions is paramount.
Similarly, application segmentation reveals distinct demand profiles. Industrial settings continue to be a primary driver, utilizing HPUs for stationary machinery and process control. Mobile applications represent another critical pillar, supporting construction, agriculture, and transportation equipment. There is also a category of specialized uses that fall under other applications, often requiring custom configurations.
Understanding the revenue contribution and growth rate of each of these segments is vital. While the overall market size is important, the strategic value lies in knowing which technology type is gaining share, which application vertical is saturating, and where the white space for innovation exists. Our detailed segmentation analysis provides this breakdown without exposing the numbers prematurely, ensuring that clients gain a clear view of where to allocate resources for maximum return.
Competitive Landscape and Strategic Positioning
The market structure is moderately concentrated, with a handful of key players commanding a significant share of total revenue. The CR3 and CR5 metrics indicate that while there are dominant forces, there is still ample room for specialized players to compete on niche capabilities, customization, and regional service excellence.
Major corporations are actively shaping the market through product innovation and strategic focus.
-
Bosch Rexroth AG: Maintains a diverse portfolio of hydraulic power units, emphasizing efficient compact and project-specific models tailored to precise customer requirements.
-
Parker-Hannifin Corp.: Focuses on eco-friendly hydraulic power units designed to reduce energy consumption, aligning with broader sustainability goals in the industrial sector.
-
Eaton Corporation plc: Provides comprehensive industrial hydraulic power solutions, leveraging its scale to serve large-scale manufacturing and infrastructure projects.
-
Danfoss Power Solutions A/S: Specializes in hydraulic power and motion control systems, integrating advanced electronics with traditional hydraulic mechanics.
-
HYDAC International GmbH: Offers hydraulic filtration and power unit solutions, addressing the critical need for fluid cleanliness and system longevity.
Beyond these industry giants, a robust ecosystem of specialized manufacturers adds depth to the market. Companies like Nachi-Fujikoshi, Dana Incorporated, and Atlas Copco contribute specific strengths, ranging from industrial precision to integrated system capabilities. Regional specialists such as Weber Hydraulik, Brevini Fluid Power, and Bucher Hydraulics provide localized expertise and custom engineering that larger conglomerates may not prioritize.
Recent activity highlights the pace of innovation. In August 2025, Parker-Hannifin announced a new line of eco-friendly hydraulic power units designed to reduce energy consumption by up to 30%, signaling a aggressive push toward efficiency. Similarly, in July 2025, Guorui Hydraulics launched a Permanent Magnet Synchronous Hydraulic Drive Integrated Power Unit featuring high-efficiency permanent magnet synchronous motors, wide speed range hydraulic pumps, and CAN bus control. These moves illustrate the competitive pressure to modernize product lines and capture value through technological differentiation.
The report includes a comprehensive profiling of all key competitors, analyzing their headquarters, strategic focus, and recent developments to help you benchmark your position and identify potential partnership or acquisition targets.
Regional Nuances and Global Reach
Geographically, the market exhibits distinct characteristics. Demand is not distributed evenly, reflecting the industrial maturity and economic priorities of different regions.
Hydraulic Pumps Market
North America represents a significant market, driven by strong manufacturing bases and infrastructure investment. Europe follows with a focus on high-precision engineering and regulatory compliance. The Asia Pacific region stands out as a dynamic growth engine, fueled by industrialization and expanding construction sectors. Latin America and the Middle East and Africa also contribute to the global total, each with unique demand patterns linked to local resource extraction and development projects.
However, relying solely on regional aggregate data can be misleading. Within each geography, the mix of electric versus diesel units, or industrial versus mobile applications, varies considerably. A strategy that works in one region may fail in another due to differences in labor costs, energy availability, and local content requirements. Our geographical analysis goes beyond surface-level numbers to explore the specific drivers and barriers within each territory, enabling a more nuanced international strategy.
Report Content and Operational Utility
This market research report is designed as a practical tool for strategic execution. It is not merely a collection of data points but a structured analysis intended to support specific business functions.
-
Market Sizing and Forecasting: Detailed revenue projections for the forecast period, allowing for budget planning and investment appraisal.
-
Segmentation Analysis: Deep dives into type, application, and regional splits to identify high-growth niches.
-
Company Profiles: Comprehensive assessments of key players, including their offerings, strategic focus, and recent moves.
-
Dynamics Assessment: Evaluation of regulatory, raw material, and technological factors impacting the supply and demand balance.
By integrating these elements, the report enables users to construct robust market entry strategies, optimize product portfolios, and anticipate competitor moves. Whether you are a manufacturer looking to expand your footprint, a supplier seeking to understand end-user demand, or an investor evaluating the sector's potential, this document provides the foundational intelligence required to make informed decisions.
Conclusion: The Imperative for Informed Strategy
The Hydraulic Power Unit market offers substantial opportunities for those equipped with the right information. The projected growth from 2026 to 2032 suggests a expanding pie, but the distribution of that growth will favor players who understand the nuances of technology shifts, regulatory compliance, and regional dynamics.
Superficial market summaries are insufficient for the complexities of today's industrial environment. To truly capitalize on the trends outlined here, stakeholders need access to the complete dataset, including the specific revenue splits, detailed competitive benchmarks, and granular regional forecasts that we have reserved for this full report.
PW Consulting invites you to leverage this research to secure a competitive advantage. We encourage you to access the full source webpage to download the complete study. There you will find the detailed intelligence necessary to transform these high-level insights into concrete operational success. The future of hydraulic power is being written now, and the decisions you make in 2026 will define your position for the rest of the decade.
For detailed analysis of this topic, please visit the official page: Hydraulic Power Unit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hemp Seeds Market Hits USD 500 Million in 2025, Projects 7.5% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Intelligence Brief: Navigating the Hemp Seeds Market Outlook 2026-2032
As the global functional food and wellness ingredients sector accelerates, hemp seeds have emerged as a cornerstone commodity bridging consumer nutrition, industrial utility, and sustainable agriculture. PW Consulting’s newly released Hemp Seeds Market research delivers a comprehensive, data-grounded assessment of this evolving landscape, designed specifically to equip executive leadership, product development teams, and supply chain strategists with the clarity required for high-stakes 2026 decision-making. Unlike broad industry summaries that rely on delayed indicators or superficial trend-spotting, this study maps the structural drivers, competitive fault lines, and regulatory inflection points that will define commercial viability over the next seven years. The following overview outlines the strategic framework, methodological rigor, and actionable intelligence contained within the full report, while preserving the granular segmentation required for precise corporate planning.
The Trajectory and Structural Signals of a Maturing Commodity Market
The hemp seeds sector has transitioned from a niche, regulation-constrained niche to a mainstream ingredient pipeline with measurable macroeconomic traction. Historical performance from 2020 through 2025 demonstrates a consistent upward arc, with annual revenue milestones reflecting sustained demand absorption across food formulation, personal care, and industrial applications. Building on this foundation, the 2026 base-year valuation establishes a clear inflection point, followed by a forecast period extending through 2032 that projects compounded annual growth at 7.5 percent. This trajectory is not merely a linear extrapolation; it reflects converging supply chain maturation, shifting consumer preference toward plant-based complete proteins, and expanding regulatory clarity that has reduced market entry friction for ingredient suppliers and branded manufacturers alike.
Strategists evaluating capital allocation, capacity expansion, or M&A targets will recognize that sustained double-digit absolute growth over a multi-year horizon signals a market moving past early adoption cycles. The compound growth rate indicates that while the category is no longer in its experimental phase, it remains far from saturation. Demand is being pulled by formulation innovation in nutritional supplements and beverage platforms, while simultaneously being pushed by agricultural processors optimizing yield, extraction efficiency, and downstream fractionation capabilities. The full study contextualizes these macro trends against historical volatility, delineating which growth phases are cyclical versus structural, and identifying the specific institutional triggers that will accelerate or constrain regional deployment.
Regulatory Architecture and the New Operational Baselines
Market velocity in hemp-derived ingredients has historically been constrained by legal ambiguity. Recent legislative and administrative actions have materially altered that landscape. The amendment enacted through Pub. L. No. 119-37 on November 12, 2025, clarified the federal definition of hemp by establishing a total THC concentration limit of not more than 0.3 percent on a dry weight basis, while explicitly excluding viable seeds from any parent plant exceeding that threshold. This provision reduces compliance uncertainty for seed-focused growers, processors, and ingredient distributors, enabling more predictable sourcing contracts and downstream certification pathways.
Parallel to statutory clarification, USDA mechanisms continue to provide structured importation pathways for hemp seeds into the United States following their removal from DEA jurisdictional authority under the 2018 Farm Bill framework. These administrative routes have streamlined cross-border supply chains, particularly for processors integrating North American grain with European and Asian finishing capacity. On the formulation side, the FDA’s 2018 GRAS evaluation, which issued no objections to hulled hemp seeds, hemp seed protein powder, and hemp seed oil as food ingredients, remains a critical benchmark. It has enabled rapid incorporation into baked goods, dairy alternatives, snack matrices, and beverage systems without requiring case-by-case premarket approval. The full report maps how these regulatory pillars interact with regional compliance variations, quality assurance protocols, and audit readiness requirements, providing operations leaders with a practical compliance roadmap rather than a theoretical legal summary.
Report Architecture: Operational Intelligence for Executive Deployment
The study is structured to translate market complexity into executable strategy. Readers will find a delineation of product architecture across whole seeds, hulled formats, extracted oils, and protein powders, with each category assessed for processing intensity, margin profiles, storage and logistics constraints, and formulation compatibility. Application pathways are examined through the lens of commercial adoption velocity, highlighting where food and beverage integration drives volume, where nutritional supplement positioning commands premium pricing, where personal care formulations leverage fatty acid and antioxidant profiles, where industrial applications utilize structural and chemical properties, and where animal feed channels absorb byproducts and lower-grade fractions. Regional demand distribution, supply chain nodes, and trade flow patterns are analyzed to identify where processing capacity aligns with consumption growth, and where infrastructural bottlenecks may create pricing dislocations or delay time-to-market for new product launches.
Beyond structural mapping, the report delivers quantitative baselines, forward-looking scenario modeling, and sensitivity analysis that allow strategy teams to stress-test assumptions around yield variability, input cost fluctuations, regulatory enforcement intensity, and competitive entry timelines. The analytical framework is calibrated for 2026 planning cycles, meaning that forecasts are anchored to current capacity utilization, recent processing line expansions, and observable shifts in procurement behavior among large-scale food manufacturers and ingredient distributors. By consolidating historical performance, base-year positioning, and multi-year projections into a single decision-ready format, the study eliminates the need for internal teams to piece together fragmented data sources or rely on outdated secondary references.
Competitive Landscape: Strategic Positioning and Recent Capacity Shifts
The market exhibits moderate concentration, with the top three participants accounting for approximately 45 percent of total revenue and the top five collectively representing roughly 55 percent. This concentration profile indicates a landscape where established processors and vertically integrated ingredient suppliers hold meaningful scale advantages, yet sufficient fragmentation remains to allow specialized entrants, regional growers, and formulation-focused brands to capture differentiated value. The competitive field spans North American grain originators, European fractionation specialists, and global distributors that bridge organic certification, bulk procurement, and retail-ready packaging.
Manitoba Harvest Hemp Foods operates as the largest hemp foods manufacturer in the category, producing and selling raw shelled hemp seeds and hemp seed oil from North American-grown and processed grain, positioning itself as a scale anchor for both retail and ingredient channels. Victory Hemp Foods has recently reinforced its processing leadership by launching North America’s largest hemp heart protein and oil processing line in April 2025, utilizing patented solvent-free fractionation to deliver allergen-free V-70 protein and V-ONE oil, an expansion that directly strengthens its value proposition for plant-based food, baking, and beverage formulators. Navitas Organics and Nutiva maintain strong consumer-facing and wholesale positions by offering organic, non-GMO, gluten-free, and vegan-certified shelled hemp seeds tailored for smoothies, baking, and superfood applications. Green Source Organics and Harvest Hemp Foods supply organic and derived hemp products across food and ingredient markets, while Canah International and Hempflax BV focus on processing and distributing seeds and oils for food and industrial ingredient applications. BAFA neu GmbH emphasizes certified organic seed production for food and animal feed, and Kanda Hemp supplies certified industrial hemp seeds for commercial grain and fiber production. Bulk Hemp Warehouse serves the raw grain and fiber segment with bulk viable whole seeds, whereas Allive and North Central Company address wholesale and snack/baking demand through bulk unhulled, hulled, and organic-compliant supply options.
Hemp Market
The strategic implication for 2026 is clear: scale processors are investing in fractionation and allergen-free certification to capture premium ingredient contracts, while mid-tier and regional players are competing on organic certification, supply reliability, and application-specific formatting. The full study evaluates these players across capacity positioning, product architecture, distribution reach, and recent operational developments, providing a comparative lens that helps procurement and partnership teams identify where scale, where specialization, and where geographic proximity deliver the highest strategic return.
Strategic Imperatives for 2026 Planning Cycles
Executives entering 2026 must treat hemp seeds not as a single commodity line but as a multi-format ingredient ecosystem with distinct margin structures, regulatory touchpoints, and formulation barriers. The most effective strategies will align procurement and capacity decisions with application-specific demand rather than aggregate volume alone. Formulators seeking clean-label protein and lipid profiles will continue to favor hulled seeds, protein powders, and oils that carry GRAS status and organic or allergen-free certifications, which means supplier qualification, batch consistency, and documentation readiness will become as critical as unit pricing.
Supply chain leaders should assess whether existing grain contracts, storage configurations, and finishing capacity match the forecast distribution of whole versus hulled demand, particularly as processors expand fractionation lines and seek to minimize solvent exposure while maintaining throughput. Market entrants and investors will benefit from understanding where regional demand concentration intersects with processing density, and where logistics costs or certification lag may create temporary arbitrage opportunities. Brand managers and innovation teams should monitor how recent legislative clarifications and administrative importation pathways reduce lead-time uncertainty, enabling faster launch cadences for hemp-integrated food, beverage, personal care, and supplement portfolios. The report provides the scenario scaffolding required to evaluate these decisions quantitatively, rather than relying on directional intuition.
Conclusion: From Market Awareness to Decisive Action
The hemp seeds market in 2026 stands at the intersection of regulatory stabilization, processing innovation, and broadening application adoption. Sustained compound growth through 2032 signals that the category has moved beyond experimental positioning into a structured ingredient pipeline with measurable economic gravity. Yet the opportunity is not uniformly distributed across formats, applications, or regions, and the firms that outperform will be those that can translate macro momentum into precise procurement, capacity, and partnership decisions. PW Consulting’s full Hemp Seeds Market research report delivers the segmented baselines, competitive mapping, regulatory context, and forward-looking scenario analysis necessary to make those decisions with confidence. Complete segmentation values, regional deployment detail, application-level revenue splits, and additional processing-line and competitive developments are available in the full study, providing the depth required for board-level planning, product roadmapping, and supply chain optimization.
Hemp Seeds Market
For detailed analysis of this topic, please visit the official page: Hemp Seeds Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 22.4% CAGR for Chargeable Flexible Battery Market to Reach $932M by 2032
By PW Consulting, 2026-09-16
The Bendable Power Paradigm: Strategic Intelligence for the Chargeable Flexible Battery Market in 2026 and Beyond
The transition from rigid power sources to conformable energy solutions is no longer a conceptual novelty in electronics design. It is an engineering imperative. As product architectures grow more complex, ergonomically demanding, and spatially constrained, manufacturers across medical technology, consumer wearables, and industrial IoT are actively seeking power systems that can bend, twist, and integrate seamlessly into unconventional form factors. PW Consulting has published a comprehensive market research study on the Chargeable Flexible Battery Market, offering executives a data-driven foundation for technology sourcing, partnership selection, and geographic expansion in the critical 2026 through 2032 horizon.
This strategic briefing introduces the scope and analytical rigor of the study. While we outline the structural dynamics and competitive forces shaping the sector, readers should note that granular segmentation metrics, pricing models, and regional revenue splits are reserved for the full report. The following analysis is designed to demonstrate the depth of our methodology and establish the commercial rationale for acquiring the complete dataset.
Market Trajectory: From Steady Growth to an Accelerating Curve
Historical tracking across the 2020 to 2025 period reveals a market that moved from incremental adoption to a structural inflection point. Revenue expanded from approximately 93.15 million USD in 2020 to an estimated 115.5 million USD by 2024, reflecting steady but measured progression driven by early-stage pilot deployments and niche product integration. The trajectory shifted noticeably in 2025, with market revenue reaching an estimated 226.52 million USD, marking a step-change that signals broader commercialization readiness across multiple end-use verticals.
The forward outlook reinforces this acceleration. Forecast modeling projects the market to reach approximately 282.97 million USD in 2026, with continued expansion through 342.56 million USD in 2027, 403.09 million USD in 2028, and 512.58 million USD in 2029. The trajectory extends toward 605.34 million USD by 2030, climbing further to 764.37 million USD in 2031 and an estimated 932.34 million USD by 2032. This progression translates to a forecast compound annual growth rate of 22.4 percent throughout the 2026 to 2032 period, indicating that flexible rechargeable power is transitioning from a supporting technology to a strategically critical component category.
Such a growth profile demands more than headline recognition. For corporate strategists, the operative question is not whether the market is expanding, but where the growth concentrates, which technology families are gaining share, and how regulatory and supply-chain dynamics will alter competitive positioning. The full report maps these variables in granular detail, with segmentation dimensions structured to support product roadmap planning, investment allocation, and market-entry timing.
Core Report Scope: An Execution-Oriented Intelligence Framework
A market study is only as valuable as its applicability to operating decisions. This report is designed to function as a practical decision-support tool rather than a high-level survey. It integrates historical performance analysis, forward-looking demand drivers, technology maturity assessment, and competitive benchmarking into a single coherent framework. The research structure enables users to evaluate both the commercial opportunity and the execution risks associated with flexible rechargeable battery adoption.
The report’s analytical coverage includes the following operational components:
- Market sizing and trajectory modeling grounded in historical data covering the 2020 to 2025 period, extended through the 2026 to 2032 forecast window.
- Technology-family evaluation distinguishing thin-film architectures from printed flexible battery formats, with emphasis on performance trade-offs, manufacturing readiness, and application fit.
- Application-side analysis examining how wearable electronics, medical devices, and consumer electronics are influencing volume demand, specification requirements, and procurement behavior.
- Regional market structure assessment designed to inform expansion planning and channel strategy without relying on publicly available approximation.
- Competitive profiling of major participants, including product focus, technological specialization, geographic footprint, and strategic posture within the flexible battery value chain.
- Regulatory and standards context, including evolving compliance expectations in key markets and their implications for product design, sourcing, and market access.
- Demand-driver mapping that connects product innovation trends, form-factor requirements, and functional performance needs to battery specification priorities.
By organizing the intelligence around these dimensions, the report supports a range of corporate functions. R&D leaders can use the technology assessment to benchmark architectural choices. Commercial teams can align product positioning with the most attractive application segments. Supply-chain and procurement stakeholders can evaluate vendor profiles with greater clarity. Executive leadership can use the forecast structure to test investment scenarios and set internal growth targets that reflect market reality rather than extrapolated assumptions.
Competitive Landscape: Differentiation in a Fragmented, Innovation-Driven Market
The chargeable flexible battery sector is characterized by a broad set of active participants, many of which compete on technological specialization, application-specific engineering, and regional manufacturing relationships rather than on scale alone. Market concentration data indicates a relatively distributed structure, with the combined share of the top three firms estimated at 25.0 percent and the top five firms at 32.0 percent. This level of dispersion signals that there is meaningful room for differentiation, and that competitive advantage will increasingly depend on proprietary cell design, integration capability, reliability under mechanical stress, and the ability to meet application-specific certification or compliance requirements.
Several established and emerging players illustrate the breadth of approaches shaping the market. Samsung SDI manufactures flexible lithium-ion rechargeable batteries targeted at wearables, smartcards, and IoT devices, reinforcing the relevance of flexible power in high-volume consumer and connected-device categories. LG Chem develops and supplies flexible rechargeable batteries optimized for wearable and flexible electronics applications, aligning product development with the mechanical and energy-density demands of next-generation form factors. Panasonic produces flexible lithium-ion rechargeable batteries engineered to withstand repeated bending and twisting, addressing durability as a core adoption barrier in wearables and smart devices.
Alongside these larger-scale participants, a number of specialized firms are advancing distinct technology positions. Blue Spark Technologies develops thin, flexible printed batteries integrated into continuous vital sign monitoring wearables, highlighting the medical and health-monitoring application pathway. Enfucell specializes in printed flexible power sources for wireless sensors and IoT, offering lithium-polymer rechargeable options that support low-power distributed sensing use cases. BrightVolt manufactures ultra-thin solid-state lithium-polymer rechargeable batteries for IoT and wearable devices, leveraging solid-state design as a potential differentiator in safety and form-factor flexibility.
Imprint Energy produces ultrathin flexible rechargeable zinc batteries for IoT smart labels and integrated electronics, expanding the material choice set available to designers seeking cost-effective or application-tailored alternatives. Cymbet develops solid-state rechargeable thin-film batteries with energy harvesting compatibility for embedded IoT and wearable applications, combining energy storage with broader system-level power strategies. Jenax manufactures J.Flex solid-state flexible lithium-ion rechargeable batteries intended for wearables and fast-charging applications, reflecting ongoing efforts to combine mechanical flexibility with improved charging performance. FlexEl offers custom thin flexible rechargeable batteries for specialized medical and industrial wearable uses, underscoring the role of bespoke engineering in high-value, lower-volume market segments.
Chargeable Flexible Battery Market
The strategic implication is clear. Buyers and competitors are not navigating a market with a single dominant solution. Instead, they are evaluating a multi-technology, multi-application space in which design strategy determines commercial success as much as manufacturing capacity does. The full report provides deeper comparative profiling and trend analysis that helps organizations identify which vendors, technology families, and partnership models are most aligned with their product architecture and market ambitions.
Market Dynamics: Technology Push, Regulatory Pressure, and Application Pull
Flexible battery adoption is advancing through a combination of simultaneous forces. On the technology side, progress in thin-film deposition, printed battery manufacturing, material flexibility, and solid-state chemistry is expanding the range of applications that can use conformable power without sacrificing reliability. On the demand side, wearables and other compact electronic devices continue to push for slimmer profiles, ergonomic integration, and uninterrupted operation, all of which increase the relevance of rechargeable flexible power sources. Medical devices and industrial IoT applications further broaden the opportunity by requiring specialized characteristics such as continuous monitoring capability, low-power efficiency, or custom form factors for embedded use.
At the same time, regulatory and standardization activity is becoming a more prominent market dynamic. The EU Battery Regulation establishes mandates affecting carbon footprint declarations, due diligence obligations, labeling, recyclability expectations, and removability considerations across rechargeable battery products. For flexible battery producers and downstream manufacturers, these requirements influence sourcing, documentation, product design, and compliance timelines. Recent developments underscore that regulatory readiness is shifting from a planning issue to an active operating constraint. European Commission industrial carbon footprint reporting for rechargeable batteries exceeding 2 kWh capacity became mandatory in February 2026. In parallel, Intertek moved toward Notified Body status under the EU Battery Regulation for flexible battery compliance, reflecting the growing institutional infrastructure needed to assess and certify flexible battery products against evolving standards.
Flexible PV Cell Market
Beyond regulatory pressure, recent patent activity illustrates how manufacturers are reinforcing their technological claims. Volt Carbon issued a second U.S. patent supporting high-cycle lithium-metal pouch cells suitable for flexible battery formats, a development that points toward improved cycle life and application versatility in next-generation cell designs. Beam Global filed a U.S. patent for a scalable flexible smart battery system intended to enhance power efficiency, indicating continued interest in system-level optimization rather than cell performance alone. These developments, while individual in scope, collectively suggest that innovation in the flexible battery field is increasingly focused on cycle durability, integration intelligence, and efficiency improvement.
A full market study must therefore account not only for what is being built, but also for what regulation, certification, and patent positioning will allow in the market ahead. The report integrates these dynamics to help organizations anticipate compliance costs, identify possible sourcing shifts, and assess whether specific technology paths offer durable advantage or merely temporary differentiation.
Strategic Value for 2026 Decision-Making
For executives making decisions in 2026, the chargeable flexible battery market presents both opportunity and complexity. Growth is strong, but the market is not uniform. Technology choices differ substantially in maturity, manufacturability, and application compatibility. Regional demand structures are not interchangeable. Regulatory expectations are evolving. Competitive positioning is shaped as much by specialized engineering as by scale. In this environment, organizations need intelligence that is detailed enough to support action, yet structured clearly enough to support prioritization.
The PW Consulting study is built for that purpose. It provides a consolidated view of historical performance, short-term momentum, and long-term expansion, with segmentation and competitive analysis calibrated to support real operating decisions. Readers seeking a broad overview may find the macro trajectory useful, but organizations that intend to source materials, select partners, enter new geographies, or justify R&D investment will need the complete segmentation detail, regional breakdowns, application-level drivers, and competitive profiles that the full report contains.
This article has outlined the analytical framework and strategic themes that define the study. It has not disclosed the core segmented data that underpin those themes. That is intentional. In a market moving at this pace, the most valuable insights are the ones that enable precise action. The full chargeable flexible battery market research report is designed to deliver that precision, supporting decision-makers who need to move from market awareness to market execution.
For detailed analysis of this topic, please visit the official page: Chargeable Flexible Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Micronized Rubber Powder Market to Hit $279.34M by 2032 at 6.5% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence Brief: The Micronized Rubber Powder Market Outlook 2026-2032
Executive Summary: A Market Poised for Structural Transformation
The global micronized rubber powder (MRP) industry is navigating a pivotal inflection point. As sustainability mandates intensify and circular economy principles transition from regulatory ideal to commercial necessity, the demand for high-performance recycled rubber solutions has accelerated. Our latest comprehensive research publication provides a granular analysis of this dynamic landscape, offering decision-makers the clarity required to navigate market volatility, supply chain constraints, and competitive disruptions across the forecast period of 2026 to 2032.
For strategic planners, procurement leaders, and investment committees, the window to secure advantageous positioning is narrowing. This article serves as a foundational overview of the market mechanics, growth trajectories, and competitive architectures detailed in our full report. It is designed to demonstrate the analytical rigor and operational relevance of our research while preserving the proprietary data necessary for precise strategic modeling. To access the complete segmentation matrices, pricing elasticity curves, and forecast scenario models, readers are invited to consult the full market brief directly.
The market has demonstrated consistent resilience over the past half-decade, evolving from a niche recycling byproduct segment into a specialized materials market characterized by technological differentiation and stringent performance standards. Understanding the forces propelling this evolution is essential for any organization seeking to capitalize on the opportunities embedded within end-of-life tire valorization and advanced polymer modification.
Historical Trajectory and Baseline Valuation (2020-2025)
Our retrospective analysis covering the period from 2020 through 2025 reveals a market that has steadily expanded despite macroeconomic headwinds, supply chain uncertainties, and fluctuating raw material costs. Over this six-year horizon, the industry consolidated its foundation, driven by increasing adoption of MRP in high-value applications and growing acceptance of recycled content mandates across key industrial sectors. The baseline valuation at the end of the historical period stands at a recorded level, reflecting a mature and increasingly sophisticated market ecosystem.
This historical growth was not uniform. It was shaped by diverging regional adoption rates, varying degrees of regulatory enforcement on tire disposal, and the gradual maturation of processing technologies. The data indicates a clear trajectory of value accumulation, with early adopters of fine-particle processing technologies capturing disproportionate margins compared to producers relying on conventional ambient grinding methods. The historical record establishes a credible foundation for forward-looking projections and underscores the importance of timing in capacity expansion and technology investment decisions.
Forward Outlook: Growth Catalysts for 2026-2032
Looking ahead, the forecast period anticipates a robust compound annual growth rate that outpaces many traditional industrial materials segments. This growth is underpinned by a convergence of structural drivers that are likely to persist throughout the decade. Regulatory frameworks worldwide are tightening requirements for tire recycling, mandating higher recovery rates and penalizing landfill disposal. Simultaneously, infrastructure spending programs in multiple economies are creating immediate demand pull for asphalt modifiers and construction additives derived from recycled rubber.
Technological advances are also reshaping the supply side. Improvements in cryogenic processing efficiency have progressively reduced energy intensity, mitigating one of the historically significant cost burdens associated with fine-particle production. At the same time, the industrial preference for powders with superior surface area and morphology is elevating the commercial relevance of specialized grades, creating pricing tiers that reward producers with advanced milling and classification capabilities. These dynamics suggest that the market of 2032 will look materially different from the market of 2026, with greater emphasis on product specification, traceability, and environmental certification.
Market Structure, Segmentation, and Value Migration
The Particle Size Dimension: Technical Differentiation as a Margin Driver
Particle size is not merely a physical specification; it is a fundamental determinant of end-use eligibility and pricing power. The market segmentation by particle size reveals a clear hierarchy of value, with finer fractions commanding preferential positioning in applications that demand intimate polymer interaction, uniform dispersion, and enhanced mechanical performance. Coarser fractions continue to serve bulk-modification roles, but the margin differential between fine and coarse grades has become increasingly pronounced as downstream formulators optimize formulations for performance and sustainability credentials.
Worldwide Micronized Silica Market
This technical segmentation has strategic implications for capacity planners. Investment in fine-grinding capability requires higher capital intensity and more complex operational control, but it opens access to application segments with lower price elasticity and stronger competitive moats. Our full report dissects the capacity allocation trade-offs across these size categories and provides scenario analysis on how shifting application preferences may alter relative demand shares over the forecast horizon.
Application Ecosystems: Where Demand Converges and Diverges
The application landscape of MRP spans multiple industrial domains, each with distinct procurement cycles, specification requirements, and growth trajectories. The automotive sector has historically represented the largest demand pool, leveraging MRP for vibration damping, component lightweighting, and recycled content integration. Construction-related applications, particularly asphalt modification and paving compounds, have emerged as a high-growth vector, supported by public-sector sustainability procurement and the demonstrated performance benefits of rubber-modified surfaces.
Industrial manufacturing, coatings, and specialty uses constitute additional demand pillars, each responding to different drivers such as polymer compounding trends, adhesive formulation requirements, and consumer-facing sustainability messaging. The interplay between these application segments creates a diversified demand base that can buffer the market against sector-specific downturns, but it also complicates forecasting, as relative demand shares shift with technological substitution, raw material pricing, and regulatory emphasis. Our detailed analysis maps these interdependencies and identifies the segments most likely to generate incremental volume growth in the coming years.
Micronized Rubber Powder Market
Regional Dynamics and Geographic Arbitrage
Geographic distribution of demand and production capacity reflects a complex interplay of regulatory environments, tire generation rates, processing infrastructure density, and logistics economics. Different regions exhibit markedly different adoption curves, with some markets leading in per-capita recycled content integration while others remain in earlier stages of capacity development. Understanding these regional asymmetries is critical for companies evaluating export opportunities, local processing investments, or strategic partnerships.
The full research publication provides a comprehensive geographic breakdown that maps demand intensity against supply availability, identifies logistics bottlenecks, and evaluates the economic viability of regional trade flows. This geographic intelligence is essential for optimizing footprint strategy and for anticipating where regulatory or infrastructure developments may create the next wave of regional demand spikes.
Competitive Architecture and Strategic Positioning
Market Concentration and the Scale Advantage
The MRP industry exhibits a moderate concentration profile, with a defined set of leading producers holding meaningful shares of global output. Competitive positioning is increasingly determined by technology tenure, processing capability, and the ability to supply certified, specification-grade materials at scale. Producers that have invested in proprietary milling technologies, integrated recycling loops, or advanced quality assurance systems are better positioned to capture premium segments and defend against commoditization pressure.
Market leaders such as Lehigh Technologies, a Michelin Group subsidiary operating from Tucker, Georgia, exemplify the integration of advanced cryogenic turbo mill technology with a diversified application portfolio spanning tires, plastics, asphalt, and construction materials. Their emphasis on lifecycle assessment and circular economy messaging aligns with the credentialing demands of downstream customers. Genan Holding A/S, headquartered in Denmark and recognized as a leading global end-of-life tire recycler, has built a reputation around ultra-fine powder production and ambient granulates, with recent product certifications reinforcing the environmental value proposition of their asphalt premix offerings.
Tinna Rubber & Infrastructure Limited, based in India, has established itself as a large-scale producer with deep integration from radial truck and bus tire feedstock through to crumb rubber modifiers, reclaim rubber, and polymer applications. Their scale and vertical integration illustrate a distinct competitive model centered on feedstock control and cost-efficient processing. Entech Inc., operating from Middlebury, Indiana, brings long operational tenure dating back to the mid-1990s, offering a broad size range of MRP and crumb rubber products complemented by integrated hauling, processing, and compounding services.
The Rubberjet Group, based in Italy, represents a different technological pathway, utilizing proprietary high-pressure water-jet technology to produce micronized rubber powder and granules from medium and large end-of-life tires and rubber tracks. Their approach underscores the ongoing innovation in processing methods and the differentiation potential that alternative milling technologies can create.
Recent Competitive Signals and Industry Developments
Recent announcements from key players illustrate the intensifying focus on environmental credentialing and product certification. In late 2025, Lehigh Technologies released a lifecycle assessment study quantifying CO2 reduction and circular economy benefits associated with their micronized powders used in asphalt modification, signaling a strategic emphasis on evidence-based sustainability claims. Concurrently, Genan Holding A/S secured Environmental Product Declaration certification for its GENAN ROAD+ PREMIXED asphalt premix, reinforcing the market trend toward third-party verified environmental performance in construction applications.
These developments are not isolated marketing events; they reflect a structural shift in procurement decision-making, where environmental documentation and performance validation are becoming prerequisites for entry into premium application segments. Companies that invest early in measurement, certification, and transparent reporting are likely to gain preferential access to specification-driven demand.
Structural Dynamics Shaping Margin and Viability
Cost Architecture and the Cryogenic Premium
The economics of MRP production are heavily influenced by process technology choice and the associated variable cost structure. For cryogenic producers, liquid nitrogen represents a significant share of variable production costs, making energy efficiency and nitrogen consumption management critical levers for margin protection. Over the past five years, improvements in cryogenic processing efficiency have materially reduced per-ton nitrogen consumption, easing a persistent cost pressure and enhancing the competitiveness of fine-grade output.
At the same time, the market has demonstrated willingness to pay a meaningful price premium for cryogenic-grade material, reflecting the functional benefits associated with superior particle morphology and surface area. This premium creates a clear economic rationale for producers to invest in or maintain cryogenic capability, but it also raises the stakes for operational execution. Cost mismanagement in the cryogenic process can quickly erode the margin advantage that the premium is meant to deliver.
Regulatory Tailwinds and Circular Economy Alignment
Policy frameworks continue to play a decisive role in shaping demand. The inclusion of natural rubber on the European Commission list of critical raw materials has heightened attention on alternative material sourcing and recycling pathways. Simultaneously, recycling regulations targeting end-of-life tires are reinforcing demand for high-value MRP as a compliant, value-adding circular economy solution. These regulatory signals are not uniform across jurisdictions, but the overall trajectory favors increased recovery, higher-value reuse, and greater documentation of environmental impact.
Organizations seeking to align their strategies with these regulatory currents must look beyond headline compliance requirements and understand the specification expectations, certification pathways, and procurement preferences emerging in regulated markets. Our report provides the detailed regulatory mapping and interpretation needed to translate policy signals into actionable commercial strategy.
Strategic Implications for 2026 Decision-Making
For executives planning allocations, capacity decisions, partnership structures, and competitive positioning in 2026, the MRP market offers both opportunity and complexity. The growth trajectory is favorable, but the distribution of value is increasingly concentrated among producers with advanced technology, certified product portfolios, and the ability to serve specification-driven applications. Companies that treat MRP as a commoditized byproduct risk ceding margin and market access to competitors who have built differentiation into their operational and commercial models.
Our full market research publication delivers the depth and granularity required to execute informed strategy. It includes detailed segmentation analysis, forward-looking volume and value projections, competitive benchmarking, cost structure evaluation, regulatory interpretation, and scenario modeling across multiple demand and supply variables. The complete dataset, including regional breakdowns, application-level demand shares, particle size valuations, and concentration metrics, is available in the full report and forms the analytical backbone for strategic planning.
To explore the full research suite, access detailed segmentation data, and obtain the complete forecast models for 2026 through 2032, request the complete Micronized Rubber Powder Market research publication. The insights within are structured to support immediate strategic action and long-range planning in a market that is rapidly redefining the value of recycled rubber materials.
For detailed analysis of this topic, please visit the official page: Micronized Rubber Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Coal Tar Pitch Market to Hit $3,044.1 Million by 2032, 4.85% CAGR
By PW Consulting, 2026-09-16
Navigating the Carbon Binders Landscape: Strategic Imperatives for the Coal Tar Pitch Market Through 2032
The global coal tar pitch market stands at a critical inflection point. As foundational carbon binders underpin both primary aluminum production and advanced graphite manufacturing, industry participants must reconcile steady demand growth with tightening environmental regulations and evolving feedstock dynamics. Our latest research evaluates the market across a comprehensive 2026 through 2032 forecast window, building on a rigorously validated historical baseline spanning 2020 to 2025. This analysis is designed to equip procurement leaders, strategy executives, and investment committees with the structural clarity required to allocate capital, secure supply corridors, and align product portfolios with long-term industrial trajectories.
Over the historical period, revenue patterns reflected a combination of cyclical demand recovery, capacity rationalization in mature regions, and gradual migration toward higher-performance grades. The market advanced from a baseline of 1,765.2 million USD in 2020 to 2,185.5 million USD in 2025, with the trajectory demonstrating both resilience and episodic volatility driven by downstream construction cycles and metallurgical output adjustments. Looking forward, the forecast horizon projects sustained expansion, positioning total market revenue near 3,044.1 million USD by 2032. This growth is anchored by a compound annual growth rate of 4.85 percent, signaling a mature yet persistently expanding addressable market rather than a speculative surge. For corporate planners, this trajectory underscores the importance of modeling demandelasticity against macro industrial indicators, rather than relying on static volume assumptions.
Market Framework and Structural Segmentation
A rigorous understanding of coal tar pitch requires disaggregating the market across both product architecture and end-use demand profiles. The report maps the landscape across multiple type categories, capturing the distinct operational requirements that separate aluminum-grade binders from impregnation and specialty variants. Aluminum-grade pitch continues to represent the dominant share of revenue, reflecting its indispensable role in carbon anode formulation for primary smelting operations. Binder and impregnation grades serve a more specialized set of downstream applications, where softening points, coking values, and rheological characteristics dictate procurement specifications. Special-grade formulations address niche performance thresholds in advanced carbon materials and refractory systems, creating a higher-margin yet technically demanding segment for producers with differentiated processing capabilities.
Coal Tar Pitch For Graphite Electrodes Market
Demand concentration across applications follows a similarly hierarchical pattern. Aluminum smelting remains the foundational consumption pillar, while graphite electrode manufacturing sustains a substantial secondary channel tied to electric-arc furnace steelmaking and industrial carbon processing. Additional application channels, including roofing formulations and specialty industrial uses, provide supplementary revenue streams that help balance cyclical volatility in the core metallurgical segments. The report examines how these application pathways interact with regional processing capacity, logistics constraints, and customer specification requirements, enabling readers to identify where supply-demand balance is most likely to tighten or loosen over the forecast period.
Regional analysis in the study is structured to highlight where manufacturing footprints, trade flows, and regulatory environments shape competitive positioning. The market is not uniformly distributed; instead, it concentrates around established carbon-processing clusters and emerging refining hubs that can offer both scale and grade flexibility. The research details how regional pricing differentials, freight exposure, and local compliance requirements influence buyer-seller dynamics, helping strategists evaluate which geographies present durable advantages and which are more susceptible to regulatory friction or feedstock disruption.
Competitive Landscape and Enterprise Positioning
The coal tar pitch sector remains moderately concentrated, with established producers leveraging integrated distillation assets, long-term customer relationships, and technical service capabilities to defend market positions. Our analysis identifies the core enterprise cohort shaping competitive dynamics, including Koppers Holdings Inc., Rain Carbon Inc., Himadri Speciality Chemical Ltd., Deza, a.s., and Shree Shyam Chemicals. Each occupies a distinct strategic niche shaped by feedstock access, geographic footprint, and grade specialization.
Coal Tar Pitch Market
Koppers Holdings Inc., headquartered in Pittsburgh, Pennsylvania, operates as an integrated producer of carbon pitch derived from coal tar distillation, with primary offerings focused on binding agents for carbon anodes serving aluminum smelters and for graphite electrodes used by electric-arc furnace steel producers. Rain Carbon Inc., based in Stamford, Connecticut, has established itself as a global leader in coal tar and petroleum distillation, manufacturing coal tar pitch with varying softening points for carbon anodes, graphite electrodes, specialty graphite, and refractory materials. Himadri Speciality Chemical Ltd., operating from Kolkata, India, stands out as a vertically integrated producer with annual pitch capacity exceeding 600,000 metric tons, offering coal tar pitch grades for aluminum, graphite electrode, and carbon black sectors, including liquid and export variants. Deza, a.s., in the Czech Republic, produces coal tar pitch and related distillation products, supplying binder-grade and impregnating grades for carbon and specialty applications. Shree Shyam Chemicals, based in Bhilai, Chhattisgarh, manufactures coal tar pitch, coal tar, and related chemicals, serving industrial-grade requirements across aluminum, graphite, chemical, and pharmaceutical sectors.
Recent Developments Shaping Supply and Corridor Strategy
Beyond structural positioning, the report tracks recent operational moves that reveal where capital is flowing and how supply arrangements are evolving. In January 2025, Rain Carbon Inc. announced a new coal tar distillation and pitch processing facility in APSEZ, Anakapalli, Andhra Pradesh, India. The initial phase targets 50,000 metric tons per year and addresses graphite, battery, and aluminum markets, with further expansion planned, signaling a deliberate push to diversify processing geography and capture demand growth in South Asia. In November 2025, Epsilon Carbon Private Limited signed a non-binding MoU with Aluminium Bahrain for the long-term supply of liquid coal tar pitch, aimed at supporting aluminum smelting demand and strengthening export security for a key downstream customer. In December 2025, Himadri Speciality Chemical Ltd. executed its first-ever liquid coal tar pitch export of 3,600 tonnes to the Middle East from the New Mangalore Port terminal, establishing a new supply corridor and demonstrating the increasing importance of logistics-enabled grade differentiation.
These developments are not isolated events. Collectively, they point to a market in which supply reliability, grade customization, and corridor diversification are becoming as strategically consequential as raw production volume. The report examines how such moves reshape competitive pressure, influence customer negotiation leverage, and alter regional import-dependency profiles for buyers seeking to de-risk procurement.
Regulatory Dynamics and the Compliance Premium
Regulatory scrutiny represents one of the most consequential variables for coal tar pitch strategy, particularly where polycyclic aromatic hydrocarbon exposure intersects with pavement applications, industrial emissions standards, and chemical handling requirements. The analysis incorporates multiple regulatory signals that are reshaping demand quality and compliance economics. Minnesota prohibits the sale and use of coal tar sealant products containing coal tar, coal tar pitch volatiles, or CAS 65996-93-2/65996-89-6 on asphalt-paved surfaces, effective January 1, 2014. New York State has proposed legislation, Senate Bill 2025-S3179A, to tighten the PAH limit in the state's coal tar ban for pavement products. Under the EU REACH framework and related directives, strict PAH controls apply to coal tar pitch production and use, with compliance costs rising for legacy grades. Tightening PAH emission and wastewater norms in Canada and New York State continue to drive compliance-driven capacity considerations and low-PAH grade development.
These regulatory threads matter because they create a structural divergence between commodity-grade volumes and specification-driven demand. As jurisdictions tighten limits on certain applications and emissions profiles, producers and buyers alike must navigate higher compliance burdens, reformulation requirements, and potential substitution pressure in affected end-use channels. The report assesses how these dynamics influence grade architecture, regional demand elasticity, and the relative attractiveness of processing investments that can accommodate tighter specifications without sacrificing cost competitiveness.
Feedstock Volatility and Industrial Demand Shifts
In addition to regulation, market participants must contend with raw material uncertainty. Coal tar feedstock volatility and shifts toward electric-arc furnace steel production continue to constrain coal tar availability for pitch distillation. This constraint is significant because it links the coal tar pitch market not only to aluminum and graphite demand, but also to broader metallurgical technology transitions and upstream coke and tar supply conditions. Where tar availability tightens, grade allocation, pricing behavior, and customer qualification timelines can all become more volatile, making supply-chain visibility and flexible contracting models increasingly valuable. The study evaluates how these pressures interact with regional availability, refining capacity utilization, and downstream qualification cycles, helping stakeholders anticipate where bottlenecks may emerge and which procurement strategies are best suited to mitigate them.
What the Full Study Delivers
This executive overview highlights the strategic contours of the coal tar pitch market, but the full research provides the operational depth that decision-makers need to convert insight into action. Our report delivers a comprehensive market sizing and forecasting framework covering historical performance and forward projections through 2032. It includes detailed segmentation analysis by type and application, together with regional evaluation that situates demand growth within local regulatory and logistical realities. The study maps the competitive landscape across key producers, examining capacity structures, product orientation, and recent developments that signal changing market power. It also assesses the regulatory and raw-material environment shaping compliance costs, feedstock constraints, and demand quality.
For executives responsible for procurement, production planning, or market entry assessments, the research is structured to answer practical questions: which grade families offer the most durable growth under tightening compliance regimes, where regional demand expansion is likely to be most consistent, how supply corridor development may affect import dependency, and what operational factors distinguish resilient producers in a concentrated market. The analysis avoids superficial generalizations in favor of scenario-aware interpretation, allowing readers to integrate findings into internal forecasting models, sourcing strategies, and investment evaluations.
Why This Research Matters for 2026 Decision-Making
The 2026 planning cycle is unlikely to resolve into a single dominant trend. Instead, leaders will need to manage multiple overlapping forces: steady structural demand growth, a moderately concentrated producer base, regulatory tightening across key jurisdictions, and feedstock availability linked to broader metallurgical transitions. In that environment, strategic advantage will accrue to organizations that can distinguish durable growth from temporary cyclical noise, align grade portfolios with shifting specification requirements, and secure supply access before capacity reallocations intensify.
Our coal tar pitch market research is designed to support that process by combining macro market visibility with segment-level interpretation. It provides the evidence base needed to evaluate whether to expand supply relationships, pursue qualification in higher-specification grades, or reassess exposure to applications facing heightened regulatory scrutiny. Just as importantly, it offers a structured competitive lens for interpreting the significance of recent capacity expansions, supply agreements, and corridor developments that may reshape buyer leverage over the coming planning cycles.
The full report contains the detailed regional, type, and application breakdowns, the extended competitive profiles, and the scenario discussion that decision-makers require for rigorous 2026 and beyond planning. Readers seeking the complete dataset and analysis are encouraged to access the full study page, where the comprehensive market intelligence is available in a format designed for strategic integration and executive review.
For detailed analysis of this topic, please visit the official page: Coal Tar Pitch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Luxury Packaging Market to Hit $253.71M by 2032 Amid 5.23% CAGR
By PW Consulting, 2026-09-16
Strategic Horizons: Navigating the Luxury Packaging Market in 2026 and Beyond
The luxury packaging sector stands at a critical inflection point. As consumer expectations evolve and regulatory pressures intensify, brands are no longer treating packaging as a mere container but as a strategic asset that communicates value, reinforces sustainability commitments, and protects brand equity. Understanding the trajectory of this market is essential for executives making capital allocation, product development, and supply chain decisions in 2026. This publication presents a comprehensive analysis of the luxury packaging landscape, offering the intelligence required to navigate an increasingly complex environment.
Worldwide Luxury Cosmetics Packaging Market
The global luxury packaging market has demonstrated consistent growth over the past half-decade. Valued at approximately 143.92 million USD in 2020, the sector expanded steadily to reach 178.23 million USD by the base year of 2025. Looking forward, the market is projected to climb to 186.79 million USD in 2026, continuing its upward trajectory through the forecast period ending in 2032, where it is expected to surpass 253.71 million USD. This expansion is underpinned by a compound annual growth rate of 5.23 percent, reflecting sustained demand across high-end consumer segments. However, aggregate figures only tell part of the story. The real strategic opportunities lie in understanding the structural shifts, material innovations, and regional dynamics that are reshaping competitive positions.
Our latest market research goes beyond top-line projections. It provides a granular examination of the forces driving growth, the constraints limiting expansion, and the strategic maneuvers required to capture value in a fragmented yet consolidating industry. For decision-makers operating in 2026, this report serves as a vital compass, illuminating pathways for investment, partnership, and innovation.
Decoding the Competitive Landscape
The luxury packaging ecosystem is characterized by a mix of established multinational players and specialized niche manufacturers. Our analysis maps the strategic positioning of key companies that are defining the market's direction, examining their operational focus, geographic reach, and innovation pipelines.
Market Leaders and Specialized Innovators
Several prominent organizations are setting the pace for the industry. DS Smith plc, headquartered in London, has cemented its reputation through a strong focus on paper-based luxury rigid boxes and premium packaging solutions. Similarly, Smurfit Westrock plc, based in Dublin, continues to advance paperboard and rigid luxury packaging while integrating sustainability innovations into its core offerings. In Milan, Pusterla 1880 S.p.A. specializes in luxury rigid boxes and premium cardboard packaging, catering to brands that demand both aesthetic excellence and structural integrity.
The Asia-Pacific region contributes significant manufacturing capabilities, exemplified by Topsion Packaging in Dongguan, China, which focuses on structurally complex rigid boxes for premium luxury applications. European fiber-based solutions are championed by Stora Enso Oyj in Helsinki, whose emphasis on circular solutions aligns with growing environmental mandates. International Paper Company, operating from Memphis, USA, provides premium paperboard and secondary paper luxury packaging at scale. Mondi plc, also headquartered in London, drives the market forward with advanced materials and designs tailored for luxury packaging. Complementing these larger entities are specialized firms such as HH Deluxe Packaging Ltd. in London, which concentrates on high-end luxury packaging and presentation solutions, and Winter and Company AG in Zug, Switzerland, known for luxury gift boxes and premium packaging. BDMO, based in Belgium, rounds out this competitive cohort with a focus on luxury cardboard packaging for cosmetics and gifts.
The competitive landscape is moderately consolidated. The top three players command a combined market share of 24.6 percent, while the top five extend their influence to 26.2 percent. This concentration indicates that while dominant players hold significant sway, substantial room remains for specialized competitors and regional leaders to carve out profitable niches. Understanding the specific strengths and strategic vulnerabilities of each competitor is essential for positioning your own offerings effectively.
Market Dynamics and Structural Shifts
Material Economics and Supply Chain Pressures
The cost environment for luxury packaging materials has become increasingly volatile. Paper prices remain elevated due to sustained global demand, higher energy costs for production, and increased reliance on recycled fibre. This pressure is compounded by regulatory and market forces affecting alternative materials. Plastic prices have risen notably, with contract increases of nearly 20 percent for polyethylene and polypropylene used in packaging. These cost dynamics directly impact margin structures and force brands to make difficult trade-offs between material choice, aesthetic quality, and cost efficiency.
Regulatory Headwinds and Opportunities
Regulatory frameworks are reshaping the operational landscape. The European Union's Packaging and Packaging Waste Regulation targets over-packaging with mandates for reduced material use in luxury segments. Compliance is no longer optional; it is a strategic imperative that influences design specifications, material sourcing, and end-of-life considerations. In the United Kingdom, Extended Producer Responsibility fees for 2025-2026 set producer charges at 192 pounds per tonne for glass and 196 pounds per tonne for paper and card. These fee structures incentivize material optimization and circular design approaches, rewarding companies that can reduce weight without compromising perceived quality.
Innovation in Action: Recent Developments Defining the Market
The pace of innovation in luxury packaging is accelerating, driven by sustainability mandates, consumer demand for experiences, and technological advancements. Recent milestones highlight the industry's commitment to redefining what luxury packaging can achieve.
Showcasing Circular Solutions
At the Luxe Pack Shanghai trade show in May 2026, Stora Enso showcased innovative fiber-based packaging solutions redefining circular luxury. This demonstration underscored the growing viability of sustainable materials that do not sacrifice the tactile and visual qualities expected in premium segments. Meanwhile, Luxe Pack New York returned with record-breaking figures, featuring premium materials, smart packaging, and a strong sustainability focus. These events signal that the intersection of luxury and sustainability is no longer a niche interest but a mainstream expectation.
Investment in Capabilities
Infrastructure investments are reinforcing the industry's innovation capacity. In April 2026, Mondi inaugurated a new innovation center in Milan dedicated to advanced materials and designs for luxury packaging. This facility will serve as a hub for developing next-generation solutions that meet evolving brand and regulatory requirements. Earlier in the year, in January 2026, James Cropper secured funding to expand production capacity for luxury packaging papers, addressing the growing demand for high-quality fiber-based substrates. These developments illustrate that leading players are committing significant resources to staying ahead of market trends.
Strategic Implications for 2026 Decision-Makers
The luxury packaging market offers substantial growth potential, but realizing that potential requires more than passive observation. Executives must adopt a proactive stance, leveraging data-driven insights to inform strategy across multiple dimensions.
Aligning Material Strategy with Regulatory and Cost Realities
With raw material costs under pressure and regulations tightening, brands must reassess their material portfolios. The shift toward fiber-based and recycled solutions is gaining momentum, but the transition must be managed carefully to maintain premium perception. Understanding the cost implications of different material choices, including regulatory fees and supply chain risks, is critical for maintaining profitability while meeting sustainability targets.
Capitalizing on Regional and Application-Specific Opportunities
Growth is not uniform across all segments. Certain applications and regions are outpacing others, driven by consumer wealth, brand investment, and cultural preferences. Identifying where demand is concentrated and which customer segments are most willing to pay for premium packaging enables more targeted product development and marketing efforts. The ability to tailor offerings to specific luxury sub-segments, whether in cosmetics, fashion, or premium beverages, can significantly enhance competitive differentiation.
Leveraging Competitive Intelligence for Strategic Positioning
The moderately consolidated nature of the market means that both large players and specialized firms have opportunities to thrive. Understanding competitor capabilities, innovation pipelines, and strategic focus areas allows companies to identify gaps in the market and position themselves effectively. Whether through partnerships, acquisitions, or organic innovation, strategic Positioning requires a clear view of the competitive terrain.
Preparing for the Future
The forecast period extending to 2032 suggests that the luxury packaging market will continue its expansion, but the composition of that growth will evolve. Companies that invest now in flexible manufacturing capabilities, sustainable material portfolios, and customer-centric design processes will be best positioned to capture long-term value. Those that delay adaptation risk being squeezed by cost pressures, regulatory constraints, and shifting consumer expectations.
Why This Research Matters Now
In a market defined by rapid change, incomplete information is a liability. The insights contained in this report are designed to equip executives with the knowledge needed to make confident, forward-looking decisions. From material economics and regulatory impacts to competitive dynamics and innovation trends, every aspect of the luxury packaging ecosystem is examined with the rigor required for high-stakes strategy development.
The data presented here represents only a fraction of what is available. Our full market research provides detailed segmentation analysis, granular regional breakdowns, application-specific growth drivers, and comprehensive competitor profiles. It includes actionable recommendations for supply chain optimization, product portfolio strategy, and market entry or expansion planning. For organizations serious about competing in the luxury packaging sector, this depth of intelligence is indispensable.
Your Next Step
The luxury packaging market is evolving at an accelerating pace. The decisions made in 2026 will shape competitive positioning for years to come. To access the complete analysis, including detailed segmentation data, regional market sizes, application breakdowns, and in-depth competitor evaluations, we invite you to explore our full market research report. Equip your organization with the strategic intelligence needed to navigate this dynamic landscape and capture the value that lies ahead.
Luxury Packaging Market
For detailed analysis of this topic, please visit the official page: Luxury Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pool Cleaners Market Hits $115M in 2025, Set to Hit $197.09M by 2032, Growing at 6.23% CAGR
By PW Consulting, 2026-09-16
Navigating the Blue Economy: Strategic Insights from the 2026 Pool Cleaners Market Intelligence Report
The landscape of aquatic maintenance is undergoing a profound transformation, driven by converging technological innovations and shifting consumer expectations. As industry leaders prepare for the remainder of the decade, access to precise, forward-looking intelligence is no longer merely advantageous; it is essential for sustained competitive advantage. This article serves as a strategic preview of our latest comprehensive research initiative, designed to equip stakeholders with the analytical clarity required to navigate the Pool Cleaners Market through 2032. By synthesizing historical performance with forward-looking projections, this report constructs a robust framework for capital allocation, product development, and market positioning.
Pool Cleaners Market
Macro Trajectory and Structural Growth Dynamics
The global pool cleaning equipment sector has demonstrated remarkable resilience and steady expansion over the past half-decade. Historical analysis reveals a consistent upward trajectory, with market valuation climbing from 85.0 million USD in 2020 to approximately 115.0 million USD by the 2025 base year. This growth reflects broader macroeconomic trends, including rising disposable incomes in mature markets, increased installation of private swimming facilities, and a growing emphasis on automated home maintenance solutions. Looking ahead, the forecast period spanning 2026 through 2032 indicates sustained momentum, with the market projected to reach 197.09 million USD by the terminal forecast year. This expansion corresponds to a compound annual growth rate of 6.23 percent, signaling a stable, moderately paced growth environment rather than a speculative boom.
It is important to recognize that such aggregate figures represent more than simple linear expansion. They embody a structural evolution in how consumers and facility managers approach water quality, chemical reduction, and time allocation. The steady CAGR underscores a mature yet innovation-driven ecosystem where incremental improvements in engineering, user experience, and energy efficiency compound over time. For executive teams, understanding this trajectory means recognizing that market share gains will increasingly depend on product differentiation, brand trust, and the ability to anticipate regional purchasing behaviors rather than on volume-driven price competition alone.
Technological Inflection Points and Product Evolution
The past eighteen months have witnessed a pronounced shift toward intelligent, connected, and highly autonomous cleaning systems. CES 2026 served as a visible showcase for this evolution, with multiple industry participants unveiling next-generation platforms that leverage artificial intelligence, advanced navigation protocols, and hybrid power architectures. These product launches are not isolated marketing events; they reflect a broader industry consensus that the next phase of value creation will be captured by manufacturers who successfully integrate smart diagnostics, adaptive cleaning patterns, and user-centric design into mainstream offerings.
Pool Chemical Market
Robotic systems have emerged as a particularly dynamic segment, increasingly favored for their operational efficiency and reduced reliance on external plumbing or manual intervention. Simultaneously, traditional suction and pressure-side categories continue to evolve, benefiting from refined filtration compatibility and enhanced durability. The interplay between these product architectures creates a complex but highly actionable landscape for engineering leaders and product managers. Our research dissects the innovation cadence across these categories, analyzing how feature adoption curves align with consumer willingness to pay, installation complexity tolerances, and long-term maintenance expectations.
Competitive Landscape and Strategic Positioning
The market exhibits a moderately concentrated structure, with the top three participants collectively commanding approximately 42.5 percent of total revenue and the top five entities holding roughly 58.0 percent. This concentration suggests an environment where established brands leverage distribution networks, service infrastructure, and brand recognition to maintain defensive moats, while newer entrants and specialized manufacturers pursue aggressive differentiation through software-driven features and cordless form factors. Understanding the equilibrium between incumbent stability and challenger agility is critical for businesses evaluating partnership opportunities, acquisition targets, or internal R&D prioritization.
Key players such as Maytronics Ltd., operating from its Israeli headquarters with a strong focus on its Dolphin-branded residential and commercial robotic systems, continue to invest heavily in navigation and propulsion refinements. Hayward Industries, Inc., based in North Carolina, maintains a broad portfolio spanning robotic and traditional cleaning categories, often emphasizing brand versatility and installer familiarity. Pentair plc, headquartered in Minnesota, provides a comprehensive suite of cleaning solutions that integrate seamlessly with wider aquatic ecosystems. Fluidra S.A., headquartered in Barcelona, leverages a portfolio encompassing Polaris, Zodiac, and Aquabot offerings, with a particular emphasis on European and global distribution channels. Aiper Intelligent LLC, operating from the United States, has positioned itself at the forefront ofcordless and AI-assisted robotic cleaners, emphasizing smart navigation and consumer usability. Meanwhile, NingBo Poolstar Pool Products Co., Ltd., based in China, functions as a significant OEM/ODM partner, supporting both branded and private-label demand across multiple product categories.
Recent product activity reinforces the intensity of this competitive environment. In January 2026, Aiper Intelligent LLC introduced the Scuba V3 and Scuba V3 Pro platforms at CES, highlighting advanced artificial intelligence and smart operational capabilities. During the same event, Maytronics Ltd. launched the Dolphin EON robotic cleaner, featuring JetIQ propulsion technology, SmartMap navigation, and a hybrid power configuration. By February 2026, iGarden, under the Fairland Group umbrella, released the M1 Pro Max bionic dual-vision robotic cleaner, an initiative that was subsequently recognized as a CES 2026 Innovation Award honoree. These developments illustrate a market where engineering differentiation, rather than pure scale, increasingly determines premium positioning.
Regulatory Pressures and Supply Chain Considerations
Beyond product innovation and competitive maneuvering, external macro-forcing mechanisms are actively reshaping cost structures and sourcing strategies. As of March 2025, the United States implemented new tariff measures affecting imported raw materials and chemicals, including a twenty-five percent tariff on steel and aluminum and a ten percent tariff on Chinese-origin imports. These policy adjustments have direct ramifications for pool equipment manufacturers, component suppliers, and assembled product importers, introducing volatility into input costs and prompting strategic reevaluation of domestic versus overseas production footprints.
Such regulatory dynamics interact with broader supply chain considerations, including freight logistics, alternative material substitution, and regional manufacturing flexibility. Companies that proactively map these cost drivers into their pricing architectures, inventory planning, and vendor diversification strategies will be better positioned to preserve margins without sacrificing market accessibility. Our analysis incorporates these external pressures into a holistic assessment of market resilience, enabling decision-makers to model scenarios that account for tariff impacts, currency fluctuations, and shifting sourcing patterns.
Probing Beyond the Surface: What This Research Delivers
While the macroeconomic trajectory and competitive framing provide a necessary foundation, the true strategic value of this research lies in its granular, decision-oriented architecture. The full study is engineered to support cross-functional teams with actionable intelligence across multiple dimensions. Key components include:
- A comprehensive segmentation analysis that isolates performance drivers across product architectures, installation environments, and geographic demand clusters, allowing leadership to identify high-conviction growth pathways without relying on generic market narratives.
- Detailed demand behavior profiling that examines purchase frequency, feature prioritization, installer influence, and post-sale service expectations, helping product and marketing teams align development roadmaps with real-world adoption patterns.
- Competitive intelligence mapping that evaluates brand positioning, innovation pacing, distribution reach, and strategic response patterns among leading manufacturers and emerging challengers, enabling precise benchmarking and gap identification.
- Supply chain and cost-structure assessments that contextualize input volatility, component dependency, and regional manufacturing considerations, supporting procurement and financial planning under varying tariff and logistics scenarios.
- Scenario-based forecasting frameworks that translate historical performance and forward indicators into actionable revenue expectations, capacity planning inputs, and market entry timing assessments.
Each analytical module is designed to answer specific strategic questions: Which product developments command premium acceptance in high-growth demand clusters? How are incumbent brands defending share against software-led entrants? Where do distribution partnerships and regional service networks create the most durable competitive advantages? By addressing these questions with methodological rigor and clearly sourced data, the study transforms raw market signals into executable strategic guidance.
Implications for 2026 Decision-Making
Entering the second half of the decade, businesses operating in or adjacent to this sector face a defining set of choices. The convergence of artificial intelligence-driven cleaning routines, cordless engineering, tariff-sensitive supply chains, and evolving consumer expectations creates an environment where reactive strategies will be quickly outpaced by proactive, data-informed positioning. Organizations that treat market intelligence as a continuous input rather than a periodic report will be better equipped to time product launches, allocate marketing spend, negotiate supplier contracts, and evaluate partnership or acquisition opportunities.
This research publication is specifically structured to serve that purpose. It provides executive teams, strategy directors, product leaders, and investment analysts with a consolidated, high-fidelity view of market mechanics, enabling them to separate structural growth from temporary noise. By grounding strategic planning in clearly delineated trend lines, competitive benchmarks, and segment-level demand dynamics, stakeholders can construct more resilient operating plans and reduce the uncertainty associated with capital deployment.
Strategic Access and Forward Engagement
The complete research deliverable extends well beyond the high-level trajectory outlined here. It contains the detailed segmentation breakdowns, competitive playbooks, regional performance context, and forecasting methodologies necessary to translate awareness into execution. For organizations seeking to calibrate product roadmaps, refine pricing architectures, evaluate market entry timing, or benchmark against the most active industry participants, the full report offers the depth required to make those decisions with confidence.
This preview demonstrates the analytical rigor and strategic orientation embedded in our research methodology. To access the complete segmentation matrices, company-specific competitive assessments, scenario-driven forecasts, and the full spectrum of data-driven insights, we invite you to visit the official source webpage and obtain the complete Pool Cleaners Market research publication. In a market defined by steady expansion, accelerating technological iteration, and shifting regulatory cost structures, precision intelligence is the most effective differentiator for businesses committed to long-term growth and market leadership.
For detailed analysis of this topic, please visit the official page: Pool Cleaners Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Navigating the Engineered Quartz Stone Market: Strategic Intelligence for 2026 and Beyond
The global demand for engineered quartz stone (EQS) has transitioned from a niche luxury preference to a mainstream standard in residential and commercial surface solutions. As we move through 2026, industry stakeholders face a complex landscape defined by robust growth trajectories, shifting regulatory frameworks, and intense competitive maneuvering. PW Consulting's latest market research provides a comprehensive navigational chart for executives, investors, and supply chain leaders seeking to capitalize on these dynamics. This executive briefing outlines the strategic value of our analysis, synthesizing historical performance, forward-looking projections, and critical market intelligence to inform high-stakes decision-making.
Market Trajectory: From Recovery to Sustained Expansion
The engineered quartz stone sector has demonstrated remarkable resilience and growth over the past half-decade. Our analysis tracks revenue performance from 2020 through the base year of 2025, capturing the market's recovery from global supply chain disruptions and its subsequent acceleration. The market valuation has climbed steadily, surpassing the 120 million USD threshold in 2025. This historic performance sets a robust foundation for the forecast period extending through 2032.
Projections indicate a continued upward trajectory, with the market expected to reach valuation levels exceeding 195 million USD by the end of the forecast window. This growth is underpinned by a compound annual growth rate (CAGR) that reflects sustained investment in surface materials across key sectors. For strategic planners, these figures are not merely statistics; they represent the total addressable market expansion that will dictate capacity planning, capital allocation, and geographic focus over the next seven years. Understanding the inflection points within this timeline allows organizations to time their market entry, product launches, and scaling initiatives with precision.
Structural Segmentation: Identifying High-Yield Opportunities
A superficial view of the EQS market obscures the nuanced value pools that drive profitability. Our research deconstructs the market across critical dimensions, providing leaders with the granularity needed to prioritize resource deployment. The analysis examines product types, application verticals, and regional performance, revealing where demand is most concentrated and where growth vectors are emerging.
Within product classifications, the market is dominated by specific formats that align with prevailing construction and renovation trends. The research details the revenue contribution and growth potential of quartz slabs, tiles, and other emerging formats. By mapping the adoption curves of these product types against buyer preferences in different end-use scenarios, firms can refine their manufacturing mixes and inventory strategies. Similarly, the application landscape is dissected to highlight the primary drivers of consumption. While certain applications remain the predominant revenue generators, the research identifies ancillary segments that offer diversification benefits and emerging opportunities for product innovation.
Regional analysis is equally critical. The report evaluates performance across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents distinct demand drivers, regulatory environments, and competitive intensities. For instance, mature markets may offer stability and high per-capita consumption, while developing regions may present higher growth rates driven by urbanization and infrastructure development. Our segmentation analysis equips clients with the insights necessary to tailor regional go-to-market strategies, balancing risk and reward across their global footprint.
Engineered Quartz Stone (EQS) Market
Competitive Landscape: Dynamics Among Key Players
The EQS market features a mix of established global giants and agile regional manufacturers, creating a competitive environment where differentiation is paramount. PW Consulting's report profiles the strategies, capabilities, and market positions of leading entities that are shaping industry standards. Understanding the moves of these key players is essential for benchmarking, partnership evaluation, and competitive positioning.
In North America, family-owned and domestic manufacturers are leveraging local production and strong brand equity to capture market share. Companies such as Cambria have built reputations around high-performance slabs and lifetime warranties, appealing to consumers and contractors who prioritize durability and trust. Similarly, MSI Surfaces has expanded its portfolio significantly, offering a wide array of styles produced through advanced machinery and patent-protected processes at its domestic facilities. These firms illustrate the importance of manufacturing proximity and design variety in securing customer loyalty.
On the global stage, pioneer brands continue to drive innovation in design and sustainability. Caesarstone, a longstanding leader since the late 1980s, maintains a strong presence through continuous product development and adaptation to regional demands. Recent capacity expansions by Caesarstone highlight the strategic focus on supporting growing demand in residential and commercial construction across major markets. Concurrently, the company has responded to industry pressures regarding worker safety by launching innovative quartz surfaces with reduced crystalline silica content, signaling a proactive approach to regulatory compliance and product safety.
European and international players are also advancing the market through technological breakthroughs and global distribution networks. The Cosentino Group stands out as a global leader, with its Silestone brand introducing HybriQ+ technology designed to lower crystalline silica content while maintaining aesthetic and performance standards. VICOSTONE, based in Turkey, has established itself as a leading manufacturer of premium quartz products for residential and commercial use, leveraging extensive collections to meet diverse design requirements. In Asia, manufacturers are expanding their reach and production capabilities. Hanwha L&C and LG Hausys represent major South Korean conglomerates producing high-quality engineered stone surfaces, with Hanwha operating facilities in both South Korea and the United States to serve local and export markets. In India, Techstone Quartz operates as an integrated manufacturer and exporter, focusing on high-quality slabs and prefabricated countertops. Meanwhile, LT Quartz in China specializes in professional quartz surfacing production and marketing, catering to a broad spectrum of applications.
Recent developments underscore the intensity of capacity and product strategy adjustments. Pokarna Limited, for example, announced significant investments to expand its engineered quartz slab production capacity, driven by rising export demand from North American and European construction sectors. These expansions, including new production lines operational in early 2026, reflect the industry's response to market growth and the strategic importance of scaling supply to meet international orders. Our competitive analysis synthesizes these developments to reveal trends in M&A activity, capacity investments, product launches, and sustainability initiatives, providing a holistic view of how the competitive battleground is evolving.
Regulatory and Operational Dynamics: Risk and Adaptation
Market growth cannot be decoupled from the regulatory and operational environment. The EQS industry is currently navigating a period of heightened scrutiny regarding health and safety, particularly concerning crystalline silica exposure during fabrication and installation. Regulatory bodies in key markets are advancing rulemaking and enforcement actions that could fundamentally alter manufacturing processes, product specifications, and liability landscapes.
In California, regulators have moved to prohibit the fabrication of artificial stone countertops with more than one percent crystalline silica, a measure driven by concerns over silicosis cases among workers. Cal/OSHA has tightened silica safety requirements and continues to enforce emergency temporary standards, compelling manufacturers and fabricators to adapt their operations. Australia has taken an even more stringent approach, banning the manufacture, supply, processing, and installation of engineered stone benchtops, panels, and slabs effective mid-2024, with prohibitions on imports added in early 2025. These regulatory shifts create both challenges and opportunities. Companies that proactively develop low-silica or silica-compliant products can turn compliance into a competitive advantage, securing contracts in markets where safety certifications are becoming a prerequisite for doing business.
Beyond regulation, cost dynamics remain a critical factor. Fluctuations in the prices of essential raw materials, such as polyester resins and quartz aggregates, directly impact profit margins. Our report analyzes these cost drivers and their volatility, offering insights into supply chain resilience and pricing strategies. Leaders must understand how material cost fluctuations interact with regional demand and competitive pricing to maintain margin integrity. The research provides frameworks for monitoring input costs, hedging strategies, and optimizing procurement to mitigate margin erosion.
Strategic Frameworks for 2026 Decision-Making
PW Consulting's Engineered Quartz Stone Market report is designed as a practical tool for execution, not just a repository of data. The study integrates quantitative forecasts with qualitative insights to support specific strategic actions. Clients will find detailed 분석의 of market drivers, restraints, and opportunities, enabling them to validate investment theses and identify whitespace. The report includes comprehensive profiles of key companies, analyzing their product portfolios, geographic reach, recent developments, and strategic positioning. This allows competitors to benchmark against industry leaders and new entrants to assess market barriers.
Furthermore, the analysis covers the entire value chain, from raw material sourcing to manufacturing technologies, distribution channels, and end-user preferences. By mapping the value chain, organizations can identify bottlenecks, partnership opportunities, and areas for vertical integration or diversification. The report also examines the impact of macroeconomic factors, construction trends, and consumer behavior shifts on demand patterns. For example, the growing emphasis on sustainable building materials and health-conscious design choices is influencing product development and marketing narratives. Our research highlights how EQS products can be positioned to align with these broader trends, such as through innovations in low-silica content, recycled content integration, and energy-efficient manufacturing processes.
The segmentation data provided in the report allows for precise targeting. Whether a firm is focusing on the dominant application segments or exploring niche applications with high growth potential, the research supports data-driven segmentation strategies. Regional breakdowns enable the calibration of market entry strategies, resource allocation, and risk management plans tailored to local conditions. The inclusion of recent industry developments ensures that the intelligence is current and actionable, capturing the latest capacity expansions, product launches, and regulatory updates that could impact business outcomes.
Engineered Stone Market
Conclusion: The Imperative for Comprehensive Intelligence
As the engineered quartz stone market accelerates toward the 2030s, the margin for strategic error narrows. The convergence of robust demand growth, evolving regulatory requirements, cost volatility, and intense competition demands a holistic and up-to-date understanding of the industry. PW Consulting's market research delivers this intelligence, combining rigorous data analysis with deep industry expertise. By revealing the underlying dynamics of market segmentation, competitive behavior, and operational risks, the report empowers stakeholders to make informed decisions that drive sustainable growth. We invite industry leaders to leverage this comprehensive analysis to navigate the opportunities and challenges of the EQS market with confidence, ensuring their strategies are aligned with the realities of 2026 and the trajectory toward 2032.
For detailed analysis of this topic, please visit the official page: Engineered Quartz Stone (EQS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Industrial Hose Market Hits $14.35B in 2025 with 6.98% CAGR Through 2032
By PW Consulting, 2026-09-16
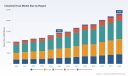
Industrial Hose Market Outlook 2026: Strategic Intelligence for Enterprise Decision Makers
The industrial hose market stands at a critical inflection point as the global economy navigates shifting supply chain dynamics, evolving regulatory frameworks, and sustained capital investment across heavy industry. Our latest comprehensive market research, Industrial Hose Market Analysis 2026, delivers the strategic intelligence needed to navigate this complex landscape. This report is not merely a data compilation, but a decision-support engine designed for executives, procurement leaders, and strategic planners who require actionable foresight rather than retrospective summaries. With a forecast horizon extending through 2032, our analysis captures both the immediate pressures shaping 2026 operations and the structural shifts that will define competitive advantage over the next half-decade.
Market Trajectory and Structural Growth Patterns
The industrial hose sector has demonstrated consistent revenue expansion over the past half-decade, with historical performance data from 2020 through 2025 establishing a clear trajectory of resilience and demand acceleration. Total market valuation has progressed from a baseline of 10,278.0 million USD in 2020, reaching 11,011.88 million USD in 2021, and advancing through 11,654.77 million USD in 2022, 12,007.18 million USD in 2023, 13,227.84 million USD in 2024, before culminating at 14,352.0 million USD in 2025. This historical arc reflects sustained capital deployment across fluid transfer infrastructure, equipment modernization cycles, and infrastructure development initiatives globally.
The forecast period from 2026 through 2032 projects continued expansion, anchored by a compound annual growth rate of 6.98 percent. Revenue is expected to reach 14,864.94 million USD in 2026, scaling toward 16,623.63 million USD by 2027, 18,166.93 million USD in 2028, 18,307.89 million USD in 2029, 20,276.98 million USD in 2030, 21,952.85 million USD in 2031, and ultimately 23,169.0 million USD by 2032. These figures represent nominal market size in USD millions, reflecting the aggregate value of hose products, assemblies, and associated fluid handling components across all industrial applications. The sustained growth rate underscores a market that continues to expand beyond cyclical recovery, driven by underlying industrial activity and technological modernization.
Importantly, our methodology isolates growth drivers from noise, enabling stakeholders to distinguish between temporary demand spikes and durable structural expansion. The 6.98 percent CAGR encompasses multiple interacting variables, including raw material cost volatility, geographic supply chain reconfiguration, regulatory compliance costs, and the ongoing shift toward high-performance composite and thermoplastic materials. executives who rely solely on headline growth figures risk misallocating resources; our analysis deconstructs these layers to reveal where sustainable value creation resides.
2026 Strategic Context: Pricing Pressures, Standards, and Operational Realities
The current operating environment is defined by intersecting cost and compliance pressures that directly influence procurement budgets, manufacturing margins, and product specification decisions. As of early 2026, stainless steel prices have stabilized near 1,995 USD per ton, a level that directly impacts hydraulic hose production costs and influences the economics of metal-reinforced assemblies. Simultaneously, natural rubber benchmark pricing has fluctuated between approximately 1.61 and 2.23 USD per kilogram, while synthetic rubber FOB pricing in China registered around 2,267 USD per ton in January 2026. These input cost dynamics do not merely affect short-term pricing; they reshape the competitive positioning of material categories, forcing manufacturers and buyers alike to reevaluate specification strategies, inventory management approaches, and total cost of ownership calculations.
Regulatory and standards evolution adds another critical dimension. The newly defined EN 854:2026 specifications establish updated requirements for textile reinforced rubber hydraulic hoses and assemblies intended for industrial and commercial applications, creating a compliance imperative that will influence product selection, certification processes, and market access for suppliers who have not aligned their portfolios accordingly. Concurrently, OSHA regulations continue to set binding workplace safety rules for hose handling and pressure systems in industrial settings, reinforcing the operational importance of durable, compliant assemblies that reduce incident risk and support audit readiness. These standards are not peripheral considerations; they embed themselves into procurement criteria, supplier qualification processes, and liability frameworks across multiple sectors.
Industrial Hose Market
Worldwide Industrial Flexible Hose Market
Trade show activity during early 2026 further illustrates the industry's active engagement with these dynamics. Companies including Salem-Republic Rubber Company, NRP Jones, Tubes International, and Elastohose have all maintained visible booth presences at major industry gatherings such as CONEXPO-CON/AGG 2026 and FLUID POWER 2026, showcasing product innovations, engaging with end-users, and signaling strategic priorities around durability, material advancement, and application-specific engineering. This sustained exhibition activity reflects an industry in active dialogue with its customer base, adapting to technical requirements and competitive expectations in real time.
Core Research Dimensions: What the Report Delivers
Our analysis is structured to provide immediate tactical value alongside long-term strategic orientation. Rather than presenting isolated data points, the report integrates quantitative benchmarking with qualitative assessment to produce a decision framework applicable across corporate functions.
Quantitative Benchmarking and Historical Reconstruction
The research reconstructs historical market performance from 2020 through 2025, calibrating base-year 2025 figures before projecting forward through 2032. This structure allows users to validate internal assumptions against audited market trajectories, identify periods of outperformance or underperformance relative to industry trends, and model scenario-based forecasts with confidence in the underlying baseline. All figures are expressed in USD millions, ensuring consistency with global financial reporting conventions and facilitating direct integration into strategic planning models.
Application and Product Category Landscape
The report maps revenue distribution across hydraulic hoses, air and water hoses, suction and discharge hoses, chemical hoses, and food and beverage hoses, while simultaneously tracking demand intensity across oil and gas, construction and infrastructure, automotive, agriculture, mining, chemicals, and food and beverage applications. By presenting these dimensions as interlocking rather than independent, our analysis reveals how material selection, performance requirements, and end-market purchasing cycles interact to shape revenue concentration and growth velocity within each product and application stream. Readers gain visibility into which categories are structurally positioned for sustained expansion and which face margin compression, substitution risk, or regulatory headwinds.
Geographic Demand Architecture
Market activity spans North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa region, each exhibiting distinct procurement patterns, infrastructure development pacing, and industrial output profiles. Our geographic assessment avoids simplistic ranking exercises in favor of examining how regional industrial structures, trade flows, and local manufacturing capacity interact to produce divergent growth paths. This regional layering enables multinational operators to prioritize market entry timing, distribution investments, and localized product strategies with greater precision.
Competitive Position Mapping and Strategic Posture Assessment
The competitive landscape includes established multinational manufacturers and specialized fabricators whose strategic positioning, product breadth, and regional reach vary considerably. Our analysis profiles organizations including Parker Hannifin Corporation, Gates Corporation, Danfoss, Continental AG, Kuriyama of America, Inc., Flexaust Inc., Southeastern Hose, Inc., and NRP Jones, examining their product portfolios, operational focus areas, and apparent strategic emphasis on fluid transfer, pressure systems, and specialized industrial applications. Rather than providing static company descriptions, we assess how each player's portfolio architecture and market orientation suggest vulnerability to pricing pressure, capacity to capture premium specification opportunities, and likelihood of influencing industry standards adoption.
Supply Chain, Procurement, and Cost Drivers
Recognizing that input costs and logistics realities fundamentally affect commercial outcomes, the report integrates raw material pricing intelligence, production cost considerations, and procurement cycle dynamics into its strategic recommendations. By linking stainless steel and rubber pricing movements to segment margins and product substitution patterns, we equip procurement teams and finance leaders with the context needed to negotiate with suppliers, time purchases, and evaluate make-versus-buy decisions more effectively.
Competitive Dynamics: Concentration, Differentiation, and M&A Potential
Market concentration metrics indicate a moderately fragmented but increasingly competitive environment, with CR3 at 24.6 percent and CR5 at 26.2 percent. These figures signal that while no single entity commands dominant market control, the top tier of suppliers collectively holds meaningful share, and the distance between leading players and the broader tail of manufacturers remains structurally significant. For strategic planners, this concentration profile suggests several actionable implications. First, pricing power is unlikely to be exercised uniformly across the market, meaning that differentiation through application engineering, certification compliance, delivery reliability, and technical support will likely determine which suppliers succeed in capturing premium positions. Second, the moderate concentration leaves room for consolidation, partnership formation, and vertical integration moves that could alter competitive balances over the forecast horizon. Third, smaller and mid-tier fabricators that specialize in custom assemblies, oilfield applications, or niche material configurations may find opportunities to compete on responsiveness and engineering service rather than price alone, particularly as end-users increasingly prioritize specification integrity and operational safety.
The strategic posture of leading and mid-tier players reflects the broader tension between scale economies and specialization. Multinational manufacturers typically compete on portfolio breadth, international distribution reach, and alignment with major industrial standards, while regional or application-focused fabricators often emphasize custom engineering, rapid turnaround, and proximity to specific end markets. Our analysis examines how these strategies are likely to perform as raw material volatility persists and as regulatory updates such as EN 854:2026 raise the baseline for compliance. Companies that have invested in material science capabilities, certified manufacturing processes, and application-specific testing infrastructure are better positioned to defend margins and capture share from less differentiated competitors.
2026 Decision Framework: Translating Market Intelligence into Action
The report is designed to answer the strategic questions that matter most to enterprise decision makers in 2026 and beyond. Rather than offering generic observations, we structure the analysis around actionable decision points.
- Where should procurement and sourcing investments be directed given current raw material pricing, input volatility, and compliance-driven specification requirements?
- Which product categories and application segments present the most attractive risk-adjusted growth exposure over the 2026 to 2032 window, and how should capital allocation reflect those opportunities?
- How do geographic demand patterns affect distribution strategy, local manufacturing decisions, and market entry timing for both incumbent operators and new entrants?
- What competitive vulnerabilities and strengths are embedded in current supplier portfolios, and how should that assessment inform partnership, sourcing, and potential acquisition evaluations?
- In what ways do evolving standards and safety regulations reshape the total cost of ownership calculus for industrial hose systems, and which suppliers are best positioned to support compliance-driven purchasing requirements?
Each of these questions is addressed through integrated quantitative data, qualitative market assessment, and competitive profiling that together provide a coherent basis for strategic planning. Our objective is to enable leaders to move from uncertainty to structured decision making, using evidence that accounts for both near-term operating realities and longer-term structural trends.
Concluding Perspective
The industrial hose market in 2026 is defined by durable growth momentum, material cost complexity, regulatory refinement, and an active competitive landscape that rewards differentiation and technical capability. The trajectory from a 14,352.0 million USD base in 2025 toward an estimated 23,169.0 million USD by 2032 reflects an industry where sustained capital spending, infrastructure development, and fluid handling modernization converge to support demand. Yet beneath these headline figures lies a richer analytical environment, one in which product category dynamics, application-specific demand intensity, regional variation, cost-driven substitution, and competitive positioning collectively determine where value is created and retained. Our full Industrial Hose Market report delivers the detailed segmentation analysis, scenario modeling, competitive profiling, and procurement intelligence required to act on this complexity with confidence. For executives and strategic planners who need more than macro-level summaries, the complete study provides the resolution necessary to inform sourcing strategy, investment prioritization, partnership evaluation, and risk management through the remainder of the decade.
For detailed analysis of this topic, please visit the official page: Industrial Hose Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pipe Joints Market Hits $228.6M in 2025, Projected to Reach $327.9M by 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for the Pipe Joints Market 2026-2032: Navigating Growth, Competition, and Regulatory Shifts
The global pipe joints market stands at a pivotal juncture as organizations prepare for the 2026 fiscal year and beyond. Infrastructure spending, industrial expansion, and evolving safety regulations are converging to reshape demand patterns across multiple sectors. For executives, procurement leaders, and strategic planners, the ability to anticipate these shifts is not merely an advantage, it is a necessity. Our latest Pipe Joints Market research delivers a comprehensive, data-driven blueprint designed to inform capital allocation, product positioning, and competitive strategy through 2032.
This insight briefing outlines the macro trajectory, competitive architecture, and emerging dynamics that will define the market landscape. It is structured to demonstrate the analytical rigor and actionable depth embedded in the full report, while intentionally reserving granular segmentation figures, regional breakdowns, and application-specific revenue allocations for the complete dataset available on our platform.
Macro Trajectory: A Resilient Growth Arc Across the Forecast Horizon
Drawing on historical performance from 2020 through 2025 and extending into a seven-year forecast period spanning 2026 to 2032, the market demonstrates a consistent upward trajectory. The overall revenue base, measured in USD millions, has progressed from 173.5 in 2020 to 181.33 in 2021, 187.78 in 2022, and 209.06 in 2023. The pace of expansion accelerated notably in 2024 and 2025, with recorded revenues of 209.42 and 228.6 respectively, reflecting stronger industrial activity, renewed construction momentum, and recovering supply chain conditions.
The forecast window projects sustained growth, with the market expected to reach 243.46 in 2026, followed by 255.59 in 2027, 269.9 in 2028, 290.04 in 2029, 293.41 in 2030, 308.93 in 2031, and a projected 327.9 by 2032. This pathway corresponds to a compound annual growth rate of 5.35 percent across the forecast horizon, signaling a market that is expanding at a steady, investable pace rather than experiencing volatile spikes. For strategic planners, this CAGR provides a reliable baseline for capacity planning, inventory forecasting, and long-term partnership structuring.
Importantly, the absolute scale of the market and the consistency of its growth underscore the foundational role that pipe joints and couplings play across critical infrastructure and industrial ecosystems. As organizations map their 2026 objectives, understanding how this trajectory aligns with regional development cycles, application-specific demand surges, and material cost normalization becomes a central component of scenario planning.
What the Report Delivers: Operational Content Designed for Execution
The full Pipe Joints Market study goes beyond top-line projections to equip decision-makers with structured, implementation-ready intelligence. The report is organized around several core analytical pillars, each calibrated to support distinct enterprise functions:
- Market sizing and forward modeling: Historical baselines and forecast pathways are presented with methodological transparency, enabling teams to anchor budgeting and demand planning in validated trajectories rather than speculative estimates.
- Segmentation architecture: The analysis dissects the market across product types, application verticals, and geographic regions. While aggregate growth signals are clear, the report provides the segmented context necessary to identify where demand is concentrating, which product categories are outpacing the broader curve, and how application-driven procurement patterns differ across industries.
- Competitive landscape and concentration metrics: Market structure is evaluated through concentration indicators, revealing the degree of fragmentation versus consolidation. This framework helps organizations assess entry barriers, partnership opportunities, and the strategic implications of operating in a market where the top three players hold a measured share and the top five maintain a slightly broader but still moderate footprint.
- Pricing and cost environment analysis: Unit economics are examined in the context of material inputs, manufacturing complexity, and specification tiers. The report situates price ranges for standard metal and alloy fittings within broader cost dynamics, giving procurement and pricing teams a reference frame for negotiations, margin planning, and make-versus-buy decisions.
- Regulatory and compliance mapping: Emerging codes and installation mandates are tracked to highlight how policy shifts influence material selection, approval workflows, and project timelines. This section is particularly relevant for firms operating in jurisdictions where nonmetallic joint specifications and manufacturer installation protocols are becoming more stringent.
- Recent industry developments and event intelligence: Product launches, trade show activity, and supplier announcements are synthesized to provide a live pulse on innovation cadence and market engagement. This ensures that strategy teams are aware of near-term product introductions and industry gatherings that may influence competitive positioning or procurement cycles.
Competitive Landscape: Key Players and the Structure of Market Participation
The pipe joints sector is characterized by a mix of established manufacturers, specialized engineering firms, and regional suppliers, each competing on dimensions such as joint integrity, installation efficiency, diameter range, and application-specific performance. The report profiles several core companies whose product portfolios and recent moves illustrate the competitive dynamics shaping the market.
Northwest Pipe Company, headquartered in Bellingham, Washington, focuses on engineered steel water pipe solutions with watertight joint systems, including its InfraShield® platform and custom mechanical couplings designed to preserve pipeline integrity under demanding service conditions. Victaulic, based in Easton, Pennsylvania, manufactures grooved mechanical pipe couplings and joining systems that emphasize faster, safer installation across industrial applications, and has continued to expand its fire protection portfolio with recent coupling introductions targeting rigid pipe joints in sprinkler systems. Teekay Couplings, operating from the United Kingdom, produces mechanical pipe couplings spanning a wide diameter range, with an emphasis on space, weight, and installation efficiency for diverse project requirements.
American Cast Iron Pipe Company, located in Birmingham, Alabama, offers restrained joint solutions such as Flex-Ring and Field Flex-Ring designs for ductile iron pipe, addressing endwise separation risks under thrust conditions. Holz Rubber Company, based in the United States, manufactures custom and standard expansion joints that absorb thermal movement and accommodate misalignment in piping systems, supporting reliability across variable operational environments.
These profiles are not isolated company snapshots; they are embedded within a broader concentration analysis that quantifies how market share is distributed and what that distribution implies for competitive strategy. In a market where the top three participants collectively hold approximately 22.8 percent and the top five reach roughly 28.5 percent, the landscape remains relatively fragmented at the top, leaving meaningful room for specialized players, regional specialists, and innovation-driven entrants to compete on performance, service, and application focus rather than scale alone.
Recent activity reinforces this dynamic. In early 2026, Victaulic introduced its style 009v FireLock coupling for rigid pipe joints in sprinkler systems, reflecting continued product development in fire protection and mechanical coupling segments. On the industry engagement front, Iran PIVEX held a January 2026 trade show featuring pipe joints and fittings from international suppliers, while the TUBE Trade Fair in Düsseldorf, scheduled for April 2026, is expected to showcase a broad array of pipe joints and coupling exhibitors. These events signal active supplier participation and sustained interest in cross-border sourcing, technology demonstration, and partnership formation.
Market Dynamics and Contextual Forces Shaping 2026 Decision-Making
Beyond sizing and competition, the research integrates the contextual forces that influence how the market behaves in practice. One notable development is the normalization of raw material costs. Steel prices for pipe joints and couplings are moderating in 2026 following earlier declines, as base metal costs stabilize. This shift has direct implications for manufacturing margins, supplier pricing strategies, and procurement timing, particularly for organizations that delayed purchasing decisions during periods of price volatility.
Pipe Joints Market
Artificial Joints Market
Regulatory evolution is equally consequential. The 2025 Ohio Fire Code mandates that nonmetallic pipe joints must be approved and installed in accordance with manufacturer instructions, reinforcing the importance of compliance documentation, approved product listings, and installer training. For firms operating in or supplying to jurisdictions with similar code trajectories, this type of requirement can affect product selection, project approval timelines, and the relative attractiveness of metallic versus nonmetallic joint solutions in specific applications.
Cost structures also vary meaningfully across specification tiers. General steel or metal pipe joints typically range from approximately USD 30 to over USD 200 per unit, while high-specification alloy fittings can reach between USD 500 and USD 2,000. These ranges illustrate how performance requirements, material grades, and application criticality drive pricing dispersion. For strategic planners, the key insight is that average market growth does not imply uniform profitability across all product categories; instead, value capture often depends on positioning within higher-specification segments, optimizing supply chain efficiency, or differentiating through installation reliability and joint performance.
Together, these dynamics create a market environment where growth is broad-based but execution is highly segmented. Companies that succeed in 2026 and beyond will be those that align their product portfolios with application demand, monitor material cost trends closely, and maintain agility in response to code changes and installation standards.
Why This Research Matters for 2026 Enterprise Decisions
As organizations finalize 2026 strategies, the pipe joints market presents both opportunity and complexity. The projected expansion from 243.46 in 2026 toward 327.9 by 2032, supported by a 5.35 percent CAGR, indicates that demand will continue to grow at a meaningful pace. however, growth at the aggregate level masks important variation across regions, product types, and end-use sectors. Without segmented visibility, companies risk overcommitting to underperforming categories, underestimating regional demand intensity, or misaligning pricing and inventory strategies with actual procurement behavior.
This research is designed to reduce that uncertainty. By combining macro forecasting with structured segmentation, competitive profiling, concentration metrics, and contextual intelligence on materials, regulation, and recent industry activity, the report provides a decision-ready framework for multiple functional teams:
- Strategy and corporate development: Evaluate where to invest, which application verticals offer the strongest near-term tailwinds, and how market concentration shapes partnership and acquisition logic.
- Sales and commercial leadership: Identify high-potential segments, tailor value propositions around joint integrity, installation efficiency, and compliance readiness, and align go-to-market plans with regional demand patterns.
- Procurement and supply chain: Time purchases in response to material cost normalization, assess supplier diversity and concentration risk, and benchmark unit economics against specification tiers.
- Product and engineering: Prioritize development toward mechanical coupling innovations, restrained joint technologies, expansion joint solutions, and fire protection systems where recent launches and trade show activity indicate active market interest.
The full report also contains the detailed regional and application-level segmentation data, granular revenue allocations, and deeper competitive benchmarking that are essential for precise planning. Those specifics are intentionally reserved for the complete dataset, ensuring that teams accessing the full study receive the uncompromised intelligence needed for targeted execution.
Looking Ahead: Positioning for Durable Advantage
The pipe joints market is not simply expanding; it is evolving in ways that reward precision, compliance awareness, and application-specific engineering. As steel costs stabilize, fire and installation codes tighten, and major suppliers continue to introduce specialized coupling and joint technologies, the competitive edge will belong to organizations that can translate market-level growth into segment-level action.
Our Pipe Joints Market research provides the foundation for that translation. It equips leadership with the historical context, forecast confidence, competitive structure, and dynamic intelligence required to make informed decisions throughout 2026 and across the remainder of the forecast period. For teams ready to move from high-level outlook to detailed planning, the complete report offers the segmentation depth, regional specificity, and application-level revenue context necessary to operationalize strategy with precision.
The 2026 market environment will reward those who prepare with data, act with segmentation discipline, and monitor the regulatory and material shifts that shape real-world demand. This study is built to support that preparation from the first strategic review through to execution.
For detailed analysis of this topic, please visit the official page: Pipe Joints Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


