



Category: market research
PW Consulting: Online Beauty & Personal Care Market to Hit $561.2B by 2032 at 8.9% CAGR
By PW Consulting, 2026-09-07
Navigating the Digital Beauty Revolution: Strategic Imperatives for 2026 and Beyond
The global beauty and personal care industry stands at a critical inflection point. As digital transformation accelerates across consumer goods, the online segment has evolved from a supplementary sales channel to a primary driver of market expansion and brand equity. For executive leadership teams planning their strategic roadmap for 2026, understanding the nuanced dynamics of this sector is not merely an advantage—it is a necessity. The convergence of shifting consumer behaviors, regulatory evolution, and intense competitive maneuvering requires a data-backed approach to decision-making.
High Security Printing Market
Recent macroeconomic indicators suggest that the sector continues to demonstrate remarkable resilience despite broader economic headwinds. The trajectory from 2020 through 2025 has established a robust foundation for sustained growth. Industry valuations have climbed steadily, reflecting a compound annual growth rate that underscores the vitality of digital commerce in this space. As we look toward the forecast period extending to 2032, the momentum indicates a significant expansion in total market valuation. This growth is not uniform; it is shaped by specific technological adoptions, supply chain optimizations, and evolving regulatory frameworks that define the operational landscape for key players.
Worldwide Mobile Phone 3D Glass Display Market
PW Consulting has synthesized extensive primary and secondary research to produce a comprehensive analysis of the Online Beauty and Personal Care Products Market. This report is designed to equip stakeholders with the intelligence required to navigate the complexities of the coming years. The following insights provide a high-level overview of the market structure, competitive forces, and strategic considerations that will define success in 2026 and beyond.
Worldwide Industrial Grade Cholesterol Market
Market Trajectory and Growth Dynamics
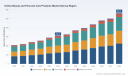
The historical performance of the market from 2020 to 2025 reveals a consistent upward trend. Starting from a valuation of USD 208.5 billion in 2020, the market expanded to USD 310.2 billion by the base year of 2025. This growth reflects the heavy migration of consumers toward digital platforms for purchasing skincare, haircare, and cosmetics. The forecast period from 2026 to 2032 projects further acceleration, with the market expected to reach USD 326.42 billion in 2026 and continue climbing toward USD 561.2 billion by 2032.
This expansion is underpinned by a compound annual growth rate of 8.9 percent throughout the forecast horizon. Such growth rates indicate that digital channels are capturing share from traditional retail at an increasing pace. However, growth is not without friction. Industry executives have identified inflation and uncertain consumer appetite for perceived value as significant risks to industry growth. Approximately 54 percent of leaders surveyed cite these economic pressures as the greatest threat to sustained expansion. This sentiment highlights the need for brands to justify premium pricing through demonstrable value, efficacy, and enhanced digital customer experiences.
Furthermore, the structure of the market remains moderately fragmented despite the presence of dominant players. Market concentration metrics indicate that the top three firms hold a combined share of 25.4 percent, while the top five control 36.7 percent. This concentration level suggests that while major incumbents hold significant influence, there is ample room for niche players and new entrants to carve out specialized positions, particularly within specific product categories or geographic regions. Understanding the balance between consolidation and fragmentation is critical for mergers and acquisitions strategy as well as organic growth planning.
Segmentation and Channel Dynamics
A deep dive into the market structure reveals distinct opportunities across product types and distribution channels. While the overall market size is impressive, the composition of revenue across different segments dictates where investment capital yields the highest return. Skincare continues to represent the largest portion of the product mix, reflecting a global consumer shift toward health-conscious beauty routines and preventative care. Haircare follows as a significant contributor, driven by professional-grade products becoming accessible through online retail. Color cosmetics, fragrances, and oral care round out the portfolio, each with unique growth drivers tied to cultural trends and hygiene awareness.
Distribution channels remain a pivotal area of analysis. Online channels have secured a substantial position in the market hierarchy. In North America specifically, online channels accounted for over 35 percent of beauty and personal care sales in 2025. This statistic underscores the digital-first behavior of consumers in mature markets. However, traditional channels such as supermarkets and hypermarkets still command significant volume, indicating a hybrid shopping behavior where consumers research online but may purchase offline, or vice versa. Specialty stores and pharmacies also maintain strong footholds, particularly for products requiring professional endorsement or specific regulatory compliance.
Regional dynamics further complicate the landscape. North America remains a powerhouse, but the Asia Pacific region represents a critical growth engine with distinct consumer preferences. Europe maintains a steady presence with a focus on premiumization and regulatory adherence. Emerging markets in Latin America and the Middle East and Africa offer high-growth potential but come with logistical and infrastructural challenges. The report provides detailed mapping of these regional variances without exposing the specific valuation figures for each locale, ensuring that strategic partners must engage with the full data set to allocate resources effectively.
Regulatory Landscape and Compliance
The regulatory environment has become increasingly complex, directly impacting product launch timelines and market access strategies. In the United States, the Modernization of Cosmetics Regulation Act (MoCRA) has fundamentally changed the compliance landscape. The FDA expanded its cosmetic database from roughly 35,000 listings to nearly 590,000 by January 2025. This drastic increase reflects a heightened focus on transparency and safety tracking.
Implementation of MoCRA has strengthened compliance requirements and enhanced consumer trust in product safety. For online retailers and brand owners, this means that data integrity regarding ingredient sourcing, manufacturing processes, and adverse event reporting is now more critical than ever. Non-compliance carries significant reputational and financial risk. The report details the specific operational changes required to align with these new standards, offering a checklist for legal and compliance teams to mitigate exposure.
Beyond the US, other jurisdictions are introducing similar frameworks. Multinational companies must navigate a patchwork of regulations that affect labeling, marketing claims, and ingredient restrictions. The strategic implication is clear: regulatory agility is now a competitive differentiator. Brands that can navigate these complexities faster than their peers will gain first-mover advantage in key markets.
Competitive Landscape and Corporate Strategy
The competitive arena is populated by a mix of e-commerce giants, specialty retailers, and traditional beauty conglomerates adapting to digital commerce. Amazon.com, Inc. remains a dominant force, leveraging its massive marketplace to provide direct-to-consumer access to a wide range of beauty and personal care products. Its influence on pricing, visibility, and logistics sets the baseline for online retail expectations.
Specialty retailers like Sephora USA, Inc. and Ulta Beauty, Inc. compete through curation, brand experience, and loyalty programs. Sephora focuses on a curated selection of skincare, makeup, and personal care items, fostering a community-driven shopping environment. Ulta Beauty operates both online and in-store, offering private-label and third-party products with a strong e-commerce presence. In November 2025, Ulta Beauty launched an invite-only marketplace, increasing body care brands and products by 39 percent year-over-year. This move signals a strategic push to expand assortment breadth and capture niche demand within the digital ecosystem.
Sally Beauty Holdings, Inc. specializes in professional and retail beauty, personal care, and hair products with nationwide shipping. Their focus on professional-grade accessibility differentiates them from mass-market retailers. Meanwhile, major brand owners like The Estée Lauder Companies Inc. are actively optimizing their distribution partnerships. Recent developments show a concerted effort to expand presence on premium marketplace platforms. For instance, The Ordinary and Estée Lauder launched in the Amazon.com.mx Premium Beauty Store in late 2025, while Origins launched in the Amazon.ca Premium Beauty Store. These listings indicate a strategy to leverage high-traffic premium placements to drive incremental volume in key international markets.
Understanding the positioning of these key companies is essential for benchmark analysis. The report provides detailed profiles of these entities, analyzing their supply chain capabilities, digital marketing strategies, and recent tactical moves. However, the specific market share percentages and detailed financial metrics for these competitors are reserved for the full report to maintain the integrity of our proprietary analysis.
Strategic Value of the Full Market Report
While the overview above highlights the macro trends and competitive tensions, it merely scratches the surface of the intelligence available. For C-suite executives, investors, and strategy managers, the devil lies in the details. The strategic value of the complete PW Consulting report lies in its ability to convert high-level trends into actionable operational plans.
Actionable Intelligence for 2026 Decision-Making
Decisions made in early 2026 will lock in capacity, inventory, and marketing budgets for the remainder of the year. Relying on aggregate data is insufficient when competitive dynamics are shifting so rapidly. The full report offers granular insights that allow stakeholders to:
- Validate Market Entry Timing: Assess whether current market conditions favor launching new product lines or expanding into specific geographic regions based on detailed demand signals.
- Optimize Channel Mix: Determine the optimal balance between direct-to-consumer websites, marketplace participation, and traditional retail partnerships to maximize margin and reach.
- Mitigate Regulatory Risk: Implement proactive compliance measures based on a detailed breakdown of MoCRA and international regulatory requirements affecting online sales.
- Benchmark Competitive Performance: Compare internal performance metrics against industry standards and key competitor moves without relying on public disclosures alone.
- Identify High-Value Segments: Pinpoint specific product categories and consumer demographics that offer the highest growth potential relative to competitive intensity.
The report includes extensive segmentation analysis that breaks down the market by type, channel, and region. This data is essential for pricing strategy, promotional planning, and inventory management. By understanding the specific contributions of skincare, haircare, color cosmetics, fragrances, and oral care to the overall revenue pool, companies can allocate R&D and marketing spend more efficiently. Similarly, understanding the shift between online, supermarkets, specialty stores, pharmacies, and direct selling channels enables logistics teams to optimize distribution networks.
Integration of Macro and Micro Data
One of the unique strengths of this study is the integration of macroeconomic context with micro-level consumption data. We do not simply present numbers; we contextualize them within the broader economic environment. For example, knowing how inflation impacts discretionary spending on premium versus mass beauty products allows brands to adjust their value propositions. Understanding the specific impact of regulatory changes on online listings helps legal teams prepare for faster time-to-market.
The forecast period from 2026 to 2032 is modeled using scenarios that account for potential economic volatility. Executives need to know not just the baseline forecast but also the risk-adjusted outcomes. The full report provides these scenarios, enabling stress-testing of strategic plans against adverse conditions. This level of depth is crucial for risk management and long-term capital allocation.
Conclusion: The Cost of Inaction
The Online Beauty and Personal Care Products Market is poised for substantial growth, but the path to capturing value is fraught with complexity. The difference between success and stagnation in 2026 will likely come down to the quality of intelligence guiding strategic choices. Companies that rely on outdated models or incomplete data risk misallocating resources in a market that rewards precision and agility.
PW Consulting's comprehensive study offers more than just data; it offers a strategic framework for navigating the next seven years. From analyzing the impact of MoCRA on compliance workflows to evaluating the strategic implications of Ulta Beauty's marketplace expansion or The Estée Lauder Companies' premium store listings, the report connects the dots between industry events and commercial outcomes.
The full dataset includes detailed segmentation splits, regional analyses, and competitive profiles that are essential for building a robust 2026 strategy. Accessing the complete report ensures that your organization is not making decisions in the dark. We invite you to review the full findings to unlock the detailed intelligence required to lead in this dynamic market.
For stakeholders ready to move beyond surface-level insights, the complete report provides the depth needed to secure a competitive advantage. The market is moving fast; ensure your strategy is built on the most accurate and comprehensive foundation available.
For detailed analysis of this topic, please visit the official page: Online Beauty and Personal Care Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Soft Ice Cream Machines Market Hits $605M in 2025, Projected to Reach $990M by 2032
By PW Consulting, 2026-09-07
Strategic Outlook: The Soft Ice Cream Machines Market in 2026 and Beyond
The global soft ice cream machines market stands at a pivotal inflection point as it enters 2026. What was once a straightforward equipment sector driven primarily by casual dining and seasonal tourism has evolved into a technologically nuanced arena shaped by shifting consumer preferences, rigorous regulatory frameworks, and strategic consolidation among leading manufacturers. For executives, procurement directors, and investment analysts, understanding the trajectory of this market is no longer optional—it is a prerequisite for capital allocation, product positioning, and supply chain resilience.
Worldwide Line Chromatic Confocal Sensor Market
Drawing on a comprehensive historical review spanning 2020 through 2025 and a forward-looking forecast period extending to 2032, our latest market research publication offers a granular, decision-ready view of the soft ice cream machines landscape. The analysis captures how the sector has grown from a 2020 baseline of approximately 450 million USD to an estimated 605 million USD in 2025, and projects a measured expansion to roughly 990 million USD by the close of the forecast window. This translates to a compound annual growth rate of 5.2 percent over the projection period, a figure that reflects steady, not speculative, momentum. The following overview outlines the strategic architecture of the report, highlights the competitive forces reshaping the industry, and demonstrates why this intelligence matters for enterprise decision-making in 2026.
Worldwide Vitamin Analysis Service Market
Market Trajectory and Structural Drivers
The historical arc of the soft ice cream machines market reveals a sector that has weathered inflationary pressure, supply chain volatility, and abrupt changes in consumer behavior without losing its long-term growth orientation. Between 2020 and 2025, revenue expansion was supported by the gradual recovery of hospitality and service segments, the normalization of dairy commodity pricing, and the steady adoption of continuous freezers in both mid-sized and entry-level commercial operations. The forecast period from 2026 onward signals a more mature phase of growth, characterized by incremental volume gains, technology-led differentiation, and regional rebalancing rather than explosive headline expansion.
Industrial Marker Pen Market
Several structural drivers underpin this trajectory. First, the commercial soft serve ecosystem continues to benefit from the reinforcement of food safety and operational hygiene mandates. Regulatory bodies in major markets have tightened requirements around certified materials, automated sanitization cycles, and consistent temperature control, effectively raising the barrier to entry for sub-tier equipment and rewarding manufacturers that embed compliance into their core engineering. Second, the rising popularity of plant-based formulations—coconut milk, almond bases, and other non-dairy alternatives—has prompted equipment designers to rethink viscosity handling, cooling efficiency, and cleaning protocols. Machines that can accommodate alternative ingredient profiles without compromising output consistency are gaining preference among forward-looking operators.
Third, macroeconomic and fiscal developments in select regions have altered the effective cost structure of soft serve products. Recent adjustments to indirect taxation on ice cream categories, including a reduction in applicable GST rates from 18 percent to 5 percent beginning in late 2025, have lowered the tax burden on soft serve offerings in relevant markets. This shift, combined with the ongoing sensitivity to ingredient costs—such as the movement in dairy pricing reflected in recent agricultural market data—places greater emphasis on equipment efficiency, portion control, and total cost of ownership. Operators are increasingly evaluating machines not solely on upfront price but on energy consumption, yield reliability, and downtime minimization.
Finally, the sector is being reshaped by the cadence of innovation disclosures and trade activity. Recent product reveals at major industry gatherings, alongside new launches of automated and electronically controlled soft serve units, illustrate how manufacturers are responding to the demand for simpler operation, faster changeovers, and more consistent dessert quality. These developments are not isolated product news; they are indicators of a market moving toward integrated solutions that blend hardware performance with digital monitoring and service support.
Report Architecture and Operational Content
Our market research is structured to convert macro trends into actionable intelligence. Rather than presenting a single aggregate view, the study decomposes the market into logical segments that mirror how buyers evaluate equipment, how manufacturers allocate R&D resources, and how distributors prioritize inventory. The report covers the full historical baseline and forward forecast, but its real value lies in the layered breakdowns that expose where growth is concentrated and where competitive intensity is rising.
At the highest level, the analysis quantifies overall market size across the historical and forecast periods, establishing a consistent baseline for scenario planning. From this anchor, the study moves into segmentation dimensions that matter operationally:
- By region, the report examines how revenue is distributed across major geographic territories, highlighting where installed bases are expanding, where mature markets are stabilizing, and where emerging demand pockets are forming.
- By machine type, the study distinguishes between multi-cylinder configurations, single-cylinder units, and other equipment variants, capturing how form factor influences throughput, footprint, cleaning workflow, and suitability for different operating environments.
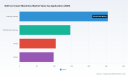
- By application, the analysis maps equipment deployment across catering operations, entertainment venues, retail shops, and other end-use settings, revealing which segments are driving procurement frequency and which are favoring higher-capacity or more specialized configurations.
Beyond segmentation, the report integrates a structured review of market dynamics that directly affect equipment purchasing and operating economics. This includes an assessment of raw material conditions relevant to dairy inputs, an evaluation of regulatory requirements imposed by food safety authorities and standards organizations, and a view of how packaging and taxation adjustments influence the broader soft serve value chain. Consumer habit shifts—especially the move toward non-dairy bases and healthier dessert positioning—are treated not as passing trends but as design inputs that manufacturers and operators must account for in product selection and menu planning.
The report also features a competitive landscape section that profiles the key companies shaping the market. Each profile focuses on the firm's specific offering within the soft ice cream machines segment, noting product lines, technological emphasis, and geographic positioning. This is complemented by a timeline of recent developments, including product reveals, launches, and trade show activity, which together provide a sense of the innovation velocity and market signaling patterns that decision-makers need to monitor.
Importantly, the publication does not merely describe the market; it translates findings into strategic questions. For a foodservice group evaluating fleet upgrades, the relevant question is whether to standardize on a single machine architecture or to diversify by application. For a manufacturer assessing market entry or expansion, the relevant question is where the concentration of demand intersects with regulatory and service requirements. For an investor, the relevant question is how the balance between established incumbents and agile new entrants will evolve under tightening compliance norms and changing ingredient economics. The report's segmentation, profiles, and dynamics sections are designed to support answers to these questions without resorting to generic commentary.
Competitive Landscape and Innovation Signals
The soft ice cream machines market is defined by a mix of long-established equipment specialists and regionally focused manufacturers, with a notable concentration of activity among a relatively small group of leading firms. Market structure indicators suggest a moderately concentrated environment, where a handful of producers account for a meaningful share of revenue while a broader tail of regional and application-specific suppliers serves niche demand. This structure has implications for pricing dynamics, service coverage, and the pace at which new features diffuse through the market.
Taylor Company, headquartered in Rockton, Illinois, represents a central force in the commercial soft serve segment. Its portfolio spans conventional soft serve freezers and frozen yogurt equipment, with the ICETRO by Taylor line extending the offering into heat-treated, high-productivity configurations. Recent activity, including a new soft serve unit exhibited in early 2026, underscores the company's continued focus on productivity and equipment versatility. ICETRO America, also under the Taylor umbrella, reinforces this direction with self-contained modular soft serve machines that incorporate automatic pasteurization and high production capacity, appealing to operators that prioritize consistent output and reduced handling risk.
Carpigiani, based in Bologna, Italy, occupies a premium position in the market, with soft serve machines tailored for ice cream vans, trucks, and retail environments. Its lineup covers single-flavor, twin-twist, and pump models, reflecting a focus on mobility, display, and multi-product flexibility. In parallel, Technogel has advanced its artisanal and industrial soft serve machines through electronic control of operating parameters, a development that aligns with the broader industry shift toward precision and repeatability. Tekno-Ice contributes to the higher-capacity end of the spectrum with Italian-made continuous freezers designed for semi-industrial and industrial soft serve production, addressing operators that require sustained output and process stability.
In the United States, Electro Freeze maintains a presence in commercial soft serve and frozen dessert equipment, with batch options and a service network that supports operators seeking local maintenance responsiveness. SaniServ, a long-standing name in the category, offers countertop and high-profit soft serve and yogurt freezers, emphasizing profitability and compact footprints for constrained service environments. On the supply side, Donper from China and Ningbo Sicen Refrigeration Equipment Co., Ltd. from Zhejiang provide commercial soft serve machines and large-capacity refrigeration-based equipment, respectively, contributing to the diversified sourcing landscape and offering alternatives for buyers balancing cost, capacity, and lead time.
Innovation signals from adjacent and complementary players also matter. A home-oriented automatic soft-serve line launched in early 2025 and a consumer-focused swirl machine with built-in freezing technology introduced around the same time illustrate how freezing and dispensing concepts are permeating different market tiers. While these are not direct replacements for commercial continuous freezers, they reflect a broader cultural and technological pull toward accessible, consistent frozen dessert experiences that can influence expectations in commercial settings as well. Meanwhile, scheduled trade activity and equipment exhibits continue to serve as focal points for product introductions and partner conversations, reinforcing the market's reliance on visible innovation cycles and industry gatherings.
Strategic Implications for 2026 Decision-Making
For enterprises operating in or adjacent to the soft ice cream machines market, the current environment demands a disciplined approach to strategy. The growth trajectory is constructive, but the sources of value are shifting from volume expansion alone to a combination of compliance assurance, operational efficiency, and product flexibility. Decision-makers should therefore orient their evaluations around several strategic dimensions.
First, equipment selection should be treated as a multi-year operating decision, not a one-time capital purchase. Regulatory expectations around hygiene, certified materials, and automated sanitization are increasing the cost of non-compliance and the reputational risk of inconsistent food safety performance. Machines that integrate these requirements by design reduce the operational burden on staff and simplify audit readiness. In a market where service coverage and parts availability influence uptime, the reliability of the supplier's support network is as important as the machine's nominal capacity.
Second, the economics of soft serve are increasingly sensitive to ingredient and energy dynamics. Dairy input pricing remains a variable that operators must monitor, and while fiscal adjustments in certain regions have eased some tax-related costs, the underlying pressure on margins persists. Equipment that supports consistent portioning, efficient cooling, and quick cleaning cycles can materially affect per-unit economics. The ability to handle non-dairy bases without major reconfiguration is becoming a differentiator for operators expanding their dessert menus or responding to local demand for plant-based options.
Third, the competitive landscape rewards clarity of positioning. With a moderate degree of concentration among leading producers and a long tail of regional and application-specific suppliers, buyers face a choice between broad-line providers that offer integrated support and specialized manufacturers that excel in particular form factors or end-use contexts. The strategic answer depends on the operator's footprint, throughput requirements, and service model. A standardized fleet may simplify training and maintenance, while a mixed deployment may better match diverse venue types. The report's segmentation detail helps decision-makers map these trade-offs to their own operating realities.
Fourth, innovation monitoring should be embedded into procurement and product planning cycles. Recent product reveals, electronic control enhancements, and modular dispenser options indicate that manufacturers are investing in ease of use, consistency, and configurability. Keeping pace with these developments allows operators to time upgrades advantageously and enables manufacturers to align R&D with demonstrable demand signals rather than speculative features. Trade shows and industry events remain valuable nodes in this monitoring process, offering concentrated views of new hardware, service programs, and partner ecosystems.
Finally, regional dynamics should inform expansion and sourcing strategies. The market's revenue distribution across territories reflects different maturity levels, regulatory environments, and consumption patterns. Operators entering new geographies or suppliers evaluating distribution partnerships need to understand where demand is stabilizing, where it is accelerating, and how local compliance and service expectations shape the viable equipment mix. This is particularly relevant in a market where the same machine family may need to be configured differently to meet region-specific hygiene standards, ingredient availability, and venue formats.
Why the Full Report Matters
This overview is intended to demonstrate the analytical rigor and strategic relevance of our Soft Ice Cream Machines Market research, while respecting the need for decision-makers to access the complete dataset before committing resources. The full report provides the underlying segmentation values, regional and type-level breakdowns, application-level deployment patterns, and company profiles that allow executives to move from directional confidence to precise planning. It also situates the market within the broader dynamics of ingredient costs, regulatory mandates, taxation shifts, and consumer habit changes, offering a single reference point for cross-functional alignment among operations, procurement, finance, and strategy teams.
In a market growing at a steady pace and undergoing simultaneous pressure from compliance, ingredient economics, and technology expectations, the cost of incomplete information is measurable. Procurement decisions made without a clear view of segmentation can lead to fleet mismatches. Investment theses built without a disciplined competitive map can overlook concentration risks or underappreciate the pace of feature diffusion. Operational plans that ignore regulatory and ingredient dynamics can underestimate total cost of ownership. Our research is designed to reduce these blind spots by combining historical continuity, forward visibility, and operational segmentation in one structured analysis.
For organizations preparing decisions in 2026—whether evaluating equipment standardization, assessing market entry, benchmarking competitors, or modeling margin sensitivity—the complete market intelligence offers a practical foundation. The report's segmentation splits, company profiles, recent development timeline, and dynamics review are built to support scenario analysis, procurement roadmaps, and competitive positioning exercises with minimal need for external supplementation.
Positioning for the Forecast Period
The soft ice cream machines market is entering a phase where disciplined execution will matter as much as market growth. The forecast period through 2032 points to continued expansion, but the distribution of that growth will be uneven across regions, machine types, and applications. Suppliers and operators alike will be rewarded for clarity: clear compliance posture, clear total cost of ownership, and clear alignment between machine capabilities and the way desserts are actually served in their target venues.
Our market research provides the structured visibility needed to navigate that complexity. By integrating historical performance, forward projections, segmentation detail, competitive profiles, and dynamic industry signals, the report equips decision-makers to distinguish between transient noise and durable shifts. For executives seeking to align capital, operations, and strategy with the realities of the soft ice cream machines market in 2026 and beyond, the full study offers the depth and specificity required to move from insight to action.
For detailed analysis of this topic, please visit the official page: Soft Ice Cream Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Methyl Diethanolamine Market to Reach $344.8M by 2032 with 6.98% CAGR
By PW Consulting, 2026-09-07
The Strategic Imperative of Methyl Diethanolamine: Navigating Growth, Supply Constraints, and Competitive Realignment Through 2032
Why 2026 Demands a Fresh Market Intelligence Framework
The Methyl Diethanolamine (MDEA) market is entering a decisive inflection point. Over the past half-decade, the sector has transitioned from a stable, back-office chemical supply chain into a dynamically priced, regionally fragmented, and capacity-constrained market where procurement timing, grade selection, and supplier diversification now directly influence operating margins and compliance posture. For executives planning capital allocation, sourcing strategies, and downstream product roadmaps in 2026, the question is no longer whether MDEA demand will grow, but how the interplay of feedstock volatility, logistics bottlenecks, and concentration-driven pricing power will reshape cost structures across gas treatment, textiles, and specialty applications.
Anti-Static Treadmill Mat Market
Our latest market research report is engineered as a decision-grade intelligence asset, not a static snapshot. It maps the trajectory from 2020 through a ten-year forecast horizon to 2032, converting historical demand signals into forward-looking strategic scenarios that boards, procurement leads, and R&D directors can operationalize immediately. The analysis is anchored in a measured compound annual growth rate of approximately 7 percent, reflecting a market that has consistently expanded from the low 160-million-dollar range in 2020 to a projected valuation exceeding 234 million dollars in 2026, and climbing toward 344 million dollars by 2032. This trajectory is not merely a function of volume growth; it is a composite of grade premiumization, application migration, and the strategic re-pricing of industrial amines in response to macro petrochemical pressures.
Integrated Stroller-Bike Market
What separates this study from conventional market summaries is its emphasis on structural drivers rather than headline figures. The report dissects the forces that will determine whether organizations can secure reliable supply at predictable cost points, where capacity expansions are most likely to shift regional availability, and which segments will absorb incremental demand versus those approaching saturation. By keeping the analytical lens on decision architecture, the research equips leaders to translate macro growth into actionable sourcing contracts, inventory buffers, and partnership strategies before price shocks or supply disruptions force reactive moves.
Worldwide Unmanned Vehicle Universal Chassis Market
Decoding the Trajectory: A Ten-Year Outlook Built for Scenario Planning
The forecast period from 2026 through 2032 is modeled around a growth environment that is steady in aggregate but highly differentiated underneath the surface. Starting from an estimated 2025 valuation of approximately 215 million dollars, the market is projected to step up to roughly 234 million dollars in 2026, then advance through subsequent years to reach 241 million dollars in 2027, 260 million dollars in 2028, 274 million dollars in 2029, 296 million dollars in 2030, 324 million dollars in 2031, and 344 million dollars in 2032. This progression reflects a market that is compounding without dramatic volatility, yet remains sensitive to input-cost cycles and capacity decisions made by leading producers.
Readers who rely on top-line growth alone risk misreading where value is being created and captured. The report deliberately avoids flattening the market into a single narrative. Instead, it separates trend signals from noise by examining how demand is distributed across application domains, how purity grades are becoming more consequential in procurement specifications, and how regional availability patterns are shifting as producers adjust logistics footprints and feedstock sourcing strategies. The objective is to help decision-makers identify which growth pockets are structurally supported and which are transient, enabling more precise capacity planning, contract negotiation, and risk hedging.
Importantly, the study translates these trajectories into practical scenario frameworks. Rather than presenting a single deterministic line, the analysis incorporates alternative pathways tied to raw material cost movements, transportation constraints, and demand intensity in core end-use sectors. This approach allows organizations to stress-test their MDEA exposure under different cost and supply assumptions, so that procurement policies and inventory strategies remain resilient even if input markets swing sharply.
- Historical demand patterns from 2020 to 2025 are used as calibration points, not just background data, so forecasts reflect how the market has actually responded to past cost and capacity shifts.
- The forecast model emphasizes grade-level relevance and application sensitivity, helping teams understand where pricing power is likely to concentrate and where substitution or spec adjustments can mitigate exposure.
- Regional and sectoral divergence is presented as a strategic map rather than a simple table, so readers can prioritize which markets warrant deeper due diligence before committing to long-term supply agreements.
What the Report Actually Delivers: A Practical Toolkit for Sourcing, Pricing, and Capacity Decisions
The MDEA market study is built for immediate operational use. It goes beyond aggregate growth figures to deliver a structured set of analyses that procurement, strategy, and operations teams can apply directly to sourcing plans, contract structures, and investment prioritization. The report is organized around real decision moments: securing volume at acceptable cost, selecting the right grade for a given process requirement, anticipating regional availability shifts, and evaluating which suppliers can reliably support long-term commitments.
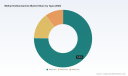
One of the core components is a deep segmentation review that examines how the market breaks down across application domains and product grades, without reducing the analysis to simplistic share percentages. The report explains why certain application areas are absorbing incremental volume, what technical or regulatory drivers are shaping demand, and how purity specifications are influencing both pricing and supplier selection. This is especially valuable for organizations that must balance process performance with cost control, since the choice between different MDEA grades can have meaningful implications for absorption efficiency, handling requirements, and downstream performance in gas treatment workflows.
The study also includes a comprehensive competitive landscape assessment that profiles the principal manufacturers shaping global supply. Rather than simply listing company names, the report evaluates how each producer is positioned in terms of product breadth, specialty-grade capabilities, geographic footprint, and brand recognition in end markets such as oil and gas acid gas removal and industrial amine applications. This competitive mapping is paired with an analysis of concentration dynamics, giving readers a realistic view of how supplier power is distributed and where alternative sourcing options may be necessary to maintain negotiation leverage.
- Detailed company profiles covering leading global producers and regional manufacturers, including their core product lines, application focus, and strategic positioning in gas treatment and specialty chemical supply chains.
- A structured review of recent market-moving events, including pricing adjustments, logistics cost pressures, and feedstock-driven re-pricing actions that signal how quickly supplier strategies can shift.
- A concentration assessment that illustrates how supply is distributed among top players, helping organizations gauge dependency risk and identify where diversification could improve sourcing resilience.
- Application and grade-level analysis that connects technical requirements to procurement strategy, so teams can align product specifications with cost, performance, and availability considerations.
Beyond the segmented deep dives, the report provides a synthesis layer designed for executive consumption. It translates complex data into a coherent narrative about where the market is becoming more price-sensitive, where capacity constraints may emerge, and which structural factors are most likely to influence the next cycle of supplier behavior. This is intended to help leaders move from data recognition to action: adjusting contract terms, re-evaluating inventory policies, and aligning internal specifications with the realities of a market that is growing steadily but not uniformly.
Competitive Realignment: The Players Setting Price, Grade, and Supply Expectations
The MDEA market is defined by a relatively concentrated supplier base that includes large multinational chemical producers alongside regional manufacturers serving specific demand centers. This structure matters because it determines how pricing signals propagate, how quickly capacity adjustments can be made, and how much flexibility buyers realistically have when negotiating long-term supply. The report profiles the organizations that are most influential in shaping availability and cost expectations, from established European and North American producers to Indian, Chinese, and Russian manufacturers with regional supply strengths.
Among the globally recognized names, BASF SE stands out as a leading producer of alkylethanolamines, including MDEA, with a strong presence in gas treatment and petrochemical applications. Dow Inc. is similarly prominent through its UCARSOL brand, which is widely associated with acid gas removal in oil and gas operations. Huntsman Corporation supplies MDEA across gas-treating applications and offers specialty grades such as JEFFTREAT 783, while Eastman Chemical Company produces Amietol M12 for industrial and specialty uses. These companies illustrate the breadth of product strategies in the market, ranging from large-volume industrial supply to more technically differentiated grades targeting specific performance requirements.
At the same time, regional producers play an increasingly important role in balancing availability and price. Advance Petrochemicals Ltd. and Amines & Plasticizers Ltd. represent Indian manufacturing capacity oriented toward gas treatment and petrochemical supply, while Maoming Yunlong Industrial Development Co. Ltd. reflects Chinese production focused on industrial and gas treatment demand. Sintez OKA Group adds another layer through its regional supply orientation in oil and gas and specialty chemicals. The presence of this diverse supplier spectrum means that procurement strategy cannot rely on a single sourcing model; instead, it must evaluate which producers offer the right combination of grade consistency, geographic reach, and responsiveness to cost changes.
- Profiles of leading multinationals and regional manufacturers, with emphasis on how their product portfolios, brand positions, and application focus shape procurement options.
- An assessment of concentration dynamics that shows how the top suppliers collectively influence pricing stability and supply risk across the market.
- A competitive lens that helps buyers understand where differentiation is real versus nominal, so they can target suppliers whose capabilities match specific gas treatment, textile, or specialty process needs.
Recent market signals reinforce the importance of monitoring supplier behavior closely. In March 2026, BASF announced a planned price increase for amines, including MDEA, effective in early April, citing logistics and raw material feedstock cost increases. This kind of action is emblematic of the broader environment: MDEA pricing is increasingly tied to transportation costs, feedstock dynamics, and macro petrochemical pressures rather than to demand alone. The report uses such developments as reference points for understanding how quickly cost structures can shift and what that means for contract timing, inventory planning, and alternative supplier evaluation.
Pricing, Feedstocks, and the Emerging Cost Architecture of MDEA Supply
One of the most operationally relevant themes in the current market is the erosion of the assumption that MDEA cost will move predictably with volume alone. Prices are being shaped by a combination of feedstock economics, logistics friction, and supplier pricing discipline in a concentrated market. As a result, procurement teams need to think beyond unit price and consider total cost exposure, including transportation, grade suitability, and the risk of sudden re-pricing when input costs rise.
The study situates these pricing dynamics within the broader petrochemical context, where global market pressures and regional disruptions can influence feedstock availability and transportation costs. This is not a theoretical concern. When leading producers adjust pricing to reflect logistics and feedstock cost increases, the effect can cascade through downstream supply chains, especially for organizations that rely on just-in-time procurement or narrowly defined specifications. The report examines how these pressures interact with concentration in the supplier base, making it important for buyers to anticipate re-pricing cycles rather than react to them after contracts are locked.
At the same time, the analysis emphasizes that cost is not the only variable. Grade selection and application fit remain central to value creation. Higher-purity or specialty grades can carry different cost implications, but they may also reduce processing inefficiencies or improve performance in demanding gas treatment environments. The research helps organizations evaluate these trade-offs by connecting specification requirements to market availability, so that purchasing decisions are aligned with both technical needs and commercial realities.
- An evaluation of how feedstock and logistics pressures are reshaping supplier pricing behavior and what that means for contract timing and inventory strategy.
- A discussion of concentration-driven pricing influence, helping teams understand where negotiation flexibility is likely to exist and where alternative sourcing may be necessary.
- Practical guidance on integrating grade selection, application performance, and total cost considerations into a coherent procurement framework.
The Roles of Grade and Application: Where Value Is Captured and Where Constraints Bite
The report treats the market's segmentation as a strategic map rather than a passive classification. Across product types, the analysis looks at how different MDEA grades are positioned and why some specifications command more attention in procurement plans than others. The presence of multiple purity levels means that buyers often face trade-offs between performance, handling complexity, and cost, and those trade-offs can become more pronounced when supply tightness or re-pricing events occur.
On the application side, the study examines the demand environment across major end-use areas without reducing the picture to a single dominant narrative. Gas treatment remains a core demand driver given the continued importance of acid gas removal in oil and gas operations, but the report also considers how other application domains contribute to overall demand and where growth may be more selective. This balanced view is essential for organizations that need to understand not just where the market is expanding, but which segments are likely to offer stable, repeatable demand versus those that may be more sensitive to economic cycles or technical substitution.
By linking grade and application analysis to procurement outcomes, the report helps teams answer practical questions: which specifications are most critical for a given process, which segments are most exposed to price volatility, and where might spec adjustments or supplier diversification reduce risk without compromising performance. This kind of linkage is what turns industry data into business value.
- A focused look at how product grades influence pricing, specification decisions, and supplier selection in real procurement environments.
- An application-oriented assessment that distinguishes between structurally supported demand and more variable segments, helping leaders prioritize sourcing attention.
- A practical framework for aligning technical requirements with market availability, so that sourcing strategies are both cost-aware and performance-appropriate.
Using This Research to Convert Uncertainty into Advantage
The central value of this market study is its ability to convert a complex, cost-sensitive, and supplier-concentrated environment into a usable strategic framework. In 2026, organizations that rely on informal market knowledge or lagging price signals are likely to face avoidable exposure when feedstock costs rise, logistics constraints tighten, or leading producers adjust pricing. The report is designed to reduce that vulnerability by giving decision-makers a clearer view of where growth is coming from, how the supplier base is structured, and which levers can improve sourcing resilience.
For procurement teams, the research supports more informed contract timing, specification choices, and supplier diversification strategies. For strategy and planning functions, it provides a grounded basis for scenario modeling around cost trajectories and availability risk. For R&D and operations leaders, it clarifies how grade selection and application fit interact with market dynamics, helping to align internal requirements with external supply realities. In each case, the goal is the same: to enable proactive decisions rather than reactive mitigation.
The report also recognizes that complete confidence in any forecast is unrealistic in a market influenced by macro petrochemical pressures and logistics volatility. That is why the analysis emphasizes structural patterns, supplier behavior signals, and decision-relevant segmentation over rigid predictions. By focusing on what is most likely to shape buyer and supplier actions over the forecast horizon, the study gives organizations a practical way to prepare for multiple outcomes instead of betting on a single one.
- A decision-oriented synthesis that helps executives and operational leaders connect market structure to sourcing, inventory, and contract strategy.
- Signal-based monitoring guidance drawn from recent pricing and cost developments, so teams can track the indicators most likely to precede supplier re-pricing or availability shifts.
- A forward-looking lens for scenario planning, enabling organizations to test how different cost, supply, and demand assumptions would affect their MDEA exposure through 2032.
Get the Full Intelligence: The Data, Profiles, and Scenario Tools Behind This Overview
This article is an introduction to the depth available in the full Methyl Diethanolamine market research report. While the discussion above highlights the strategic logic, competitive structure, and pricing dynamics shaping the market, the complete study contains the granular segmentation detail, supplier profiles, concentration analysis, and scenario frameworks that leaders need to make precise sourcing and planning decisions. The full report is where the headline trajectory is connected to the operational details that determine whether a strategy will hold up under real market conditions.
For teams responsible for procurement, cost planning, or market positioning, the full report offers the level of specificity required to move from general awareness to targeted action. If your objective is to understand where MDEA demand is structurally headed, how supplier concentration affects pricing power, and which grade and application considerations should shape your sourcing posture, the complete research package provides the full analytical foundation.
The market is growing, but not uniformly. Costs are being repriced, supplier behavior is shifting, and application demand is distributed across segments with different risk profiles. In that environment, the organizations that perform best will be the ones that base their decisions on detailed, decision-grade intelligence rather than on surface-level metrics. The full report is built for exactly that purpose.
Discover the complete segmentation analysis, competitive profiles, concentration insights, and forward-looking scenario tools by accessing the full market research study. The detailed data and structured frameworks inside are designed to support the next cycle of procurement, strategy, and operational decisions across the MDEA value chain.
For detailed analysis of this topic, please visit the official page: Methyl Diethanolamine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Intelligence: The Shellac Market Outlook for 2026 and Beyond
As we navigate the complex landscape of global commodity markets in 2026, few sectors offer the nuanced blend of heritage, regulatory scrutiny, and sustainable innovation quite like the natural resin industry. At PW Consulting, we have just completed a comprehensive deep-dive into the Shellac Market, delivering a forecast model that extends from 2026 through 2032. This report is not merely a collection of statistics; it is a strategic tool designed to inform procurement, investment, and operational decisions in a market characterized by concentrated supply chains and evolving consumer preferences.
Horizontal Fan Coil Units Market
The shellac industry stands at a critical juncture. Driven by the global shift towards natural ingredients and eco-friendly finishes, demand dynamics are reshaping how stakeholders approach sourcing and production. Our latest research encapsulates the trajectory of this market, providing a clear view of the growth corridors and the competitive forces that define them. For executives and strategists looking to secure their supply lines or identify new revenue streams, understanding the macro trends is only the beginning. The true value lies in the granular analysis of market segmentation, regulatory impacts, and competitor positioning that our full report provides.
Home Building Material E-Commerce Platform Market
Market Trajectory and Macro Economic Indicators
Our analysis begins with a rigorous examination of historical performance and future projections. The Shellac Market has demonstrated consistent resilience and steady expansion over the past five years. According to our data, the global revenue generated by the shellac industry has climbed from approximately 143.25 Million USD in 2020 to an estimated 170.28 Million USD in 2025. This historical progression sets a robust baseline for our forecast period, which spans from 2026 to 2032.
Worldwide Construction Vehicle Axle Market
Looking ahead, the market is projected to reach a valuation of 221.57 Million USD by the end of 2032. This growth trajectory implies a Compound Annual Growth Rate (CAGR) of 3.95 percent during the forecast period. While these aggregate figures provide a high-level view of economic health, the strategic implications run deeper. The steady upward momentum suggests a market that is not subject to volatile boom-and-bust cycles typical of some commodity sectors, but rather one driven by structural increases in consumption across specific application verticals.
It is important to note that while the overall market size is expanding, the distribution of value across different segments varies significantly. Strategic decision-makers must understand where the value is being generated. Our full report dissects these segments to reveal which regions and applications are outperforming the baseline CAGR, allowing clients to allocate resources more effectively. For instance, while the global aggregate grows steadily, certain regional markets exhibit higher sensitivity to raw material availability and regulatory changes, creating unique opportunities for localized supply chain optimization.
Supply Chain Dynamics and Regional Powerhouses
The structural integrity of the shellac supply chain is a paramount concern for any organization involved in its trade or utilization. Our research highlights a significant geographic concentration in the production and export of raw and refined shellac. India remains the dominant force in this arena, accounting for a substantial majority of the global lac resin supply. This dominance is rooted in the specific agro-climatic conditions of regions like Chhattisgarh, where the lac insect secretions are harvested.
The concentration of supply in a single geographic region presents both opportunities and risks. On one hand, it offers a consolidated sourcing hub for international buyers. On the other, it necessitates a deep understanding of the local labor dynamics and environmental regulations that govern production. Our industry context analysis indicates that the Indian shellac industry employs a significant workforce across hundreds of factories and processing units, known locally as bhattas. The stability of this labor force and the adherence to safety standards are critical variables that influence export reliability.
Furthermore, the geopolitical landscape plays a crucial role in trade flows. India's export strategy is heavily oriented towards key markets in Europe and the United States. Trade bodies and government agencies are actively facilitating these connections, recognizing the economic importance of this niche export sector. Recent initiatives have focused on connecting global buyers with Indian suppliers through dedicated expos and trade promotions. These events are not merely ceremonial; they are strategic interventions designed to secure long-term contracts and enhance the visibility of Indian shellac products in high-value markets.
Key Industry Developments and Trade Facilitation
In May 2026, significant activity was observed in the trade promotion sphere. SHEFEXIL, a key export promotion council, announced the second annual Bharat Nutraverse 2026 expo. This event, organized with the support of the Government of India, serves as a critical bridge between global buyers and Indian shellac and nutraceutical suppliers. Such initiatives underscore the government's commitment to elevating the quality and global reach of these products. For market participants, these events represent vital opportunities to forge new partnerships and stay abreast of regulatory updates concerning food-grade and pharmaceutical certifications.
Competitive Landscape and Player Positioning
The global shellac market is characterized by a mix of specialized manufacturers, exporters, and distributors. Our report provides a detailed competitive analysis of the key entities shaping the market. The competitive intensity is moderated by the specialized nature of the product, yet the market concentration ratios indicate that a handful of major players hold a significant share of the revenue. Specifically, the CR3 and CR5 metrics suggest a moderately concentrated market where scale and quality certification are key differentiators.
Leading the charge in India are several established manufacturers who cater to diverse global requirements. Companies such as D. Manoharlal (Shellac) Pvt. Ltd. and SK Shellac Company have built reputations on supplying top-grade shellac, dewaxed flakes, and refined products specifically tailored for food, cosmetic, and pharmaceutical coatings. Their ability to maintain consistent quality while scaling production is a critical factor in their market standing. Similarly, Vishnu Shellac Factory and Jagdamba LAC Factory focus on serving European and North American specialty markets, positioning themselves around heritage quality and food-grade compliance.
On the international front, European and American distributors and manufacturers play a pivotal role in refining and distributing these materials to end-users. Stroever Schellack Bremen (SSB) GmbH & Co. KG in Germany supplies premium shellac grades for food, pharmaceutical, and industrial applications, leveraging machine-made refining processes to ensure purity. In the UK, A.F. Suter and Co. Ltd operates as a key wholesaler and distributor, managing the import and export of high-quality shellac, waxes, gums, and resins. These entities often act as the crucial link between raw material producers and final formulation companies, adding value through logistics and quality assurance.
In the Asia Pacific region, beyond India, players like Chuxiong DES Shellac Co., Ltd. in China are notable for their emphasis on sustainable raw material base development and the production of food-grade high-purity refined shellac. Meanwhile, niche players like Shellac Finishes in Eastern India focus specifically on the woodworking and furniture restoration segments, importing and manufacturing fresh dewaxed shellac flakes. This segmentation of competitor focus allows for a targeted analysis of where competitive pressure is highest in specific value chains.
Strategic Implications for Competitive Intelligence
Understanding the profile of these competitors is essential for benchmark analysis. Our report goes beyond basic company profiles to analyze their strategic moves, capacity expansions, and certification statuses. For a procurement manager, knowing which supplier has the strongest foothold in pharmaceutical-grade certifications can mitigate supply risk. For an investor, identifying which manufacturers are aligning with sustainability trends can highlight long-term viability. The full deliverable includes detailed profiles of these key companies, offering a comparative view of their offerings and market reach.
Segmentation Analysis: Type, Application, and End-Use
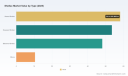
One of the most valuable aspects of our research is the granular breakdown of the market by type and application. The shellac market is not monolithic; it is divided into distinct product categories such as waxed, dewaxed, bleached, and other variants. Each type commands a different price point and serves different functional requirements. For example, dewaxed shellac is often preferred for specific industrial and wood finishing applications where clarity and penetration are key, while waxed variants may find preference in other contexts.
Similarly, the demand drivers vary significantly across application verticals. The Food & Beverage sector represents a major consumption base, driven by the demand for natural glazing agents and coatings. Pharmaceutical applications require rigorous adherence to safety standards, creating a high-barrier entry point that benefits certified suppliers. The Cosmetics industry utilizes shellac for its natural properties in formulations, while the Woodworking sector relies on it for traditional finishes and restoration work.
Our analysis delves into the revenue contributions of each of these segments without losing sight of the interdependencies. A surge in demand for natural cosmetics, for instance, can ripple through to increase pressure on raw material availability, affecting pricing across the board. By understanding these linkages, clients can better anticipate cost fluctuations. However, the precise percentage splits and specific revenue contributions for each segment are detailed exclusively in the full report to maintain the depth of commercial confidentiality we offer our subscribers.
Regulatory and Quality Standards
Regulation is a defining force in the shellac market. As the product moves into food and pharmaceutical channels, compliance becomes non-negotiable. Organizations like SHEFEXIL support manufacturers in obtaining the necessary food-grade and pharmaceutical certifications under global safety standards. This regulatory support is vital for maintaining access to lucrative markets in Europe and North America. The cost of compliance and the time required to achieve certification are strategic factors that our report evaluates for each major region and company type.
Strategic Recommendations for 2026 Decision Makers
Based on our comprehensive analysis, we offer several strategic considerations for stakeholders operating in the Shellac Market in 2026.
- Diversify Sourcing Strategies: Given the high concentration of raw material production in India, companies should evaluate multi-sourcing strategies or secure long-term contracts to mitigate geopolitical or climate-related disruptions in the primary supply region.
- Invest in Certification: For players aiming to penetrate high-value segments like pharmaceuticals and premium food products, prioritizing regulatory compliance and certification is a direct pathway to margin expansion and market access.
- Monitor Sustainability Trends: The industry trend towards natural and eco-friendly solutions is accelerating. Manufacturers and brands that can verify the sustainability of their supply chain will gain a competitive advantage in marketing and procurement negotiations.
- Leverage Trade Events: Participation in industry-specific expos, such as the Bharat Nutraverse, provides direct access to innovation and networking opportunities that can lead to exclusive distribution agreements.
- Analyze Regional Nuances: While global averages provide a direction, regional dynamics differ. Strategies should be tailored to specific geographic markets, considering local consumption patterns and regulatory environments.
Conclusion
The Shellac Market is poised for continued growth, underpinned by a shift towards natural ingredients and steady demand across diverse industries. However, realizing the value of this growth requires more than just observing the headline numbers. It demands a deep understanding of the supply chain vulnerabilities, the competitive tactics of key players, and the regulatory frameworks that govern trade.
PW Consulting's full Shellac Market Report offers the detailed intelligence necessary to navigate this landscape with confidence. We have outlined the macro trajectory and the key players here, but the specific data points, regional splits, and competitor benchmarks that drive precise decision-making are contained within our comprehensive document. For organizations committed to strategic excellence in 2026 and beyond, accessing this level of detail is not optional; it is essential.
We invite you to explore the full findings of our study to uncover the specific opportunities that align with your organizational goals. The market is moving; ensure your strategy moves with it.
For detailed analysis of this topic, please visit the official page: Shellac Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Downlights Market to Hit $2.16B by 2032, Growing at 5.5% CAGR
By PW Consulting, 2026-09-07
Navigating the Downlights Market: Strategic Intelligence for 2026 Decision-Makers
The global lighting industry is undergoing a structural transformation, driven by energy efficiency mandates, rapid technological iteration, and shifting macroeconomic pressures. Within this landscape, the downlights sector represents a critical intersection of architectural design, commercial functionality, and residential aesthetics. As organizations plan their capital expenditures and product roadmaps for the remainder of the decade, relying on fragmented market signals is no longer sufficient. PW Consulting's comprehensive Downlights Market study offers a rigorous, data-backed foundation for strategic planning, providing executives with the clarity needed to navigate an increasingly complex environment.
Quartz Sand、Quartz Grit and Quartz Slab Market
This industry insight serves as a strategic preamble to our flagship research publication. It outlines the macroeconomic trajectory, competitive dynamics, and regulatory forces shaping the sector, while demonstrating the analytical depth embedded in the full report. The objective is to equip leadership teams with a nuanced understanding of where value is being created, where risks are concentrated, and how to position portfolios for sustainable growth through 2032.
Worldwide Twin Screw and Barrel Market
Market Trajectory and Structural Growth Drivers
The downlights market has demonstrated consistent expansion over the past half-decade, reflecting both mature adoption cycles and emerging demand vectors. Historical data from 2020 through 2025 reveals a sector that has successfully navigated supply chain disruptions, component cost inflation, and evolving end-user expectations. The global market reached a valuation of approximately 1,487.5 million USD in the base year of 2025, building upon steady year-over-year gains that trace back to the 1,200 million USD baseline established in 2020.
Multi-player Real-time Online Editing Market
Looking forward, the forecast period spanning 2026 to 2032 projects a compound annual growth rate of 5.5 percent. This trajectory suggests a market poised to exceed 2,159 million USD by the close of the forecast window. Such growth is not merely incremental; it reflects a convergence of structural factors that will redefine competitive positioning over the next seven years. Building renovation cycles, stringent energy codes, and the ongoing migration toward smart-integrated lighting ecosystems are all contributing to sustained demand across multiple end-use environments.
For executive teams, the implications of this trajectory are clear. Revenue planning cannot rely on linear extrapolation. Instead, strategic models must account for cyclical procurement patterns, regional tariff fluctuations, and the accelerating pace of product lifecycle compression. The full study deconstructs these variables into actionable modeling frameworks, enabling finance and strategy functions to stress-test assumptions against multiple macroeconomic scenarios.
Forecast Architecture and Scenario Planning
The forecast methodology underpinning our analysis integrates historical performance data with forward-looking indicators, including construction activity indices, regulatory compliance timelines, and semiconductor availability cycles. Rather than presenting a single-point projection, the report structures its outlook across baseline, optimistic, and conservative scenarios. This approach allows organizations to quantify exposure to key risk factors while identifying upside opportunities tied to specific product innovations or regional policy shifts.
Decision-makers will find particular value in the report's treatment of demand elasticity across different procurement environments. By mapping how pricing dynamics, lead times, and specification requirements interact with purchasing behavior, the study provides a practical lens for revenue forecasting, inventory optimization, and capacity planning. These insights are especially critical for organizations managing multi-year product portfolios or negotiating long-term supplier agreements in a volatile component market.
Competitive Landscape and Strategic Positioning
The downlights market is characterized by a moderately concentrated competitive structure, where scale, specification expertise, and brand credibility play decisive roles in capturing high-value contracts. Concentration metrics indicate that the top three participants command a combined share of approximately 52 percent, while the top five collectively account for 75 percent of total market revenue. This distribution underscores the importance of differentiated value propositions for mid-tier and emerging players seeking to expand their footprint without engaging in unsustainable price competition.
Several established manufacturers illustrate the strategic pathways available within this environment. Acuity Brands Inc, headquartered in Atlanta, Georgia, has built a prominent position through its Juno recessed LED downlight platform, serving residential, commercial, and retrofit applications with a focus on specification-grade reliability. JESCO Lighting Group LLC, based in Port Washington, New York, targets the architectural lighting segment with contemporary LED downlights designed for commercial, institutional, and residential environments, emphasizing aesthetic integration and performance consistency.
Ledra Brands Inc, operating out of Irvine, California under its Alphabet Lighting brand, offers the NU series downlights engineered for plenum spaces, with tamper-resistant and fire-rated configurations that address stringent safety requirements in high-specification projects. Satco Products, Inc., located in Brentwood, New York, has carved out a niche in commercial and slim-fit LED downlights featuring remote driver architectures and emergency backup capabilities, catering to applications where flexibility and code compliance are paramount. Signify Holding, based in Eindhoven, Netherlands, leverages the Philips brand to deliver professional LED downlights and recessed lighting systems, combining global distribution reach with well-established specification relationships. Zumtobel Group, headquartered in Dornbirn, Austria, provides architectural lighting solutions that integrate LED downlights and panels for professional interior applications, positioning itself at the intersection of design-led specification and building performance.
Product Innovation as a Competitive Differentiator
Recent product introductions highlight how leading participants are responding to evolving specification requirements and installation efficiency demands. In January 2026, Satco launched an LED Fire Rated Slimfit Downlight with remote driver and CCT selectable features, directly addressing the need for flexible color temperature options within code-compliant form factors. This followed a December 2025 introduction of LED Slimfit Downlights for the Performer series, which emphasized improved performance metrics for routine commercial and residential deployments.
In May 2026, Ultraleds announced an integrated LED downlight series featuring IP65 rating and fire-rated construction, targeting faster installation workflows in environments where durability and environmental protection are critical. Earlier in the cycle, in August 2025, Fluxwerx introduced the Speak series downlight with both fixed and adjustable options, positioning the product as a new paradigm for recessed lighting by offering design flexibility without compromising specification integrity. These developments illustrate a broader industry shift toward modular designs, configurable performance parameters, and installation-friendly architectures that reduce labor costs and accelerate project timelines.
The full report provides a detailed mapping of product positioning across these and other key participants, analyzing how feature sets, certification portfolios, and channel strategies influence competitive outcomes. Rather than offering a static company directory, the study evaluates strategic intent, identifying which organizations are prioritizing volume-driven segments, which are focusing on specification-intensive projects, and where convergence or divergence is likely to shape future market share dynamics.
Regulatory, Tariff, and Supply Chain Dynamics
No strategic assessment of the downlights market would be complete without a rigorous examination of the external forces that directly influence cost structures, compliance timelines, and competitive accessibility. Three interconnected dynamics deserve particular attention from leadership teams: regulatory mandates, tariff exposure, and semiconductor supply volatility.
On the regulatory front, the ENERGY STAR Downlights Specification Version 1.0, finalized on November 16, 2023, took full effect on January 1, 2025, establishing new performance thresholds for energy efficiency and operational consistency. This mandate has reshaped specification requirements for many procurement teams, particularly in commercial and public-sector projects where compliance documentation and validated performance data carry significant weight. Organizations that have aligned their product portfolios with these standards are better positioned to compete in regulated bidding environments, while those lagging in compliance face increasing friction in key channels.
Tariff exposure has introduced additional complexity to the cost landscape. The escalation of U.S.-China tariffs to a combined rate of 104 percent in 2025 has significantly affected component and fixture costs for lighting manufacturers, influencing sourcing strategies and pricing architectures across the value chain. Earlier in the cycle, U.S. tariffs on Chinese goods increased from 10 percent to 20 percent in February 2025, raising compliance and material costs for LED downlight production and prompting many participants to reevaluate supplier diversification, inventory buffering, and regional assembly strategies.
Supply chain dynamics have compounded these pressures. Persistent semiconductor supply-chain volatility extended lead times for LED drivers and control ICs to 12-16 weeks during peak periods in 2025, disrupting production scheduling and forcing manufacturers to make difficult trade-offs between inventory carrying costs and order fulfillment reliability. These lead-time extensions are not merely operational inconveniences; they affect quotation validity, project bidding timelines, and the ability to honor fixed-price contracts in environments where raw material and component costs can shift rapidly.
Pricing responses from major participants reflect these pressures. Acuity Brands implemented a third price increase for luminaires and electronics in July 2025, driven by new global tariffs and market volatility. Such moves illustrate how cost pass-through strategies are being calibrated in real time, and why procurement and finance teams must incorporate dynamic pricing assumptions into their planning models rather than relying on historical average costs. The full study quantifies these dynamics within dedicated analytical sections, providing a structured framework for evaluating tariff exposure, supplier concentration risk, and the financial implications of specification compliance across different segments.
Strategic Implications for Procurement and Product Planning
For organizations operating in or adjacent to the downlights market, the convergence of regulatory, tariff, and supply chain forces creates both risk and opportunity. On the risk side, reliance on narrow supplier bases, inflexible pricing contracts, or product lines that lag behind current compliance standards can erode margins and limit bidding competitiveness. On the opportunity side, manufacturers and distributors that proactively diversify component sourcing, integrate compliant performance characteristics early, and design for installation efficiency can capture advantage in specification-driven procurement environments.
The report's dynamics section goes beyond descriptive analysis to offer structured implications for sourcing strategy, inventory policy, and product portfolio management. By linking external events to operational and financial outcomes, the study helps teams translate macro-level disruptions into tactical decisions that preserve margin integrity and service reliability.
Application Segments and Regional Demand Architecture
Demand for downlights is distributed across multiple end-use environments, each with distinct specification priorities, procurement cycles, and price sensitivity profiles. Commercial applications represent the largest revenue share within the market, reflecting the ongoing intensity of workplace renovation, hospitality upgrades, and institutional project activity. Residential demand forms a substantial secondary pillar, supported by homeowner renovation cycles, new housing activity, and a growing preference for recessed lighting solutions that combine aesthetic subtlety with LED performance. Industrial applications, while smaller in absolute terms, contribute specialized demand tied to facility upgrades, safety-rated installations, and environments where durability and code compliance intersect.
Regional demand patterns further shape competitive strategy. North America, Europe, and Asia Pacific each represent significant revenue pools, but they differ markedly in terms of specification culture, code enforcement intensity, channel structure, and sensitivity to component cost fluctuations. Latin America and the Middle East and Africa constitute smaller but strategically relevant markets, often influenced by project-driven procurement, import dependency, and evolving building standards. Understanding how these regional contexts interact with product type, application requirements, and tariff exposure is essential for organizations deciding where to allocate sales resources, inventory, and product development effort.
The full study provides a structured analysis of how these regional and application dynamics interact, without reducing the landscape to simplistic share rankings. Instead, it focuses on the qualitative and quantitative factors that drive demand concentration, specification pull-through, and channel effectiveness in each context. This approach enables organizations to assess where their current capabilities align with market opportunity and where targeted investment may be required to capture growth effectively.
Why This Study Matters for 2026 Strategic Planning
The decisions made in 2026 will shape competitive positioning well beyond the current forecast horizon. Product portfolio investments, supplier agreements, pricing architectures, and channel strategies all require an evidence base that accounts for both historical performance and forward-looking disruption. PW Consulting's Downlights Market report is designed to serve as that evidence base, offering a level of analytical rigor that supports executive decision-making rather than merely describing market conditions.
Several attributes distinguish this study from broader industry summaries. First, it integrates historical data, base-year valuation, and multi-year forecasts into a coherent analytical narrative, allowing readers to evaluate growth sustainability rather than isolated data points. Second, it contextualizes competitive dynamics within the realities of product innovation, specification requirements, and channel behavior, helping organizations interpret market share movements in terms of strategic intent and capability alignment. Third, it embeds regulatory, tariff, and supply chain analysis directly into the market framework, ensuring that external volatility is treated as a core planning variable rather than an incidental footnote.
For strategy, finance, and product leadership, the report provides a foundation for scenario modeling, portfolio rationalization, and channel investment decisions. For sales and specification teams, it offers insight into the demand drivers and compliance requirements that influence procurement behavior across commercial, residential, and industrial environments. For supply chain and operations leaders, it frames the cost and lead-time dynamics that affect inventory policy, quotation strategy, and supplier diversification priorities.
The study also addresses the practical need for clarity in a market where terminology, specification standards, and product architectures evolve rapidly. By establishing a consistent analytical framework and defining the relationships between product types, applications, regions, and competitive forces, the report reduces the friction associated with cross-functional alignment. This is particularly valuable for organizations operating across multiple business units or geographies, where shared market intelligence can improve coordination and reduce interpretive variance.
What the Full Report Delivers
Beyond the macro-level context and competitive framing outlined here, the complete Downlights Market study provides detailed coverage designed to support operational and strategic execution. The report examines segmentation structures across product types, application environments, and geographic regions, enabling readers to evaluate where growth is concentrated and how demand characteristics differ across contexts. It includes concentration analysis that clarifies the competitive hierarchy and identifies the structural conditions that shape market entry, expansion, and retention strategies.
The publication also features company profiling that goes beyond basic corporate information to assess strategic positioning, product architecture, and the practical implications of recent launches and specification developments. Recent industry developments are integrated into the analysis to show how product introductions, regulatory milestones, and cost pressures are influencing near-term market behavior. In addition, the report incorporates structured treatment of industry context factors, including regulatory specifications, tariff developments, semiconductor supply dynamics, and pricing actions, linking each to its likely impact on market participants.
Readers will also find forward-looking analysis that connects market size and growth trajectory to the underlying drivers of demand, providing a basis for evaluating opportunity magnitude and planning resource allocation accordingly. The study is structured to support a range of use cases, from high-level strategic planning to more granular product and channel decisions, while maintaining a consistent analytical standard throughout.
Conclusion: Positioning for Informed Growth
The downlights market is not defined by a single trend or disruption. It is shaped by the interaction of regulatory mandates, tariff realities, supply chain behavior, product innovation cycles, and regional specification cultures. organizations that approach this environment with fragmented intelligence risk misallocating resources, underestimating compliance exposure, or misreading competitive intent. Those that invest in structured, data-grounded analysis are better equipped to align product portfolios, pricing strategies, and channel efforts with the realities of demand and cost.
PW Consulting's Downlights Market study is built to support that level of decision-making. By combining historical context, forecast architecture, competitive analysis, and dynamic industry factors into a single integrated framework, the report provides the intelligence necessary to plan with confidence across the 2026 to 2032 horizon. The overview presented here illustrates the scope and depth of the analysis, while leaving the core segmentation data, detailed company evaluations, and scenario-specific quantification for the full publication.
Leaders seeking to translate market complexity into actionable strategy will find the complete study an essential reference for 2026 planning and beyond. It offers the analytical precision required to evaluate growth opportunity, manage risk exposure, and position portfolios for durable performance in a sector where specification, compliance, and cost dynamics continue to evolve at pace.
For detailed analysis of this topic, please visit the official page: Downlights Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Cloud CDN Market Hits $11.7B in 2025, Projected to Reach $28.49B by 2032
By PW Consulting, 2026-09-07
Unlocking the Edge: Strategic Imperatives in the Cloud Content Delivery Network Market Through 2032
The digital infrastructure landscape is undergoing a profound transformation. As enterprises accelerate their migration to cloud-native architectures and consumers demand instantaneous content delivery across geographies, the Cloud Content Delivery Network Market has emerged as a critical backbone of global digital commerce. Our latest comprehensive market research report provides a definitive analysis of this sector, offering senior decision-makers the intelligence required to navigate investment, procurement, and competitive positioning through the forecast period ending 2032. This article serves as a strategic preview of the findings, highlighting the macroeconomic trajectory, the evolving competitive architecture, and the operational dynamics that will define enterprise success in the coming years.
Worldwide Self-propelled Feeding System Market
Market Trajectory and Macroeconomic Context
The historical performance of the Cloud Content Delivery Network sector demonstrates sustained resilience and accelerating adoption. Between 2020 and 2025, the market expanded from a base valuation of 6.5 billion USD to 11.7 billion USD, reflecting a compound annual growth trajectory that underscores the infrastructure criticality of edge delivery networks. This growth has been fueled by parallel trends: the exponential increase in video streaming consumption, the performance demands of modern web applications, and the rising need for API acceleration across distributed microservices environments.
Worldwide Custom Piano Market
Looking forward, our forecast modeling projects the market to reach 13.74 billion USD in 2026, with momentum carrying through to a projected valuation of 28.49 billion USD by 2032. This forward curve implies a compound annual growth rate of 13.5 percent across the forecast horizon. Such a rate places cloud CDN infrastructure among the more dynamic segments of the broader cloud services ecosystem, outpacing many traditional IT spend categories. The growth is not merely a function of organic expansion but reflects structural shifts in how enterprises architect their digital presence. Edge computing capabilities are increasingly bundled with security, serverless compute, and real-time analytics, transforming CDN from a passive content cache into an active application delivery plane.
Worldwide Cosmetics Regulatory Consultant Market
For enterprise strategists, these aggregate figures provide essential context for budget planning and capacity modeling. However, the headline numbers represent only the surface layer of actionability. The true strategic value of our research lies in the decomposition of these trends across technology types, application verticals, and regional deployment patterns. Decision-makers must understand where capital is flowing, which workloads are driving procurement, and how geopolitical and regulatory variables will reshape regional demand curves. Our report dissects these dimensions without obscuring the underlying mechanics, enabling executives to test scenarios against granular data rather than relying on top-down extrapolations.
Competitive Architecture: Navigating a Concentrated yet Dynamic Landscape
The competitive structure of the cloud CDN market presents a nuanced picture for both investors and enterprise buyers. Market concentration metrics indicate that the top three providers command approximately 65 percent of total revenue, while the top five entities extend their collective share to roughly 80 percent. This concentration reflects the economies of scale inherent in operating globally distributed edge networks, the high barriers to entry associated with peering agreements and Points of Presence deployment, and the enterprise preference for vendors with proven reliability at scale.
Within this consolidated framework, several incumbent and specialized players continue to differentiate through platform architecture and strategic pivots. Akamai Technologies Inc., headquartered in Cambridge, Massachusetts, has long anchored the market through its Akamai Connected Cloud platform, which integrates a massively distributed edge network with cloud computing, security, and content delivery services. The company's strategic positioning extends beyond traditional CDN caching into broader cloud infrastructure services, a pivot validated by recent financial disclosures and landmark enterprise commitments. In early 2026, Akamai reported full-year 2025 revenue of 4.208 billion USD, representing a 5 percent year-over-year increase, with Cloud Infrastructure Services revenue growing 25 percent to 630 million USD. Subsequent developments reinforced this trajectory, including a seven-year, 1.8 billion USD commitment from a leading U.S.-based frontier model provider, marking the largest customer deal in the company's history. Alongside these growth signals, Akamai has navigated cost-side pressures by notifying customers and partners of a 3 percent interim surcharge effective April 2026, with potential adjustments up to 10 percent on contract renewals tied to rising expenses for servers, RAM, SSDs, and energy. Regulatory and security positioning has also advanced, with Akamai on track to achieve FedRAMP High and DOD Impact Level 4 and 5 accreditations in 2026, while simultaneously announcing an intent to acquire LayerX to enforce AI usage control across browser environments.
Cloudflare, Inc., based in San Francisco, California, continues to press its differentiation through the Workers and edge compute platform, which delivers a global network purpose-built for content delivery, security, and application performance. The company's recent financial results underscore strong momentum, with Q1 2026 revenue reaching 639.8 million USD, a 34 percent year-over-year increase, alongside non-GAAP income from operations of 73.1 million USD. This performance reflects the growing appeal of edge compute platforms that allow developers to run logic closer to end users, reducing latency and centralizing security policy enforcement at the perimeter.
Fastly, Inc., also headquartered in San Francisco, has carved a distinct niche with its Compute@Edge platform, emphasizing high-performance content delivery and serverless application execution. The company reported record Q1 2026 financial results, with revenue of 173.02 million USD and an adjusted gross margin of 65.1 percent. Remaining performance obligations expanded 63 percent year-over-year, signaling strong forward demand and contract visibility. Fastly's trajectory highlights the ongoing relevance of specialized, developer-centric edge platforms even within a market increasingly dominated by hyperscale and diversified cloud providers.
The hyperscale cloud providers maintain a significant presence through integrated CDN offerings that align closely with broader cloud ecosystems. Amazon Web Services, Inc., headquartered in Seattle, Washington, operates Amazon CloudFront, a global edge network designed for content delivery and streaming services, tightly coupled with AWS storage and compute primitives. Microsoft Corporation, based in Redmond, Washington, provides Azure CDN and Front Door for optimized content delivery within cloud environments, enabling enterprises to leverage existing Azure investments while extending performance to the edge. Alphabet Inc., headquartered in Mountain View, California, offers Google Cloud CDN for global edge delivery and streaming optimization, integrating with Google's broader network infrastructure and analytics capabilities. These hyperscaler offerings benefit from procurement consolidation advantages and ecosystem lock-in, though they also face competitive pressure from independent providers that emphasize neutrality, multi-cloud portability, and specialized edge compute capabilities.
Our report provides detailed company profiles, strategic positioning matrices, and capability comparisons across these key players. We examine how each vendor's architecture, pricing philosophy, security posture, and geographic footprint influence enterprise selection criteria. The analysis extends to recent developments, including pricing adjustments, accreditation achievements, and strategic acquisitions that signal where each competitor is placing its bets. By mapping these dynamics, the report equips procurement teams and strategy leaders with a comparative lens to evaluate vendor fit beyond brand recognition.
Market Segmentation Dynamics: Workloads, Types, and Regional Variation
Understanding where demand originates within the cloud CDN market is essential for aligning technology investments with revenue-generating workflows. Our segmentation analysis distinguishes three primary frameworks: by type, by application, and by region. Each lens reveals distinct growth drivers and procurement behaviors that aggregate figures obscure.
By type, the market encompasses Video Streaming, Web Performance, and API Acceleration workloads. Video Streaming represents the largest revenue concentration, reflecting the persistent growth of on-demand media, live event delivery, and user-generated content platforms that require low-latency, high-throughput edge distribution. Web Performance remains a foundational category, as enterprises optimize page load times, reduce bounce rates, and improve search rankings through edge caching and content optimization. API Acceleration addresses the rising complexity of distributed application architectures, where microservices, mobile backends, and third-party integrations demand consistent low-latency communication across global user bases. The interplay among these categories varies by vendor capability and enterprise maturity, and our report details how workload mix influences pricing, contract structure, and service level expectations.
By application, demand concentrates across Media and Entertainment, E-commerce, Gaming, and Others. Media and Entertainment organizations rely on CDN infrastructure to manage bursty traffic patterns, global audience distribution, and rights-managed content delivery. E-commerce platforms depend on edge performance to reduce checkout friction, protect against traffic spikes during promotional events, and maintain brand credibility through fast, secure experiences. Gaming operators utilize CDN capabilities to distribute updates, manage matchmaking latency, and support real-time content delivery for both cloud gaming and traditional title distribution. The Others category captures a growing set of enterprise use cases, including SaaS delivery, financial services compliance-driven caching, and IoT telemetry aggregation at the edge. Our segmentation analysis provides relative revenue contributions across these application areas, enabling readers to benchmark their industry's position and anticipate cross-industry adoption patterns.
Regional variation introduces additional strategic complexity. North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa each present distinct procurement dynamics shaped by infrastructure maturity, regulatory environments, and enterprise digital transformation pacing. North America maintains the largest revenue share, reflecting the concentration of hyperscale cloud providers, high enterprise IT spend, and early adoption of edge compute use cases. Europe demonstrates strong demand driven by data localization requirements, multilingual content delivery, and regulatory frameworks influencing data routing and caching strategies. Asia Pacific represents a high-growth region characterized by rapid mobile adoption, diverse language and content requirements, and expanding cloud infrastructure investment across both developed and emerging markets. Latin America and the Middle East and Africa, while smaller in absolute terms, offer meaningful growth opportunities as enterprises in these regions accelerate their digital presence and as global vendors extend Points of Presence to improve latency and local compliance. Rather than presenting static percentage allocations that age quickly, our report frames regional dynamics through growth trajectories, deployment drivers, and the strategic implications of vendor network expansion. This approach allows decision-makers to assess market entry timing, partnership opportunities, and capacity planning with greater precision.
Industry Dynamics: Pricing, Regulation, and Infrastructure Pressure
Beyond the structural growth narrative, the cloud CDN market is navigating a period of operational and regulatory intensity that directly affects enterprise planning. Cost pressures on infrastructure providers are translating into pricing adjustments that procurement teams must anticipate. As noted in recent industry communications, infrastructure vendors have signaled interim surcharges and renewal price adjustments linked to rising costs for servers, memory, storage components, and energy. These adjustments reflect broader supply chain dynamics and the capital intensity of maintaining globally distributed edge networks. Enterprises should incorporate such pricing variability into total cost of ownership models and negotiate contract structures that account for potential mid-cycle adjustments.
Regulatory and accreditation developments are simultaneously reshaping eligibility and deployment options for government, defense, and regulated industry workloads. Advancements in security accreditations, including trajectories toward FedRAMP High and defense impact level accreditations, expand the addressable market for providers that can demonstrate compliance with stringent security controls. For enterprises operating in regulated sectors, the availability of accredited edge infrastructure influences vendor selection, data residency strategies, and risk management frameworks. Our report examines how these regulatory developments intersect with CDN deployment models and what they imply for enterprise compliance roadmaps.
Pricing transparency and interconnect dynamics also warrant attention. Cloud providers continue to refine pricing for peering, interconnect, and carrier services, with list price adjustments effective across major regions. These changes affect the cost structure of hybrid and multi-cloud delivery architectures, particularly for enterprises that rely on direct peering or carrier partnerships to optimize traffic routing. Understanding the direction and magnitude of such pricing shifts helps enterprises forecast egress and interconnection costs, evaluate alternative routing strategies, and assess whether vendor consolidation or diversification better serves cost management objectives.
Strategic acquisitions and product expansions further signal where the market is heading. Moves to extend edge platforms into browser-based AI usage control, serverless compute, and advanced security enforcement illustrate the convergence of content delivery with broader application and security capabilities. Enterprises evaluating CDN investments should consider these expansions not as peripheral features but as indicators of how vendors intend to deepen platform stickiness and expand the scope of edge-mediated workloads. Our report analyzes these developments within the context of vendor roadmaps and competitive differentiation.
What the Full Report Delivers: Operational Intelligence for Decision-Makers
This preview highlights the strategic shape of the market, but the complete research study provides the depth required for concrete action. The report is structured to support multiple decision contexts, from enterprise procurement and vendor selection to investment analysis and competitive strategy. It includes detailed market sizing across historical and forecast periods, decomposed across type, application, and region, with methodology notes that clarify assumptions and data sources. Readers gain access to segmentation splits that quantify revenue contributions without reducing the analysis to static snapshots, allowing for scenario testing and demand forecasting aligned to specific enterprise contexts.
The competitive analysis section delivers company profiles for the leading providers, with emphasis on platform offerings, recent financial results, strategic announcements, and operational developments. These profiles are paired with concentration analysis and positioning commentary that help readers interpret market share in the context of capability depth, pricing philosophy, and ecosystem integration. The report also incorporates industry context on pricing adjustments, regulatory accreditations, and infrastructure cost dynamics, mapping these factors to practical implications for contract negotiation, compliance planning, and total cost of ownership assessment.
For technology leaders, the report provides actionable guidance on evaluating edge platform capabilities, understanding the trade-offs between hyperscale integrated offerings and independent specialized providers, and aligning CDN procurement with broader cloud and security architectures. For investors and analysts, the study offers a structured view of growth drivers, concentration risks, and the operational variables that will influence margin trajectories and competitive positioning through 2032. For procurement teams, segmentation and regional analysis support demand planning, multi-vendor strategy evaluation, and negotiation preparation informed by market-wide pricing and cost dynamics.
We have deliberately reserved the most granular data points, scenario models, and detailed vendor comparison matrices for the full report. This approach ensures that readers who engage with the complete study receive actionable intelligence rather than generalized observations. The preview presented here establishes the strategic context and demonstrates the analytical rigor of the research, while the full publication delivers the specific figures, segmentation breakdowns, and competitive assessments needed to translate market intelligence into decisive action.
Strategic Takeaways for Enterprise Decision-Makers
As enterprises plan for the 2026 to 2032 horizon, several priorities emerge from the market dynamics outlined in this research. First, organizations should treat cloud CDN infrastructure as a strategic application delivery layer rather than a commodity caching service. The convergence of edge compute, security enforcement, and content delivery means that vendor selection increasingly influences developer productivity, security posture, and user experience outcomes. Second, procurement strategies should account for pricing variability and infrastructure cost pressures by incorporating flexibility into contract terms, evaluating multi-vendor approaches where appropriate, and modeling total cost of ownership against workload-specific performance requirements. Third, regulatory and accreditation developments should be factored into compliance roadmaps, especially for enterprises operating in government, defense, and regulated industry contexts where accredited edge infrastructure expands or constrains vendor options.
Finally, the concentration of market share among leading providers does not diminish the relevance of specialized platforms or the importance of differentiation in procurement decisions. Enterprises with unique performance, latency, or multi-cloud portability requirements may find that specialized edge compute platforms or independent CDN providers offer capabilities that align more closely with their architectural goals. Conversely, organizations prioritizing procurement consolidation and ecosystem integration may benefit from hyperscale offerings that simplify operations and align with existing cloud investments. The optimal path depends on workload mix, geographic distribution, compliance needs, and long-term platform strategy, all of which our full report examines in detail.
The Cloud Content Delivery Network Market is positioned for sustained expansion, driven by the structural demands of digital content, application performance, and edge-mediated security. Our research provides the intelligence framework to navigate this growth with clarity, enabling decision-makers to move beyond aggregate market narratives and engage with the segmentation, competitive, and operational details that shape real-world outcomes. We invite readers to access the complete study for the full breadth of data, analysis, and strategic guidance required to make informed decisions in this evolving market.
For detailed analysis of this topic, please visit the official page: Cloud Content Delivery Network (CDN) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Tufting Machine Market Hits $202.04M in 2025, Projected 6.9% CAGR Through 2032
By PW Consulting, 2026-09-07
Strategic Imperatives in the Tufting Machine Market: Navigating Growth and Complexity in 2026
The global textile manufacturing landscape is undergoing a significant transformation, driven by shifting consumer preferences, technological advancements, and macroeconomic pressures. Within this ecosystem, the tufting machine market stands out as a critical bellwether for industrial textile production. As businesses plan their capital expenditure and capacity expansion strategies for the remainder of the decade, understanding the nuanced dynamics of this sector is no longer optional—it is a strategic necessity. PW Consulting's latest comprehensive study on the Tufting Machine Market offers a definitive roadmap for stakeholders aiming to capitalize on emerging opportunities while mitigating inherent risks.
Worldwide Sprocket Gear Hob Market
This analysis serves as an introduction to the depth and breadth of our findings. It is designed to highlight the strategic value of the report for executive decision-makers, investors, and industry analysts. While we outline the overarching trends and structural components here, the specific data points required for precise modeling and benchmarking are detailed within the full publication.
Intermodal Cranes Market
Market Trajectory and Historical Context
The tufting machine industry has demonstrated remarkable resilience and growth over the past half-decade. Based on our aggregated data covering the period from 2020 through 2025, the market has evolved from a post-pandemic recovery phase into a period of sustained expansion. The historical revenue stream illustrates a consistent upward trajectory, reflecting renewed confidence in textile infrastructure investments.
Smart Hand Dryer Market
Looking forward, our forecast period extends from 2026 to 2032. The projected growth rate during this interval suggests a robust market environment. Our analysis indicates a Compound Annual Growth Rate (CAGR) that underscores the sector's vitality. This growth is not merely a function of inflation but is rooted in tangible increases in production capacity and adoption rates across various manufacturing hubs. While the headline CAGR of 6.9% provides a macro-level view, the true strategic insight lies in understanding the velocity of growth across different phases of the forecast period. Early years may show steady increments, but later years could reflect acceleration driven by new technology adoption cycles.
For a firm planning a five-year capital strategy, knowing the aggregate market size is useful, but understanding the inflection points within that timeline is invaluable. Our report dissects these phases, allowing planners to align procurement and investment cycles with market peaks and troughs. Without access to the full granular data, stakeholders risk misaligning their expansion plans with actual market absorption rates.
Segmentation Dynamics and Operational Implications
One of the most critical aspects of strategic planning in the tufting industry is understanding where demand is concentrated. The market is not a monolith; it is fractured into distinct segments based on machine type, application, and geography. Each segment carries its own risk profile, margin structures, and growth drivers.
Machine Type Stratification
The market is dominated by specific categories of machinery, each serving different production needs. High-volume broadloom production relies heavily on specific cut pile technologies, while decorative and specialized textile applications often require loop pile or multi-level loop configurations. Our report provides a detailed breakdown of how revenue is distributed across these categories. Understanding the revenue unit distribution among Cut Pile, Loop Pile, Multi-Level Loop Pile, and Other machine types is essential for manufacturers deciding which technological lines to prioritize. For instance, a shift in consumer preference toward high-pile interiors might favor specific loop technologies, whereas industrial flooring might sustain demand for cut pile systems. The full report details the relative market weight of each category, enabling equipment vendors to tailor their R&D and manufacturers to optimize their floor layout.
Application End-Uses
Demand for tufting machines is derivative of demand for the final products. The primary application remains carpets and rugs, representing the largest share of the consumption basket. However, other sectors such as automotive interiors and textile wall coverings are gaining traction. The automotive sector, in particular, presents a unique value proposition due to the higher quality specifications required for vehicle interiors. Textile wall coverings represent a growing niche driven by interior design trends in commercial spaces.
Our analysis explores the revenue units associated with each application vertical. We examine how the 104.79 million USD revenue unit baseline for carpets and rugs compares to the 40.71 million USD unit interest in automotive interiors, and how these figures are projected to evolve. For a machinery supplier, knowing which application segment is growing fastest helps in targeting sales channels. For a producer, it helps in diversifying revenue streams. The complete report elaborates on the specific growth catalysts within each application segment, including regulatory changes in automotive materials and design trends in residential housing.
Regional Landscape
Geography plays a pivotal role in market dynamics. Manufacturing hubs in Asia Pacific, established markets in North America and Europe, and emerging regions in Latin America and the Mideast and Africa all contribute to the global total. The revenue units are distributed across these regions, with North America showing significant activity at 66.05 million USD units, followed closely by Europe at 56.17 million USD units, and Asia Pacific at 55.15 million USD units.
However, raw revenue numbers do not tell the whole story. Production costs, labor availability, and logistical infrastructure vary wildly between these regions. A strategic investor needs to know not just where the revenue is generated, but where the capacity is being installed. Our regional analysis goes beyond top-line figures to discuss installation rates and capacity utilization trends. We advise clients on where to locate distribution centers or assembly plants based on these nuanced regional insights. The full document provides the specific regional breakdowns necessary for localization strategies.
Competitive Landscape and Vendor Positioning
The tufting machine market is characterized by a mix of established legacy manufacturers and agile new entrants. Market concentration is a key metric for assessing competitive risk. Our data indicates a moderately concentrated landscape, where the CR3 stands at 52.0 percent and the CR5 at 61.0 percent. This suggests that while there are dominant players, there is still ample room for specialized competitors to thrive.
Key Industry Players
Several companies define the current competitive arena. Tuftco Corporation, headquartered in Chattanooga, Tennessee, remains a cornerstone of the industry. Their focus on integrated tufting machines with full production lines from yarn to finished carpet allows them to serve carpet mills worldwide with a comprehensive solution. This vertical integration offers clients reduced complexity but may come with higher capital entry barriers.
Similarly, Card-Monroe Corp. (CMC), also based in Chattanooga, competes heavily in the high-speed segment. Their machinery supports broadloom carpet, patterned carpet tiles, and synthetic turf, with a presence spanning 38 countries. Their ability to operate across diverse geographies makes them a benchmark for global service capabilities.
In Europe, Vandewiele NV represents the high-tech end of the spectrum. Their tufting division utilizes advanced patterning technology such as ICN, Myriad, and Colortec. This positions them strongly in markets where design complexity and customization are premium drivers, such as high-end carpets and turf.
On the other end of the spectrum, companies like Tuft Love in the USA focus on durability and performance for residential use, catering to a different customer base than the industrial mills served by Tuftco or CMC. Meanwhile, the Asian manufacturing sector is represented by players like TMT Machinery and Haochuan Group. TMT Machinery emphasizes high-speed machines with enhanced automation and energy efficiency, a critical factor in regions with rising energy costs. Haochuan Group offers a range from automatic CNC rug machines to tufting guns, bridging the gap between industrial production and custom artisanal work.
Technology and Innovation Trends
Innovation is the primary differentiator in this market. Recent developments highlight the pace of change. For example, Card-Monroe Corp. and Vandewiele Group both showcased their latest technologies at the ICFE 2026 exhibition in Istanbul, Turkey. These trade shows are critical barometers for industry direction. In late 2025, TMT Machinery launched its new TMT-8600 high-speed carpet tufting machine at the INDEX Saudi Arabia textile exhibition, signaling a push toward high-efficiency hardware in the Middle East region.
Furthermore, product launches such as the AK-V tufting gun by Tufting Europe in 2024 demonstrate continuous refinement in tooling precision and noise reduction. These incremental improvements accumulate to create significant productivity gains over the lifecycle of the machinery. Our report analyzes how these technological shifts impact total cost of ownership and output quality. We assess which technologies are becoming commoditized and which remain proprietary advantages. Understanding the adoption curve of technologies like CNC automation and energy-efficient motors is crucial for long-term asset planning.
Industry Dynamics and External Pressures
Macroeconomic and regulatory factors exert significant pressure on the tufting machine market. Strategic planners must account for variables beyond simple demand and supply.
Raw Material Volatility
The cost of inputs is a perpetual concern. Recent industry data indicates that polypropylene prices increased by 34 percent year-to-date through April 2026, driven by rising crude oil and naphtha costs. Since tufted carpets and textiles are heavily reliant on synthetic fibers, this cost pressure trickles down to machine utilization rates. If material costs rise too high, production volumes may contract, affecting the frequency of machine replacement or upgrade cycles. Our analysis models various commodity price scenarios to help clients stress-test their investment plans against raw material volatility.
Regulatory and Classification Standards
Compliance is another layer of complexity. The HS code 8447.90 for tufting machines is in effect worldwide, but regulatory landscapes are shifting. Expected US HTS mandates and EU Combined Nomenclature refinements in 2025 require manufacturers and importers to stay vigilant regarding classification and tariff structures. Misclassification can lead to significant cost penalties or supply chain delays. Our report includes a regulatory watchlist that tracks these changes, ensuring that clients remain compliant as they expand across borders.
Labor and Automation
Labor costs continue to drive the adoption of automation. There is a macro trend showing increasing demand for residential and commercial carpets driving nearly 40 percent growth in tufting machine adoption. This demand surge often coincides with tightness in skilled labor markets. Consequently, the value proposition of fully automatic and CNC-controlled machines increases. Tuftco, for instance, supplied over 4,500 high-speed tufting machines in 2023, contributing to the production of 6.7 million square meters of tufted carpets. This scale of output highlights the efficiency gains possible with modern machinery compared to manual or semi-automatic processes. Our report quantifies the labor savings and productivity improvements associated with different machine tiers, assisting HR and operations directors in building business cases for automation.
The Strategic Value of Comprehensive Intelligence
In a market defined by complex segmentation, volatile input costs, and rapid technological iteration, intuition is insufficient. Decisions regarding capital expenditure, market entry, or vendor selection require robust data. PW Consulting's Tufting Machine Market report is designed to fill the information gap between general industry knowledge and actionable intelligence.
The report provides a structured framework for analysis. It begins with the executive summary, offering a high-level view of the market health and key takeaways. It then dives into the methodology, ensuring transparency in how data was collected and modeled. The detailed market overview section dissects the historical and forecast data, providing the specific revenue units and growth rates needed for financial modeling. The segmentation analysis offers the breakdowns discussed earlier, allowing users to isolate specific niches rather than viewing the market as a whole.
Furthermore, the competitive landscape section does more than list companies; it analyzes their strategic positioning, recent developments, and potential vulnerabilities. This is crucial for mergers and acquisitions activity or for identifying potential partners. The industry dynamics section contextualizes the data within the broader economic and regulatory environment, ensuring that predictions are grounded in reality rather than optimism.
Why This Report Matters for 2026 Decision-Making
As we move through 2026, the window for strategic positioning is narrowing. Companies that wait for the market to fully mature may find themselves priced out of key segments or lagging in technology adoption. Conversely, those who invest without clear data risk overcapacity in shrinking segments.
Our report allows you to:
- Validate Capacity Expansion: Use precise forecast data to justify new machinery purchases to stakeholders.
- Identify High-Growth Niches: Pinpoint specific machine types or applications that offer the best return on investment.
- Assess Competitive Threats: Understand the capabilities of key rivals like Tuftco, CMC, and Vandewiele to anticipate market shifts.
- Mitigate Risk: Account for raw material price swings and regulatory changes in your long-term planning.
- Optimize Supply Chains: Leverage regional insights to determine the best locations for manufacturing or distribution.
The difference between a good strategy and a great one often lies in the quality of the underlying data. While this article provides a snapshot of the market's direction, the full report contains the depth required to execute strategy. It transforms abstract trends into concrete metrics.
Conclusion
The tufting machine market is poised for continued growth, underpinned by steady demand in core applications and emerging opportunities in specialized sectors. However, navigating this growth requires more than a surface-level understanding. It demands a deep dive into segmentation data, competitive moves, and macroeconomic drivers. The interplay between rising raw material costs, regulatory adjustments, and technological advancements creates a complex environment where information is a primary asset.
PW Consulting remains committed to providing the clarity needed to thrive in this environment. Our Tufting Machine Market research is the tool designed to empower your leadership team with the confidence to make bold, data-backed decisions. We invite you to explore the full findings of this study to unlock the detailed intelligence necessary for securing your position in the evolving textile manufacturing landscape. The future of tufting is not just about making carpets; it is about engineering efficiency and precision in a demanding global market. Ensure your strategy is built on the most comprehensive foundation available.
For detailed analysis of this topic, please visit the official page: Tufting Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: AMOLED Revenue Hits $25B in 2025, Forecast to Surge to $47.75B by 2032 at 9.75% CAGR
By PW Consulting, 2026-09-07
The AMOLED Market in 2026: Strategic Imperatives and the Road to 2032
The global display industry is entering a decisive inflection point. As mobile devices, wearables, automotive cabins, and consumer electronics converge toward richer visual experiences, AMOLED technology has evolved from a premium differentiator into a structural requirement for product competitiveness. For executives navigating capital allocation, supply chain resilience, and product roadmaps, the ability to separate durable growth from cyclical noise is now a strategic necessity.
Worldwide Automotive Electric Heating Film Market
Our newly released AMOLED Market research study provides a comprehensive view of this landscape, anchoring executive decision-making in rigorous historical analysis and forward-looking modeling. Covering the historical period from 2020 to 2025 and extending through the forecast horizon of 2026 to 2032, the study quantifies how the market has scaled from approximately 12.45 billion USD in 2020 to an estimated 25.0 billion USD in 2025. Looking ahead, the market trajectory reflects a compound annual growth rate of 9.75 percent, with projected revenue reaching 27.78 billion USD in 2026 and advancing toward 47.75 billion USD by 2032. These headline figures provide the framework, but the real strategic value lies in the underlying mechanics: how technology transitions, application diversification, regional supply footprints, and competitive concentration shape opportunity and risk.
Non-Slip Fitness Mat Market
This article offers a preview of the study's strategic logic. It demonstrates the analytical depth that executives can rely on, while deliberately withholding the granular segmentation data that forms the backbone of actionable planning. The full report remains the essential instrument for teams that need to convert market intelligence into investment decisions, sourcing strategies, and product positioning.
Worldwide Industrial Flow Sensor Market
Why 2026 Is a Strategic Reckoning Year for AMOLED
The 2026 landscape is shaped by simultaneous advances on multiple fronts: panel generation upgrades, foldable form factor maturation, automotive display expansion, and an increasingly complex materials and intellectual property environment. Against this backdrop, high-level market sizing is necessary but insufficient. Decision-makers need to understand how revenue flows across technology variants, which applications absorb volume and value at different stages of adoption, and where geographic concentration creates pricing leverage or exposure.
The study's base year of 2025 and forecast window through 2032 were selected precisely because they capture the period in which AMOLED transitions from smartphone-led dominance toward broader application absorption. Over the historical 2020 to 2025 cycle, the market demonstrated a pattern of accelerating adoption punctuated by supply constraints and premiumization effects. The forecast period continues that momentum, though with a critical nuance: growth will not be uniform across segments or geographies. Some application categories will expand rapidly as attachment rates rise, while others will remain niche but strategically important as platform differentiators.
Because the full segmentation breakdown is reserved for the complete report, organizations that rely only on top-line numbers risk misreading where future margin pools and volume drivers will concentrate. The study's architecture is designed to resolve that ambiguity by mapping market size against type, application, and regional supply dynamics in a way that supports internally consistent scenario planning.
Inside the Research: What the Study Delivers
Our AMOLED Market report is built for strategy, procurement, finance, and product leadership teams that need defensible assumptions rather than generic market narratives. The study combines historical reconstruction with forward modeling, and it organizes the market in a way that mirrors the actual operating logic of the display supply chain.
Scope and Structural Design
The report aligns its analytical framework with the core dimensions that determine competitive exposure and commercial opportunity:
- Historical reconstruction from 2020 through 2025, establishing the actual growth path behind the headline market size
- Forecast modeling from 2026 through 2032, anchored on the 9.75 percent CAGR and a revenue trajectory measured in billions of USD
- Segmentation by technology type, enabling readers to understand how rigid, flexible, foldable, and transparent AMOLED panels contribute differently to overall market value
- Segmentation by application, distinguishing the roles of smartphones, wearables, televisions, automotive, and emerging use cases in shaping demand
- Regional breakdown across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa
- Market concentration analysis, revealing how consolidated the competitive field is and where pricing power may reside
Rather than presenting isolated figures, the study integrates these dimensions so that leadership teams can examine consistency across layers. For example, the relationship between premium device adoption and flexible or foldable panel demand is analyzed in context, not as an abstract trend. The same applies to automotive display integration, where design cycles, qualification requirements, and regional vehicle production patterns influence the pace of AMOLED uptake.
Actionable Outputs for Decision-Making
The report translates market modeling into tools that support concrete decisions. Readers can use the analysis to:
- Benchmark internal forecasts against externally validated market trajectories and identify where assumptions diverge
- Assess segment-level attractiveness without relying on fragmentary industry anecdotes
- Evaluate supply-side concentration and the implications for sourcing, negotiation leverage, and continuity risk
- Frame product roadmap choices around the technologies and applications most likely to drive value over the decade
- Prepare for input cost volatility and structural materials constraints that influence panel economics
Importantly, the study does not treat regional or application splits as static snapshots. It contextualizes them within the broader competitive and technology environment so that executives can understand not just where the market is, but how it is likely to move.
Competitive Landscape: Concentration, Capability, and Recent Shifts
One of the most strategically significant features of the AMOLED market is the degree of concentration among leading manufacturers. The study examines market concentration through the lens of controlled share among the top players, with the top three accounting for approximately 55.0 percent of market revenue and the top five reaching roughly 72.0 percent. This level of concentration has direct implications for pricing dynamics, qualification pathways, and the degree of dependence that downstream brands and OEMs may face.
The competitive environment is anchored by a set of companies with distinct technological positioning and geographic advantages. Samsung Display, headquartered in Yongin, South Korea, remains the world's largest AMOLED producer by volume and revenue. Its portfolio spans flexible, rigid, QD-OLED, and foldable AMOLED panels for smartphones, wearables, laptops, and automotive applications, making it a central reference point for the entire industry. LG Display, based in Seoul, South Korea, is a major AMOLED panel supplier with particular strength in WOLED and tandem OLED panels for smartphones, TVs, and automotive displays. In China, BOE Technology Group in Beijing has emerged as a key AMOLED manufacturer producing flexible, foldable, and rigid AMOLED panels for smartphones, wearables, and automotive applications. AUO Corporation, located in Hsinchu, Taiwan, is an active producer of AMOLED and OLED panels for consumer electronics and automotive displays, while Visionox, headquartered in Shenzhen, China, supplies AMOLED displays including foldable and high-resolution panels for smartphones and wearables.
These companies are not merely participants in a static market; they are actively reshaping it through capacity expansion, product launches, and technology licensing relationships. The report evaluates the strategic significance of recent developments rather than simply listing them. For instance, Samsung Display's start of AMOLED display sample production at its 8.6-Gen IT production line in Asan in January 2026 represents a meaningful shift in production scale and application targeting, with mass production verified and samples shipped to customers including Apple for 2026 MacBook Pro laptops. That development matters because it signals the extension of AMOLED into larger IT devices, a category where display economics, thermal management, and substrate requirements differ materially from smartphones.
Similarly, Samsung Display's March 2026 launch of its latest foldable AMOLED panel series, featuring enhanced durability and ultra-thin form factors targeting premium smartphones and automotive dashboards, illustrates how foldable technology is moving beyond early adopters into higher-reliability use cases. At the same event ecosystem level, BOE showcased a new foldable flexible OLED display at AWE 2026 with structural refinement and material innovation for seamless form factors, reinforcing the competitive intensity around foldable implementations and the increasing importance of material and structural engineering.
These developments are not isolated product news; they are indicators of where value and differentiation are being created. The study contextualizes them within broader competitive dynamics, including the licensing environment. For example, Samsung Display has been granted non-exclusive license rights under various patents owned or controlled by Samsung Electronics to BOE for manufacturing and selling OLED displays. This kind of arrangement affects not only direct competition but also the overall pace at which new entrants can scale differentiated products without being constrained by proprietary barriers.
Segment Dynamics, Materials, and the Cost of Premium Performance
Technology segmentation is central to understanding both the upside and the limits of AMOLED growth. The report separates the market into rigid AMOLED, flexible AMOLED, foldable AMOLED, and transparent AMOLED, because each category carries different manufacturing complexity, cost profiles, and end-market fit. Rigid panels may offer scale and maturity in certain applications, while flexible and foldable approaches unlock design freedoms that are strategically attractive but technically demanding. Transparent AMOLED adds another layer of differentiation with specialized use cases, though typically at a smaller scale relative to mainstream display categories.
The materials layer is equally important. Premium AMOLED performance depends on substrate quality and process precision, and those requirements translate directly into cost. OLED glass substrates command a 30 to 60 percent price premium over LCD equivalents due to tighter surface roughness specifications below 0.5 nm Ra. This premium is not a minor input detail; it shapes panel economics, influences the relative attractiveness of different device categories, and affects the pace at which cost-sensitive applications can adopt AMOLED at volume.
On the materials front, Corning Incorporated introduced a next-generation ultra-thin glass substrate for foldable smartphones in 2024, an advance that highlights the ongoing push to reconcile durability with thinness and weight. Such substrate innovations matter because foldable adoption is not simply a question of consumer preference; it is also a function of reliability, hinge engineering, and the supply base's ability to produce consistent panels at scale. The study incorporates these kinds of material-level shifts into its interpretation of segment growth rather than treating them as peripheral technical news.
Because segment-level detail is one of the areas where organizations most often need precision, the full report provides the specific breakdowns that allow teams to evaluate where rigid, flexible, foldable, and transparent AMOLED are likely to generate the most value. That level of detail is essential for anyone making architecture choices, sourcing commitments, or portfolio prioritization decisions.
Regional Supply Footprints and Structural Risk Factors
Geography remains a defining feature of AMOLED market strategy. The study maps regional distribution across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, not as a set of disconnected percentages, but as a framework for understanding where demand concentration, production capability, and supply risk converge. Asia Pacific, in particular, stands out as a major axis of activity given its concentration of panel manufacturing, device assembly, and consumer electronics demand. Yet the strategic story is not simply about which region is largest; it is about how regional dynamics interact with technology transitions and competition.
Regional planning becomes more complex when supply chains are exposed to trade policy and materials control risks. US-China trade restrictions on advanced materials and potential export controls on high-purity glass precursor chemicals represent systemic supply chain risk. For companies that depend on specialized substrates, precursor chemicals, and tightly controlled process inputs, these risks affect not only cost but also continuity of supply and the feasibility of certain sourcing strategies.
The study treats these risks as strategic variables rather than background noise. It examines how regional concentration may amplify or mitigate exposure, how qualification cycles influence sourcing flexibility, and how companies can position themselves against disruptions that may not appear in a single year's forecast but can have outsized effects over a multi-year planning horizon. For that reason, the regional analysis in the report is designed to support scenario-based resilience planning, not just opportunity sizing.
How to Use the Full Study in 2026 Planning
The preview above outlines the analytical framework and the strategic logic behind the study. What it cannot do, by design, is replace the full report. The real decision-grade value lies in the segmentation detail, the consistency checks across type, application, and region, and the competitive interpretations that connect recent developments to longer-term positioning. Organizations that need to align product strategy, sourcing, capacity planning, and investment cases will find that the complete study offers the specificity required to move from directional confidence to executable assumptions.
In practice, the report is most valuable when used as a shared reference point across functions. Strategy teams can use it to test growth narratives; procurement and supply chain teams can use it to evaluate supplier concentration and materials exposure; finance can use it to calibrate revenue and cost trajectories; and product teams can use it to weigh the timing and commercial logic of technology adoption. The 9.75 percent CAGR and the headline progression from 25.0 billion USD in 2025 toward 47.75 billion USD by 2032 provide the macro frame, but the segmented structure is what turns that frame into an operational tool.
The study also helps leadership teams avoid the common mistake of treating AMOLED as a single homogeneous category. The distinctions among rigid, flexible, foldable, and transparent formats, and among smartphone-led, wearable, television, automotive, and other applications, are not cosmetic. They determine where scale is achievable, where premium pricing can be defended, and where new entrants or incumbents can build durable advantage.
Conclusion: From Market Awareness to Decision Advantage
The AMOLED market in 2026 is large, growing, and increasingly contested. The combination of strong historical momentum, a clear forward CAGR, and active technology development across major manufacturers creates a landscape rich with opportunity, but also rich with complexity. Concentration among leading producers, premium materials requirements, licensing relationships, and geopolitical supply risks all shape the practical meaning of the market's growth trajectory.
Our AMOLED Market research is designed to help executives interpret that complexity with discipline. It provides the historical grounding, the forecast structure, the segmentation logic, and the competitive context needed to make informed decisions in 2026 and beyond. The macro story is clear; the operational story is where real advantage is created. For that operational story, the full report is the essential source, offering the detailed segmentation and competitive intelligence that turn market awareness into decision advantage.
For detailed analysis of this topic, please visit the official page: AMOLED Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electric Truck Market to Hit $10.16B by 2032, 29.5% CAGR Through 2032
By PW Consulting, 2026-09-07
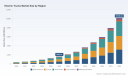
Electric Trucks Market 2026: Strategic Intelligence for Executive Decision-Making
The commercial transportation sector stands at a definitive inflection point. As regulatory mandates tighten and total cost of ownership models shift in favor of electrification, the transition from diesel to electric powertrains is no longer a question of if, but how fast. For logistics executives, fleet operators, and investors, the ability to navigate this transition with precision is the difference between capturing market share and being left behind by competitors who have already locked in supply chains, charging infrastructure, and regulatory compliance pathways.
Portable Vlogging Camera Market
PW Consulting's latest Electric Trucks Market research report provides a comprehensive, data-driven foundation for these critical decisions. Spanning a historical analysis from 2020 through 2025 and a detailed forecast period extending to 2032, this study offers the granularity required to allocate capital efficiently, mitigate supply chain risk, and position organizations ahead of the regulatory curve. The following overview outlines the strategic landscape, the macroeconomic forces at play, and the competitive dynamics that define the electric truck ecosystem in 2026 and beyond.
WBG Semiconductor Material (SiC-GaN) Market
Market Trajectory and Scale: A Decade of Accelerated Adoption
The historical data underscores a pattern of exponential growth that has fundamentally altered the baseline for commercial vehicle forecasting. From a market valuation of approximately 392.3 million USD in 2020, the sector expanded to 1,662.14 million USD by 2025. This represents a compound annual growth trajectory that reflects not merely incremental adoption but a structural reordering of the commercial vehicle market. The momentum is projected to sustain through the forecast period, with the market expected to reach 2,118.75 million USD in 2026 and continue its ascent to 10,158.53 million USD by 2032.
Optical Glass Inspection Services Market
Such growth rates, underpinned by a forecast compound annual growth rate of 29.5 percent, signal that electrification is moving from early-adopter phases into mainstream commercial deployment. For enterprise strategists, this implies that the window for establishing first-mover advantages in fleet conversion, charging network partnerships, and regional regulatory compliance is rapidly narrowing. The report's forecast model accounts for the interplay of battery cost trajectories, infrastructure rollout rates, and policy enforcement timelines, providing a realistic range of scenarios for capacity planning and investment timing.
It is critical to recognize that this expansion is not uniform across all segments or geographies. The research dissects the market into distinct operational categories, propulsion architectures, and regional demand centers, enabling decision-makers to identify where volume concentrations will emerge and where regulatory or infrastructural friction may alter adoption curves. The following sections distill the structural components of this landscape.
Segmentation Dynamics: Powertrain Architectures and Duty Cycles
The electric truck market is not a monolithic entity. It is bounded by duty cycles, payload requirements, and charging feasibility, which collectively dictate the viability of specific propulsion technologies. The report segments the market by propulsion type, capturing the distinct characteristics of battery electric, plug-in hybrid, and fuel cell electric configurations. Battery electric vehicles dominate the current revenue share, reflecting the maturity of lithium-ion supply chains and the operational suitability of battery architectures for regional haul and urban delivery cycles. Plug-in hybrid solutions represent a transitional bridge for applications where range anxiety or insufficient charging infrastructure remains a constraint, while fuel cell electric platforms are carving out niches in heavy-duty long-haul operations where rapid refueling and high vehicle utilization are paramount.
By vehicle type, the market is stratified into heavy-duty, medium-duty, and light-duty categories. Heavy-duty trucks command the largest share of revenue, driven by the high cost of diesel assets in long-haul and regional distribution networks and the substantial fuel savings achievable through electrification. Medium-duty trucks, encompassing step vans, box trucks, and municipal service vehicles, represent a high-growth segment fueled by last-mile delivery expansion and municipal zero-emission mandates. Light-duty electric trucks serve specialized commercial applications, including service fleets and proprietary delivery operations, where payload flexibility and maneuverability are prioritized over maximum range.
Battery pricing dynamics are a critical variable in the unit economics of these segments. Industry data indicates that average battery prices for electric vehicles declined by 8 percent in 2025, driven by manufacturing efficiency gains and shifts in battery chemistries. This cost compression directly improves the total cost of ownership for fleet operators and expands the addressable market for electric trucks in segments where upfront capital costs have historically been a barrier. The report quantifies how these cost curves intersect with vehicle utilization rates, charging time availability, and residual value assumptions to produce segment-specific ROI profiles.
Regional Demand Centers and Policy-Driven Deployment
Geographic demand for electric trucks is shaped by a combination of regulatory ambition, industrial density, and infrastructure readiness. North America, Europe, and Asia Pacific represent the three primary demand centers, each governed by distinct policy frameworks and market structures. In North America, the U.S. Advanced Clean Trucks Rule mandates that manufacturers sell an increasing percentage of zero-emission trucks as an increasing percentage of annual sales from model year 2025 through 2035. This regulatory signal has catalyzed fleet procurement strategies and infrastructure investments across major logistics corridors. Similarly, New Jersey's Advanced Clean Trucks Rule requires manufacturers producing vehicles over 8,500 pounds GVWR to sell increasing percentages of zero-emission trucks, reinforcing the regulatory momentum at the state level.
In Europe, the push toward decarbonization is equally pronounced, with fleet operators aligning procurement strategies to meet national and supranational emissions targets. The region's dense urban environments and well-developed charging networks in key industrial corridors provide a favorable backdrop for medium-duty and heavy-duty electric truck deployment. Asia Pacific presents a differentiated landscape, with electric truck sales more than doubling in 2025 worldwide and reaching 9 percent of all truck sales. Nearly 30 percent of the Chinese market has been captured by new Chinese manufacturers, illustrating the intensity of domestic competition and the speed at which local supply chains have scaled. The Chinese electric truck market is almost exclusively served by Chinese manufacturers using local batteries, with one provider supplying a dominant share of the total cell capacity. This concentration highlights the strategic importance of localized battery supply and the competitive insulation that domestic manufacturers enjoy in their home markets.
Latin America and the Middle East and Africa, while currently smaller in absolute revenue terms, are emerging as monitoring zones for future policy adoption and pilot deployments. The report provides detailed regional revenue trajectories that allow strategists to assess where policy tailwinds or infrastructure investments may unlock secondary demand centers within the forecast horizon.
Competitive Landscape: Incumbents, Challengers, and Technology Positioning
The electric truck market features a diverse mix of established commercial vehicle manufacturers, technology-driven entrants, and regional specialists. This competitive mosaic is defined by differing approaches to vehicle architecture, battery integration, charging ecosystem partnerships, and geographic focus. Understanding the positioning of key participants is essential for assessing supply risk, partnership opportunities, and potential market consolidation.
Volvo Trucks North America has solidified its presence in the North American market with the VNR Electric series and next-generation FH, FM, and FMX Electric trucks. In April 2026, Volvo launched the FH Aero Electric with a range of up to 700 km, alongside next-generation FH, FM, and FMX Electric models with improved flexibility and ranges up to 470 km. The following month, Volvo expanded capabilities for the VNR Electric in North America with new configurations and supporting infrastructure. With over 750 units operating in North America, Volvo has built a substantial operational footprint that provides real-world performance data and a template for enterprise fleet integration.
Daimler Truck has expanded its e-truck portfolio with the Mercedes-Benz eActros 600 long-haul electric truck and additional variants. In April 2026, Daimler showcased the eActros Lowliner variant and the eActros 600 Expedition vehicle at trade exhibitions, signaling a strategy of broadening the application envelope of its electric platforms. The eActros 600 is positioned as a solution for long-haul operations, a segment where range and payload have historically been the primary constraints on electrification.
Tesla is preparing to commence volume production of the Tesla Semi electric semi-truck in 2026. The entry of a technology company with significant vertical integration capabilities into the heavy-duty truck segment introduces a new competitive dynamic, particularly around battery efficiency, software-defined vehicle architecture, and direct-to-customer sales models. The timing of volume production aligns with a period of heightened fleet interest in long-haul electrification.
MAN Truck & Bus has brought the eTGX, eTGS, eTGM, and eTGL electric truck series to series production active since 2025, complemented by the Charge&Go charging service. This integrated approach to vehicle and charging infrastructure reflects a growing industry trend where manufacturers are expanding their value proposition beyond the vehicle itself to include energy management solutions.
Harbinger Motors has focused on medium-duty electric and hybrid-electric trucks and vans, leveraging in-house motor and battery manufacturing. In October 2025, Harbinger launched medium-duty electric vehicle sales in Canada through a dealer network with upfitter partnerships, extending its market reach beyond the United States. This expansion underscores the growing cross-border demand for medium-duty electrification and the importance of dealer and upfitter relationships in scaling deployment.
Workhorse Group produces the W56 electric step vans and commercial delivery trucks, with 100-unit orders and promotional pricing active in 2026. This focused approach to the step van and delivery segment targets a specific operational niche where predictable routes and centralized charging can maximize the economic benefits of electrification.
BYD Company Ltd. continues to leverage its integrated Chinese battery supply chain to produce electric heavy-duty trucks and commercial vehicles at scale. The company's ability to vertically integrate battery production with vehicle manufacturing provides a cost and supply chain advantage in markets where local battery sourcing is a strategic priority. Tata Motors produces electric commercial and heavy-duty trucks in India and global markets, positioning itself to capitalize on the growing electrification demand in emerging economies where total cost of ownership sensitivity is high and policy incentives are evolving.
Scania AB maintains an active e-truck lineup with regional projects that demonstrate the practical deployment of electric heavy-duty vehicles in structured fleet operations. Rivian produces electric commercial and work vehicles including electric trucks, extending its technology platform from consumer vehicles into the commercial segment. Slate Auto is targeting deliveries of affordable electric pickup trucks for late 2026, expanding the definition of commercial electrification into the light-duty pickup segment where fleet adoption for service and construction applications is growing.
The market concentration reflects a moderately fragmented competitive environment. The top three participants account for 38.0 percent of market revenue, while the top five hold 42.0 percent. This concentration level suggests that while scale advantages exist, there is significant room for specialized entrants and regional players to capture value in specific duty cycles or geographies. The report's competitive analysis includes detailed company profiles, product positioning, and strategic assessments that enable readers to evaluate supply chain resilience and partnership potential.
Fleet Deployment Milestones and Infrastructure Realities
The transition from pilot programs to scaled fleet deployment is a defining characteristic of the 2026 market landscape. In January 2026, GMA Trucking Procurement enabled the largest known Class 8 battery-electric truck deployment in Texas with 40 trucks by Nevoya for the Houston-Dallas corridor. This deployment represents a significant operational validation of battery-electric heavy-duty trucks in a major logistics corridor, providing real-world data on range performance, charging logistics, and maintenance requirements under commercial service conditions.
Such deployments are critical for the broader market because they generate the operational evidence that fleet managers, regulators, and financiers require to accelerate adoption. The report examines the infrastructure requirements associated with these deployments, including depot charging capacity, grid connection feasibility, and the role of public and semi-public charging networks in supporting regional haul operations. The interplay between vehicle range, charging time, and route structure is analyzed to provide practical guidance on fleet sizing, charging station placement, and energy procurement strategies.
The decline in battery prices by 8 percent in 2025 is a supportive factor for these deployments, but infrastructure constraints, permitting timelines, and utility interconnection processes remain operational risks that must be managed proactively. The research provides a framework for assessing these risks and developing mitigation strategies that align fleet rollout schedules with infrastructure readiness.
Regulatory Tailwinds and Market Signal Interpretation
Regulatory mandates are a primary driver of electric truck adoption, but their impact varies by jurisdiction and vehicle class. The U.S. Advanced Clean Trucks Rule and state-level implementations such as New Jersey's Advanced Clean Trucks Rule create a structured demand signal that manufacturers must respond to through product portfolio adjustments and production planning. For fleet operators, these mandates translate into procurement requirements that influence vehicle replacement cycles and fleet composition planning.
The International Energy Agency Global EV Outlook 2026 reports that electric truck sales more than doubled in 2025 worldwide, reaching 9 percent of all truck sales, with nearly 30 percent of the Chinese market captured by new Chinese manufacturers. This global acceleration provides context for the regional dynamics discussed in the report and highlights the divergent competitive structures that are emerging across markets. In regions where domestic manufacturers have strong battery supply chain integration, competitive intensity is higher and pricing pressure is more pronounced. In markets where international manufacturers are gaining traction, differentiation through vehicle performance, service networks, and financing solutions becomes a critical success factor.
For strategic planners, the key insight is that regulatory targets are not static. They represent ratcheting requirements that will continue to tighten through the forecast period. The report models the interaction between regulatory compliance timelines and fleet turnover rates, enabling organizations to anticipate the timing of mandate-driven procurement needs and to structure leasing, purchasing, and infrastructure investments accordingly.
Operational Insights and Decision Frameworks Within the Report
The full research report delivers a depth of operational intelligence that goes beyond headline market figures. It provides detailed segmentation analysis across regions, vehicle types, and propulsion technologies, allowing users to construct scenario-based demand forecasts that reflect their specific operational context. The report includes company profiles for the leading participants in the market, covering their product offerings, geographic presence, and strategic positioning. These profiles are designed to support supplier evaluation, partnership due diligence, and competitive benchmarking.
Recent developments are tracked and contextualized, including product launches, market expansions, and fleet deployments. These events are integrated into the broader market narrative to illustrate how individual company actions contribute to market evolution and to identify emerging best practices in vehicle specification, charging infrastructure planning, and fleet integration. The research also examines the supply chain dynamics that underpin vehicle production, including battery cell sourcing, motor manufacturing, and component localization trends.
For finance and investment teams, the report provides the revenue trajectory data and segment-level context needed to assess market opportunity sizing, capital allocation priorities, and the risk-return profile of electric truck exposure across different value chain positions. The forecast period through 2032 allows for multi-year planning horizons that align with fleet replacement cycles and infrastructure investment payback periods.
Strategic Imperatives for 2026 and Beyond
As the electric truck market enters a phase of accelerated scaling, the strategic implications for enterprises are clear. First, the timing of fleet electrification decisions must account for the ratcheting nature of regulatory mandates and the lead times required for vehicle procurement, charging infrastructure installation, and driver and maintenance training. Early planning reduces the risk of being forced into rushed procurement decisions at unfavorable pricing or with limited vehicle availability.
Second, the competitive landscape is evolving rapidly, with established manufacturers expanding their electric portfolios, technology entrants moving toward volume production, and regional specialists capturing niche opportunities. Understanding the strengths, limitations, and strategic intentions of each participant is essential for making informed supplier selection and partnership decisions. The report's competitive profiles and recent development tracking provide the basis for this analysis.
Third, the total cost of ownership calculus for electric trucks is improving, driven by battery cost declines and the increasing cost of diesel and compliance with emissions regulations. However, the economics remain segment-specific and route-dependent. The report's segmentation analysis and operational insights enable organizations to identify the applications where electrification delivers the strongest financial and strategic returns, and to prioritize those applications in their fleet transition plans.
Fourth, infrastructure readiness is a critical enabler of scaled deployment. The report's examination of charging requirements, grid considerations, and real-world deployment examples such as the Houston-Dallas corridor provides practical guidance for aligning vehicle rollout with infrastructure development. This alignment is essential for avoiding operational disruptions and maximizing the utilization of electric assets.
Fifth, the global nature of the market means that strategies must account for regional differences in competitive intensity, regulatory frameworks, and supply chain structures. The report's regional analysis supports the development of market-specific strategies that reflect local conditions while maintaining alignment with global corporate objectives.
Accessing the Full Strategic Intelligence
The electric truck market in 2026 presents a complex environment defined by rapid growth, evolving competition, regulatory acceleration, and shifting technology economics. Navigating this environment requires more than headline market figures. It requires a detailed, structured understanding of segment dynamics, regional demand patterns, competitive positioning, and the operational realities of fleet deployment.
PW Consulting's Electric Trucks Market research report provides this comprehensive intelligence. The full report contains the detailed segmentation data, company profiles, recent development tracking, and scenario-based forecasts that enterprise decision-makers need to allocate resources, manage risk, and capture opportunity in the electric truck transition. The macro-level trajectory, competitive landscape, and market dynamics summarized here are intended to demonstrate the scope and rigor of the research, while the complete dataset and analytical frameworks remain available through the full report.
To access the complete market size breakdowns, regional revenue trajectories, segment-level growth rates, company profiles, and forecast models, we invite you to explore the full report on the PW Consulting website. The detailed intelligence contained within is designed to support strategic planning, investment decisions, and operational execution across the 2026 to 2032 forecast horizon.
The transition to electric commercial vehicles is reshaping the logistics and transportation industry. Organizations that invest in rigorous market intelligence today will be better positioned to make informed decisions, build resilient supply chains, and capitalize on the growth opportunities that this transformation creates. PW Consulting's Electric Trucks Market report is built to provide that foundation, combining historical analysis, forward-looking forecasts, and competitive intelligence into a single, actionable resource for executive decision-making.
For detailed analysis of this topic, please visit the official page: Electric Trucks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pediatric Hearing Aids Market to Reach $3.39M by 2032 at 6.3% CAGR
By PW Consulting, 2026-09-07
Navigating the Next Wave: Strategic Intelligence for the Global Pediatrics Hearing Aids Market (2026-2032)
The pediatric hearing aids sector is undergoing a profound transformation, driven by converging forces of technological innovation, evolving reimbursement frameworks, and an expanding recognition of early auditory intervention as a cornerstone of child development. For corporate strategists, investors, and healthcare market leaders, understanding the trajectory of this specialized market is no longer optional it is a strategic imperative. PW Consulting is pleased to introduce our latest comprehensive research study, meticulously crafted to equip decision-makers with the precision intelligence required to navigate the 2026-2032 forecast horizon.
Highly Transparent Synthetic Hydrotalcite Market
Built upon a rigorous analytical foundation spanning 2020 through 2025 historical data, this report maps a highly structured forecast period that extends through 2032. At the macro level, the global pediatric hearing aids market has demonstrated consistent, measurable expansion. Revenue growth has accelerated steadily over the past half-decade, with the market surpassing the two-billion-dollar threshold in 2025 and continuing its upward trajectory into 2026. The compounded annual growth rate projected across the forecast window stands at 6.3 percent, reflecting both underlying demographic realities and the accelerating commercialization of child-specific auditory technologies. By the close of the forecast period, the market is positioned to reach a substantially elevated revenue baseline, underscoring the long-term structural demand that stakeholders must prepare for.
Worldwide Nursing Underwear Market
This executive overview is designed as a strategic preview. It highlights the analytical architecture, competitive intelligence, and market dynamics that will be unpacked in full within the complete study. Readers will gain a clear understanding of how the research connects macro-level momentum to actionable corporate strategy, while preserving the granular segmentation, regional breakdowns, and pricing matrices that form the core value proposition of the full report.
Eco-friendly Camping Tableware Market
The Strategic Imperative for 2026 Decision-Making
Market entrants, incumbents, and allied healthcare stakeholders face a uniquely complex landscape in 2026. Unlike mature adult hearing aid segments, the pediatric market operates at the intersection of clinical necessity, parental decision-making, pediatric audiologist preferences, school-based screening programs, and highly regulated reimbursement pathways. These intersecting variables create both formidable barriers to entry and highly defensible positioning opportunities for organizations equipped with precise market intelligence.
The strategic value of this research lies in its ability to translate broad growth trajectories into decision-ready frameworks. For product developers, the report decodes where innovation investment yields the strongest clinical adoption and where engineering complexity must be balanced against pediatric usability and durability requirements. For commercial and sales leadership, the analysis illuminates the procurement behaviors of audiologists, hospital networks, and early intervention programs, mapping the influence pathways that ultimately drive prescription and fitting volumes. For policy and market access teams, the study contextualizes how recent coding updates, state-level coverage adjustments, and regulatory clearances are reshaping the commercial environment for pediatric auditory devices.
A critical insight emerging from the 2026 environment is the growing premium on child-specific differentiation. Generic adaptations of adult hearing aid architectures increasingly fail to meet the functional, aesthetic, and acoustic demands of younger patients. Stakeholders that recognize this shift and align their development roadmaps, clinical training investments, and reimbursement positioning accordingly will be better positioned to capture share in a market where trust, clinical efficacy, and ease of use are decisive purchase drivers.
Furthermore, the forecast period coincides with heightened scrutiny around access, early detection, and equitable intervention. Organizations that anticipate these macro trends and embed them into their commercial planning will gain a structural advantage. This report is engineered to support that anticipation, providing a disciplined, evidence-based foundation for scenario planning, resource allocation, and competitive positioning.
Decoding the Market Architecture: Structure, Momentum, and Concentration
The pediatric hearing aids market exhibits a distinctive structural profile that differentiates it from broader adult and general audiology segments. Understanding this architecture is essential for any organization evaluating product sequencing, channel strategy, or clinical partnership development. The market is shaped by technology formats that balance acoustic performance, physical fit, and pediatric suitability, by clinical typologies of hearing loss that dictate intervention pathways, and by geographic realities that influence screening infrastructure, reimbursement maturity, and adoption velocity.
Historical revenue performance across the 2020-2025 window reflects a market that has consistently expanded, albeit with variations in pace tied to broader healthcare access dynamics and technology adoption cycles. The upward trajectory has brought the market firmly into a multi-billion-dollar revenue tier, with 2025 establishing a clear inflection point as more refined pediatric product lines and stronger clinical awareness converged. The forecast sequence that follows carries this momentum forward, projecting continued expansion through 2032 at a sustained compounded annual rate of 6.3 percent. This rate is neither speculative nor aggressive it is grounded in observed adoption patterns, product pipeline maturity, and the structural importance of early auditory intervention in pediatric care pathways.
From a concentration standpoint, the market remains moderately consolidated. The three largest players collectively account for approximately 42 percent of revenue, while the top five extend that share to roughly 48 percent. This level of concentration signals a competitive environment where scale, brand trust, and clinical engagement matter significantly, yet where meaningful share remains accessible to specialized entrants and regionally focused players who can deliver differentiated value. The implication for corporate strategy is clear: competitive advantage will not be derived from scale alone, but from the precision with which organizations align product offerings, clinical education, and reimbursement navigation to the specific needs of pediatric care delivery.
The segmentation architecture explored in the full report provides the granular lens required for targeted strategy. Product design variations reflect differing priorities in acoustic performance, retention, aesthetics, and pediatric adaptability, each appealing to distinct clinical and parental preferences. Hearing loss typologies further differentiate clinical demand, influencing the type of intervention most appropriate for a given patient profile and shaping the product mix that audiologists and implant specialists recommend. Geographic distribution adds another layer of strategic relevance, as regional differences in screening initiatives, healthcare financing, and provider density influence both volume potential and route-to-market design. In the complete study, these dimensions are fully mapped, enabling stakeholders to evaluate where to concentrate investment, where to adapt positioning, and where to expect competitive friction.
Competitive Landscape: Navigating an Innovator-Driven Arena
The competitive field in pediatric hearing aids is characterized by a blend of established audiology leaders, specialized technology developers, and implantable solution providers, each pursuing pediatric relevance through distinct strategic lenses. Rather than competing solely on price or general hearing performance, leading organizations are investing heavily in child-specific engineering, clinical engagement, and reimbursement-aligned service models. This has produced a landscape where differentiation is increasingly defined by the depth of pediatric understanding embedded in product design and commercial execution.
Several major players have built dedicated pediatric portfolios that reflect a deliberate commitment to this segment. Sonova Holding AG has advanced a focused pediatric offering with models engineered for children experiencing mild-to-profound hearing loss, signaling a clear strategy of pediatric specialization within a broader portfolio. William Demant Holding A/S, operating through its Oticon brand, has moved toward AI-enhanced sound processing and user-intent sensing tailored to younger users, aligning premium technology development with pediatric usability. Starkey Hearing Technologies has concentrated on pediatric-friendly solutions and program structures designed to meet the needs of children across varied age groups, emphasizing accessibility and tailored support. GN Store Nord A/S supplies pediatric instruments and infant-appropriate models, reinforcing the importance of early-life intervention within its commercial architecture. WS Audiology has extended its Signia platform into pediatric use with child-oriented series, while Widex A/S has developed offerings spanning babies, infants, and older children, reflecting a comprehensive age-range approach.
Beyond conventional hearing aid manufacturers, the competitive field also includes implantable and bone conduction specialists whose pediatric applications expand the intervention continuum. MED-EL develops both implantable and non-implantable hearing solutions with pediatric applications, while Cochlear Limited manufactures implantable cochlear systems designed specifically for pediatric patients. Oticon Medical AB contributes pediatric bone conduction and implant solutions, illustrating how regulatory clearances and implant-based technologies are extending the competitive perimeter beyond traditional air conduction devices. ReSound, operating under the GN Store Nord umbrella, further reinforces the pediatric hearing aid style landscape with models designed for children across age ranges.
What unites these competitors is a recognition that pediatric adoption depends on more than technical specification. Clinical education, fitting workflows, parental confidence, durability in active use environments, and integration with early intervention programs all influence prescription behavior. The full report analyzes these behavioral drivers in detail, examining how each major player positions itself within the pediatric ecosystem, where their product development focus lies, and how their commercial activities shape the competitive dynamic. This competitive mapping is critical for stakeholders evaluating partnership opportunities, competitive response strategies, or market entry pathways.
Recent product activity further underscores the pace of innovation. In April 2026, Oticon Inc. introduced a pediatric hearing aid family featuring second-generation AI-powered sound processing and 4D user-intent sensors, positioning the launch as a differentiated advance in pediatric auditory technology. Developments of this kind signal a broader industry direction: the convergence of intelligent sound processing, contextual sensing, and child-appropriate design is becoming an increasingly important battleground for competitive differentiation.
Market Dynamics and the Evolving Operating Environment
Strategic planning in the pediatric hearing aids market cannot be separated from the regulatory, reimbursement, and operational dynamics that shape commercial viability. In 2026, stakeholders are operating within an environment where policy updates, coding changes, and coverage adjustments directly influence access, prescribing behavior, and the economic calculus of pediatric intervention.
One significant regulatory development is the release of updated procedural coding frameworks that include new hearing device services codes effective from early 2026. These changes affect how pediatric hearing aid fittings, follow-up services, and related clinical activities are documented and billed, with downstream implications for provider workflows, reimbursement predictability, and the commercial economics of pediatric audiology practices. For manufacturers and market access teams, such coding shifts create both implementation requirements and opportunities to align service models with emerging billing realities.
Reimbursement landscapes are also evolving at the state and program level. In California, for example, the Department of Health Care Services updated its 2026 action plan related to hearing aid coverage for children, reflecting ongoing efforts to refine access pathways and coverage structures for pediatric patients. Adjustments of this nature matter because pediatric hearing aid adoption is highly sensitive to out-of-pocket exposure, public program coverage, and the clarity of reimbursement processes for families and providers. Organizations that monitor and anticipate these changes can better align pricing strategies, clinical support resources, and patient assistance frameworks.
Regulatory clearances for pediatric-relevant technologies continue to expand the intervention toolkit. The FDA clearance of a pediatric-relevant bone conduction hearing system through a 510(k) submission illustrates how implant-adjacent and bone conduction options are becoming more embedded in pediatric care considerations. Such clearances broaden the clinical options available for specific hearing loss profiles and can influence how specialists evaluate intervention pathways for younger patients. They also introduce new competitive dynamics for companies operating across both conventional and implantable solution categories.
On the commercial side, cost remains a central consideration for families, providers, and program administrators. Pediatric hearing aids typically carry a meaningful per-unit expense, with average costs broadly ranging from one thousand to four thousand dollars. This price reality reinforces the importance of reimbursement navigation, value-based communication, and durable product design that can withstand the wear-and-tear associated with pediatric use. For commercial leaders, it also highlights the need to articulate clinical and lifestyle value in ways that resonate with audiologists, parents, and funding bodies alike.
Taken together, these dynamics create an operating environment that rewards organizations capable of integrating regulatory awareness, reimbursement strategy, and product innovation into a coherent commercial plan. The full report provides the structured analysis required to translate these moving parts into practical strategy, including the implications for channel design, clinical engagement, and market access positioning.
What the Full Study Delivers: A Practical Intelligence Framework
This research study is built to support concrete decision-making rather than abstract market commentary. The complete report provides a structured, evidence-based framework that connects high-level market trajectory to the operational questions faced by product, commercial, clinical, and market access teams. It is designed to serve as a reference point for strategic planning, competitive assessment, and investment prioritization across the 2026-2032 horizon.
At the core of the study is a detailed market sizing and forecast architecture that traces historical performance and projects forward with methodological transparency. This foundation enables stakeholders to evaluate growth momentum, identify inflection points, and align internal planning assumptions with externally validated trajectories. Beyond headline figures, the report examines how different product types, hearing loss categories, and regional environments shape demand patterns and adoption pathways, providing the segmentation depth required for targeted strategy.
The competitive analysis component translates company profiles and recent developments into an actionable landscape view. Rather than presenting static corporate summaries, the study assesses how major players position themselves within the pediatric space, where their product emphasis lies, how they engage clinical stakeholders, and what their recent activity suggests about future strategic direction. This approach helps readers evaluate competitive vulnerability, identify white-space opportunities, and anticipate likely responses to market shifts.
In addition to structural and competitive analysis, the report incorporates the regulatory and reimbursement context that shapes commercial execution. It examines how coding changes, coverage updates, and regulatory clearances influence access dynamics and provider behavior, offering practical context for market access planning and clinical partnership development. Cost considerations are addressed within this framework, connecting pricing realities to reimbursement pathways, parental affordability, and the broader value proposition that must be communicated across the care ecosystem.
The full study also integrates forward-looking scenario considerations that help organizations stress-test their strategies against alternative market conditions. By connecting product innovation trajectories, clinical adoption factors, and policy evolution to potential demand outcomes, the report equips readers to plan with greater confidence in an environment where multiple variables evolve simultaneously. This scenario orientation is especially valuable for organizations evaluating new product introductions, geographic expansion, or partnership structures in a specialized and rapidly evolving segment.
Conclusion: Aligning Strategy with the Next Phase of Pediatric Auditory Care
The pediatric hearing aids market is entering a phase defined by stronger clinical emphasis on early intervention, accelerating technology differentiation, and an evolving reimbursement and regulatory backdrop. Growth is no longer solely a function of population dynamics or general audiology expansion it is increasingly shaped by how effectively organizations design for pediatric needs, engage clinical stakeholders, and navigate access pathways. In this environment, strategic intelligence is a decisive advantage.
PW Consulting’s full market research study offers the depth, structure, and competitive context required to make informed decisions in 2026 and beyond. It is intended for leaders who need more than directional trends they need a rigorous, decision-ready understanding of market size dynamics, segmentation behavior, competitive positioning, and the policy and reimbursement forces that shape commercial outcomes. The preview presented here highlights the strategic architecture of the study while reserving the detailed segmentation, regional breakdowns, and pricing intelligence for the complete report.
For organizations preparing product roadmaps, commercial plans, market access strategies, or investment evaluations, the full study provides the precision intelligence necessary to move from awareness to action. We invite strategic decision-makers to access the complete report and leverage its insights to strengthen positioning, refine execution, and align capabilities with the next phase of growth in the global pediatric hearing aids market.
For detailed analysis of this topic, please visit the official page: Pediatrics Hearing Aids Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


