



Category: market research
PW Consulting: Electronic Packaging Materials Market to Hit $3,729.9M by 2032, Growing at 7.8% CAGR
By PW Consulting, 2026-09-07
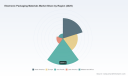
Navigating the Next Wave: Strategic Intelligence for the Electronic Packaging Materials Market (2026–2032)
As the global electronics industry enters a defining phase of architectural transformation, the materials that enable miniaturization, thermal management, and signal integrity are no longer peripheral inputs—they are strategic assets. The electronic packaging materials sector has moved beyond incremental improvement into a period of structural realignment, where material science, regulatory pressure, and assembly-node migration intersect simultaneously. Our newly published market research synthesizes five years of historical performance with a seven-year forward view, giving corporate strategists, procurement leaders, and R&D directors the evidence base needed to act decisively through 2032.
Unified Commerce Platform Market
For decision-makers operating in 2026, the question is no longer whether the packaging materials landscape will change, but how to position supply chains, product roadmaps, and partnership portfolios ahead of the curve. This analysis translates macroeconomic signals, competitive realignments, and emerging regulatory economics into actionable strategic context, while deliberately preserving granular segmentation insights for the full report. The objective is straightforward: equip leadership teams with the framing required to allocate capital, prioritize supplier relationships, and anticipate margin pressures before they become competitive disadvantages.
Worldwide Reproductive System Anatomical Model Market
Market Trajectory and the Architecture of Growth
The electronic packaging materials market has demonstrated a pronounced expansion pattern over the historical review window, with revenues rising from approximately $1,800.5 million in 2020 to $2,215.0 million in 2025. That progression was not linear, of course; short-term adjustments reflected broader electronics demand cycles, material availability constraints, and shifting semiconductor packaging priorities. Yet the underlying trajectory has converged toward a sustained upward slope, and our forecast modeling extends that momentum through 2032, with the total market projected to reach $3,729.9 million by the terminal year of the outlook period.
The implied compound annual growth rate over the 2026–2032 forecast window stands at 7.8 percent, a figure that places the sector above the broader industrial materials baseline and signals durable demand aggregation. Growth at that pace does not emerge from a single application surge or one regional engine; it reflects compounding contributions across device complexity, substrate innovations, and packaging format transitions. For enterprise planners, a 7.8 percent CAGR is a meaningful benchmark when evaluating capacity planning, long-term supplier commitments, and R&D investment horizons. It also underscores that material categories tied closely to advanced assembly and interconnection will likely outpace legacy substitution flows, creating asymmetrical opportunity zones within an otherwise unified market structure.
Worldwide MTB Helmet Market
Strategically, this trajectory matters because it reframes packaging materials from a commodity-adjacent category into a growth-supported input sector. Companies that continue to treat electronic packaging materials purely through the lens of unit cost optimization risk missing the structural value migration that accompanies format migration and node scaling. The full research report dissects how growth is distributed across material classes and end-use contexts, allowing procurement and product strategy teams to align sourcing decisions with forward demand concentration rather than backward price benchmarks.
Competitive Architecture and Strategic Positioning
Fragmented yet Focused: How Concentration Shapes Market Dynamics
One of the most operationally important findings in the 2026 outlook is the market’s concentration profile. The top three participants collectively account for roughly 18.5 percent of total sector revenue, while the top five reach approximately 25.6 percent. Those numbers tell a clear story: this is a market with recognized incumbents and specialized material specialists, but it is far from an oligopoly. Dispersion of that kind creates both opportunity and execution risk.
On the opportunity side, fragmentation means that technology differentiation, regional distribution strength, and application-specific formulation expertise can still generate meaningful premium positioning. It also means that midstream manufacturers and assembly operators have a real choice in supplier architecture—single-source dependency is not structurally forced by market economics alone. On the execution-risk side, the same dispersion requires disciplined supplier qualification, technical validation, and compliance monitoring. The firms that convert fragmentation to advantage are typically those that build portfolio relevance across multiple packaging formats while maintaining deep capability in one or two material technology families.
Incumbents at the Forefront: Profiles and Strategic Implications
Across the competitive landscape, several organizations have established themselves as reference points for capability and scale. Their activities through early 2026 provide useful signals for anyone evaluating partnership pathways or benchmarking technology roadmaps.
- 3M Company, headquartered in St. Paul, Minnesota, continues to anchor its electronics materials presence around chip packaging and interconnection solutions alongside semiconductor production materials. Its most recent 10-K filing for the fiscal year ended December 31, 2025 confirms the continued operation of its Electronics Materials Solutions segment with chip packaging and interconnection offerings, signaling that this capability set remains a defined business-line priority rather than a residual product line.
- Henkel AG & Co. KGaA, based in Düsseldorf, Germany, maintains a strong focus on epoxy-based structural adhesives, underfill materials, and packaging solutions. Its half-year financial report for 2025 described continued growth in industrial adhesives and specialty materials, including electronics packaging, which reinforces the strategic relevance of adhesive and underfill chemistry in current packaging architectures.
- Heraeus Holding GmbH, located in Hanau, Germany, provides materials and material systems for assembly and advanced semiconductor packaging. Its 2024 financial report highlighted growth within its Semiconductor & Electronics business platform, specifically in advanced packaging materials—an indicator that high-performance material systems remain an active investment and revenue focus.
- NAMICS Corporation, operating out of Japan, concentrates on advanced materials for semiconductor devices and packages. The company’s positioning reflects the broader demand pull for precision materials that support tighter tolerance assembly and higher thermal and mechanical reliability requirements.
- PacTech USA Packaging Technologies, Inc., with its operational base in Germany, focuses on wafer-level bumping and packaging technologies and services. That service-and-technology orientation matters because it bridges material supply with process integration, an increasingly important combination as packaging formats become more customized and node-specific.
Together, these profiles illustrate a market where chemical formulation, substrate interface engineering, and process-level packaging expertise all carry strategic weight. The competitive environment rewards firms that can align material supply with application-specific process needs, and it pressures laggards that rely on generic catalog selling without application engineering depth. Our report goes further into each company’s positioning, strategic moves, and likely implications for sourcing strategy and technical collaboration, but the immediate takeaway for 2026 planning is clear: supplier selection is becoming less about price lists and more about capability alignment across advanced assembly requirements.
Macro Pressure Points: Materials, Regulation, and Cost Architecture
Raw Material Signals and the Cost Environment
Cost discipline in electronic packaging materials cannot be separated from upstream material economics. Throughout early 2026, pricing indicators for polymer-based inputs have sent mixed but strategically relevant signals. According to the U.S. Bureau of Labor Statistics, the Producer Price Index for plastic materials and resin manufacturing registered 329.454 in April 2026, up from 312.442 in March 2026. That month-over-month movement points to near-term price volatility in resin-dependent supply chains. At the same time, broader annual tracking reported by IbisWorld showed the Producer Price Index for plastic materials and resin declining to 285.0 in 2026, a 9.5 percent decrease from the prior year. Taken together, these data points highlight a market where short-term monthly swings can coexist with a longer-term easing or repricing trend, depending on basis, timing, and material grade.
For procurement teams, the practical implication is not to anchor budgets on a single index printout, but to build contracting and inventory strategies that can accommodate both directionality and volatility. In a market growing at a mid-to-high single-digit CAGR, even modest raw material repricing can alter margin expectations across packaging material categories. The full report links these macro cost signals to segment-level exposure, helping leaders identify where resin-linked categories, specialty formulations, or high-performance compounds may face more pronounced cost transmission.
Regulatory Reconfiguration: Compliance as a Competitive Variable
Regulatory developments are reshaping the packaging materials economic equation in ways that go well beyond environmental compliance. The Packaging and Packaging Waste Regulation entered into force on 11 February 2025 and applies generally from 12 August 2026, introducing requirements for increased recycled plastic content in packaging. While this regulation is not exclusively about electronic packaging materials, it intersects with material sourcing strategies wherever plastic-based packaging solutions are part of the supply chain or product delivery architecture. The compliance timeline means that companies must already be operationalizing sourcing adjustments, supplier documentation, and content verification as they move through 2026.
In parallel, several U.S. states including Oregon and Maine have launched extended producer responsibility packaging programs with fees calculated by weight beginning in 2026. These state-level mechanisms expand the financial footprint of packaging decisions and increase the importance of weight efficiency, material choice, and packaging minimization in total cost modeling. For companies that consume electronic packaging materials in broader product distribution or device packaging chains, EPR fees introduce another variable into landed-cost and lifecycle cost calculations.
Strategically, regulation should not be treated as a compliance footnote. When recycled-content mandates and weight-based EPR fees begin affecting material selection and packaging geometry, they also influence supplier prioritization, qualification cycles, and long-term cost structure. The market study incorporates these dynamics into its forward assessment so that strategists can gauge where regulatory exposure may reinforce or disrupt existing sourcing preferences.
What the Research Delivers for 2026 Decision-Making
Operational Depth Behind the Outlook
A market overview can describe direction; it cannot, by itself, support procurement strategy, technology roadmapping, or competitive benchmarking. The full report is built to bridge that gap. It combines historical reconstruction, forward modeling, segment-level analysis, and company-specific profiling into a single decision-support structure. Rather than stopping at headline totals, the research maps the structural logic behind growth, identifies where material classes and application contexts diverge in growth intensity, and traces the competitive behavior of firms that are actively shaping the market’s next phase.
Practically, the report is designed for teams that need to answer questions such as:
- Where is demand concentration most likely to intensify across material types and end-use contexts through 2032?
- Which supplier capabilities are becoming more valuable as packaging formats become more application-specific?
- How should raw material volatility and regulatory cost mechanisms be incorporated into sourcing and pricing strategies?
- What company-level developments signal near-term shifts in technology emphasis or capacity orientation?
- How does market concentration shape negotiation leverage, qualification strategy, and supply continuity risk?
These are not abstract planning questions. In a market expanding from roughly $2.3 billion in 2026 to nearly $3.7 billion by 2032, the allocation of limited technical, procurement, and capital resources will determine which organizations capture value and which merely follow it. The report provides the structured intelligence needed to make those allocation calls with greater confidence.
Why 2026 Is a Strategic Inflection Point
The current year is especially consequential because multiple forces are converging at once. Demand growth remains robust enough to justify capacity and technology investment, but raw material pricing is showing both near-term volatility and longer-term directional change. Regulatory frameworks are moving from policy language to operational enforceability, and they are doing so while companies are still adjusting supply chains to advanced packaging requirements. At the same time, the competitive field remains sufficiently dispersed that differentiation is possible, but concentrated enough that technology leadership and application expertise can create durable advantages.
In that environment, the most effective strategic move is to replace assumption-based sourcing and reactive compliance with evidence-based planning. That means understanding not only the total market size and growth rate, but also where growth is concentrated, which material and application pathways are most exposed to cost and regulatory shifts, and how leading participants are aligning their portfolios with advanced packaging needs. Our research is structured to support exactly that decision sequence.
From Signal to Strategy: Accessing the Full Intelligence
The figures and developments summarized here establish the strategic backdrop; the complete report delivers the operational architecture behind them. While this preview highlights macro trajectory, concentration dynamics, competitive profiles, and regulatory-material pressure points, the full publication contains the segmentation detail, company benchmarking, and segment-level exposure analysis required to translate strategy into execution.
For teams building sourcing strategies, evaluating supplier partnerships, aligning R&D priorities, or preparing for regulatory-driven cost shifts, the difference between headline awareness and segment-specific intelligence can be substantial. The research was designed to close that gap. It provides a rigorous view of how the electronic packaging materials market is likely to evolve through 2032, which participants are shaping that evolution, and what cost and compliance variables will influence margin and sourcing outcomes along the way.
The strategic message for 2026 is clear: this market is expanding at a pace and with a structural complexity that rewards informed positioning. Organizations that incorporate forward-looking market intelligence into supplier selection, material qualification, and cost strategy will be better placed to manage volatility, meet compliance expectations, and capture growth where it is most concentrated. Those that rely on backward-looking assumptions will face a more difficult alignment problem as advanced packaging requirements and regulatory economics continue to reshape the field.
For the complete segmentation analysis, competitive benchmarking, and region- and application-level intelligence that supports precise 2026 decision-making, the full Electronic Packaging Materials Market research report is available through our official market research page.
For detailed analysis of this topic, please visit the official page: Electronic Packaging Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: EVA Resin Market Hits $112.02M in 2025, Projected 8.83% CAGR Through 2032
By PW Consulting, 2026-09-07
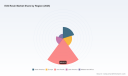
Strategic Intelligence for the EVA Resin Market: Navigating Growth, Volatility, and Competitive Shifts Through 2032
The global ethylene-vinyl acetate resin market is entering a decisive growth phase, shaped by converging forces in packaging, renewable energy, and sustainable material innovation. For executives planning 2026 budgets, capacity investments, and product roadmaps, the landscape demands more than surface-level trend tracking. It requires a disciplined, data-grounded view of where value is accumulating, which applications will drive the next wave of demand, and how supply-side dynamics will compress or expand margins in the years ahead. PW Consulting’s latest EVA Resin Market research is designed precisely for that purpose: a structured, decision-ready intelligence package that translates historical performance and forward-looking projections into actionable strategy.
Worldwide Projection Display Chip Market
This market study covers the trajectory from 2020 through 2032, with 2025 established as the base year and a full forecast window extending to 2032. The market, measured in millions of USD, moved from 87.51 in 2020 to 92.52 in 2021, then climbed to 94.29 in 2022, 99.52 in 2023, and 110.15 in 2024. The momentum continued into 2025 with a recorded size of 112.02, followed by a projected 125.56 in 2026, 132.54 in 2027, 144.11 in 2028, 159.3 in 2029, 168.6 in 2030, 182.73 in 2031, and 199.92 in 2032. This progression underpins a forecast CAGR of 8.83 percent, signaling a market that is expanding at a pace well above cyclical commodity norms and reflecting structural demand rather than one-off spikes.
Worldwide Laminated Shim Market
The strategic importance of these numbers lies not in the figures themselves, but in what they imply for portfolio planning. A market advancing from just over 112 near-term to nearly 200 by the end of the forecast period requires leaders to answer a different set of questions: where will volume concentrate, which application segments will capture disproportionate share, and how should sourcing and capacity decisions be sequenced to protect margin against raw material volatility? The research addresses these questions with a framework built for operating decisions rather than abstract market narration.
왜 이 연구가 2026 년 의사결정의 기준이 되는가
2026 년은 EVA 수지 공급망에서 단순한 연간 계획이 아니라 전환점이 될 가능성이 높습니다. 수요 구조는 포장재와 태양광 캡슐화를 중심으로 성숙하고 있으며, 발포체와 핫멜트 접착제 역시 용도별 기술 차별화가 본격화되고 있습니다. 동시에 에틸렌 기반 원재료 가격의 변동은 생산원가의 구조적 변수로 작용하고 있어, 구매 전략과 재고 설계, 장기 계약 조건을 통합한 접근이 필요합니다.
이 보고서는 각 의사결정 단계에 맞춘 인사이트 경로를 제공합니다. 먼저 시장 규모와 성장률의 시계열 흐름을 통해 현재 단계가 회복 국면인지, 구조적 확장 국면인지 판단할 수 있도록 구성했습니다. 다음으로 유형, 용도, 지역별 흐름을 종합해 어느 축에서 수요가 더 빠르게 형성되는지 확인할 수 있으며, 경쟁 강도 및 집중도 지표를 통해 신규 진출, 제휴, 또는 차별화 포지셔닝의 현실성을 점검하도록 설계했습니다. 마지막으로 최근 공급 확대와 제품 출시, 규제 환경 변화를 함께 다루어 수량적 전망만이 아니라 운영 리스크와 기회 요인을 동시에 읽을 수 있게 했습니다.
실무적으로 이 연구는 다음과 같은 질문에 답하는 데 활용됩니다.
- 2026 년 이후 성장 속도가 빨라지는 구간과 상대적으로 완만하게 움직이는 구간을 어떻게 구분할 것인가
- 포장, 태양광, 발포, 접착제 등 주요 용도 중 우선순위 투자 대상은 어디이며, 그 판단의 근거는 무엇인가
- 원재료 가격 변동과 공급 차질이 마진에 미치는 영향을 완화하기 위해 조달, 생산, 배합 전략을 어떻게 재설계할 것인가
- 지역별로 다른 규제, 관세, 인증 요건이 사업성 평가에 어떤 차이를 만들며, 어떤 시장 진입 방식이 현실적인가
- 경쟁사가 최근 발표한 설비 확장이나 신규 등급 출시가 자사 포지션에 어떤 영향을 주는가
핵심은 수치를 나열하는 것이 아니라, 수치를 전략 언어로 바꾸는 데 있습니다. 보고서가 제시하는 전망은 단순한 목표치가 아니라, 투자 타이밍, 제품 믹스 조정, 공급망 재편의 기준으로 쓰일 수 있도록 구성되어 있습니다.
보고서의 실전형 구성: 무엇을 담고 있는가
이 시장 연구는 경영진, 사업 개발, 조달, 연구개발, 영업 전략 담당자가 각각 필요로 하는 깊이를 한 문서 안에서 접근할 수 있도록 설계되었습니다. 중심에는 장기 시장 궤적과 성장 동인이 있으며, 그 주변으로 유형 체계, 용도 구조, 지역 분포, 경쟁 구도, 그리고 외부 환경 변수가 유기적으로 연결됩니다.
먼저 시장 규모 시리즈는 2020 년부터 2032 년까지의 흐름을 연속적으로 제시해 기준 연도 대비 현재 위치와 향후 확장 폭을 함께 확인할 수 있게 합니다. 이를 통해 2026 년을 기점으로 본격화되는 성장 경로 상에서 어느 구간이 가장 큰 증분 수요를 만들어내는지, 어떤 타이밍에 선제적 대응이 필요한지 해석할 수 있습니다. 성장률 지표 역시 단순 산출값이 아니라, 시장 성숙도와 수요 전환 속도를 함께 고려하는 관점에서 해석되도록 정리되어 있습니다.
유형별 분석에서는 저밀도, 중밀도, 고밀도 EVA 의 용도 적합성과 수요 형성 방식이 어떻게 다른지 다룹니다. 각 유형은 동일한 수지 범주에 속하면서도 포장재 적합성, 접착 성능, 발포 특성, 태양광 모듈 요구사양 등 각기 다른 기술적 매력과 비용 구조를 갖습니다. 보고서는 이러한 차이가 실제 수요와 가격 협상력에 어떤 영향을 주는지 이해할 수 있도록 구성되어 있으며, 특정 세부 수치보다는 유형별 전략적 의미를 읽도록 돕습니다.
용도 측면에서는 포장재 필름, 태양광 셀 캡슐화, 발포체, 핫멜트 접착제, 기타 응용으로 나누어 수요 동인과 성장 조건을 설명합니다. 포장재는 물량 기반과 유통·소비재 드라이빙이 강한 영역이고, 태양광 캡슐화는 모듈 보급과 신뢰성 요구 측면에서 구조적 수요가 형성되는 영역입니다. 발포체와 접착제는 가공 특성과 최종 용도 집단의 요구사항에 따라 차별화 기회가 존재하는 영역입니다. 보고서는 각 용도의 성장률이 단순한 시장 점유율이 아니라 제품 사양, 규제 반응, 공정 효율, 대체재 압력과 어떻게 연결되는지 보여주도록 구성되어 있습니다.
지역 분석에서는 북미, 유럽, 아시아 태평양, 라틴아메리카, 중동 및 아프리카를 아우르며 지역별 성장 배경과 수요 중심, 공급망 접근성의 차이를 비교합니다. 어느 지역이 단기 확대 기회가 큰지, 어느 지역이 규제나 현지화 요건 때문에 진입 방식이 달라지는지, 어느 지역이 생산 거점이나 조달 거점으로 기능할 수 있는지에 대한 판단을 지원하도록 정리되어 있습니다. 세부 지역별 수치보다는 상대 위치와 성장 조건, 리스크 요인의 차이를 읽는 데 초점을 둡니다.
경쟁 구도 부문에서는 참여 기업의 제품 포트폴리오와 최근 움직임을 함께 검토해 시장의 집중도와 차별화 가능성을 평가합니다. 보고서의 경쟁 분석은 단순 기업 목록이 아니라, 각사가 어떤 응용 축을 중심으로 역량을 쌓고 있는지, 최근 설비 확장이나 바이오 기반 등급 출시가 어떤 전략적 방향성과 연결되는지 해석하도록 설계되어 있습니다.
마지막으로 시장 동학 섹션에서는 원재료 가격 상관성, 공급 차질, 관세와 규제 요건, 환경 기준과 컴플라이언스 이슈가 EVA 수지의 원가와 수요에 미치는 영향을 다룹니다. 특히 에틸렌과 비닐 아세테이트 관련 흐름이 생산원가에 미치는 영향, 지역별 관세 스케줄과 협정에 따른 수입 조건 변화, VOC 및 미세플라스틱 관련 규제와 reformulation 압력이 제품 설계와 공급 전략에 어떤 제약을 주는지 설명합니다. 이는 재무 모델링과 운영 계획을 동시에 검토할 때 필요한 배경입니다.
경쟁 구도와 최근 움직임의 전략적 의미
EVA 수지 시장은 상위 기업들의 집중도가 높은 구조로 이해할 필요가 있습니다. 시장 집중도 지표는 상위 3 개사 기준 65.0 퍼센트, 상위 5 개사 기준 85.0 퍼센트로 보고되며, 이는 신규 진입이나 범용 물량 경쟁만으로는 구조적 이점을 확보하기 어렵다는 점을 시사합니다. 결과적으로 경쟁 우위는 규모 그 자체보다 용도 적합성, 공급 안정성, 기술 차별성, 그리고 지속가능성 기반 제품 전략에서 형성될 가능성이 큽니다.
주요 참여 기업들을 살펴보면, 각사는 서로 다른 응용 축과 브랜드 자산을 중심으로 시장을 공략하고 있습니다. Dow Inc. 는 ELVAX™를 비롯한 EVA 공중합체 수지를 중심으로 포장, 접착제, 전선 및 케이블, 태양광 캡슐화 응용을 다루고 있으며, 폭넓은 응용 커버리지를 기반으로 다양한 가공 요건에 대응하는 포지션을 취하고 있습니다. ExxonMobil Corporation 은 폴리올레핀 플랜트를 통해 포장, 태양광, 폴리올레핀 응용용 EVA 공중합체를 공급하고 있으며, 최근 Baytown 폴리올레핀 플랜트의 가동 확대로 포장 및 태양광용 EVA 공중합체 생산능력을 확장한 바 있습니다.
Celanese Corporation 은 Ateva® 브랜드 EVA 수지를 통해 핫멜트 접착제, 코팅, 태양광 캡슐런트 중심의 응용에 접근하고 있으며, 접착과 코팅 성능을 요구하는 용도에서 기술 기반 차별화가 가능한 구조를 갖추고 있습니다. LG Chem Ltd. 는 신발, 포장, 산업용 응용을 위한 EVA 공중합체를 생산하며, 아시아 기반의 공급 역량과 다용도 포트폴리오를 통해 지역별 수요와 연결하는 전략을 취하고 있습니다. Lotte Chemical Corporation 은 접착제, 포장, 건설용 EVA 수지를 공급해 산업 전반의 수요층을 폭넓게 포괄하는 방향을 지향합니다.
Hanwha Solutions Corporation 은 포장 및 필름 응용용 EVA 수지를 다루며 필름 가공과 포장 용도에서의 적용성을 강조합니다. Braskem S.A. 는 사탕수수 기반의 I'm green™ 바이오 EVA 수지를 통해 지속가능성 중심 제품군에서 존재감을 구축하고 있으며, 원재료 소싱과 탄소 관련 차별화 측면에서 주목을 받고 있습니다. Formosa Plastics Corporation 은 다양한 산업용으로 EVA 공중합체를 제조하며, 범용 응용에서의 공급 안정성과 폭넓은 가공 대응이 강점 영역으로 볼 수 있습니다.
여기에 최근 발표된 사업 움직임이 시장 방향을 더 선명하게 만듭니다. Borealis 는 2025 년 5 월 신발 중창용 Borenewables EVA 등급을 출시하며 지속가능성 이니셔티브를 강화했고, 2025 년 10 월에는 조류 유래 소재와 EVA 를 혼합한 Bloom Materials 라인을 도입해 친환경 소재 포트폴리오를 확장했습니다. ExxonMobil 은 2024 년 4 월 발표 이후 2025 년까지 이어지는 Baytown 폴리올레핀 플랜트의 신규 운영을 통해 포장 및 태양광용 EVA 공중합체 생산능력을 확대했습니다.
이러한 움직임은 몇 가지 공통된 전략적 신호를 줍니다. 첫째, 용량 확대는 단순한 물량 증가가 아니라 포장재와 태양광이라는 수요 강세 응용에 대한 공급 안정화 의도를 담고 있습니다. 둘째, 바이오 기반 및 혼합 소재 등급의 출시는 규제 환경과 고객 요구 변화에 선제적으로 대응하는 차별화 경로로 볼 수 있습니다. 셋째, 지역별 기업 구성이 다양하게 형성되어 있어, 아시아 기반의 공급 역량과 미주·유럽 기반의 기술·브랜드 포트폴리오가 서로 다른 경쟁 축으로 작동하고 있습니다. 보고서는 이러한 개별 움직임을 시장 전체 맥락에서 해석해, 어떤 기업의 전략이 단기 물량 확보에 가까운지, 어떤 움직임이 중장기 포지셔닝에 가까운지 구분할 수 있도록 돕습니다.
원재료, 규제, 공급 리스크가 비즈니스에 미치는 영향
EVA 수지 사업의 수익성과 운영 안정성은 결국 원재료 흐름과 규제 환경의 조합에서 결정됩니다. 산업 데이터에 따르면 글로벌 에틸렌 가격은 원유 가격과 높은 상관관계를 유지하며, 2022 년 이후의 에너지 crisis 영향이 지속되면서 EVA 공중합체 생산원가에 직접적인 변동성을 초래하고 있습니다. 에틸렌과 VAM 은 통상 생산원가의 70~80 퍼센트 수준을 차지하므로, 이 구간의 가격 움직임은 판매 가격 협상, 계약 구조, 재고 전략, 생산 스케줄링에 직접적인 영향을 줍니다.
공급 측면에서는 중국과 중동 지역의 지정학적 긴장과 플랜트 셧다운이 비닐 아세테이트 모노머 공급에 차질을 일으켜 2024~2025 년 동안 가격 변동과 계약 조정으로 이어졌습니다. 이는 단순히 원재료 가격 문제가 아니라, 계약 조건 재설계, 대체 소싱 경로 확보, 생산 계획의 유연성 확보라는 운영 과제로 연결됩니다. 특히 수요가 빠르게 확장되는 구간에서는 공급 안정성이 가격 경쟁력만큼 중요해질 수 있어, 조달 전략의 재점검이 필요합니다.
규제 환경은 지역별로 차별화되어 있으며, 같은 수지라도 적용되는 요건과 비용이 달라질 수 있습니다. 일본 관세 스케줄에서는 에틸렌-비닐 아세테이트 공중합체가 HS 390130 으로 분류되며 4.1 퍼센트의 기본 세율이 적용되고, RCEP 요건 충족 수입품에는 2.8 퍼센트의 경감 세율이 적용됩니다. 이는 수입 경로 설계, 원산지 관리, 협정 활용 여부에 따라 실효 비용 구조가 달라질 수 있음을 의미합니다. EU REACH 및 관련 지침은 플라스틱 소재의 VOC 배출에 대한 더 엄격한 제한을 부과하고 있어, 포장 및 자동차 부문에서 EVA 기반 제품의 reformulation 노력이 촉발되고 있습니다.
미국과 유럽의 규제 동향도 간과할 수 없습니다. 미국 EPA 와 ECHA 는 EVA 유래 소재의 VOC 및 미세플라스틱 배출 관련 모니터링과 규제를 계속하고 있으며, 북미와 유럽에서의 생산에 컴플라이언스 요건이 영향을 미치고 있습니다. 규제 대응은 단순한 법적 준수를 넘어 제품 배합, 포장 설계, 고객과의 사양 협의, 그리고 장기적으로는 제품 포지셔닝과 차별화 방식까지 연결될 수 있습니다.
이러한 동학은 EVA 수지 시장을 단순한 성장 시장으로 보기보다, 원가 구조와 규제 대응력, 공급 안정성이 함께 작용하는 복합 경쟁 시장으로 이해해야 한다는 점을 보여줍니다. 보고서는 이 요소들을 시장 전망 및 경쟁 분석과 분리해 설명하지 않고, 서로 어떻게 겹치는지 읽을 수 있도록 배치해 경영 판단의 일관성을 높이도록 구성했습니다.
어떤 의사결정을 위해 이 연구를 활용해야 하는가
이 연구의 가치는 전망 수치 자체보다, 그 수치를 어떤 의사결정 프레임에 넣고 활용할 수 있는지에 있습니다. 2026 년을 포함한 중기 계획을 세우는 조직이라면 다음과 같은 활용 경로를 고려할 수 있습니다.
- 사업 포트폴리오 검토 시, 어떤 용도 또는 지역이 더 높은 성장 탄력성을 보이는지 확인하고 우선순위 조정 근거로 활용한다
- 공급망 및 조달 전략 수립 시, 원재료 가격 상관성과 공급 차질 사례를 반영해 계약 구조, 재고 수준, 대체 소싱 가능성을 재설계한다
- 생산능력 및 투자 검토 시, 수요 성장 경로와 경쟁사의 용량 확대가 장기적으로 어떤 수급 균형을 만들 수 있는지 가정 검증에 활용한다
- 제품 개발 및 reformulation 계획에서 규제 변화와 고객 요구 변화를 반영해 예상 비용, 인증, 시장 수용성을 함께 검토한다
- 경쟁 대응 전략 설계 시, 주요 기업의 브랜드, 응용 커버리지, 최근 제품 출시 패턴을 기준으로 우리 포지션의 차별 지점을 정의한다
특히 중요한 점은 세부 수치의 단순 확보가 아니라, 수치가 의미하는 전략적 결론을 추출하는 일입니다. 예를 들어 특정 유형의 점유율이나 특정 용도의 절대 금액이 아니라, 그 흐름이 우리 제품 라인, 고객사 구조, 생산 거점, 규제 노출과 어떻게 맞닿아 있는지를 함께 읽어야 실제 의사결정에 활용할 수 있습니다. 이 보고서는 바로 그 연결을 돕도록 설계되어 있습니다.
결론: 성장 전망보다 중요한 것은 해석의 정밀도와 실행 연결성
EVA 수지 시장은 2026 년 이후 2032 년까지 확장 궤도를 이어갈 가능성이 높으며, 그 과정에서 포장, 태양광, 발포, 접착제 등 주요 용도의 수요 동인과 원재료·규제 환경의 변화가 복합적으로 작용합니다. 시장이 커지는 국면일수록 기회는 넓어지지만, 경쟁은 더 정교해지고 원가 구조는 더 민감해집니다. 따라서 성장률은 출발점일 뿐이며, 실제로는 유형 선택, 용도 집중, 지역 진입 방식, 공급 안정성, 규제 대응, 그리고 경쟁사의 최근 행보가 함께 평가되어야 합니다.
PW Consulting 의 EVA Resin Market 연구는 이러한 다차원 판단을 지원하기 위해, 시장 규모 시계열과 성장 경로, 유형·용도·지역의 구조, 경쟁 집중도와 주요 기업 전략, 그리고 원재료 및 규제 동학을 하나의 일관된 프레임으로 정리했습니다. 세부 구간별 수치, 세부 지역별 비중, 세부 용도별 금액과 같은 핵심 분할 데이터는 전체 그림을 이해하는 데 필수적이지만, 실제 전략 수립 단계에서는 보다 정밀한 비교와 내부 데이터와의 결합이 필요합니다. 이 연구의 fuller insights, full segmentation breakdowns, and complete scenario detail 은 하단 링크를 통해 확인하실 수 있습니다.
Access the full EVA Resin Market report and detailed market intelligence here
이 소개 글은 연구의 범위와 방향, 그리고 2026 년 의사결정에 주는 의미를 개괄적으로 보여드리기 위한 것입니다. 실제 실행 가능한 판단과 내부 계획 수립을 위해서는 시장 구조, 경쟁 위치, 원가·규제 변수를 함께 포함한 전체 보고서를 검토하시기를 권장합니다.
For detailed analysis of this topic, please visit the official page: EVA Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Magnetic Couplings Market Hits $215M in 2025, Projected 6.98% CAGR
By PW Consulting, 2026-09-07
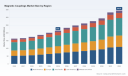
Strategic Intelligence: Navigating the Magnetic Couplings Market in 2026 and Beyond
The industrial landscape of 2026 is defined by a singular imperative: the integration of efficiency, safety, and reliability into core operational machinery. For senior executives and strategic planners, understanding the trajectory of enabling technologies is no longer optional; it is a prerequisite for resilient supply chain management and capital allocation. The Magnetic Couplings Market represents a critical nexus in this evolution, bridging the gap between traditional mechanical drive systems and the demands of modern, hermetic, and energy-efficient industrial processes.
Worldwide Hydraulic Servo Drive Market
PW Consulting is pleased to present a comprehensive market study designed to equip stakeholders with the foresight necessary to navigate this dynamic sector. This article serves as a strategic overview, highlighting the macroeconomic trends, competitive tensions, and operational drivers that define the market landscape from 2026 through 2032. It is intended to demonstrate the depth of our analysis while respecting the proprietary nature of the granular data contained within the full report.
Worldwide Mini Pleat HEPA Filter Market
Market Trajectory and Historical Context
Understanding where the market is going requires a clear view of where it has been. The Magnetic Couplings Market has exhibited consistent growth over the past half-decade, driven by a steady shift toward non-contact torque transmission solutions. In 2025, the market established a significant baseline, reflecting the cumulative impact of industrial automation upgrades and stricter environmental compliance measures across chemical and process industries.
Dust-Free Bag Vacuum Cleaner Market
Our analysis tracks this evolution from 2020 through the base year of 2025, providing a robust historical dataset that validates growth trends. The momentum has carried forward into 2026, where the market value is projected to reach new heights. This trajectory is not merely linear; it reflects compounding adoption rates in key verticals where leakage prevention and maintenance reduction are paramount. Looking ahead, the forecast period extends to 2032, offering a long-term view for investment planning. The compound annual growth rate observed over this forecast horizon underscores a sustained expansion phase, suggesting that magnetic couplings are transitioning from niche components to standard considerations in drive engineering.
For strategic decision-makers, these top-line figures validate the sector's stability. However, the true value lies in understanding the velocity of this change. The progression from the 2025 baseline to the 2032 outlook indicates a market that is maturing but still possesses significant runway for penetration. Companies that align their product development and market entry strategies with this growth curve stand to capture disproportionate value.
Drivers of Adoption and Market Dynamics
The expansion of the magnetic couplings sector is not happening in a vacuum. It is propelled by a confluence of macroeconomic trends, regulatory pressures, and technological necessities. In 2026, three distinct forces are shaping the demand landscape.
First, the push for energy efficiency remains a dominant theme. Industrial operations are under increasing pressure to reduce carbon footprints and operational expenditures. Magnetic couplings offer a pathway to optimized drive systems that minimize friction losses and enable variable speed control without the wear associated with mechanical contact. This is particularly relevant in sectors where pump and mixer operations run continuously, such as in chemical processing and water management.
Second, safety and environmental regulations are tightening globally. Industries handling hazardous materials, including petrochemicals and pharmaceuticals, face stricter requirements for hermetic sealing and leakage prevention. Magnetic couplings provide the necessary barrier-free separation between motor and pump shafts, eliminating the risk of seal failure and subsequent hazardous emissions. Compliance with these evolving standards is becoming a critical driver for procurement teams evaluating replacement and new installation projects.
Third, the broader trend toward industrial automation and robotics is creating new application niches. As manufacturing processes become more sophisticated, the demand for precise, contactless torque transmission increases. This extends beyond traditional heavy industry into medical devices and precision instrumentation, where reliability and cleanliness are essential. The market dynamics reflect this diversification, with demand signals strengthening across multiple application verticals.
Supply Chain and Raw Material Considerations
While demand drivers paint a positive picture, the supply side presents complexities that strategic leaders must monitor closely. The manufacturing of magnetic couplings, particularly those utilizing high-performance permanent magnets, is deeply tied to the rare-earth materials market.
Recent industry data indicates that raw material costs can account for a substantial majority of the total cost structure for neodymium-based magnetic couplings. Specific elements such as neodymium, praseodymium, and dysprosium represent the lion's share of these expenses. This concentration of cost means that price volatility in the rare-earth sector directly impacts the profitability and pricing strategies of coupling manufacturers.
Furthermore, geopolitical factors have come into sharp focus following regulatory changes in key producing regions. Notably, restrictions implemented in late 2025 regarding rare-earth and magnet exports have introduced fluctuations in global supply availability. Market participants witnessed a decline in export volumes during this period, which rippled through the supply chain. For companies relying on global sourcing strategies, these disruptions highlight the importance of supply chain security and diversification.
In response, some manufacturers are emphasizing localized production capabilities and engineered solutions that reduce dependency on volatile imports. This shift is influencing the competitive landscape, favoring firms with robust supply chain management and the ability to offer stable pricing despite market fluctuations. Strategic procurement and long-term supplier partnerships are becoming differentiating factors in this environment.
Competitive Landscape and Industry Players
The market is characterized by a mix of established engineering firms and specialized magnet manufacturers. Our analysis identifies a concentrated competitive environment where key players hold significant market share. The data suggests a moderate to high level of concentration, indicating thatwhile the market is open to innovation, scale and technical expertise remain critical barriers to entry.
Several companies are defining the standards for performance and application integration. In Europe, firms such as DST Dauermagnet-SystemTechnik GmbH and KTR Systems GmbH are recognized for their specialized permanent magnetic couplings designed for hermetic separation in demanding process industries. KTR's MINEX series, for instance, highlights the focus on pumps and agitators where leak prevention is critical. Similarly, mayr power transmission GmbH integrates magnetic couplings with safety brakes and torque limiters, addressing the needs of automation and robotics applications.
In the United States, companies like Magnetic Technologies Ltd. and MagnaDrive Corporation focus on custom solutions for seal-less pumps and energy-efficient drives. MagnaDrive's emphasis on torque-limiting couplings for mining and power generation illustrates the diversification of applications into heavy infrastructure. Dexter Magnetic Technologies brings expertise in synchronous and hysteresis couplings for high-precision fields such as medical devices and aerospace, showcasing the technology's reach beyond traditional industrial uses.
The presence of established industrial groups also shapes the landscape. EagleBurgmann provides magnetic coupling solutions specifically for hydrocarbon pumps in petrochemical and nuclear industries, leveraging deep domain knowledge in sealing technology. Eclipse Magnetics and Magnet Applications contribute by offering bespoke magnet assemblies and engineered solutions, with a noted emphasis on U.S.-based manufacturing to support supply chain security.
In Asia, SDM Magnetics Co., Ltd. represents the manufacturing capacity available in the region, focusing on sintered neodymium and custom assemblies for industrial automation. This global distribution of players ensures that supply capabilities exist across major regions, though logistics and trade policies continue to influence regional availability.
Recent Developments and Product Innovation
The pace of innovation remains high as companies seek to differentiate their offerings in a growing market. Recent activity in 2026 demonstrates a continued focus on showcasing integrated solutions and launching specific product lines tailored to emerging needs.
At major industry events such as ConExpo 2026, larger transmission groups like Regal Rexnord showcased integrated power transmission solutions that included magnetic couplings. This visibility at high-profile trade shows signals the technology's increasing relevance in broader power transmission ecosystems. Simultaneously, component specialists like Miki Pulley introduced contactless link magnetic couplings designed specifically for non-contact torque transmission, highlighting ongoing refinement in core product designs.
Further back in the recent timeline, Magnetic Technologies Ltd. announced new coupling models aimed at precision industrial applications, reinforcing the trend toward higher specification requirements. These developments indicate that competitors are not merely copying existing architectures but are actively engineering improvements to handle more demanding torque profiles and environmental conditions.
For buyers and partners, keeping track of these product launches is essential. The introduction of new models often signals shifts in capabilities, such as higher torque limits, improved thermal stability, or easier integration with motor systems. These incremental innovations can accumulate to create significant operational advantages over the lifecycle of the equipment.
Strategic Segmentation Insights
Understanding the market requires breaking it down by key dimensions, though the specific weightings often hold the proprietary key to investment timing. Our report delves into segmentation by region, type, and application, providing the granularity needed to identify high-potential pockets of growth.
Regionally, the market is distributed across major global economies. North America, Europe, and Asia Pacific represent significant bases of activity, each with distinct regulatory and industrial drivers. While aggregate figures show robust activity across these regions, the relative strength varies based on local manufacturing density and environmental mandate strictness. Latin America and the Middle East and Africa also contribute, often driven by specific large-scale infrastructure projects in petrochemical and water treatment sectors.
By product type, the market is anchored by disc-type and synchronous couplings, which handle the bulk of transactional volume in industrial settings. Disc-type couplings are broadly used for their simplicity and effectiveness in torque transmission, while synchronous types offer precise speed matching for specialized applications. Other types cater to niche requirements, ensuring that the technology can be adapted to a wide range of mechanical interfaces.
In terms of application, underwater environments represent a significant use case, driven by the need for reliable, sealed systems in subsea operations. The petrochemical sector remains a foundational application area, where safety regulations mandate hermetic solutions for pumps and mixers. The electronic sector, while smaller in volume terms, represents a high-growth niche where precision and miniaturization are key. Understanding which segments are outpacing the general market trend is vital for portfolio strategy.
Market Concentration and Competitive Intelligence
The competitive structure of the magnetic couplings market influences pricing power and innovation speed. Our analysis highlights a concentrated market environment, where a core group of firms commands a substantial portion of revenue. This concentration suggests that relationships with top-tier suppliers are critical for end-users seeking compliance and reliability.
For new entrants or those looking to expand, the concentration levels imply that competing on price alone is insufficient. Differentiation through customization, service support, and supply chain reliability is necessary to erode the share of incumbents. The presence of both specialized magnetic firms and large industrial conglomerates creates a dual dynamic where niche expertise competes with broad solution integration.
Strategic players are increasingly leveraging their ability to offer end-to-end solutions. By combining magnet manufacturing expertise with coupling design and integration services, leading companies reduce friction for customers who prefer single-source accountability. This trend is expected to continue, reinforcing the position of firms with comprehensive capabilities.
The Strategic Value of Comprehensive Market Intelligence
While the overview provided here captures the essential currents of the Magnetic Couplings Market, the complexities of 2026 and beyond require deeper data. Executive decisions regarding capital investment, supplier selection, and market entry demand precision that only a structured market study can provide.
The full PW Consulting report offers detailed breakdowns of market size and forecast figures across the entire forecast period. It unpacks the segmentation data to reveal which specific regions and applications are offering the highest return potential. This level of detail allows strategists to move beyond general trends and identify actionable opportunities.
Furthermore, the report provides a comprehensive competitive profiling section that goes beyond public summaries. It analyzes recent developments, product launches, and strategic moves in detail, offering a timeline of activity that helps predict competitor behavior. Understanding the impact of raw material fluctuations and regulatory changes on specific company supply chains is also part of the deep dive available in the full document.
Access to this level of intelligence reduces risk. It allows procurement leaders to anticipate price shifts driven by rare-earth costs. It enables product managers to align R&D with the most promising application verticals. It supports sales teams in targeting regions where regulatory tailwinds are strongest. In a market where concentration is high and supply chains are sensitive, information asymmetry is a significant advantage.
Conclusion: Positioning for 2026 and Beyond
The Magnetic Couplings Market is poised for continued expansion, underpinned by irreversible trends in energy efficiency, safety regulation, and automation. The forecast data projects a steady climb in market value through 2032, offering a stable growth environment for those who can navigate supply chain complexities and competitive intensity.
Success in this sector will belong to organizations that combine technological aptitude with strategic market awareness. They must understand not just the performance of the coupling, but the economics of the materials that build it and the regulatory frameworks that mandate its use. With moderate market concentration and a diverse player base, there are opportunities for both established players to defend share and agile firms to capture niche segments.
This article serves as a primer to the extensive analysis available in our latest market research. To fully equip your organization with the data required to make informed 2026 decisions, we invite you to explore the complete report. The detailed segmentation splits, granular forecast trajectories, and deep competitive profiles contained within will provide the actionable intelligence necessary to secure a strategic foothold in this evolving industry.
For access to the full market study and comprehensive data tables, please visit the source page to download the complete intelligence package. Equip your team with the precision data needed to turn market dynamics into strategic advantage.
For detailed analysis of this topic, please visit the official page: Magnetic Couplings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Trypsin Market Hits USD 96.5M in 2025, Projects 5.5% CAGR to Reach USD 140.75M by 2032
By PW Consulting, 2026-09-07
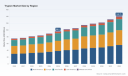
Strategic Navigation in the Global Trypsin Market: 2026 Outlook and Decision Intelligence
The global trypsin market stands at a critical inflection point as industrial biotechnology, pharmaceutical manufacturing, and advanced diagnostics converge around increasingly stringent performance and regulatory expectations. Market intelligence compiled by PW Consulting indicates that the sector expanded from approximately 75.0 million USD in 2020 to 96.5 million USD in 2025, reflecting a disciplined yet accelerating trajectory shaped by bioprocessing scale-up, cell-based therapeutics, and the maturation of recombinant production platforms. The forecast period spanning 2026 to 2032 points toward sustained momentum, with a projected compound annual growth rate of 5.5 percent and a market valuation expected to reach 140.75 million USD by the close of the outlook window. For executives, procurement leaders, and R&D strategists, these figures are not merely summary statistics. They represent a structural realignment in how enzymes are sourced, qualified, and integrated into production workflows. This introduction outlines the strategic architecture of our newest report, demonstrates how macro-level intelligence can be operationalized, and clarifies the decision-grade content that awaits inside the full study.
Worldwide Granules Packing Machine Market
From Historical Trajectory to Forward-Looking Commitment
The market's historical arc from 2020 through 2025 illustrates a pattern of resilience punctuated by incremental but compounding growth. Annual revenue moved from 75.0 million USD in 2020 to 76.92 million USD in 2021, 81.49 million USD in 2022, 84.02 million USD in 2023, 89.51 million USD in 2024, and 96.5 million USD in 2025. This sequence signals a market that has moved beyond the post-pandemic stabilization phase and entered a period of deliberate expansion. Buyers no longer treat trypsin as a commoditized laboratory reagent. Instead, they evaluate it as a process-critical input whose purity profile, supply reliability, and regulatory posture directly affect batch success rates, downstream purification economics, and time-to-clinic for advanced therapies.
Intelligent Communication Software Market
The forecast landscape reinforces this shift. Revenue is projected to advance to 102.28 million USD in 2026, 105.51 million USD in 2027, 114.94 million USD in 2028, 118.85 million USD in 2029, 122.2 million USD in 2030, 131.51 million USD in 2031, and 140.75 million USD in 2032. The 5.5 percent CAGR is not an abstract figure; it is a decision parameter. It shapes capital allocation for capacity expansion, informs supplier diversification strategies, and helps R&D organizations align enzyme qualification roadmaps with long-term manufacturing plans. Leaders who internalize this growth rhythm can time sourcing commitments, negotiate contract structures with better visibility, and anticipate the competitive intensity that accompanies a maturing supply base.
Worldwide Cone Pizza Machine Market
Why This Research Matters for 2026 Decision-Making
Strategic decisions in the trypsin market are increasingly cross-functional. Procurement must balance cost discipline against the risk of supply interruption; R&D must reconcile experimental flexibility with the need to lock in GMP-grade formats for commercial programs; quality and regulatory teams must interpret evolving expectations around animal-origin-free alternatives and batch consistency; and business development teams must gauge which applications are accreting share versus plateauing. Our report was constructed to serve this cross-functional reality. Rather than offering a single-dimensional volume estimate, it delivers a modular intelligence framework that can be layered into sourcing strategy, pipeline planning, competitive benchmarking, and scenario modeling.
For 2026, the most consequential decisions revolve around format selection, supplier qualification, and application alignment. Recombinant and animal-origin-free variants are gaining traction precisely because they reduce exposure to biological variability and simplify the regulatory narrative. At the same time, legacy animal-derived forms continue to serve specific laboratory and process niches. Understanding where each format creates advantage, and under what compliance or cost conditions, is central to competitive positioning. The report translates these choice points into actionable analysis, helping teams avoid over-indexing on price alone or under-investing in qualification lead time.
Competitive Architecture at a Glance
The trypsin market exhibits moderate concentration, with the top three firms accounting for roughly 28.0 percent of revenue and the top five firms reaching approximately 35.0 percent. This structure indicates a landscape where established life-science and specialty enzyme players maintain meaningful influence, while specialized manufacturers and technology-focused entrants continue to carve out differentiated positions. Competitive advantage is no longer defined solely by catalog breadth. It is increasingly determined by the ability to deliver consistently qualified material, offer application-specific formulations, and align product architecture with regulatory expectations in biomanufacturing and diagnostic workflows.
Several flagship organizations illustrate how differentiated strategies are unfolding in practice. Novo Nordisk Pharmatech A/S, headquartered in Køge, Denmark, has focused its trypsin offering on high-purity animal-free recombinant materials produced via E. coli fermentation under GMP conditions, with supply directed toward biomanufacturing, cell dissociation, and vaccine production. In October 2024, the company launched TrypsiNNex®, a GMP-grade animal-free recombinant trypsin featuring more than 70 percent beta-trypsin content and batch variability below 5 percent, validated for biopharmaceutical manufacturing. This launch signals a broader move toward controlled, scalable recombinant supply for mission-critical process steps.
Thermo Fisher Scientific Inc., based in Waltham, Massachusetts, continues to anchor its trypsin portfolio around porcine-derived materials alongside animal-origin-free alternatives such as TrypLE, supporting cell culture dissociation and bioprocessing applications. The company’s breadth of infrastructure and integrated bioprocessing ecosystem positions it as a multi-format enabler for organizations that need to bridge research and commercial production without fragmenting their supplier base. Promega Corporation, located in Madison, Wisconsin, emphasizes high-performance formats for analytical and proteomics workflows, including sequencing-grade modified trypsin, Trypsin Gold, Trypsin Platinum in recombinant form, and immobilized variants tailored for mass spectrometry. Its positioning reflects the growing importance of enzyme quality in generating reproducible analytical data and advancing proteomics pipelines. Merck KGaA, through Sigma-Aldrich in Darmstadt, Germany, remains a reference point for laboratory-grade cell culture trypsin and associated research products, reinforcing the continued role of established reagent channels in early-stage development and scientific supply chains.
Beyond these core players, recent product and regulatory activity shows that the competitive field is being reshaped by formulation innovation and safety evaluations. In February 2026, EFSA adopted a safety opinion concluding that there were no safety concerns for the food enzyme serine protease, or trypsin, derived from a genetically modified Fusarium venenatum strain. That determination, published in the EFSA Journal in March 2026, broadens the regulatory conversation around recombinant enzyme acceptance and underlines how safety qualification can unlock new application pathways. Meanwhile, c‑LEcta expanded the recombinant supply landscape in October 2025 with the launch of CellTrypase, a GMP-grade recombinant animal-free trypsin-like enzyme validated for major biopharmaceutical production cell lines. Together, these developments point to an environment in which format credibility, regulatory clearance, and cell-line compatibility are becoming decisive competitive factors.
Market Dynamics Under the Microscope
The contemporary trypsin market is governed by a set of interacting forces that directly affect sourcing strategy and product planning. One of the most consequential is the regulatory drift toward recombinant and animal-origin-free formats for cell-therapy inputs and advanced biomanufacturing. Guidance endorsed by the European Medicines Agency in 2025 elevated recombinant trypsin to preferred status for cell-therapy inputs, reinforcing a directionality that procurement and quality teams can no longer treat as optional. In parallel, recombinant suppliers are expected to demonstrate compliance with stringent FDA 21 CFR 211 and ISO 13485 requirements, and to provide evidence of batch-to-batch consistency below 5 percent variability. These expectations reshape the value proposition of enzyme selection: consistency, documentation, and traceability now carry commercial weight comparable to unit pricing.
A second dynamic concerns the practical limits of animal-derived sourcing. Extraction from porcine and bovine sources is accompanied by complex purification steps and yield losses that commonly range from 5 to 15 percent, driven by variability in raw biological material. This inherent variability has implications for both cost predictability and process control, especially when manufacturers require tight lot-to-lot reproducibility. As a result, many organizations are reassessing the trade-off between legacy supply convenience and the longer-term advantages of controlled recombinant platforms. The trend does not imply the elimination of animal-derived trypsin, but it does encourage selective deployment where its characteristics are genuinely advantageous and where supply risk can be managed.
A third dynamic is the widening of application relevance. Trypsin is increasingly embedded in workflows that extend beyond traditional cell culture dissociation. Its role in biomanufacturing, vaccine production, proteomics, and advanced diagnostics connects enzyme supply to broader value chains where downstream success depends on upstream material performance. This linkage raises the stakes for qualification strategy and creates opportunities for suppliers that can provide application-validated formats, robust technical support, and clear regulatory alignment. Market growth is therefore not simply a function of demand volume; it is also a function of how effectively the supply base can answer cross-application requirements without sacrificing consistency or compliance.
What the Report Delivers: Decision-Grade Content Overview
The full report is organized to convert market intelligence into operational clarity. It provides a detailed assessment of market size and growth behavior across the historical and forecast periods, with a structured lens on the forces that shape expansion and the conditions that may accelerate or moderate it. The analysis includes a thorough segmentation review by region, by type, and by application, allowing readers to evaluate where demand is concentrating, which formats dominate specific use contexts, and how application portfolios are evolving. Importantly, the report avoids superficial breakdown by offering interpretive commentary alongside segment structure, so that buyers and strategists can understand the practical significance of each grouping rather than reading isolated share figures in isolation.
The study also contains a competitive analysis section that examines the strategic behavior of leading participants. Company-specific profiles describe the trypsin-related offerings, production philosophies, and application focus that define each player’s market position. These profiles are paired with an assessment of recent developments, including product launches, safety evaluations, and regulatory actions that alter the competitive field. By linking product architectures to market events, the report helps readers anticipate which suppliers are strengthening their position in biomanufacturing, which are deepening their analytical and proteomics relevance, and which are expanding the recombinant supply envelope for GMP environments.
Operational content extends to supply chain and procurement considerations. The report addresses raw material variability, purification complexity, format transition risk, and the practical implications of qualification requirements. It also maps regulatory context, including the implications of recent guidance and safety opinions for sourcing choices and compliance planning. For organizations that must align R&D flexibility with commercial readiness, this material supports a more disciplined approach to supplier selection, contract design, and specification lock-in. Readers will find scenario-oriented commentary that connects market growth to supply strategy, helping executive teams translate trajectory data into procurement timing, supplier diversification, and capacity planning decisions.
Translating Market Intelligence into 2026 Action
For companies making sourcing, investment, or product decisions in 2026, the strategic value of the report lies in its ability to connect external market behavior with internal decision processes. Leaders can use the growth projection as a checkpoint for whether to lock in long-term supply agreements, diversify across format types, or accelerate qualification of recombinant options. The competitive analysis supports supplier evaluation by clarifying what each major player emphasizes and where differentiation is emerging. The dynamics section helps quality, regulatory, and operations teams anticipate the requirements that will shape vendor qualification and batch acceptance. And the segmentation framework enables teams to identify which applications and format families warrant deeper engagement, without being distracted by granular share details before the proper internal review is complete.
The most effective use of this intelligence is not passive consumption but active integration. Procurement teams can compare supplier narratives against consistency requirements and application validation needs. R&D leaders can map enzyme format transitions onto pipeline milestones and clinical-readiness timelines. Business and strategy leaders can use the market trajectory to test assumptions about capacity expansion, geographic focus, and portfolio investment. In each case, the report is designed to support, not replace, internal judgment, providing a credible external baseline against which internal plans can be calibrated.
Why the Full Study Deserves a Place in Your Decision Process
Trypsin may appear at first glance to be a narrow reagent category, but its market behavior reflects broader shifts in biotechnology, pharmaceutical manufacturing, and diagnostics. As the sector moves from 2026 into the latter half of the decade, companies that treat enzyme supply as a strategic variable rather than a routine purchase will be better positioned to manage consistency risk, align with evolving regulatory expectations, and capture share in applications where material performance matters most. The full PW Consulting report offers the depth required to make those choices with confidence. It pairs market-size and growth analysis with segmentation insight, competitor profiling, regulatory context, and operational implications, all structured to support real-world decision workflows.
The preview above establishes the analytical foundation and the strategic relevance of the market, but the complete intelligence is contained in the full study. Inside, readers will find the detailed regional, type, and application breakdowns, the extended competitive assessment, and the decision frameworks needed to convert growth signals into sourcing and planning actions. For teams preparing for 2026 commitments and beyond, the report offers a structured lens on where the trypsin market is heading and how to position accordingly.
For detailed analysis of this topic, please visit the official page: Trypsin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Wall Mounted Gas Boiler Market Hits $6,277M in 2025, Projections Hit $9,099M by 2032 at 5.49% CAGR
By PW Consulting, 2026-09-07
Navigating the Wall Mounted Gas Boiler Market: Strategic Intelligence for 2026 and Beyond
The global heating infrastructure sector is undergoing a structural transformation driven by tightening efficiency mandates, evolving fuel compatibility requirements, and a decisive shift toward space-optimized thermal solutions. Within this landscape, the wall mounted gas boiler market has emerged as a critical battleground for manufacturers, distributors, and policy-aware investors. As operational footprints narrow and regulatory ceilings tighten, enterprise leaders require more than high-level trend statements. They need granular, forward-looking intelligence that maps technological inflection points, regional demand elasticity, and competitive positioning into actionable decision frameworks. This market research study is designed precisely for that purpose, offering a comprehensive analytical foundation to navigate the 2026–2032 forecast horizon with confidence.
Worldwide Aluminum Ski Poles Market
Drawing on a rigorous historical baseline spanning 2020 through 2025 and extending into a detailed forward projection, the study captures the market's compounding trajectory. Total revenue has progressed from approximately 4,257.8 million USD in 2020 to an estimated 6,277.15 million USD in 2025, reflecting a sustained expansion pattern that has consistently outpaced broader building equipment benchmarks. The forecast period anticipates continued growth, with projected valuations climbing toward 6,754.87 million USD in 2026, advancing to 7,217.42 million USD in 2027, and reaching approximately 9,099.16 million USD by 2032. This progression corresponds to a compound annual growth rate of 5.49 percent, a figure that signals resilient underlying demand rather than speculative short-term momentum. For executives calibrating capital allocation, capacity planning, and product portfolio roadmaps, these directional indicators provide a necessary anchor. Yet macro trajectories alone do not capture where value is concentrating, which product architectures are gaining share, or how competitive dynamics will reshape pricing and distribution models. That deeper layer of analysis resides within the full report.
Ludus Duodecim Scriptorum Market
Why the 2026 Decision Window Demands Specialized Market Intelligence
The current operating environment for wall mounted gas boilers is defined by simultaneous regulatory pressure, technological maturation, and supply chain recalibration. Since January 2025, EU Member States have been restricted from subsidizing or incentivizing stand-alone fossil fuel boiler sales, while updated energy efficient product design rules have begun systematically phasing out the least-efficient models from commercial channels. Concurrently, all newly installed gas boilers in the EU must now achieve a minimum efficiency rating of 92 percent under ErP standards, a threshold that aligns with broader revisions to the Energy Performance of Buildings Directive. These regulatory shifts are not isolated compliance checkboxes; they are actively restructuring demand patterns, accelerating the replacement cycle for older non-condensing units, and elevating the strategic importance of high-efficiency condensing architectures. Furthermore, EU legislation requires Member States to prepare for a complete phase-out of fossil fuel boilers by 2040, a long-horizon mandate that is already influencing product development cycles, investor expectations, and channel partner strategies in the present day.
Worldwide Shared Kitchen Market
For enterprise decision-makers, the implication is clear: generalized industry commentary cannot substitute for structured, data-backed analysis. Capacities must align with efficiency-driven replacement demand rather than speculative volume growth. Product roadmaps must integrate modulating burner technologies, hydrogen-compatible readiness pathways, and heat exchanger material strategies that balance performance with longevity. Distribution and installation ecosystems must adapt to pre-commissioned, low-noise, compact designs that reduce on-site labor and improve seasonal efficiency outcomes. The 2026 forecast year represents a critical inflection point where these factors converge, making this study's timing strategically relevant for procurement leaders, product managers, regional expansion planners, and competitive intelligence teams.
Research Architecture: From Macro Trajectory to Operational Playbooks
This study is constructed to bridge high-level market directionality with operational specificity. Rather than presenting static data tables, the report translates historical performance, forward estimates, and structural segmentation into decision-ready narratives. The analytical framework moves systematically through market sizing, segmentation logic, competitive profiling, regulatory impact mapping, and emerging product architecture trends. Each section is designed to surface implications for pricing strategy, capacity investment, channel development, and technology adoption timelines.
The report's operational utility is reinforced by a structured breakdown of market composition across key dimensions. Historical and projected revenue trajectories are contextualized within type, application, and regional demand patterns, allowing readers to identify where volume concentration is forming and which segments are experiencing the strongest efficiency-driven substitution effects. The study also examines market concentration dynamics, providing context around competitive density and the strategic positioning of dominant players. Throughout, the analysis deliberately avoids oversimplified regional or application percentage breakdowns in this preview, preserving the more granular, intersectional insights for the full dataset where they can be properly contextualized against pricing environments, installation infrastructure maturity, and policy implementation timelines.
Beyond quantitative mapping, the report integrates qualitative assessments of product architecture evolution. This includes an evaluation of condensing versus non-condensing technology adoption, the material science considerations shaping heat exchanger durability, and the performance implications of modulating output ranges, intelligent combustion adaptation, and pre-commissioned installation designs. These technology-level observations are directly linked to efficiency compliance pathways, seasonal performance outcomes, and end-user total cost of ownership, creating a practical bridge between engineering decisions and commercial strategy.
Competitive Landscape and Strategic Positioning Dynamics
The wall mounted gas boiler market is characterized by a concentrated but highly differentiated competitive field. Leading manufacturers have invested heavily in efficiency optimization, footprint reduction, installation speed, and future fuel compatibility. The report provides in-depth company profiles that move beyond generic brand recognition to examine specific product architectures, efficiency claims, and strategic development trajectories.
European manufacturers continue to anchor the upper tier of the market with engineered condensing platforms designed to meet stringent efficiency thresholds. Vaillant Group has emphasized intelligent combustion adaptation and high seasonal efficiency within its ecoTEC plus gas condensing wall-hung portfolio, while also advancing H2-ready capability pathways that align with long-term decarbonization expectations. Viessmann Manufacturing Company has focused on compact, pre-commissioned quick-install design through its Vitodens series, with recent developments reinforcing the strategic importance of small-footprint, low-noise units that deliver Class A efficiency outcomes. Robert Bosch GmbH has positioned its high-efficiency wall-hung condensing boilers around modulating burner technology, extending performance flexibility while also developing hydrogen-ready options that anticipate shifting fuel infrastructure requirements.
Parallel momentum is evident among other globally active players. Ariston Holding N.V. has advanced its Clas ONE and Alteas ONE+ series by integrating patented XtraTech stainless steel heat exchangers with strong ErP ratings, emphasizing durability and efficiency in residential and light commercial applications. Navien Inc. has expanded its presence through NHB-H and NCB-H series wall-hung condensing combi boilers that combine high-capacity modulating output with Wi-Fi control options, targeting installations where flexible output management and remote monitoring are commercially valuable. In the broader European manufacturing base, Ferroli S.p.A. continues to push high-output wall-hung condensing solutions such as the Force W line, supporting residential and cascade installations with capacities reaching substantial kW ranges, while also showcasing hydrogen-ready product developments at major trade platforms. Immergas S.p.A. has strengthened its competitive profile through Victrix Superior and Victrix Pro series units that leverage Aqua Celeris technology and emphasize sanitary comfort ratings alongside condensing performance. BDR Thermea Group has continued to refine its Quinta Ace wall-hung condensing line, offering aluminium or stainless-steel heat exchanger options tailored to both residential and commercial deployment scenarios.
These competitive profiles are not evaluated in isolation. The report situates each player within broader strategic themes: how product efficiency claims map to regulatory thresholds, how installation-friendly design features influence channel adoption, how hydrogen-ready development paths may shape future portfolio premiums, and where heat exchanger material selection affects lifecycle reliability and warranty economics. Recent milestones illustrate these dynamics in action. In February 2026, Viessmann launched the compact Vitodens 025-W wall-mounted gas condensing combi boiler with 24 kW and 28 kW outputs, achieving ERP efficiency of 92 percent (Class A) with seasonal efficiency up to 98 percent, a small footprint, low noise profile, and pre-commissioned unit configurations. Earlier, in June 2025, BDR Thermea Group introduced the Quinta Ace S wall-hung boiler series, combining advanced characteristics of its prior Quinta Ace platform with improved efficiency for residential applications. Around the same period, Ferroli highlighted its Force W wall-hung condensing boilers through touring van showcases and signaled new hydrogen-ready product developments, signaling an active transition toward future-compatible system designs.
This preview intentionally frames competitive positioning at a strategic level while reserving detailed share comparisons, technology adoption intensity metrics, and product-level performance cross-references for the full report. The goal is to give decision-makers enough structural clarity to recognize where competitive pressure is intensifying and which capability sets are becoming table stakes, without diluting the proprietary segmentation depth that supports precise benchmarking.
Market Dynamics: Regulation, Materials, and the Efficiency Imperative
Market dynamics in the wall mounted gas boiler segment are increasingly shaped by the intersection of policy compliance, material performance, and installation economics. Efficiency mandates are no longer peripheral considerations; they are central drivers of product eligibility, channel acceptance, and end-user replacement behavior. As noted, updated EU rules require newly installed gas boilers to achieve a minimum efficiency rating of 92 percent ErP, and the broader policy trajectory points toward the systematic removal of lower-efficiency models from active sale channels. This regulatory environment reinforces demand for condensing architectures that can consistently meet or exceed seasonal efficiency expectations while maintaining compact form factors suitable for wall mounting in space-constrained residential and commercial settings.
At the component level, material selection is exerting a meaningful influence on product durability and competitive differentiation. Sector analysis indicates that stainless steel heat exchangers have achieved dominant adoption in condensing boilers, accounting for approximately 68 percent of use cases, owing to superior corrosion resistance and extended lifespan in condensing operating environments. This material preference is not merely a technical detail; it affects warranty structures, service interval expectations, total cost of ownership calculations, and the commercial credibility of efficiency claims over the product lifecycle. Manufacturers that align heat exchanger engineering with condensing duty cycles gain an advantage in both performance reliability and downstream service economics, factors that increasingly matter as installation volumes shift toward higher-efficiency replacements and repeat purchase cycles lengthen.
Installation and operational behavior also shape demand trajectories. Pre-commissioned designs, low-noise operation, compact footprints, and integrated control capabilities are becoming commercially relevant because they reduce on-site labor complexity, improve fit within constrained mechanical spaces, and support smarter building integration. These attributes are especially important as distributors and installers prioritize products that minimize commissioning time while meeting stringent efficiency standards. The study examines how these dynamics interact with regional installation infrastructure maturity, channel training requirements, and the pace at which legacy non-condensing units are being replaced by condensing alternatives.
To support structured evaluation, the report outlines the strategic dimensions that enterprise teams should monitor throughout the forecast period:
- Regulatory alignment pathways and how efficiency thresholds influence product eligibility, promotional eligibility, and replacement cycle acceleration
- Technology substitution patterns between condensing and non-condensing architectures, including the performance and commercial implications of modulating output and intelligent combustion adaptation
- Material and durability considerations, particularly the role of stainless steel heat exchangers in extending service life and supporting long-term efficiency claims
- Installation ecosystem factors such as pre-commissioned design, footprint compression, noise reduction, and control integration that affect channel preference and end-user adoption
- Future fuel compatibility developments, including hydrogen-ready design strategies that position product portfolios for longer-horizon infrastructure transitions
These dynamics are not treated as isolated trends. The study maps their interaction across product development, distribution strategy, and regional deployment conditions, helping readers identify where operational readiness must be strengthened and where market opportunities are likely to concentrate.
Strategic Takeaways for 2026 Planning Cycles
The wall mounted gas boiler market is entering a phase where efficiency compliance, installation efficiency, and future fuel compatibility converge to redefine competitive advantage. Historical growth from 2020 through 2025 demonstrates a market that has consistently expanded under real demand conditions, while the 2026–2032 forecast horizon suggests continued momentum with a compound annual growth rate of 5.49 percent. Total revenue projections moving from an estimated 6,754.87 million USD in 2026 toward approximately 9,099.16 million USD by 2032 reflect a trajectory that rewards organizations capable of aligning product architecture, channel execution, and regulatory foresight.
Yet the strategic value of this study lies in what it enables beyond the headline numbers. It provides a structured basis for evaluating where condensing technology adoption is most advanced, which efficiency and material strategies are becoming commercially decisive, how leading manufacturers are differentiating through modulating output, pre-commissioned installation, and hydrogen-ready development, and where regional and application-level demand patterns are likely to influence capacity and distribution decisions. These insights are essential for teams planning product portfolio adjustments, regional expansion, competitive benchmarking, and investment prioritization.
This preview is intentionally designed to demonstrate analytical depth while reserving the most actionable segmentation data, detailed company comparisons, and intersectional market breakdowns for the complete report. The full study delivers the precision that enterprise decision-makers need to move from broad directional awareness to targeted strategic execution. For leaders who require a reliable foundation for 2026 planning and beyond, the complete market research offers the detailed intelligence necessary to translate market dynamics into informed, confident action.
For detailed analysis of this topic, please visit the official page: Wall Mounted Gas Boiler Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Neuropathy Pain Treatment Market to Hit $12.94 Billion by 2032, Driven by 7.64% CAGR
By PW Consulting, 2026-09-07
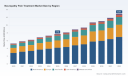
Strategic Horizon 2026: Navigating the Neuropathy Pain Treatment Market
The global landscape for neuropathy pain treatment is undergoing a profound transformation, driven by an aging population, the rising prevalence of diabetes, and significant advancements in pharmacological understanding. As we approach 2026, the decision-making window for pharmaceutical leaders, healthcare investors, and strategic planners is narrowing. Understanding the trajectory of this market is no longer optional; it is a critical imperative for capitalizing on emerging opportunities and mitigating regulatory risks. PW Consulting's latest market research offers a comprehensive lens through which to view these dynamics, providing the granular intelligence necessary to navigate a sector defined by both robust growth and complex therapeutic challenges.
Worldwide Air Traffic Control Hardware Solutions Market
The convergence of chronic disease management and pain mitigation has created a fertile ground for investment. However, the heterogeneity of neuropathic conditions requires a nuanced approach to market entry and portfolio expansion. This report serves as a strategic compass, detailing the economic contours and competitive forces that will define the industry over the next half-decade. By dissecting the market from multiple analytical angles, we provide stakeholders with the foresight needed to align their commercial strategies with the evolving demands of clinicians and patients alike.
Worldwide Compound Extruder Market
Market Trajectory and Economic Outlook
The historical data from 2020 through 2025 establishes a clear precedent of steady expansion, setting the stage for accelerated growth in the forecast period. The market has demonstrated resilience even amidst global supply chain disruptions and shifting healthcare priorities. In the base year of 2025, the overall market revenue reached 7.76 Billion USD. This figure represents a significant accumulation of value over the preceding five years, reflecting the increasing adoption of standardized pain management protocols and the broadening of therapeutic indications.
Worldwide Head Mounted Transmitter Market
Looking forward to the forecast period spanning 2026 to 2032, the momentum is projected to sustain and even intensify. The Compound Annual Growth Rate (CAGR) is estimated at 7.64 percent, signaling a healthy expansion rate that outpaces many traditional therapeutic sectors. By the end of the forecast horizon in 2032, the market is expected to surpass the 12.94 Billion USD mark. This trajectory implies a substantial increase in total addressable market size, offering lucrative avenues for stakeholders who can position themselves effectively ahead of this curve.
For corporate strategists, these macroeconomic figures are more than just statistics; they represent the scale of opportunity available for new product launches, pipeline acquisitions, and geographic expansion. The growth from 8.14 Billion USD in 2026 to nearly 13 Billion USD by 2032 suggests that demand will not be limited to mature markets but will increasingly draw from emerging economies where healthcare infrastructure is improving. The consistent year-over-year increments indicate a stable demand environment, reducing the volatility risk often associated with niche therapeutic areas.
Therapeutic Segments and Clinical Drivers
The utility of this research lies in its ability to deconstruct the aggregate market numbers into actionable therapeutic insights. The landscape is dominated by distinct drug classes that cater to different physiological mechanisms of pain. Anticonvulsants remain a cornerstone of treatment, holding a significant portion of the market share due to their established efficacy in managing nerve pain. Antidepressants also constitute a major pillar, particularly for patients where pain coexists with mood disorders, a common comorbidity in chronic neuropathy cases.
Beyond these mainstream categories, specialized formulations including opioids and capsaicinoids serve specific patient profiles where first-line treatments may be insufficient or contraindicated. The segmentation by drug class reveals a diversified ecosystem where innovation is not confined to a single molecule type. This diversity allows pharmaceutical companies to strategize based on their existing intellectual property portfolios or licensing capabilities. For instance, companies with strong anticonvulsant pipelines can leverage the dominant position of this class, while those focused on novel delivery mechanisms might target the capsaicinoid segment for localized pain relief solutions.
Equally critical is the breakdown by indication, which maps the revenue potential to specific disease states. Diabetic neuropathy continues to be the primary driver of demand, reflecting the global diabetes epidemic. Chemotherapy-induced neuropathy represents a growing segment, driven by advancements in oncology treatments that extend survival rates but leave patients managing long-term side effects. Postherpetic neuralgia and sciatic neuropathy further fragment the market, requiring targeted marketing and clinical engagement strategies. Understanding the revenue weight of each indication allows businesses to prioritize resources toward the highest value patient populations without neglecting niche areas that may offer premium pricing opportunities.
- Drug Class Dynamics: Evaluation of anticonvulsants, antidepressants, opioids, capsaicinoids, and other emerging classes.
- Indication Focus: Analysis covering diabetic neuropathy, chemotherapy-induced neuropathy, postherpetic neuralgia, sciatic neuropathy, and other conditions.
- Clinical Guidelines: Integration of current therapeutic recommendations influencing prescribing behaviors.
Competitive Landscape and Strategic Positioning
The market structure is characterized by a moderate level of concentration, suggesting room for both established giants and agile niche players to compete. The top three companies collectively hold approximately 45.2 percent of the market, while the top five firms account for 58.3 percent. This concentration indicates that while market leaders exert significant influence through brand recognition and formulary access, a substantial portion of the revenue remains distributed among secondary competitors. This distribution creates opportunities for companies to carve out specific niches or acquire assets to consolidate their position.
Key industry players are actively shaping the competitive environment through product lifecycle management and generic entry strategies. Pfizer, headquartered in New York, continues to leverage its flagship products such as Lyrica and Lyrica CR, maintaining a strong presence in diabetic peripheral neuropathy and postherpetic neuralgia treatments. Meanwhile, companies like Eli Lilly and Company focus on antidepressant-based solutions like Cymbalta for diabetic peripheral neuropathy, diversifying the pharmacological approaches available to prescribers.
The generic segment is equally dynamic, with manufacturers like Torrent Pharmaceuticals Limited and Sunshine Biopharma expanding access to essential medications. Torrent produces generic pregabalin, offering cost-effective alternatives to branded options, while Sunshine Biopharma has recently entered the space with generic gabapentin products. Almatica Pharma LLC further complements this landscape by managing a portfolio of gabapentin products including Neurontin, Gralise, and Horizant. These companies collectively ensure that price competition remains a factor, influencing overall market pricing strategies and reimbursement negotiations.
- Brand Leaders: Strategies employed by major pharmaceutical firms to protect market share through extended-release formulations and new indications.
- Generic Entrants: The impact of ANDA approvals and generic launches on pricing pressure and market accessibility.
- Portfolio Diversification: How companies are balancing branded innovation with generic volume to maximize revenue streams.
Regulatory and Reimbursement Dynamics
Navigating the regulatory environment is as critical as understanding the clinical science. Recent regulatory actions have set new standards for drug development and labeling, particularly in complex areas like chemotherapy-induced peripheral neuropathy. In January 2025, the FDA issued a guidance document specifically addressing the development of drug and biological products for the prevention and treatment of this condition. This move signals a heightened regulatory focus on oncology-related neuropathic pain, potentially accelerating the approval pathways for targeted therapies in this segment while raising the bar for clinical evidence requirements.
Simultaneously, reimbursement policies and therapeutic guidelines are shaping prescribing habits at the point of care. In January 2025, the Texas Health and Human Services Commission updated its therapeutic drug class review, categorizing pregabalin and gabapentin as first-line agents for neuropathic pain. Additionally, duloxetine and milnacipran are recognized as additional first-line options. These classifications directly influence formulary decisions and insurance coverage, making compliance with regional health authority guidelines a prerequisite for market success. Companies must ensure their value propositions align with these preferred status designations to secure favorable reimbursement terms.
Controlled substance regulations also remain a pivotal consideration. Pregabalin is classified as a Schedule V controlled substance under federal regulations, requiring strict prescription protocols. This classification impacts distribution logistics, pharmacy stocking decisions, and patient access pathways. Strategic planners must account for these regulatory constraints when designing supply chain networks and sales force training programs. The interplay between efficacy, safety, and regulatory control creates a complex operating environment where compliance is not just a legal necessity but a competitive differentiator.
Strategic Implications for 2026 Decision Makers
As organizations prepare their strategies for 2026, the insights contained in this report offer several critical takeaways. First, the projected growth to over 12.94 Billion USD by 2032 underscores the importance of long-term capacity planning and R&D investment. Companies that hesitate to enter or expand within this space risk ceding share to competitors who are already positioning themselves for the upcoming wave of demand. Second, the segmentation data highlights the need for precision marketing. A one-size-fits-all approach is insufficient when the revenue drivers vary significantly across drug classes and indications.
Third, the competitive analysis suggests that partnership and licensing opportunities may be more viable than de novo development for certain players. Given the concentration levels and the activity of generic manufacturers, acquiring existing pipelines or partnering with generic producers can accelerate time-to-market. Finally, the regulatory updates regarding chemotherapy-induced neuropathy and controlled substance scheduling require immediate attention. Strategic plans must incorporate compliance workflows and advocacy efforts to navigate these evolving requirements successfully.
The timing of market entry is also paramount. With recent product launches such as Sunshine Biopharma's generic gabapentin in June 2025, the window for establishing a foothold in certain generic segments is narrowing. Early movers who can secure distribution agreements and clinician loyalty before the market becomes saturated will gain a distinct advantage. Conversely, late entrants must offer distinct value propositions, such as improved delivery systems or combination therapies, to justify their presence.
Navigating the Data Depth
While this overview provides a high-level strategic framework, the full scope of opportunity requires a deeper dive into the specific data points that drive these conclusions. The aggregate figures and trends discussed here are derived from a comprehensive dataset that includes detailed regional performance, granular revenue splits by segment, and extensive company profiles. Understanding the specific market share percentages, regional revenue distributions, and precise forecast models for each sub-segment is essential for building a robust business case.
For instance, while we have discussed the dominance of North America and the growth potential in Asia Pacific at a conceptual level, the exact revenue contributions and growth rates for each territory are crucial for investment allocation. Similarly, the specific valuation of each drug class and indication segment informs pricing strategies and portfolio prioritization that cannot be fully appreciated without the complete dataset. The nuances hidden within the segmentation splits determine where the highest margins lie and which customer segments are most resilient to pricing pressure.
To access the complete intelligence required for definitive strategic planning, stakeholders are encouraged to consult the full Neuropathy Pain Treatment Market research report. The full document contains the granular tables, detailed methodological explanations, and proprietary forecasts that transform general insights into actionable business intelligence. In a market moving toward 12.94 Billion USD, having the precise data behind the trends is the difference between a good strategy and a great one.
Conclusion
The neuropathy pain treatment market stands at a pivotal juncture in 2026. With a solid historical foundation, a robust CAGR of 7.64 percent, and a complex mix of regulatory and competitive forces, the sector offers significant potential for growth. However, realizing this potential requires more than general awareness; it demands precise, data-driven decision-making. From the dominance of anticonvulsants and antidepressants to the regulatory nuances of Schedule V substances and FDA guidance, every factor plays a role in shaping the commercial landscape.
PW Consulting's analysis provides the necessary depth to navigate this environment, offering a clear view of the market concentration, key player strategies, and therapeutic shifts. By leveraging these insights, organizations can align their resources with the highest value opportunities, mitigate regulatory risks, and capture share in a market destined for substantial expansion. The path forward is clear for those equipped with the right intelligence, making this research an indispensable tool for leaders aiming to define their position in the next era of pain management.
For detailed analysis of this topic, please visit the official page: Neuropathy Pain Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Medical Device Polymers Market to Reach $18.49 Billion by 2032, Growing at 7.8% CAGR
By PW Consulting, 2026-09-07
Navigating the Next Wave of Growth: Strategic Imperatives in the Polymers for Medical Devices Market
Executive Preview from PW Consulting
The global healthcare infrastructure is undergoing a material transformation. As medical device manufacturers push for lighter, more durable, and increasingly patient-specific solutions, the polymers that form the structural and functional backbone of these products have become a critical strategic battleground. PW Consulting’s latest in-depth market assessment tracks this evolution across a seven-year forecast horizon, translating macroeconomic shifts into actionable decision intelligence for executives, product developers, and supply chain leaders. This article outlines the strategic architecture of the research, highlights the structural forces reshaping competitive positioning, and demonstrates why a disciplined, data-grounded approach to polymer sourcing and R&D allocation will define market winners through the end of the decade.
Auxiliary Photosensitive Chemicals Market
Decision-makers evaluating capital allocation, supplier partnerships, or new product portfolios require more than headline figures. They need to understand how regulatory cadence, regional manufacturing footprints, and high-performance material substitution patterns intersect to create margin opportunities and compliance bottlenecks. The research framework presented here is designed precisely for that purpose: it maps observable market growth against the operational realities of medical-grade compounding, sterilization validation, and cleanroom conversion, while deliberately leaving the granular breakdowns for the complete dataset available on our source portal.
Big Data Replication Software Market
Macro Trajectory and the Strategic Opening for 2026 Decision-Making
The polymers incorporated into medical devices have moved from supporting roles into primary design determinants. Over the historical window, the sector demonstrated sustained expansion as device complexity increased and single-use architectures gained prevalence. The most recent baseline year reflects a consolidated global revenue level that underscores how deeply polymer selection is now embedded in device economics. Looking forward, the forecast period extends through the early 2030s, projecting a compound annual growth rate in the high-single-digit range. This trajectory is not uniform: it is conditioned by sterilization requirements, implant-grade validation cycles, and the pace at which manufacturers transition from legacy materials to engineered alternatives.
Worldwide Solvent Based Fire Retardant Coating Market
For 2026 planning cycles, the strategic implication is clear. The growth corridor offers room for suppliers to capture share through differentiated biocompatibility profiles, regional supply resilience, and faster qualification pathways. It also creates risk for OEMs that treat polymer procurement as a commoditized line item rather than a design-and-compliance decision. Executives who integrate the full segmentation logic, regional supply constraints, and application-specific qualification timelines into their budget models will be positioned to mitigate lead-time volatility and secure preferential access to medical-grade lots during periods of constrained conversion capacity.
What the Research Delivers: Actionable Intelligence Beyond Headline Growth
A robust market study must bridge the gap between aggregate revenue projections and the operational questions that procurement, regulatory, and R&D teams face daily. The PW Consulting report is structured to serve as a working reference rather than a static snapshot. Its architecture combines historical normalization, forward modeling, and qualitative benchmarking so that readers can stress-test assumptions against multiple scenarios.
- Historical trajectory analysis spanning the 2020 to 2025 window, aligning revenue evolution with known demand shocks, supply chain disruptions, and material substitution cycles.
- Forward modeling through the forecast horizon, with year-by-year progression that allows planners to map procurement peaks, capacity ramp schedules, and milestone gate reviews.
- Segmentation logic that separates material families, application contexts, and geographic demand clusters, enabling targeted sensitivity analysis rather than blunt aggregate planning.
- Competitive benchmarking across principal suppliers, including product-line positioning, specialty resin portfolios, and geographic manufacturing footprints.
- Regulatory and compliance cross-references that tie material selection to biocompatibility testing regimes, sterilization validation expectations, and change-control documentation requirements.
- Scenario-ready architecture, allowing users to adjust assumptions around regional capacity, conversion bottlenecks, and premium-grade pricing dynamics without rebuilding the model from scratch.
Each section is designed to feed directly into budgeting, supplier qualification, and product roadmap decisions. The complete dataset, including granular regional splits and application-level breakdowns, is reserved for the full report environment so that subscribers can run internal comparisons without relying on second-hand summaries.
Competitive Architecture: Seven Supplier Archetypes Shaping the Field
The market’s competitive structure reflects the technical demands of medical-grade production. High-performance thermoplastics, biostable elastomers, and emerging biodegradable systems each require specialized compounding, documentation, and conversion capabilities. The companies highlighted in the research illustrate how supplier strategies diverge across engineering excellence, regional localization, and sustainability-aligned material development.
Specialized Implant and High-Performance Resin Providers
Several European and American incumbents anchor the premium segment through implant-grade polymers and surgical tool materials. One German specialty supplier has built recognition around bioresorbable polymer systems and PEEK-based implantable solutions, complemented by filaments engineered for additive manufacturing workflows. A Belgian high-performance materials leader contributes PEEK, PPSU, and broader PAEK families that target long-term implant contact, sterilization resilience, and tooling applications where thermal and chemical stability are non-negotiable. These players compete not merely on resin chemistry but on qualification support, lot traceability, and the ability to co-develop formulations that reduce device-level validation burden.
Engineering Plastics and Device-Touch Materials
Another tier of competitors focuses on medical-grade engineering plastics that balance mechanical performance with manufacturability. A large German chemical group supplies polymer families tailored to surgical instruments, fluid handling components, and patient-contact parts, emphasizing formulations designed for sterilization compatibility and dimensional stability. A separate German materials company has expanded its device-touch portfolio with polycarbonate and thermoplastic polyurethane lines for intravenous systems, wearable platforms, and sterilization-resistant assemblies. A U.S.-based specialty firm extends this logic with polyesters, polyacetal, ultra-high-molecular-weight polyethylene, and liquid crystal polymers that support precision components, injection delivery systems, and orthopedic applications.
Tubing, Conversion, and PVC-Alternatives Specialists
Not all competitive advantage resides in resin synthesis. Conversion and tubing specialists translate medical-grade polymers into finished or semi-finished components under cleanroom conditions, where process control and regulatory documentation are integral to product value. One German converter has concentrated on thermoplastic and silicone processing for tubing, catheters, and injection systems, reflecting how downstream capability can become a differentiator when device makers seek to shorten assembly complexity. Alongside this, a U.S.-based polymer supplier has pushed styrenic block copolymers and related elastomeric systems as flexible, non-PVC options for tubing and component designs, aligning with broader sustainability and solubility concerns in disposable architectures.
Recent Developments That Signal Strategic Direction
Recent events reinforce the direction of travel. A major materials group localized production of a medical-grade thermoplastic polyurethane at a Taiwan site to strengthen regional supply for device manufacturers. A separate high-performance materials company introduced a white PPSU resin aimed at medical devices, surgical instruments, and biopharma workflows, expanding the palette of visually inspectable, high-purity resins. On the regulatory side, a light-activated polymer formulation received clearance for a 3D-printed nerve repair cuff device, illustrating how additive manufacturing and novel resin chemistry are converging in clinical applications. In parallel, a biomedical materials partner entered a co-development arrangement to advance next-generation bioresorbable systems for devices and drug delivery, signaling that biodegradable and bioresorbable pathways remain an area of active investment. Another supplier introduced a medical-grade polyurethane tailored for wearable devices with enhanced biocompatibility, reinforcing how wearable and patient-monitoring architectures are pulling material requirements toward skin-contact performance and long-term comfort.
Regulatory and Operational Dynamics That Redefine Competition
The market’s growth ceiling is not determined by demand alone. It is defined by the compliance environment surrounding polymeric materials used in direct patient contact, terminally sterilized assemblies, and implantable systems. Biocompatibility expectations under internationally recognized testing series shape material selection at the design stage. Packaging integrity and microbial barrier performance require validation pathways that influence how medical-grade polymers are integrated into finished device architectures. For implantable and long-term contact applications, manufacturers must operate under production control expectations that include change-notification discipline and supply continuity planning. These requirements introduce a structural premium on suppliers that can maintain lot-to-lot consistency, provide robust documentation, and support change management without triggering re-qualification delays.
The operational layer adds further nuance. Specialized conversion and compounding for medical-grade polymers typically depends on cleanroom environments and skilled operators to preserve biocompatibility and regulatory adherence. This means that raw resin availability does not automatically translate into device-ready supply. Lead times, conversion capacity, and qualification readiness often matter more to device OEMs than headline pricing. At the same time, regulatory encouragement around biodegradable polymers in disposable devices and packaging is reinforcing sustainability-oriented material substitution, particularly where waste reduction and single-use optimization intersect with clinical workflow improvements. Together, these dynamics create a market in which technical compliance and supply resilience are competitive advantages, not overhead.
Strategic Priorities for 2026 Planning
Given the interaction between growth momentum, regulatory constraints, and supplier specialization, several priorities emerge for executives shaping 2026 strategy.
- Treat medical-grade polymer selection as a design-and-compliance decision. Material performance, sterilization tolerance, and documentation readiness should be evaluated alongside cost, because qualification timelines can dominate total program economics.
- Map regional supply resilience against conversion capacity. Raw resin forecasts are necessary but insufficient; cleanroom conversion, tubing extrusion, and device-level assembly readiness can become the binding constraint during demand surges.
- Monitor high-performance and biodegradable substitution patterns. As implantable, surgical, and wearable applications continue to expand, premium resin families and bioresorbable systems are shaping new value pools that reward early qualification and specification leadership.
- Build supplier partnerships around change control and traceability. In categories where notification procedures and lot consistency matter, relationship depth and documentation capability can reduce downstream risk more effectively than transactional sourcing.
- Integrate sustainability drivers without over-indexing on narrative. Regulatory encouragement, packaging optimization, and PVC-alternative adoption are real demand signals, but strategic advantage comes from verifying material performance, sterilization compatibility, and supply continuity before scaling commitments.
Why the Complete Dataset Changes the Decision
Aggregated growth figures establish direction, but the operational decisions that determine outcomes live in the segmentation details. Regional demand distribution, application-level concentration, and material-family splits shape where margin pools form, where qualification bottlenecks emerge, and how supplier portfolios should be weighted in a sourcing strategy. The full report environment provides that structure without sacrificing analytical rigor, allowing teams to compare scenarios internally while preserving confidentiality and decision speed.
For organizations preparing for 2026 budgeting, product roadmap reviews, or supplier qualification cycles, the complete intelligence set offers a practical bridge between market growth and execution readiness. The research has been built to support those conversations with a clear, testable, and continuously relevant view of how polymers in medical devices are likely to evolve across the forecast horizon.
Accessing the Full Intelligence
The complete market assessment is available through our source portal, where subscribers can access the full segmentation architecture, regional and application-level breakdowns, supplier benchmarking tables, and the scenario-ready forecast models that underpin this analysis. Given the technical specificity of medical-grade polymer sourcing and the pace of regulatory and product developments, the most valuable use of this research is interactive: teams can test assumptions against the detailed splits, align procurement calendars with regional capacity signals, and prioritize qualification investments where material substitution and compliance risk intersect.
PW Consulting’s Polymers in Medical Devices Market study is designed for decision-makers who need more than directional confidence. It provides the structural detail required to translate market growth into sourcing strategy, R&D prioritization, and regulatory readiness. For executives preparing for the 2026 planning cycle, the complete dataset offers the precision necessary to move from headline growth to executable advantage.
For detailed analysis of this topic, please visit the official page: Polymers in Medical Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: High Silica Zeolite Market Hits $1.19M in 2025, Projects 1.2% CAGR to 2032
By PW Consulting, 2026-09-07
Navigating the High Silica Zeolite Market: Strategic Intelligence for 2026 Decision Makers
Introduction: The Intersection of Stability and Niche Growth
The High Silica Zeolite market represents a specialized segment within the broader industrial catalyst and adsorbent landscape. For executives and strategists operating in 2026, understanding the trajectory of this market is not merely about tracking commodity prices; it is about anticipating shifts in refining efficiency, petrochemical throughput, and environmental compliance standards. As global industries pivot towards more sustainable operational frameworks, the demand for high-performance molecular sieves becomes increasingly critical. This market research briefing serves as a foundational tool for organizations seeking to align their supply chains, R&D investments, and partnership strategies with the evolving realities of the high silica zeolite sector.
Worldwide Elderly Hearing Aids Market
Our analysis covers the period from 2020 through 2032, providing a robust historical baseline alongside a forward-looking forecast. The data indicates a market that is mature yet resilient, characterized by steady progression rather than volatile spikes. By examining the interplay between technological specifications, regional manufacturing capabilities, and key corporate maneuvers, stakeholders can derive actionable insights that mitigate risk and identify emerging opportunities.
Worldwide Elderly Culture and Entertainment Market
Market Size and Trajectory: A Long-Term Perspective
Understanding the macroeconomic contours of the high silica zeolite market is essential for long-term capital allocation. The market has demonstrated a consistent presence over the past half-decade, maintaining a stabilized revenue profile in million USD terms. Historical data from 2020 to 2025 shows a market that has navigated various economic cycles while preserving its core value proposition. As we move into the forecast period extending to 2032, the growth trajectory suggests a gradual expansion.
Email Newsletter Tool Market
The compound annual growth rate (CAGR) projected for the forecast period stands at 1.2 percent. While this figure may appear modest compared to high-growth technology sectors, it reflects the mature nature of the industrial catalyst market. For investors and corporate planners, this steady growth rate indicates a lower-risk environment where value is derived from efficiency gains, product differentiation, and strategic consolidation rather than pure volume expansion. The forecast model anticipates fluctuations in yearly revenue, highlighting specific periods of consolidation followed by moderate upticks. This granular temporal analysis allows clients to prepare for inventory management and capacity planning with greater precision.
It is crucial to note that while the overall market size provides the umbrella view, the real strategic value lies in understanding the underlying drivers that sustain this trajectory. The stability observed in the 2020 to 2025 window was supported by consistent demand from downstream industries, even as global supply chains faced disruptions. The forecast to 2032 suggests that this demand will persist, albeit shaped by new regulatory pressures and technological advancements in catalyst formulation.
Segmentation Dynamics: Types, Applications, and Regional Influence
A superficial view of market size is insufficient for tactical decision-making. The true complexity of the high silica zeolite market lies in its segmentation. Our research dissects the market across type, application, and region, revealing where value is actually generated and consumed.
From a product type perspective, the market is stratified among several key zeolite variants. The dominance of specific types, such as ZSM-5, reflects their entrenched position in established refining processes. However, the presence of other types like USY and Beta indicates a diversified demand structure. Understanding the proportion of revenue attributed to each type helps manufacturers decide where to focus production capabilities. For instance, a type with a higher share of the market mix may require different scaling strategies compared to a niche variant with specialized performance characteristics. The report details the revenue splits across these categories without exposing the specific percentage breakdown here, encouraging a deeper dive into the full dataset for precise modeling.
Application-wise, the market is heavily influenced by the petroleum and petrochemical sectors. These industries remain the primary consumers of high silica zeolites due to their reliance on cracking and alkylation processes. However, the report also captures the remainder of the market, which includes emerging applications that may offer higher margins or growth potential. Identifying the weight of these application segments is vital for suppliers looking to diversify their client base beyond traditional refining customers.
Regionally, the market exhibits distinct characteristics. North America, Europe, and Asia Pacific represent significant portions of the market landscape. Each region presents unique regulatory environments, manufacturing hubs, and consumption patterns. For example, regulatory shifts in Europe regarding emissions and efficiency can drive demand for specific high-performance zeolites differently than in Asia Pacific, where industrial output growth might be the primary driver. The report segments the market by these geographic zones to help companies tailor their go-to-market strategies. Specific regional revenue splits are reserved for the comprehensive report to maintain the precision of our competitive intelligence.
Competitive Landscape: Key Players and Strategic Positioning
The high silica zeolite market is not a commodity free-for-all; it is defined by a select group of sophisticated manufacturers who command significant influence. Our analysis identifies key companies that shape the industry dynamics, ranging from specialized zeolite producers to large chemical conglomerates. The market concentration metrics indicate that while the market is not overly monopolized, there is a clear tier of leaders who drive pricing and innovation standards.
Tosoh Corporation, headquartered in Tokyo, stands as a leading producer of HSZ-series high silica zeolites. Their focus on SiO2/Al2O3 ratios above 10 positions them strongly in petroleum refining and petrochemical hydrocracking. Recent developments highlight the volatility inherent in this sector; for instance, in August 2025, Tosoh reported decreased HSZ shipments for automotive applications in both domestic and European markets. This kind of company-specific intelligence is crucial for competitors analyzing market share shifts and for customers assessing supply reliability.
Zeolyst International, based in Pennsylvania, operates as a global supplier of synthetic high-silica zeolite powders. Their positioning spans petroleum refining, petrochemicals, and emission control, making them a versatile player. Similarly, W.R. Grace & Co. in Maryland continues to manufacture high-performance catalysts for refining processes, leveraging decades of chemical engineering expertise. These US-based entities compete closely with European giants such as Clariant AG and BASF SE. Clariant, located in Muttenz, supplies synthetic high silica zeolites for industrial catalyst and adsorbent applications, while BASF in Ludwigshafen produces zeolite catalysts including high-silica variants for refining and petrochemical sectors.
Honeywell International Inc., through its UOP division in Charlotte, supplies high-silica zeolite catalysts for petroleum refining and chemical processes, integrating zeolite technology into broader process solutions. Additionally, Zeochem AG in Rotkreuz, Switzerland, manufactures high-silica zeolites for catalysts and adsorbents in refining and petrochemical industries. The interactions between these companies—whether through competition, patent landscapes, or supply chain dependencies—define the market's competitive intensity. Understanding the headquarters, operational focus, and recent shipment trends of these entities allows strategists to map out potential partnership opportunities or competitive threats.
Industry Dynamics: Raw Materials and Regulatory Pressures
Market dynamics are often driven by factors external to the zeolite production itself. Raw material availability and pricing form the bedrock of cost structures. According to data from the USGS in February 2026, US natural zeolite production rose to an estimated 81,000 tons in 2024, with ex-works unit values averaging $145 per metric ton. While natural zeolites differ from synthetic high silica variants, the broader zeolite ecosystem influences supply chain logistics and raw material sourcing strategies for chemical manufacturers. Fluctuations in natural zeolite production can signal broader geological or economic trends affecting the mineral sector.
Furthermore, regulatory environments play a pivotal role in shaping demand. The same USGS report noted that US natural zeolite production and sales increased due to growing demand for animal feed, odor control, soil amendment, and water purification applications. While these are not the primary focus of high silica synthetic zeolites, they illustrate the regulatory push towards environmental stewardship and resource efficiency that permeates the entire industry. For high silica zeolite manufacturers, this translates into pressure to develop catalysts that enable cleaner refining processes or more efficient chemical conversions. Compliance with emission standards and the drive for energy efficiency in petrochemical plants are indirect but powerful drivers of demand for advanced zeolite materials.
Operational noise in the industry, such as shipment variations reported by major players like Tosoh, underscores the importance of real-time monitoring. A decrease in automotive application shipments in specific regions can ripple through the supply chain, affecting inventory levels and pricing strategies. Our report integrates these dynamic factors to provide a living view of the market, rather than a static snapshot.
Report Content Overview: Operational Intelligence for Execution
To translate these high-level insights into execution, our comprehensive market research report provides a detailed operational toolkit. The document is structured to support various functional teams within an organization, from strategy and finance to operations and sales.
The scope of the analysis covers the historical period from 2020 to 2025 and the forecast period from 2026 to 2032. All financial data is presented in USD millions, ensuring consistency for global reporting standards. The report includes detailed segmentation splits that allow users to isolate specific market niches. By breaking down the market by region, type, and application, clients can benchmark their own performance against the broader industry averages.
Beyond market sizing, the report delves into company profiles for the key industry participants. These profiles include headquarters locations, corporate URLs, and summary assessments of their product portfolios and market focus. This information is invaluable for vendor selection, partnership due diligence, and competitive benchmarking. The inclusion of recent developments, such as shipment updates and product launches, ensures that the intelligence is current and relevant for immediate decision-making.
Additionally, the report contextualizes the market within the broader industry environment by incorporating data on raw materials and regulatory trends. This holistic approach ensures that users understand not just the 播报 numbers, but the forces that influence them. The concentration metrics, such as CR3 and CR5 percentages, provide insight into market competitiveness and barrier to entry. By understanding the level of consolidation, new entrants can assess the viability of market participation, while incumbents can evaluate the risk of disruption.
Strategic Imperatives for 2026 and Beyond
As organizations plan their strategies for the remainder of the decade, several imperatives emerge from this market analysis. First, maintaining supply chain resilience is paramount. Given the specialized nature of high silica zeolite production and the concentration of key manufacturing hubs, disruptions can have outsized effects. Diversifying sourcing channels and understanding the capacity limits of key suppliers like Tosoh or Zeolyst can prevent operational bottlenecks.
Second, innovation in catalyst formulation remains a key differentiator. With the market growing at a steady CAGR, volume growth alone may not suffice to capture significant value. Companies that invest in developing zeolite variants with higher efficiency, longer lifecycle, or better adaptability to new refining technologies will likely command premium positioning. The report's segmentation data helps identify which types and applications are yielding the most value, guiding R&D investment priorities.
Third, regulatory compliance should be viewed as a strategic opportunity rather than a cost center. As environmental regulations tighten globally, the demand for catalysts that enable cleaner processes will rise. Aligning product development with these regulatory trends can open up new revenue streams. The industry context regarding environmental applications, even in adjacent sectors like natural zeolites, signals a broader shift towards sustainability that high silica zeolite producers can leverage.
Finally, competitive intelligence must be continuous. The actions of major players, such as shipment adjustments or shifts in focus areas, provide leading indicators of market trends. Monitoring the activities of companies like Honeywell UOP or BASF allows strategists to anticipate shifts in pricing, availability, and technology standards. Our report provides the framework for this ongoing monitoring by establishing a baseline of company capabilities and recent performance.
Conclusion: Accessing Comprehensive Intelligence
The High Silica Zeolite Market is a complex, mature ecosystem where strategic advantages are gained through depth of knowledge rather than broad generalizations. The steady growth trajectory, combined with the specialized nature of the product segments and the influence of key corporate players, requires a nuanced approach to planning. This briefing has outlined the macro landscape, the competitive forces, and the operational dynamics that define the sector. However, the full value of this research lies in the detailed data tables, specific segmentation percentages, and granular forecast models that support precise financial modeling and strategic planning.
For organizations ready to deepen their understanding and secure their position in this market, accessing the full comprehensive report is the logical next step. The detailed intelligence contained within allows for scenario planning, precise market entry analysis, and robust competitive benchmarking. In a market where margins and efficiency are critical, having access to verified, granular data is the ultimate competitive asset. We invite stakeholders to explore the complete findings to ensure their 2026 decisions are built on the most accurate and actionable industry intelligence available.
For detailed analysis of this topic, please visit the official page: High Silica Zeolite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Smart Card Fare Markets to Reach $2.43B by 2032, Driven by 9.1% CAGR
By PW Consulting, 2026-09-07
Smart Cards Automated Fare Collection Systems Market: A Strategic Compass for 2026 Decision-Making
The global transit landscape is undergoing a fundamental transformation, driven by the convergence of smart card technology, open-loop payment ecosystems, and the urgent demand for seamless multimodal mobility. As municipal authorities and transport operators accelerate their digital modernization agendas, the Smart Cards Automated Fare Collection Systems Market has emerged as a critical battleground for technology providers, systems integrators, and public sector stakeholders. Our latest market research publication offers a rigorous, data-grounded examination of this evolving sector, delivering the strategic intelligence required to navigate the opportunities and complexities that will define the 2026–2032 forecast horizon.
Environmentally Friendly Recycled Plastic Solution Market
This article serves as a strategic preview of the full report. It highlights the macro trajectory, the structural dynamics reshaping competitive positioning, and the operational insights embedded within our analysis. Readers seeking precise segment valuations, regional breakdowns, and granular competitor benchmarking will find the complete dataset exclusively available through the full research publication.
Backgammon Market
The Macro Trajectory: Sustained Expansion at a Defining Inflection Point
Analyzing historical performance from 2020 through the 2025 base year, the market has demonstrated consistent upward momentum, with total revenue expanding from approximately 0.85 billion USD to 1.32 billion USD over the six-year observational window. This trajectory reflects not only steady deployment cycles across mature transit networks but also the accelerating adoption of contactless smart card interfaces in markets previously reliant on legacy paper ticketing or fragmented validation systems.
Worldwide Acoustic Module Market
Looking ahead, the forecast period spanning 2026 to 2032 projects a compound annual growth rate of 9.1 percent, positioning the sector for robust expansion. By the close of the forecast window in 2032, aggregate market revenue is projected to reach 2.43 billion USD. This growth is underpinned by several structural drivers: the continued shift toward cashless and account-based ticketing architectures, the integration of mobile wallet and biometric validation modalities, and the broader modernization of rail and bus networks in both developed and emerging economies.
The momentum observed from 2024 to 2025—where revenue climbed from 1.21 billion USD to 1.32 billion USD—signals a market that is transitioning from early-adoption capitalization to a more mature, scale-driven phase. Organizations evaluating procurement timelines, technology roadmaps, or partnership strategies must recognize that the next several years will reward those who align their investment cycles with this projected acceleration. Our research dissects the inflection points within this curve, mapping where demand concentration is likely to intensify and which deployment models will capture disproportionate share.
Market Architecture and Operational Realities
Automated fare collection ecosystems are inherently multifaceted, comprising hardware deployments, software platforms, and backend settlement infrastructures that must interoperate across diverse operational environments. The market is structured across distinct hardware and software categories, including farebox installations, ticket vending machines, and onboard and off-board validators, each carrying different capital intensity profiles and lifecycle replacement schedules.
Hardware components such as fare gates, validators, and ticket vending machines require substantial investment, and industry data indicates that approximately 47 percent of transit agencies face financial limitations during system implementation. This cost reality introduces a critical strategic variable: procurement decisions are increasingly evaluated not merely on technical compatibility but on total cost of ownership, vendor financing flexibility, and the ability to phase deployments without disrupting service continuity. Our report examines how these budget constraints are reshaping vendor selection criteria, inflationary pressure on component supply chains, and the growing preference for modular, upgradeable architectures over monolithic turnkey installations.
On the regulatory and standards front, the push toward open-loop payment interoperability has gained decisive traction. National transportation authorities are completing nationwide open-loop EMV roll-outs across rail networks, with road-vehicle extensions planned in follow-on phases. For operators and technology vendors alike, this regulatory trajectory demands preparation for costs that extend beyond hardware procurement to encompass network integration, security certification, and ongoing transaction settlement reconciliation. Agencies rolling out open-loop payments must plan for equipment upgrades and backend connectivity that meet emerging security and interoperability benchmarks. Our analysis isolates the regulatory timelines, compliance requirements, and risk vectors that decision-makers must factor into multi-year capital planning.
Competitive Landscape: Concentration, Capability, and Strategic Positioning
The market exhibits moderate concentration, with the top three players capturing approximately 26.5 percent of aggregate revenue and the top five firms accounting for roughly 29.4 percent. This concentration profile suggests a landscape that is neither overwhelmingly consolidated nor excessively fragmented—an environment where scale advantages coexist with meaningful room for specialized technology providers to differentiate through niche capabilities, regional partnerships, or modular product architectures.
Several established leaders define the competitive frontier. Cubic Corporation, headquartered in San Diego, California, continues to operate as a leading provider of integrated turnkey automated fare collection systems for public transport, offering full NFC and contactless smart card interfaces alongside fare processing engines, central computer systems, card management frameworks, and outsourcing services spanning bus, rail, and multimodal operations. Thales Group, based in Paris, functions as a global systems integrator delivering contactless smart card automatic fare collection systems, fare gates, validators, card readers, account-based ticketing platforms, and mobile wallet integration for mass transit and public transport ticketing. Scheidt & Bachmann GmbH, headquartered in Braunschweig, Germany, provides advanced fare collection systems using smart card technology, including account-based ticketing solutions such as the Fare Go Suite for seamless secure mobility with smart cards, mobile apps, contactless cards, and biometric options. Atos SE, located in Bezons, France, delivers complete mobility solutions for public transport including contactless payment systems, smart ticketing technology, transit fare management software, and integrated automated fare collection platforms.
At the component and semiconductor level, NXP Semiconductors, headquartered in Eindhoven, Netherlands, supplies secure NFC and RFID ICs, smart card interfaces, and contact readers for automated fare collection systems, including MIFARE Plus and RAIN RFID solutions enabling hands-free access and interoperable public transport ticketing. Omron Corporation, based in Kyoto, Japan, provides station device systems, transportation IC card solutions, and fare collection equipment supporting contactless smart cards and seamless validation for rail and public transport networks. Siemens AG, headquartered in Munich, Germany, offers integrated public transport ticketing solutions enabling cashless payments with tokens such as smart cards or barcodes linked to user accounts for seamless fare collection in bus, rail, and multimodal systems. These players collectively represent the spectrum of capability that operators evaluate when designing or upgrading fare collection infrastructures.
Our report maps each key company’s product portfolio, geographic footprint, partnership ecosystems, and recent strategic moves, enabling readers to assess where capability overlap exists, where white-space opportunities may emerge, and which vendors are best positioned to support specific deployment scenarios. The full publication provides detailed competitive profiling that goes beyond surface-level descriptions to examine integration complexity, certification portfolios, and service-level execution track records.
Recent Market Developments: Signals of Acceleration
Recent operational milestones illustrate the pace at which transit authorities are recalibrating their fare collection strategies. In March 2026, MARTA began upgrading its fare collection equipment and payment options to enable open payment using bank cards and mobile wallets while continuing to support existing Breeze smart cards. This simultaneous support for legacy smart cards and new open-loop channels reflects a pragmatic transition posture—operators must protect existing rider bases while expanding payment accessibility. Around the same period, Saint Louis Metro introduced next-generation fare collection with upgraded digital tools, new ticket vending machines, and state-of-the-art validators at all stations, signaling the continued relevance of on-site hardware refresh cycles even as backend payment architectures evolve.
Beyond North American deployments, international developments underscore the global nature of this modernization wave. In July 2025, the Land Bank of the Philippines launched a pilot automated fare collection system for MRT-3 enabling EMV payments and serving as a payment-gateway integrator for nationwide settlements. This initiative exemplifies the convergence of banking infrastructure, transit operations, and national payment standardization—a model with implications for other markets seeking to unify settlement rails across transport modes.
These events, among many others documented in the full report, are not isolated announcements; they are indicators of a structural shift. Transit agencies and operators have made real progress in modernizing fare collection through contactless and open-loop payment systems, yet the pace of adoption varies significantly by geography, regulatory environment, and capital availability. Our research contextualizes these developments within broader deployment patterns, helping stakeholders distinguish between headline announcements and actionable trend signals.
What the Full Report Delivers: Operational Intelligence for 2026 Planning
The complete Smart Cards Automated Fare Collection Systems Market research publication is designed as a decision-support tool rather than a static data repository. It integrates quantitative forecasting with qualitative industry analysis to answer the questions that procurement leaders, investment analysts, and technology strategists face when evaluating market entry, expansion, or partnership opportunities.
The report covers the following operational dimensions in depth:
- Historical market sizing from 2020 through the 2025 base year, with year-over-year revenue movement contextualized against deployment cycles, technology refresh patterns, and macroeconomic influences on transit capital budgets.
- A forward-looking forecast spanning 2026 to 2032, presenting revenue projections that account for expected adoption curves, hardware replacement timelines, and the diffusion of account-based and open-loop payment models across different operational environments.
- Segment-level analysis across hardware and software categories, including farebox installations, ticket vending machines, and validators deployed in onboard and off-board configurations. The full report examines how these categories interact, where capital intensity differs, and how lifecycle replacement schedules create recurring revenue opportunities for solution providers.
- Regional market dynamics that reflect distinct regulatory frameworks, infrastructure maturity, and transit ridership patterns. Decision-makers will find contextual analysis that explains why certain regions exhibit different adoption velocities and what that means for vendor go-to-market strategies.
- Competitive profiling of the key companies shaping the market, with attention to product architectures, integration capabilities, geographic presence, and recent strategic developments that indicate future positioning.
- Industry context analysis covering infrastructure cost realities, regulatory mandates such as open-loop EMV roll-outs, and the practical implications of network integration and equipment upgrade requirements for agencies transitioning to open payment environments.
- Strategic recommendations that translate market data into actionable guidance for technology vendors, systems integrators, transit operators, and investment stakeholders evaluating the sector’s growth trajectory and risk profile.
By combining macro revenue projections with segment-level structural analysis and competitive benchmarking, the report enables readers to model scenarios, prioritize investment targets, and anticipate where vendor capabilities will need to evolve to meet emerging operator requirements. The dataset underlying these insights is constructed to support both top-down market sizing and bottom-up segment evaluation, giving users the flexibility to approach the market from multiple analytical angles.
Why This Research Matters for 2026 Decisions
The 2026 to 2032 period will reward organizations that can distinguish between temporary deployment spikes and durable structural shifts. Smart card-based automated fare collection is no longer a niche transit function; it is a core component of the broader mobility payment infrastructure, intersecting with banking networks, mobile platforms, and national digital identity initiatives. Companies that underestimate the pace of open-loop integration, the capital constraints facing transit agencies, or the competitive intensity among established integrators risk misallocating resources or missing partnership windows.
Conversely, organizations that ground their strategy in rigorous market intelligence can identify where demand is concentrating, which deployment models are gaining traction, and how regulatory timelines are compressing decision cycles. The market’s 9.1 percent projected CAGR reflects genuine growth momentum, but growth at this scale also intensifies competition for contracts, accelerates technology obsolescence, and raises the bar for integration reliability. Our research equips decision-makers with the context needed to navigate these pressures rather than react to them after the fact.
For technology vendors and component suppliers, the report clarifies where product roadmaps should prioritize interoperability, where certification and security compliance will become gating factors, and how regional demand variation should influence go-to-market sequencing. For transit operators and public authorities, the analysis supports more informed procurement planning by highlighting the cost realities of hardware deployment, the integration complexity of open-loop transitions, and the vendor ecosystems best aligned with specific operational requirements. For investors and market analysts, the publication offers a structured view of market concentration, growth drivers, and competitive differentiation that supports valuation models and sector allocation decisions.
Accessing the Full Intelligence
This preview has outlined the strategic framework and macro contours of the Smart Cards Automated Fare Collection Systems Market as analyzed in our latest research publication. The complete report expands on every dimension introduced here, providing the detailed segment valuations, regional revenue distributions, competitor benchmarking matrices, and deployment scenario analyses that organizations require to make confident, evidence-based decisions.
Precise segmentation data, including regional revenue splits, type-specific market shares, and application-level breakdowns, is available exclusively within the full report. Readers seeking to evaluate specific market opportunities, benchmark vendors against defined criteria, or model forecast scenarios for internal planning should consult the complete publication to access the underlying dataset and accompanying analytical commentary.
The transit sector’s migration toward contactless, interoperable, and account-based fare collection is accelerating. The organizations that will capture value in this environment are those that combine strategic foresight with rigorous market intelligence. Our Smart Cards Automated Fare Collection Systems Market research is built to provide that foundation, enabling stakeholders to act with clarity as the 2026 to 2032 forecast period unfolds.
For detailed analysis of this topic, please visit the official page: Smart Cards Automated Fare Collection Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Orthopedic Surgical Power Tools Market Hits $194M in 2025, Forecast to $263M by 2032
By PW Consulting, 2026-09-07
Navigating the Next Decade: Strategic Imperatives in the Orthopedic Surgical Power Tools Market
The landscape of orthopedic surgery is undergoing a quiet but profound transformation. As surgical precision becomes increasingly linked to patient outcomes, the reliability and performance of surgical power tools have moved from being mere utilities to critical strategic assets. For stakeholders operating within the medical technology sector, understanding the trajectory of the Orthopedic Surgical Power Tools Market is no longer optional—it is a prerequisite for sustainable growth. Our latest market research provides a comprehensive lens through which to view these dynamics, offering a roadmap for navigating the complexities of the period from 2026 through 2032.
Worldwide Yaw Gear Box for Wind Power Market
This analysis serves as an introduction to the deeper intelligence contained within our full report. While the broader trends provide context, the specific data points required for precise forecasting and competitive positioning are detailed in the complete study. Here, we outline the macro-economic environment, the competitive forces at play, and the regulatory currents that will define the industry over the next decade.
Worldwide Hard Cover Making Machine Market
Market Trajectory and Historical Context
To understand where the market is going, one must first appreciate where it has been. The period from 2020 to 2025 established a baseline of resilience and gradual expansion. Over this historical window, the global revenue for orthopedic surgical power tools climbed from 165.0 million USD to approximately 194.0 million USD. This growth was not linear; it reflected the broader challenges and recoveries within the global healthcare infrastructure during recent years. The stabilization observed in 2023 followed by renewed momentum in 2024 and 2025 signals a maturing market that is absorbing shocks and returning to a growth trajectory.
Wood Clear Finish Market
Looking forward, the forecast period from 2026 to 2032 projects a continued upward trend. The market is expected to expand from an estimated 207.96 million USD in 2026 to 263.9 million USD by 2032. This progression represents a Compound Annual Growth Rate (CAGR) of 4.45 percent. While this rate may appear moderate compared to emerging technology sectors, it is significant within the context of regulated medical devices. It suggests steady demand driven by procedural volume increases rather than volatile speculative investment. For business leaders, this consistency implies that long-term capital allocation decisions can be grounded in predictable demand fundamentals, provided that product portfolios remain aligned with evolving surgical needs.
Core Drivers and Industry Dynamics
Several underlying factors are propelling this market expansion. The aging global population continues to drive demand for joint replacement and trauma repair procedures, which are primary use cases for orthopedic power tools. Furthermore, the shift toward minimally invasive surgery (MIS) places higher demands on the precision and ergonomics of surgical instrumentation. Surgeons require tools that offer consistent torque and control in tighter surgical fields, pushing manufacturers to innovate beyond traditional mechanical designs.
However, growth is not solely a function of demand; it is also constrained and shaped by operational realities. Reusable orthopedic surgical power tools require routine sterilization and maintenance, contributing to higher hospital costs compared to single-use alternatives. This dynamic creates a complex decision matrix for healthcare providers. While reusable instruments offer longevity, the associated labor and sterilization costs, including autoclave monitoring per AAMI ST-79 standards, must be weighed against the convenience of disposable options. This tension influences procurement strategies and product design roadmaps.
Regulatory compliance remains a critical gatekeeper. All orthopedic surgical power tools require FDA 510(k) clearance or CE marking under EU MDR. Compliance with ISO 13485 quality management and ANSI/AAMI standards is mandatory for orthopedic surgical power tools. These requirements ensure safety but add layers of complexity to product launches and market entry. Additionally, reimbursement landscapes are shifting. The 2026 CPT code updates include new codes for osteotomy procedures with externally controlled intramedullary lengthening devices effective January 1, 2026. Such updates can alter the economic viability of specific procedures, thereby influencing the demand for the tools used to perform them.
Competitive Landscape and Strategic Positioning
The market is characterized by a consolidated structure where major players hold significant sway. Market concentration data indicates that the top three companies hold a 62.0 percent share, while the top five control 75.0 percent of the market. This level of concentration suggests that competitive moves by industry giants ripple quickly through the ecosystem, affecting pricing, supply chain dynamics, and innovation pacing.
Several key companies define the current competitive terrain, each with distinct strategic focuses:
- Stryker Corporation: Based in Kalamazoo, Michigan, Stryker continues to reinforce its position through targeted product launches. In June 2026, the company launched the TPX HD premium small bone power tool for demanding orthopaedic procedures including total joint revisions, minimally invasive surgery, and oral maxillofacial cases. This move highlights a strategy focused on high-performance tools for complex revisions and specific specialties.
- Zimmer Biomet Holdings, Inc.: Located in Warsaw, Indiana, Zimmer Biomet emphasizes modularity in its approach. Their X Series Power System serves hip, knee, trauma, and shoulder procedures with modular design. This flexibility allows healthcare providers to standardize across different procedure types, potentially locking in long-term contracts.
- DePuy Synthes: Headquartered in West Chester, Pennsylvania, DePuy Synthes focuses on consistent power in demanding applications. Their orthopaedic power tool systems are designed to withstand the rigors of high-volume surgical environments.
- CONMED Corporation: Based in Largo, Florida, CONMED offers Hall Power tools for large and small bone procedures. Their strategy often centers on reliability and broad applicability across different orthopedic needs.
- B. Braun Melsungen AG: From Melsungen, Germany, this company provides integrated surgical power tools for orthopedic applications, leveraging its broader European presence to influence regional standards and adoption.
- MicroAire Surgical Instruments: Located in Charlottesville, Virginia, MicroAire focuses on powered instruments including PAL handpiece and Series 7000 for orthopedic procedures, catering to niche requirements within the broader tool category.
- ACF Medical: Based in Yunusemre, Manisa, Turkey, ACF Medical offers CE-certified battery-powered systems and saw blades for arthroplasty and trauma, representing the competitive pressure from emerging manufacturing hubs.
- Advanced Orthopaedic Solutions, Inc.: From Torrance, California, this firm focuses on technologically superior instruments for minimally invasive and precise orthopedic procedures, aligning closely with the macro trend toward MIS.
The competitive environment is not static. Companies are constantly balancing R&D investment against the need for regulatory approval. The launch of new tools like the TPX HD indicates a competitive race toward higher precision and better ergonomics. However, the high barriers to entry created by regulatory standards and established distribution networks protect incumbents while making it difficult for new entrants to gain significant traction without differentiated technology.
Segmentation Nuances and Regional Considerations
While the overall market size provides the headline numbers, the true strategic value lies in understanding how this value is distributed across different segments. The market is not a monolith; it is composed of distinct categories such as surgical drills, surgical saws, and other instruments and accessories. Demand varies significantly depending on the specific surgical application, ranging from large bone procedures to small bone and high-speed orthopedic power tools. Each segment carries its own growth drivers and competitive intensity.
Geography also plays a pivotal role in market dynamics. Revenue generation is not evenly distributed across the globe. Certain regions demonstrate higher adoption rates due to established healthcare infrastructure and reimbursement frameworks, while others offer growth potential due to improving access and increasing surgical volumes. However, detailed regional breakdowns, including specific percentage splits and revenue amounts for regions such as North America, Europe, and Asia Pacific, are critical data points that require careful analysis. These details form the backbone of any localized market entry or expansion strategy.
Similarly, the balance between different instrument types influences inventory planning and R&D focus. Some tool categories see consistent demand due to their ubiquity in standard procedures, while others may experience faster growth linked to specific technological advancements or surgical technique shifts. Understanding the revenue contribution of each type and application is essential for optimizing product mix. Our full report contains the granular segmentation data necessary to dissect these variances and identify high-value opportunities within each category.
Strategic Recommendations for 2026 and Beyond
For executives and strategists, the insights derived from this market analysis point to several actionable imperatives. First, product development must align with the dual demands of precision and durability. As surgical techniques evolve toward minimally invasive approaches, tools must offer enhanced torque and ergonomics without compromising reliability. The recent industry moves toward premium small bone power tools exemplify this direction.
Second, regulatory strategy cannot be an afterthought. With FDA 510(k) clearance and EU MDR requirements setting the baseline, companies must build compliance into their design controls early. The mandatory nature of ISO 13485 quality management means that quality systems are a competitive differentiator as well as a license to operate. Companies that can demonstrate superior quality management may gain preference in procurement processes where risk mitigation is prioritized by hospital groups.
Third, cost considerations for end-users must be factored into value propositions. The ongoing debate between reusable and single-use alternatives affects total cost of ownership calculations for hospitals. Manufacturers need to articulate the economic benefits of their tools, whether through longevity, reduced maintenance costs, or improved surgical outcomes that reduce readmission rates. The impact of sterilization processes and maintenance requirements on hospital budgets is a key talking point for sales and marketing teams.
Fourth, monitoring reimbursement trends is vital. Changes such as the 2026 CPT code updates can shift procedure volumes overnight. Strategic planning should include scenario modeling based on potential reimbursement shifts to ensure that product portfolios remain viable under different payment structures. Understanding which procedures are financially favored by payers allows companies to tailor their marketing and development efforts toward supported indications.
Finally, competitive intelligence should be continuous. With market concentration remaining high, tracking the product launches and strategic moves of the top players is essential. A launch by a market leader often demands a response, whether through innovation, partnership, or targeted marketing. Keeping abreast of developments such as new product introductions in the upper half of 2026 ensures that strategies remain relevant and responsive.
Conclusion: The Value of Comprehensive Intelligence
The Orthopedic Surgical Power Tools Market presents a landscape of steady growth tempered by regulatory and operational complexities. The projected expansion to 263.9 million USD by 2032 offers a compelling opportunity, but realizing value within this market requires more than a surface-level understanding of the trends. It demands a deep dive into segmentation, regional nuances, and competitive specific strategies.
The data provided in this overview sets the stage, highlighting the macro trajectory and the key players defining the industry. However, the specific percentage splits, regional revenue breakdowns, and detailed segment analysis hold the keys to precise strategic planning. These details allow for accurate forecasting, targeted market entry, and optimized resource allocation.
Our comprehensive report unlocks this deeper layer of intelligence. It provides the detailed segmentation data by region, type, and application that is necessary to move from general strategic direction to specific tactical execution. For organizations committed to leading in this space, accessing the full dataset is the next logical step. The full report contains the granular breakdowns required to validate assumptions and refine forecasts for the 2026 to 2032 period.
In an industry where precision defines success, your market intelligence should be equally precise. We invite you to explore the complete study to secure the detailed competitive and segment-level data required to navigate the upcoming decade with confidence.
For detailed analysis of this topic, please visit the official page: Orthopedic Surgical Power Tools Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


