



Category: market research
PW Consulting: X-Ray Food Inspection Market Hits $230M in 2025, Projects 9.7% CAGR to $437.6M by 2032
By PW Consulting, 2026-09-07
Strategic Intelligence for 2026: Navigating the X-ray Food Inspection Equipment Market
Executive Overview
As the global food processing industry faces intensifying pressure to guarantee consumer safety while optimizing throughput, the X-ray food inspection equipment sector has transitioned from a luxury expense line to a foundational pillar of manufacturing operations. Our latest comprehensive analysis, "X-ray Food Inspection Equipment Market," serves as an essential strategic compass for executives, operations leaders, and investors planning their moves for the 2026 fiscal year and beyond. This report is not merely a collection of historical data; it is a forward-looking intelligence tool designed to illuminate the complex interplay between regulatory mandates, technological innovation, and shifting consumer habits.
Worldwide API Process Development and Manufacturing Market
The urgency for this level of granular insight cannot be overstated. Food manufacturers are no longer evaluated solely on the quality and taste of their products, but increasingly on the safety protocols embedded within their production lines. Inline inspection technologies have become the eyes of the modern factory, detecting contaminants that were once only identifiable after costly recalls. Understanding where the market is heading, who is leading the charge, and what technical capabilities are becoming standard requirements is critical for maintaining competitive advantage. This article outlines the strategic landscape, offering a preview of the depth and utility contained within our full market research deliverable.
New Energy Vehicle Carbon Fiber Parts Market
Market Trajectory and Macro Dynamics
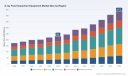
The financial trajectory of the X-ray food inspection market demonstrates robust and sustained expansion, reflecting the industry-wide prioritization of hazard analysis and critical control points. Historical data from the past half-decade establishes a clear upward trend in revenue generation and equipment adoption. From a base valuation of approximately 173.0 million USD in 2020, the sector experienced steady growth, reaching 185.11 million USD in 2021, 198.77 million USD in 2022, and stabilizing at 201.3 million USD in 2023. The acceleration became more pronounced thereafter, with revenues climbing to 219.16 million USD in 2024 and an estimated 230.0 million USD in 2025.
Worldwide Aluminum PTC Heating Element Market
These historical figures are not just retrospective markers; they set the stage for the aggressive forecast period extending through 2032. For 2026, the market is projected to reach 244.19 million USD, signaling a pivotal year for capital expenditure decisions. The momentum continues to build, with projections indicating 283.3 million USD by 2027, 294.61 million USD in 2028, 328.38 million USD in 2029, 365.7 million USD in 2030, 407.91 million USD in 2031, and a substantial 437.6 million USD by 2032. This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 9.7 percent over the forecast horizon.
It is worth noting a contextual macro data point indicating the broader market context; some industry data frames the total ecosystem value at a higher aggregate level, citing a figure of 2.23 billion USD for 2026 when considering the wider scope of contaminant detection and compliance services. Regardless of the specific valuation lens, the directional consensus is unmistakable: demand for enhanced detection capabilities and compliance with food safety mandates is driving sustained investment. This expansion is not accidental. It is the direct result of a market maturing around the necessity of automated, high-speed inspection that can keep pace with modern processing volumes without compromising safety standards.
Segmentation Dynamics and Application Realities
While the aggregate growth numbers provide the headline narrative, the true strategic value lies in understanding how demand is distributed across different equipment types and application sectors. The market is broadly segmented into Unpackaged Product Testing Equipment, Packaged Product Testing Equipment, and Bulk Product Testing Equipment. Each category faces distinct operational challenges and regulatory scrutiny. Unpackaged product inspection remains vital for raw ingredient handling and early-stage processing, while packaged product inspection addresses the critical need for final barrier checks before distribution. Bulk equipment serves high-volume commodity streams where density variations and foreign material risks require specialized sensitivity.
Similarly, the application landscape reveals diverse opportunities for inspection integration. Key sectors driving volume include Confectionery and Cereals, Meat and Sausage Products, Dairy Products, the Canning Industry, and Bakery Products. Each segment presents unique detection challenges. For instance, dense products like meat and sausage blends require systems capable of differentiating between bone fragments and natural density variations, whereas bakery and confectionery lines demand high-speed throughput without sacrificing the ability to detect thin glass or low-density plastics. The increasing consumer preference for processed and packaged foods has heightened requirements for inline inspection to detect bone fragments, glass, and other contaminants in high-volume lines, forcing manufacturers to rethink their quality assurance architectures.
The full report provides a detailed breakdown of these segmentation splits, offering actionable intelligence on which sub-segments are experiencing the fastest adoption rates and how budget allocations are shifting across categories. Understanding these nuances allows companies to target their R&D investments and sales strategies more effectively, ensuring resources are directed toward the highest growth potential areas rather than generalized market assumptions.
Regulatory Compliance and Operational Integration
In the food inspection industry, technology does not exist in a vacuum; it operates within a tightly regulated environment. Compliance is a primary driver of equipment procurement. In the United States, X-ray inspection systems for food must comply with FDA radiation safety guidelines and 21 CFR 179 standards to ensure no radiation hazard in industrial quality control applications. This regulatory baseline is non-negotiable and shapes the design, certification, and deployment considerations for every system entering the market. Manufacturers must ensure their equipment not only detects contaminants but also adheres to strict radiation emission limits, a factor that influences brand reputation and operational licensing.
Beyond radiation safety, the integration of inspection data into broader quality management systems is becoming a mandatory expectation. Food manufacturers must integrate X-ray data with plant-level quality management systems for FSMA and HACCP compliance in the United States and Europe. This requirement is transforming X-ray machines from standalone detection devices into intelligent nodes within a connected factory ecosystem. The ability to log inspection events, generate audit-ready compliance reports, and trigger automated rejection mechanisms without manual intervention is now a core requirement for many procurement teams. Equipment that cannot seamlessly feed data into enterprise quality systems risks obsolescence or relegates the operator to costly manual workarounds.
Globally, certification landscapes vary but carry equal weight. For example, Thermo Scientific X-ray inspection machines are certified to global standards including UNE 73-302 in Spain and GB18871-2002 in China prior to sales. These regional standards reflect local regulatory preferences and safety expectations, meaning that a successful global market entry strategy requires careful attention to certification pathways. Our analysis details how key players navigate these diverse regulatory environments, ensuring that their technologies are deployable across borders without prohibitive compliance delays.
Competitive Landscape and Key Player Strategies
The market is characterized by a high degree of concentration, with significant share held by a group of established multinational and specialized players. Our analysis identifies a highly competitive landscape where senior firms command a substantial portion of the market. Specifically, concentration metrics indicate a CR3 of 65.5 percent and a CR5 of 85.2 percent, highlighting the dominance of top-tier incumbents and the high barriers to entry for new competitors. This consolidated environment means that strategic partnerships, technology licensing, and targeted acquisitions are common mechanisms for shifting competitive positioning.
Leading the pack is Eagle Product Inspection, headquartered in Lutz, Florida, United States. Eagle specializes in advanced X-ray inspection systems for the food industry, including high-sensitivity models like the Pack 550 PRO and MAXIMIZER series for contaminant detection, fat analysis, and multi-view imaging in poultry, meat, and packaged foods. Eagle has demonstrated an aggressive product cadence recently. In early 2026, they enhanced the Pack 550 PRO x-ray system to advance HACCP critical control point verification on packaged food lines. Followed this by highlighting the Pack 430 PRO for FSMA-aligned inspection performance and efficiency in poultry processing, and strengthened a pipeline of X-ray systems for upstream foreign material prevention under tightening USDA and FSMA compliance. Furthermore, Eagle demonstrated three X-ray systems at IPPE for sausage blends and raw poultry, reinforcing their strong presence in protein processing. These moves illustrate a focused strategy on aligning hardware capabilities with specific regulatory frameworks and high-risk protein segments.
Mettler-Toledo International Inc., based in Greifensee, Switzerland, remains a formidable force via its Safeline brand. They offer comprehensive X-ray inspection systems including high-speed contaminant detection, intelligent software, and automated setup for food processing lines. Their strength lies in the integration of sophisticated software ecosystems that simplify operator training and reduce changeover times, addressing a key bottleneck in multi-SKU production environments.
Loma Systems, headquartered in Farnborough, Hampshire, United Kingdom, provides X-ray inspection systems for food, packaging, and pharmaceutical industries, featuring dual-energy and high-sensitivity models like the X5DE series for low-density contaminant detection. In a significant expansion move, Loma launched the X5DE Dual Energy X-ray Inspection System into North America for high-throughput convenience food, snacks, bakery, and meat/poultry lines. This geographic expansion underscores the critical importance of regional availability and support networks in winning large-scale integrator contracts.
In Asia, Anritsu Corporation of Atsugi, Kanagawa, Japan, manufactures X-ray inspection systems with advanced sensors for fine metal and bone fragment detection, including the DualX+ series for challenging food applications. Ishida Co., Ltd. of Kyoto, Japan, offers X-ray inspection systems using Photo-Counting Dual Energy technology for superior detection in packaged foods and high-throughput lines. These Japanese players bring precision engineering and sensor innovation that appeals to markets demanding the highest reliability in difficult-to-inspect products.
Thermo Fisher Scientific Inc., based in Waltham, Massachusetts, United States, delivers X-ray inspection machines for food and beverage, certified to global standards with high-resolution imaging for contaminant and defect detection. Their broad scientific instrument heritage allows them to bridge the gap between laboratory-grade analysis and industrial inline speed. Minebea Intec of Hamburg, Germany, provides X-ray inspection systems for food and pharmaceutical industries, including multi-view and bulk inspection models with AI-enhanced capabilities. The integration of AI into bulk and multi-view inspection marks a trend toward predictive quality management rather than simple binary pass/fail decisions.
Sesotec GmbH of Schönberg, Germany, focuses on X-ray inspection and metal detection systems for food processing, with intelligent sorting and analysis for foreign body and material identification. Fortress Technology Inc. of Toronto, Ontario, Canada, manufactures X-ray inspection systems for food safety, including high-care applications and high processing rates with sanitary designs, catering to environments where hygiene and rapid sanitation cycles are paramount. FlexXray, based in Arlington, Texas, United States, provides X-ray food inspection and contaminant retrieval services with FDA/USDA-registered facilities for packaged and bulk food products. Their service-oriented model highlights a growing niche where inspection technology is bundled with specialized recovery and verification services, offering a distinct value proposition for brands facing acute contamination events.
Technological Frontiers and Future Outlook
As the forecast period extends toward 2032, the technological trajectory of the market is shifting toward deeper intelligence and greater integration. The baseline capability of detecting dense foreign materials like metal, stone, and bone is now table stakes. The competitive differentiator is moving toward the detection of low-density contaminants such as glass, certain plastics, and calcified cartilage, which require advanced dual-energy imaging and sophisticated material discrimination algorithms. Systems that can maintain high sensitivity for these elusive contaminants without slowing line speeds are capturing premium market share.
Artificial intelligence and machine learning are beginning to permeate the inspection landscape. AI-enhanced capabilities allow systems to adapt to product variations, reducing false rejects that disrupt production and cause throughput losses. In bulk and multi-view applications, AI can analyze complex density patterns to distinguish between genuine defects and natural product irregularities, a capability that directly impacts profitability by reducing waste and rework. Furthermore, the convergence of inspection data with plant-level analytics platforms enables predictive maintenance of the inspection equipment itself, minimizing unplanned downtime during critical production runs.
The role of the X-ray unit is also evolving from a passive detector to an active data generator. As manufacturers integrate X-ray data with quality management systems, the inspection machine becomes a source of real-time process intelligence. Trends in reject rates, contaminant types, and line performance metrics can feed back into upstream process controls, closing the loop on quality assurance. This shift aligns with broader Industry 4.0 initiatives and the push for smart factories, where every stage of production is measurable, analyzable, and optimizable.
Report Structure and Strategic Utility
The full "X-ray Food Inspection Equipment Market" research report is structured to provide immediate operational relevance for decision-makers. It opens with a detailed executive summary and market definition, followed by a rigorous methodology section that ensures transparency and reproducibility of the findings. The core of the report comprises comprehensive market sizing and segmentation analysis, exploring revenue streams across equipment types, application verticals, and geographic regions. These sections do not merely present figures; they contextualize them within the operational realities of different market participants, helping readers benchmark their own performance and identify white spaces for growth.
A substantial portion of the report is dedicated to competitive profiling. Each key company is evaluated on its strategic positioning, product portfolio breadth, geographic footprint, technological differentiation, and recent strategic moves. The inclusion of recent developments, such as specific product launches, trade show demonstrations, and expansion announcements, provides a real-time pulse on how competitors are reacting to market signals. This allows readers to anticipate competitor responses to regulatory changes, new technology standards, or shifts in end-user demand.
The report also covers deep dives into market dynamics, including the regulatory environment, consumer habit shifts, and macroeconomic factors influencing capital equipment spending. Supply chain considerations, after-sales service requirements, and the economics of ownership versus service-based inspection models are explored to give a holistic view of the market ecosystem. Strategic recommendations are provided for equipment manufacturers, system integrators, food processors, and investors, outlining actionable paths to capture value in a growing, high-stakes sector.
Conclusion: The Strategic Imperative for 2026
The X-ray food inspection equipment market stands at an inflection point. The convergence of regulatory tightening, consumer demand for safer packaged foods, and the availability of sophisticated dual-energy and AI-driven detection technologies is creating a rich environment for growth. However, this growth is not evenly distributed. Success in 2026 and the subsequent forecast years will depend on the ability to navigate segmentation nuances, comply with a fragmented but strict regulatory landscape, and leverage competitive intelligence to position offerings against well-entrenched incumbents.
This article has provided a high-level view of the market dynamics, the leading players, and the strategic themes shaping the industry. Yet, the full depth of the analysis, including precise segmentation breakdowns, competitive benchmark metrics, regional deployment trends, and tailored strategic recommendations, is reserved for the complete report. For executives and analysts responsible for charting the course of food safety technology investments, the detailed intelligence within our research library is an indispensable asset. We invite you to access the full report to gain the comprehensive insights necessary to make informed, high-confidence decisions for the year ahead and the decade to come.
For detailed analysis of this topic, please visit the official page: X-ray Food Inspection Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: High Class KVM Switches Revenue Hits $280M in 2025, 7.8% CAGR to 2032
By PW Consulting, 2026-09-07
Beyond Peripheral Control: Strategic Intelligence for the High Class KVM Switches Market
Executive Context: Why This Market Matters in 2026
The infrastructure landscape of modern enterprise computing has undergone a fundamental shift. As organizations consolidate data center footprints, expand edge deployments, and demand higher-resolution control environments, the role of high-class KVM (Keyboard, Video, Mouse) switches has evolved from basic hardware consolidation to a critical security and operational linchpin. For leadership teams evaluating capital allocation, vendor partnerships, and technology roadmaps in 2026, understanding the trajectory of this specialized segment is no longer optional—it is a prerequisite for informed decision-making.
Conventional Special Color Masterbatch Market
This article serves as a strategic preview of the comprehensive market study recently released by PW Consulting. Our analysis distills a decade of historical performance, forward-looking economic modeling, and granular competitive intelligence into an actionable framework. Below, we outline the macro-environment, the structural forces reshaping demand, and the tactical intelligence you will gain by accessing the full report. Specific numerical breakdowns, granular regional allocations, and detailed application-level revenue shares are intentionally reserved for the complete publication. To obtain the full intelligence package required for board-level strategy, we invite you to visit the official source page.
Worldwide GPCR Assay Services Market
Macro Trajectory: A Market in Structural Expansion
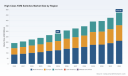
Over the past half-decade, the high-class KVM switches sector has demonstrated consistent, compounding growth. Historical revenue records from 2020 through 2025 trace a clear upward arc, reflecting sustained enterprise investment in centralized control infrastructure. Building on that foundation, our forecast horizon extends through 2032, modeling a trajectory that anticipates continued double-digit absolute expansion. The compound annual growth rate projected across this window underscores a market that is not merely recovering from cyclical pauses but is instead being structurally reinforced by broader IT modernization mandates.
Electronic Grade Ethyl Acetate Market
Several macro-level vectors are fueling this momentum. The proliferation of high-density compute clusters, the migration toward mixed-signal and high-resolution control rooms, and the increasing regulatory emphasis on secure remote access have collectively elevated KVM switching from a peripheral consideration to an integrated architectural requirement. Organizations that previously treated these devices as tactical hardware are now evaluating them through the lens of long-term operational resilience, cryptographic compliance, and total cost of ownership across multi-year deployment cycles.
The revenue progression observed from the early 2020s through the base year of 2025, and the modeled escalation through the end of the decade, signals that market participants who align product strategy, supply chain planning, and GTM motions with these structural tailwinds are positioned to capture disproportionate share. Conversely, legacy portfolios that fail to address emerging resolution, latency, and security mandates risk gradual erosion in relevance.
Strategic Catalysts Reshaping Demand Horizons
The growth narrative is not monolithic. It is being sculpted by a constellation of interrelated catalysts that vary in intensity across deployment contexts. Foremost among these is the escalating energy and compute density within data center environments. Power consumption trends in large-scale U.S. data center operations have risen sharply as AI-driven workloads expand, with projections pointing toward significant increments in total electricity demand through the late 2020s. This density surge compels operators to rethink how they monitor, manage, and secure physical infrastructure at scale, driving demand for high-performance KVM solutions that can deliver reliable visual fidelity and low-latency control without adding undue operational overhead.
Simultaneously, the regulatory environment around cryptographic security has entered a decisive transition phase. As of late September 2026, validation frameworks will transition remaining legacy certificates to a historical status, mandating migration to next-generation cryptographic module standards for secure IT infrastructure. For KVM switch deployments—particularly those used in segmented or air-gapped environments—this regulatory shift is reshaping procurement criteria. Buyers are increasingly prioritizing platforms validated under these updated standards, and vendors must navigate certification timelines, validation pathways, and integration requirements to remain competitive in government-adjacent and highly regulated enterprise segments.
Additional dynamics include the widespread adoption of secure KVM architectures that incorporate tamper protection and network isolation principles, often aligned with recognized secure product profiling standards. In parallel, manufacturing and deployment ecosystems are tightening around quality management expectations, where certified quality systems have become a baseline expectation for global data center rollouts. These forces combine to create a market where technical performance, certification readiness, and supply chain discipline are equally determinative of commercial success.
Technology Segmentation: The Digital-Analog Balance and Resolution Arms Race
The market is structurally divided between digital and analog high-class KVM switch categories, each serving distinct operational profiles. The digital segment continues to gain strategic prominence as organizations pursue IP-native architectures, remote access capabilities, and integration with broader data center orchestration tooling. Digital platforms are increasingly expected to support higher video resolutions, maintain sub-frame latency for time-sensitive control scenarios, and embed security features directly into the signal path. The analog segment, meanwhile, retains relevance in environments where deterministic signal characteristics, specific cabling topologies, or legacy interface compatibility remain paramount.
Within both segments, resolution and latency have emerged as the primary axes of competitive differentiation. Four-megapixel and beyond resolutions are no longer niche specifications; they are rapidly becoming baseline expectations in broadcast control rooms, mission-critical operations centers, and premium enterprise desktop configurations. vendors are responding with advanced compression methodologies, optimized delivery pipelines, and refined display interface support. The push toward ultra-low latency in high-resolution contexts is particularly pronounced in professional control-room and broadcast applications, where visual lag can directly affect operator decision quality and workflow integrity.
A parallel thread is the emphasis on form factor, thermal design, and scalability. Fanless operation, modular matrix expansion, and multi-monitor configurations are increasingly valued as organizations seek to reduce maintenance burden and accommodate varied physical layouts. Design recognition and ergonomic refinement are also becoming meaningful differentiators in segments where the KVM switch is a visible component of the operator environment rather than a hidden rack element. These qualitative dimensions, while harder to quantify in isolation, materially influence purchasing committees and end-user satisfaction over the equipment lifecycle.
Industry Applications: Where Value Is Concentrated
Demand for high-class KVM switches is not evenly distributed across use cases. Several application domains stand out as primary value centers, each with distinct performance expectations, procurement cycles, and integration requirements. Data center management remains the most significant anchor, driven by the need to centralize control over dense, distributed, and increasingly automated compute infrastructure. In this context, KVM solutions function as a critical access layer that enables operators, engineers, and security teams to interact with headless or remote nodes without compromising security posture or adding complex software dependency chains.
Broadcast stations represent another high-intensity adoption vector. Here, the intersection of high-resolution video handling, low-latency signal routing, and reliable switcher performance is non-negotiable. Production environments require KVM infrastructure that can keep pace with multi-source monitoring, director workflows, and live operation constraints. The aviation controls industry similarly imposes rigorous demands, where operational reliability, deterministic performance, and secure access patterns are central to mission-critical oversight functions.
Beyond these dominant verticals, a diverse set of professional environments contribute meaningful demand. Control rooms, enterprise IT helpdesk consolidation, secure facility management, and specialized professional workstations all generate tailored requirements. The full report maps these application territories with comparative precision, including the relative scale of each segment, the evolving procurement criteria within them, and the specific product capabilities that resonate most strongly with their operational rhythms.
Competitive Landscape: Incumbents, Innovations, and Positioning
The competitive field is populated by established players with deep domain expertise, each pursuing differentiated routes to market. Vertiv Group Corporation, headquartered in Columbus, Ohio, continues to advance its high-end Avocent portfolio while expanding its KVM-over-IP offering with the recently introduced MergePoint Unity 2 platform. This launch emphasizes FIPS 140-3 cryptographic alignment, four-megapixel support, and enterprise-grade centralized control for data centers and edge environments, signaling a deliberate move toward security-first positioning in regulated and distributed deployments.
Raritan, operating under Legrand and based in Somerset, New Jersey, maintains a strong foothold in ultra-high-performance KVM-over-IP. Its Dominion KX IV series is engineered for four-megapixel video at thirty frames per second, with fanless operation and scalable matrix configurations tailored to large enterprise data centers. The emphasis on thermal economy and scalable architecture reflects a product philosophy centered on long-term operational simplicity in dense IT environments.
IHSE GmbH, located in Oberteuringen, Germany, has built its reputation on high-resolution extension and switching for professional control-room and broadcast applications. Through a series of recent product introductions showcased at major industry events, the company has pushed next-generation extender technology with advanced compression approaches designed for low-latency four-megapixel and eight-megapixel performance. These releases underscore a focus on professional environments where visual fidelity and timing precision are directly tied to mission outcomes.
Adder Technology Limited, based in Cambridge, United Kingdom, delivers high-performance IP KVM and extender solutions optimized for broadcast, control rooms, and mission-critical settings. Its portfolio emphasizes low-latency delivery and high video quality, aligning with applications where operator responsiveness and image clarity are paramount. The company’s positioning reflects a consistent commitment to specialized environments rather than broad commoditized segments.
ATEN International Co., Ltd., headquartered in Taipei, Taiwan, manufactures premium desktop and enterprise KVM switch series with support for high-resolution multi-monitor configurations. Its design-led approach has been recognized with the prestigious Red Dot Award for Product Design for its Desktop KVM Switch Series, highlighting the growing importance of industrial aesthetics, user experience, and ergonomic refinement in professional-grade hardware. The blend of performance and design distinguishes ATEN in segments where end-user interaction quality matters as much as backend capability.
Shenzhen CKL Technology Co., Ltd., based in Shenzhen, China, specializes in high-end multi-monitor KVM switches capable of consolidating control across numerous computers with integrated video splitting and extension functionality. Its offerings target enterprise and professional setups that require dense workstation consolidation without sacrificing display fidelity. This concentration on multi-source management reflects the broader industry push toward workspace simplification and centralized operational control.
Strategic Developments Shaping the Near-Term Battlefield
Recent product launches and certifications reveal how aggressively these incumbents are moving to capture emerging demand. Vertiv’s February 2026 introduction of the Avocent MergePoint Unity 2 platform illustrates the priority placed on cryptographic compliance and secure remote access for enterprise and edge data centers. IHSE’s sequence of announcements in early and mid-2025, including a new extender generation presented at a major industry showcase and a DisplayPort-based series leveraging advanced compression technology, demonstrates sustained investment in resolution and latency performance for professional environments. ATEN’s May 2026 recognition with a top-tier product design award further reinforces the strategic significance of form factor and user-centered design as competitive differentiators.
These developments are not isolated product news; they are strategic signals. Each release and certification reflects a vendor’s read on where the market is heading and which capability bundles will matter most in upcoming procurement cycles. The full report deconstructs these moves into a structured competitive positioning framework, enabling readers to compare product roadmaps, identify capability gaps, and anticipate vendor responses to regulatory and technology inflection points.
Inside the Research: What Decision-Makers Will Gain
The complete PW Consulting study is designed as a decision-support instrument rather than a static market snapshot. It combines historical performance records, forward-looking economic modeling, segmentation analysis, competitive profiling, and regulatory context into a cohesive intelligence package. Readers will find structured coverage across the following dimensions:
- Market Sizing and Trajectory: A detailed assessment of overall market magnitude, historical progression, and forecast evolution, anchored in a rigorous methodology that captures both baseline momentum and scenario-dependent variation across the projection window.
- Segmentation Intelligence: A structured breakdown of market composition by region and by type, with comparative analysis of digital versus analog high-class KVM switches and the economic weight of each pathway. Regional and application-level allocations are presented with sufficient granularity to inform market-entry, expansion, and prioritization decisions, while core numerical splits are reserved for the full report to preserve analytical depth.
- Application Mapping: A comparative examination of how demand distributes across data center management, broadcast stations, aviation controls, and other professional environments, including the operational requirements and procurement behaviors that differentiate each vertical.
- Competitive Profiling: In-depth analyses of leading vendors, including corporate positioning, product strategy, recent developments, and inferred strategic priorities. The report maps how each player is aligning its portfolio with emerging resolution, latency, security, and design expectations.
- Regulatory and Standards Context: A synthesis of the compliance landscape shaping procurement criteria, including cryptographic validation transitions, secure KVM architecture expectations, and quality management requirements that affect global deployment readiness.
- Strategic Implications and Scenarios: Forward-looking interpretation of how market forces are likely to interact through the end of the decade, helping leadership teams stress-test investment assumptions, vendor selection criteria, and product roadmap decisions.
By design, the study balances transparency with strategic confidentiality. Macro indicators such as overall market scale and the compound annual growth rate are integrated into the narrative to establish analytical credibility, while the most granular revenue allocations, regional percentages, and application-level figures are held within the full document. This approach ensures that the complete report delivers maximum commercial value to readers who require precise, decision-grade numbers for planning and forecasting.
Guidance for Leadership: Turning Intelligence into Action
For executives, procurement leaders, and strategy teams, the immediate question is how to convert market awareness into executable advantage. Three practical imperatives emerge from the current landscape.
First, align technology roadmaps with the resolution and latency frontier. As four-megapixel and higher resolutions migrate from premium differentiator to baseline expectation in key verticals, portfolios that lag in video quality, compression efficiency, or interface support will face growing friction in competitive evaluations. Organizations should assess their current product capabilities against the performance bands now being demanded in data center, broadcast, and control-room environments, and prioritize development or partnership moves that close any gaps.
Second, treat cryptographic compliance as a strategic gate, not a checklist item. With the impending migration of legacy validation certificates to historical status, secure infrastructure requirements are being reset. KVM solutions positioned for government-adjacent, regulated, or security-sensitive deployments must demonstrate readiness under updated cryptographic standards. Vendors and buyers alike should map certification timelines, integration dependencies, and validation pathways to avoid procurement delays or post-deployment compliance exposure.
Third, evaluate competitive positioning through a multi-dimensional lens. The strongest performers are combining technical performance with thermal economy, scalability, design quality, and certification readiness. When benchmarking vendors or planning product investments, decision-makers should weigh these dimensions together rather than isolating any single attribute. A portfolio that excels in one area but falters in another may lose out to a more balanced competitor in real-world evaluation committees.
Accessing the Full Intelligence
This article provides a strategic preview of the forces shaping the high-class KVM switches market and the analytical framework behind PW Consulting’s latest study. It is intended to establish the professional depth and decision relevance of the full research while preserving the granular data that buyers, investors, and product strategists need to act with precision.
To obtain the complete market sizing breakdown, segmentation allocations, competitive profiles, regulatory synthesis, and scenario-based guidance, please visit the official report page. The full publication is structured for immediate application in capital planning, vendor evaluation, market-entry analysis, and technology roadmap development. In a market defined by rapid resolution advancement, evolving security mandates, and intensifying competitive moves, timely access to granular intelligence is the difference between reactive positioning and deliberate advantage.
The trajectory from 2020 through the projected horizon reflects more than aggregate growth. It reflects a structural reevaluation of how organizations control, secure, and scale their computing infrastructure. Those who understand the composition of that growth, the competitive dynamics driving it, and the regulatory currents shaping procurement will be best positioned to navigate the years ahead. The complete report delivers that understanding in full.
For detailed analysis of this topic, please visit the official page: High Class KVM Switches Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: HBVE Market Hits $221M in 2025, Projects 5.25% CAGR Toward 2032
By PW Consulting, 2026-09-07
Strategic Intelligence in the Hydroxybutyl Vinyl Ether Market: Navigating Growth and Complexity Through 2032
The global chemical landscape is undergoing a structural transformation driven by demand for specialty monomers that enable next-generation performance materials. Among these, Hydroxybutyl Vinyl Ether (HBVE) has emerged as a critical enabler for high-durability coatings, UV-curable systems, and advanced adhesive formulations. As procurement leaders, R&D directors, and strategic planners evaluate their positioning for the 2026–2032 horizon, access to rigorous, forward-looking market intelligence is no longer optional—it is a competitive necessity.
Worldwide PA Filament Market
Our latest HBVE market research report delivers a comprehensive, data-grounded assessment of the industry trajectory, competitive architecture, and regulatory operating environment. This article previews the strategic dimensions covered in the full publication. It is designed to demonstrate analytical depth while reserving granular segmentation data, pricing frameworks, and region-specific revenue allocations for the complete report. Readers seeking the full quantitative architecture are encouraged to access the source publication for complete intelligence.
Worldwide Iontophoresis Market
Market Trajectory: From Historical Baseline to Forecasted Expansion
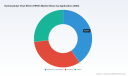
Understanding where the HBVE market stands today requires a clear view of its historical evolution and its projected growth path. The market has demonstrated consistent expansion over the past half-decade, reflecting steady adoption across industrial coatings, adhesive systems, and specialty chemical intermediates. Historical data captures a market that grew from approximately $180.75 million in 2020 to $221.0 million in 2025, underscoring a pattern of sustained, compounding demand rather than volatile, event-driven spikes.
Worldwide Thermoplastic Material for Clear Orthodontic Aligner Market
Our forecast modeling extends this trajectory through 2032, projecting the overall market size to reach $315.5 million by the end of the forecast period. This outlook translates to a compound annual growth rate of 5.25 percent across the 2026–2032 window. Such a growth profile signals a mature but steadily expanding category, where incremental innovation in formulation science, regulatory compliance readiness, and supply chain optimization will determine market share evolution rather than abrupt demand shocks.
The forecast framework is built on historical sensitivity analysis, capacity adjustment assumptions, and application-level demand modeling. Importantly, the full report dissects the underlying drivers of this trajectory across regional demand centers and application verticals, providing decision-makers with the granularity needed to align procurement planning, capacity investments, and formulation roadmaps. The headline figures illustrate directionality; the complete study reveals the structural mechanics behind that direction.
Report Scope and Practical Deliverables for Strategic Teams
A market research publication earns its value through actionable structure. Our HBVE study is organized to support cross-functional decision-making, spanning commercial strategy, technical procurement, regulatory compliance, and competitive positioning. Below is a structured overview of the core components integrated into the analysis.
- Executive market sizing and forecast modeling across the 2026–2032 period, with sensitivity scenarios that capture feedstock variability, regional demand shifts, and regulatory developments.
- Demand-side segmentation by application, mapping consumption patterns across end-use sectors and providing context on how adhesive and coating formulations drive HBVE utilization.
- Regional demand architecture, detailing consumption intensity, supply proximity dynamics, and trade flow considerations that influence sourcing strategies.
- Competitive landscape profiling that goes beyond corporate headcounts to examine product positioning, brand architectures, technical documentation footprints, and capacity readiness.
- Value chain and feedstock context, including upstream dependencies such as 1,4-butanediol sourcing and how raw material linkage shapes cost sensitivity and supply continuity.
- Regulatory and compliance mapping that tracks registration status across major chemical inventories and occupational exposure frameworks, helping teams anticipate documentation requirements and supply eligibility.
- Recent corporate developments and product documentation updates that signal strategic emphasis, technical readiness, and application targeting by key market participants.
Each section is constructed to be read independently by specialists and collectively by integrated strategy teams. Marketers can extract positioning insights; procurement teams can assess supply concentration and regional availability; R&D and formulation groups can align technical datasheets and compatibility requirements with available market offerings; and executives can integrate the consolidated growth outlook into investment and capacity planning. The complete report also includes structured appendices that translate narrative analysis into tabular formats suitable for internal modeling and board-level review.
Competitive Landscape: Leading Participants and Strategic Postures
The HBVE market features a mix of established multinational chemical manufacturers and focused regional producers. Competitive differentiation in this space is rarely driven by volume alone; it is shaped by technical documentation quality, application-specific branding, regulatory readiness, and the ability to support formulation engineers with consistent monomer specifications. Our analysis profiles the principal companies shaping supply and innovation in this category, highlighting how each participant positions its HBVE offerings.
BASF SE, headquartered in Ludwigshafen, Germany, maintains a prominent role as a supplier of HBVE as an unsaturated monomer with hydroxyl functionality for fluoropolymer resins in high-durability coatings. Recent activity underscores BASF’s emphasis on technical clarity and application breadth. In May 2025, the company updated its Vinyl Monomers overview catalog to include verified CAS 17832-28-9 status for intermediates. A subsequent datasheet update in July 2025 confirmed availability for monomer, cross-linking, and reactive monomer applications. These documentation moves signal an intent to support diverse formulation pathways while reinforcing product traceability and specification reliability.
Ashland Inc., based in Wilmington, Delaware, markets HBVE under its Rapi-Cure HBVE brand for UV-curable coatings and adhesives in labels, commercial printing, and flexible packaging. Ashland’s value proposition centers on curing performance and application specificity, aligning HBVE supply with end-formulation needs in high-speed printing and packaging workflows. A July 2025 product stewardship summary update reaffirmed the material’s role in UV/EB curing systems for coatings and adhesives, reinforcing Ashland’s focus on technical stewardship and application-aligned documentation.
On the regional supply side, a cluster of Chinese manufacturers contributes meaningful capacity and market reach. Hubei Xinjing New Material Co., Ltd. operates as an active manufacturer with annual capacity around 3,800 metric tons for coatings and adhesive applications, positioning the company as a capacity-relevant player for demand in Asia-Pacific and export-oriented supply chains. Chongqing RICI Chemical Co., Ltd. produces HBVE for industrial coatings and adhesives with a focus on Asia-Pacific markets, while Henan Newblue Chemical Co., Ltd., based in Zhengzhou, supplies industrial-grade 4-Hydroxybutyl Vinyl Ether with 99 percent purity, emphasizing specification consistency for downstream users.
Additional China-based participants broaden the supply field. Shanghai Nianxing Industrial Co., Ltd. supplies HBVE for chemical intermediates and specialty applications. Boai NKY Enterprise Co., Ltd. produces and supplies HBVE for coatings and UV-curable systems. Chongqing Rici Chemical also appears as an active producer of HBVE used in high-performance materials, reinforcing the density of regional manufacturing capability. The presence of multiple producers indicates that supply availability is broadly supported, yet differentiation remains in purity profiles, documentation rigor, brand positioning, and regional logistics competence.
From a concentration standpoint, the competitive structure is fragmented enough to provide procurement flexibility while still featuring recognizable leaders in technical branding and multinational reach. The full report quantifies concentration dynamics and evaluates how market share distribution interacts with pricing behavior, supply resilience, and customer negotiation leverage. Rather than relying on broad descriptors, the study maps how each participant’s product communications, capacity posture, and regional footprint shape competitive pressure points across the value chain.
Market Dynamics: Feedstock Linkages, Regulatory Frameworks, and Supply Chain Realities
HBVE market dynamics are influenced by more than end-user demand. Feedstock dependency, regulatory eligibility, occupational exposure management, and cross-border compliance inventories collectively determine how easily supply can move, how formulations are validated, and how quickly new applications can scale. These dynamics are embedded throughout the forecast, segmentation, and competitive analysis in the full study.
A central upstream consideration is the reliance on 1,4-butanediol as a key feedstock for vinyl ether synthesis. This linkage connects HBVE supply economics to broader intermediate chemical markets and means that cost sensitivity, availability constraints, and manufacturing scheduling can be influenced by conditions in the 1,4-butanediol supply base. For procurement teams, this underscores the importance of understanding not only HBVE pricing signals but also the upstream context that shapes those signals. The full report situates this relationship within market-level cost dynamics and capacity planning assumptions.
Regulatory readiness is equally important. HBVE is registered under EU REACH and included in China’s Catalog of Hazardous Chemicals 2015, which means suppliers and downstream users must navigate documentation, handling requirements, and market access conditions across key regions. In parallel, HBVE appears on the German GESTIS DNEL Substance List with exposure limit parameters, reflecting the need for workplace exposure management in production and formulation settings. These frameworks do not necessarily restrict market participation, but they establish compliance expectations that influence supplier selection, logistics planning, and technical validation cycles.
On the global inventory side, HBVE compliance is supported by listings under TSCA, PICCS, ENCS, IECSC, and DSL inventories. This broad inventory coverage facilitates international supply by aligning the material with major chemical regulatory registries. For multinational formulators and distributors, such compliance breadth reduces friction in cross-border transactions and supports sourcing diversification strategies. The complete report translates these regulatory facts into operational implications, including how registration status affects supply reliability, documentation burdens, and regional market entry considerations.
Recent industry activity reinforces the strategic importance of documentation and technical transparency. The July 2025 datasheet updates from both BASF and Ashland reflect a pattern in which suppliers emphasize verified application use, monomer functionality, and curing system compatibility. These updates matter because HBVE buyers—especially in coatings and adhesives—frequently require reproducible specifications, clear handling guidance, and formulation-friendly technical narratives. Accordingly, market participation is not only about capacity; it is increasingly about the quality and timeliness of technical information that supports procurement approval and product validation.
Demand-side applications remain the central pull factor. HBVE consumption is concentrated in contexts where hydroxyl functionality and vinyl ether reactivity deliver performance value, particularly in adhesives and sealants and in coatings. The broader application landscape also includes intermediate and specialty use cases that extend the material’s reach beyond high-volume formulation categories. The full report breaks down application consumption patterns and explains how formulation requirements, curing technologies, and end-market performance standards shape demand intensity. It deliberately avoids presenting simplistic share figures in isolation, instead embedding application context within regional demand structures and competitive supply dynamics to show how value moves through the market.
Why This Study Matters for 2026 Decision-Making
Strategic decisions made in 2026 will compound over the forecast period. Whether the objective is to secure resilient HBVE supply, identify high-return application opportunities, assess competitor movement, or build internal forecasting models, decision-makers need more than headline growth figures. They need a structured view of how the market is sized, how it is expected to grow, where demand is concentrated, how competition is organized, and which regulatory and feedstock factors will shape operational reality.
This study is designed to meet that need. It provides a forecast-aligned framework that links historical performance to forward projections, then layers in segmentation, competitive profiling, and regulatory context so that leaders can stress-test assumptions rather than accept averages at face value. For procurement, this means clearer visibility into supply concentration and regional availability. For R&D and formulation teams, it means clearer alignment between available monomer specifications and application requirements. For strategy and investment planning, it means a defensible growth outlook anchored in documented market structure and participant behavior.
The full report also enables scenario-based thinking. Because the HBVE market is influenced by upstream feedstock dynamics, regulatory documentation cycles, and application-specific performance demands, decisions benefit from sensitivity analysis rather than single-point forecasts. The publication includes modeled ranges and structural assumptions that help teams evaluate how changes in regional demand, regulatory interpretation, or supplier documentation activity could affect sourcing strategies and market entry plans.
What the Complete Report Unlocks
This preview establishes the strategic foundation. The complete HBVE market research report goes further by supplying the detailed architecture needed for execution. It integrates comprehensive market sizing and forecast tables, application-level demand analysis, regional consumption structures, company profiles with strategic positioning insights, and regulatory mapping tied to operational implications. It also captures recent product documentation activity and market developments that signal near-term supplier emphasis and application targeting.
Readers looking for exact regional revenue splits, precise application-level market allocations, or specific procurement-ready benchmarks will find those details in the full study. The decision to reserve that granularity here is intentional. Our objective is to demonstrate analytical rigor and contextual depth while directing stakeholders to the complete publication for the quantitative detail and structured appendices required for internal modeling, procurement negotiation, and strategic planning.
For teams responsible for 2026 planning and beyond, the HBVE market presents a steady growth opportunity intertwined with technical, regulatory, and supply-chain complexity. Navigating that complexity successfully depends on having intelligence that is both strategically framed and operationally detailed. The complete report is built for that purpose, offering a clear path from high-level market trajectory to decision-ready specificity.
For detailed analysis of this topic, please visit the official page: Hydroxybutyl Vinyl Ether (HBVE) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Kitchen Knife Market Hits $213.5M in 2025, Projected 6.1% CAGR Through 2032
By PW Consulting, 2026-09-07
Strategic Intelligence for the Kitchen Knife Market: Navigating Growth, Consolidation, and Trade Shifts Through 2032
As consumer kitchens evolve and culinary expectations rise, the global kitchen knife market stands at a decisive inflection point. For executives, investors, and product leaders, understanding where value is being created, how competitive dynamics are shifting, and which structural forces will shape margins over the next seven years is no longer optional. The latest Kitchen Knife Market research from PW Consulting was designed precisely for this moment of decision. It moves beyond surface-level growth statements and delivers a rigorous, forward-looking intelligence framework that can be embedded directly into product roadmaps, sourcing strategies, pricing models, and regional expansion plans.
Worldwide Amorphous Vinyl Alcohol Resin Market
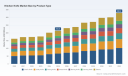
This study is anchored in a comprehensive historical review and a disciplined forecast horizon. Drawing on 2020 through 2025 as the foundational baseline, the analysis projects market behavior through 2032, enabling leadership teams to stress-test assumptions against both cyclical recovery patterns and longer-term structural demand. The macro trajectory is clear and strategically meaningful: total market revenue has expanded steadily from 162.5 million USD in 2020 to 213.5 million USD in 2025, with the forecast period extending that momentum toward 328.4 million USD by 2032. Sustained at a forecast CAGR of 6.1 percent, this growth path signals more than simple volume expansion. It reflects a market in which product differentiation, material performance, and end-use positioning increasingly determine which players capture premium share and which compete primarily on price.
Worldwide Automatic Conveyor Material Bars Equipment Market
What makes this intelligence especially relevant for 2026 planning is the combination of durable demand drivers and sudden external shocks. On one side, rising home cooking engagement continues to reshape residential purchasing behavior, pushing buyers toward specialized, durable, and aesthetically refined tools. On the other, trade policy and input-cost pressure have introduced real uncertainty into import-dependent supply chains. The research integrates these forces rather than treating them separately, allowing decision-makers to see how demand strength, material economics, and regulatory exposure interact inside the same operating environment.
Fiber Glass PLY Yarn Market
Our objective with this publication is straightforward: give organizations a reliable basis for action without overloading them with raw data dumps. Instead, the report translates market structure into strategic questions. Which product categories are consolidating value fastest? Where do material preferences create defensible pricing power? How should commercial and residential channels be evaluated differently when forecasting demand? Which regional markets offer near-term expansion potential without overexposing the business to tariff or logistics risk? These are the questions this study is built to answer.
What the Report Covers: Actionable Structure for Real Decision Cycles
The research is organized to serve multiple internal audiences simultaneously. It is not a single-purpose document; it is a modular intelligence asset that can be used by product strategy, sales leadership, supply chain planning, and corporate development teams. The study begins by mapping the market’s overall size and trajectory, then decomposes that total into the structural segments that matter most for operational planning. Rather than presenting numbers in isolation, the report frames segmentation through a commercial lens: how categories relate to one another, where usage contexts create different buying criteria, and how material choices influence both consumer perception and manufacturing cost.
A central strength of the analysis is its practical segmentation logic. The report evaluates product types ranging from chef’s knives and utility knives to paring, bread, boning, carving, and other specialized formats, showing how each fits into broader usage patterns and purchase missions. This breakdown is valuable because it helps teams avoid treating the kitchen knife category as a single homogeneous market. In reality, the decision to buy a high-frequency everyday blade differs from the decision to purchase a task-specific tool, and those differences shape SKU strategy, packaging, bundling, and channel targeting.
Material composition is analyzed with equal rigor. The study examines stainless steel, carbon steel, ceramic, titanium, and other materials not only as manufacturing inputs but as value signals in the marketplace. Material choice has become a defining element of positioning, influencing perceived sharpness, edge retention, corrosion resistance, care requirements, and premium appeal. Because these attributes directly affect pricing architecture and consumer retention, the report ties material trends back to commercial outcomes rather than stopping at technical description.
End-use segmentation further sharpens the strategic picture. By separating residential and commercial demand, the analysis clarifies where volume concentration lies and where growth is being generated by distinct purchasing logic. Commercial buyers evaluate durability, replacement cycles, standardization, and total cost of use differently from residential consumers, who may prioritize design, brand identity, and specialized performance. Understanding these divergent demand profiles is essential for companies deciding whether to compete across both orbits or concentrate on the segment where they can defend a stronger value proposition.
Regional analysis completes the structural foundation. The report examines market activity across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, with attention to how local culinary traditions, channel maturity, import dependence, and purchasing power affect demand behavior. This regional framing is particularly important in a market where manufacturing hubs, distribution capabilities, and consumer preferences vary widely and where tariff exposure can quickly alter relative competitiveness.
Beyond segmentation, the study integrates forward-looking scenario considerations. It does not simply extend a trend line. It identifies the variables most likely to accelerate or compress growth, including consumer spending patterns, raw material and manufacturing cost shifts, product certification and standards expectations, and product safety dynamics. By separating stable structural drivers from intermittent disruptions, the report helps teams distinguish between temporary volatility and permanent market change.
Competitive Landscape: Ten Companies, Distinct Positionings, and a Concentration Profile That Matters
No market intelligence is complete without a clear view of who is competing, how they are positioning, and where concentration is rising. The Kitchen Knife Market study profiles a set of influential manufacturers whose strategies illustrate the range of ways to compete in this space. These companies do not all pursue the same value equation. Some emphasize U.S.-based production and service-oriented warranties, others lean into German forged precision, while several position around Japanese-style performance blades or budget-friendly durability. Together, they show how brand origin, manufacturing philosophy, product breadth, and service promise can each become the backbone of a competitive position.
Buck Knives illustrates a U.S.-focused approach centered on high-quality domestic kitchen cutlery. Its recent Fall 2024 kitchen line expanded into models such as a new cleaver, santoku, and petite chef knife, signaling continued investment in product variety within a quality-driven identity. WÜSTHOF represents the premium forged German tradition, and its 2025 Partner series launch broadened everyday-use options with an 8-inch chef’s knife, a 7-inch hollow edge santoku, and a 6-inch utility knife. Victorinox, based in Switzerland, maintains a strong reputation for durability-focused design through its Swiss Classic and Swiss Modern collections, and its catalog updates and limited edition releases show how established brands continue to deepen engagement with both everyday users and collectors.
On the Japanese-style side, Yoshida Metal Industry Co. Ltd. highlights the performance conversation through high-performance hollow-edge and forged blades marketed under respected brand names. Zwilling J. A. Henckels AG demonstrates the scale and breadth possible within premium German-style kitchen knife lines, using quality and innovation as recurring themes across a wide portfolio. Cutco Corporation underscores a different commercial model: large-scale U.S.-made kitchen cutlery supported by lifetime warranties and sharpening services, a value proposition that ties product sales to long-term customer relationships.
The competitive set also includes companies built around specialized manufacturing philosophies and market entry points. Steelport Knife Co. focuses on premium carbon steel handcrafted U.S.-made knives made with all-American materials, positioning craftsmanship as the core differentiator. Rada Cutlery targets durable, budget-friendly kitchen cutlery designed for everyday professional and home use, showing that affordability and reliability can coexist as a clear market position. Dexter-Russell Company continues to supply budget kitchen cutlery and tools with a strong U.S. manufacturing presence, reinforcing the importance of accessible price points in certain channel contexts.
This diversity matters because the market is not dominated by a single playbook. The report’s concentration analysis helps leadership understand how much share is held by the leading competitors and what that implies for pricing behavior, channel leverage, and new-entry risk. With the top three competitors accounting for approximately 32.5 percent of market concentration and the top five reaching about 38.2 percent, the landscape is consolidated enough to reward scale and brand strength, yet still open enough for differentiated entrants to capture meaningful positioning in specific segments or channels. For strategy teams, that concentration profile raises practical questions: Should a business aim to compete broadly or win narrowly? Is the goal to outperform on product architecture, service, distribution, or brand storytelling? The report provides the context needed to answer those questions with more confidence.
Market Dynamics and 2026 Realities: Trade Policy, Input Costs, and Demand Signals
Strategic planning for 2026 cannot rely on historical patterns alone. The kitchen knife market is being shaped by several overlapping dynamics that influence both demand and cost structure. One of the most visible is the evolving trade environment. Proposed U.S. tariffs of 10 percent or higher on most trading partners, including China and Japan, began reshaping imported kitchen knife economics in 2026. For companies dependent on cross-border sourcing or imported finished goods, this changes the calculus around landed cost, retail pricing, margin protection, and sourcing diversification.
The pressure is not hypothetical. By mid-2025, U.S. steel and aluminum tariffs had already increased wholesale costs of Japanese knives by an estimated 23 percent for U.S. importers. That kind of cost shock does more than compress margins in the short term. It alters competitive positioning, forcing some brands to absorb cost, others to adjust pricing, and many to reassess supply-chain dependencies. The report integrates these cost dynamics into the larger market narrative so that teams can anticipate where price elasticity, product substitution, and channel renegotiation are likely to become acute.
At the same time, consumer demand is being pulled in a distinctly premium direction. Rising interest in home cooking and specialized kitchen tools is strengthening residential demand for higher-quality and more specialized knives. This trend supports the market’s broader growth trajectory, but it also invites a more discerning buyer base. Consumers are increasingly attentive to edge quality, material integrity, aesthetics, and long-term usability. For commercial organizations, that means product claims must be credible, consistency must be reliable, and brand trust must be built through performance rather than marketing alone.
Standards and certification remain an underappreciated strategic dimension. Collections such as Victorinox’s Swiss Classic and Swiss Modern lines reflect the market’s expectation that durability and sharpness must meet rigorous requirements for both professional and household use. As buyers become more informed and channels become more quality-conscious, certification and standards compliance can serve as both a barrier to entry and a trust multiplier for established players. The report addresses these expectations directly, explaining how they affect product development priorities and market access.
Importantly, the study also provides reassurance on a key operational question: there were no active recalls or safety warnings for kitchen knives during the 2024 to 2026 window. Instead, industry attention has concentrated on sharp-edge performance, quality certifications, and consistent manufacturing standards. That focus matters because it signals where competitive credibility is being earned. In a category where the product’s core function is literally edge performance, safety and quality assurance are not side issues; they are central to brand durability and buyer confidence.
Why This Research Matters for 2026 Decisions
The strategic value of this report lies in its ability to convert market complexity into executable judgment. For product leaders, the segmentation and material analysis supports more disciplined SKU rationalization, innovation prioritization, and price-point architecture. For commercial and sales teams, the residential-versus-commercial distinction and regional perspectives help shape channel tactics, bundling decisions, and regional go-to-market sequencing. For procurement and supply chain executives, the tariff and input-cost findings provide a basis for scenario planning around sourcing, inventory timing, and margin defense. For corporate development and investor-facing teams, the concentration profile and competitive profiles offer a grounded view of where market power resides and where opportunity may still be captured through differentiation.
Just as importantly, the report is designed to support decisions under uncertainty. Growth is positive, but growth alone does not guarantee profitable exposure. Tariffs can alter relative cost advantage. Raw material pressures can change the economics of imported versus domestically produced lines. Consumer preference can shift toward specialized performance or back toward everyday utility depending on broader household spending behavior. A market growing at a 6.1 percent CAGR still contains winners and losers, and the difference is usually determined by how well a company anticipates structural change rather than simply responds to it.
This is why the study intentionally balances breadth with depth. It gives leadership the macro trajectory, the segment logic, the competitive map, and the dynamic pressures that matter most, while avoiding the trap of overwhelming the reader with fragmented data. The goal is to make the intelligence usable immediately: to inform a pricing review, support a sourcing reassessment, guide a product launch sequence, or strengthen a regional expansion case.
How to Use This Intelligence and Where to Go Next
PW Consulting designed this Kitchen Knife Market research as a decision-grade resource rather than a static market summary. The executive overview presented here captures the strategic frame and the market logic, but the full report contains the detailed segment breakdowns, competitive comparisons, regional evaluations, and scenario-based observations needed to turn direction into action. Organizations that rely only on high-level growth figures risk missing the operational nuances that determine execution quality in a market this sensitive to cost, channel behavior, and product differentiation.
For teams preparing 2026 plans, the report offers a way to align internal stakeholders around a shared evidence base. It helps product, sales, sourcing, and strategy functions speak the same language about where growth is coming from, which segments deserve investment, and where external pressures could disrupt assumptions. That alignment is often the difference between a plan that looks solid in a presentation and one that holds up under operational reality.
Readers seeking the complete segmentation detail, competitive profiles, regional evaluations, and forward-looking scenario analysis are encouraged to access the full report through the source page. There, the macro narrative is reinforced by the layer of structured market intelligence that supports precise, confident decisions across product, channel, and supply strategy.
Conclusion: A Market That Rewards Clarity, Discipline, and Early Positioning
The kitchen knife market is expanding with steady momentum, but its real strategic importance lies in how value is distributed across product types, materials, end uses, regions, and competitors. Growth creates opportunity, yet opportunity is captured only when companies understand the forces that shape buyer behavior and cost exposure at the same time. The combination of durable residential demand, premiumization trends, trade-policy uncertainty, and shifting input costs makes 2026 a year in which informed strategic positioning can produce meaningful advantage.
PW Consulting’s Kitchen Knife Market research was built to give organizations that advantage. It translates a dynamic market into a usable intelligence framework, helping leaders move from observation to action with greater confidence. For executives who need to decide where to compete, how to price, what to source, and which segments to prioritize, this study provides the foundation for decisions that are not just timely, but durable.
For detailed analysis of this topic, please visit the official page: Kitchen Knife Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Cancel for Any Reason Travel Insurance Market to Reach $2,035.12 Million by 2032 as CAGR Hits 13.23 Percent
By PW Consulting, 2026-09-02
Cancel for Any Reason Travel Insurance Market 2026: Strategic Intelligence for Enterprise Decision-Makers
Executive Overview: The Flexibility Imperative in Modern Travel Risk Management
The global travel insurance landscape is undergoing a structural transformation driven by heightened consumer demand for autonomy and the unpredictable nature of modern trip disruption. Within this shifting environment, the cancel for any reason travel insurance market has emerged as a critical niche, evolving from a peripheral add-on into a strategic product category that addresses the fundamental anxiety of nonrefundable financial commitment. Our latest Worldwide Cancel for Any Reason Travel Insurance Market research provides a comprehensive, data-rich examination of this rapidly expanding sector, offering enterprise stakeholders the analytical rigor required to navigate the complexities of product design, pricing architecture, and competitive positioning through the forecast period ending in 2032.
Worldwide Cancel for Any Reason Travel Insurance Market
The period from 2020 through 2025 established a volatile yet highly instructive baseline for the industry. Market revenue climbed from modest historical levels to surpass the 850 million dollar threshold by the base year, reflecting a compounding effect of post-pandemic travel rebounds, inflationary pressures on trip costs, and an accelerated consumer preference for non-standard cancellation flexibility. Looking forward, the trajectory indicates sustained momentum, with annualized growth rates projected at a robust double-digit pace that underscores the category's transition from a discretionary luxury to a mainstream expectation among discerning travelers. This research report dissects the forces propelling this expansion, mapping the interplay between consumer psychology, regulatory frameworks, distribution innovation, and carrier strategy to deliver an actionable intelligence asset for executives, product managers, and investors operating across the travel protection ecosystem.
Worldwide Cancel for Any Reason Travel Insurance Market
Macro Market Trajectory and Structural Growth Drivers
The numerical architecture of the market tells a story of accelerated adoption and deepening market penetration. Over the five-year historical window, revenue expansion demonstrated consistent upward pressure, with each successive year building upon the preceding momentum. By 2025, the aggregate market had consolidated its position as a significant contributor to the broader travel insurance umbrella, and the forecast horizon projects this trajectory to accelerate further. The compound annual growth rate anchored at approximately 13.23 percent through the 2026 to 2032 interval signals that the category is not merely growing alongside travel volumes but is outpacing traditional coverage segments by capturing unmet demand for unconditional flexibility.
Worldwide Cancel for Any Reason Travel Insurance Market
Several structural catalysts underpin this expansion. First, the rising average cost of international and domestic travel, driven by airfare inflation, hotel rate escalation, and premium experience packaging, has magnified the financial stakes of trip cancellation. When nonrefundable expenditures represent a larger share of household or corporate travel budgets, the willingness to pay a premium for a safety valve increases proportionally. Second, the psychological shift among leisure and business travelers toward risk aversion has normalized the purchase of supplemental protection layers that standard cancellation policies fail to address. Conventional trip cancellation coverage remains tethered to a predefined list of covered reasons, leaving a substantial gap for cancellations motivated by personal preference, scheduling conflicts, or emergent but non-medical concerns.
Third, the insurtech revolution has lowered the friction associated with add-on acquisition. Digital-first platforms now enable seamless integration of cancel for any reason riders at the point of booking, transforming what was once a cumbersome, agent-mediated process into a frictionless consumer experience. This technological democratization has expanded the addressable market beyond high-net-worth individuals and corporate travel departments into the broader leisure traveler segment, amplifying volume growth and intensifying competitive pressure on incumbents to innovate or risk disintermediation. The interplay of these drivers creates a fertile environment for sustained revenue expansion, but also introduces complexity in product structuring, claims management, and regulatory compliance that demands rigorous analytical oversight.
Competitive Landscape: Strategic Positioning Among Leading Carriers
The marketplace is characterized by a concentrated yet dynamically competitive field, with a handful of established carriers commanding a disproportionate share of volume while a cohort of agile specialists and insurtech-enabled entrants vies for differentiation through product innovation, pricing architecture, and user experience. Market concentration metrics indicate that the top three players collectively account for roughly 38 percent of total revenue, while the top five extend their footprint to just over half of the market. This distribution suggests a landscape where scale advantages in marketing, distribution partnerships, and claims infrastructure confer meaningful moats, yet ample room remains for specialized providers to capture niche segments through targeted value propositions.
Among the dominant forces, Allianz Travel Insurance has leveraged its global brand equity and comprehensive plan architecture to embed cancel for any reason functionality within premium-tier offerings such as the OneTrip Prime and OneTrip Premier plans. By providing up to 80 percent reimbursement of prepaid nonrefundable trip costs and permitting cancellation as late as the day of departure, Allianz has positioned its cancel anytime upgrade as a high-fidelity solution for travelers who prioritize maximum liquidity and temporal flexibility. This aggressive reimbursement ceiling serves as a benchmark that pressures competitors to calibrate their own benefit structures, creating a upward drift in industry reimbursement norms.
Seven Corners has carved a distinct positioning by emphasizing accessibility and rapid efficacy. Its cancel for any reason add-on, available across plans including the Trip Protection Basic tier, offers up to 75 percent reimbursement and is distinguished by notably short waiting periods. This configuration appeals to last-minute planners and travelers who require immediate coverage activation without lengthy pre-purchase constraints, addressing a specific friction point in the consumer journey. Travel Insured International approaches the segment through its Worldwide Trip Protector suite, particularly the Platinum and Deluxe variants, where optional cancel for any reason benefits reimburse up to 75 percent for cancellations not otherwise covered. This approach integrates the add-on into a broader protection ecosystem, encouraging cross-selling and deepening customer lifetime value.
IMG, through its iTravelInsured family encompassing Travel LX, Travel SE, and Choice plans, offers cancel for any reason as an optional add-on with up to 75 percent reimbursement, though its availability is subject to state-specific restrictions that illustrate the regulatory fragmentation inherent to the category. Trawick International stands out for its product innovation, having introduced an industry-first embedded cancel for any reason offering on its Safe Travels AnyReason plan, which delivers 75 percent reimbursement without an additional fee. This structural breakthrough reframes the value equation for consumers, transforming the add-on from a cost center into an integrated benefit and challenging competitors to reconsider their pricing and packaging strategies.
WorldTrips, Travelex Insurance Services, Travel Guard under AIG, World Nomads, and Generali Global Assistance each contribute unique variations to the competitive mosaic. WorldTrips emphasizes flexibility across its Atlas Journey series, while Travelex focuses on value optimization and emergency coverage integration. Travel Guard leverages the AIG corporate infrastructure to deliver optional coverage with percentage-based reimbursement, appealing to travelers who trust established financial institution backing. World Nomads targets the adventure and independent travel demographic with optional upgrades on Explorer and Epic plans, though availability remains constrained for certain jurisdictions. Generali Global Assistance positions its premium plans with up to 75 percent reimbursement, aligning with the mid-to-high reimbursement band that has become a competitive standard.
Emerging and specialty players such as Tin Leg and Faye are gaining recognition for their competitive plan structures and differentiated benefit profiles. Tin Leg has been identified among the top providers for 2026 based on plan competitiveness, while Faye distinguishes itself through add-ons that complement cancel for any reason with non-medical evacuation benefits, addressing the broader risk profile of travelers who seek holistic protection beyond financial reimbursement. This diverse competitive field ensures that innovation remains a persistent force, with carriers continuously refining reimbursement percentages, waiting period constraints, eligibility criteria, and bundling strategies to capture share in a market that rewards both brand trust and product agility.
Distribution Architecture and Consumer Segmentation Dynamics
The pathway through which cancel for any reason coverage reaches the end consumer has evolved into a multi-channel ecosystem where digital direct channels command a dominant share of revenue, while traditional intermediated routes retain significant relevance for specific traveler profiles. Online direct and insurtech platforms account for the largest portion of market revenue, reflecting the structural shift toward consumer-led purchasing behavior, price transparency, and instantaneous plan customization. These channels benefit from lower acquisition costs, algorithmic underwriting capabilities, and seamless integration with booking workflows, enabling carriers to scale distribution without proportional increases in overhead. The insurtech paradigm also facilitates rapid A/B testing of pricing tiers, benefit configurations, and user interface designs, accelerating the iteration cycle that keeps products aligned with evolving consumer expectations.
Travel agencies and online travel agencies represent the second substantial distribution pillar, channeling revenue through a model that leverages the trust relationship between agents and travelers, as well as the convenience of bundled purchase during itinerary construction. This channel is particularly effective for complex itineraries, multi-stop journeys, and luxury travel segments where consumers prefer guided decision-making and value the reassurance of expert recommendation. Traditional insurance brokers constitute the third channel, maintaining a stronghold among corporate travel departments, high-net-worth individuals, and travelers with specialized risk profiles who require personalized consultation and bespoke policy structuring. While this channel operates at a smaller aggregate scale compared to digital direct and OTA-mediated flows, it commands higher average premiums and fosters deeper client relationships that enhance retention and cross-sell potential.
Segmentation by traveler type reveals a pronounced concentration of revenue among individual and leisure travelers, who collectively generate the largest share of market income. This dominance reflects the broader cultural shift toward experiential travel, the proliferation of solo and small-group adventure itineraries, and the financial vulnerability of individual households to nonrefundable loss. Business and corporate travelers form the second substantial segment, driven by the persistent need for itinerary flexibility in an environment characterized by shifting meeting schedules, remote work adoption, and geopolitical unpredictability that disrupts corporate travel planning. Group and family travelers, while representing a smaller revenue share, contribute meaningful volume through multi-policy purchases and sensitivity to cancellation flexibility that protects collective investment in shared experiences.
An important behavioral metric underscores the category's growth potential: approximately 10 percent of travel insurance plans purchased currently include cancel for any reason coverage. This penetration rate, while modest relative to total travel insurance volumes, reveals a substantial untapped addressable market. As consumer awareness deepens, as distribution channels streamline add-on acquisition, and as standard cancellation policies continue to exhibit rigidity in the face of non-covered cancellation triggers, the proportion of travelers electing cancel for any reason protection is poised to expand. This latent demand represents a strategic growth vector for carriers that can effectively communicate the value proposition, simplify the purchasing process, and align reimbursement structures with realistic consumer expectations.
Regulatory Nuances, Operational Mechanics, and Market Volatility
The commercial viability and consumer appeal of cancel for any reason coverage are inextricably linked to a regulatory and operational framework that varies across jurisdictions and imposes specific structural requirements on product design. A foundational regulatory reference point comes from the New York Department of Financial Services, whose Insurance Circular Letter No. 4, issued in 2020, delineates that cancel for any reason benefits do not technically qualify as traditional insurance. This classification carries profound implications for how carriers structure offerings, permitting the benefit to be sold either as an incidental benefit or within standalone contracts, while also clarifying that cancel for any reason coverage may not be available under certain standard policy configurations. This regulatory clarity, while providing a compliance pathway, also introduces complexity for carriers operating across multiple states, where the treatment of the benefit must be calibrated to local insurance codes and supervisory expectations.
A particularly sensitive regulatory dimension concerns eligibility restrictions in specific jurisdictions. New York residents face limitations on access to cancel for any reason coverage under certain provider plans, a constraint rooted in state-specific insurance regulations that restrict the offering of benefits that fall outside conventional insurance definitions. This geographic inconsistency creates a fragmented market where product availability, reimbursement structures, and purchasing windows differ across state lines, requiring carriers to maintain nuanced compliance infrastructures and consumers to navigate variable eligibility criteria. The implication for market analysis is significant: aggregate revenue figures must be interpreted with an understanding that regulatory boundaries shape distribution potential, and strategic forecasts must account for the possibility of regulatory evolution that could either expand or constrain the addressable market in key jurisdictions.
Operational mechanics further define the category's value proposition and consumer adoption patterns. Cancel for any reason coverage typically mandates purchase within a time-sensitive window, commonly spanning 10 to 21 days from the initial trip deposit, and requires that the policyholder insure 100 percent of nonrefundable trip costs to qualify for the add-on benefit. Additionally, most plans stipulate cancellation at least 48 hours before scheduled departure. These constraints serve dual purposes: they prevent adverse selection by ensuring coverage is purchased before cancellation intent crystallizes, and they establish a clear operational boundary that carriers can price and administer with predictable risk profiles. For consumers, these requirements introduce a disciplined purchasing cadence that, while potentially friction-inducing, reinforces the perception of cancel for any reason as a genuine risk mitigation tool rather than a loophole for arbitrary refund extraction.
Reimbursement architecture remains a central competitive battleground. Standard cancel for any reason reimbursement ranges from 50 percent to 75 percent of prepaid nonrefundable trip costs, with select carriers pushing toward higher ceilings. Allianz, for instance, offers up to 80 percent reimbursement through its cancel anytime upgrade, setting a premium benchmark that influences consumer expectations and competitive calibration across the industry. The 50 to 75 percent band represents a pragmatic equilibrium between consumer value and carrier risk management, ensuring that the add-on remains financially sustainable while delivering meaningful partial recovery that justifies the premium cost. As market competition intensifies, carriers may explore differentiation through higher reimbursement tiers, reduced add-on fees, or bundled value propositions that combine cancel for any reason with ancillary protections such as medical evacuation, baggage coverage, or travel delay benefits.
Recent market developments illuminate the category's sensitivity to external volatility. In early March 2026, interest in cancel for any reason coverage rose approximately 27 percent compared to preceding periods, a surge linked to geopolitical volatility and operational uncertainty that amplified traveler demand for flexible cancellation options. This spike demonstrates the category's role as a responsive risk management instrument that gains prominence during periods of instability, and it suggests that macroeconomic and geopolitical shocks can serve as accelerants for adoption. Trawick International's August 2024 launch of the Safe Travels AnyReason plan, featuring embedded cancel for any reason coverage with 75 percent reimbursement and no additional fee, represents a product-level innovation that reframes consumer value perception and pressures competitors to reconsider their pricing and packaging architectures. These events, viewed collectively, reinforce the thesis that the cancel for any reason segment is both reactive to external conditions and driven by continuous product evolution.
Report Architecture and Core Analytical Deliverables
Our Worldwide Cancel for Any Reason Travel Insurance Market research is structured to deliver operational intelligence that transcends high-level market sizing and penetrates the tactical decisions that shape product strategy, investment allocation, and competitive positioning. The report begins with a comprehensive market overview that synthesizes historical performance from 2020 through 2025, establishes the base year revenue foundation, and projects forward through a detailed forecast horizon extending to 2032. This temporal architecture enables readers to assess trend consistency, identify inflection points, and evaluate the sustainability of growth trajectories under varying demand scenarios.
The segmentation analysis deconstructs revenue flows across regional markets, distribution channels, and traveler types, providing a granular view of where value is generated and how structural shifts in consumer behavior or channel dynamics may alter future revenue distribution. Rather than presenting static snapshots, the report integrates forward-looking indicators that illuminate the relative growth potential of each segment, allowing decision-makers to prioritize resource allocation, expansion initiatives, and partnership development in alignment with projected demand concentration. The regional analysis maps revenue intensity, growth velocity, and regulatory context across key geographies, while the distribution channel examination traces the evolving balance between digital direct sales, OTA-mediated purchases, and traditional brokerage relationships. The traveler type breakdown isolates the distinct demand drivers, purchasing behaviors, and coverage preferences that differentiate individual, business, and group segments, enabling targeted product and marketing strategies.
A dedicated competitive landscape section profiles the leading carriers and emerging specialists, dissecting their product architectures, reimbursement structures, distribution strategies, and recent innovations. This analysis extends beyond descriptive profiling to evaluate strategic positioning, competitive advantages, vulnerability points, and potential consolidation or partnership dynamics. By mapping the competitive field with precision, the report equips readers with the insight required to anticipate competitor moves, identify white space opportunities, and calibrate their own value propositions against established benchmarks. The regulatory and operational dynamics section synthesizes jurisdictional considerations, purchasing window requirements, reimbursement norms, and compliance pathways, providing a risk-aware framework for product development and market entry planning.
Additional report components include detailed reimbursement analysis, consumer behavior insights, distribution friction assessment, and scenario-based forecasting that stress-tests growth assumptions under varying macroeconomic, regulatory, and competitive conditions. The report also integrates comparative benchmarking of plan features, pricing structures, and benefit configurations, enabling carriers to evaluate their offerings against industry norms and identify optimization opportunities. Throughout, the analysis maintains a focus on actionable intelligence: rather than merely describing market conditions, it provides structured frameworks for interpreting data, identifying strategic implications, and translating insight into executable decisions.
Strategic Implications for Enterprise Stakeholders
The cancel for any reason travel insurance market presents a compelling strategic opportunity for carriers, distributors, investors, and technology providers who can align their capabilities with the category's structural growth drivers and competitive dynamics. For incumbent carriers, the imperative is to leverage scale advantages in brand recognition, distribution partnerships, and claims infrastructure while simultaneously investing in product innovation that differentiates their offerings in an increasingly crowded field. Reimbursement architecture, waiting period flexibility, bundled value propositions, and user experience design represent levers that can shift competitive positioning and capture share from competitors whose product configurations lag behind evolving consumer expectations.
For insurtech platforms and digital-first distributors, the opportunity lies in tightening the integration between booking workflows and cancel for any reason acquisition, reducing friction to the point where add-on purchase becomes a default consideration rather than a deliberate afterthought. Algorithmic pricing, dynamic benefit customization, and personalized recommendation engines can enhance conversion rates and improve risk selection, while seamless claims processing and transparent reimbursement communication can reinforce trust and drive repeat purchase behavior. The dominance of online direct and insurtech channels in revenue generation underscores the strategic importance of digital excellence, and carriers that fail to optimize their digital interfaces risk ceding share to more agile competitors.
Investors evaluating exposure to this market should focus on carriers that demonstrate a balanced combination of revenue growth, margin discipline, regulatory compliance maturity, and product innovation velocity. Market concentration metrics suggest that scale players retain meaningful advantages, but the presence of specialized providers capturing niche demand indicates that differentiated value propositions can sustain viable competitive positions. The regulatory fragmentation surrounding cancel for any reason coverage, particularly the jurisdictional restrictions affecting certain states, introduces both risk and opportunity: carriers with robust compliance infrastructures can navigate these constraints more effectively, while regulatory evolution that clarifies or expands permissible offering structures could unlock additional addressable demand.
Corporate travel managers and enterprise risk officers should view cancel for any reason coverage as a strategic component of comprehensive travel risk management, particularly in environments characterized by scheduling volatility, geopolitical instability, and operational uncertainty. While standard cancellation policies address enumerated risks, the flexibility offered by cancel for any reason add-ons provides a supplementary safeguard that protects against non-covered disruption and reduces the financial exposure of nonrefundable commitments. As travel programs increasingly prioritize employee flexibility and itinerary autonomy, the inclusion of cancel for any reason options in corporate travel policies may become a differentiating factor in talent attraction and retention, as well as a practical risk mitigation tool.
Conclusion: Positioning for Sustained Growth Through Informed Strategy
The worldwide cancel for any reason travel insurance market stands at the intersection of consumer demand evolution, technological distribution innovation, regulatory complexity, and competitive intensity. The historical growth trajectory from 2020 through 2025, the projected double-digit compound annual growth rate through 2032, and the recent demand surges triggered by geopolitical and operational volatility collectively affirm that this category is not a transientfad but a structural component of the modern travel protection ecosystem. Carriers, distributors, and investors who approach this market with rigorous analytical frameworks, disciplined product strategy, and adaptive competitive positioning will be best equipped to capture the value embedded in this expanding segment.
Access to granular segmentation data, forward-looking scenario analysis, competitive benchmarking, and regulatory pathway assessment is essential for stakeholders who require the depth of intelligence necessary to make informed strategic decisions. The complete research report provides the comprehensive data architecture, segment-level projections, distribution channel dynamics, traveler type breakdowns, and competitive profiling that enable precise planning and risk-aware execution. Readers seeking the full spectrum of market intelligence, including detailed revenue projections, segment concentration metrics, and carrier-specific strategic assessments, are encouraged to access the complete report through the source webpage, where the complete dataset and analytical appendices are available for download and review.
For detailed analysis of this topic, please visit the official page: Worldwide Cancel for Any Reason Travel Insurance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Worldwide Bioceramic Root Canal Sealer Market To Reach 566.65 Million USD By 2032 At 9.48 CAGR
By PW Consulting, 2026-09-02
Strategic Intelligence for the Bioceramic Root Canal Sealer Market: Navigating Growth and Innovation in 2026
The global dental market is undergoing a profound transformation, driven by an aging population, increased awareness of oral health, and a shift towards minimally invasive, bioactive materials. Within this landscape, the bioceramic root canal sealer market has emerged as a critical segment, offering superior sealing capabilities, biocompatibility, and ease of use compared to traditional resin-based alternatives. As we approach 2026, understanding the trajectory, competitive dynamics, and regulatory nuances of this market is essential for stakeholders aiming to capitalize on its robust growth. This article provides a strategic overview of the market landscape, drawing insights from our latest comprehensive analysis, Worldwide Bioceramic Root Canal Sealer Market, to highlight the key opportunities and challenges shaping the industry.
Worldwide Bioceramic Root Canal Sealer Market
Market Trajectory and Growth Drivers
Our analysis reveals a compelling growth narrative for the bioceramic root canal sealer market. Valued at USD 195.4 million in 2020, the market has demonstrated consistent resilience and expansion, reaching USD 300.2 million in 2025. This historical performance underscores the rapid adoption of bioceramic technologies as endodontists and general practitioners seek materials that enhance clinical outcomes and operational efficiency. Looking ahead, the market is projected to accelerate, with revenues expected to reach USD 566.65 million by 2032. This growth translates to a Compound Annual Growth Rate (CAGR) of 9.48% over the forecast period from 2026 to 2032.
Worldwide Bioceramic Root Canal Sealer Market
Several macroeconomic and clinical factors are fueling this expansion. The rising prevalence of dental caries and periodontal diseases globally is driving the volume of endodontic procedures. Concurrently, there is a paradigm shift in clinical preference towards hydraulic calcium silicate-based sealers that set via hydration from dentinal tubule moisture, offering no shrinkage and high biocompatibility. These materials are increasingly favored for their ability to promote healing and form hydroxyapatite, aligning with the broader industry trend towards bioactive dentistry. Furthermore, the availability of premixed, ready-to-use injectable formats is reducing preparation time and minimizing waste, thereby improving the value proposition for dental practices.
Worldwide Bioceramic Root Canal Sealer Market
While the market has historically been led by North America, which accounted for a significant share of revenue in the base year, the growth story is increasingly global. Europe continues to represent a strong market with established reimbursement frameworks and high clinical standards. Meanwhile, the Asia Pacific region is witnessing accelerated adoption, supported by expanding healthcare infrastructure and a growing middle class accessing advanced dental care. Latin America and the Middle East and Africa, though smaller in current revenue contribution, present emerging opportunities as distribution networks mature and awareness of bioceramic benefits spreads. Our report delves into these regional nuances without exposing specific percentage splits, providing a qualitative assessment of market maturity and potential entry strategies for each geography.
Segmentation Dynamics: Type and Application
The market is segmented by product type and application, each exhibiting distinct growth characteristics. In terms of type, Premixed Injectable Sealers have established themselves as a dominant category, reflecting the industry's demand for convenience, consistency, and reduced handling errors. These ready-to-use formulations are engineered to offer high flowability and radiopacity, ensuring precise placement and effective sealing of complex canal anatomies. The Powder-Liquid and Two-Paste Systems segment remains relevant, particularly in settings where customization of mix ratios is preferred or where specific clinical protocols require traditional handling methods. However, the trend towards single-use syringes and preloaded syringes is driving a structural shift in favor of premixed options.
By application, Dental Clinics represent the primary end-use environment, accounting for the largest share of market consumption. The high volume of root canal treatments performed in private practices and specialized endodontic centers drives the demand for reliable, user-friendly sealers. Hospitals constitute a significant secondary application, often handling complex cases or catering to public health sectors where bulk procurement and standardized protocols are prevalent. Academic and Research Institutes also contribute to the market, serving as early adopters of new technologies and validating long-term clinical performance through studies. The intersection of these applicationsegments creates a comprehensive demand profile that manufacturers must address through targeted product positioning and educational outreach.
Competitive Landscape: Titans and Innovators
The competitive landscape of the bioceramic root canal sealer market is characterized by a mix of established multinational dental manufacturers and agile innovators who are rapidly gaining traction. The market exhibits a moderate level of concentration, with the top three companies collectively holding a substantial share, while the top five players command an even larger portion of the revenue. This concentration suggests that while there are dominant incumbents, there is still room for specialized players to differentiate through product features, regional distribution strength, and clinical advocacy.
Dentsply Sirona, headquartered in Charlotte, NC, USA, stands as a market leader with a comprehensive portfolio. Their offerings include ProRoot Bio Sealer, a bioceramic sealer with high bioactive cement content designed for enhanced setting, pH, and hydroxyapatite formation, alongside the AH Plus Bioceramic Sealer. In September 2025, Dentsply Sirona launched ProRoot Bio Sealer and AH Plus Ribbon, with US availability expected in October 2025. These launches emphasize stronger adhesion, faster healing, high pH, and hydroxyapatite formation, reinforcing the company's commitment to advancing bioactive endodontics.
Septodont, based in Saint-Maur-des-Fossés, France, is another key player renowned for its BioRoot RCS. This bioactive bioceramic permanent root canal sealer offers outstanding adhesion to dentin and gutta-percha, a tight seal with no shrinkage, and high purity. Septodont also provides the BioRoot Flow variant, catering to clinicians seeking versatility in handling and flow characteristics. Their focus on clinical evidence and purity standards has solidified their reputation among endodontists seeking predictable outcomes.
Kerr Endodontics, part of Envista and based in Brea, CA, USA, markets the ZenSeal and ZenSeal Pro bioceramic root canal sealers. These products consist of tricalcium silicate, dicalcium silicate, and radiopacity agents in a hydrophilic matrix. Kerr emphasizes high flowability, minimized waste, high radiopacity, and value per application. In July 2025, Kerr Dental released ZenSeal, highlighting these attributes to address the practical needs of busy clinical environments.
EdgeEndo, operating under HSG-S Corp in Albuquerque, NM, USA, has carved a niche with its EdgeBioCeramic Sealer, a resin-free, highly flowable, premixed option for cold obturation. They also offer EdgeBioCeramic ThermalFlow Root Canal Sealer, optimized for lower viscosity in warm obturation techniques. Trusted in millions of cases, EdgeEndo's products appeal to clinicians who prioritize resin-free formulations and adaptability to different obturation methods.
Angelus, headquartered in Londrina, Brazil, produces Bio-C Sealer and BIO-C Sealer ION+, ready-to-use bioceramic sealers with biologically active ingredients that support sealing and healing. Their premixed syringe presentation with applicator tips enhances usability. Similarly, Brasseler USA, based in Savannah, GA, offers BC Sealer Ion+, a next-generation premixed bioceramic sealer based on Akermanite. This product is highlighted for enhanced handling, ion release, versatility, osteogenic/angiogenic properties, and long-term sealing capabilities.
International players are also exerting significant influence. Prevest DenPro, located in Jammu, India, markets Cerafill RCS, a ready-to-use injectable premixed bioceramic filling and sealing material. C-Root Dental Medical, based in China, provides C-Root SP premixed bioceramic sealer featuring a patented strontium silicate formula. Dentonics, based in the USA, offers Master-dent Bioceramic Root Canal Sealer, a premixed alumina-free calcium silicate-based hydrophilic formula for efficient obturation. SS White Dental, from Lakewood, NJ, supplies a bioceramic sealer engineered to penetrate, fill, and seal main and lateral canals, described as biological as pulp tissue. Vista Apex, also based in the USA, markets a bioactive endodontic sealer as a hydraulic, ready-to-use injectable paste that utilizes dentinal tubule moisture for the setting reaction.
Recent developments underscore the dynamic nature of this competitive field. In October 2024, Longly Biotechnology (Wuhan) CO., LTD received FDA 510(k) clearance for i-MTA SP Injectable Root Canal Bioceramic Sealer, a premixed ready-to-use hydraulic bioceramic paste. Similarly, in May 2024, Enpuno Biotechnology Co., Ltd received FDA 510(k) clearance for NRSP Injectable Root Canal Bioceramic Sealer, offering multiple models of premixed ready-to-use injectable white hydraulic bioceramic paste. These clearances highlight the active commercial pathways for manufacturers, particularly from China, to enter regulated markets and expand the global supply base.
Industry Dynamics: Regulation, Reimbursement, and Standards
Navigating the bioceramic root canal sealer market requires a keen understanding of the regulatory and reimbursement environment. In the United States, root canal filling materials, including bioceramic sealers, are regulated as Class II devices under 21 CFR 872.3820 with product code KIF. This classification mandates 510(k) premarket notification, where manufacturers must demonstrate substantial equivalence to predicate devices and compliance with relevant standards. The regulatory pathway ensures safety and efficacy but also imposes time and resource requirements on new entrants.
Technical standards play a pivotal role in product development and market acceptance. Bioceramic root canal sealers must conform to ISO 6876 standards for dentistry root canal sealing materials. These standards encompass various performance criteria, including flow rate requirements, which are often referenced in literature as not less than 20 mm per ISO 6786/2001 references. Compliance with these standards is a baseline expectation for credible products and is frequently cited in product documentation and clinical reviews. Manufacturers must invest in rigorous testing to validate flow, setting time, solubility, and sealing ability to meet these benchmarks.
On the reimbursement front, bioceramic sealers are typically utilized in root canal treatments that are billed under standard endodontic procedure codes. Our analysis indicates that no specific new CPT or DRG updates have been isolated exclusively to bioceramic variants in public sources. This means that reimbursement generally follows the broader procedure code for endodontic therapy, and the choice of sealer may not directly alter the reimbursement amount. However, the value proposition of bioceramic sealers lies in their potential to reduce procedural complications, improve success rates, and enhance patient satisfaction, which can indirectly support practice growth and retention. Stakeholders must consider how product benefits align with clinical efficiency and patient outcomes to justify the adoption of these materials within existing reimbursement frameworks.
The trend towards premixed, ready-to-use injectable pastes or syringes that set via hydration from dentinal tubule moisture is a defining characteristic of the segment. These hydraulic calcium silicate-based formulations offer no shrinkage and high biocompatibility, distinguishing them from older resin-based or zinc oxide-eugenol sealers. This technological shift is driving product innovation and shaping clinician preferences, as the ease of use and biological advantages become increasingly recognized in the professional community.
Strategic Outlook for 2026 and Beyond
As we move into 2026, the bioceramic root canal sealer market presents a landscape rich with opportunities for strategic engagement. The projected CAGR of 9.48% indicates a healthy growth environment that rewards manufacturers and distributors who can effectively position their products, expand their geographic footprint, and build strong clinical advocacy networks. The increasing number of FDA 510(k) clearances for bioceramic sealers from diverse manufacturers suggests a broadening of supply options and potential price competition, which may accelerate adoption in price-sensitive markets while challenging incumbents to maintain differentiation through innovation and service excellence.
Key strategic considerations for industry participants include:
- Product Differentiation and Innovation: With a crowded field of premixed injectable sealers, companies must continue to innovate in areas such as flowability, radiopacity, ion release, and handling characteristics. Formulations that offer unique benefits, such as enhanced osteogenic/angiogenic properties or compatibility with both cold and warm obturation techniques, can capture specific clinician segments. The launch of products like ProRoot Bio Sealer and ZenSeal demonstrates the ongoing commitment to refining these attributes.
- Regulatory Strategy and Market Access: Understanding the nuances of Class II regulation and ISO compliance is critical. For manufacturers targeting the US market, a robust 510(k) pathway is essential. For global expansion, adapting to regional regulatory requirements and standards is equally important. Recent clearances for companies like Longly Biotechnology and Enpuno Biotechnology illustrate the viability of navigating these pathways, opening doors for broader market participation.
- Clinical Education and Advocacy: Given the technical nature of bioceramic materials, clinician education remains a powerful driver of adoption. Manufacturers that invest in continuing education, hands-on workshops, and evidence-based marketing can build trust and accelerate the transition from traditional sealers to bioceramic alternatives. Partnerships with key opinion leaders and academic institutions can further validate product performance and influence prescribing habits.
- Distribution and Regional Penetration: While North America and Europe are mature markets, the growth potential in Asia Pacific, Latin America, and the Middle East and Africa should not be overlooked. Tailoring distribution strategies to local healthcare infrastructure, reimbursement environments, and price sensitivities can unlock new revenue streams. Companies with strong regional presence or partnerships can leverage these opportunities to capture market share ahead of competitors.
- Supply Chain and Operational Efficiency: As demand grows, ensuring consistent supply and quality control is paramount. Premixed products require careful manufacturing and storage protocols to maintain integrity. Companies that can optimize their supply chains, minimize waste, and deliver reliable products will gain a competitive edge, particularly in high-volume dental clinic settings where efficiency is valued.
Conclusion: The Value of Comprehensive Market Intelligence
The bioceramic root canal sealer market is at an inflection point, characterized by technological advancement, competitive intensity, and expanding global demand. The data points to a market that is not only growing in size but also evolving in complexity, with diverse product types, applications, and regional dynamics. For decision-makers in the dental industry, a superficial understanding is insufficient. Success requires a granular grasp of market size projections, segmentation splits, competitive profiles, regulatory constraints, and emerging trends.
Our Worldwide Bioceramic Root Canal Sealer Market report is designed to provide this depth. It offers a detailed analysis of the market from 2020 through 2032, encompassing historical data, forecast projections, and a thorough examination of segmentation, competition, and industry dynamics. The report goes beyond high-level metrics to deliver actionable insights, including profiles of key companies, recent product launches and regulatory clearances, and an assessment of the factors influencing market trajectory. By accessing this comprehensive intelligence, stakeholders can formulate strategies that are grounded in data, responsive to market realities, and positioned for long-term success.
We invite you to explore the full report to gain the complete picture. The detailed breakdowns of regional performance, type-specific growth rates, application-level consumption patterns, and company share analysis provide the precision needed to make informed investment, product development, and market entry decisions. In a market moving at a 9.48% CAGR, the difference between guessing and knowing can define your competitive advantage. Let our analysis be your guide to navigating the bioceramic root canal sealer landscape with confidence and clarity.
For detailed analysis of this topic, please visit the official page: Worldwide Bioceramic Root Canal Sealer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Projects 6.45 Percent CAGR in Worldwide Medical Conductive Gel Market Reaching USD 681.19 Million by 2032 Based on 2025 Base Year Data
By PW Consulting, 2026-09-02
Strategic Intelligence in the Worldwide Medical Conductive Gel Market: Navigating Growth and Complexity Through 2032
The global medical conductive gel market stands at a critical inflection point where material science, regulatory evolution, and shifting clinical workflows converge. For executives, procurement leaders, and product strategists operating in the medical device and healthcare sectors, understanding this landscape is no longer optional—it is a prerequisite for informed capital allocation, supply chain resilience, and competitive positioning. As we approach 2026, the demand for precise, forward-looking intelligence has intensified. This article introduces the strategic architecture of our latest Worldwide Medical Conductive Gel Market research, outlining how the study translates macro trends, competitive dynamics, and regulatory currents into actionable decision support for enterprise leaders.
Worldwide Medical Conductive Gel Market
Market Trajectory and the Strategic Imperative for 2026 Decision-Making
Over the past half-decade, the worldwide medical conductive gel market has demonstrated steady expansion, reflecting broader growth in diagnostic imaging, electrophysiological monitoring, and therapeutic electrical stimulation. Historical revenue progression from 2020 through 2025 illustrates a market that has consistently advanced despite supply chain volatility and shifting procurement frameworks. Baseline figures for 2025 establish a substantial revenue foundation, while forward projections through 2032 outline a sustained upward trajectory anchored by a compound annual growth rate of 6.45 percent across the forecast horizon.
Worldwide Medical Conductive Gel Market
What makes this growth profile strategically significant is not merely its magnitude, but its composition. The market is unfolding across multiple use-case domains, each with distinct performance requirements, regulatory pathways, and purchasing behaviors. Ultrasound applications continue to represent a substantial share of total revenue, while ECG and EEG conductive media, TENS-related formulations, and other specialized medical gels collectively form a diversified demand base. This breadth means that companies cannot rely on a single product narrative or end-user segment to drive long-term value creation. Instead, strategy must account for how clinical adoption patterns, device innovation cycles, and channel economics interact across the portfolio.
Worldwide Medical Conductive Gel Market
For 2026 planning, the most consequential question is how organizations will align their capabilities with the segments where differentiation is most defensible. The research is structured to help decision-makers answer that question by mapping revenue flows, volume concentrations, and structural dependencies without exposing the precise numeric splits that constitute the full analytical core. The objective is to provide enough contextual fidelity to prioritize initiatives, while preserving the detailed segmentation intelligence that justifies the full study.
Why 2026 Demands a Different Analytical Lens
Several converging forces reshape how conductive gel markets should be evaluated this year. First, device manufacturers are increasingly designing electrodes and monitoring platforms with material compatibility in mind, which places conductive gels at the center of product performance rather than as interchangeable consumables. Second, reimbursement frameworks and coding practices influence how end users justify procurement, particularly in electrical stimulation and neuromuscular applications where per-unit billing conventions affect volume decisions. Third, regulatory expectations around biocompatibility, sterilization, and classification continue to mature, creating both compliance burdens and opportunities for suppliers who can demonstrate rigorous quality systems.
These dynamics mean that historical parity in revenue growth is insufficient for competitive advantage. Companies need to understand where value is being created along the chain—from custom hydrogel platforms and OEM partnerships to specialized skin preparation formulations and bulk-roll hydrogel supplies—and which end-user environments are expanding most rapidly in terms of procedure volume, procurement consolidation, and channel preferences. The study is designed to illuminate these relationships through a multi-layered analytical framework that integrates market sizing, segmentation, and competitive intelligence into a coherent strategic narrative.
Inside the Report: Operational Intelligence for Enterprise Strategy
The Worldwide Medical Conductive Gel Market research is built around practical utility. It is intended to support scenario planning, product portfolio evaluation, go-to-market positioning, and M&A or partnership diligence. The report structure is organized to move from macro market architecture to granular competitive and operational insights, allowing users to navigate according to their immediate decision context.
- Macro market architecture and forecast logic: The study establishes baseline sizing for the overall market, traces historical progression, and projects forward through the 2032 horizon. The analytical approach connects demand drivers, device utilization trends, and supply-side capacity considerations to explain why the trajectory unfolds as projected, rather than presenting growth figures in isolation.
- Segmentation depth without data exposure: Revenue is examined across product type, end-user setting, and geographic footprint. The report discusses relative structural weight, procurement behaviors, and performance characteristics that differentiate segments, giving readers a clear sense of where concentration and opportunity lie while retaining the exact numeric breakdowns for the full publication.
- Competitive landscape and company profiling: Detailed profiles of leading manufacturers and emerging producers are included, covering product offerings, manufacturing posture, certification status, and strategic positioning. This allows readers to assess where incumbents maintain advantage, where custom manufacturing and OEM relationships create differentiation, and where regional producers are expanding capability.
- Regulatory and quality system mapping: The report integrates applicable classification frameworks, biocompatibility expectations, sterilization considerations, and coding context into the market narrative so that procurement and compliance teams can interpret demand trends in light of regulatory reality.
- Recent market events and clearance activity: Notable regulatory clearances and product developments are analyzed for their implications on competitive dynamics, signal quality expectations, and adjacent application expansion, particularly where salt-free or chloride-free formulations and microcurrent-oriented gels are gaining attention.
By combining these elements, the research enables users to move beyond generic market summaries and into decision-grade interpretation. Whether the goal is to assess potential market entry, benchmark a product roadmap, evaluate supplier options, or anticipate procurement shifts, the study provides the connective tissue between data and strategy.
Competitive Landscape: Incumbents, Specialists, and Regional Contenders
The competitive structure of the medical conductive gel market reflects a blend of long-established manufacturers with broad electrophysiology portfolios and specialized producers focused on custom hydrogel platforms, skin preparation, or regional supply. This mix creates a market environment where differentiation often comes from formulation expertise, regulatory readiness, OEM integration, and the ability to serve both standardized and bespoke application requirements.
Parker Laboratories remains a prominent reference point in the space, with product lines such as Spectra 360 and Signagel addressing long-term monitoring, ECG, defibrillation, biofeedback, and EMG contexts. Its positioning illustrates how established brands compete on formulation variety, signal performance, and familiarity within clinical workflows. Axelgaard Manufacturing similarly emphasizes bulk-roll hydrogel production and specialized AG-series products for stimulating, iontophoresis, sensing, and defibrillation use cases, with a manufacturing footprint that reinforces its domestic supply proposition. Weaver and Company occupies a more focused position through conductive pastes and skin prep formulations designed for rigorous EEG and ECG signal standards, reflecting a technician-centric value proposition centered on reproducibility and electrical contact quality.
On the custom and OEM-oriented side, NEXGEL operates through FDA-registered, ISO-certified facilities with cGMP manufacturing capable of producing hydrogel platforms with or without active ingredients, which positions the company for tailored medical conductive applications. R&D Medical Products extends this theme by developing conductive hydrogels for surface mount electrodes, intraoperative nerve monitoring, skin adhesive wearables, and OEM partnerships, indicating a trajectory toward integration with advanced monitoring and wearable devices.
A substantial cohort of manufacturers based in China contributes to the market's production capacity and product diversity. Companies such as Top-Rank Health Care, Yangzhou Boen Medical Technology, Jining Jinnot Medical Gel Factory, and Shenzhen TianyiHeng Technology each focus on conductive gel supply for diagnostic and therapeutic devices, with varying degrees of customization in conductivity and viscosity. Their presence underscores the importance of regional supply dynamics, cost structures, and the ability to serve both domestic device ecosystems and export channels. In Europe, Ultragel Medical Ltd has built a long-standing export footprint in contact and conductive gels for ultrasound diagnostics and electromedical procedures, reflecting a niche but internationally active position.
Recent regulatory clearances add texture to the competitive picture. In late 2025, Motive Health Inc. received FDA 510(k) clearance for a muscle stimulator device using salt-free, chloride-free conductive gel for NMES and TENS electromedical procedures. Separately, in early 2025, Shenzhen Ulike Smart Electronics Co., Ltd. secured clearance for Jmoon Conductive Gel intended for use with microcurrent devices to improve skin conductivity. These developments are noteworthy because they signal expanding regulatory acceptance for specialized gel formulations in adjacent therapeutic and aesthetic-electromedical applications, and they hint at how formulation choices can become part of device-level differentiation rather than remaining purely consumable-level decisions.
Market concentration indicators further clarify the competitive environment. The share held by the top three and top five participants reflects a moderately consolidated landscape, but one that still leaves meaningful room for specialized manufacturers and regional suppliers to compete on customization, service, and application-specific performance. Understanding how concentration interacts with segment-level demand is central to evaluating which competitive strategies are most sustainable in 2026 and beyond.
Regulatory, Reimbursement, and Quality Dynamics Shaping Demand
Conductive gels occupy a regulatory space where classification depends on intended use, contact conditions, and whether the product is supplied separately or as part of a device system. In the United States, conductive gels supplied separately for electromedical procedures are classified under 21 CFR 882.1275 as electroconductive media, generally falling within Class II for product code GYB. This classification pathway shapes premarket expectations and reinforces the importance of documentation, intended-use clarity, and quality system maturity for suppliers targeting regulated markets.
Biocompatibility remains a foundational requirement for products that contact skin. ISO 10993-1 guidance informs evaluation of biological safety based on contact duration and nature, and this framework is actively referenced in FDA expectations related to electrocardiograph electrodes and associated conductive media. For manufacturers, this means that material selection, extractables and leachables considerations, and testing strategies must align with the clinical exposure profile of the end application. Where devices incorporating or using conductive gels require sterilization, ISO 11135 for ethylene oxide processes may also be relevant, adding another layer of operational planning for products that must meet validated sterilization requirements without compromising gel performance or packaging integrity.
In the European context, non-invasive conductive gels such as ultrasound gels may be classified as Class I medical devices under EU MDR Rule 1 when they contact only intact skin and are not absorbed or dispersed. This classification pathway reduces certain regulatory burdens relative to higher-risk device categories, but it does not remove the need for careful conformity assessment, labeling discipline, and post-market vigilance. The interplay between classification logic and product use case is therefore a strategic consideration for manufacturers deciding how to position products across geographies and application sets.
Reimbursement context also influences demand behavior. HCPCS code A4558 covers conductive gel or paste for use with electrical devices such as TENS or NMES, billed per ounce, and this coding convention remains active under CMS frameworks as of 2026. While reimbursement mechanics vary by payer and care setting, the existence of a billable code for conductive media in electrical stimulation contexts creates a structural link between procedure volume, consumable procurement, and revenue workflows. For market participants, this reinforces the value of understanding not only how products perform clinically, but also how they fit into billing, inventory, and cost-per-procedure calculations within end-user organizations.
Strategic Takeaways for 2026 and Beyond
Taken together, the market environment for medical conductive gels in 2026 is characterized by steady expansion, diversified demand, and a competitive field that rewards formulation expertise, regulatory readiness, and application-level integration. Several strategic themes emerge for organizations preparing their next planning cycle.
First, product strategy should be guided by end-use specificity rather than generic volume assumptions. Because different applications impose different requirements on conductivity, viscosity, skin compatibility, sterilization, and signal stability, the most defensible positions tend to be those aligned with clearly defined clinical and device-integration needs. The research supports this by examining how segment-level behavior diverges across product types and end-user settings, helping teams identify where specialized positioning can protect margin and improve stickiness.
Second, supply chain and manufacturing posture matter more than ever. Custom hydrogel platforms, cGMP production capability, OEM partnerships, and domestically anchored manufacturing can all serve as differentiators, particularly when device manufacturers seek consistency, auditability, and rapid iteration. The presence of both established incumbents and regionally concentrated producers means that procurement strategies must weigh cost, quality assurance, compliance documentation, and responsiveness in combination rather than in isolation.
Third, regulatory and reimbursement awareness should be embedded in product and market planning. Classification nuances, biocompatibility expectations, sterilization considerations, and coding frameworks all influence how quickly a product can be adopted and how easily it can be justified within procurement and billing workflows. The study integrates these factors into the market narrative so that strategic decisions reflect not only demand potential but also the practical conditions under which demand translates into commercial outcomes.
Fourth, competitive intelligence should be interpreted with an eye toward concentration and fragmentation. The market is not uniformly consolidated, and the balance between top-player share and the remaining competitive field varies by segment and region. This creates opportunities for targeted positioning, especially where incumbents are less specialized or where regional supply chains can offer differentiated service and responsiveness. Understanding these patterns is essential for evaluating partnership options, entry strategies, and defensive positioning.
Access the Full Intelligence
This article provides a strategic preview of the landscape and the analytical value embedded in our Worldwide Medical Conductive Gel Market research. It is designed to demonstrate the depth, structure, and decision relevance of the study while preserving the full segmentation data, exact regional and application-level breakdowns, and detailed quantitative projections for the complete publication. For executives who need to move from directional understanding to precise planning, the full report delivers the market sizing logic, segmentation architecture, competitive profiling, and regulatory context necessary to support confident 2026 decisions and multi-year strategy development.
The market will continue to evolve as device design, regulatory expectations, reimbursement practices, and procurement behaviors interact across regions and end-user settings. Organizations that invest in detailed, structured intelligence now will be better positioned to allocate resources, prioritize product and supply decisions, and respond to competitive shifts with clarity. We invite you to access the complete study for the full set of data, profiles, and forward-looking analysis that underpin the strategic framework outlined here.
For detailed analysis of this topic, please visit the official page: Worldwide Medical Conductive Gel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Multi-junction VCSEL Chips Market to Reach 1,977.53 Million by 2032 with 22.21% CAGR
By PW Consulting, 2026-09-02
Strategic Intelligence for the Multi-Junction VCSEL Inflection Point: Why the 2026 Decision Window Demands Precision
The global market for multi-junction VCSEL chips has crossed a structural threshold. What was once a niche photonics component confined to selective 3D sensing pilots has matured into a high-growth, capital-intensive semiconductor segment where architectural decisions made in 2026 will shape competitive positioning through the end of the decade. Our newly released Worldwide Multi-junction VCSEL Chips Market research study is built for executives who require more than directional sentiment. It is a decision-grade intelligence asset designed to translate a rapidly compounding revenue trajectory into actionable procurement, capacity, partnership, and market-entry strategies.
Worldwide Multi-junction VCSEL Chips Market
The macro arc is unmistakable. After establishing a base in 2025, the total addressable market has expanded from roughly $112.45 million in 2020 to $485.78 million in 2025, and the forward path steepens further: the segment is projected to reach approximately $626.0 million in 2026, accelerating toward $773.3 million in 2027, $948.99 million in 2028, and $1,161.39 million by 2029. The progression continues through $1,374.72 million in 2030, $1,672.1 million in 2031, and ultimately approaches $1,977.53 million in 2032. This expansion is tied to a compound annual growth rate of 22.21 percent across the 2026–2032 forecast horizon, denominated in USD millions. A trajectory at this velocity does more than reward early positioning. It punishes late ambiguity. Companies that treat multi-junction VCSEL procurement as a commodity buying exercise now will discover that performance density, supply assurance, and qualification timelines have already become the differentiators that separate winners from stranded capacity.
Worldwide Multi-junction VCSEL Chips Market
That is precisely why this study exists. It does not simply forecast. It decomposes the forces that will govern where growth materializes, who can deliver at scale, and what risks will determine margin and continuity in a market where substrate geopolitics, geopolitical trade controls, and automotive qualification regimes intersect.
Worldwide Multi-junction VCSEL Chips Market
Why 2026 Is a Decision-Defining Year
The most immediate clarification this research provides is that the 2026–2032 window is not a linear extension of the prior five years. It is a different operating regime. The market is no longer being pulled by a single flagship use case. Instead, demand is coalescing across multiple high-value applications that each impose distinct performance, reliability, and cost requirements on multi-junction architectures. For automotive LiDAR, that means power density, thermal behavior, and long-term qualification discipline. For consumer electronics, it means form-factor constraints, optical efficiency, and volume scalability. For industrial sensing, it means robustness, customization, and repeatability. For optical communications, it means signal integrity, integration compatibility, and data-rate alignment. Each application category places a different burden on chip architecture, packaging, test, and supply, and the report maps how these diverging requirements will reshape competitive advantage over the forecast period.
Equally important, the period ahead will be defined by how companies navigate material and substrate volatility. Gallium arsenide availability has become a strategic variable rather than a procurement footnote. Export controls and duty adjustments have tightened the flow of GaAs-related substrates and epitaxial inputs, while lead times for stocked and custom substrates, plus the additional cycle time required for custom epi recipes, have lengthened planning horizons. These are not abstract supply concerns. They directly affect time-to-qualification, program continuity, and the economics of scale-up. The study embeds this operating reality into its forecasts and strategic framing so that leadership teams can pressure-test sourcing strategies, qualification timelines, and regional exposure rather than reacting after disruption occurs.
What the Study Delivers: An Execution-Minded Content Architecture
The report is structured to move from market framing to operational decision support. Rather than stopping at headline sizing, it provides a granular, analyst-vetted architecture that executives can use immediately in planning cycles. The study includes the following core deliverables:
- A full historical reconstruction from 2020 through the 2025 base year, paired with an eight-year forecast extending through 2032, all expressed in USD millions. This enables backcasting of assumptions and stress-testing of growth scenarios against actual prior performance.
- A market segmentation framework organized by junction count, geographic footprint, and end-use application. These cuts reveal where multi-junction architectures are accumulating value, where performance premiums are emerging, and which demand vectors will most influence capacity planning and product roadmaps.
- Concentrated competitive profiling of the companies most actively shaping the multi-junction VCSEL landscape. Each profile is built around technology posture, product architecture, qualification status, and recent strategic moves, allowing readers to benchmark suppliers, evaluate partners, and anticipate competitor behavior.
- A market structure read focused on concentration dynamics, helping stakeholders understand how share, capability, and bargaining power are distributed across the supplier base.
- Integrated coverage of the regulatory and materials environment, including export-control regimes, tariff adjustments, substrate lead-time parameters, and handling constraints associated with epitaxial processing. This context is mapped directly to region, segment, and supply-chain dynamics rather than treated as disconnected news.
- A forward-looking events and developments section that ties product launches, demonstrations, and adoption signals to the broader market trajectory, ensuring that near-term announcements are interpreted in context rather than in isolation.
The intent is to make the study usable at multiple levels of the organization. Corporate strategy teams can use it to frame long-range positioning. Business unit leaders can use it to align product plans and sourcing strategy. Procurement and supply-chain executives can use it to evaluate exposure, redundancy, and qualification sequencing. R&D and engineering leaders can use it to prioritize architecture trade-offs and qualification investments.
The Competitive Field: Capability, Qualification, and Scale as Strategic Currency
The multi-junction VCSEL market is not a fragmented commodity arena. It is a concentrated, capability-driven field where differentiation increasingly comes from architecture expertise, qualification depth, process control, and the ability to convert performance density into reliable volume supply. Our research profiles the companies that are actively setting the tone for this competitive phase.
Lumentum Holdings Inc., headquartered in San Jose, California, has positioned itself around multi-junction VCSEL arrays in its M Series, including 70W, 100W, and 400W 905 nm models intended for automotive and industrial LiDAR as well as 3D sensing. Its automotive-qualified offerings emphasize high power density in a compact form factor, a combination that matters wherever system volume and thermal envelope are constrained. In a market where automotive programs reward proven qualification and repeatable supply, that posture is strategically significant.
Coherent Corp., based in Saxonburg, Pennsylvania, provides 940 nm multi-mode VCSEL arrays built on a multi-junction architecture that is designed to deliver high power at relatively low current. Its example performance point, approximately 4.6 W at 2.7 A, supports 3D sensing, short-range LiDAR, and automotive in-cabin applications, with AECQ-102 qualification reinforcing automotive readiness. The emphasis on low-current efficiency and in-cabin use cases reflects a broader industry shift toward diversified automotive photonics placements beyond exterior sensing alone.
ams-OSRAM AG, including its Vixar lineage and headquartered in Premstätten, Austria, has developed VCSEL technology encompassing multi-junction structures for 3D sensing and addressable arrays. Its historical role in pioneering commercial multi-junction VCSEL with high power conversion efficiency gives it a distinct technology-reference position in the segment, particularly for teams evaluating efficiency-driven design trade-offs.
TRUMPF Photonic Components GmbH, based in Ulm, Germany, manufactures multi-junction VCSEL arrays across single, double, and triple-junction configurations for consumer electronics, automotive, and industrial sensing. Its distinguishing characteristic is control across the full process chain, from design through manufacturing in a cleanroom facility. For customers prioritizing supply integrity, process traceability, and end-to-end manufacturability, vertical integration is a meaningful value proposition.
The Asia-based supplier base is expanding capability and scale with notable momentum. Raysees Technology Co., Ltd., operating in China, specializes in multi-junction VCSEL chips with power conversion efficiency above 50 percent, peak optical power above 100W, addressable arrays, and small divergence for dToF, 3D vision, and LiDAR. It has advanced to mass production on 6-inch wafers with yield above 90 percent, a combination that signals maturity in both performance and manufacturing reliability.
LEMON Photonics Technologies Co., Ltd., also in China, produces vehicle-grade 905 nm and 940 nm multi-junction VCSEL chips for automotive and 3D sensing applications as part of a broader laser chip portfolio. Its vehicle-grade focus underscores the growing importance of qualified automotive-grade photonics within the regional supply base.
Suzhou Everbright Photonics Co., Ltd., also referred to as Changguang Huaxin Optoelectronics Technology Co., Ltd., is headquartered in Suzhou, Jiangsu, China. It develops and mass-produces high-performance multi-junction VCSEL arrays, including 6-junction and higher configurations for LiDAR, with wavelengths near 940 nm, high energy density, low divergence, and 6-inch wafer production capability. The presence of higher-junction configurations in volume production indicates that the segment is pushing beyond baseline dual- and triple-junction offerings into more specialized high-energy-density architectures.
QSI, or Quantum Semiconductor International, is based in South Korea and develops multi-junction VCSEL array devices using epi growth technology for wavelengths spanning 790–940 nm. Its target applications include LiDAR and heating systems, with optical power above 10W per chip. This wider wavelength range and application breadth reflect the way multi-junction platforms are being leveraged across more than one end-use domain.
Recent developments reinforce that the competitive story is still unfolding in real time. In March 2026, Lumentum showcased a breakthrough optical scale-up demonstration at OFC 2026 using high-density multimode 1060 nm VCSEL array technology for AI infrastructure interconnects. That move highlights how multi-junction and high-density VCSEL know-how is being extended into data-communications and AI infrastructure contexts, widening the potential demand base beyond sensing alone. In September 2025, TRUMPF Photonic Components unveiled a new 100G VCSEL at ECOC 2025 as a drop-in replacement optimized for high-volume supply in data communications. That launch illustrates how VCSEL suppliers are aligning product roadmaps to the volume economics of data-rate-driven interconnect markets. At the same time, industry commentary from August 2025 continued to note the ongoing adoption of multi-junction VCSEL arrays for solid-state LiDAR in automotive applications, confirming that the automotive demand thesis remains actively reinforced across the supply chain.
Concentration, Control, and the Strategic Meaning of Market Structure
A market growing at this pace is never just about total size. Structure matters. The study’s concentration read shows that the top three companies account for approximately 62.45 percent of market share, while the top five reach roughly 78.9 percent. That level of concentration has direct strategic implications. It suggests that a relatively compact group of suppliers holds disproportionate influence over qualification pathways, scale-up credibility, and the pace at which new architectures become commercially dependable. For buyers, this means supplier selection is not a simple price comparison but a risk-adjusted assessment of technical depth, program continuity, and qualification leverage. For entrants and expanders, it means that displacing incumbents requires more than competitive pricing; it requires demonstrable advantages in efficiency, form factor, qualification readiness, or supply assurance that can withstand program-level scrutiny.
Concentration also interacts with the macro forecast. When growth is fast but supplier base is concentrated, market share moves can be meaningful even when absolute revenue gains appear incremental at first. Small shifts in design-in wins, qualification approvals, or regional supply commitments can compound into larger trajectory differences over a multi-year horizon. The report provides the analytical scaffolding to evaluate those shifts without relying on intuition or headline press releases.
The Materials and Regulatory Layer: Where Strategy Meets Constraint
No serious multi-junction VCSEL strategy can ignore the materials and regulatory environment. The report integrates a set of constraints and developments that are reshaping sourcing logic across the segment.
On the materials side, China imposed export controls on gallium arsenide in 2023 and on indium phosphide in 2025, requiring permits for every customer order and affecting substrate supply for VCSEL epitaxy. These controls are not limited to headline scarcity. They introduce permit-cycle uncertainty into procurement planning, which can affect program scheduling and the reliability of just-in-time sourcing assumptions. Alongside that, GaAs substrate lead times range from 6–12 weeks for stocked sizes to 10–20 weeks for custom, with an additional 8–16 weeks for custom epi recipes due to hydride and arsine handling constraints. That extended planning horizon means substrate and epi scheduling have become strategic variables, not operational minutiae.
On the regulatory and trade side, international commerce in gallium and arsenic compounds is tightly controlled under ITAR/EAR and dual-use regulations in the EU and US, requiring end-use declarations for VCSEL-related materials. This adds compliance burden and traceability requirements to the supply chain, particularly for companies operating across multiple jurisdictions or supporting programs with sensitive end-use profiles. U.S. Section 301 tariff adjustments in 2025 further increased duties on certain Chinese-origin GaAs-related imports up to 60 percent, affecting epitaxial wafer supply chains. That duty escalation changes the cost calculus for globally distributed sourcing models and can make regional redundancy, supplier diversification, or localized process steps more attractive than they appeared before the adjustment.
Geopolitical tensions and China’s export restrictions on rare earths and semiconductor materials in 2025 also contributed to supply volatility for gallium feedstock critical to GaAs VCSEL substrates. The combined effect is a materials environment in which continuity, compliance, and lead-time realism must be engineered into strategy rather than treated as contingencies. The study maps these factors to region, segment, and supply dynamics so that executives can see not just that constraints exist, but how they distribute across the market and where exposure is most consequential.
How to Use This Intelligence in the 2026 Planning Cycle
The research is designed to be activated, not merely read. In practice, that means using it to answer a set of high-stakes questions that leadership teams face right now:
- Where should multi-junction VCSEL capacity and design-in investments be prioritized given the divergence of application requirements across automotive LiDAR, consumer electronics, industrial sensing, and optical communications?
- Which supplier capabilities, qualification statuses, and process-control advantages are most likely to determine program success over the forecast period, and how should sourcing strategies be structured to reduce single-point exposure?
- How should organizations model the impact of substrate lead times, export controls, tariff adjustments, and dual-use compliance on cost, schedule, and supply continuity?
- Where do higher-junction and higher-power-density architectures create differentiation potential, and where do they add execution risk that must be managed through qualification and yield discipline?
- How can recent product demonstrations and launches be interpreted as signals about where the demand base is broadening, especially as VCSEL technology extends toward AI infrastructure interconnects and high-volume data communications?
These questions cannot be answered reliably with top-line totals alone. They require the intersection of forecast, segmentation, competitive profiling, concentration analysis, and materials context that the study provides. That is the core value proposition: the report converts a high-growth market signal into an operational decision framework.
What Remains in the Full Study
This article is intentionally a preview. It establishes the direction, magnitude, and strategic texture of the multi-junction VCSEL opportunity, and it situates the market within a 2026–2032 growth arc of 22.21 percent CAGR, with total market size advancing from $626.0 million in 2026 toward $1,977.53 million in 2032. It also outlines the competitive and regulatory environment that will shape execution. What it does not do is expose the full segmented revenue values, regional revenue amounts, application-level dollar splits, or detailed junction-count revenue breakdowns that the complete study contains. Those figures are essential for precise budgeting, sourcing modeling, and competitive positioning, and they are built into the full report so that readers can operationalize the numbers directly.
The full Worldwide Multi-junction VCSEL Chips Market research study provides the complete historical-to-forecast series, the detailed segmentation revenue breakdown by region, junction count, and application, the concentrated supplier profiles with strategic interpretation, the concentration metrics, and the integrated regulatory and materials analysis, all presented in a format designed for internal distribution and decision-making. If your team needs to translate a fast-moving photonics market into procurement strategy, program timing, partnership choices, and risk-managed capacity planning, the complete dataset is where that translation becomes actionable.
2026 is not simply another forecast year for multi-junction VCSEL chips. It is the year in which the market’s growth velocity, application diversification, supplier concentration, and materials constraints converge into a single strategic environment. Companies that build their plans on detailed, current, and structured intelligence will be better positioned to convert that environment into durable advantage. The full study is available for teams ready to move from directional confidence to precision planning.
For detailed analysis of this topic, please visit the official page: Worldwide Multi-junction VCSEL Chips Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Beneficial Nematodes Market to Reach $318.89 Million by 2032, Growing at 8.99% CAGR
By PW Consulting, 2026-09-02
Strategic Intelligence Brief: Worldwide Beneficial Nematodes Market 2026-2032
The global transition toward sustainable agriculture is no longer a peripheral trend; it is a structural realignment of crop protection economics. Within this shift, beneficial nematodes—specifically entomopathogenic nematodes—have emerged as critical biological tools for managing soil-dwelling and foliar insect pests. As chemical nematicides face tightening regulatory scrutiny and consumer demand for residue-free produce accelerates, biological control agents are capturing expanding market share. Our latest Worldwide Beneficial Nematodes Market study provides a comprehensive, data-rich roadmap for executives navigating this high-growth segment through 2032.
Worldwide Beneficial Nematodes Market
This intelligence brief previews the strategic architecture of the report, highlighting the macroeconomic trajectories, competitive dynamics, regulatory tailwinds, and operational realities that will define investment decisions in 2026 and beyond. The full study contains detailed segment projections, actionable market-entry frameworks, and granular competitive benchmarking designed to support precise, evidence-based decision-making.
Worldwide Beneficial Nematodes Market
Macroeconomic Trajectory: A Decade of Accelerated Expansion
The worldwide beneficial nematodes market has demonstrated consistent compounding growth over the past half-decade, and forward projections indicate that momentum will intensify through the end of the decade. Drawing on historical performance data from 2020 through 2025 and extending the forecast horizon to 2032, the study maps a market trajectory that firms cannot afford to overlook.
Worldwide Beneficial Nematodes Market
Baseline valuation data reveals a market that has steadily expanded its revenue base, moving from over 115 million USD in 2020 to approximately 174.45 million USD by 2025. This five-year ramp establishes a robust foundation for the forecasted acceleration that follows. The compound annual growth rate (CAGR) projected for the 2026-2032 forecast period stands at 8.99 percent, a figure that underscores the structural, rather than cyclical, nature of this expansion.
Forward projections illustrate a market that scales materially each year: revenue is expected to cross 191 million USD in 2026, continue climbing through 207.85 million USD in 2027 and 218.25 million USD in 2028, and then experience a step-change acceleration toward 251.74 million USD in 2029. By the close of the forecast window, the market is positioned to reach approximately 318.89 million USD in 2032. This upward curve reflects converging drivers—regulatory substitution, integrated pest management (IPM) adoption, and expanding application footprints across agricultural and horticultural sectors.
For corporate strategists, these figures translate into a clear imperative: the window for establishing competitive positioning, securing supply chain resilience, and capturing share in high-growth verticals is open now. Delaying strategic engagement risks ceding ground to competitors who are already scaling production capacity, expanding distribution networks, and investing in formulation innovation.
Report Architecture: Operational Depth for Executive Decision-Making
This study is engineered for practitioners who require more than headline figures. The report delivers a multidimensional analysis structured to support market entry, portfolio optimization, competitive positioning, and risk assessment. The following components form the analytical backbone of the publication:
- Historical Reconstruction and Baseline Validation: A rigorous reconstruction of market performance from 2020 through 2025, establishing validated baselines that anchor all forward projections. This section reconciles reported revenue data with underlying volume and pricing dynamics to ensure forecast reliability.
- Forward Forecast Modeling (2026-2032): Multi-scenario projections that account for baseline, accelerated, and constrained growth pathways. The modeling framework incorporates driver sensitivity, regulatory pacing, and supply-side capacity constraints to produce actionable revenue trajectories.
- Segmentation Analysis by Species and Type: A detailed dissection of the market by nematode species, including Steinernema feltiae , Steinernema carpocapsae , Heterorhabditis bacteriophora , and other species. The analysis evaluates relative commercial significance, target pest profiles, formulation compatibility, and application-specific performance characteristics.
- Application Verticals Analysis: A comprehensive review of end-use deployment across agriculture, greenhouse and nursery operations, turf and ornamentals, and home and garden contexts. This section maps value-chain dynamics, customer acquisition pathways, and seasonal demand patterns that shape revenue realization.
- Regional Demand and Distribution Mapping: An evaluation of market geography that assesses demand intensity, distribution infrastructure maturity, regulatory environment variation, and logistical considerations across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa.
- Competitive Benchmarking and Strategic Group Mapping: Profiles of leading producers and distributors, including BASF SE, Biobest Group, Andermatt Biocontrol AG, Koppert Biological Systems, Bioline Agrosciences, Applied Bio-Nomics, Arbico Organics, BioLogic Company, and Natural Insect Control. The analysis evaluates production scale, product portfolio breadth, geographic reach, IPM integration capabilities, and strategic differentiators.
- Market Concentration and Competitive Structure: An assessment of market fragmentation versus consolidation dynamics, including concentration metrics that illuminate the balance of power among top-tier players and the opportunities available to mid-tier and niche entrants.
- Regulatory, Technical, and Operational Dynamics: A synthesis of the regulatory environment, production technology constraints, storage and viability considerations, and compatibility profiles that shape commercialization feasibility and time-to-market for new offerings.
- Strategic Recommendations and Investment Frameworks: Actionable guidance tailored to different stakeholder profiles—established chemical and biologicals manufacturers, specialized biocontrol producers, distribution-focused entrants, and regional market developers—covering capacity investment, partnership strategy, formulation innovation, and channel expansion.
Each analytical component is supported by primary and secondary research, triangulated to produce consistent, defensible conclusions. The report is designed to function as both a strategic reference document and an operational planning tool, enabling teams to align product development, supply chain planning, and commercial execution with verified market realities.
Competitive Landscape: Differentiation in a Maturing Biologicals Sector
The beneficial nematodes market features a diverse competitive field that spans multinational agricultural chemistry conglomerates, specialized biocontrol producers, and regional distributors with deep local-market relationships. Understanding the strategic postures of these actors is essential for identifying white space, anticipating competitive responses, and calibrating market-entry approaches.
Large-scale producers such as BASF SE operate one of the world's largest specialist nematode production facilities and offer established product ranges like Nemasys for biological control across agriculture, turf, and horticulture. Their scale advantages in manufacturing, formulation science, and global distribution create high barriers for smaller entrants attempting to compete on volume and consistency. Meanwhile, specialized firms including Biobest Group, Andermatt Biocontrol AG, Koppert Biological Systems, and Bioline Agrosciences have built strong reputations around entomopathogenic nematode products integrated into IPM programs for greenhouse, outdoor, and protected cropping environments. These companies compete on technical expertise, strain-specific efficacy, and close collaboration with growers and crop advisors.
Regional and niche players such as Applied Bio-Nomics, Arbico Organics, BioLogic Company, and Natural Insect Control serve important distribution and orientation roles, particularly in North American markets where organic farming, home garden pest control, and turf management create distinct demand channels. Their strategies often emphasize accessibility, customer education, and tailored product mixes that align with local growing conditions and certification requirements.
Market concentration data indicates that the top three competitors account for approximately 42.5 percent of aggregate revenue, while the top five players represent roughly 58.2 percent. This concentration profile suggests a market that is meaningfully consolidated at the top yet remains sufficiently fragmented to allow regional specialists and focused technology developers to capture profitable niches. Strategic success in this environment depends on clarity about whether a company intends to compete on scale and broad portfolio coverage, on technical differentiation and IPM integration, or on regional reach and customer intimacy.
Recent industry developments reinforce the velocity of strategic activity. In April 2026, Pheronym was awarded 378,000 USD in NSF Phase IIB supplemental funding to accelerate commercialization and scale manufacturing of its Nemastim technology, which improves beneficial nematode performance in field applications. This milestone signals growing investor and public-sector confidence in adjunctive technologies that enhance nematode efficacy and field reliability. In March 2026, PI AgSciences received U.S. EPA federal registration for PHC68949, a novel biochemical peptide technology that activates systemic acquired resistance and strengthens root tissues against parasitic nematodes across crops including soybeans, corn, and potatoes. While PHC68949 targets plant-parasitic nematodes rather than insect pests, its regulatory approval illustrates the broader enabling environment for biological and biochemical crop protection tools, which can create positive spillover demand for complementary biocontrol solutions.
Regulatory and Technical Dynamics Shaping Commercial Viability
Regulatory architecture is a defining force in the beneficial nematodes market. Unlike many synthetic chemical nematicides, entomopathogenic nematodes are positioned as reduced-risk biological alternatives that align with organic farming standards and IPM frameworks. This positioning results in fewer regulatory hurdles, faster product registration pathways in many jurisdictions, and growing inclusion in government-endorsed sustainable agriculture programs. As chemical residues face increasing restrictions and retailer standards tighten, biological controls gain preferential treatment that directly supports adoption growth.
Technical and operational realities, however, impose discipline on commercialization strategies. Commercial production of beneficial nematodes requires synchronized development of infective juveniles on artificial media or host insects, and viability is highly sensitive to storage temperature and shipping media. These constraints mean that product consistency, cold-chain logistics, and formulation stability are not merely cost-center concerns but critical determinants of field performance and customer trust. Companies that invest in robust production protocols, reliable temperature management, and evidence-based shelf-life engineering gain competitive advantages that are difficult for less disciplined entrants to replicate.
Importantly, entomopathogenic nematodes used for insect pest control do not harm plants, beneficial insects such as ladybugs or earthworms, or human health, distinguishing them clearly from plant-parasitic nematodes. This safety profile strengthens their appeal across organic and conventional systems alike and supports broader stakeholder acceptance among growers, consumers, and regulators. It also reduces liability risk and simplifies communication with environmentally conscious market segments.
Strategic Implications for 2026 Decision-Makers
The convergence of sustained demand growth, regulatory tailwinds, and technological innovation creates a favorable environment for strategic action. Yet the same factors also raise the stakes for execution quality. Companies entering or expanding in this market must address several interrelated priorities:
- Production Capacity and Supply Chain Resilience: Scaling infective juvenile production while maintaining viability standards requires deliberate investment in fermentation or host-based systems, quality control infrastructure, and logistics networks that protect product integrity through storage and transit.
- Formulation and Efficacy Innovation: Differentiation increasingly hinges on formulation science, strain selection, and adjunctive technologies that improve field performance under variable conditions. Partnerships with technology developers and targeted R&D investments can produce defensible product advantages.
- Application-Specific Go-to-Market Design: Because demand patterns vary significantly across agriculture, greenhouse and nursery, turf and ornamentals, and home and garden contexts, successful commercial strategies require tailored pricing, packaging, distribution, and educational support aligned with each vertical's purchasing behavior and operational rhythms.
- Regulatory Strategy and Certification Alignment: Early engagement with registration processes, organic certification requirements, and regional compliance frameworks can reduce time-to-market and unlock preferential procurement channels in sustainable agriculture programs.
- Competitive Positioning and Partnership Strategy: Whether pursuing scale, specialization, or regional depth, companies must define a coherent strategic identity and identify partnerships—whether with distributors, research institutions, or technology providers—that amplify their strengths and compensate for capability gaps.
Why the Full Report Matters Now
The preview above establishes the strategic contours of the worldwide beneficial nematodes market, but the complete study delivers the segment-level precision, competitive intelligence, and scenario-based forecasting that executives require to convert direction into action. The full report contains detailed regional demand assessments, type-specific growth profiles, application-vertical revenue breakdowns, and granular competitor analysis that cannot be summarized at the headline level without losing the operational granularity needed for planning.
For organizations evaluating market entry, expanding product portfolios, negotiating partnerships, or allocating production and distribution investment, the study provides a verified evidentiary base that reduces uncertainty and supports faster, more confident decisions. The 8.99 percent CAGR across the 2026-2032 forecast period, the step-change acceleration projected from 2029 onward, and the concentration dynamics among top-tier competitors all point to a market in which early, well-informed positioning confers durable advantage.
Access the complete Worldwide Beneficial Nematodes Market study to obtain the full segmentation detail, competitive benchmarking, regional analysis, and strategic frameworks required to build and execute a winning approach in this rapidly evolving market.
For detailed analysis of this topic, please visit the official page: Worldwide Beneficial Nematodes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Presses Play on Strong 5.06 CAGR in Worldwide Pressure Sensitive Graphic Film Market | 2025 Revenue Valuation at 6.8 Billion USD to Surge Past 9 Billion by 2032
By PW Consulting, 2026-09-02
Navigating the Pressure Sensitive Graphic Film Market: Strategic Imperatives for 2026 and Beyond
The global market for pressure sensitive graphic film is entering a decisive phase. As brands, signmakers, and converters navigate shifting cost structures, evolving regulatory frameworks, and accelerating demand for sustainable print media, the window for strategic repositioning is narrowing. Our latest Worldwide Pressure Sensitive Graphic Film Market study is designed to cut through the noise and deliver the kind of forward-looking intelligence that shapes capital allocation, product roadmaps, and regional expansion decisions in 2026 and beyond.
Worldwide Pressure Sensitive Graphic Film Market
This report is not a rearview mirror. It is a working document for executives who need to anticipate demand shifts, benchmark competitive moves, and calibrate supply chain strategy before market signals become obvious. Below, we outline the analytical architecture of the study, the structural forces reshaping the industry, and the competitive dynamics that will separate leaders from laggards in the coming years.
Worldwide Pressure Sensitive Graphic Film Market
A Market at an Inflection Point: Macro Trajectory and Strategic Context
Over the historical window from 2020 through 2025, the worldwide market for pressure sensitive graphic film demonstrated steady, compounding growth, reflecting the durable integration of adhesive graphics into vehicle branding, architectural visualization, retail signage, and promotional displays. The trajectory carries clear momentum into the forecast period of 2026 to 2032, with a projected compound annual growth rate that underscores a market still expanding at a meaningful pace rather than plateauing. This growth is not uniform; it is being re-shaped by material substitution, digital printing adoption, and compliance pressures that vary significantly by geography and end-use sector.
Worldwide Pressure Sensitive Graphic Film Market
For decision-makers, the headline trajectory matters, but the actionable intelligence lies in understanding what is driving it. Demand is being pulled by several converging forces: the continued rollout of large-format digital printing in commercial and architectural settings, fleet and vehicle graphics programs that prioritize durability and conformability, and a broader push toward visually compelling, removable, and repositionable graphics in built environments. At the same time, cost volatility in plastic feedstocks and the emergence of recycling-oriented regulation are rewriting the economics of material selection. Companies that treat these as peripheral concerns risk margin erosion; those that embed them into product design and sourcing strategy will find new openings in premium and compliance-aligned segments.
Importantly, the market's size and growth path also reflect a concentrated competitive structure. The landscape is shaped by a limited number of scale players and specialist manufacturers, which means pricing power, technology differentiation, and channel relationships matter disproportionately. In such an environment, strategic clarity about where to compete, what performance attributes to prioritize, and how to prepare for regulatory shifts becomes a direct lever on financial outcomes.
What This Study Delivers: Analytical Depth Built for Executive Action
Our Worldwide Pressure Sensitive Graphic Film Market research is built to answer the questions that boardrooms and strategy teams actually face. Rather than presenting a single aggregate figure, the study decomposes the market across the dimensions that drive real-world planning: material type, end-use application, and regional demand patterns. Each dimension is examined not just for size, but for the growth logic, adoption barriers, and competitive implications that sit behind it.
The report combines historical reconstruction with forward modeling, enabling readers to assess how recent market behavior informs the forecast horizon. It integrates observable industry dynamics, including raw material cost movements, regulatory calendars, and product-level innovation signals, so that the forecast is anchored in the operational realities manufacturers and converters face on the ground. The analysis is structured to support several concrete use cases:
- Portfolio and product strategy: Identifying which material families and performance profiles align with near-term demand and which are exposed to substitution risk or regulatory friction.
- Regional prioritization: Mapping where demand intensity, competitive density, and compliance requirements create the most favorable conditions for investment or market entry.
- Competitive positioning: Understanding how leading manufacturers differentiate through adhesive technology, conformability, durability, and sustainability claims, and where whitespace may exist.
- Supply chain and sourcing planning: Interpreting feedstock cost trends and regulatory timelines that affect input economics and downstream customer requirements.
- M&A and partnership screening: Locating capability gaps and technology assets that are strategically relevant in a consolidating, technology-intensive sector.
The study is written for practitioners who need to move from insight to decision. It avoids superficial segmentation and instead focuses on the operating logic of the market: how pressure sensitive adhesive technology translates into product performance, how converters and end-users evaluate trade-offs among durability, conformability, printability, and environmental compliance, and how leading players are using innovation and channel strength to defend or expand their positions.
Structural Forces Reshaping Demand and Economics
Several forces are simultaneously expanding opportunity and raising the bar for competitiveness. Understanding them in combination is essential, because their interaction determines which product configurations and business models will thrive.
Raw Material Cost Trends and Margin Architecture
Input cost dynamics remain a central concern for producers and converters alike. Recent indicators point to a favorable direction in certain plastic material and resin cost measures, with year-over-year declines reported in key US price indices for plastic materials and resins. For pressure sensitive graphic film manufacturers, such movements can relieve cost pressure on core feedstocks and create temporary margin room. However, the strategic implication is not simply that costs are down. The larger lesson is that material cost cycles can shift rapidly, and companies that rely on static pricing assumptions or inflexible sourcing arrangements may leave value on the table when input conditions improve, only to face compression again when sentiment reverses.
The report incorporates these cost signals into the broader forecast context, helping readers interpret whether current conditions are likely to support price stability, encourage volume recovery, or accelerate substitution toward alternative material formats. It also frames the question every procurement and product leader should be asking: how resilient is our cost structure if feedstock indices move in the opposite direction over the forecast horizon?
Regulatory Pressure as a Market Design Force
Regulation is no longer a compliance footnote; it is becoming a market design force. In Europe, the Packaging and Packaging Waste Regulation introduces mandatory minimum recycled content targets for plastic packaging beginning in 2030, alongside design-for-recycling criteria, packaging minimization measures, and eco-modulated fee structures. The regulatory architecture creates clear expectations for recyclability and recycled content that can cascade into adjacent graphic and labeling applications, especially where film components are evaluated within packaging systems.
In the United States, multiple states are advancing Extended Producer Responsibility programs for packaging, with registration, reporting, and fee obligations rolling out across different timelines. These programs shift a portion of post-consumer management costs onto producers, reinforcing the importance of material choice, recoverability, and documented end-of-life performance. Pressure sensitive graphic films used in packaging contexts can fall within these obligations depending on jurisdiction and application, which means the regulatory footprint is not limited to traditional packaging converters. It extends to any participant whose products intersect with regulated packaging streams.
These developments are not abstract. They affect customer expectations, specification requirements, and the relative attractiveness of different material options. They also create a strategic fork: companies that integrate recyclability, recycled content pathways, and compliance documentation into their product architecture can position themselves as preferred suppliers in sustainability-sensitive accounts, while those that treat regulation as a downstream problem may find themselves constrained by customer specifications and cost pass-throughs.
Competitive Landscape: Differentiation, Scale, and Innovation Signals
The market is contested by a mix of large, diversified industrial players and focused specialty manufacturers. The result is a competitive field where performance claims, adhesive technology, conformability, weatherability, and print-process compatibility are key differentiators. Scale players bring broad distribution, brand trust, and multi-application portfolios, while specialist firms often compete on product depth within specific graphic film categories, including cast and calendered vinyl, overlaminates, and digital print media.
Several leading participants illustrate the breadth of strategic positioning now visible in the industry. 3M Company continues to emphasize premium large format graphic films and reflective and commercial graphics solutions built on pressure-sensitive adhesive technology, spanning advertising, fleet signage, vehicle wraps, and architectural applications. Avery Dennison Corporation maintains a strong presence through its MPI series cast and calendered films, Supreme Wrapping Films, and overlaminates, serving fleet graphics, architectural, commercial signage, and digital printing use cases. ORAFOL Europe GmbH is recognized for self-adhesive specialty graphic films under its ORACAL, ORAJET, and ORAGUARD brands, with a focus on digital print media, laminating, and protective films for the graphic arts industry. Arlon Graphics LLC produces pressure-sensitive cast and calendered vinyl films for fleet and vehicle wraps, wall wraps, promotional signage, and architectural graphics. LINTEC Corporation supplies pressure-sensitive materials and graphic films suited to large-format digital printing and construction-related graphic applications.
The field also includes other notable participants whose product orientations highlight different strategic angles. DuPont de Nemours Inc. participates through advanced film materials suitable for graphic and labeling applications. Hexis S.A.S. specializes in high-performance pressure-sensitive graphic vinyl films for vehicle wrapping, signage, and architectural graphics. Fedrigoni S.P.A. offers materials in the graphic film sector, including pressure-sensitive solutions for premium graphic and labeling uses, while Ritrama, part of the Fedrigoni Group, produces pressure-sensitive films and materials focused on graphic arts and visual communication applications.
What matters strategically is not just who is present, but how they are competing. The market is shaped by a mix of technology leadership, brand and distribution strength, and responsiveness to application-specific requirements. In a concentrated landscape, a relatively small number of firms account for a meaningful share of activity, which magnifies the importance of product innovation, customer specification wins, and the ability to align material performance with evolving sustainability expectations.
Recent Innovation and Education Signals: What They Reveal
Recent industry activity offers a useful lens on where competitive advantage is being built. In mid-2025, Avery Dennison introduced a PVC-free overlaminate developed with its ADReva Technology, a solvent-free polyurethane-based film emphasizing sustainability, conformability, and durability for graphic films. This launch is significant not only as a product addition; it signals a broader directional shift toward solvent-free, PVC-free constructions that address both performance and sustainability concerns in digital printing and overlamination applications. For buyers and competitors alike, such moves redefine the benchmark for what a modern overlay or protective film should deliver.
Around the same period, ORAFOL released an educational series comparing cast versus calendered PVC digital print media for pressure-sensitive graphic films. Educational content of this kind is not merely marketing. It reflects an effort to shape specification behavior, reduce application误用, and reinforce the value of material selection logic in a market where end-users and print service providers often navigate complex trade-offs among conformability, durability, print quality, and cost. In a market with concentrated suppliers and sophisticated application requirements, education can be a subtle but effective tool for competitive differentiation.
Together, these developments illustrate a market in which innovation is increasingly tied to sustainability credentials, material architecture, and application guidance. They also suggest that competitive advantage will be determined not only by scale, but by the ability to translate technical performance into customer-facing value and compliance alignment.
Why This Research Matters for 2026 Decision-Making
2026 is a year in which strategic assumptions need to be tested against a market that is simultaneously growing, regulating, and innovating. Companies that rely on simplified demand stories or static cost assumptions risk misalignment with the realities facing customers and competitors. The strategic questions that matter now include: which material types and application segments offer the most defensible growth, which regional markets present the best risk-adjusted opportunity, and how should product roadmaps respond to sustainability and recyclability expectations without sacrificing performance or cost competitiveness?
The Worldwide Pressure Sensitive Graphic Film Market study is designed to provide the context and structure needed to answer those questions. It connects market size and trajectory to the operating logic of the industry, integrates regulatory and cost dynamics into the forecast environment, and maps competitive differentiation in a way that supports practical planning. The objective is to give executives a defensible basis for prioritizing investments, adjusting portfolios, and preparing for the next phase of market development.
Because the study is built around the dimensions that matter for execution, it can be used by product teams evaluating material and formulation directions, by commercial teams assessing where to concentrate sales and specification efforts, and by corporate strategy groups weighing expansion, partnership, or capability-acquisition options. It is equally relevant for organizations seeking to benchmark their position against the leading participants and for those evaluating how regulatory and cost trends may alter the economics of specific product lines.
What Lies Inside: A Guided Preview of the Study Architecture
The full report is organized to move from market structure to competitive logic to forward outlook, with analytical support that ties each layer together. While the complete figures, segment detail, and regional breakdowns are available in the published version, the study's architecture is designed around several core components that matter for strategic planning:
- Market sizing and trajectory: A historical-to-forecast view that frames the scale of the market and the pace of growth across the 2026 to 2032 horizon, enabling readers to calibrate expectation and prioritize where growth attention should be focused.
- Segmentation logic by material type: An examination of how different film material families relate to performance, cost, and end-use suitability, and what that implies for substitution, differentiation, and demand shifts.
- Application-based demand analysis: A breakdown of the principal end-use areas driving consumption, including vehicle wraps and graphics, indoor and outdoor signage, architectural and building graphics, and promotional and retail displays, with attention to the growth logic and specification dynamics in each.
- Regional demand context: A geographic view that situates market opportunity and competitive intensity across major regions, supporting decisions about where to allocate commercial effort and capacity attention.
- Competitive profiling: Company-level profiles that capture strategic orientation, product focus, and market presence for leading participants, providing a basis for benchmarking and positioning analysis.
- Industry dynamics integration: Incorporation of raw material cost movements, regulatory developments, and innovation signals that affect market economics and customer expectations, ensuring the forecast is grounded in operational reality.
This structure is intended to be practical rather than encyclopedic. Each section is built to answer a decision-relevant question: where is demand coming from, why is it shifting, who is positioned to capture it, and what external forces will alter the playing field over the forecast period.
How to Use This Intelligence in Practice
The value of the study is maximized when it is integrated into existing planning rhythms. For product and R&D leadership, the material and application analysis can inform formulation priorities, performance targets, and the evaluation of sustainability-aligned alternatives. For commercial and sales leadership, the regional and application view can shape territory emphasis, specification support, and account targeting in sectors where performance and compliance requirements are tightening. For procurement and supply chain teams, the cost and regulatory context can support sourcing strategy, contract structuring, and scenario planning around input volatility and compliance-driven customer requirements.
For corporate strategy and corporate development teams, the competitive profiles and market structure assessment can support benchmarking, partnership evaluation, and identification of capability gaps. In a market where a relatively concentrated set of players accounts for a substantial share of activity, understanding the strategic posture of the leading firms is particularly valuable for assessing both competitive risk and potential collaboration or acquisition opportunities.
Most importantly, the study is designed to be used before decisions are locked in, not after outcomes are known. It provides the scaffolding to ask better questions, pressure-test assumptions, and align cross-functional teams around a shared understanding of where the market is going and what it will take to compete effectively.
Positioning for the Next Phase of Market Development
The pressure sensitive graphic film market is not static. It is being shaped by the interaction of durable demand for high-quality graphics, the expansion of digital printing and large-format applications, the recalibration of material economics, and a regulatory environment that is making recyclability and recycled content more than aspirational language. In that context, the companies that will fare best are those that treat sustainability, performance, and cost as an integrated design challenge rather than a set of separate trade-offs.
They are also the companies that will pay close attention to competitive dynamics. With a concentrated field of capable participants, differentiation through adhesive technology, conformability, durability, and application-specific guidance is not optional. Nor is responsiveness to customer specifications that increasingly reflect recycling and content expectations. The market rewards clarity of strategy, technical credibility, and the ability to convert innovation into customer value.
Our Worldwide Pressure Sensitive Graphic Film Market study is intended to equip leaders with the insight needed to navigate this environment with confidence. It provides the market context, segment logic, competitive mapping, and dynamic factors that matter for 2026 decision-making and for the years that follow. The full report offers the complete dataset and detailed analysis required to turn that context into concrete action.
For executives who need to understand not just where the market stands, but where it is heading and how to position for the opportunities and risks ahead, this research offers a direct path from high-level trajectory to operational strategy. The market's direction is clear enough to demand preparation; the details are specific enough to reward those who invest in understanding them.
For detailed analysis of this topic, please visit the official page: Worldwide Pressure Sensitive Graphic Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


