



Category: market research
Pad Printing Supplies Market: Why 5.65% CAGR Reshapes Industry Dynamics
By PW Consulting, 2026-09-21
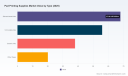
Strategic Shifts and Commercial Opportunities in the Global Pad Printing Supplies Market
The pad printing supplies market has evolved from a niche decorating technique into a critical enabler of mass customization, product identification, and industrial marking across multiple manufacturing verticals. Over the 2020-2025 period, the sector demonstrated steady expansion, reaching a valuation of 182.0 million USD in 2025. Forward projections indicate the market will scale to 267.3 million USD by 2032, supported by a compound annual growth rate of 5.65 percent through the forecast horizon. This trajectory reflects a maturing yet still dynamic landscape where incremental technological improvements, regulatory tightening, and shifting end-user expectations are reshaping competitive priorities. For executives and investors, the market no longer rewards pure volume play; it rewards precision in formulation, compliance readiness, and the ability to integrate consumable supply with automated production workflows.
The growth pattern is not uniform across all segments. Historical momentum has been anchored by established industrial applications, but the forward curve is increasingly influenced by regions and use cases that demand higher durability, stricter chemical compliance, and faster turnaround. The market structure remains moderately fragmented, with the top three players capturing roughly a third of total revenue and the top five accounting for just under half. This concentration level signals a space where scale advantages exist but are not insurmountable, and where differentiated value propositions can still secure meaningful share. The following analysis examines the structural challenges, demand drivers, competitive positioning, and forward trends that will determine which organizations capture the next wave of value.
Market Landscape and Core Challenges
The pad printing supplies market has built its recent growth on a foundation of recurring industrial demand, but the operating environment is being reshaped by three overlapping pressures that decision-makers cannot treat as background noise. The first is the compliance burden surrounding ink chemistry and material safety. Formulators and converters are no longer competing only on adhesion, color fidelity, or drying speed. They are increasingly evaluated against a widening set of regulatory expectations that govern volatile organic compound emissions, restricted substances, and end-use safety. Products intended for toys, consumer electronics, packaging decoration, or medical-adjacent components must pass through certification and documentation requirements that vary by jurisdiction. This raises the cost of entry for new formulations and forces suppliers to treat compliance as a core product attribute rather than a post-launch add-on.
The second challenge is the tension between automation throughput and consumable consistency. As pad printing moves from manual or semi-manual cells to integrated automated lines, the tolerance for variation shrinks. Pad wear, cliché durability, ink viscosity stability, and cup performance become process reliability issues rather than simple replenishments. Manufacturers that upgrade equipment often discover that the limiting factor is not the machine itself but the consistency of the consumables feeding it. This creates a structural demand for higher-grade pads, more stable ink systems, and tighter technical support, while also exposing suppliers that rely on commodity-grade inputs to quality and claim risks.
The third challenge is cost volatility in raw materials and logistics, layered with a shift in buyer behavior toward total cost of ownership. Price-per-liter comparisons are losing relevance in many procurement cycles because they ignore waste reduction, line downtime, rework, and compliance risk. Buyers are increasingly scrutinizing whether a marginally cheaper ink generates higher hidden costs through slower curing, more frequent pad changes, or failed audits. Suppliers that compete primarily on unit price face margin compression, while those that can demonstrate measurable process efficiency and reduced compliance exposure are better positioned to defend their positioning. Together, these challenges reframe the market from a transactional supplies business into a performance and risk-management partnership.
Key Drivers of Market Evolution
Technological Innovation and Formulation Advances
Technology is reshaping the pad printing supplies market along two reinforcing paths: ink performance and process integration. On the ink side, the industry is moving toward systems that balance print quality with environmental and safety constraints. Solvent-based formulations continue to hold a strong position where adhesion and metering stability are critical, but the innovation frontier is increasingly defined by how cleanly those systems can operate and how easily they fit into controlled production environments. UV-curable options have gained relevance where rapid hardening, reduced handling, and energy-efficient processing are priorities, especially in high-speed decorative and marking applications. Ceramic-based inks remain essential for products that must withstand elevated temperatures and harsh surface conditions, maintaining their role in demanding industrial and household contexts. The broader trend is not replacement of one chemistry by another, but the expansion of application-specific toolkits that let manufacturers match consumables to substrate, curing method, and end-use exposure.
Worldwide Specialty Ink Market
Beyond chemistry, the integration of consumables with automation is becoming a differentiator. Suppliers that support custom mixing, automated ink delivery, pad replacement schedules, and cliché management reduce the operational friction that often slows line optimization. When consumables are treated as part of a controlled process rather than as standalone purchases, manufacturers achieve more predictable output and fewer interruptions. This shift is particularly visible in high-volume environments where even small improvements in metering consistency or pad life translate into meaningful throughput gains. The strategic implication is that value is migrating from the mere supply of materials toward the supply of repeatable, documented process performance.
Regulatory and Compliance Pressure as a Market Filter
Regulatory expectations are increasingly functioning as a market filter, shaping both product design and customer selection. Standards and directives associated with chemical safety, restricted substances, and end-use certification are no longer isolated concerns for specific niches. They influence purchasing decisions across packaging decoration, electronics marking, and consumer goods. In practice, this means that documentation, substance control, and test evidence have become commercial assets. Ink systems that can demonstrate alignment with major compliance frameworks reduce the burden on downstream manufacturers and lower the risk of downstream audit failures or product holds.
Recent market activity illustrates this shift clearly. One major supplier introduced a solvent-based and sustainable pad printing ink system designed to support recycling of recovered packaging materials while maintaining durability for toys, electronics, automotive components, and promotional items. The same offering was positioned as free from phthalates and BPA and suitable for printing on the non-food contact side of packaging, with conformance claims tied to multiple regulatory frameworks. Separately, another supplier achieved certification for a group of eco-focused pad printing inks, emphasizing freedom from naphtha, PAH, and cyclohexanone, with compliance references to REACH, RoHS, and EN 71-3. These moves are not isolated product launches; they signal a broader market dynamic in which environmental and safety credentials are becoming decision-critical, especially where procurement teams must justify material choices to internal stakeholders and external auditors alike.
Digital Textile Printing Ink Market
Demand-Side Shifts in Manufacturing and Branding
Demand is being shaped by a combination of industrialization, product complexity, and brand expectations. Manufacturers are printing more than logos; they are applying identification marks, functional labels, safety information, and decorative finishes that must survive handling, cleaning, and time. The growth of short-run customization and rapid product variation also increases the value of flexible pad printing supplies that can adapt to frequent changeovers without sacrificing quality. In electronics, smaller components and tighter tolerances increase the need for precise deposition and stable ink behavior. In glass and plastic products, surface diversity demands inks and pads that can maintain adhesion across varying textures and finish types. In ceramic and porcelain applications, the need for durability under heat and moisture keeps specialty ink systems relevant.
At the same time, downstream brands and contract manufacturers are placing greater weight on process reliability and material documentation. Procurement is increasingly influenced by the need to reduce variability across shifts, minimize rework, and avoid supply-chain surprises caused by reformulation or compliance gaps. This makes supply consistency, technical support, and change-management capability more valuable than ever. Buyers are not simply purchasing pads, inks, and plates; they are purchasing predictability.
Supply Chain and Cost Structure Realignment
Cost structure is being rethought around durability, waste, and support rather than headline price. Volatile input costs and logistics uncertainty have made it harder for suppliers to compete on discount alone, while buyers are more willing to pay for solutions that reduce line waste or improve uptime. The result is a gradual realignment toward value-based positioning, where suppliers justify their pricing through measurable operational benefits. This also favors companies with stronger technical service models, more controlled formulation pipelines, and the ability to provide custom mixes or region-specific compliance support. For customers, the supply chain is becoming a source of process advantage rather than just a procurement function.
Competitive Positioning and Strategic Differentiation
The competitive landscape is defined by a mix of established ink and consumables specialists, regional machine-and-consumable integrators, and suppliers that combine equipment, tooling, and consumables under one roof. The distinct strategic advantage in this market is rarely derived from a single product feature. It is built from the combination of formulation capability, compliance readiness, automation support, and service responsiveness. Companies that treat pad printing supplies as a system rather than a commodity are better positioned to retain customers through line upgrades, regulation changes, and application expansion.
On the ink and consumables side, several players are competing on specialized chemistry and certification strength. One German-based supplier maintains a broad portfolio covering inks, clichés, printing pads, ink and doctoring cups, auxiliary materials, and laser cliché production, positioning itself as a full-line provider for pad printing operations. Another German formulates a wide range of solvent-based and UV-curable inks oriented toward industrial decoration, marking, and identification, emphasizing breadth across application types. In the United States, a major international supplier has pushed eco-oriented formulations, including solvent-based and UV pad printing inks designed without phthalates or BPA for packaging and product decoration, appealing to buyers who need both performance and cleaner substance profiles. A separate U.S. consumables specialist has emphasized eco-certified formulations, with a portion of its SB Eco Series inks achieving GOTS certification and aligning with REACH, RoHS, and EN 71-3 requirements. This certification-driven positioning is strategically important because it converts compliance into a marketable advantage rather than a hidden cost.
A second competitive cluster revolves around integration with equipment and automation. One U.S. supplier focuses on custom pad printing machines, tooling, fixtures, and consumables for high-volume automated applications, effectively combining hardware and consumables to reduce sourcing complexity. Another U.S. player offers a wide range of pad printing machines, fixtures, inks, pads, printing plates, and operates a large North American ink warehouse, leveraging distribution scale and inventory depth as a service advantage. A silicone and consumables-focused supplier produces in-house silicone pads, inks, plates, fixtures, and accessories, giving it tighter control over the pad supply chain and a direct route to custom specifications. Yet another U.S. company emphasizes custom-mixed inks, printing pads, cliché plates, and full automation support, highlighting the importance of flexibility in demanding production environments.
The competitive pattern suggests two parallel value routes. The first is depth in formulation and compliance, where differentiation comes from certification, substance control, and application-specific ink performance. The second is breadth and integration, where differentiation comes from equipment compatibility, inventory availability, custom mixing, and process support. Companies that can bridge both routes, even partially, gain a stronger hold on customers because they reduce the number of separate sourcing decisions and make it easier to standardize across multiple lines or sites.
Market structure is likely to evolve through selective consolidation and targeted specialization rather than across-the-board merger activity. Larger players with distribution scale and compliance infrastructure can absorb smaller regional suppliers or geographic distributors, especially where customers value single-source reliability. At the same time, niche specialists can prosper by owning a specific application, chemistry, or certification niche that larger generalists cannot serve as precisely. New entrants face a meaningful barrier in formulation know-how, certification timelines, and established technical service relationships, but they can still gain traction by addressing underserved compliance needs or automation-centric consumable packages. The most durable strategy appears to be building defensible positioning through either regulatory readiness and documented performance, or integrated automation support and customizability, while avoiding reliance on price alone.
Forward Trends and Commercial Implications
Compliance and Eco-Aligned Formulations Will Become Baseline Expectations
Over the next three to five years, the market is likely to see compliance-friendly and lower-impact formulations move from premium differentiators to baseline requirements in many application areas. Buyers serving consumer-facing, electronics, and packaging-adjacent markets will increasingly expect substance control, test evidence, and documentation as standard deliverables. This trend favors suppliers with established certification pathways and formulation discipline, while raising the risk for those that treat compliance as reactive. The commercial opportunity lies in building repeatable compliance narratives that simplify customer purchasing and reduce audit friction. The uncertainty is that regulatory expectations can diverge by region and application, creating a moving target for global suppliers and requiring localized documentation strategies.
Automation-Ready Consumables and Process-Locked Partnerships
As more production lines adopt higher levels of automation, consumables will be evaluated for their behavior inside controlled systems rather than in isolation. This should increase demand for inks and pads that support consistent metering, stable curing or drying, predictable wear, and easier integration with auto-ink delivery or changeover workflows. Suppliers that provide custom mixing, process tuning, and technical support will be better positioned to lock in long-term relationships, because the value they deliver is tied to line performance rather than unit transactions. The opportunity is to design consumables and service packages that reduce downtime and variability. The risk is that automation increases the stakes of inconsistency; a single recurring failure mode can erode trust quickly and push buyers toward more controlled supply alternatives.
Application Expansion and Regional Rebalancing
Forward growth is likely to be supported by continued application expansion across glass and plastic products, ceramic and porcelain items, electronic components, and other industrial uses, with regional demand patterns shifting as manufacturing footprints and export channels evolve. Regions with expanding industrial output, packaging activity, and consumer goods production will create incremental demand for marking, decoration, and identification supplies. The commercial opportunity is to align product portfolios and service coverage with the applications and geographies that are scaling fastest, rather than assuming legacy demand patterns will persist unchanged. The downside is that regional expansion can expose suppliers to new compliance regimes, logistics constraints, and competitive responses, making localized positioning and supply resilience more important than generic global messaging.
Actionable Implications for Decision-Makers
For manufacturing and operations leaders, the priority is to treat pad printing supplies as a process variable with measurable business impact. Procurement should evaluate ink systems, pads, and cliché solutions against line throughput, waste, changeover time, and compliance exposure, not just purchase price. Where production is moving toward higher automation or stricter end-use requirements, teams should prioritize suppliers that can provide documented performance, stable formulation pipelines, and responsiveness to custom specifications. Establishing clear acceptance criteria for consistency and certification documentation can reduce the risk of downstream failures and make supplier comparisons more objective.
For investors and corporate development teams, the market presents opportunities in players with credible compliance positioning, formulation depth, and integration with automation-focused customers. Businesses that have built certification readiness, custom-mixing capability, or strong regional distribution and inventory support are better placed to defend margins and capture share from purely transactional competitors. At the same time, due diligence should account for regulatory variability, raw-material exposure, and the durability of customer relationships beyond single projects. The most attractive profiles typically combine technical differentiation with recurring consumable demand and clear alignment to end-use compliance needs.
PW Consulting
For procurement and sourcing professionals, the strategic task is to move from transactional purchasing to supplier partnership models that reduce total operating risk. That includes evaluating eco-oriented and certified formulations where relevant, aligning consumable selection with equipment and line requirements, and ensuring that documentation and compliance claims are part of the sourcing decision. Where multiple sites or product families are involved, standardization on a smaller set of validated consumables can improve consistency and simplify audits, provided the selected options remain flexible enough for application-specific needs. In markets where compliance expectations are rising, sourcing decisions made without adequate documentation can create hidden cost and operational risk.
For organizations seeking deeper segmentation data, company-level positioning, and scenario-based guidance across regions and applications, the full PW Consulting market research report provides a more detailed breakdown of revenue splits, competitive profiles, and forecast assumptions. The report supports more precise planning by extending the core market view into actionable detail for procurement strategy, investment screening, and long-range capacity or portfolio decisions.
For detailed analysis of this topic, please visit the official page: Pad Printing Supplies Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Automotive Drive Shaft Market 2026: Beyond The 5.2% CAGR—Strategic Shifts Reshaping Growth
By PW Consulting, 2026-09-21
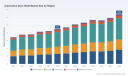
Strategic Trends and Commercial Opportunities in the Automotive Drive Shaft Market
The automotive drivetrain is undergoing one of its most significant structural transformations in decades. As propulsion architectures diversify and vehicle platforms evolve, the drive shaft has shifted from a standardized mechanical component to a strategically differentiated element of vehicle performance, efficiency, and packaging. Market tracking indicates that the global automotive drive shaft sector has grown from approximately $6.9 billion in 2020 to an estimated $9.03 billion in 2025, with a projected compound annual growth rate of 5.2 percent across the 2026–2032 horizon. The trajectory points toward a market surpassing $12.8 billion by the end of the forecast period, reflecting both volume expansion and a steady shift toward higher-performance, lightweight, and application-specific designs.
Beneath the headline growth figures lies a more nuanced reality. The sector is no longer driven solely by total vehicle production; it is increasingly shaped by propulsion mix, regional platform strategies, material substitution, and the consolidation of driveline technology portfolios. For executives, investors, and procurement leaders, the question is no longer whether the market is expanding, but where value is being created, which capabilities are becoming non-negotiable, and how prevailing cost and regulatory pressures will reshape competitive dynamics over the next five years.
Market Landscape and Core Challenges
The current market structure reflects a maturing but directionally shifting ecosystem. Growth over the historical period was supported by steady passenger vehicle demand, incremental content gains in vehicle platforms, and early-stage electrification programs that required rethinking torque delivery and packaging constraints. The commercial vehicle segment continues to provide meaningful volume stability, while the passenger car segment anchors the majority of revenue. Within product categories, hollow shaft designs dominate the revenue split, driven by their weight advantages, torsional efficiency, and broader adoption in modern front-wheel and all-wheel-drive architectures. Solid shafts retain a strong presence where durability, load capacity, and cost predictability remain paramount, particularly in heavier commercial applications and certain rear-drive configurations.
Worldwide Intermediate Shaft for Vehicle Market
Against this backdrop, three core challenges are reshaping how suppliers, OEMs, and investors should read the market.
- Propulsion-mode fragmentation. The transition from conventional internal combustion architectures to hybrid and electric platforms is not a 1:1 replacement of existing driveline content. Electric and hybrid vehicles alter torque characteristics, packaging envelopes, and NVH requirements, forcing suppliers to redesign joint interfaces, support structures, and shaft geometries. This creates short-term engineering complexity and lengthens validation cycles, even as it opens longer-term opportunities for propulsion-agnostic driveline systems.
- Material cost volatility and sourcing pressure. Steel continues to serve as the foundational material for many drive shaft applications because of its balance of strength, toughness, and supply chain maturity. At the same time, aluminum and composite solutions are gaining ground where weight reduction and efficiency targets are most stringent. The practical challenge is that raw material price swings for steel, aluminum, and composites can push component costs upward by as much as 15 percent in a single year, complicating quotation stability, margin planning, and long-term program commitments.
- Competitive concentration with room for differentiation. The market remains relatively fragmented at the top, with the leading three players accounting for roughly 24.6 percent of revenue and the top five reaching about 26.2 percent. That level of concentration signals a sector where scale, customer relationships, and engineering breadth matter, but also where differentiation is still possible through application-specific engineering, regional manufacturing footprints, and value-added design services. In practical terms, market share alone does not guarantee resilience unless it is paired with program wins in higher-growth configurations and cost-competitive execution.
Key Demand Drivers
Technology Innovation and Design Breakpoints
The most consequential driver of near-term market change is the engineering redefinition of what a drive shaft must accomplish. Lightweight aluminum and carbon fiber composites are increasingly specified by EV manufacturers as standard options to meet efficiency and emissions requirements, signaling a structural shift in component specifications rather than a temporary trend. This push toward weight reduction intersects with higher torque density in electrified powertrains, which places new demands on joint durability, balance, and vibration damping. Suppliers that can deliver hollow shaft designs with tighter tolerances, optimized wall profiles, and advanced joint integration are better positioned to capture content in vehicles where every kilogram and every decibel of NVH performance matters.
Technically, the opportunity is not limited to material substitution. The growth of high-angle CV joints, telescopic solutions, and integrated driveline architectures reflects a broader demand for packaging flexibility in crossovers, EVs, and premium passenger vehicles. Product launches in this space are increasingly framed around supporting multiple propulsion types within a single platform strategy, which suggests that future winning components will be judged as much on adaptability as on baseline performance.
Policy and Regulatory Environment
Regulatory expectations continue to influence design choices indirectly but powerfully. Efficiency mandates, emissions targets, and durability standards create incentives for weight reduction, friction reduction, and longer service life. In electric vehicle programs, these requirements can translate into more aggressive use of aluminum and composites, as well as tighter specifications for rotating components. The regulatory environment also affects commercial vehicle demand, where emissions and payload considerations shape axle and driveline selection. While policy does not prescribe a single drivetrain architecture, it consistently raises the cost of inefficiency, which benefits suppliers capable of delivering lighter, more integrated, and more reliable driveline solutions.
Demand-Side Shifts in Consumer and OEM Behavior
On the demand side, the expansion of SUVs, crossovers, and premium passenger vehicles has increased the relevance of driveline systems that can accommodate varied packaging constraints and higher performance expectations. Passenger cars continue to represent the dominant revenue base, but the composition of that demand is changing. OEMs are prioritizing platforms that can be reused across propulsion types, which favors suppliers with modular, propulsion-agnostic capabilities. At the same time, commercial vehicle demand remains a critical anchor for solid shaft and heavy-duty applications, particularly where strength, load capacity, and total cost of ownership outweigh the emphasis on minimal weight.
The commercial-vehicle side also introduces a different purchasing logic. Fleet operators and commercial OEMs focus heavily on lifecycle cost, serviceability, and reliability under sustained load. That creates a dual-track market: one track oriented toward efficiency and lightweight integration in passenger vehicles, another oriented toward robustness and cost predictability in commercial applications. Suppliers that can manage both tracks without diluting engineering focus tend to be more resilient across cycles.
Supply Chain and Cost Structure Dynamics
Cost structure is becoming a strategic battleground. Established steel supply chains provide reliability and scale, but they are exposed to price volatility and regional availability constraints. Aluminum and composites can improve performance and packaging, yet they introduce additional complexity in sourcing, processing, and validation. The practical consequence is that cost competitiveness is increasingly determined not just by material choice, but by supplier integration, manufacturing efficiency, and the ability to manage mix shifts without sacrificing delivery reliability. Programs that require rapid transitions between material grades or joint configurations amplify the importance of flexible production and strong supplier relationships.
This environment favors suppliers that can combine engineering support with disciplined cost execution. In practice, the winners are those who can help OEMs navigate the trade-offs between weight, strength, NVH, and cost while keeping programs on schedule. That is especially true as recent industry developments show major players investing in driveline technologies that span EVs and conventional platforms, indicating that breadth of capability is becoming a commercial advantage.
Competitive Landscape and Leading Strategies
The competitive field is anchored by a set of established driveline specialists, each with a distinct strategic posture. GKN Automotive remains focused on sideshafts, CV joints, and propeller shafts across ICE, hybrid, and electric vehicles, emphasizing propulsion-agnostic drive systems. That positioning reflects an effort to stay relevant across propulsion transitions rather than betting on a single powertrain future. Nexteer Automotive has built a reputation around premium telescopic drive shafts and high-angle CV joints for OEM applications, with a recent emphasis on driveline technologies designed to support both EVs and premium driving experiences across propulsion types. In the first quarter context, Dana Incorporated reported strong results alongside new business wins in drivetrain solutions, illustrating how program-level victories can reinforce commercial momentum even as broader market conditions remain mixed.
The competitive picture also includes major driveline and metal-forming players such as American Axle & Manufacturing, which supplies front and rear axles and driveshafts for global OEMs, and Hyundai WIA Corporation, which produces driveline systems and drive shafts for both passenger and commercial applications. Neapco Holdings rounds out the landscape with driveline components including driveshafts and CV joints for OEM and aftermarket use. Together, these companies highlight a market where scale, geographic reach, and application coverage matter, but differentiation increasingly depends on engineering integration and program execution.
Recent corporate and product activity underscores how the landscape is evolving. The announcement of a combination involving Dauch Corporation and Dowlais Group, integrating GKN Automotive driveline technologies, signals a consolidation path aimed at broadening technical portfolios and strengthening competitive scale. At the same time, product-level moves such as Nexteer’s introduction of three driveline technologies for EVs and premium applications show that innovation remains a central competitive lever. The pattern suggests a market that is neither fully consolidated nor static; rather, it is being shaped by selective integration, technology broadening, and continued investment in next-generation driveline architectures.
Strategic differentiation is emerging along several axes. One is propulsion-agnostic engineering: the ability to support multiple powertrain types with shared platform logic reduces OEM complexity and increases the value of suppliers that can deliver flexible component families. Another is material and design leadership, especially where lightweight solutions can be adopted without compromising durability or cost targets. A third is regional manufacturing and customer proximity, which supports faster response times, lower logistics exposure, and better alignment with local content expectations. In this environment, scale alone is inadequate; competitive advantage is increasingly tied to technical breadth, portfolio coherence, and the capacity to convert innovation into repeatable program wins.
Forward-Looking Trends and Commercial Opportunities
Trend 1: Propulsion-Agnostic Driveline Architectures Will Become a Standard Expectation
Over the next three to five years, OEMs are likely to continue prioritizing platforms that can accommodate multiple propulsion modes. That dynamic favors drive shaft and driveline solutions that can be adapted across ICE, hybrid, and electric applications without sacrificing performance or packaging efficiency. The commercial opportunity lies in offering modular component families, joint configurations, and integration support that reduce redesign effort and accelerate time-to-production. Suppliers that can demonstrate flexibility without compromising quality or cost structure will be better positioned to secure multi-program relationships.
The associated risk is execution complexity. Supporting diverse propulsion modes increases engineering workload, validation requirements, and inventory complexity. Companies that overextend across too many configurations without disciplined platform logic may face margin erosion and operational strain.
Trend 2: Lightweight Materials Will Expand, but Steel Will Remain Foundational
Industry direction points toward broader adoption of aluminum and composite solutions in applications where efficiency targets and packaging constraints are most demanding. At the same time, steel’s strength, toughness, and established supply chain will keep it central to many drive shaft applications, particularly where cost, durability, and volume manufacturing reliability matter most. The commercial opportunity here is not a simple swap from one material to another; it is the ability to offer the right material choice for each application while managing volatility in raw material costs. Suppliers with strong sourcing strategies, material expertise, and cost-forecasting discipline can convert material transitions into differentiated value rather than margin risk.
A key uncertainty is the pace and consistency of material adoption. If lightweight material specifications become more standardized across EV platforms, adoption could accelerate quickly and reward early movers with strong process capability. If volatility in raw material pricing persists, OEMs may adopt a more cautious stance, prioritizing total cost of ownership over absolute weight reduction in certain segments.
Trend 3: Consolidation and Portfolio Broadening Will Reshape Competitive Access
The market is likely to continue experiencing selective consolidation and portfolio integration as companies seek broader driveline capabilities, greater scale, and stronger positions across propulsion types. This creates two related opportunities. For larger players, integration can expand technical coverage and improve competitive positioning in high-value programs. For smaller or more specialized suppliers, the opportunity lies in focusing on niches where application knowledge, speed, or regional proximity creates defensible value. Investors and executives should watch for combinations that deepen technology portfolios, as well as for supplier strategies that emphasize end-to-end driveline integration rather than single-component competition.
The risk is that consolidation can also raise customer concentration concerns and reduce flexibility in some procurement relationships. Buyers may need to balance the benefits of integrated supply against the desire for multi-source resilience, especially in programs where supply continuity is critical.
PW Consulting
Actionable Guidance for Decision-Makers
For Manufacturers and Suppliers
Focus engineering investment on propulsion-agnostic designs and lightweight material capabilities, but pair that investment with disciplined cost management. The market is rewarding suppliers that can support multiple propulsion types while maintaining stable quotations and reliable delivery. Strengthen program-management and validation capacity so that new product introductions do not become bottlenecks. Where possible, build modular component strategies that reduce redesign risk and enable faster response to OEM platform decisions.
For Investors
Evaluate exposure not just by market size, but by technology breadth, application mix, and sensitivity to material cost volatility. Companies with strong positions in high-growth configurations, diversified propulsion coverage, and credible integration strategies are better placed to capture the next phase of growth. Monitor corporate consolidation activity closely, since combinations that broaden driveline portfolios may change competitive intensity and margin dynamics. Be mindful that revenue growth can mask uneven profitability if material volatility or program mix shifts are not managed effectively.
For Procurement and OEM Sourcing Leaders
Treat supplier selection as a multi-factor decision that includes technical flexibility, material strategy, and regional execution capability, not only unit price. Given raw material volatility, consider sourcing frameworks that provide visibility into cost drivers and allow for structured adjustments without destabilizing program economics. Where lightweight materials are specified for efficiency or emissions reasons, ensure that suppliers have validated processes and sufficient capacity to support scale-up. Diversifying across propulsion-capable suppliers can reduce program risk, especially when platform strategies span multiple powertrain types.
Closing Perspective
The automotive drive shaft market is moving from a period of steady volume-driven growth into a phase where technology choice, propulsion mix, material economics, and supplier integration matter as much as overall demand. The sector’s expansion toward the $12.8 billion range by 2032 is meaningful, but the more important story is how value is being redistributed across product types, applications, and competitive positions. Companies that can align engineering flexibility with cost discipline, while navigating material volatility and shifting propulsion requirements, are the ones most likely to convert market growth into durable advantage.
For decision-makers seeking a sharper read on regional dynamics, application-level demand patterns, material segment shifts, and company-specific positioning, a more detailed research asset can provide the granularity needed to translate these trends into procurement, investment, and product strategy. A full market report offers deeper segmentation detail, competitive benchmarking, and scenario-based guidance tailored to specific business decisions, making it a practical next step for teams that need to move from strategic direction to execution.
Cardan Shaft Market
For detailed analysis of this topic, please visit the official page: Automotive Drive Shaft Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
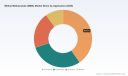
Strategic Trends and Commercial Opportunities in the Global Methyl Methacrylate Market
The global methyl methacrylate (MMA) market has entered a period of structural transformation, driven by shifting capacity dynamics, evolving sustainability mandates, and expanding downstream applications. Valued at approximately 162.5 million USD in 2025, the market reflects steady expansion from 113.25 million USD in 2020, with a projected compound annual growth rate of 7.9 percent through 2032. This trajectory signals robust underlying demand, yet the growth path is neither uniform nor frictionless. Industry participants must navigate supply chain reconfigurations, regional price volatility, and intensifying competitive pressures while aligning product portfolios with emerging end-use requirements. Understanding the interplay between technological advancement, regulatory shifts, and demand-side evolution is essential for capturing value in the coming years.
The market concentration remains notably high, with the top three players holding roughly 65 percent of global capacity and the top five accounting for an estimated 85 percent. Such concentration shapes pricing dynamics, influences capacity expansion decisions, and creates both barriers and opportunities for new entrants. While the monomer remains the dominant form consumed across applications, the broader methacrylate ecosystem encompasses a range of derivatives that extend value creation beyond raw monomer supply. Companies that successfully integrate upstream efficiency with downstream formulation expertise are positioned to command stronger margins and deeper customer relationships.
Market Scale and Growth Trajectory
The historical expansion of the MMA market demonstrates consistent growth punctuated by cyclical supply disruptions and regional demand fluctuations. The transition from 2020 through 2025 saw incremental gains as downstream sectors resumed activity following global disruptions, while the forecast period through 2032 points toward accelerated expansion fueled by infrastructure investment, electrified mobility adoption, and electronics miniaturization. Growth is not evenly distributed across regions or applications, but the aggregate trajectory reflects a market that is repricing itself around sustainability premiums, supply reliability, and application-specific performance requirements.
Revenue projections indicate that the market will surpass 180 million USD by 2026 and continue climbing toward 272.5 million USD by 2032. This expansion reflects both volume growth and structural shifts in product mix, as high-performance grades and sustainably produced variants capture a larger share of downstream spending. The pace of growth will depend on how quickly capacity transitions align with demand signals, how regulatory frameworks shape production economics, and how quickly end-use industries adopt next-generation materials.
Key Challenges and Inflection Points
Several structural challenges are redefining the MMA market landscape. First, the transition from traditional C3-based production pathways to alternative feedstock routes introduces both operational complexity and capital intensity. Companies investing in newer production technologies must manage ramp-up risk, supply chain adaptation, and customer qualification timelines, all while maintaining competitive pricing in a market sensitive to raw material spreads.
Second, regional capacity realignment is reshaping supply reliability and pricing architecture. Strategic plant closures, capacity transfers, and geographic shifts in production footprint have altered regional supply balances, creating short-term volatility and forcing downstream buyers to recalibrate sourcing strategies. The interplay between legacy capacity retirement and new facility commissioning has produced uneven supply conditions that reward agile procurement and penalize rigid long-term contracting.
Third, sustainability compliance and carbon footprint differentiation are emerging as decisive commercial factors. End-use industries increasingly demand materials with lower lifecycle emissions, verified recycling integration, and transparent environmental reporting. Producers that cannot demonstrate credible sustainability performance risk losing share to competitors with lower-carbon production pathways or stronger ESG credentials. This dynamic is particularly pronounced in construction, automotive, and electronics, where regulatory pressure and corporate sustainability targets are accelerating material substitution decisions.
Key Drivers Reshaping the Market
Technological Innovation and Production Pathways
Technological advancement remains a primary catalyst for market evolution. Alternative production routes that utilize different feedstock inputs are gaining traction, offering potential advantages in carbon intensity, feedstock flexibility, and integration with circular material flows. One notable development involves the commercialization of a C2-based production pathway that integrates chemical recycling for closed-loop operations, reducing the carbon footprint associated with traditional MMA synthesis. The successful ramp-up of full industrial-scale operation at a major North American facility signals a shift toward lower-emission production models, provided that feedstock availability, operational reliability, and cost competitiveness can be sustained.
Such innovations are not merely technical achievements; they alter competitive positioning by enabling producers to differentiate on sustainability credentials, supply reliability, and long-term cost structure. Companies that can validate performance at scale, secure feedstock partnerships, and communicate environmental benefits to downstream customers are likely to capture premium positioning. Conversely, reliance on legacy production methods without parallel sustainability investments may expose suppliers to margin compression as buyers prioritize lower-carbon alternatives.
Policy and Regulatory Environment
Regulatory frameworks and policy signals are exerting growing influence on capacity planning, feedstock selection, and regional investment decisions. Environmental compliance requirements, emissions reporting mandates, and sustainability-related procurement standards are reshaping the cost calculus for both producers and downstream users. In some cases, regulatory uncertainty has prompted reassessment of large-scale capacity projects, with firms pausing or redirecting investments as they evaluate long-term policy trajectories and market demand alignment.
At the same time, sustainability-driven regulations are creating incentives for process innovation and material efficiency. Producers that proactively align operations with emerging compliance expectations can reduce future retrofit risk and position themselves as preferred suppliers for customers facing their own sustainability mandates. The regulatory landscape is therefore not simply a constraint; it is a filter that rewards operational agility and penalizes complacency.
Demand-Side Evolution and Application Expansion
Downstream demand patterns are shifting as end-use industries pursue performance, lightweighting, and durability improvements. The automotive sector continues to drive volume through applications that require transparent, weather-resistant, and impact-tolerant materials, with electric vehicle platforms creating additional demand for specialized acrylic components and interior trim solutions. Construction activity, supported by infrastructure renewal and modernization initiatives, sustains demand for signage, glazing, and durable surface materials that benefit from MMA-derived performance characteristics.
Electronics and medical applications represent additional growth vectors. Electronics manufacturers are increasingly relying on high-purity acrylic materials for components that demand dimensional stability, optical clarity, and thermal resistance. Medical device and healthcare applications are expanding as biocompatible and sterilizable acrylic materials gain acceptance in diagnostic, procedural, and consumer health products. These application segments are not only adding volume; they are also elevating the value of specialized grades, which command stronger margins and require closer technical collaboration between suppliers and end users.
Supply Chain Dynamics and Cost Structure
Supply chain conditions and raw material cost movements are directly influencing pricing stability and margin outcomes. Global MMA prices experienced upward pressure in early 2026, with momentum intensifying toward the end of the quarter as supply tightened and production costs increased. Such price dynamics highlight the sensitivity of the market to feedstock availability, energy costs, and production utilization rates. Companies that manage feedstock sourcing, energy efficiency, and inventory positioning effectively are better equipped to navigate price volatility and protect margins.
PW Consulting
Capacity realignment across key regions has further complicated supply reliability. Strategic decisions to close certain legacy facilities while commissioning newer, more efficient plants have altered regional supply balances, creating temporary dislocations and forcing downstream buyers to adapt sourcing strategies. In parallel, some producers have adjusted product offerings and geographic sales strategies to optimize portfolio performance, reflecting a broader trend toward disciplined capacity management and targeted market participation.
Competitive Landscape and Leading Strategies
The MMA market is characterized by a concentrated set of global producers, each pursuing distinct strategic priorities to defend or expand their market position. Leading players are differentiating through a combination of production technology, geographic footprint, sustainability commitments, and application-specific product development. The competitive environment rewards scale, operational excellence, and the ability to align supply capabilities with evolving downstream requirements.
Strategic Positioning of Major Players
Major producers are pursuing multiple levers to strengthen competitive advantage. One prominent global producer has focused on expanding its methacrylate leadership through large-scale capacity investments and technology differentiation, maintaining a dominant position in global methacrylate production. Another key player has advanced sustainability-oriented production approaches, emphasizing lower-carbon pathways and closed-loop operations to appeal to customers with stringent environmental targets. Integrated producers supplying monomer and derivatives for coatings, adhesives, and polymer applications are leveraging vertical integration and technical service capabilities to deepen customer relationships and stabilize demand.
Regional presence and supply chain resilience are also central to competitive positioning. Producers with North American operations have invested in capacity expansions and facility modernizations to strengthen regional supply reliability, while Asian-focused manufacturers have adjusted pricing and product strategies in response to regional market conditions. Companies with dedicated division structures for MMA and acrylic resins are increasingly emphasizing high-performance grades for electronics, automotive, and optical applications, reflecting a strategic shift toward value-added segments rather than commodity volume competition.
Specialist producers focusing on methacrylate derivatives and sustainable PMMA solutions are carving out niches by combining application expertise with environmental credentials. Their strategy often centers on technical customization, supply consistency, and sustainability reporting that resonates with downstream customers facing procurement mandates. Meanwhile, global distributors and suppliers of methacrylate-based systems for coatings, adhesives, and polyurethane applications are expanding their geographic reach and product portfolios to capture demand across diverse end-use markets.
Poly Methyl Methacrylate (PMMA) Market
Market Evolution and Competitive Dynamics
The competitive landscape is evolving along several axes. Consolidation and capacity optimization are enabling established players to streamline operations, retire less efficient assets, and redirect capital toward higher-return projects. At the same time, the emergence of alternative production technologies and sustainability-focused differentiation is creating space for companies that can operationalize new pathways at scale. New entrants face meaningful barriers due to capital intensity, feedstock logistics, customer qualification requirements, and the prominence of incumbent technical service networks, but targeted entry into specialty grades or regional supply gaps remains plausible for well-positioned organizations.
Pricing power and margin resilience are increasingly tied to sustainability credentials, supply reliability, and application-specific expertise. Producers that can demonstrate consistent performance, lower lifecycle emissions, and responsive technical support are better positioned to negotiate favorable commercial terms and retain customers during supply disruptions. The market is therefore moving toward a more value-driven competition model, where volume alone is insufficient to secure long-term advantage.
Future Outlook and Emerging Opportunities
Trend 1: Sustainability as a Structural Differentiator
Lower-carbon production and circular material integration are set to become central competitive dimensions over the next three to five years. Producers that successfully scale alternative feedstock routes, chemical recycling integration, and verified emissions reductions will gain preferential access to customers with sustainability procurement mandates. This trend creates opportunities for suppliers to command premiums for certified low-carbon grades, secure long-term commitments from environmentally focused end users, and differentiate from competitors reliant on higher-emission pathways. The risk lies in greenwashing exposure and the need for credible verification, as downstream buyers increasingly scrutinize sustainability claims and demand transparent reporting.
Trend 2: Regional Supply Rebalancing and Sourcing Strategy Shifts
The ongoing realignment of production capacity across regions will continue to influence pricing, availability, and contract structures. As legacy facilities are retired and newer plants reach full operational scale, regional supply balances will evolve, creating both disruption and opportunity. Buyers that diversify sourcing, develop contingency supply arrangements, and align contract terms with capacity transition timelines will be better insulated from volatility. Producers that can offer reliable regional supply, flexible delivery models, and transparent capacity reporting will strengthen their negotiating position and customer retention.
Trend 3: Application Specialization and High-Performance Grade Expansion
Demand for specialized acrylic materials in automotive, electronics, medical, and advanced construction applications is expected to grow as performance requirements become more stringent. This trend favors producers with strong formulation capabilities, technical service infrastructure, and the ability to co-develop solutions with end users. Opportunities exist for suppliers to capture higher margins through grade customization, application-specific certification, and integrated product systems that address multiple performance criteria. The risk is that overinvestment in unproven application segments or inadequate technical support could limit returns, particularly if downstream adoption timelines extend or substitution alternatives emerge.
Methacrylic Acid (MAA) (CAS 79-41-4) Market
Actionable Insights for Decision Makers
The evolving MMA market environment requires proactive strategy adjustments across the value chain. Decision makers should align sourcing, investment, and product development plans with the structural trends shaping supply, pricing, and sustainability expectations.
- For manufacturers and producers, priority should be placed on operationalizing lower-carbon production pathways, securing feedstock and energy cost advantages, and building technical service capabilities that support application-specific sales. Investing in scale where it delivers cost and sustainability benefits, while maintaining disciplined capacity management, can strengthen margin resilience and customer retention.
- For investors, attention should focus on companies with credible sustainability roadmaps, visible capacity transition plans, and exposure to higher-growth application segments such as automotive electrification, electronics miniaturization, and medical devices. Assessing feedstock flexibility, regional supply positioning, and ESG verification readiness can help identify businesses positioned for durable value creation.
- For procurement and sourcing leaders, diversifying supplier bases, developing scenario-based contracting, and incorporating sustainability criteria into supplier selection can reduce exposure to regional disruptions and price volatility. Establishing clear performance and compliance requirements, while maintaining flexibility for capacity transition periods, will support supply continuity and cost control.
Detailed segmentation data, capacity flow analysis, pricing trajectory modeling, and company-level assessments can provide the precision needed to convert these strategic directions into execution plans. Organizations seeking to deepen their market intelligence and align decisions with granular demand, supply, and competitive signals will benefit from comprehensive research that maps the full landscape and isolates actionable opportunities.
For detailed analysis of this topic, please visit the official page: Methyl Methacrylate (MMA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Cat Litter Market 2026: Why 5.5% CAGR and Clay Dominance Signal a Strategic Shift
By PW Consulting, 2026-09-21
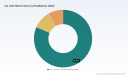
Strategic Shifts Defining the Global Cat Litter Market (2025–2032)
The global cat litter market has evolved from a low-differentiation commodity category into a strategically contested space shaped by material science, consumer expectations, and tightening operational standards. With the market reaching an estimated USD 11.81 billion in 2025 and expanding at a compound annual growth rate of approximately 5.5 percent through 2032, the category’s trajectory reflects broader shifts in pet care, sustainability, and retail consolidation. Growth is not uniform, and the value creation path is increasingly segmented by formulation performance, supply chain resilience, and brand trust. For executives and investors, the opportunity lies less in chasing volume and more in aligning product portfolios, manufacturing capabilities, and distribution strategies with structural demand changes.
Several factors sharpen the strategic stakes. Household penetration of cats continues to rise in mature markets, while emerging markets are building foundational pet care consumption patterns. At the same time, raw material dynamics, formulation innovation, and regulatory scrutiny of manufacturing hygiene are reshaping competitive benchmarks. The sector’s concentration, with a small group of players holding the majority of industry revenue, suggests that scale, distribution relationships, and brand equity remain powerful moats. Yet the appearance of rapid product experimentation, especially around biodegradable and silica-based formats, indicates that incumbents cannot rely solely on legacy formulations or traditional retail placements.
Three friction points define the current transition. First, raw material price volatility and supply geography create margin exposure for both traditional clay-based and silica-based lines, forcing manufacturers to balance cost control with performance consistency. Second, consumer preference is bifurcating: one segment prioritizes low-cost, high-clumping mineral products, while another increasingly demands natural, low-dust, or flush-friendly alternatives. Third, operational integrity is becoming a strategic differentiator after a high-profile contamination incident involving a widely distributed litter brand, which triggered regulatory review and heightened retailer vigilance. These dynamics do not merely create risk; they establish the criteria by which leading players will be judged over the next several years.
Key Demand and Supply Drivers Reshaping the Category
Technological and formulation innovation is shifting from incremental improvements toward targeted performance solutions. The most notable advances cluster around rapid clumping, odor neutralization, low-dust engineering, and compatibility with automated cleaning systems. Recent product introductions have emphasized fast absorption, instant clumping behavior, and suitability for self-cleaning litter boxes, signaling that convenience is becoming a performance specification rather than a marketing phrase. Alongside this, odor-control strategies are incorporating activated carbon and mineral blends that address the household cleanliness expectations of urban consumers and multi-pet households. The practical implication is that product leadership increasingly depends on formulation precision and repeatability rather than on broad distribution alone.
Worldwide Prescription Cat Food Market
Regulatory and quality standards are also exerting a more direct influence on market behavior. Following a voluntary recall tied to rodent and avian contamination and insanitary storage conditions affecting Tidy Cats products distributed by Gold Star Distribution, Inc., the FDA elevated the recall classification for certain pet products to Class II after reviewing contamination hazards. This sequence matters beyond the immediate compliance event. It demonstrates that hygiene, traceability, and storage controls are becoming procurement concerns for retailers and distributors, especially in markets where consumer trust can shift quickly after a publicized safety issue. For manufacturers, the strategic response is not simply to meet baseline requirements but to embed operational hygiene into product handling, packaging integrity, and distribution protocols as a visible competitive attribute.
Demand-side behavior is changing through a combination of premiumization and value sensitivity. Cat owners are not a monolithic group: some remain highly price-conscious and gravitate toward familiar mineral-based options, while others willingly pay for natural, plant-based, or starch-derived formulations that align with environmental expectations and low-dust preferences. This split is reinforced by the growth of subscription and direct-to-consumer models in certain regions, which reward consistency, packaging convenience, and reliable replenishment. The result is a market where brand trust and usage experience can justify premium positioning even as mainstream segments continue to compete on cost-per-use and retail availability.
Worldwide Natural Cat Litter Products Market
Supply chain and cost structure dynamics add another layer of complexity. Clay remains the dominant raw material base, which means pricing exposure is tied to extraction, processing, freight, and energy costs. Silica-based options face different economics, including synthesis and material intensity considerations. At the same time, natural and biodegradable inputs depend on agricultural and processing supply chains that can vary in consistency, seasonality, and regional availability. Companies that can manage formulation flexibility, lock in dependable sourcing, and minimize waste in conversion processes are better positioned to protect margins through cycles of input inflation. For buyers and distributors, this reinforces the importance of supplier diversification and specification clarity when evaluating long-term contracts.
Competitive Positioning and the Emerging Landscape
The competitive field is anchored by a concentrated group of manufacturers with strong mineral-based capabilities and well-known retail brands, alongside a widening set of regional and formulation-focused producers. TOLSA SA and Laviosa Chimica Mineraria SpA represent established bentonite and mineral-based production profiles with international reach. Oil DRI Corporation of America specializes in absorbent material formulations, while InterSand operates as a North American bentonite and cat litter producer and exporter. On the branded side, The Clorox Company and its Fresh Step portfolio maintain broad retail distribution, and Dr. Elsey's competes in the premium clumping and natural segments. These players benefit from scale, shelf relationships, and formulation familiarity, but their strategic challenge is to sustain relevance as product experimentation and retail assortment complexity increase.
A parallel competitive track is emerging around natural, biodegradable, and plant-based options. Brands such as Naturally Fresh, World's Best Cat Litter, and Kent Corporation illustrate the positioning of pine and plant-based formulations, while manufacturers like Shandong Aiyu Pet Products, Changzhou Sanmei Pet Products, and Anhui Hengjie Group reflect a broader Asian production base spanning cassava, tofu, zeolite, and mixed formats. Several of these companies have expanded visibility through trade activity and product catalog updates. For example, recent exhibition presentations highlighted pure tofu cat litter with natural soybean residue, strong clumping, odor locking with activated carbon, and low dust, while other launches emphasized rapid absorption, instant clumping, and suitability for automatic litter boxes. This activity signals that Asia-based producers are not only competing on cost but increasingly on specification performance and OEM customization capability.
The strategic differentiation among leaders is becoming less about category ownership and more about segmentation mastery. Incumbents with strong mineral-based positions can defend share through consistent performance, packaging innovation, and retail execution. Premium natural brands can build loyalty through perceived safety, environmental alignment, and user experience. Meanwhile, OEM-oriented manufacturers with flexible formulation capabilities can serve private-label programs, regional distributors, and product-development partners seeking to move quickly into biodegradable or mixed-material formats. This creates a landscape where M&A, joint supply arrangements, and brand acquisitions are plausible tools for players seeking to fill portfolio gaps or enter new geographic channels.
Market structure is likely to evolve through both consolidation and fragmentation. Consolidation may occur as larger consumer goods and distribution players acquire regional brands or integrate upstream sourcing to secure input stability. Fragmentation may continue as new entrants target specialized needs, including low-dust formulations, flush-compatible options, and automatic litter box compatibility. The Company is also likely to see increased importance of brand trust and retail compliance, especially after recent contamination-related scrutiny. In practice, this means that competitive advantage will be determined by a combination of formulation consistency, operational discipline, distribution access, and the ability to communicate product benefits in ways that resonate with increasingly discerning buyers.
PW Consulting
Forward-Looking Trends and Commercial Implications
One of the most important forward-looking trends is the growing role of performance-specific formulations in product selection. Not all litter is evaluated primarily on price anymore; automatic cleaning devices, odor sensitivity, dust exposure, and tracking behavior increasingly influence purchase decisions. Over the next three to five years, this should drive further refinement in clumping speed, absorption capacity, and low-dust manufacturing controls. The commercial implication is that product specifications will become more consequential in procurement decisions, and successful players will need to validate performance claims with repeatable production quality rather than relying on broad category messaging.
A second trend is the continued expansion of natural and biodegradable alternatives as a meaningful, though still minority, share of activity. As plant-based, starch-based, and tofu-derived options gain visibility, the strategic question is not whether they will replace conventional mineral products, but where they will hold strongest appeal and how they can be produced consistently at scale. Distribution will matter as much as formulation, because eco-oriented products often require clearer consumer education, distinct shelf positioning, and reliable replenishment cycles. Companies that can stabilize input supply, maintain clumping and odor-control performance, and communicate environmental benefits without sacrificing usability are likely to capture the most durable demand within this segment.
A third trend concerns supply chain integrity and regulatory responsiveness becoming more visible in brand credibility. The recent recall and subsequent FDA classification update have reinforced that hygiene, storage, and distribution conditions are not back-office concerns; they are customer-facing trust signals. Over the coming years, this is likely to translate into tighter audit expectations, stronger quality assurance requirements from retailers, and greater emphasis on traceability in sourcing and logistics. The upside is that disciplined operators can use compliance and safety assurances as differentiators, especially in markets where consumers and retailers are especially sensitive to product cleanliness and brand reliability.
These trends carry both opportunity and uncertainty. On the opportunity side, there is room for manufacturers to capture value through formulation leadership, private-label partnerships, premiumization, and regional expansion into channels that reward consistency and freshness of product design. There is also scope for investors to identify companies with defensible sourcing, scalable OEM capabilities, or brands positioned in high-trust segments. On the risk side, raw material volatility, consumer skepticism after safety incidents, and fragmentation of retail channels could pressure margins and slow share shifts. Demand may also evolve unevenly across regions, meaning that growth assumptions need to be tested against local pet ownership patterns, retail structure, and price sensitivity.
Strategic Actions for Decision-Makers
For manufacturers, the priority is to align formulation roadmaps with the ways consumers now evaluate performance. This means investing in clumping reliability, odor control, dust reduction, and compatibility with automated litter systems, while also building supply flexibility across mineral, silica, and natural inputs. Equally important is operational hygiene and traceability, which should be treated as brand assets rather than minimum compliance steps. Companies that can combine specification leadership with dependable production quality will be better positioned to defend premium pricing and secure retailer confidence.
For investors, the most useful discipline is to evaluate competitive positions through the lens of margin resilience and channel access rather than headline category growth alone. Opportunities are likely strongest where companies demonstrate scalable sourcing, formulation versatility, or brand strength in premium or eco-oriented segments. At the same time, diligence should account for input exposure, regulatory sensitivity, and the risk that safety incidents can quickly alter retail placement and consumer trust. Portfolio selection should favor operators that can sustain product consistency and adapt to shifting material economics.
For procurement and distribution leaders, the strategic focus should be on supplier qualification, specification clarity, and contingency planning. Diversifying across mineral and natural-based sources can reduce exposure to single-material volatility, while explicit performance requirements can reduce the risk of assortment inconsistencies. Given the elevated attention to storage and contamination risks, procurement teams should also strengthen audit expectations and handling standards across the distribution chain. In practice, this means treating litter procurement as a quality and reliability decision as much as a cost decision.
For decision-makers seeking to move from directional insight to actionable planning, the market’s segmentation details, regional demand patterns, formulation economics, and competitive moves warrant closer examination. Many of the richest strategic choices—whether in product development, channel expansion, supplier selection, or capital allocation—depend on granular data that cannot be fully captured in a high-level review. Access to a more detailed market study can help translate these trends into specific scenarios, segment-level demand estimates, and tailored recommendations aligned with each organization’s position.
For detailed analysis of this topic, please visit the official page: Cat Litter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Roadmarking Paints Market 5.8% CAGR: Strategic Shifts Behind the $10.6B 2032 Trajectory
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Roadmarking Paints Market
The global roadmarking paints market has entered a phase of mature expansion, characterized by steady demand recovery across infrastructure sectors and a gradual shift in material preferences. With a market valuation of 7.18 billion USD in 2025, the sector has demonstrated consistent revenue growth from 5.52 billion USD in 2020, reflecting a compound annual growth rate of 5.8 percent through the forecast period extending to 2032. This trajectory suggests that the industry is moving beyond post-pandemic normalization into a structure defined by regulatory evolution, material innovation, and geographic demand divergence. At first glance, the numbers indicate a reliable growth engine for coatings and infrastructure suppliers. A closer look reveals a market navigating cost volatility, tightening environmental specifications, and intensifying competition among established players and emerging regional suppliers.
The current landscape is shaped by three interconnected dynamics that decision-makers cannot afford to overlook. First, the transition toward low-emission and waterborne coating systems is accelerating, but the pace of adoption remains uneven across regions and project types. Second, raw material price fluctuations, particularly in thermoplastic compounds, specialty resins, and optical glass components, are compressing margins and forcing procurement strategies to become more flexible. Third, infrastructure spending is increasingly being directed toward high-visibility, safety-critical applications, which elevates the standard for durability and reflectivity but also raises the bar for supplier qualification. These forces create a market that is expanding in aggregate yet becoming more selective in how value is captured.
Navigating the Current Inflection Points
The market’s growth narrative is not uniform. While overall demand continues to climb, several structural pressures are reshaping how manufacturers, contractors, and public agencies evaluate roadmarking solutions. The expansion of urban and interurban road networks, combined with periodic resurfacing programs, sustains baseline demand. However, the composition of that demand is shifting. Projects are increasingly scrutinized for lifecycle cost, environmental footprint, and compliance with updated technical specifications. This means that suppliers offering conventional solvent-based products without clear pathways to compliant alternatives face growing friction in specification lists and bidding processes.
At the same time, the industry is witnessing a quiet recalibration of cost expectations. Budget-constrained infrastructure programs are more sensitive to upfront material pricing, which can slow the uptake of premium thermoplastic and specialized cold plastic systems. The tension between performance requirements and cost containment is not simply a procurement inconvenience; it is a strategic variable that determines which product categories gain traction in different project environments. Suppliers that can balance performance, compliance, and total cost of ownership are positioned to secure more consistent wins, while those locked into single-format portfolios may encounter narrowing windows of opportunity.
A third inflection point lies in the standardization and enforcement of roadmarking specifications. Updated technical benchmarks for ready-mixed paints and related marking materials are raising the minimum threshold for adhesion, durability, and reflectivity. These updates are not merely administrative; they influence which formulations are acceptable for public works, how frequently markings must be renewed, and what documentation suppliers must provide. For companies operating across multiple markets, alignment with evolving specifications is becoming a competitive differentiator rather than a baseline requirement.
Key Drivers Reshaping Market Dynamics
Technological Innovation and Material Evolution
Material science is quietly redefining what roadmarking paints can do. Waterborne formulations have advanced significantly in terms of drying time, abrasion resistance, and wet-edge performance, making them increasingly viable for high-traffic corridors where downtime is costly. At the same time, thermoplastic and cold plastic systems continue to be valued for their durability and reflective performance in demanding applications, but their deployment is increasingly tied to project economics and supply availability. The practical outcome is a market where performance claims must be substantiated by application-specific evidence, not just laboratory benchmarks.
Innovation is also extending beyond the paint itself. Improvements in optical glass quality, bead shape consistency, and bond strength are influencing the longevity of marked lines, which in turn affects maintenance cycles and total project cost. Suppliers that integrate material formulation with application technology, including spray equipment compatibility and line-width precision, are delivering more predictable outcomes for contractors and road authorities. This convergence of formulation and application engineering is reducing variability in the field, which is increasingly important as agencies compare bids on the basis of lifecycle performance rather than unit price alone.
Policy and Regulatory Pressures
Regulatory expectations are becoming a central force in product selection. Concerns over volatile organic compound emissions and broader environmental impact are prompting many procurement entities to favor lower-emission alternatives. This does not automatically eliminate solvent-based systems from the market, but it does raise the importance of documentation, emission profiles, and regional compliance pathways. In practice, regulation is acting as both a constraint and a catalyst: it limits the unconstrained use of older chemistries while creating demand for suppliers who can demonstrate credible low-emission performance without sacrificing durability.
Technical specifications are also evolving. Updated standards for ready-mixed road marking paints and related systems are tightening expectations around consistency, application conditions, and performance verification. For manufacturers, this means that product development cycles must account for specification alignment in key markets. For distributors and contractors, it means that stocking decisions and bidding strategies need to reflect the likely direction of regulatory enforcement. The companies that treat specification updates as early signals rather than late obstacles are better positioned to maintain preferred status on project shortlists.
Demand-Side Shifts in Infrastructure and User Behavior
Demand is being influenced by more than road construction volume. Public safety priorities, traffic growth, and the operational needs of airports and commercial parking facilities are all contributing to more frequent marking cycles and higher visibility requirements. Roads and highways remain the dominant application context, but the strategic importance of parking areas and airport tarmacs should not be underestimated. These environments often require specialized markings that can withstand different stress factors, from heavy vehicle turning loads to aircraft pavement conditions, and they tend to be less price-sensitive when reliability is at stake.
There is also a behavioral shift on the part of procurement teams. Buyers are increasingly comparing solutions on a total-cost basis that includes application efficiency, drying time, weather tolerance, and expected service life. This is changing the conversation from “which paint is cheapest per liter” to “which system delivers the best outcome over the project cycle.” Suppliers that can articulate these trade-offs clearly, and back them with field-relevant performance data, are gaining influence in specification decisions.
Supply Chain and Cost Structure Realignment
Cost structures in the roadmarking paints market are under pressure from multiple directions. Volatility in raw material pricing, especially for thermoplastic compounds and specialty glass components, creates uncertainty for both manufacturers and buyers. The challenge is compounded by differences in sourcing availability across resin suppliers and regional supply networks, which can affect lead times and price consistency. For companies relying on fixed-price contracts or tight bidding windows, this volatility can quickly translate into margin compression or project risk.
In response, supply chain resilience is becoming a strategic priority. Some suppliers are diversifying input sources, renegotiating terms with material partners, or adjusting product portfolios to reduce exposure to the most volatile components. Others are investing in formulation efficiency to stretch high-cost inputs while maintaining performance. The broader implication is that cost advantage in this market is increasingly determined by procurement agility and formulation discipline, not simply by scale. Firms that can manage input variability while preserving product consistency will be better equipped to offer stable pricing and reliable fulfillment, which are increasingly valued in competitive procurement environments.
Competitive Landscape and Strategic Positioning
The market is characterized by a concentrated core of established coatings and infrastructure material providers alongside a broader base of regional and specialized players. This structure creates a competitive environment where scale, product breadth, and technical service capability matter, but so does local specification knowledge and adaptability to regional procurement practices. The presence of major global names reflects the importance of cross-market reach, integrated product portfolios, and the ability to support large infrastructure programs with consistent supply and technical documentation.
Several leading companies illustrate the different ways to compete. PPG Industries has built recognition around waterborne and solvent-based traffic paint systems, emphasizing formulation families designed for road marking applications. Its positioning reflects a broader strategy of offering choices that align with varying regulatory and performance requirements while maintaining a consistent technical backbone. Swarco, with operations spanning multiple regions, provides a mix of solvent-based, waterborne, and two-component systems, which allows it to match products to project-specific conditions and specification environments. This breadth supports flexibility in bidding and application scenarios.
Meon Ltd has carved out a role focused on line marking paints and cold plastic systems for roads, parking lots, and airports, highlighting the value of serving multiple application contexts with a coherent product set. Axalta Coating Systems contributes a portfolio that includes spirit-soluble and modified alkyd formulations, showing continued relevance for markets where established chemistries still fit within accepted specifications. Cloverdale Paint Inc underscores another competitive angle: regional specification alignment. Its waterborne traffic paint formulations approved for Canadian infrastructure specifications illustrate how regulatory fit and local qualification can be decisive in securing market access.
Differentiation Beyond Product Catalog Breadth
In a market where many players offer overlapping product categories, differentiation is increasingly determined by how well a supplier can reduce risk and uncertainty for the buyer. Technical support, specification readiness, application guidance, and consistent quality control are becoming part of the core value proposition. Companies that can help contractors and public agencies navigate formulation choices, meet updated standards, and manage application conditions are building a defensible position that is harder to replicate than price alone.
This also means that the competitive battleground is shifting from pure product features to service-integrated solutions. Suppliers that combine reliable product performance with practical field support, clear compliance documentation, and predictable supply are better positioned to win repeat business and preferred supplier status. In contrast, competitors that rely primarily on catalog breadth without strong technical and service integration may find themselves vulnerable when buyers compare total project risk and lifecycle outcomes.
Portfolio Evolution and Market Structure Trends
The competitive landscape is likely to continue evolving through a combination of consolidation, portfolio specialization, and selective entry by regional players. Larger firms may pursue broader coverage through acquisitions or geographic expansion, aiming to strengthen supply continuity and specification reach. Smaller and mid-sized suppliers may compete by focusing on niche applications, regional specifications, or specialized material systems that larger players deprioritize. At the same time, new entrants with differentiated formulations or application-focused technologies could gain traction in segments where durability, drying speed, or environmental compliance are especially valued.
One important trend is the growing importance of portfolio coherence. Buyers are less interested in isolated product lines and more interested in suppliers that can address a range of marking needs across roads, parking areas, and airports with consistent quality and clear technical guidance. This favors companies that can offer a structured portfolio rather than fragmented offerings, while still retaining the flexibility to serve project-specific requirements. Another trend is the increasing relevance of regional compliance knowledge. As specifications become more localized and more stringent, suppliers with strong familiarity with local standards and procurement practices are gaining an edge in winning formal qualifications and specification inclusions.
Forward Outlook: Trends Shaping the Next 3 to 5 Years
Over the next several years, the roadmarking paints market is likely to be shaped by three reinforcing trends. The first is the continued migration toward lower-emission and more durable marking systems, driven by regulatory expectations, safety priorities, and total-cost considerations. This will not result in a single dominant chemistry across all contexts. Instead, it will produce a more segmented market in which waterborne, thermoplastic, and cold plastic solutions coexist, each anchored to specific application profiles and specification regimes.
Traffic Marking Paints Market
The second trend is the growing emphasis on supply chain stability and cost predictability. As raw material volatility and specification updates continue to influence procurement decisions, suppliers that can manage input risk, maintain consistent quality, and offer transparent pricing logic will be rewarded with stronger customer relationships and more resilient order flow. This trend favors organizations that treat supply chain management as a strategic capability rather than an operational back-office function.
The third trend is the increasing role of performance verification and lifecycle thinking in specification and bidding processes. Buyers are likely to place greater weight on demonstrated durability, reflectivity retention, application efficiency, and compliance readiness. This creates opportunities for suppliers that can provide credible evidence of field performance and support buyers in evaluating total project outcomes. It also introduces risk for companies that depend on price-based competition without a clear performance narrative or specification alignment.
These trends open commercial opportunities in several areas. Suppliers with strong waterborne or low-emission portfolios can benefit from specification shifts in markets where emission constraints are tightening. Companies with robust thermoplastic and cold plastic capabilities can focus on high-durability applications where performance justifies premium positioning, especially if they can manage cost exposure effectively. There is also room for service-led differentiation, where technical support, application guidance, and specification expertise become the basis for preference rather than product features alone. At the same time, uncertainty remains. Raw material cost swings, uneven regulatory enforcement, and project budget constraints can all slow adoption or shift demand between product categories. Firms that monitor these variables closely and adjust portfolios and procurement strategies accordingly will be better prepared to capture upside while limiting downside.
Strategic Implications for Decision-Makers
For Manufacturers and Material Formulators
Portfolio strategy should be guided by the need to balance compliance, durability, and cost control. Rather than treating product lines as static offerings, manufacturers can benefit from aligning formulations with the specification trajectories of key markets and identifying where performance claims can be credibly extended. Investment in application-relevant testing, clear documentation, and supply chain flexibility can strengthen competitive positioning more reliably than incremental catalog expansion alone. Companies should also consider where they can reduce exposure to volatile inputs without compromising field performance, since cost stability is increasingly part of the value proposition.
PW Consulting
For Investors and Strategic Buyers
The market offers exposure to steady infrastructure-linked demand, but value creation will likely come from companies that can manage regulatory transitions, supply variability, and application performance in an integrated way. Due diligence should pay attention to specification alignment, regional qualification strength, and the ability to serve multiple application environments with coherent product and service offerings. Businesses that rely heavily on single-format dependency or on price competition in volatile input conditions may face narrower margins for error. Strategic acquisitions or partnerships that expand compliance coverage, regional reach, or service capability can create advantages in a market where buyer preferences are shifting toward reliability and lifecycle value.
For Procurement Teams and Infrastructure Buyers
Evaluating roadmarking solutions with a total-cost perspective can reduce project risk and improve long-term outcomes. This means accounting for application speed, drying behavior, weather tolerance, expected service life, and compliance readiness alongside unit pricing. Early engagement with suppliers on specification alignment and performance expectations can help avoid mismatches during bidding and execution. Procurement teams can also benefit from tracking specification updates and material availability trends, since these often signal which product categories will become easier or harder to source at competitive terms in upcoming project cycles.
Paint Market
For all of these audiences, the value of detailed market intelligence lies in its ability to connect broad trends to specific decisions. Segment-level demand patterns, regional specification trajectories, raw material exposure by product category, and competitive positioning by application context all influence how the market will evolve beyond the headline growth narrative. A more granular view helps manufacturers prioritize formulation and portfolio choices, helps investors identify where durable advantage is being built, and helps procurement teams structure sourcing strategies that are resilient to both regulatory and cost-side uncertainty.
The roadmarking paints market is not simply expanding; it is restructuring around performance expectations, environmental mandates, and supply chain realities. Companies that interpret these signals early and align their strategies accordingly are more likely to convert market growth into sustained commercial advantage. For decision-makers seeking a deeper, segment-level view of demand splits, regional specification trends, raw material exposure, and competitive positioning across product types and application contexts, the full PW Consulting market report provides the additional granularity needed to support planning, procurement, and investment decisions with greater confidence.
For detailed analysis of this topic, please visit the official page: Roadmarking Paints Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Heat Exchanger Market: How 5.5% CAGR and Asia Pacific's 6.9B Size Redefine Growth
By PW Consulting, 2026-09-21
The Heat Exchanger Market: Strategic Shifts and Commercial Opportunities in a Transforming Industrial Landscape
The global heat exchanger market has entered a phase of steady, structurally driven expansion. Between 2020 and 2025, revenue climbed from approximately $14.5 billion to $20.01 billion, reflecting an environment where thermal management has become inseparable from industrial efficiency, energy transition goals, and operational resilience. The forward trajectory points to continued growth through 2032, with a compound annual growth rate of 5.5 percent and projected revenue reaching nearly $29.5 billion by the end of the forecast period. This expansion is not merely cyclical. It is being shaped by overlapping forces: stricter energy and emissions regulations, the electrification of process heat, the cooling demands of digital infrastructure, and a recalibration of supply chains after years of disruption.
For executives and investors, the market presents a familiar paradox. Demand is broad and durable, yet the profitability and competitive positioning of individual players depend heavily on product specialization, regional supply dependencies, and the ability to navigate certification and materials constraints. Understanding where value is created—and where margin pressure is intensifying—requires looking beyond top-line growth and examining the structural dynamics that will separate resilient operators from those exposed to cost volatility and substitution risk.
Market Status and Core Challenges
The current market structure reflects a mature but still evolving industry. Revenue is distributed across multiple product configurations, end-use sectors, and geographic regions, with no single segment dominating to the point of rendering others irrelevant. That dispersion is both a strength and a source of strategic complexity. Manufacturers must balance standardized high-volume offerings with engineered solutions that command higher margins but require deeper customer integration. At the same time, the industry is operating under heightened scrutiny on safety, performance verification, and traceability, which raises the barrier to entry for undifferentiated competitors but also increases compliance burdens for established players.
Heat Transfer Equipment Market
Several challenges stand out as true inflection points.
- Materials cost escalation is reshaping economics. The cost of metallic heat exchanger equipment has risen from less than $100 per kilowatt thermal to a range between $500 and $1,000 per kilowatt thermal. This shift directly affects project economics, particularly for large industrial and power-generation installations where thermal capacity is a primary cost driver. Manufacturers and buyers are now forced to weigh material selection, design optimization, and lifecycle performance more carefully than in the past.
- Regulatory and certification frameworks are tightening the operational baseline. Pressure vessel and heat exchanger fabrication increasingly depends on recognized stamps and certification programs that verify design integrity and performance. Compliance with established mechanical codes and industry certification schemes is no longer optional; it is a precondition for supplying critical industrial, HVAC, and refrigeration applications. These requirements improve safety and interoperability, but they also lengthen qualification cycles and constrain the speed at which new entrants can scale.
- Trade and import dynamics are altering supply reliability. Projections indicate substantial increases in U.S. imports of heat exchange units within specific tariff classifications through 2025. This pattern points to a market that is becoming more internationally interdependent, with sourcing strategies shifting in response to capacity constraints, regional manufacturing investments, and the need to secure consistent supply for downstream projects.
Together, these forces create a market where growth is achievable, but only for participants who can align product strategy with cost discipline, certification readiness, and supply-chain certainty. The days of competing primarily on price are giving way to competition on verified performance, delivery reliability, and application-specific engineering.
Core Drivers of Market Change
Technology Innovation and Product Differentiation
Product innovation is moving along two complementary paths: performance enhancement in established designs and targeted development for emerging cooling and thermal-management needs. In industrial applications, the emphasis remains on improving heat-transfer efficiency, reducing footprint, and extending service life under harsher operating conditions. In parallel, new product introductions are increasingly oriented toward sectors where thermal control is becoming a bottleneck, such as data center cooling and district energy systems.
Recent product activity illustrates this shift. New brazed plate heat exchanger models have been introduced specifically for data center cooling and district energy applications, signaling that manufacturers are tailoring designs to high-density thermal loads and integrated energy networks rather than treating these as generic secondary markets. At the same time, the continued expansion of large-scale plate heat exchanger manufacturing capacity in the United States reflects a strategic bet on domestic production for a product category where throughput, lead time, and proximity to customers can be decisive advantages.
For businesses, the implication is clear: technology leadership is increasingly defined by application fit rather than generic product breadth. Companies that can match thermal performance to specific operating environments—while maintaining manufacturability and serviceability—are better positioned to defend margins and capture premium projects.
Policy and Regulatory Environment
Policy and standards are not background conditions; they are actively shaping demand patterns and competitive eligibility. Mechanical design and fabrication standards for shell and tube units, certification programs for brazed and fusion-bonded plate heat exchangers, and pressure vessel stamping requirements all create a shared technical language across buyers, engineers, and suppliers. That commonality reduces transaction risk in complex projects, but it also means that compliance competence has become a core capability rather than a back-office function.
The regulatory environment also interacts with broader energy and sustainability agendas. As industries face pressure to reduce energy consumption and emissions, thermal recovery and heat integration become more valuable. Heat exchangers that enable waste-heat recovery, efficient process heating, and lower refrigeration loads are increasingly evaluated against energy-performance criteria that extend beyond initial capital cost. In practical terms, this favors suppliers that can document efficiency gains, support lifecycle assessments, and align product specifications with project-level compliance requirements.
Demand-Side Shifts in Key Sectors
Demand is being reshaped by changes in how companies use energy, how facilities are designed, and how critical infrastructure is cooled. Industrial operators are looking for equipment that supports continuous operation with fewer interruptions and lower operating expense. Commercial and infrastructure projects are placing greater emphasis on thermal systems that can scale with load variability and integrate into broader energy strategies. These shifts are not uniform across sectors, but they share a common theme: thermal management is moving from a supporting utility to a strategic performance variable.
PW Consulting
This demand evolution is visible in the localization of manufacturing and the diversification of application-focused product lines. Facility expansions in North America are intended to improve supply reliability for regional customers, while new models designed for data centers and district energy reflect an understanding that future growth will be tied to specific high-value use cases. For buyers, this means that procurement decisions are increasingly influenced by operational continuity, lead-time predictability, and the ability to match equipment to changing load profiles.
Supply Chain and Cost Structure Transformation
The cost structure of heat exchanger production is being re-evaluated in response to materials inflation, fabrication complexity, and the need for dependable delivery. The sharp increase in metallic equipment costs per unit of thermal capacity is a clear signal that design choices and procurement strategies must be recalibrated. Suppliers that rely on rigid material specifications without exploring optimization opportunities may face margin compression, while those that integrate material efficiency, standardized yet customizable platforms, and robust fabrication processes can better absorb input-cost volatility.
At the same time, trade flows and import projections suggest that sourcing strategies are becoming more dynamic. Companies are balancing domestic production with international supply to manage risk, cost, and capacity. This balancing act is especially important in segments where project timelines are tight and certification or quality documentation must be maintained across the supply chain. The organizations that succeed will be those that treat supply chain design as part of product strategy, not as a separate logistics function.
Competitive Landscape and Leading Strategies
The competitive field includes a mix of specialized manufacturers, broad thermal-system providers, and service-oriented firms that support installation, repair, and maintenance. This diversity is one of the market’s defining features. Some companies compete through large-scale shell and tube solutions for industrial and power generation applications. Others focus on plate and frame, brazed plate, or dry cooling systems for HVAC, refrigeration, and process industries. A further group builds its position on custom fabrication, ASME-aligned pressure vessel work, or aftermarket services that extend asset life and reduce downtime.
Graphite Heat Exchanger Market
Several strategic patterns are evident among the more prominent players.
- Application anchoring. Leading manufacturers tend to differentiate by anchoring their offerings in specific end-use environments. Some build their identity around industrial and power applications, others around refrigeration and cooling, and others around engineered systems for refining and process sectors. This focus allows them to develop deeper technical credibility and repeatable project references in their chosen domains.
- Certification and standards as competitive infrastructure. Companies that operate confidently within recognized mechanical and performance standards are better positioned to win bids in regulated or safety-critical environments. Stamping readiness, documented quality systems, and alignment with widely accepted design standards reduce friction in project approval and procurement.
- Capacity and supply localization. Recent facility investments in the United States and Mexico highlight a strategic emphasis on regional production capability. Expanding domestic or nearshore manufacturing can improve delivery speed, reduce exposure to long-distance logistics risk, and strengthen relationships with customers who prioritize supply reliability.
- Aftermarket and service differentiation. Firms that provide repair, maintenance, and heat recovery services create additional value streams while reinforcing customer relationships. In asset-intensive industries, the ability to keep existing equipment operating efficiently can be as strategically important as selling new units.
The market is not consolidating into a single dominant model, and that is deliberate. The diversity of applications, sizes, materials, and certification requirements makes full horizontal consolidation difficult. Instead, the landscape is evolving through a combination of specialization, selective capacity expansion, and targeted product launches. New entrants face a meaningful hurdle because they must establish trust in performance, compliance, and delivery before they can compete for large projects. Meanwhile, established players are expanding where demand is strongest and where manufacturing scale or technical specialization gives them an advantage.
International activity also remains important. Large exhibitions and technology gatherings in Asia continue to draw hundreds of companies showcasing new equipment, materials, and process technologies. This global exchange of innovation matters because it influences product roadmaps, material choices, and competitive benchmarks across regions. Companies that monitor these developments closely can identify emerging design directions and supply-chain shifts before they become mainstream.
Future Trends and Commercial Opportunities
Trend One: Application-Specific Thermal Solutions Will Command Greater Value
Over the next three to five years, the market is likely to reward manufacturers that move from generic product catalogs to solution-oriented portfolios tailored to high-priority applications. Data centers, district energy, industrial heat recovery, and specialized refrigeration systems are all areas where thermal performance has direct operational and economic consequences. Equipment that is designed for these contexts—rather than adapted after the fact—will increasingly be preferred in procurement decisions.
The commercial opportunity lies in combining technical customization with repeatable engineering platforms. If a company can standardize core design elements while varying capacity, materials, and integration features for specific applications, it can achieve both efficiency in production and relevance in the market. The risk is that over-customization can erode the cost advantages of scale, so the balance between flexibility and standardization will be a critical managerial challenge.
Trend Two: Cost and Materials Strategy Will Become a Competitive Weapon
Given the significant increase in metallic equipment costs per unit of thermal capacity, cost management will move up the strategic agenda. Companies that succeed will not simply pass through higher input costs; they will actively redesign for material efficiency, evaluate alternative configurations where appropriate, and work with customers to optimize total cost of ownership rather than initial price. Procurement teams, in turn, will increasingly seek evidence that installed equipment will perform efficiently over time, reducing operating expense and exposure to future materials volatility.
This trend creates opportunities for suppliers that can offer transparent performance data, lifecycle cost modeling, and design choices that align material use with actual thermal requirements. It also raises the stakes for buyers, who must weigh short-term price against long-term reliability and efficiency. Misaligned purchasing decisions could lead to higher operating costs or premature replacement cycles, especially in demanding service environments.
Trend Three: Supply Reliability and Regional Manufacturing Will Shape Market Access
As import patterns shift and major manufacturers invest in North American production capacity, supply reliability is becoming a competitive differentiator. Projects that depend on tight installation schedules or operate in environments where downtime is costly will naturally favor suppliers that can demonstrate consistent delivery and strong regional support. This does not mean international supply will disappear, but it does suggest that regional manufacturing and service presence will be valued more highly than in the past.
The opportunity here is for manufacturers to align capacity investments with the customer segments most sensitive to lead time and service response. For investors, the relevant question is whether capacity expansion is attached to durable demand or merely to short-term pricing conditions. Overbuilding without clear application demand can create pressure on utilization and pricing, while targeted expansion in growing segments can strengthen market position and improve margins over time.
Uncertainty and Risk Considerations
Several uncertainties should temper overly optimistic planning. Materials cost trajectories remain volatile, and any further escalation could pressure project economics and delay capital decisions. Regulatory and certification requirements may become more demanding in certain jurisdictions, increasing qualification time and reducing flexibility in sourcing. Trade dynamics could also shift if tariff structures, import patterns, or domestic content expectations change. Finally, demand growth may be uneven across sectors, with some applications expanding rapidly while others remain constrained by broader industrial activity or capital spending cycles.
These risks do not undermine the market’s long-term direction, but they do reinforce the need for scenario-based planning. Companies that treat demand, cost, and supply assumptions as fixed are more exposed to disruption than those that prepare for a range of outcomes.
Actionable Guidance for Decision Makers
For manufacturers, the priority is to sharpen the link between product strategy and application demand. That means identifying the segments where thermal performance, certification readiness, and delivery reliability matter most, and then concentrating engineering and manufacturing investment there. It also means reviewing material and fabrication choices with a clear eye on cost exposure, exploring where standardization can protect margins without sacrificing application fit. Companies that can offer verified performance, predictable lead times, and strong service support will be better positioned to win and retain high-value projects.
For investors, the key is to distinguish between capacity that is tied to structural demand and expansion that is primarily reactive. Look for evidence that growth is anchored in application-driven need, supported by clear operational advantages, and aligned with compliance and supply reliability. Companies with diversified but focused portfolios, strong certification capabilities, and a credible aftermarket or service presence often have more resilient business models than those relying on undifferentiated volume alone. Monitoring regional manufacturing investments and product launches in emerging applications can also provide early signals about where competitive advantages are being built.
For procurement and operations leaders, the focus should shift from transactional price comparison to total value assessment. That includes evaluating equipment against lifecycle efficiency, serviceability, delivery risk, and compliance documentation. In environments where downtime, energy cost, or regulatory exposure is significant, the cheapest initial option may not be the most economical over the life of the asset. Building procurement criteria that reflect operational reality can reduce vulnerability to supply delays, performance shortfalls, and avoidable operating expenses.
Because the market is evolving across technology, regulation, cost structure, and regional supply simultaneously, the full picture is difficult to capture from headlines or isolated announcements alone. Detailed segmentation data, company-level positioning, and scenario analysis are needed to convert these broad dynamics into concrete decisions about product investment, sourcing, and market entry. For organizations that want to move faster and with more confidence, a comprehensive research perspective can help identify where growth is most durable, where margin pressure is most likely, and which strategic choices will matter most over the next several years.
For detailed analysis of this topic, please visit the official page: Heat Exchanger Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Grinding Wheels Market: Strategic Trends and Commercial Opportunities (2026–2032)
1. Market Landscape and Core Challenges
The global grinding wheels market has demonstrated steady expansion over the past five years, moving from a valuation of approximately USD 5,450 million in 2020 to an estimated USD 6,665 million in 2025. Looking ahead, the market is projected to reach USD 8,770 million by 2032, representing a compound annual growth rate of 4.1 percent across the 2026–2032 forecast period. This trajectory reflects a mature but resilient market that is increasingly shaped by shifting industrial priorities rather than raw volume growth alone.
While the top-line figures suggest continuity, the underlying structure tells a more nuanced story. Market concentration remains moderate, with the top three players accounting for roughly 28.5 percent of industry revenue and the top five reaching 35.2 percent. This fragmentation indicates that value is not solely captured by scale; differentiation in product performance, regional service capabilities, and application-specific engineering are becoming decisive competitive factors. The market is large enough to accommodate specialized players, yet consolidating around firms that can integrate abrasives knowledge with machine-tool compatibility and end-user process expertise.
Key Structural Challenges
Several intersecting pressures are redefining how grinding wheels businesses compete and plan for the near term.
- Performance-pressure vs. cost trade-offs. End users are increasingly unwilling to accept incremental wear rates or inconsistent surface finishes in exchange for lower unit prices. Grinding wheels are now evaluated as part of total cost-per-part equations, where dressing frequency, wheel life, and machine downtime carry as much weight as purchase price. This shifts competitive advantage toward suppliers who can demonstrate measurable productivity gains rather than competing purely on commodity pricing.
- Regulatory complexity and standardization. Revised safety and marking frameworks are raising the compliance bar for both wheels and the machines they run on. Updated standards have clarified arbor hole dimensions and anti-overspeed requirements, while newer machine classification schemes require risk-based safety measures, including burst guard strength calculations. At the same time, labeling obligations now extend to maximum operating speed, shelf life or expiry date, dimensions, usage restrictions, traceable manufacturing numbers, mounting instructions, and ISO-type markings. These requirements elevate quality assurance and documentation costs, particularly for cross-border trade and multi-market portfolios.
- Raw material and input volatility. The abrasive grain base remains heavily weighted toward aluminum oxide, which continues to command a substantial share of the broader abrasive grains market. Any disruption to grain supply, binder systems, or additive availability can ripple through wheel pricing and formulation stability. Suppliers that lack diversified sourcing or formulation flexibility face margin exposure when input costs move unexpectedly.
The practical implication is that the grinding wheels market is entering a phase where operational and regulatory excellence are as commercially significant as product performance. Companies that treat compliance, consistency, and process integration as strategic capabilities are better positioned to protect margins and secure long-term contracts.
2. Key Drivers Shaping the Market
Market momentum is being directed by a combination of technological, regulatory, demand-side, and supply-chain forces. Rather than operating in isolation, these drivers are reinforcing one another and reshaping what buyers expect from grinding wheel suppliers.
Technology Innovation and Breakthroughs
Precision-shaped grain technology and advanced bonding approaches are changing the performance envelope of conventional grinding wheels. Products built on controlled grain geometry can deliver more consistent cutting action and predictable wear behavior, which matters increasingly in high-value metalworking, automotive, and aerospace applications. At the same time, developments in diamond and CBN abrasives are extending the role of superabrasive solutions beyond niche operations into more mainstream grinding processes, especially where component tolerances, surface integrity, and throughput are critical.
Recent industry activity underscores this direction. During 2026 trade events, multiple participants showcased grinding-related technologies that blur the line between wheel design and machine-process compatibility. Diamond and CBN abrasives applicable to grinding wheels were highlighted as part of broader precision grinding solutions, while large-format double disc grinding wheels for face and fine grinding demonstrated continued investment in high-productivity processes. Grinding machine providers also presented equipment compatible with electroplated and dressable CBN grinding wheels, reflecting a growing emphasis on process-integrated performance rather than standalone consumable supply. In parallel, resin-bonded grinding wheel offerings continued to appear at hardware-focused exhibitions, signaling sustained interest in flexible bonding solutions for a wide range of workshop and industrial applications.
Policy and Regulatory Environment
Regulations are increasingly shaping both product design and commercial readiness. Updated standards for grinding wheels and accessories have tightened requirements around dimensional consistency and speed safety, making specification accuracy and manufacturing control more important. Machine-related classifications that assign risk levels and mandate appropriate safety measures, including burst guard strength calculations, are also influencing how wheels are selected, validated, and deployed in industrial settings.
For suppliers, these developments raise the value of robust documentation, traceable production, and consistent marking practices. For buyers, they create a stronger expectation that wheel suppliers can support compliance as part of the product proposition. The broader effect is a market where higher safety and quality standards are becoming a competitive filter rather than a back-office obligation.
Demand-Side Shifts in Transport and Steel Industries
Demand for grinding wheels remains closely tied to industrial sectors where precision metal removal, surface conditioning, and tooling support are essential. The transport industry and steel industry continue to represent significant application anchors, reflecting the ongoing need for grinding solutions across component manufacturing, maintenance, and fabrication workflows. Beyond these sectors, the wider application base remains substantial, underscoring the market's diversification across general industrial metalworking, toolmaking, and precision grinding tasks.
What is changing is not simply the volume of activity, but the performance criteria attached to it. Transport and steel-related production environments are placing greater emphasis on consistency, reduced rework, and process reliability. As a result, buyers are more inclined to evaluate grinding wheels based on how effectively they support downstream quality and machine utilization. This demand-side evolution favors suppliers that can align product recommendations with specific process conditions, machine types, and finishing objectives.
PW Consulting
Supply Chain and Cost Structure Dynamics
Cost structures across the grinding wheels value chain are being influenced by input availability, formulation complexity, and the cost of maintaining consistent quality at scale. Since a large share of abrasive grain demand is tied to aluminum oxide, grain pricing and supply reliability can have an outsized impact on margin planning. Binder systems, additives, and manufacturing precision add further layers of variability, particularly for products that must meet application-specific performance targets.
At the same time, logistics and regional demand patterns are reshaping how suppliers think about inventory positioning and production footprints. Markets with strong industrial activity are placing a premium on responsiveness, technical support, and local specification expertise. Suppliers that can balance formulation consistency with regional service capability are gaining an advantage in segments where downtime and specification errors carry significant operational costs.
3. Competitive Landscape and Leading Strategies
The competitive field in grinding wheels is broad and varied, combining large multinational abrasive businesses with focused regional producers and specialized technology providers. The market's moderate concentration suggests room for differentiation, but also intensifying competition for customers who increasingly prioritize performance reliability, application fit, and compliance support.
Worldwide Floor Grinding Tools Market
Strategic Positioning of Core Players
Several established companies illustrate the different ways value is being pursued in this market.
- Saint-Gobain Abrasives leverages its Norton Abrasives brand to serve industrial metalworking, automotive, and aerospace applications with vitrified, resin-bonded, and CBN grinding wheels. Its positioning reflects a focus on broad application coverage and a portfolio that spans conventional and superabrasive solutions.
- Norton Abrasives continues to emphasize its established manufacturing footprint in conventional aluminum oxide, silicon carbide, and superabrasive grinding wheels. Its relevance lies in the combination of product familiarity and the ability to address a wide range of standard and demanding grinding tasks.
- 3M Abrasives differentiates through precision-shaped grain technology in products such as its Cubitron II and silver series depressed-center and cut-off grinding wheels. The emphasis on controlled grain geometry highlights a strategy centered on performance consistency and process efficiency rather than commodity substitution.
- Tyrolit Group specializes in metal and precision grinding wheels, including vitrified and superabrasive products for automotive, aerospace, and toolmaking. Its profile suggests a strategy rooted in application-specific engineering and precision grinding expertise.
- Klingspor produces abrasive discs, cut-off wheels, and bonded grinding wheels, reflecting a practical, broad-based offering for workshop and industrial users. Its strength lies in versatility and coverage across common abrasive product categories.
- Camel Grinding Wheels manufactures resin-bonded and vitrified grinding wheels, cut-off wheels, and coated abrasives, positioning itself across a mix of bonded and coated solutions that serve both general and specialized applications.
- Carborundum Universal Limited operates as a leading abrasives producer for industrial applications in India and globally. Its relevance in the broader market highlights the importance of regional strength, cost-competitive production, and expanding international reach.
Taken together, these profiles show two ongoing patterns. One is the continued importance of portfolio breadth and application coverage among larger players. The other is the growing relevance of technology-led differentiation, especially where grain design, superabrasive compatibility, and process-specific recommendations can justify preferential selection.
Market Evolution and Strategic Trends
The competitive landscape appears to be moving along several recognizable paths.
- Technology-led segmentation. Suppliers are increasingly competing on process-enabling features such as grain geometry, wheel dressing compatibility, and performance stability under specific operating conditions. This creates subtle but commercially meaningful differentiation even within broadly similar product categories.
- Application and sector alignment. Companies with clearer alignment to high-value end markets, including automotive, aerospace, and precision toolmaking, are better placed to command attention from buyers who value consistency and technical support over lowest-cost supply.
- Regional presence and responsiveness. Strong local service, specification assistance, and supply reliability remain critical, especially in active industrial regions where downtime and process mismatches are expensive. This continues to support the relevance of regional leaders alongside global portfolios.
- Integration with grinding process ecosystems. The growing visibility of machine-compatible wheel solutions, including electroplated and dressable CBN options and large-format grinding formats, indicates a widening competitive field where wheel suppliers are increasingly evaluated in the context of overall grinding performance.
The market is not necessarily trending toward rapid consolidation into a single dominant model. Instead, it is becoming more layered: global portfolios provide scale and breadth, regional specialists offer responsiveness and local expertise, and technology-focused players compete on measurable process advantages. For buyers and investors alike, the most relevant question is not only who sells grinding wheels, but who can most reliably translate product characteristics into reduced total cost and improved process outcomes.
4. Future Trends to Watch (2026–2032)
Based on current market direction, regulatory development, and product activity, several trends are likely to shape commercial decision-making over the next three to five years.
Trend 1: Performance Differentiation Will Matter More Than Category Growth
With a projected CAGR of 4.1 percent through 2032, market expansion will provide a supportive backdrop, but growth alone will not determine competitive success. The more decisive battleground will be performance differentiation: wheel life consistency, surface finish quality, dressing behavior, and the ability to reduce total cost per part. Suppliers that can validate these outcomes with practical evidence will have stronger positioning in demanding metalworking, transport, and steel-related applications.
The commercial opportunity lies in moving the conversation from specification matching to process improvement. This includes helping buyers select wheels based on machine type, material removal requirements, and quality targets rather than defaulting to habitual choices. The risk is that companies relying on undifferentiated product lines may face margin pressure as buyers compare solutions more rigorously.
Trend 2: Safety, Traceability, and Compliance Will Become Commercial Levers
Updated standards for wheel marking, dimensional requirements, and anti-overspeed provisions, together with machine risk classification and burst guard considerations, are reinforcing the importance of documentation and manufacturing control. Over time, these requirements are likely to become embedded in procurement expectations, particularly in environments where safety, auditability, and supply consistency are heavily scrutinized.
This creates opportunity for suppliers that can package compliance as part of a dependable supply proposition. Traceable manufacturing numbers, clear usage restrictions, shelf life or expiry information, and complete dimensional and speed markings are increasingly part of the credibility equation. The uncertainty lies in how quickly different regions and customer types adopt consistent procurement practices around these requirements, which could create uneven implementation burdens.
Trend 3: Superabrasive and Process-Integrated Solutions Will Expand Their Reach
The continued visibility of diamond and CBN abrasives in grinding-related applications, alongside machine solutions designed for electroplated and dressable CBN wheels, points toward broader adoption of advanced grinding approaches in selected high-value processes. Large-format grinding wheels and precision-focused formats also indicate that specific high-productivity applications will continue to drive specialized demand.
For suppliers, the opportunity is to develop credible offerings where superabrasive or precision formats deliver clear advantages in tolerance, surface integrity, or throughput. For buyers, the strategic value depends on identifying the applications where these solutions justify their cost through measurable process gains. The risk is over-extension: superabrasive solutions are not universally advantageous, and misaligned adoption can erode return on investment if process conditions are not properly matched.
Grinding Media Market
5. Strategic Actions for Decision Makers
The grinding wheels market is evolving in a way that rewards preparation, evidence, and process-oriented thinking. The following actions can help different stakeholder groups respond effectively.
For Manufacturers and Product Leaders
- Prioritize differentiation through measurable performance attributes such as consistent wear behavior, predictable dressing response, and compatibility with precision grinding processes.
- Strengthen documentation and marking practices to align with evolving safety and traceability expectations, reducing friction in regulated or audit-sensitive procurement environments.
- Invest in application-specific support where transport, steel, and precision metalworking demand clearer guidance on wheel selection and process integration.
For Investors and Strategic Planners
- Assess exposure not only to overall market growth, but to segments where performance differentiation, compliance readiness, and region-specific service can sustain pricing power.
- Watch for signals of technology-led competition, including precision grain designs and superabrasive process compatibility, as indicators of where value may shift over the forecast period.
- Consider supply-chain resilience in abrasive grains and binder inputs as a strategic factor, especially in portfolios sensitive to formulation consistency and input cost volatility.
For Procurement and Operations Leaders
- Evaluate grinding wheels within total cost-per-part frameworks, incorporating wheel life, dressing frequency, rework reduction, and machine utilization rather than unit price alone.
- Verify that suppliers can meet updated marking, speed, and traceability expectations, especially where operational safety and compliance documentation are increasingly important.
- Align specifications with actual process conditions and machine compatibility, including where electroplated or dressable CBN solutions may be justified by precision and throughput requirements.
The market's trajectory suggests that the most consequential decisions will come from understanding where grinding wheels create process value, not just where they fit into a consumables budget. Detailed segmentation data, region-specific demand patterns, application-level performance profiles, and company-level competitive positioning can sharpen these decisions considerably. For readers seeking deeper, segment-level data and tailored interpretation for specific business situations, the full market research report provides a more granular view of the categories, regions, and competitive dynamics shaping the grinding wheels market through 2032.
For detailed analysis of this topic, please visit the official page: Grinding Wheels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
BMP-2 Market Set to Hit $347 Million: 5 Shifts Reshaping Bone Healing Through 2032
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Bone Morphogenetic Protein 2 Market Through 2032
The bone morphogenetic protein 2 (BMP-2) market has entered a phase of measured expansion characterized by steady clinical adoption, evolving regulatory frameworks, and shifting reimbursement dynamics. After reaching approximately $238.12 million in 2025, the market is projected to scale toward $346.71 million by 2032, reflecting a compound annual growth rate of 5.5 percent over the forecast horizon. This trajectory signals a mature but still growing sector where incremental innovation, 신중한 임상 적용, and healthcare payment 정책调整 will determine competitive positioning rather than explosive volume expansion. For executives and investors evaluating orthobiologics, understanding the structural forces behind this growth curve is essential for allocating capital, shaping R&D priorities, and anticipating procurement shifts.
Market Landscape and Core Challenges
The BMP-2 segment operates within a concentrated competitive environment. The top three players collectively command over half of total revenue, while the five largest firms account for nearly three-quarters of market share. This concentration reflects the high barriers to clinical validation, regulatory clearance, and surgeon familiarity that shield established products from rapid displacement. At the same time, the distribution of volume across geographies and clinical applications reveals where growth is accumulating and where friction persists.
Several structural challenges define the current inflection point for BMP-2 stakeholders:
- Clinical adoption boundaries and safety perception. While recombinant BMP-2 has demonstrated efficacy in specific fusion and trauma indications, historical concerns around ectopic bone formation, inflammatory responses, and dosing limitations continue to influence prescribing behavior. Surgeons and hospital committees increasingly weigh off-the-shelf osteoinductive agents against alternative graft strategies, requiring manufacturers to reinforce indication-specific evidence and refine delivery systems.
- Reimbursement complexity and procedural coding evolution. The trajectory of BMP-2 utilization is closely tied to how procedural codes and payment rules recognize osteobiologic adjuncts. Recent clarifications from the Centers for Medicare & Medicaid Services maintained recognition of multiple FDA-approved indications beyond primary anterior lumbar interbody fusion, including acute open tibial shaft fractures, sinus augmentation, and localized alveolar ridge augmentations. Such policy continuity reduces uncertainty for specific use cases, yet broader reimbursement variability across payers and institutional formularies still creates uneven demand patterns.
- Supply chain resilience and cost structure pressures. Recombinant protein manufacturing demands controlled bioprocessing, stringent quality assurance, and reliable delivery vehicle production. Any disruption in raw material sourcing, fill-finish capacity, or cold-chain logistics can affect product availability and pricing stability. Simultaneously, healthcare systems under margin pressure are scrutinizing the cost-per-fusion or cost-per-procedure calculus, pushing suppliers to justify value through outcomes data and total episode cost considerations.
These challenges are not insurmountable, but they reshape the commercial playbook. Market participants that treat clinical evidence, coding alignment, and manufacturing reliability as integrated strategic priorities are better positioned to convert steady demand into durable share gains.
Key Drivers Shaping Market Trajectory
The expansion path of BMP-2 through the late 2020s and into the early 2030s is being pulled by a handful of interlocking forces. Each driver carries distinct implications for product design, commercial access, and partnership strategy.
Technological Innovation and Delivery Engineering
Innovation in BMP-2 is less about discovering new protein variants and more about improving how the molecule is presented, localized, and released at the surgical site. Advanced absorbable carriers, tunable resorption profiles, and combination approaches that pair osteoinductive signals with structural scaffolds are reducing variability in bone formation while addressing safety concerns associated with high initial doses. Incremental formulation and device integration are enabling surgeons to deploy recombinant BMP-2 in a broader set of anatomies with greater confidence. For manufacturers, these refinements create differentiation beyond the molecule itself, turning delivery performance into a commercial moat.
Demineralized Bone Matrix (DBM) Market
Regulatory Frameworks and Coding Clarity
Regulatory and coding environments act as gatekeepers for reimbursement and, by extension, for routine clinical use. The 2026 ICD-10-PCS updates affirmed ongoing FDA-approved indications for recombinant BMP-2 products, including new codes for introduction of recombinant BMP-2 into joints and retention of indications for acute open tibial shaft fractures, sinus augmentation, and localized alveolar ridge augmentations. Such clarifications reduce ambiguity for specific procedural contexts, making it easier for hospitals to justify use within established pathways. At the same time, the broader regulatory landscape continues to emphasize post-market evidence, indication-specific labeling, and appropriate use criteria. Companies that proactively align clinical data packages with procedural coding realities and payer expectations can accelerate adoption in eligible segments while limiting off-label exposure.
Demand-Side Shifts in Surgical Practice and Patient Populations
Demand for bone graft substitutes is influenced by demographic trends, surgical volume patterns, and evolving preferences among spine, trauma, and craniofacial surgeons. An aging population and the rising prevalence of degenerative spinal conditions support continued procedural volume in fusion and reconstruction settings. In parallel, minimally invasive and lateral approaches are expanding the range of cases where locally applied osteoinductive agents can add value. Surgeons increasingly look for products that integrate smoothly into their preferred techniques, simplify operative workflow, and provide predictable outcomes. This behavior favors suppliers that invest in surgeon education, procedural compatibility, and real-world evidence generation tailored to specific clinical narratives.
PW Consulting
Cost Structure and Value-Based Procurement
Hospital procurement is moving toward total cost-of-care thinking rather than isolated device pricing. In fusion and trauma cases, the economic argument for BMP-2 hinges on reducing revision rates, accelerating fusion or healing, and streamlining recovery pathways. When suppliers can demonstrate that their product contributes to fewer complications or shorter downstream resource utilization, the conversation shifts from unit price to episode value. At the same time, manufacturers must manage input costs, scale production efficiently, and maintain margin discipline. The tension between value demonstration and cost control creates an opening for organizations that can translate clinical performance into economic language that procurement teams and value analysis committees understand.
Competitive Landscape and Leading Strategies
The competitive structure of the BMP-2 market reflects the advantages of first-mover clinical recognition, robust manufacturing capability, and deep surgeon relationships. Medtronic stands out as a central player, with its INFUSE Bone Graft platform built around recombinant human BMP-2 delivered on an absorbable collagen sponge. The product’s established footprint in anterior lumbar interbody fusion, oblique lateral interbody fusion, posterolateral fusion, and acute open tibial shaft fractures gives the company a strong reference base and procedural familiarity advantage. The recent CMS coding updates that sustain multiple FDA-approved indications reinforce the commercial viability of these use cases and support continuity in surgical adoption where evidence and technique align.
Strategic positioning among leading participants tends to converge on several differentiating levers:
- Indication anchoring and evidence depth. Companies that maintain rigorous, indication-specific clinical data and update labeling in step with regulatory expectations can defend their core territories and expand within approved boundaries. This reduces reliance on off-label usage and strengthens payer and hospital committee confidence.
- Delivery system integration. Differentiating through carrier technology, handling characteristics, and compatibility with emerging surgical approaches allows suppliers to compete on more than molecule identity. Integration with instruments, sleeves, or minimally invasive delivery workflows can improve adoption by reducing operative friction.
- Commercial engagement and education. Surgeon training, case-based education, and support for value analysis committees help convert product attributes into real-world utilization. In a market where procedural familiarity matters, sustained engagement can protect share even as alternatives evolve.
- Manufacturing reliability and supply assurance. Consistent production quality and predictable availability are critical in orthobiologics. Any lapse can disrupt surgical scheduling and erode trust quickly. Leading firms invest in process robustness, capacity planning, and quality systems to minimize these risks.
Looking forward, the market is likely to experience selective consolidation, strategic partnerships, and cautious new entry rather than a flood of disruptors. High clinical and regulatory hurdles favor incumbents, but opportunities remain for companies that bring differentiated delivery technologies, targeted indications, or region-specific commercialization capabilities. New entrants may focus on underserved anatomical sites, alternative carrier platforms, or localized market access strategies where incumbent coverage is thinner. The overall pattern points to a competitive environment where defensible niches, evidence leadership, and execution reliability determine outcomes more than broad-based price competition.
Future Trends and Commercial Implications for 2027–2032
Several trends will shape how the BMP-2 market evolves through the end of the decade. Each trend carries clear commercial consequences for manufacturers, investors, and healthcare buyers.
Refinement of Indication-Specific Use and Procedural Alignment
Over the next several years, BMP-2 utilization is expected to become more precisely aligned with procedural contexts where the evidence base and delivery approach are strongest. Rather than broad diffusion, growth will likely concentrate in applications such as spinal fusion, selected trauma scenarios, reconstruction, and oral maxillofacial procedures where osteoinductive adjuncts address specific biological gaps. This trend creates value for suppliers that can map product attributes to surgical workflows, support appropriate-use guidance, and generate real-world data that resonate with hospital committees. The commercial opportunity lies in helping customers match the right formulation and delivery approach to the right case, improving both outcomes and reimbursement capture.
Carrier and Combination Technology as a Differentiator
The next wave of competitive advantage will increasingly come from how BMP-2 is delivered and combined with structural or resorbable materials. Innovations in controlled release, scaffold integration, and handling characteristics can improve localization, reduce dose variability, and expand compatibility with newer surgical approaches. Companies that lead in carrier engineering and device integration may command stronger positioning in high-value procedural segments, while also creating switching costs through workflow familiarity. For investors, technology-led differentiation in delivery platforms can offer a more durable growth narrative than volume alone.
Reimbursement Harmonization and Regional Expansion
Reimbursement dynamics will remain a swing factor. Where procedural coding and payer policies converge with clinical indications, adoption can stabilize and grow; where they diverge, demand will remain fragmented. The recent maintenance of multiple FDA-approved indications through ICD-10-PCS updates illustrates how coding clarity can reinforce commercial viability in defined use cases. At the same time, regional variation in surgical volumes, healthcare financing, and access to advanced osteobiologics will influence growth rates across geographies. The trend suggests that commercial success will depend on localized reimbursement strategy, surgeon engagement, and supply readiness tailored to each market’s payment environment. Risk surfaces when reliance on a narrow set of indications or a single geographic concentration leaves the business exposed to policy shifts or volume slowdowns.
Strategic Actions for Decision Makers
Different stakeholders face distinct imperatives as the BMP-2 market moves toward 2032. The following actions are designed to translate market dynamics into practical decisions.
Angiopoietin 2 Market
For Manufacturers and Commercial Leaders
- Anchor product strategy in indication-specific evidence and procedural compatibility. Align clinical data, labeling, and education with the fusion, trauma, reconstruction, and oral maxillofacial contexts where surgeons are most likely to deploy recombinant BMP-2.
- Invest in delivery system differentiation and workflow integration. Enhance carrier performance, handling, and compatibility with preferred surgical approaches to create practical value beyond molecule identity.
- Build reimbursement readiness into the commercial plan. Monitor coding updates, payer policies, and institutional value analysis criteria, and prepare economic narratives that connect clinical performance to episode-level value.
For Investors and Strategic Capital Allocators
- Prioritize companies with defensible evidence positions, reliable manufacturing, and clear delivery differentiation. In a concentrated market, execution quality and clinical trust are often the real barriers to entry and the basis for durable share.
- Focus on value drivers rather than headline volume. Evaluate how candidates translate outcomes, workflow benefits, and reimbursement alignment into sustainable economics, especially under increasing procurement scrutiny.
- Watch for selective consolidation and niche entry. opportunities may arise from targeted indications, regional access plays, or platform technologies that improve localization and safety profiles without requiring broad molecule replacement.
For Procurement and Clinical Operations Leaders
- Evaluate BMP-2 products through total episode value rather than unit price alone. Consider impact on fusion success, revision risk, recovery pathways, and downstream resource use when comparing alternatives.
- Align product selection with procedural planning and coding realities. Ensure that chosen products fit the surgical approaches, indications, and documentation requirements that support reimbursement in your setting.
- Establish clear criteria for supplier reliability and evidence maturity. Consistent supply, quality assurance, and up-to-date clinical support reduce operational risk and help standardize appropriate use across service lines.
The BMP-2 market is moving through a period where incremental innovation, regulatory clarity, and value-based procurement will determine who captures growth and who merely defends share. For organizations seeking to navigate this environment with precision, detailed segmentation data, competitive benchmarking, and region-specific reimbursement insights can materially sharpen strategy. The full research report provides deeper breakdowns across type, application, and geographic dynamics, along with expanded competitor tracking and scenario analysis, offering a practical foundation for product planning, investment decisions, and procurement prioritization.
For detailed analysis of this topic, please visit the official page: Bone Morphogenetic Protein (BMP) 2 Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
7 Strategic Shifts Driving the Electronic Components Market to $717.6B by 2032
By PW Consulting, 2026-09-21
The Electronic Components Market: Strategic Trends and Commercial Opportunities Through 2032
The electronic components sector has transitioned from a commodity-driven business into a technology-intensive, strategically critical industry. Over the historical period from 2020 through 2025, global revenue climbed from approximately $300 billion to over $438 billion, reflecting an average compound annual growth rate of 7.36 percent across the full forecast horizon extending to 2032, when the market is projected to exceed $717 billion. This trajectory is not merely a recovery from supply disruptions of the early 2020s; it reflects a structural realignment driven by electrification, connectivity mandates, industrial automation, and a reconfiguration of global manufacturing footprints. The current landscape presents a paradox for decision makers: demand volumes are robust and accelerating, yet availability, cost structures, and competitive positioning are being reshaped by forces that do not always move in tandem.
Understanding where value will concentrate, which capabilities will command premiums, and how supply-chain architecture will evolve requires looking beyond headline volumes. The segmentation of the market by component type reveals a hierarchy of strategic relevance that is not always intuitive. Active components continue to anchor the largest share of revenue, reflecting their centrality to integrated circuits, analog and power management, and embedded control functions. Passive components represent a substantial and often underestimated revenue pool, driven by demand for capacitors, inductors, resistors, and RF modules that scale directly with the complexity of electronic assemblies. Electromechanical components, while smaller in relative terms, serve as critical enablers for connectors, switches, and sensors that bridge electrical and mechanical systems. By application, consumer electronics remains the largest end-use driver, followed by telecommunications, industrial, medical, automotive, and a diversified remainder that spans aerospace, test and measurement, and specialized instrumentation. Regionally, Asia Pacific leads in volume, with North America and Europe maintaining meaningful shares supported by design activity, high-value manufacturing, and policy-driven incentives.
Any realistic strategy must be built on these structural realities. The market's growth is not uniform across products or geographies; it is uneven, with pockets of intense competition, long lead times, and pricing volatility coexisting alongside segments where differentiation and reliability command durable margins. For executives and investors, the task is to map their exposure to the segments where the economics are most favorable, and to anticipate the inflection points that will separate winners from laggards.
Market Context: Baseline Dynamics and Critical Junctures
A Growth Profile That Rewards Timing and Positioning
The market's expansion from 2020 to 2025 was propelled by a confluence of restocking after pandemic-era shortages, the acceleration of automotive electrification, the proliferation of connected devices, and sustained capital expenditure in industrial and infrastructure electronics. The forward trajectory through 2032 reflects continued momentum, but with a widening dispersion of opportunity. The overall growth rate of 7.36 percent over the forecast period is meaningful, yet it conceals divergent sub-trends: components tied to high-growth applications will outpace the average, while mature commodity categories may experience pricing pressure and cyclical volatility. The implication is that aggregate market size is a useful sanity check, but it is insufficient for tactical planning. Companies need to align their portfolios with the application and technology vectors that are expanding faster than the baseline.
Three Junctures Redefining the Playing Field
First, supply-chain resilience has moved from an operational concern to a strategic lever. Lead-time variability remains a practical challenge for certain categories, particularly automotive-grade microcontrollers and specialized discrete devices, where procurement teams report extended delivery windows for select product lines. This is not a transient inconvenience; it is a structural feature of a market where qualified production capacity for high-reliability parts does not always scale in lockstep with demand. Organizations that treat sourcing strategy as a core competency, rather than a transactional function, can convert lead-time risk into negotiating leverage and preferential access.
Second, the regulatory and sustainability agenda is reshaping cost structures and competitive dynamics. Carbon-related mechanisms, including the EU Carbon Border Adjustment Mechanism, have begun publishing certificate pricing data, signaling that environmental compliance will be increasingly priced into cross-border trade. For component manufacturers and distributors, this creates both operational complexity and differentiation potential: firms that can demonstrate transparent, lower-carbon supply chains and efficient material utilization will be better positioned for markets where procurement criteria are expanding beyond performance and price.
Third, the balance between integration and fragmentation is shifting. Large incumbents continue to consolidate capabilities across analog, power, microcontrollers, and sensing to serve high-value applications, while independent distributors and niche specialists gain relevance by offering speed, accessibility, and hard-to-source inventory. At the same time, new manufacturing initiatives and partnerships are being deployed to stabilize supply in discrete and power categories, indicating that regional diversification and capacity partnerships are becoming permanent features of the landscape rather than one-off remedies.
Key Drivers Reshaping the Market
Technology Innovation and Breakthroughs
The most consequential technology trends are converging around power semiconductors, analog and precision ICs, and the integration of sensing with processing. Wide-bandgap devices based on silicon carbide and gallium nitride are expanding the addressable range for higher-efficiency power conversion, a theme especially relevant for electric vehicles, industrial drives, and renewable-energy systems. Companies with strong positions in power semiconductors and discrete devices are investing in manufacturing and product roadmaps that target these applications, while also extending into intelligent sensing and connectivity solutions that bridge functional domains. In parallel, the push toward physically aware and secure architectures is prompting collaboration around hardware anchored in AI edge platforms, with security and reliability increasingly treated as core product attributes rather than add-ons. These advancements are not abstract; they translate into higher value per unit, longer lifecycle relevance, and greater switching costs for customers who standardize on qualified solutions.
Policy and Regulatory Environment
Policy is now an active force in shaping where production occurs, what qualifies as a compliant component, and how trade flows are priced. Incentive programs and local-content expectations have encouraged investment in new fabrication and assembly capacity across multiple regions, reducing over-concentration risk while simultaneously complicating multi-site qualification. Regulatory instruments tied to carbon intensity are becoming operational realities, with certificate pricing now visible to market participants. This trend elevates the strategic importance of supply-chain transparency, material efficiency, and energy-aware manufacturing. For buyers, it introduces a new dimension to supplier evaluation; for manufacturers, it rewards those who can quantify and reduce the footprints associated with their products. Policy is no longer a background condition. It is a variable in cost, access, and go-to-market strategy.
Demand-Side Shifts in Consumer and Enterprise Behavior
On the demand side, two patterns stand out. Consumer electronics continues to anchor a large share of total volume, fueled by the ongoing refresh cycles of smartphones, wearables, home appliances, and connected accessories, each of which places incremental demands on passive components, RF modules, and power management. Simultaneously, enterprise demand is being reshaped by automation, data infrastructure, and the electrification of mobility and industrial equipment. Automotive and industrial applications are increasingly value-dense, with requirements that span high-reliability microcontrollers, power devices, secure connectivity, and long lifecycle support. Medical electronics is another segment where precision analog, sensing, and power management converge to support diagnostic, monitoring, and treatment devices. The practical takeaway is that demand is not only growing, it is becoming more application-specific, more certification-intensive, and more loyal to qualified suppliers, which raises the value of domain expertise.
Supply-Chain Architecture and Cost Structures
Capital intensity, lead-time discipline, and component availability are interacting to redefine cost structures. In memory-related ecosystems, production capacity has lagged rapidly growing demand, an imbalance visible in export flows from major manufacturing centers and a symptom of how quickly demand can outpace supply in certain technology nodes. In the automotive and industrial arenas, extended lead times for specific microcontroller series illustrate that even mature categories can experience bottlenecks when qualified capacity and demand are misaligned. At the same time, new partnerships in power discrete manufacturing, the opening of additional fabrication and assembly sites, and the expansion of distribution catalogs are all aimed at smoothing availability. The net effect is a market where cost is increasingly a function of reliability, qualification status, and supply assurance, not just unit price. Companies that manage inventory intelligently, qualify alternate sources prudently, and maintain visibility into production pipelines will be better positioned to absorb volatility and protect margins.
Competitive Landscape and Leading Strategies
Incumbents Anchored in Technology Gravity
The competitive field is anchored by firms with deep portfolios and established design-ins across analog, power, microcontrollers, precise sensing, and discrete devices. Several large players have built their advantage around a combination of technical breadth, application familiarity, and long-term customer relationships in automotive, industrial, and medical markets. Analog-focused companies emphasize precision and signal integrity for demanding environments. Power-semiconductor leaders are extending their relevance through wide-bandgap platforms and secure, intelligent solutions for edge and mobility applications. Microcontroller specialists serve automotive and industrial customers with architectures optimized for reliability and integration. Passive component manufacturers and connector specialists, meanwhile, compete on miniaturization, electrical performance, and the ability to scale volume with consistent quality. These positions are not easily replicated because they depend on sustained R&D investment, qualification history, and the trust that arises when components are embedded in safety-critical or high-value systems.
Strategic Moves That Are Reshaping the Landscape
Recent activity shows a market in motion. A power MOSFET manufacturing partnership was formed to strengthen supply stability, illustrating how discrete and power markets are addressing availability through collaboration and expanded fabrication reach. New manufacturing capacity has come online, including a power module plant in Southeast Asia, underscoring the multi-region footprint that major producers are building to serve global demand more flexibly. On the distribution side, catalog expansion and targeted campaigns are improving access to new parts and highlighting application areas such as industrial automation. Participation in major industry events has been used to advance hardware security and edge-compute solutions, signaling that safeguarding and intelligent processing are extensions of core component strategy. Taken together, these moves reflect a landscape where incumbents are reinforcing technology leadership and supply assurance, while distributors and specialists differentiate through breadth, speed, and application focus.
Integration, Differentiation, and the Rise of Niche Strengths
The market is not consolidating into a single mold. Instead, it is bifurcating in a productive way. Some segments reward scale, integrated portfolios, and the ability to support long-lifecycle applications with stable supply. Others reward specialization, speed to market, and the ability to source or rapidly introduce parts that are difficult to obtain. Independent distribution continues to play a meaningful role by connecting customers with new products and hard-to-find inventory, and by offering supply-chain services that go beyond transaction processing. This dual structure means that competitive advantage is context-specific: a manufacturer competing for automotive-grade design wins will pursue a different playbook than a distributor competing for rapid availability and broad catalog depth. The most resilient organizations are those that understand where they sit in this spectrum and invest accordingly.
Looking Ahead: Three Trends to Watch Through 2032
1. Power and Wide-Bandgap Economics Will Keep Improving, but Qualification Will Be the Gatekeeper
As efficiency requirements intensify across automotive, industrial, and energy applications, the addressable market for advanced power semiconductors and supporting components will expand. Yet growth will be uneven because adoption depends on qualification, system integration, and total-cost-of-ownership evidence. Organizations that can shorten qualification cycles, provide application support, and demonstrate reliability across lifecycle conditions will capture more design wins. The risk is that expectations for rapid adoption outrun the practical pace of validation, particularly in automotive and medical applications where certification timelines are long and unforgiving. Strategy should therefore pair technology roadmaps with customer-facing qualification and support capabilities.
2. Sustainability Metrics Will Be Priced Into Procurement and Product Design
With carbon-related mechanisms becoming operational and certificate pricing now visible, environmental performance is transitioning from a compliance topic to a procurement variable. Expect more purchasing decisions to incorporate supply-chain transparency, material sourcing, and energy intensity as evaluation criteria. This trend creates opportunity for manufacturers and distributors that can document and improve their footprints, and it raises the cost of opacity. The uncertainty lies in how quickly and uniformly these criteria will be applied across regions and customers. Firms that treat sustainability as a measurable, certifiable attribute rather than a narrative will have an advantage in negotiations and market access.
Electronics Market
3. Supply Assurance Will Become a Differentiated Value, Not Just a Cost Center
The combination of lead-time variability in select categories, capacity investments across multiple regions, and the strategic use of partnerships points toward supply assurance as a core competitive element. Buyers will increasingly value partners that can provide visibility, inventory flexibility, and qualification-ready alternatives. Manufacturers and distributors that invest in pipeline visibility, multi-site production options, and responsive catalog management will be able to command loyalty in segments where availability is a deciding factor. The downside risk is geopolitical and operational: the continued importance of advanced semiconductor manufacturing hubs means that regional disruptions can have disproportionate effects. Resilience planning, rather than assumption of continuity, will be a necessary discipline.
Strategic Recommendations for Decision Makers
For Manufacturers and Product Leaders
Align product roadmaps with the applications and technologies where value density is rising, especially power management, precision analog, sensing, secure connectivity, and reliable microcontrollers for automotive and industrial use. Prioritize qualification and lifecycle support as core capabilities, because design-in decisions in high-stakes applications are often driven by risk reduction as much as by performance. Use regional capacity and partnership options to improve supply assurance without overcommitting to a single geography. Treat sustainability data as a product attribute that can support customer requirements and mitigate future trade friction. Finally, resist the temptation to chase every volume opportunity; concentrate resources where differentiation, certification, and application expertise create durable returns.
PW Consulting
For Investors and Strategic Planners
Assess exposure to sub-segments with the most favorable growth and margin dynamics rather than relying on aggregate market size alone. Favor business models that combine technology leadership with supply assurance, because these two attributes together tend to protect share and pricing. Watch for consolidation among players seeking to broaden portfolios and shorten customer time-to-integration, and monitor the role of independent distribution as a source of market intelligence and rapid introduction capability. Be mindful of policy risk and raw-material dynamics, and model scenarios that reflect extended lead times in certain categories and the possibility of pricing volatility in commodity-like segments. The most resilient investments are those that account for both upside from electrification and connectivity and the operational complexity that accompanies them.
Worldwide Rail Components Market
For Procurement, Supply-Chain, and Sourcing Leaders
Build sourcing strategies that incorporate qualification readiness, lead-time transparency, and alternate-source planning, especially for automotive-grade and industrial parts where delivery windows can be extended. Treat distributor relationships as strategic channels for new product access and hard-to-source inventory, not merely as transactional routes. Incorporate environmental and supply-chain transparency criteria into supplier evaluations, since these are increasingly part of purchasing decisions. Maintain a disciplined approach to inventory and pipeline visibility, balancing the cost of holding buffer stock against the cost of interrupted production. Where feasible, negotiate for improved visibility, regional delivery options, and design-in support, because these capabilities can reduce risk more effectively than price concessions alone.
Closing Perspective
The electronic components market is large, growing, and structurally complex. The aggregate trajectory points toward sustained expansion, but the real opportunities are distributed unevenly across technologies, applications, and geographies. Companies that map their activities to the segments where demand is intensifying, qualification matters, and supply assurance is valued will be best positioned to convert growth into durable advantage. For leaders seeking to move from broad trends to specific, actionable insight, the full research report provides detailed segment-level data and tailored recommendations to support portfolio, investment, and sourcing decisions with greater precision.
For detailed analysis of this topic, please visit the official page: Electronic Components Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Footwear Market 2026: Beyond the 4.7% CAGR Story and What's Really Driving Growth
By PW Consulting, 2026-09-21
The Strategic Agenda for the Footwear Market: Navigating Growth, Tariffs, and Sustainability Through 2032
1. Market Overview and Core Challenges
The global footwear market has demonstrated resilient expansion over the past five years, growing from approximately $389.5 billion in 2020 to an estimated $483.0 billion in 2025. This trajectory reflects a compound annual growth rate of 4.7% over the historical period, driven by consistent consumer demand, evolving product categories, and geographic shifts in consumption patterns. Looking ahead to the forecast horizon of 2026 through 2032, the market is projected to reach $663.9 billion by the end of the period, with year-on-year increments reflecting both baseline growth and the compounding effect of structural changes across the value chain.
Several converging forces now place the industry at a strategic inflection point. First, tariff architectures and trade policy volatility have reshaped cost structures and sourcing logic. In the United States, average footwear tariffs stand at roughly 23.6%, with certain categories exposed to duties of 48% or higher, and importers paid an estimated $6.221 billion in duties during 2025. This environment compels brands and distributors to rethink landed cost, inventory positioning, and supplier diversification with greater urgency than in prior cycles. Second, regulatory momentum around sustainability and product traceability is accelerating. The EU Ecodesign for Sustainable Products Regulation requires Digital Product Passports for footwear by 2027, raising the bar for transparency, material disclosure, and lifecycle accountability across markets that interact with European supply chains and consumers. Third, the competitive field remains concentrated yet dynamic, with the top three firms capturing roughly 52% of market share and the top five approximately 58%, leaving meaningful room for specialized players, regional champions, and new entrants that can differentiate on performance, comfort, or sustainability claims.
These dynamics create a dual mandate for leadership teams: protect near-term margin and supply continuity while building optionality for regulatory compliance and shifting consumer preferences. The firms that treat these pressures as isolated compliance tasks risk forfeiting share to competitors who embed them into product roadmaps, sourcing strategies, and channel planning.
2. Key Drivers Shaping Market Trajectory
Technology and material innovation continue to redefine product value propositions across athletic, casual, and specialized segments. Advances in midsole geometries, lightweight foams, knit uppers, and comfort-focused constructions have expanded the performance envelope of everyday footwear, while sustainability-oriented materials and processes are increasingly tied to both consumer appeal and compliance readiness. Recent expositions underscore this direction: the Footwear Show New York Expo in June 2026 highlighted sustainable innovations, sculptural heels, and minimalist sneakers as focal points for buyers, signaling that aesthetic experimentation and eco-conscious design are moving in tandem rather than in competition.
Policy and standards environments are exerting an equally powerful pull on decision-making. Beyond tariff exposure, the impending Digital Product Passport requirement in the EU is prompting manufacturers and brand owners to build traceability infrastructure, consolidate material data, and align design choices with recyclability and durability targets. This is not solely a European concern; global suppliers serving multinational accounts are increasingly asked to provide standardized data packages that travel with products across jurisdictions, raising the baseline for documentation and process discipline throughout the supply chain.
Demand-side behavior is evolving around comfort, versatility, and occasion-blurring usage. Footwear and accessories led outdoor retail sales growth in 2024, with a modest rebound continuing into 2025, illustrating how health-oriented activity, leisure travel, and hybrid lifestyles are sustaining demand beyond core athletic use cases. At the same time, consumers are scrutinizing durability, comfort, and authenticity claims more closely, rewarding brands that can credibly connect product performance with responsible sourcing. This creates openings for comfort-led casual lines, performance-oriented running offerings, and specialized work or outdoor boots that serve distinct functional needs while adhering to higher design standards.
Supply chain and cost structures are being reconfigured in response to trade frictions and capacity considerations. Global footwear brands and suppliers have adapted sourcing footprints under U.S. tariff pressures, and acquisitions increased in 2025 as companies sought to offset cost impacts and secure capabilities. This shift is visible not only in brand-level M&A but also in the strengthening of domestic and allied production capacity for specialized categories, including military and tactical footwear, where compliance requirements and national sourcing priorities intersect. Collectively, these supply-side responses are recalibrating lead times, inventory risk, and the economics of made-to-order versus forecast-driven production.
Industry forecasts anticipate low single-digit growth for the broader fashion sector in 2026, with footwear positioned as a key subsector affected by tariff uncertainties and consumer caution. This outlook reinforces the need to prioritize productivity, assortment discipline, and differentiated value over volume-driven expansion in the near term.
3. Competitive Landscape and Strategic Positioning
The market features a broad set of established players spanning athletic and lifestyle performance, comfort-led casual lines, outdoor and work footwear, and specialized tactical or safety boots. Companies such as Nike, adidas America, ASICS America, Puma, New Balance, Crocs, Skechers, and Brooks Running anchor the athletic and lifestyle segments, each emphasizing distinct blends of performance, style, and mass-market accessibility. Nike and adidas continue to leverage global brand equity and broad category coverage across athletic and lifestyle footwear, while ASICS and Brooks Running concentrate on performance-oriented running and training offerings that serve dedicated user bases. Puma complements this field with athletic and lifestyle positioning that bridges sport and culture, and New Balance has strengthened its dual identity across performance running and casual footwear.
In the comfort and casual space, Crocs, Skechers, Clarks, ECCO, Geox, and Rieker illustrate the breadth of consumer appeal around ease, fit, and everyday wearability. Crocs focuses on casual, comfortable, and lifestyle footwear with recognizable design signatures, while Skechers emphasizes comfort-driven casual styles. Clarks, ECCO, Geox, and Rieker each bring differentiated perspectives on comfort, breathability, and orthopedic-friendly design, appealing to segments that prioritize long-wear comfort and functional materials. Premium casual and lifestyle positioning is further reinforced by ECCO’s design-led approach and Geox’s specialization in breathable comfort footwear, giving consumers multiple entry points into the casual category.
Outdoor, work, and safety footwear represents a distinct strategic layer, with firms such as Timberland, Wolverine World Wide, Red Wing Shoe Company, Danner, Belleville Boot Company, McRae Industries, Made Plus, and Steinberg Systems addressing durability, protection, and specialized compliance needs. Timberland offers outdoor, work, and lifestyle footwear that bridges function and style, while Wolverine World Wide’s brand portfolio spans work, outdoor, and broader footwear segments. Red Wing and Danner emphasize work, outdoor, and safety-oriented boots, with Red Wing also extending into casual boot offerings. Belleville Boot Company and McRae Industries serve military and tactical requirements, with McRae noted for Berry Amendment-compliant combat boots and Belleville for military and tactical footwear. Made Plus has entered the conversation with next-generation performance footwear that combines performance and sustainability focus, while Steinberg Systems contributes to the work and safety footwear manufacturing base.
Sports Footwear Market
Recent developments indicate a market in which membership, capacity, and trade events are reinforcing supply-side alignment and product innovation. McRae Industries was welcomed as the newest USFMA manufacturer member in May 2026, underscoring its legacy in Berry Amendment-compliant military combat boots. YKK Americas joined the association in April 2026, expanding national capacity for military boot production following its acquisition of Collt’s Manufacturing. In February 2026, USFMA added Gusbi, Autec Automation, and Robot System Automation as Italian footwear machinery leaders to enhance U.S. production capacity for domestic manufacturers. On the commercial side, the Footwear Show New York Expo in June 2026 showcased sustainable innovations, sculptural heels, and minimalist sneakers to buyers, and the 26th International Shoes & Leather Exhibition in Ho Chi Minh City was scheduled for July 2026 to promote new machinery, materials, and sustainable footwear initiatives. These events and membership moves reflect a broader tendency to strengthen production capabilities, align on compliance and traceability, and surface product directions that blend sustainability with design differentiation.
Strategically, the landscape is evolving through both consolidation and fragmentation. Concentration among leading firms remains significant, yet the breadth of specialized players indicates that differentiation by function, comfort, compliance, and materials can support durable positions even in a concentrated market. New entrants and established niche players can gain traction by solving specific problems—whether that is performance-per-wear in running, all-day comfort in casual settings, or regulated compliance in defense and industrial applications—while larger incumbents pursue scale, brand breadth, and channel leverage. The net effect is a market in which leadership is increasingly defined not only by volume but by the ability to align product, supply, and compliance narratives with the priorities of distinct customer groups.
4. Future Trends and Commercial Opportunities (2026–2031)
One defining trend for the next several years is the integration of compliance and traceability into product design and sourcing decisions. As Digital Product Passport requirements take effect and sustainability expectations rise, footwear that can demonstrate material provenance, durability, and end-of-life considerations will gain advantages in regulated channels and among informed consumers. This creates commercial opportunities for manufacturers and brand owners that invest early in data collection, material standardization, and design-for-circularity, turning compliance from a cost center into a trust signal that supports premium positioning and retailer relationships.
A second trend is the continued recalibration of supply chains around cost, resilience, and category-specific needs. Tariff exposure and acquisition activity through 2025 have accelerated shifts in sourcing geography, supplier consolidation, and the selective development of domestic or allied capacity for specialized products. Over the forecast period, firms are likely to pursue more flexible manufacturing arrangements, closer coordination between brands and tier-one suppliers, and greater use of automation and machinery partnerships to improve responsiveness. The expansion of production capacity for military and tactical footwear, supported by machinery and membership developments, illustrates how category-specific requirements can drive targeted capacity investments that differentiate suppliers in regulated segments.
A third trend is the broadening of usage occasions and the corresponding rise of hybrid product strategies. Footwear and accessories have led outdoor retail sales growth, and the modest rebound into 2025 suggests sustained appetite for products that support active leisure, travel, and everyday wear. This environment favors lines that balance performance, comfort, and style, such as minimalist sneakers, sculptural heel designs, and comfort-focused casual footwear. Brands that can bridge athletic-derived technologies with lifestyle aesthetics, or that can offer durable outdoor and work products with consumer-facing design appeal, are well positioned to capture spend across overlapping occasions.
PW Consulting
These trends carry both opportunity and uncertainty. Growth is expected to continue, but low single-digit industry growth in 2026 and ongoing tariff uncertainties mean that volume-led expansion will be less reliable than disciplined assortment planning, cost control, and differentiated value creation. Additionally, regulatory timelines, consumer receptivity to sustainability claims, and the pace of supply chain restructuring will vary by region and category, requiring scenario-based planning rather than single-point forecasts. Firms that prepare for multiple pathways—by building traceability readiness, diversifying sourcing options, and maintaining agile product development cycles—will be better placed to capture upside while limiting exposure to shocks.
5. Actionable Recommendations for Decision-Makers
For manufacturers and brand owners, the priority is to align product roadmaps with compliance and consumer value at the same time. This means embedding traceability and material disclosure considerations into design phases, prioritizing constructions and materials that support both performance and sustainability narratives, and evaluating sourcing options against tariff exposure and lead-time reliability. Companies should also assess where specialized capacity—such as regulated military or safety footwear, comfort-led casual lines, or performance running—can be strengthened through equipment partnerships, selective acquisitions, or closer supplier integration, particularly as machinery and membership developments continue to expand production capabilities.
Military Footwear Market
For investors, the strategic question is where differentiation is durable enough to support margin and share gains in a concentrated yet diverse market. Opportunities are likely to be found in segments where function, comfort, and compliance intersect, in suppliers that can provide traceability and data infrastructure, and in brands that combine athletic-derived technology with lifestyle appeal. Due diligence should weigh tariff sensitivity, regulatory readiness, assortment discipline, and the credibility of sustainability claims, while monitoring consolidation activity and capacity investments that may reshape competitive dynamics. A selective approach that favors defensible niches and operationally resilient business models is better suited to a low single-digit growth environment than broad-based volume bets.
For procurement and distribution leaders, the imperative is to manage landed cost and assortment risk without sacrificing the product variety that drives demand. Diversifying sourcing where feasible, negotiating with visibility into tariff exposure, and prioritizing suppliers that can deliver consistent data packages for compliance will reduce friction as Digital Product Passport requirements and retailer expectations intensify. Procurement teams should also align category strategies with usage trends, ensuring that comfort, outdoor-adjacent, and lifestyle-led lines are represented in ways that reflect actual consumer behavior rather than legacy category boundaries. Building supplier relationships that emphasize transparency, responsiveness, and proven compliance readiness will become a structural advantage in negotiations and assortment planning.
Across these audiences, timely access to detailed market intelligence supports better decisions. Detailed segmentation data, competitor benchmarking, and scenario analysis can clarify where growth is most attainable, which compliance investments matter earliest, and how sourcing shifts affect cost and service levels. For decision-makers who need granular breakdowns, supplier-level insight, and tailored recommendations, the full research report provides the depth required to translate these strategic trends into concrete plans.
For detailed analysis of this topic, please visit the official page: Footwear Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


