



Category: market research
Contact Image Sensor Market: What the 7.2% CAGR and 2032 $2.5B Trajectory Really Mean
By PW Consulting, 2026-09-21
The Contact Image Sensor Market: Navigating Structural Shifts and Strategic Growth Trajectory Through 2032
Market Landscape and Critical Inflection Points
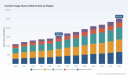
The Contact Image Sensor market has transitioned from a mature, incremental growth phase into a period of strategic redefinition. Revenue crossed the 1.5 billion USD threshold in the 2025 base year, building on a steady upward trajectory from approximately 1.09 billion USD in 2020. The expansion has been broad-based, with consistent year-over-year gains reflecting steady adoption across imaging, document handling, and industrial inspection workflows. Projected forward through 2032, the market is expected to reach roughly 2.52 billion USD, underpinned by a compound annual growth rate of 7.2 percent. This growth profile signals more than legacy replacement cycles; it indicates structural demand formation tied to digitization, automation, and quality control imperatives across multiple verticals.
Within this trajectory, the market exhibits a balanced spatial distribution across developed and emerging economies, with North America, Europe, and Asia Pacific each contributing meaningfully to aggregate demand. Type segmentation shows monochrome and color imaging maintaining substantial and relatively comparable footprints, reflecting a market where application requirements, rather than pure technology preference, dictate adoption. On the application side, scanners and copy machines continue to anchor volume, while surface inspection systems and banknote readers represent higher-value, specification-driven segments. The concentration profile remains notably consolidated, with the top three participants capturing a disproportionate share of revenue and the top five commanding an even larger portion of total market activity. This structure shapes pricing dynamics, innovation pacing, and the strategic options available to both incumbents and new entrants.
Despite the favorable growth math, the industry is passing through a set of inflection points that will determine which participants capture disproportionate value over the next several years.
1. The Shift From Commodity Imaging to High-Specification Inspection
The market is no longer driven primarily by basic document digitization. Instead, a growing portion of demand is migrating toward inspection-grade performance, where resolution, line speed, contrast handling, and dimensional repeatability matter more than unit cost alone. This shift changes the value equation for Contact Image Sensors: devices that once competed on price and availability must now demonstrate imaging fidelity, environmental robustness, and integration readiness. Suppliers that treat the sensor as a commoditized component risk being squeezed into low-margin volume streams, while those that align performance with application-specific tolerances can command stronger positioning.
2. Integration Complexity as a Competitive Moat and Barrier
As end systems become more compact and performance expectations rise, the sensor is increasingly evaluated as part of a broader optical and electrical subsystem rather than as an isolated component. Illumination design, signal processing, module form factors, and OEM integration support are becoming integral to commercial success. This creates a higher bar for market entry and rewards companies that can deliver complete, validated solutions rather than discrete sensor SKUs. At the same time, it places pressure on assembly, calibration, and support capabilities, which can erode differentiation if not managed deliberately.
3. Regulatory and Export Control Sensitivities Emerging in High-Performance Segments
Performance-driven adoption is beginning to intersect with trade and export control considerations. Equipment and sensing technologies capable of sub-micron surface repeatability or high-accuracy measurement are increasingly subject to regulatory scrutiny in select jurisdictions. While this does not constrain the entire Contact Image Sensor market, it introduces a meaningful overlay for high-specification machine vision and inspection applications. Companies operating in these segments must anticipate compliance requirements earlier in product development, rather than treating them as post-design checks.
Key Drivers Shaping Market Trajectory
The 7.2 percent growth path through 2032 is not a uniform expansion. It is being shaped by a combination of technology, regulation, demand behavior, and supply-side economics that reward participants who align their roadmaps with where value is actually forming.
Technology Innovation and Performance Leapfrogging
Innovation in Contact Image Sensors is increasingly centered on resolution, line rate, and dynamic range, particularly for inspection and machine vision use cases. The push toward higher dpi and extended scan lengths is enabling more demanding defect detection, surface characterization, and print-quality verification tasks. Recent product expansion from Teledyne DALSA illustrates this direction clearly: the extension of its AxCIS family with new 1,800 dpi and 1,500 mm models, delivering monochrome line rates up to 80 kHz with HDR capability, reflects a market moving toward faster, higher-fidelity line-scan imaging for semiconductor wafer, battery, and print inspection. This type of advancement does more than add specification points; it expands the addressable set of applications where Contact Image Sensors can compete against alternative imaging architectures.
Equally important is the growing emphasis on customization and color capability. CMOS Sensor Inc’s focus on custom-designed Contact Image Sensors supporting color imaging and diverse application needs underscores a parallel trend: differentiation is increasingly tied to tailoring sensor characteristics to specific workflows. In a consolidated market, the ability to adapt resolution, color response, and integration parameters can be the difference between being specified in a system design or being bypassed by a more flexible alternative.
Regulation, Compliance, and the Redefinition of Eligible Applications
Policy and trade controls are becoming a more visible factor in how high-performance sensing technologies are deployed and sold. Canada’s Export Control List, updated in May 2025, includes sensors and lasers in Category 6 with specific clauses for equipment capable of measuring surfaces with sub-micron repeatability or 0.5 mm accuracy. This does not halt market growth, but it does introduce a segmentation effect: some high-specification inspection applications will require additional compliance consideration, documentation, and channel discipline. For suppliers, the practical implication is that performance leadership must be paired with regulatory literacy, especially where accuracy and repeatability become selling points. For buyers, it means that sourcing strategies need to account for documentation, origin, and end-use classification more carefully than in the past.
Demand-Side Evolution: From Office Imaging to Industrial and Security Workflows
A major driver of sustained demand is the broadening of application contexts beyond traditional document handling. Scanners and copy machines remain substantial demand anchors, but surface inspection systems and banknote readers represent segments where the sensor is tied to operational integrity, security, and quality assurance. In these environments, imaging is not a convenience feature; it is a control function. That shift increases the willingness to invest in sensor performance and reliability, while also raising the cost of failure.
At the same time, large-format document and print workflows continue to create niche but strategically meaningful demand. ColorTrac’s focus on CIS-based large-format scanners for wide-format printing and document handling points to a segment where scan width, document handling, and imaging consistency matter more than aggressive cost reduction. This kind of application specialization often offers steadier margins than high-volume commodity scanning, especially where the sensor is tightly coupled to a defined system architecture.
Supply Chain and Cost Structure Realignment
Cost dynamics are being reshaped by both component-level innovation and broader supply-chain realignment. On one hand, advances in CMOS sensor ICs and illumination integration allow higher performance without necessarily increasing system complexity in a linear fashion. On the other hand, the consolidation of supply around a limited number of capable providers means that continuity, qualification, and long-term availability are becoming strategic purchasing considerations. The market’s concentration profile means that buyers cannot assume frictionless switching between suppliers; qualification cycles, firmware or interface compatibility, and support arrangements can create real sticking points.
A significant structural signal comes from Mitsubishi Electric Corporation, which issued a notice of Contact Image Sensor business transfer to affiliated Miyoshi Electronics Corporation effective April 1, 2028, with production relocation and a long-term customer supply commitment. This type of organizational move matters because it signals how incumbents are restructuring their manufacturing and support footprint to preserve continuity while repositioning operational control. For customers and partners, the key question is not whether supply will continue, but how transition timing, production relocation, and documentation will be managed without disrupting qualification or field performance.
Cmos Image Sensor For Adas Market
Competitive Landscape and Emerging Strategic Postures
The Contact Image Sensor market is defined by a small group of capable players with distinct differentiation strategies. Rather than competing solely on price, leading participants are carving out positions based on performance class, integration support, application specialization, and continuity assurance. This creates a landscape where strategic advantage is less about being the largest sensor vendor and more about being the most reliable solution partner for specific high-value application sets.
Incumbent Performance Leadership and Application Alignment
Mitsubishi Electric Corporation has built its positioning around high-performance Contact Image Sensors with original CMOS sensor ICs and illumination solutions aimed at surface inspection, copy machines, and banknote applications. The emphasis on original ICs and illumination integration indicates a strategy centered on controlling critical subsystems rather than assembling interchangeable parts. This approach aligns well with inspection and security-oriented applications where image consistency and lighting uniformity directly affect system performance. At the same time, the announced business transfer to Miyoshi Electronics Corporation reflects a long-cycle move to reorganize production and supply responsibility while preserving customer commitments. For the market, this suggests continuity in the near term, but also an evolving ownership and operational structure that participants should monitor as the 2028 transition approaches.
High-Speed Line-Scan Focus for Machine Vision
Teledyne DALSA has positioned itself around high-speed, high-resolution integrated line-scan Contact Image Sensors for machine vision inspection, with the AxCIS family targeting semiconductor wafer, battery, and print applications. The company’s recent expansion into 1,800 dpi and 1,500 mm models with 80 kHz monochrome line rates and HDR reinforces a strategy aimed at the upper end of performance requirements. This is a meaningful competitive posture because it ties product leadership directly to inspection scenarios where speed and resolution translate into throughput and defect-detection confidence. In a market where some volumes remain price-sensitive, this focus allows Teledyne DALSA to compete on specification-driven value rather than pure unit economics.
Customization and OEM-Ready Integration as Differentiators
CMOS Sensor Inc and FRAMOS GmbH represent a different but complementary set of strategic angles. CMOS Sensor Inc emphasizes custom-designed Contact Image Sensors with support for color imaging and application-specific customization, positioning flexibility as a commercial advantage where standard SKUs do not fully match system requirements. FRAMOS GmbH focuses on integration of high-quality CIS modules into compact scanning and machine vision systems, including electrical and optical specification support and OEM equipment compatibility. Together, these profiles highlight an important market reality: in a consolidated environment, many wins are decided by integration ease, specification tailoring, and the ability to reduce time-to-deployment for equipment manufacturers.
PW Consulting
Application-Locked Niche Positioning
ColorTrac’s CIS-based large-format scanners for wide-format printing and document handling demonstrate the value of application-locked specialization. In wide-format workflows, scan width, mechanical handling, and imaging consistency can be more decisive than marginal sensor cost differences. This kind of positioning can be resilient because it is tied to a defined use case with limited substitution, although it also depends on continued demand in the underlying printing and document-handling segments.
Market Structure Evolution: Consolidation, Selective Specialization, and Entry Risk
The market’s concentrated revenue distribution implies that broad-based new entry will face meaningful barriers. Qualification cycles, integration support demands, and the established relationships between sensor suppliers and equipment manufacturers all raise the bar for entry. At the same time, the landscape is not static. There is room for selective specialization, especially where a new or expanding participant can match a high-specification requirement, provide better integration support, or offer a more flexible customization model for a defined application set. The more probable structural evolution is not a wholesale reshuffling of leaders, but a continued sorting of the market into performance-driven inspection segments, integration-heavy OEM relationships, and application-specialized niches. Consolidation pressure may intensify where scale, qualification depth, and supply continuity matter most, while differentiation opportunities remain stronger where customization and application alignment are valued over pure volume.
Outlook: Three Strategic Trends for the Next Three to Five Years
Trend 1: Inspection-Grade Imaging Will Become the Core Growth Engine
Over the next several years, the most attractive growth pocket is likely to remain inspection and machine vision applications, where resolution, speed, and dynamic range translate directly into operational value. This trend favors suppliers that can deliver repeatable high-performance modules and the surrounding support needed for industrial integration. The commercial opportunity lies not only in selling sensors, but in enabling end systems that can justify higher specification investment through improved defect detection, throughput, and audit readiness.
The associated risk is performance overreach without application fit. Specifying sensors for the highest available resolution or line rate does not automatically produce better outcomes if illumination, processing, or mechanical constraints are not addressed in tandem. In inspection-driven segments, the winners are likely to be those who can align sensor capability with system-level tolerances and validation requirements.
Trend 2: Long-Cycle Supply Continuity and Organizational Restructuring Will Shape Purchasing Confidence
As production footprints and business structures evolve among major participants, supply continuity will become an increasingly prominent purchasing criterion. The Mitsubishi Electric-to-Miyoshi Electronics transfer is a clear example of how incumbents may reorganize manufacturing responsibility while attempting to preserve long-term supply commitments. For buyers, this creates both reassurance and planning complexity: continuity is intended, but transition timing, engineering support, and documentation will need active management.
Strategically, this trend increases the value of supplier stability, qualified second sources where feasible, and clear roadmap visibility. For participants on the supply side, the opportunity lies in making transitions predictable and minimizing qualification disruption. The uncertainty is that organizational changes can alter support models, response times, and regional availability even when nominal supply continues.
Trend 3: Regulation Will Act as a Segment Filter Rather Than a Market-Wide Constraint
Trade and export-control developments are likely to function as a segmentation mechanism, particularly influencing high-accuracy, sub-micron-class inspection applications. The practical effect is not a blanket slowdown, but a need for earlier compliance consideration in product definition, documentation, and channel strategy. Companies that proactively address classification and end-use considerations will encounter fewer surprises when targeting high-specification projects across multiple regions.
Worldwide 3D Image Sensor Market
The risk here is complacency. As accuracy and repeatability become stronger competitive differentiators, the same attributes can attract regulatory attention. This creates a feedback loop in which performance leadership must be matched by compliance readiness, especially for suppliers and buyers operating in cross-border equipment programs.
Actionable Implications for Decision Makers
For Equipment Manufacturers and Integrators
Treat sensor selection as a system-level decision rather than a discrete component purchase. In inspection and high-specification scanning applications, prioritize suppliers that can support illumination integration, module form factors, electrical and optical specification alignment, and OEM deployment needs. Where applications require color imaging or specialized customization, evaluate flexibility and development support early, because late-stage adaptation can erode time-to-market advantages.
Also, build continuity planning into sourcing strategy. In a concentrated market, switching costs are not just pricing-related; they include qualification, compatibility, and support dependencies. Mapping transition risk, including production relocation or business structure changes, should be part of long-term procurement planning.
For Investors and Strategic Partners
Look beyond headline market size and focus on where specification-driven value is forming. The most compelling exposure is likely in segments where imaging performance directly affects quality, security, or throughput, and where integration support is a meaningful part of the commercial proposition. In those areas, differentiation is less fragile than in commoditized scanning volumes, and competitive position can be more durable when tied to application lock-in and validation requirements.
At the same time, monitor organizational and supply-chain transitions among leading participants. Restructuring can create both opportunity and risk, depending on how smoothly production, support, and documentation are managed. The strategic question is whether a transition strengthens continuity or introduces uncertainty in qualification and service.
For Procurement and Operations Leaders
Strengthen qualification frameworks and documentation expectations, especially for higher-accuracy and inspection-oriented deployments. Where regulatory sensitivity may apply, coordinate early with internal compliance and trade-control functions so that accuracy and repeatability claims do not create unintended classification exposure. Establish clearer criteria for supplier stability, support responsiveness, and long-term availability, since these factors will increasingly determine operational resilience in a concentrated market.
Finally, avoid assuming that specification parity equals substitutability. Two sensors may appear similar on a datasheet while differing substantially in integration effort, support model, or transition risk. Procurement decisions that incorporate total deployment cost and continuity risk are better positioned than decisions based solely on unit price or headline performance.
The Contact Image Sensor market is moving into a phase where growth is increasingly tied to performance specificity, integration readiness, and supply continuity rather than broad volume expansion alone. That shift creates clearer routes to differentiation for participants who align their capabilities with the right application sets, but it also raises the stakes for buyers who must navigate consolidation, transition planning, and emerging regulatory considerations. For decision makers seeking detailed segment splits, regional revenue structures, concentration analysis, and company-level tracking through 2032, a full scope market intelligence report can provide the more granular framework needed to translate these trends into concrete sourcing, investment, and product decisions.
For detailed analysis of this topic, please visit the official page: Contact Image Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The Shipping Software Market: Strategic Trends and Commercial Opportunities Through 2032
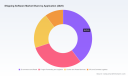
The shipping software market has entered a decisive growth phase, driven by the compounding effects of e-commerce expansion, digital fulfillment mandates, and enterprise modernization programs. Valued at approximately $2.19 billion in 2025, the market has expanded consistently over the past half-decade and is projected to accelerate toward a ~$3.87 billion valuation by 2032, reflecting a compound annual growth rate of 8.5 percent over the 2026–2032 forecast window. This trajectory is not merely a function of volume growth; it signals a structural reorientation in how shippers, logistics providers, and merchant networks orchestrate transportation execution, rate optimization, and customer-facing delivery experiences. The sector is no longer defined by simple label printing or carrier selection. It has evolved into a critical control layer that connects order management, warehouse operations, freight procurement, and post-purchase engagement into a unified operational fabric.
Despite the favorable expansion path, the market is navigating a series of inflection points that will shape competitive outcomes over the next several years. The following analysis examines the forces driving this transformation, maps the strategic positioning of leading participants, and outlines the commercial opportunities and risks that executives and investors should monitor as the landscape matures.
Market Context: Growth Trajectory and Structural Headwinds
The market's expansion over the 2020–2025 period demonstrates resilient demand across multiple buyer segments, with the 2025 valuation establishing a foundation for more aggressive growth in the forecast period. The projected acceleration toward the late 2020s and early 2030s reflects both incremental adoption and deeper enterprise penetration, as organizations move from point solutions to integrated shipping orchestration platforms. Growth is being reinforced by the ongoing shift to cloud-based architectures, which now represent the dominant deployment model, and by sustained demand from commerce-driven fulfillment environments that require rapid carrier selection, automation, and customer visibility.
However, several structural challenges are reshaping how vendors position their offerings and how buyers evaluate procurement decisions. Three dynamics merit particular attention.
Operational Cost Pressure and Infrastructure Economics
Shipping software buyers are increasingly sensitive to total cost of ownership, not only in license or subscription terms but also in the underlying infrastructure and integration costs required to operate at scale. Cloud hosting and infrastructure expenses can range from several hundred to multiple thousands of dollars per month depending on transaction volume and architecture choices, while API usage at scale introduces incremental fee structures that can accumulate quickly as call volumes rise. For enterprises processing high parcel volumes, these operational costs become material line items that influence platform selection, vendor negotiation, and architectural decisions around multi-carrier abstraction layers. The practical implication is that shipping software is no longer evaluated solely on feature breadth; buyers are scrutinizing cost predictability, usage-based pricing transparency, and the efficiency of underlying integration patterns.
Regulatory Shifts and Data Transfer Economics
Changing regulatory frameworks are beginning to influence cloud economics and data handling requirements, with implications for how shipping platforms manage cross-border data flows, carrier integrations, and customer information. Forthcoming requirements such as the EU Data Act, taking effect in early 2027, are expected to affect cloud transfer fees and pricing dynamics for data-intensive workloads. Shipping software that depends on continuous data exchange across carriers, marketplaces, and global fulfillment nodes will need to account for evolving compliance expectations and potential cost shifts tied to data movement. This creates both a compliance burden and a strategic consideration for vendors offering global multi-carrier capabilities, as regulatory alignment increasingly factors into enterprise procurement criteria.
Labor Dynamics, Incident Cost, and Operational Resilience
While shipping software is a technology category, its value proposition is tightly linked to labor efficiency and operational continuity. Workforce spending remains a dominant cost center across logistics-heavy environments, and downtime or incident response can carry significant financial consequences when fulfillment operations are disrupted. Shipping platforms are therefore expected to demonstrate not only automation depth but also reliability, rapid issue resolution, and integration stability. The market is tilting toward solutions that reduce manual intervention, streamline exception handling, and minimize operational friction during peak shipping periods. Resilience is becoming a competitive differentiator.
Core Drivers Reshaping the Shipping Software Landscape
The current growth cycle is being propelled by several interrelated forces. Understanding how these drivers interact provides a clearer view of where value is being created and where competitive advantage is likely to consolidate.
Technology Innovation and API-Centric Architecture
One of the most consequential shifts in the market is the move toward API-first shipping orchestration. Cloud-based shipping APIs now enable rate shopping, label creation, address verification, tracking, and return workflows across hundreds of carriers through standardized integration layers. This architecture reduces development overhead for merchants and platforms that need to connect multiple carriers without building bespoke integrations one by one. It also supports modular adoption, where shipping functionality can be embedded into commerce platforms, order management systems, or fulfillment workflows without requiring a monolithic replacement of existing systems.
The rise of versionless or continuously updated software models further reinforces this trend. Rather than waiting for periodic releases, buyers increasingly expect incremental feature delivery, ongoing carrier rule updates, and dynamic automation capabilities that adapt to changing shipping conditions. At the same time, advanced functionality such as branded tracking, predictive delivery estimates, and returns management is extending the value of shipping software beyond execution into customer experience and post-purchase engagement. This expansion broadens the addressable use case and increases the strategic importance of shipping platforms within the commercial technology stack.
Demand-Side Evolution in Commerce and Fulfillment
buyer behavior is reshaping requirements on multiple fronts. E-commerce and retail fulfillment continue to exert strong demand for scalable shipping automation, multi-carrier rate optimization, and seamless platform integrations with ecosystems such as Shopify, WooCommerce, and other commerce environments. At the same time, freight forwarding, logistics providers, courier and postal services, and third-party logistics operators are seeking more capable multi-carrier execution tools that can handle mixed parcel and LTL workflows, broker rating, and enterprise system integration.
A notable shift is the growing expectation that shipping software should support brand-consistent delivery experiences and flexible fulfillment choices. Shoppers increasingly expect transparent tracking, accurate delivery estimates, and easy returns, while merchants want to manage carrier selection dynamically based on cost, speed, and service levels. This pushes vendors to integrate rate optimization, delivery promise communication, and post-purchase visibility into a single workflow rather than treating them as separate concerns.
Salon Software Market
Supply Chain Complexity and Multilayer Logistics Requirements
Shipping software is also being reshaped by the increasing complexity of supply chain execution. Organizations are managing more intricate fulfillment networks, cross-region shipping obligations, and hybrid parcel/LTL operations. In this environment, the ability to consolidate carrier management, support enterprise integrations with ERP and warehouse systems, and provide multi-carrier abstraction becomes a practical necessity rather than a convenience feature.
This complexity favors platforms that can act as an intermediate control layer between enterprise systems and carrier ecosystems. For large shippers and logistics service providers, the value lies in reducing fragmentation, standardizing rate and label workflows, and enabling centralized decision-making across carrier options. As a result, the market is seeing heightened interest in solutions that combine parcel execution with broader transportation and supply chain management capabilities, as well as in connectors that link shipping software to major enterprise platforms.
Partnerships, Enterprise Integrations, and Ecosystem Expansion
A growing number of partnerships are extending shipping software reach into enterprise environments. Recent integration activity has connected multi-carrier parcel shipping capabilities with major cloud SCM and ERP ecosystems, enabling organizations to embed shipping execution within broader enterprise workflows. These collaborations are strategically important because they lower adoption friction for large buyers and accelerate deployment in environments where standalone shipping tools would otherwise require extensive customization.
PW Consulting
This ecosystem-oriented approach is also visible in product refinements that target operational specificity, such as expanded automation rules for regional address handling, broker rating enhancements, and multi-carrier support improvements. Rather than positioning shipping software as a static utility, leading vendors are investing in capabilities that adapt to changing carrier rules, regional requirements, and enterprise integration needs. The trend suggests that competitive advantage will increasingly belong to platforms that can combine API flexibility, enterprise connectivity, and ongoing operational updates within a manageable cost structure.
Competitive Dynamics and Strategic Positioning
The shipping software market is characterized by a broad set of participants spanning standalone shipping platforms, API-centric providers, enterprise supply chain vendors, and large technology companies with shipping integrations. Market concentration remains moderate, indicating that no single player dominates the entire landscape, but a cluster of established vendors holds meaningful share through product breadth, carrier relationships, and ecosystem reach.
Differentiation Among Leading Participants
Competitive positioning generally falls along a few distinct axes. Some vendors emphasize multi-carrier rate comparison, label automation, and shipment execution for SMB and mid-market commerce users. Others focus on API-first abstraction layers that let platforms and enterprises integrate shipping functionality at scale. A third group anchors its strategy in enterprise-grade supply chain and transportation management, where shipping execution is part of a broader operational suite. A fourth segment extends into post-purchase experience, using branded tracking and delivery communication as a differentiator that supports customer retention and brand consistency.
- Multi-carrier execution and automation remain foundational. Vendors in this space compete on carrier breadth, rate shopping intelligence, and the ability to handle high-volume fulfillment workflows with minimal manual intervention.
- API and platform integration capabilities are increasingly decisive for technology-forward buyers. Providers that offer clean abstraction layers, address verification, and scalable tracking support can embed themselves more easily into commerce and logistics ecosystems.
- Enterprise integration and ERP alignment create stickiness in larger accounts. Shipping solutions that connect cleanly to enterprise resource planning and warehouse systems reduce operational silos and support consolidated procurement and execution.
- Customer-facing shipping experiences are becoming a competitive lever. Branded tracking, estimated delivery communication, and returns management extend the software's role from operational utility to commercial enablement.
Evolution of the Market Structure
The market appears to be moving toward a dual pattern of consolidation and specialization. On one hand, larger enterprise vendors and well-resourced platform providers are strengthening their positions through integration depth, carrier reach, and broader supply chain alignment. On the other hand, specialized players continue to compete by targeting clearly defined buyer needs, such as e-commerce shipping automation, API-centric parcel orchestration, or post-purchase engagement tools.
New entrants and incumbent expansion both remain viable paths, but the bar is rising. Buyers increasingly expect carrier coverage, integration flexibility, automation depth, and predictable operating costs. As a result, pure point solutions must demonstrate a strong niche advantage or a clear path to integration breadth, while broader platforms must prove they can deliver shipping-specific usability and carrier-level accuracy without becoming overly complex. The competitive frontier is shifting toward solutions that can operate as a reliable intermediary across carriers, enterprise systems, and customer-facing workflows while keeping cost structures transparent.
Recent Moves and What They Signal
Recent industry activity underscores the strategic importance of product continuity, leadership focus, and ecosystem integration. Recognition of leading vendors in shipping software reflects the market's heightened attention to operational reliability and solution maturity. Leadership appointments in sending technology and shipping solutions indicate that organizations are investing in focused management attention for core shipping capabilities. Product updates that expand automation rules, regional support, and broker rating functionality show that vendors are tuning their platforms for practical operational complexity rather than merely adding surface-level features.
Partnership activity connecting multi-carrier parcel shipping with major cloud SCM environments is particularly telling. These moves lower the barrier for enterprises to adopt advanced shipping functionality within existing systems and suggest that integration readiness is becoming a competitive necessity. At the same time, feature launches around broker rating and carrier management point to a wider recognition that shipping software must support nuanced procurement decisions, not just execution. Taken together, these developments indicate a market that is maturing rapidly and rewarding vendors that can combine technical agility with operational relevance.
Forward Outlook: Three Trends to Watch Through 2032
Looking ahead, the shipping software market is likely to be shaped by a small number of high-impact trends. These developments will influence vendor strategy, buyer expectations, and the allocation of investment capital.
Real Estate Software Market
Trend 1: From Execution Tool to Orchestration Platform
Shipping software is increasingly positioned as an orchestration layer rather than a transactional utility. That means broader responsibility for rate optimization, carrier selection logic, exception handling, delivery communication, and returns workflows. Over the next three to five years, platforms that can unify these functions in a configurable, API-accessible architecture will likely capture more enterprise value. The commercial opportunity lies in selling not just shipping labels or rate comparison, but operational control, cost optimization, and customer experience consistency across channels and regions.
The risk here is complexity creep. As platforms broaden their scope, they must preserve usability, carrier accuracy, and deployment speed. Buyers may resist solutions that become too heavy or expensive relative to the value they deliver. The winners will be those that expand capability without sacrificing integration clarity or cost predictability.
Trend 2: Ecosystem Embedding and Enterprise Interoperability
Enterprise adoption will continue to favor shipping software that fits cleanly into broader technology environments. Integration with ERP, cloud SCM, order management, and warehouse systems will be a key enabler of scale, especially for organizations that want centralized governance over carrier selection and fulfillment execution. Partnerships and prebuilt connectors will likely become more important than custom integration work as buyers seek faster time-to-value and lower operational risk.
This creates opportunity for vendors that invest in ecosystem alignment and enterprise-grade reliability. It also raises the stakes for smaller providers that lack integration depth, unless they can win through niche focus, superior developer experience, or distinctive post-purchase capabilities. A practical uncertainty is the pace and consistency of enterprise platform evolution, which can affect integration roadmaps and dependency management.
Trend 3: Cost Transparency, Compliance, and Operational Resilience
As infrastructure and API usage costs become more visible in buyer evaluations, platforms that offer predictable pricing, efficient data handling, and resilient operations will gain an advantage. At the same time, regulatory developments affecting data transfer and cloud economics will require vendors and buyers to plan for evolving compliance obligations. Shipping software that handles cross-border data flows, carrier integrations, and customer information will need to demonstrate both operational efficiency and regulatory awareness.
The commercial implication is that cost structure and compliance readiness will become more differentiated factors in procurement decisions. Buyers will likely favor solutions that make usage economics easier to forecast and that reduce the burden of adapting to new regulatory requirements. The risk side includes potential shifts in cloud transfer costs, API pricing pressure at scale, and the operational impact of downtime or incident response during high-volume periods. Resilience will not be a nice-to-have; it will be part of the value equation.
Strategic Implications for Decision-Makers
The shipping software market offers meaningful opportunities, but the right course of action depends on the role an organization plays in the value chain. The following recommendations are intended to translate market dynamics into practical strategic choices.
For Shipping Software Vendors and Technology Manufacturers
Product strategy should emphasize orchestration breadth without sacrificing integration simplicity. vendors that can combine multi-carrier execution, API accessibility, enterprise interoperability, and customer-facing delivery tools will be better positioned to capture expanding demand across commerce, logistics, and enterprise segments. Equally important is cost structure discipline: usage-based economics, cloud hosting assumptions, and API fee exposure should be modeled clearly so that pricing remains competitive as transaction volumes grow.
Investment in automation depth and operational adaptability also deserves priority. Regional address handling, broker rating, carrier rule changes, and peak-season operational needs are not edge cases; they are central to reliable fulfillment at scale. Vendors that keep pace with these requirements while maintaining a clear developer and administrator experience will strengthen their competitive standing.
For Investors and Strategic Allocators
The market's 8.5 percent CAGR trajectory and expanding enterprise penetration suggest continued demand, but differentiation will matter more over time. Investors should look beyond headline growth and assess whether a company has durable advantages in carrier relationships, integration ecosystems, automation depth, or post-purchase engagement. Concentration dynamics indicate room for both scaled incumbents and specialized challengers, but long-term winners are likely to be those that can defend margins while expanding scope.
It is also prudent to monitor operating cost exposure and compliance readiness as selection criteria that may influence churn, expansion, and competitive displacement. Companies that can articulate a clear path to efficient scale, predictable cost profiles, and resilient operations will generally present stronger investment theses than those relying primarily on feature volume.
For Procurement Leaders and Enterprise Buyers
Buyers should evaluate shipping software as a strategic operational layer, not merely a transactional tool. Key evaluation criteria should include carrier coverage, integration compatibility with existing ERP or cloud SCM environments, automation capabilities for rate selection and fulfillment workflows, and the predictability of ongoing usage costs. Post-purchase functionality such as branded tracking and returns management should be assessed for their contribution to customer experience and operational efficiency, not treated as optional extras.
Given the pace of change in carrier rules, regulatory expectations, and enterprise integration patterns, buyers should also prioritize vendors with a demonstrated ability to update product capabilities and maintain interoperability over time. Selecting a platform that can grow with the organization while keeping cost and complexity under control will reduce the risk of future rework or displacement.
Conclusion
The shipping software market is entering a period in which growth, complexity, and strategic differentiation are converging. Demand is being sustained by commerce expansion, enterprise modernization, and the need for more capable multi-carrier execution and visibility tools. At the same time, buyers are becoming more discriminating about cost transparency, integration readiness, regulatory alignment, and operational resilience. For vendors, the opportunity lies in building platforms that combine API flexibility, enterprise interoperability, and customer-facing delivery value without allowing cost or complexity to erode competitiveness. For investors and buyers, the priority is to identify solutions and partners that can scale efficiently while adapting to a rapidly changing operational and regulatory environment.
Given the breadth of segmentation, regional variation, and evolving enterprise requirements across the shipping software landscape, detailed segmentation data and tailored commercial assessment can help decision-makers move from high-level trends to specific procurement, investment, and product decisions. PW Consulting's full research report provides deeper coverage of market segmentation, competitive positioning, and actionable recommendations designed to support planning across vendor, investor, and buyer perspectives.
For detailed analysis of this topic, please visit the official page: Shipping Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Diesel Fuel Injection Systems Market Gains 5.5% CAGR Amid Regional Power Shifts
By PW Consulting, 2026-09-21
Diesel Fuel Injection Systems Market: Navigating the Tipping Point Toward Sustainable Efficiency
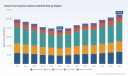
The diesel fuel injection systems market is currently navigating a complex period of structural adjustment. Drawing from historical data spanning 2020 to 2025 and a forecast period extending to 2032, the market exhibits a clear narrative of recent contraction followed by a projected recovery. In 2020, the market revenue stood at approximately $98,208 million. Over the subsequent five years, the sector experienced a steady decline in revenue, reaching a base year valuation of $75,142 million in 2025. This contraction reflects the lingering effects of global supply chain disruptions and the initial phases of regulatory pressure on internal combustion engines.
However, the trajectory shifts markedly from 2026 onward. The market is expected to rebound, growing at a compound annual growth rate (CAGR) of 5.5% through 2032. By the end of the forecast period, revenue is projected to surpass $109,400 million. This growth is not merely a return to pre-pandemic levels but indicates a maturing market where value is derived from higher-performance, precision-engineered systems rather than volume alone. The market remains moderately fragmented, with a top-three concentration ratio of 25.4% and a top-five concentration ratio of 30.5%, suggesting that while dominant players hold significant sway, there is ample room for specialized competitors and niche innovations to capture value.
PW Consulting
These macroeconomic figures provide the backdrop for a deeper investigation into the operational realities facing executives and investors. The following analysis dissects the core challenges, driving forces, and competitive maneuvers defining this sector, offering a strategic lens for decision-making in a transforming landscape.
Market Landscape: The Contraction-Recovery Paradox
The revenue decline observed from 2020 to 2025 masks a critical underlying dynamic: the qualitative evolution of the product mix. While unit volumes may have faced headwinds due to economic fluctuations and the gradual transition toward electrification in light-duty segments, the revenue erosion was partially mitigated by the increasing adoption of high-pressure common rail technologies. As legacy systems are phased out, the average value per unit in the installed base shifts toward more sophisticated injection architectures capable of meeting stringent efficiency and emission targets.
This period of contraction has forced a recalibration of expectations. Market participants who previously relied on steady volume growth are now focusing on margin preservation and technological differentiation. The recovery projected for 2026 and beyond suggests that the market has absorbed the initial shocks of regulatory and economic volatility. The growth phase is driven by the need to retrofit and upgrade existing fleets, the expansion of commercial vehicle markets in high-growth regions, and the continuous push for thermal efficiency in heavy-duty applications where diesel remains the dominant power source.
Key Challenges and Inflection Points
Three critical challenges define the current operational environment and serve as inflection points for strategic planning:
- Regulatory Tightening as a Dual-Edged Sword: Emission standards continue to escalate, requiring precise control over fuel injection timing and quantity. While this drives demand for advanced systems, it also increases the complexity and cost of compliance. Manufacturers must balance the engineering requirements of meeting standards such as EPA and Euro norms with the commercial reality of price-sensitive end markets. Nonconformance penalties further raise the stakes, making reliability and validation paramount.
- Material and Supply Chain Pressures: The trend toward higher operating pressures—exceeding 2,000 bar in many common rail systems—demands components fabricated from high-performance steels and specialized alloys. These materials are subject to price volatility and supply constraints. Any disruption in the availability of critical raw materials can impact production schedules and cost structures, forcing manufacturers to rethink sourcing strategies and inventory management.
- The Electrification Cross-Pressure: The long-term shift toward electrification in passenger cars and light commercial vehicles creates a structural headwind for traditional diesel injection volumes in these segments. Manufacturers must determine how to allocate R&D resources between defending existing diesel markets with incremental improvements and investing in technologies that support alternative fuels or hybrid architectures.
Core Drivers of Market Dynamics
Understanding the recovery trajectory requires a granular look at the forces propelling change. The market is not growing simply due to macroeconomic recovery; it is being reshaped by specific technological, regulatory, and demand-side innovations.
Technological Innovation: The Push for Higher Pressure and Precision
The technical arms race in diesel fuel injection centers on pressure, speed, and control. Leading systems now operate at pressures exceeding 2,500 bar, with some architectures pushing toward 3,000 bar. This is not merely an engineering milestone but a functional necessity. Higher injection pressures improve atomization, leading to more complete combustion, lower particulate emissions, and better fuel economy.
Recent developments highlight this trajectory. For instance, innovations unveiled in 2026 demonstrate a focus on supporting future emissions standards through 500-bar-plus fuel injection capabilities and alternative fuel compatibility. This signals that the industry is preparing for a diversified fuel landscape where diesel injection technology must adapt to new energy carriers while maintaining performance benchmarks. Furthermore, the ability to achieve ultra-fast actuation in injectors allows for multiple injection events per cycle, giving engine control units finer granularity over combustion dynamics. These capabilities are essential for meeting the dual mandates of power output and emission compliance.
Regulatory and Policy Environment: Compliance as a Market Filter
Policy continues to be a primary determinant of market structure. Heavy-duty engines, in particular, are subject to rigorous standards that require optimized fuel injection timing and quantity, often in conjunction with aftertreatment systems. Regulations are not static; they evolve, imposing stricter limits on nitrogen oxides and particulates.
This regulatory environment acts as a filter. It raises the barrier to entry for manufacturers who cannot demonstrate consistent compliance and reliability. At the same time, it creates a sustained demand for upgrade kits and retrofit solutions. The introduction of modular common rail fuel system upgrade kits for legacy engines illustrates how regulators and market needs converge. By converting older high-pressure injection systems with newer components, manufacturers can extend the life of existing assets while achieving efficiency gains, such as the verified 5% improvement noted in recent upgrade initiatives. This trend underscores a market where service and upgrade revenue streams are becoming increasingly relevant alongside new equipment sales.
Diesel Engines Market
Demand-Side Shifts: Commercial Vehicles and Off-Highway Resilience
While passenger car volumes face long-term uncertainty, the demand profile for diesel injection systems is being bolstered by the commercial vehicle and off-highway segments. Heavy-duty trucks, mining equipment, and agricultural machinery rely on the torque, durability, and energy density of diesel power. In these applications, the operational imperative is efficiency and uptime, and advanced injection systems deliver tangible value by reducing fuel consumption and maintenance intervals.
The off-highway sector, in particular, benefits from the ruggedness of modern injection architectures. High-pressure systems designed for extreme operating conditions ensure that engines perform reliably in remote or demanding environments. As global infrastructure projects and mining activities expand, especially in Asia Pacific and other developing regions, the demand for high-performance engines equipped with advanced injection systems remains robust. This demand provides a stable revenue base that cushions the market against volatility in the light-duty segment.
Supply Chain and Cost Structure Evolution
The cost structure of diesel fuel injection systems is undergoing a transformation driven by material science and manufacturing efficiency. The reliance on specialized steels and alloys for components that withstand extreme pressures means that cost management is no longer solely about labor arbitrage. It involves securing resilient supply chains for critical raw materials and investing in advanced manufacturing processes such as precision machining and additive manufacturing for complex geometries.
Diesel Common Rail Injection System Market
Companies are increasingly looking at vertical integration and long-term supplier partnerships to mitigate risk. The ability to control the quality and supply of key components becomes a competitive differentiator. Moreover, as systems grow more complex, the integration of software and sensors adds a new layer to the cost and value equation. The shift from purely mechanical systems to electronically controlled, sensor-rich architectures means that value capture is moving toward intellectual property, calibration expertise, and system-level integration.
Competitive Landscape and Strategic Positioning
The market features a mix of global tier-one suppliers and specialized engine manufacturers with strong fuel system capabilities. The top players have carved out distinct positions based on technology focus, application coverage, and geographic reach.
Bosch remains a dominant force, leveraging its extensive portfolio of common-rail systems with piezo injectors capable of high pressures. Its strength lies in the breadth of coverage across passenger cars, light commercial, and heavy-duty vehicles, supported by a comprehensive fuel supply ecosystem. Bosch's ability to deliver full-system solutions, including pumps and rails, provides a holistic value proposition to OEMs seeking single-source reliability.
Denso Corporation has established itself through its i-ART common rail technology, which integrates advanced control capabilities. Its focus on medium- and large-sized vehicles, with pressures up to 2,500 bar and the integration of SCR and DPF controls, highlights a strategy centered on system-level emissions management. By linking injection performance directly to aftertreatment optimization, Denso offers a solution that addresses the full emission compliance chain.
BorgWarner has expanded its footprint through strategic acquisitions, such as the 2020 acquisition of Delphi Technologies. This move bolstered its portfolio with EUI and DFi7 injectors for heavy-duty and passenger segments, alongside PLD systems. BorgWarner's trajectory reflects a consolidation strategy, using scale to offer a wide array of injection technologies while maintaining the specialized engineering heritage of its acquired units.
PHINIA occupies a strong niche in light- and medium-duty engines, producing injector families and high-pressure pumps that support emissions standards through 3,000 bar operation. Its upcoming focus on 500-bar-plus innovations and alternative fuel support indicates a forward-looking stance, positioning the company to cater to OEMs preparing for evolving regulatory and fuel landscapes.
Cummins Inc. distinguishes itself with deep integration into heavy-duty and mining engines. Its common rail systems, including the Modular Common Rail Fuel System, feature ultra-fast actuated injectors and dual-stage pumps delivering up to 2,600 bar. Cummins emphasizes verified efficiency gains, such as the 5% improvement delivered by its MCRS upgrade kits. This focus on measurable performance outcomes appeals to fleet operators and OEMs in demanding applications where fuel cost and operational efficiency are critical.
Strategies of Leaders and Market Evolution
The strategies of these leaders reveal common themes. First, there is a clear push toward higher pressure and faster actuation, which serves as a technological moat. Second, integration is key; players that can offer injectors, pumps, rails, and control software as a coherent system reduce complexity for customers and lock in value. Third, the ability to support legacy engine upgrades and alternative fuel readiness is becoming a strategic imperative, extending the relevance of diesel injection technology beyond new engine production.
The market is likely to see continued consolidation among smaller players who cannot match the R&D investment requirements of high-pressure systems. At the same time, new entrants may emerge in the form of specialized component suppliers or software-centric firms focusing on injection control algorithms. The moderate concentration ratios suggest that while the leaders hold significant share, the market structure allows for competitive differentiation through niche technologies and regional expertise.
Future Trends and Commercial Opportunities
Looking ahead to the next three to five years, several trends are poised to shape the market and create actionable opportunities.
Trend 1: Retrofit and Upgrade Economy Gains Momentum
As regulations tighten and older fleets face compliance pressures, the market for retrofit solutions will expand. Upgrade kits that convert legacy inline pump systems to modern common rail architectures, increasing injection pressure and accumulator volume, will see growing demand. This trend offers commercial opportunities for manufacturers with strong aftermarket channels and technical support capabilities. It also appeals to operators seeking to extend asset life while meeting emission standards without full vehicle replacement.
Trend 2: Integration of Alternative Fuel Compatibility
Diesel injection systems are not disappearing; they are evolving. The push toward alternative fuels means that injection hardware and control strategies must adapt to different fuel properties. Innovations supporting alternative fuels alongside traditional diesel will become a key differentiator. Companies that develop flexible injection platforms capable of handling multiple fuel types will capture value in a transitioning energy landscape. This trend also opens opportunities for partnerships with fuel producers and alternative energy developers.
Trend 3: Software-Defined Injection and Data Analytics
As electronic control becomes more pervasive, the value of software in optimizing injection timing, quantity, and pressure profiles will grow. Advanced calibration and real-time adaptation based on sensor feedback will drive efficiency gains. This shift creates opportunities for firms that can provide sophisticated control algorithms, diagnostic tools, and data analytics services. The integration of injection data with broader fleet management systems could unlock new value streams, enabling predictive maintenance and performance optimization.
Risks and Uncertainties
Despite the positive outlook, risks remain. The pace of electrification in certain segments could accelerate, eroding long-term demand for diesel systems faster than anticipated. Raw material costs and supply chain disruptions could pressure margins. Regulatory shifts could introduce new compliance requirements that demand rapid redesign cycles. Additionally, geopolitical factors affecting trade and supply routes may impact the availability of critical components. Companies must maintain agility and diversify their technology portfolios to navigate these uncertainties.
Strategic Recommendations for Decision Makers
For executives, investors, and procurement leaders, the current market dynamics call for a proactive and nuanced approach.
For Manufacturers and Technology Developers
- Invest in High-Pressure and Multi-Fuel Platforms: Prioritize R&D in systems that exceed current pressure norms and can accommodate alternative fuels. This ensures relevance as emission standards tighten and energy sources diversify.
- Expand Aftermarket and Upgrade Capabilities: Develop modular upgrade kits and retrofit solutions that allow customers to modernize existing fleets. This creates a recurring revenue stream and strengthens customer relationships beyond the initial sale.
- Strengthen Supply Chain Resilience: Secure long-term agreements for critical materials and explore vertical integration where feasible. Diversify sourcing to mitigate the risk of disruptions in high-performance alloy supply.
For Investors
- Assess Technology Moats and System Integration: Evaluate potential investments based on their ability to deliver high-pressure solutions, integrated system architectures, and software-defined control. Companies with strong IP in piezo actuation or advanced control algorithms are well-positioned for sustained value creation.
- Monitor Retrofit and Commercial Vehicle Exposure: Companies with a strong footprint in commercial vehicles, off-highway applications, and aftermarket upgrade services may offer more stable growth profiles than those heavily reliant on passenger car volumes.
- Watch for Consolidation and Niche Disruptors: The market may see further consolidation among mid-tier players. Simultaneously, look for niche entrants with specialized technologies in areas such as alternative fuel injection or data-driven optimization.
For Procurement and Fleet Operators
- Evaluate Total Cost of Ownership, Not Just Unit Price: Advanced injection systems that offer verified efficiency gains and lower emission compliance costs can deliver significant long-term savings. Consider the impact of fuel savings, maintenance intervals, and regulatory compliance when selecting systems.
- Plan for Fleet Modernization and Retrofits: Assess the compatibility of existing engines with available upgrade kits. Proactive planning for retrofits can help manage compliance timelines and reduce downtime.
- Engage with Suppliers on Long-Term Support: Ensure that suppliers can provide ongoing technical support, calibration services, and parts availability. Strong supplier partnerships are critical for maintaining operational reliability in demanding applications.
As the diesel fuel injection systems market enters a phase of recovery and technological refinement, the landscape offers clear pathways for those who can align their strategies with the driving forces of efficiency, compliance, and adaptability. The interaction between regulatory demands, material science, and system integration continues to reshape value creation in this sector. Decision makers who maintain a close pulse on technology roadmaps, competitive moves, and regional demand shifts will be best positioned to capitalize on the opportunities ahead. For those seeking a comprehensive breakdown of segment trajectories, regional nuances, and granular competitive intelligence, the full suite of detailed research available through PW Consulting provides the depth required to inform precise strategic moves and tailored recommendations.
For detailed analysis of this topic, please visit the official page: Diesel Fuel Injection Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The District Heating and Cooling Market: Strategic Trends and Commercial Opportunities Through 2032
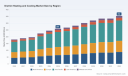
The district heating and cooling (DHC) sector has entered a phase of structural expansion, driven by urban decarbonization mandates, technological maturation, and shifting consumer expectations around energy resilience. Market valuation reached approximately USD 260 billion in 2025, reflecting a compound annual growth rate of 4.5 percent across the 2026-2032 forecast horizon. The trajectory from 2020 onward demonstrates consistent upward momentum, with recent acceleration tied to policy enforcement and capital reallocation toward low-carbon thermal infrastructure. This growth is not merely cyclical; it represents a reconfiguration of how cities and industrial clusters source, distribute, and optimize thermal energy.
At this scale, the market carries meaningful implications for capital allocation, technology roadmapping, and partnership strategy. Understanding where value is created—and where friction persists—requires looking beyond headline figures to the operational, regulatory, and competitive forces shaping deployment decisions. The following analysis examines the current market reality, the forces accelerating change, the competitive dynamics among established players, and the strategic implications for executives navigating the next five years.
Market Reality: Scale, Structure, and Core Challenges
The thermal infrastructure market has grown from roughly USD 180 billion in 2020 to the current USD 260 billion baseline, with forward projections pointing toward USD 354 billion by 2032. This expansion reflects both incremental capacity additions and a structural shift toward integrated heating and cooling networks that serve multi-consumer zones. Geographically, the market is diversified across mature and emerging deployment regions, with Asia Pacific representing the largest demand pool, followed by North America and Europe. Europe and parts of the Middle East have concentrated heavily on cooling infrastructure in high-density urban and commercial environments, while Northern European and select Asian markets have prioritized heating network modernization and renewable integration.
Three challenges define the current inflection point:
- Infrastructure capital intensity and deployment timelines. District networks require extensive piping, substations, valve assemblies, and balancing equipment. Concession-based expansions frequently span tens of kilometers and involve multi-year construction, permitting, and interconnection sequencing. Capital planning must accommodate prolonged payback periods, material procurement risk, and coordination with municipal authorities.
- Decarbonization compliance pressure. Regulatory frameworks are tightening renewable share requirements and performance measurement methodologies for both heating and cooling. Operators and equipment suppliers must demonstrate measurable emissions reductions while maintaining reliability, particularly in markets where fossil-based backup still provides peak-load stability.
- Systems integration and operational complexity. Modern networks increasingly blend multiple heat sources—industrial waste heat, data center exhaust, geothermal, biomass, and large-scale heat pumps—into unified distribution systems. This introduces control coordination challenges, flow balancing complexity, and the need for advanced monitoring and predictive maintenance to protect efficiency targets.
These challenges are not blockers; they are the organizing constraints that determine which business models scale and which stall. Companies that treat thermal infrastructure as a systems problem—spanning source generation, distribution, control hardware, and consumer-side efficiency—gain a meaningful advantage in winning concessions, securing supply contracts, and delivering performance guarantees.
PW Consulting
Key Drivers Accelerating Market Transformation
Multiple forces are converging to reshape demand patterns, investment priorities, and technology adoption curves. The following drivers explain why growth is accelerating and where competitive advantage is being formed.
Technology Innovation and System-Level Breakthroughs
Thermal networks are transitioning from single-source, linear distribution models to multi-source, digitally coordinated systems. Heat pumps, advanced substations, motorized control valves, and heat exchangers now enable finer temperature control, better load-matching, and higher renewable penetration. Waste heat recovery has emerged as a particularly valuable capability. Large data center operators and industrial facilities are increasingly viewed as thermal asset owners rather than pure electricity consumers, with excess heat routed into neighboring district networks. This shift changes the economics of thermal supply: low-marginal-cost heat becomes available where population and commercial density intersect with suitable infrastructure corridors.
Practical examples illustrate how this is unfolding. Operator activity in Espoo has demonstrated the commencement of large-scale heat pump plants utilizing excess heat from major data center operations, producing substantial district heating output and covering a significant share of local demand. Such deployments show that data-center-adjacent thermal integration is moving from feasibility studies into operating reality. At the same time, equipment manufacturers continue to refine skid-mounted substation solutions and valve assemblies that reduce on-site integration friction, helping network builders standardize components across expansions.
Policy and Regulatory Momentum
Policy has become a central determinant of deployment economics. In the European Union, binding national targets now require increasing the share of renewables in district heating and cooling, supported by revised methodologies for counting renewable cooling performance. The EU Heating and Cooling Strategy, expected in the second quarter of 2026, is positioned to accelerate decarbonization implementation and clarify compliance pathways. These policy signals matter because they influence concession award criteria, public funding eligibility, and long-term off-take certainty.
Funding mechanisms are reinforcing the regulatory direction. Calls such as LIFE-2025-CET-DHC provide support at up to 95 percent for proposals focused on efficient district heating and cooling networks that integrate renewable energy and waste heat. For project developers and equipment providers, this creates a pathway to reduce capital exposure on pilot and early-scale deployments, particularly in regions where municipal balance sheets are constrained. Meanwhile, national and municipal authorities continue to structure concessions that tie network expansion to decarbonization outcomes, as shown in recent green heating network agreements that add tens of kilometers of distribution capacity and serve tens of thousands of households through biomass and recovered energy.
Demand-Side Shifts in Urban, Industrial, and Commercial Settings
Demand is no longer driven solely by legacy residential heating contracts. Industrial clusters remain a major consumer segment, but the composition of demand is broadening. Commercial complexes, education campuses, healthcare facilities, and mixed-use urban districts are increasingly evaluated through the lens of thermal efficiency, continuity of supply, and emissions performance. Cooling demand in hot climates and densely built environments is also accelerating the case for centralized chilled water systems, particularly where peak electricity pricing and grid constraints make decentralized cooling less attractive.
Partnership structures reflect this broadening demand base. Recent expansions of district cooling systems serving education group buildings demonstrate how institutional clients are being integrated into larger sustainability programs, with completion timelines aligned to academic and operational cycles. Large-scale cooling plant inaugurations with significant refrigeration tonnage further indicate that high-capacity centralized cooling is becoming a standard asset class in regions where cooling is a dominant load. These demand-side shifts create opportunities for operators to secure long-term service relationships and for equipment suppliers to tailor control and heat exchange solutions to multi-building portfolios.
Supply Chain and Cost Structure Dynamics
The cost structure of district networks is being reshaped by material intensity, component standardization, and financing availability. Piping, substations, valves, and heat exchangers remain essential physical inputs, and large concession-driven expansions highlight how material procurement and installation logistics influence project pace. At the same time, standardization of skid-based substation packages and advanced control hardware can reduce customization cost and accelerate commissioning. Financing innovation also matters: where public grants, climate funds, and long-term concession revenue streams exist, the cost of capital becomes a decisive factor in who can pursue expansion aggressively.
A nuanced risk in the cost picture is the tension between rapid expansion and performance assurance. Faster network growth can strain quality control, balancing, and maintenance planning if supply chains are not aligned to technical specifications. Operators and manufacturers that invest in repeatable engineering processes and remote monitoring capabilities can protect margins while scaling, whereas fragmented procurement approaches may create operational inefficiencies that erode the value of expansion.
Competitive Landscape: Positioning, Differentiation, and Market Evolution
The competitive environment combines global operators, regional specialists, and equipment manufacturers, each competing on a different axis of value creation. The structure is moderately concentrated, but the variation in business models means that direct comparison requires attention to whether a company competes as a network operator, a technology supplier, or both.
Danfoss operates from an equipment and control standpoint, providing advanced control valves, motorized control valves, ball valves, heat exchangers, and complete substation or skid solutions for district heating and cooling networks and building applications. Its differentiation lies in component-level precision and integration support, positioning it as a critical supplier for operators seeking to standardize control architectures and improve balancing across networks. For DHC projects, Danfoss-type solutions can reduce engineering complexity and improve the reliability of temperature and flow regulation across varied load conditions.
Veolia competes as an operator and developer, with a strong orientation toward fifth-generation systems that use geothermal and waste heat, and a clear decarbonization focus. Its advantage is the ability to bundle development, operation, and low-carbon sourcing into a single value proposition, which is appealing to municipalities and institutional clients that want emissions reduction outcomes without managing multiple vendor relationships. Veolia’s positioning suggests a strategy centered on asset development and long-term service contracts tied to sustainability performance.
Fortum illustrates the operator-as-system-integrator model, running heating and cooling networks while capturing waste heat from data centers and targeting carbon-neutral supply by 2030. The recent start of operations at large-scale heat pump plants that draw on data center excess heat demonstrates a strategy of turning adjacent industrial heat into a competitive supply advantage. By combining operational scale with innovative sourcing, Fortum shows how a regional operator can build differentiation through source diversification and decarbonization commitments.
ENGIE operates a broad international footprint, with hundreds of heating networks and a substantial number of cooling networks across multiple countries, alongside significant heat and cooling production capacity. Its strategy appears oriented toward scale, international replication, and strategic partnerships that extend network reach into institutional and commercial demand pools. Recent concession activity securing long-term rights for green district heating network expansion and partnership expansions for sustainable cooling delivery indicate a focus on securing multi-year growth pipelines through public-sector and institutional collaboration.
Emicool represents a regionally concentrated but strategically important cooling operator, with large-scale plant assets and an emphasis on energy-efficient cooling supply. In high-cooling-load environments, operators like Emicool compete on plant efficiency, reliability, and the ability to serve dense commercial and residential zones with centralized chilled water infrastructure. Its relevance highlights the importance of regional specialization: in markets where cooling dominates thermal demand, expertise in plant design, load management, and operational efficiency becomes the core competitive battleground.
The broader market trajectory suggests continued evolution along three lines:
- Integration and consolidation. Larger operators are likely to pursue network acquisitions, concession portfolios, and partnership expansions to secure growth corridors and diversify heat and cooling sources.
- Specialization and regional depth. Regional specialists will continue to win in high-demand cooling markets and in niche heating segments where local regulatory, climatic, or industrial conditions create durable advantages.
- Technology supplier relevance. Manufacturers of control hardware, heat exchangers, and substation skids will gain importance as networks become more complex and operators seek standardized, monitorable, and efficient component ecosystems.
New entrants are most likely to appear where data center heat recovery, geothermal integration, or grant-funded renewable network development create viable project structures. However, successful entry typically requires access to land-use coordination, financing, and operational expertise, not merely technology capability.
Future Trends and Commercial Opportunities for the Next 3-5 Years
Several trends are likely to define the medium-term market, each carrying distinct commercial implications.
Underfloor Heating Market
Trend 1: Multi-source thermal integration becomes standard. Networks will increasingly combine waste heat from industrial and data center operations, geothermal, biomass, and large-scale heat pumps within unified control frameworks. This trend creates opportunities for operators that can secure heat supply agreements, for technology providers that enable source-agnostic control and balancing, and for financiers that structure projects around diversified thermal supply contracts. A practical commercial pathway is to align heat sourcing with urban and industrial land-use planning, ensuring that new heat loads are identified before network expansions are finalized.
Trend 2: Policy-driven decarbonization expands public funding and concession availability. Continued regulatory tightening and dedicated funding instruments will support projects that demonstrate renewable share growth and measurable emissions reductions. The commercial opportunity is not only in capturing grants but in designing projects that qualify for sustained support and that can be replicated across multiple municipalities. Developers that standardize project templates—combining proven sourcing, standardized substation and valve assemblies, and measurable performance reporting—can reduce delivery risk and improve scalability.
Trend 3: Cooling infrastructure scales as a strategic asset class. In high-temperature and high-density environments, district cooling will increasingly be treated as critical infrastructure rather than an optional convenience. Large-capacity plants and campus-linked cooling expansions indicate a pipeline of demand that favors operators with strong plant efficiency, reliable chilled water distribution, and the ability to integrate with building-level efficiency programs. Suppliers that support optimized heat exchange, cold storage integration, and load forecasting can differentiate within this pipeline.
Risk considerations. Deployment timelines can slip if permitting, material availability, or interconnection sequencing become constrained. Performance claims tied to renewable share or emissions reduction may face scrutiny if measurement methodologies evolve or if supply conditions change. In addition, rapid expansion without strong operational control can create balancing issues that undermine efficiency and customer satisfaction. Commercial planning should therefore incorporate contingency thinking around permitting, component standardization, and post-commissioning maintenance capacity.
Strategic Actions for Decision-Makers
Different stakeholders face different priorities, but all benefit from a clear view of where value is created in the thermal infrastructure value chain. The following actions are most relevant in the current environment.
Heat Cost Allocator Market
For Equipment Manufacturers and Technology Providers
Prioritize standardization and integration support. Substation skids, control valves, and heat exchangers that can be deployed repeatedly across multiple networks reduce engineering friction and improve project predictability. Emphasize coordination capabilities that help operators manage multi-source inputs, variable loads, and balancing requirements. Where possible, align product roadmaps with the growing relevance of waste heat recovery and renewable integration, since those themes are shaping both concession criteria and funding eligibility.
For Investors and Developers
Focus on corridors with aligned policy incentives, identifiable waste-heat sources, and credible long-term demand. Data center-adjacent heating, geothermal-enabled networks, and institutional cooling portfolios represent areas where project structures can combine revenue visibility with decarbonization goals. Evaluate not only technical feasibility but also the availability of grants, concession stability, and the operational capability required to run complex multi-source networks. Projects that can demonstrate repeatable deployment templates will generally attract more favorable capital terms and partnership interest.
For operators and procurement teams, the priority is performance assurance and supply resilience. Select components and partners that support long-term balancing, monitoring, and maintenance rather than lowest-first-cost procurement alone. In cooling-heavy markets, prioritize plant efficiency, redundancy, and load-forecasting capability. In heating markets, emphasize source diversification and control hardware that can accommodate future renewable and waste-heat integration without major redesign.
Across all roles, the strategic value of granular market intelligence is high. Macro trends indicate direction, but concession timelines, funding eligibility details, regional cooling and heating demand patterns, and component-level deployment preferences determine execution success. Decision-makers who can map these details to their own project pipelines, procurement plans, or investment theses are better positioned to move quickly when opportunities appear.
The district heating and cooling market is expanding on the back of policy pressure, multi-source heat integration, and growing recognition of thermal networks as decarbonization infrastructure. Growth will not be uniform; it will concentrate where regulatory support, demand density, and source availability align. For executives and investors, the practical task is to identify where those conditions overlap and to build capabilities—technical, operational, and commercial—that allow participation at the right scale. For those seeking deeper segmentation detail, competitive benchmarking, and tailored strategic recommendations, the full PW Consulting research report provides the supporting data and analysis needed to translate these market signals into concrete action.
For detailed analysis of this topic, please visit the official page: District Heating and Cooling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Dibasic Ester Market: Strategic Trends & Commercial Opportunities Through 2032
The dibasic ester (DBE) market has transitioned from a niche solvent portfolio to a strategically relevant segment within specialty chemicals, driven by tightening environmental regulations and evolving application requirements. Over the historical period from 2020 to 2025, the market demonstrated resilient expansion, reaching a base-year valuation of approximately 162.0 million USD in 2025. Forward projections indicate a compound annual growth rate of 6.5 percent across the 2026 to 2032 forecast horizon, with revenue scaled in millions of USD. This trajectory reflects a market that has moved past early-adoption friction and is now embedding DBE formulations into mainstream industrial, coating, and cleaning applications where performance, regulatory compliance, and sustainability must align.
The structural expansion is not uniform across all regions and end-use categories, but the overall momentum is clear. Asia Pacific continues to scale rapidly as manufacturing hubs reconfigure solvent portfolios, North America and Europe anchor demand through regulatory-driven reformulation, and emerging regions are gradually capturing share as cost-effective DBE grades become more accessible. Market concentration remains moderate, with the top three participants holding roughly 35 percent of industry revenue and the top five reaching approximately 45 percent. This fragmented-yet-concentrated structure signals room for both consolidation and differentiated positioning, depending on how companies navigate product quality, feedstock sourcing, and regional compliance requirements.
Worldwide Dibutyl Maleate (DBM) Market
Market Landscape And Core Challenges
The current DBE landscape is defined by a need to balance performance consistency with environmental compliance, while simultaneously managing feedstock volatility and regional specification fragmentation. Two to three structural challenges stand out as critical inflection points for operators and buyers alike.
First, regulatory pressure across major markets is accelerating solvent reformulation, but compliance pathways are not harmonized. Manufacturers and formulators must navigate differingVOC thresholds, hazardous air pollutant restrictions, and regional certification timelines. This creates adaptation costs and can delay product commercialization, especially for companies serving multiple jurisdictions with a single formulation strategy. Second, feedstock economics and supply chain resilience remain sensitive. Even as bio-based routes mature, parity with petrochemical equivalents fluctuates with agricultural commodity prices, fermentation scale-up timelines, and logistics constraints. Operators that rely on single-source raw materials or narrow regional procurement face margin pressure during periods of input cost instability. Third, application-specific performance expectations are rising. Paints and coatings, industrial cleaners, plasticizers, paint strippers, and other specialty uses each impose distinct solvency, evaporation, and safety profiles. Delivering consistent quality across these segments without compromising cost structure requires tighter process control and more advanced quality assurance capabilities.
Together, these challenges are reshaping how participants design production footprints, manage formulation partnerships, and prioritize product grades. They also create a clear divergence between suppliers that can offer compliant, traceable, and performance-validated solutions and those competing primarily on price in commoditized niches.
Key Drivers Shaping Market Dynamics
The expansion of the DBE market is being propelled by a combination of technological, regulatory, demand-side, and supply chain forces. Each driver reinforces the others, making DBE increasingly attractive as a multifunctional solvent and intermediate across industrial applications.
Technological innovation and process breakthroughs are expanding the value proposition of DBE beyond conventional solvent replacement. Purification advances, fractionation techniques, and custom blending capabilities have improved consistency, odor profiles, and application compatibility. This has enabled higher-performance use cases where formulators need predictable evaporation rates, low residue, and compatibility with resin systems. Companies with proprietary fractionation and blending know-how are increasingly differentiating through specification-grade products rather than generic solvent volumes.
Policy and regulatory environments are acting as a powerful catalyst. Ongoing reviews of legacy solvents and evolving emission standards are pushing formulators toward alternatives with lower VOC profiles and reduced hazardous air pollutant exposure. In parallel, broader sustainability frameworks are encouraging substitution away from chlorinated and high-VOC solvents, particularly in European markets and other regions with strict environmental enforcement. The cumulative effect is a reformulation pipeline where DBE is prioritized as a practical, performance-aligned alternative.
Demand-side behavior is also shifting. Industrial buyers are increasingly treating solvent selection as a risk-management decision rather than a purely cost-driven purchase. Procurement teams prioritize compliance documentation, biodegradability profiles, and supply reliability, especially in coatings, pharmaceutical-adjacent applications, and electronics-related cleaning processes. This change in buying logic favors suppliers that can provide transparent product attributes, consistent lot-to-lot quality, and application support.
PW Consulting
Supply chain and cost structure dynamics are evolving alongside these demand shifts. Bio-based feedstock routes have progressed toward commercial viability, with certain fermentation-derived intermediates reaching cost levels that are within a reasonable range of conventional petrochemical equivalents. This progress reduces the premium historically associated with greener solvent pathways and opens the door to broader adoption, provided that scale, production reliability, and integration with existing DBE manufacturing lines can be sustained. At the same time, partnerships between specialty fermentation players and established DBE producers are laying the groundwork for commercial-scale bio-succinate-related projects, which could further strengthen the sustainability narrative and expand the feedstock base over the next several years.
Competitive Landscape And Leading Strategies
The DBE competitive field is a mix of global specialty chemical players, regional manufacturers, and application-focused producers. Their strategic positioning varies by geography, product purity requirements, feedstock strategy, and end-use specialization, but several competitive themes are visible across the market.
Some leading participants emphasize recycled-content and biodegradable solvent solutions, positioning their DBE offerings as compliant, performance-tested options for coatings, polyurethane polyols, recycling solvents, and soil stabilization. Others differentiate through high-performance solvent grades derived from mixed acid streams and fractionation expertise, targeting coatings, resins, and industrial applications where clarity, low odor, and processing ease matter. European-based manufacturers leverage regional production and specialty distribution channels to serve industrial solvents and performance materials, while multinational portfolios maintain breadth across geographies and application categories. Certain players focus on high-purity grades for pharmaceutical, personal care, and electronics-adjacent markets, where exacting quality standards become a barrier to entry and a source of margin resilience. In Asia, large-scale production capacity and growing specification-grade capabilities are enabling regional suppliers to capture demand from paint, coating, printing ink, and dispersant applications while progressively upgrading quality for more demanding contracts.
These different strategic postures are producing a market that is both consolidating and fragmenting at the same time. Consolidation is likely where scale, feedstock integration, and regulatory compliance create advantages for larger portfolios and well-capitalized producers. Fragmentation persists where regional formulation needs, purity specifications, and application-specific service requirements reward localized expertise and narrower specialization. New entrants and capacity expansions tend to succeed when they bring a clear position—whether in bio-based content, ultra-high purity, cost-efficient large-volume production, or application-tailored blends—rather than attempting to compete across all segments without differentiation.
Recent corporate activity underscores the strategic importance of this positioning. Investments in bio-based DBE production facilities signal a long-term commitment to sustainability-linked demand and feedstock diversification. Product launches targeting low-VOC formulations for automotive applications illustrate how regulatory and performance requirements can converge into commercially viable specialty grades. These moves are not isolated announcements; they indicate how participants are aligning R&D, regulatory preparation, and application development to capture reformulation demand in specific end markets.
Forward Outlook: Trends And Commercial Opportunities
Looking ahead across the 2026 to 2032 window, several trends are likely to shape how the DBE market evolves and where commercial opportunities emerge.
One major trend is the continued acceleration of solvent reformulation as regulatory review and emission standards tighten further. This creates opportunities for suppliers that can offer compliant, application-validated DBE grades with strong documentation and technical support. Companies that proactively align product portfolios with regional compliance expectations will be better positioned to secure long-term formulation partnerships, especially in coatings and industrial cleaning segments where reformulation cycles can be lengthy and switching costs are meaningful.
A second trend is the greater commercial maturity of bio-based and fermentation-derived intermediates for DBE-related product families. As production scales and cost gaps narrow, sustainability credentials become more commercially actionable rather than purely aspirational. This opens opportunities for differentiation through lower-carbon sourcing, recycled content integration, and tailored bio-based blends. It also raises the strategic importance of feedstock contracts, fermentation partnerships, and production reliability, since buyers will increasingly evaluate not only performance but also supply continuity and traceability.
A third trend is the growing premium on specification-grade quality and application-specific service. As DBE moves deeper into demanding markets—including pharmaceutical-adjacent, electronics, and advanced coatings—the ability to deliver consistent purity, predictable behavior, and technical problem-solving becomes a competitive advantage. This favors producers that invest in quality control, custom blending, and application engineering, and it creates room for segmented pricing rather than undifferentiated commodity competition.
These trends carry commercial opportunities, but they also contain risks. Regulatory timelines can shift, and regional enforcement intensity may vary, affecting the pace of substitution. Feedstock availability and cost parity may be influenced by agricultural market dynamics, energy prices, and logistics disruptions. Capacity additions could intensify competition in certain regions or grades, particularly where differentiation is limited. Finally, application migration is not automatic; performance validation, customer testing, and formulation compatibility can slow adoption even when regulatory and sustainability incentives are strong. Participants that monitor these uncertainties and build flexible sourcing, product, and service strategies will be better prepared to capture upside while managing downside exposure.
Divinylbenzene (DVB) Market
Strategic Actions For Decision-Makers
For manufacturers, the priority is to define a clear DBE positioning that matches both market demand and internal capability. Companies should evaluate whether they can win through scale and cost efficiency, through high-purity specialty grades, through bio-based or recycled-content differentiation, or through application-specific formulation support. Investments in fractionation, blending, quality assurance, and technical service often matter as much as raw capacity, because buyers increasingly choose suppliers that reduce reformulation risk and improve process reliability. Feedstock strategy also deserves close attention, especially where bio-based routes and partnerships can strengthen long-term resilience and align with customer sustainability expectations.
For investors, the market calls for discipline in distinguishing durable advantage from short-term capacity expansion. The most attractive opportunities are likely to sit with participants that combine regulatory readiness, consistent quality, and credible sustainability pathways with a defensible application focus. Capacity announcements alone do not guarantee differentiation; the key questions are whether a company can protect margins through specification leadership, secure reliable feedstock supply, and sustain customer relationships in reformulation-intensive segments. Monitoring partnerships, product launches, and regional compliance shifts can provide early signals about where share and value creation are consolidating.
For procurement and sourcing leaders, DBE should be evaluated as part of a broader solvent strategy rather than as a simple price comparison. Factors such as compliance documentation, biodegradability and VOC characteristics, lot consistency, technical support, and supply continuity can have a material impact on formulation risk and operational reliability. Building relationships with suppliers that can support multiple regional requirements and provide transparent product information may reduce exposure to reformulation delays and quality variability. Where possible, securing longer-term supply arrangements for critical grades can help manage volatility in both feedstock costs and regional availability.
As the DBE market continues to evolve, the companies and buyers that act early on regulatory alignment, feedstock strategy, and specification-grade differentiation will be best positioned to translate market momentum into commercial advantage. For decision-makers seeking more granular segmentation data, regional demand patterns, and tailored strategic recommendations, the full research report provides a deeper view of the market structure and the operational choices that will determine competitive outcomes through 2032.
For detailed analysis of this topic, please visit the official page: Dibasic Ester (DBE) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Consumer Pressure Washers: 4.8% CAGR Growth and Where the Market Is Moving
By PW Consulting, 2026-09-21
Strategic Shifts and Commercial Opportunities in the Consumer Pressure Washers Market
The consumer pressure washers market has demonstrated resilient growth over the past half-decade, transitioning from a mature, cyclical segment to one characterized by technological differentiation and evolving regulatory pressures. Market valuation reached approximately 215 million USD in 2025, expanding from roughly 163 million USD at the start of the historical review period in 2020. The trajectory suggests a steady advance toward 345 million USD by 2032, underpinned by a compound annual growth rate of 4.8 percent across the forecast window. This expansion is not merely a function of population growth or disposable income trends; it reflects a structural recalibration in how consumers and light commercial operators approach surface maintenance, driven by convenience expectations, sustainability mandates, and rapid iteration in motor and battery architecture.
Despite the positive top-line momentum, the sector confronts several inflection points that will separate agile operators from those constrained by legacy product architectures or static distribution assumptions. First, regulatory tightening at the municipal and national levels is beginning to reshape allowable use cases, particularly where water consumption, runoff management, or electrical safety standards intersect with consumer-grade equipment. Second, the cost and availability dynamics of core components—particularly lithium-ion cells, rare-earth motors, and polymer composites—are pressuring margin structures and forcing manufacturers to reconsider bill-of-materials strategies. Third, competitive intensity at the consumer end of the spectrum is elevating customer acquisition costs while compressing the window for product lifecycle differentiation, as feature parity spreads across mainstream retail channels. These forces collectively demand a more granular approach to product positioning, regional go-to-market planning, and risk mitigation.
Electricity, Autonomy, and the Redefinition of Consumer Utility
Technological innovation remains the primary engine of market evolution, with the most consequential advances unfolding in electric powertrain design and battery integration. Gas-powered units continue to hold meaningful share, particularly among users who prioritize high continuous output and portability in off-grid settings, but electric architectures are capturing incremental share among urban and suburban consumers who value quieter operation, lower maintenance burdens, and indoor storage compatibility. The broader trend is not a simple substitution of power sources; rather, it reflects a segmentation of use cases. High-cycle residential cleaning tasks, such as driveway and siding maintenance, increasingly favor electric platforms that can be deployed without fuel handling or combustion-related ventilation concerns. Meanwhile, battery-powered models are expanding the boundary of convenience by eliminating cord constraints, though their adoption remains tied to runtime improvements, charge-cycle durability, and price thresholds that make premium battery packs accessible to mainstream buyers.
Within this context, manufacturers are investing in horizontal series architectures and modular accessories that simplify assembly, reduce service friction, and create cross-sell pathways. Companies that have emphasized compact electric lines for home and garden applications are aligning product roadmaps with the expectation that consumers will favor equipment that is easy to store, quick to start, and straightforward to maintain. This shift is also reshaping purchasing behavior: buyers are increasingly comparing total cost of ownership rather than sticker price alone, weighing factors such as filter replacement intervals, pump life, and the availability of replacement nozzles or hoses. The practical implication is that innovation is no longer measured solely by pressure output or flow rate; it is increasingly defined by ecosystem completeness and the degree to which a unit integrates with the user’s existing cleaning routines.
PW Consulting
Regulatory Signals and the Rebalancing of Adoption Pathways
Policy and regulatory developments are introducing both constraints and catalysts. In several jurisdictions, water conservation rules are narrowing the permissible frequency or scope of aesthetic pressure washing, which can dampen repeat purchases for non-essential cleaning while simultaneously elevating demand for high-efficiency nozzle designs, flow-restriction features, and equipment that performs effectively at lower water volumes. These constraints are prompting manufacturers and retailers to rethink product messaging, shifting emphasis from raw power toward precision, water management, and compliance-friendly operation. Where local ordinances increasingly target runoff or noise, equipment that can satisfy municipal expectations while maintaining perceived effectiveness gains a structural advantage in retail placement and consumer trust.
Safety regulation is simultaneously sharpening the focus on electrical integrity and component certification. Recalls tied to missing ground-fault protection or inadequate insulation have underscored the importance of rigorous design validation, particularly for corded electric models that operate in wet environments. These events reinforce a broader truth for the category: consumer confidence in electric pressure washers depends heavily on perceived reliability and clear safeguards. Manufacturers that standardize on integral protection mechanisms, transparent labeling, and traceable quality controls are better positioned to insulate their brands from reputational and liability exposure. In practice, regulatory risk is becoming a design input rather than a post-market afterthought, and companies that embed compliance into product architecture early are likely to face lower retrofitting costs and fewer market interruptions.
Demand-Side Evolution and the New Purchasing Calculus
On the demand side, the market is being reshaped by a blend of practical maintenance needs and discretionary cleaning behavior. Home exterior cleaning remains the largest application context, driven by the visibility of surface wear, seasonal grime accumulation, and the growing preference for DIY approaches that avoid service-call expenses. Car washing and garden or patio maintenance form the next tier of demand, with consumer preferences increasingly influenced by time savings, storage limitations, and the desire for equipment that can transition between tasks without extensive reconfiguration. This multi-purpose expectation is encouraging manufacturers to optimize for quick accessory swaps, adjustable pressure settings, and ergonomic handling, since a single unit that can address multiple surfaces expands its perceived value within the household.
High Pressure Washers Market
Behavioral shifts are also evident in how consumers evaluate and purchase equipment. Retail visibility, digital research, and post-purchase service access increasingly influence brand choice as much as baseline specifications. Buyers are comparing warranty terms, parts availability, and online tutorial support alongside motor type and pressure rating. In this environment, the ability to provide clear guidance on safe operation, appropriate chemical use, and routine upkeep becomes a competitive lever. The commercial opportunity lies in packaging equipment with educational content, maintenance kits, and accessible replacement parts, thereby transforming a transactional sale into a longer-term relationship that reduces premature abandonment of the product and supports repeat purchases of consumables and accessories.
Supply Chain and Cost Structure Pressures
Cost structures across the value chain are being recalibrated by component availability, freight variability, and the capital intensity of battery technology. Electric and battery-powered models are particularly sensitive to cell pricing and electronics supply, which can create uneven margin profiles across product tiers. In response, manufacturers are pursuing design simplification, supplier consolidation, and regional assembly strategies that reduce exposure to single-source dependencies. There is also a growing emphasis on standardizing pumps, motors, and hose interfaces across multiple product lines, which allows firms to aggregate procurement volume and streamline inventory management. The strategic implication is clear: cost competitiveness in this market is increasingly derived from platform discipline and supply chain flexibility rather than from marginal negotiation on individual parts.
At the same time, logistics and after-sales service networks are gaining strategic importance. Because pressure washers are used infrequently but critically, consumers expect timely access to replacement components and practical troubleshooting support. Distributors and retailers that can offer efficient parts fulfillment and knowledgeable service guidance are better positioned to defend margin and foster loyalty. This dynamic is nudging the market toward tighter coordination between manufacturers, channel partners, and service providers, particularly in regions where residential ownership is concentrated and seasonal demand spikes place pressure on inventory and support capacity.
Competitive Landscape and Strategic Positioning
The competitive environment is moderately concentrated, with leading players commanding a combined share that leaves ample room for differentiated challengers and regional specialists. Headquartered in Germany, Alfred Kärcher SE & Co. KG has built recognition around compact electric lines for home and garden use, emphasizing accessibility in entry-level series and an expanding family of horizontal-format models that appeal to storage-conscious consumers. The company’s approach illustrates how a brand can anchor its consumer offering in ease of use, familiar design cues, and a product ladder that bridges routine household cleaning with light hobbyist applications. By maintaining a clear focus on the residential use case, the firm reinforces a reputation for practical reliability and broad retail availability.
Greenworks Tools, based in North Carolina, has strengthened its presence by leaning into battery-powered and electric pressure washers distributed through major retail channels. The company’s strategy highlights the value of aligning product design with the purchasing habits of DIY consumers who expect cordless flexibility, straightforward assembly, and compatibility with broader outdoor power equipment ecosystems. This orientation supports cross-category brand exposure and gives retailers a cohesive narrative around backyard maintenance. In practice, the company’s positioning demonstrates how battery platform consistency and retail accessibility can translate into a recognizable consumer identity, especially among buyers who prefer a unified tool ecosystem over standalone appliances.
FNA Group, operating under Simpson Cleaning in Wisconsin, has carved out a premium residential and commercial electric pressure washer offering that emphasizes durability and a higher-performance perception. The brand’s presence in both consumer and light commercial contexts allows it to borrow credibility from professional-grade expectations while still addressing the home market. This dual orientation is strategically useful because it supports a tiered narrative: entry-level electric units capture convenience-driven buyers, while premium electric models provide a pathway for users who anticipate heavier use or demand more robust construction. The result is a portfolio that can span multiple price points without diluting the core promise of electric reliability.
Mi-T-M Corporation, headquartered in Iowa, has focused on residential and commercial pressure washers that include hot water options and a broader equipment ecosystem. By incorporating temperature control into select offerings, the company addresses use cases where grease removal or Winter-related cleaning tasks benefit from heated flow, differentiating its lineup from standard cold-water consumer units. This specialization illustrates how a manufacturer can expand perceived utility by targeting specific cleaning challenges, thereby creating a reason for consumers and light business operators to choose a more capable machine even at a higher price point.
The landscape is evolving through a combination of consolidation, specialization, and channel-driven new entry. Larger players are expanding their reach by standardizing platforms and acquiring complementary brand equity, while smaller firms are competing through niche features, regional distribution depth, and specialized service arrangements. Trade activity continues to serve as a visible pulse point for the category. Major outdoor product demonstrations and new product showcases, such as the POWERCLEAN® 2026 event scheduled for late 2026, provide a recurring forum where manufacturers introduce refinements in nozzle technology, pump assemblies, and cordless platforms. Similarly, appearances at events like the PPC Pro Show allow suppliers to test market reaction to equipment variations and gauge interest from both retail and light commercial buyers. These gatherings are not merely promotional; they function as timing markers for product launches, channel negotiations, and competitive benchmarking.
Differentiation is increasingly determined by the integration of product design, regulatory readiness, and channel experience. Brands that can offer clear safety certifications, intuitive controls, efficient water usage, and easy parts access are better equipped to command shelf space and sustain consumer confidence. At the same time, the market is not consolidating uniformly; regional preferences, purchasing channels, and use-case priorities create pockets where specialized offerings can thrive. For new entrants, the most viable path is often to identify an underserved combination of power source, accessory ecosystem, or service promise rather than to race directly into the most crowded price segments.
Future Trends and Commercial Implications
Over the next three to five years, one dominant trend will be the continued rebalancing between gas, electric, and battery-powered architectures, shaped less by total displacement than by use-case segmentation. Electric models will strengthen their foothold in semi-urban and suburban households where storage constraints, noise sensitivity, and maintenance simplicity matter, while gas units retain relevance for longer-duration tasks and locations with limited electrical access. Battery-powered lines will expand as runtime and charge-cycle performance improve, but their growth will depend on the ability to lower effective ownership cost through standardized packs, interchangeable batteries across product families, and retail programs that make premium battery hardware accessible. The commercial opportunity lies in designing product families that let consumers upgrade from entry-level electric to battery-capable configurations without replacing the entire system.
A second trend will be the normalization of compliance-oriented feature design. As water conservation rules and electrical safety standards become more visible in local markets, equipment that demonstrates efficient flow, integral protection mechanisms, and clear usage guidance will gain a reputational and practical edge. This creates an opportunity for manufacturers and channel partners to lead with transparency: product materials that explain appropriate use cases, maintenance expectations, and local regulatory compatibility can reduce returns, limit liability exposure, and strengthen retail trust. In markets where aesthetic pressure washing is being restricted, compliant efficiency becomes a selling point rather than a concession.
A third trend will be the shift toward multi-purpose household cleaning systems. Consumers increasingly prefer units that can move between home exteriors, vehicles, and patio or garden surfaces with minimal setup change. This favors designs with quick-connect accessories, adjustable pressure regulation, and accessories that address a range of soils and surfaces. The strategic reward for companies that solve this versatility challenge is higher basket value, stronger repeat purchase potential for attachments and consumables, and reduced competitive vulnerability to single-feature rivals. The uncertainty to watch is the risk of over-engineering: adding features that complicate storage, increase weight, or obscure the core cleaning task can erode the convenience advantage that drives consumer adoption in the first place.
Strategic Guidance for Decision Makers
Manufacturers should prioritize platform discipline and compliance integration as part of the core product roadmap rather than treating them as downstream adjustments. Standardizing pumps, motors, and accessory interfaces across a coherent family of electric and battery-capable models can reduce procurement fragmentation, improve inventory turnover, and make after-sales support more efficient. At the same time, embedding safety and water-efficiency considerations early in the design process can limit retrofit cycles and create a clearer value proposition in regulated markets. Companies that align product messaging with real household use cases—storage footprint, quick setup, maintenance simplicity, and multi-surface versatility—will be better positioned to capture share from generic commodity competition.
Investors evaluating exposure to this market should focus on the companies and segments that demonstrate platform leverage, retail channel strength, and a credible response to regulatory and safety dynamics. Battery platform compatibility, parts accessibility, and the ability to cross-sell accessories are indicators of durable consumer relationships, while reliance on a narrow feature set or a single distribution chute increases vulnerability to competitive pressure and regulatory shifts. Due diligence should also examine how a company manages component cost volatility and whether its product roadmap reflects a realistic balance between performance, safety, and user convenience. Opportunities are likely to accrue to firms that can articulate a differentiated use-case story and execute on service and parts fulfillment as part of the brand experience.
Pressure Washers Market
Procurement and channel leaders should approach sourcing and assortment decisions with an eye toward total cost of ownership and compliance readiness. Evaluating suppliers on the basis of electrical safety design, ease of maintenance, availability of replacement components, and clarity of operating guidance can reduce downstream friction and improve customer satisfaction. Where local water-use restrictions or safety recalls have altered purchasing expectations, assortment plans that emphasize efficient, well-documented equipment can strengthen retailer credibility and reduce exposure to non-compliant products. Building relationships with manufacturers that provide transparent documentation and reliable parts supply will pay dividends during seasonal demand peaks and in post-purchase support scenarios.
The convergence of technology, regulation, and consumer behavior means that the most actionable intelligence is highly segmented and forward-looking. Detailed product-level data, regional demand profiles, and scenario-based forecasts are essential for translating these broad dynamics into specific sourcing, launch, and investment decisions. PW Consulting’s Consumer Pressure Washers Market research report provides that deeper layer of granularity, including segment performance, regional breakdowns, and competitive benchmarking tailored to decision-critical questions. For executives, planning teams, and investors seeking to move beyond market-level overviews into actionable strategy, the full report offers the detailed structure needed to align product, channel, and capital decisions with the trajectory of the market.
For detailed analysis of this topic, please visit the official page: Consumer Pressure Washers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
DMC Market 2026: Why 8.1% CAGR Signals a Battery-Grade Structural Shift
By PW Consulting, 2026-09-21
Strategic Shifts and Commercial Opportunities in the Dimethyl Carbonate Market: 2025–2032
Market Landscape and Structural Challenges
The dimethyl carbonate (DMC) market has matured from a niche solvent and chemical intermediate into a strategically positioned segment driven by parallel growth in polymers, energy storage, and green chemistry. Between 2020 and 2025, the market expanded steadily from approximately 1,120 million USD to 1,676 million USD, reflecting an accelerated adoption curve across multiple end-use sectors. Projections for the 2026–2032 window point to a compound annual growth rate of 8.1%, with the market expected to reach roughly 2,896 million USD by the end of the forecast period. This trajectory is not merely a function of volume growth; it reflects a structural repositioning of DMC as a cross-sector enabler, where the same molecule serves distinct value propositions depending on the grade, application, and regional regulatory context.
Yet the market's momentum is accompanied by structural friction points that will define competitive positioning over the next several years. First, the DMC value chain remains moderately fragmented, with the top three players capturing roughly a quarter of total revenue and the top five accounting for about a third. This concentration level indicates room for consolidation, but also suggests that scale advantages are not yet fully decisive. Companies are competing across different grade segments and geographies, which complicates direct comparison and rewards players who can align production capabilities with specific customer requirements rather than those who compete solely on volume.
Second, the market sits at the intersection of multiple demand drivers that do not always pull in the same direction. Polycarbonate synthesis, battery electrolyte formulations, and solvents/reagents applications each impose different purity, consistency, and logistical requirements. Industrial-grade volumes tend to prioritize cost efficiency and broad availability, while battery-grade and pharmaceutical-grade DMC require tighter specifications, more rigorous quality control, and often distinct supply relationships. This divergence creates operational complexity for producers who must manage multiple product lines without allowing one segment to cannibalize investment in another.
Third, regional dynamics are reshaping the competitive map. Asia Pacific represents the largest market footprint, reflecting both manufacturing intensity and end-use demand concentration, while North America and Europe maintain significant but smaller shares. Latin America and the Middle East/Africa regions account for comparatively smaller portions of the market today, yet their relevance can shift quickly when trade policy, logistics costs, or localized production decisions change. The market's geographic distribution is not static; it responds to capacity siting decisions, import/export classifications, and the timing of downstream demand buildouts.
For executives, this landscape signals that DMC is no longer a commodity with a single pricing logic. Strategic value comes from aligning grade capabilities, regional presence, and application-specific service models with where end-demand is actually tightening or expanding.
Key Drivers Reshaping Demand and Supply
Technology Innovation and Grade Specialization
One of the most consequential developments in the DMC market is the widening gap between industrial and high-purity grades. Battery-grade DMC, in particular, has emerged as a critical input for lithium-ion electrolyte formulations, where moisture control, impurity thresholds, and batch consistency directly affect cell performance and manufacturing yield. The same molecule used as a solvent or reagent in pharmaceutical and fine-chemical synthesis also requires high-purity handling, but the specification drivers differ: battery applications emphasize electrochemical compatibility and large-scale repeatability, while pharmaceutical use cases emphasize residue limits, traceability, and regulatory documentation.
Technological progress is therefore not just about producing more DMC; it is about widening the range of grades that can be reliably delivered at scale. Transesterification and oxidative carbonylation routes continue to underpin much of the production landscape, but the operational differentiator has shifted toward purification, quality assurance, and the ability to serve tightly specified customers without sacrificing throughput. Producers that can connect process control with customer qualification processes are gaining an advantage that is not visible in headline volume figures but matters heavily in procurement decisions.
Policy and Regulatory Environment
Regulatory classification and environmental policy are increasingly shaping where and how DMC is adopted. In multiple jurisdictions, DMC is positioned as a lower-toxicity alternative to more hazardous solvents, and this framing creates a steady tailwind for substitution in coatings, cleaning formulations, and certain synthesis pathways. The U.S. EPA's continued emphasis on low-toxicity green alternatives under Clean Air Act classifications reinforces a broader narrative: DMC benefits from being part of the regulatory answer to solvent risk reduction, not just a chemical with favorable performance attributes.
Trade and customs classification decisions also influence market flow. A notable example occurred in mid-2025, when U.S. Customs and Border Protection issued a ruling involving DMC imports from Saudi Arabia. Such determinations may appear procedural, but they can alter sourcing strategies, lead to re-routing of supply, and affect the relative attractiveness of different origin points. In a market where regional availability, freight costs, and import status intersect, regulatory clarity can be as commercially important as raw material pricing.
Lithium Batter Ethylene Carbonate Market
Demand-Side Transformation in Energy Storage and Polymers
The battery sector is a central pillar of near-term DMC demand. As lithium-ion battery manufacturing scales and electrolyte formulations continue to evolve, the need for consistent battery-grade carbonate solvents has grown alongside cell production. This is not a single-technology bet; it is a broader alignment between energy storage deployment, electric mobility, and stationary storage buildouts that increases the addressable base for electrolyte-related DMC. At the same time, polycarbonate synthesis remains a substantial application area, supported by durable demand in engineering plastics and related specialty applications. The dual pull from energy storage and polymer manufacturing gives DMC a diversified demand profile that can buffer the market against downturns in any single sector.
Importantly, demand-side growth is not uniform across customers. Large battery and polymer buyers increasingly evaluate suppliers on reliability, specification consistency, and the ability to support qualification cycles. In practice, this means that commercial access to DMC is becoming more relationship- and capability-driven than price-only, especially in the higher-grade segments.
Dimethyl Terephthalate (DMT) Market
Supply Chain Volatility and Cost Structure Sensitivity
Raw material dynamics remain a persistent pressure point. Methanol pricing, in particular, has shown sharp movements that directly affect DMC production economics. In early 2026, methanol prices in China moved above 400 USD per ton, rising more than 40% from early March levels amid geopolitical tension and supply disruptions. Northeast Asia pricing also firmed, with China FOB levels reaching roughly 425 USD per metric ton and India FOB levels climbing toward 807 USD per metric ton, reflecting tighter Middle East supply conditions. These movements illustrate how quickly cost structures can shift when feedstock availability is disrupted.
For DMC producers and buyers alike, the implication is that cost management cannot rely on static assumptions. Procurement planning, inventory positioning, and contract structures need to account for volatility in methanol and related logistics inputs. On the production side, companies with flexible feedstock strategies, integrated operations, or strong regional supply relationships are better positioned to absorb shocks without compromising grade reliability.
Competitive Landscape and Leading Strategies
The DMC competitive set is shaped by a mix of established chemical manufacturers and specialty players, many with strong positions in Asia and Japan, alongside Western suppliers focused on high-purity and application-specific offerings. Several themes define how the leading companies are positioning themselves.
Japanese producers, such as UBE Corporation, Kowa Company, and Kishida Chemical, illustrate a strategy rooted in grade breadth, process maturity, and targeted capacity deployment. UBE's focus on both DMC and ethyl methyl carbonate, including battery-grade material for lithium-ion electrolytes, reflects an effort to serve the energy storage chain directly. The company's presence across multiple geographies, including U.S. and European operations, shows an intent to align production footprint with regional demand rather than rely solely on export-oriented volume. Kowa and Kishida Chemical, meanwhile, emphasize industrial, pharmaceutical, and high-purity applications, suggesting a playbook that prioritizes specification control and customer-specific grades over undifferentiated scale.
Lotte Chemical represents a different but overlapping logic: DMC is positioned both as a monomer for polycarbonates and as a specialty chemical input, with production located in Korea to serve regional industrial demand. This dual-use orientation allows the company to capture value across polymer and specialty channels, provided it can manage the operational requirements of each. In the specialty space, Tokyo Chemical Industry and Merck KGaA highlight the importance of purity and application support. Merck's pharmaceutical and chemical synthesis positioning, including battery-electrolyte grade options, underscores how high-purity DMC can be sold into multiple premium segments when supported by the right documentation and quality systems. TCI's focus on research and industrial grades with high-purity offerings shows that even smaller-scale positioning can be commercially relevant when it aligns with laboratory, pilot, and specialized production needs.
Chinese producers form a defining part of the market's growth dynamics. Shandong Shida Shenghua Chemical, Hualu Hengsheng Group, and Dongying City Longxing Chemical each operate large-scale DMC production using oxidative carbonylation and related routes, supplying industrial, battery, and pharmaceutical grades. Their strategy is largely oriented around scale, regional supply, and expanding capacity to meet growing domestic and export demand. The presence of multiple large-scale Chinese producers contributes to the region's market weight, but also intensifies competition on cost, grade availability, and supply reliability.
Recent developments illustrate how these strategic directions are being executed. In February 2026, UBE Corporation began groundbreaking and construction of a new DMC and EMC plant in Louisiana, USA, with 100,000 tons per year of DMC capacity, targeted for operation in the second half of fiscal 2026 to meet North American battery and semiconductor demand. This move is strategically significant because it ties capacity addition directly to regional end-demand growth and reduces reliance on longer logistics chains for important customer segments. Similarly, in November 2025, Jiangsu Sailboat Petrochemical announced a collaboration with Asahi Kasei for a new high-purity DMC and ethylene carbonate facility in Lianyungang, China, expanding battery-grade supply. That partnership reflects a broader pattern: high-purity and battery-grade capacity is increasingly being scaled through coordinated projects rather than isolated plant buildouts.
Looking ahead, the competitive landscape is likely to evolve along three lines. First, consolidation pressure may increase where scale, grade control, and regional reach create advantages that smaller players struggle to match. Second, differentiation will likely deepen by grade and application, with battery-grade and pharmaceutical/reagent-grade segments becoming more distinct in terms of customer requirements and margin dynamics. Third, new entrants and capacity additions in key regions may alter local supply balances, especially where demand growth is fastest and import dependence is high. The companies that win will be those that can combine technical reliability with commercial agility, not simply those with the largest nameplate capacity.
Future Trends and Commercial Implications
Trend 1: Battery-Grade DMC as a Strategic Sub-Segment
Battery-grade DMC is poised to become one of the most strategically important sub-segments of the market over the next three to five years. The combination of electrolyte formulation needs, scaling battery manufacturing, and qualification-driven purchasing creates a demand profile that rewards consistency, documentation, and supply reliability. Commercial opportunity here is not limited to volume; it extends to long-term supply alignment, technical support, and the ability to meet evolving customer specifications. The risk is that overcapacity in lower-grade segments does not automatically translate into battery-grade competitiveness, because the value drivers differ and qualification cycles can be slow.
Trend 2: Regionalization of Supply and Demand
The market is moving toward greater regional alignment between production and end-use. Capacity additions in North America and continued expansion in Asia illustrate a pattern in which producers are siting assets closer to major demand centers to reduce logistics exposure and improve service levels. This regionalization can benefit buyers through shorter lead times and more stable supply, but it also introduces new complexity: regional availability may diverge, and trade or customs classifications can influence where material is sourced. Companies that map regional demand against local capacity, import status, and logistics risk will be better positioned to manage sourcing decisions.
Trend 3: Green Solvent Substitution and Regulatory Tailwinds
DMC's positioning as a lower-toxicity solvent alternative continues to provide a structural adoption pathway in selected applications. As regulatory expectations around solvent use tighten and corporate sustainability goals influence procurement choices, DMC can benefit from substitution where performance and compliance align. The commercial opportunity lies in applications where the molecule's safety and environmental profile translates into tangible qualification advantages. The uncertainty is that substitution is application-specific and not automatic; performance trade-offs, cost, and supply consistency still determine outcomes.
Risk Considerations
Several uncertainties warrant attention. Methanol price volatility can compress margins or shift sourcing behavior quickly, particularly when geopolitical events or Middle East supply disruptions occur. Regulatory classification changes, customs rulings, and trade policy shifts can alter effective market access and redirect flows. Capacity additions may outpace demand in certain grades or regions, creating localized oversupply even as other segments remain tight. Finally, the qualification and consistency requirements of premium-grade customers mean that operational execution matters as much as strategic intent; a misstep in quality or reliability can have outsized commercial consequences in battery and pharmaceutical channels.
Actionable Recommendations for Decision-Makers
For manufacturers and producers: Prioritize grade-specific capability building over undifferentiated scale. The market's most valuable growth is increasingly tied to battery-grade and high-purity segments, where specification control, quality systems, and customer qualification support differentiate suppliers. At the same time, producers should structure feedstock and inventory strategies to withstand methanol price volatility, and evaluate regional capacity options that reduce exposure to logistics disruption and trade classification uncertainty. Where possible, align new capacity with identifiable regional demand rather than generic volume assumptions.
PW Consulting
For investors: Assess exposure by grade and application, not just by company name. The DMC market is bifurcating in terms of value drivers: industrial volumes may follow cost and availability logic, while battery-grade and pharmaceutical-grade segments reward quality, consistency, and long-term supply relationships. Investment theses should account for regional capacity additions, feedstock sensitivity, and the timing of demand buildouts in energy storage and specialty applications. Also consider the risk that capacity expansions in one segment do not translate into pricing power if premium-grade demand does not keep pace.
For procurement and sourcing teams: Treat DMC sourcing as a grade- and region-specific decision. Industrial buyers may prioritize cost stability, but battery and pharmaceutical buyers should place greater weight on specification consistency, documentation, and supplier qualification track records. Given methanol-driven cost volatility and the potential impact of customs and trade rulings, it is prudent to maintain diversified sourcing options where feasible and to monitor regulatory developments that can affect origin eligibility and import feasibility. Building longer-term alignment with suppliers that can demonstrate consistent quality may reduce disruption risk more effectively than frequent spot-market switching.
Across all roles, the strategic value of DMC intelligence lies in connecting macro growth trends with grade-level realities, regional supply dynamics, and the operational requirements of end-demand. Detailed segmentation data, competitive capacity mapping, and scenario-based cost analysis can sharpen decisions that headline market numbers alone cannot resolve. For organizations that need a closer look at grade-specific demand splits, regional dynamics, and company-level positioning, deeper research resources can help translate the broader trend picture into actionable sourcing, investment, and capacity strategies.
For detailed analysis of this topic, please visit the official page: Dimethyl Carbonate (DMC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The Laser Rangefinder Market: Strategic Trends and Commercial Opportunities Through 2032
The laser rangefinder market has evolved from a specialized instrumentation niche into a strategically critical sector spanning defense modernization, precision engineering, and autonomous systems. Between 2020 and 2025, global revenue expanded from approximately 218.0 million USD to 328.0 million USD, reflecting a compound annual growth rate of 8.85 percent projected through 2032. By the end of the forecast period, market value is expected to surpass 580.0 million USD. This trajectory is not merely a function of incremental demand growth; it signals a structural shift in how ranging technology is embedded across platforms, industries, and operational workflows. For executives and investors evaluating exposure to this space, the period ahead will reward those who understand not just where the market is growing, but why certain segments are accelerating, how competitive positioning is reshaping, and which capabilities will separate leaders from followers.
PW Consulting
Market Landscape and Core Challenges
The current market structure reflects both maturity in established applications and rapid experimentation in emerging ones. Hand-held laser rangefinder products continue to represent the larger revenue share, driven by widespread adoption in surveying, forestry, sports, and field engineering. Telescope laser rangefinder solutions, while smaller in absolute terms, carry disproportionate strategic weight due to their integration into defense fire-control systems, aerospace platforms, and high-precision industrial metrology. The application mix similarly reveals a dual dynamic: military and defense remains the dominant demand driver, but construction and engineering, industrial automation, sports and recreation, and forestry collectively represent a growing base of commercial users who increasingly demand compact, eye-safe, and connected ranging solutions.
Despite the favorable top-line trajectory, the industry faces several structural challenges that will shape competition and investment returns over the next few years.
Technological Convergence and Integration Complexity
Ranging technology is no longer evaluated in isolation. Customers now expect laser rangefinder modules to interoperate seamlessly with cameras, inertial measurement units, LiDAR arrays, and edge-processing pipelines. This integration demands tighter mechanical packaging, thermal management, software-defined calibration, and robust communication protocols. Suppliers that treat ranging as a standalone component risk losing relevance to vendors offering validated subsystem solutions. The challenge for manufacturers is balancing modular flexibility with platform-specific optimization without inflating development cycles or compromising reliability.
Regulatory and Safety Pressures
Eye-safety requirements, spectral regulations, and export control frameworks continue to shape product design and market access. Eye-safe wavelengths around 1.54 µm and 1.535 µm have become standard expectations for defense, aerospace, and many commercial applications, pushing suppliers to invest in erbium-glass and related gain media. Simultaneously, regional certification regimes for construction and industrial equipment add compliance overhead. Companies that proactively design to these constraints early in the development cycle gain a meaningful time-to-market advantage, while those that treat compliance as an afterthought face rework costs and delayed deployments.
Supply Chain Sensitivity and Cost Structure Variability
The market operates with a moderately concentrated competitive structure, where the top three players account for roughly 29.6 percent of revenue and the top five reach approximately 38.2 percent. This concentration does not imply a uniform cost environment. Component availability, semiconductor bottlenecks, precision optics sourcing, and specialized assembly capabilities can create regional cost asymmetries. Suppliers reliant on single-source subassemblies face margin volatility when demand spikes or when geopolitical factors disrupt logistics. As a result, resilience in supplier networks and disciplined design-for-manufacturability have become strategic differentiators rather than back-office concerns.
Key Drivers Shaping Market Growth
The 8.85 percent compound annual growth rate through 2032 is not a generic forecast; it reflects the interaction of several reinforcing drivers. Understanding these drivers helps decision-makers separate temporary demand spikes from durable secular trends.
Defense Modernization and Multi-Domain Integration
Military and defense demand continues to anchor market growth. Modern air defense, ground vehicle fire control, naval combat systems, and unmanned aerial platforms require accurate, low-latency ranging that can operate in contested environments and under stringent size, weight, and power constraints. Recent contract activity illustrates how defense procurement is converting into sustained module and system orders. In March 2025, Lumibird secured orders from Rheinmetall Air Defense to supply VIDAR laser rangefinders for Skyranger 30 short-range air defense integration, with deliveries scheduled through 2028. A month later, the company announced a contract from Saab AB for OdiPro laser rangefinders supporting Swedish and Danish armed forces CV90 platforms. By June 2025, Lumibird had also received a contract from Saab for 57 VIDAR laser rangefinders for Danish Navy frigates, with deliveries planned across 2025 and 2026. These awards highlight a recurring pattern: defense customers are locking in multi-year supply commitments for ranging modules that will be embedded in platform lifecycles lasting well beyond the initial delivery window.
For commercial strategists, the implication is clear. Defense-driven revenue tends to be less cyclical than spot-market commercial demand, but it also demands rigorous qualification, traceability, and integration support. Companies that build repeatable qualification pathways and maintain configurable module architectures can capture platform programs without sacrificing agility.
Miniaturization and Autonomy-Ready Form Factors
A second powerful driver is the push toward ultralight, low-SWaP ranging modules suitable for drones, gimbals, robotics, and mobile autonomy. As payloads shrink and mission profiles diversify, the value of a ranging module is no longer defined solely by maximum distance; it is increasingly measured by its contribution to stabilization, obstacle detection, target tracking, and sensor fusion. LightWare LiDAR introduced the GRF-500 laser rangefinder module in March 2025, extending gimbal range to 500 meters for drone and autonomy applications. Analog Modules, Inc. followed in September 2024 with the miniaturized Model 7552A-04 laser rangefinder receiver/range processor designed for high-performance tactical applications. In December 2025, Safran Vectronix released the LRF 3019 compact laser rangefinder module targeting advanced drone tracking and multi-sensor applications. Together, these releases show a market moving toward rangefinder solutions that are not only smaller but also more purpose-built for embedded perception and tracking.
This trend expands the addressable market beyond traditional handheld and tripod-based use cases. It also raises the performance bar: modules must maintain accuracy and repeatability while operating under vibration, variable temperature, and limited power budgets. Suppliers that can deliver validated SWaP-optimized modules with clear integration documentation will find themselves positioned at the intersection of multiple growth vectors.
Commercial Productivity Demands and Field Instrumentation
Demand-side changes in construction, engineering, forestry, and industrial operations are also reshaping purchasing behavior. Field teams increasingly prioritize reflectorless measurement, faster data capture, and compatibility with digital workflows such as BIM, GIS, and automated inventory systems. Laser Technology, Inc. has long served these professional measurement segments with reflectorless laser rangefinders in its TruPulse series for surveying, forestry, construction, and government applications. Meanwhile, companies such as ERDI TECH LTD and JIOptics have expanded offerings around eye-safe 1535 nm modules and long-range instruments spanning commercial, military, and professional use cases up to 15 kilometers. The broader message is that commercial buyers are no longer comparing products on distance alone; they are evaluating total workflow value, including calibration stability, data output formats, durability, and integration with existing field software.
As commercial operators face pressure to reduce rework, accelerate surveying cycles, and improve asset visibility, ranging instruments that reduce human error and speed data handover will gain preference. This creates room for vendors that invest in user experience, ruggedization, and ecosystem compatibility alongside core ranging performance.
Supply-Side Dynamics and Regional Capability Shifts
Cost structures and manufacturing footprints are evolving as regional capability clusters mature. Established European and North American suppliers continue to strengthen high-end defense and aerospace positions, while select Asian manufacturers have expanded into both professional and consumer-oriented segments with competitive pricing and rapid product iteration. Shenzhen Laser Explore Tech. Co., Ltd. reflects this broader pattern, producing eye-safe and standard laser rangefinders, riflescopes, and night-vision solutions for hunting, golf, and outdoor applications. JIOptics, with long-range laser rangefinders up to 15 kilometers for commercial, military, and professional use, further illustrates how volume-oriented and performance-oriented lines are being developed in parallel.
The strategic implication is that the market is not bifurcating into premium versus commodity in a simple way. Instead, different customer segments are developing distinct requirement sets, and suppliers are responding with portfolio breadth. Companies that can manage multiple quality tiers, maintain separate design and production pathways, and protect intellectual property in high-value modules will be better positioned to serve both defense programs and commercial volume markets without cross-contaminating brand expectations or margin structures.
Competitive Landscape and Leading Strategies
The competitive field combines established defense and optics specialists with agile module developers and volume-focused manufacturers. No single company dominates the entire value chain, and leadership is increasingly defined by segment focus, integration depth, and program execution rather than by a single flagship product.
Differentiated Positioning Among Leading Players
JENOPTIK AG has built a profile around compact solid-state and diode-pumped laser rangefinder modules, including ELEM series options reaching up to 60 kilometers with eye-safe 1.54 µm Erbium:glass technology for military vehicle and fire-control integration as well as industrial metrology. Its emphasis on module-level design positions the company as a supplier that can be embedded into broader system architectures. Safran Electronics & Defence, through its Ultisense offerings, provides both integrated laser rangefinder modules and full systems for military and aerospace applications, reflecting a strategy that spans component and system-level value. This dual capability can reduce integration risk for platform customers who prefer single-source responsibility for critical subsystems.
LightWare LiDAR has carved out a distinctive position in ultralight microLiDAR sensors and rangefinder modules, with GRF and SF series products optimized for drone gimbals, autonomy, robotics, and industrial sensing. This focus on small, weight-sensitive platforms differentiates the company from traditional surveying and defense vendors and aligns it closely with the miniaturization and autonomy trends described earlier. Attollo Engineering similarly targets the low-SWaP segment with the WASP™-200 series, designed for defense UAVs, gimbals, and handheld systems, reinforcing how several suppliers are converging on embedded, weight-conscious ranging for mobility platforms.
On the commercial professional side, Laser Technology, Inc. continues to differentiate through reflectorless measurement capabilities for field professionals, while ERDI TECH LTD and JIOptics extend the competitive field with eye-safe module options and long-range instruments that serve mixed commercial and professional demand. Analog Modules, Inc. contributes a tactical-leaning, miniaturized receiver and range processor portfolio for moving-target and long-range applications, demonstrating that specialized signal-processing and receiver designs remain important for demanding use cases. Lumibird’s recent defense contracts and module portfolio, including OdiPro and VIDAR series products, underscore the ongoing importance of platform integration, multi-year program execution, and demonstrated performance in air defense, naval, and ground vehicle contexts.
Evolving Market Structure: Consolidation, Segmentation, and New Entrants
The competitive landscape is likely to evolve along three parallel tracks. First, selective consolidation and partnership activity may increase as platform customers seek reduced integration complexity and suppliers aim to bundle modules with sensors, processing, or software support. Second, segmentation will deepen as the requirements of defense platforms, industrial automation, and consumer-adjacent applications diverge further, making a single product architecture insufficient for capturing the full market. Third, new entrants and adjacent technology providers—particularly those coming from drone autonomy, robotics perception, and smart instrumentation—will continue to test incumbents on form factor, price, and ease of integration.
In this environment, competitive advantage is less about claiming the longest range in isolation and more about proving reliability, interoperability, and total cost of ownership within a specific platform or workflow. Companies that publish clear integration guidelines, support qualification processes, and maintain predictable supply timelines will earn preference even when their headline specifications are not the absolute maximum on the market.
Golf GPS Market
Future Outlook: Three Trends Defining the Next Three to Five Years
Embedded Ranging as a Standard Subsystem
Over the next few years, laser rangefinder modules are likely to become less visible as standalone products and more embedded as standard subsystems within larger platforms. In defense, this means deeper integration with fire control, target tracking, and multi-sensor fusion. In commercial autonomy and robotics, it means ranging becoming part of the basic perception stack rather than a specialized add-on. The commercial opportunity here lies in designing modules that anticipate integration early: standardized mechanical interfaces, robust calibration procedures, and software-friendly data outputs. Suppliers that treat integration as a product feature rather than a service add-on will capture more platform-level engagements.
Eye-Safe, Multi-Wavelength, and Application-Tuned Designs
Eye-safety and wavelength selection will continue to influence product roadmaps, but the future is not one-wavelength-fits-all. Different applications will optimize for different trade-offs among range, eye safety, atmospheric performance, detector cost, and regulatory acceptance. The strategic opportunity is to develop application-tuned variants rather than a single universal design. This includes scalable module families that share core architecture while allowing wavelength, optics, and processing choices tailored to specific operational profiles. Companies that manage this portfolio complexity efficiently will be able to serve both regulated defense contexts and commercial environments without diluting focus.
Workflow Integration and Total Value Selling
As commercial and professional buyers become more sophisticated, purchasing decisions will increasingly weigh workflow compatibility, data usability, and durability alongside raw ranging performance. This shift opens the door for value selling that emphasizes reduced measurement time, fewer repeat visits, better data handoff to digital systems, and lower training burden. The risk for suppliers that compete only on specifications is margin erosion from price-based comparisons. The opportunity for those that demonstrate measurable operational improvements is stronger pricing power and longer customer relationships. Decision-makers should expect this trend to accelerate as digital construction, precision forestry, and automated inspection become more widespread.
Risks and Uncertainties to Monitor
Several uncertainties could affect the pace and distribution of growth. Export control and procurement policy shifts may alter the timing of defense program awards or redirect demand toward local sourcing requirements. Component supply disruptions can compress margins or delay deliveries, especially for modules dependent on specialized optics, detectors, or precision assembly. Competitive entry from adjacent technology spaces may compress differentiation in certain price-sensitive segments. Finally, if macroeconomic conditions slow capital investment in construction, industrial modernization, or platform procurement, near-term demand could diverge from long-term structural trends. These risks do not negate the growth outlook, but they reinforce the importance of portfolio balance, supply resilience, and program diversification.
Laser Distance Measuring Devices Market
Strategic Actions for Decision-Makers
The market’s trajectory creates distinct implications depending on a reader’s role. The following actions are intended to translate market dynamics into practical next steps.
For Manufacturers and Component Suppliers
Prioritize modular architectures that can be configured for multiple platforms without full redesigns, and invest in qualification pathways that reduce cycle time for defense and professional customers. Align product roadmaps with application-specific requirements rather than chasing a single maximum-range headline. Strengthen documentation, calibration support, and integration guidance so that the module becomes easier to adopt within larger systems. Where volume commercial segments are targeted, separate design, quality, and production pathways from high-end defense lines to protect margin and brand positioning.
For Investors and Corporate Development Teams
Evaluate exposure not just by product category but by end-use resilience and program visibility. Defense-linked module and system positions can offer multi-year revenue visibility, but they require disciplined execution and compliance readiness. Commercial segments tied to productivity workflows, autonomy, and field instrumentation can offer faster iteration and broader addressability, but they demand strong user experience and ecosystem fit. Consider the value of suppliers that can operate across quality tiers or that hold differentiated capabilities in SWaP optimization, eye-safe wavelengths, or signal processing, as these attributes are likely to command disproportionate relevance as platforms become more integrated.
For Procurement and Platform Integration Teams
Shift evaluation criteria beyond distance and price toward total system fit. Assess eye-safety compliance, environmental ruggedness, calibration stability, data output compatibility, and supplier support for qualification and integration. Where possible, validate modules within representative workflows or platform conditions before committing to multi-unit deployments. For long-lived platforms, negotiate supply continuity and obsolescence management as part of the procurement framework, because ranging subsystems often need to remain available and supported across the platform lifecycle.
Why Deeper Intelligence Matters Now
The laser rangefinder market is large enough to matter and dynamic enough to reward targeted strategy. Aggregate growth figures point to a steadily expanding opportunity, but the real strategic value lies in understanding how demand is distributed across applications, how module requirements are changing under SWaP and safety constraints, and how competitive positioning is being reshaped by integration depth and program execution. The difference between a generic growth narrative and an actionable strategy is detail: segment-level demand trajectories, regional capability shifts, qualification requirements, and supplier capability mapping.
For executives and investors who need to move from market awareness to investment and operating decisions, a more granular view of subsegments, pricing dynamics, demand intensity by application, and company-level capability profiles can significantly reduce uncertainty. PW Consulting’s broader research on this market provides that deeper segmentation, forecast detail, and competitive benchmarking to support planning across manufacturing, investment, and procurement contexts.
The next phase of growth in laser ranging will belong to organizations that treat accuracy, integration, and workflow value as a single design problem rather than a set of separate specifications. Those who align product strategy, supply resilience, and customer support with that reality will be best positioned as the market moves from 2025 toward 2032 and beyond.
For detailed analysis of this topic, please visit the official page: Laser Rangefinder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Voluntary Carbon Offsets: The Real Drivers Behind 30.7% CAGR Growth
By PW Consulting, 2026-09-21
The Voluntary Carbon Offsets Market: Strategic Trends and Commercial Opportunities in a Rapidly Evolving Landscape
The voluntary carbon offsets market has entered a phase of structural transformation that demands attention from executives, strategists, and investors. After a period of volatility, the sector is expanding at a compound annual growth rate of 30.7 percent between 2026 and 2032, with revenue projected to reach approximately 13.56 billion USD by 2032. The trajectory is not merely a continuation of recent growth; it reflects a recalibration of how companies approach decarbonization beyond their own operations, how project developers structure supply, and how standards bodies and regulators attempt to harmonize credibility. The market's total size stood at roughly 2.1 billion USD in 2025, a figure that underscores both the scale of momentum and the distance still to travel before voluntary offsets become a routine component of corporate climate strategy. For decision-makers, the opportunity lies not in treating this as a commodity play but in understanding the mechanics of integrity, segmentation, and timing that will separate durable value creation from speculative exposure.
Carbon Financial Service (CFS) Market
Market Reality and Core Challenges
At a high level, the market's expansion is anchored by a growing recognition that emissions reduction alone is insufficient for organizations with net-zero ambitions. Corporate demand for voluntary credits has become the largest application segment, reflecting a broad commitment to neutralize residual emissions and support supply chain decarbonization. Parallel demand from energy and utilities, consumer goods and retail, and agriculture illustrates how the market is spreading across value chains with distinct risk profiles and performance requirements. The regional distribution of activity is similarly broad, with North America representing the largest share, followed by Europe, Asia Pacific, Latin America, and the Middle East and Africa, each bringing different regulatory expectations, project pipelines, and buyer maturity. Market concentration remains relatively low, with the top three and top five firms holding modest combined shares, indicating that scale advantages are still forming and that fragmentation persists across project origination, verification, and distribution.
Yet the expansion narrative is shadowed by challenges that define the current turning point. The first is the persistent tension between price signaling and perceived quality. Nature-based credits typically trade in a low single-digit dollar range per tonne, while technology-based carbon dioxide removal credits can exceed 170 dollars per tonne, creating a pricing landscape that forces buyers to make difficult trade-offs between volume, durability, and additionality. This spread is not an anomaly; it is the market's way of differentiating project types under constrained supply of high-integrity options. Companies that treat price as the only variable risk overpaying for low-confidence claims or under-investing in credits that align with their disclosure expectations.
Carbon Offset/Carbon Credit Trading Service Market
The second challenge centers on the credibility infrastructure itself. The Integrity Council for the Voluntary Carbon Market has established Core Carbon Principles as a global benchmark, and certification programs and methodologies have been assessed against these principles, with some REDD+ methodologies and broader program frameworks receiving approval. At the same time, implementing regulations are raising transparency requirements for certification schemes, and new methodologies are being introduced to address long-standing quality concerns. This is progress, but it also means that the definition of a reliable credit is being rewritten in real time. Buyers and sellers are navigating a moving target, and the cost of misalignment is rising as auditors, regulators, and stakeholders demand clearer provenance and more robust impact evidence.
The third challenge is the strategic uncertainty around how voluntary credits should be used in relation to internal decarbonization and Scope 3 emissions. Organizations are still forming their own doctrines about when an offset qualifies as a bridging tool rather than a substitute for operational change, and how much reliance on external credits is appropriate in supply chain engagement. Until these postures stabilize, demand can be lumpy and project pipelines can misprice risk, particularly for removal credits that require longer lead times and higher capital intensity. The result is a market that is simultaneously scaling and questioning its own foundations, a combination that creates both opportunity and caution.
Key Drivers Shaping the Market
Technology innovation and the maturation of carbon dioxide removal options are reshaping supply dynamics. Advances in monitoring, verification, and digital documentation are lowering the friction of project development and improving the traceability of impact, while new removal pathways are expanding the range of durable credits available. These developments matter because they influence both the cost curve and the confidence curve. Where historical supply relied heavily on avoidance and reduction projects, there is now growing emphasis on removal projects that offer longer-lived storage and stronger alignment with net-zero framing. The shift is not a replacement but a rebalancing, and it has implications for procurement planning, capital allocation, and reporting architecture. Companies that understand which technologies are moving from pilot to commercial viability can anticipate where premium pricing will persist and where competitive pressure will compress margins.
Policy and regulatory activity is reinforcing this rebalancing by setting clearer expectations for what qualifies as high-integrity and how claims should be substantiated. Recent framework adoptions and implementing regulations in major markets have begun to standardize transparency and certification requirements, while coalitions and standard-setting bodies have introduced jurisdictional approaches and corporate supply chain instruments designed to channel voluntary credit use toward credible outcomes. For example, efforts to advance jurisdictional REDD+ and the introduction of new REDD+ methodologies respond directly to concerns about baseline integrity and additionality, and the anticipation of corporate scope 3 standards signals that buyers will need to integrate credits into a more rigorous decarbonization narrative. The practical implication is that policy is no longer a peripheral risk; it is becoming a design constraint for project portfolios and procurement strategies. Organizations that embed regulatory trajectory into their scenario planning can avoid stranded claims and better align with credible benchmarks.
Demand-side behavior is changing in ways that go beyond volume growth. Consumers and corporate buyers are increasingly sensitive to the provenance of the credits they purchase, the co-benefits associated with project types, and the degree to which offsets support broader transition goals. This behavioral shift is pushing distributors and developers to differentiate on narrative and evidence rather than on volume alone. It is also encouraging more tailored engagement across sectors, where the motivations of a consumer-facing brand differ from those of an energy provider or an agricultural producer. The lesson for decision-makers is that segmentation is becoming the basis for competitive advantage: the same credit may command different justification in different contexts, and the most effective procurement strategies are those that match credit selection to organizational risk tolerance, stakeholder expectations, and disclosure architecture.
Cost structures across the supply chain are also evolving. As verification practices tighten and project developers respond to quality benchmarks, transaction costs and due diligence requirements are rising, particularly for removal and jurisdictional projects. At the same time, improved tooling and data availability are beginning to reduce the burden of screening and monitoring. The net effect is a market in which the cost of access is climbing for low-quality supply but easing for credible supply that can be documented efficiently. Companies that invest early in robust sourcing processes and clear internal criteria are likely to secure more stable relationships and better terms over time, while those that rely on ad hoc purchasing risk exposure to price volatility and reputational uncertainty.
Competitive Landscape and Leading Strategies
The competitive field includes a range of firms with distinct operating models, from consultative providers that bundle credit access with sustainability strategy services to developers and sellers that emphasize integrity and project selection. Some organizations focus on high-integrity project portfolios and transparency, while others concentrate on renewable energy, energy efficiency, or conservation forestry initiatives. A number of players operate as project sourcing and brokerage entities, offering flexibility in procurement, and others manage and certify projects globally, leveraging geographic breadth and verification relationships. This diversity reflects the market's early-stage structure, where differentiation is often built on reputation, methodology expertise, and the ability to connect buyers with projects that meet specific requirements.
Leading firms are typically positioning around one or more of the following advantages. One is trust and verification, where organizations build credibility by aligning with recognized standards and emphasizing transparency in methodology selection and impact documentation. Another is vertical specialization, where firms focus on project types or sectors that match their expertise and buyer demand, such as nature-based conservation or technology-based removal, allowing them to develop deeper technical capability and more consistent quality. A third advantage is service integration, where credits are offered alongside advisory support, measurement, and reporting assistance, helping customers navigate the complexity of using offsets responsibly. These strategic stances matter because the market is rewarding firms that reduce uncertainty for buyers, not simply those that aggregate volume. In a landscape where quality differentiation is increasingly central, the winners are likely to be those that can combine credible supply with clear guidance and reliable execution.
The market structure is evolving toward selective consolidation and parallel differentiation. On one hand, larger players are expanding their capabilities across origination, verification support, and distribution to capture scale benefits and reduce transaction friction. On the other hand, specialized entrants are targeting niches that require particular expertise, such as jurisdictional approaches, removal technology, or sector-specific procurement programs. New entrants are also emerging as standards, methodologies, and regulatory expectations create fresh requirements that incumbents may not fully address. This combination suggests a market that will continue to fragment in the short run as different needs are served by different models, but that may consolidate over time as buyers prefer fewer, more reliable relationships and as scale benefits in due diligence and data management become more pronounced. For participants, the implication is to monitor not only who grows, but where capabilities are being built and where quality assurance is most valued by buyers.
Forward Outlook: Trends and Commercial Opportunities
The first major trend over the next three to five years is a shift toward higher-integrity credits and a premium on removal and jurisdictional projects that can demonstrate durable impact and clear additionality. As corporate buyers refine their use of voluntary credits and regulators encourage greater transparency, demand is likely to tilt toward credits that withstand scrutiny, even if they carry higher costs. The commercial opportunity for companies is to build procurement strategies that treat integrity as a design parameter rather than an afterthought, securing access to credible supply early and structuring internal criteria to avoid reliance on credits that may become difficult to defend. This also creates value for developers and intermediaries that can document impact efficiently and align with evolving benchmarks, as the market is likely to reward those who can reduce uncertainty at scale.
A second trend is the integration of voluntary credits into broader supply chain decarbonization and corporate transition narratives. As scope 3 engagement matures and new corporate programs are anticipated, credits will increasingly be used as part of a coordinated approach that combines supplier engagement, internal reduction, and selective offsetting. The opportunity here lies in matching credit selection to the specific requirements of value chain partners, designing programs that support credible claims, and preparing reporting architectures that can accommodate evolving standards. Companies that treat this as a cross-functional effort, rather than a procurement transaction, are better positioned to use credits as a strategic lever rather than a compliance exercise.
The third trend is the gradual standardization of quality assessment and transparency, driven by benchmark principles, regulatory transparency requirements, and methodological innovation. While full harmonization remains a distant goal, the direction is clear: assessment will become more structured, claims will need stronger documentation, and differentiation between project types will be more explicit. The opportunity is for organizations to build internal competence in evaluating quality, to align with credible benchmarks, and to communicate choices clearly to stakeholders. The risk is that those who delay assessment capabilities may face higher transaction costs, limited access to preferred supply, or pressure to retrofit claims that no longer meet expectations. Uncertainty will persist because standards will continue to evolve and because project performance can vary, but the trajectory favors structured, evidence-based procurement over opportunistic buying.
Strategic Recommendations for Decision-Makers
For manufacturers and industrial operators with net-zero commitments, the priority is to define a clear doctrine for how voluntary credits complement internal reduction and supplier engagement. This means establishing criteria for credit type, quality thresholds, and acceptable use cases, then integrating these criteria into procurement and reporting processes. The practical benefit is reduced risk of rework, stronger alignment with stakeholder expectations, and better positioning as standards mature. A second step is to develop supplier-facing programs that use credits as part of a broader engagement model, especially where scope 3 influence is meaningful. Companies that combine credit selection with data collection and joint improvement plans can use voluntary markets to accelerate transition rather than simply offset residual emissions.
For investors and capital allocators, the strategic focus should be on identifying where value is being created through credibility, scale, and service integration rather than volume alone. Projects and platforms that can demonstrate robust documentation, align with recognized benchmarks, and reduce due diligence friction are likely to have stronger long-term economics. Equally important is attention to risk, since the market's growth depends on continued regulatory clarity and sustained buyer confidence. Diversification across project types and geographies, combined with disciplined underwriting of quality and execution, can help manage the inherent uncertainty while preserving exposure to structural demand.
For purchasers and procurement teams, the most valuable posture is disciplined sourcing supported by internal expertise. This includes building a curated supplier base, defining due diligence checklists aligned with quality benchmarks, and planning for the cost and lead time associated with higher-integrity credits, particularly removal projects. It also means preparing communication strategies that explain why certain credits are selected and how they fit into the broader decarbonization plan. The payoff is more resilient procurement, clearer stakeholder narratives, and greater flexibility as standards and availability evolve. For organizations seeking deeper segmentation data and tailored recommendations for specific sectors, geographies, and procurement models, the full research report provides a more detailed view of market structure, project trends, and strategic options.
The voluntary carbon offsets market is no longer a niche experiment. Its growth rate, expanding application base, and evolving integrity framework make it a meaningful component of climate strategy for many organizations. The businesses that will benefit most are those that treat the market as a system to be understood and managed, not as a simple marketplace for credits. By aligning procurement with credible quality signals, preparing for more structured standards, and integrating offsets into broader decarbonization and supply chain strategy, leaders can convert a complex and fast-moving sector into a durable source of strategic advantage.
PW Consulting
For detailed analysis of this topic, please visit the official page: Voluntary Carbon Offsets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Cationic Starch Market: Strategic Trends and Commercial Opportunities in a Maturing Industrial Landscape
The global cationic starch market has entered a phase of steady, structurally driven expansion. Valued at approximately USD 1,712.5 million in 2025, the market has grown consistently from its 2020 baseline of USD 1,362.5 million. Forward projections anticipate a compound annual growth rate of 4.89 percent through 2032, pushing total valuation past USD 2,300 million. This trajectory reflects more than cyclical demand recovery; it signals a fundamental recalibration of how industrial formulators, paper manufacturers, and material scientists approach modified biopolymers. Cationic starch has transitioned from a niche sizing and retention aid to a functional ingredient embedded across multiple value chains. Yet beneath the headline growth figures lie structural frictions, competitive realignments, and technological inflection points that will separate prepared operators from passive participants over the next five years.
Market Current State and Core Challenges
A Market Balancing Scale and Complexity
The past five years have demonstrated reliable volume expansion, but the composition of that growth reveals divergent regional maturity and application concentration. Asia Pacific currently anchors the largest share of global demand, driven by capacity additions in paperboard, packaging, and textile processing. North America and Europe maintain high-value, specification-driven consumption patterns, while Latin America and the Middle East and Africa represent emerging but structurally constrained demand pockets. The application landscape remains heavily tilted toward paper making performance, which continues to absorb the majority of industrial volumes. Textile processing, adhesives, and diversified industrial uses contribute meaningful but comparatively smaller demand streams. This concentration is both a stability anchor and a vulnerability: when end-user sectors face cyclical downturns or input cost shocks, the entire value chain feels the pressure.
Key Challenges and Inflection Points
Three structural tensions are reshaping how operators approach the market.
-
Raw material volatility and feedstock dependency. Corn, potato, tapioca, and wheat remain the foundational inputs for cationic starch production. Price fluctuations in these commodities directly translate into margin compression or pricing instability for downstream manufacturers. Recent USDA projections point to a season-average corn price around USD 4.20 per bushel for the 2025/26 period, supported by record crop estimates and elevated ending stocks. Forward economic outlooks suggest stagnation near USD 4.10 per bushel for the 2026 marketing year, influenced by sustained high production and supply increases. While favorable crop conditions can temporarily ease cost pressure, the underlying dynamic remains: raw material price volatility for corn, potato, cassava, and wheat represents the most immediate threat to production cost predictability. Major corn-producing regions, including the United States, Brazil, Argentina, and China, account for over 85 percent of global corn production used in cationic starch feedstock, concentrating supply risk in a handful of agricultural basins.
-
Environmental compliance and process footprint. Regulatory scrutiny and internal sustainability mandates are forcing manufacturers to confront the environmental implications of traditional starch modification. The 2025 Technical Report on cornstarch highlights environmental impacts including particulate matter emissions from corn wet-milling operations. As jurisdictions tighten emission standards and corporate buyers demand lower carbon and waste profiles, producers face a compliance-cost dilemma: invest in cleaner process technology, accept higher operational complexity, or risk losing specification-sensitive customers who are auditing supplier environmental performance.
-
Application saturation and functional differentiation. Paper making performance continues to dominate demand, but incremental volume growth in this segment increasingly depends on replacing legacy synthetic additives or optimizing existing formulations rather than expanding total addressable usage. The market is shifting from volume-driven adoption to performance-driven substitution. Operators that offer only commodity-grade cationic starch without clear functional advantages in retention, drainage, strength enhancement, or compatibility with recycled fiber streams will face pricing pressure and margin erosion.
Key Drivers of Market Dynamics
Technological Innovation and Enzymatic Modification
The most consequential shift in the cationic starch landscape is the move toward precision modification and process efficiency. Traditional chemical quaternization remains functional, but it carries energy intensity, waste handling requirements, and batch-to-batch variability. Recent industry activity points to a pivot toward enzymatic and bio-assisted modification routes that reduce energy consumption, improve functional consistency, and align with sustainability expectations. In September 2025, Avebe introduced a proprietary enzymatic modification process designed to reduce energy consumption in cationic starch production. This development is not merely a technical curiosity; it represents a cost-structure lever and a compliance advantage. Lower energy intensity translates into reduced operating expense and a smaller environmental footprint, both of which matter to specification-driven buyers and regulated jurisdictions. In June 2025, Cargill announced a strategic partnership with a biotech startup focused on enzyme-assisted starch modification, targeting next-generation bio-based cationic starches. This signals that large agribusiness and ingredient players are actively investing in the next iteration of functional starch chemistry rather than incrementally optimizing legacy processes.
For operators, the implication is clear: modification technology is becoming a competitive moat. Companies that control or access enzymatic, bio-assisted, or low-energy modification platforms can offer buyers combination of performance consistency, lower process cost, and sustainability credentials. Those locked into high-energy, chemically intensive routes will face increasing cost and compliance headwinds.
Policy and Regulatory Environment
Regulatory dynamics are reshaping both the input side and the output side of the value chain. On the input side, agricultural reporting and commodity forecasting shape procurement strategy. On the output side, environmental reporting and industrial emission standards influence where and how production can scale. The 2025 Technical Report on cornstarch brought particulate matter emissions from corn wet-milling operations into sharper focus, reinforcing the need for emissions control investments and process redesign. While regulation often reads as a constraint, it can also function as a filter that rewards operators with modernized infrastructure and disciplined environmental management.
At the same time, non-GMO and clean-label expectations are crossing over from food applications into industrial procurement criteria. In March 2025, Ingredion launched an eco-friendly cationic starch derived from non-GMO corn for papermaking and food applications. This move illustrates how sourcing claims and ingredient provenance are becoming part of the commercial narrative even in industrial contexts. Buyers who prioritize supply chain transparency, reduced chemical footprint, or alignment with internal sustainability targets create opening for suppliers that can document and verify such attributes.
Demand-Side Shifts: Paper, Packaging, and Industrial Substitution
Demand behavior is evolving along two parallel tracks. First, paper and board manufacturers continue to seek functional additives that improve strength, retention, and drainage while supporting recycled fiber integration. Cationic starch’s role in surface sizing, dry strength, and retention systems keeps it relevant, but the purchasing mindset is shifting from basic availability to total cost of ownership, including dosage efficiency, compatibility with existing chemistry, and consistency across batches. Second, adjacent applications such as textile processing and adhesives are expanding but remain sensitive to downstream industrial activity and formulation preferences. Textile manufacturers explore starch-based modifiers for warp sizing and fabric finishing where biodegradability and process compatibility matter. Adhesive formulators evaluate cationic starch for specific bonding and rheology requirements. These segments do not yet rival paper making in volume, but they provide diversification pathways for producers capable of meeting tighter specification profiles.
A recent procurement signal underscores the ongoing industrial demand cadence. In October 2025, an Indian paper mill awarded a tender for procurement of cationic starch in jumbo bags for Unit 1 board machine operations. While individual tender awards are routine, they reflect the operational reality that paper production units continue to embed cationic starch into scheduled procurement and capacity utilization plans. The broader takeaway is that demand is not disappearing; it is becoming more structured, specification-aware, and sensitive to total performance economics.
Supply Chain and Cost Structure Evolution
The supply chain for cationic starch is increasingly defined by the intersection of agricultural output, regional processing capacity, and logistics economics. Because major corn-producing regions account for the overwhelming share of feedstock used in cationic starch production, supply chain resilience is tied to crop cycles, storage dynamics, and trade flows in those basins. Elevated ending stocks and record crop estimates can ease near-term price pressure, but sustained high production also shapes farmer economics and future planting decisions, creating a feedback loop that procurement teams must monitor.
Cost structure evolution is also being driven by scale advantages, integration levels, and process technology. Integrated wet-milling operations can capture margin across multiple derivative streams, while specialized producers focus on functional consistency and customer-specific modification. The most resilient cost positions combine feedstock access, efficient modification, and disciplined energy management. Operators that rely on fragmented sourcing or outdated process routes will find it harder to maintain stable pricing and margin in a market where buyers increasingly compare total cost rather than unit price alone.
Competitive Landscape and Leading Strategies
Strategic Positioning of Core Players
The competitive field blends large global ingredient and agribusiness players with regional starch specialists and paper-adjacent operators. Each group pursues a distinct strategic position.
-
Global integrated players. Companies such as ADM operate through corn wet-milling operations, producing cationic starch for paper surface sizing and industrial applications. Their strategic advantage lies in feedstock access, scale, and the ability to cross-leverage derivatives across multiple end markets. In August 2025, ADM acquired a regional specialty starch producer to expand its functional starch derivatives portfolio. This move reflects a consolidation logic: expand capability, deepen application coverage, and capture additional margin through portfolio breadth. Acquisition-driven expansion allows integrated players to add functional specialties without building from scratch, accelerating time to market for differentiated products.
-
Regional and feedstock-specialist producers. Companies including Starch Asia, Mahalaxmi Starch Products, Bharat Starch, and Formonix Starch represent a diversified set of regional manufacturers with focused product lines and cost-competitive production bases. Starch Asia produces and supplies cationic starch derived from prime tapioca starch for worldwide markets including Asia, Europe, and the USA. Its positioning emphasizes feedstock selection and export reach. Mahalaxmi Starch Products manufactures cationic starch powder primarily for industrial applications such as papermaking, while Bharat Starch focuses on enhancing paper strength and productivity. Formonix Starch manufactures cationic starch from maize, tapioca, and potato for the paper industry, illustrating feedstock flexibility as a response to customer preference and regional availability. These players often compete on responsiveness, specification adaptation, and regional cost structures, making them relevant partners for buyers seeking tailored grades or supply diversification.
-
End-user and co-located operators. TNPL procures cationic starch for use in board machine operations within its paper production. This highlights a distinct position in the value chain where production and consumption are partially integrated. Such operators prioritize supply reliability, grade compatibility, and cost predictability, and their procurement behavior can influence regional demand patterns and supplier selection criteria.
Portfolio Differentiation and Competitive Evolution
The market is not consolidating into a single homogeneous structure; it is bifurcating along capability lines. At one end, integrated global players are expanding functional portfolios and investing in next-generation modification technologies to capture specification-sensitive demand and sustainability-oriented procurement. At the other, regional and feedstock-focused producers are competing through grade flexibility, responsive service, and cost positions tied to local feedstock availability and operational efficiency. Between these poles, acquisition activity, partnership models, and process innovation are redrawing the competitive map.
Cationic Conditioning Polymers Market
Several dynamics are shaping this evolution.
-
Integration versus specialization. Integrated players gain feedstock leverage and portfolio breadth, but they must manage complexity across multiple derivatives and end markets. Specialists can move faster on customer-specific grades and regional requirements, but they face raw material exposure and scale limitations. The most resilient strategies often combine focused specialization with selective partnerships or acquisitions that add capability without over-extending operational scope.
-
Technology as a barrier and enabler. Enzymatic modification, low-energy processes, and non-GMO or bio-based sourcing are becoming differentiators that influence customer selection. Companies that can demonstrate measurable performance benefits, lower process footprint, or verified sourcing attributes are better positioned to defend pricing and win specification-driven contracts.
-
Procurement structure and relationship depth. As paper mills and industrial buyers shift toward total cost evaluation, suppliers that provide consistent quality, technical support, and reliable logistics gain relationship depth that pure price competition cannot easily displace. Tender activity and scheduled procurement cycles reward dependable supply and specification accuracy as much as unit cost.
The competitive landscape is therefore moving toward a dual structure: global players pursuing portfolio and technology leadership, and regional specialists competing on flexibility, feedstock selection, and service intensity. New entrants and expanding regional producers will continue to test incumbents in specific grades and geographies, while larger players use acquisition and partnership to close capability gaps.
Future Trends and Commercial Opportunities
Trend One: Performance-Based Substitution and Dosage Efficiency
Over the next three to five years, demand growth will increasingly depend on replacing less efficient additives and optimizing dosage rather than simply expanding total volume in mature applications. Cationic starch that delivers measurable improvements in retention, drainage, strength, or compatibility with recycled fiber streams will capture preference in paper and board manufacturing. Opportunity lies in formulation partnerships, technical service, and grade optimization that reduce total additive cost per ton of finished product. Suppliers that can quantify performance per unit of dosage will have a stronger commercial position than those competing solely on price per unit of starch.
Trend Two: Low-Energy and Bio-Assisted Modification as Standard Expectations
Process technology will shift from differentiator to baseline expectation. Enzymatic modification, enzyme-assisted routes, and low-energy production methods are already appearing in product introductions and partnership announcements. As energy costs, environmental reporting, and buyer sustainability criteria intensify, lower-footprint modification will become a procurement consideration rather than a niche claim. Commercial opportunity will accrue to operators that can scale these processes reliably, maintain functional consistency, and document performance and environmental advantages. The risk is that any technology advantage will be time-limited if competitors adopt similar routes or if regulatory thresholds raise the floor for acceptable process footprint.
Trend Three: Feedstock Strategy and Regional Cost Arbitrage
Because feedstock price volatility remains the most immediate threat to production cost predictability, feedstock strategy will become a core competitive lever. Operators will need to manage crop cycle exposure, evaluate regional feedstock mixes, and consider flexibility across corn, potato, tapioca, and wheat where formulation and processing allow. Regions with favorable crop economics, storage infrastructure, and trade logistics may sustain cost advantages, but those advantages can shift with planting decisions, export dynamics, and stock levels. Commercial opportunity exists for producers that can blend feedstock flexibility with consistent functional output, allowing them to adapt to input price movements without sacrificing product performance or customer specification.
Risks and Uncertainties
-
Commodity price reversals. Favorable crop estimates and elevated stocks can compress input costs temporarily, but weather events, trade policy shifts, or demand surges in other corn-using sectors can reintroduce volatility. Procurement teams and producers must plan for cyclical rather than linear input cost paths.
-
Regulatory tightening and compliance cost. Emissions reporting, particulate matter controls, and broader environmental expectations may raise capital and operating requirements for wet-milling and modification operations. Companies with outdated infrastructure may face disproportionate cost increases.
-
Application concentration risk. Heavy reliance on paper making performance means that downturns in paper and board demand or shifts toward alternative additives can slow volume growth. Diversification into textile, adhesives, and other industrial uses can reduce exposure, but those segments require different specification capabilities and go-to-market approaches.
-
Technology diffusion and margin compression. As enzymatic and low-energy processes become more widely accessible, the differentiation window narrows. Early advantage can translate into pricing power only if paired with scale, reliability, and customer lock-in through technical service and specification integration.
Strategic Implications for Decision Makers
For Manufacturers and Producers
-
Invest in modification technology that lowers energy intensity and improves batch consistency. Process upgrades that reduce cost and environmental footprint create dual benefits: operating leverage and customer-facing sustainability credentials.
-
Build feedstock flexibility into product architecture where feasible. The ability to shift across corn, potato, tapioca, or wheat inputs without sacrificing functional output can protect margins during commodity swings and expand customer reach across regions with different feedstock economics.
-
Strengthen technical service and specification support. As buyers evaluate total cost of ownership and dosage efficiency, suppliers that help optimize formulations, reduce variability, and integrate with customer processes will deepen relationships and defend pricing better than those competing on unit price alone.
-
Use selective acquisition or partnership to close capability gaps. Portfolio expansion into functional derivatives, bio-based grades, or regional capacity can accelerate positioning, but discipline is essential to avoid over-extending operational complexity.
For Investors
-
Evaluate exposure to technology-driven margin expansion. Companies with access to enzymatic or low-energy modification, non-GMO or bio-based sourcing claims, and documented process efficiency are better positioned to capture specification-sensitive demand and defend profitability under regulatory and cost pressure.
-
Assess feedstock strategy and regional cost resilience. Understand how each target manages commodity exposure, whether through integration, geographic positioning, or feedstock flexibility. Favorable crop cycles can mask structural cost weaknesses that reappear when input prices shift.
-
Look for application diversification that is real rather than nominal. Expansion into textile, adhesives, or other industrial uses can reduce concentration risk, but only if the company has the specification capability, customer relationships, and technical support to compete in those segments.
-
Monitor consolidation signals. Acquisition activity among integrated players and partnerships with biotech or enzyme developers indicate where capability is being concentrated. Markets where technology and portfolio breadth are converging may reward scaled, well-positioned operators and create acquisition opportunities for others.
For Procurement and Sourcing Leaders
-
Shift evaluation criteria from unit price to total cost of ownership. Consider dosage efficiency, consistency, logistics reliability, technical support, and process footprint. A lower unit price can be offset by higher dosage, variability, or integration friction.
Worldwide Cationic Reagent Market -
Diversify supplier base with purpose. Qualification of regional specialists and feedstock-flexible producers can reduce concentration risk and improve responsiveness, but ensure that each supplier meets specification, quality, and compliance requirements relevant to your operations.
-
Incorporate sustainability and sourcing attributes into supplier selection where they align with internal mandates. Non-GMO, low-energy process claims, and verified feedstock provenance can matter for customer-facing requirements and internal procurement policy, provided they are supported by documentation and consistent performance.
-
Plan for commodity volatility rather than assume stable input costs. Engage suppliers on feedstock strategy, pricing mechanisms, and flexibility. Procurement contracts that acknowledge cyclical input dynamics and allow reasonable adjustment can reduce exposure to abrupt cost shocks.
Accessing Deeper Intelligence
The trajectory of the cationic starch market will be shaped by the interaction of feedstock economics, process technology, application substitution, and regulatory expectations. Companies that treat these forces as isolated variables will miss the cumulative effect on cost structure, customer selection, and competitive positioning. Deeper visibility into segment-level demand patterns, regional cost dynamics, specification trends, and supplier capability mapping can materially improve strategic timing and resource allocation.
For decision makers seeking granular segmentation, regional demand splits, application-specific volume trajectories, and customized scenario analysis, full research coverage is available through PW Consulting’s comprehensive report. The complete study provides detailed breakdowns across regions, types, and applications, along with company-level profiles and forward scenarios designed to support procurement planning, portfolio strategy, and investment evaluation.
The market is not entering a period of dramatic disruption; it is entering a period of disciplined differentiation. Operators that align technology, feedstock strategy, and customer-facing performance will capture the most resilient share of growth, while those relying on commodity positioning alone will face narrowing margins and increasing selection pressure. The next strategic move matters more than the last one.
PW Consulting
For detailed analysis of this topic, please visit the official page: Cationic Starch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


