



Category: market research
PW Consulting: Corrugating Grease Market Poised to Reach USD 295.56 Million by 2032, Says New Insights
By PW Consulting, 2026-07-13
Corrugating Grease Market — 2026 Strategic Outlook and Decision Playbook
Executive summary
As corrugated packaging rebounds and industrial maintenance priorities refocus on uptime and lifecycle cost, corrugating greases are moving from a commoditized maintenance item to a strategic input for plant reliability and packaging safety. PW Consulting’s latest market study, built on a 2020–2025 historical base and a 2026–2032 forecast horizon, quantifies the market and translates that data into a practical playbook for management teams preparing 2026 budgets and strategic choices.
Corrugating Grease Market
Key macro markers: the global corrugating grease market shows clear expansion into the latter half of the decade, underpinned by a steady compound annual growth rate (CAGR) of 4.62% across our forecast window and a base-year market size that informs FY-2026 planning. Our research triangulates demand-side recovery in corrugated packaging volumes, technology shifts in high-temperature greases, and raw-material structural changes to surface the highest-impact decision levers for 2026.
Corrugating Grease Market
Why this matters for 2026 decisions
- Procurement and operations leaders face a narrow window (next 12–18 months) to lock in lubricant strategies that affect maintenance intervals, inventory carrying costs, and operational safety through 2030.
- Suppliers and OEMs must align product roadmaps and service propositions around heat-resistant chemistries and certifications relevant to food-contact packaging lines.
- Private equity and corporate M&A teams will find the sector’s current concentration and margin dynamics useful for identifying consolidation or joint-service opportunities.
Market dynamics and structural drivers
Several structural themes are shaping the corrugating grease market:
Corrugating Grease Market
- Packaging recovery: The corrugated packaging market’s rebound supports sustained maintenance spend on corrugating equipment, creating a predictable baseline for grease demand.
- Formulation pressure from raw materials: Lithium soap and lithium complex thickeners remain significant components of global grease production, but volumes have experienced near-term pressure amid competing demand (notably from electric-vehicle battery supply chains) and a broader shift to alternative thickeners. Tighter upstream controls and regulatory scrutiny on lithium extraction are accelerating formulation experimentation across suppliers.
- Regulatory and certification pull: NSF H1 registration and similar food-contact certifications are material procurement differentiators for grease used on corrugating lines involved in packaging foodstuffs. Certification status is increasingly a must-have in commercial negotiations with major packagers.
- Supplier concentration and bargaining dynamics: The market exhibits a moderate degree of concentration among leading suppliers, creating both opportunities for premium, service-led offerings and vulnerability for buyers that rely on a narrow supplier base.
Technology and formulation trends
High-temperature, low-volatility chemistries continue to dominate technical conversations. Fully fluorinated PFPE/PTFE-based greases remain the benchmark for single-facer and heated-roll applications because of their film strength and thermal stability at elevated temperatures. At the same time, synthetic hydrocarbon and other engineered high-temperature synthetics are making inroads where cost or regulatory considerations require alternatives to fluorinated systems.
Manufacturers must weigh trade-offs: top-tier PFPE systems offer superior thermal performance and maintenance interval extensions but come with higher upfront material cost and tighter supplier concentration. Non-fluorinated high-temperature synthetics and novel thickener-systems provide cost and regulatory latitude, but require thorough compatibility and wear testing before plant-wide conversion.
Competitive landscape — what leading suppliers are doing
PW Consulting’s competitive review highlights differentiated strategies from incumbents and specialist suppliers:
- Chemours (Krytox) leverages its Krytox Performance CORR product family to anchor premium positioning: established industry standards for high-temperature corrugator bearings and strong brand recognition among maintenance teams. Their value proposition is thermal performance combined with proven uptime benefits.
- FUCHS Lubricants (including Nye Lubricants) competes on a combined product-and-service model. Their food-grade, PTFE-thickened solutions and Total Corrugator Plant Lubrication service illustrate a route to lock-in through plant conversions and lifecycle services that reduce total cost of ownership for buyers.
- LUBCON and IKV Tribologie operate as focused specialists, targeting technical niche applications and compliance-driven segments with NSF H1-registered products, quick-response technical support, and regional presence that appeals to converters with specific certification needs.
- Adjacent chemistry and materials developments — for example, coatings and inks with improved grease resistance showcased by suppliers in late-2025 — change the operational interface between grease and substrate. These cross-supply chain interactions are emerging negotiating points between packaging material suppliers and lubrication providers.
Strategic implications and recommended moves for 2026
For executive teams building 2026 plans, the report highlights a set of prioritized actions that create optionality and de-risk exposure to raw-material and regulatory shocks:
- Procurement diversification: Establish dual-source contracts for premium high-temperature greases and map alternative-thickener suppliers to mitigate single-supplier risk. Include supply continuity clauses and multi-year pricing collars tied to raw-material indices.
- Certification roadmap: Require NSF H1 (or equivalent) compliance where lines produce food packaging. Make certification a gate in supplier RFPs and include periodic re-audits in vendor terms.
- Service-led conversions: For converters aiming to reduce downtime, pilot plant conversions using service packages (lubrication audits, conversion trials, and predictive monitoring) rather than spot-product switches. Track maintenance interval improvements and capture actual TCO impacts to justify roll-outs.
- R&D and testing protocols: Allocate budget to qualification testing for non-fluorinated alternatives — including thermal cycling, wear particles monitoring, and substrate interaction tests — before committing to fleet-wide changes.
- Cross-supply chain coordination: Coordinate procurement and technical teams with ink and coating suppliers to ensure grease compatibility, particularly as packaging surface technologies evolve.
- Scenario planning and hedging: Use scenario-based planning to model upstream raw-material constraints and regulatory changes (including potential REACH-like actions) and build contingency capex and inventory strategies accordingly.
What PW Consulting’s report delivers (practical content)
The full report is built for action: it combines robust market-sizing and forecast models with operationally focused tools that can be executed during 2026 planning cycles. Highlights include:
- A verified market-size baseline and a transparent CAGR forecast to 2032, enabling finance teams to quantify near-term budget envelopes for lubricant spend.
- Supplier scorecards and a competitive playbook describing product portfolios, certification coverage, service models, and win-loss patterns observed in customer conversions.
- A regulatory and raw-material risk map with trigger points for formulation sensitivity and sourcing contingency options.
- Technical evaluation templates and an equipment-level pilot checklist for safe, repeatable grease qualification in plant environments.
- Commercial negotiation levers and contracting templates designed to protect buyers from supply shocks while allowing suppliers to monetize performance improvements.
- Scenario analytics that connect packaging demand forecasts to grease consumption patterns under multiple recovery and cost-inflation assumptions.
How to use this intelligence in 2026 planning cycles
Executives, procurement leads, and plant managers should use the report in three immediate ways:
- Inform the 2026 procurement RFP: use supplier scorecards and certification filters to structure RFPs that prioritize continuity, compliance, and demonstrable performance gains.
- Design pilot programs: deploy the report’s pilot checklist across representative lines to measure real-world maintenance interval shifts, lubricant consumption, and interfacing risks with inks and substrates.
- Support capital allocation: feed forecast scenarios into maintenance-capex planning to determine whether investments in bearings, seals, or advanced lubrication systems produce superior ROI versus repeated lubricant-based interventions.
Decision primers for specific stakeholders
- C-suite and strategy teams — incorporate supplier concentration metrics and sensitivity to raw-material regulation in portfolio scenarios and M&A screening.
- Procurement — implement multi-source strategies with contractual protections linked to performance metrics and certification maintenance.
- Operations — prioritize pilot-based conversions and embed grease compatibility checks into change-control procedures.
- R&D — accelerate qualification of non-lithium thickener systems and alternative synthetics where regulatory or cost risk is material.
Conclusion and next steps
The corrugating grease market is not a niche of purely technical interest — it is a lever for uptime, packaging safety, and cost control. Our research shows a clear growth trajectory through the rest of the decade and identifies the practical interventions that create value in 2026 planning cycles. PW Consulting’s full report contains the granular segmentation, supplier-by-supplier benchmarking, and downloadable operational templates that decision teams need to execute with confidence.
To access the complete dataset, segmentation tables, supplier contact map, and the operational playbook, download the full report or contact PW Consulting’s Industrial Lubricants practice. For immediate inquiries and enterprise licensing options, visit: pwconsulting.com/reports/corrugating-grease-market.
For detailed analysis of this topic, please visit the official page: Corrugating Grease Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rare Earth Metal Recycling to Grow at 17.5% CAGR, Reach USD 773.06 Million by 2032 — Asia‑Pacific Leads with USD 134.7M in 2025
By PW Consulting, 2026-07-13
Rare Earth Metal Recycling Market: Strategic Outlook for 2026 — PW Consulting Preview
Executive summary
PW Consulting’s latest Rare Earth Metal Recycling Market report (base year 2025; historical period 2020–2025; forecast 2026–2032) delivers a tactical playbook for corporate leaders, investors, and policy-makers preparing for a market that is transitioning from pilot stage to industrial scale. The market has expanded rapidly—from approximately USD 110 million in 2020 to USD 250 million in 2025—and our modelling projects continued rapid growth through the forecast horizon, yielding a multi-fold increase by 2032 under a scenario-driven compound annual growth rate (CAGR) of 17.5% for the forecast period. This growth trajectory is underpinned by technology maturation, supportive industrial finance, and geopolitical realignment of critical minerals supply chains.
Rare Earth Metal Recycling Market
Why this report matters for decisions in 2026
-
Action timing: 2026 is a pivot year for rare earth recycling as several projects move from demonstration to commercial commissioning. Decisions on plant siting, feedstock agreements, and offtake partnerships taken in 2026 will determine competitive positioning for the remainder of the decade.
Rare Earth Metal Recycling Market -
Capital allocation: Our analysis connects capital deployment to near-term capacity additions and price sensitivities. Companies and financiers who deploy capital with the right technology-, feedstock- and policy-alignment stand to capture outsized returns as the recycling supply pool scales.
Rare Earth Metal Recycling Market -
Risk management: Regulatory shifts and raw-material price volatility are already affecting economics. The report supplies scenario-based stress tests that inform hedging, inventory, and vertical-integration choices that should be considered by 2026 planners.
Macro picture — what the numbers tell us
The rare earth recycling market has moved beyond niche recovery to a structurally growing industry. Measured in USD Million, the market more than doubled between 2020 and 2025, and our forecast shows a clear path to substantially larger market value by 2032 under a 17.5% CAGR across 2026–2032. That pace is consistent with accelerating collection programs, technology improvements in recovery yields, and rising economics driven by magnet demand in electrification and renewables.
Concentration metrics are notable: the three largest recyclers control a meaningful share of the market, while the top five firms consolidate an even greater portion. That concentration profile creates both opportunity and incumbent risk—opportunity for new entrants who can unlock differentiated feedstock access or proprietary recovery routes, and risk for smaller players exposed to feedstock or capital constraints.
Market drivers and near-term disruptors
-
Supply-side restructuring: Government financing and industrial policy in the U.S. and allied markets have catalyzed commercial projects and recycling hubs. Public-private capital is reducing project financing barriers, accelerating timelines for select facilities.
-
Raw material economics: Prices for Nd-Pr alloys and related rare earth inputs have experienced acute upward pressure in early 2026, materially improving the economics of recycling projects and shortening payback periods for higher-capex processes.
-
Technology differentiation: Multiple technical routes—hydrogen-based processes, chromatography, proprietary solvent and pyrometallurgical hybrids—are proving competitive in different feedstock and scale contexts. Technology choice drives plant footprint, capital intensity, and product specification.
-
Regulatory and geopolitical dynamics: Export controls, licensing rules, and extraterritorial provisions introduced by key producing nations are reshaping trade flows and compliance burdens. Parallel supportive measures from buyer-country governments are accelerating domestic recycling capability.
Competitive landscape — who to watch
The market is populated by a combination of specialist recyclers, incumbent mineral producers pivoting into circularity, and technology-focused start-ups. Key companies profiled in our report include established and scaling operators with differentiated approaches to feedstock, chemistry, and value capture. Highlights include:
-
Cyclic Materials — advancing mixed rare earth oxide production through proprietary processes and expanding capacity in North America to capture end-of-life magnet flows from EVs, wind turbines, and electronics.
-
Neo Performance Materials — integrating recycling capabilities with magnet production, with international plant activity that signals a hybrid upstream–downstream strategy.
-
REEcycle Inc. — commercializing a high-efficiency process to recover rare earths from NdFeB magnets in batteries and e‑waste.
-
HyProMag (Maginito/Mkango partnership) — deploying hydrogen-based short-loop recycling for NdFeB scrap with commercial-scale plans in the U.S. market.
-
ReElement Technologies — using chromatography-based processing, supported by strategic defence funding to scale U.S. processing capacity.
-
Global industrial players (Umicore, Hitachi Metals, Lynas, MP Materials) — expanding recycling as part of broader critical-material strategies, leveraging existing refining, manufacturing, or mining positions to offer integrated supply solutions.
-
Specialist recyclers and new entrants (Oryx Metals, RarEarth) — developing niche, low-hazard chemistries for motor and magnet recycling in regional markets.
Recent 2026 developments underscore the move to industrialization: large announced campus investments, site selections for magnet manufacturing with closed-loop recycling, and university-industry facility launches demonstrate that commercially meaningful capacity is being deployed now—accelerating feedstock demand for collectors and processors alike.
Strategic implications and recommendations for 2026 decision-makers
-
Secure strategic feedstock partnerships now. Early long-term agreements with OEMs, motor remanufacturers, and e‑waste aggregators provide cost and quality visibility that materially improves project returns. Our scoring matrices identify the differentiated value of short-loop (scrap) versus long-loop (end-of-life) feedstock.
-
Match technology to feedstock and offtake. Not all recovery technologies are equal across feedstock streams. Our techno-economic roadmaps quantify break-even yields and product specifications; match technology selection to your targeted product stream rather than selecting technology independently.
-
Layer capital strategies: blend measurable public financing opportunities with staged private capital to shorten time-to-commercial while de‑risking scale-up. We map grant/loan programs against project timelines and provide a practical funding playbook for 2026–2028 execution.
-
Design for product quality and standards. Magnet-grade outputs require tight impurity control; recycling projects must incorporate downstream purification or partner with magnet manufacturers to realize premium pricing. Our recommended process flows include pragmatic quality checkpoints to retain value.
-
Develop compliance and trade contingency plans. With export controls and extraterritorial licensing in flux, build compliance-first sourcing and technology governance frameworks. The report includes a jurisdictional risk matrix and a checklist for contract language that protects IP and supply continuity.
-
Consider industrial clustering to capture scale. Co-location with magnet manufacturing, battery plants, or existing refining capacity reduces logistics and intermediate handling costs—our location decision model weights cost, feedstock availability, and policy incentives.
What the report contains — operationally useful deliverables
This report is intentionally practical. It is designed to be a working tool for 2026 planning and includes:
-
Market sizing and growth scenarios (2020–2032) with transparent assumptions and sensitivity analyses for pricing, collection rates, and technology adoption.
-
Technology evaluation frameworks that compare recovery yield, unit economics, capital intensity, and environmental footprint across leading process routes.
-
Commercial due diligence templates for feedstock agreements, offtake contracts, and EPC procurement specific to recycling plants.
-
Project financial models with modular inputs for plant size, feedstock grade, and product mix—enabling rapid scenario testing for 2026 investment decisions.
-
A competitive intelligence chapter profiling market players, their strategic moves, and a forward-looking map of announced capacities and likely commercialization timelines (redacted at segment granularity in this preview to protect proprietary forecasting detail).
-
Regulatory and policy appendices summarizing recent export controls, public financing programs, and recommended compliance actions.
How to use this intelligence in 2026
Leaders should use the report to create an executable 24–36 month plan aligned with capital cycles and policy windows. We recommend three immediate actions:
-
Run a rapid portfolio fit exercise using our technology–feedstock matrix to prioritize piloting vs. partnering vs. building.
-
Begin targeted feedstock negotiations with the top local collectors/OEMs identified in our market map, locking minimum viable throughput to de-risk financing conversations.
-
Engage with funding stakeholders—public and private—using our investor-ready capex and cash-flow models to secure trancheable finance tied to measurable performance milestones.
Why PW Consulting’s forecast is strategically distinct
Our approach blends granular project-level techno-economics with system-level trade-flow analysis and a disciplined policy-risk overlay. The report’s forecasts are not a single baseline; they are a suite of scenarios that reflect the key variables we see driving 2026 outcomes—feedstock collection efficacy, technology learning rates, policy levers, and raw material price dynamics. We show not only where value pools are likely to emerge but also the tactical moves that can capture them.
Trailer principle — what this preview omits and where to find it
This press release intentionally highlights strategic implications and high-level market trajectory. To preserve the utility of the intelligence for commercial decision-making, detailed segment-level tables (regional splits, application shares, and company-level revenue estimates) and the full project-by-project capacity schedule are reserved for subscribers of the full report. Those exhibits include the exact flows, unit economics, and sensitivity tables that corporate planners need to execute in 2026.
Next steps
Executives preparing decisions in 2026 should contact PW Consulting to access the full Rare Earth Metal Recycling Market report and the accompanying financial model. Our advisory team is available to run a tailored 48-hour strategic diagnostics session, deploying the report’s datasets against your assets, partner list, and capital constraints to produce an actionable 90‑day plan.
About PW Consulting
PW Consulting is a strategy advisory and industry analysis firm specializing in critical-materials value chains. Our Rare Earth Metal Recycling Market report synthesizes technical, commercial, and policy intelligence to help clients convert market transition into competitive advantage.
For detailed analysis of this topic, please visit the official page: Rare Earth Metal Recycling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 7.38% CAGR for Metal Ion Free (MIF) Photoresist Developer Market Through 2032
By PW Consulting, 2026-07-13
Metal Ion Free (MIF) Photoresist Developer Market — Strategic Imperatives for 2026
Executive summary
PW Consulting’s new market study on Metal Ion Free (MIF) Photoresist Developers delivers the evidence-based framework executives need to make high-stakes semiconductor materials decisions in 2026. Built on a 2020–2025 historical baseline with 2025 as the base year and a 2026–2032 forecast horizon, the report quantifies a sustained growth trajectory: the global MIF developer market expands from under USD 1.0 Billion in 2020 to roughly USD 1.40 Billion in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 7.38% through the 2026–2032 forecasting window, approaching the low‑to‑mid USD 2.3 Billion range by 2032. These macro dynamics create discrete opportunities and risks for process engineers, procurement leads, and corporate strategists preparing for the 2026 budget cycle and beyond.
Metal Ion Free (MIF) Photoresist Developer Market
Why 2026 is a decisive inflection point
-
Node migration and yield sensitivity: As semiconductor manufacturers consolidate mature nodes and ramp advanced logic, the tolerance for ionic contamination tightens — elevating the strategic importance of MIF developers for device reliability and yield. 2026 is when many capital and process decisions finalized in 2024–25 will enter execution, making timely vendor choices critical.
Metal Ion Free (MIF) Photoresist Developer Market -
Supply-side dynamics and cost pass-through: Upstream feedstock (notably tetramethylammonium hydroxide, TMAH) and regional demand swings have resulted in directional price softness in early‑to‑mid 2025. Buyers and planners must decide in 2026 whether to lock long-term supply agreements, pursue spot procurement, or invest in formulation co-development to secure predictable margins.
Metal Ion Free (MIF) Photoresist Developer Market -
Regulatory and sustainability inflection: Emphasis on low-ionic, environmentally compliant developers has accelerated vendor product launches and partnerships. 2026 procurement strategies should explicitly incorporate environmental compliance, recyclability of process chemistries, and vendor roadmaps for lower-environmental-impact formulations.
Market trajectory and what it means for decisions
The market’s historical compounding and our forecasted 7.38% CAGR together indicate steady, above‑inflation growth driven by semiconductor production resilience and incremental yield-driven migrations to MIF chemistries. For 2026 planning this translates into three practical implications:
-
Invest in qualification pipelines now: Lead times for developer qualification—lab evaluations, pilot production runs, and inline integration—can exceed a single fiscal year when combining supplier audits, wafer‑level testing, and supply agreements. Firms that begin cross-functional qualification in early 2026 can materially shorten time-to-production for critical nodes in 2027.
-
Prioritize supplier portfolio design: Given the market concentration metrics (the top three suppliers capture a majority share and the top five an even larger portion), strategic sourcing should balance performance specialization with supplier diversification to mitigate single‑source exposure.
-
Embed price and supply scenarios in budgeting: Because raw material pricing exhibited softness in Q2 2025, 2026 procurement should model both continued softening and potential rebound scenarios tied to demand cycles in foundry and memory segments.
Key market dynamics shaping 2026 strategies
-
Feedstock concentration: TMAH remains the dominant upstream input with standard normalities used across most MIF developer formulations. Any supply disruption or regulatory action affecting TMAH will have an outsized impact on downstream availability and qualification schedules.
-
Regulatory and purity drivers: MIF developers are increasingly the default where ionic purity matters (chemically amplified and DNQ-based resists, sub‑0.5 µm work). Decision-makers must align product selection with device reliability specifications rather than price alone.
-
Product differentiation: Vendors are competing not just on purity and normality but on adjunct performance attributes—wetting agents, residue control, and compatibility with immersion or in‑line track systems. Procurement and process teams should score suppliers against a multidimensional performance matrix instead of a unit price list.
-
Sustainability and compliance: Recent launches and partnerships show suppliers investing in eco‑friendlier MIF formulations. Incorporating environmental KPIs into supplier scorecards will be a differentiator for OEMs and fabs pursuing sustainable manufacturing mandates.
Competitive landscape — what matters to buyers and strategists
The MIF developer vendor ecosystem blends large, vertically integrated chemical companies with fast‑moving specialty formulators and distribution partners. PW Consulting’s analysis identifies several strategic postures that matter in 2026:
-
Global chemistry leaders: Long‑standing players with broad portfolios offer scale, technical support, and global logistics that suit high-volume foundries. Their recent moves include eco‑friendly product introductions and strategic partnerships to support customized process solutions—important for partners seeking co‑development and security of supply.
-
Regional and specialty formulators: Smaller manufacturers and niche suppliers provide quick‑turn customization and lab‑scale to production transition capability. These firms are ideal partners for product differentiation and pilot projects where fast iteration matters.
-
Distributors and lab-to-production bridges: Specialized distribution companies play a critical role in bringing major brands into small/mid‑volume fabs and R&D labs, offering technical dispersion and local regulatory navigation.
For procurement and strategy teams: evaluate suppliers across three dimensions—technical fit (compatibility with resist systems and track equipment), operational resilience (lead times, multi-site supply), and strategic flexibility (co‑development, IP, and environmental roadmap).
Recent vendor activity and implications
-
Product launches focused on environmental performance and process compatibility indicate vendors expect sustainability and compliance to be purchasing criteria in 2026. Buyers should request detailed life‑cycle and regulatory documentation during RFPs.
-
Partnerships between major suppliers and device manufacturers suggest a trend toward collaborative product customization. Corporates considering process differentiation should assess the strategic value of exclusive or semi‑exclusive development agreements.
-
Price signals from 2025 and early 2026 imply buyers can achieve short‑term cost relief, but should guard against complacency—securing long‑term stability often requires premium terms or co‑investment in qualification and supply resilience.
Actionable 2026 playbook — recommendations at a glance
-
Start an accelerated qualification sprint: Launch cross‑functional (procurement, process, quality) trials for at least two supplier candidates per critical node. Target pilot completion within 6–12 months and align budget approvals to that timeline.
-
Adopt a layered sourcing strategy: Combine one lead global supplier for scale and two regional/specialty partners for flexibility. Include contractual clauses for price review tied to key raw material indices, and inventory buffers for critical ramp periods.
-
Negotiate co‑development and IP terms: Where process differentiation matters, structure agreements that secure priority access to new MIF formulations while retaining manufacturing rights or preferred status during ramp phases.
-
Integrate sustainability KPIs: Require transparency on formulation lifecycle impacts and vendor roadmaps for lower environmental footprint chemistries as a condition for long-term sourcing commitments.
-
Scenario test budgets: Build P&L sensitivity for sustained price softness, short-term supply shocks, and accelerated demand—update capital and working capital models quarterly in 2026.
What PW Consulting’s report includes (practical deliverables)
The full market study translates these strategic implications into operational tools: a validated market sizing and forecast model (USD, revenue expressed in Million units), segmentation by region/chemistry/application, vendor profiles and capability maps, supply‑chain heat maps, raw‑material pricing scenarios, regulatory impact analysis, a risk matrix, M&A and partnership targets, and an execution playbook for procurement and process teams. Importantly, the report pairs numerical forecasts with qualification checklists, supplier scoring templates, and a buyer’s negotiation playbook that clients can deploy immediately.
Accessing the full intelligence
This release is a strategic “trailer”: it surfaces the evidence and frameworks that will shape successful 2026 strategies while preserving the granular segmentation and supplier‑level data that our clients rely on for tactical decisions. For procurement teams, process engineering leads, corporate development professionals, and investors preparing commitments in 2026, the full report provides the downloadable datasets, interactive models, and due‑diligence appendices necessary to act with confidence.
Contact
To request an executive briefing or to license the complete PW Consulting MIF Photoresist Developer Market Report (including the downloadable forecast model and supplier scorecards), contact our Industry Strategy Desk at insights@pwconsulting.com. Time‑sensitive advisory slots for 2026 strategy sessions are available on a limited basis.
For detailed analysis of this topic, please visit the official page: Metal Ion Free (MIF) Photoresist Developer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Liposomal Glutathione Market to Expand at 8.79% CAGR Through 2032
By PW Consulting, 2026-07-13
Liposomal Glutathione Market 2026 Strategic Outlook — Actionable Intelligence for Corporate Decision-Makers
PW Consulting’s latest market intelligence on Liposomal Glutathione synthesizes five years of historical performance with a rigorous 2026–2032 forecast to inform near-term corporate strategy. The global market recorded steady expansion through 2020–2025, reaching an estimated USD 186.15 Million in the base year (2025). Our model anticipates continued momentum at a compound annual growth rate (CAGR) of 8.79% for 2026–2032, with the market evolving from roughly USD 206.29 Million in 2026 to an expected USD 335.89 Million by 2032. These macro trajectories create both clear opportunities and strategic challenges for incumbent players, new entrants, ingredient suppliers, and channel partners.
Liposomal Glutathione Market
Why this report matters for 2026 planning
-
Decision support under uncertainty: the market is in a structural growth phase driven by bioavailability demand, premium consumer positioning, and formulation innovation. Our scenarios quantify upside and downside pathways to help allocate CAPEX and commercial spend.
Liposomal Glutathione Market -
Operational risk mitigation: the report identifies supply-chain pinch points and proposes sourcing strategies for reduced L‑glutathione and phospholipid inputs — critical for continuity in 2026 procurement cycles.
Liposomal Glutathione Market -
Go‑to‑market design: we map effective commercial models (DTC, specialty retail, practitioner channels, and B2B formulation licensing) and provide playbooks for rapid execution.
-
M&A and partnership intelligence: our competitive analysis and concentration metrics highlight likely target profiles and timing windows for acquisitive growth or strategic alliances.
What you will find in the report — practical, executable deliverables
-
Dynamic market model (2020–2032) delivered in Excel, enabling user-defined scenarios and sensitivity testing of pricing, penetration, and channel mix assumptions.
-
Commercial playbooks tailored for product types and route-to-market strategies, including sample promotional narratives and positioning frameworks for premium vs. mass segments.
-
Supply-chain scorecards and a supplier short-list for raw glutathione and phosphatidylcholine, with risk heatmaps and recommended mitigation levers.
-
Regulatory and labeling toolkit that translates DSHEA-era constraints into compliant marketing language and evidence strategies that support allowable structure–function claims.
-
Product development checklist covering formulation choices, stability testing, PK/PD study templates, and third-party validation pathways to substantiate bioavailability claims.
-
Competitive intelligence dossier on leading brands and manufacturer profiles, plus a prioritized list of M&A/partnership targets and value-creation hypotheses.
Macro and market-structure takeaways (data‑driven)
The category has transitioned from niche to mainstream over the last five years. The growth profile through 2025 reflects rising consumer awareness of antioxidant strategies and a premium willingness to pay for demonstrable bioavailability improvements. Our forecasted 8.79% CAGR captures sustained adoption across channels and iterative product innovation rather than a one‑time spike.
Market concentration is moderate: the top three players account for a meaningful share, while the top five increase that share further but leave room for disruptive entrants and mid-sized specialists. This structure implies the sector is neither a pure oligopoly nor highly fragmented; strategic consolidation and brand consolidation remain highly plausible, particularly for companies that can pair formulation IP with distribution scale.
Competitive landscape — positioning and strategic implications
-
Quicksilver Scientific — Known for liquid and spray formats emphasizing enhanced bioavailability. Strategic strengths: clinician awareness and formulation recognition. Strategic implication: further investment in comparative bioavailability data and clinician education can solidify premium pricing and justify channel exclusives.
-
LivOn Laboratories — Proprietor of a recognized liposomal encapsulation technology marketed for oral delivery. Strategic strengths: proprietary processing and brand equity with nutraceutical formulators. Strategic implication: consider licensing models to monetize technology across adjacent antioxidant ingredients or pursue selective co‑branded partnerships.
-
Seeking Health — Positions on ingredient sourcing (non‑GMO sunflower phospholipids) and practitioner channels. Strategic strengths: supply‑chain story and clinician trust. Strategic implication: opportunity to expand practitioner-led educational programs and evidence-generation to defend premium segment share.
-
Core Med Science — Focused on high-potency formulations across capsules and liquids. Strategic strengths: product potency claims and broad format offering. Strategic implication: vertical integration or supply agreements for reduced L‑glutathione could protect margins as raw-material pricing evolves.
-
Empirical Labs — Active in liquid formulations for detox and antioxidant positioning. Strategic strengths: niche detox audience and targeted marketing. Strategic implication: cross-selling into adjacent detox or functional wellness bundles and clinical partnerships can expand lifetime value.
Regulatory, raw-material and research context
Key regulatory reality: in the U.S., liposomal glutathione is marketed as a dietary supplement under DSHEA and is not subject to pre-market FDA approval. This creates a compliance landscape where labeling, substantiation of claims, and advertising rigor are decisive competitive differentiators rather than product approval gates. Companies must adopt conservative claim language, maintain audit-ready documentation, and implement robust adverse event monitoring.
Raw-material dynamics are central. Reduced L‑glutathione produced via yeast fermentation is the predominant source, while liposomes are typically formed from phosphatidylcholine derivatives. Supply tightness, quality divergence across suppliers, and geopolitical sourcing risk for phospholipids can all materially affect cost of goods sold and product shelf stability. Our supply‑chain module provides a prioritized mitigation plan including secondary sourcing, long‑term contracts, and on‑site QC protocols.
Research and promotional constraints: standard consumer-facing disclaimers remain necessary. Investing in human PK/PD and bioavailability studies is a high‑leverage move: credible clinical data enables stronger trade partnerships, premium pricing, and reduced risk during regulatory or marketing scrutiny.
Prescriptive strategic moves for 2026
-
Invest selectively in human bioavailability data and third‑party validations to convert curiosity into enduring willingness to pay.
-
Secure diversified supply lines for reduced L‑glutathione and phospholipids now; consider multi-year offtake agreements to stabilize input costs.
-
Prioritize GMP-certified manufacturing and transparent QC reporting to differentiate on quality — not just marketing.
-
Adopt hybrid commercial models that blend practitioner endorsement with DTC storytelling for maximal reach and margin control.
-
Pursue bolt‑on M&A for formulation IP or channel capability rather than headline-grabbing buyouts; small strategic acquisitions can accelerate scale at lower valuation multiples.
-
Systematize compliance and claims governance across markets to avoid costly reworks or enforcement actions as the category matures.
-
Explore licensing of liposomal platforms to white-label partners as a lower-capex route to enlarge addressable market footprint.
The PW Consulting difference — how we support 2026 decisions
Our Liposomal Glutathione Market report is designed as an operational toolkit for corporate leaders: the deliverable set includes a flexible financial model, a competitor and supplier database, regulatory compliance templates, and a prioritized roadmap of initiatives keyed to ROI and timing. For firms preparing 2026 budgets, the combination of modeled scenarios and tactical playbooks reduces execution risk and accelerates time-to-market for prioritized initiatives.
Note: this release presents high‑confidence macro results and strategic guidance. To preserve the tactical value of the dataset for subscribers and to encourage direct engagement, detailed segmental breakdowns, regional splits, application-level datapoints, and company market-share tables are withheld here. The full report and supporting Excel model contain the granular tables and heatmaps that decision-makers require to execute precise, investable strategies.
Next steps
-
If you are evaluating portfolio moves, distribution strategies, or sourcing arrangements for 2026, begin with a scenario workshop using our model to identify breakeven investment levels and prioritized actions.
-
Contact PW Consulting to access the full report and the downloadable market model; the detailed segmentation, company share tables, and supplier shortlists are available to subscribers and advisory clients.
2026 will be a defining year for companies that convert formulation credibility, supply‑chain resilience, and disciplined commercial execution into defensible market positions. PW Consulting’s Liposomal Glutathione Market intelligence equips leaders with the foresight and tools to act decisively — without revealing the proprietary segmentation that makes those actions investable.
For detailed analysis of this topic, please visit the official page: Liposomal Glutathione Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Polarizer for OLED Market to Expand at a 10.32% CAGR Through 2032
By PW Consulting, 2026-07-13
Polarizer for OLED Market — Strategic Briefing (PW Consulting)
Executive summary
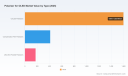
As companies set budgets and strategic priorities for 2026, the polarizer segment for OLED displays sits at a pivotal inflection point. PW Consulting’s forthcoming Polarizer for OLED Market report synthesizes robust quantitative modelling with on-the-ground commercial intelligence to inform executive decisions on product development, capacity allocation, sourcing, and M&A. At the macro level, the OLED polarizer market is recovering and re-accelerating: the global market reached roughly USD 2.19 billion in our 2025 base year and is projected to expand at a compound annual growth rate (CAGR) of about 10.32% across our 2026–2032 forecast horizon — reaching a materially larger market size by 2032. This growth coexists with accelerating substitution risks from polarizer-less technologies, concentrated supplier structures, and raw-material cost volatility — factors that together make 2026 a make-or-break year for many OEMs and suppliers.
Polarizer for OLED Market
Why this matters for 2026 planning
-
Timing of investment: With a strong near-term growth trajectory, suppliers face trade-offs between capacity expansion and preserving capital for R&D into alternate optical stacks. The opportunity to capture incremental volume in 2026 is real, but so is the risk of overbuilding for a market being reshaped by pol-less innovations.
Polarizer for OLED Market -
Risk management: Raw-material exposure (notably PVA and iodine) creates a dual challenge — cost-pass-through limits with end customers, and supply concentration risks. Companies that lock flexible sourcing arrangements or integrate upstream are positioned to protect margins in 2026.
Polarizer for OLED Market -
Customer alignment: Panel-makers and system OEMs continue to pilot polarizer-free architectures for specific product segments. Suppliers must prioritize cross-functional partnerships with display integrators in 2026 to retain design-ins and avoid being disintermediated.
Market snapshot (high level)
Our model, calibrated to 2020–2025 historical performance and updated through early 2026 intelligence, quantifies a market that has grown steadily from the 2020 base and stands at approximately USD 2.19 billion in 2025. Under the central forecast scenario the market expands at a 10.32% CAGR during 2026–2032, reflecting continued OLED adoption across consumer electronics, large-format displays, and specialized automotive/industrial applications. The market remains moderately concentrated: the top three suppliers account for roughly 68% of market share and the top five approach the mid‑80s percent range — a structure that creates both resilience and vulnerability depending on how quickly substitution trends proceed.
Note: This briefing intentionally omits detailed segmentation figures by region, product type, and application. The full report contains the granular splits, growth rates by segment, and model sensitivities that underpin the scenarios summarized here.
Competitive landscape — strategic implications
Supplier competition is bifurcating into (1) scale-focused incumbents maintaining cost and supply leadership, and (2) specialist innovators pursuing ultra-thin, flexible and high-contrast solutions. Key companies we track exhibit distinct positioning:
-
Nitto Denko Corporation (Japan) — A global leader in ultra-thin polarizers with strong IP and long-standing design relationships in smartphones and premium displays. Nitto’s scale and product breadth make it a de facto partner for panel-makers migrating toward flexible and foldable form factors.
-
Sumitomo Chemical (Japan) — Focused on high-performance PVA-based films for premium applications. Its strengths are in optical performance and material science, positioning it to defend premium price points but leaving it exposed to raw-material inflation unless hedged.
-
LG Chem / Shanjin Optoelectronics (Korea/China) — Retains OLED-specific manufacturing capabilities, particularly for larger-size and flexible panels. Close ties with panel ecosystems give LG Chem strategic leverage for volume commitments and co-development.
-
Samsung SDI (Ace Digitech) (Korea) — Notable for polarizers tailored to foldable and premium OLEDs and for potential strategic moves tied to Samsung’s broader display roadmap. Business positioning is subject to ongoing strategic review, but the company’s integration into a major panel ecosystem is a competitive differentiator.
-
BenQ Materials (Taiwan) — Specialist in bendable circular polarizers, gaining share in the foldable segment. Smaller scale than the largest incumbents but high relevance in fast-growing subsegments.
-
Other regional manufacturers (Japan, China, Taiwan, Korea) — A cadre of medium and smaller players are expanding capacity and capability, often targeting cost-sensitive segments or regional OEMs. Their growing presence contributes to supply competition and to the industry’s ability to respond to regional trade shifts.
Strategic takeaway: market concentration gives incumbents pricing power in the near term but does not insulate them from technology-driven commoditization. Partnerships with panel-makers, selective capex, and focused R&D into flexible/ultra-thin materials will be decisive in 2026.
Technology disruption and demand substitution
Three concurrent trends are reshaping demand:
-
Polarizer-less innovations: Independent market analyses forecast meaningful adoption of polarizer-free OLED modules in certain device classes over the coming decade. Pilots and awards (e.g., recent recognitions for polarizer-free display innovations) indicate commercial momentum that could materially reduce some polarizer volumes, particularly where thickness and cost are paramount.
-
Alternative optical stacks: Approaches such as OLED Transmittance Control Film (OTF) are gaining traction in specific TV applications as a way to optimize cost and thinness. These alternatives do not instantly negate the polarizer market but change the mix of required optical films and the value chain.
-
Segment-specific trajectories: Replacement risk is uneven — some applications (e.g., high-contrast smartphone panels, certain automotive displays) will maintain polarizer demand longer due to optical performance requirements, while others may move faster toward pol-less designs.
Supply chain and input risk
Manufacturing of polarizer films is materially dependent on polyvinyl alcohol (PVA) and iodine for dyeing and performance. Key observations for 2026 planning:
-
Input concentration: The iodine supply chain is concentrated geographically; this creates price volatility and raises secure-supply concerns. Market-level estimates suggest the iodine sector itself will be a multibillion-dollar market in 2026, with major national suppliers accounting for a large share of output.
-
Margin pressure: Historical gross margins for polarizer operations at several Chinese and Taiwanese producers cluster in the mid‑teens to low‑twenties percent. That margin band constrains the ability of suppliers to fully absorb raw-material spikes without contractual or commercial consequences.
-
Trade & tariff dynamics: Policy shifts — such as potential changes to previously tariff-free treatments of polarizers and sub-films — plus ongoing US-China trade tensions create sourcing and competitiveness implications. Companies should stress-test 2026 supplier strategies against alternative tariff scenarios.
Actionable recommendations for 2026
-
Prioritize dual-track investment: allocate a portion of R&D and capex budgets to defend core polarizer technology (ultra-thin, flexible, circular polarizers) while funding targeted pilots for pol-less optical solutions with key panel customers.
-
Hedge raw-material exposure: secure multi-year supply agreements for PVA and iodine, consider strategic inventory buffering, and evaluate upstream investments or alliances to stabilize cost and availability.
-
Forge closer OEM partnerships: negotiate long-term design-in commitments, co-development agreements, and risk-sharing contracts with panel-makers to protect revenue streams as optical architectures evolve.
-
Reassess geographic footprint: model tariff scenarios and re-align production footprints and sourcing to mitigate trade risk while preserving access to growth markets.
-
Targeted M&A and JV playbook: prioritize acquisitions or minority investments that fill capability gaps (e.g., pol-less optics, flexible substrates, or iodine/PVA upstream exposure) and that can be integrated rapidly to capture 2026 market opportunities.
-
Adopt scenario-driven planning: use our three-tier scenarios (conservative, central, rapid substitution) to set contingency budgets and trigger points for capacity adjustments across 2026.
What the PW Consulting report contains (practical deliverables)
-
Market sizing and forecasts (2020–2032) with driver decomposition and sensitivity modelling for pol-less adoption rates and component substitution.
-
Supplier scorecards and cost-to-serve benchmarking for the top global firms, including capability maps and strategic positioning assessments.
-
Supply-chain heatmaps identifying raw-material risk, single points of failure, and mitigation levers for 2026 procurement cycles.
-
Commercial playbooks for OEMs and suppliers: pricing strategies, contract templates for long-term sourcing, and co-development agreement templates.
-
M&A screen: prioritized targets, valuation heuristics, and integration risk checklists to accelerate 2026 deal-making.
-
Regulatory and geopolitical impact analysis with tariff sensitivity scenarios and alternative sourcing strategies.
-
Executive dashboards and negotiation-ready slide decks to support board-level decision-making in 2026.
Closing perspective
2026 represents both an opportunity window and a stress test for players across the polarizer value chain. The macro trajectory is favorable — double-digit CAGR through our forecast period — yet the pace and shape of technology substitution, input volatility, and trade dynamics will determine winners and losers. PW Consulting’s Polarizer for OLED Market report provides the quantitative backbone and commercial playbooks necessary to make high-conviction decisions in 2026 without waiting for perfect foresight.
To access the complete analysis, including the withheld segment-level intelligence and supplier-specific scorecards, please consult the full Polarizer for OLED Market report on our website or contact our industry team for an enterprise briefing.
For detailed analysis of this topic, please visit the official page: Polarizer for OLED Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Marine Electric Motor Market to More Than Double to USD 16.42 Billion by 2032 on a 12.25% CAGR
By PW Consulting, 2026-07-13
Marine Electric Motor Market — 2026 Strategic Brief: Why this report will shape your electrification decisions
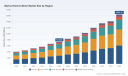
PW Consulting’s latest Marine Electric Motor Market report (base year 2025) synthesizes quantitative projection models, supplier intelligence, technology roadmaps and procurement-grade decision tools to guide boardroom and commercial teams through the critical 2026 planning window. The market is transitioning from niche retrofit projects to mainstream vessel architectures: global demand has more than doubled since 2020 and is projected to expand at a compound annual growth rate of approximately 12.25% into the forecast horizon. On a headline basis, the market grew from around USD 4.1 billion in 2020 to roughly USD 7.3 billion in 2025 and is forecast to exceed USD 8.3 billion in 2026, accelerating toward an estimated USD 16.4 billion by 2032. These dynamics create discrete tactical and strategic inflection points for shipowners, OEMs, suppliers and investors in 2026.
Marine Electric Motor Market
Why this matters to executives in 2026
- Investment timing: With robust near-term growth, capital allocation decisions made in 2026 will determine access to constrained production capacity and the ability to secure preferential OEM engagement.
- Procurement strategy: Rapid product evolution and supply-side concentration on critical raw materials mean single-source procurement or late contracting can significantly raise TCO and delivery risk.
- Product roadmap alignment: From small recreational outboards to high-power inboard systems, technology choices made now (type of motor, magnet technology, integration strategy) will lock in lifecycle efficiency and retrofit flexibility for a decade.
- Regulatory compliance and commercial opportunity: New IMO measures and tightened energy-efficiency planning raise both compliance risk and market demand; early movers capture first-mover commercial advantages in retrofit and newbuild segments.
What the PW Consulting report delivers — practical, decision-ready content
- Proprietary demand model with scenario variants (base, accelerated decarbonization, supply-constrained) and downloadable forecast datasets calibrated to 2020–2025 historicals and extended to 2032.
- Fully auditable financial templates: capex/opex lines, TCO calculators, and payback analyses tailored to propulsion and auxiliary installations across vessel archetypes.
- Supplier scorecards and negotiation playbooks: capability matrices, technology readiness, warranty and service footprints, and recommended commercial terms segmented by buyer profile.
- Supply-chain heatmaps and risk registers: material exposure (magnets, copper), manufacturing bottlenecks, and logistics vectors—plus mitigation options such as strategic inventory, long-term offtake, and co-investment models.
- Technology deep dives: permanent-magnet architectures, synchronous/asynchronous options, novel topologies (including recent trapezoidal stator radial-flux designs), and integration pathways for hybrid-electric systems.
- Case studies and implementation roadmaps: sample retrofit and newbuild programs with stepwise milestones, certification checklists, and expected operational outcomes.
- M&A and partnership screening tools: valuation heuristics for target assessment, strategic fit matrices and playbooks for technology licensing or joint development agreements.
Market dynamics shaping 2026 opportunity
- Regulatory push: The IMO’s 2025–2027 policy package — including a global fuel standard and strengthened SEEMP requirements — creates a deterministic demand tailwind for low- and zero-emission propulsion. These rules enter force in 2027 and are already prompting fleets to accelerate electrification pilots and design-for-electrification in newbuild contracts.
- Raw material and energy supply constraints: The industry faces concentration risk for rare earth elements used in high-power permanent-magnet motors, with primary production concentrated in a small number of jurisdictions. Parallel pressure on copper supply driven by broader electrification increases material cost volatility and project scheduling risk in 2026.
- Technology maturation and product proliferation: Smaller, higher-power-density motor topologies and integrated pod and inboard systems are moving from prototype demonstrations to catalog entries, shortening the commercialisation curve for advanced propulsion units.
- Capital markets and financing: Growing availability of green financing and incentive structures for decarbonization makes financed electrification projects more accessible — but lenders increasingly require robust lifecycle models and demonstrated supplier security before funding.
Competitive landscape — who matters and what to watch
The market is characterized by a mix of large industrial incumbents and agile specialist challengers. Leading global suppliers and a cohort of fast-moving innovators are each carving distinct strategic plays; together they shape OEM sourcing, pricing dynamics and integration choices.
Marine Electric Motor Market
- ABB (Zurich, Switzerland) — Strengths: integrated electric propulsion systems and strong installed base in commercial and specialized vessels. Strategic implication: ABB is a default partner for operators seeking turnkey electrification in larger vessel segments; competitors should anticipate bundled solutions and lifecycle service contracts.
- Siemens (Munich, Germany) — Strengths: high-efficiency motors and integrated drives for heavy maritime and offshore applications. Strategic implication: Siemens will continue to anchor large-scale projects where electrification is paired with complex power management and automation.
- Ingeteam / Indar (Zamudio, Spain) — Strengths: broad power range and proven reliability on merchant and specialized ships. Strategic implication: strong contender for retrofits and mid-to-high power newbuilds where established marine credibility is required.
- TECO-Westinghouse (Round Rock, USA) — Strengths: rugged marine-grade motors and long heritage in shipboard systems. Strategic implication: appeals to fleets prioritizing durability and long service lifecycles, particularly in demanding operating profiles.
- Torqeedo, ePropulsion, Evoy, Elco Motor Yachts — Strengths: nimble innovation in outboards, pod drives and leisure/commercial segments with high-efficiency small- to medium-power units. Strategic implication: these firms are accelerating product cycles for small craft and will influence standards, charging/installation norms and aftersales partnerships.
- WEG, Nidec — Strengths: scale manufacturing capability and adaptable motor platforms. Strategic implication: positioned to provide cost-competitive alternatives and to support OEMs requiring volume production and global service footprints.
Recent product and trade-show activity through 2025–2026 demonstrates two parallel flows: incumbents scaling proven architectures for large vessels, and smaller players accelerating power-density improvements and integration for leisure and short-haul commercial craft. Expect continued alliance activity between system integrators and magnet or inverter specialists as manufacturers seek performance-density gains while managing supply-chain exposure.
Marine Electric Motor Market
Supply-chain and technology risk mitigation
- Diversify magnet sourcing and consider magnetless architectures where lifecycle economics and reliability support substitution. Contractual hedges, consortia purchasing, and strategic equity stakes in upstream suppliers are viable options for materially exposed buyers.
- Lock early delivery slots with high-quality manufacturers for 2026–2027 production windows; consider staggered procurement to manage cashflow and avoid single-point delivery risk.
- Invest in holistic TCO models that incorporate commodity volatility, maintenance intervals and potential regulatory penalties to ensure procurement decisions are resilient across scenarios.
Six strategic recommendations for 2026 decision-makers
- Run fast pilots with clear metrics: short-run retrofit pilots (6–18 months) with pre-agreed data sharing enable suppliers and shipowners to derisk full-scale rollouts.
- Adopt a layered supplier strategy: combine a primary systems partner for integration with two qualified secondary suppliers for critical components and aftersales to manage continuity risk.
- Embed material-hedging clauses into supplier contracts: indexed pricing bands, capped pass-throughs and minimum acceptance quantities reduce exposure to rare earth and copper swings.
- Use PW Consulting’s scenario tools to stress-test fleet electrification pathways against regulatory timelines and fuel-cost scenarios before committing to fleet-wide conversion plans.
- Pursue strategic partnerships with inverter and battery suppliers early to capture integration benefits and improve certification timelines.
- Prioritise modularity in design specifications to enable technology refreshes without full-system replacement, protecting investments against rapid product evolution.
How PW Consulting supports execution
Our Marine Electric Motor Market report bundles the quantitative forecast workbook with actionable deliverables — vendor scorecards, procurement RFx templates, capex/opex calculators and a step-by-step implementation playbook. The deliverables are designed for rapid hand-off to procurement, technical and finance teams so that 2026 programs move from approval to contract award with control over timing, cost and compliance exposure.
For decision-makers planning capital allocation, supplier negotiations or M&A activity this year, the report provides the calibrated market view and negotiation playbooks required to convert the current growth trajectory into durable competitive advantage. To access the full dataset, segmented intelligence and the downloadable toolset, please visit PW Consulting’s Marine Electrification insights page to obtain the complete report and advisory options.
For detailed analysis of this topic, please visit the official page: Marine Electric Motor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Flutes Instrument Market Poised for Steady Expansion at a 4.31% CAGR in 2026–2032 Forecast
By PW Consulting, 2026-07-13
Flutes Instrument Market — Strategic Preview for 2026: Actionable Intelligence from PW Consulting
Executive summary
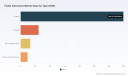
PW Consulting’s new Flutes Instrument Market report delivers a focused, decision-ready briefing for executives planning resource allocation, product strategy, and channel investments in 2026 and beyond. The global market for flutes stood at USD 467.18 Million in 2025 and has demonstrated steady recovery from the pandemic era, rising from USD 382.15 Million in 2020. Our 2026–2032 forecast projects the market to grow at a compound annual growth rate (CAGR) of 4.31%, reaching approximately USD 627.72 Million by 2032. These headline metrics underline a market large enough to justify targeted strategic plays, yet sufficiently specialized to reward companies that execute differentiated value propositions.
Flutes Instrument Market
Why this report matters for 2026 corporate planning
- Timing for resource reallocation: With a mid-single-digit CAGR and evident post-2020 momentum, 2026 is a pivotal year for shifting investment from broad-based volume plays to targeted innovation (e.g., premiumization, sustainable packaging, and new educational channels).
- Risk-calibrated market entry: Trade friction and tariff volatility introduce execution risk for import-dependent models; our intelligence identifies where to localize manufacturing, adjust pricing frameworks, and design compliant supply chains.
- Channel and product prioritization: The market structure favors firms that align product tiers (student, intermediate, professional) with the right distribution and service models—school programs, institutional contracting, and premium direct-to-consumer experiences.
- M&A and partnership signals: Moderate market concentration (top-3 vendors account for ~43% and top-5 for ~56% of market sales) means consolidation and strategic alliances can quickly shift competitive dynamics—use our report to evaluate targets and partnership rationales.
Data-driven positioning without the spoilers
To preserve the strategic value of this preview, we present high-level, verifiable metrics (overall market size, growth rate, concentration) while deliberately reserving granular regional, application and type splits for the full report. Clients will find rich tables, dynamic dashboards, and downloadable models that unpack those segment-level figures, enabling revenue-scenario modeling and price-volume forecasting tailored to your business. This “trailer” approach demonstrates our method and findings while inviting teams to access the full dataset for executable plans.
Flutes Instrument Market
What’s inside the full PW Consulting report (practical deliverables)
- Market sizing and baseline time series (2020–2025) with scenario-based forecasts (2026–2032) that support budgeting and three-tier planning (conservative, base, aggressive).
- Segmentation frameworks (by geographic market, instrument type, and end-use) with interactive sensitivity analysis and break-even maps for manufacturing, import, and distribution choices.
- Channel and go-to-market playbooks: recommended direct-to-consumer, distributor, and institutional strategies for each product tier, including margin calculators and lead-time impact models.
- Supply-chain and cost-pressure analysis: import tariff scenarios, sourcing alternatives, manufacturing footprint optimization, and inventory buffers tuned to instrument lead times.
- Competitive benchmarking: detailed company profiles, product positioning matrices, go-to-market strengths, IP and craftsmanship differentiation, and acquisition targets with quantified fit scores.
- Risk register and mitigation plans covering regulation, trade policy, currency exposure, and demand shocks from education budgets.
- Practical implementation templates: product roadmap prioritization, trade-show and institutional sales calendars, and a 12–24 month M&A diligence checklist.
Competitive landscape — who matters and why
The flute market blends global brands, regional volume players, and a cluster of highly specialised artisanal makers. Strategic implications differ by competitor archetype:
Flutes Instrument Market
- Global integrated manufacturers (e.g., Yamaha Corporation): Scale across student through professional tiers, global distribution reach, and brand trust make them natural partners for institutional programs. Recent moves toward sustainable packaging reinforce a combined product-and-brand experience play that competitors should monitor and, where relevant, emulate.
- Volume/education specialists (e.g., Trevor James, Jupiter, Conn-Selmer/Armstrong): These makers dominate accessibility and price-sensitive channels. They are positioned to capture demand from school programs and beginner segments; incumbents should consider product-adjacent services (rental, maintenance) to protect margin.
- Premium Japanese makers (e.g., Muramatsu, Miyazawa, Altus, Sankyo): Their Japan-based craftsmanship and R&D focus attract professional and advancing players. They set quality benchmarks that define high-price tiers and act as natural partners for artist endorsements and orchestral supply contracts.
- US artisan cluster (Powell, Wm. S. Haynes, Brannen Brothers, Burkart, Di Zhao, and peers): The Boston and broader New England ecosystem delivers ultra-premium, custom instruments prized by orchestras and soloists. Recognition of Greater Boston as a global premium hub in 2025 amplifies brand value for these makers—opportunities exist to scale bespoke services via limited editions, artist collaborations, and experiential marketing.
- Hybrid strategies (Gemeinhardt, Pearl): Firms blending local manufacturing for specific components with offshore assembly achieve favorable cost-quality balance for mid-tier and professional instruments. These models are resilient in tariff environments if component localization is strategically deployed.
Recent developments that should inform 2026 strategy
- Yamaha’s 2025 sustainable packaging redesign demonstrates how product presentation and ESG credentials can be a low-friction lever to improve perceived value at entry price points.
- Regional recognition: the 2025 spotlight on Boston’s artisanal cluster elevates premium makers’ bargaining power with orchestras and collectors, creating aftermarket and service opportunities beyond primary instrument sales.
- The Musical Instrument Museum’s “Magical Flute” exhibition (launched December 2025) is enlarging public interest and can be leveraged by brands for co-marketing, provenance storytelling, and cross-channel promotions.
- Policy and trade noise: 2025 U.S. tariffs on woodwind instruments have reached effective levels up to 27.4% in some cases; export figures showed an 8.4% decline in U.S. musical instrument exports in early–mid 2025 versus prior averages. These disturbances matter for pricing strategy and sourcing decisions in 2026.
- Demand drivers: continued government investments in music education across emerging Asian markets present structural expansion opportunities for student-focused manufacturers and for companies willing to build institutional relationships.
Strategic plays for 2026 — prioritized and actionable
- Localize selectively: Protect margin and access by localizing critical components or assembly in tariff-sensitive markets. Use our cost-benefit templates to identify the break-even point for localization vs. import.
- Product tier segmentation: Differentiate offers by lifecycle stage—promote rental and service bundles in educational markets, emphasize customization and limited editions for premium buyers, and support mid-tier with upgrade paths and trade-in programs.
- Capitalize on sustainability and experience: Align packaging, materials sourcing and repair services with ESG narratives; invest in premium unboxing and post-sale service for higher lifetime value.
- Partnerships with public institutions: Establish curricula and rental agreements with schools and conservatories in growth markets, leveraging government music-education initiatives to secure volume and visibility.
- Digital and direct engagement: Build D2C channels focused on configurators, virtual try-before-you-buy tools, and artist-led content to shorten the consideration cycle for intermediate and professional buyers.
- M&A and alliance playbook: Target bolt-on artisanal brands to capture premium margins, or consolidate distribution in strategic territories to mute tariff impact.
How PW Consulting’s report translates into a 2026 action plan
Executives will find an immediately usable 90–day activation plan inside the full report: prioritized initiatives by expected return and implementation complexity, vendor and partner shortlists, and a set of KPIs for quarterly tracking. The report’s downloadable financial model lets teams stress-test scenarios—tariff shocks, demand surges from education programs, and premiumization rate changes—so CFOs can model cash flow and capital allocation implications quickly.
Closing — next steps
For decision-makers preparing budgets and strategic roadmaps in 2026, PW Consulting’s Flutes Instrument Market report provides the empirical foundation and tactical tools necessary to convert market signals into competitive advantage. This brief exposes the market shape, concentration dynamics, and near-term risks; the full report contains the granular segment data, model access, and company-level detail required to operationalize those insights.
Access the full report and the interactive dataset on PW Consulting’s website to download the executive toolkit, request a bespoke briefing, or arrange a scenario workshop tailored to your organization’s product and distribution footprint.
For detailed analysis of this topic, please visit the official page: Flutes Instrument Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Medical Fiber Laser Market to Expand at 11.24% CAGR (2026–2032), Driving Rapid Clinical Adoption
By PW Consulting, 2026-07-13
Medical Fiber Laser Market 2026: Strategic Imperatives from PW Consulting’s New Industry Brief
PW Consulting’s latest industry brief on the Medical Fiber Laser Market synthesizes five years of historical performance (2020–2025) and delivers a forward-looking, decision-grade view across the 2026–2032 forecast horizon. This report is written for CEOs, corporate development teams, product leaders, and private equity investors preparing high-conviction strategies for 2026. It combines rigorous market-sizing, competitive mapping, regulatory and reimbursement intelligence, and executable commercial playbooks — while deliberately reserving the granular segment-level tables for the full report to preserve client value.
Medical Fiber Laser Market
Market snapshot: trajectory and scale
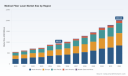
At a macro level the market demonstrates robust, sustained expansion. PW Consulting’s topline sizing shows the global medical fiber laser market growing from USD 554.4 Million in 2020 to USD 950.29 Million in the base year 2025, and accelerating through the forecast to reach USD 2,023.26 Million by 2032 — a compound annual growth rate (CAGR) of 11.24% over the 2026–2032 period. This growth reflects broad-based adoption across urology, dermatology, dentistry and soft-tissue surgical specialties, increased availability of compact thulium and erbium fiber platforms, and dynamic commercial models (capital sale, subscription, and single-use consumables).
Medical Fiber Laser Market
Why this matters for 2026 enterprise decision-making
- Timing of investment: The market’s double-digit CAGR means that choices made in 2026 (R&D allocation, manufacturing scale-up, or distribution partnerships) will have outsized impact on revenue capture across the forecast window.
- Commercial model selection: As platforms migrate from capital equipment only to hybrid capital + recurring consumables models, companies must validate unit economics and lifecycle margin curves before committing to wide rollout.
- Regulatory rhythm: The device class and 510(k)-centric regulatory environment favors fast followers and modular claims strategies; readiness in regulatory dossiers will materially accelerate access to high-value clinical channels.
- M&A and partnership windows: With market concentration moderate at scale (CR3 ~42.5%, CR5 ~61.8%), there is clear room for consolidation and strategic partnerships that can shift share rapidly in targeted subsegments.
Five strategic imperatives for 2026
- Prioritize platform/consumable economics: Map lifecycle margins across device and fiber consumables; use PW Consulting’s pricing-sensitivity model to simulate adoption under varied reimbursement scenarios.
- Build clinical adoption playbooks: Translate improved procedural outcomes (e.g., reduced retropulsion in stone surgery with thulium designs) into reproducible hospital procurement wins via KOL-driven protocols and bundled training.
- Regulatory-first product development: Design product roadmaps with modular 510(k) strategies to minimize iterative regulatory cycles and accelerate geographic launches where pathways are established.
- Flexible go-to-market: Test hybrid commercial routes — direct sales in leading markets, distributor partnerships in selectively strategic markets, and OEM/white-label deals for specialty fibers.
- Targeted M&A and alliances: Acquire or partner for either high-margin consumable streams or niche IP (e.g., specialized laser fiber designs or wavelength-specific systems) that strengthen total addressable market coverage without diluting core competencies.
Competitive landscape — what the market signals
PWC’s competitive scan identifies established laser OEMs, surgical-device companies with distribution muscle, and specialist fiber producers as distinct but overlapping competitor archetypes. Leading names in the space include IPG Photonics (IPG Medical), Coherent, Quanta System, Acclaro Medical, Boston Scientific, Cook Medical, Light Guide Optics, and Olympus — each bringing differentiated advantages in wavelength expertise, fiber design, channel access or regulatory scale.
Medical Fiber Laser Market
- IPG Photonics (IPG Medical): Known for thulium fiber platforms and surgical fiber delivery serving urology applications; distribution relationships amplify reach into high-volume procedural channels.
- Coherent: Recently launched purpose-designed thulium platforms for urology, reflecting incumbent OEM strategies to target therapeutic use-cases with tailored support assemblies.
- Quanta System: European-origin TFL systems focused on urology and delicate soft-tissue procedures; distribution partnerships strengthen cross-border access.
- Acclaro Medical: Focused on a differentiated erbium-doped fluoride fiber platform for dermatology, supported by clinical evidence generation to expand indications.
- Boston Scientific & Cook Medical: Strategic distributors and channel anchors that can accelerate adoption by pairing fiber systems with established clinical offerings and salesforces.
- Light Guide Optics & Olympus: Specialized in fibers and integrated systems respectively, these players highlight the importance of delivery-device compatibility and regulatory clearances for market acceptance.
Recent milestones shaping 2026 strategy
- Acclaro Medical’s clinical presentations in March 2026 expanded dermatology evidence for a 2910 nm erbium-based fiber platform, a signal that clinical data continues to be the decisive barrier to mainstream uptake.
- Light Guide Optics’ FDA 510(k) clearance (late 2024/announced in formal 2025 filings) for surgical laser fibers underscores the priority of regulatory-cleared delivery devices in commercial contracts.
- Boston Scientific’s late-2025 regulatory update for holmium fiber consumables evidences ongoing lifecycle management by incumbents to maintain share through packaging, shelf-life and compatibility enhancements.
- New market entrants and Chinese-origin OEMs securing 510(k) clearances in 2025 signal intensifying competitive supply and downward pressure on specific component pricing — a commercial risk and an opportunity for higher-volume players.
Regulatory and reimbursement dynamics
Medical fiber laser systems and surgical fibers are regulated predominantly under established Class II pathways in major markets. Devices typically pursue 510(k) clearances demonstrating substantial equivalence for indications such as soft tissue ablation, coagulation and lithotripsy. Compliance with GMP, labeling, and post-market surveillance remain non-negotiable operational requirements. On reimbursement, procedures using fiber lasers generally map to existing CPT/DRG codes for laser surgery; there were no fiber-laser-specific procedure codes as of 2025 — meaning reimbursement upside will be earned through demonstrated value rather than new coding lanes.
What the PW Consulting report delivers (practical contents)
The full PW Consulting report is designed as a playbook not a textbook. Highlights include:
- Proprietary market-sizing and scenario models (2020–2032) with sensitivity to pricing, adoption latency, and reimbursement shocks.
- Go-to-market decision matrices that prioritize markets, channels and customer segments by expected ROI and time-to-contribution.
- Regulatory pathway maps for the U.S., EU and selected APAC markets, including checklist-level guidance for 510(k) strategies and labeling claims shaping clinical trials.
- Commercialization templates: sample contracting terms, consumable margin waterfall models, and distributor scorecards proven in laser device rollouts.
- Competitive benchmarking (profiles, product roadmaps, recent filings) and a short-list of pragmatic M&A targets with rationale and valuation comparables.
- Clinical adoption playbooks and KOL engagement frameworks that translate technical advantages (e.g., reduced retropulsion, high-frequency dusting capability) into purchasing decisions.
Risk scenarios and mitigation
PW Consulting models three practical risk scenarios — baseline, aggressive-competition, and reimbursement-adverse — each with explicit triggers and mitigation actions. Key risks include faster-than-expected entrant pricing pressure, regulatory delays for claim expansion, and slower hospital adoption cycles. Mitigations emphasized in the report include staged capacity investments, dual-sourcing for critical fiber components, and prioritized evidence-generation partnerships to secure early adopters.
How to use these insights in 90/180/360 day plans
- 90 days: Validate product-market fit with a compact pilot using the report’s clinical and purchasing playbooks; secure regulatory pre-submission meetings where appropriate.
- 180 days: Execute channel tests (direct vs. distributor), lock initial consumable pricing bands, and begin targeted clinical studies designed with our KOL templates.
- 360 days: Ramp manufacturing commitments aligned to scenario-based demand forecasts and evaluate M&A targets prioritized by the report’s strategic filters.
Conclusion — why this brief matters to C-suite teams
Medical fiber lasers occupy a high-leverage corner of the medtech landscape: accelerating technological innovation, shifting commercial economics, and a regulatory environment that rewards disciplined execution. PW Consulting’s report turns market complexity into an actionable strategic path: quantify opportunity, prioritize investments, hedge against regulatory and competitive shifts, and design commercial models to capture recurring revenue. For executives planning resource allocation in 2026, the insights in this brief are decision-enabling — and the full report contains the confidential segment-level analytics, modeled scenarios, and tactical playbooks required to operationalize these insights.
To access the complete report, which includes full segment tables, vendor scorecards, and downloadable financial models, please visit our report landing page or contact PW Consulting’s Sales & Insights team for a tailored executive briefing.
For detailed analysis of this topic, please visit the official page: Medical Fiber Laser Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Manga & Anime Licensing Market to Expand at 11.5% CAGR, Reaching USD 37,388 Million by 2032
By PW Consulting, 2026-07-13
PW Consulting: Strategic Preview — Manga & Anime Licensing Market Outlook (2026–2032)
Executive summary
The global manga and anime licensing market is entering a strategic inflection point. After accelerating through the early 2020s, the market expanded from roughly USD 10 billion in 2020 to an estimated USD 17.5 billion by 2025. Our analysis projects continued robust growth through the 2026–2032 forecast window at a compound annual growth rate of approximately 11.5%, with the total addressable licensing market approaching the mid‑tens of billions by the early 2030s. For executives planning 2026 budget cycles, content slate decisions, or distribution alliances, this report provides the evidence base and applied frameworks necessary to convert market momentum into durable revenue and IP ownership advantages.
Manga And Anime Licensing Market
Why this matters for 2026 decision-making
-
Market scale and velocity: Sustained double‑digit CAGR through the forecast period shifts licensing from a niche income stream into a core strategic revenue pillar for media conglomerates, publishers, game companies, and consumer brands. Capital allocation, talent pipelines, and M&A theses must reflect that reality by 2026.
Manga And Anime Licensing Market -
Vertical integration premium: Companies that control creation, distribution, and merchandise channels are better positioned to capture downstream licensing economics. Recent transactions and JV activity highlight a premium being placed on integrated IP pipelines.
Manga And Anime Licensing Market -
Platform and regional dynamics: Streaming platforms, D2C merchandising, and gaming tie‑ins are redefining monetization windows. Meanwhile, regulatory, local market, and anti‑piracy actions are reshaping risk-adjusted returns across territories—making market entry and licensing term design more complex and consequential.
What PW Consulting’s report delivers — practical, executable content
We designed this study as a decision tool for C‑suite and licensing teams. The report combines market sizing and forecasting with practitioner‑grade playbooks and contractual tools, including:
-
Proprietary total market and trend models that reconcile historical performance (2020–2025) with scenario‑based forecasts for 2026–2032, enabling sensitivity analysis for macro and micro drivers.
-
Go‑to‑market blueprints for licensors and licensees — covering streaming exclusives, timed theatrical windows, merchandising roadmaps, and app/game integration strategies.
-
IP valuation and royalty benchmarking methodology, including step‑by‑step templates for structuring advance/royalty blends, minimum guarantees, and territory carve‑outs that balance upside capture with distribution partner incentives.
-
Localization and distribution playbooks that prioritize translation, cultural adaptation, and regulatory compliance to maximize per‑market yield while managing cost and speed to market.
-
Risk frameworks addressing copyright enforcement, anti‑piracy enforcement levers, AI ingestion and content‑use exposure, and regulatory shifts—each with operational controls and contract clauses you can implement immediately.
-
M&A and JV decision matrices for acquiring IP owners, stakes in studios, or distribution platforms — complete with target prioritization criteria and integration checklists.
-
Executive dashboards and investor‑grade slide packs summarizing KPIs such as revenue per title, lifetime merchandising yield, and channel mix scenarios (digital, physical, theatrical, experiential).
Competitive landscape — who matters and why
The market’s competitive architecture blends traditional IP holders, platform aggregators, and media conglomerates. The report maps strategic positioning for each major actor and highlights near‑term moves that will affect licensing bargaining power.
-
Crunchyroll (Sony Pictures Entertainment): Continues to expand both streaming reach and direct‑to‑consumer merchandising capabilities, recently launching branded online stores across Southeast Asia. This intensifies platform leverage for exclusive windows and merchandise co‑development.
-
Toei Animation: As a steward of several high‑value legacy franchises, Toei’s licensing approach remains a bellwether for how classic IP will be stewarded across emerging platforms and experiential channels.
-
Aniplex (Sony Music Entertainment Japan): Deepening production capacity through recent studio acquisitions, Aniplex is converting production control into scalable licensing pipelines that increase capture of downstream revenues.
-
Shueisha / VIZ / Shogakukan / Kodansha: These publishers continue to dominate manga IP origination. Their partnership and distribution arrangements in North America and beyond will be determinative for print‑digital balance and English‑language adaptations.
-
Bandai Namco: An example of a commercial model that monetizes IP across games, toys, and merchandise at scale—reported licensing‑related revenues demonstrate the revenue ceiling for well‑executed franchise commercialization.
-
Netflix and other global streamers: Aggressive commissioning of originals and co‑productions is altering licensing windows and creating alternative revenue pools for studios willing to prioritize global exclusivity over territory‑by‑territory licensing.
-
Specialist licensors and distributors (Sentai, GKIDS, Square Enix): Niche players retain strategic value through theatrical distribution expertise, collector‑market credibility, and rights management for titles that are cultural or fiscally specialized.
Recent industry developments with strategic implications
-
Consolidation and production scaling: Studio acquisitions and JV launches (including notable 2025–2026 moves) are shortening the path from IP creation to worldwide licensing — favoring organizations that can operationalize cross‑border production pipelines quickly.
-
Retail & D2C acceleration: Platform operators are increasingly controlling merchandising channels, which changes margin pools and bargaining dynamics for licensees and retail partners.
-
Regulatory and rights landscape: Government policy signals (domestic support principles for creative industry growth and clarified guidance on AI/copyright use) are reducing legal ambiguity but raising compliance requirements that must be embedded in licensing agreements.
-
Piracy enforcement pressure: Recent legal actions against piracy platforms are creating enforcement precedents that licensors can leverage in contract negotiations and anti‑counterfeiting strategies.
Strategic actions for 2026 planning
Based on our scenario work and company‑level analysis, we recommend that leaders prioritize the following actions in their 2026 plans:
-
Shift from channel‑first to IP‑first capital allocation: Prioritize investments that grow and protect original IP portfolios (sequels, cross‑media adaptation rights, merchandising exclusives) rather than short‑term distribution deals.
-
Design flexible licensing terms: Embed performance collars, renegotiation triggers tied to streaming metrics, and downstream revenue‑share mechanisms to capture value as titles scale globally.
-
Operationalize anti‑piracy and AI governance: Adopt contractual clauses and technical controls that reflect recent national guidelines on AI use and international enforcement trends to limit rights leakage.
-
Invest in D2C and experiential channels: Accelerate direct merchandising platforms and event strategies to capture higher lifetime per‑fan revenue, while using platform partnerships to extend reach selectively.
-
Prioritize market access strategies for high‑growth geographies: Use hybrid partnerships (local distributors + global platforms) to mitigate regulatory complexity while preserving monetization upside.
-
Use M&A as capability playbooks: Acquire studios or minority stakes where production control will materially shorten time to monetization and boost negotiated licensing economics.
Why PW Consulting’s intelligence is unique
We combine granular, reproducible market models with implementable legal and commercial templates. The report is built around the executive workflows of licensing teams — from VP licensing to CFO — and includes scenario stress tests, integration checklists, and reproducible financial models validated against public filings and market behaviors.
Next steps — how to access the full intelligence
This release is a strategic preview designed to establish the decision context for 2026. To protect client value and commercial confidentiality we have intentionally withheld detailed regional and application splits, as well as title‑level revenue tables. Subscribers to the full PW Consulting Manga & Anime Licensing Market report receive:
-
Complete model files with downloadable forecasts and sensitivity toggles.
-
Full segmentation by region, type, and application (broken down to actionable units for commercial negotiation).
-
Contract templates, sample term sheets, and royalty benchmarking tables keyed to revenue and channel scenarios.
-
Customized advisory sessions to apply the models to your 2026 planning and go‑to‑market execution.
Contact PW Consulting to request a briefing or to license the full report and datasets. Our team of industry experts will walk you through the models and translate findings into a prioritized action plan tailored to your commercial objectives.
For detailed analysis of this topic, please visit the official page: Manga And Anime Licensing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Low‑Powered Electric Motorcycle & Scooter Market to Expand at a 12.15% CAGR
By PW Consulting, 2026-07-13
Low Powered Electric Motorcycle And Scooter Market: Strategic Imperatives for 2026
PW Consulting today publishes a forward-looking industry brief accompanying our full Low Powered Electric Motorcycle And Scooter Market report (base year 2025). The market reached a definitive scale in 2025 — and, under our base forecast, is expected to expand at a compound annual growth rate of approximately 12.15% through 2032. This trajectory reshapes competitive dynamics, supplier economics and regulatory risk profiles. The analysis that follows is curated to help boards, corporate strategy teams, private equity investors and mobility operators make informed, immediate decisions in 2026. For full segmented datasets, interactive models and annexes, please refer to the complete report on the PW Consulting site.
Low Powered Electric Motorcycle And Scooter Market
Why 2026 is a Pivotal Inflection Point
-
Cost and component dynamics are shifting the unit economics. A material reduction in battery-pack and critical mineral prices over 2024–2025 has improved margin potential for manufacturers and opened space for new business models (battery ownership, swapping and subscription-based services).
Low Powered Electric Motorcycle And Scooter Market -
Regulatory attention is intensifying. Governments and standards bodies have tightened safety and classification rules for electric two‑wheelers, while internationally recognised frameworks (including vehicle safety regulations and UL safety outlines for vehicle systems) are influencing product design and time-to‑market requirements.
Low Powered Electric Motorcycle And Scooter Market -
Market structure remains neither hyper‑consolidated nor atomistic: a small set of large producers coexists with many regional and specialist players, creating both pressure for scale and opportunities for targeted acquisitions or rapid market entry via partnerships.
-
Urban mobility and logistics economics continue to evolve. The segment that serves personal commuting is still a primary volume driver, but commercial last‑mile use cases are changing product specifications and aftersales needs.
What PW Consulting’s Report Delivers — Practical, Decision‑Ready Tools
-
Forecast Model: A company-calibrated market model (2026–2032) with scenario capabilities (base, upside and downside) that allow executives to stress-test capital allocation and pricing strategies.
-
Cost & Supply Chain Toolkit: Bottom-up supply‑chain cost models for battery pack composition, motor and power electronics that quantify sensitivity to commodity swings and supplier concentration.
-
Competitive Benchmarking: Strategic profiles and capability matrices for the leading OEMs and new entrants, focused on product architecture, go‑to‑market muscle, software/IP and manufacturing flex.
-
Regulatory & Safety Matrix: A consolidated compliance checklist mapped to key markets and product classes, including recommended testing sequence and timeline to certification.
-
Go‑to‑Market Playbooks: Channel, fleet and subscription playbooks with KPIs for deployment pilots, dealer enablement and urban operator partnerships.
-
M&A & Partnership Framework: Rapid screening criteria, valuation levers and integration blueprints for targets that deliver scale, technology or distribution advantages.
-
Operational Templates: Pilot scorecards, warranty economics calculators, battery lifecycle management procedures and a risk heatmap for supply and regulatory shocks.
Key Strategic Implications for Executives in 2026
-
Re‑think battery strategy: With continued downward pressure on pack prices and raw lithium cost volatility, firms must decide between owning battery assets, enabling swap ecosystems, or outsourcing to capture margin without capital strain.
-
Prioritise software and services as a differentiation axis: Connectivity, fleet management and subscription features are shifting value from pure hardware to bundled recurring revenue — a critical factor in valuation and margin expansion.
-
Design for compliance and resilience: Incorporate safety certification pathways and thermal management standards into early stage product development to avoid costly rework and market delays.
-
Localise manufacturing selectively: Prioritise localized assembly or cell sourcing in markets where regulation, import duty structures and logistics materially affect price competitiveness.
-
Tailor product roadmaps to dual demand streams: Maintain a clear product split between high‑volume personal commuting designs and more robust platforms for commercial last‑mile use, with differentiated service propositions.
-
Prepare for consolidation opportunities: Given the market’s mid‑level concentration, strategic M&A and alliances can rapidly improve scale and provide access to distribution or technology that would be expensive to build organically.
Competitive Landscape — How Incumbents and Challengers are Positioning
The competitive map is being redrawn along three axes: scale/cost, software-enabled differentiation and ecosystem plays (battery swapping, aftersales and fleet management). Leading manufacturers and new entrants exemplify these vectors.
-
Large-scale incumbents focus on cost and distribution: Several established OEMs leverage manufacturing scale to defend volume-oriented segments and export markets.
-
Smart, connected challengers push software and services: Vendors with integrated IoT, telematics and battery-swapping approaches are transforming retention economics and recurring revenue potential.
-
Regional specialists and legacy brands pursue premium or heritage positioning: Iconic marques and premium innovators are converting brand equity into electrified portfolios targeted at urban buyers willing to pay for design and performance.
Notable corporate positions reviewed in the report include high-volume manufacturers, IoT‑centric platform players, battery‑swap ecosystem builders, India’s high-growth producers and traditional motorcycle OEMs moving into electric segments. Recent market signals that we have analysed include a mainstream manufacturer’s launch of a new scooter platform in late 2025, and a strategic summit by a notable producer showcasing a full‑size model with a third‑party motor and removable lithium-ion battery. These moves demonstrate both product diversification and continued investment in battery systems and modular platforms.
Operational Playbook — Tactical Actions for 2026
-
Supply chain triage: Run a 60‑day battery and motor supplier stress test, mapping alternate sources and qualification lead times.
-
Rapid pilots: Deploy 3–5 pilot vehicles with integrated telematics and warranty telemetry to generate real-world reliability datasets and unit economics before scaling.
-
Regulatory fast‑lane: Engage early with certification bodies and adopt the UL and national vehicle safety frameworks as project milestones to avoid launch pauses.
-
Dealer & fleet alignment: Reconfigure channel incentives to prioritise battery health, service subscriptions and residual value guarantees that reduce consumer total cost of ownership.
Investor & M&A Lens — What Buyers Should Prioritise
-
Value drivers are shifting: IP in software/telemetry and recurring revenue models command premium multiples relative to pure hardware; battery-ownership and swap revenues are key differentiators.
-
Due diligence focus: Assess supply‑contract resiliency, product certification status, and aftersales economics (warranty claims, battery health metrics) — these factors materially affect post‑deal integration risk.
-
Integration roadmap: Successful consolidation requires rapid harmonisation of SKUs, cross‑platform telematics and unified warranty policies to unlock cost synergies.
How to Use This Report Over 90 Days
-
Day 0–30: Strategic reset — senior leadership review, scenario stress‑tests of forecast model, and supplier concentration mapping.
-
Day 30–60: Tactical execution — launch pilot programmes, commence regulatory certification paths, and begin partner negotiations for battery and software partnerships.
-
Day 60–90: Decision cadence — finalise capex allocations, commit to manufacturing footprints or partnership structures, and shortlist M&A targets if inorganic growth is required.
Concluding Recommendation
For companies operating in, or entering, the low-powered electric motorcycle and scooter market, 2026 is the year to convert optionality into repeatable advantage. The combination of improving battery economics, evolving regulatory expectations and the growing importance of software and service revenues creates a clear playbook: secure resilient supply chains, architect products for certifiability, and build recurring‑revenue service layers that protect margin and increase customer lifetime value.
This briefing is a strategic preview intended to demonstrate our analytical depth and practical orientation. The full PW Consulting report contains the complete market model, segmented demand analyses, company share tables and downloadable templates that underpin the recommendations above. Access the full intelligence pack and the interactive scenario model on PW Consulting’s report page to translate these insights into your 2026 decisions.
For detailed analysis of this topic, please visit the official page: Low Powered Electric Motorcycle And Scooter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


