



Category: market research
Si OLED Microdisplay Market Poised for 29.85% CAGR Through 2032 — PW Consulting
By PW Consulting, 2026-07-13
Si‑OLED Microdisplay Market — Strategic Imperatives for 2026
Executive snapshot
The silicon‑backed OLED (Si‑OLED or OLEDoS) microdisplay market has moved from a niche specialist domain into a verified commercial growth story. Our analysis shows the market expanding from roughly USD 345.5 million in 2020 to about USD 1,492.5 million in 2025, with an accelerated trajectory at the start of the forecast window. PW Consulting projects the market to reach approximately USD 1,930.6 million in 2026 and to exceed USD 9.2 billion by 2032, reflecting an aggressive compound annual growth rate of roughly 29.85% across the 2026–2032 forecast period. For leadership teams planning 2026 strategy, this combination of rapid revenue expansion and concentrated supplier capabilities creates a narrow window for decisive action: scale when clarity exists, but hedge while the value chain reconfigures.
Si Oled Microdisplay Market
Why this research matters for 2026 decision-makers
- Timing of capacity commitments: With demand forecasts steepening in 2026, capital decisions made this year will determine who benefits from the next wave of AR/VR, enterprise, and defense contracts. Mistimed investment risks either costly idle capacity or missed market share.
- Product differentiation strategy: Resolution, brightness, contrast, power efficiency and silicon backplane expertise are the primary levers. Prioritizing one axis (e.g., ultra‑high resolution for enterprise AR) over another (e.g., extreme brightness for head‑mounted optics in defense) will shape design-in success.
- Supply chain resilience: Si‑OLED blends semiconductor CMOS processes with OLED materials and optics. Firms that map and secure critical upstream inputs and partner for optical engines will reduce time‑to‑market and failure risk.
- Commercial route options: The market rewards OEM partnerships, module integrators, vertical integration and licensing — simultaneously. Choosing which route to scale in 2026 will influence margins and exit options by 2028.
Demand and technology dynamics shaping 2026 choices
Si‑OLED microdisplays are winning design cycles because they deliver pixel densities and compact footprints that incumbent panel technologies struggle to match. The convergence of high‑resolution silicon backplanes (fabricated with standard CMOS processes) and OLED emissive layers enables near‑eye systems that meet the twin constraints of optical throughput and device ergonomics. Two tangible technology vectors accelerating adoption are peak luminance (to enable bright outdoor or high-dynamic-range near‑eye experiences) and energy efficiency (to extend untethered battery life). Recent R&D milestones from research institutions attest to both extremes: prototypes pushing multi‑megacandela luminance in monochrome microdisplays for specialized optics, and alternative driving schemes that update only required pixels for significantly reduced power draw.
Si Oled Microdisplay Market
On the demand side, the classic consumer AR/VR use case is now complemented by robust enterprise, industrial and defense pull. Near‑term procurement cycles and public sector programs are increasing the addressable market for high‑performance Si‑OLED modules, while consumer AR roadmaps are beginning to incorporate silicon‑backed solutions where pixel density and compact optics are decisive.
Si Oled Microdisplay Market
Competitive landscape — players and strategic postures
The competitive field combines established semiconductor and display incumbents, defense‑oriented specialists, and fast‑scaling pure‑plays. Each cohort presents different advantages and trade‑offs for partners, customers and investors:
- Sony Semiconductor Solutions Corporation: Leverages deep CMOS and imaging expertise to offer high‑resolution, high‑brightness Si‑OLED SKUs and scale manufacturing. Their product releases have set benchmarks in pixel density and luminance for AR/VR optical engines.
- eMagin Corporation: U.S.‑based, with cleanroom production and a history of delivering rugged, high‑brightness microdisplays for defense and industrial customers. Their compliance posture and defense pedigree make them a preferred partner where export controls and certifications are decisive.
- SeeYA Technology (Seeya Technology): A pure‑play OLEDoS manufacturer that has moved from development to mass production and public financing, indicating capital to expand silicon‑OLED capacity and R&D. Their growth trajectory exemplifies how focused players can scale rapidly with the right financing and domestic market support.
- Kopin Corporation: A diversified microdisplay supplier with a long trail of fielded defense solutions and customizable offerings for enterprise and healthcare applications.
- BOE, Seiko Epson, MICROOLED, OLiGHTEK, OLEDWorks: These firms represent a mix of large panel manufacturers, optics‑engineers and niche specialists that can serve both module‑level integration and OEM partnerships. Their combined presence increases options for buyers but also raises the bar on performance and integration capabilities.
Across the competitive field, leadership currently concentrates among a few suppliers with the manufacturing scale, IP breadth and customer access to influence component pricing and qualification timelines. New entrants with strong IP or a focused go‑to‑market strategy can still displace incumbent positions, particularly where they solve a specific optical or thermal constraint.
Recent industry signals that matter for 2026 planning
- Market entrants leveraging public capital to accelerate fabs and R&D highlight the importance of watching financing cycles and capacity additions in 2026.
- Prototype breakthroughs from research institutes that demonstrate high pixel density and novel low‑power driving schemes suggest potential step changes in product architectures over the next 12–24 months.
- Large program awards and defense procurements for OLED‑based head‑mounted displays (including fighter jet programs) indicate a growing, defense‑grade addressable market that will be subject to export controls, certification timelines and long lead procurement cycles.
What the PW Consulting Si‑OLED Microdisplay report delivers (operationally actionable)
Our full study is structured for executives who need to convert market intelligence into executable plans. Highlights include:
- A validated demand model with base‑year calibration (2020–2025) and scenario forecasts to 2032 that isolate near‑term (2026–2028) inflection points and long‑run market sizing.
- Supplier and capability maps that align manufacturing process risks (CMOS fab dependencies, OLED materials sourcing, optics assembly) with typical qualification timelines.
- Decision frameworks for CapEx vs. outsourcing, including a timing matrix that shows break‑even windows for greenfield fabs, capacity leases and strategic JV models.
- Commercial playbooks for OEMs: preferred procurement models, price/volume negotiation levers, and channel strategies (module integrator vs. direct supply).
- Technology roadmaps and R&D investment prioritization guides that link pixel architecture choices to end‑use P&L outcomes (e.g., AR enterprise adoption rates or defense specifications).
- Regulatory and export control impact analysis, plus practical mitigation strategies for defense‑sensitive supply chains.
Note: To preserve client value, the report summarizes segmentation outcomes and competitive positioning in high resolution. This article intentionally omits the granular regional, application and size‑band splits that are available in the gated report and data annex.
Immediate recommendations for 2026 (concise playbook)
- Prioritize flexible capacity commitments: favor scalable production lines or partnerships that allow output to step up as design wins convert into orders.
- Lock critical upstream inputs (CMOS wafer access, OLED materials, specialized optics) with multi‑year contracts or dual‑sourced suppliers to minimize single‑point failures.
- Invest in one clear product differentiator early — either resolution/pixel technology or ultralow‑power driving schemes — and position marketing and BD resources around that capability.
- Engage defense procurement teams early if pursuing military opportunities: build ITAR/compliance capabilities and plan for extended qualification cycles and lifecycle support commitments.
- Consider targeted M&A or JV activity for gaps in optics, packaging or silicon expertise rather than broad vertical integration unless a clear ROI case exists.
- Enable modular designs in product roadmaps to work across multiple optical engines and to accelerate design wins across enterprise and consumer variants.
How PW Consulting’s research de‑risks executive choices in 2026
Our methodology combines primary interviews with OEMs, tier‑1 integrators, and fab partners, triangulated with transaction and financing data, product roadmaps from leading suppliers, and bottom‑up engineering cost models. The result is a defensible, scenario‑based guide that translates market size and growth into concrete operational decisions: who to partner with, when to invest in capacity, and what performance metrics to prioritize to capture the most valuable design‑in opportunities.
Next steps
For executives preparing 2026 strategic plans — whether your focus is manufacturing scale, product roadmaps, channel strategy, or M&A — our Si‑OLED Microdisplay Market report provides the templates and data required to choose with conviction. The full report contains the detailed regional, application and display‑size splits, supplier scorecards, and downloadable model files referenced here. To obtain the comprehensive dataset, methodology appendix and executive workshops, please visit our report page or contact PW Consulting’s microdisplay practice for a briefing.
For detailed analysis of this topic, please visit the official page: Si Oled Microdisplay Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Acquired Immunodeficiency Syndrome Market — 5.42% CAGR to 2032
By PW Consulting, 2026-07-13
Acquired Immunodeficiency Syndrome Market — 2026 Strategic Preview
Executive snapshot
PW Consulting’s latest market study uses a 2025 base year and spans historical analysis (2020–2025) with detailed forecasts through 2032. At the macro level, the global AIDS market stands at approximately USD 36,250 Million in 2025 and is projected to expand to roughly USD 38,946 Million in 2026, continuing to grow to an anticipated market size in excess of USD 52 Billion by 2032. This trajectory represents a mid-single-digit compound annual growth rate (CAGR) across the forecast window — a rate that underpins both steady baseline demand for antiretrovirals and material upside from structural shifts in product modality, pricing and access.
Acquired Immunodeficiency Syndrome Market
Why 2026 matters for corporate decision‑makers
-
Inflection of treatment modalities: 2024–2026 is the period when long-acting injectables and novel combination regimens move from early adoption to mainstream commercialization in high-income and middle-income markets. Several regulatory approvals and late‑stage clinical reads in early 2026 materially change choice architecture for physicians, payers and procurement agencies.
Acquired Immunodeficiency Syndrome Market -
Rapid movement on access and pricing: public‑private partnerships and voluntary licensing agreements announced in 2025–2026 create clear roadmaps for generic supply into low‑ and middle‑income countries, changing demand timing and pricing elasticity across procurement cohorts.
Acquired Immunodeficiency Syndrome Market -
Policy and coverage consolidation: near‑universal adoption of “treat all” policies and expanding viral suppression targets are shifting procurement volumes and the unit economics of novel prevention products, making 2026 the year strategic investments in market access and supply chain scale either pay off or materially underperform.
What this report delivers — practical, transaction‑ready intelligence
The study is built to inform boardroom decisions and commercial execution plans in 2026. Key deliverables include:
-
Top‑down market sizing and forecast model (2026–2032) with scenario‑switching capability for alternate adoption, price and access assumptions.
-
Clinical pipeline and modality impact analysis — assessing likely uptake curves for long‑acting injectables, novel oral regimens, and once‑weekly/bi‑annual prevention approaches.
-
Payer and procurement playbooks covering tender dynamics, price‑volume thresholds, and contractual structures that optimize realization in public and private channels.
-
Commercial go‑to‑market roadmaps for innovators and generics, including segmentation of revenue pools by channel, optimized salesforce deployment, and digital distribution strategies.
-
Supply‑chain and manufacturing readiness assessment with COGS levers, scale‑up timelines, and contingency plans for API constraints and regulatory releases.
-
Regulatory and policy risk matrix, including likely approval timelines, compulsory licensing exposure, and donor funding sensitivity analysis.
-
Deal and M&A playbook: valuation benchmarks, partnership structures, and integration priorities tailored to both originators and generic manufacturers.
-
Interactive appendices: country‑level forecasts, pricing sensitivity tables, and downloadable financial models for scenario work by commercial teams.
Competitive landscape — who matters and why
The industry environment is bifurcating: a small set of originator companies continue to command premium positioning through differentiated single‑tablet regimens and long‑acting modalities, while a broad base of generics concentrates on volume supply and low‑cost procurement channels. Competitive dynamics in 2026 are driven by product modality leadership, licensing partnerships, and the ability to stitch commercial and public health strategies together at scale.
-
Gilead Sciences — continues to anchor commercial leadership through established single‑tablet regimens and first‑mover positioning in twice‑yearly injectable PrEP. Their late‑stage clinical data and access partnerships with generics materially shape price and availability timelines globally. Strategic watchers should track Gilead’s combination programs and their sequencing strategy for innovative regimens versus discounting to public channels.
-
ViiV Healthcare — remains the specialist HIV player with a depth of long‑acting clinical know‑how; its portfolio of injectables and INSTI‑based regimens provides a compelling alternative for both treatment and prevention. ViiV’s advantage is focused product stack and strong relationships with HIV treatment programs.
-
Merck & Co. — the regulatory approval of new oral regimens in 2026 expands the competitive set for switch strategies in virologically suppressed patients. Collaborations with other innovators on once‑weekly approaches make the company an important alliance partner and potential disruptor in regimen economics.
-
Large pharma (J&J/Janssen, BMS, AbbVie, Boehringer, Roche) — these incumbents maintain niche clinical assets (notably protease and NNRTI classes) and diagnostic linkages that are strategically valuable in integrated care pathways and differentiated reimbursement negotiations.
-
Generics and specialty producers (Cipla, Viatris, Teva, Aurobindo, Dr. Reddy’s, Hetero, Emcure) — the generics cohort is executing on both procurement supply and technology transfer deals that will accelerate price erosion in public tenders. Their role in manufacturing scalable, low‑cost versions — and in some cases, generic launches of novel molecules on agreed licensing terms — will be decisive for market share in LMICs.
Recent developments that alter competitive calculus
-
Regulatory and clinical milestones in early 2026 have expanded the set of commercially viable regimens, reducing single‑product dependency for payers and raising the bar for differentiated clinical value.
-
Access partnerships announced in 2025–2026 — including voluntary licensing and low‑price arrangements for prevention products — materially change procurement cost curves for public buyers beginning in 2027, forcing originators to refine dual‑track commercial models.
-
Public‑health adoption of WHO‑preferred regimens and widespread “treat all” policies have stabilized baseline demand, while unmet prevention needs keep upside open for high‑efficacy, low‑touch products.
Strategic Imperatives for 2026 — a prioritized to‑do list
-
Reassess portfolio mix against modality risk: prioritize investment in modalities expected to reach scale in the next 24 months (e.g., long‑acting injectables) while rationalizing marginal line extensions.
-
Lock in supply and licensing partnerships early: secure API capacity and voluntary licensing agreements to protect margins against accelerated generic entry in LMIC tenders.
-
Design differentiated reimbursement value propositions: develop outcome‑and‑adherence based contracting pilots with major payers and donors.
-
Stress‑test commercial models with procurement scenarios: model price thresholds, tender timing and mix shifts between hospital, retail and online channels to quantify revenue risk.
-
Operationalize a rapid regulatory playbook: align global regulatory filings with country rollout plans to avoid mismatches between label availability and distribution contracts.
-
Prioritize M&A and alliance targets that fill short‑term capability gaps — e.g., manufacturing scale, long‑acting formulation expertise, or country distribution networks.
-
Invest in demand generation and provider education for new modalities to accelerate uptake and justify premium pricing where clinical differentiation exists.
Risks to monitor (the 18‑month watchlist)
-
Accelerated generic entry and aggressive public procurement pricing in LMICs that compress margins for originators.
-
Regulatory delays or unexpected safety signals for novel modalities that could slow adoption.
-
Donor funding volatility and shifting priorities within major buyers that reallocate volumes between prevention and treatment programs.
-
Manufacturing or API bottlenecks that impede scale‑up for injectable programs tied to inflexible dosing schedules.
Why PW Consulting’s 2026 market study is uniquely valuable
This research is constructed to move beyond descriptive market commentary and into immediately usable strategy. It combines a transparent top‑down forecast (with a 2025 base and 2026–2032 scenarios), granular commercial playbooks, and an interactive model that allows teams to stress‑test pricing, access, and uptake assumptions. The study integrates clinical milestone timelines, supplier readiness assessments, and procurement dynamics so that commercial, access and R&D leaders can prioritize investments with confidence.
Next steps — the trailer
We have presented the strategic contours and highlighted the disruptors, but the full decision‑grade intelligence — including country‑level forecasts, price‑volume matrices, channel revenue splits, and the downloadable scenario model — is intentionally reserved for the complete report and accompanying data pack. For teams preparing budgets, alliance strategies or M&A diligence in 2026, securing the full dataset and model will materially shorten time‑to‑decision and improve outcome predictability.
Contact PW Consulting to access the complete Acquired Immunodeficiency Syndrome Market study, the interactive forecast model, and a tailored briefing that prioritizes the actions your executive team must take before the close of 2026.
For detailed analysis of this topic, please visit the official page: Acquired Immunodeficiency Syndrome Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Climbing Equipment Market to Reach USD 2,932.8M by 2032; 6.8% CAGR - PW Consulting Insight
By PW Consulting, 2026-07-13
Climbing Equipment Market — Strategic Preview for 2026 Decision‑Makers
As PW Consulting’s senior industry analyst, I present a concise, decision‑focused preview of our new Climbing Equipment Market research (base year 2025; historical window 2020–2025; forecast 2026–2032). The market is on a sustained upward trajectory, expanding at a compounded annual growth rate of 6.8% through the forecast window. By 2025 the global market reached a substantive scale and — under our central scenario — continues toward a materially larger market by 2032. This briefing lays out the strategic implications you must act on in 2026: where to prioritize investment, how to defend margins amid cost shocks and standards turbulence, and which competitive moves will deliver disproportionate returns. Note: this preview demonstrates our analytical depth while intentionally withholding detailed segment breakouts and specific regional/application splits; the full intelligence package on the PW Consulting site contains the granular models and actionable datapoints.
Climbing Equipment Market
Why this report matters for 2026
- Timing: 2026 is a pivot year — product cycles, standards updates, and fresh product launches converge. Companies that align portfolio, compliance and supply chain plans now will capture the next wave of growth.
- Durable growth with tactical volatility: The market’s multi‑year growth trajectory coexists with near‑term cost and regulatory shocks. Strategic moves in 2026 should balance growth capture with margin protection.
- Proof points for capital allocation: Whether prioritizing R&D, manufacturing footprint changes, or M&A, executives need market sizing, scenario P&Ls, and risk overlays calibrated to a 6–8% CAGR environment to justify 3–5 year investments.
- Governance and safety: Recent standards changes and recalls have elevated compliance from operational hygiene to strategic risk — 2026 budgets must reflect that reality.
Market trajectory and the drivers shaping 2026 decisions
The climbing equipment market posted robust recovery and expansion in the early 2020s and enters 2026 with momentum across core demand generators: continued consumer participation (indoor and outdoor), premiumization of kit, and diversified use cases (recreation, gym, rescue and work‑at‑height). Against this constructive backdrop, several structural and episodic factors materially affect near‑term strategy:
Climbing Equipment Market
- Standards and safety: The UIAA’s 2025 suite of revisions (including helmets, energy absorbing systems, and load sharing devices) raises the bar on compliance and testing. These changes will alter product development pipelines, labeling requirements, and certification timelines — a practical consideration for product release cadences in 2026.
- Recall and liability risk: High‑profile recalls over recent years have increased reputational and legal exposure for manufacturers and retailers. Firms must embed enhanced traceability and warranty playbooks into 2026 plans.
- Input cost volatility: Entry‑level participants reported equipment cost inflation of 14–21% between 2022 and 2024; combined with tariff actions on steel and aluminum introduced in 2025, metal‑intensive product categories face margin compression unless mitigated by sourcing or pricing moves.
- Product innovation cadence: Major vendors are staging new product waves each season (winter releases and spring product launches were documented into 2026). This compresses the time to market advantage and increases the value of agile development and rapid validation channels.
- Channel and experience dynamics: Growth of indoor facilities, performance training, and rental models (gear hire) is changing unit economics and product life cycles; these trends reshape the addressable market for consumables versus long‑life durable goods.
Competitive landscape — tactical implications for 2026
The market structure remains fragmented, with a moderate share held by established global brand leaders and many specialist firms occupying high‑value niches. Our competitive mapping of leading players points to clear positioning and strategic levers that matter in 2026:
Climbing Equipment Market
- Black Diamond Equipment — Broad hardware and device portfolio; global brand strength balanced with recall‑related risk. Recommendation: accelerate transparency initiatives (traceability, lifetime registries) and emphasize service/inspection programs to rebuild trust.
- Petzl — Safety‑led innovation and strong mechanized device portfolio. Recommendation: leverage safety credentials into premium, certified upgrade kits for institutional buyers (gym chains, rescue services).
- Mammut — Technical ropes and apparel leadership. Recommendation: double down on bundled systems (rope + harness + helmet) for premium trade customers and guided programs to lock in multi‑item purchases.
- Arc’teryx — Premium performance apparel and harnesses with strong brand equity. Recommendation: exploit premium margins via limited‑edition product drops and certified partnerships with elite gyms and pro teams.
- Edelrid / Beal / Sterling Rope — Rope and testing prowess; subject to batch quality scrutiny. Recommendation: invest in visible laboratory accreditation and third‑party testing communication to differentiate on safety provenance.
- CAMP / Grivel / DMM / Metolius / Trango / Mad Rock — Specialized hardware and alpine kit. Recommendation: focus on manufacturing resilience (nearshoring or dual sourcing for metal components) and exploit technical provenance in narrow, high‑margin niches.
- La Sportiva / Scarpa — Footwear specialists. Recommendation: expand aftermarket services (resoling programs, fit clinics) and capture lifetime value from shoe owners through loyalty programs.
- Singing Rock — PPE and work‑at‑height crossover. Recommendation: position climbing‑grade PPE as dual‑use for industrial customers — a fast path to larger, recurring contracts.
The top three and top five concentration metrics indicate moderate market concentration, leaving room for both category consolidation and emergent specialists to scale. In short: scale matters, but so does technical differentiation and safety credibility.
Risk matrix and mitigations for 2026
- Regulatory tightening and certification delays — Mitigation: accelerate pre‑compliance testing and allocate product roadmaps with certification buffers.
- Recall or quality incidents — Mitigation: implement full SKU traceability, quick‑reaction repair/replace programs, and insurance strategies combined with public communications playbooks.
- Raw material/tariff shocks — Mitigation: diversify suppliers, negotiate cost‑index clauses, and selectively reprice with transparent consumer communications.
- Channel disruption (gym closures, retail consolidation) — Mitigation: expand D2C, subscription/rental models, and B2B partnerships with gym operators and outdoor education providers.
- Brand dilution from counterfeit/grey market — Mitigation: digital authentication, selective geo‑pricing, and tightened distributor controls.
What the PW Consulting report delivers — practical components
This preview sits atop a comprehensive, execution‑oriented study designed for leadership teams making 2026 resource allocation choices. The full report contains:
- Validated market sizing and forecast models (2020–2032) with scenario analysis and sensitivity testing around cost, participation, and regulatory variables.
- Competitive benchmarking and capability maps that highlight where incumbents are vulnerable and where entrants can create defensible niches.
- Product roadmaps aligned to UIAA/EN/ASTM standards, including time‑to‑compliance estimates and development cost envelopes.
- Supply chain heatmaps and suggested supplier playbooks — including nearshoring vs. offshore scenarios and raw material hedging templates.
- Commercial playbooks: go‑to‑market options for premiumization, D2C rollout, gym channel partnerships, rental models, and institutional sales to rescue/industrial buyers.
- M&A and alliance candidate shortlists, valuation frameworks, and integration checklists tuned to climbing equipment economics.
- Operational checklists for recalls, traceability, warranty policies, and crisis communications.
- Primary interview excerpts with gym operators, pro athletes, procurement leads and technical officers to ground strategic recommendations in practitioner realities.
Immediate 90‑day actions for executives (practical, non‑incremental)
- Initiate a product compliance audit: map every SKU against newly revised UIAA and applicable regional standards; prioritize re‑certification of critical stock-keeping units.
- Stress‑test supplier contracts against tariff scenarios and identify two alternate metal component sources to reduce single‑point exposure.
- Design and pilot a traceability program (QR/serial) for high‑risk SKUs to shorten recall response time and restore consumer confidence.
- Revisit pricing strategy: deploy targeted premiumization for validated safety upgrades while protecting entry‑level accessibility through value‑led bundles.
- Fast‑track partnerships with regional gym chains and rental operators to introduce lifecycle services (inspections, repairs, trade‑in) that capture aftermarket revenue.
Final notes — positioning for 2026 and beyond
2026 presents a classic strategic inflection: a predictable growth trajectory underlaid by episodic risk drivers that favor companies who combine technical excellence with commercial agility. Executives who invest early in compliance, supply‑chain resilience, and authentic safety communication will both protect margins and capture market share. Conversely, firms that delay tackling certification backlogs or ignore supplier concentration will face margin erosion and heightened recall vulnerability.
PW Consulting’s full Climbing Equipment Market report translates this strategic framing into models, playbooks, and deal pipelines you can operationalize immediately. For teams making capital allocation, product prioritization, or M&A decisions in 2026, this intelligence is designed to move from insight to action within quarters — not years.
To access the complete dataset, segmented forecasts, and executable annexes (including the granular region/application splits and company‑level opportunity maps withheld from this preview), visit the PW Consulting Climbing Equipment Market report page.
For detailed analysis of this topic, please visit the official page: Climbing Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Silica Gel Orange Market to Reach USD 207.94M by 2032 at 5.12% CAGR
By PW Consulting, 2026-07-13
Silica Gel Orange Desiccant Market — 2026 Strategic Preview (PW Consulting)
Executive snapshot
By 2025 the global silica gel orange desiccant market had reached roughly USD 146.6 million (base year 2025). Our model projects a near-term uplift to about USD 154.7 million in 2026 and a steady climb to approximately USD 207.9 million by 2032 — a 2026–2032 compound annual growth rate (CAGR) of roughly 5.12%. These headline dynamics reflect sustained demand from moisture-sensitive industries, a regulatory-driven shift toward cobalt-free indicating chemistries, and steady input-cost volatility from silica-sourced feedstocks.
Silica Gel Orange Desiccant Market
Why this preview matters for 2026 decision-makers
- Timing. 2026 is a pivot year: buyers and manufacturers face accelerating regulatory pressure to phase out hazardous indicator chemistries even as firms race to capture premiumized, eco-labelled desiccant slots in electronics, pharma, and premium packaging.
- Margin sensitivity. Raw material trends — notably movements in sodium silicate pricing — are compressing traditional pricing cushions. Sharp procurement and hedging choices this year will determine 2026 gross-margin outcomes.
- Fragmentation = opportunity. The market remains fragmented (top‑3 firms account for under 20% of global revenue), creating openings for scale plays, selective consolidation, and differentiated product strategies without immediate domination risk from incumbents.
- Practical urgency. Operational decisions made in 2026 (formulation selection, long‑term supplier contracts, production capacity reconfiguration) will lock in cost and compliance profiles for the next five years.
What PW Consulting’s full study gives you (practical deliverables)
This report is built as an actionable playbook, not an academic exercise. Highlights of what you’ll find inside:
Silica Gel Orange Desiccant Market
- Market sizing and scenario-based forecasts (historical 2020–2025; base year 2025; forecast 2026–2032) with sensitivity runs that isolate price, regulatory adoption, and end-market substitution impacts.
- Granular demand drivers by application and by form factor, with channel‑level margins and manufacturer economics (note: detailed sub‑segment tables are reserved for the full report).
- Raw material impact matrix — including modeled exposure to sodium silicate price swings and recommended hedging structures for producers and large-volume buyers.
- Regulatory & ESG playbook: compliance timelines, substitution pathways (practical steps to eliminate cobalt chloride), and endorsement criteria for “cobalt‑free” claims.
- Commercial toolkits: procurement scorecards, sample of RFP language tailored for indicating desiccants, distributor selection matrix, and a tiered pricing model to accelerate negotiation cycles.
- Competitive landscape and vendor shortlists with capability maps, production footprints, and patent/technology scans to support supplier selection and M&A origination.
- Risk heatmaps and mitigation plans (supply interruptions, feedstock price shock, regulatory delistings) and a prioritized 18‑month action plan for revenue protection and margin recovery.
Market dynamics to prioritize in 2026
Three dynamics will shape outcomes this year and into the forecast horizon.
Silica Gel Orange Desiccant Market
- Regulatory & product evolution: There is a clear, industry‑level transition toward cobalt‑free orange indicating silica gels. Leading suppliers and new product launches are positioning around recyclable, cobalt‑free indicator chemistries — an imperative for food, pharmaceutical and healthcare packaging where hazardous-substance scrutiny is highest.
- Feedstock and cost pressure: Sodium silicate remains the primary feedstock. Benchmarks in early 2026 indicate average pricing in the band of roughly USD 0.48–0.63/kg, with a benchmark of about USD 0.58/kg recorded in February 2026 and modest monthly increases. These movements are translating into incremental production cost for silica gel makers and will require proactive procurement strategies or formula optimization to preserve margins.
- Market structure and route-to-market complexity: The sector is fragmented — small to medium regional producers coexist with specialized global players. This fragmentation favors buyers who can run multi-sourced procurement strategies, and it favors nimble manufacturers that can differentiate through ESG credentials, product performance, and service levels (rechargeability, dust-free quality, mechanical strength of beads/pouches).
Competitive landscape — the incumbents and what they signal
The competitive set is diverse: global manufacturers, regional OEM suppliers, and specialty chemical houses. Key vendors profiled in our study include:
- Sorbchem India — long-established manufacturer offering organic-indicator orange beads and global bulk supply capabilities.
- Aharnish Desiccant — positions on high-performance, self-indicating formulations with broad industrial reach.
- AGM Container Controls — US-based supplier emphasizing non‑toxic, pollution‑free options tailored to packaging and container markets.
- DryCon and Innoveda (IIGT Chem) — global suppliers focusing on high adsorption capacity and environmentally safer indicating beads.
- Baltimore Innovations — UK supplier with multiple indicator formats and forms for industrial users.
- DryTec Industries, Best Silica Gel Packaging, Sorbstar, Cilicant, Wisesorbent, and others — a mix of OEM and export-focused firms active in bulk and branded channels.
Recent industry moves underline the tenor of competition: Clariant launched a recyclable orange silica gel line in early 2025 eliminating cobalt chloride; Best Silica Gel Packaging and other regional players have been promoting cobalt‑free, SGS‑tested alternatives; Airnov has re-positioned its healthcare packaging offerings to emphasize indicating types. These shifts collectively raise the bar for sustainability and regulatory compliance across buyer categories.
Strategic implications and recommended actions for 2026
Below are prioritized, executable moves we recommend to commercial, procurement, and product teams preparing for 2026:
- Procurement: establish dual‑track sourcing. Run a two-tier sourcing strategy: secure near‑term cost stability with incumbent suppliers via 6–12 month price collars while qualifying cobalt‑free alternative suppliers for longer term contracts. Parallel inventory and vendor-financing solutions will cushion input-price swings.
- Product & compliance: fast‑track cobalt‑free validation. Prioritize lab validation and supply‑chain documentation to support cobalt‑free claims for products intended for food, pharma and healthcare customers. Update packaging and TDS/COA templates now to avoid late-stage rework in 2026.
- Commercial: segment the go‑to‑market. Differentiate offerings by form factor (beads vs. granular/pouch), performance attributes (rechargeability, dust-free, crushing strength), and ESG certification. Use an outcomes-based pricing pilot for high-value segments (e.g., electronics packaging and specialty pharmaceuticals).
- Operational: model capacity and contingency. Run capacity utilization scenarios that incorporate a 5–10% shock to feedstock availability and price. Identify co‑sourcing regions and logistics flexes (air vs. sea) for sensitive customer segments.
- M&A & partnerships: hunt for bolt‑on tech and regional footholds. Given market fragmentation and low top‑3 concentration, targeted acquisitions or JV’s can be accretive to scale and add proprietary indicator chemistries or regional distribution networks quickly.
How PW Consulting recommends you use this intelligence
The full study is designed to plug directly into three decision processes:
- Board‑level strategy reviews: use the scenario decks and 18‑month action plan to align investment in sustainable formulations and capacity with revenue and margin targets.
- Procurement RFPs & supplier due diligence: adopt our supplier scorecard and price‑sensitivity model to compress sourcing cycles from months to weeks.
- New product launches: leverage the product benchmarking and regulatory checklist to accelerate market entry for cobalt‑free indicating desiccants and to support customer certifications.
Trailer — what we’re not revealing here (and why you should read the full report)
This preview intentionally demonstrates the analytical depth of our work while withholding the granular sub‑segment tables, regional & application split percentages, and unit‑price curves that buyers and sellers use to form contracts and bids. Those core inputs — the exact regional and application shares, detailed per‑form revenue filters, and the full company financial and capability matrices — are available only in the complete PW Consulting report and data pack. If you are planning procurement negotiations, capital allocation, or M&A activity in 2026, the devil is in those undisclosed cells.
Next step
PW Consulting can provide an executive briefing and a tailored data extract aligned to your priorities (procurement, product, M&A). For commercial teams looking to convert the 2026 opportunity into measurable margin improvement, our short workshop format (two half-days) combines the report’s scenarios with a bespoke supplier negotiation playbook.
Contact PW Consulting’s Silica Gel Orange Desiccant team to schedule a briefing and obtain the full dataset and templates that support rapid, defensible decisions in 2026.
For detailed analysis of this topic, please visit the official page: Silica Gel Orange Desiccant Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Zellweger Spectrum Disorders Market to Reach USD 493.39M by 2032 at 6.72% CAGR
By PW Consulting, 2026-07-13
Zellweger Spectrum Disorders Market — Strategic Briefing for 2026 Decision-Makers
Executive snapshot
PW Consulting’s targeted industry briefing introduces the Zellweger Spectrum Disorders (ZSD) market as an emergent, specialty rare-disease segment where near-term commercial decisions will determine mid-decade winners and platform owners. Our market model indicates a clear, evidence-backed growth trajectory (compound annual growth rate of approximately 6.7% across the 2026–2032 forecast window) from a mid-2020s baseline to a materially larger market by the end of the decade. This growth reflects a mix of continued uptake of approved adjunctive therapies, expansion in diagnostic capture, and the accelerating probability of disruptive gene-editing and genetic-medicine interventions progressing through preclinical and clinical pipelines.
Zellweger Spectrum Disorders Market
Why this matters for 2026 strategy
-
Timing and option value: With the field still dominated by a small number of commercial incumbents and diagnostic service providers, 2026 is a pivot year for strategic investments — defined by whether organizations will lock in access to diagnostic funnels, secure payer visibility, or position for future disease-modifying entrants.
Zellweger Spectrum Disorders Market -
Capital allocation and portfolio sequencing: The market’s steady expansion at ~6.7% CAGR forces a re-evaluation of R&D prioritization versus near-term commercial plays (diagnostics, supportive care, and adjunctive bile acid therapies). Firms must balance investment in incremental product improvements and distribution leverage against optionality for transformative therapies coming from gene- and base-editing research.
Zellweger Spectrum Disorders Market -
Payer and access dynamics: Payers are already forming expectations around cost-effectiveness for adjunctive therapies and diagnostics, while preparing frameworks for one-time or high-cost gene therapies. How companies engage with payers in 2026 will materially affect launch dynamics for any novel disease-modifying agent.
Market architecture — what the full report models (high level)
Our full study applies a multi-layered market architecture combining epidemiology, diagnosis rates, therapeutic uptake curves, and unit economics to produce forward-looking revenue scenarios. The report contains:
-
A rigorous epidemiology module calibrated to published incidence and newborn-screen adjustments, with sensitivity cases for regional clustering (e.g., documented founder populations) and improved diagnostic penetration.
-
Diagnosis and patient flow modelling that links genetic and biochemical testing capacity to patient identification, with explicit assumptions on diagnostic yield and referral capture over time.
-
Therapeutic adoption curves segmented by product type (adjunctive bile acid therapy, symptomatic/supportive treatments) and end-user channels (hospital, specialty clinic, homecare), with transparent assumptions and alternative scenarios for accelerated approval or limited indication expansions.
-
Payer pathway and pricing architecture that evaluates reimbursement levers, co-pay dynamics, and real-world evidence requirements.
-
Commercial opportunity maps and channel strategies for market entry, expansion, and loyalty programs focused on clinicians, genetic counselors, and center-of-excellence networks.
Note: this briefing intentionally omits granular split tables and regional/unit amounts that are included in the full report; these are provided to subscribing clients to preserve competitive discretion.
Clinical and R&D landscape — near-term inflection points
The clinical landscape today is defined by an established adjunctive treatment for hepatic manifestations and an ecosystem of diagnostic and supportive care. Key dynamics shaping near-term strategy:
-
Established standard: An FDA-approved adjunctive cholic acid product remains the only marketed therapy specifically indicated for certain liver manifestations tied to peroxisomal disorders. Its continued commercial availability and guideline reaffirmation have stabilized a baseline addressable market for treatment of liver-related morbidity.
-
Transformational science: Cutting-edge genome editing—illustrated by recent preclinical base-editing correction of a common PEX1 mutation in animal models—raises the probability of future curative-class interventions. These advances will compress timelines for strategic planning: companies must build optionality today (partnerships, manufacturing readiness, payer engagement) to capture asymmetric upside if therapies translate clinically.
-
Unmet needs beyond the liver: No therapies as of 2026 have established safety and effectiveness for extrahepatic manifestations, making neurometabolic and developmental outcomes a critical area for differentiation and long-term value creation.
Competitive landscape — positioning and implications
The competitive ecosystem combines a few commercial product sponsors with a broader array of diagnostic and platform players. From our strategic vantage point, three archetypes drive market dynamics:
-
Therapeutic incumbents that own approved adjunctive treatment and clinician mindshare. These organizations have monetized the hepatic treatment niche and built distribution and reimbursement relationships that create near-term barriers to entry.
-
Diagnostic and platform providers whose genetic panels and testing services act as the primary funnel for identifiable patients. Their role in accelerating diagnosis—and therefore treatment initiation—gives them outsized influence on capture rates and real-world outcomes data.
-
Emergent science leaders (academic and biotech) developing gene-editing and precision-medicine approaches that could reframe disease economics and payer willingness to fund high-cost, one-time interventions.
Representative organizations featured in our competitive matrix include established therapeutic sponsors, genome diagnostics firms, and life-science tools companies that support the testing and clinical workflows. Each entity’s core competency (commercial reach, diagnostic coverage, platform-readiness) is mapped to tactical playbooks in the full report — enabling readers to prioritize partnerships, licensing, or bolt-on M&A that accelerate pathway control.
Commercial dynamics and payer strategy
Commercial success in ZSD will require a three-pronged approach:
-
Capture diagnostics: Align with genetic testing labs and newborn-screen expansion advocates to reduce diagnostic delay and increase the addressable treated population.
-
Evidence generation: Invest early in real-world evidence and registry infrastructure that demonstrates long-term hepatic and extrahepatic outcomes, cost offsets, and quality-of-life benefits; anticipate payer demand for outcome-based agreements.
-
Channel optimization: Design differentiated go-to-market approaches for tertiary centers, specialty clinics, and homecare support services; leverage telehealth and genetic counseling to extend reach while controlling costs.
M&A, partnerships, and manufacturing considerations
Given the concentrated nature of commercial activity and the rising prospect of gene-editing therapeutics, corporate development strategies should be selective and scenario-driven. The full study includes a prioritized list of inorganic targets and partnership archetypes mapped to three strategic objectives: near-term revenue capture, diagnostics funnel control, and platform readiness for curative therapies. Manufacturing readiness — particularly for specialty formulations and, later, viral or non-viral vectors — is a gating factor for large-capacity moves and should be evaluated against likely regulatory and payer timelines.
What PW Consulting’s full report delivers (practical takeaways)
-
Action-oriented financial models: downloadable Excel with base case, optimistic, and conservative scenarios; transparent assumptions you can tweak to test your strategic options.
-
Market-entry and partnership playbooks: step-by-step approaches for diagnostics companies, therapeutics sponsors, and clinical service providers.
-
Payer-engagement templates: evidence dossiers, budget-impact models, and suggested outcome-measure bundles tailored to different health-system archetypes.
-
Regulatory and clinical milestones calendar: tracking preclinical advances and guideline updates that will reset commercial timelines.
These deliverables are designed to move leaders from analysis to decision (license, invest, partner, or wait) within a 90–180 day planning horizon.
Immediate recommendations for 2026
-
Diagnostics-first strategy for commercial teams: negotiate prioritized access to testing panels and build joint physician education programs to accelerate diagnosis-to-treatment time.
-
Payer-focused evidence generation: sponsor pragmatic registries now to capture hepatic and extrahepatic outcomes; structure data collection to support potential outcomes-based contracts for future high-cost interventions.
-
Option value preservation: secure collaboration options with gene-editing and vector-development groups rather than full M&A if capital is constrained; preserve flexibility to scale if clinical translation occurs.
-
Commercial readiness: ensure cold-chain, specialty pharmacy relationships, and center-of-excellence networks are in place to support potential rapid expansion of treated populations.
Closing — the strategic opportunity
The ZSD market presents a classic rare-disease strategic paradox: steady, cash-generating near-term pathways co-exist with high-impact optionality from potential future curative therapies. PW Consulting’s analysis shows a materially growing addressable market over the 2026–2032 period, underpinned by diagnostic momentum and incremental therapeutic uptake. However, the true inflection point will be set by the clinical translation of gene-editing approaches and the payer frameworks that follow—events for which companies must prepare now.
For clients seeking the complete dataset, granular segmentation (regional, product-type, and end-user splits), and the tactical playbooks required to act in 2026, PW Consulting’s full Zellweger Spectrum Disorders Market report and interactive model are available on our research portal. Access to the complete materials will enable you to move from strategic intent to executable plans with clarity and confidence.
For detailed analysis of this topic, please visit the official page: Zellweger Spectrum Disorders Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Integral Total Station Market Reaches USD 1,956.6M in 2025 (2020–2025)
By PW Consulting, 2026-07-13
Integral Total Station Historic Market: Strategic Briefing for 2026 Decision-Makers
Executive snapshot
Between 2020 and 2025 the integral total station market expanded from a lower‑mid single‑billion scale to an estimated USD 1.96 billion (base year 2025), reflecting steady demand across surveying, construction, mining and related infrastructure sectors. Our forward view anticipates continued expansion through the 2026–2032 forecast window at a compound annual growth rate of 6.75%, bringing the market to roughly USD 3.09 billion by 2032. These headline figures signal a maturing market where product differentiation, workflow integration and service economics will increasingly determine winners and losers.
Integral Total Station Historic Market
Why this study matters for 2026 strategy
For executives planning capital allocation, product roadmaps, M&A, or go‑to‑market pivoting in 2026, the arithmetic above is only the starting point. What matters is how that growth is being captured—and by whom. Our Integral Total Station Historic Market research turns the macro trajectory into operational levers: which technology shifts compress total cost of ownership, where aftermarket and software monetization deliver margin uplift, how supply‑chain pinch points erode delivery certainty, and what competitive moves compress incumbent advantage. In short, the study translates a market growth rate into actionable scenarios that inform 12–36 month decisions.
Integral Total Station Historic Market
Scope and practical outputs of the report
- Validated historical time series (2020–2025) and a transparent forecast model (2026–2032) with sensitivity scenarios for low/high capital‑spend and supply‑chain stress.
- Competitive benchmarking across product categories and business models: feature parity tables, pricing band analysis, and aftermarket revenue estimates.
- Service and deployment playbooks for OEMs, system integrators and large users—covering field service, theft/security economics, software subscription design, and training/enablement.
- Supply‑chain risk map: critical component sourcing, single‑supplier exposures, and mitigation options including alternative sourcing, component redesign and buffer inventories.
- Regulatory and standards checklist to align product calibration, certification and project compliance with ISO and ALTA/NSPS requirements.
- M&A and partnership scorecards highlighting integration risk, revenue capture potential and estimated payback timelines under multiple synergies assumptions.
Competitive landscape: structure and strategic implications
The market reveals a clear oligopolistic tendency: the top three vendors account for a dominant share, and the top five consolidate an even greater portion of market value. Measured concentration (CR3 and CR5) indicates that leadership is not marginal; it is structural. This concentration creates both barriers and vulnerabilities—barriers to new entrants at scale, but vulnerabilities for incumbents exposed to rapid technological shifts or service disruptions.
Integral Total Station Historic Market
Leading incumbents combine hardware excellence with adjacent software and services. Examples of recent strategic activity illustrate the evolution:
- Leica Geosystems (Hexagon) has doubled down on device security and cloud services—introducing an integrated theft‑deterrence/security offering for high‑value robotic stations and rolling out a cloud‑based data management platform for real‑time access and analysis. These moves are defensive (protect high‑value assets) and offensive (monetize data flows).
- Trimble has continued product innovation on robotic stations, prioritizing automation and improved on‑device processing to shrink field workflows and cut post‑processing effort.
- Topcon’s collaboration with construction contractors points to a channel strategy that embeds instruments into project delivery rather than treating them as one‑off capital buys.
From a strategic lens, these behaviors highlight two winning axes: (1) verticalization—expanding from instruments to workflow/platform offerings that lock customers into recurring revenue, and (2) integration—with construction and engineering firms to secure volume through project‑level partnerships.
Technology, supply chain and standards dynamics
Three technical and operational trends are shaping near‑term competitive advantage:
- Sensor and component dynamics: critical sensors (optical, image and pressure sensors used in EDM and angle measurement) experienced moderate price pressure and episodic tight supply in 2025. For OEMs this translated into either margin compression or delayed deliveries—depending on inventory and procurement agility.
- Software and data services: cloud‑enabled device management, security functions (asset locating/theft deterrence) and integrated analytics are moving from premium differentiators to expected features for professional users. Firms that convert device telemetry into actionable project insights can extract higher aftermarket value.
- Standards and compliance: adherence to ISO calibration protocols and project accuracy frameworks (including ALTA/NSPS requirements) is increasingly non‑negotiable for large infrastructure customers. Compliance becomes a commercial enabler when embedded into sales and warranty offerings.
Strategic playbook for 2026
Below are pragmatic options for different player types—each aligned to the market backdrop and near‑term operational realities:
- For OEMs with scale: accelerate platformization—bundle device, cloud management and security into subscription tiers; prioritize aftermarket service networks to increase lifetime value; shore up component sourcing via strategic supplier agreements and dual‑sourcing for critical sensors.
- For mid‑tier and niche vendors: find white‑space in vertical workflows (e.g., mining, utilities) by co‑developing process‑specific modules; pursue cost‑leadership in manual station segments with focused field‑durability claims and local service partnerships.
- For large contractors and surveyors: shift procurement strategy from CAPEX to blended CAPEX/OPEX—leverage managed‑service contracts to gain predictable refresh cycles and faster access to advanced features; insist on cloud‑enabled device telemetry to measure productivity gains.
- For private equity and corporate development teams: prioritize roll‑up targets that strengthen aftermarket service capability or add software monetization, and stress‑test valuation assumptions against scenarios where component scarcity adds 6–12 month lead times for new product ramps.
Decision frameworks and KPIs to track in 2026
We recommend four KPIs to convert market insight into measurable outcomes:
- Installed base monetization rate: percentage of devices on active cloud/service subscriptions.
- Aftermarket revenue per installed device—leading indicator of service economics and customer stickiness.
- Time‑to‑fulfilment for new device orders—sensitive to sensor supply and critical for time‑bound infrastructure contracts.
- Compliance readiness score—measure of organizational alignment to ISO/ALTA calibration and reporting obligations.
Use cases: how clients have applied this research
Recent applications of our analysis include:
- An OEM reworked its pricing architecture and introduced a three‑tier subscription model anchored to device telemetry—expected to raise recurring revenue share by mid‑2027.
- A construction conglomerate redesigned procurement to prefer managed instrument fleets, reducing on‑site instrument loss and improving field productivity—supporting faster project close‑outs.
- An investor adjusted acquisition timing for a target firm after modelling lead‑time exposure for critical sensors, avoiding an overpay in a stressed supply scenario.
What this briefing does not disclose—and why that matters
To preserve actionable advantage for clients and to respect the commercial sensitivity of primary‑level segmentation, this preview intentionally omits granular subsegment breakdowns (regional/application splits and product‑level revenues). These are central to tactical decisions—pricing by region, SKU rationalization, and M&A valuation—and are available in the full Integral Total Station Historic Market report. The objective here is to demonstrate analytical depth and to show how headline growth translates into strategic choices, while directing practitioners to the full dataset and modelling toolbox for execution.
Immediate next steps for executives (90‑day plan)
- Run a short‑form stress test of your supply chain for critical sensors—identify single points of failure and evaluate buffer or dual‑sourcing options.
- Audit installed devices for telemetry capability and design a pilot subscription offer—measure uptake and churn after a single project cycle.
- Map competitive moves in your served geographies—prioritize defensive feature development (security, cloud sync) where incumbents are scaling platform offers.
- Engage with PW Consulting for the full dataset and scenario model to quantify the revenue and margin impact of each action above.
Concluding perspective
The integral total station market is no longer just a hardware business; it is becoming a workflow and data business with hardware as the anchor. Growth is solid, predictable and visible at the macro level, but the real value accrues to organizations that can convert instrument sales into sustained service streams, manage supplier risk effectively, and align with customers’ project delivery models. Our full market study equips leaders with the granular segmentation, scenario models and commercial playbooks needed to convert the 6.75% CAGR and the roughly USD 3.09 billion terminal market opportunity into concrete, defensible revenue and margin outcomes.
For access to the complete data tables, segment‑level forecasts, company scorecards and the full strategic toolkit, consult the Integral Total Station Historic Market report on PW Consulting’s publication portal.
For detailed analysis of this topic, please visit the official page: Integral Total Station Historic Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Multi-Junction GaAs Solar Cells Market — 13.01% CAGR (2026–2032)
By PW Consulting, 2026-07-13
Multi-Junction Gallium Arsenide (GaAs) Solar Cells: Strategic Imperatives for 2026
Executive snapshot
As the GaAs multi-junction solar cell market accelerates toward broader commercial and space-driven adoption, 2026 becomes a defining inflection point for industrial players, investors, and satellite integrators. Our PW Consulting market model shows a robust compound annual growth rate of 13.01% across the forecast horizon, with global industry revenues expanding from a base-year level in 2025 to a materially larger market by 2032. The sector’s dynamics are shaped by technology maturation (higher cell conversion efficiencies and lightweight form-factors), concentrated supply chains, and an evolving geopolitical and trade policy environment — all of which demand decisive strategic responses this year.
Multi Junction Gallium Arsenide Solar Cells Market
Why 2026 matters: five strategic implications
-
Acceleration from niche to scale: The market has moved beyond early-adopter space projects into scaled deployments tied to LEO constellations, high-performance UAVs, and renewed interest in concentrated PV systems. This is driving predictable revenue expansion and creating new commercial structures where power-to-mass and radiation performance are premium decision variables.
Multi Junction Gallium Arsenide Solar Cells Market -
Technology is a differentiator — but so is supply security: Breakthroughs in triple- and quadruple-junction architectures, epitaxial lift‑off, and inverted metamorphic processes are improving on-orbit productivity. At the same time, primary feedstock concentration and periodic export controls are amplifying the value of procurement strategies and long-term material agreements.
Multi Junction Gallium Arsenide Solar Cells Market -
Higher market concentration creates winner-takes-most dynamics: The top-tier suppliers command a meaningful share of industry revenues, resulting in strong bargaining power for suppliers who can demonstrate flight heritage, radiation hardening, and mass-optimized solutions. This drives premium pricing for validated product lines and creates barriers for new entrants.
-
Policy and trade interventions will shape near-term sourcing decisions: National R&D programs aimed at reducing III‑V costs, combined with episodic tariff activity and short-term export policy shifts, introduce both opportunity (subsidized innovation) and risk (supply interruptions) that must be modeled into 2026 capex and procurement plans.
-
Investment timing is critical: With a clear path for multi-year revenue growth backed by a double-digit CAGR, 2026 is the year for targeted capital deployment — but only when paired with disciplined due diligence on technology roadmaps, supply continuity, and regulatory exposure.
Data-driven context you can act on
PW Consulting’s bottom-up market build reconciles historical performance (2020–2025) with scenario-based forecasts for 2026–2032. The 2025 base year anchors our model, and the outlook projects meaningful expansion through 2032 under a central scenario that reflects continued demand from satellite constellations, incremental CPV deployment, and aerospace platforms that prize power‑density improvements. Our market concentration metrics underline competitive dynamics: the three largest firms together control a significant majority of the market, and the top five firms capture an even larger share — a structural reality that shapes contracting, pricing, and partnership strategies.
Competitive landscape: profiles and strategic takeaways
-
Spectrolab Inc. (Boeing subsidiary) — With extensive flight heritage and proven high-efficiency multi-junction products for space missions, Spectrolab remains a go-to supplier for prime integrators. Strategic implication: firms seeking immediate low-technical-risk adoption should evaluate partnership and qualification pathways with legacy suppliers, while monitoring potential price premiums tied to heritage products.
-
AZUR SPACE Solar Power GmbH — A European specialist that spans space and terrestrial CPV markets and supplies major primes. Strategic implication: European OEMs and integrators will continue to favor suppliers with local certification and established relationships; non‑EU players should assess compliance and localization strategies when targeting European programs.
-
EMCORE Corporation — Recent announcements of efficiency milestones underscore the company’s technology-led position. Strategic implication: buyers and investors should track efficiency-vs-cost tradeoffs and consider staged procurement that exploits early access to higher-efficiency cells while protecting against integration risk.
-
MicroLink Devices — Focuses on lightweight, flexible cells via ELO and IMM processes. Strategic implication: platforms where mass is the binding constraint (small sats, high-end UAVs) should prioritize engagement with innovators that can demonstrate manufacturability at scale.
-
SolAero Technologies (now under Rocket Lab ownership) — Emphasizes power-to-mass performance for satellite constellations. Strategic implication: vertical integration trends (supplier-owned launches/platforms) warrant careful competitive benchmarking for both customers and investors.
-
Sharp, Alta Devices, CESI and others — These firms present varied capabilities spanning high-efficiency space cells, thin-film approaches, and qualification services. Strategic implication: a layered sourcing and qualification strategy, combining incumbents and specialists, reduces technological and supply risk.
Supply chain and raw-material risk
GaAs device economics are sensitive to III‑V feedstock availability, gallium sourcing dynamics, and specialized manufacturing equipment. China’s dominant role in primary gallium production and episodic trade policy changes can create near-term volatility that propagates through procurement and inventory strategies. Public sector initiatives (notably in the U.S.) to subsidize III‑V research and manufacturability aim to lower cost curves over time, but they do not negate the need for near-term risk mitigation.
Regulatory and geopolitical context
Policy interventions — including tariff adjustments, export control measures, and targeted R&D funding — will affect short- and medium-term decisions on where to build capacity, how to structure supply agreements, and which regions to prioritize for qualification and certification. For 2026 planning, the most actionable steps are those that combine scenario planning with contractual levers to protect continuity while preserving optionality to capture upside if trade conditions ease.
Practical 2026 playbook: where to focus capital and management attention
-
Secure material and equipment continuity: Negotiate multi-year gallium supply agreements, evaluate diversified secondary sourcing, and pre‑order long‑lead epitaxy and metallization capital equipment where strategic. Stress-test procurement against adverse trade scenarios.
-
Segmented product strategy: Define clear go-to-market paths for (a) heritage, flight‑qualified cells targeting primes; (b) high‑efficiency offerings aimed at performance‑constrained missions; and (c) lightweight/versatile cells for next‑gen smallsat and UAV programs.
-
Partner and qualify early: For integrators, start parallel qualification tracks with incumbents and innovators to avoid single‑source risk while accelerating time-to-deploy.
-
Commercial innovation: Evaluate outcome‑linked contracting (performance-per-kilogram or launched‑power-based pricing) and bundled service models (cells + panel integration + on-orbit performance guarantees) to capture premium value.
-
M&A and investment posture: Target asset-level acquisitions that add unique process IP (ELO, IMM), raw-material access, or flight-qualification records. Use staged earnouts tied to efficiency and reliability milestones.
-
Operational readiness: Invest in accelerated qualification frames, test‑laboratory expansion, and cross‑functional teams that can turn prototype efficiencies into manufactured yields without long qualification tails.
What PW Consulting’s full study delivers (high-level)
Our comprehensive report — anchored to a 2025 base and forecasting through 2032 — combines quantitative rigor with practical, transaction-ready insights. Key deliverables include:
-
A detailed market model with scenario toggles (policy, raw material shocks, adoption curves) and transparent assumptions for revenues and unit economics.
-
Supplier benchmarking and scorecards covering technology readiness, flight heritage, manufacturing capacity, and supply‑chain exposure.
-
Technology roadmaps showing achievable efficiency, mass, and cost trajectories for triple- and quadruple-junction approaches and thin‑film variants.
-
Procurement and contracting playbooks tailored to manufacturers, systems integrators, and investors, including negotiation templates for long-term feedstock contracts and manufacturing equipment procurement.
-
Risk matrices and stress-tests covering raw-material concentration, tariff scenarios, export controls, and geopolitical shocks.
-
An M&A shortlist and integration checklist calibrated for 2026‑specific opportunities, plus a 100‑day implementation plan for acquirers or strategic partners.
Final counsel for decision-makers in 2026
With a structurally growing market, demonstrable technology advances, and concentrated supply power centered among a few established vendors, 2026 will reward organizations that combine disciplined capital allocation with proactive supply-chain strategies and accelerated product qualification. Short-term protection against raw-material and trade volatility must be balanced with strategic investments that secure differentiated product performance. Whether you are a systems integrator preparing to scale a constellation, a supplier deciding on capacity expansion, or an investor sizing acquisition targets, the right mix of tactical procurement and strategic partnerships this year will materially influence market position across the forecast horizon.
Next steps
PW Consulting’s full Multi-Junction GaAs Solar Cells Market report provides the granular segmentation, supplier-level benchmarking, and scenario models needed to operationalize the recommendations above. To access the complete dataset and bespoke advisory options, contact PW Consulting’s Industry Team for a briefing and tailored engagement plan.
For detailed analysis of this topic, please visit the official page: Multi Junction Gallium Arsenide Solar Cells Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Oil & Gas Drones Market to Reach USD 103.8B by 2032 at 19.12% CAGR
By PW Consulting, 2026-07-13
Oil & Gas Drones Market — Strategic Outlook for 2026 Decision-Makers
As energy companies accelerate digital transformation of field operations, unmanned aerial systems (UAS) have moved from niche pilots to enterprise-grade inspection, monitoring, and emergency-response platforms. Our latest PW Consulting market study provides the strategic intelligence executives need to make defensible investments in 2026 and beyond. At a macro level, the oil & gas drones market has transitioned from a fragmented, project-driven spend to a predictable, high-growth market: global revenue reached USD 30,501.38 Million in the report base year (2025) and is forecast to exceed USD 103,803.52 Million by 2032, reflecting a compound annual growth rate (CAGR) of 19.12% over the forecast period. Market concentration remains modest (CR3 ~22.15%, CR5 ~34.20%), underlining continued room for new entrants and differentiation.
Oil Gas Drones Market
Why this research matters for 2026 strategic choices
-
Timing is decisive: 2026 is a pivot year where regulatory clarity, maturing sensor stacks, and demonstrated ROI from early adopters converge — creating a narrow window to lock in advantageous commercial terms and operational baselines.
Oil Gas Drones Market -
Capital allocation decisions hinge on credible scenario modeling. Our study translates the market’s high-level growth path into investment scenarios tailored to asset-heavy operators, mid-tier service providers, and technology vendors.
Oil Gas Drones Market -
Procurement and vendor strategy must balance performance, supply-chain resilience, and regulatory compliance; the report gives procurement teams the framework they need to avoid “platform lock” while securing service-level guarantees.
Market trajectory and executive takeaways
The historical growth trend from 2020 through 2025 shows rapid adoption across pipeline patrols, offshore asset monitoring, leak detection, and emergency response workflows. The market scaled from documented levels in 2020 to USD 30,501.38 Million in 2025. Under our central forecast, the market expands to USD 36,361.66 Million in 2026 and accelerates through the late 2020s to cross USD 100 billion by 2032. This magnitude and speed of expansion justify treating UAS as core operational infrastructure rather than optional field technology.
From a decision-making perspective, three macro implications are immediate:
-
Shift from CapEx experiments to recurring, integrated Opex models (managed services, data subscriptions, and SLA-backed inspection contracts).
-
Prioritize platforms and sensors that enable multi-mission use; flexibility drives utilization rates and shortens payback.
-
Embed regulatory and security risk into procurement criteria — compliance capabilities materially affect deployable scope and timelines.
What the report contains — practical, operational, and commercial tools
This research is intentionally tactical. Rather than high-level forecasts alone, the report is a playbook for implementation teams and C-suite sponsors. Key deliverables include:
-
Operational playbooks for safe, compliant UAS deployment covering flight authorization, BVLOS enablement strategies, and hazardous-material handling under new guidance.
-
Procurement templates and vendor evaluation matrices that score platforms by mission fit (e.g., thermal, LiDAR, chemical/gas sensing), endure requirements, and supply-chain risks.
-
Data architecture and analytics blueprints for integrating aerial data into existing asset integrity and SCADA systems, including recommended formats, retention policies, and ML-ready pipelines.
-
Financial models (CapEx/Opex scenarios) with sensitivity analyses for utilization rates, service vs. buy decisions, and accelerated ROI pathways for scale deployments.
-
Regulatory compliance checklists and suggested lobby/engagement strategies for jurisdictions with evolving UAS rules and critical-infrastructure restrictions.
-
Actionable case studies and “lessons learned” from early enterprise rollouts — highlighting what reduced operational downtime, lowered inspection costs, and improved safety outcomes.
Competitive landscape — how vendors are positioning and what it means for buyers
The vendor ecosystem blends established UAV OEMs, specialist analytics firms, and service integrators. Each archetype brings distinct strengths and constraints that matter to 2026 buyers:
-
Platform-centric incumbents (e.g., DJI Enterprise) deliver mature multirotor systems with expansive payload ecosystems. Their advantage is end-to-end hardware availability and large install bases — attractive for rapid scaling but sensitive to supply-chain and jurisdictional restrictions.
-
Specialist manufacturers and sensor integrators (e.g., Flyability, Acecore Technologies, Microdrones) differentiate on mission-specific capabilities such as confined-space inspection robustness, modular LiDAR integration, and high-performance airframes for harsh environments.
-
Service-first players (e.g., Terra Drone, Cyberhawk Innovations) offer managed inspection programs and analytics-as-a-service, reducing up-front CapEx for operators that prefer outcome-based contracts.
-
Autonomy and software leaders (e.g., Skydio, PrecisionHawk) compete on flight autonomy, obstacle avoidance, and data-processing platforms that accelerate actionable insight generation.
-
Tactical UAS suppliers and long-endurance vendors (e.g., AeroVironment, Insitu/Boeing) are focused on remote, persistent surveillance use-cases where range and endurance trump short-range agility.
For buyers, the recommendation is to adopt a “best-of-breed assembly” approach: lock down the mission-critical payload and analytics stack, while keeping airframe selection flexible where possible. Given the current concentration ratios, partnerships and regional ecosystems will determine long-term total-cost and service quality.
Regulatory context and industry dynamics — the 2026 reality
Regulatory shifts in late 2024–2026 materially change program design and procurement windows. Notable context for 2026 planning includes:
-
PHMSA’s recent integration guidance (published April 2026) explicitly recognizes UAS for pipeline right-of-way patrols — creating operational pathways for wide-area patrol programs backed by a compliance framework.
-
FAA and PHMSA’s November 2025 guidance clarifies risk-based transport of hazardous materials by UAS, enabling new logistics and emergency-response use cases previously constrained by ambiguity.
-
U.S. contractors face restrictions (effective December 22, 2025, guidance) on using covered foreign entities on federally funded projects — an important procurement constraint that affects sourcing, warranty, and support expectations.
-
State-level rules, such as Florida’s statute restricting drone operations near critical infrastructure (2025 updates), create patchwork governance that requires tailored operational playbooks per region.
These regulatory changes are both an accelerant and a filter: they increase addressable use-cases while raising the bar for compliance, documentation, and vendor traceability. Companies that move early with compliant, auditable programs will secure competitive advantage and regulatory goodwill.
Strategic implications and five immediate actions for 2026
-
Establish a cross-functional “UAS Center of Excellence” that unites operations, HSE, legal, and procurement to standardize policies and scale capability.
-
Run a 12-month pilot portfolio that includes at least two mission archetypes (e.g., pipeline ROW patrol and offshore platform thermography) to validate operational workflows and data handoffs.
-
Implement dual-sourcing and vendor contingency clauses focused on firmware provenance, parts availability, and export/compliance constraints to mitigate supply and regulatory risk.
-
Adopt a data-first approach: require vendors to deliver ML-ready datasets and open APIs to avoid vendor lock-in and accelerate analytics maturity.
-
Translate regulatory developments into executable flight-authority maps and compliance playbooks by jurisdiction — keep these updated and use them as procurement pass/fail gates.
How to use PW Consulting’s full report
The executive brief you are reading is a strategic primer. The full PW Consulting Oil & Gas Drones Market study supplies the granular tools operational teams require to execute. Subscribers will receive:
-
Detailed segmentation across use-cases and airframe types, with proprietary scenario-based demand curves and sensitivity to sensor adoption rates (note: detailed segment tables are held in the full report to preserve proprietary modeling).
-
Vendor assessment scorecards with methodical scoring across performance, regulatory compliance, support footprint, and total cost of ownership.
-
Ready-to-use flight operations templates, procurement RFP language, and contractual clauses for warranties, data ownership, and cybersecurity obligations.
-
Customized roadmap workshops and executive briefings to convert market intelligence into a 12–36 month implementation plan aligned with your asset and regulatory footprint.
Closing — why act now
2026 represents an operational inflection point for oil & gas companies and their service ecosystems. The convergence of favorable regulation for specific applications, rapid capability advances in autonomy and sensing, and a multi-billion-dollar growth trajectory means that early, well-governed deployments yield outsized returns — operational resilience, safety improvements, and measurable cost reductions. PW Consulting’s study is designed to be immediately actionable for teams that must move from pilot to program with confidence.
For the full market segmentation, vendor scorecards, and hands-on templates that operationalize these insights, refer to the complete PW Consulting Oil & Gas Drones Market report.
For detailed analysis of this topic, please visit the official page: Oil Gas Drones Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rative Dentistry Market to grow 6.51% CAGR to USD 32.42B by 2032
By PW Consulting, 2026-07-13
Rative Dentistry Market 2026: Strategic Preview for Executive Decision-Making
As PW Consulting’s senior strategic advisor and chief industry analyst, I present a succinct yet rigorous preview of our Rative Dentistry Market research — calibrated to inform board-level decisions and corporate strategy for 2026. This briefing synthesizes the macro trajectory, competitive dynamics, regulatory headwinds and practical implications executives must account for when allocating capital, designing product roadmaps, and shaping go-to-market plays. It purposefully demonstrates analytical depth while reserving the granular segment-by-segment tables and split forecasts for the full report.
Rative Dentistry Market
Why this study matters for 2026
The restorative dentistry market is on a clear growth path: our work uses 2025 as the base year and projects performance through 2032 under a structured forecasting framework. The market reached approximately USD 20.85 billion in 2025 and is modeled to expand at a compound annual growth rate of 6.51% across the 2026–2032 forecast window, reaching an expected market size above USD 32 billion by 2032. That pace points to durable volume expansion and pricing upside driven by material science advances, digital workflow penetration, and broader systemic incentives for oral health integration.
Rative Dentistry Market
For executives, this macro picture frames three enduring strategic questions for 2026:
Rative Dentistry Market
- Where on the value chain should we concentrate investment to capture the fastest-growing pockets (materials, digital systems, implants, or consumables)?
- How aggressively should we pursue inorganic growth given competitive concentration and mid-market consolidation opportunity?
- What operational changes are required to mitigate raw-material volatility and regulatory complexity while accelerating clinical adoption?
Market trajectory: what the headline numbers conceal
The headline CAGR and market totals validate that restorative dentistry remains an investable, innovation-rich segment. Yet beneath this steady growth lie three structural shifts that materially alter competitive playbooks:
- Material innovation: Next-generation bioactive composites and ion-releasing fillers are shifting clinical preference toward solutions that actively support remineralization and reduce secondary caries risk. Early launches and clinical data have begun to rebase value propositions from “fit and finish” toward demonstrable biological benefit.
- Digitalization and same‑day workflows: The maturation of CAD/CAM systems and chairside restoratives has compressed procedure timelines and increased the economic value of integrated platforms that bundle hardware, software and consumables.
- Policy and reimbursement tailwinds: Emerging incentives to integrate oral health screening into broader care pathways (for example, a new Medicare-related incentive structure in the U.S.) are creating additional referral and utilization levers for restorative services.
These forces interact: innovative materials increase procedure value, digital workflows lower delivery cost and time, and reimbursement incentives expand addressable demand. For decision-makers, the combined effect magnifies returns for strategically timed investments in product and channel capabilities.
Competitive landscape — concentrated but open to moves
The market exhibits a mid-level concentration profile: our metrics indicate that the top three players capture a meaningful share, and the top five further consolidate nearly half of market revenue. That configuration produces a landscape where global champions maintain scale advantages while a long tail of specialist and regional players create pockets of dislocation and opportunity.
- Dentsply Sirona: A global leader pairing comprehensive restorative portfolios with CAD/CAM systems and broad consumable lines. Recent product launches in bioactive composites and a solid financial outlook signal continued investment in integrated restorative solutions.
- 3M: Strong in advanced direct restorative materials and bonding systems; recognized for durable, aesthetic composites and cement technologies.
- Straumann Group: Deep expertise in implant and digital restorative workflows; recent annual disclosures emphasize digital and regenerative product launches that strengthen end-to-end restorative propositions.
- Ivoclar Vivadent, GC, Zimmer Biomet, Envista (Kerr/Nobel), and select specialist suppliers: Each holds differentiated capabilities — from high‑aesthetic ceramics and bioactive glass ionomers to implant systems and prosthetic platforms — creating a competitive mosaic where partnerships and selective M&A are logical strategic tools.
Executives facing growth or defense decisions should evaluate three levers: scale (to defend pricing and distribution), differentiation (material or digital-led), and platform orchestration (connectivity between clinics, labs and suppliers). Our qualitative and quantitative profiling in the full report maps these levers to near-term commercial outcomes, but we reserve detailed segment-level share tables for subscribers.
Operational and regulatory dynamics that will shape 2026 actions
Operational resilience matters more than ever. Key dynamics we modeled and stress-tested include:
- Raw material cost volatility: The composites supply chain is sensitive to synthetic monomer and specialty filler pricing. Procurement strategies should combine longer-term supply contracts, multi-sourcing and pass-through pricing mechanisms embedded in distributor agreements.
- Quality and compliance: ISO 13485-aligned quality management systems remain a gating item for major market access and for supporting rapid regulatory filings. Companies without robust QMS risk delayed launches and shortened commercial windows.
- Environmental and clinical standards: Policies encouraging the use of amalgam separators and the broader push toward mercury-free restorative alternatives are reshaping product developmental priorities and facility investments.
- Reimbursement & incentives: The addition of oral health incentives into broader payment programs (notably in the U.S.) creates new justification for investments in screening-enabled restorative pathways and cross-referral systems between medical and dental providers.
These operational inputs feed directly into capital allocation decisions. For example, allocating R&D spend to bioactive, fluoride-releasing or low-shrinkage chemistries should be balanced against investments in regulatory capacity and clinical evidence generation to accelerate reimbursement capture.
Practical, action-oriented outputs inside the report
PW Consulting’s full study is designed as a decision toolkit rather than a static market narrative. Key deliverables include:
- A top-down market model with scenario analyses (base, upside and downside) through 2032, enabling sensitivity testing across price, penetration and adoption curves.
- Proprietary competitive heat maps and capability matrices that score rivals on product breadth, digital integration, clinical evidence and distribution strength.
- Go-to-market playbooks for incumbents and new entrants: channel optimization, lab-clinic partnerships, and differentiated service bundles that increase lifetime value per patient.
- Regulatory and reimbursement roadmaps tailored to major markets, with tactical checklists to accelerate product approvals and payer engagement.
- M&A and partnership screening: target archetypes, valuation benchmarks, and integration risk matrices reflecting prevailing market concentration dynamics.
Each module is accompanied by executable annexes — for example, negotiation templates for supplier contracts, sample clinical economic models, and a phased rollout plan for implementing chairside CAD/CAM capabilities across multi-site clinic groups.
Investment and M&A implications for 2026
Given the market’s growth profile and concentration metrics, strategic options that consistently emerge from our analysis are:
- Build-or-buy decisions favoring bolt-on acquisitions that add a technical differentiator (e.g., bioactive chemistries or proprietary digital integration) rather than generic volume plays.
- Selective vertical integration into critical consumables to protect margins and ensure supply continuity, combined with partnerships for capital-intensive hardware.
- Portfolio optimization where firms rationalize lower-growth commodity lines to free resources for high-margin, innovation-led products and digital services.
Private equity and corporate strategists will find the market structure conducive to platform plays that combine a strong channel partner with differentiated proprietary technology; our report includes candidate profiles and diligence checklists for these opportunities.
What this preview deliberately withholds — and why
To preserve the value of the research as a strategic asset, this introduction intentionally avoids publishing the detailed regional, product-type and end-user splits that underpin our modeling and scenario outputs. Those granular split metrics — which include region- and application-level growth drivers, price elasticity estimates, and sub-segment revenue projections — are available in the full report and associated data pack. Withholding segment-level tables is intended to protect the commercial sensitivity of the analysis and to provide an incentive for stakeholders to engage directly with the full deliverables.
How to use this intelligence in your 2026 planning cycle
Leaders should treat this research as both a forecasting engine and a decision-support library. Immediate steps we recommend before committing capital in 2026:
- Run the report’s scenario models against your internal pipeline to see how product launches and pricing moves change enterprise value under conservative and aggressive adoption assumptions.
- Prioritize short-term investments in regulatory capacity and clinical evidence generation for any bioactive or novel restorative product you plan to commercialize within 18–24 months.
- Revisit procurement and hedging strategies for critical resin and filler inputs; convert spot exposures into contracted supply where possible to stabilize margins.
- Map potential M&A targets using the capability matrices in the report to identify the fastest routes to product differentiation and geographic scale.
Closing perspective
Restorative dentistry in 2026 is not a market of marginal improvements; it is a sector in which material science, digital workflows and changing care economics converge to reshape where value will accrue. The market’s steady CAGR and expanding total size create a favorable backdrop, but success will be determined by choices around differentiation, operational discipline and evidence-backed commercialization. PW Consulting’s full Rative Dentistry Market study translates these strategic imperatives into operational plans — the deeper data, segment-level forecasts, and executable annexes are contained in the report and supplementary data packs.
For boards, investment committees, and corporate strategy teams preparing 2026 plans, this preview sets the strategic frame. To access the complete market model, competitor scorecards, and tactical playbooks referenced here, please consult PW Consulting’s full research release.
For detailed analysis of this topic, please visit the official page: Rative Dentistry Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fertility ELISA Kits Market to Top USD 1,021.3M in 2026 at 6.12% CAGR
By PW Consulting, 2026-07-13
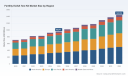
Fertility ELISA Test Kit Market — Strategic Preview for 2026 Decision-Making
As PW Consulting’s lead industry analyst, I present a focused, decision-oriented preview of our forthcoming Fertility ELISA Test Kit Market report. This briefing translates the report’s core macro findings into actionable strategic levers for executives planning investments, product strategies, regulatory programs, and go‑to‑market moves in 2026. It demonstrates the depth of our analysis while intentionally withholding the granular segment tables and model outputs that subscribers will access on the report page.
Fertility Elisa Test Kit Market
Headline market trajectory — what matters to 2026 planning
The global fertility ELISA test kit market has exhibited steady expansion through the 2020–2025 period and reached a definitive base in 2025. Our model indicates a compound annual growth rate (CAGR) of 6.12% across the 2026–2032 forecast window. Concretely, the market expanded meaningfully during the historical window and is projected to approach roughly USD 1.44 billion by 2032 — a trajectory that creates a predictable runway for mid‑sized investments, selective product launches, and consolidation plays.
Fertility Elisa Test Kit Market
Why this trajectory is strategically relevant in 2026:
Fertility Elisa Test Kit Market
- Predictability at the macro level enables multi‑year regulatory and manufacturing investments with a reasonable ROI horizon.
- Moderate growth rather than hypergrowth favors disciplined, differentiated product strategies (e.g., premium assays, service bundles, automation) rather than aggressive volume plays only.
- Stability in the base market size supports M&A transactions aimed at capability certainty (assay panels, manufacturing scale, or distribution reach) rather than pure market share capture.
Market structure and competitive intensity — concentration and opportunity
The market exhibits a mid‑level concentration: the top three players account for just under two‑fifths of market share, while the top five collectively control a little over half. This constellation creates a mixed competitive environment: established incumbents command important clinical and distribution footprints, but meaningful share remains available to specialized entrants and regional players.
Strategic implications:
- Incumbent players can leverage scale and regulatory dossiers to defend pricing and channel access; challengers must therefore rely on superior clinical differentiation, lower total cost of ownership, or targeted clinical partnerships to accelerate adoption.
- Private equity and corporate M&A strategies can be value‑accretive by acquiring niche assay portfolios or localized manufacturing to plug capability gaps for larger players seeking near‑term growth.
Competitive landscape: capabilities that determine winners
Our competitive assessment focuses on firms that demonstrate distinct assay portfolios, regulatory positioning, and commercial breadth across fertility and endocrine testing:
- Ansh Labs (Webster, TX) — Notable for immunoassay specialization and monoclonal antibody platforms applied to AMH testing. Their mix of RUO and CE‑marked products illustrates a staged regulatory commercialization approach and a clinically respected assay lineage relevant to ovarian reserve and IVF outcome assessment.
- DRG International (Springfield, NJ) — A producer of classic competitive binding and immunoassays such as estradiol and other steroid hormone tests. Their product set and assay formats make them a logical partner for labs and clinics that require validated hormone monitoring during ovulation induction and menstrual dysfunction management.
- Monobind Inc. (Lake Forest, CA) — Offers broad IVD ELISA menus including FSH, LH, prolactin, and beta‑hCG, enabling lab consolidation of assay workflows. Monobind’s IVD breadth is a strategic asset where buyers prefer a single‑vendor test menu for endocrine and reproductive panels.
- Sure Bio‑Tech (USA) — Export‑oriented supplier with compliance to GMP/ISO 13485 and CE marking; positions itself as a cost‑competitive source for routine fertility assays while emphasizing manufacturing compliance and international distribution.
Each profile above reflects technology choice (e.g., monoclonal antibody specificity vs. competitive binding formats), regulatory footprints (RUO, CE, pathways to FDA clearance), and commercial focus (specialist assay developer vs. broad IVD supplier). Our full report maps these dimensions against adoption vectors in clinics, hospitals, and diagnostic laboratories to identify realistic near‑term champions and acquisition targets.
Regulatory, quality, and reimbursement environment — constraints and accelerants
Three non‑negotiable externalities will shape winners and losers in 2026:
- Regulatory pathways: Fertility ELISA kits — especially those intended to inform clinical decisions like menopausal status or ovarian reserve — are subject to formal regulatory review (e.g., FDA clearance or de novo authorization for specified claims) and CE marking for European commercialization. The intended use claim is often the gating factor for both clinical adoption and commercial reimbursement potential.
- Quality systems: ISO 13485 compliance and GMP practice are baseline requirements for market access and large‑scale distribution; suppliers that can demonstrate robust manufacturing traceability and lot consistency command higher trust with laboratory buyers and institutional procurement teams.
- Reimbursement and coding: Fertility hormone assays typically flow through established clinical laboratory coding structures rather than a dedicated fertility ELISA code. That creates both simplicity (standard lab reimbursement processes) and complexity (lack of fertility‑specific reimbursement premiums), requiring suppliers to make compelling health‑economic and workflow arguments to justify premium pricing.
Where the practical value lies — what the full report delivers
PW Consulting’s full report is engineered as a practitioner’s toolkit for 2026 strategy execution. Subscribers will receive:
- Market sizing and validated forecast model (2020–2032) with driver‑level sensitivity and scenario outputs that allow executives to stress‑test investment cases.
- Competitive benchmarking matrix linking assay technology, regulatory status, manufacturing capacity, and commercial channels to identify defensible niches and M&A targets.
- Regulatory pathway playbooks (FDA, CE, and selected APAC pathways), including typical timelines, documentation checklists, and cost‑rate assumptions for product launches and intended‑use expansions.
- Go‑to‑market frameworks for three archetypal players — incumbent large IVD, specialty assay developer, and a scaled distributor — with tailored pricing, channel, and partnership strategies to maximize adoption in clinics and labs.
- Operational readiness assessments for scaling manufacturing (capacity planning, QC automation, raw material sourcing) and supply chain risk matrices addressing critical reagent and antibody supplier concentration.
- Investment and M&A decision tools: valuation comparables, synergy templates, and integration checklists focused on assay portfolio consolidation and cross‑selling opportunities.
To honor the “trailer” approach of this preview, we are intentionally omitting the granular segment breakdowns (by region, product type, and end‑user) and the underlying financial model that supports our forecasts. These are available with subscription to the complete report and come with an interactive model file.
Action agenda for 90 days and 12 months — prioritized moves
For executives looking to translate insight into action in 2026, prioritize the following:
- 90‑day moves: finalize regulatory gap analyses for any pipeline assays with clinical claims; initiate targeted partnership discussions with IVF clinic networks for pilot validations; perform a quick win supply‑chain audit focused on critical antibody sources.
- 12‑month initiatives: allocate budget for regulatory submissions aligned with prioritized intended uses, execute at least one channel partnership (e.g., national distributor or reference lab), and evaluate acquisition targets that deliver either complementary assay panels or manufacturing scale to compress time‑to‑market.
Concluding counsel — the competitive posture for 2026
The fertility ELISA kit market in 2026 is neither a winner‑take‑all battlefield nor a stagnant commodity patch. It is a growth market with moderate concentration, technical entry barriers, and clear regulatory gating. Firms that combine clinical differentiation (assay specificity/precision), credible regulatory strategy, and disciplined commercial execution will capture disproportionate value. Companies that treat this market as a simple volume play will face margin pressure and payer scrutiny.
PW Consulting’s complete Fertility ELISA Test Kit Market report equips leaders with the granular segmentation, model files, and execution playbooks needed to make high‑confidence decisions. For the full dataset, regional and product splits, and downloadable financial model, visit our report page — the granular intelligence there is designed to immediately inform board‑level investment deliberations and commercial operating plans for 2026.
For detailed analysis of this topic, please visit the official page: Fertility Elisa Test Kit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


